Peter Kenyon
CEO at RAMSDENS HOLDINGS PLC
Replay available
Full Year Results hosted by Ramsdens Holdings (LSE:RFX) on Investor Meet Company, held 2025-01-15.
On 6ix: 6ix.com/event/ramsdens-holdings-plc-rfx-full-year-results
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:01 Good afternoon, and welcome to the RAMSDENS HOLDINGS PLC Full Year Results Investor Presentation. Throughout this recorded presentation, investors will be in listen only mode. Questions are encouraged, and they can be submitted at any time using the Q and A tab situated on the right hand corner of your screen. Simply type in your questions and press send. The company may not be in a position to answer every question received during the meeting itself. However, the company can review all questions submitted today and publish responses where it is appropriate to do so. Before we begin, I would
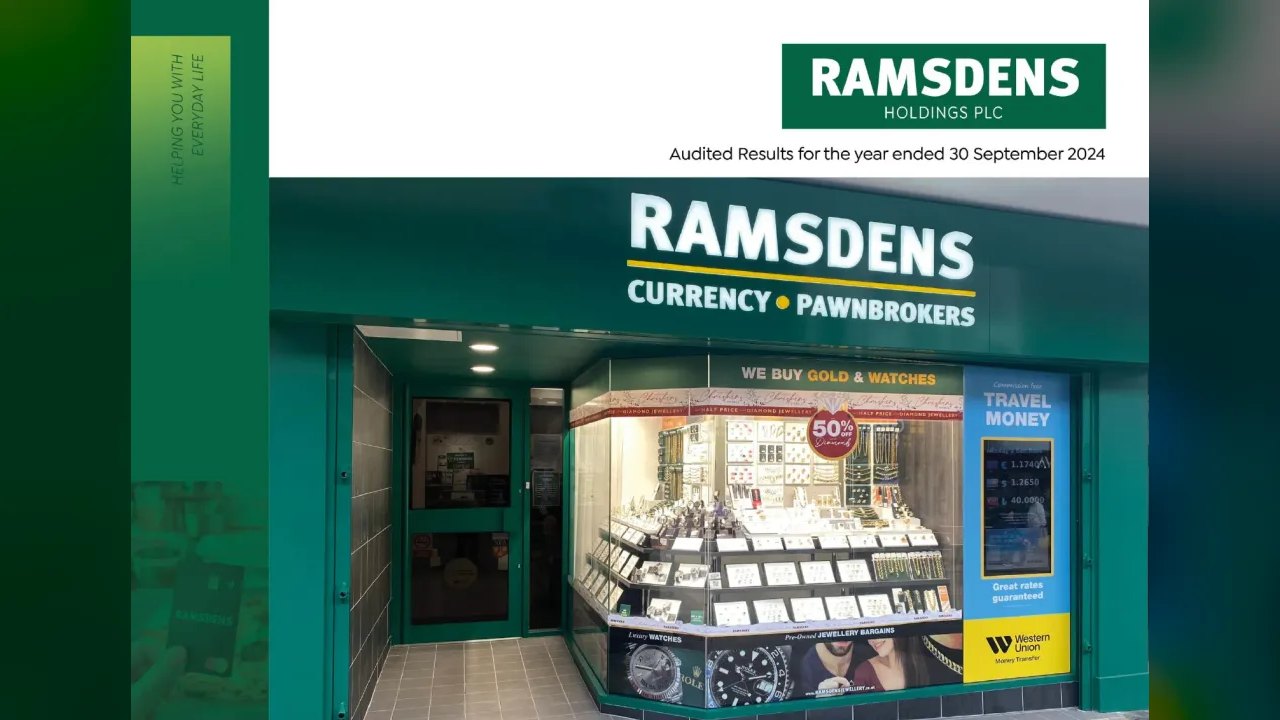
0:31 like to submit the following poll. And I would now like to hand you over to CEO, Peter Kenyon. Good afternoon to you. Thanks, Alex. Welcome, everybody. I think what we will do is we've done before, we will if I give a quick overview in case there's anybody new to RAMSDENS. So that's a picture of our new Burnley store last year. I think we have some t's and c's in the presentation. So this is us. You know, that's a map of where the stores are. That's a mix of our main services, and you can see it's a reasonably balanced pie chart between foreign currency, pawnbroking, retail jewelry, and the purchase of precious metals, which I often call gold buying because that's the primary income that we get from it.
1:22 We have a 169 stores as of September 24. Post that period, of course, one at the, Teaside Airport. It's a 168 as of today. We're mainly located in the North Of England, Scotland, and and Southern Wales, but we do have a pocket of stores in Kent and Essex. And we're headquartered in Teaside with a building in Middlesbrough and a building in Stockton. Customers are kind to us, and we have quite a strong trust pilot rating there. So into some of the the highlights of of the past year, strong performance. PBT up 12%, and we'll go through that in in detail with the moving parts. You can see that the four key income streams are all up year on year, and, again, we'll go into those in detail.
2:09 Net assets, we have a stronger balance sheet. We've increased our basic EPS, and we've increased our dividends for those looking for income, if you like, as well as growth from their investment in RAMSDENS. Clear growth strategy hasn't changed, since coming to the market. It was the same prior to that, that, obviously, we want to get more from existing store estate. So that's getting better across the income streams, but also relocating where appropriate. Grow our online presence and opportunity to earn more income from our online activities, expand the store estate. We opened seven newbies in the year, and we've opened Grantham just after the year end. We have a pipeline of research towns, and I'll go through where we are with that at the appropriate time.
2:54 And we acquired our brewery franchisee during the year, which has been a very good acquisition for us. So into the actual income streams, We start off with purchase of purchase of precious metals. Why do we start off with that one? Well, I think, you can see in the bottom right hand, part of your screen and the graph of of the gold price and how since March, it has really kicked on March 24. And, obviously, into quarter one this year, we have the weakness of sterling. Sterling has weakened by about 8% since the budget against the dollar, and that pushes the sterling gold price higher. So, obviously, we get a tailwind with this. And if you like, we have some, you know, maybe excess profits of where we thought we might be, But it's been you know, we we buy a weight of of gold from customers, and then we have choices. If we melt it, it goes through this segment.
3:54 If we were to retail the golds, to refurbish it and retail it, it will go through the retail jewelry. So this is purely about melting gold, and you can see how it has improved over the years, with an increase in gold price over the, like, same period. Now what comes up may come down, but at this point in time, I think everyone looking forward with the uncertainties that we have, weakness of sterling, probably in the short term, you think gold will stay high. And that's the basis of, if you like, our thinking in the short term. Moving on to foreign currency exchange, which is the biggest service by, percentage of gross profit. So what we do in this segment, so we sell foreign currency notes to you as you're going on holiday.
4:41 We will buy your foreign currency notes back from you when you come back from holiday. We have a multicurrency card, and we also do international money transfers or international payments. So taking those each at a turn, the sales of foreign currency, sales of notes has been good. You know, we're doing more transactions. We are doing it for a slightly lower amount, but we're doing it for a slightly higher margin, and that is up 6% year on year. Our purchases, like we said, our interims have regrettably it's a lower average transaction value. It's a lower transaction count, and it's a slightly worse margin. Now why is that happening? Well, people are taking slightly less on holiday, spending all that they have, and not coming back. And if they do have some some cash when they do come back, then maybe we'll keep it for the next time because people are traveling. People are still going on holiday.
5:37 Now the sales and the growth of the sales that we have in, you might say we're taking market share, maybe it's a bigger market. But it's the the sales of the foreign currency gives the the confidence that the cash to card risk is maybe not imminent, but we have our own card. So where are we with our, RAMSDENS multicurrency card? It launched in September 23. We have over 17,000 cards issued in the year, 21,000 now, and it's going really well. The it gives us access to, if you like, the spend that the customer might have whilst they're abroad. And it it will grow year on year, and, obviously, when we can strip out a meaningful amount of income, we will report on it separately. But it is growing quite nicely.
6:28 Mastercard are very happy with where we are after twelve months. And to give you an idea, in December, there was about 300,000 pounds loaded onto the card, but there's also 600,000 reloaded onto the card where the customer, if like, hasn't been into a RAMSDENS branch and is spending that money abroad. And that's obviously transactions and income driving for us that we had no access to before. The last income stream is international payments. International payments was done through in partnership, if you like, with RFX. We we passed the customer on to them. They gave good service, but I think with two people trying to take profit from the income stream, neither of us were really pushing, in fact, the RAMSDENS international payments. So we now have our own authorization.
7:18 We would expect to be live offering the service in H1 this financial year, and, obviously, we'll report on how successful that is taking forward. One thing that I would probably just add on, click and collect in the new website. So the jury website sorry. The currency website launched in July 23, and one of the things that you can see there is the click and click volumes are now 12% of the total of FX. So we've been quite successful in attracting the customer, which is while lower margin is a high transaction valued about £650. Onto pawnbroking next. So a solid year. You can see that the income result well, the gross profit is up 16% year on year, but the loan book is only up 4%.
8:03 The income trails the loan book growth, so we have to grow the loan book and then the interest income follows. And that was happened, if you like, last year. Had good growth in f y twenty three, and the income follows in f y twenty four. It's a very solid book. Happy where we are with with everything there. Repayment rates are still very strong. The growth in quarter one is still growing, you know, but, it's about 2%, two and a half percent in quarter one of the current financial year. And you can see that if, like, the book building coming back out of COVID, it was also building pre COVID, and it was just, like, steady incremental growth as the store estate, grew and, if you like, inflationary pressure into customers' bills, making them borrow a little bit more.
8:53 We now have a new website, RAMSDENS Pawnbrokers. That launched at the end of November. A while, if you like, got six weeks of data, I mean, it's encouraging data. We've been testing, making sure all the system works on the new website. So customers who want to pay part payments or pay their loans off, all that functionality we're ensuring that's been working. We've been soft launching the acquiring new leads for new lending, and making sure that we have the processes correct for handling those leads efficiently and effectively, whether that is lent at distance, whether that's lent by who's visiting the customer, or whether the customer goes into a store. We've been making sure all that works. The systems are good, and we're now ready to press the button on a bit of paper click advertising and acquire customers. Now, obviously, the first year, it might be a case of acquire the customers and what's the cost to acquire those customers.
9:48 But pawnbroking excuse me. Pawnbroking is very sticky. It's about 90% repeat customer rate. And, hopefully, we're building new customers here through the website for the long term. So pawnbroking, good, solid part of our business. And then the last income stream is retail. So retail had a bit of a mixed year. H one was,
10:13 tougher. H two was a little easier. H one, we had good growth in our secondhand jewelry. And then h two, we had good growth in our secondhand jewelry. So our value for money secondhand jewelry has done really well. In terms of premium watch sales, which is there in the chart, 38% of our retail revenue, the first half of the year, we had a bit of downward pressure, into the pricing that it's sort of leveled off at the start of twenty four. And then March and April, we started to sell more watches as the customer had more confidence that they were not going to buy an asset that maybe would fall in price. And probably at the same time, watches in Switzerland were recording that their sales of premium watches were also increasing.
11:01 Now the growth in premium watches carried on through h two and has carried on into quarter one where we've reported our revenue was up 15%. You can see that the growth in the the retail revenue and the growth in retail profit has been driven off a a relatively flat, slightly down jewelry retail stock. And one of the things that we were doing in the first half of the year was really concentrating on what stock do we have, how much stock do we have that's in our replenishable lines. You know? So have we got enough for, let's say, the next two months worth of sales? Give us time to replenish it from what we might buy from customers. Or have I got, you know, six, seven months worth of supply, and therefore, I don't really need to, you know, put more into stock, and therefore, the weight of the the gold that we bought from customers might be, processed through for its intrinsic value rather than held to be retailed at a later date.
11:57 So we've had a bit of a, a review. We're in a good place again, and we're now investing in stock to take us forward to, to take our retail revenue higher and, obviously, our retail gross profit higher because that's the main thing that we concentrate on. So what does that mean into our profit and loss? I'll hand you on to Martin. Thanks, Peter. As Peter said at the start, one of the most pleasing elements is that whilst revenue is up 14%, actually, all of the key revenue streams are up. So foreign currency, pawnbroken, retail and precious metals. So we've seen very, very strong growth in in precious metals, and that's really been driven probably from March onwards when the gold price particularly started increasing. It increased right through to the end of the year.
12:45 And we've mentioned in q one, again, you know, that that period is about 40% up on on last year, and that's that shows a level of growth, if you like, in h two versus h one that's continued. So very, very strong h two for for precious metals. Again, very strong h two for retail as well. And, again, that's continued into q one of of the new year. So very, very good. And and that gross profit, if you like, fall through is very strong as well. So the margins within the products is very, very consistent. So as Peter said, with with currency, there's a slight mix change. We're buying less probably from customers, but the rates that we sell currency at, that margin is very consistent. It's slightly better than it was a year ago. There's probably a slightly higher cost to deliver the currency to the stores, so that's quite a a smaller cost.
13:36 You take, you know, pawnbroken rates are the same. Our interest rates are are the same. We've not increased those during the year. And jewelry retail, that's had a headwind in in one respect of the increased gold price. So for the the cost of that jewelry is increasing, but we've been able to pass that on to the consumer through increased pricing. And that's been really encouraging that volumes haven't been impacted by that. The margins within the segments, again, very consistent. Admin expenses have increased 11%. And, again, this is very consistent with with what we said in the last few years really is, yes, there's more stores in there that adds a a level of cost, but by far, the the biggest inflationary cost increases people. So it's around 22,700,000 of our admin expense in 2024 is is people, and that's increased around 2,600,000 in the year. So that's that's a real strong increase.
14:32 And, obviously, as we look forward, that continues to be the case. So in the next year, in in f y twenty five, it's gonna cost around 800,000 annualized. So from April 25, the the national insurance cost is around 800,000. We're only gonna take half of that in the current year. Obviously, 2026 will will have a full cost of that. The the the real living wages is our entry level pair. It's gone up 5% from April 25. So whilst, again, that's laid on top of the national insurance cost that had been increasing faster than that. So, actually, relative to recent years, that's a lower increase in wage cost. But, obviously, we've been able to grow the income streams to out out grow that, and we're still seeing good strong growth in our profits.
15:18 Profit before tax, 11.4, up from 10.1. The the other cost in their finance cost is is increasing. That's part of that cost is the IFRS 16 rental cost. It's actually attached to having more stores and, therefore, more rent, and, therefore, the interest cost increases. That's around a 100,000. And there's around 200,000 increase in real bank borrowing interest cost, and that's a higher interest rate for the year and a slightly bigger facility from March. So we've we've refinanced in March to get a bigger facility. Income tax. So we've had a transitional year previously, but in the current year, the full the full year is a 25% corporation tax rate. And and the effective rate because of the the mix of add backs in the tax computation is around 27% income tax rate. So that that's now a rate which we expect to continue into the future, but that's why the income tax is growing quicker, if you like, than the profit. And that's why EPS growth is not necessarily in line with profit before tax.
16:23 But you see that being more sensible going forward in terms of that alignment. As Peter said, the pie chart in the bottom left there just gives a, you know, a very, very balanced mix of those diversified income streams. That that really puts us in a a really strong place.
16:38 And and, you know, having those different income streams means that we can we can share that increase in employment costs whilst others, you know, if if you just have a foreign currency business, you don't have to pass that on through your margin. Actually, we've got that diversification, we're we're well positioned to be able to take that increased cost and share it across different products.
17:02 Onto the cash flow statement. And I think this is the first year for a long time where we've not had significant working capital investment. So we've had coming out of well, probably since COVID, real reinvestment in the balance sheet for growth, for for inventory in particular. So we've seen such good growth in in retail in recent years, and we've continually invested in stock. We've actually been able to continue that growth, but from a a flat base of inventory. And that means, obviously, that cash then falls through operating cash. And equally, the growth in the loan book, which a lot of that came in in '23 and '24 is only a modest increase that, again, is is meant the cash falls through to operating activity. So you can see there a stark difference in in f y twenty four in terms of that cash generation.
17:52 The CapEx, we as Peter said, we've opened seven stores. We purchased one. We actually relocated three as well in the period. And we actually purchased our head office. We got a new office in in Stockton to facilitate bigger capacity within our jewelry processing team in particular, and obviously, the the wider growth of the business. That's a leasehold property that we purchased around a million pounds, and that actually shows through the cash flow in the in the lease liability payments because of because it's a long leasehold, nine hundred and ninety five years. The refinance happened in March. We now have a, it's four years left of a five year facility. It's a 15,000,000 RCF. We do have access to a 5,000,000 accordion, so we can borrow up to 20,000,000 if we would need that.
18:39 It's at slightly better terms. It's 2.15 over base. And, you know, that we've got three covenants which are you know, we're very, very strong performance against those, so it's not restricted in terms of our use of the facility. We borrowed around 8,500,000 at the year end. And typically, you know, that's not changed in terms of our seasonality and our need to use that facility through the summer. And actually, we repay a lot of that borrowing through the winter as the currency in the till is is taken out seasonally and then put back in in the summer. We've declared a a final dividend of 7.6p, and that's up from 7.1p last year and takes the total to 11.2 for the year. Again, that's going in line with EPS, and and equates to around 43% payout ratio, which, you know, I think longer term, we say we will pay up to 50% of our EPS out as dividends, and that still gives us opportunity to grow the dividend into the future.
19:44 Into the balance sheet. Very, very consistent with what we've seen historically. You know what? I think just to remind everyone, the inventories that we buy include, you know, pre owned jewelry that we actually buy below the intrinsic value. We obviously have pre owned watches, and we have new jewelry as as well within there. The trade on the receivables is the pawnbroken lending. So that's asset backed, again, mainly with gold jewelry and watches. And then the cash in the till and the currency in the till and the cash in the banks. So the the reason we have strong cash balances and still borrow money is the requirements of having that cash availability, particularly the currency in the stores. There's 8,200,000 of currency in the stores at the year end. Mentioned the new 15,000,000 facility and the covenants are shown there in terms of the the types of equivalent they are.
20:36 Net assets increasing. So 53,600,000, that's the reinvestment of of the profitability into the balance sheet. And, again, very, very strong access to to to give us the facilities we need to grow over the next few years.
20:54 Okay. Into strategy and how do we grow the business. People who've seen this presentation before will have seen this slide with slightly different photographs. So the one on the left is Cumberland, which is relocated, and the one on the right is the brewery store that we acquired. And I'm sure the lady on the phone is something that we've got from purchased through our iStock library. Into the the the component parts then, if we drive growth from our core estates, how do we do that? Well, we've got the four income streams. We really want to invest in our people. Everyone has a individual development discussion every six months. We ensure that they're happy. We look at what we want to train them in, across the four key services.
21:41 We And have an opportunity in every single store to improve our income from each of these four services. So we keep pushing with a structure of operations director, four regional managers, 16 area managers of the stores to improve what we do on a day in, day out basis. Also, within our, obviously, existing store estate is some young stores, stores that we've opened over the last, if you like, two years, stores that we've opened during the year, you know, that might be loss making now, but might be profitable next year, and hopefully profitable into the future thereafter. We every store that is over three years old is profitable and contributing to our head office costs. So we have a very, if you like, good model that we use.
22:31 Relocations where, if you like, we we know we're gonna get a return better than the investment in in in the store, in the shop fit, etcetera. And we purposely have a flexible lease portfolio to allow us to do that. There's a a slide in the appendices where it tells you our average time to release break is. Our stores are regularly maintained, repainted, carpet sliding, all that sorts of goods to make sure that they still look good for our customers, and we present an attractive retail environment and slash financial services environment where they can, you know, undertake whatever transaction they wish to do with ourselves. So that's the store estate.
23:16 As I said, we have a a model that is working, so why don't we have more of those stores? So seven in the year. Grantham was opened after the year end. Now there's been a slight know, we we haven't got we have got stores in the pipeline that will open. There'll be another four. I suspect it will open in f y twenty five, And we have a lot of research towns, so different towns. There's one town that we'll name that we've been to before. How did we look at it? Had two shopping centers. The council has now bought both shopping centers. It's relocated into one shopping center that's gonna have a, like, a a retail nucleus, and we're taking one of the last two stores that are free in that shopping center because everything has been condensed.
24:04 When we had the two half full shopping centers, it was a town that was a don't know where to go, don't know which one are back, so we'll go to a different location. So quite discerning in in the in the towns that we we choose. I think the change of government slowed things down as well in that we didn't know what the government would do when they had the chance to do a budget. And we concentrated on our websites, which I'll come to next. But, so we had a slight pause, but it was an intentional pause in the store of states just to see what the government may or may not do. Now we know what they have done and the impact of it. We can deal with it and move forward. Onto online. So on a website basis, the graph in the top right hand side is splitting our online revenue from h one to h two.
24:55 And we've really done that, for 2024 just to show how poor, restrictive, whatever word you wish to use for h one is, and then for how good h two is. So, you know, let's remember that Black Friday, Cyber Monday, Christmas, and January sales is all in h one, and yet h two has performed so much better. We were 8% behind and 8% overall, so 60% up in the second half of the year.
25:28 This is online. Online jewelry retail is also a catalog. There are about 15,000 items on that website, so acts as a catalog for our branch staff to use. We have good momentum. We're investing. We're using AI or about to use AI to describe our products, and that will save us some headcount. That headcount will redeployed into the processing so we can get more items onto line online moving forward. Currency website, that went July 23. 23% growth in click and collect in FX '24. And as I've said, it is, 12% of our total FX sales now. Pawnbroking launched November. Expectations to grow our customer base over the years. Year one might be, if you like, neutral with the cost to acquire, but high hopes to come from that website.
26:22 And then what should launch quarter one in 2025, so if you like, know, January, February, March, is a new website aimed at RAMSDENS HOLDINGS. So what we set out to do was segregate RAMSDENS for cash for websites, or one website into four websites where we could improve our SEO, improve our pay per click, and really develop for, online income streams that also support our branch network. So it is a an online and a high street, operation. The last one, the acquisition opportunities, we've got a nice picture of of Burry there. Something will come up. I mean, it's a very small industry, the pawnbroker industry. It's it's dominated by ourselves, H and T and cash converters in terms of stores.
27:10 There's a lot of people with one store, but the gold price is good. There's not many pawnbrokers rushing to my door at this moment in time saying, will I buy their business? We had one, but it wasn't located where we wanted to be during the year. So we didn't bid for it, but we had the opportunity. We've also looked at foreign currency businesses, and we've also looked at jewelers. But we have a very good store model that we can open. We have strengthened the brand. We can design the store how we want it. So acquisitions have to be attractive to us against, if you like, building our own store network, which we've done successfully in the past. So that's, like, the four growth strategies for us, and and we we do that with a strong underpinning ESG systems and and and
27:58 very simply, environmental, we want to do the right thing. You know? So let's be good citizens. Let's recycle where we can. Let's turn off the lights in the rooms that we're not in, all that type of activity. Socially, we want to look after our people. We pay the reliving wages, our entry pay.
28:16 We're heavily invested in staff development, and 91% of staff say that their branch or department is a happy place to work, and they're happy at work. And we want to drive that to a 100 where possible. And then we're you know, we wanna do a little bit for our community. Our branch managers choose the local charities they wish to support with coin collections. But over the year, we've donated £46,000 to charity. We aim to, like, pay about 9.5 percent of our post tax profit to charity to support a lot and a lot of good causes. Governance, while we're aimless, didn't you? Obviously, some of are investing in, some considering to invest in them. That brings a regulatory bar for us to to adhere to, but we're also FCA authorized, so we have to make sure that we adhere to everything that happens with that. We're members of the QCA.
29:09 We follow their code of conduct.
29:12 Within the board, we've had a refresh in recent years with Steve Smith retiring from the board and Karen Ingham joining us. Our chair, Andy Meehan, will retire in March after the AGM. And Chris Muir has joined the board who comes with a FTSE background. So he's ex SCS of late and another, you know, bright person joining the board to challenge both Martin and I. So I think he will you know, he he's already brought some new ideas, and, obviously, we will wish
29:43 Andy, well once he retires and thank him for all his, if you like, guidance in the ten years he's been my chair. Into the summary and outlook. Look. It's been a great year. Profit is up. We've strengthened our balance sheet. We've increased the dividends. We've got a good model and, a history of growing this business. We've invested online, and it's growing online. It's growing in stores. We think we have a a positive outlook, and we've made a good start into FY twenty five. And the highlights are there that strong gold price continues 40% over in quarter one against, you know, weaker like for likes, Pawnbroking, steady, good quality growth in the loan book.
30:30 Indates are absolutely fine. Expires are all within the norms. Jewelry retail revenue up by more than 15%. Again, I suppose a bit of a weak comparison, but that is a great growth against the economic backdrop. Foreign currency, like more of the sales doing well, purchases slightly back, but 3% growth. Again, solid growth for us. Martin's gone through the increases in the employment costs just to flex it. It is not all some sunshine, and there are a few showers there to, for us to to get through. But in all, we are confident of our future and in a good place. So I think, you know, we're ready to see what questions you have for us. Perfect.
31:15 Peter, Martin, thank you very much indeed for your presentation. Ladies and gentlemen, please do continue to submit your questions using the Q and A tab situated on the top right corner of your screen. While the company take a few moments to review those questions submitted today, I would like to remind you that a recording of this presentation along with a copy of the slides and the published q and a can be accessed by our investor dashboard. Peter Martin, as you can see, we have received a number of questions throughout today's presentation. And if I may now hand back to you and kindly ask you to read out the questions where appropriate to do so, and I'll pick up from you both at the end. Okay. I think, the first one is, you know, thank you for your kind comments, Pavel. But the the crux of the question is, will we consider, buying back our shares?
32:03 We've answered that in our section one seven two consideration because it's been asked a couple of times. At this moment in time, we're not proposing any share buybacks. We're rewarding shareholders with a good dividend, and we think we still still have opportunities to grow this business. And that's where we're, like, allocating our capital. So we keep it under watch. It's not something that we are not blind to. We we understand the issues with the the depressed share prices, etcetera. And we let's say, we'll keep that under watch. Lawrence, can we give us a sense of the assumed average gold price in the 2025 forecast? I actually don't know what the detailed forecast is that Liberum have put forward for the gold price, but I think he thinks that it will probably stay around in nine carat terms and in sterling terms, probably about £25.
32:59 So probably a little bit lower than where we are currently, but probably a decent average of what it has been in quarter one.
33:10 Mark has asked, company has significant net cash. He's cautious with regards to additional stores, trades on a single digit PE. Is now not the time to buy back shares? So I'll move on. No. Another one. I know our cash balances sorry. Sorry. Has asked cash balances increased once again. Are there any plans to buy back shares? Let's move on. George has asked with a 4% gross in profit from a 5% increase in gold purchases. How sensitive is profitability to the gold price fluctuations, and what strategies are in place to mitigate this volatility?
33:50 So we have always targeted, if you like, a pound profit when we buy the gold. So it depends how much weight we're buying off the customer. It depends whether the items are retailable or not retailable, determines what we will pay to the customer for the goods. And then with the weight of gold that we have bought, there's always going to be about 35%, which will go straight through and be sold for its intrinsic value. And at the other end of the scale, it's probably about 15 to 20% that is good retail quality that we want to refurbish and put out there for sale into our retail stock. Then there's a chunk in the middle that we have an option with. If the gold price is high, we might scrap all of that. If we're needing the retail stock to grow retail and push retail along, then we may choose to to do that. So we have options, if you like, with our gold buying, but the key that we need, it all drives off what's the weight of gold that we're buying, and that was up 5% in the quarter.
34:43 I think with the gold price, it's probably important. When you look at the the segments, obviously, it impacts some of the others negatively. So whilst retail, for instance, if the gold price was to fall, then actually there's a benefit to the retail business because the cost price, the input cost produces. So it's not all you know, it won't all just disappear out of precious metals. There is some benefit. And, generally, in a gold price reducing environment, typically, the consumer is feeling better and retail and and FX might actually improve as well. So it's it's hard to really quantify the the the direct impact of the gold price. Okay. Thanks, Martin. Andrew has asked, are you seeing generally larger average transactions in the stores in the Southeast?
35:28 For pawnbroking across the estate, the average is about £350. It's north of 500. I think it's 517 in our southern stores. So, yes, the loans in the Southern stores are higher. Retail, not necessarily, foreign currency, not necessarily, like, average transaction values. Malcolm has asked how many new stores were proposed to open in f y twenty five. Well, one in Grantham is open, another four, I suspect, in the eight and a half months that we have left in f y twenty five. What do you expect working capital outflow to be in '20 in f y twenty five? I'll let you spoke too. Yeah. I mean, it's it really does depend on the growth in retail. We've seen such strong growth in q one.
36:18 I think we obviously have that that will impact how much stock we buy. But certainly, new stores with less new stores, if we do four new stores or five new stores, you're probably around a million pound of investment in in retail stock for that. And and then you've got, you know, some you know, the pawnbroken loan book growth is only around four percent currently. So that that number again is is gonna be less than a million pounds you would sell on that sort of basis. So it's relatively low, is is that, but it would be higher if we perform better. And I think, you know, we've got the cash to to do that if if trade is good. Yeah. We have that that curse of opportunities. Given pressure on employment cost increases, can you grow revenues fast enough to make meaningful growth in profits? I hope so.
37:05 Yeah. We look. We we talked about it. Martin talked about it when he went through. We have four good income streams here that can take the burden of the increase of of of wages going up £2,000,000 annually. So, you know, we can eco power foreign currency margin. We can increase our retail prices. Gold pricing is strong, and we've always got the fallback that we can increase our pawnbroking interest rates because I think it's like elastic demand. We have the strength in that, but, you know, we want to be fair to our customers. But we want to we wanna grow the business with scale as well as slight increases in price. Mark has asked how are like for like profit figures and revenue?
37:51 We've not disclosed that, So to answer, just don't have the details absolutely to hand. Can you expand on the potential benefits of the recent authorization by the FCA to make international money transfers and the launch of the in house service. Yeah. So we've had a successful joint venture slash partnership with RFX for about seven years. It generated a decent income stream for the pair of us at about 250,000. We you know, there's no advertisement. There was conversations that happened in store. We didn't have control over the pricing. The service is very good from, and, you know, there was nothing wrong in that. But we got to a period in time where if we're going to take this income stream seriously and push it, then we need to have a 100% control of it. So that's the decision that we took. We got the authorization. We got a couple of things to to finish off before we fully launch the service.
38:52 But I you know, again, you've gotta acquire a customer base. You gotta grow that customer base. Hopefully, we'll retain all of the customers that we pass through to talk. And, you know, let's see. Two, three years, we'll be reporting on this as a as a meaningful income stream. Pebble, has the single exceptionally expensive pawn watch, believe it was, and recurrent loan on it now been resolved. Yes. That's resolved. It's no longer in the book. Rosita's asked should get stronger glasses, by the way. I think I'll push pull a screen nearer to me. Don't you find debit cards like Monzo and Wise impact your foreign currency sales, and is there any future in it? Is there any future in, is that Monzo or future in Wise or our currency sales?
39:41 Hey. Look. Sales of cash is up. So Monzo has been here for quite a while. Revolut's been here for quite a while. And, yeah, our cash sales of currency and the profit from it is up 6% in the last twelve months. And our foreign currency income, again, is up 3% in the quarter, and we have our own card as well. So it's a competitor, and Monzo has its strengths and weaknesses as do some of the other competitors. We think we've got a good, solid, strong offer to offer our customers, and, hopefully, we can both grow cash on the card. Lawrence, could you provide more detail on the operational advantages of the new head office? So we were bursting at the seams in in our Middlesbrough head office, so we needed more space. I needed more space so that I could process more jewelry.
40:38 I needed more space so I could photograph more jewelry. I needed more space so that I could process watches. And to do that, I needed to move certain departments out of the building. So if I you know, you you look at it across, you had accounts, compliance and risk, HR, all those type of administrative services that don't need a secured building to be in. So we have bought another building in Stockton and moved the admin center there, and that's how we're we're managing. So it's a space issue to recruit people to process more gold that's getting handled. Rebecca said, Sally St. Giles Mall Sally St. Giles Mall, your ELDINGS branch is located in as announced it's due to close.
41:25 What are your plans for that store and its staff going forward, please? Quite a detailed question. Yeah. We, the landlord of the St. Giles Center has decided to close the doors on Monday. It hasn't quite closed as yet. Someone might come in, and, hopefully, that might get sorted because it should. That that center is the hub of the town, but we are in negotiations with other landlords for a relocation of that store. We will there will be a RAMSDENS that remains in Elgin in which unit it is and when that is will be, decided in the near future. In the short term, our customers will be requested to go to INNOVENS, Our staff will be looked after because that's what we do at RAMSDENS.
42:14 What sort of revenues could the in house international money transfer service bring? Again, we haven't put a number on that, Lawrence. I wouldn't do it, and I wouldn't have invested a year trying to get the authorization if I didn't, want it to be meaningful. So we'll report on how successful we are, in the future, but it is something that would be additional, if you like, to the, the numbers that, Liberum have. That's great, Peter and Martin. Thank you for addressing all those questions for investors today. But before we direct investors to provide you with their feedback, which I know is particularly important to the company, Peter, could I please ask you for a few closing comments? Hey. There's a lot of questions there on share buybacks. We're very, very conscious of this issue with retail investors.
43:02 If I was a bit blase in answering it, you know, there there isn't an intention. It is something that we do think about, and we'll keep it under thought. It's just not at this moment in time. And the rest of it is that we, you know, we sit here. We know we've got a a good business that's doing well, and we're looking forward to continuing to grow it and continuing to, like, grow the net worth of the business, grow that balance sheet, grow the profitability, and, hopefully, you know, along the way, shareholders are rewarded with an increased price and a dividend income stream. Fantastic. Peter, Martin, thank you once again for updating investors today. Could I please ask investors not to close this session as you will now be automatically redirected to provide your feedback in order that the board can better understand your views and expectations?
43:48 This will only take a few moments to complete, and I'm sure will be greatly valued by the company. On behalf of the management team of RAMSDENS HOLDINGS PLC, we would like to thank you for attending today's presentation, and good afternoon to you all.
Follow Ramsdens Holdings PLC into a list and get an email when it puts out news.
CEO at RAMSDENS HOLDINGS PLC
CFO at RAMSDENS HOLDINGS PLC