Peter Kenyon
CEO at RAMSDENS HOLDINGS PLC
Replay available
Annual Results hosted by Ramsdens Holdings (LSE:RFX) on Investor Meet Company, held 2026-01-15.
On 6ix: 6ix.com/event/ramsdens-holdings-plc-rfx-annual-results
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
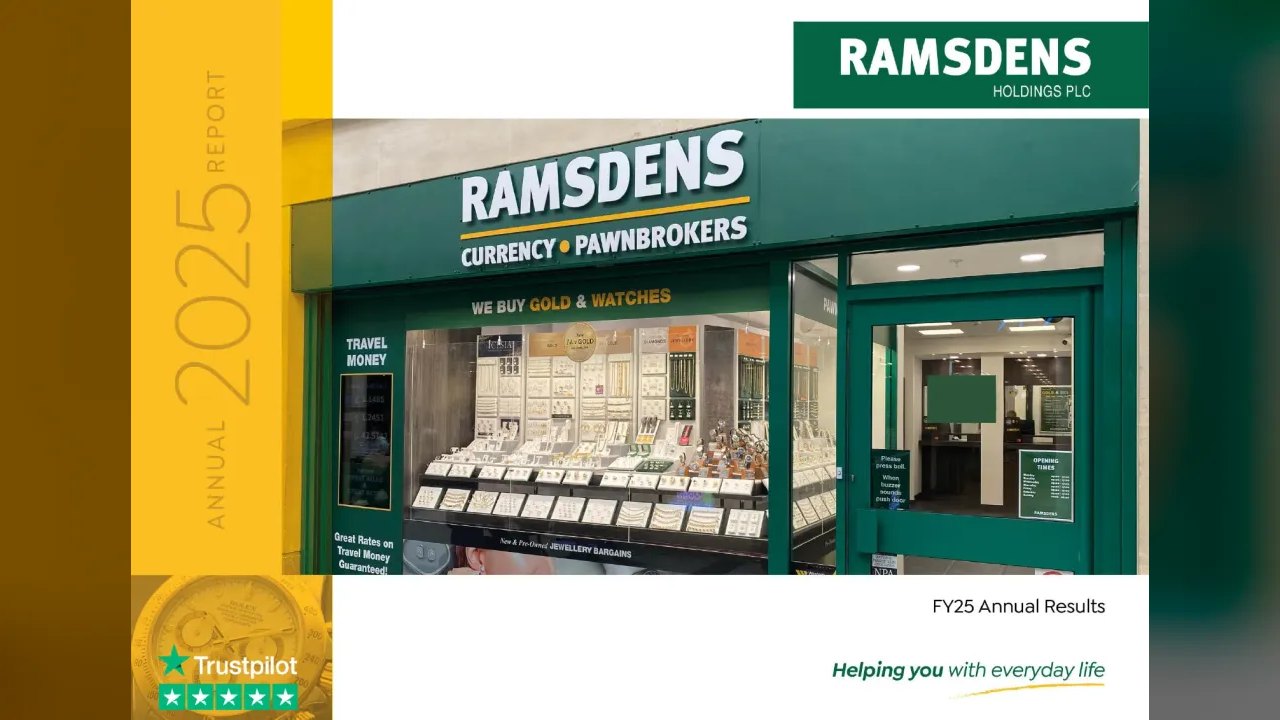
0:01 Good afternoon, ladies and gentlemen. Welcome to the RAMSDENS HOLDINGS PLC Annual Results Presentation. Throughout today's recording meeting, investors will be in listen only mode. Questions are encouraged. They can be submitted at any time just using the Q and A tab on the right hand corner of your screen. Simply press your type your questions and press send. The company may not be in a position to answer every question received during the meeting itself. However, the company can review your questions submitted today and publish responses where it's appropriate to do so. Before we begin, we'd like to submit the following poll. I'm sure the company would be most grateful for your participation. I'd now like to hand over to the management team today, Peter, Martin. Good afternoon. Thanks, Mark. Well, welcome, everybody. Let's say, hopefully, we have as many questions as normal. We're quite happy to answer them as we always have been. The picture on the front, that's our Burton store that was opened about twelve months ago, a usual disclaimer.
0:50 Contents page with a typical jewelry window there, segmenting the the different jewelry we have on offer new on secondhand. So who we are? The the key thing, bottom right hand corner, we're diversified. For income streams, it's a pretty even pie chart. There's also gonna be swings from year to year. You can see the numbers there ranging from 21 to 29% of gross profit. A map of where we are in The UK, we're still a very predominantly northern business. We are headquartered on Teeside. We have a processing center in Middlesbrough and, if not, an office in Stockton. We have dedicated websites for each service. You can see some of the Trustpilot responses below, and we'll talk about if that four key services, how they work, how we make our money, as we go through this, presentation.
1:49 But I think a lot of you are probably familiar with the business. The highlights. So, obviously, record turnover over 100,000,000 for the first time. Record profit 16,200,000, which is 43% upon last year's 11,400,000. Some of that is gold enabled, and we'll go back through that one. But it's enabled us to put the dividend up, which just so happens to be 43% up to two in its totality. We've called some of that out as a special dividend. Again, we'll explain why we've done that. Those results were, like, slightly ahead of market expectations. Some operational highlights. I'll come back to the websites, two new stores. We'll talk about new store opening programs.
2:34 Launched a new in house international money transfer service. We have been doing it for about seven years, but we're now doing it on our own, and 40,000 currency cards are now an issue. In terms of the outlook, we've had a strong start in q one. That's in the r and s. You've seen that. We've also, said we're very, happy to say we will exceed 18,000,000, this year in PBT. And, from yesterday, you can now see Cavendish's research, our new Nomad and broker on our ramsdensplc.com website. Our plan is to open eight to 12 stores in this financial year, and then, Dan, I'll come back into that, but we are on track to do so. We believe, underlyingly, all of our core income streams are making progress. We're in a really good position, and we've got an established growth strategy, which you've if you've heard this before, is not going to be too much different.
3:34 So top two, graphs show really our record, since coming to AIM. Both are very positive. We've always talked about a staircase in profit before tax growth. It's obviously shot up in f y twenty five aided by the gold price increases. And, again, let's say, we'll explain that. The dividend growth, again, incremental growth in FY twenty five. There's a special interim in yellow and a special dividend in in blue that's topping that up a little bit as well. Martin will cover the the balance sheet in detail, but net asset is 62,900,000 and a very good class of net assets too. Net cash on the balance sheet, and we're generating a 20% return on equity for '25 f y twenty five.
4:25 Again, our diversified income streams are there just if you like to show. But, you know, one of our strengths, and thinking about our strengths is strong foundations that we have. Financials are slightly gloss over. I've talked those. We'll go through them in detail. I have four IT programmers, our sales ledger CRM system, cash book is all ours. It's a bespoke system. It's perfect for our needs. We think it's market leading. Staff who use it think it's intuitive, and we can develop that ourselves. It's bought and paid for expense as we go along with the salaries of the four developers. And that's in been enable us to develop the websites to be enable us to launch the IMT service, which, again, all our software is all in house.
5:17 We have a strong consumer brand, customers are kind in their Trustpilot feedback, trusted high street name, which is a big differentiator when we get into car currency cards and getting into international payments because there are a 170 stores that you can walk into and ask a question, which is not the same with some of our competitors. Years of advertising, TV, sports sponsorship have helped develop that that brand. And we think we've got a great culture in the business. We, you know, we're we're aimless, we've got our strong governance. We're also FC authorized. We've had that for years. So we've got good governance, a strong ethos, we'll bring out in the in the palm broking to do the right thing. Low staff turnover for retailer, we're about 20%, 20 something percent.
6:06 That's lower than typical retail, which is 50 to 51. And if you go down the country into the South, it's probably 50 to a 100% turnover a year. So we want to keep our staff happy. We pay the reliving wages, our minimum pay, and we invest in our people because their efforts are the people who make the difference, and generate the results for, you know, the business and the shareholders. So growth strategy, the pictures might have changed, but the strategy hasn't. So driving growth from our core estate and growing the online presence. So growth from the core estate established stores, in my opinion, all have an opportunity to get better, whether that's more FX, more retail, buying more gold, or growing your own book.
6:59 I'm not worried whether they you know, if they're two years old, they have definitely got opportunities to mature and grow. If they're 20 years old, they've still got opportunity to grow. Had a store that was in my is it worth it category. I've changed the manager in the last six months, and that store has had an immediate turnaround. Every store in our state has the ability to improve. The website side of things, we had a legacy website called RAMSDENS for cash. We still have it for its domain authority. But we now have four separate websites for our four key income streams. So why have we done that? Well, our pawnbroking and our gold buying website to if you like, from a business development, are to drive customers to come into stores.
7:45 So people come to the site. We see that they look at branch locator, and then hopefully they're then following on in store, to do a pawnbroken loan or to sell their gold. Our pawnbroken website also facilitates the customer repaying their loans early if they wish to do so. Moving on to foreign currency website, click and collect, home delivery. You can top up your card, and you can ask about, and make payment on an international payment should you wish to do so. And jewelry retailing, it's probably the older platform. It's about four years old on that platform. It's currently getting replatformed as we speak. Hopefully, we'll launch this month. And the reason for that and the reason that we're doing it is to aid customers searching the product that they may wish to buy.
8:35 It's a bit clunky in the current way. Hopefully, the new version will be more streamlined, more effective, and lead to more sales. It'll also help the branches because, as we said previously, our website is a catalog of stock across the whole of the estate that our stores can tap into. So continuous improvement, absolutely what we're about, and I've said immature stores will continue to grow. We do look at relocations if it's appropriate, so there'll be a couple this year. On the right hand side, this is, like, is outside of the existing estate. So more stores, and I'll come back to that one, or something will crop up. So Gemini, Palm Brooks and Jewelers on the Isle Of Sheppey. Tony wanted to retire, 71 years old.
9:22 It was a good acquisition for us. We're very happy to to buy that, look after his staff, and take the business forward. In terms of the store estate, what we have and what we usually get questions on is if we let our model. So that's where we're at, and two stores opened in, the last or in f y twenty five in Grantham And Burton. We actually closed our Tea Side airport kiosk store, and we merged two stores in the center of Glasgow. So we stayed, if you like, neutral, a 180 168 stores and a franchised store. So why did we take, if you like, our foot off the the gas in terms of expanding the store estate over the last, like, twelve months or in that financial year when we'd average about seven and a half stores for the two prior years?
10:13 Well, there's a change of government. There was a November 24 budget, and we had no idea what they would do. Having had the budget and they significantly changed the rules of the game, if you like, with the increases into employer's national insurance by both lowering the threshold and increasing the rate, we thought there might be a bit of a high street bloodbath. That's actually happened, but later than I thought. So if you think about the last three, four months, you go Claire's Poundland, works have closed a few. River Island want to close a few. There are you know, it's been in the press. There have been several high street closures, hospitality trading, big impact into them. So we took we took a cautious approach. And and in the last twelve months, we, you know, revisited all the stores that we've opened over the last five years.
11:06 We know we have a really, really strong model for the high street supported by our websites. So we're happy to grow again, and we've said that we will grow eight to 12 stores, in this financial year and beyond. We've already opened in Wakefield. I've got four stores that will open prior to, if, like, end of February first week in, March. And we're in a good place to deliver eight to 12 new stores in this financial year. We've got a really good strong pipeline of good deals of stores that are in the right locations next to retailers that I think will be around the next twelve months. So, you know, quite discerning about what we do, and we have plenty of opportunities to grow the estate.
11:52 In terms of the financials, about 500,000 for a new store, 225,000 is probably something cost in the CapEx and and making it secure and putting the safe scene and and and all the things that we do in a new store, and about 275,000 of working capital, which is jewelry or cash and growing a loan book. We share with you, an indicative, model of a first year loss, which is really preopening expenses of rent before, you know, while we're shop fitting, staff recruited before we're trading, and it's that type of operation that creates the loss. And then really, the first year is is pretty neutral thereafter. And then we're building the income streams and profit in years two, three, and four.
12:40 That is the hurdle to open a store. If we don't believe we can't deliver a 20% return on capital from a new store, we don't open it. We'll look somewhere else. So that's our new stores and our strategy to grow the business. So I'll hand over to Martin who'll run through the the financials in more detail. Thanks, Peter. As Peter said, you know, it's been a very, very strong year, record revenue, over a 100,000,000 for the first time. So revenue up 22%, and gold buying and retail have been a big part of that step forward. We'll talk about the income streams individually shortly. Gross profit margins within each product is relatively consistent. So you can see that that most of that 18% growth in gross profit is very similar to that top line growth in in revenue.
13:31 The number of stores in the year, as Peter said, there was two new stores and one merged and one closure. So there's a slight increase in in admin costs from the extra two stores. We've had the maturity of all the stores opened in the prior year for the full year. And we've had the increase in in in people costs, which has been a significant part of the the growth in admin expenses. So up to 12% increase in admin expenses, that's about 4,500,000. It's about 3.6, 3,700,000 of that is due to the people cost increase. So that's more people in terms of the newer stores. It's more people in head office supporting that website growth and supporting the jewelry retail processing center, for instance. But it's also, you know, the rate the cost increase of the real living wage and the increase in national insurance cost, which Peter mentioned.
14:24 The finance cost in the in the business have reduced in the year by 20%. It's about half of the of the finance cost is is rental interest cost. It's IFRS 16, and it's to do with the rents in the business rather than borrowing cost. But the borrowing cost has reduced in the year due to having less debt throughout the year and the lower base rate, and that's contributes about a 200,000 reduction in overall finance costs. It's a very low finance cost for the size of the business, and we use that RCF that we have very efficiently to borrow money through the summer to effectively fund the extra FX that goes into the tills as the the volumes increase with travel. So profit before tax is up 43% at 16,200,000.
15:09 The tax rate is very similar, point 3,000,000. And tax in the year, very consistent with the profitability and profit after tax 11,900,000, which is 37p in terms of basic EPS. So we just touch on each individual segment separately and give a bit more color in terms of what's happening and the dynamics within them. So purchase of precious metals, predominantly gold buying. What you can see is revenue is up 44 percent. So the volume of gold we've purchased in the year is up around 14%. So a lot of this growth has come through the higher gold price. So we think about the growth in volume, the 14%.
15:55 So, you know, some of that actually is coming h two, and we would say that's definitely being contributed through the website. So we launched a brand new gold buying website in February 2025, and we've been working to promote that, especially into the second half of the year. We've seen a lot of traffic to that website, a lot of traffic going on to the branch of theatre pages. And therefore, we know people have used that website to then go into store and sell us gold, and therefore, the volume increase, some of that is is driven by that activity. It's not all driven by gold price increase. The gold price awareness definitely helps build customer volume, but actually the price itself, you know, it's the fact that people are reminding you in the press that the price is higher, the price is higher than people.
16:42 You know, I'm not just to sell more of the gold. Very few people actually understand the absolute gold price in terms of that driving them to to to take that step. The gross profit, 52% up. And you can see you can see here the gold price in terms of nine carat gold. We've set out just how much this has moved in the last year. So in f y twenty four, the average price was £21. In the last year, in '28 in '25, that price has moved to £28. That's a 34% increase. And as we sit here today, it's moved significantly higher again. So we've said in the r and s that q one, the gold buying profit for q one has increased a further 50% for that quarter. Gold price today is over £40 a gram in nine carat terms.
17:29 So we're very cautious when we look forward in terms of what that gold price can be. So we're obviously not banking on a £40 gold price into the future forever. But certainly, as the gold price is higher, the amount of profit you make per transaction is is higher, and that is what's fallen through into f y twenty five and also into q one of the new financial year. So on to revenues oh, on to retail. Sorry. So jewelry retail has been a real success. We've seen 20% increase here in revenue as well. This has got actually the headwind of of the gold price. The gold price means the input input price of jewelry has increased, It's increased substantially through the year. What we've been able to do is actually manage our pricing to the customer to maintain our margin. So we've actually you can see here the gross margin overall has been very consistent. It's 37% across the the mix of our retail, and we've been able to pass that on and still see growth, very good growth in our overall retail segment.
18:36 The graph in the bottom left just shows where we've been really with retail on that journey. You know, in the last four years, we've more than doubled our retail. There's a lot of sort of self help in in this income stream. We've put more stock in. We've improved the window displays. You can see the picture on the right there. It's very modular in design now where we can present the windows in a much more, you know, structured way and very consistent way through through the network. So we put more stock in during the year. There's about a £8,000,000 investment in stock, and that some of that is the cost of the stock is higher, and some of that is obviously more stock and more range to the to the stores as well. So very, very strong performance in a in a environment wherein discretionary spend has been probably a tough year for a lot of retailers.
19:23 We're very, very happy with with our progress in in jewelry retail. The the the segment at the bottom just shows how the split of the the categories sit within retail. So pre owned jewelry is about 38%. That's performed exceptionally well in the last twelve months. So the growth in pre on jewelry is actually 35% in revenue terms. So we've seen a very, very strong step forward in that as people look for value when the overall pricing has increased. It's about half of that growth is in pricing and half of it is in is in volume as well. So of that 35%, you know, it's not it's not all gold price driven. It's some of that is is volume driven as well. Watch pricing is obviously not affected by the gold price, and we've still seen 13% increase in our premium watch sales. And our new jewelry, which is only up 10%, is probably all in pricing and very little volume difference in the last twelve months.
20:21 Online is up 14%. So again, retail growth online as we still develop that website further. You know, we still think there's a big opportunity in retail as we move forward. Onto pawnbroken. So pawnbroken loan book in the year is up 7%. A lot of that growth came in h two, in the second half of the year. And, again, we we've launched a website. It was launched in November. We actually started promoting it more, like, February once we got our existing customers who used the website to pay for their existing loans. Once we made sure that works and we got that comfort with how that new website worked, we started to then to try and promote it more widely.
21:07 Again, we see good customer traffic to the website. We see a lot of people using the branch to get the pages. We do get inquiries about lending direct through the website, but a lot of people, again, are using the website as a signpost to go into store. And we've seen the lending pick up in h two. And, again, we've seen in q one significant growth again in the loan books. The loan book at the year end is 11,400,000. As we've said in the RNS, the loan book at the end of December is 12,800,000. So it's a step forward again into q one of the new year. We are lending slightly more to a customer, but we're not lending anywhere near the increase in the gold price. The gold price, as we've just seen, is is significantly higher than it was. It's up probably 50% over over the last year, and and we've, you know, we've lent probably 10% more on average to our customers on a pure gold basis.
22:01 So LTV or loan to value has been very, very conservative, and it's a lot lower than it would be in long run averages. So there's an opportunity for gold price that's high to lend more to our customers, and we see that continued growth, we think, into the next twelve months as we sort of as a gold price, if it stays higher than it's been for the last twelve months, we can lend more across that. We've actually seen repayments improve on pawnbroken. So repayment levels for customers despite maybe a cost of living struggle, people have typically paid back paid us back a bit quicker and paid us back slightly more than historic norms, which has been why the partly why the the yield in the loan book is slightly higher than it was a year ago.
22:48 We've worked hard with our older loans, people who've lent for more than the initial term of six months. Anyone who's lent for more than twelve months, we actually offer a reduced in a reduced interest rate, and we got more emphasis in our conversations and help with those customers to actually pay down more of their capital. And we've seen aged lending actually reduced, which is why that also helps the yield on the loan book. But actually takes away some of the loan book growth in the short term, but actually will give us, you know, strong customer outcomes in the long term and keep those customers into the future. They get their goods back quicker, they can borrow again in the future. So Pawnbroken is in a very, very good place. We've seen good incremental growth. We've not followed the gold price up and lent significantly more than we have historically.
23:41 And we think the website has started to make a difference, and we think that still is a huge opportunity to grow Pawnbroken into the future. Onto currency. So overall, our total currency exchange, you can see in the table there at the top, is 1% up. So it's slightly higher than it was the a year before. And what we've seen there is the average transaction is actually slightly down. So people have exchanged slightly less. It's about 2% down. And we anecdotally, there's there's probably two reasons for that either of, you know, they've taken less money abroad with them because they've had less to take. They've maybe traveled for a shorter period. I think some travel companies have said the average I mean, of people who maybe substitute a ten day holiday a seven day holiday to keep the cost of travel down given how expensive it's it's been in the last twelve months. So we've we've seen slightly lower values.
24:37 We've served a very similar number of customers, but what we've seen is some substitution effectively from higher value, higher margin product into lower margin products. So more people have used our click and collect service online. So you buy in advance, typically, at a slightly lower rate. And so more people have used the currency card, which again is at a slightly lower margin because of the cost to supply the card. So you can see gross profit is slightly down at 3%, but we still are serving very similar number of customers, maybe slightly more. And those customers are then, you know, very, very much understand the wider business and and they're using us for gold buying and they're using us for retail and the profitability of that customer is still very, very strong.
25:26 The currency card has been, you know, a step forward again. So we have 20,000 a year ago. You have 40,000 customers using that card. And as that layers in, that that, again, offers long term customer capture, and that customer uses that card multiple times while they're traveling. We've also had a slight reduction in the purchasing back of currency. So because the average transaction is lower, people then have left with less money and they sell less back. So you can see that the purchase of currency down about 5%. And again, that's contributed to the mix of the overall gross profit being slightly down. Cash flow statement. As Peter said, when we open a store, you know, the CapEx, the cash goes in at the start. The business end is very, very cash generative.
26:16 So when we have options in how we invest that cash, usually, we open, you know, probably on average seven or eight stores a year, which is a big use of cash. Actually, in the year, we've not done that. We've only opened two. So we've had more cash available to invest in inventory. I think the inventory has worked. You know, we've improved the retail performance, and therefore, we put more of that cash to work into inventory. And we've had longboat growth, which is the growth in the trading receivables. The the cash generation, the strength of that gives gives us the options to to invest in the period. The the income tax is probably a bit strange in that we've had six quarterly payments for tax. Usually, it's helpful, but we've transitioned from quarterly in arrears to to quarterly in the year. So there's about £2,000,000 there of one off cash out the door for tax, and that will normalize as we move into new year.
27:11 The dividend in the year, we've declared a 16p dividend overall. We're very conscious of the gold buying step forward that we've achieved with the gold price, and therefore, we've called out 2.5p of that as a special dividend. We still give an underlying dividend increase of over 20%. But overall, the dividend increase of 43% is that it reflects a very similar payout to last year, which is around about 43% of EPS. So our philosophy on dividend is very, you know, very consistent. It's broadly up to half of that profit out as a dividend and either half to grow the business. We are very conscious of a high gold price, and that's why we structured the dividend in this way, particularly in this year.
28:02 As Peter alluded to, we've got a very, very strong balance sheet. You know, we get asked a lot about inventories, especially the gold jewelry stock we hold. That, you know, is recorded in the balance sheet at cost. We don't revalue that to the gold price, for instance. So it's around about 9,000,000 of watch inventory we hold. The rest of that is typically gold stock, and the pre owned portion of that is held up below its intrinsic value. Trade and receivable is the pawnbroken lending plus the interest associated with that. And again, that collateral that supports that is a very, very strong coverage and therefore, again, that's a very, very strong asset class. The cash in the balance sheet of 15,000,000 does include the currency in the till. So it's around 9,000,000 of FX. And what happens there is the swing in FX through the year is we have about 4 to 5,000,000 of FX in the till in the winter, and it jumps up to around 10,000,000.
28:57 In the summer, that 5,000,000 of cash we use from our RCF, there's also around 3 or 4,000,000 of sterling cash that you need to cover that cycle as well as we sell around about 3,000,000 of currency per day in the summer. And therefore, as people pay us that money each day, it takes a day, a day and a half to get that back through the cycle into the bank. So it's a very, very efficient balance sheet. We have no structural debt on the balance sheet. The RCF effectively is repaid in the winter. Today, we have zero drawn on the RCF, which is why we have a very low finance cost as a business. Okay. Thanks, Martin. In in summary, you know, we were we set off in f y twenty five. We have steadily beat the expectations at the start of that year and have delivered 43% growth in PBT.
29:53 FY twenty six has started strongly, and we have, said that we'll make over 18,000,000. So it's another good start into the current year. The two graphs you've seen before early in the presentation are just really reiterating our track record on AIM, and the intention is to grow a more profitable business that has a very strong balance sheet and is able to reward shareholders. Strategy hasn't changed. We've had a following wind with the gold price, but, you know, we've taken advantage of that. Underlyingly, the trade you know, the business is in a really good place, happy with the progress that we've made since last year and made a little bit more progress in the gold buying, which is a bit more transactional or rewarded dividends with that.
30:42 So that's the presentation. Thanks, Mark. That's great. Thank you very much indeed to you both. Ladies and gentlemen, please do continue to submit your questions just using the Q and A tab situated on the right hand corner of the screen. I just want the guys to take a couple of moments to review your questions submitted already. I'd just like to remind you, recording this presentation along with a copy of the slides and the published Q and A can be accessed via your Investor Meet company dashboard. Peter Martin, you've received a number of questions from investors. So thank you firstly to everybody for your engagement this afternoon. If I may just hand back to you to just navigate us through that Q and A and I'll pick up from you at the end. Alright. Thanks, Mark. Excuse me. Leading forward, you know, the eyesight's getting going as I get older. So question one, can you explain the extent to which your earnings vary depending upon the price of gold and silver?
31:31 But, obviously, I'll not talk about the gold going up any further, but lots of people think that will happen. Let's concentrate on if you like the gold going backwards. When we run if I take pawnbroking conservatively lend, if the gold price fell back 30%, 33%, our lending would still be in long run averages. So I don't think there's much impact into the pawnbroking segment. If the gold price is lower and we get less further scrapping, we're probably giving less surpluses back to consumers. So it's probably no detriment to ourselves, but, obviously, consumers who are currently getting surpluses higher than the bad before may lose out a little bit. Into retail, I think, again, where cost basis have changed for jewelry retailers, I think there'd be a reluctance if they can start buying their products at a lower price whether they just take advantage of that.
32:27 We've talked about if that special dividend, and is that an indicator to, if you like, the the variety or the variability of the gold price? It might be. But you know what? If the gold price is lower, will retail be in a better place because the world's in a better place? Will foreign currency be in a better place because foreign currency is in a better place? So it it isn't just a simple a simple answer. And, you know, we talked through the the gold buying. We have options. So if we buy a weight of gold, while we might take advantage of the gold price and scrap it straight away and get its intrinsic value, The gold price is lower. Why don't we take a year because we haven't got any structural debt and and repay it through, you know, retail it through our stores and earn more margins? So it isn't a it isn't a linear question.
33:15 As for silver, it's it's so low volume. It doesn't it doesn't, doesn't cause any any any movement on the Richter scale. It is my understanding RAMSDENS HOLDINGS is intended to open several new branches every year, but recently, the board changed its mind about this policy. Is there any particular reason why the company has had a change of mind? Well, I think it was just a pause, not a change, and I explained it about the the government policy and what I thought would happen to the retail landscape happened probably slower than I thought it would have done. Steven has asked, has the lack of opening branches and the relevant preopening costs helped profitability in the year? Not really. I mean, you know, we've said that's our model. I'm trying to make sure that our new stores make profit as soon as they possibly can, and RAMSDENS are both making profit in year one.
34:12 Steven, again, any thoughts about leaving AIM? Oh, in which way? No. We haven't got any thoughts about leaving AIM. That's that's the market we're on. Other people might have, but, now we're, powering up for for our existing, investors. Where do you expect to open the new branches, please? Commercial reasons. It's across The UK. There'll be some in the Northwest. There'll be some in the Southeast. Operationally, I don't want to, overload, any of my area managers with too many new stores. So we spread the new stores across the estate, and we have opportunities still to do that and ripple the estate. By that, I can put trained staff in the store. It performs better from the outset.
35:15 So that's that's the structure. That's what we're following. Due to the continued strength of precious metals is an opportunity for RAMSDENS to create a coin focused bullion website to buy, sell similar to Atkinson's or CHARD. The big store estate would no doubt lend itself to a click collect, not just direct to the customer. So it actually probably conflicts with some of the margins that we enjoy in our gold buying segment. So it's something that we've picked up and put down, but I'm not seeing it on the short term horizon. David's been a shareholder for a bit now. Thank you, David. I'm very pleased with the cautious steady growth. Well done. Thank you very much. Gary, earnings are very tied to the gold price. If the gold prices fall back to $2,000, level it trade that two years ago, what would the impact be on earnings? Would they fall back would they fall back to twenty twenty three levels?
36:11 I all the reports I read, Gary, is is is $2,000 is not on anybody's horizon in the near term. We'd react and move the business, but I don't think that our you know, some of our earnings are not necessarily tied to the gold price as I've explained. David, what do you see as the maximum number of stores nationwide? I don't think there is a maximum. I was explaining earlier to some city investors. We have a a town in Scotland. Population's about nine and a half thousand. That store makes us a £180,000 profit. So I think there's plenty of opportunities for us to go at across The UK. You know, we've only got a 170 stores. We could double the estate and and, you know, quite easily, really. Over time because we're funding that without structural debt through our own cash generation.
37:05 David, don't leave aim, please. Okay? Paul, congratulations on the fabulous results. Regarding watches, the potential for watches specifically seems huge. Any plans to build up inventory and take on established pre owned players through the website? Well, we do. Our our watch retailing is about 20,000,000, and growing. You know, it grew 13% in the last twelve months, and we very much do wish to drive that forward. It's been good business for us. The hardest part of some of the watches is repairing them quick enough if we buy it. You know, so we buy somebody's unwanted watch because they're trading up whatever the the reason may be. We often have to refurbish it, regulate it, service it, and get it ready, and and that's not a quick process.
37:54 But that that I'm obviously working on that as well to try and improve our efficiency with some of our our watches. Simon, Cavendish FY '27 forecast show a decline in profitability between '26 and '27. What key assumptions are driving that reduction? Is it expected gold price softness? I don't know whether it's expected gold price softness, but I wouldn't have thought anybody listening is expecting me to, having a conversation with Kevin is saying, I expect what I expect the gold price to be nine months or twelve months or eighteen months from now. So, you know, we were happy with our '27 projections coming out of, you know, midpoints of, like, '25, and it's just too far into the future. It's a very volatile world.
38:41 So there's you know, the the predictions in '27 are very you know? On the current gold price of where it is today, you know, $4,600 an ounce, it it they're probably seen as conservative. Sven, perhaps a left field question, but will the acquisition of HT during '25 affect the strategy for RAMSDENS in any way? So far, no. They're doing what they're doing. You know, it's a large business. It's been a successful business. I know that they're growing their store incrementally, and and, yeah, they you know, it I'll leave I'll leave them to manage their business and take it forward. I'm concentrating on what what we can control and how we can grow our profitability, how we can grow our dividend, how we can strengthen our balance sheet. So it's, RAMSDENS I'm mainly interested, but, obviously, I do watch what they're doing.
39:36 I seem to have rattled through those quite quickly. You've certainly done a good job there. Thank you very much indeed. Of course, if any other questions do make themselves available, Peter and Marty will will make those available to post today's meeting. Look, I know investor feedback is particularly important to you both. I'll shortly redirect those on the call to give you their thoughts or expectations through feedback. But perhaps, if I may, just come back to you, Peter, for a couple of closing comments. I think it's we've had a very good year. Yes, the gold price has given us a following win, but our business is in a really good position to continue to grow and deliver shareholder rewards. So that's what we're aiming to do. That's great. Perfectly clear. Thank you once again. Can I please ask investors not to close this session as we're now automatically redirect you so that you can provide your feedback in order that management can really better understand your views and expectations?
40:25 This may take a couple of moments to complete, but I shall be very gratefully appreciated by the company. I'm part of the management team of RAMSDENS HOLDINGS PLC. We'd like to thank you for attending today's presentation. I wish you all a good rest of your day. Thank you once again for your time.
Follow Ramsdens Holdings PLC into a list and get an email when it puts out news.
CEO at RAMSDENS HOLDINGS PLC
CFO at RAMSDENS HOLDINGS PLC