Dennys — Investor Presentation (November 2014)
30 slides from Dennys's investor presentation, Nov 13, 2014
Slide 1: November 2014 Investor Presentation
November 2014 Investor Presentation
Slide 2: Forward-Looking Statements and Non-GAAP Financial Measures
2 Forward-Looking Statements and Non-GAAP Financial Measures Denny’s Corporation urges caution in considering its current trends and any outlook on earnings disclosed in this presentation. In addition, certain matters discussed may constitute forward-looking statements. These forward-looking stateme
Slide 3: Denny's Investment Highlights
3 Denny’s Investment Highlights Iconic brand with 96% brand awareness in the U.S.* and nearly 1,700 restaurants in all 50 states in the U.S. and 11 countries & U.S. territories * Source: Denny’s BrandTracker, Year End 2013. ** See Appendix for reconciliation of Net Income to Adjusted EBITDA, Adjuste
Slide 4: Driving Shareholder Returns with America's Diner Revitalization
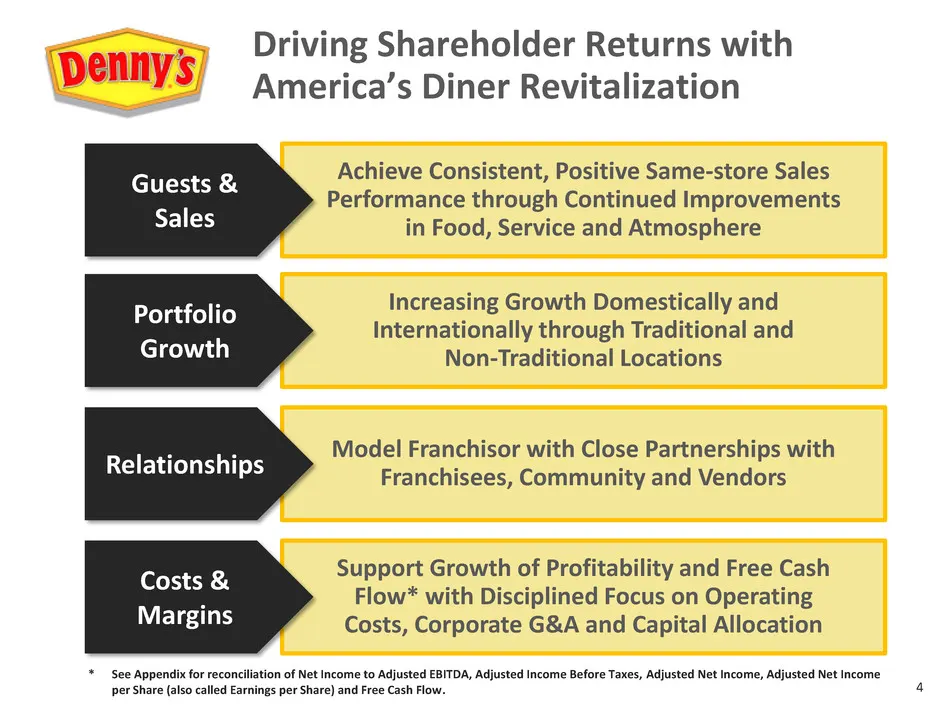
4 Achieve Consistent, Positive Same-store Sales Performance through Continued Improvements in Food, Service and Atmosphere Driving Shareholder Returns with America’s Diner Revitalization Guests & Sales Increasing Growth Domestically and Internationally through Traditional and Non-Traditional Locatio
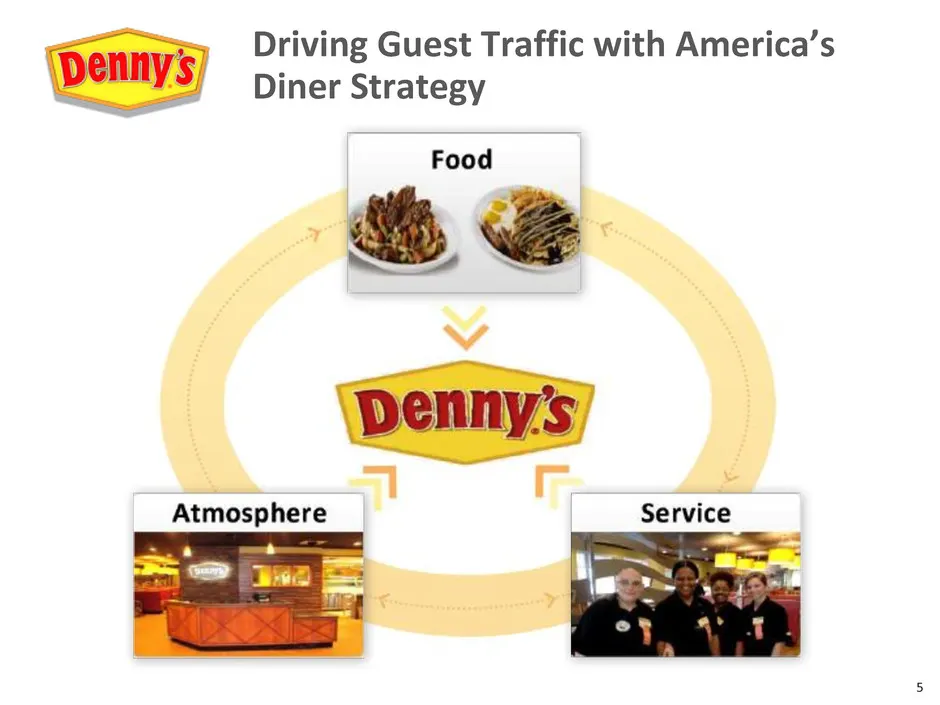
Slide 5: Driving Guest Traffic with America's Diner Strategy
5 Driving Guest Traffic with America’s Diner Strategy
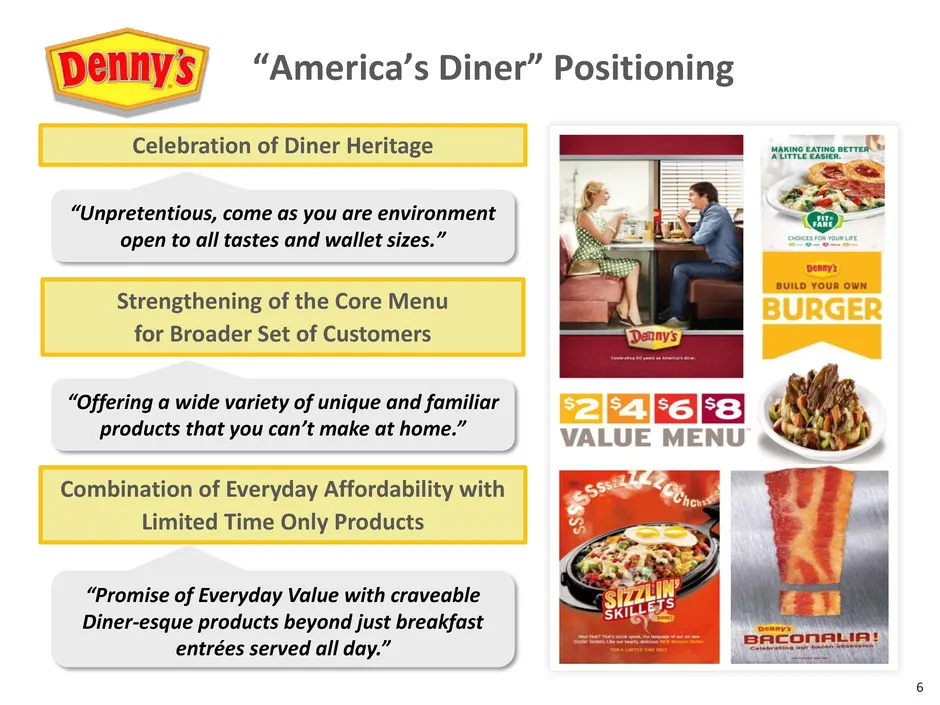
Slide 6: "America's Diner" Positioning
6 “America’s Diner” Positioning “Unpretentious, come as you are environment open to all tastes and wallet sizes.” Celebration of Diner Heritage “Offering a wide variety of unique and familiar products that you can’t make at home.” “Promise of Everyday Value with craveable Diner-esque products beyond
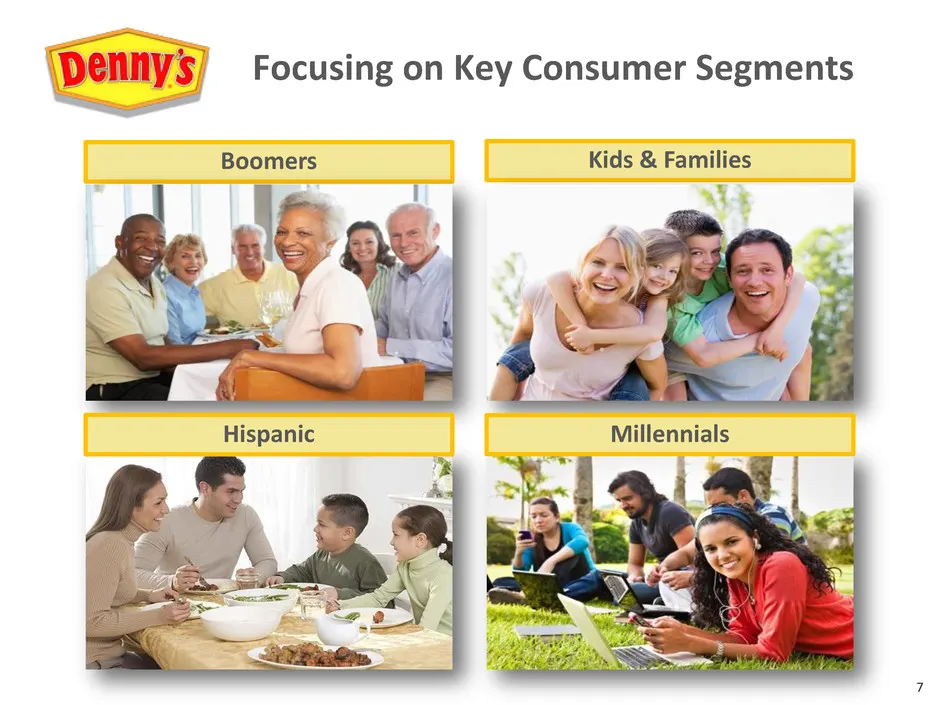
Slide 7: Focusing on Key Consumer Segments
7 Kids & Families Boomers Millennials Hispanic Focusing on Key Consumer Segments
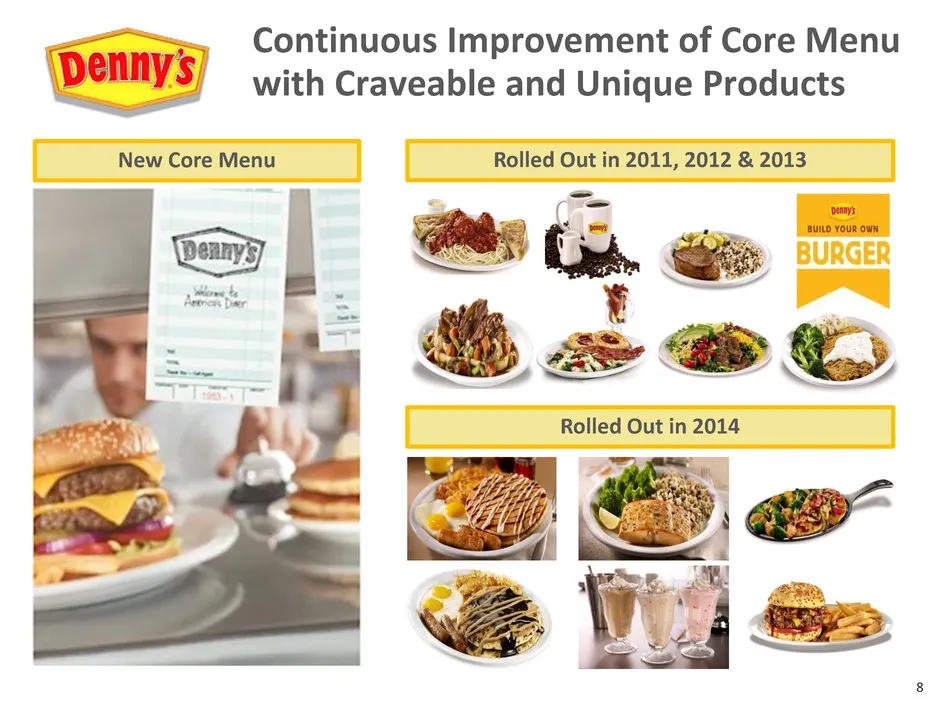
Slide 8: Continuous Improvement of Core Menu with Craveable and Unique Products
8 Continuous Improvement of Core Menu with Craveable and Unique Products Rolled Out in 2014 Rolled Out in 2011, 2012 & 2013 New Core Menu
Slide 9: Leading Everyday Value Platform
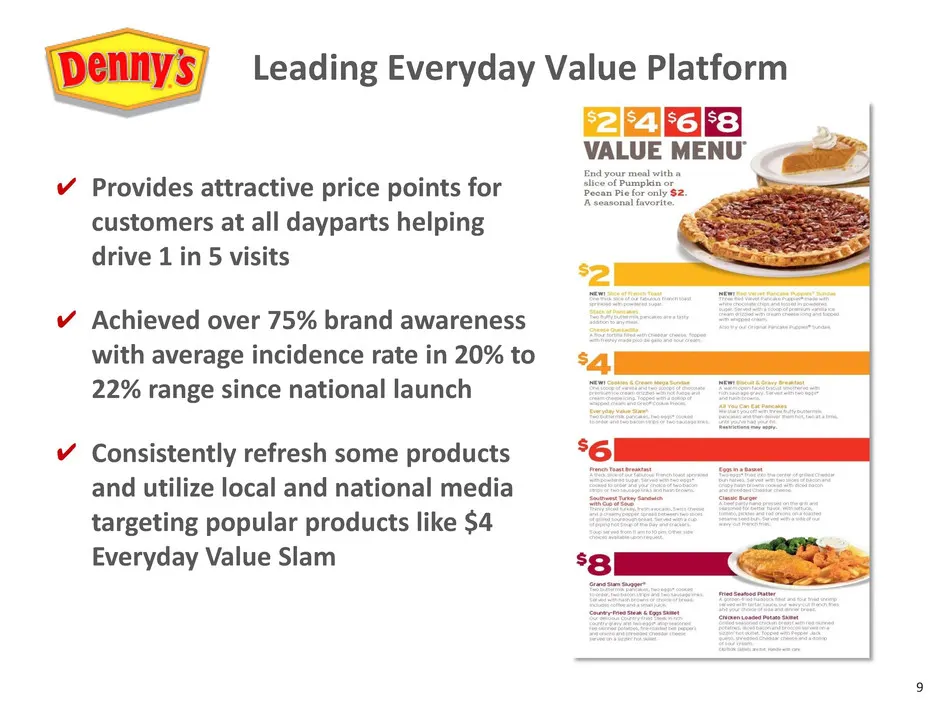
9 Leading Everyday Value Platform Provides attractive price points for customers at all dayparts helping drive 1 in 5 visits Achieved over 75% brand awareness with average incidence rate in 20% to 22% range since national launch Consistently refresh some products and utilize local and national media
Slide 10: Strong and Consistent Pipeline of Limited Time Only Products
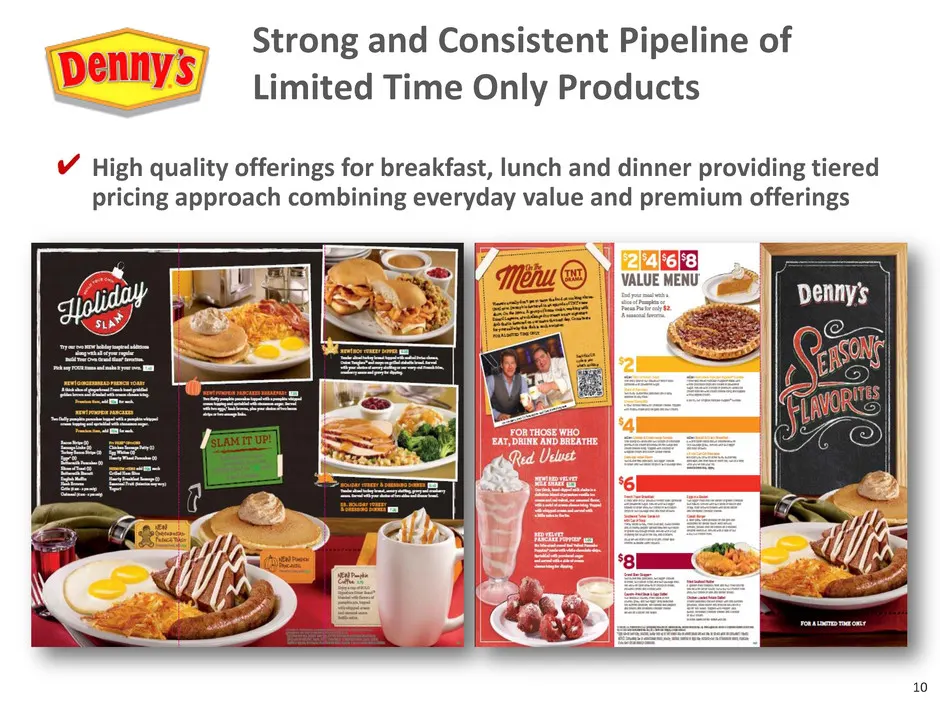
10 Strong and Consistent Pipeline of Limited Time Only Products High quality offerings for breakfast, lunch and dinner providing tiered pricing approach combining everyday value and premium offerings
Slide 11: Improving Guest Service
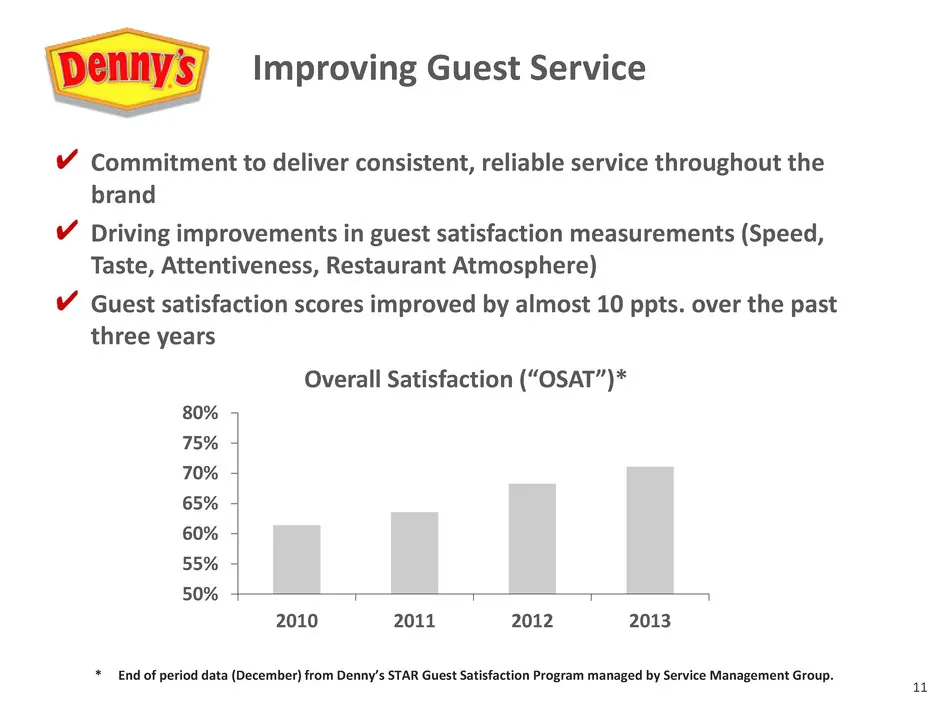
11 50% 55% 60% 65% 70% 75% 80% 2010 2011 2012 2013 Overall Satisfaction (“OSAT”)* Commitment to deliver consistent, reliable service throughout the brand Driving improvements in guest satisfaction measurements (Speed, Taste, Attentiveness, Restaurant Atmosphere) Guest satisfaction scores improved by
Slide 12: New Heritage Remodel Program: Exterior
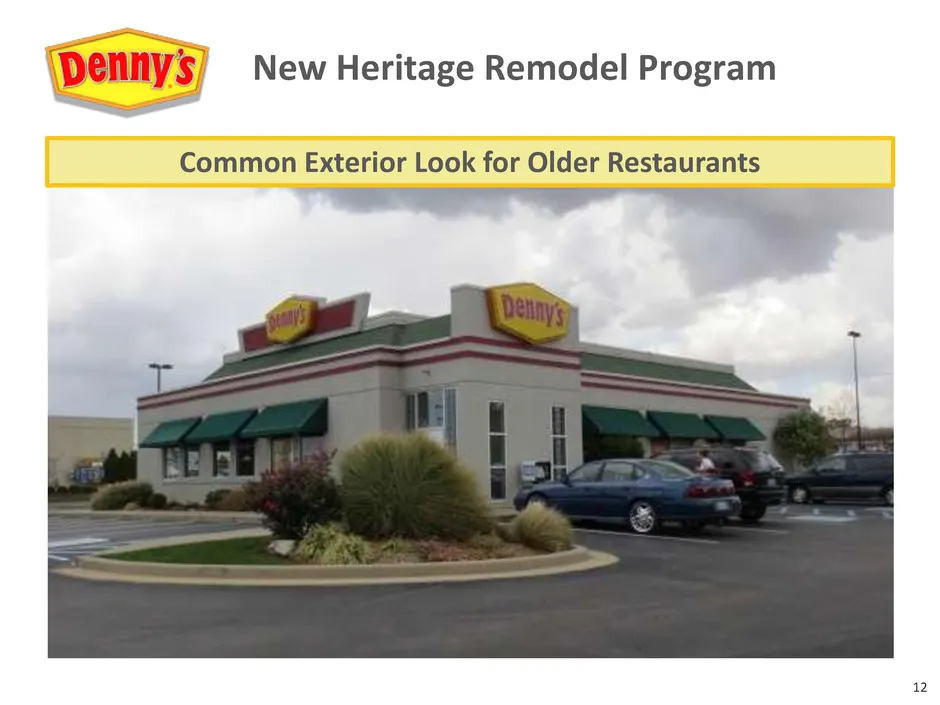
12 New Heritage Remodel Program Common Exterior Look for Older Restaurants
Slide 13: New Heritage Remodel Program: Interior
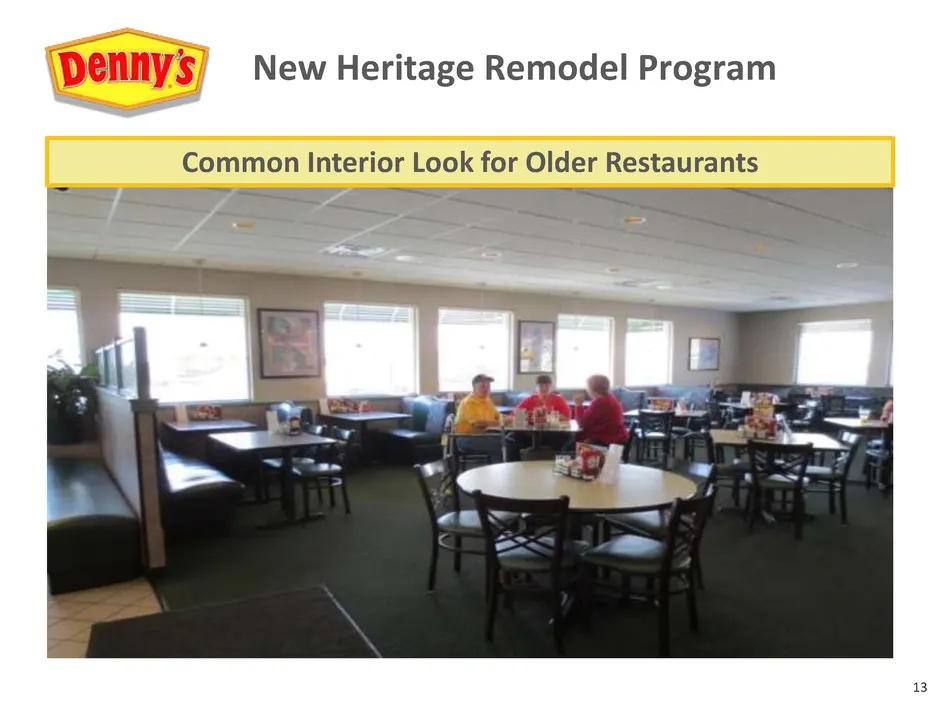
13 New Heritage Remodel Program Common Interior Look for Older Restaurants
Slide 14: New Heritage Remodel Program
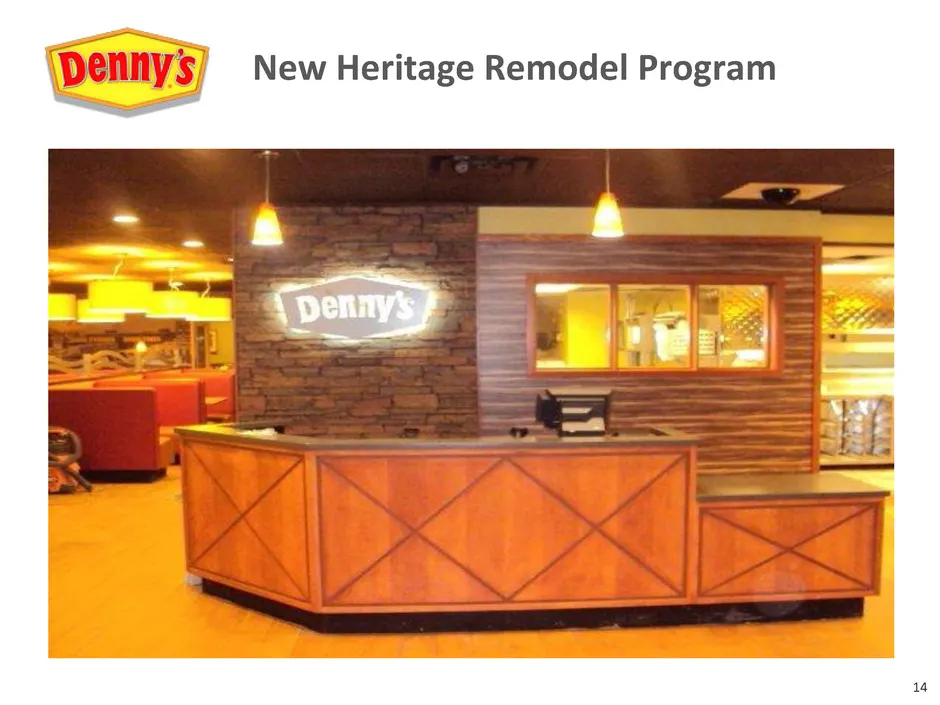
14 New Heritage Remodel Program
Slide 15: New Heritage Remodel Program
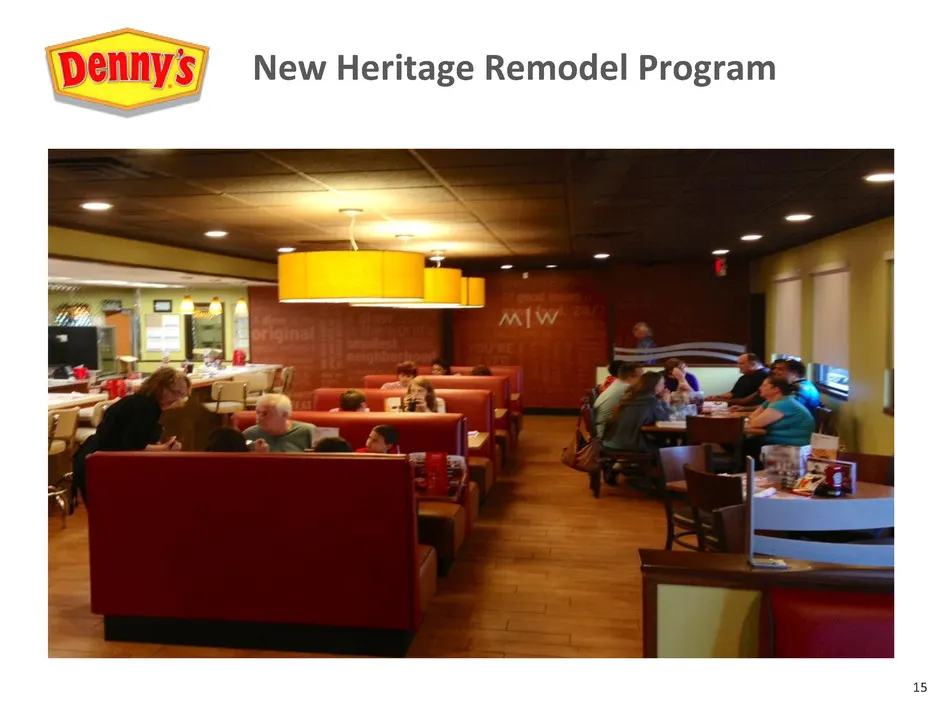
15 New Heritage Remodel Program
Slide 16: Enhancing Denny's Atmosphere with New Heritage Remodel Program
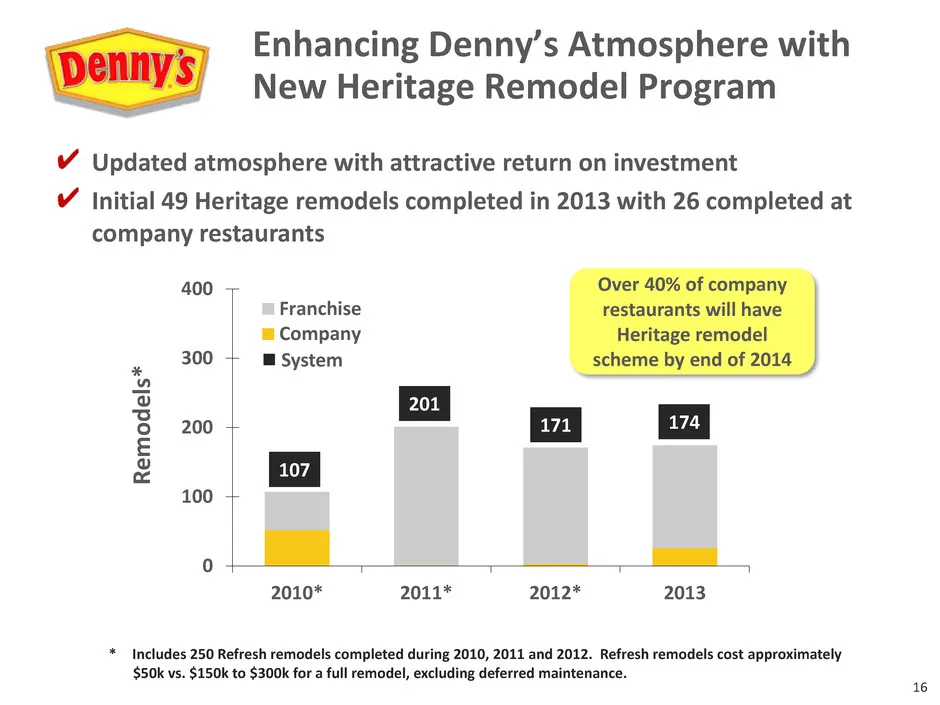
16 Enhancing Denny’s Atmosphere with New Heritage Remodel Program Updated atmosphere with attractive return on investment Initial 49 Heritage remodels completed in 2013 with 26 completed at company restaurants 0 100 200 300 400 2010* 2011* 2012* 2013 R e m o d el s* Franchise Company * Includes 250
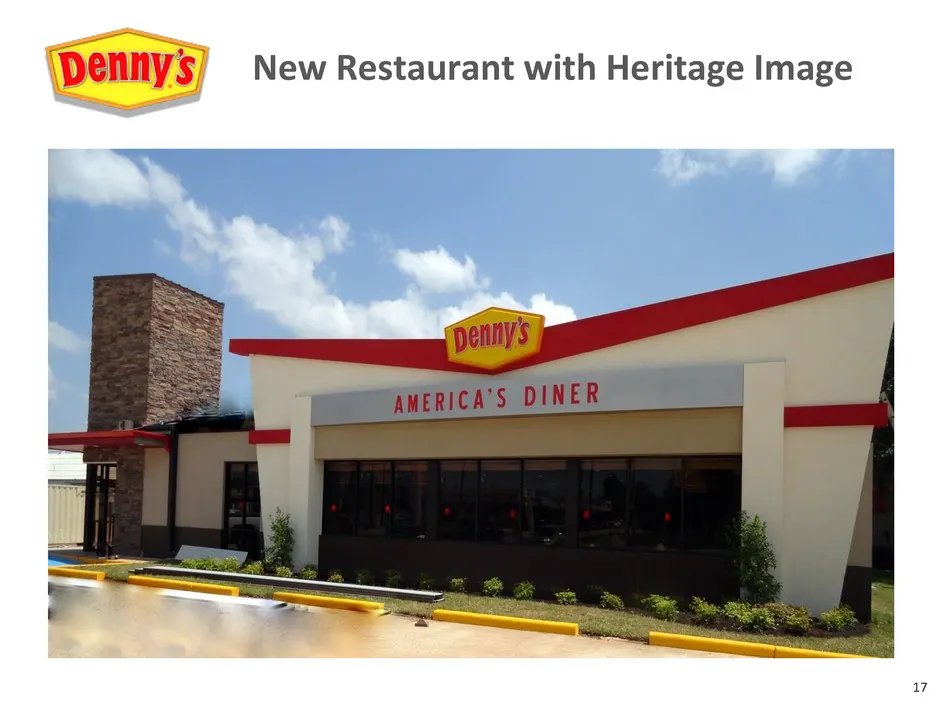
Slide 17: New Restaurant with Heritage Image
17 New Restaurant with Heritage Image
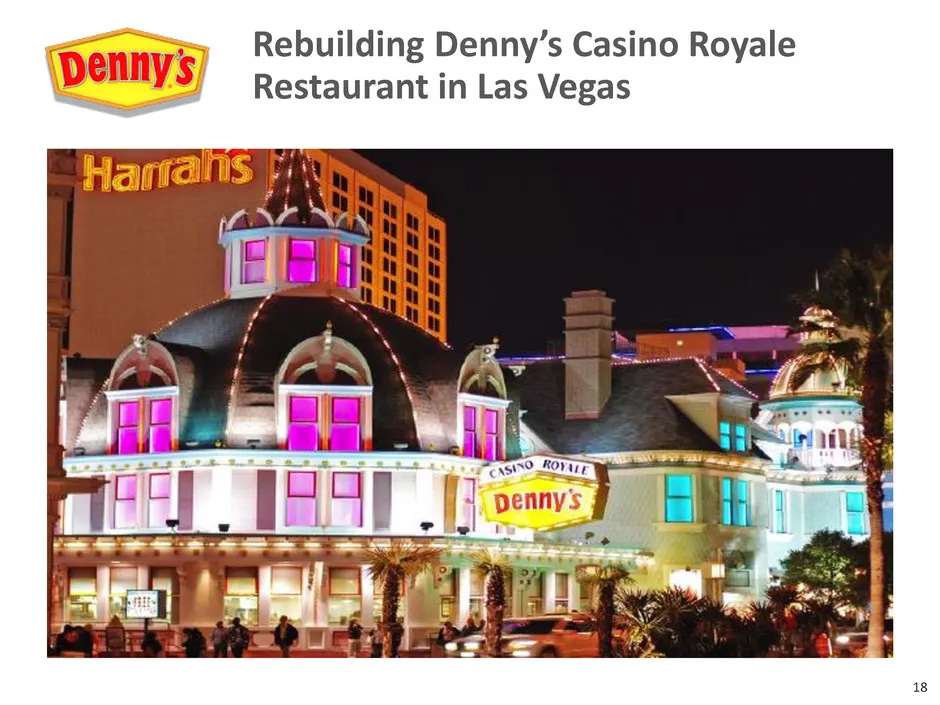
Slide 18: Rebuilding Denny's Casino Royale Restaurant in Las Vegas
18 Redevelopment of location by landlord provides opportunity to rebuild Denny’s highest volume restaurant Rebuilding Denny’s Casino Royale Restaurant in Las Vegas
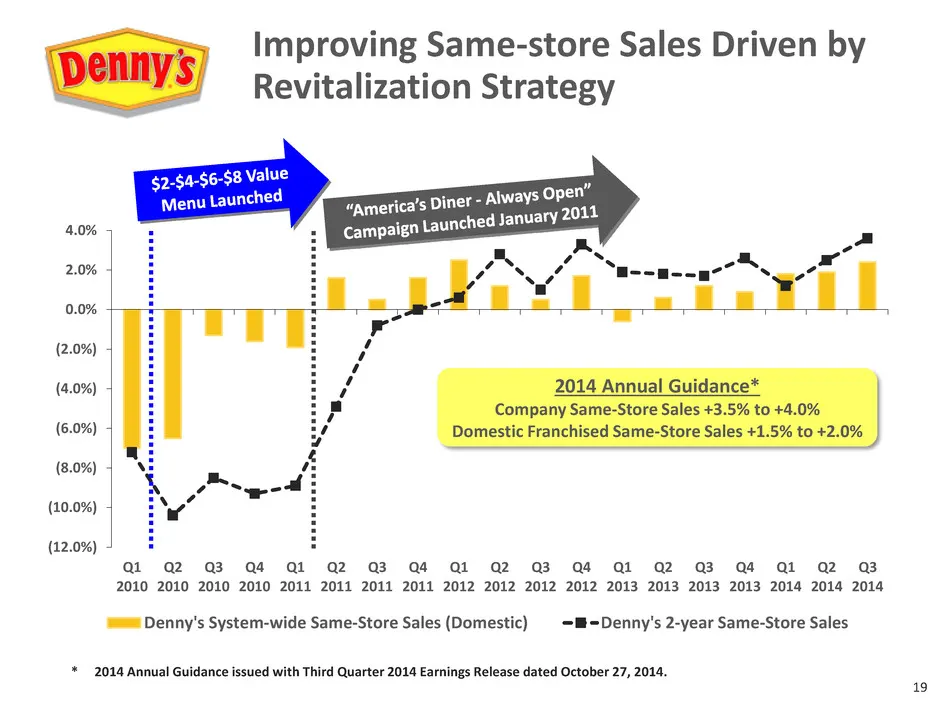
Slide 19: Improving Same-store Sales Driven by Revitalization Strategy
19 (12.0%) (10.0%) (8.0%) (6.0%) (4.0%) (2.0%) 0.0% 2.0% 4.0% Q1 2010 Q2 2010 Q3 2010 Q4 2010 Q1 2011 Q2 2011 Q3 2011 Q4 2011 Q1 2012 Q2 2012 Q3 2012 Q4 2012 Q1 2013 Q2 2013 Q3 2013 Q4 2013 Q1 2014 Q2 2014 Q3 2014 Denny's System-wide Same-Store Sales (Domestic) Denny's 2-year Same-Store Sales Improv
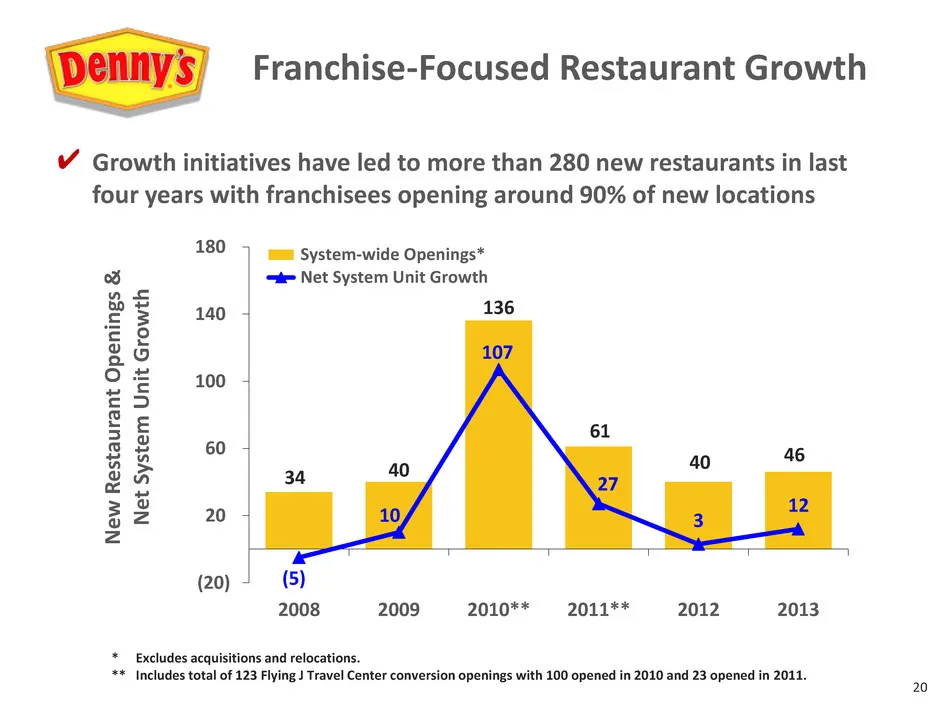
Slide 20: Franchise-Focused Restaurant Growth
20 34 40 136 61 40 46 (5) 10 107 27 3 12 (20) 20 60 100 140 180 2008 2009 2010** 2011** 2012 2013 New R e st au ra n t Op e n in gs & Net Sy st e m U n it G ro w th System-wide Openings* Net System Unit Growth * Excludes acquisitions and relocations. ** Includes total of 123 Flying J Travel Center c
Slide 21: Strong market share in many top markets
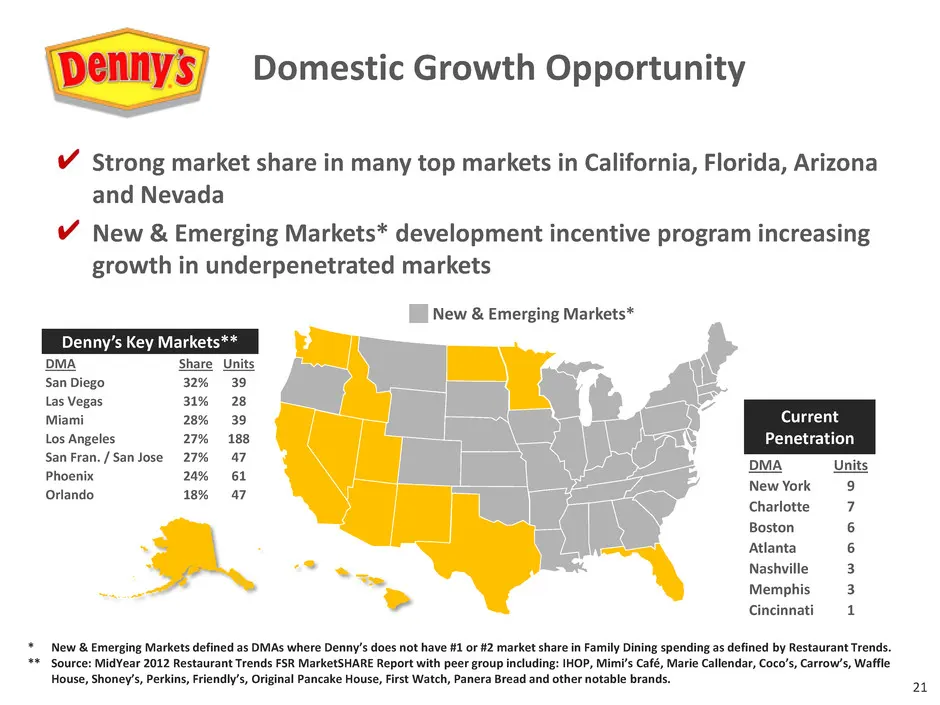
21 Strong market share in many top markets in California, Florida, Arizona and Nevada New & Emerging Markets* development incentive program increasing growth in underpenetrated markets Denny’s Key Markets** DMA Share Units San Diego 32% 39 Las Vegas 31% 28 Miami 28% 39 Los Angeles 27% 188 San Fran.
Slide 22: Growing International Footprint
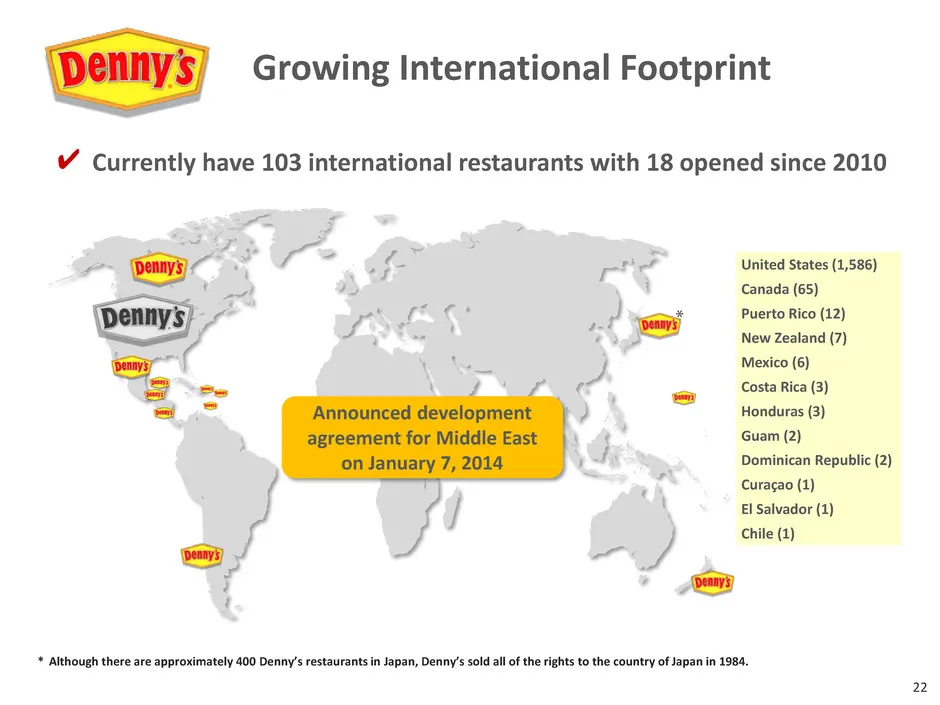
22 * Although there are approximately 400 Denny’s restaurants in Japan, Denny’s sold all of the rights to the country of Japan in 1984. United States (1,586) Canada (65) Puerto Rico (12) New Zealand (7) Mexico (6) Costa Rica (3) Honduras (3) Guam (2) Dominican Republic (2) Curaçao (1) El Salvador (1
Slide 23: Growing Non-Traditional Locations
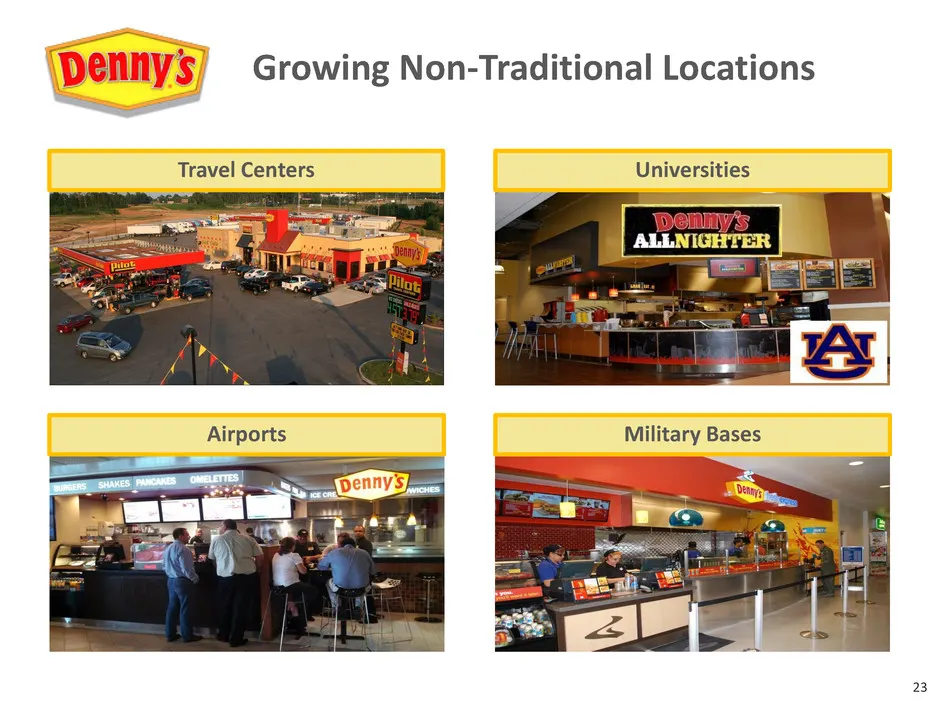
23 Travel Centers Airports Universities Military Bases Growing Non-Traditional Locations
Slide 24: Growing Adjusted Earnings per Share
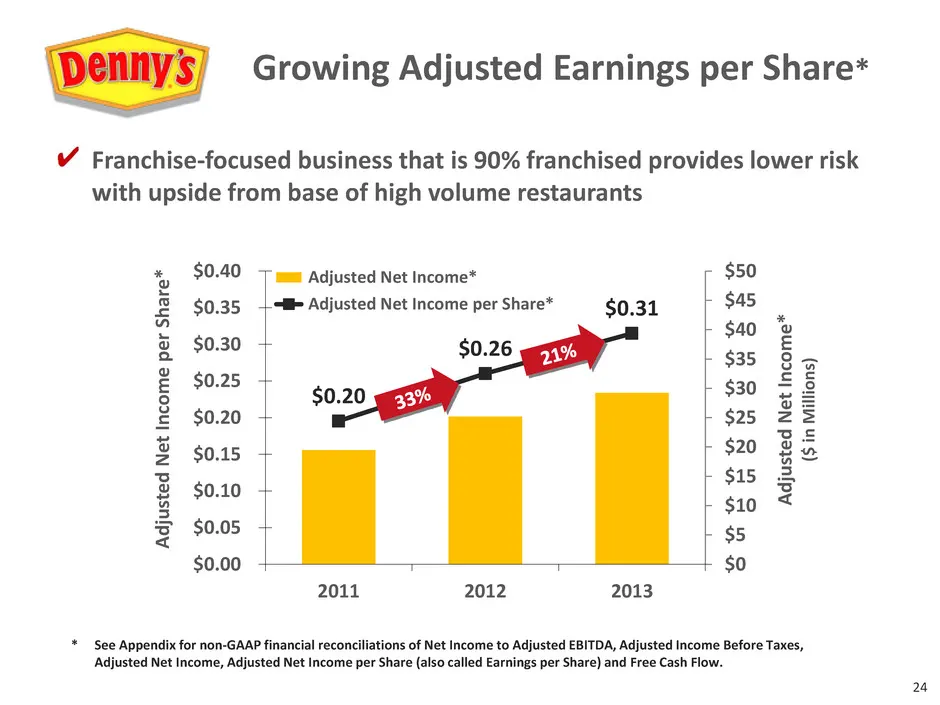
24 $0.20 $0.26 $0.31 $0 $5 $10 $15 $20 $25 $30 $35 $40 $45 $50 $0.00 $0.05 $0.10 $0.15 $0.20 $0.25 $0.30 $0.35 $0.40 2011 2012 2013 A d ju st ed N et In co me * ($ in Mil lio n s) A d ju st ed N et In co me p er Sha re * Adjusted Net Income* Adjusted Net Income per Share* * See Appendix for non-GAAP
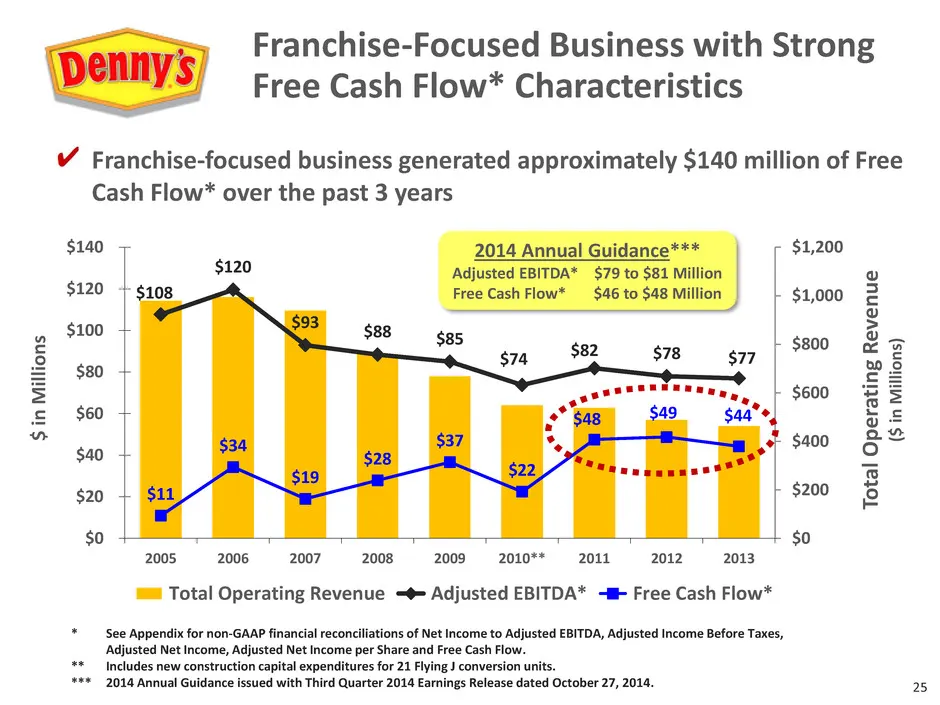
Slide 25: Franchise-Focused Business with Strong Free Cash Flow Characteristics
25 $108 $120 $93 $88 $85 $74 $82 $78 $77 $11 $34 $19 $28 $37 $22 $48 $49 $44 $0 $200 $400 $600 $800 $1,000 $1,200 $0 $20 $40 $60 $80 $100 $120 $140 2005 2006 2007 2008 2009 2010** 2011 2012 2013 To tal Op e ra ti n g R ev e n u e ($ in Mil lio n s) $ in M ill io n s Total Operating Revenue Adjusted
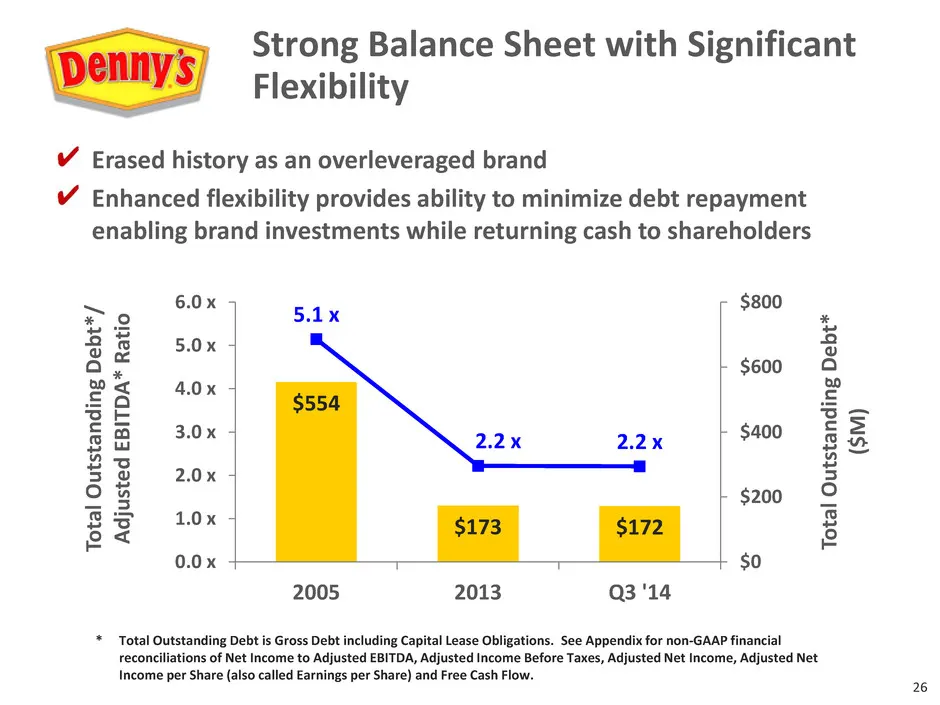
Slide 26: Strong Balance Sheet with Significant Flexibility
26 Strong Balance Sheet with Significant Flexibility $554 $173 $172 5.1 x 2.2 x 2.2 x 0.0 x 1.0 x 2.0 x 3.0 x 4.0 x 5.0 x 6.0 x 2005 2013 Q3 '14 $0 $200 $400 $600 $800 To tal Out st an d in g D e b t* / A d ju st e d EBI TD A* R ati o To tal Out st an d in g D e b t* ($M ) Erased history as an overl
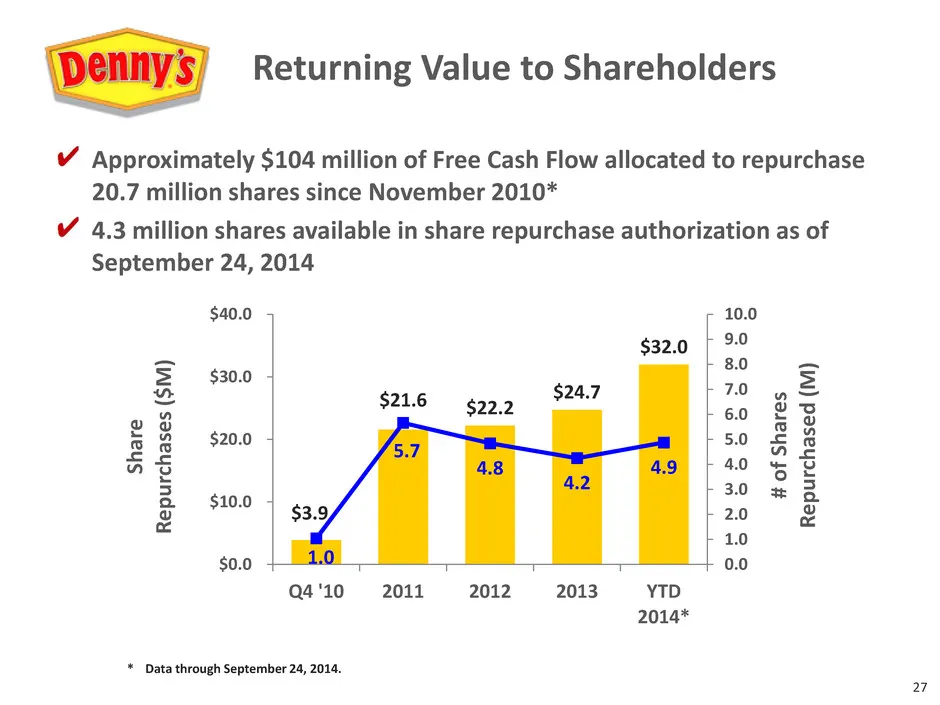
Slide 27: Returning Value to Shareholders
27 $3.9 $21.6 $22.2 $24.7 $32.0 1.0 5.7 4.8 4.2 4.9 0.0 1.0 2.0 3.0 4.0 5.0 6.0 7.0 8.0 9.0 10.0 Q4 '10 2011 2012 2013 YTD 2014* $0.0 $10.0 $20.0 $30.0 $40.0 # o f Sha re s R e p u rc h as e d (M ) Sha re R e p u rc h as e s ($M ) Approximately $104 million of Free Cash Flow allocated to repurchase
Slide 28: Denny's Investment Highlights
28 Denny’s Investment Highlights Iconic brand with 96% brand awareness in the U.S.* and nearly 1,700 restaurants in all 50 states in the U.S. and 11 countries & U.S. territories * Source: Denny’s BrandTracker, Year End 2013. ** See Appendix for reconciliation of Net Income to Adjusted EBITDA, Adjust
Slide 29: Appendix
APPENDIX
Slide 30: Non-GAAP Financial Reconciliations
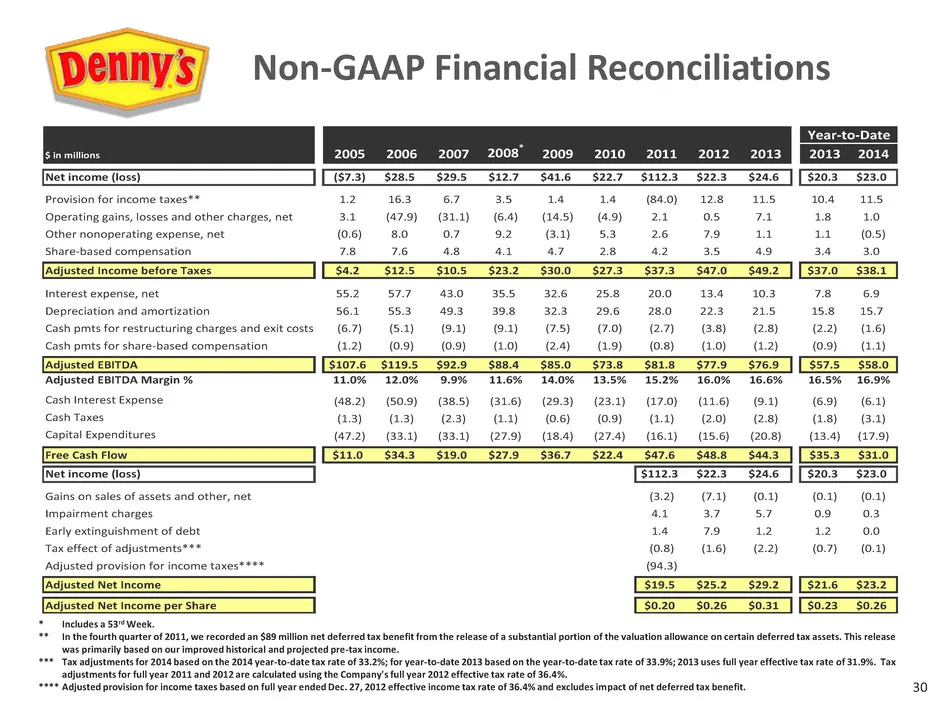
30 * Includes a 53rd Week. ** In the fourth quarter of 2011, we recorded an $89 million net deferred tax benefit from the release of a substantial portion of the valuation allowance on certain deferred tax assets. This release was primarily based on our improved historical and projected pre-tax inco
Source: SEC EDGAR · 8-K filed Nov 13, 2014
More decks from Dennys Corp
 Investor Presentation (August 2025)30 slides · Aug 4, 2025
 Investor Presentation (May 2025)32 slides · May 2025
 Investor Presentation (February 2025)32 slides · February 2025
 Investor Presentation (January 2025)32 slides · Jan 13, 2025
 Investor Day (October 2024)137 slides · Oct 22, 2024
 Q2 2024 Earnings Presentation22 slides · Jul 30, 2024