Southern Community Financial Corp
Southern Community Financial — Investor Presentation (February 2006)
25 slides from Southern Community Financial's investor presentation, Feb 6, 2006
Slide 1: Southern Community Financial Corporation
Coguthern FINANCIAL CORPORATION
Slide 2: Forward-Looking Statements
This presentation may contain, in addition to historical information, various "forward-looking statements" that represent our judgment concerning the future and are subject to risks and uncertainties that could cause Southern Community's actual operating results and financial position to differ mate
Slide 3: Corporate Profile
Corporate Profile CORPORATE PROFILE Started - November 18, 1996 State Chartered, Fed Member and Report to the SEC SCFC Operates 19 Banking Offices in 8 Counties Financial Services Branch in Raleigh, NC New Branch in Mooresville, NC (Charlotte) VCS Management, LLC Small Business Investment Company -
Slide 4: Corporate Profile
Corporate Profile CORPORATE PROFILE Created a diverse, full service financial institution for the long term 3rd largest community bank headquartered in N.C.; largest in the Triad Region Positioned competitively to transition new relationships Reputation for service, community focus - -7-
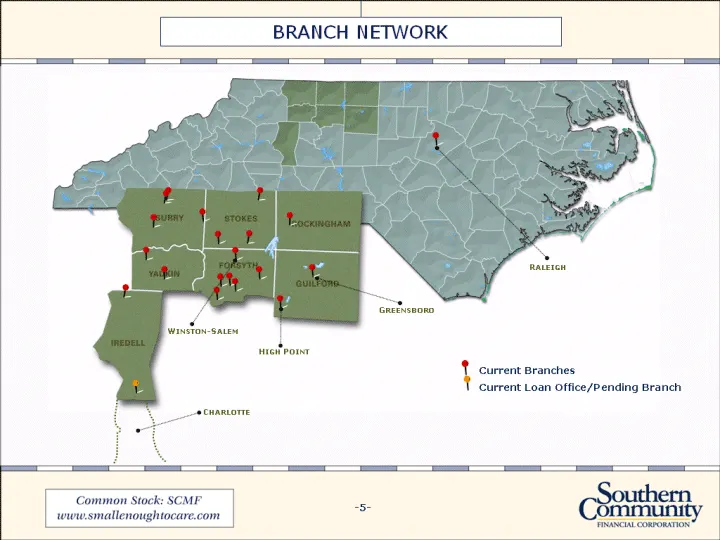
Slide 5: Branch Network
Branch Network BRANCH NETWORK Current Branches Current Loan Office/Pending Branch CHARLOTTE WINSTON-SALEM GREENSBORO HIGH POINT - -9- RALEIGH
Slide 6: Target Markets
Target Market TARGET MARKETS Small & Medium Sized Businesses Owners Managers Professionals Residential Builders / Developers Retail Customers - -11-
Slide 7: Our Market Area
Our Market Area OUR MARKET AREA Piedmont Region is the 12-county area of NC that stretches from Raleigh in the East to Charlotte in the West. Southern Community headquarters located in Winston-Salem, center of the Piedmont. Population for the Piedmont Triad (one of the top 50 MSAs, includes Greensbo
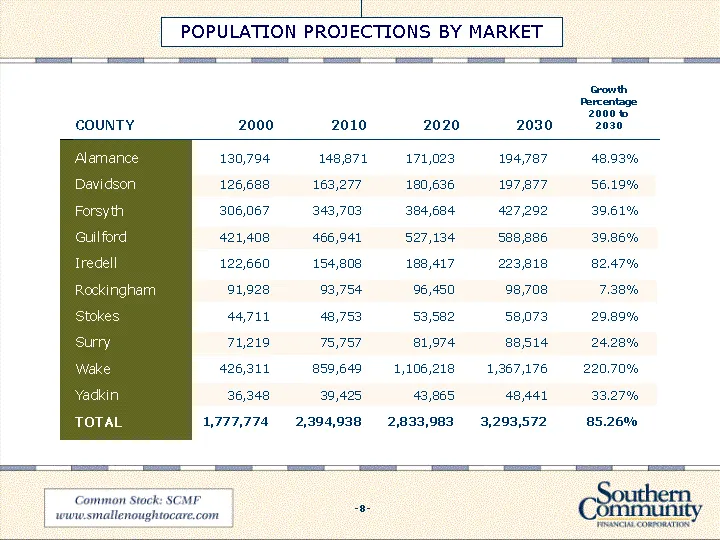
Slide 8: Population Projections by Market
POPULATION PROJECTIONS BY MARKET - -15-
Slide 9: Sound Infrastructure
SOUND INFRASTRUCTURE Leadership of Management and Board Corporate Governance Regulatory Compliance Customer Security Soundness in Lending Risk Management Team - -17-
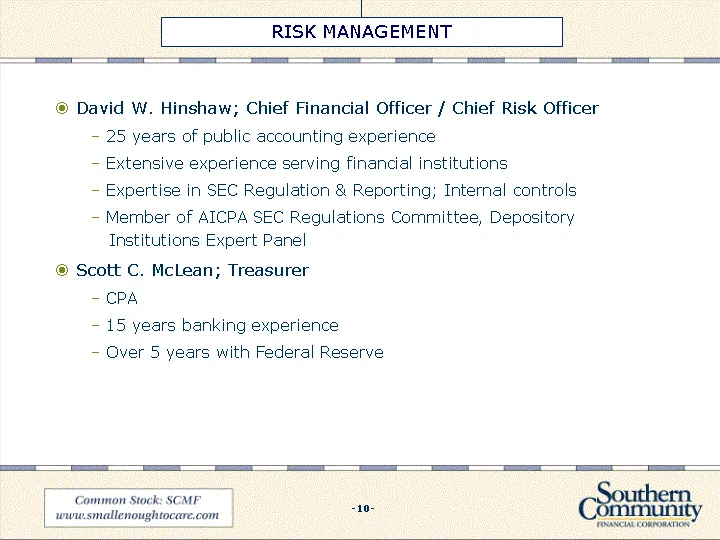
Slide 10: Risk Management
RISK MANAGEMENT David W. Hinshaw; Chief Financial Officer / Chief Risk Officer 25 years of public accounting experience Extensive experience serving financial institutions Expertise in SEC Regulation & Reporting; Internal controls Member of AICPA SEC Regulations Committee, Depository Institutions Ex
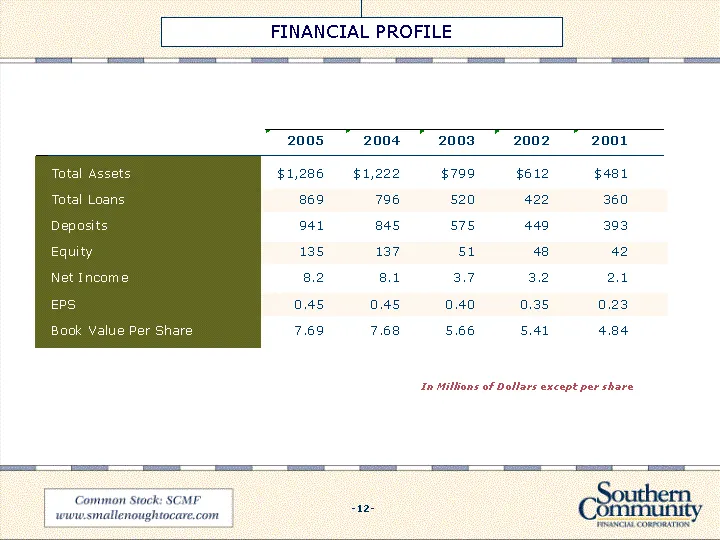
Slide 11: Financial Profile
FINANCIAL PROFILE - -23- In Millions of Dollars except per share
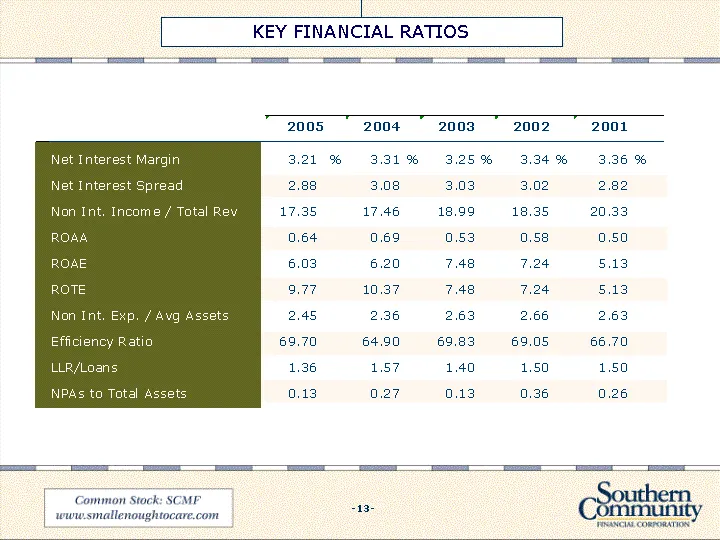
Slide 12: Key Financial Ratios
KEY FINANCIAL RATIOS a a ee 2003” 2002 2001 Net Int 325% 3.34% 3.36 Net Int 3033.02 2.82 Non Int. Ir 1899 18.35 20.93 OAA 053 Ose 0.50 OAE 7480 7.24 5.13 OTE 7487.24 5.13 Non Int. Exp 263 2.66 2.63 69.83 69.05 66.70 1401.50 1.80 0130.36 0.26 [. ‘Common Stock: SCMP ewu:smallenoughtocare.com ae
Slide 13: Balance Sheet Management
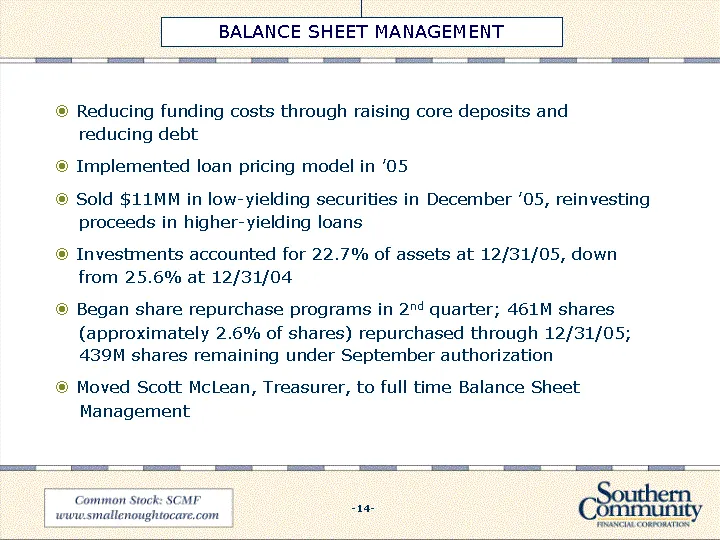
BALANCE SHEET MANAGEMENT Reducing funding costs through raising core deposits and reducing debt Implemented loan pricing model in '05 Sold $11MM in low-yielding securities in December '05, reinvesting proceeds in higher-yielding loans Investments accounted for 22.7% of assets at 12/31/05, down from
Slide 14: Deposit Portfolio Composition
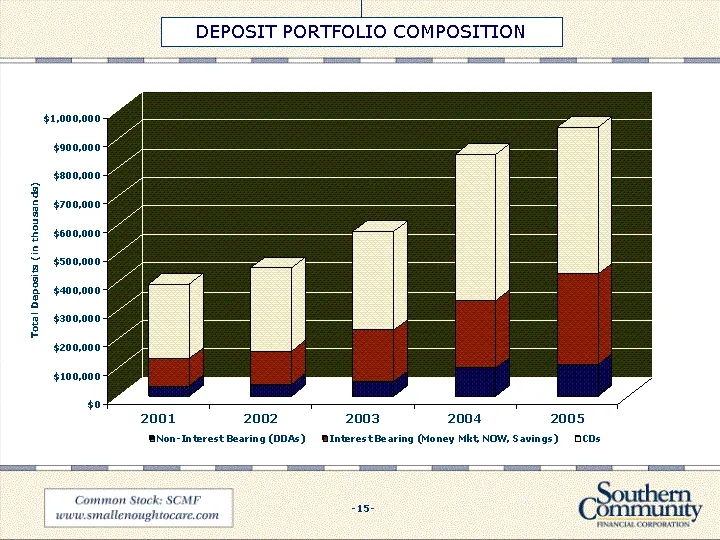
DEPOSIT PORTFOLIO COMPOSITION - -29-
Slide 15: Funding Mix
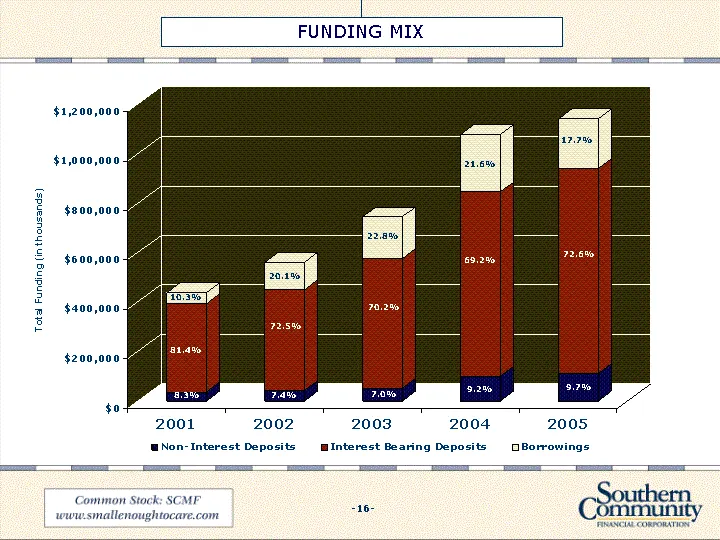
FUNDING MIX - -31- 8.3% 7.4% 7.0% 9.2% 9.7% 81.4% 72.5% 70.2% 69.2% 72.6% 10.3% 20.1% 22.8% 21.6% 17.7%
Slide 16: Investment Portfolio Composition
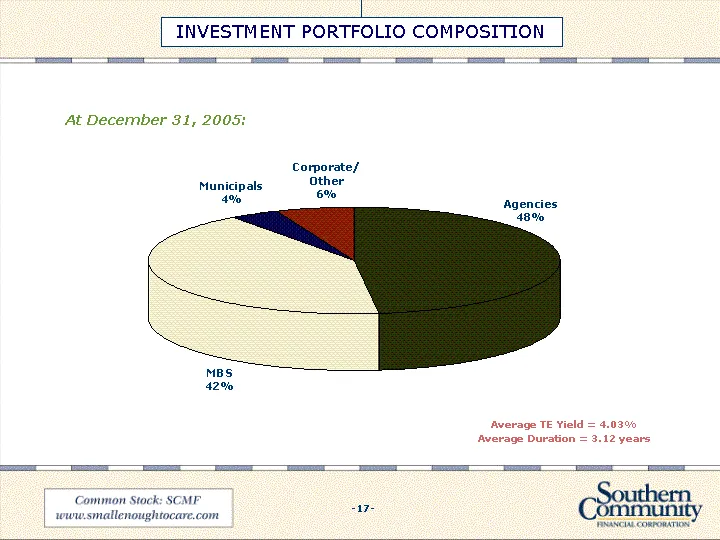
Agencies MBS Municipals Corporate/Other East 48 42 4 6 INVESTMENT PORTFOLIO COMPOSITION At December 31, 2005: Average TE Yield = 4.03% Average Duration = 3.12 years - -33-
Slide 17: Loan Portfolio Composition
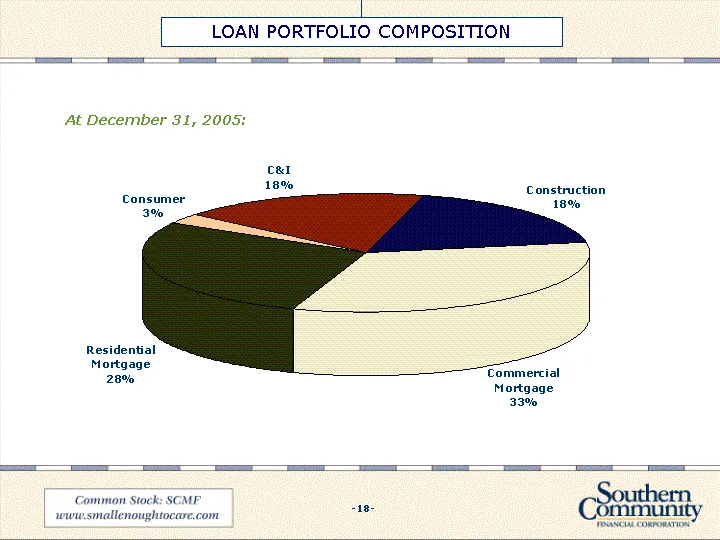
Commercial Mortgage Residential Mortgage Consumer Construction C&I East 33 28 3 18 18 LOAN PORTFOLIO COMPOSITION At December 31, 2005: - -35-
Slide 18: Asset Quality and Reserves
ASSET QUALITY AND RESERVES Lend to Established Businesses with Historical Cash Flow Do Not Participate in Large Syndications Independent Loan Review NPAs Are Low - 0.13% of Total Assets $11.8 Million in ALLL, 1.36% of Loans, 8.37x NPLs - -37-
Slide 19: Expense Control
EXPENSE CONTROL Holding Line Managers Accountable Rewarding cost savings measures Evaluating all decisions in light of the current environment Creating efficiencies through automation 2006 will be impacted by the opening of the Greensboro (12/05) and Mooresville (estimated Q3 '06) banking offices, o
Slide 20: Consolidation Creates Opportunity
CONSOLIDATION CREATES OPPORTUNITY Wachovia - their target customer is larger - $50MM-$100MM in sales Bank of America-National Retail Strategy - abandoned local base SunTrust / Acquired NCFC /Acquired CCB, which operated as a N.C. Community bank. Less decision making in our market. (Total of $1.2 bil
Slide 21: Positioned for Growth
POSITIONED FOR GROWTH Well capitalized Sound, excellent quality Infrastructure and people in place to support a much larger institution A leader in: - -Service - -Business Banking - -Construction Lending Competitive , entrepreneurial, determined - -43-
Slide 22: Positioned for Growth
POSITIONED FOR GROWTH Very experienced, proven commercial banking team Strong Construction lending division, growing and producing excellent fee income Southern Community Advisors (Wealth Management Group) Enhanced Mortgage division, new manager, more aggressive posture in new markets Retail Bank to
Slide 23: Focus and Strategy
FOCUS AND STRATEGY Our Future Strategy: Expand Market Through de novo Locations or Accretive Acquisitions Diversify Our Revenue - Expand Mortgage Operations - Build Southern Community Advisors our Wealth Management Division Leverage Commercial Bank Loans & Relationships Leverage Infrastructure and P
Slide 24: Why Invest in Southern Community?
WHY INVEST IN SOUTHERN COMMUNITY? Reputation Service Focus Competitive Sound Credit and Risk Culture Strong Management Team, Committed Employees Consolidation Opportunities - well positioned in North Carolina Inside Ownership (13.2% as of 12/31/05) Long term focus to build a solid, competitive, high
Slide 25: Closing Questions & Answers
CLOSING QUESTIONS & ANSWERS NASDAQ "SCMF" NASDAQ "SCMFO" - -51-
Source: SEC EDGAR · 8-K filed Feb 6, 2006
More decks from Southern Community Financial Corp
 KBW Investor Conference 201030 slides · Jul 27, 2010
 Investor Presentation (May 2009)26 slides · May 4, 2009
 Conference Presentation (February 2009)26 slides · Feb 6, 2009
 Southeast SuperCommunity Bank Conference (February 2008)28 slides · Feb 11, 2008
 America's Community Bankers Community Bank Investor Conference 200724 slides · Nov 2, 2007
 Emerging Growth Institutional Investor Forum 200727 slides · Mar 26, 2007