Southern Community Financial Corp
Southern Community Financial — Emerging Growth Institutional Investor Forum 2007
27 slides from Southern Community Financial's conference presentation, Mar 26, 2007
Slide 1: Emerging Growth Institutional Investor Forum
March 27, 2007 Emerging Growth Institutional Investor Forum Sidoti & Co., LLC
Slide 2: Forward Looking Statements
This presentation may contain, in addition to historical information, various “forward-looking statements” that represent our judgment concerning the future and are subject to risks and uncertainties that could cause Southern Community’s actual operating results and financial position to differ mate
Slide 3: Corporate Profile
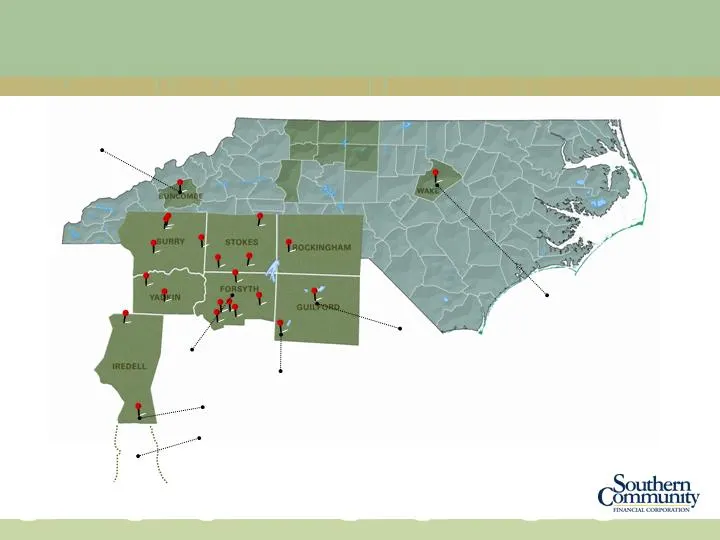
Started November 18, 1996 State chartered, Fed member and report to the SEC SCFC operates 22 banking offices in 9 NC counties Recently expanded into Raleigh & Asheville, NC New banking office in Mooresville, NC (Charlotte) opened in August 2006 VCS Management, LLC Small business investment company C
Slide 4: Why Invest In Southern Community?
Competitive & driven for the long term Our people: Strong, entrepreneurial management team; committed employees Have built the infrastructure & capacity to support significant growth Strength of our commercial banking and construction team Diverse, full-service financial institution; positioned to c
Slide 5: Southern Community Services
Full service retail and commercial banking Full service construction lending division Mezzanine financing Mortgage division Asset management, brokerage, trust Tax-free exchange Cash management/online services Lock box Courier Southern Community Services
Slide 6: Why Invest In Southern Community? Ownership and Capital
Inside ownership (12.4% as of 12/31/06) Well capitalized, 136.2MM in equity, over 17.4MM shares outstanding, market cap of 169.98MM Strength of credit administration & regulatory compliance Strong credit culture/fundamentals Why Invest In Southern Community?
Slide 7: Asset Quality And Reserves
Lend to established businesses with historical cash f low Independent loan review NPAs are 0.25% of total assets (as of 12/31/06) $13.0 million in ALLL, 1.26% of loans, 4.95x coverage of NPLs (as of 12/31/06) Asset Quality And Reserves
Slide 8: Why Invest In Southern Community? Market Position
Long term focus to build a solid, competitive, high performance institution 3 rd largest Community Bank in NC – Consolidation opportunities Deposit share – #3 in Forsyth County #5 in Triad (Greensboro/High Point/Winston-Salem) Positioned in four of the top five markets in fast-growing NC NC is #1 in
Slide 9: Why Invest In Southern Community? Trust and Service
One of only 8 community banks in NC offering trust services Strong reputation for service and community involvement (97% customer approval rating) Our culture: High-service standards and focus – Heart for Service Most experienced, competitive and deepest commercial/ construction departments in NC Ve
Slide 10: Best Commercial Bank In NC
Commercial Bank Offer any type of business loan Full cash management services Small business banking Commercial Finance Asset-based lending Receivables purchasing & financing Operate full-service lock box Small Business Investment Corporation Venture capital – Mezzanine financing Subordinated debt w
Slide 11: Target Markets
Small & medium sized businesses Owners Managers Professionals Residential builders/developers – over $200 million outstanding Retail customers Target Markets
Slide 12: Branch Network
C HARLOTTE W INSTON -S ALEM Headquarters G REENSBORO H IGH P OINT R ALEIGH M OORESVILLE Branch Network A SHEVILLE
Slide 13: Population Projections By Market
Alamance Davidson Rockingham Stokes Surry Yadkin TOTAL Population Projections By Market Entire US: 28.9% State of NC: 51.9% COUNTY 2000 2030 Growth % 2000 to 2030 130,794 194,787 48.93% Buncombe (Asheville) 206,766 278,494 34.69% 147,246 197,877 34.39% Forsyth (Winston-Salem) 306,067 427,292 39.61%
Slide 14: NC Growth Projections
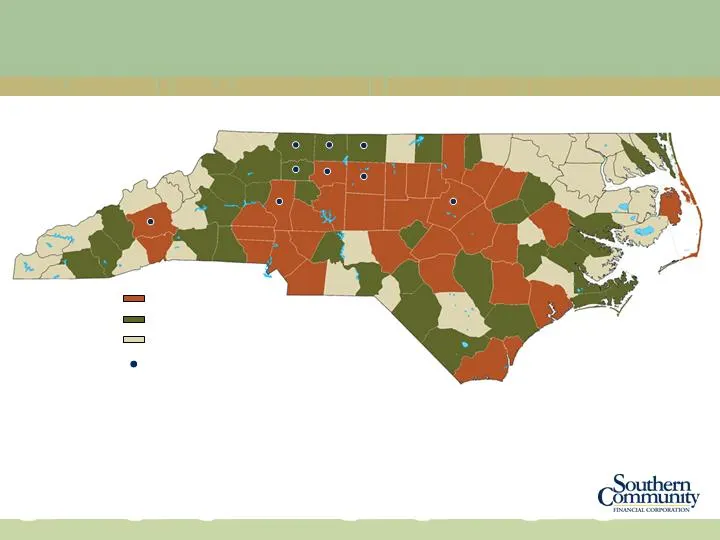
NC Growth Projections High Growth County Medium Growth County Low Growth County Based on Raymond James’ Projected Economic Indicator Change ’06-’11, which measures prospective wealth creation using changes in population and median household income County With Southern Community Branch
Slide 15: Deposit Initiatives
Incentive for commercial/retail bankers Focused campaigns Deposit specialist Targeting Business banking Changing our funding mix Deposit Initiatives
Slide 16: Deposit Portfolio Composition
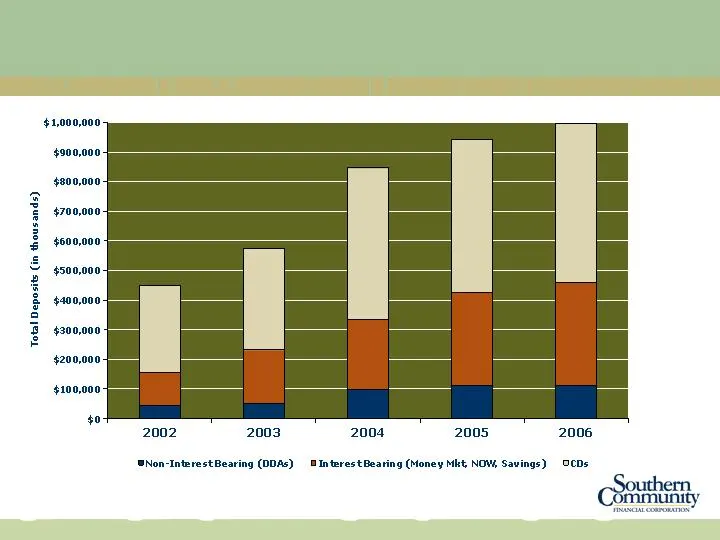
11.8% 11.7% 9.0% 9.3% 33.5% 27.9% 31.1% 25.8% 10.6% 38.4% 54.7% 60.4% 59.9% 64.9% Deposit Portfolio Composition 51.0%
Slide 17: Market Share – NC Statewide
TOTAL Southern Bancshares (NC)(NC) Bank of Granite Corp. (NC) South Financial Group Inc. (SC) Capital Bank Corp. (NC) Fidelity Bancshares (NC) Inc. (NC) FNB United Corp. (NC) First Bancorp (NC) First Charter Corp. (NC) Royal Bank of Canada SunTrust Banks Inc. (GA) First Citizens BancShares Inc. (NC)
Slide 18: Market Share – Our Markets
TOTAL Crescent Financial Corp. (NC) Capital Bank Corp. (NC) Paragon Commercial Corp. (NC) Yadkin Valley Financial (NC) Fidelity Bancshares (NC) Inc. (NC) FNB Financial Services Corp. (NC) High Point Bank Corp. (NC) Piedmont FS&LA (NC) Royal Bank of Canada First Citizens BancShares Inc. (NC) SunTrust
Slide 19: Financial Profile
Total Assets Total Loans Deposits Equity Net Income EPS Book Value Per Share Tangible Book Value Per Share In Millions of Dollars except per share Financial Profile * Reflects impact of investment portfolio restructure 2006 2005 2004 2003 2002 $1,436 $1,288 $1,223 $799 $612 1,033 1,025 4.2 * 7.7 8.1
Slide 20: Key Financial Ratios
Net Interest Margin Net Interest Spread Non Int. Income / Total Rev ROAA ROAE ROTE Non Int. Exp. / Avg Assets Efficiency Ratio LLR/Loans NPAs to Total Assets Key Financial Ratios * Reflects impact of investment portfolio restructure 2006 2005 2004 2003 2002 3.30 % 3.20 % 3.26 % 3.22 % 3.34 % 2.92 2.
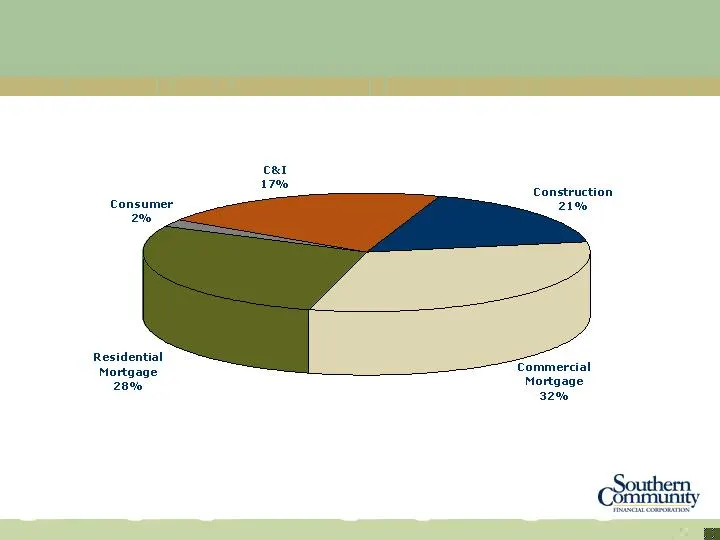
Slide 21: Loan Portfolio Composition
At December 31, 2006: Approximately 58% Floating Loan Portfolio Composition
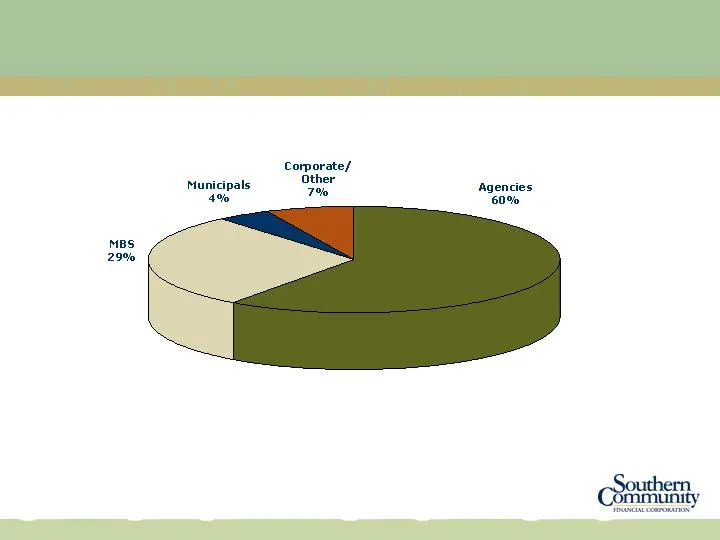
Slide 22: Investment Portfolio Composition
At December 31, 2006: Total Dollars = Approximately $255 million Average Yield = 4.38% % of Assets = 17.8% Investment Portfolio Composition
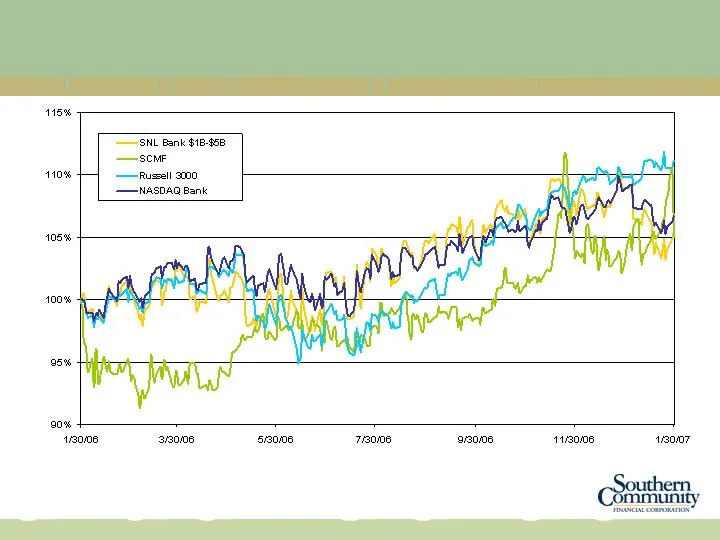
Slide 23: Market Performance (Last 12 Months)
Initial investors have seen a return of 2.83 times their investment, or a CAGR of 12.5% Market Performance (Last 12 Months)
Slide 24: Consolidation Creates Opportunity
Wachovia – Target customer is larger Bank of America – National Retail Strategy SunTrust – Less local decision making in our markets Royal Bank of Canada / Centura – Focused internally BB&T – Focused internally Consolidation Creates Opportunity
Slide 25: Focus And Strategy
Focus And Strategy Expand market through de novo locations or accretive acquisitions Diversify our revenue Expand mortgage operations Build our wealth management division Leverage commercial bank loans & relationships Leverage infrastructure & people Enhance profitability Build core deposit base Bui
Slide 26: Why Southern Community Is Different
Desire and commitment Depth and breadth of our services Strength of commercial and construction services Proven ability to grow revenue, deposits and loans Market footprint and position in NC Infrastructure Soundness Our people/culture Why Southern Community Is Different
Slide 27: Southern Community Financial Corporation
COMMA FINANCIAL CORPORATION
Source: SEC EDGAR · 8-K filed Mar 26, 2007
More decks from Southern Community Financial Corp
 KBW Investor Conference 201030 slides · Jul 27, 2010
 Investor Presentation (May 2009)26 slides · May 4, 2009
 Conference Presentation (February 2009)26 slides · Feb 6, 2009
 Southeast SuperCommunity Bank Conference (February 2008)28 slides · Feb 11, 2008
 America's Community Bankers Community Bank Investor Conference 200724 slides · Nov 2, 2007
 Southeast SuperCommunity Bank Conference (February 2007)26 slides · Feb 14, 2007