Southern Community Financial Corp
Southern Community Financial — Investor Presentation (May 2009)
26 slides from Southern Community Financial's investor presentation, May 4, 2009
Slide 1: May 2009 Investor Meetings
www.smallenoughtocare.com May 2009 Investor Meetings
Slide 2: Forward Looking Statements
www.smallenoughtocare.com 2 This presentation may contain, in addition to historical information, various “forward-looking statements” that represent our judgment concerning the future and are subject to risks and uncertainties that could cause Southern Community’s actual operating results and finan
Slide 3: Corporate Profile
www.smallenoughtocare.com 3 Corporate Profile
Slide 4: Corporate Profile
www.smallenoughtocare.com 4 Commercial bank chartered on November 18, 1996 and headquartered in Winston-Salem, North Carolina Strong management team with an average of 17 years of in- market and 29 years of total banking experience Fifth largest community bank based in North Carolina with total asse
Slide 5: Operating in High Growth Markets
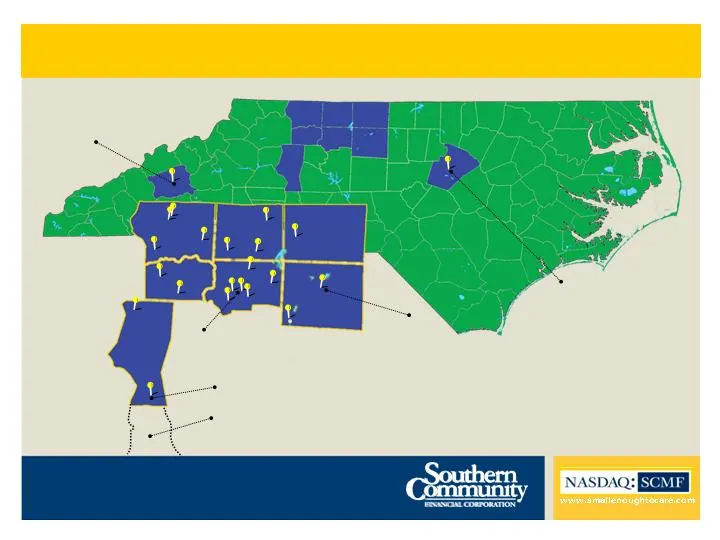
www.smallenoughtocare.com 5 Operating in High Growth Markets C HARLOTTE W INSTON -S ALEM Headquarters G REENSBORO H IGH P OINT STOKES R ALEIGH M OORESVILLE A SHEVILLE BUNCOMBE WAKE ROCKINGHAM SURRY FORSYTH GUILFORD YADKIN IREDELL 22 banking offices in 9 counties across central North Carolina
Slide 6: High Growth Demographics
6 High Growth Demographics County Percent of SCMF Franchise (%) Actual Population Proj. Pop. Growth by 2013 (%) Median HH Income ($) Proj. HH Income Growth by 2013 (%) Forsyth 61.7 345,969 9.2 55,540 14.0 Surry 10.4 73,908 2.0 41,210 13.5 Yadkin 7.9 38,716 3.2 44,288 13.1 Guilford 6.8 468,153 7.5 56
Slide 7: Deposit Growth Opportunities
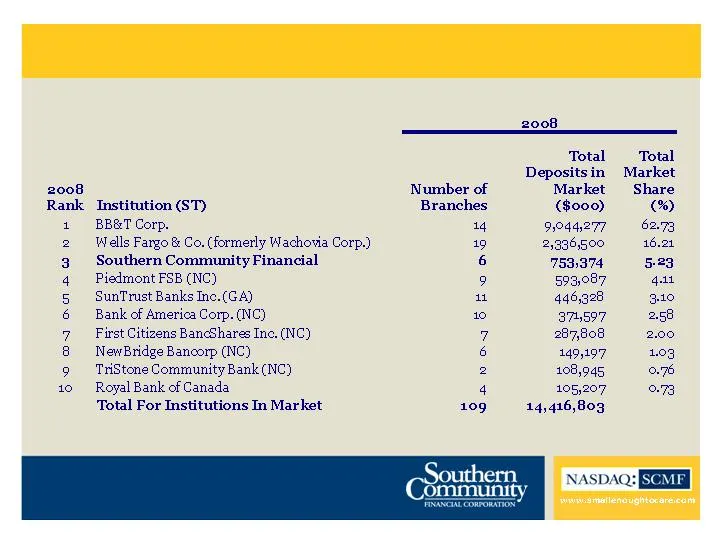
7 Deposit Growth Opportunities There is a significant opportunity to gain deposit market share in Forsyth County: Source: SNL Financial, FDIC Summary of Deposits ; Data as of June 30, 2008
Slide 8: Growth Strategies & Outlook
www.smallenoughtocare.com 8 Growth Strategies & Outlook
Slide 9: Successfully Navigating the Current Environment
9 Successfully Navigating the Current Environment Asset Quality: Lend to established businesses with historical cash flow Independent loan review Manageable risk in loan portfolio is contained within residential construction and development loans Several construction lenders have contractor’s and/or
Slide 10: Key Focus
10 Key Focus Net Interest Margin & Capital: Continue to focus on core deposit gathering Loan and deposit pricing becoming more rational Opportunities created through market disruption (new relationship acquisitions) Completed $42.8 million offering under Treasury’s Capital Purchase Program in Decemb
Slide 11: Deposit and Fee Income Initiatives
11 Deposit and Fee Income Initiatives ME Banking product (premium rate DDA) exceeding projections: Stated rate is 4%, but actual cost of funds closer to one-year rates when all costs and fees earned are considered 303 new accounts opened during 1Q09 Average account balance of nearly $6,800 Easy Acce
Slide 12: Expectations for 2Q and 2H 2009
12 Expectations for 2Q and 2H 2009 Loan loss provision, charge-offs, and reserve coverage to remain at current levels NPLs not expected to significantly increase Modest net interest margin compression in 2Q Anticipate net interest margin and overall profitability to improve in 2 nd half 2009 Opportu
Slide 13: Long Term Strategy: Build out existing markets
www.smallenoughtocare.com 13 Build out existing markets De novo growth + accretive acquisitions Build non interest income Expand mortgage operations & wealth management division Mortgage refinance activity has intensified Leverage commercial relationships, infrastructure and people Enhance profitabi
Slide 14: Financials
www.smallenoughtocare.com 14 Financials
Slide 15: 1Q09 Key Themes
15 1Q09 Key Themes Asset Quality, Net Results & Deposit Growth Residential construction and development lending continue to be the largest portion of manageable risk in the loan portfolio Continue to proactively monitor our loan portfolio Problem real estate team moved 13 properties ($1.5 million) o
Slide 16: First Quarter 2009 Financial Highlights
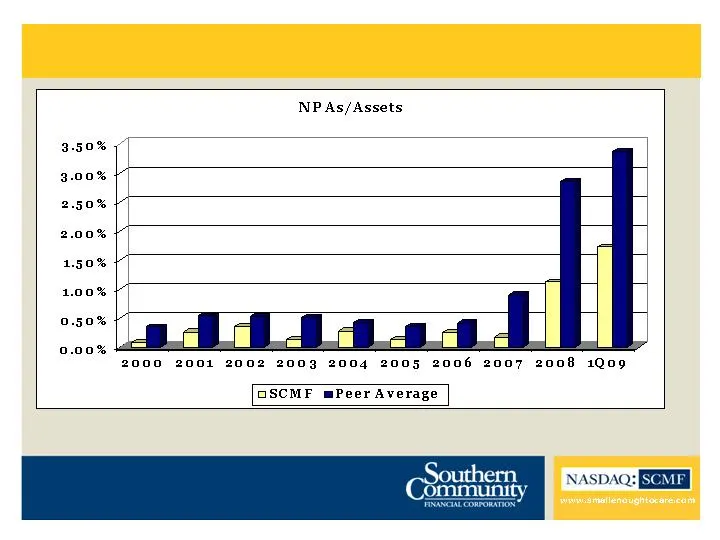
16 First Quarter 2009 Financial Highlights Net loss of $49.70 million, or $2.96 per diluted common share included a one-time, non-cash goodwill impairment charge of $49.5 million Net income of $425 thousand, excluding goodwill impairment and preferred dividends of $627 thousand NPLs were $21.25 mill
Slide 17: First Quarter 2009 Financial Highlights
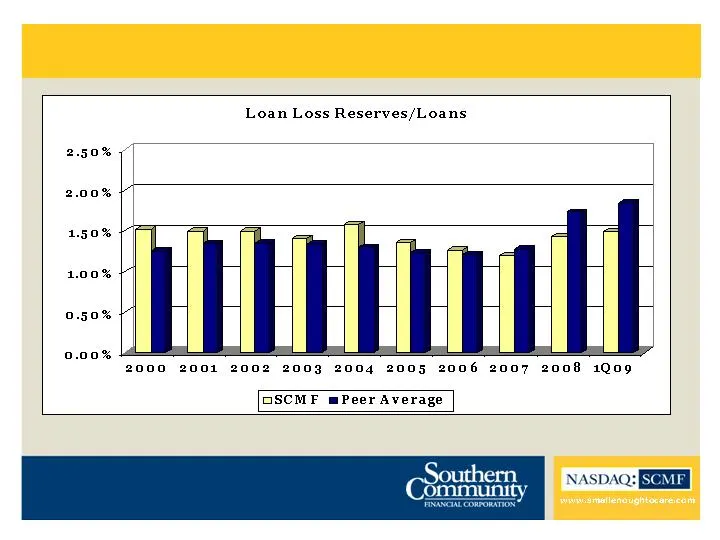
17 First Quarter 2009 Financial Highlights Allowance for loan losses was $19.31 million or 1.49% of total loans and .95 times NPLs, compared to $18.85 million or 1.43% and 1.31 times NPLs at December 31, 2008 Net interest income decreased 3% compared to 4Q08, and increased 13% compared to 1Q08 Net i
Slide 18: Asset Quality: Consistently Outperform our Peers
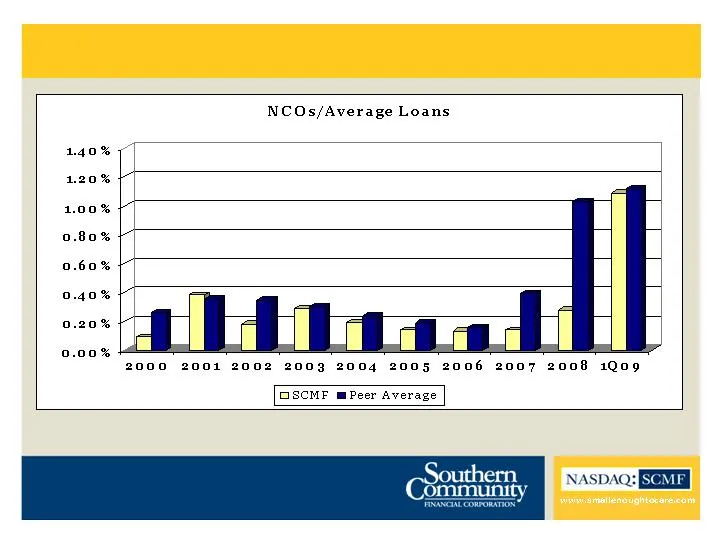
18 Asset Quality: Consistently Outperform our Peers Source: SNL Financial; Peers include publicly traded commercial banks based in AL, AR, FL, GA, MS, NC, SC, TN, VA, and WV with total assets between $1 billion and $5 billion
Slide 19: Asset Quality: Consistently Outperform our Peers
19 Asset Quality: Consistently Outperform our Peers Source: SNL Financial; Peers include publicly traded commercial banks based in AL, AR, FL, GA, MS, NC, SC, TN, VA, and WV with total assets between $1 billion and $5 billion
Slide 20: Reserve Coverage In Line With Peers Despite Stronger Asset Quality
20 Reserve Coverage In Line With Peers Despite Stronger Asset Quality Source: SNL Financial; Peers include publicly traded commercial banks based in AL, AR, FL, GA, MS, NC, SC, TN, VA, and WV with total assets between $1 billion and $5 billion
Slide 21: Capital Ratios Bolstered by TARP Infusion
www.smallenoughtocare.com 21 Capital Ratios Bolstered by TARP Infusion All ratios shown above are at the holding company level * To Risk Weighted Assets ** To Average Assets (1) Includes $42.75 million TARP investment closed on December 5, 2008 (2) Minimum for Well Capitalized Banks 3/31/09 1 12/31/
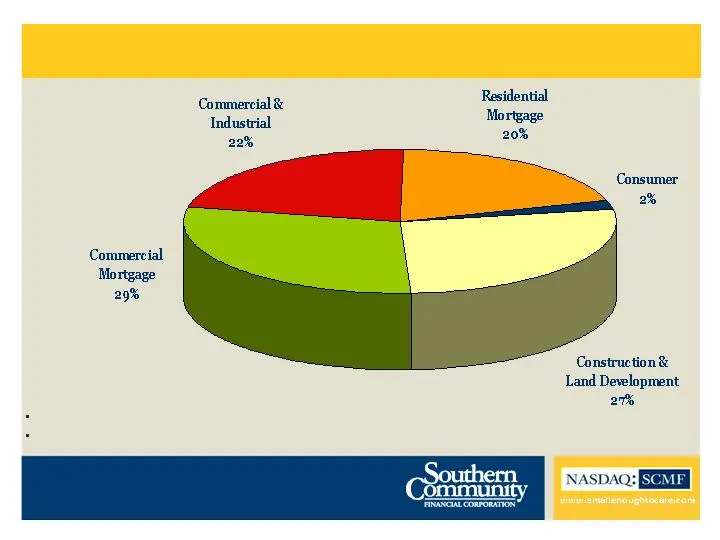
Slide 22: A Diversified Loan Portfolio
www.smallenoughtocare.com 22 As of 3/31/09 Approximately 56% of loans are variable rate loans (mostly prime-based) Approximately 32% of CRE loans are owner-occupied A Diversified Loan Portfolio
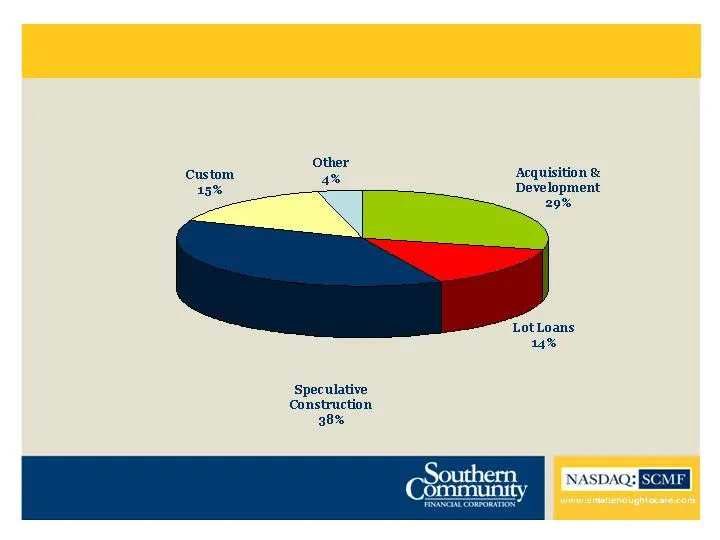
Slide 23: Residential Construction Loan Portfolio
23 Residential Construction Loan Portfolio As of 3/31/09:
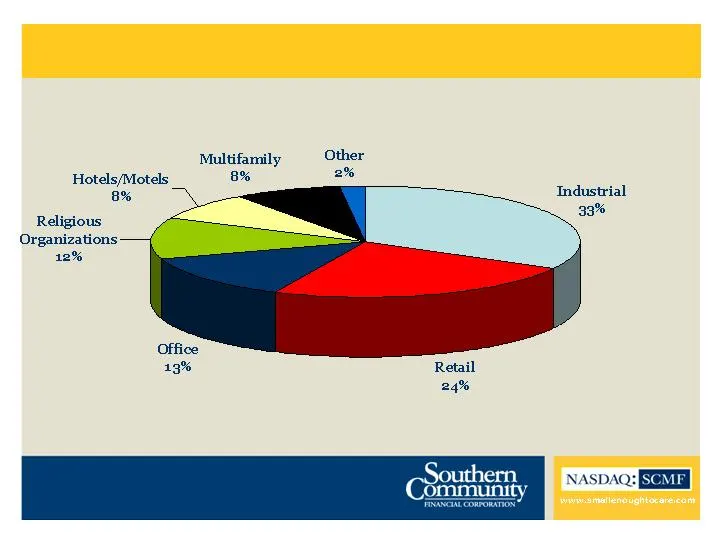
Slide 24: CRE Loans by Property Type
24 CRE Loans by Property Type As of 3/31/09:
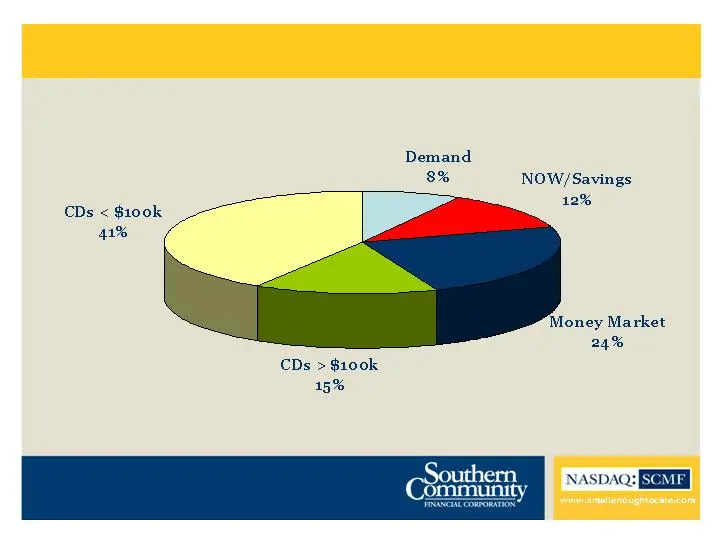
Slide 25: Deposit Composition
25 Deposit Composition As of 3/31/09
Slide 26: Small Enough To Care
www.smallenoughtocare.com 26 Small Enough To Care
Source: SEC EDGAR · 8-K filed May 4, 2009
More decks from Southern Community Financial Corp
 KBW Investor Conference 201030 slides · Jul 27, 2010
 Conference Presentation (February 2009)26 slides · Feb 6, 2009
 Southeast SuperCommunity Bank Conference (February 2008)28 slides · Feb 11, 2008
 America's Community Bankers Community Bank Investor Conference 200724 slides · Nov 2, 2007
 Emerging Growth Institutional Investor Forum 200727 slides · Mar 26, 2007
 Southeast SuperCommunity Bank Conference (February 2007)26 slides · Feb 14, 2007