Aleris International — Bear Stearns Commodities, Metal and Consumer/Industrial Goods Conference (December 2005)
32 slides from Aleris International's conference presentation, Dec 8, 2005
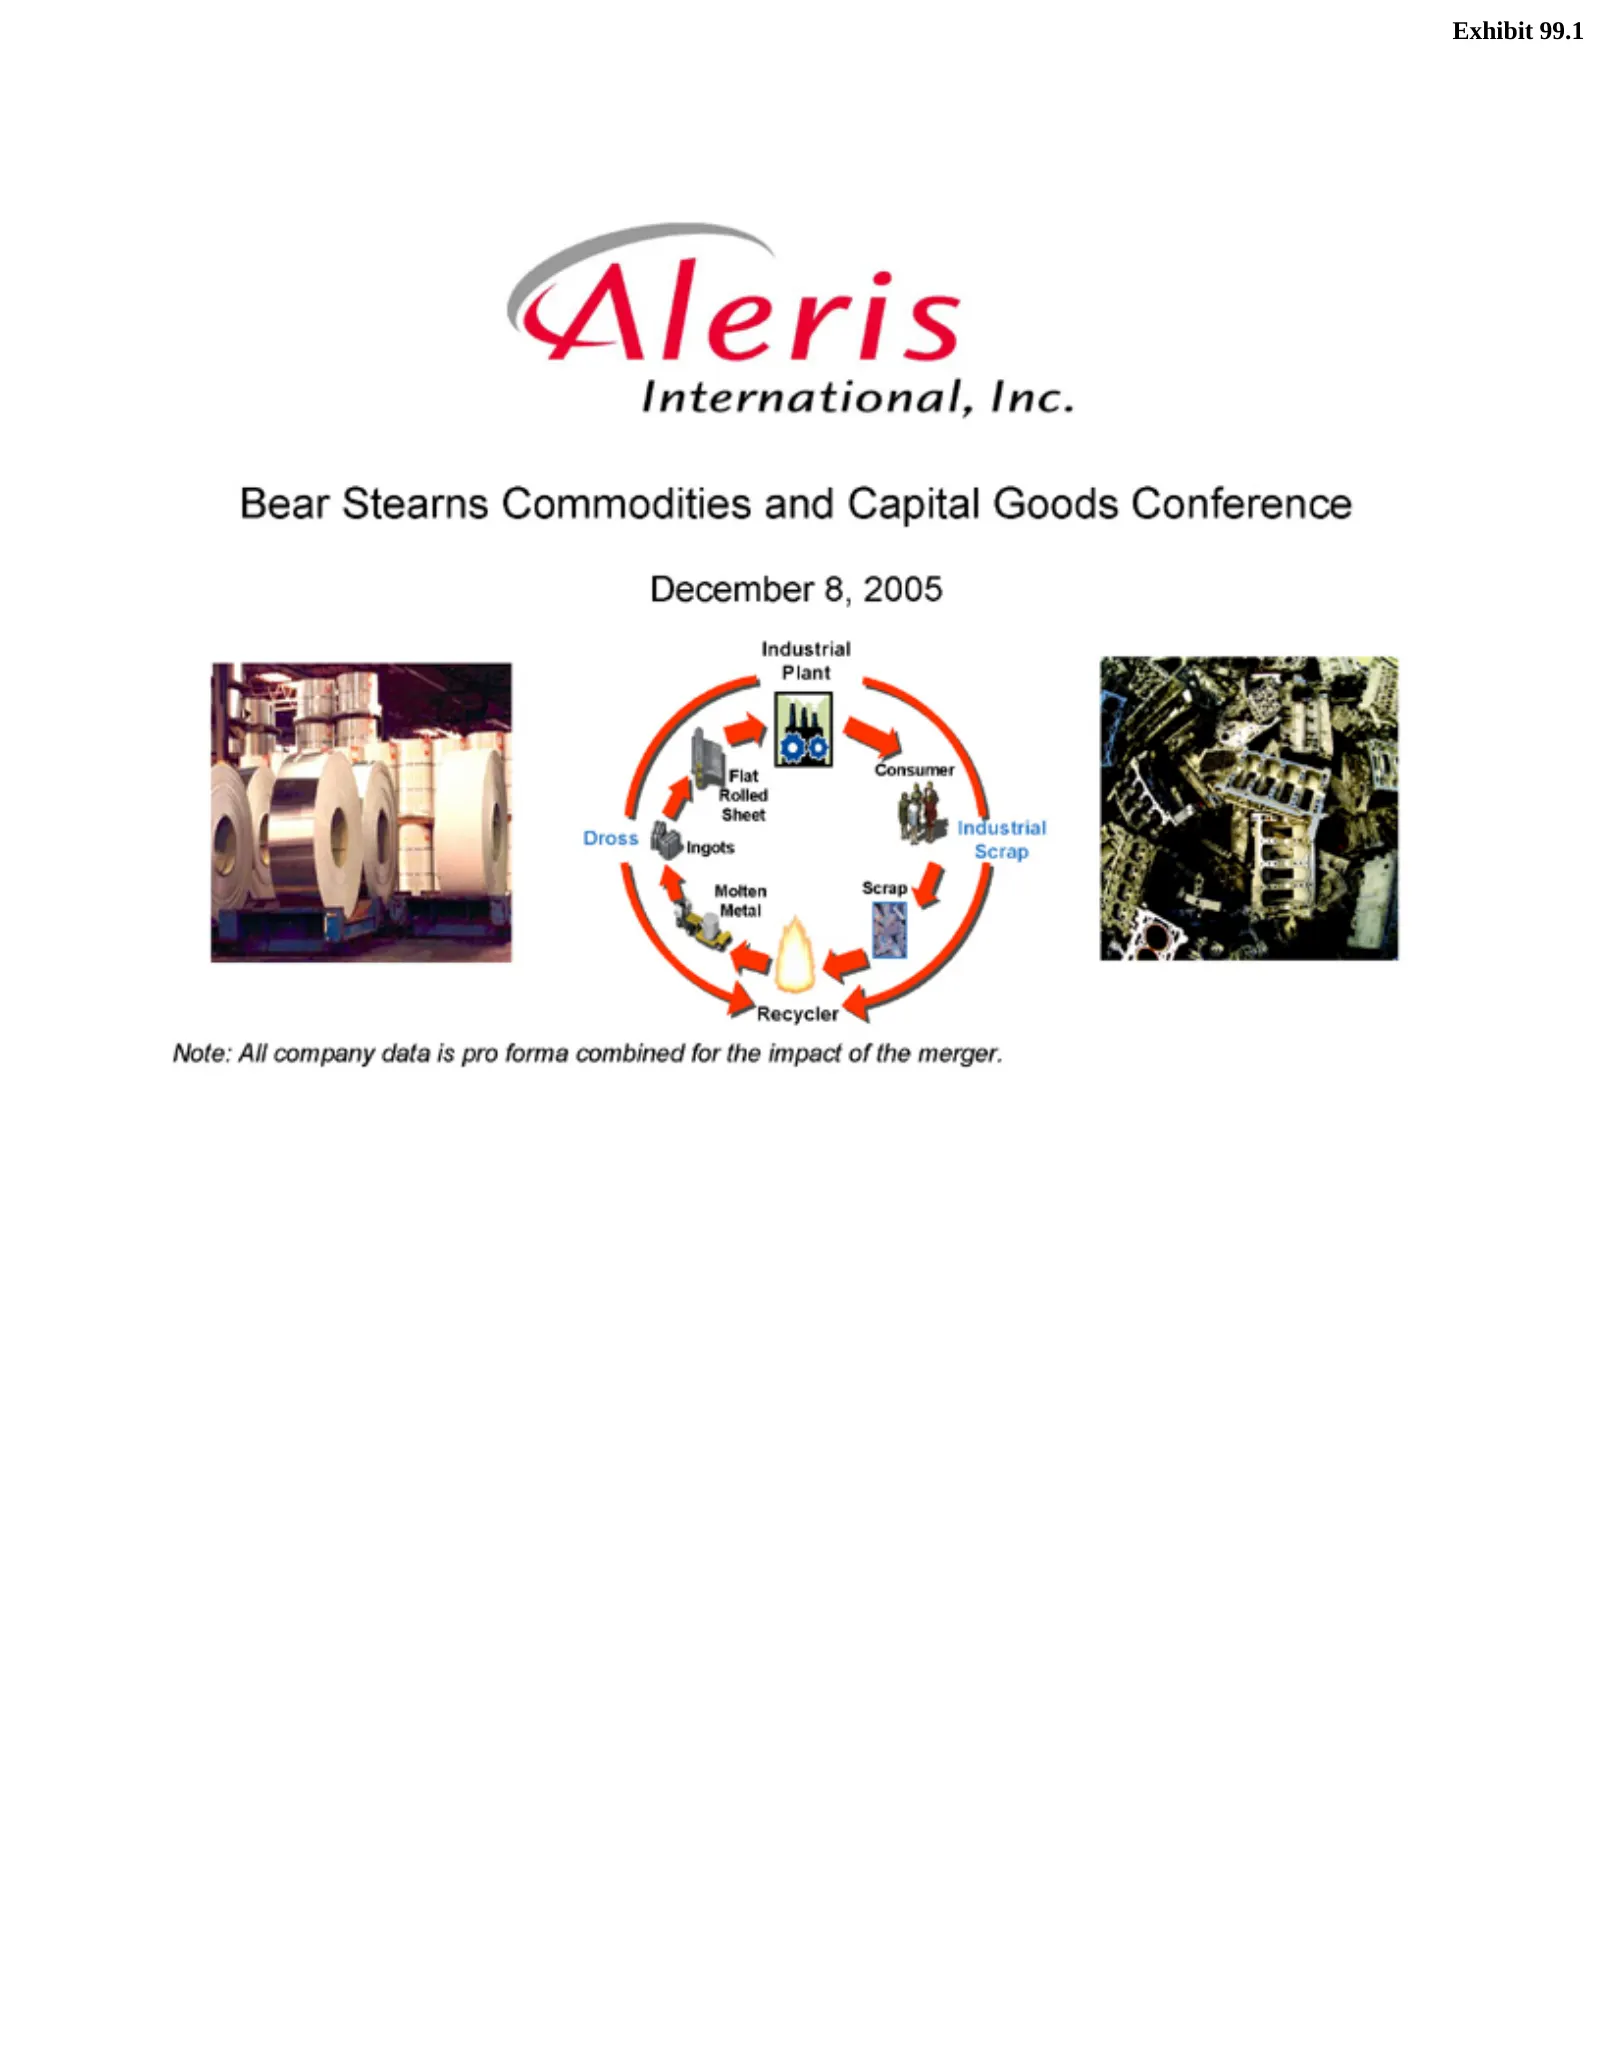
Slide 1: Bear Stearns Commodities, Metal and Consumer/Industrial Goods Conference
Exhibit 99.1 BearConsumer December Flat Industrial Ingots Note: Recycler Stearns All Scrap company Plant Dross 8, Molten Commodities 2005 Rolled data Scrap Sheet is pro Metal andforma Capital combined Goods Conference for the impact of the merger.
Slide 2: Safe Harbor Statements
Safe Harbor Statements harbor statements. cause information Alflex currency releases comparable 2 actual 05-1208division provisions which transaction. contained ItGAAP Bearcontained results ispresented sold important ofinformation. Stearnsto in the The in differ herein July this Securities our above
Slide 3: Merger Overview
Merger Overview
Slide 4: The Merger
The Merger December Commonwealth Revenue: (1) 4 LTM$2.4 Celebrating 05-1208 9,12004 Bear asBillion of Industries, Year September (1) Headquarters: as Aleris Stearns Inc. Conf/gb 30, 2005. Beachwood, OH NYSE Symbol: ARS Tomorrow!
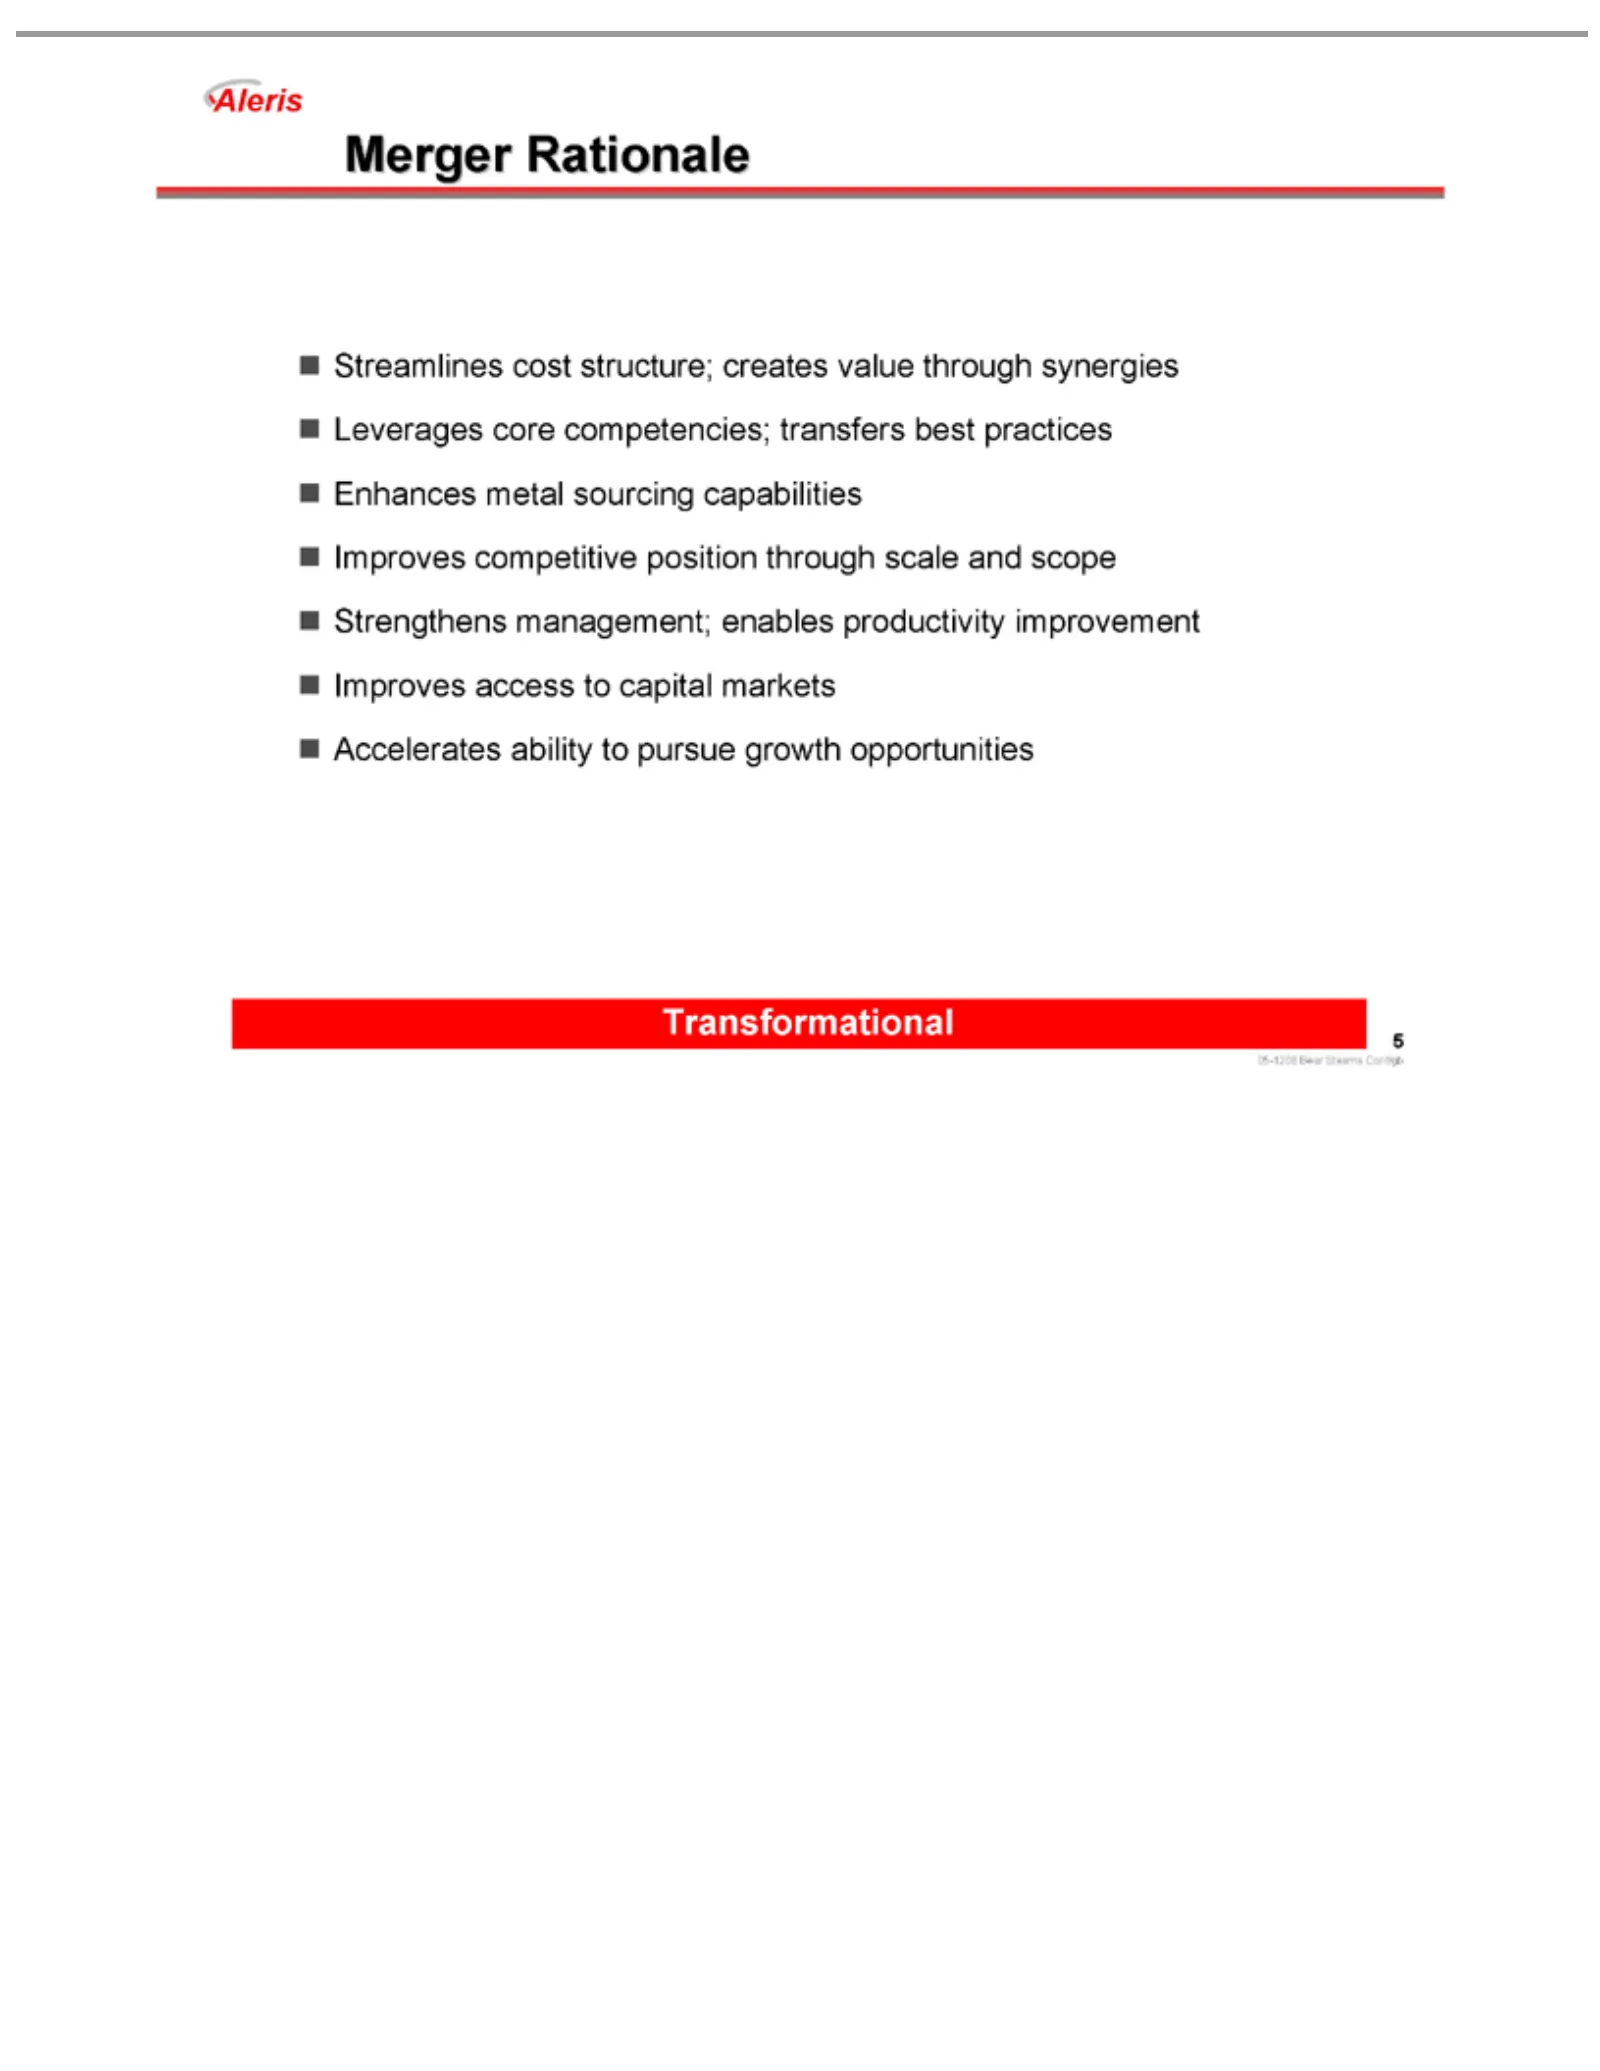
Slide 5: Transformational Merger Rationale
Transformational Merger Streamlines Leverages Enhances Strengthens Improves Accelerates 5 05-1208Rationale competitive access metal core Bearability cost management; competencies; sourcing to structure; Stearnsto capital pursue position capabilities enables markets Conf/gbcreates growth transfers th
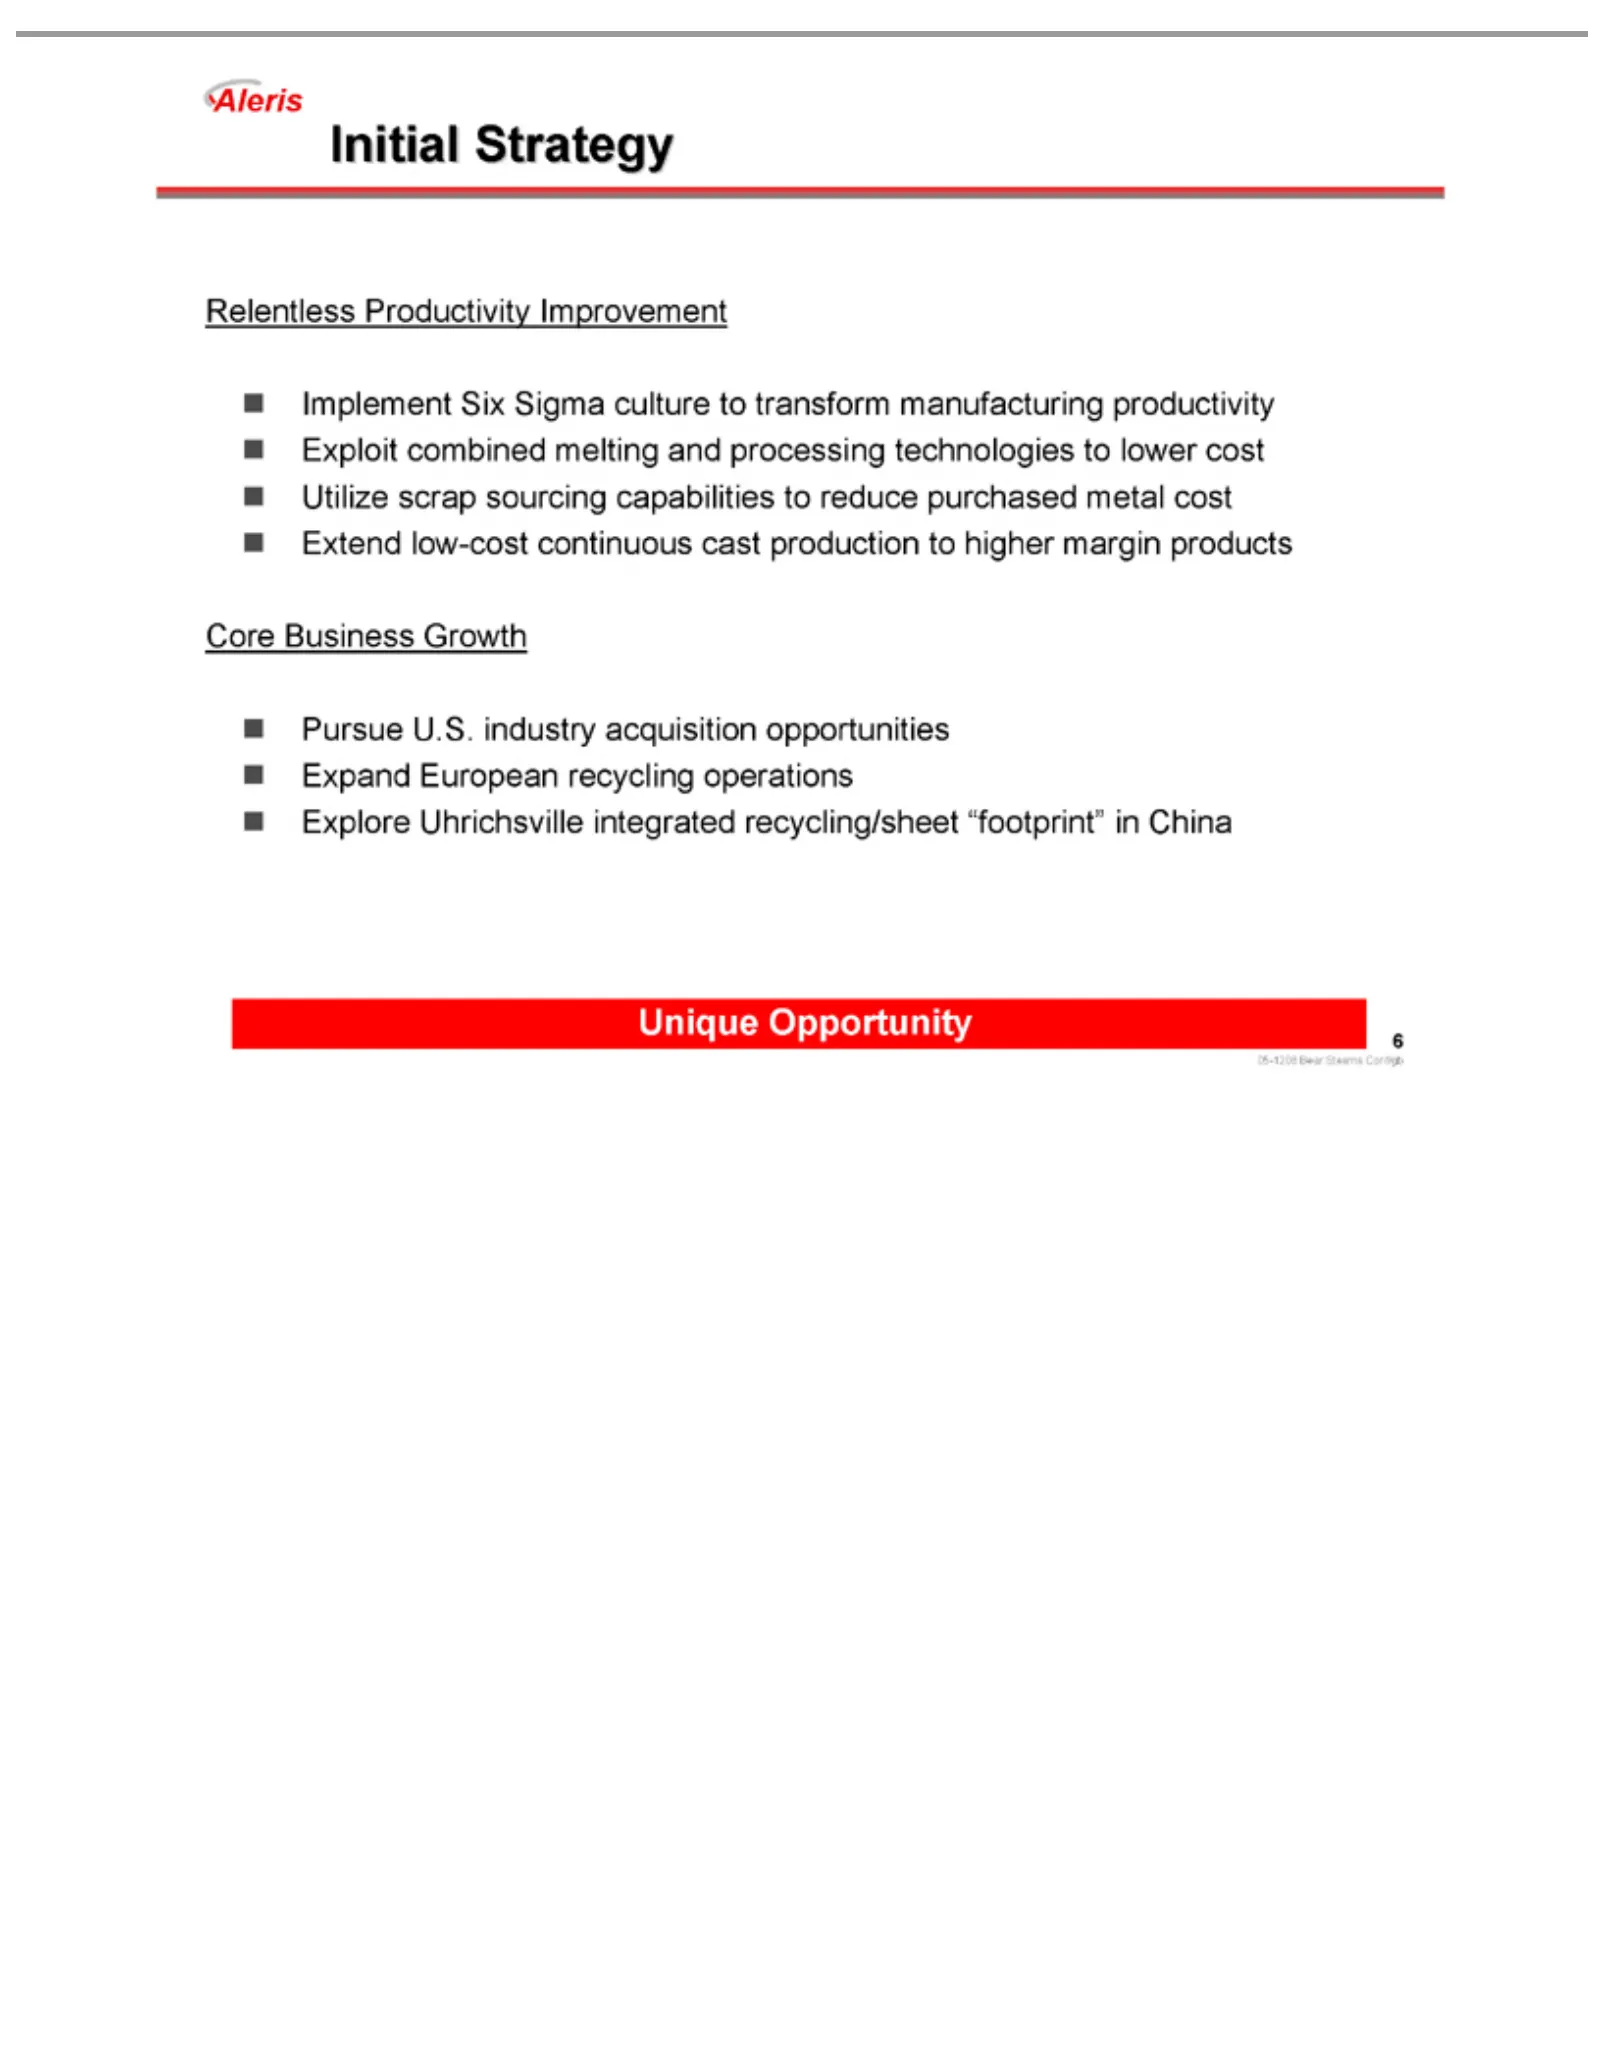
Slide 6: Initial Business Strategy
InitialBusiness Relentless Implement metal Core Pursue Explore Unique 6 05-1208cost Strategy U.S. Opportunity Uhrichsville Extend Productivity Six Bearindustry Growth Sigma low-cost Stearnsacquisition integrated culture Improvement continuous Conf/gb to recycling/sheet transform opportunities castma
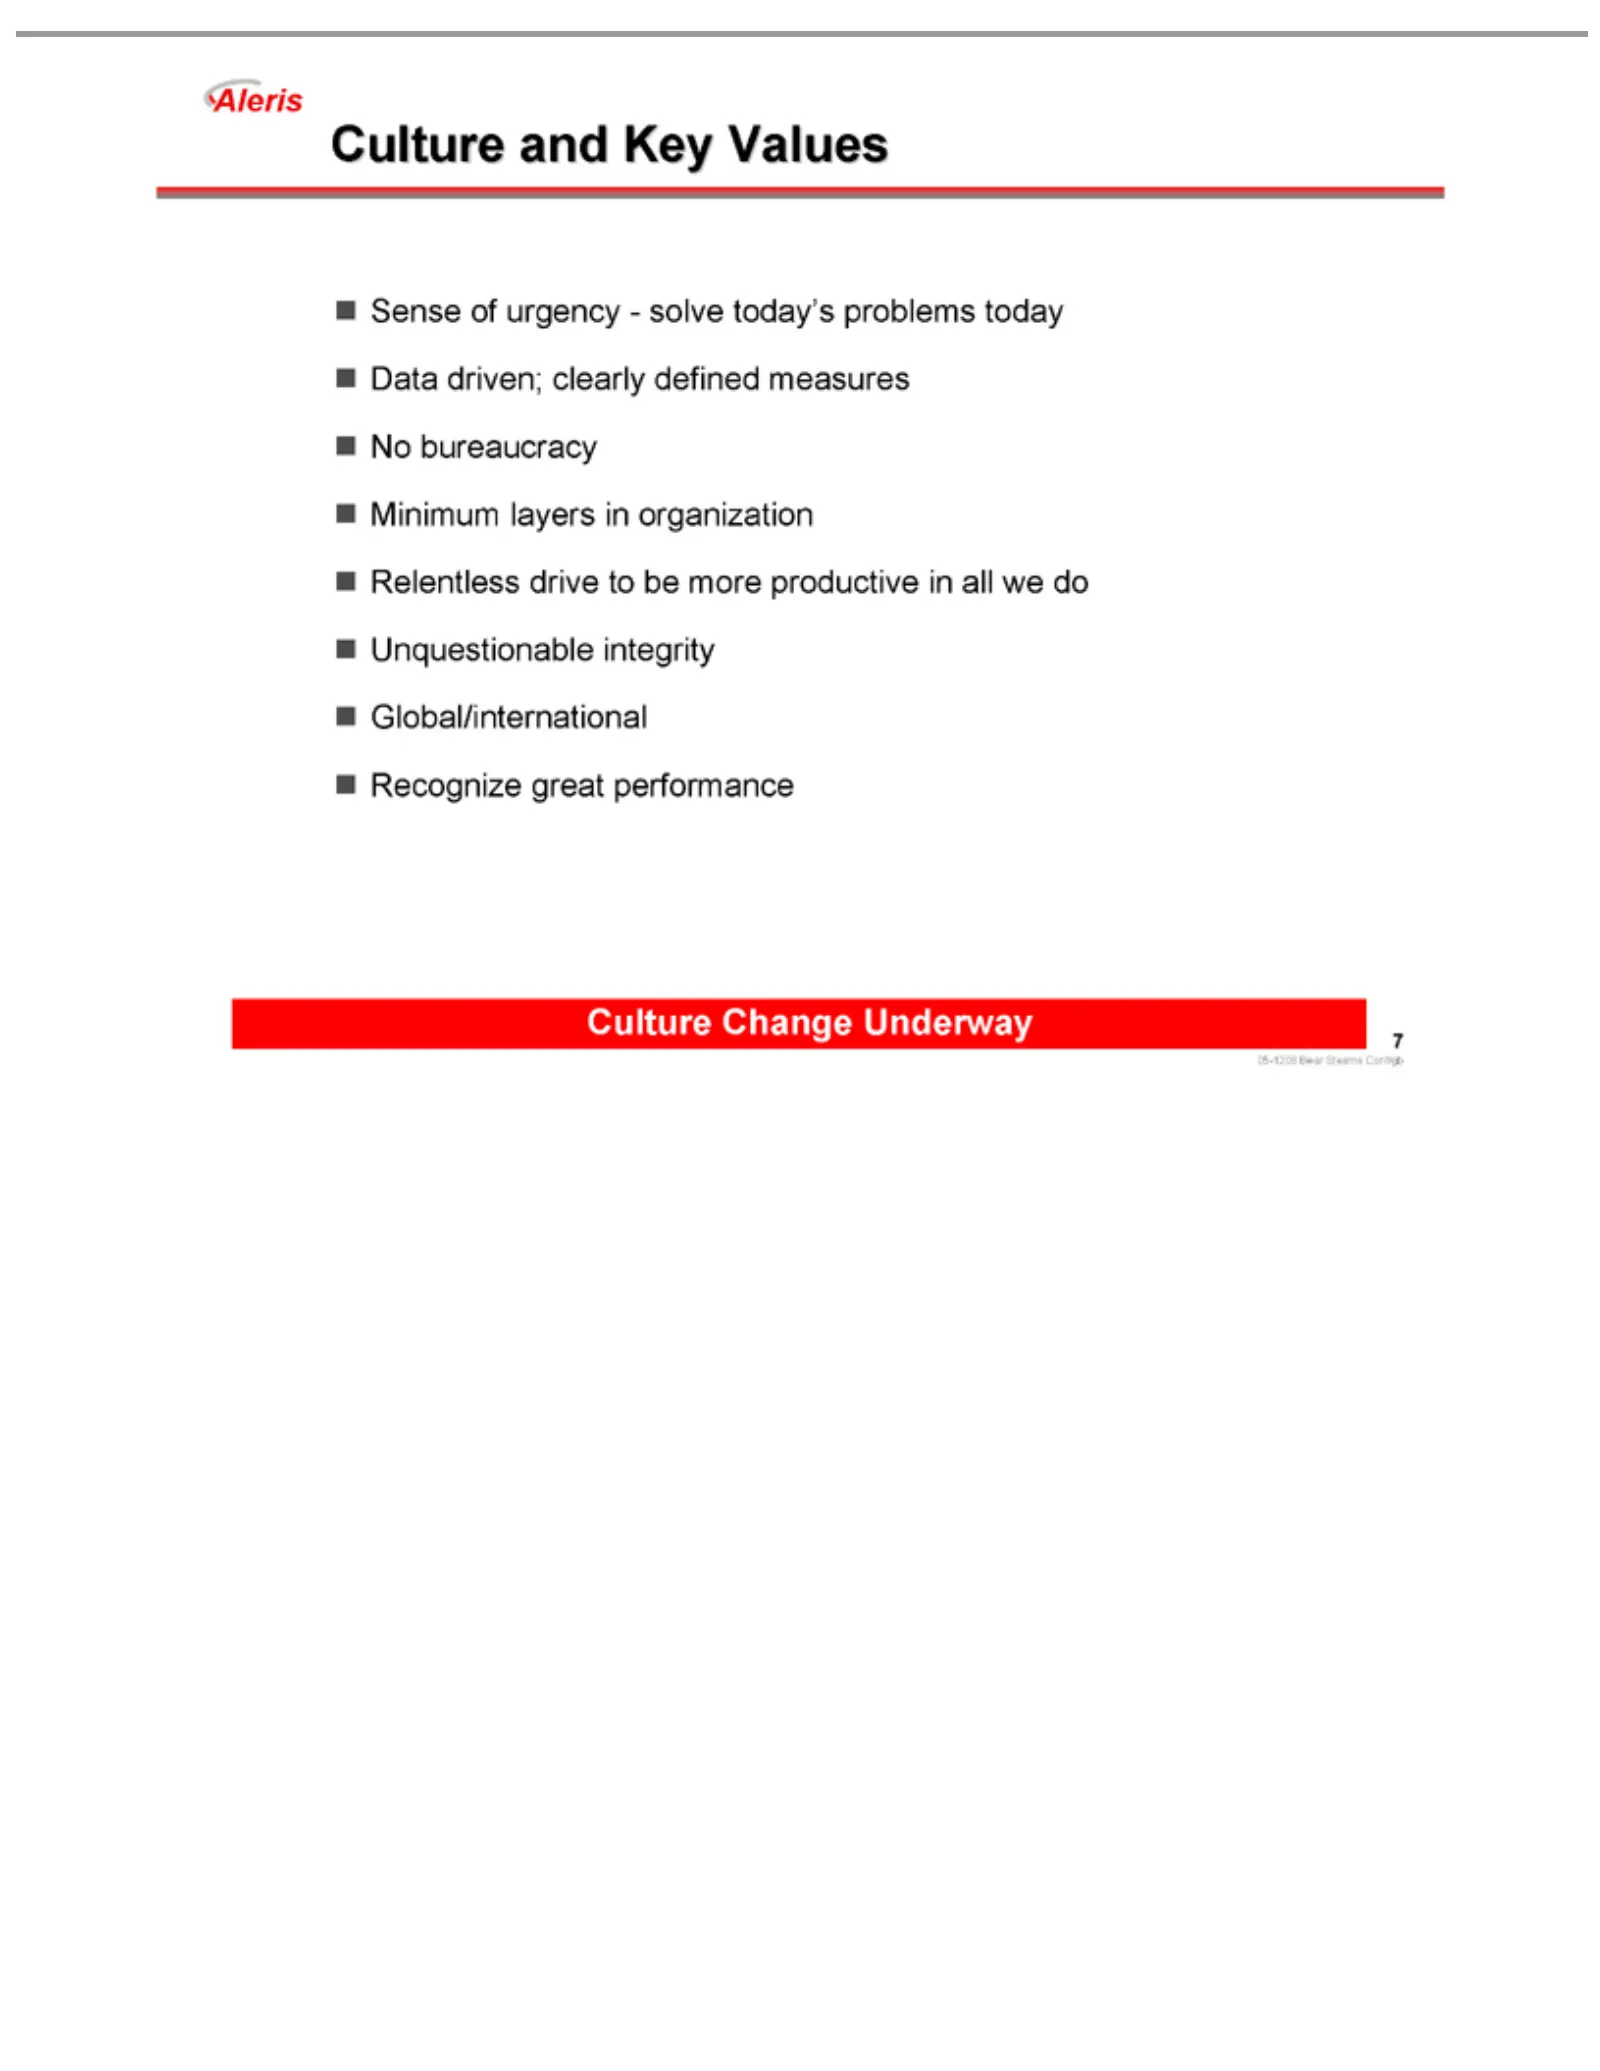
Slide 7: Culture of Change
Sense ofChange Unquestionable Culture 7 05-1208 and urgency—solve Key Bear integrity Underway Values Stearns Global/international today’s problems today Conf/gb Recognize Data driven; great clearly performance defined measures No bureaucracy Minimum layers in organization Relentless drive to be more
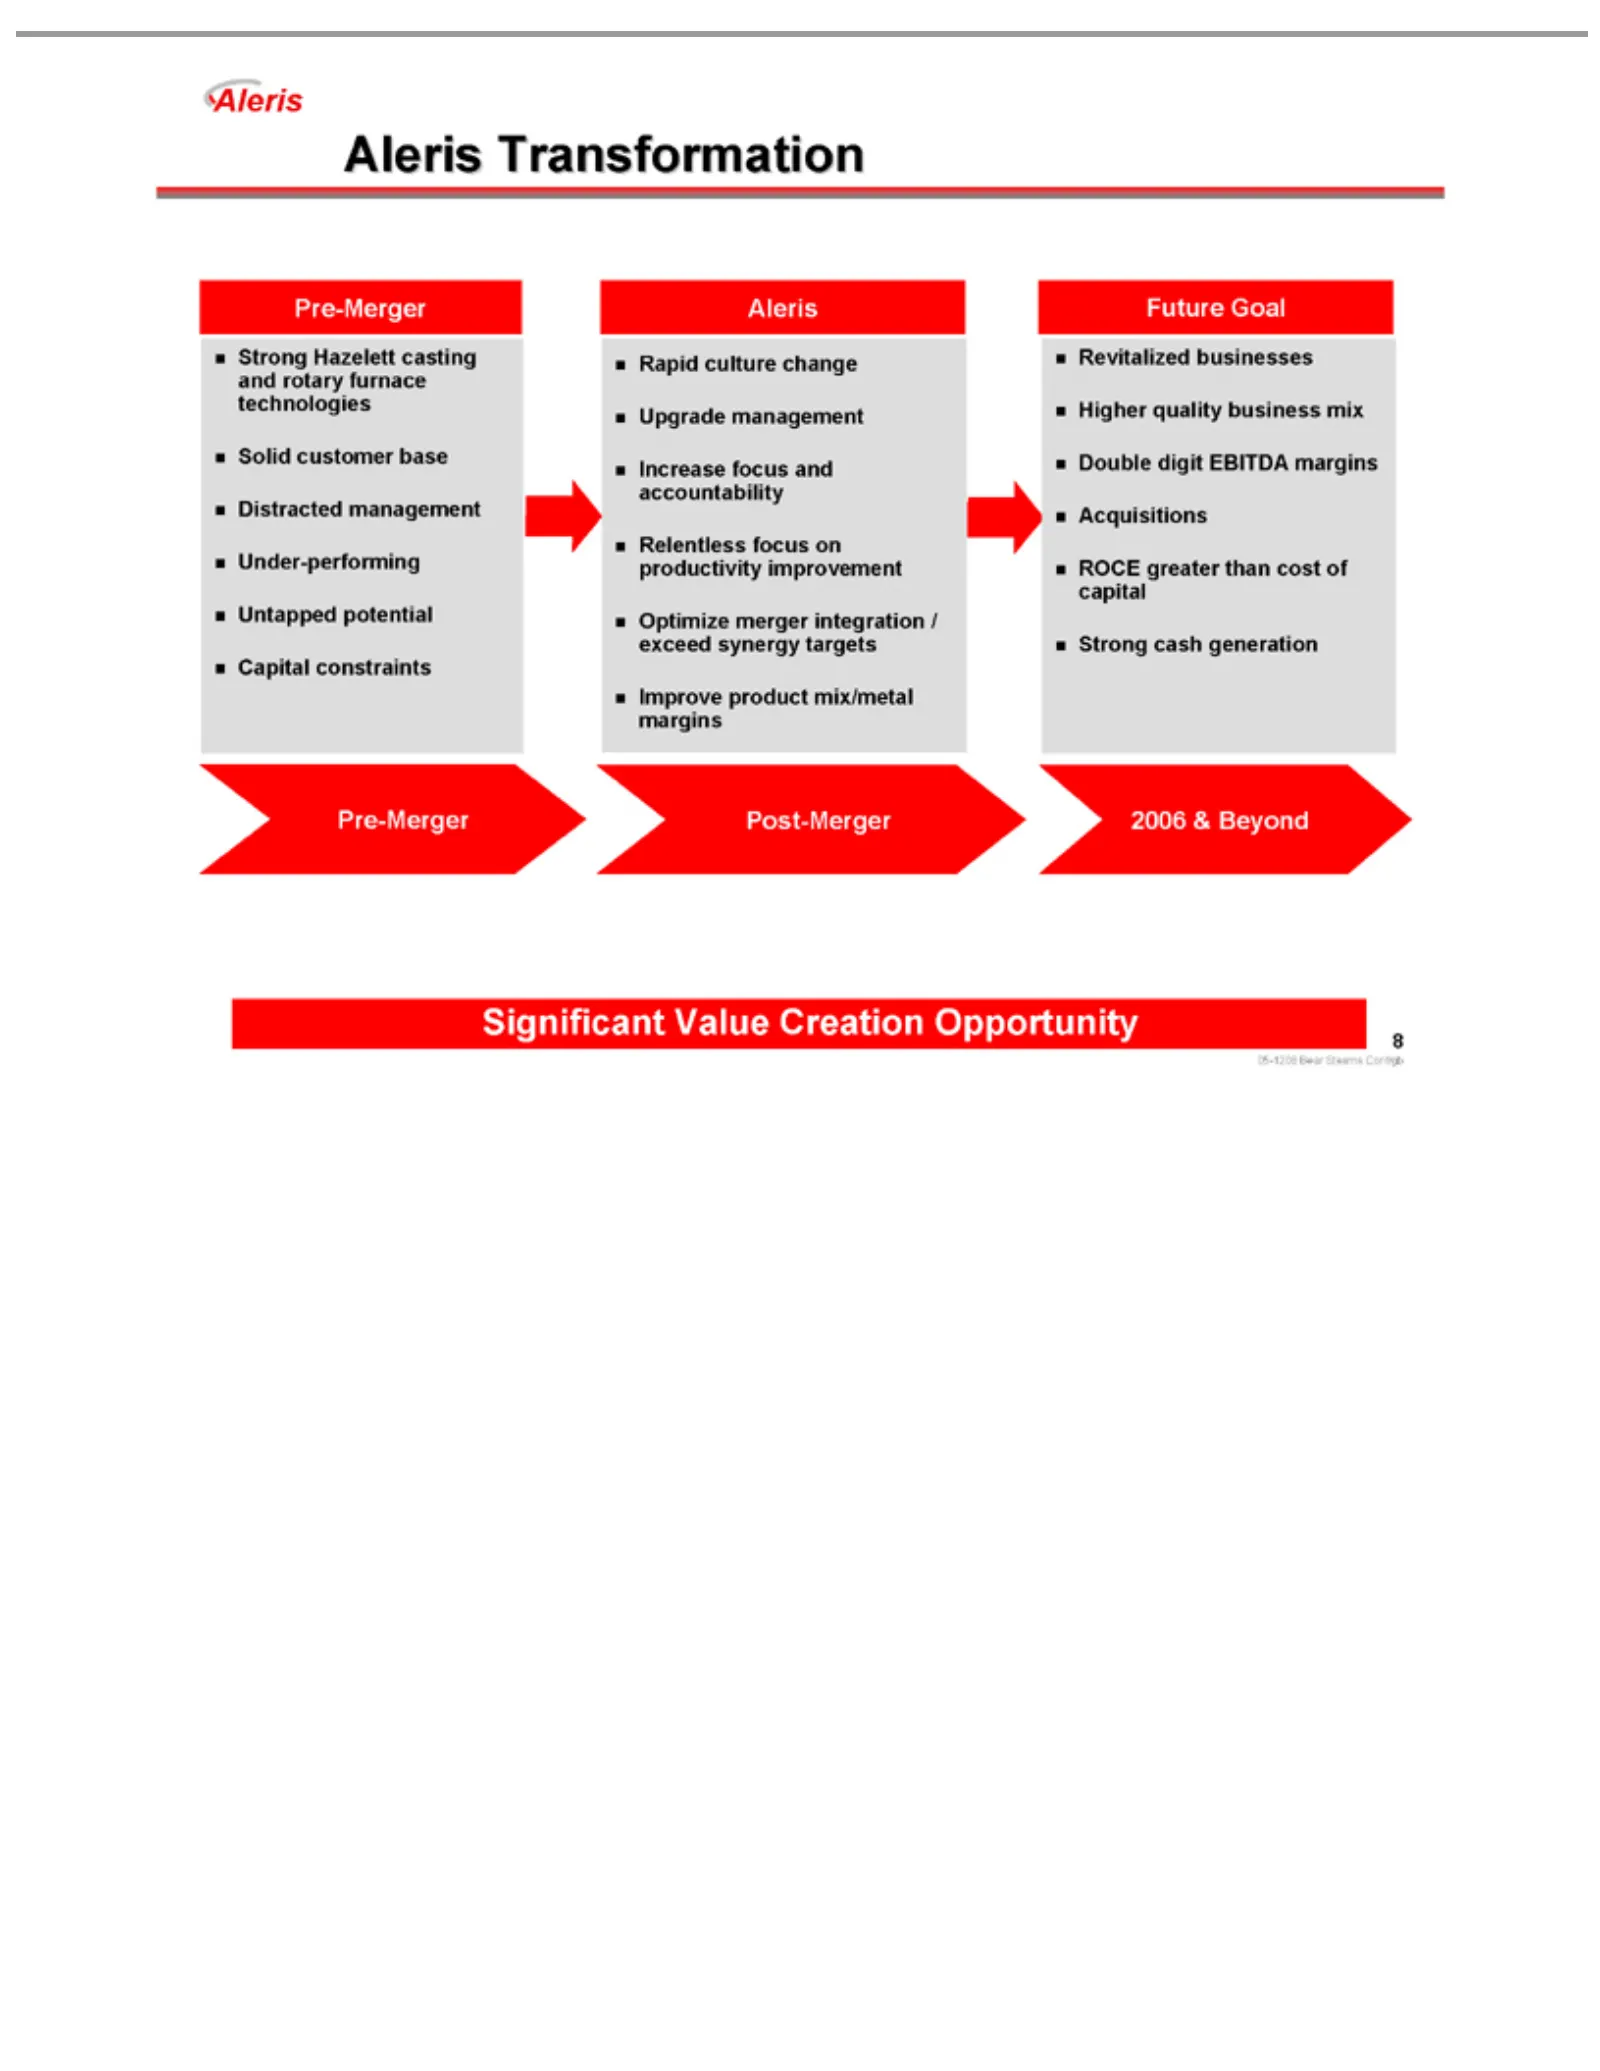
Slide 8: Aleris Transformation
Solid customer Rapid Aleris Upgrade Increase Relentless Optimize Improve Future Revitalized ROCE Strong Pre-Merger Significant 8 05-1208culture Transformation Goal Hazelett cash greater focus product management merger focus Value businesses Post-Merger Beargeneration change than and base casting on
Slide 9: Company Overview
Company Overview
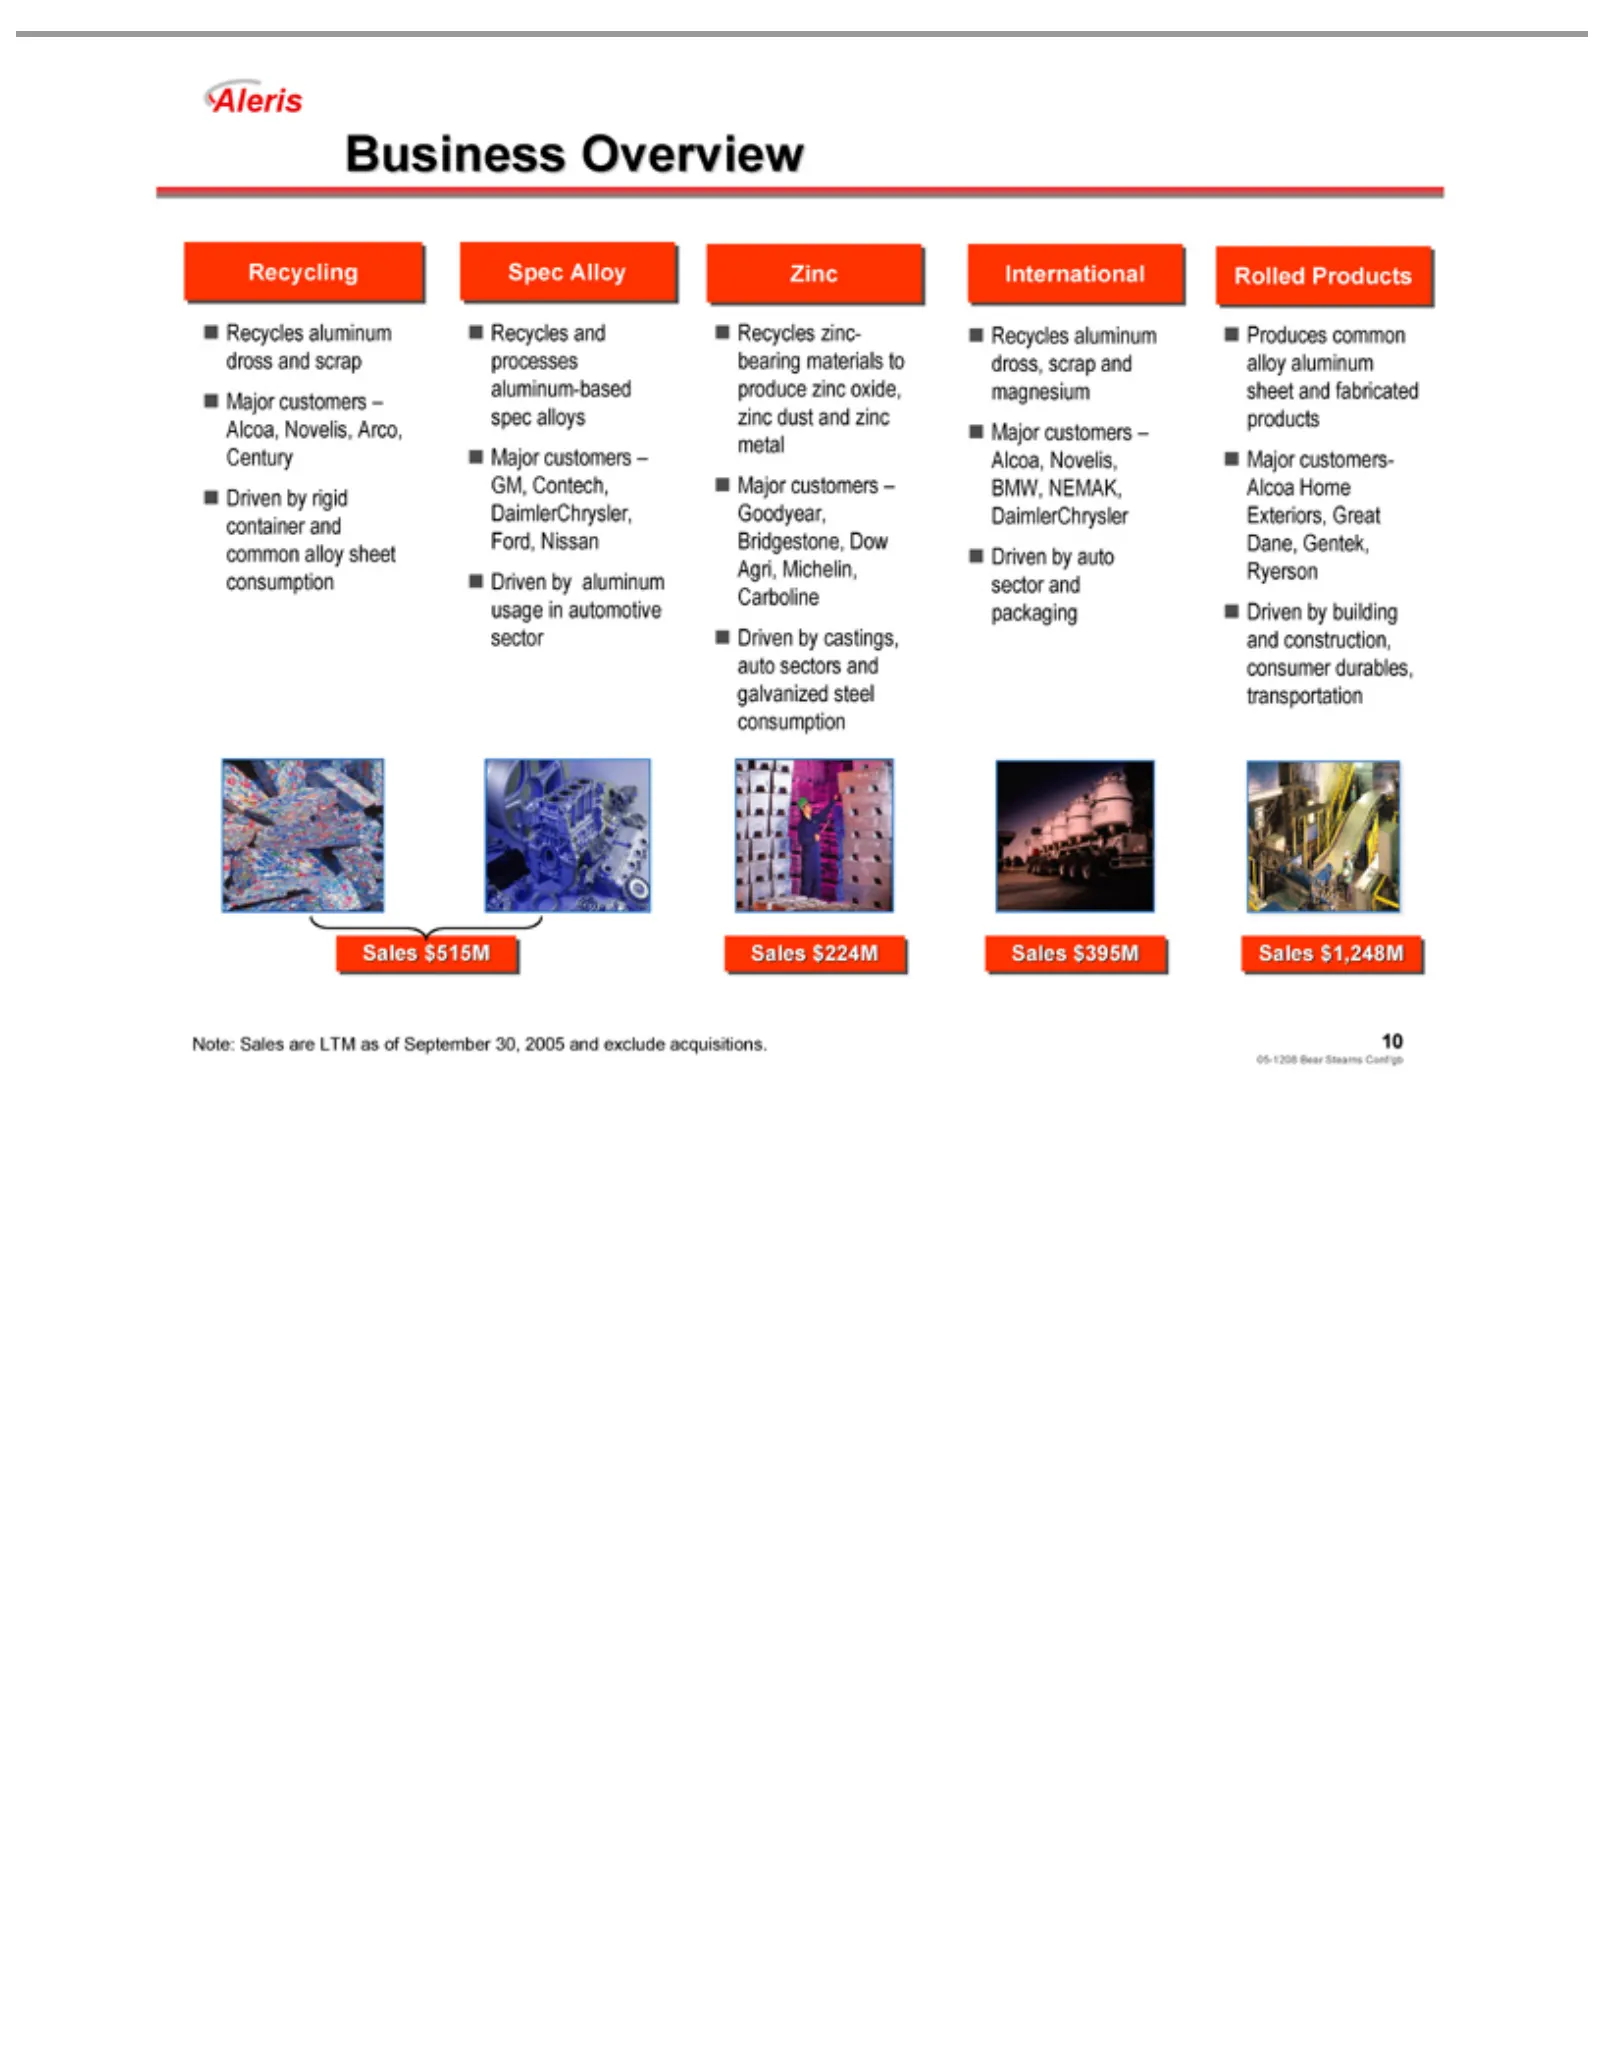
Slide 10: Business Overview
Business Recycling Spec Zinc galvanized Recycles International Rolled Produces Sales transportation Note: 05-1208 Alloy $515M Sales Products Bear Overview and zinc-bearing aluminum common steel are Sales processes Stearns LTM consumption alloy $224M dross dross, asConf/gb materials aluminum-based of
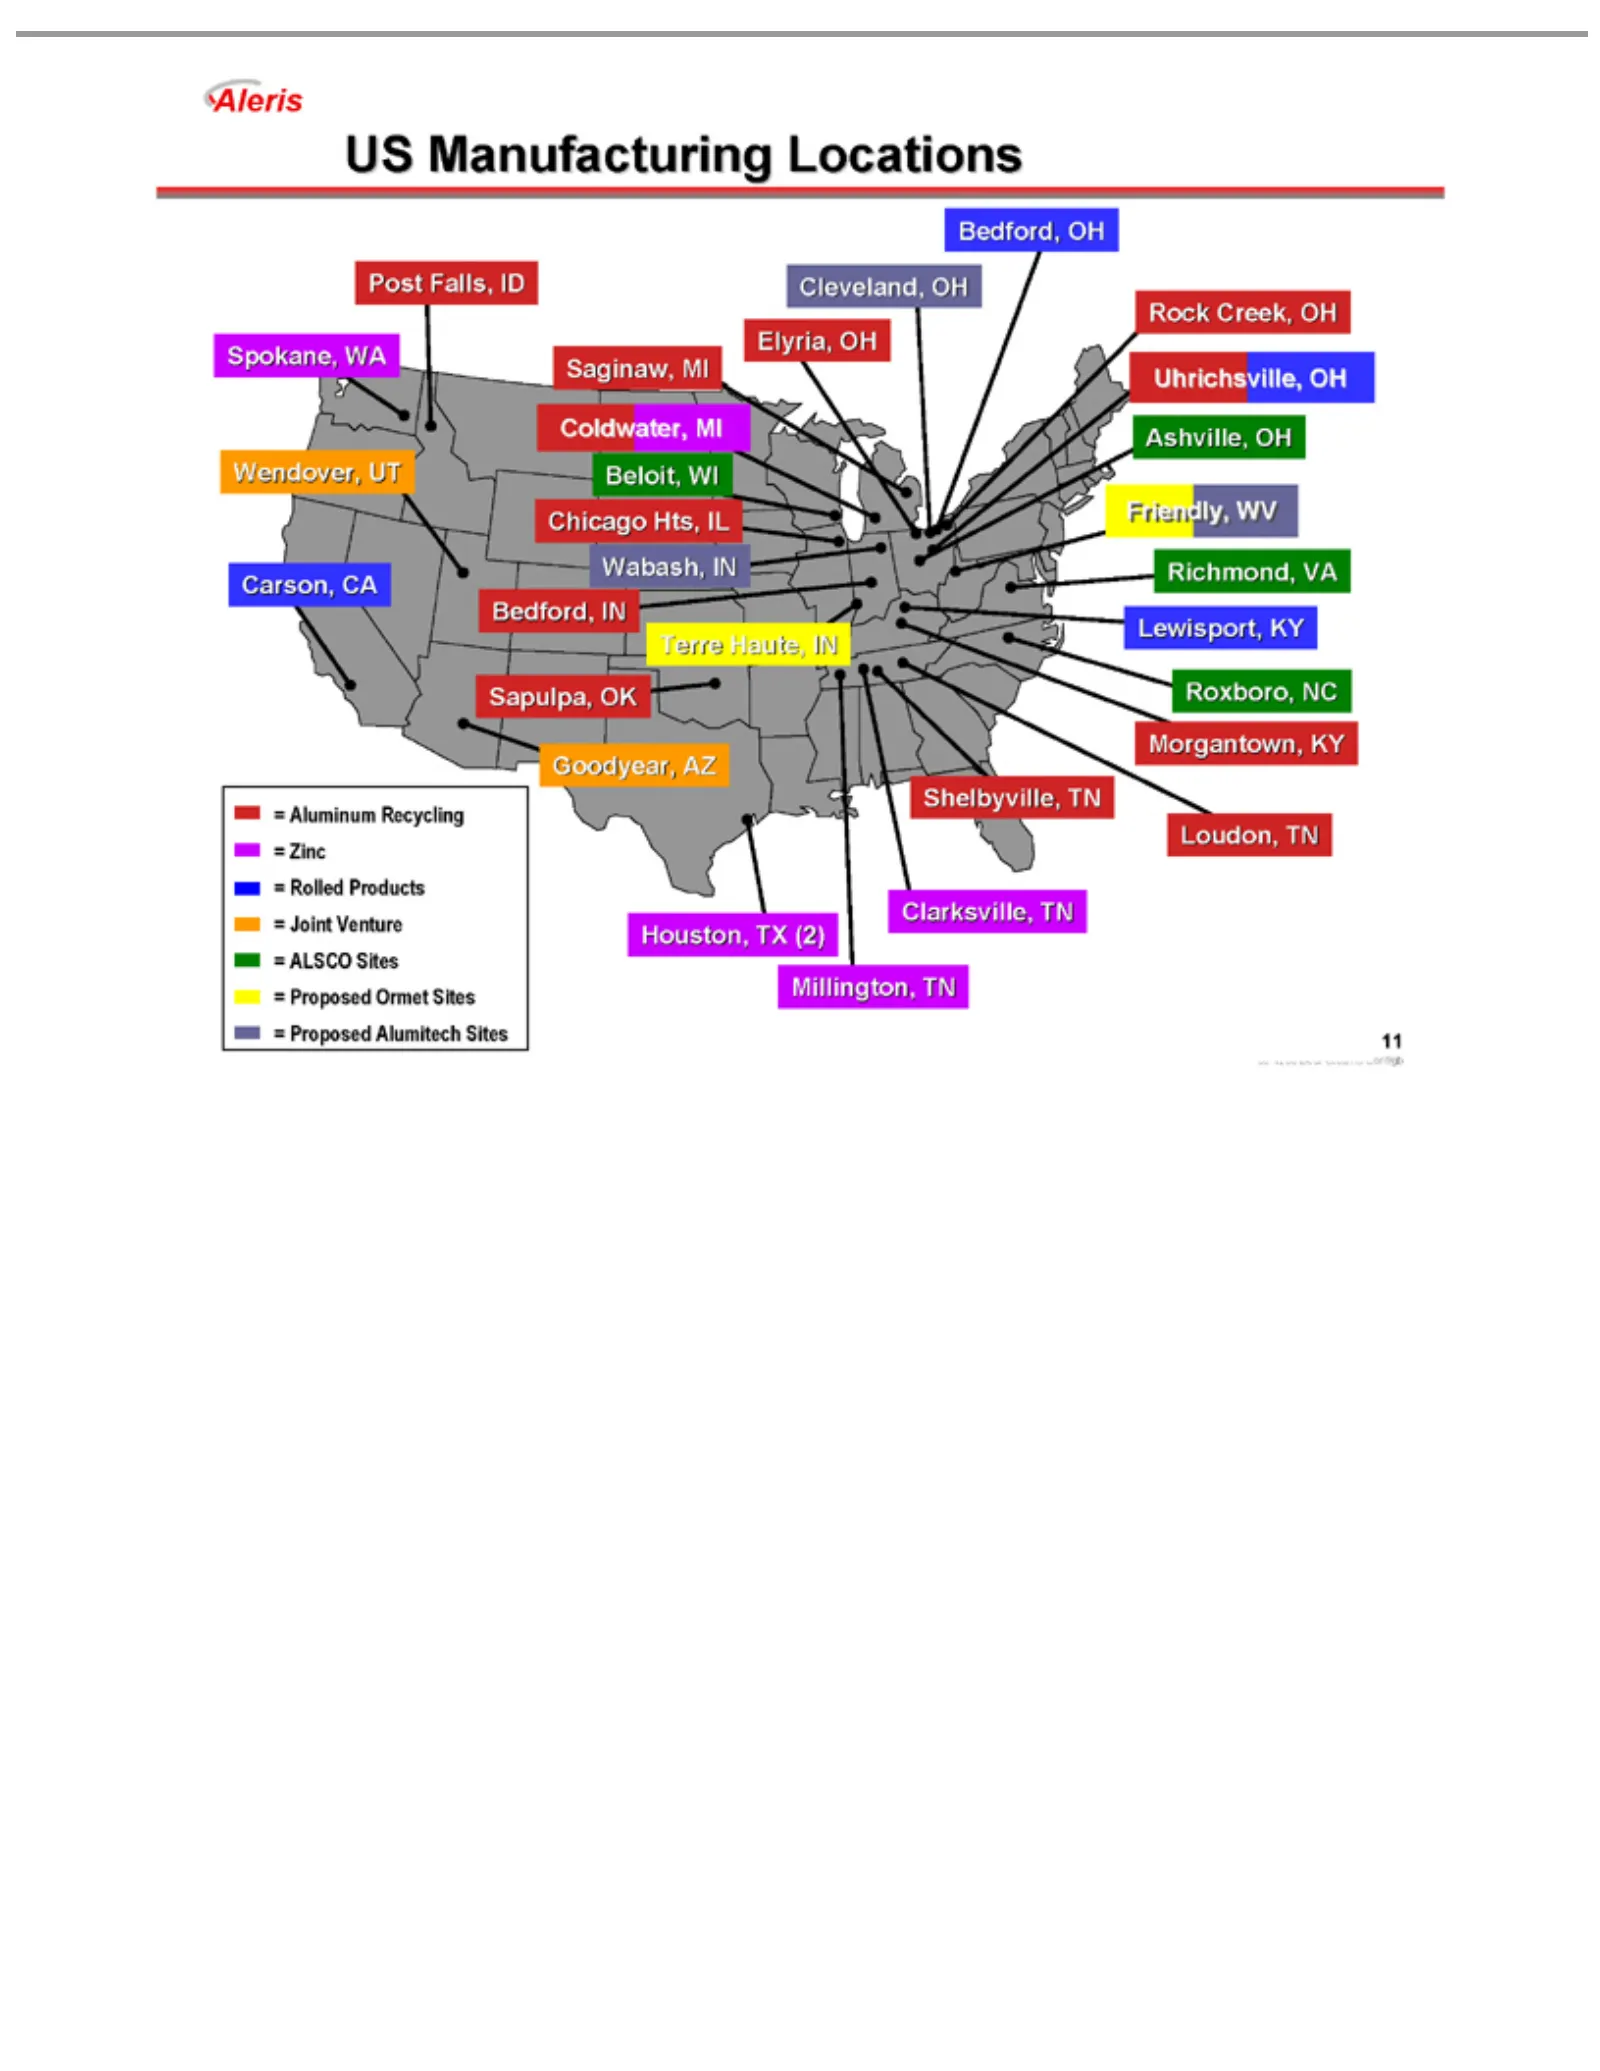
Slide 11: US Locations
US Post Spokane, Wendover, Carson, Saginaw, Coldwater, Beloit, Wabash, Terre Sapulpa, Goodyear, Bedford, Cleveland, Elyria, Rock Friendly, Richmond, Lewisport, Roxboro, Morgantown, Loudon, Houston, Shelbyville, Clarksville, Millington, = Conf/gb 11Aluminum Manufacturing Falls, Haute, Creek, WI OH CA
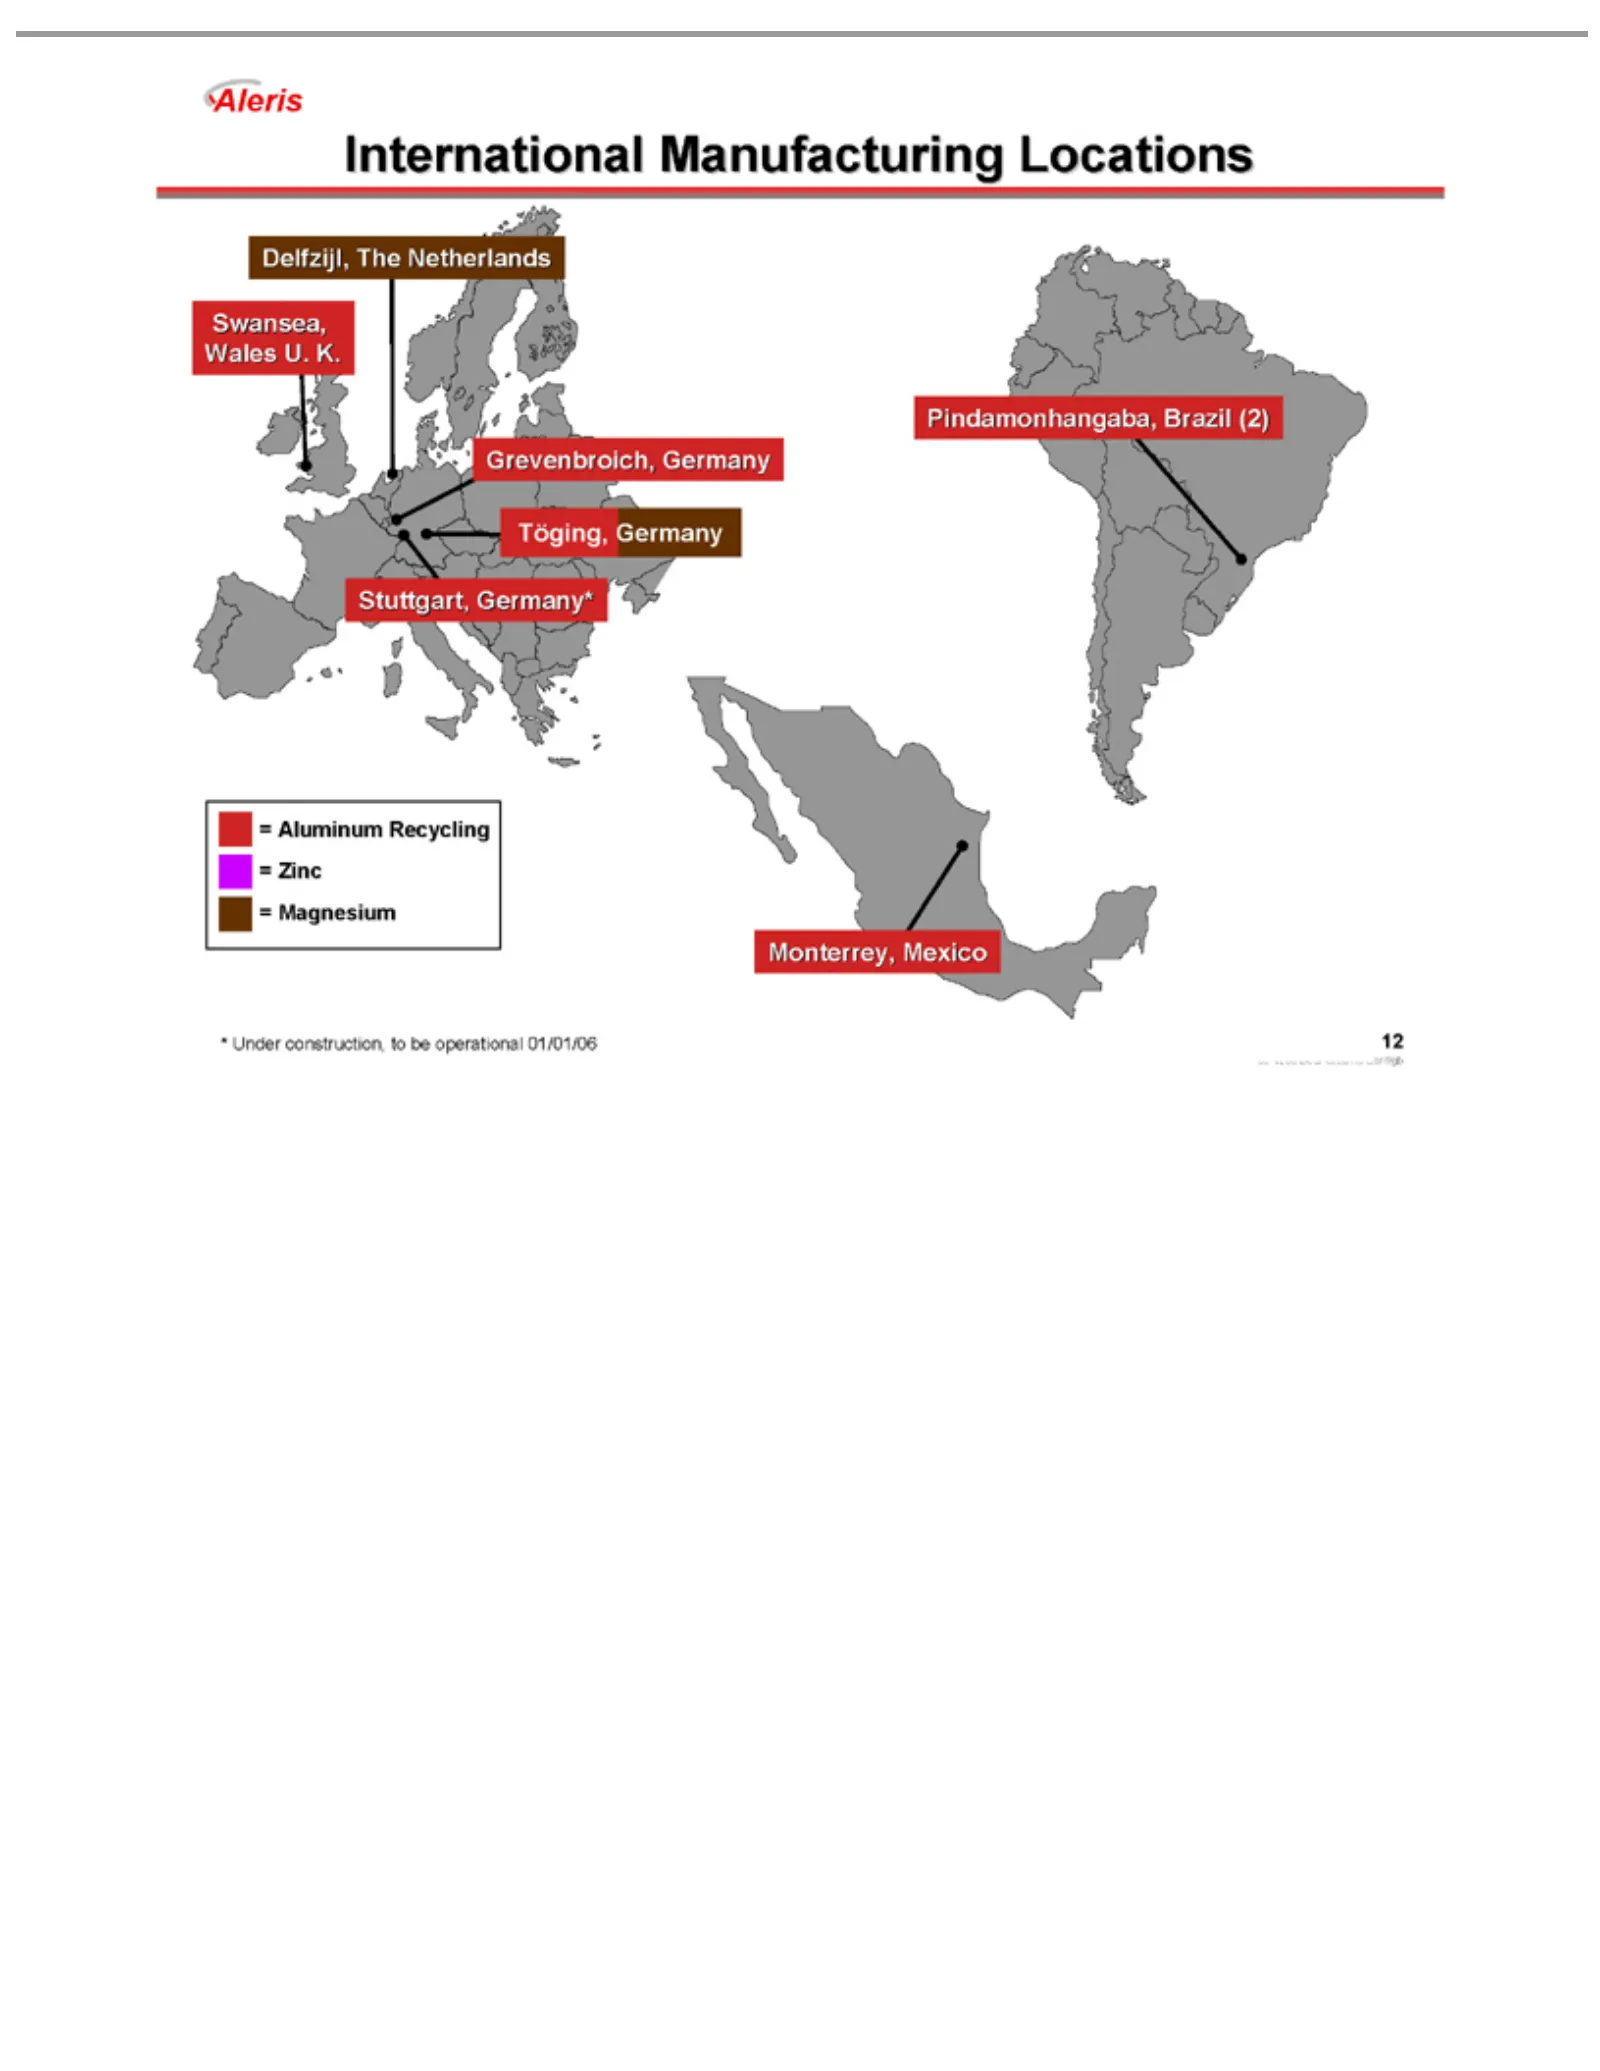
Slide 12: International Locations
International Delfzijl, Swansea, Grevenbroich, Töging, Stuttgart, Pindamonhangaba, Monterrey, = * 12Aluminum Conf/gb Under Germany The Germany* Wales Mexico Netherlands Recycling Manufacturing construction, Germany U. K. Brazil = Zinc (2)to Locations be = Magnesium operational 01/01/06
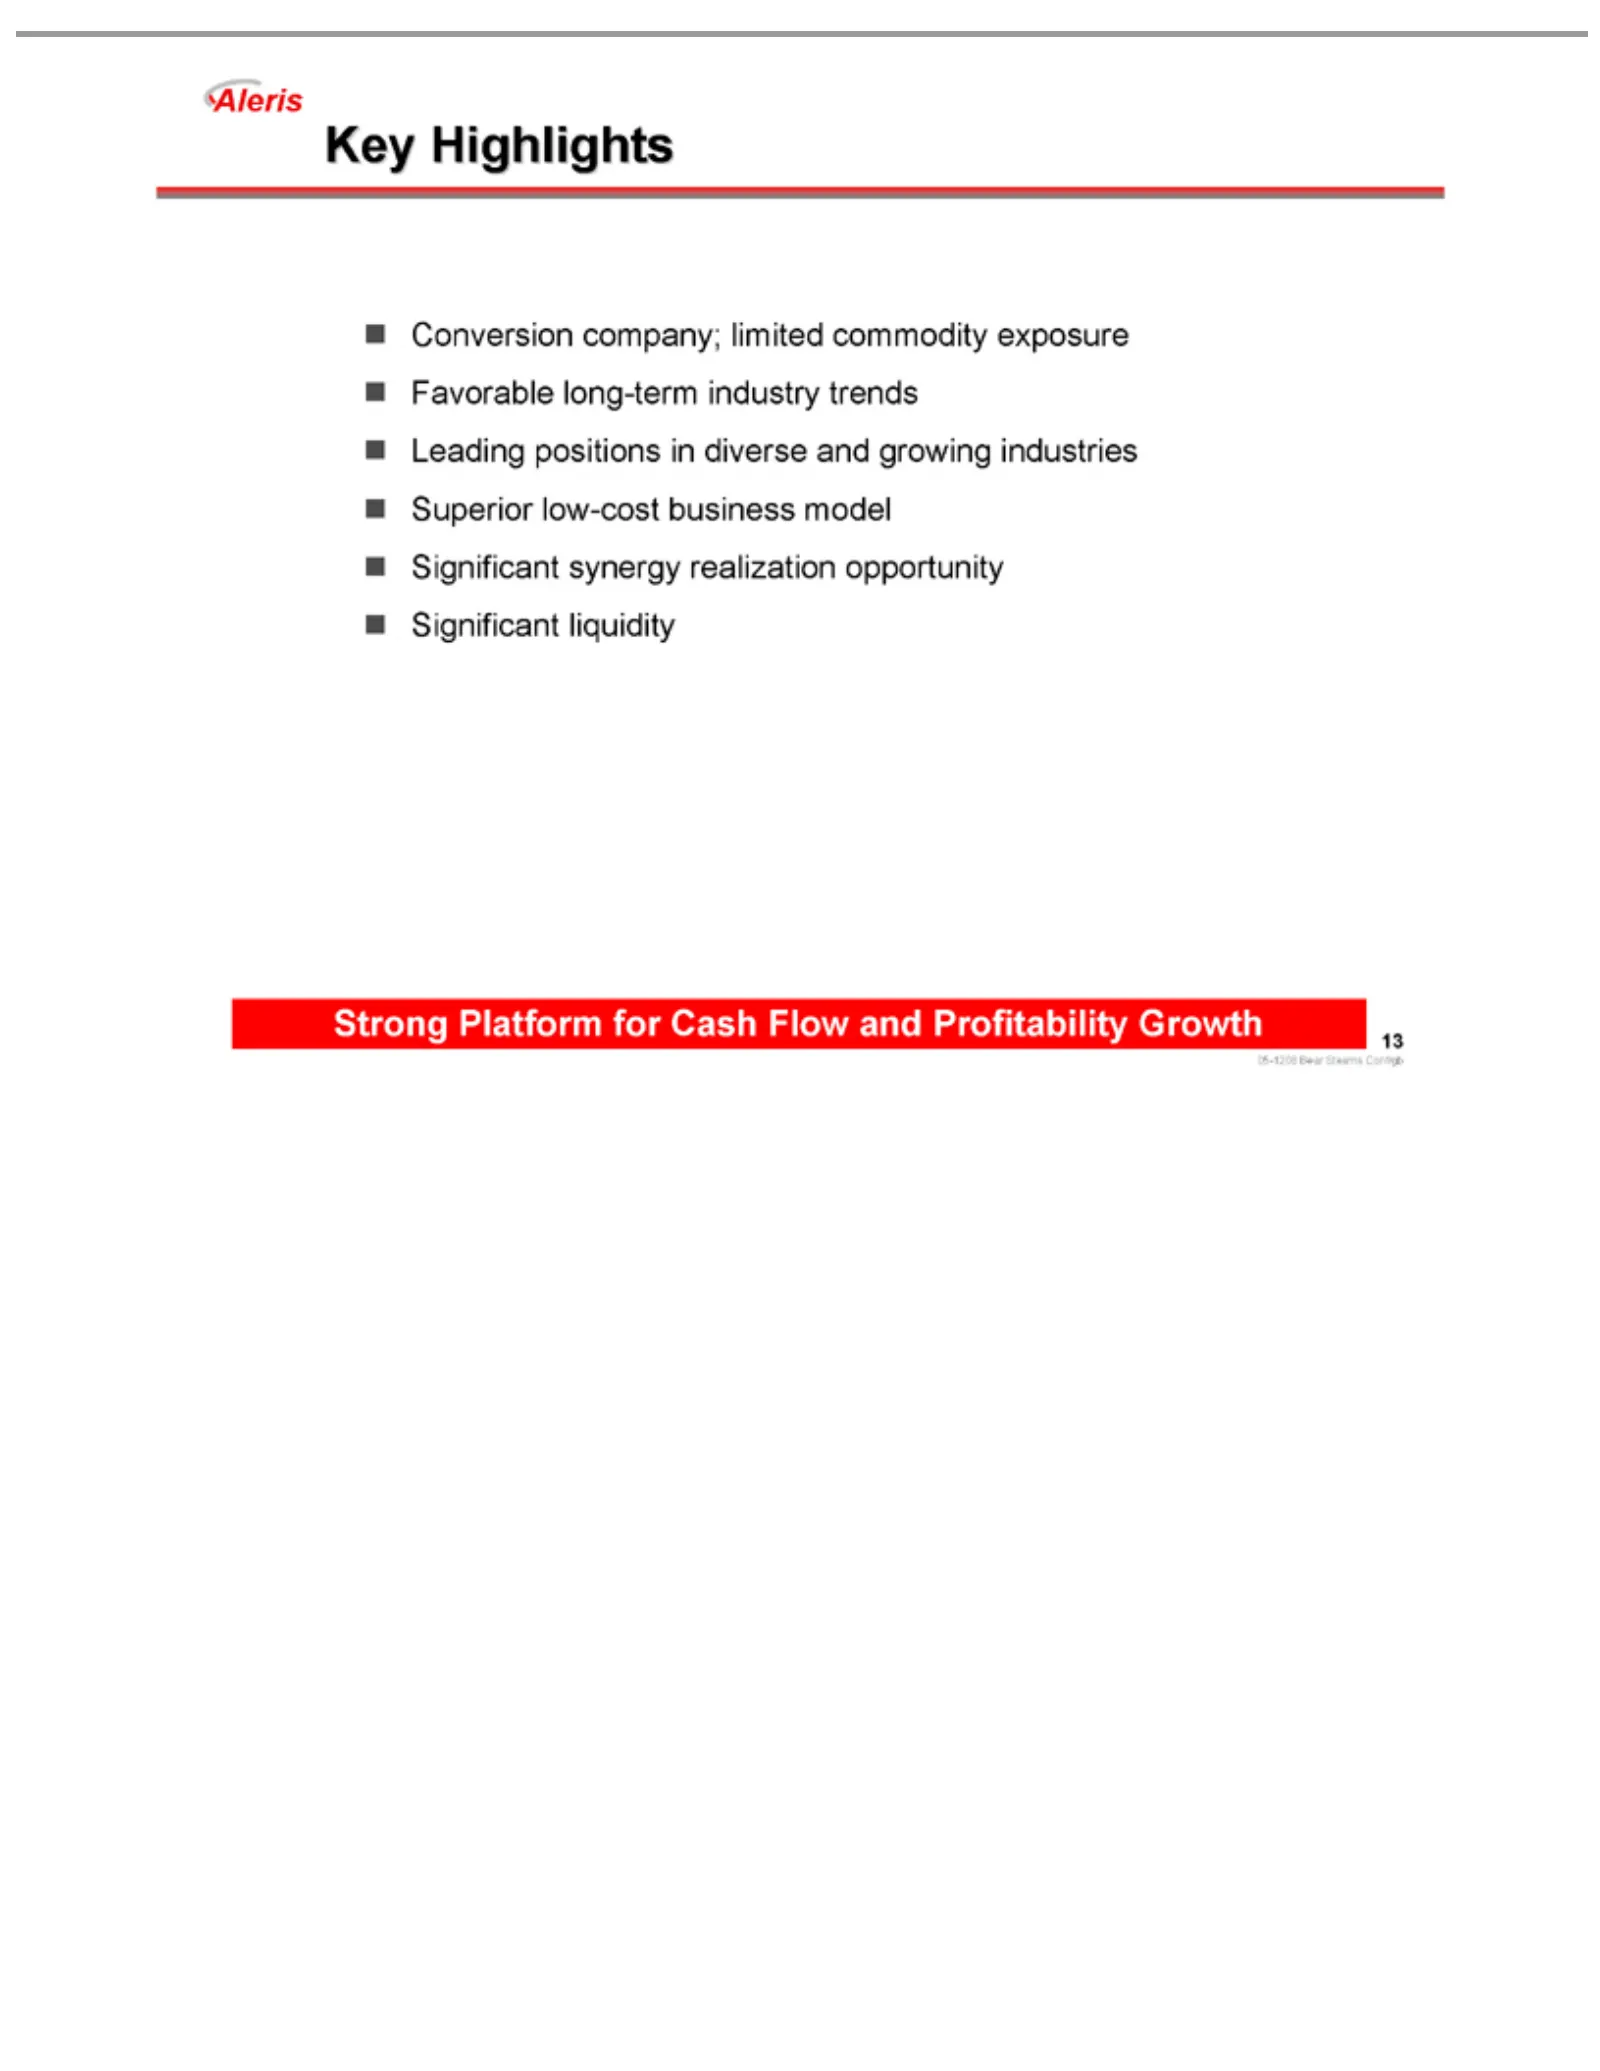
Slide 13: Key Highlights
Key Highlights Conversion realization Strong 05-1208 13 Platform Bear opportunity company; Stearns for Cash Conf/gb limited Significant Flowcommodity andliquidity Profitability exposure Growth Favorable long-term industry trends Leading positions in diverse and growing industries Superior low-cost b
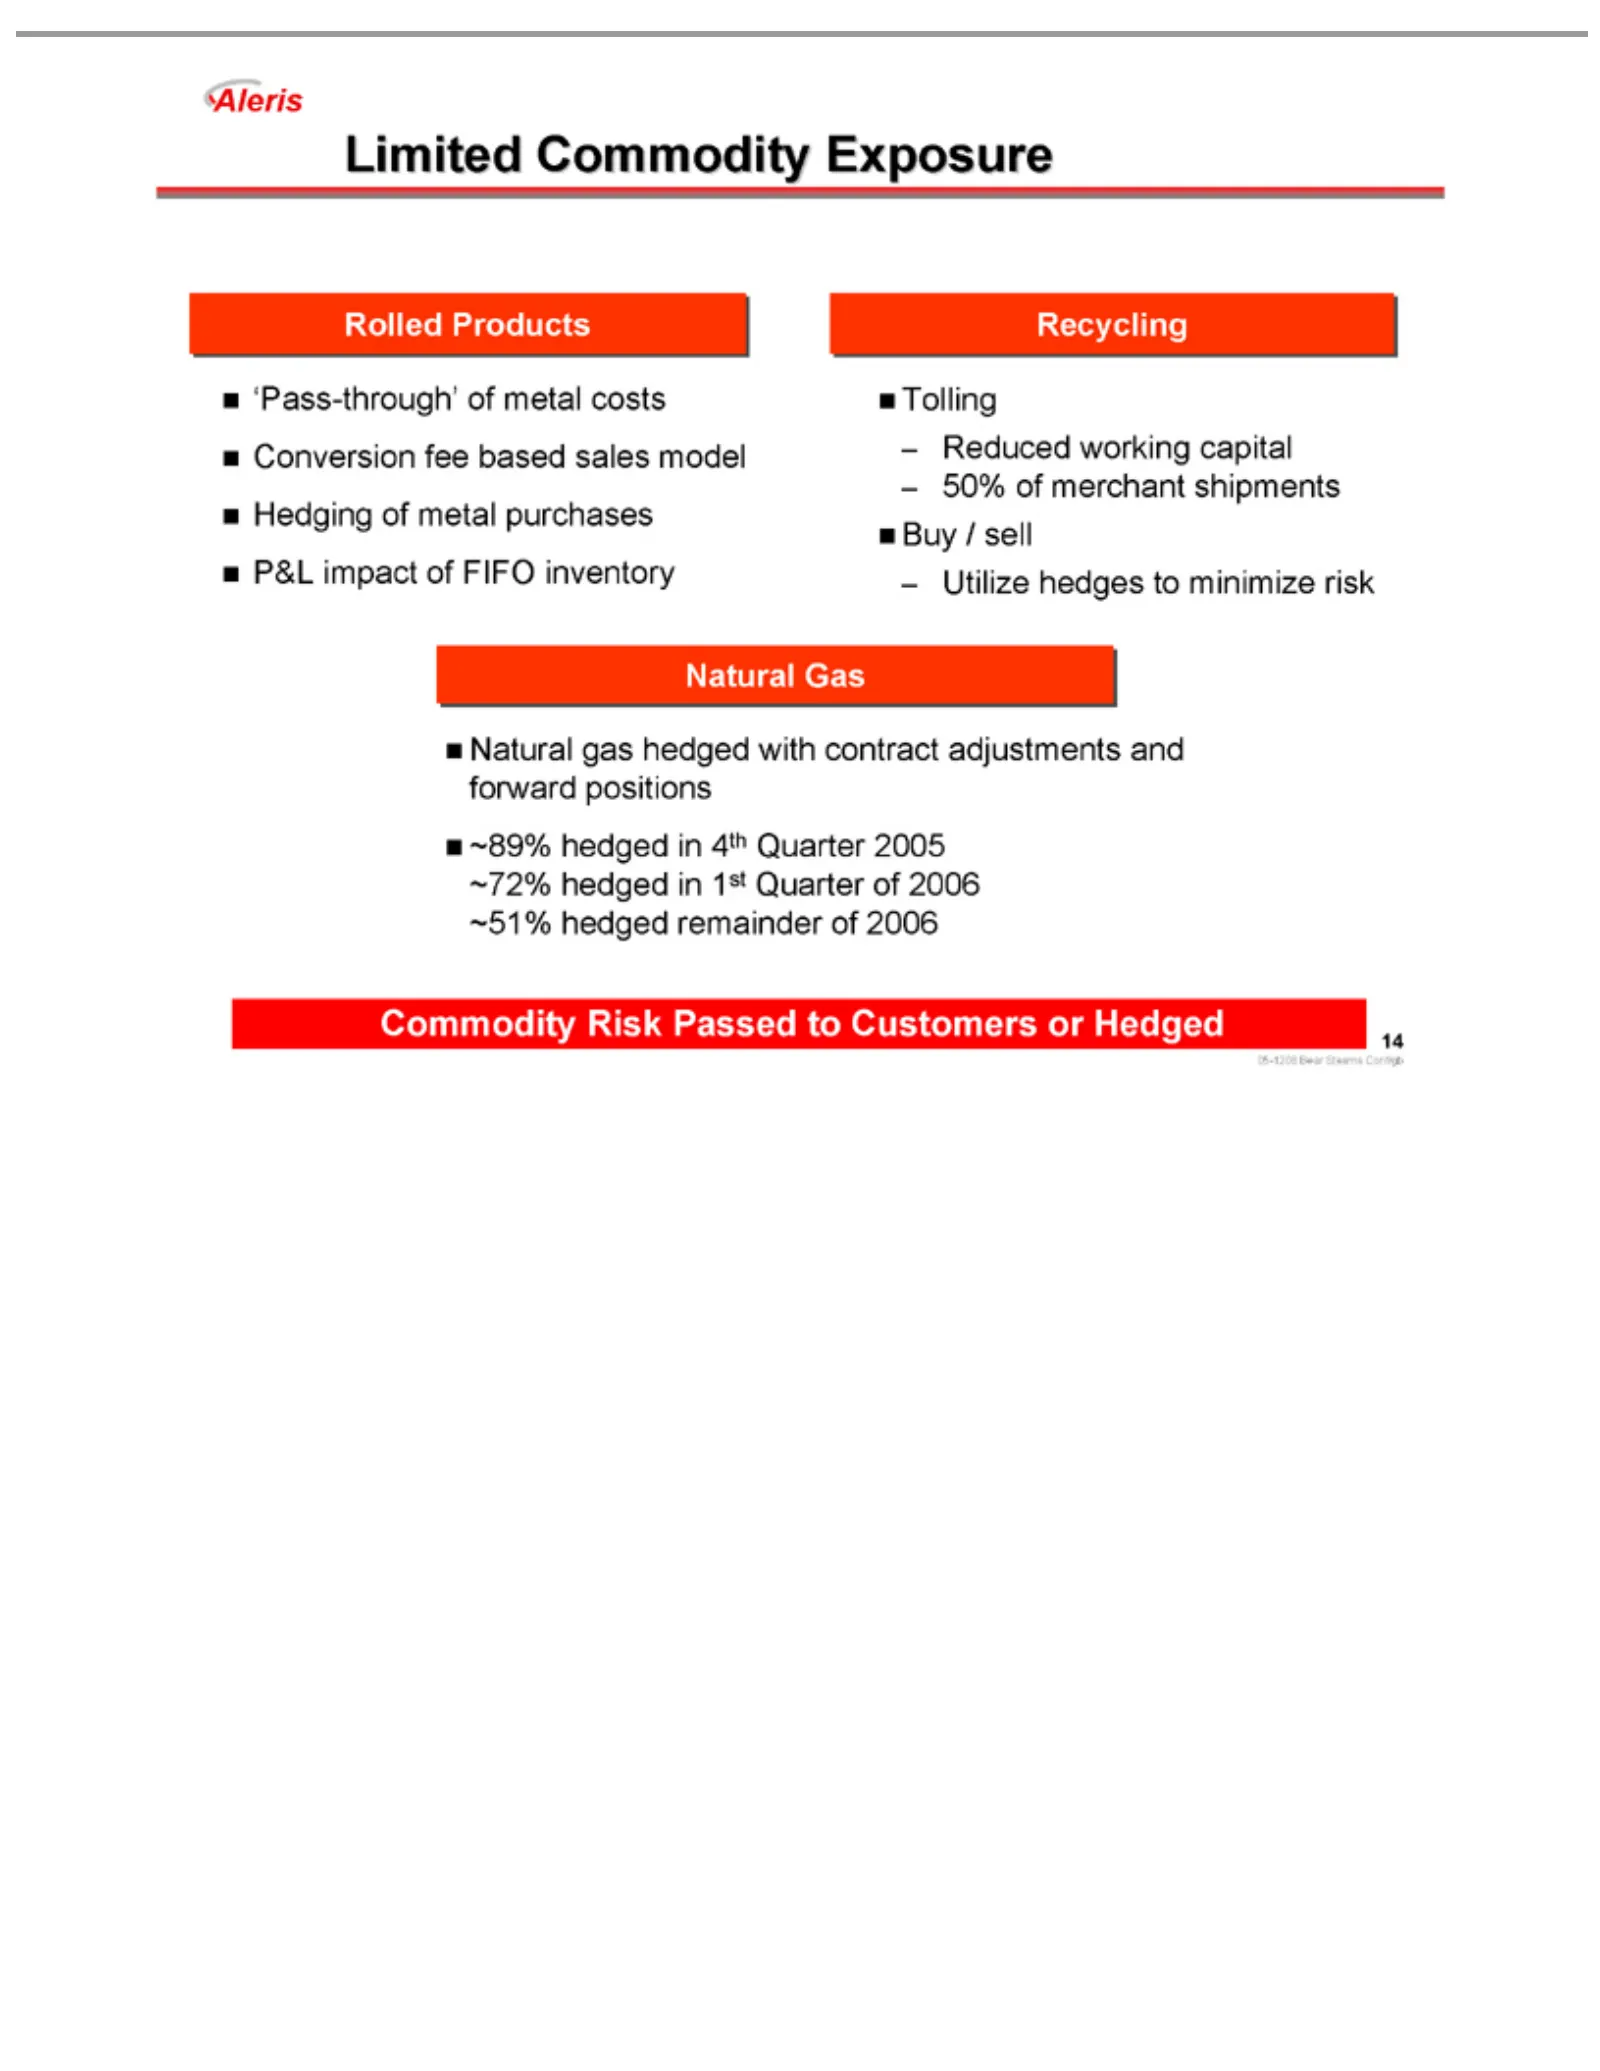
Slide 14: Limited Commodity Risk Exposure
Limited Rolled ‘Pass-through’ Recycling Reduced Tolling Buy Utilize Natural ~89% Commodity 05-1208 14 / sell hedged Products hedges Gas gas Commodity Bear working hedged Risk Stearns in to of4th minimize Passed metal capital with Quarter Exposure Conf/gb costs contract to 50% risk Customers 2005 Con
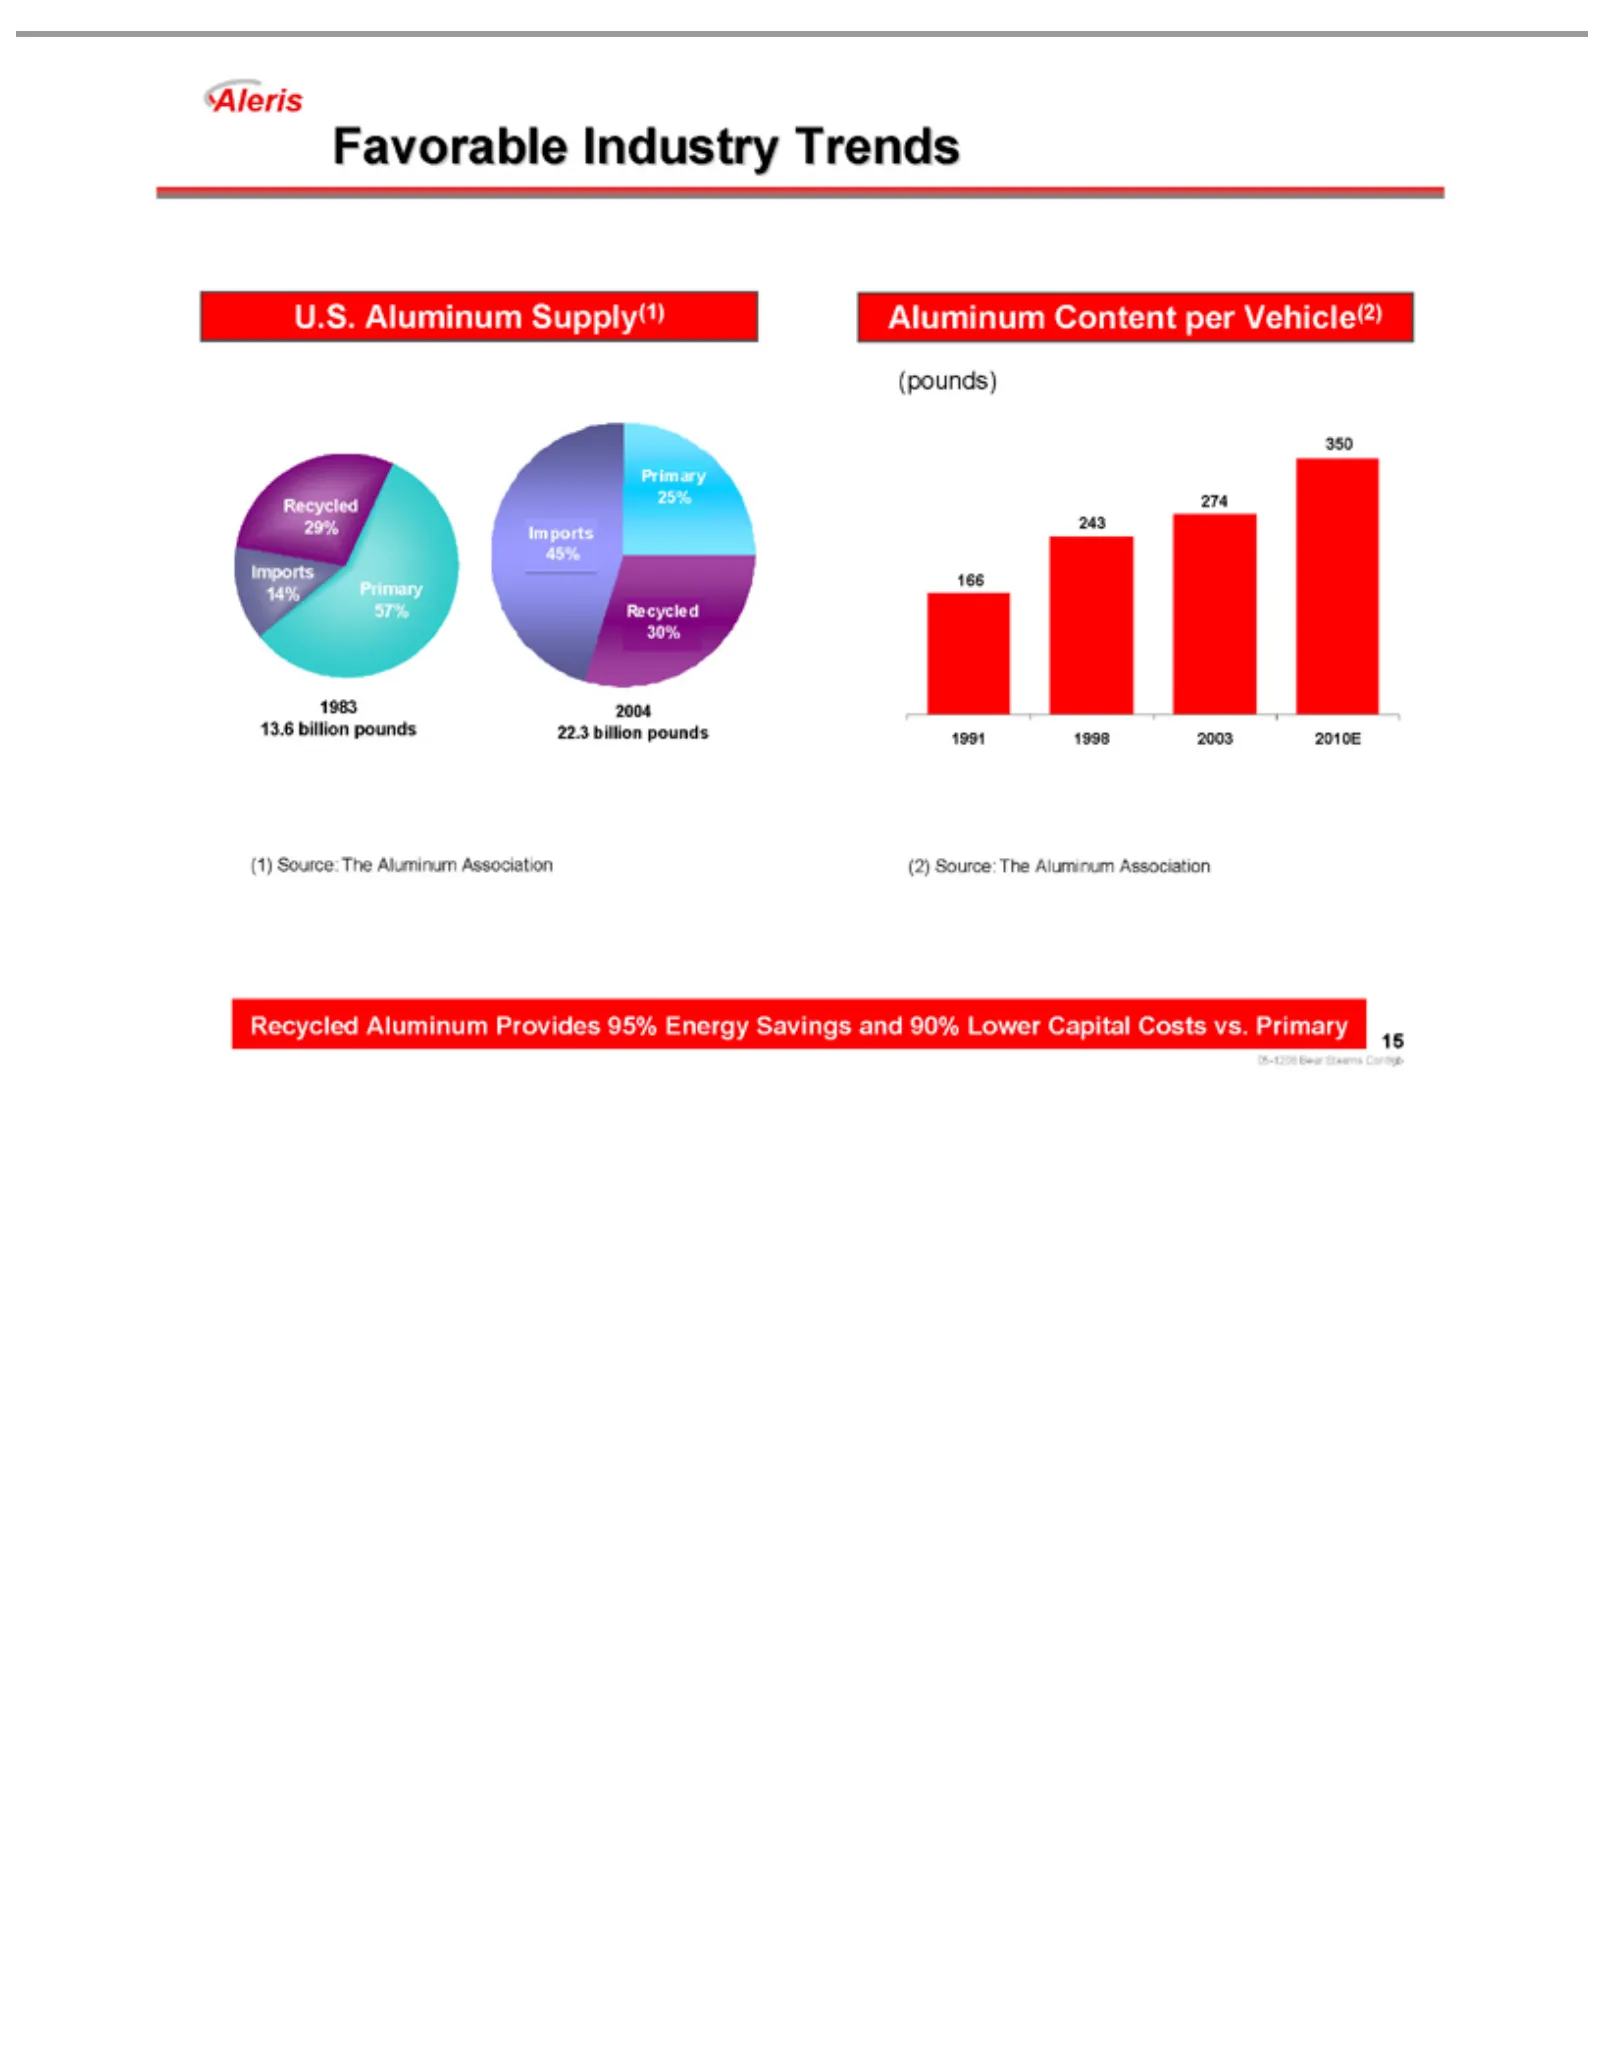
Slide 15: Favorable Industry Trends
Favorable U.S. 14% 1983 Primary Imports Recycled 2004 Aluminum 274 350 (pounds) 1991 166 (1) (2) 15 243 Aluminum Primary 13.6 22.3 1998 Recycled 05-1208 45% 25% 29% 30% Industry billion 2003 Content Source: Bear 57% AluminumSupply(1) 2010E pounds TheTrends per Vehicle(2) Aluminum StearnsProvides Con
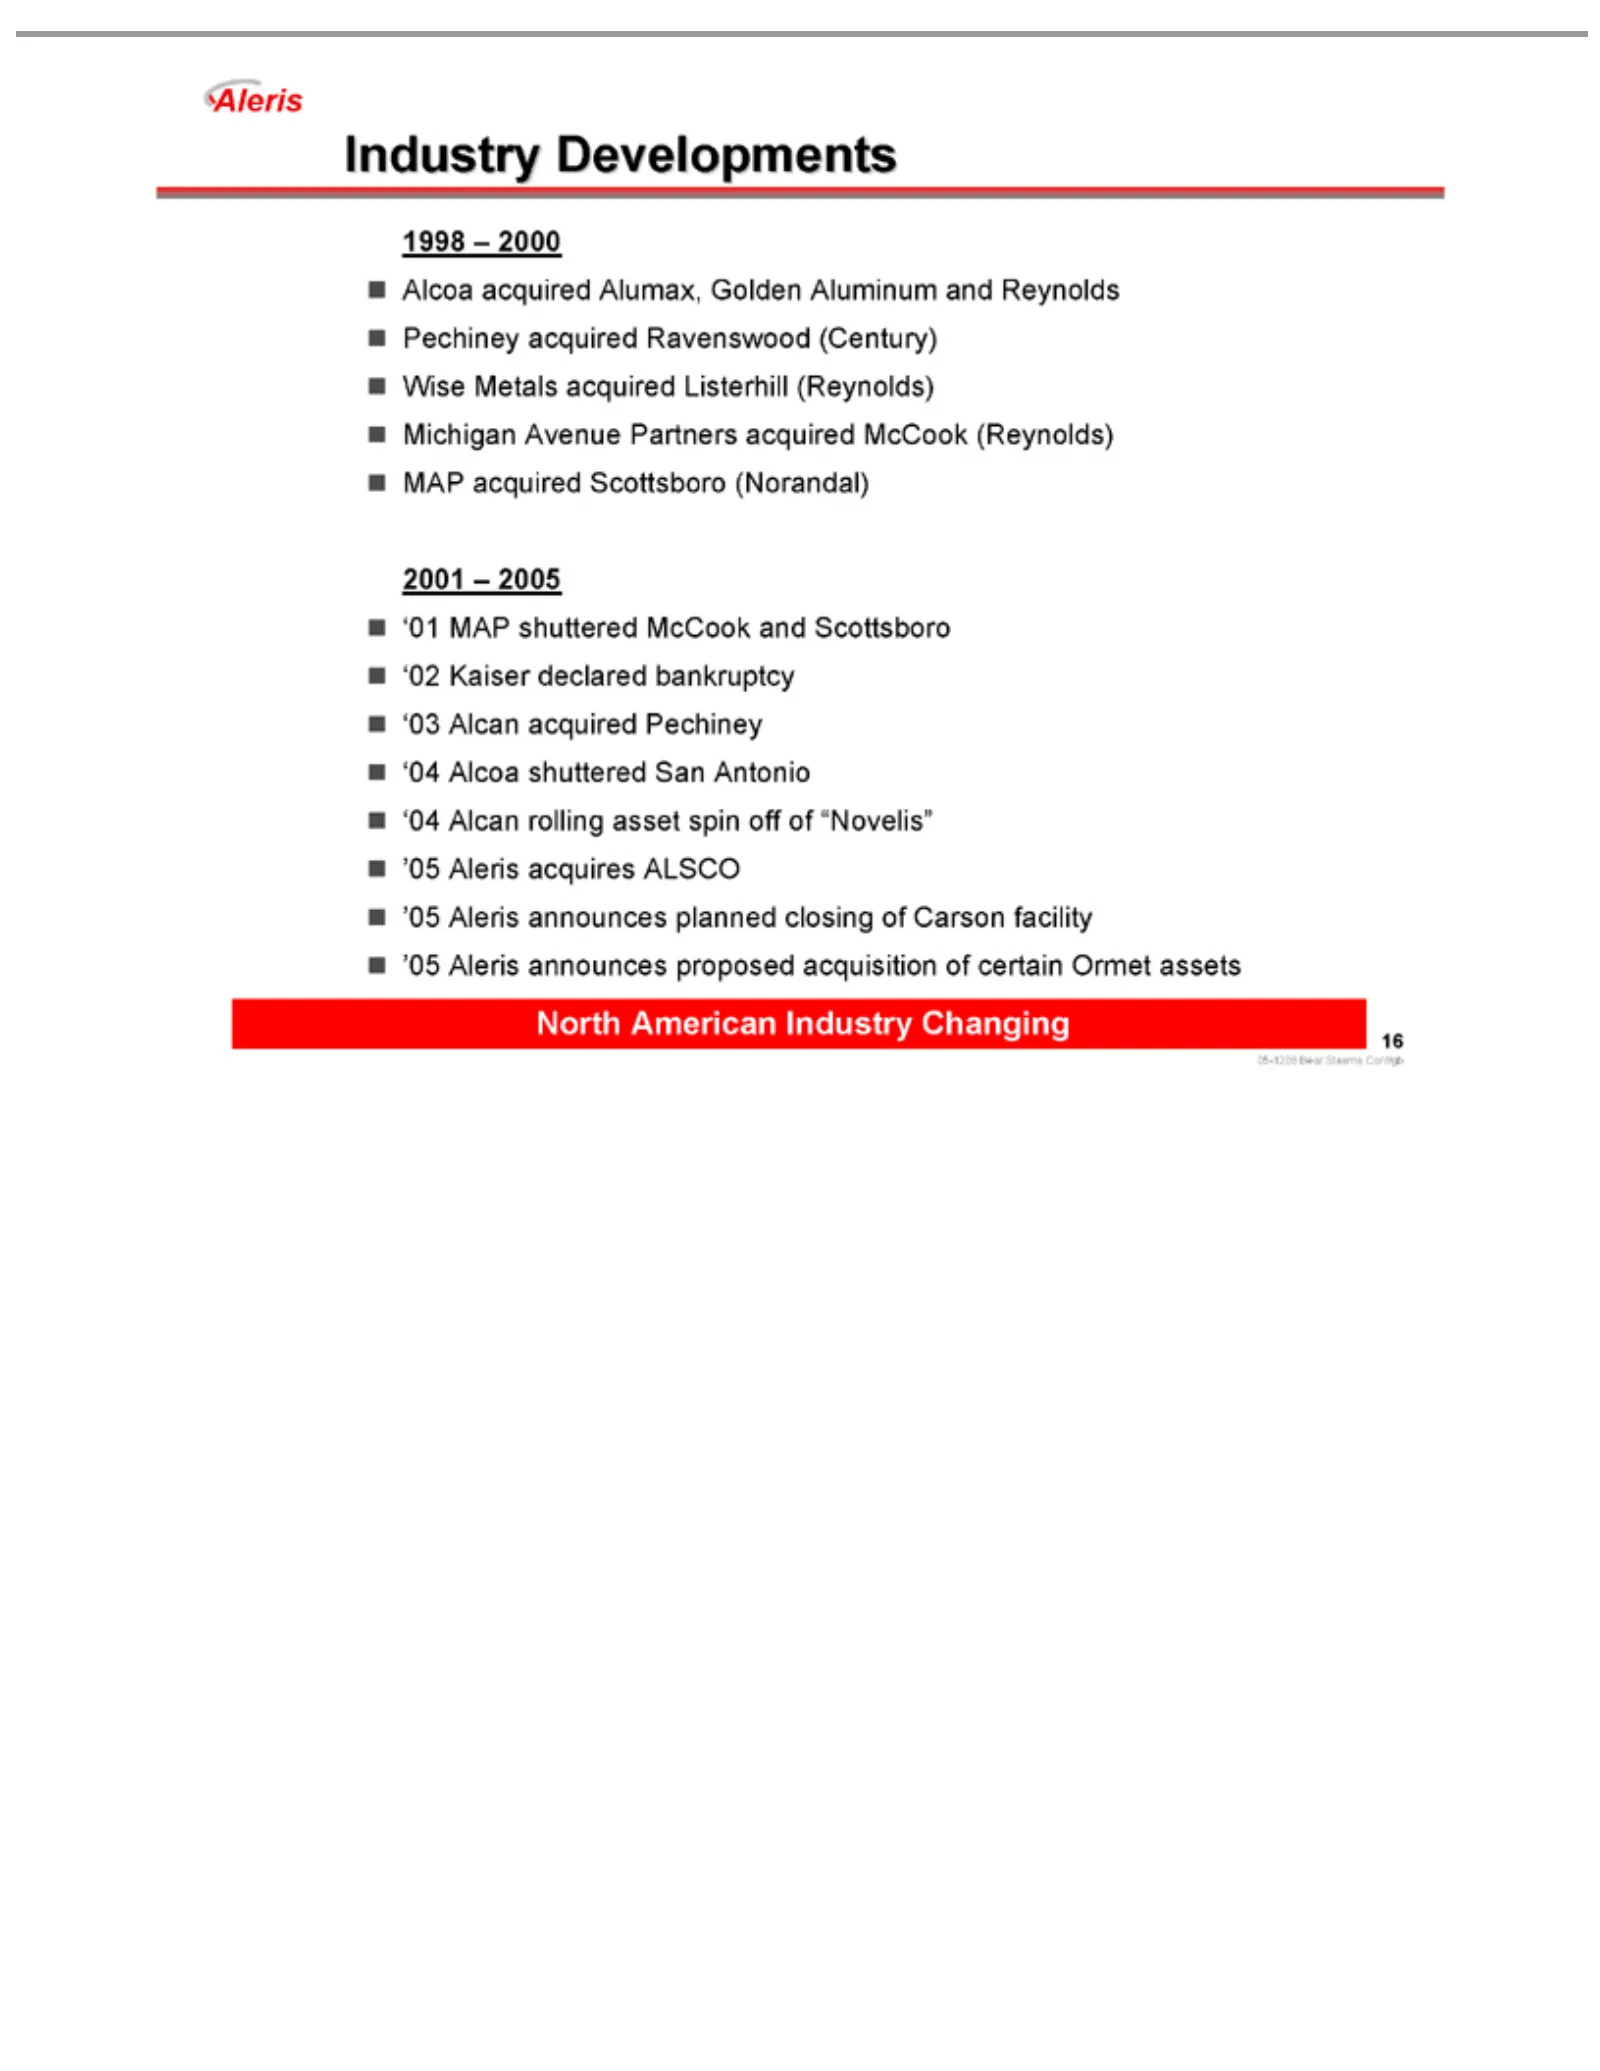
Slide 16: Industry Developments
Industry 1998 Alcoa (Reynolds) 2001 ‘01 acquires ‘05 North 05-1208 16 Aleris MAP –American acquired 2000 2005 ALSCO Developments Bear shuttered announces MAP Stearns Alumax, Industry acquired McCook planned proposed Conf/gb Golden Changing Scottsboro and closing acquisition Aluminum Scottsboro of (N
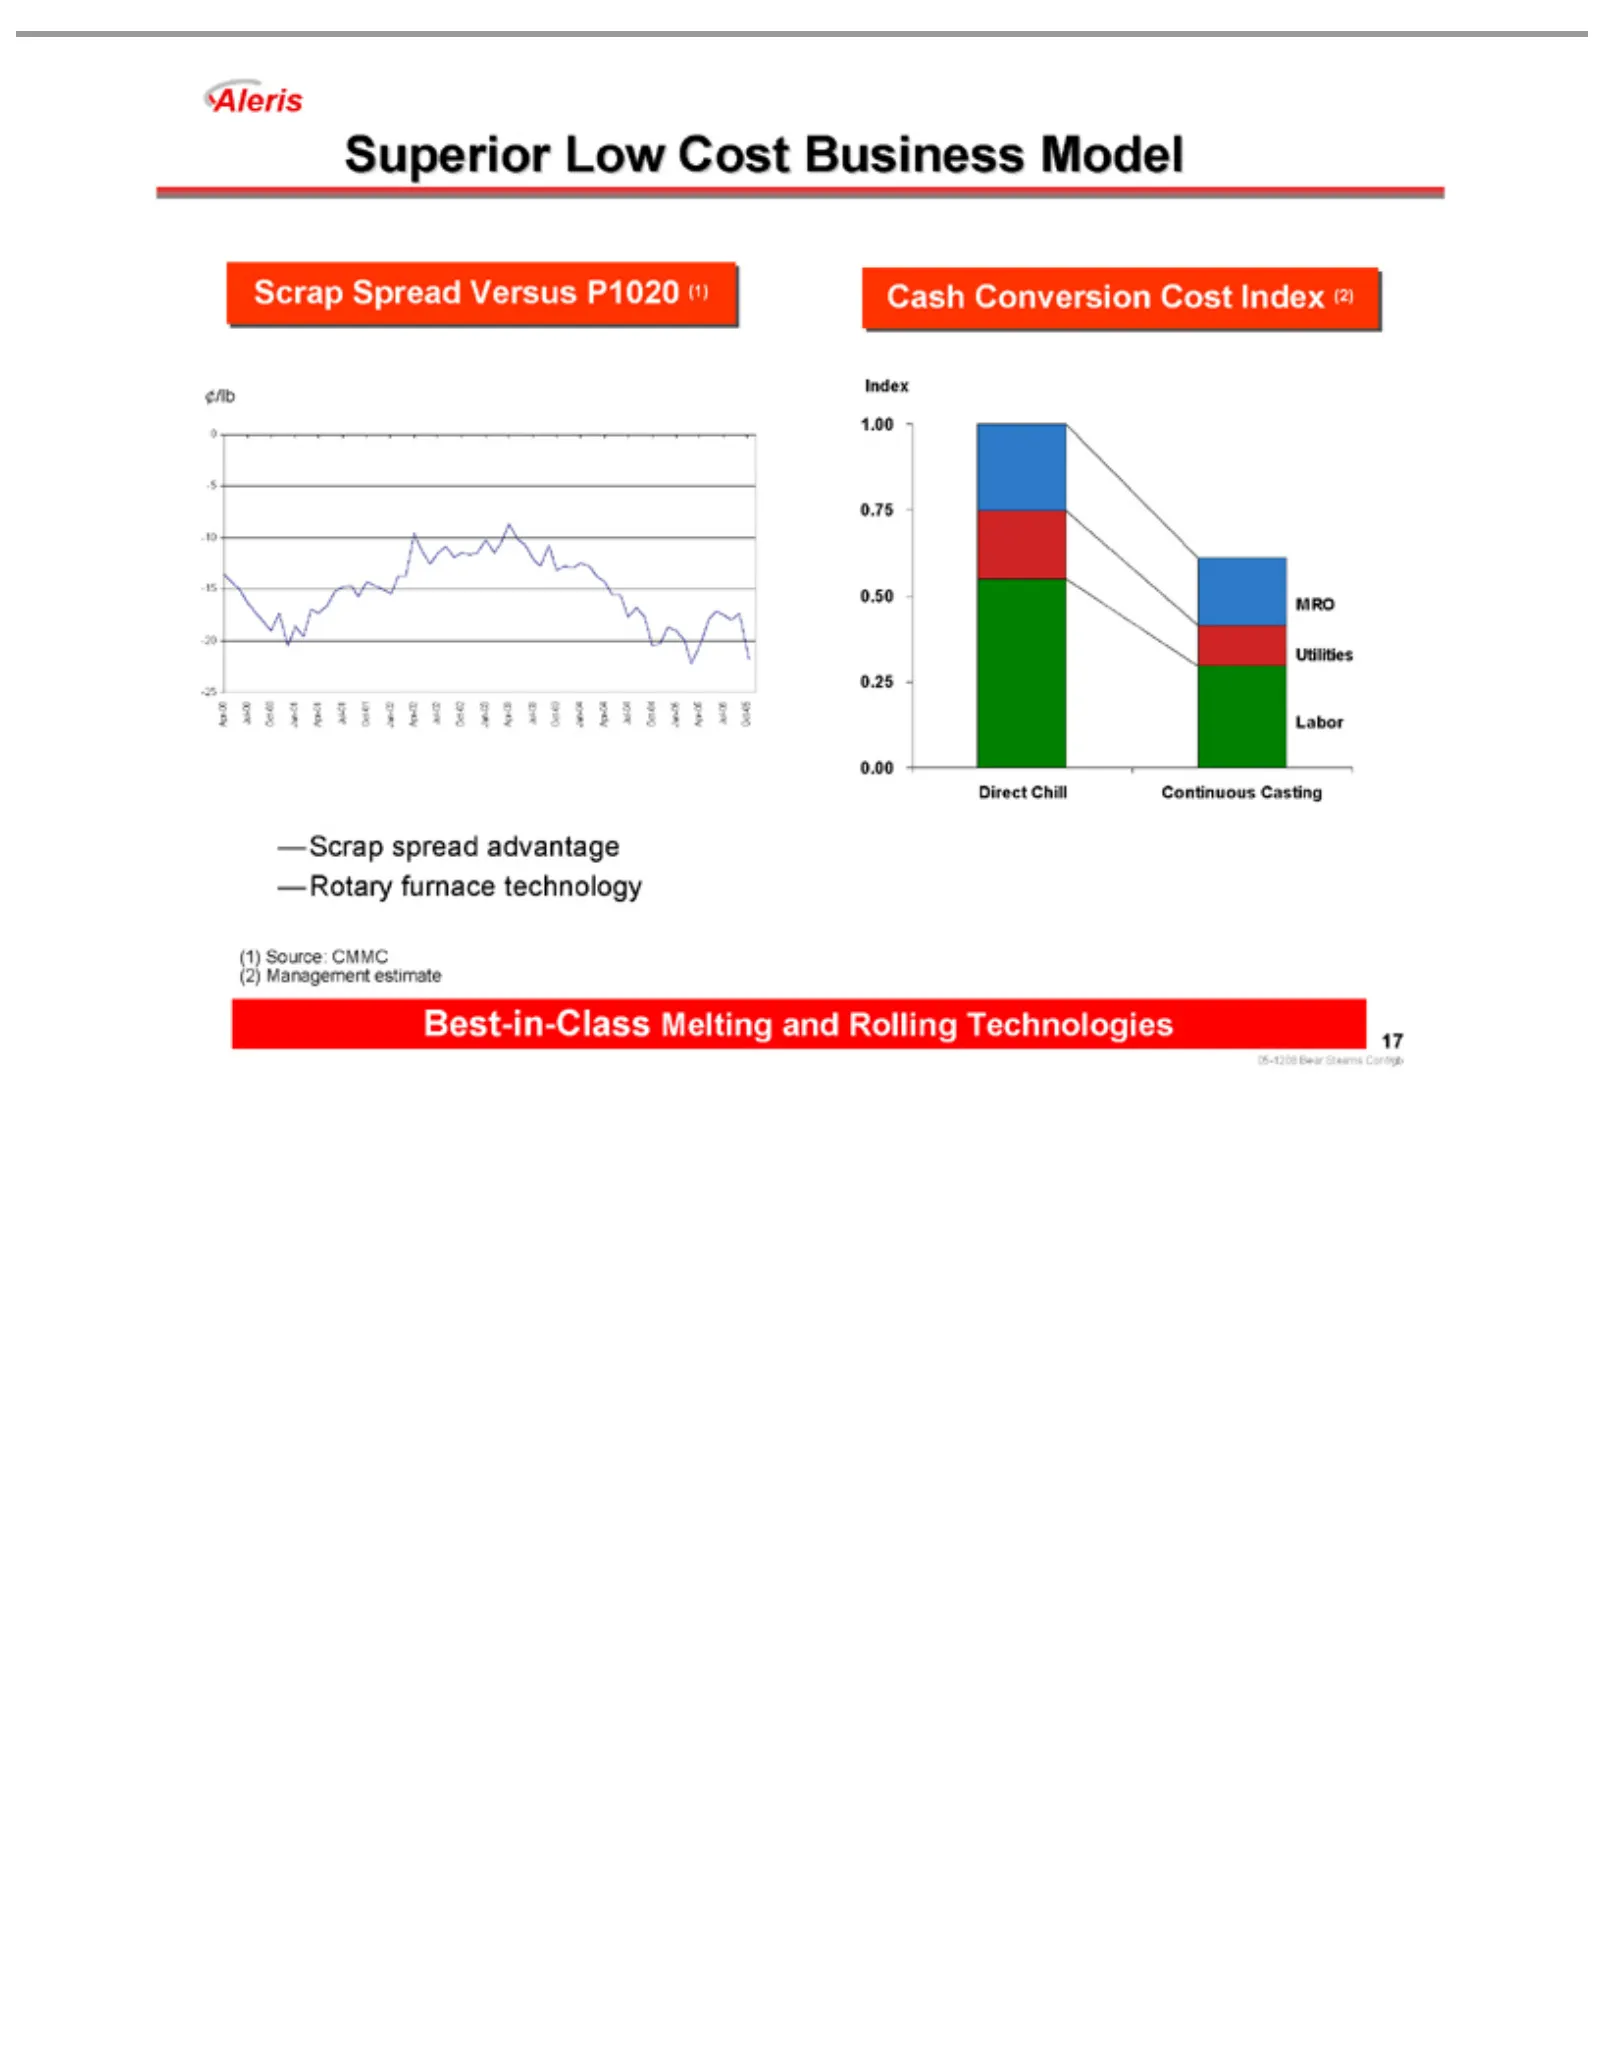
Slide 17: Superior Business Model
Superior Scrap Cash 0 ¢/lb Apr-00 1.00 Index Direct MRO —Scrap (1) 17-5 -10 0.75 Conversion Spread Utilities Chill Jul-00 Source: -15 spread Low 0.50 Best-in-Class 05-1208 -20 Continuous Bear Versus Cost Oct-00 0.25 Labor advantage CMMC -25 Cost Business 0.00 Melting StearnsP1020 Jan-01 Index Castin
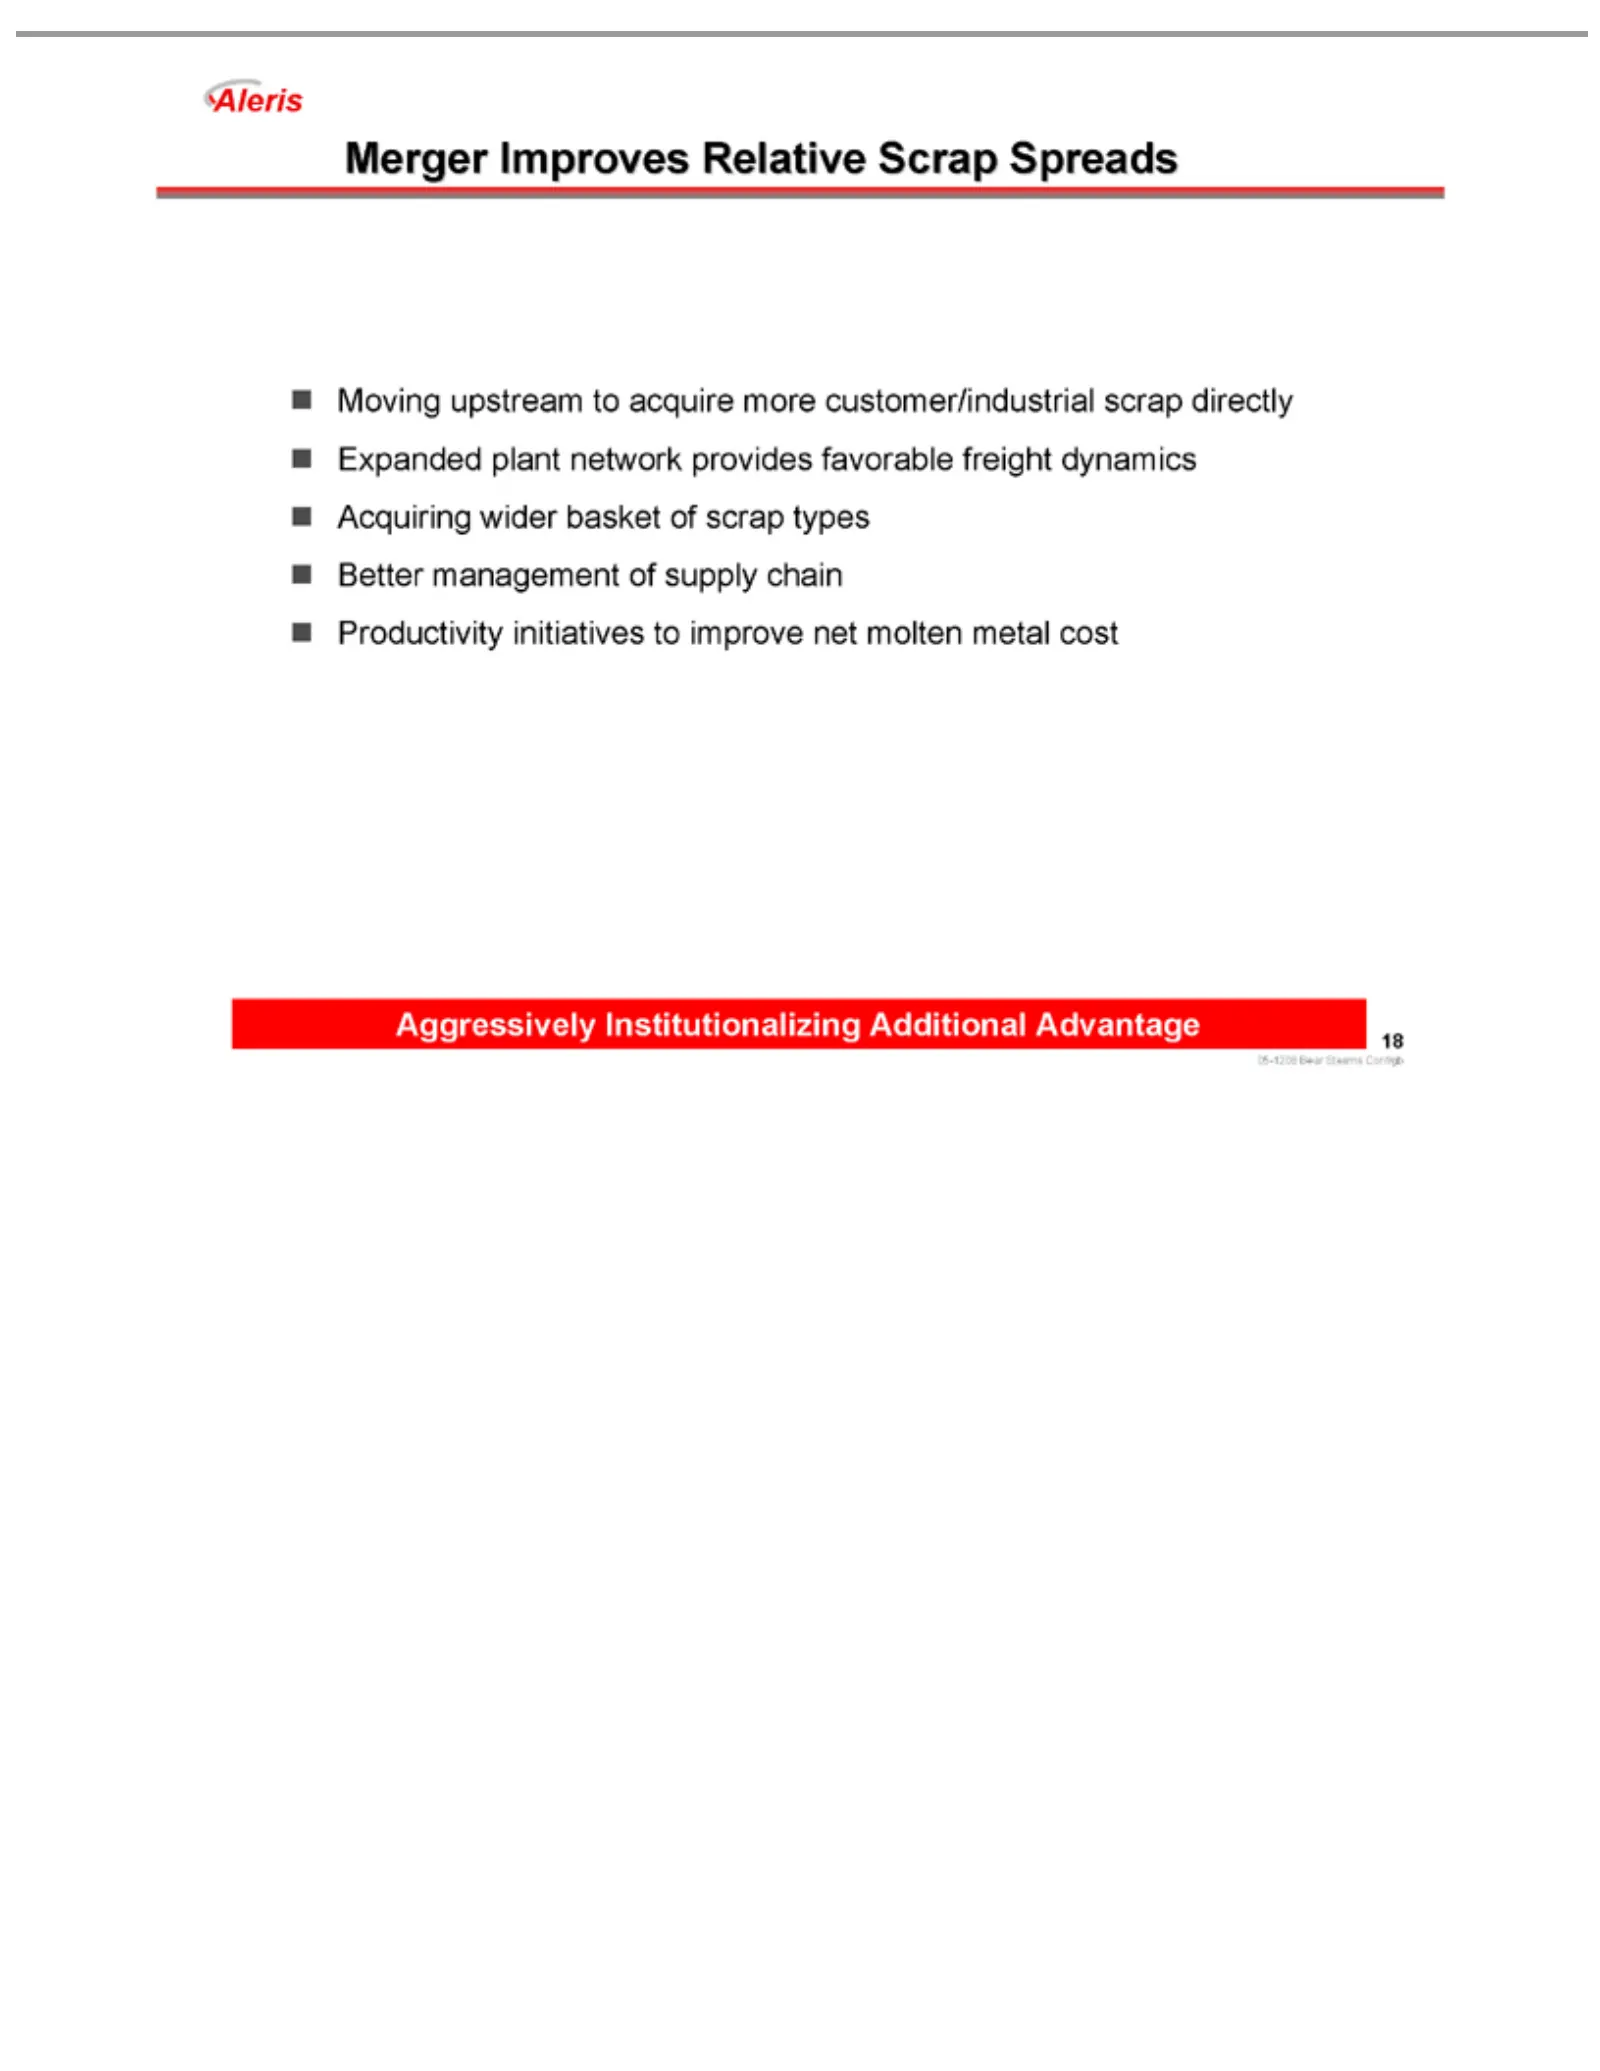
Slide 18: Merger Improves Scrap Advantage
Merger Moving chain Aggressively 05-1208 18 Productivity Improves upstream Bear Institutionalizing Stearns Relative to initiatives acquire Conf/gb Scrap more toAdditional improve Spreads customer/industrial net Advantage molten metal scrap cost directly Expanded plant network provides favorable frei
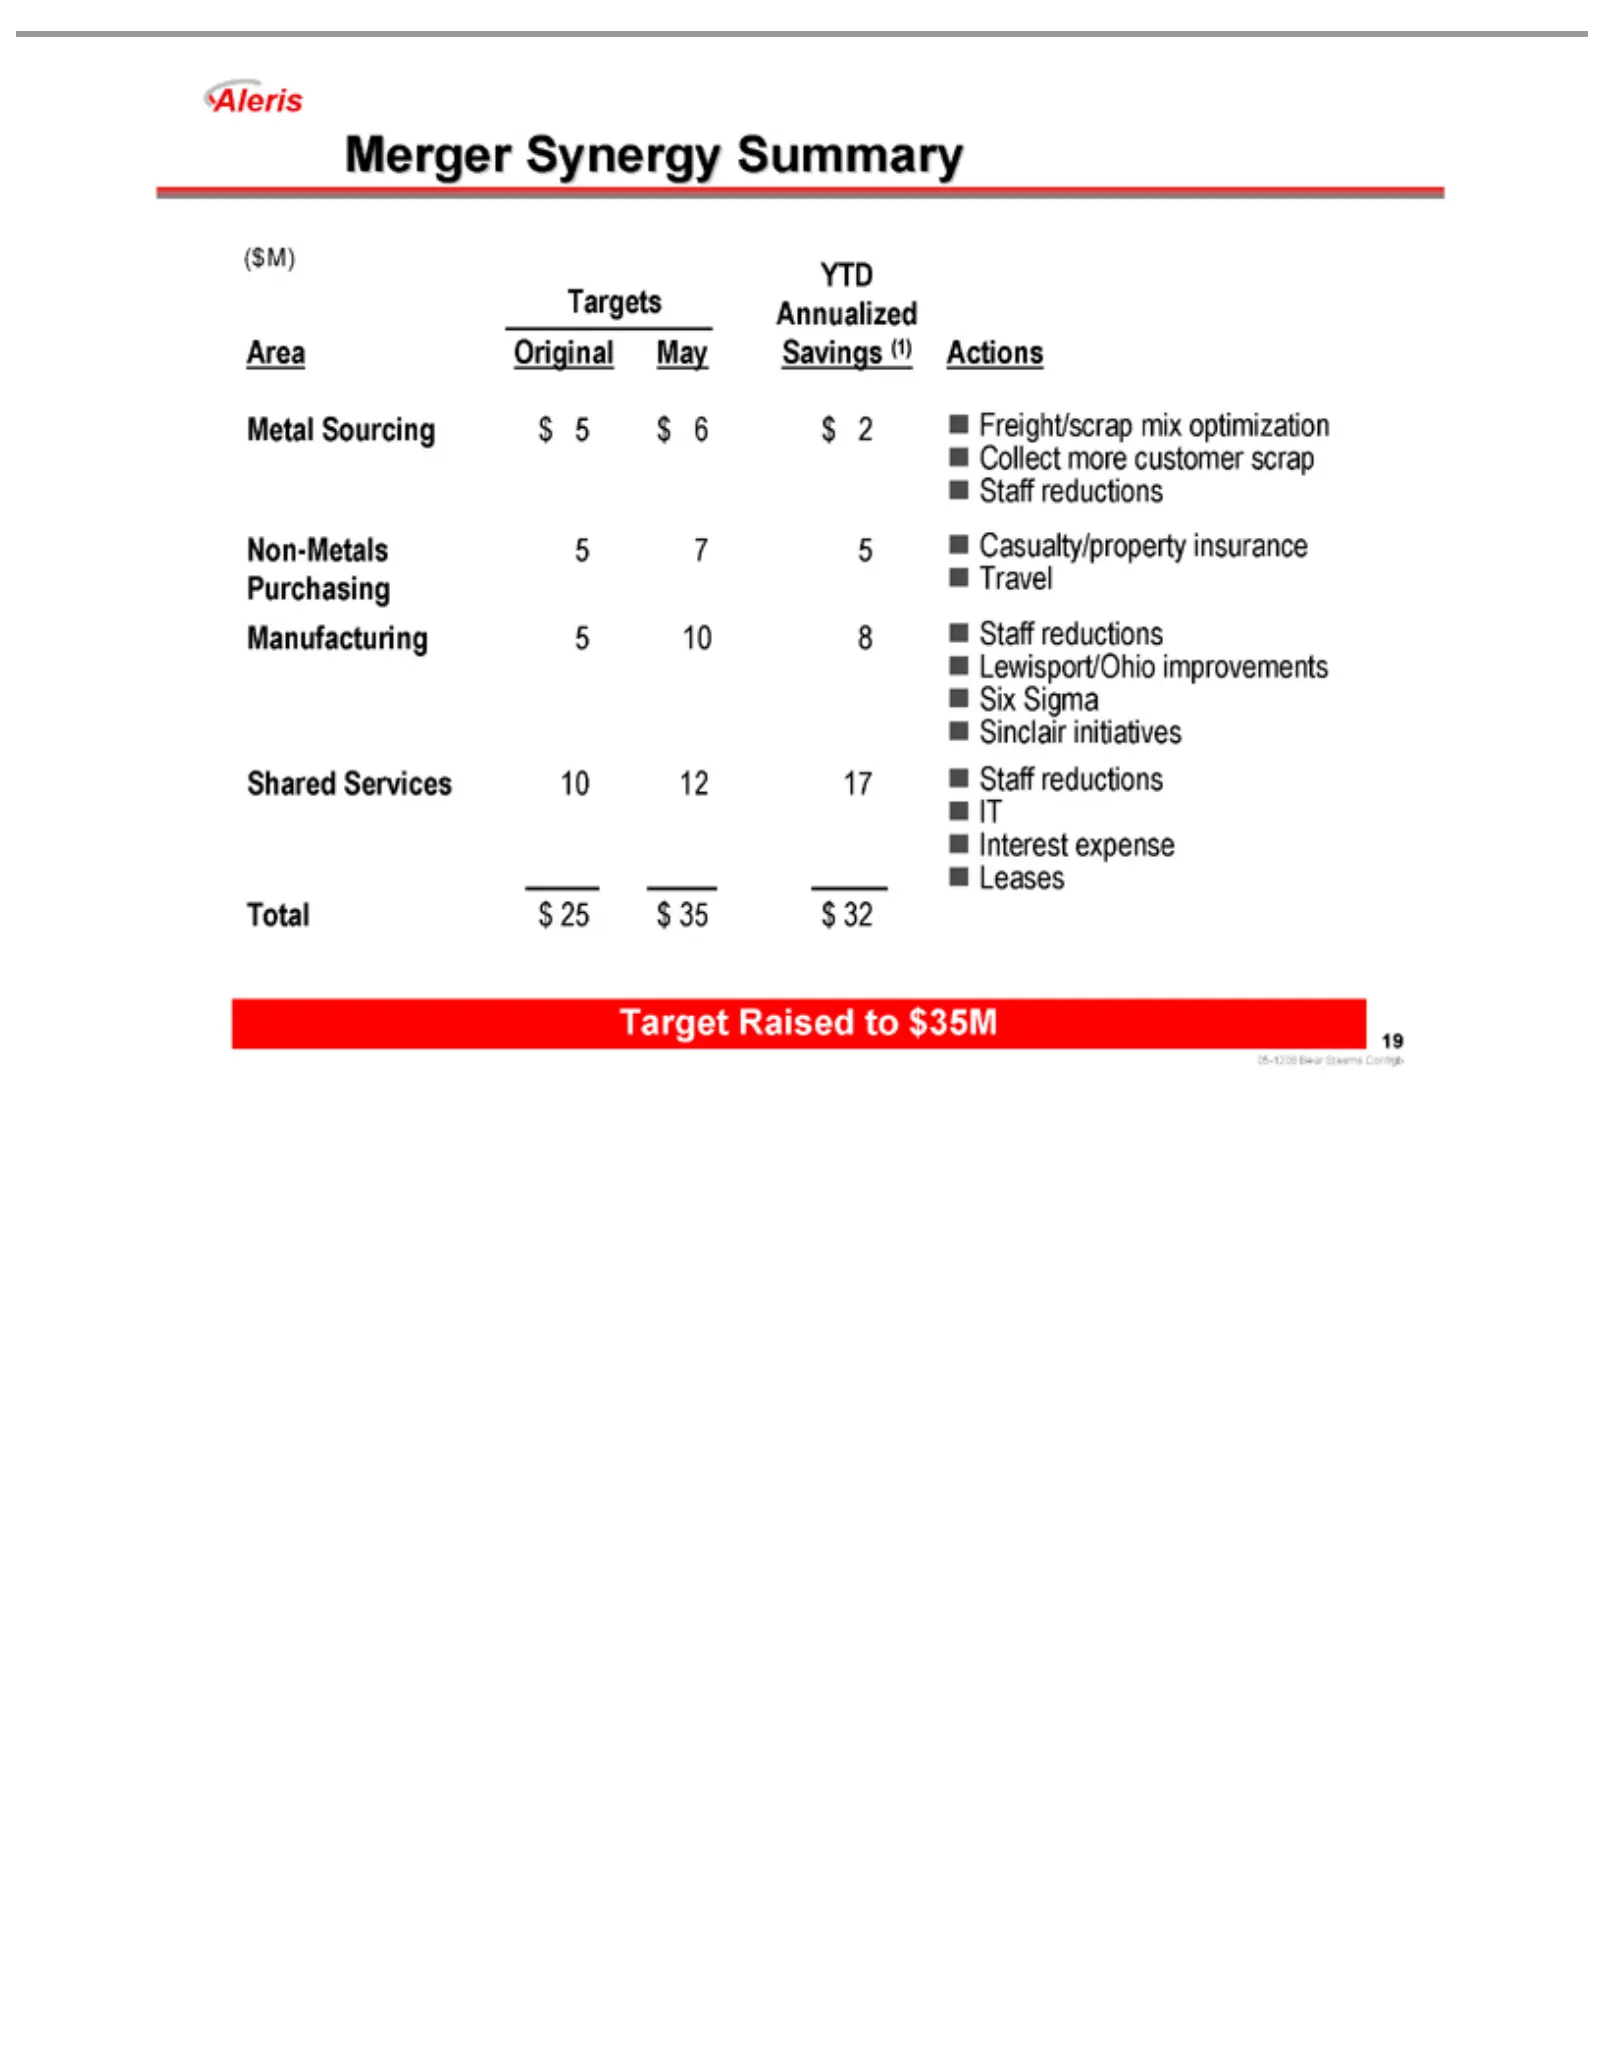
Slide 19: Merger Synergy Targets
Merger Targets YTD ($M) Area Metal Non-Metals Manufacturing Shared Total Freight/scrap Actions Collect Casualty/property Travel Lewisport/Ohio Six Sinclair Staff Interest IT Target Leases 05-1208 19 Sigma reductions Original $25 Sourcing Raised Services Annualized more Synergy expense initiatives Be
Slide 20: Recent Developments
Recent Developments
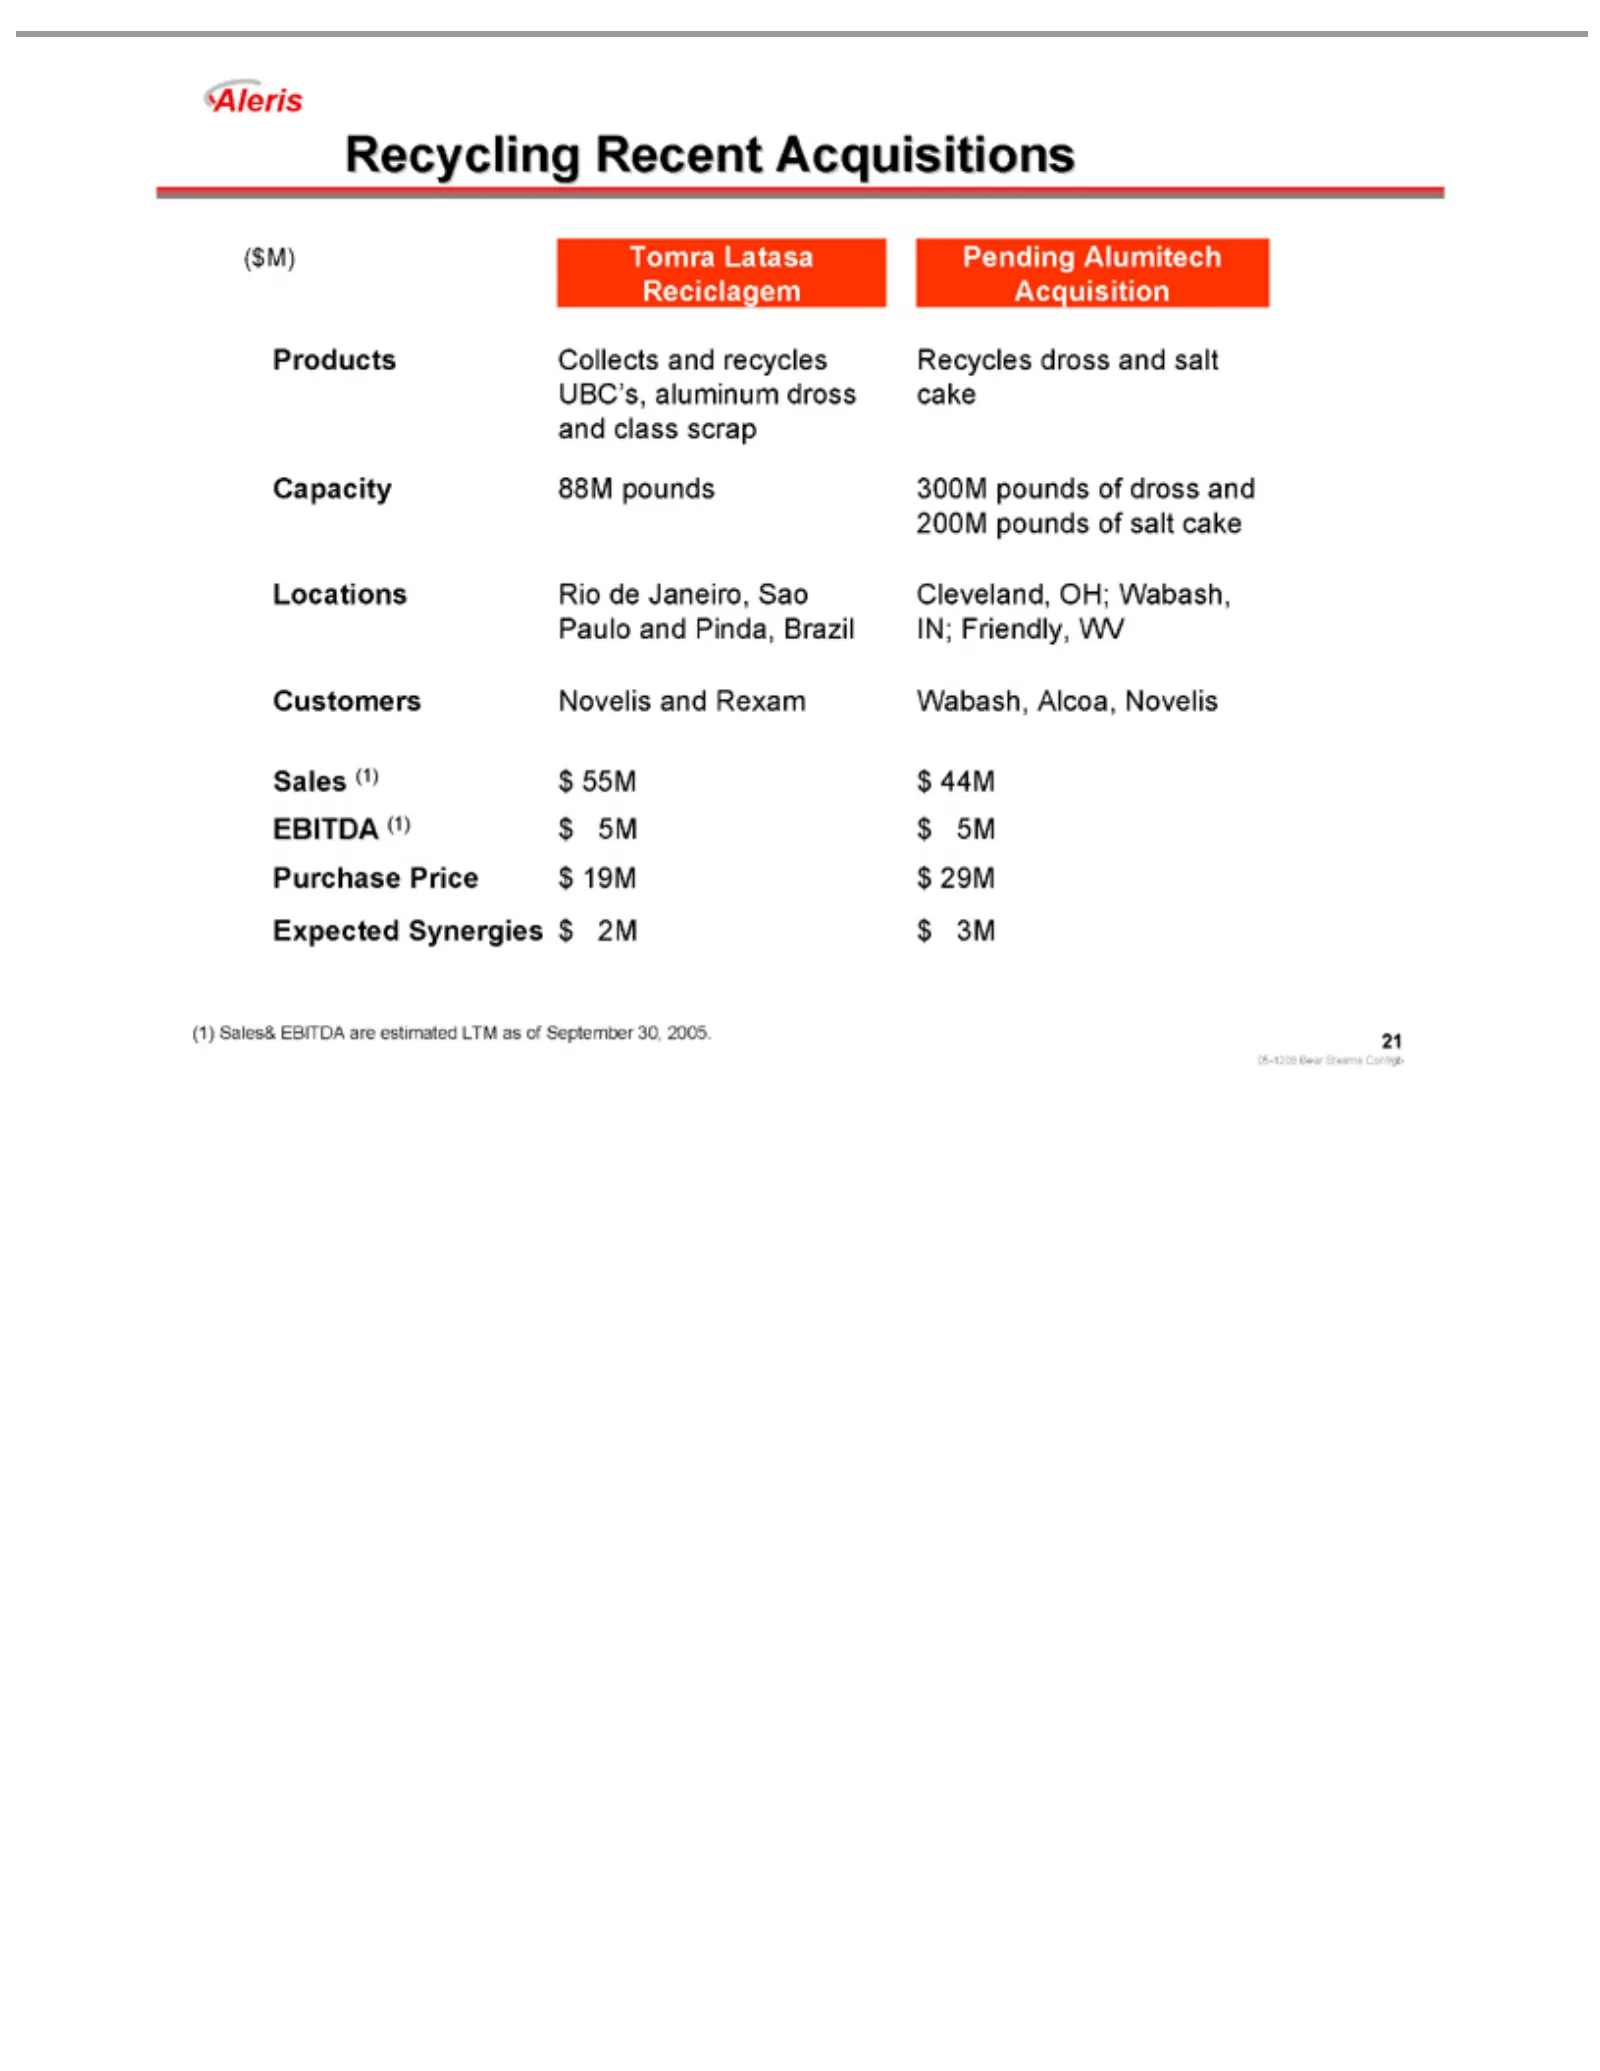
Slide 21: Recycling Recent Acquisitions
Recycling ($M) Products Capacity Locations Customers Sales EBITDA Purchase Expected (1) Tomra (1)Sales& 05-1208 Collects $55M 88M Price (1) Synergies Rio Recent Novelis BearLatasa $5M de pounds $19M EBITDA $44M Janeiro, Acquisitions and $5M and StearnsReciclagem $2M $29M recycles 300M Rexam are $3M
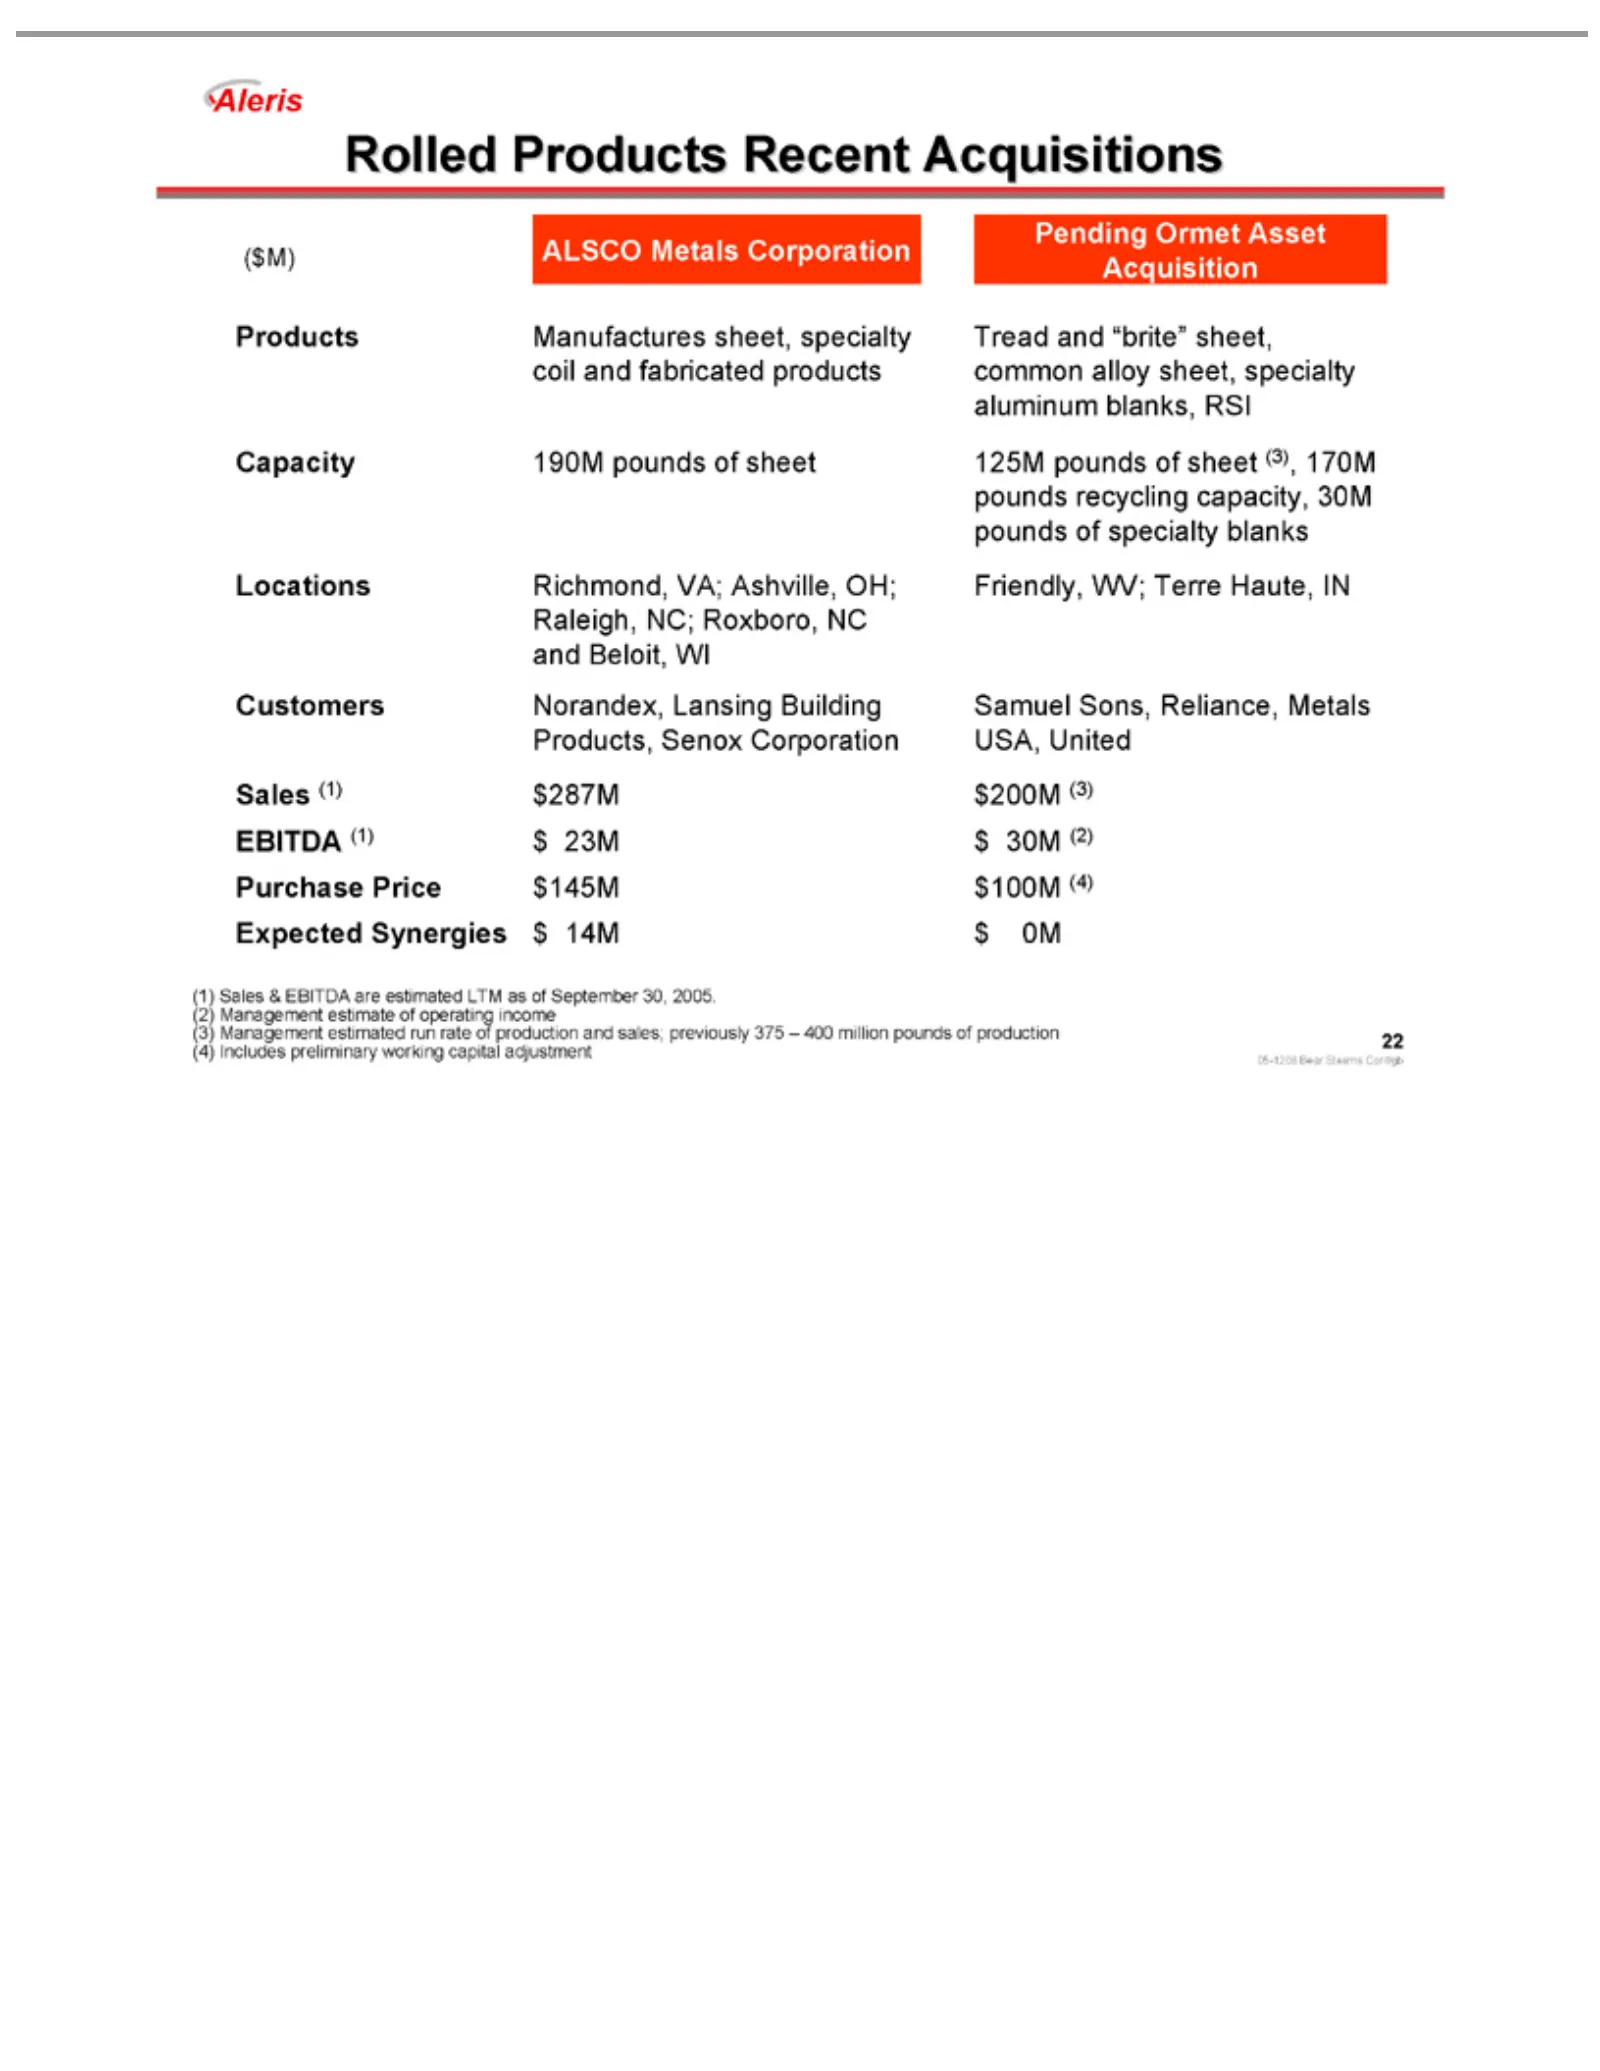
Slide 22: Rolled Products Recent Acquisitions
Rolled ($M) Products Capacity Locations Customers Sales EBITDA Purchase Expected (1) 22 (3) ALSCO (1) 05-1208Products Sales Manufactures $287M 190M Price (1) Synergies Richmond, Norandex, Management Bear$23M & Metals $145M pounds EBITDA Recent $200M $30M Stearns$14M Corporation VA; Lansing $100M she
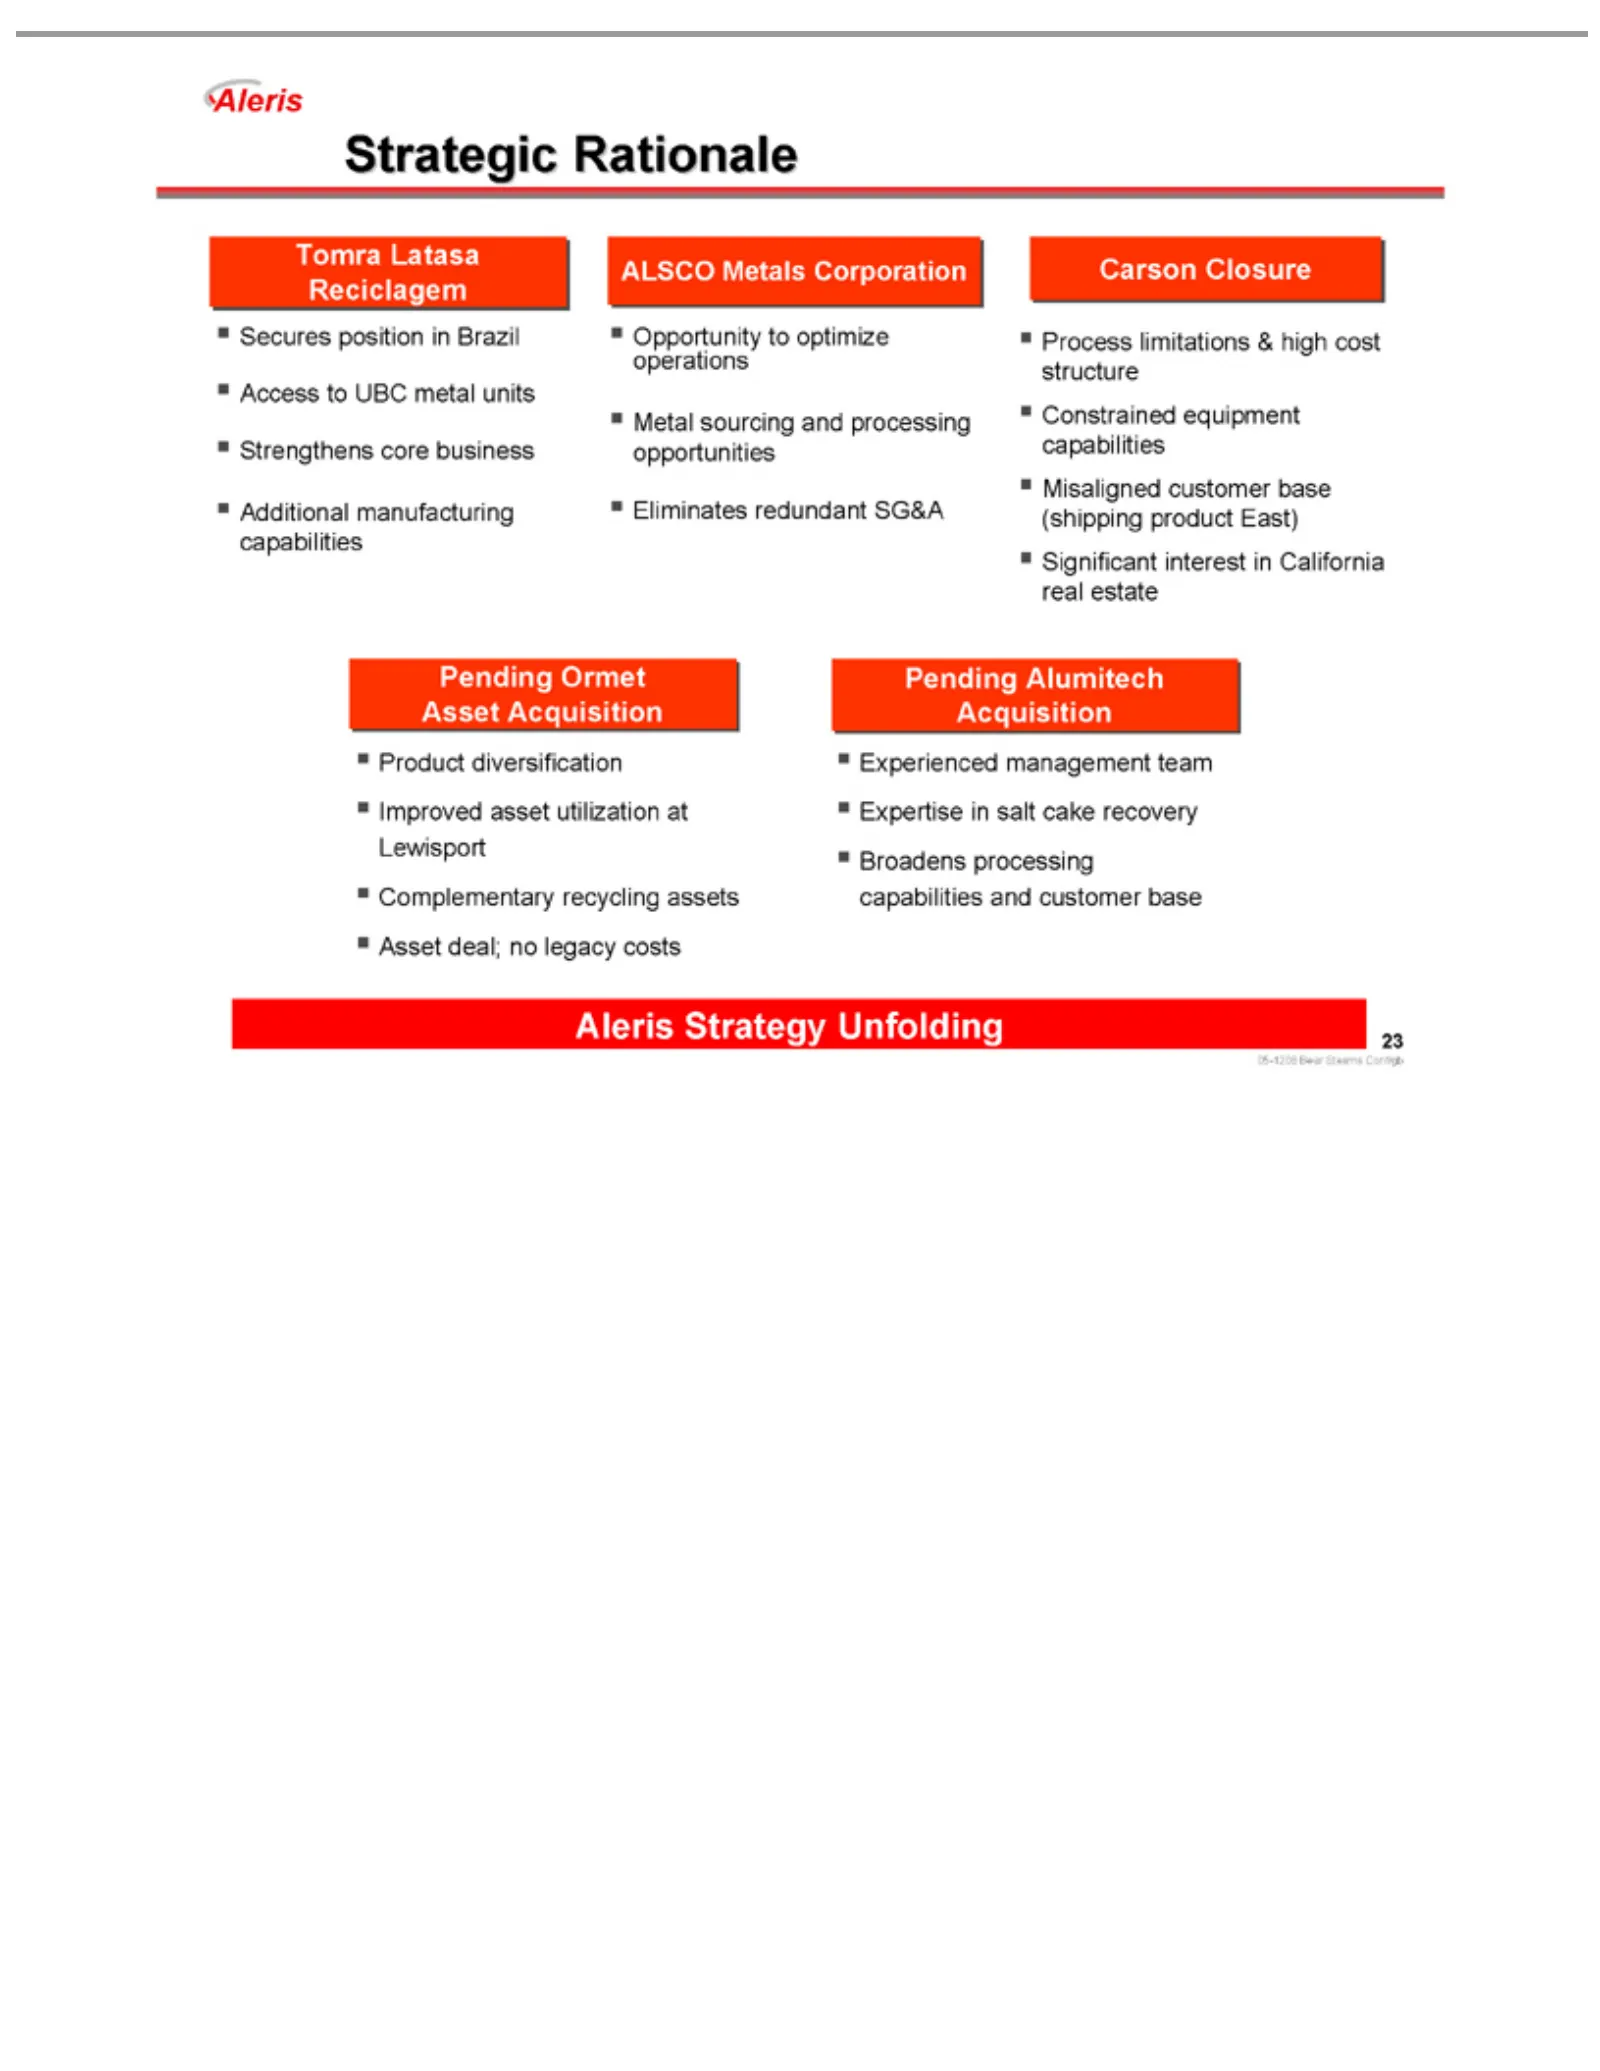
Slide 23: Strategic Rationale for Acquisitions
Strategic Tomra Secures Access Strengthens Additional Significant Pending Product Improved Complementary Asset Aleris 05-1208 23 deal; Strategy Latasa to position diversification Ormet Bear Rationale UBC asset manufacturing interest no core Reciclagem Stearns legacy Unfolding Asset utilization metal
Slide 24: Aleris Financial Summary
Aleris Financial Summary
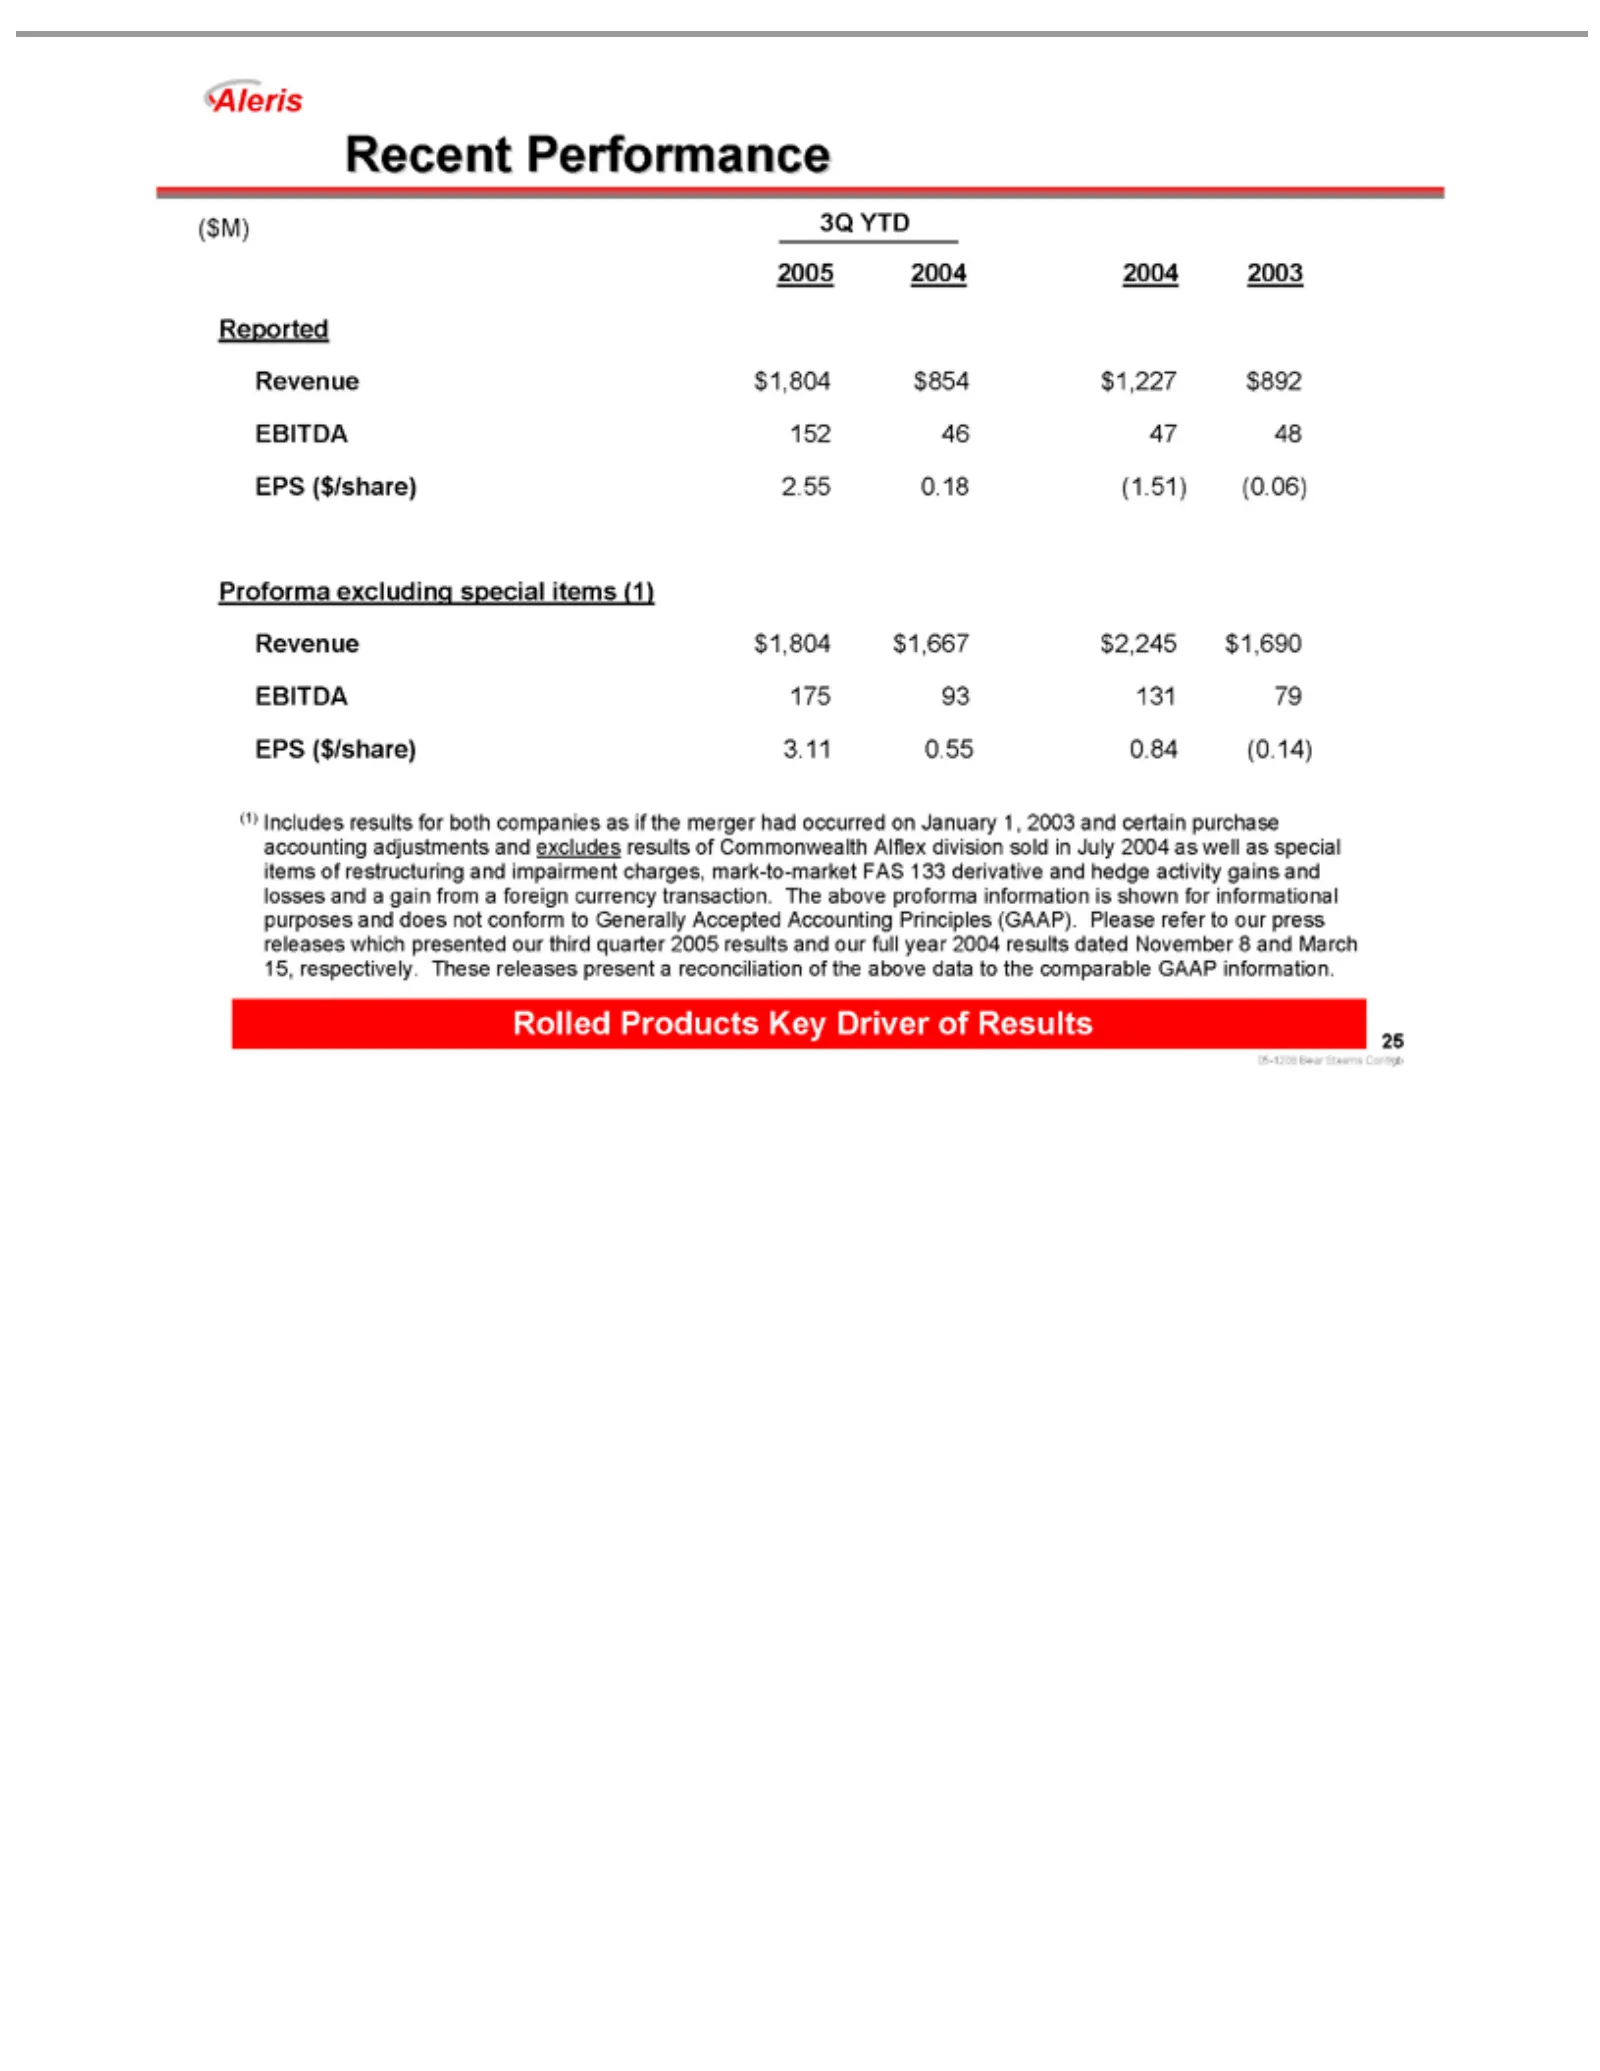
Slide 25: Recent Performance
Recent ($M) 2005 Reported Proforma Revenue EBITDA EPS (1) July above third Rolled 05-1208 25 Includes 2004 ($/share) quarter 2004 3Q proforma Products Performance Bear YTD $1,804 152 175 excluding as 2004 results 2005 well 46 93 Stearns 2.55 3.11 information Key $854 $1,667 2003 47 131 as results 0.
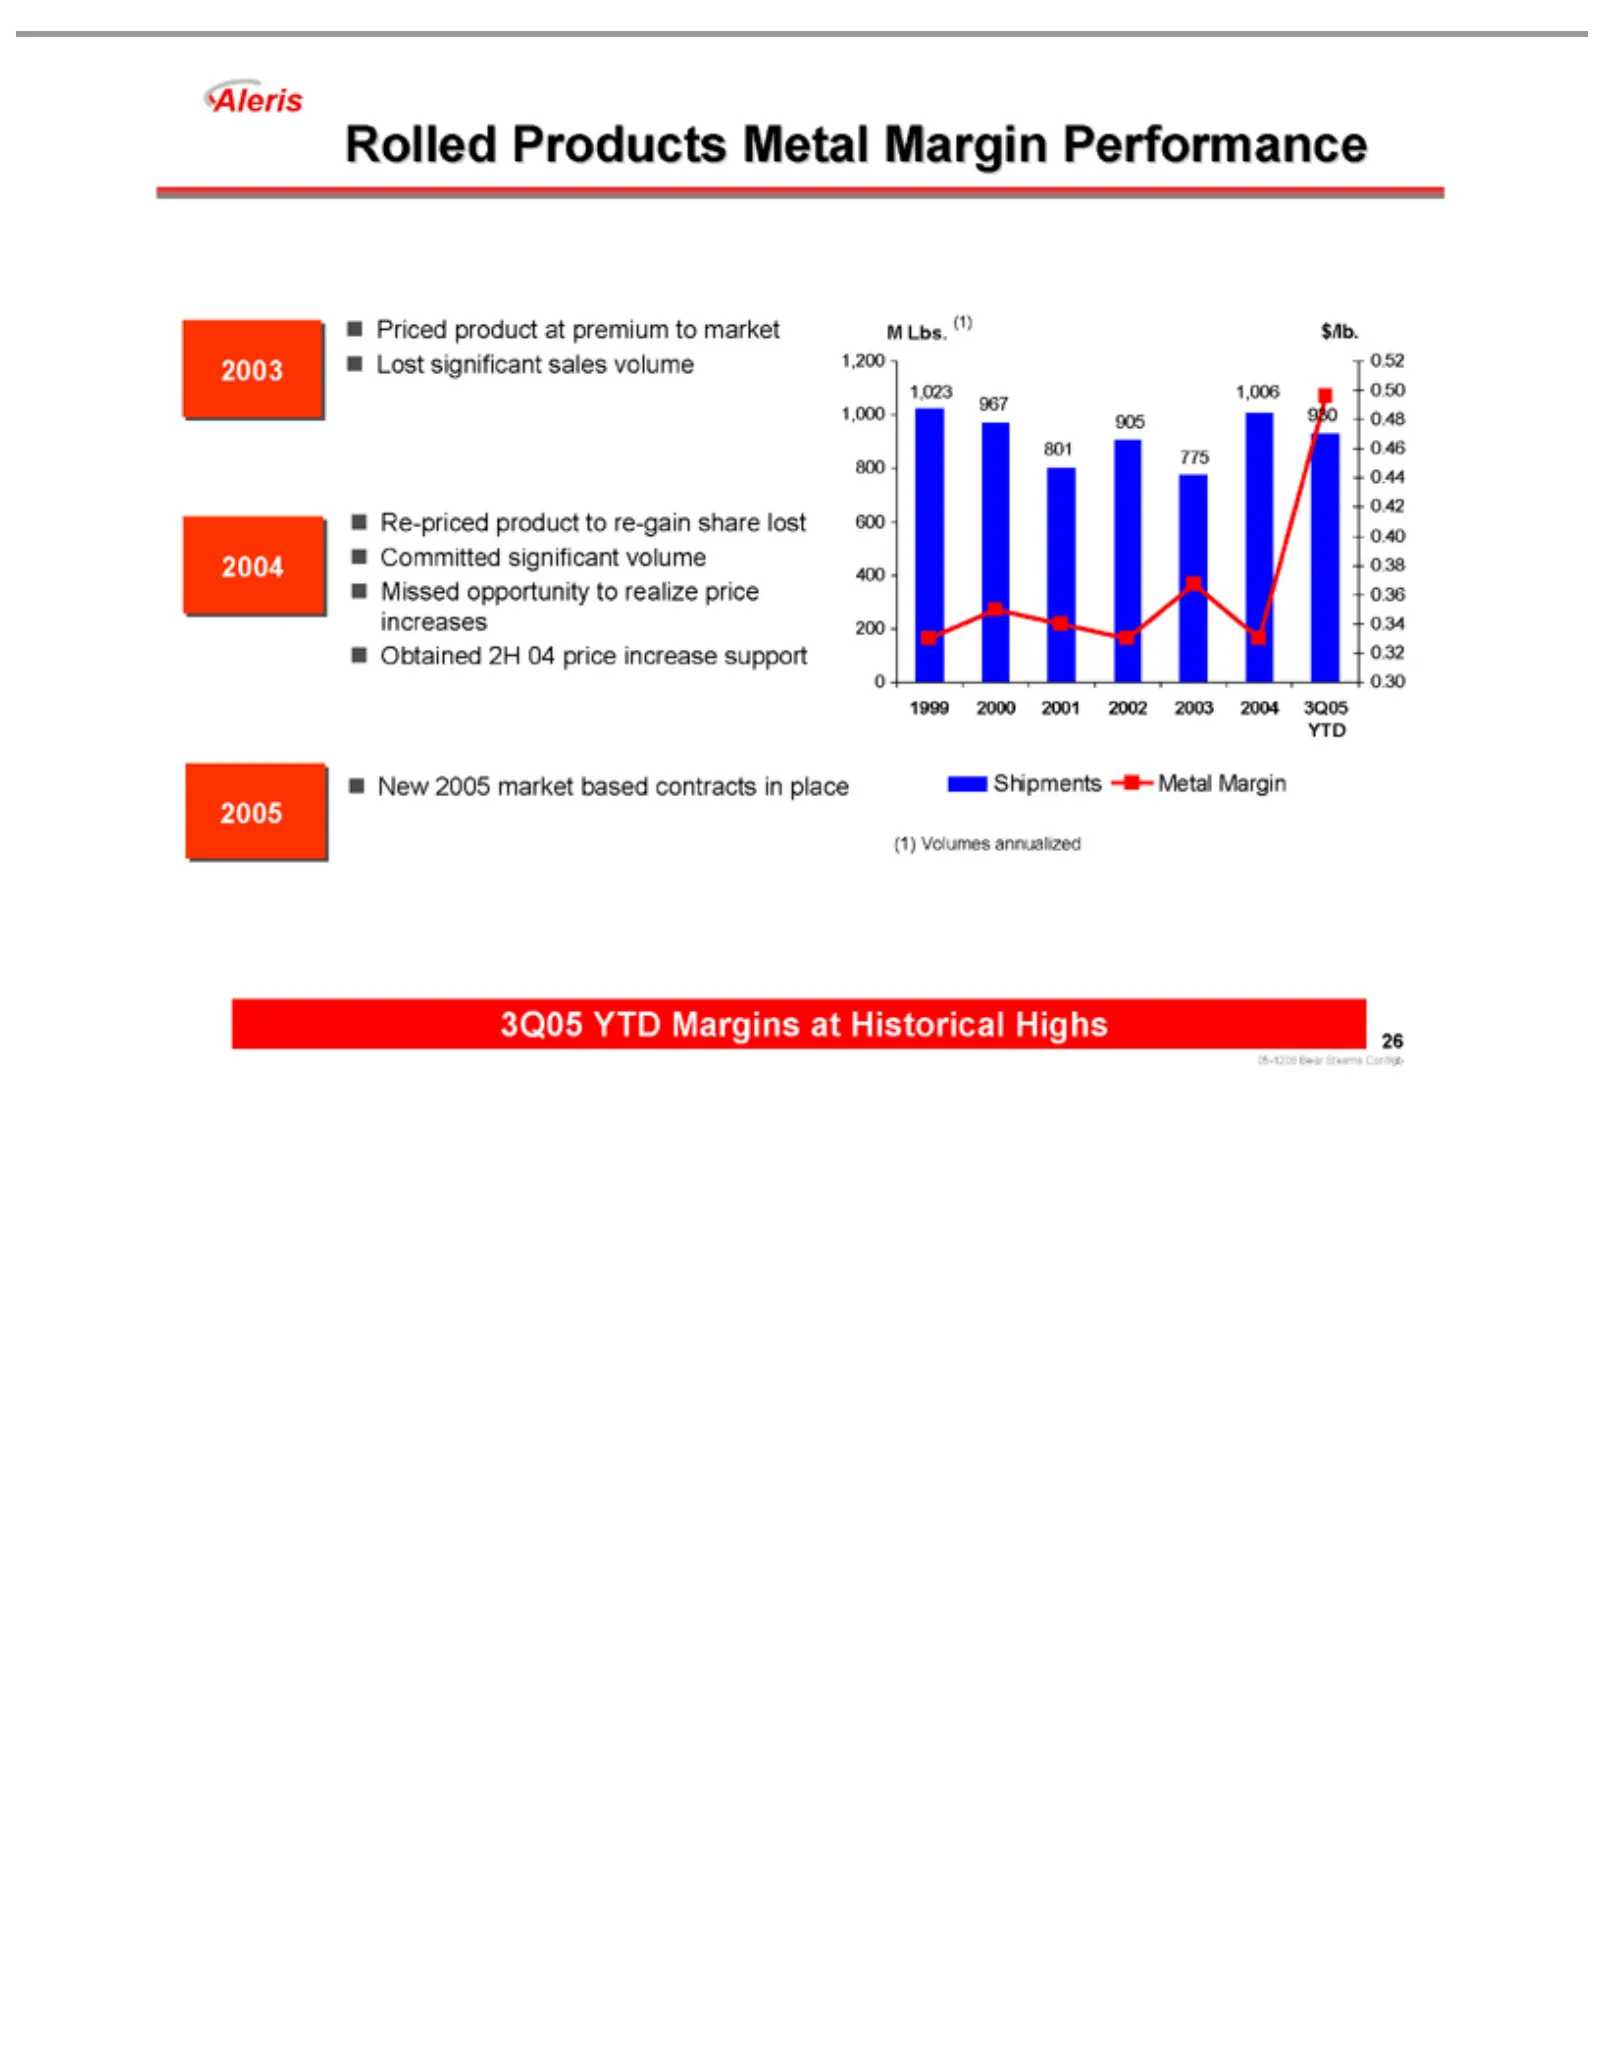
Slide 26: Rolled Products Performance
Rolled 2003 Priced Re-priced New M 1,200 1999 1,023 0.52 Shipments (1) 26 Lbs. 3Q05 0.50 2005 2004 2000 05-12081,000 1,006 product Products YTD(1) Volumes 0.48 product market Metal 2005 2001 Bear800 967 0.46 atMetal 600 2002 905 annualized Margin premium Marginsbased to0.44 Stearns 400 930 re-gain a
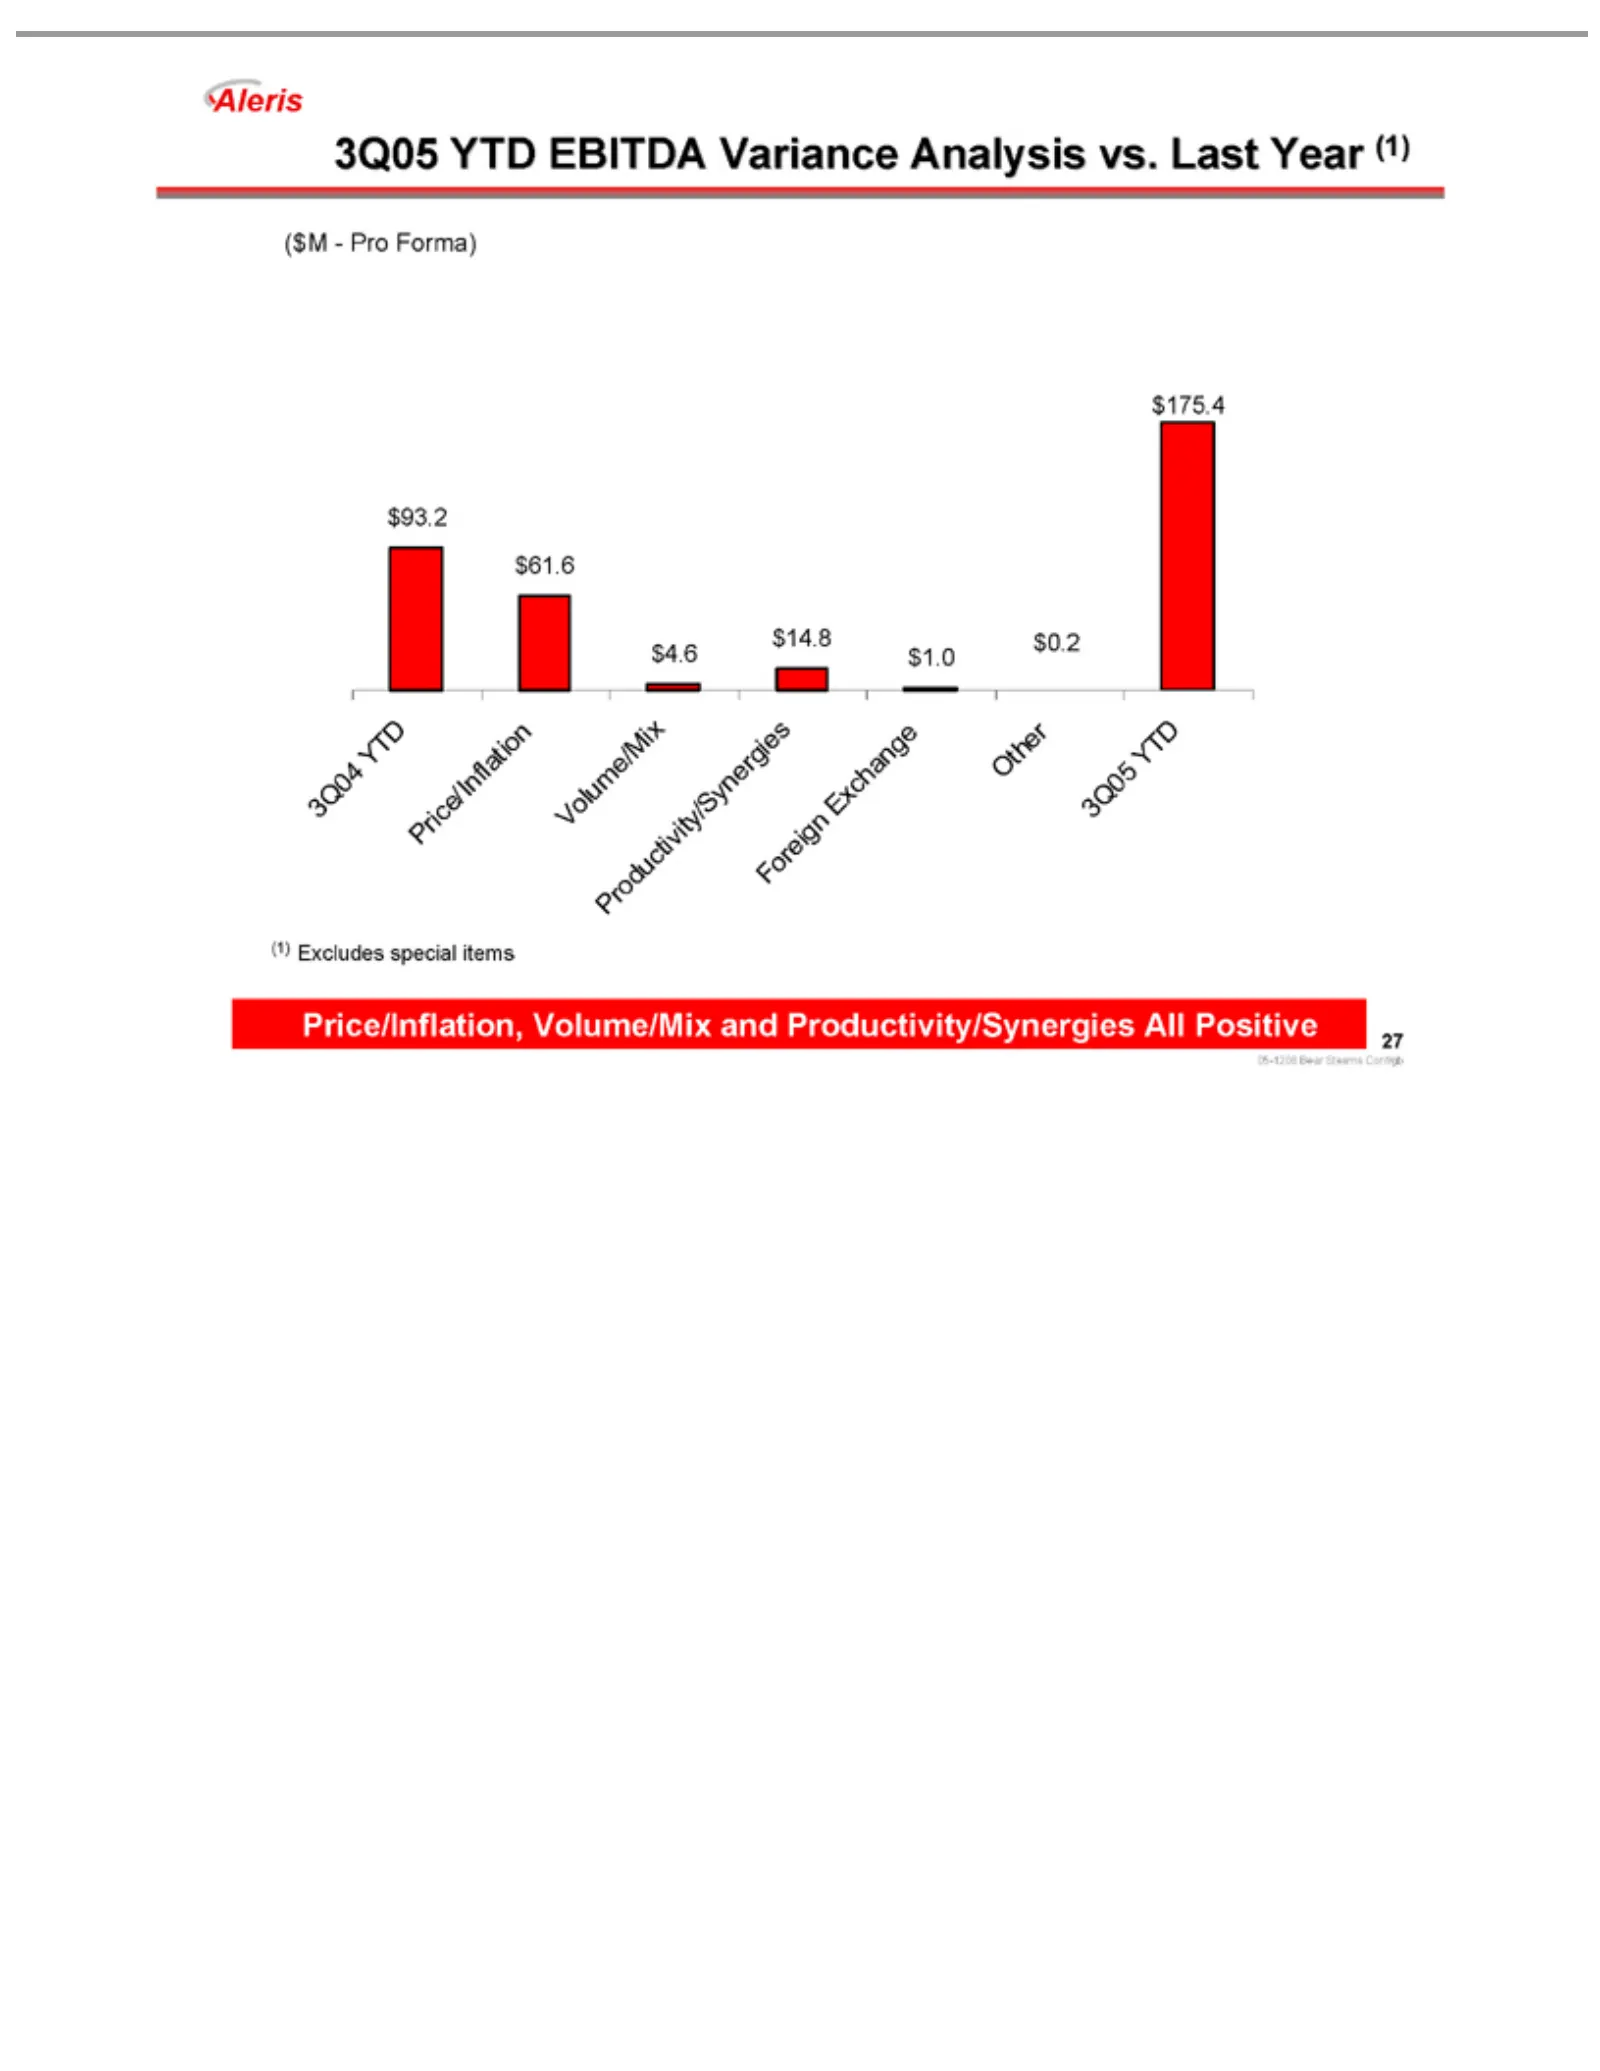
Slide 27: EBITDA Variance Analysis vs. Last Year
3Q05 ($ $93.2 $14.8 (1) 27 M—Pro 3Q04 4YTD $61.6 $0.2 Excludes $4.6 Forma) EBITDA Price/Inflation, 05-1208 YTDBear special$1.0 $175.4 Variance Price/Inflation Stearns Volume/Mix items Conf/gb Analysis Price/Inf Volume/Mix and vs. Last Year (1)All Positive Productivity/Synergies Productivity/Synergie
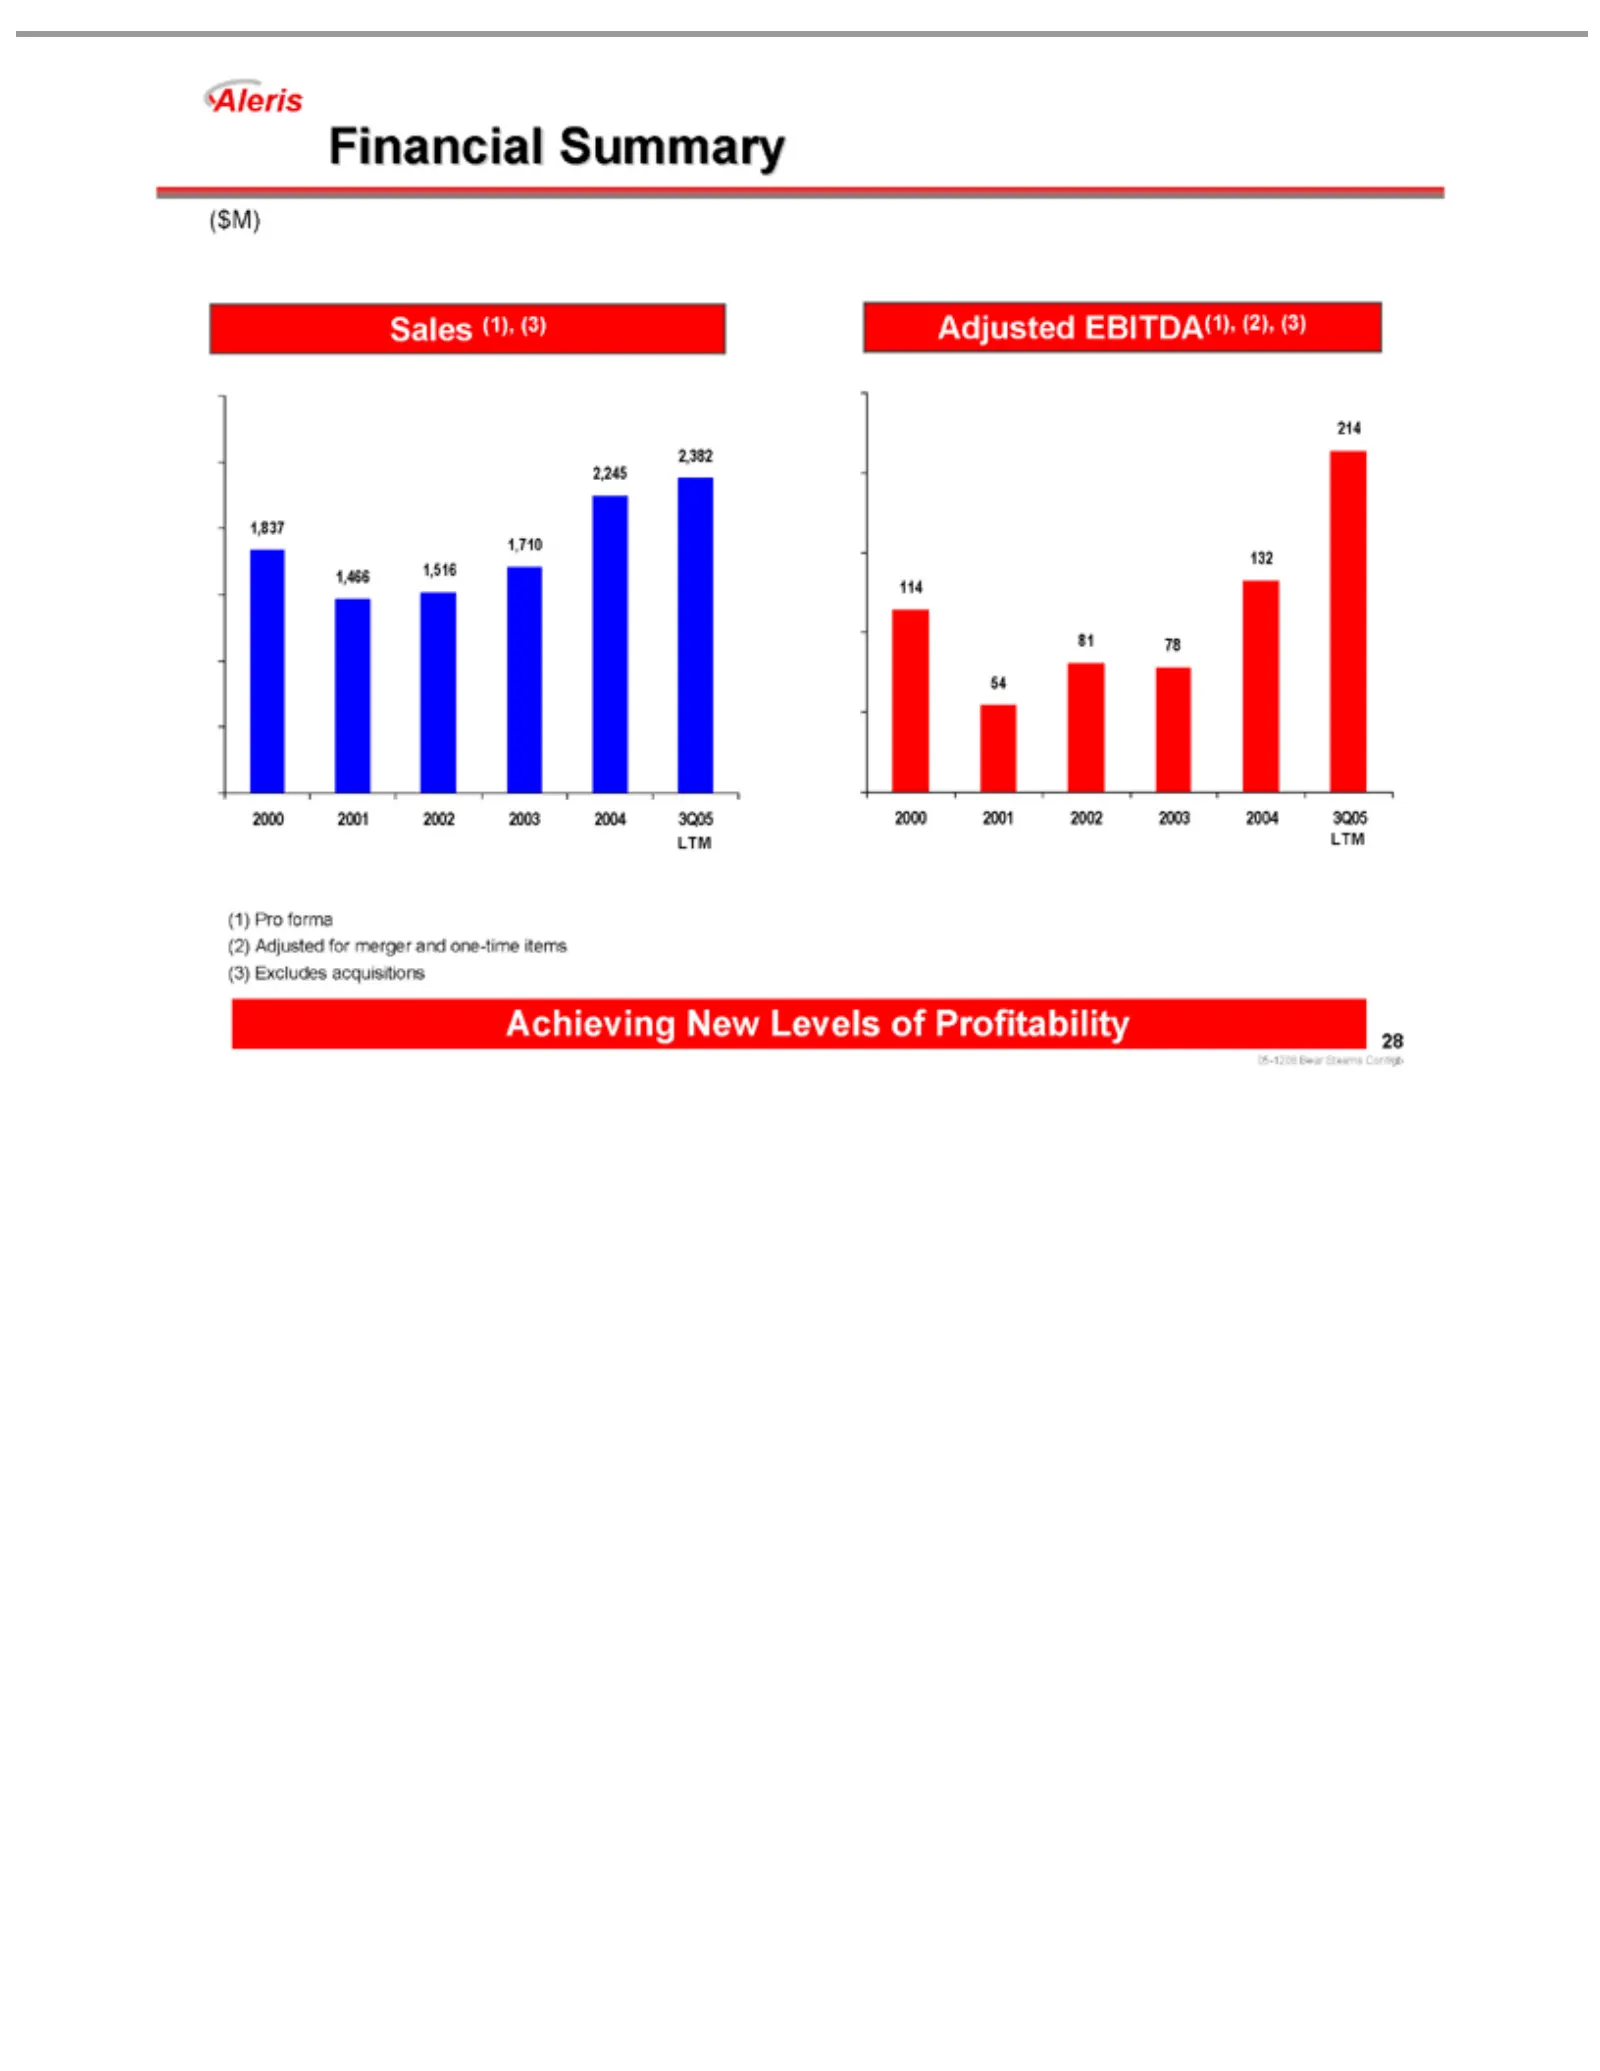
Slide 28: Financial Summary
Financial ($ Sales 2,382 1,710 1,837 3,000 132 214 81 250 2000 (1) LTM (2) 28 M) 78200 114 2001 (1), 2,245 1,466 2,500 54 Achieving 05-1208 Pro 150 Summary (3) 2002 forma 1,516 2,000 100 Adjusted Adjusted Bear New 2003 100 1,500 for Stearns 50 2004 EBITDA(1), of0 1,000 merger LevelsConf/gb3Q05 and50
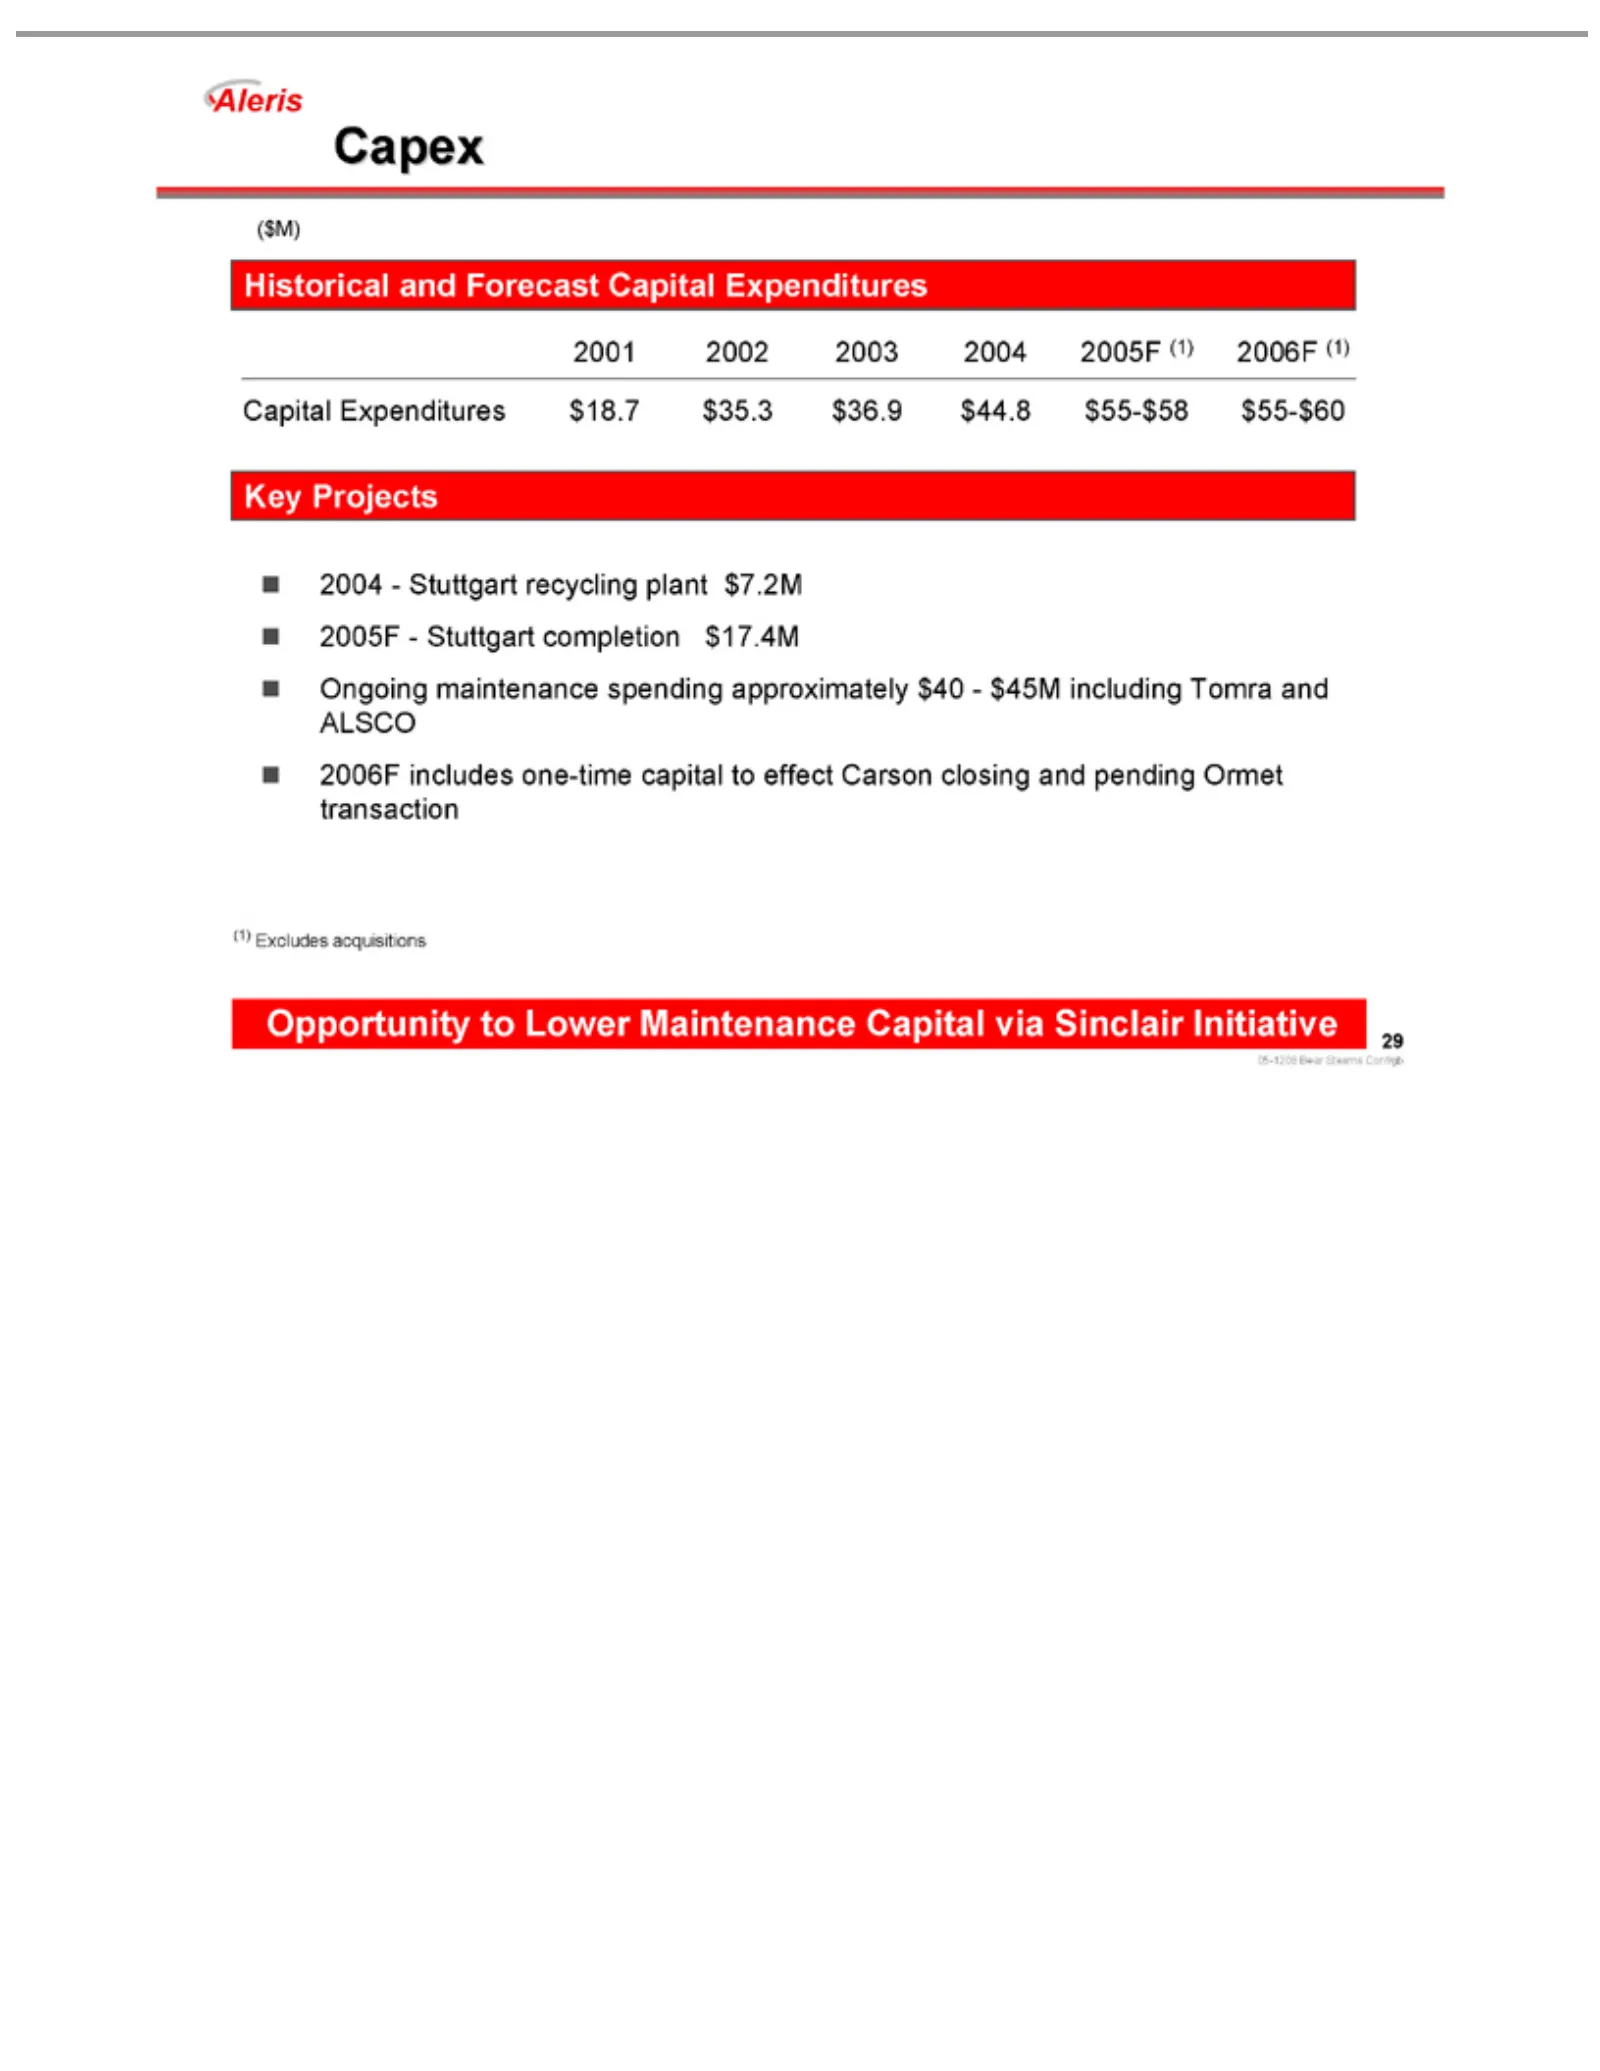
Slide 29: Historical and Forecast Capital Expenditures
Historical ($M) Capex 2001 Capital Key 2004—Stuttgart Ongoing 2006F (1) 29 Projects 2002 includes Expenditures Excludes maintenance Opportunity 05-1208 and 2003 Bear Forecast one-time recycling 2004 acquisitions toStearns Lower $18.7 2005F spending Capital capital plant $35.3 Conf/gb(1)Expenditures
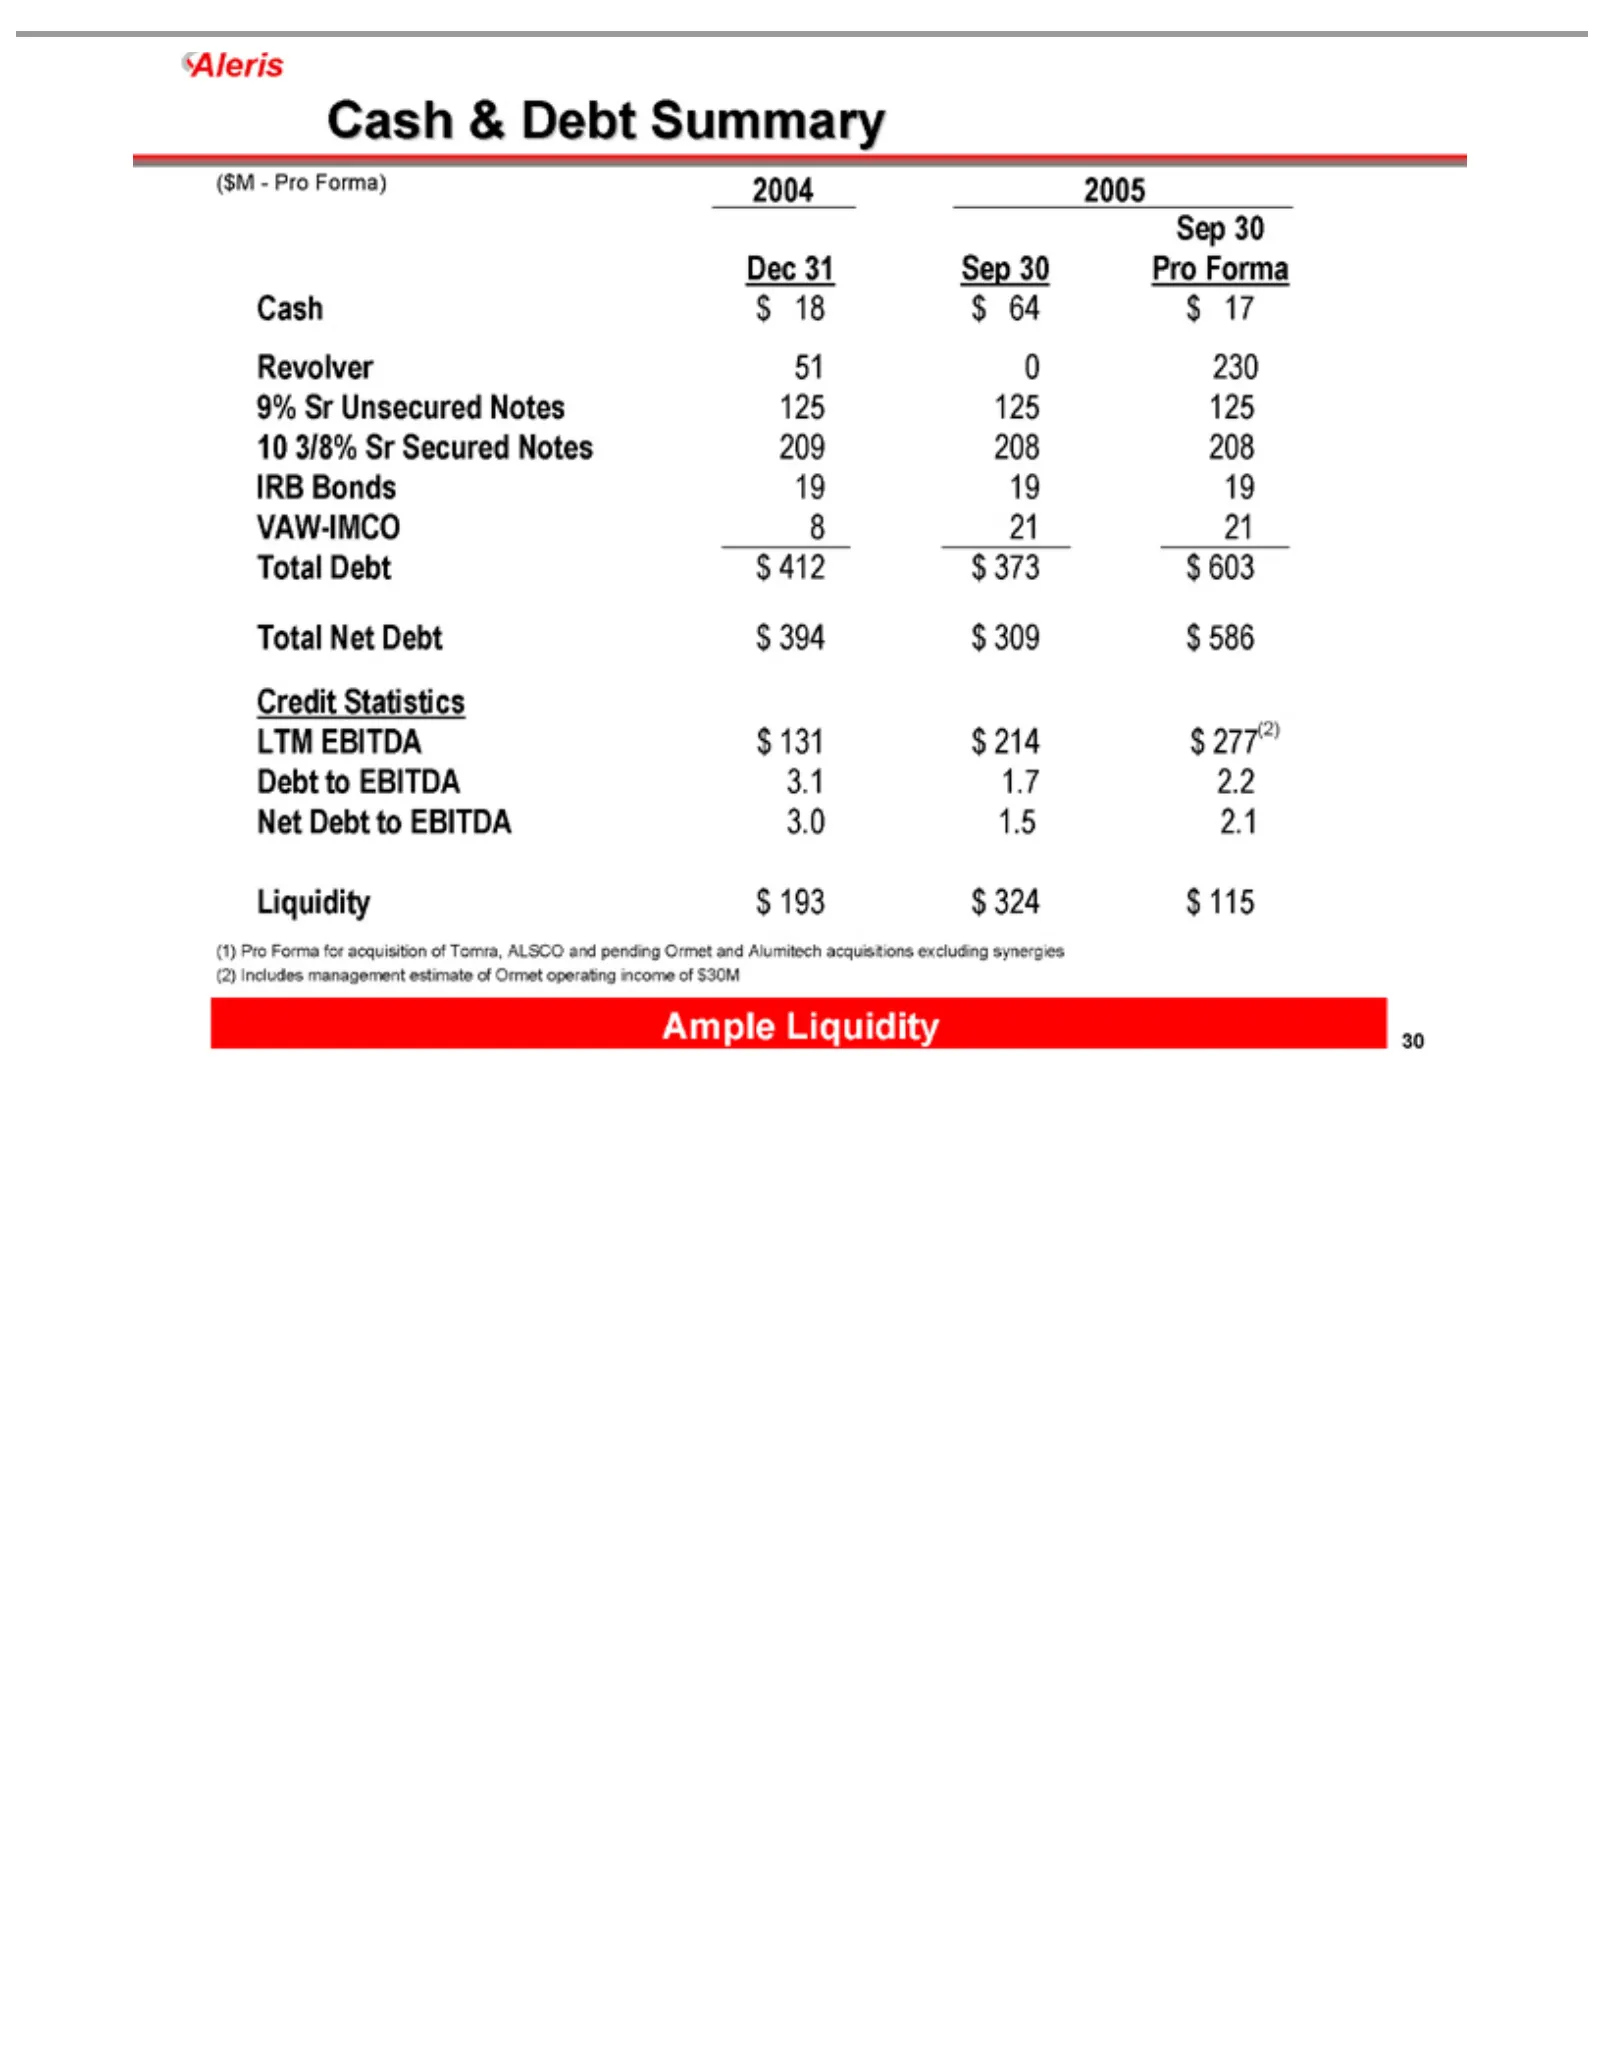
Slide 30: Pro Forma Debt and Liquidity Summary
($M—Pro Sep Dec Cash Revolver 9% 10 IRB VAW-IMCO Total Credit LTM Debt Net Liquidity (1) Ample 05-1208 30 3/8% Pro Sr Debt 30 31 Bonds to & $18 EBITDA Debt Net Unsecured Statistics Liquidity Forma Sep EBITDA Debt Bear Sr to 51 $193 Debt $64 Forma) $412 19 Secured 30 EBITDA 08Summary Stearns $17 230
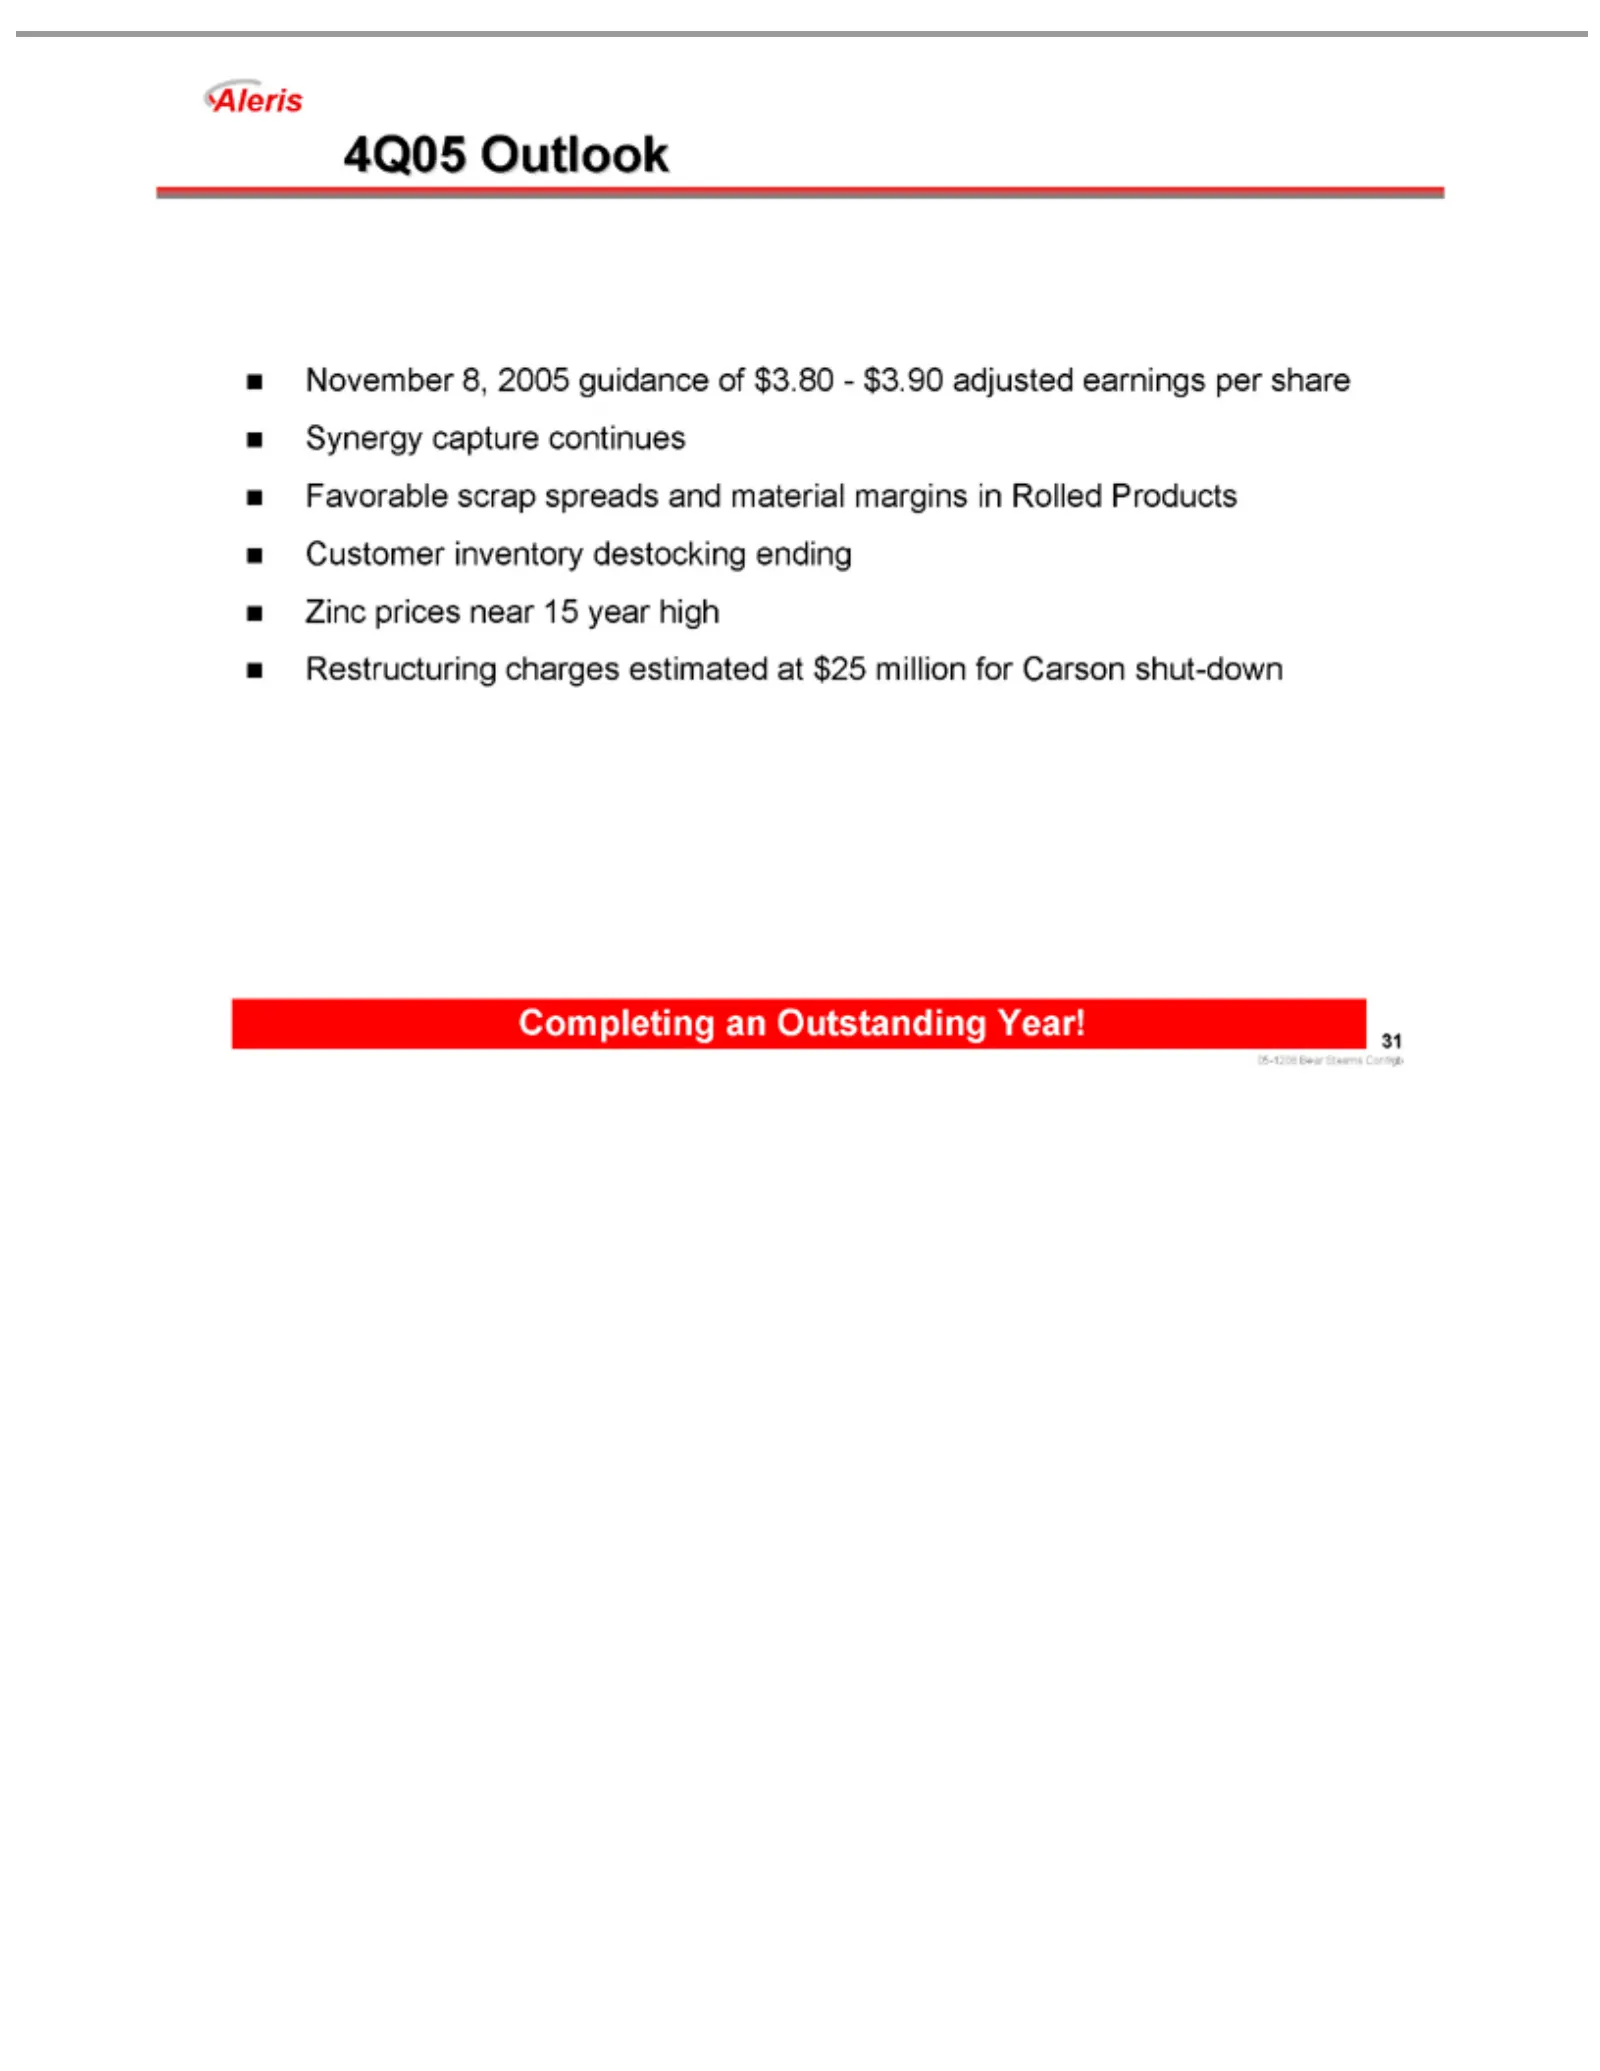
Slide 31: 4Q05 Outlook
4Q05 Outlook November ending Completing 05-1208 31 Zinc Bear 8,an prices 2005 Stearns Outstanding near guidance Conf/gb 15 year Year! of $3.80—$3.90 high Restructuring adjusted charges earnings estimated per share at $25 Synergy millioncapture for Carson continues shut-down Favorable scrap spreads a
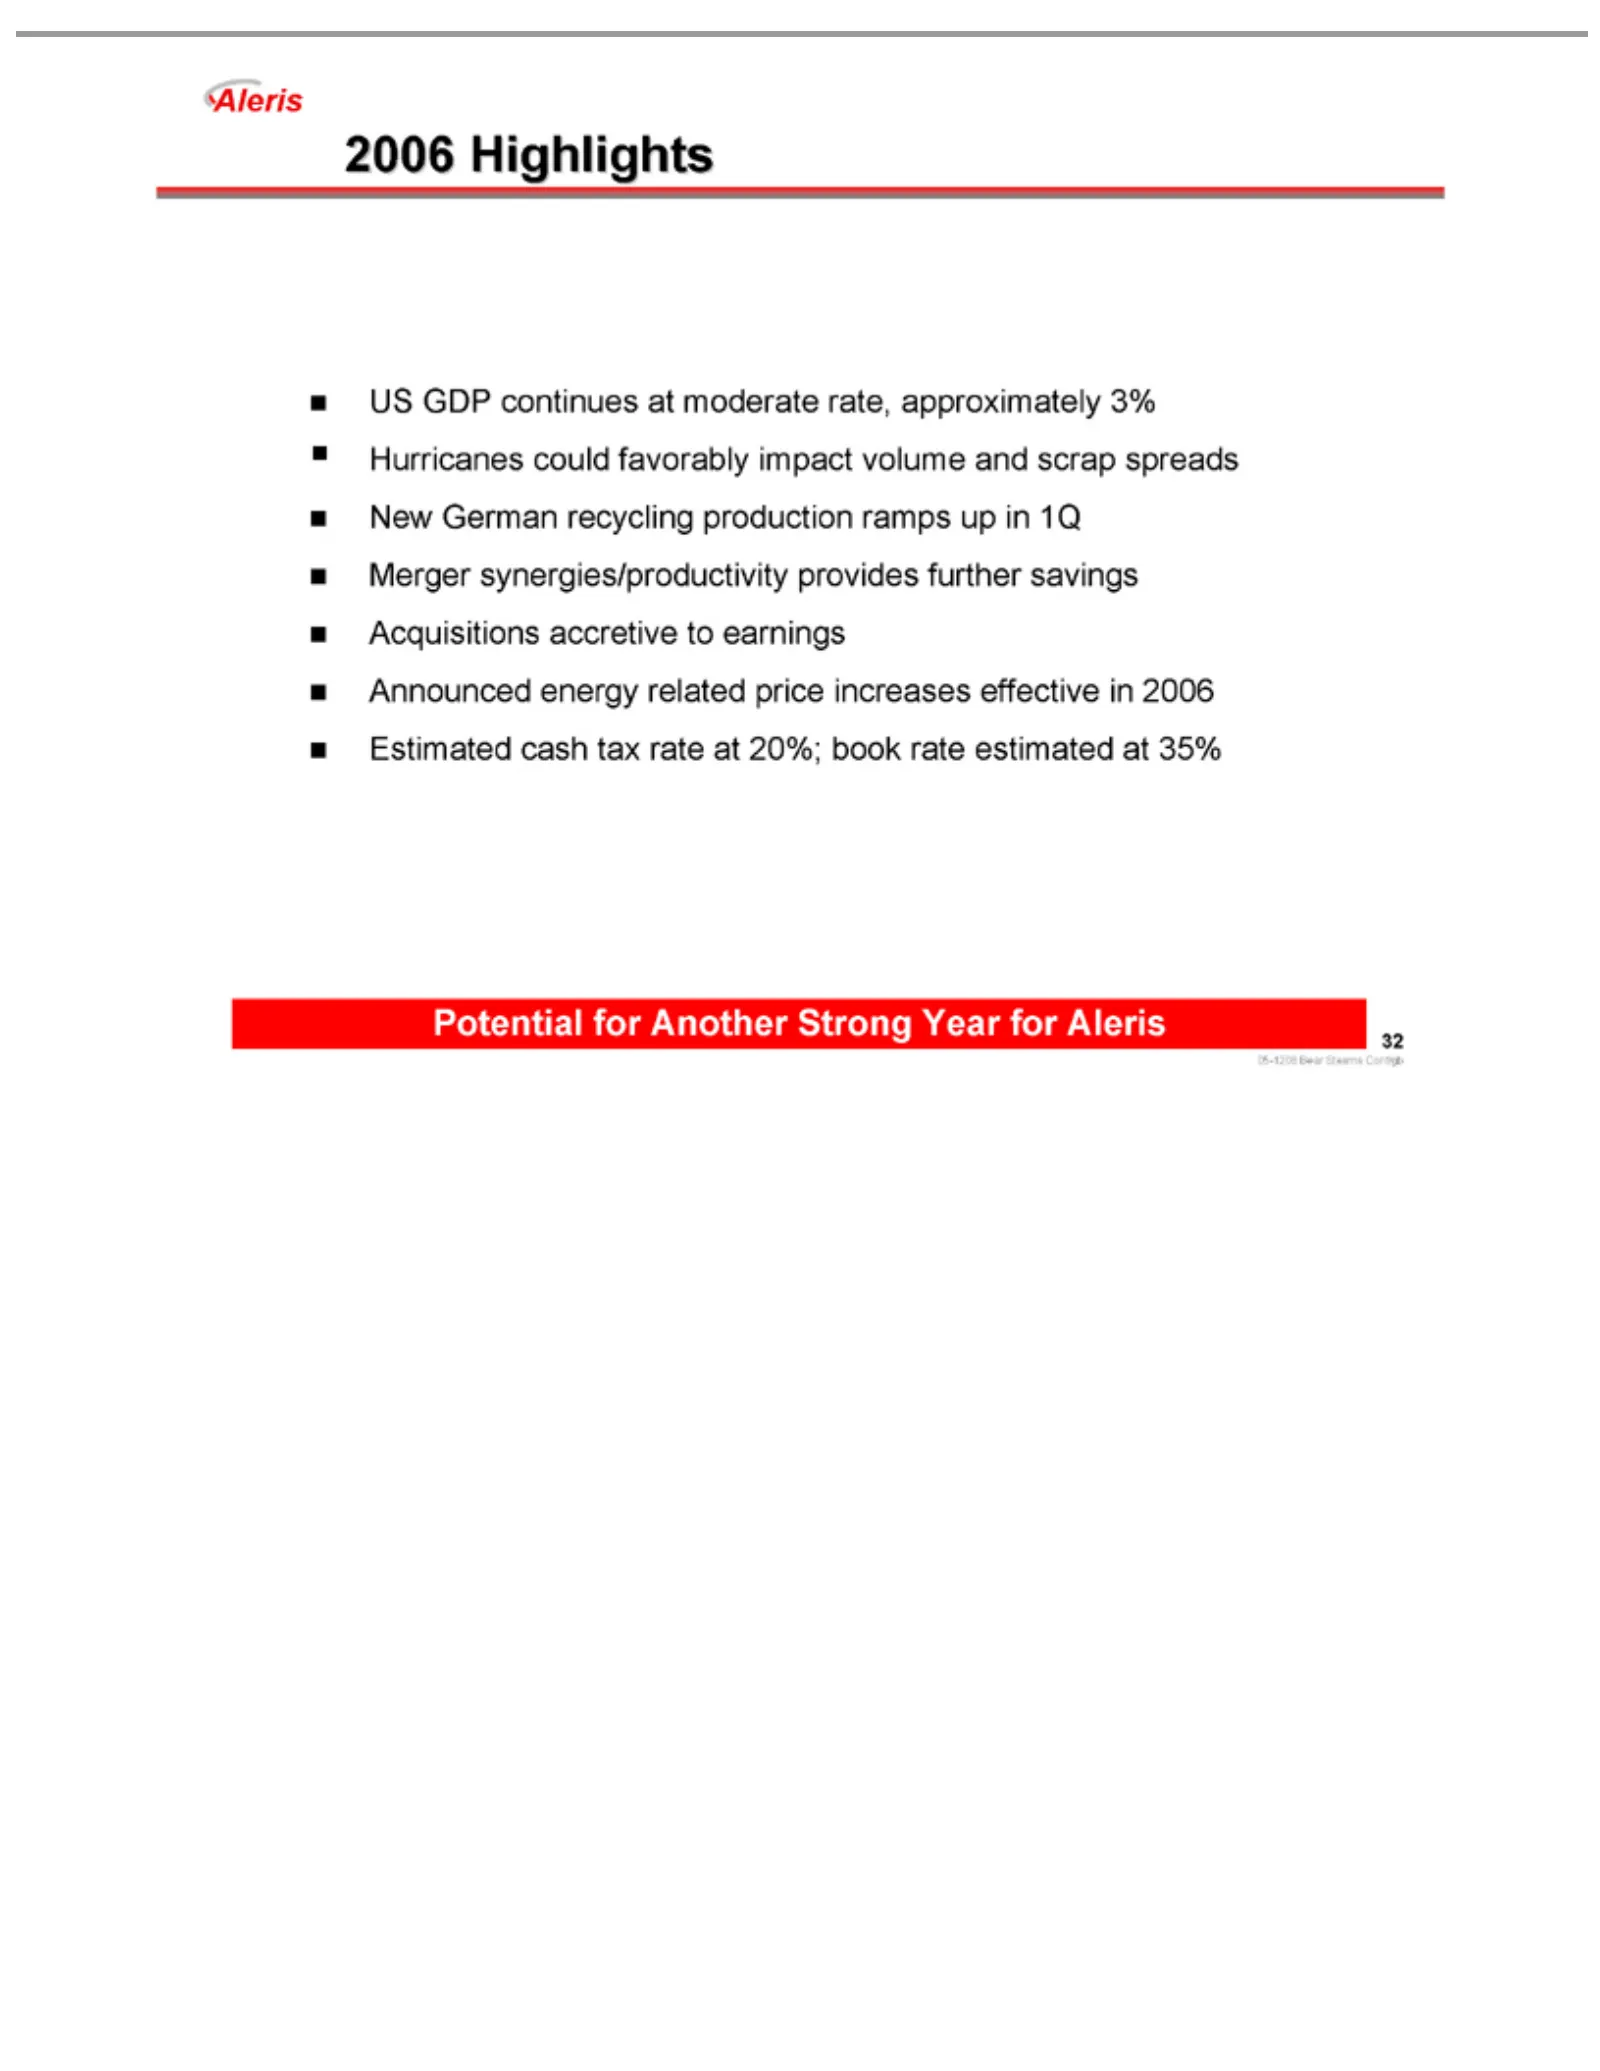
Slide 32: 2006 Highlights
2006GDP US Merger estimated Potential 05-1208 32 Highlights synergies/productivity Bear continues for at 35% Another Stearns at Strong moderate Conf/gbYear provides rate, forapproximately Aleris further savings 3% Acquisitions Hurricanes could accretive favorably to earnings impactAnnounced volume a
Source: SEC EDGAR · 8-K filed Dec 8, 2005
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
 Investor Presentation (October 2007)14 slides · Oct 3, 2007