Metro Bancorp — Investor Presentation (August 2013)
45 slides from Metro Bancorp's investor presentation, Aug 15, 2013
Slide 1: Metro Bancorp
METRO BANCORP - \ = ~~ . ae - et ARG 7~ ‘on = = ey j | la | if mT % a a any nie August 15, 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains projections and other forward- looking statements regarding future events, strategic corporate objectives or the future financial performance of Metro. We wish to caution you that these forward-looking statements may differ materially from actual
Slide 3: Overview
Overview • Headquartered in Harrisburg • Total Assets: $2.7 billion • Total Deposits: $2.2 billion • Total Loans: $1.6 billion • Stores: 33 • Team Members: 980 • NASDAQ Traded, Ticker : METR • Shares Outstanding: $14.1 million • Market Capitalization: $309.2 mm (as of 7/31/13) 3
Slide 4: History of Growth
History of Growth • Began Operations in June 1985 • Reached $500 million in Assets – 2001 • Reached $1 billion in Assets – 2003 • Completed $19.6 million Public Stock Offering – 2004* • Reached $2 billion in Assets – 2008 • Competed $82.5 million Public Stock Offering – 2009* 4 * 2004 and 2009 stock
Slide 5: Experienced Management Team
Experienced Management Team Gary L. Nalbandian- Chairman/President/CEO Founding Chairman/Director: Since 1985 Mark A. Zody, CPA – Chief Financial Officer Since1988; 25 Years of Banking Experience Percival B. Moser – Chief Operating Officer Since 2011; 32 Years of Banking Experience 5
Slide 6: Experienced Management Team
Experienced Management Team James R. Ridd – Chief Credit Officer Since 1990; 28 Years of Banking Experience Adam L. Metz – Chief Lending Officer Since 2004; 17 Years of Banking Experience Steven W. Cribbs – Chief Risk Officer Since 2010; 14 Years of Banking Experience 6
Slide 7: #3 in Market Share – Harrisburg Metro Area
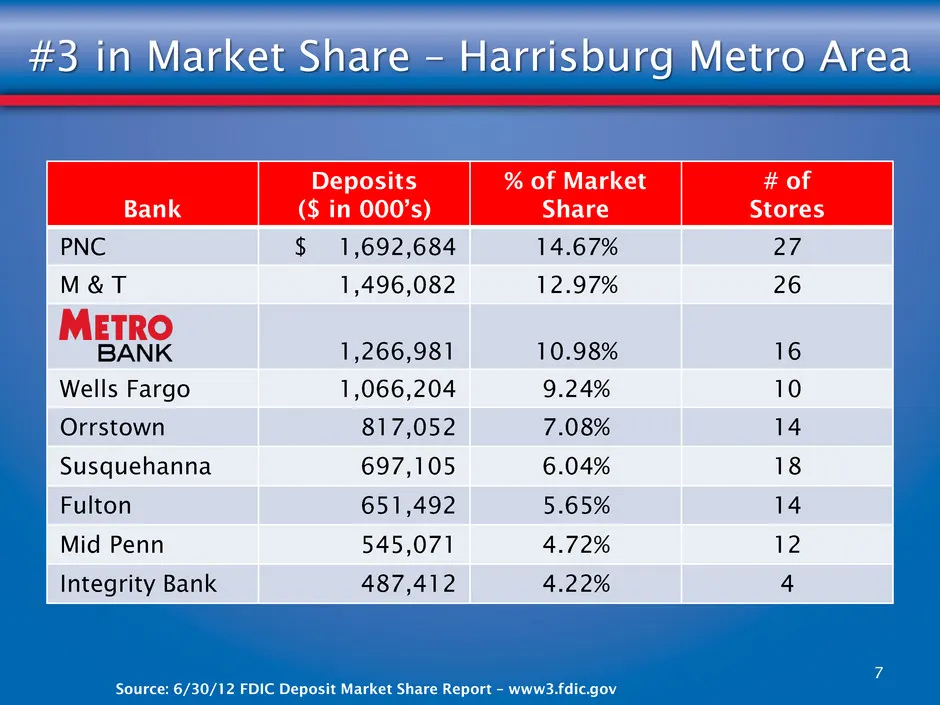
#3 in Market Share – Harrisburg Metro Area Bank Deposits ($ in 000’s) % of Market Share # of Stores PNC $ 1,692,684 14.67% 27 M & T 1,496,082 12.97% 26 1,266,981 10.98% 16 Wells Fargo 1,066,204 9.24% 10 Orrstown 817,052 7.08% 14 Susquehanna 697,105 6.04% 18 Fulton 651,492 5.65% 14 Mid Penn 545,071 4
Slide 8: Market Potential
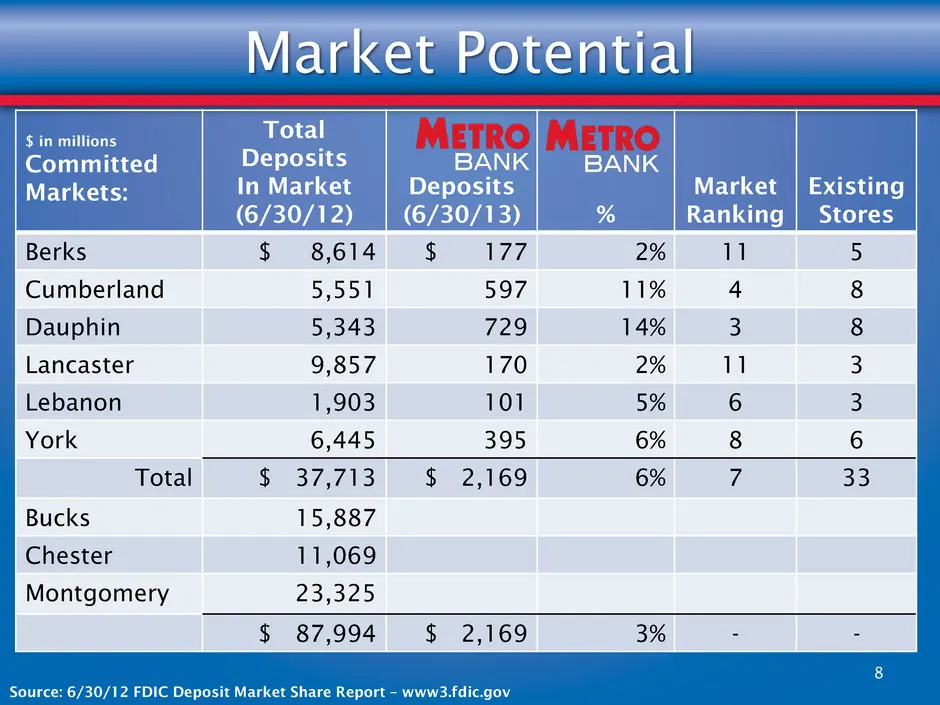
Market Potential 8 $ in millions Committed Markets: Total Deposits In Market (6/30/12) Deposits (6/30/13) % Market Ranking Existing Stores Berks $ 8,614 $ 177 2% 11 5 Cumberland 5,551 597 11% 4 8 Dauphin 5,343 729 14% 3 8 Lancaster 9,857 170 2% 11 3 Lebanon 1,903 101 5% 6 3 York 6,445 395 6% 8 6 Tot
Slide 9: The Model
The Model • Manage for Growth and Profitability • Deliver AMAZING Service • Fund Loan Growth through Strong Deposit Growth • Maintain Low Risk Profile • Continue to Increase Shareholder Value 9
Slide 10: The Culture
The Culture • Culture Matches the Model • Clear and Pervasive • Hire for Attitude and Train for Skills • Consistently Reinforce 10
Slide 11: The Training
The Training • Unique Structure: Metro University • Forty-Five in House Courses and E-Learning • Oversee Talent Development • Individual Curriculums for Management, Lending and Professional Development 11
Slide 12: The Execution
The Execution • Believe in The Model • Invest in Facilities and People • 100% Execution • Quality Control • Work Together to Say YES to the Customer 12
Slide 13: The Brand
The Brand MODEL (value differentiating) + CULTURE (unique) + EXECUTION (fanatical) = THE DIFFERENCE 13
Slide 14: Financial Review
FINANCIAL REVIEW METRO BANK
Slide 15: 2012 Accomplishments
2012 Accomplishments Gaining Momentum • Grew net loans $89 million and grew deposits $160 million • Increased revenues by $3.6 million • Reduced noninterest expenses by $2.9 million • Restored profitability to net income of $10.9 million, EPS of $0.77 per common share • Continued improvement in asse
Slide 16: First Half of 2013 Highlights
First Half of 2013 Highlights* Continued Momentum 16 • Record net income for the second quarter and for the first six months • Net income up $2.2 mm, or 41%, over 2012 • EPS of $0.54/share, up 41% over 2012 • Continued diligent expense management • Lower loan loss provision • Total net loans up $139
Slide 17: Total Assets
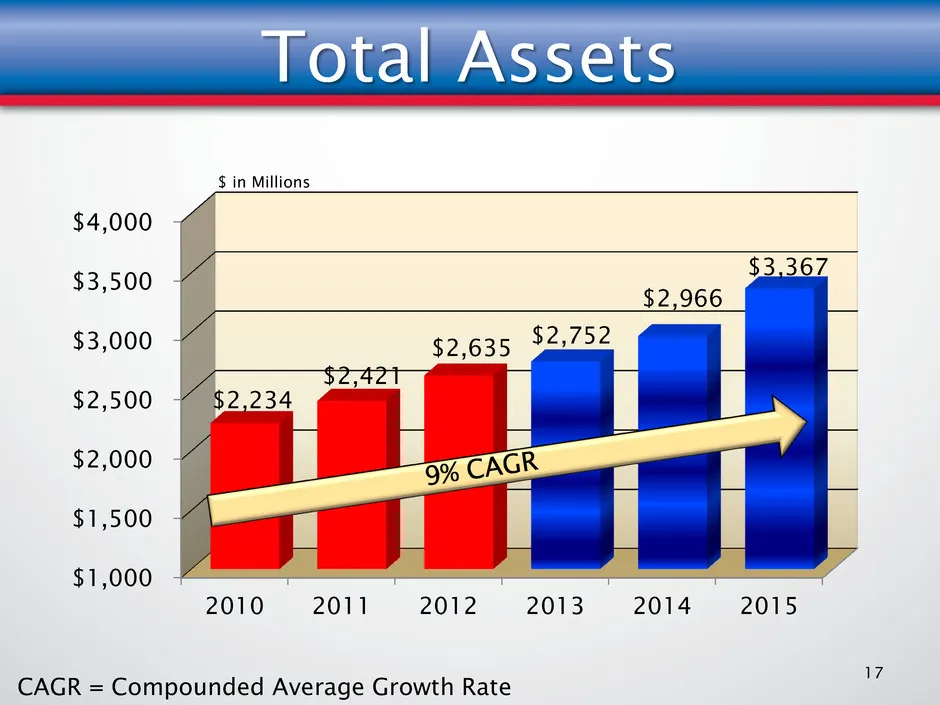
Total Assets $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 $4,000 2010 2011 2012 2013 2014 2015 $2,234 $2,421 $2,635 $2,752 $2,966 $3,367 17 $ in Millions CAGR = Compounded Average Growth Rate
Slide 18: Total Deposits
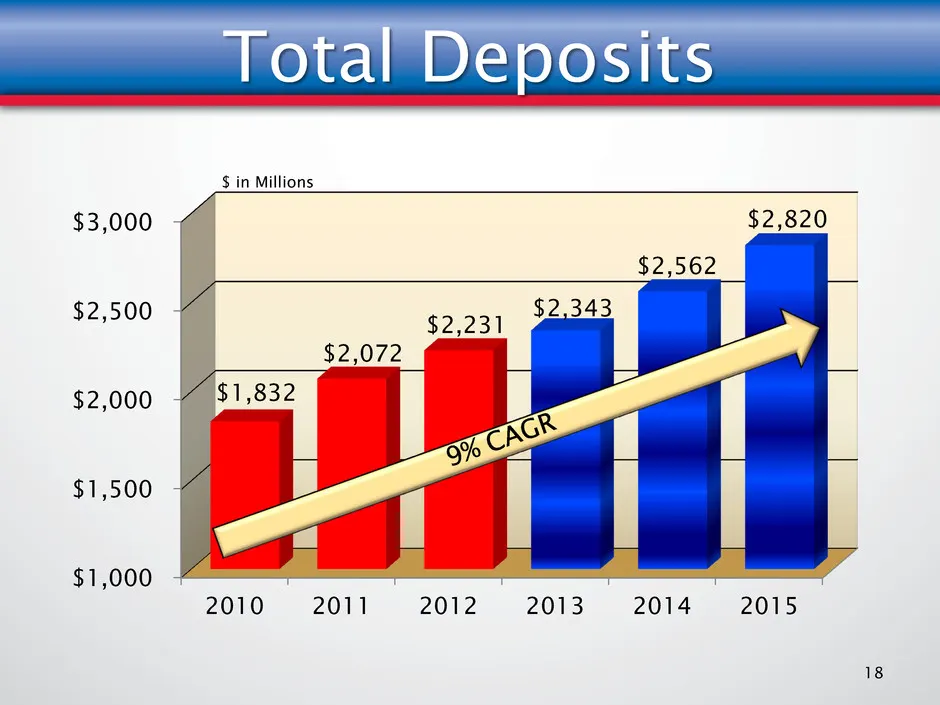
Total Deposits $1,000 $1,500 $2,000 $2,500 $3,000 2010 2011 2012 2013 2014 2015 $1,832 $2,072 $2,231 $2,343 $2,562 $2,820 18 $ in Millions
Slide 19: Strong Core Deposit Foundation
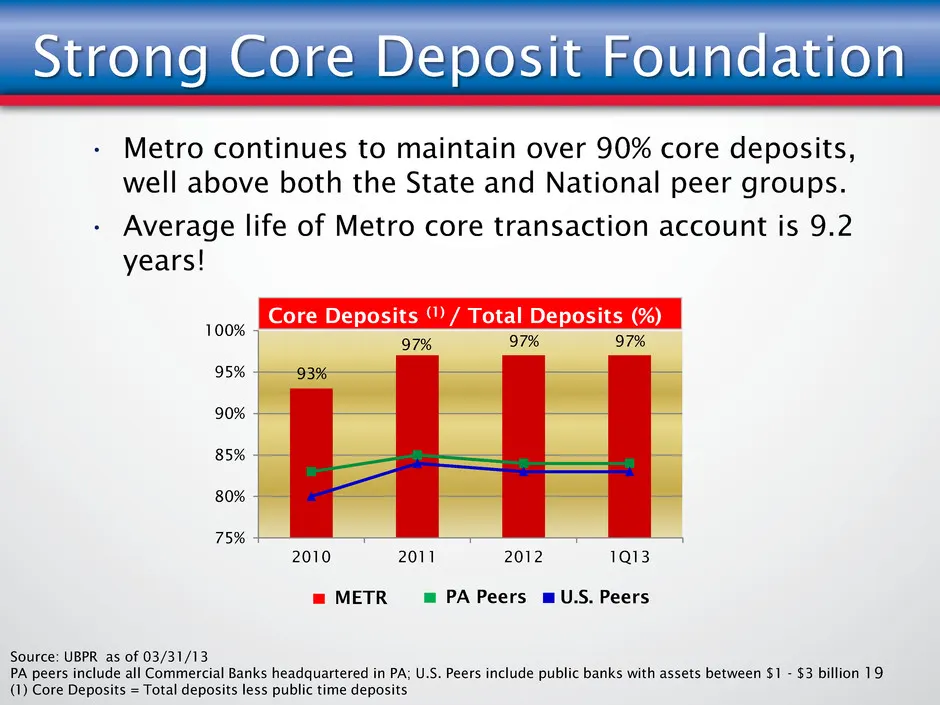
Strong Core Deposit Foundation 19 93% 97% 97% 97% 75% 80% 85% 90% 95% 100% 2010 2011 2012 1Q13 Source: UBPR as of 03/31/13 PA peers include all Commercial Banks headquartered in PA; U.S. Peers include public banks with assets between $1 - $3 billion (1) Core Deposits = Total deposits less public tim
Slide 20: Deposit Mix
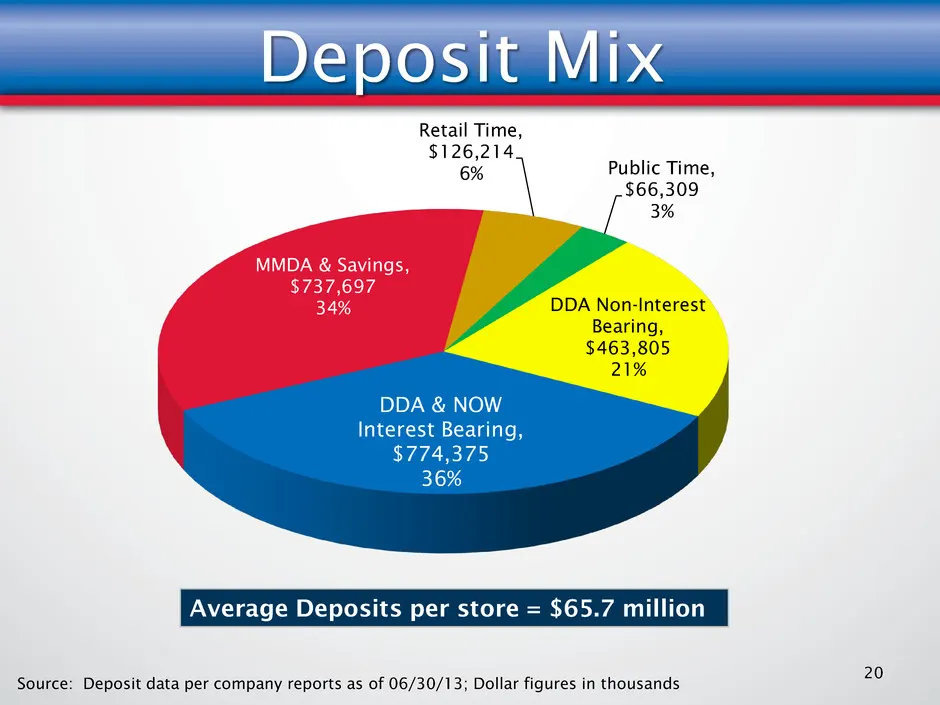
DDA Non-Interest Bearing, $463,805 21% DDA & NOW Interest Bearing, $774,375 36% MMDA & Savings, $737,697 34% Retail Time, $126,214 6% Public Time, $66,309 3% Average Deposits per store = $65.7 million Source: Deposit data per company reports as of 06/30/13; Dollar figures in thousands Deposit Mix 20
Slide 21: Total Loans (net)
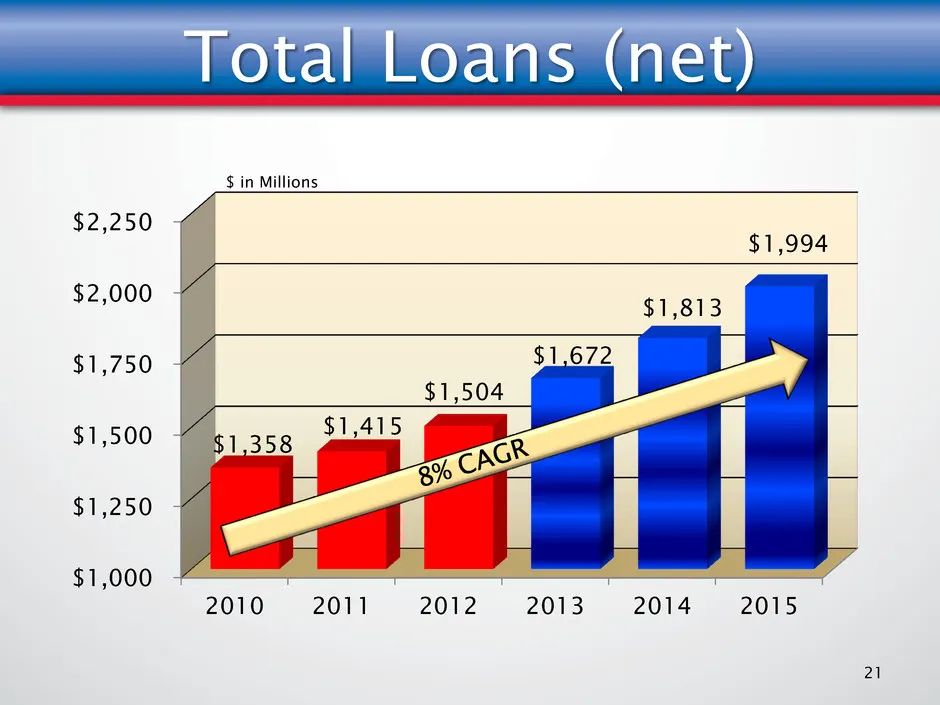
Total Loans (net) $1,000 $1,250 $1,500 $1,750 $2,000 $2,250 2010 2011 2012 2013 2014 2015 $1,358 $1,415 $1,504 $1,672 $1,813 $1,994 21 $ in Millions
Slide 22: Net Interest Margin: A Key Source of Franchise Strength
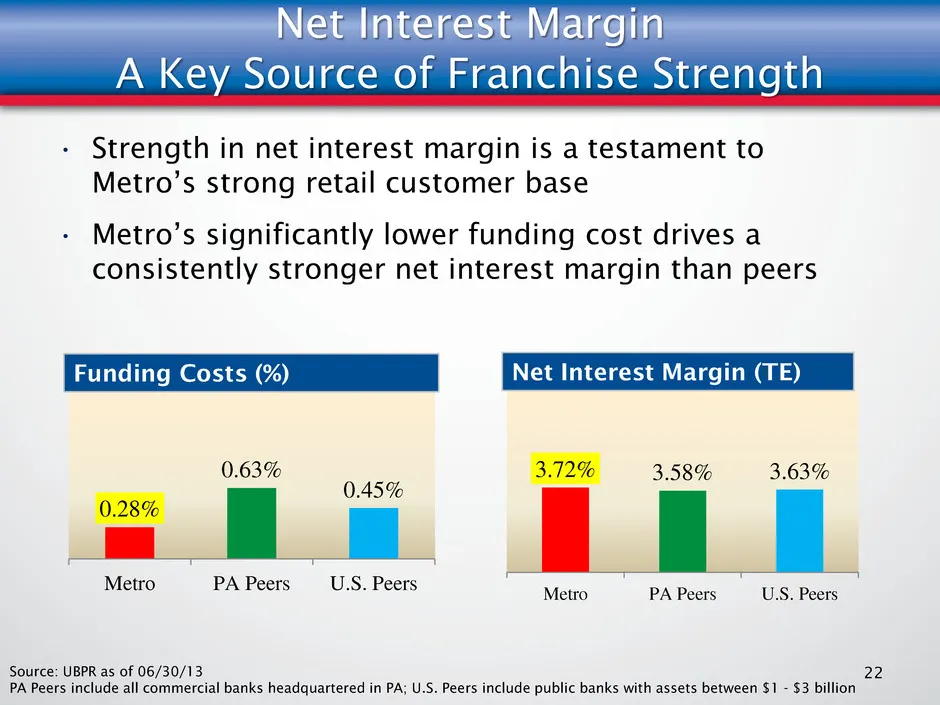
3.72% 3.58% 3.63% Metro PA Peers U.S. Peers Net Interest Margin A Key Source of Franchise Strength 22 • Strength in net interest margin is a testament to Metro’s strong retail customer base • Metro’s significantly lower funding cost drives a consistently stronger net interest margin than peers Sourc
Slide 23: Net Interest Income Growth
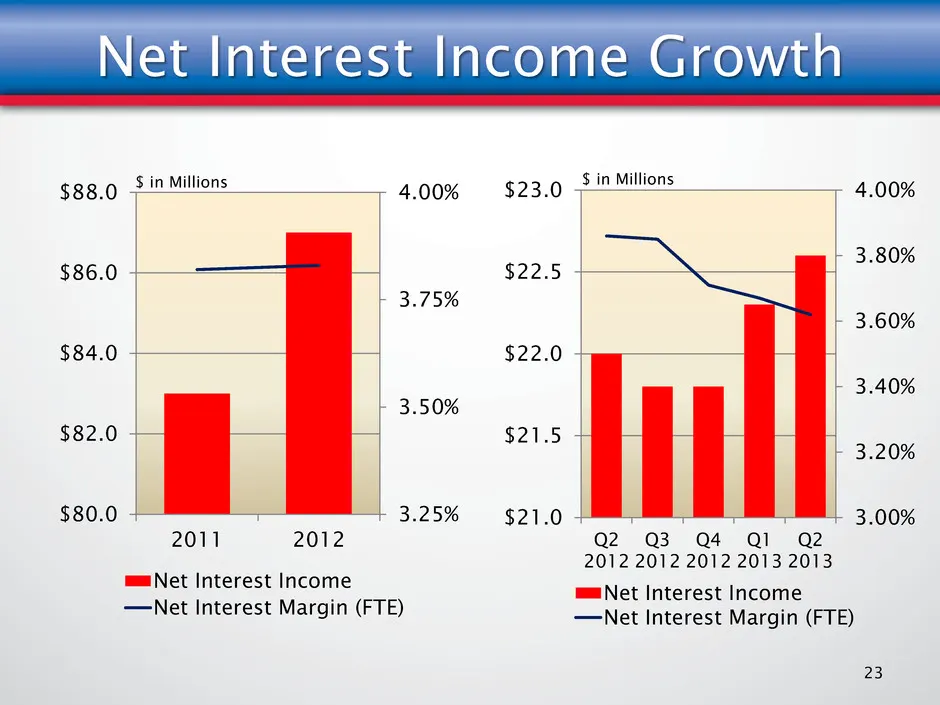
Net Interest Income Growth 3.00% 3.20% 3.40% 3.60% 3.80% 4.00% $21.0 $21.5 $22.0 $22.5 $23.0 Q2 2012 Q3 2012 Q4 2012 Q1 2013 Q2 2013 Net Interest Income Net Interest Margin (FTE) 3.25% 3.50% 3.75% 4.00% $80.0 $82.0 $84.0 $86.0 $88.0 2011 2012 Net Interest Income Net Interest Margin (FTE) 23 $ in Mil
Slide 24: Revenue Growth
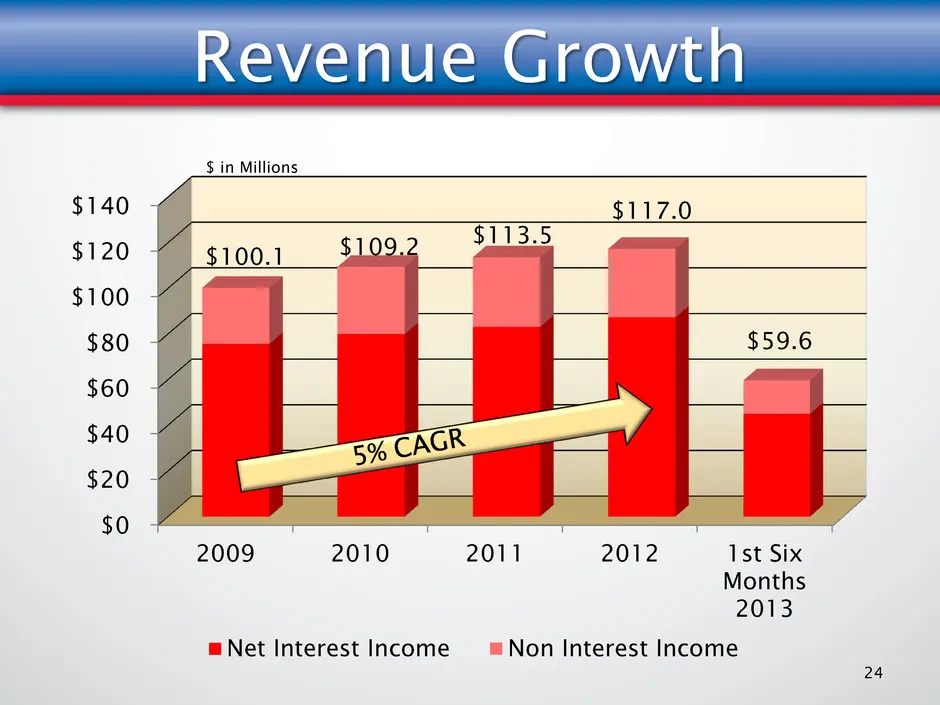
Revenue Growth $0 $20 $40 $60 $80 $100 $120 $140 2009 2010 2011 2012 1st Six Months 2013 Net Interest Income Non Interest Income 24 $ in Millions $100.1 $109.2 $113.5 $117.0 $59.6
Slide 25: Prudent Expense Management
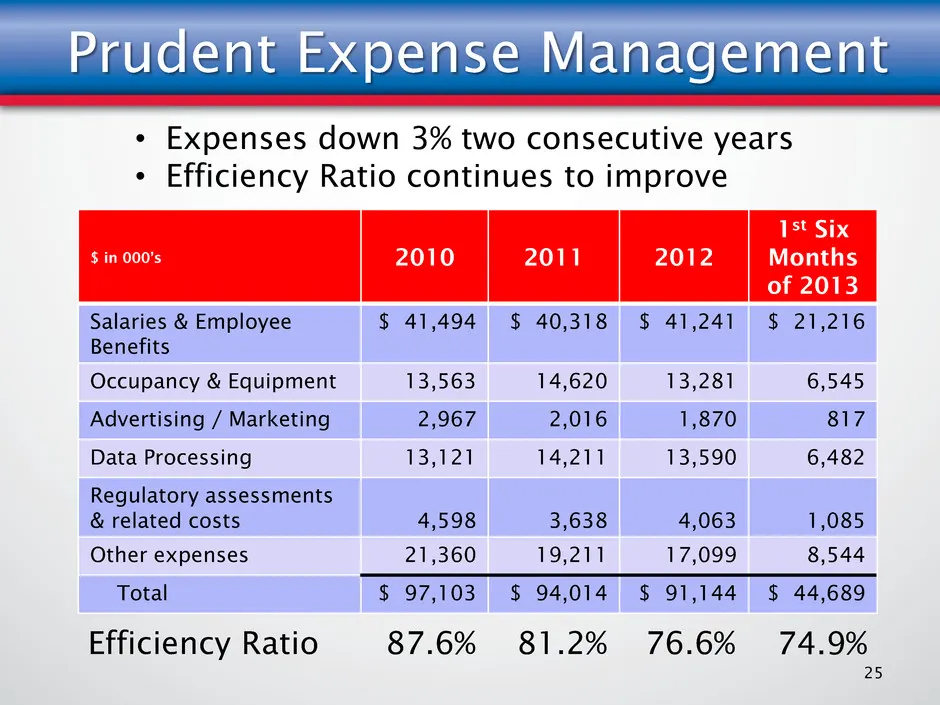
Prudent Expense Management $ in 000’s 2010 2011 2012 1st Six Months of 2013 Salaries & Employee Benefits $ 41,494 $ 40,318 $ 41,241 $ 21,216 Occupancy & Equipment 13,563 14,620 13,281 6,545 Advertising / Marketing 2,967 2,016 1,870 817 Data Processing 13,121 14,211 13,590 6,482 Regulatory assessment
Slide 26: Improved Profitability
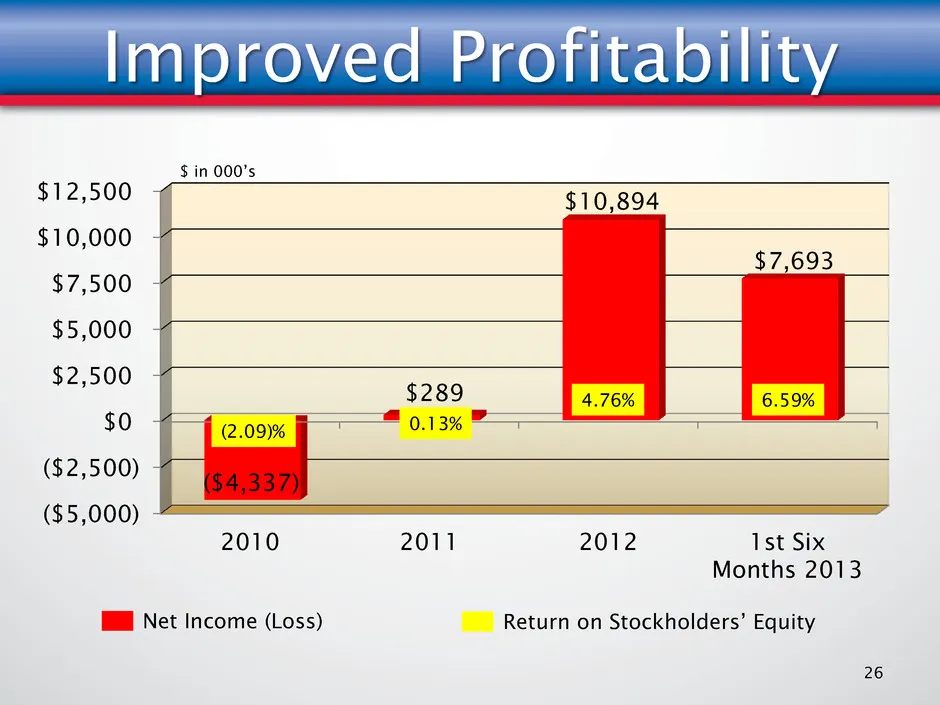
Improved Profitability ($5,000) ($2,500) $0 $2,500 $5,000 $7,500 $10,000 $12,500 2010 2011 2012 1st Six Months 2013 ($4,337) $289 $10,894 $7,693 26 Net Income (Loss) (2.09)% 0.13% 4.76% $ in 000’s Return on Stockholders’ Equity 6.59%
Slide 27: Quarterly Net Income and Earnings Per Share
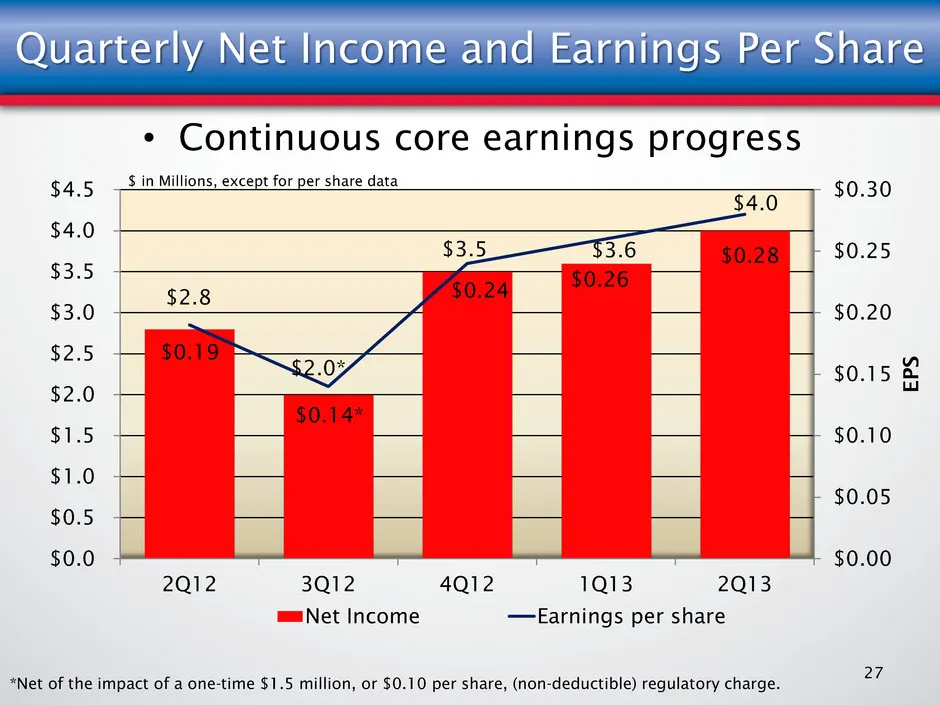
$2.8 $2.0* $3.5 $3.6 $4.0 $0.19 $0.14* $0.24 $0.26 $0.28 $0.00 $0.05 $0.10 $0.15 $0.20 $0.25 $0.30 $0.0 $0.5 $1.0 $1.5 $2.0 $2.5 $3.0 $3.5 $4.0 $4.5 2Q12 3Q12 4Q12 1Q13 2Q13 E P S Net Income Earnings per share Quarterly Net Income and Earnings Per Share 27 $ in Millions, except for per share data *N
Slide 28: Investment Portfolio
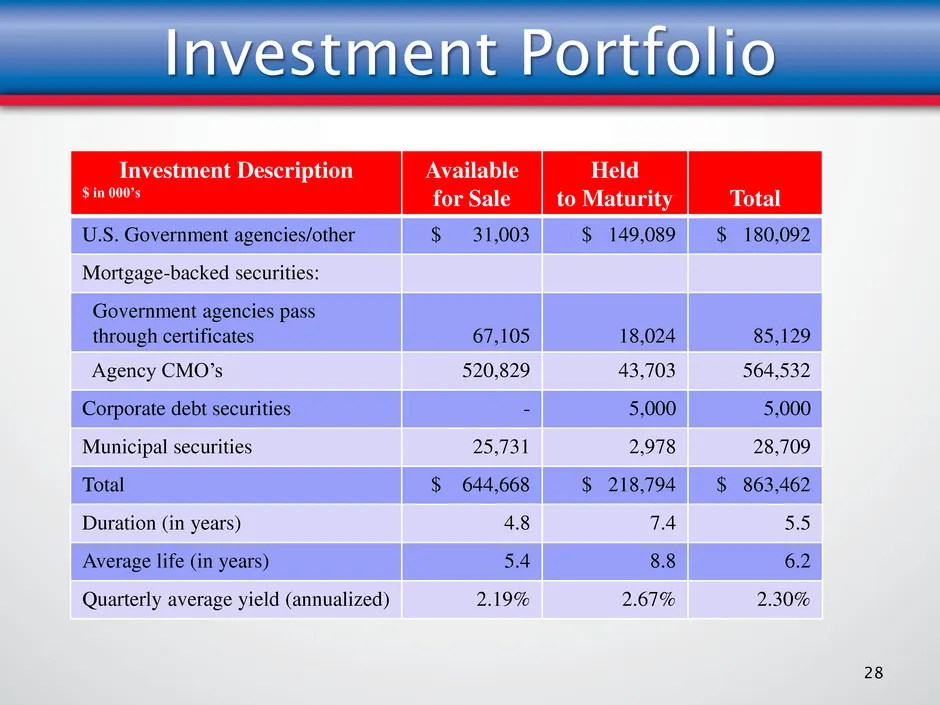
Investment Portfolio Investment Description $ in 000’s Available for Sale Held to Maturity Total U.S. Government agencies/other $ 31,003 $ 149,089 $ 180,092 Mortgage-backed securities: Government agencies pass through certificates 67,105 18,024 85,129 Agency CMO’s 520,829 43,703 564,532 Corporate de
Slide 29: Strong Capital Position
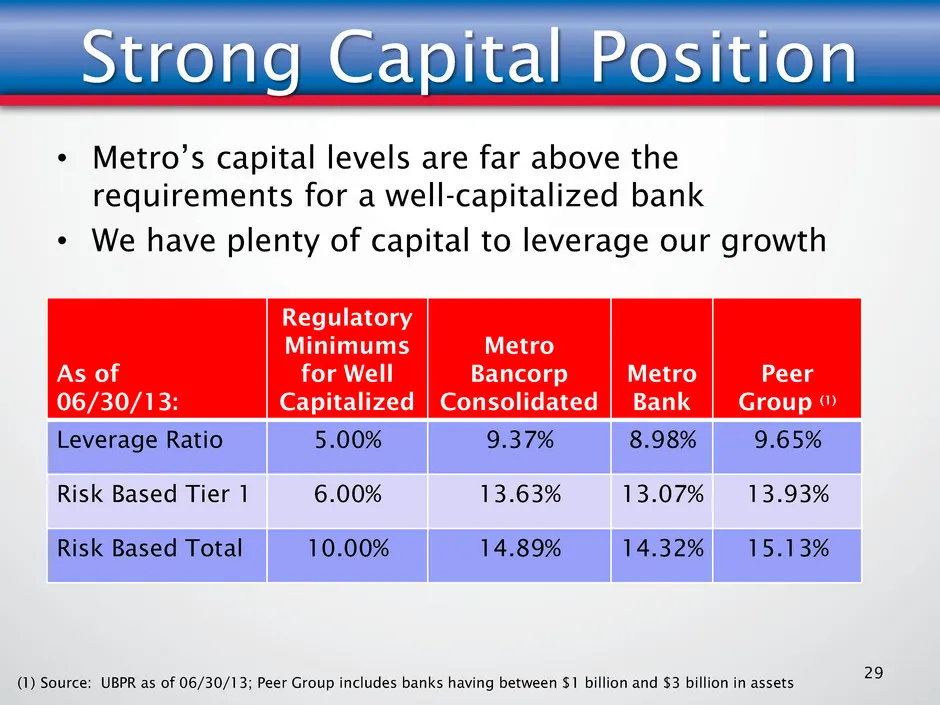
Strong Capital Position • Metro’s capital levels are far above the requirements for a well-capitalized bank • We have plenty of capital to leverage our growth 29 As of 06/30/13: Regulatory Minimums for Well Capitalized Metro Bancorp Consolidated Metro Bank Peer Group (1) Leverage Ratio 5.00% 9.37% 8
Slide 30: Lending & Asset Quality
LENDING & ASSET QUALITY imETRO BANK
Slide 31: Consistent, Quality Loan Growth
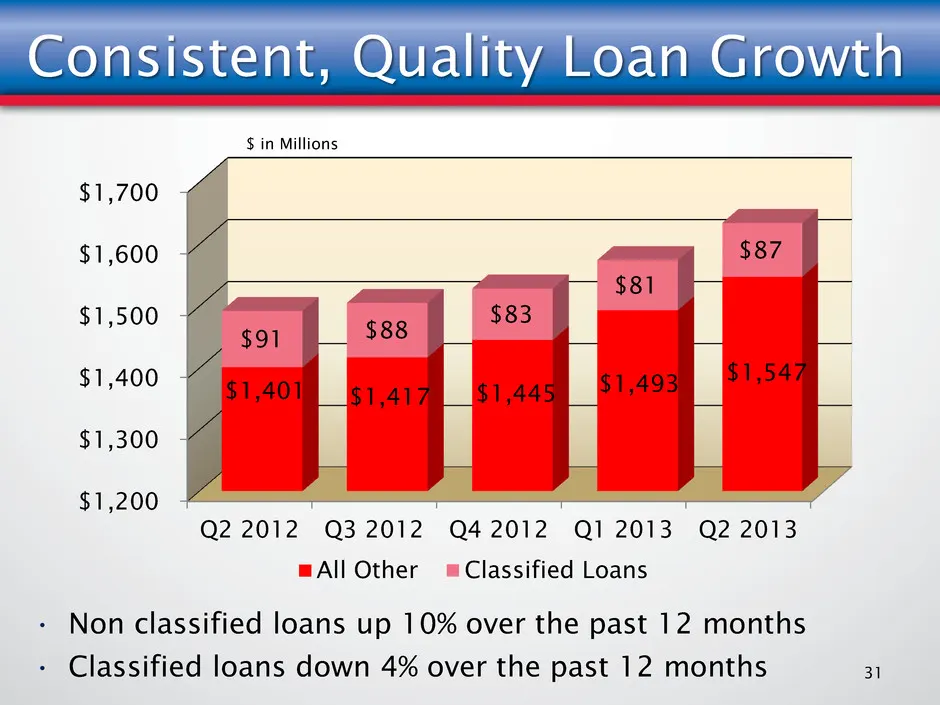
Consistent, Quality Loan Growth $1,200 $1,300 $1,400 $1,500 $1,600 $1,700 Q2 2012 Q3 2012 Q4 2012 Q1 2013 Q2 2013 $1,401 $1,417 $1,445 $1,493 $1,547 $91 $88 $83 $81 $87 All Other Classified Loans 31 $ in Millions • Non classified loans up 10% over the past 12 months • Classified loans down 4% over t
Slide 32: Loan Portfolio Mix
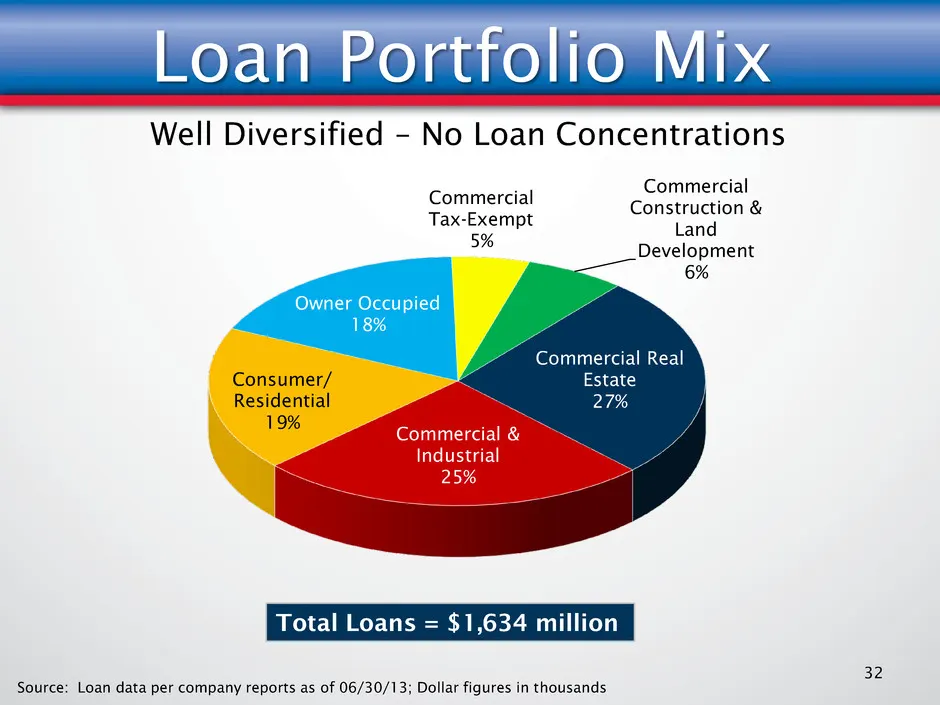
Commercial Real Estate 27% Commercial & Industrial 25% Consumer/ Residential 19% Owner Occupied 18% Commercial Tax-Exempt 5% Commercial Construction & Land Development 6% Total Loans = $1,634 million Source: Loan data per company reports as of 06/30/13; Dollar figures in thousands Loan Portfolio Mix
Slide 33: Real Estate & Construction Loans
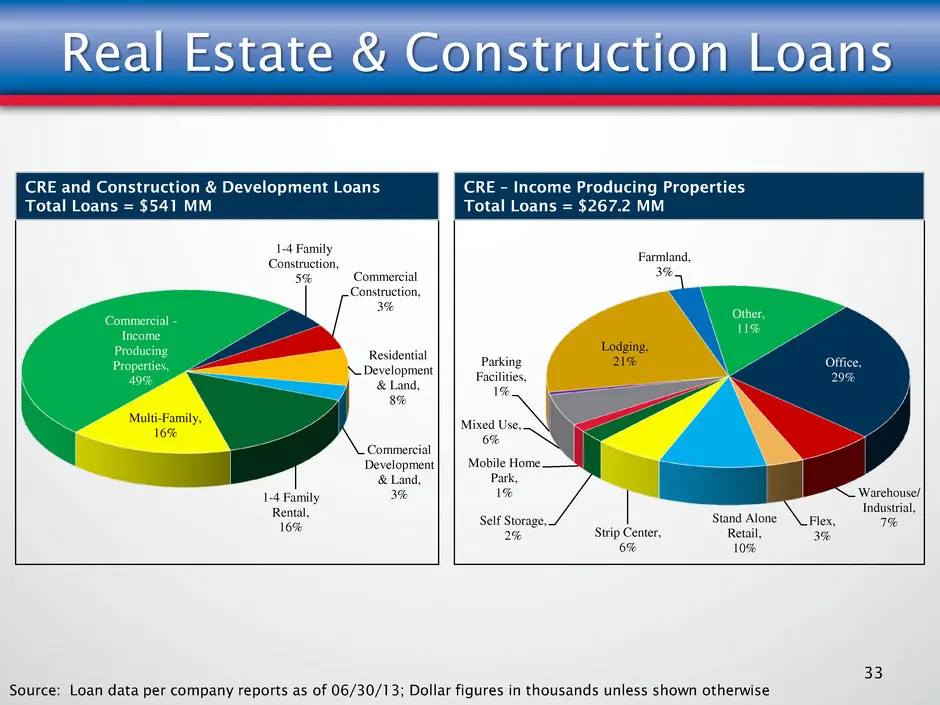
1-4 Family Construction, 5% Commercial Construction, 3% Residential Development & Land, 8% Commercial Development & Land, 3% 1-4 Family Rental, 16% Multi-Family, 16% Commercial - Income Producing Properties, 49% Source: Loan data per company reports as of 06/30/13; Dollar figures in thousands unless
Slide 34: Large Loan Relationships
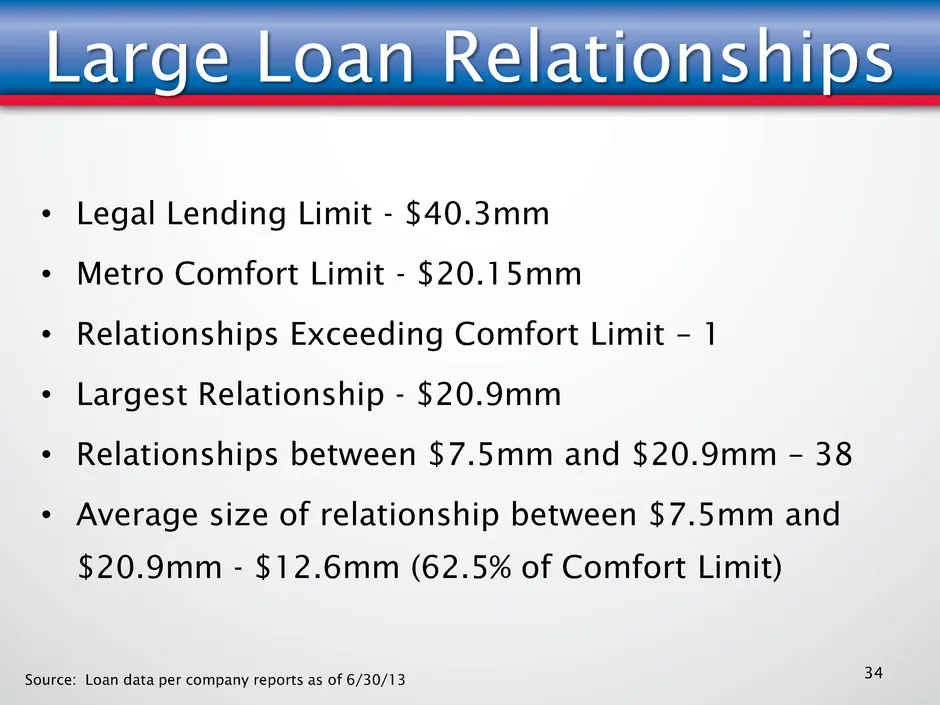
Large Loan Relationships • Legal Lending Limit - $40.3mm • Metro Comfort Limit - $20.15mm • Relationships Exceeding Comfort Limit – 1 • Largest Relationship - $20.9mm • Relationships between $7.5mm and $20.9mm – 38 • Average size of relationship between $7.5mm and $20.9mm - $12.6mm (62.5% of Comfort
Slide 35: Loan Performance
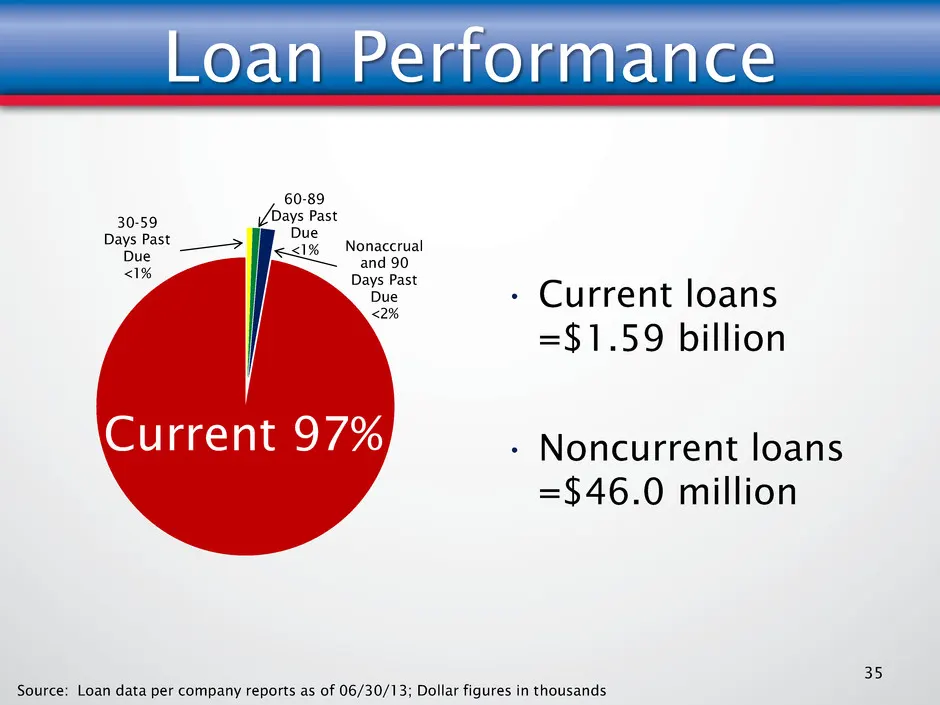
Source: Loan data per company reports as of 06/30/13; Dollar figures in thousands Loan Performance 35 30-59 Days Past Due <1% 60-89 Days Past Due <1% Nonaccrual and 90 Days Past Due <2% Current 97% • Current loans =$1.59 billion • Noncurrent loans =$46.0 million
Slide 36: Asset Quality and Loan Loss Reserve Trends
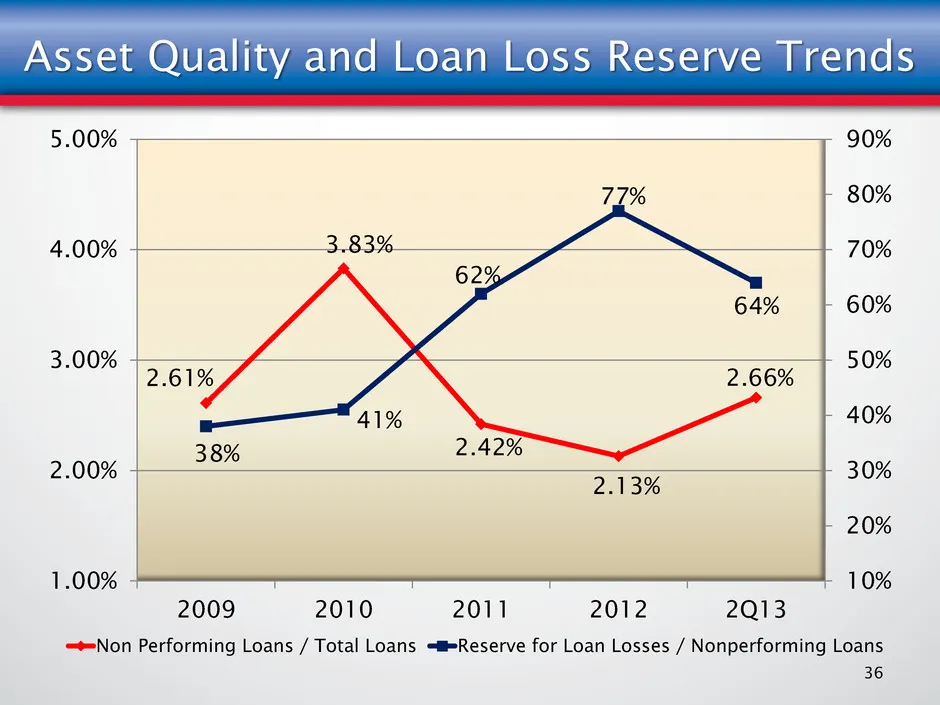
Asset Quality and Loan Loss Reserve Trends 36 2.61% 3.83% 2.42% 2.13% 2.66% 38% 41% 62% 77% 64% 10% 20% 30% 40% 50% 60% 70% 80% 90% 1.00% 2.00% 3.00% 4.00% 5.00% 2009 2010 2011 2012 2Q13 Non Performing Loans / Total Loans Reserve for Loan Losses / Nonperforming Loans
Slide 37: Net Loan Charge-Offs/Avg. Loans
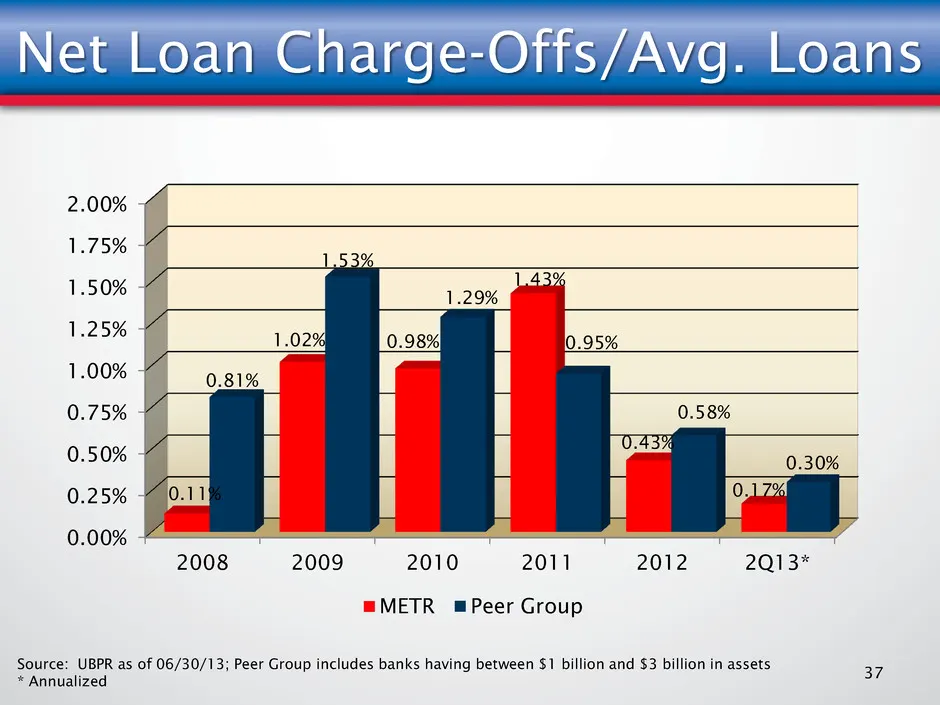
Net Loan Charge-Offs/Avg. Loans 0.00% 0.25% 0.50% 0.75% 1.00% 1.25% 1.50% 1.75% 2.00% 2008 2009 2010 2011 2012 2Q13* 0.11% 1.02% 0.98% 1.43% 0.43% 0.17% 0.81% 1.53% 1.29% 0.95% 0.58% 0.30% METR Peer Group 37 Source: UBPR as of 06/30/13; Peer Group includes banks having between $1 billion and $3 bill
Slide 38: Criticized & Classified Loan Vintage Analysis
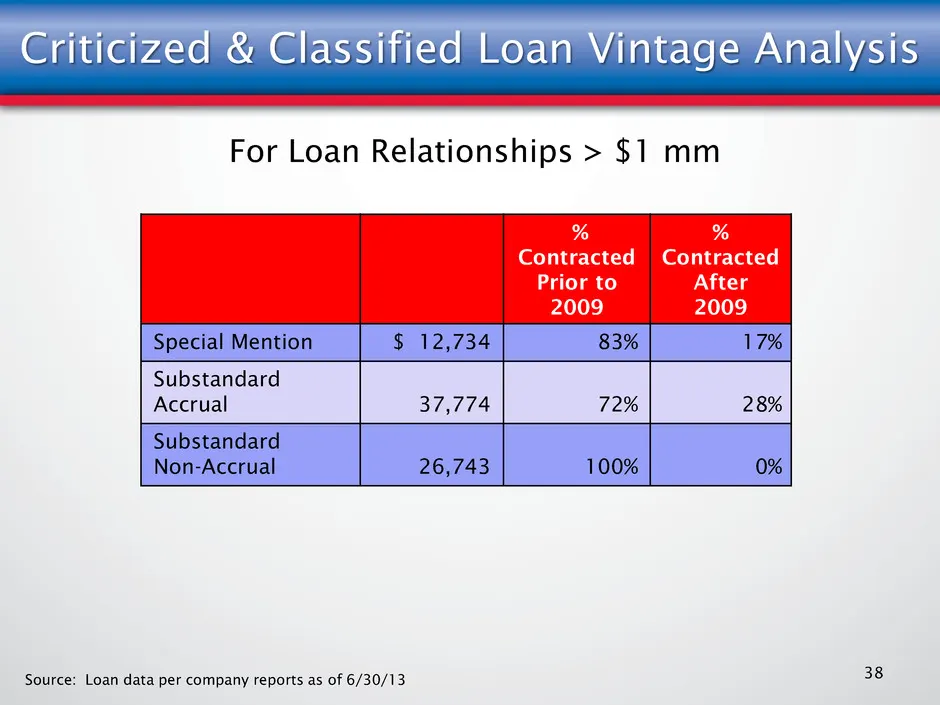
Criticized & Classified Loan Vintage Analysis % Contracted Prior to 2009 % Contracted After 2009 Special Mention $ 12,734 83% 17% Substandard Accrual 37,774 72% 28% Substandard Non-Accrual 26,743 100% 0% 38 Source: Loan data per company reports as of 6/30/13 For Loan Relationships > $1 mm
Slide 39: Common Stock
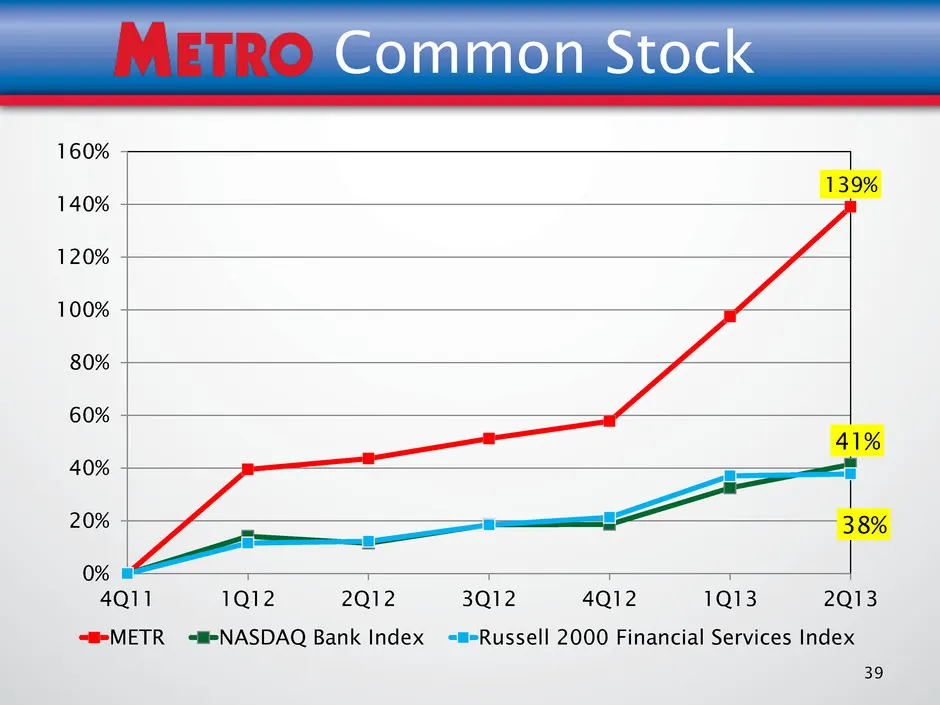
39 Common Stock 139% 41% 38% 0% 20% 40% 60% 80% 100% 120% 140% 160% 4Q11 1Q12 2Q12 3Q12 4Q12 1Q13 2Q13 METR NASDAQ Bank Index Russell 2000 Financial Services Index
Slide 40: 2013 and Beyond
2013 and Beyond Enhance long-term shareholder value by: • Increasing revenue through organic loan growth, deposit growth and fee income growth • Growing market share – customers, households and share of wallet • Diligently managing asset quality as well as other enterprise risks • Improving EPS and
Slide 41: The Future
THE FUTURE imETRO BANK
Slide 42: Five Year Growth
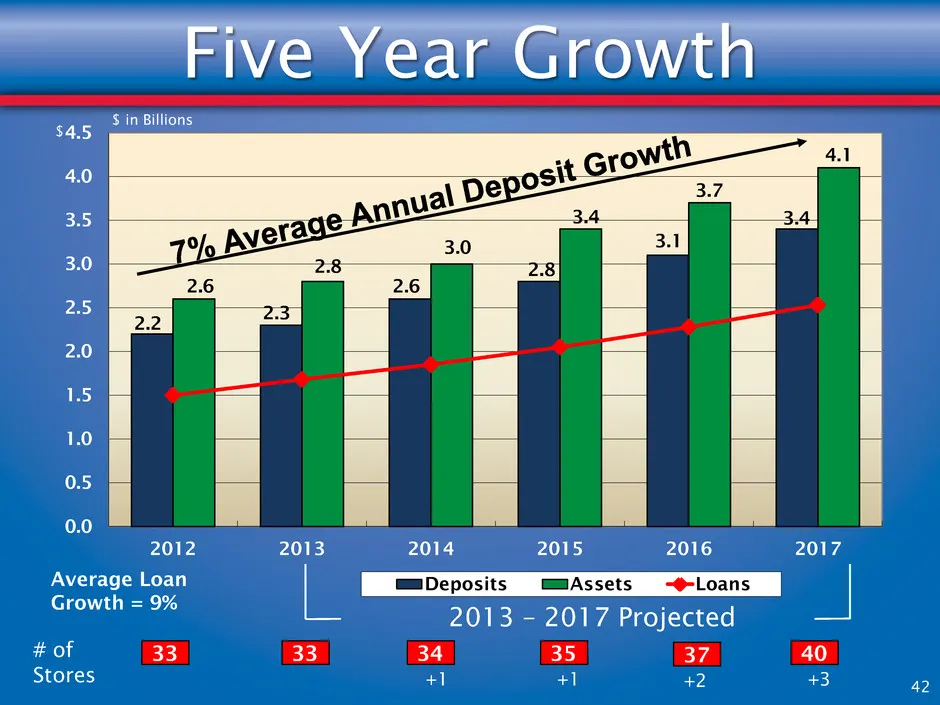
2.2 2.3 2.6 2.8 3.1 3.4 2.6 2.8 3.0 3.4 3.7 4.1 0.0 0.5 1.0 1.5 2.0 2.5 3.0 3.5 4.0 4.5 2012 2013 2014 2015 2016 2017 Deposits Assets Loans # of Stores 33 33 34 35 $ 2013 – 2017 Projected +1 +1 $ in Billions 40 +3 37 +2 Five Year Growth 42 Average Loan Growth = 9%
Slide 43: Expand the Footprint
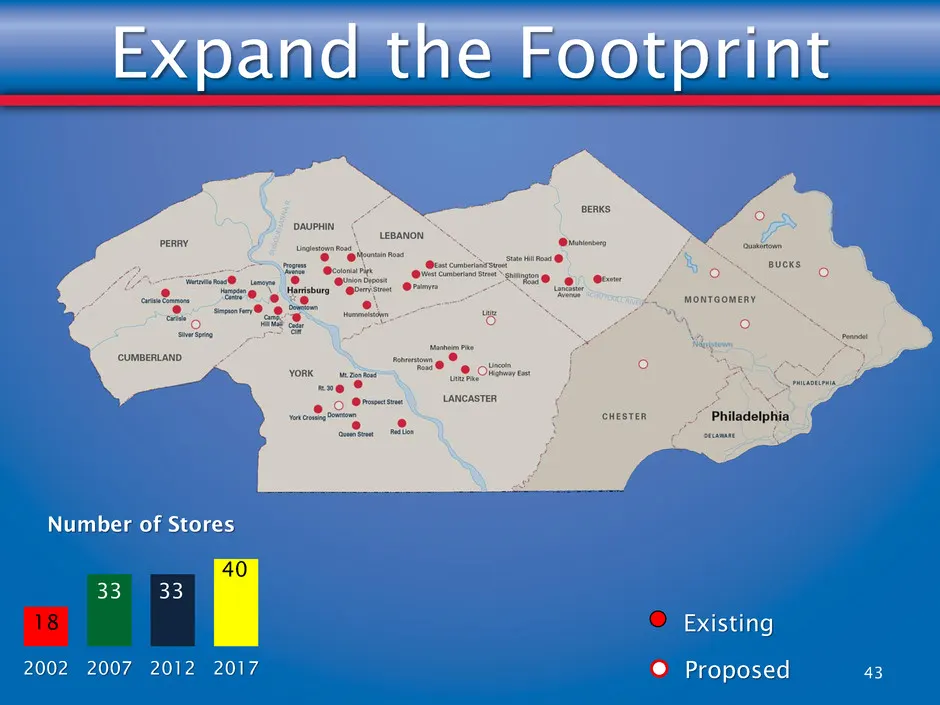
Existing Proposed Expand the Footprint 43 18 33 33 40 2002 2007 2012 2017 Number of Stores
Slide 44: The Store is the Brand
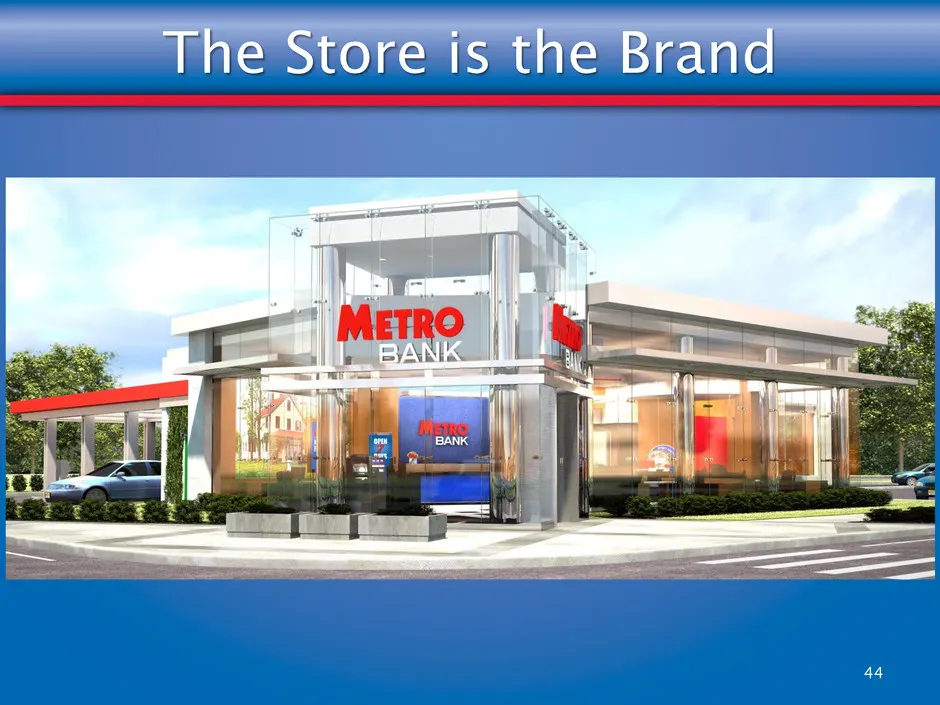
The Store is the Brand 44
Slide 45: Summary
Summary • Unique Deposit-Driven/Retail Focus • Service, Not Rate, Drives Growth • Growth is Essential to Success and Value 45
Source: SEC EDGAR · 8-K filed Aug 15, 2013
More decks from Metro Bancorp Inc
 Merger or Acquisition (August 2015)15 slides · Aug 4, 2015
 Shareholder Meeting (June 2015)35 slides · Jun 19, 2015
 Shareholder Meeting (May 2014)35 slides · May 22, 2014
 Sandler O'Neill & Partners 2013 East Coast Financial Services Conference46 slides · Nov 13, 2013
 Shareholder Meeting (May 2013)37 slides · May 17, 2013
 Sterne Agee Financial Institutions Investor Conference February 201342 slides · Feb 11, 2013