Aleris International — MSCI Aluminum Products Conference 2005
23 slides from Aleris International's conference presentation, Nov 17, 2005
Slide 1: Aluminum Producer's Point of View
Exhibit 99.1 MSCI Aluminum Producer’s Steven J. Demetriou Point of Products View Chairman November Conference & Chief 17,Executive 2005 Officer
Slide 2: Safe Harbor Statements
Safe Harbor Statements harbor statements. cause information Alflex currency releases comparable 2 actual division provisions which transaction. contained ItGAAP contained results ispresented sold important ofinformation. to in the The in differ herein July this Securities our above to2004 from prese
Slide 3: Outline of Discussion
DiscussionofOutline Introduction Examples 3 to Supplier-Distributor Aleris Outlook for Collaboration Aluminum SheetPossible Optimization Solutionsoffor theMills Supply & Distributors Chain
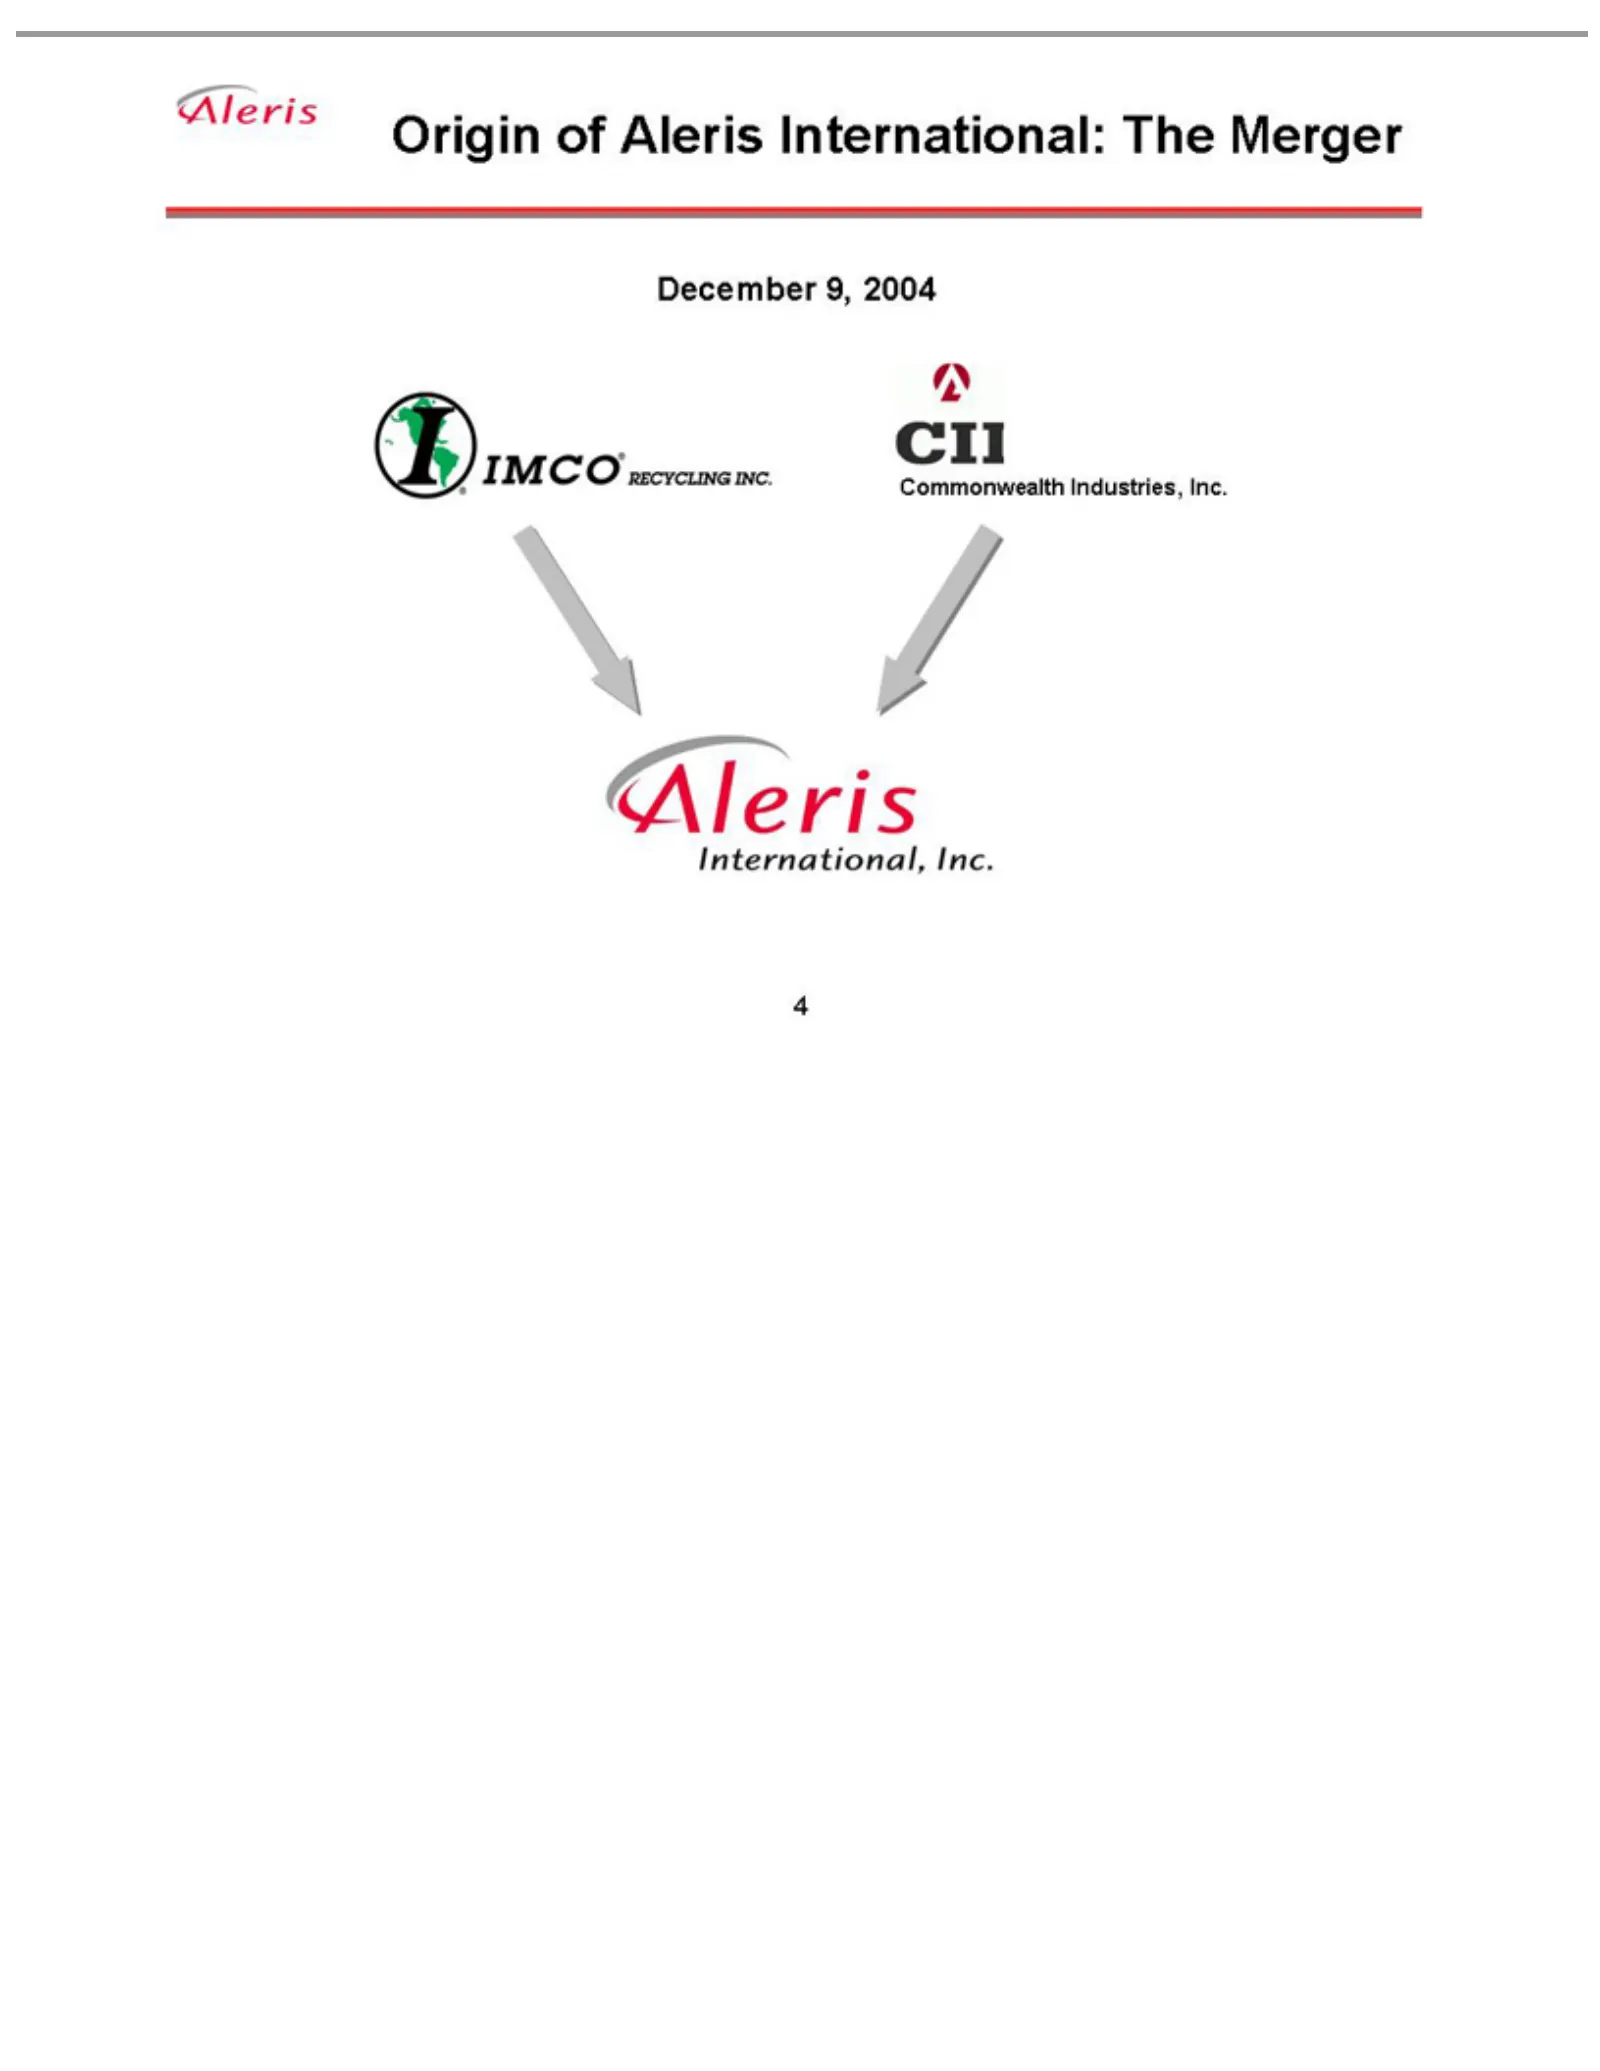
Slide 4: Origin of Aleris: The Merger
Origin of Aleris December Commonwealth 4 9, 2004 International: Industries, Inc.The Merger
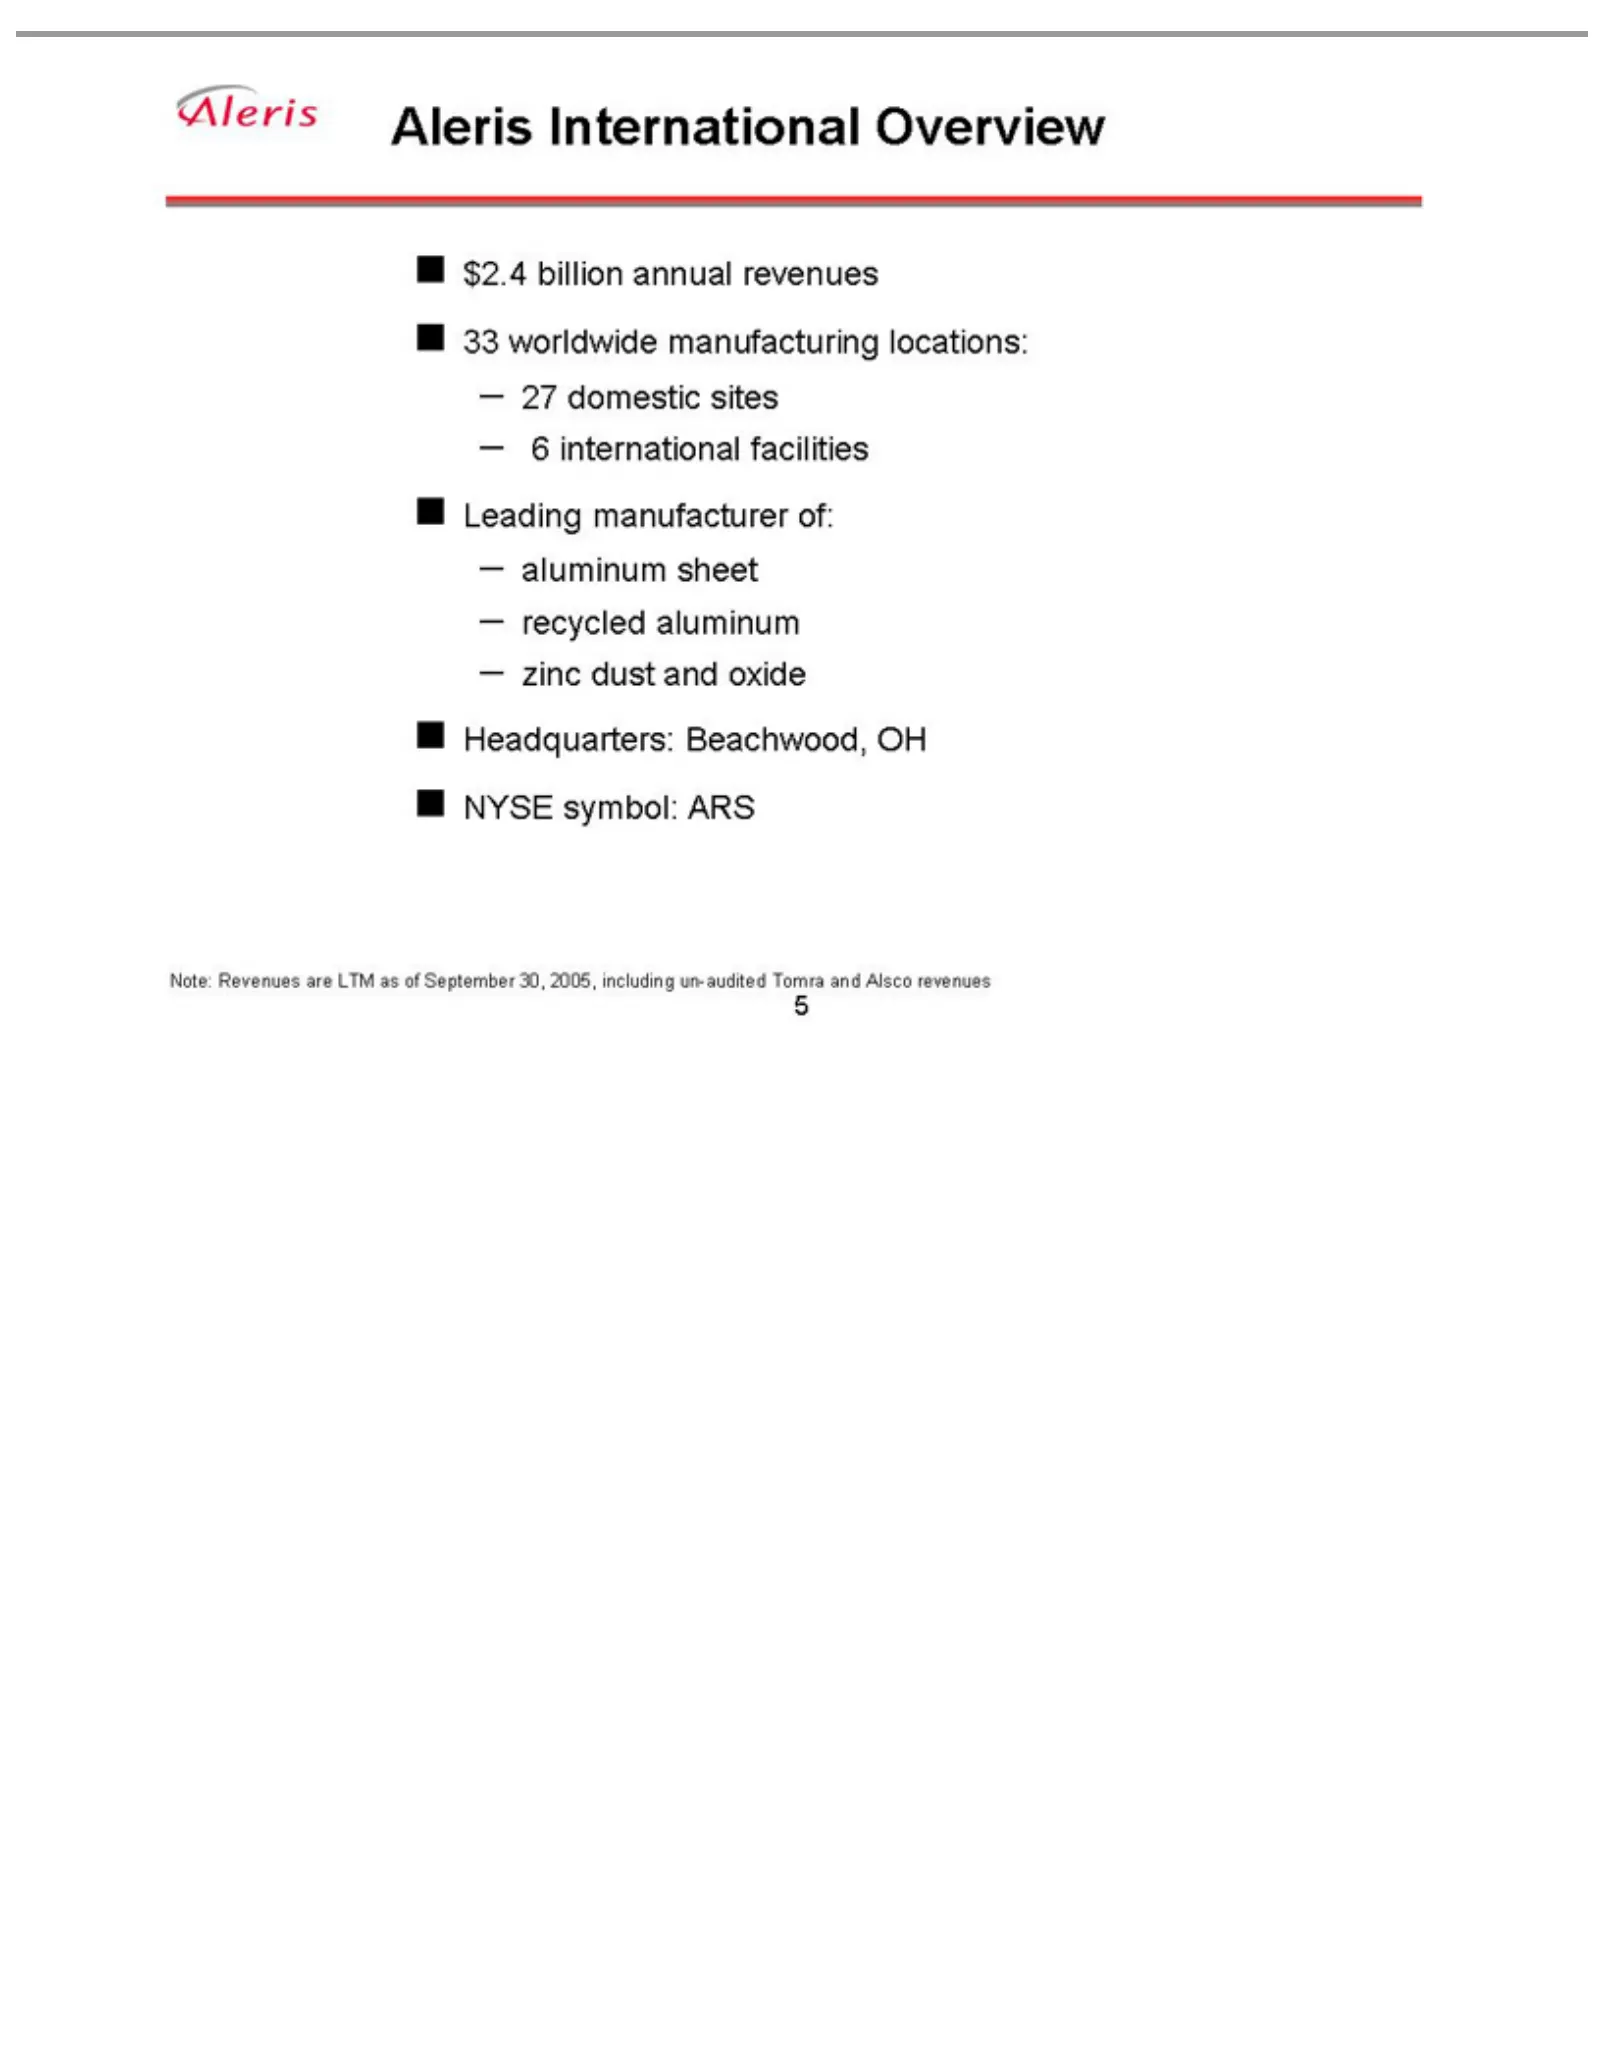
Slide 5: Aleris Overview
Aleris 33 27 6 NYSE Note: 5 international worldwide domestic Revenues International symbol: sites manufacturing facilities ARS are Overview LTMLeading as oflocations: $2.4 September manufacturer billion 30, annual 2005, of: revenues aluminum includingsheet un-audited recycled Tomra aluminum and Alsc
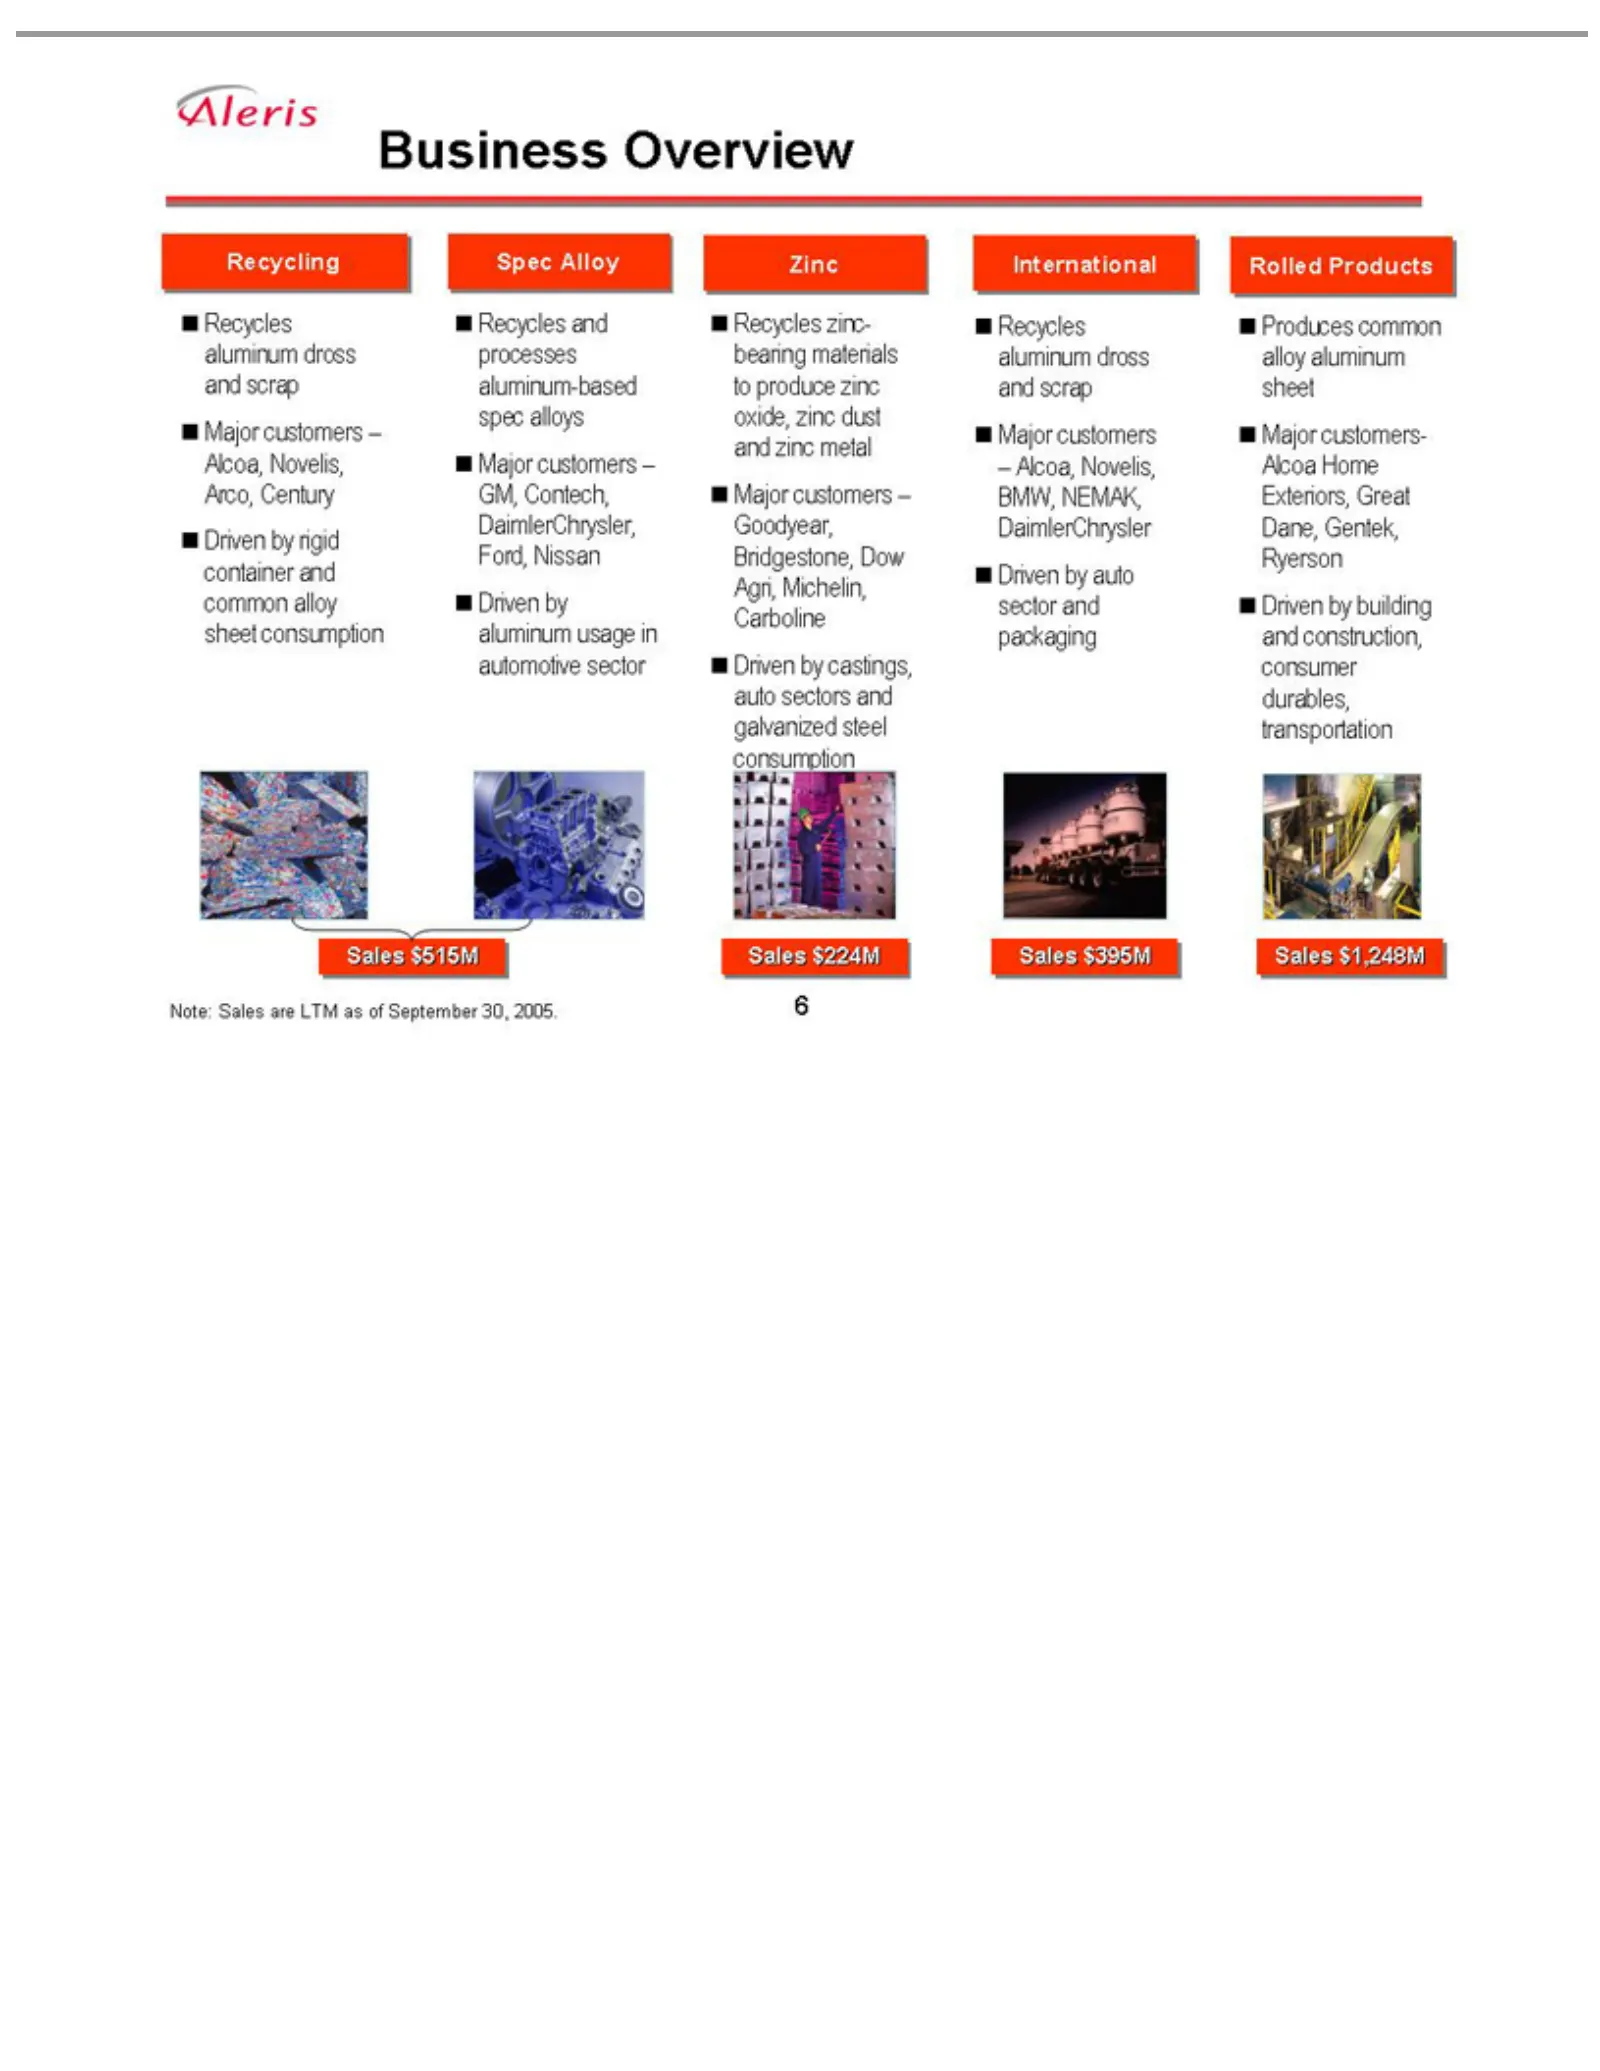
Slide 6: Business Overview
Business Recycling Spec Zinc galvanized Recycles International – Rolled Produces Sales Note: 6 Alcoa, Alloy $515M $224M $395M $1,248M Sales Products Novelis, Overview and zinc-bearing aluminum common steel areprocesses LTM consumption BMW, alloy dross asmaterials aluminum-based of aluminum NEMAK, an
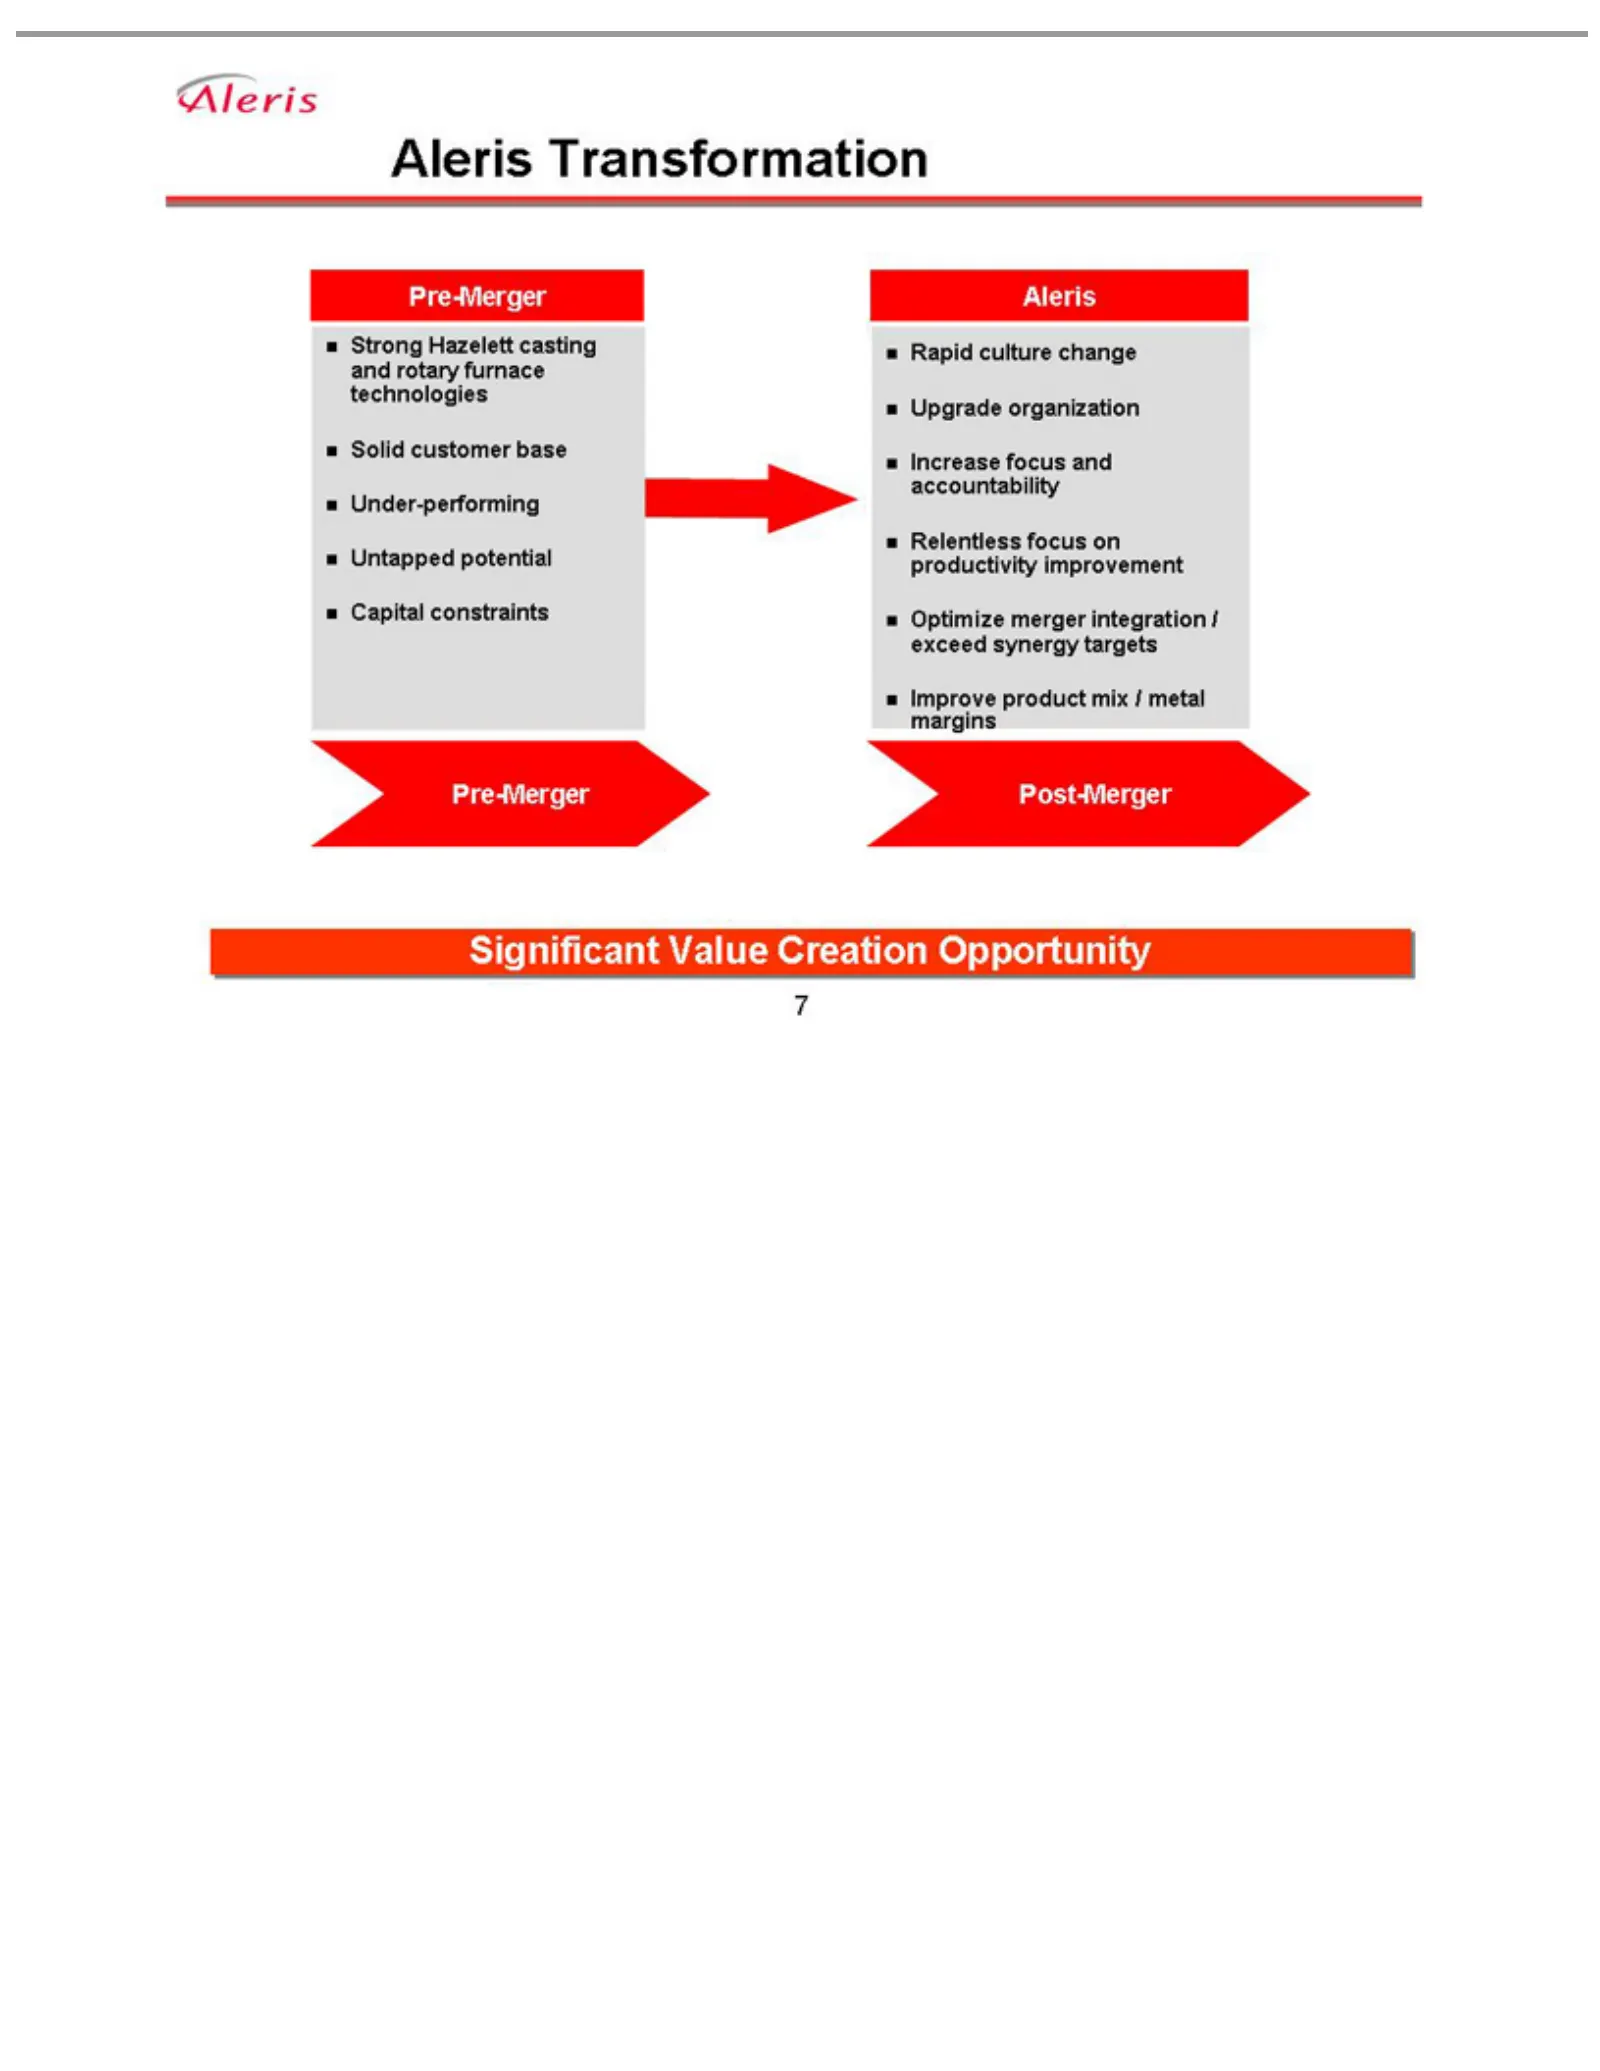
Slide 7: Pre-Merger vs Post-Merger Transformation
Strongcustomer Solid Rapid Aleris Pre-Merger Upgrade Increase Relentless Optimize Improve Significant Post-Merger 7 culture Transformation Hazelett focus product organization merger focus Value change and base casting on mix integration Creation accountability productivity Under-performing / metal a
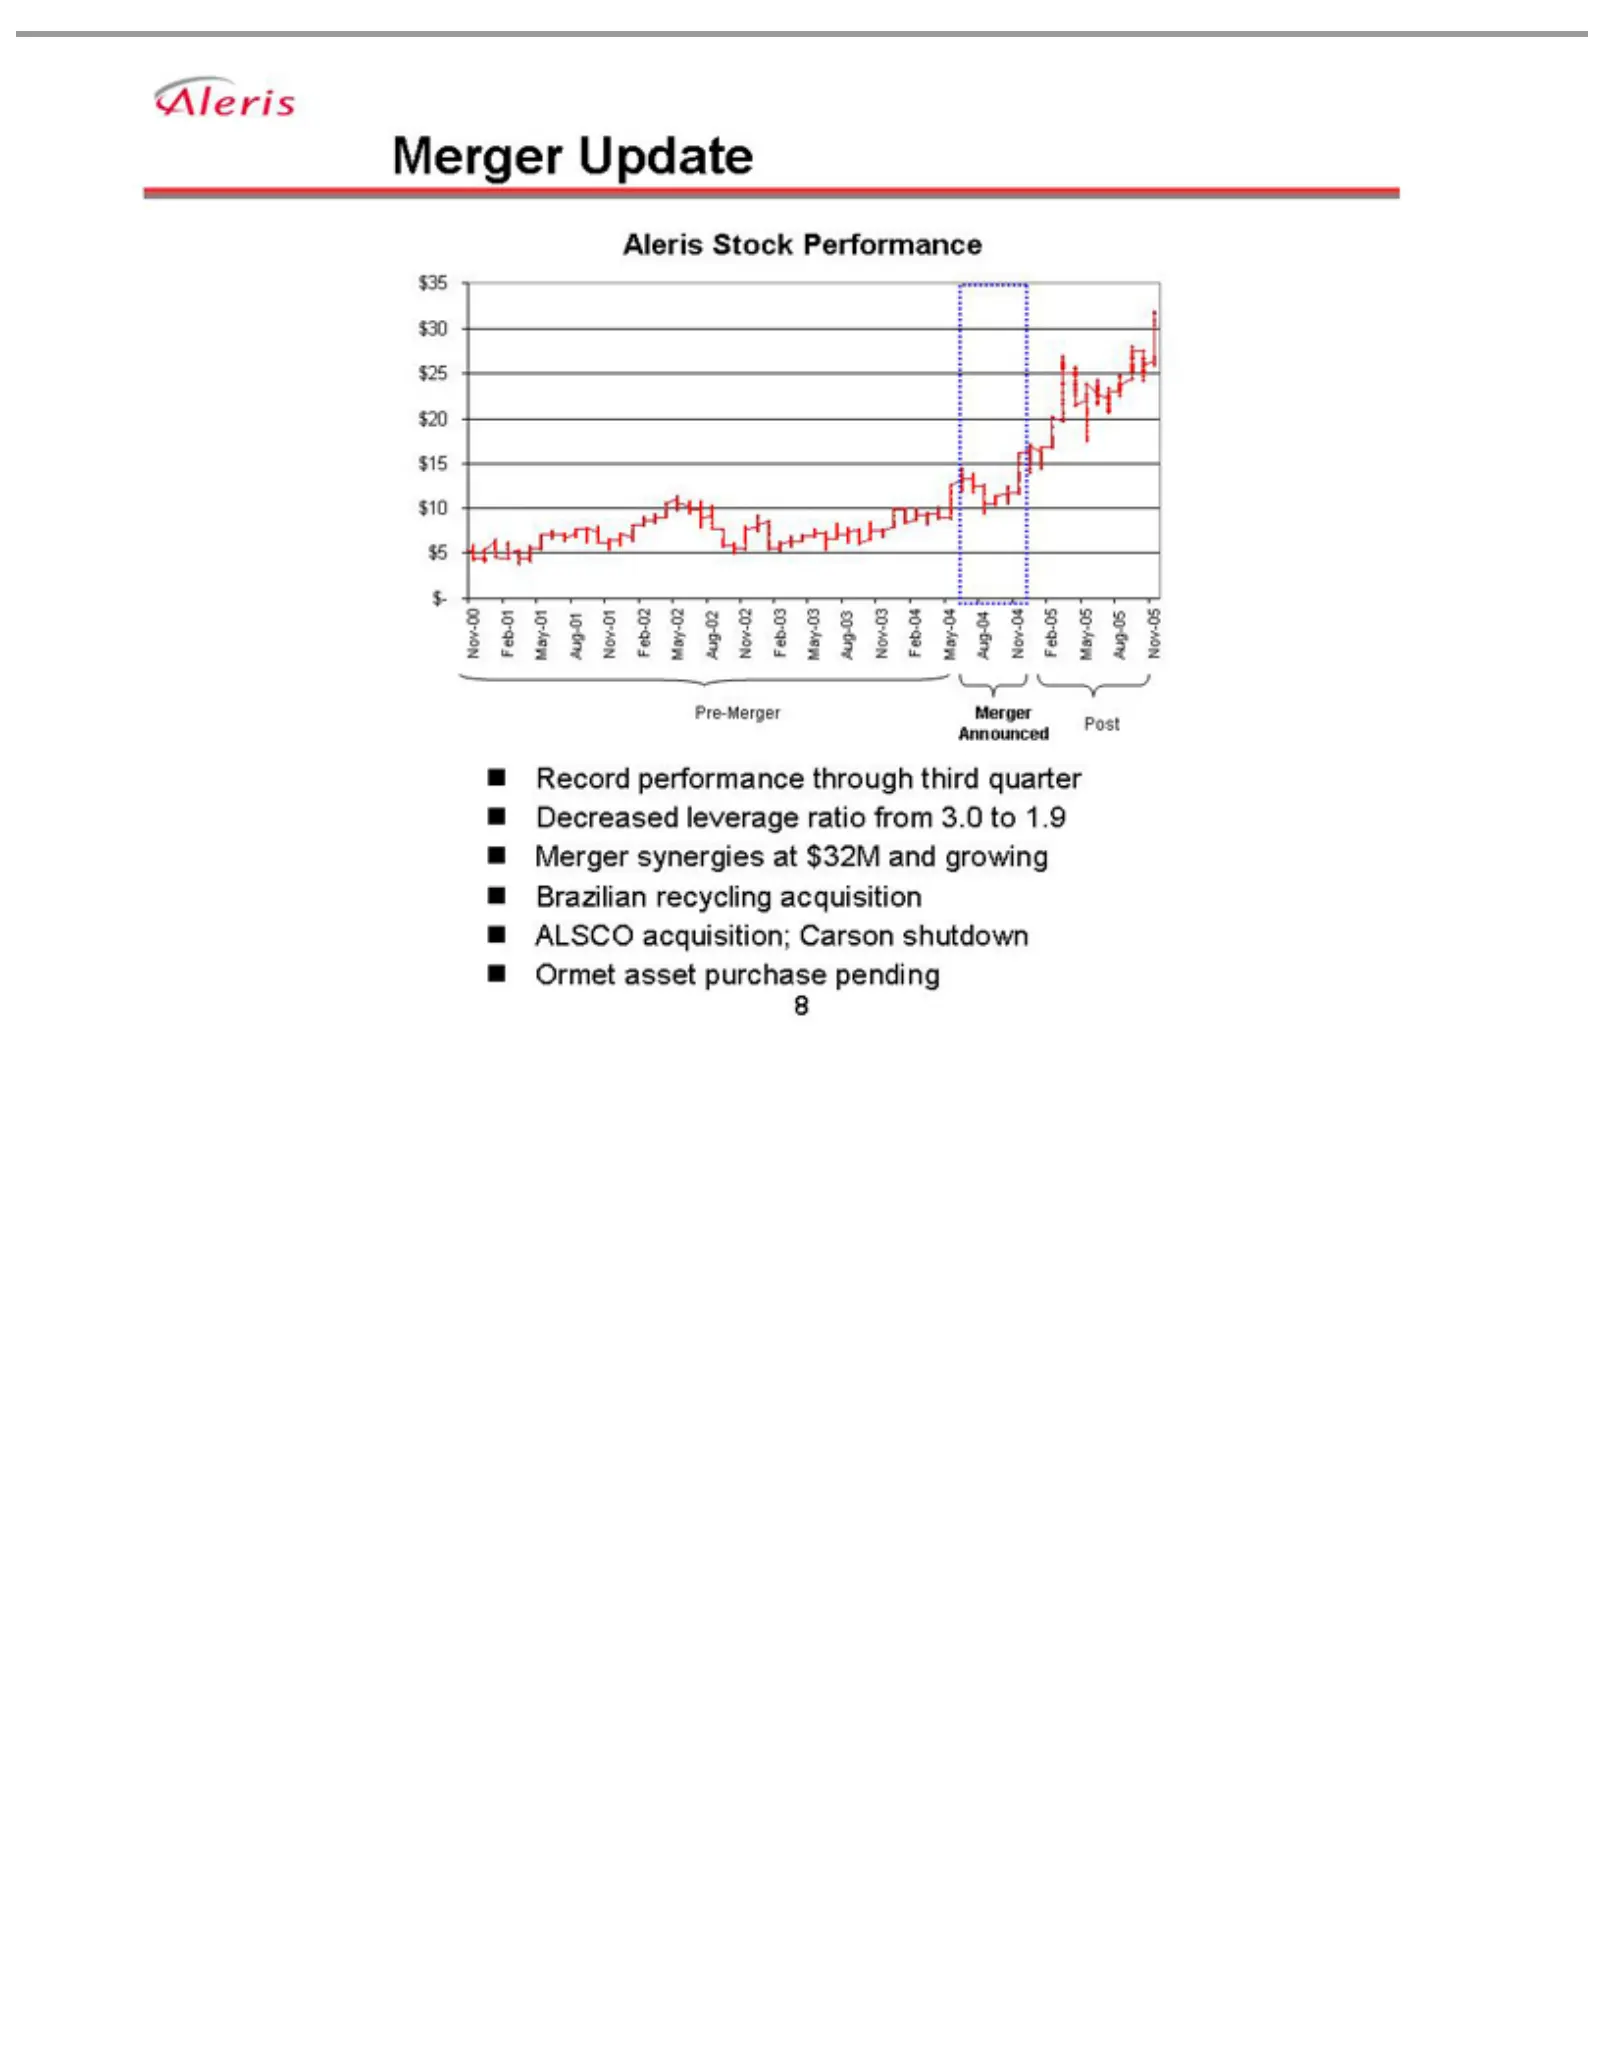
Slide 8: Aleris Stock Performance
Aleris Stock Nov-00 Merger Pre-Merger Record Post Ormet 8 asset Announced performance Update Feb-01 purchase Performance May-01 through pending Aug-01 $35third $30 Nov-01 quarter $25 $20 Feb-02 Decreased $15 $10 May-02 $5 leverage $-Aug-02 ratio Nov-02 from 3.0 Feb-03 to 1.9 May-03 MergerAug-03 syne
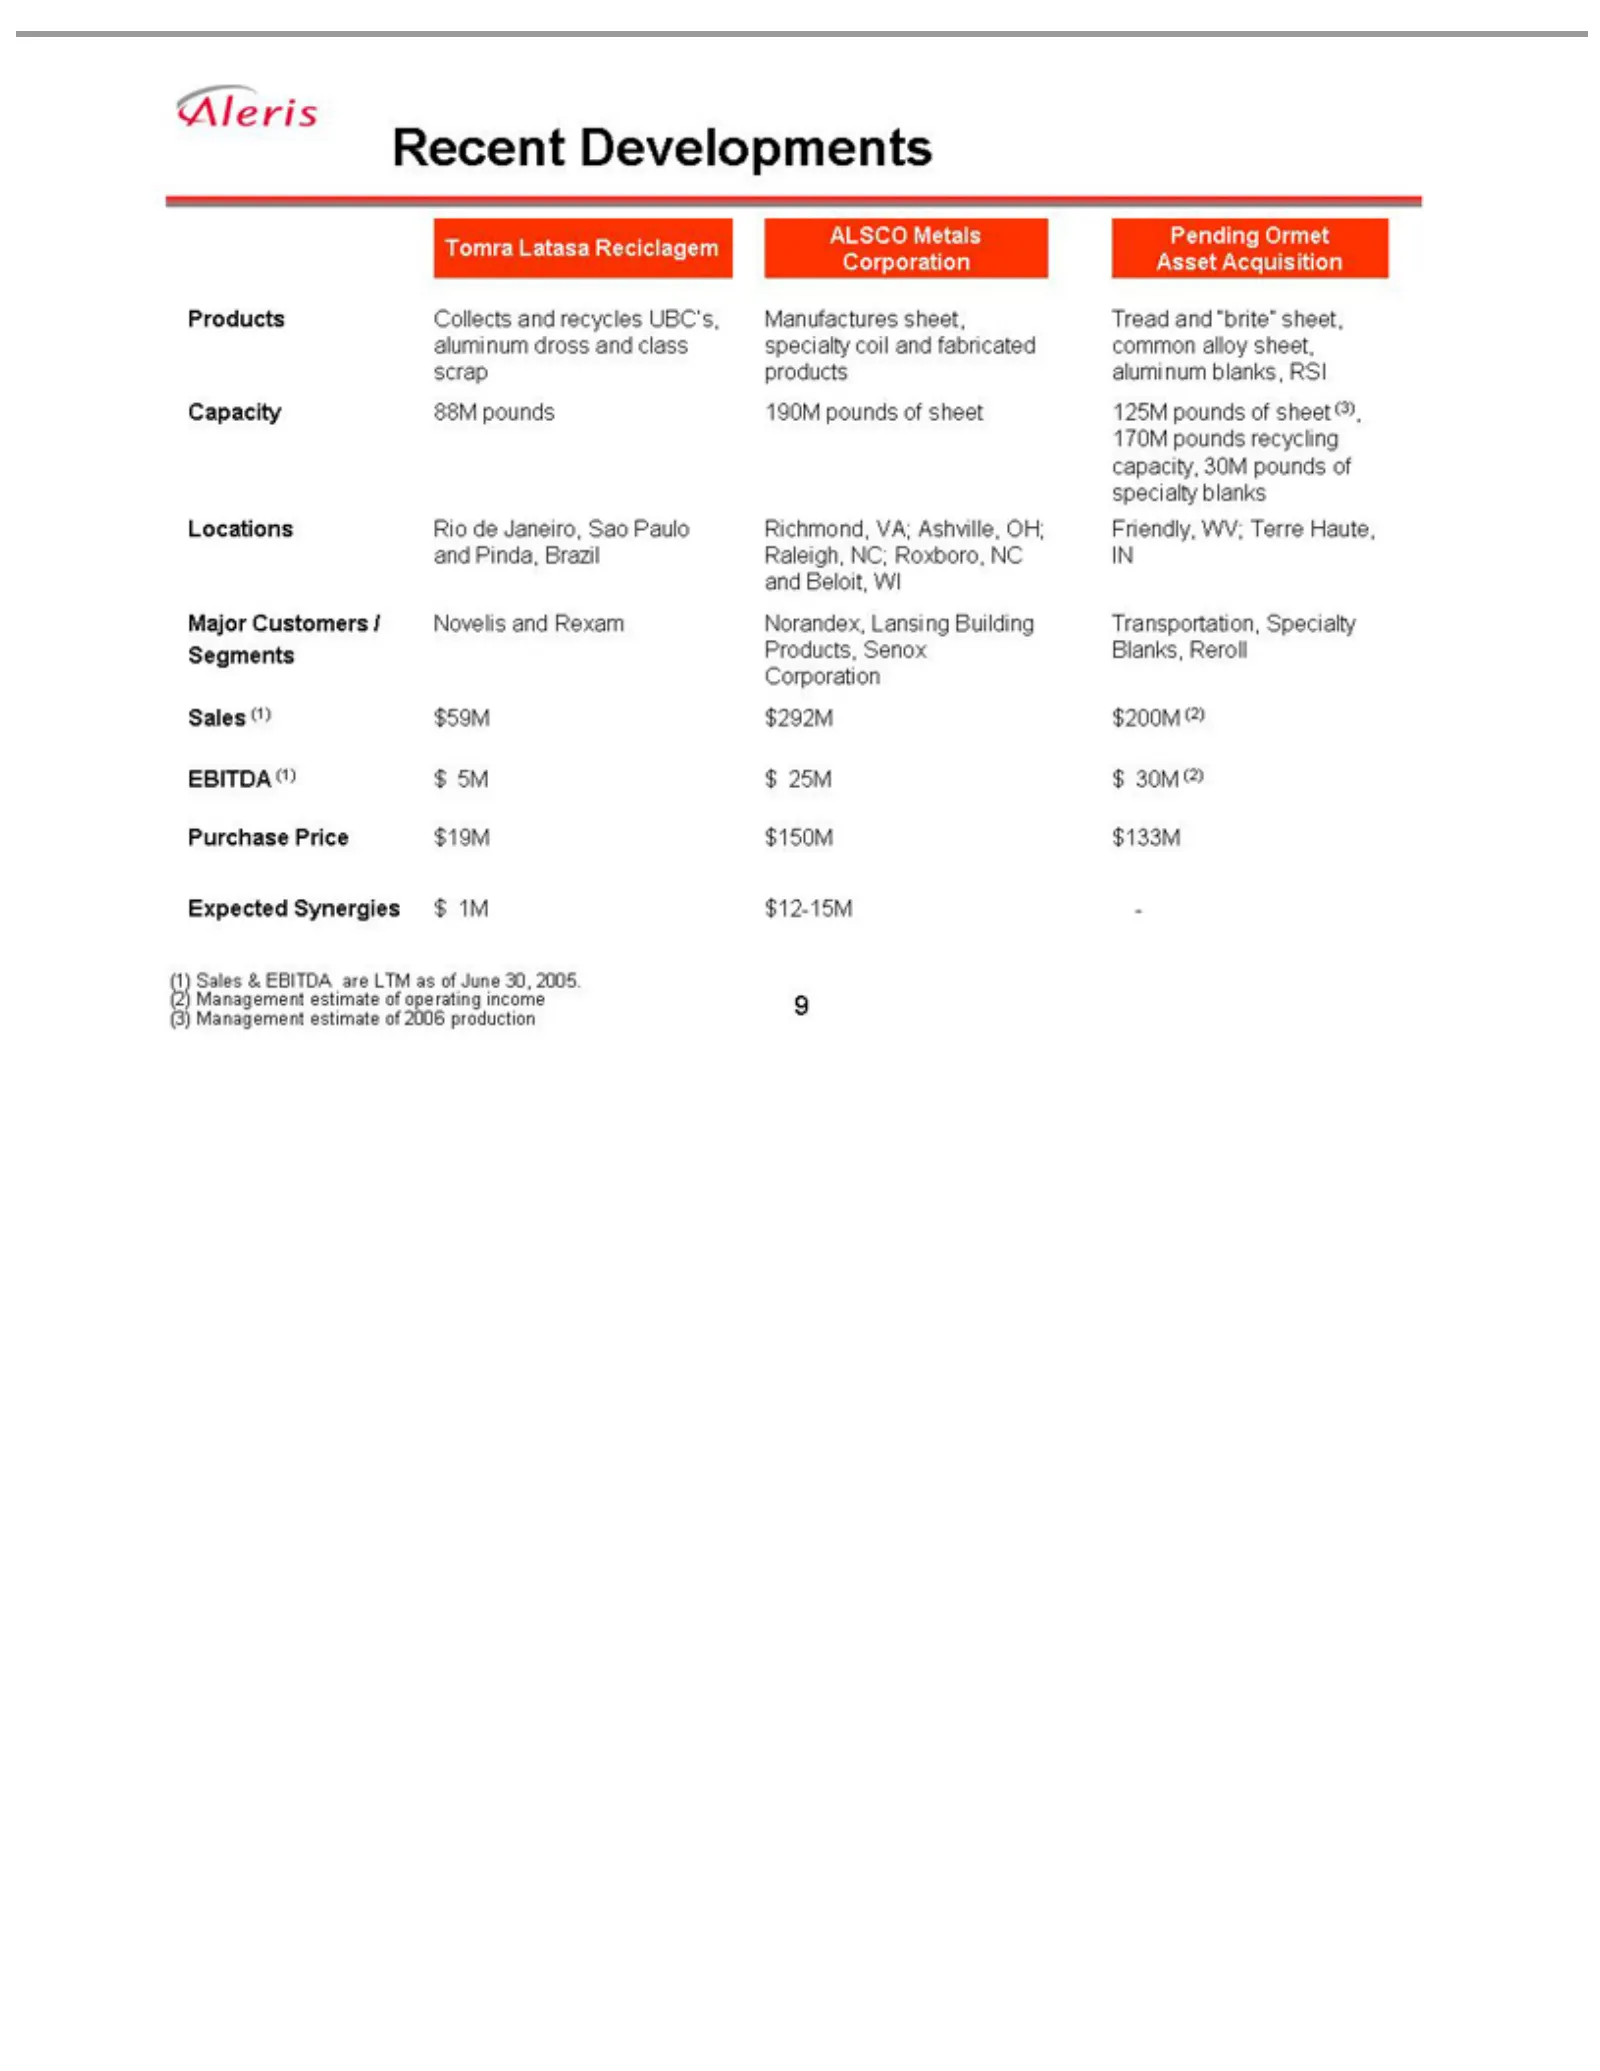
Slide 9: Recent Developments
Recent Tomra Products Capacity Locations Major Sales EBITDA Purchase Expected (1) 9 Sales (1) Customers Latasa Developments Collects $59M & 88M Price (1) Synergies Rio EBITDA $5M Reciclagem de pounds $19M $292M Janeiro, /and $25M Segments $1M are $150M recycles 190M $200M $30M LTM $12-15M Sao ALSCO
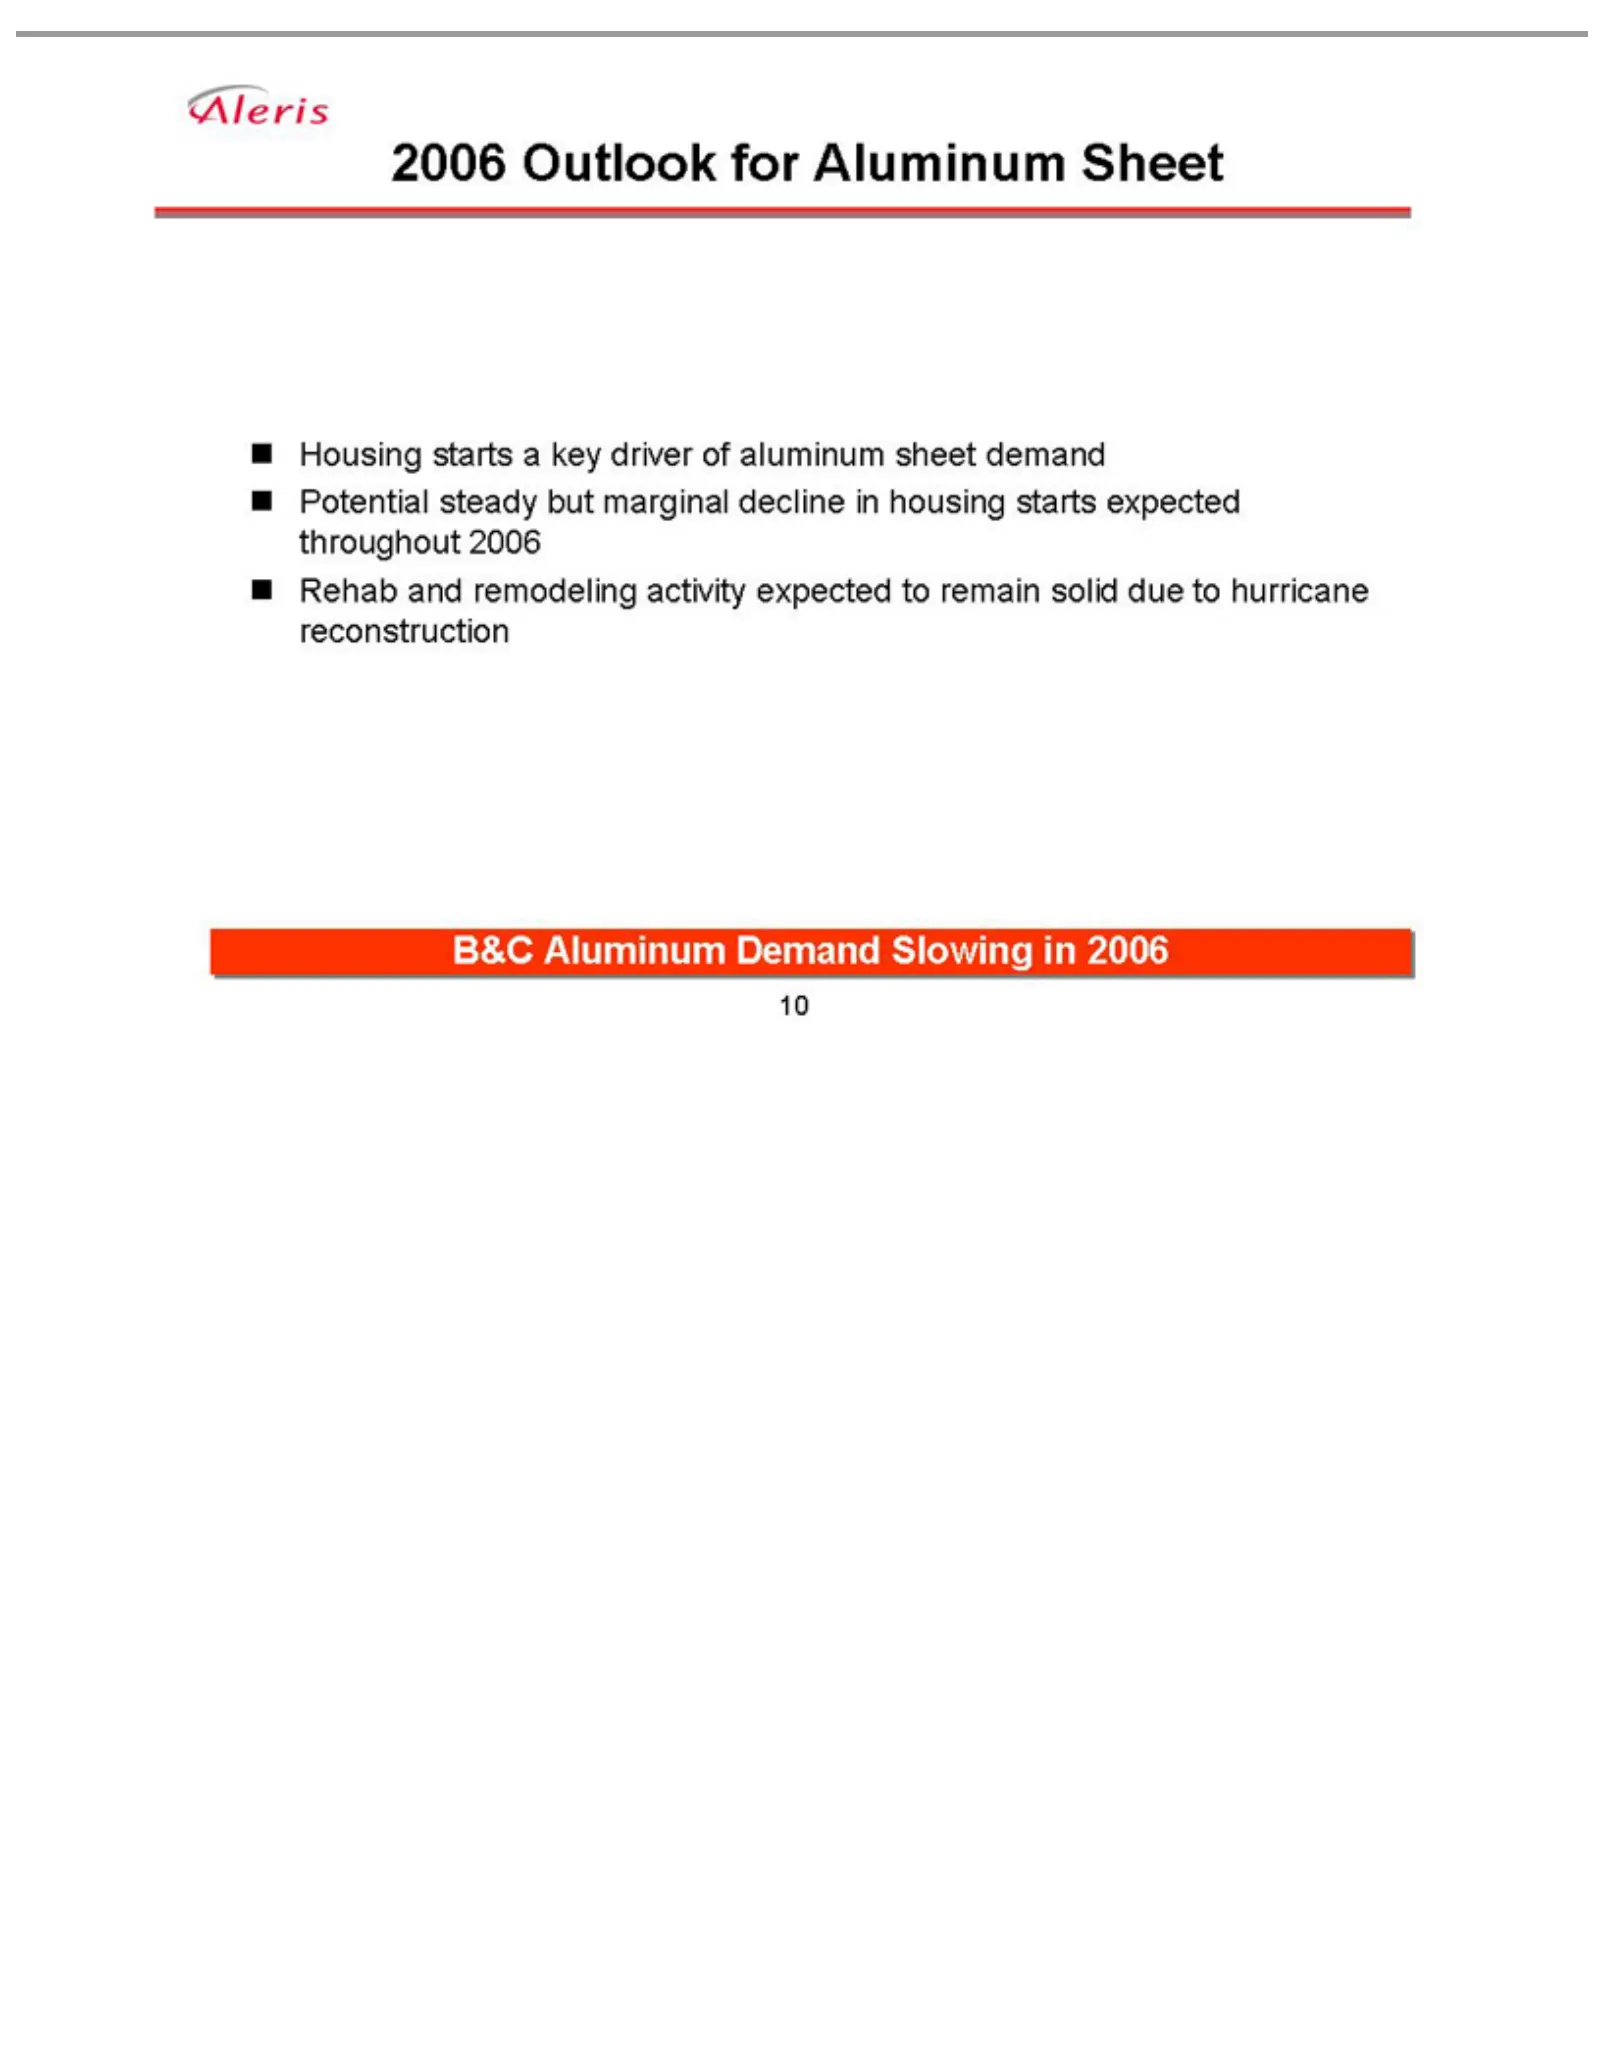
Slide 10: 2006 Outlook: Housing
2006 Outlook Housing Potential Rehab B&C 10 Aluminum andstarts steady remodeling for a but key Demand Aluminum marginal driver activity Slowing ofSheet decline aluminum expected in in 2006 housing to sheet remain demand starts solidexpected due to hurricane throughout reconstruction 2006
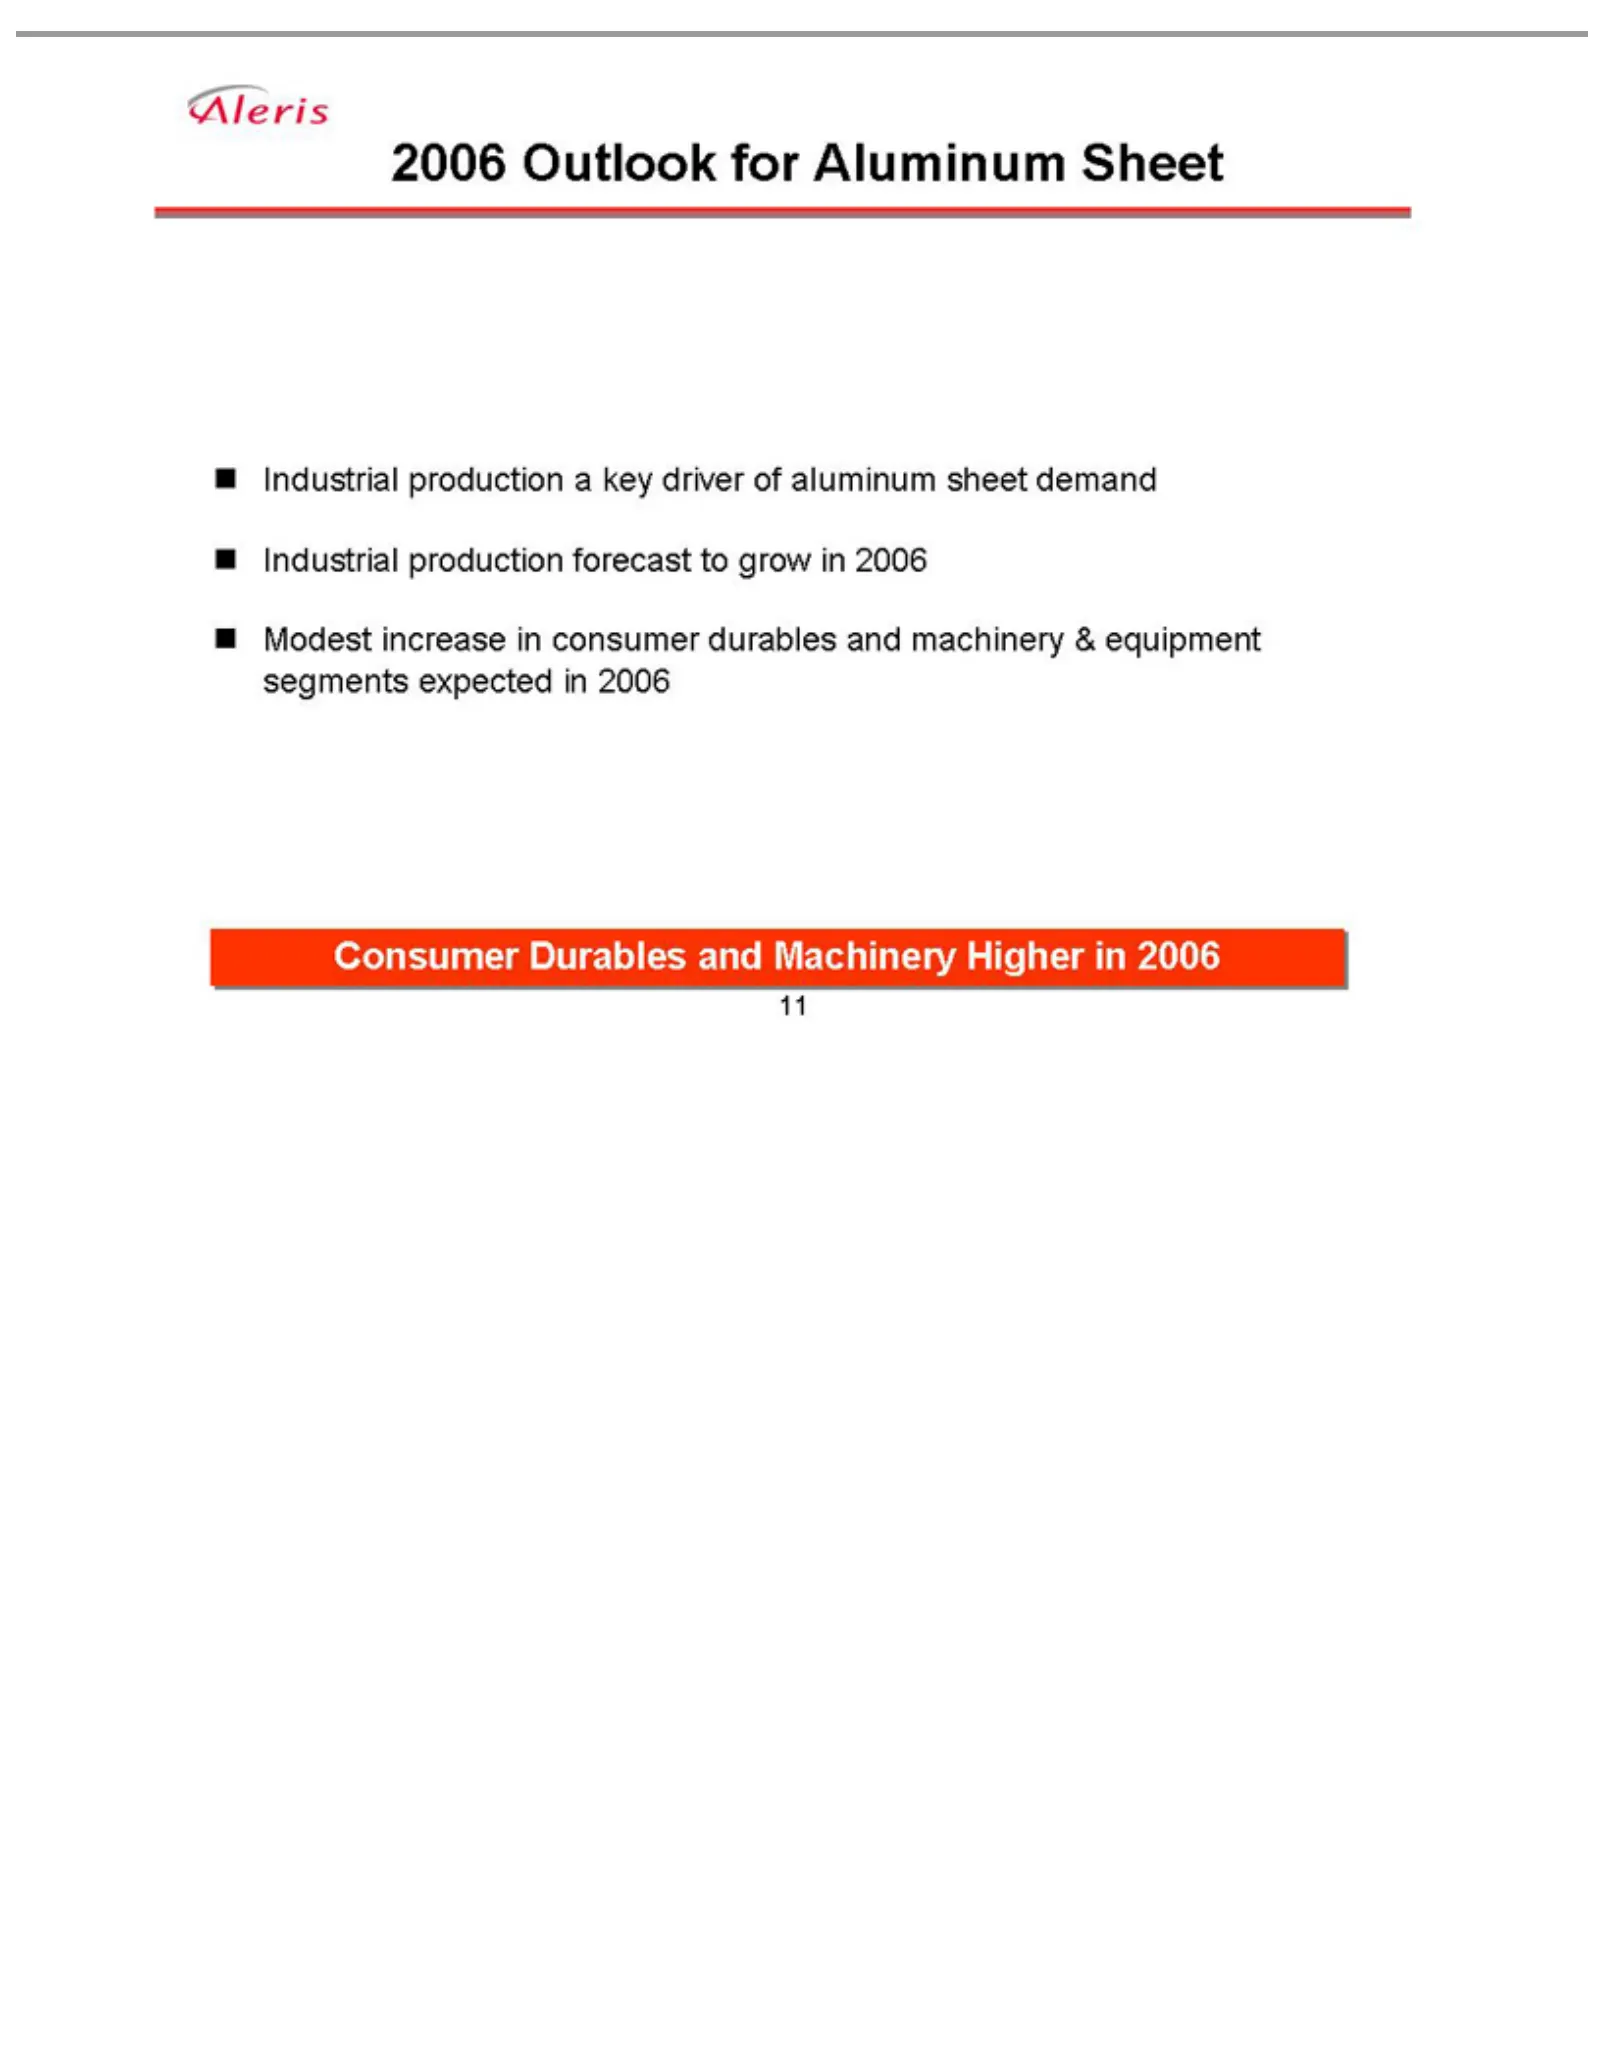
Slide 11: 2006 Outlook: Industrial
2006 Outlook Industrial Modest Consumer 11 increase production Durables forinAluminum consumer and a key forecast Machinery driver Sheet durables to grow ofHigher aluminum in and 2006 machinery in 2006 sheet demand & equipment segments expected in 2006
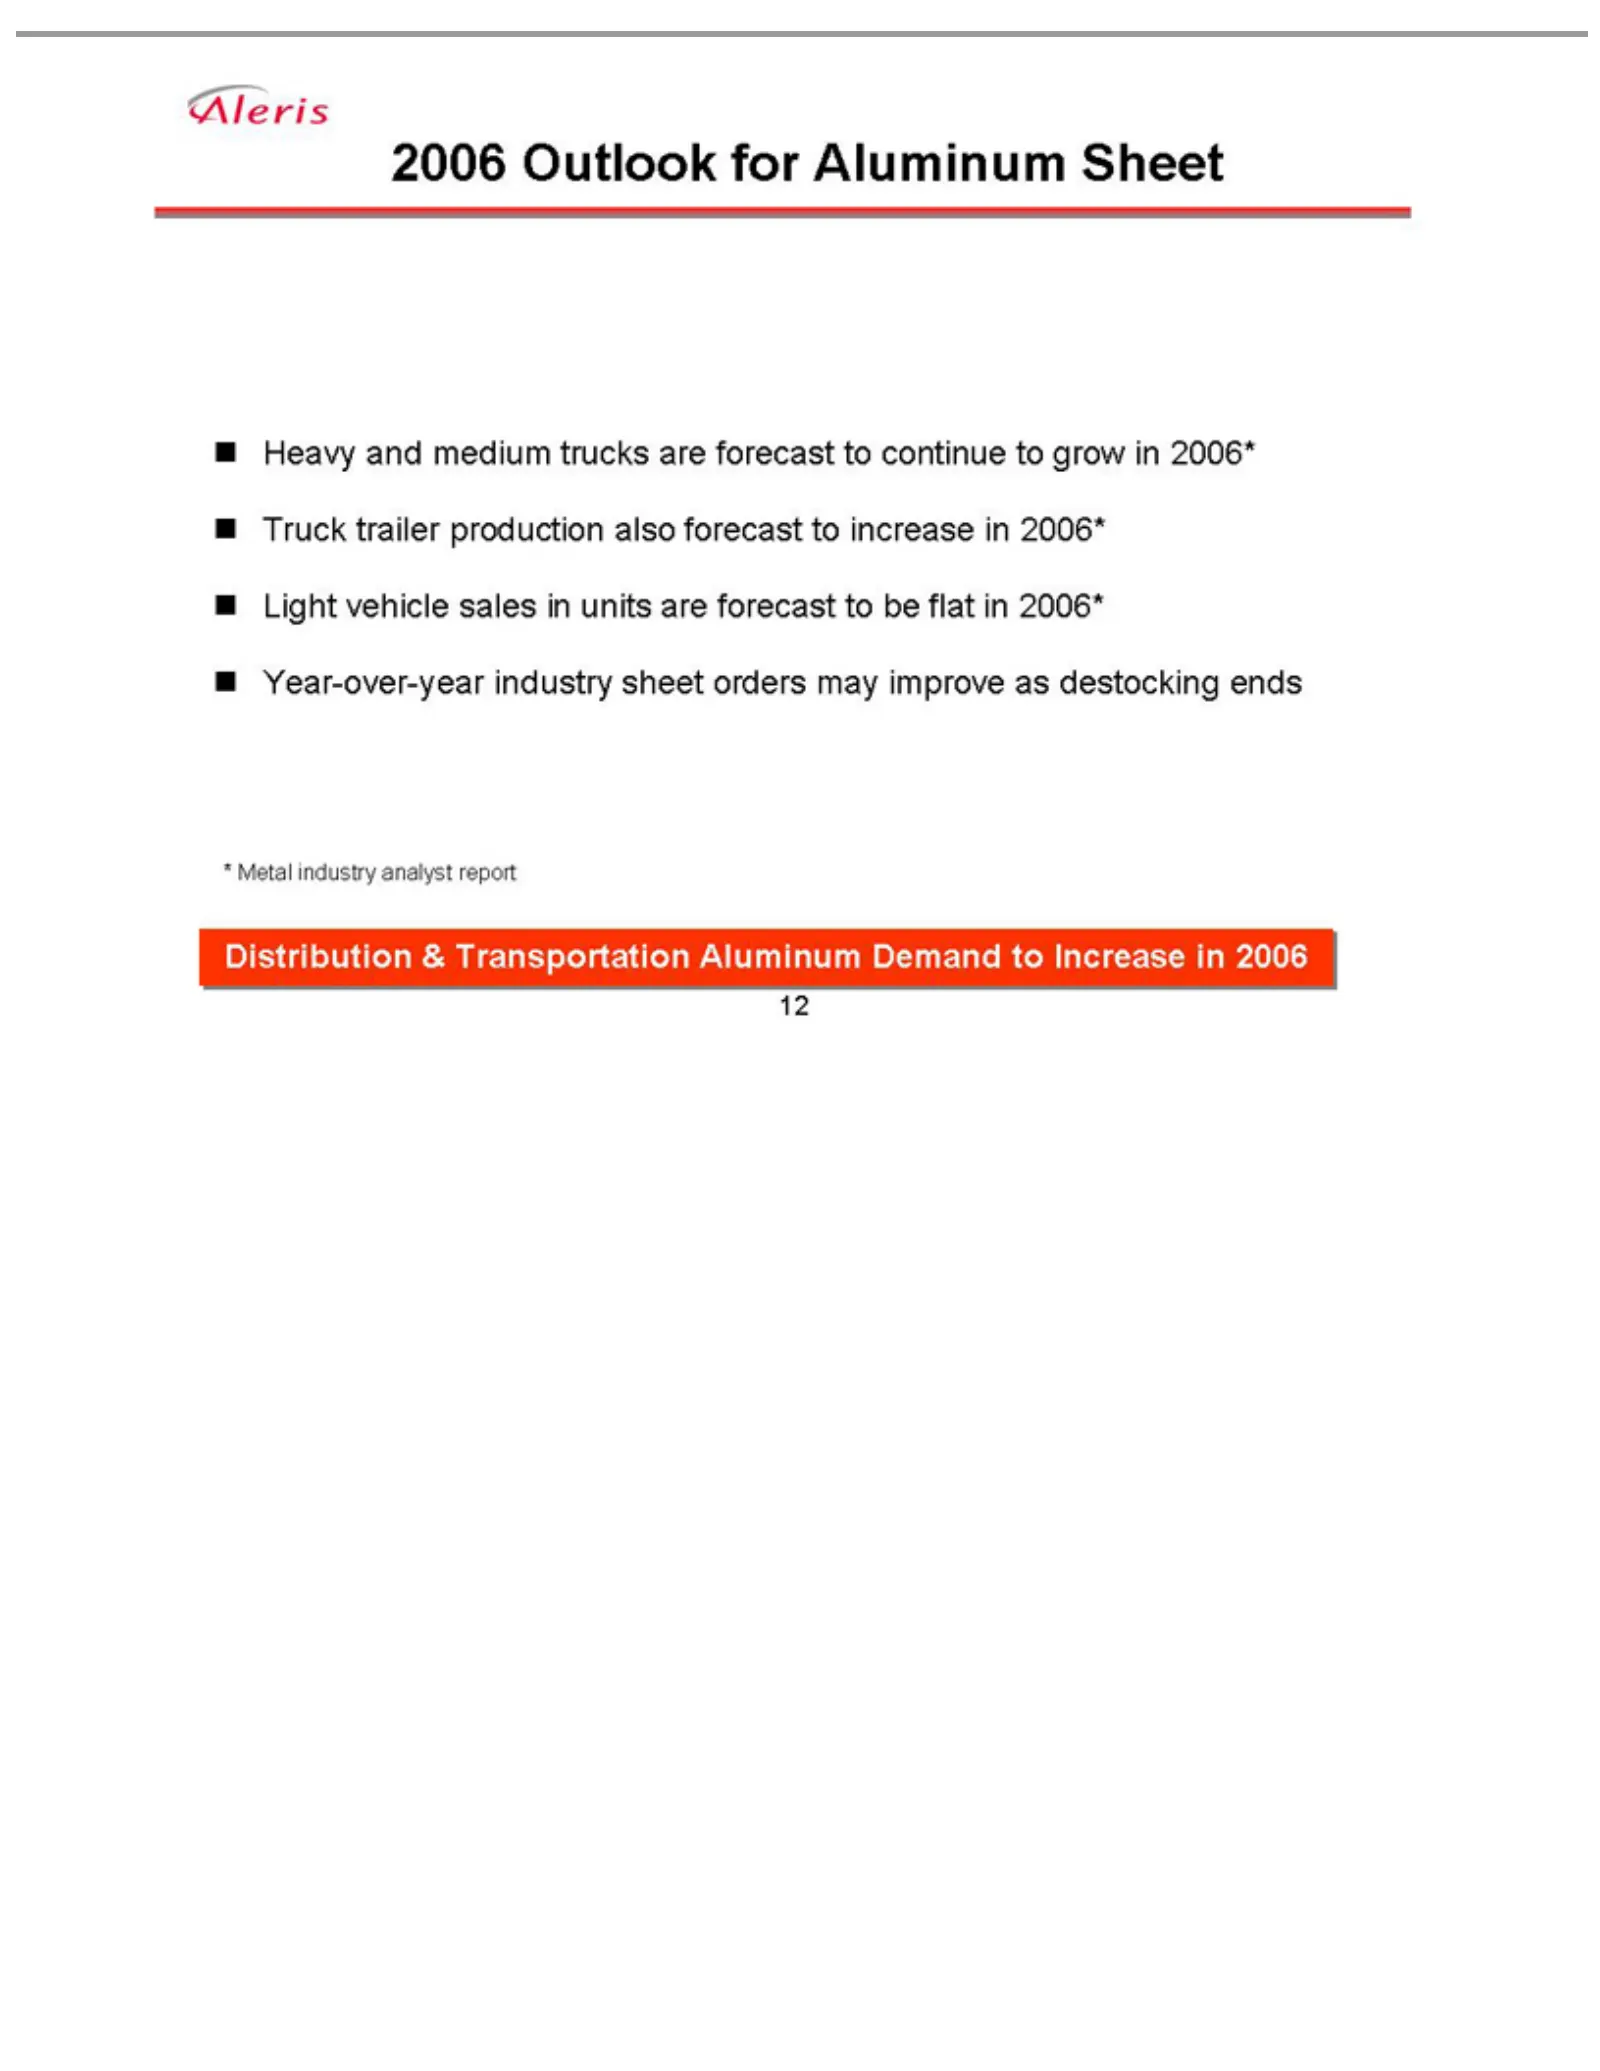
Slide 12: 2006 Outlook: Transportation
2006industry Heavy year * 12 Outlook and Metal medium Distribution &sheet for industry Aluminum orders trucks analyst may areSheet Transportation forecast report improvetoascontinue Aluminum destocking Demand grow ends in 2006* to Increase Truck trailer production also forecast to increase in 2006*
Slide 13: Mill-Distributor Supply Chain Issues
Mill-Distributor Why Inaccurate OPPORTUNITY Increasing Volatile Surges Surge 13 the &inmetal Purge focus demand demand inventories; values; on Environment Supply the sub-optimize forecasting; supply increases higher ChainHurts chain carrying Issues inventory working supplier Service (millcosts –prod
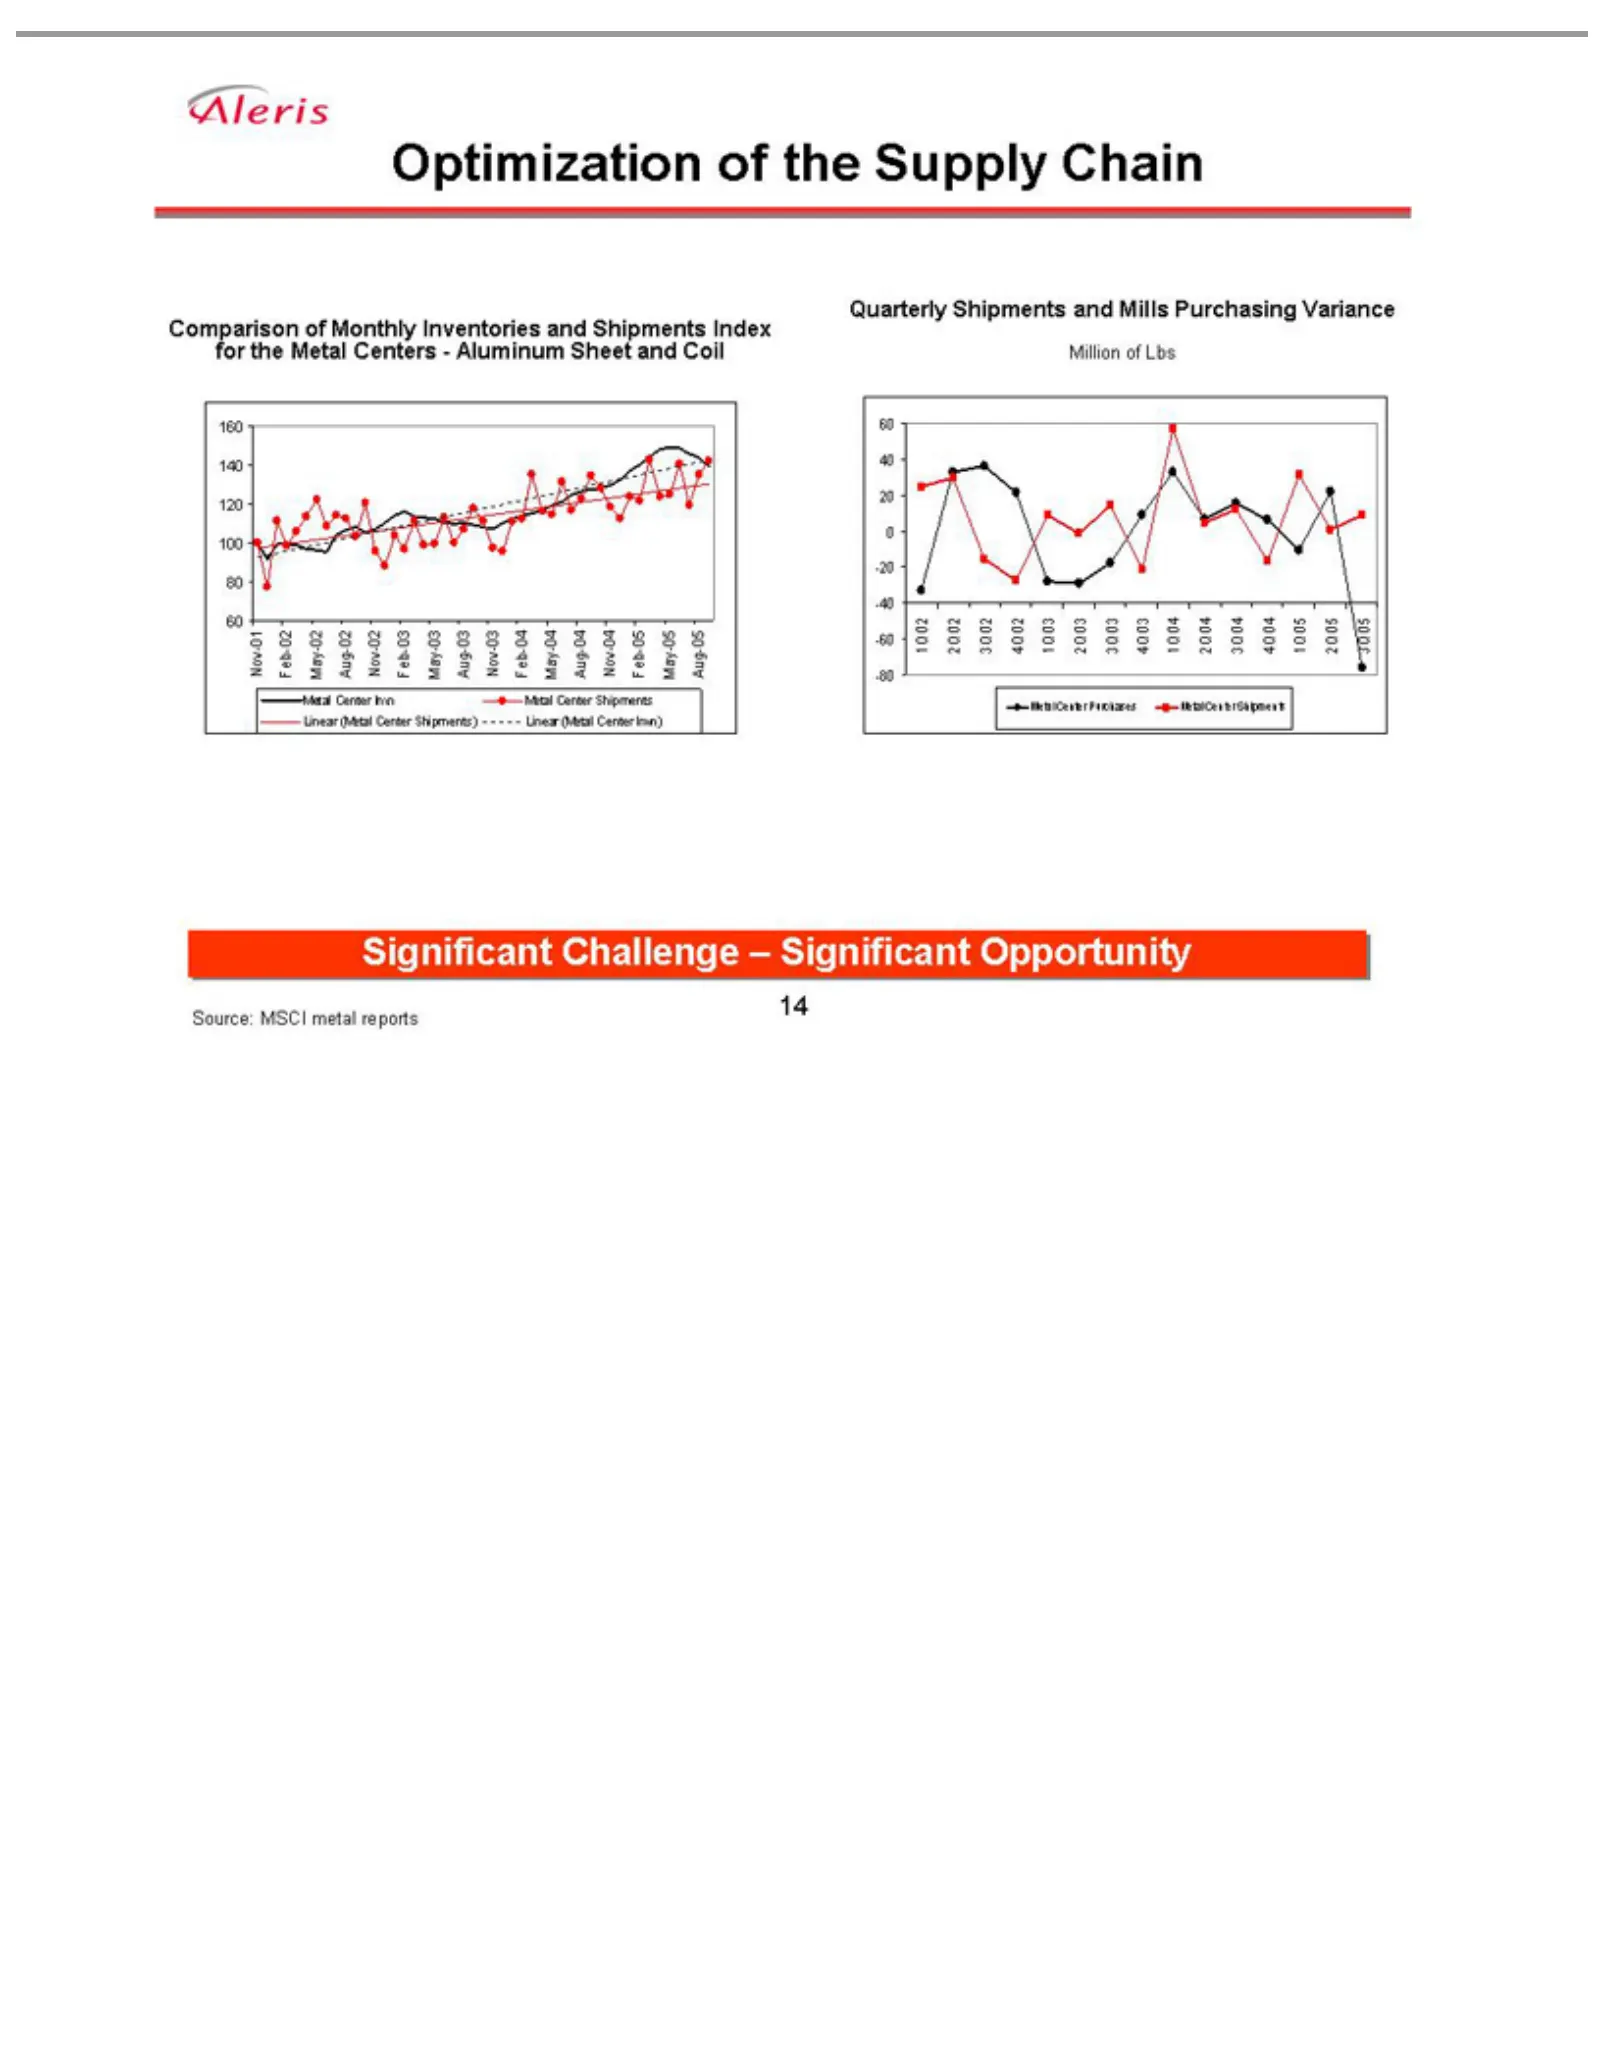
Slide 14: Optimization Opportunity: Metal Center Inventories and Shipments
Optimization Comparison 160 Nov-01 May-02 May-03 May-04 May-05 Linear Quarterly Million 60 1Q02 Metal Significant Source: 14 40140 2Q02 20 Center (Metal of MSCI Feb-02 Aug-02 Aug-03 Aug-04 Aug-05 120 0Shipments Lbs -20 Challenge 3Q02 of 100 Invn Purchases Shipments of Center metal -40 Monthly the No
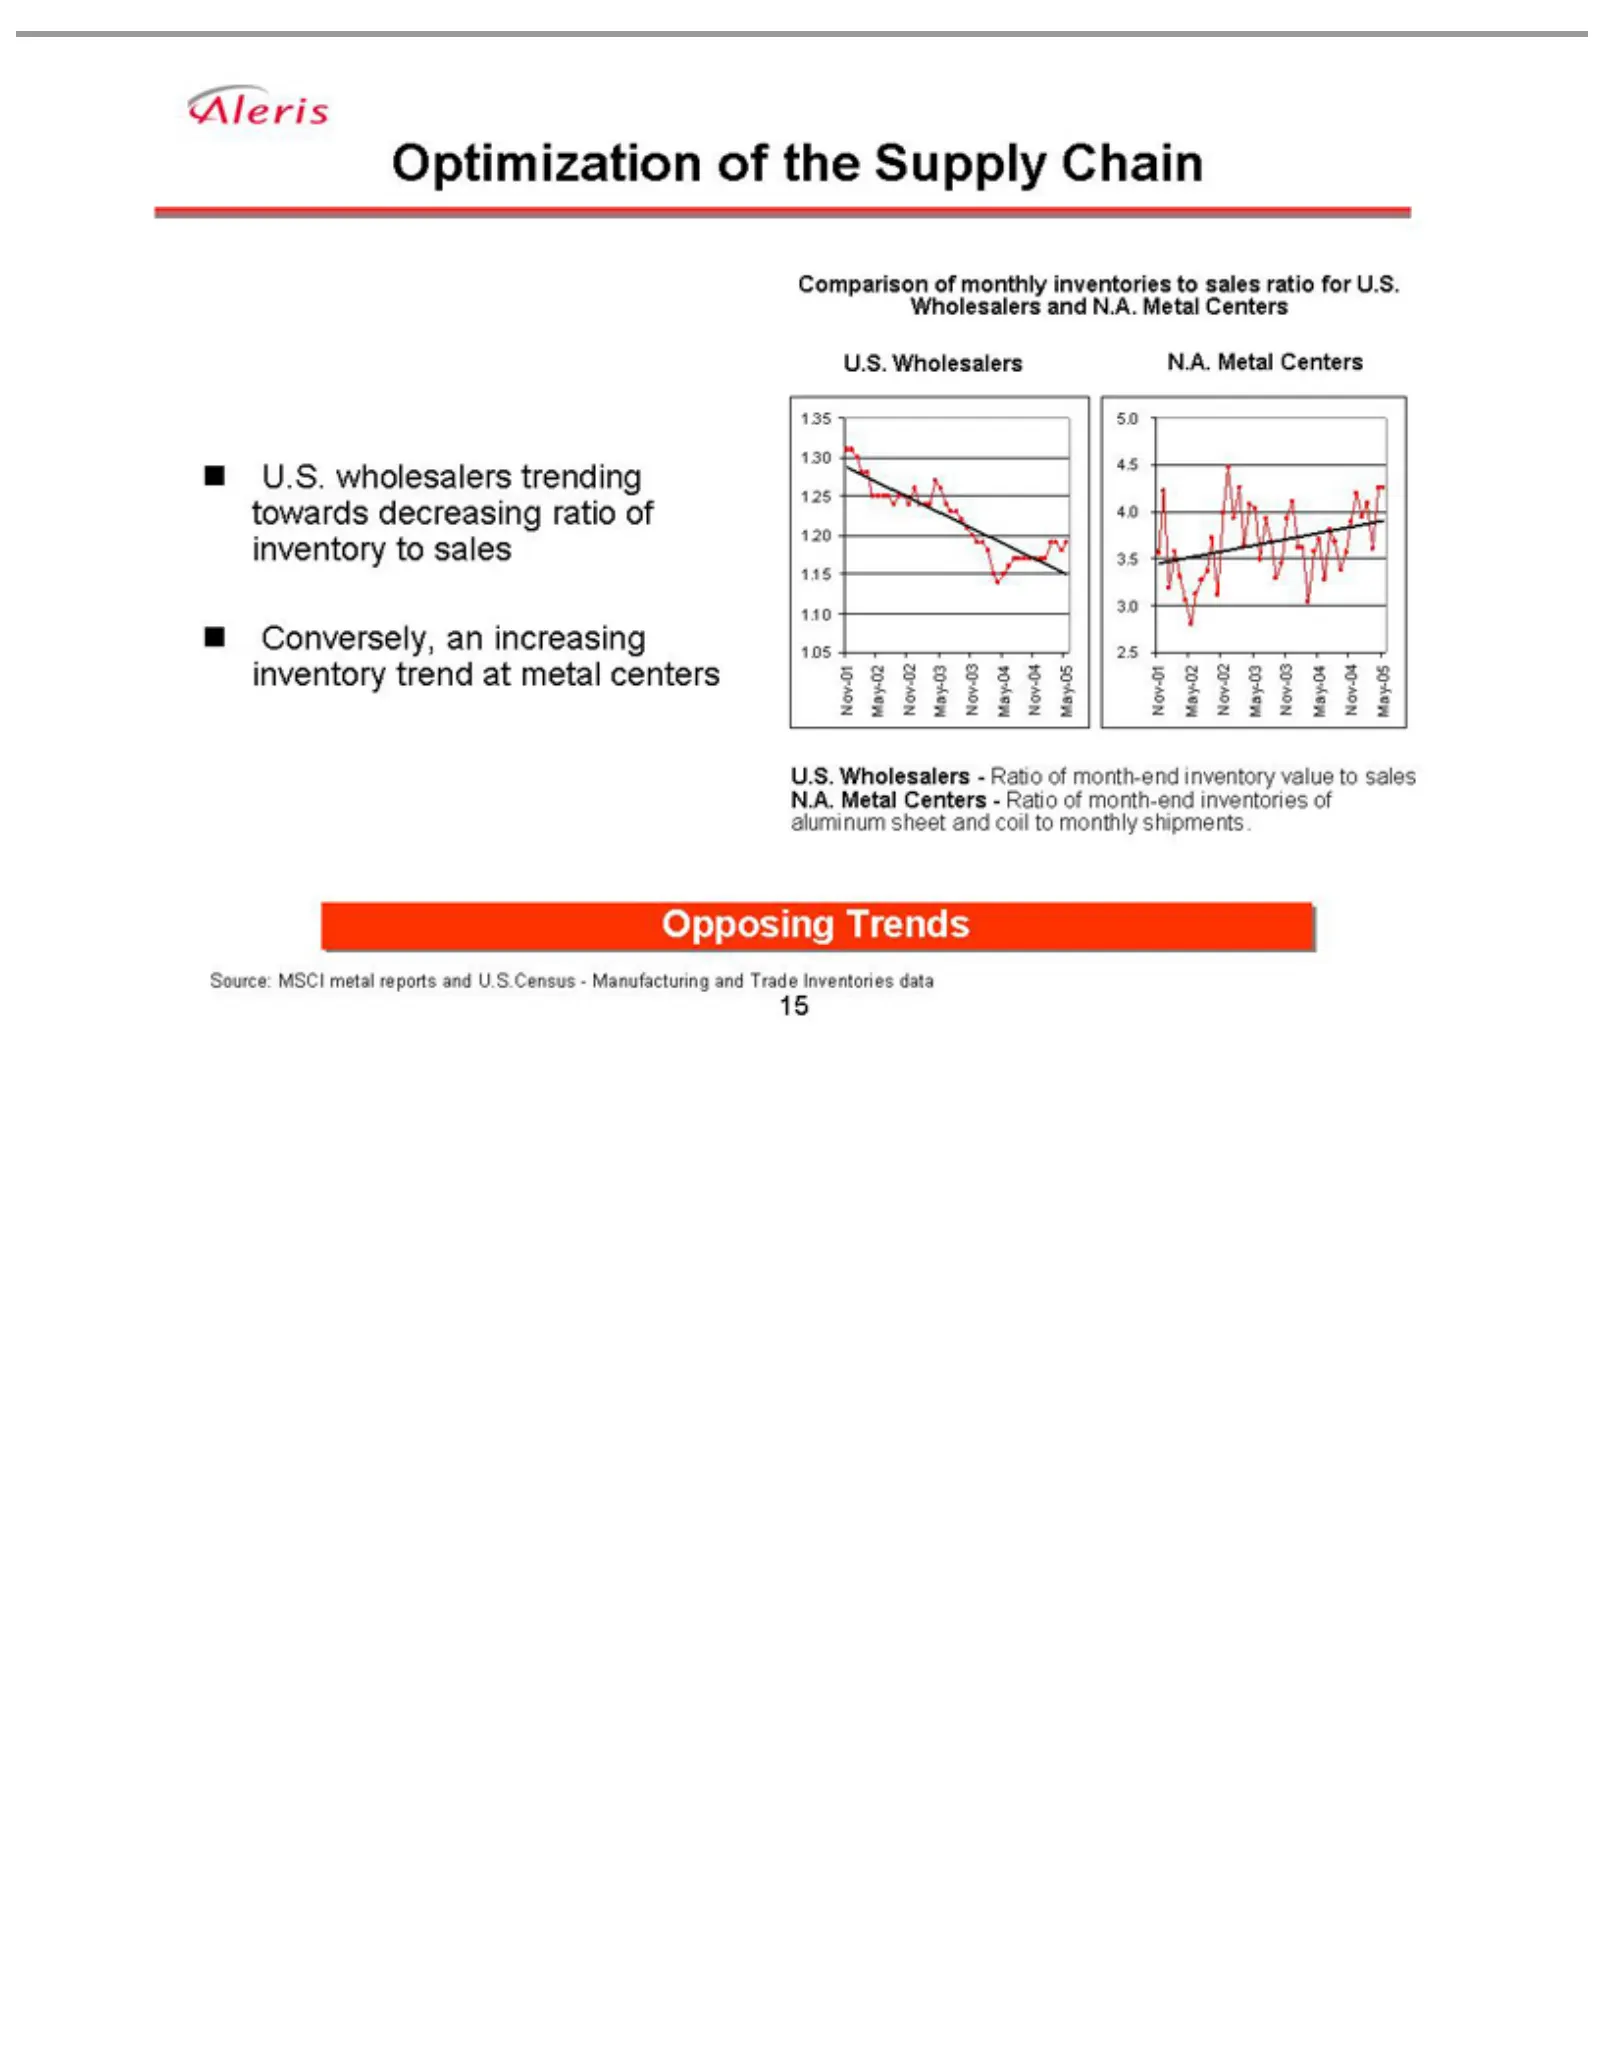
Slide 15: Optimization Opportunity: Inventory to Sales Ratio
Optimization Conversely, Comparison Wholesalers N.A. 1.35 Nov-03 5.0 Nov-01 May-03 May-04 U.S. May-05 Opposing Source: 15 4.5 1.30 Wholesalers Wholesalers—Ratio wholesalers Metal 4.0 MSCI May-04 May-02 Nov-03 Nov-04 1.25 Trends 3.5 Centers an of and ofmetal 1.20 3.0 increasing monthly the Nov-04 Nov
Slide 16: Examples of Supplier-Distributor Collaboration
Examplesdemand Technology Baseline Inventory Real-time Optimizing 16 availability and ofthe driven Supplier-Distributor continuously Flow using information of and recent Information manufacturing synchronized, sales sharing Collaboration volume and lead results planning and times near-term in (provi
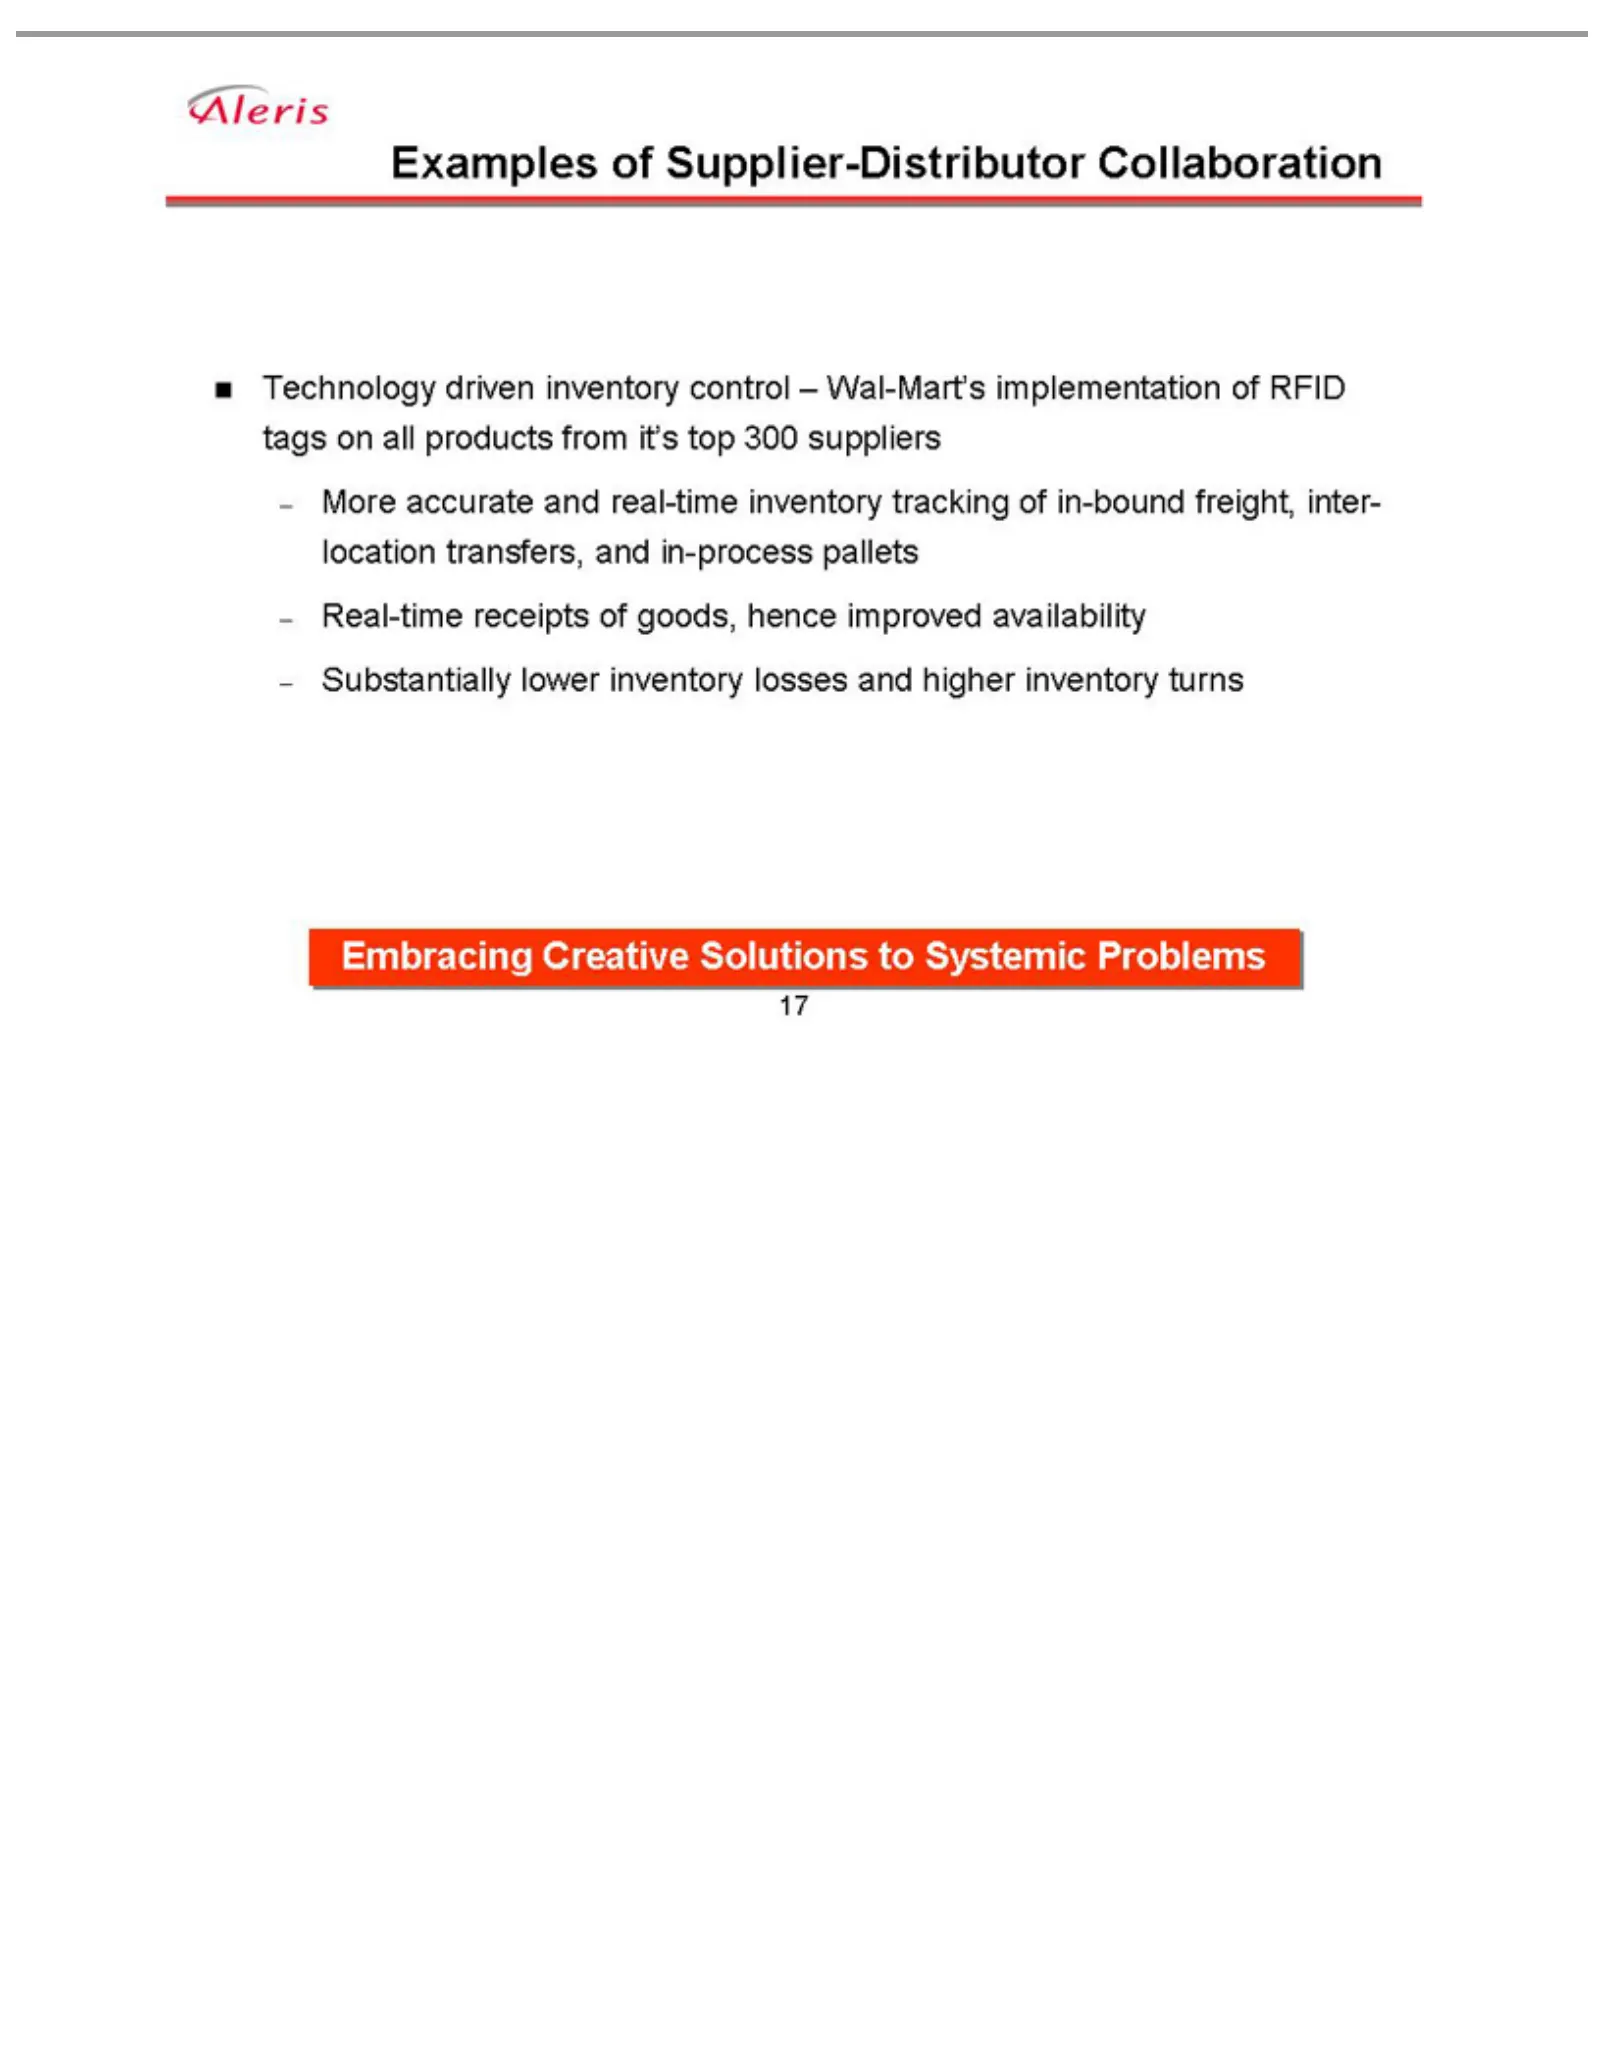
Slide 17: Examples of Supplier-Distributor Collaboration
Examples Technology More Real-time Substantially Embracing 17 accurate receipts ofCreative driven Supplier-Distributor lower and of real-time inventory inventory Solutions goods, hence inventory control losses to Systemic Collaboration improved and – tracking Wal-Mart’s higher Problems availability
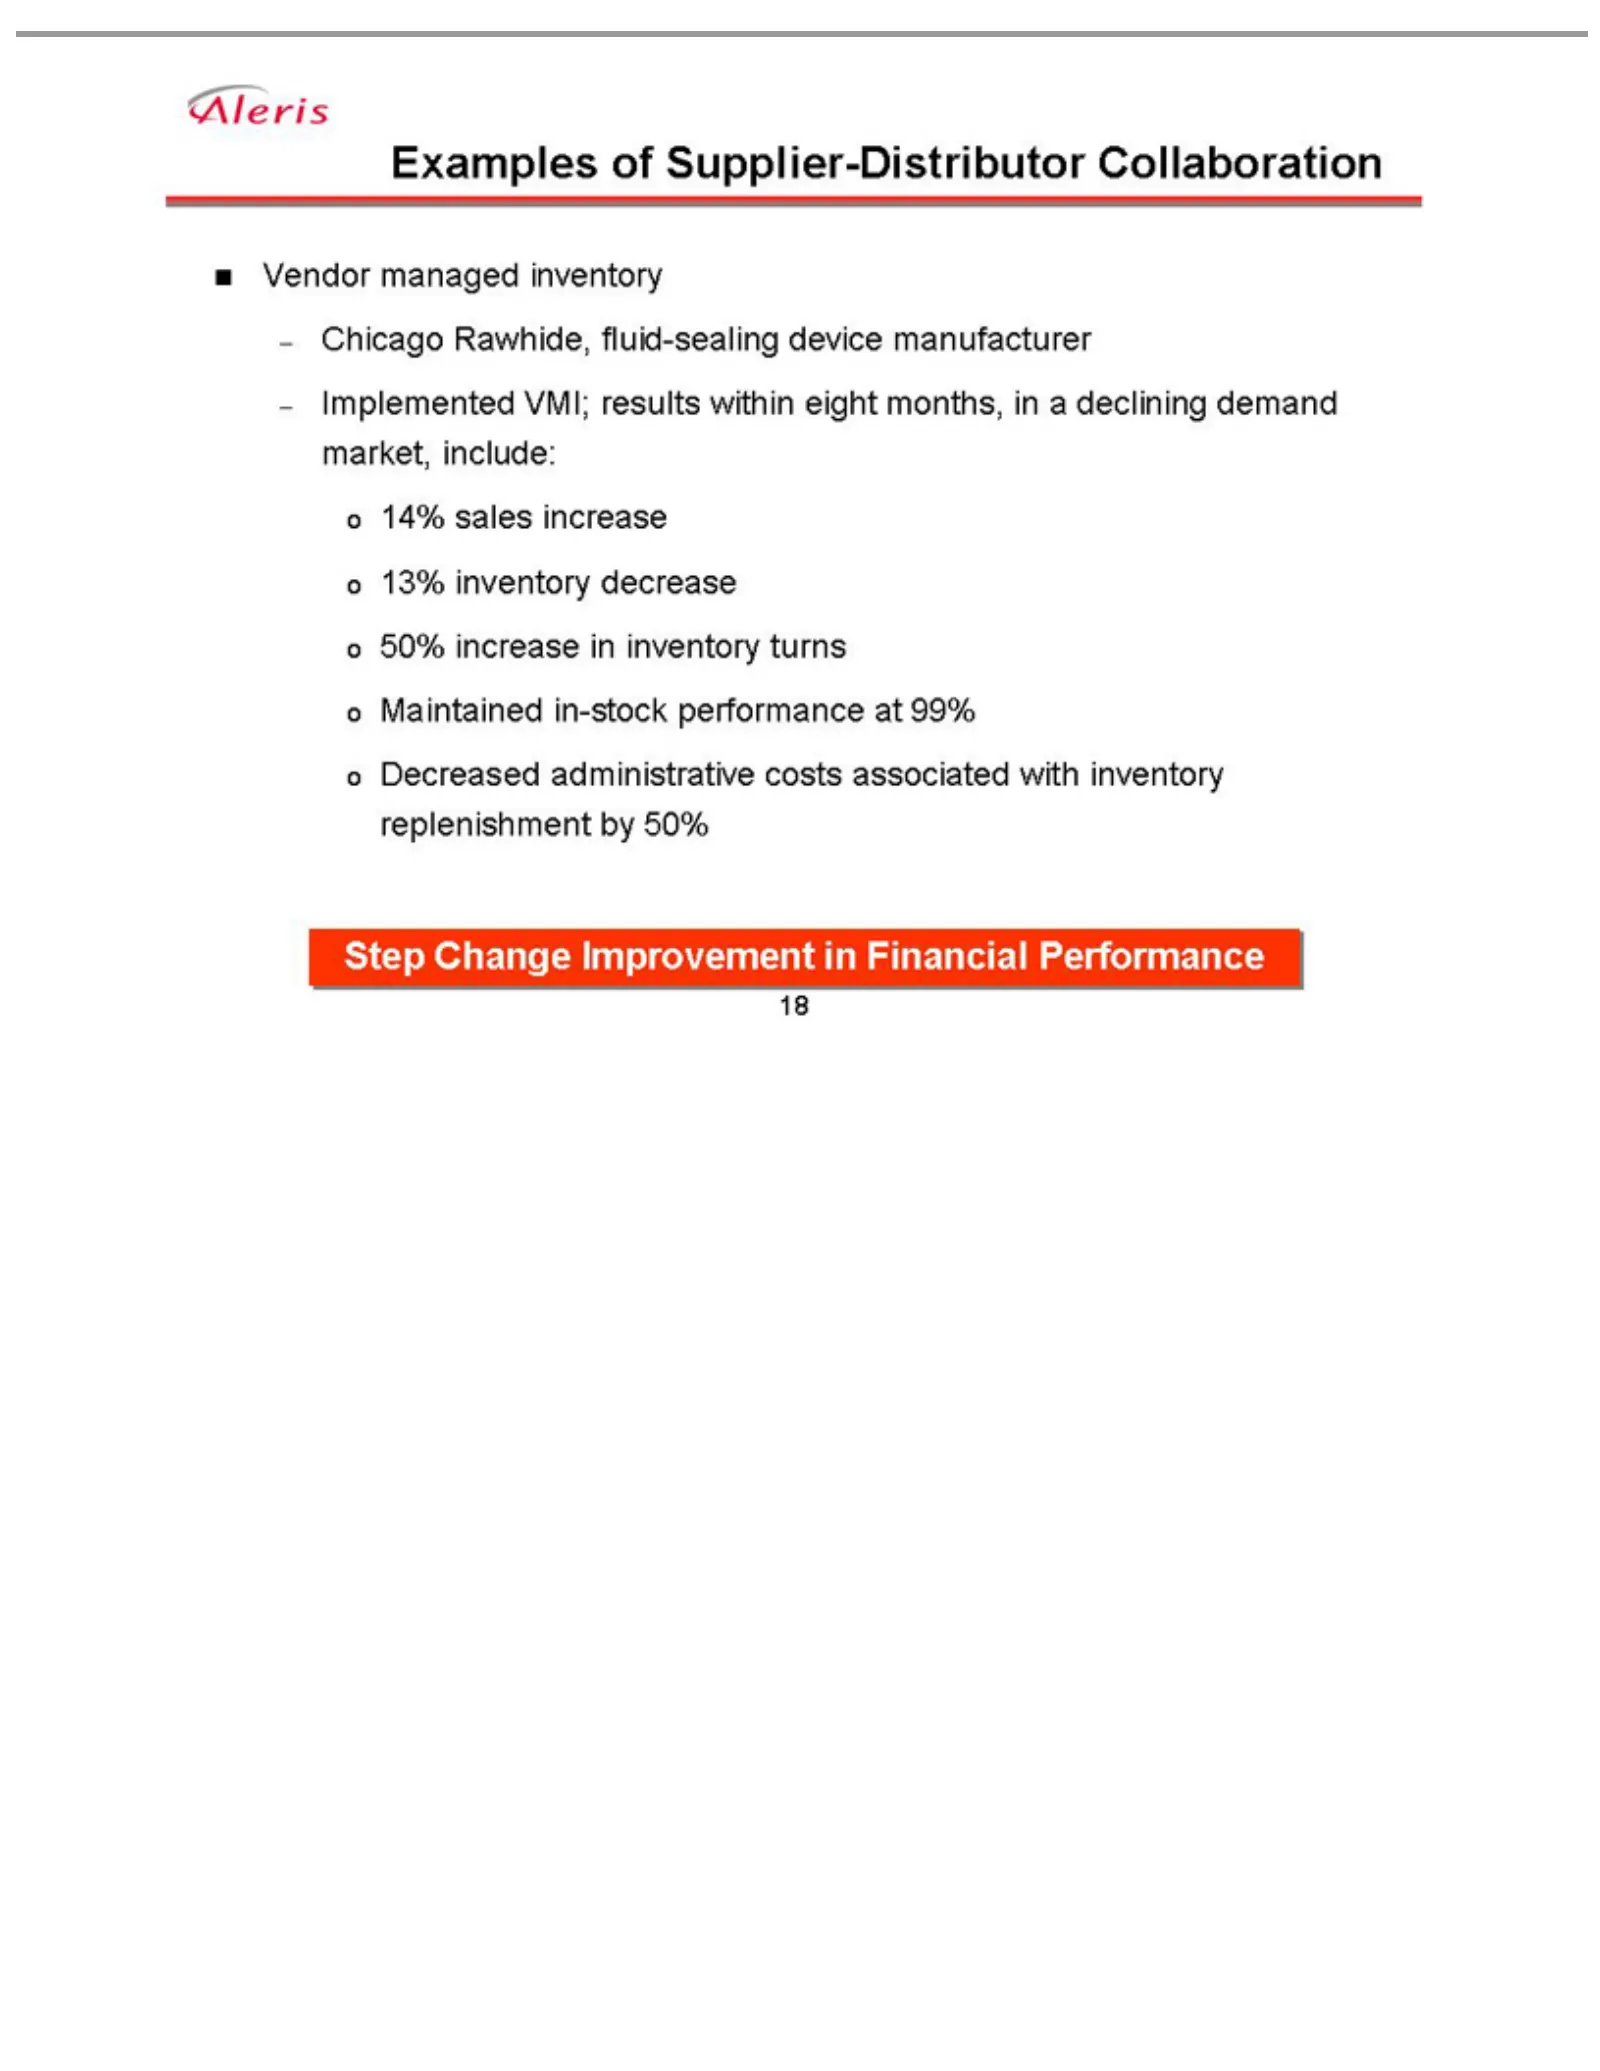
Slide 18: Examples of Supplier-Distributor Collaboration
Examples Vendor Chicago Implemented 14% Maintained Decreased Step 18 Change sales managed Rawhide, of increase administrative in-stock Supplier-Distributor Improvement VMI; inventory fluid-sealing 13% results performance inventory costs within in Financial associated device at Collaboration eight de
Slide 19: Possible Solution for Mills & Distributors
Possible Inventory Open Active Lead MSCI 19 time communications Data collaboration Solution reductions improvement Indicates for between through: Mills No between programs Turn & aDistributors Improvement mill a mill – and utilize anda distributor a“lean” distributor in Many tools on Years toinvento
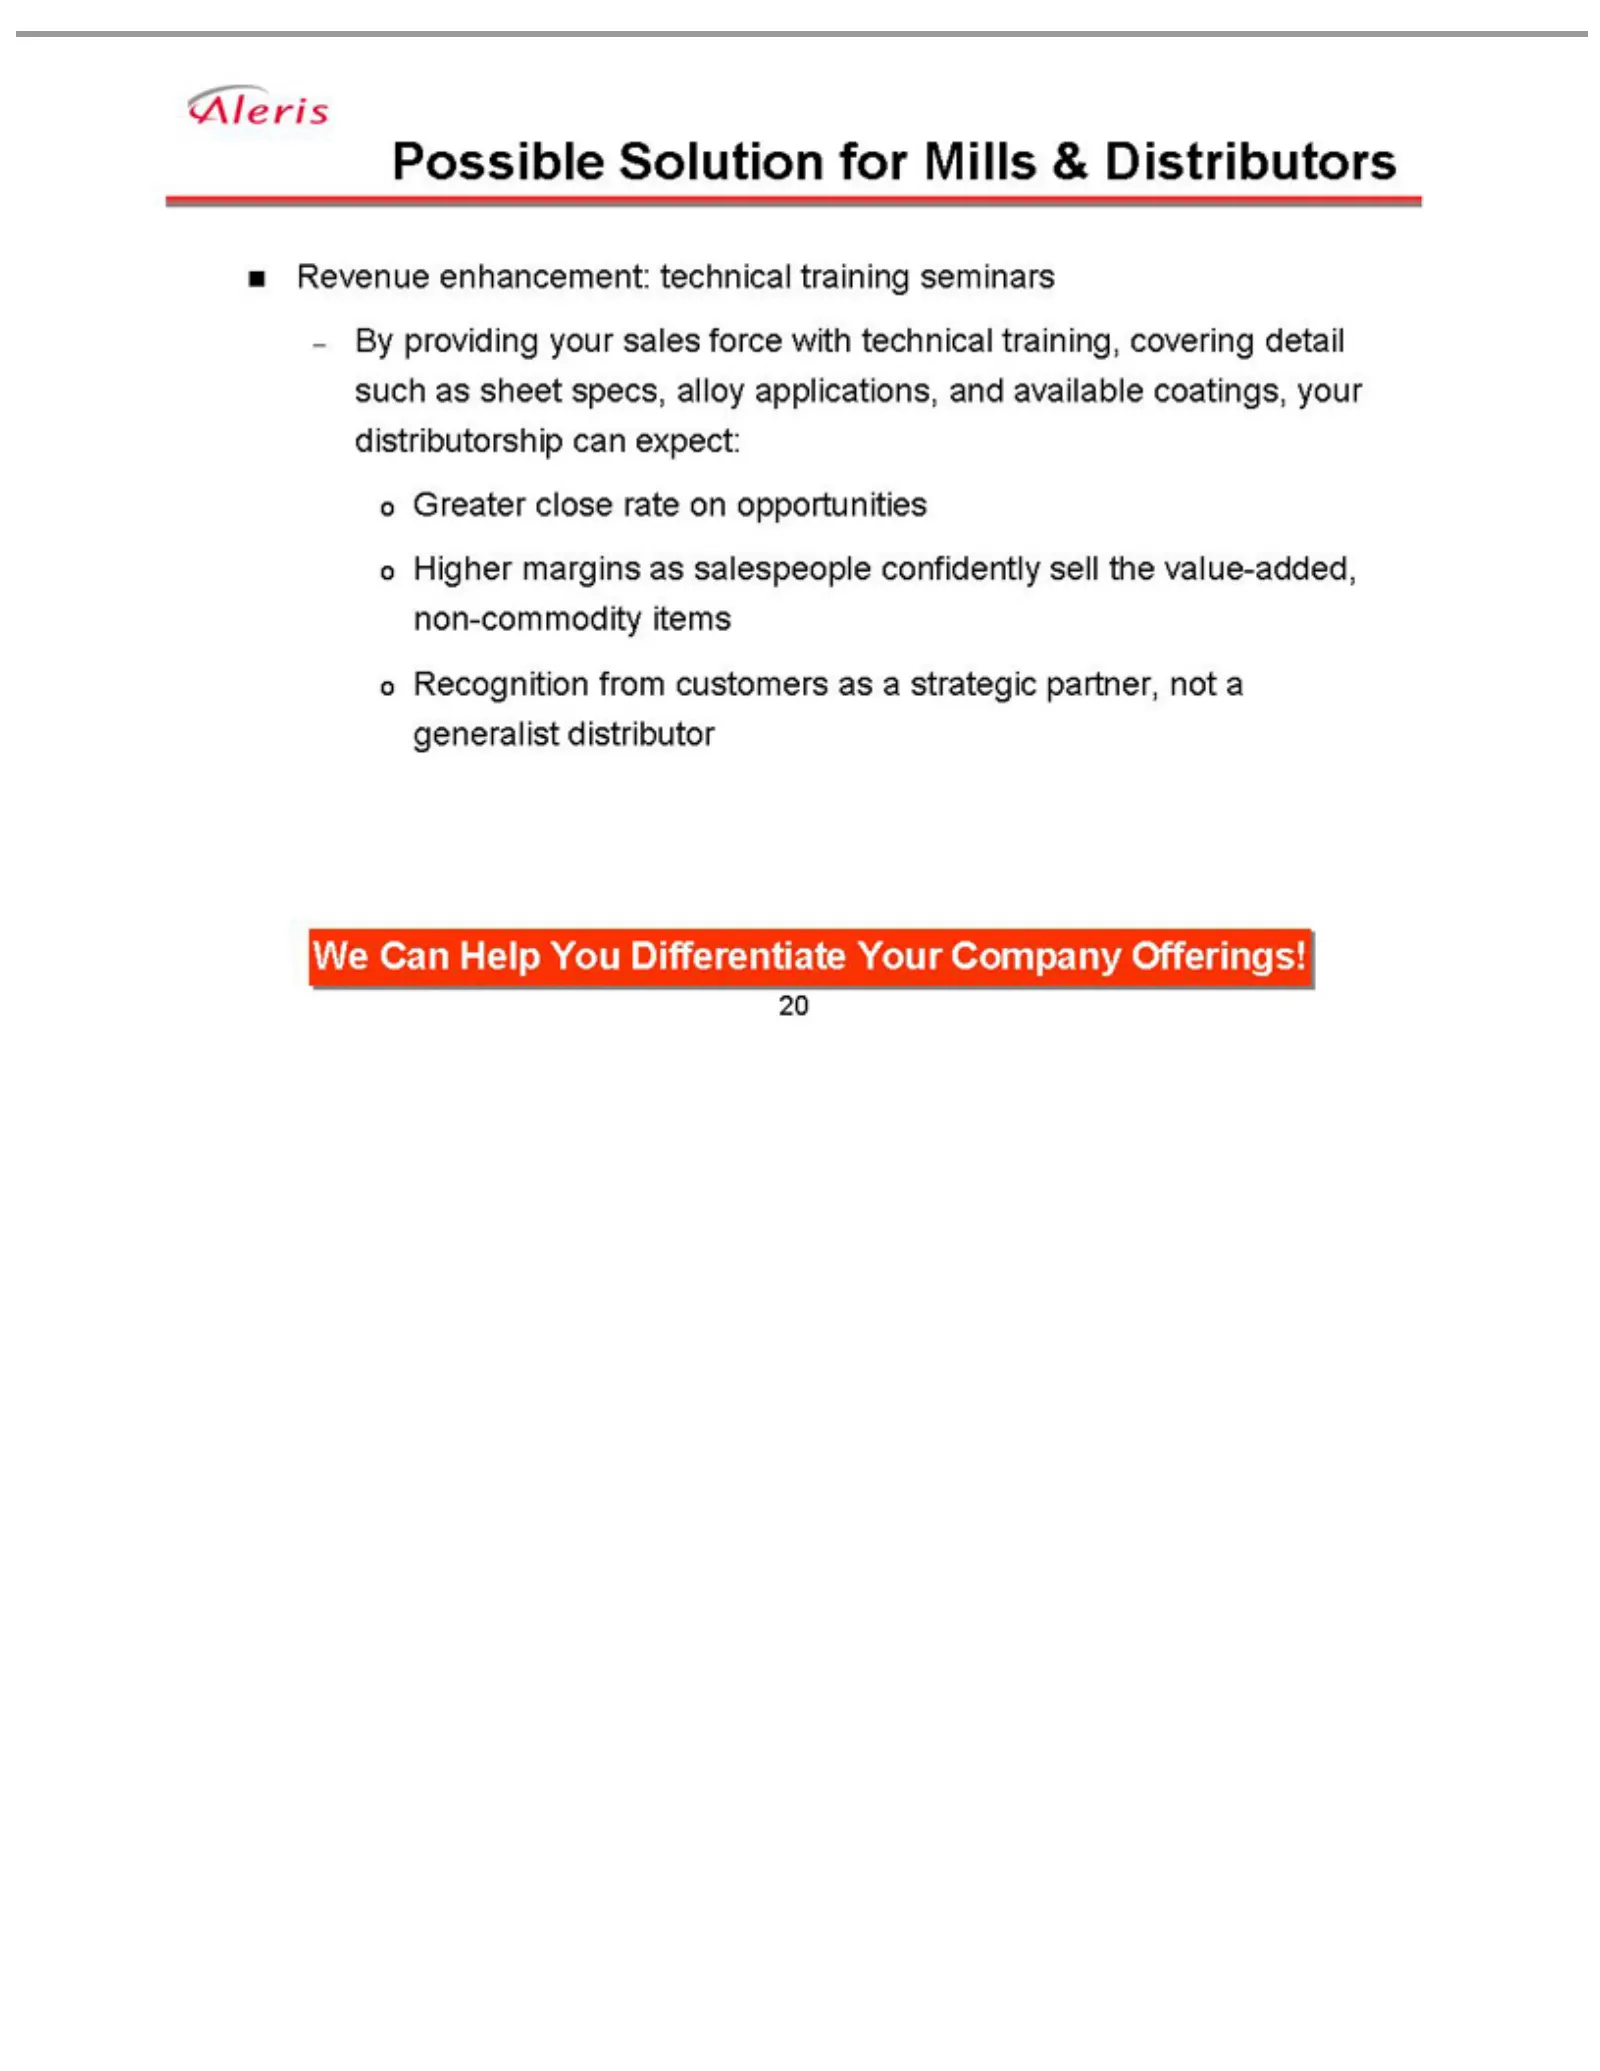
Slide 20: Possible Solution: Revenue Enhancement
Possible Revenue By Greater Higher We 20 providing Canmargins close Help Solution enhancement: rate your Youasfor on Differentiate salespeople sales opportunities Mills technical force & Distributors with confidently Your training technical Company seminars sell training, the Offerings! value-added,
Slide 21: Possible Solution: Revenue Enhancement
Possible Revenue Reinforces Encourages Portrays Does More 21 not Effective to Solution enhancement: require the theexisting customer Selling customer afor passport Mills of product joint ato Aluminum’s strong &and think sales Distributors knowledge time supply more calls zone Attributes with creativ
Slide 22: Possible Solution: Inventory Efficiency and Productivity
Possible Revenue Inventory White Efficiency 22 papers Solution enhancement: availability, Leads and to for technical Productivity Mills metal increased & bulletins values, Distributors service ordering, are always and product production up to date support status, and immediately intransit tracking;
Slide 23: Summary and Thank You
We are Summary The Thank 23 prospects You excited forfor Your about a continued Continued the futurepositive Support of Aleris economic ofInternational Aleris!environment are encouraging Together with our MSCI customers, we are enthusiastic about the opportunities to create unique value
Source: SEC EDGAR · 8-K filed Nov 17, 2005
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
 Investor Presentation (October 2007)14 slides · Oct 3, 2007