Aleris International — Investor Day (May 2005)
50 slides from Aleris International's investor day presentation, May 25, 2005
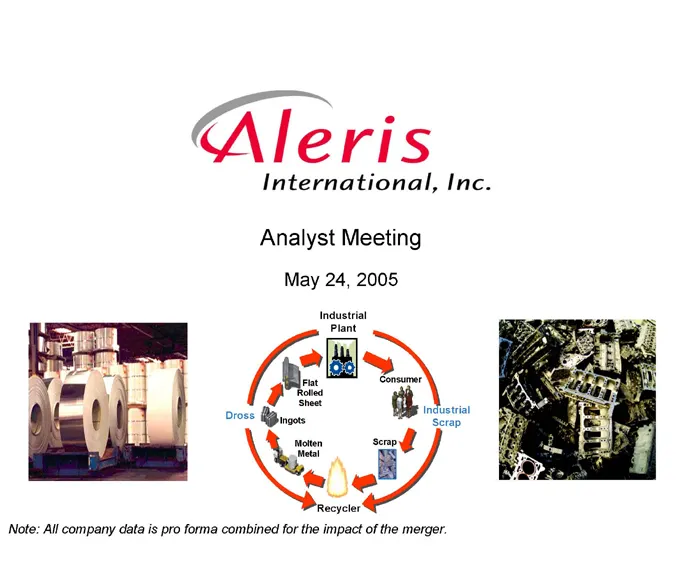
Slide 1: Analyst Meeting
Analyst Meeting May 24, 2005 Industrial Plant Consumer Industrial Scrap Scrap Recycler Molten Metal Dross Ingots Flat Rolled Sheet Note: All company data is pro forma combined for the impact of the merger.
Slide 2: Safe Harbor
Safe Harbor Statements contained in this presentation that state the company’s or its management’s expectations or predictions of the future are forward-looking statements intended to be covered by the safe harbor provisions of the Securities Act of 1933 and the Securities Exchange Act of 1934. The
Slide 3: Merger Overview
Merger Overview
Slide 4: The Merger
The Merger December 9, 2004 Revenue: $2.4 Billion (1) Headquarters: Beachwood, OH NYSE Symbol: ARS (1) 1Q05 LTM pro forma
Slide 5: A New Beginning
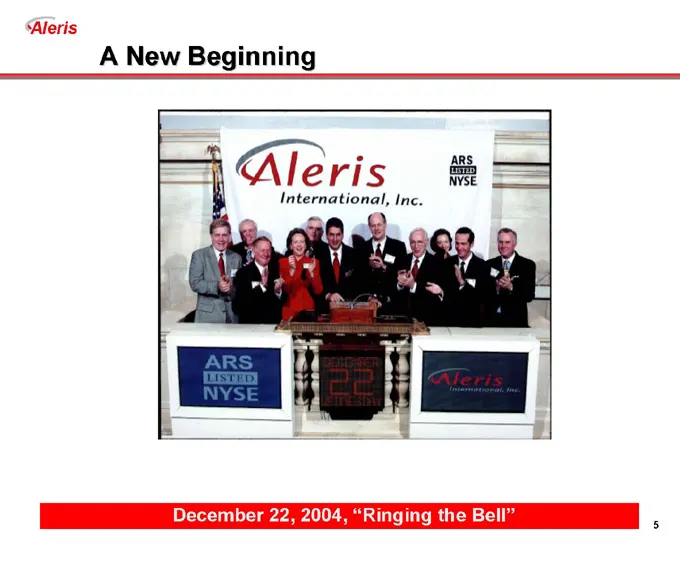
A New Beginning December 22, 2004, “Ringing the Bell”
Slide 6: Merger Rationale
Merger Rationale Streamlines cost structure; creates value through synergies Leverages core competencies; transfers best practices Enhances metal sourcing capabilities Improves competitive position through scale and scope Strengthens management; enables productivity improvement Improves access to ca
Slide 7: Initial Strategy
Initial Strategy Relentless Productivity Improvement Implement Six Sigma culture to transform manufacturing productivity Exploit combined melting and processing technologies to lower cost Utilize scrap sourcing capabilities to reduce purchased metal cost Extend low-cost continuous cast production to
Slide 8: Acquisition Criteria
Acquisition Criteria Focus on core rolled product and recycling businesses; exploit capabilities Diversify end-uses within rolled products and recycling Geographic expansion in faster growing economies of Eastern Europe, South America, Asia and China Upgrade management talent Target greater than 15%
Slide 9: Mission Statement
Mission Statement To become a leading global provider of scrap-based aluminum and zinc products and services focused on generating the highest level of quality and productivity to exceed stakeholder expectations Focus on providing outstanding value to customers through delivery performance, quality,
Slide 10: Organizational Overview
Organizational Overview
Slide 11: Management Team
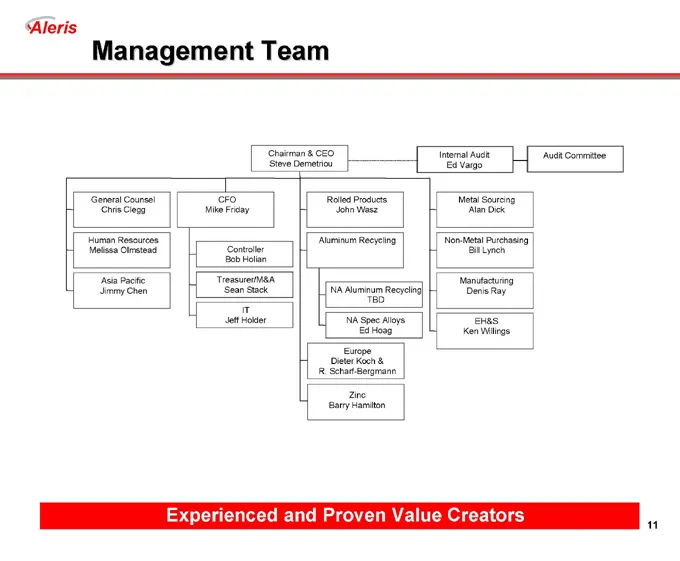
Management Team Chairman & CEO Steve Demetriou Internal Audit Ed Vargo Audit Committee General Counsel Chris Clegg Human Resources Melissa Olmstead Asia Pacific Jimmy Chen CFO Mike Friday Controller Bob Holian Treasurer/M&A Sean Stack IT Jeff Holder Rolled Products John Wasz Aluminum Recycling NA Al
Slide 12: Culture and Key Values
Culture and Key Values Sense of urgency - solve today’s problems today Data driven; clearly defined measures No bureaucracy Minimum layers in organization Relentless drive to be more productive in all we do Unquestionable integrity Global/international Recognize great performance Culture Change Unde
Slide 13: Successful Aleris Leader
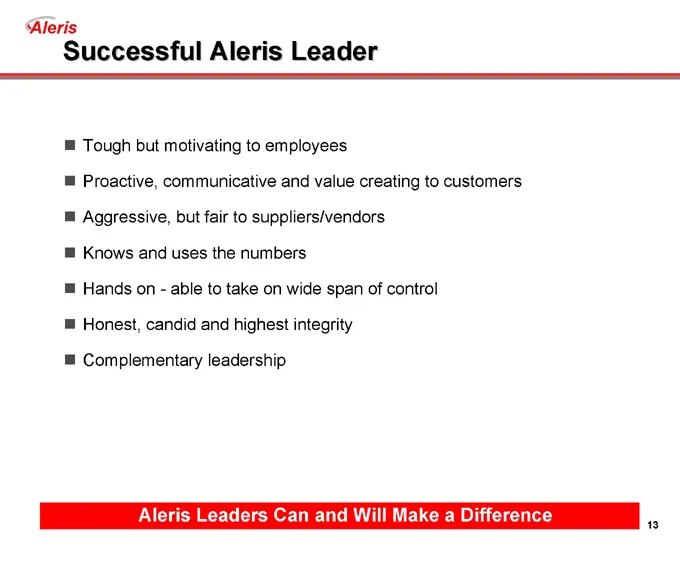
Successful Aleris Leader Tough but motivating to employees Proactive, communicative and value creating to customers Aggressive, but fair to suppliers/vendors Knows and uses the numbers Hands on - able to take on wide span of control Honest, candid and highest integrity Complementary leadership Aleri
Slide 14: Aleris Transformation
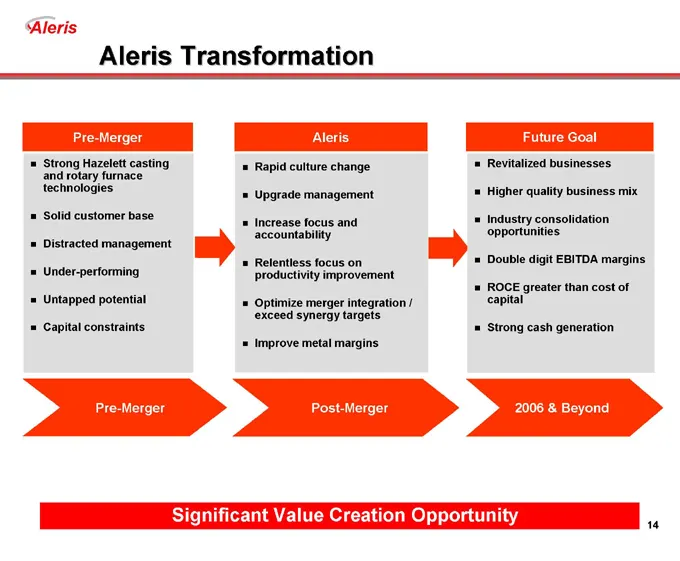
Aleris Transformation Pre-Merger Strong Hazelett casting and rotary furnace technologies Solid customer base Distracted management Under-performing Untapped potential Capital constraints Aleris Rapid culture change Upgrade management Increase focus and accountability Relentless focus on productivity
Slide 15: Company Overview
Company Overview
Slide 16: Business Overview
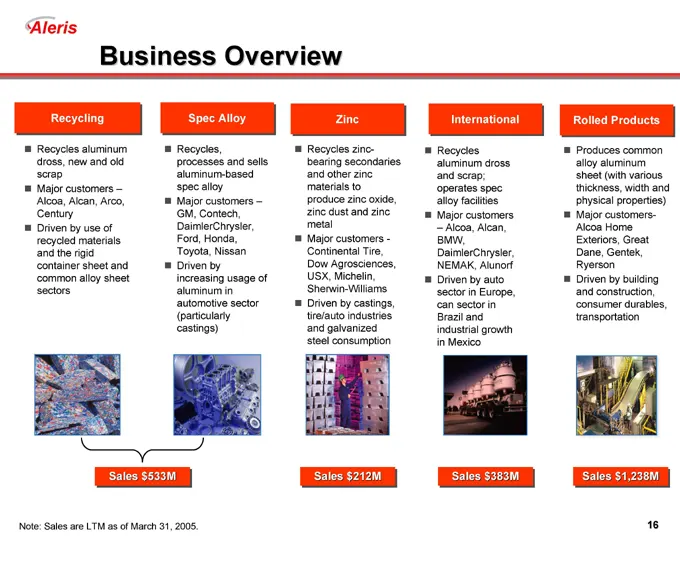
Business Overview Recycling Recycles aluminum dross, new and old scrap Major customers – Alcoa, Alcan, Arco, Century Driven by use of recycled materials and the rigid container sheet and common alloy sheet sectors Spec Alloy Recycles, processes and sells aluminum-based spec alloy Major customers – G
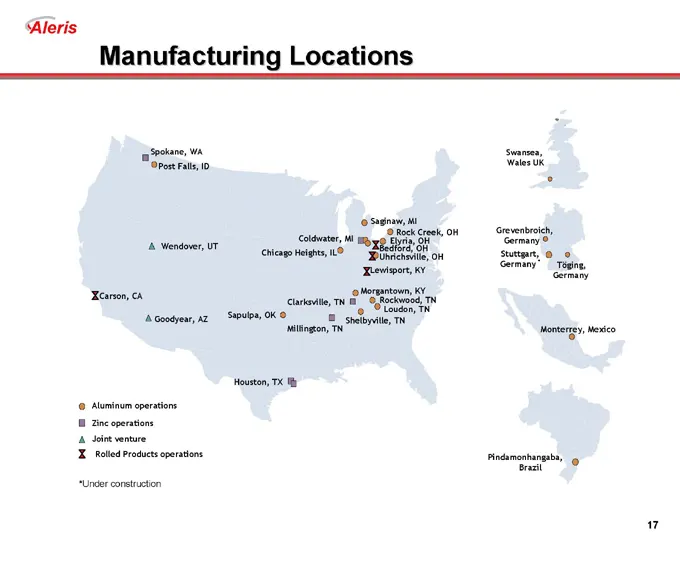
Slide 17: Manufacturing
Manufacturing Locations Spokane, WA Post Falls, ID Wendover, UT Carson, CA Goodyear, AZ Swansea, Wales UK Grevenbroich, Germany Stuttgart, Germany * Töging, Germany Monterrey, Mexico Sapulpa, OK Chicago Heights, IL Coldwater, MI Saginaw, MI Houston, TX Aluminum operations Zinc operations Joint ventu
Slide 18: Key Highlights
Key Highlights Conversion company; limited commodity exposure Favorable long-term industry trends Leading positions in diverse and growing industries Superior low-cost business model Significant synergy realization opportunity Diverse end-use applications Significant liquidity Strong Platform for Ca
Slide 19: Limited Commodity Exposure
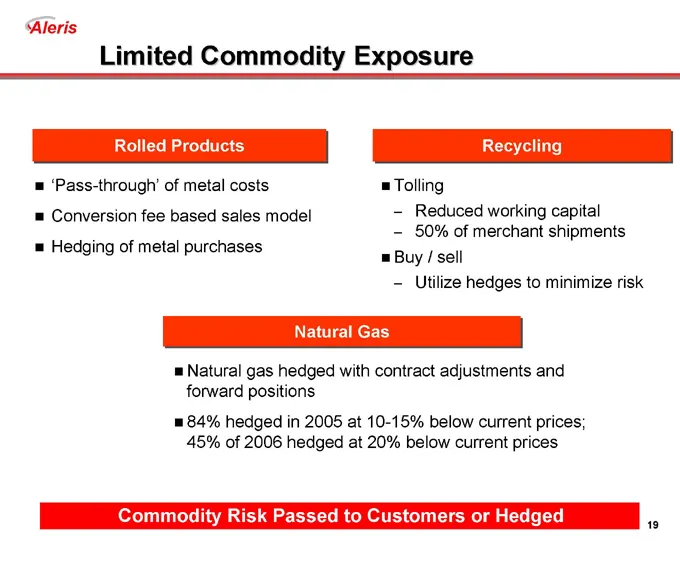
Limited Commodity Exposure Rolled Products ‘Pass-through’ of metal costs Conversion fee based sales model Hedging of metal purchases Recycling Tolling Reduced working capital 50% of merchant shipments Buy / sell Utilize hedges to minimize risk Natural Gas Natural gas hedged with contract adjustments
Slide 20: Favorable Industry Trends
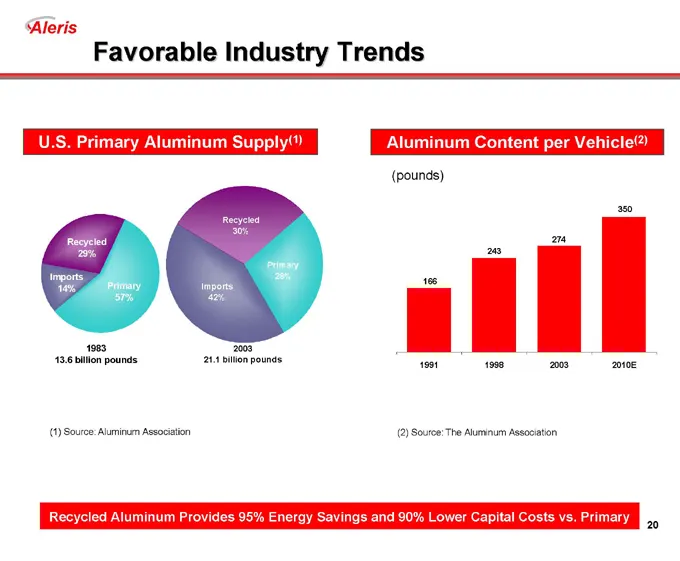
Favorable Industry Trends U.S. Primary Aluminum Supply(1) Recycled 30% Primary 28% Imports 42% Recycled 29% Primary 57% Imports 14% 1983 13.6 billion pounds 2003 21.1 billion pounds (1) Source: Aluminum Association Aluminum Content per Vehicle(2) (pounds) 243 274 350 1991 1998 2003 2010E (2) Source:
Slide 21: Leading Industry Positions
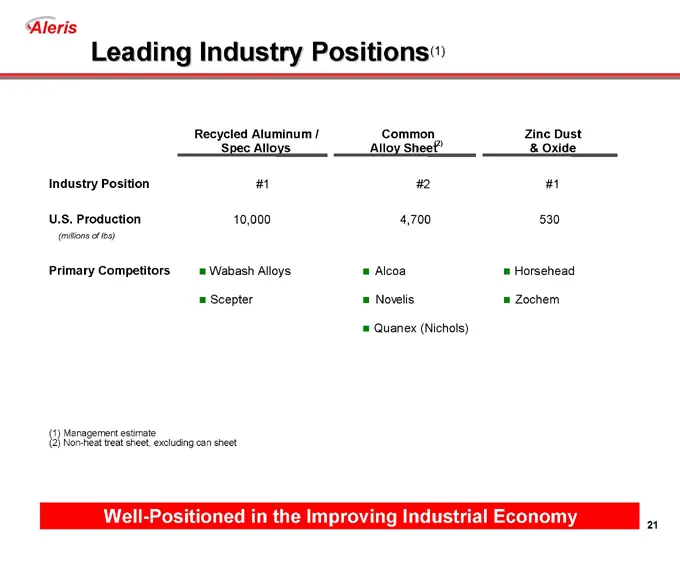
Leading Industry Positions(1) Recycled Aluminum / Spec Alloys Common Alloy Sheet (2) Zinc Dust & Oxide Industry Position #1 #2 #1 U.S. Production 10,000 4,700 530 (millions of lbs) Primary Competitors Wabash Alloys Alcoa Horsehead Scepter Novelis Zochem Quanex (Nichols) (1) Management estimate (2) N
Slide 22: Superior Low Cost Business Model
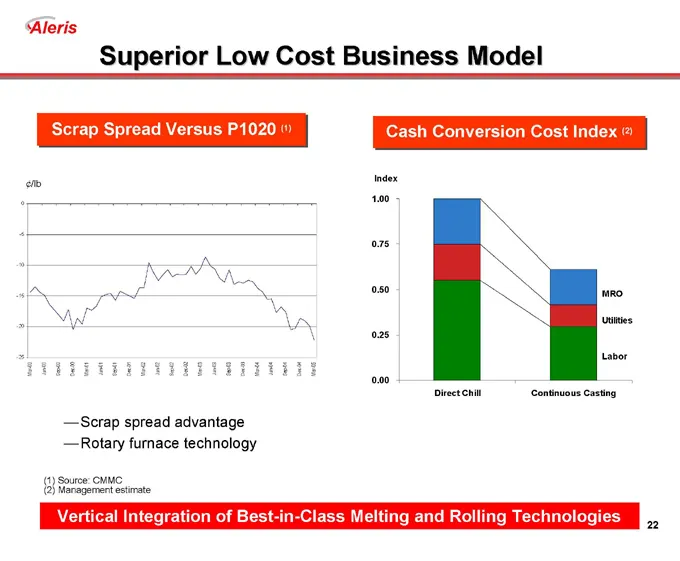
Superior Low Cost Business Model Scrap Spread Versus P1020 (1) ¢/lb 0 -5 -10 -15 -20 -25 Mar-00 Jun-00 Sep-00 Dec-00 Mar-01 Jun-01 Sep-01 Dec-01 Mar-02 Jun-02 Sep-02 Dec-02 Mar-03 Jun-03 Sep-03 Dec-03 Mar-04 Jun-04 Sep-04 Dec-04 Mar-05 Cash Conversion Cost Index (2) Index 1.00 0.75 0.50 0.25 0.00 Di
Slide 23: Merger Improves Relative Scrap Spreads
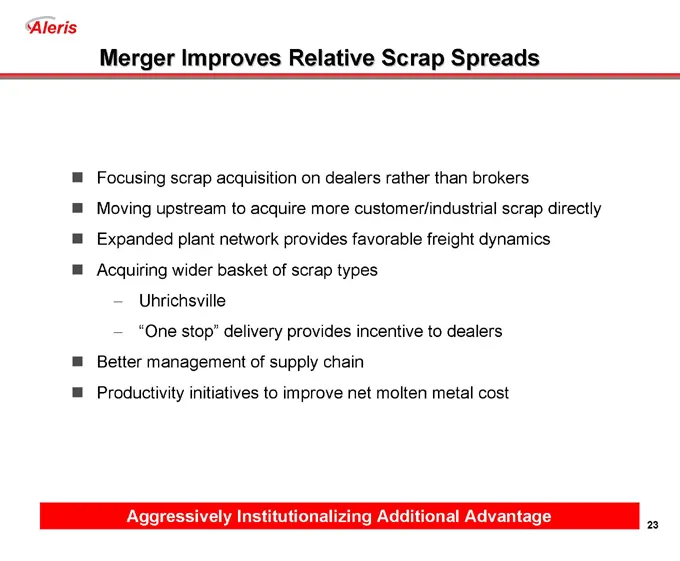
Merger Improves Relative Scrap Spreads Focusing scrap acquisition on dealers rather than brokers Moving upstream to acquire more customer/industrial scrap directly Expanded plant network provides favorable freight dynamics Acquiring wider basket of scrap types Uhrichsville “One stop” delivery provid
Slide 24: Key Business Drivers
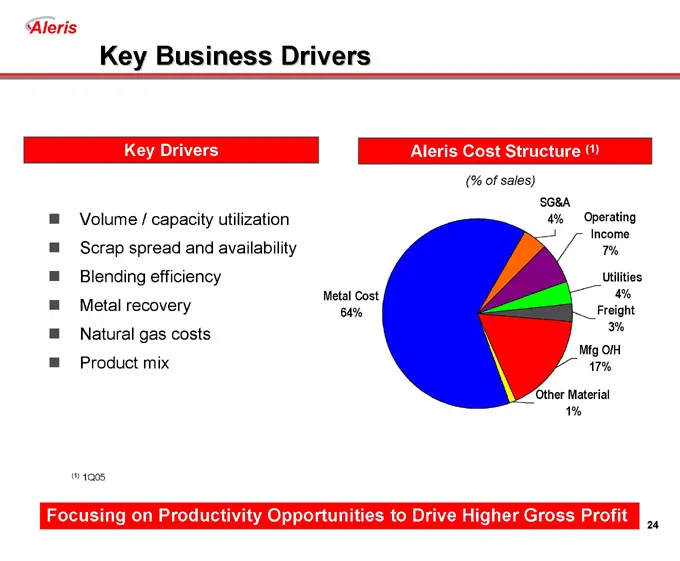
Key Business Drivers Key Drivers Volume / capacity utilization Scrap spread and availability Blending efficiency Metal recovery Natural gas costs Product mix Aleris Cost Structure (1) (% of sales) Metal Cost 64% Other Material 1% Mfg O/H 17% Freight 3% Utilities 4% Operating Income 7% SG&A 4% (1) 1Q
Slide 25: Core Competency
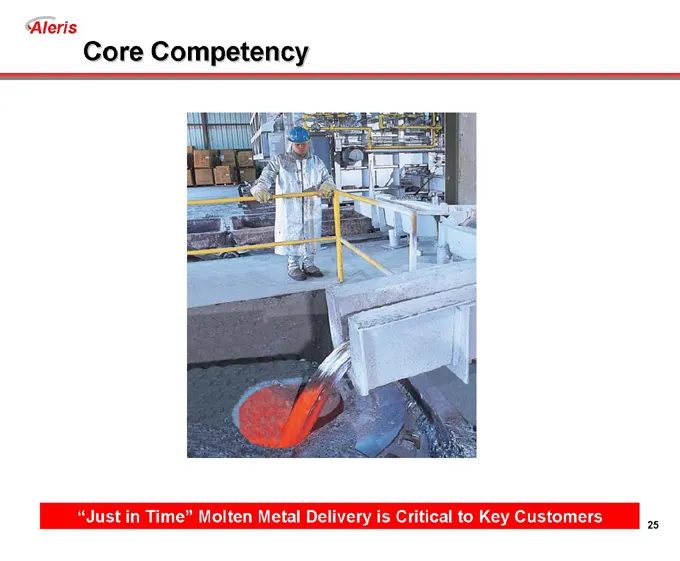
Core Competency “Just in Time” Molten Metal Delivery is Critical to Key Customers
Slide 26: Core Competency
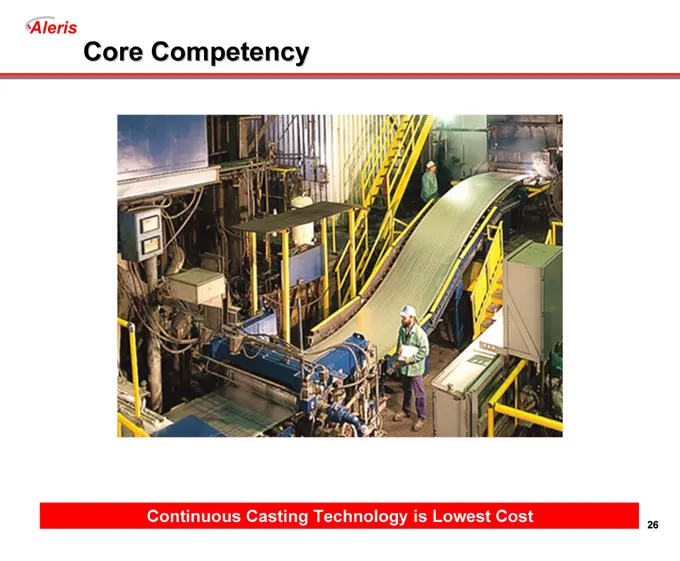
Core Competency Continuous Casting Technology is Lowest Cost
Slide 27: Synergy Summary
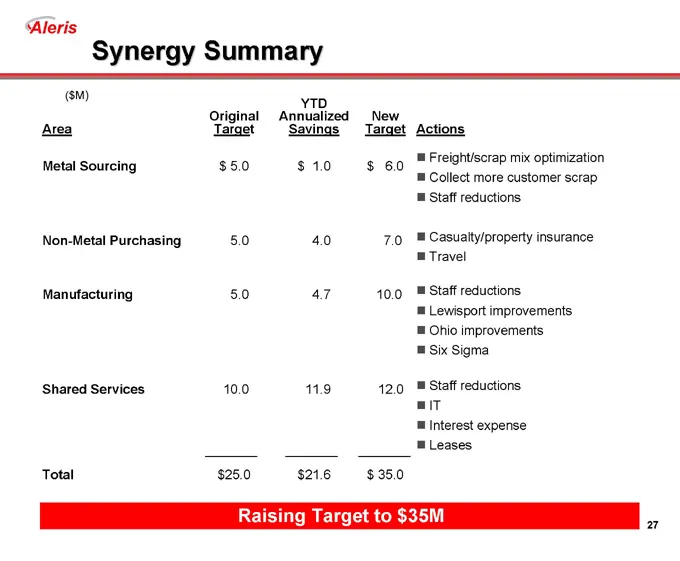
Synergy Summary ($M) Area Original Target YTD Annualized Savings New Target Actions Freight/scrap mix optimization Metal Sourcing $5.0 $1.0 $6.0 Collect more customer scrap Staff reductions Non-Metal Purchasing 5.0 4.0 7.0 Casualty/property insurance Travel Manufacturing 5.0 4.7 10.0 Staff reduction
Slide 28: Estimated Synergy Capture Profile
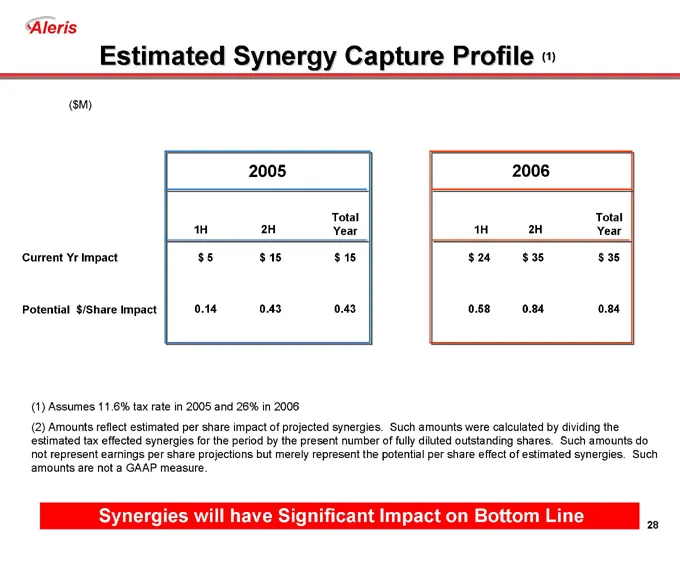
Estimated Synergy Capture Profile (1) ($M) 2005 2006 Total Year Total Year 1H 2H 1H 2H Current Yr Impact $5 $15 $15 $24 $35 $35 Potential $/Share Impact 0.14 0.43 0.43 0.58 0.84 0.84 (1) Assumes 11.6% tax rate in 2005 and 26% in 2006 (2) Amounts reflect estimated per share impact of projected synerg
Slide 29: Rolled Products
Rolled Products
Slide 30: Non-Heat Treat Sheet (NHTS) Products
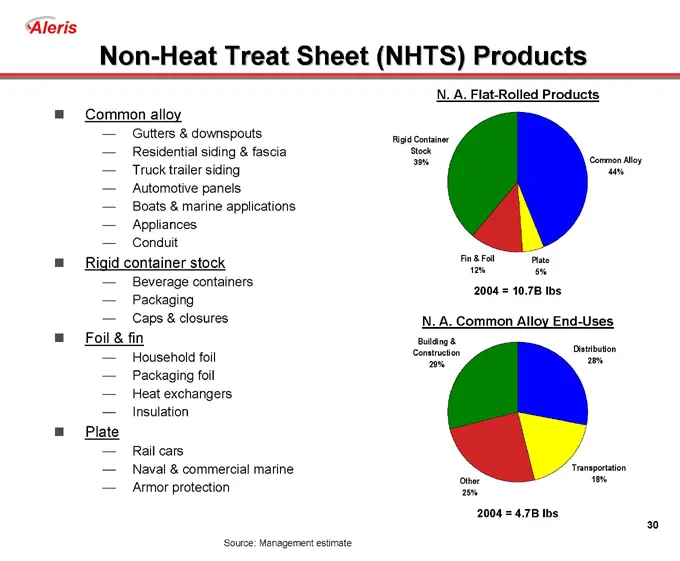
Non-Heat Treat Sheet (NHTS) Products Common alloy Gutters & downspouts Residential siding & fascia Truck trailer siding Automotive panels Boats & marine applications Appliances Conduit Rigid container stock Beverage containers Packaging Caps & closures Foil & fin Household foil Packaging foil Heat e
Slide 31: NHTS Shipments
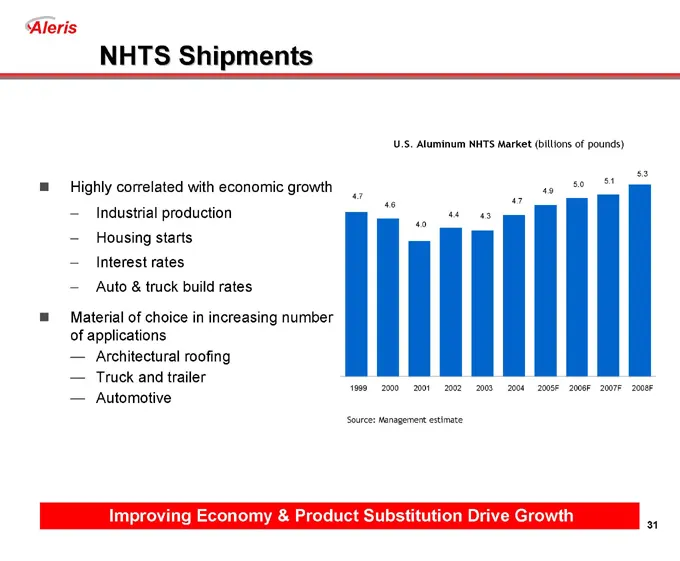
NHTS Shipments Highly correlated with economic growth Industrial production Housing starts Interest rates Auto & truck build rates Material of choice in increasing number of applications Architectural roofing Truck and trailer Automotive 4.7 4.6 4.0 4.4 4.3 4.7 4.9 5.0 5.1 5.3 1999 2000 2001 2002 20
Slide 32: Sources of Scrap
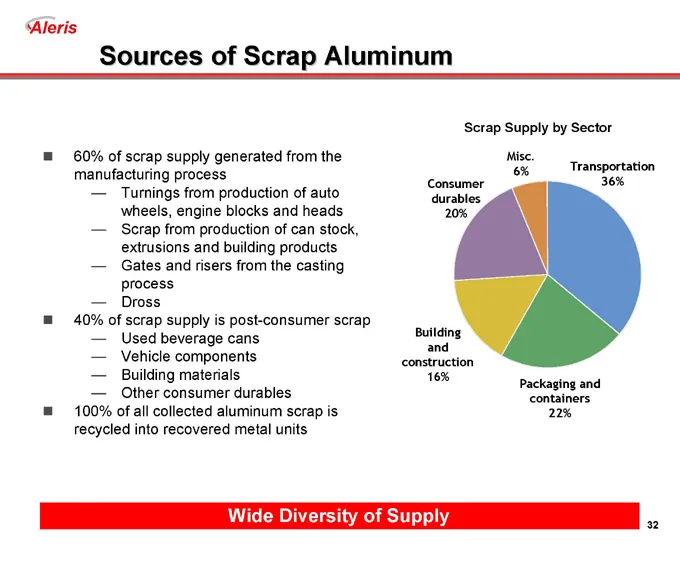
Sources of Scrap Aluminum 60% of scrap supply generated from the manufacturing process Turnings from production of auto wheels, engine blocks and heads Scrap from production of can stock, extrusions and building products Gates and risers from the casting process Dross 40% of scrap supply is post-con
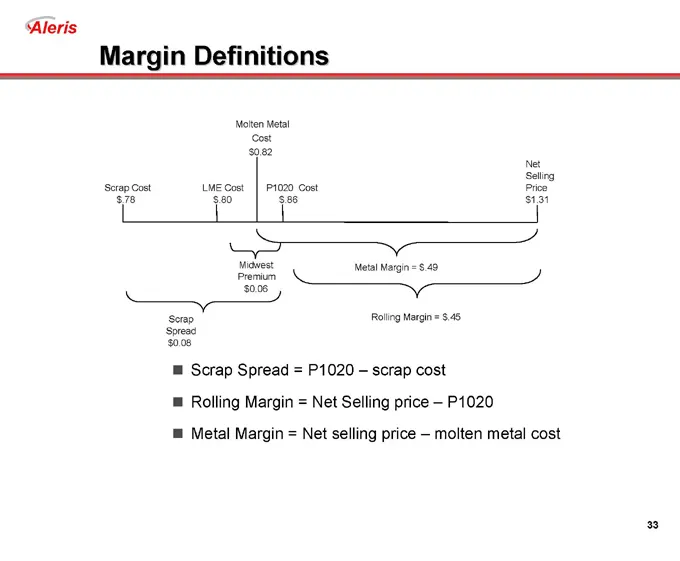
Slide 33: Margin Definitions
Margin Definitions Scrap Cost $.78 LME Cost $.80 Molten Metal Cost $0.82 P1020 Cost $.86 Net Selling Price $1.31 Midwest Premium $0.06 Metal Margin = $.49 Scrap Spread $0.08 Rolling Margin = $.45 Scrap Spread = P1020 – scrap cost Rolling Margin = Net Selling price – P1020 Metal Margin = Net selling
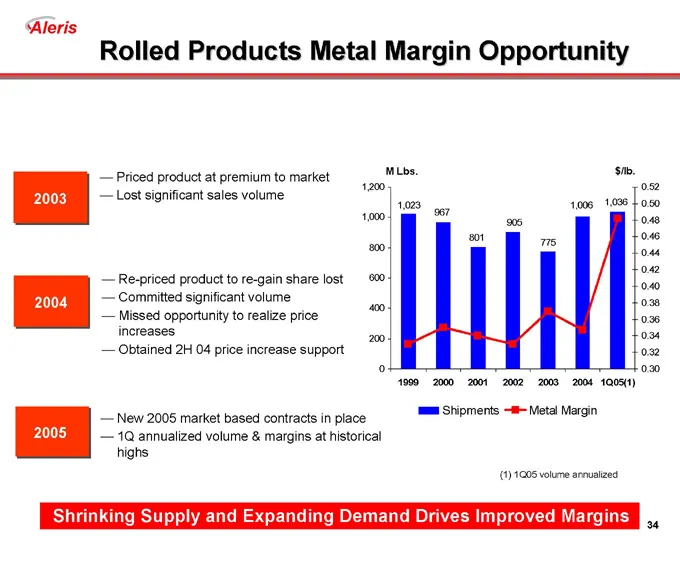
Slide 34: Rolled Products Metal Margin Opportunity
Rolled Products Metal Margin Opportunity Priced product at premium to market 2003 Lost significant sales volume Re-priced product to re-gain share lost 2004 Committed significant volume Missed opportunity to realize price increases Obtained 2H 04 price increase support New 2005 market based contract
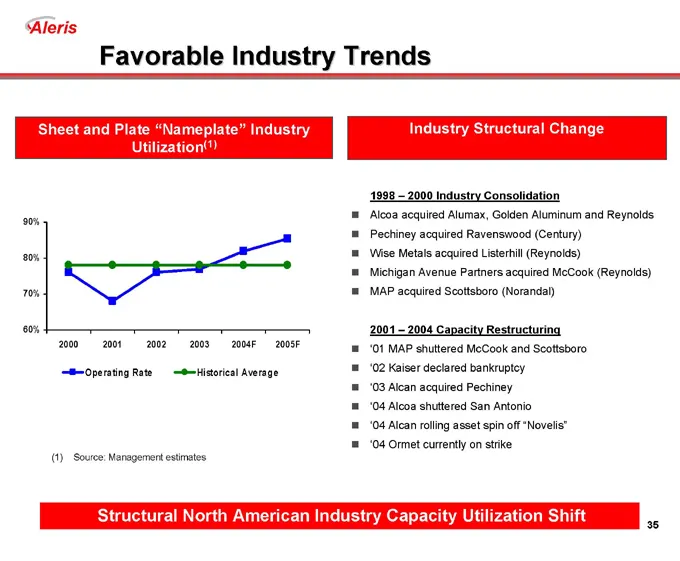
Slide 35: Favorable Industry Trends
Favorable Industry Trends Sheet and Plate “Nameplate” Industry Utilization(1) 2000 2001 2002 2003 2004F 2005F 90% 80% 70% 60% Operating Rate Historical Average (1) Source: Management estimates Industry Structural Change 1998 – 2000 Industry Consolidation Alcoa acquired Alumax, Golden Aluminum and Re
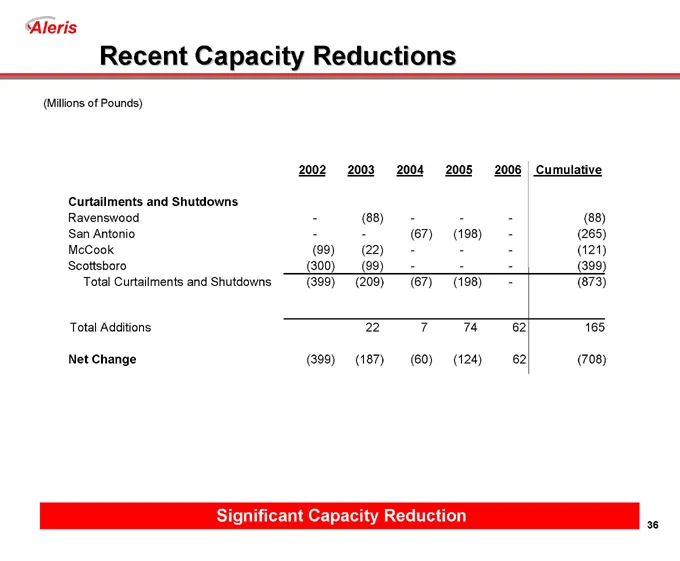
Slide 36: Recent Capacity Reductions
Recent Capacity Reductions (Millions of Pounds) 2002 2003 2004 2005 2006 Cumulative Curtailments and Shutdowns Ravenswood - (88) - - - (88) San Antonio - - (67) (198) - (265) McCook (99) (22) - - - (121) Scottsboro (300) (99) - - - (399) Total Curtailments and Shutdowns (399) (209) (67) (198) - (873
Slide 37: Financial Summary
Financial Summary
Slide 38: Recent Performance
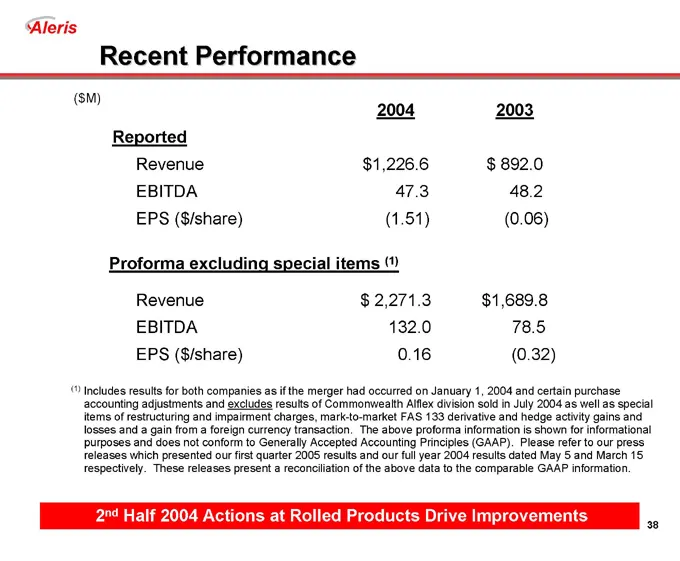
Recent Performance ($M) 2004 2003 Reported Revenue $1,226.6 $892.0 EBITDA 47.3 48.2 EPS ($/share) (1.51) (0.06) Proforma excluding special items (1) Revenue $2,271.3 $1,689.8 EBITDA 132.0 78.5 EPS ($/share) 0.16 (0.32) (1) Includes results for both companies as if the merger had occurred on January
Slide 39: 1Q Performance
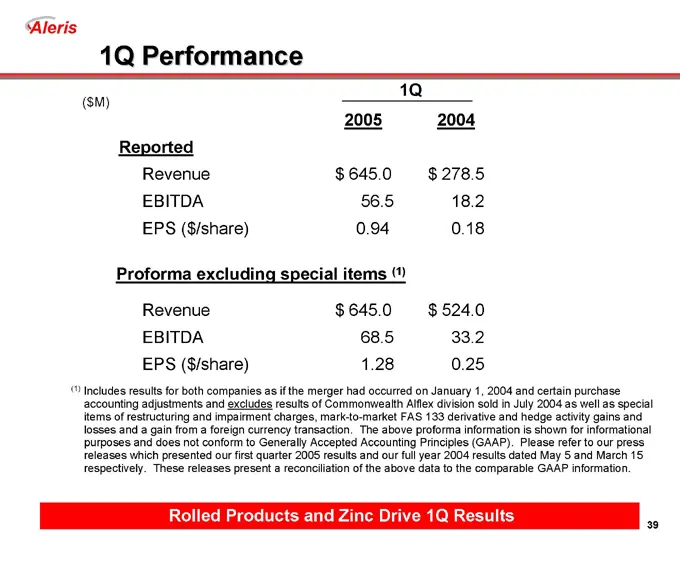
1Q Performance 1Q ($M) 2005 2004 Reported Revenue $645.0 $278.5 EBITDA 56.5 18.2 EPS ($/share) 0.94 0.18 Proforma excluding special items (1) Revenue $645.0 $524.0 EBITDA 68.5 33.2 EPS ($/share) 1.28 0.25 (1) Includes results for both companies as if the merger had occurred on January 1, 2004 and ce
Slide 40: 1Q EBITDA Variance
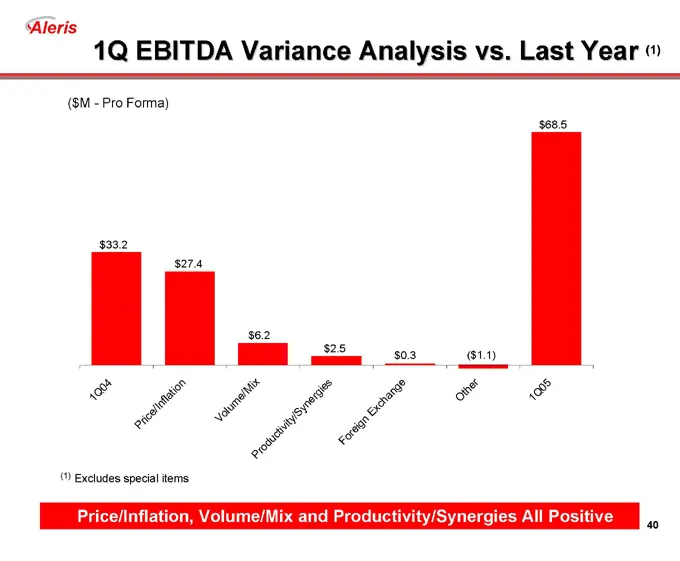
1Q EBITDA Variance Analysis vs. Last Year (1) ($M - Pro Forma) $33.2 $27.4 $6.2 $2.5 $0.3 ($1.1) $68.5 1Q04 Price/Inflation Volume/Mix Productivity/Synergies Foreign Exchange Other 1Q05 (1) Excludes special items Price/Inflation, Volume/Mix and Productivity/Synergies All Positive
Slide 41: 2Q EBITDA Variance
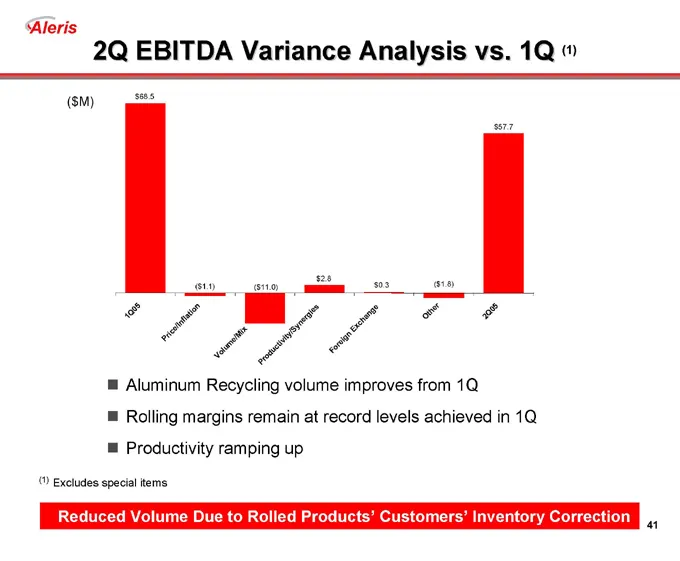
2Q EBITDA Variance Analysis vs. 1Q (1) ($M) $68.5 ($1.1) ($11.0) $2.8 $0.3 ($1.8) $57.7 1Q05 Price/Inflation Volume/Mix Productivity/Synergies Foreign Exchange Other 2Q05 Aluminum Recycling volume improves from 1Q Rolling margins remain at record levels achieved in 1Q Productivity ramping up (1) Exc
Slide 42: Financial Summary
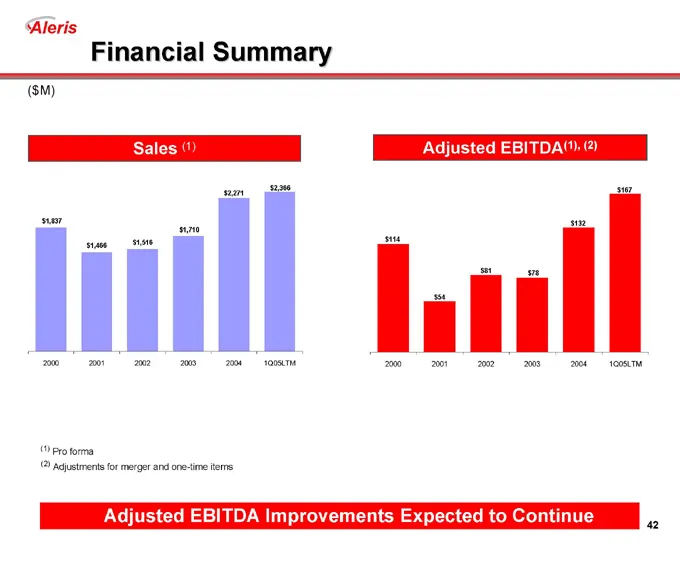
Financial Summary ($M) Sales (1) $1,837 $1,466 $1,516 $1,710 $2,271 $2,366 2000 2001 2002 2003 2004 1Q05LTM Adjusted EBITDA(1), (2) $114 $54 $81 $78 $132 $167 2000 2001 2002 2003 2004 1Q05LTM (1) Pro forma (2) Adjustments for merger and one-time items Adjusted EBITDA Improvements Expected to Continu
Slide 43: Capex
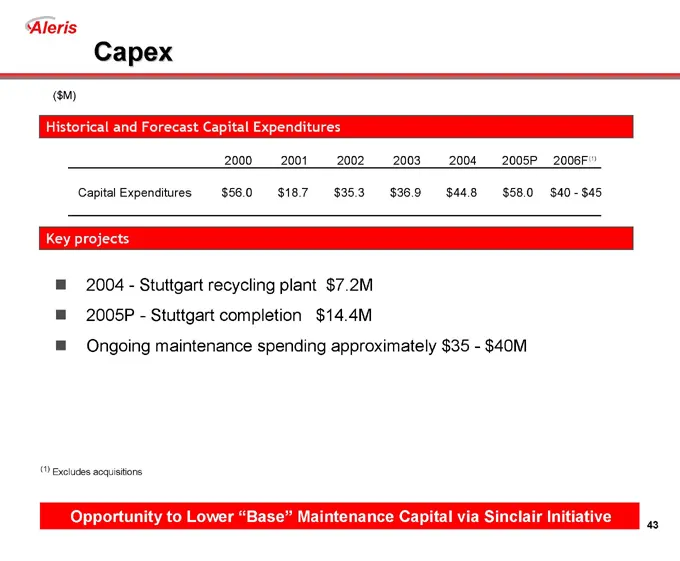
Capex ($M) Historical and Forecast Capital Expenditures 2000 2001 2002 2003 2004 2005P 2006F (1) Capital Expenditures $56.0 $18.7 $35.3 $36.9 $44.8 $58.0 $40 - $45 Key projects 2004 - Stuttgart recycling plant $7.2M 2005P - Stuttgart completion $14.4M Ongoing maintenance spending approximately $35 -
Slide 44: Cash & Debt Summary
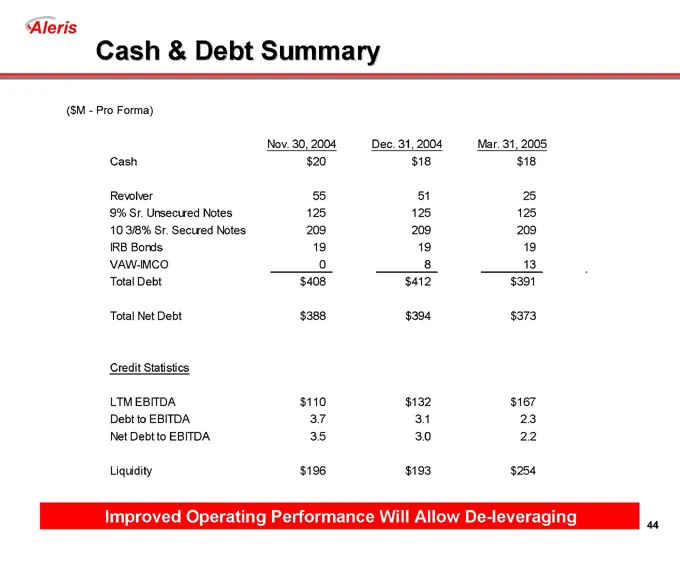
Cash & Debt Summary ($M - Pro Forma) Nov. 30, 2004 Dec. 31, 2004 Mar. 31, 2005 Cash $20 $18 $18 Revolver 55 51 25 9% Sr. Unsecured Notes 125 125 125 10 3/8% Sr. Secured Notes 209 209 209 IRB Bonds 19 19 19 VAW-IMCO 0 8 13 Total Debt $408 $412 $391 Total Net Debt $388 $394 $373 Credit Statistics LTM
Slide 45: Corporate Expenses
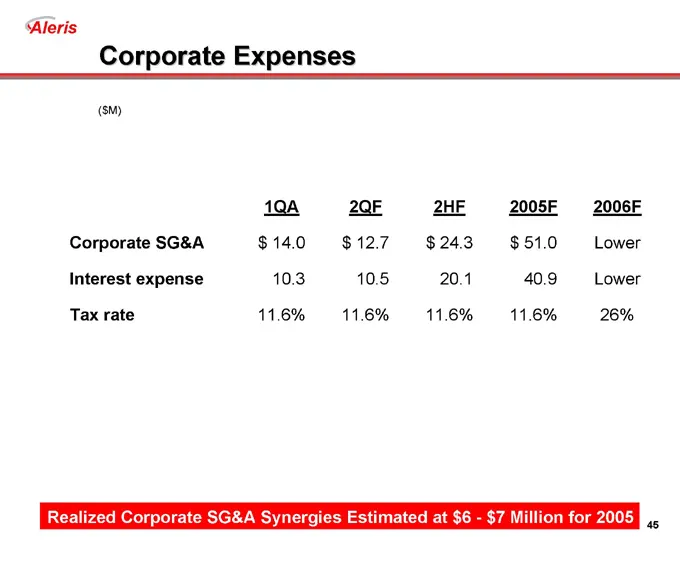
Corporate Expenses ($M) 1QA 2QF 2HF 2005F 2006F Corporate SG&A $14.0 $12.7 $24.3 $51.0 Lower Interest expense 10.3 10.5 20.1 40.9 Lower Tax rate 11.6% 11.6% 11.6% 11.6% 26% Realized Corporate SG&A Synergies Estimated at $6 - $7 Million for 2005
Slide 46: Financial Goals
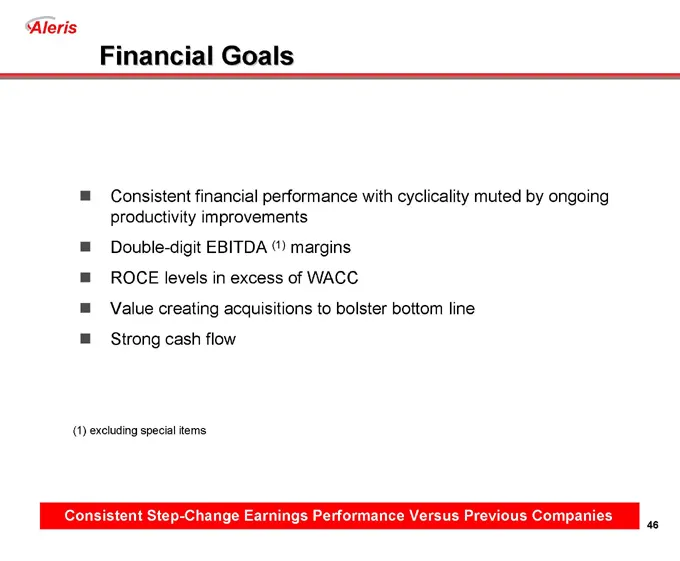
Financial Goals Consistent financial performance with cyclicality muted by ongoing productivity improvements Double-digit EBITDA (1) margins ROCE levels in excess of WACC Value creating acquisitions to bolster bottom line Strong cash flow (1) excluding special items Consistent Step-Change Earnings P
Slide 47: 2Q05 Outlook
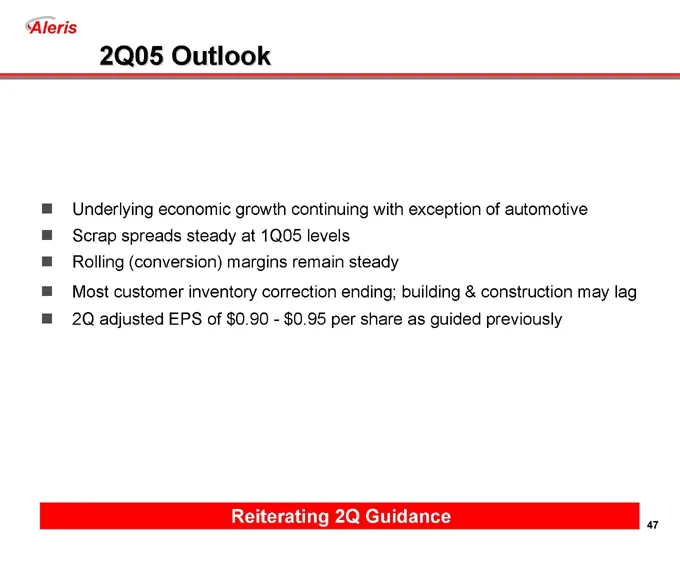
2Q05 Outlook Underlying economic growth continuing with exception of automotive Scrap spreads steady at 1Q05 levels Rolling (conversion) margins remain steady Most customer inventory correction ending; building & construction may lag 2Q adjusted EPS of $0.90 - $0.95 per share as guided previously Re
Slide 48: 2H05 and Full-Year Outlook
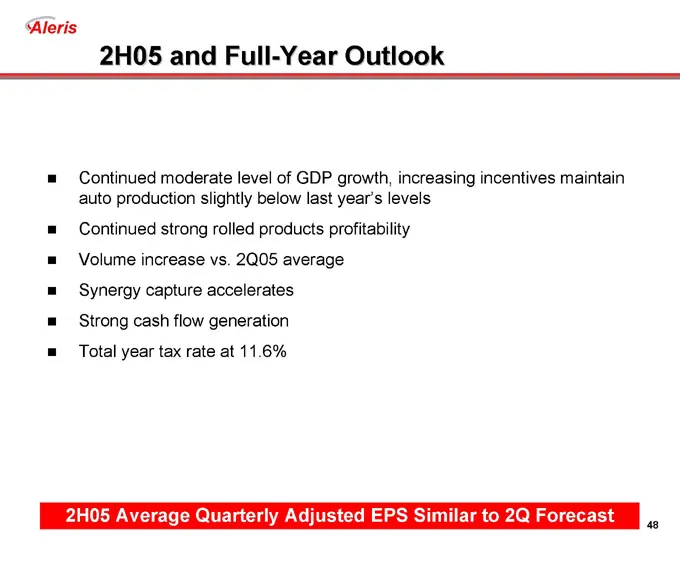
2H05 and Full-Year Outlook Continued moderate level of GDP growth, increasing incentives maintain auto production slightly below last year’s levels Continued strong rolled products profitability Volume increase vs. 2Q05 average Synergy capture accelerates Strong cash flow generation Total year tax r
Slide 49: 2006 Highlights
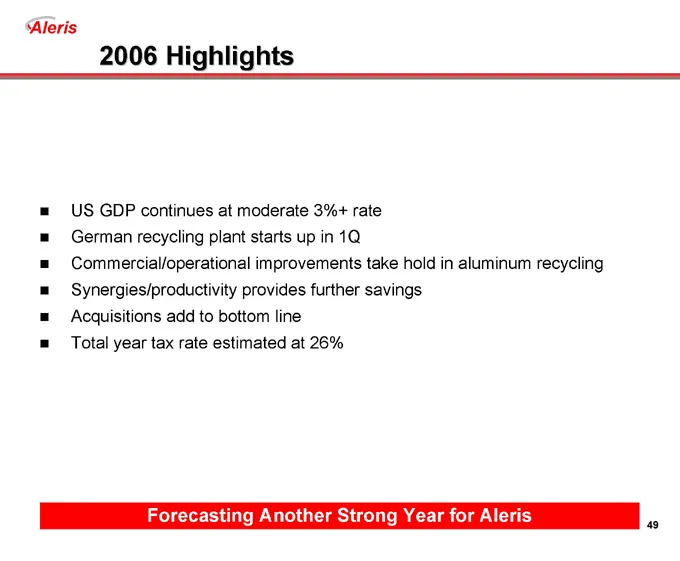
2006 Highlights US GDP continues at moderate 3%+ rate German recycling plant starts up in 1Q Commercial/operational improvements take hold in aluminum recycling Synergies/productivity provides further savings Acquisitions add to bottom line Total year tax rate estimated at 26% Forecasting Another St
Slide 50: Q&A
Q&A
Source: SEC EDGAR · 8-K filed May 25, 2005
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
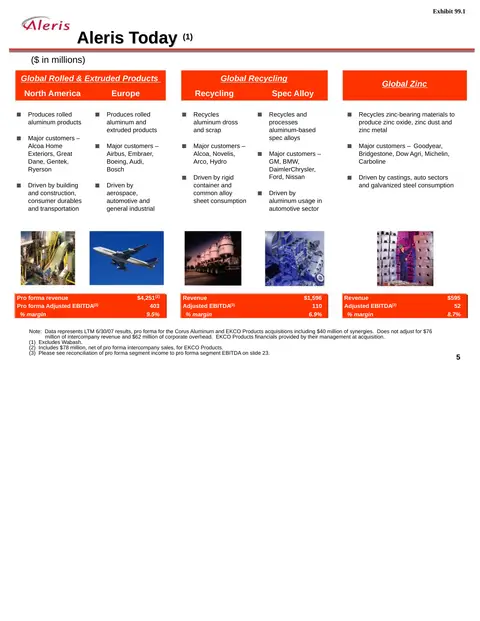 Investor Presentation (October 2007)14 slides · Oct 3, 2007