Aleris International — Investor Day (December 2005)
39 slides from Aleris International's investor day presentation, Dec 9, 2005
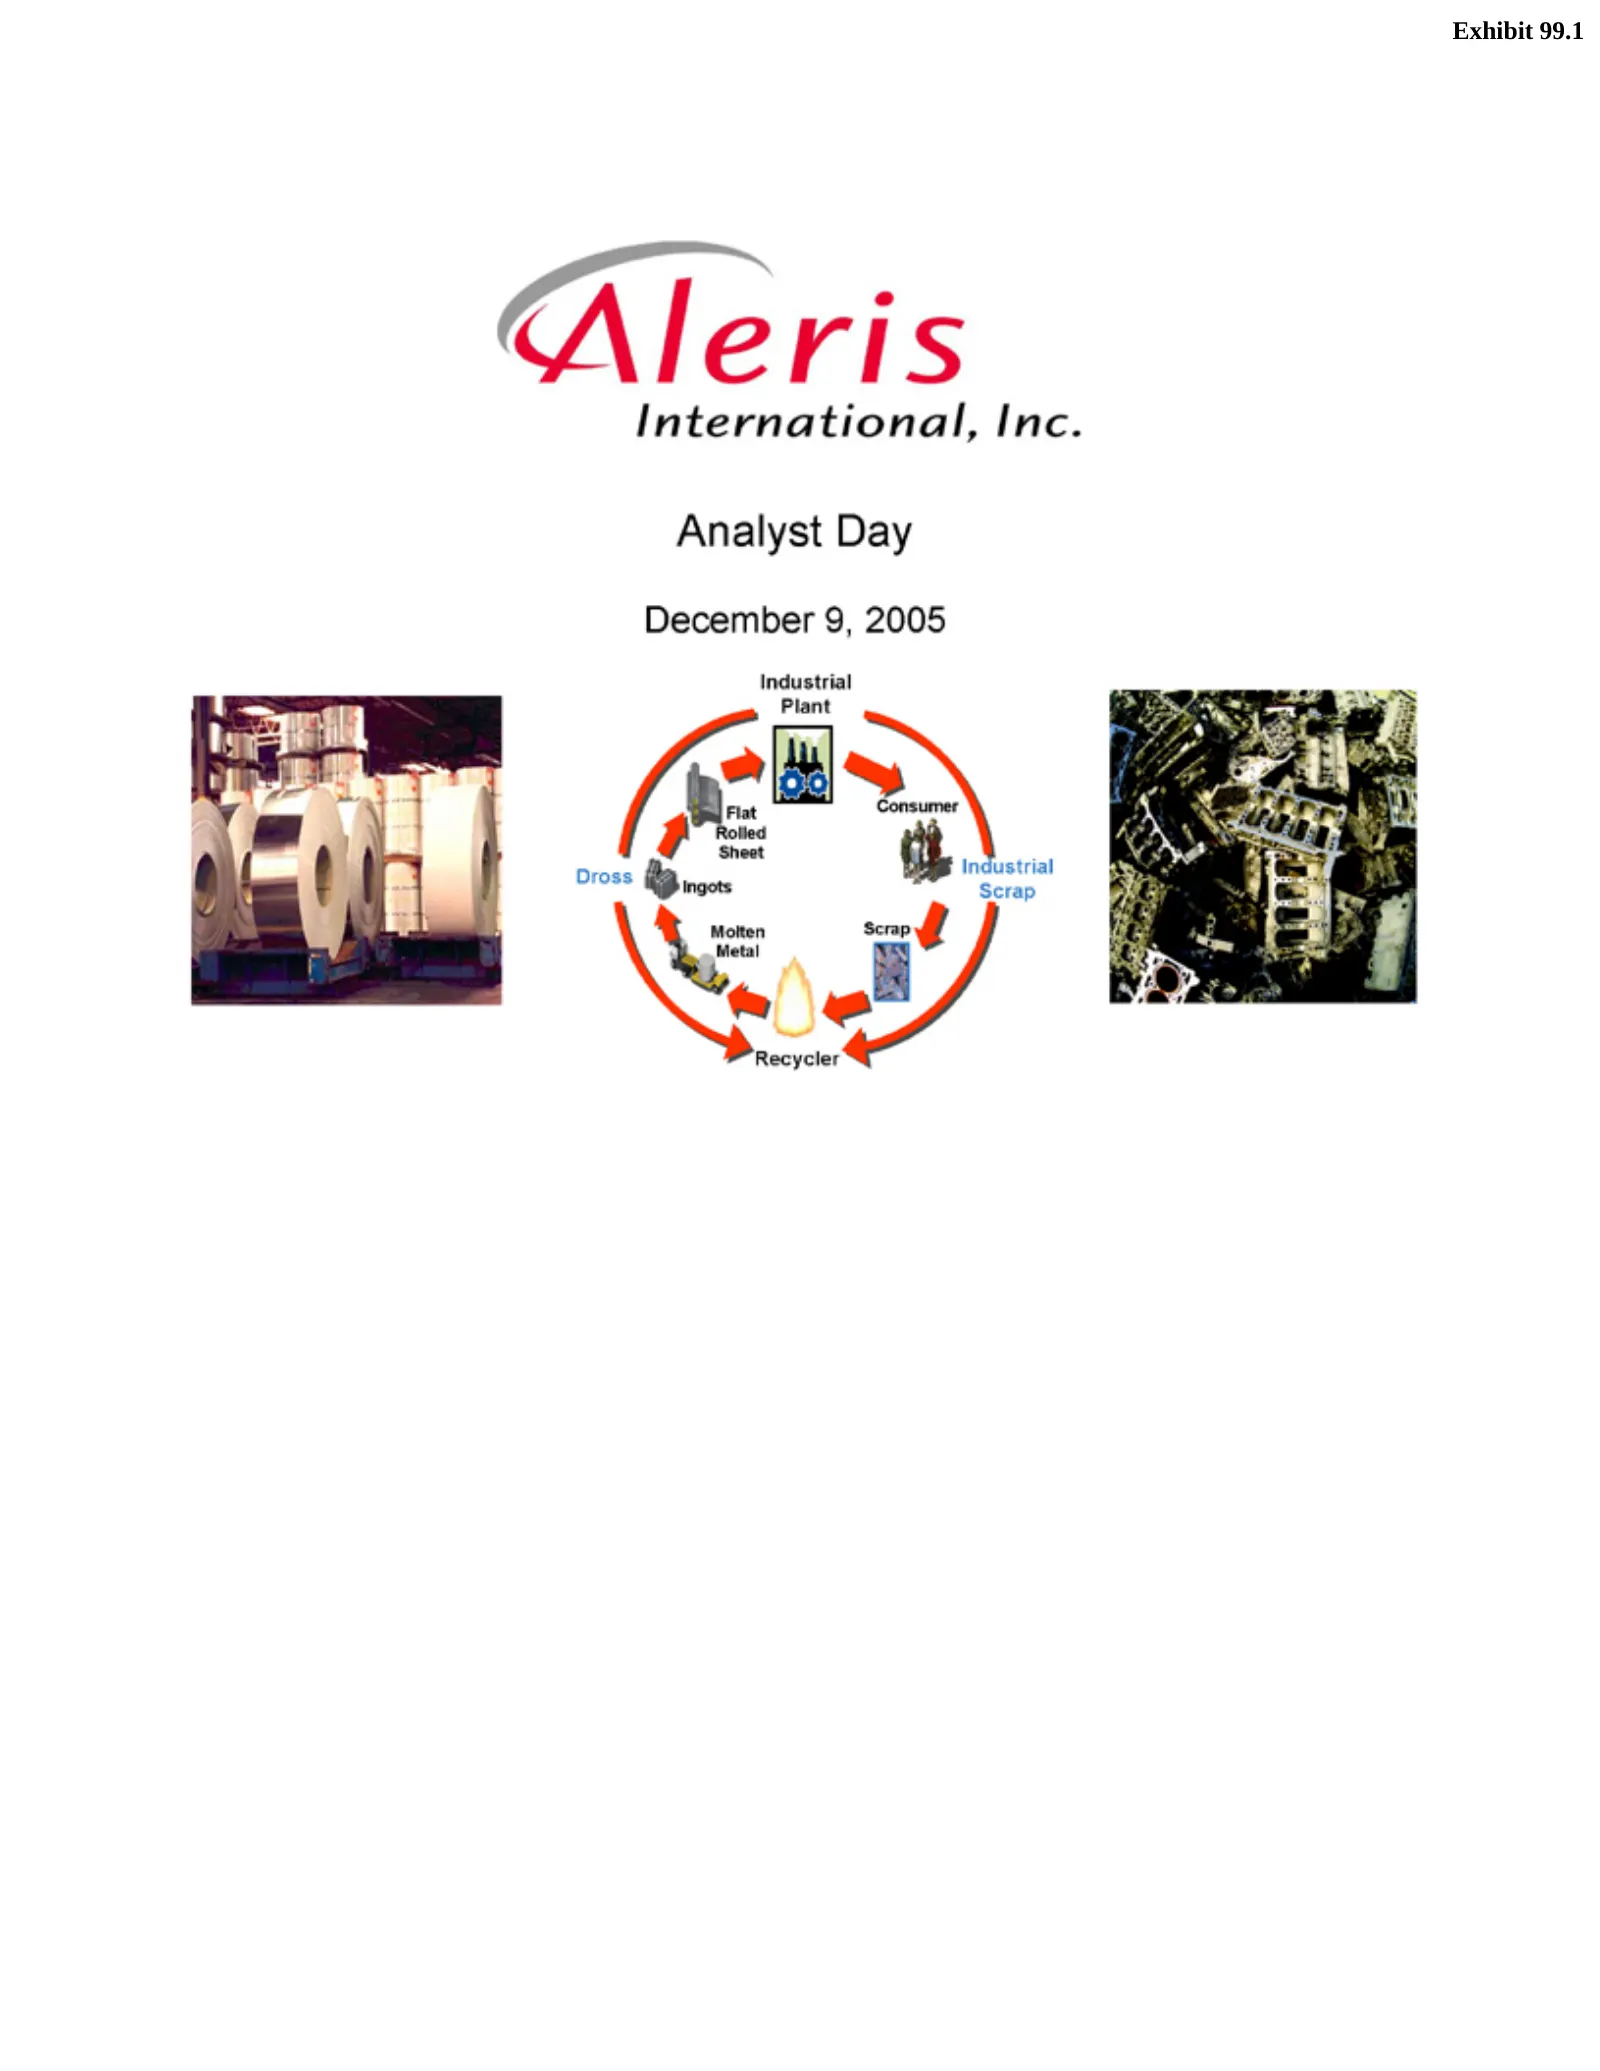
Slide 1: Analyst Day December 9, 2005
Exhibit 99.1 Analyst December Flat Industrial Consumer Molten Ingots Dross Recycler ScrapRolled Metal Day Plant Scrap 9,Sheet 2005
Slide 2: Safe Harbor Statements
Safe Harbor Statements harbor statements. cause 2 actual provisions contained Itresults is important oftothe in differ this Securities to from presentation note that those Actthe ofexpressed that 1933 company’s state andor the the forecast, actual company’s Securities results see Exchange its orcoul
Slide 3: Merger Overview
Merger Overview
Slide 4: The Merger
The Merger December Commonwealth Revenue: (1) LTM$2.4 Celebrating9,One 2004 asBillion of Industries, September Year (1)Aleris as Headquarters: Inc.30, 2005.4 Beachwood, OH NYSE Symbol: ARS Today!
Slide 5: Merger Rationale
Merger Rationale Streamlines Leverages Enhances Strengthens Improves Accelerates 5 Transformational competitive access metal core ability cost management; competencies; sourcing to structure; to capital pursue position capabilities enables markets creates growth transfers through productivity value
Slide 6: Initial Business Strategy
InitialBusiness Relentless Implement Exploit Utilize Extend Core Pursue Explore Unique 6 Strategy scrap U.S. low-cost Opportunity combined Uhrichsville Productivity Six industry sourcing Growth Sigma continuous melting acquisition integrated culture capabilities Improvement and cast toprocessing rec
Slide 7: First Year Accomplishments
First Year Initiated Established Exceeded Restructured Stabilized Completed S&P Improved Surpassed Positioning 7 corporate massive Accomplishments merger liquidity aluminum $1B or for credibility and announced credit in Sustainable announced cultural synergy market position sheet rating andcap four
Slide 8: Culture of Change and Key Values
Sense Data No Minimum Relentless Unquestionable Recognize Global/international Culture 8 bureaucracy driven; ofChange and urgency layers drive great Key clearly integrity Underway to performance Values in - be solve organization defined moretoday’s productive measures problems in all today we do
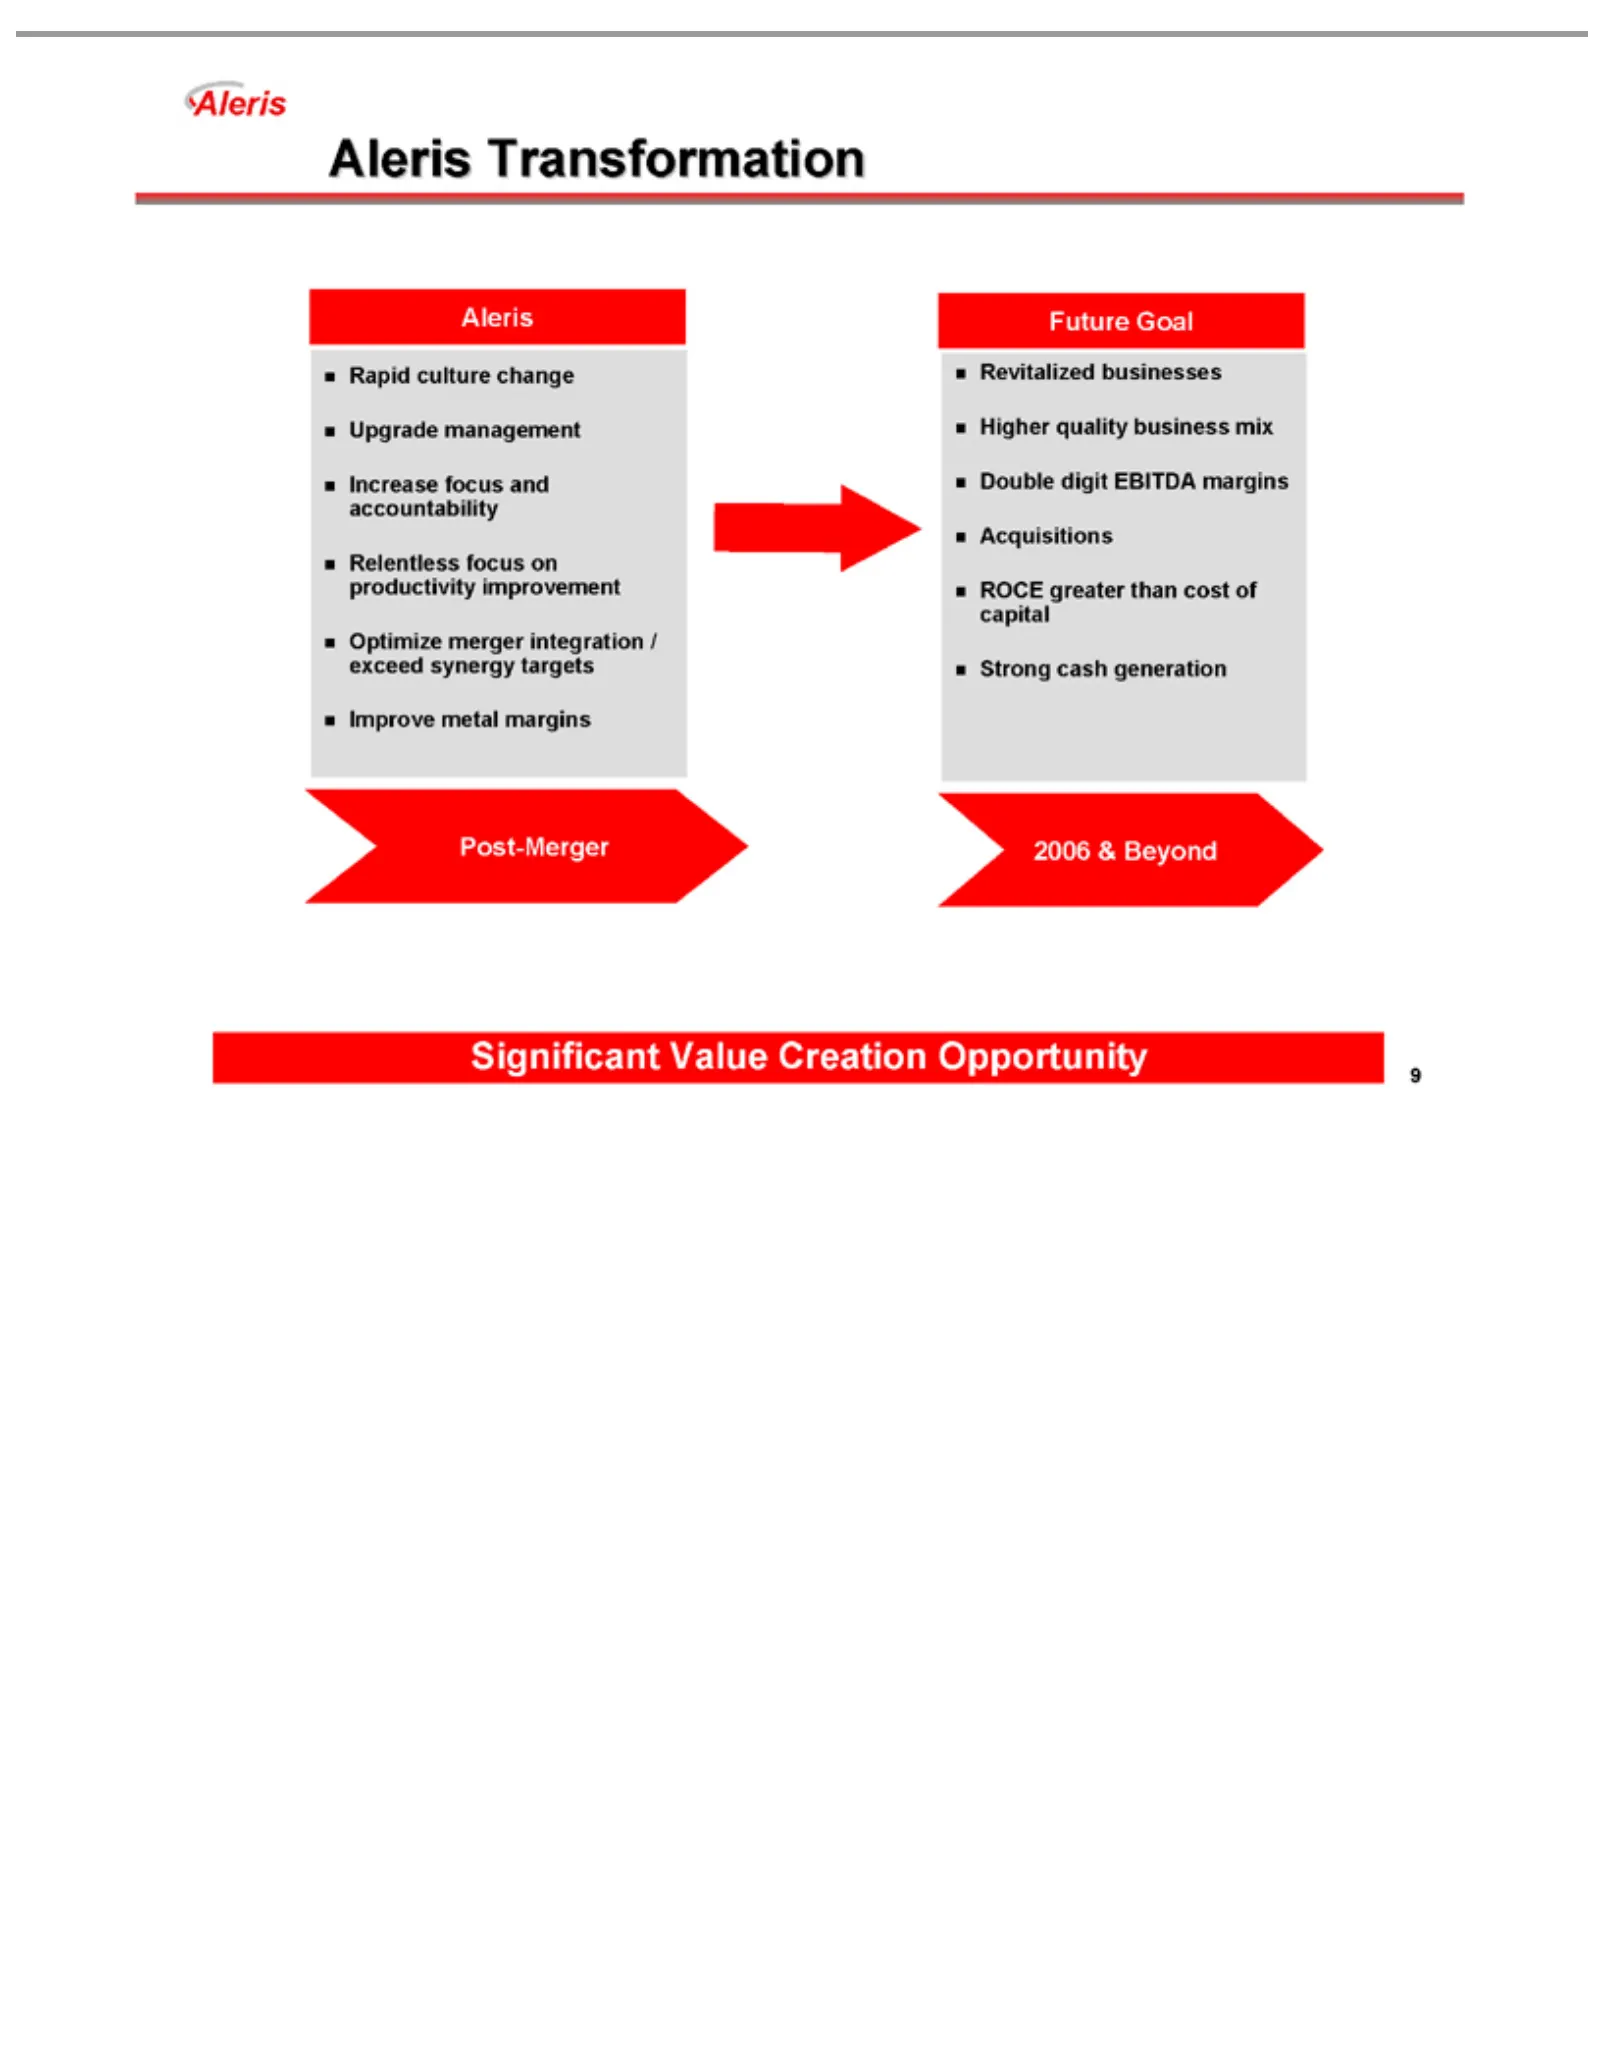
Slide 9: Post-Merger Transformation Goals
Rapid&culture Aleris Upgrade Increase Relentless Optimize Improve Future Post-Merger Revitalized ROCE Strong 2006 Significant 9 Transformation Goal cash greater Beyond focus metal management merger focus Value businesses generation change than and margins on integration Creation accountability cost
Slide 10: Company Overview
Company Overview
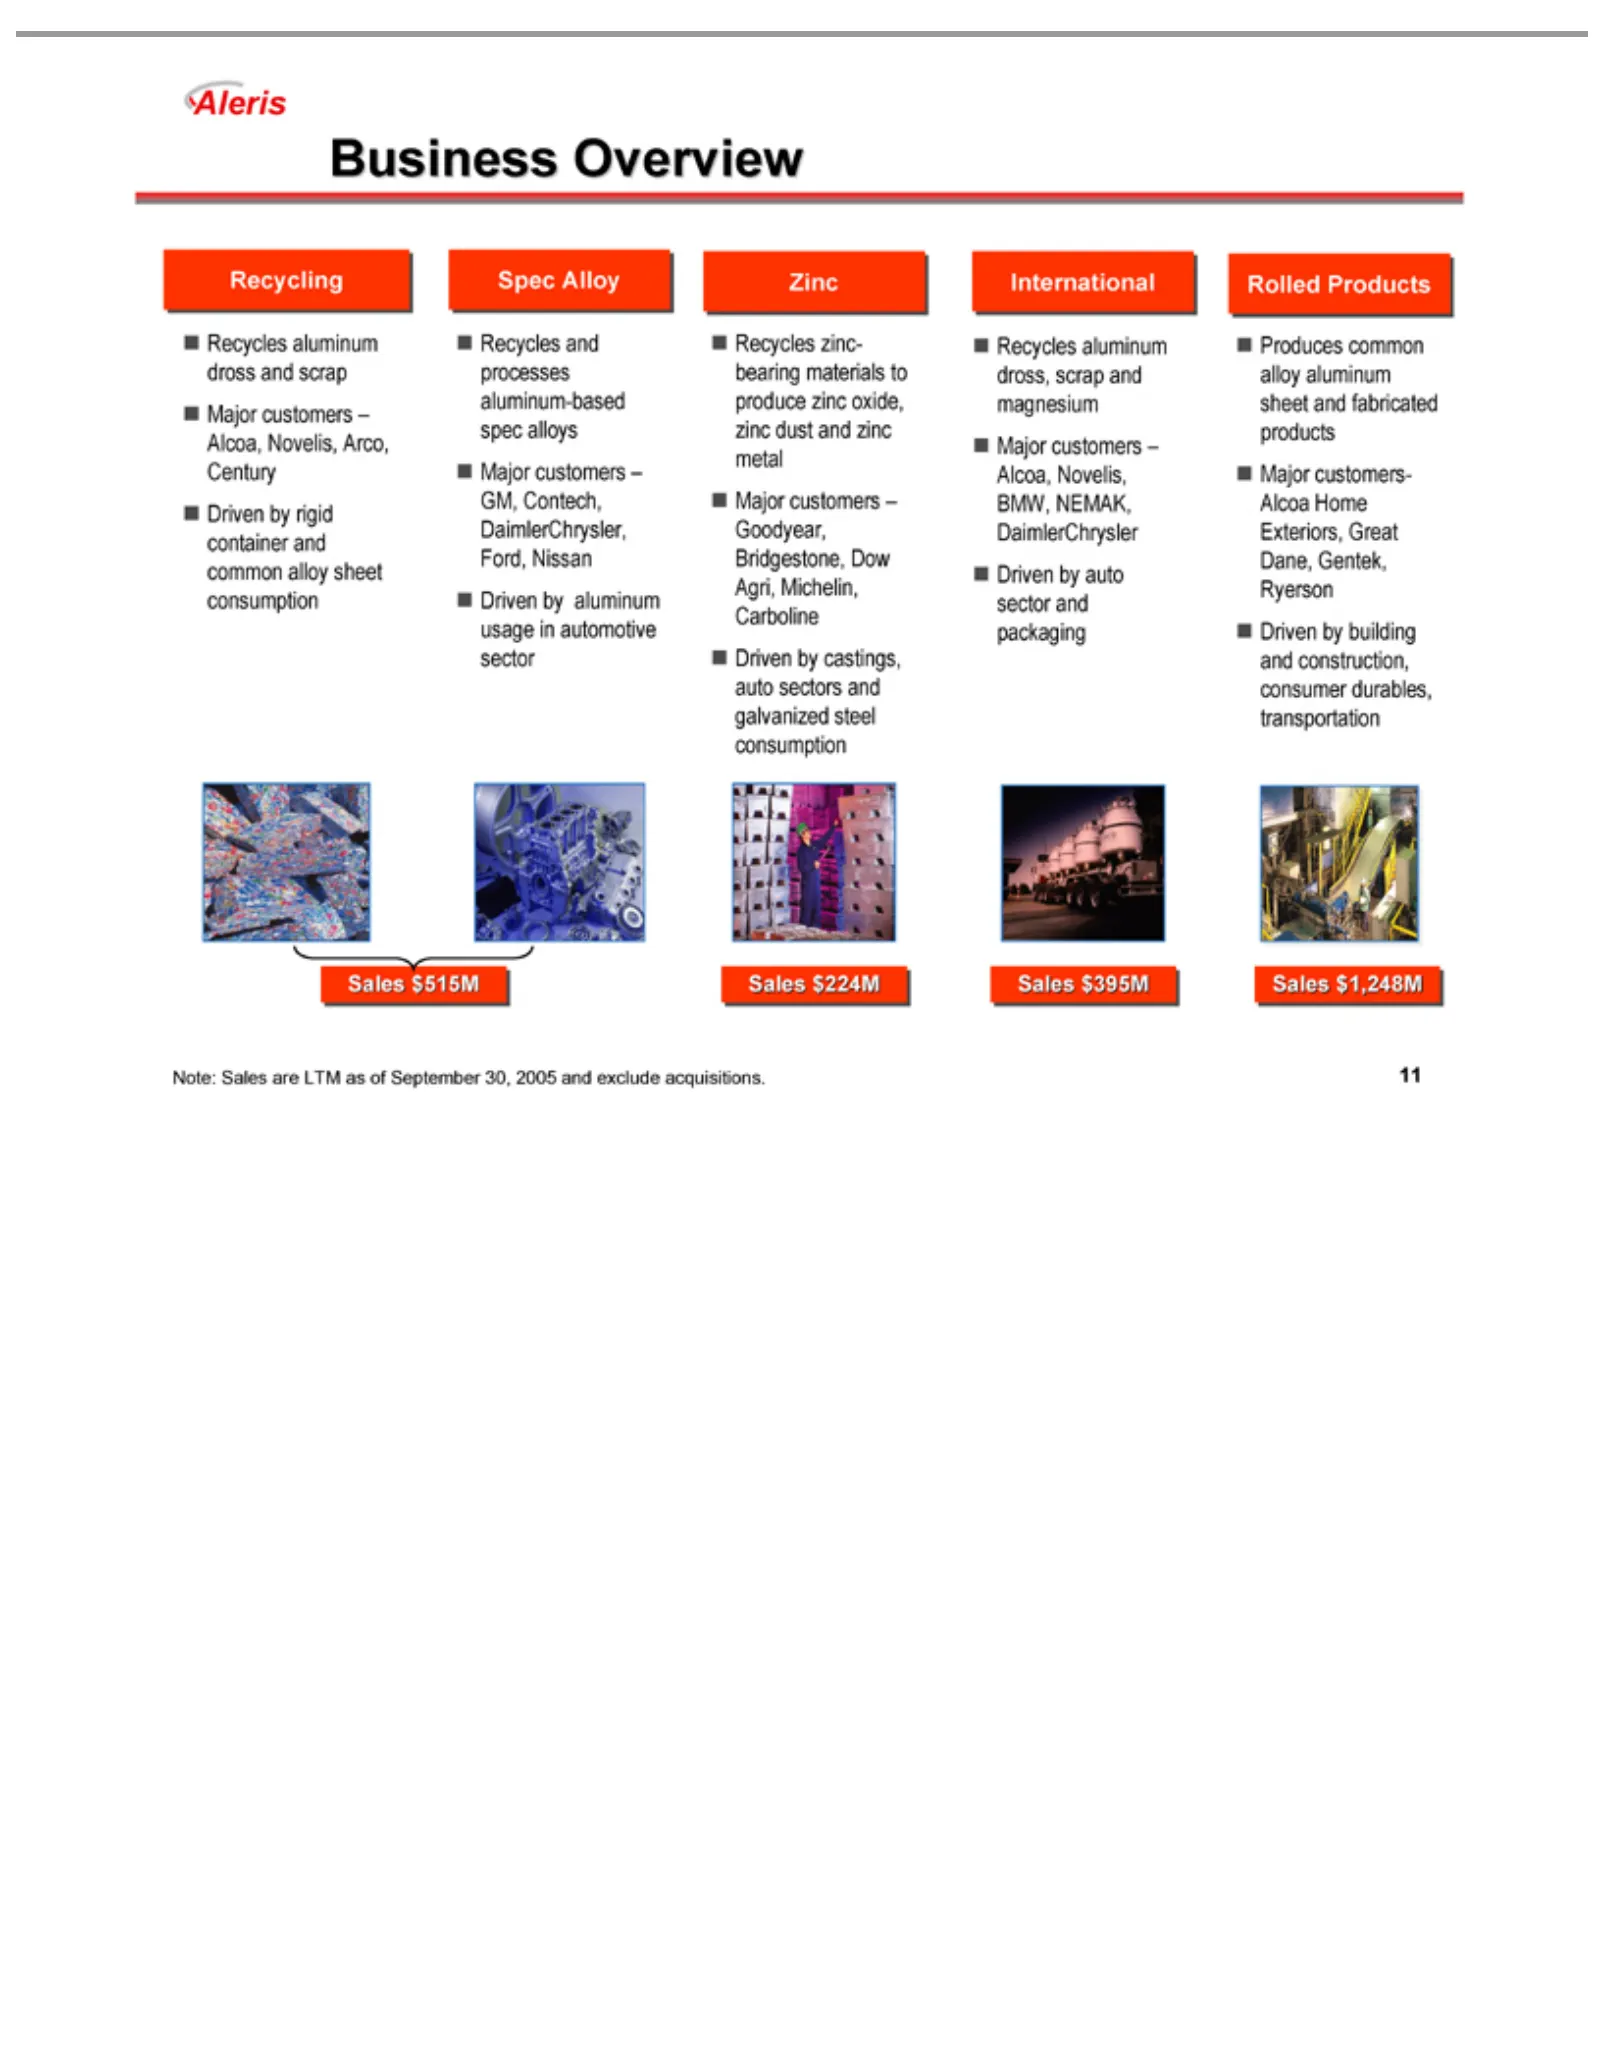
Slide 11: Aleris Business Overview
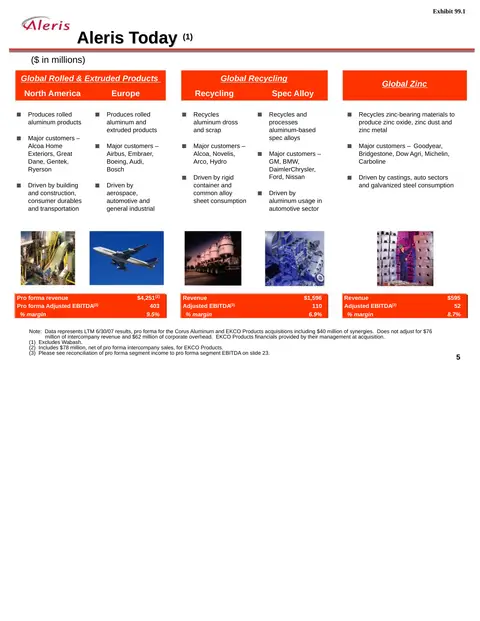
Business Recycling Spec Zinc Recycles International Rolled Produces Major Driven Sales Note: Alloy $515M Sales customers customers-Alcoa Products byOverview and zinc-bearing aluminum common rigid aluminum castings, auto building are Sales processes sector LTM container – alloy –Alcoa, GM, Goodyear,
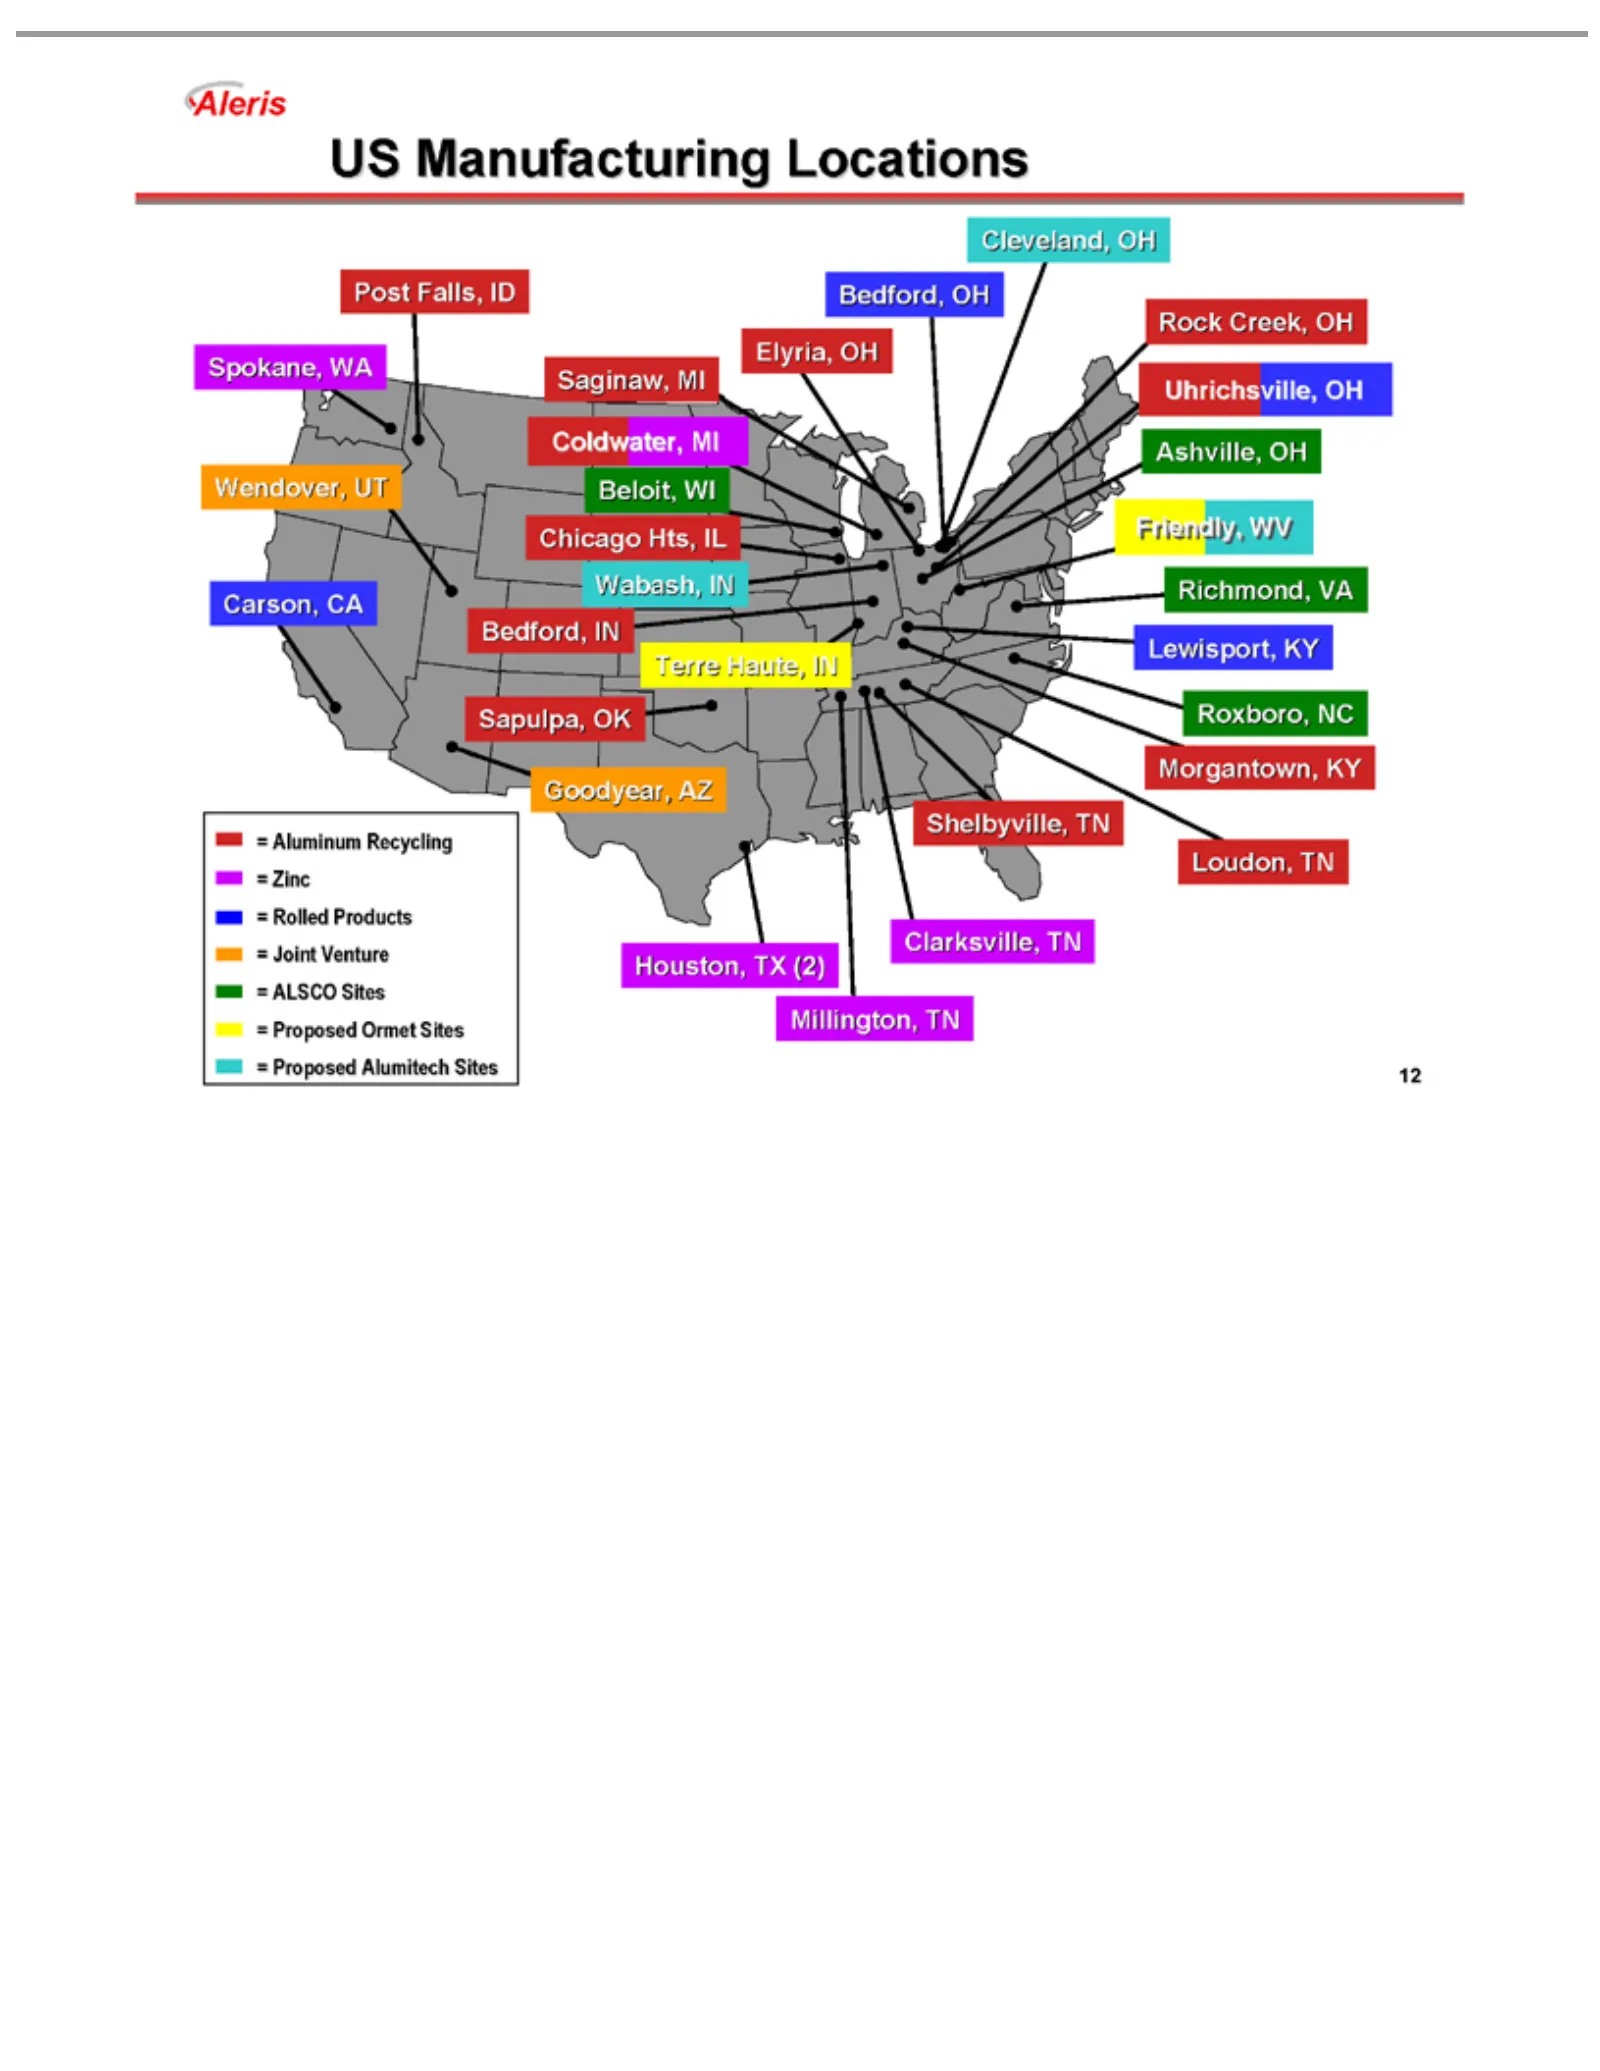
Slide 12: US Manufacturing Locations
US Post Spokane, Wendover, Carson, Saginaw, Coldwater, Beloit, Wabash, Terre Sapulpa, Goodyear, Bedford, Elyria, Cleveland, Rock Friendly, Richmond, Lewisport, Roxboro, Morgantown, Loudon, Shelbyville, Clarksville, Houston, Millington, = 12Aluminum Manufacturing Falls, Haute, Creek, WI OH CA TN IN O
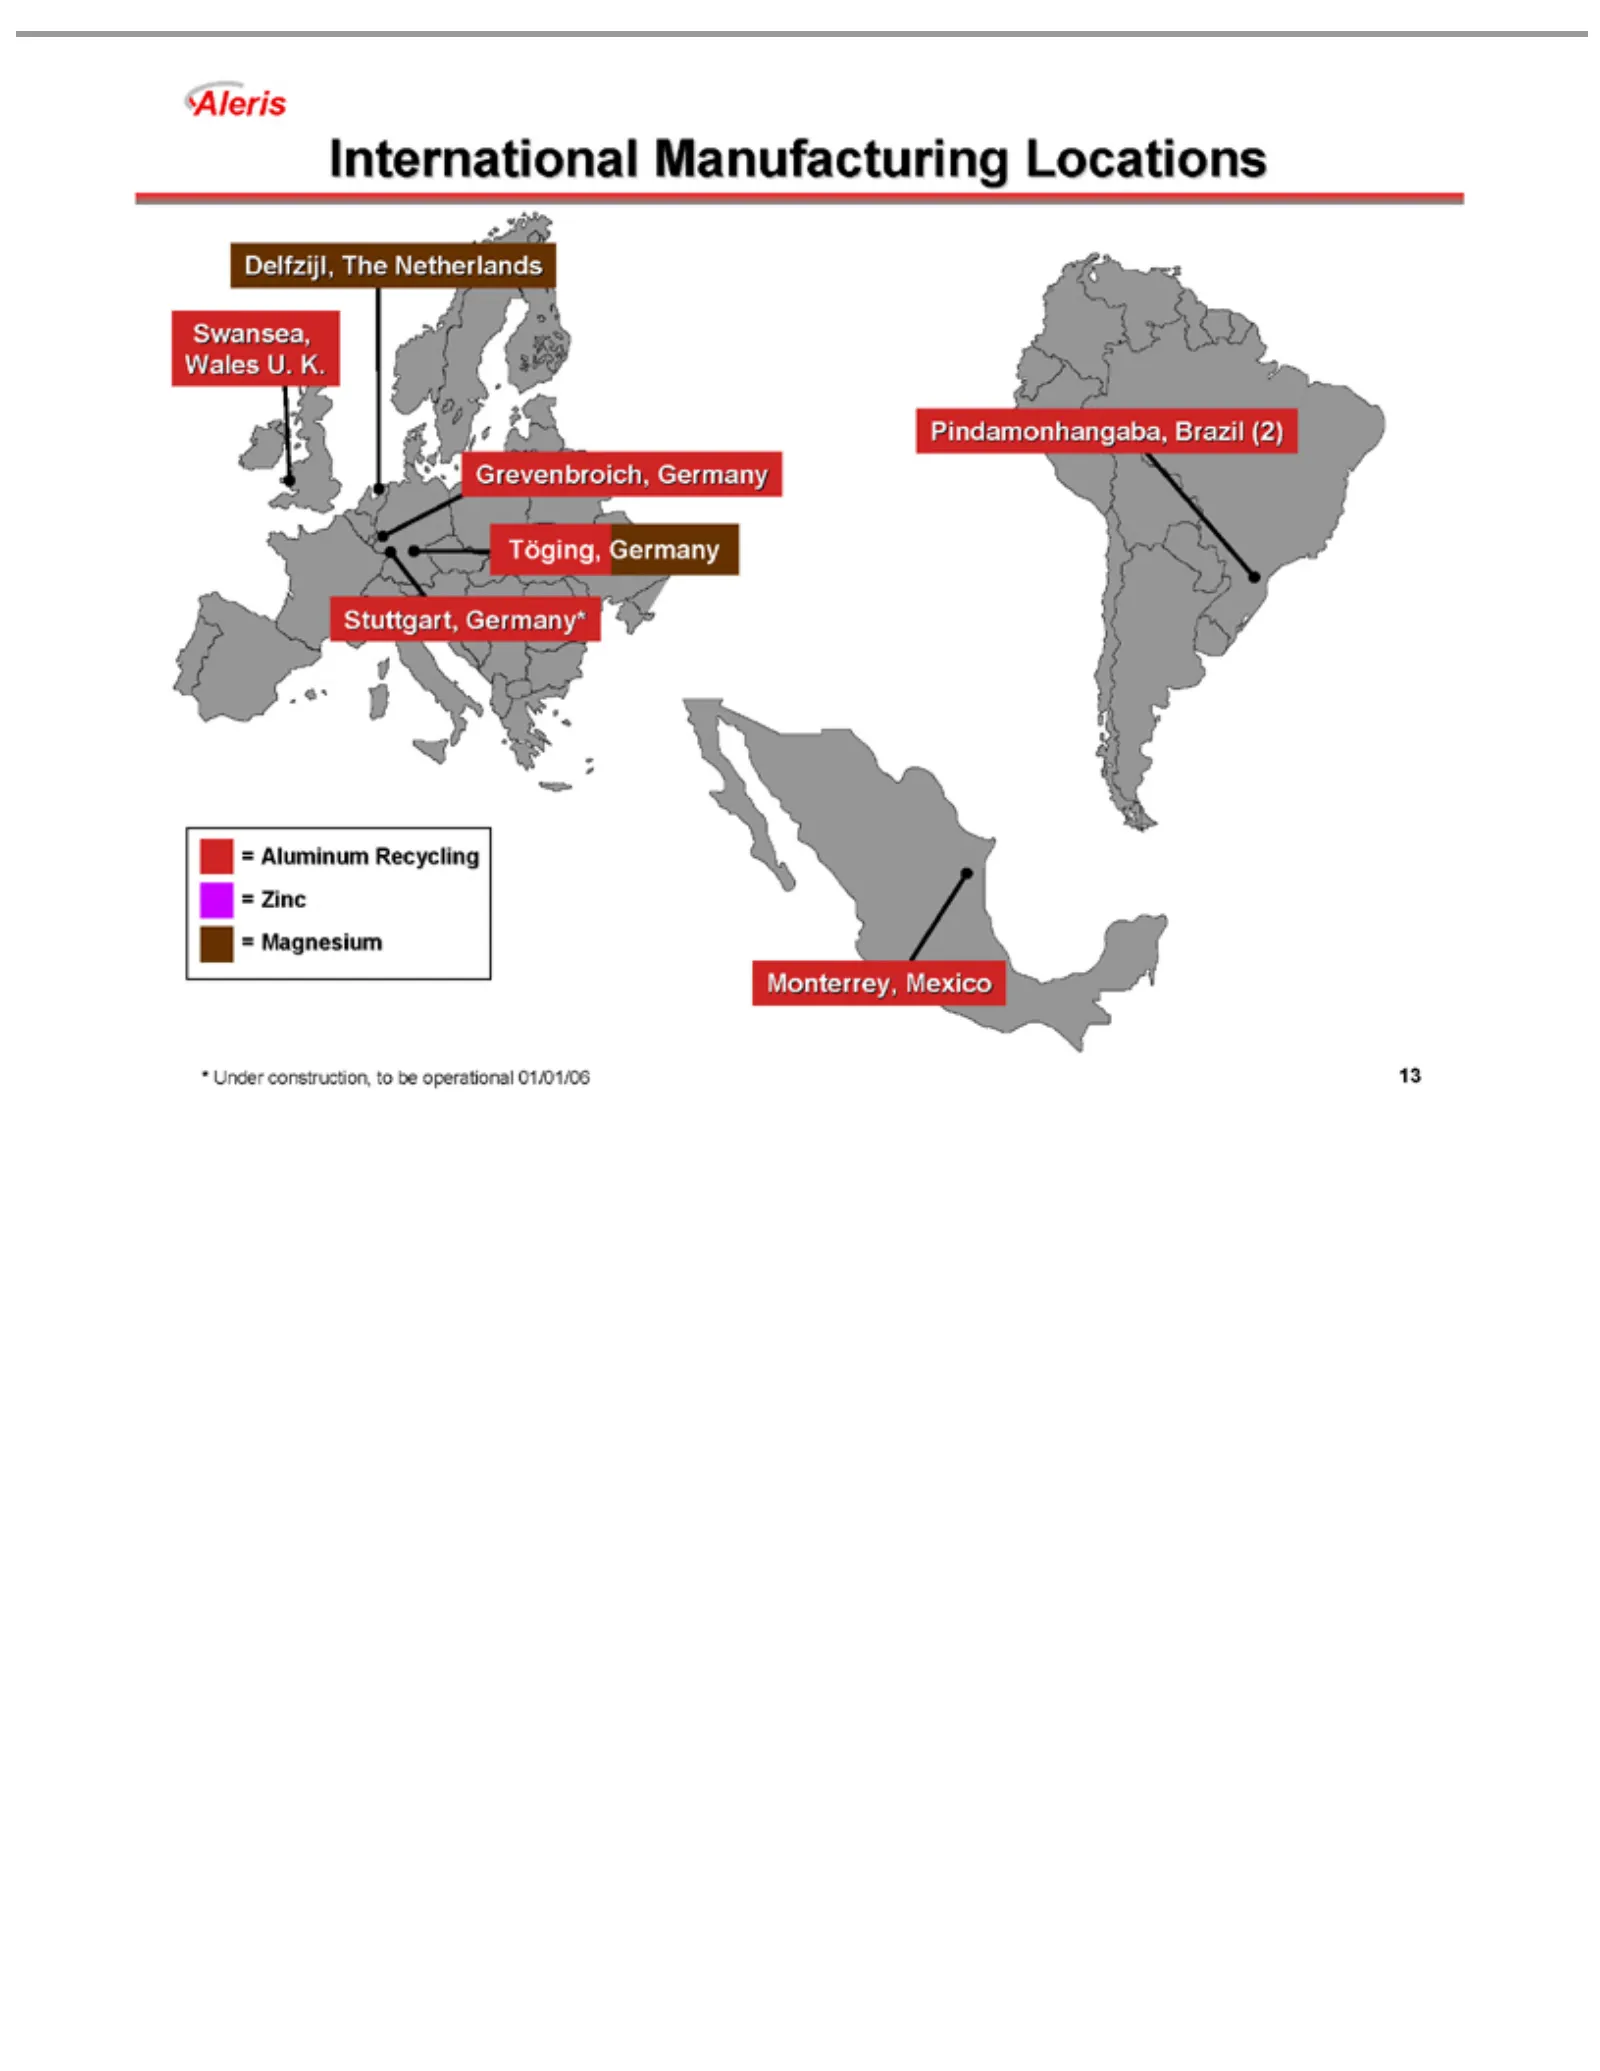
Slide 13: International Locations
International Delfzijl, Swansea, Grevenbroich, Töging, Stuttgart, = Monterrey, * 13Aluminum Under Germany The Germany* Wales Mexico Netherlands Recycling Manufacturing construction, Germany U. K. = Zincto Locations be = Magnesium operational 01/01/06
Slide 14: Key Highlights
Key Highlights Conversion Favorable Leading Superior Significant Strong 14 Platform positions low-cost long-term synergy liquidity company; forbusiness inrealization Cash diverse industry limited Flow model and trends commodity opportunity and growing Profitability industries exposure Growth
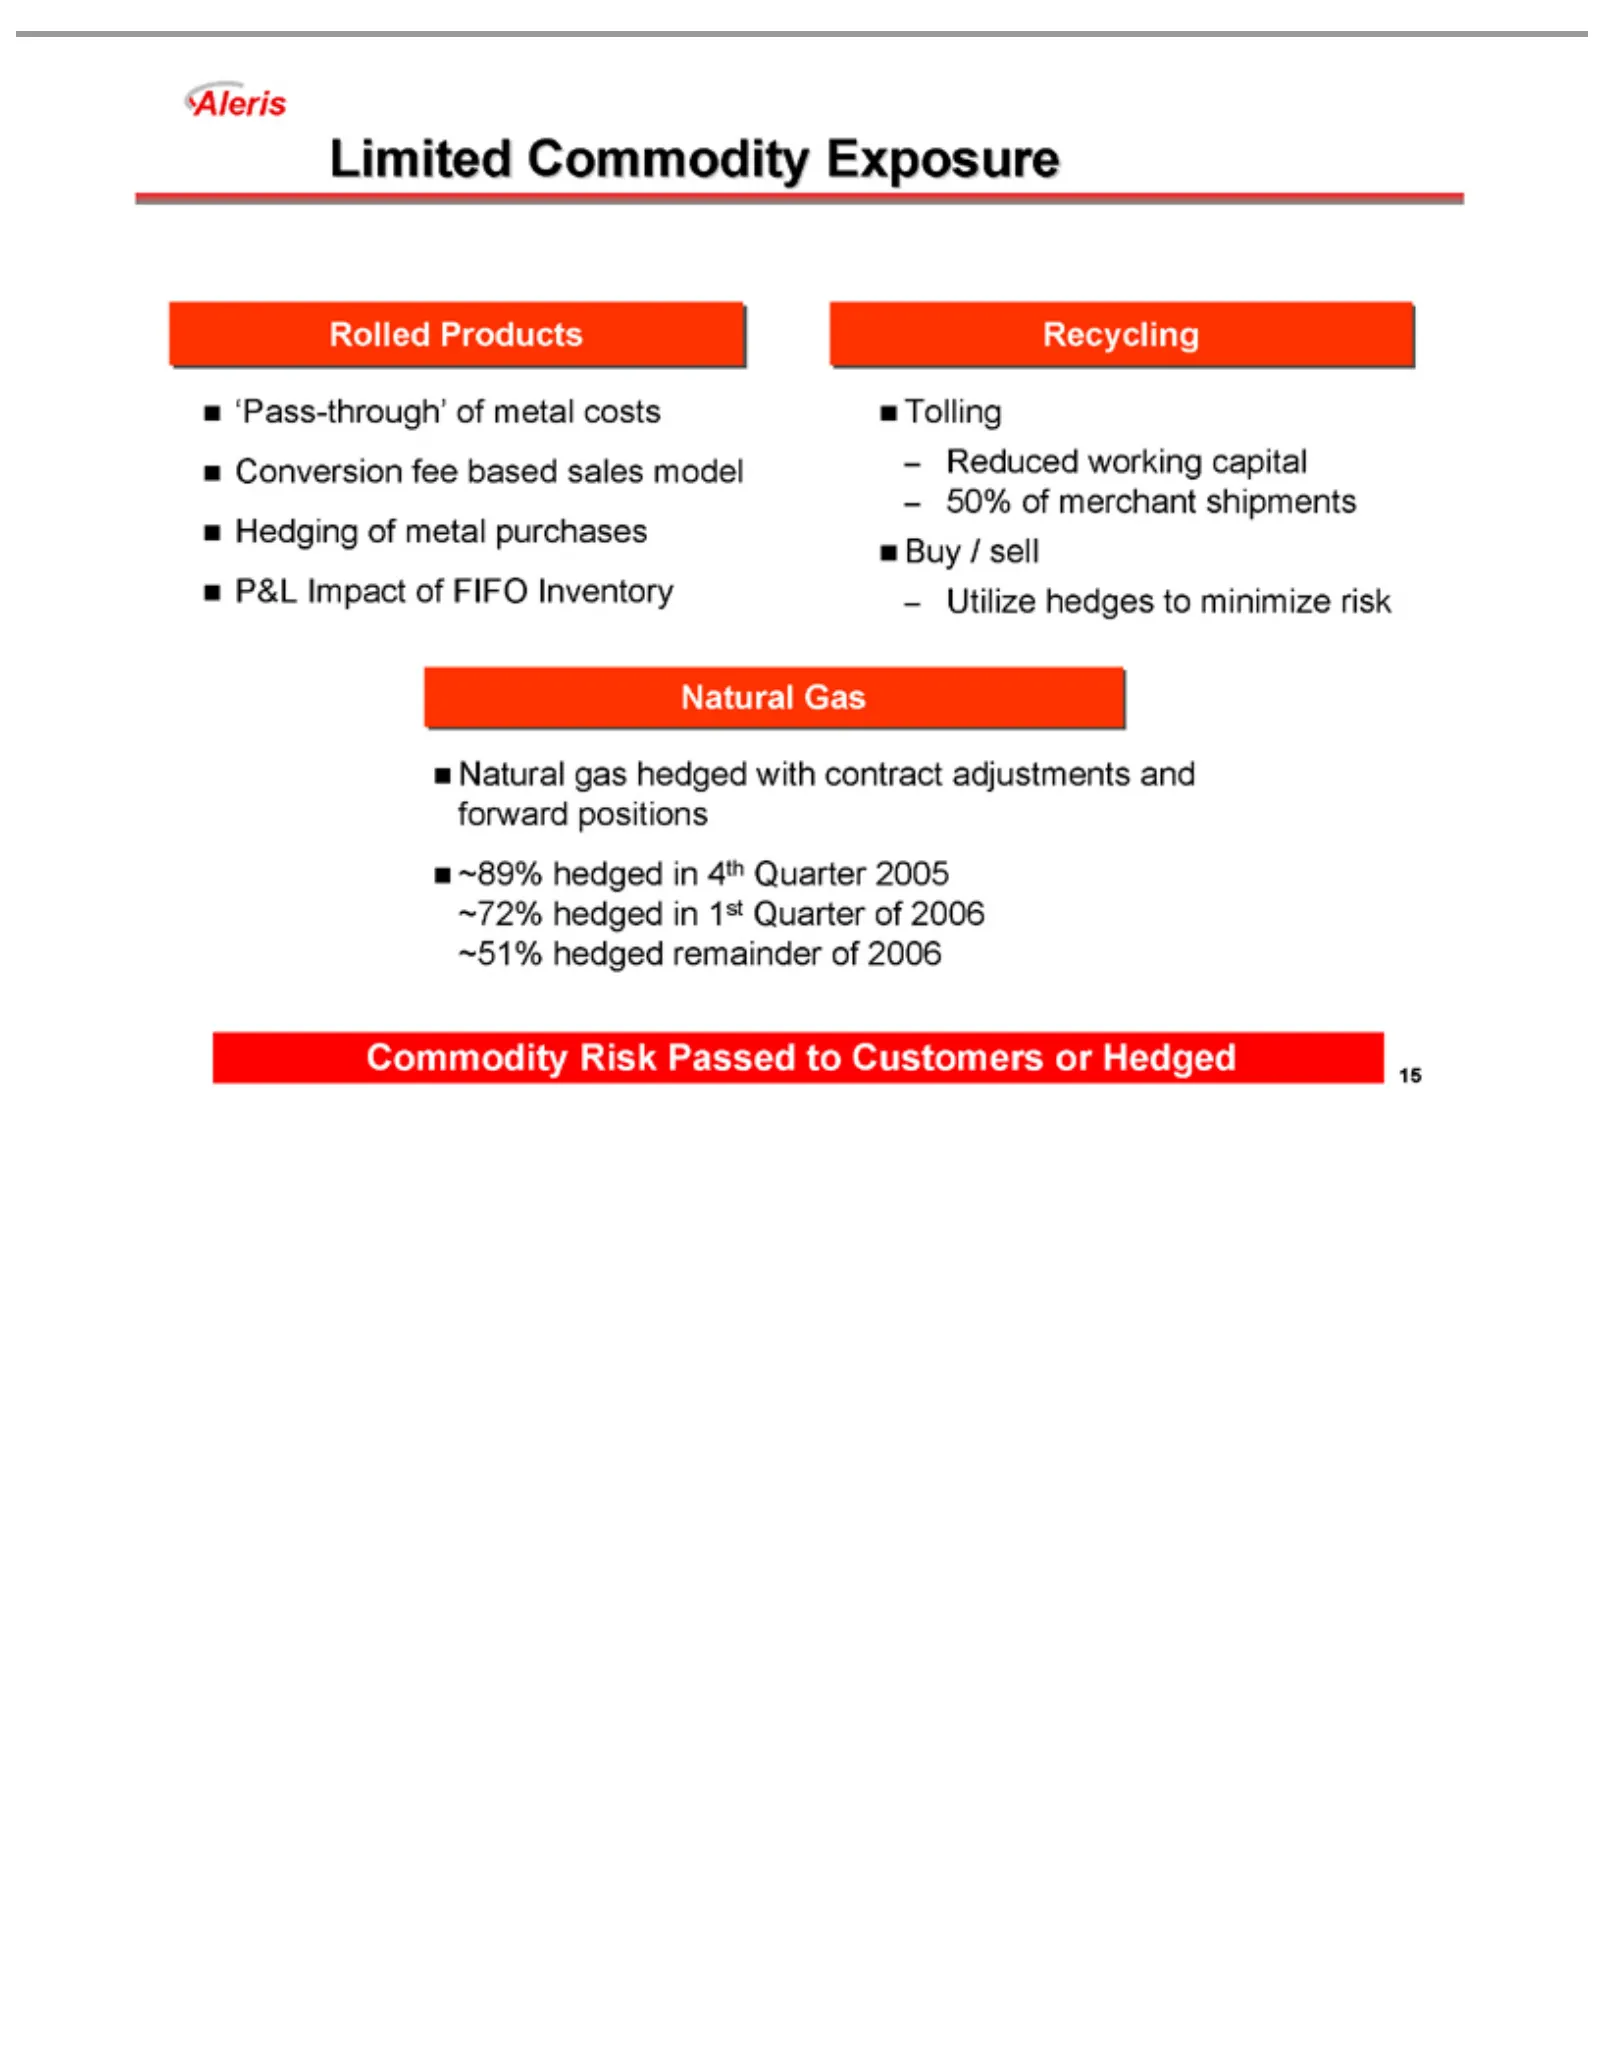
Slide 15: Limited Commodity Exposure
Limited Rolled ‘Pass-through’ Conversion Hedging P&L Reduced Tolling Recycling Buy Utilize Natural ~89% Commodity 15 /Impact sell hedged Products hedges Gas gas Commodity of working metal hedged fee Risk ofin to of FIFO based 4th minimize Passed metal purchases capital with Quarter Exposure Inventor
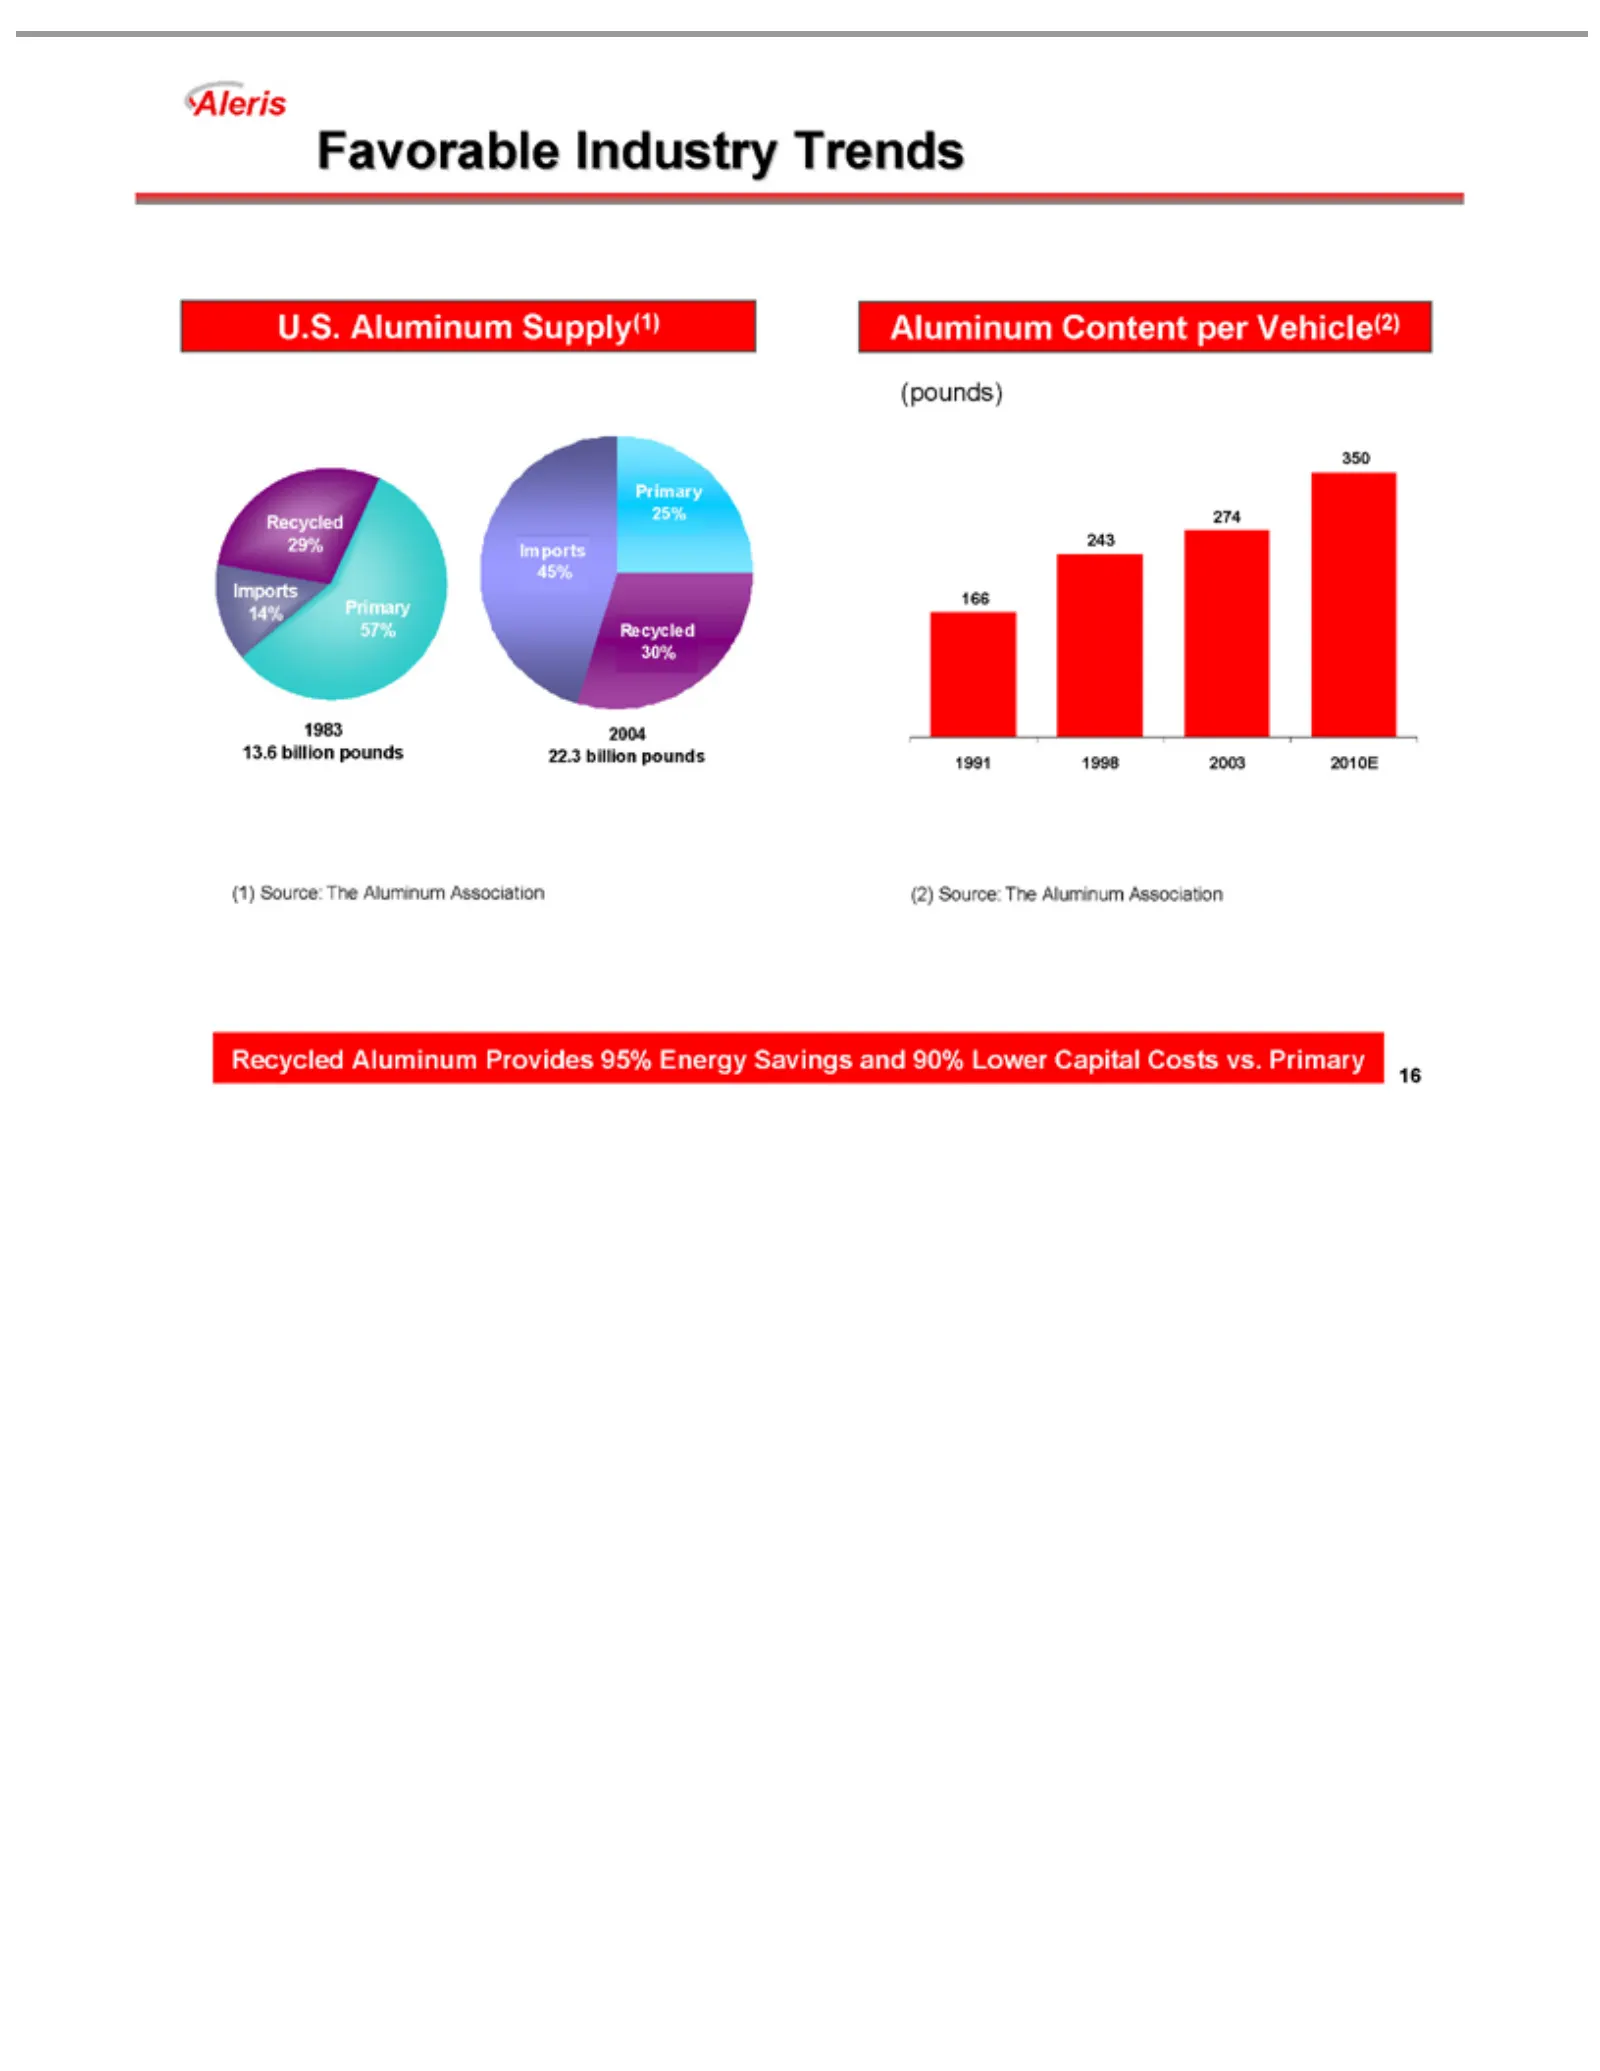
Slide 16: Favorable Industry Trends
Favorable U.S. Imports Primary 1983 13.6 Aluminum 274 350 (pounds) 1991 166 (1) 16 243 Aluminum billion 2004 1998 Recycled Source: 45% 14% 25% 57% 29% 30% Industry 2003 Content pounds The Supply(1) 2010E Aluminum Trends per 22.3 Aluminum Vehicle(2) billion95% Provides Association pounds (2) Source:
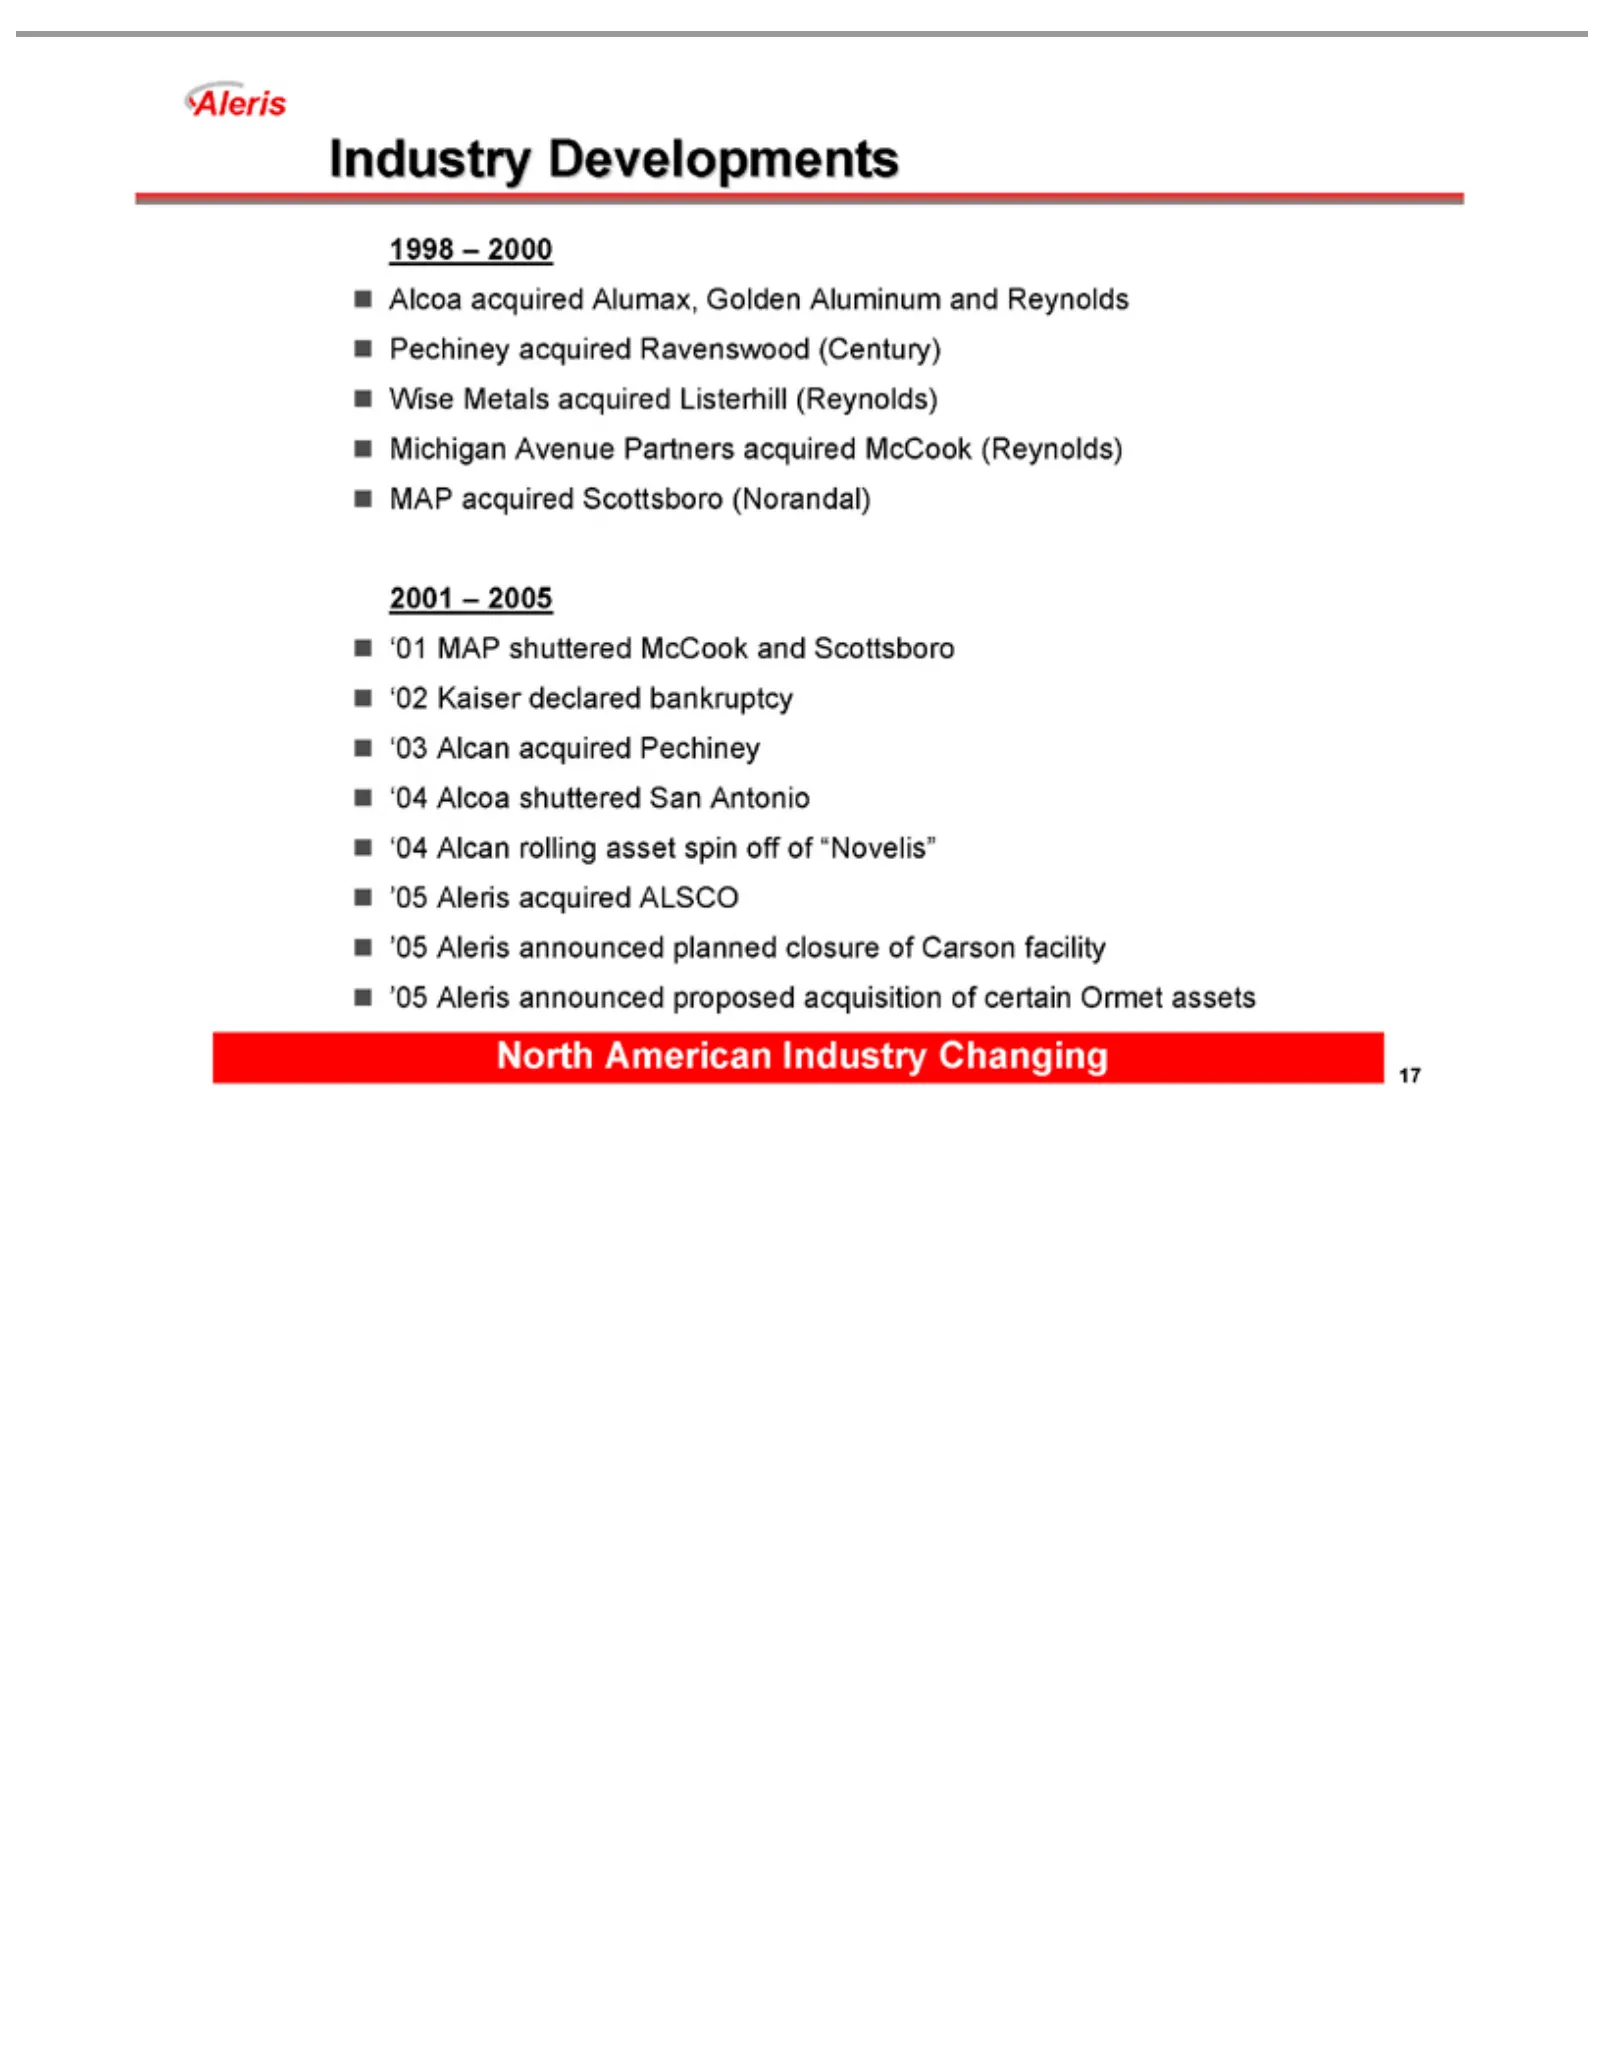
Slide 17: Changing North American Industry Developments
Industry 1998 Alcoa Pechiney Wise Michigan MAP 2001 ‘01 ‘02 ‘03 ‘04 ‘05 North 17 Alcoa Alcan Aleris MAP Kaiser –Metals acquired American acquired 2000 2005 Developments acquired shuttered Avenue acquired shuttered rolling announced declared acquired Scottsboro Alumax, Industry asset Partners Ravensw
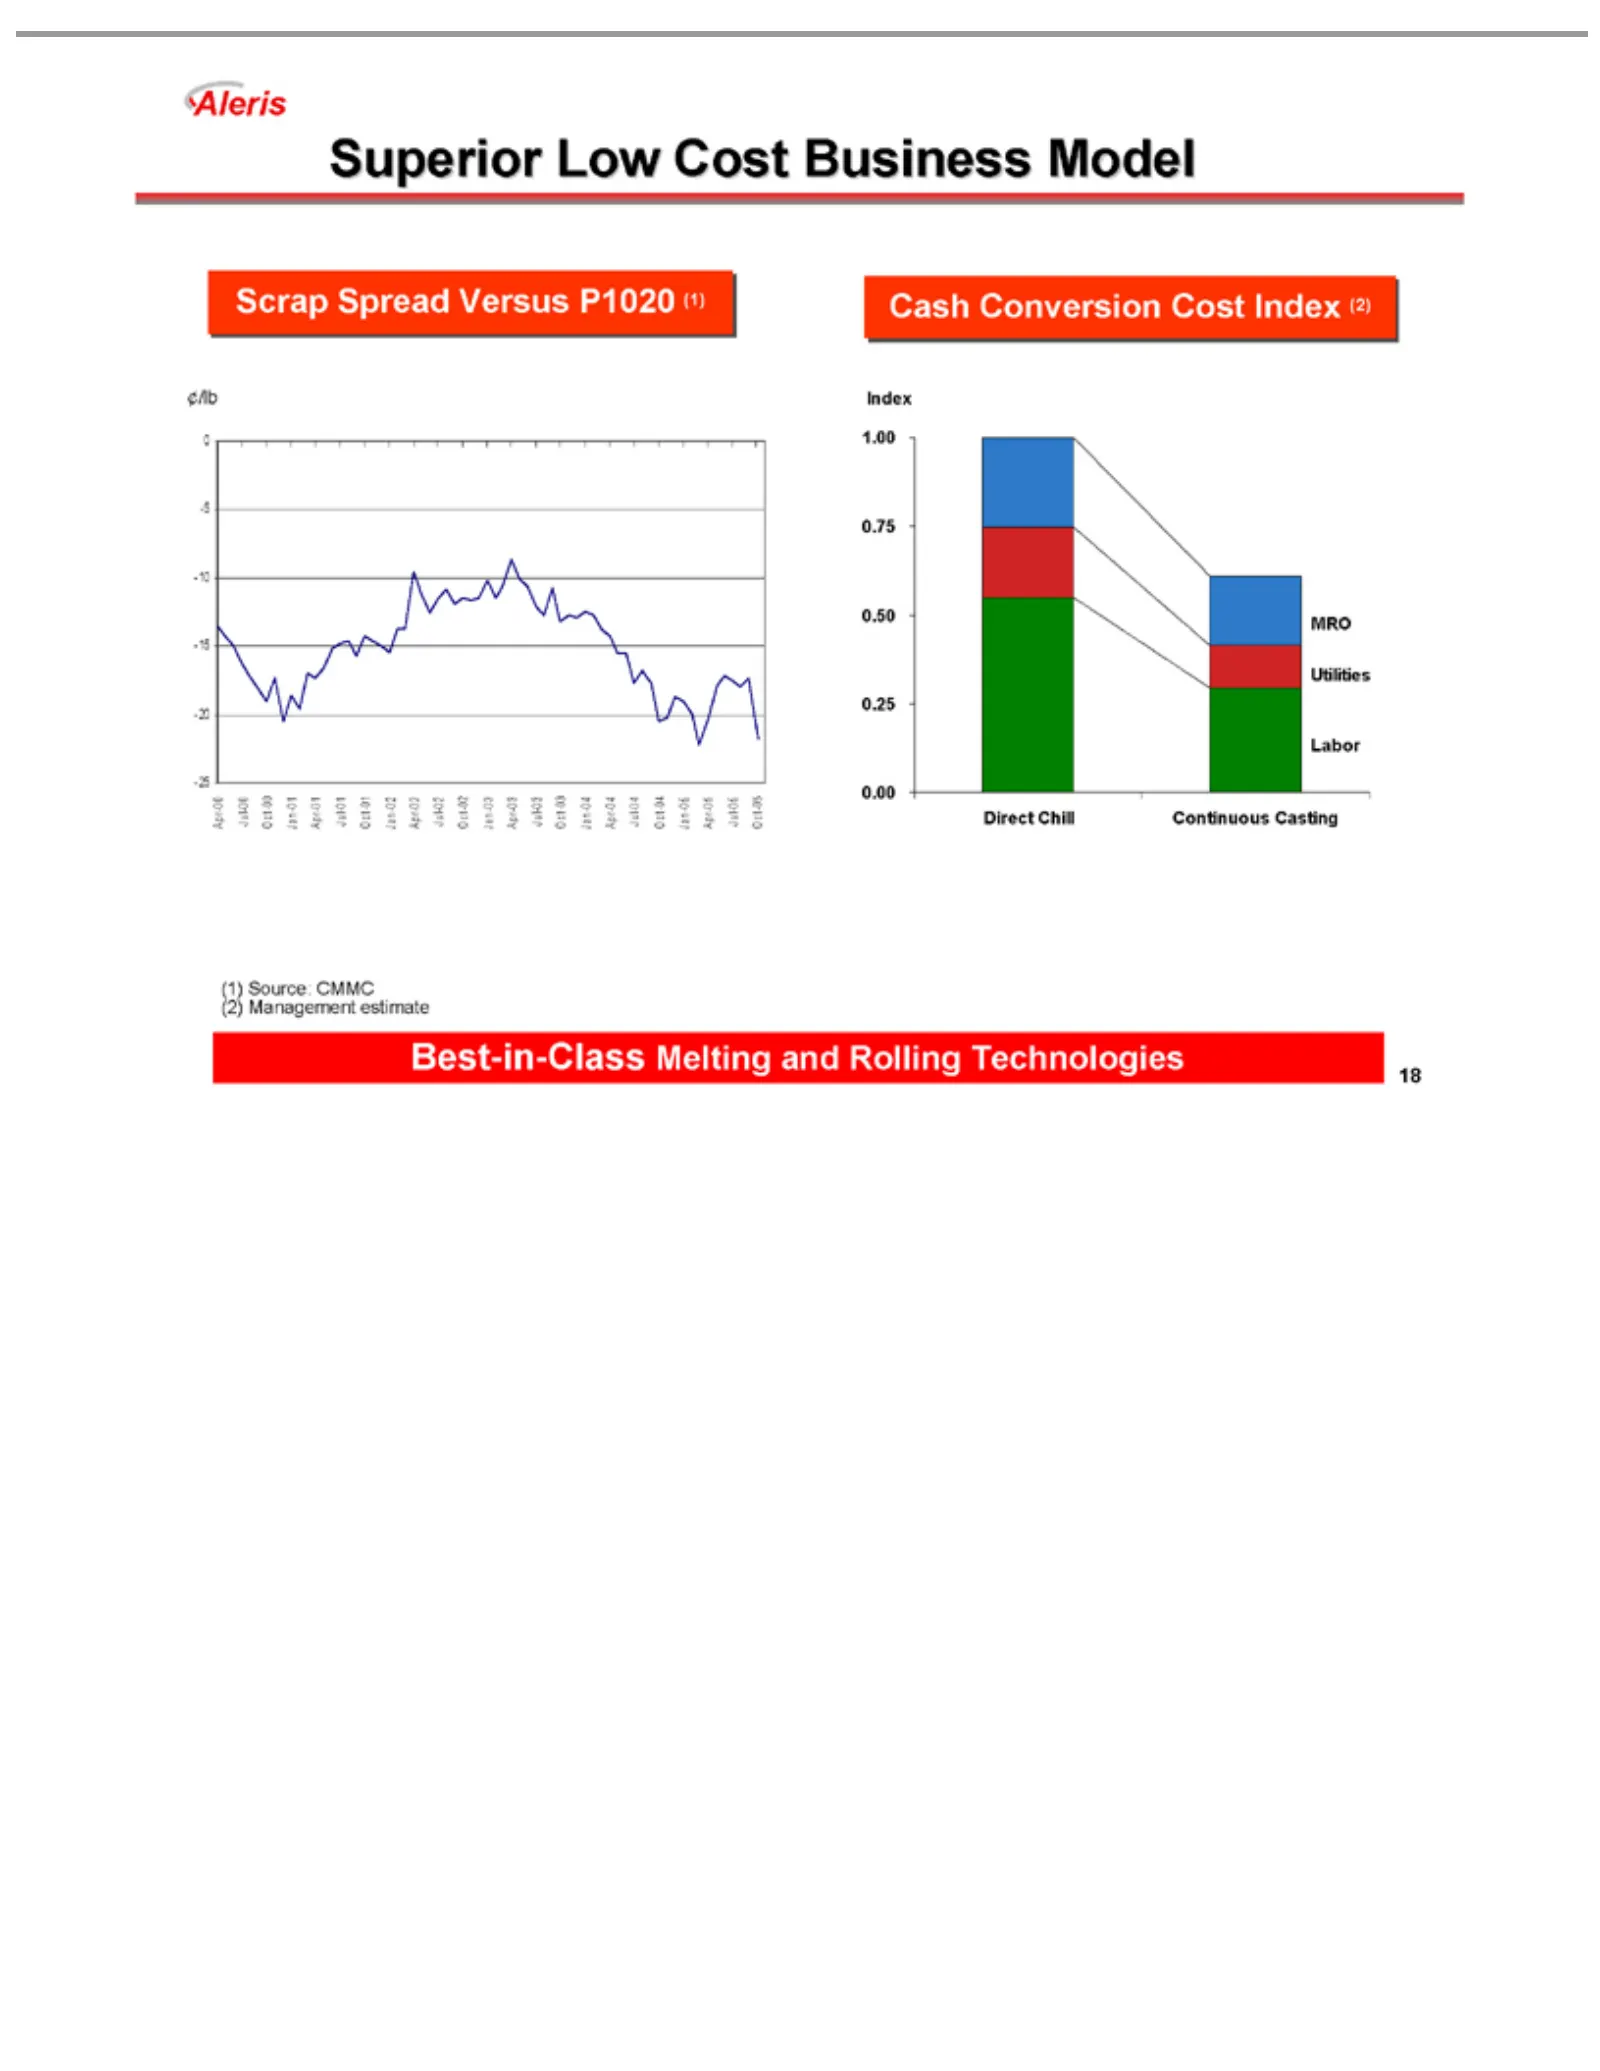
Slide 18: Superior Scrap Management Business Model
Superior Scrap -25 Apr-00 Utilities MRO 0.50 0.75 1.00 Index Direct 0.00 Labor (1) Best-in-Class 18 Source: -20Spread Chill Jul-00 -15 0.25 LowCMMC -10 Continuous Versus Melting Cost Oct-00 -5 0Business (2) ¢/lb P1020 Jan-01 and Management Casting Rolling (1) Model Apr-01 Cash Technologies Jul-01 Co
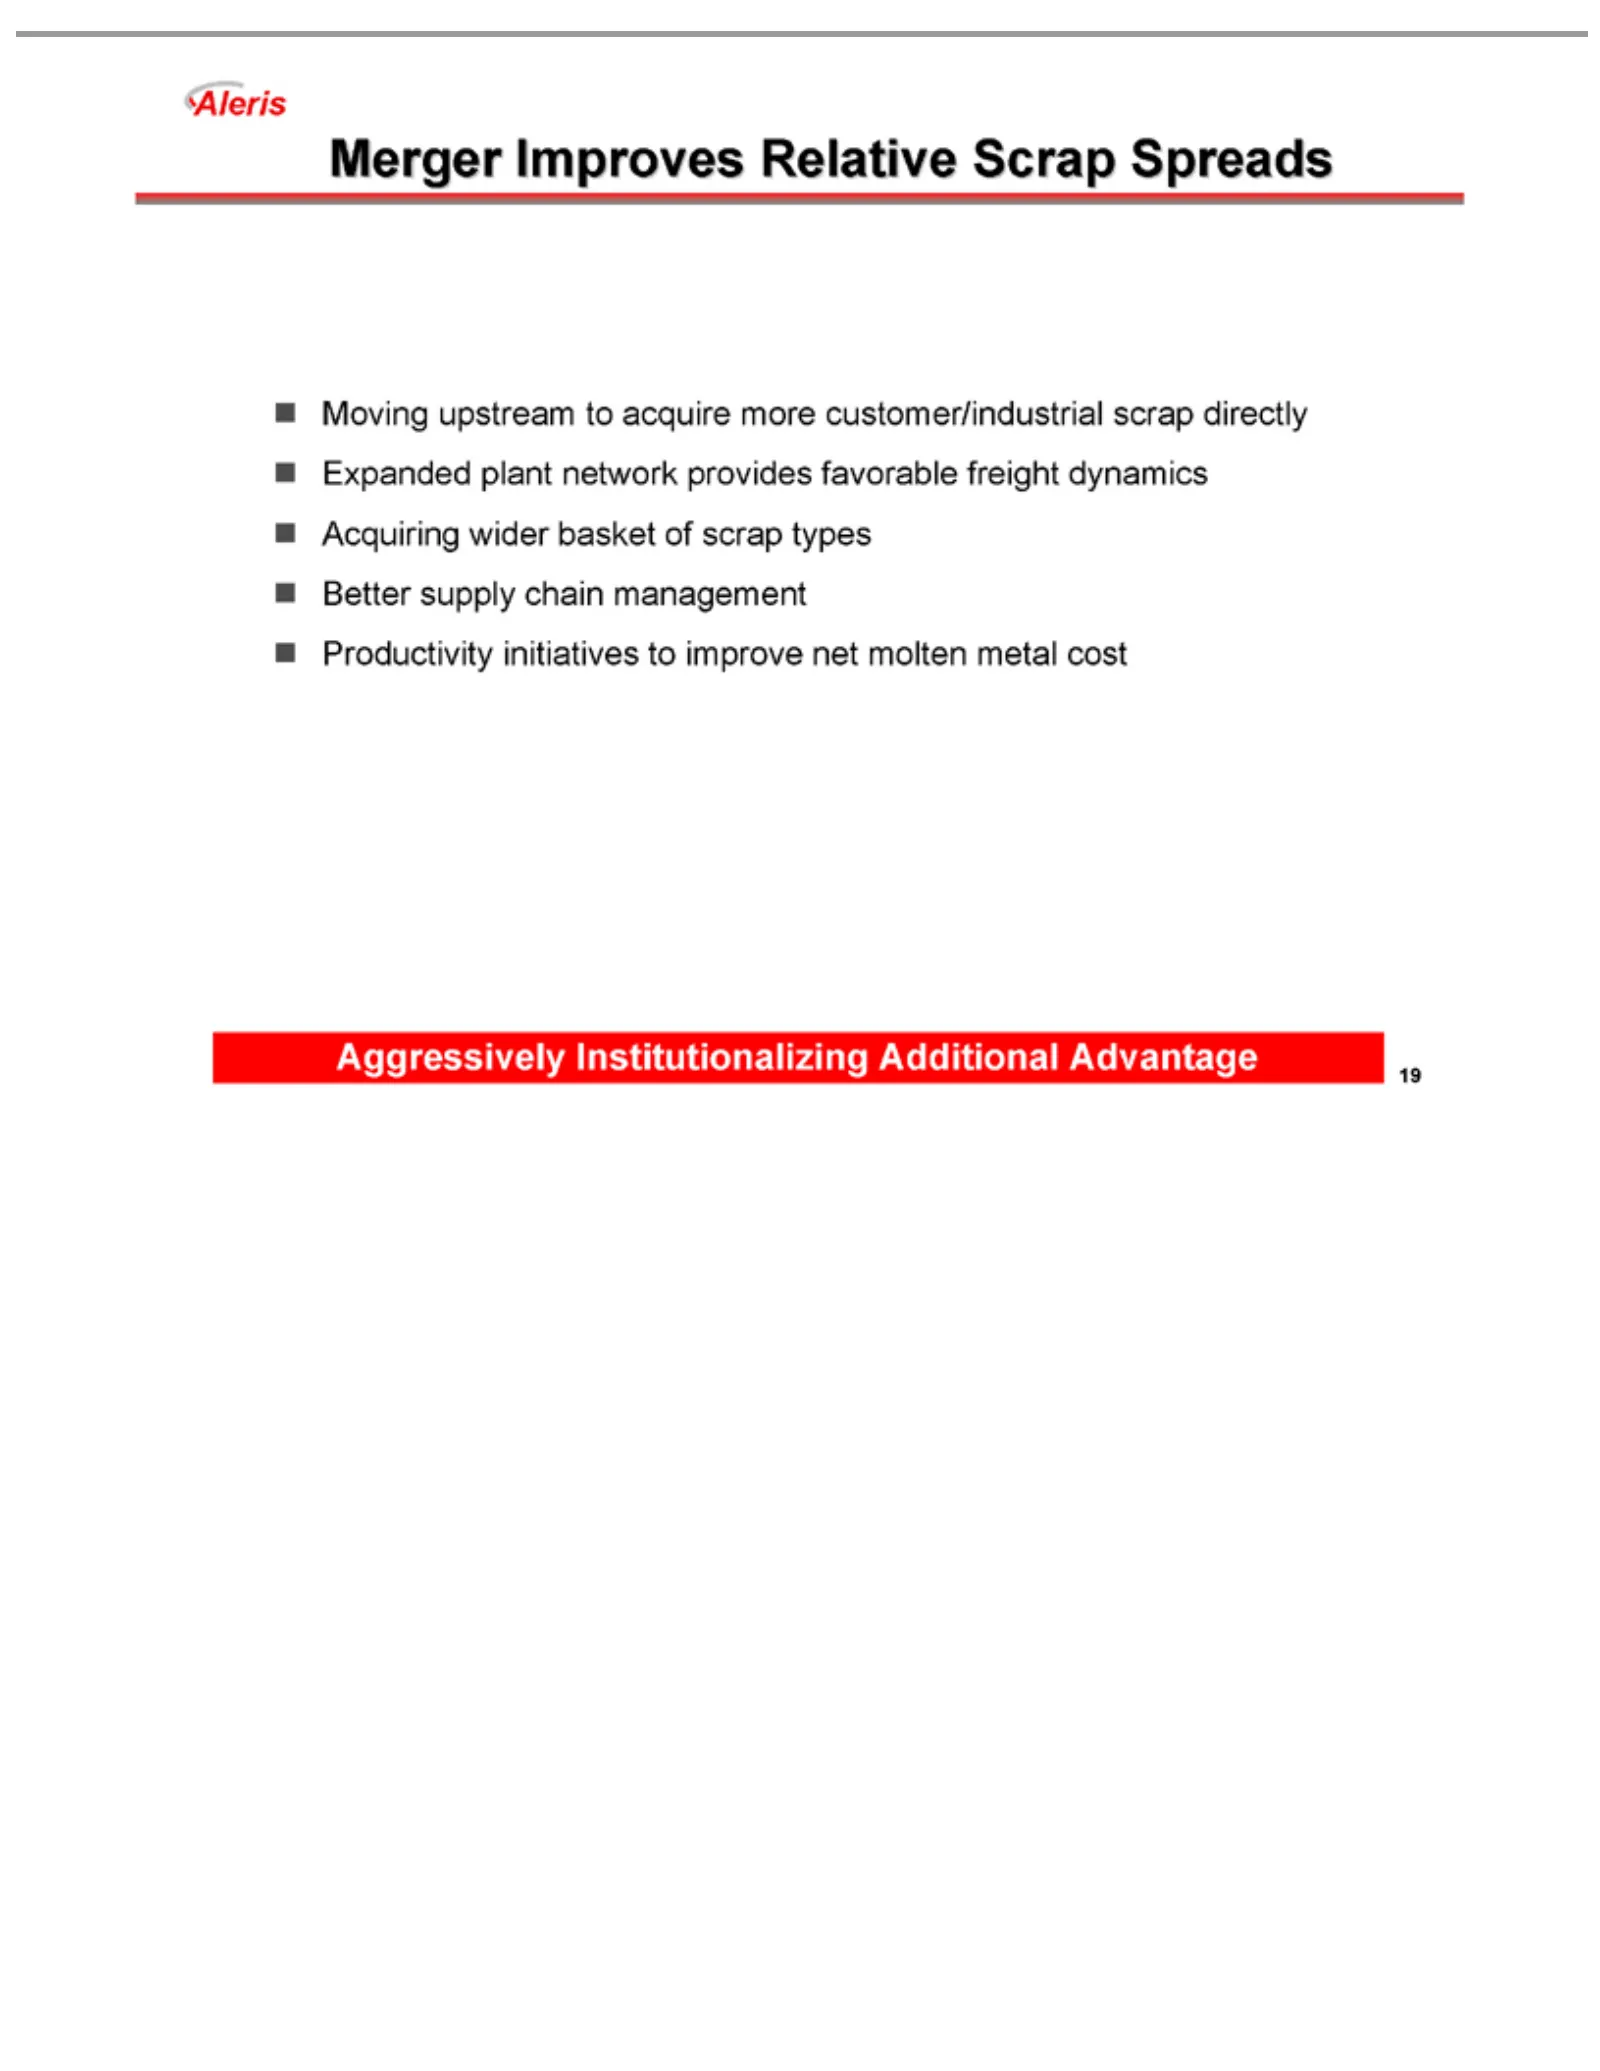
Slide 19: Merger Improves Relative Scrap Spreads
Merger Improves Moving management Aggressively 19 upstream Productivity Institutionalizing Relative to acquire initiatives Scrap more Additional Spreads customer/industrial to improve Advantage net molten scrapmetal directly costExpanded plant network provides favorable freight dynamics Acquiring wi
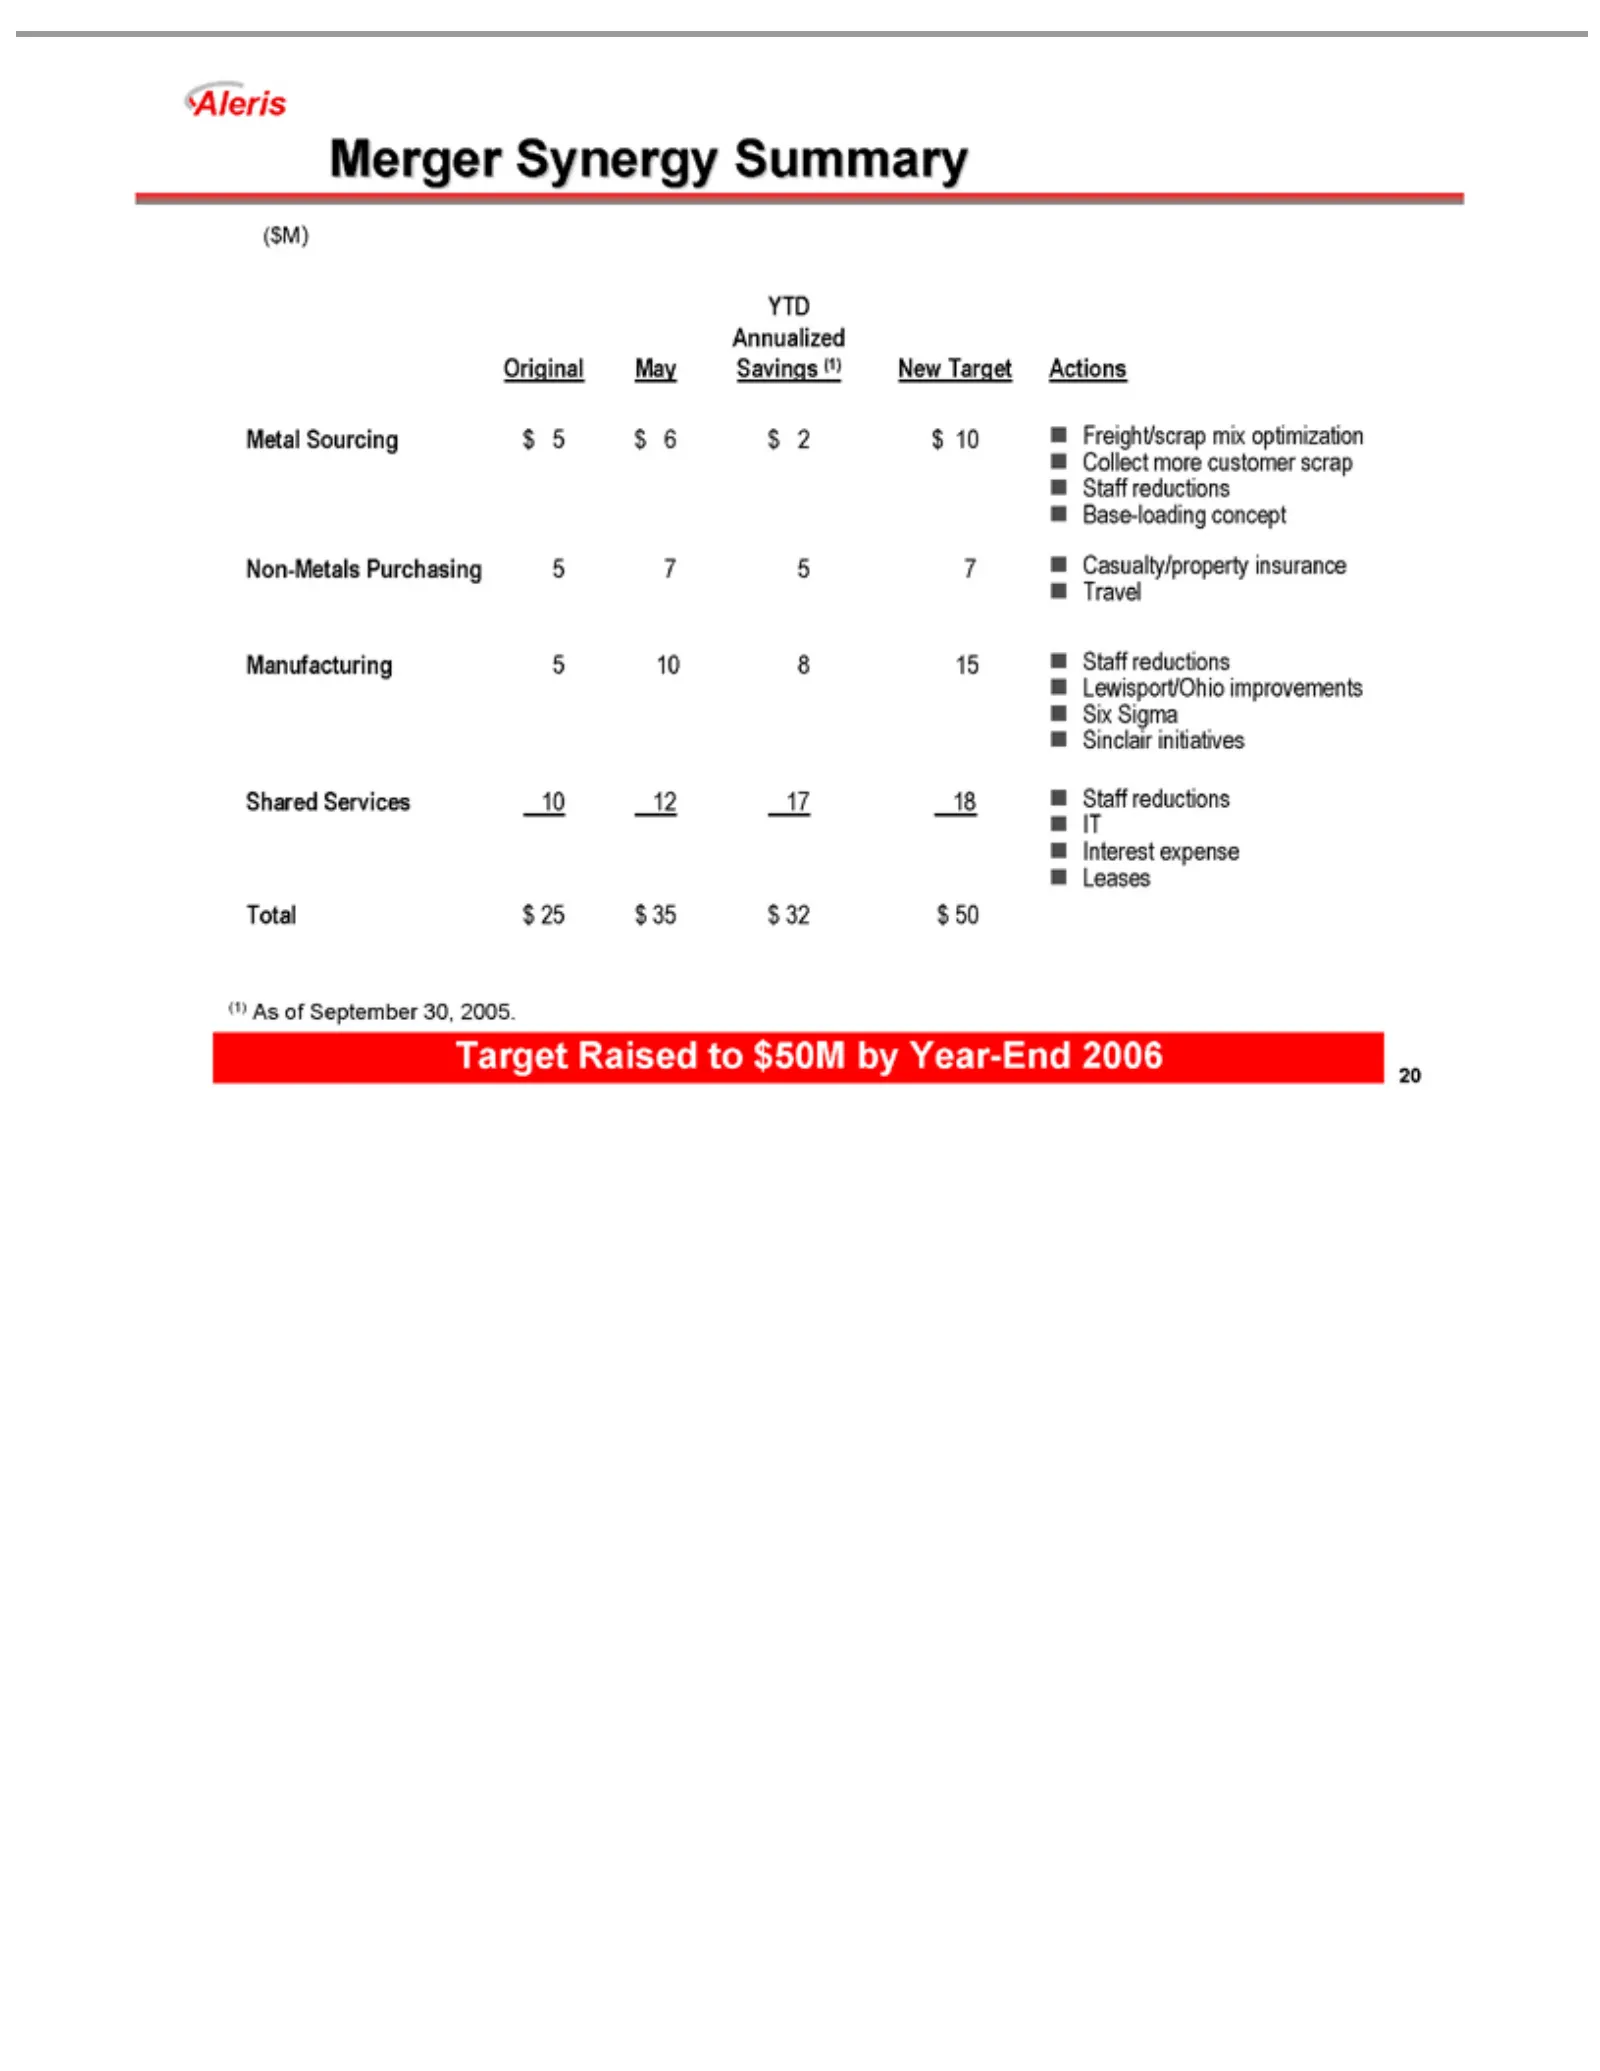
Slide 20: Merger Synergy Summary
Merger ($M) Metal Non-Metals Manufacturing Shared Total Freight/scrap Actions Lewisport/Ohio Staff Interest (1) 20 Targetreductions $25 Original Sourcing Services Synergy As expense $35 ofPurchasing Raised mix September $32 May 5$5 to improvements IT 10 Leases Summary 10 optimization $50 $6 12 YTD $
Slide 21: Recent Developments
Recent Developments
Slide 22: Recycling Acquisitions: Tomra and Alumitech
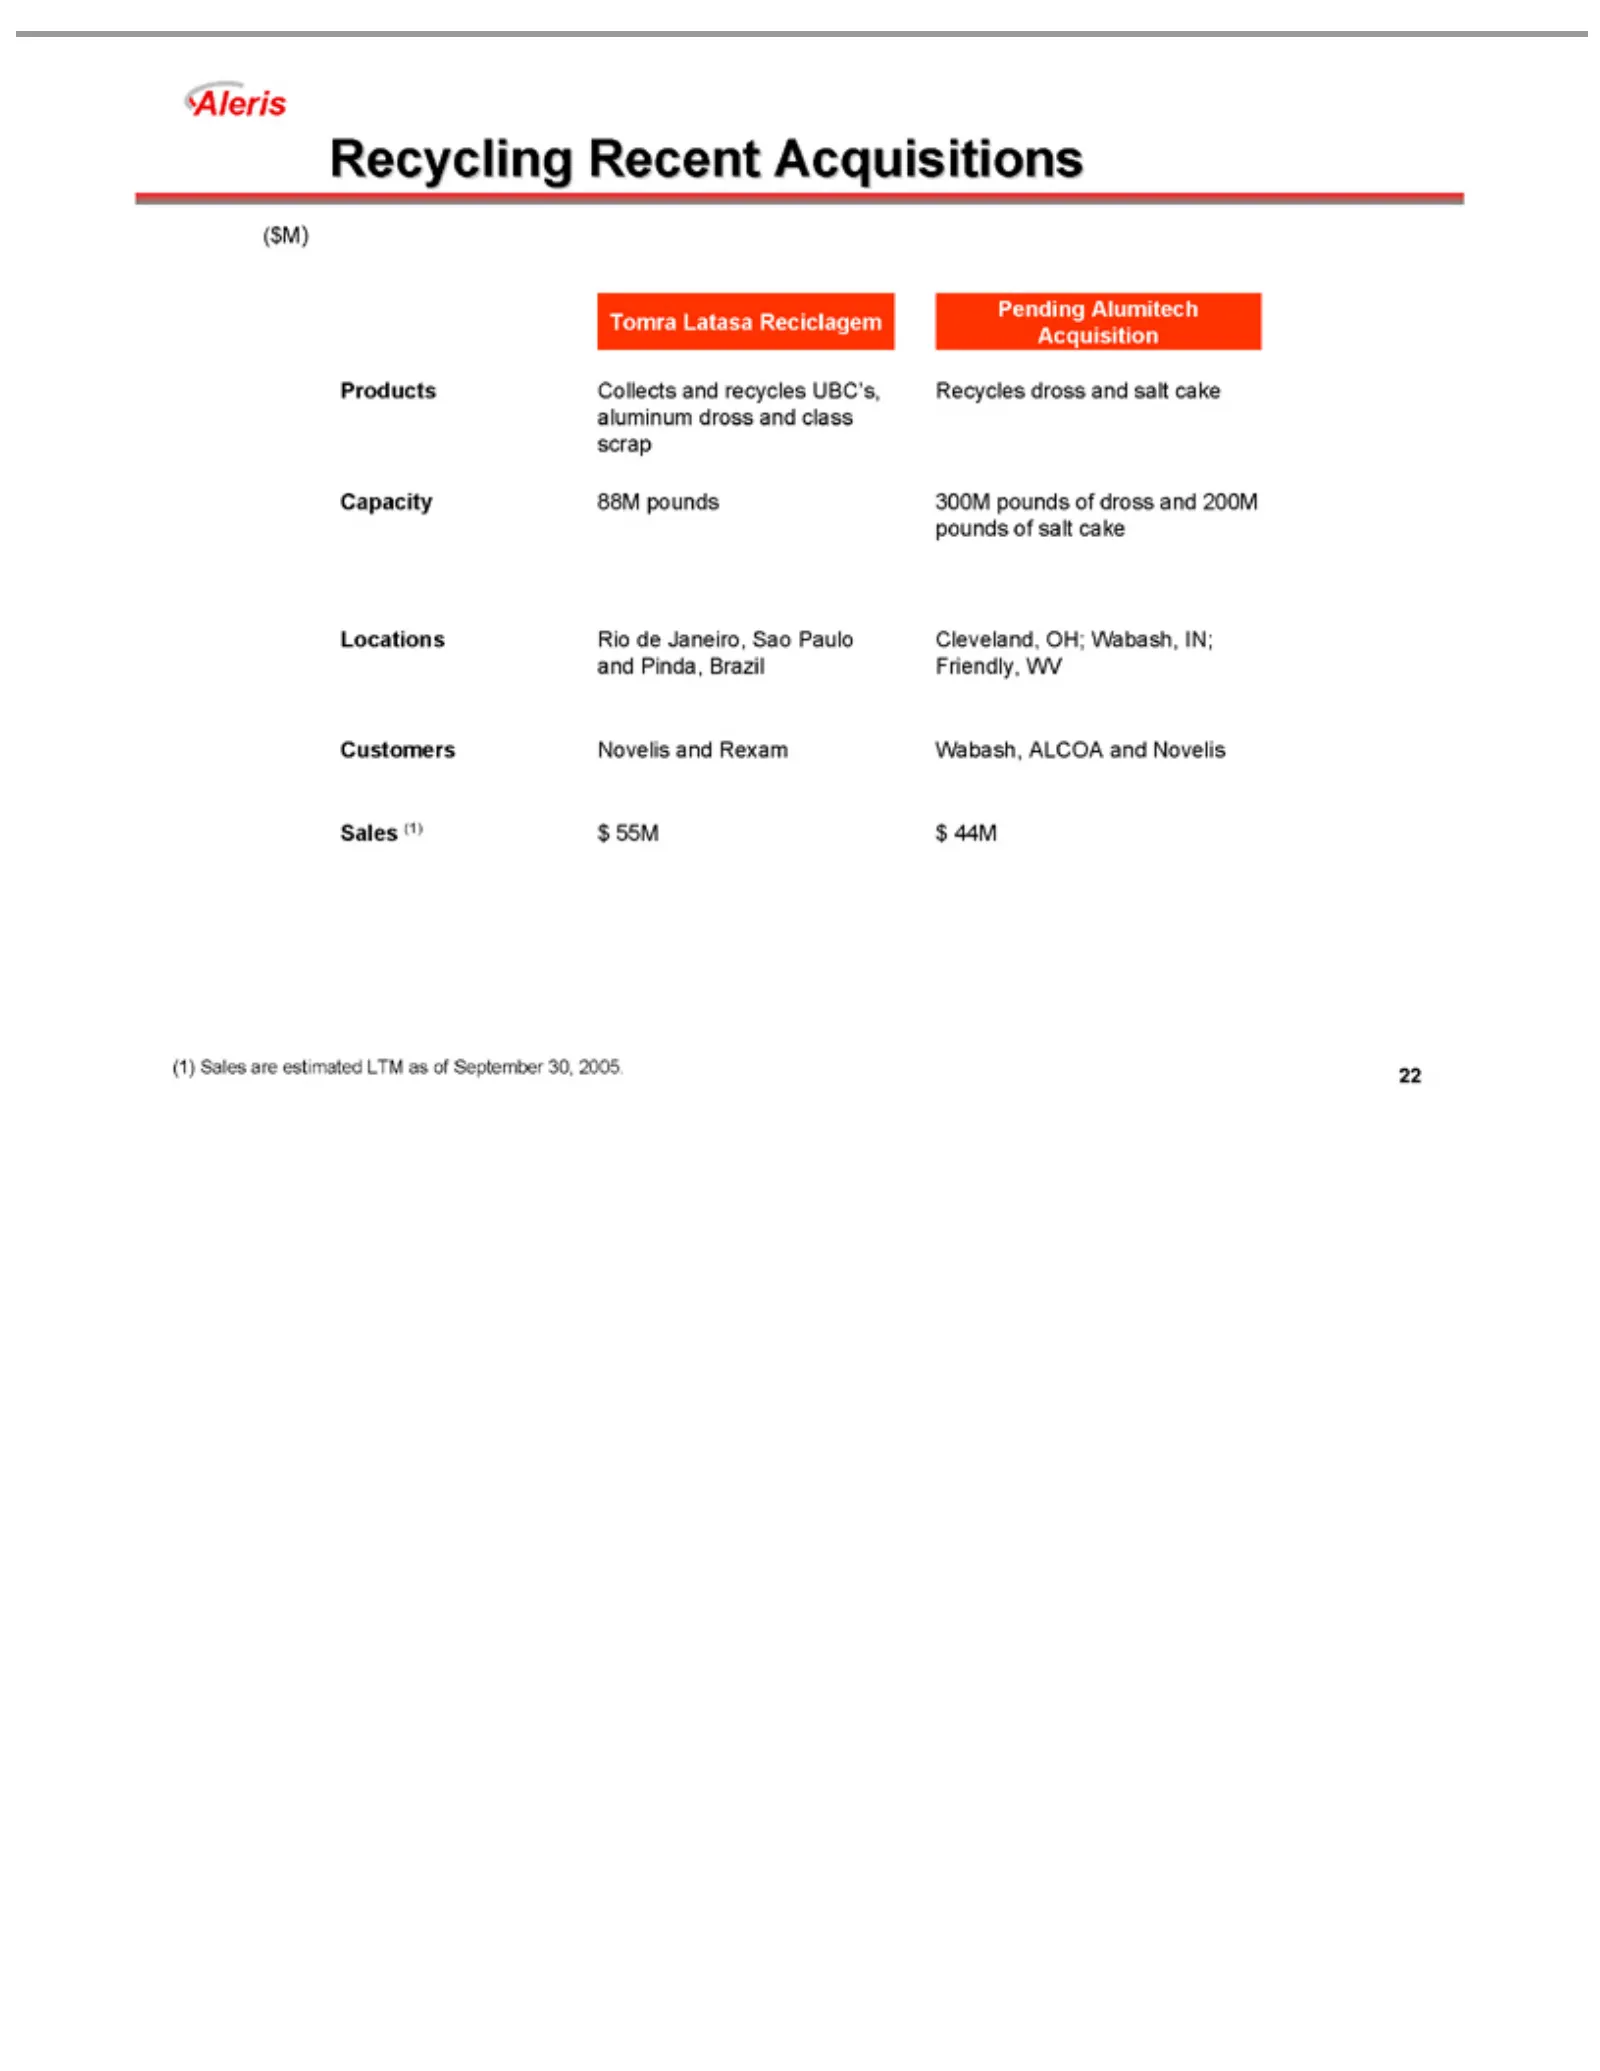
Recycling Tomra ($M) Products Capacity Locations Customers Sales (1) (1) Latasa Sales Collects $55M 88M Rio Recent Novelis are Reciclagem de pounds $44M estimated Janeiro, Acquisitions and andrecycles 300M Rexam Sao Pending LTM pounds Paulo UBC’s, Wabash, asAlumitech of and ofSeptember aluminum dros
Slide 23: Rolled Products: ALSCO and Ormet
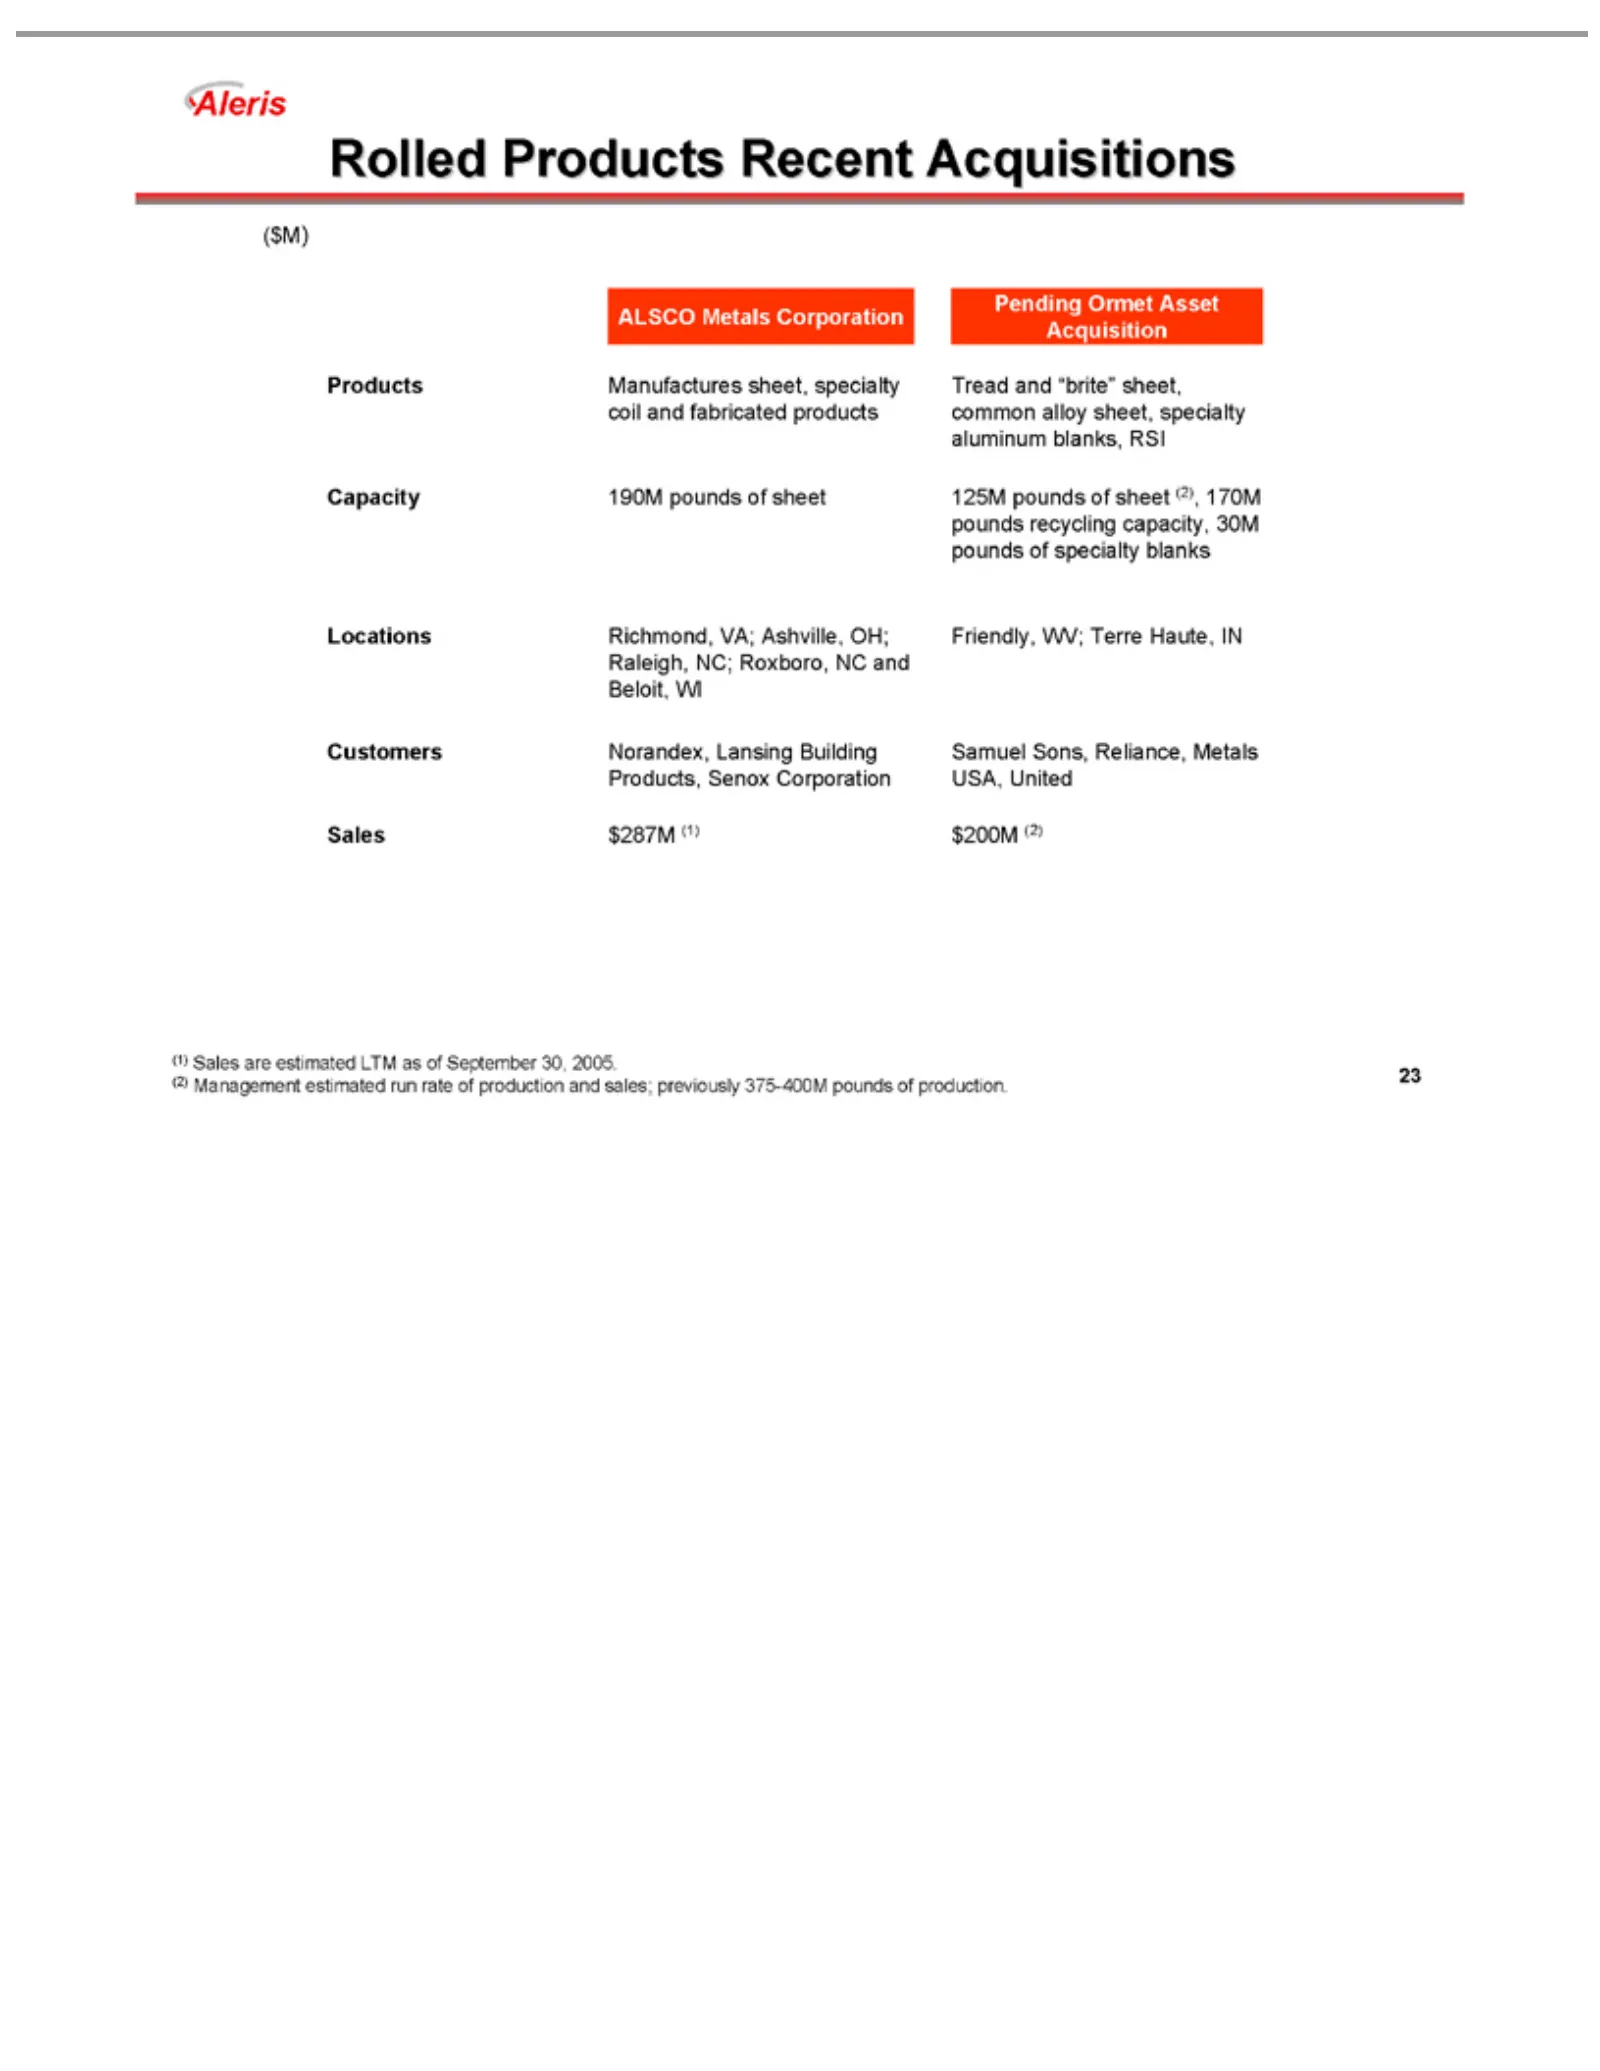
Rolled ($ ALSCO Products Capacity Locations Customers Sales (1) 23 (2)M) $287M Products Sales Metals Manufactures 190M Richmond, Norandex, (1) arepounds Corporation ManagementRecent $200M estimated VA; Lansing sheet, of Acquisitions (2) Ashville, sheet LTM Pending estimatedspecialty Building 125M as
Slide 24: Strategic Rationale for Pending Acquisitions
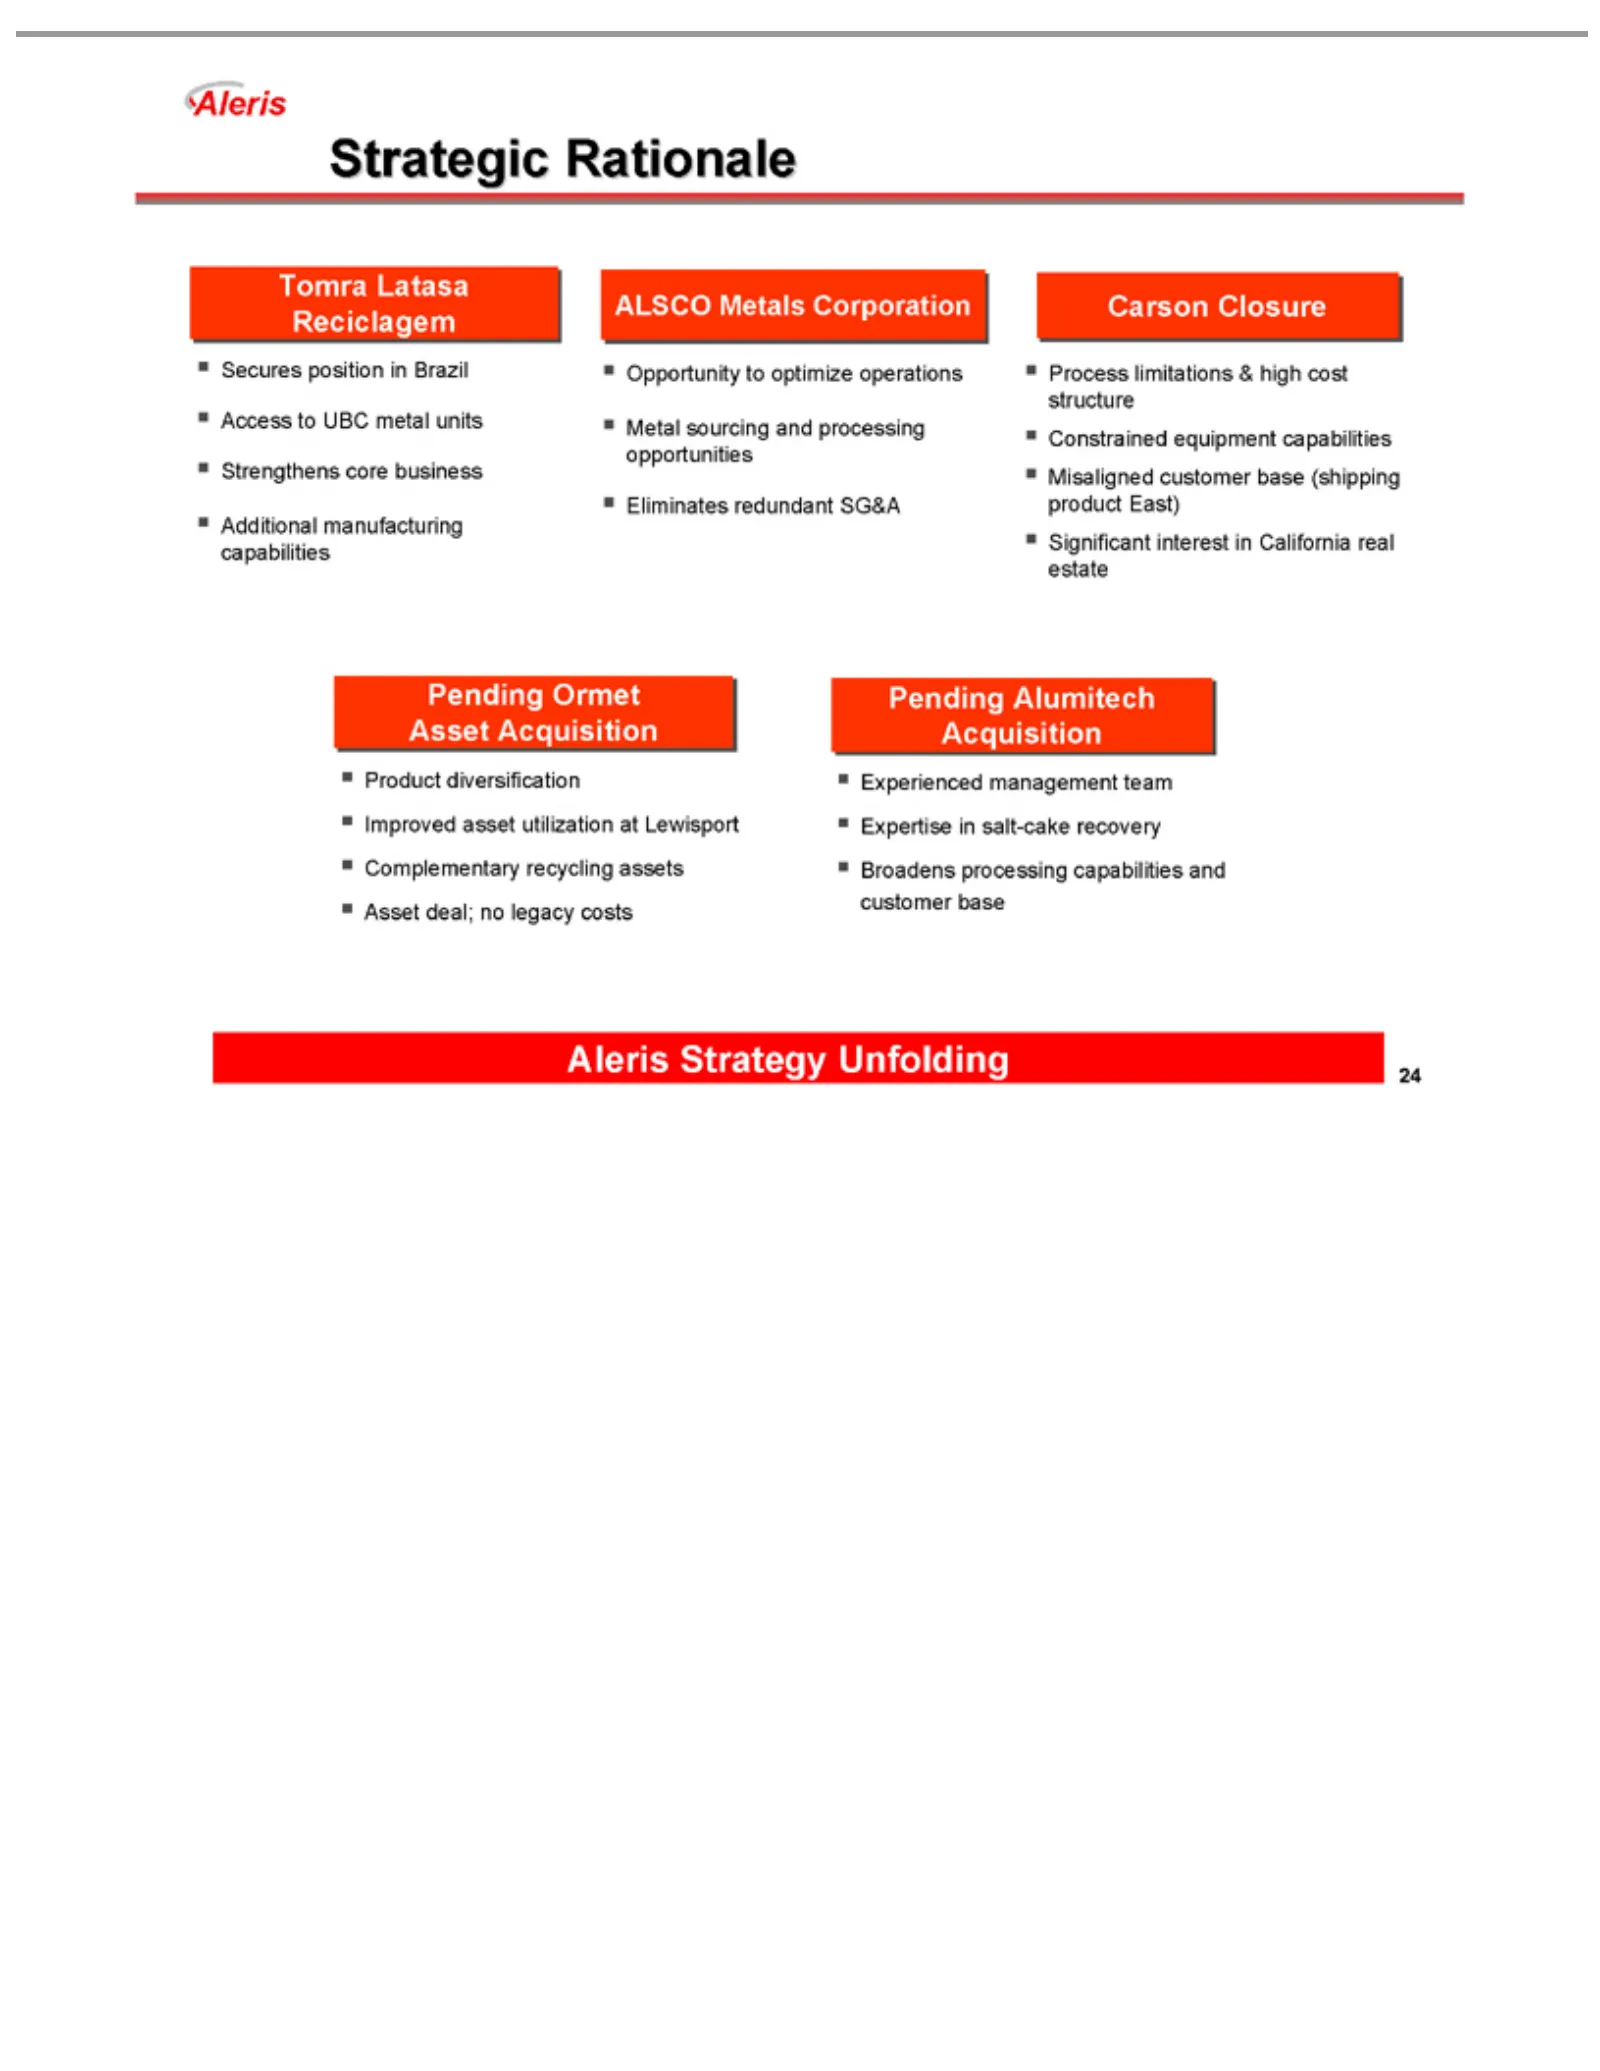
Strategic Tomra Secures Access structure Strengthens Additional Pending Product Improved Complementary Asset Aleris 24 deal; Strategy Latasa to position diversification Alumitech Ormet Rationale UBC asset manufacturing no core Reciclagem legacy Unfolding Asset utilization metal recycling in business
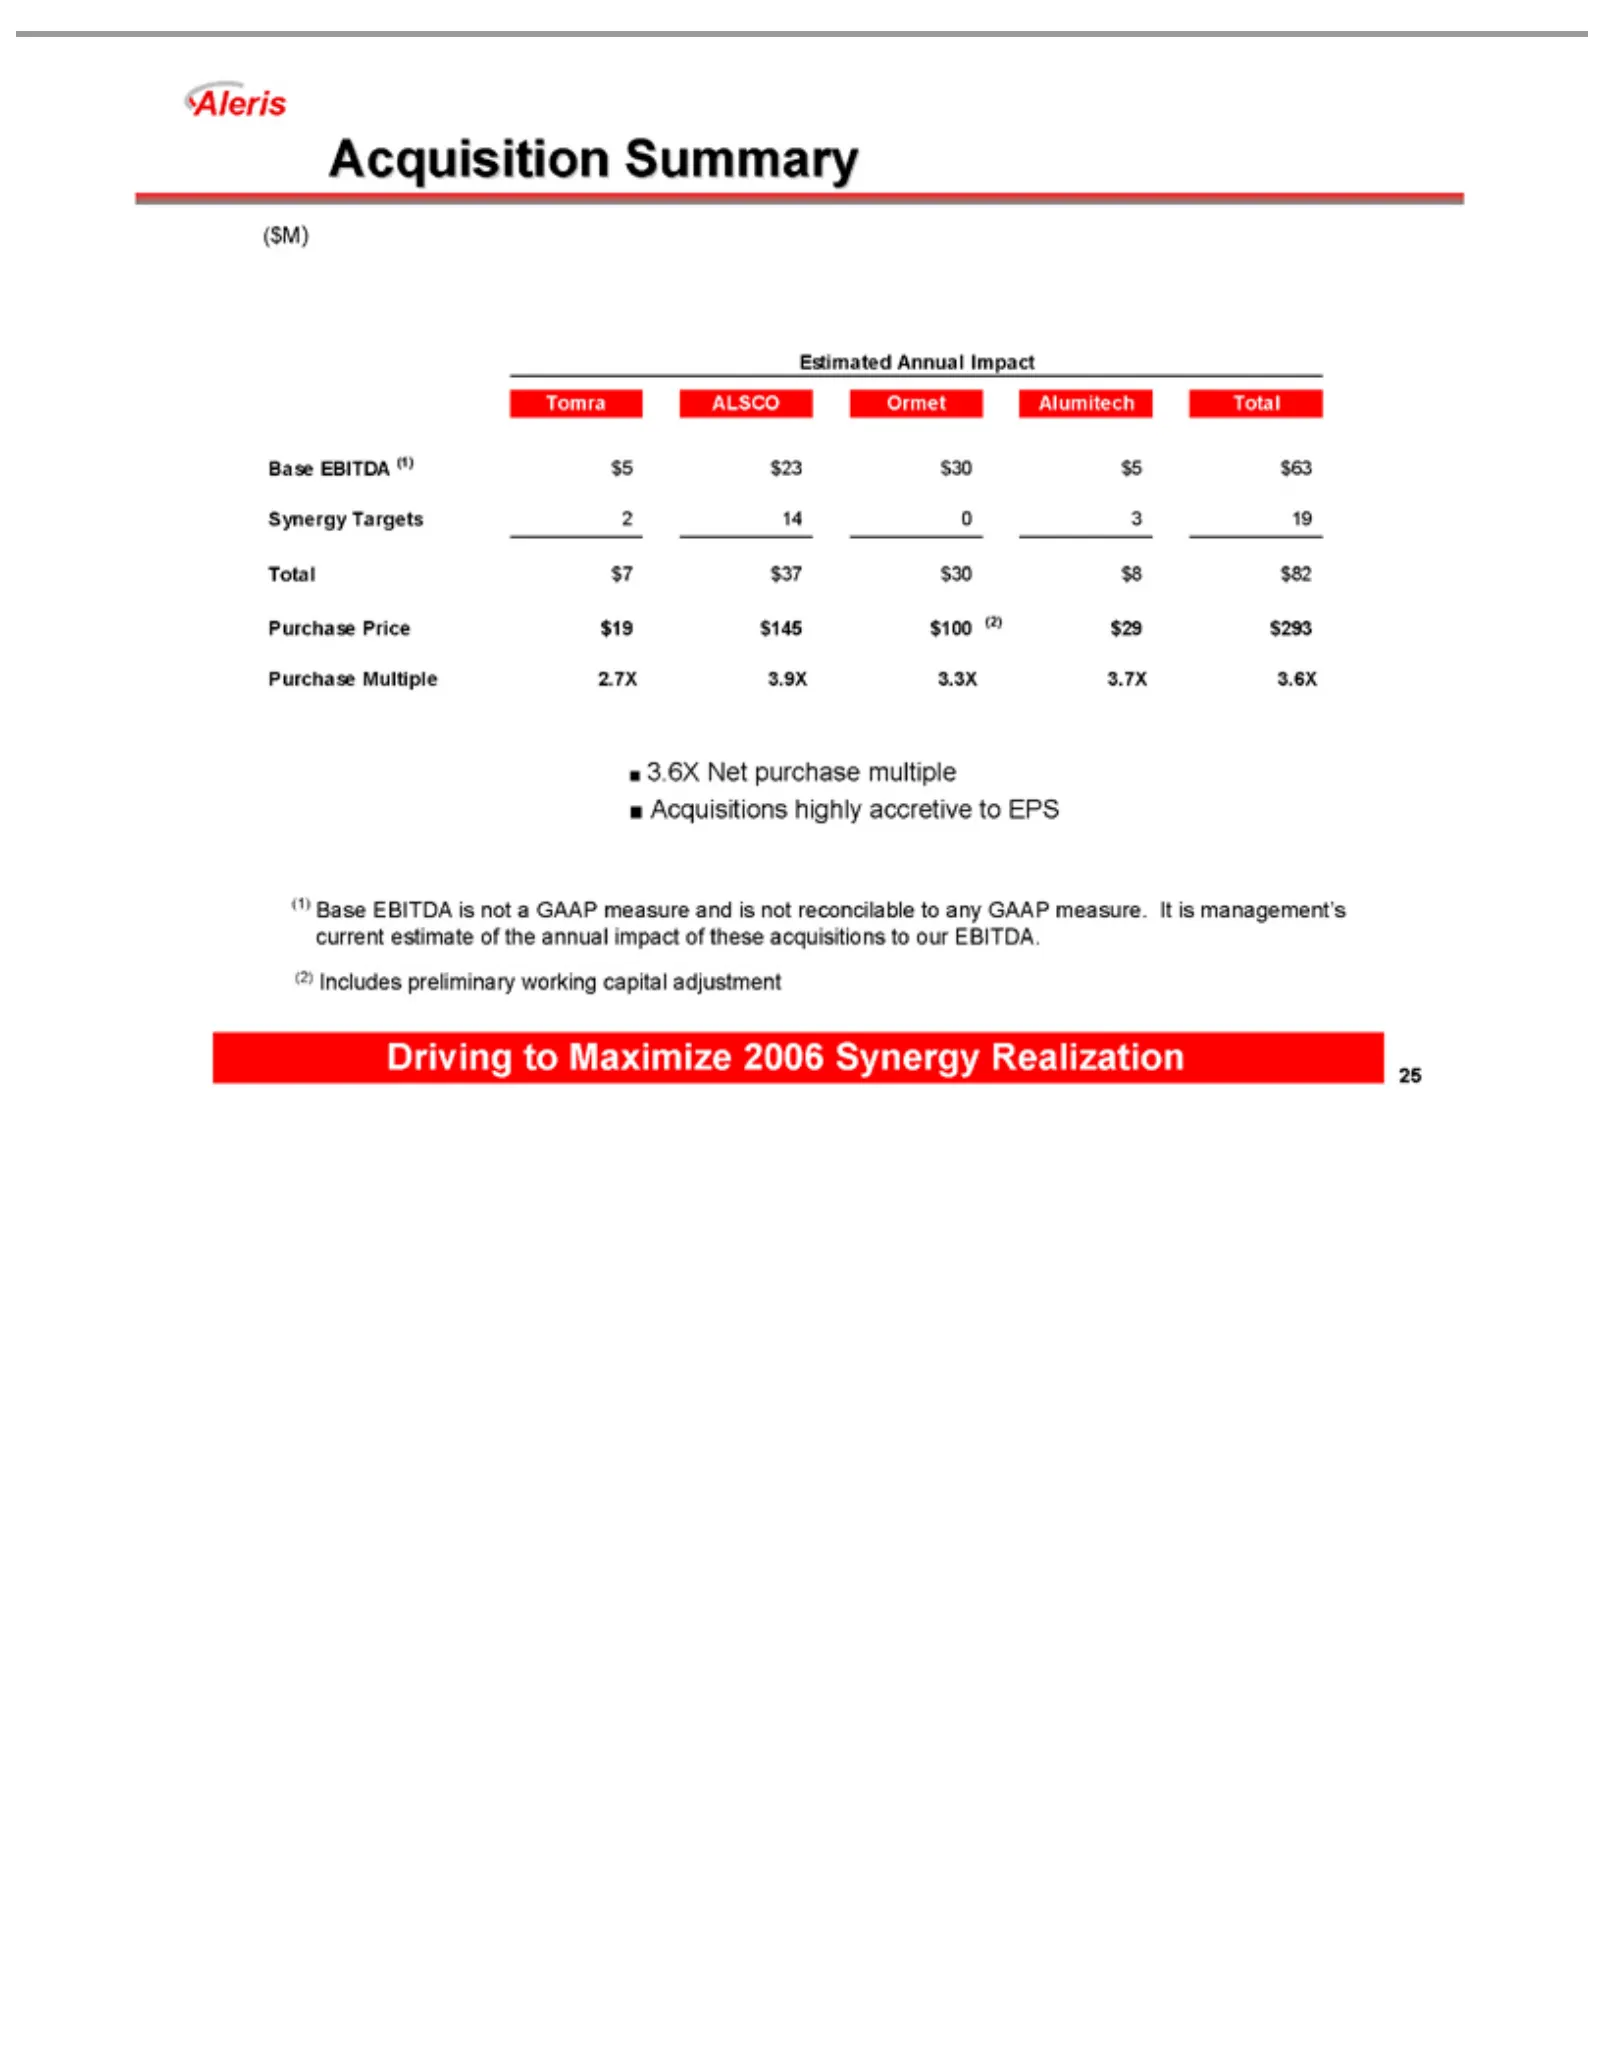
Slide 25: Acquisition Summary
Acquisition Aleris Estimated ($M) Tomra Base Synergy Total Purchase 3.6X Acquisitions (1) (2) 25 Base EBITDA Net $7 DrivingALSCO Includes $37 Targets EBITDA toPrice Multiple purchase Annual Summary $30 highly (1) $19 Ormet 2preliminary Maximize$8 Impact 14 is $5 2.7X multiple $145 accretive $82 not
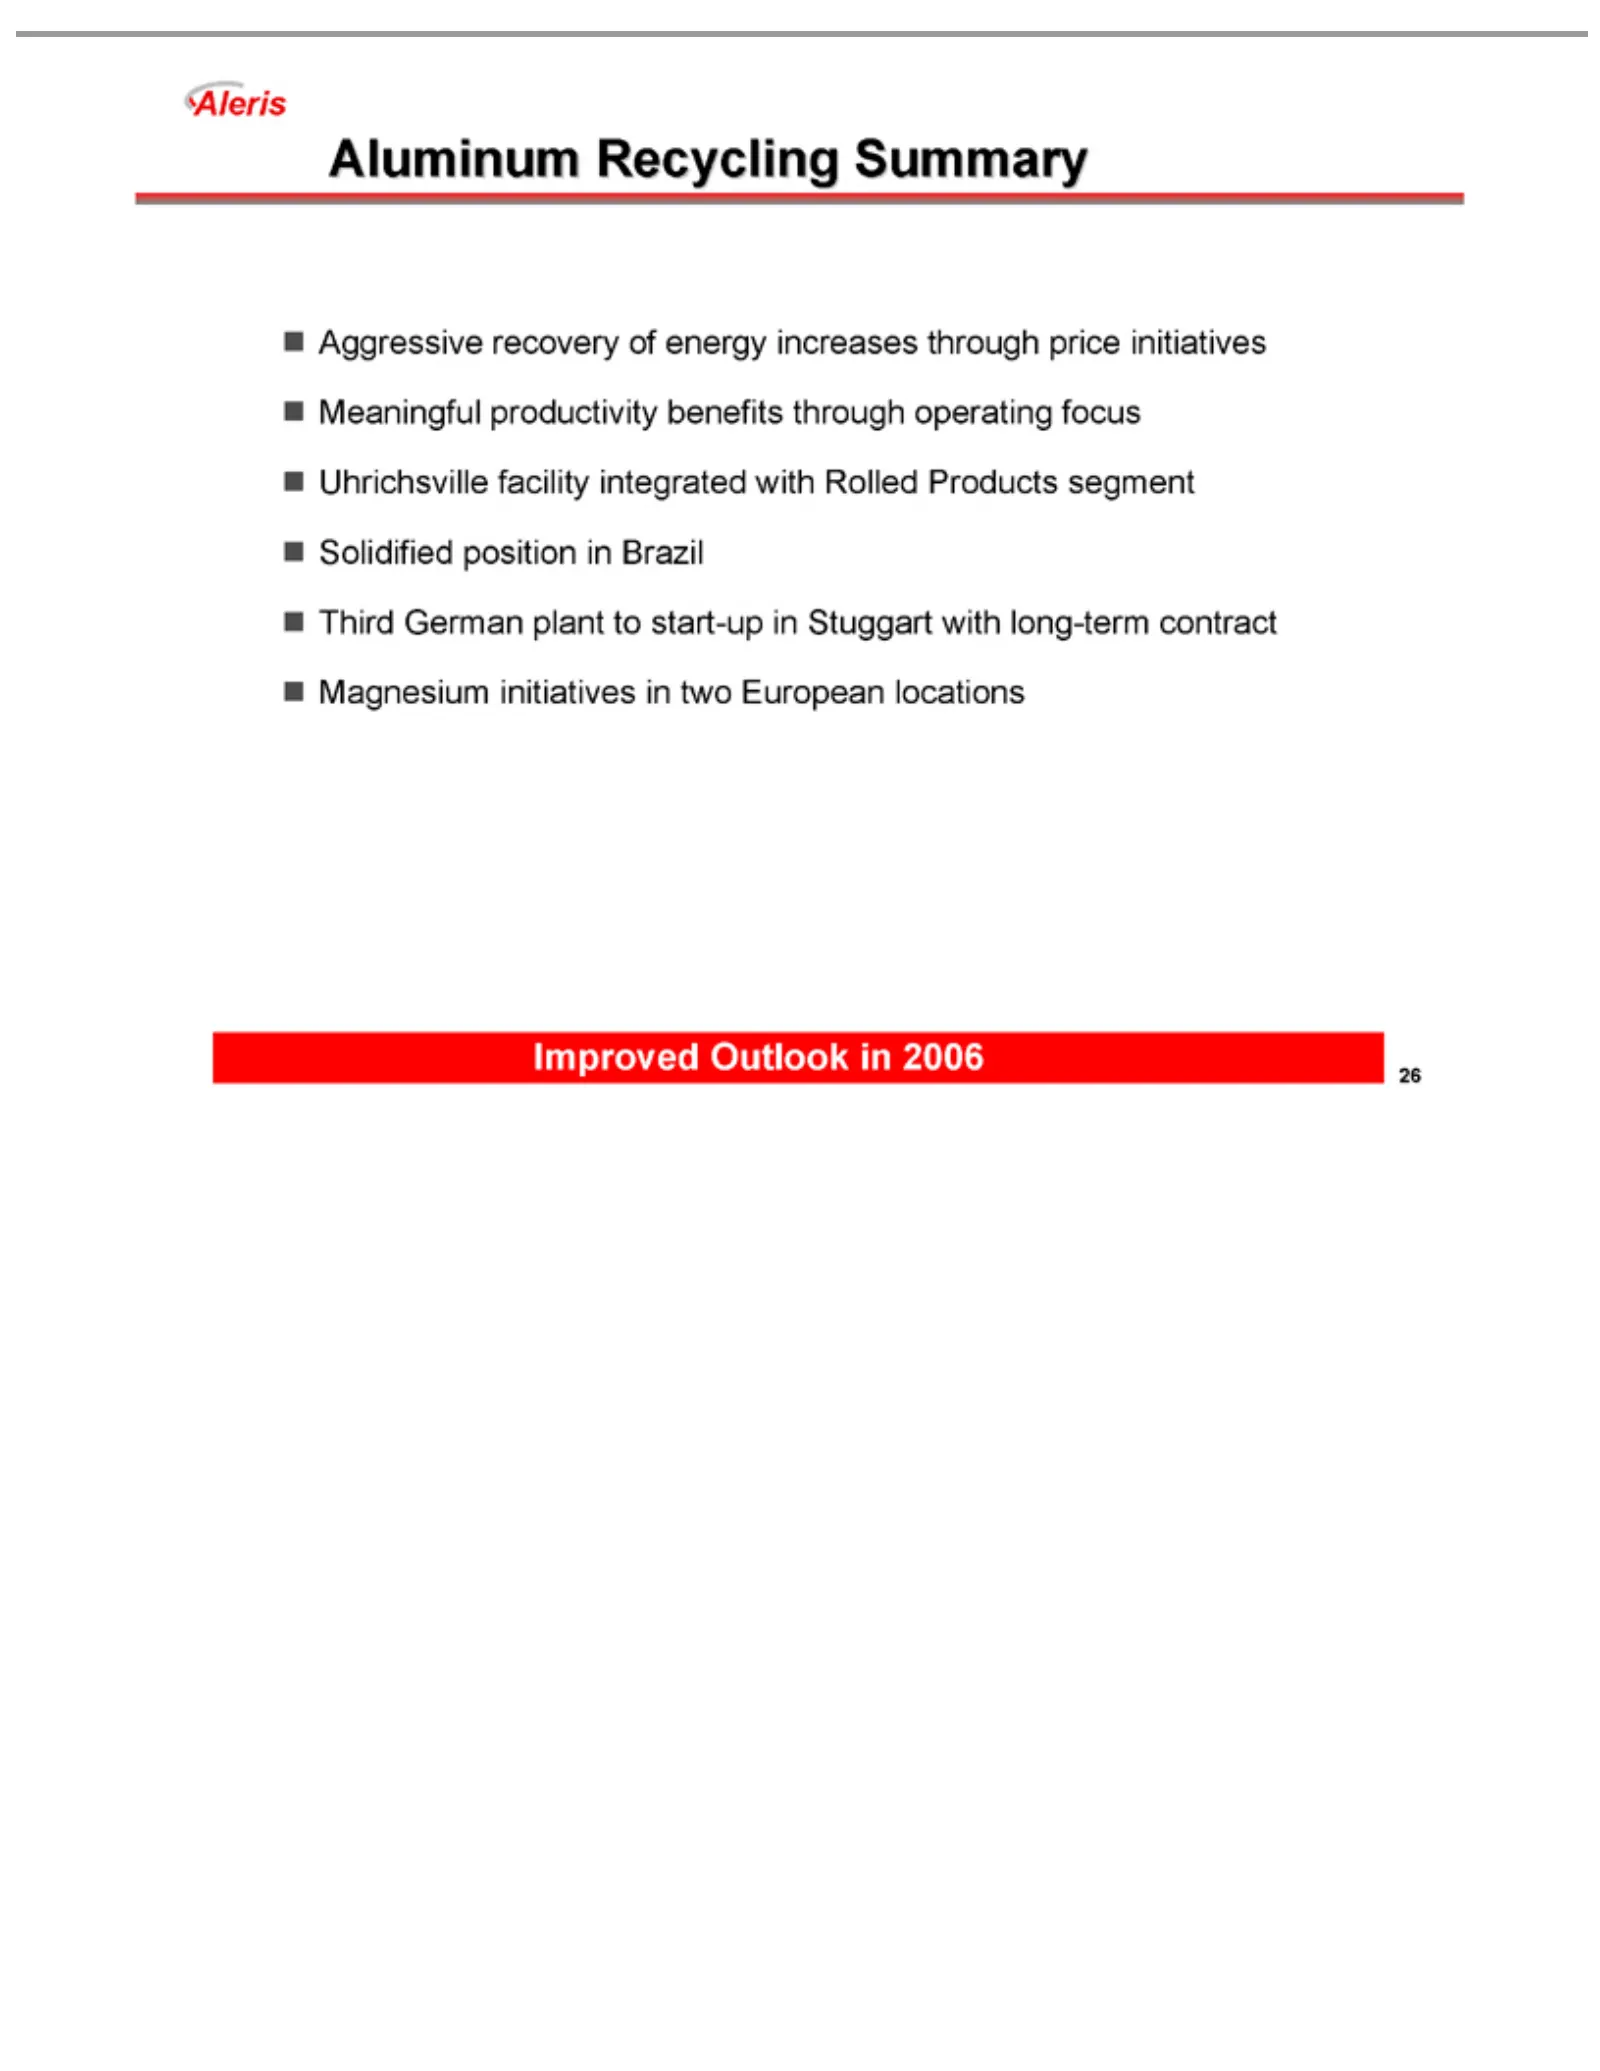
Slide 26: Aluminum Recycling Summary
Aluminum Aleris Aggressive Meaningful Uhrichsville Solidified Third Magnesium Improved 26 German Outlook position Recycling recovery productivity initiatives facility plantinto integrated of 2006 Brazil Summary in start-up energy benefits two European with in increases through Stuggart Rolled locati
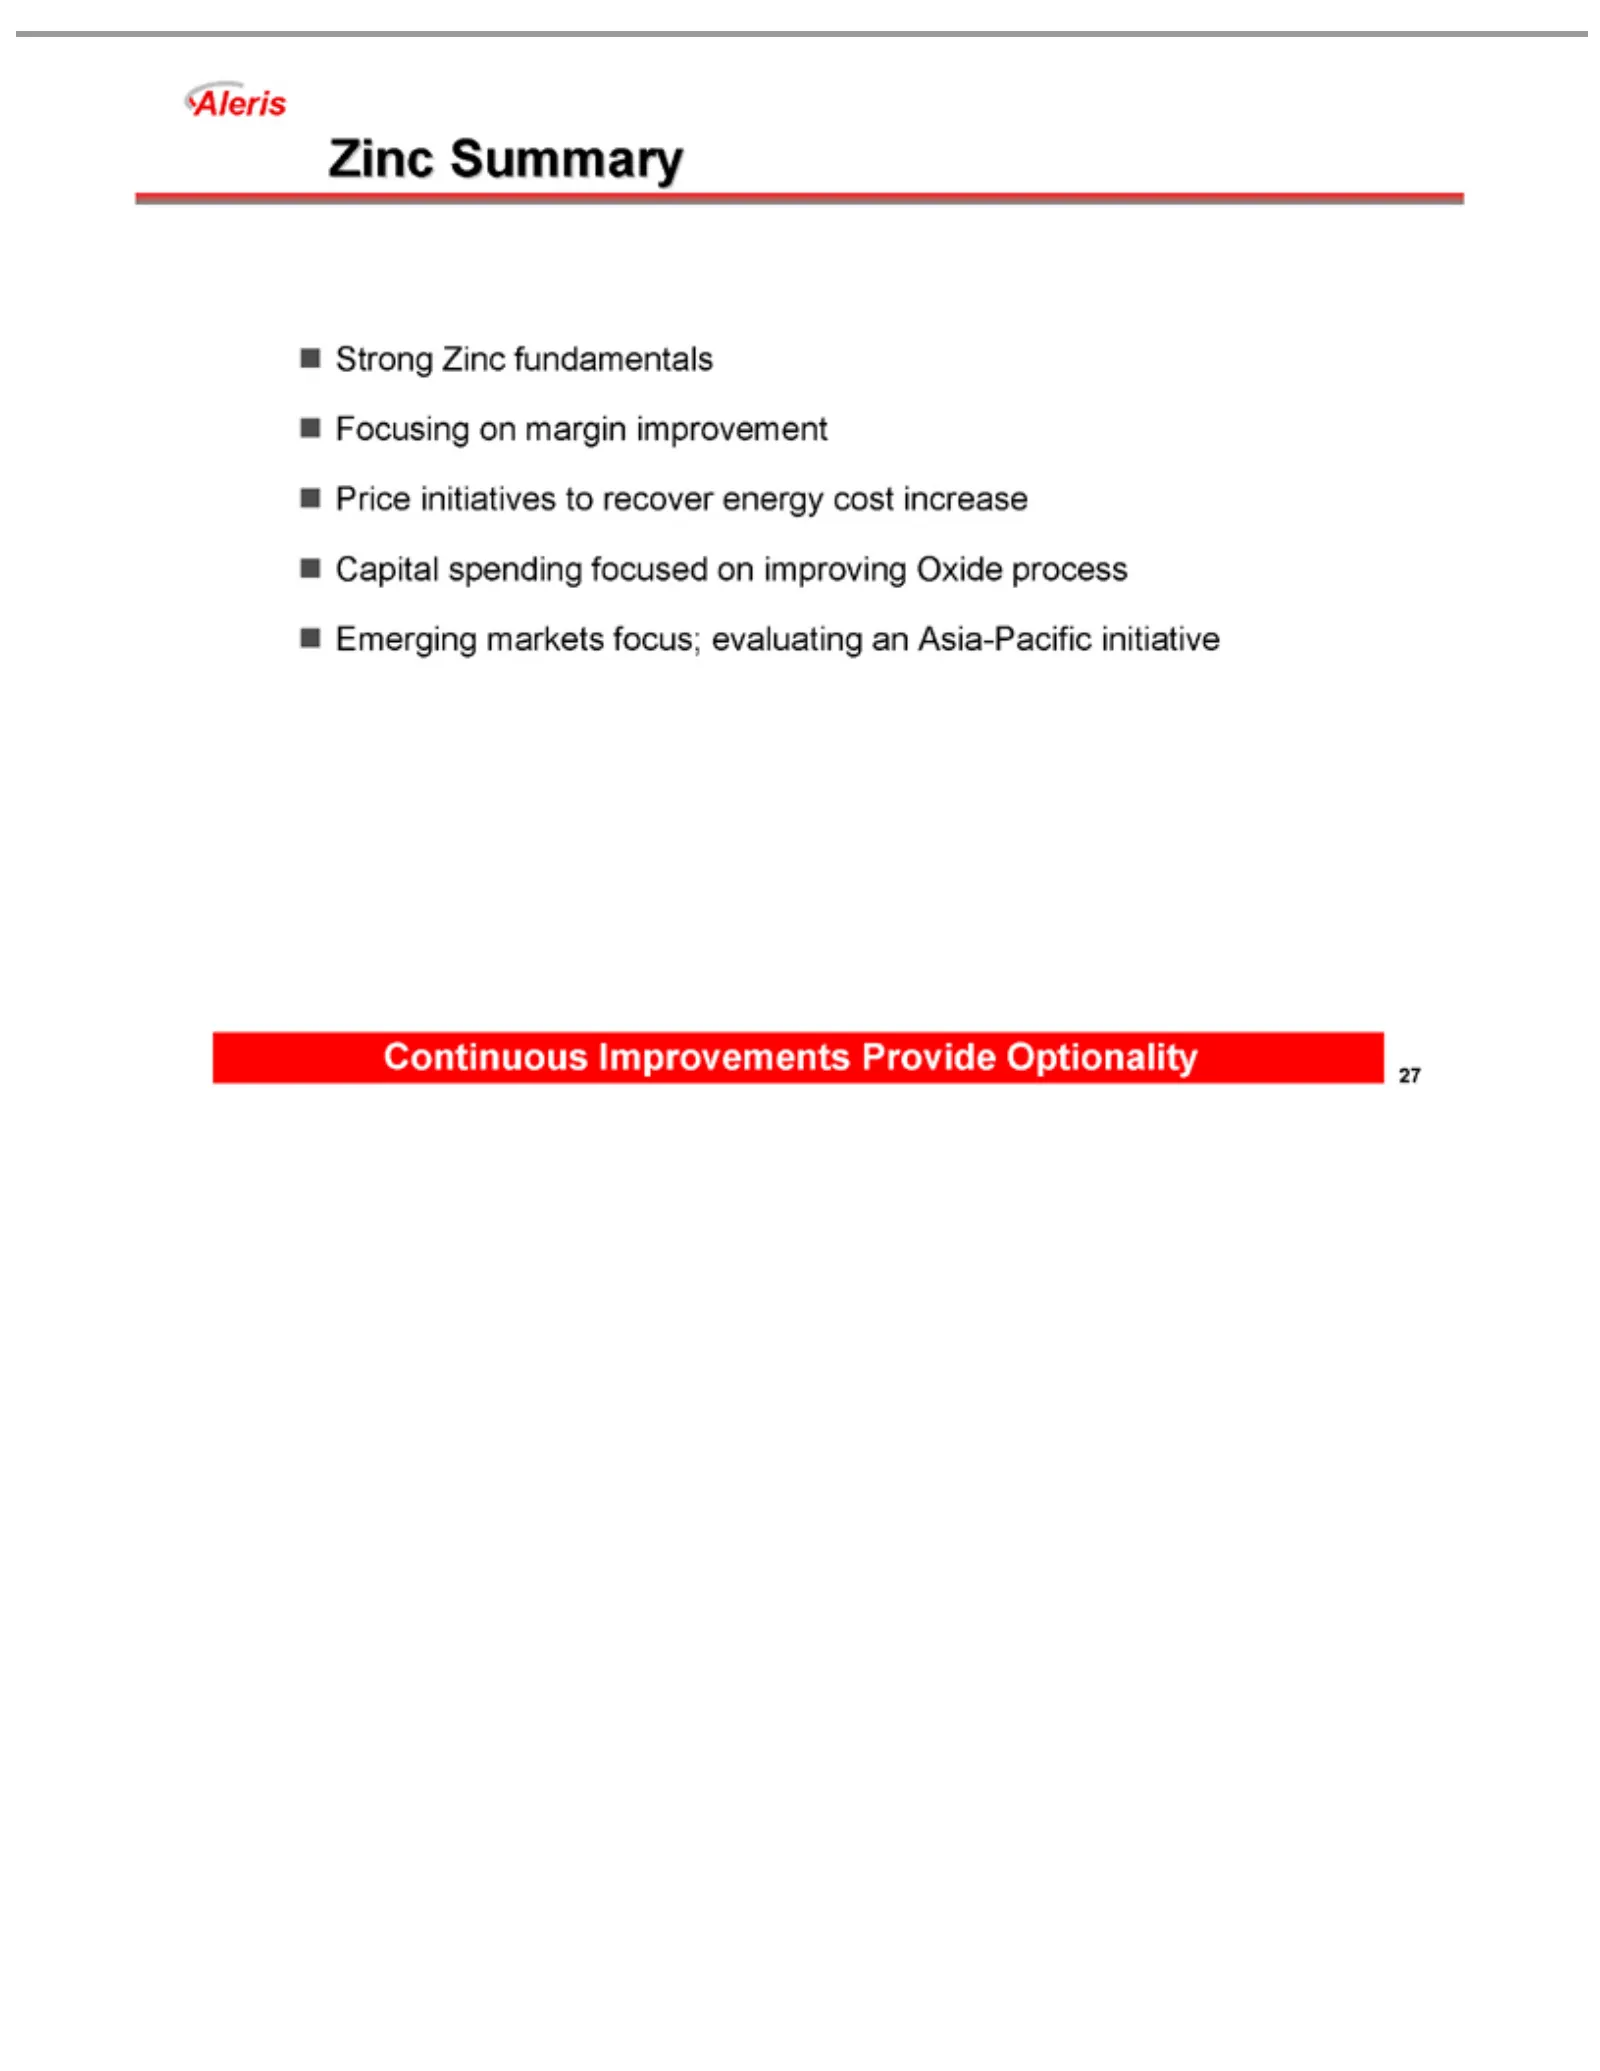
Slide 27: Zinc Summary
Zinc Summary Aleris Strong Focusing Price Continuous 27 initiatives Zinc onImprovements fundamentals margin to recover improvement energy Providecost Optionality increase Capital spending focused on improving Oxide process Emerging markets focus; evaluating an Asia-Pacific initiative
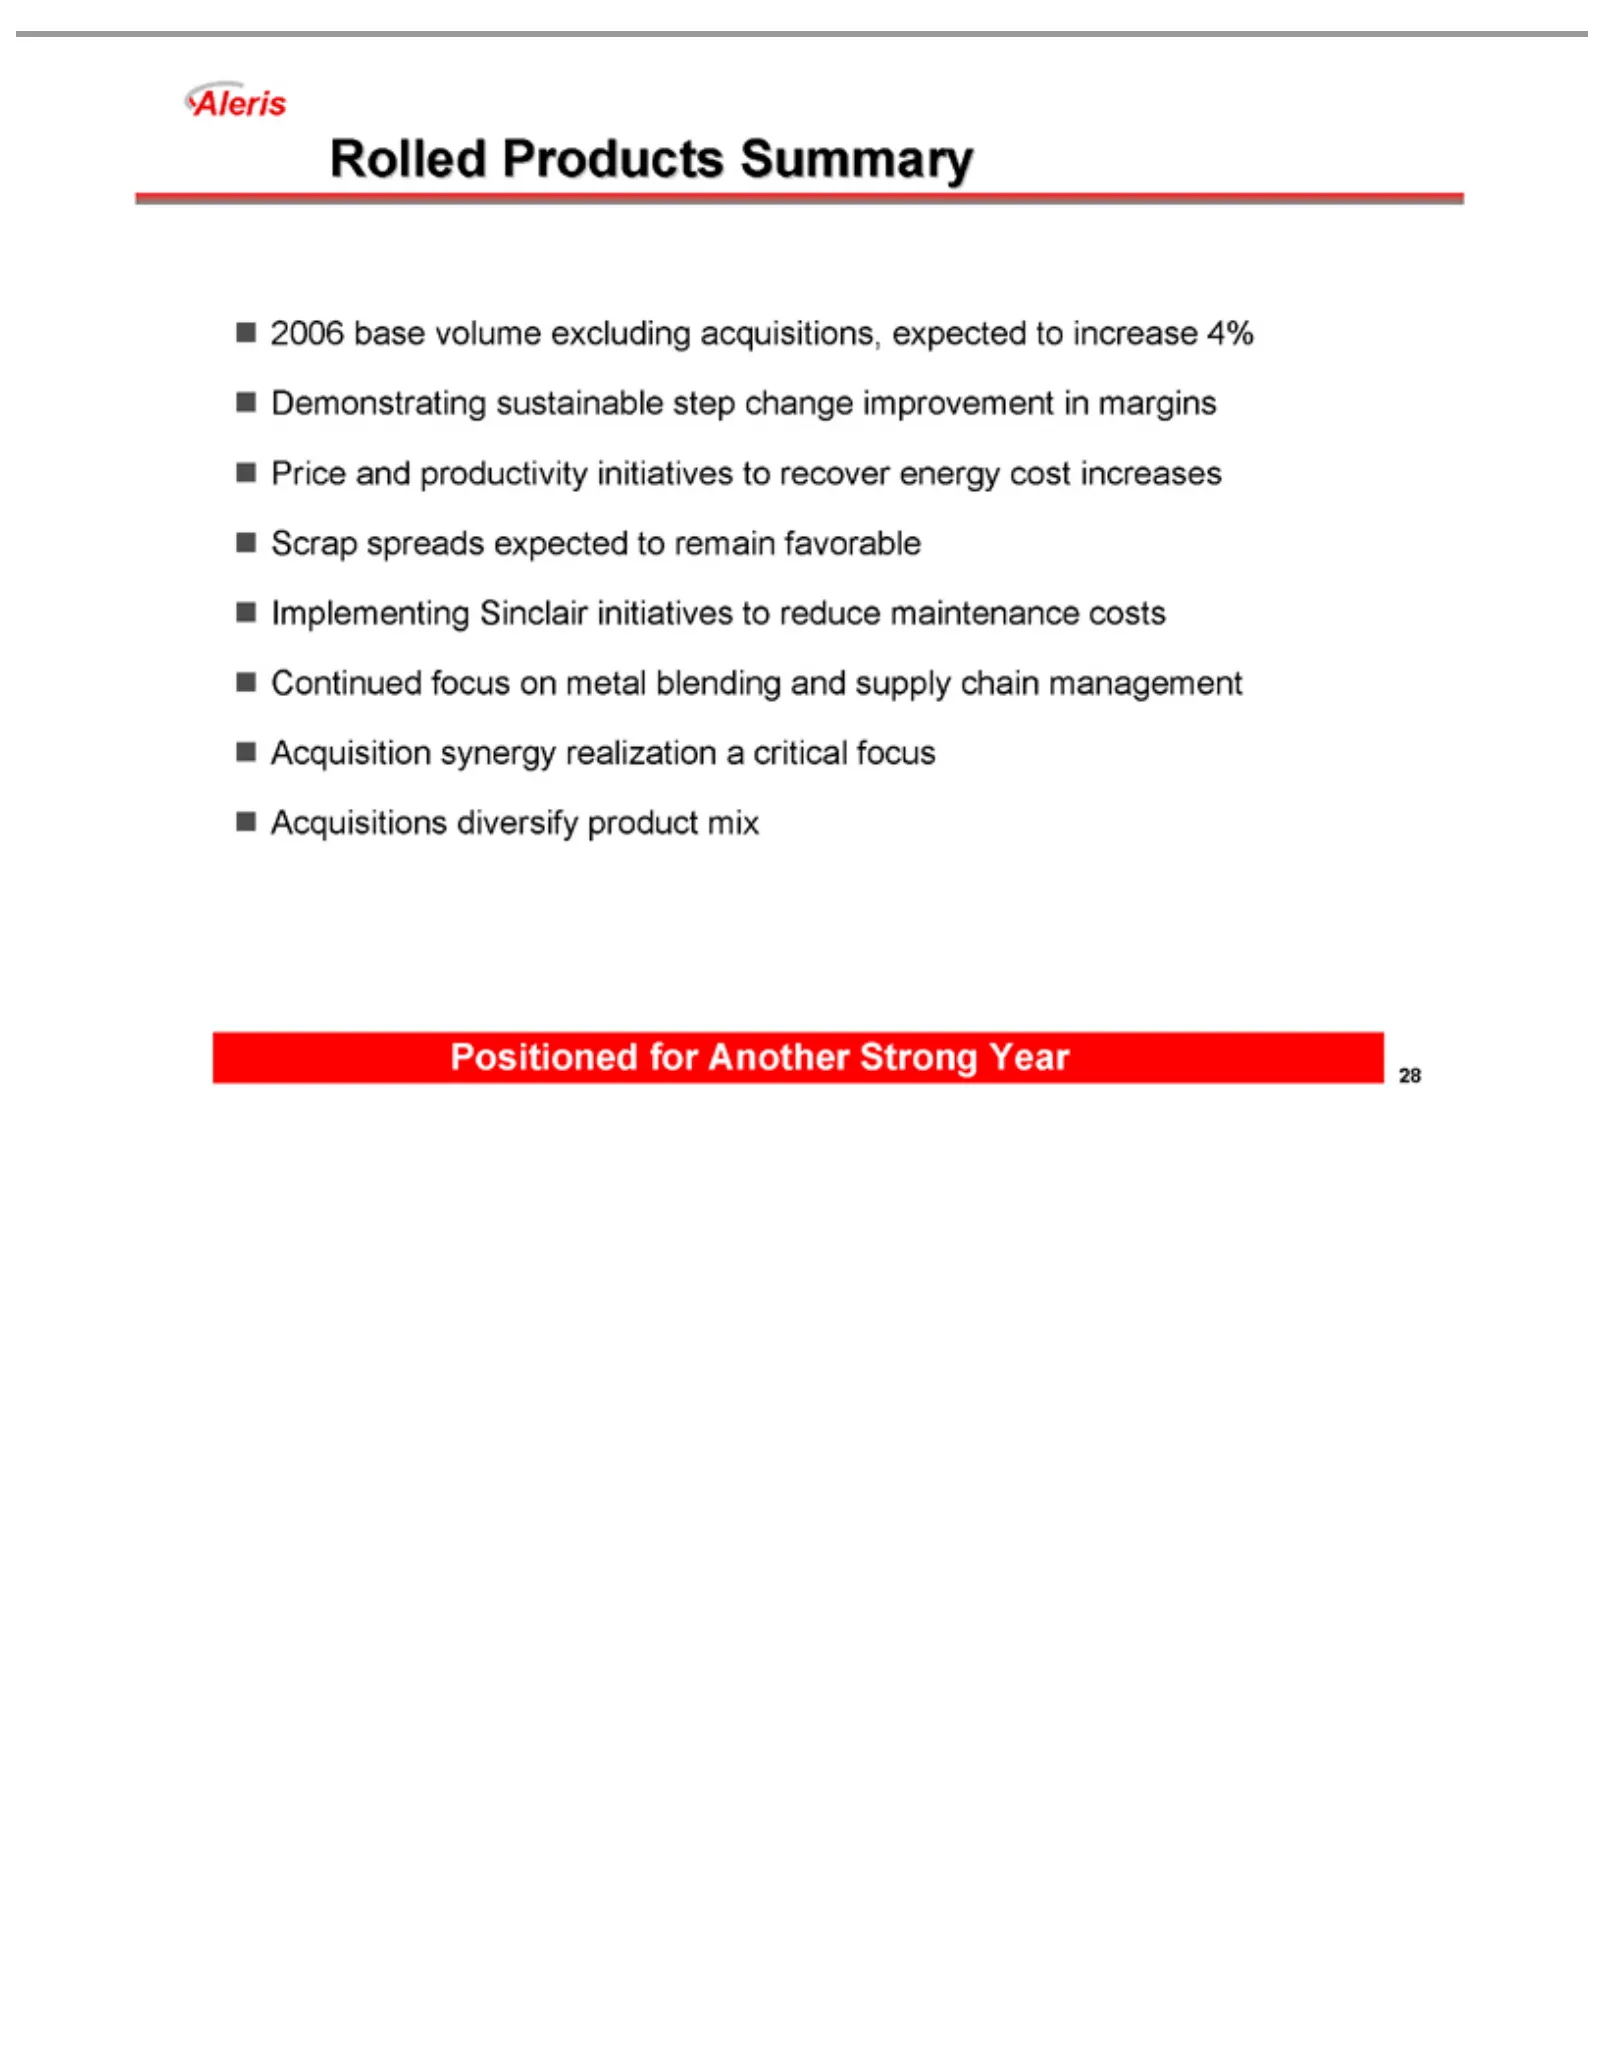
Slide 28: Rolled Products Summary
Rolledbase Aleris 2006 Demonstrating Price Scrap Implementing Continued Acquisition Acquisitions Positioned 28 and spreads Products productivity volume focus for synergy diversify expected Another Sinclair sustainable Summary onexcluding metal realization product initiatives Strong to blending remai
Slide 29: Aleris Financial Summary
Aleris Financial Summary
Slide 30: Recent Aleris Performance
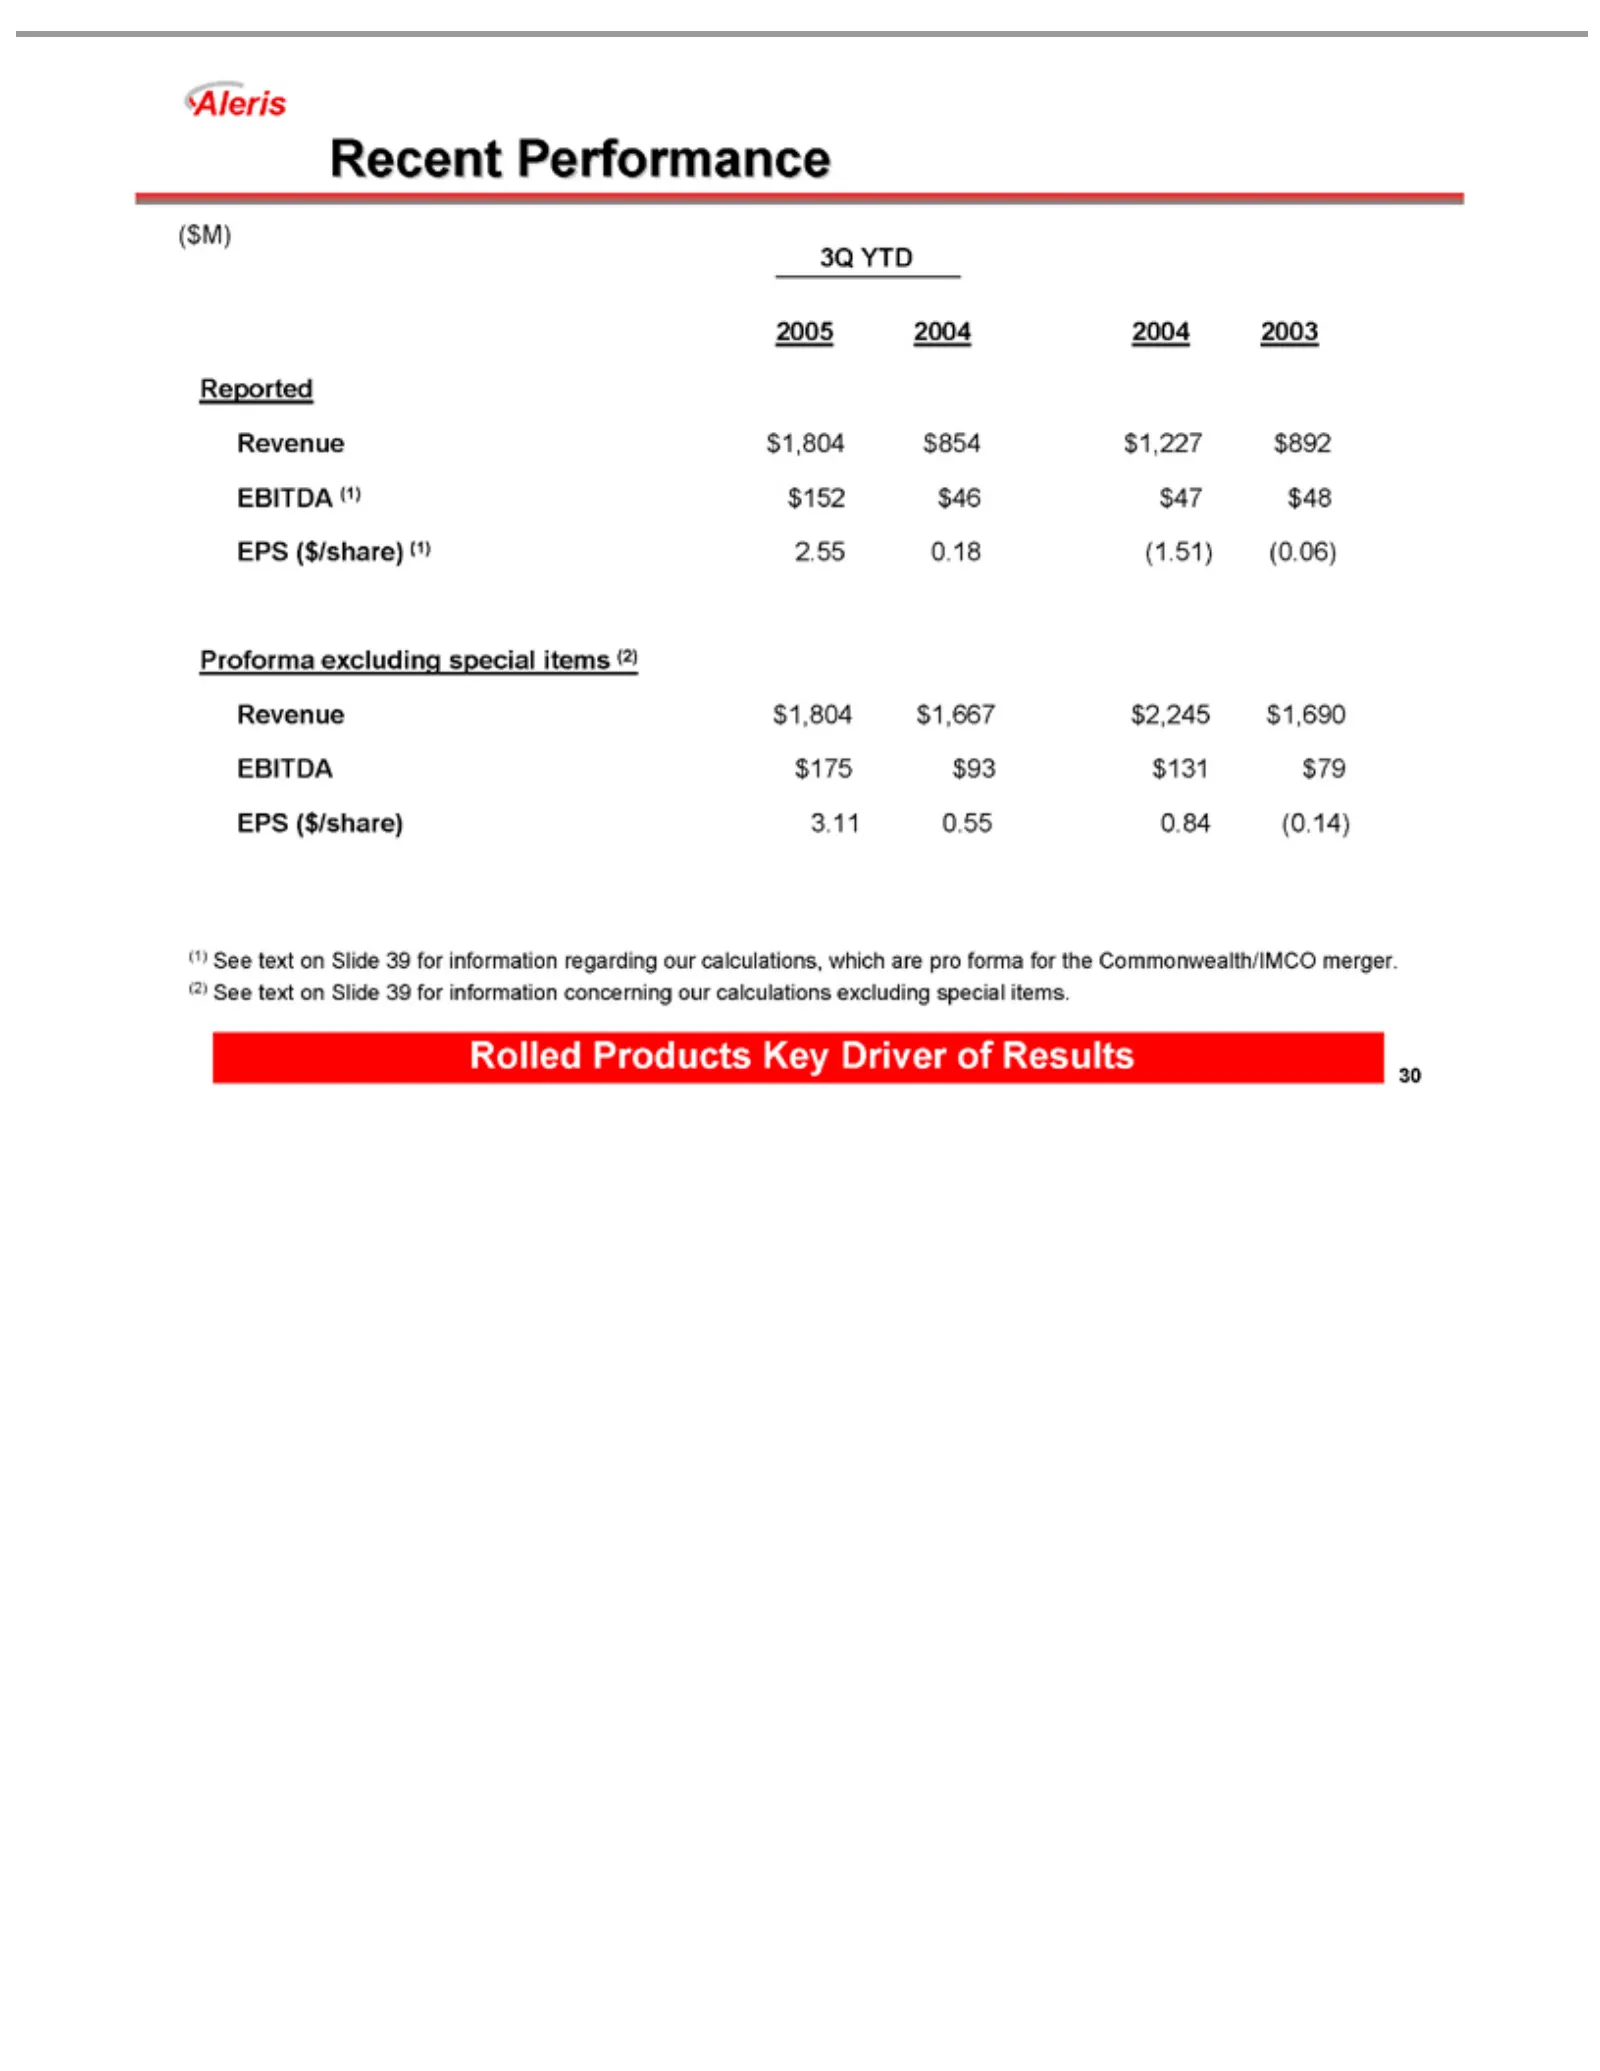
Recent Aleris 3Q ($M) 2005 Reported Proforma Revenue EBITDA EPS (1) excluding Rolled 30 See YTD ($/share) 2004 Products Performance text $1,804 (1) $175 excluding special 2004 on $152 (1) 3.11 Slide $93 Key $854 $1,667 2003 2.55 items. $46 0.55 $131 special 39 Driver $1,227 0.18 $47 for 0.84 $2,245
Slide 31: Rolled Products Metal Margins
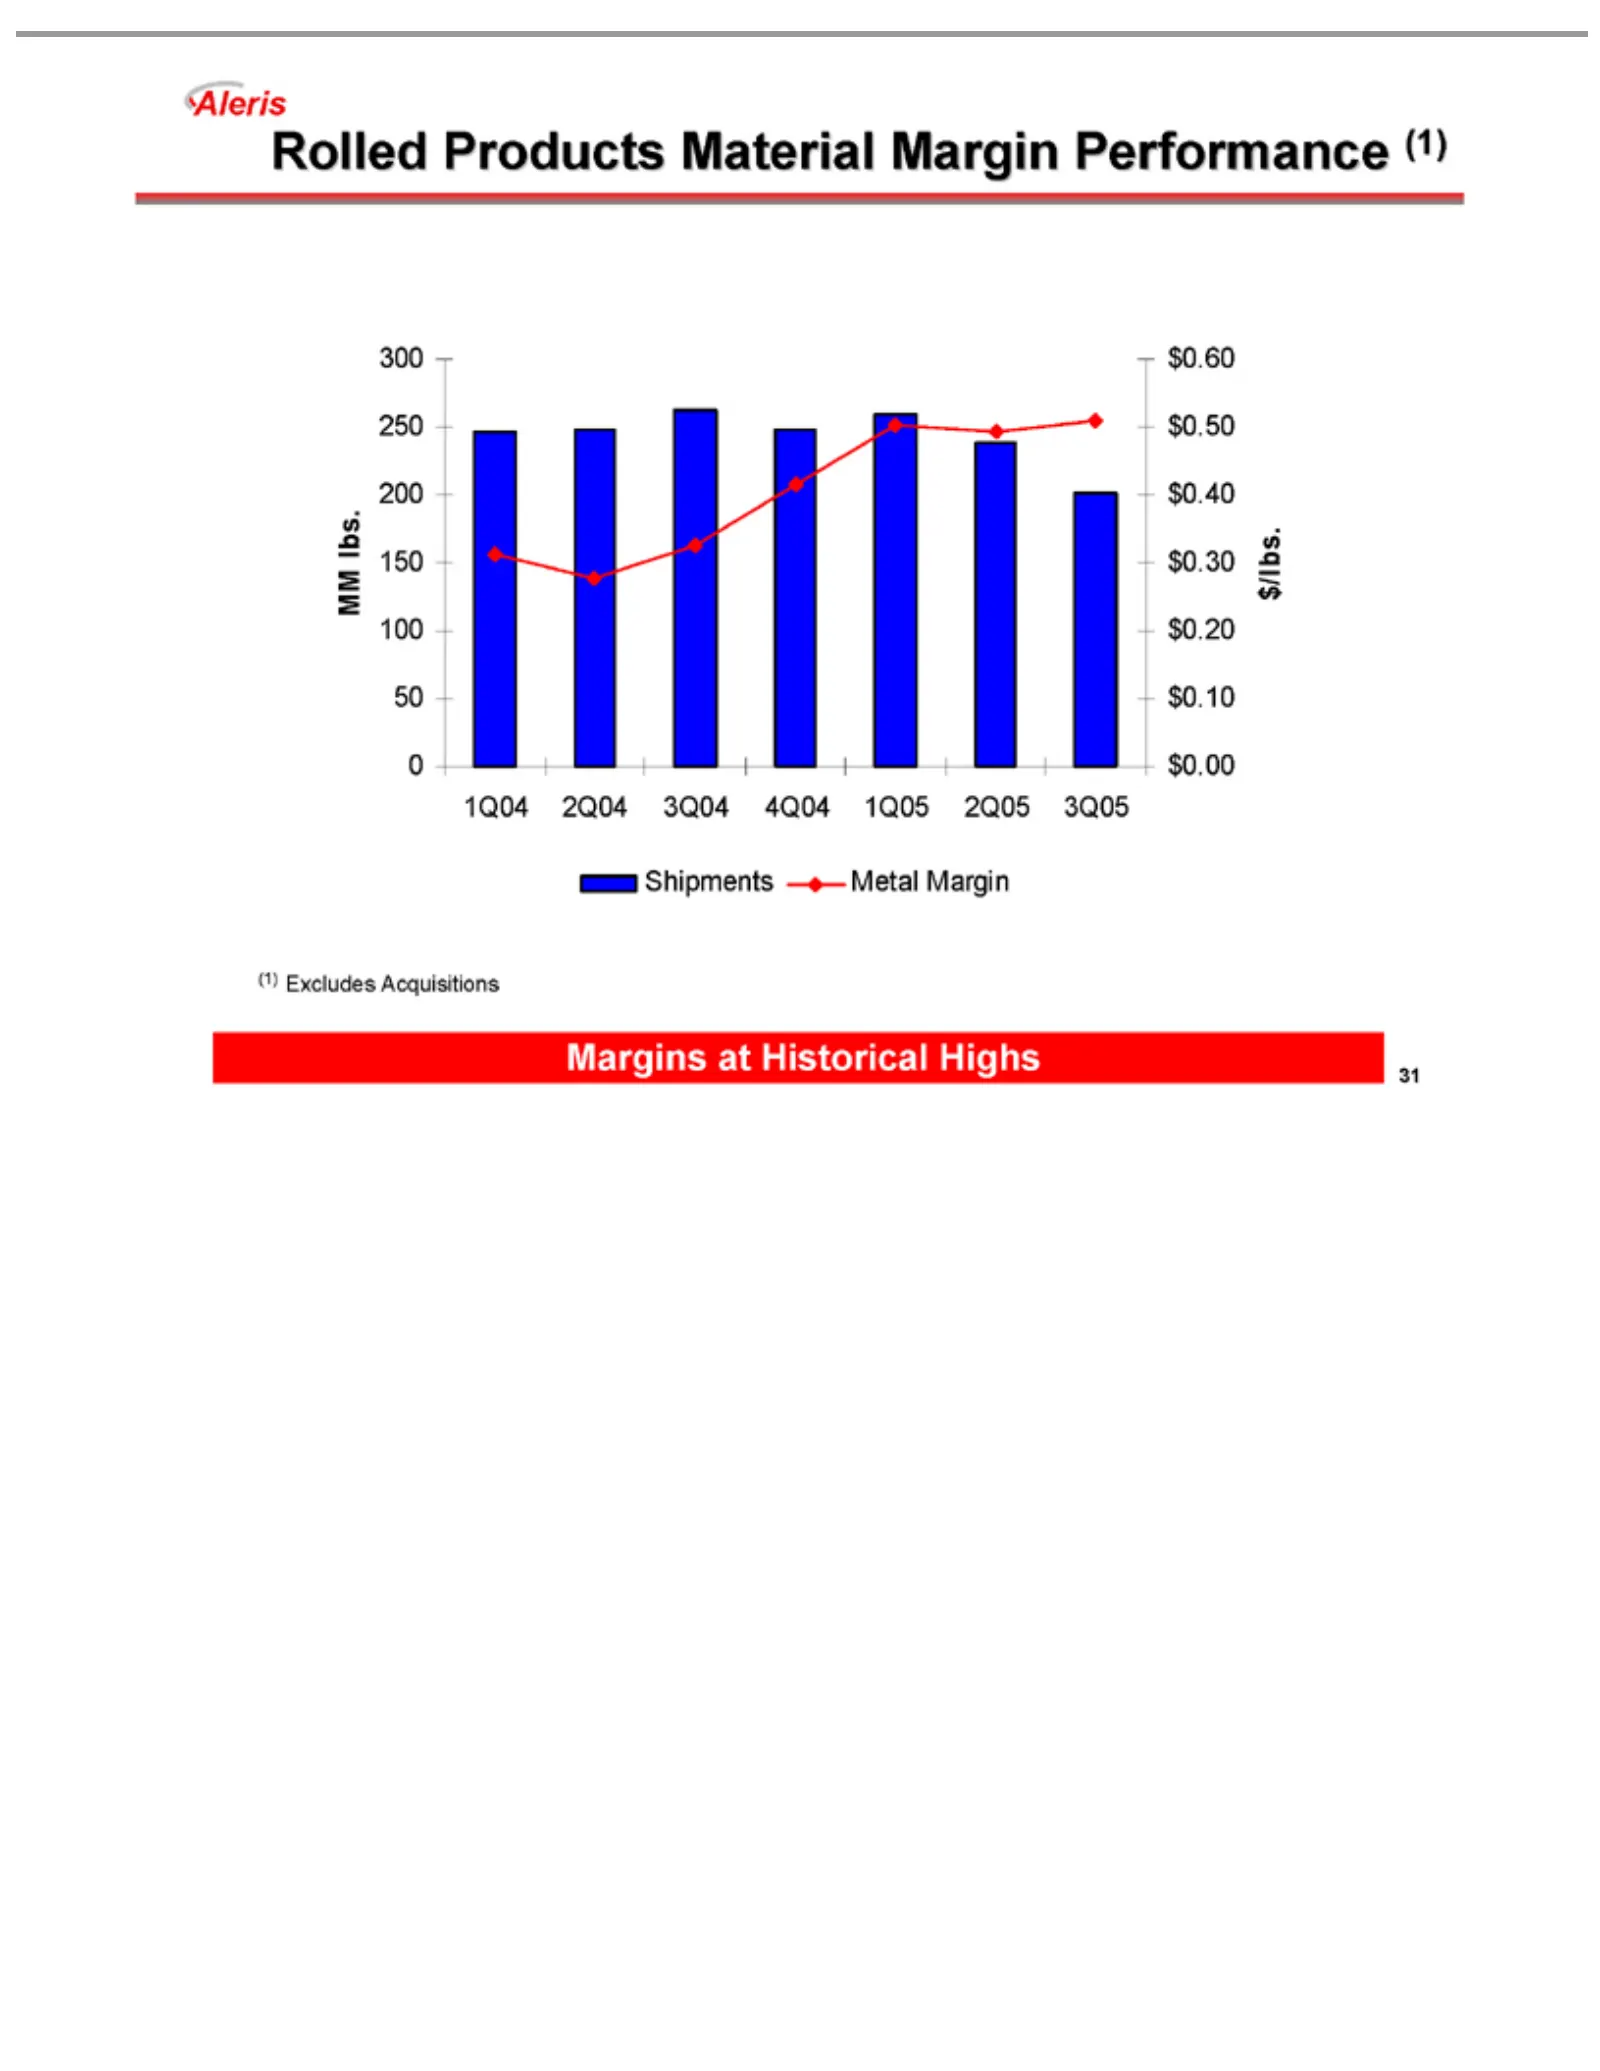
Rolled Aleris 0 50 100 200 250 300 $ $0.20 $0.30 $0.40 $0.50 MM $/lbs. 150 $0.00 1Q04 Shipments (1) 310.60 0.10lbs Margins 2Q04 Products Excludes at Metal 3Q04Material Margin Acquisitions 4Q04 Historical 1Q05 Margin Highs 2Q05 Performance 3Q05 (1)
Slide 32: 3Q05 YTD EBITDA Variance Analysis
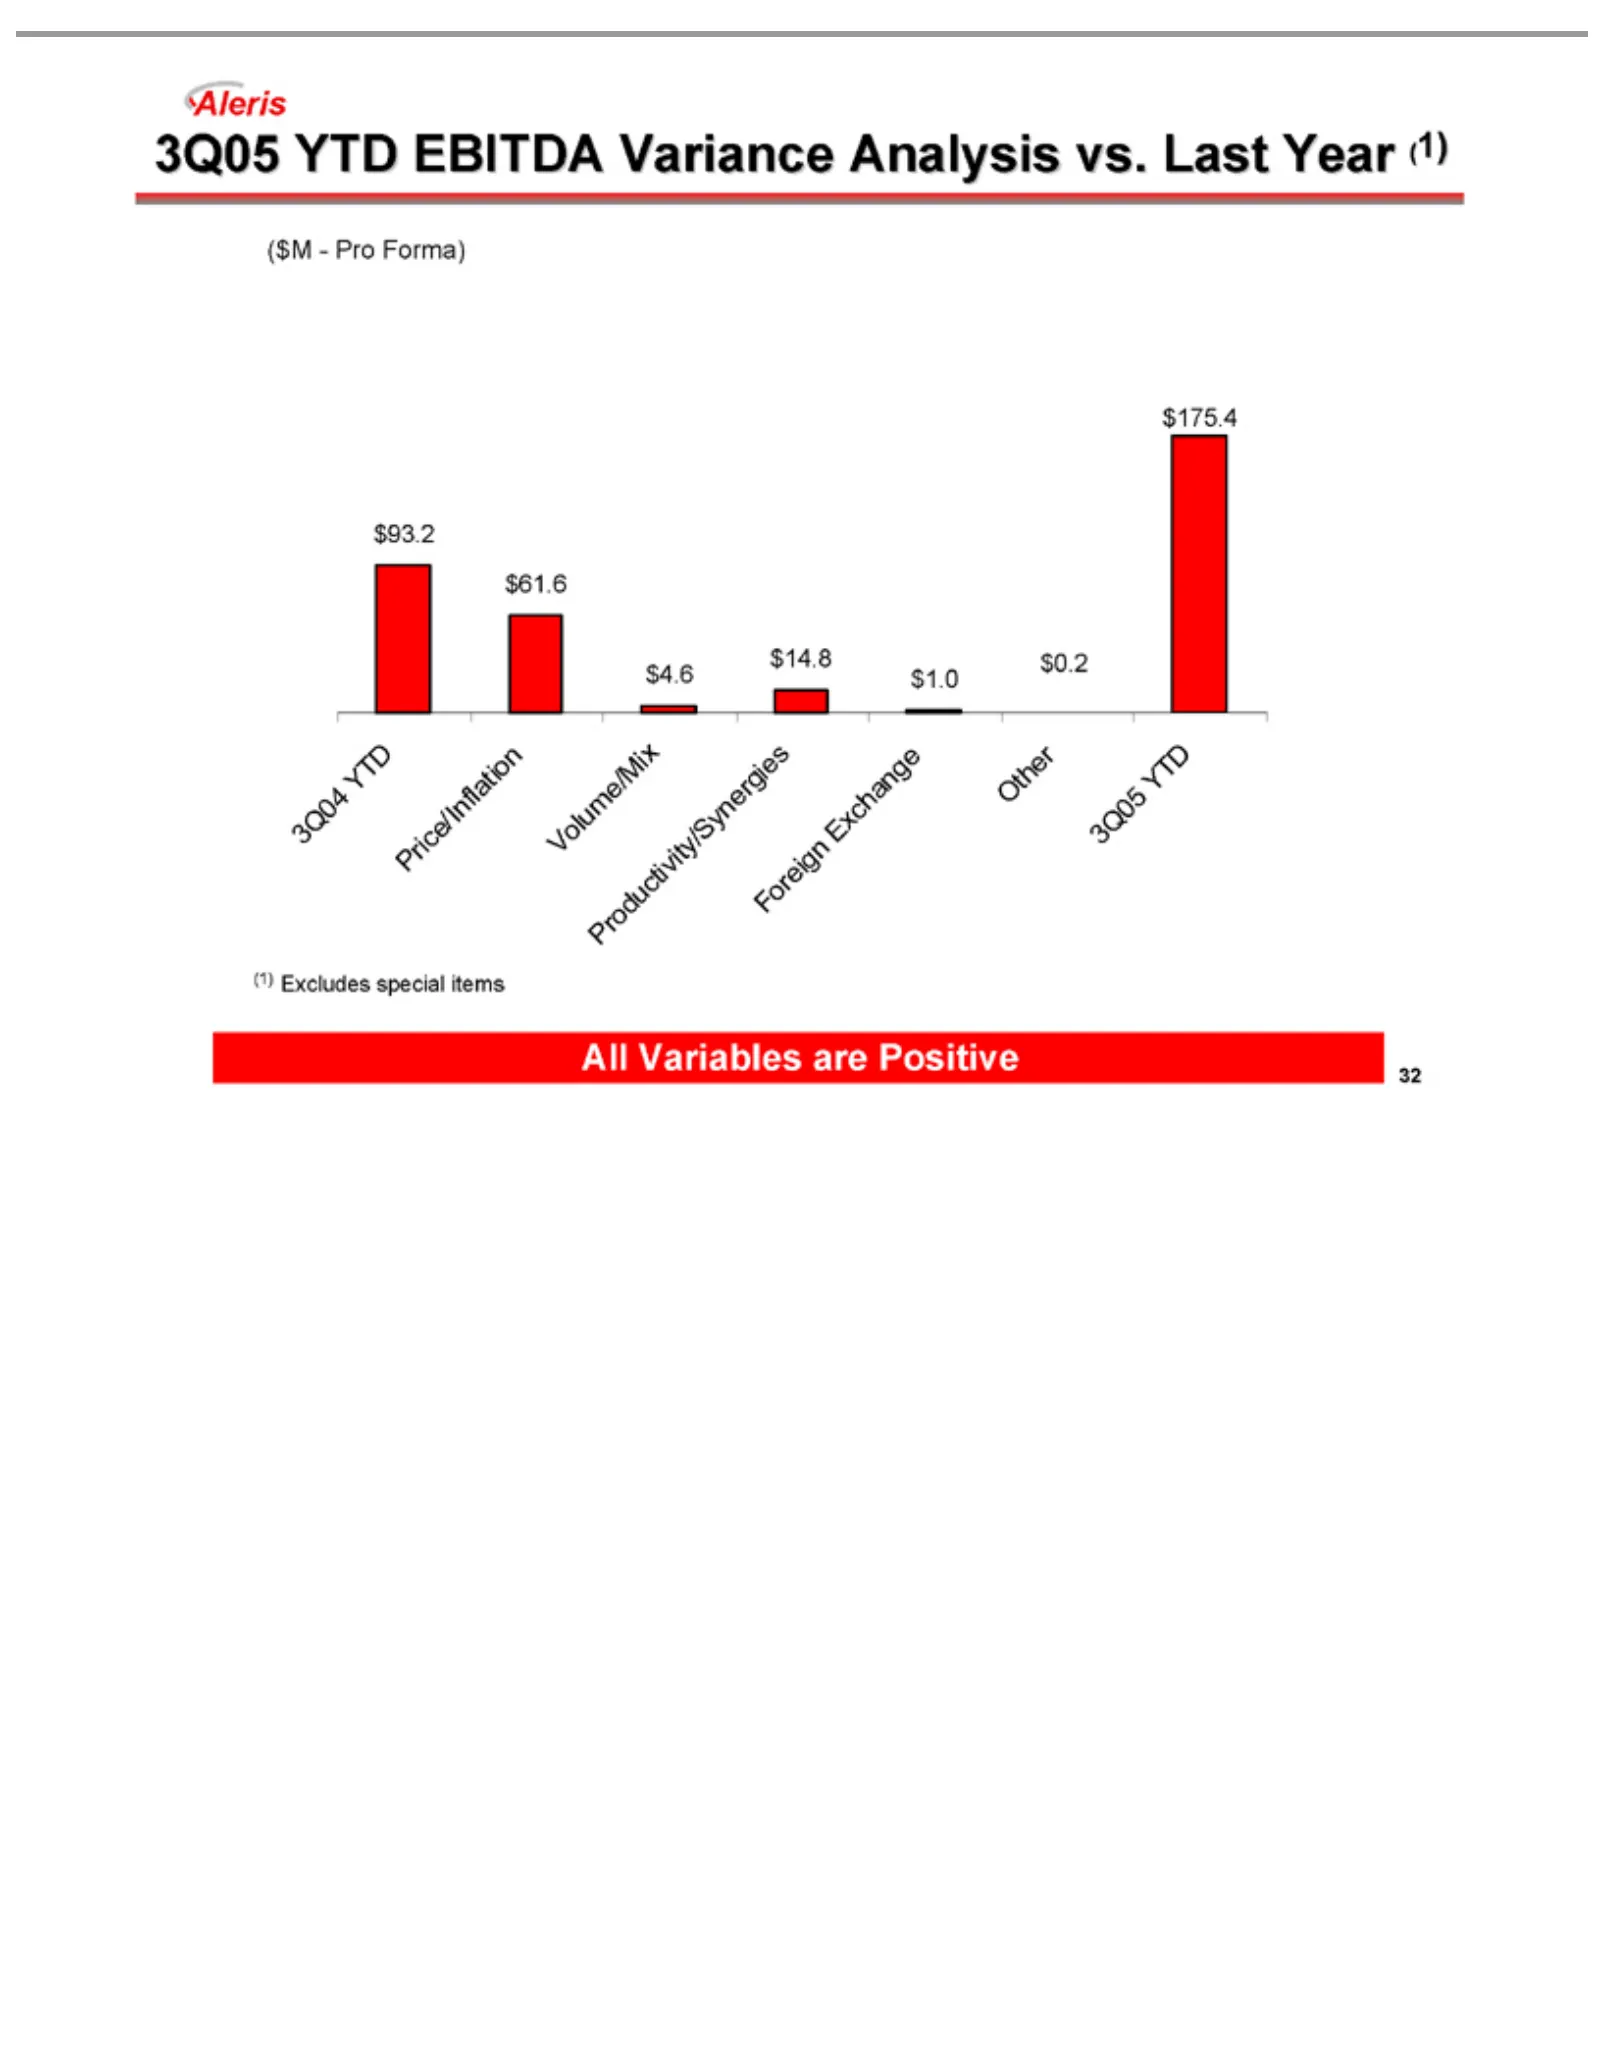
3Q05 Aleris ($M 3Q04 Price/Inflation (1) All 32 Excludes Variables - YTD Pro Forma) EBITDA $93.2 special are Volume/Mix Positive $61.6 items Variance $4.6Productivity/Synergies $14.8 Analysis $1.0 vs. $0.2Last $175.4 YearForeign (1) Exchange Other 3Q05 YTD
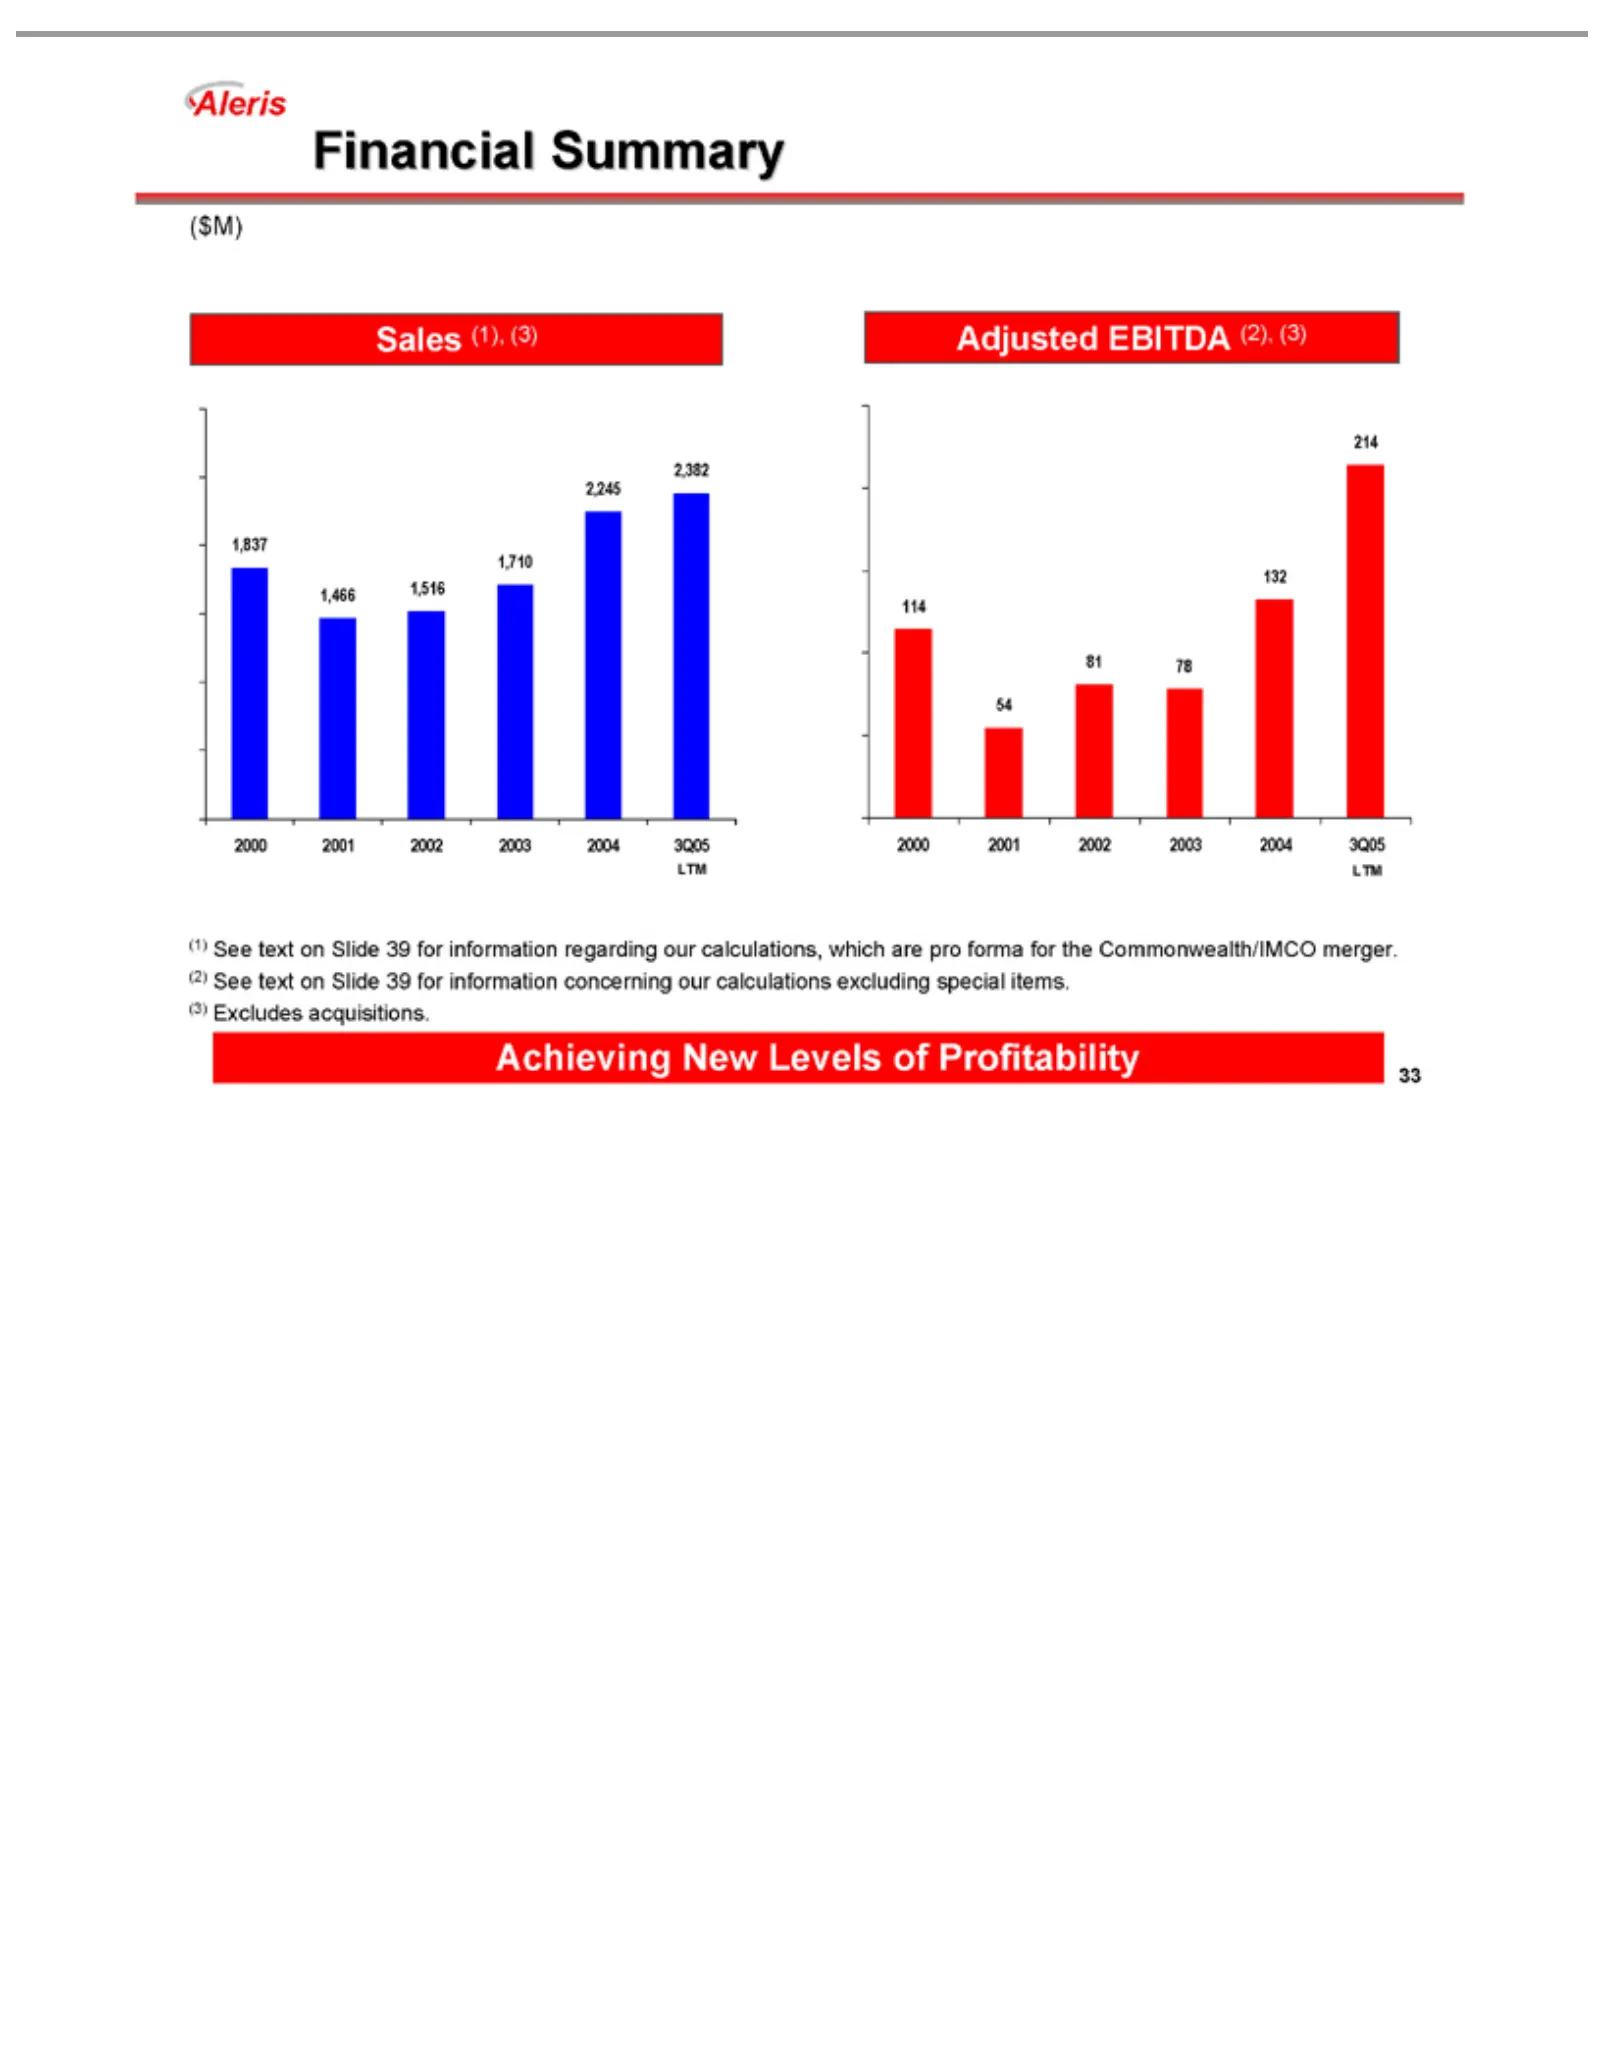
Slide 33: Achieving New Levels of Profitability
Financial Aleris Sales ($M) 3,000 2,500 214 2,245 2,000 1,710 132 1,500 81 50 54 1,000 0 2000 LTM (1) excluding (3) Achieving 330500 78 See Excludes 1,466 2001 LTM (1), 250 2,382 200 1,837 150 114 text Summary (3) special 100 1,516 New 2002 on acquisitions. Adjusted Slide Levels 2003 items. 392004 E
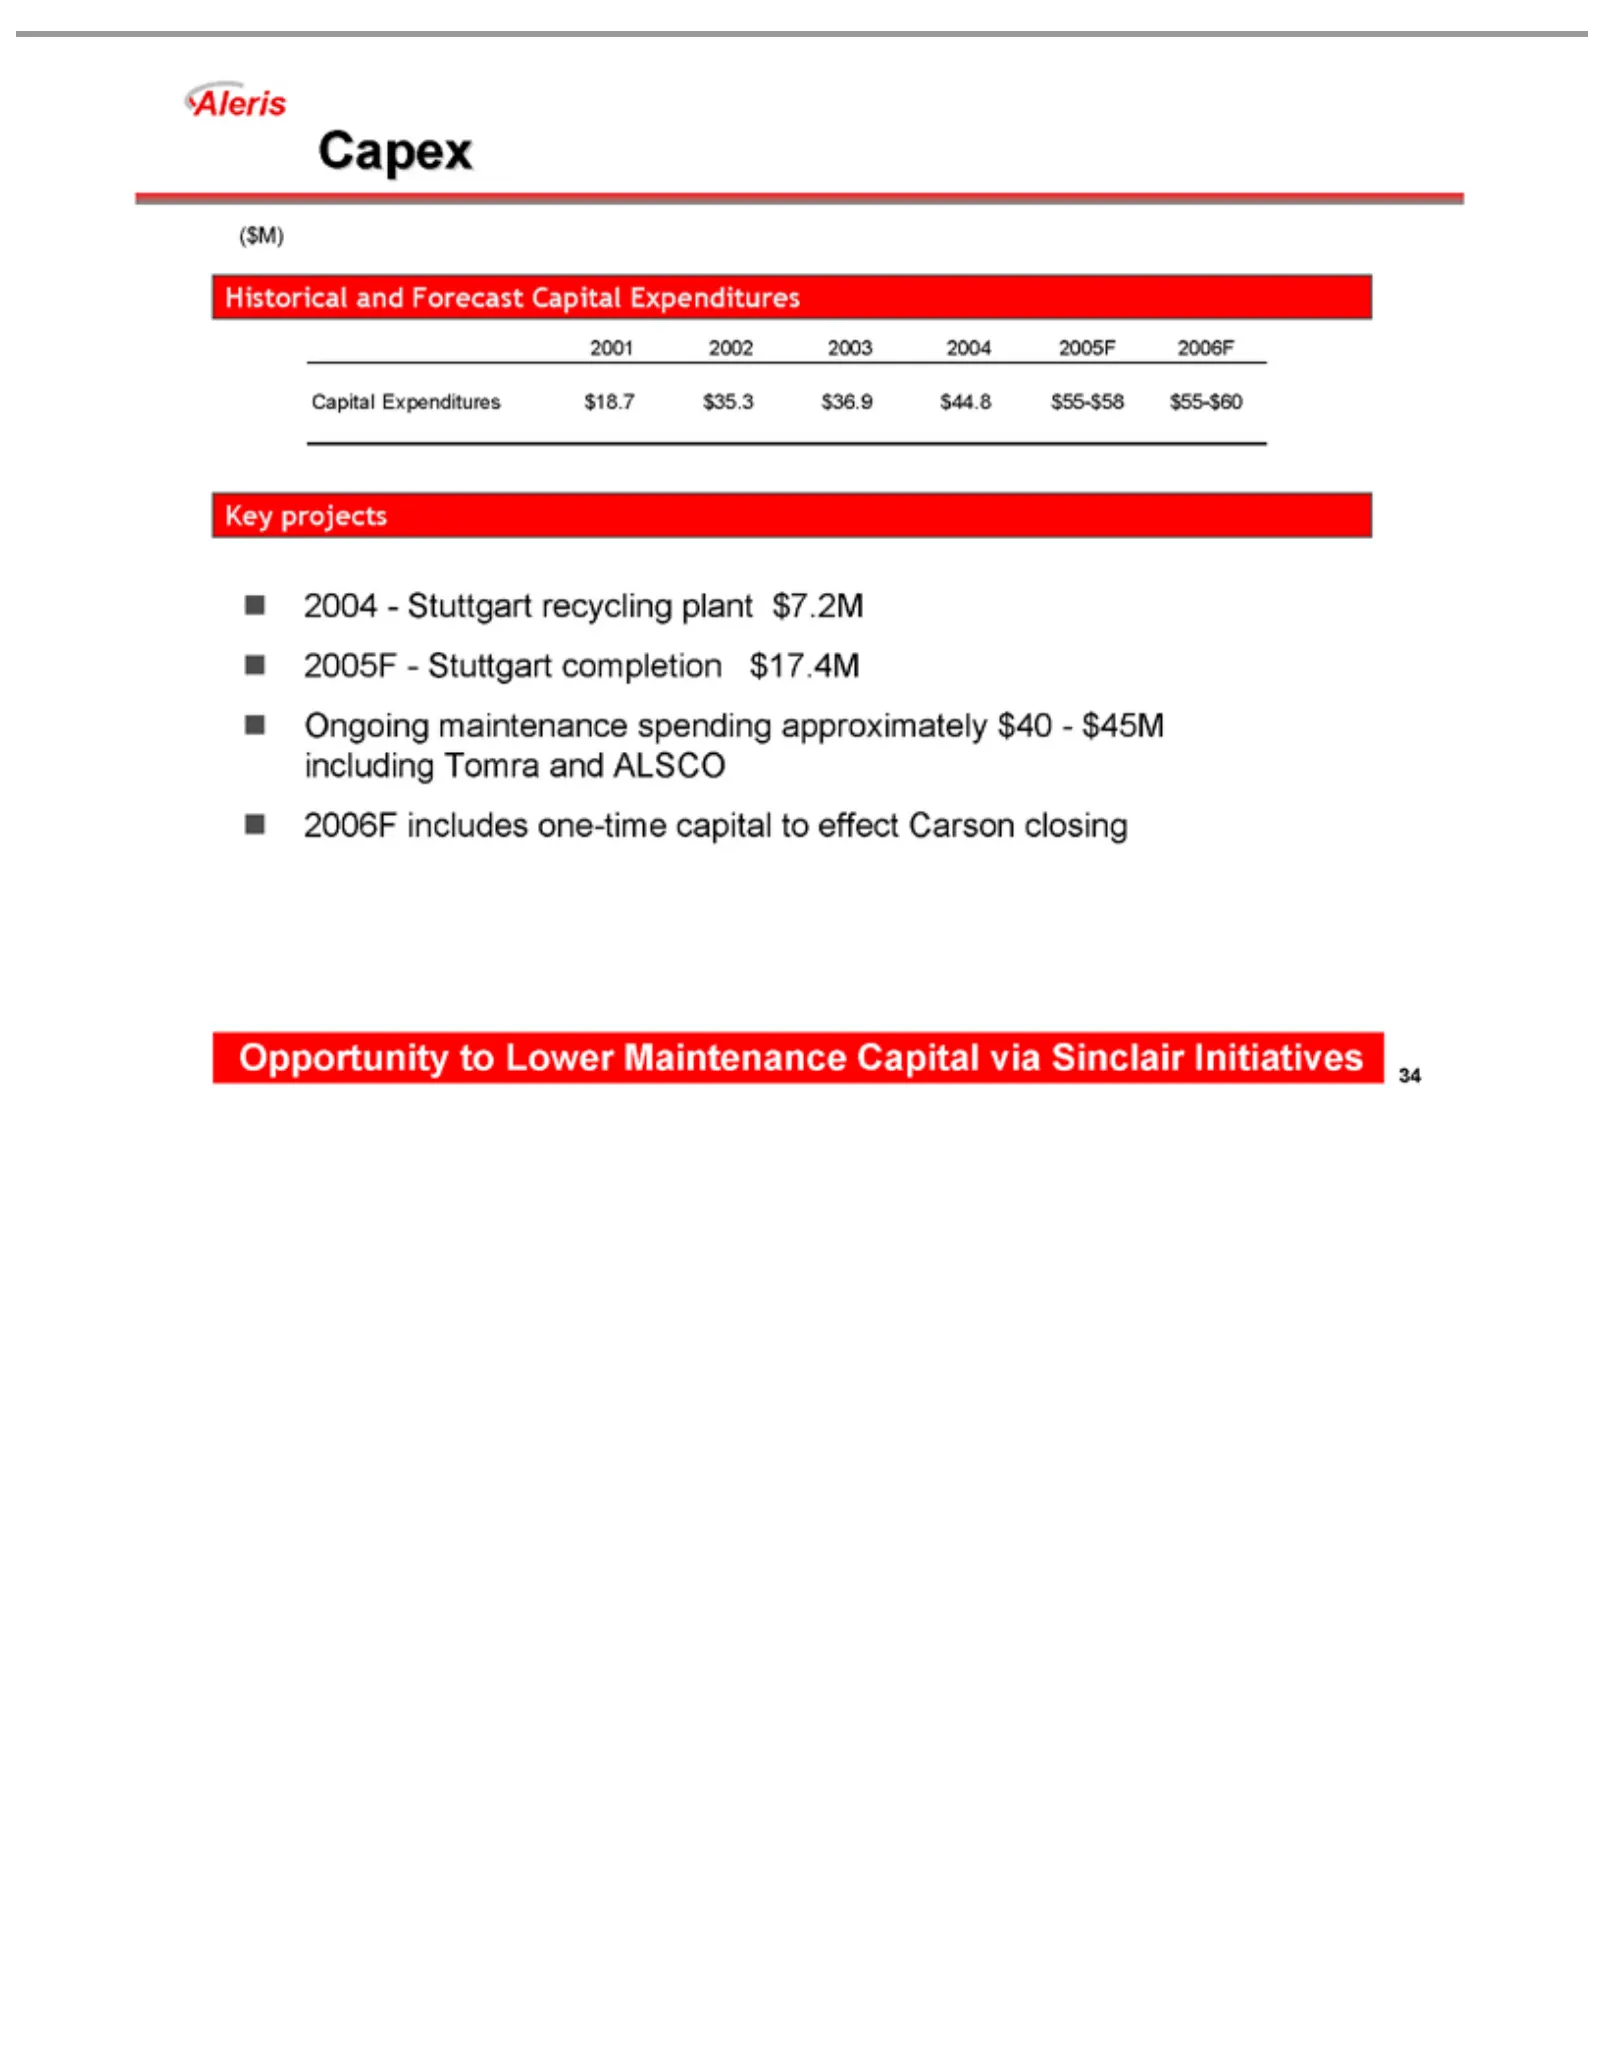
Slide 34: Historical and Forecast Capital Expenditures
Historical ($M) Capex Aleris 2001 Capital Key 2004—Stuttgart 2005F—Stuttgart Ongoing 2006F Opportunity 34 projects 2002 includes Expenditures maintenance and 2003 toForecast Lower one-time recycling 2004 completion $18.7 2005F Maintenance spending Capital capital plant $35.3 2006F $17.4M Expenditure
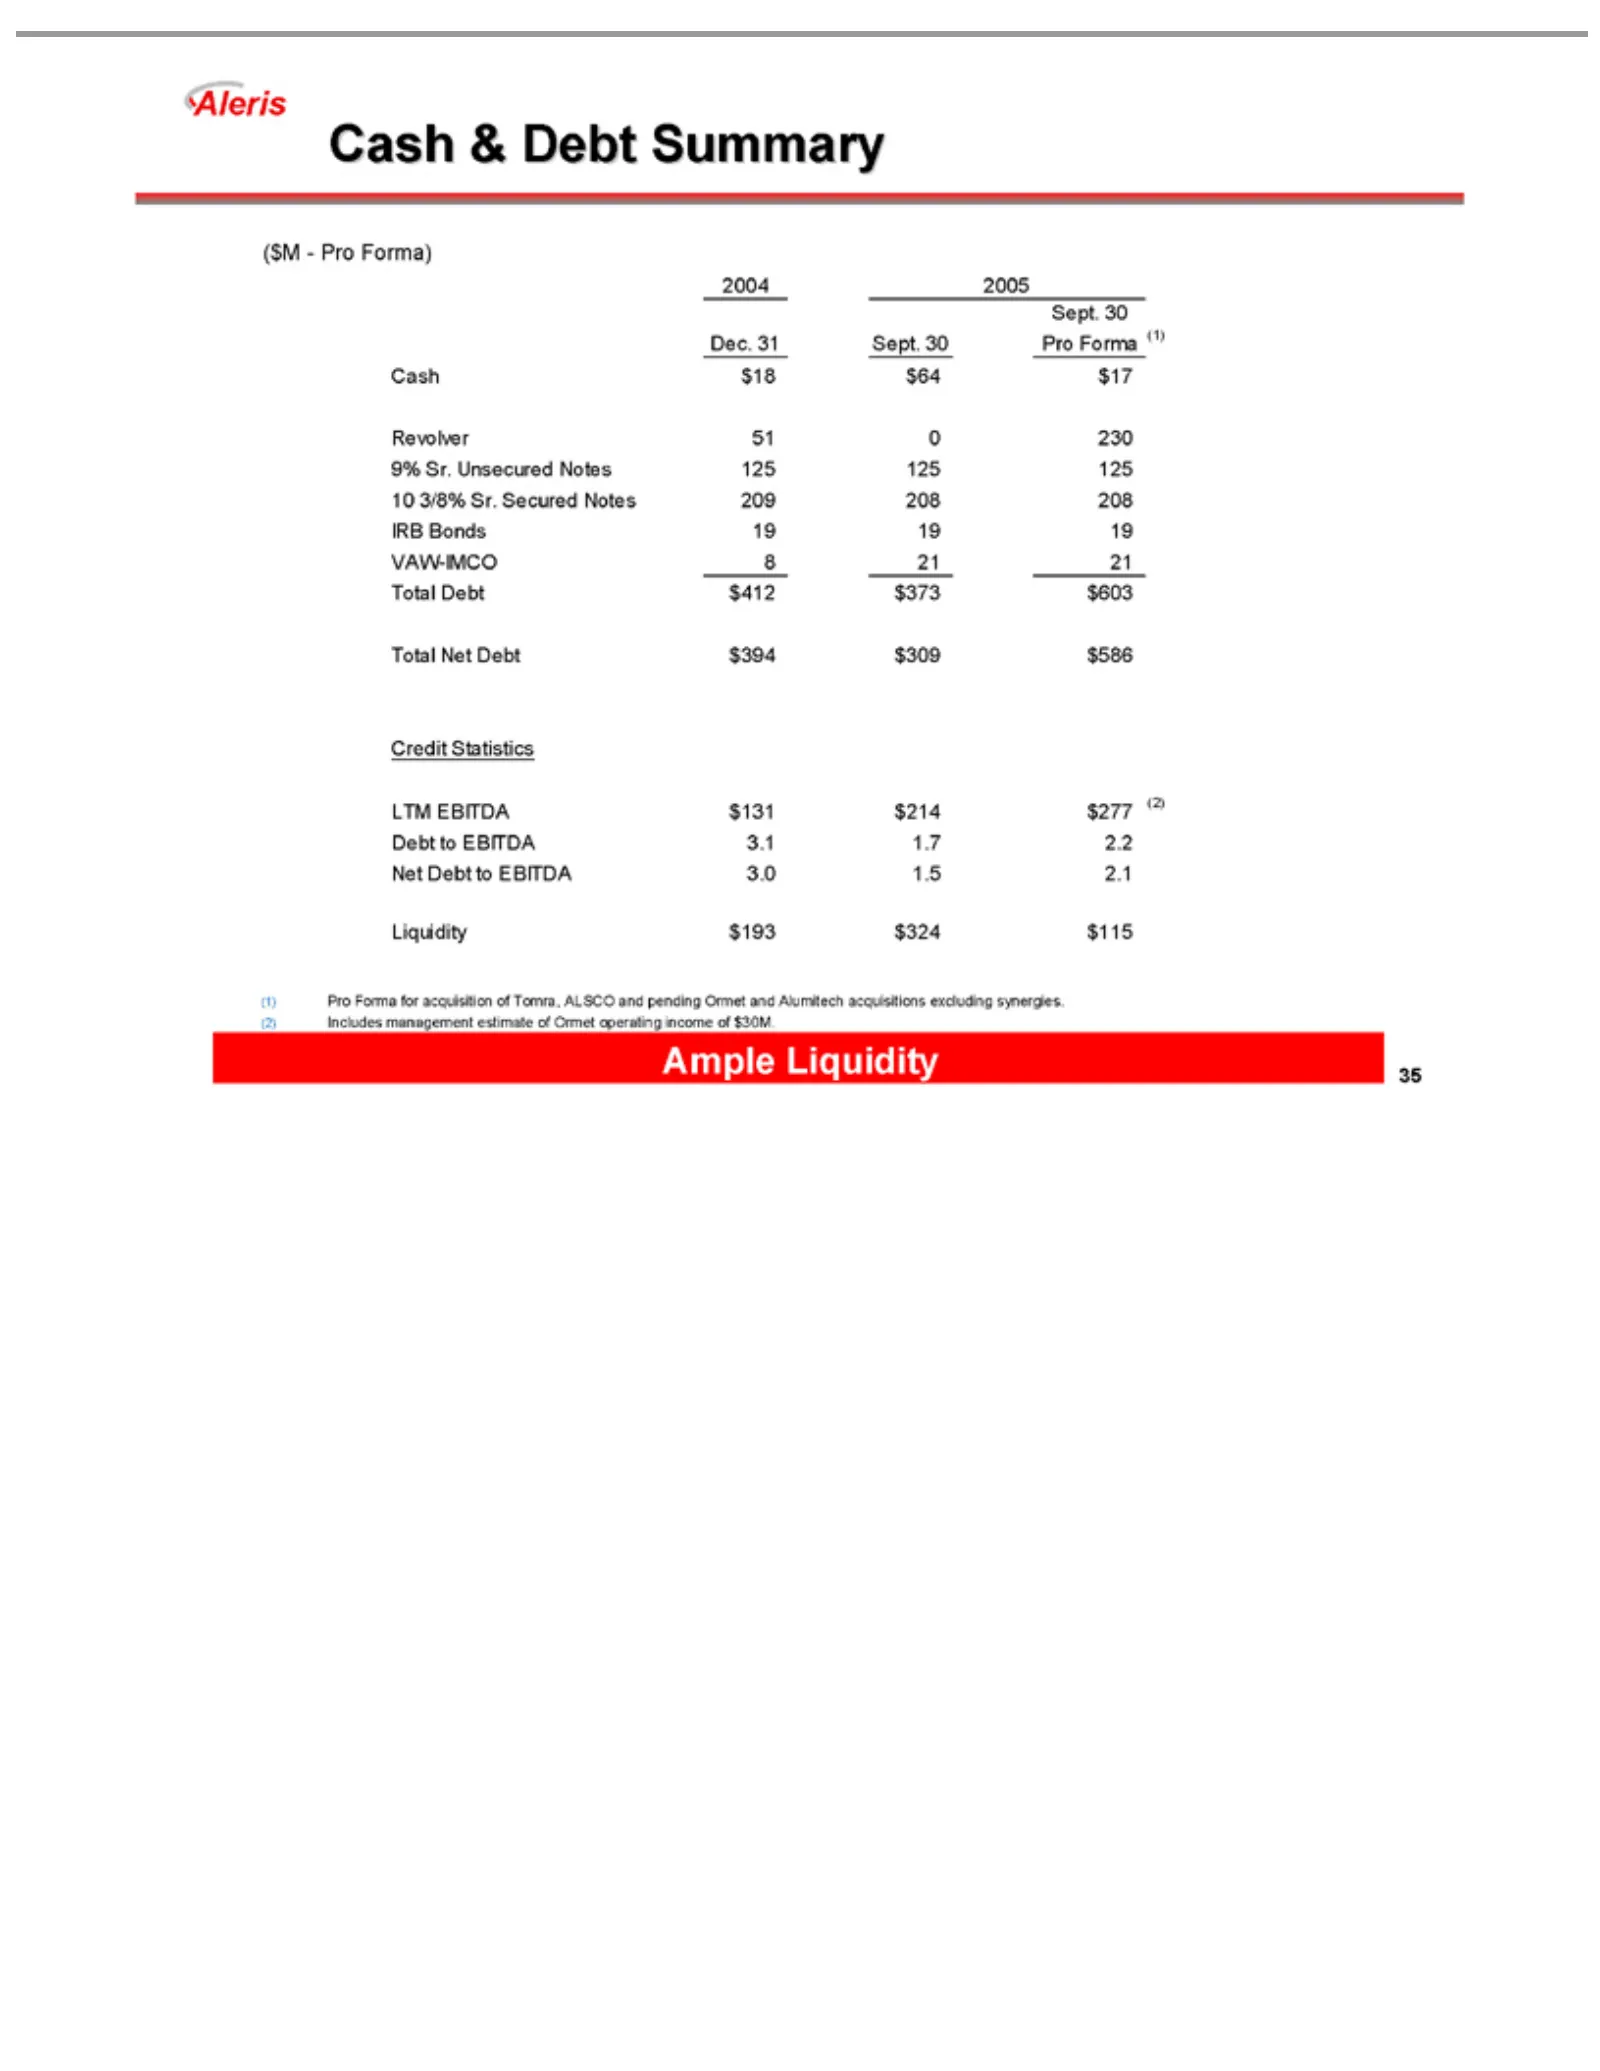
Slide 35: Ample Liquidity and Credit Statistics
Aleris ($M 2004 Dec. Cash Revolver 9% 10 IRB VAW-IMCO Total Credit LTM Debt Net Liquidity (1) Ample 35 3/8% Pro Sr. Debt Bonds -31 to 2005 $18 EBITDA Debt Net Pro Cash Statistics Unsecured Liquidity Forma EBITDA Sept. Sr. to 51 $193 Debt $64 Forma) $412 19 EBITDA & Secured 0830 $17 230 for Debt 19 2
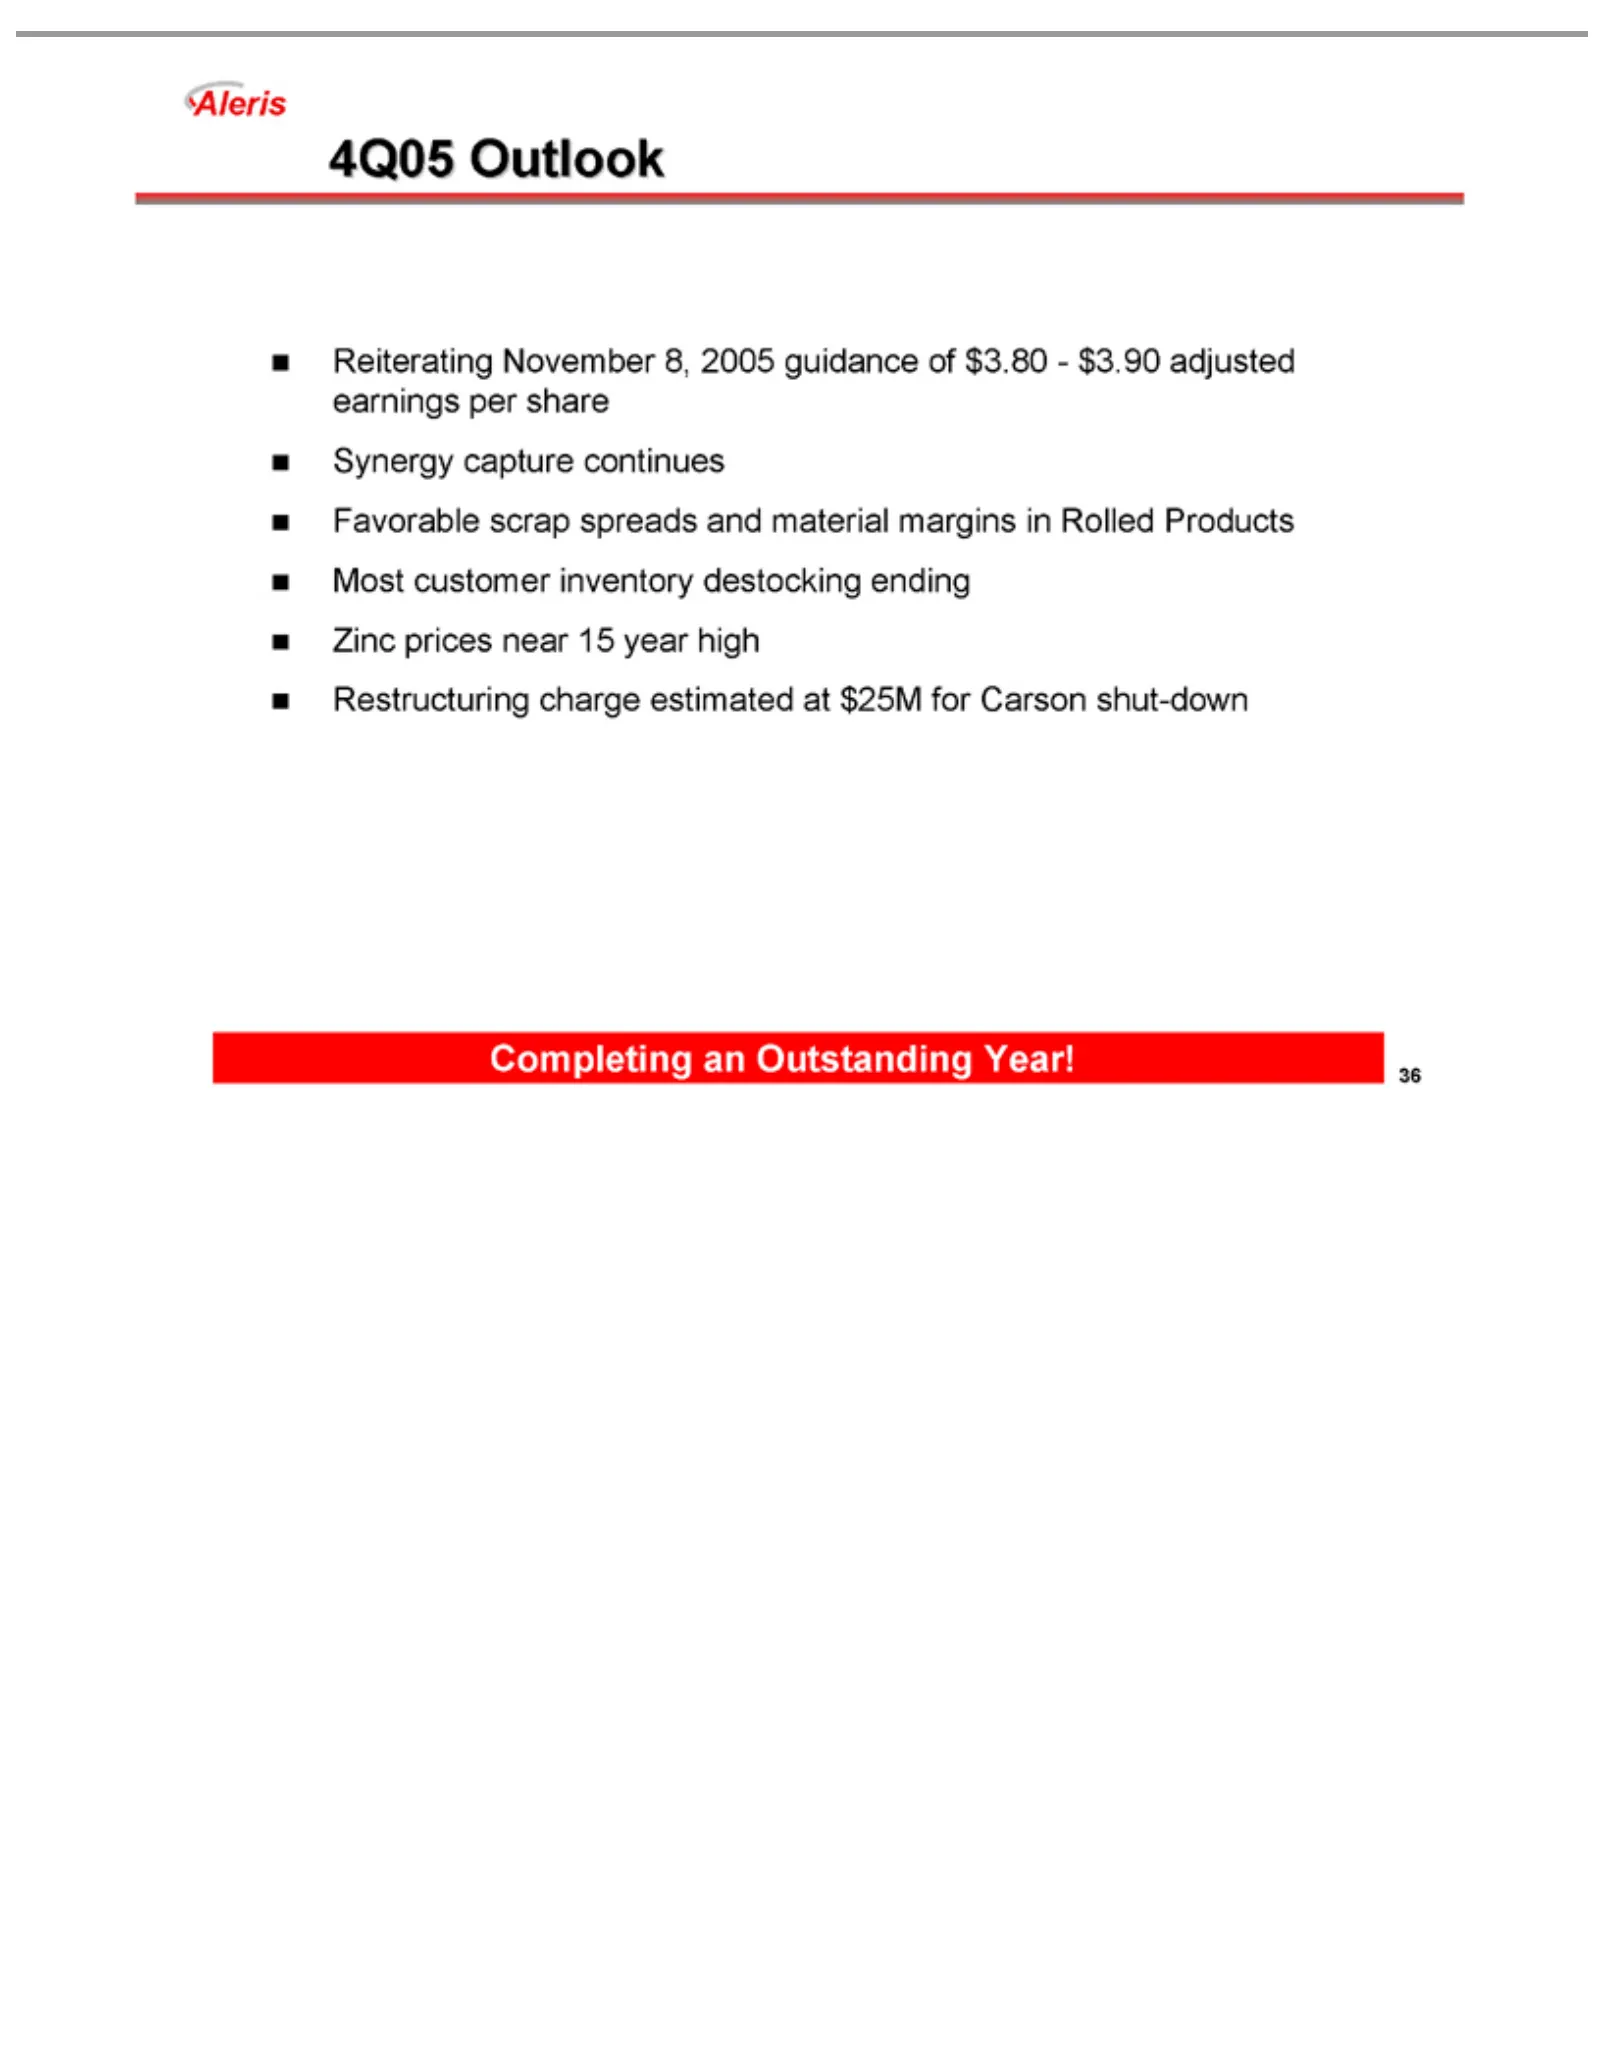
Slide 36: 4Q05 Outlook
4Q05prices Aleris Reiterating Synergy Favorable Most Zinc Restructuring Completing 36 customer Outlook capture scrap November near ancharge Outstanding inventory spreads 15 continues year estimated 8,and high 2005 destocking Year! material guidance at $25M ending margins of for$3.80—$3.90 Carson in
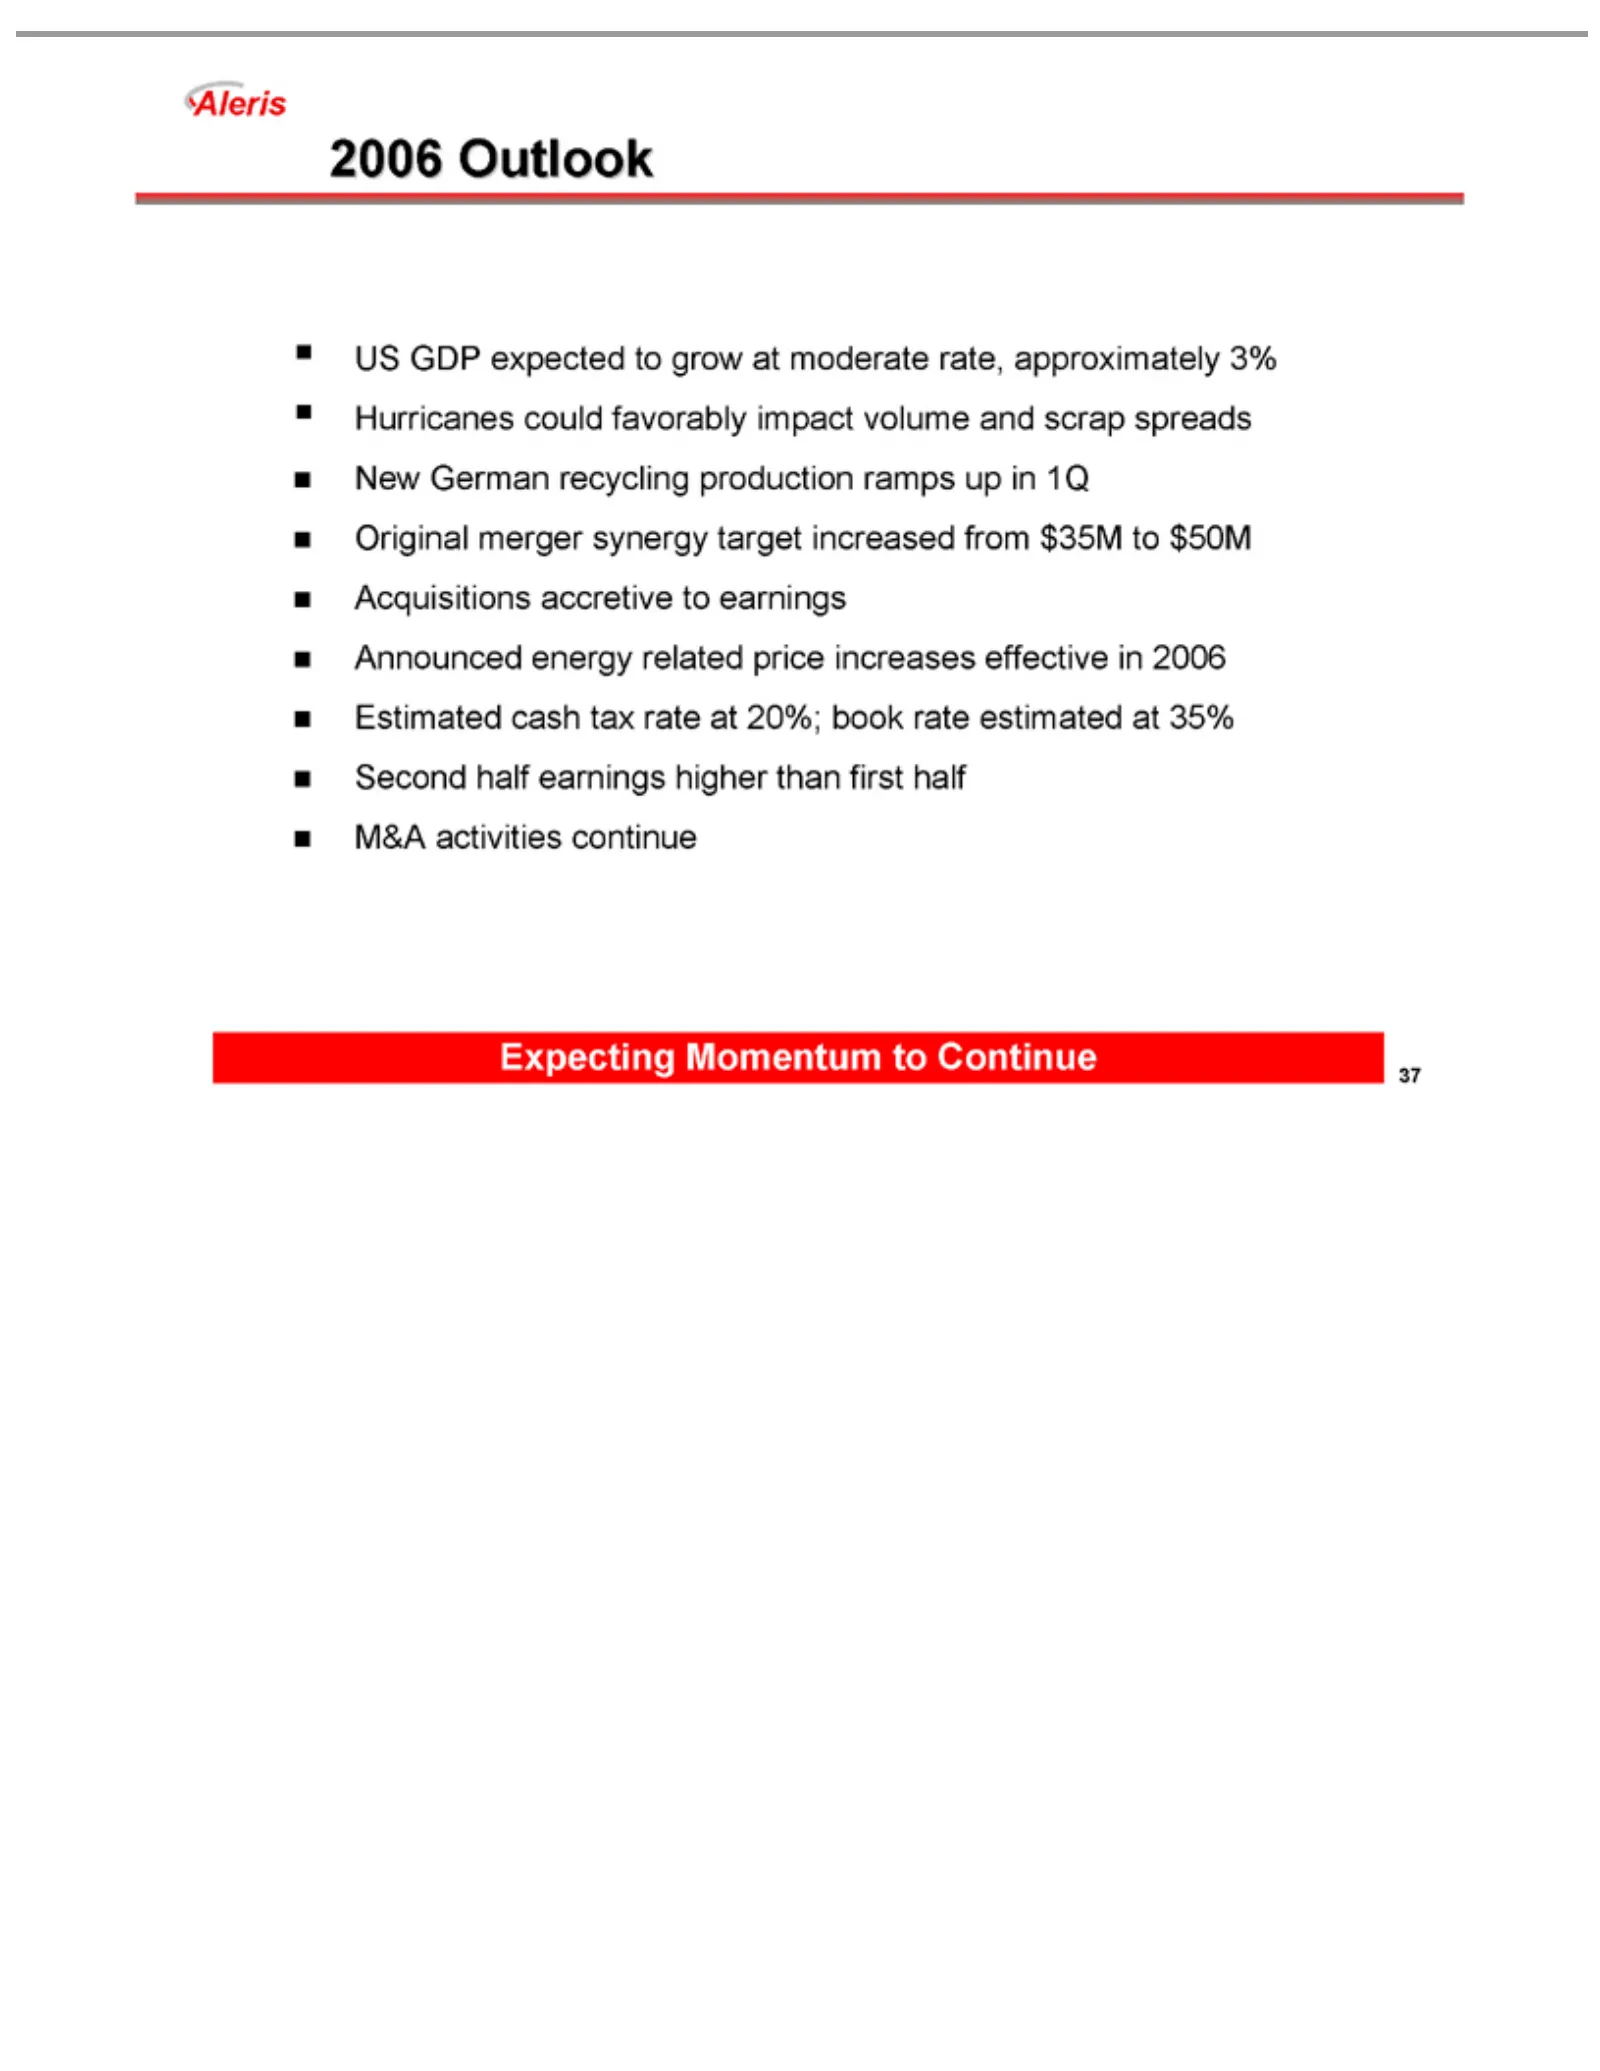
Slide 37: 2006 Outlook
2006GDP Aleris US New Original Acquisitions Announced Estimated Second M&A Expecting 37 German Outlook activities half merger expected cash Momentum energy earnings accretive recycling tax continue synergy to rate related grow higher toat production target earnings Continue 20%; price atthan moderat
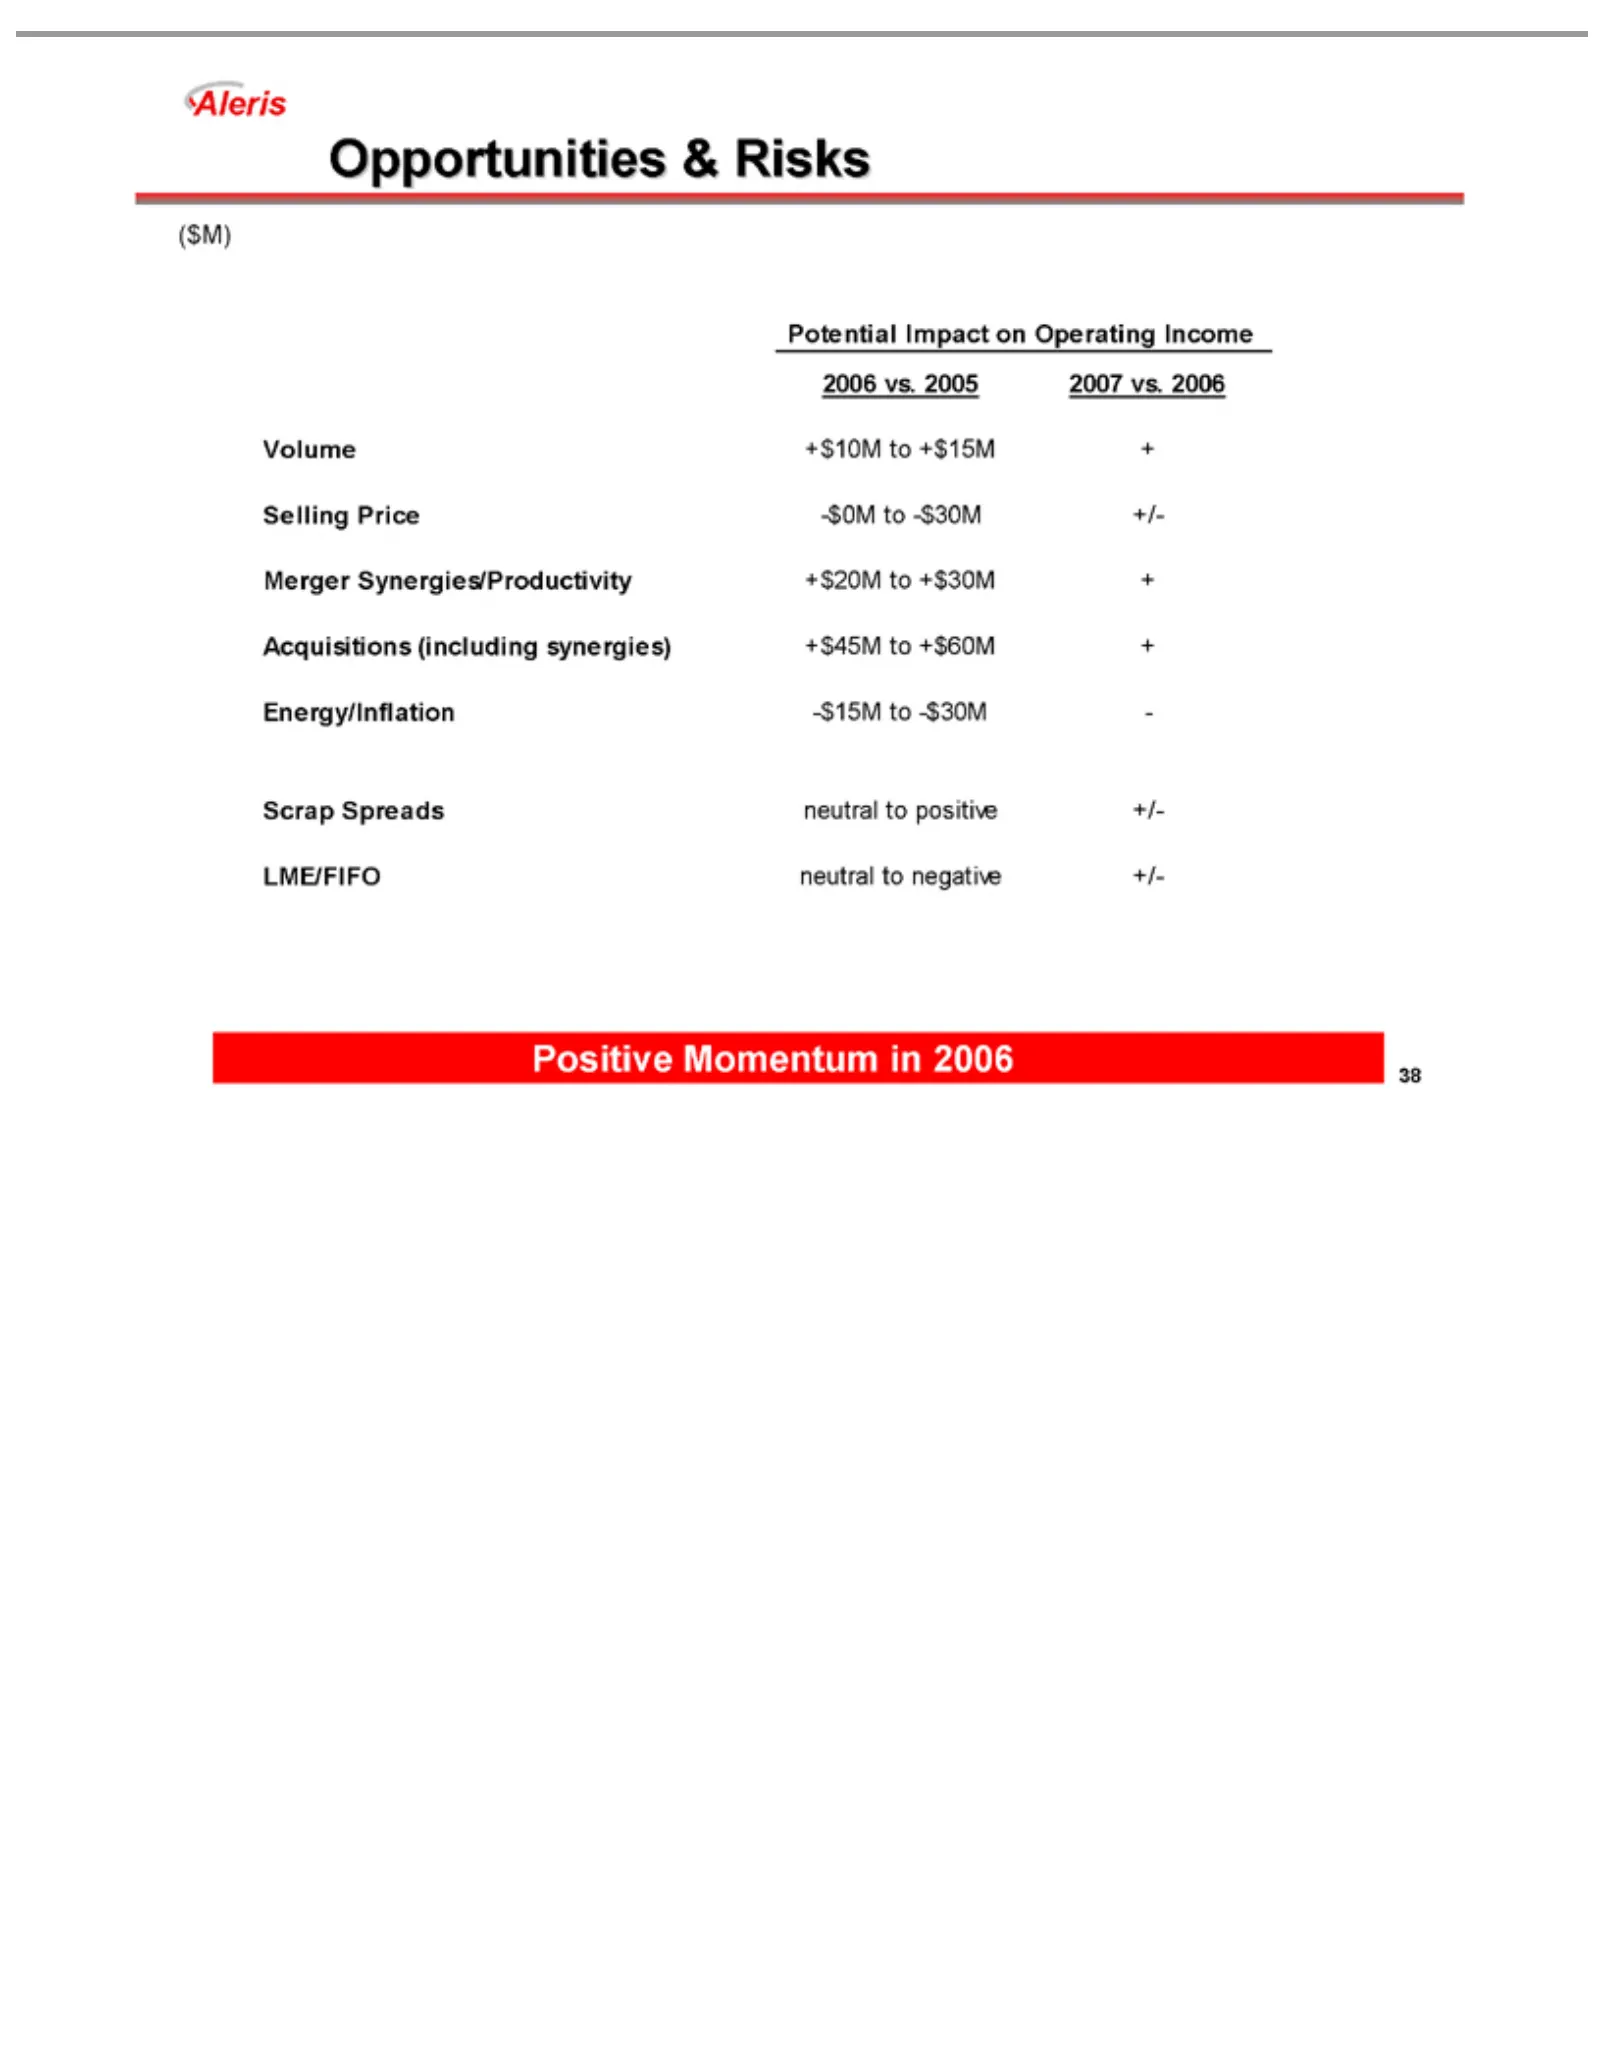
Slide 38: Potential 2006 Opportunities and Risks
Opportunities Aleris Potential ($M) 2006 Volume Selling Merger Acquisitions Energy/Inflation Scrap LME/FIFO Positive 38 vs. Spreads Price Synergies/Productivity +$10M Momentum 2005 Impact neutral (including -$0M &2007 neutral to Risks on -$15M +$15M to Operating vs. innegative -$30M to2006 2006 syne
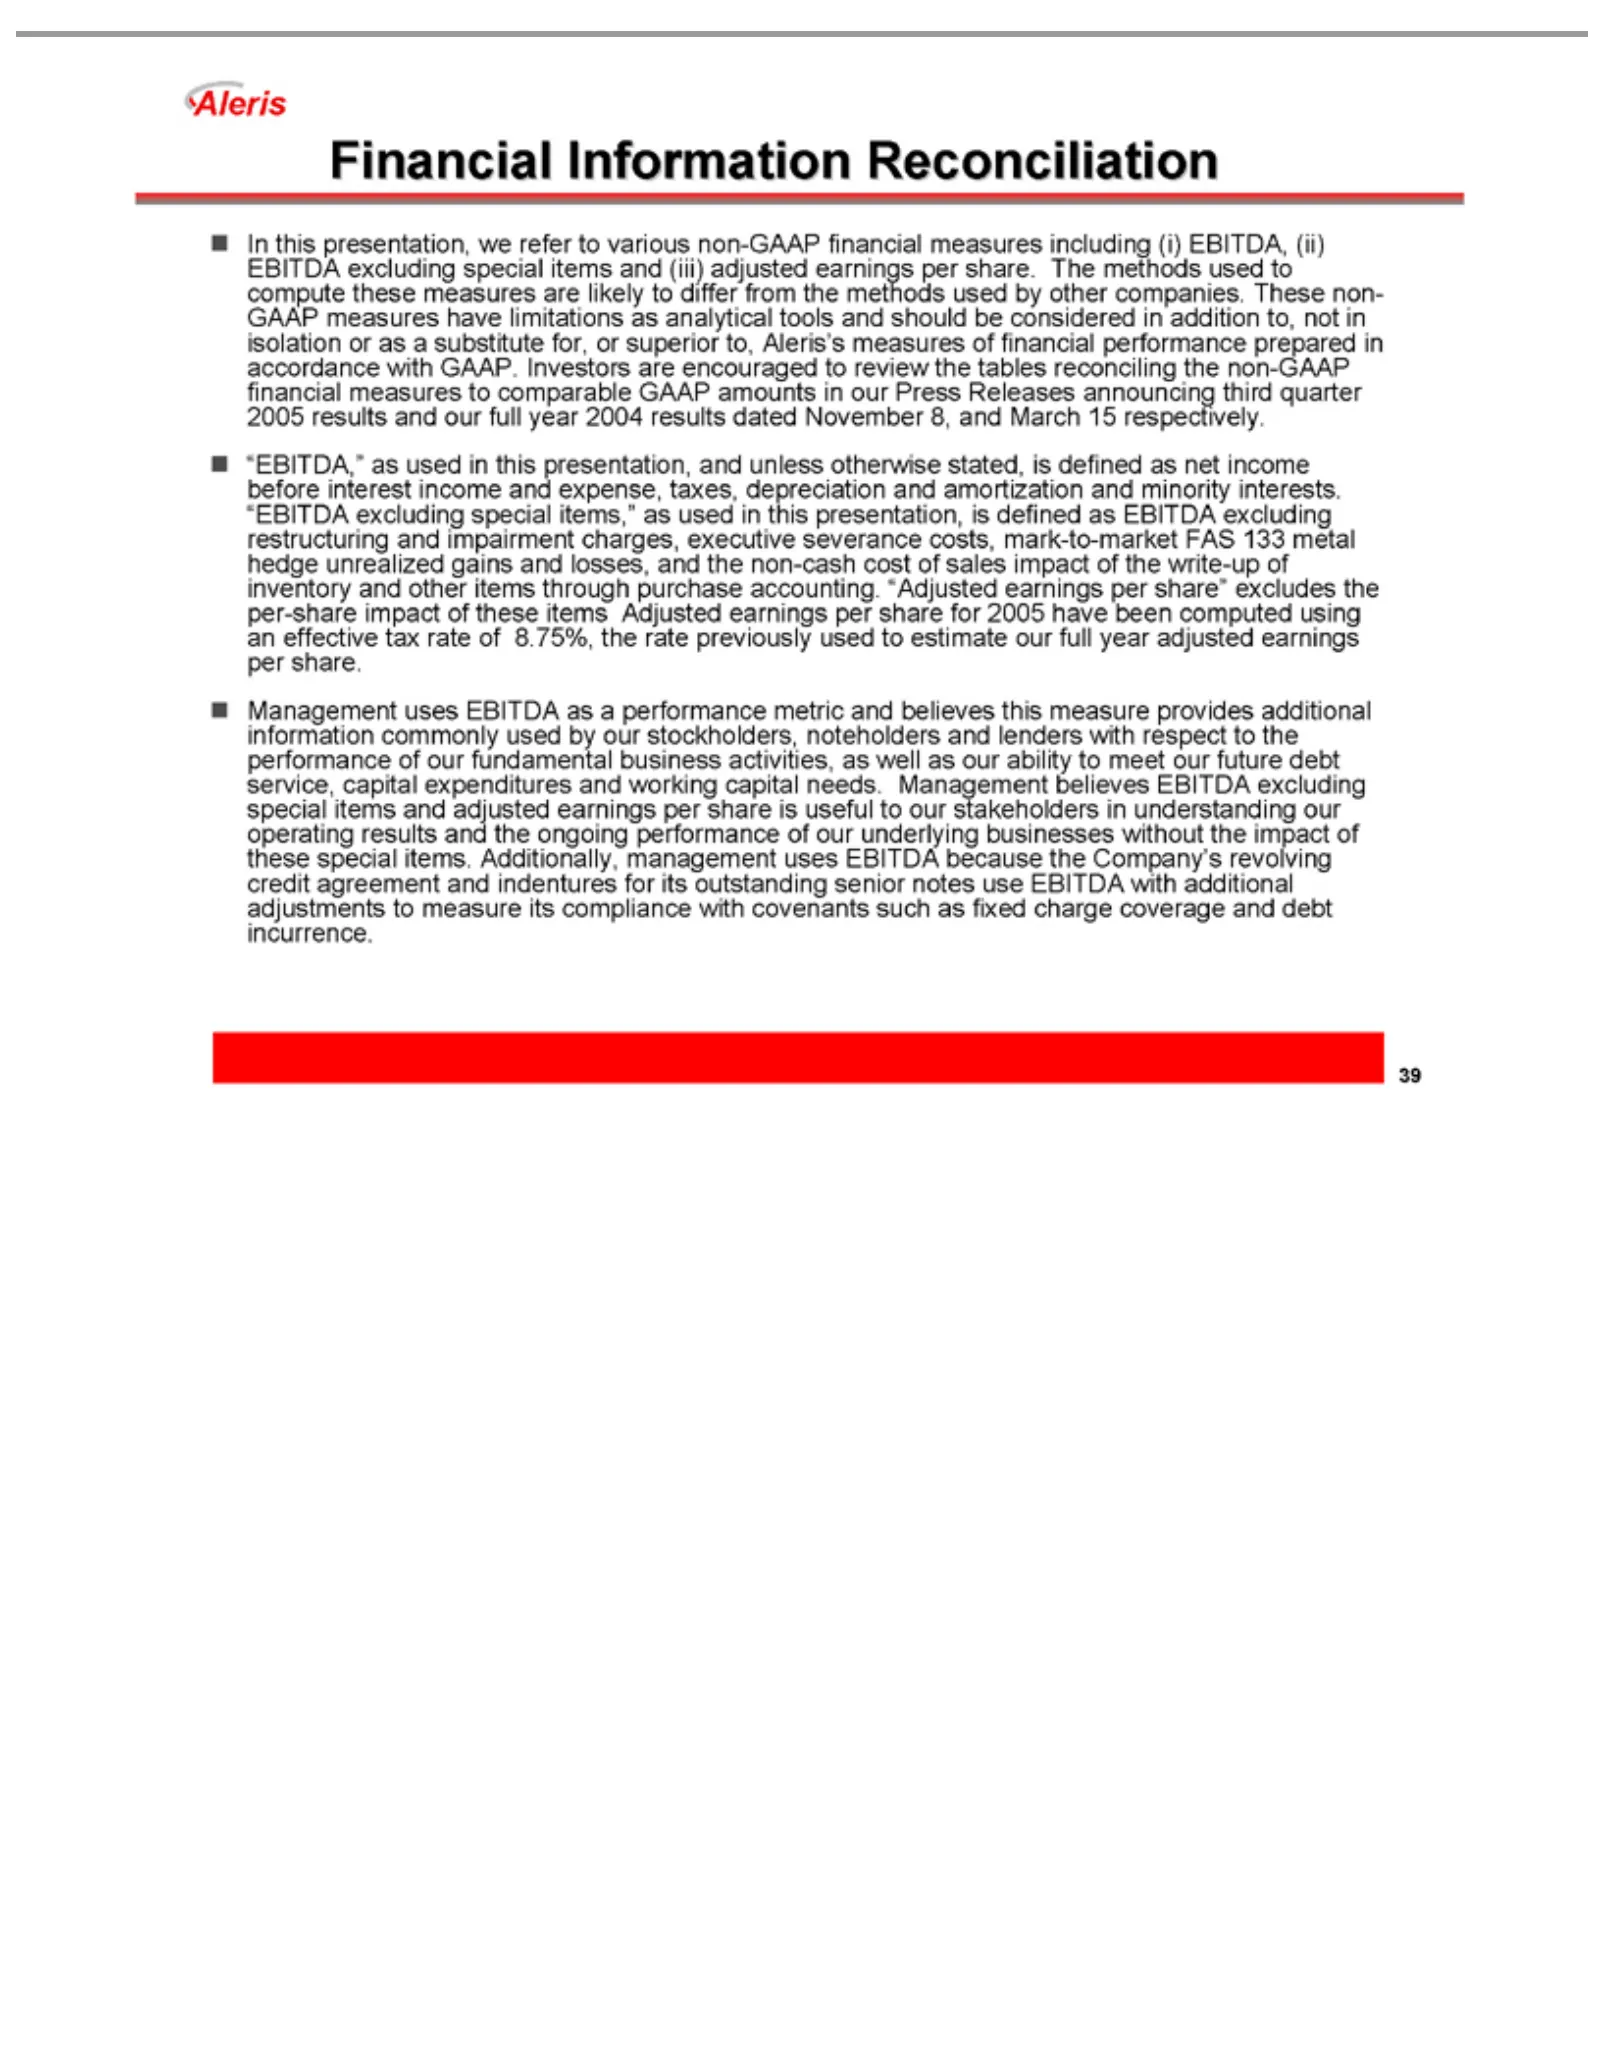
Slide 39: Financial Information
Financial Aleris In these or measures “EBITDA,” “EBITDA hedge share Management share. performance special measure 39 thisameasures as impact unrealized presentation, substitute items items. its to Information excluding compliance comparable as of and uses Additionally, used are our these for, gains
Source: SEC EDGAR · 8-K filed Dec 9, 2005
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
 Investor Presentation (October 2007)14 slides · Oct 3, 2007