Dennys — Investor Presentation (August 2017)
33 slides from Dennys's investor presentation, Aug 8, 2017
Slide 1: Investor Presentation August & September 2017
1 INVESTOR PRESENTATION August & September 2017
Slide 2: Forward-Looking Statements and Non-GAAP Financial Measures
2 FORWARD-LOOKING STATEMENTS AND NON-GAAP FINANCIAL MEASURES Denny’s Corporation urges caution in considering its current trends and any outlook on earnings disclosed in this presentation. In addition, certain matters discussed may constitute forward-looking statements. These forward-looking stateme
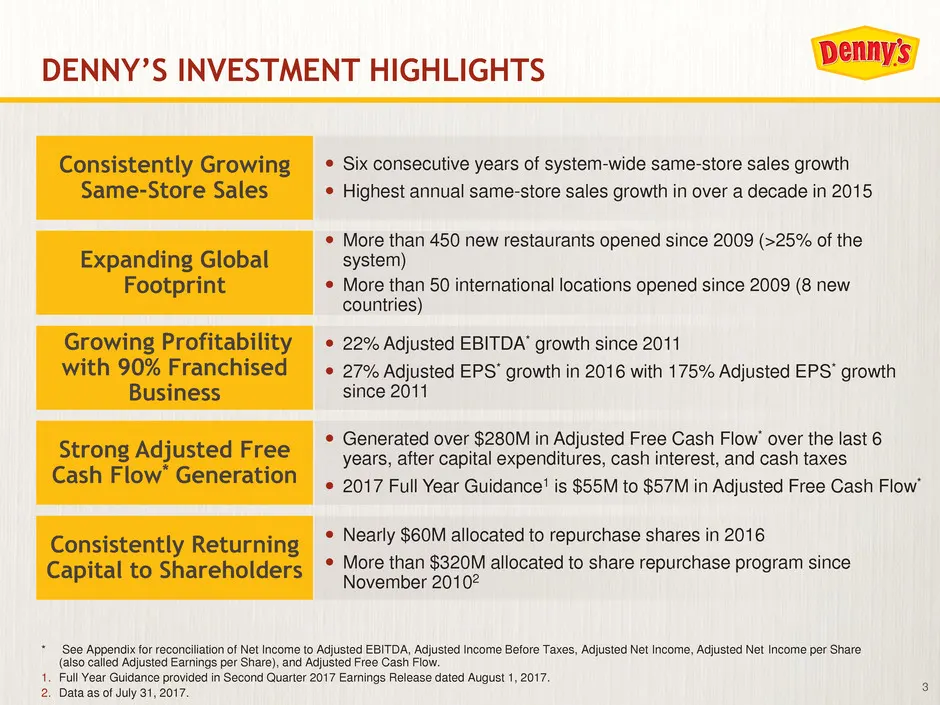
Slide 3: Denny's Investment Highlights
3 DENNY’S INVESTMENT HIGHLIGHTS * See Appendix for reconciliation of Net Income to Adjusted EBITDA, Adjusted Income Before Taxes, Adjusted Net Income, Adjusted Net Income per Share (also called Adjusted Earnings per Share), and Adjusted Free Cash Flow. 1. Full Year Guidance provided in Second Quarte
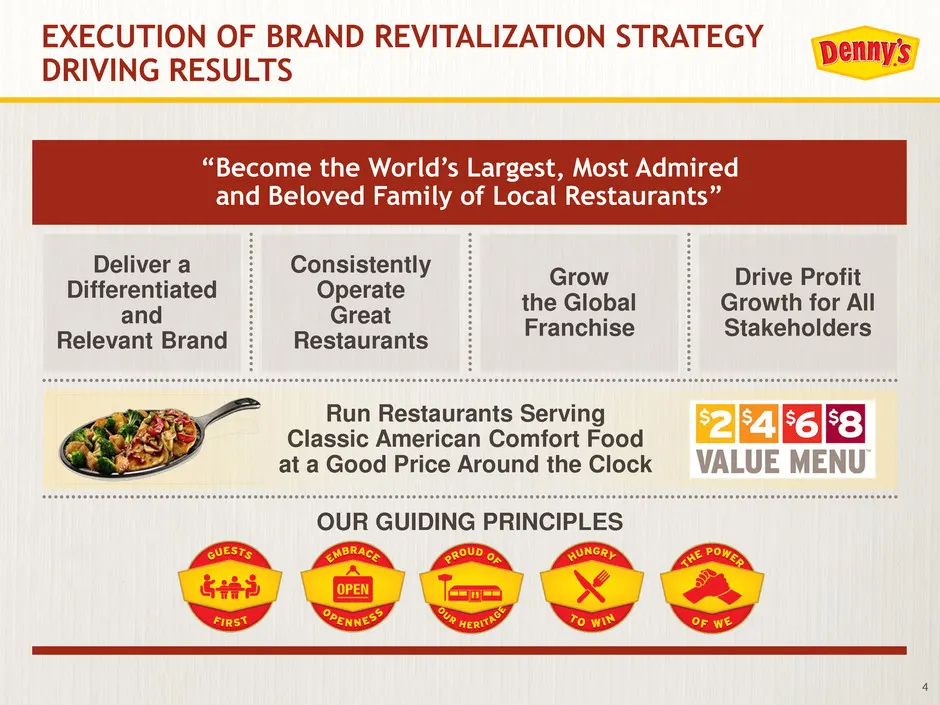
Slide 4: Execution of Brand Revitalization Strategy Driving Results
4 Run Restaurants Serving Classic American Comfort Food at a Good Price Around the Clock EXECUTION OF BRAND REVITALIZATION STRATEGY DRIVING RESULTS Drive Profit Growth for All Stakeholders Grow the Global Franchise Consistently Operate Great Restaurants Deliver a Differentiated and Relevant Brand “B
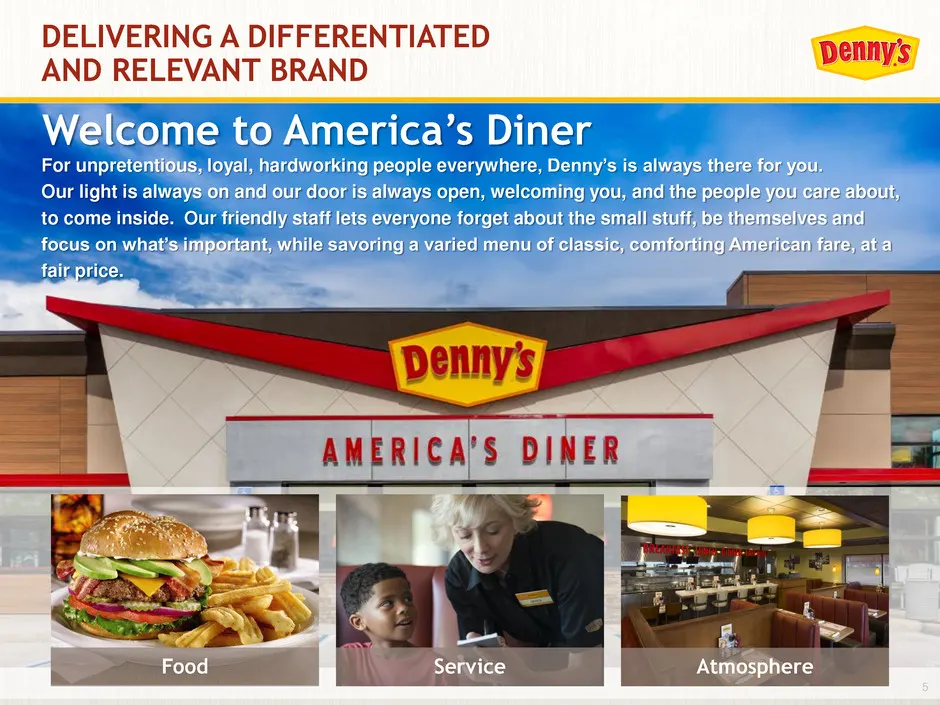
Slide 5: Delivering a Differentiated and Relevant Brand
5 For unpretentious, loyal, hardworking people everywhere, Denny’s is always there for you. Our light is always on and our door is always open, welcoming you, and the people you care about, to come inside. Our friendly staff lets everyone forget about the small stuff, be themselves and focus on what
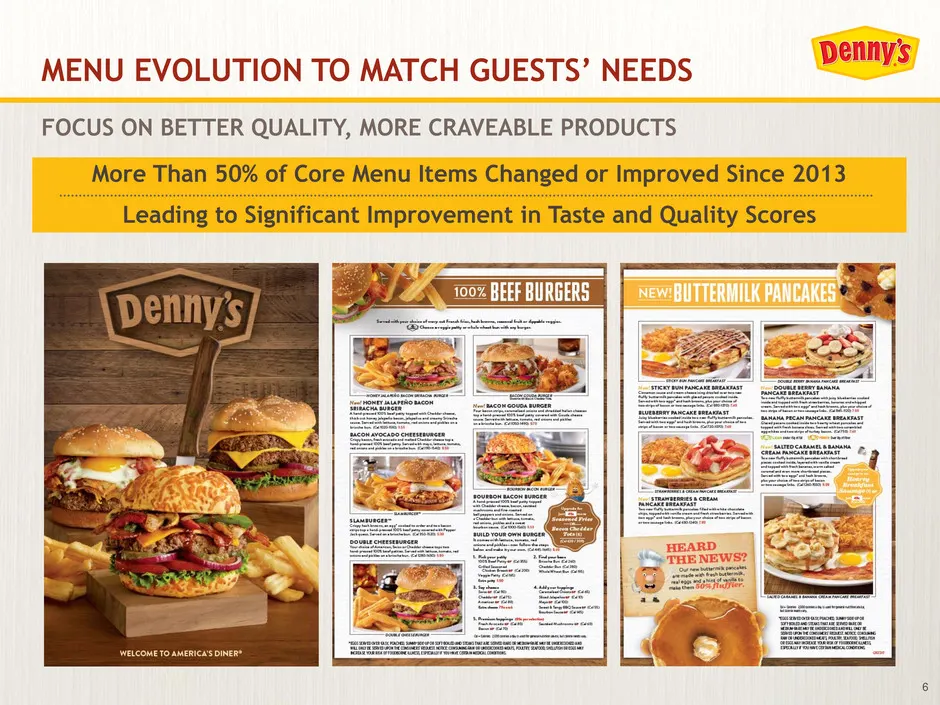
Slide 6: Menu Evolution to Match Guests' Needs
6 MENU EVOLUTION TO MATCH GUESTS’ NEEDS FOCUS ON BETTER QUALITY, MORE CRAVEABLE PRODUCTS More Than 50% of Core Menu Items Changed or Improved Since 2013 Leading to Significant Improvement in Taste and Quality Scores
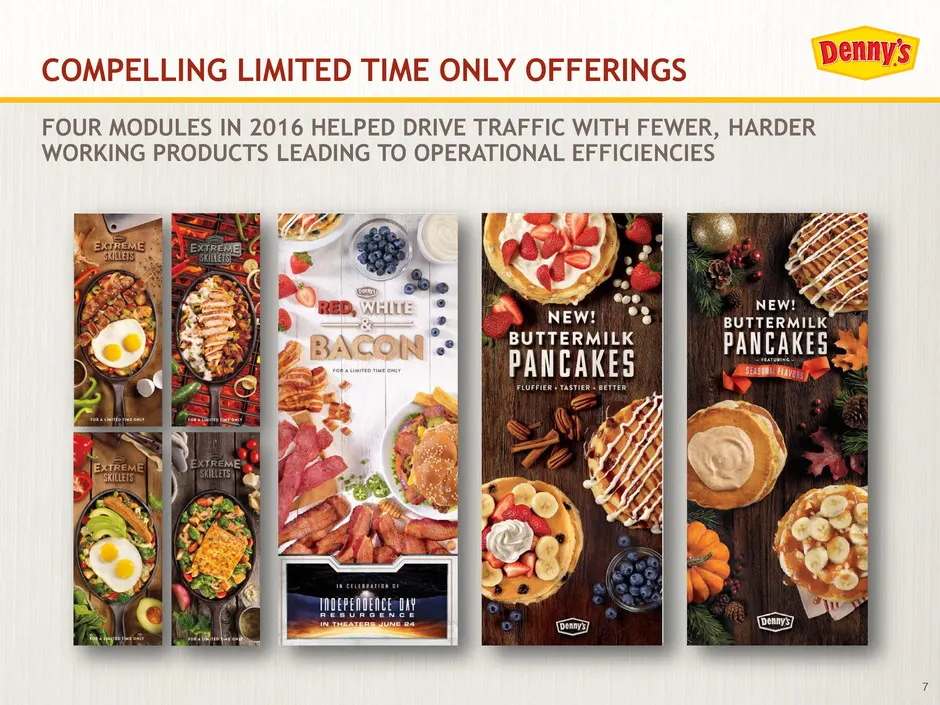
Slide 7: Compelling Limited Time Only Offerings
7 COMPELLING LIMITED TIME ONLY OFFERINGS FOUR MODULES IN 2016 HELPED DRIVE TRAFFIC WITH FEWER, HARDER WORKING PRODUCTS LEADING TO OPERATIONAL EFFICIENCIES
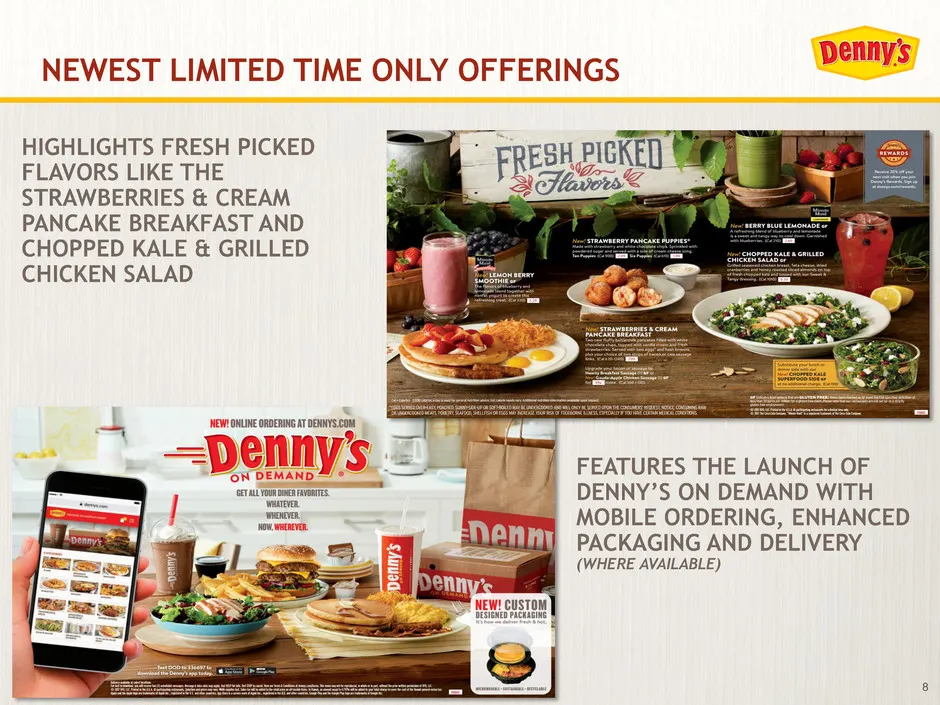
Slide 8: Newest Limited Time Only Offerings
8 NEWEST LIMITED TIME ONLY OFFERINGS HIGHLIGHTS FRESH PICKED FLAVORS LIKE THE STRAWBERRIES & CREAM PANCAKE BREAKFAST AND CHOPPED KALE & GRILLED CHICKEN SALAD FEATURES THE LAUNCH OF DENNY’S ON DEMAND WITH MOBILE ORDERING, ENHANCED PACKAGING AND DELIVERY (WHERE AVAILABLE)
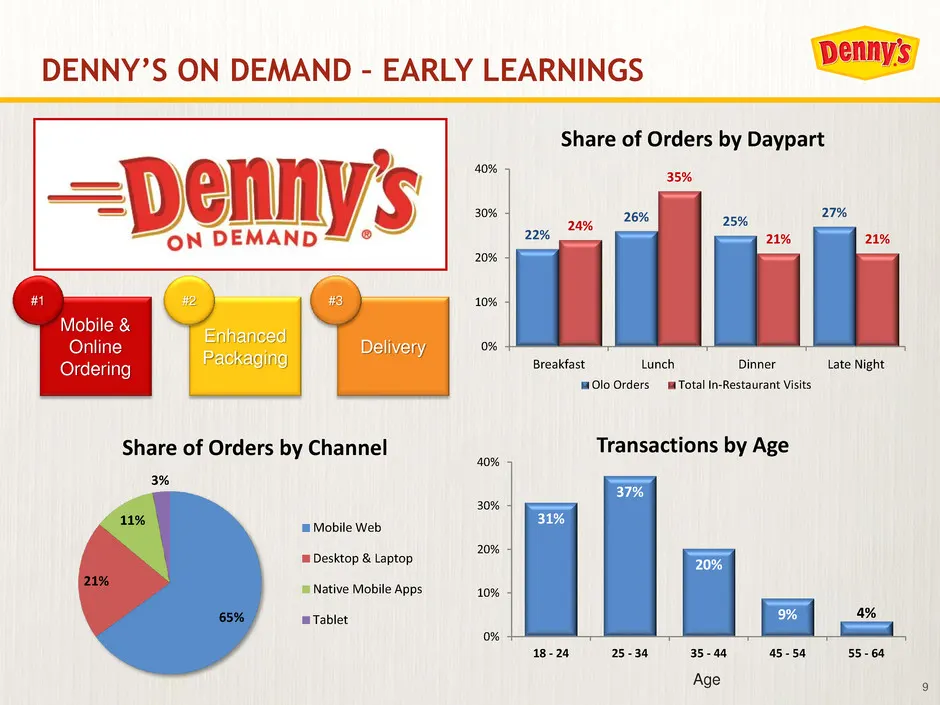
Slide 9: Denny's On Demand – Early Learnings
9 22% 26% 25% 27% 24% 35% 21% 21% 0% 10% 20% 30% 40% Breakfast Lunch Dinner Late Night Share of Orders by Daypart Olo Orders Total In-Restaurant Visits 65% 21% 11% 3% Share of Orders by Channel Mobile Web Desktop & Laptop Native Mobile Apps Tablet Age DENNY’S ON DEMAND – EARLY LEARNINGS Mobile & Onl
Slide 10: Everyday Value Menu Helping to Drive Traffic
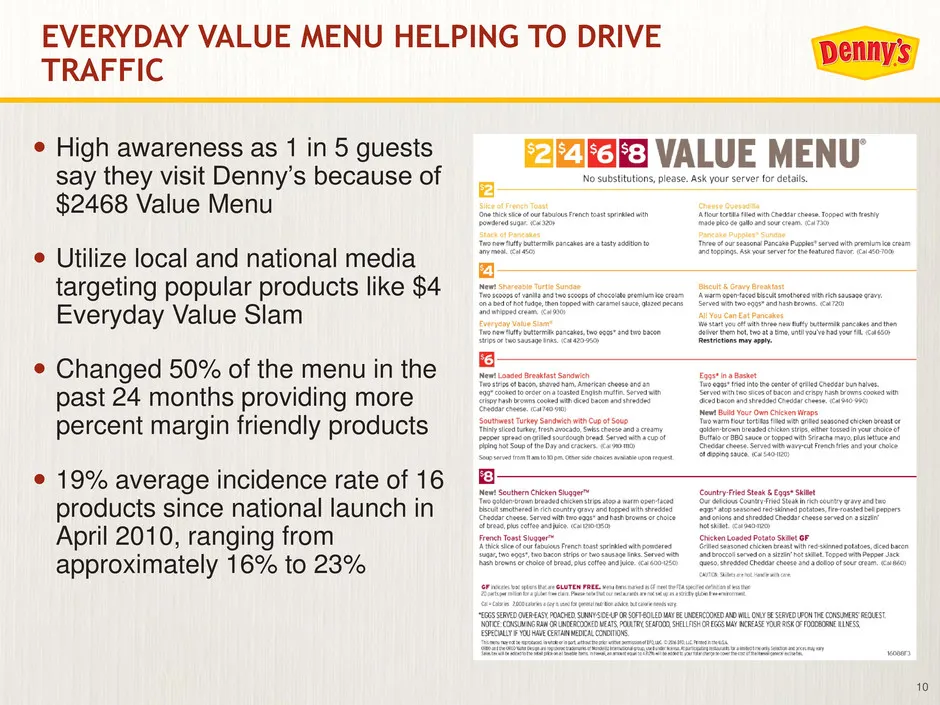
10 EVERYDAY VALUE MENU HELPING TO DRIVE TRAFFIC High awareness as 1 in 5 guests say they visit Denny’s because of $2468 Value Menu Utilize local and national media targeting popular products like $4 Everyday Value Slam Changed 50% of the menu in the past 24 months providing more percent margin
Slide 11: Engaging Key Customer Segments Through Traditional and New Media
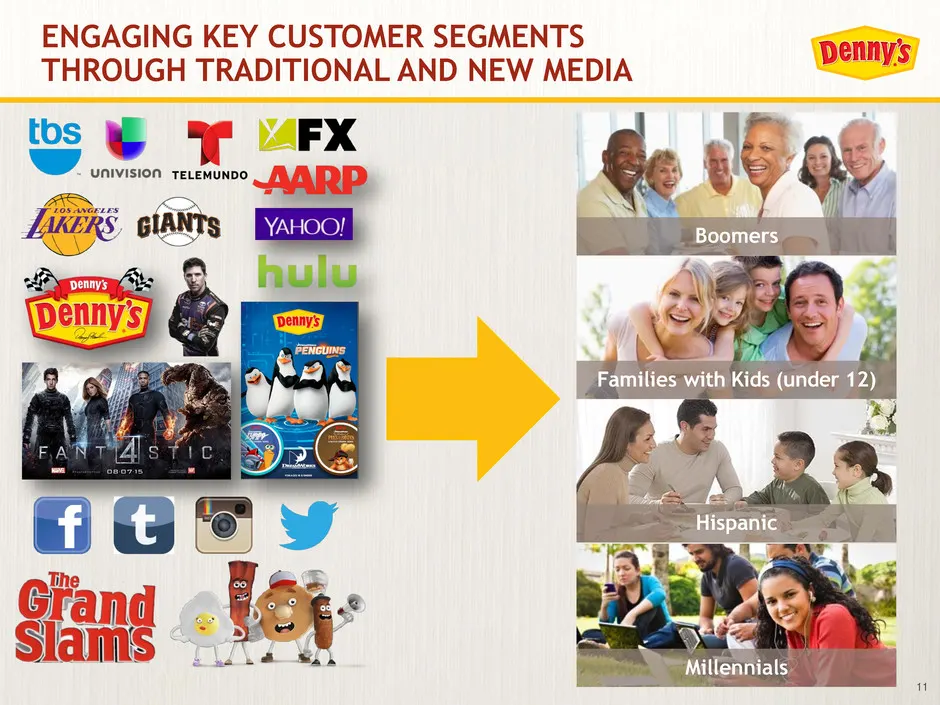
11 ENGAGING KEY CUSTOMER SEGMENTS THROUGH TRADITIONAL AND NEW MEDIA Boomers Families with Kids (under 12) Hispanic Millennials
Slide 12: Remodel Program Enhancing Traffic and Scores
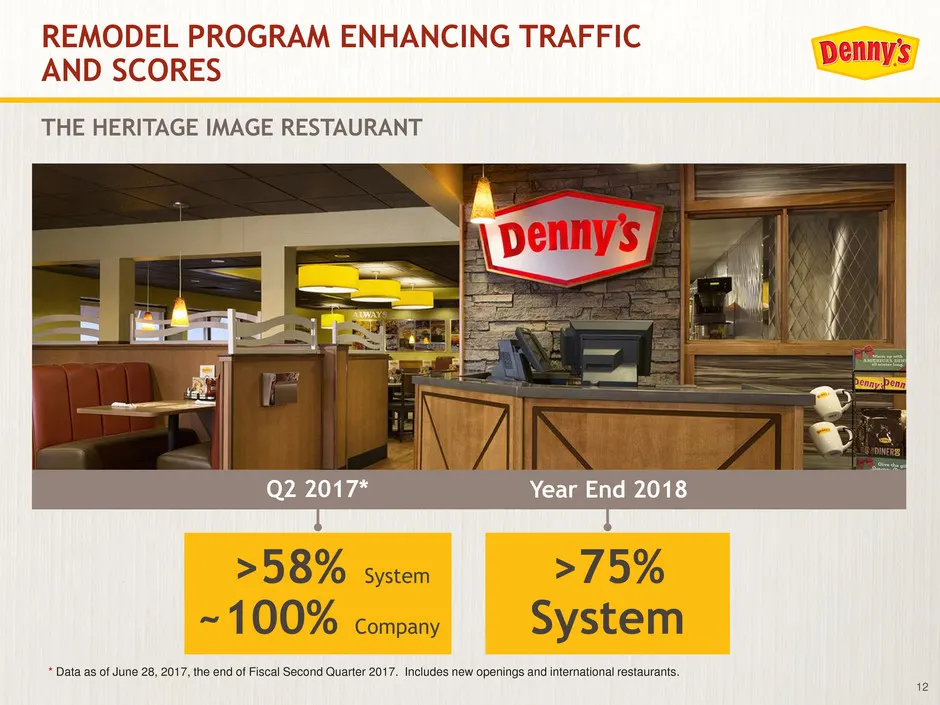
12 >75% System >58% System ~100% Company REMODEL PROGRAM ENHANCING TRAFFIC AND SCORES THE HERITAGE IMAGE RESTAURANT * Data as of June 28, 2017, the end of Fiscal Second Quarter 2017. Includes new openings and international restaurants. Q2 2017* Year End 2018
Slide 13: Heritage Image Key to Revitalizing Legacy Brand
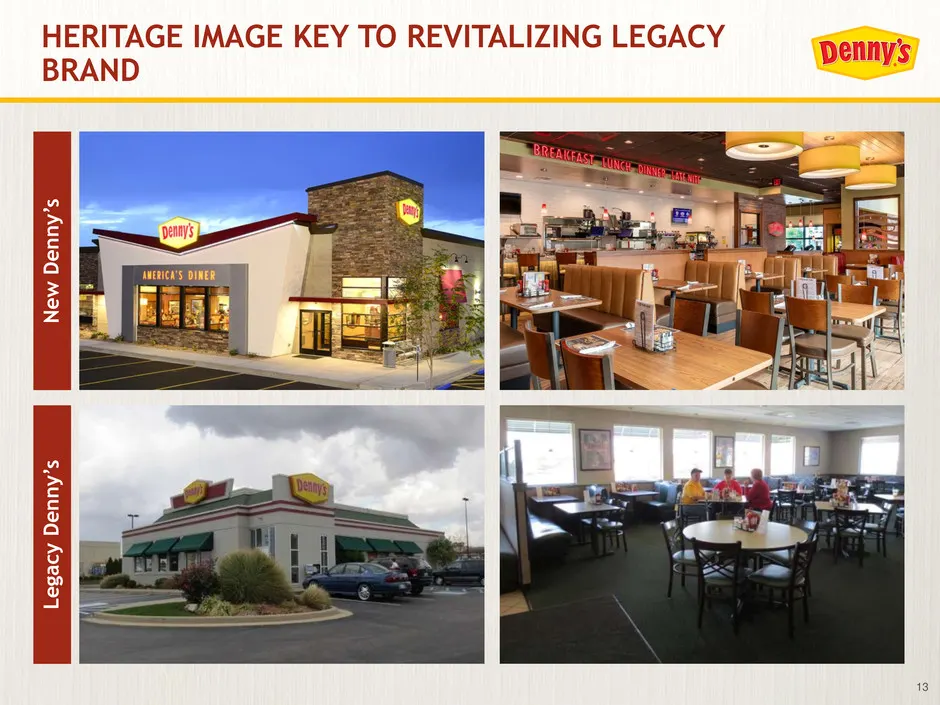
13 HERITAGE IMAGE KEY TO REVITALIZING LEGACY BRAND L e gacy D e n n y’ s New D e n n y’ s
Slide 14: Focus on Operating Great Restaurants
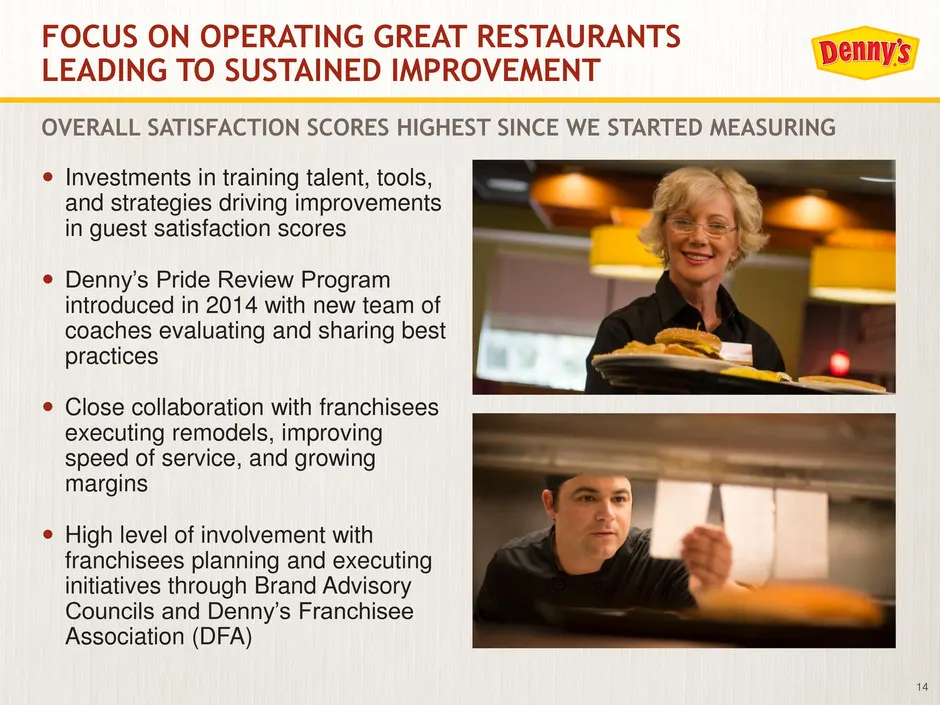
14 Investments in training talent, tools, and strategies driving improvements in guest satisfaction scores Denny’s Pride Review Program introduced in 2014 with new team of coaches evaluating and sharing best practices Close collaboration with franchisees executing remodels, improving speed of
Slide 15: Expanding Global Footprint
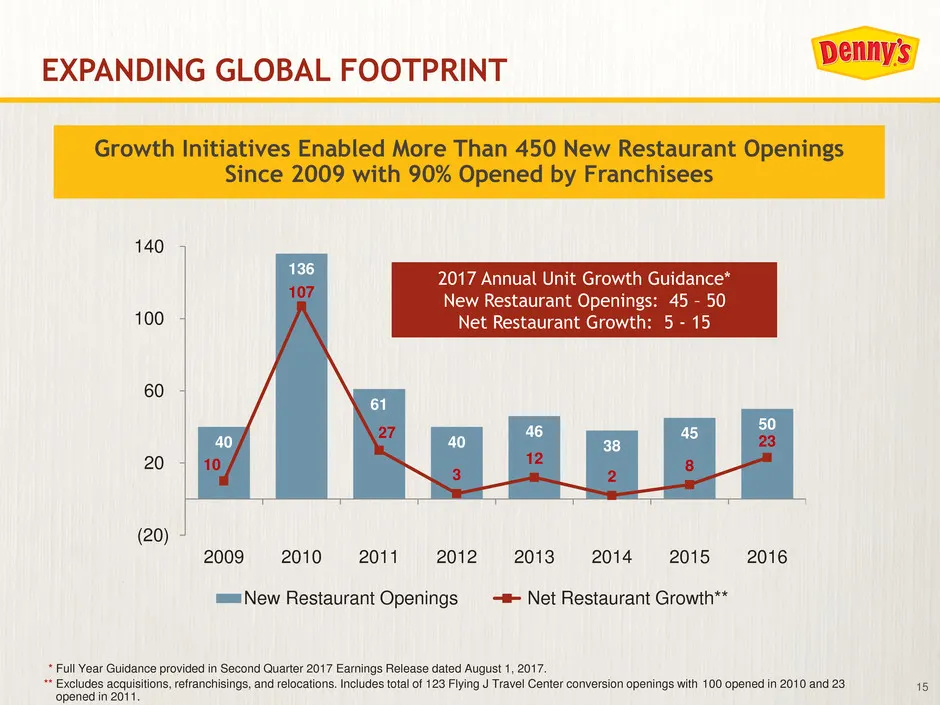
15 EXPANDING GLOBAL FOOTPRINT Growth Initiatives Enabled More Than 450 New Restaurant Openings Since 2009 with 90% Opened by Franchisees 40 136 61 40 46 38 45 50 10 107 27 3 12 2 8 23 (20) 20 60 100 140 2009 2010 2011 2012 2013 2014 2015 2016 New Restaurant Openings Net Restaurant Growth** * Full Ye
Slide 16: Domestic Expansion Opportunity
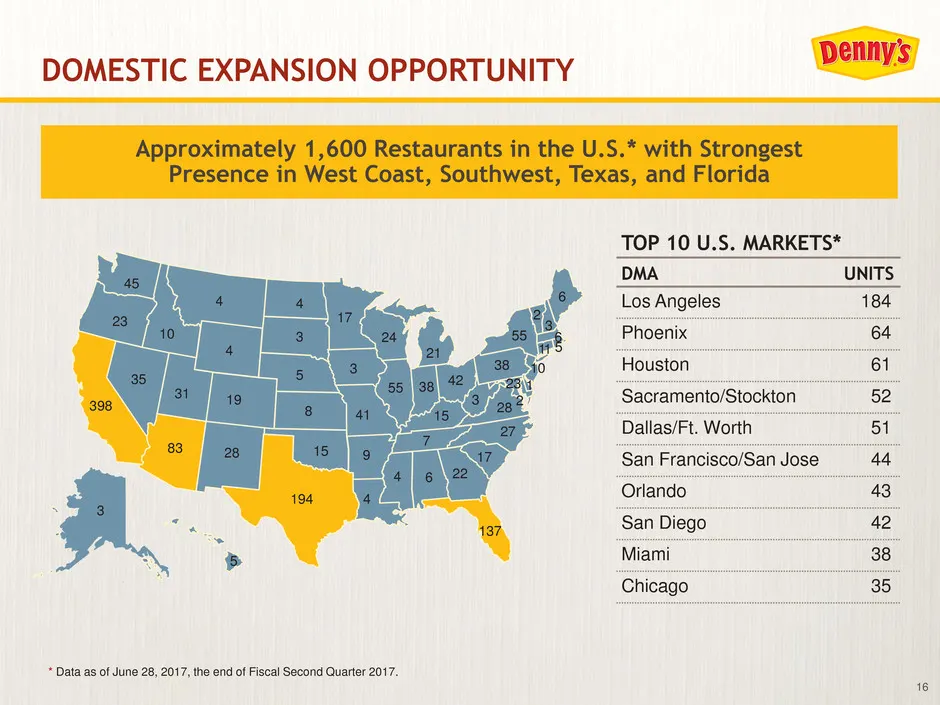
16 398 3 5 23 45 194 28 83 35 10 4 4 19 31 15 8 5 3 4 17 3 41 9 4 4 6 22 137 17 27 7 24 55 15 21 38 42 38 3 28 55 6 10 23 1 2 3 11 5 6 2 DOMESTIC EXPANSION OPPORTUNITY TOP 10 U.S. MARKETS* DMA UNITS Los Angeles 184 Phoenix 64 Houston 61 Sacramento/Stockton 52 Dallas/Ft. Worth 51 San Francisco/San Jo
Slide 17: Growing Number of International Locations
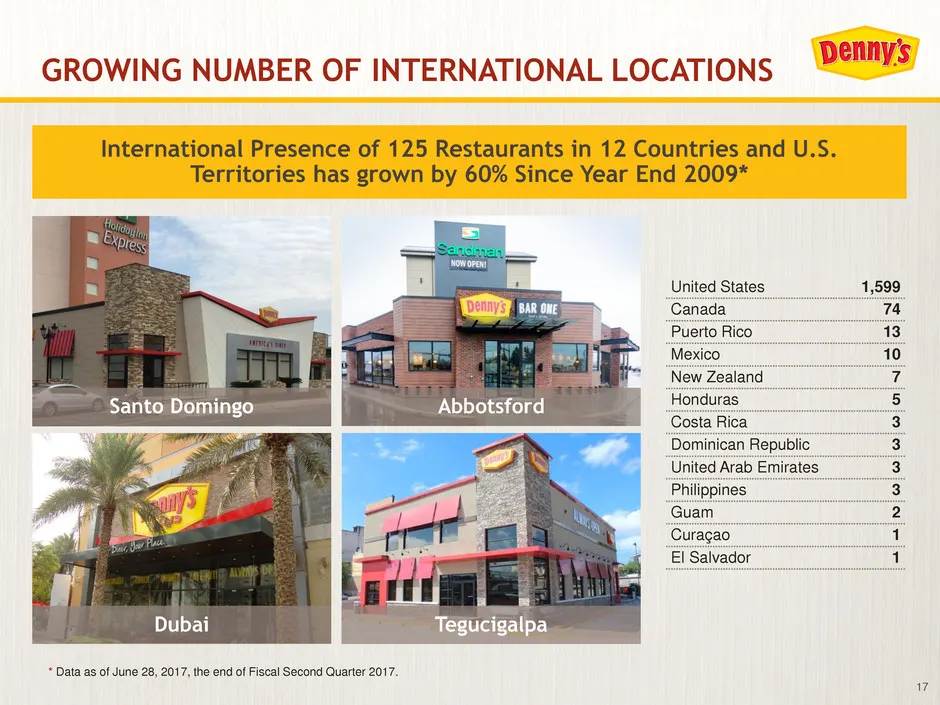
17 GROWING NUMBER OF INTERNATIONAL LOCATIONS United States 1,599 Canada 74 Puerto Rico 13 Mexico 10 New Zealand 7 Honduras 5 Costa Rica 3 Dominican Republic 3 United Arab Emirates 3 Philippines 3 Guam 2 Curaçao 1 El Salvador 1 International Presence of 125 Restaurants in 12 Countries and U.S. Territ
Slide 18: Growing Base of Non-Traditional Locations
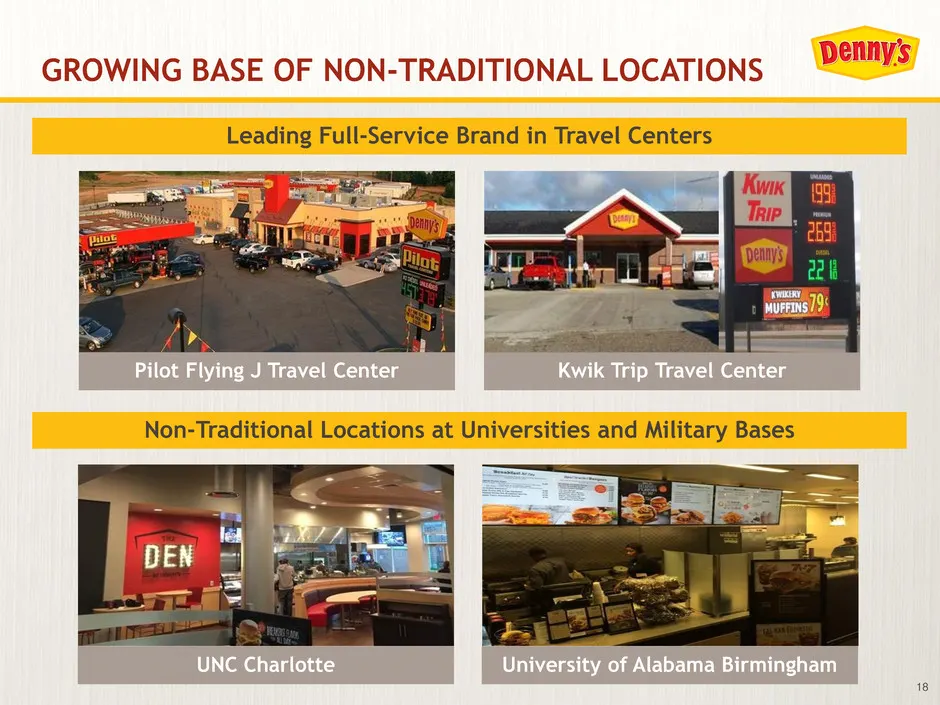
18 GROWING BASE OF NON-TRADITIONAL LOCATIONS UNC Charlotte Leading Full-Service Brand in Travel Centers Non-Traditional Locations at Universities and Military Bases University of Alabama Birmingham Pilot Flying J Travel Center Kwik Trip Travel Center
Slide 19: Strong Partnership with Franchisees
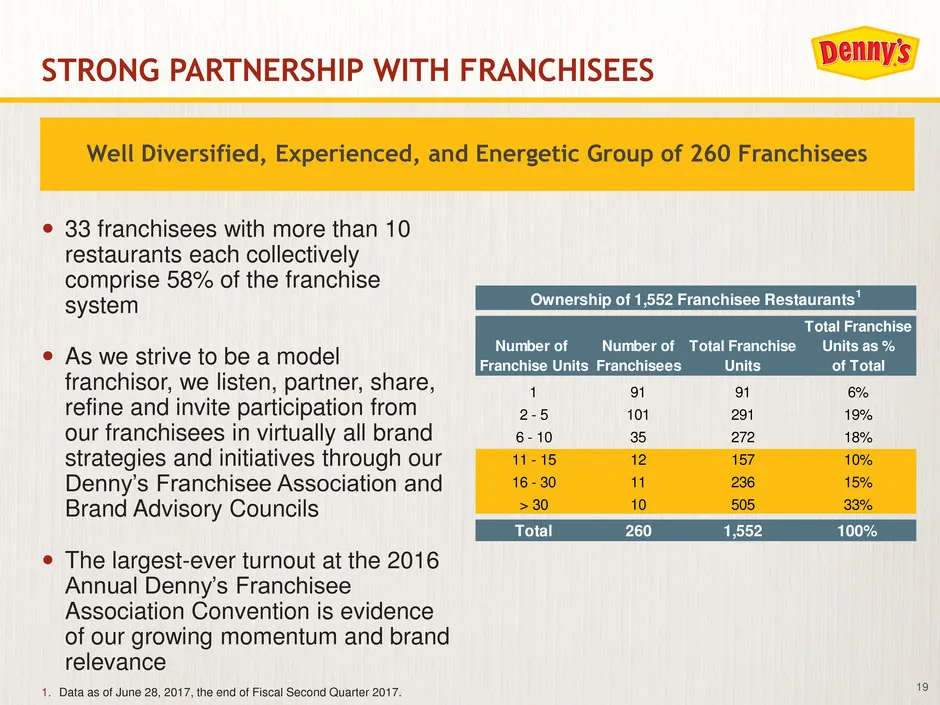
19 33 franchisees with more than 10 restaurants each collectively comprise 58% of the franchise system As we strive to be a model franchisor, we listen, partner, share, refine and invite participation from our franchisees in virtually all brand strategies and initiatives through our Denny’s Fran
Slide 20: Total System Sales and Adjusted EBITDA Growth
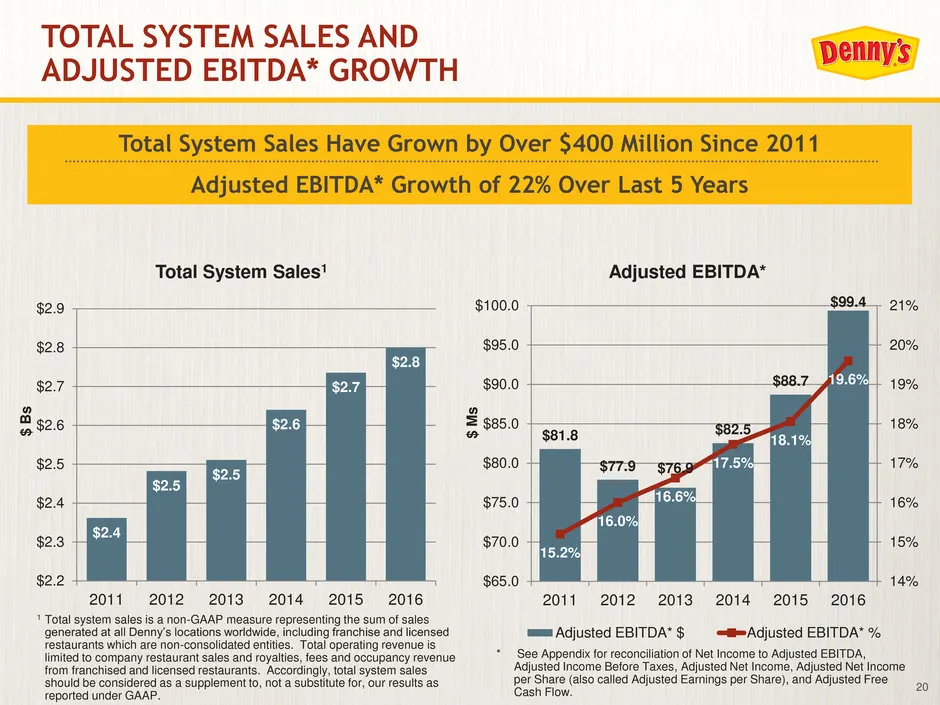
20 TOTAL SYSTEM SALES AND ADJUSTED EBITDA* GROWTH $2.4 $2.5 $2.5 $2.6 $2.7 $2.8 $2.2 $2.3 $2.4 $2.5 $2.6 $2.7 $2.8 $2.9 2011 2012 2013 2014 2015 2016 $ B s Total System Sales1 $81.8 $77.9 $76.9 $82.5 $88.7 $99.4 15.2% 16.0% 16.6% 17.5% 18.1% 19.6% 14% 15% 16% 17% 18% 19% 20% 21% $65.0 $70.0 $75.0 $8
Slide 21: Company Sales and Margins
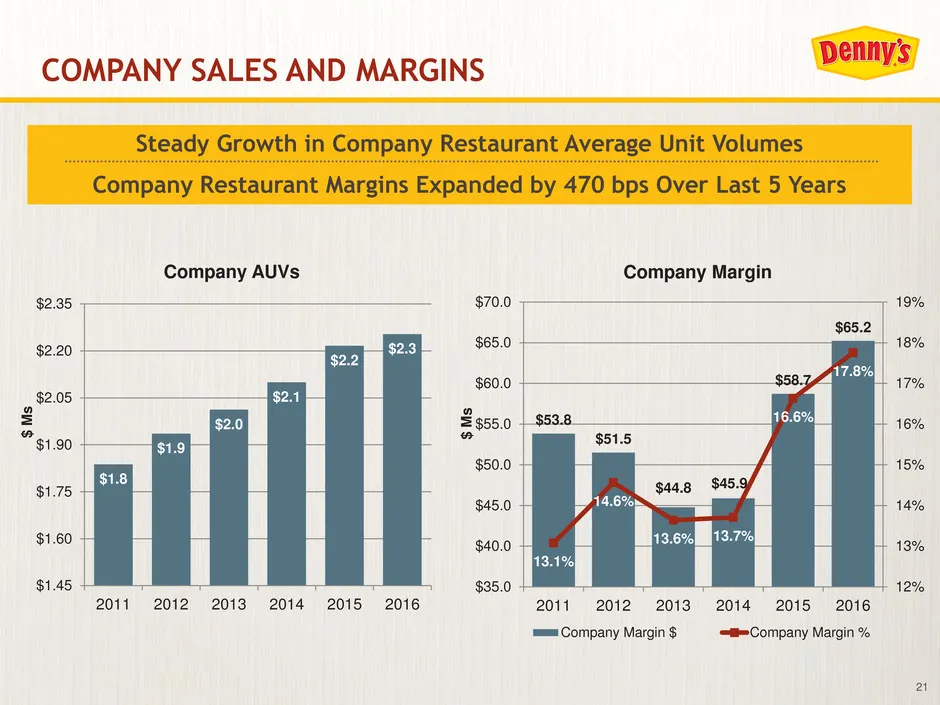
21 COMPANY SALES AND MARGINS $1.8 $1.9 $2.0 $2.1 $2.2 $2.3 $1.45 $1.60 $1.75 $1.90 $2.05 $2.20 $2.35 2011 2012 2013 2014 2015 2016 $ M s Company AUVs $53.8 $51.5 $44.8 $45.9 $58.7 $65.2 13.1% 14.6% 13.6% 13.7% 16.6% 17.8% 12% 13% 14% 15% 16% 17% 18% 19% $35.0 $40.0 $45.0 $50.0 $55.0 $60.0 $65.0 $70.
Slide 22: Franchise Sales and Margins
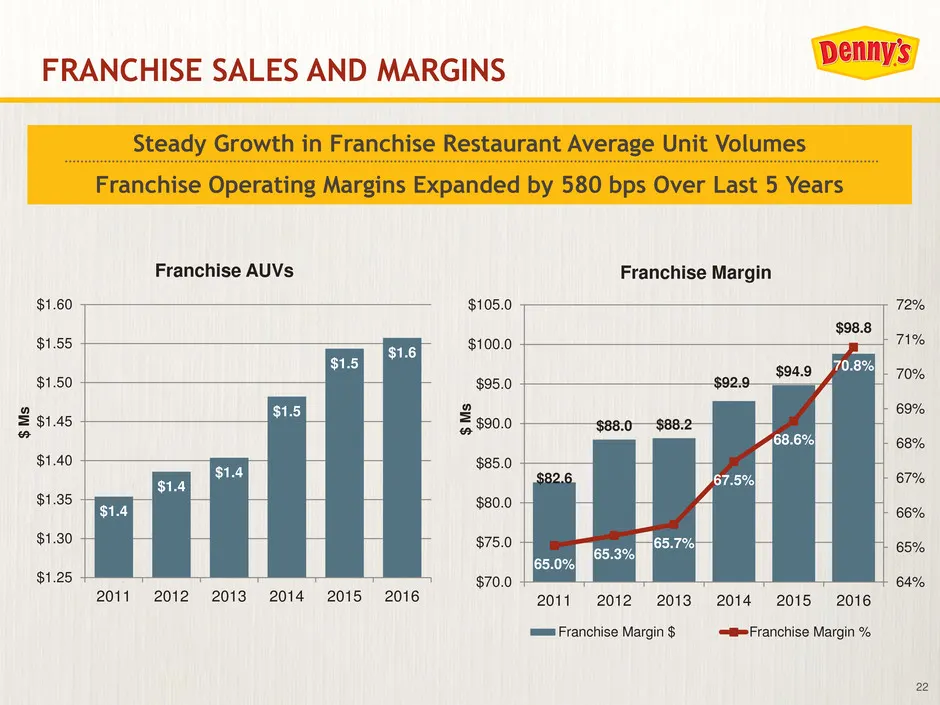
22 FRANCHISE SALES AND MARGINS $1.4 $1.4 $1.4 $1.5 $1.5 $1.6 $1.25 $1.30 $1.35 $1.40 $1.45 $1.50 $1.55 $1.60 2011 2012 2013 2014 2015 2016 $ M s Franchise AUVs $82.6 $88.0 $88.2 $92.9 $94.9 $98.8 65.0% 65.3% 65.7% 67.5% 68.6% 70.8% 64% 65% 66% 67% 68% 69% 70% 71% 72% $70.0 $75.0 $80.0 $85.0 $90.0 $9
Slide 23: Consistently Growing Same-Store Sales
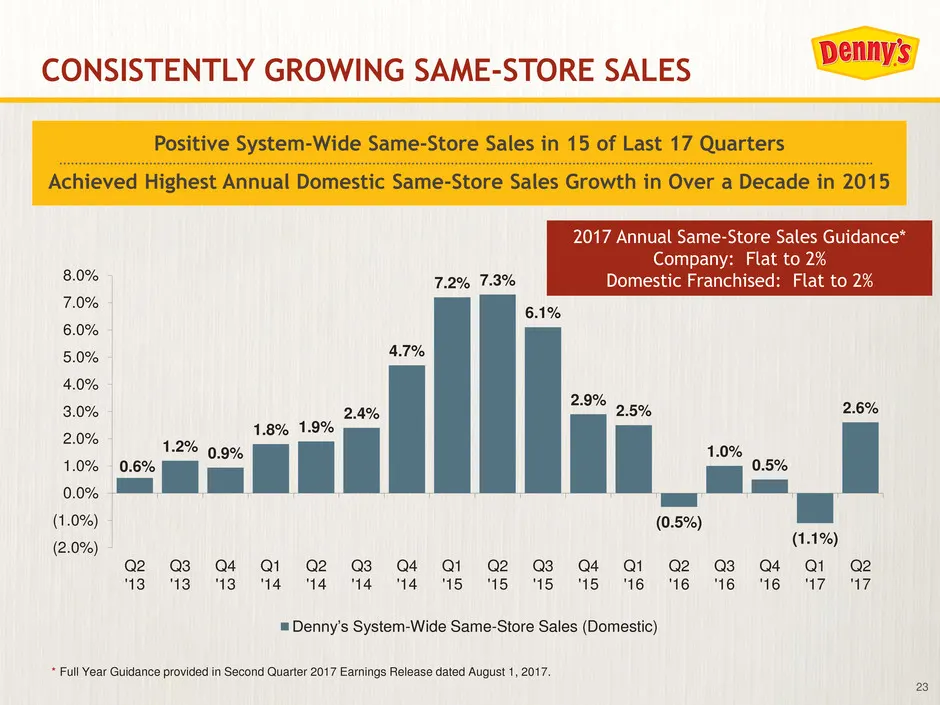
23 CONSISTENTLY GROWING SAME-STORE SALES 0.6% 1.2% 0.9% 1.8% 1.9% 2.4% 4.7% 7.2% 7.3% 6.1% 2.9% 2.5% (0.5%) 1.0% 0.5% (1.1%) 2.6% (2.0%) (1.0%) 0.0% 1.0% 2.0% 3.0% 4.0% 5.0% 6.0% 7.0% 8.0% Q2 '13 Q3 '13 Q4 '13 Q1 '14 Q2 '14 Q3 '14 Q4 '14 Q1 '15 Q2 '15 Q3 '15 Q4 '15 Q1 '16 Q2 '16 Q3 '16 Q4 '16 Q1 '17
Slide 24: Growing Adjusted Net Income per Share
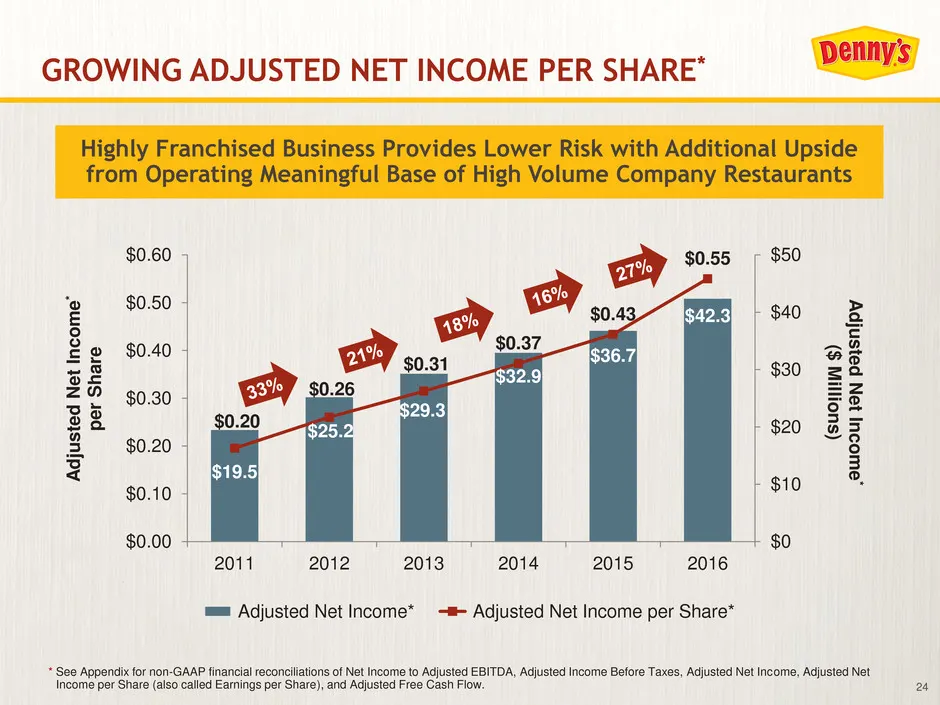
24 GROWING ADJUSTED NET INCOME PER SHARE* Highly Franchised Business Provides Lower Risk with Additional Upside from Operating Meaningful Base of High Volume Company Restaurants $19.5 $25.2 $29.3 $32.9 $36.7 $42.3 $0.20 $0.26 $0.31 $0.37 $0.43 $0.55 $0 $10 $20 $30 $40 $50 $0.00 $0.10 $0.20 $0.30 $0.
Slide 25: Strong Adjusted Free Cash Flow Generation
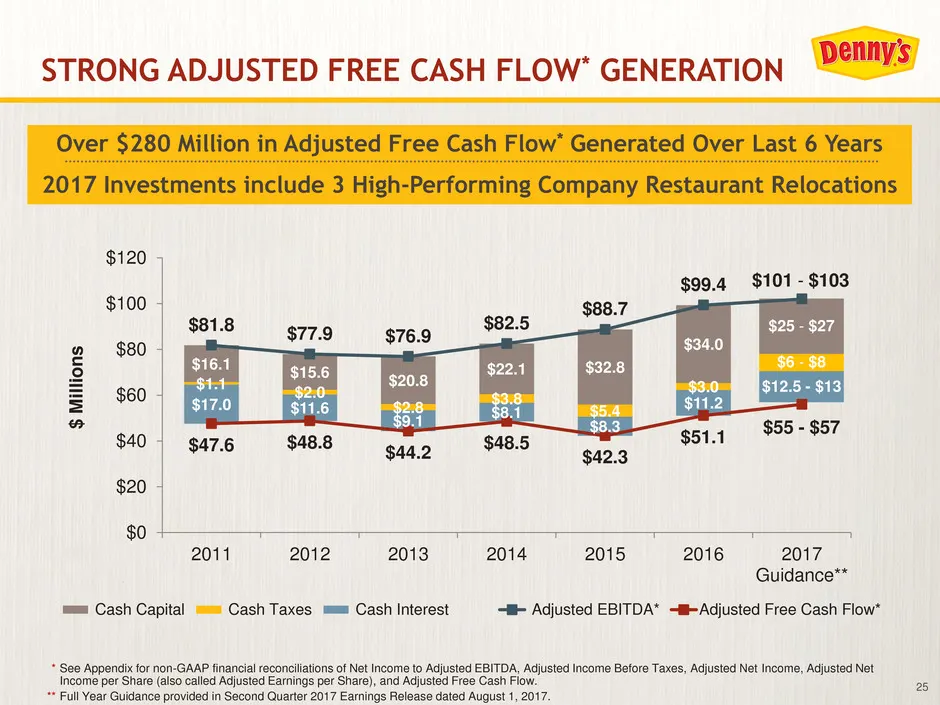
25 $6 - $8 $12.5 - $13 $25 - $27 STRONG ADJUSTED FREE CASH FLOW* GENERATION * See Appendix for non-GAAP financial reconciliations of Net Income to Adjusted EBITDA, Adjusted Income Before Taxes, Adjusted Net Income, Adjusted Net Income per Share (also called Adjusted Earnings per Share), and Adjusted
Slide 26: Solid Balance Sheet with Flexibility
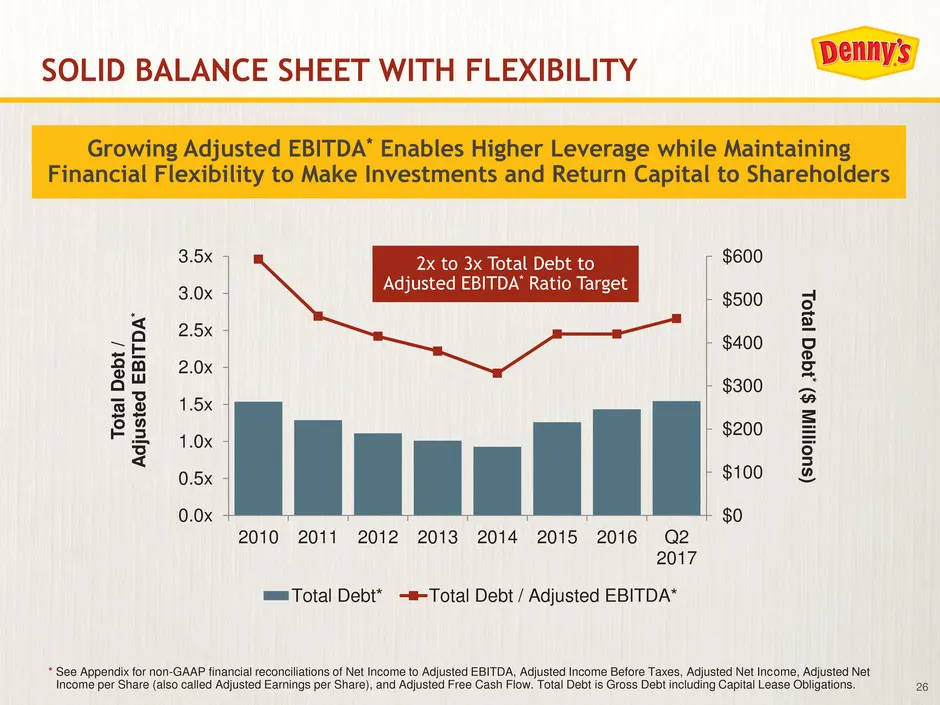
26 SOLID BALANCE SHEET WITH FLEXIBILITY Growing Adjusted EBITDA* Enables Higher Leverage while Maintaining Financial Flexibility to Make Investments and Return Capital to Shareholders 0.0x 0.5x 1.0x 1.5x 2.0x 2.5x 3.0x 3.5x 2010 2011 2012 2013 2014 2015 2016 Q2 2017 $0 $100 $200 $300 $400 $500 $600
Slide 27: Consistently Returning Excess Capital to Shareholders
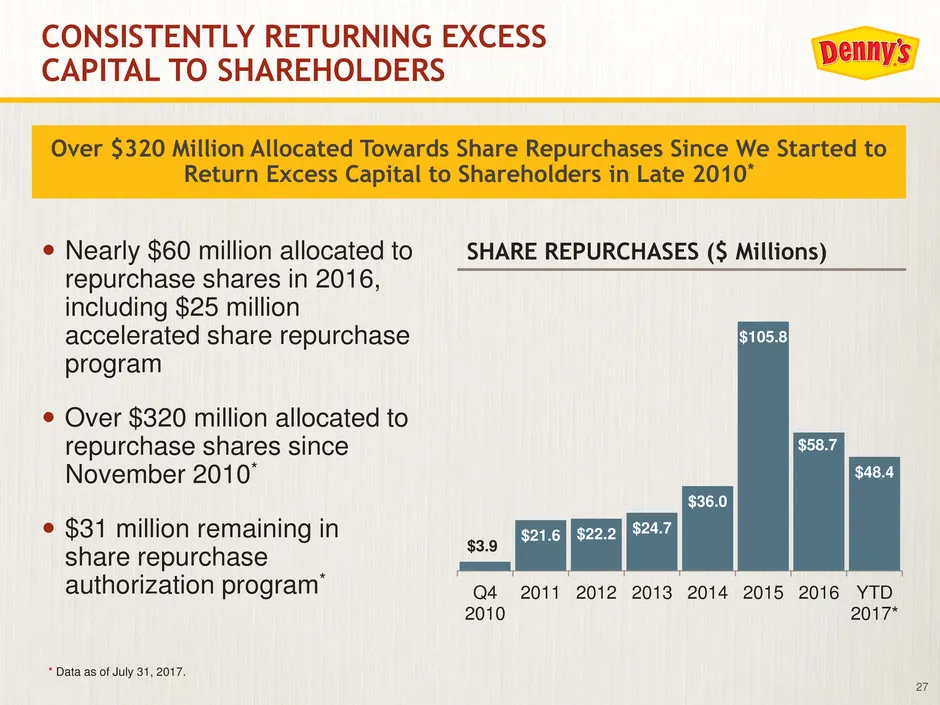
27 Nearly $60 million allocated to repurchase shares in 2016, including $25 million accelerated share repurchase program Over $320 million allocated to repurchase shares since November 2010* $31 million remaining in share repurchase authorization program* CONSISTENTLY RETURNING EXCESS CAPITAL
Slide 28: Stock Price Outperformance
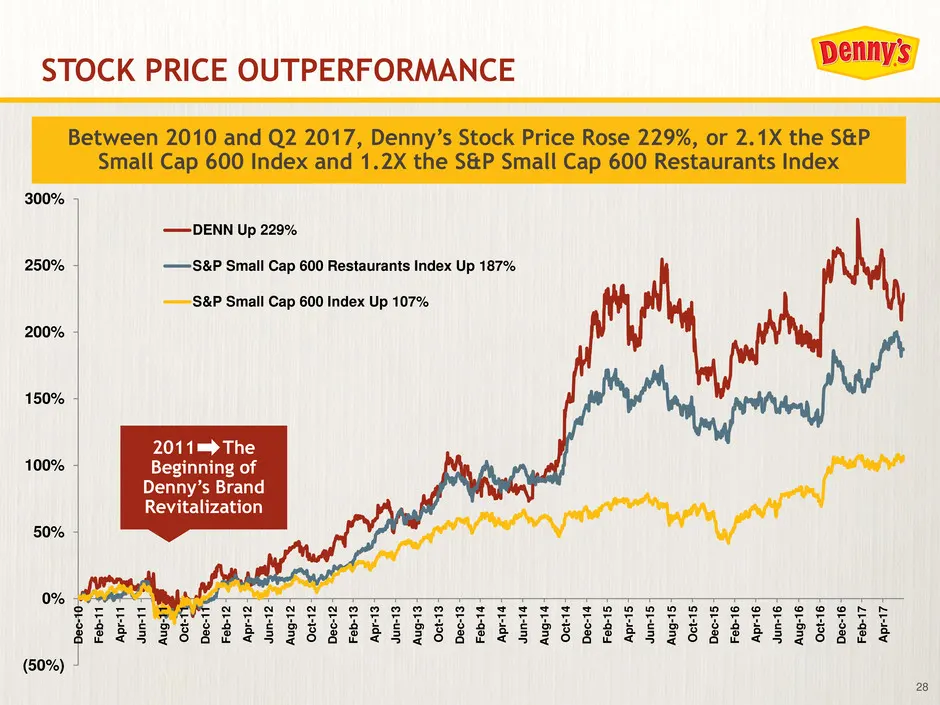
28 STOCK PRICE OUTPERFORMANCE 2011 The Beginning of Denny’s Brand Revitalization Between 2010 and Q2 2017, Denny’s Stock Price Rose 229%, or 2.1X the S&P Small Cap 600 Index and 1.2X the S&P Small Cap 600 Restaurants Index (50%) 0% 50% 100% 150% 200% 250% 300% De c -1 0 F e b -1 1 Apr-1 1 J u n -1 1
Slide 29: Denny's Investment Highlights
29 Consistently growing same-store sales through brand revitalization strategies to enhance food, service, and atmosphere Expanding global footprint with traditional and non-traditional distribution points Growing profitability with 90% franchised business provides lower risk profile with upsi
Slide 30: Appendix
30 APPENDIX
Slide 31: Experienced and Committed Leadership Team
31 EXPERIENCED AND COMMITTED LEADERSHIP TEAM John C. Miller, President and CEO since 2011 with over 30 years experience in restaurant operations and management. Prior to joining Denny’s, served as President of Taco Bueno and spent 17 years with Brinker International where positions held included Pre
Slide 32: Awards and Commendations
32 TDn2K Global Best Practices Award 2016 Nation’s Restaurant News Power List (John C. Miller) Diversity Journal’s Women Worth Watching Award (April Kelly-Drummond) Diversity Journal Awards of Excellence Honorable Mention Savoy Top Influential Women in Corporate America (April Kelly-Drummo
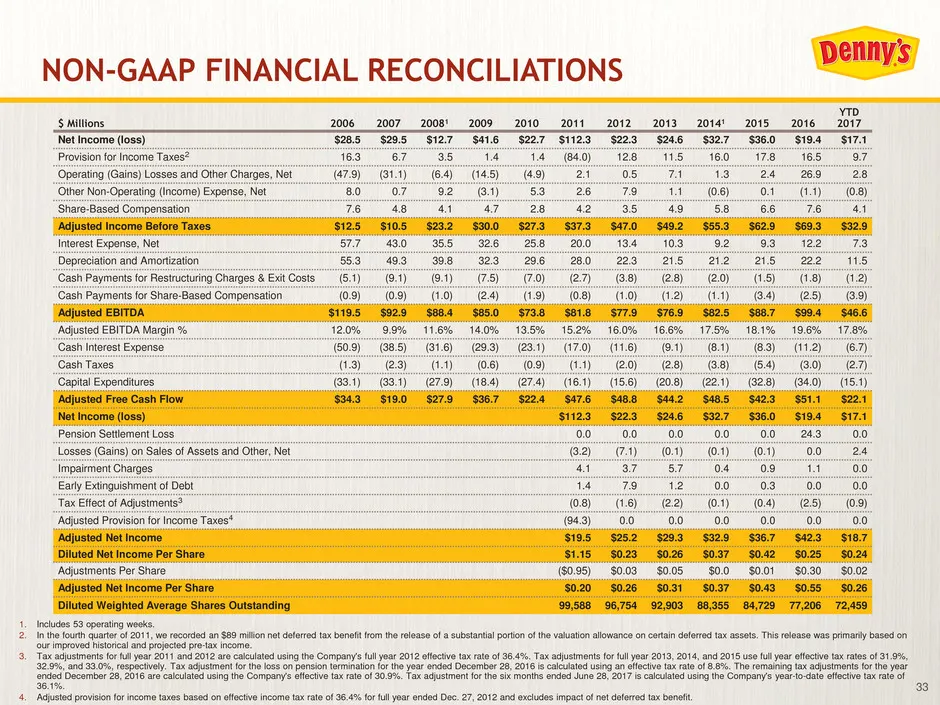
Slide 33: Non-GAAP Financial Reconciliations
33 NON-GAAP FINANCIAL RECONCILIATIONS 1. Includes 53 operating weeks. 2. In the fourth quarter of 2011, we recorded an $89 million net deferred tax benefit from the release of a substantial portion of the valuation allowance on certain deferred tax assets. This release was primarily based on our imp
Source: SEC EDGAR · 8-K filed Aug 8, 2017
More decks from Dennys Corp
 Investor Presentation (August 2025)30 slides · Aug 4, 2025
 Investor Presentation (May 2025)32 slides · May 2025
 Investor Presentation (February 2025)32 slides · February 2025
 Investor Presentation (January 2025)32 slides · Jan 13, 2025
 Investor Day (October 2024)137 slides · Oct 22, 2024
 Q2 2024 Earnings Presentation22 slides · Jul 30, 2024