Justin Hales
Chief Executive Officer
Replay available
Camplify Holdings (ASX:CHL) Q4 2026 earnings call, held 2026-08-26. Watch the replay and read the transcript on 6ix.
On 6ix: 6ix.com/event/camplify-holdings-limited-chl-q4-2026-earnings-call
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
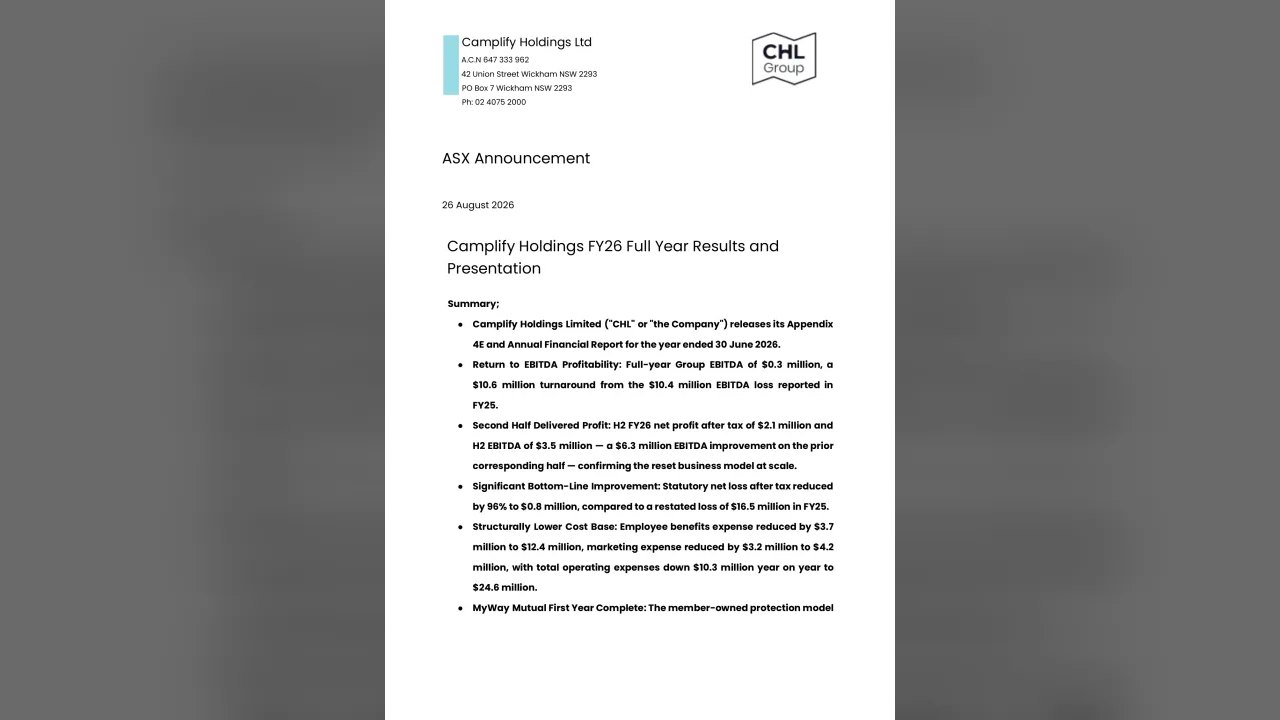
0:03 12 months ago, we told the market that FY26 would be about one thing, becoming a profit-focused organisation first and foremost. Today's result shows that we delivered on that commitment. FY26 was a year of two halves. In the first half, we completed the hard structural work, the cost reduction programs and scaling of the MyWayMutual. In the second half, the reset business delivered. Here are the headline numbers. Full year, group EBITDA of $0.3 million. A $10.6 million turnaround from the $10.4 million loss in FY25. Importantly, half two at EBITDA of $3.5 million and a H2 net profit after tax of $2.3 million. a $6.3 million EBITDA improvement from the prior corresponding half.
0:56 Statutory net loss after tax reduced 96% to $0.8 million from a restated $16.5 million loss PCP. We closed with cash of $10 million, no debt. PCP cash increased from $8.4 million in FY25. Importantly, the second half was profitable through the most significant external shock this business has faced. The June quarter escalation in the Middle East and the fuel volatility followed cut forward bookings by 29% within weeks. We stepped down cost immediately, held our margins and remained profitable through the quarter. Our most profitable half as a listed company was also one of our most difficult quarters.
1:42 This is clearly evidence that our strategy is working. Beyond the financial results, the FY26 delivered structural improvements across the business. We launched and scaled the MyWay Mutual, moving owner protection in-house, now our single largest driver of our margin transformation. We executed the JB Group strategic investment with a placement of $3.2 million and a board improvement of share and zero. We went from a 12-month product backlog to a 45-day product cycle delivery team, shipping more product changes in 12 months than we have in our previous three years combined. We improved customer satisfaction, retention and higher conversion rates.
2:27 We launched our Camplify Exchange RV sales marketplace. We permanently reduced our cost base. Employee costs down $3.7 million and marketing down $3.2 million. I want to hand over to Brett to walk you through our financial results and business metrics. Thanks, Justin. So despite those testing global conditions, it was a transitional year for Camplify. As a group EBITDA is positive 0.3 mil, that 10.6 mil turnaround. And with the statutory loss narrowed to 8 million, importantly, the group was profitable through that entire second half. I won't say the second half was, by no account, smooth. The Middle East fuel line certainly cut forward bookings by that 29%. What we've seen since then, Australia's fairly much recovered and is moving back ahead, and we've managed to close the year with $10 million in cash and no debt.
3:22 The next slide shows well the half-year trends. This one slide goes back three full financial years, just splitting into the two halves. It shows that, as I said, we've been working steadily to close that EBITDA loss. So it's now a 3.5 mil profit in the last half on revenue that's fairly stable. The revenue has been jumping around over those six halves due to the TAP program in New South Wales closing down. That was quite a big number in the early halves. That's pretty much stopped. It was now moved into other areas with that. What really changed was the cost base beneath the numbers. The cost of sales dropped down to $5.9 million in the last half, really with the benefit of MyWay Mutual Protection now fully in-house.
4:13 We've also taken close management of the employee cost down to $5.8 million and kept marketing quite tight at 2.1 for the last three halves, basically. That's helped improve that EBITDA margin from a negative 13% a year ago to now a positive 17% for the half. I do want to allay some investor concerns that we've been too harsh on marketing. In some good news, we have actually been focused more on the top of funnel and through the whole marketing funnel rather than just on the social medias. And we had enough budget to actually release our first TV commercial in Australia, which is now live on Channel 7. and we've included the link on the YouTube video. So I do recommend everyone to have a look at that and like it later on.
4:58 Back to the numbers. So the three drivers that are behind the financial result, really the first is that margin, the gross margin rose to 63%. It was tracking at 58% last financial year. And as I said, it's really moved forward, particularly in the last half. Secondly is that cost discipline, staff cost down 3.7 million year on year, the market down 3.2 million year on year. The third driver is the revenue mix. Whilst revenue was 6.8% lower, we have tried to really push out the lower margin volumes that were Good for GTV, but not so good for EBITDA. And now focus on growing that recurring revenue.
5:43 And there's premium membership fees. Now we've got a full year of the mutual under our belt. We're seeing a more normalized pattern there. So the revenue from subscriptions is up about 30%. Cash flow wise, we now move to quarterly cash flow reporting. So we are quite transparent how that cash cycle moves. We closed the financial year at $10 million up from $8.4 million. That includes a $3.2 million placement back in November for the JB Group. Operating cash outflows narrowed from $4.5 million the prior year to $1.2 million. and with the seasonality we expect the cash to start building again as we move in towards summer in Australia and New Zealand and then unwind fairly quickly afterwards and as I said now on with the quarterly ASX reporting we're quite transparent how that cycle works on the balance sheet side net assets stands at 41.3 mil um A critical thing has been getting the net current liability position moving forward to 6.4 million, somewhat better than last year.
6:48 And 5.9 million of that is actually deferred fees, which as long as there's no cancellations, we'll pick that up through profit at a later point. So overall, the net assets are trending in a positive direction and that's been assisted by the capital raise and moving the business back into profitability. On the segment side, Each of our markets were fairly impacted by the Middle East war and the global headwinds. You can see in the quarterly figures that pretty much all numbers dropped in the fourth quarter. But as I said, we are tracking better locally. There was quite a strong tailwind in the summer bookings here in Australia and New Zealand, which did help us. So Q3 was very strong, but as I said, Q4 was quite dramatic shutdown. But as I said, the business has responded quickly on margins and has held well.
7:43 Moving to future bookings, the pipeline is recovering. We've had solid bookings in the Australian market. New Zealand is quite late in their booking trends, a lot of last-minute bookings, and Europe is now the back end with their summer season basically over, so we expect a few months to be very quiet in Europe. But as I said, forward bookings are back up again which is good news. So a solid close to the financial year despite those global headwinds and very pleasing to see the second half figures back into a profit. I'll hand back to Justin now. Thanks Brett. Just to stay with forward bookings for a moment I know that's a number that many of you watch closely. Future bookings sits at 19 million as Brett mentioned just below the 22.9 million PCP The context that matters there is that number fell 29% within weeks of the June shock, since recovered by 2.25 million, so 13%.
8:43 Our data shows that customers aren't cancelling their holidays, they are booking closer to travel date, and the momentum and trend that we have in that number we're very confident on. We're now seeing not only domestic in Australia but a bit more return to action in the last couple of weeks in international trips as well, particularly for Australia and New Zealand. So we believe that with an elevated fuel price and general aviation costs in the Australian market that a domestic road trip will become more appealing this year and we're very confident on that number moving in for the rest of the year. I want to spend a moment on the MyWay Mutual because it really is a defining structural achievement of the year. FY26 owner protection move from an external insurer to a member owned mutual.
9:38 Members get broader coverage and faster claims decisions. Shareholders get the protection margin retained inside the group rather than that paid to an insurer as profit. Year one performance, $2.7 million paid out across 2,447 claims to a 99% approval rate on decided claims and a 68% loss ratio. Inside our target range for the full first year funded. The fund paid its own claims and cleared a surplus and our exposure is capped through an excess of loss reinsurance. The fund carries attritional claims reinsurance through that process as well. Claims turnaround at 85 days is not what we want and it is our clearest improvement target for FY27.
10:28 With claims capacity resourced ahead of the January peak, a wider repair network and a new member claims benefits all coming, we are really confident about the ability for us to really deliver with that product and create a real innovation in what we can do with that overall protection product as we continue to roll it out in both Australia and New Zealand as a number one focus. On the JB Group, this partnership has gone well beyond the placement. Just recently, we've agreed that all new vans across the five JB Group brands, including JB, New Age, Network RV, Victory and Traveller, now include a complimentary Club Camplify membership for 12 months as part of a bundle.
11:19 New vehicle supply flows directly into our membership ecosystem and also has the ability to look at managed services pilot being able to be further rolled out with JB in FY27. Our unwavering focus for FY27 includes delivering full-year profitability, generating positive cash flow, achieving cost-effective growth in core markets, and the further role of our insurance programs, including the expansion of our products into the northern hemisphere markets. expanding member services in the Australian footprint, particularly with that relationship with JB. What's different about the outlook compared to previous years is the starting point.
12:04 The cost basis reset, the second half ran at the level we planned. The mutual enters its first year of scale with margins already transformed. The JB rollout proves the pilot programs and network works and the balance sheet supports the plan with $10 million in cash and no debt. An example of member services expansion is our Camplify Exchange, Australia's RV marketplace built for buying and selling. We launched that just recently, a few months ago. We already have 493 listings live with 12 dealer partners. Every listing shows what a van could earn on Camplify. Buyers can try it before they buy through a Camplify rental. It's also a direct integration with dealer stock and the ability for them to move into a full rental environment using the Camplify rental marketplace as well as the ability to sell and our customers to buy.
13:01 Exchange completes the RB lifecycle for our customers. Try it on Camplyfy, buy it on the exchange, rent it out to offset your ownership, sell it when it's time to upgrade, and provide protection with Club Camplyfy, protected by the MyWay Mutual. One customer, the whole lifecycle inside the group. On the screen now, you can see our board and executive team who have driven this result. Very great support from our team. We have an excellent team now across our board and executive. So in summary, FY26 for CHL, we turned a $10.4 million EBITDA loss into a positive EBITDA result. We delivered a profitable second half through genuine external demand shock.
13:48 We launched and scaled the MyWay Mutual, transformed our margin profile. We executed the JB Group Partnership, connecting manufacturers' supplies into our membership ecosystem. We permanently reset the cost base while improving product delivery speed, conversion and retention. And we've positioned the business extremely well for FY27 and beyond. The hard structural work is behind us. FY27 is about execution, operating leverage, with the second half of FY26 as the starting point, not the target. We remain committed to our plan and positive about our ability to deliver against these objectives. Thank you to Brett and the team and our shareholders. And I now open up for questions via the Q&A function.
14:40 And just a question here. We'll open up from Owen. Big turnaround. Can you guys hear me okay? We can. Yep. Thanks, Evan. Hey, Justin. Big turnaround. Well done. Don't see that in the macro. That's been pretty tough for consumer. Just on the cost base now, that's a big reset, but the trend has been negative throughout 26. What's the right level of cost? Do we analyze that second half now of kind of six mil into next year, or is it run rate a bit lower this year? Yeah, Brett, I might hand over to you to answer that one. I think certainly from our marketing perspective, we've sort of kept our marketing revenue percentage fairly consistent for this year.
15:34 From an employee benefit perspective, we expect it to be there, thereabouts of where we kind of traded that for a full year, maybe slightly down on that. Brett, any other key comments around that? Yeah, I think the cost reset was really a focus of Q4 with the impact of the Middle East tensions. So we do have a lower number going forward. Marketing is probably the only area that, as I said, we will allow that to go back up if revenues move in the right direction. But most of the other areas, we are seeing some, yeah, quite heavy savings coming through from AI these days. So we have scaled back teams using more automated systems and things. So we're not expecting a dramatic change in the core operational cost going forward.
16:21 And just to understand that in the past, the gross profit margins had a drag around the insurance side. Obviously, GP margins improved in 26. Can you just maybe talk through on the mutual, just... what the gross profit margins are inside that business and then what target is. Yeah, I think at the moment the loss ratio overall is running around 75%. We are putting in place, for example, the strategy with JV Vans is to aim to try and improve the overall spending on repairs. We see it a very tight market for repairs on caravans. very difficult to get them into repair shops, very difficult to get them back out on the road in a quick manner. So having the work with JB Vans will help us to get that more efficient.
17:12 The overall costs, the mutual, I'm seeing probably about a $2 million annual saving just by switching over to the mutual. We've got better control over the claims process, better control over the AER processes, work with hires and overall a very positive outcome for Australia and New Zealand. And we are looking to push those same efficiencies into the European market as quickly as we can. Yeah, I think in general, you know, we've got a new insurance system going live in a couple of months time as part of that claims management and costs will be a key thing that we focus on and rolling out a true nationwide repair network. so we're getting better and better on a case-by-case basis at the cost basis of each one of those claims and we're seeing you know pushing that down as we you know work with our preferred repair network so we'll look to sort of scale out a little bit more in the Australia New Zealand market and certainly think there's a lot that we can do in the European market.
18:15 And we're in some fairly advanced discussions to improve those products and margins in that market as well. So, you know, very confident that we can, from a cost perspective in insurance, we can get better and better. And premium membership grew 40-odd percent, a big strong number there. Can't see it in the deck or the notes there. Maybe can you talk through the RVs or caravans in the marketplace now and the percentage that are premium members? Overall, the numbers from a fleet perspective were fairly flat, maybe slightly up. But certainly, we've certainly had a very strong movement into premium membership, which has been good.
19:08 And that's something that we're looking to build more on, particularly as we roll out better products in the European market as well. but you know particularly now with the offerings that we can open up from a my way mutual club campify perspective with the personal offering there's a lot more that we can do around that and as part of that sales process now with with JB. So every customer will receive a complimentary membership from JB as part of that sale. So they're one of the biggest, if not the biggest in Australia now in terms of new vehicles sold across the RV segment. So that brings customers into that pipeline, which is exactly what we wanted to do.
19:59 a certain percentage of those will go on to be marketplace customers and be premium members and a certain percentage will be personal members. So we'll be able to grow both of those membership bases, which grows recurring revenue for us. And we've got the runs on the board in terms of maintaining that product from a loss ratio perspective. And I think really we can build and build and build on that overall membership number. Well done. Thanks very much, Alan. Okay, just another question that's come in around future bookings. So the question was, in those future bookings or those that have completed recently, can you give us an idea on average booking values and length? are you seeing hirers shorten length of hire due to cost pressure?
20:56 So on a seasonalized basis on a PCP, no significant change to average booking values that we're seeing and no length changes. maybe the only difference would be in the New Zealand market in the short term with a little bit less European traffic in the last couple of months that would have had a little bit of an impact but looking forward into the upcoming season we see that being fairly consistent so no major changes in any of those key metrics nothing material anyway anything to add on that one Brett? Yeah, just the full year numbers, just quick looking at those. Yeah, we saw about a 4% increase in the average spend per trip across the full financial year and about a 2% increase in the average days spent on each trip.
21:47 So it's good that overall those parameters are both moving in the right direction, predominantly in the first three quarters. Yeah, not as strong in the last, yeah, straight after the fuel crisis. That's another question. Can you talk about work being done on LLM integration or MCP work? Any meaningful traffic delivered to CHL via LLMs or too early? I think from a direct LLM traffic perspective, we are seeing a little bit. nothing material at this stage. I think the main thing that we are doing is focusing really on the core systems that drive traffic through those, which is content. So we've really built a very, very big content library and are continuing to do that.
22:36 The last six months, I think the team have built 1,200 or maybe 2,000 particular content pages directly aimed at customers. And what we're seeing is that a huge increase in relatively speaking SEO hire traffic. as a result of that. So some of that's been driven by LLM, some of that's been driven by traditional sort of SEO. But I think we're becoming more and more of an authority on this level. The more content we have, the more quality listings, the better reviews, the better YouTube content all those things you know we're seeing that they're having an impact so you know that that's excellent I think the key thing also around that is that organic traffic generally converts it at a better rate and we're seeing that in our conversion metrics so our conversion metrics you know sort of going up and to the right, which means that more of that funnel that's coming into the pipeline from a higher perspective is being placed in a paid booking.
23:46 And that's helping us to be able to manage that marketing investment as part of that, but also to deliver a better outcome for customers. So really, we're seeing some great wins in all those regards as part of that. So they're the only questions that have come in. So with that, we'll close the presentation. Thank you, everyone, for being on the call. Thank you to shareholders for support. Look forward to our next update shortly. Thank you.
Follow Camplify Holdings Ltd. into a list and get an email when it puts out news.
Chief Executive Officer