PowerSecure International — Investor Presentation (February 2008)
23 slides from PowerSecure International's investor presentation, Feb 20, 2008
Slide 1: PowerSecure
Power Weetite February 20, 2008
Slide 2: Forward Looking Statements Safe Harbor
Forward Looking Statements Safe Harbor All forward-looking statements made in this presentation are made under the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward-looking statements, which are all statements other than statements of historical facts and includ
Slide 3: The Electric Power Industry is Large and Growing
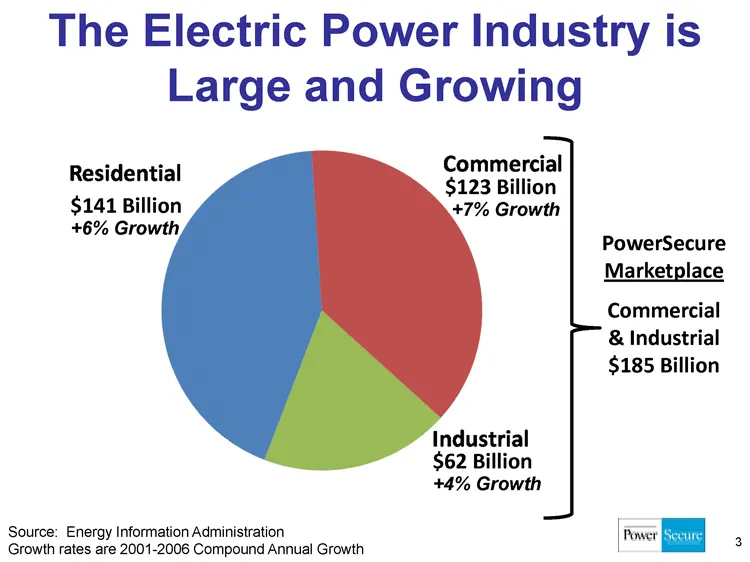
The Electric Power Industry is Large and Growing Residenttial $141 Billion +6% Growth Commercial $123 Billion +7% Growth Industrial $62 Billion +4% Growth PowerSecure Marketplace Commercial & Industrial $185 Billion Source: Energy Information Administration Growth rates are 2001-2006 Compound Annual
Slide 4: With Continued Long-term Increases in Demand Projected
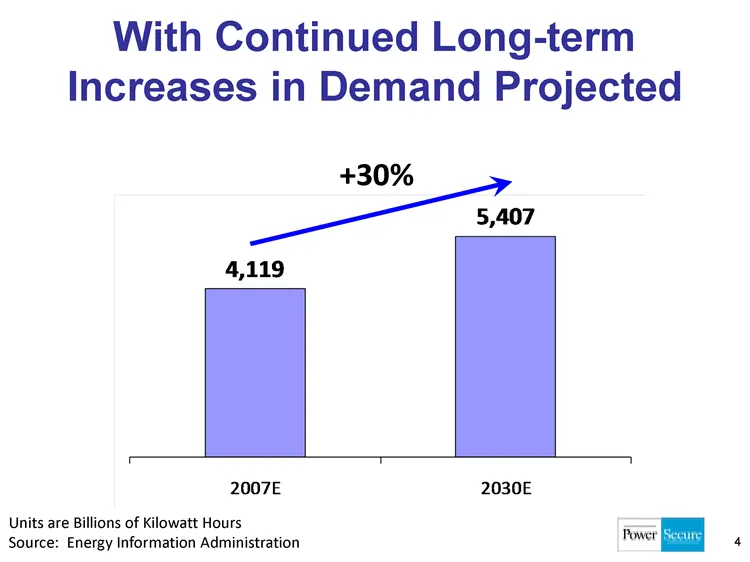
With Continued Long-term Increases in Demand Projected +30% 4,119 5,4007 2007E 2030E Units are Billions of Kilowatt Hours Source: Energy Information Administration
Slide 5: However, Utilities are Increasingly Constrained
However, Utilities are Increasingly Constrained Capital Investment Process Cumbersome Increasing Burden of Environmental Constraints Evolving Regulatory Process/Environment Focus on Large "Step-Function" Capital Investment Projects
Slide 6: And Electricity Prices Continue to Rise
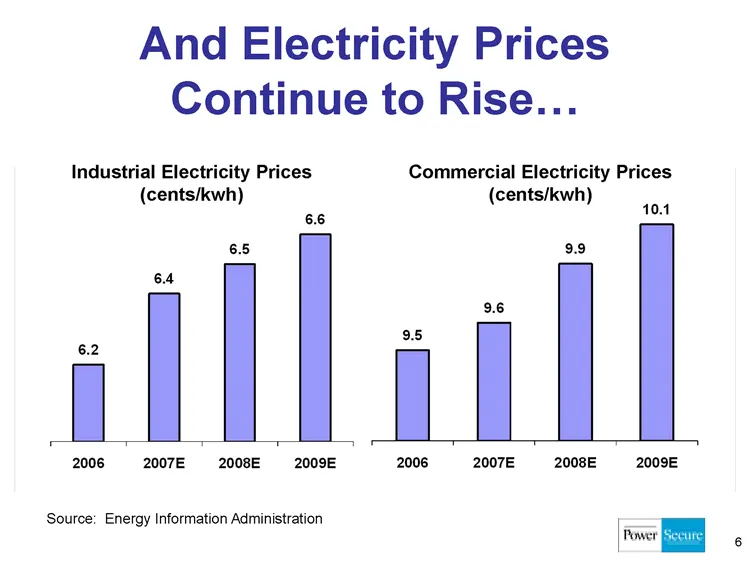
And Electricity Prices Continue to Rise 6 Industrial Electricity Prices (cents/kwh) Commercial Electricity Prices (cents/kwh) 6.2 6.4 6.5 6.6 2006 2007E 2008 2009 9.5 9.6 9.9 10.1 2006 2007E 2008E 2009E Source: Energy Information Administration
Slide 7: Electricity Prices Increase Exponentially During Peak Demand Periods
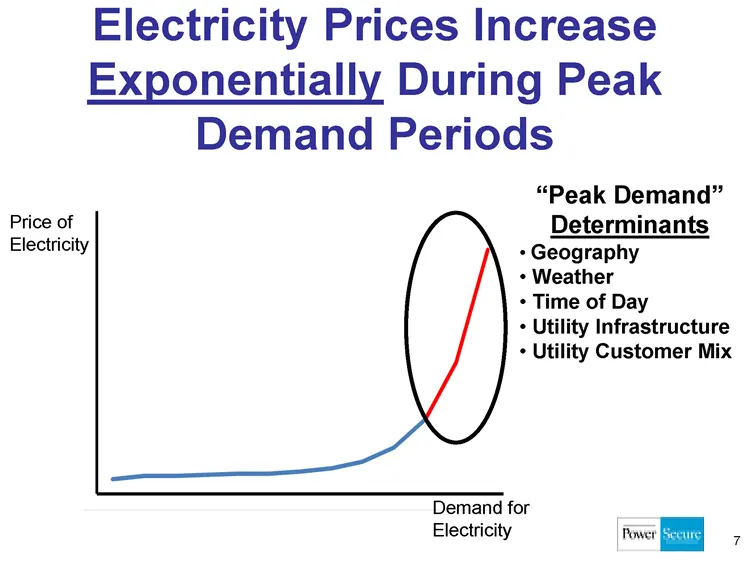
Electricity Prices Increase Exponentially During Peak Demand Periods Price of Electricity "Peak Demand" Determinants Geography Weather Time of Day Utility Infrastructure Utility Customer Mix Demand for Electricity
Slide 8: Providing Opportunity for our Distributed Generation Solutions to Deliver Efficiencies
Providing Opportunity for our "Distributed Generation" Solutions to Deliver Efficiencies Utility Customers "Load Curtailment"/"Demand Response" = Reducing Power Load on Grid Commercial and Industrial Customers "Peak Shaving" = Reducing Electricity from Utility During Peaks
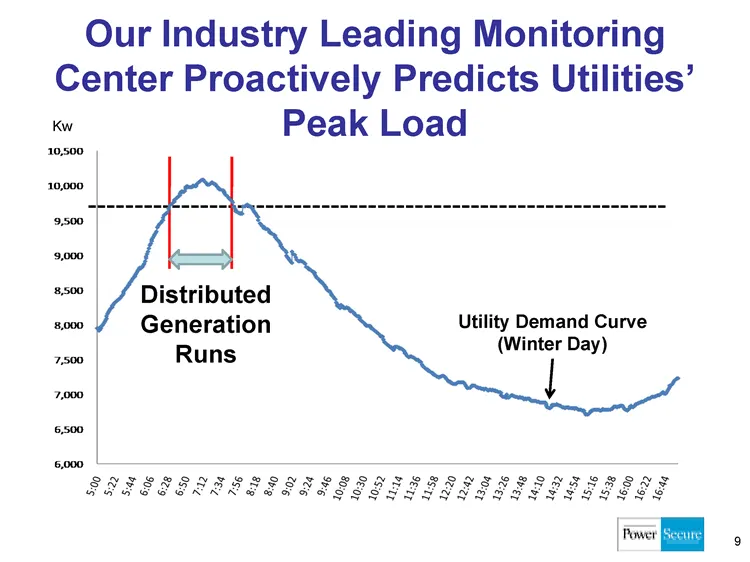
Slide 9: Our Industry Leading Monitoring Center Proactively Predicts Utilities' Peak Load
Our Industry Leading Monitoring Center Proactively Predicts Utilities' Peak Load Distributed Generation Runs Utility Demand Curve (Winter Day) Kw 10,500 10,000 9,500 9,000 8,500 7,500 7,000 6,500 6,000 5:00 5:22 5:44 6:06 6:28 6:50 7:12 7:34 7:56 8:18 8:40 9:02 9:24 9:46 10:08 10:30 10:52 11:14 11:3
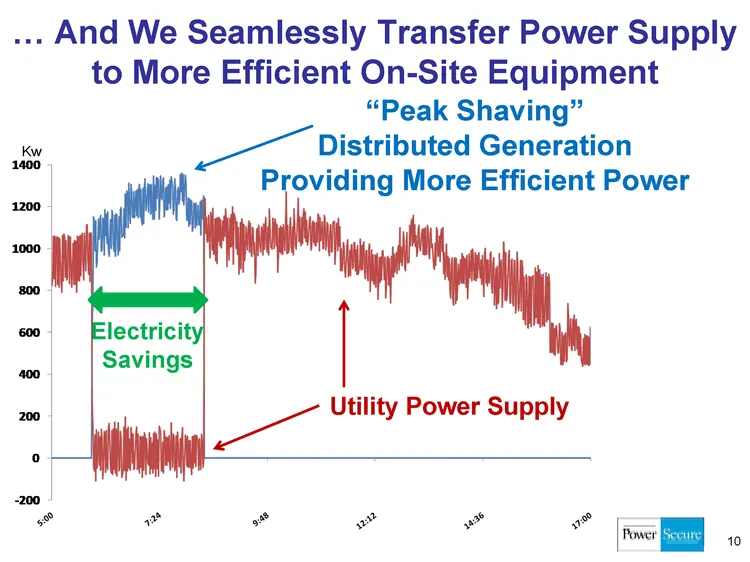
Slide 10: And We Seamlessly Transfer Power Supply to More Efficient On-Site Equipment
And We Seamlessly Transfer Power Supply to More Efficient On-Site Equipment 10 Kw Utility Power Supply "Peak Shaving" Distributed Generation Providing More Efficient Power Electricity Savings 1400 1200 800 600 400 200 0 -200 5:00 7:24 9:48 12:12 14:36 17:00
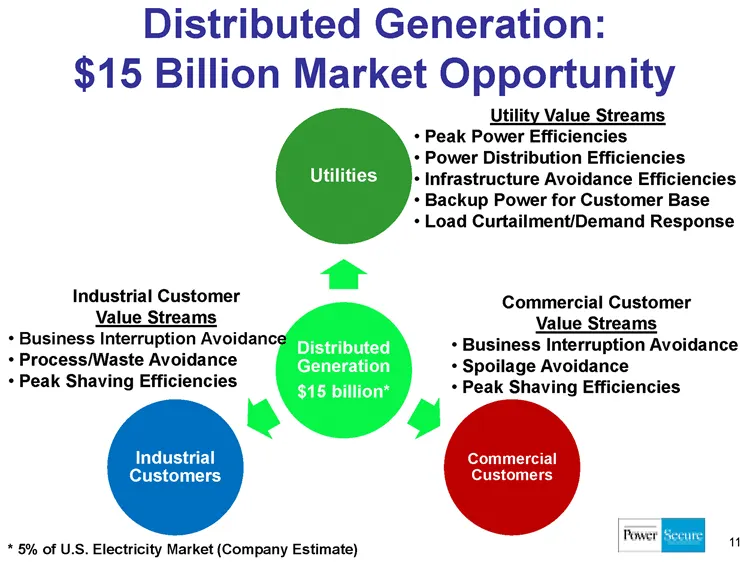
Slide 11: Distributed Generation: $15 Billion Market Opportunity
Distributed Generation: $15 Billion Market Opportunity Utility Value Streams Peak Power Efficiencies Power Distribution Efficiencies Infrastructure Avoidance Efficiencies Backup Power for Customer Base Load Curtailment/Demand Response Industrial Customer Value Streams Business Interruption Avoidance
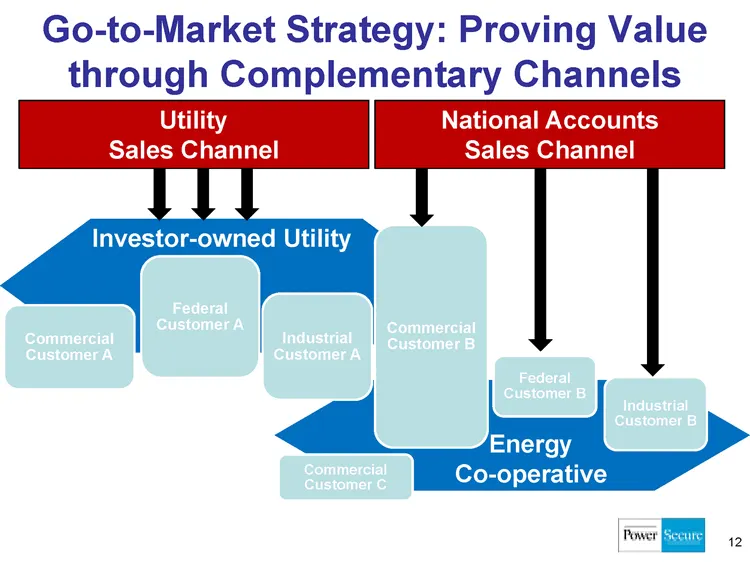
Slide 12: Go-to-Market Strategy: Proving Value through Complementary Channels
Go-to-Market Strategy: Proving Value through Complementary Channels Utility Sales Channel National Accounts Sales Channel Investor-owned Utility Commercial Customer A Federal Customer A Industrial Customer A Commercial Customer B Federal Customer B Industrial Customer B Energy Co-operative Commercia
Slide 13: Our Customer Value Proposition is Strong
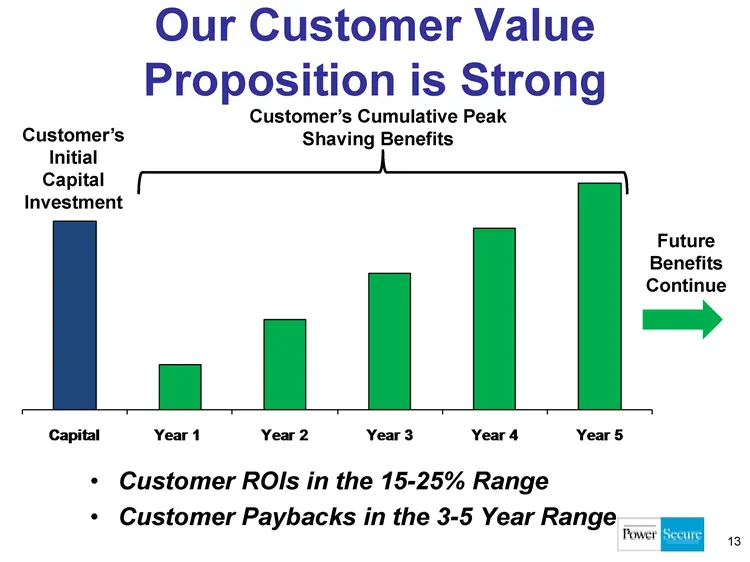
Our Customer Value Proposition is Strong Customer's Cumulative Peak Shaving Benefits Customer's Initial Capital Investment Future Benefits Continue Capital year 1 year 2 year 3 year 4 year 5 Customer ROIs in the 15-25% Range Customer Paybacks in the 3-5 Year Range
Slide 14: Business Model: Matching Economics to Customer's Needs
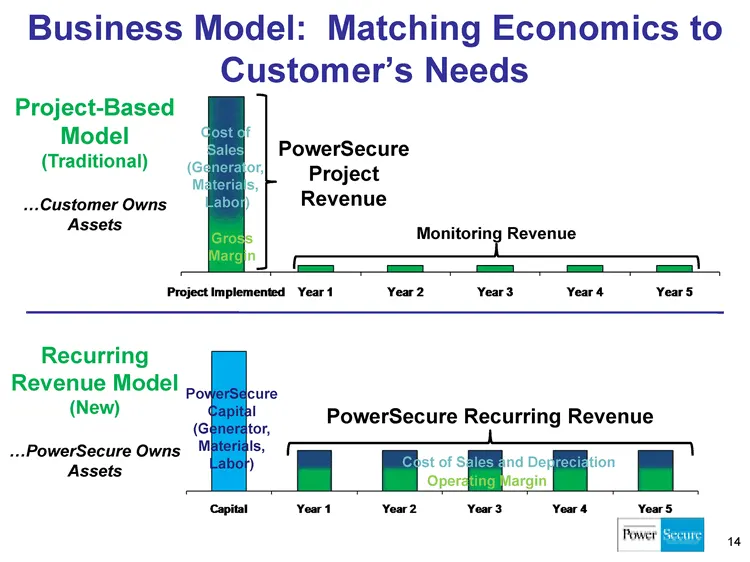
Business Model: Matching Economics to Customer's Needs Project-Based Model (Traditional) Customer Owns Assets Cost of Sales (Generator, Materials, Labor) PowerSecure Project Revenue Monitoring Revenue Project implemented year 1 year 2 year 3 year 4 year 5 Recurring Revenue Model (New) PowerSecure Ow
Slide 15: Market Leadership
Market Leadership First to Bring Turnkey Distributed Generation Concept to Market (Profitable Day 1) Deep Understanding of Utilities and their Customers Proven track record of execution and dependability Strong ROI-based Customer Value Proposition Strong Relationships - Our Culture Seeks to Build Fo
Slide 16: With Strong, Sustainable Competitive Advantages
With Strong, Sustainable Competitive Advantages Superior Engineering Unmatched Proactive Electricity Grid Forecasting Capabilities Seamless "Parallel Switchgear" Technology Expert in Utility Tariff Systems Expert in Utility Interconnect Requirements Dedicated, Dependable Distributed Generation Asset
Slide 17: And Growing Complementary Businesses
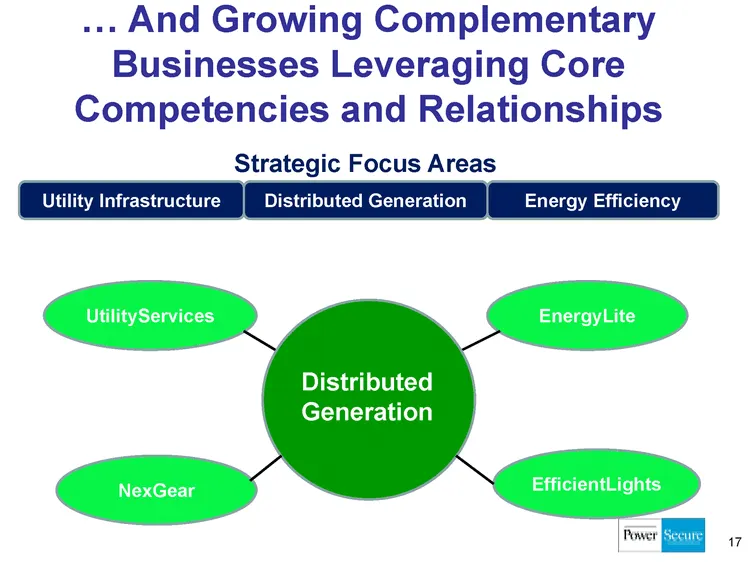
And Growing Complementary Businesses Leveraging Core Competencies and Relationships 17 Strategic Focus Areas Utility Infrastructure Distributed Generation Energy Efficiency UtilityServices Distributed Generation EnergyLite NexGear EfficientLights
Slide 18: A Track Record of Profitable Growth
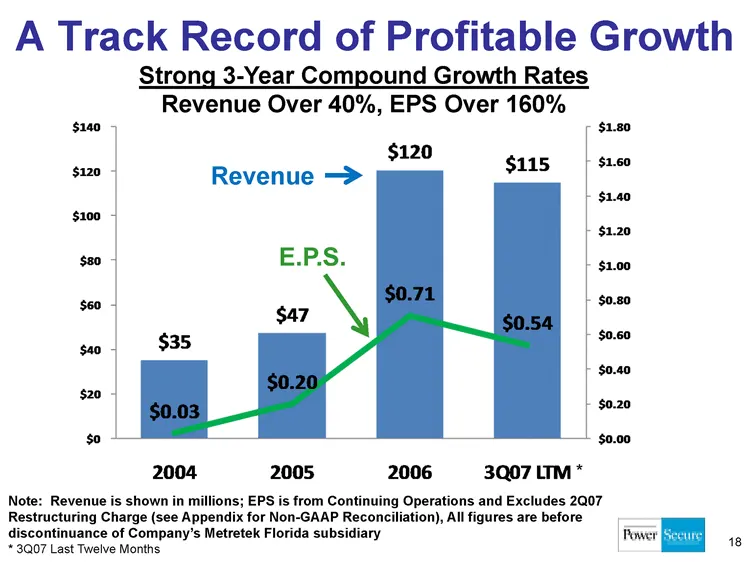
A Track Record of Profitable Growth 18 Note: Revenue is shown in millions; EPS is from Continuing Operations and Excludes 2Q07 Restructuring Charge (see Appendix for Non-GAAP Reconciliation), All figures are before discontinuance of Company's Metretek Florida subsidiary * 3Q07 Last Twelve Months Str
Slide 19: And a Strong Balance Sheet Positions us for the Future
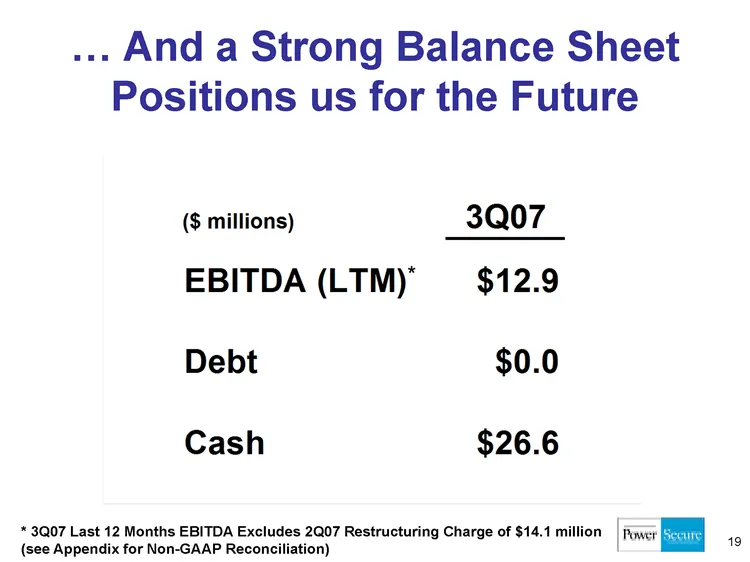
And a Strong Balance Sheet Positions us for the Future * 3Q07 Last 12 Months EBITDA Excludes 2Q07 Restructuring Charge of $14.1 million (see Appendix for Non-GAAP Reconciliation) ($ millions) 2Q07 EBITDA (LTM)* $12.9 Debt $0.0 Cash $26.6
Slide 20: Our Future is Bright
Our Future is Bright Large and Growing Marketplace U.S. and International Strong Market Position Focus on Core and Complementary Businesses Dedicated Employees who are Industry Experts Culture of Profitable Growth 20 L30179 24 PowerSecure Investor Presentation 2-20-08.pdf
Slide 21: Appendix (Non-GAAP Measures)
Appendix (Non-GAAP Measures)
Slide 22: Non-GAAP Reconciliations
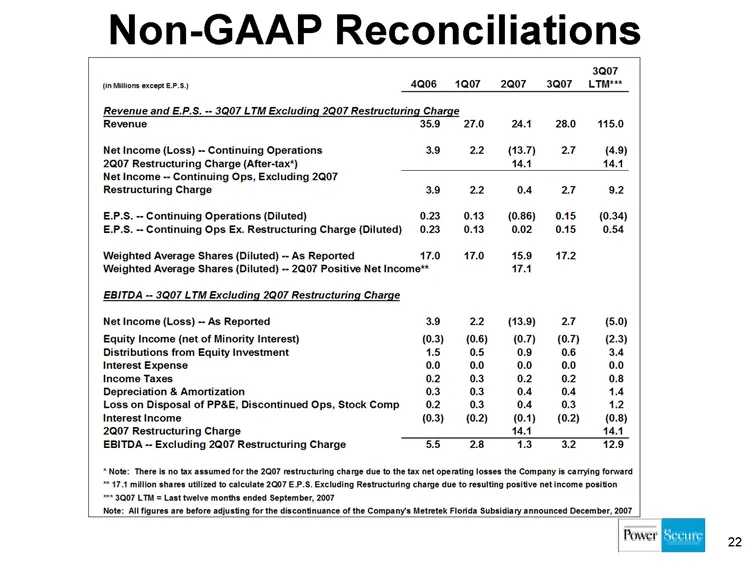
Non-GAAP Reconciliations (in Millions except E.P.S.] 4Q06 1Q07 2Q07 3Q07 3Q07 LTM*** Revenue and E.P.S. -- 3Q07 LTM Excluding 2Q07 Restructuring Charge Revenue Net Income (Loss) -- Continuing Operations 2Q07 Restructuring Charge (After-tax*) Net Income -- Continuing Ops, Excluding 2Q07 Restructuring
Slide 23: Non-GAAP Measures
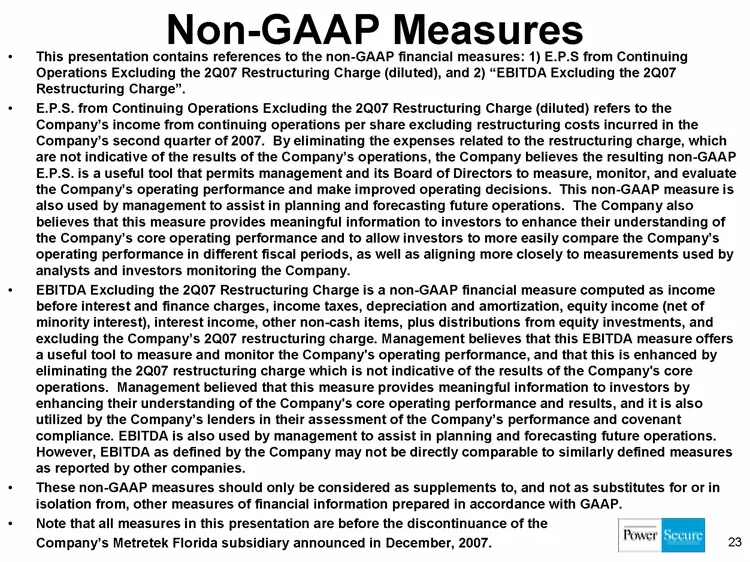
Non-GAAP Measures This presentation contains references to the non-GAAP financial measures: 1) E.P.S from Continuing Operations Excluding the 2Q07 Restructuring Charge (diluted), and 2) "EBITDA Excluding the 2Q07 Restructuring Charge". E.P.S. from Continuing Operations Excluding the 2Q07 Restructuri
Source: SEC EDGAR · 8-K filed Feb 20, 2008
More decks from PowerSecure International Inc
 Investor Presentation (January 2016)19 slides · Jan 13, 2016
 Q3 2015 Earnings Presentation19 slides · Nov 9, 2015
 Investor Presentation (September 2015)19 slides · Sep 2, 2015
 Investor Presentation (August 2015)16 slides · Aug 10, 2015
 Investor Presentation (May 2015)21 slides · May 26, 2015
 Investor Presentation (May 2015)18 slides · May 6, 2015