Escalera Resources — Double Eagle Petroleum — IPAA Oil and Gas Investment Symposium 2010
13 slides from Escalera Resources's conference presentation, Apr 12, 2010
Slide 1: Double Eagle Petroleum Co. IPAA Oil and Gas Investment Symposium
Double Eagle Petroleum Co. IPAA Oil and Gas Investment Symposium New York, April 13, 2010
Slide 2: Disclaimer
2 Disclaimer This presentation may contain projections and other forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended. Any such projections or statements reflect the Company's current views with respect to future events and financial perform
Slide 3: Corporate Profile
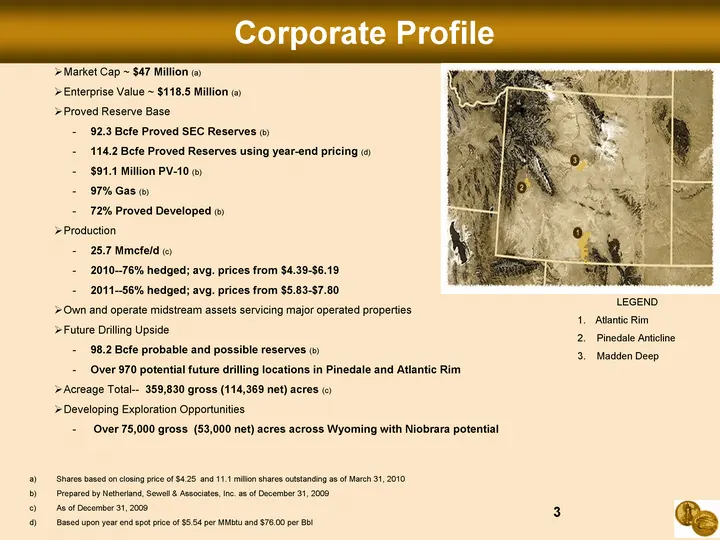
Corporate Profile Market Cap ~ $47 Million (a) Enterprise Value ~ $118.5 Million (a) Proved Reserve Base 92.3 Bcfe Proved SEC Reserves (b) 114.2 Bcfe Proved Reserves using year-end pricing (d) $91.1 Million PV-10 (b) 97% Gas (b) 72% Proved Developed (b) Production 25.7 Mmcfe/d (c) 2010--76% hedged;
Slide 4: DBLE is compelling to investors on a production and proved reserves basis
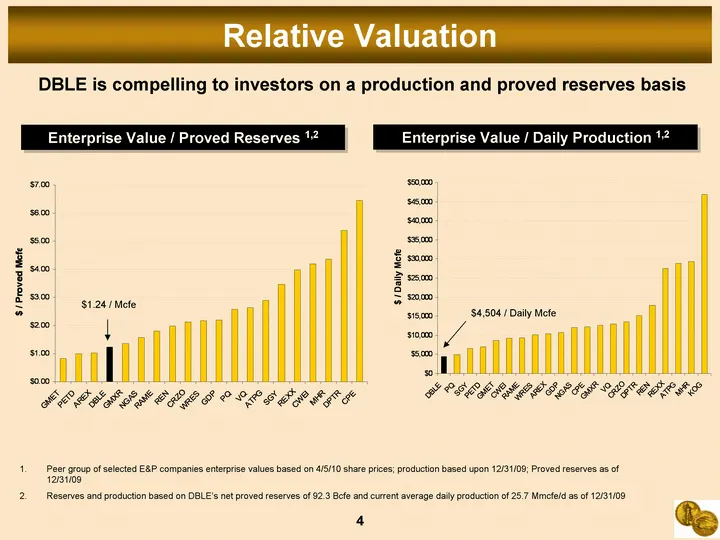
DBLE is compelling to investors on a production and proved reserves basis 4 Enterprise Value / Proved Reserves 1,2 $1.24 / Mcfe $4,504 / Daily Mcfe Relative Valuation Peer group of selected E&P companies enterprise values based on 4/5/10 share prices; production based upon 12/31/09; Proved reserves
Slide 5: Historical Highlights
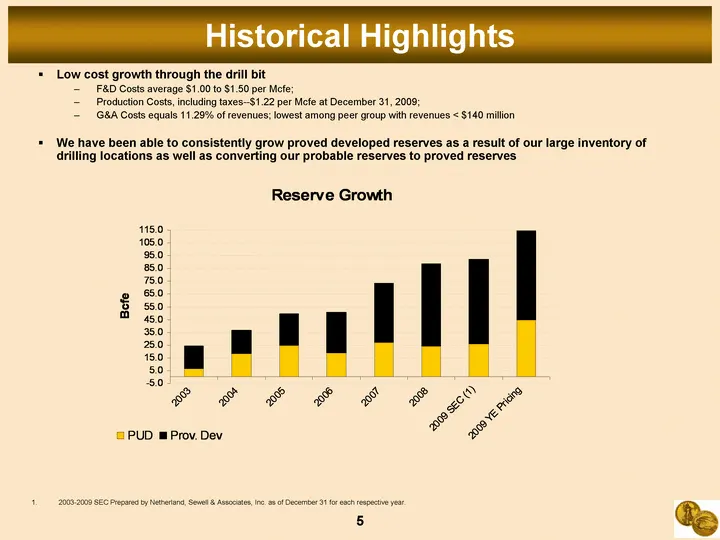
5 Historical Highlights Low cost growth through the drill bit F&D Costs average $1.00 to $1.50 per Mcfe; Production Costs, including taxes--$1.22 per Mcfe at December 31, 2009; G&A Costs equals 11.29% of revenues; lowest among peer group with revenues < $140 million We have been able to consistently
Slide 6: Quality Asset Portfolio-Overview
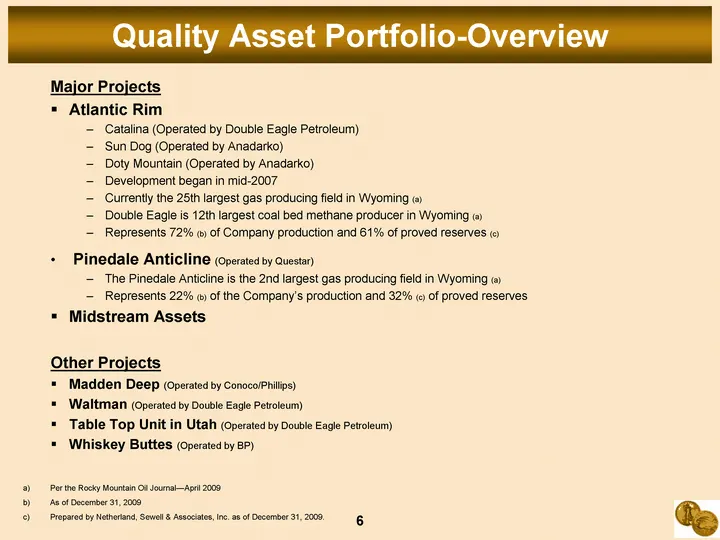
6 Quality Asset Portfolio-Overview Major Projects Atlantic Rim Catalina (Operated by Double Eagle Petroleum) Sun Dog (Operated by Anadarko) Doty Mountain (Operated by Anadarko) Development began in mid-2007 Currently the 25th largest gas producing field in Wyoming (a) Double Eagle is 12th largest co
Slide 7: Historical drilling activity
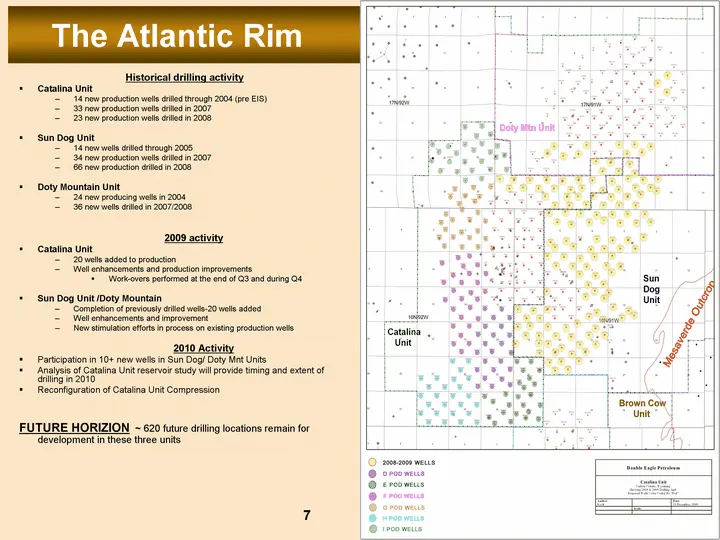
7 Historical drilling activity Catalina Unit 14 new production wells drilled through 2004 (pre EIS) 33 new production wells drilled in 2007 23 new production wells drilled in 2008 Sun Dog Unit 14 new wells drilled through 2005 34 new production wells drilled in 2007 66 new production drilled in 2008
Slide 8: Catalina Unit Historical Economics
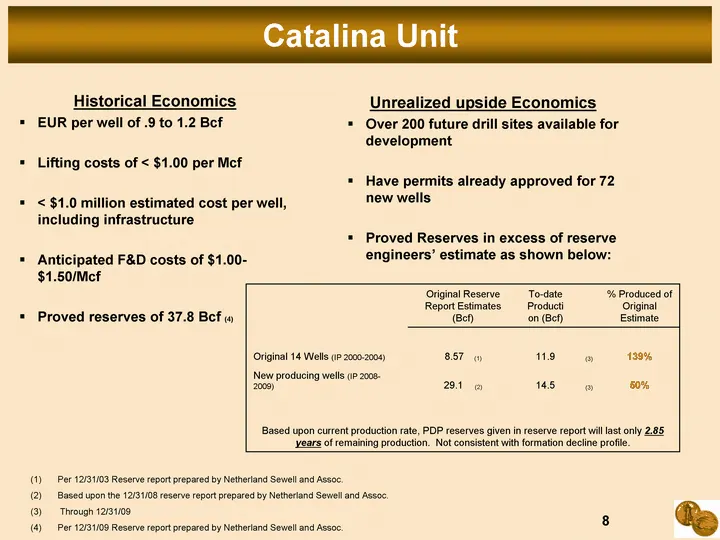
8 Catalina Unit Historical Economics EUR per well of .9 to 1.2 Bcf Lifting costs of < $1.00 per Mcf < $1.0 million estimated cost per well, including infrastructure Anticipated F&D costs of $1.00- $1.50/Mcf Proved reserves of 37.8 Bcf (4) Unrealized upside Economics Over 200 future drill sites avail
Slide 9: Pinedale Anticline
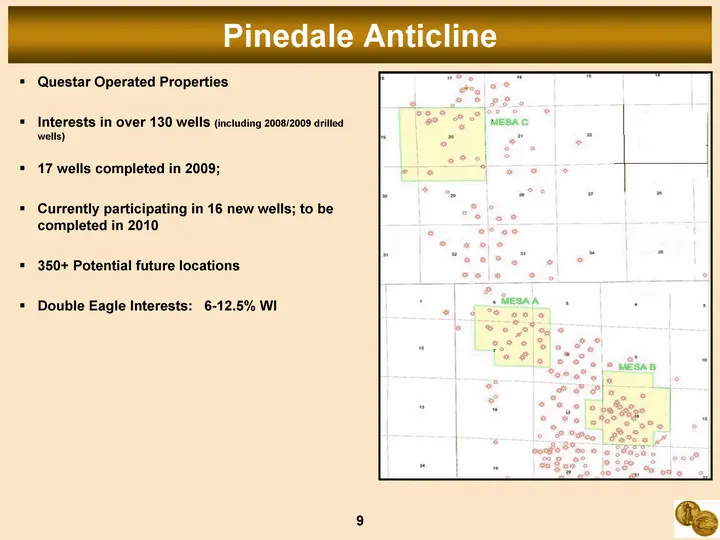
9 Pinedale Anticline Questar Operated Properties Interests in over 130 wells (including 2008/2009 drilled wells) 17 wells completed in 2009; Currently participating in 16 new wells; to be completed in 2010 350+ Potential future locations Double Eagle Interests: 6-12.5% WI
Slide 10: Midstream Infrastructure
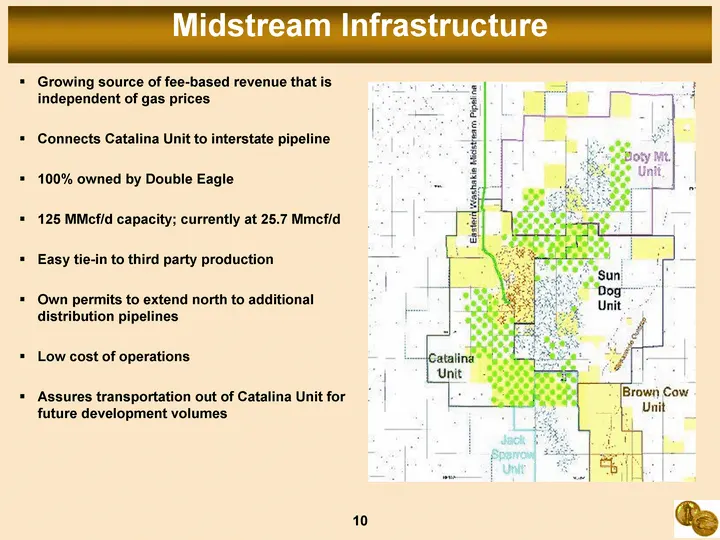
10 Midstream Infrastructure Growing source of fee-based revenue that is independent of gas prices Connects Catalina Unit to interstate pipeline 100% owned by Double Eagle 125 MMcf/d capacity; currently at 25.7 Mmcf/d Easy tie-in to third party production Own permits to extend north to additional dis
Slide 11: Developing Exploration Potential
11 Developing Exploration Potential Table Top Unit Filed for EIS review with USFS, awaiting approval Assessing need for additional seismic work; to be performed 2011 Potential 2-3 TCF target Niobrara Formation Niobrara Shale is up and coming play. Potentially similar to Bakken, Barnett or Marcellus;
Slide 12: Value Proposition
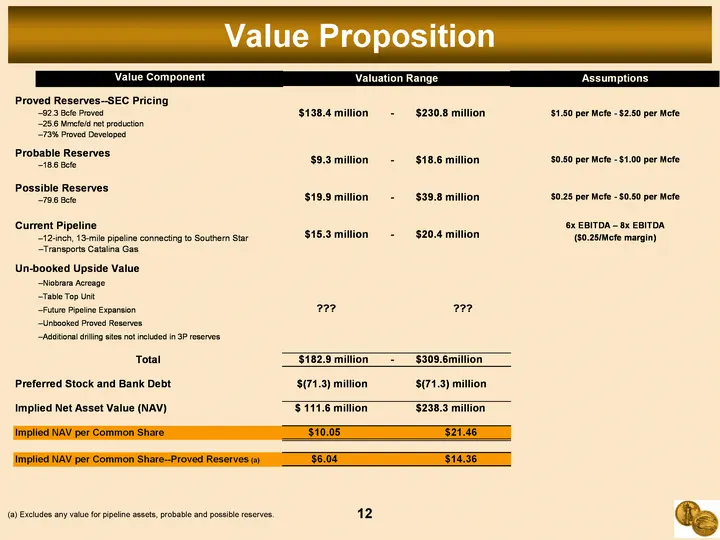
12 Value Proposition (a) Excludes any value for pipeline assets, probable and possible reserves.
Slide 13: Questions
Questions
Source: SEC EDGAR · 8-K filed Apr 12, 2010
More decks from Escalera Resources Company
 EnerCom: The Oil & Gas Conference 201420 slides · Aug 20, 2014
 IPAA OGIS Toronto 201421 slides · Jun 5, 2014
 IPAA Oil & Gas Conference April 201426 slides · Apr 9, 2014
 Double Eagle Petroleum — Euro Pacific Global Investment Conference 201318 slides · Sep 3, 2013
 Double Eagle Petroleum — EnerCom's The Oil & Gas Conference 201318 slides · Aug 14, 2013
 Double Eagle Petroleum — OGIS Conference New York 201316 slides · Apr 15, 2013