Escalera Resources — Double Eagle Petroleum — Euro Pacific Global Investment Conference 2013
18 slides from Escalera Resources's conference presentation, Sep 3, 2013
Slide 1: Euro Pacific Global Investment Conference New York September 10, 2013
1 Euro Pacific Global Investment Conference New York September 10, 2013 Double Eagle Petroleum Co. KSH
Slide 2: Corporate Information & Disclaimer
2 Corporate Information & Disclaimer NASDAQ: DBLE Shares Outstanding: 11,341,379 52 Week Price Range: $2.86-$6.20 50 Day Average Volume: 19,056 *information quoted above as of August 29,2013 Corporate Office: 1675 Broadway, Suite 2200 Denver, CO 80202 www.dble.com This presentation may contain proje
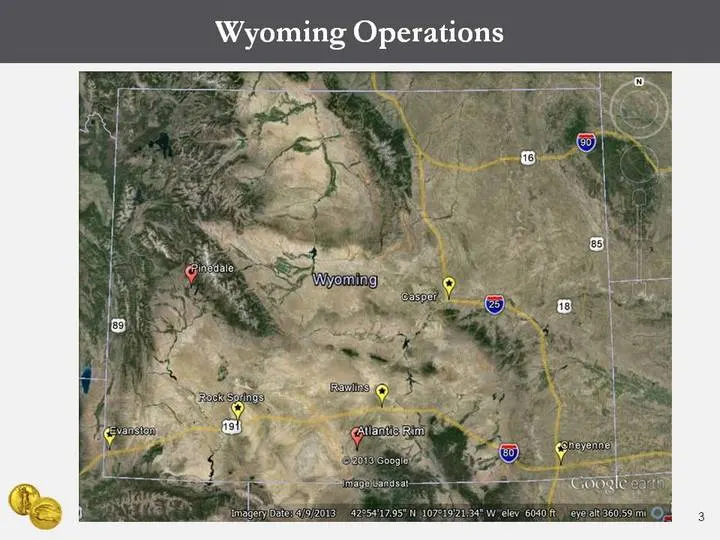
Slide 3: Wyoming Operations
Wyoming Operations 3
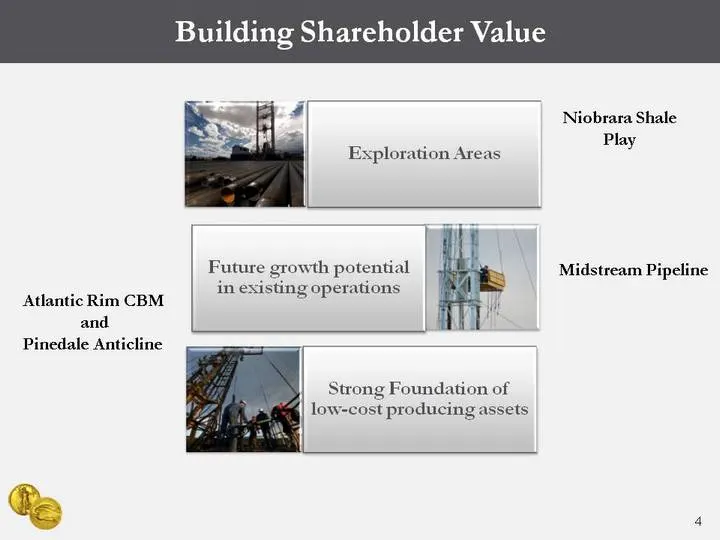
Slide 4: Building Shareholder Value
Building Shareholder Value Building Shareholder Value 4 Niobrara Shale Play Midstream Pipeline Atlantic Rim CBM and Pinedale Anticline
Slide 5: Proven Execution: Cost Control
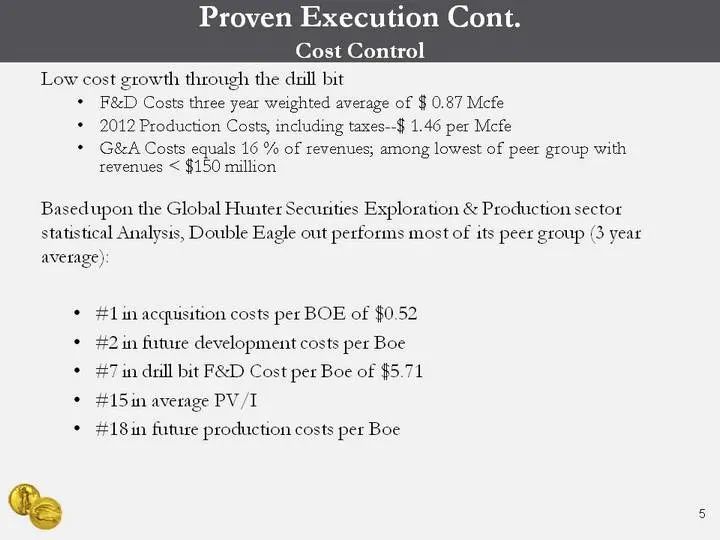
5 Proven Execution Cont. Cost Control Low cost growth through the drill bit F&D Costs three year weighted average of $ 0.87 Mcfe 2012 Production Costs, including taxes--$ 1.46 per Mcfe G&A Costs equals 16 % of revenues; among lowest of peer group with revenues < $150 million Based upon the Global Hu
Slide 6: Proven Execution: Reserve Growth 2003-2012
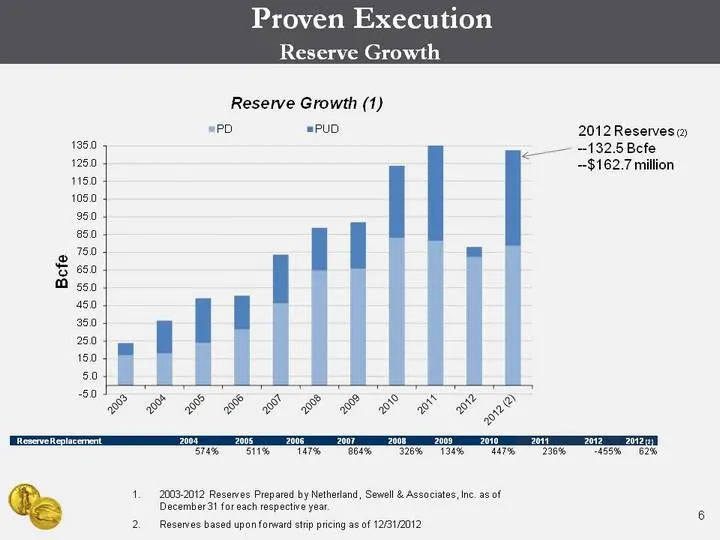
6 Proven Execution Reserve Growth 2003-2012 Reserves Prepared by Netherland, Sewell & Associates, Inc. as of December 31 for each respective year. Reserves based upon forward strip pricing as of 12/31/2012 Reserve Replacement Reserve Replacement 2004 2005 2006 2007 2008 2009 2010 2011 2012 2012 (2)
Slide 7: Building Shareholder Value: Niobrara Shale Play
Building Shareholder Value Building Shareholder Value 7 Niobrara Shale Play
Slide 8: Niobrara Shale Acreage
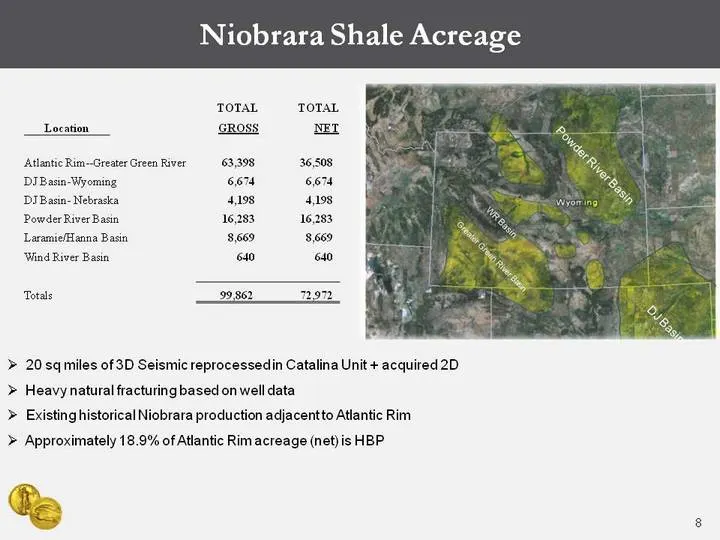
8 Niobrara Shale Acreage Powder River Basin Greater Green River Basin DJ Basin WR Basin 20 sq miles of 3D Seismic reprocessed in Catalina Unit + acquired 2D Heavy natural fracturing based on well data Existing historical Niobrara production adjacent to Atlantic Rim Approximately 18.9% of Atlantic Ri
Slide 9: Niobrara Shale-Atlantic Rim Appraisal Well
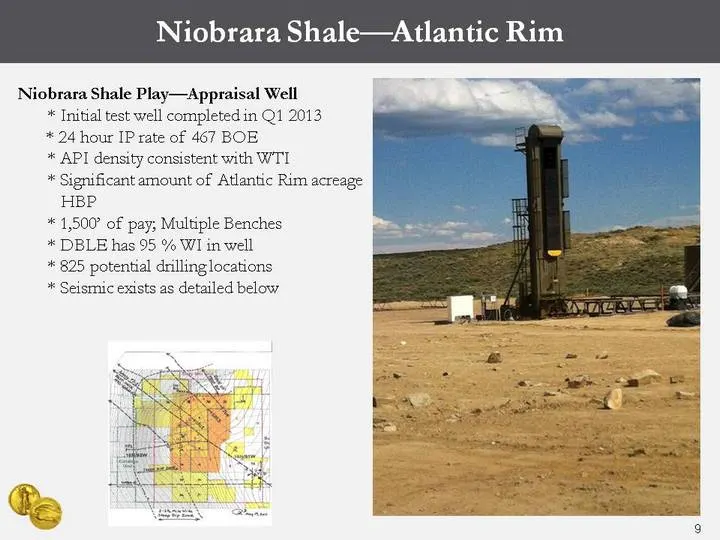
Niobrara Shale-Atlantic Rim 9 Niobrara Shale Play-Appraisal Well * Initial test well completed in Q1 2013 * 24 hour IP rate of 467 BOE * API density consistent with WTI * Significant amount of Atlantic Rim acreage HBP * 1,500' of pay; Multiple Benches * DBLE has 95 % WI in well * 825 potential drill
Slide 10: Niobrara Shale Central Wyoming & Colorado
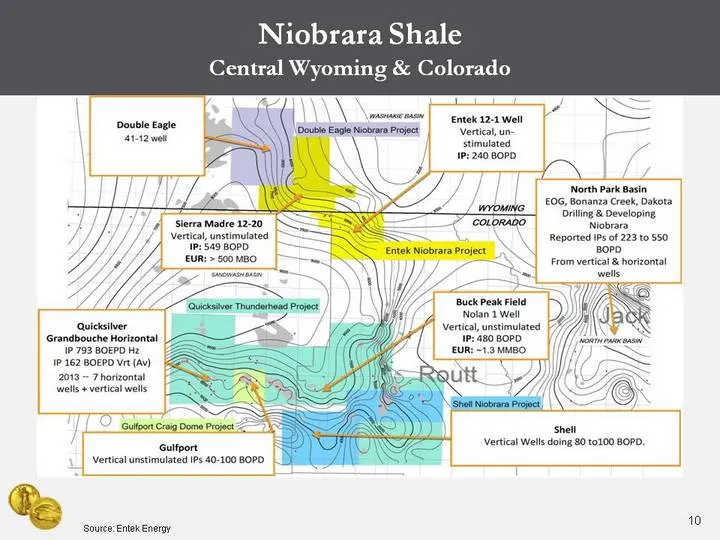
10 Niobrara Shale Central Wyoming & Colorado Source: Entek Energy
Slide 11: Niobrara Shale Central Wyoming & Colorado Recent Activity
11 Niobrara Shale Central Wyoming & Colorado Recent Activity Quicksilver and Shell establish an AMI in Sand Wash Basin to develop ~850,000 acres of Niobrara potential. Three wells have been permitted Entek and East Resources establish an AMI in Sand Wash Basin of Wyoming to develop ~ 87,000 acres of
Slide 12: Building Shareholder Value: Pinedale Anticline, Midstream Pipeline, Atlantic Rim CBM
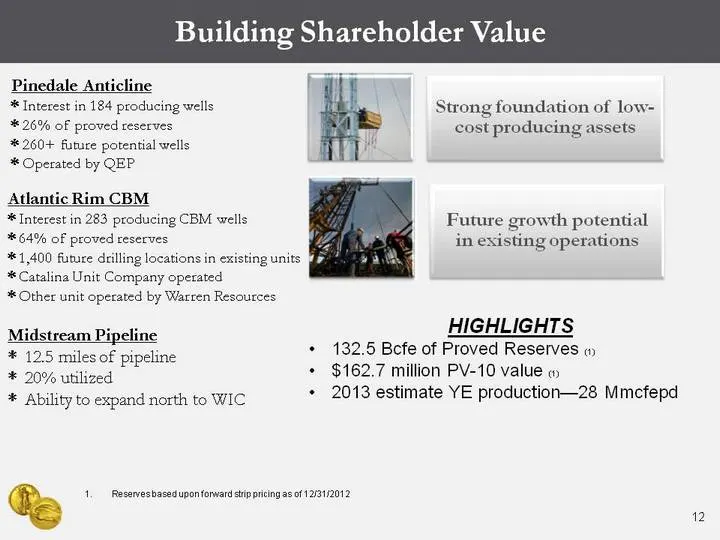
Building Shareholder Value Building Shareholder Value 12 Pinedale Anticline * Interest in 184 producing wells * 26% of proved reserves * 260+ future potential wells * Operated by QEP Midstream Pipeline * 12.5 miles of pipeline * 20% utilized * Ability to expand north to WIC Atlantic Rim CBM * Intere
Slide 13: Atlantic Rim Project in the Greater Green River Basin
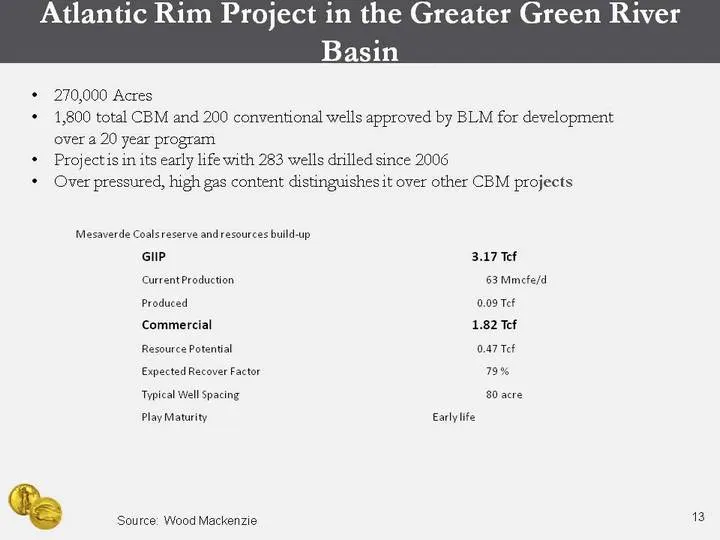
Atlantic Rim Project in the Greater Green River Basin 13 270,000 Acres 1,800 total CBM and 200 conventional wells approved by BLM for development over a 20 year program Project is in its early life with 283 wells drilled since 2006 Over pressured, high gas content distinguishes it over other CBM pro
Slide 14: The Atlantic Rim: Historical drilling activity
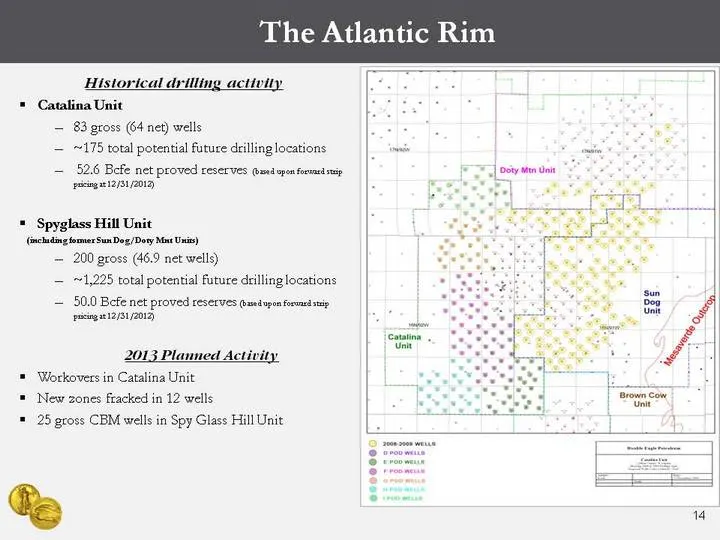
14 Historical drilling activity Catalina Unit 83 gross (64 net) wells ~175 total potential future drilling locations 52.6 Bcfe net proved reserves (based upon forward strip pricing at 12/31/2012) Spyglass Hill Unit (including former Sun Dog/Doty Mnt Units) 200 gross (46.9 net wells) ~1,225 total pot
Slide 15: Pinedale Anticline Producing Assets
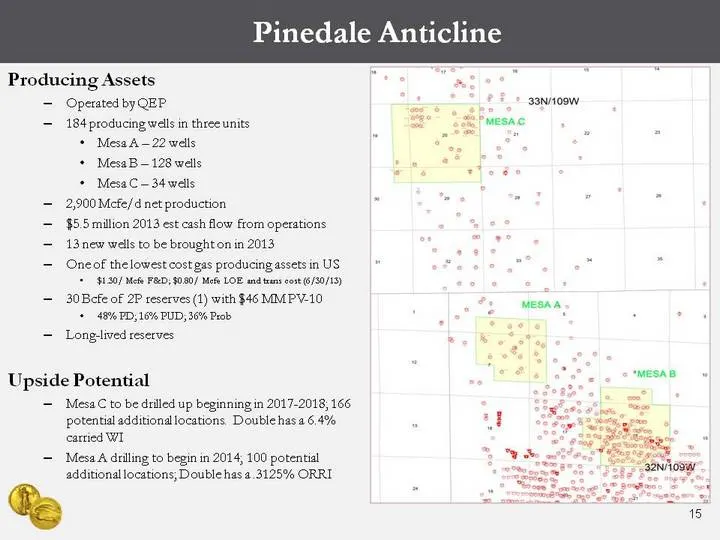
15 Producing Assets Operated by QEP 184 producing wells in three units Mesa A - 22 wells Mesa B - 128 wells Mesa C - 34 wells 2,900 Mcfe/d net production $5.5 million 2013 est cash flow from operations 13 new wells to be brought on in 2013 One of the lowest cost gas producing assets in US $1.30/ Mcf
Slide 16: Midstream Infrastructure
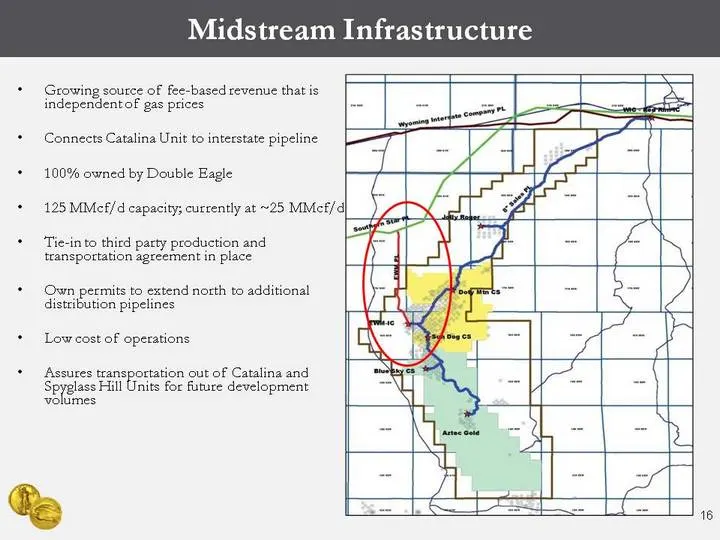
Midstream Infrastructure Growing source of fee-based revenue that is independent of gas prices Connects Catalina Unit to interstate pipeline 100% owned by Double Eagle 125 MMcf/d capacity; currently at ~25 MMcf/d Tie-in to third party production and transportation agreement in place Own permits to e
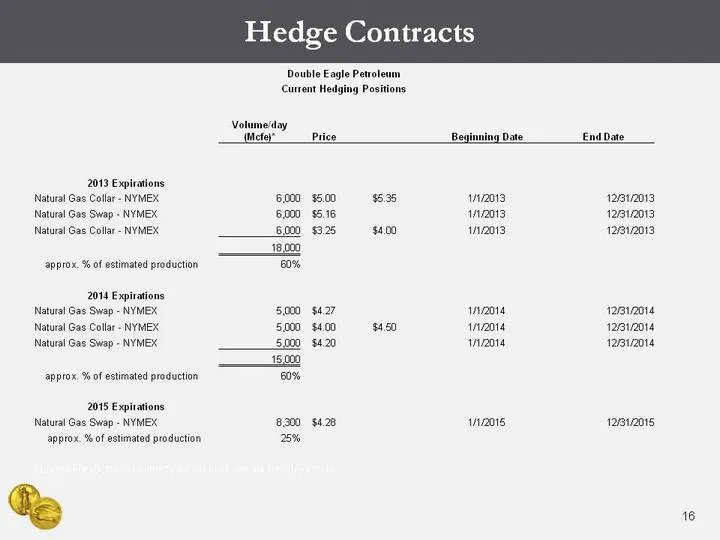
Slide 17: Hedge Contracts
Hedge Contracts 16 Double Eagle Petroleum Double Eagle Petroleum Double Eagle Petroleum Double Eagle Petroleum Double Eagle Petroleum Double Eagle Petroleum Current Hedging Positions Current Hedging Positions Current Hedging Positions Current Hedging Positions Current Hedging Positions Current Hedgi
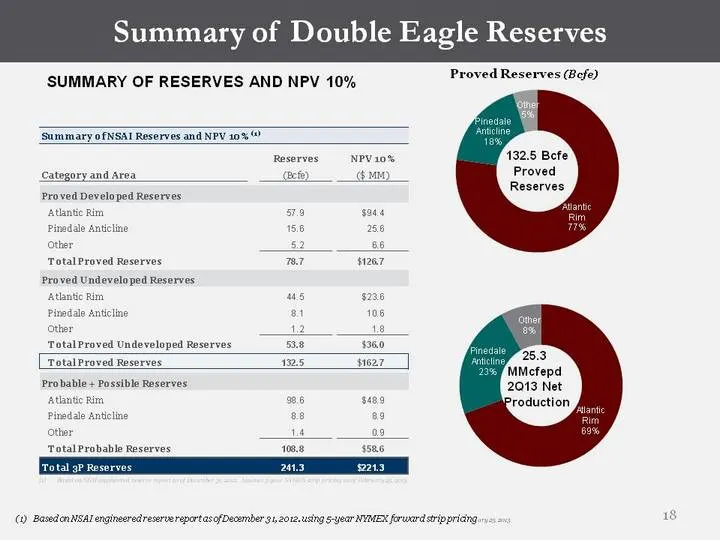
Slide 18: Summary of Reserves and NPV 10%
Summary of Reserves and NPV 10% 18 Proved Reserves (Bcfe) Based on NSAI engineered reserve report as of December 31, 2012. Assumes 5-year NYMEX strip pricing as of February 25, 2013. 132.5 Bcfe Proved Reserves 25.3 MMcfepd 2Q13 Net Production Summary of Double Eagle Reserves Based on NSAI engineered
Source: SEC EDGAR · 8-K filed Sep 3, 2013
More decks from Escalera Resources Company
 EnerCom: The Oil & Gas Conference 201420 slides · Aug 20, 2014
 IPAA OGIS Toronto 201421 slides · Jun 5, 2014
 IPAA Oil & Gas Conference April 201426 slides · Apr 9, 2014
 Double Eagle Petroleum — EnerCom's The Oil & Gas Conference 201318 slides · Aug 14, 2013
 Double Eagle Petroleum — OGIS Conference New York 201316 slides · Apr 15, 2013
 Double Eagle Petroleum — Investor Presentation (August 2012)18 slides · Aug 14, 2012