Emclaire Financial — Shareholder Meeting (April 2012)
48 slides from Emclaire Financial's shareholder meeting presentation, Apr 25, 2012
Slide 1: 2012 Annual Meeting of Shareholders
2012 Annual Meeting of Shareholders Parent Holding Company of The Farmers National Bank of Emlenton April 25, 2012 – 9:00 AM Emlenton, Pennsylvania William C. Marsh Chairman, President & CEO
Slide 2: Introductions
Introductions From Bank/Company : • Board of Directors • Executive Management • Other Officers and Employees Guests : • Independent Accountants – Leah Blazek; Crowe Horwath, LLP • Market Maker – Bob Wagner; Boenning & Scattergood, Inc. 2
Slide 3: Forward Looking Statements
Forward Looking Statements This presentation contains certain forward - looking statements and information relating to the Company that are based on the beliefs of management as well as assumptions made by and information currently available to management. These forward - looking statements relate t
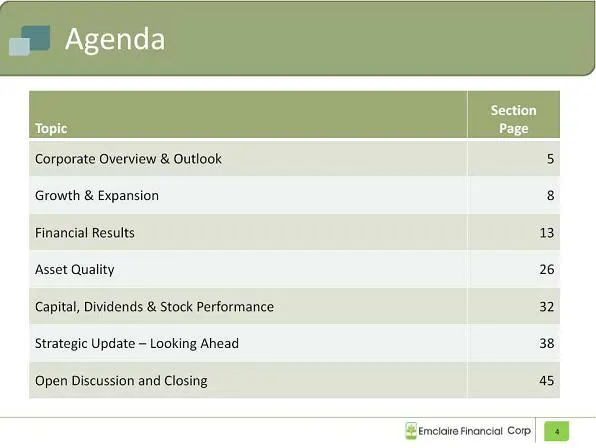
Slide 4: Agenda: Sections and Topics
Section Topic Page Corporate Overview & Outlook 5 Growth & Expansion 8 Financial Results 13 Asset Quality 26 Capital, Dividends & Stock Performance 32 Strategic Update Looking Ahead 38 Open Discussion and Closing 45
Slide 5: Corporate Overview
Corporate Overview • Record earnings – 2011 and 1Q 2012 • Continued core balance sheet growth – loans/deposits • Consistent organic growth – earnings and footings • Asset quality improvement • Capital level improvement • Continue to improve professional staff – additions/training 5
Slide 6: Economic Outlook
Economic Outlook • Market interest rate environment low and to remain low • Unemployment improving – nationally and particularly in region • Real estate values stabilizing – Western Pennsylvania held firmer than nationally • Bank earnings and valuations recovering nationally • Gasoline prices – up a
Slide 7: Regulatory Outlook
Regulatory Outlook • Dodd - Frank & Consumer Financial Protection Bureau – Safe Act (mortgage lending business) – Like traditional Consumer Product Safety Commission; but for financial companies – All impacts mainly larger financial companies • Overdraft rules • FDIC insurance premiums • OCC / OTS m
Slide 8: Growth & Expansion
Growth & Expansion 8 • History of Growth • Franchise • Five Year Balance Sheet Look • Growth Components
Slide 9: History of Growth – 10,000X
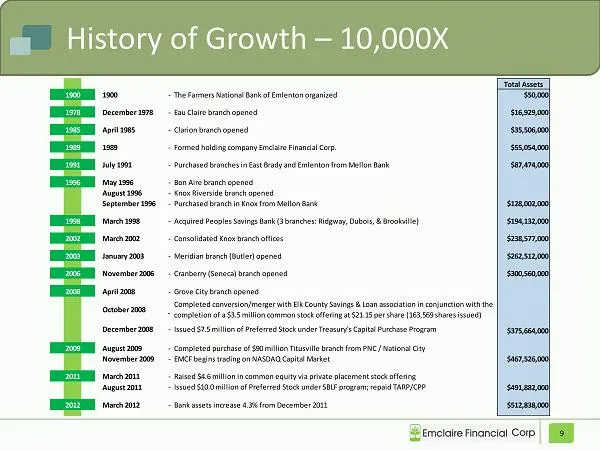
History of Growth – 10,000X 9 Total Assets 1900 -The Farmers National Bank of Emlenton organized $50,000 December 1978 -Eau Claire branch opened $16,929,000 April 1985 -Clarion branch opened $35,506,000 1989 -Formed holding company Emclaire Financial Corp. $55,054,000 July 1991 -Purchased branches i
Slide 10: Banking Franchise
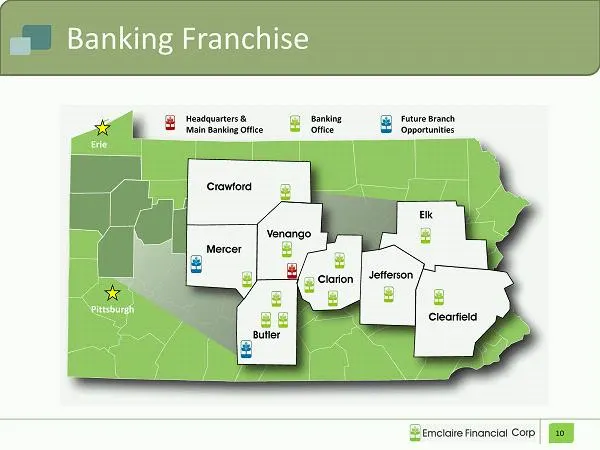
Banking Franchise Headquarters & Main Banking Office Banking Office Erie Pittsburgh Future Branch Opportunities 10
Slide 11: Balance Sheet Growth
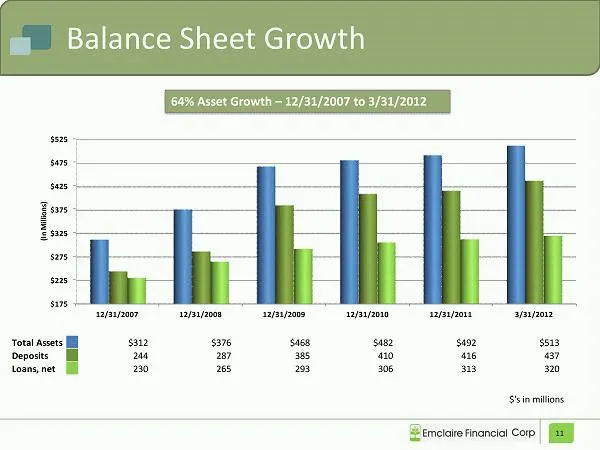
Balance Sheet Growth 64% Asset Growth – 12/31/2007 to 3/31/2012 11 $175 $225 $275 $325 $375 $425 $475 $525 12/31/2007 12/31/2008 12/31/2009 12/31/2010 12/31/2011 3/31/2012 (In Millions) Total Assets $312 $376 $468 $482 $492 $513 Deposits 244 287 385 410 416 437 Loans, net 230 265 293 306 313 320 $’s
Slide 12: Sources of Balance Sheet Growth
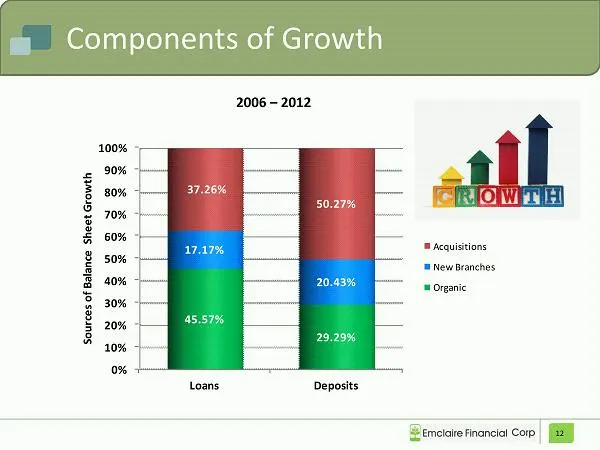
0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% Loans Deposits 45.57% 29.29% 17.17% 20.43% 37.26% 50.27% Sources of Balance Sheet Growth Acquisitions New Branches Organic Components of Growth 12 2006 – 2012
Slide 13: Financial Results
Financial Results 13 • Consolidated Financial Highlights • Balance Sheet Review • 2011 Results • 2012 First Quarter Results • Core Results • Efficiency
Slide 14: Consolidated Financial Highlights: Balance Sheet
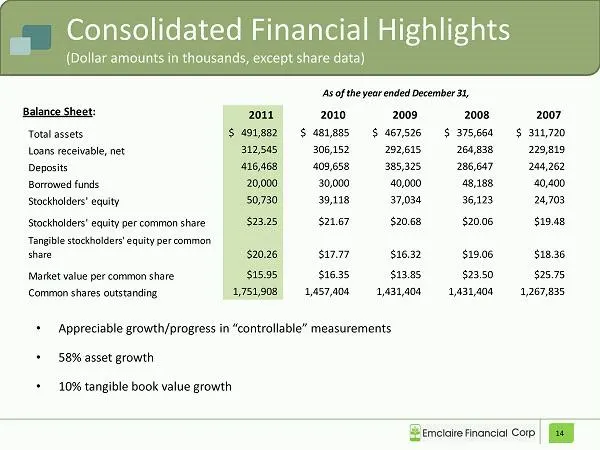
Consolidated Financial Highlights (Dollar amounts in thousands, except share data) 14 • Appreciable growth/progress in “controllable” measurements • 58% asset growth • 10% tangible book value growth 2011 2010 2009 2008 2007 Total assets 491,882$ 481,885$ 467,526$ 375,664$ 311,720$ Loans receivable,
Slide 15: Consolidated Financial Highlights: Income Statement
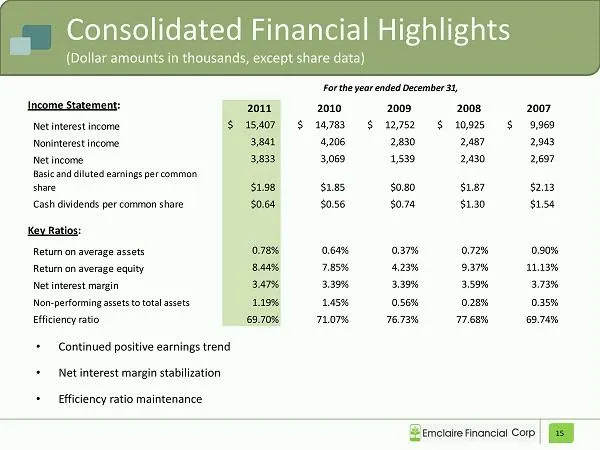
Consolidated Financial Highlights (Dollar amounts in thousands, except share data) 15 • Continued positive earnings trend • Net interest margin stabilization • Efficiency ratio maintenance 2011 2010 2009 2008 2007 Net interest income 15,407$ 14,783$ 12,752$ 10,925$ 9,969$ Noninterest income 3,841 4,
Slide 16: Consolidated Balance Sheets
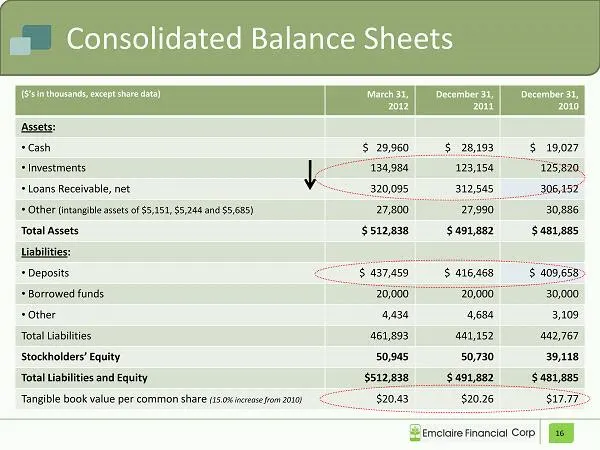
Consolidated Balance Sheets ($’s in thousands, except share data) March 31, 2012 December 31, 2011 December 31, 2010 Assets : • Cash $ 29,960 $ 28,193 $ 19,027 • Investments 134,984 123,154 125,820 • Loans Receivable, net 320,095 312,545 306,152 • Other (intangible assets of $5,151, $5,244 and $5,68
Slide 17: Consolidated Balance Sheets: Growth Comparison
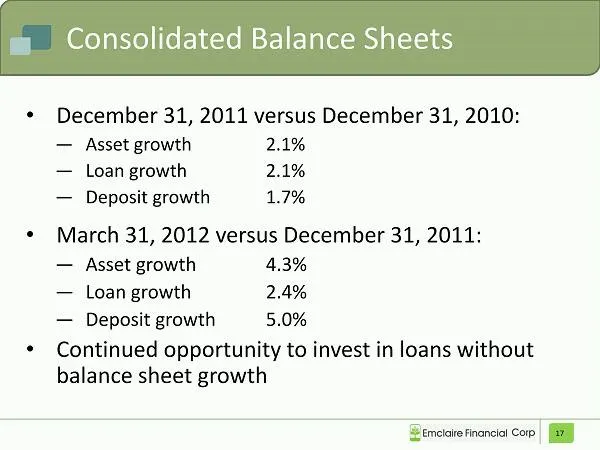
Consolidated Balance Sheets • December 31, 2011 versus December 31, 2010: — Asset growth 2.1% — Loan growth 2.1% — Deposit growth 1.7% • March 31, 2012 versus December 31, 2011: — Asset growth 4.3% — Loan growth 2.4% — Deposit growth 5.0% • Continued opportunity to invest in loans without balance sh
Slide 18: Earnings – 2011 vs. 2010
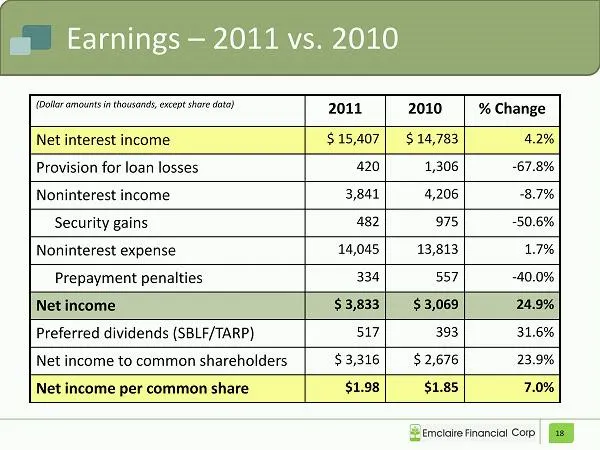
Earnings – 2011 vs. 2010 18 (Dollar amounts in thousands, except share data) 2011 2010 % Change Net interest income $ 15,407 $ 14,783 4.2% Provision for loan losses 420 1,306 - 67.8% Noninterest income 3,841 4,206 - 8.7% Security gains 482 975 - 50.6% Noninterest expense 14,045 13,813 1.7% Prepaymen
Slide 19: Earnings – 2011 vs. 2010 Commentary
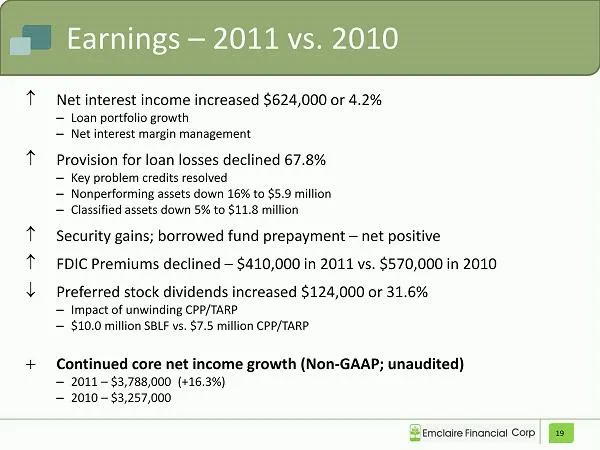
Earnings – 2011 vs. 2010 Net interest income increased $624,000 or 4.2% – Loan portfolio growth – Net interest margin management Provision for loan losses declined 67.8% – Key problem credits resolved – Nonperforming assets down 16% to $5.9 million – Classified assets down 5% to $11.8 million
Slide 20: Earnings Considerations
Earnings Considerations 20 Headwinds: • Regulatory burden & compliance costs • Interest rate environment • Technology and security costs • Healthcare costs • Mild loan demand Opportunities: • Noninterest revenue growth • Improved operating efficiencies • Realized reduction in FDIC premiums • Expansi
Slide 21: Earnings – 1Q 2012 vs. 1Q 2011
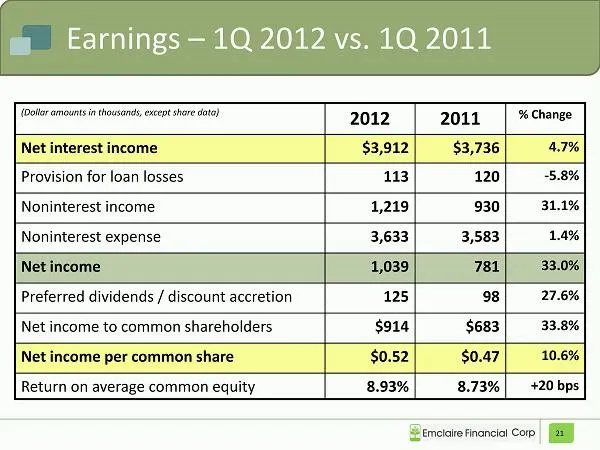
Earnings – 1Q 2012 vs. 1Q 2011 (Dollar amounts in thousands, except share data) 2012 2011 % Change Net interest income $3,912 $3,736 4.7% Provision for loan losses 113 120 - 5.8% Noninterest income 1,219 930 31.1% Noninterest expense 3,633 3,583 1.4% Net income 1,039 781 33.0% Preferred dividends /
Slide 22: Earnings – 1Q 2012 vs. 1Q 2011 Commentary
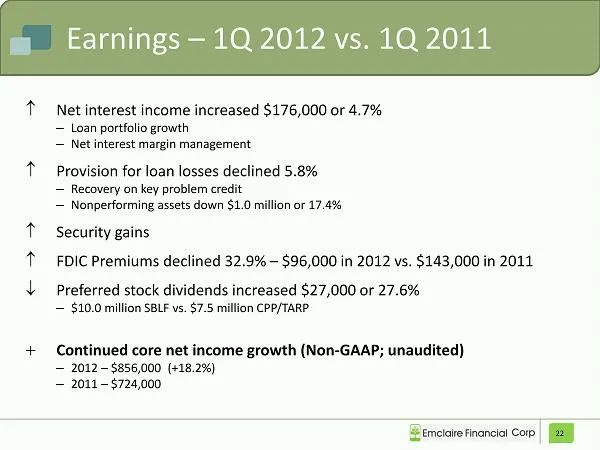
Earnings – 1Q 2012 vs. 1Q 2011 Net interest income increased $176,000 or 4.7% – Loan portfolio growth – Net interest margin management Provision for loan losses declined 5.8% – Recovery on key problem credit – Nonperforming assets down $1.0 million or 17.4% Security gains FDIC Premiums decli
Slide 23: Core Revenue Growth
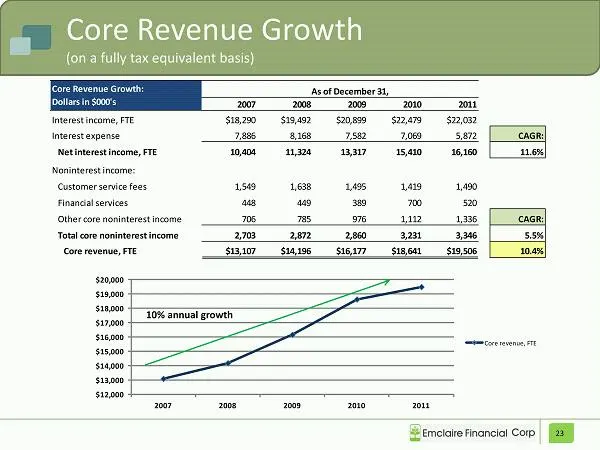
$12,000 $13,000 $14,000 $15,000 $16,000 $17,000 $18,000 $19,000 $20,000 2007 2008 2009 2010 2011 Core revenue, FTE Core Revenue Growth (on a fully tax equivalent basis) 23 10% annual growth 2007 2008 2009 2010 2011 Interest income, FTE $18,290 $19,492 $20,899 $22,479 $22,032 Interest expense 7,886 8
Slide 24: Core Earnings Growth
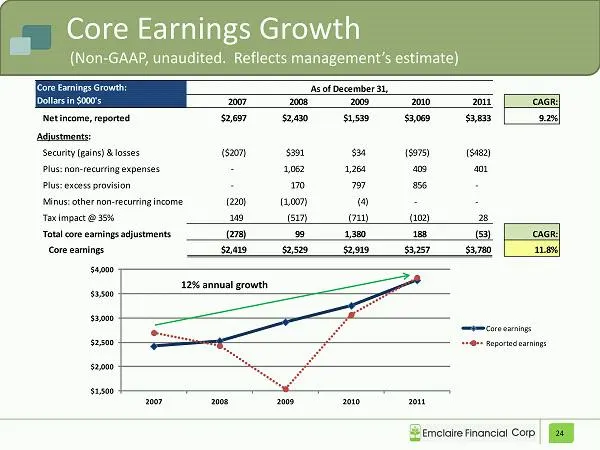
$1,500 $2,000 $2,500 $3,000 $3,500 $4,000 2007 2008 2009 2010 2011 Core earnings Reported earnings Core Earnings Growth (Non - GAAP, unaudited. Reflects management’s estimate) 24 12% annual growth 2007 2008 2009 2010 2011 CAGR: Net income, reported $2,697 $2,430 $1,539 $3,069 $3,833 9.2% Adjustments
Slide 25: Efficiency
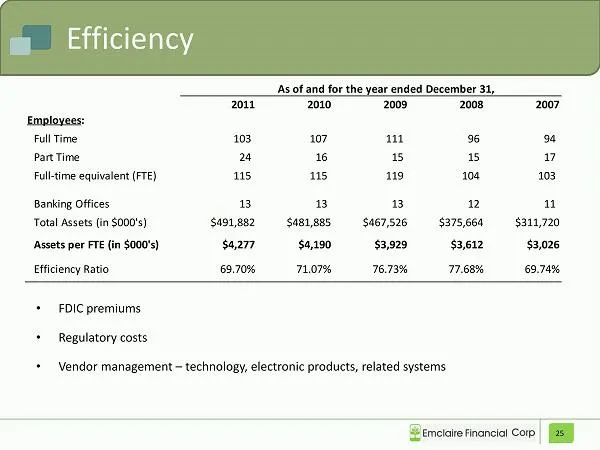
Efficiency 25 • FDIC premiums • Regulatory costs • Vendor management – technology, electronic products, related systems 2011 2010 2009 2008 2007 Employees: Full Time 103 107 111 96 94 Part Time 24 16 15 15 17 Full-time equivalent (FTE) 115 115 119 104 103 Banking Offices 13 13 13 12 11 Total Assets
Slide 26: Asset Quality
Asset Quality 26 • Overview • Classified Assets • Delinquency Trends • Loan Portfolio Growth
Slide 27: Asset Quality Overview
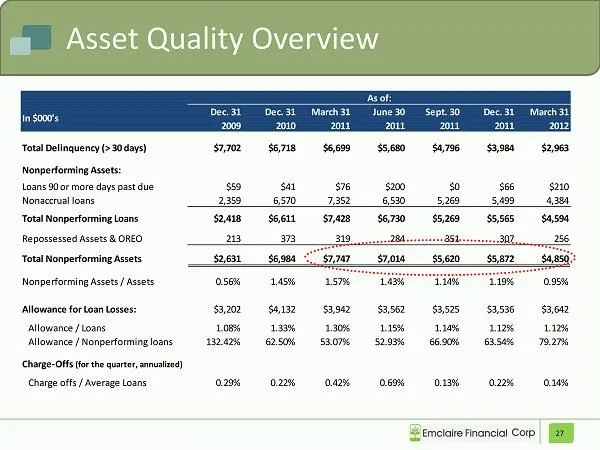
Asset Quality Overview 27 Dec. 31 Dec. 31 March 31 June 30 Sept. 30 Dec. 31 March 31 2009 2010 2011 2011 2011 2011 2012 Total Delinquency (> 30 days) $7,702 $6,718 $6,699 $5,680 $4,796 $3,984 $2,963 Nonperforming Assets: Loans 90 or more days past due $59 $41 $76 $200 $0 $66 $210 Nonaccrual loans 2,
Slide 28: Peer Group
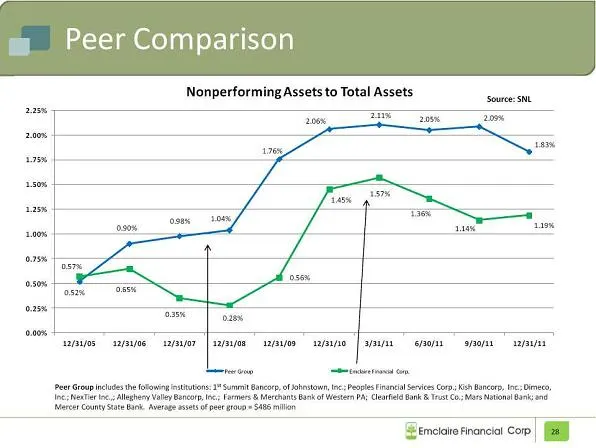
Peer Group includes the following institutions: 1 st Summit Bancorp, of Johnstown, Inc.; Peoples Financial Services Corp.; Kish Bancorp, Inc.; Dimeco, Inc.; NexTier Inc.,; Allegheny Valley Bancorp, Inc.; Farmers & Merchants Bank of Western PA; Clearfield Bank & Trust Co.; Mars National Bank; and Mer
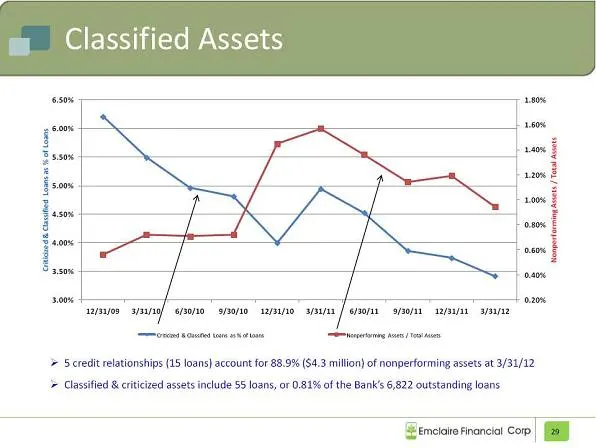
Slide 29: Classified & Criticized Assets
5 credit relationships (15 loans) account for 88.9% ($4.3 million) of nonperforming assets at 3/31/12 Classified & criticized assets include 55
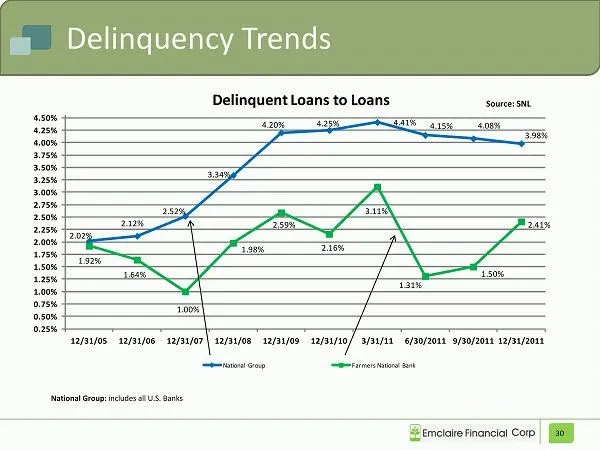
Slide 30: Delinquency Trends
2.02% 2.12% 2.52% 3.34% 4.20% 4.25% 4.41% 4.15% 4.08% 3.98% 1.92% 1.64% 1.00% 1.98% 2.59% 2.16% 3.11% 1.31% 1.50% 2.41% 0.25% 0.50% 0.75% 1.00% 1.25% 1.50% 1.75% 2.00% 2.25% 2.50% 2.75% 3.00% 3.25% 3.50% 3.75% 4.00% 4.25% 4.50% 12/31/05 12/31/06 12/31/07 12/31/08 12/31/09 12/31/10 3/31/11 6/30/2011
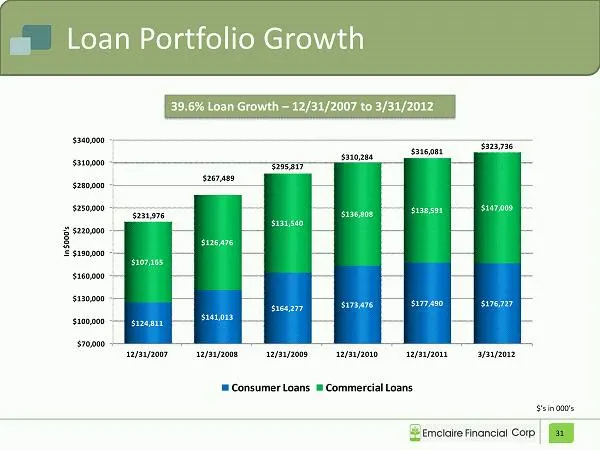
Slide 31: Loan Portfolio Growth
Loan Portfolio Growth 39.6% Loan Growth – 12/31/2007 to 3/31/2012 31 $70,000 $100,000 $130,000 $160,000 $190,000 $220,000 $250,000 $280,000 $310,000 $340,000 12/31/2007 12/31/2008 12/31/2009 12/31/2010 12/31/2011 3/31/2012 $124,811 $141,013 $164,277 $173,476 $177,490 $176,727 $107,165 $126,476 $131,
Slide 32: Capital, Dividends & Stock Performance
Capital, Dividends & Stock Performance 32 • Private Placement Offering • Regulatory Capital – Bank • Capital Management • Stock Performance
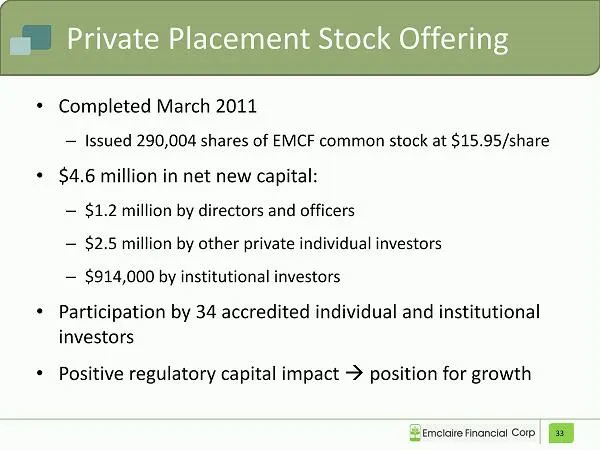
Slide 33: Private Placement Stock Offering
Private Placement Stock Offering • Completed March 2011 – Issued 290,004 shares of EMCF common stock at $15.95/share • $4.6 million in net new capital: – $1.2 million by directors and officers – $2.5 million by other private individual investors – $914,000 by institutional investors • Participation
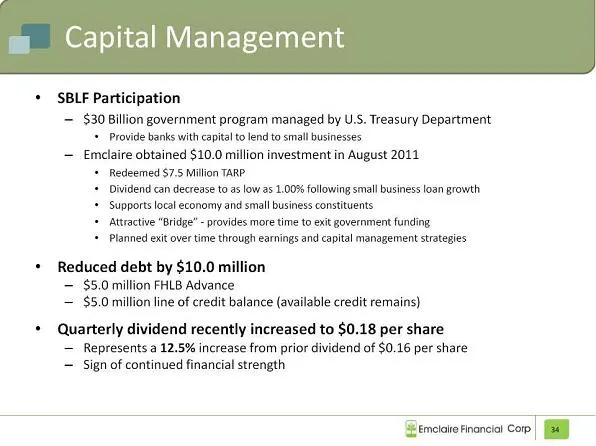
Slide 34: Capital Management: SBLF Participation
Capital Management SBLF Participation $30 Billion government program managed by U.S. Treasury Department Provide banks with capital to lend to small businesses Emclaire obtained $10.0 million investment in August 2011 Redeemed $7.5 Million TARP Dividend can decrease to as low as 1.00% following smal
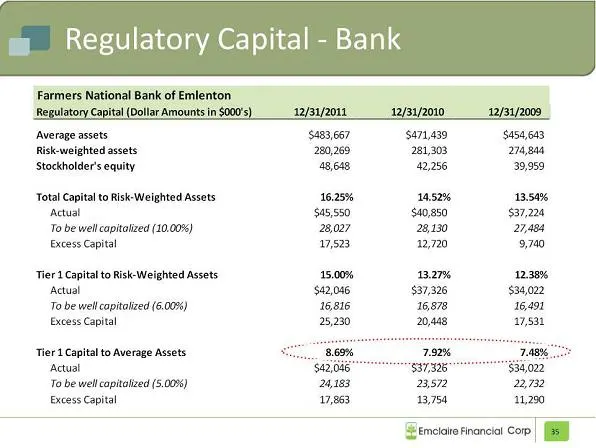
Slide 35: Regulatory Capital - Bank
Regulatory Capital - Bank Farmers National Bank of Emlenton Regulatory Capital (Dollar Amounts in $000's) 12/31/2011 12/31/2010 12/31/2009 Average assets $ 483,667$ 471,439$ 454,643 Risk-weighted assets280,269 281,303 274,844 Stockholder's equity48,648 42,256 39,959 Total Capital to Risk-Weighted As
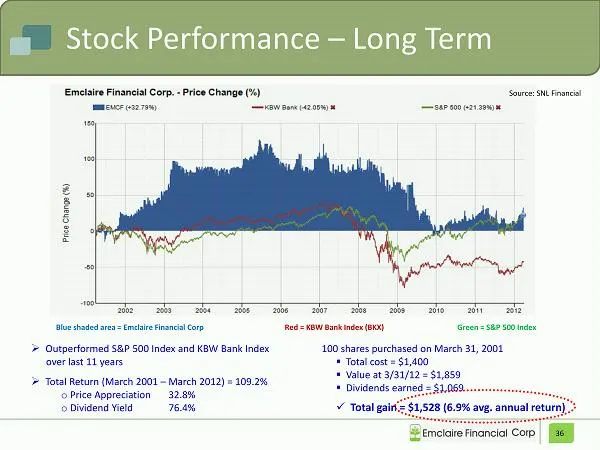
Slide 36: Stock Performance – Long Term
Blue shaded area = Emclaire Financial Corp Red = KBW Bank Index (BKX) Green = S&P 500 Index Source: SNL Financial Stock Performance – Long Term 36 » Outperformed S&P 500 Index and KBW Bank Index over last 11 years » Total Return (March 2001 – March 2012) = 109.2% o Price Appreciation 32.8% o Dividen
Slide 37: Stock Performance – Short Term
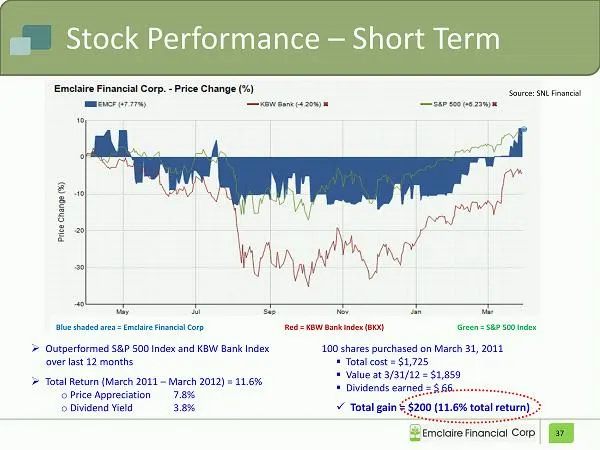
Blue shaded area = Emclaire Financial Corp Red = KBW Bank Index (BKX) Green = S&P 500 Index Source: SNL Financial Stock Performance – Short Term 37 » Outperformed S&P 500 Index and KBW Bank Index over last 12 months » Total Return (March 2011 – March 2012) = 11.6% o Price Appreciation 7.8% o Dividen
Slide 38: Strategic Update – Looking Ahead
Strategic Update – Looking Ahead 38 • Market Assessment • Planned New Banking Offices • Strategy Recap
Slide 39: Market Assessment
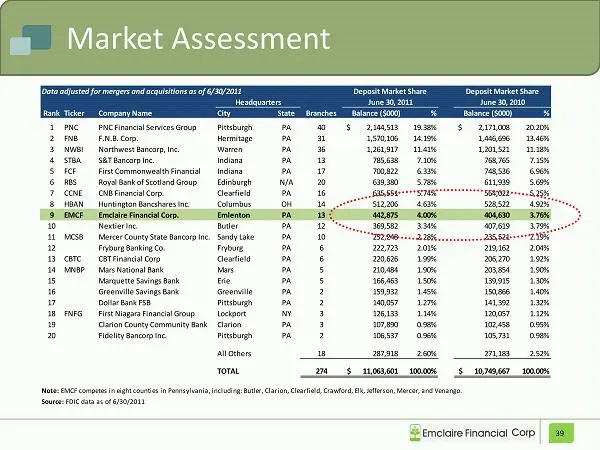
Market Assessment 39 Data adjusted for mergers and acquisitions as of 6/30/2011 RankTicker Company Name City State Branches Balance ($000) % Balance ($000) % 1 PNC PNC Financial Services Group Pittsburgh PA 40 2,144,513$ 19.38% 2,171,008$ 20.20% 2 FNB F.N.B. Corp. Hermitage PA 31 1,570,106 14.19% 1,
Slide 40: Market Assessment by County
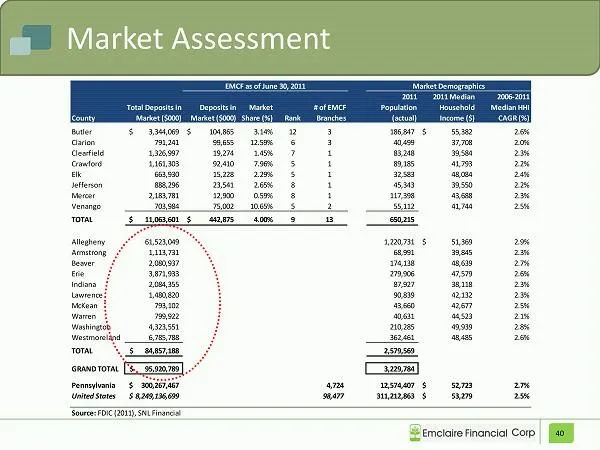
Market Assessment 40 County Butler 3,344,069$ 104,865$ 3.14% 12 3 186,847 55,382$ 2.6% Clarion 791,241 99,655 12.59% 6 3 40,499 37,708 2.0% Clearfield 1,326,997 19,274 1.45% 7 1 83,248 39,584 2.3% Crawford 1,161,303 92,410 7.96% 5 1 89,185 41,793 2.2% Elk 663,930 15,228 2.29% 5 1 32,583 48,084 2.4%
Slide 41: Future Office – Cranberry Twp., PA
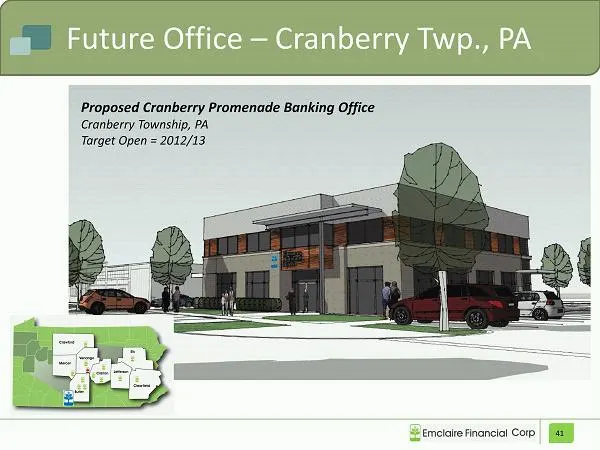
Future Office – Cranberry Twp., PA 41 Proposed Cranberry Promenade Banking Office Cranberry Township, PA Target Open = 2012/13
Slide 42: Future Office - Hermitage, PA
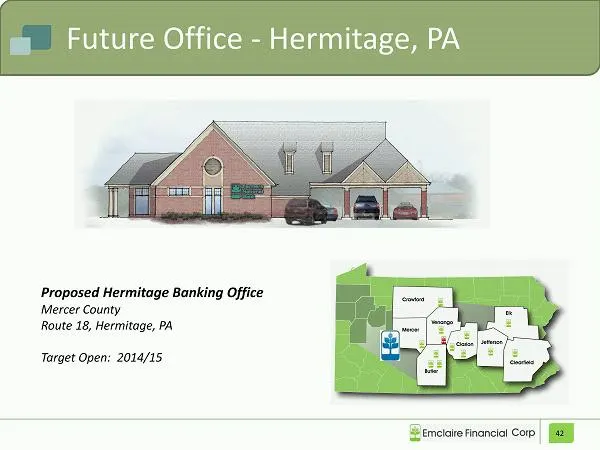
Future Office - Hermitage, PA Proposed Hermitage Banking Office Mercer County Route 18, Hermitage, PA Target Open: 2014/15 42
Slide 43: Strategy Recap
Strategy Recap • Earnings – Margin management and noninterest revenue focus – Disciplined expense control • Balance Sheet - Growth – De Novo opportunities – Acquisition opportunities – Organic growth – Expand commercial lending – (security/loan mix) – In market penetration – New markets • Risk Manag
Slide 44: Well Positioned
Well Positioned • Capital • Franchise • Systems & Technology • People …To execute our strategies and enhance shareholder value… …Our people working diligently, and doing the “right thing” has resulted in and will result in positive financial performance… 44
Slide 45: Open Discussion
Open Discussion 45 • Questions and Answers
Slide 46: Closing
Closing 46 • Thank you all for attending • Thank you to board, management group and staff • Special thank you
Slide 47: Special Thank You
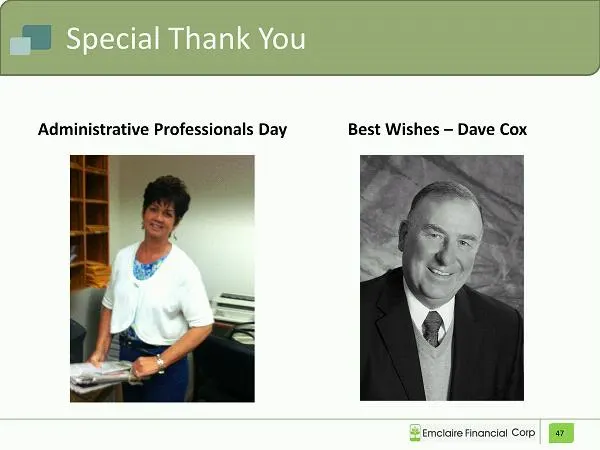
Special Thank You Administrative Professionals Day Best Wishes – Dave Cox 47
Slide 48: 2012 Annual Meeting of Shareholders
2012 Annual Meeting of Shareholders Parent Holding Company of The Farmers National Bank of Emlenton April 25, 2012 – 9:00 AM Emlenton, Pennsylvania William C. Marsh Chairman, President & CEO
Source: SEC EDGAR · 8-K filed Apr 25, 2012
More decks from Emclaire Financial Corp
 Merger or Acquisition (March 2022)13 slides · Mar 24, 2022
 Shareholder Meeting (April 2021)36 slides · Apr 21, 2021
 Shareholder Meeting (April 2020)32 slides · Apr 22, 2020
 Raymond James Emerging Bank Symposium (September 2019)23 slides · Sep 4, 2019
 Shareholder Meeting (April 2019)32 slides · Apr 24, 2019
 Shareholder Meeting (April 2018)28 slides · Apr 25, 2018