North Valley Bancorp — Keefe Bruyette and Woods Banking Conference 2014
43 slides from North Valley Bancorp's conference presentation, Jul 29, 2014
Slide 1: Keefe Bruyette and Woods Banking Conference
Richard P. Smith, President & CEO Keefe Bruyette and Woods Banking Conference New York, NY July 29, 2014
Slide 2: Safe Harbor Statement
SAFE HARBOR STATEMENT Certain comments included in this presentation may involve forward- looking statements, for which TriCo claims the protection of the "safe harbor" provisions created by Federal securities laws. Such forward- looking statements are subject to risks and uncertainties which may ca
Slide 3: Agenda
AGENDA Company Overview Recent Activities & Focus Merger announcement Key Revenue Drivers Challenges & Opportunities Financials Questions 3
Slide 4: Overview
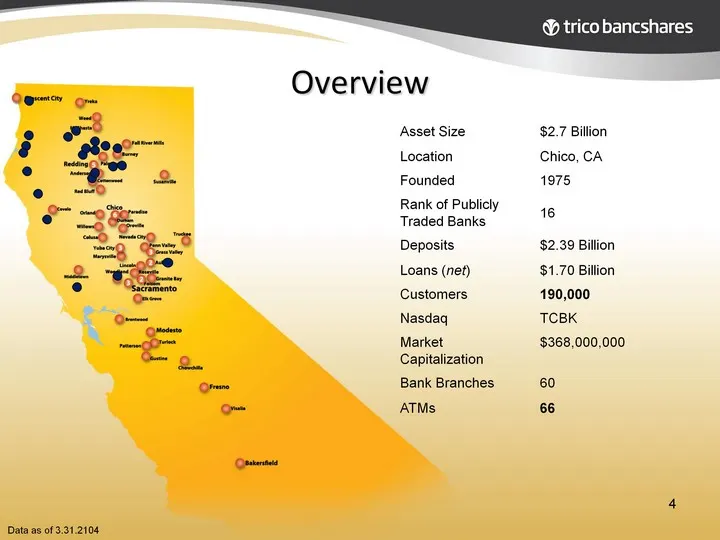
Overview Data as of 3.31.2104 Asset Size $2.7 Billion Location Chico, CA Founded 1975 Rank of Publicly Traded Banks 16 Deposits $2.39 Billion Loans (net) $1.70 Billion Customers 190,000 Nasdaq TCBK Market Capitalization $368,000,000 Bank Branches 60 ATMs 66 4
Slide 5: Executive Team
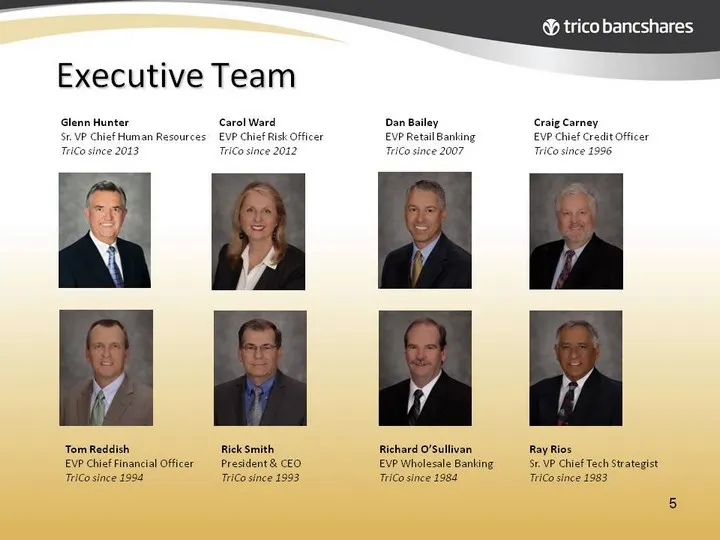
Executive Team Rick Smith President & CEO TriCo since 1993 Tom Reddish EVP Chief Financial Officer TriCo since 1994 Richard O'Sullivan EVP Wholesale Banking TriCo since 1984 Craig Carney EVP Chief Credit Officer TriCo since 1996 Glenn Hunter Sr. VP Chief Human Resources TriCo since 2013 Ray Rios Sr.
Slide 6: Recent Activities
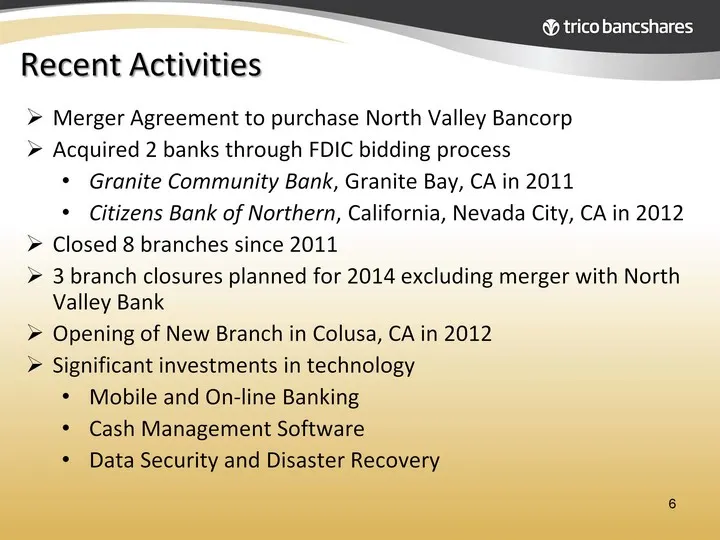
Recent Activities Merger Agreement to purchase North Valley Bancorp Acquired 2 banks through FDIC bidding process Granite Community Bank, Granite Bay, CA in 2011 Citizens Bank of Northern, California, Nevada City, CA in 2012 Closed 8 branches since 2011 3 branch closures planned for 2014 excluding m
Slide 7: Transaction Highlights
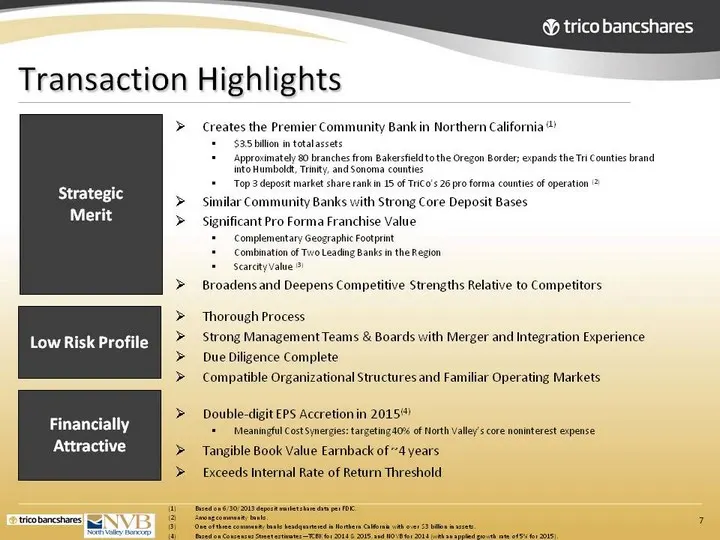
Transaction Highlights Creates the Premier Community Bank in Northern California (1) $3.5 billion in total assets Approximately 80 branches from Bakersfield to the Oregon Border; expands the Tri Counties brand into Humboldt, Trinity, and Sonoma counties Top 3 deposit market share rank in 15 of TriCo
Slide 8: Merger Summary
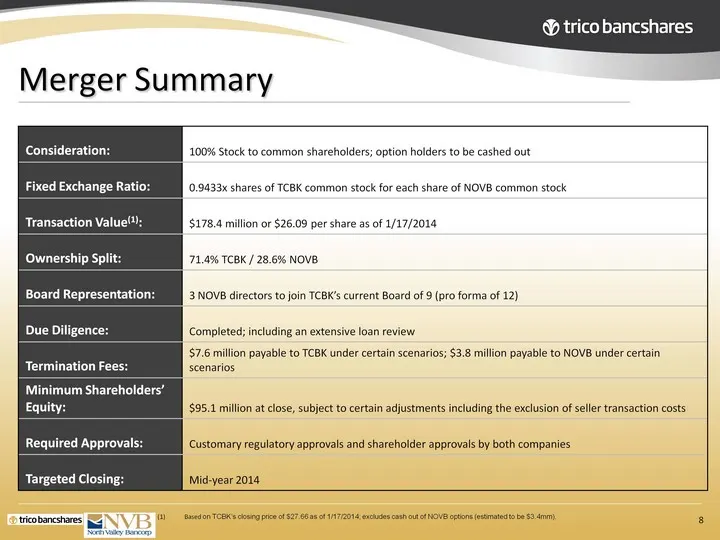
Merger Summary Based on TCBK's closing price of $27.66 as of 1/17/2014; excludes cash out of NOVB options (estimated to be $3.4mm). Consideration: 100% Stock to common shareholders; option holders to be cashed out Fixed Exchange Ratio: 0.9433x shares of TCBK common stock for each share of NOVB commo
Slide 9: Transaction Assumptions
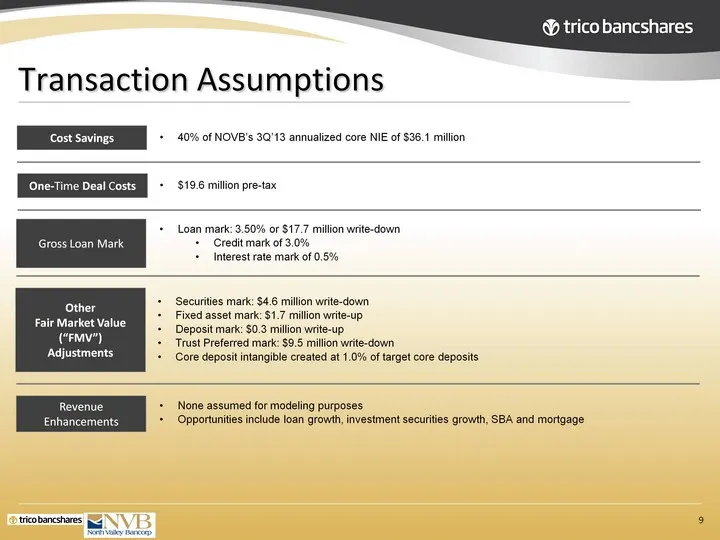
Transaction Assumptions 40% of NOVB's 3Q'13 annualized core NIE of $36.1 million $19.6 million pre-tax Cost Savings Other Fair Market Value ("FMV") Adjustments One-Time Deal Costs Securities mark: $4.6 million write-down Fixed asset mark: $1.7 million write-up Deposit mark: $0.3 million write-up Tru
Slide 10: Positioned for today, prepared for the future
Positioned for today, prepared for the future. Strong and growing bank capital Competitive product set to compete with banks both large and small Superior reputation versus large bank competitors Continue to see organic growth in current environment Strong focus on risk management and new regulatory
Slide 11: What is long term success?
What is long term success? A winning culture with a motivated and talented work force Significant and growing market share Low cost core deposit base Diversified revenues sources Efficient operations Strong risk management practices Rewarding our shareholders 11
Slide 12: Key Drivers of Bank Revenues
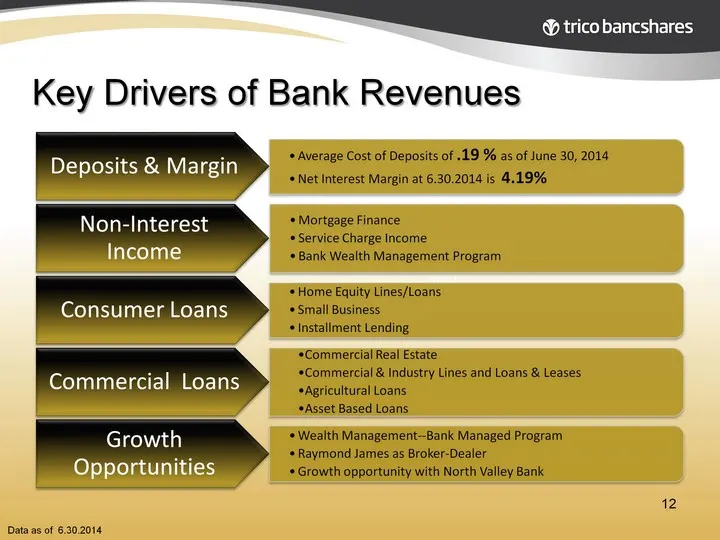
Data as of 6.30.2014 39% Key Drivers of Bank Revenues 12
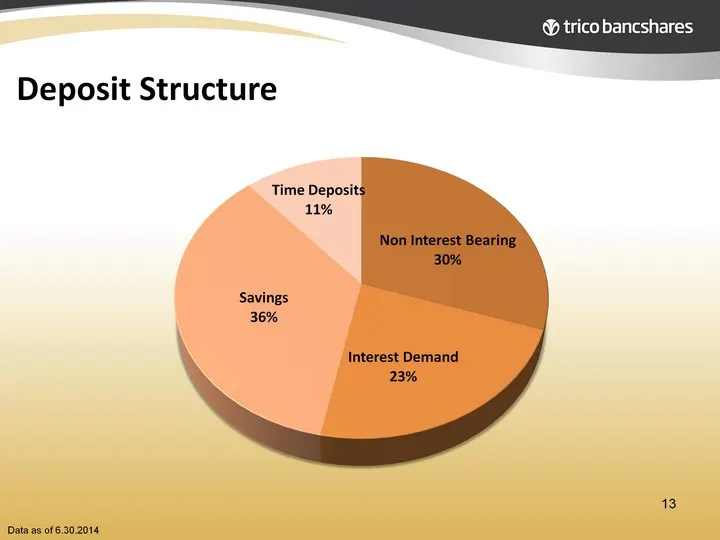
Slide 13: Data as of 6.30.2014 13 (CHART)
Data as of 6.30.2014 13 (CHART)
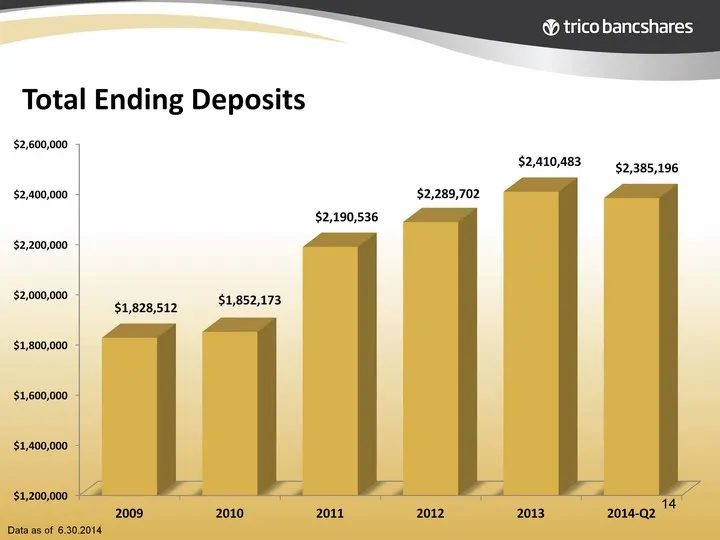
Slide 14: Data as of 6.30.2014 14 (CHART)
Data as of 6.30.2014 14 (CHART)
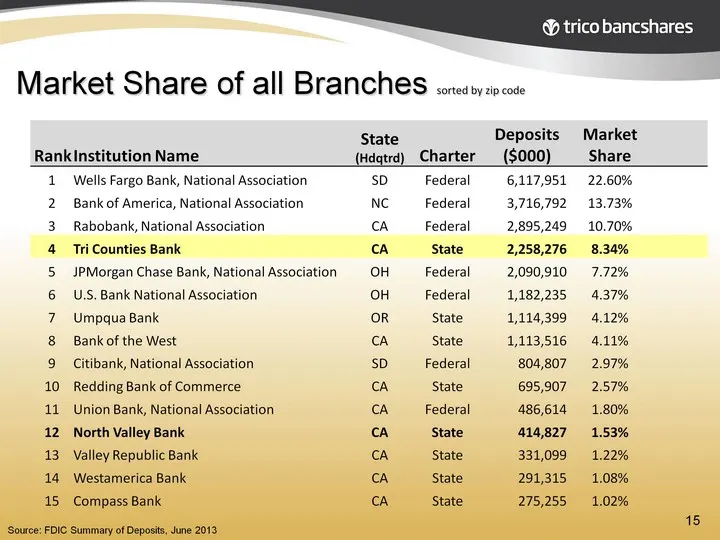
Slide 15: Market Share of all Branches sorted by zip code
Market Share of all Branches sorted by zip code Source: FDIC Summary of Deposits, June 2013 Rank Institution Name State (Hdqtrd) Charter Deposits ($000) Market Share 1 Wells Fargo Bank, National Association SD Federal 6,117,951 22.60% 2 Bank of America, National Association NC Federal 3,716,792 13.7
Slide 16: Non-Interest Income
Consistently Represents Approximately 25+% of Total Bank Revenues Residential Home Mortgage Lending Refinances have slowed to low levels Increasing numbers of purchase transactions but overall slow activity Wealth Management Revenues New opportunities with North Valley Bank Lower revenues from servi
Slide 17: Consumer Loans
Reduced demand for consumer loans Home equity values have increased Economic uncertainty Reluctance to borrow Underperforming job market Auto loans are most in demand Home equity lines/loans increasing in demand Consumer Loans 17
Slide 18: Data as of 6.30.2014 18 (CHART)
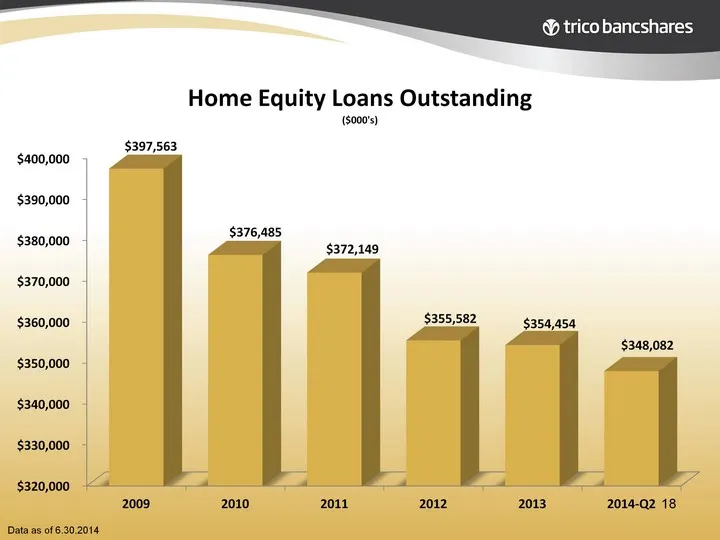
Data as of 6.30.2014 18 (CHART)
Slide 19: Loan Portfolio by Type
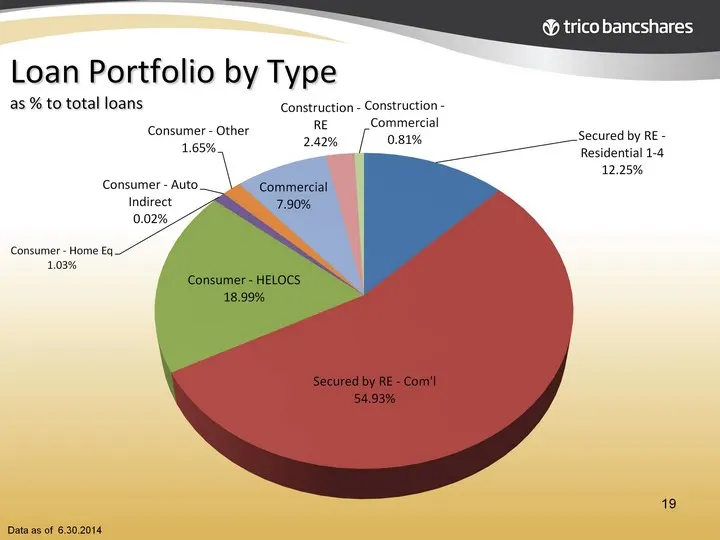
Loan Portfolio by Type as % to total loans Data as of 6.30.2014 19 (CHART)
Slide 20: Commercial Loans
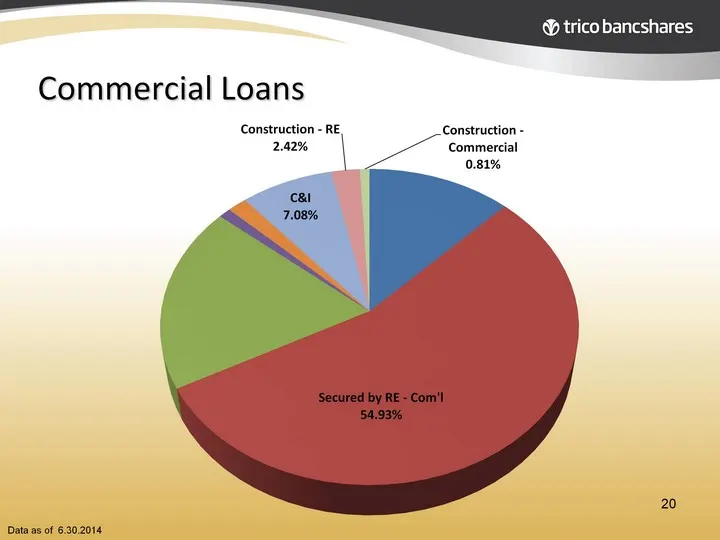
20 Commercial Loans Data as of 6.30.2014 (CHART)
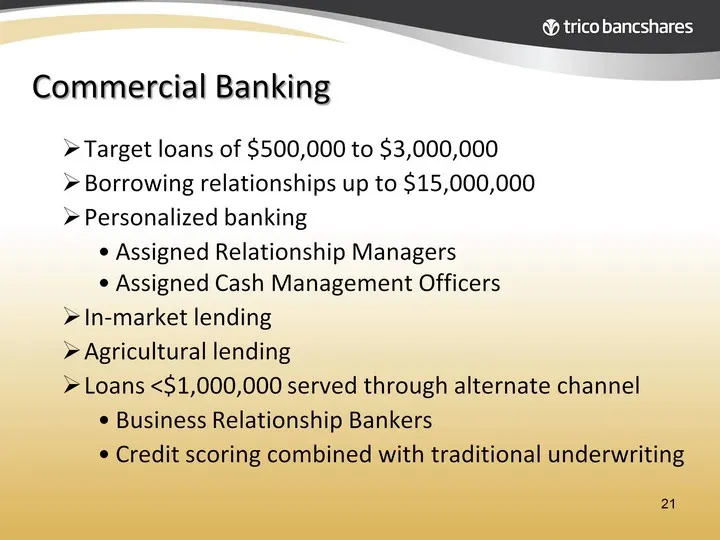
Slide 21: Commercial Banking
Commercial Banking Target loans of $500,000 to $3,000,000 Borrowing relationships up to $15,000,000 Personalized banking Assigned Relationship Managers Assigned Cash Management Officers In-market lending Agricultural lending Loans <$1,000,000 served through alternate channel Business Relationship Ba
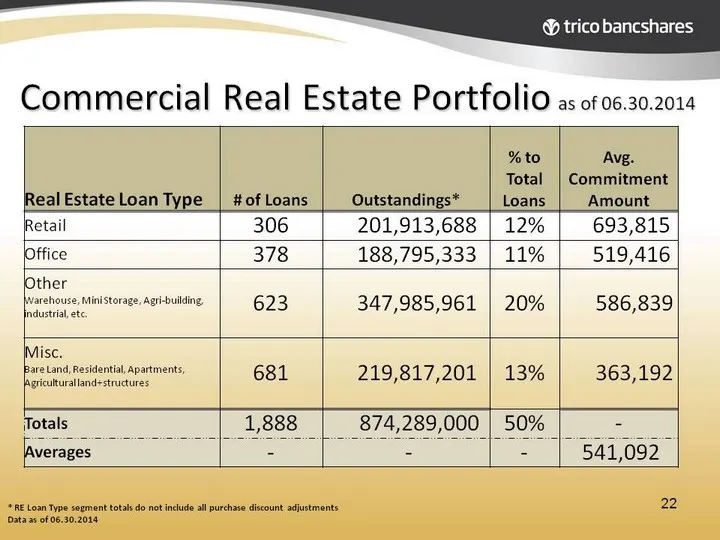
Slide 22: Commercial Real Estate Portfolio
Commercial Real Estate Portfolio as of 06.30.2014 * RE Loan Type segment totals do not include all purchase discount adjustments Data as of 06.30.2014 Real Estate Loan Type # of Loans Outstandings* % to Total Loans Avg. Commitment Amount Retail 306 201,913,688 12% 693,815 Office 378 188,795,333 11%
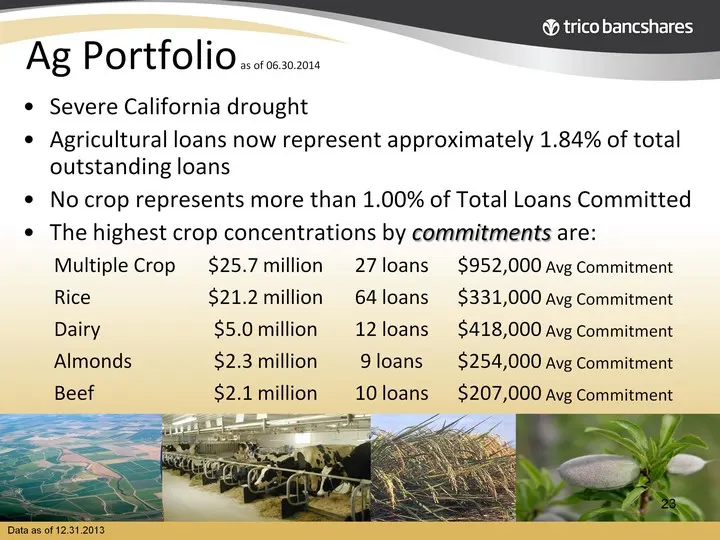
Slide 23: Ag Portfolio
Ag Portfolio as of 06.30.2014 Severe California drought Agricultural loans now represent approximately 1.84% of total outstanding loans No crop represents more than 1.00% of Total Loans Committed The highest crop concentrations by commitments are: Data as of 12.31.2013 Multiple Crop $25.7 million 27
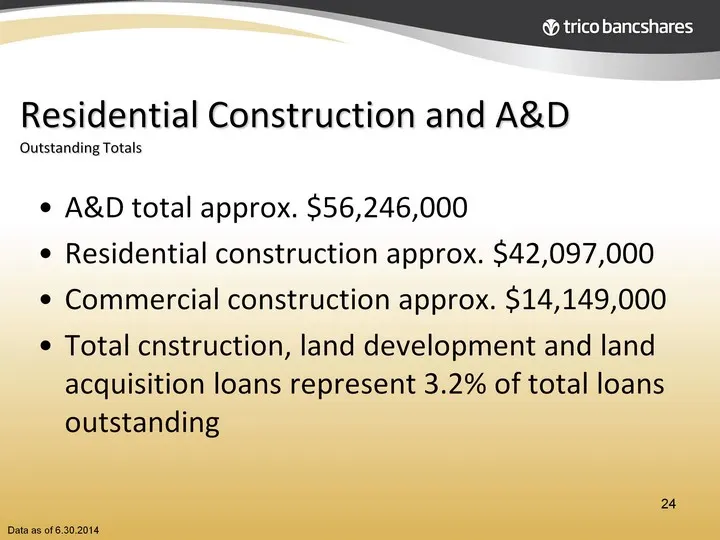
Slide 24: Residential Construction and A&D
Residential Construction and A&D Outstanding Totals A&D total approx. $56,246,000 Residential construction approx. $42,097,000 Commercial construction approx. $14,149,000 Total cnstruction, land development and land acquisition loans represent 3.2% of total loans outstanding Data as of 6.30.2014 24
Slide 25: (CHART)
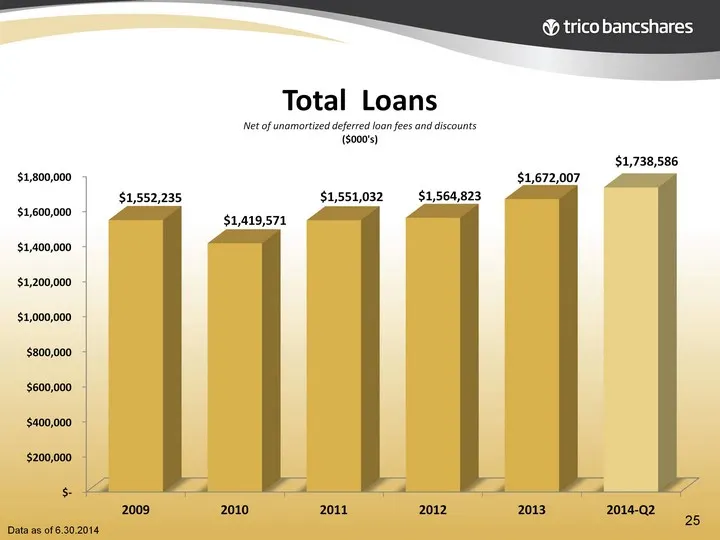
Data as of 6.30.2014 (CHART) 25
Slide 26: Mergers and Acquisitions
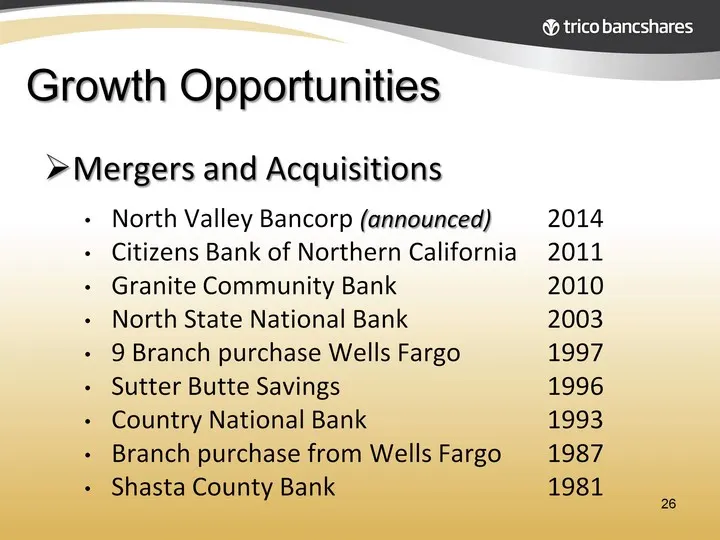
Mergers and Acquisitions North Valley Bancorp (announced) 2014 Citizens Bank of Northern California 2011 Granite Community Bank 2010 North State National Bank 2003 9 Branch purchase Wells Fargo 1997 Sutter Butte Savings 1996 Country National Bank 1993 Branch purchase from Wells Fargo 1987 Shasta Cou
Slide 27: What keeps us up at night?
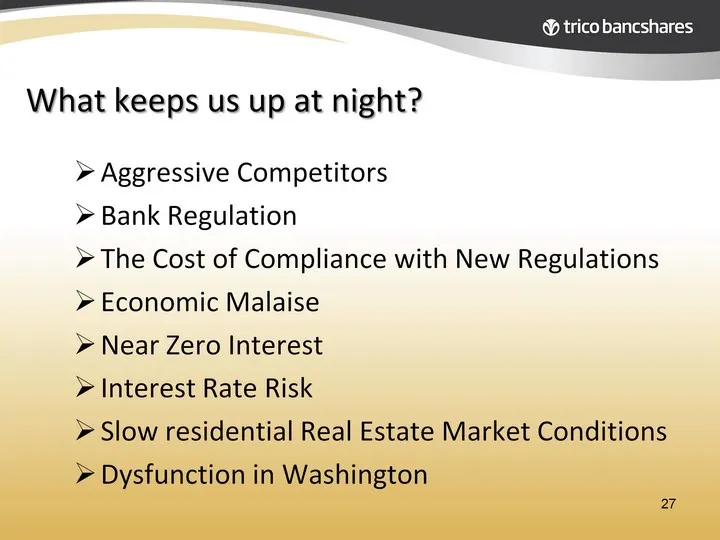
What keeps us up at night? Aggressive Competitors Bank Regulation The Cost of Compliance with New Regulations Economic Malaise Near Zero Interest Interest Rate Risk Slow residential Real Estate Market Conditions Dysfunction in Washington 27
Slide 28: Challenges Within Bank Strategies
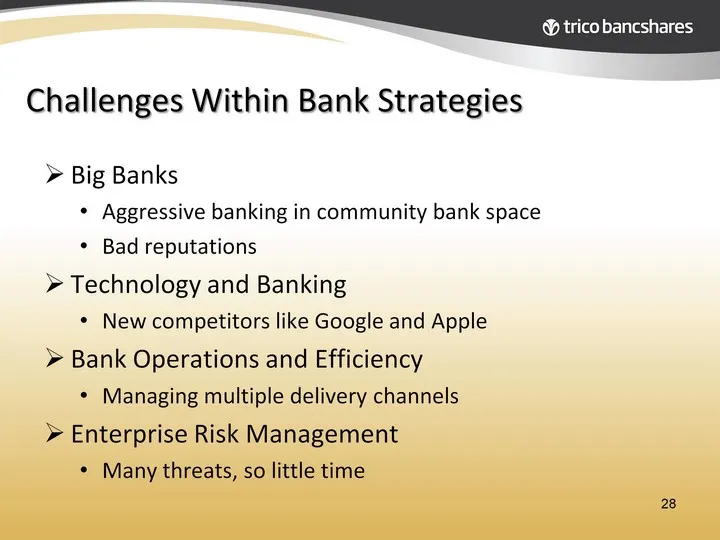
Challenges Within Bank Strategies Big Banks Aggressive banking in community bank space Bad reputations Technology and Banking New competitors like Google and Apple Bank Operations and Efficiency Managing multiple delivery channels Enterprise Risk Management Many threats, so little time 28
Slide 29: Financials
® trico bancshares Financials
Slide 30: 3.31.2014 (CHART)
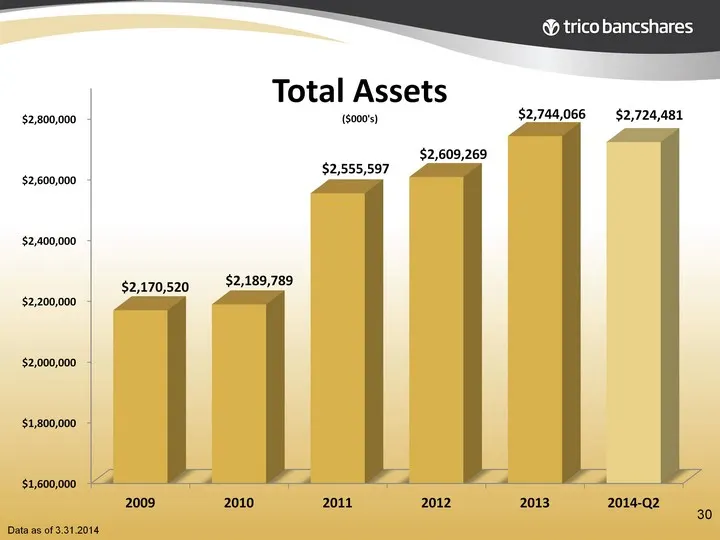
Data as of 3.31.2014 (CHART) 30
Slide 31: Data as of 6.30.2014 31 (CHART)
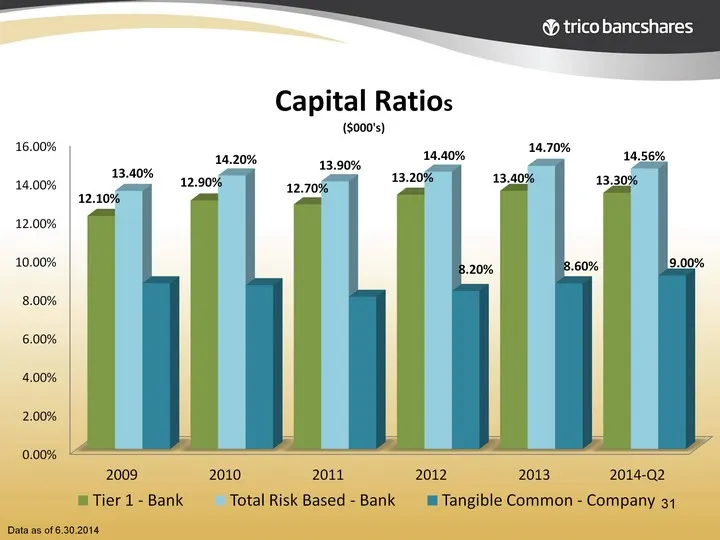
Data as of 6.30.2014 31 (CHART)
Slide 32: (CHART)
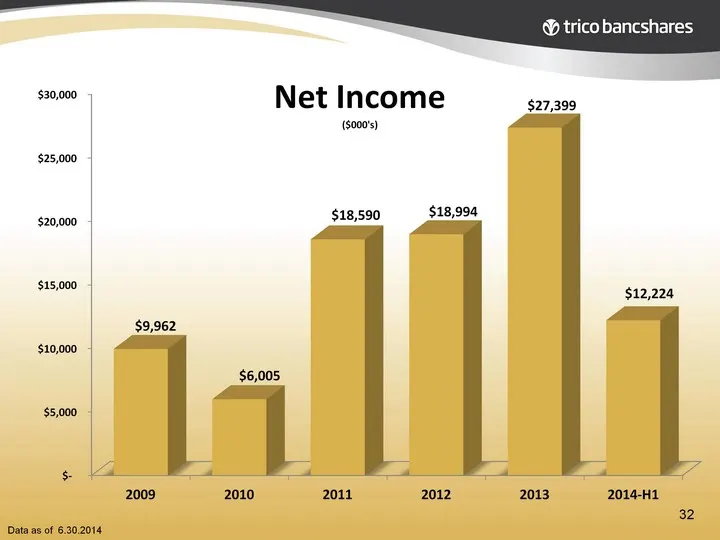
Data as of 6.30.2014 (CHART) 32
Slide 33: Data as of 6.30.2014 33 (CHART)
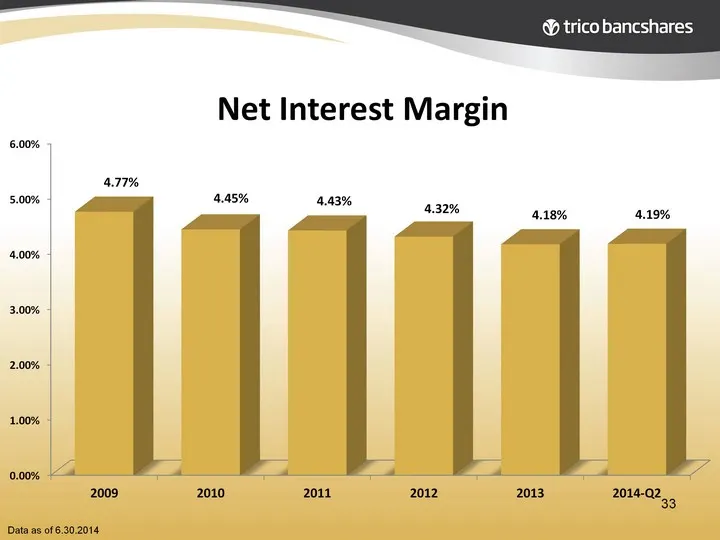
Data as of 6.30.2014 33 (CHART)
Slide 34: Data as of 6.30.2014 34 (CHART)
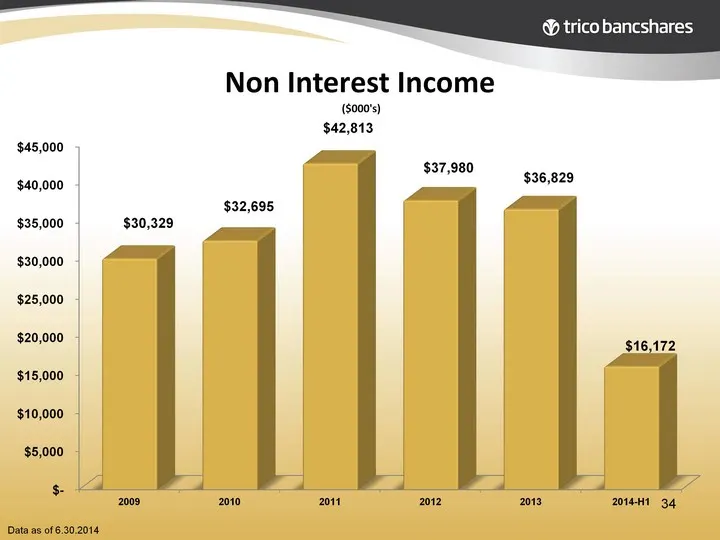
Data as of 6.30.2014 34 (CHART)
Slide 35: Data as of 6.30.2014 35 (CHART)
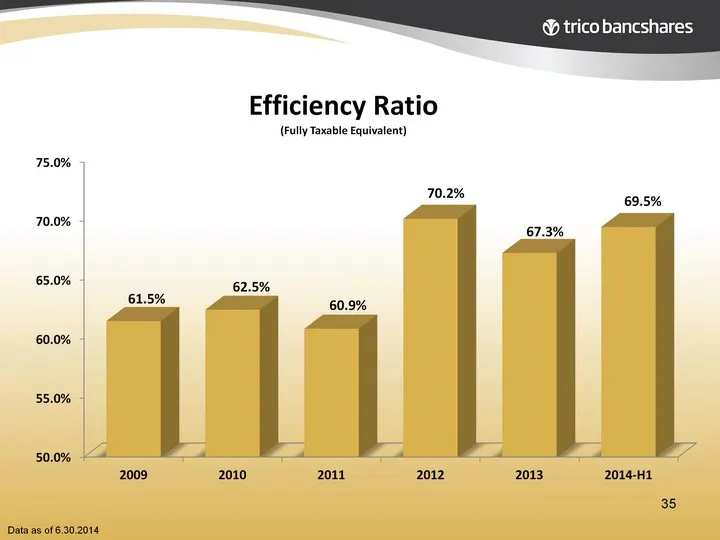
Data as of 6.30.2014 35 (CHART)
Slide 36: Data as of 6.30.2014 36 (CHART)
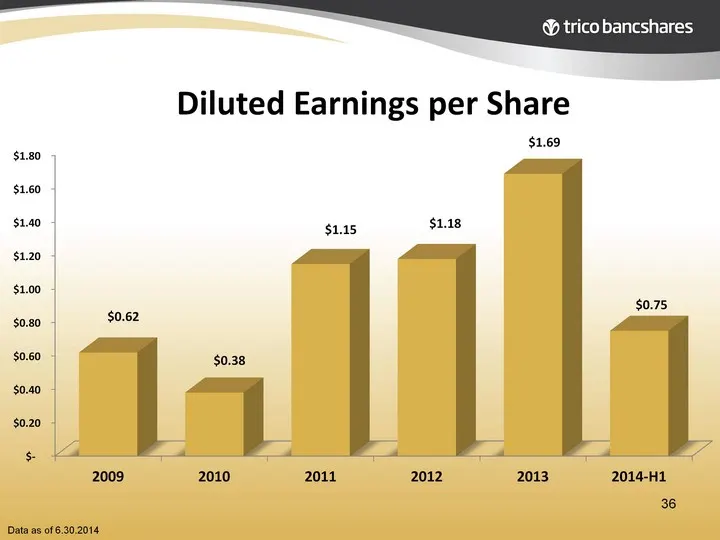
Data as of 6.30.2014 36 (CHART)
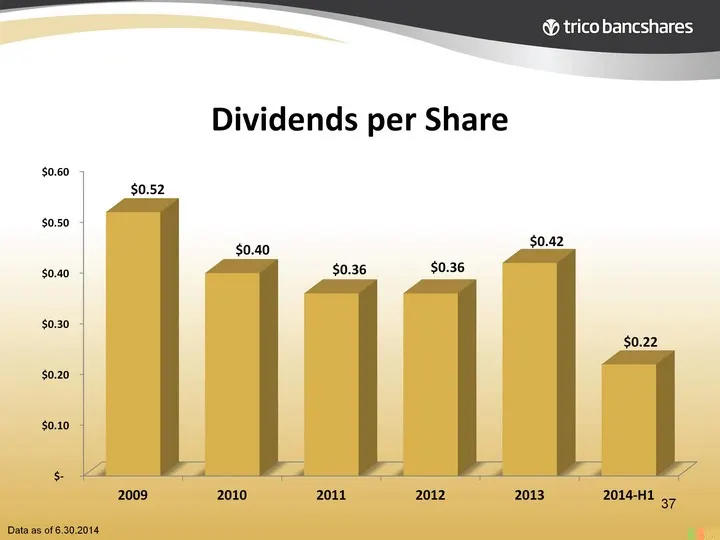
Slide 37: Data as of 6.30.2014 37 (CHART)
Data as of 6.30.2014 37 (CHART)
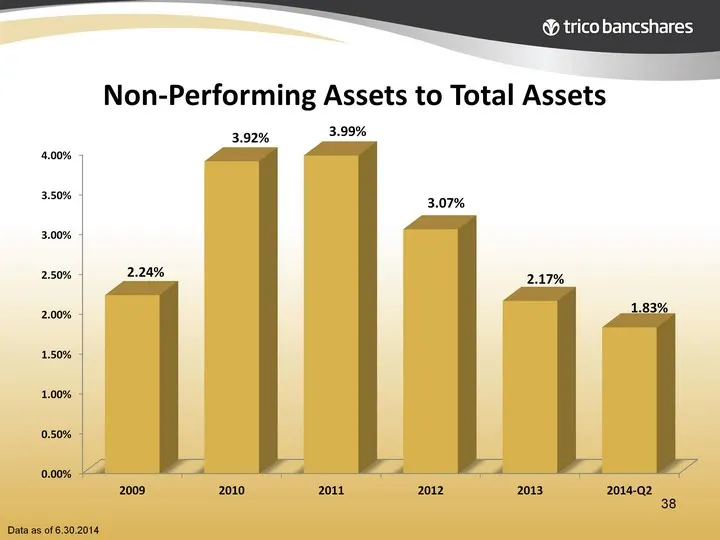
Slide 38: Data as of 6.30.2014 38 (CHART)
Data as of 6.30.2014 38 (CHART)
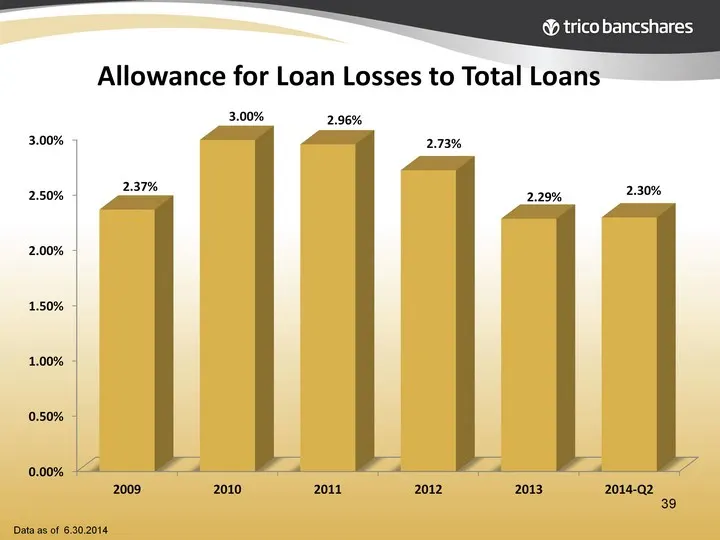
Slide 39: Data as of 6.30.2014 39 (CHART)
Data as of 6.30.2014 39 (CHART)
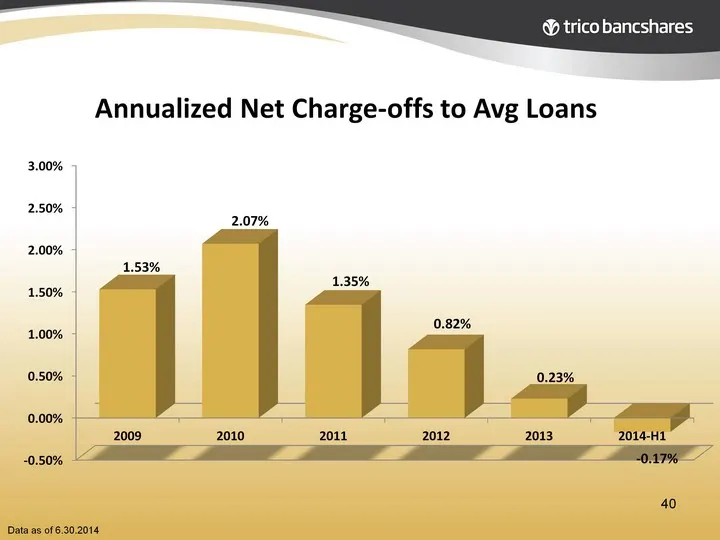
Slide 40: Data as of 6.30.2014 40 (CHART)
Data as of 6.30.2014 40 (CHART)
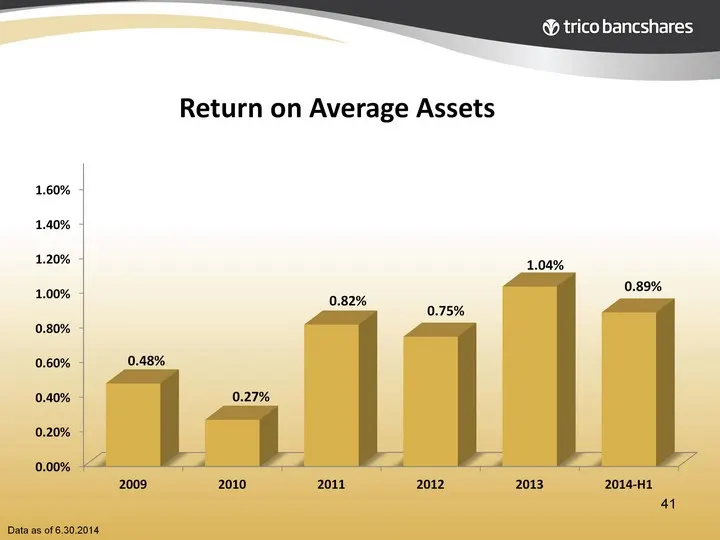
Slide 41: Data as of 6.30.2014 41 (CHART)
Data as of 6.30.2014 41 (CHART)
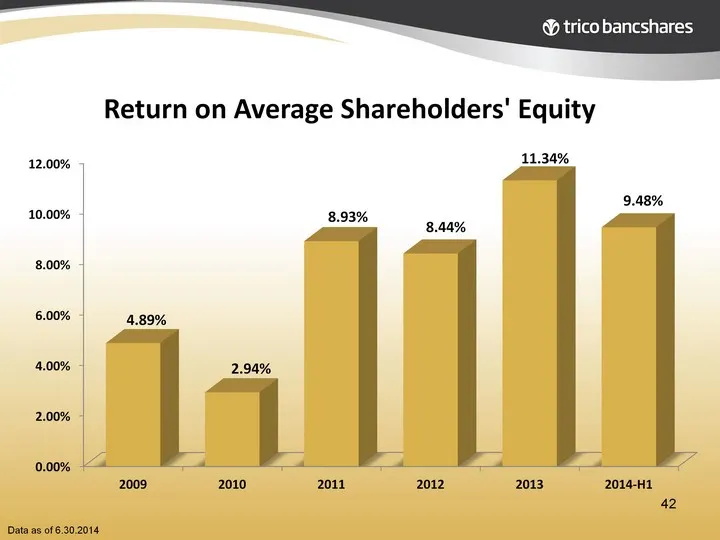
Slide 42: Data as of 6.30.2014 42 (CHART)
Data as of 6.30.2014 42 (CHART)
Slide 43: TriCo Bancshares is committed to
TriCo Bancshares is committed to: Improving the financial success and well-being of our shareholders, customers, communities and employees.
Source: SEC EDGAR · 425 filed Jul 29, 2014
More decks from North Valley Bancorp
 Merger or Acquisition (January 2014)14 slides · Jan 22, 2014
 West Coast Financial Services Conference (March 2012)13 slides · Mar 2, 2012
 Sandler O'Neill & Partners West Coast Financial Services Conference 201114 slides · Mar 7, 2011
 D. A. Davidson & Co. Annual Financial Services Investor Conference 200925 slides · May 5, 2009
 Sandler O'Neill & Partners West Coast Financial Services Conference 200917 slides · Feb 27, 2009
 D.A. Davidson & Co. Annual Financial Services Investor Conference 200827 slides · May 5, 2008