Santander Holdings USA Inc · NYSE:SNUS/PH
Santander Holdings USA — Debt Investor Presentation (May 2022)
30 slides from Santander Holdings USA's debt investor presentation, May 6, 2022
Slide 1: Santander Holdings USA, Inc. First Quarter 2022 Fixed Income Investor Presentation
May 6, 2022 SANTANDER HOLDINGS USA, INC. First Quarter 2022 Fixed Income Investor Presentation 1
Slide 2: Important Information
Important Information This presentation of Santander Holdings USA, Inc. (“SHUSA”) contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the financial condition, results of operations, business plans and future performance of SHUSA.
Slide 3: Index
Index 1 2 3 4 At a Glance Summary Results Appendix 3
Slide 4: Santander Group
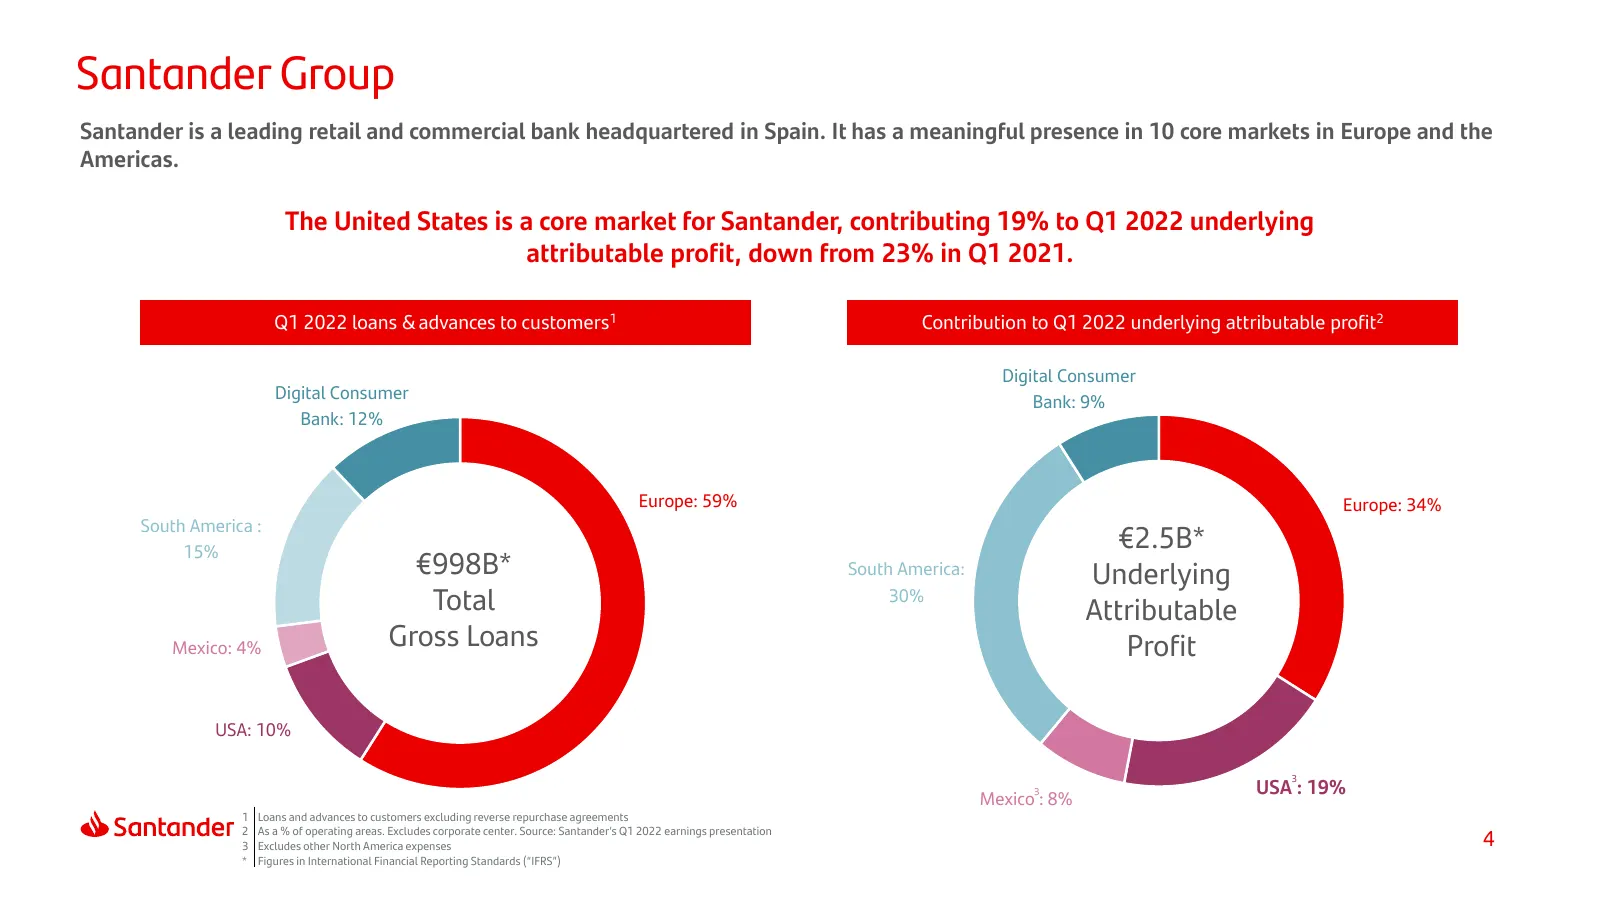
Santander Group Santander is a leading retail and commercial bank headquartered in Spain. It has a meaningful presence in 10 core markets in Europe and the Americas. The United States is a core market for Santander, contributing 19% to Q1 2022 underlying attributable profit, down from 23% in Q1 2021
Slide 5: Q1 2022 Highlights
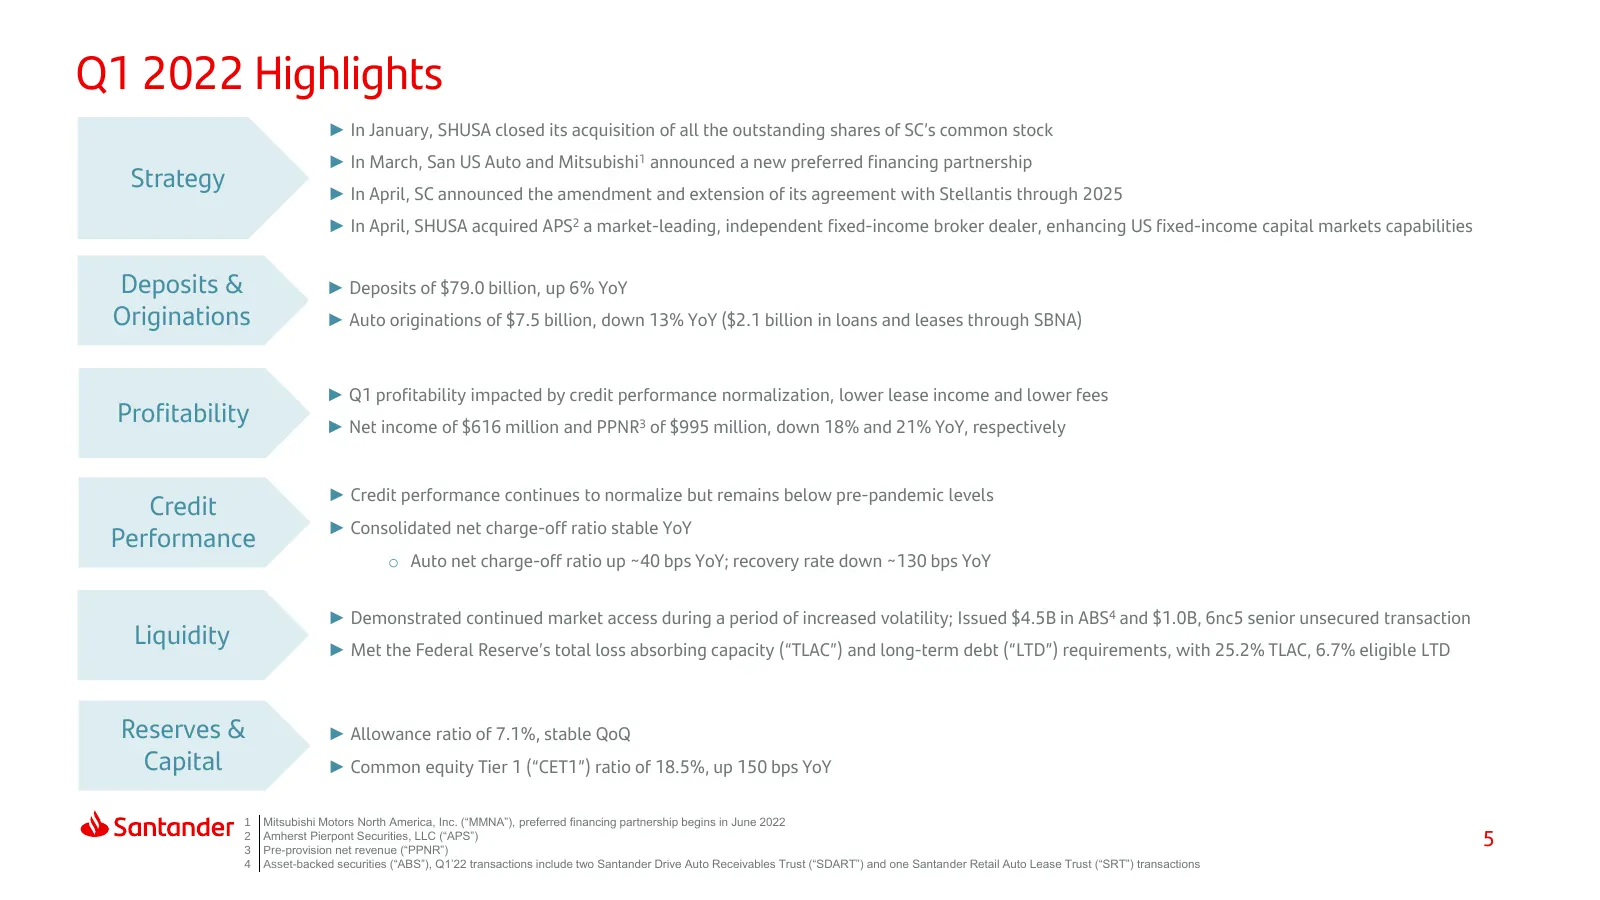
Q1 2022 Highlights ► In January, SHUSA closed its acquisition of all the outstanding shares of SC’s common stock ► In March, San US Auto and Mitsubishi1 announced a new preferred financing partnership Strategy ► In April, SC announced the amendment and extension of its agreement with Stellantis thro
Slide 6: Index
Index 1 2 3 4 At a Glance Summary Results Appendix 6
Slide 7: Santander Holdings USA, Inc. ("SHUSA")
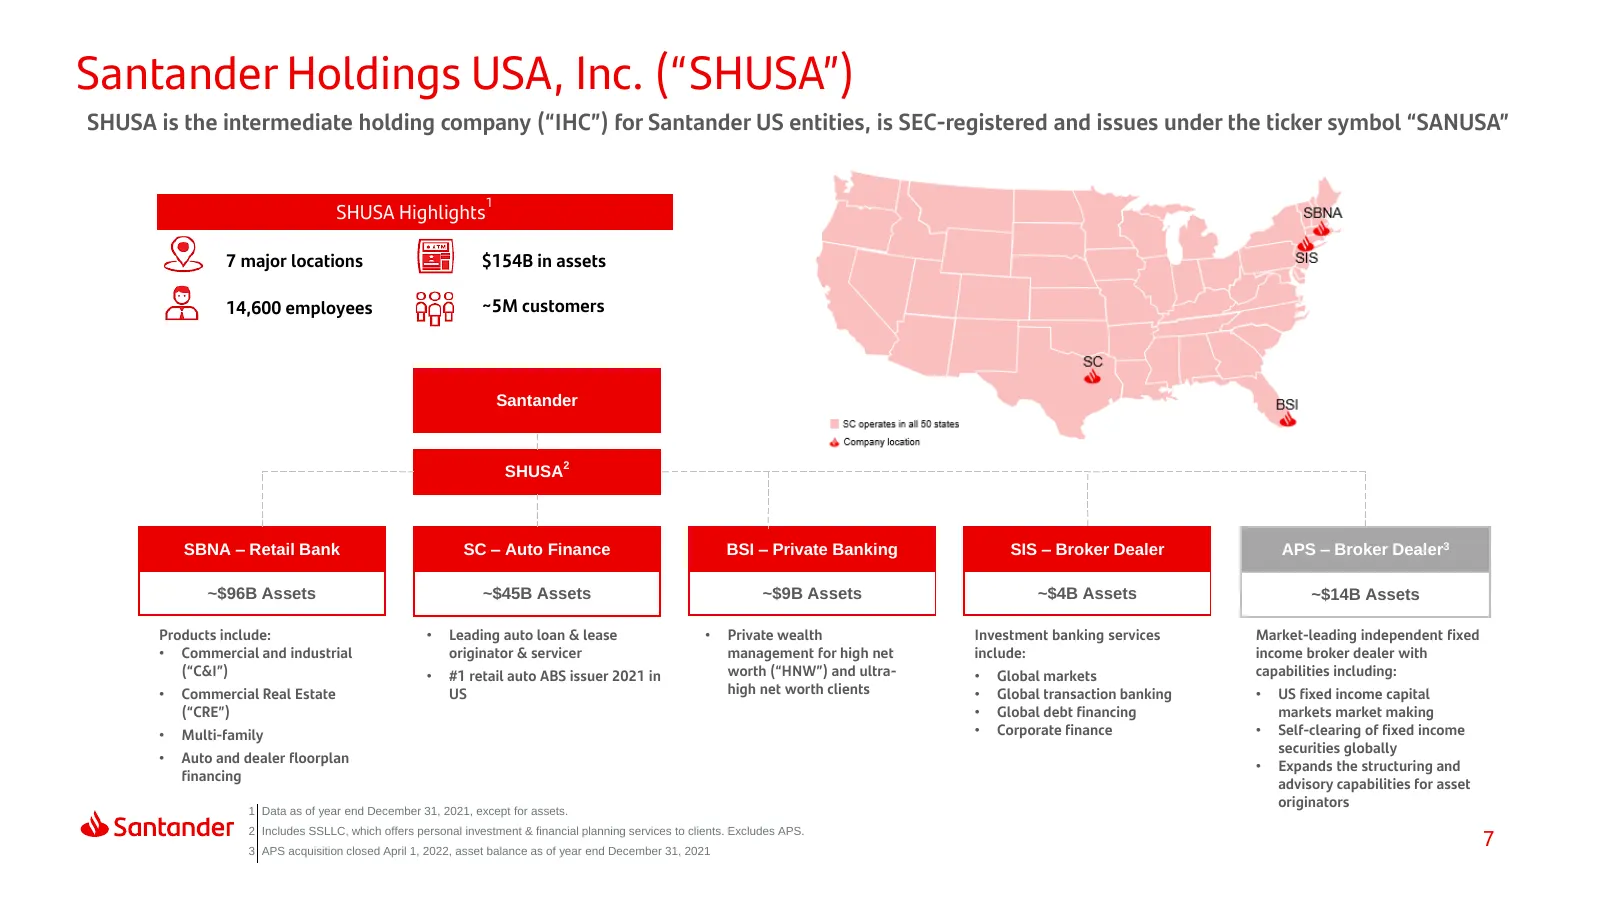
Santander Holdings USA, Inc. (“SHUSA”) SHUSA is the intermediate holding company (“IHC”) for Santander US entities, is SEC-registered and issues under the ticker symbol “SANUSA” 1 SHUSA Highlights 7 major locations $154B in assets 14,600 employees ~5M customers Santander SHUSA2 SBNA – Retail Bank SC
Slide 8: SHUSA Overview
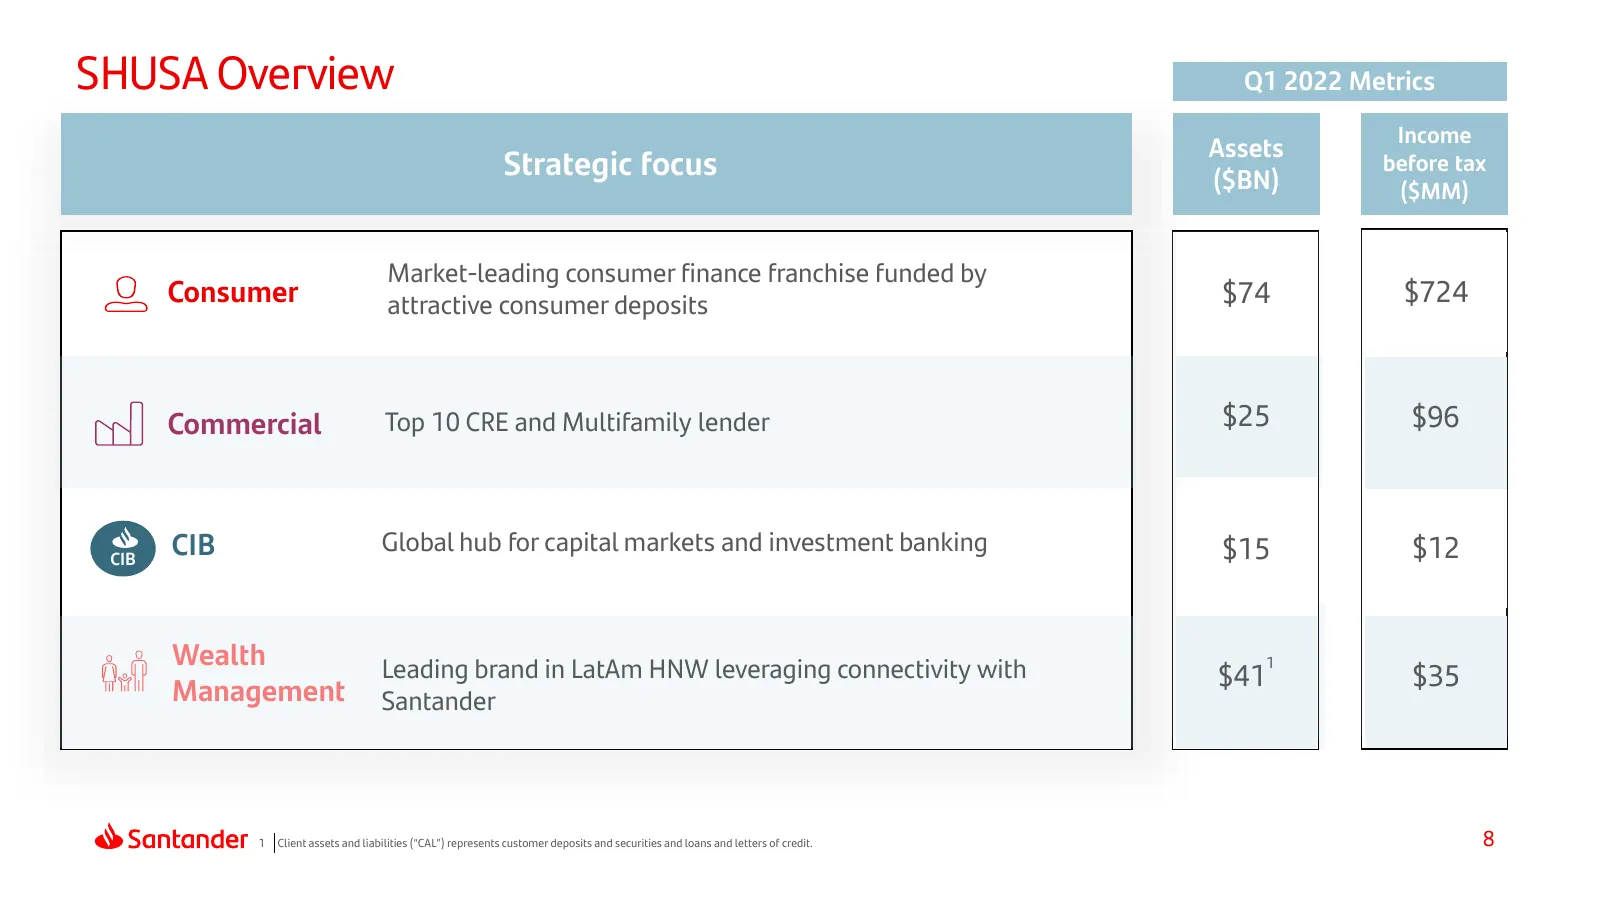
SHUSA Overview Q1 2022 Metrics Income Assets Strategic focus ($BN) before tax ($MM) Strategic focus Market-leading consumer finance franchise funded by Consumer attractive consumer deposits $74 $724 Commercial Top 10 CRE and Multifamily lender $25 $96 CIB CIB Global hub for capital markets and inves
Slide 9: Balance Sheet Overview
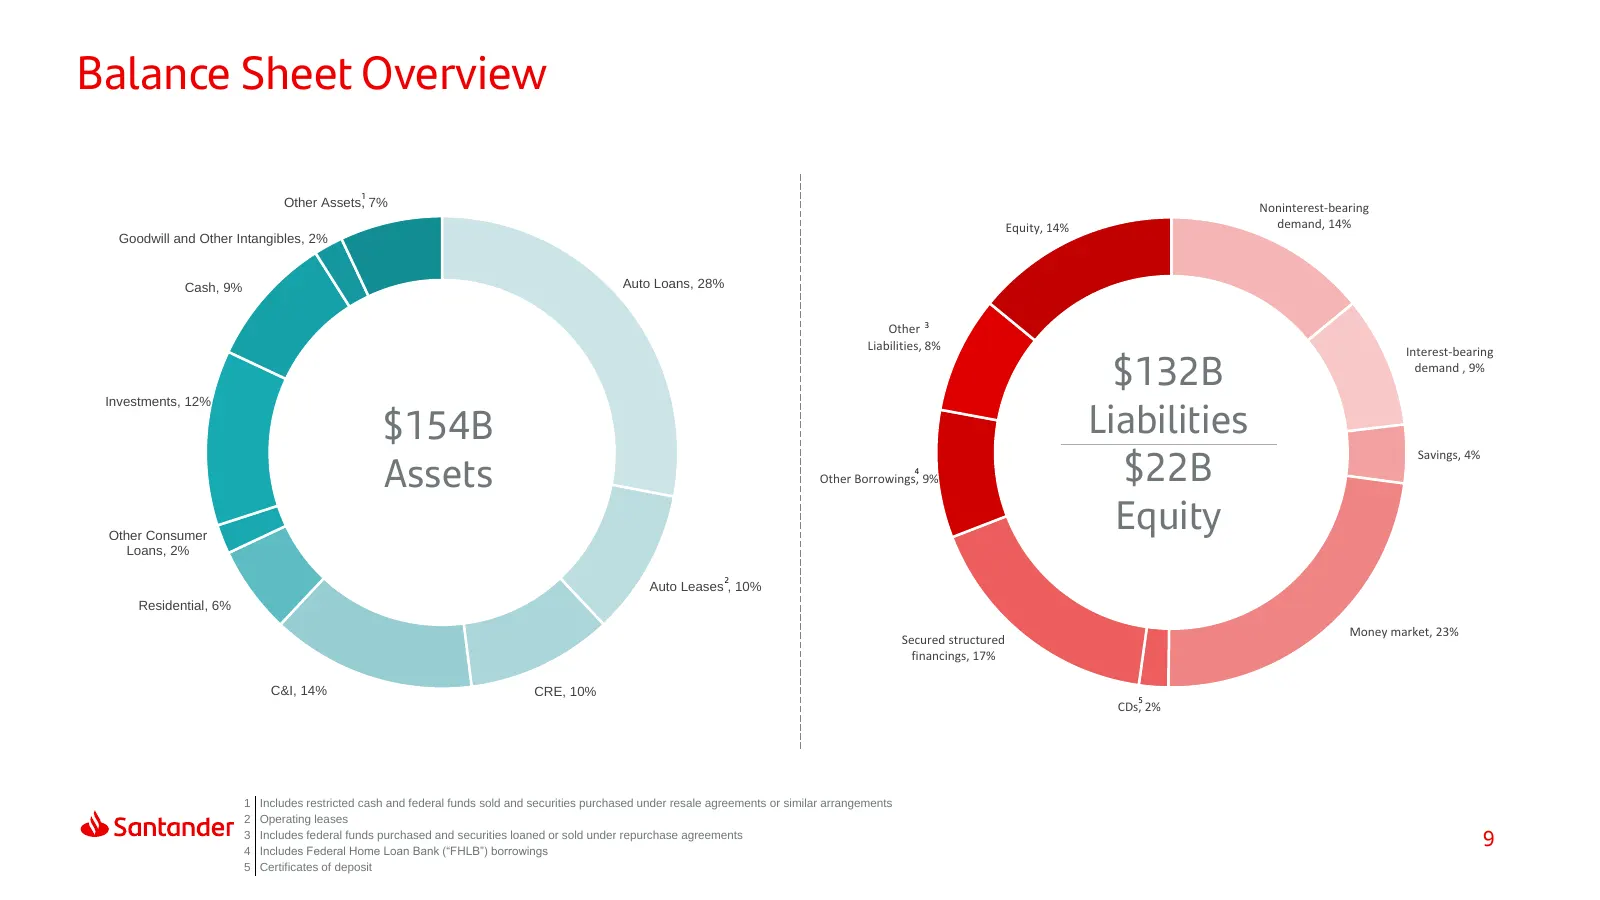
Balance Sheet Overview 1 Other Assets, 7% Noninterest-bearing Equity, 14% demand, 14% Goodwill and Other Intangibles, 2% Cash, 9% Auto Loans, 28% Other 3 $132B Liabilities, 8% Interest-bearing demand , 9% $154B Liabilities Investments, 12% Assets $22B Savings, 4% 4 Other Borrowings, 9% Other Consume
Slide 10: Balance Sheet Trends
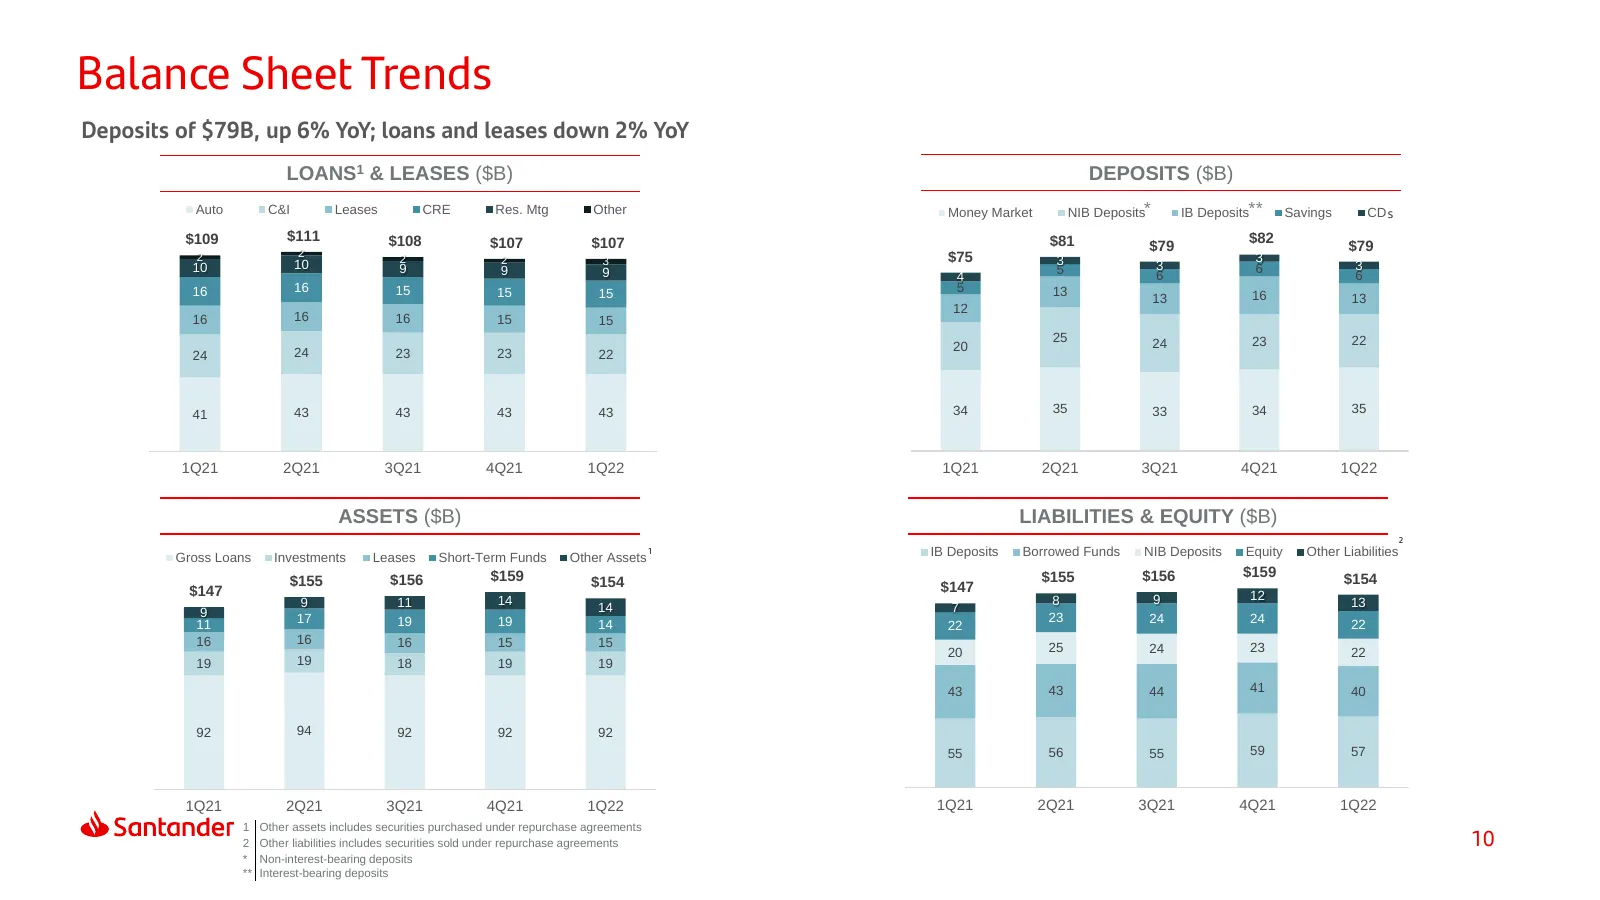
Balance Sheet Trends Deposits of $79B, up 6% YoY; loans and leases down 2% YoY LOANS1 & LEASES ($B) DEPOSITS ($B) Auto C&I Leases CRE Res. Mtg Other Money Market NIB Deposits* IB Deposits** Savings CD s $109 $111 $108 $107 $107 $81 $82 2 $79 $79 2 10 2 2 3 $75 3 3 10 9 9 5 3 6 3 9 4 6 6 16 16 15 15
Slide 11: Quarterly Profitability
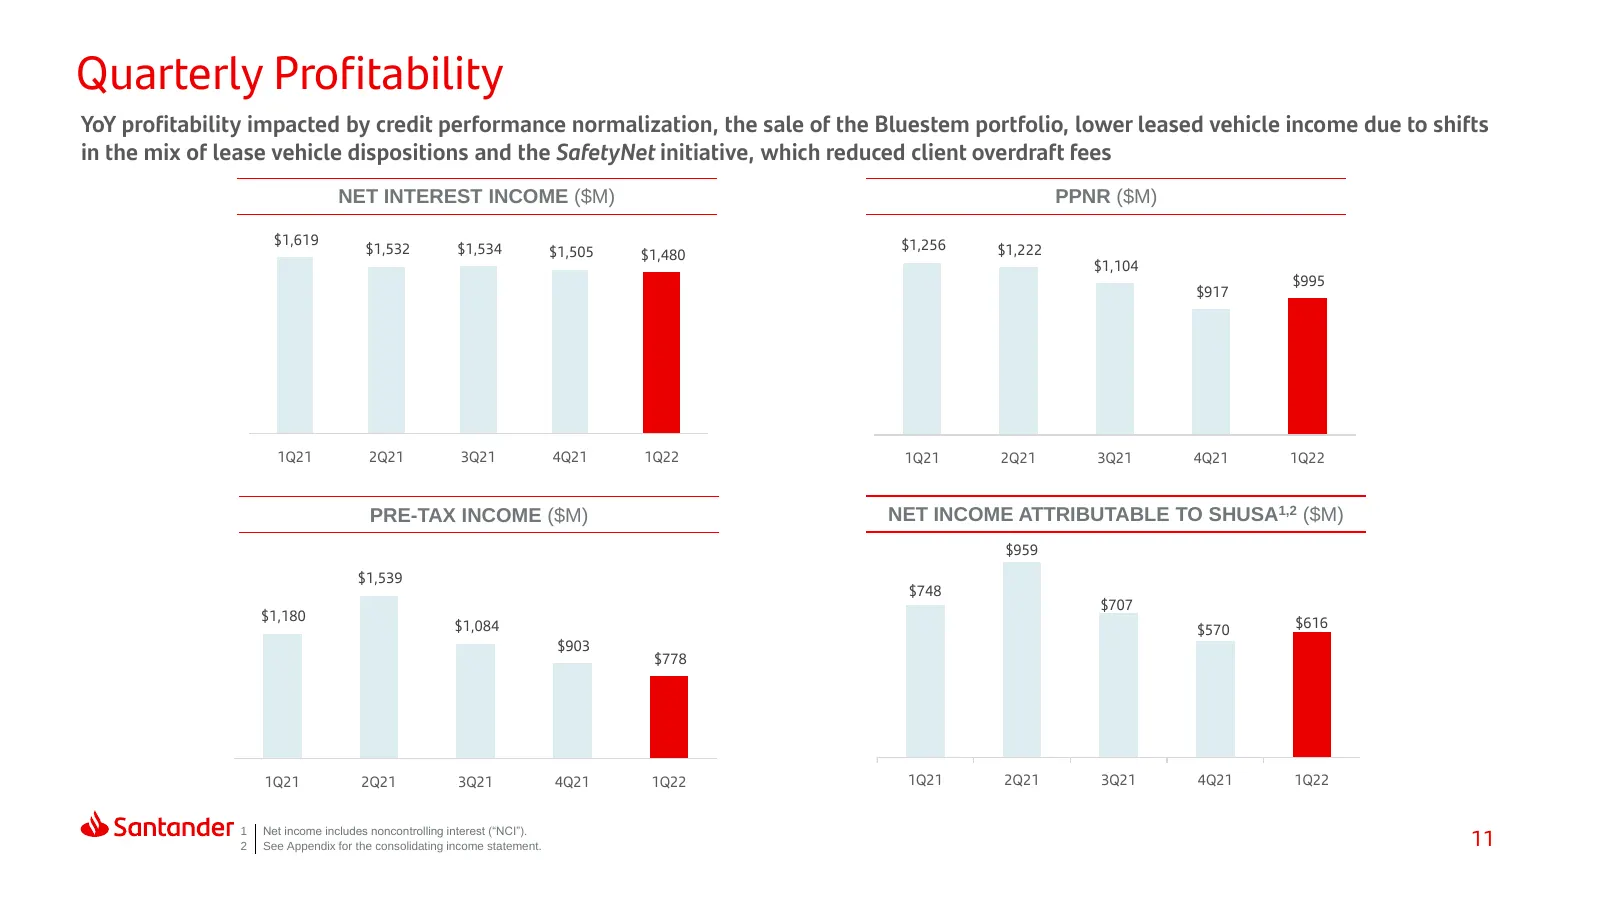
Quarterly Profitability YoY profitability impacted by credit performance normalization, the sale of the Bluestem portfolio, lower leased vehicle income due to shifts in the mix of lease vehicle dispositions and the SafetyNet initiative, which reduced client overdraft fees NET INTEREST INCOME ($M) PP
Slide 12: Net Interest Margin & Interest Rate Risk Sensitivity
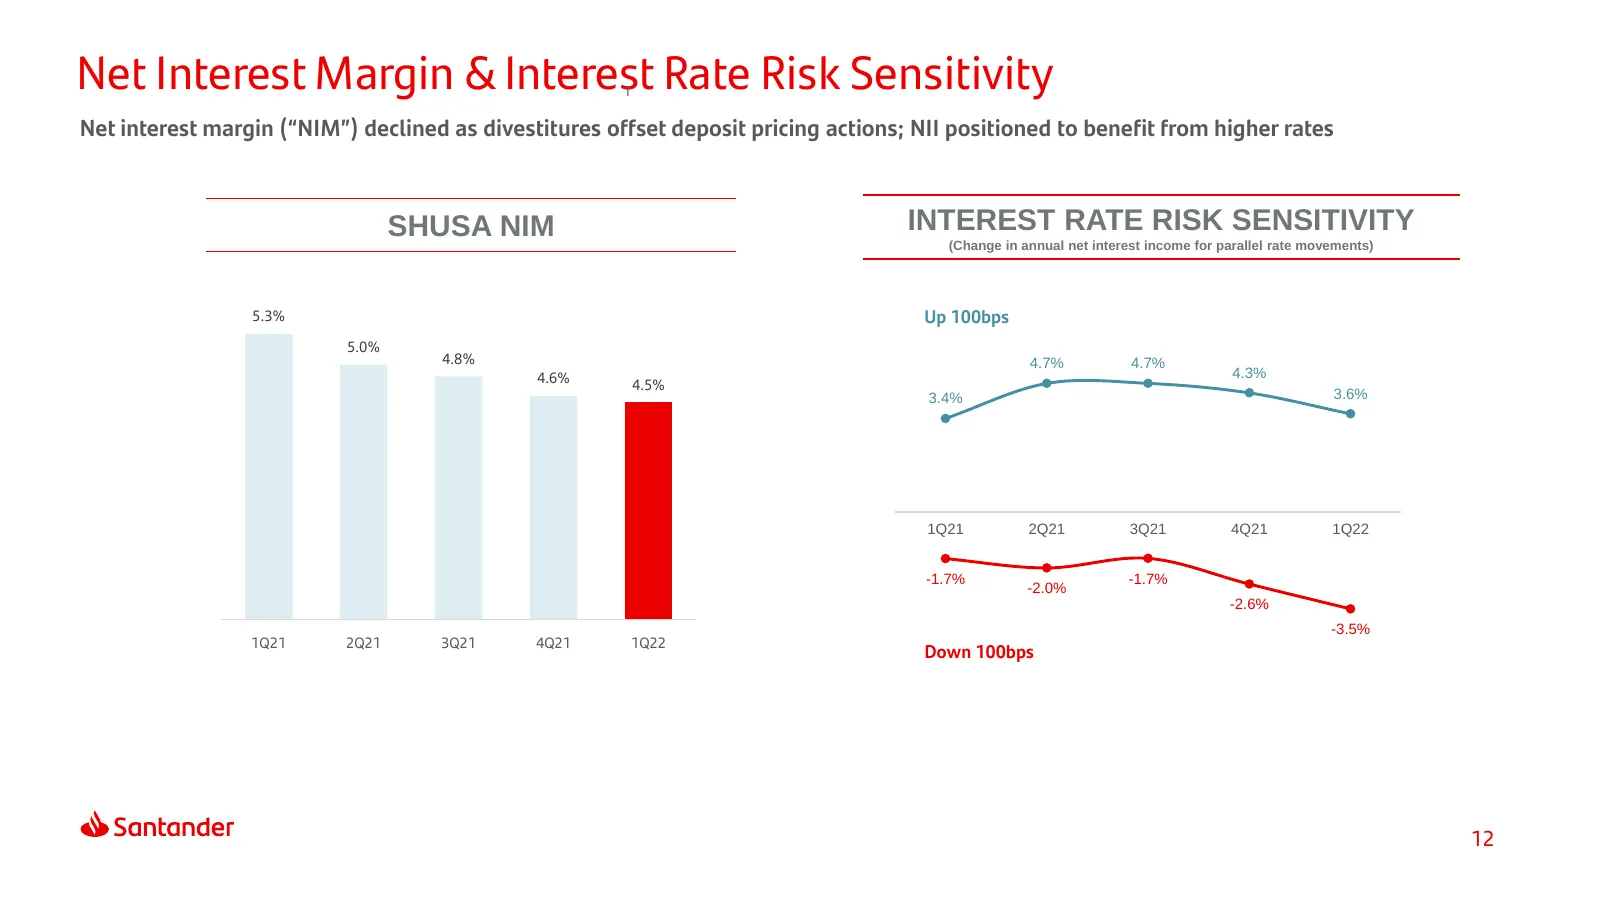
Net Interest Margin & Interest Rate Risk Sensitivity 1 Net interest margin (“NIM”) declined as divestitures offset deposit pricing actions; NII positioned to benefit from higher rates SHUSA NIM INTEREST RATE RISK SENSITIVITY (Change in annual net interest income for parallel rate movements) 5.3% Up
Slide 13: ESG Strategy Implementation
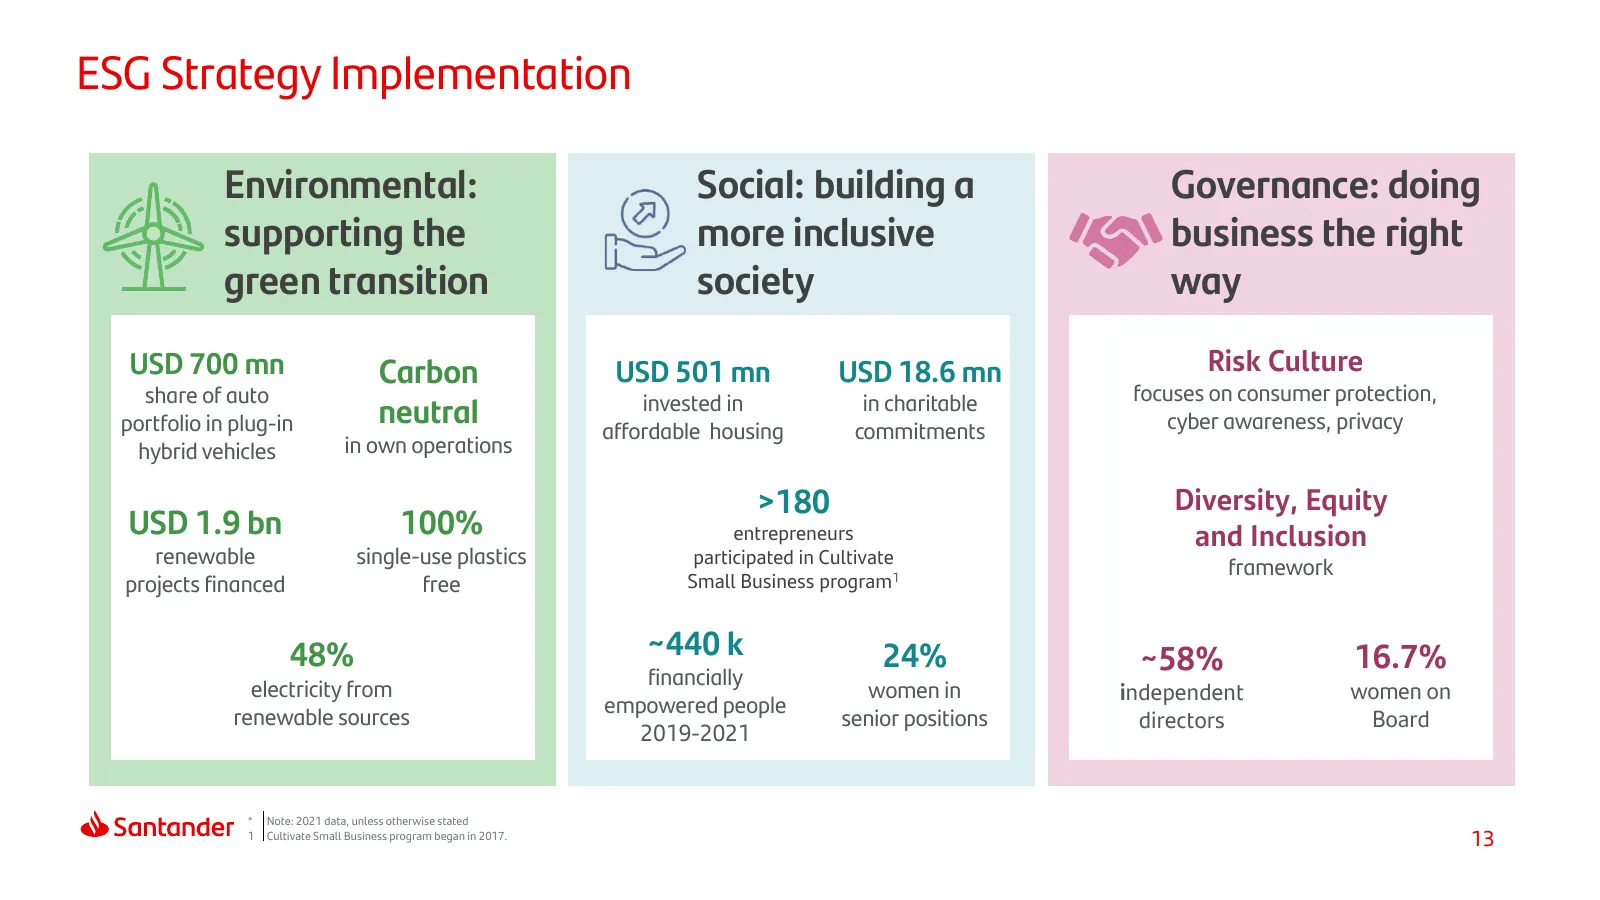
ESG Strategy Implementation Environmental: Social: building a Governance: doing supporting the more inclusive business the right green transition society way USD 700 mn Carbon USD 501 mn USD 18.6 mn Risk Culture share of auto invested in in charitable focuses on consumer protection, portfolio in plu
Slide 14: Index
Index 1 2 3 4 At a Glance Summary Results Appendix 14
Slide 15: Auto Originations
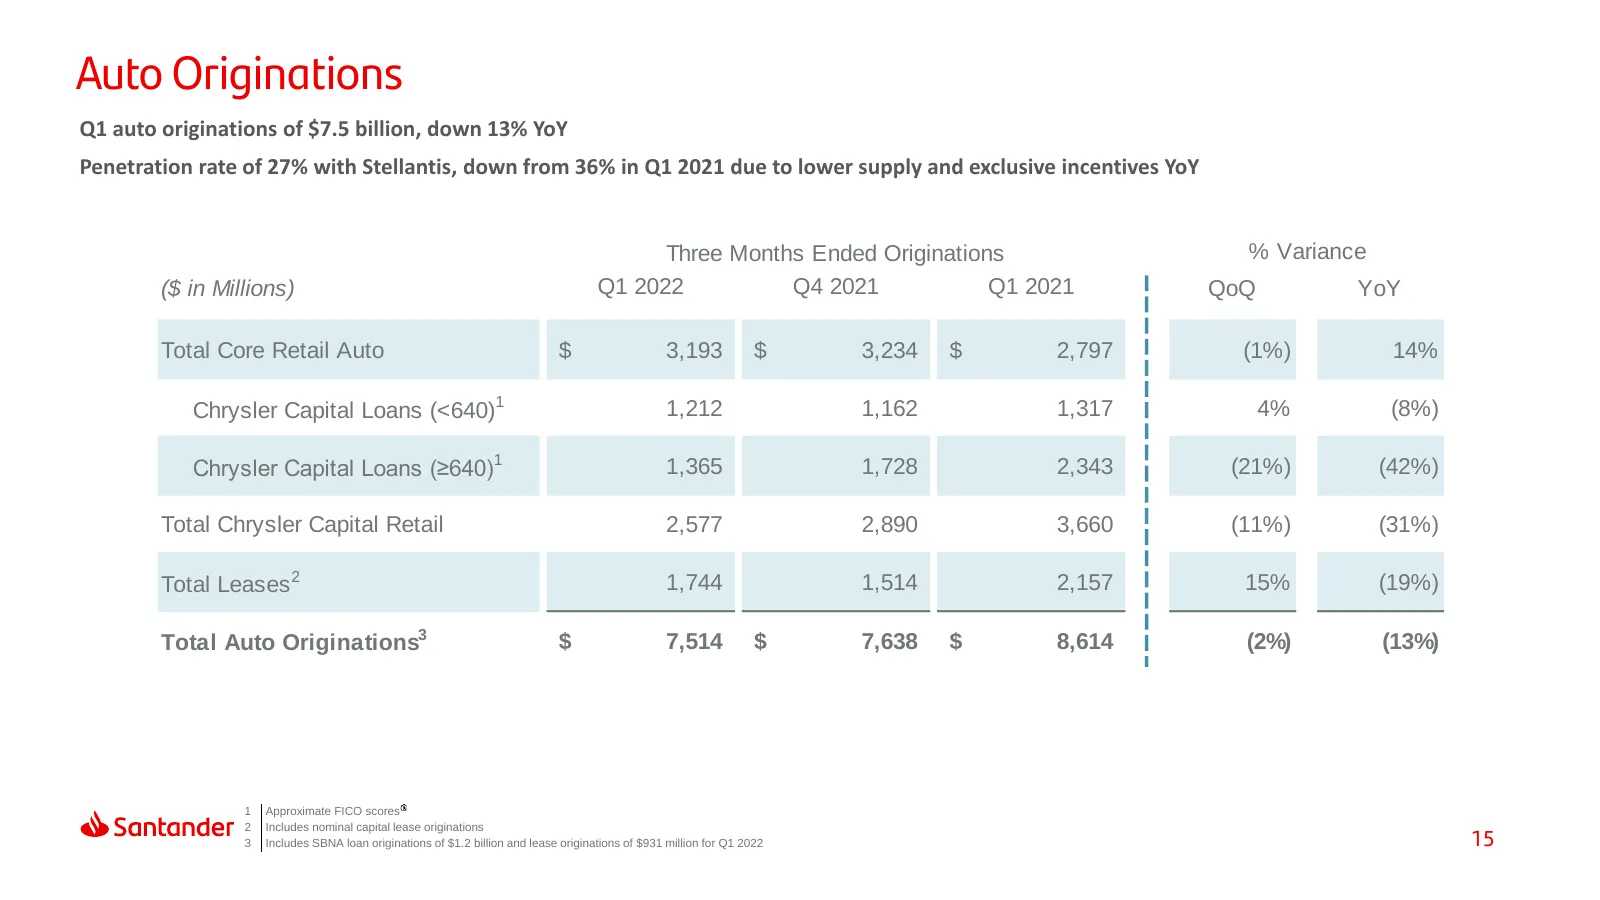
Auto Originations Q1 auto originations of $7.5 billion, down 13% YoY Penetration rate of 27% with Stellantis, down from 36% in Q1 2021 due to lower supply and exclusive incentives YoY Three Months Ended Originations % Variance ($ in Millions) Q1 2022 Q4 2021 Q1 2021 QoQ YoY Total Core Retail Auto $
Slide 16: Asset Quality
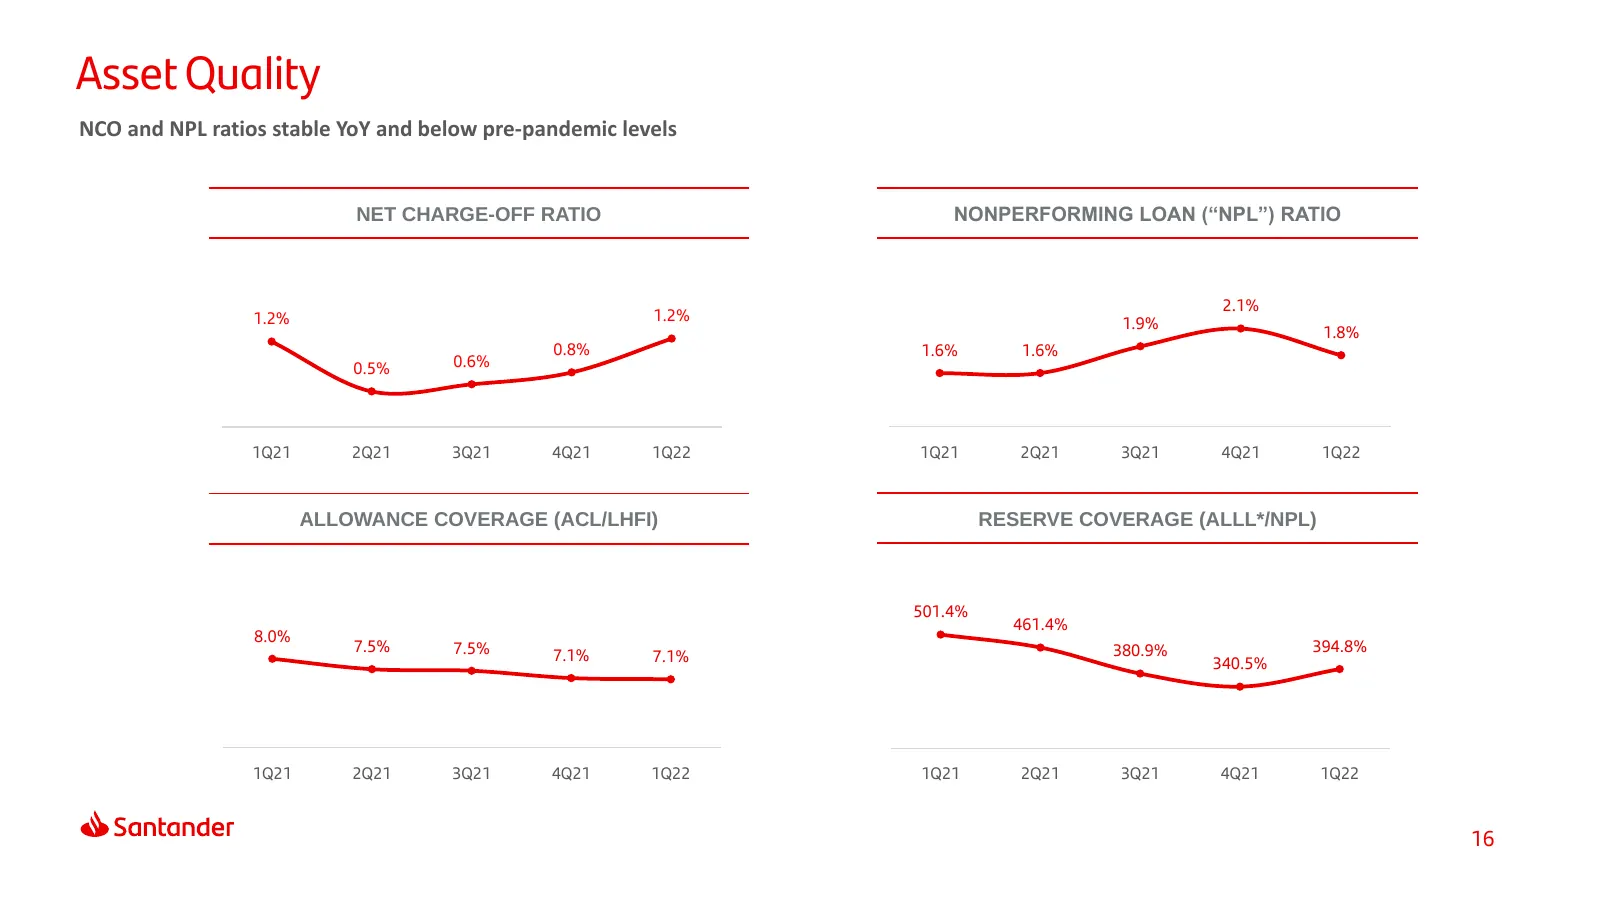
Asset Quality NCO and NPL ratios stable YoY and below pre-pandemic levels NET CHARGE-OFF RATIO NONPERFORMING LOAN (“NPL”) RATIO 2.1% 1.2% 1.2% 1.9% 1.8% 0.8% 1.6% 1.6% 0.5% 0.6% 1Q21 2Q21 3Q21 4Q21 1Q22 1Q21 2Q21 3Q21 4Q21 1Q22 ALLOWANCE COVERAGE (ACL/LHFI) RESERVE COVERAGE (ALLL*/NPL) 501.4% 461.4%
Slide 17: Allowance For Credit Losses ("ACL")
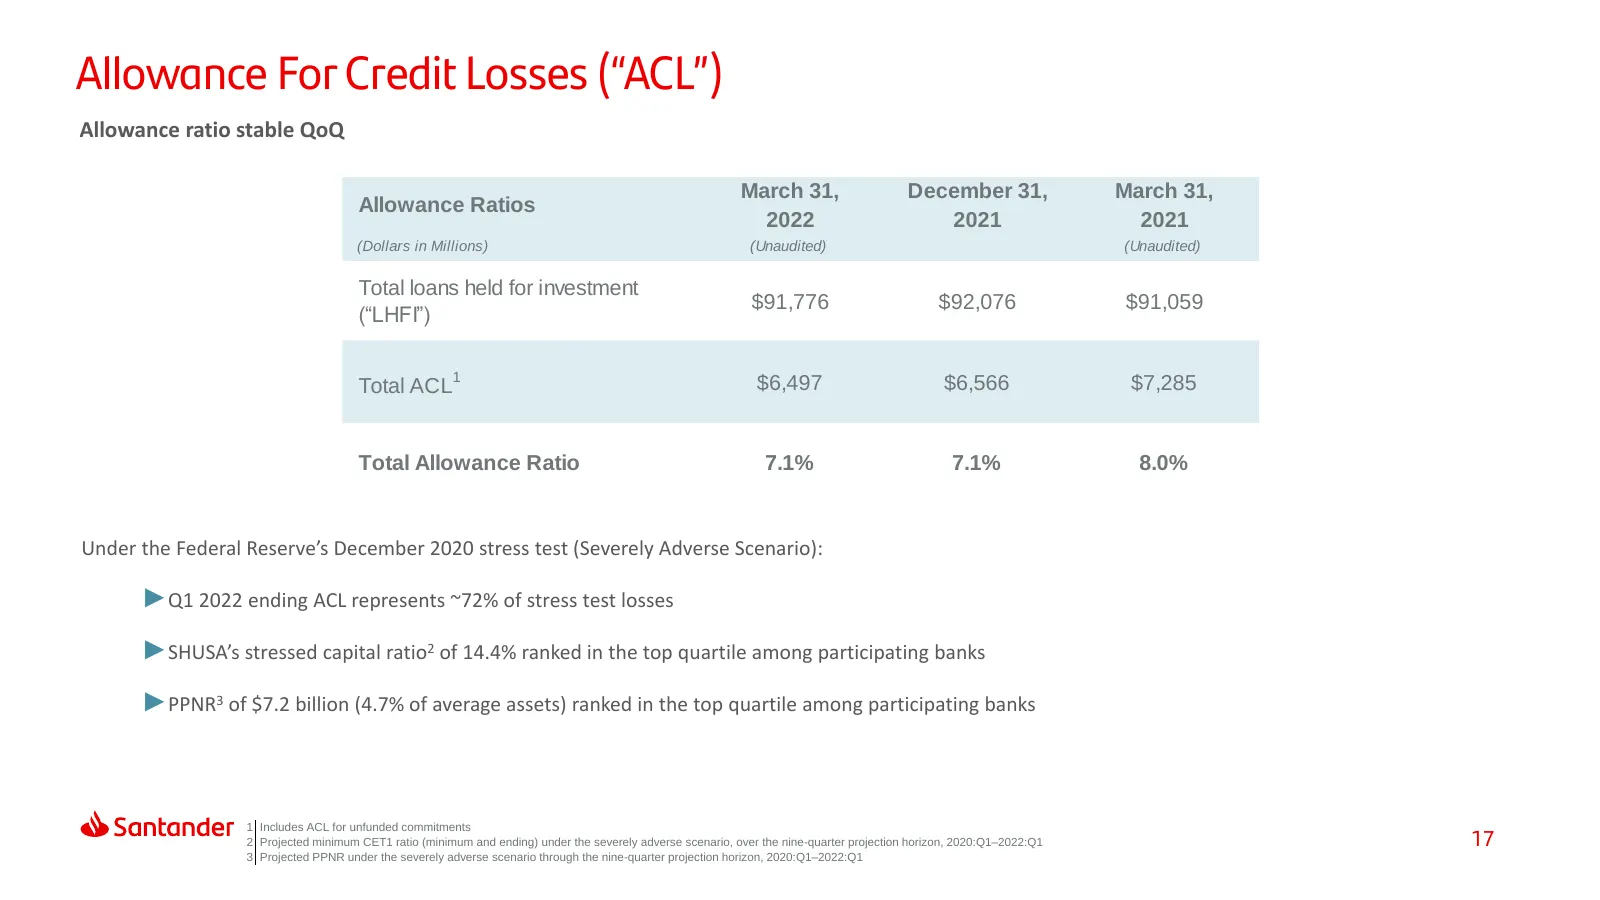
Allowance For Credit Losses (“ACL”) Allowance ratio stable QoQ March 31, December 31, March 31, Allowance Ratios 2022 2021 2021 (Dollars in Millions) (Unaudited) (Unaudited) Total loans held for investment $91,776 $92,076 $91,059 (“LHFI”) Total ACL1 $6,497 $6,566 $7,285 Total Allowance Ratio 7.1% 7.
Slide 18: Borrowed Funds Profile
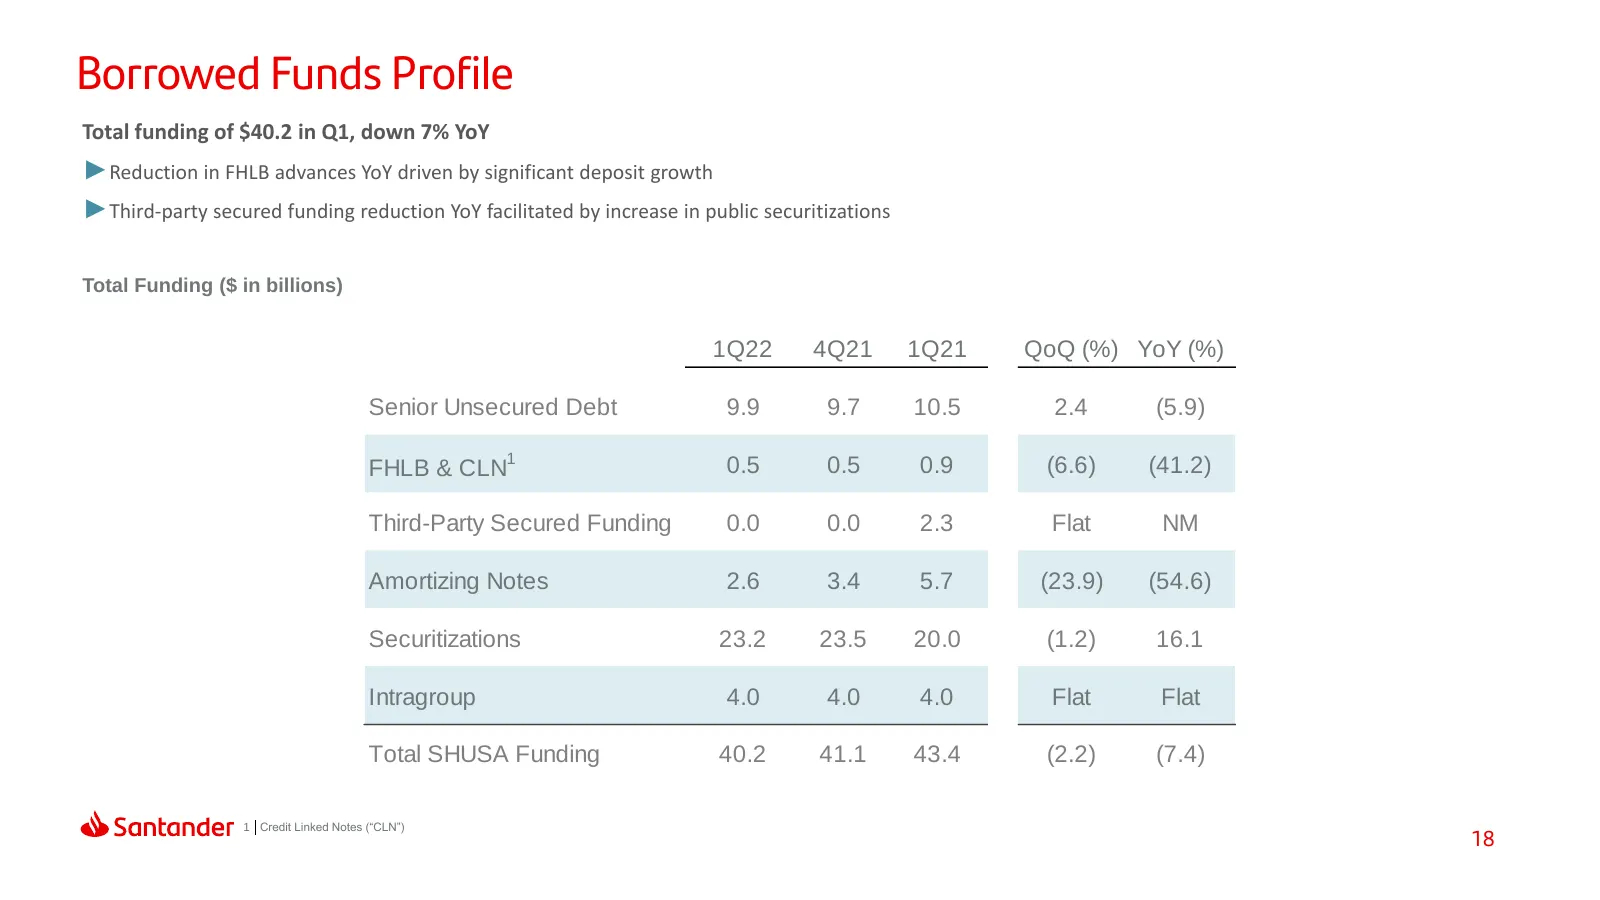
Borrowed Funds Profile Total funding of $40.2 in Q1, down 7% YoY ►Reduction in FHLB advances YoY driven by significant deposit growth ►Third-party secured funding reduction YoY facilitated by increase in public securitizations Total Funding ($ in billions) 1Q22 4Q21 1Q21 QoQ (%) YoY (%) Senior Unsec
Slide 19: Debt & Total Loss-Absorbing Capacity
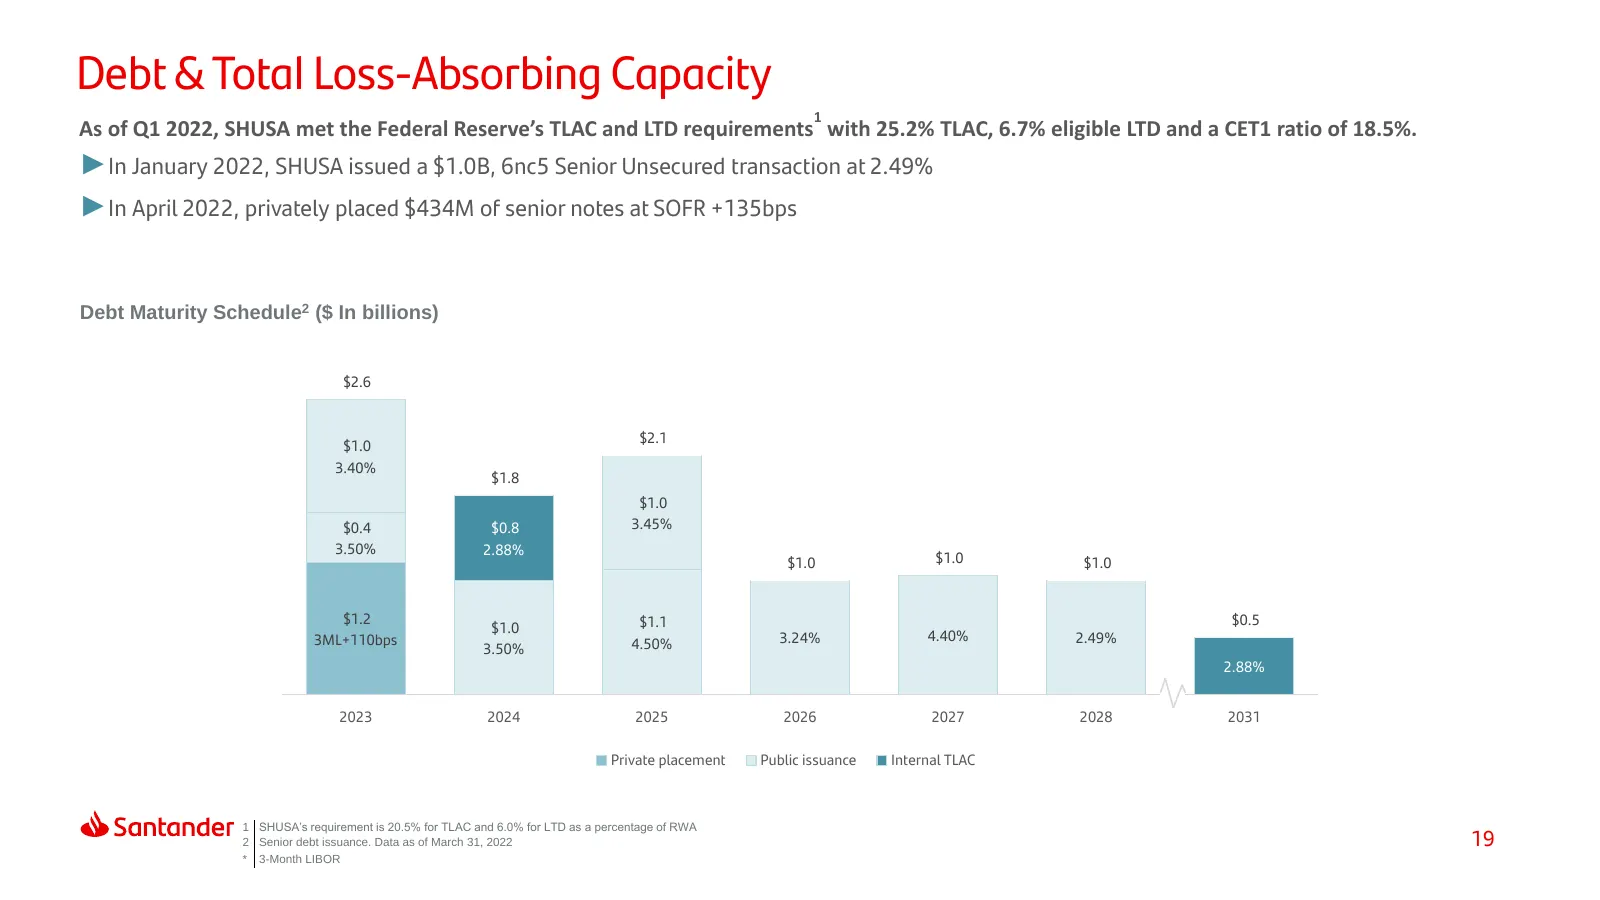
Debt & Total Loss-Absorbing Capacity 1 As of Q1 2022, SHUSA met the Federal Reserve’s TLAC and LTD requirements with 25.2% TLAC, 6.7% eligible LTD and a CET1 ratio of 18.5%. ►In January 2022, SHUSA issued a $1.0B, 6nc5 Senior Unsecured transaction at 2.49% ►In April 2022, privately placed $434M of s
Slide 20: Capital Ratios
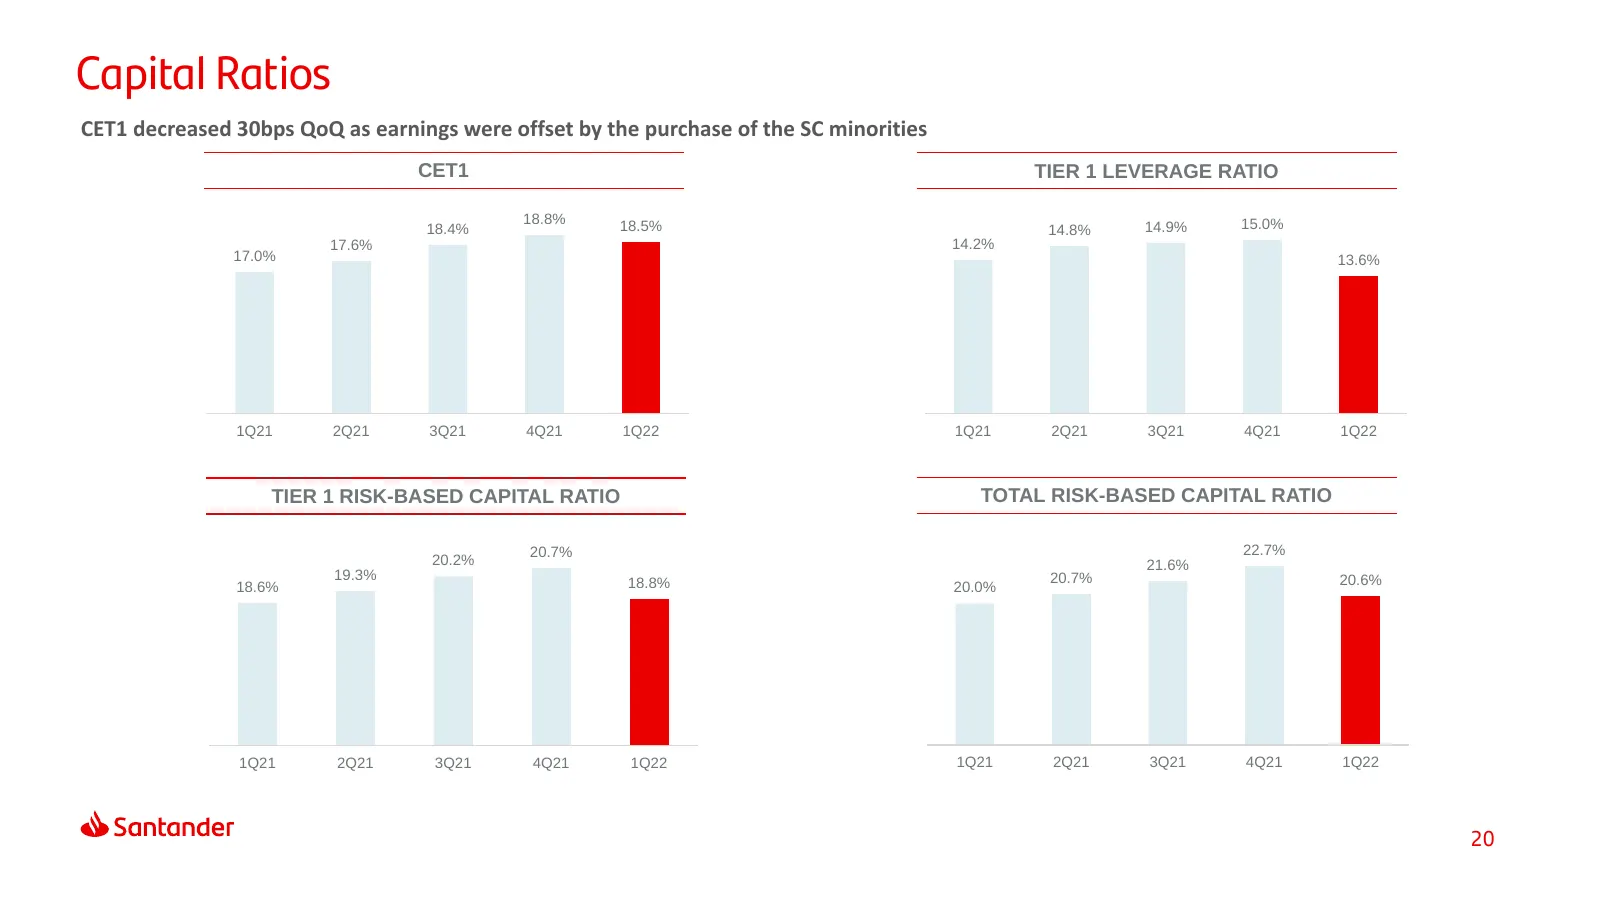
Capital Ratios CET1 decreased 30bps QoQ as earnings were offset by the purchase of the SC minorities CET1 TIER 1 LEVERAGE RATIO 18.8% 18.5% 15.0% 18.4% 14.8% 14.9% 17.6% 14.2% 17.0% 13.6% 1Q21 2Q21 3Q21 4Q21 1Q22 1Q21 2Q21 3Q21 4Q21 1Q22 TIER 1 RISK-BASED CAPITAL RATIO TOTAL RISK-BASED CAPITAL RATIO
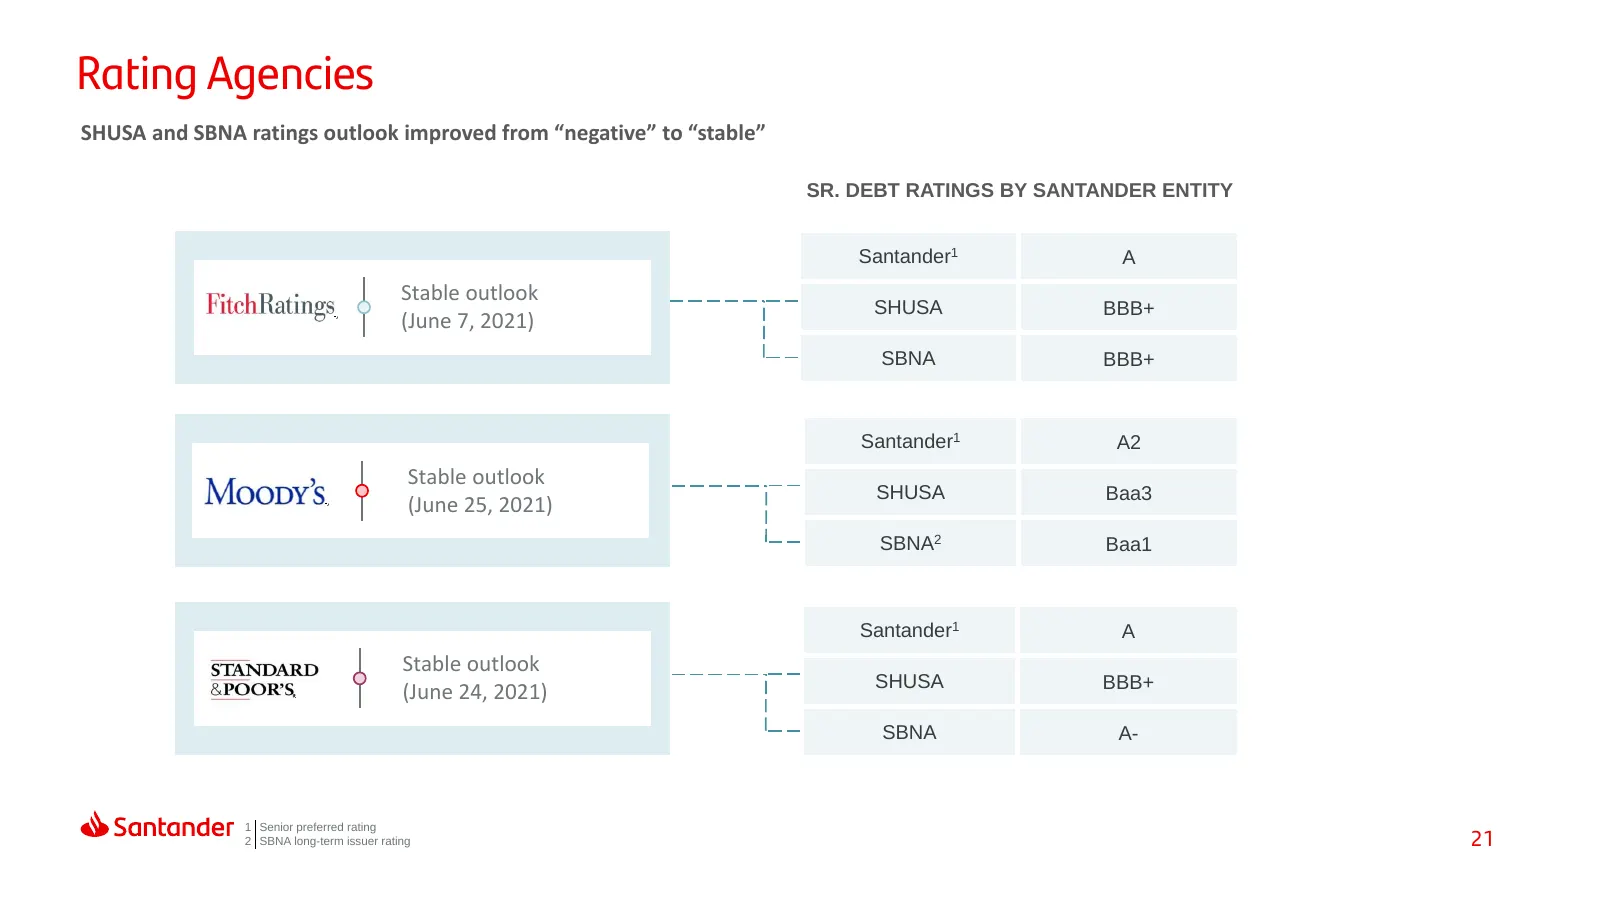
Slide 21: Rating Agencies
Rating Agencies SHUSA and SBNA ratings outlook improved from “negative” to “stable” SR. DEBT RATINGS BY SANTANDER ENTITY Santander1 A Stable outlook SHUSA BBB+ (June 7, 2021) SBNA BBB+ Santander1 A2 Stable outlook SHUSA Baa3 (June 25, 2021) SBNA2 Baa1 Santander1 A Stable outlook SHUSA BBB+ (June 24,
Slide 22: Index
Index 1 2 3 4 At a Glance Summary Results Appendix 22
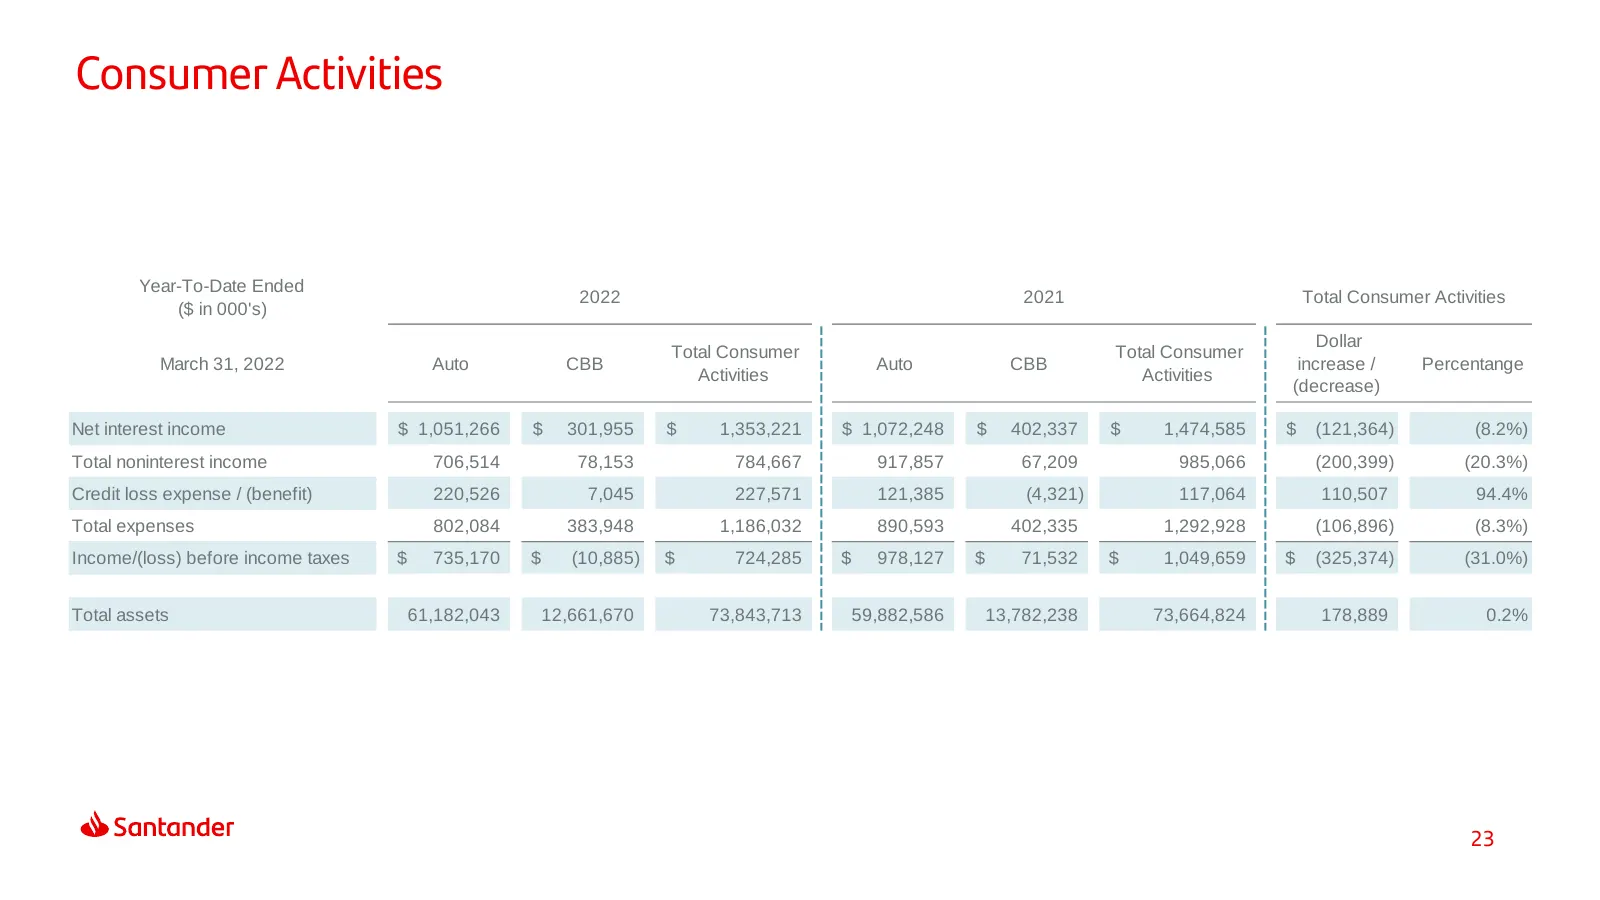
Slide 23: Consumer Activities
Consumer Activities Year-To-Date Ended 2022 2021 Total Consumer Activities ($ in 000's) Dollar Total Consumer Total Consumer March 31, 2022 Auto CBB Auto CBB increase / Percentange Activities Activities (decrease) Net interest income $ 1,051,266 $ 301,955 $ 1,353,221 $ 1,072,248 $ 402,337 $ 1,474,58
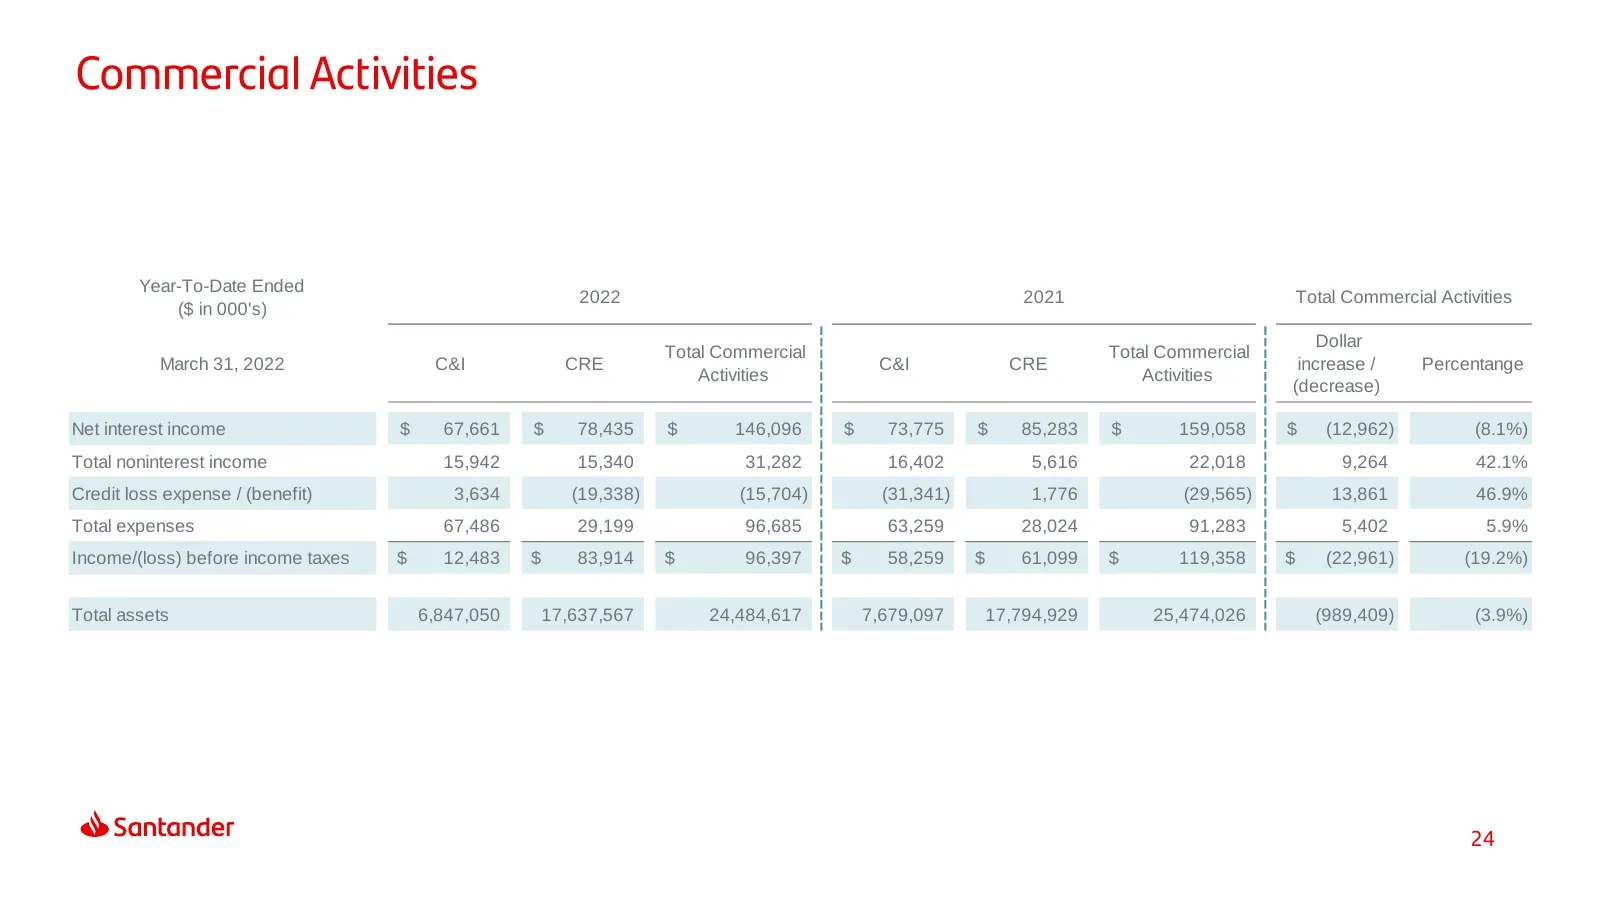
Slide 24: Commercial Activities
Commercial Activities Year-To-Date Ended 2022 2021 Total Commercial Activities ($ in 000's) Dollar Total Commercial Total Commercial March 31, 2022 C&I CRE C&I CRE increase / Percentange Activities Activities (decrease) Net interest income $ 67,661 $ 78,435 $ 146,096 $ 73,775 $ 85,283 $ 159,058 $ (1
Slide 25: CIB and Wealth Management
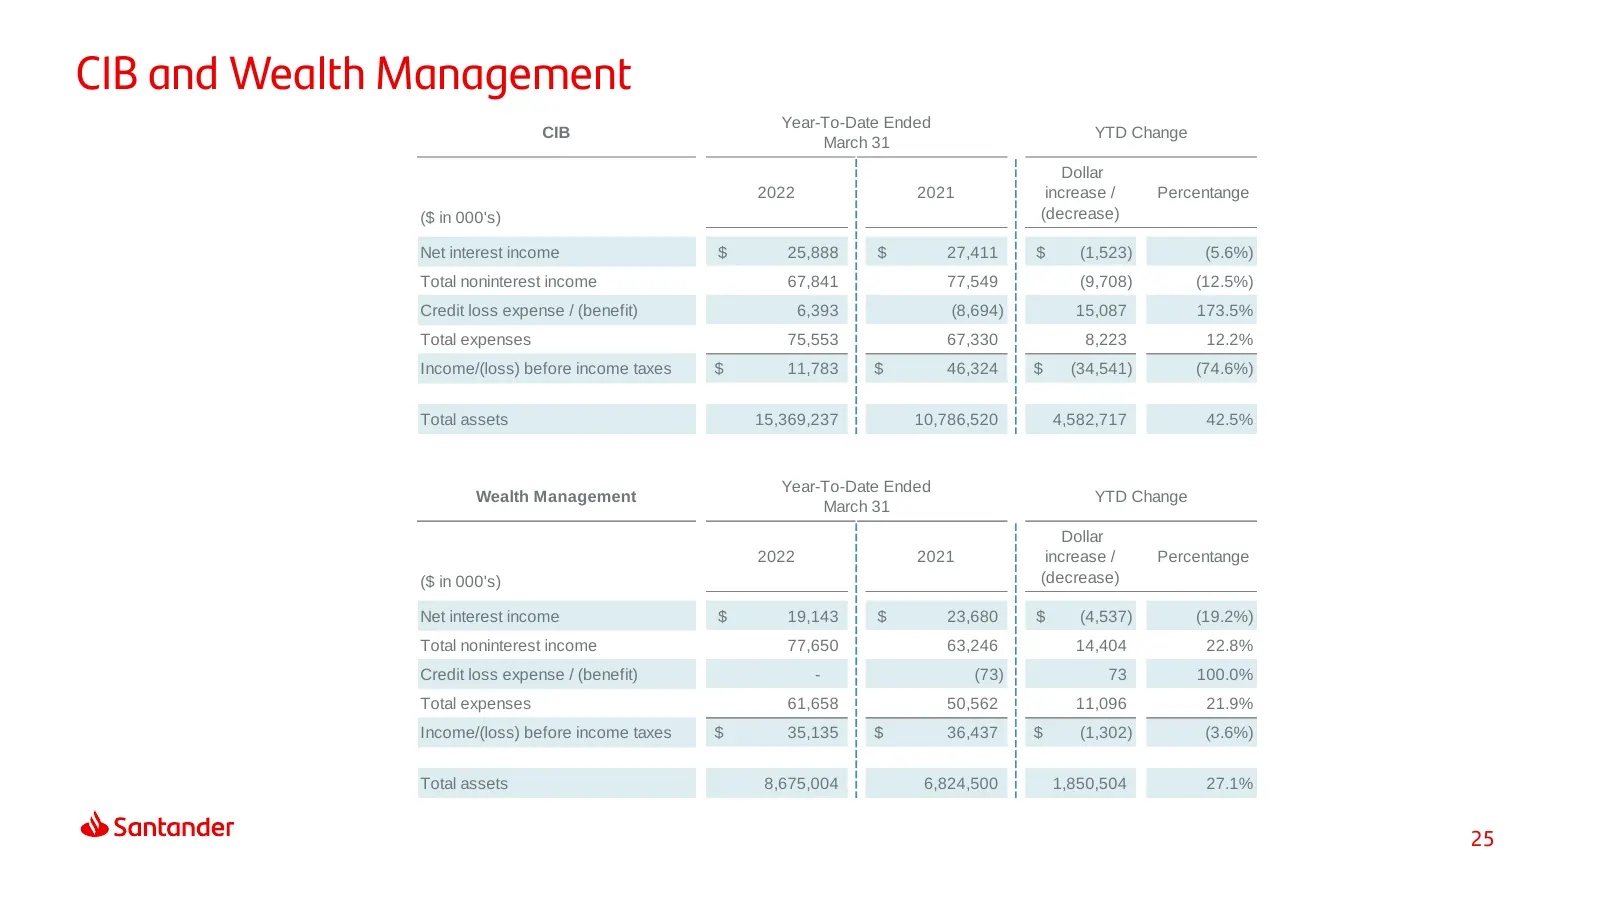
CIB and Wealth Management Year-To-Date Ended CIB YTD Change March 31 Dollar 2022 2021 increase / Percentange ($ in 000's) (decrease) Net interest income $ 25,888 $ 27,411 $ (1,523) (5.6%) Total noninterest income 67,841 77,549 (9,708) (12.5%) Credit loss expense / (benefit) 6,393 (8,694) 15,087 173.
Slide 26: Other
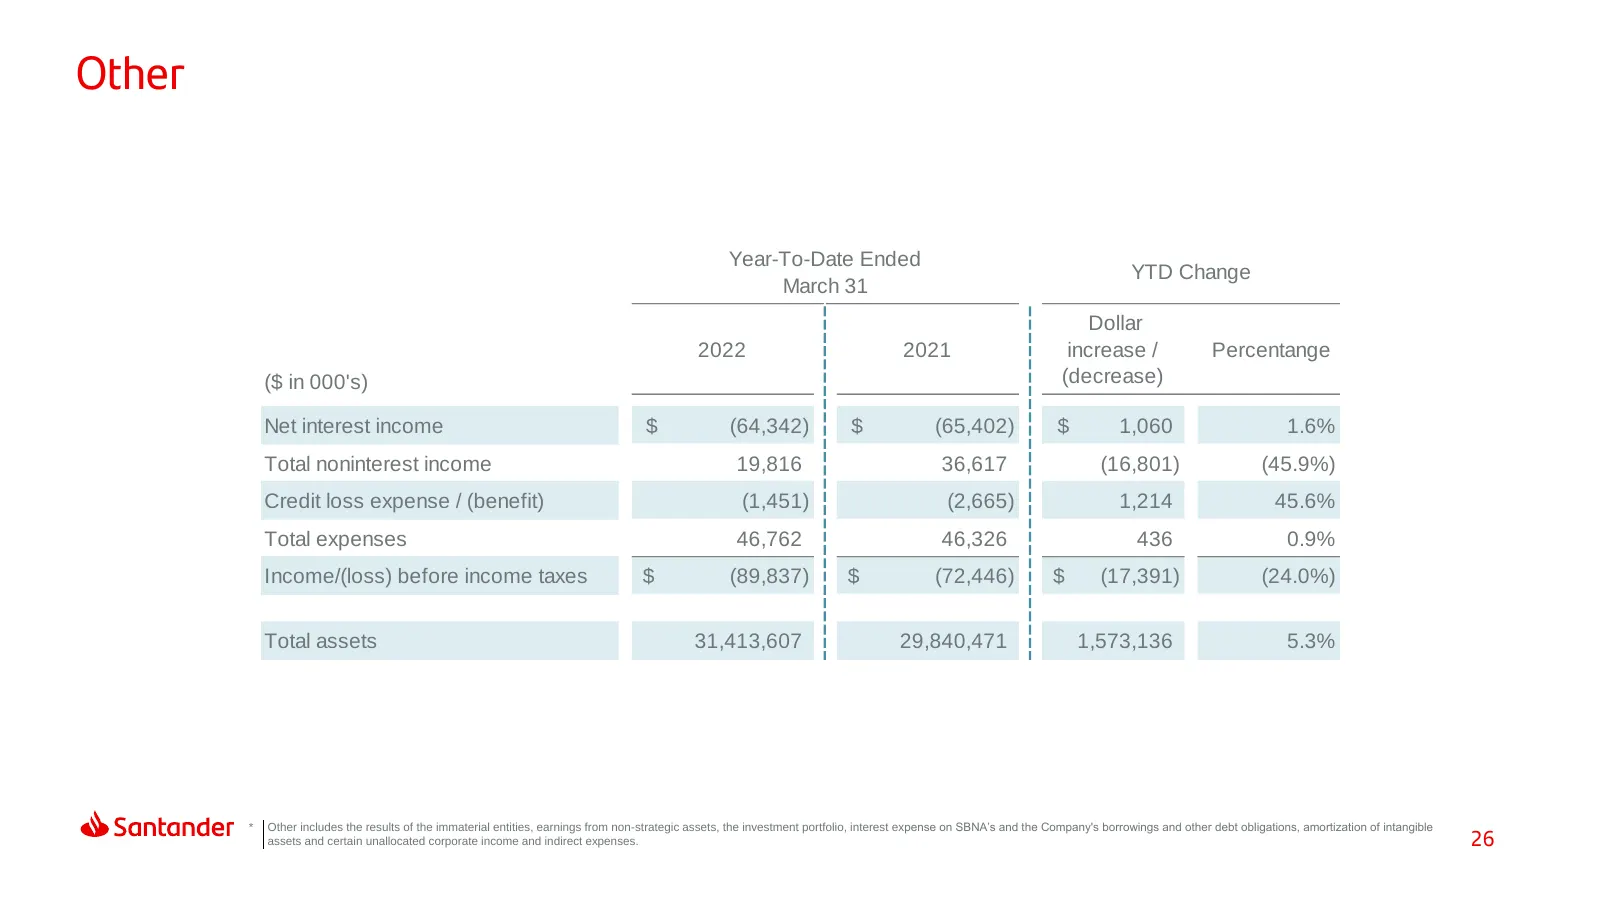
Other Year-To-Date Ended YTD Change March 31 Dollar 2022 2021 increase / Percentange ($ in 000's) (decrease) Net interest income $ (64,342) $ (65,402) $ 1,060 1.6% Total noninterest income 19,816 36,617 (16,801) (45.9%) Credit loss expense / (benefit) (1,451) (2,665) 1,214 45.6% Total expenses 46,76
Slide 27: SHUSA: Quarterly Trended Statement Of Operations
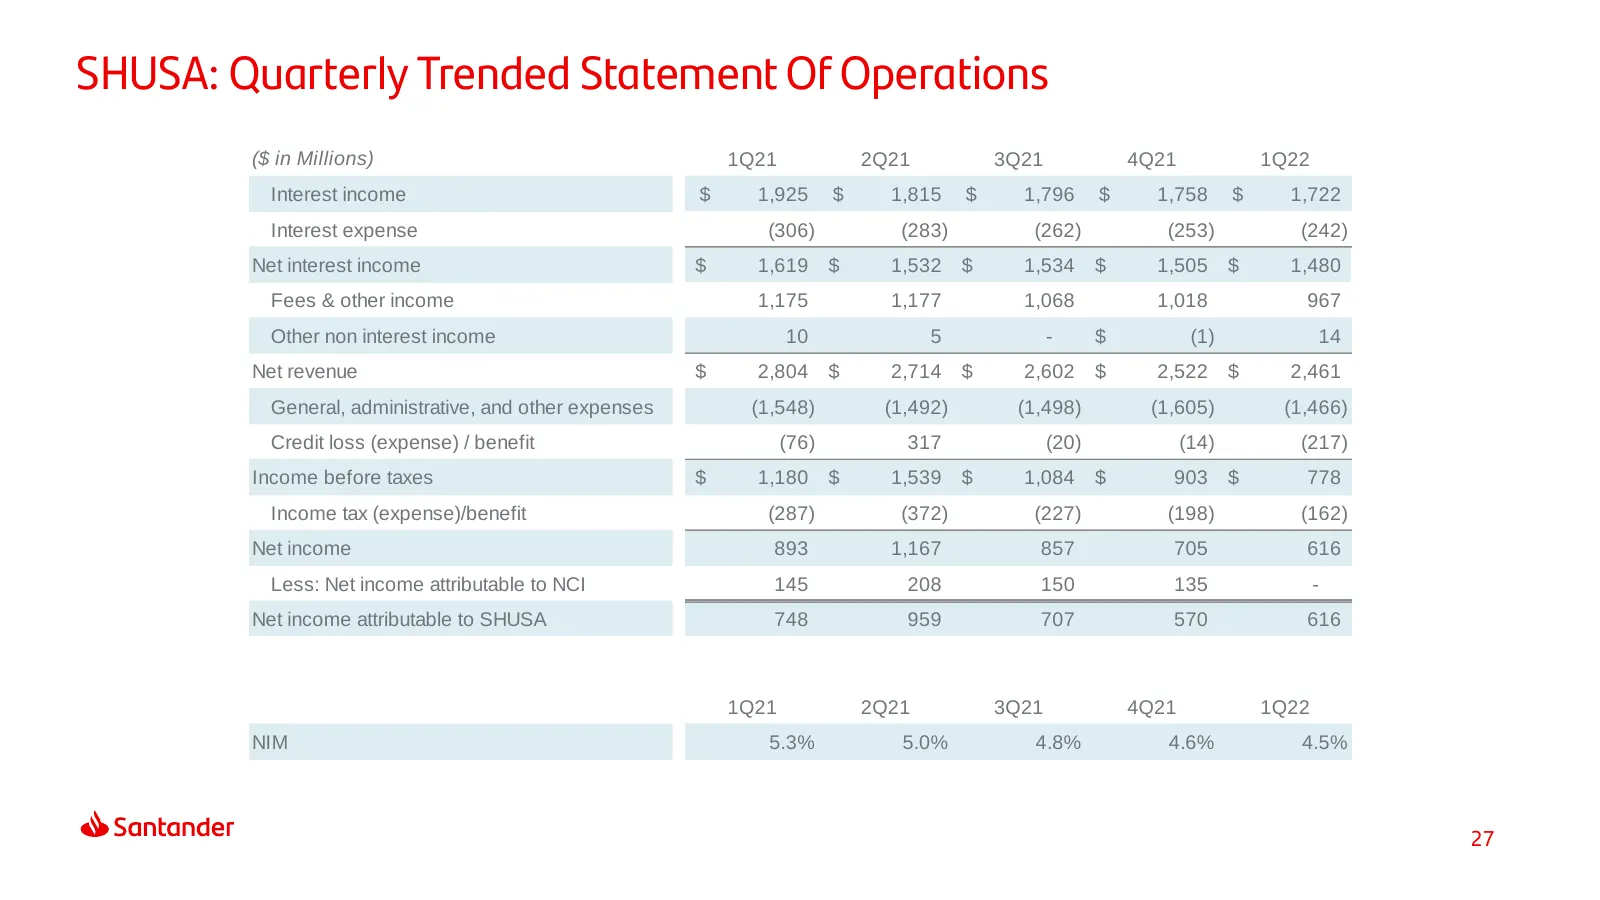
SHUSA: Quarterly Trended Statement Of Operations ($ in Millions) 1Q21 2Q21 3Q21 4Q21 1Q22 Interest income $ 1,925 $ 1,815 $ 1,796 $ 1,758 $ 1,722 Interest expense (306) (283) (262) (253) (242) Net interest income $ 1,619 $ 1,532 $ 1,534 $ 1,505 $ 1,480 Fees & other income 1,175 1,177 1,068 1,018 967
Slide 28: SHUSA: Non-GAAP Reconciliations
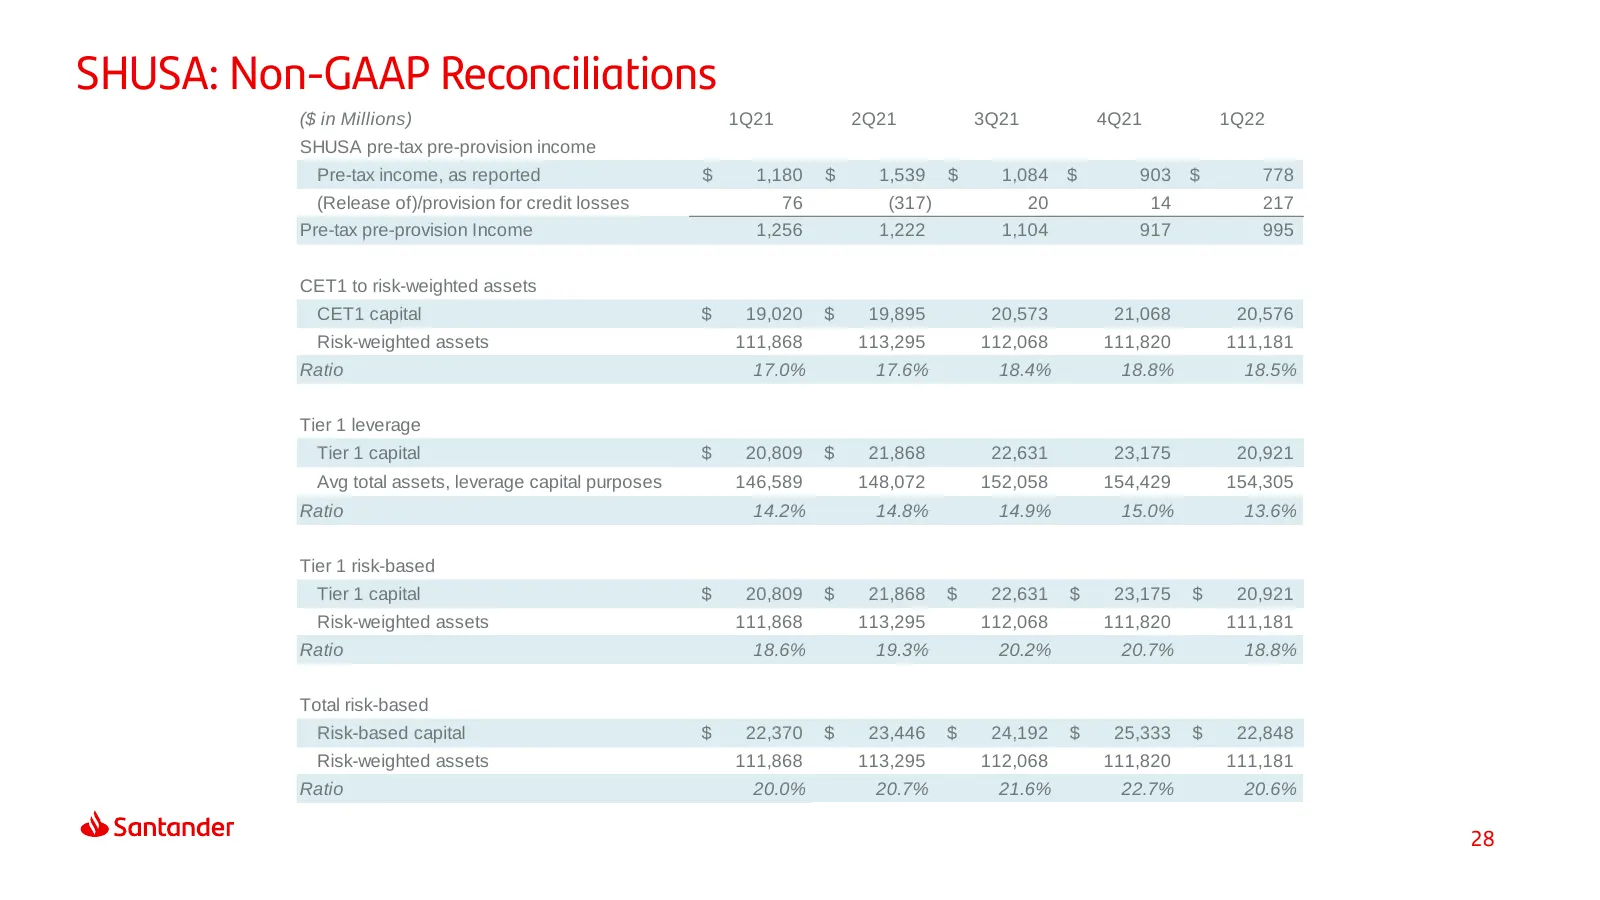
SHUSA: Non-GAAP Reconciliations ($ in Millions) 1Q21 2Q21 3Q21 4Q21 1Q22 SHUSA pre-tax pre-provision income Pre-tax income, as reported $ 1,180 $ 1,539 $ 1,084 $ 903 $ 778 (Release of)/provision for credit losses 76 (317) 20 14 217 Pre-tax pre-provision Income 1,256 1,222 1,104 917 995 CET1 to risk-
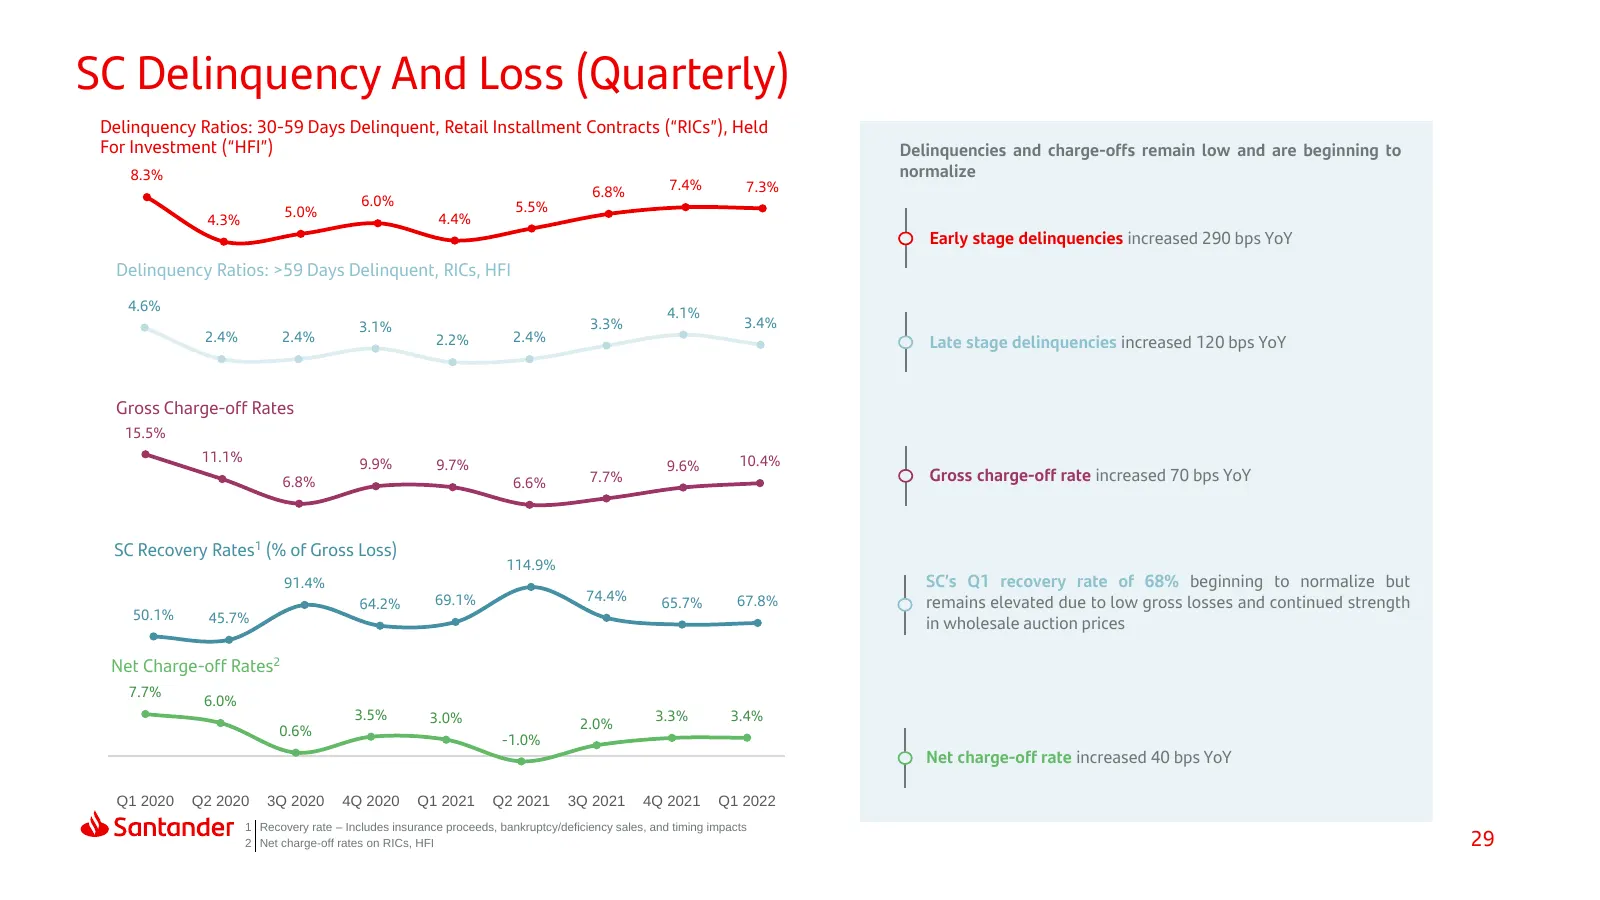
Slide 29: SC Delinquency And Loss (Quarterly)
SC Delinquency And Loss (Quarterly) Delinquency Ratios: 30-59 Days Delinquent, Retail Installment Contracts (“RICs”), Held For Investment (“HFI”) Delinquencies and charge-offs remain low and are beginning to 8.3% normalize 6.8% 7.4% 7.3% 6.0% 5.5% 5.0% 4.4% 4.3% Early stage delinquencies increased 2
Slide 30: Thank You.
Thank You. Our purpose is to help people and businesses prosper. Our culture is based on believing that everything we do should be:
Source: company website
More decks from Santander Holdings USA Inc
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026