Massey Energy — Credit Suisse Energy Summit 2011
26 slides from Massey Energy's conference presentation, Feb 10, 2011
Slide 1: Running Right - Credit Suisse Energy Summit 2011
aA Alpha Natural Resources a ~ RUNNING RIGHT Credit Suisse Energy Summit 2011 February 10, 2011 Kevin Crutchfield, CEO
Slide 2: Forward Looking Statements
A Alpha Natural Resources ‘nome nein Forward Looking Statements Information set forth herein contsins“forwarchlooking statem ent as defined in the Private Securities Litigation Reform Act of 1995, which involve a number of risks and Uncertainties. Alpha and Massey caution readers that shy forward:lo
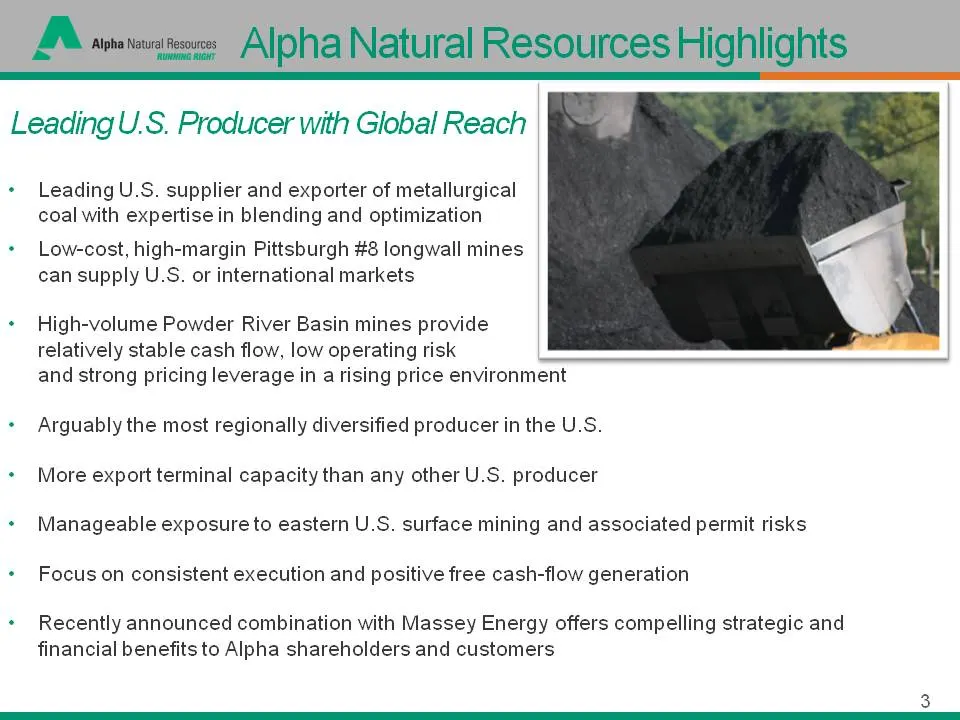
Slide 3: Alpha Natural Resources Highlights
AA mene Alpha Natural Resources Highlights Leading U.S. Producer with Global Reach + Leading U.S. supplier and exporter of metallurgical coal with expertise in blending and optimization + Low-cost, high-margin Pittsburgh #8 longwall mines can supply U.S. or international markets + High-volume Powder
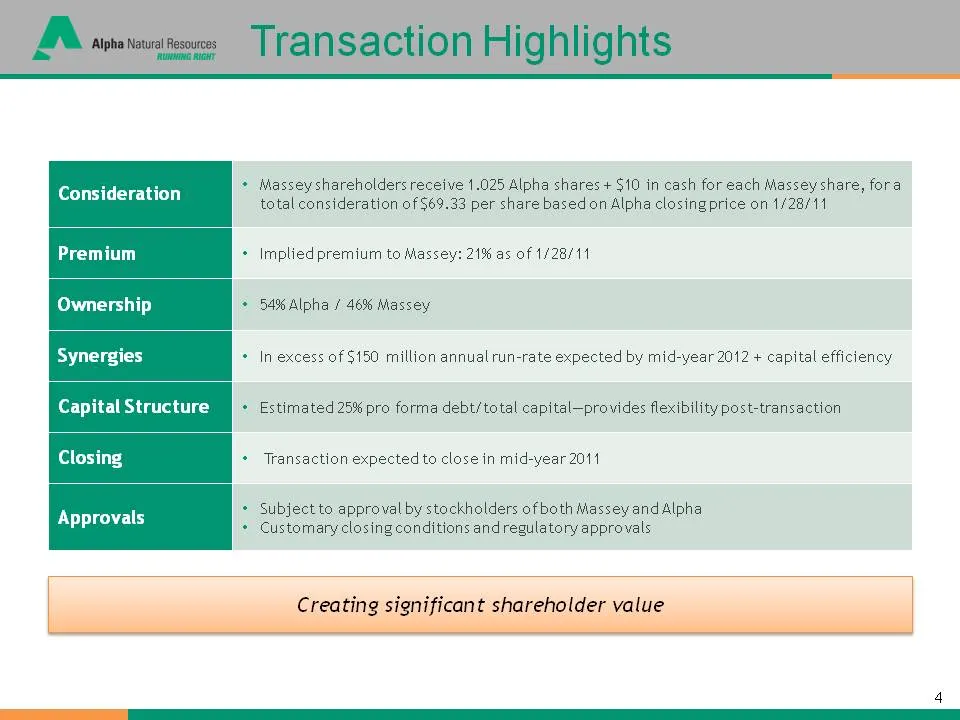
Slide 4: Transaction Highlights
AA sm sixee ~Transaction Highlights * Massey shareholders receive 1.025 Alpha shares + $10 in cash for each Massey share, fora total consideration of $69.33 per share based on Allpha closingprice on 1/28/11 Consideration + Implied premium to Massey: 21% as of 1/28/11 Jownersnin ES + Inexcess of $150
Slide 5: A Compelling Combination
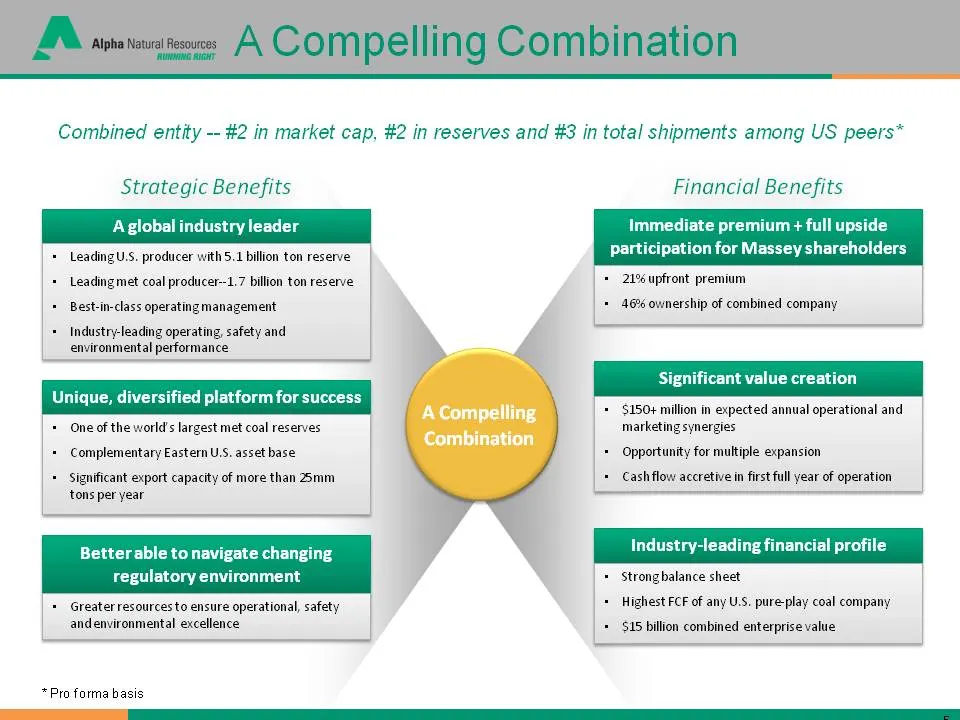
A smear A Compelling Combination Combined entity -- #2 in market cap, #2 in reserves and #3 in total shipments among US peers* Strategic Benefits Financial Benefits Aglobal industry leader Immediate premium + full upside + LeadingU.S, producer with 5.1 billion ton reserve n for Massey shareholders +
Slide 6: Combined company, a leading provider of total coal and met coal globally
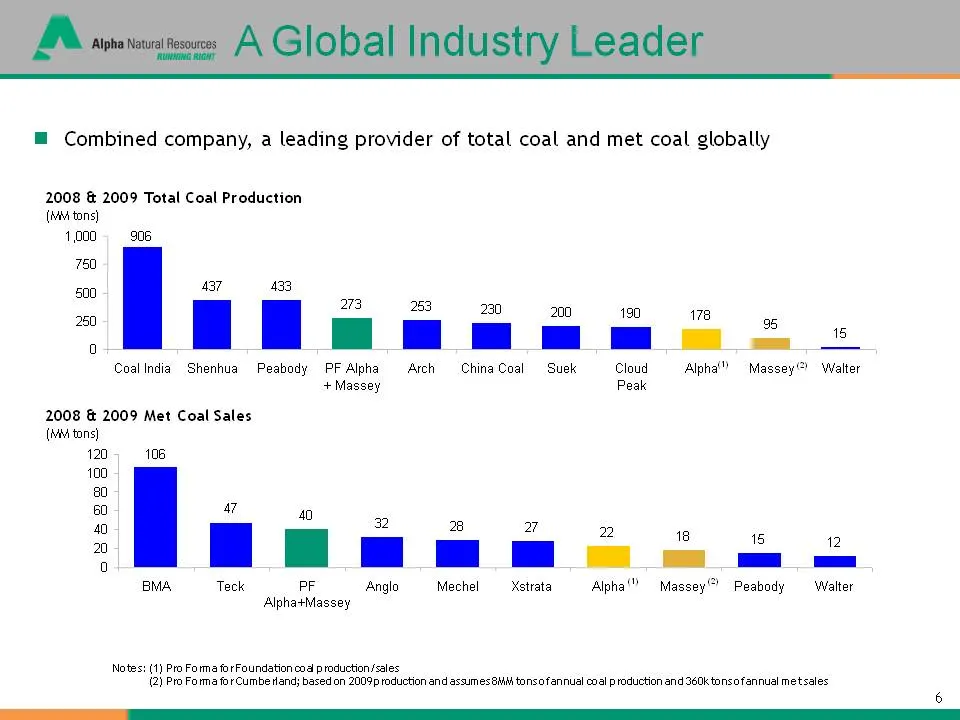
@ Combined company, a leading provider of total coal and met coal globally 2008 & 2009 Total Coal Production (WM tons} 4 Ae = aL eee Coal India Shenhua Peabody PF Alpha Arch China Coal Suek Cloud. «== Alpha!” Massey") Walter + Massey Peak 2008 & 2009 Met Coal Sales (i tons) 120) 106 ‘00 an. a 18 15
Slide 7: Significant Expected Synergies
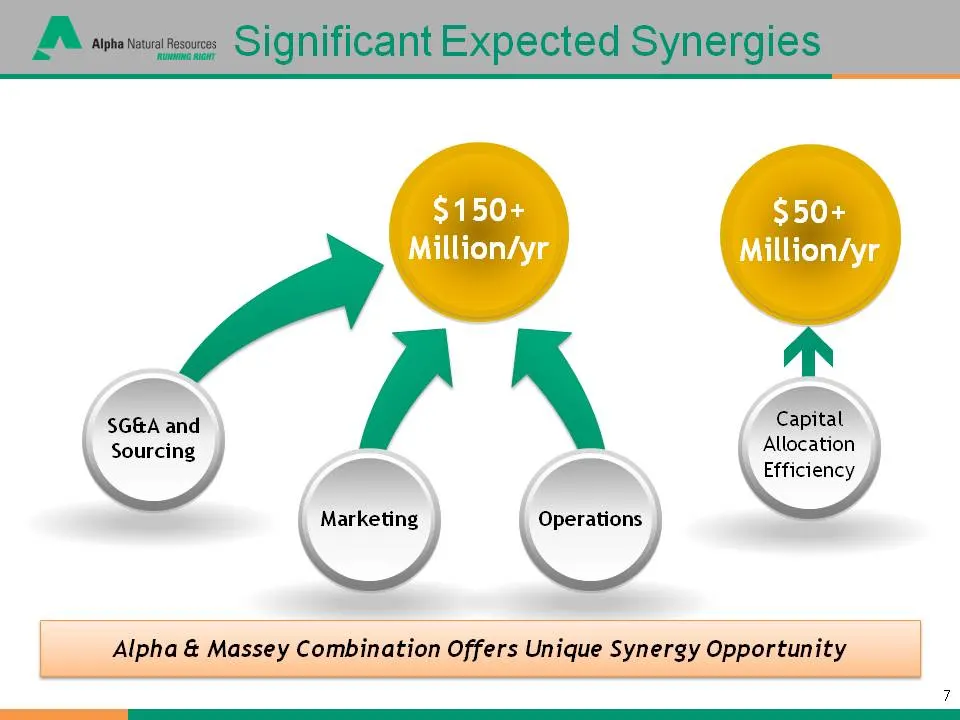
A vmmitere Significant Expected Synergies Zn SG&A and Capital \. Sourcing Allocation \ J \\ Efficiency Marketing Operations Alpha & Massey Combination Offers Unique Synergy Opportunity
Slide 8: Alpha Natural Resources
Alpha Natural Resources 8
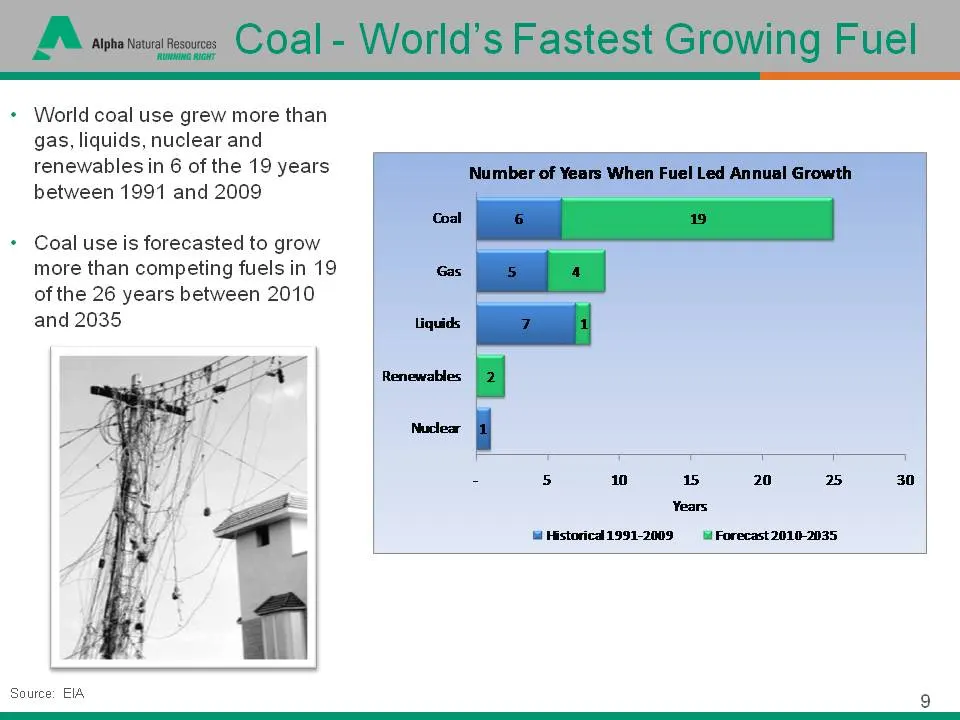
Slide 9: World coal use growth versus competing fuels
+ World coal use grew more than gas, liquids, nuclear and renewables in 6 of the 19 years between 1991 and 2009 + Coal use is forecasted to grow more than competing fuels in 19 of the 26 years between 2010 and 2035 Source: EIA Coal Gas Number of Years When Fuel Led Annual Growth Years li Historic 19
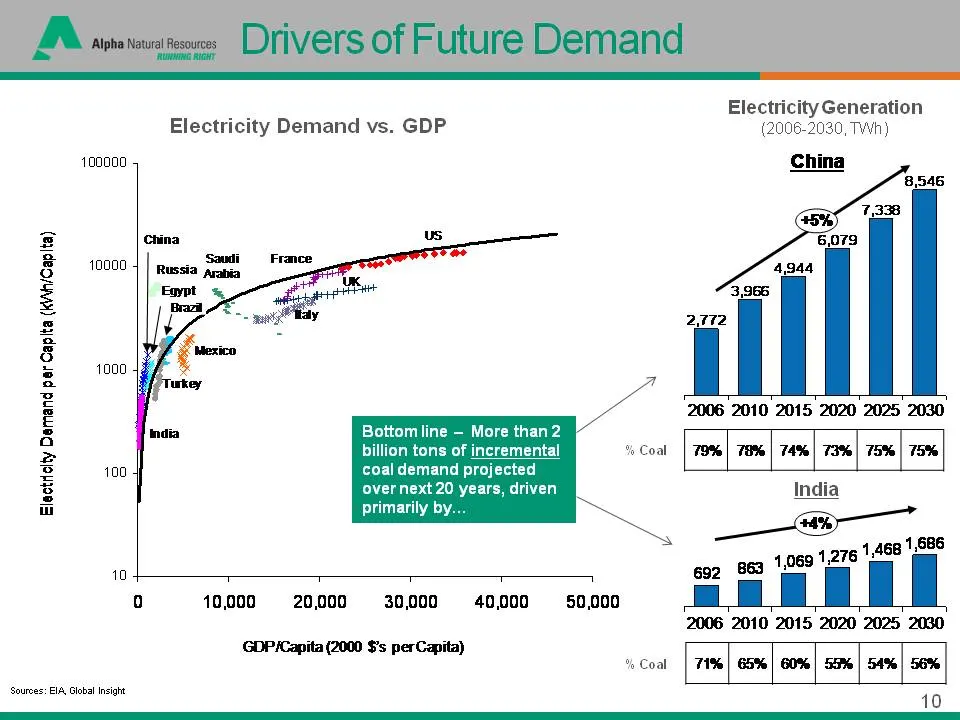
Slide 10: Electricity Demand per Capita and incremental coal demand
10000 1000 1000 100 Electricity Demand per Capita (kVWh/Capita) 10 Sources: EIA Global Insight Electricity Demand vs. GDP Bottom line — More than 2 billion tons of incremental coal demand projected over next 20 years, driven primarily by... Q 10,000 20,000 30,000 40,000 GDPiCapita (2000 $'s perCapit
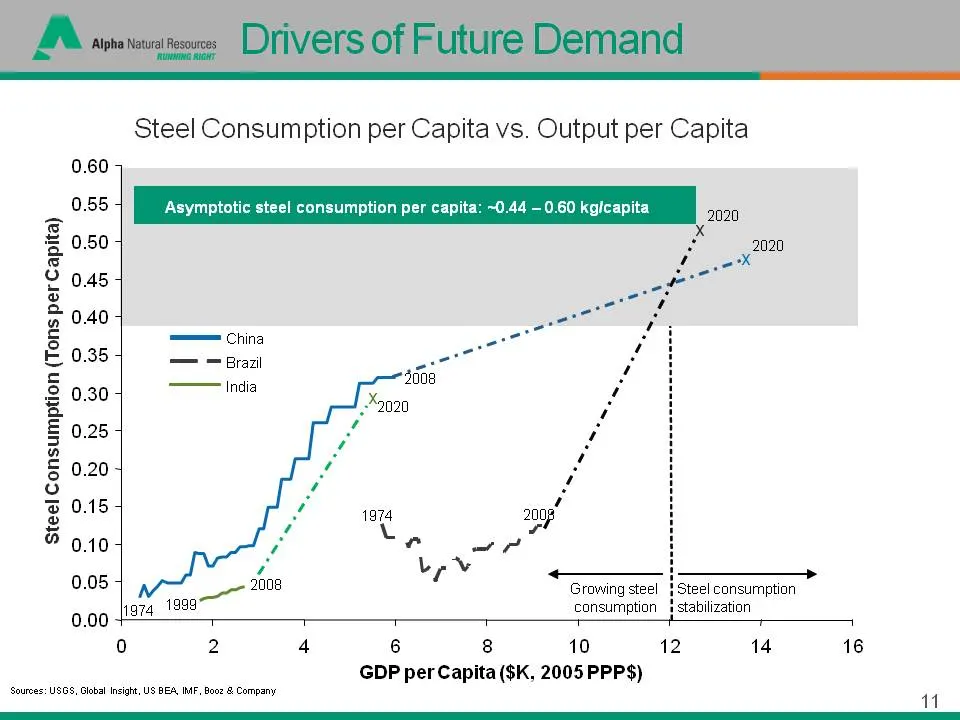
Slide 11: Asymptotic steel consumption per capita
(ESB) Asymptotic steel consumption per cay Steel Consumption per Capita vs. Output per Capita 60 kgicapita supa —_ _ | Growing steel} Steel consumption azg 1999 consumption {stabilization 0 2 4 6 8 10 12 14 16 GDP per Capita ($K, 2005 PPP$) Sources: USGS, Global Insight, US BEA, MF, Booz & Company 1
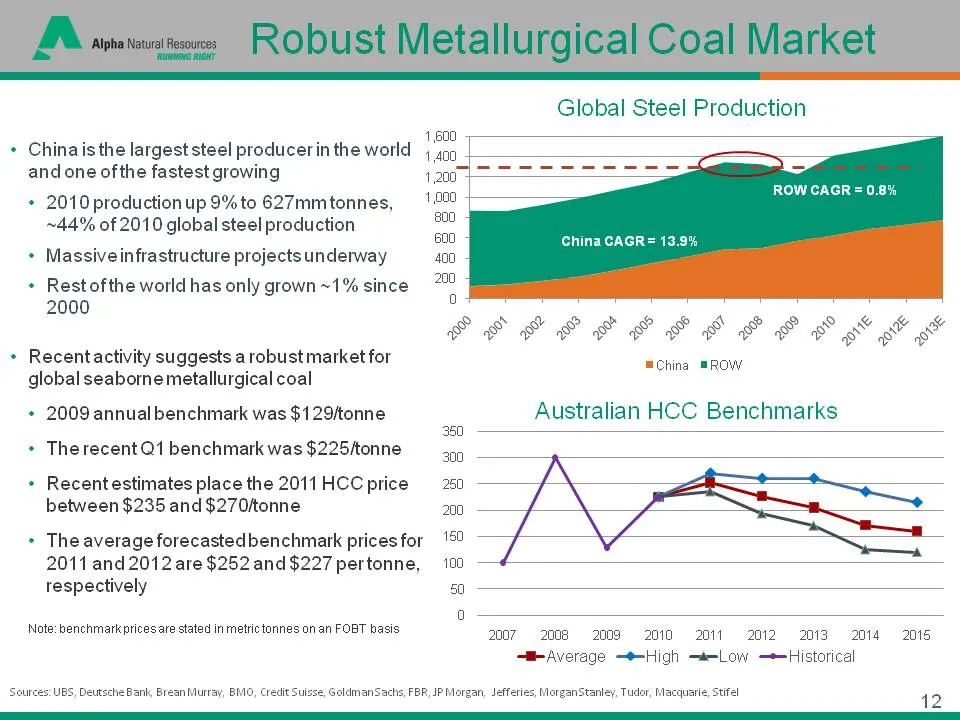
Slide 12: Robust Metallurgical Coal Market
AA vmionsteeee Robust Metallurgical Coal Market Global Steel Production a ' 1,600 * Chinais the largest steel producerinthe world {sop and one ofthe fastest growing 4297 ROW CAGR =0¥ + 2010 productionup9%to 627mmtonnes, 10% ~44% of 2010 global steel production China CAGR= 13.9% + Massiveinfrastructu
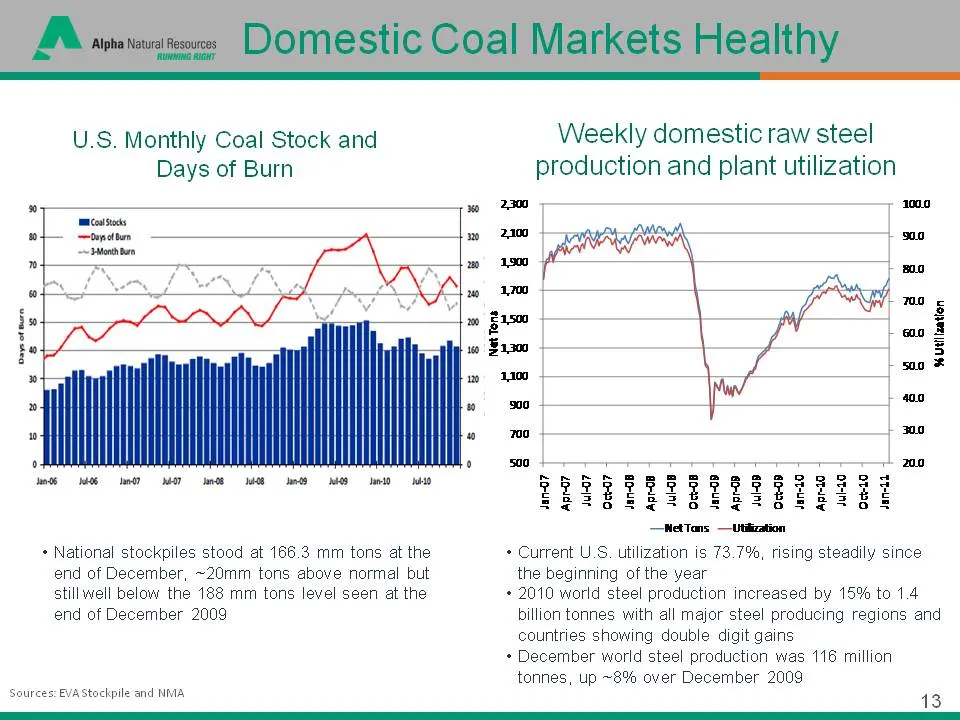
Slide 13: U.S. Monthly Coal Stock and Weekly domestic raw steel production
U.S. Monthly Coal Stock and Weekly domestic raw steel Days of Burn production and plant utilization » we «= «2,300 1000 as ae ee als Yi yi | a | mo © = PO» +0 Satyr mam Z ‘ — poem “oad we ZB1300 A. 7 me 5 um «1100 al » soo aag 0 sao . 80 20 ii gs + National stockpiles stood at 166.3 mm tons at the +
Slide 14: Alpha Natural Resources Overview
A Alpha Natural Resources mn Alpha Natural Resources Overview Leading U.S. Producer With Global Reach 14
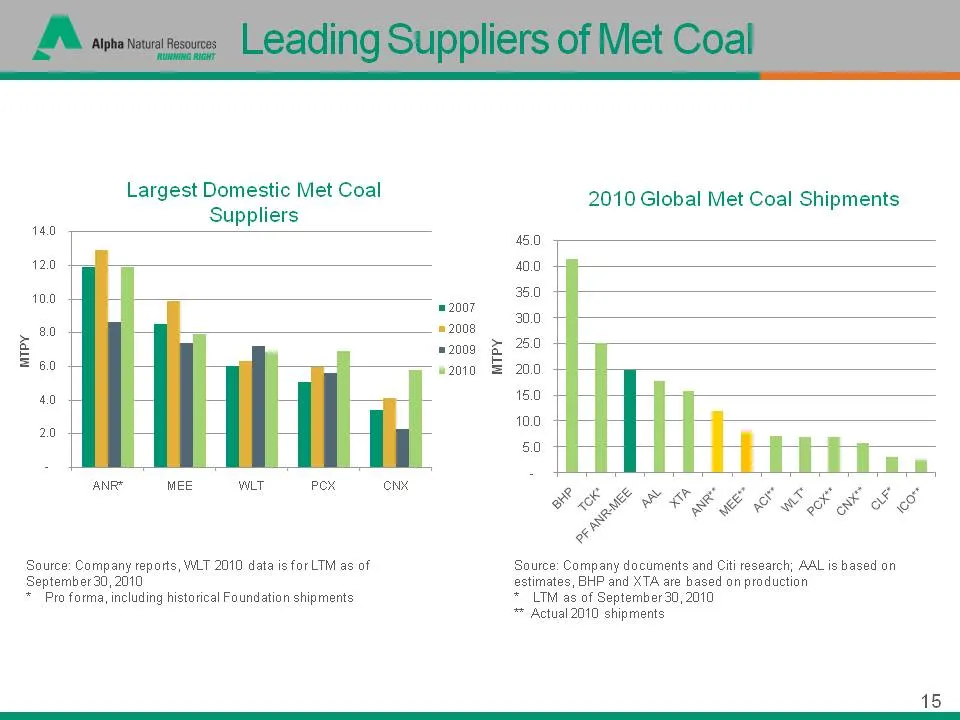
Slide 15: Largest Domestic Met Coal Suppliers; 2010 Global Met Coal Shipments
Largest Domestic Met Coal 2010 Global Met Coal Shipments Suppliers ie 45.0 12.0 + 40.0 36.0 10.0 2007 30.0 80 = 2008 z s 2000 E250 = 60 e210 3 200 40 16.0 10.0 20 50 ANR® MEE WLT POX CNX . Source: Company reports, WLT 2010 data is for LTM as of Source: Company documents and Citi research; AALis base
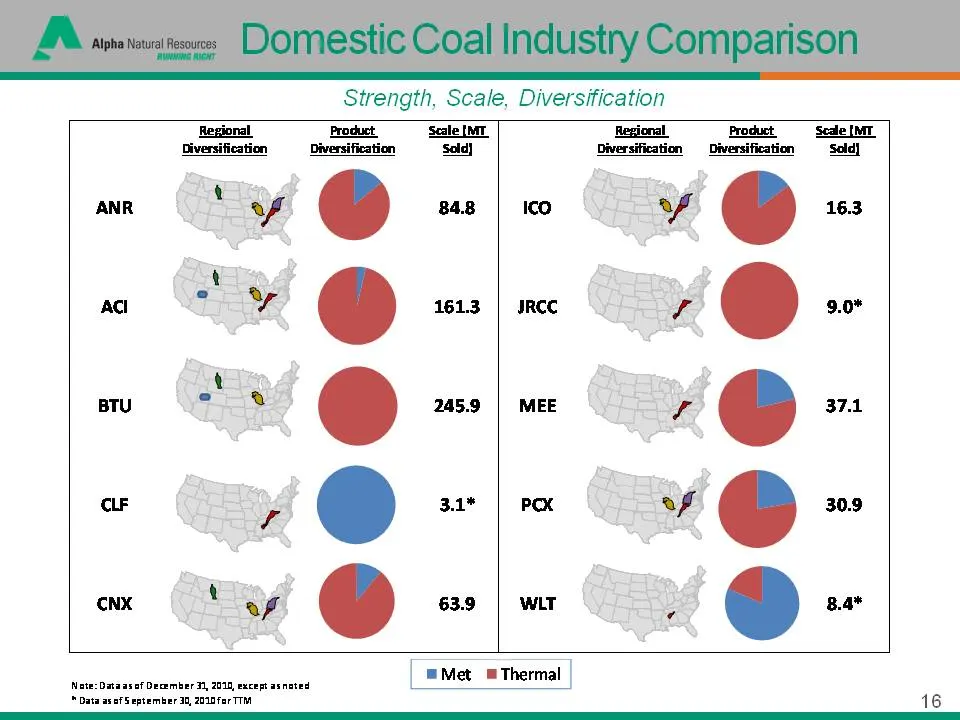
Slide 16: Reserves by company, met and thermal
ANR C y & 84.8 t “2 ac - vy ] & BTU oy CLF Ra ns CNX cee va 161.3 245.9 3.1* 63.9 Ico JRCC PK WLT 9.0* 37.1 30.9 3.4* Nate: Dataset December 3, 2010, except asnoted * Data asef September 30, 2710ferTTM = Met = Thermal | 16
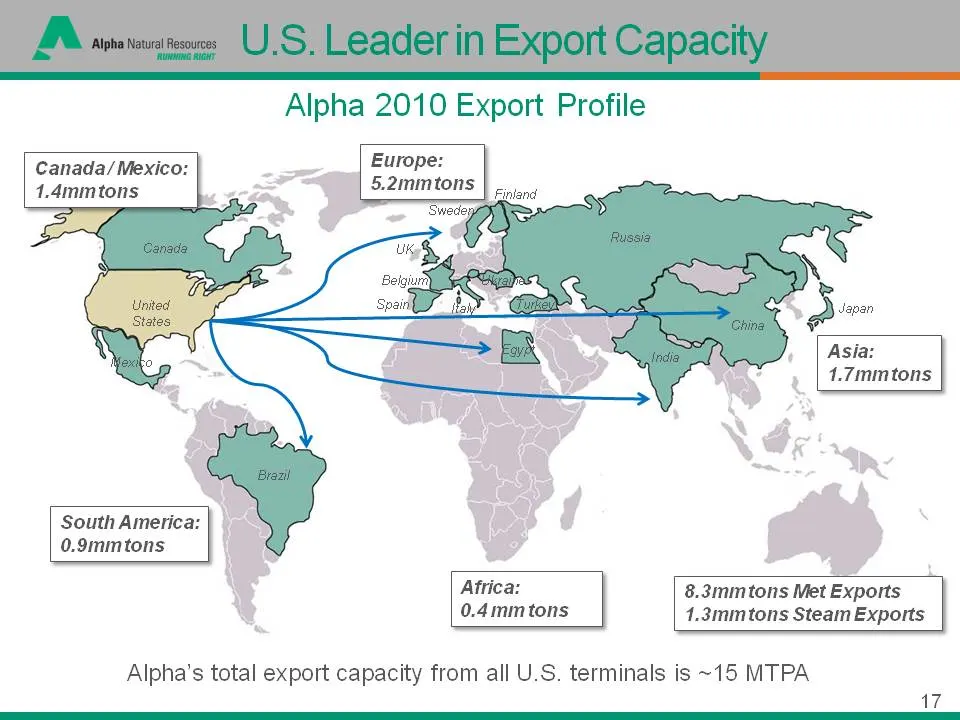
Slide 17: Alpha 2010 Export Profile
Canada/Mexico: 1.4mmtons South America: 0.9mmtons Alpha 2010 Export Profile Europe: 5.2mmtons ‘Swede Uke Belgiuy Spain ER Asia: Finland Soon 1.7mmtons Africa: 8.3mmtons Met Exports 0.4mm tons 1.3mmtons Steam Exports Alpha’s total export capacity from all U.S. terminals is ~15 MTPA 17
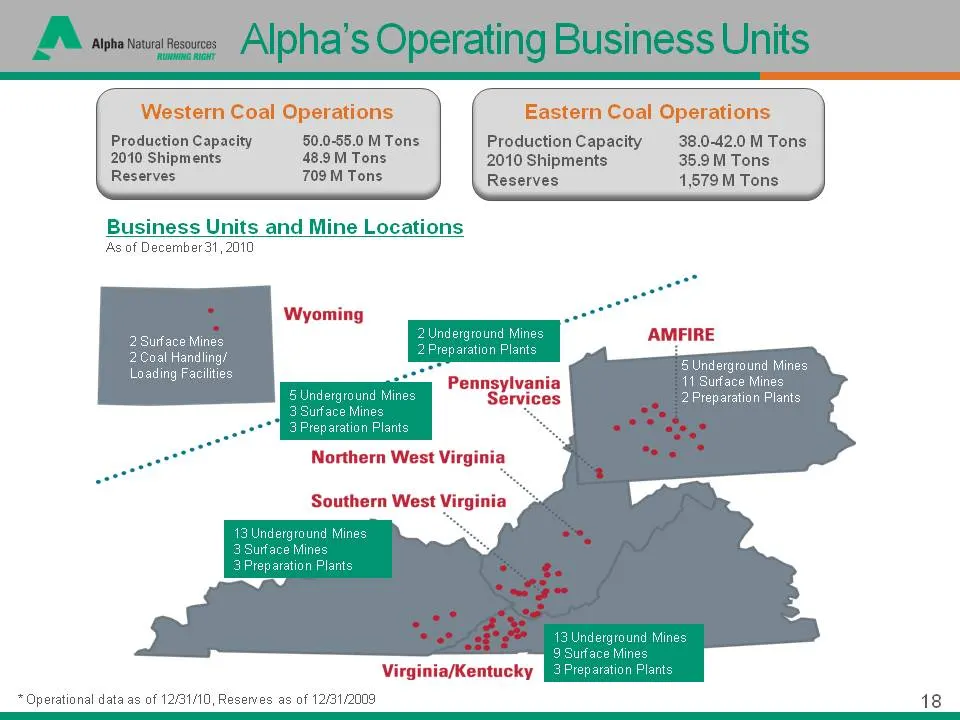
Slide 18: Business Units and Mine Locations
Production Capacity 38.0-42.0 M Tons 2010 Shipments 35.9M Tons Reserves 1,579 M Tons Production Capacity 50.0-55.0 M Tons 2010 Shipments 48.9 M Tons Reserves 709 M Tons Business Units and Mine Locations As of December31,2010 in val Handling? dling reparation Pla * Operational data as of 12/21/10, Re
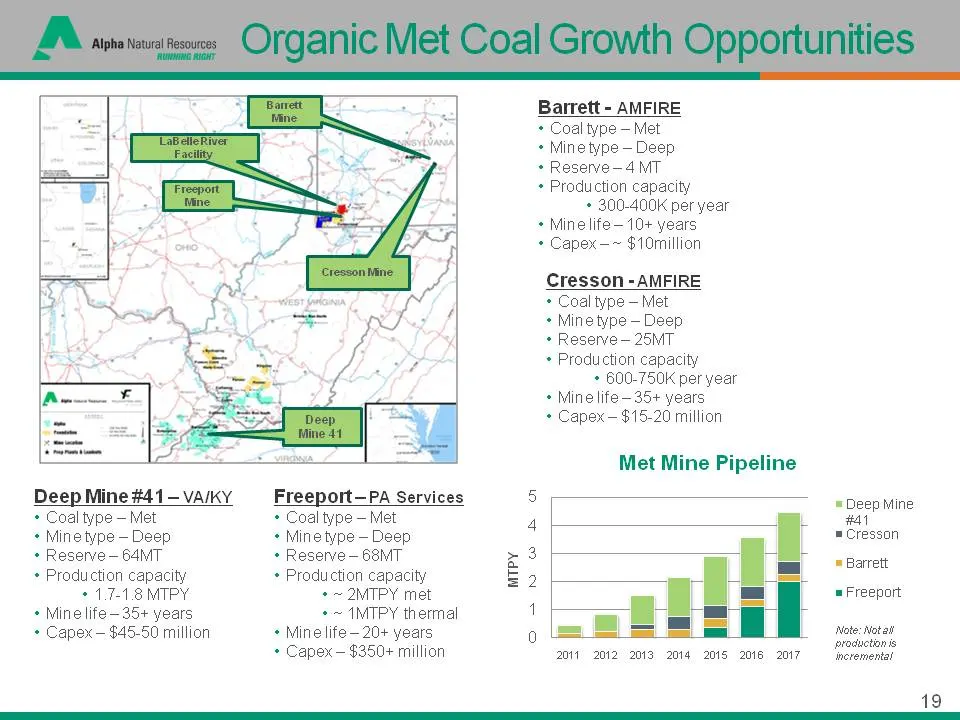
Slide 19: Met Mine Pipeline
Deep Mine #41 — VA/KY + Coal type — Met + Mine type — Deep + Reserve - 64MT + Production capacity + 1.7-18MTPY + Mine life-35+ years + Capex —$45-50 million Freeport—PA Services + Coal type — Met + Mine type — Deep + Reserve - 68MT + Production capacity + ~ 2MTPY met +~1IMTPY thermal + Mine life—20+
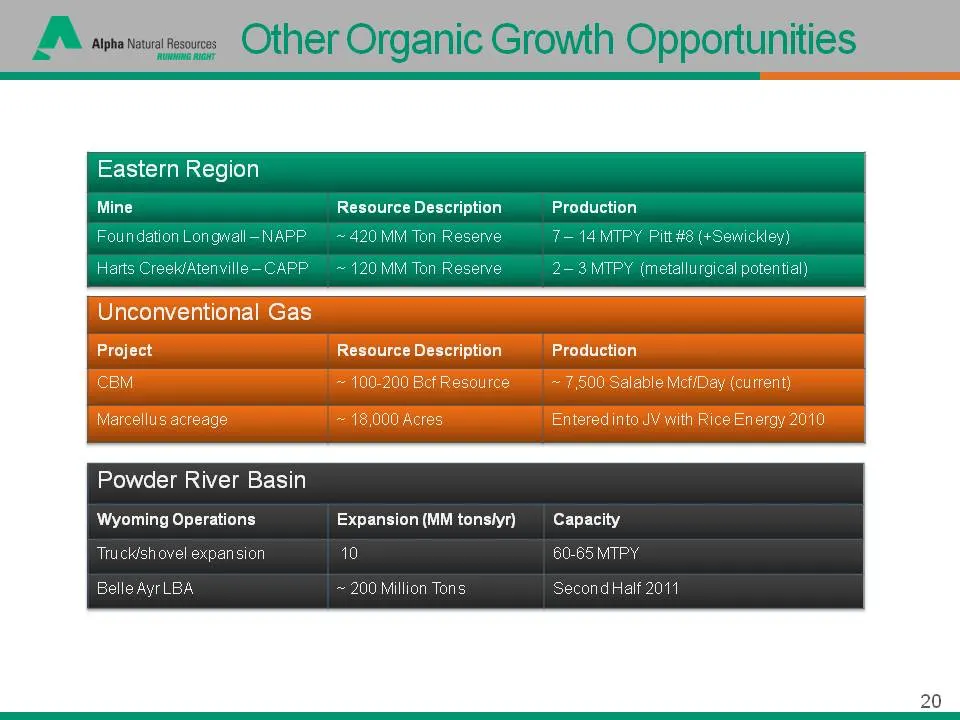
Slide 20: Other Organic Growth Opportunities
AA svateeee Other Organic Growth Opportunities Eastern Region Resource Description Production ~ 420 MM Ton Re e 7-14 MTPY Pitt ~ 120 MM Ton Re Powder River Basin Wyoming Operations Expansion (MM tonslyr) Capacity Tr n 10 10 Million Tor
Slide 21: Financial Strength to Enhance Shareholder Value
A Alpha Natural Resources ‘nome ne Financial Strength to Enhance Shareholder Value 21
Slide 22: Revenue, Adjusted EBITDA, Adjusted EPS and Free Cash Flow
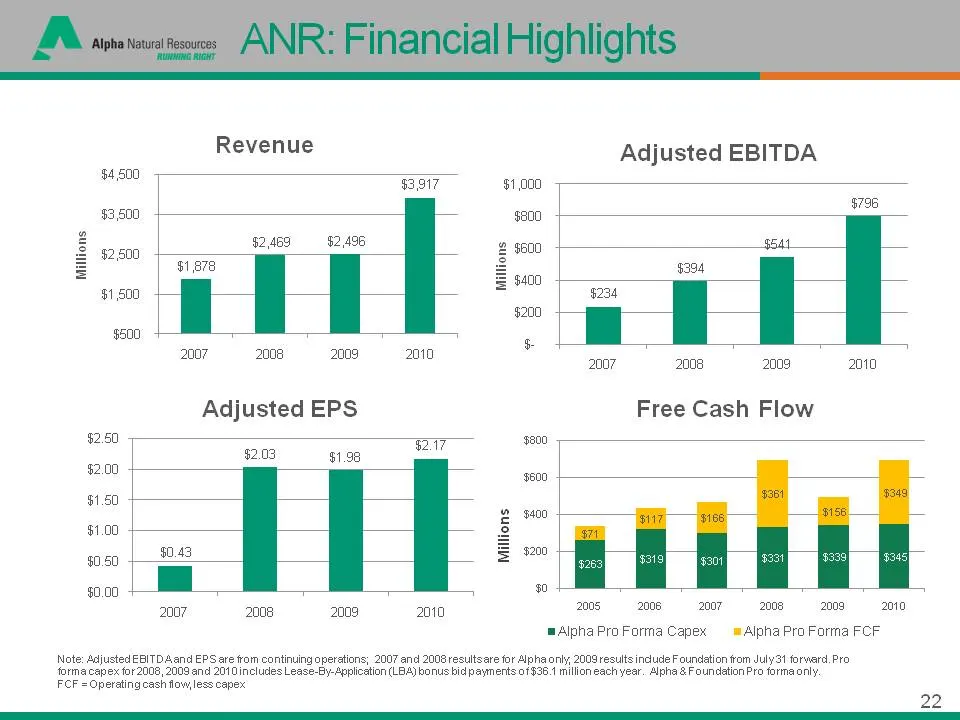
Revenue Adjusted EBITDA $4,500 Bor pF 96 $3,500 cf §2,500 $2,469 $2,496 $544 , $294 $1,500 $234 $600 $ i 2007 2008 2009 2010 2007 2008 2009 2010 Adjusted EPS Free Cash Flow $2.50 $2.00 a Med a $1.50 $1.00 $0.43 $0.50 0 | a ai ane ae zoos 2008-2007, 2008/0030 mAlpha Pro Forma Capex = Alpha Pro Forma
Slide 23: Leverage of approximately 1.0x and liquidity of approximately $1.8 billion
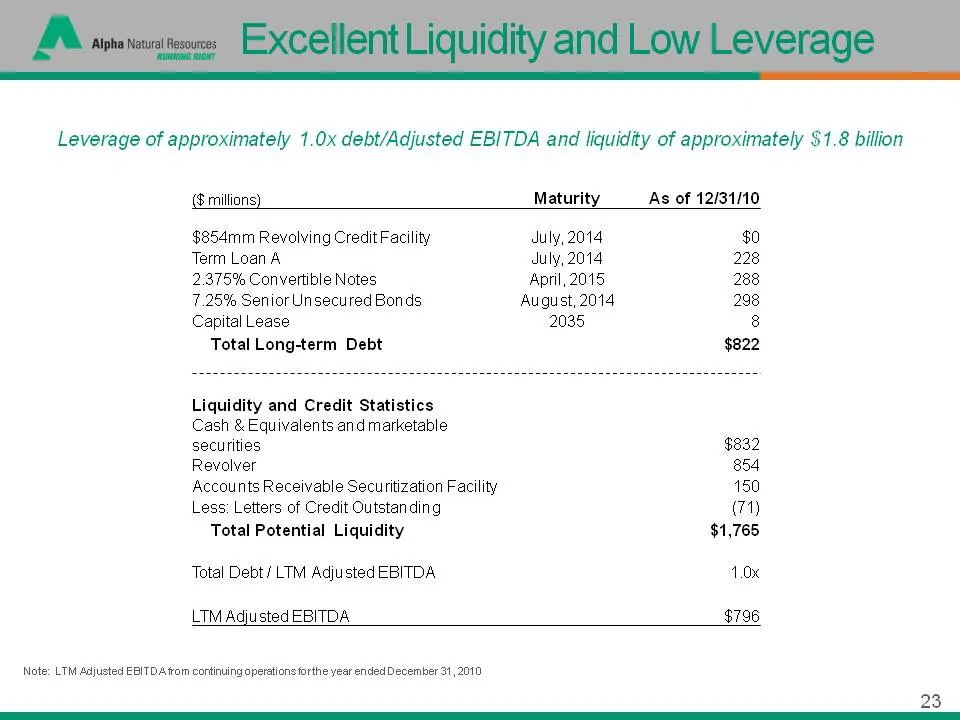
Leverage of approximately 1.0x debt/Adjusted EBITDA and liquidity of approximately $1.8 billion (Smilions) Maturity As of 12/31/10 $854mm Revolving Credit Facility July, 2014 $0 Term Loan A July, 2014 228 2.375% Convertible Notes April, 2015 288 7.25% Senior Unsecured Bonds August, 2014 298 Capital
Slide 24: Recent Valuation Comparison
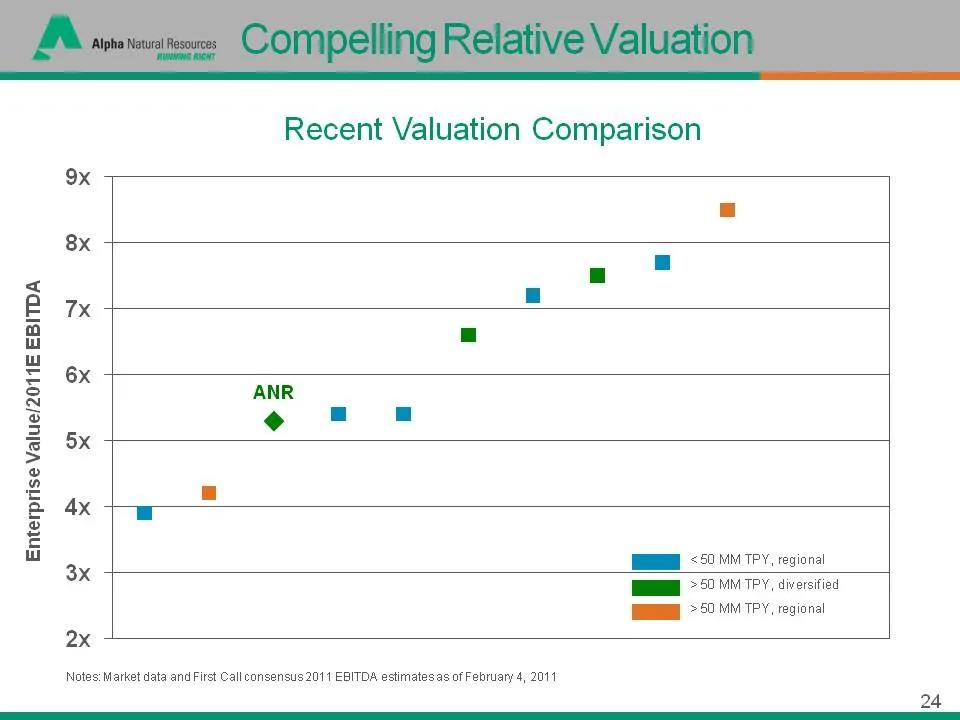
9x 8x IX 6x 5x 4x Enterprise Value/2011E EBITDA 3x 2x Recent Valuation Comparison ANR ME <50 MM TPY, regional HE > EO MM TPY, diversified HE > 50 MM TPY, regional Notes: Market data and First Call consensus 201 1 EBITDA estimatesas of February 4, 2014 24
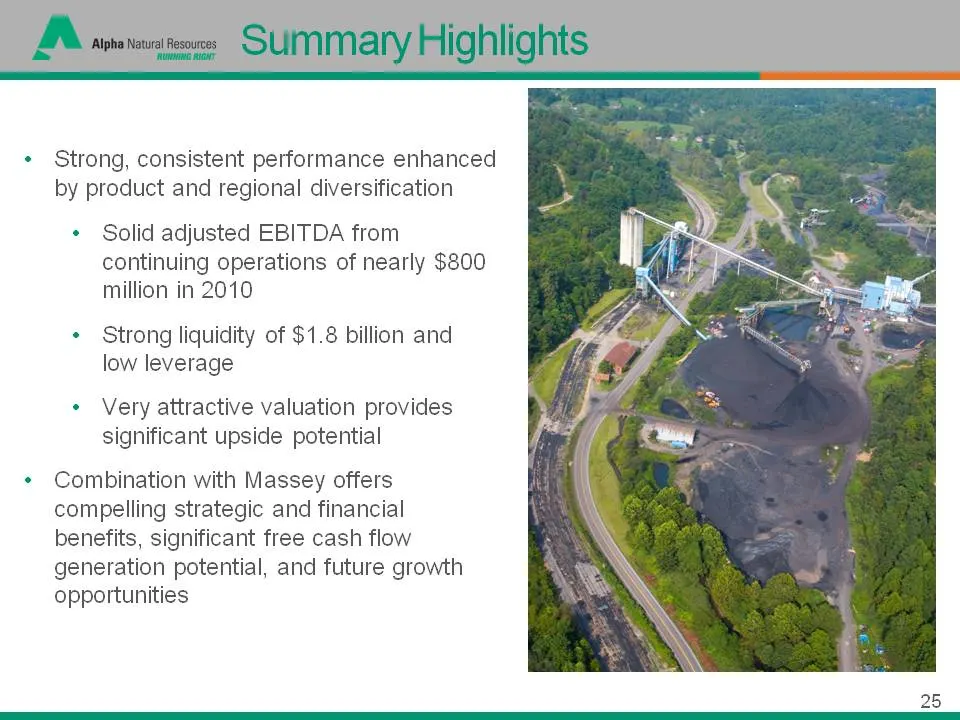
Slide 25: Summary: strong, consistent performance
+ Strong, consistent performance enhanced by product and regional diversification + Solid adjusted EBITDA from continuing operations of nearly $800 million in 2010 * Strong liquidity of $1.8 billion and low leverage + Very attractive valuation provides significant upside potential * Combination with
Slide 26: Alpha Natural Resources
A ‘Alpha Natural Resources ‘roman A Alpha Natural Resources y~ www.alphanr.com
Source: SEC EDGAR · 425 filed Feb 10, 2011
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010
 Howard Weil Energy Conference 200851 slides · Apr 7, 2008