Consumers Energy Company · NYSE:CMS/PB
Consumers Energy — American Gas Association, May 18 & 19, 2015
44 slides from Consumers Energy's conference presentation, May 15, 2015
Slide 1: CMS Energy – American Gas Association, May 18 & 19, 2015
CMS Energy CMS Listed NYSE American Gas Association May 18 & 19, 2015 Ludington Pumped Storage Fourth Largest in the world Ray Compressor Station #1 LDC in gas storage Cross Winds® Energy Park #2 in renewable sales in the Great Lakes area
Slide 2: CMS Energy Investor Meeting May 21, 2015
CMS Energy CMS Listed NYSE Investor Meeting May 21, 2015 Ludington Pumped Storage Fourth Largest in the world Ray Compressor Station #1 LDC in gas storage Cross Winds® Energy Park #2 in renewable sales in the Great Lakes area
Slide 3: Forward-looking statements and non-GAAP measures
This presentation is made as of the date hereof and contains “forward-looking statements” as defined in Rule 3b-6 of the Securities Exchange Act of 1934, Rule 175 of the Securities Act of 1933, and relevant legal decisions. The forward-looking statements are subject to risks and uncertainties. All f
Slide 4: Who Has the Best Track Record?
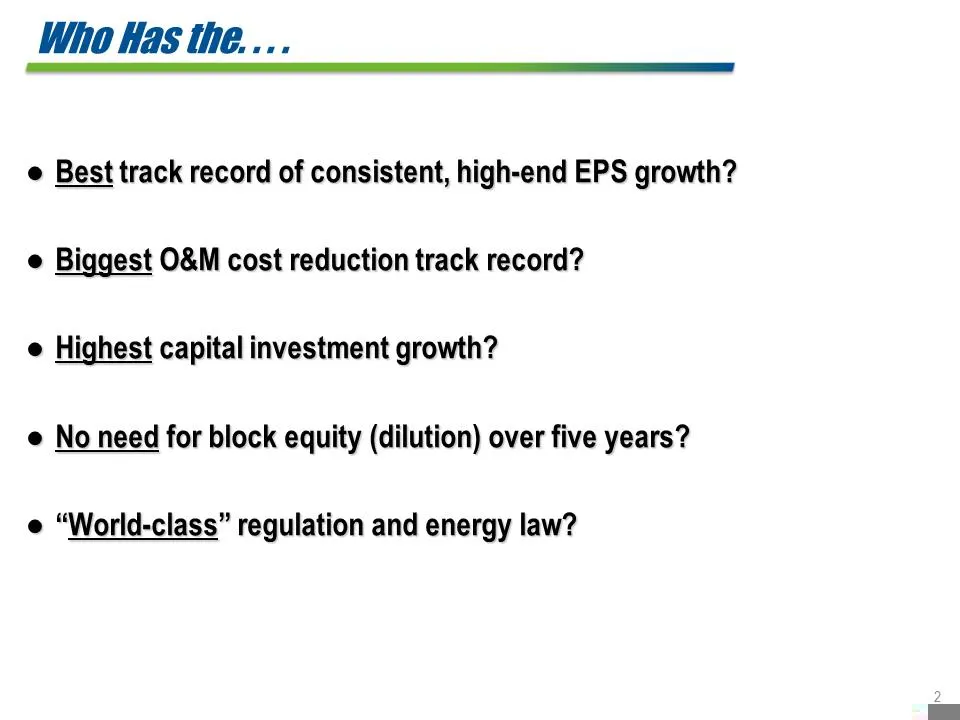
.Best track record of consistent, high-end EPS growth? .Biggest O&M cost reduction track record? .Highest capital investment growth? .No need for block equity (dilution) over five years? .“World-class” regulation and energy law? Who Has the. . . .
Slide 5: CMS Energy
CMS Energy
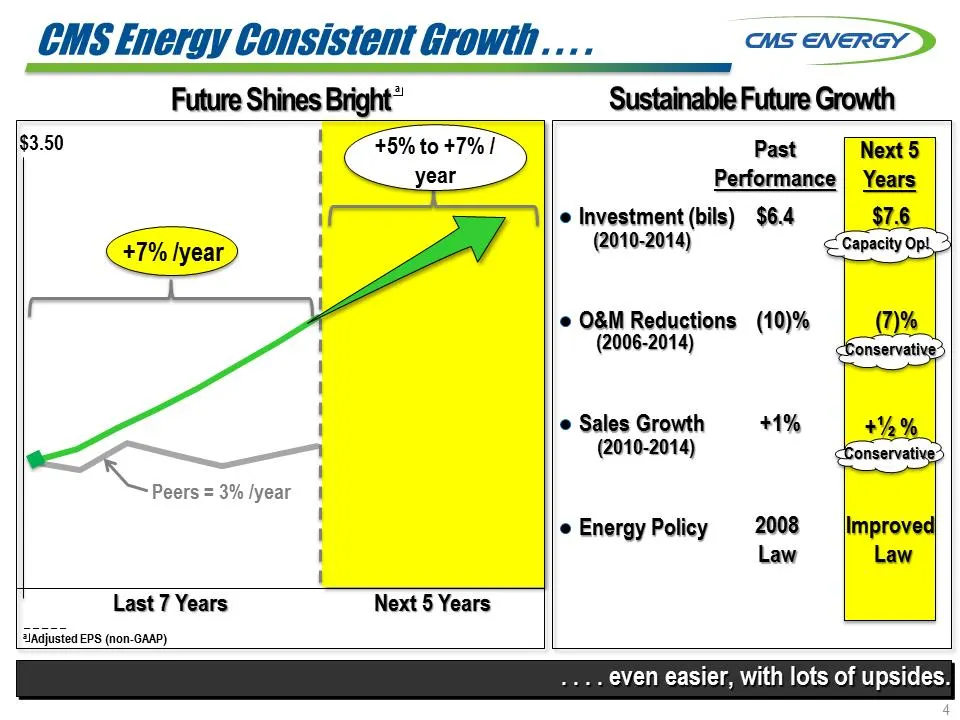
Slide 6: Consistent Growth, Sustainable Future Growth
CMS Energy Con sistent Growth . . . . . . . . even easier, with lots of upsides. Sustainable Future Growth Investment (bils) O&M Reductions Sales Growth Energy Policy Future Shines Bright $6.4 (10)% +1% $7.6 (7)% +½ % Past Performance Next 5 Years Improved Law (2010-2014) (2006-2014) (2010-2014) 200
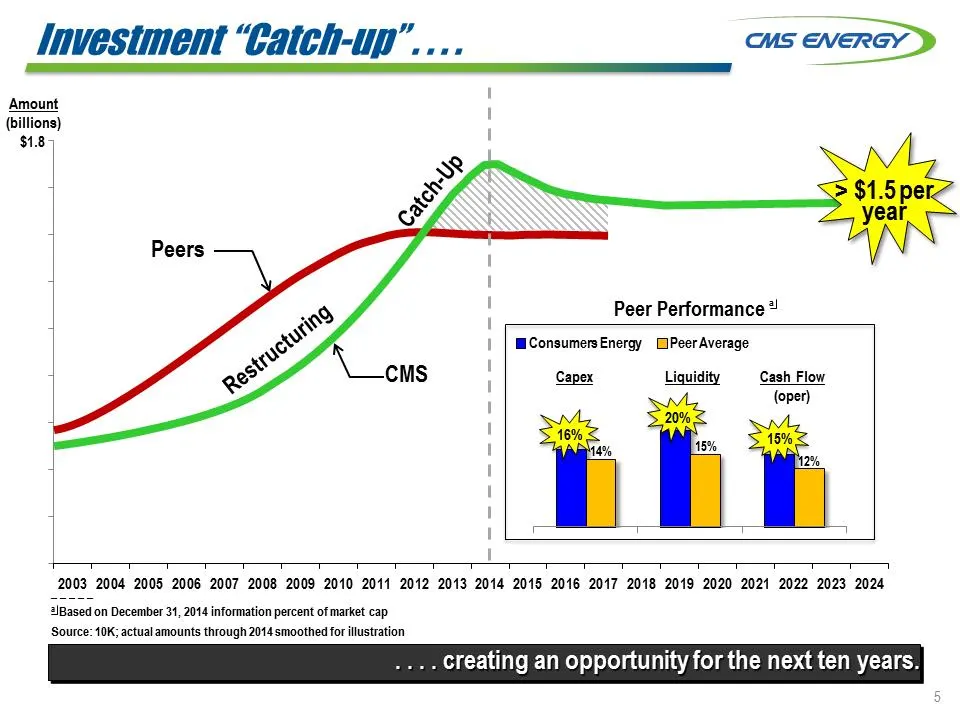
Slide 7: Investment catch-up creating an opportunity for the next ten years
2003200420052006200720082009201020112012201320142015201620172018201920202021202220232024. . . . creating an opportunity for the next ten years. Amount (billions) $1.8 CMS Peers _ _ _ _ _ a Based on December 31, 2014 information percent of market cap Source: 10K; actual amounts through 2014 smoothed
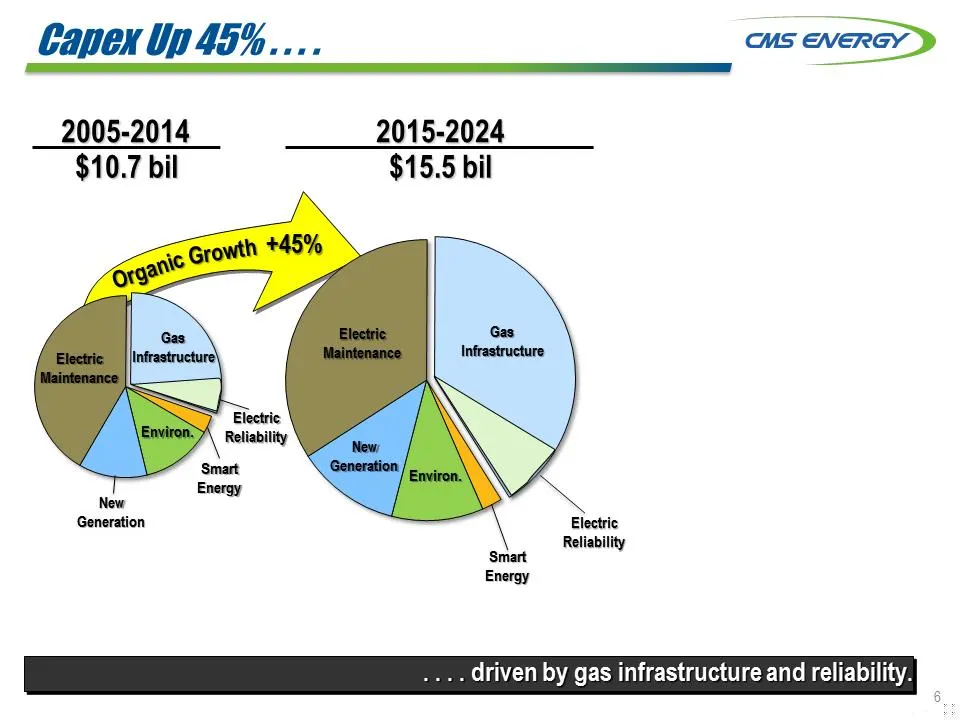
Slide 8: Capex Up 45% driven by gas infrastructure and reliability
Capex Up 45% . . . . . . . . driven by gas infrastructure and reliability. 2015-2024 2005-2014 $10.7 bil $15.5 bil +45% Capex Up 45% . . . . . . . . driven by gas infrastructure and reliability.Electric Maintenance New Generation Environ. Smart Energy Electric Reliability Electric Maintenance Gas In
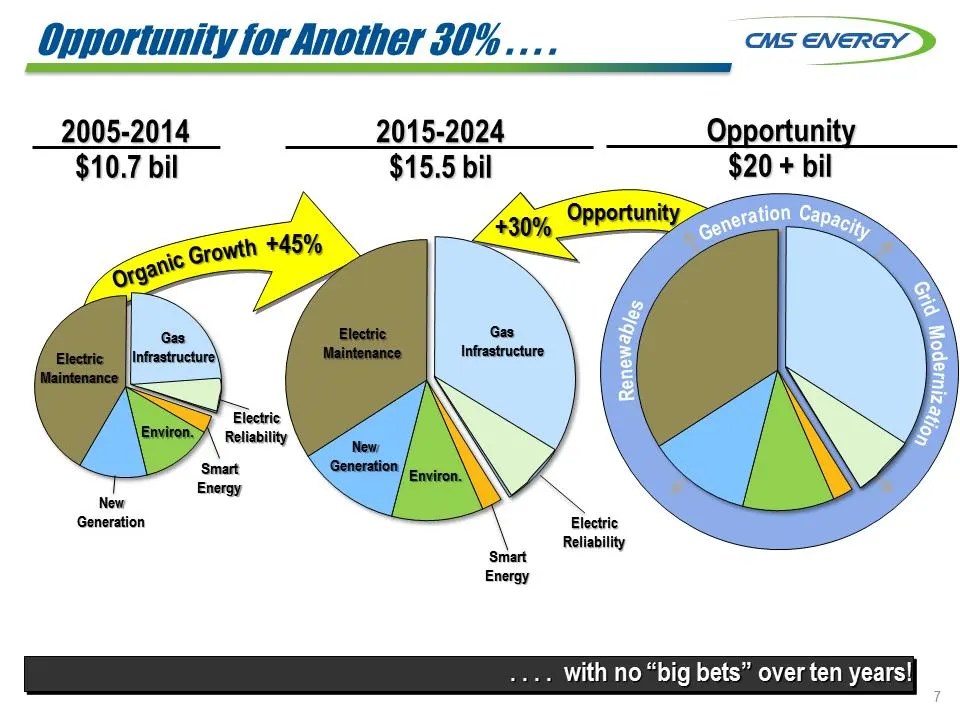
Slide 9: Opportunity for Another 30% with no big bets over ten years
Opportunity for Another 30% . . . . . . . . with no “big bets” over ten years! 2015-2024 2005-2014 $10.7 bil $15.5 bil +45% Opportunity for Another 30% . . . . . . . . with no “big bets” over ten years!+30% Electric Maintenance Gas Infrastructure New Generation Environ. Smart Energy Electric Reliabi
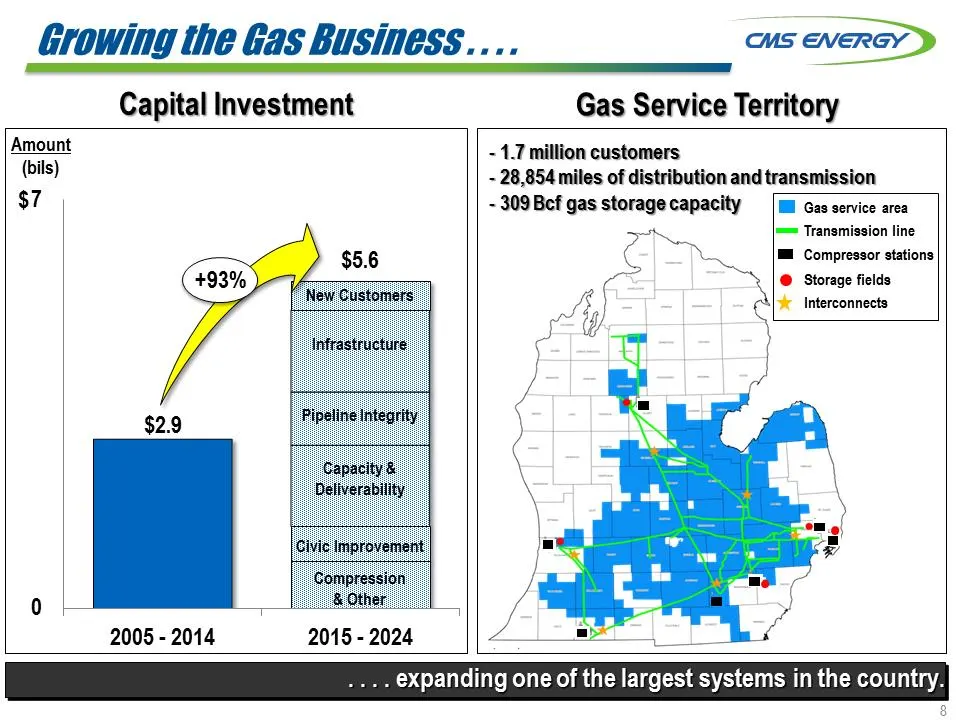
Slide 10: Growing the Gas Business
G rowing the Gas Business . . . . . . . . expanding one of the largest systems in the country. Amount (bils) $5.6 Capital Investment $ +93% Pipeline Integrity Civic Improvement Capacity & Deliverability Compression & Other Infrastructure New Customers Gas service area Transmission line Compressor st
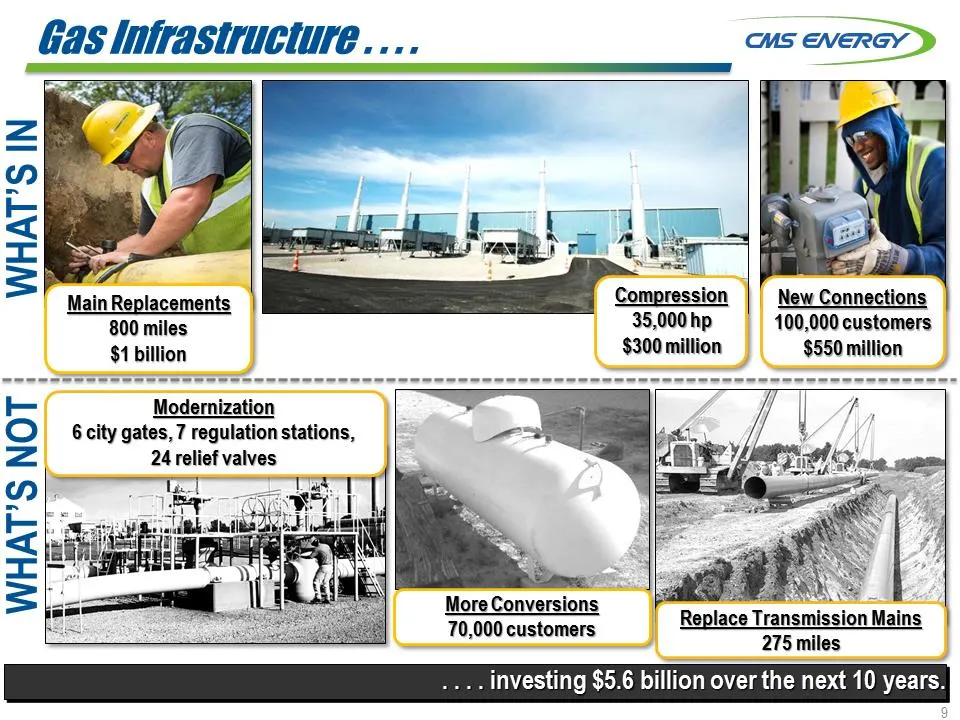
Slide 11: Gas Infrastructure investing $5.6 billion over ten years
Gas Infrastructure . . . . . . . . investing $5.6 billion over the next 10 years. Main Replacements 800 miles $1 billion Modernization 6 city gates, 7 regulation stations, 24 relief valves New Connections 100,000 customers $550 million Replace Transmission Mains 275 miles WHAT’S IN WHAT’S NOT More C
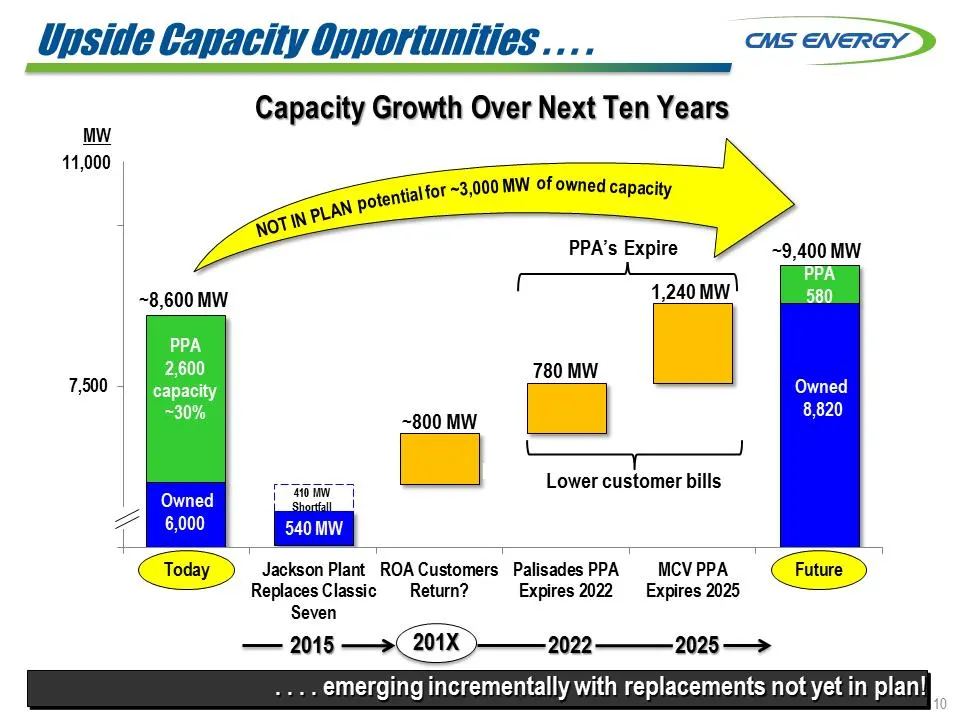
Slide 12: Capacity opportunities emerging incrementally
. . . . emerging incrementally with replacements not yet in plan! 7,50010,000TodayJackson PlantReplaces ClassicSevenROA CustomersReturn?Palisades PPAExpires 2022MCV PPAExpires 2025Future~800 MW 1,240 MW MW PPA 2,600 capacity ~30% ~8,600 MW 540 MW 410 MW Shortfall Owned 6,000 780 MW ~9,400 MW 11,000
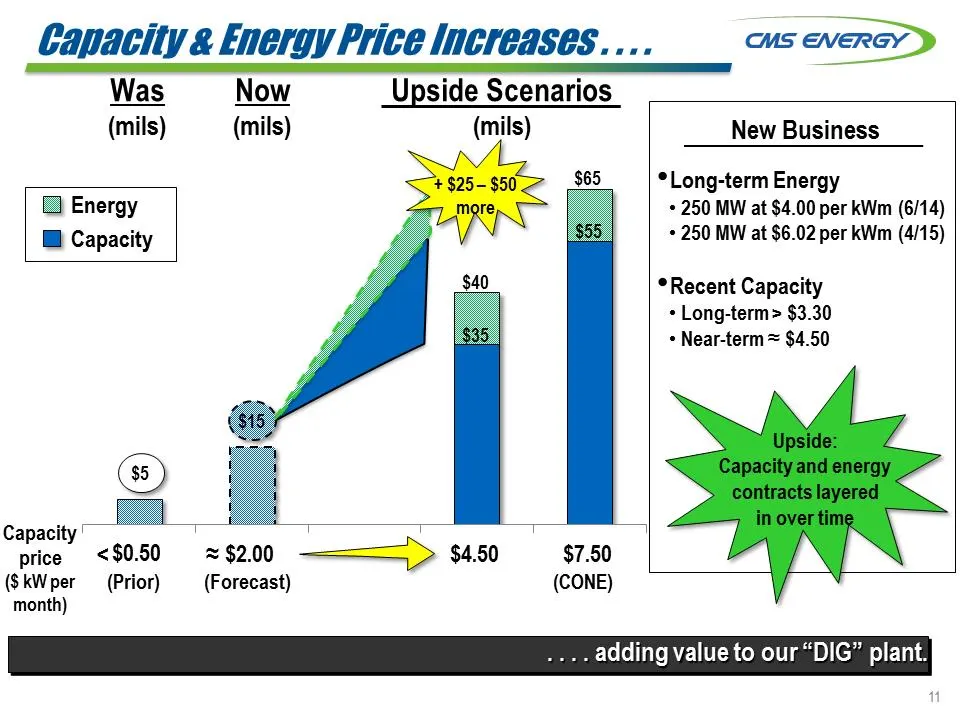
Slide 13: Capacity & Energy Price Increases adding value to DIG plant
Capacity & Energy Price Increases . . . . . . . . adding value to our “DIG” plant. $0.50$2.00$4.50$7.50Capacity price ($ kW per month) Was (mils) Upside Scenarios (mils) $55 $35 New Business •Long-term Energy •250 MW at $4.00 per kWm (6/14) •250 MW at $6.02 per kWm (4/15) •Recent Capacity •Long-term
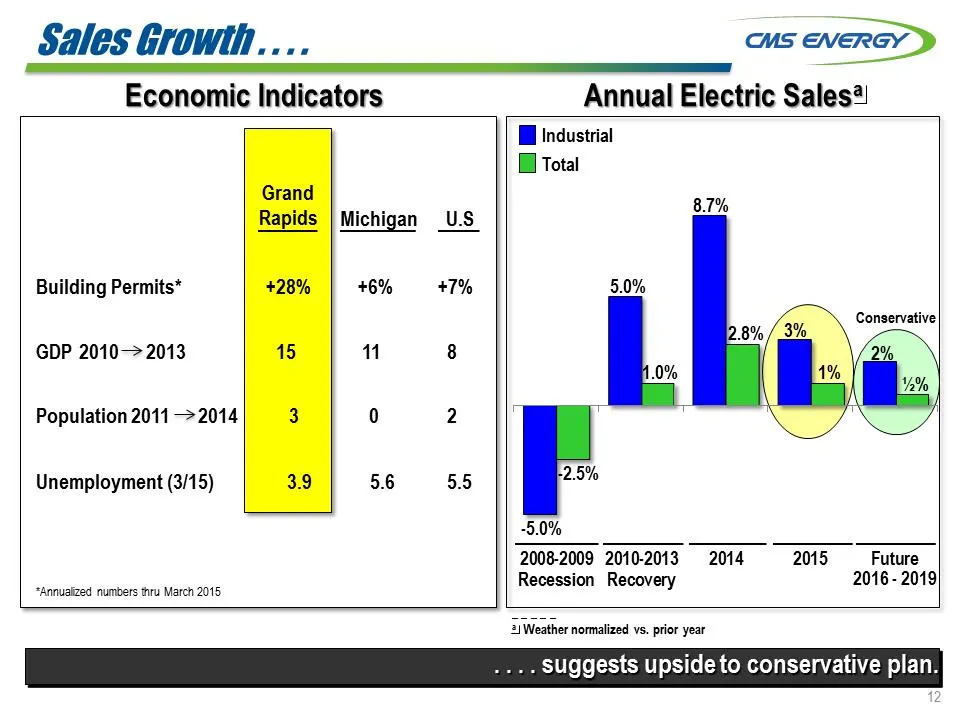
Slide 14: Sales Growth suggests upside to conservative plan
Sales Growth . . . . . . . . suggests upside to conservative plan. Annual Electric Salesa 2008-2009Recession2010-2013Recovery20142015Future -5.0% -2.5% 5.0% 8.7% 2.8% 3% 1% Industrial Total _ _ _ _ _ a Weather normalized vs. prior year ½% 2% Conservative 2016 - 2019 Economic Indicators Grand Rapids
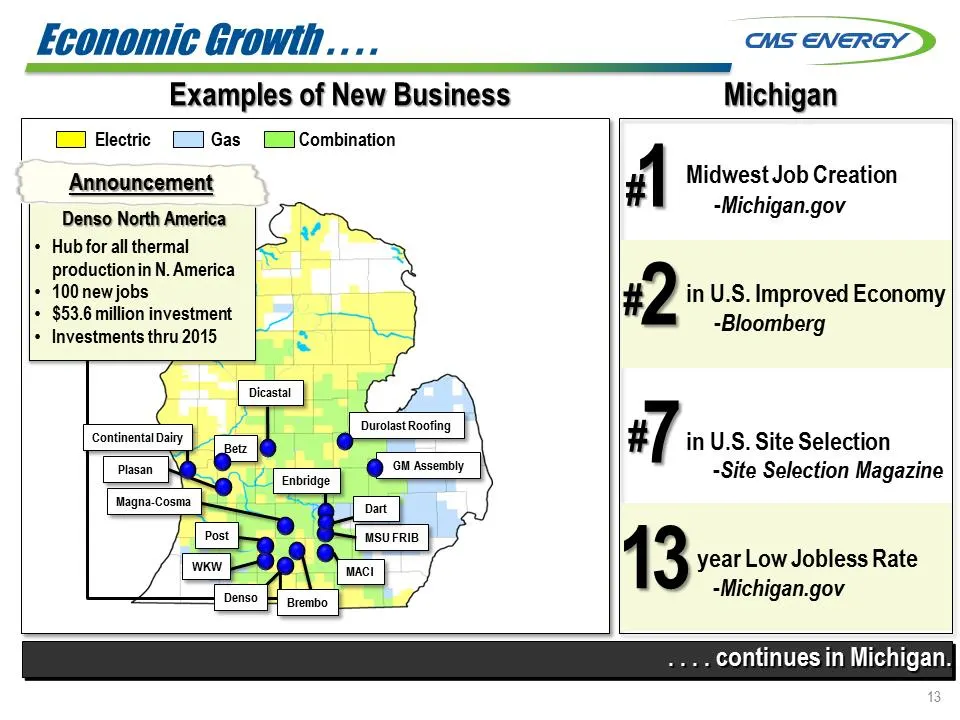
Slide 15: Economic growth continues in Michigan
Mich_Map. . . . continues in Michigan. Electric Gas Combination Betz MSU FRIB Durolast Roofing GM Assembly Examples of New Business Michigan Denso North America •Hub for all thermal production in N. America •100 new jobs •$53.6 million investment •Investments thru 2015 Announcement Enbridge MACI Dar
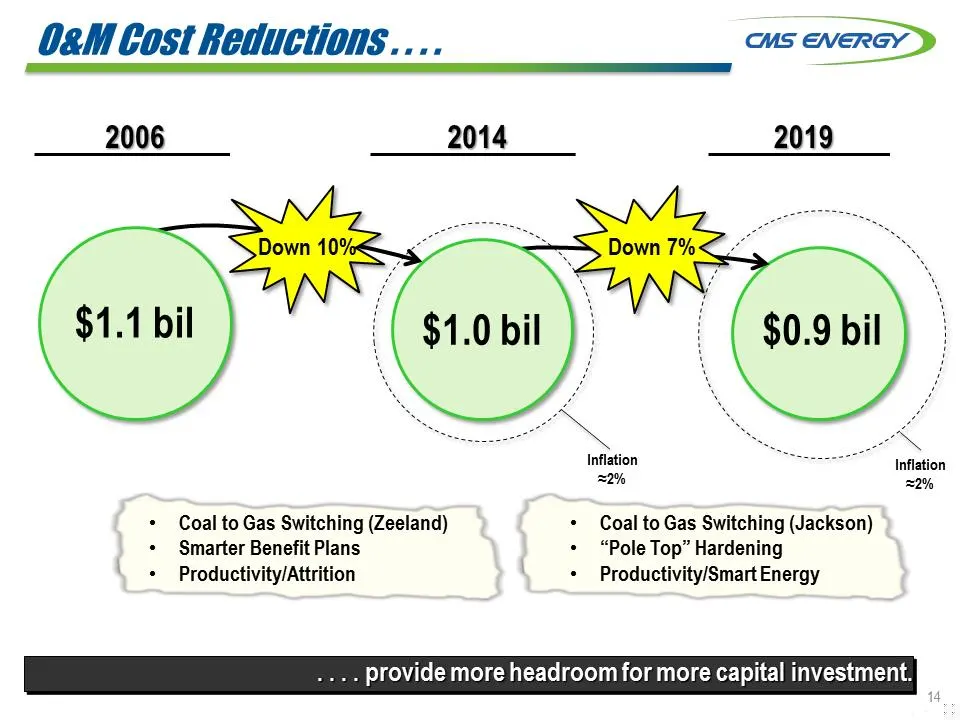
Slide 16: O&M Cost Reductions provide more headroom
O&M Cost Reductions . . . . . . . . provide more headroom for more capital investment. Down 10% $1.1 bil $0.9 bil 2006 2014 2019 $1.0 bil •Coal to Gas Switching (Zeeland) •Smarter Benefit Plans •Productivity/Attrition •Coal to Gas Switching (Jackson) •“Pole Top” Hardening •Productivity/Smart Energy
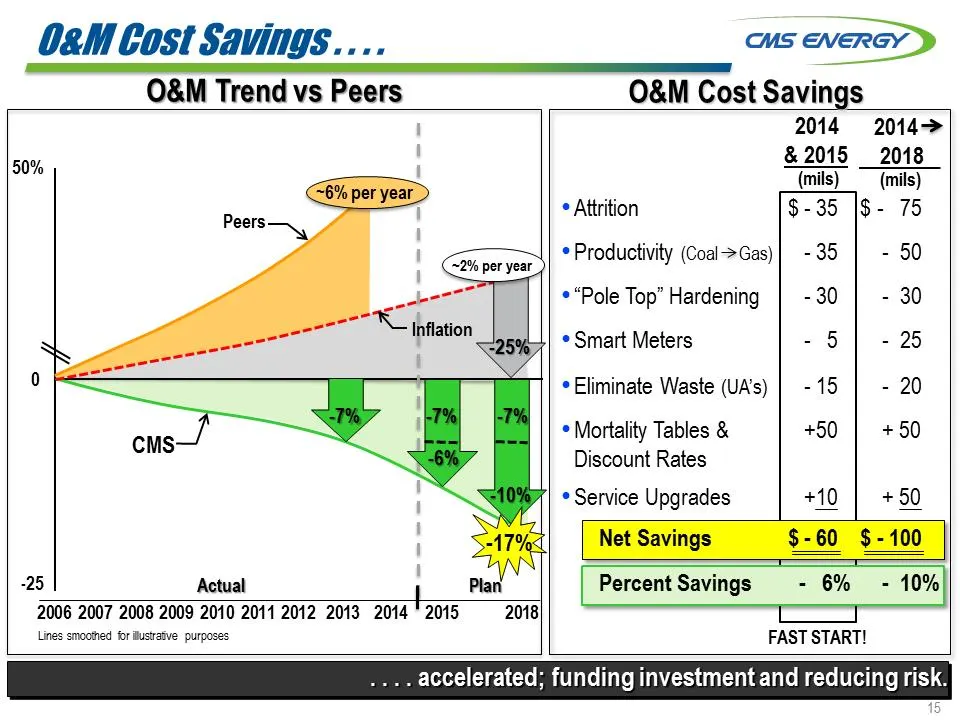
Slide 17: O&M cost savings accelerated
20062007200820092010201120122013. . . . accelerated; funding investment and reducing risk. 50% -25 Lines smoothed for illustrative purposes O&M Trend vs Peers 2014 Actual Plan O&M Cost Savings Peers CMS 0 -10% ~2% per year -25% -7% O&M Cost Savings . . . . 2018 ~6% per year Inflation 2015 FAST START
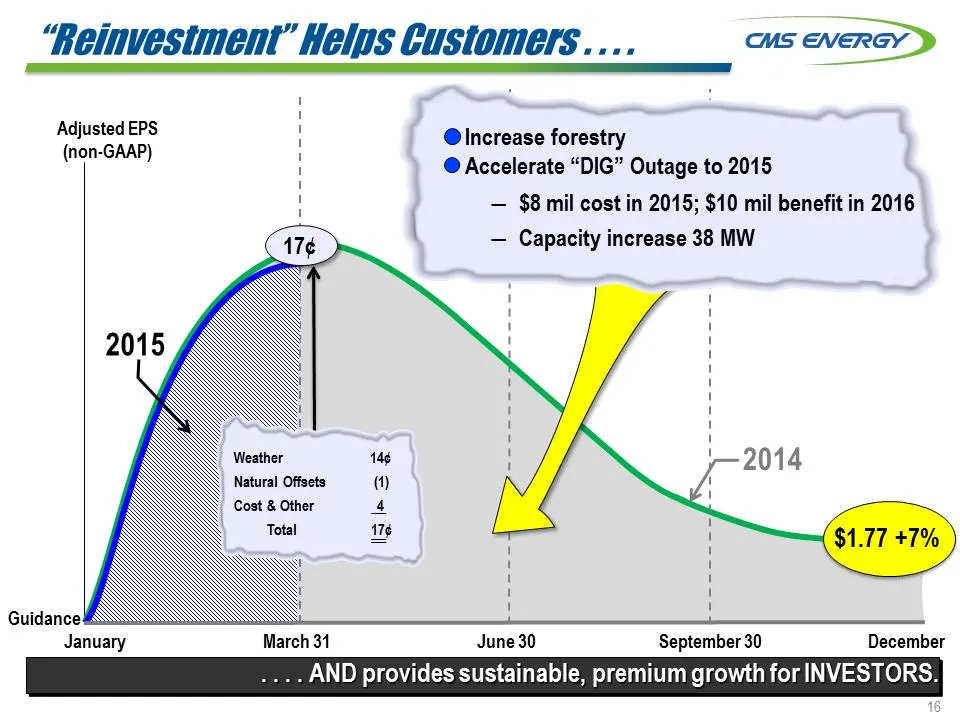
Slide 18: 2015 adjusted EPS guidance
. . . . AND provides sustainable, premium growth for INVESTORS. 2014 Adjusted EPS (non-GAAP) Guidance January March 31 June 30 September 30 December $1.77 +7% 2015 “Reinvestment” Helps Customers . . . . 17¢ Weather 14¢ Natural Offsets (1) Cost & Other 4 Total 17¢ Increase forestry Accelerate “DIG” O
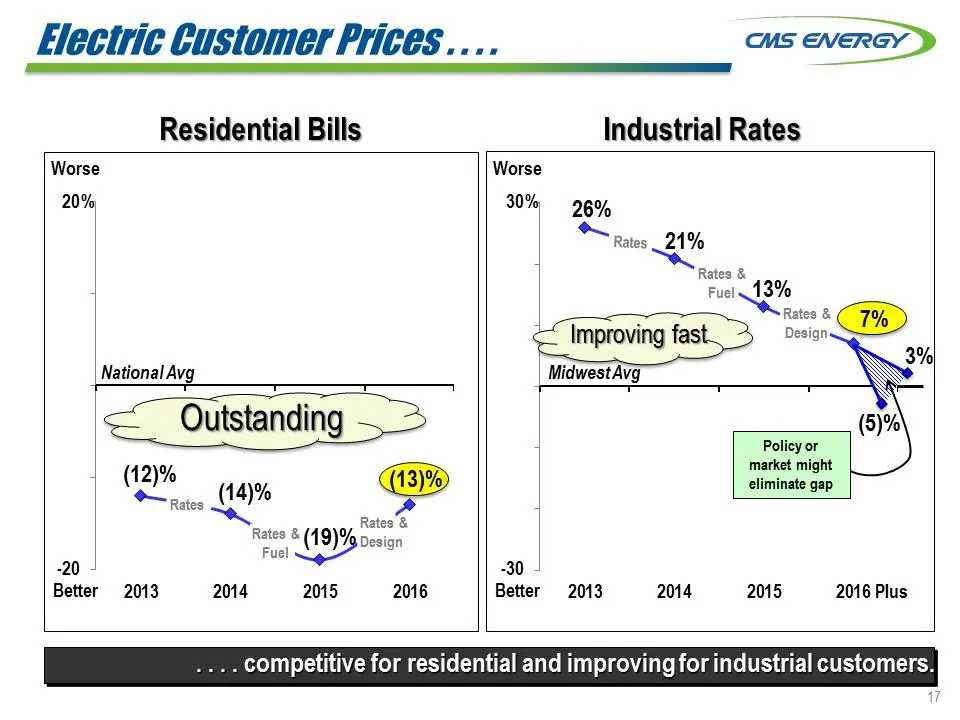
Slide 19: Electric customer prices competitive and improving
. . . . competitive for residential and improving for industrial customers. -2013201420152016Industrial Rates (12)% (14)% (19)% (13)% National Avg % Better Worse Rate s Rates & Fuel Rates & Design - 201320142015201626% 21% 13% Midwest Avg % 7% Better Worse BetterRates & Fuel Rates & Design 3% (5)% P
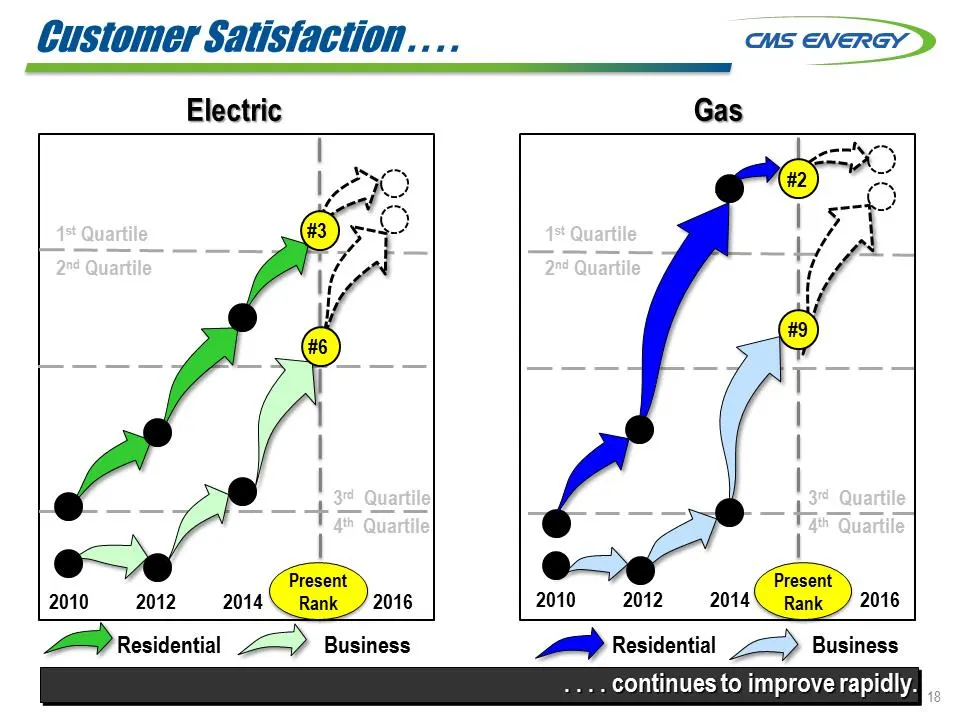
Slide 20: Customer Satisfaction
Customer Satisfaction . . . . Electric 1st Quartile 2nd Quartile 4th Quartile 2010 2012 2014 2016 Residential3rd Quartile . . . . continues to improve rapidly. Gas 1st Quartile 2nd Quartile 4th Quartile 3rd Quartile 2010 2012 2014 2016 Present Rank Present Rank Residential Business Residential Busin
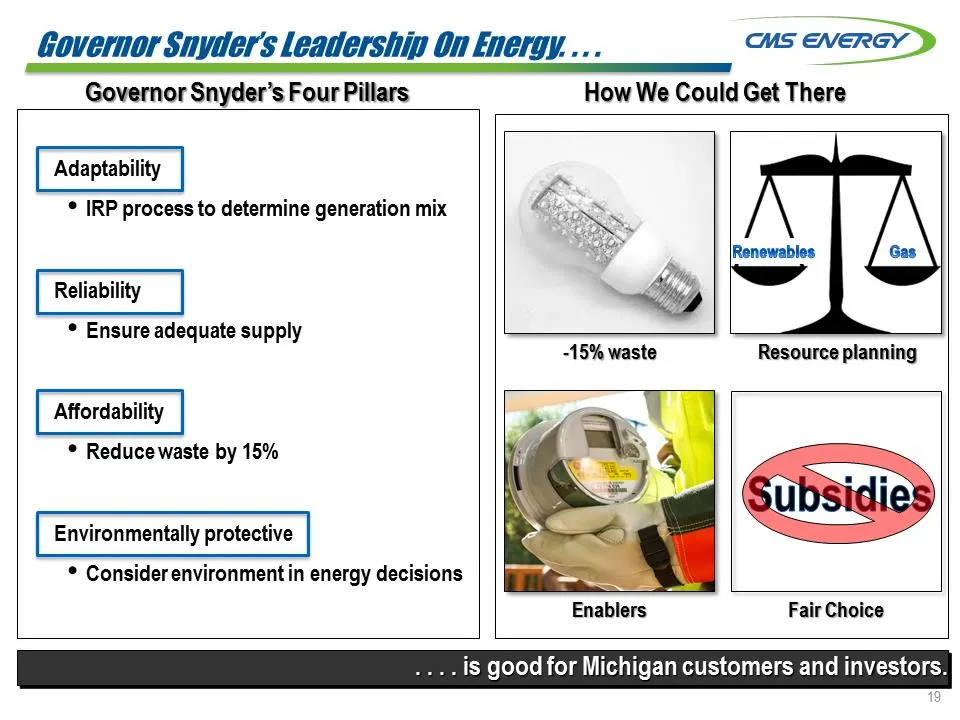
Slide 21: Governor Snyder's Leadership on Energy
. . . is good for Michigan customers and investors. Governor Snyder’s Leadership On Energy. . . . How We Could Get There Governor Snyder’s Four Pillars GasRenewablesSubsidies-15% waste Resource planning Enablers Fair Choice Adaptability •IRP process to determine generation mix Reliability •Ensure ad
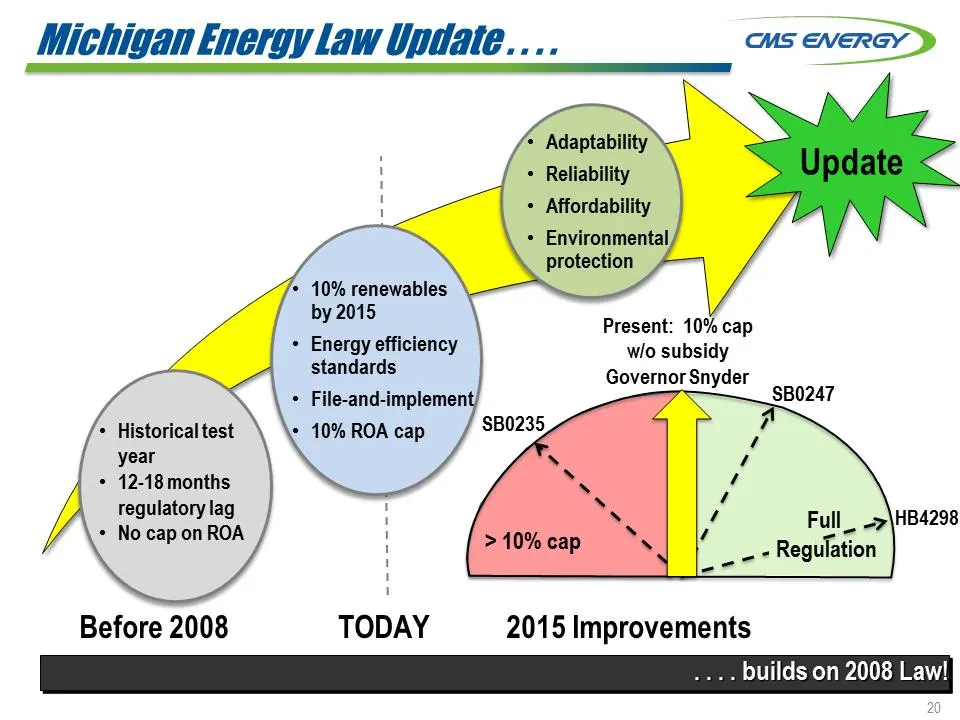
Slide 22: Michigan Energy Law Update
Michigan Energy Law Update . . . . •Historical test year •12-18 months regulatory lag •No cap on ROA •10% renewables by 2015 •Energy efficiency standards •File-and-implement •10% ROA cap Adaptability Reliability Affordability Environmental protection Before 2008 TODAY 2015 Improvements . . . . build
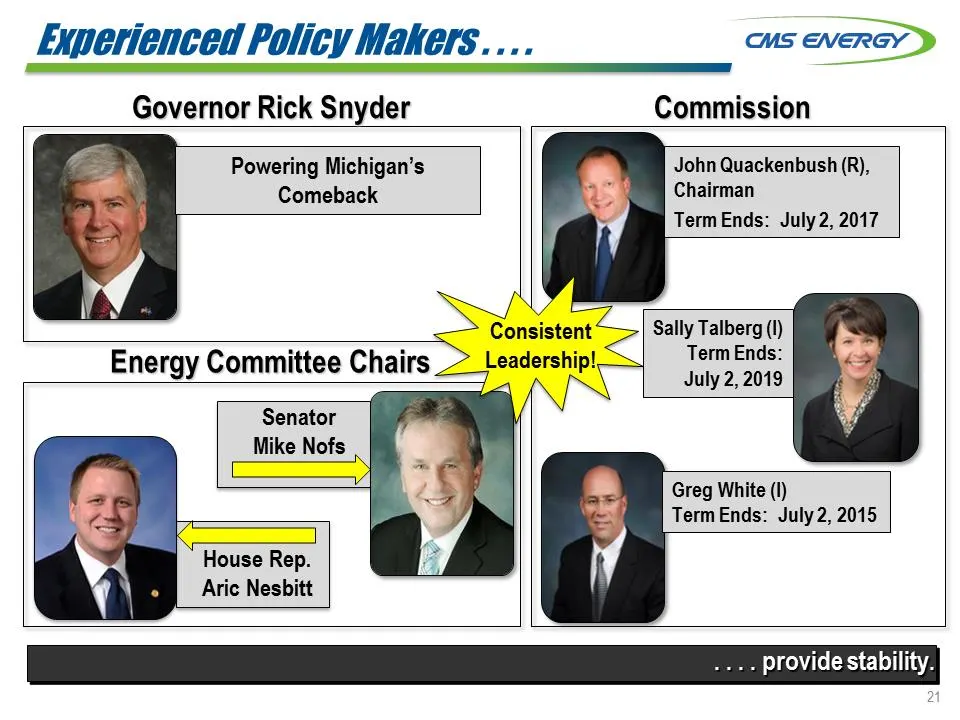
Slide 23: Commission and policy makers provide stability
. . . . provide stability. John Quackenbush (R), Chairman Term Ends: July 2, 2017 Greg White (I) Term Ends: July 2, 2015 Sally Talberg (I) Term Ends: July 2, 2019 Commission Powering Michigan’s Comeback Governor Rick Snyder Energy Committee Chairs Senator Mike Nofs House Rep. Aric Nesbitt Consistent
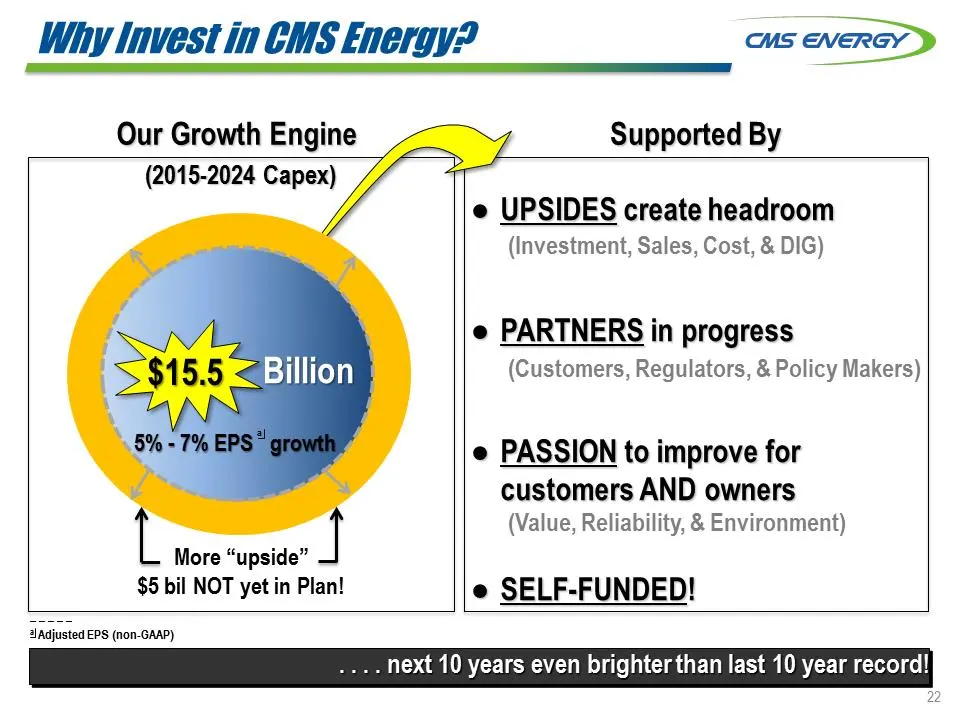
Slide 24: Why Invest in CMS Energy?
. . . next 10 years even brighter than last 10 year record! Supported By .UPSIDES create headroom .PARTNERS in progress .PASSION to improve for customers AND owners .SELF-FUNDED! Our Growth Engine Billion $15.5 More “upside” $5 bil NOT yet in Plan! (2015-2024 Capex) 5% - 7% EPS growth (Investment, S
Slide 25: Appendix
Appendix
Slide 26: Michigan's Energy Future
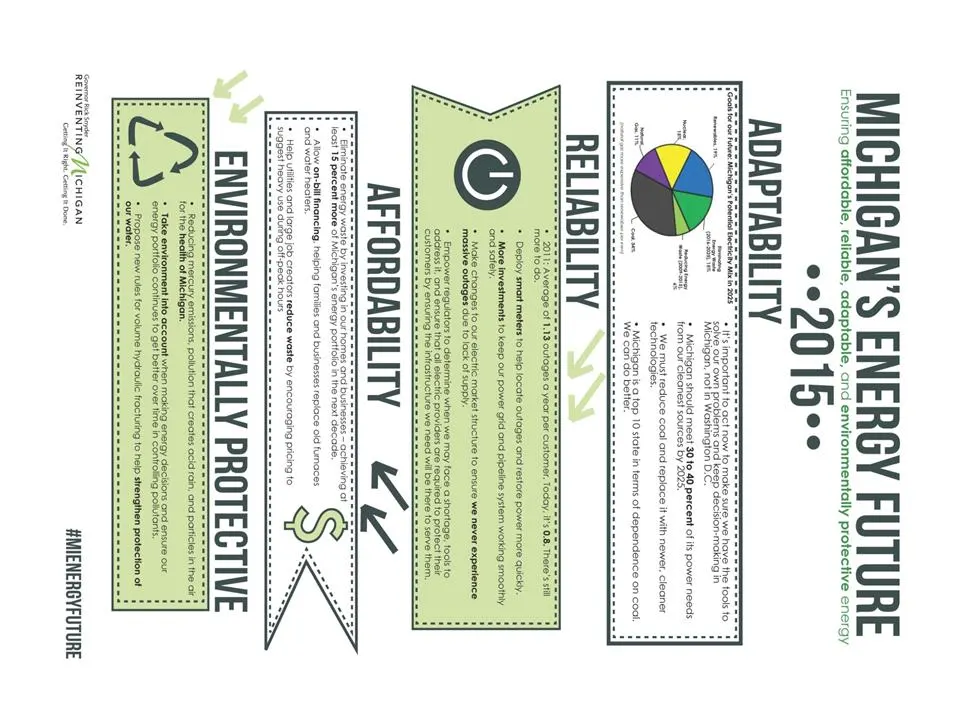
MICHIGAN’S ENERGY FUTURE Ensuring affordable, reliable, adaptable, and environmentally protective energy --2015+° swloger 6 yeor per customer. Today. 1's 08 There's + Deploy smart meters help locate outages and restore power more auicky. + Mote investments 10 Keep our power ri ond pipeline system wo
Slide 27: Carbon Tonnage Reduction
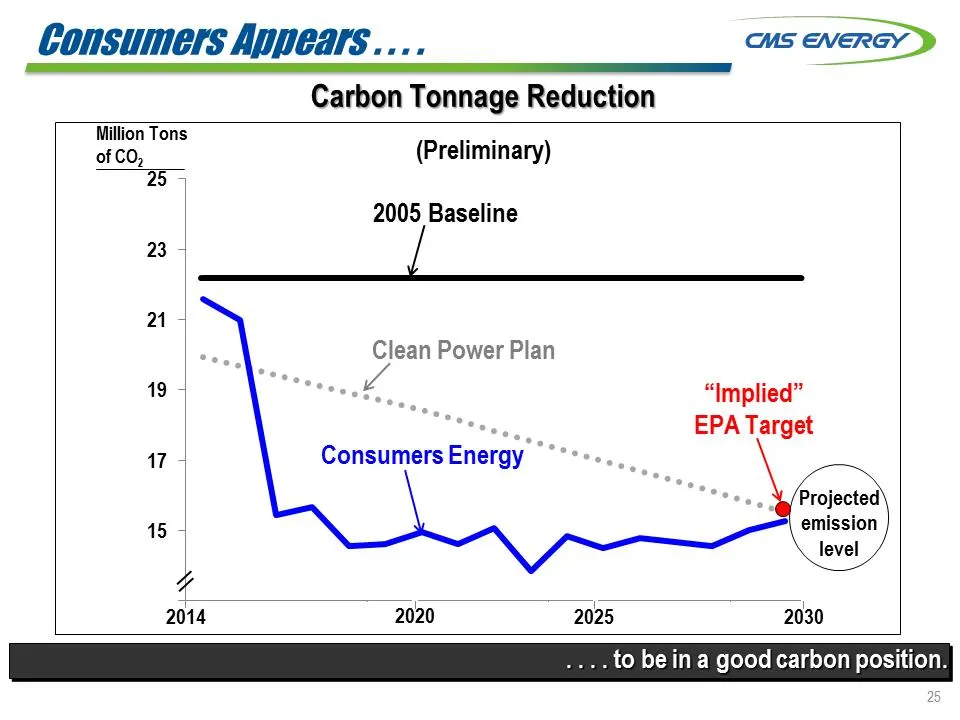
. . . to be in a good carbon position. Carbon Tonnage Reduction (Preliminary) 131517192123252005 Baseline Million Tons of CO2 Consumers Energy 2014 2030 2020 2025 2029 Clean Power Plan Projected emission level “Implied” EPA Target Consumers Appears . . . .
Slide 28: Generation Strategy: New Supply Sources
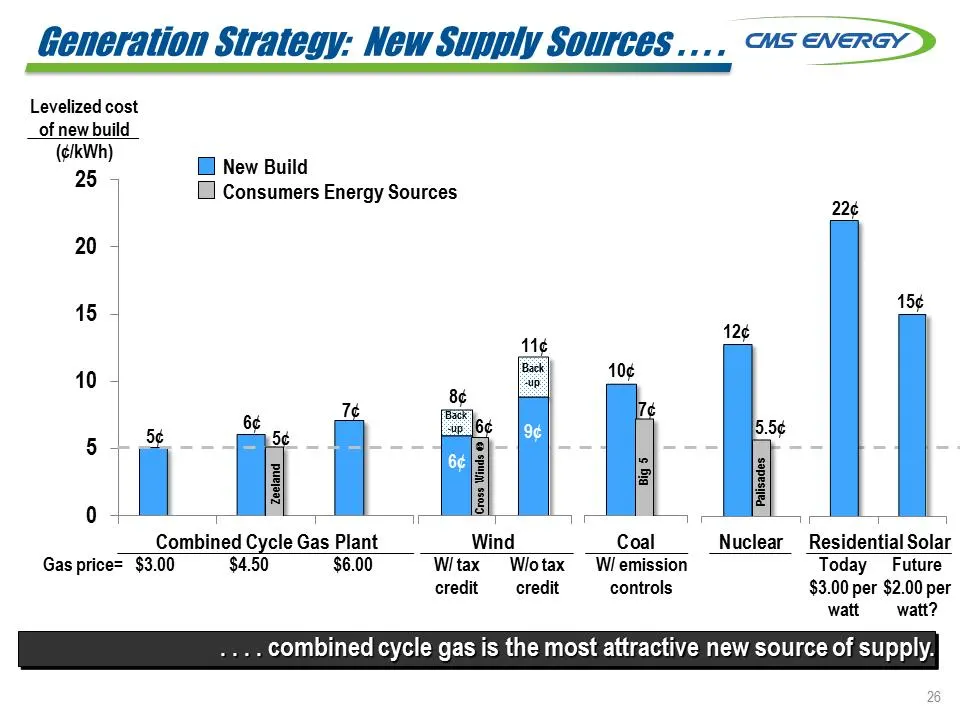
Generation Strategy: New Supply Sources . . . . 0510152025CoalNuclear. . . . combined cycle gas is the most attractive new source of supply. Levelized cost of new build (¢/kWh) Gas price= $3.00 $4.50 $6.00 W/ tax credit W/o tax credit W/ emission controls Today $3.00 per watt 5¢ 6¢ 7¢ 6¢ 9¢ 10¢ 12¢
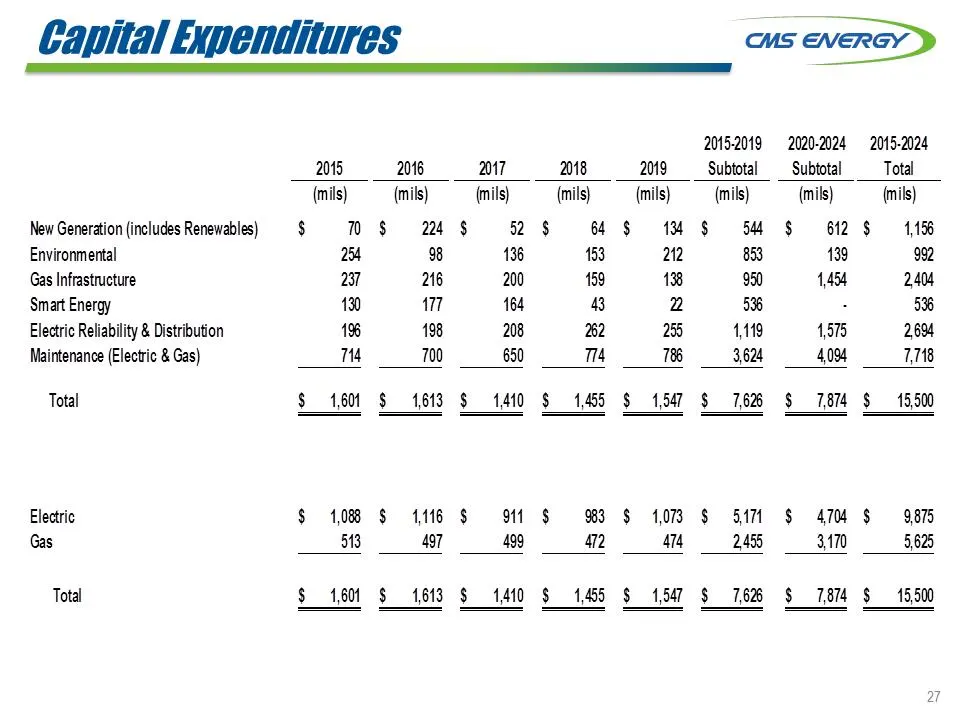
Slide 29: Capital Expenditures
Capital Expenditures 2015-20192020-20242015-202420152016201720182019SubtotalSubtotalTotal(mils)(mils)(mils)(mils)(mils)(mils)(mils)(mils)New Generation (includes Renewables) 70$ 224$ 52$ 64$ 134$ 544$ 612$ 1,156$ Environmental254 98 136 153 212 853 139 992 Gas Infrastructure237 216 200 159 138 950 1
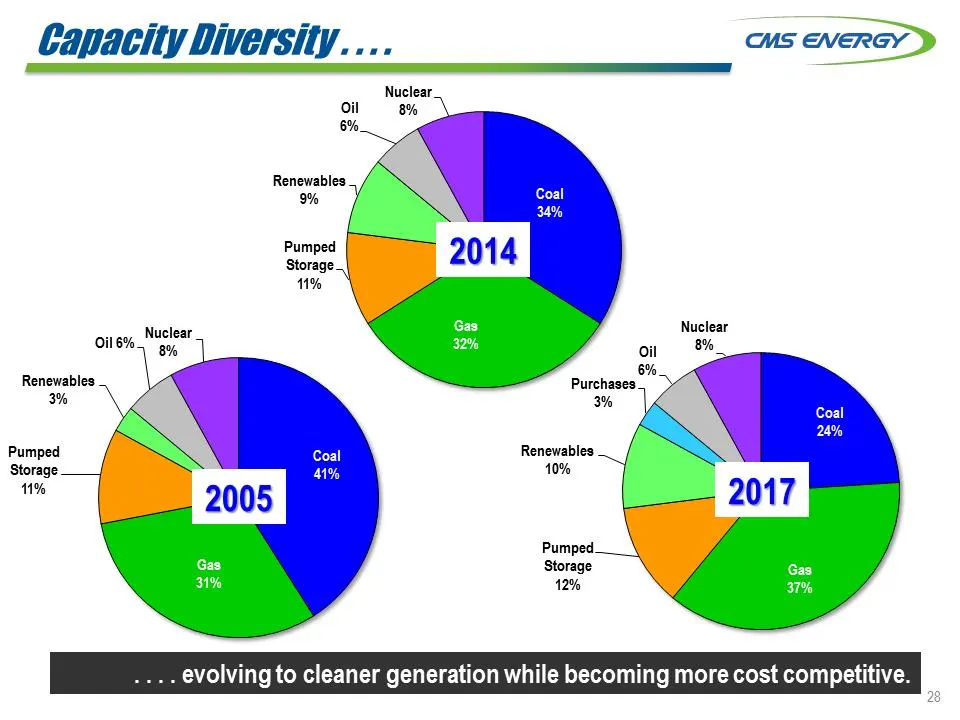
Slide 30: Capacity Diversity
Capacity Diversity . . . . Coal 34% Gas 32% Pumped Storage 11% Renewables 9% Oil 6% Nuclear 8% Coal 24% Gas 37% Pumped Storage 12% Renewables 10% Purchases 3% Oil 6% Nuclear 8% . . . . evolving to cleaner generation while becoming more cost competitive. Coal 41% Gas 31% Pumped Storage 11% Renewables
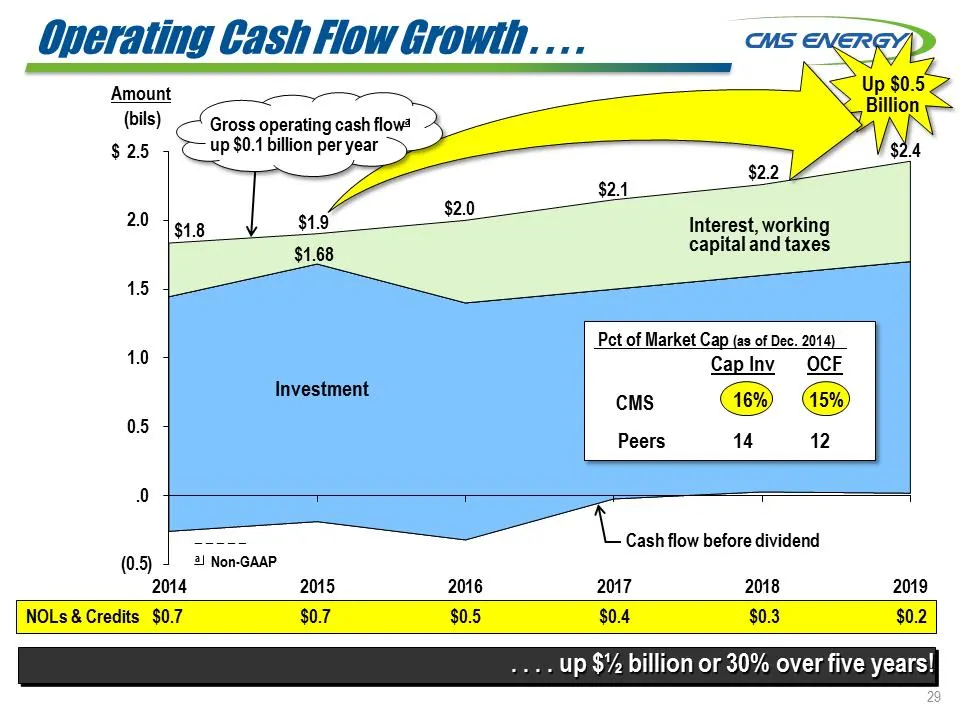
Slide 31: Operating Cash Flow Growth
Operating Cash Flow Growth . . . . (0.5)0.00.51.01.52.02.5201420152016201720182019Amount (bils) $ Cash flow before dividend a Non-GAAP NOLs & Credits $0.7 $0.7 $0.5 $0.4 $0.3 $0.2 up $½ billion or 30% over five years! $2.2 Interest, working capital and taxes $1.8 $2.4 $1.68 Pct of Market Cap (as of
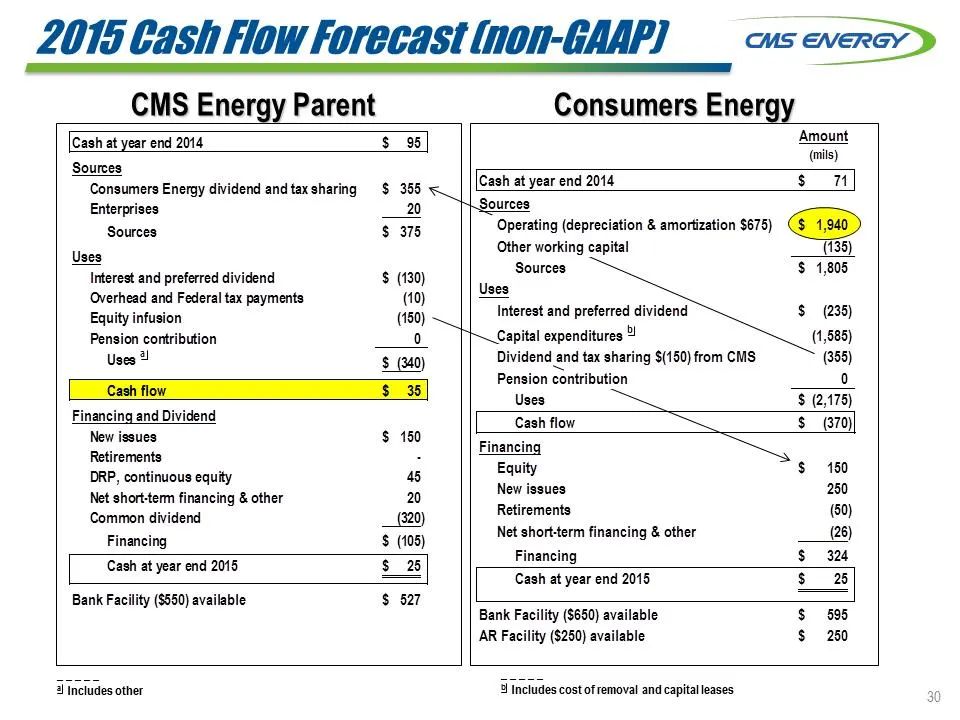
Slide 32: 2015 Cash Flow Forecast (non-GAAP)
2015 Cash Flow Forecast (non-GAAP) CMS Energy Parent Cash at year end 201495$ SourcesConsumers Energy dividend and tax sharing355$ Enterprises20 Sources375$ UsesInterest and preferred dividend(130)$ Overhead and Federal tax payments(10) Equity infusion(150) Pension contribution0Uses a(340)$ Cash flo
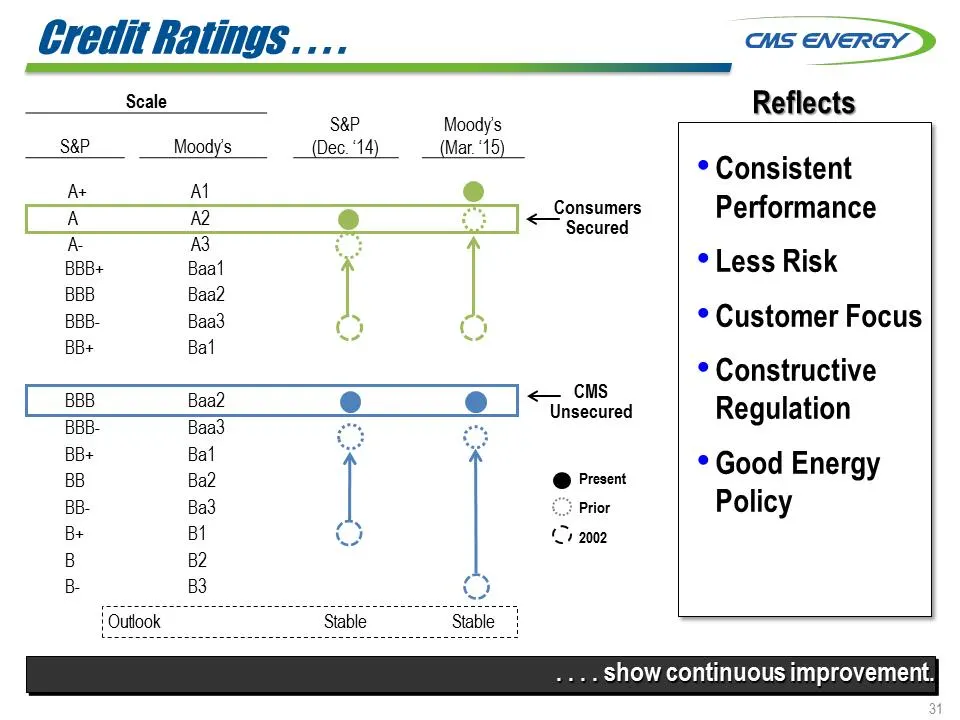
Slide 33: Credit Ratings show continuous improvement
Credit Ratings . . . . . . . . show continuous improvement. •Consistent Performance •Less Risk •Customer Focus •Constructive Regulation •Good Energy Policy Reflects Present Prior 2002 Scale S&P Moody’s S&P (Dec. ‘14) Moody’s (Mar. ‘15) A+ A1 A A2 A- A3 BBB+ Baa1 BBB Baa2 BBB- Baa3 BB+ Ba1 BBB Baa2 B
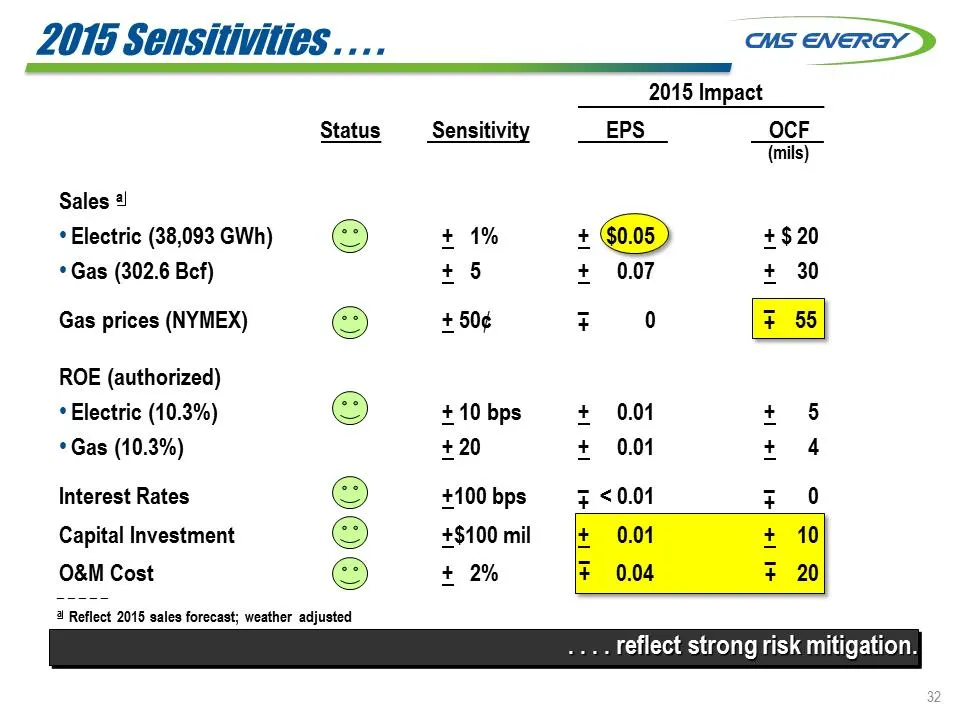
Slide 34: 2015 Sensitivities
2015 Sensitivities . . . . _ _ _ _ _ a Reflect 2015 sales forecast; weather adjusted 2015 Impact Status Sensitivity EPS OCF Sales a •Electric (38,093 GWh) •Gas (302.6 Bcf) + 1% + 5 + $0.05 + 0.07 + $ 20 + 30 Gas prices (NYMEX) + 50¢ 0 55 ROE (authorized) •Electric (10.3%) •Gas (10.3%) + 10 bps + 20
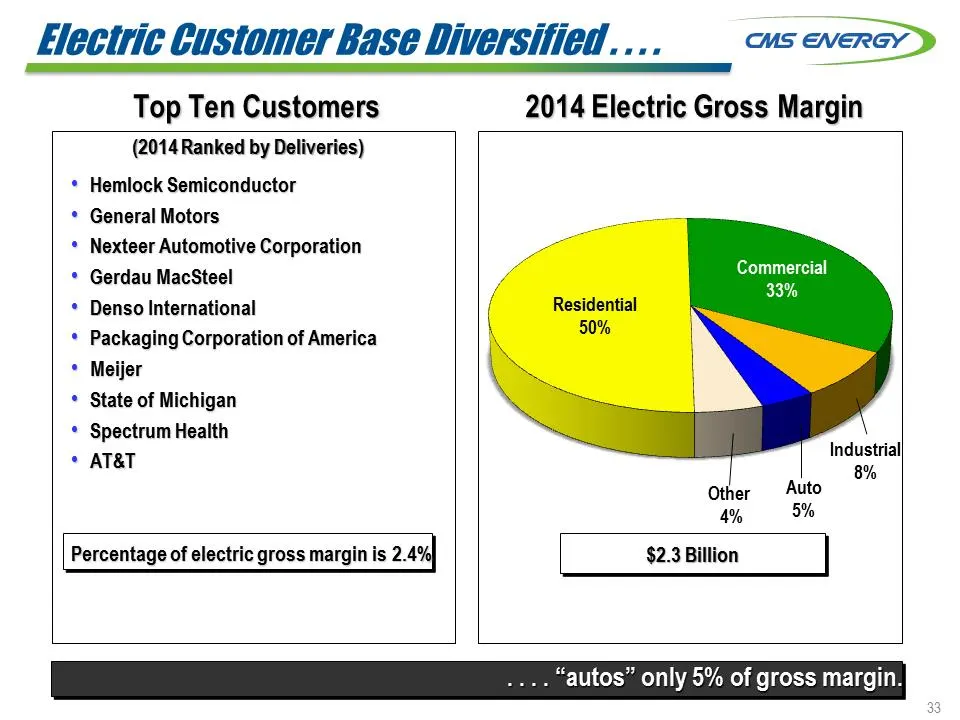
Slide 35: Electric Customer Base Diversified
. . . . “autos” only 5% of gross margin. •Hemlock Semiconductor •General Motors •Nexteer Automotive Corporation •Gerdau MacSteel •Denso International •Packaging Corporation of America •Meijer •State of Michigan •Spectrum Health •AT&T Percentage of electric gross margin is 2.4% Top Ten Customers $2.3
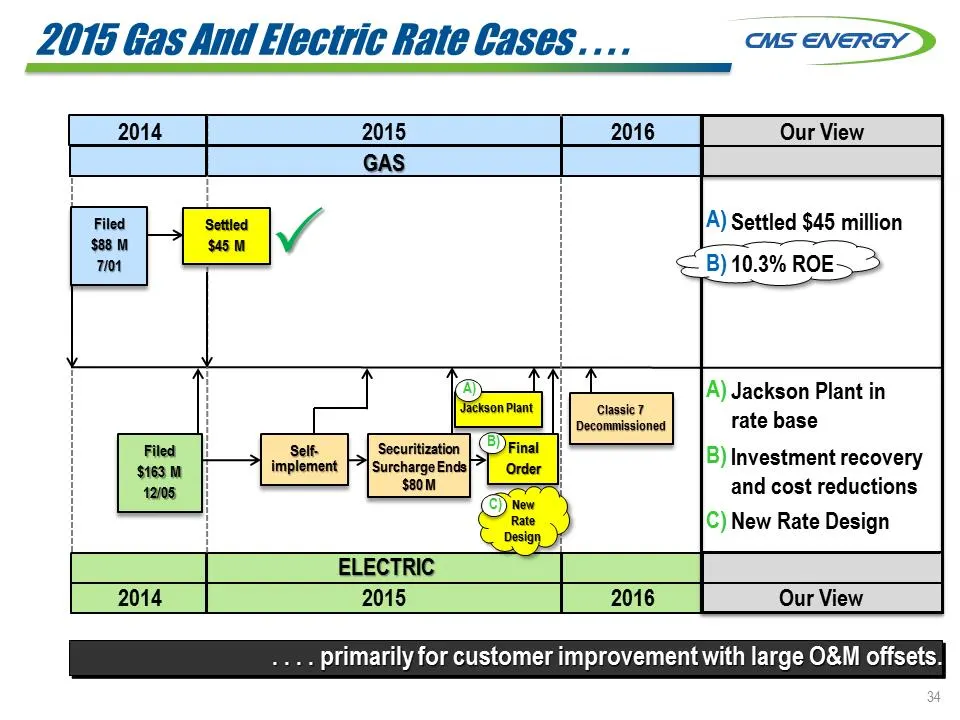
Slide 36: 2015 Gas and Electric Rate Cases
2 016 2015 2014 Filed $88 M 7/01 . . . . primarily for customer improvement with large O&M offsets. ELECTRIC GAS Our View Our View Filed $163 M 12/05 Securitization Surcharge Ends $80 M 2016 2015 2014 Jackson Plant in rate base Investment recovery and cost reductions New Rate Design A) B) C) Settled
Slide 37: GAAP Reconciliation
GAAP Reconciliation
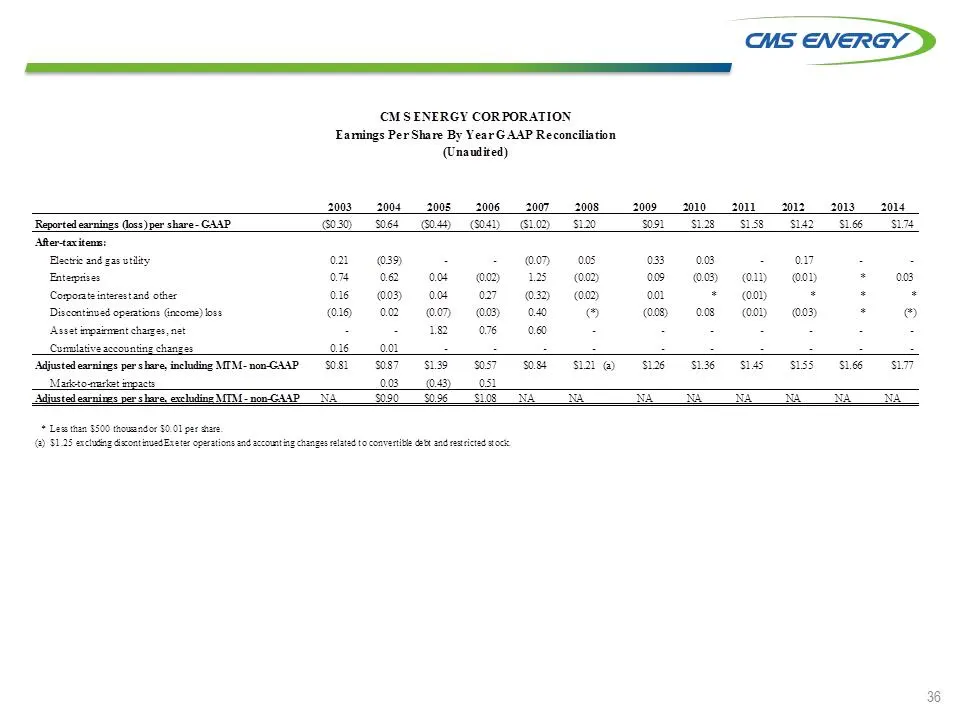
Slide 38: Reported to adjusted earnings per share reconciliation
2 00320042005200620072008200920102011201220132014Reported earnings (loss) per share - GAAP($0.30)$0.64($0.44)($0.41)($1.02)$1.20$0.91$1.28$1.58$1.42$1.66$1.74After-tax items:Electric and gas utility0.21(0.39)- - (0.07)0.050.330.03- 0.17- - Enterprises0.740.620.04(0.02)1.25(0.02)0.09(0.03)(0.11)(0.01
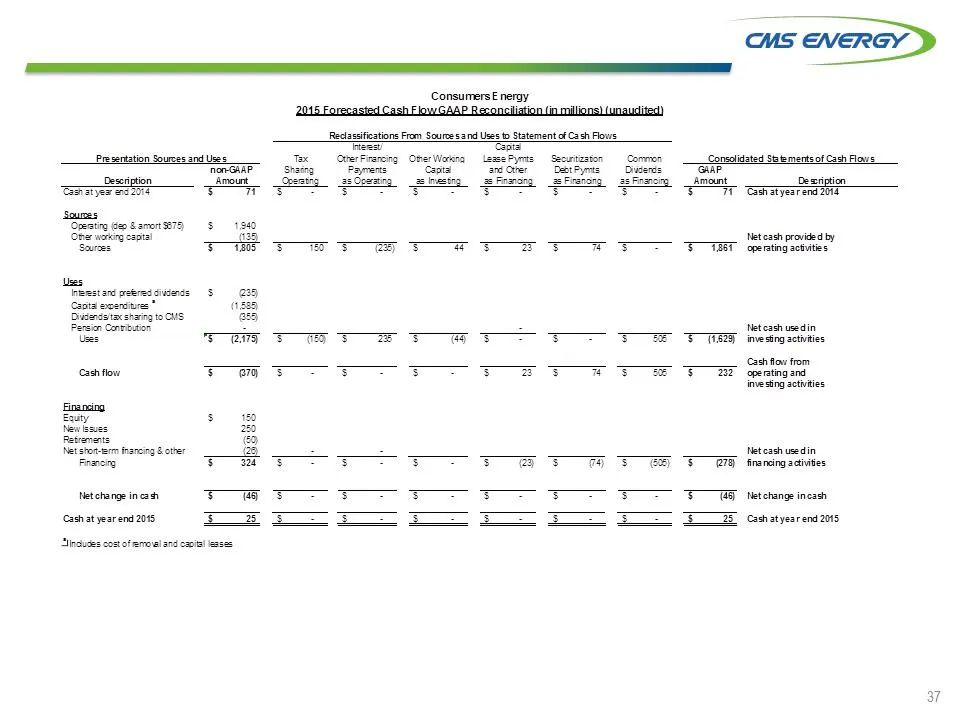
Slide 39: Cash flow GAAP reconciliation
Interest/CapitalTaxOther FinancingOther Working Lease PymtsSecuritizationCommonnon-GAAPSharing PaymentsCapitaland OtherDebt PymtsDividends GAAPAmountOperatingas Operatingas Investingas Financingas Financingas FinancingAmountDescriptionCash at year end 201471$ -$ -$ -$ -$ -$ -$ 71$ Cash at year end 2
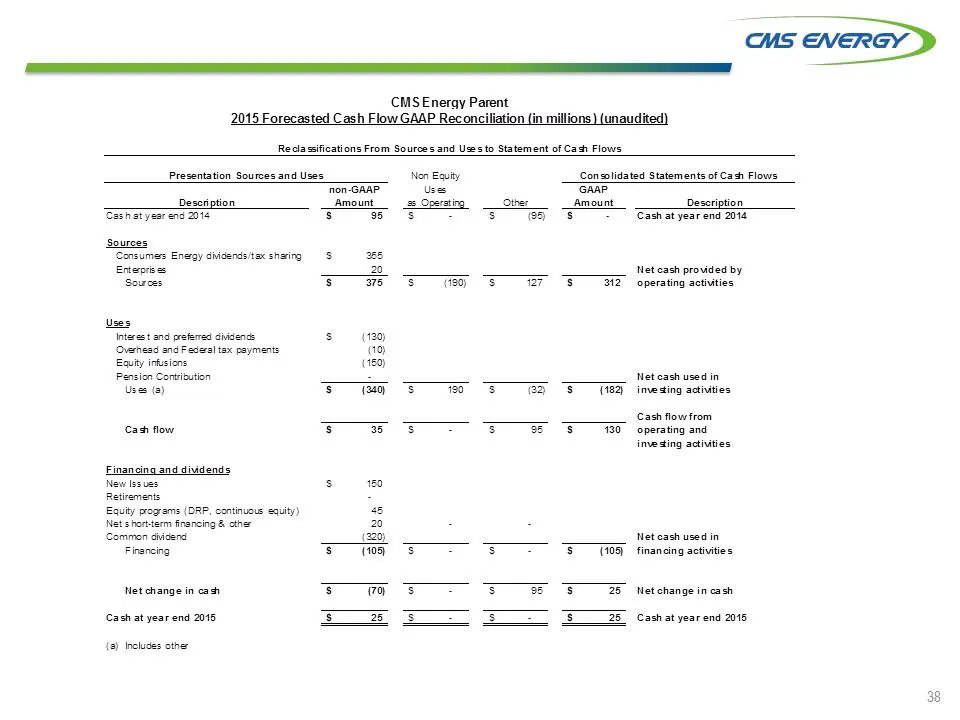
Slide 40: CMS Energy Parent cash flow reconciliation
Non Equitynon-GAAPUsesGAAPAmountas OperatingOtherAmountDescriptionCash at year end 201495$ -$ (95)$ -$ Cash at year end 2014SourcesConsumers Energy dividends/tax sharing355$ Enterprises20 Net cash provided bySources375$ (190)$ 127$ 312$ operating activitiesUsesInterest and preferred dividends(130)$
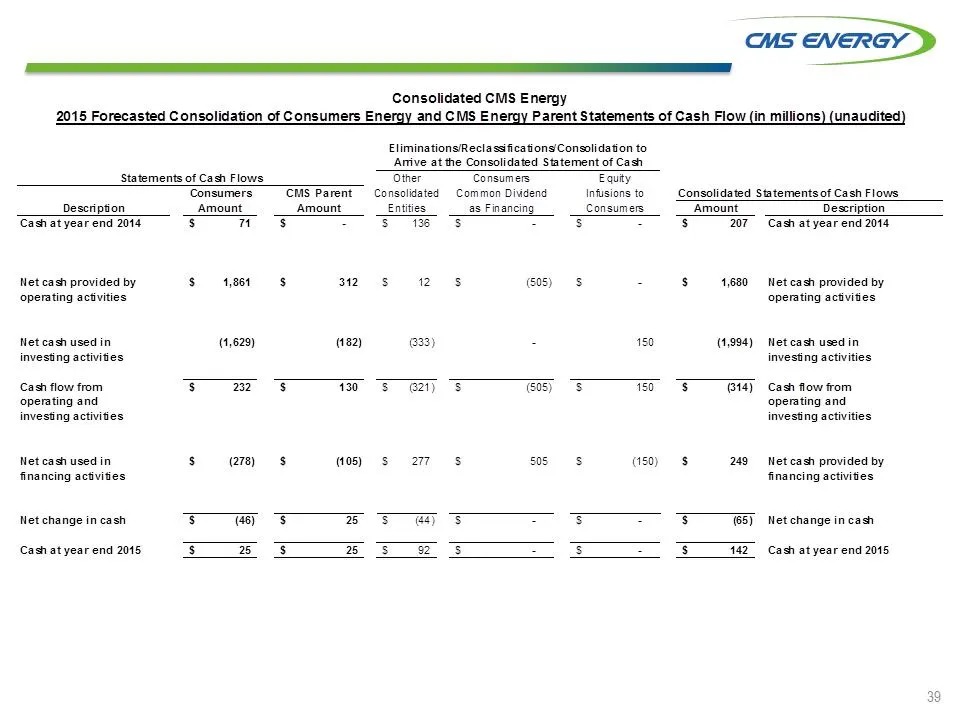
Slide 41: Consolidated Statements of Cash Flows
OtherConsumersEquityConsumersCMS ParentConsolidatedCommon DividendInfusions toConsolidated Statements of Cash FlowsDescriptionAmountAmountEntitiesas FinancingConsumersAmountDescriptionCash at year end 201471$ -$ 136$ -$ -$ 207$ Cash at year end 2014Net cash provided by1,861$ 312$ 12$ (505)$ -$ 1,680
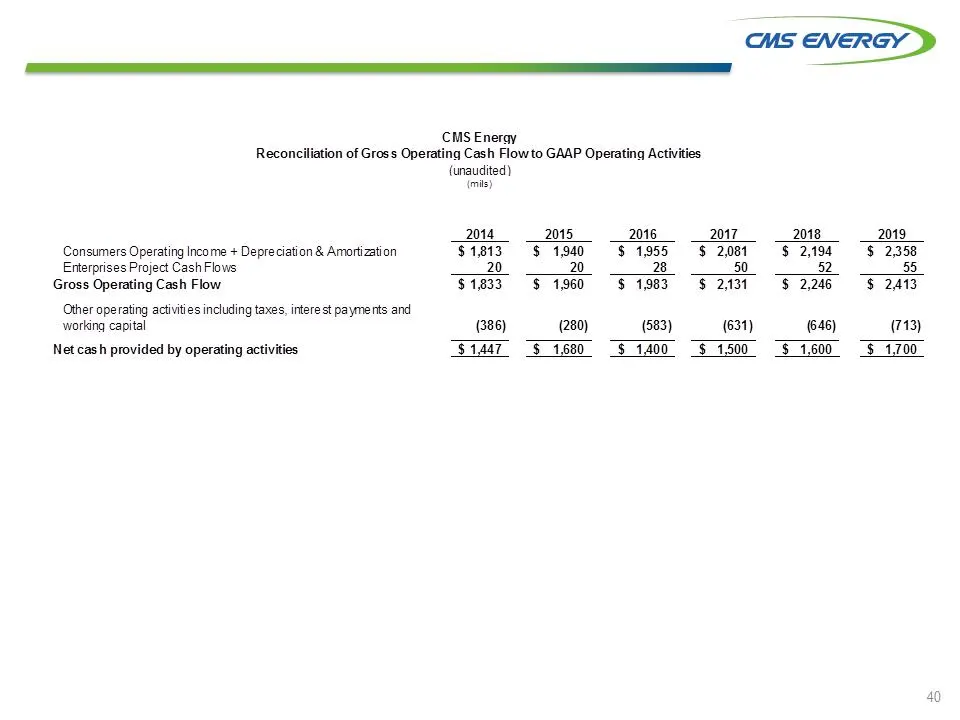
Slide 42: Gross Operating Cash Flow to GAAP reconciliation
201420152016201720182019Consumers Operating Income + Depreciation & Amortization1,813$ 1,940$ 1,955$ 2,081$ 2,194$ 2,358$ Enterprises Project Cash Flows20 20 28 50 52 55 Gross Operating Cash Flow1,833$ 1,960$ 1,983$ 2,131$ 2,246$ 2,413$ (386) (280) (583) (631) (646) (713) Net cash provided by operat
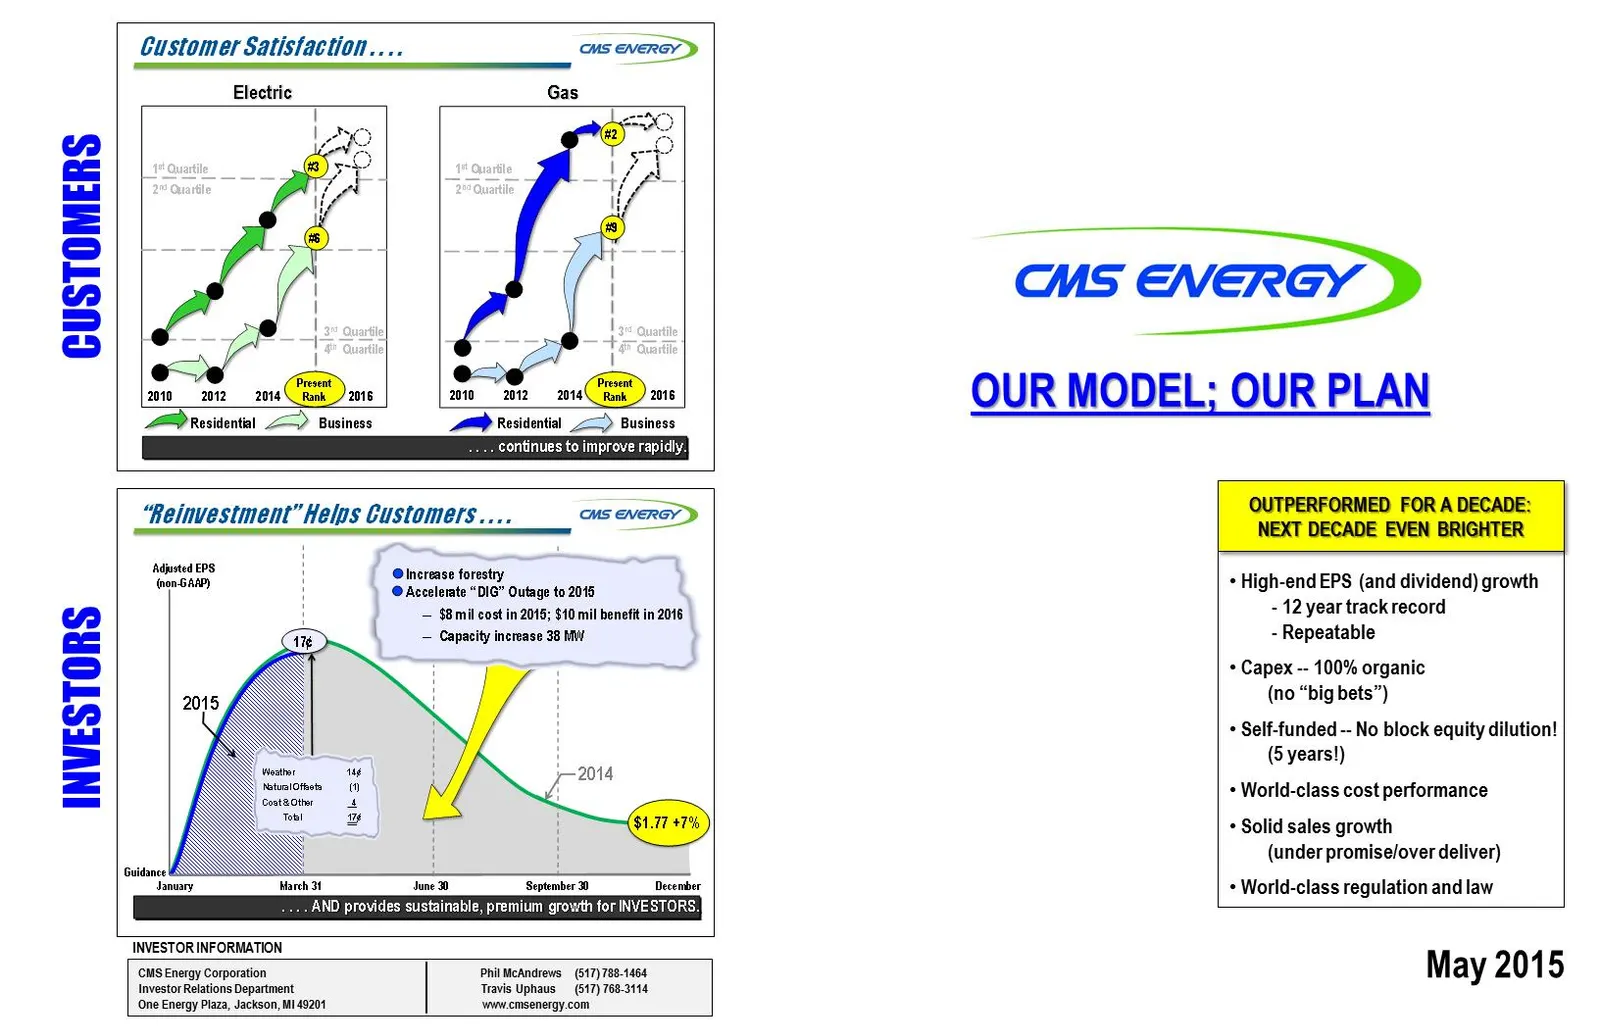
Slide 43: Investor Information
May 2015 OUR MODEL; OUR PLAN INVESTOR INFORMATION CMS Energy Corporation Phil McAndrews 517 7881464 Investor Relations Department Travis Uphaus 517 7683114 One Energy Plaza, Jackson, MI 49201 www.cmsenergy.com CUSTOMERS INVESTORS 12. . . . AND provides sustainable, premium growth for INVESTORS.2014A
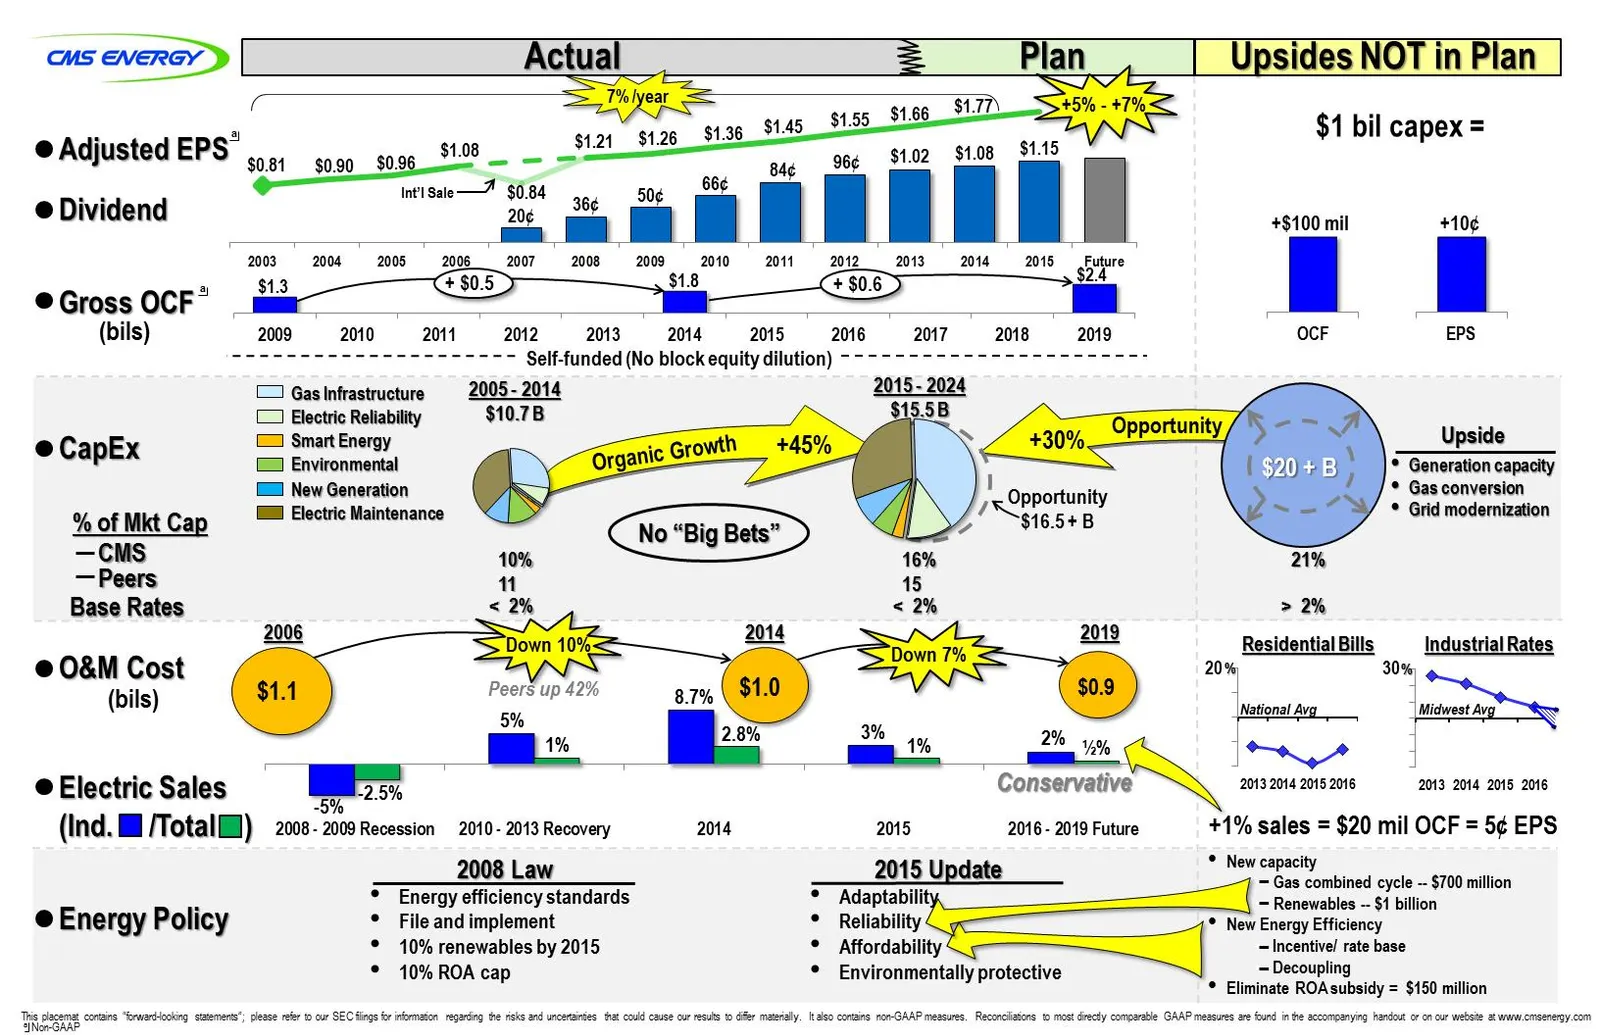
Slide 44: Our Model; Our Plan
Adjusted EPS Gross OCF Dividend CapEx CMS O&M Cost Electric Sales (Ind. /Total ) Energy Policy 10% 11 16% 15 21% •Energy efficiency standards •File and implement •10% renewables by 2015 •10% ROA cap •Adaptability •Reliability •Affordability •Environmentally protective 2015 Update 2008 Law 2009201020
Source: SEC EDGAR · 8-K filed May 15, 2015
More decks from Consumers Energy Company
 FY2024 Earnings Presentation33 slides · Feb 6, 2025
 Technical Presentation (August 2024)8 slides · August 2024
 Technical Presentation (August 2024)8 slides · August 2024
 Corporate Update (August 2024)8 slides · August 2024
 Corporate Update (August 2024)8 slides · August 2024
 Corporate Update (September 2023)22 slides · Sep 28, 2023