Wachovia Corp New
Wachovia Corp New — Q1 2008 Earnings Presentation
45 slides from Wachovia Corp New's earnings presentation, Apr 14, 2008
Slide 1: Wachovia Corporation 1Q08 Financial Highlights
Exhibit (99)(b) Wachovia Corporation 1Q08 Financial Highlights April 14, 2008
Slide 2: 1Q08 Quarterly highlights
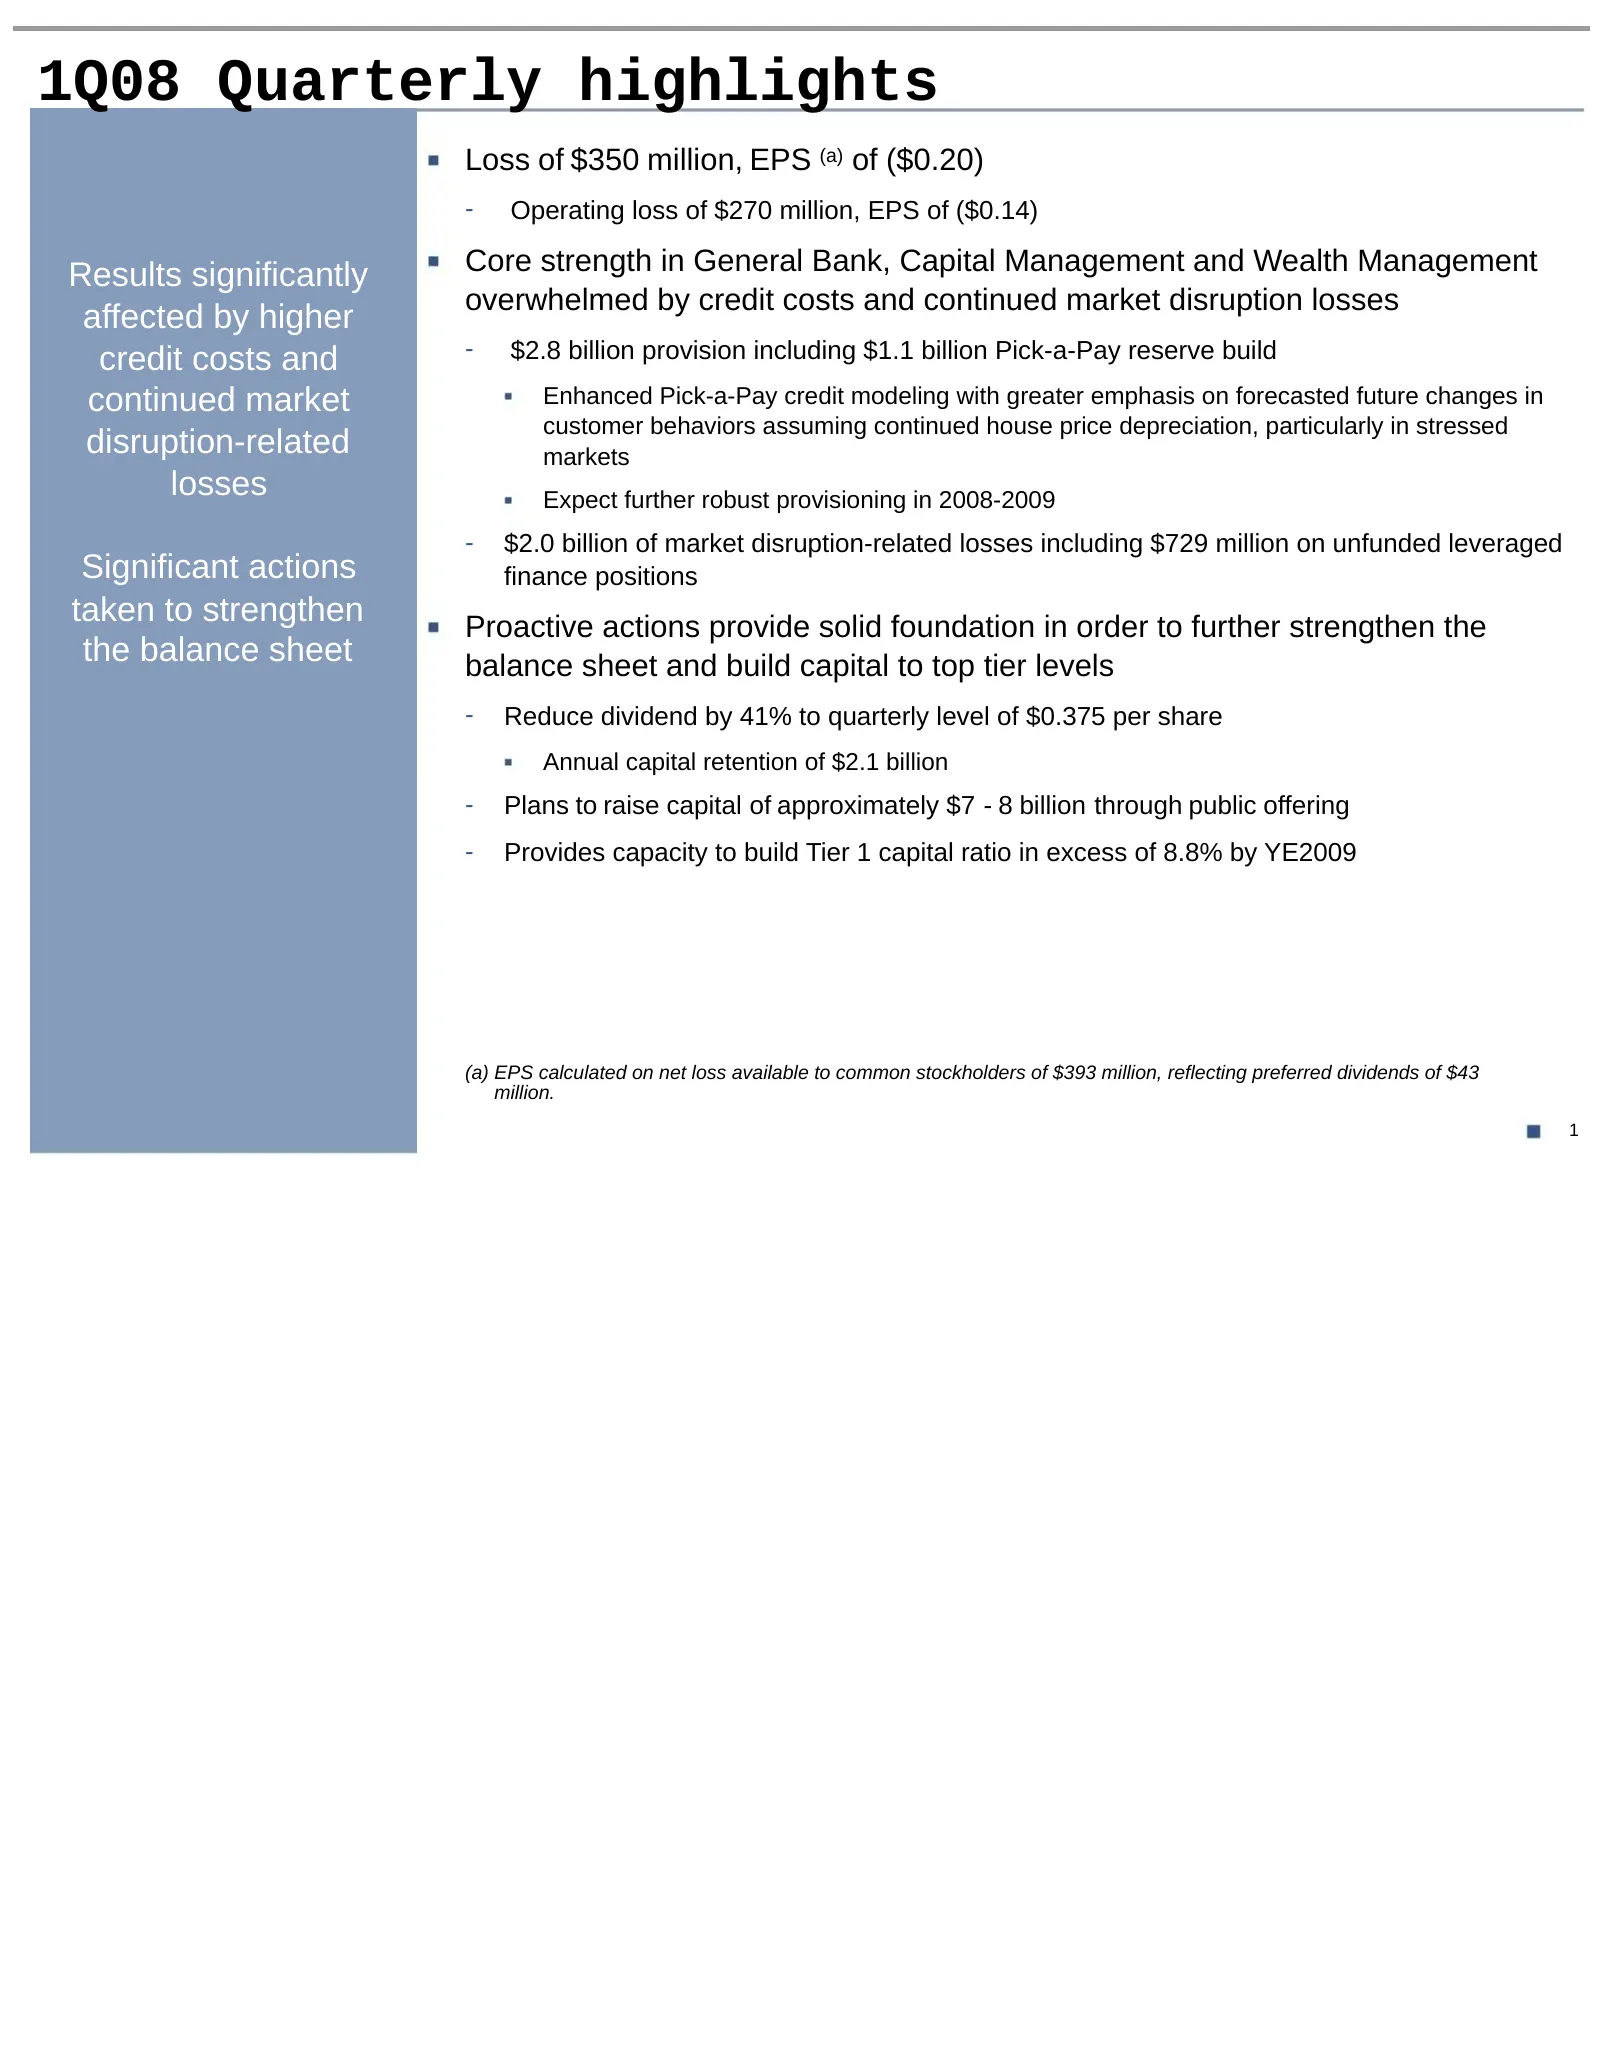
1Q08 Quarterly highlights Loss of $350 million, EPS (a) of ($0.20) - Operating loss of $270 million, EPS of ($0.14) Results significantly Core strength in General Bank, Capital Management and Wealth Management overwhelmed by credit costs and continued market disruption losses affected by higher cred
Slide 3: Financial highlights
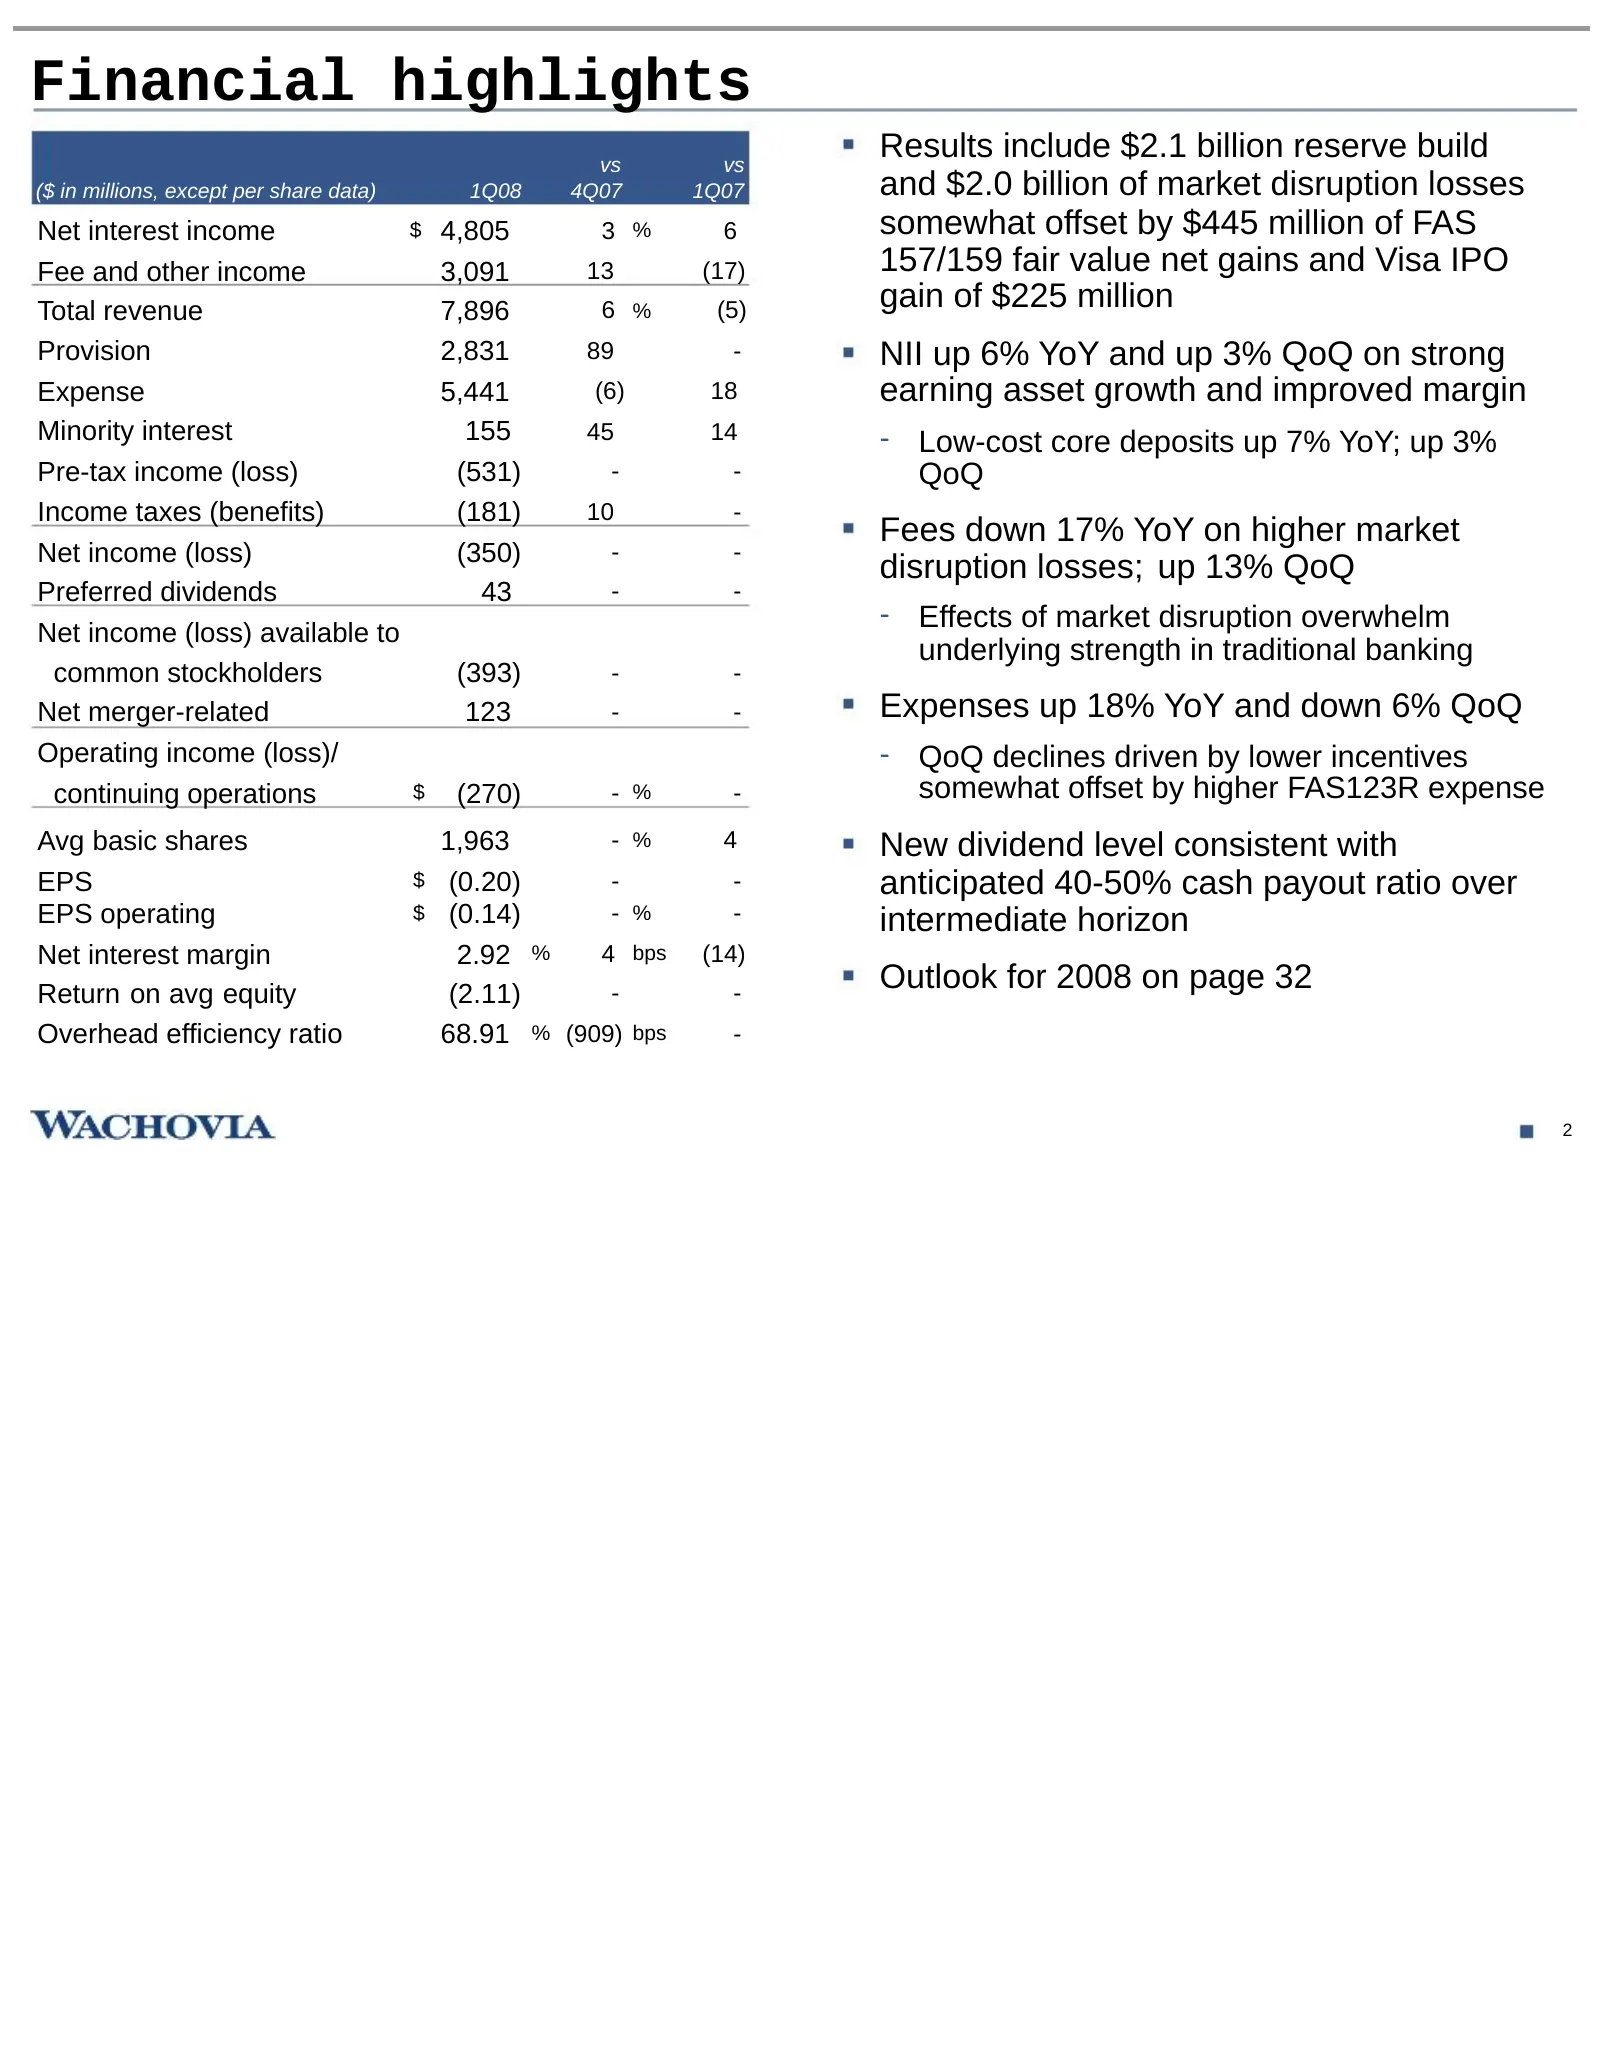
Financial highlights vs vs Results include $2.1 billion reserve build ($ in millions, except per share data) 1Q08 4Q07 1Q07 and $2.0 billion of market disruption losses Net interest income $ 4,805 3 % 6 somewhat offset by $445 million of FAS Fee and other income 3,091 13 (17) 157/159 fair value net
Slide 4: Balance sheet strengthening: Building capital and reserves
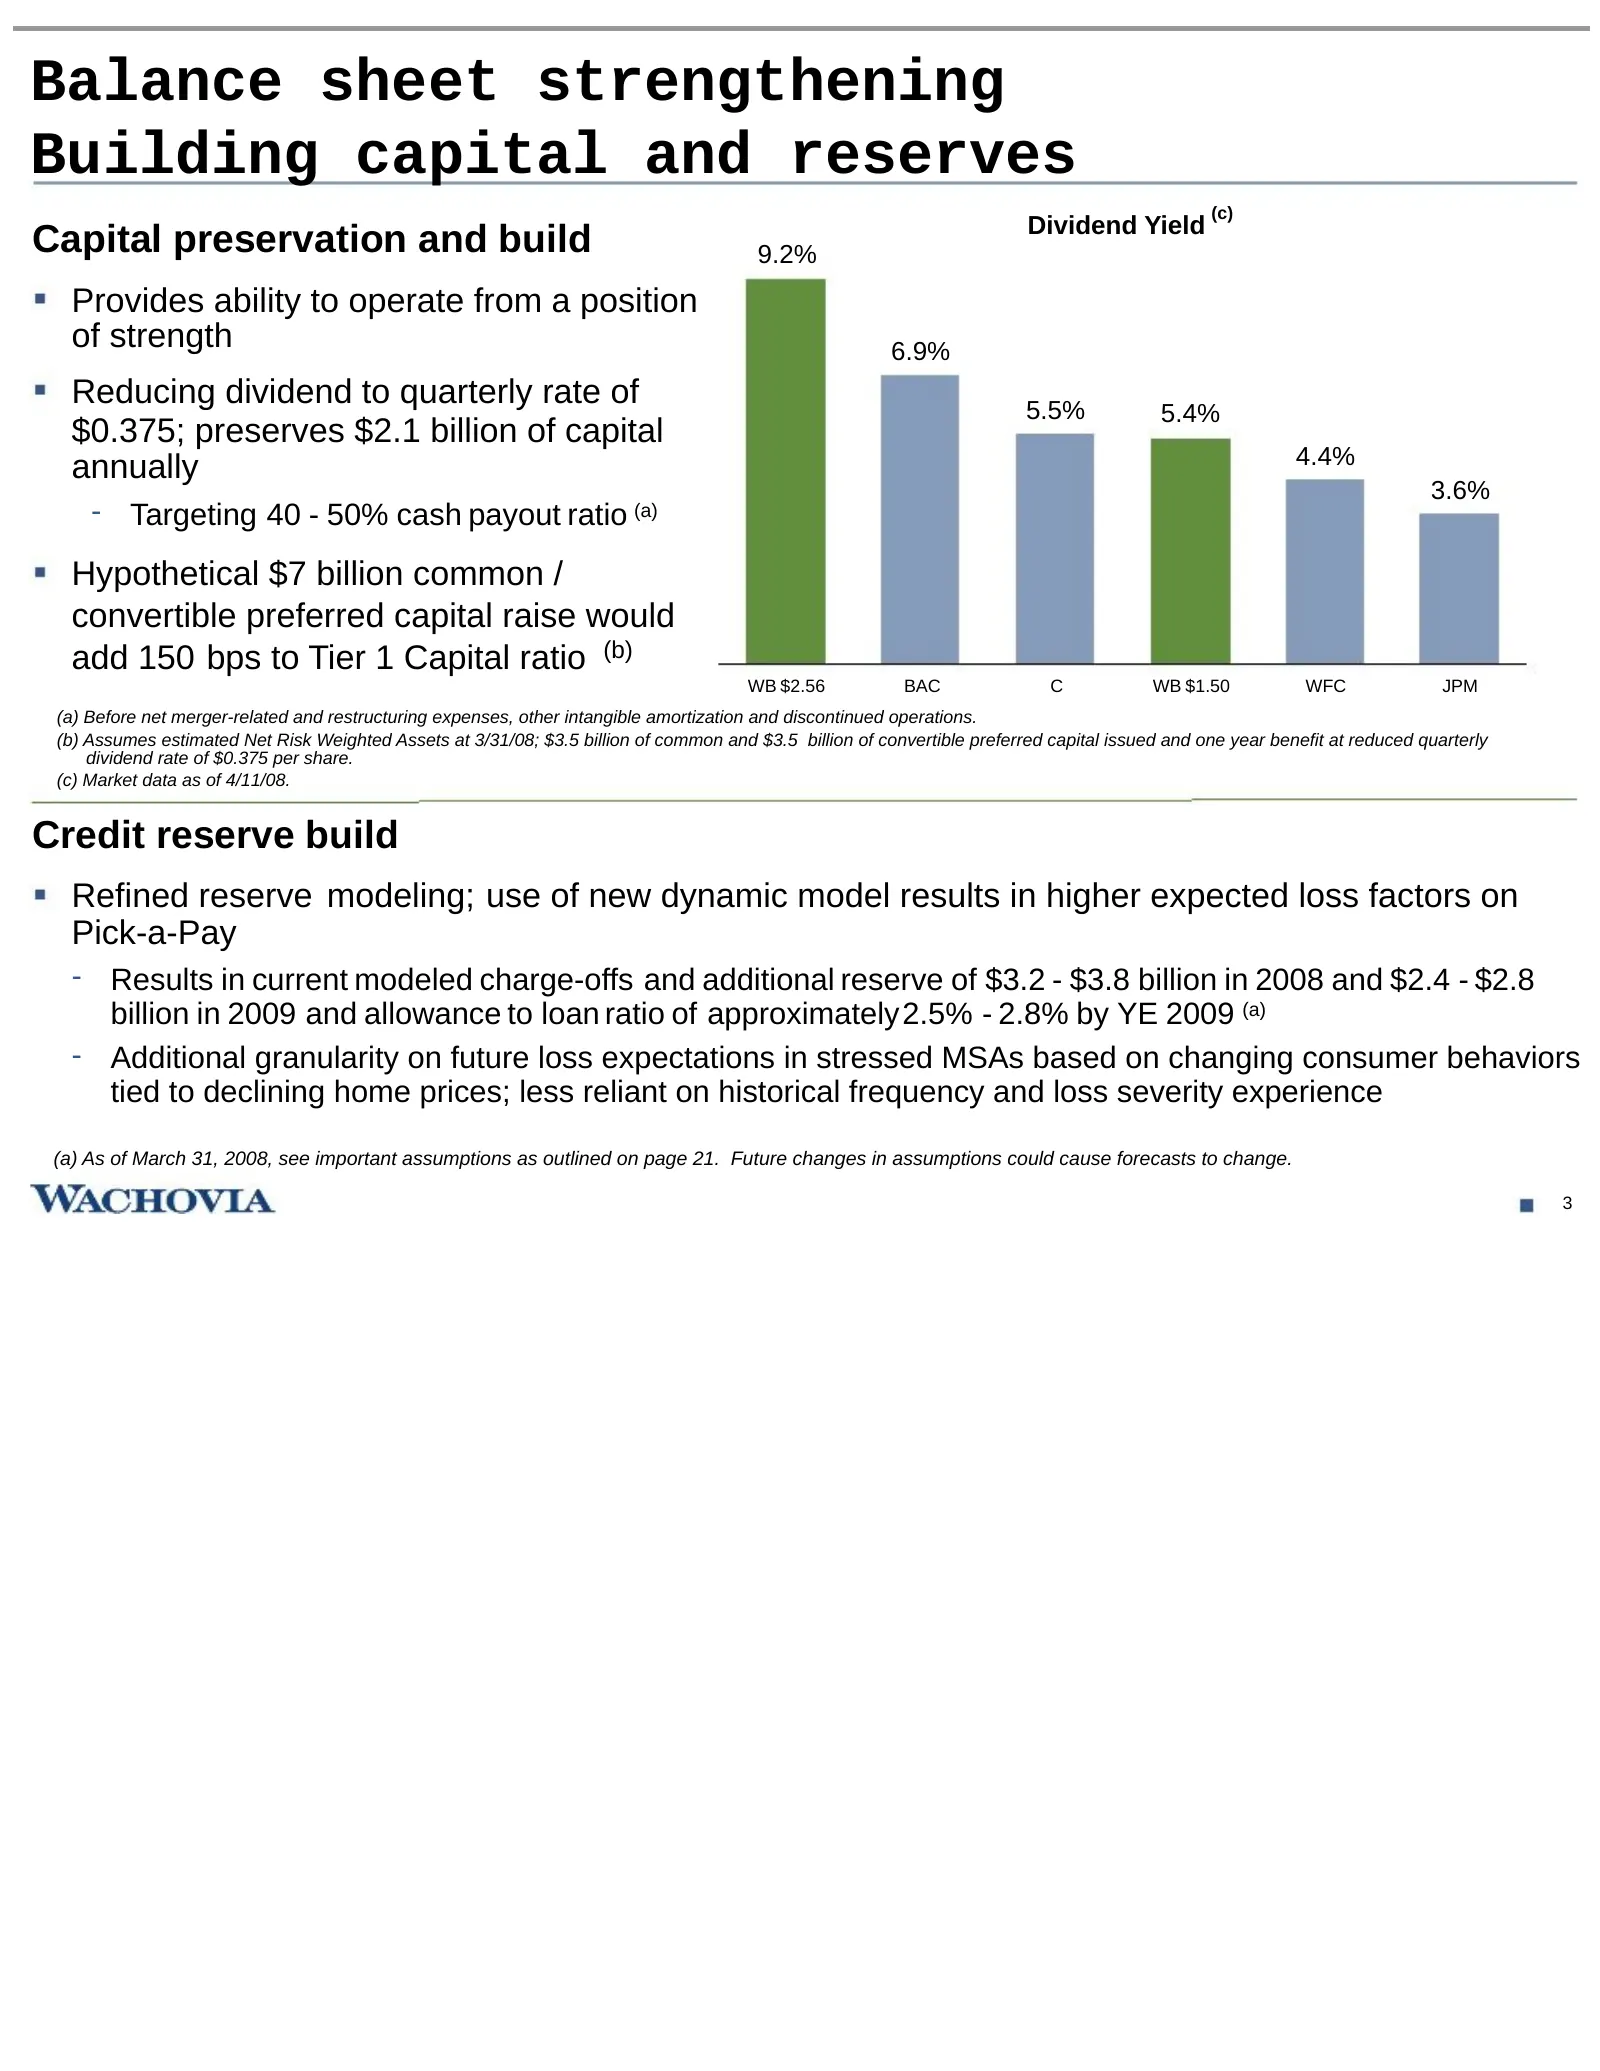
Balance sheet strengthening Building capital and reserves (c) Dividend Yield Capital preservation and build 9.2% Provides ability to operate from a position of strength 6.9% Reducing dividend to quarterly rate of 5.5% 5.4% $0.375; preserves $2.1 billion of capital annually 4.4% 3.6% - Targeting 40 -
Slide 5: Strong liquidity and capital position
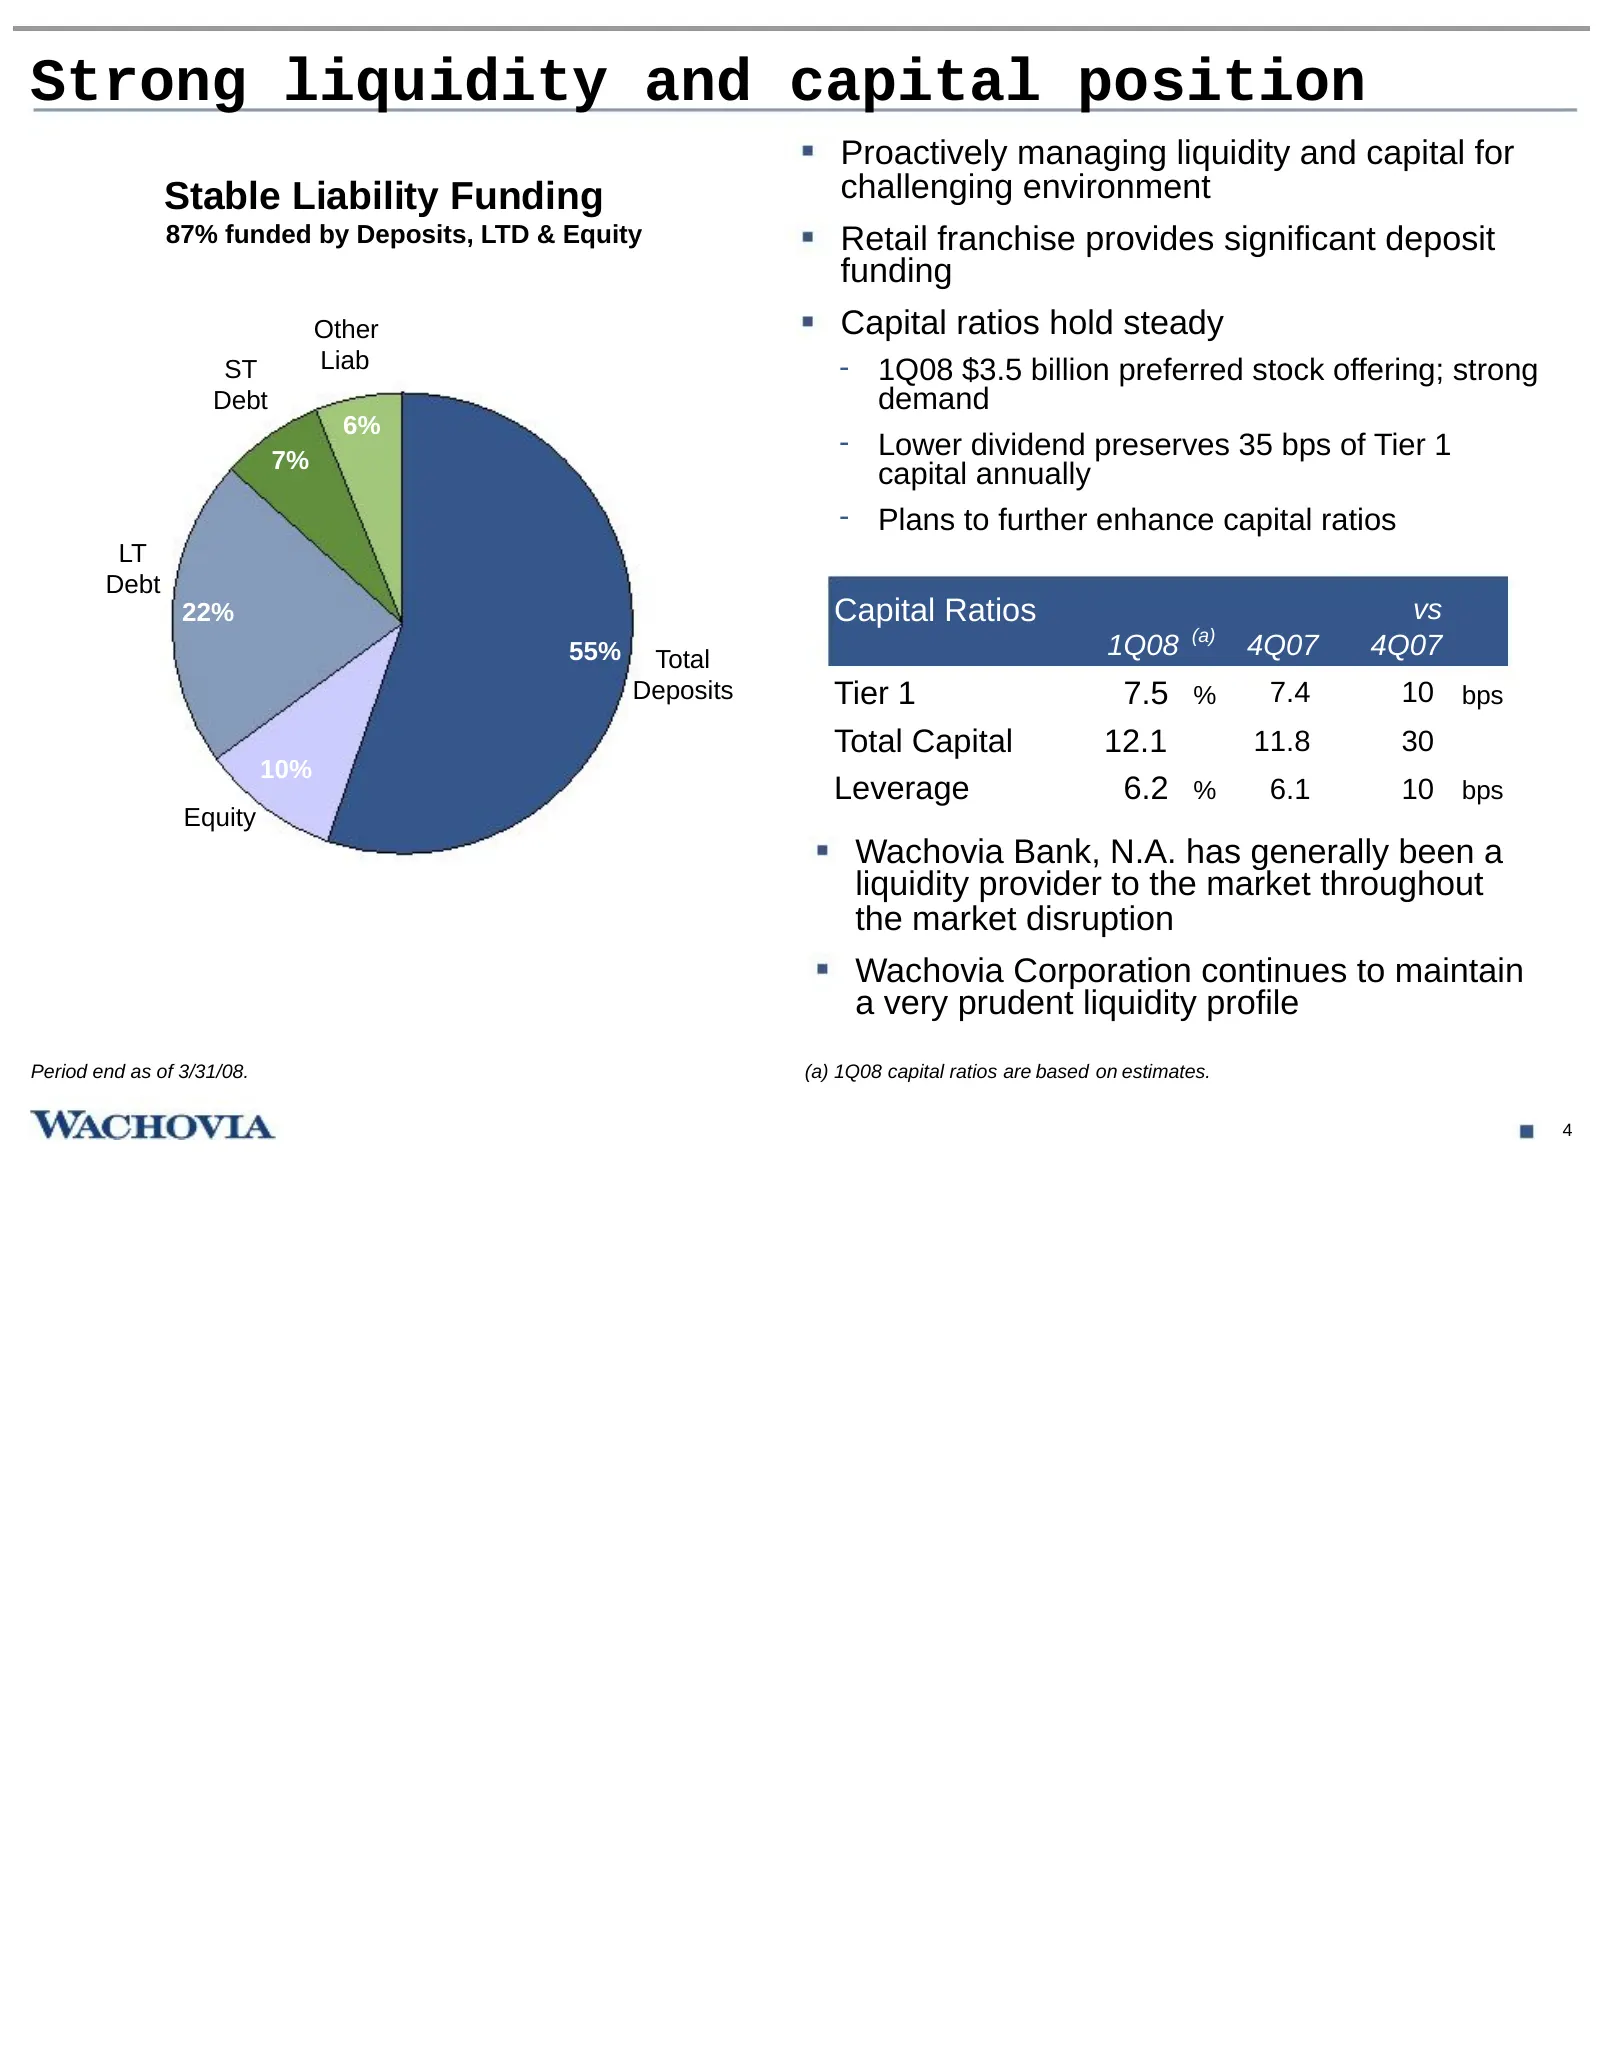
Strong liquidity and capital position Proactively managing liquidity and capital for Stable Liability Funding challenging environment 87% funded by Deposits, LTD & Equity Retail franchise provides significant deposit funding Other Capital ratios hold steady ST Liab - 1Q08 $3.5 billion preferred stoc
Slide 6: Market disruption losses and write-downs
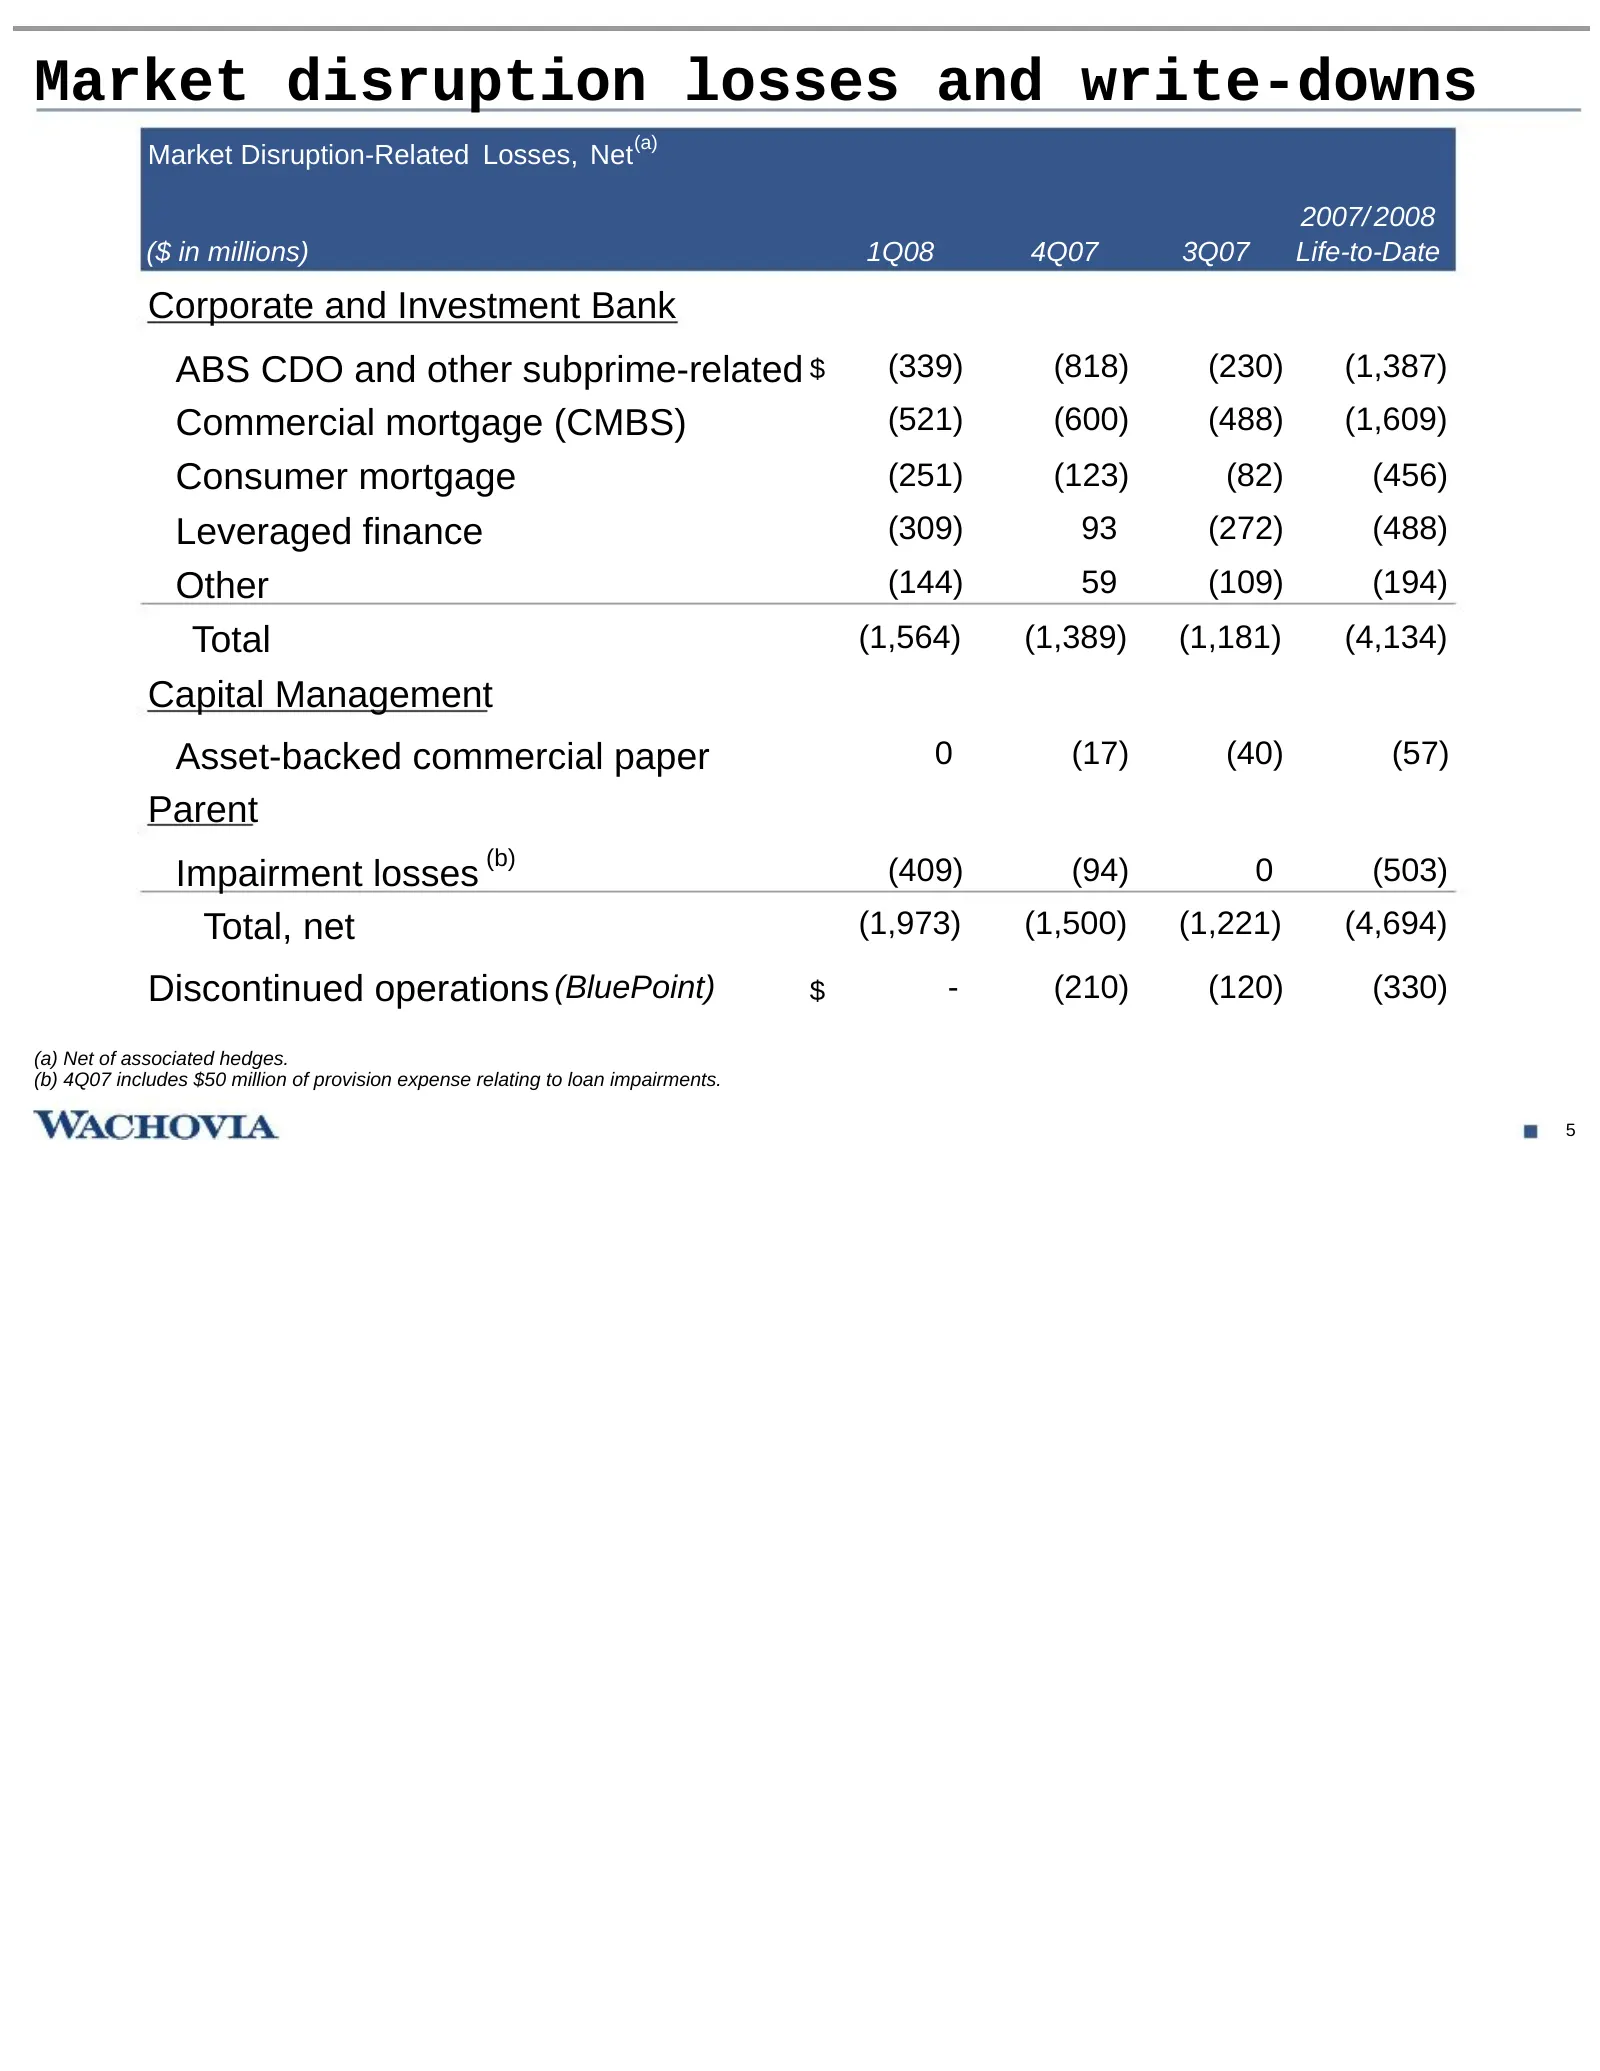
Market disruption losses and write-downs (a) Market Disruption-Related Losses, Net 2007/ 2008 ($ in millions) 1Q08 4Q07 3Q07 Life-to-Date Corporate and Investment Bank ABS CDO and other subprime-related $ (339) (818) (230) (1,387) Commercial mortgage (CMBS) (521) (600) (488) (1,609) Consumer mortgag
Slide 7: Average deposit growth
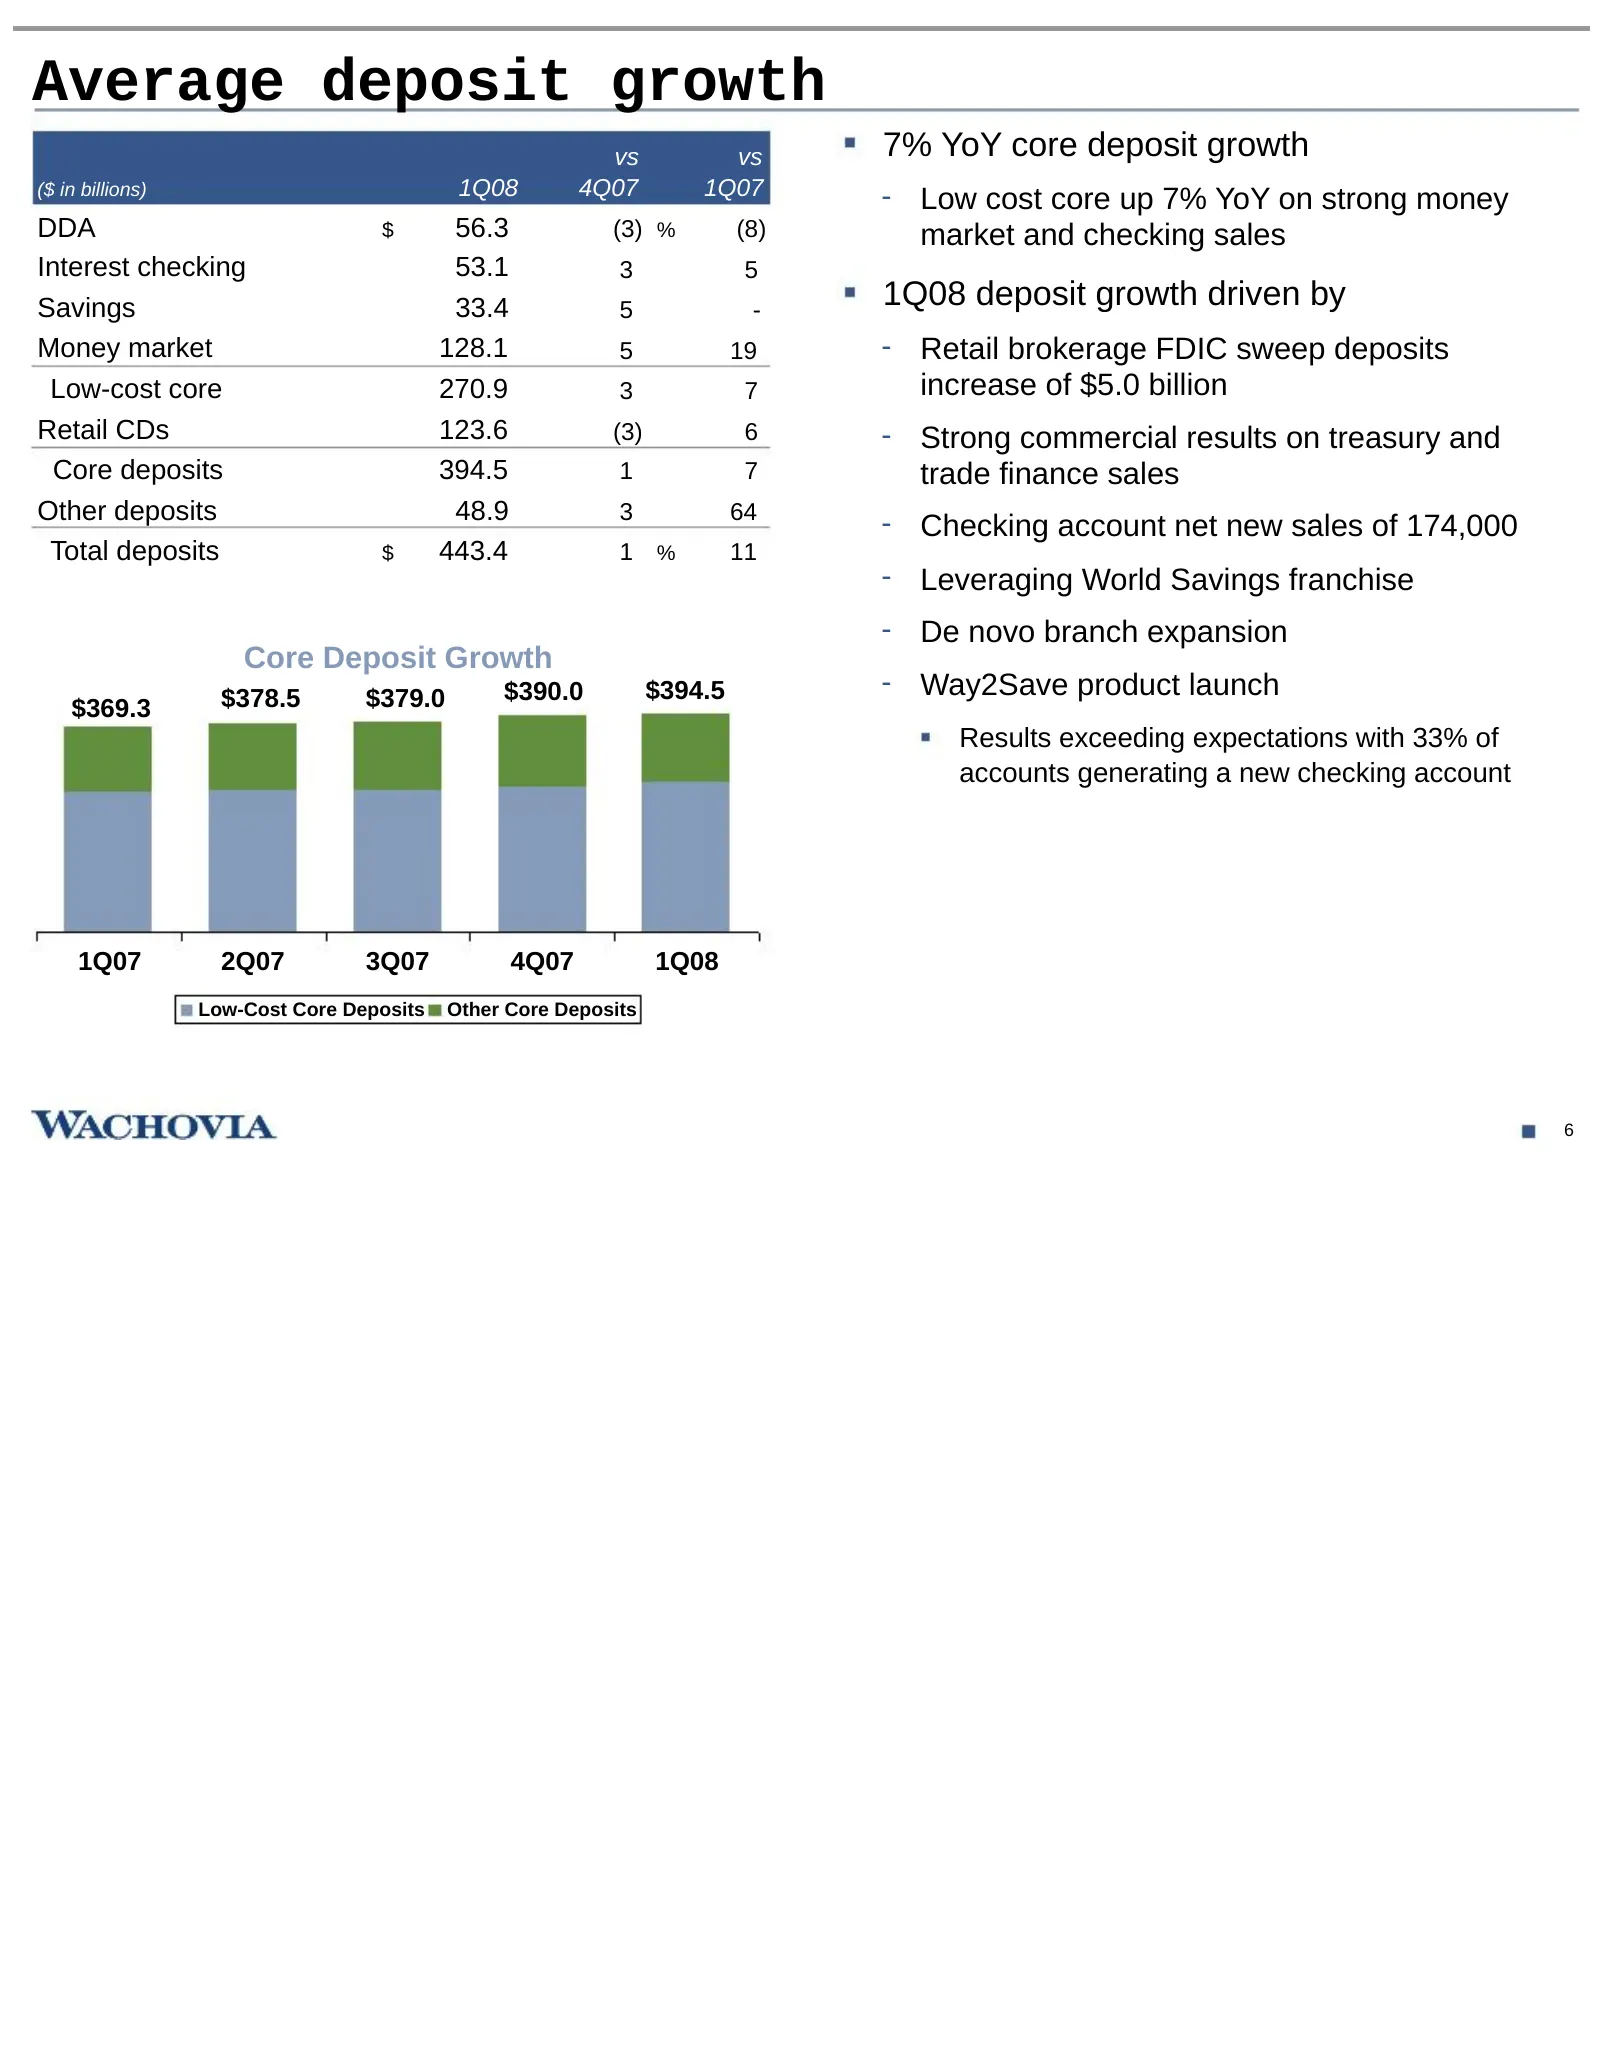
Average deposit growth vs vs 7% YoY core deposit growth ($ in billions) 1Q08 4Q07 1Q07 - Low cost core up 7% YoY on strong money DDA $ 56.3 (3) % (8) market and checking sales Interest checking 53.1 3 5 Savings 33.4 5 - 1Q08 deposit growth driven by Money market 128.1 5 19 - Retail brokerage FDIC sw
Slide 8: Average loan growth
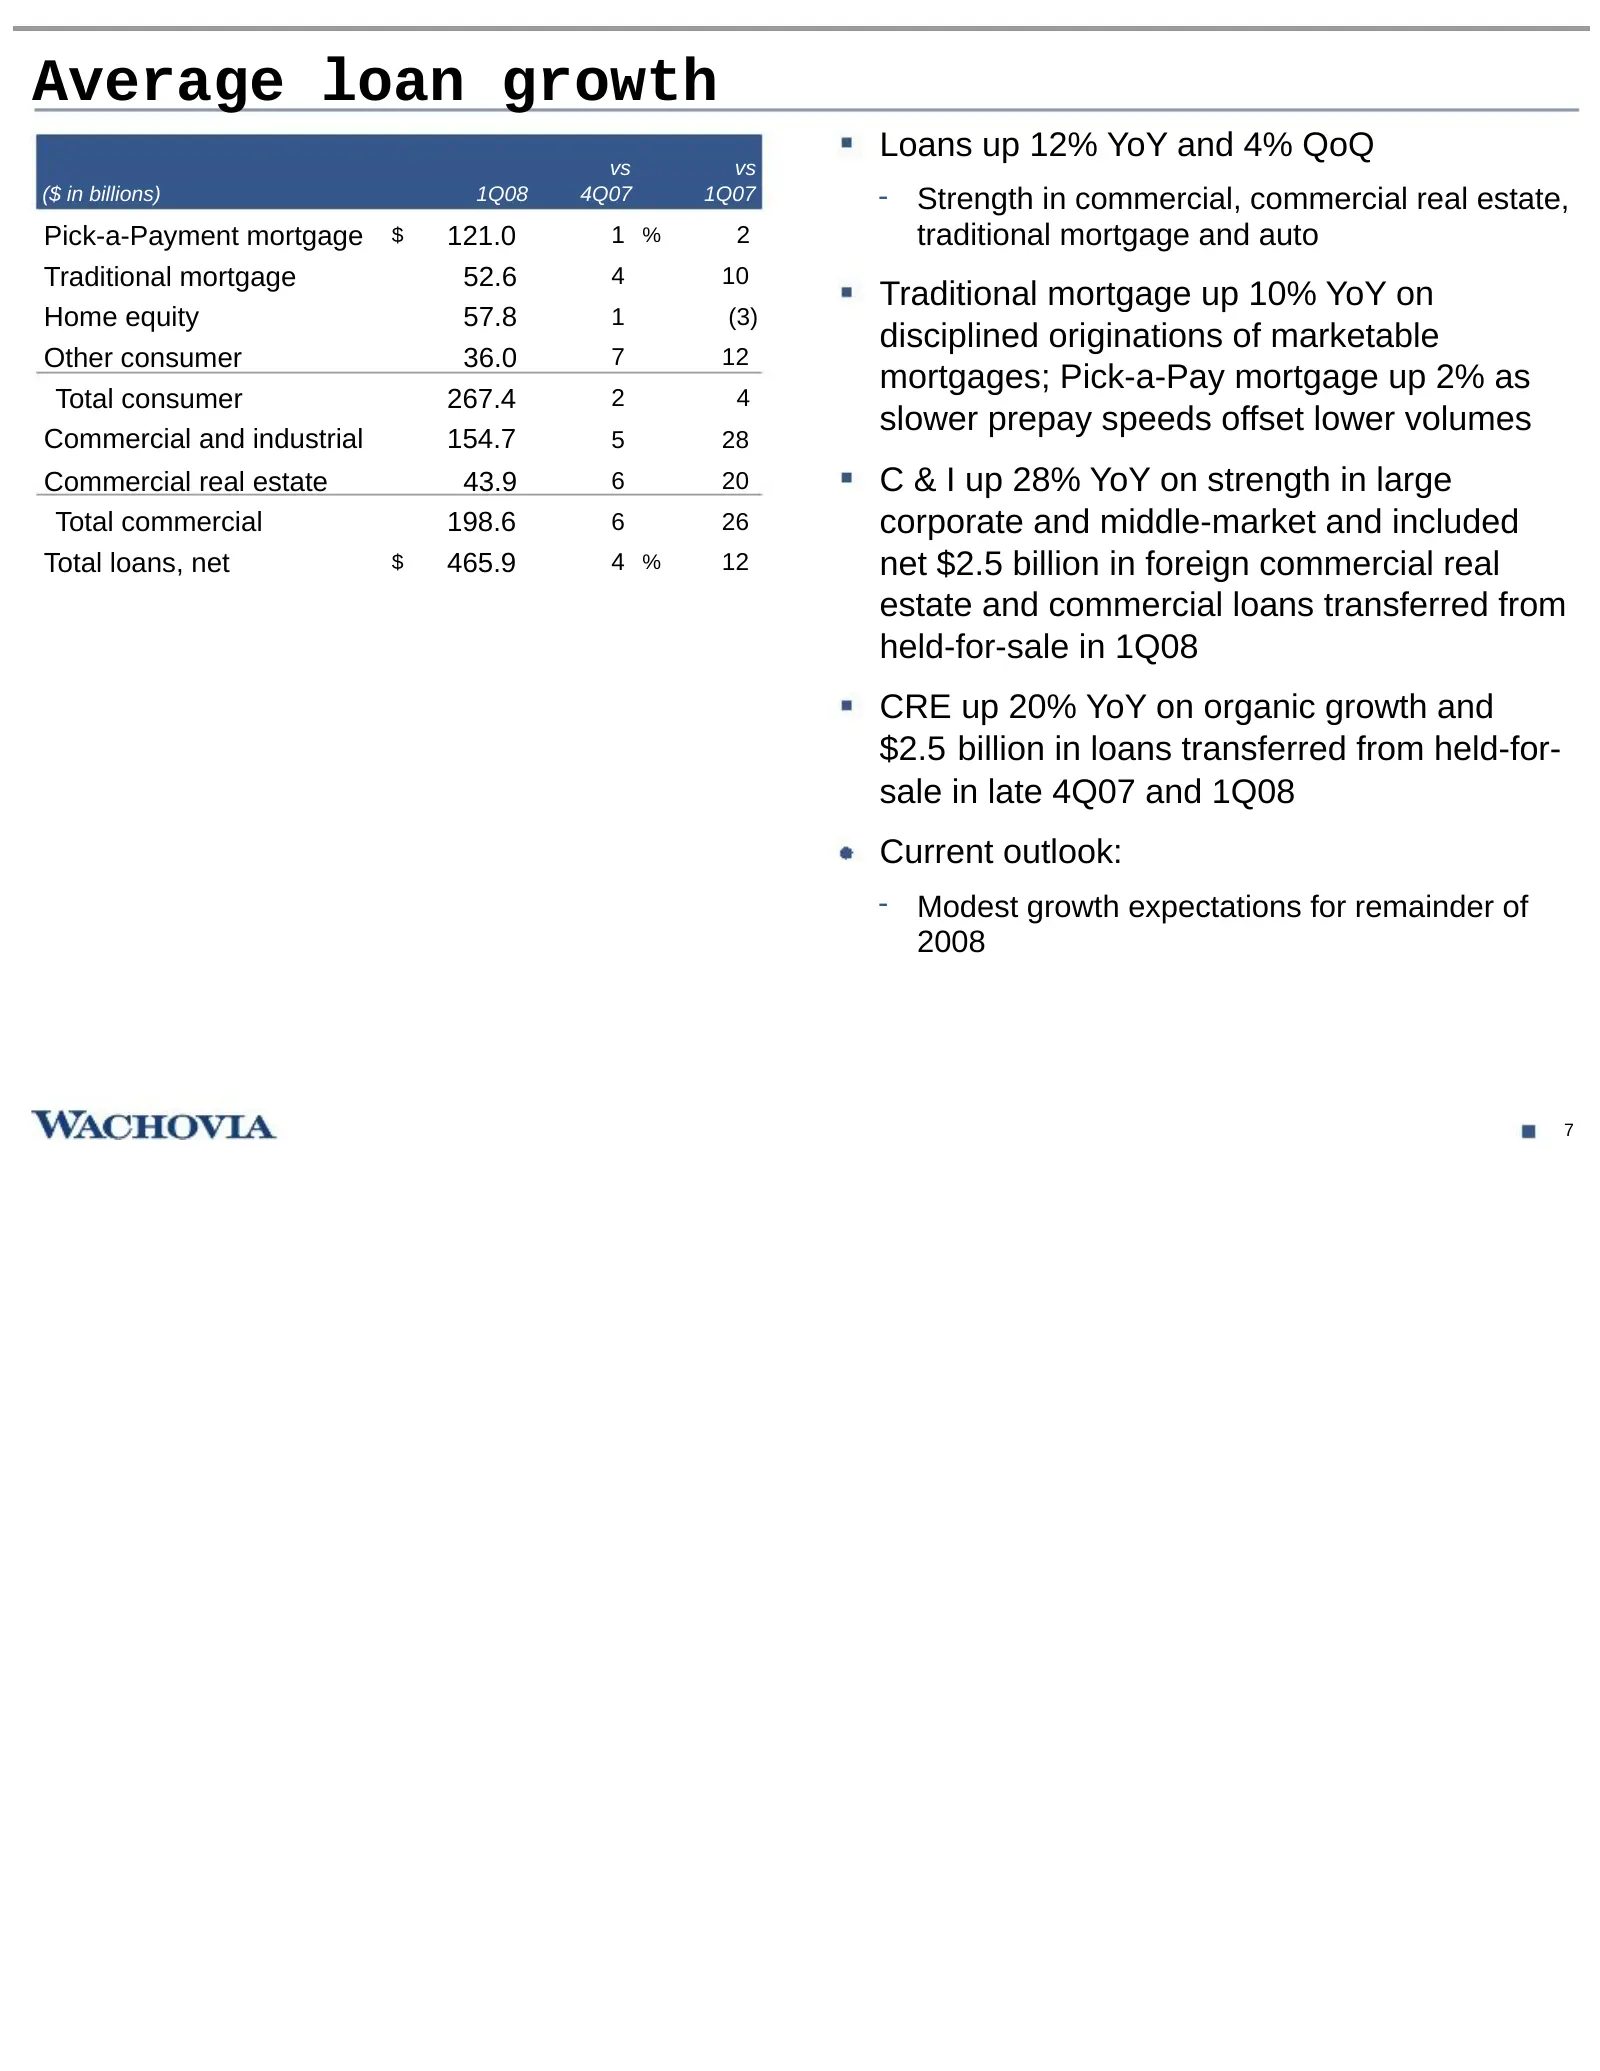
Average loan growth Loans up 12% YoY and 4% QoQ vs vs ($ in billions) 1Q08 4Q07 1Q07 - Strength in commercial, commercial real estate, Pick-a-Payment mortgage $ 121.0 1 % 2 traditional mortgage and auto Traditional mortgage 52.6 4 10 Traditional mortgage up 10% YoY on Home equity 57.8 1 (3) discipli
Slide 9: General Bank key metrics
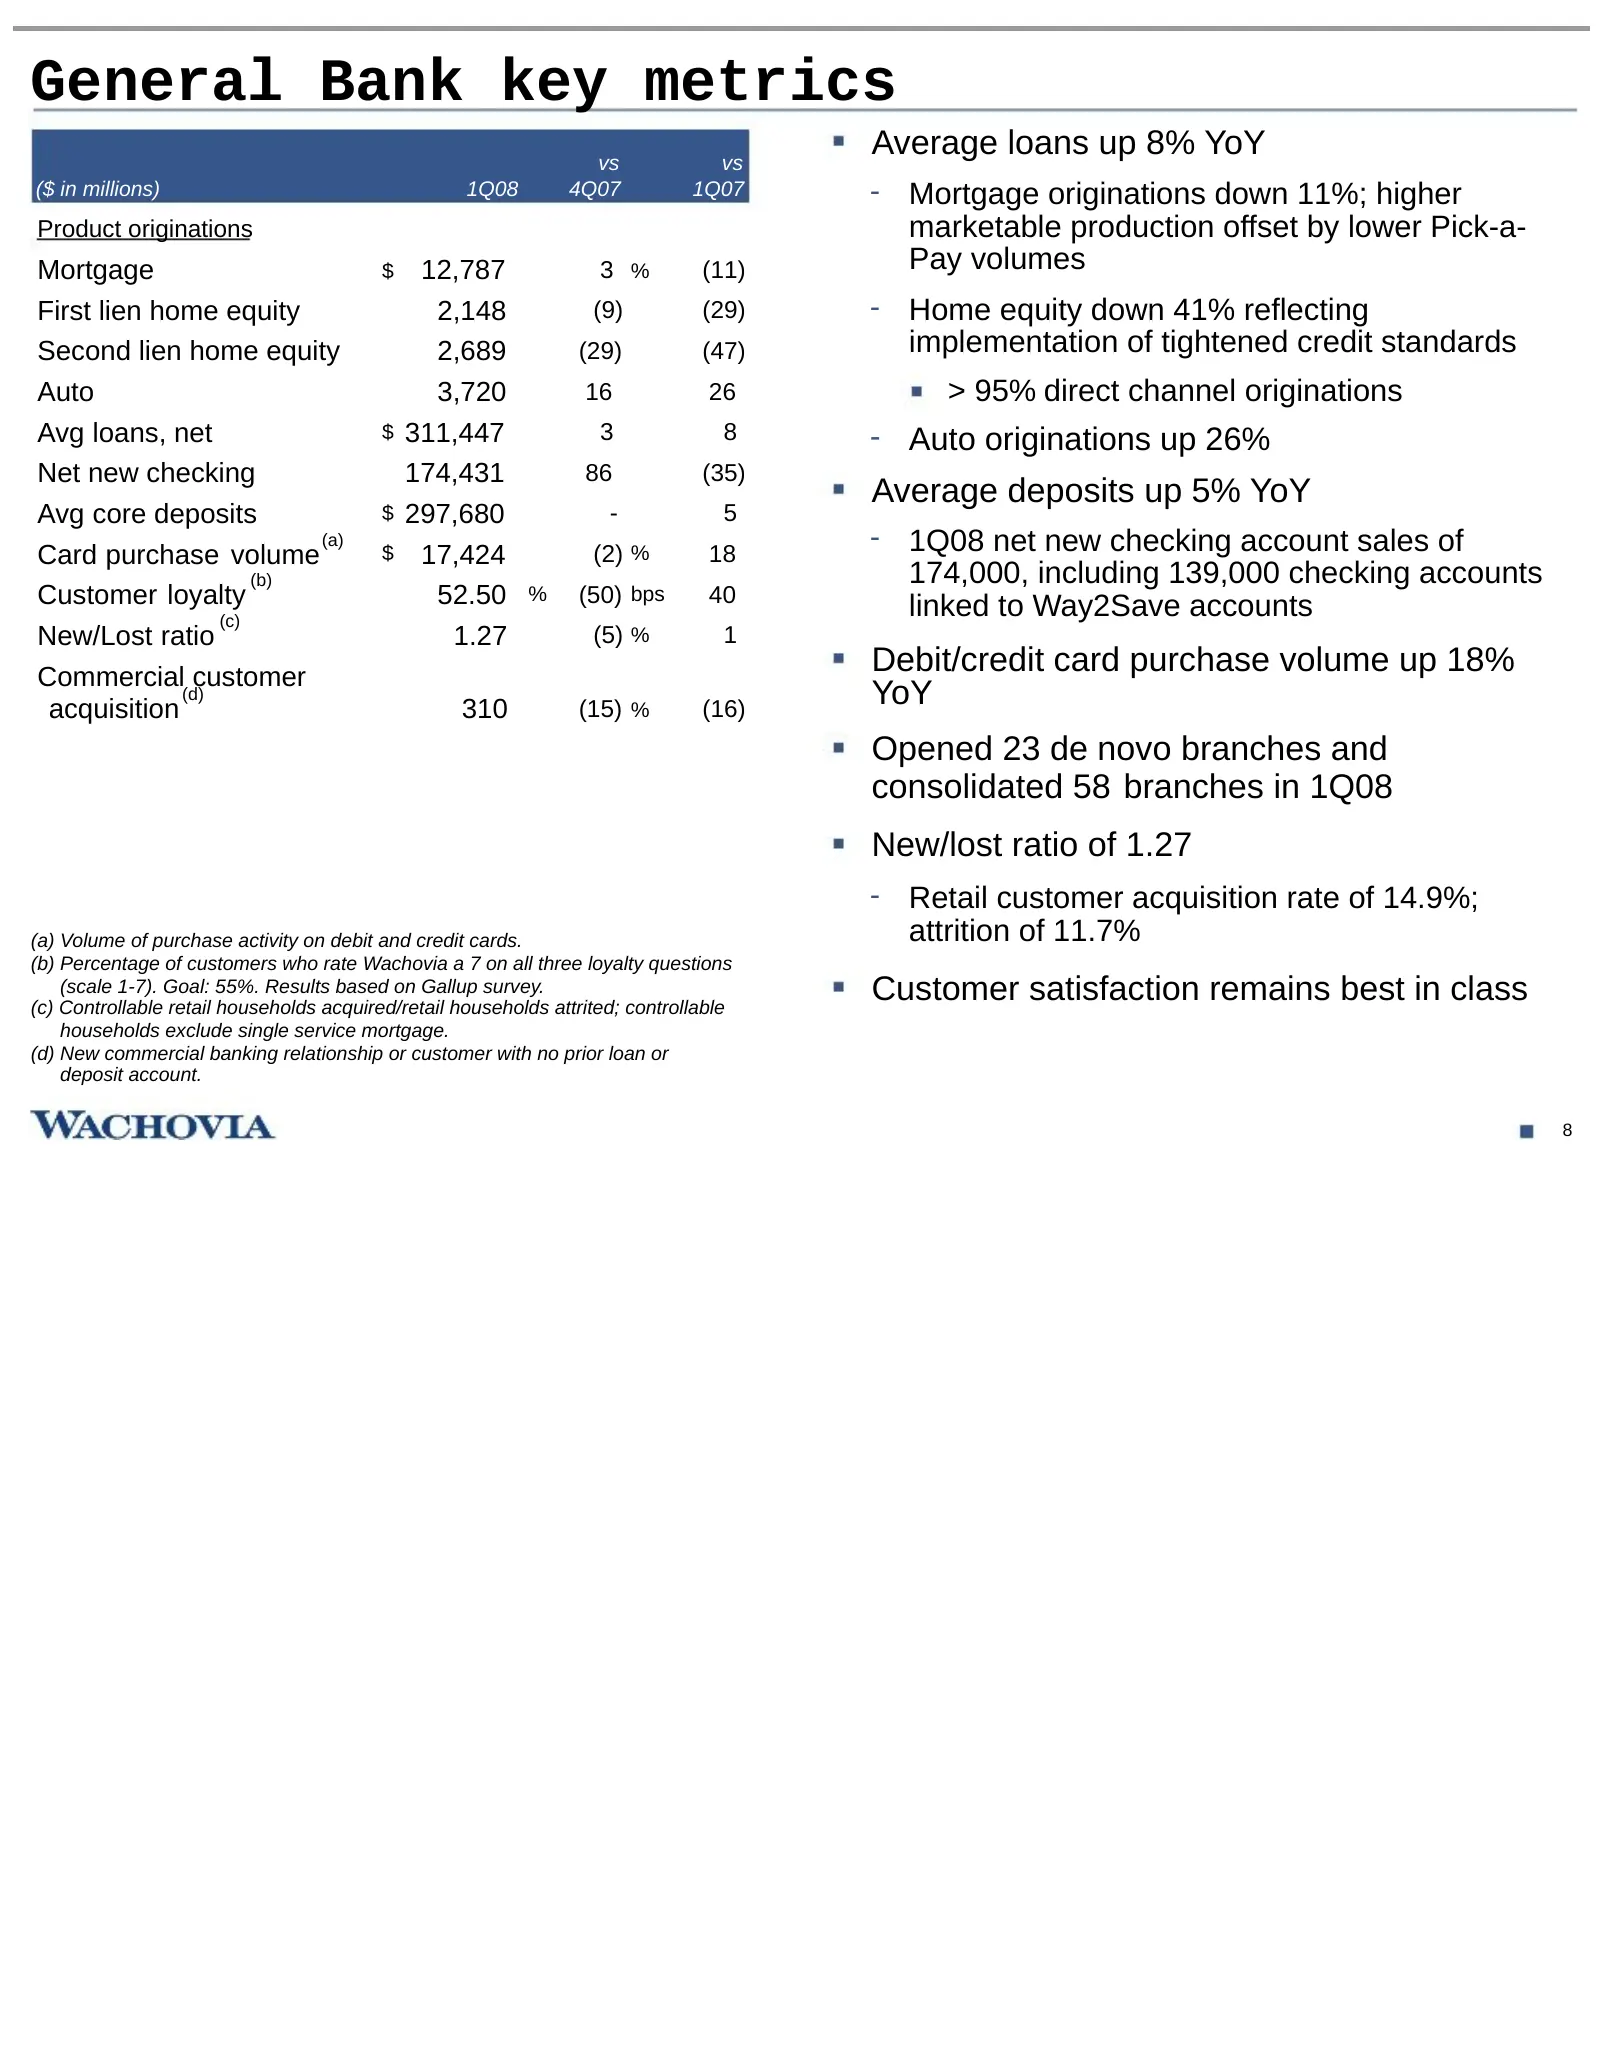
General Bank key metrics vs vs Average loans up 8% YoY ($ in millions) 1Q08 4Q07 1Q07 - Mortgage originations down 11%; higher Product originations marketable production offset by lower Pick-a- Mortgage $ 12,787 3 % (11) Pay volumes First lien home equity 2,148 (9) (29) - Home equity down 41% reflec
Slide 10: General Bank summary
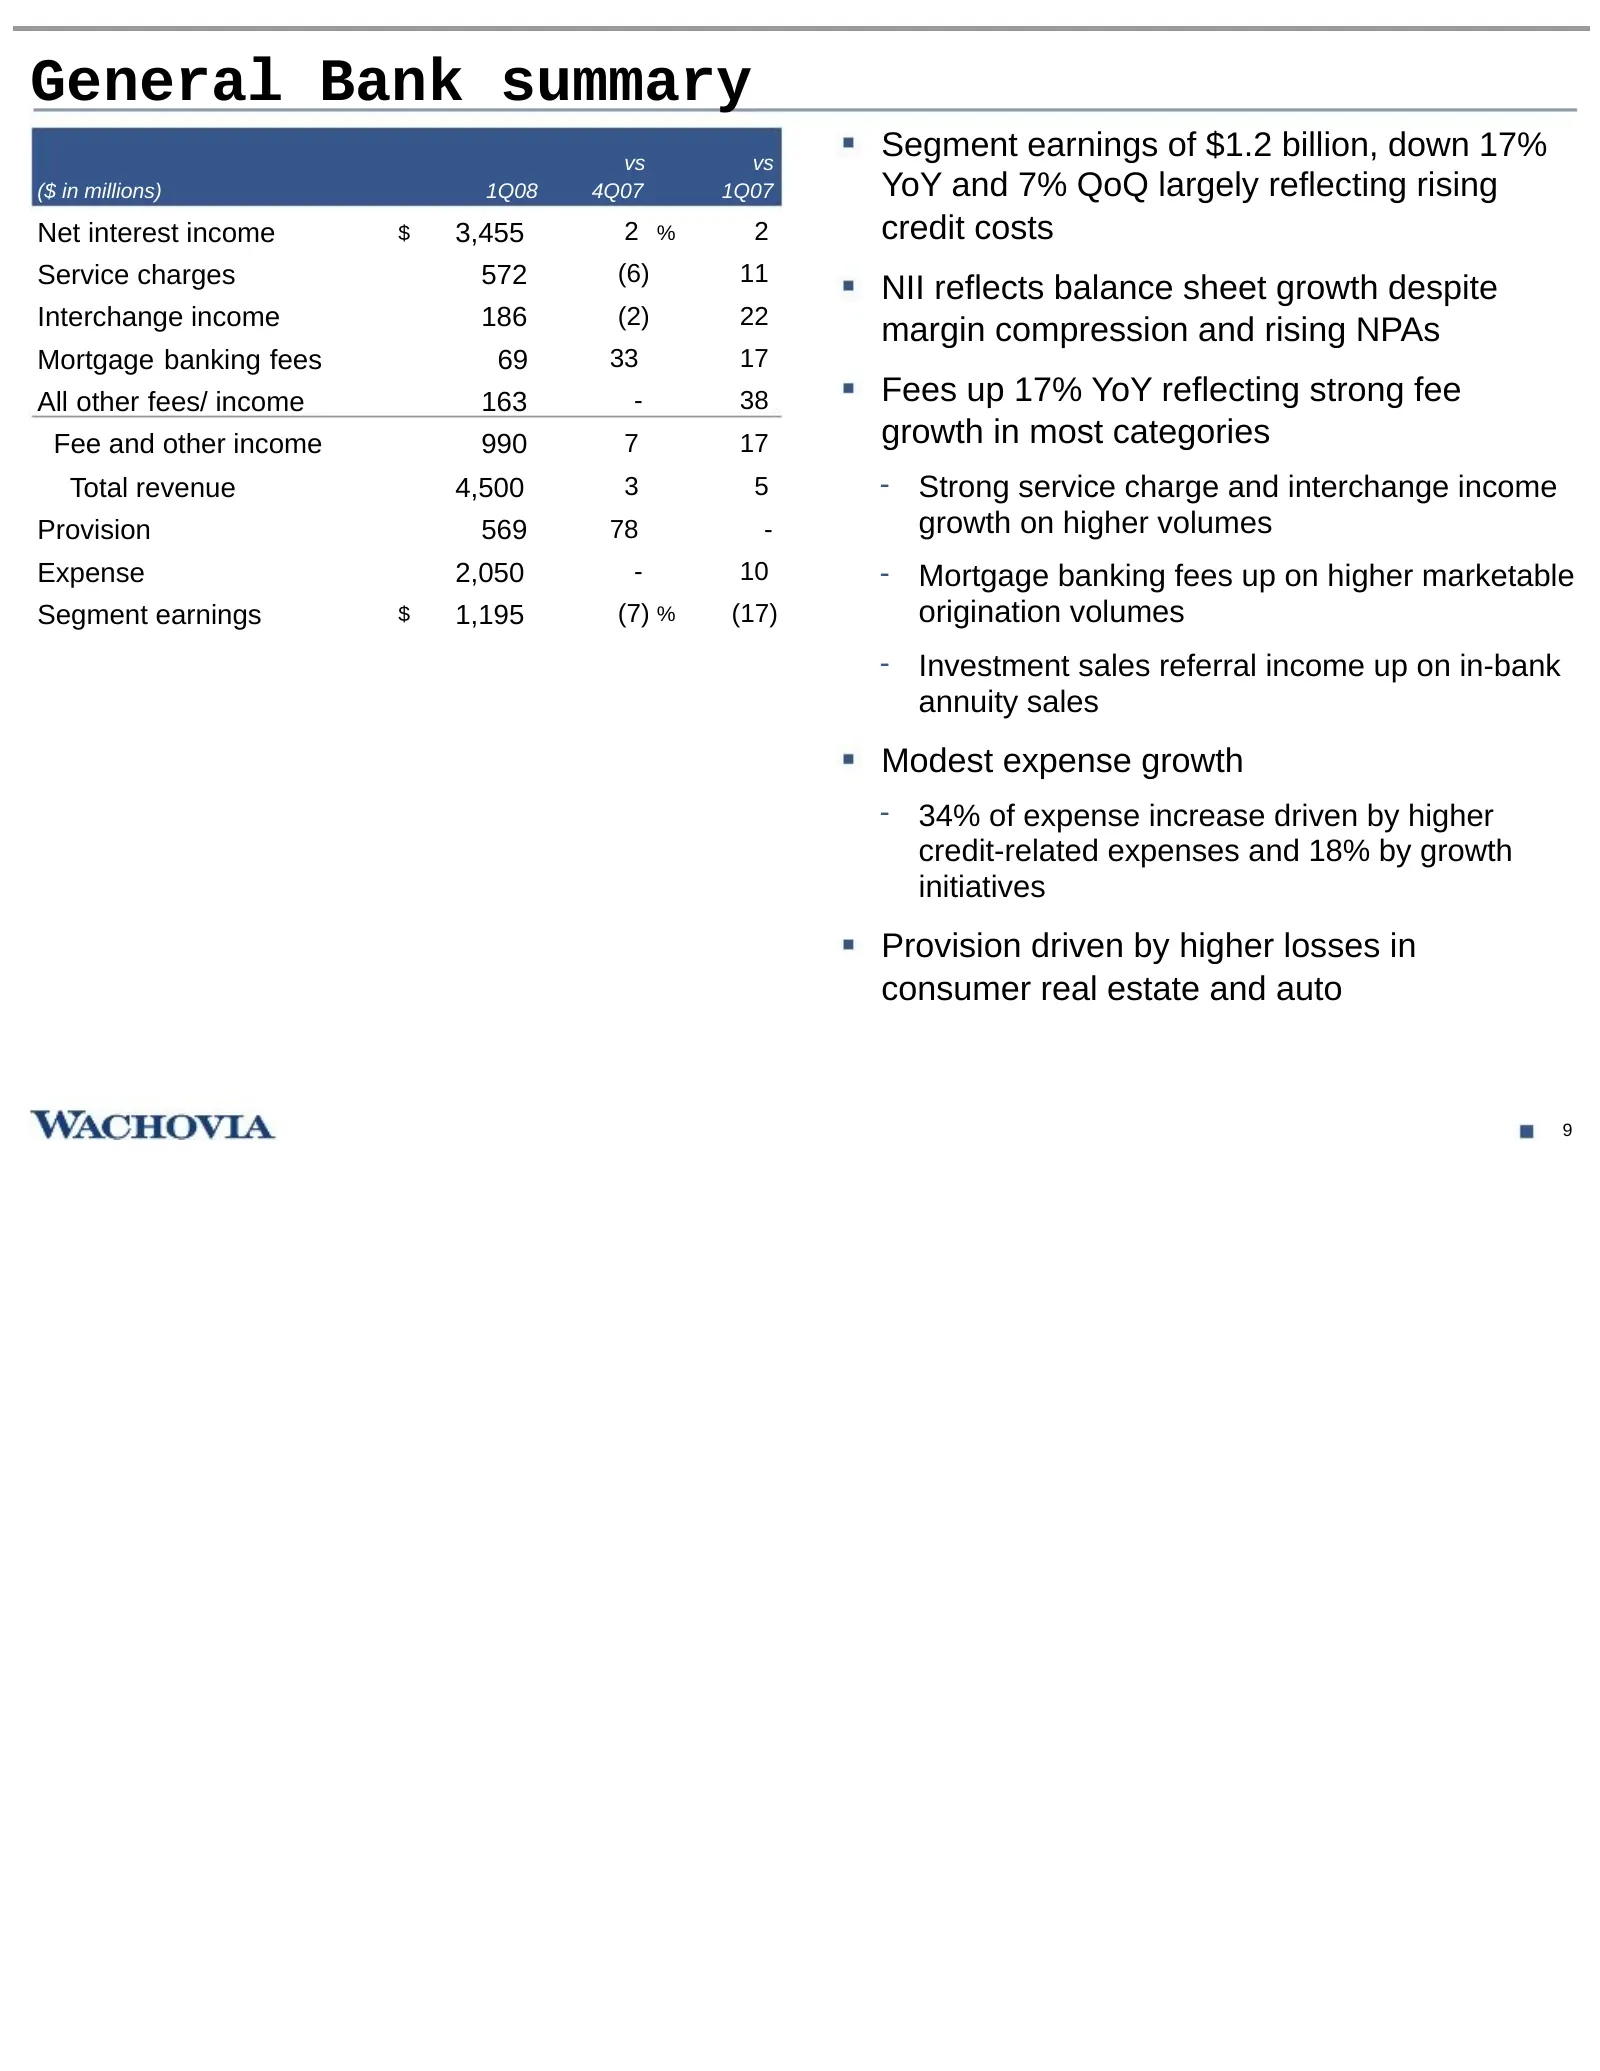
General Bank summary vs vs Segment earnings of $1.2 billion, down 17% ($ in millions) 1Q08 4Q07 1Q07 YoY and 7% QoQ largely reflecting rising Net interest income $ 3,455 2 % 2 credit costs Service charges 572 (6) 11 NII reflects balance sheet growth despite Interchange income 186 (2) 22 margin compr
Slide 11: Wealth Management summary
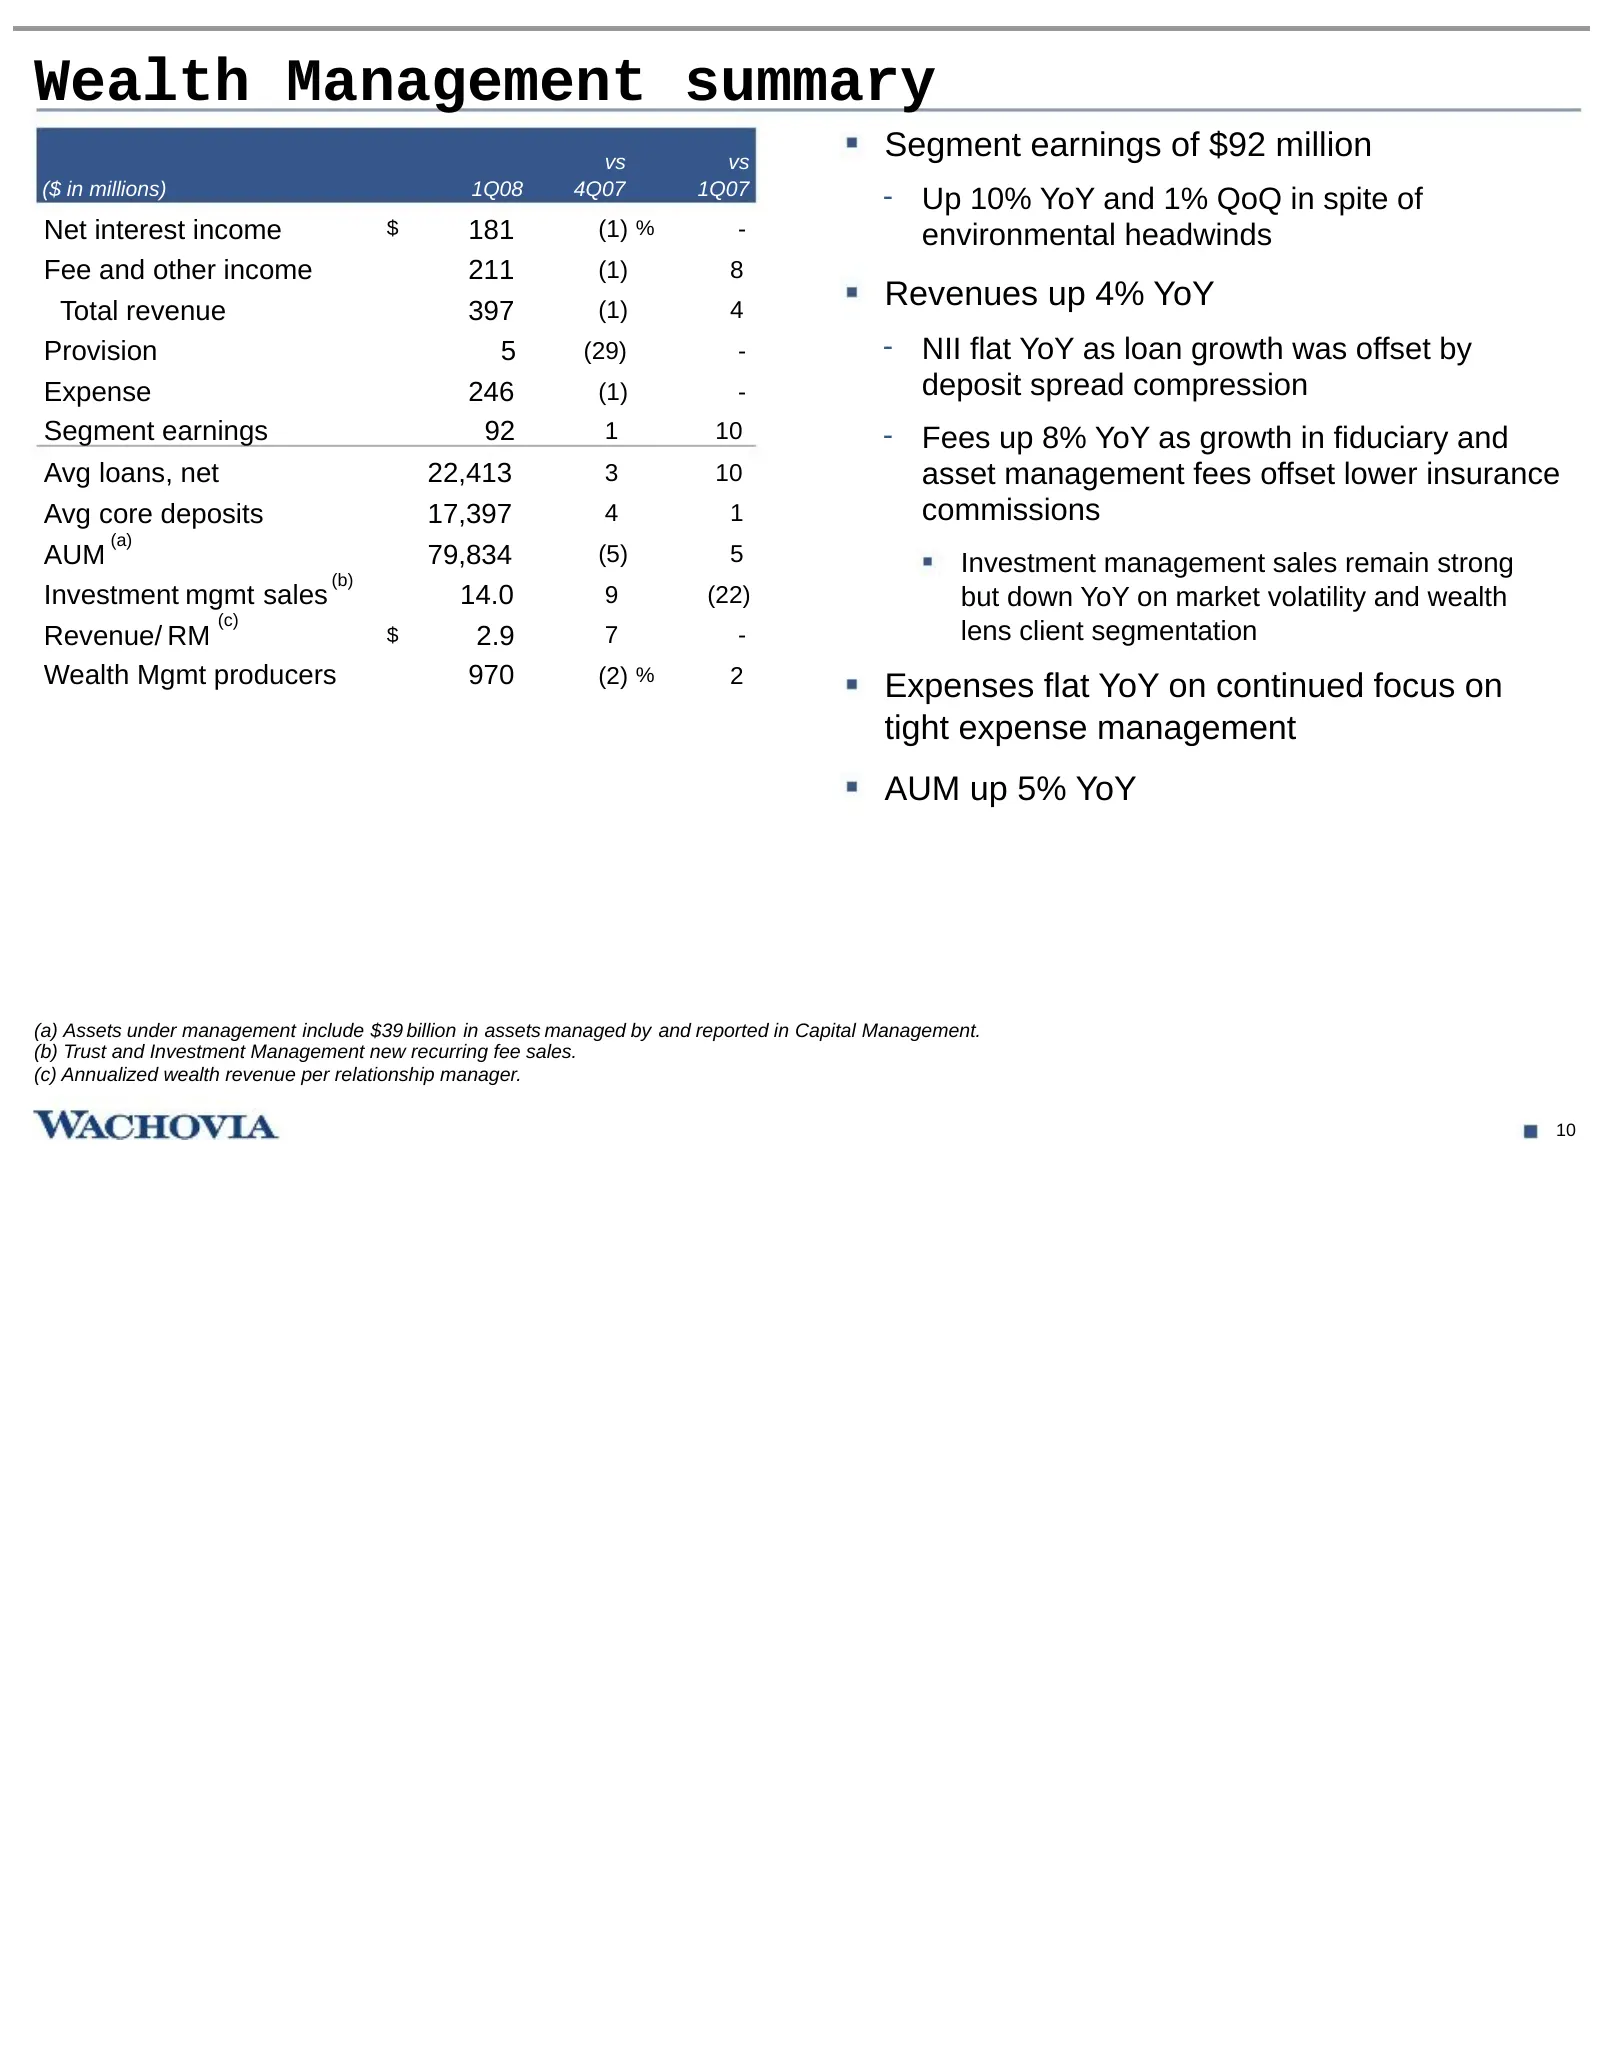
Wealth Management summary vs vs Segment earnings of $92 million ($ in millions) 1Q08 4Q07 1Q07 - Up 10% YoY and 1% QoQ in spite of Net interest income $ 181 (1) % - environmental headwinds Fee and other income 211 (1) 8 Total revenue 397 (1) 4 Revenues up 4% YoY Provision 5 (29) - - NII flat YoY as
Slide 12: Corporate and Investment Bank summary
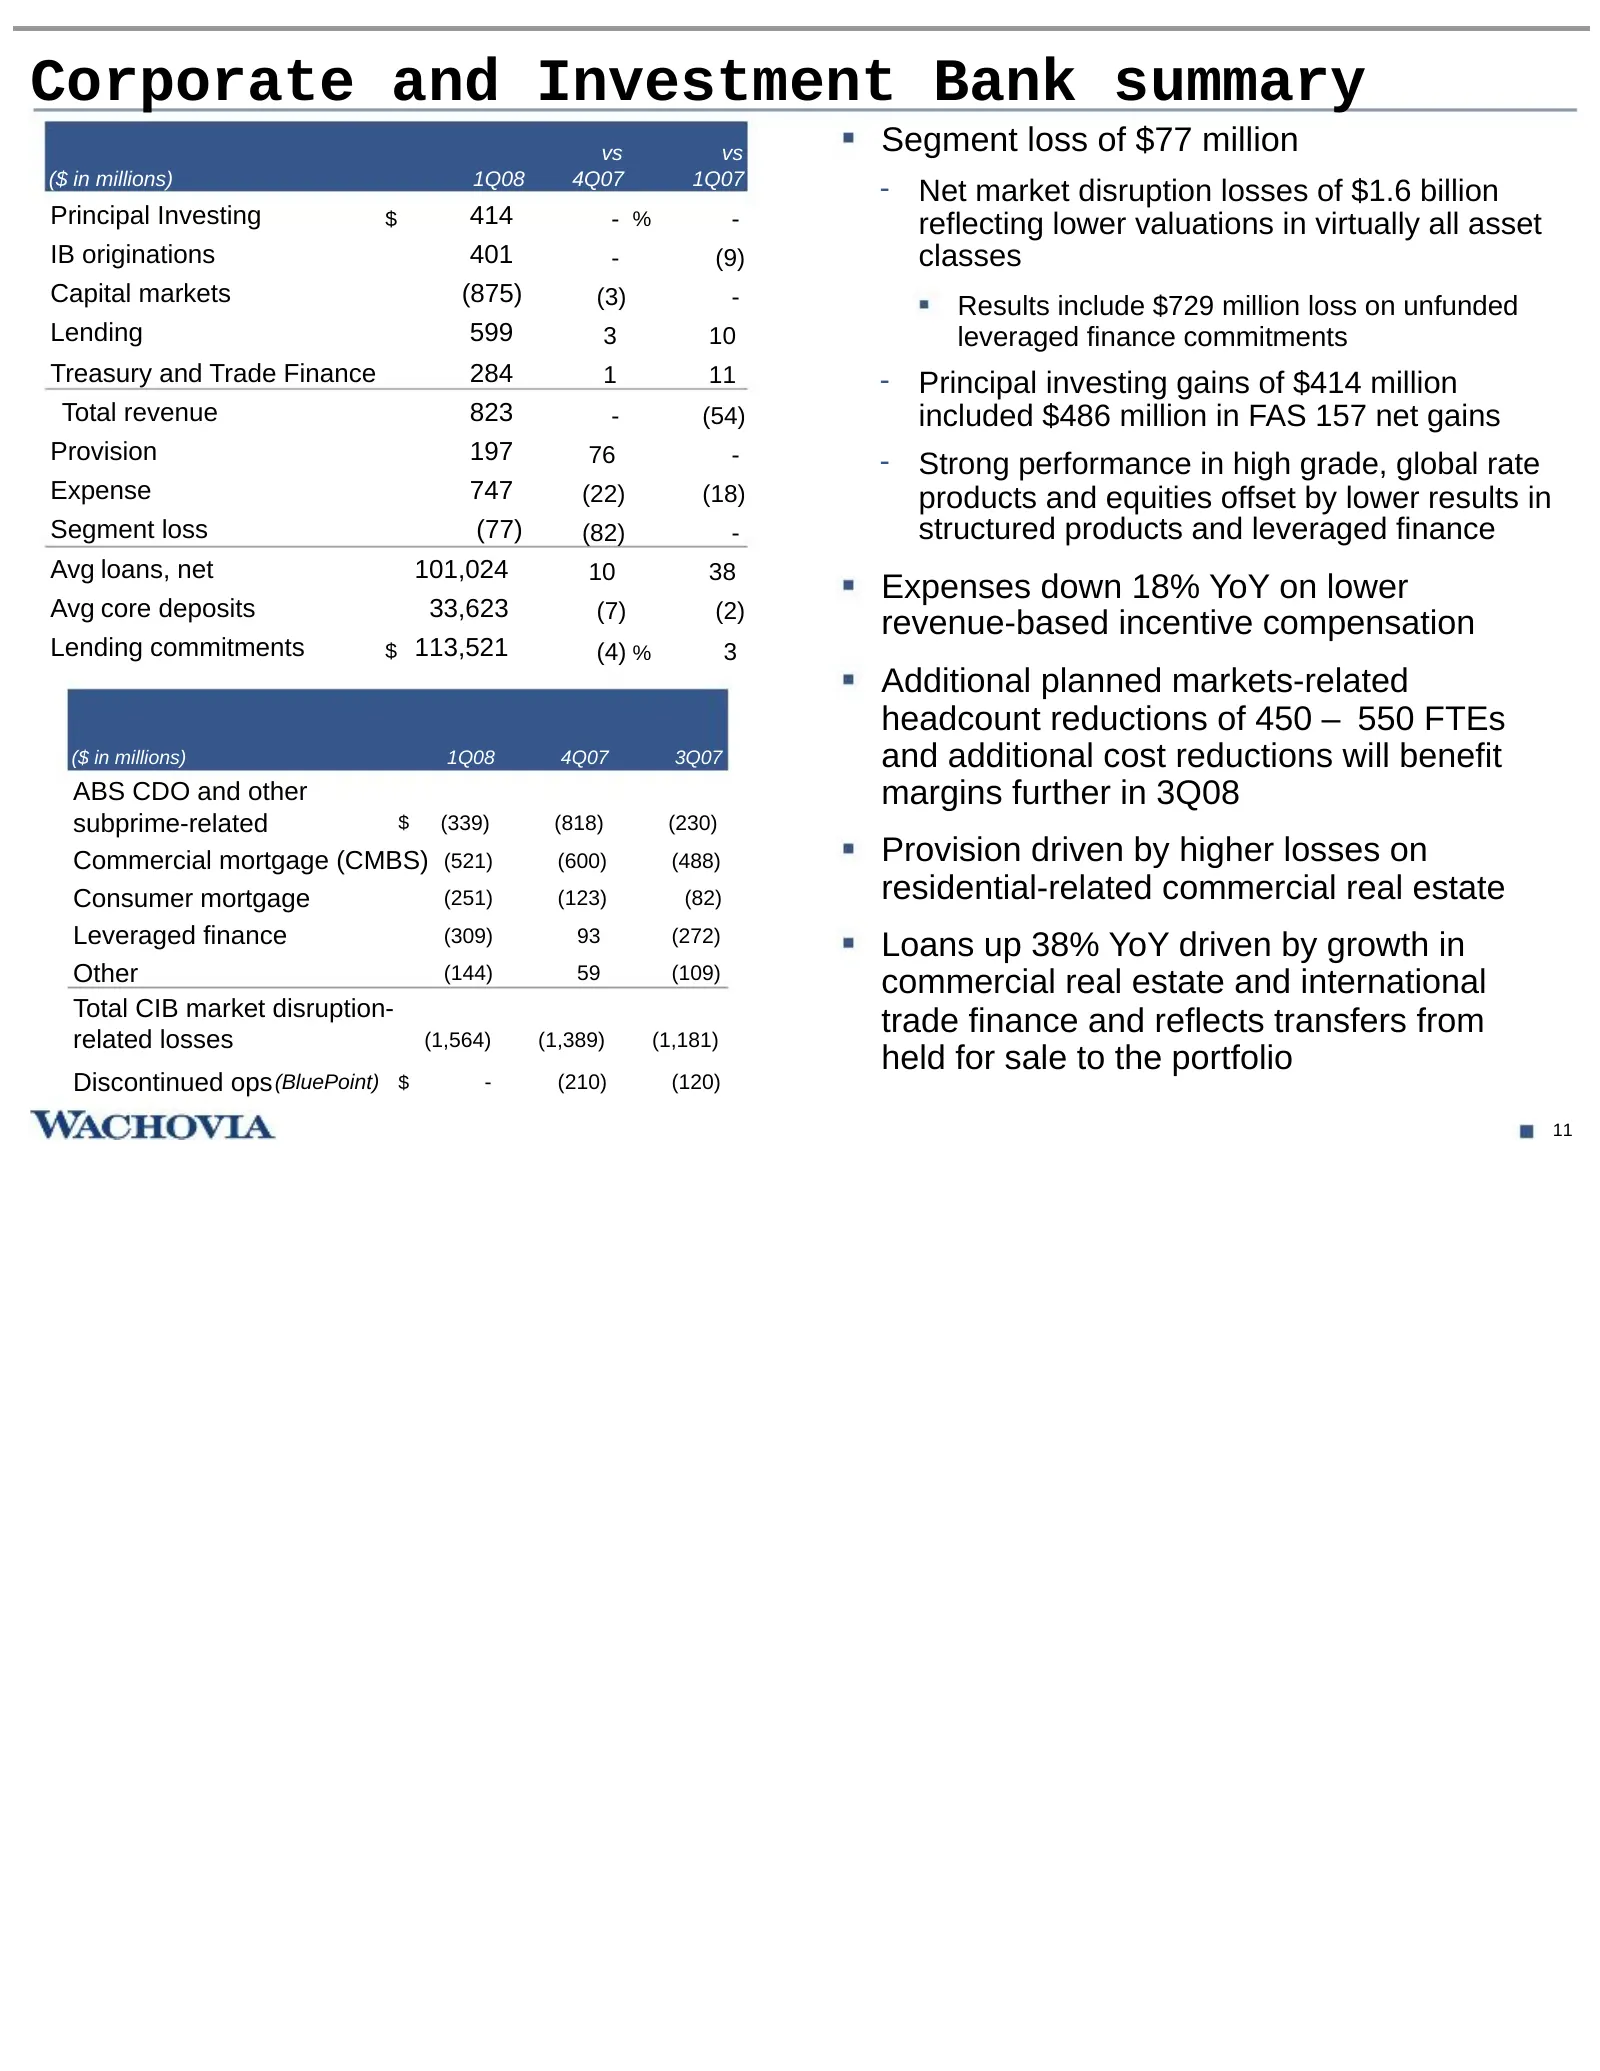
Corporate and Investment Bank summary vs vs Segment loss of $77 million ($ in millions) 1Q08 4Q07 1Q07 - Net market disruption losses of $1.6 billion Principal Investing $ 414 - % - reflecting lower valuations in virtually all asset IB originations 401 - (9) classes Capital markets (875) (3) - Resul
Slide 13: Commercial mortgage and leveraged finance: Distribution-related exposure
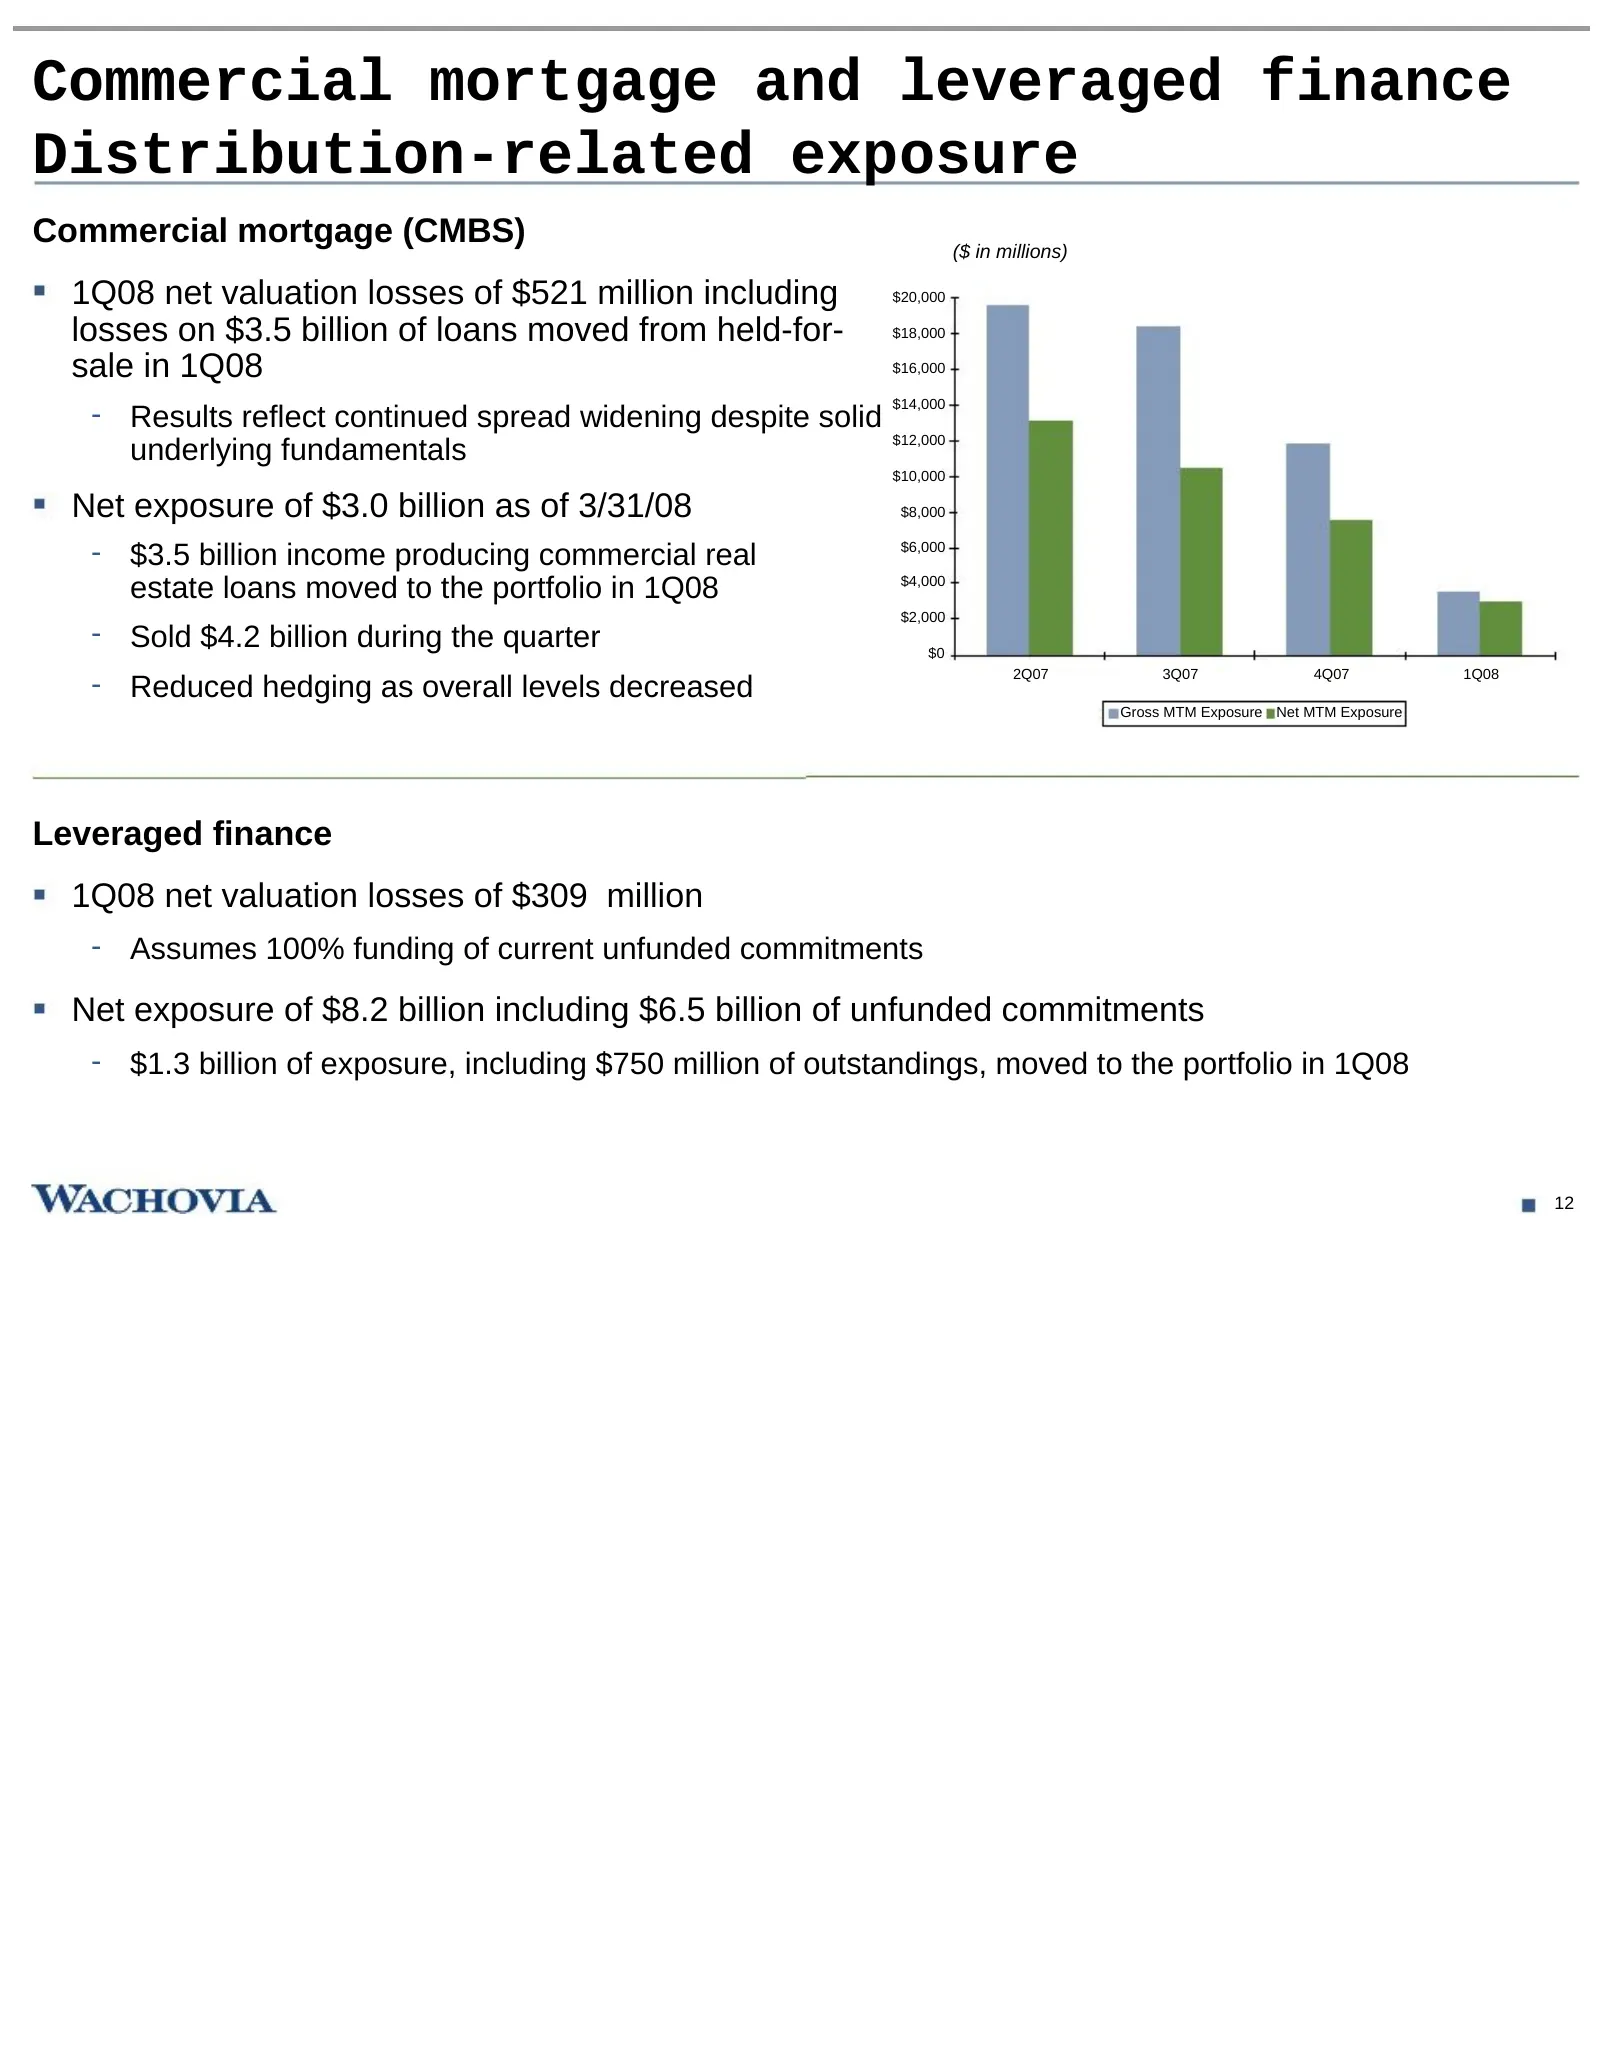
Commercial mortgage and leveraged finance Distribution-related exposure Commercial mortgage (CMBS) ($ in millions) 1Q08 net valuation losses of $521 million including $20,000 losses on $3.5 billion of loans moved from held-for- $18,000 sale in 1Q08 $16,000 - Results reflect continued spread widening
Slide 14: Corporate and Investment Bank: Remaining distribution exposure
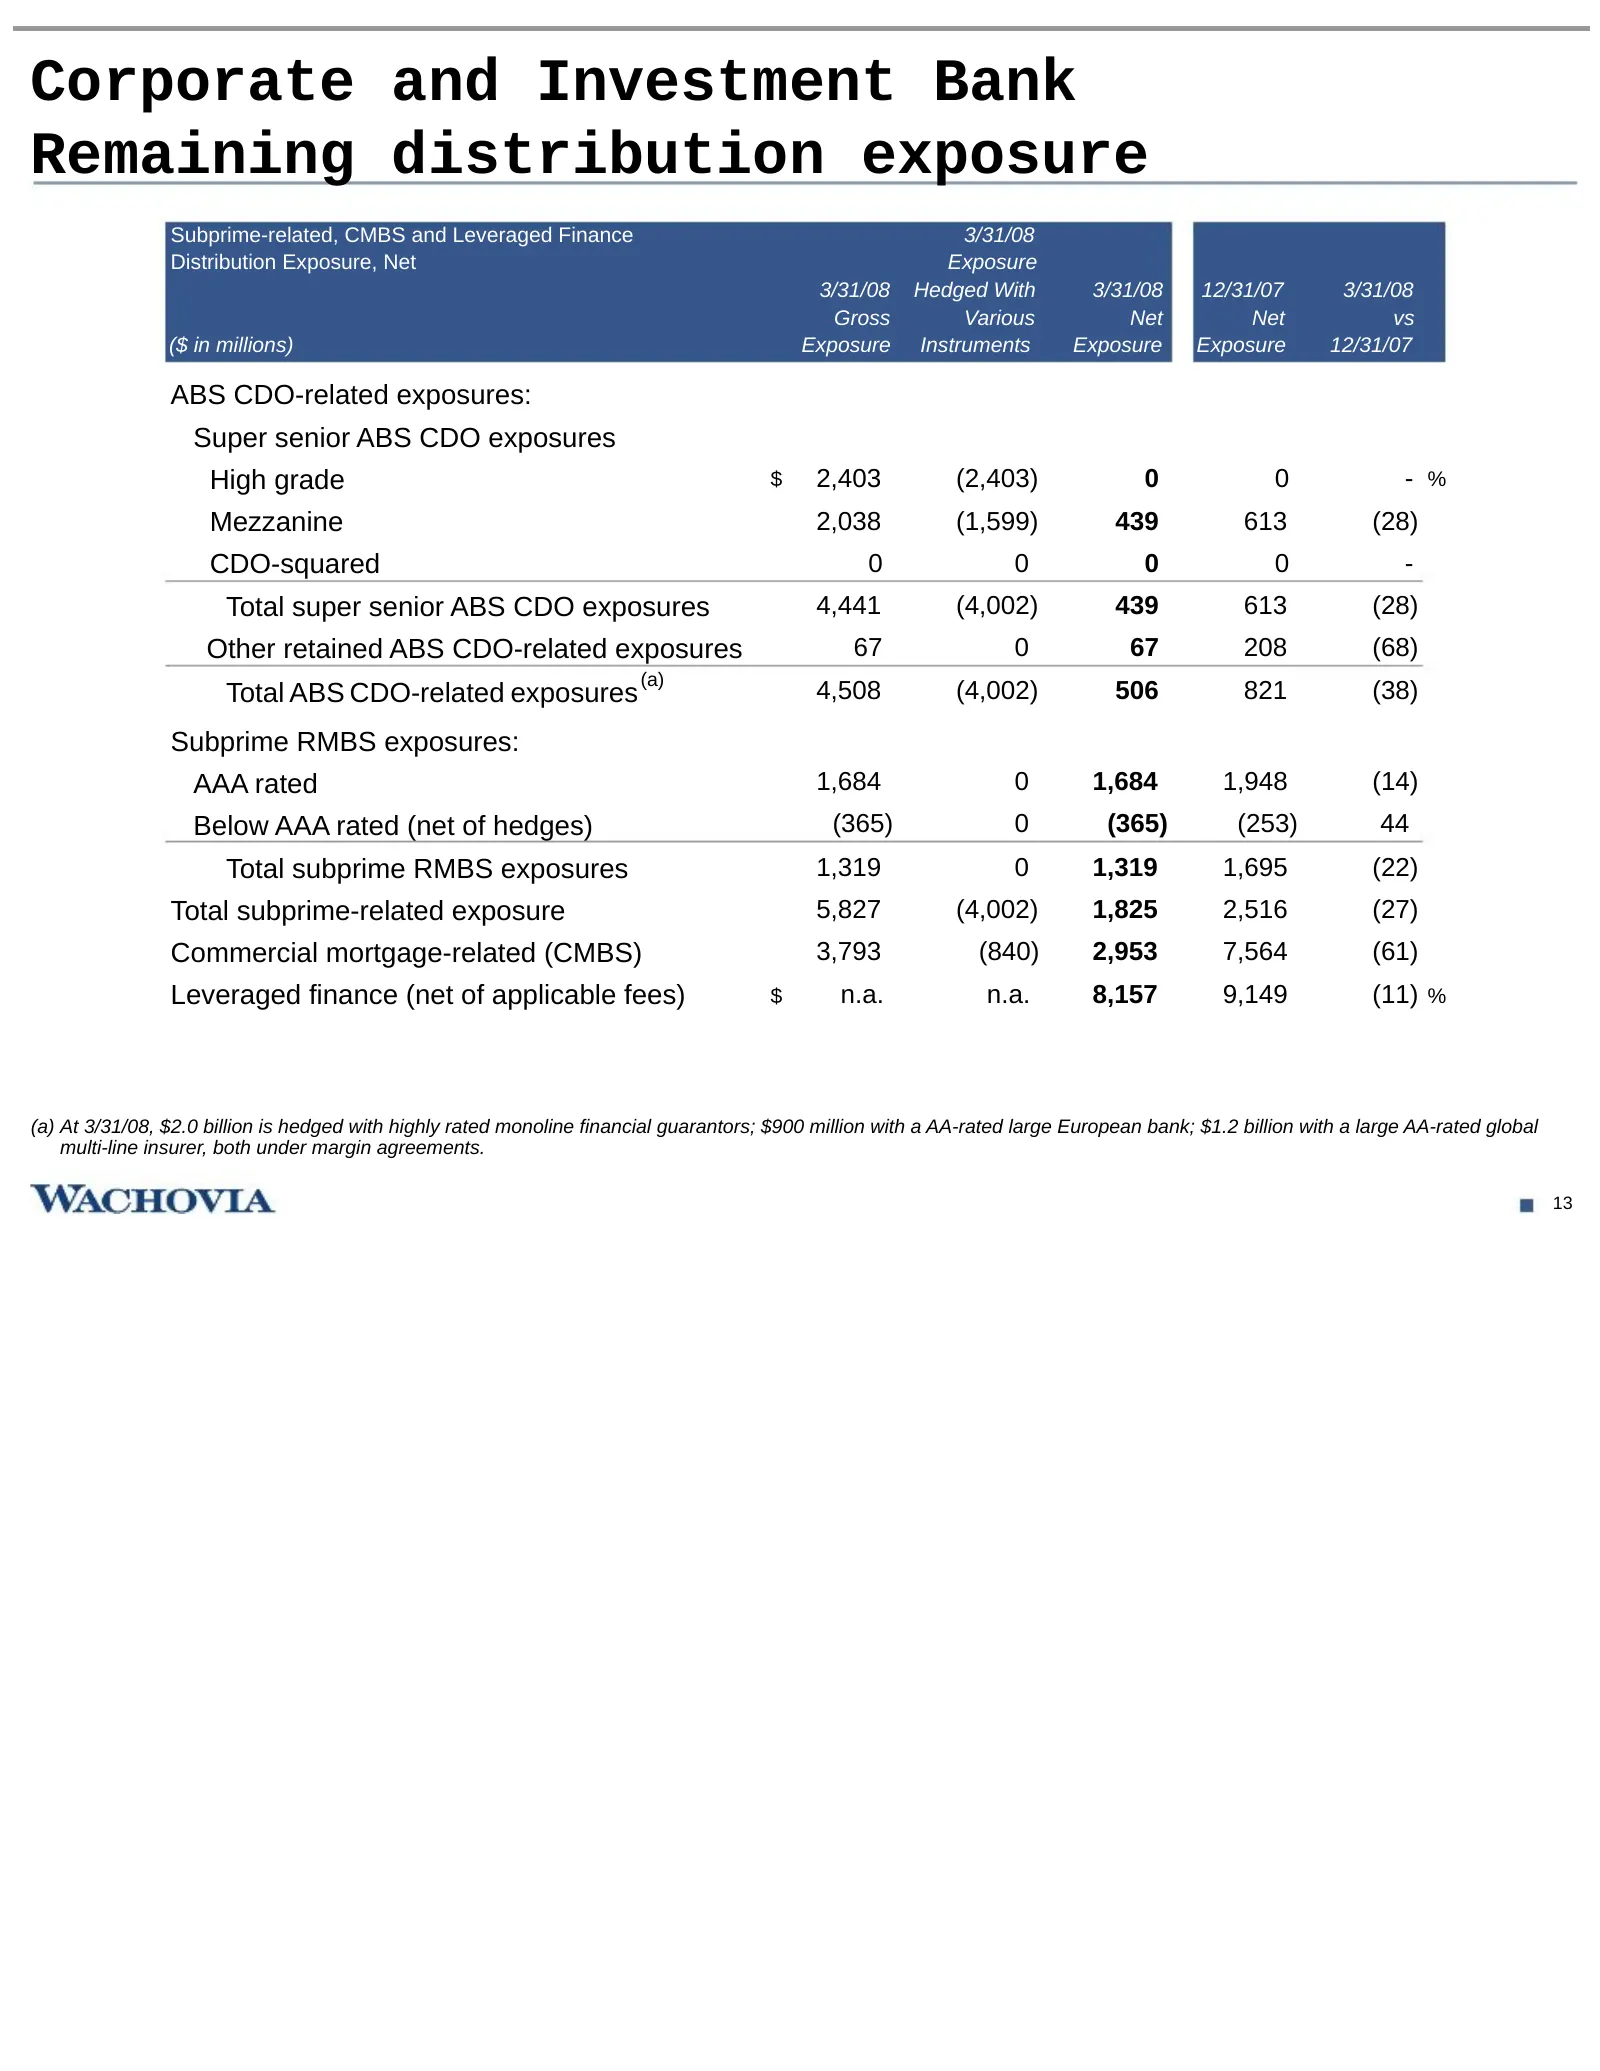
Corporate and Investment Bank Remaining distribution exposure Subprime-related, CMBS and Leveraged Finance 3/31/08 Distribution Exposure, Net Exposure 3/31/08 Hedged With 3/31/08 12/31/07 3/31/08 Gross Various Net Net vs ($ in millions) Exposure Instruments Exposure Exposure 12/31/07 ABS CDO-related
Slide 15: Capital Management key metrics
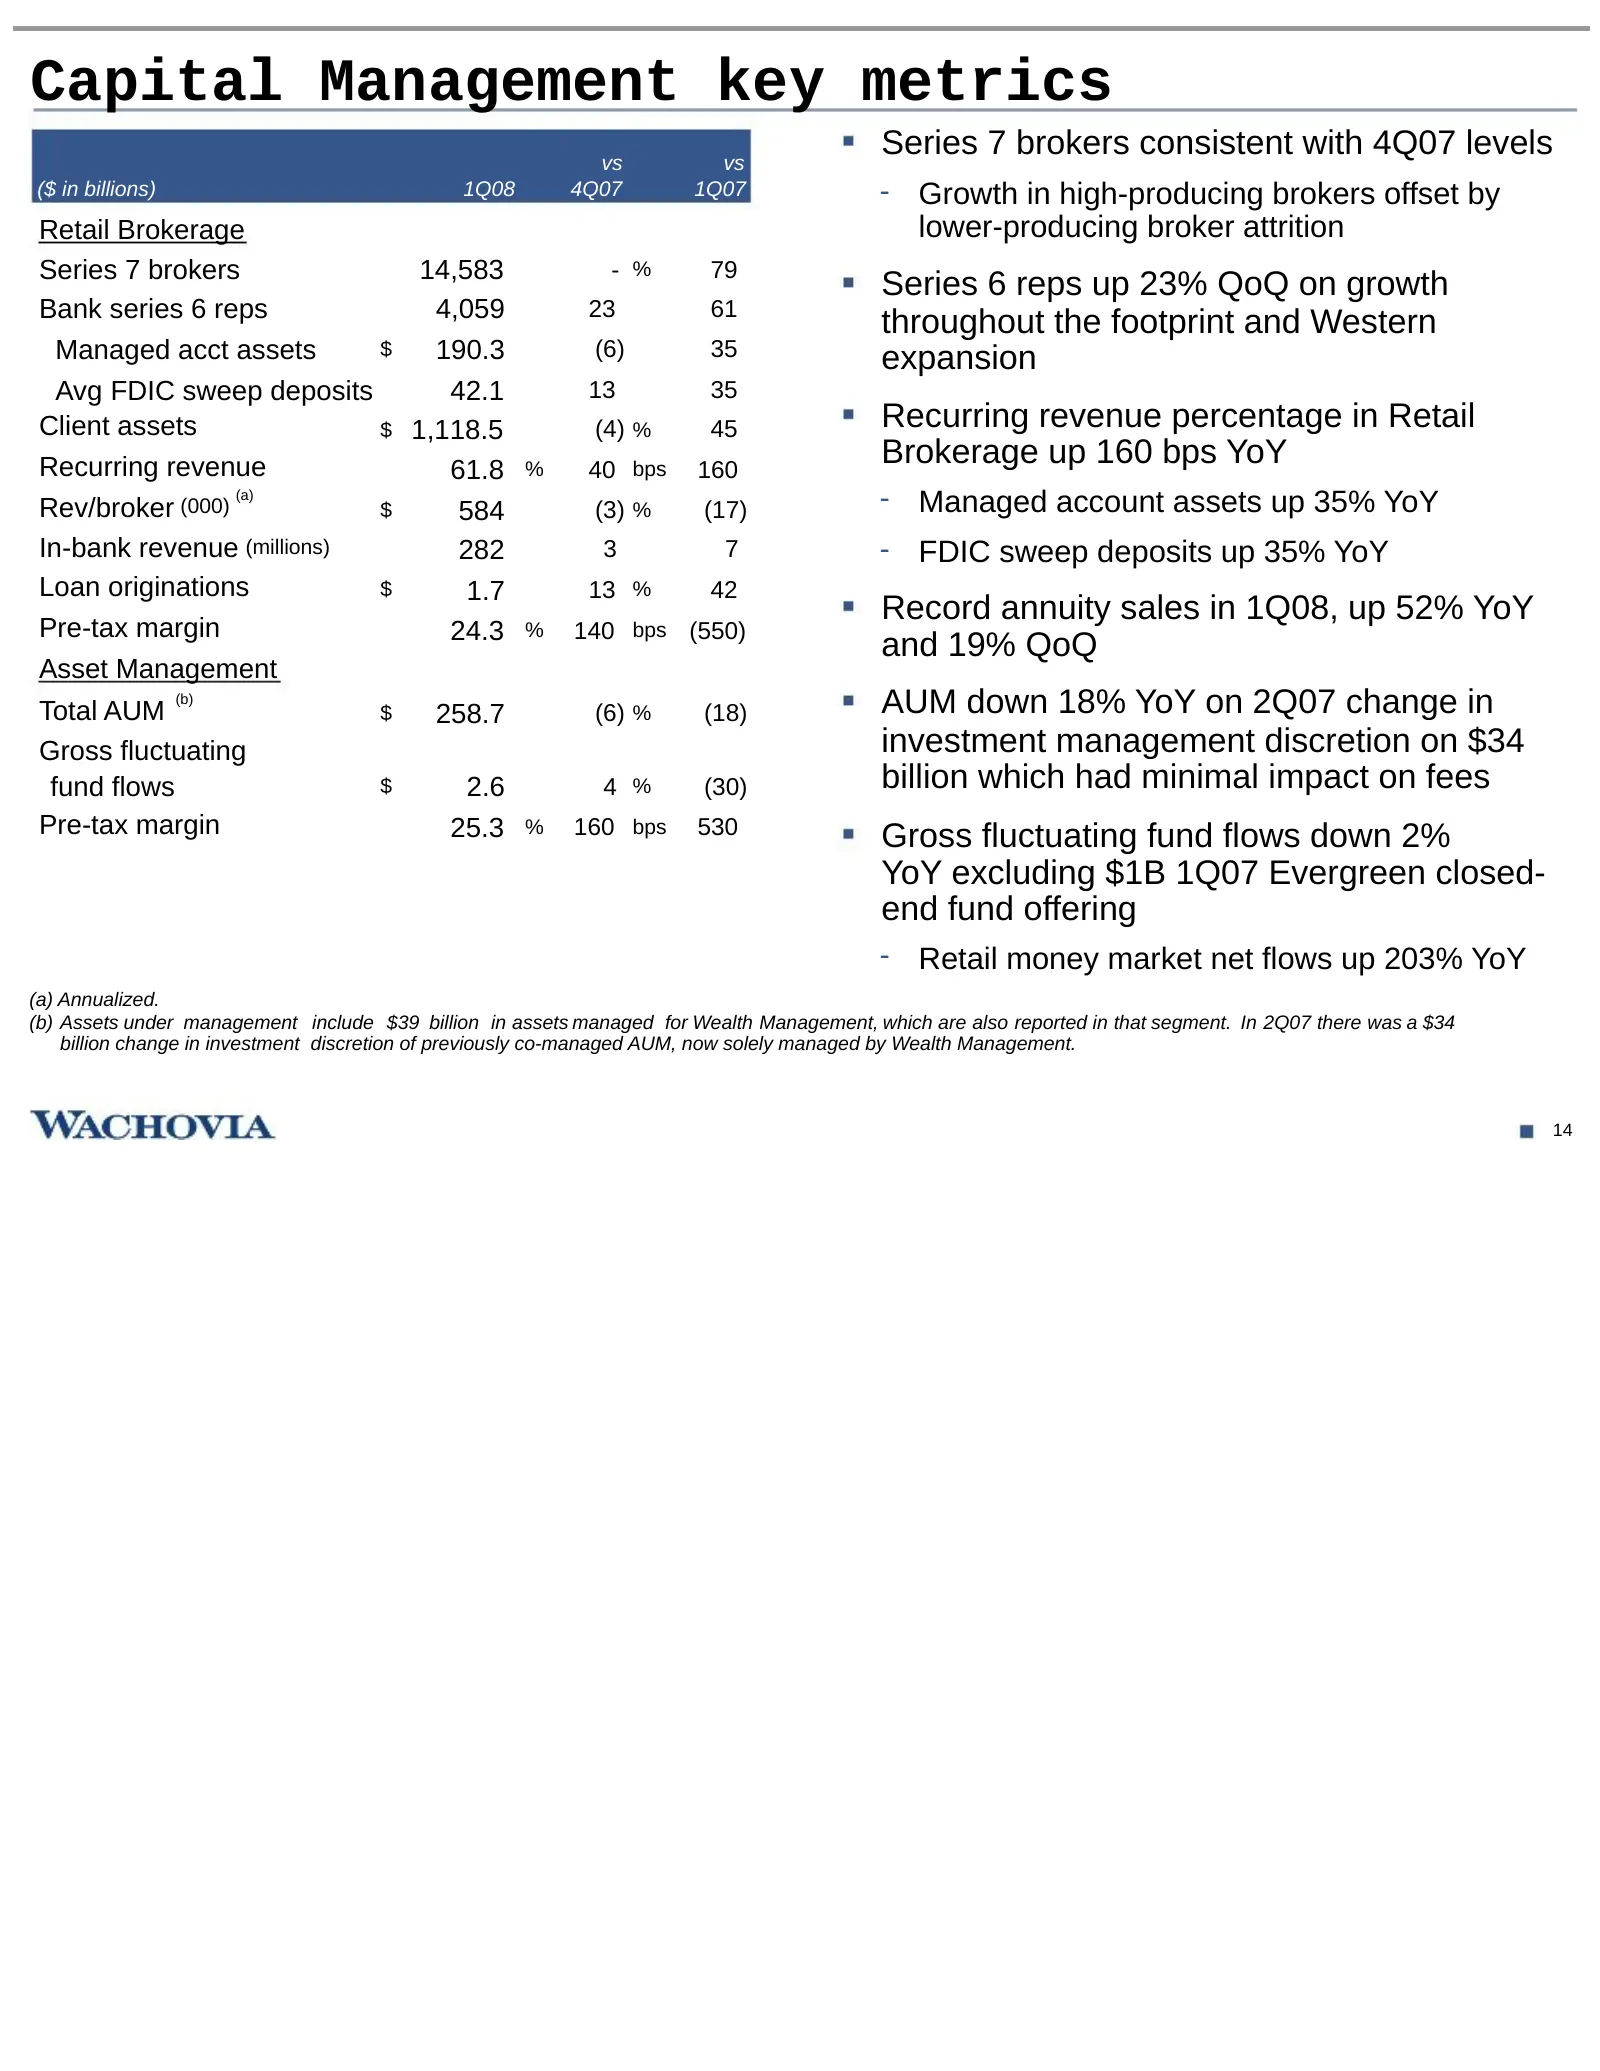
Capital Management key metrics vs vs Series 7 brokers consistent with 4Q07 levels ($ in billions) 1Q08 4Q07 1Q07 - Growth in high-producing brokers offset by Retail Brokerage lower-producing broker attrition Series 7 brokers 14,583 - % 79 Series 6 reps up 23% QoQ on growth Bank series 6 reps 4,059 2
Slide 16: Capital Management summary
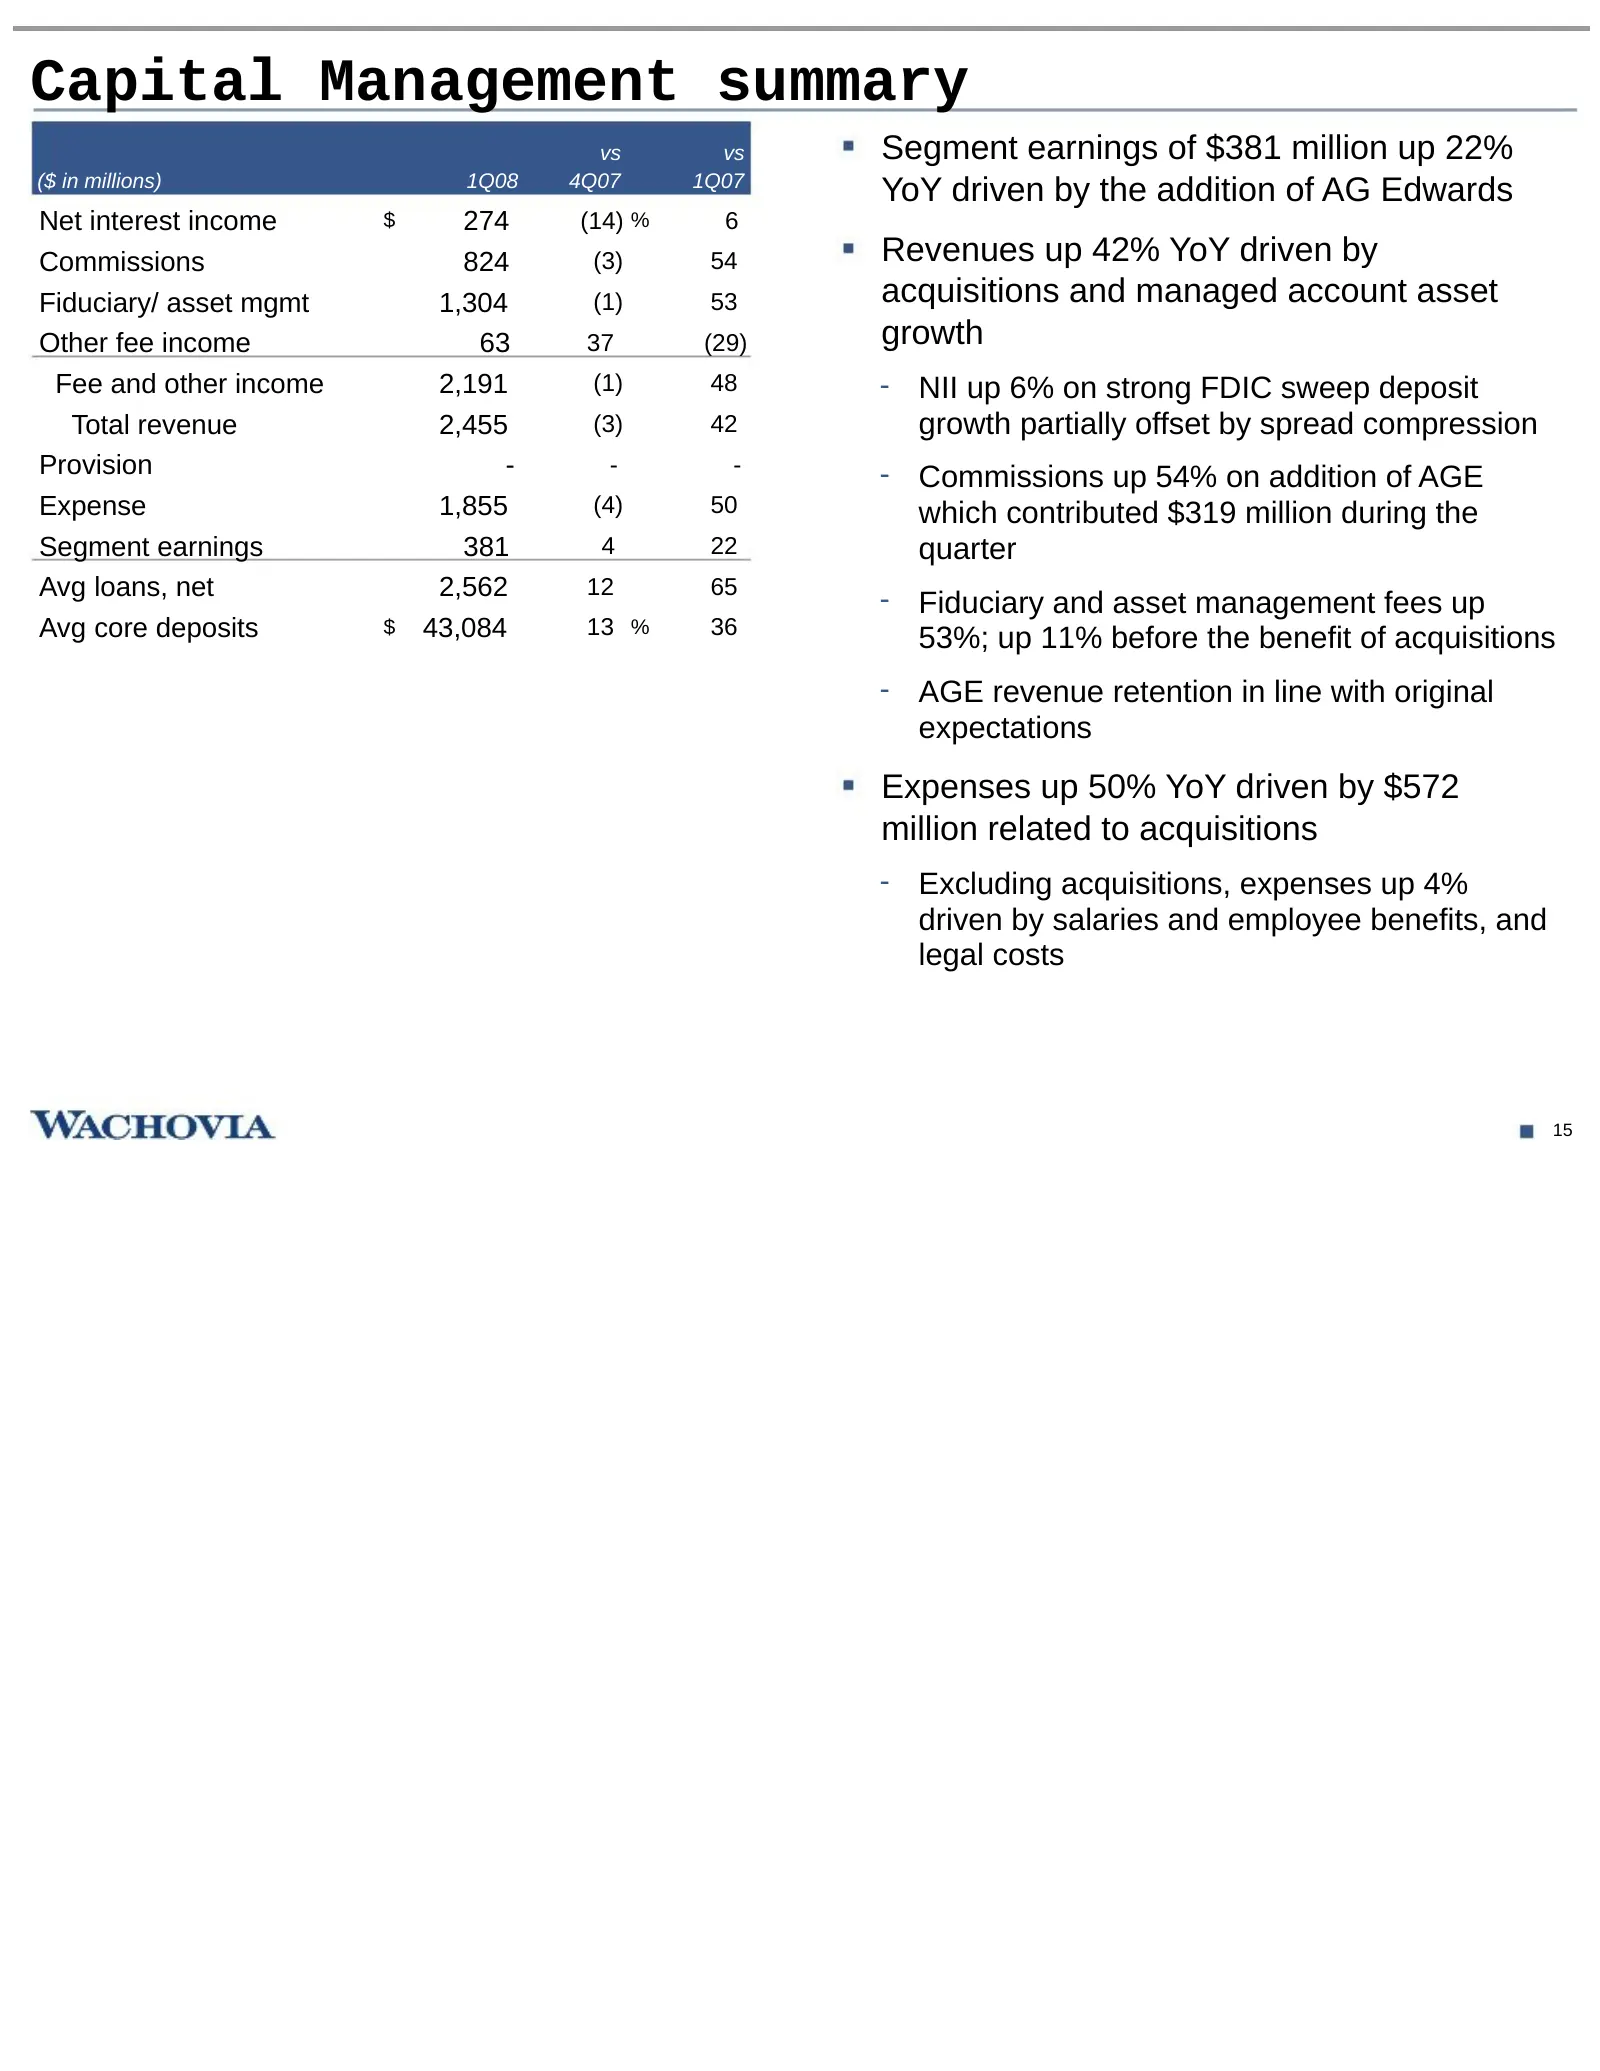
Capital Management summary vs vs Segment earnings of $381 million up 22% ($ in millions) 1Q08 4Q07 1Q07 YoY driven by the addition of AG Edwards Net interest income $ 274 (14) % 6 Commissions 824 (3) 54 Revenues up 42% YoY driven by Fiduciary/ asset mgmt 1,304 (1) 53 acquisitions and managed account
Slide 17: Credit quality
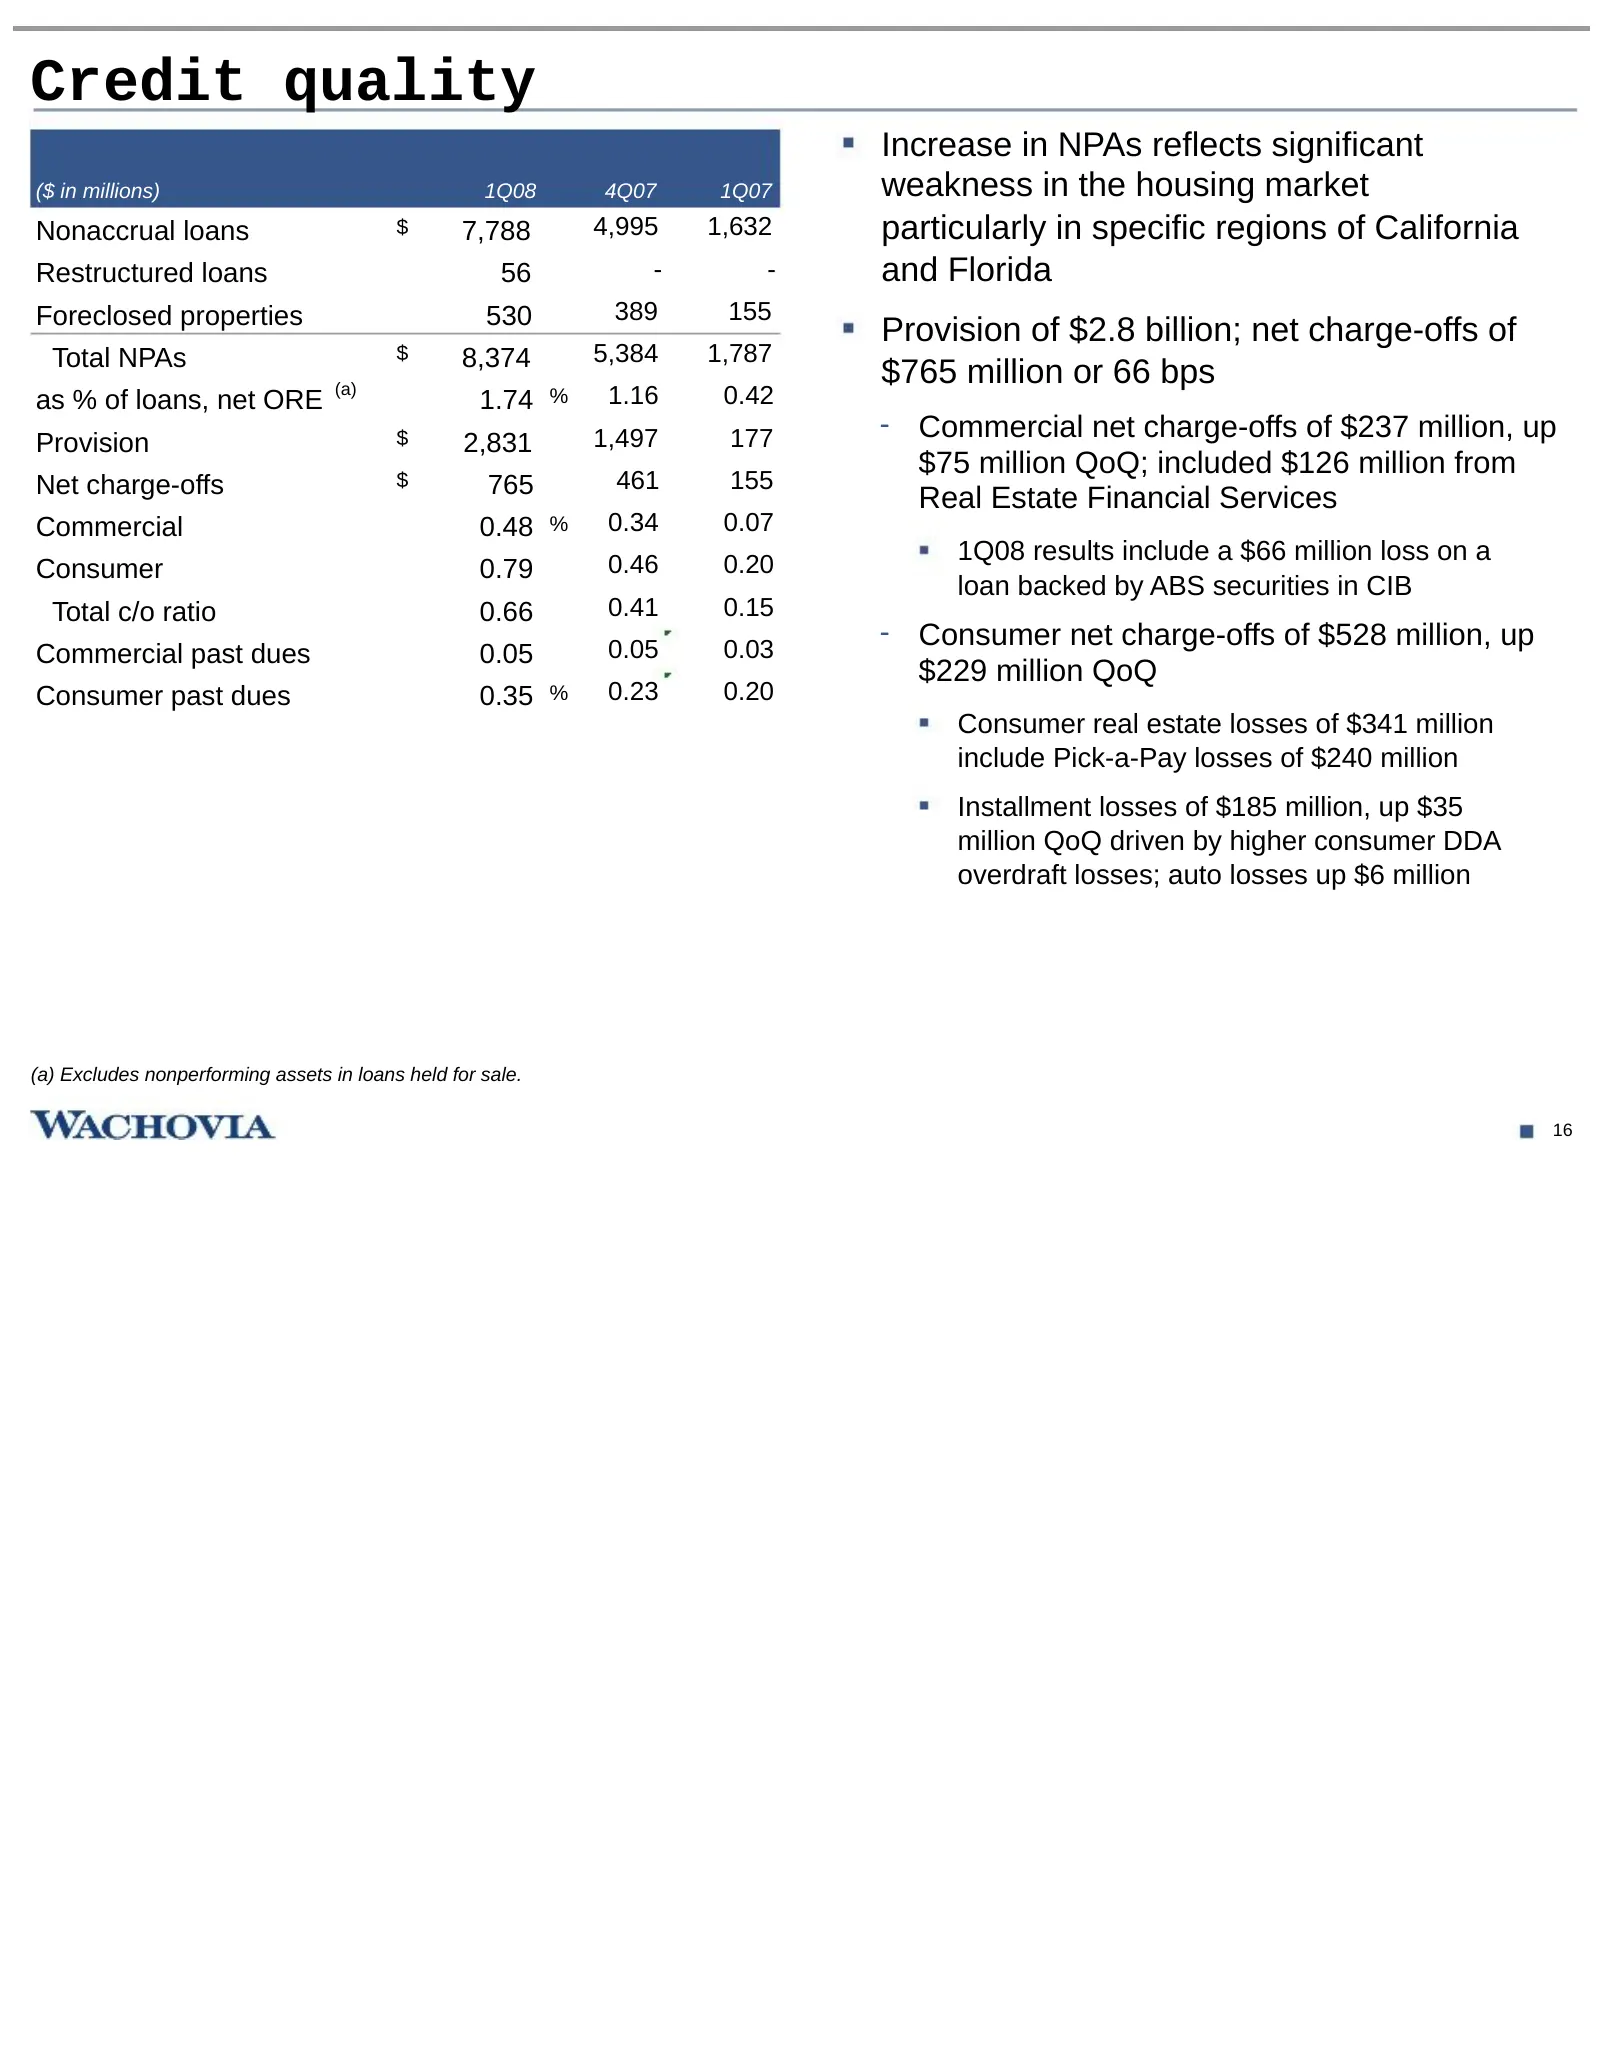
Credit quality Increase in NPAs reflects significant ($ in millions) 1Q08 4Q07 1Q07 weakness in the housing market Nonaccrual loans $ 7,788 4,995 1,632 particularly in specific regions of California Restructured loans 56 - - and Florida Foreclosed properties 530 389 155 Provision of $2.8 billion; ne
Slide 18: Allowance for credit losses
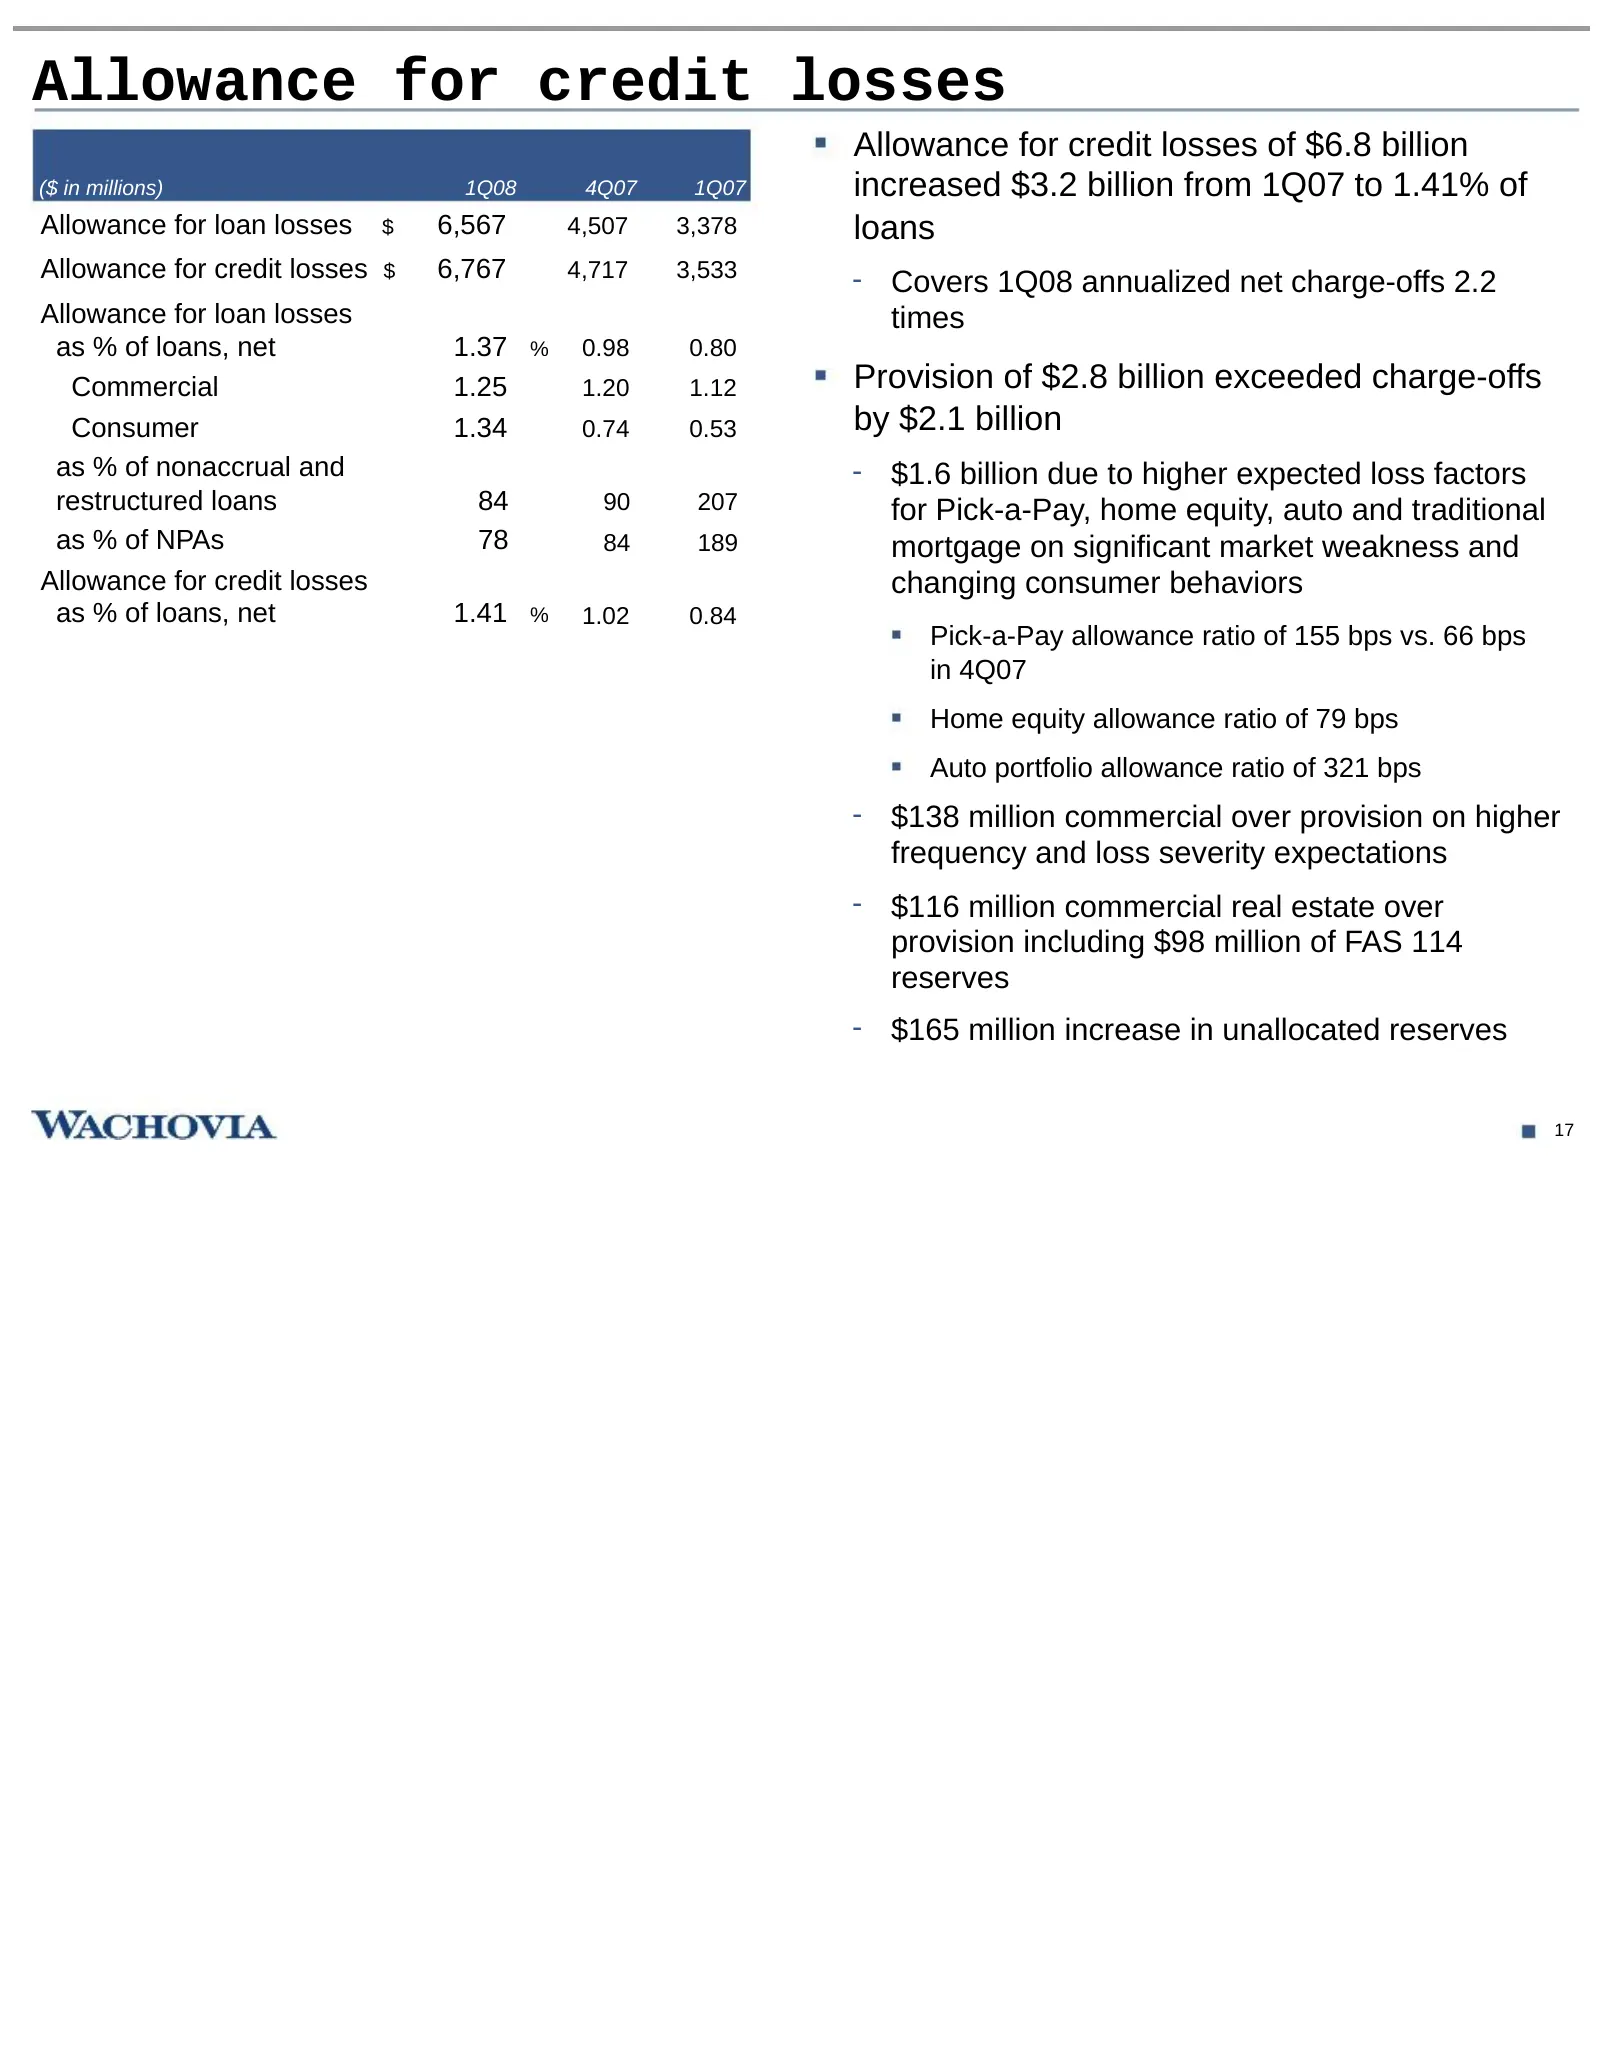
Allowance for credit losses Allowance for credit losses of $6.8 billion ($ in millions) 1Q08 4Q07 1Q07 increased $3.2 billion from 1Q07 to 1.41% of Allowance for loan losses $ 6,567 4,507 3,378 loans Allowance for credit losses $ 6,767 4,717 3,533 - Covers 1Q08 annualized net charge-offs 2.2 Allowan
Slide 19: Mortgage portfolio
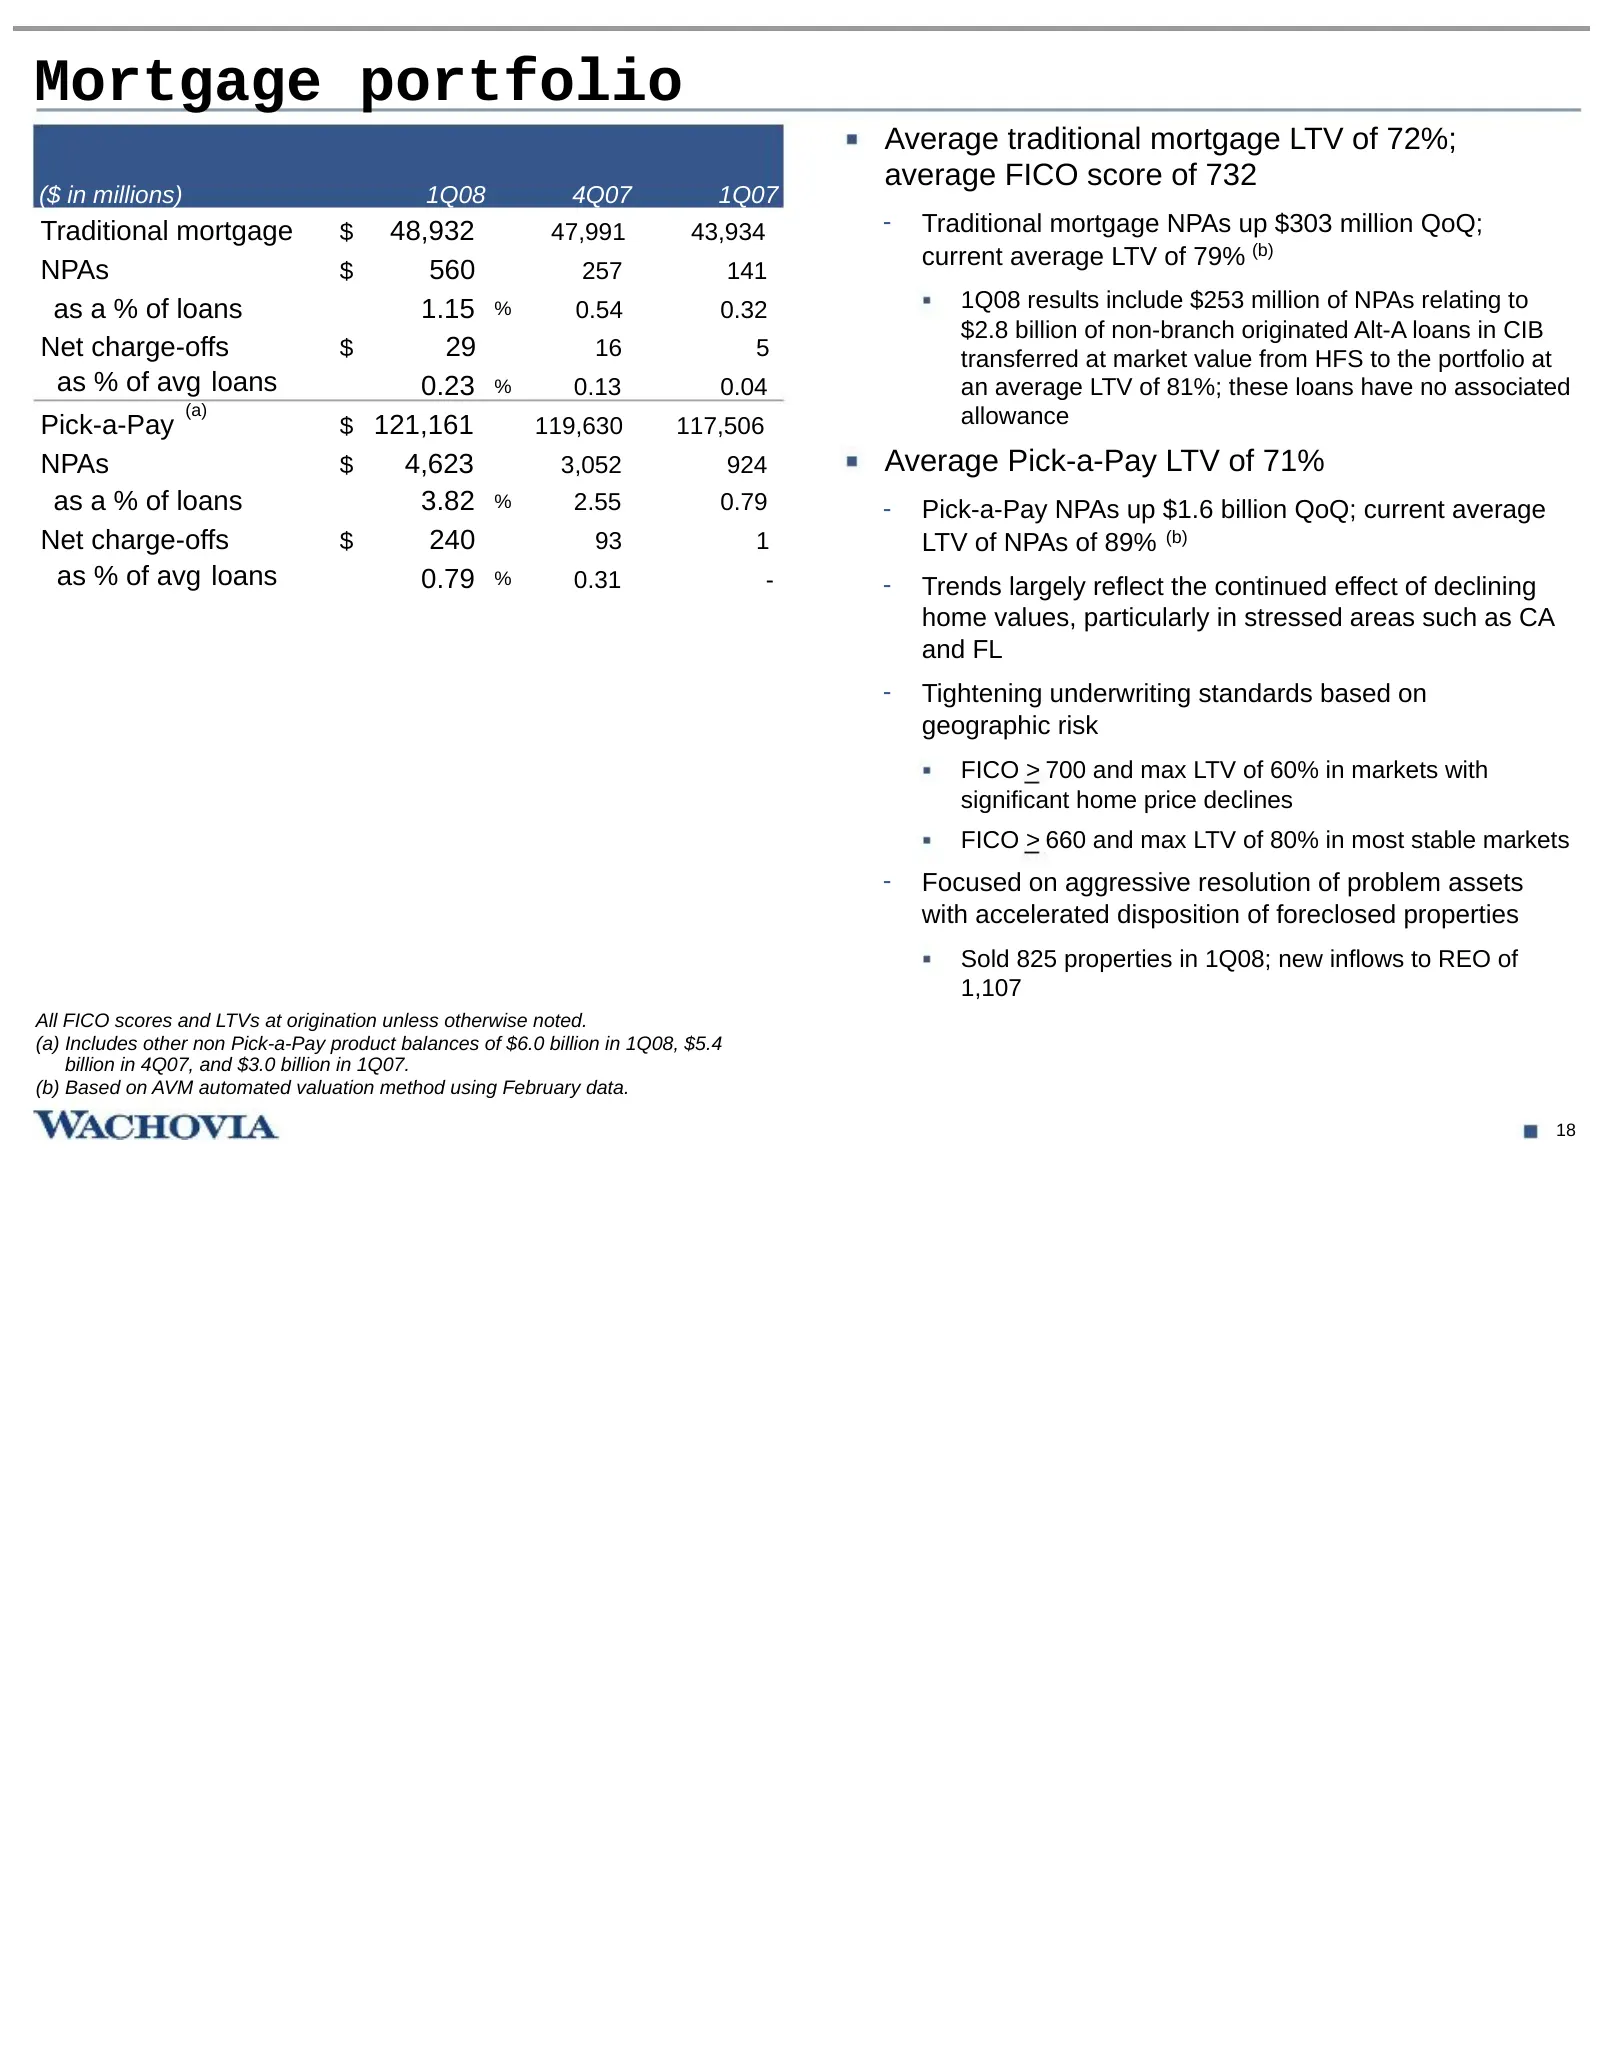
Mortgage portfolio Average traditional mortgage LTV of 72%; average FICO score of 732 ($ in millions) 1Q08 4Q07 1Q07 Traditional mortgage $ 48,932 47,991 43,934 - Traditional mortgage NPAs up $303 million QoQ; current average LTV of 79% (b) NPAs $ 560 257 141 as a % of loans 1.15 % 0.54 0.32 1Q08 re
Slide 20: Wachovia Mortgage 90+ days past due vs. industry
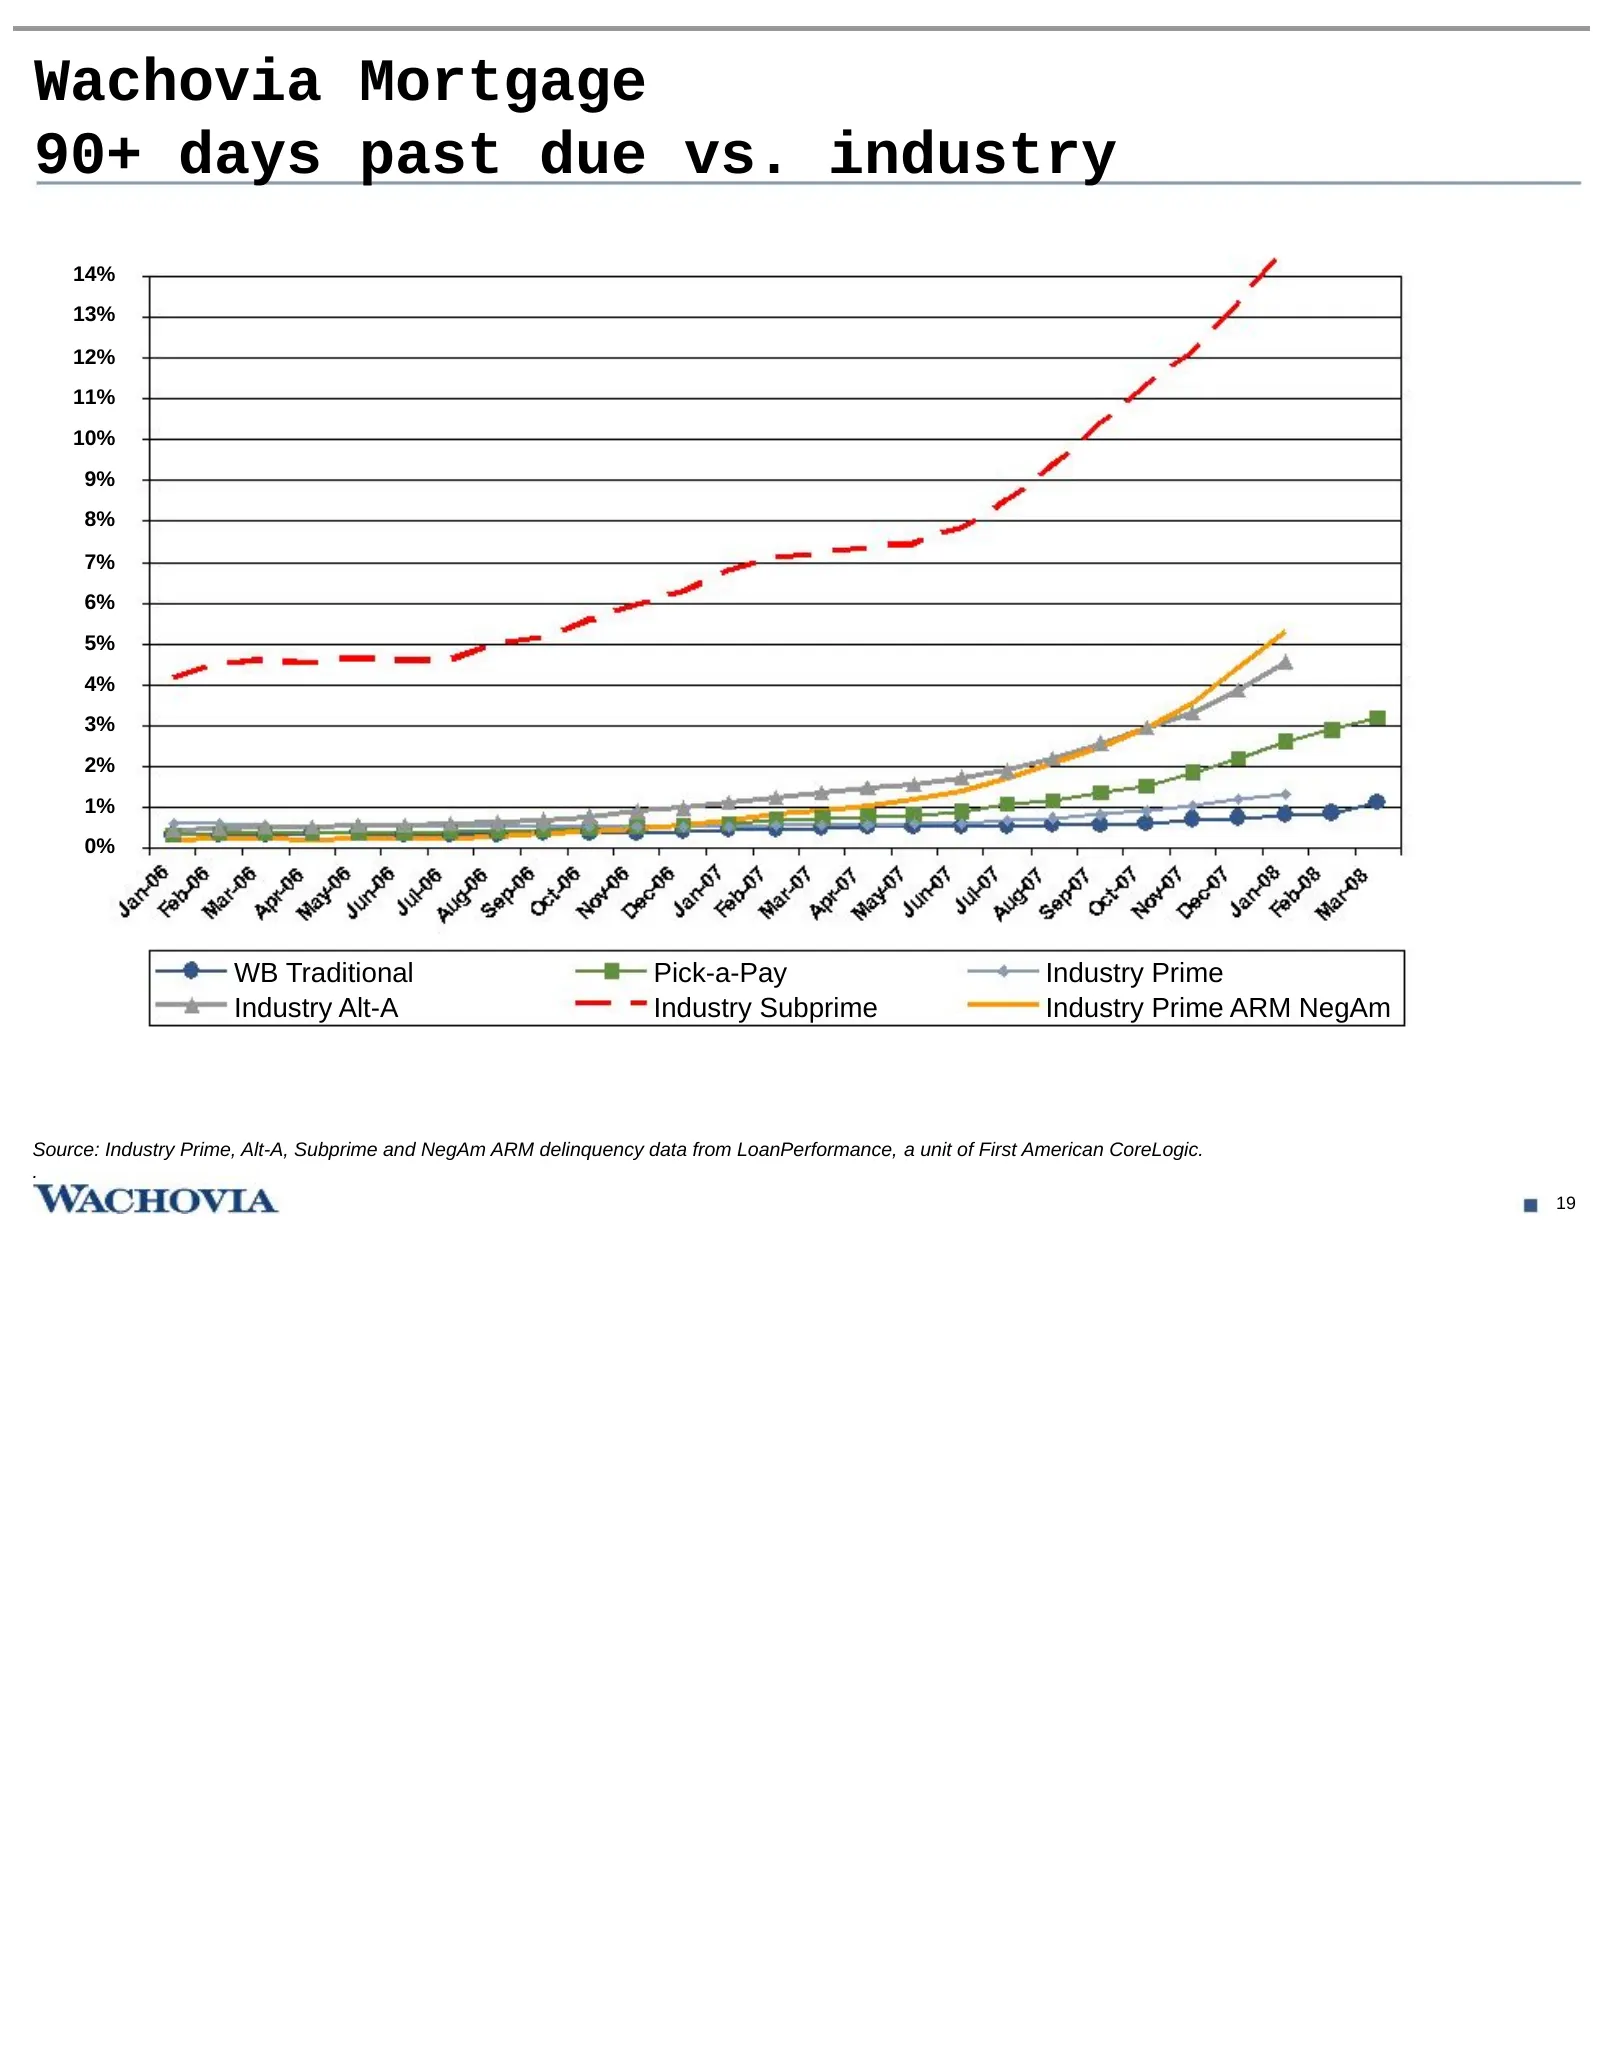
Wachovia Mortgage 90+ days past due vs. industry 14% 13% 12% 11% 10% 9% 8% 7% 6% 5% 4% 3% 2% 1% 0% WB Traditional Pick-a-Pay Industry Prime Industry Alt-A Industry Subprime Industry Prime ARM NegAm Source: Industry Prime, Alt-A, Subprime and NegAm ARM delinquency data from LoanPerformance, a unit of
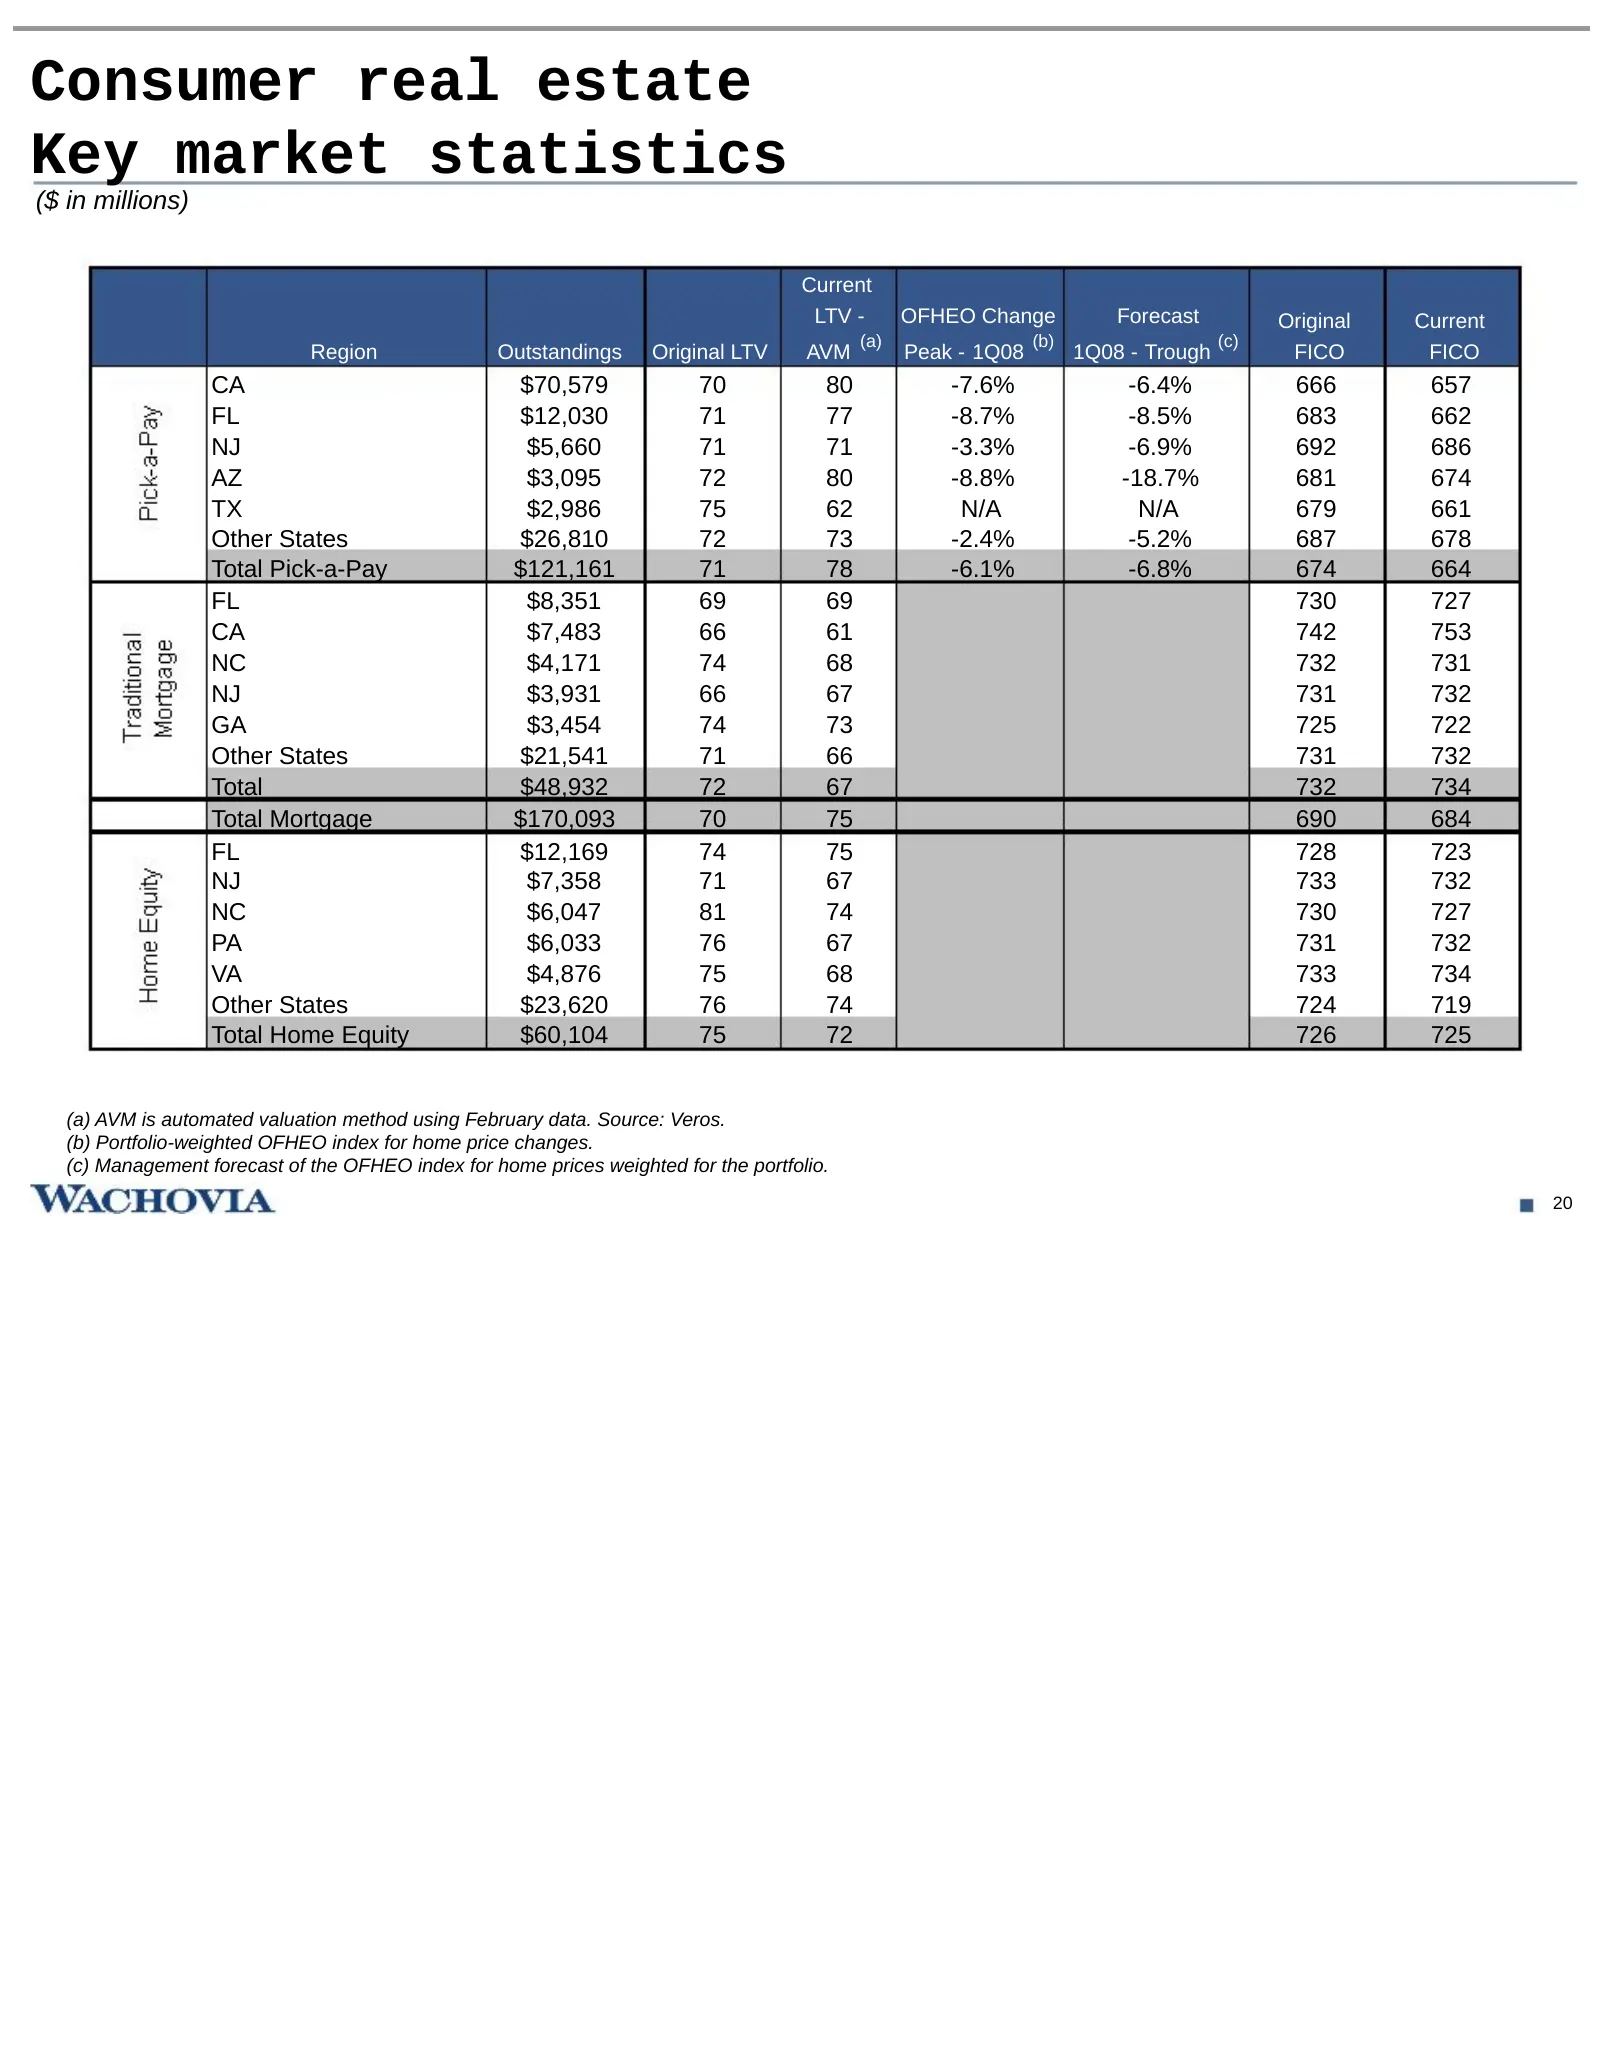
Slide 21: Consumer real estate: Key market statistics
Consumer real estate Key market statistics ($ in millions) Current LTV - OFHEO Change Forecast Original Current (a) (b) (c) Region Outstandings Original LTV AVM Peak - 1Q08 1Q08 - Trough FICO FICO CA $70,579 70 80 -7.6% -6.4% 666 657 FL $12,030 71 77 -8.7% -8.5% 683 662 NJ $5,660 71 71 -3.3% -6.9% 6
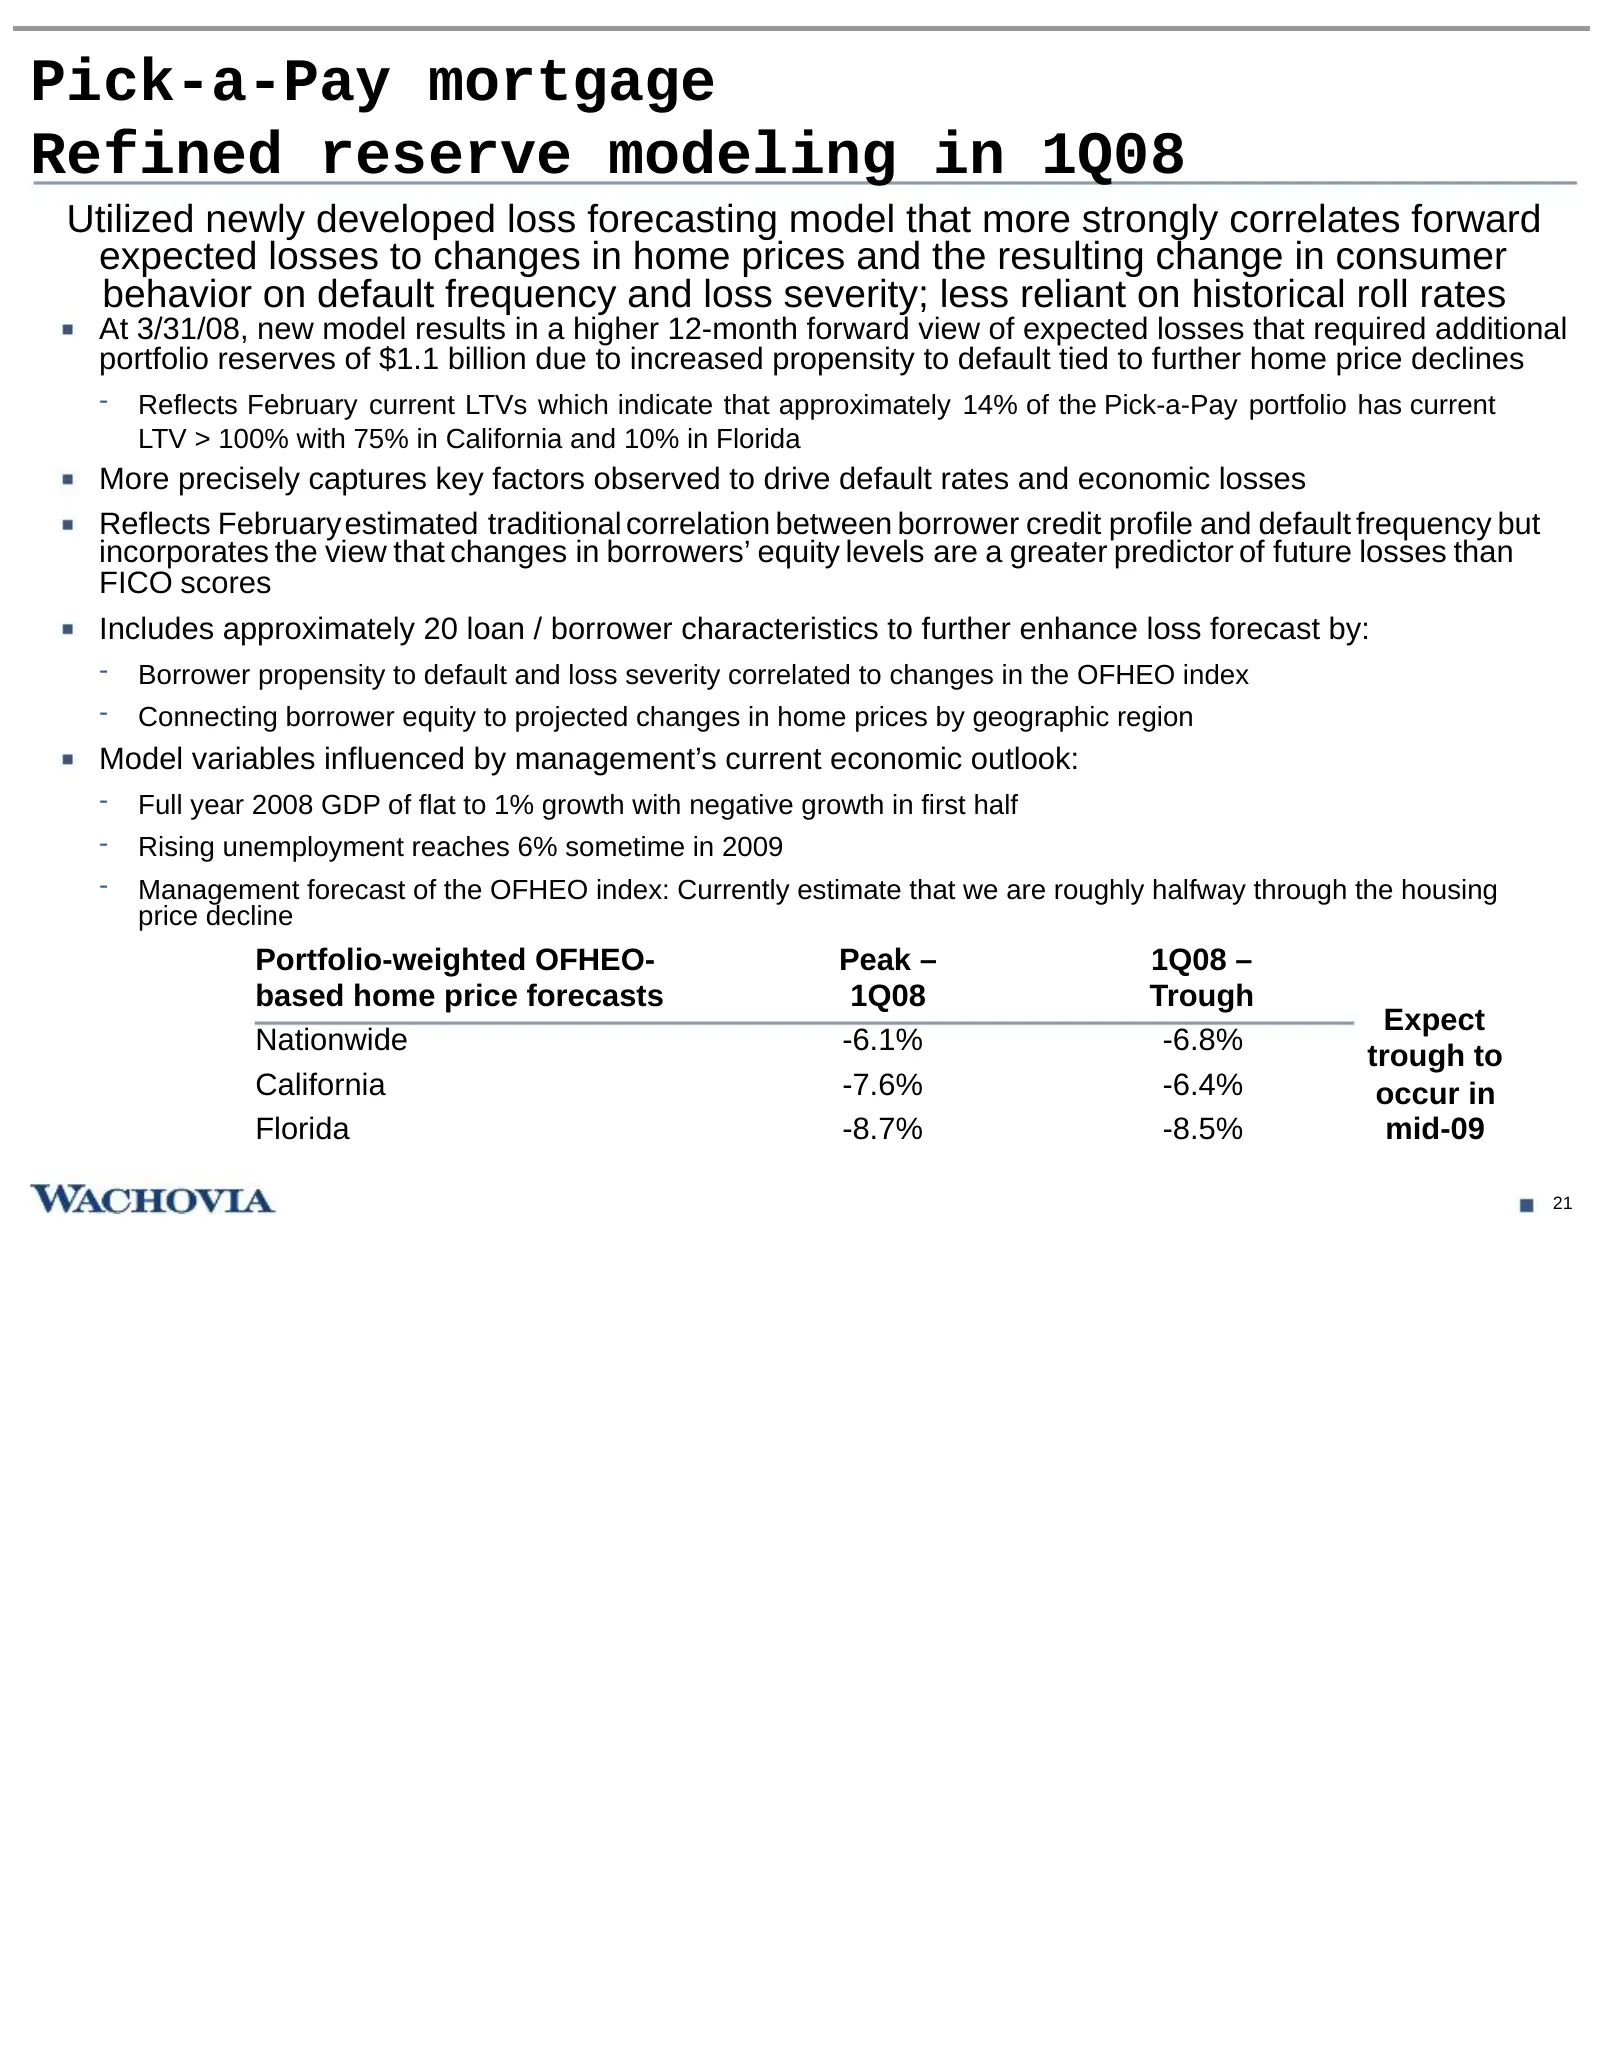
Slide 22: Pick-a-Pay mortgage: Refined reserve modeling in 1Q08
Pick-a-Pay mortgage Refined reserve modeling in 1Q08 Utilized newly developed loss forecasting model that more strongly correlates forward expected losses to changes in home prices and the resulting change in consumer behavior on default frequency and loss severity; less reliant on historical roll r
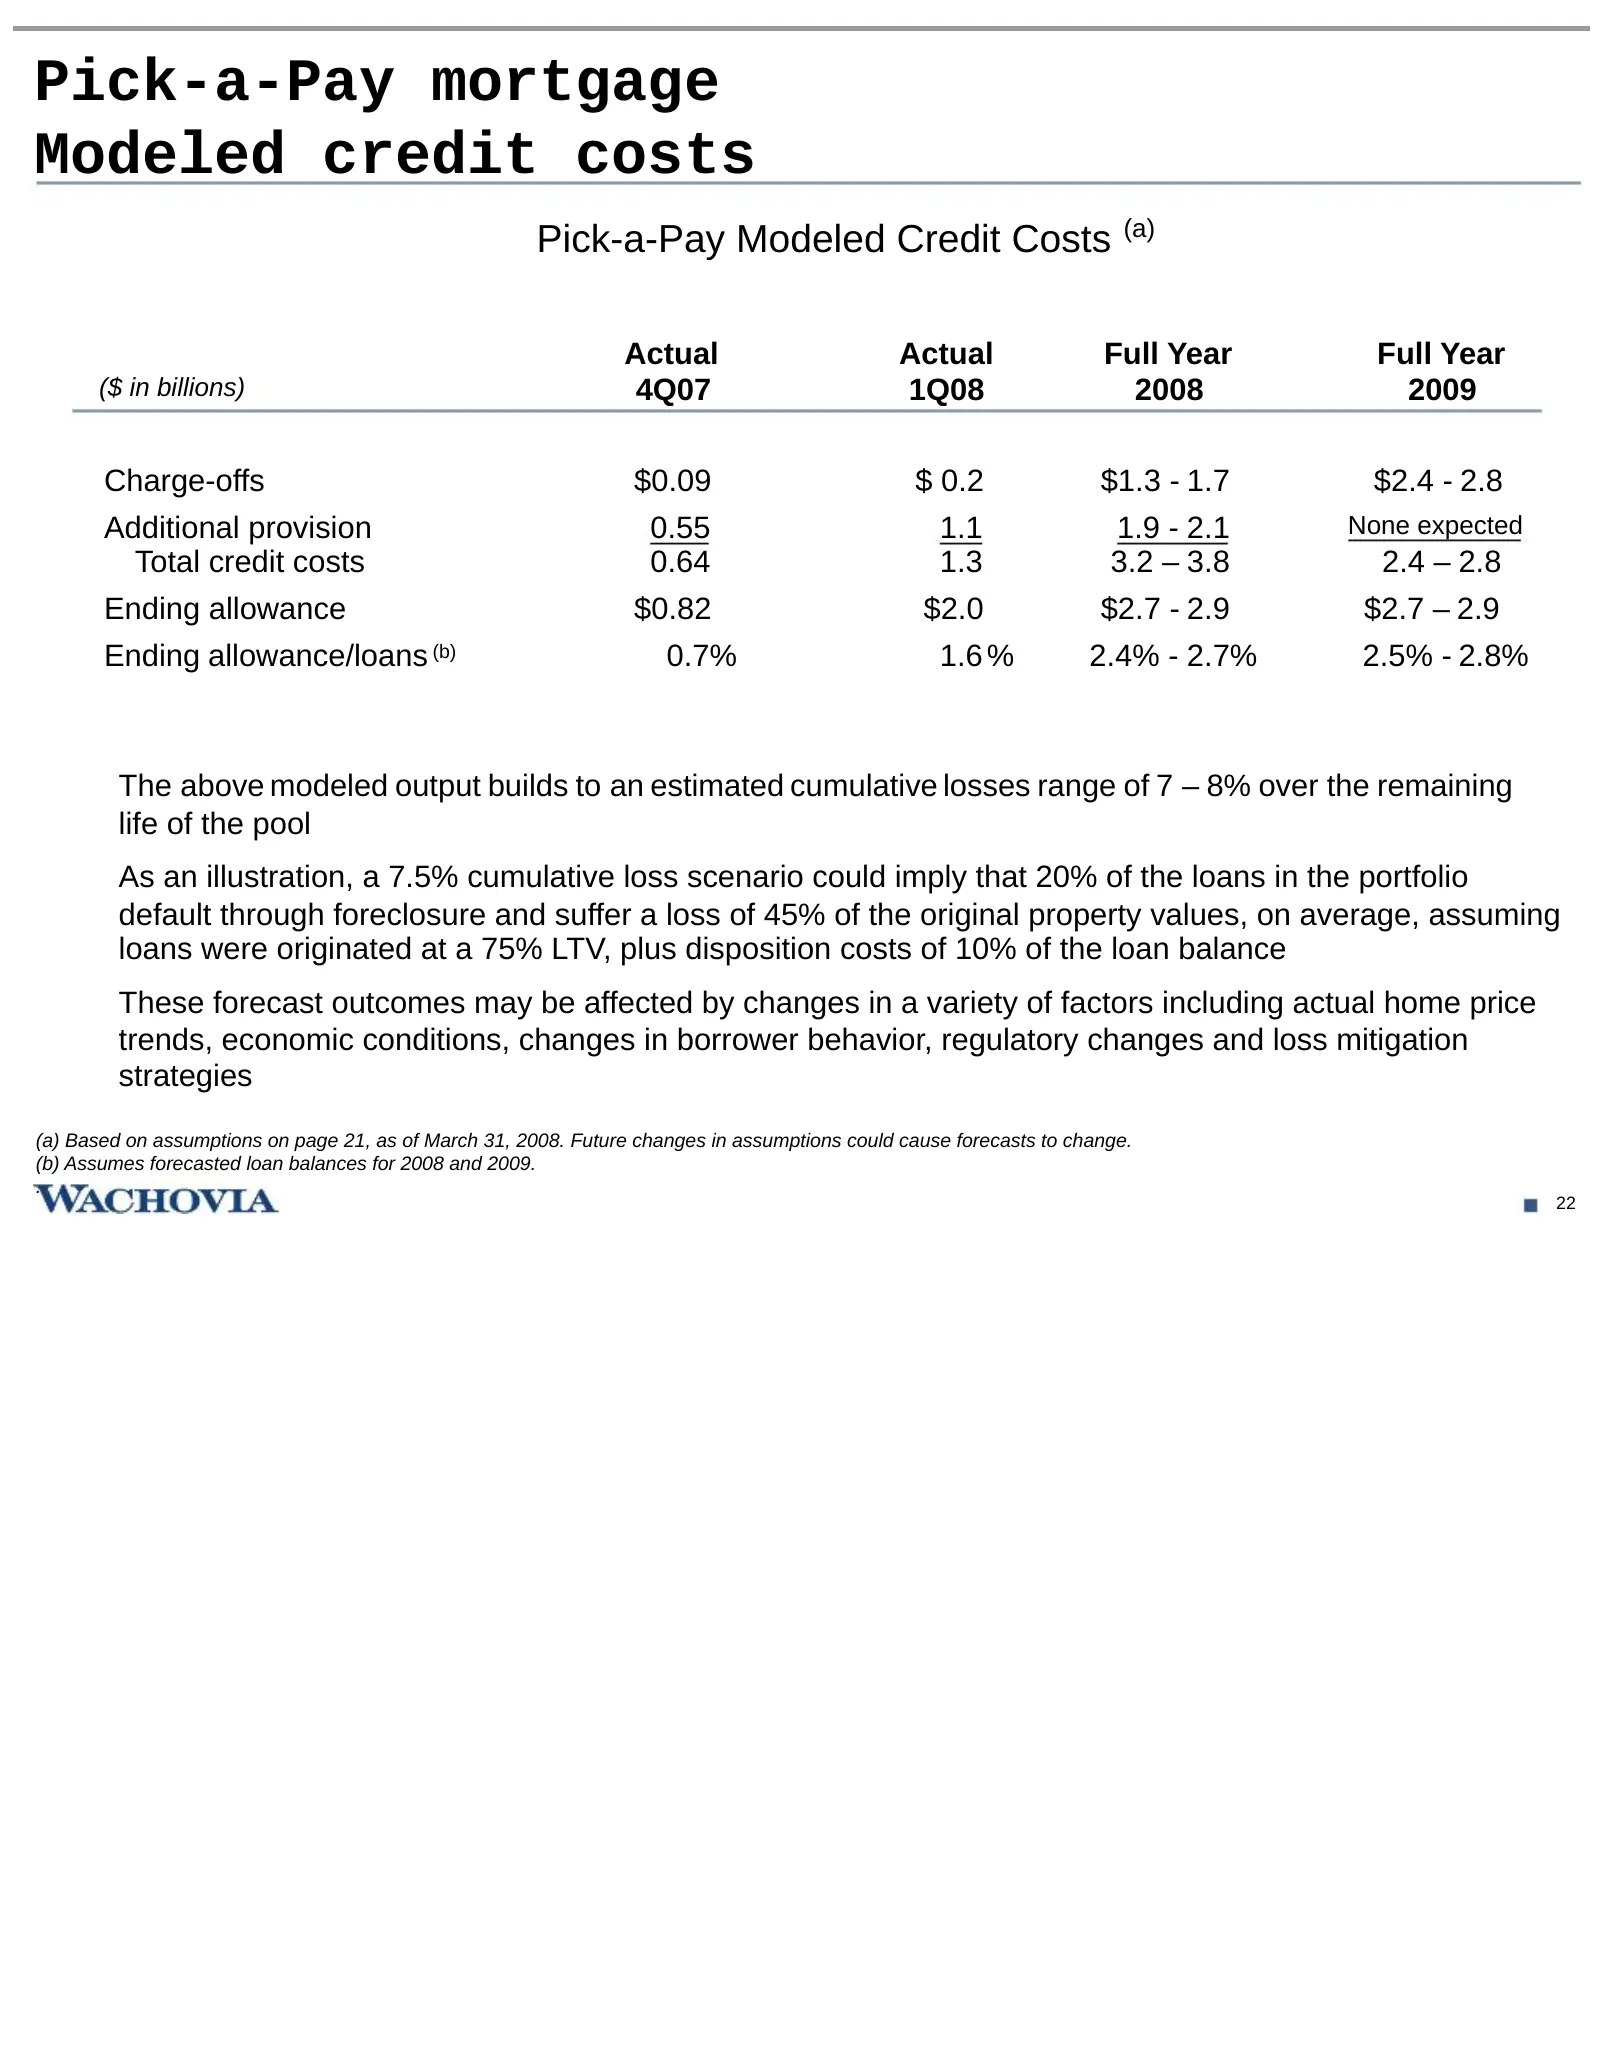
Slide 23: Pick-a-Pay mortgage: Modeled credit costs
Pick-a-Pay mortgage Modeled credit costs Pick-a-Pay Modeled Credit Costs (a) Actual Actual Full Year Full Year ($ in billions) 4Q07 1Q08 2008 2009 Charge-offs $0.09 $ 0.2 $1.3 - 1.7 $2.4 - 2.8 Additional provision 0.55 1.1 1.9 - 2.1 None expected Total credit costs 0.64 1.3 3.2 – 3.8 2.4 – 2.8 Endin
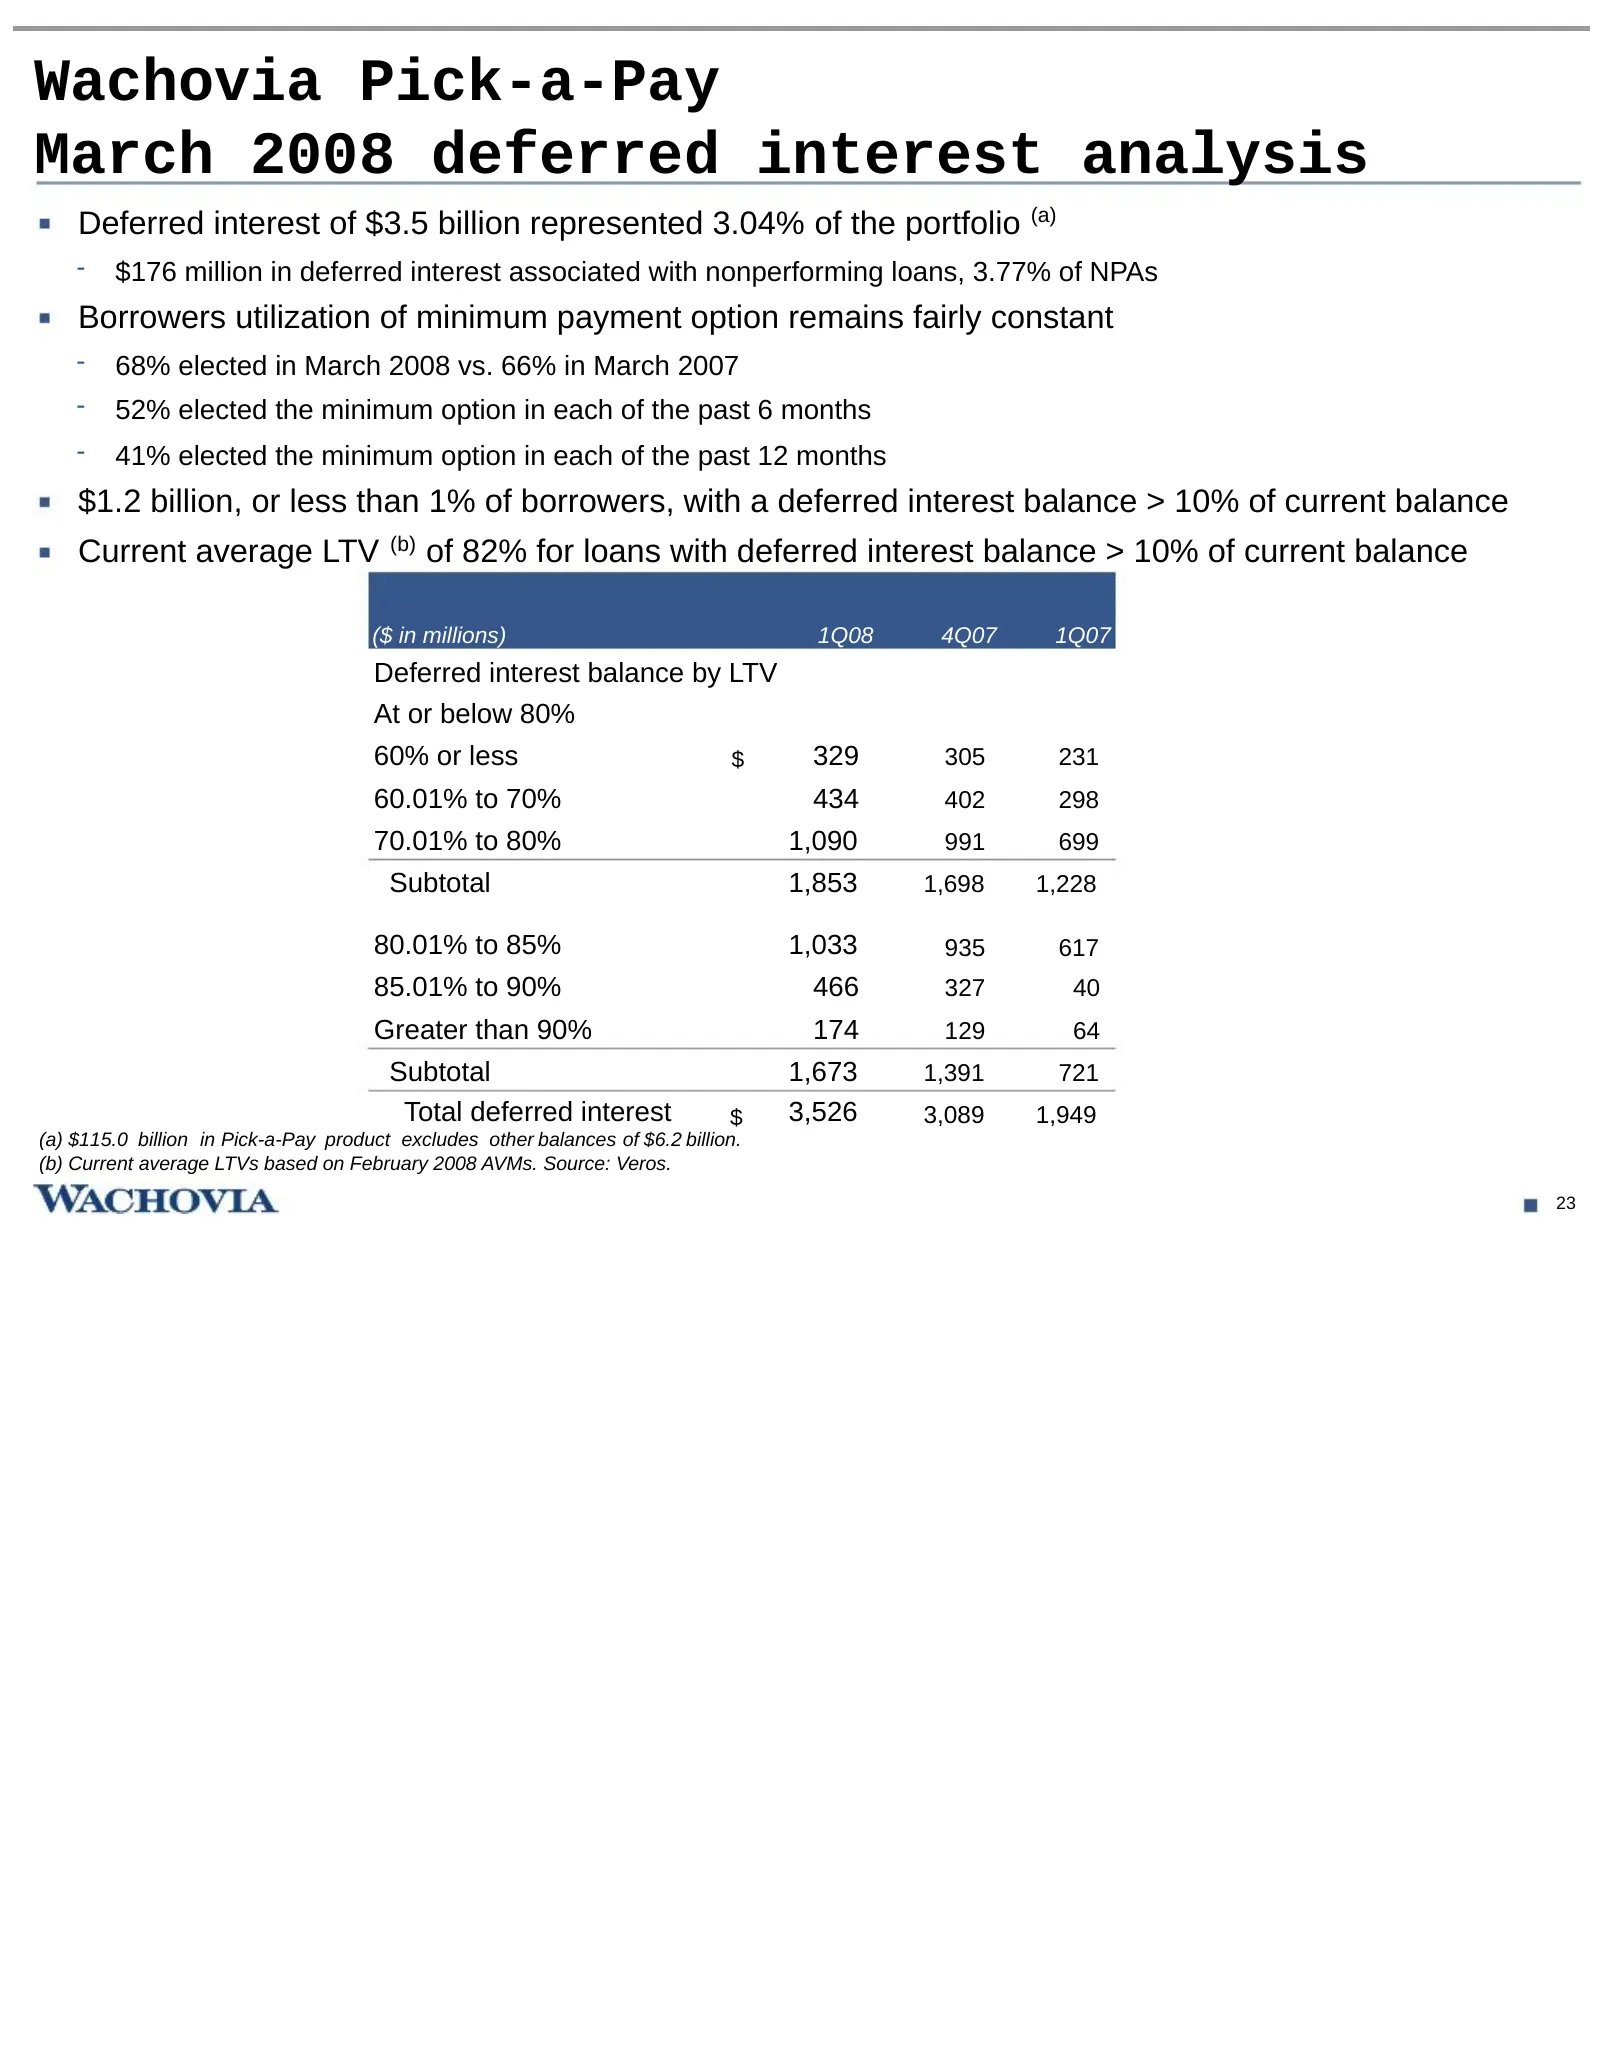
Slide 24: Wachovia Pick-a-Pay: March 2008 deferred interest analysis
Wachovia Pick-a-Pay March 2008 deferred interest analysis Deferred interest of $3.5 billion represented 3.04% of the portfolio (a) - $176 million in deferred interest associated with nonperforming loans, 3.77% of NPAs Borrowers utilization of minimum payment option remains fairly constant - 68% elec
Slide 25: Wachovia Pick-a-Pay: Proactively managing risk
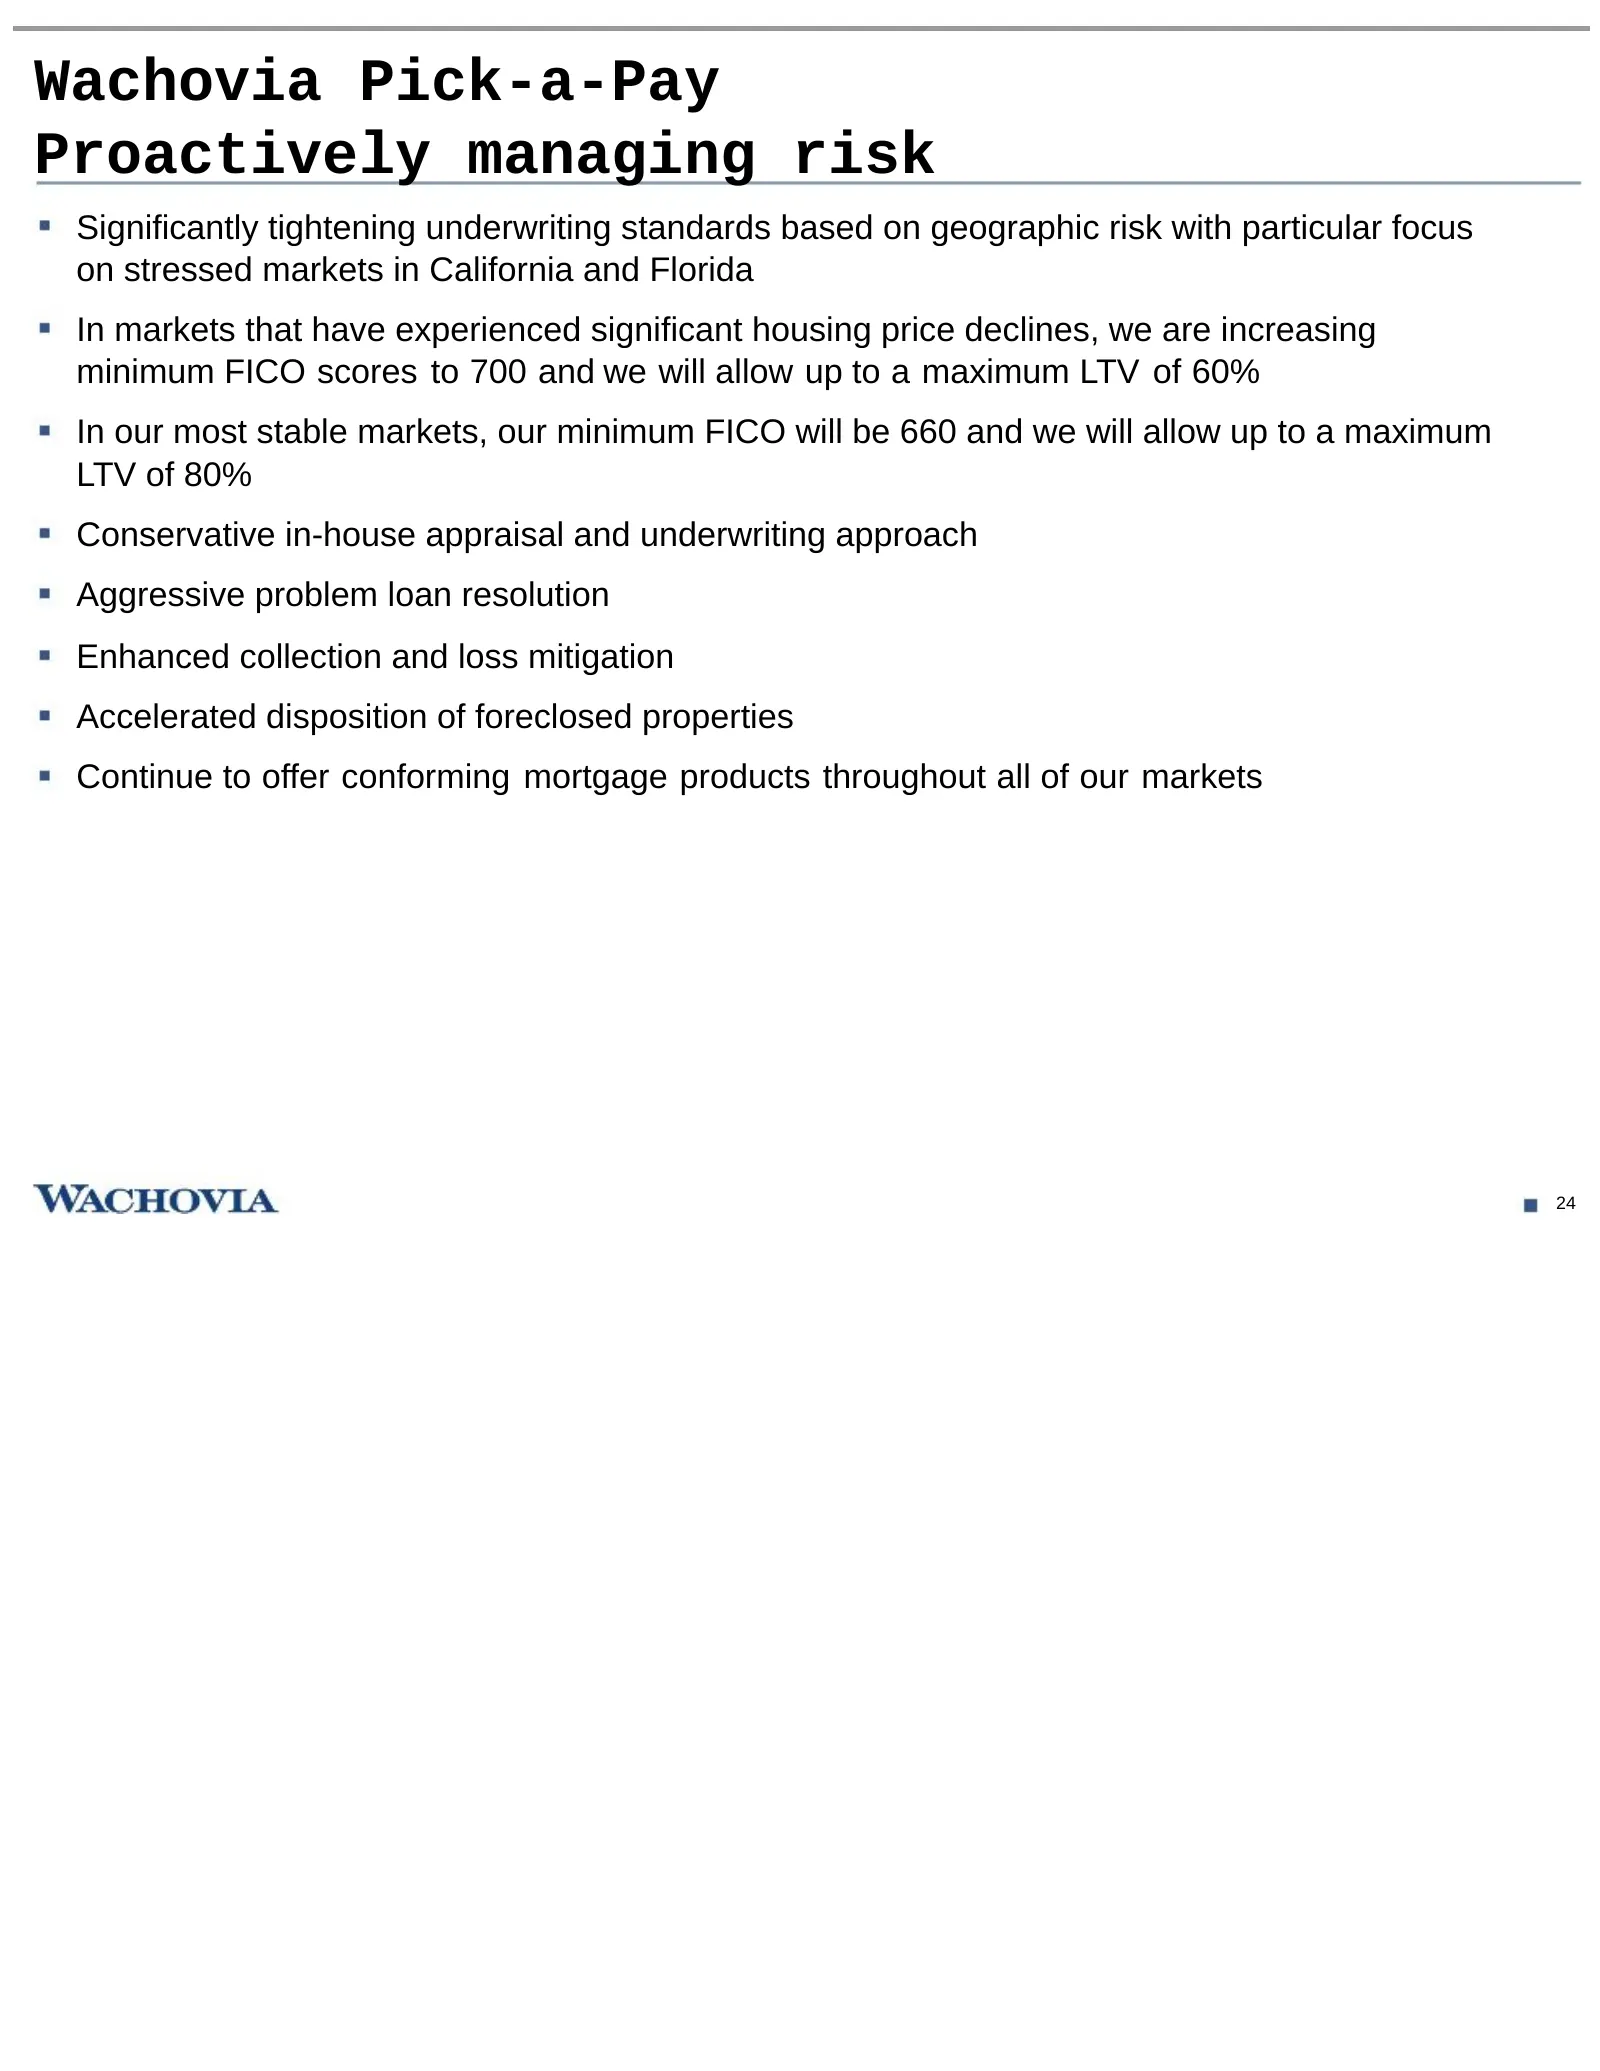
Wachovia Pick-a-Pay Proactively managing risk Significantly tightening underwriting standards based on geographic risk with particular focus on stressed markets in California and Florida In markets that have experienced significant housing price declines, we are increasing minimum FICO scores to 700
Slide 26: Home equity loans and lines
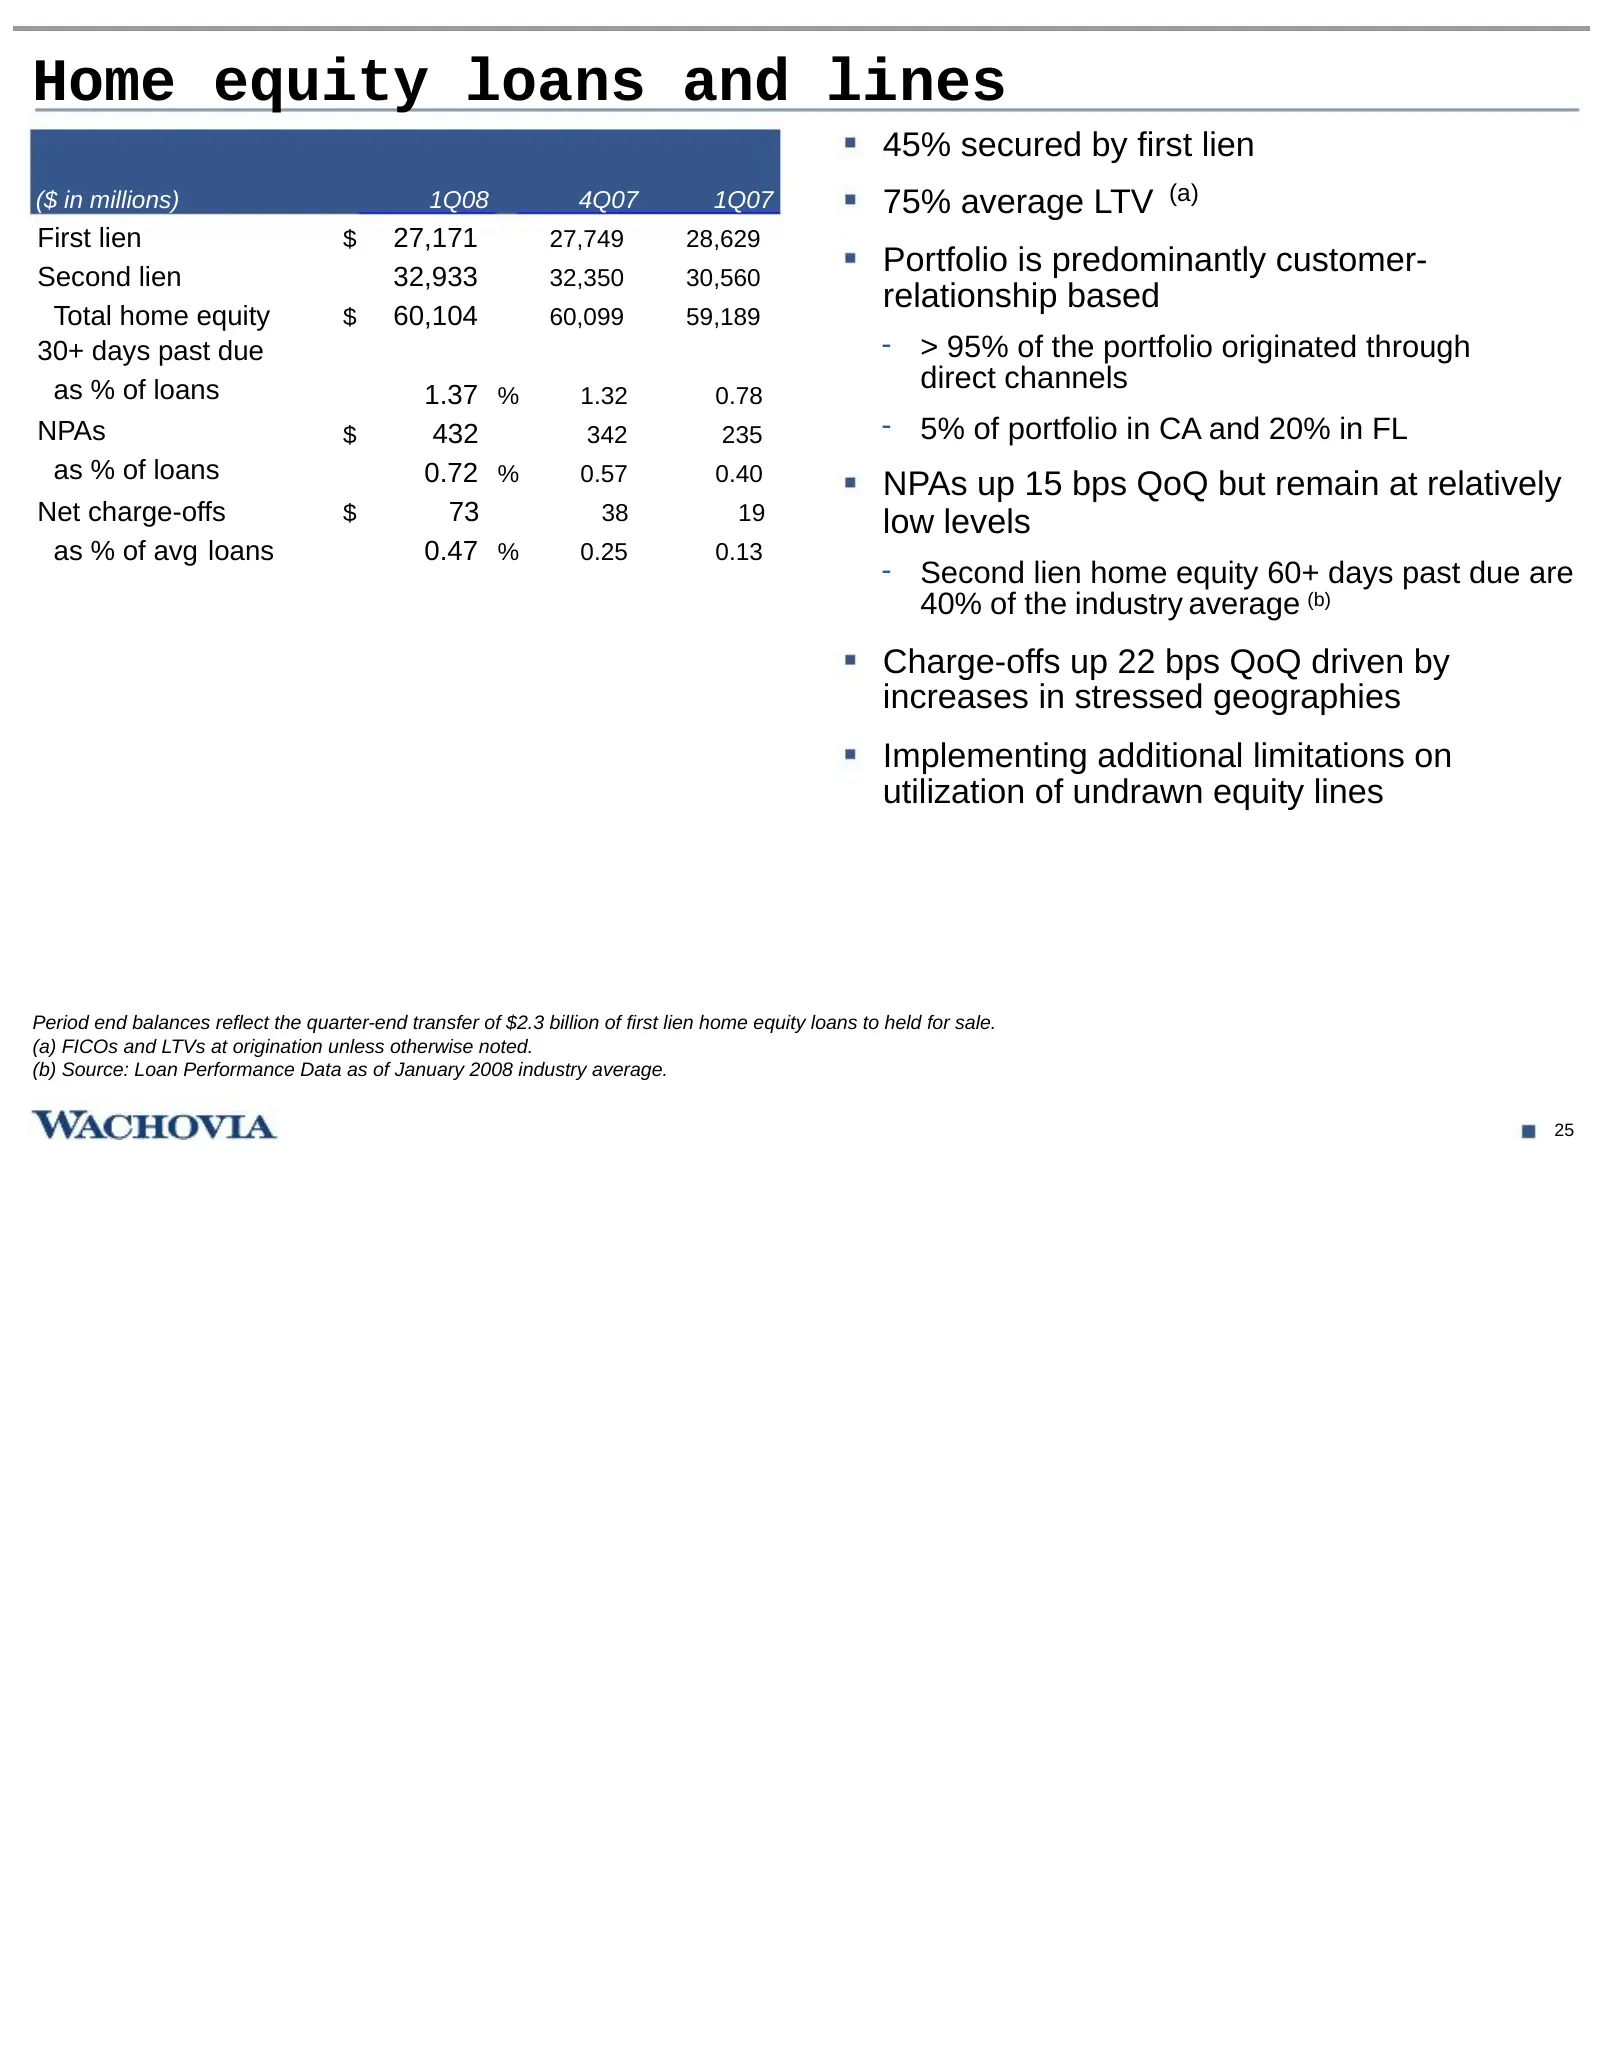
Home equity loans and lines 45% secured by first lien ($ in millions) 1Q08 4Q07 1Q07 75% average LTV (a) First lien $ 27,171 27,749 28,629 Second lien 32,933 32,350 30,560 Portfolio is predominantly customer- relationship based Total home equity $ 60,104 60,099 59,189 30+ days past due - > 95% of th
Slide 27: Second lien home equity 60+ days past due vs. industry
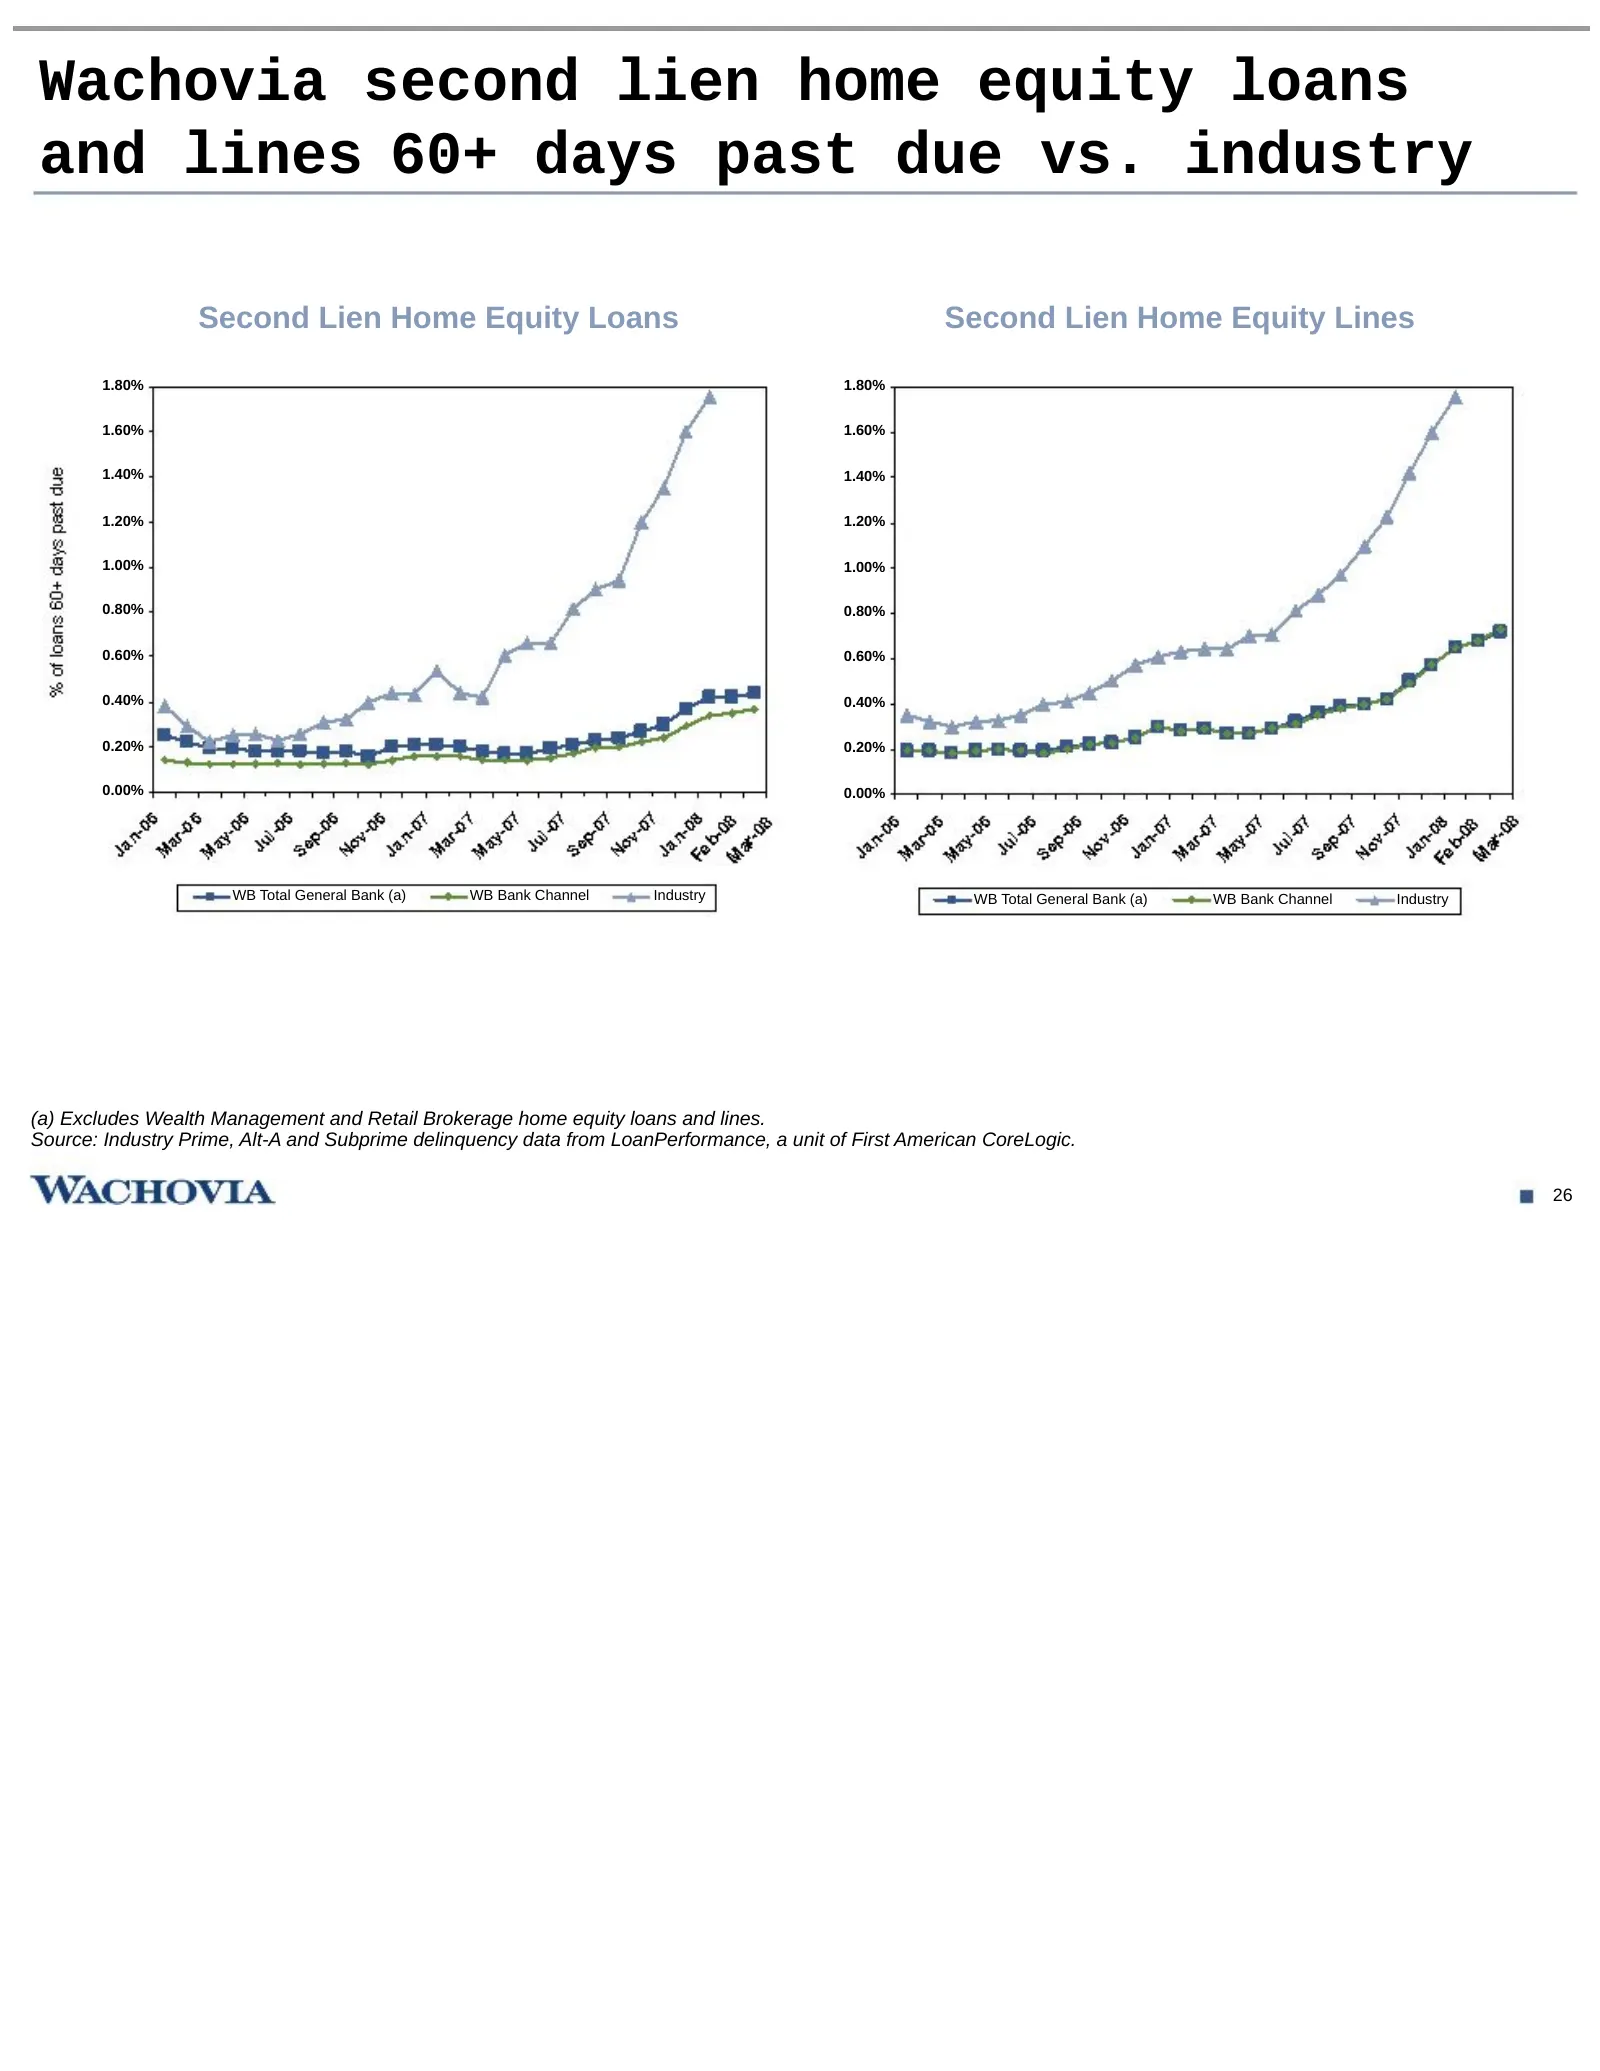
Wachovia second lien home equity loans and lines 60+ days past due vs. industry Second Lien Home Equity Loans Second Lien Home Equity Lines 1.80% 1.80% 1.60% 1.60% 1.40% 1.40% 1.20% 1.20% 1.00% 1.00% 0.80% 0.80% 0.60% 0.60% 0.40% 0.40% 0.20% 0.20% 0.00% 0.00% WB Total General Bank (a) WB Bank Channe
Slide 28: Managed auto portfolio
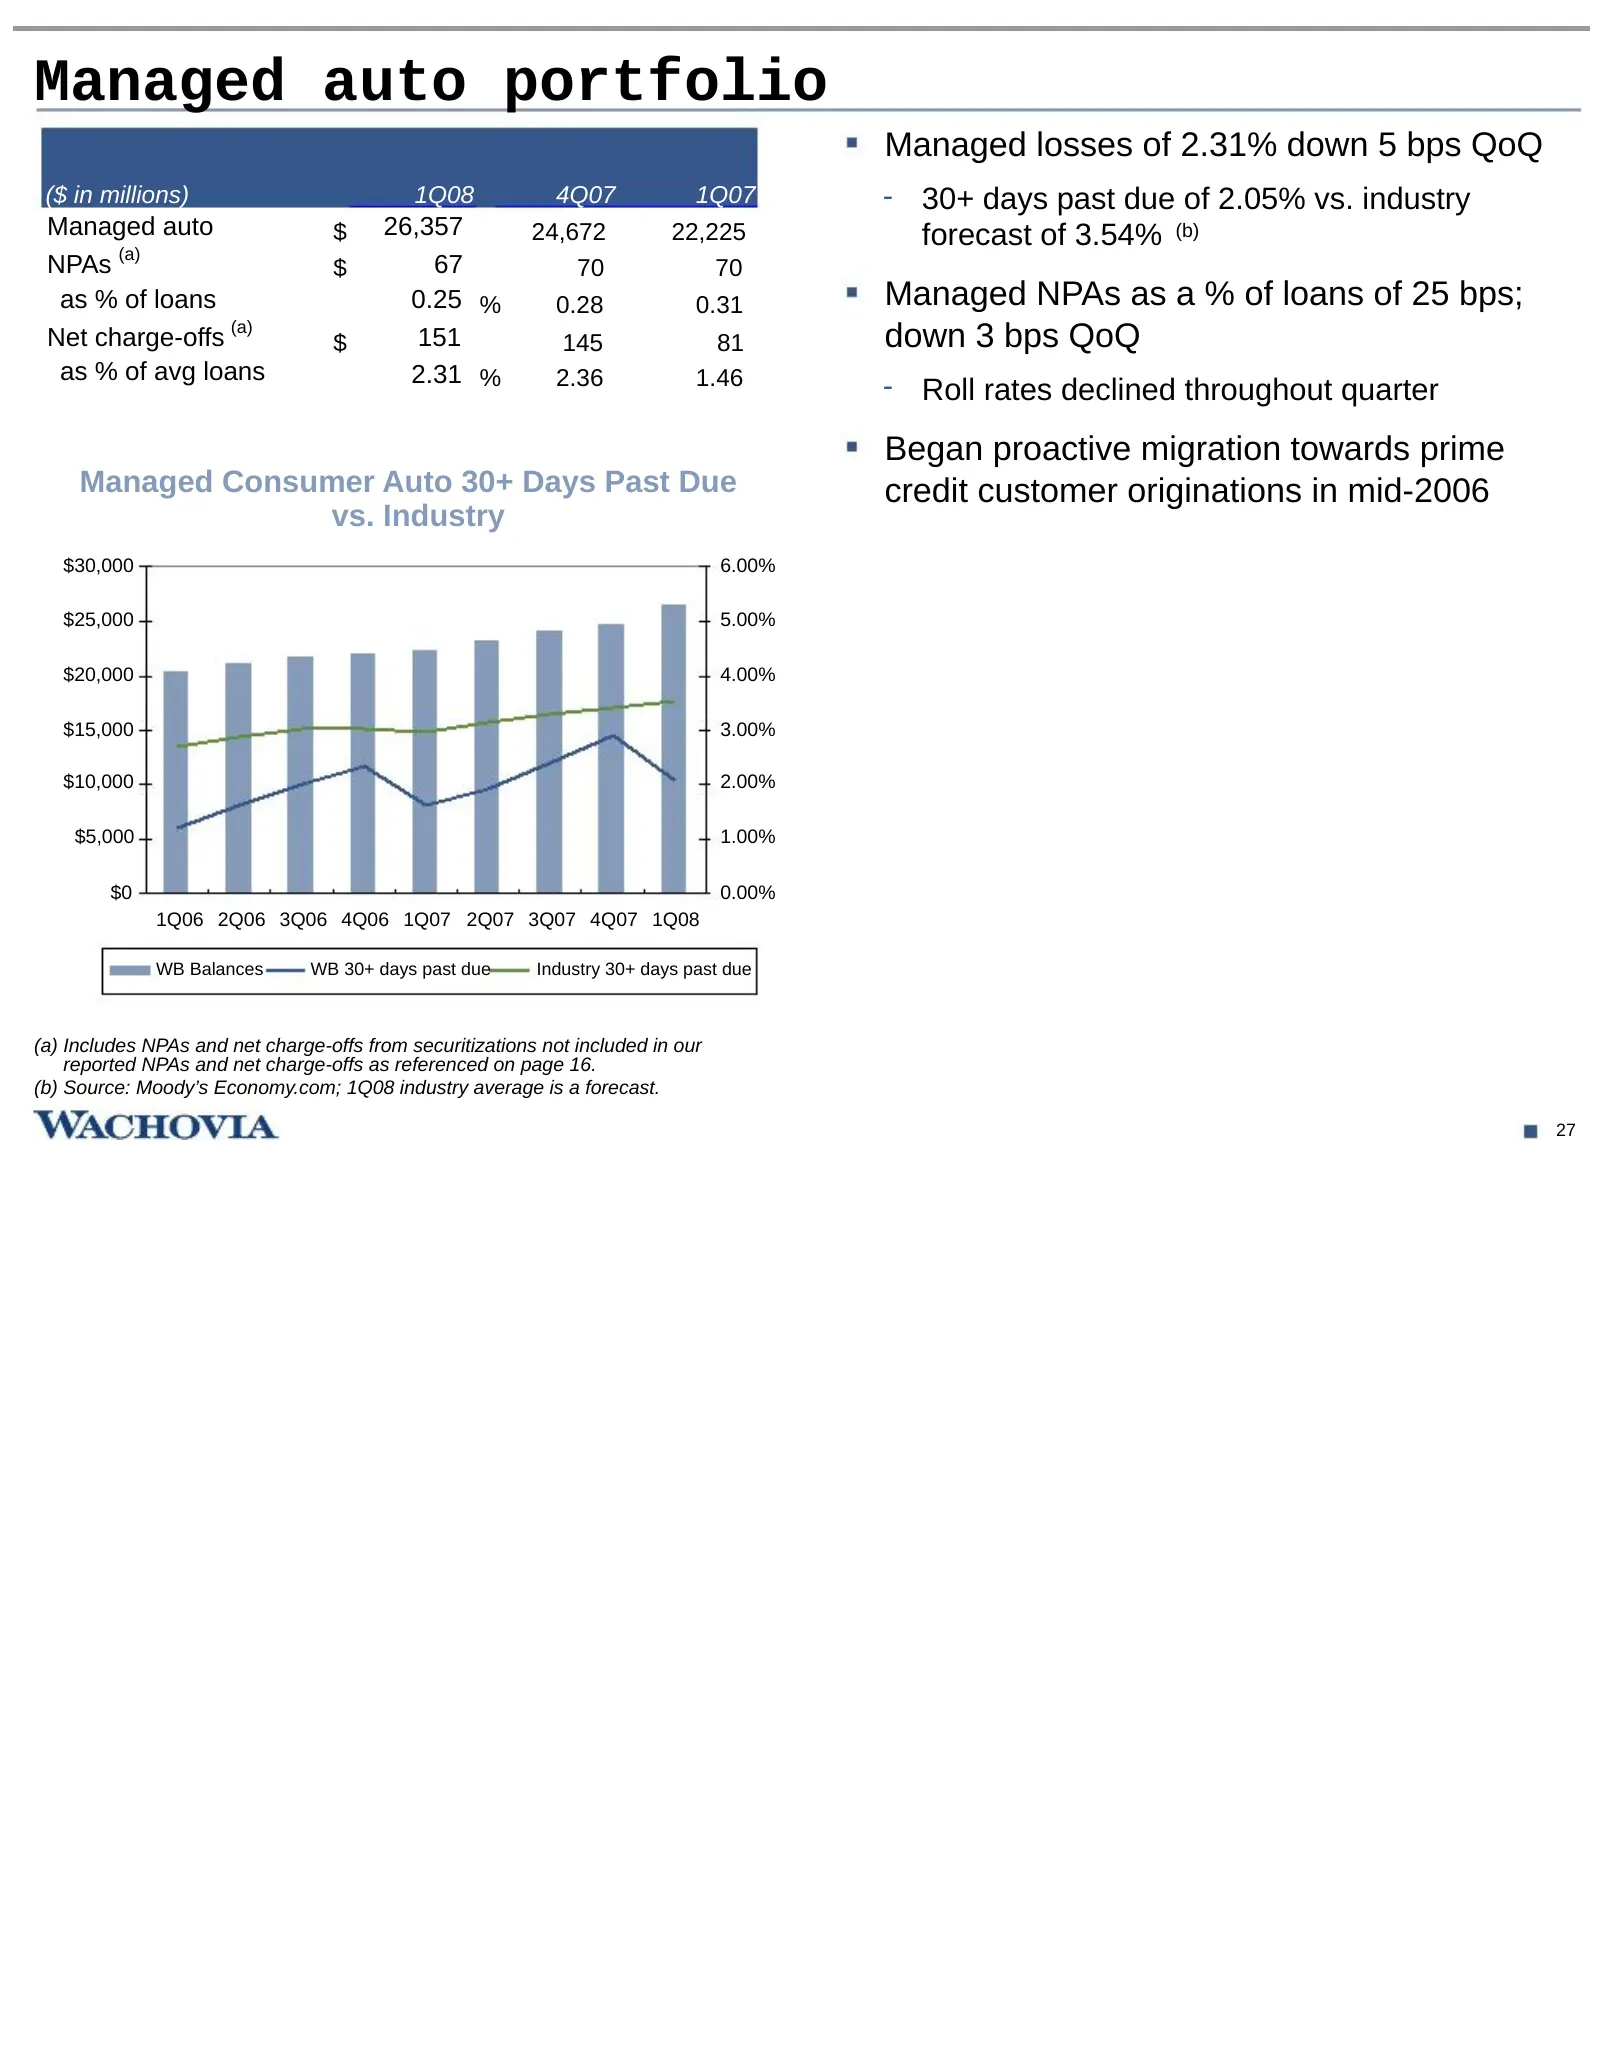
Managed auto portfolio Managed losses of 2.31% down 5 bps QoQ ($ in millions) 1Q08 4Q07 1Q07 - 30+ days past due of 2.05% vs. industry Managed auto $ 26,357 24,672 22,225 forecast of 3.54% (b) NPAs (a) $ 67 70 70 as % of loans 0.25 % 0.28 0.31 Managed NPAs as a % of loans of 25 bps; Net charge-offs
Slide 29: Commercial Real Estate: Real Estate Financial Services portfolio
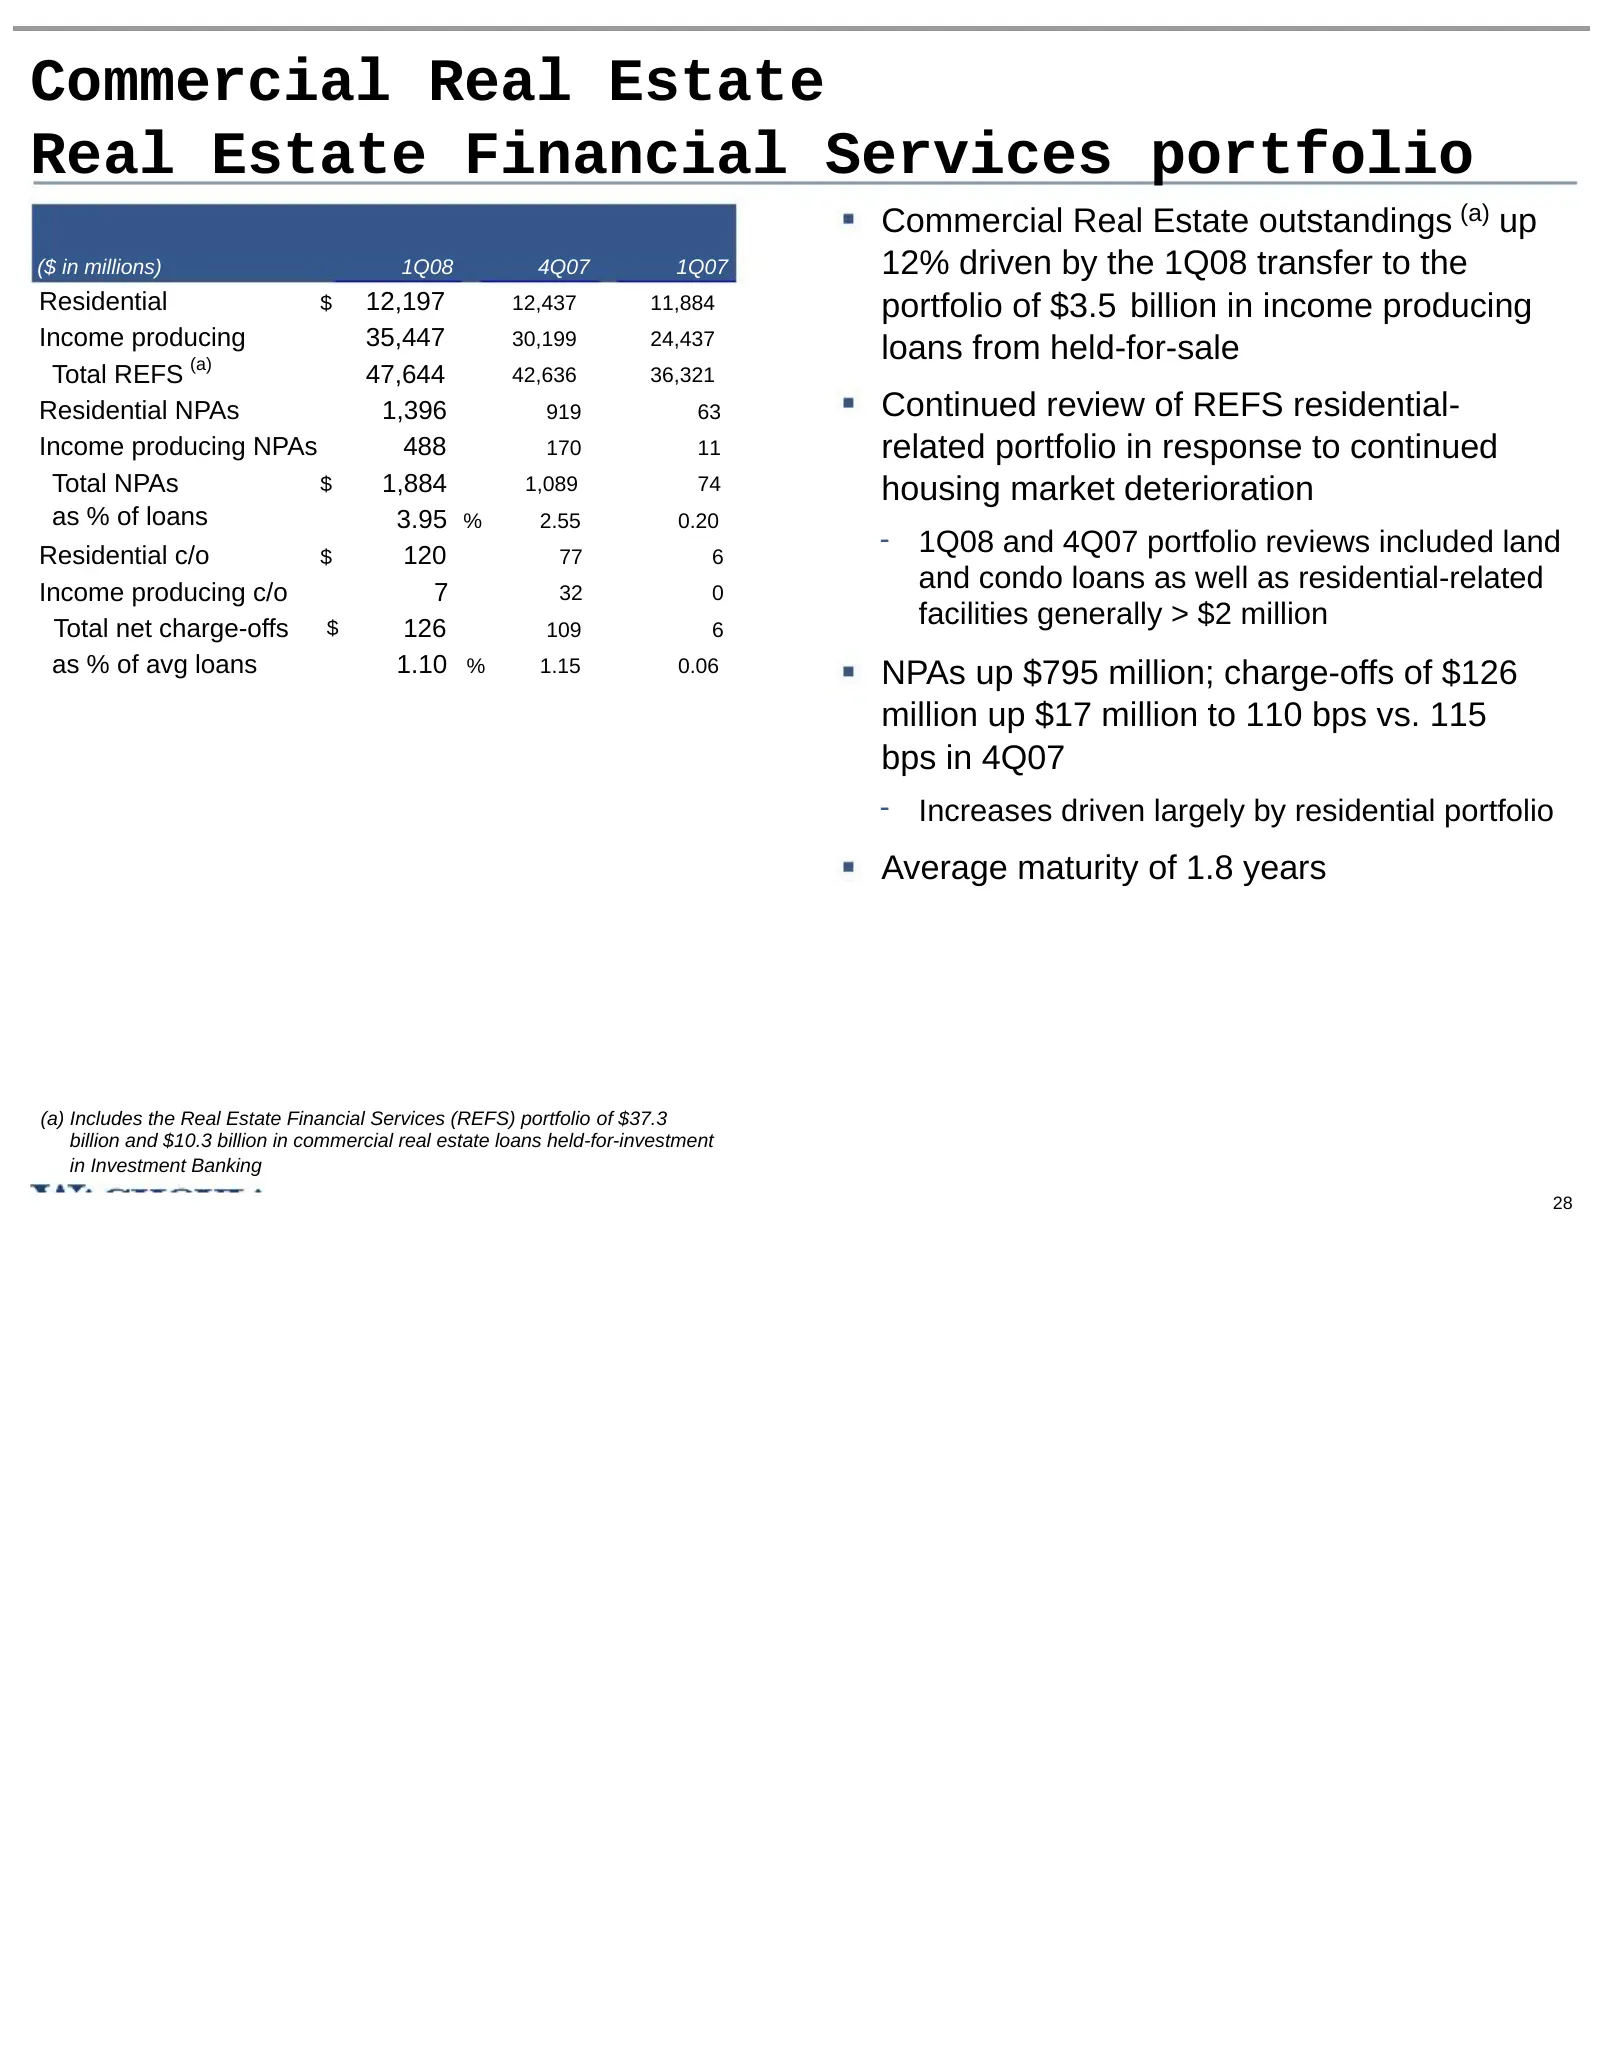
Commercial Real Estate Real Estate Financial Services portfolio Commercial Real Estate outstandings (a) up ($ in millions) 1Q08 4Q07 1Q07 12% driven by the 1Q08 transfer to the Residential $ 12,197 12,437 11,884 portfolio of $3.5 billion in income producing Income producing 35,447 30,199 24,437 loan
Slide 30: Real Estate Financial Services: Well diversified loan portfolio
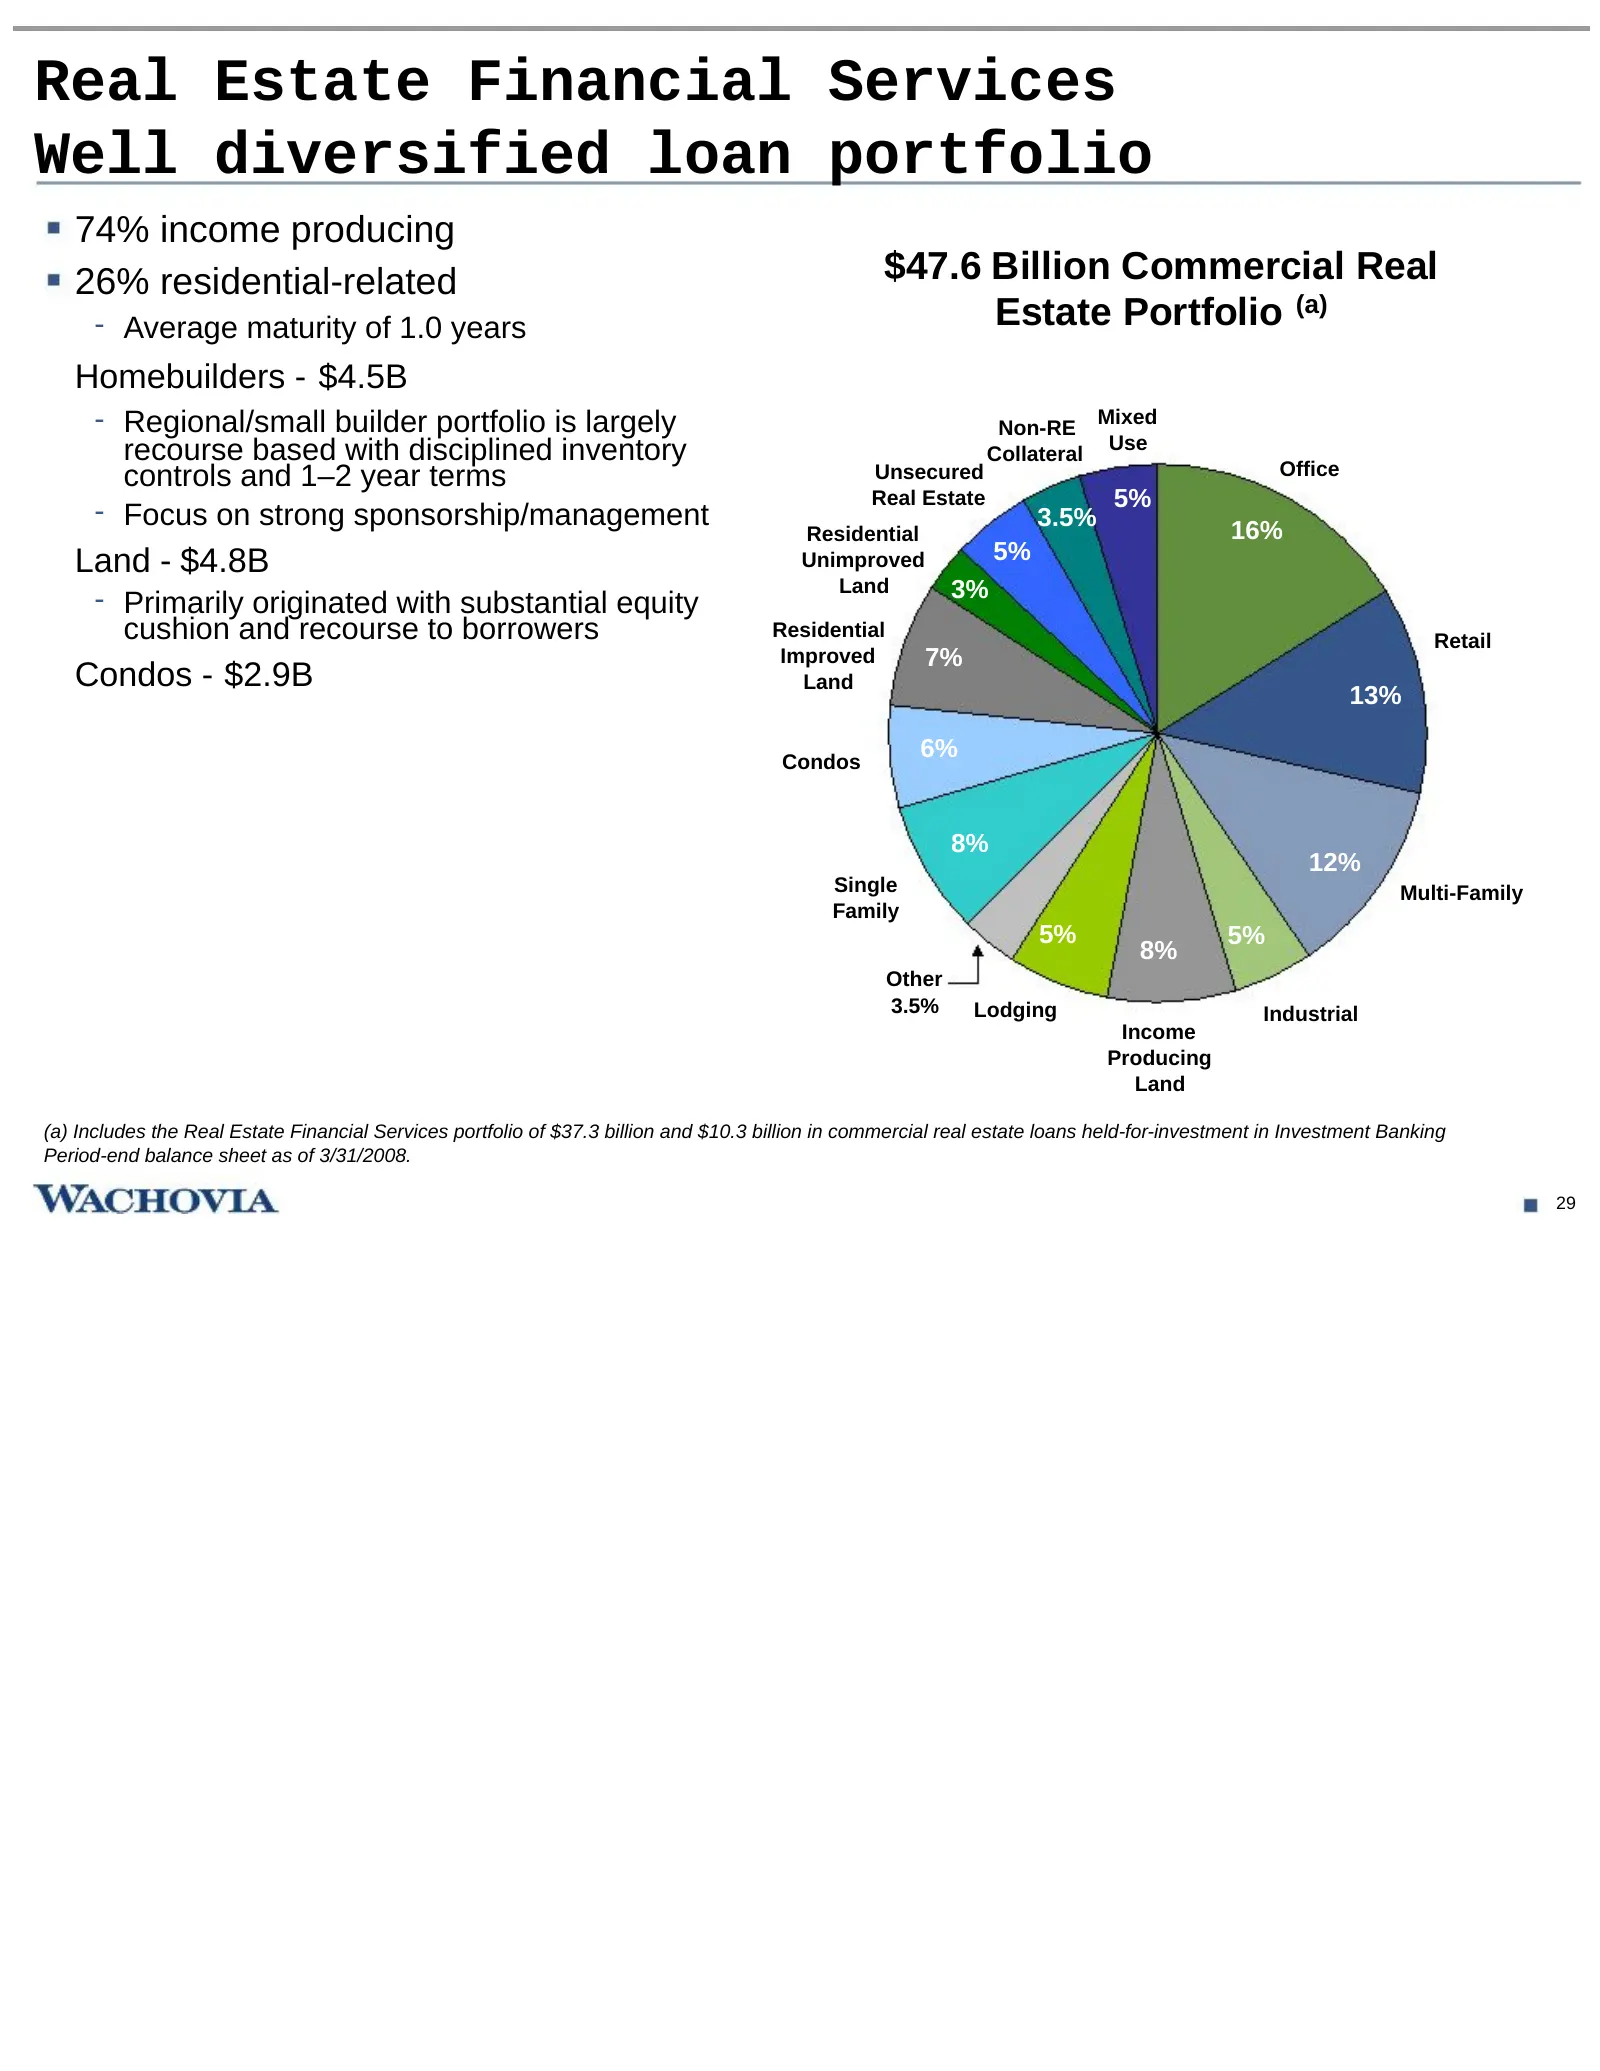
Real Estate Financial Services Well diversified loan portfolio 74% income producing 26% residential-related $47.6 Billion Commercial Real - Average maturity of 1.0 years Estate Portfolio (a) Homebuilders - $4.5B - Regional/small builder portfolio is largely Non-RE Mixed recourse based with disciplin
Slide 31: Real Estate Financial Services: Geographic concentrations
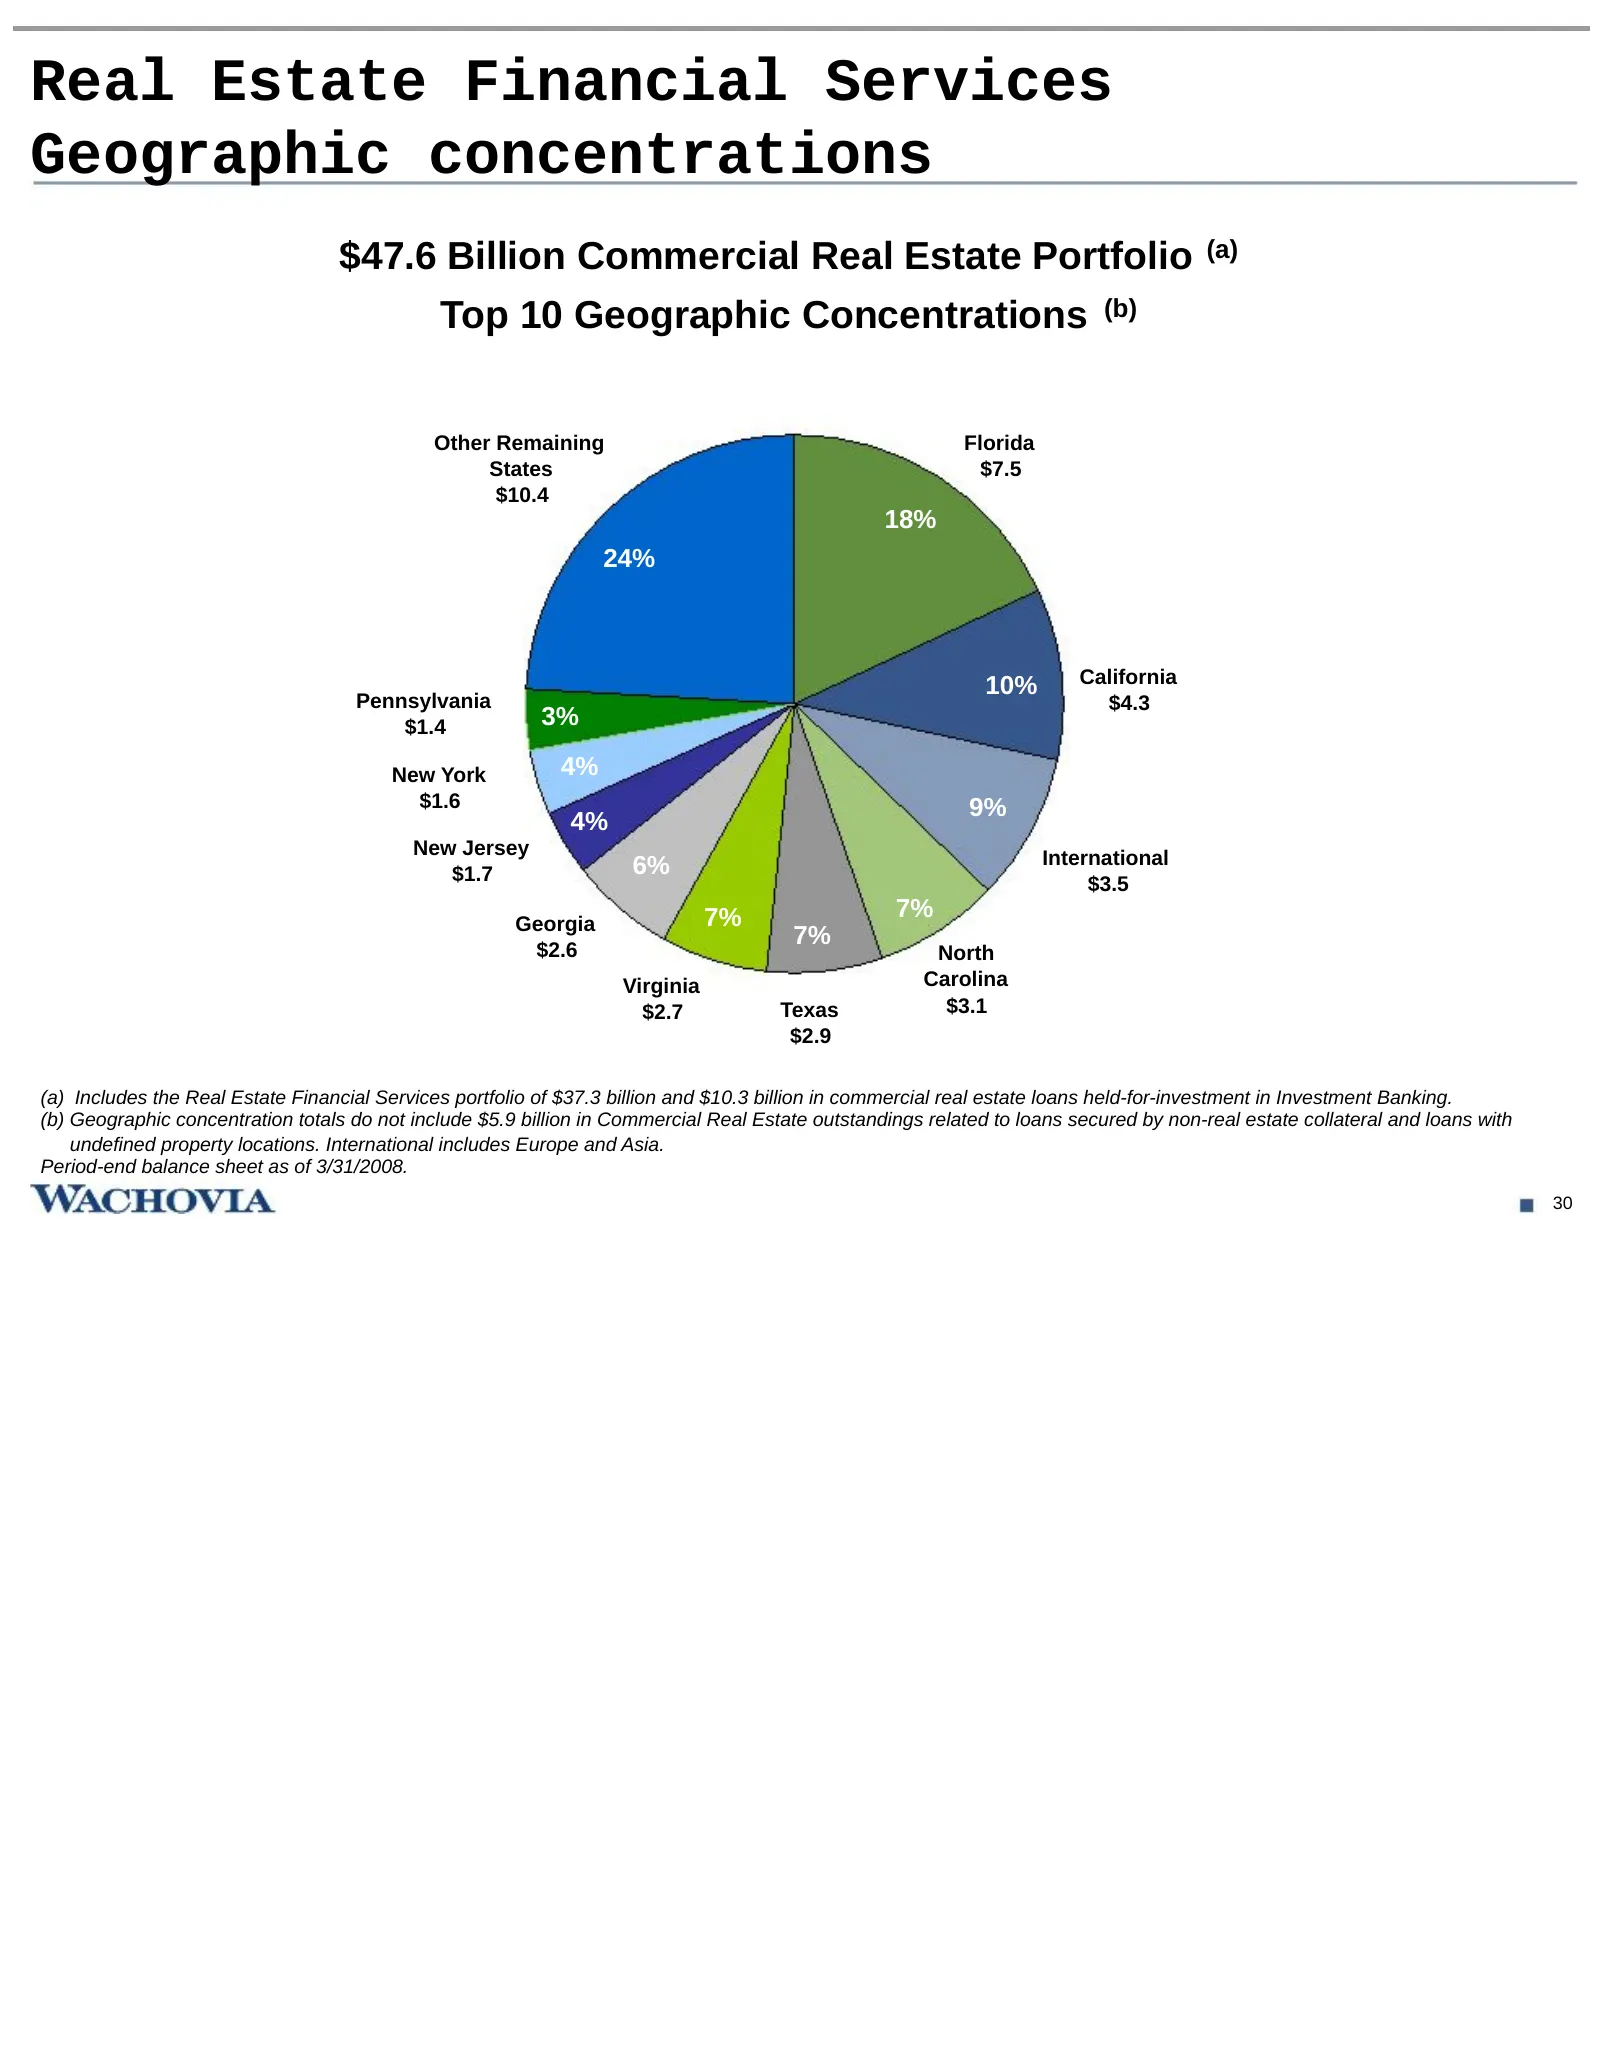
Real Estate Financial Services Geographic concentrations $47.6 Billion Commercial Real Estate Portfolio (a) Top 10 Geographic Concentrations (b) Other Remaining Florida States $7.5 $10.4 18% 24% 10% California Pennsylvania $4.3 $1.4 3% New York 4% $1.6 9% 4% New Jersey International $1.7 6% $3.5 7%
Slide 32: Middle-market and large corporate
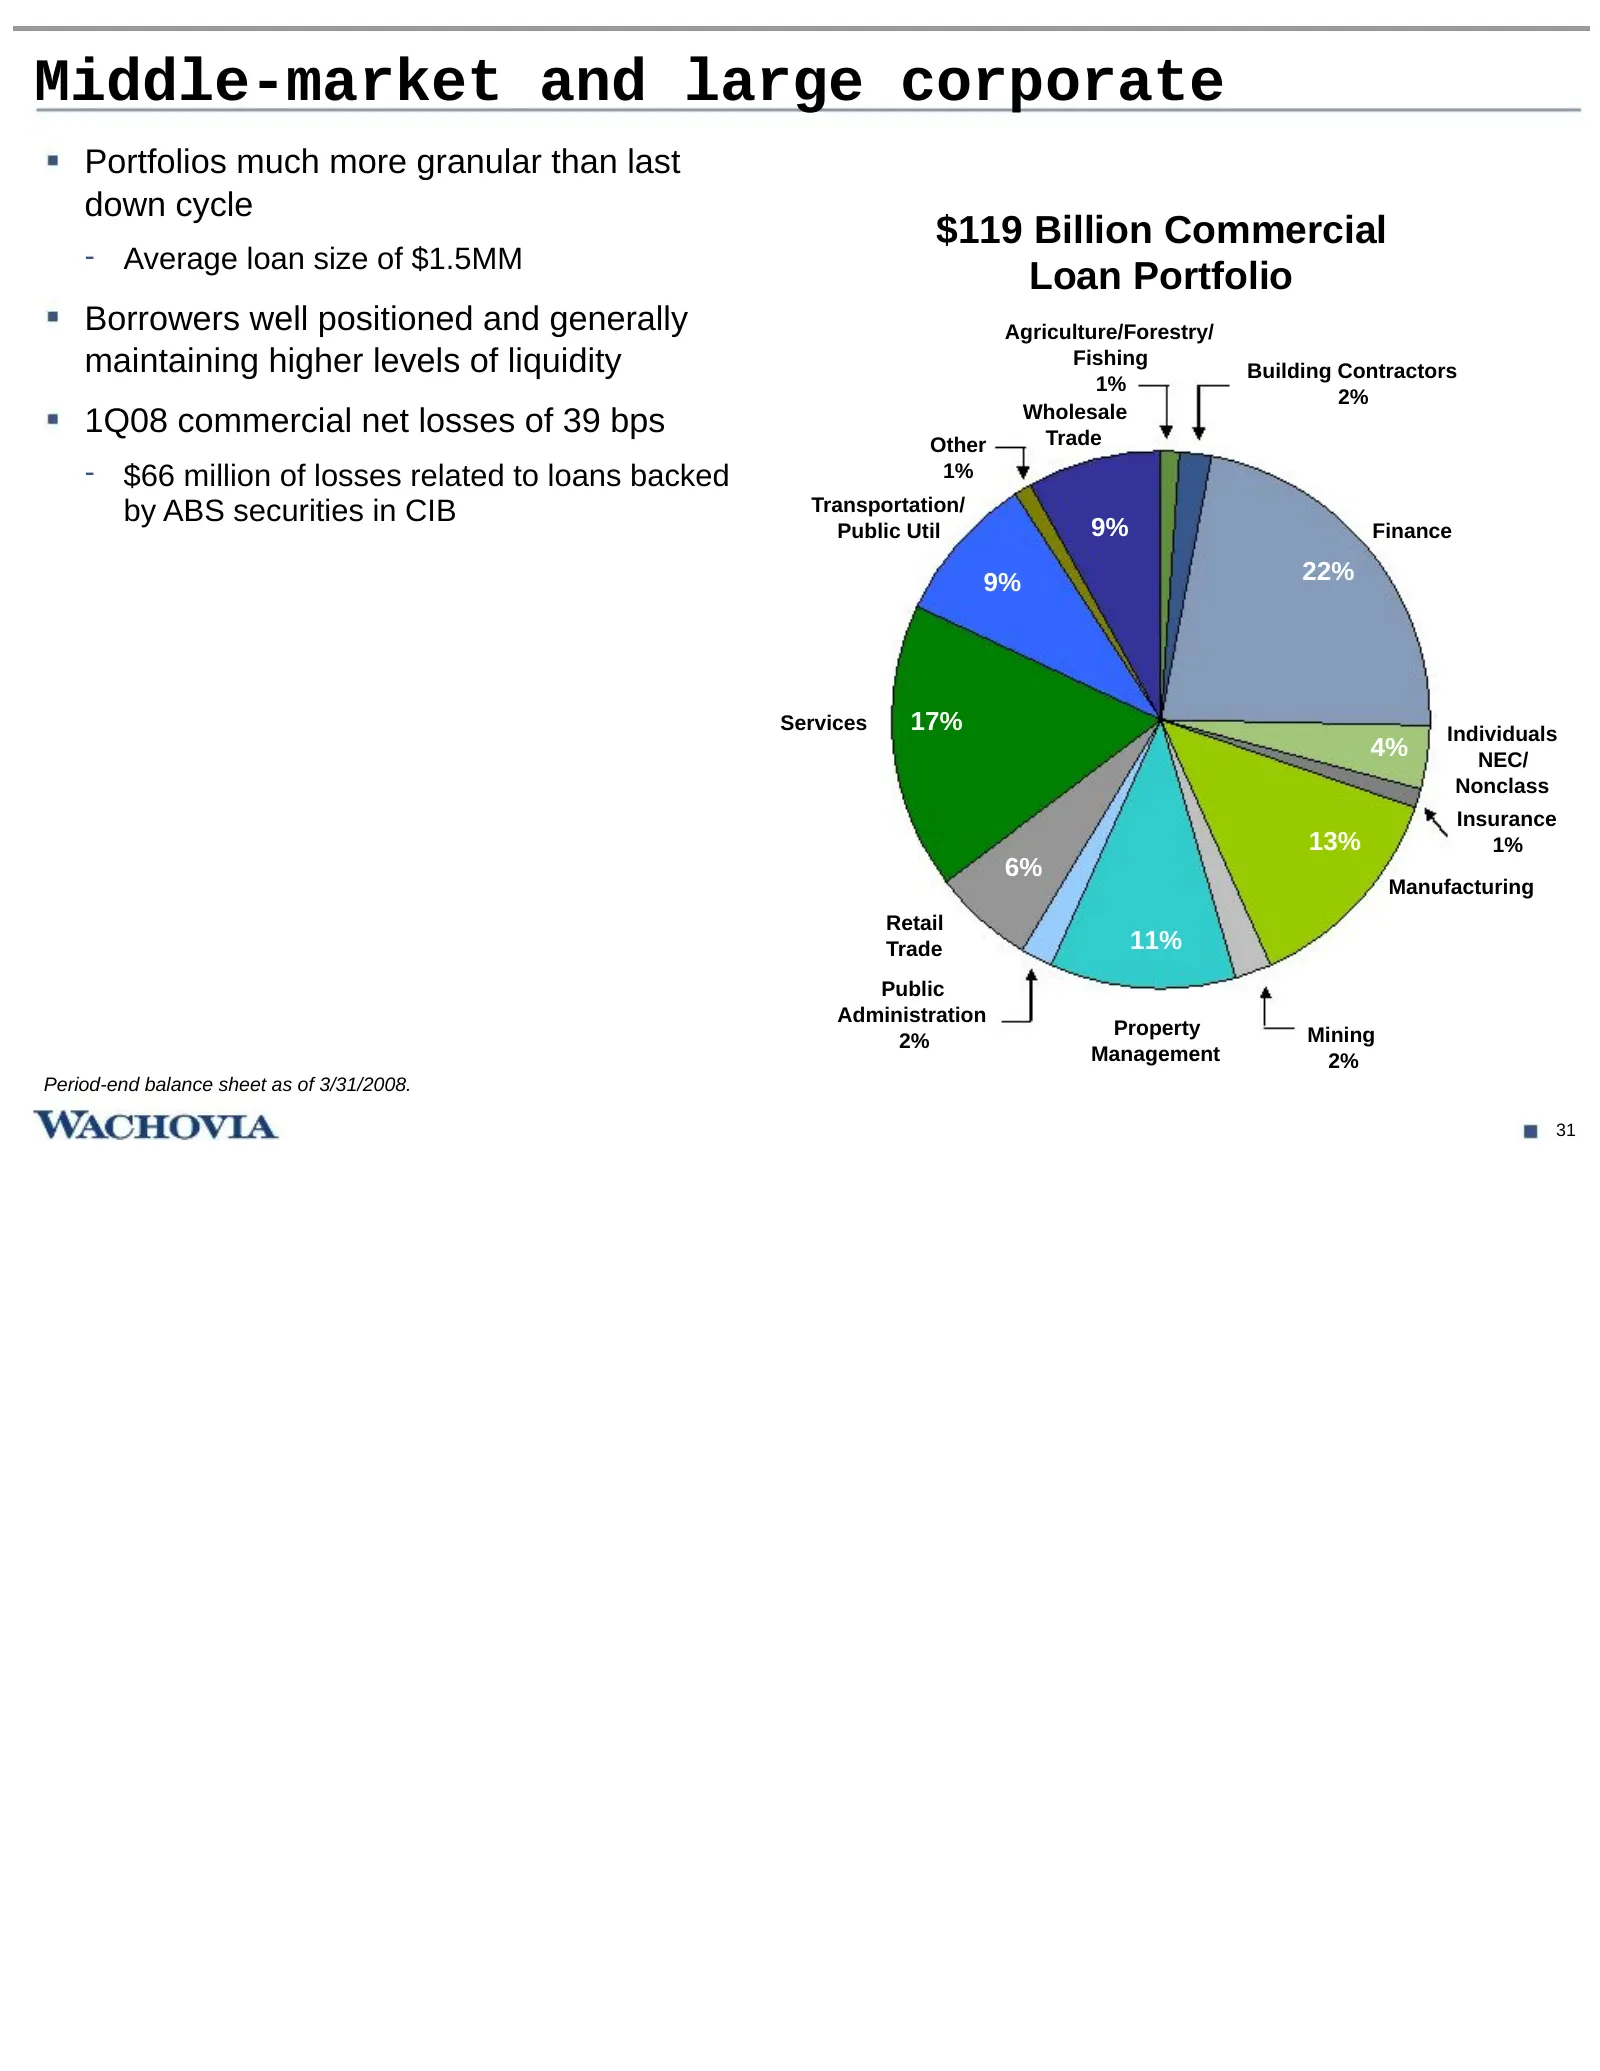
Middle-market and large corporate Portfolios much more granular than last down cycle $119 Billion Commercial - Average loan size of $1.5MM Loan Portfolio Borrowers well positioned and generally Agriculture/Forestry/ maintaining higher levels of liquidity Fishing Building Contractors 1% 2% Wholesale
Slide 33: Summary and Outlook
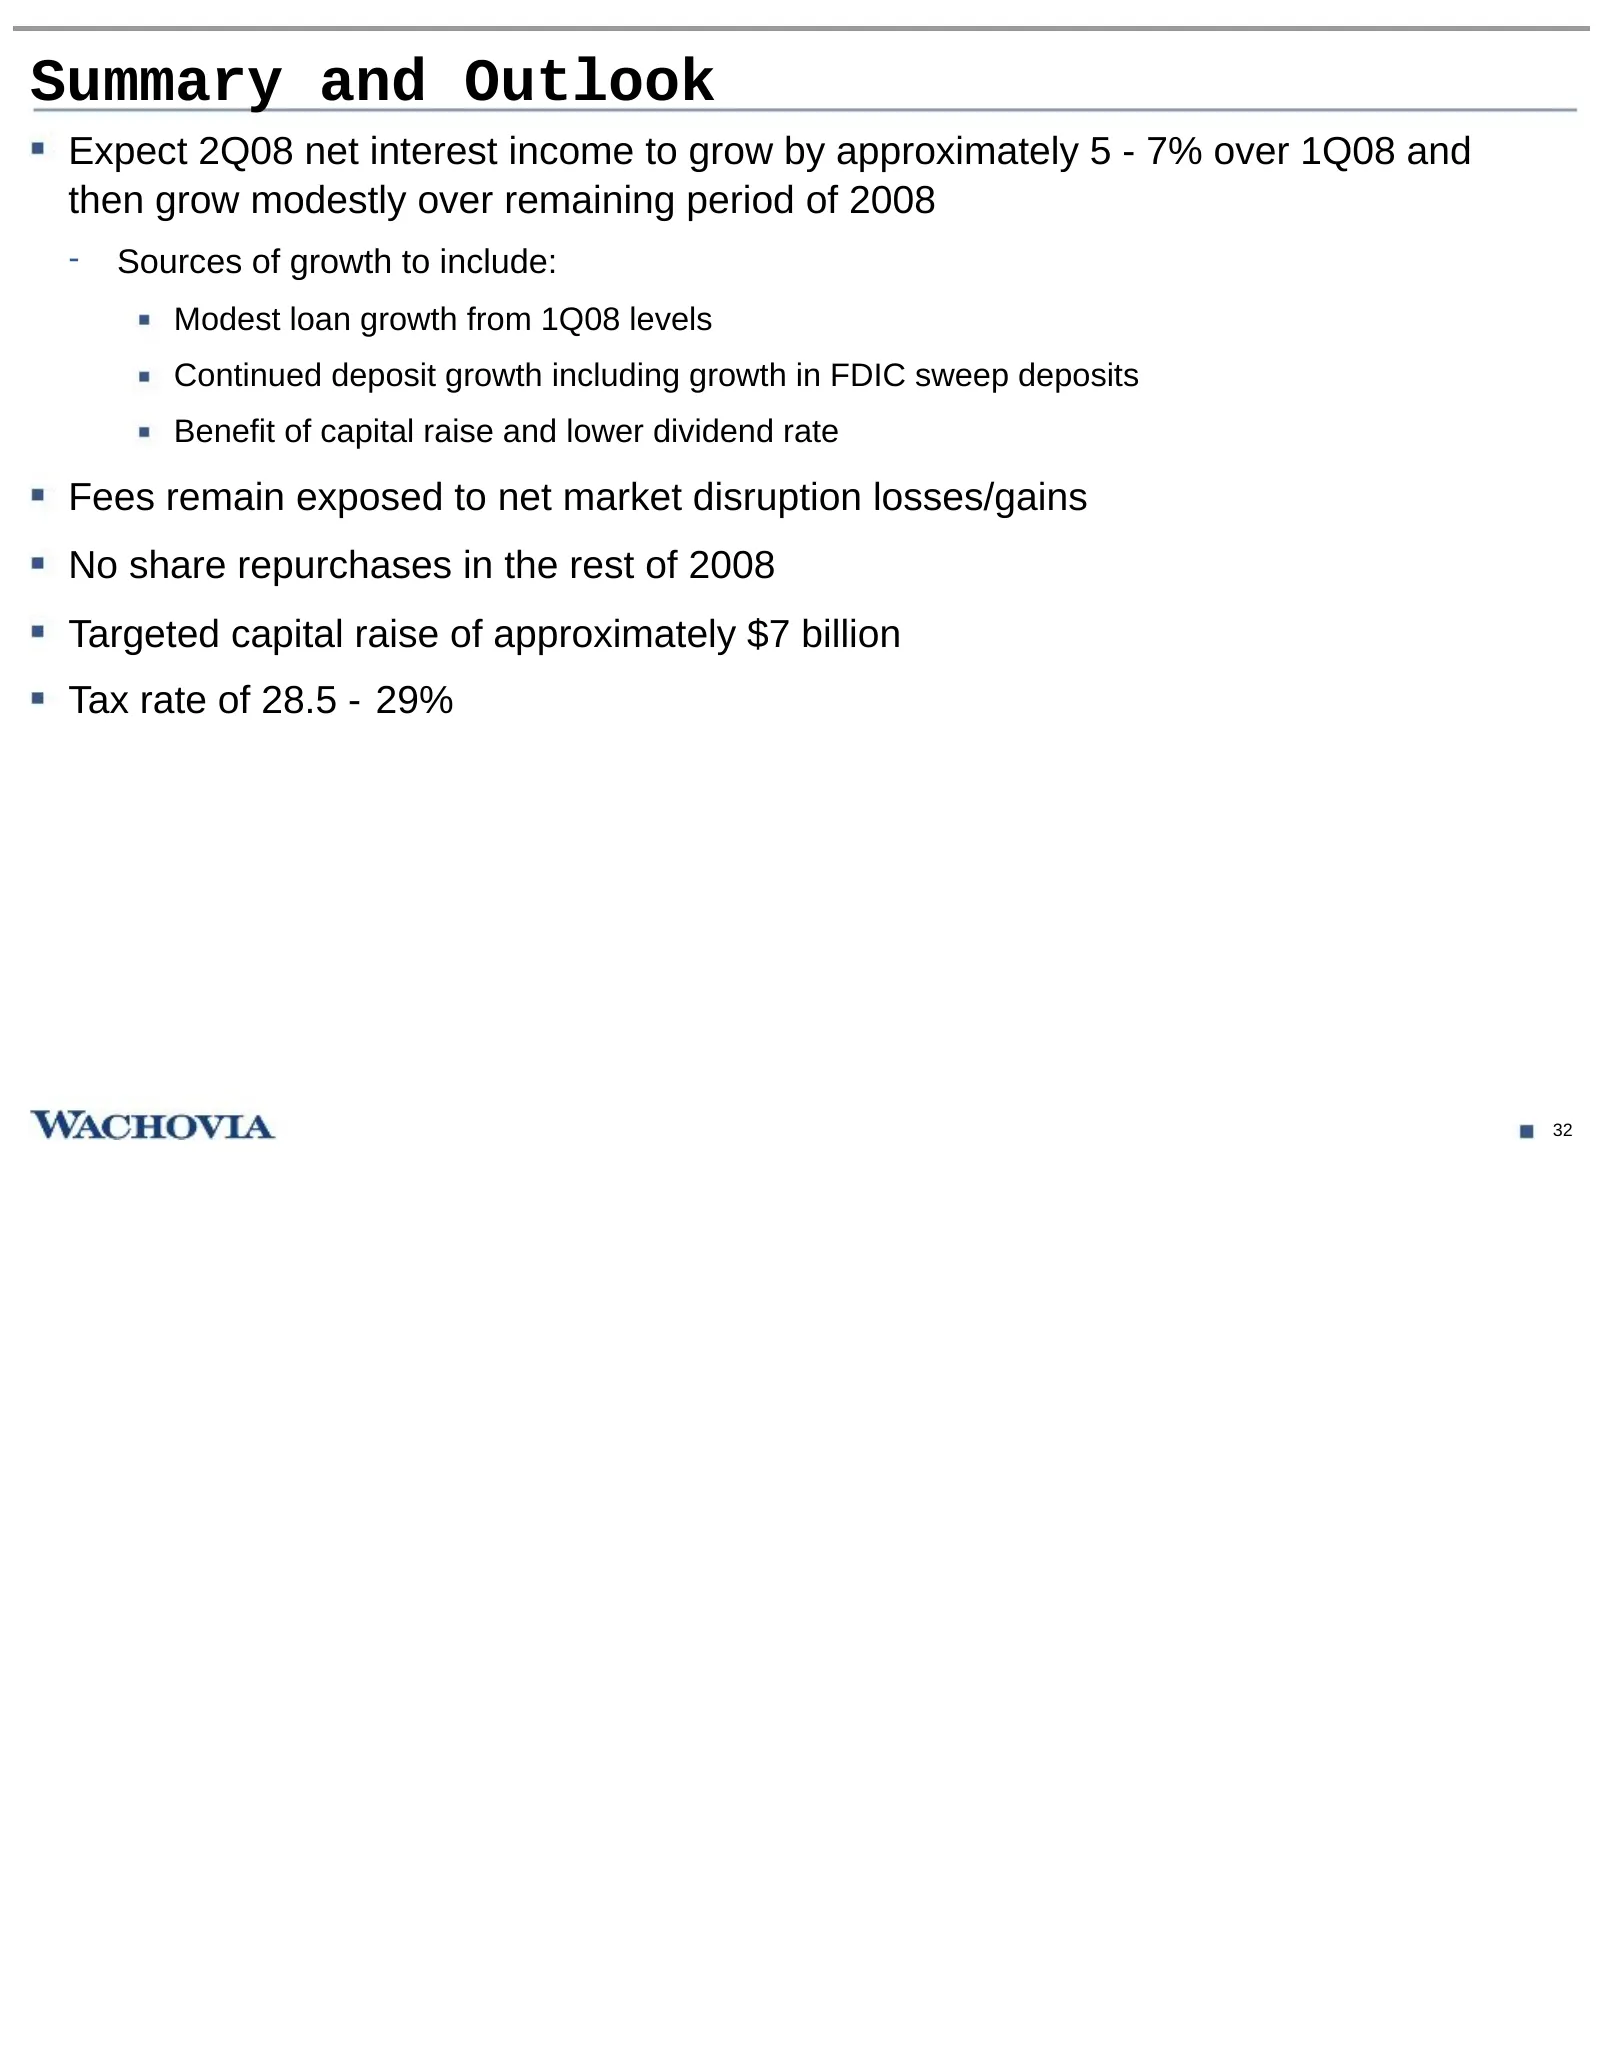
Summary and Outlook Expect 2Q08 net interest income to grow by approximately 5 - 7% over 1Q08 and then grow modestly over remaining period of 2008 - Sources of growth to include: Modest loan growth from 1Q08 levels Continued deposit growth including growth in FDIC sweep deposits Benefit of capital r
Slide 34: Appendix
Appendix WACHOVIA.
Slide 35: Consumer real estate portfolio
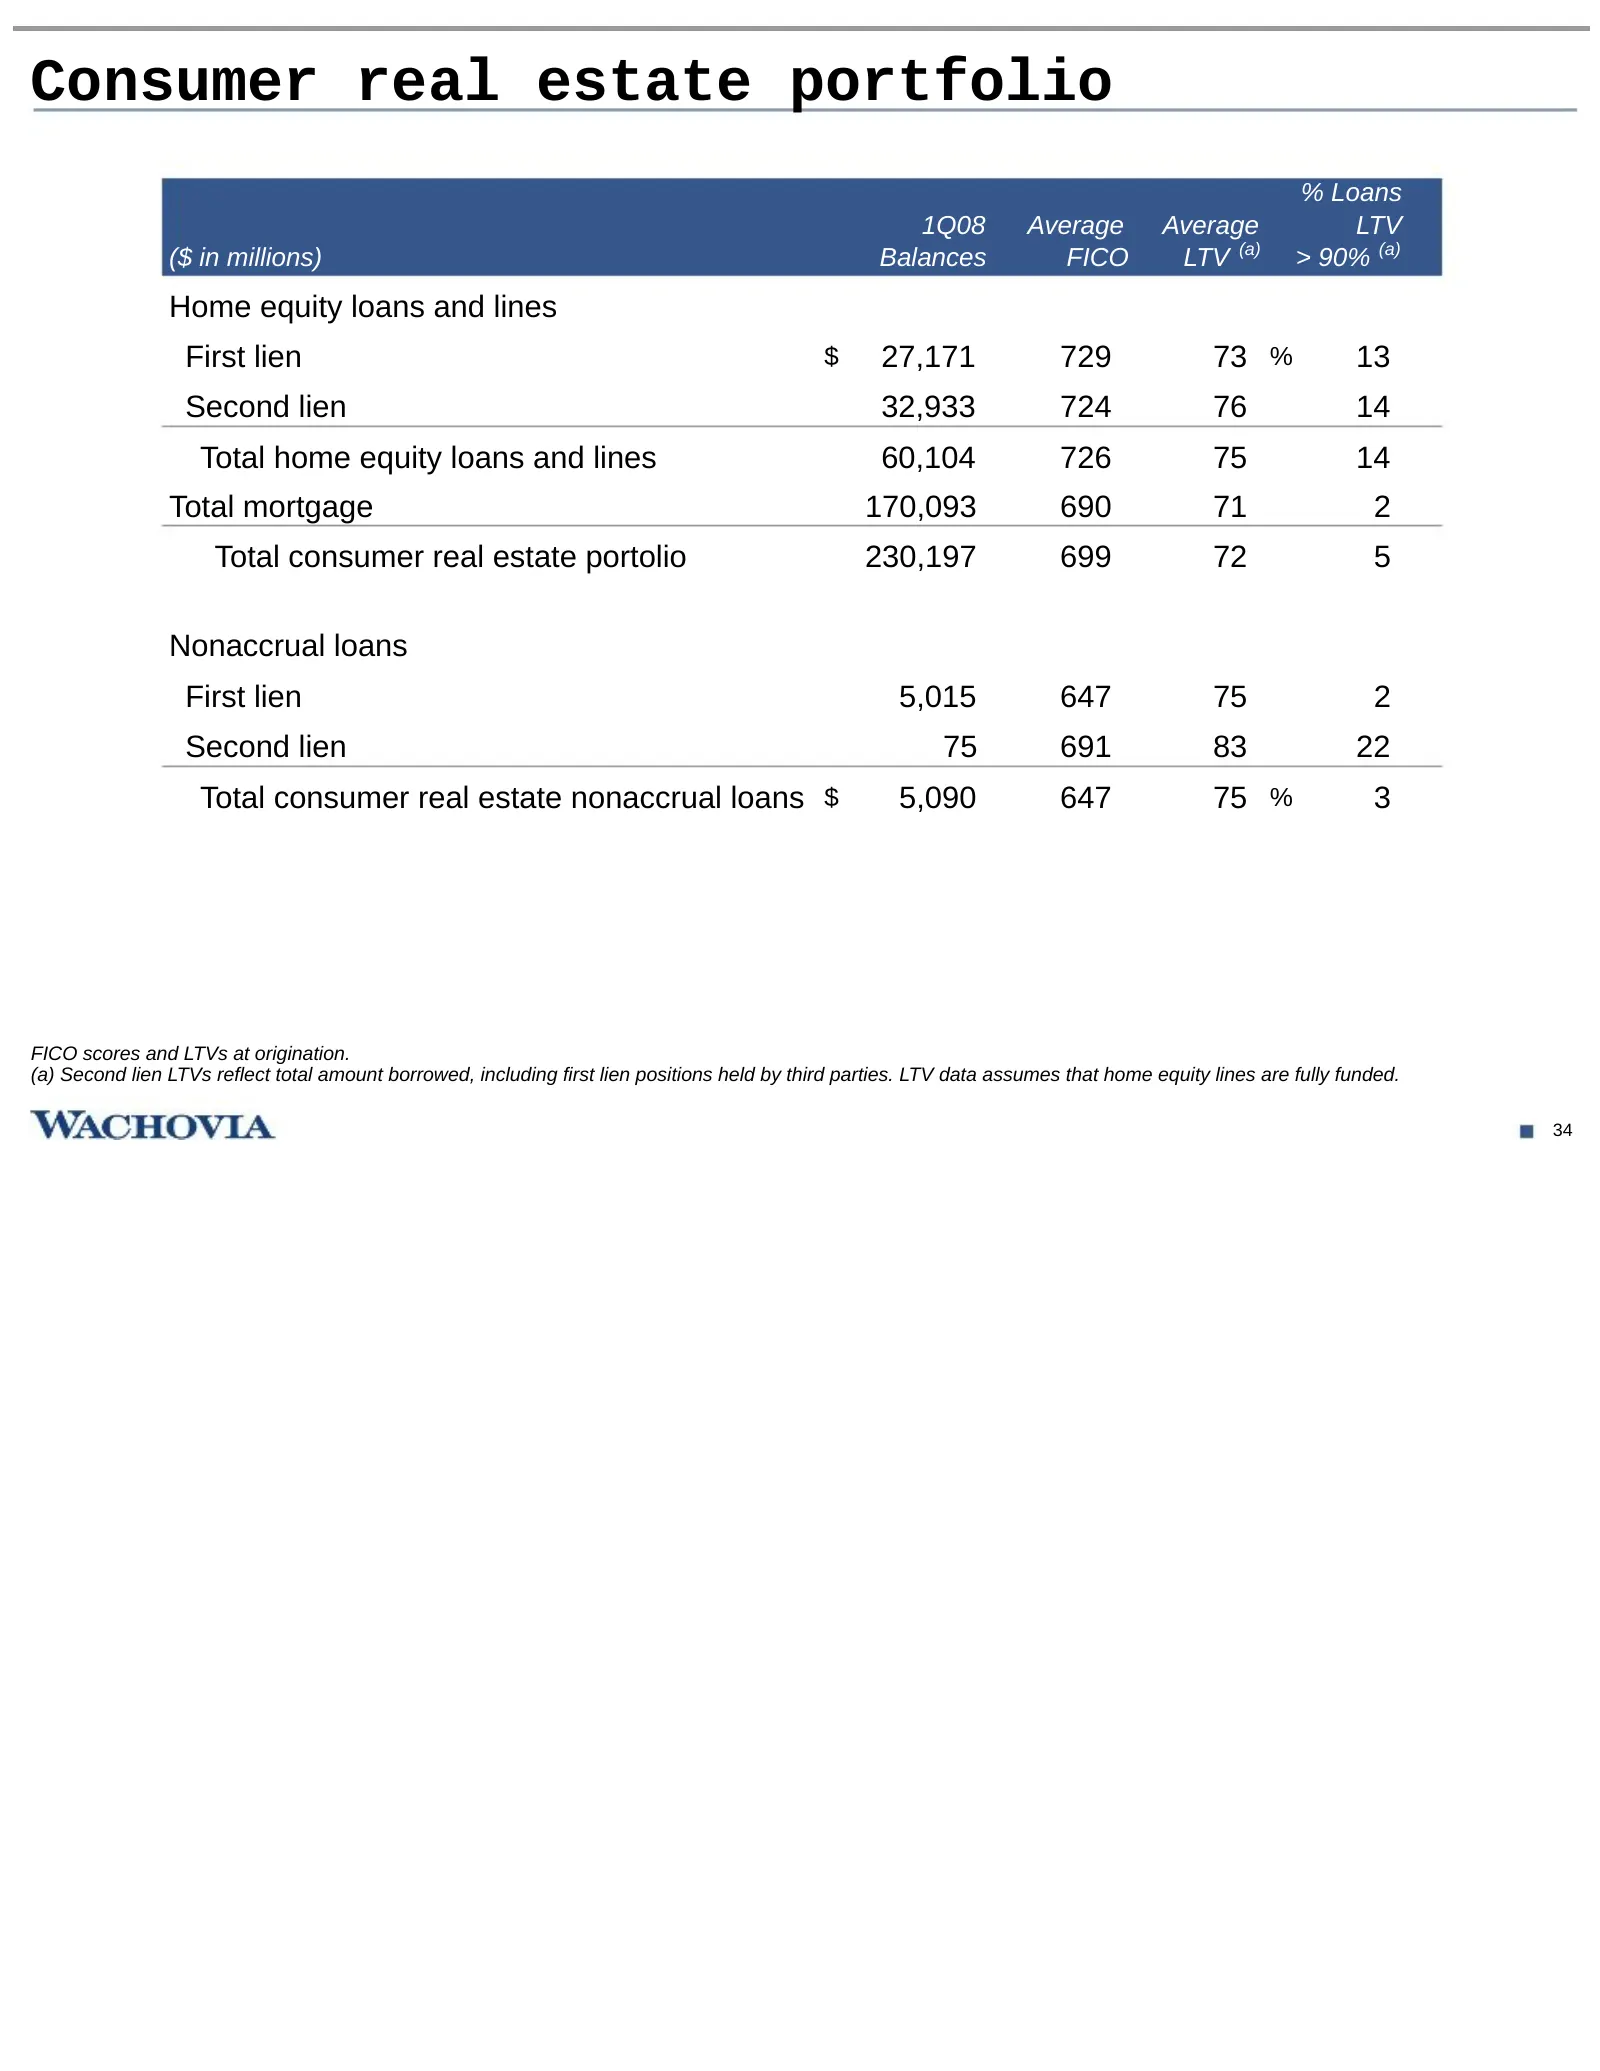
Consumer real estate portfolio % Loans 1Q08 Average Average LTV ($ in millions) Balances FICO LTV (a) > 90% (a) Home equity loans and lines First lien $ 27,171 729 73 % 13 Second lien 32,933 724 76 14 Total home equity loans and lines 60,104 726 75 14 Total mortgage 170,093 690 71 2 Total consumer r
Slide 36: Wachovia Mortgage 90+ days past due by vintage vs. industry
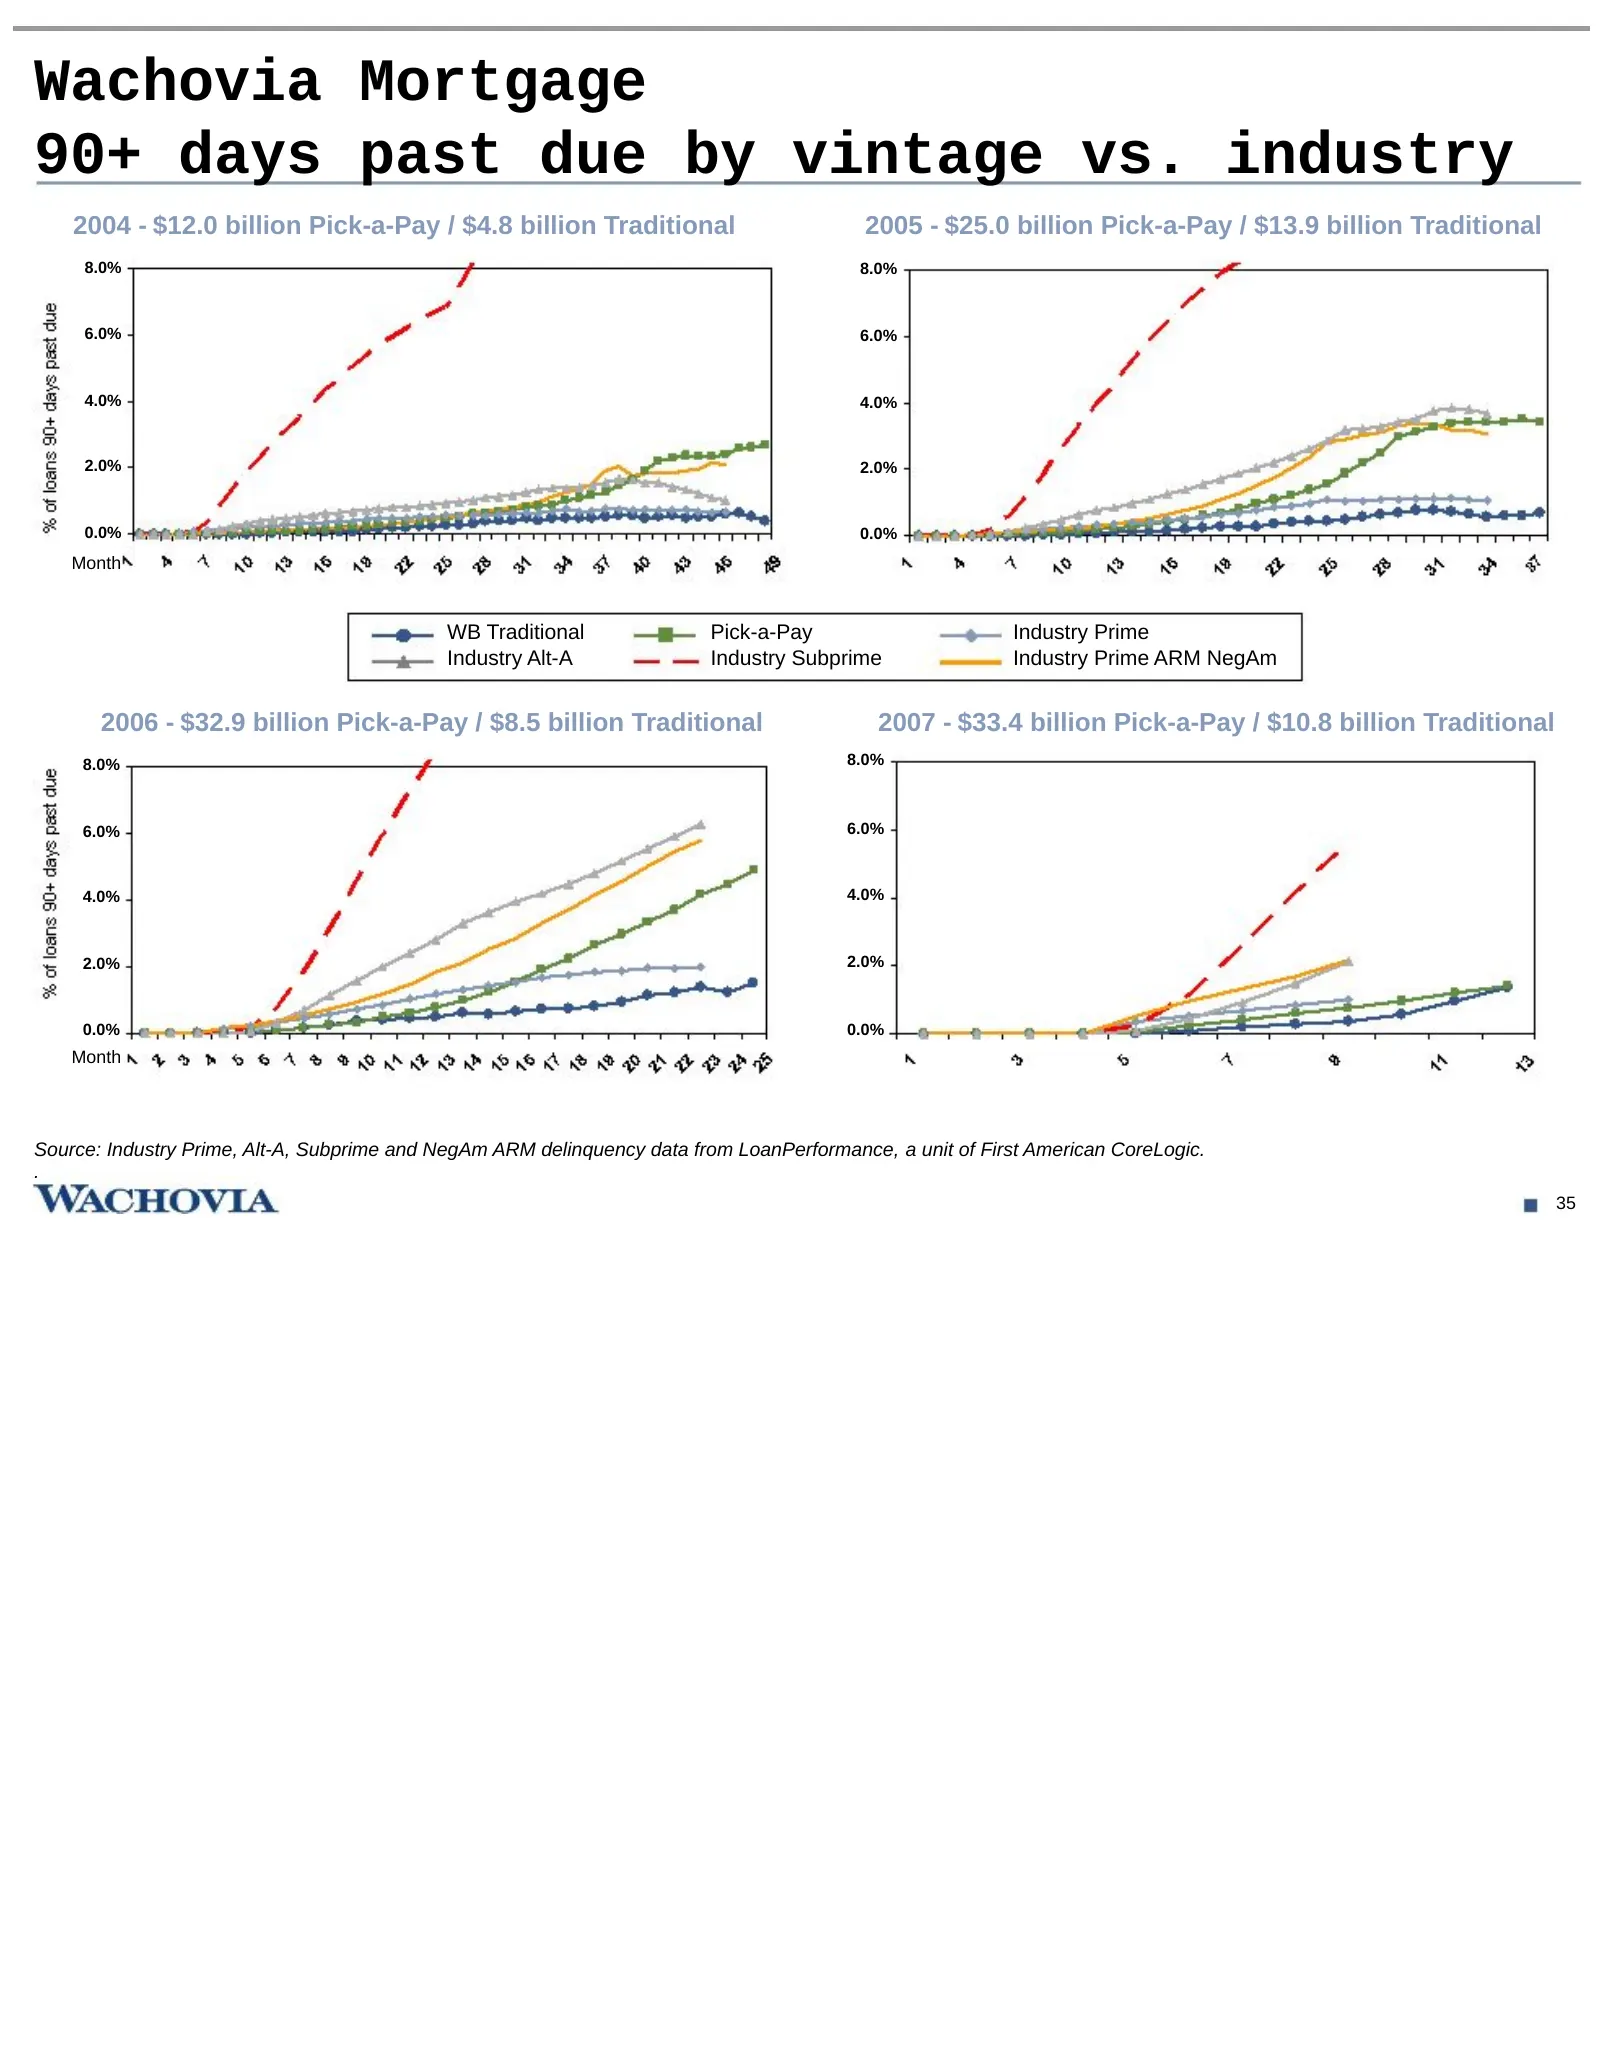
Wachovia Mortgage 90+ days past due by vintage vs. industry 2004 - $12.0 billion Pick-a-Pay / $4.8 billion Traditional 2005 - $25.0 billion Pick-a-Pay / $13.9 billion Traditional 8.0% 8.0% 6.0% 6.0% 4.0% 4.0% 2.0% 2.0% 0.0% 0.0% Month WB Traditional Pick-a-Pay Industry Prime Industry Alt-A Industry
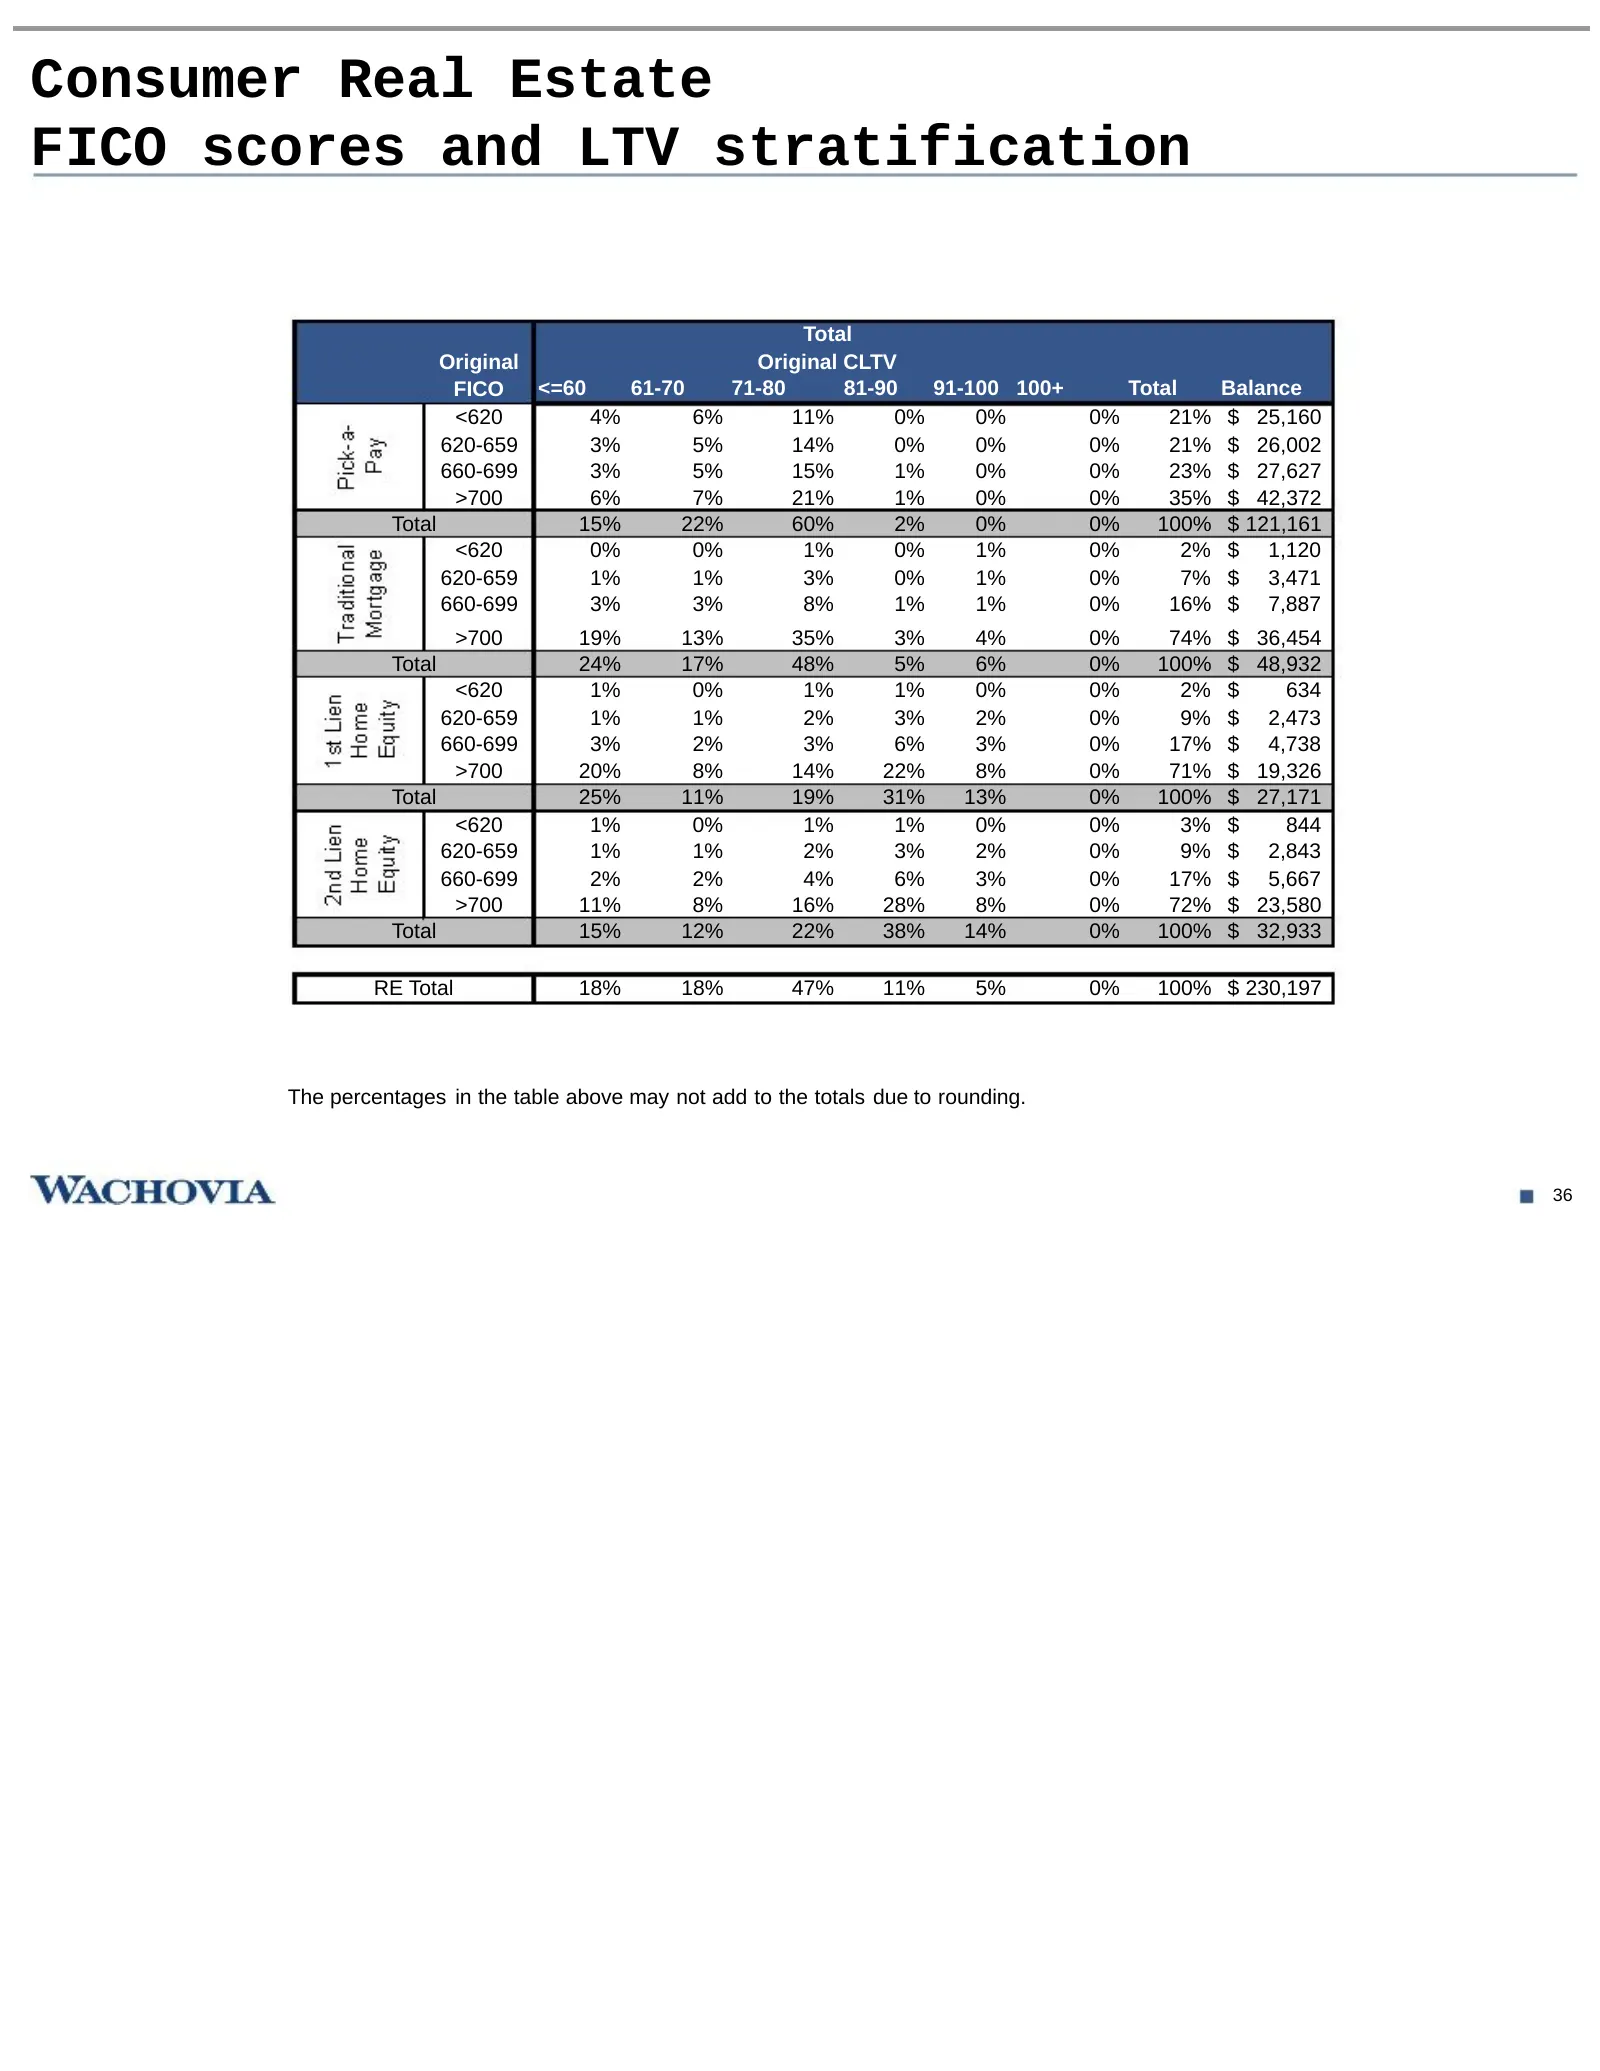
Slide 37: Consumer Real Estate FICO scores and LTV stratification
Consumer Real Estate FICO scores and LTV stratification Total Original Original CLTV FICO <=60 61-70 71-80 81-90 91-100 100+ Total Balance <620 4% 6% 11% 0% 0% 0% 21% $ 25,160 620-659 3% 5% 14% 0% 0% 0% 21% $ 26,002 660-699 3% 5% 15% 1% 0% 0% 23% $ 27,627 >700 6% 7% 21% 1% 0% 0% 35% $ 42,372 Total 1
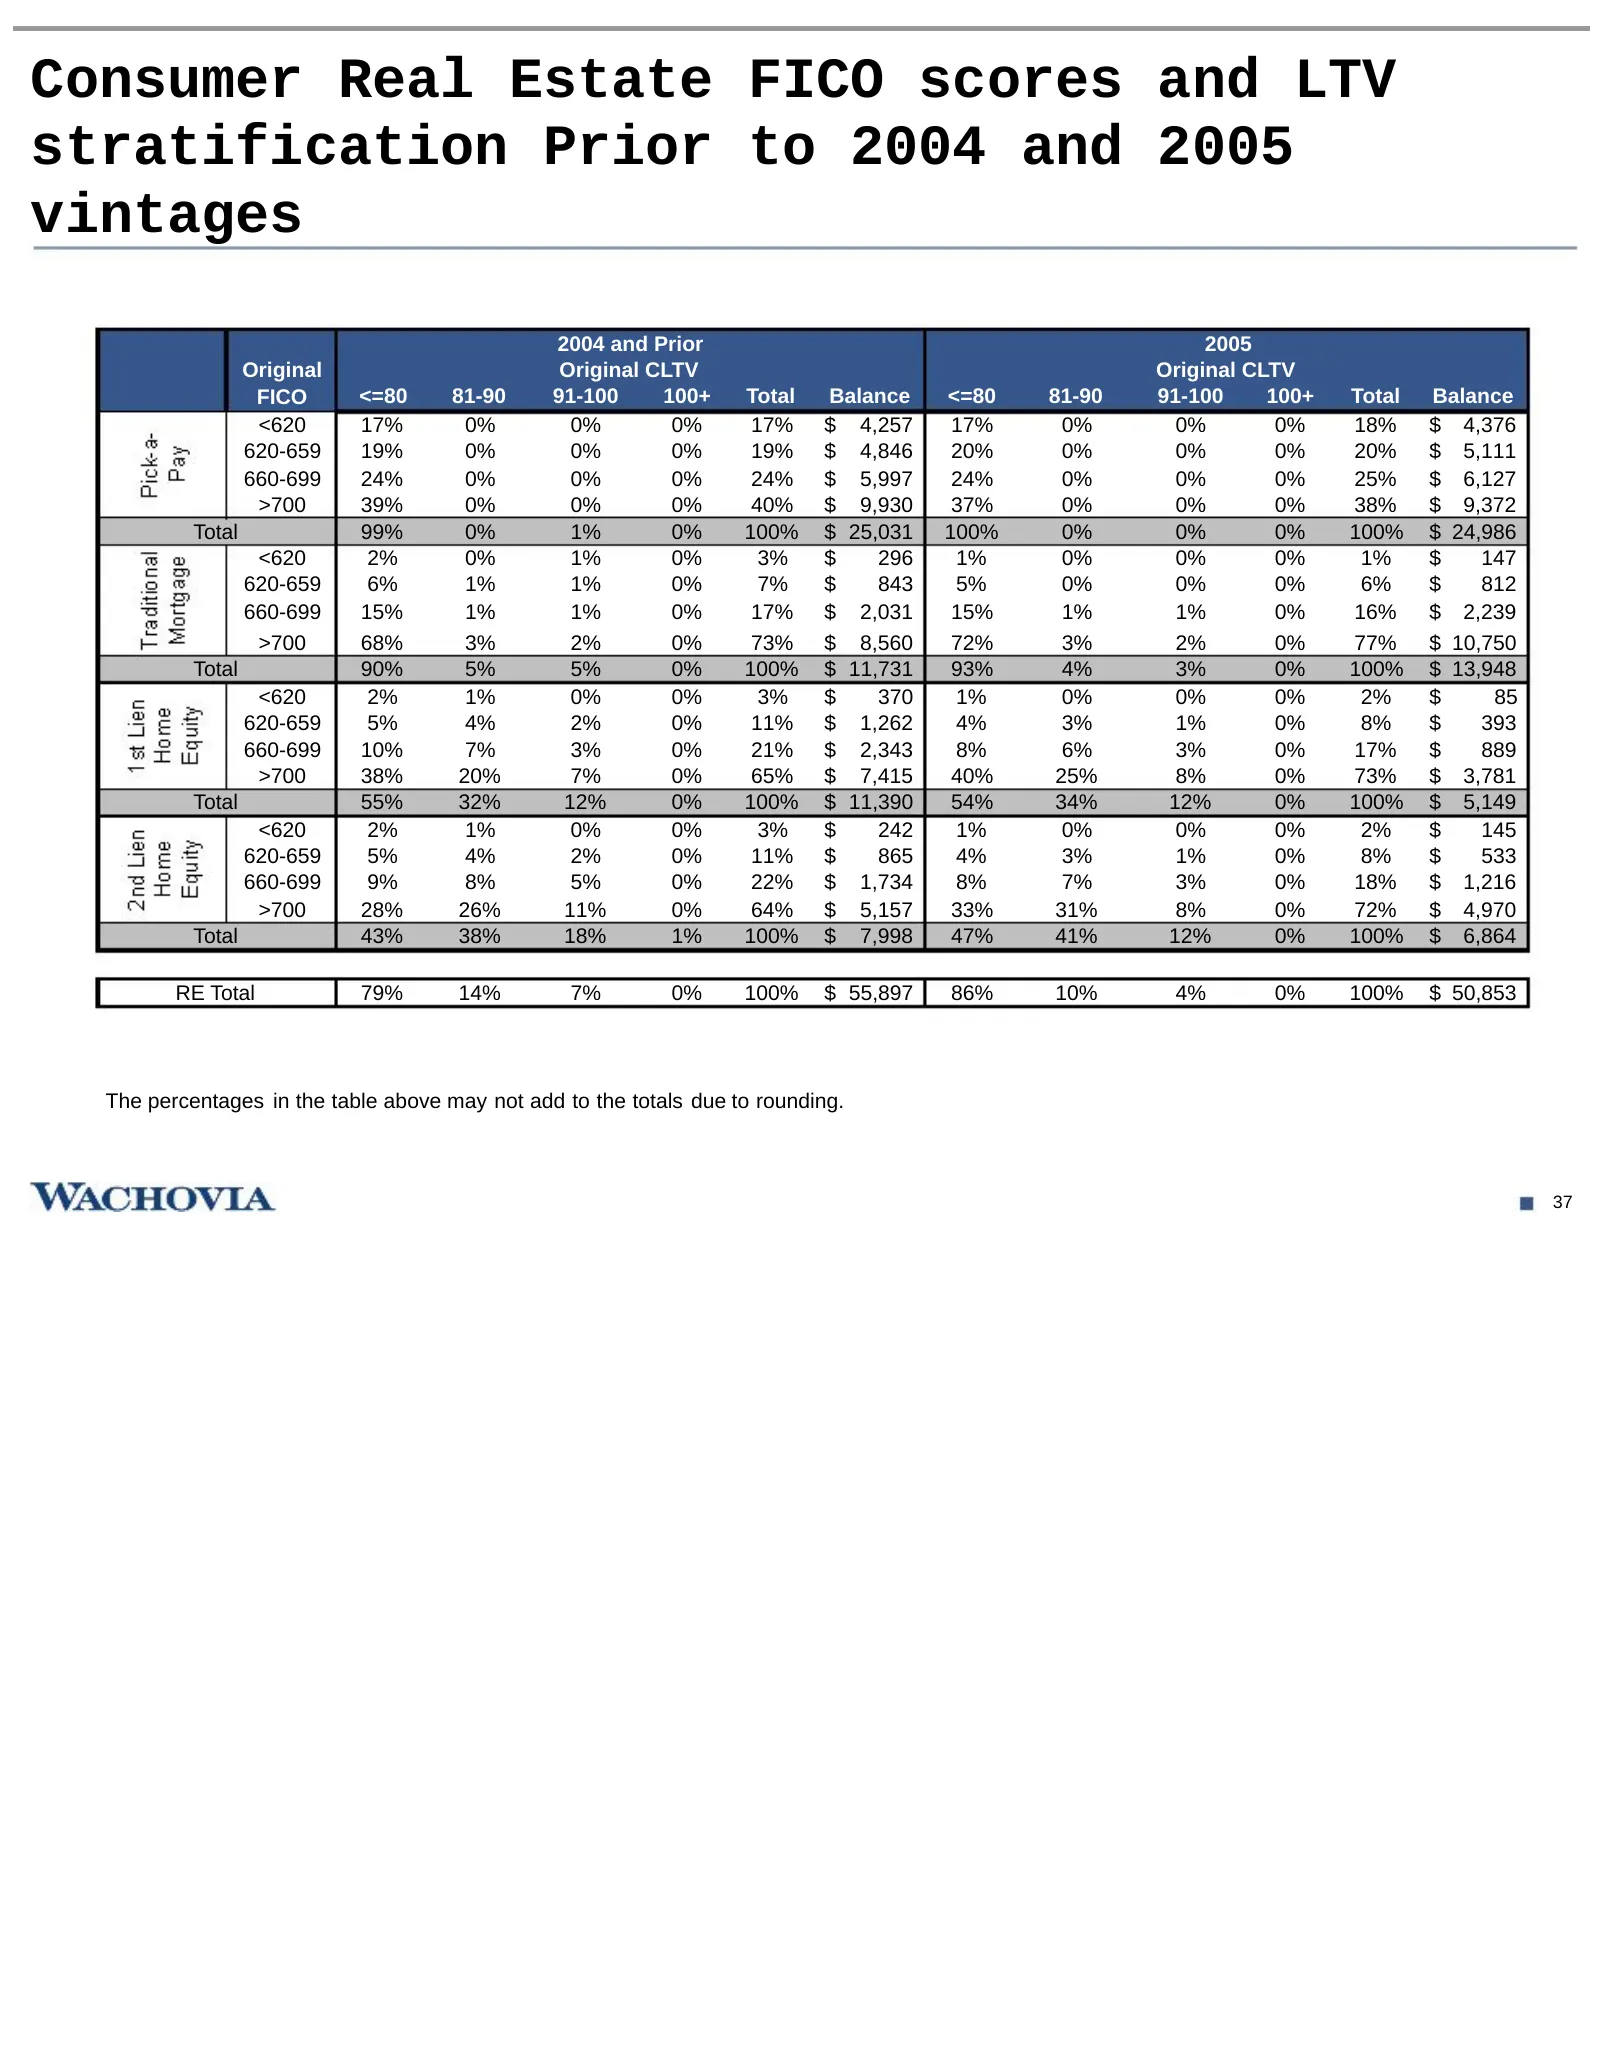
Slide 38: FICO and LTV stratification: 2004 and prior, 2005 vintages
Consumer Real Estate FICO scores and LTV stratification Prior to 2004 and 2005 vintages 2004 and Prior 2005 Original Original CLTV Original CLTV FICO <=80 81-90 91-100 100+ Total Balance <=80 81-90 91-100 100+ Total Balance <620 17% 0% 0% 0% 17% $ 4,257 17% 0% 0% 0% 18% $ 4,376 620-659 19% 0% 0% 0%
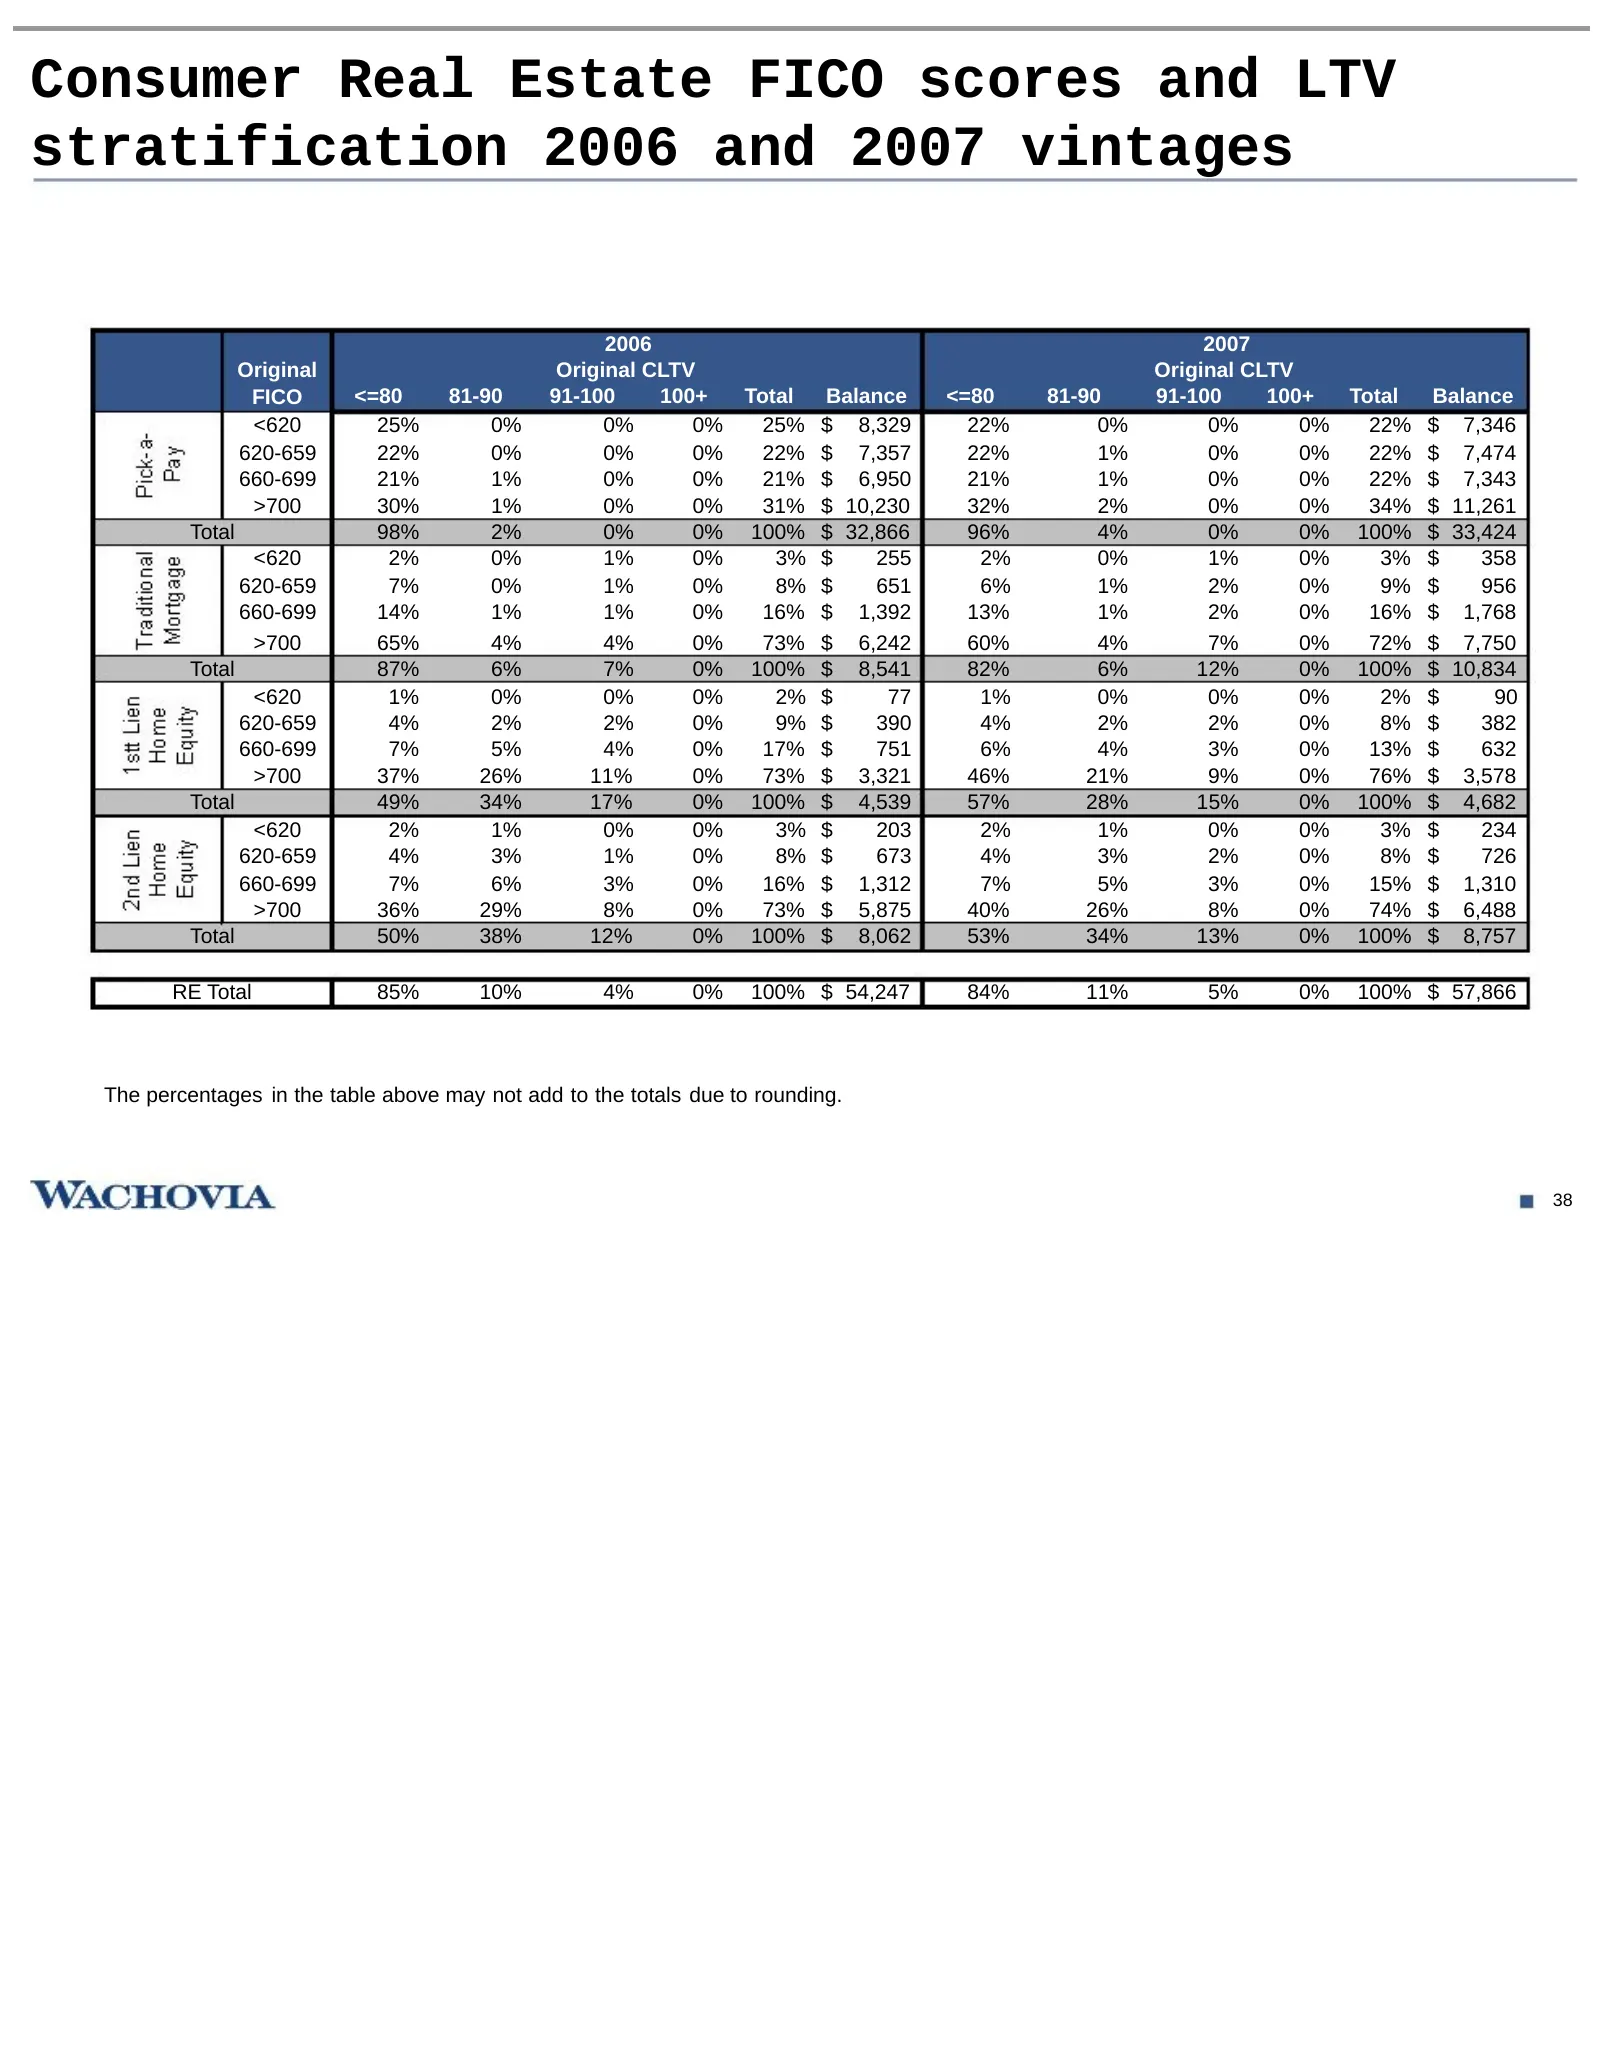
Slide 39: FICO and LTV stratification: 2006 and 2007 vintages
Consumer Real Estate FICO scores and LTV stratification 2006 and 2007 vintages 2006 2007 Original Original CLTV Original CLTV FICO <=80 81-90 91-100 100+ Total Balance <=80 81-90 91-100 100+ Total Balance <620 25% 0% 0% 0% 25% $ 8,329 22% 0% 0% 0% 22% $ 7,346 620-659 22% 0% 0% 0% 22% $ 7,357 22% 1%
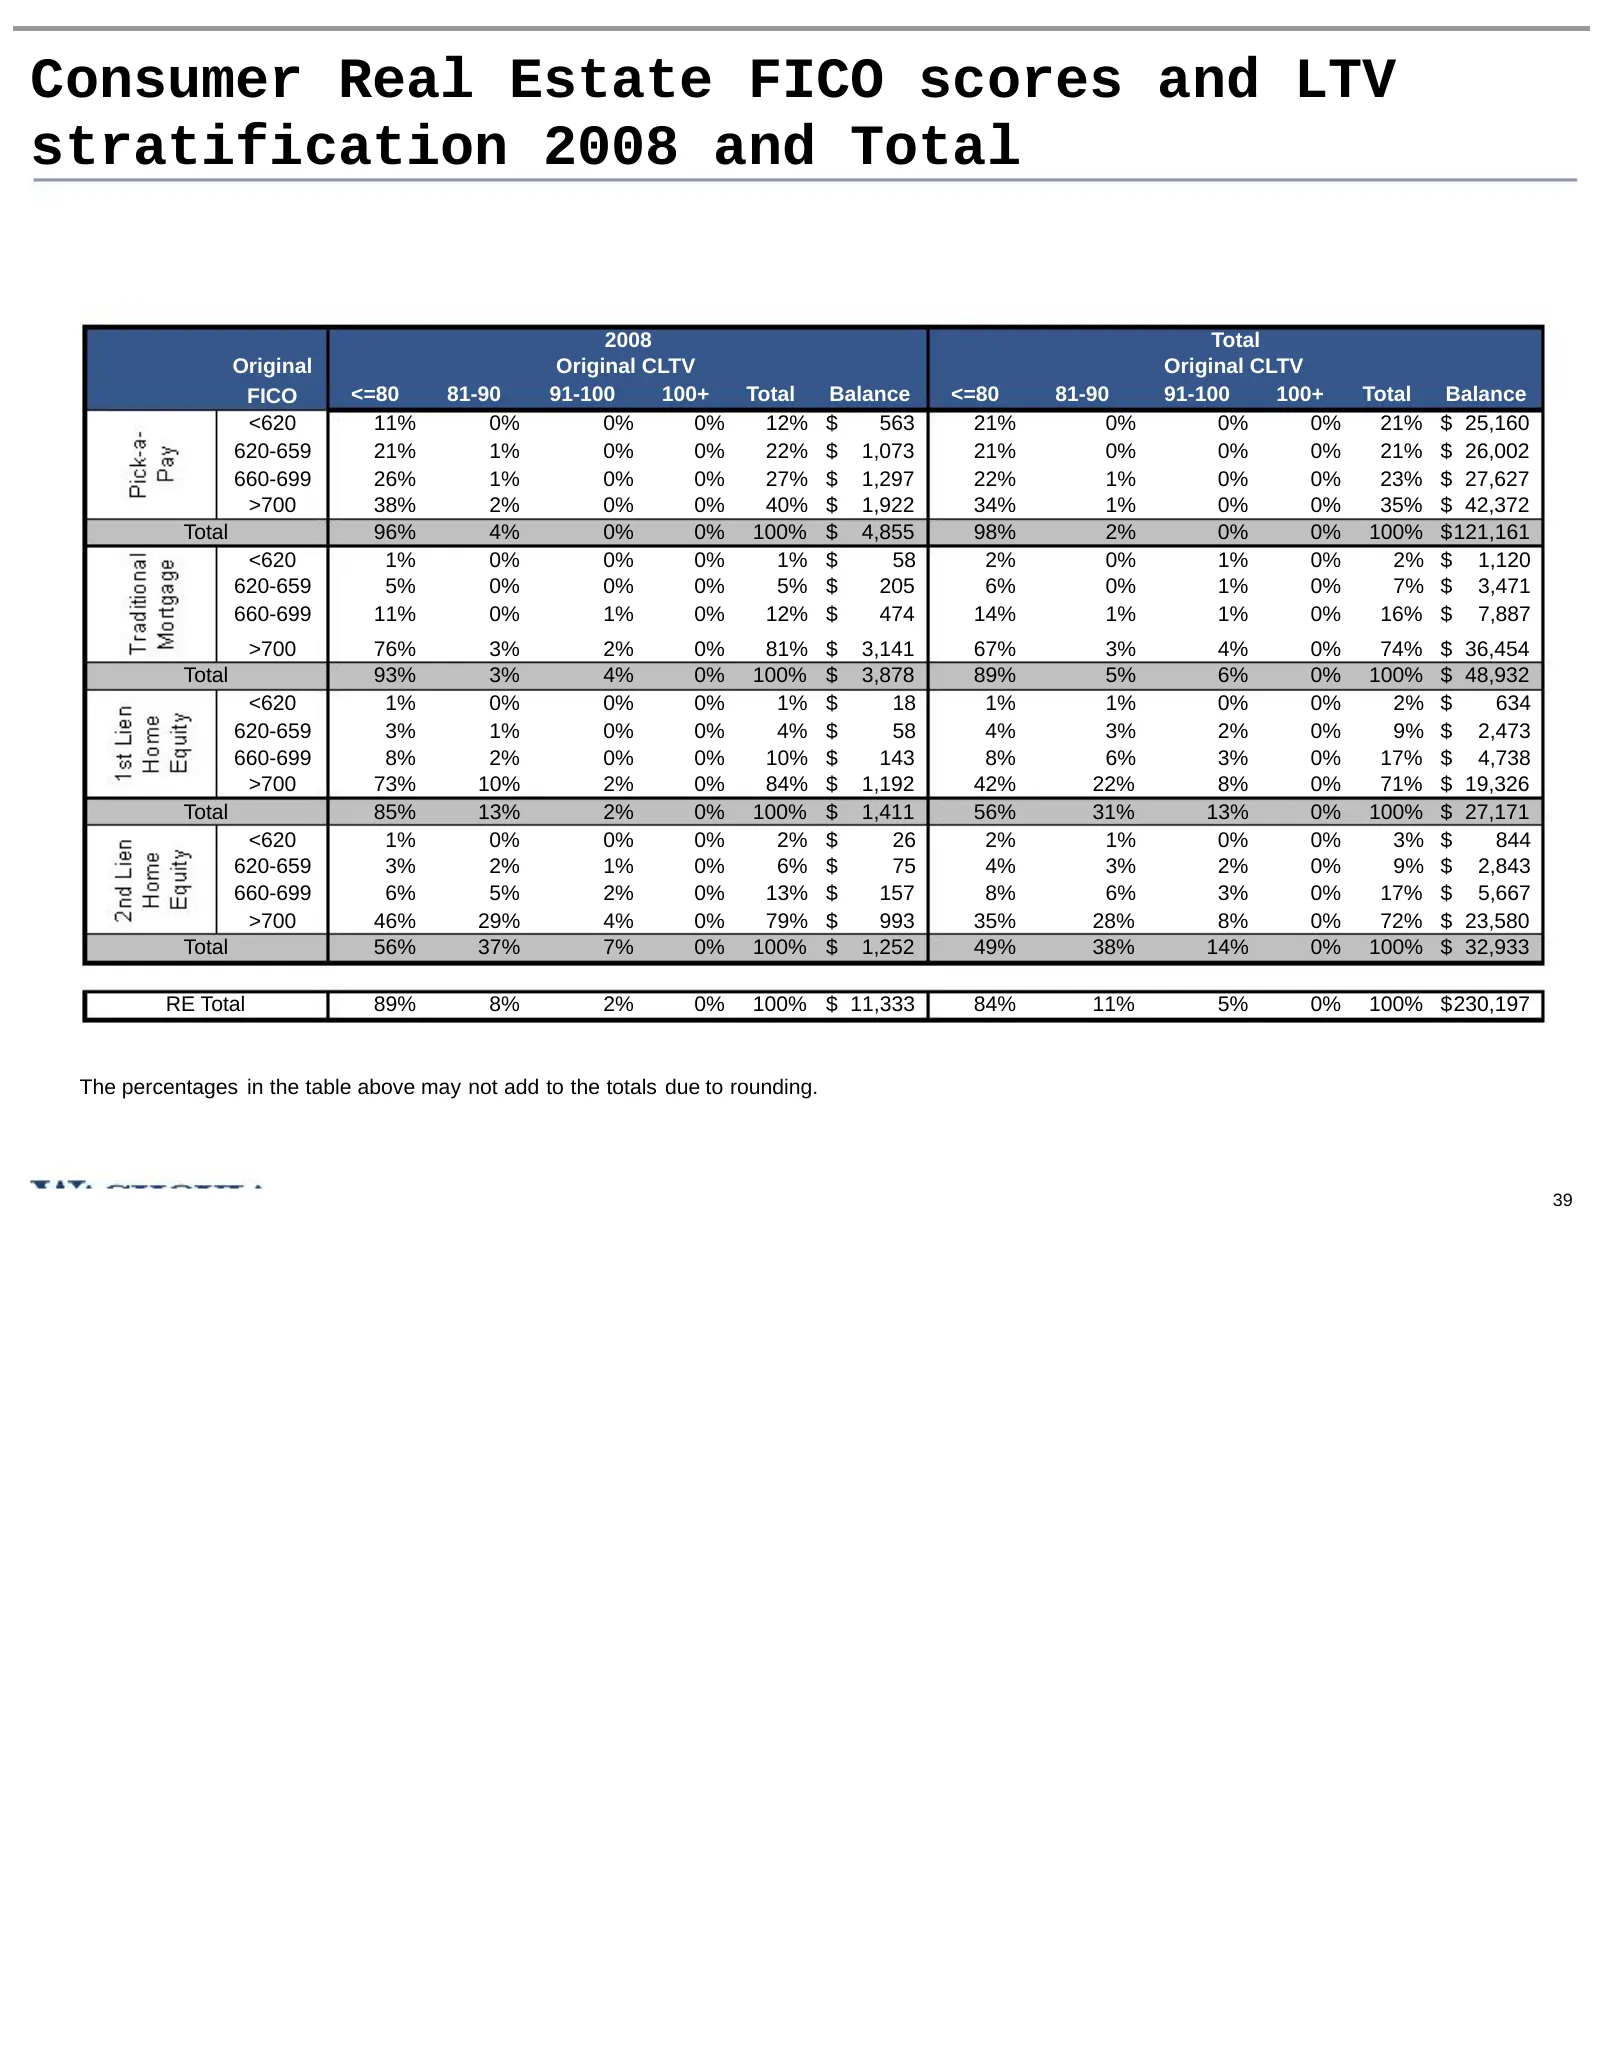
Slide 40: FICO and LTV stratification: 2008 and Total
Consumer Real Estate FICO scores and LTV stratification 2008 and Total 2008 Total Original Original CLTV Original CLTV FICO <=80 81-90 91-100 100+ Total Balance <=80 81-90 91-100 100+ Total Balance <620 11% 0% 0% 0% 12% $ 563 21% 0% 0% 0% 21% $ 25,160 620-659 21% 1% 0% 0% 22% $ 1,073 21% 0% 0% 0% 21
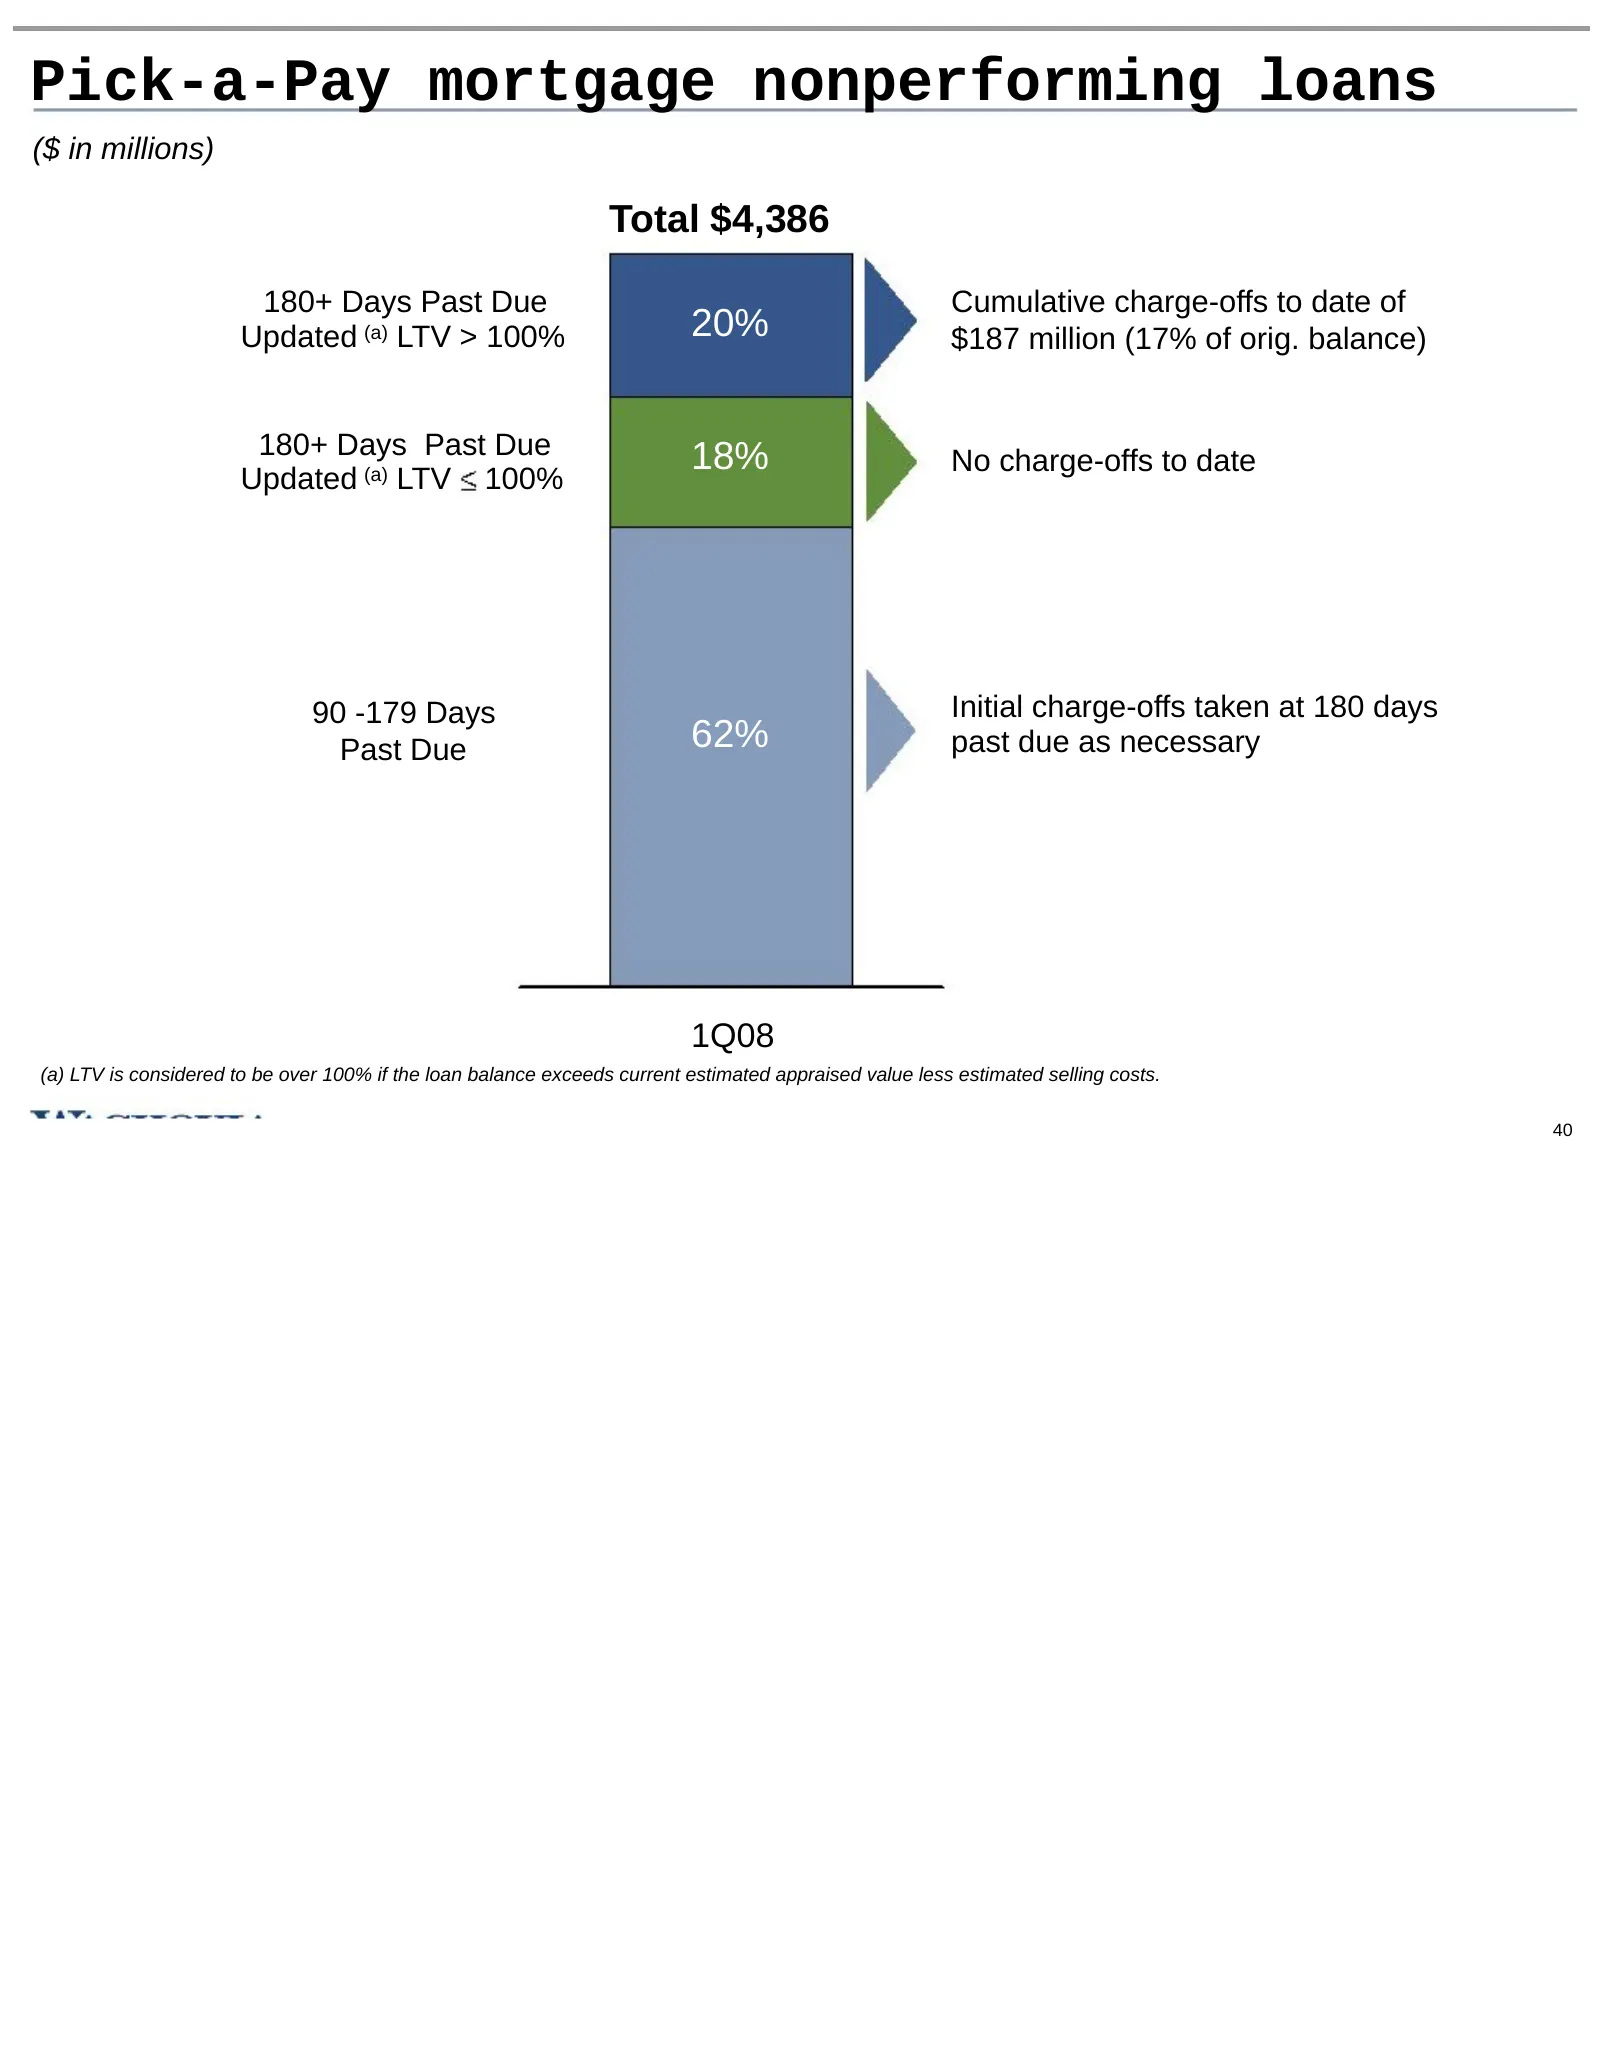
Slide 41: Pick-a-Pay mortgage nonperforming loans
Pick-a-Pay mortgage nonperforming loans ($ in millions) Total $4,386 180+ Days Past Due Cumulative charge-offs to date of Updated (a) LTV > 100% 20% $187 million (17% of orig. balance) 180+ Days Past Due 18% No charge-offs to date Updated (a) LTV 100% 90 -179 Days Initial charge-offs taken at 180 da
Slide 42: Pick-a-Pay reserve model: Our use of OFHEO in reserve modeling
Pick-a-Pay reserve model Our use of OFHEO in reserve modeling Office of Federal Housing Enterprise Oversight (OFHEO) is a widely recognized source of data that measures average price changes in home sales financed by conventional mortgages, purchased by Fannie Mae or Freddie Mac, and therefore the d
Slide 43: Cautionary statement
Cautionary statement The foregoing materials and management’s discussion of them may contain, among other things, certain forward-looking statements with respect to Wachovia, as well as the goals, plans, objectives, intentions, expectations, financial condition, results of operations, future perform
Slide 44: Notes on non-GAAP financial measures
Notes on non-GAAP financial measures The information contained herein includes certain non-GAAP financial measures. Please refer to our First Quarter 2008 Quarterly Earnings Report for additional information reconciling non-GAAP financial measures and for an important explanation of our use of non-G
Slide 45: Notes on non-GAAP financial measures
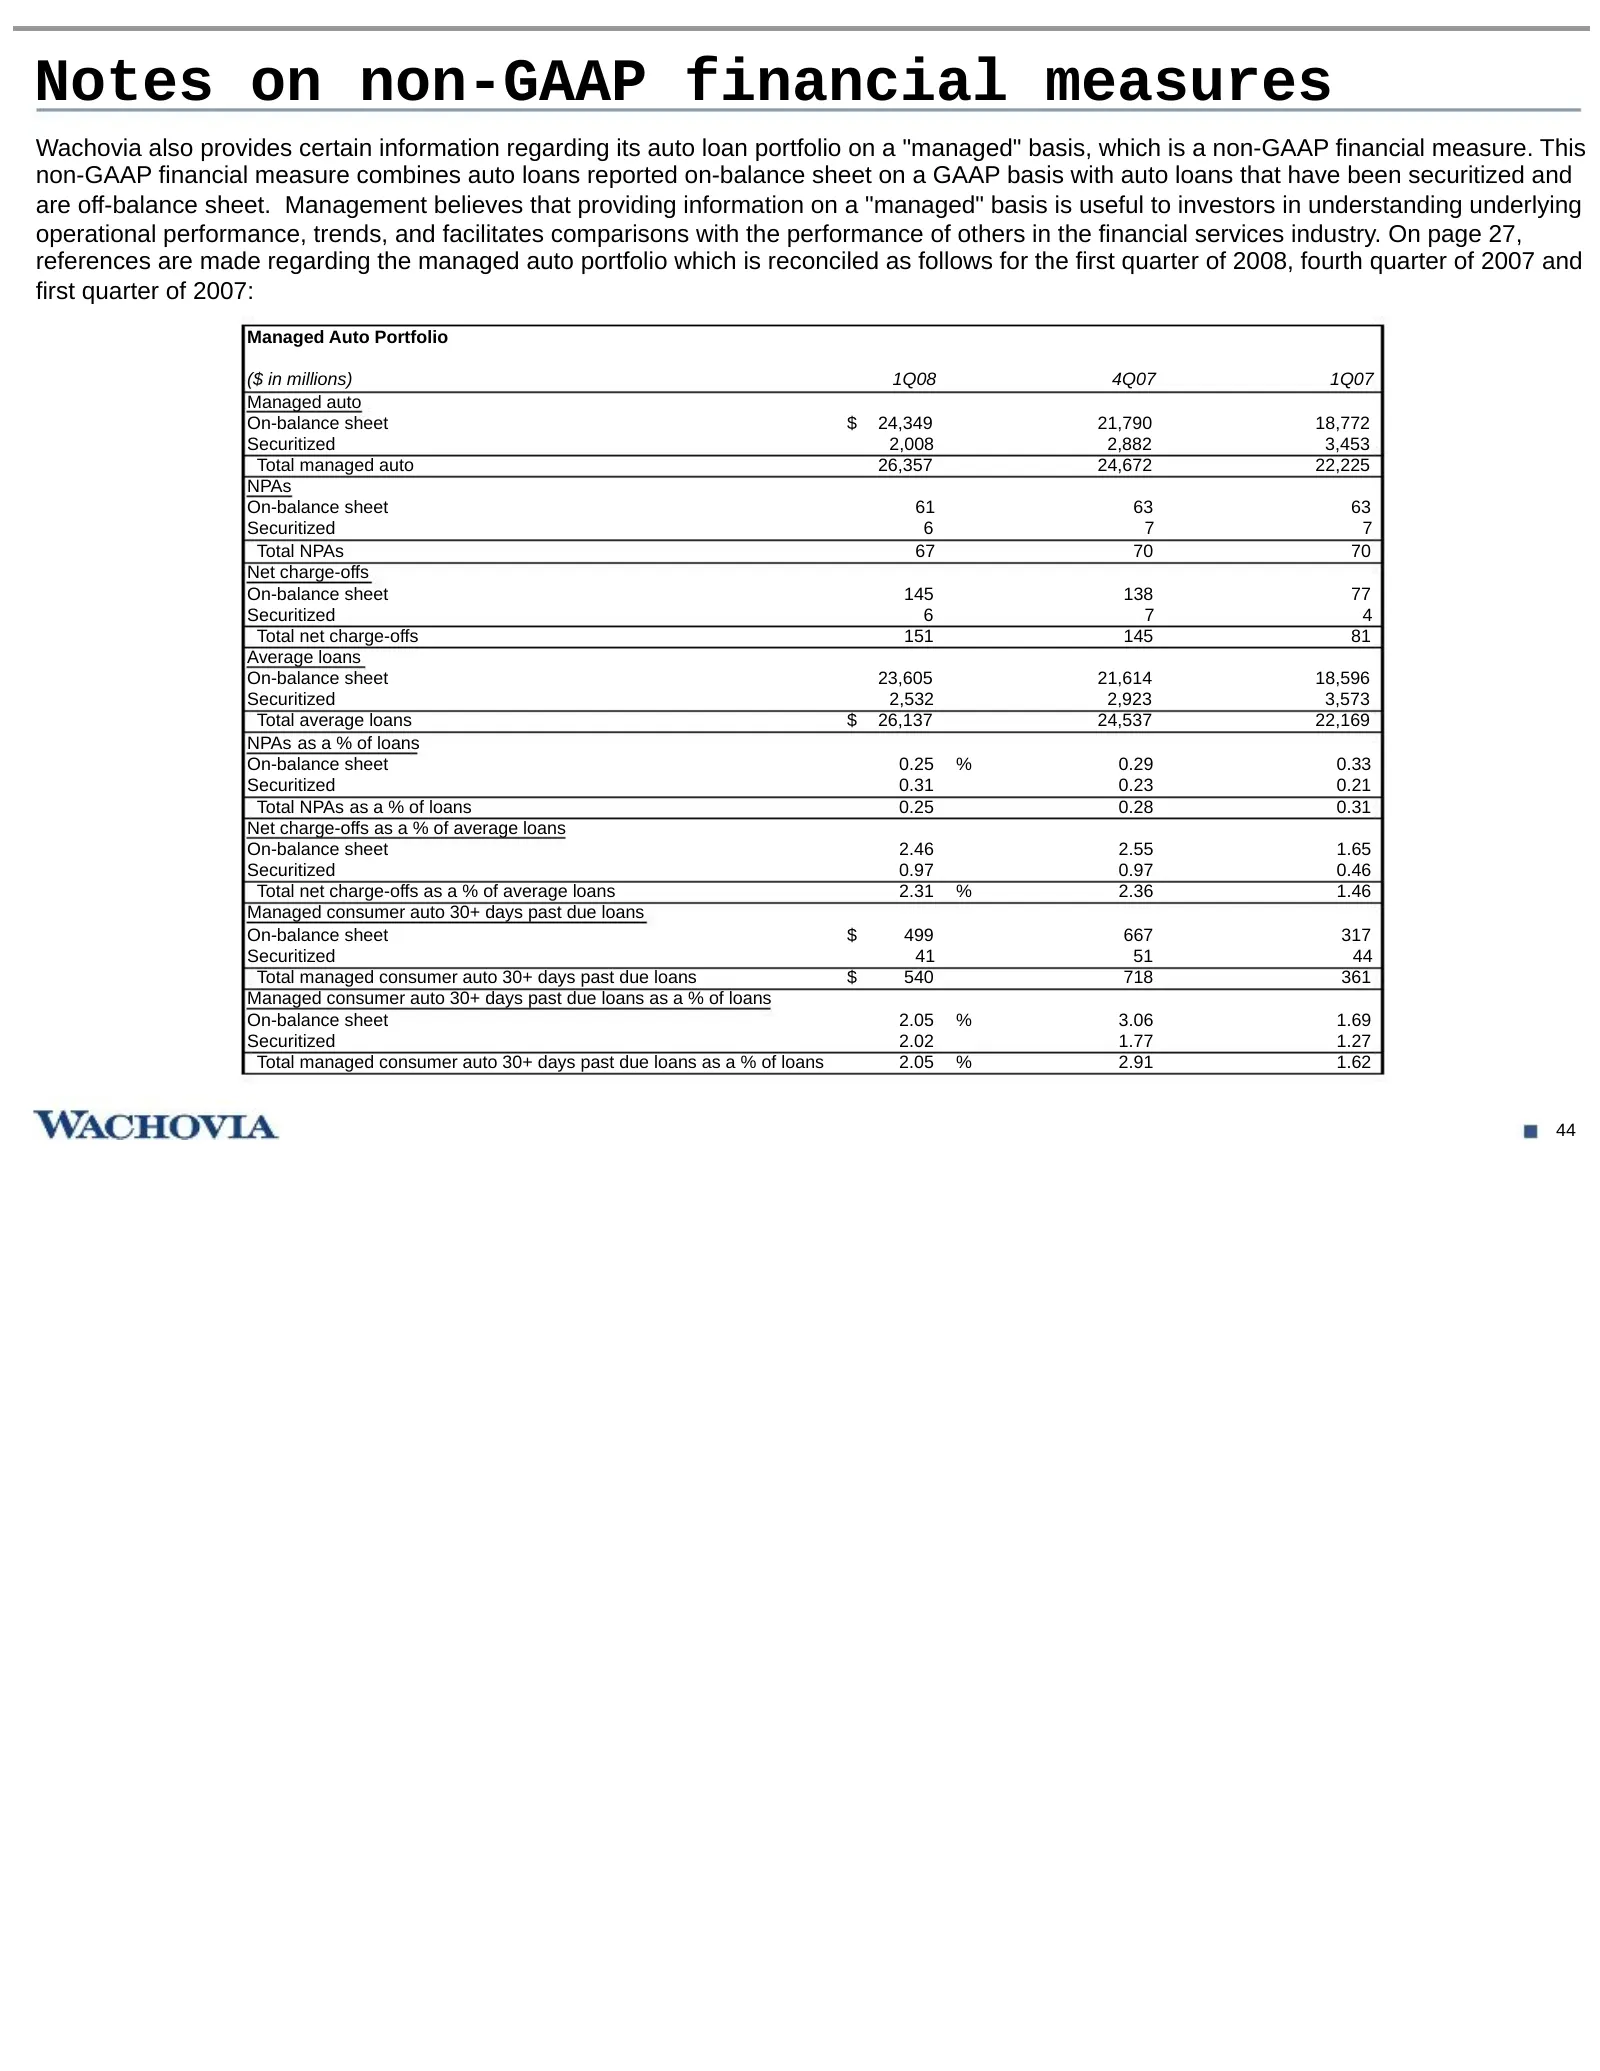
Notes on non-GAAP financial measures Wachovia also provides certain information regarding its auto loan portfolio on a "managed" basis, which is a non-GAAP financial measure. This non-GAAP financial measure combines auto loans reported on-balance sheet on a GAAP basis with auto loans that have been
Source: SEC EDGAR · 8-K filed Apr 14, 2008
More decks from Wachovia Corp New
 Q3 2008 Earnings Presentation41 slides · Oct 22, 2008
 Merger or Acquisition (October 2008)15 slides · Oct 3, 2008
 Lehman Brothers Global Financial Services Conference 200828 slides · Sep 9, 2008
 Q2 2008 Earnings Presentation56 slides · Jul 22, 2008
 IPO Roadshow (April 2008)104 slides · Apr 14, 2008
 Q4 2007 Earnings Presentation30 slides · Jan 22, 2008