Massey Energy — Investor Presentation (August 2006)
22 slides from Massey Energy's investor presentation, Aug 15, 2006
Slide 1: Investor Meetings
Investor Meetings Bear Stearns August 16, 2006 Don L. Blankenship / Chairman, President & Chief Executive Officer Baxter F. Phillips, Jr. / Executive Vice President & Chief Administrative Officer Exhibit 99.1 * *
Slide 2: Safe Harbor Statement
FORWARD-LOOKING STATEMENTS: certain statements in this presentation are forward-looking as defined by the private securities litigation reform act of 1995. Due to known and unknown risks, the company’s actual results may differ materially from its expectations or projections. Factors potentially con
Slide 3: Massey Energy Company
Massey Energy Company A leading provider of high- quality steam and metallurgical coal in Central Appalachia. * *
Slide 4: Massey's competitive advantage is based on our market-leading reserve base
2,260 Massey’s competitive advantage is based on our market-leading reserve base Note: 65 million tons of Massey reserves are located in Northern Appalachia
Slide 5: Our reserves represent an estimated one-third of total Central Appalachia reserves
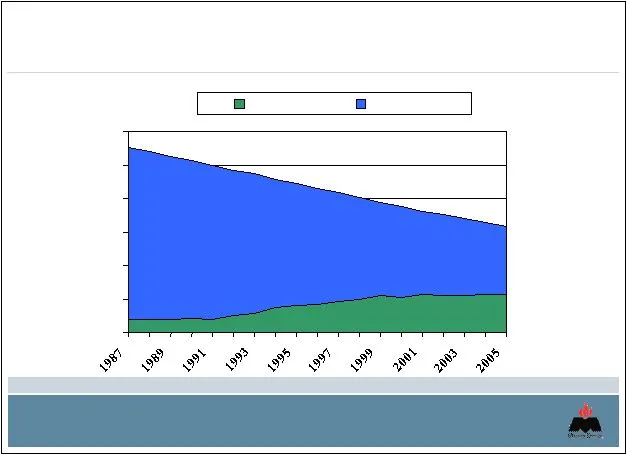
0.8 2.3 MEE Non-MEE (Central Appalachia Reserve Tons In Billions) Source: Energy Venture Analysis, Inc., Company estimates 11.0 6.3 Our reserves represent an estimated one-third of total Central Appalachia reserves
Slide 6: Central Appalachian production has been declining
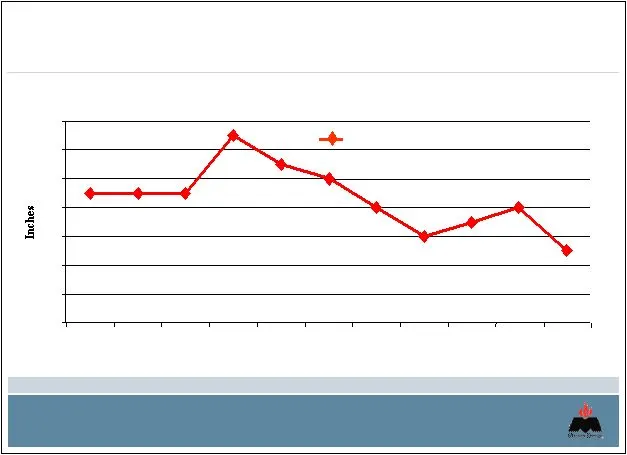
Source: Energy Information Administration Central Appalachian production has been declining, largely due to the diminishing supply of economic reserves Average seam thickness
Slide 7: Reserve degradation in Central Appalachia has negatively impacted productivity
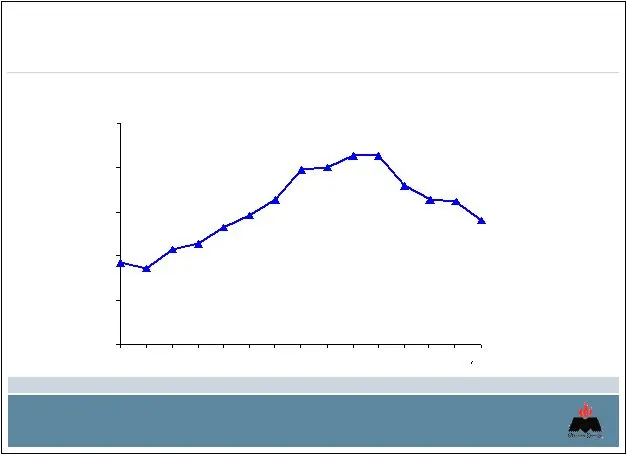
Reserve degradation in Central Appalachia has negatively impacted productivity Source: Energy Information Administration , MSHA 2.00 2.50 3.00 3.50 4.00 4.50 (tons per employee hour)
Slide 8: CAPP production projections: declining supply and rising costs to continue for competitors
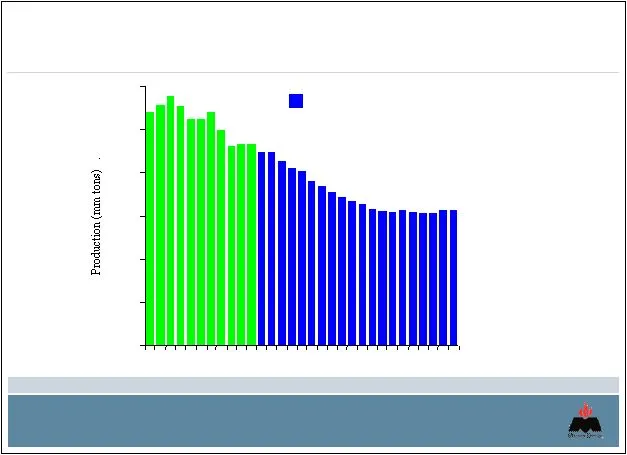
Source: Energy Information Administration historical information and projections CAPP Production Projections The trend of declining supply and rising costs are expected to continue for our competitors
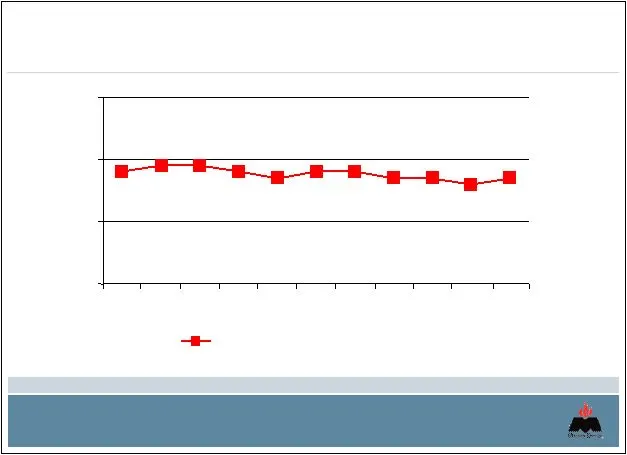
Slide 9: Massey's underground reserves have evidenced little degradation
Massey’s numerous and high-quality underground reserves have evidenced little degradation 2006P 2008P 2010P Underground mine tons/foot
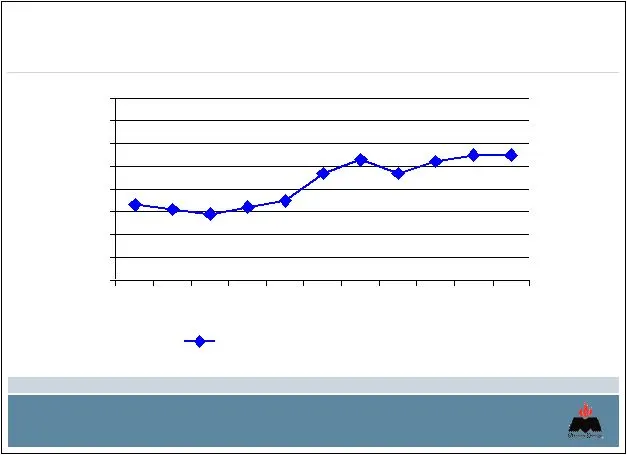
Slide 10: Massey's surface mine reserves have not evidenced significant degradation
Massey’s extensive surface mine reserves have not evidenced significant degradation 2006P 2008P 2010P Surface mine tons/yard (ratio)
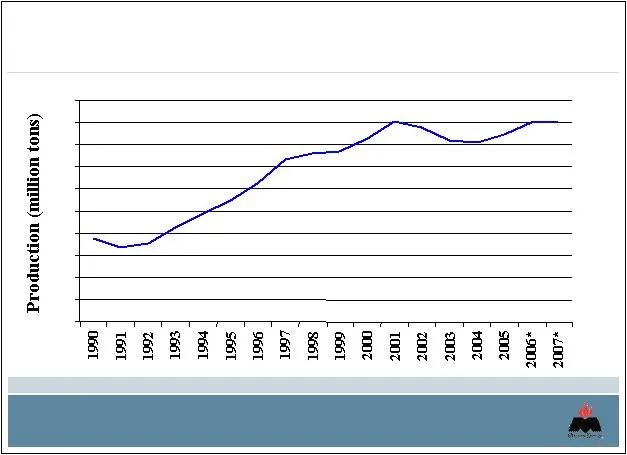
Slide 11: Massey's production in Central Appalachia continued to increase
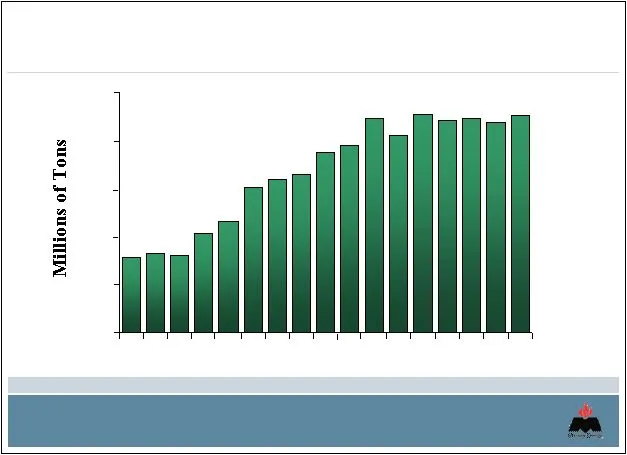
Massey’s production in Central Appalachia continued to increase due to our growing reserve base and low costs
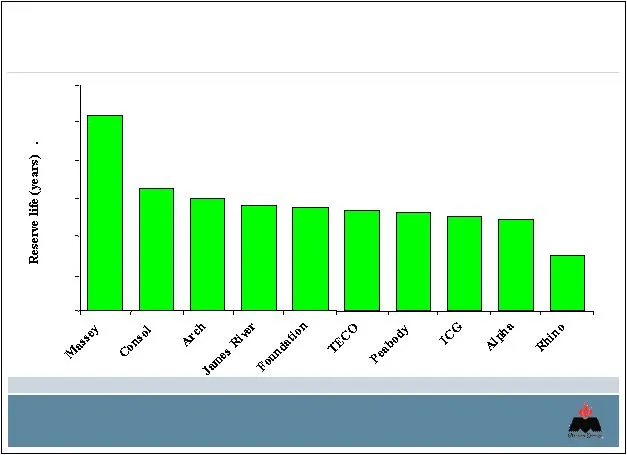
Slide 12: Massey is better able to sustain production volume at a low cost
Massey is better able to sustain production volume at a low cost due to its extensive reserve base in Central Appalachia Source: Production estimates based on internal estimates and company reports .
Slide 13: Massey has a diversity of product to meet customer needs
100% 42% 63% 37% 2,260 mil. 943 mil. 1,413 mil. 847 mil. Total Compliance -1% Sulfur + 1% Sulfur Massey has a diversity of product to meet customer needs Reserves @ 12/31/05 (tons) 22% Metallurgical 9% Industrial 69% Utility 2005 Produced Tons Sold
Slide 14: Massey's asset base provides a significant cost advantage
• Massey’s asset base provides a significant cost advantage vs. our Central Appalachian competitors - and we believe it will increase as regional reserves are depleted • This accelerating cost advantage translates into shareholder value not captured by traditional earnings or EBITDA multiples Shareh
Slide 15: Massey remains a low-cost producer in Central Appalachia
Massey remains a low-cost producer in Central Appalachia $41.00 – 41.50 Central Appalachia competitors $35.62 Massey 2005 Average Cash Cost ($/ton)* * Cash costs exclude DD&A and includes SG&A Source: Competitors’ cash costs developed from competitors’ company reports
Slide 16: Massey Margin Advantage
Massey Margin Advantage 22% of total production vs. competitor average of 9% Metallurgical production advantage: Premium reserves Lower royalties Best practices Equipment infrastructure Lower legacy liability expense Cost Advantage: Over the long-term, Massey is expected to record higher per ton mar
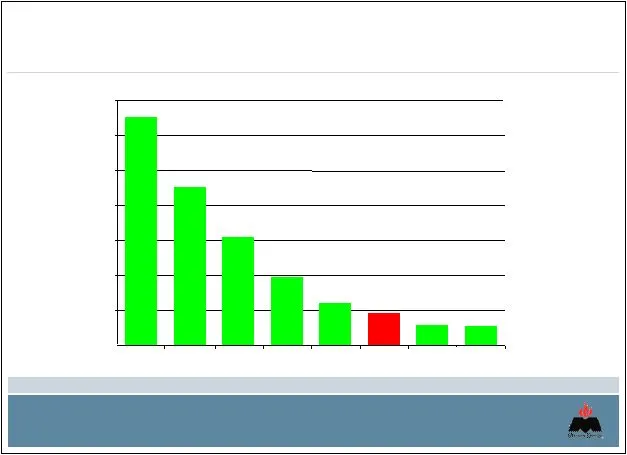
Slide 17: Low Legacy Liabilities
Low Legacy Liabilities 2005 Legacy Liabilities as a Percentage of Net Worth* * Net worth defined as shareholders equity less intangibles Source : Company reports CONSOL Foundation James River Peabody Alpha Massey ICG Arch
Slide 18: Massey's increasing competitive advantage
• Massey’s increasing competitive advantage should translate into increased and sustainable shareholder value • Over time, Massey should realize cash flow growth with or without volume growth - via margin expansion Massey Competitive Advantage
Slide 19: Current Massey focus on further margin expansion through management of cash costs
Current Massey focus on further margin expansion through management of cash costs • Re-start Aracoma longwall • Continue to increase surface mine capacity • Idle four high cost underground mining sections • Shut Rockhouse longwall • Optimize staffing to improve productivity
Slide 20: Massey Creating Long-term Value
• Foremost producer in Central Appalachia with increasing market share • Leading Central Appalachian reserve base enables long- term organic growth • Capital discipline to optimize leverage and liquidity requirements • Safety, community and environmental stewardship programs that improve ‘Our Total
Slide 21: Disclaimer
Disclaimer FORWARD-LOOKING STATEMENTS: certain statements in this presentation are forward-looking as defined by the private securities litigation reform act of 1995. Such forward-looking statements are based on facts and conditions as they exist at the time such statements are made as well as predi
Slide 22: Doing the Right Thing…with Energy
Doing the Right Thing…with Energy
Source: SEC EDGAR · 8-K filed Aug 15, 2006
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Credit Suisse Energy Summit 201126 slides · Feb 10, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010