MainSource Financial Group Inc
MainSource Financial — Investor Presentation (November 2012)
35 slides from MainSource Financial's investor presentation, Nov 16, 2012
Slide 1: MainSource Financial Group
<M, MainSource FINANCIAL GROUP
Slide 2: Disclosure Regarding Forward Looking Statements
Disclosure Regarding Forward Looking Statements This presentation may include forward-looking statements regarding, among other things, MainSource’s business strategy, financial position and prospects, dividend policy, business results, strategic initiatives, credit quality including reserve levels,
Slide 3: Franchise Overview
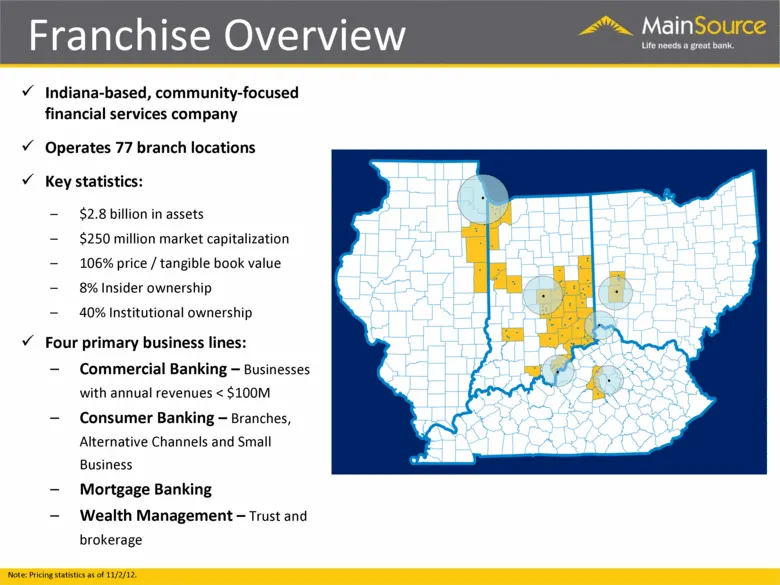
Indiana-based, community-focused financial services company Operates 77 branch locations Key statistics: $2.8 billion in assets $250 million market capitalization 106% price / tangible book value 8% Insider ownership 40% Institutional ownership Four primary business lines: Commercial Banking – Busin
Slide 4: Historical Highlights
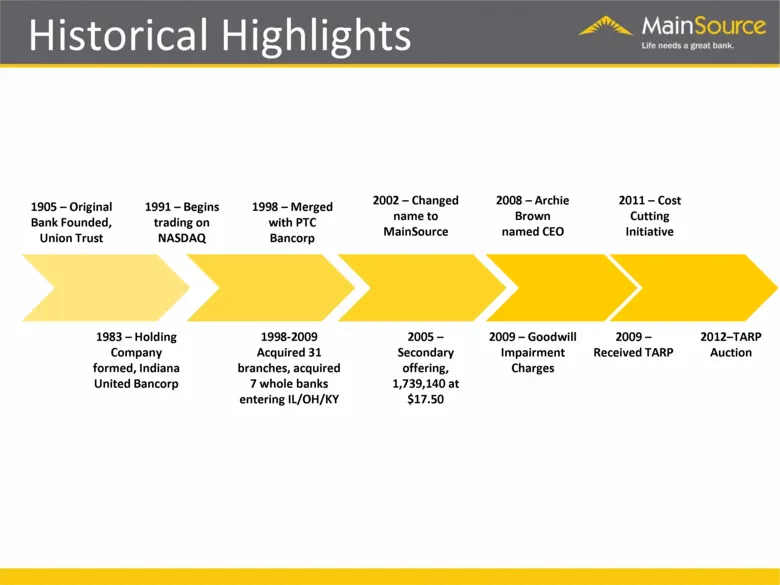
Historical Highlights 1905 – Original Bank Founded, Union Trust 1983 – Holding Company formed, Indiana United Bancorp 1991 – Begins trading on NASDAQ 1998 – Merged with PTC Bancorp 1998-2009 Acquired 31 branches, acquired 7 whole banks entering IL/OH/KY 2002 – Changed name to MainSource 2005 – Secon
Slide 5: High Quality People
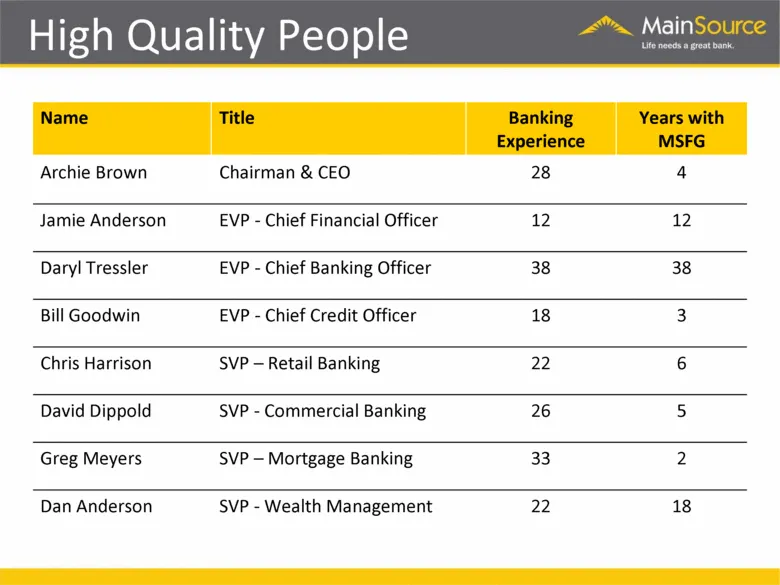
Name Title Banking Experience Years with MSFG Archie Brown Chairman & CEO 28 4 Jamie Anderson EVP - Chief Financial Officer 12 12 Daryl Tressler EVP - Chief Banking Officer 38 38 Bill Goodwin EVP - Chief Credit Officer 18 3 Chris Harrison SVP – Retail Banking 22 6 David Dippold SVP - Commercial Bank
Slide 6: Core Strategy
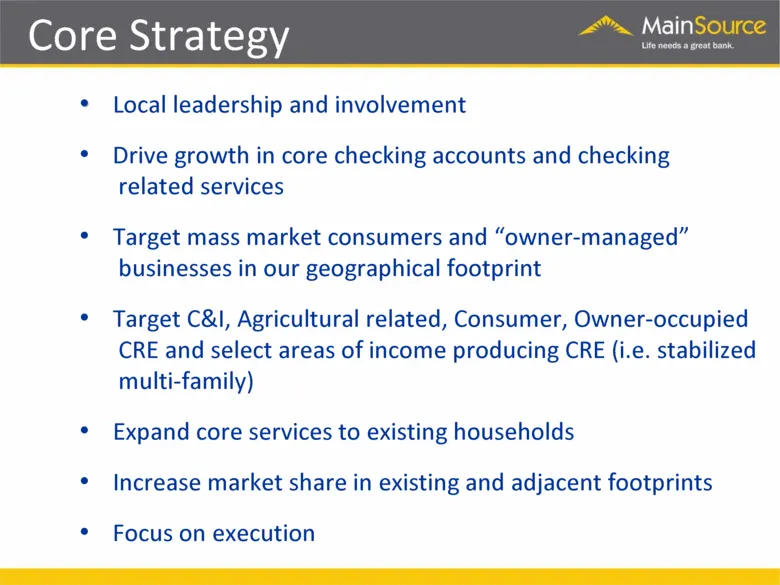
Local leadership and involvement Drive growth in core checking accounts and checking related services Target mass market consumers and “owner-managed” businesses in our geographical footprint Target C&I, Agricultural related, Consumer, Owner-occupied CRE and select areas of income producing CRE (i.e
Slide 7: Total Assets and Loans
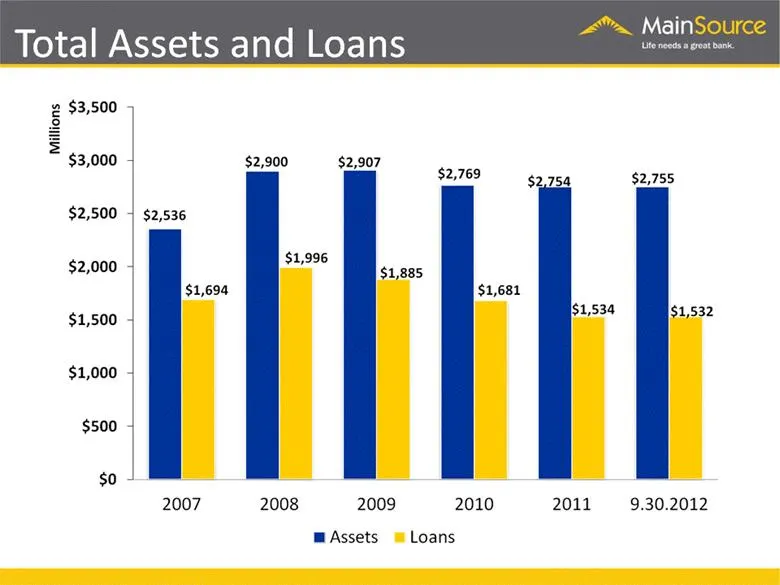
tal Assets and Loans 2 $3,500 $3,000 ~ $2,900 $2,907 $2,769 $9754 $2,755 $2,500 ~ $2,536 $1,996 $2,000 ~ $1,885 $1,694 $1,681 $1,500 - $1,534 $1,532 $1,000 ~ $500 ~ $o + 2007 2008 2009 2010 2011 -9.30.2012 MAssets ™ Loans
Slide 8: Growing Core Funding
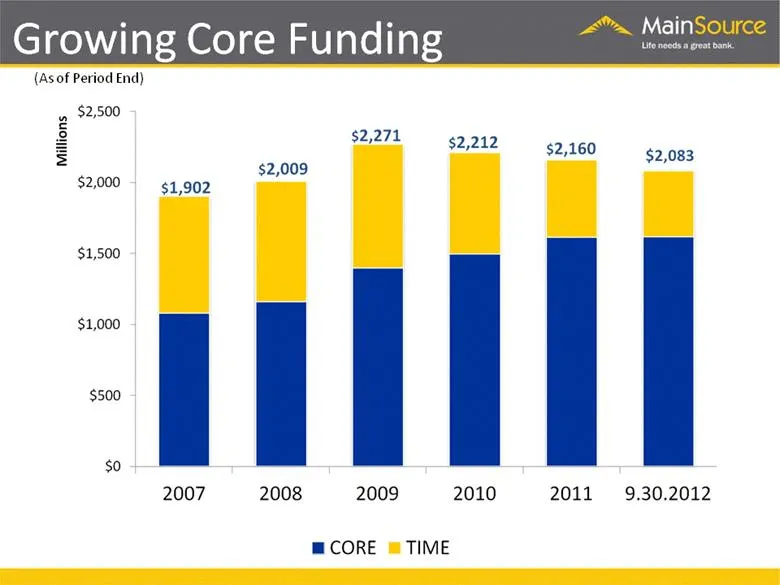
Growing Core Funding (As of Period End)
Slide 9: Investment Portfolio
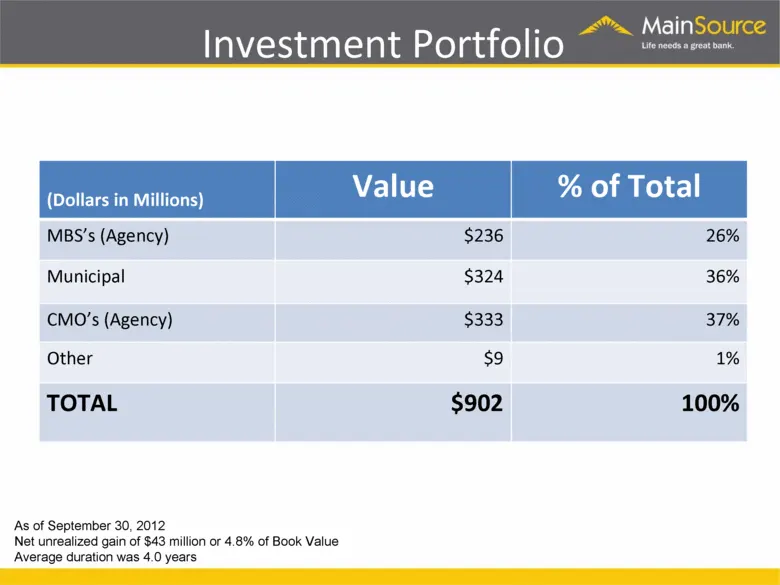
Investment Portfolio (As of 9.30.12) (Dollars in Millions) Value % of Total MBS’s (Agency) $236 26% Municipal $324 36% CMO’s (Agency) $333 37% Other $9 1% TOTAL $902 100% As of September 30, 2012 Net unrealized gain of $43 million or 4.8% of Book Value Average duration was 4.0 years
Slide 10: Loan Portfolio
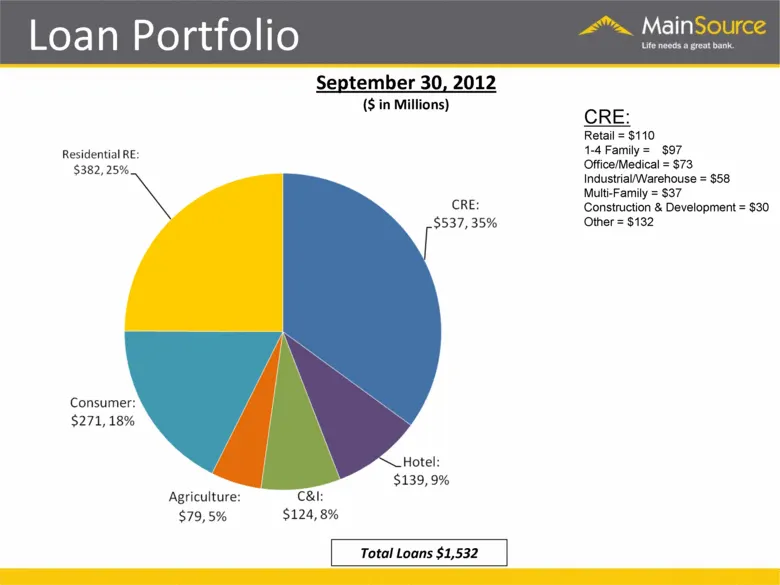
Loan Portfolio Total Loans $1,532 September 30, 2012 ($ in Millions) CRE: Retail = $110 1-4 Family = $97 Office/Medical = $73 Industrial/Warehouse = $58 Multi-Family = $37 Construction & Development = $30 Other = $132
Slide 11: Asset Quality
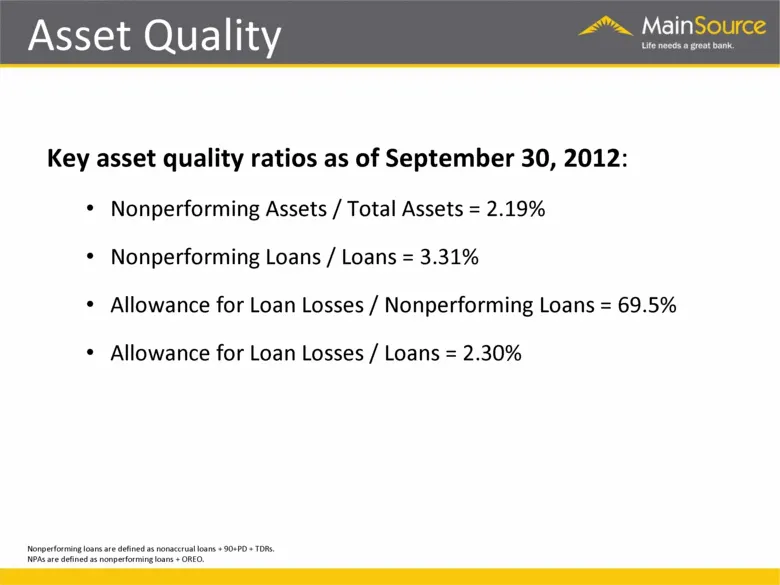
Key asset quality ratios as of September 30, 2012: Nonperforming Assets / Total Assets = 2.19% Nonperforming Loans / Loans = 3.31% Allowance for Loan Losses / Nonperforming Loans = 69.5% Allowance for Loan Losses / Loans = 2.30% Nonperforming loans are defined as nonaccrual loans + 90+PD + TDRs. NPA
Slide 12: Risk Trends
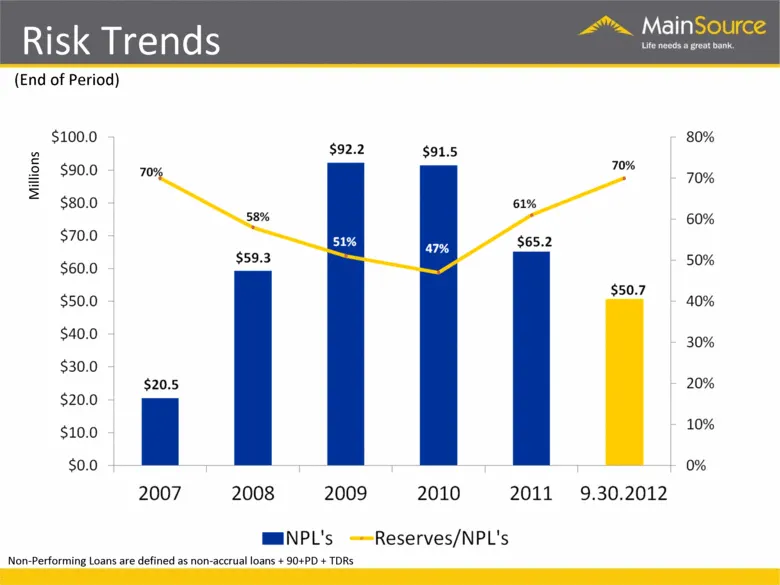
Risk Trends Millions (End of Period) Non-Performing Loans are defined as non-accrual loans + 90+PD + TDRs
Slide 13: Adversely Classified Assets
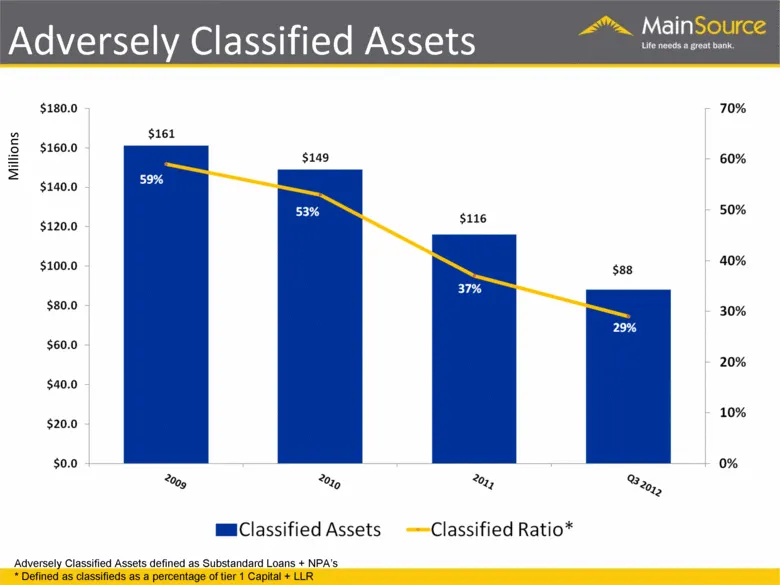
Adversely Classified Assets Millions Adversely Classified Assets defined as Substandard Loans + NPA’s * Defined as classifieds as a percentage of tier 1 Capital + LLR
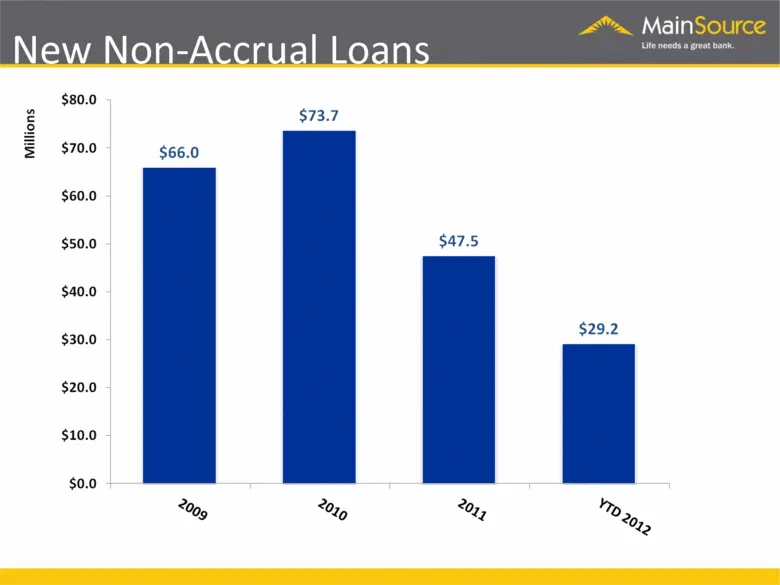
Slide 14: $80.0 $73.7 $70.0 $66.0 $60.0 50. $50.0 $47.5 $40.0 $30.0 $29.2 $20.0 $10.0 $0.0
$80.0 $73.7 $70.0 $66.0 $60.0 50. $50.0 $47.5 $40.0 $30.0 $29.2 $20.0 $10.0 $0.0 ) 00g 7) 204,
Slide 15: Provision & Net Charge-Offs
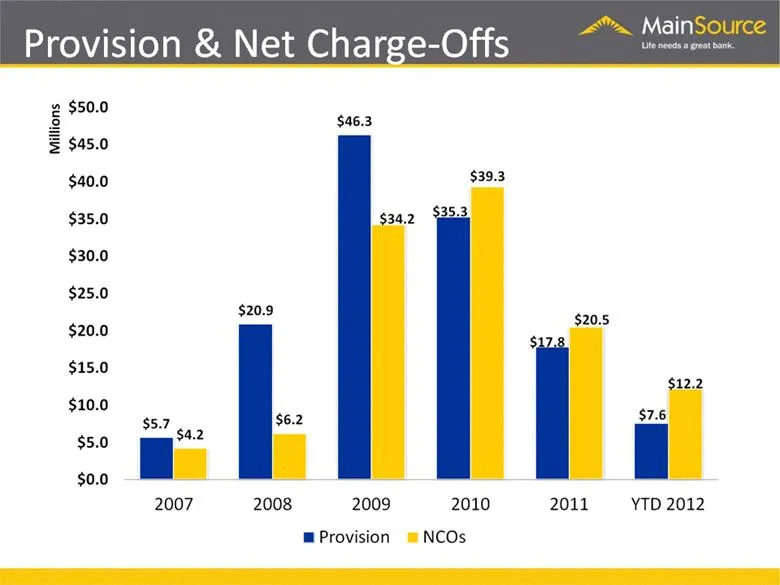
Provision & Net C $46.3 $39.3 $34.2 - $20.9 $208 % $12.2 $6.2 Ul 2008 2009 2010 2011 YTD 2012 @ Provision NCOs
Slide 16: Credit Process
Credit approval is centralized and includes committees for larger loans Cash flow orientation with emphasis on primary and secondary sources of repayment. Personal guarantees are required on virtually all business loans Lend in geographical footprint Credit Process
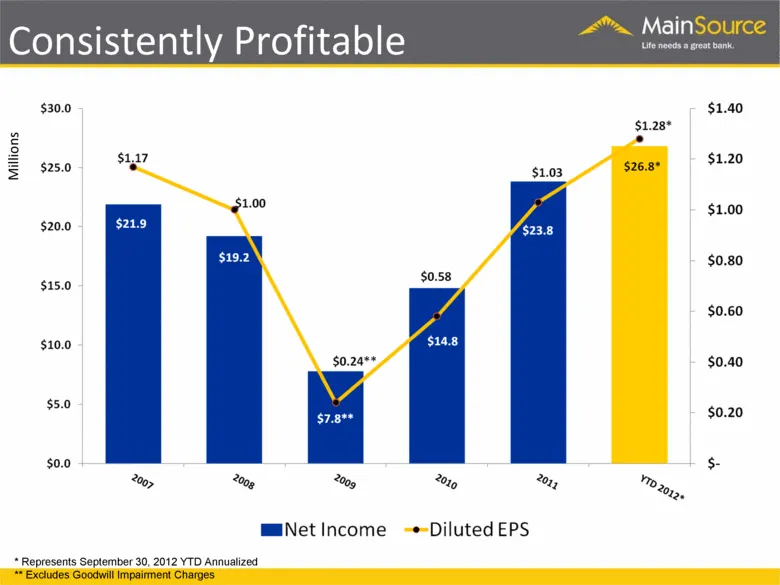
Slide 17: Consistently Profitable
Consistently Profitable Millions * Represents September 30, 2012 YTD Annualized ** Excludes Goodwill Impairment Charges
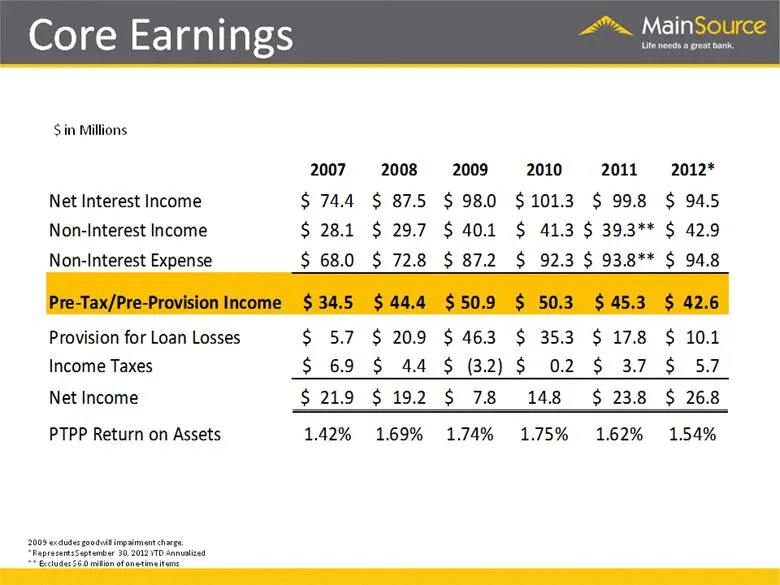
Slide 18: Core Earnings
$ in Millions 2009 excludes goodwill impairment charge. *Represents September 30, 2012 YTD Annualized ** Excludes $6.0 million of one-time items Core Earnings 2007 2008 2009 2010 2011 2012* Net Interest Income 74.4 $ 87.5 $ 98.0 $ 101.3 $ 99.8 $ 94.5 $ Non-Interest Income 28.1 $ 29.7 $ 40.1 $ 41.3 $
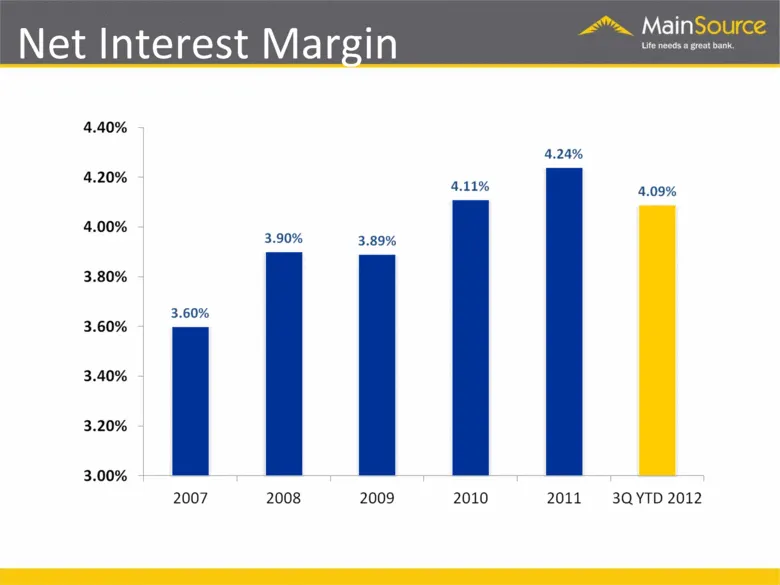
Slide 19: 4.40% 4.20% 4.00% 3.80% 3.60% 3.40% 3.20% 3.00% 4.24% 4.11% 4.09% 3.90% 3.89% I
4.40% 4.20% 4.00% 3.80% 3.60% 3.40% 3.20% 3.00% 4.24% 4.11% 4.09% 3.90% 3.89% I : : 2007 2008 2009 2010 2011 = 3QYTD 2012
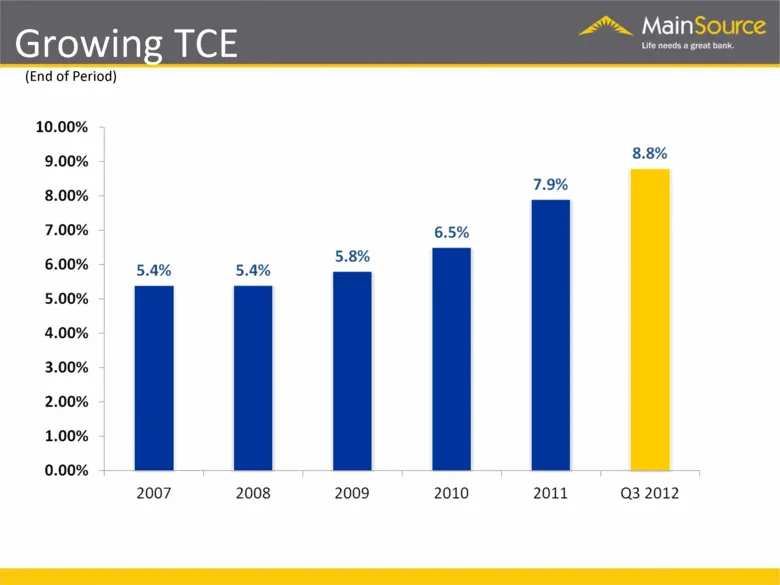
Slide 20: 2% MainSource
2% MainSource (End of Period) 10.00% 9.00% aoe 8.00% 7.9% 7.00% 6.5% 6.00% 5. 40 aoe 5.00% 4.00% 3.00% 2.00% 1.00% 0.00% 2007 2008 2009 2010 2011 Q3 2012
Slide 21: Strong Regulatory Capital
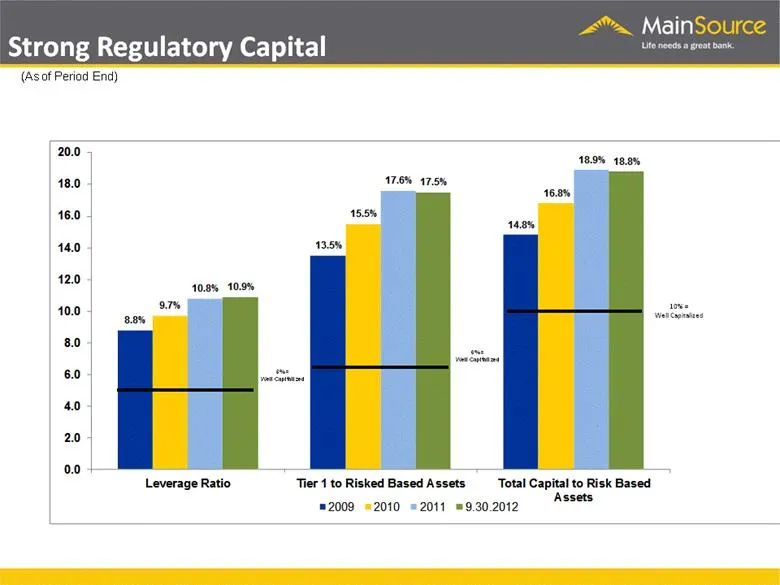
5% = Well Capitalized 6% = Well Capitalized 10% = Well Capitalized Strong Regulatory Capital (As of Period End) 8.8% 13.5% 14.8% 9.7% 15.5% 16.8% 10.8% 17.6% 18.9% 10.9% 17.5% 18.8% 0.0 2.0 4.0 6.0 8.0 10.0 12.0 14.0 16.0 18.0 20.0 Leverage Ratio Tier 1 to Risked Based Assets Total Capital to Risk B
Slide 22: 3rd Quarter 2012 Highlights
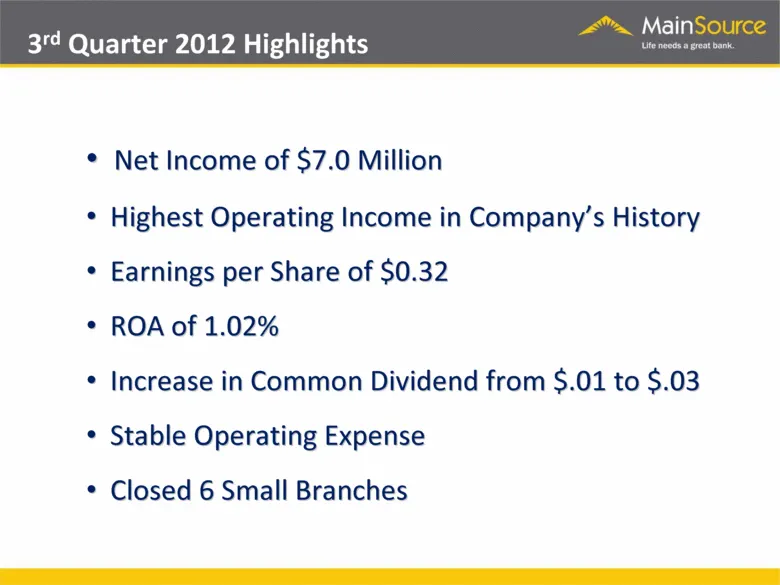
Net Income of $7.0 Million Highest Operating Income in Company’s History Earnings per Share of $0.32 ROA of 1.02% Increase in Common Dividend from $.01 to $.03 Stable Operating Expense Closed 6 Small Branches 3rd Quarter 2012 Highlights
Slide 23: 2012 Strategic Priorities
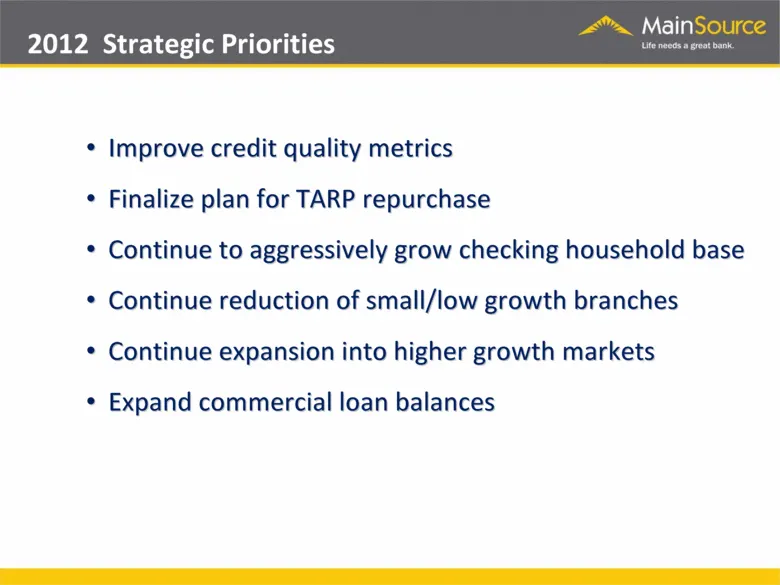
Improve credit quality metrics Finalize plan for TARP repurchase Continue to aggressively grow checking household base Continue reduction of small/low growth branches Continue expansion into higher growth markets Expand commercial loan balances 2012 Strategic Priorities
Slide 24: New Checking Accounts Opened
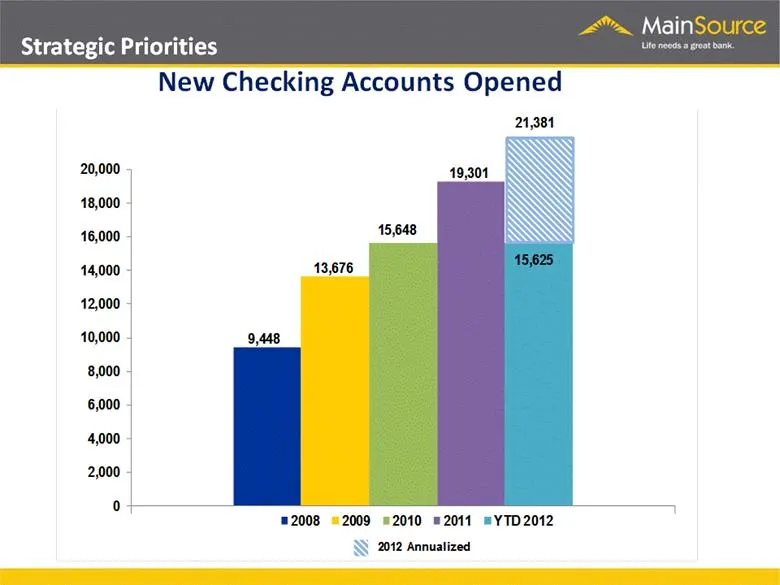
New Checking Accounts Opened Strategic Priorities 9,448 13,676 0 2,000 4,000 6,000 8,000 10,000 12,000 14,000 16,000 18,000 20,000 2008 2009 2010 2011 YTD 2012 15,648 19,301 15,625 21,381 2012 Annualized
Slide 25: Total Checking Accounts
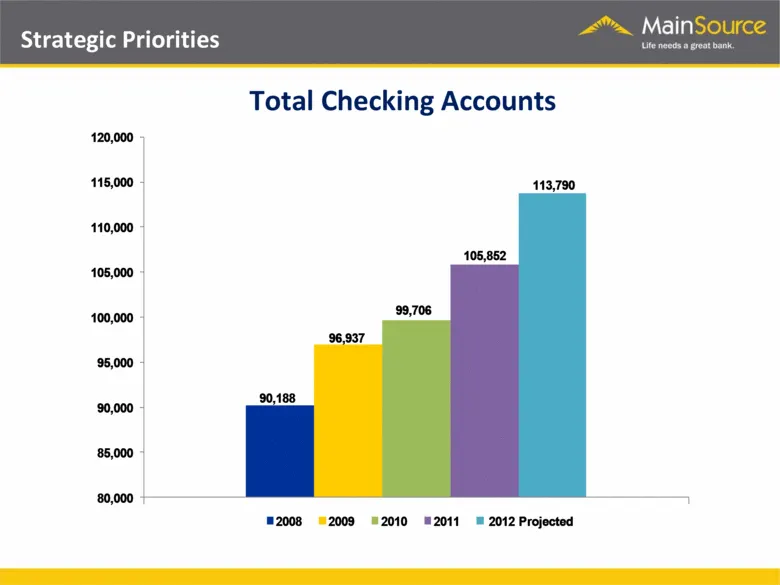
Total Checking Accounts Strategic Priorities 90,188 96,937 80,000 85,000 90,000 95,000 100,000 105,000 110,000 115,000 120,000 2008 2009 2010 2011 2012 Projected 99,706 105,852 113,790
Slide 26: Strategic Expansion
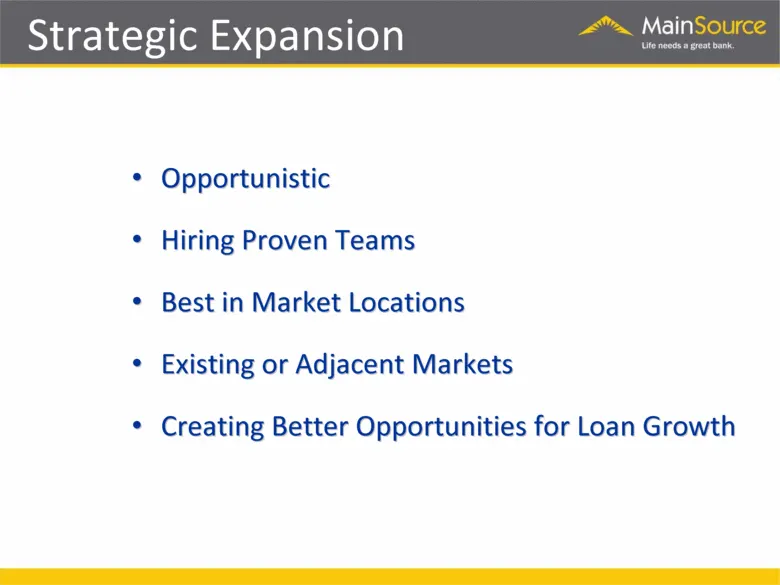
Opportunistic Hiring Proven Teams Best in Market Locations Existing or Adjacent Markets Creating Better Opportunities for Loan Growth Strategic Expansion
Slide 27: Columbus, Indiana
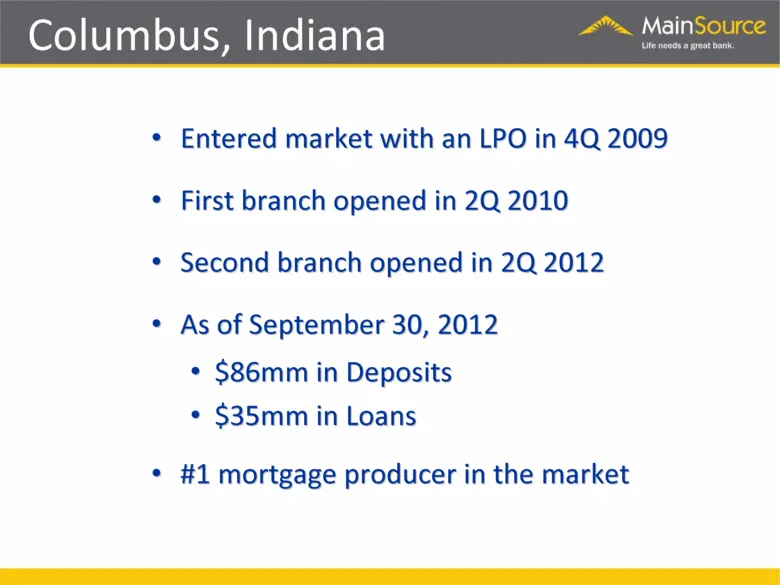
Entered market with an LPO in 4Q 2009 First branch opened in 2Q 2010 Second branch opened in 2Q 2012 As of September 30, 2012 $86mm in Deposits $35mm in Loans #1 mortgage producer in the market Columbus, Indiana
Slide 28: Seymour, Indiana
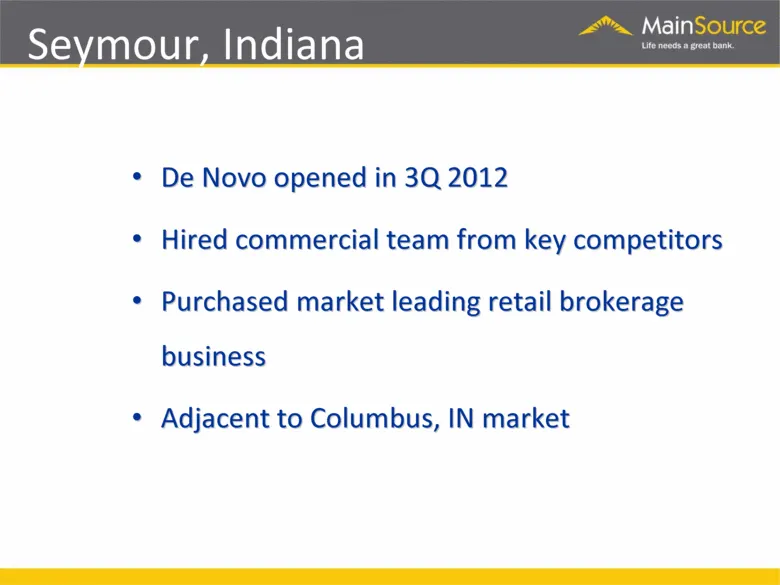
De Novo opened in 3Q 2012 Hired commercial team from key competitors Purchased market leading retail brokerage business Adjacent to Columbus, IN market Seymour, Indiana
Slide 29: Indianapolis Expansion
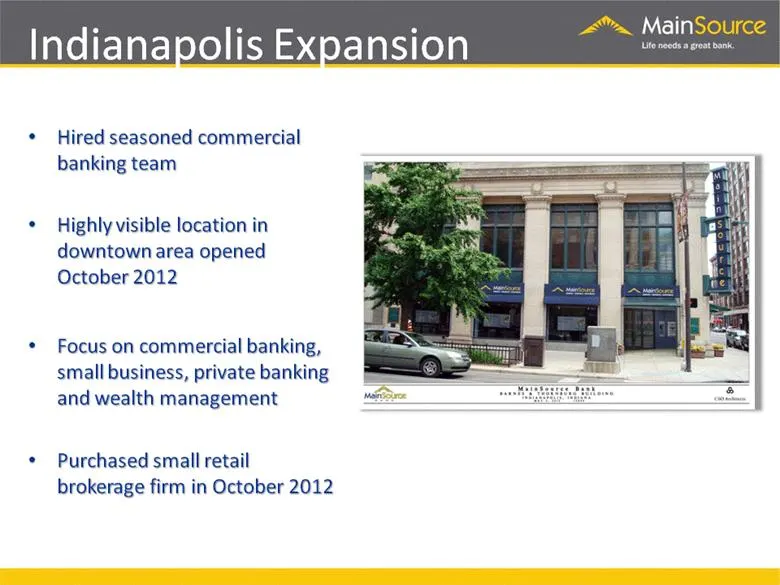
Hired seasoned commercial banking team Highly visible location in downtown area opened October 2012 Focus on commercial banking, small business, private banking and wealth management Purchased small retail brokerage firm in October 2012 Indianapolis Expansion
Slide 30: Shelbyville, KY/East Louisville
Announced branch purchase on August 28th, 2012 Closing in 4Q 2012 $35mm in Deposits and Loans Creates entry point for Eastern Louisville loan presence Shelbyville, KY/East Louisville
Slide 31: 2% MainSource
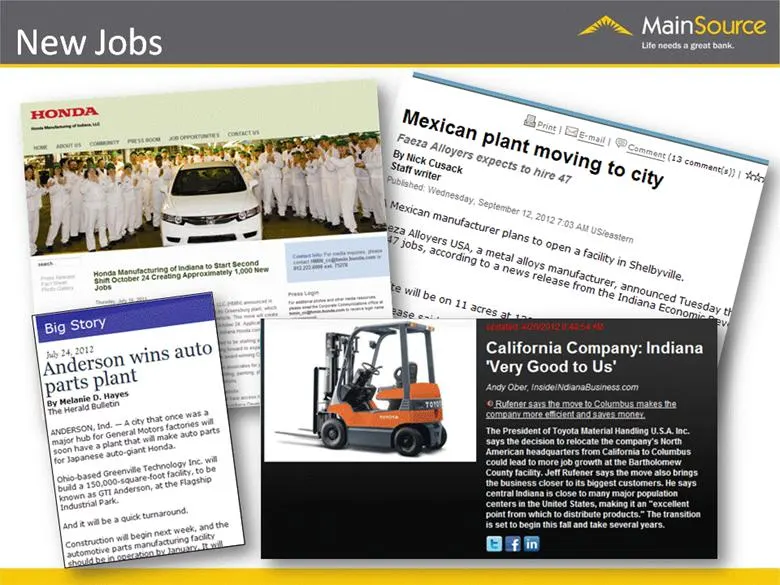
2% MainSource Ute needa goat Dank, California Company ‘Very Good to Us’
Slide 32: 2% MainSource
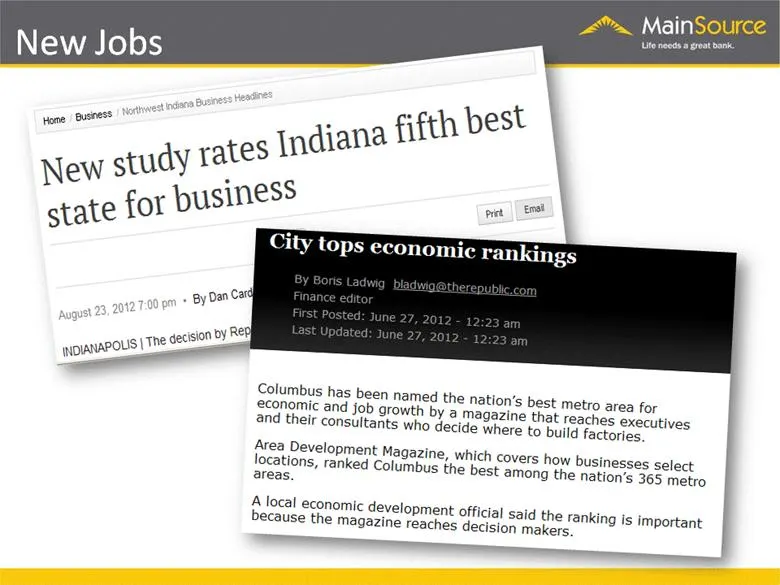
2% MainSource Ue need grat Bank. City tops economic rankings sion by Rep yANAPOUS |The dectsiOR wo Columbus has been named the nation’s best metro area for Sad omic and Job growth by a magazine that reaches executives and their consultants who decide where te Suit factories. f.local economic develop
Slide 33: Investment Highlights
Proven and experienced management team High quality deposit franchise Positive asset quality trends Focus on shareholder value Improving local economies Attractive valuation Investment Highlights
Slide 34: Investment Thesis
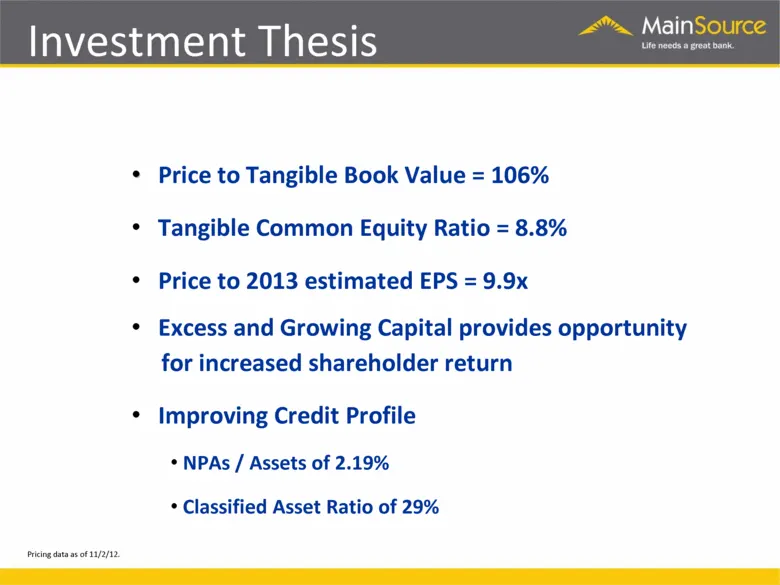
for increased shareholder return Improving Credit Profile NPAs / Assets of 2.19% Classified Asset Ratio of 29% Pricing data as of 11/2/12. Investment Thesis Price to Tangible Book Value = 106% Tangible Common Equity Ratio = 8.8% Price to 2013 estimated EPS = 9.9x Excess and Growing Capital provides
Slide 35: MainSource Financial Group
<M, MainSource FINANCIAL GROUP
Source: SEC EDGAR · 8-K filed Nov 16, 2012
More decks from MainSource Financial Group Inc
 Merger or Acquisition (October 2017)25 slides · Oct 31, 2017
 Merger or Acquisition (July 2017)23 slides · Jul 31, 2017
 Merger or Acquisition (July 2017)19 slides · Jul 26, 2017
 Shareholder Meeting (May 2017)67 slides · May 3, 2017
 Merger or Acquisition (December 2016)7 slides · Dec 19, 2016
 Investor Presentation (September 2016)34 slides · Sep 22, 2016