Heartland Financial USA — Investor Presentation (March 2017)
53 slides from Heartland Financial USA's investor presentation, Mar 2, 2017
Slide 1: Investor Presentation March 2017
Investor Presentation Lynn B. Fuller Chairman and CEO Bryan R. McKeag Chief Financial Officer March 2017 Trading Symbol: HTLF | www.htlf.com
Slide 2: Safe Harbor
2 Safe Harbor This presentation may contain, and future oral and written statements of the Company and its management may contain, forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 with respect to the financial condition, results of operations, pla
Slide 3: Agenda
3 Agenda Heartland’s growth story Key tenets of Heartland’s business model Financial Highlights
Slide 4: Heartland: Tremendous Growth in Assets and Shareholder Return
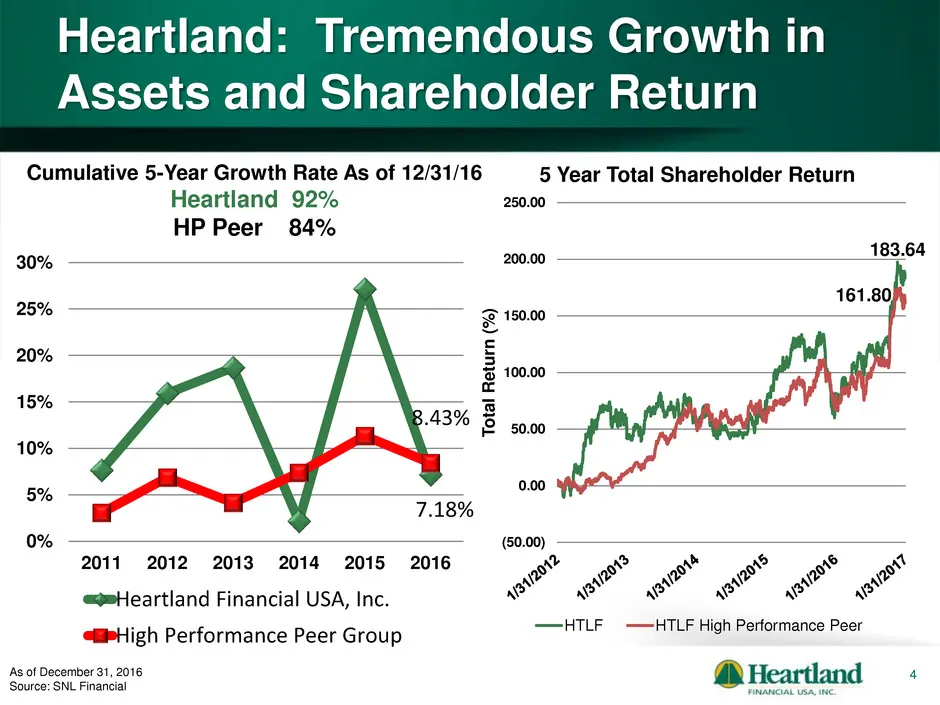
4 Cumulative 5-Year Growth Rate As of 12/31/16 Heartland 92% HP Peer 84% Heartland: Tremendous Growth in Assets and Shareholder Return As of December 31, 2016 Source: SNL Financial 7.18% 8.43% 0% 5% 10% 15% 20% 25% 30% 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc. High Performance Peer
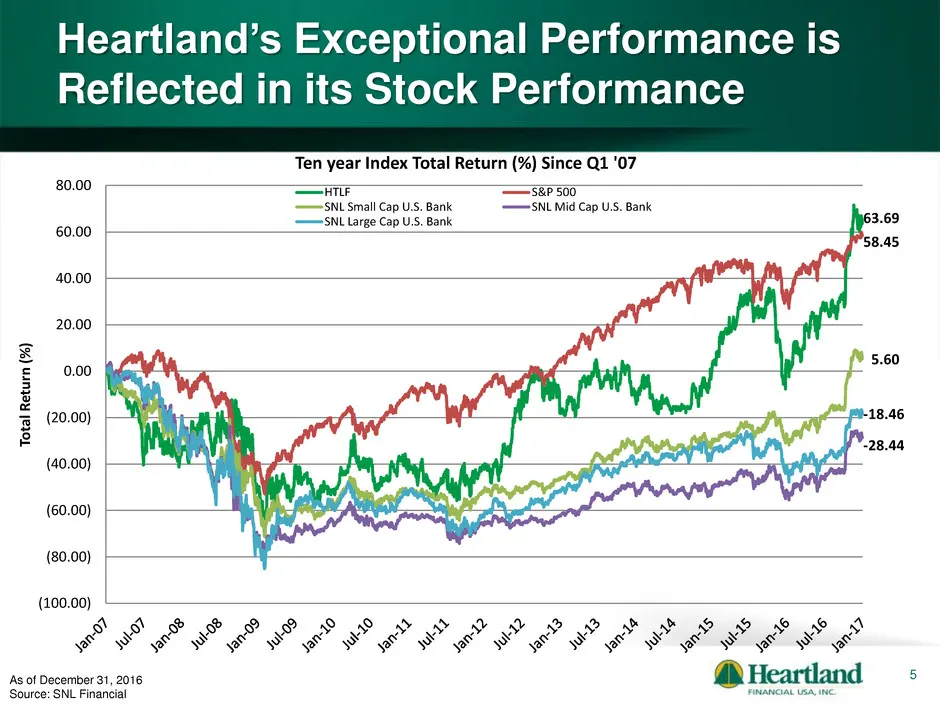
Slide 5: Heartland's Exceptional Performance is Reflected in its Stock Performance
5 Heartland’s Exceptional Performance is Reflected in its Stock Performance As of December 31, 2016 Source: SNL Financial (100.00) (80.00) (60.00) (40.00) (20.00) 0.00 20.00 40.00 60.00 80.00 To ta l R et u rn (% ) Ten year Index Total Return (%) Since Q1 '07 HTLF S&P 500 SNL Small Cap U.S. Bank SNL
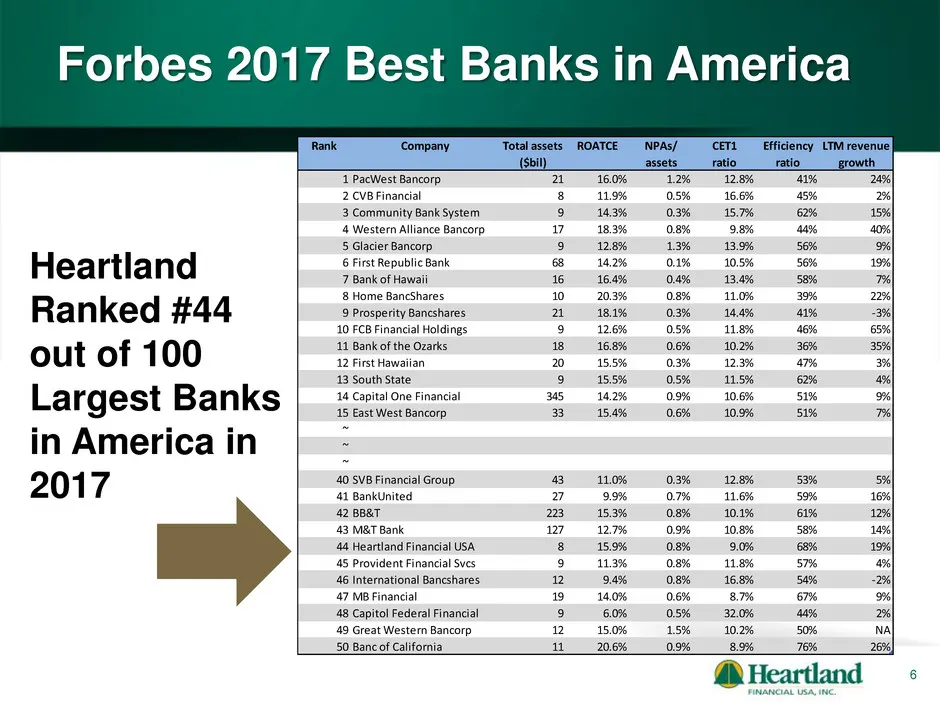
Slide 6: Heartland Ranked #44 out of Largest Banks in America in 2017
6 Heartland Ranked #44 out of 100 Largest Banks in America in 2017 Forbes 2017 Best Banks in America Rank Company Total assets ROATCE NPAs/ CET1 Efficiency LTM revenue ($bil) assets ratio ratio growth 1 PacWest Bancorp 21 16.0% 1.2% 12.8% 41% 24% 2 CVB Financial 8 11.9% 0.5% 16.6% 45% 2% 3 Community
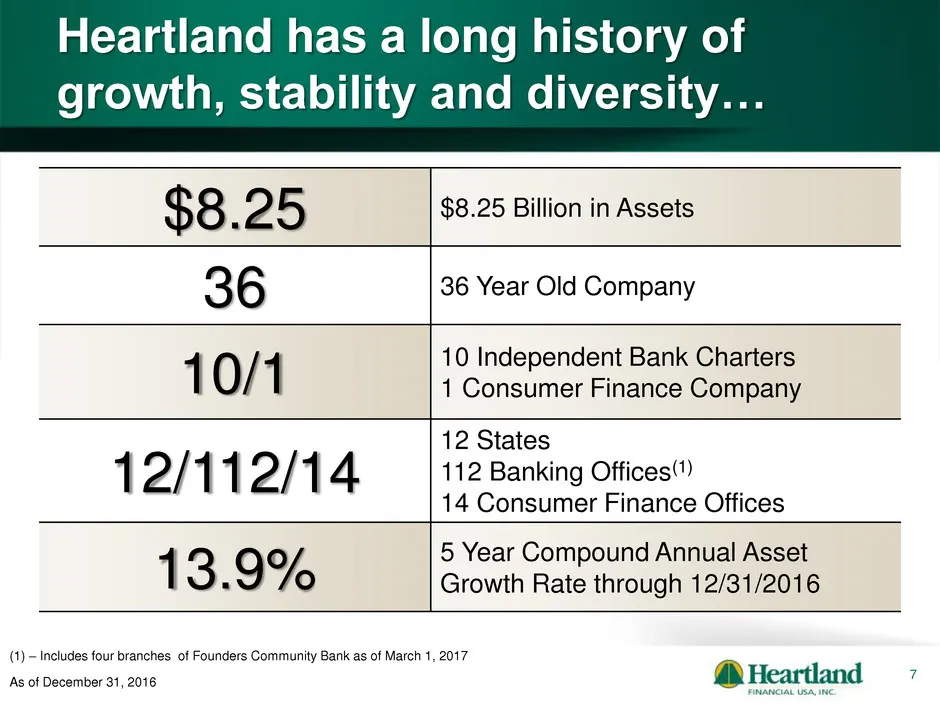
Slide 7: Heartland has a long history of growth, stability and diversity
7 $8.25 $8.25 Billion in Assets 36 36 Year Old Company 10/1 10 Independent Bank Charters 1 Consumer Finance Company 12/112/14 12 States 112 Banking Offices(1) 14 Consumer Finance Offices 13.9% 5 Year Compound Annual Asset Growth Rate through 12/31/2016 Heartland has a long history of growth, stabili
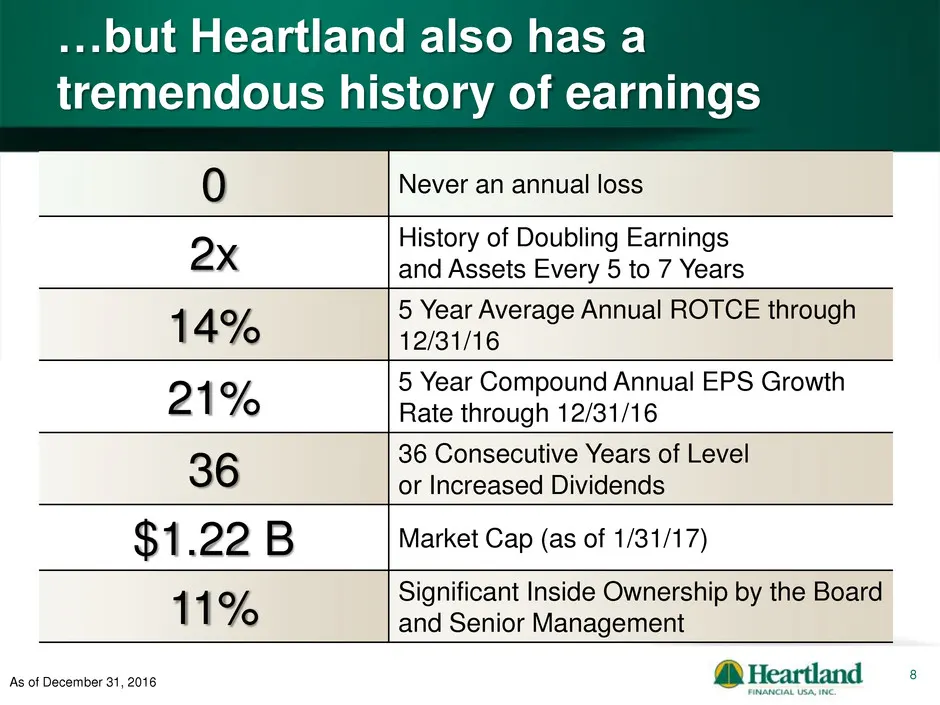
Slide 8: Heartland also has a tremendous history of earnings
8 0 Never an annual loss 2x History of Doubling Earnings and Assets Every 5 to 7 Years 14% 5 Year Average Annual ROTCE through 12/31/16 21% 5 Year Compound Annual EPS Growth Rate through 12/31/16 36 36 Consecutive Years of Level or Increased Dividends $1.22 B Market Cap (as of 1/31/17) 11% Significa
Slide 9: An Expanding Franchise
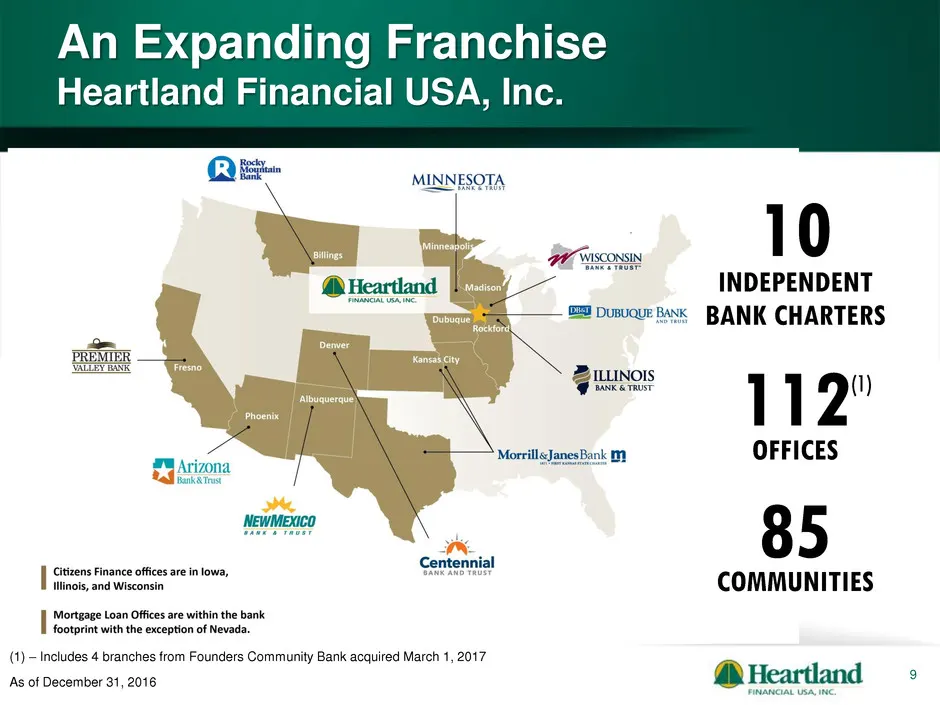
9 An Expanding Franchise Heartland Financial USA, Inc. 10 INDEPENDENT BANK CHARTERS 112 OFFICES 85 COMMUNITIES As of December 31, 2016 (1) – Includes 4 branches from Founders Community Bank acquired March 1, 2017 (1)
Slide 10: Expansion Timeline
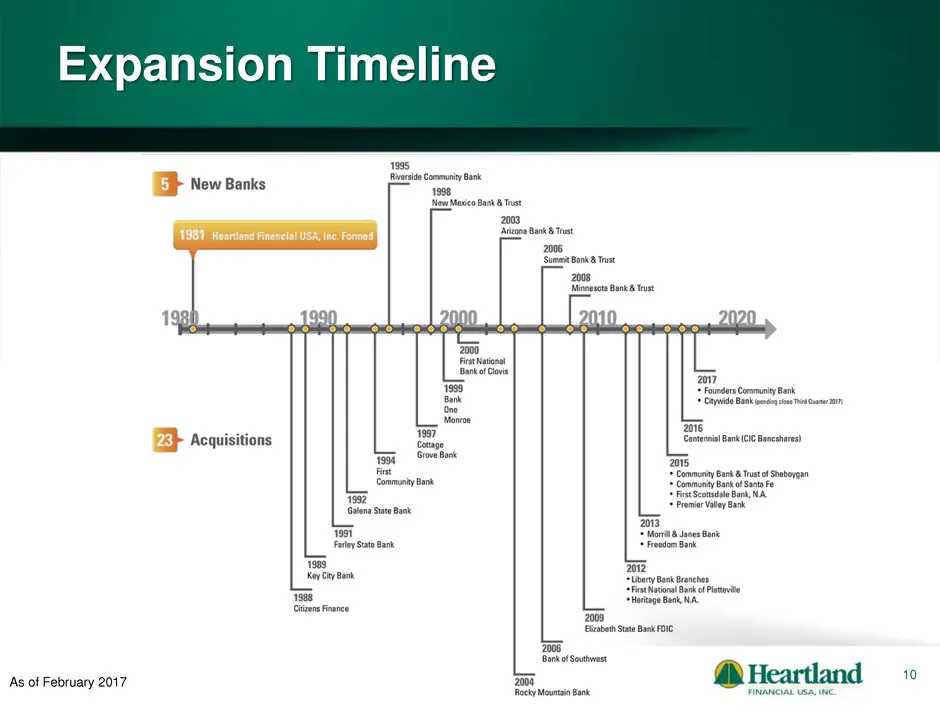
10 Expansion Timeline As of February 2017
Slide 11: Acquisition and Organic Asset Growth
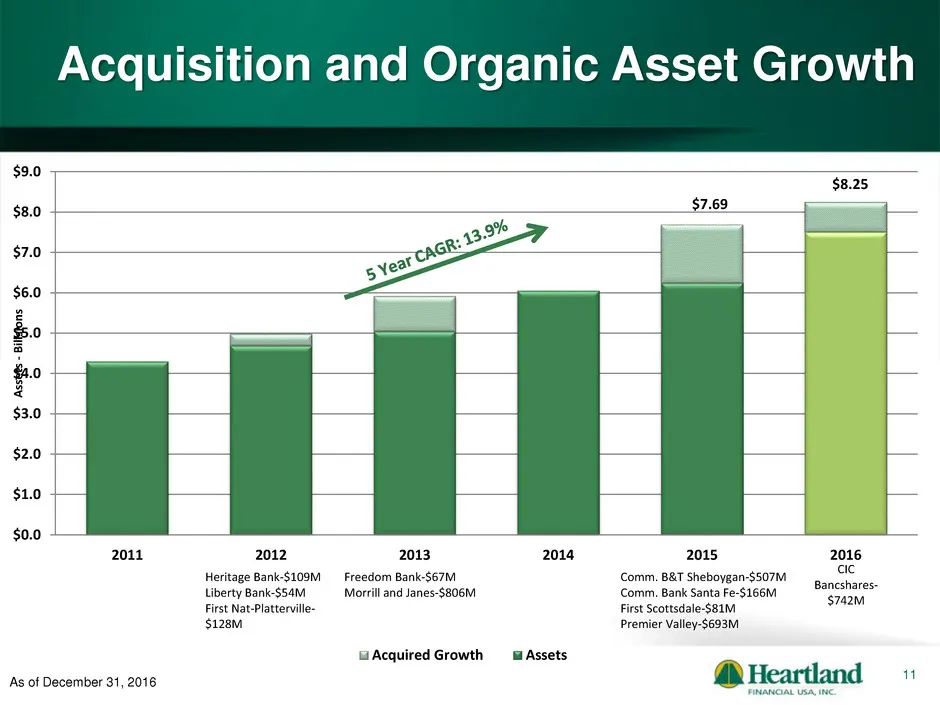
11 Acquisition and Organic Asset Growth As of December 31, 2016 $0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 $8.0 $9.0 2011 2012 2013 2014 2015 2016 A ssets - B ill si o n s Acquired Growth Assets $8.25 $7.69 Heritage Bank-$109M Liberty Bank-$54M First Nat-Platterville- $128M Freedom Bank-$67M Morrill an
Slide 12: Heartland has established core competencies in M&A
12 12 bank acquisitions announced and 11 closed since 2012 Opportunities abound across entire footprint Heartland’s community bank model is attractive to sellers Focus on expanding existing markets >= $1 Billion in assets Transactions that demonstrate an IRR > 15% Commitment to sharehold
Slide 13: Centennial Bank (CIC Bancshares)
13 Centennial Bank (CIC Bancshares) Announced October 2015 Closed February 2016 with systems integration completed in June 2016 Assets of approximately $742.8 million 14 branches-Serving Denver metro & surrounding mountain resort communities Approximately $76.9 million stock and cash trans
Slide 14: Founders Community Bank
14 Founders Community Bank Announced October 2016 Closed February 2017 with systems integration mid-March 2017 Assets of approximately $196.9 million as of 12/31/16 4 branches and one lending center in San Luis Obispo County on the Central Coast of California Approximately $31.1 million st
Slide 15: Citywide Banks
15 Citywide Banks Announced February 2017 Expected close and integration in third and fourth quarters of 2017 Assets of approximately $1.4 billion as of 12/31/16, marking Heartland’s largest acquisition 12 branches all located in the Denver Metro/Front Range area Approximately $203 million
Slide 16: Market Overview: Expanding in High Growth Markets
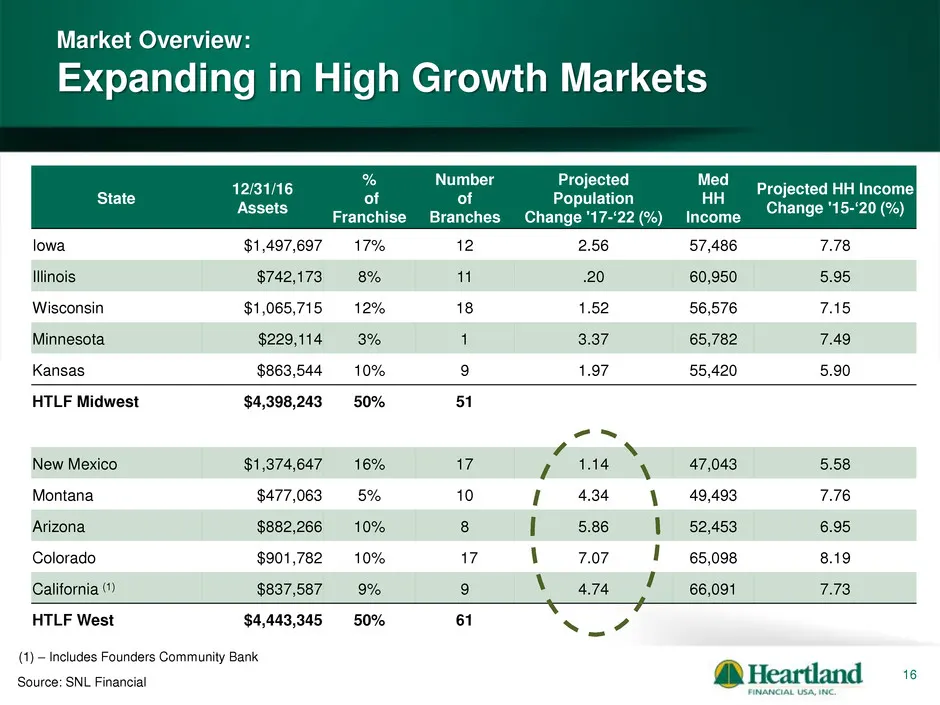
16 State 12/31/16 Assets % of Franchise Number of Branches Projected Population Change '17-‘22 (%) Med HH Income Projected HH Income Change '15-‘20 (%) Iowa $1,497,697 17% 12 2.56 57,486 7.78 Illinois $742,173 8% 11 .20 60,950 5.95 Wisconsin $1,065,715 12% 18 1.52 56,576 7.15 Minnesota $229,114 3% 1
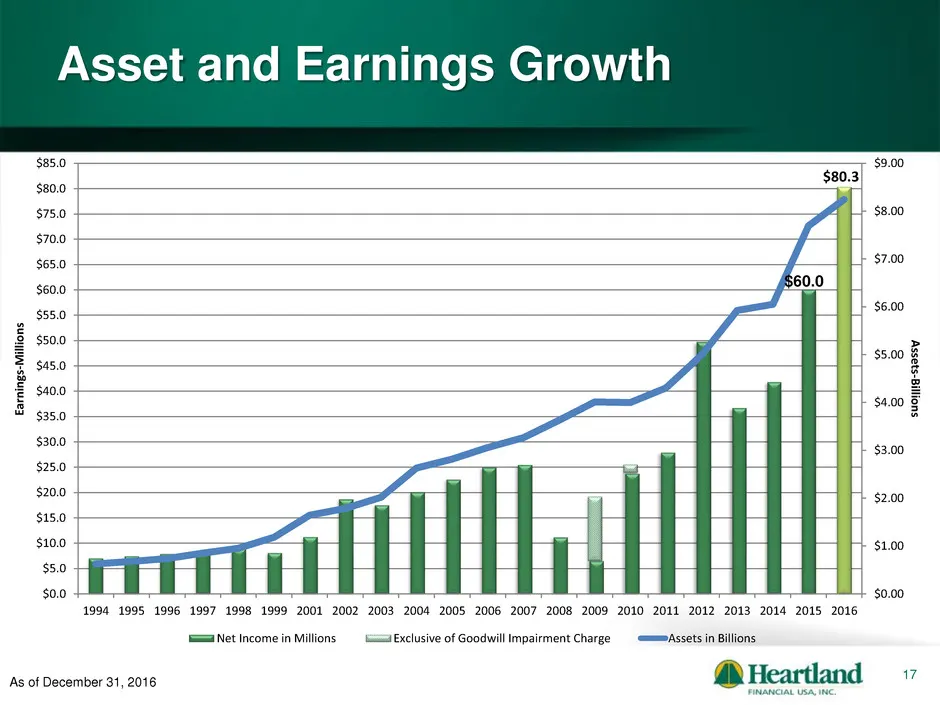
Slide 17: Asset and Earnings Growth
17 Asset and Earnings Growth As of December 31, 2016 $60.0 $80.3 $0.00 $1.00 $2.00 $3.00 $4.00 $5.00 $6.00 $7.00 $8.00 $9.00 $0.0 $5.0 $10.0 $15.0 $20.0 $25.0 $30.0 $35.0 $40.0 $45.0 $50.0 $55.0 $60.0 $65.0 $70.0 $75.0 $80.0 $85.0 1994 1995 1996 1997 1998 1999 2001 2002 2003 2004 2005 2006 2007 2008
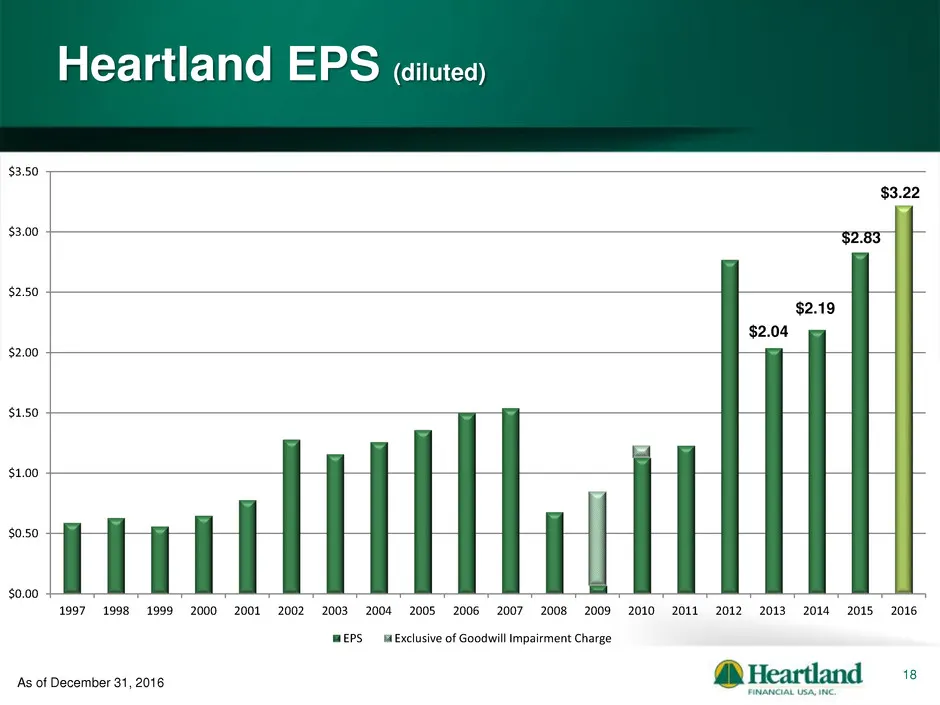
Slide 18: Heartland EPS (diluted)
18 Heartland EPS (diluted) As of December 31, 2016 $2.04 $2.19 $2.83 $3.22 $0.00 $0.50 $1.00 $1.50 $2.00 $2.50 $3.00 $3.50 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 EPS Exclusive of Goodwill Impairment Charge
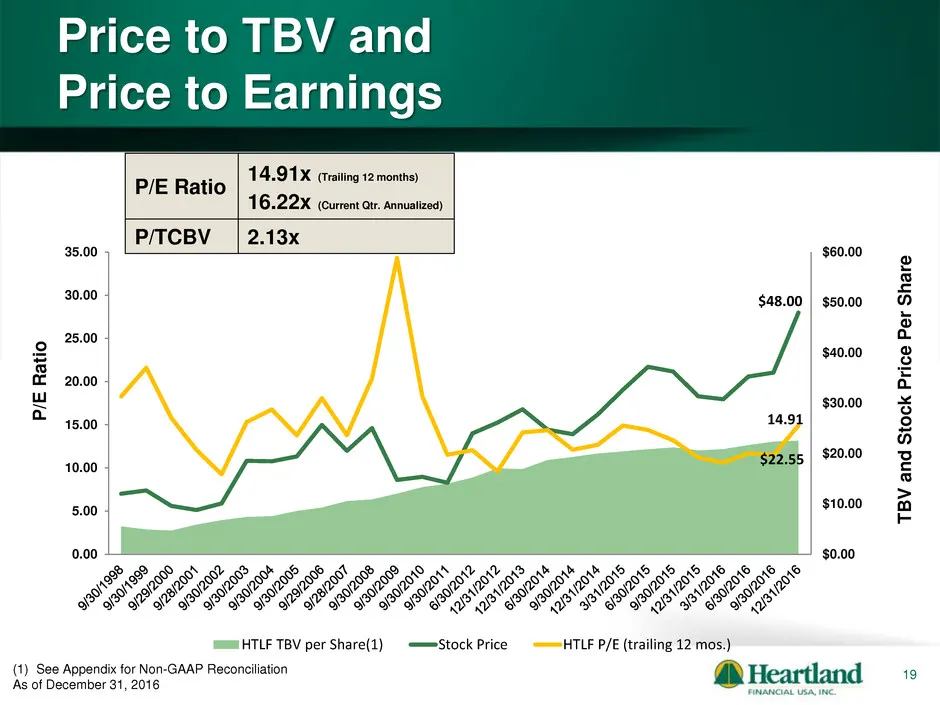
Slide 19: Price to TBV and Price to Earnings
19 Price to TBV and Price to Earnings (1) See Appendix for Non-GAAP Reconciliation As of December 31, 2016 T B V a n d St o ck P ri ce Pe r S h a re P/E Ratio 14.91x (Trailing 12 months) 16.22x (Current Qtr. Annualized) P/TCBV 2.13x P /E R at io $22.55 $48.00 14.91 0.00 5.00 10.00 15.00 20.00 25.00
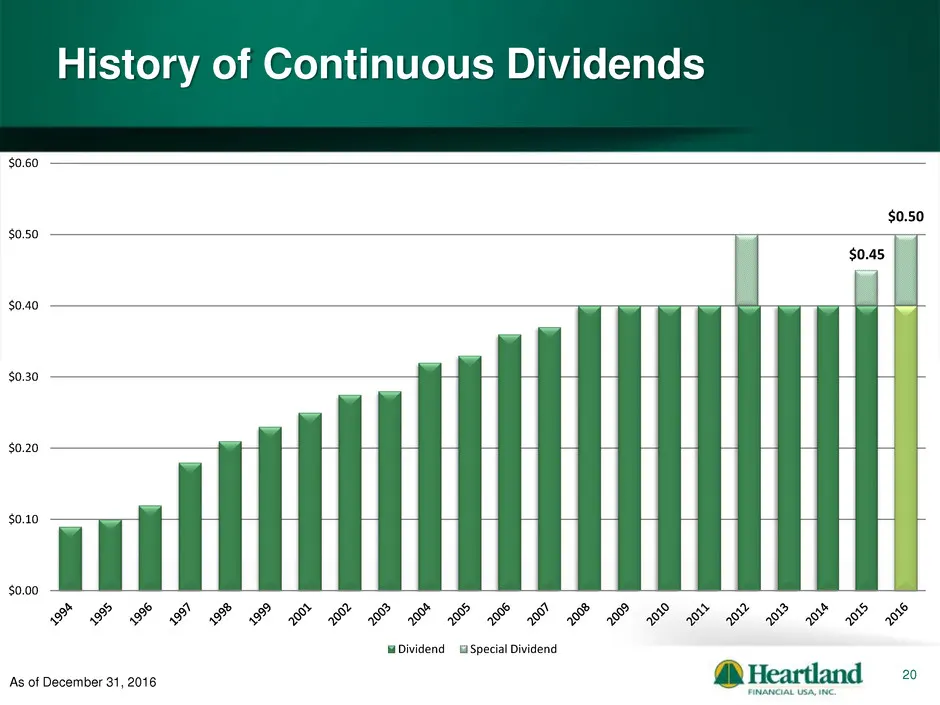
Slide 20: History of Continuous Dividends
20 History of Continuous Dividends As of December 31, 2016 $0.50 $0.45 $0.00 $0.10 $0.20 $0.30 $0.40 $0.50 $0.60 Dividend Special Dividend
Slide 21: Agenda
21 Agenda Heartland’s growth story Key tenets of Heartland’s business model Financial Highlights
Slide 22: Three Core Pillars: Local Bank Delivery, Revenue Enhancement, Cost Savings
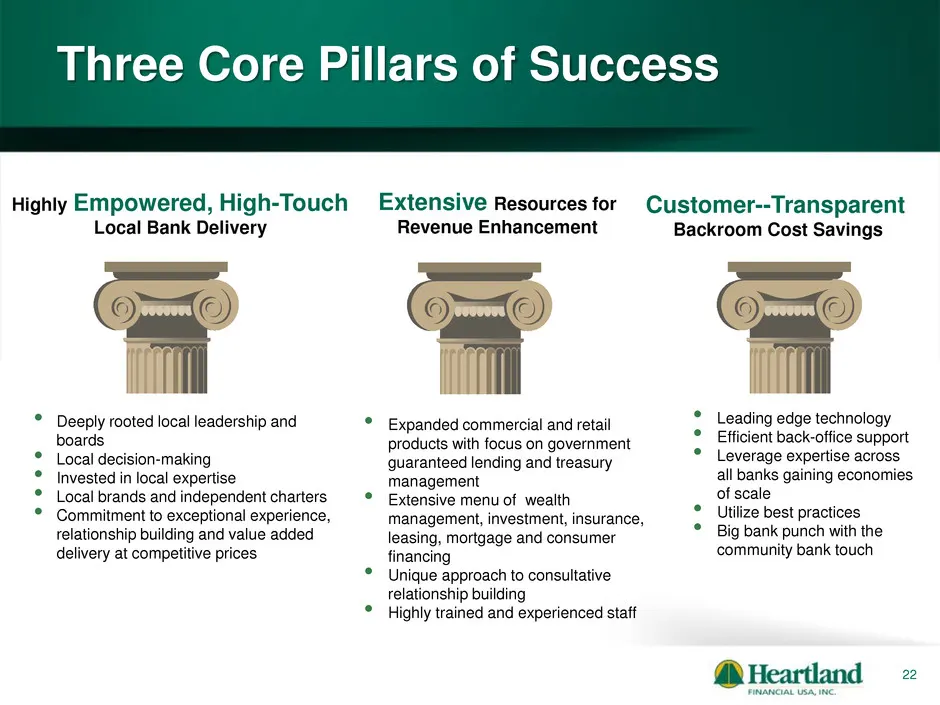
22 Highly Empowered, High-Touch Local Bank Delivery • Deeply rooted local leadership and boards • Local decision-making • Invested in local expertise • Local brands and independent charters • Commitment to exceptional experience, relationship building and value added delivery at competitive prices E
Slide 23: Primary Target Markets
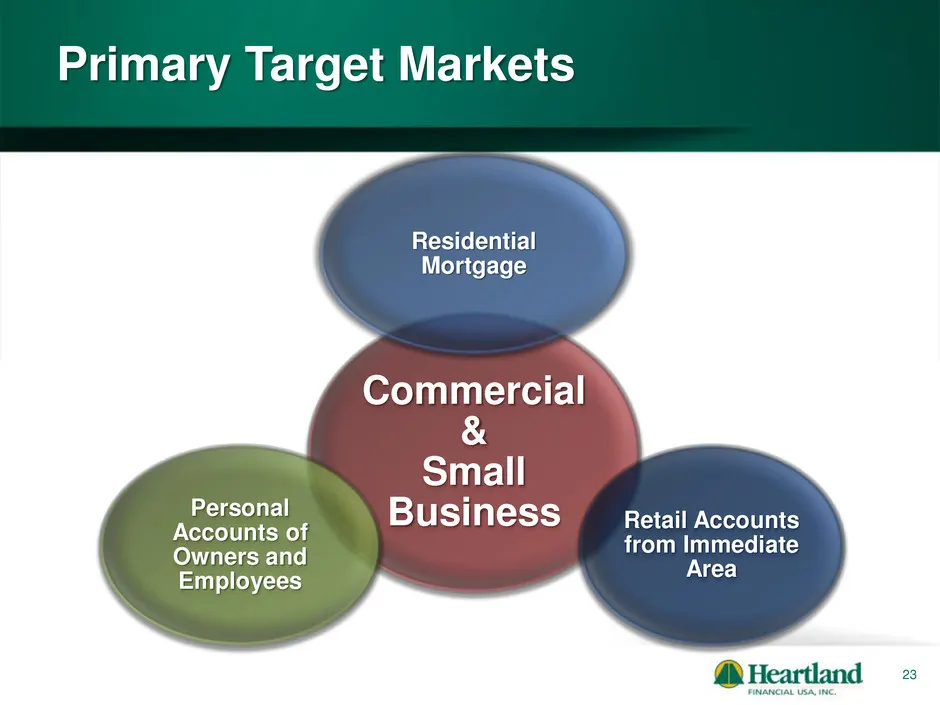
23 Primary Target Markets Commercial & Small Business Residential Mortgage Retail Accounts from Immediate Area Personal Accounts of Owners and Employees
Slide 24: 5 Primary Business Lines
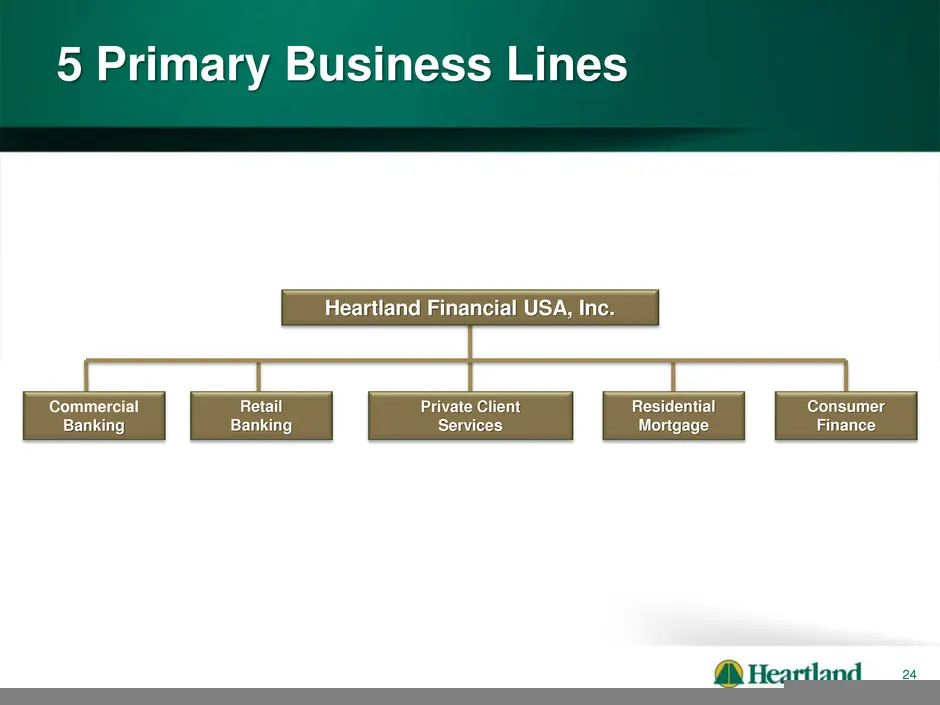
24 Heartland Financial USA, Inc. Commercial Banking Retail Banking Private Client Services Consumer Finance Residential Mortgage 5 Primary Business Lines
Slide 25: Solid Capital Ratios
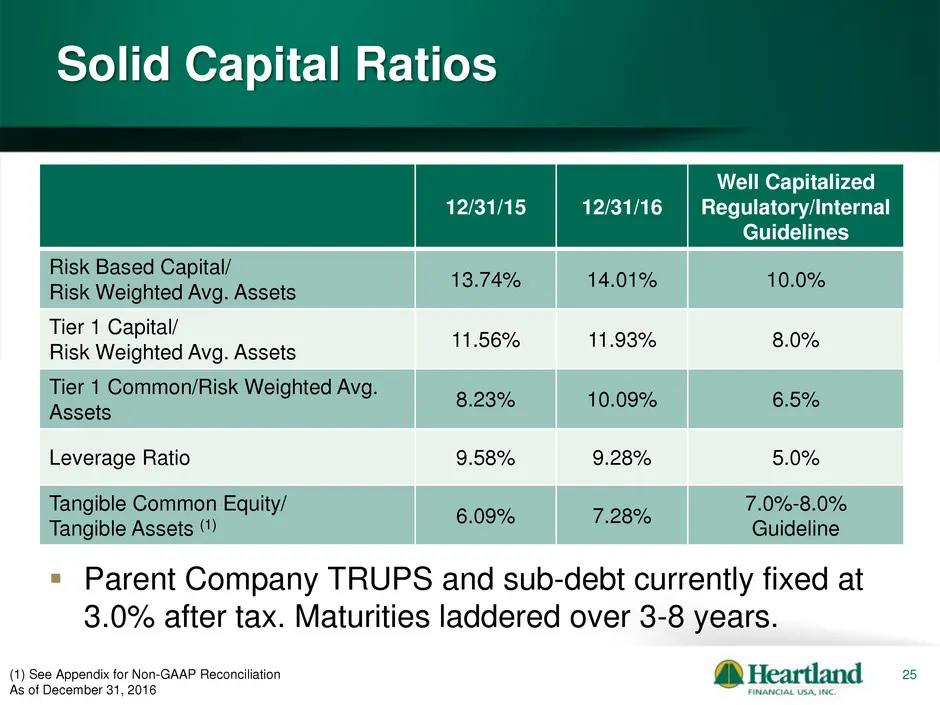
25 Solid Capital Ratios 12/31/15 12/31/16 Well Capitalized Regulatory/Internal Guidelines Risk Based Capital/ Risk Weighted Avg. Assets 13.74% 14.01% 10.0% Tier 1 Capital/ Risk Weighted Avg. Assets 11.56% 11.93% 8.0% Tier 1 Common/Risk Weighted Avg. Assets 8.23% 10.09% 6.5% Leverage Ratio 9.58% 9.28
Slide 26: HTLF core facts summary
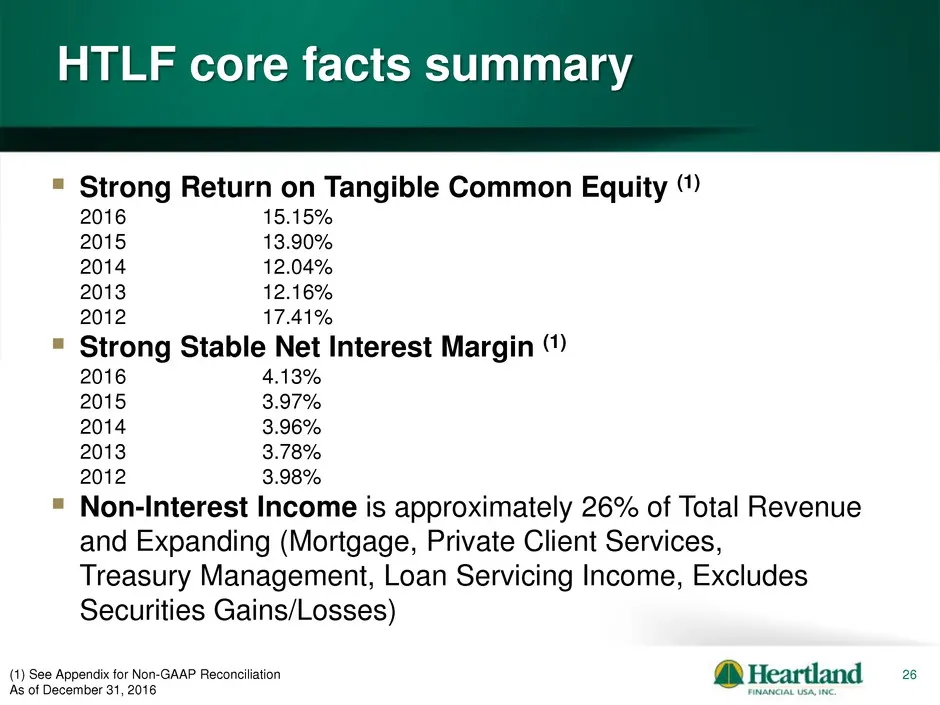
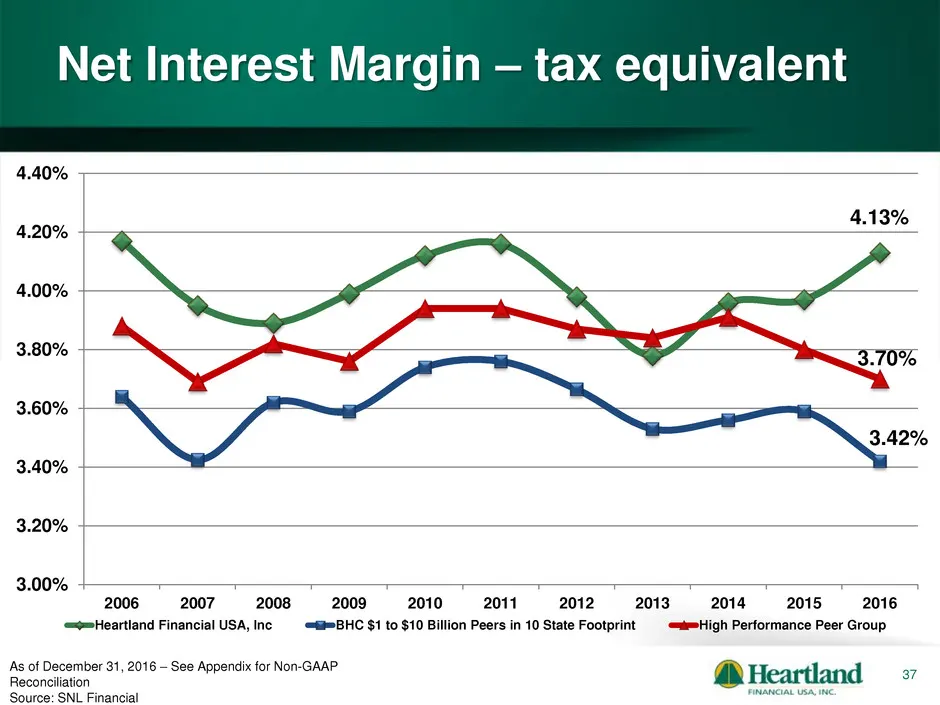
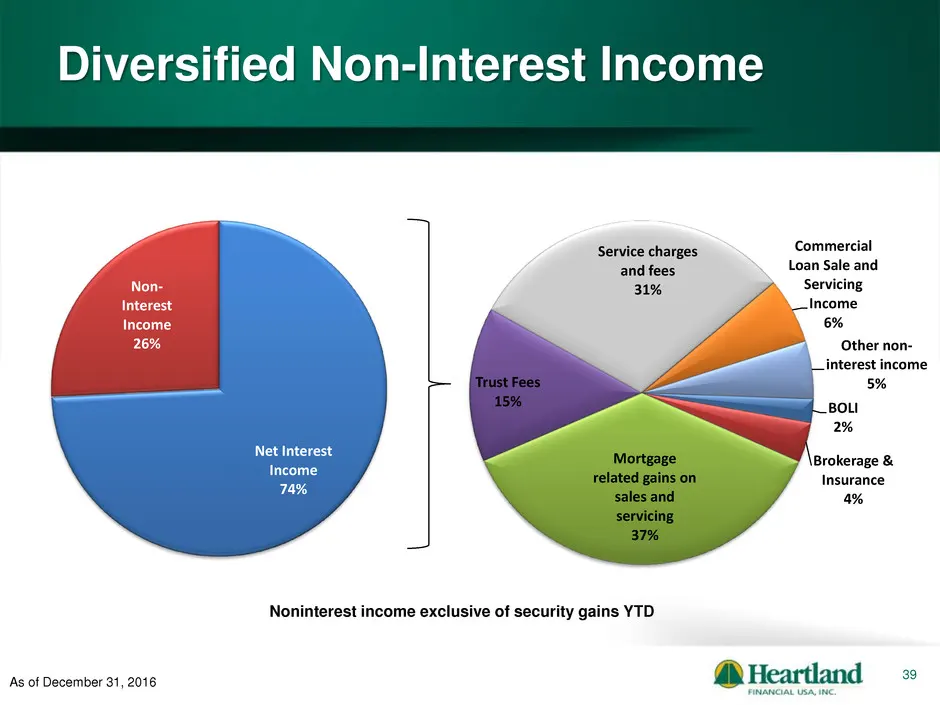
26 Strong Return on Tangible Common Equity (1) 2016 15.15% 2015 13.90% 2014 12.04% 2013 12.16% 2012 17.41% Strong Stable Net Interest Margin (1) 2016 4.13% 2015 3.97% 2014 3.96% 2013 3.78% 2012 3.98% Non-Interest Income is approximately 26% of Total Revenue and Expanding (Mortgage, Private Cli
Slide 27: HTLF core facts summary (cont.)
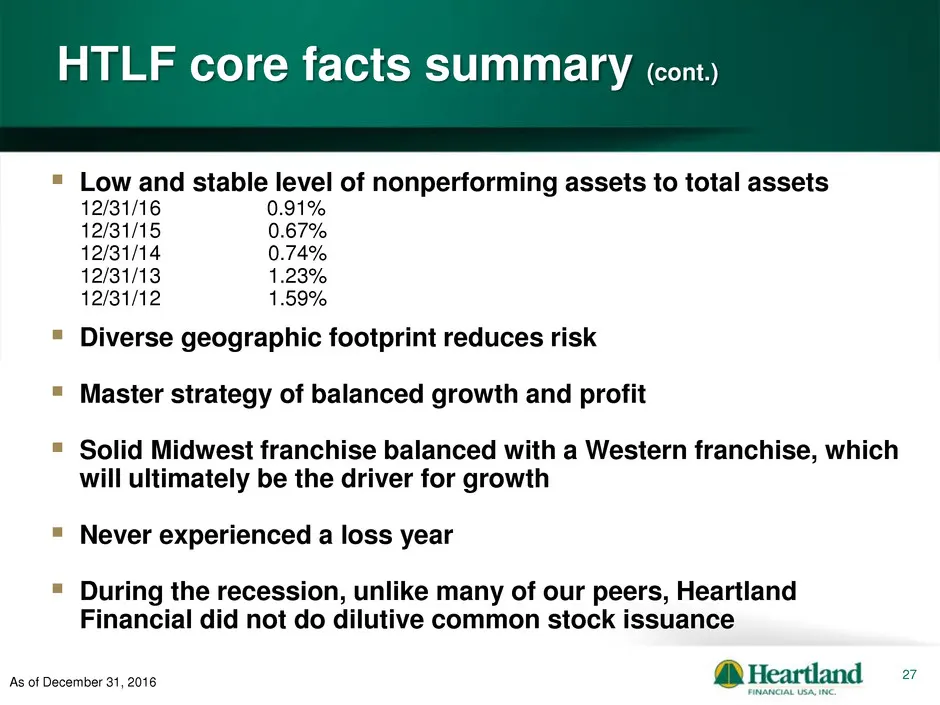
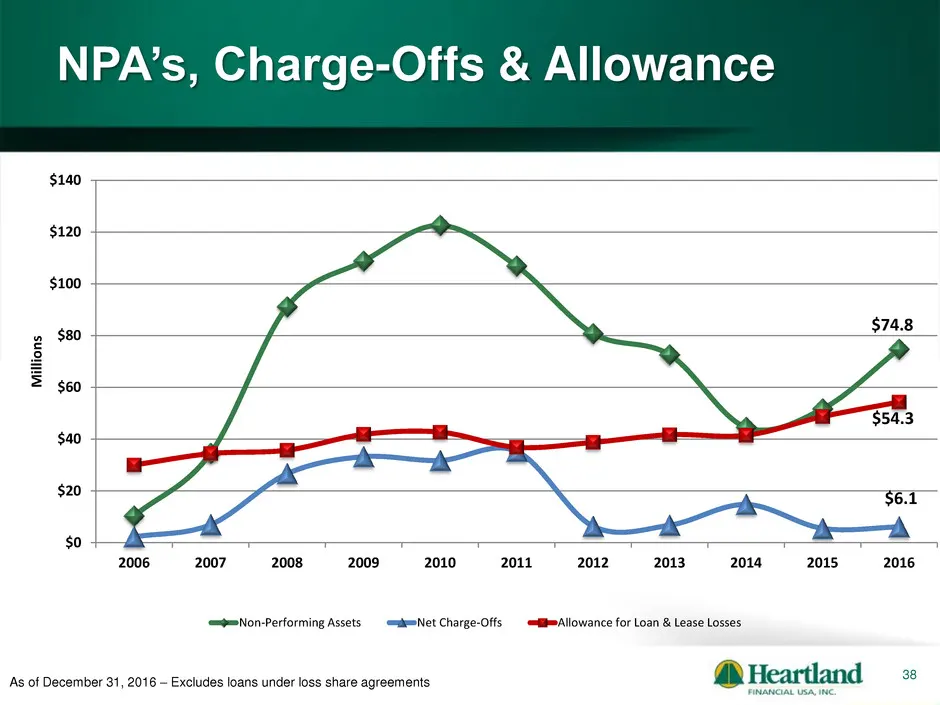
27 Low and stable level of nonperforming assets to total assets 12/31/16 0.91% 12/31/15 0.67% 12/31/14 0.74% 12/31/13 1.23% 12/31/12 1.59% Diverse geographic footprint reduces risk Master strategy of balanced growth and profit Solid Midwest franchise balanced with a Western franchise, which
Slide 28: Agenda
28 Heartland’s growth story Key tenets of Heartland’s business model Financial Highlights Agenda
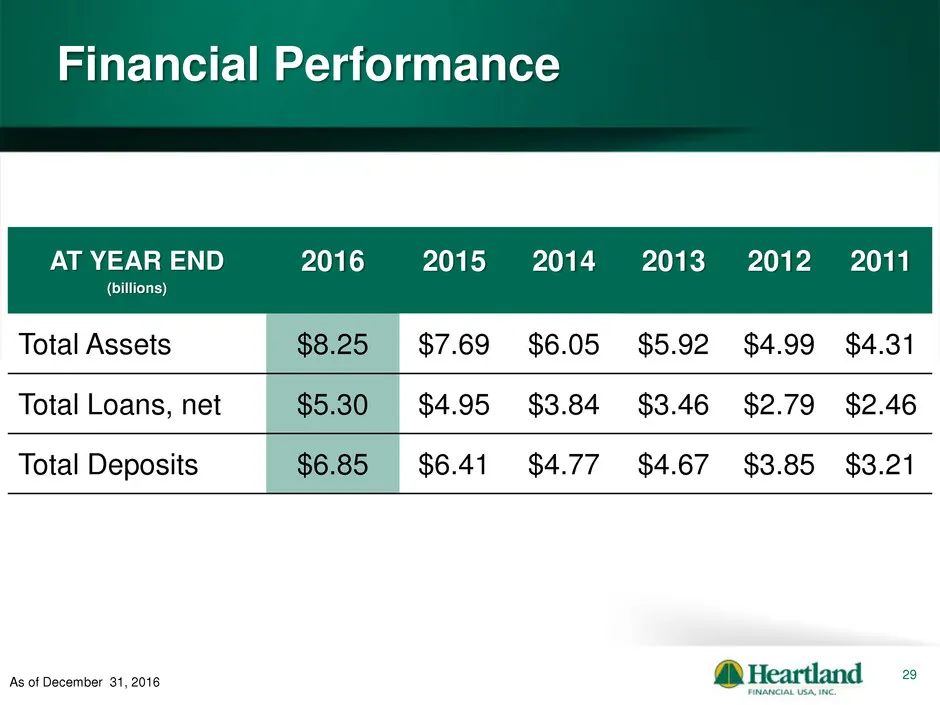
Slide 29: Financial Performance
29 Financial Performance As of December 31, 2016 AT YEAR END (billions) 2016 2015 2014 2013 2012 2011 Total Assets $8.25 $7.69 $6.05 $5.92 $4.99 $4.31 Total Loans, net $5.30 $4.95 $3.84 $3.46 $2.79 $2.46 Total Deposits $6.85 $6.41 $4.77 $4.67 $3.85 $3.21
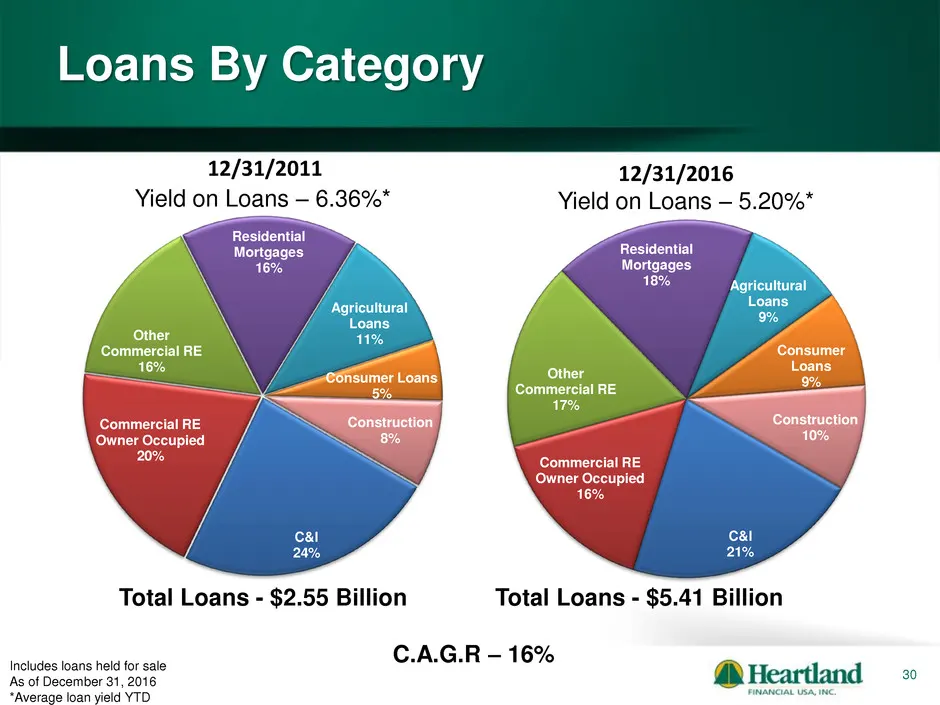
Slide 30: Loans By Category
30 Loans By Category Includes loans held for sale As of December 31, 2016 *Average loan yield YTD Yield on Loans – 6.36%* C.A.G.R – 16% Yield on Loans – 5.20%* C&I 24% Commercial RE Owner Occupied 20% Other Commercial RE 16% Residential Mortgages 16% Agricultural Loans 11% Consumer Loans 5% Construc
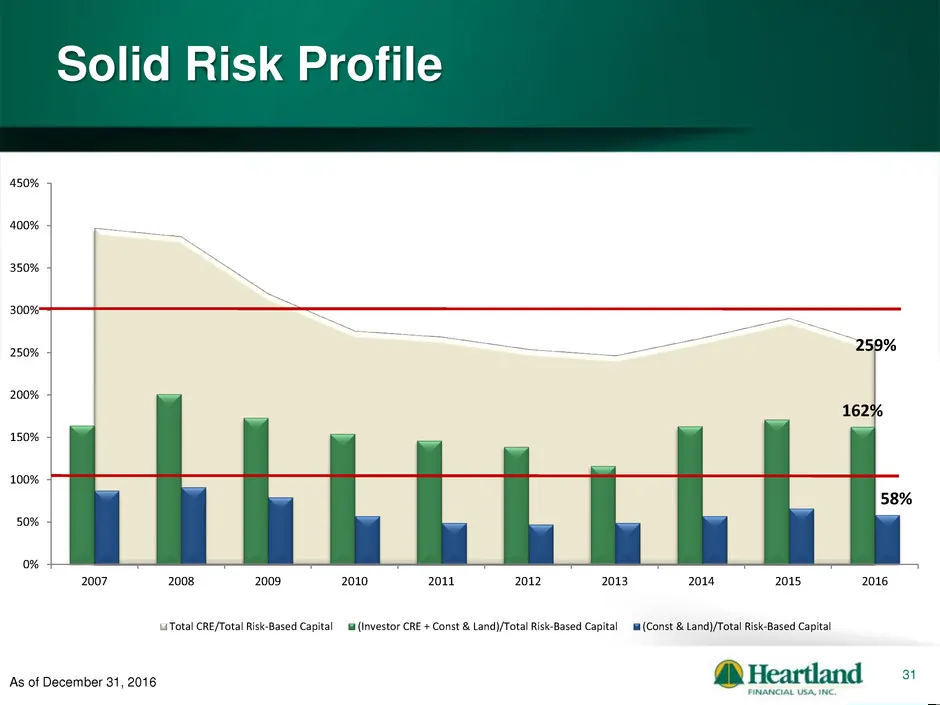
Slide 31: Solid Risk Profile
31 Solid Risk Profile As of December 31, 2016 162% 58% 0% 50% 100% 150% 200% 250% 300% 350% 400% 450% 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Total CRE/Total Risk-Based Capital (Investor CRE + Const & Land)/Total Risk-Based Capital (Const & Land)/Total Risk-Based Capital 259%
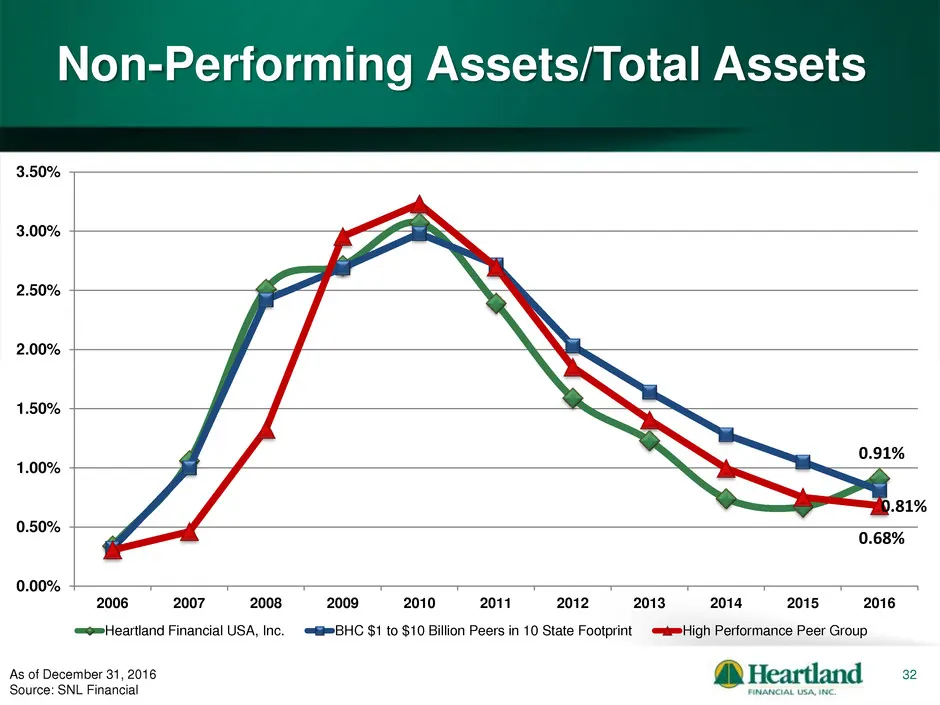
Slide 32: Non-Performing Assets/Total Assets
32 Non-Performing Assets/Total Assets As of December 31, 2016 Source: SNL Financial 0.91% 0.81% 0.68% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc. BHC $1 to $10 Billion Peers in 10 State Footprint High Performanc
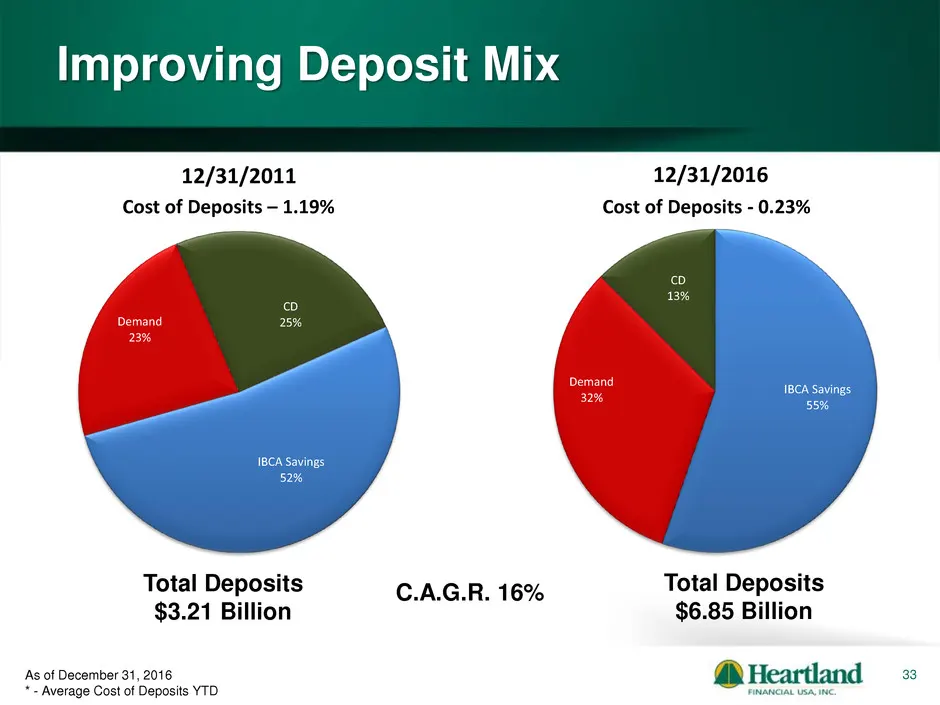
Slide 33: Improving Deposit Mix
33 IBCA Savings 52% Demand 23% CD 25% 12/31/2011 IBCA Savings 55% Demand 32% CD 13% 12/31/2016 As of December 31, 2016 * - Average Cost of Deposits YTD Improving Deposit Mix Total Deposits $3.21 Billion Total Deposits $6.85 Billion C.A.G.R. 16% Cost of Deposits – 1.19% Cost of Deposits - 0.23%
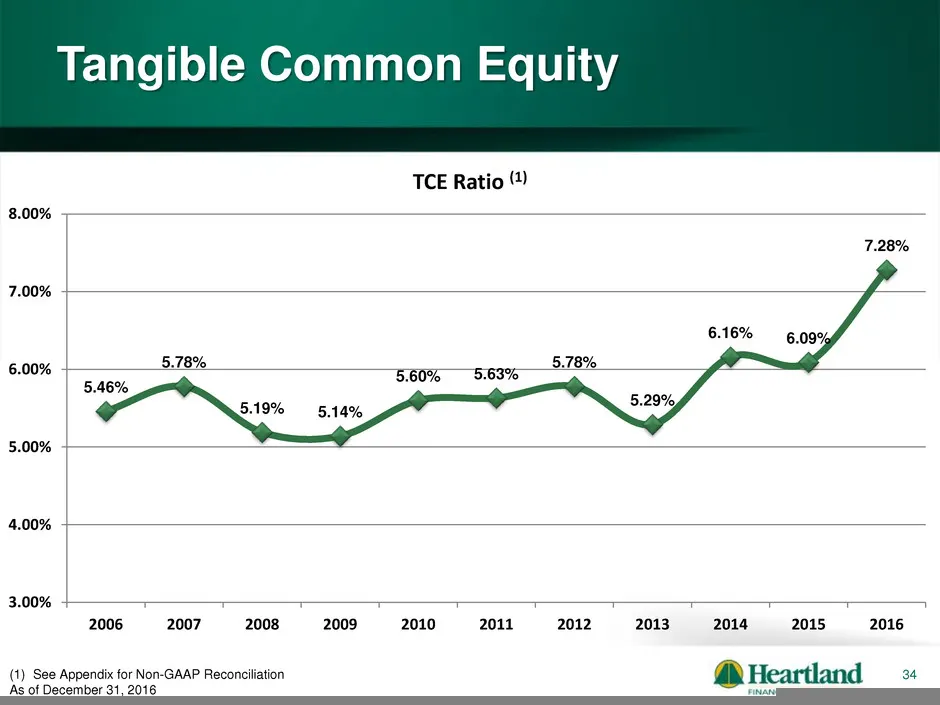
Slide 34: Tangible Common Equity
34 Tangible Common Equity (1) See Appendix for Non-GAAP Reconciliation As of December 31, 2016 5.46% 5.78% 5.19% 5.14% 5.60% 5.63% 5.78% 5.29% 6.16% 6.09% 7.28% 3.00% 4.00% 5.00% 6.00% 7.00% 8.00% 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 TCE Ratio (1)
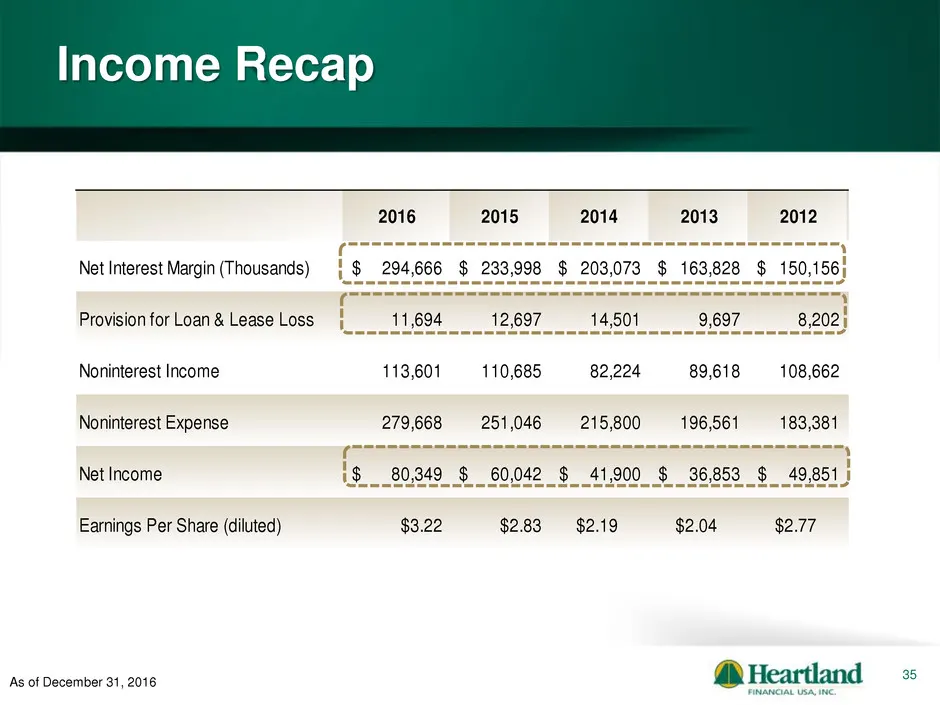
Slide 35: Income Recap
35 As of December 31, 2016 Income Recap 2016 2015 2014 2013 2012 Net Interest Margin (Thousands) 294,666$ 233,998$ 203,073$ 163,828$ 150,156$ Provision for Loan & Lease Loss 11,694 12,697 14,501 9,697 8,202 Noninterest Income 113,601 110,685 82,224 89,618 108,662 Noninterest Expense 279,668 251,046
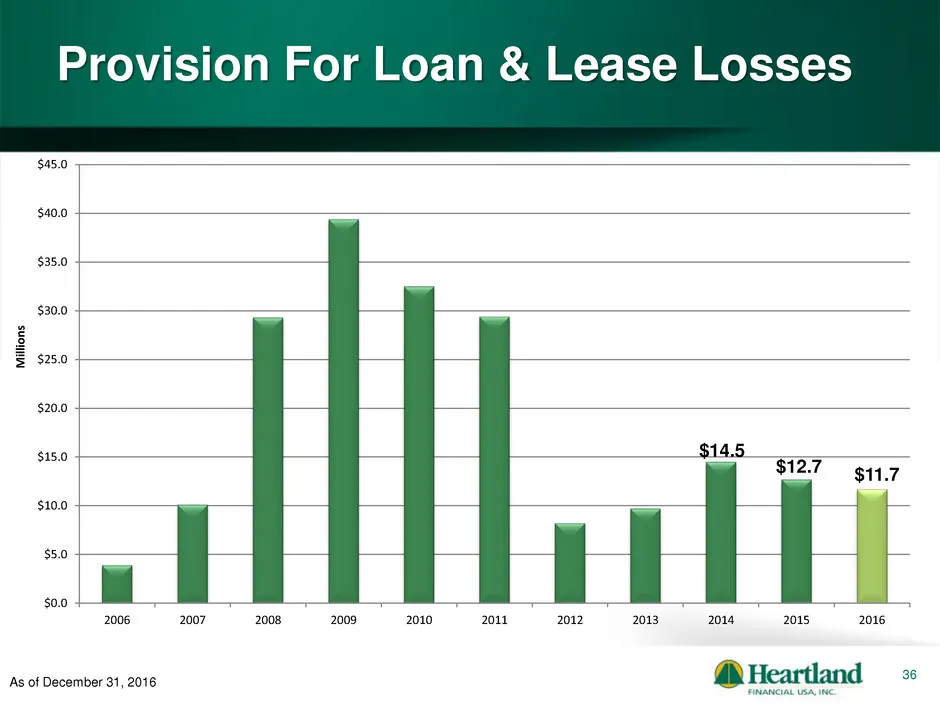
Slide 36: Provision For Loan & Lease Losses
36 Provision For Loan & Lease Losses As of December 31, 2016 $14.5 $12.7 $11.7 $0.0 $5.0 $10.0 $15.0 $20.0 $25.0 $30.0 $35.0 $40.0 $45.0 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 M ill io n s
Slide 37: Net Interest Margin
37 Net Interest Margin – tax equivalent As of December 31, 2016 – See Appendix for Non-GAAP Reconciliation Source: SNL Financial 4.13% 3.42% 3.70% 3.00% 3.20% 3.40% 3.60% 3.80% 4.00% 4.20% 4.40% 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc BHC $1 to $10 Billion
Slide 38: NPA's, Charge-Offs & Allowance
38 NPA’s, Charge-Offs & Allowance $74.8 $6.1 $54.3 $0 $20 $40 $60 $80 $100 $120 $140 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 M ill io n s Non-Performing Assets Net Charge-Offs Allowance for Loan & Lease Losses As of December 31, 2016 – Excludes loans under loss share agreements
Slide 39: Diversified Non-Interest Income
39 Diversified Non-Interest Income As of December 31, 2016 Noninterest income exclusive of security gains YTD Net Interest Income 74% Non- Interest Income 26% BOLI 2% Brokerage & Insurance 4% Mortgage related gains on sales and servicing 37% Trust Fees 15% Service charges and fees 31% Commercial Loa
Slide 40: Revenue Enhancement: Mortgage Lending
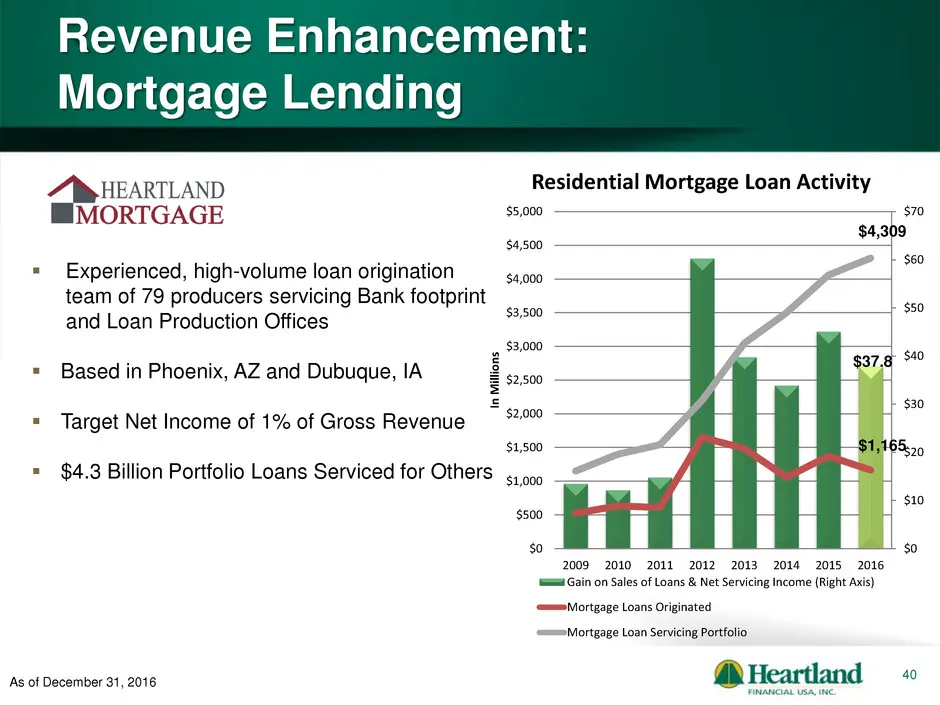
40 Revenue Enhancement: Mortgage Lending As of December 31, 2016 Experienced, high-volume loan origination team of 79 producers servicing Bank footprint and Loan Production Offices Based in Phoenix, AZ and Dubuque, IA Target Net Income of 1% of Gross Revenue $4.3 Billion Portfolio Loans Serv
Slide 41: Revenue Enhancement: Private Client Services
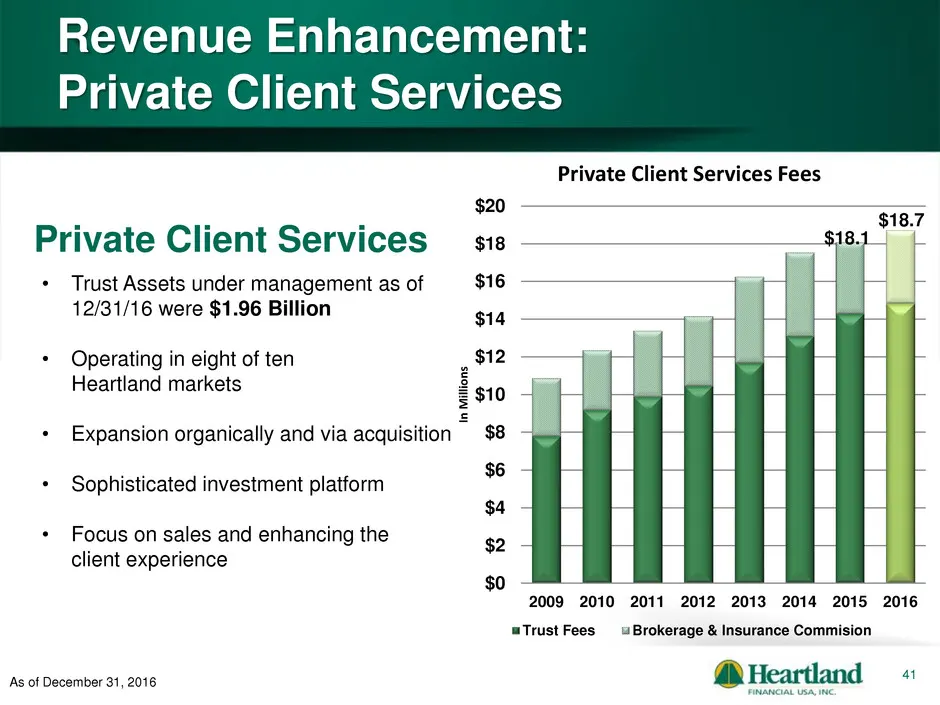
41 • Trust Assets under management as of 12/31/16 were $1.96 Billion • Operating in eight of ten Heartland markets • Expansion organically and via acquisition • Sophisticated investment platform • Focus on sales and enhancing the client experience Private Client Services Revenue Enhancement: Private
Slide 42: Revenue Enhancement: Treasury Management
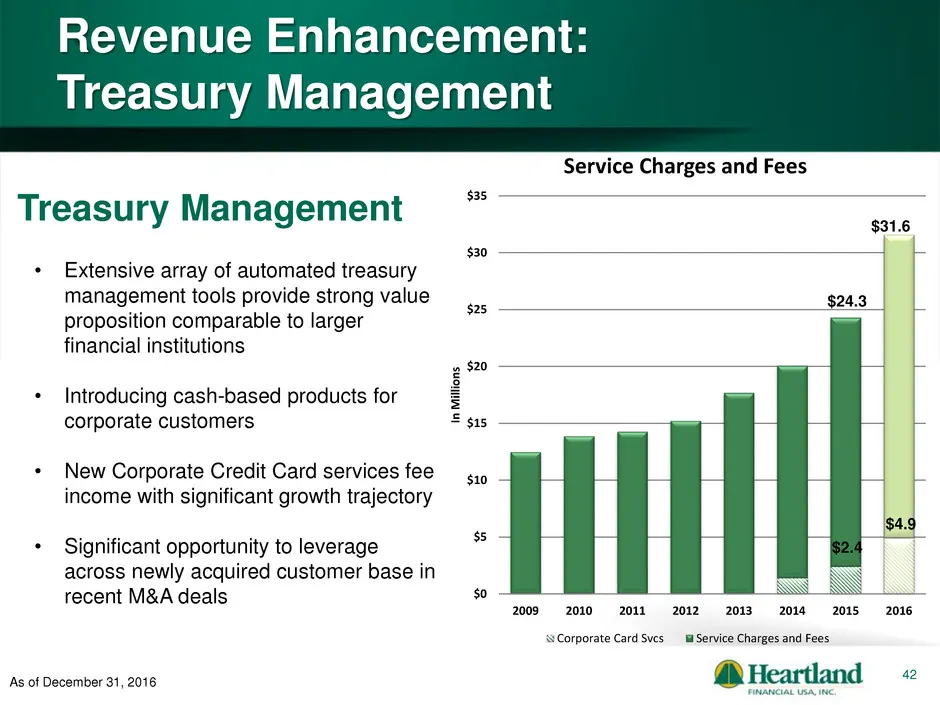
42 Treasury Management • Extensive array of automated treasury management tools provide strong value proposition comparable to larger financial institutions • Introducing cash-based products for corporate customers • New Corporate Credit Card services fee income with significant growth trajectory •
Slide 43: Net Income
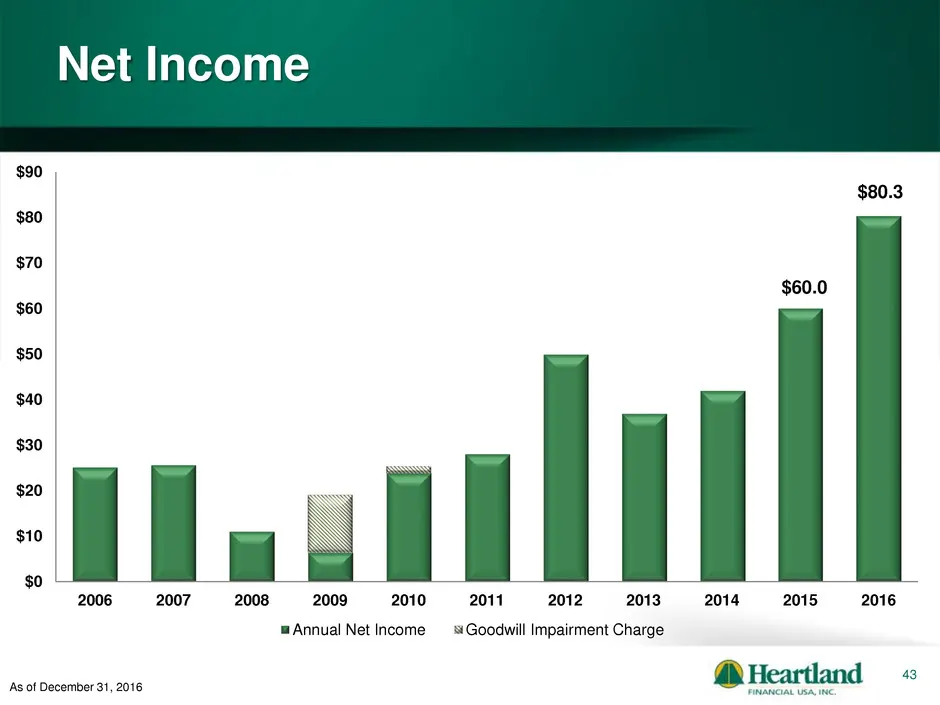
43 Net Income As of December 31, 2016 $60.0 $80.3 $0 $10 $20 $30 $40 $50 $60 $70 $80 $90 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Annual Net Income Goodwill Impairment Charge
Slide 44: Efficiency Ratio
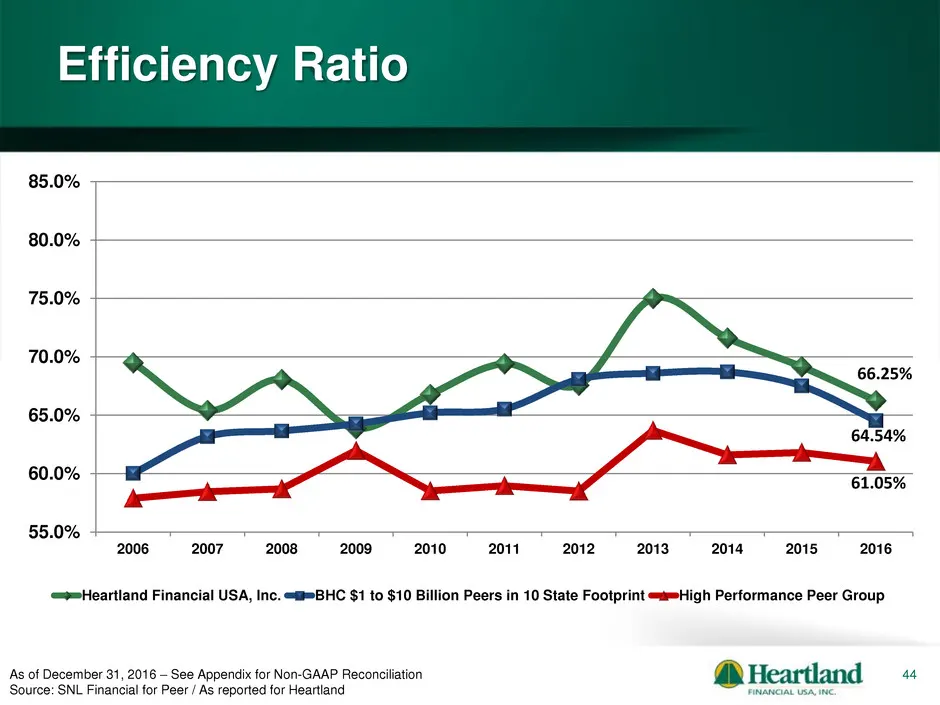
44 Efficiency Ratio As of December 31, 2016 – See Appendix for Non-GAAP Reconciliation Source: SNL Financial for Peer / As reported for Heartland 66.25% 64.54% 61.05% 55.0% 60.0% 65.0% 70.0% 75.0% 80.0% 85.0% 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc. BHC $1
Slide 45: Return on Average Common Equity
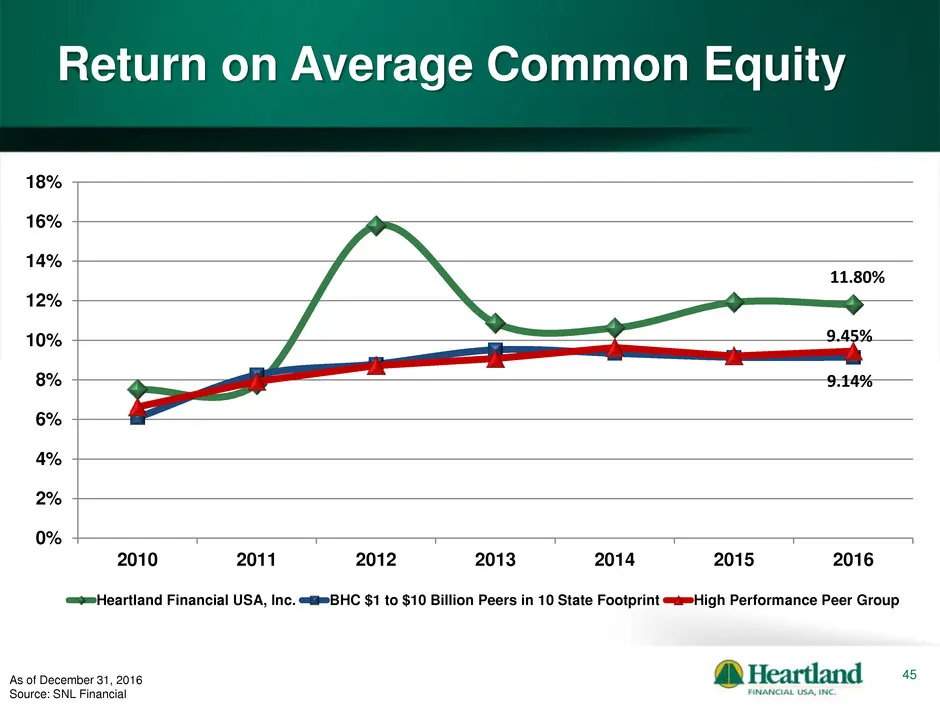
45 Return on Average Common Equity As of December 31, 2016 Source: SNL Financial 11.80% 9.14% 9.45% 0% 2% 4% 6% 8% 10% 12% 14% 16% 18% 2010 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc. BHC $1 to $10 Billion Peers in 10 State Footprint High Performance Peer Group
Slide 46: Return on Average Tangible Common Equity
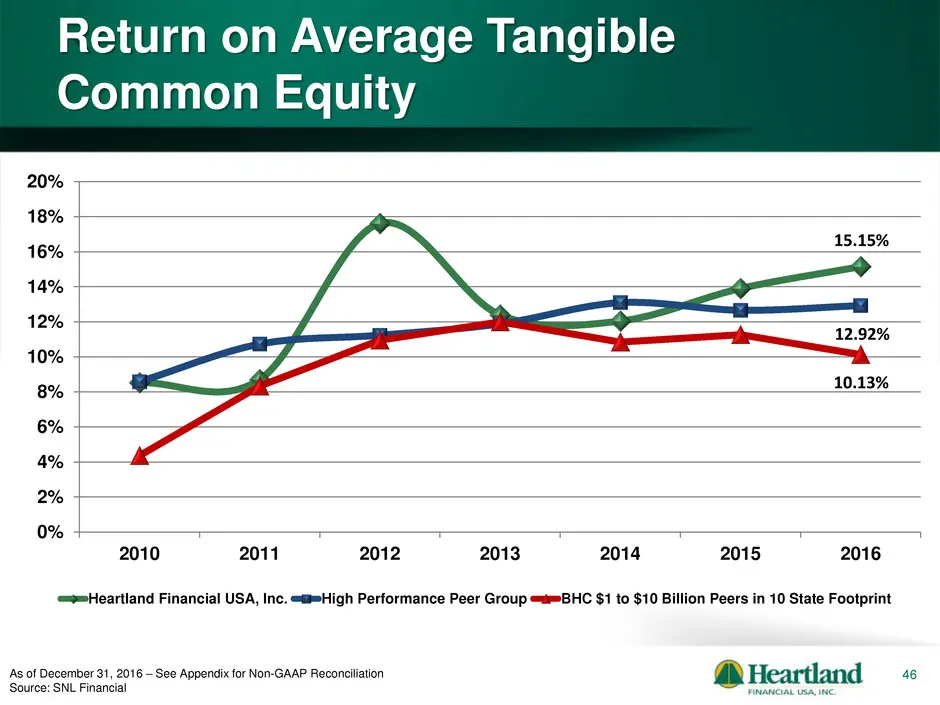
46 Return on Average Tangible Common Equity As of December 31, 2016 – See Appendix for Non-GAAP Reconciliation Source: SNL Financial 15.15% 12.92% 10.13% 0% 2% 4% 6% 8% 10% 12% 14% 16% 18% 20% 2010 2011 2012 2013 2014 2015 2016 Heartland Financial USA, Inc. High Performance Peer Group BHC $1 to $10
Slide 47: Analyst Ratings (February 2017)
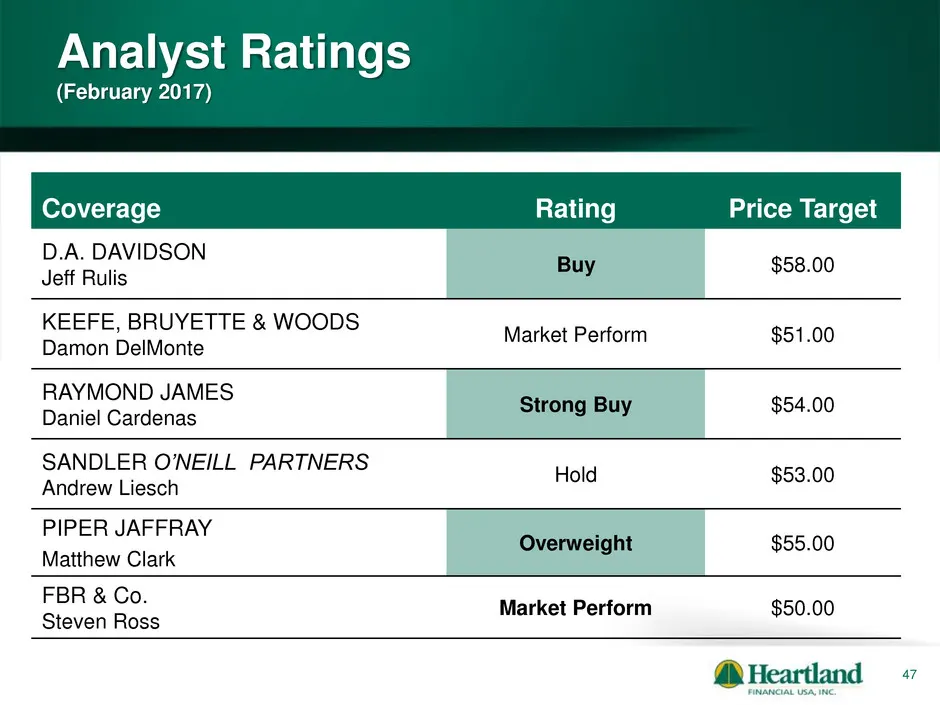
47 Analyst Ratings (February 2017) Coverage Rating Price Target D.A. DAVIDSON Jeff Rulis Buy $58.00 KEEFE, BRUYETTE & WOODS Damon DelMonte Market Perform $51.00 RAYMOND JAMES Daniel Cardenas Strong Buy $54.00 SANDLER O’NEILL PARTNERS Andrew Liesch Hold $53.00 PIPER JAFFRAY Matthew Clark Overweight $
Slide 48: Investment Summary
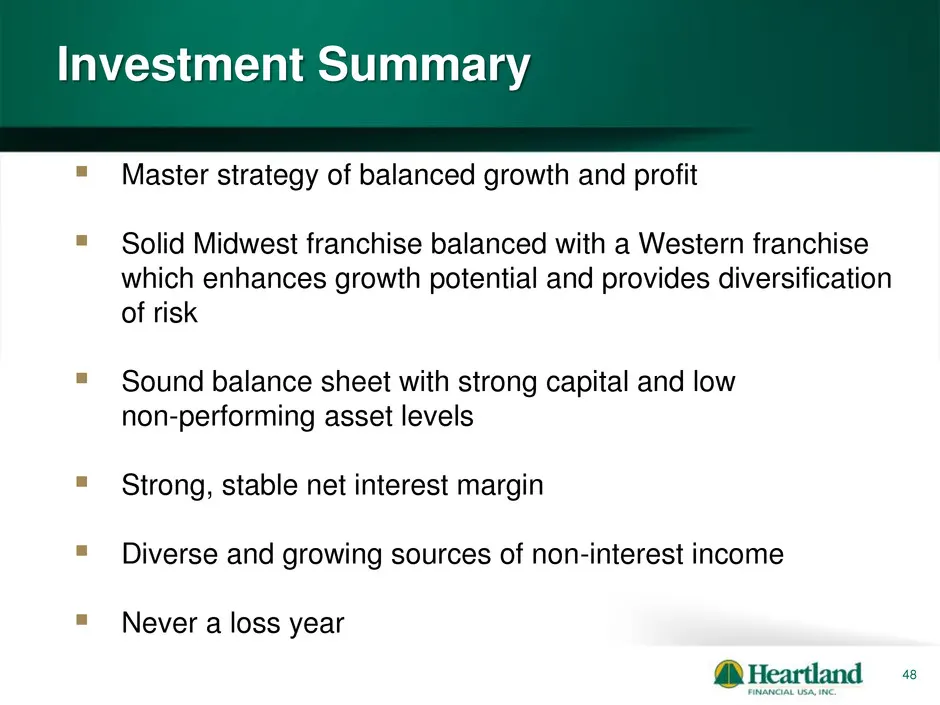
48 Master strategy of balanced growth and profit Solid Midwest franchise balanced with a Western franchise which enhances growth potential and provides diversification of risk Sound balance sheet with strong capital and low non-performing asset levels Strong, stable net interest margin Div
Slide 49: Contact Information
Contact Information LYNN B. FULLER Chi MHeartland OF o1 Prana Ane ihe aay siscied FAX (369) 589-2011 1398 CENTRALAVENUE PO.80X 778 _DUBUQUE.IA 52004-0778 BRYAN R. McKEAG EXECUTIVE VICE PRESIDENT (CHIEF FINANCIAL OFFICER PHONE: (563) 589-1994 ‘CEL: (920) 284.0732 Fast) 5091951 EE (886) 739-2100 sero
Slide 50: Reconciliation of Return on Average Common Tangible Equity and Efficiency Ratio
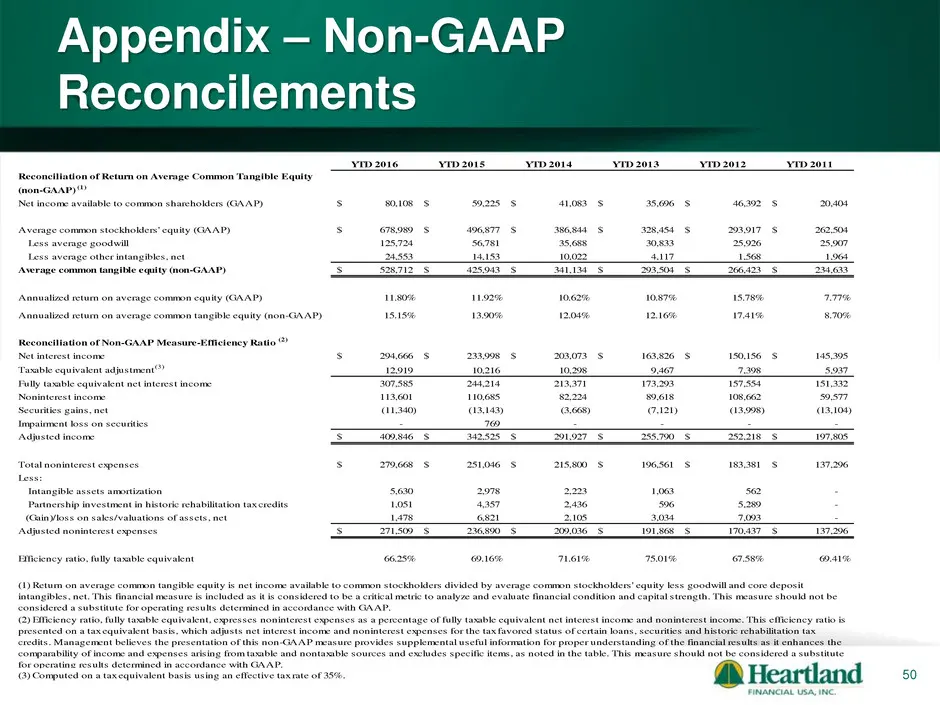
50 YTD 2016 YTD 2015 YTD 2014 YTD 2013 YTD 2012 YTD 2011 Reconciliation of Return on Average Common Tangible Equity (non-GAAP) (1) Net income available to common shareholders (GAAP) 80,108$ 59,225$ 41,083$ 35,696$ 46,392$ 20,404$ Average common stockholders' equity (GAAP) 678,989$ 496,877$ 386,844$
Slide 51: Appendix – Non-GAAP Reconcilements (Continued)
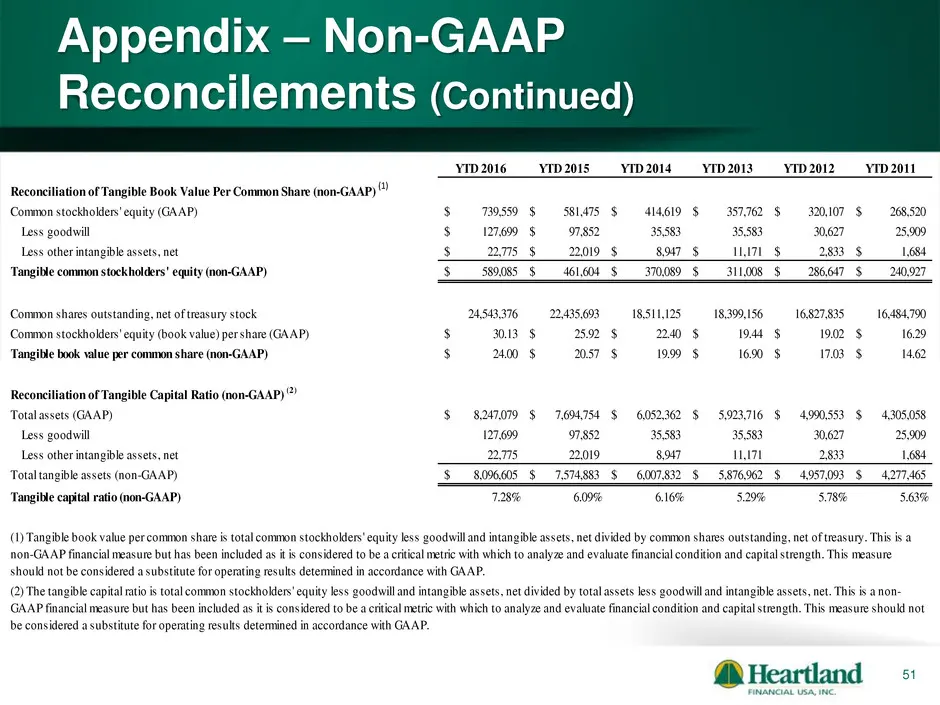
51 Appendix – Non-GAAP Reconcilements (Continued) YTD 2016 YTD 2015 YTD 2014 YTD 2013 YTD 2012 YTD 2011 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) (1) Common stockholders' equity (GAAP) 739,559$ 581,475$ 414,619$ 357,762$ 320,107$ 268,520$ Less goodwill 127,699$ 97,852$ 35,583
Slide 52: Appendix – Non-GAAP Reconcilements (Continued)
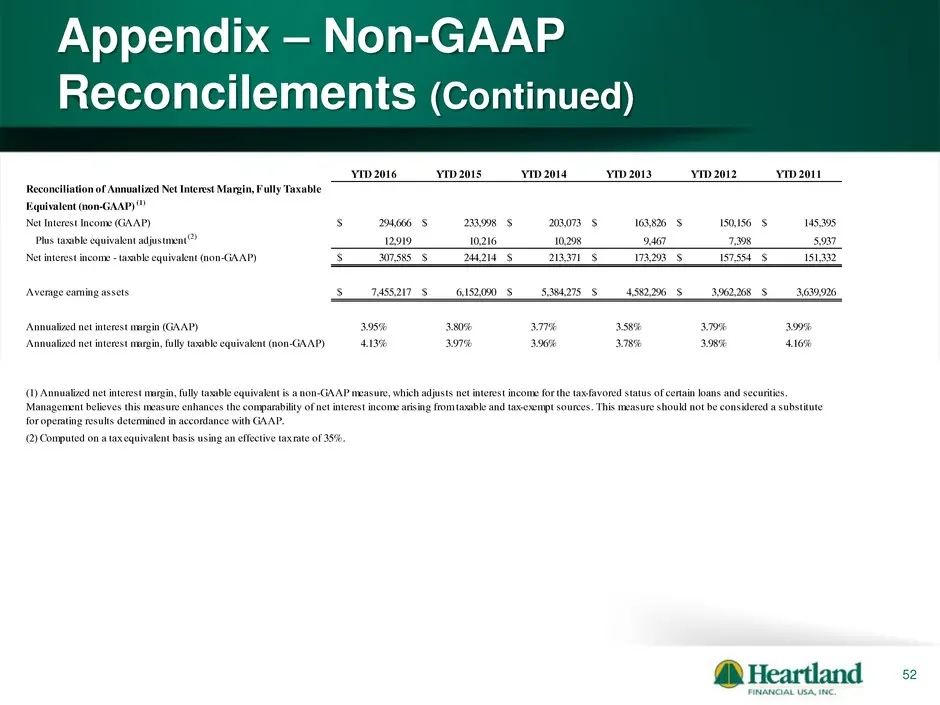
52 Appendix – Non-GAAP Reconcilements (Continued) YTD 2016 YTD 2015 YTD 2014 YTD 2013 YTD 2012 YTD 2011 Reconciliation of Annualized Net Interest Margin, Fully Taxable Equivalent (non-GAAP) (1) Net Interest Income (GAAP) 294,666$ 233,998$ 203,073$ 163,826$ 150,156$ 145,395$ Plus taxable equivalent a
Slide 53: Mission Statement
Mission Statement: Through excellence In customer service and Respect for the individual, EVERYONE PROFITS Trading Symbol: HTLF | www.htlf.com
Source: SEC EDGAR · 8-K filed Mar 2, 2017
More decks from Heartland Financial USA Inc
 Merger or Acquisition (July 2024)6 slides · Jul 31, 2024
 Merger or Acquisition (May 2024)6 slides · May 2, 2024
 Merger or Acquisition (May 2024)27 slides · May 2, 2024
 Q4 2023 Earnings Presentation54 slides · Feb 13, 2024
 Q4 2023 Earnings Presentation35 slides · Jan 29, 2024
 Q3 2023 Earnings Presentation55 slides · Nov 15, 2023