Escalera Resources — Double Eagle Petroleum — Sidoti & Company Semi-Annual New York Microcap Conference (January 2012)
19 slides from Escalera Resources's conference presentation, Jan 6, 2012
Slide 1: Sidoti & Company Semi-Annual New York Microcap Conference
1 Sidoti & Company Semi - Annual New York Microcap Conference January 9, 2012 Double Eagle Petroleum Co
Slide 2: Corporate Information & Disclaimer
2 Corporate Information & Disclaimer This presentation may contain projections and other forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended. Any such projections or statements reflect the Company's current views with respect to future even
Slide 3: Double Eagle Petroleum Co. Overview
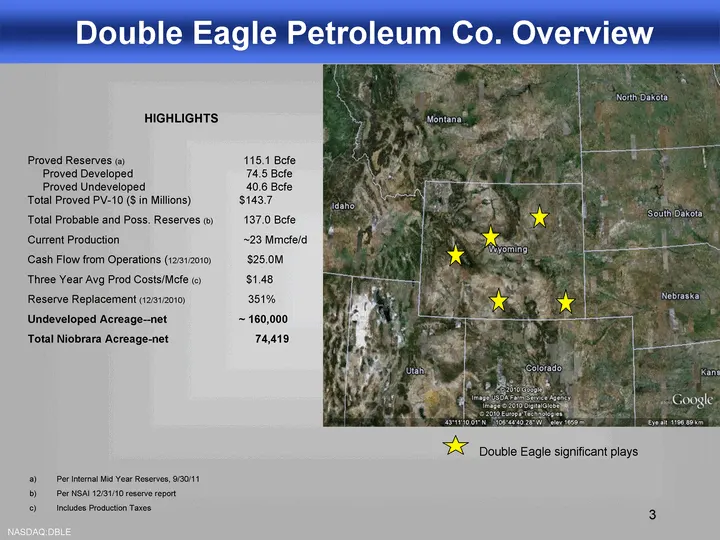
3 Double Eagle Petroleum Co. Overview HIGHLIGHTS Proved Reserves (a) 115.1 Bcfe Proved Developed 74.5 Bcfe Proved Undeveloped 40.6 Bcfe Total Proved PV-10 ($ in Millions) $143.7 Total Probable and Poss. Reserves (b) 137.0 Bcfe Current Production ~23 Mmcfe/d Cash Flow from Operations (12/31/2010) $25
Slide 4: Financial Summary
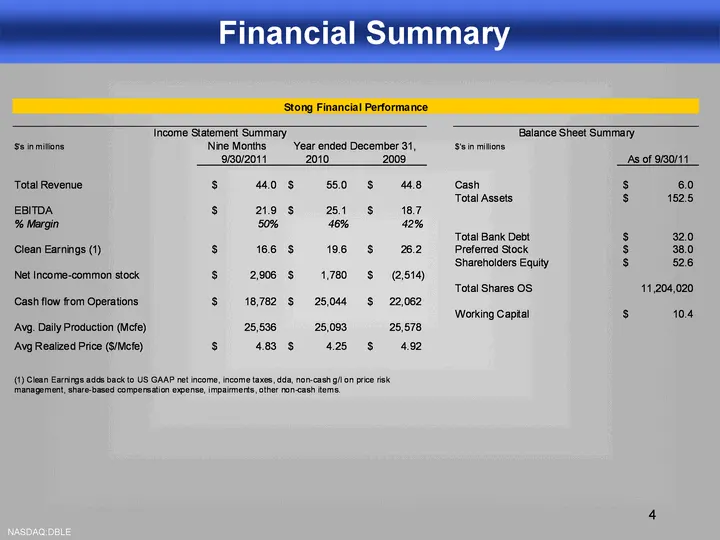
Financial Summary Thcome Statement Summary Balance Sheet Summary ‘Seinmisons Nine Months Year ended December 31, Sein mitons 90/2011 2010 2009 As of 930/11, Total Revenue S$ 440 $ 550 $ 448 Cash s 60 Total Assets S$ 1625 EBITDA $2198 21 S$ 187 % Margin 50% 46% 12% Total Bank Debt s 320 Clean Earning
Slide 5: Double Eagle's Value Proposition
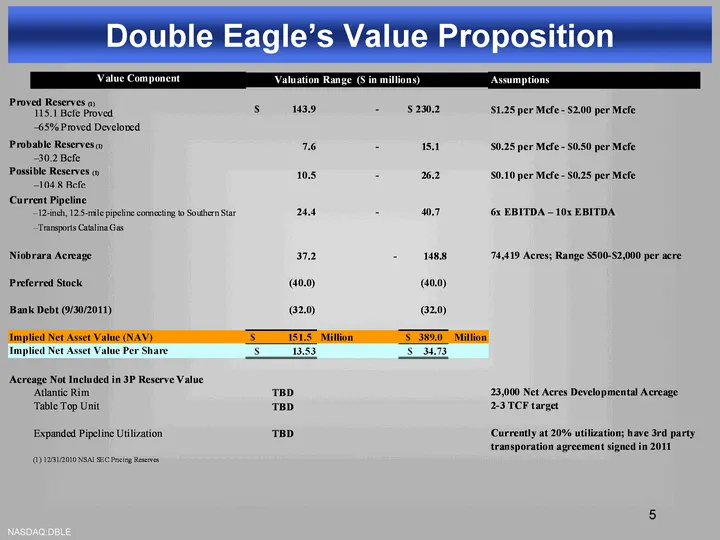
5 Double Eagle's Value Proposition
Slide 6: Proven Execution 2003-2010
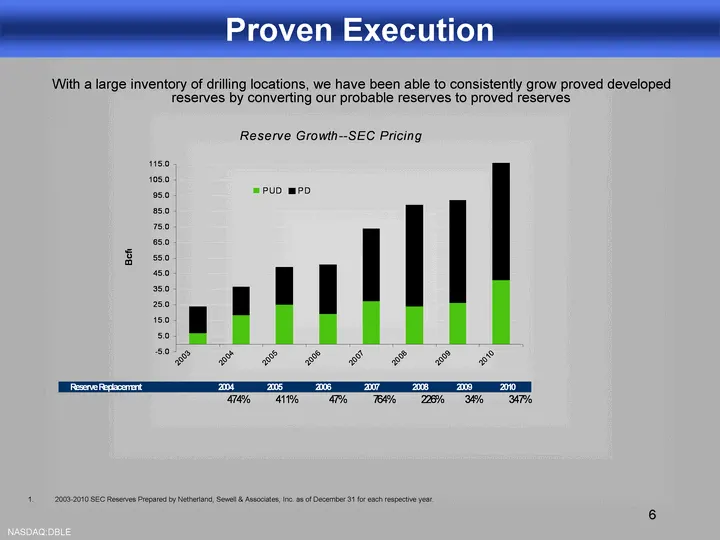
6 Proven Execution 2003-2010 SEC Reserves Prepared by Netherland, Sewell & Associates, Inc. as of December 31 for each respective year. With a large inventory of drilling locations, we have been able to consistently grow proved developed reserves by converting our probable reserves to proved reserve
Slide 7: Proven Execution: Low cost growth through the drill bit
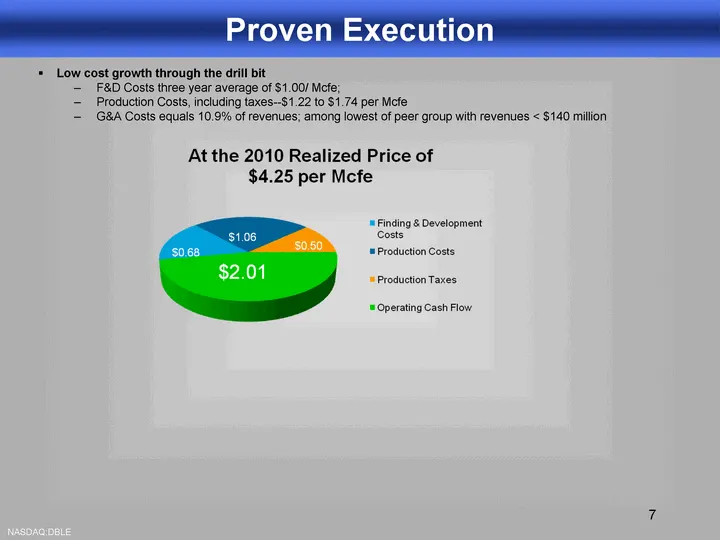
7 Proven Execution Low cost growth through the drill bit F&D Costs three year average of $1.00/ Mcfe; Production Costs, including taxes--$1.22 to $1.74 per Mcfe G&A Costs equals 10.9% of revenues; among lowest of peer group with revenues < $140 million
Slide 8: Building Blocks for Shareholder Value
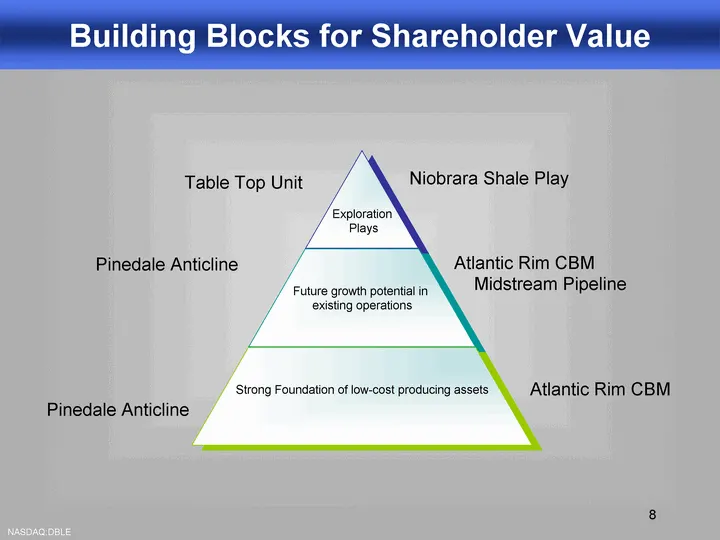
8 Building Blocks for Shareholder Value Atlantic Rim CBM Midstream Pipeline
Slide 9: Building Blocks for Shareholder Value
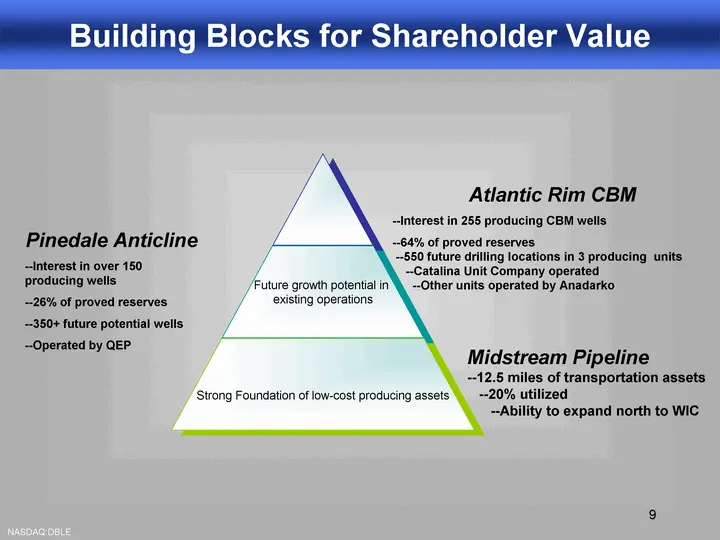
9 Building Blocks for Shareholder Value Midstream Pipeline --12.5 miles of transportation assets --20% utilized --Ability to expand north to WIC Atlantic Rim CBM --Interest in 255 producing CBM wells --64% of proved reserves --550 future drilling locations in 3 producing units --Catalina Unit Compan
Slide 10: The Atlantic Rim: Historical drilling activity
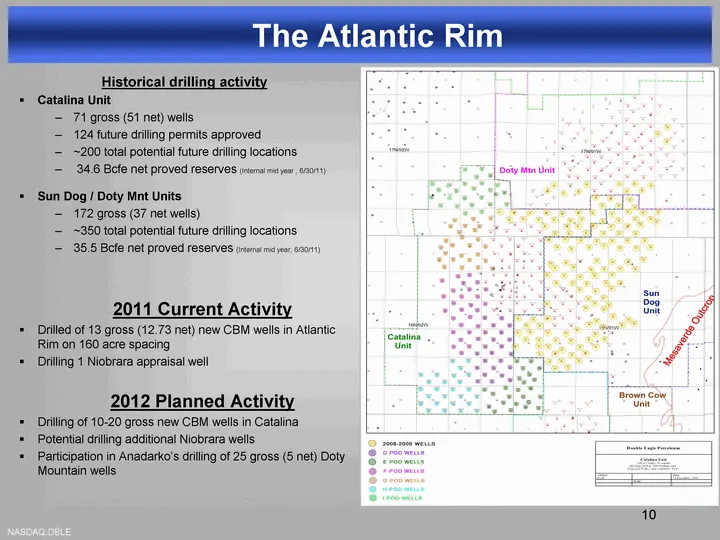
10 Historical drilling activity Catalina Unit 71 gross (51 net) wells 124 future drilling permits approved ~200 total potential future drilling locations 34.6 Bcfe net proved reserves (Internal mid year , 6/30/11) Sun Dog / Doty Mnt Units 172 gross (37 net wells) ~350 total potential future drilling
Slide 11: Pinedale Anticline
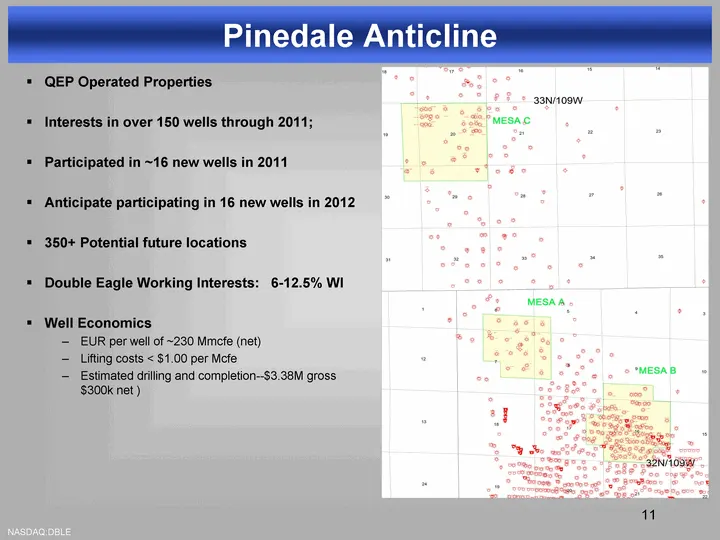
11 Pinedale Anticline QEP Operated Properties Interests in over 150 wells through 2011; Participated in ~16 new wells in 2011 Anticipate participating in 16 new wells in 2012 350+ Potential future locations Double Eagle Working Interests: 6-12.5% WI Well Economics EUR per well of ~230 Mmcfe (net) Li
Slide 12: Midstream Infrastructure
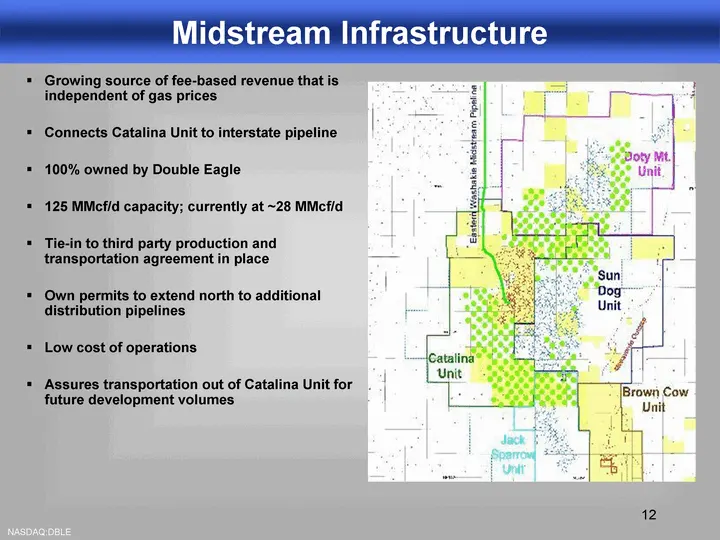
12 Midstream Infrastructure Growing source of fee-based revenue that is independent of gas prices Connects Catalina Unit to interstate pipeline 100% owned by Double Eagle 125 MMcf/d capacity; currently at ~28 MMcf/d Tie-in to third party production and transportation agreement in place Own permits t
Slide 13: Building Blocks for Shareholder Value
13 Building Blocks for Shareholder Value
Slide 14: Exploration Play-Niobrara Shale
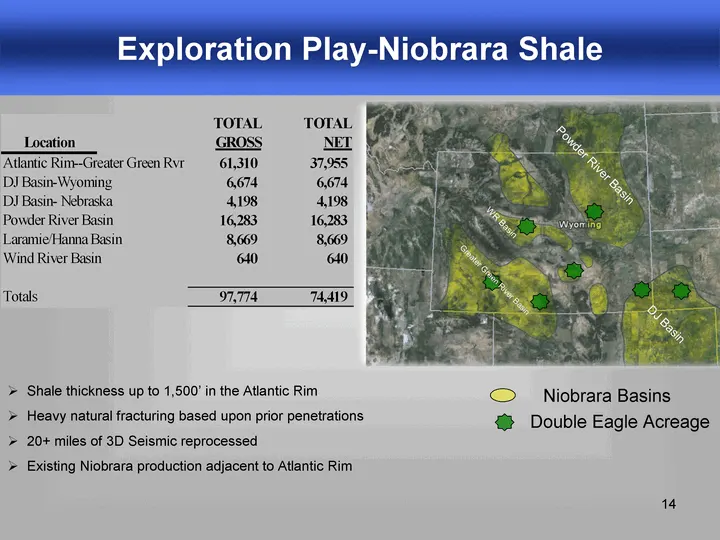
14 Exploration Play-Niobrara Shale Niobrara Basins Double Eagle Acreage Powder River Basin Greater Green River Basin DJ Basin WR Basin Shale thickness up to 1,500' in the Atlantic Rim Heavy natural fracturing based upon prior penetrations 20+ miles of 3D Seismic reprocessed Existing Niobrara product
Slide 15: Exploration Play-Niobrara Shale Central Wyoming & Colorado
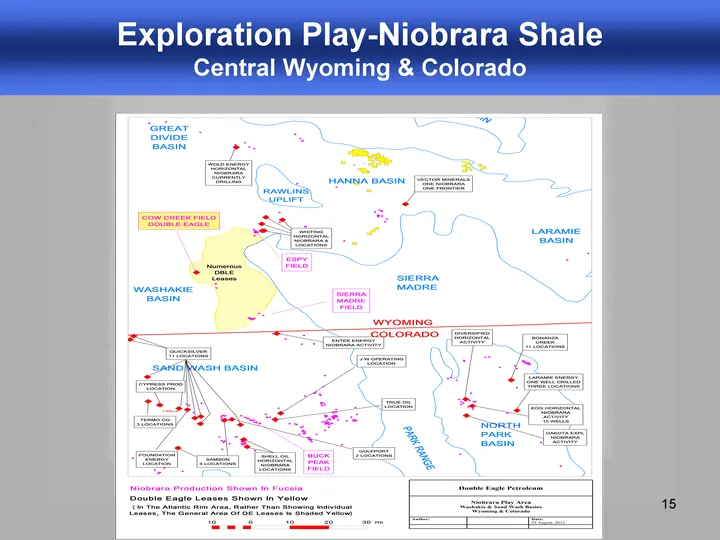
15 Exploration Play-Niobrara Shale Central Wyoming & Colorado
Slide 16: Exploration Play-Niobrara Shale DJ Basin
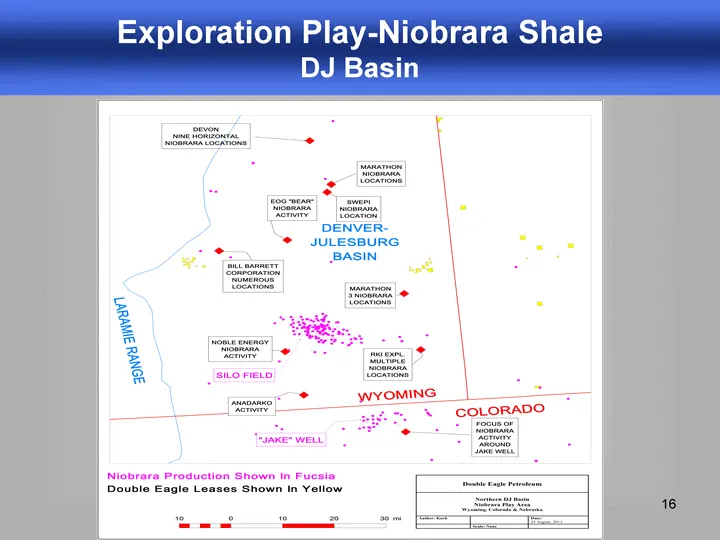
16 Exploration Play-Niobrara Shale DJ Basin
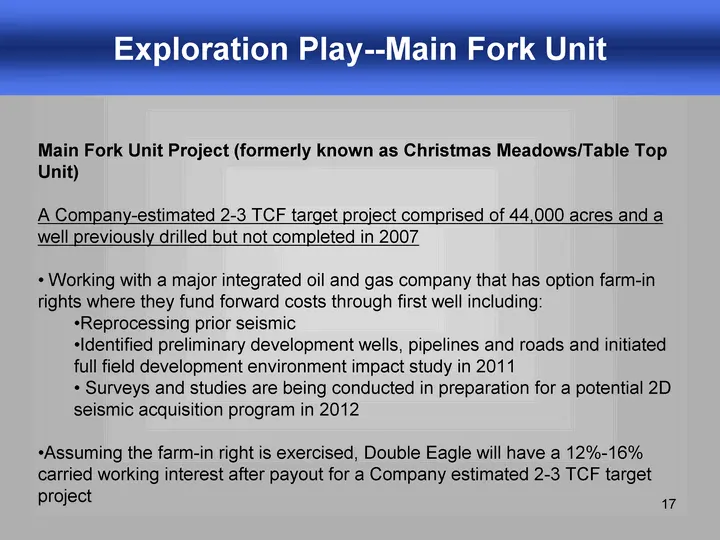
Slide 17: Exploration Play--Main Fork Unit
17 Exploration Play--Main Fork Unit Main Fork Unit Project (formerly known as Christmas Meadows/Table Top Unit) A Company-estimated 2-3 TCF target project comprised of 44,000 acres and a well previously drilled but not completed in 2007 Working with a major integrated oil and gas company that has op
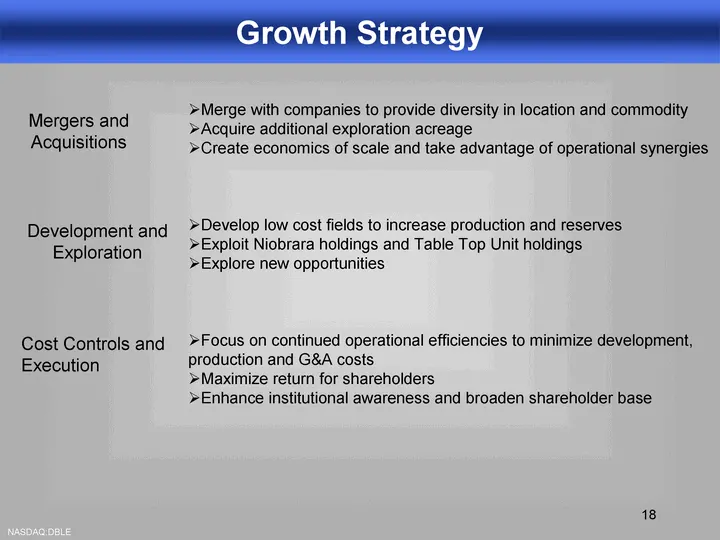
Slide 18: Growth Strategy
18 Growth Strategy Mergers and Acquisitions Merge with companies to provide diversity in location and commodity Acquire additional exploration acreage Create economics of scale and take advantage of operational synergies Develop low cost fields to increase production and reserves Exploit Niobrara ho
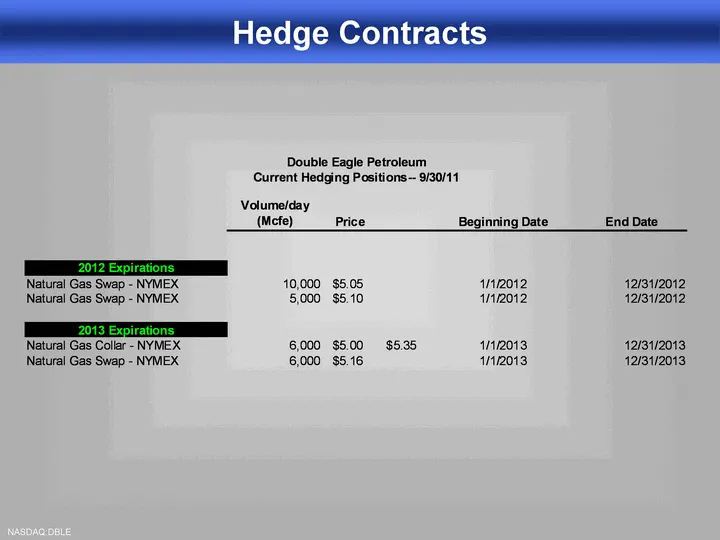
Slide 19: Hedge Contracts
Hedge Contracts Double Eagle Petroleum Current Hedging Positions ~ 9/30/11 Volumelday (Mcfe) ice Beginning Date End Date Natural Gas Swap - NYMEX 10,000 $5.05 42012 12/31/2012 Natural Gas Swap - NYMEX 5,000 $5.10 4112012 12/31/2012 Natural Gas Collar - NYMEX 6,000 $5.00 $5.35 11112013 12/31/2013, Na
Source: SEC EDGAR · 8-K filed Jan 6, 2012
More decks from Escalera Resources Company
 EnerCom: The Oil & Gas Conference 201420 slides · Aug 20, 2014
 IPAA OGIS Toronto 201421 slides · Jun 5, 2014
 IPAA Oil & Gas Conference April 201426 slides · Apr 9, 2014
 Double Eagle Petroleum — Euro Pacific Global Investment Conference 201318 slides · Sep 3, 2013
 Double Eagle Petroleum — EnerCom's The Oil & Gas Conference 201318 slides · Aug 14, 2013
 Double Eagle Petroleum — OGIS Conference New York 201316 slides · Apr 15, 2013