Santander Holdings USA Inc · NYSE:SNUS/PH
Santander Holdings USA — Debt Investor Presentation (May 2024)
33 slides from Santander Holdings USA's debt investor presentation, May 6, 2024
Slide 1: Santander Holdings USA, Inc. First Quarter 2024 Fixed Income Investor Presentation
May 6, 2024 SANTANDER HOLDINGS USA, INC. First Quarter 2024 Fixed Income Investor Presentation 1
Slide 2: Important Information
Important Information This presentation of Santander Holdings USA, Inc. (“SHUSA”) contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the financial condition, results of operations, business plans and future performance of SHUSA.
Slide 3: Index
Index 1 2 3 4 At a Glance Results Capital & Appendix Liquidity 3
Slide 4: SHUSA
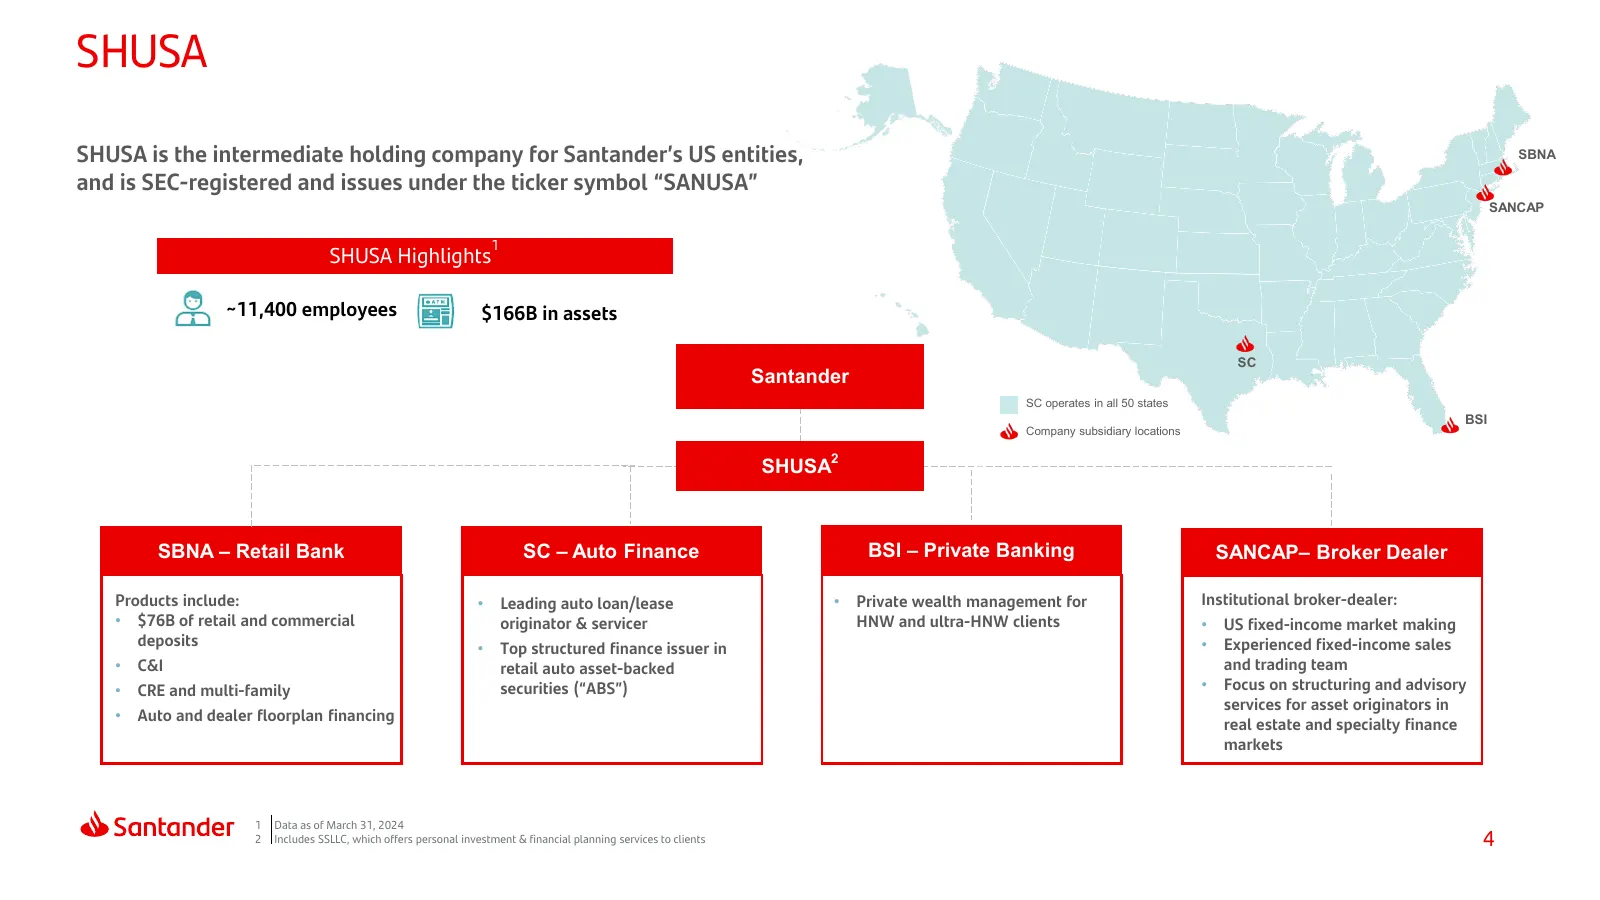
SHUSA SHUSA is the intermediate holding company for Santander’s US entities, SBNA and is SEC-registered and issues under the ticker symbol “SANUSA” SANCAP 1 SHUSA Highlights ~13,200 employees ~11,400 $166B in assets SC Santander SC operates in all 50 states BSI Company subsidiary locations SHUSA2 SB
Slide 5: SHUSA Q1 2024 Highlights
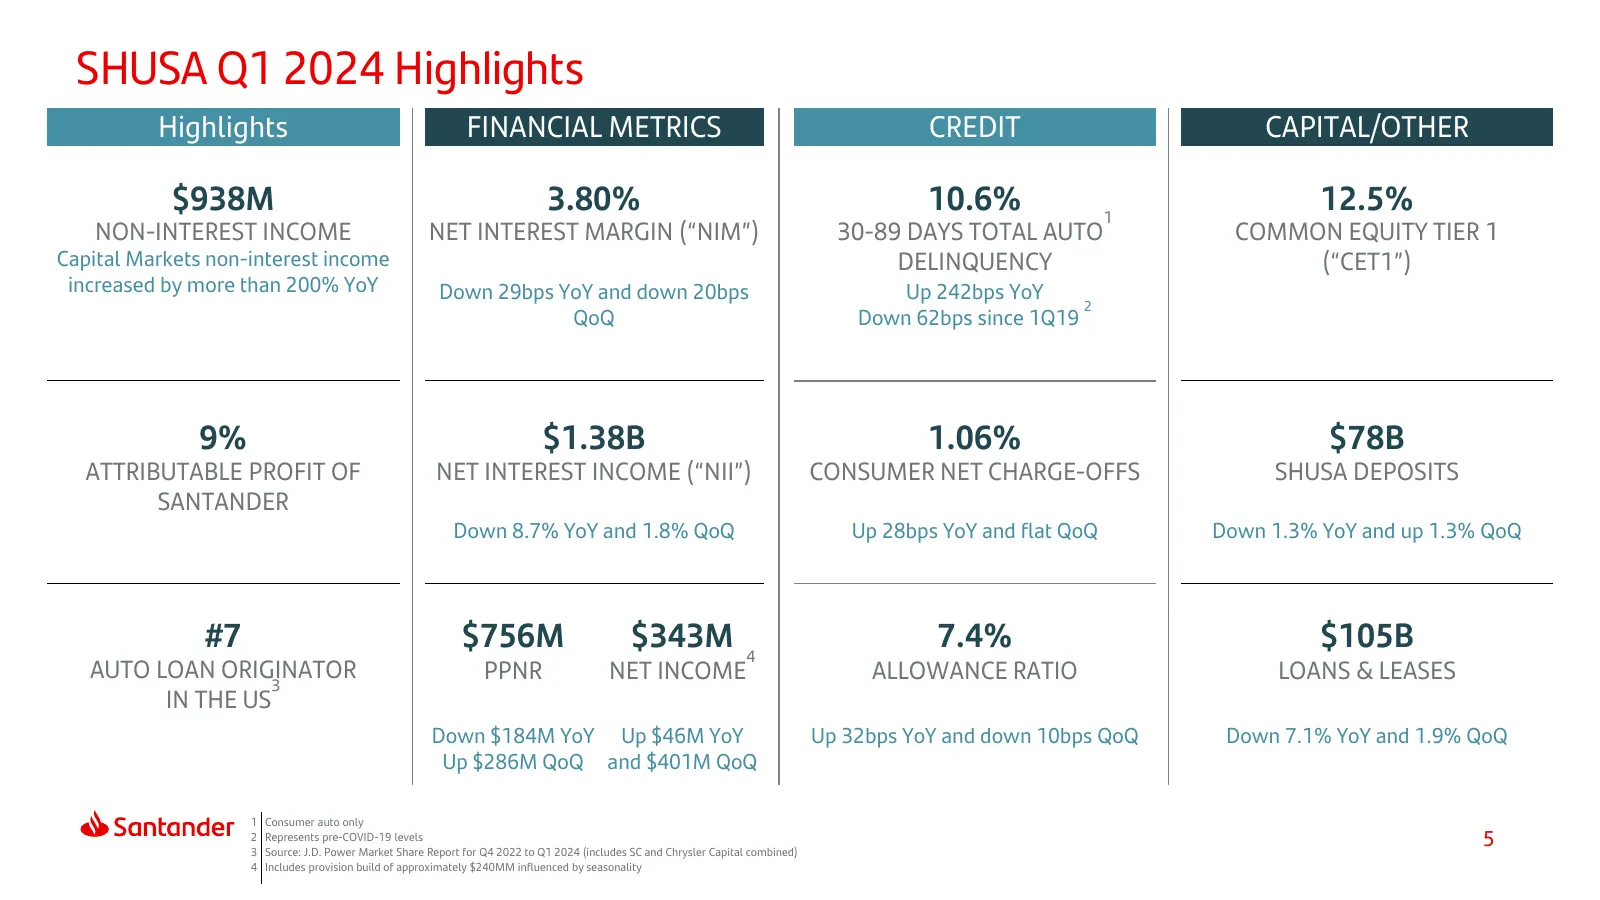
SHUSA Q1 2024 Highlights Highlights FINANCIAL METRICS CREDIT CAPITAL/OTHER $938M 3.80% 10.6% 1 12.5% NON-INTEREST INCOME NET INTEREST MARGIN (“NIM”) 30-89 DAYS TOTAL AUTO COMMON EQUITY TIER 1 Capital Markets non-interest income DELINQUENCY (“CET1”) increased by more than 200% YoY Down 29bps YoY and
Slide 6: Strategic Focus
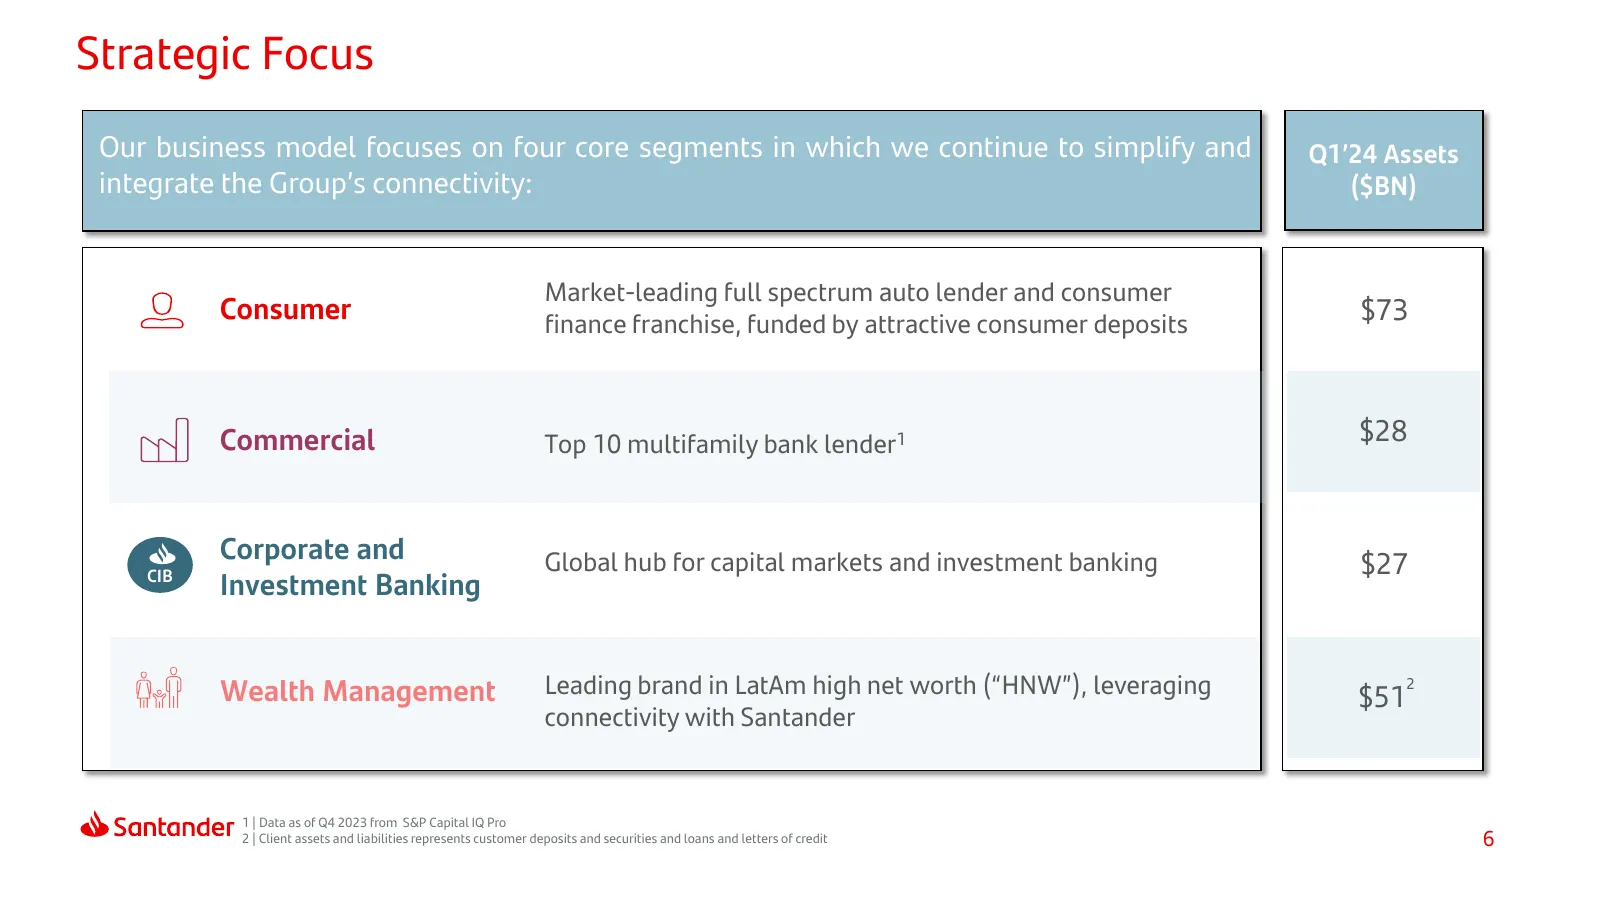
Strategic Focus Our business model focuses on four core segments in which we continue to simplify and Q1’24 Assets integrate the Group’s connectivity: ($BN) Market-leading full spectrum auto lender and consumer Consumer finance franchise, funded by attractive consumer deposits $73 Commercial Top 10
Slide 7: Index
Index 1 2 3 4 At a Glance Results Capital & Appendix Liquidity 7
Slide 8: Quarterly Profitability
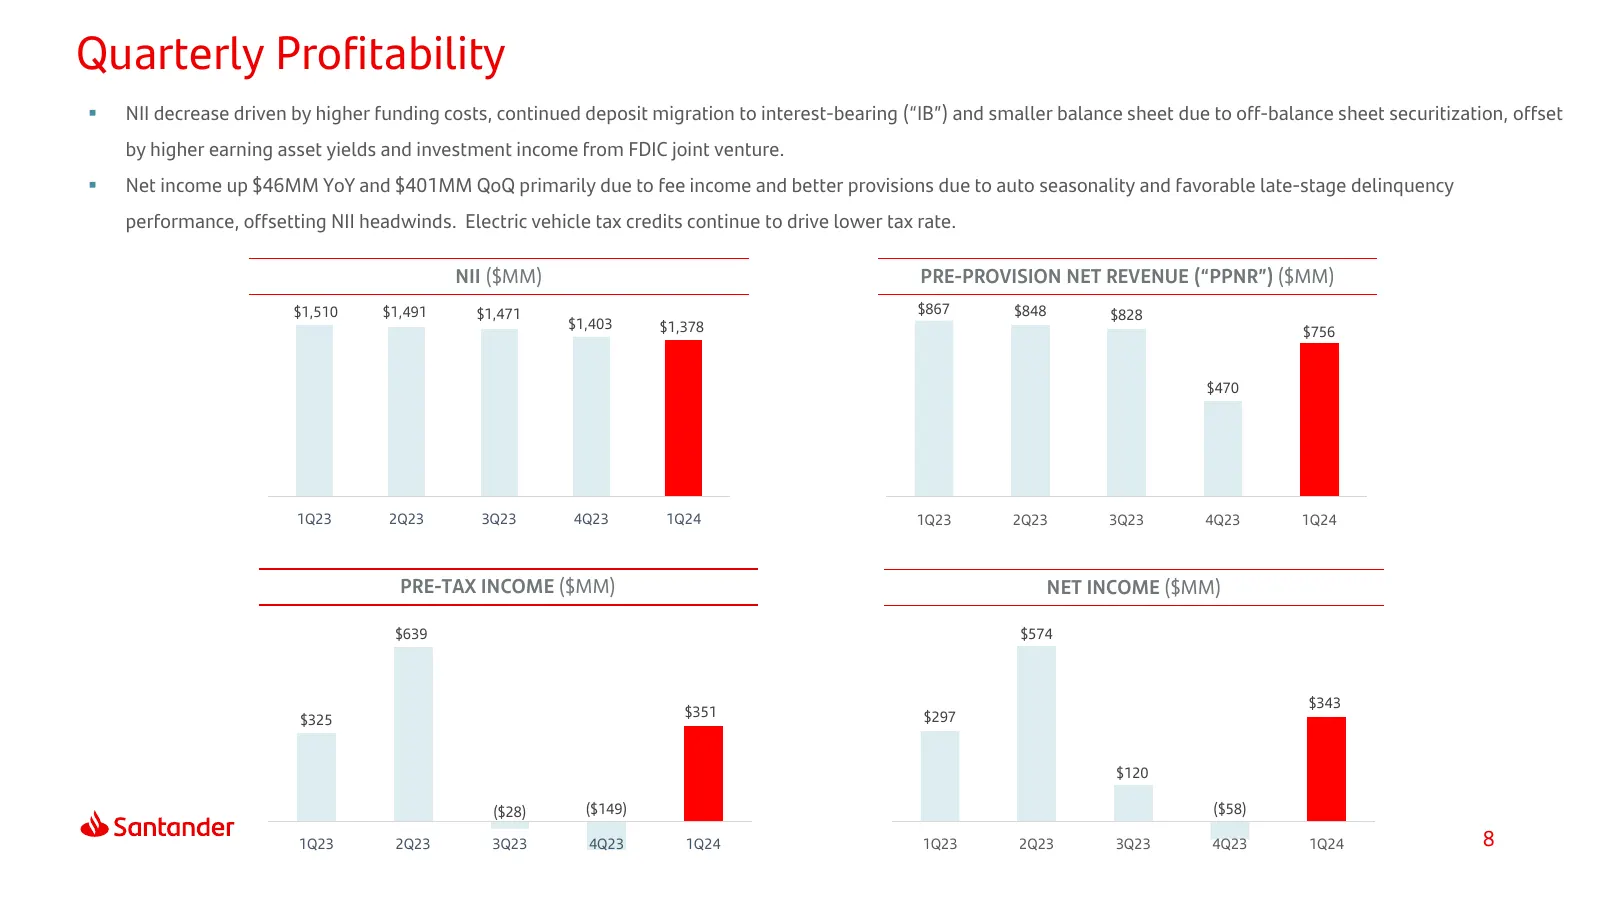
Quarterly Profitability NII decrease driven by higher funding costs, continued deposit migration to interest-bearing (“IB”) and smaller balance sheet due to off-balance sheet securitization, offset by higher earning asset yields and investment income from FDIC joint venture. Net income up $46MM
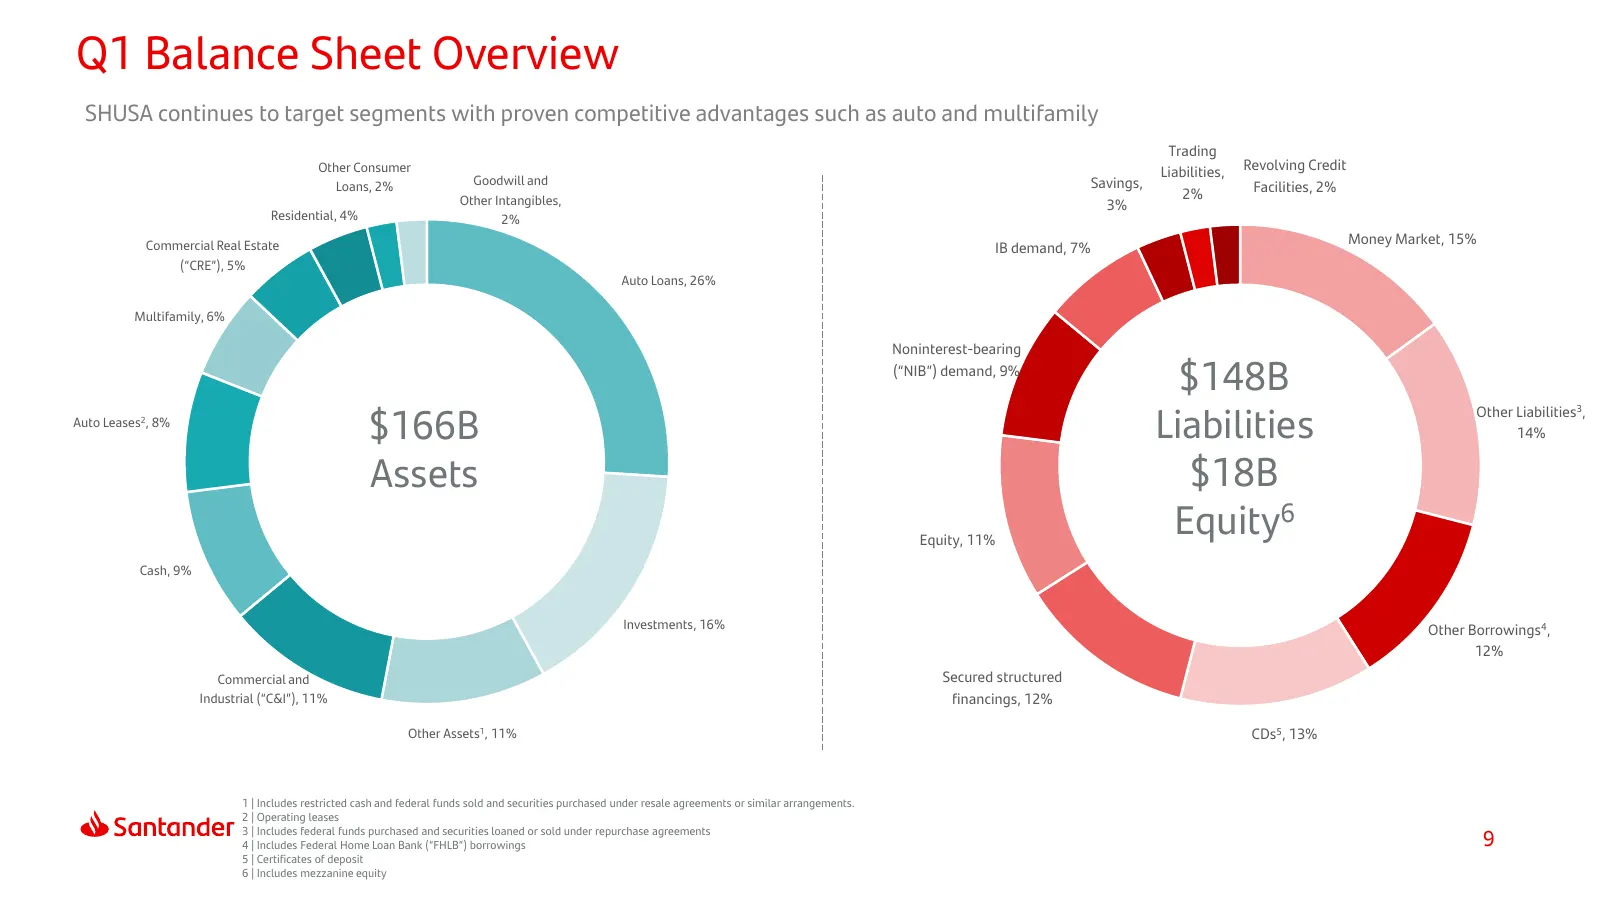
Slide 9: Q1 Balance Sheet Overview
Q1 Balance Sheet Overview SHUSA continues to target segments with proven competitive advantages such as auto and multifamily Trading Other Consumer Liabilities, Revolving Credit Loans, 2% Goodwill and Savings, Facilities, 2% Other Intangibles, 2% 3% Residential, 4% 2% Commercial Real Estate Money Ma
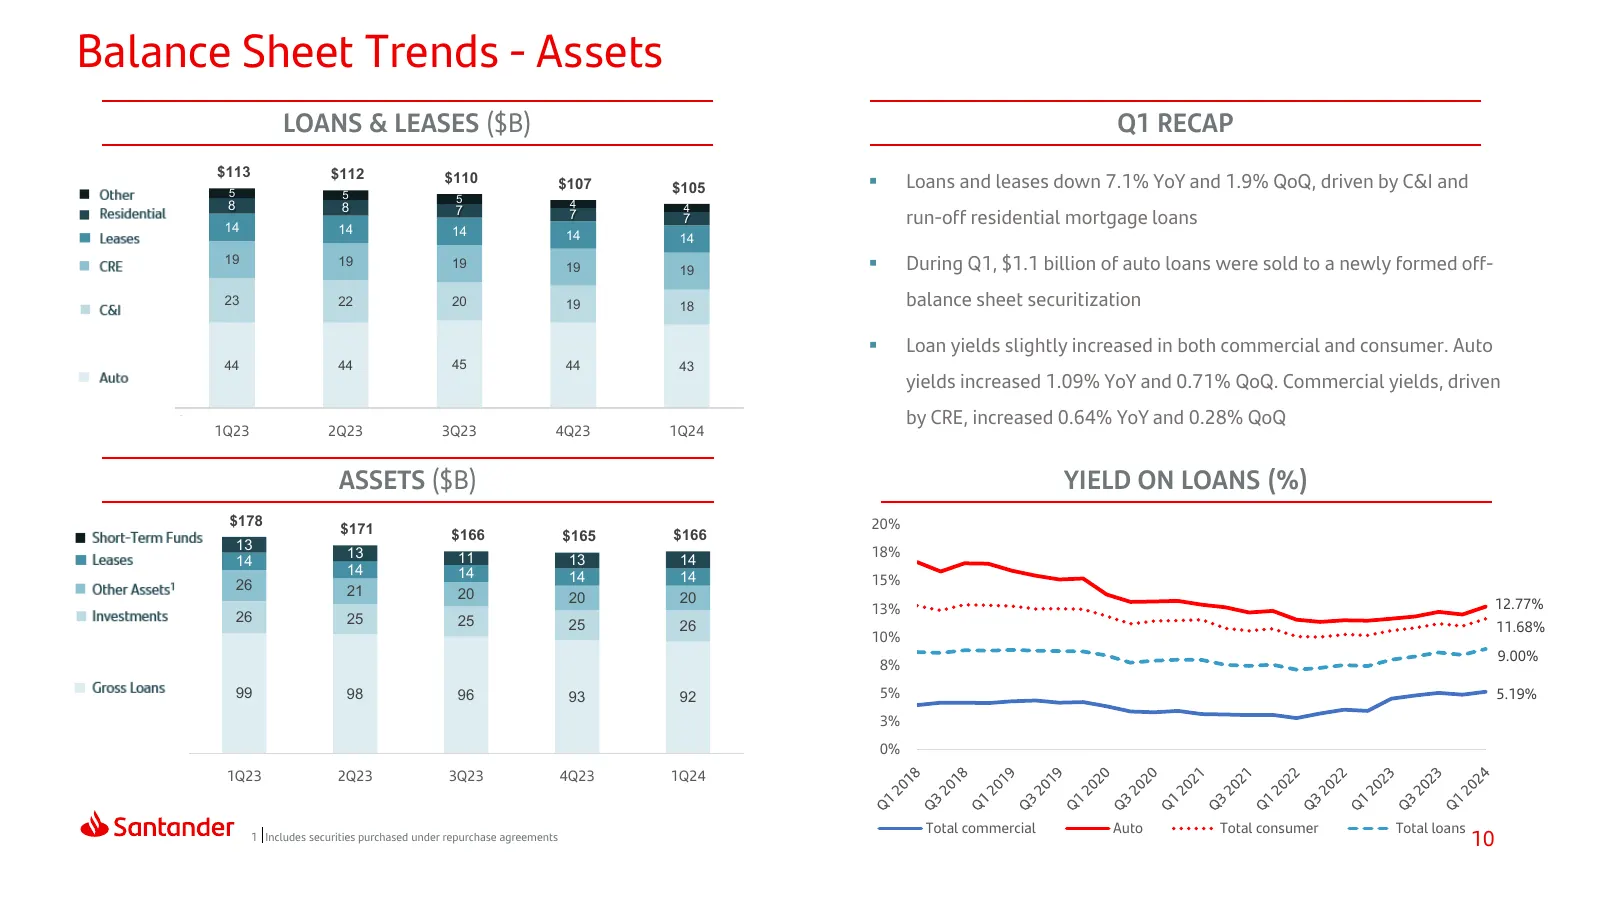
Slide 10: Balance Sheet Trends - Assets
Balance Sheet Trends - Assets LOANS & LEASES ($B) Q1 RECAP $113 $112 5 $110 $107 $105 Loans and leases down 7.1% YoY and 1.9% QoQ, driven by C&I and 5 5 8 8 4 4 7 14 14 7 7 run-off residential mortgage loans 14 14 14 19 19 19 19 19 During Q1, $1.1 billion of auto loans were sold to a newly forme
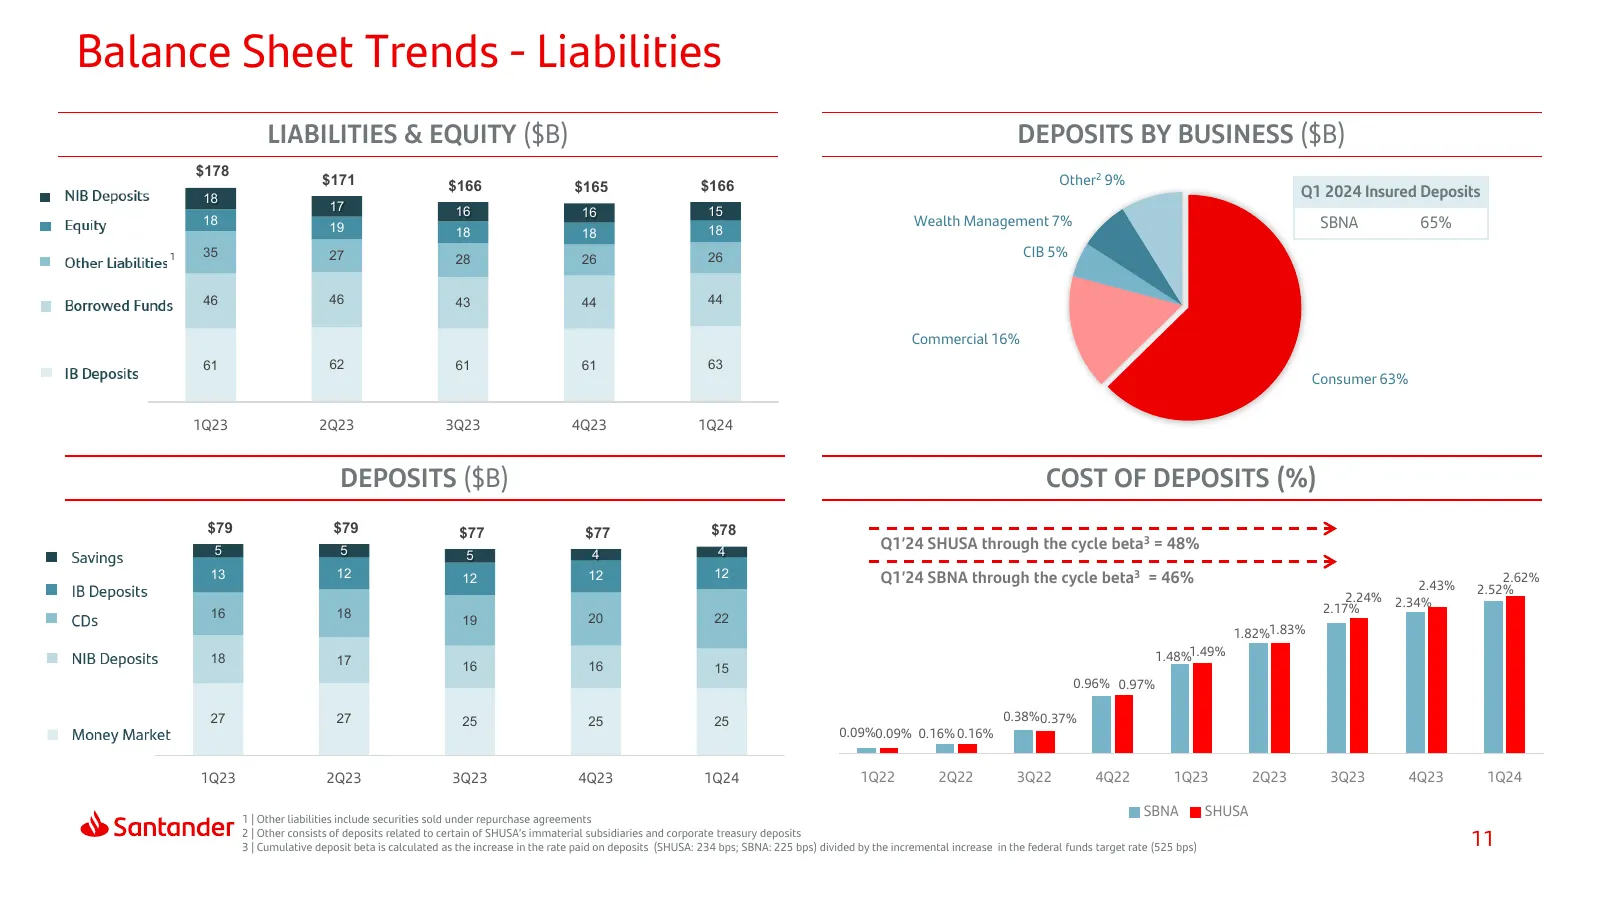
Slide 11: Balance Sheet Trends - Liabilities
Balance Sheet Trends - Liabilities LIABILITIES & EQUITY ($B) DEPOSITS BY BUSINESS ($B) $178 $171 $166 $165 $166 Other2 9% 18 Q1 2024 Insured Deposits 17 16 16 15 18 19 Wealth Management 7% SBNA 65% 18 18 18 1 35 27 28 26 26 CIB 5% 46 46 43 44 44 Commercial 16% 61 62 61 61 63 Consumer 63% 1Q23 2Q23 3
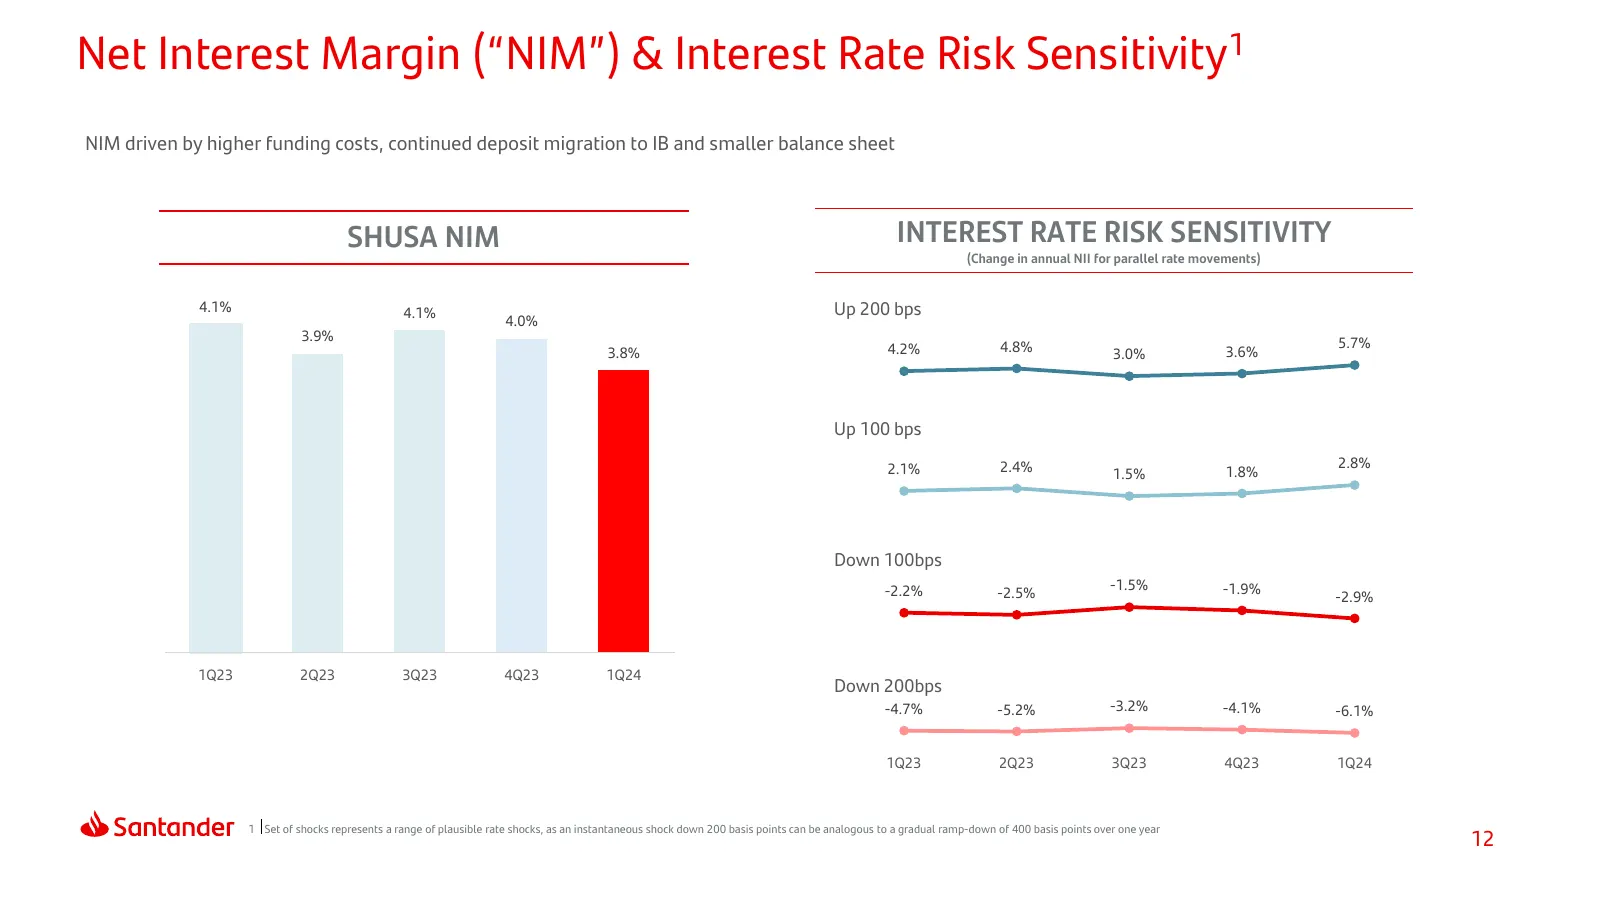
Slide 12: Net Interest Margin & Interest Rate Risk Sensitivity
Net Interest Margin (“NIM”) & Interest Rate Risk Sensitivity1 NIM driven by higher funding costs, continued deposit migration to IB and smaller balance sheet SHUSA NIM INTEREST RATE RISK SENSITIVITY (Change in annual NII for parallel rate movements) 4.1% 4.1% Up 200 bps 4.0% 3.9% 5.7% 3.8% 4.2% 4.8%
Slide 13: Auto Originations
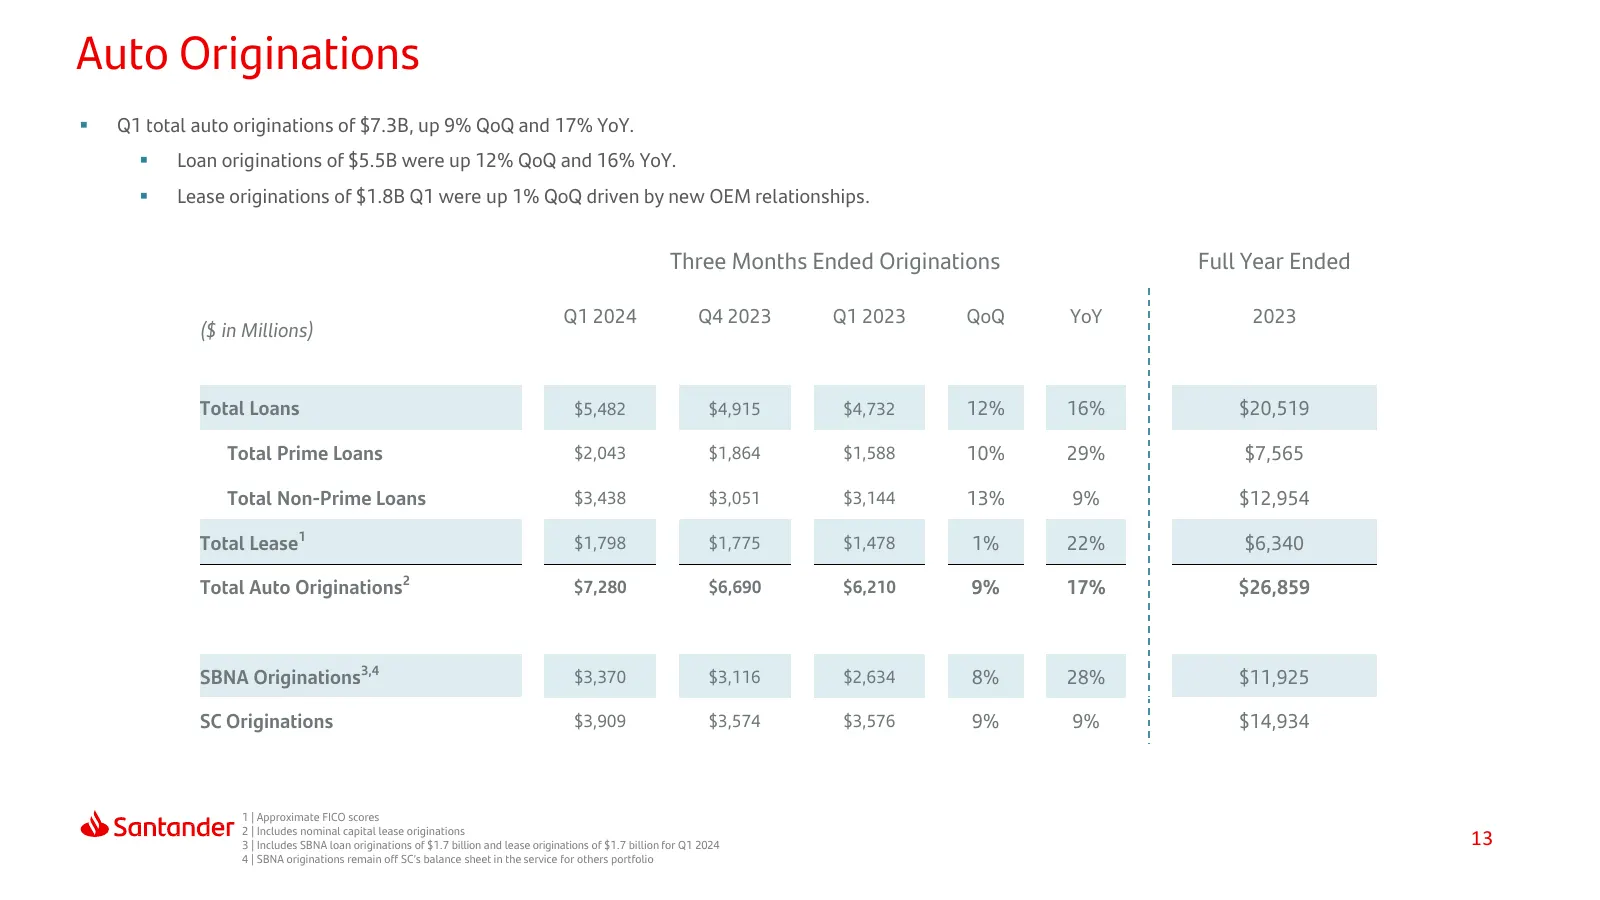
Auto Originations Q1 total auto originations of $7.3B, up 9% QoQ and 17% YoY. Loan originations of $5.5B were up 12% QoQ and 16% YoY. Lease originations of $1.8B Q1 were up 1% QoQ driven by new OEM relationships. Three Months Ended Originations Full Year Ended Q1 2024 Q4 2023 Q1 2023 QoQ YoY 2
Slide 14: Loan Delinquency by Business Portfolio
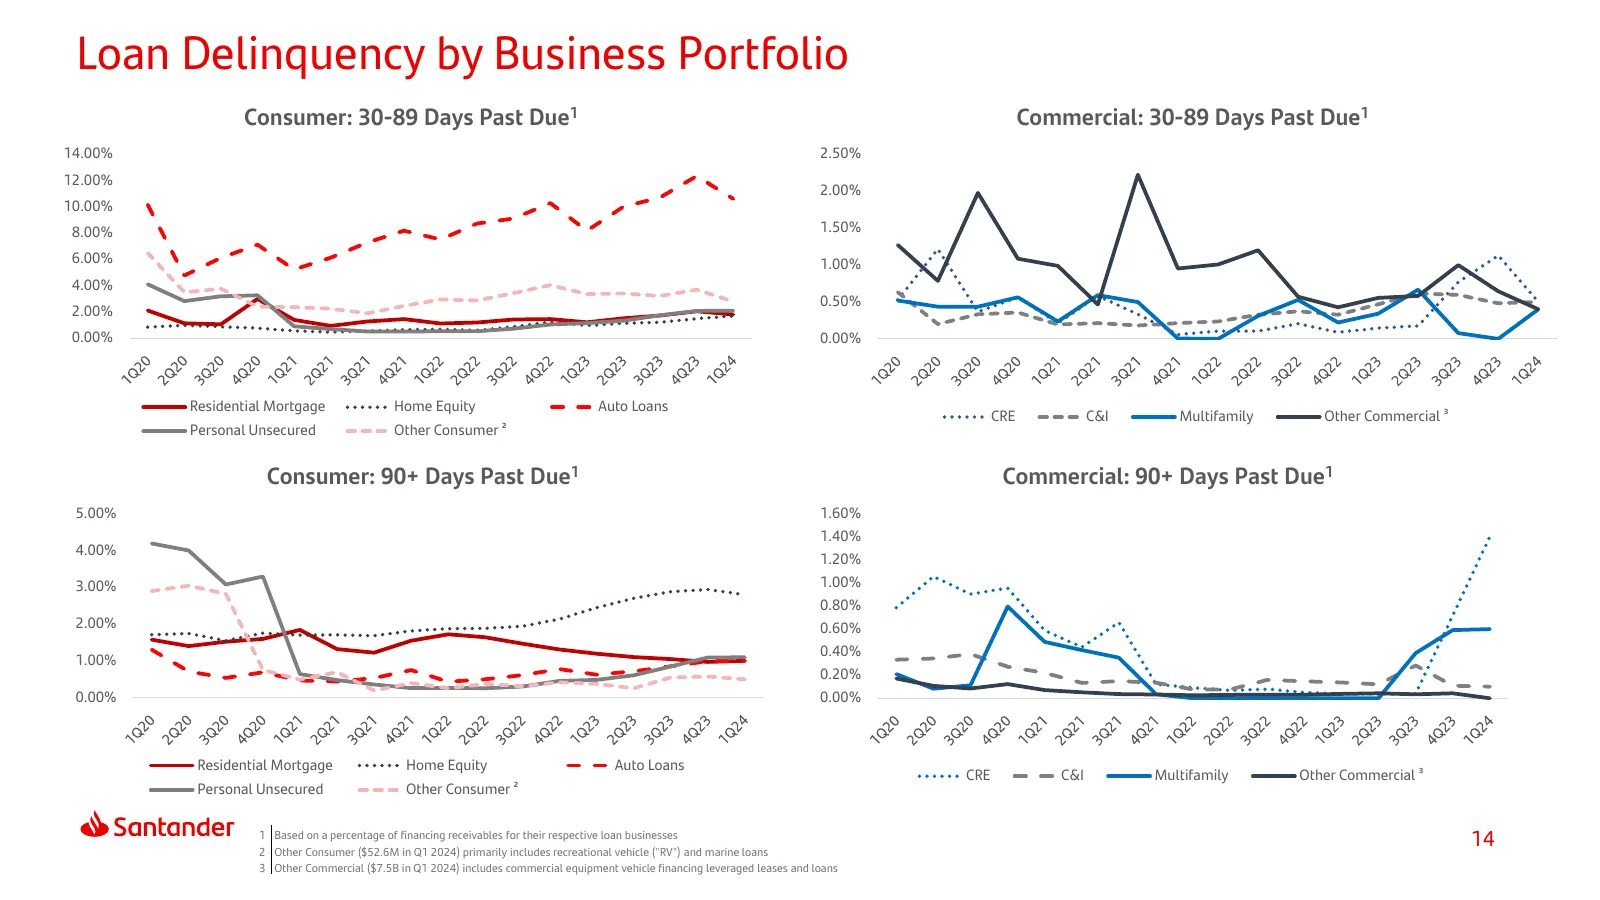
Loan Delinquency by Business Portfolio Consumer: 30-89 Days Past Due1 Commercial: 30-89 Days Past Due1 14.00% 2.50% 12.00% 2.00% 10.00% 8.00% 1.50% 6.00% 1.00% 4.00% 0.50% 2.00% 0.00% 0.00% Residential Mortgage Home Equity Auto Loans CRE C&I Multifamily Other Commercial ³ Personal Unsecured Other Co
Slide 15: Charge-offs and Recoveries by Business Portfolio
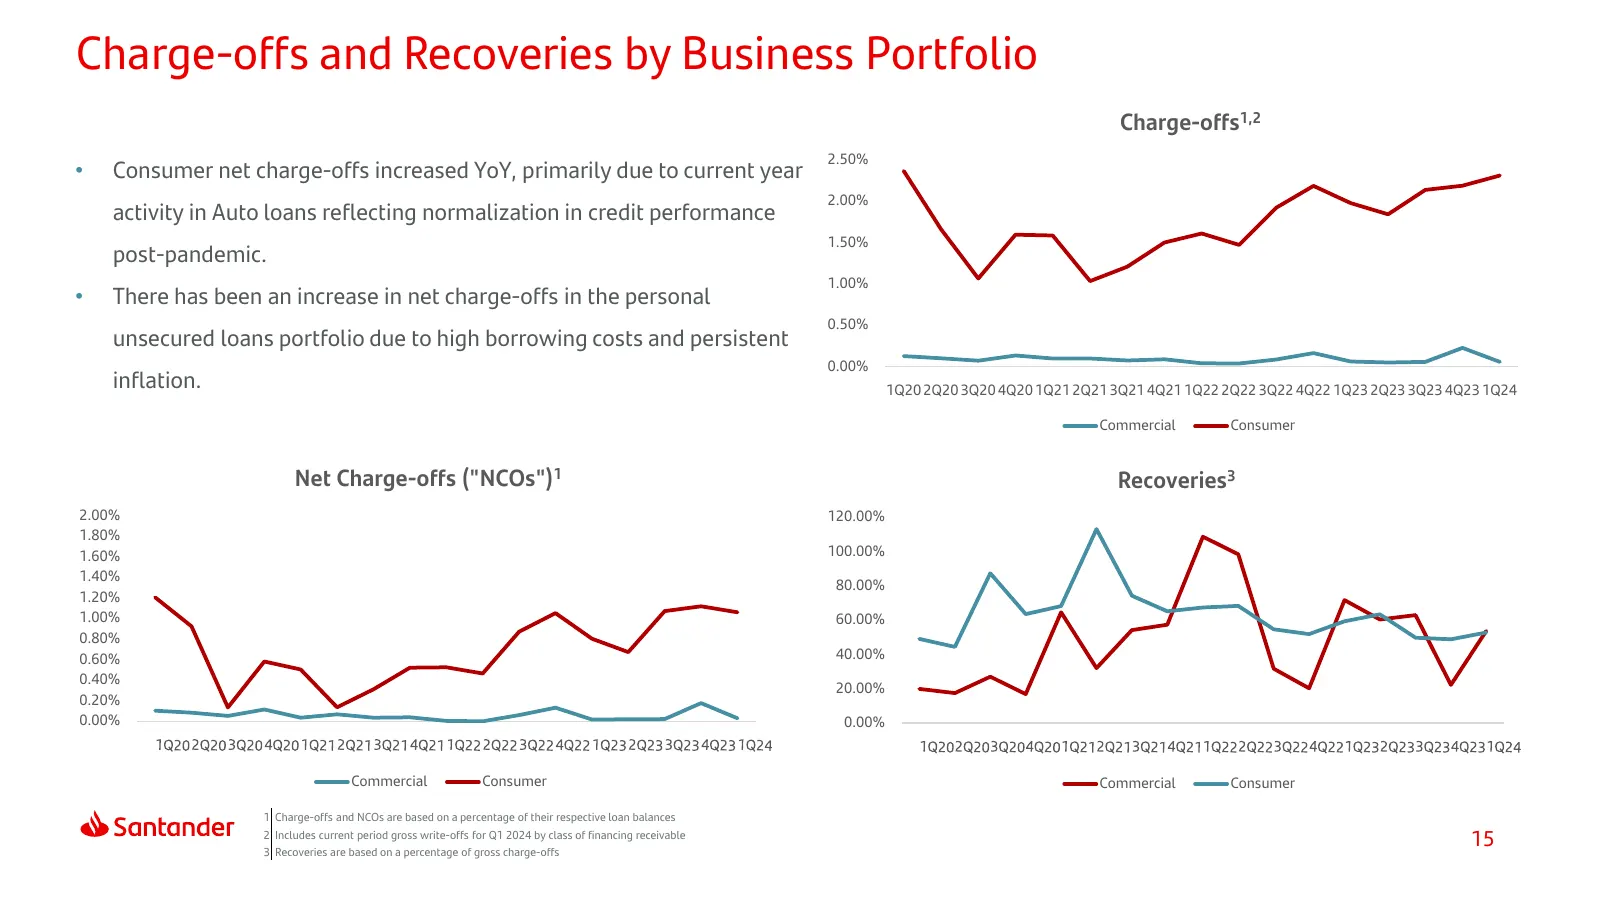
Charge-offs and Recoveries by Business Portfolio Charge-offs1,2 2.50% • Consumer net charge-offs increased YoY, primarily due to current year 2.00% activity in Auto loans reflecting normalization in credit performance 1.50% post-pandemic. 1.00% • There has been an increase in net charge-offs in the
Slide 16: Allowance For Credit Losses ("ACL")
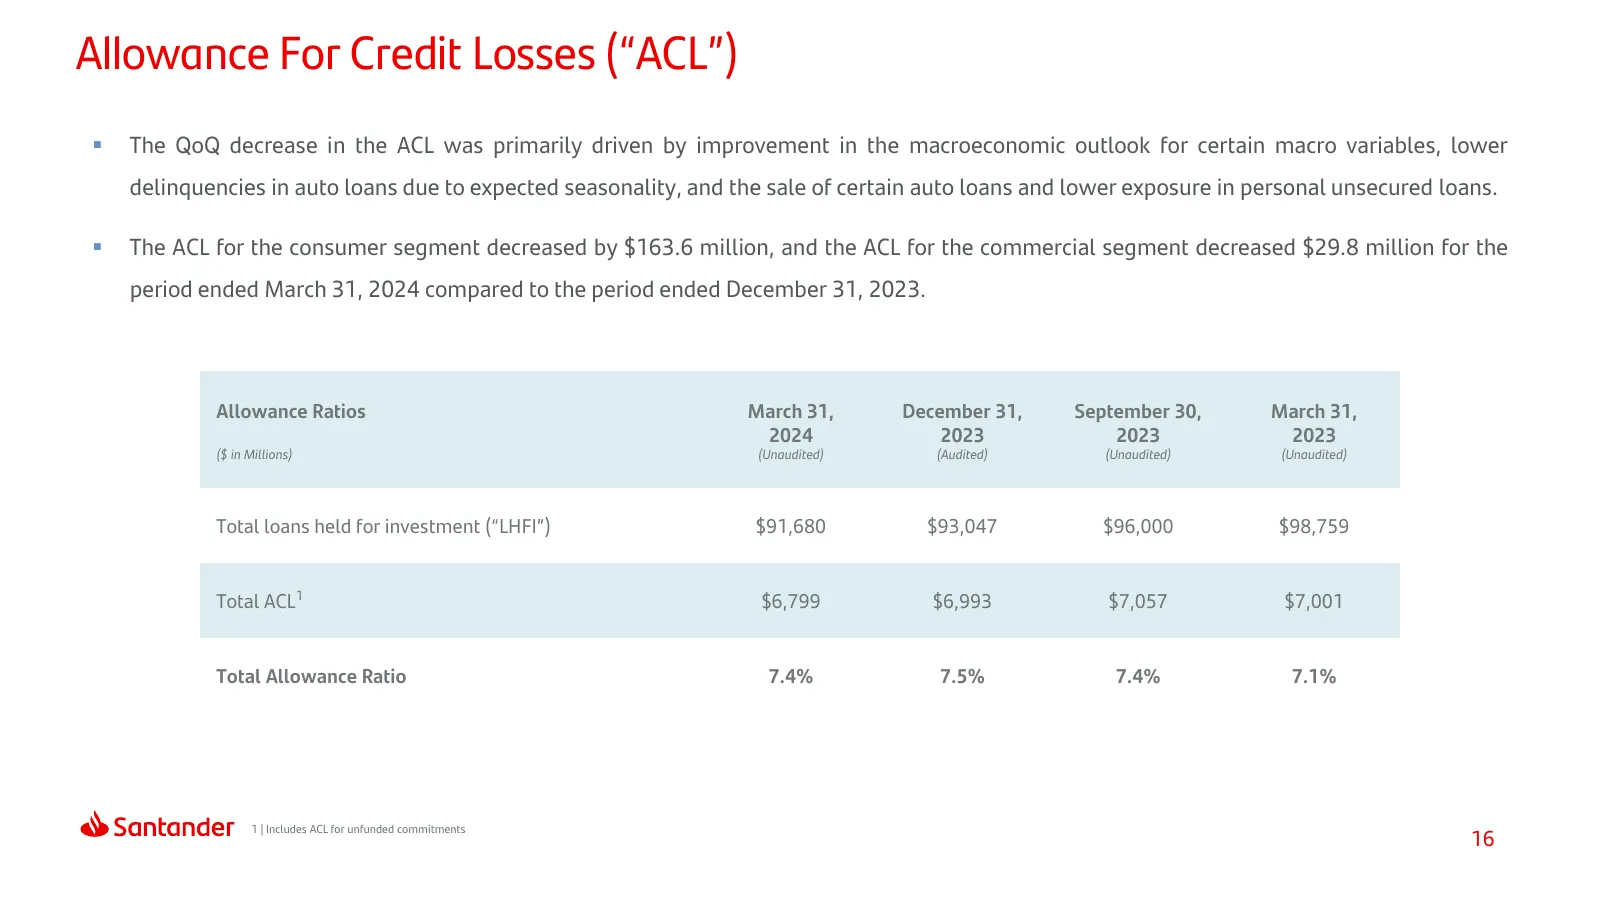
Allowance For Credit Losses (“ACL”) The QoQ decrease in the ACL was primarily driven by improvement in the macroeconomic outlook for certain macro variables, lower delinquencies in auto loans due to expected seasonality, and the sale of certain auto loans and lower exposure in personal unsecured l
Slide 17: Index
Index 1 2 3 4 At a Glance Results Capital & Appendix Liquidity 17
Slide 18: Overall borrowings and SBNA contingent liquidity stable QoQ
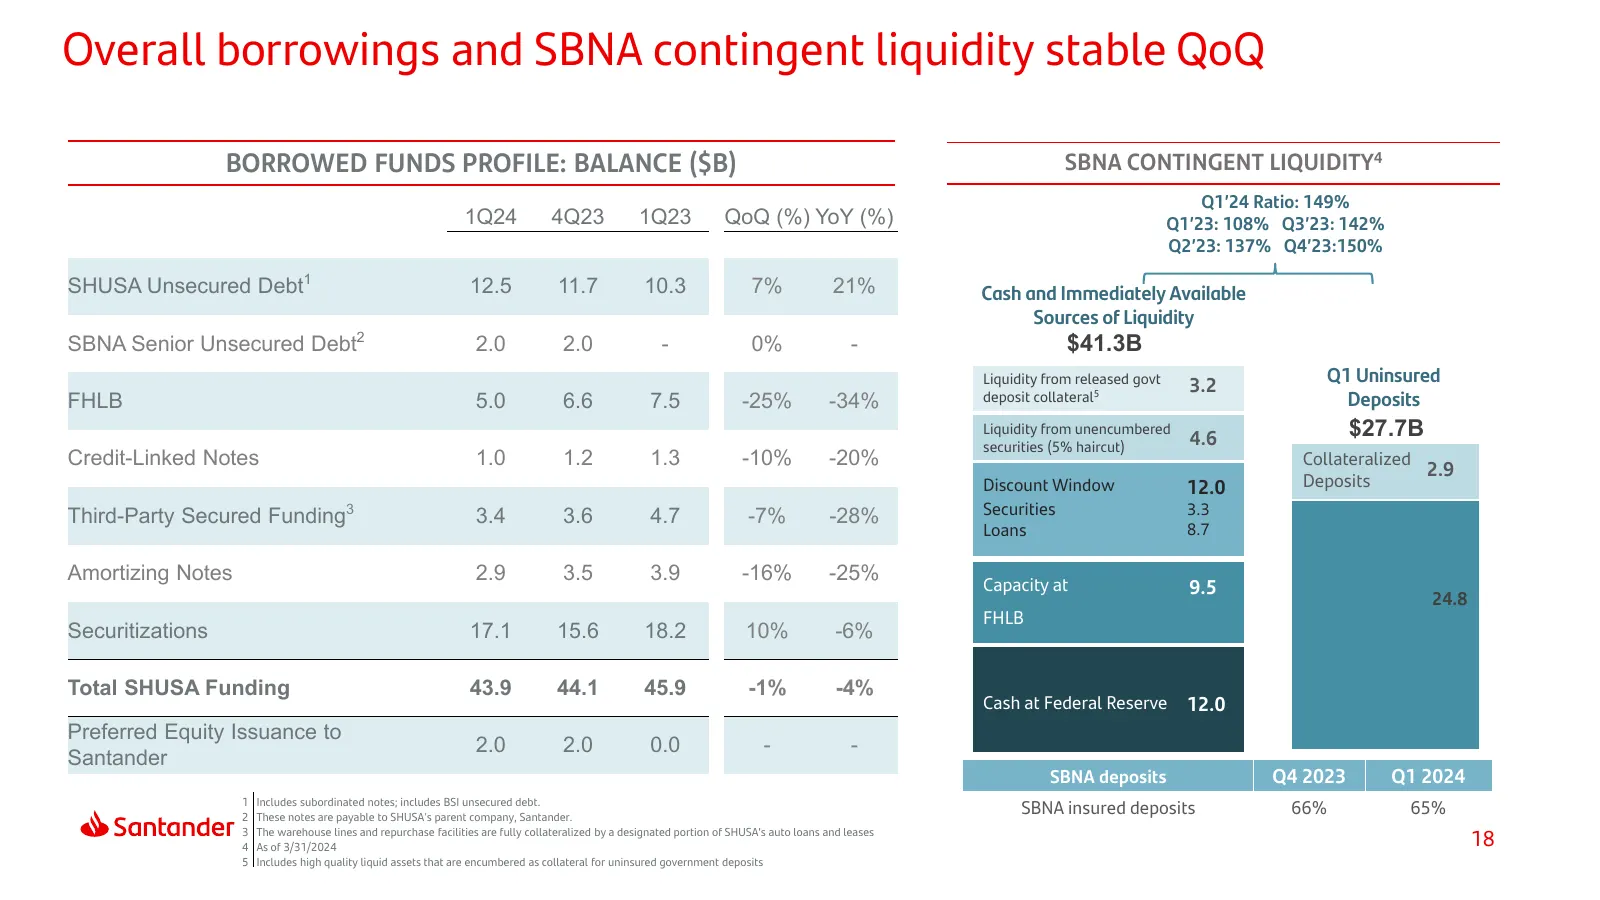
Overall borrowings and SBNA contingent liquidity stable QoQ BORROWED FUNDS PROFILE: BALANCE ($B) SBNA CONTINGENT LIQUIDITY4 Q1’24 Ratio: 149% 1Q24 4Q23 1Q23 QoQ (%) YoY (%) Q1’23: 108% Q3’23: 142% Q2’23: 137% Q4’23:150% SHUSA Unsecured Debt1 12.5 11.7 10.3 7% 21% Cash and Immediately Available Sourc
Slide 19: Debt & Total Loss-Absorbing Capacity ("TLAC")
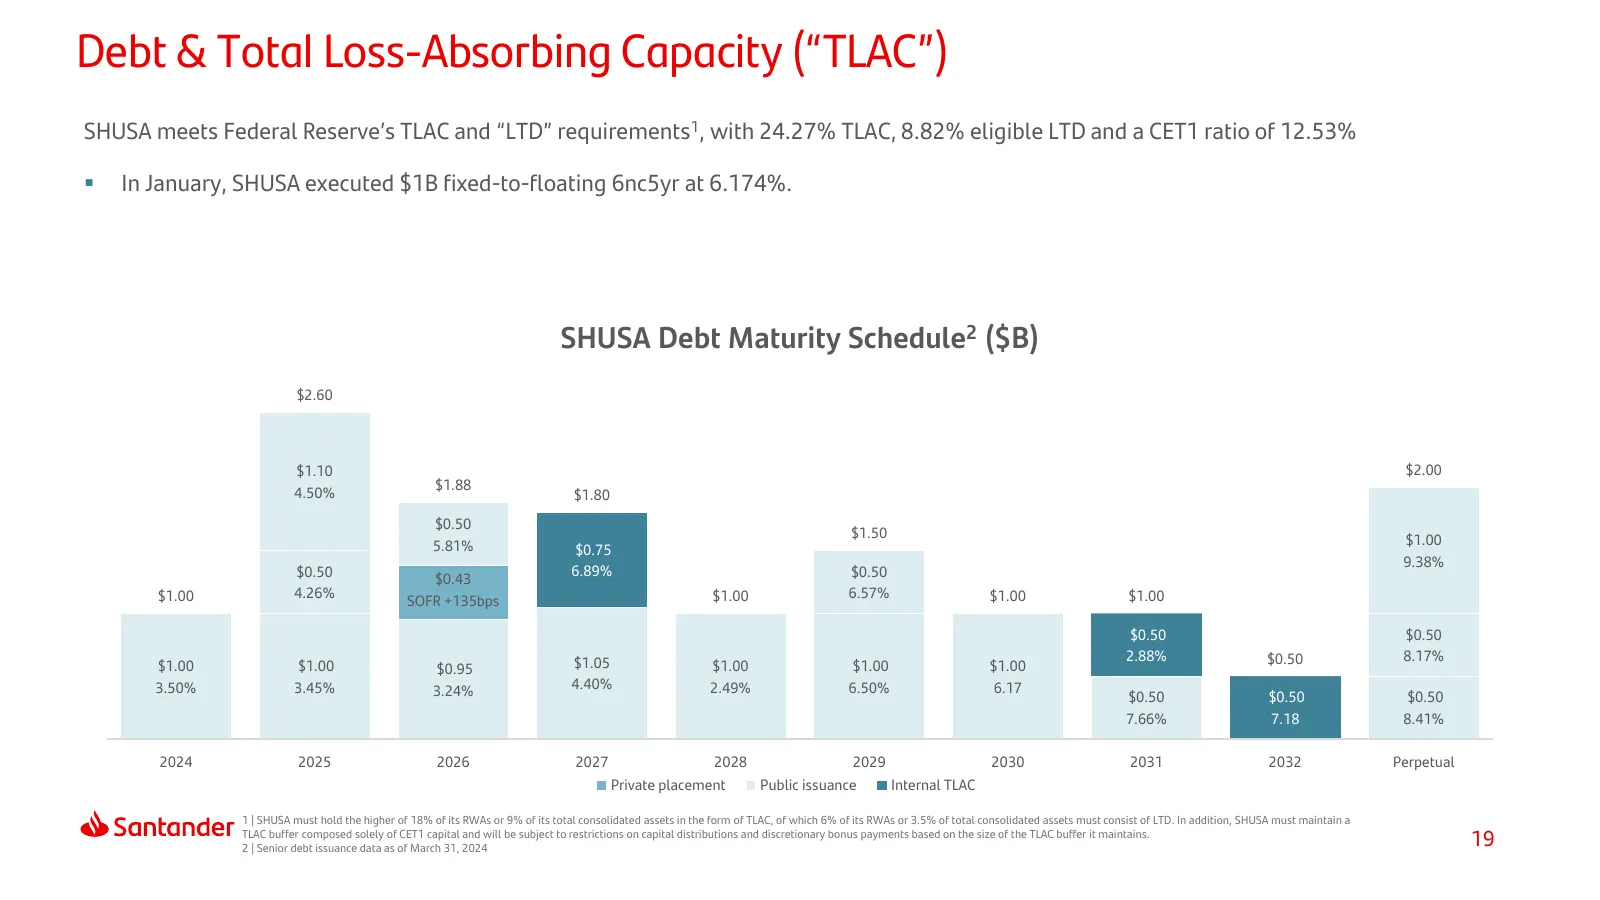
Debt & Total Loss-Absorbing Capacity (“TLAC”) SHUSA meets Federal Reserve’s TLAC and “LTD” requirements1, with 24.27% TLAC, 8.82% eligible LTD and a CET1 ratio of 12.53% In January, SHUSA executed $1B fixed-to-floating 6nc5yr at 6.174%. SHUSA Debt Maturity Schedule2 ($B) $2.60 $1.10 $2.00 $1.88 4.
Slide 20: Capital Ratios
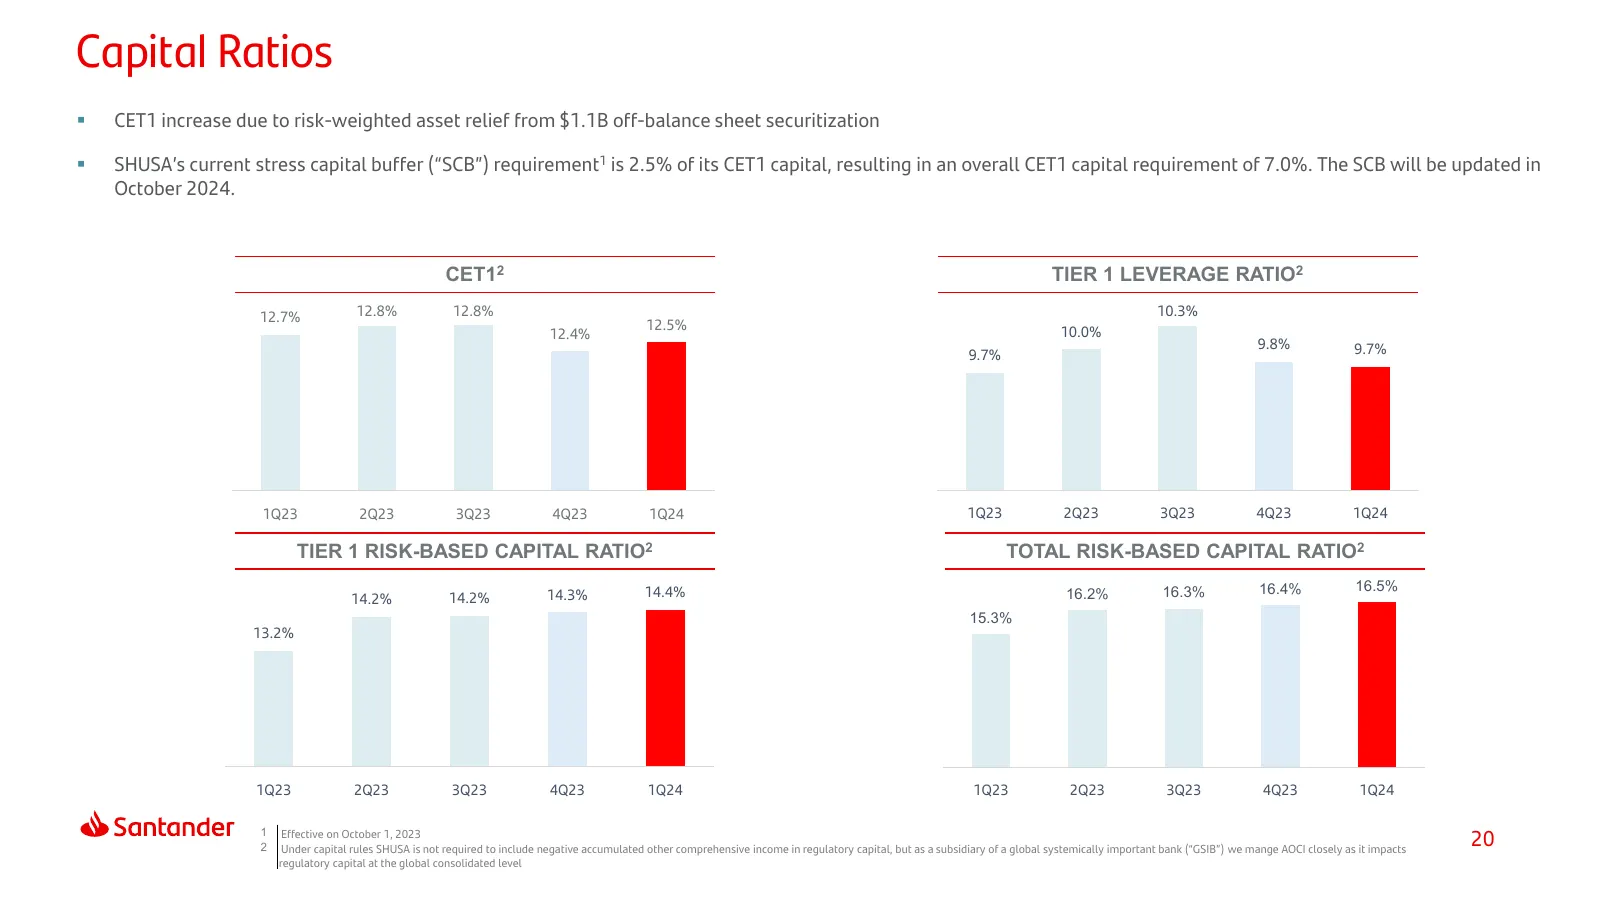
Capital Ratios CET1 increase due to risk-weighted asset relief from $1.1B off-balance sheet securitization SHUSA’s current stress capital buffer (“SCB”) requirement1 is 2.5% of its CET1 capital, resulting in an overall CET1 capital requirement of 7.0%. The SCB will be updated in October 2024. CE
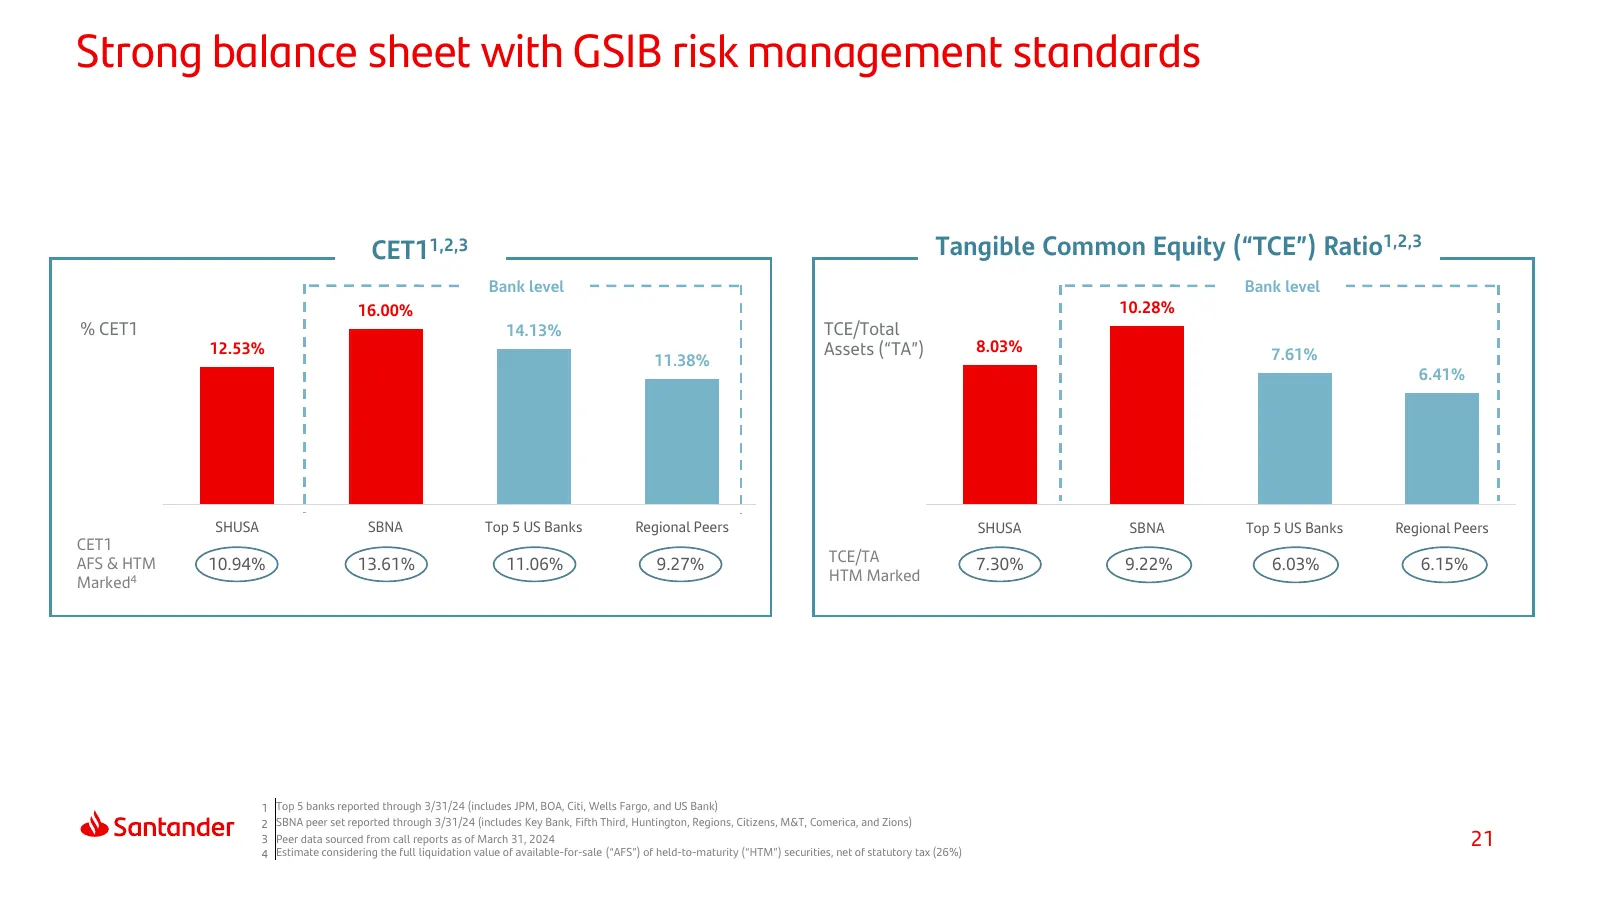
Slide 21: Strong balance sheet with GSIB risk management standards
Strong balance sheet with GSIB risk management standards CET11,2,3 Tangible Common Equity (“TCE”) Ratio1,2,3 Bank level Bank level 16.00% 10.28% % CET1 14.13% TCE/Total 12.53% Assets (“TA”) 8.03% 7.61% 11.38% 6.41% SHUSA SBNA Top 5 US Banks Regional Peers SHUSA SBNA Top 5 US Banks Regional Peers CET
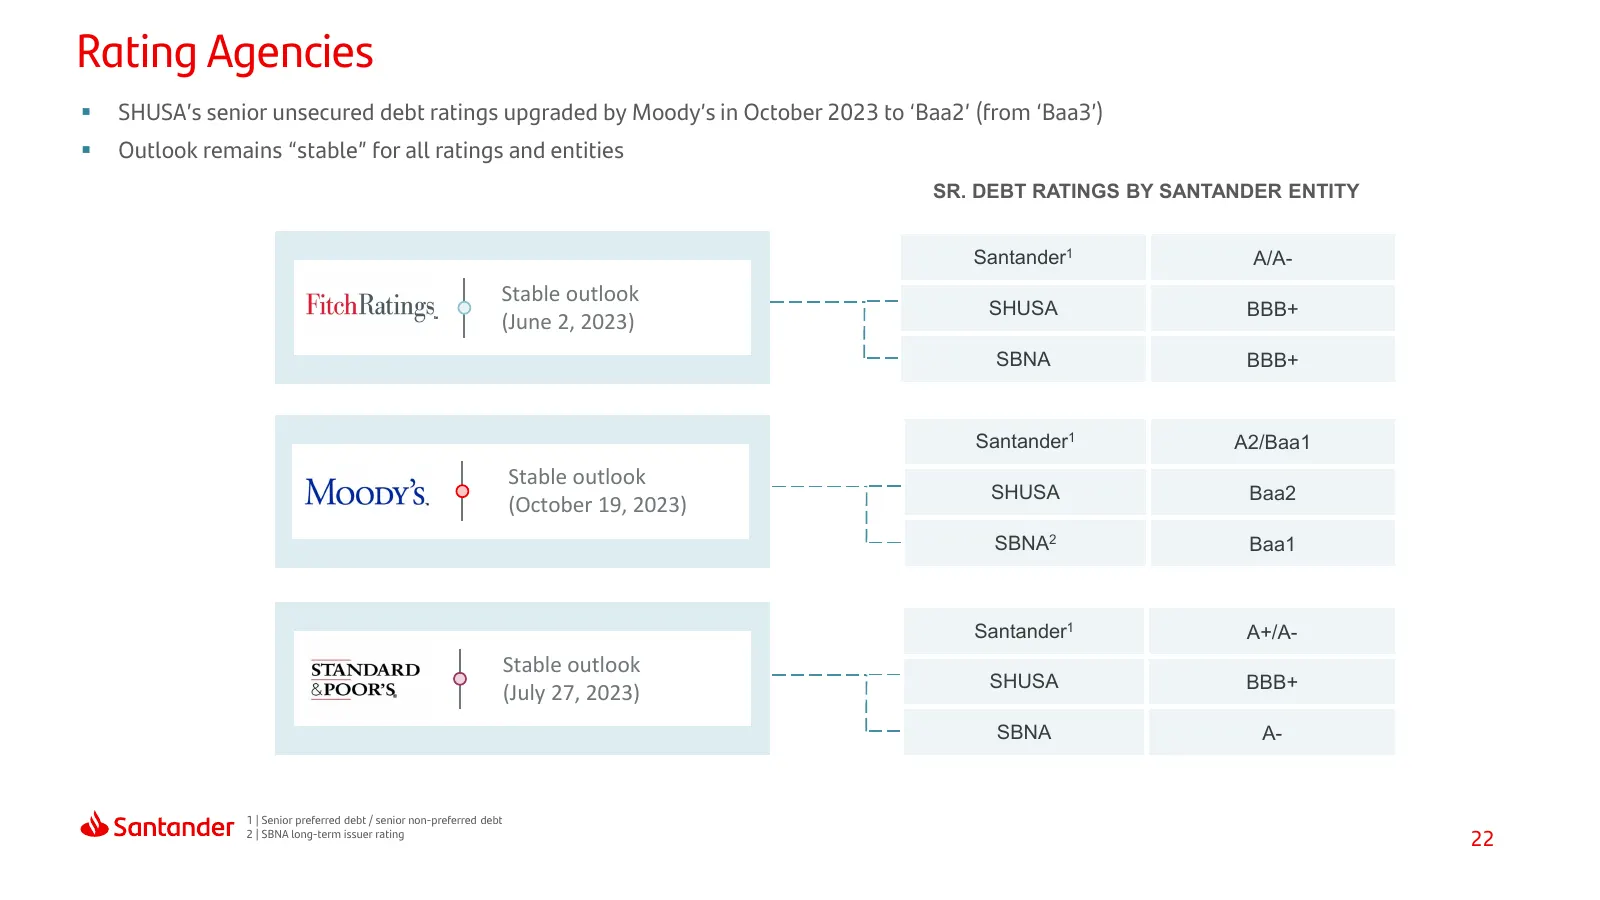
Slide 22: Rating Agencies
Rating Agencies SHUSA’s senior unsecured debt ratings upgraded by Moody’s in October 2023 to ‘Baa2’ (from ‘Baa3’) Outlook remains “stable” for all ratings and entities SR. DEBT RATINGS BY SANTANDER ENTITY Santander1 A/A- Stable outlook SHUSA BBB+ (June 2, 2023) SBNA BBB+ Santander1 A2/Baa1 Stabl
Slide 23: Index
Index 1 2 3 4 At a Glance Results Capital & Appendix Liquidity 23
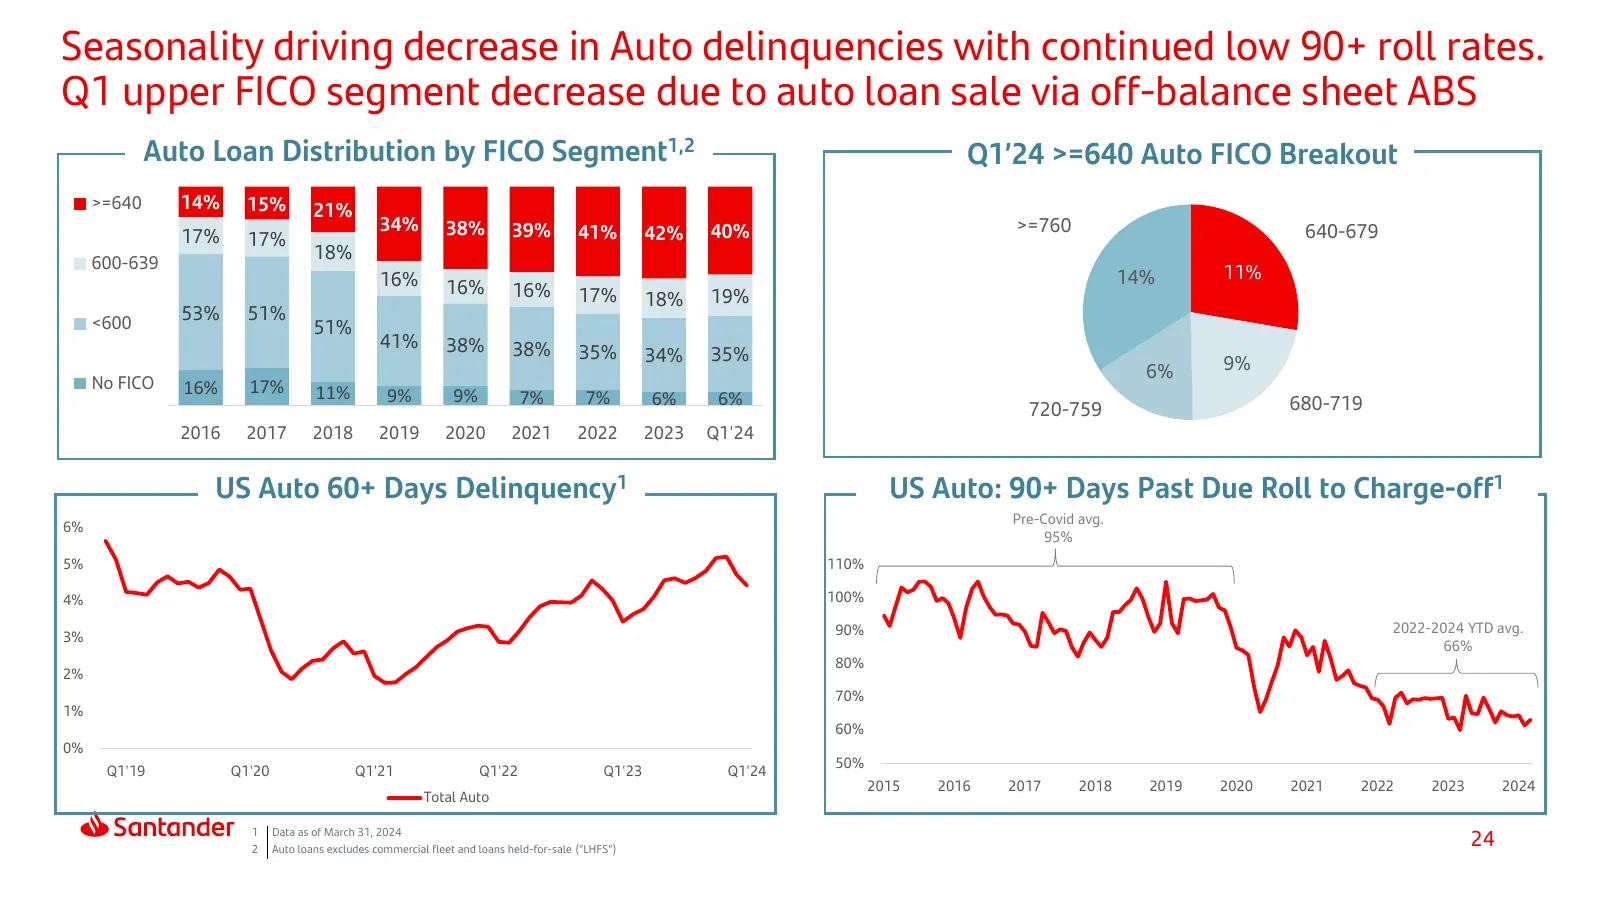
Slide 24: Seasonality driving decrease in Auto delinquencies with continued low 90+ roll rates
Seasonality driving decrease in Auto delinquencies with continued low 90+ roll rates. Q1 upper FICO segment decrease due to auto loan sale via off-balance sheet ABS Auto Loan Distribution by FICO Segment1,2 Q1’24 >=640 Auto FICO Breakout >=640 14% 15% 21% 34% 38% 39% 41% 42% 40% >=760 640-679 17% 17
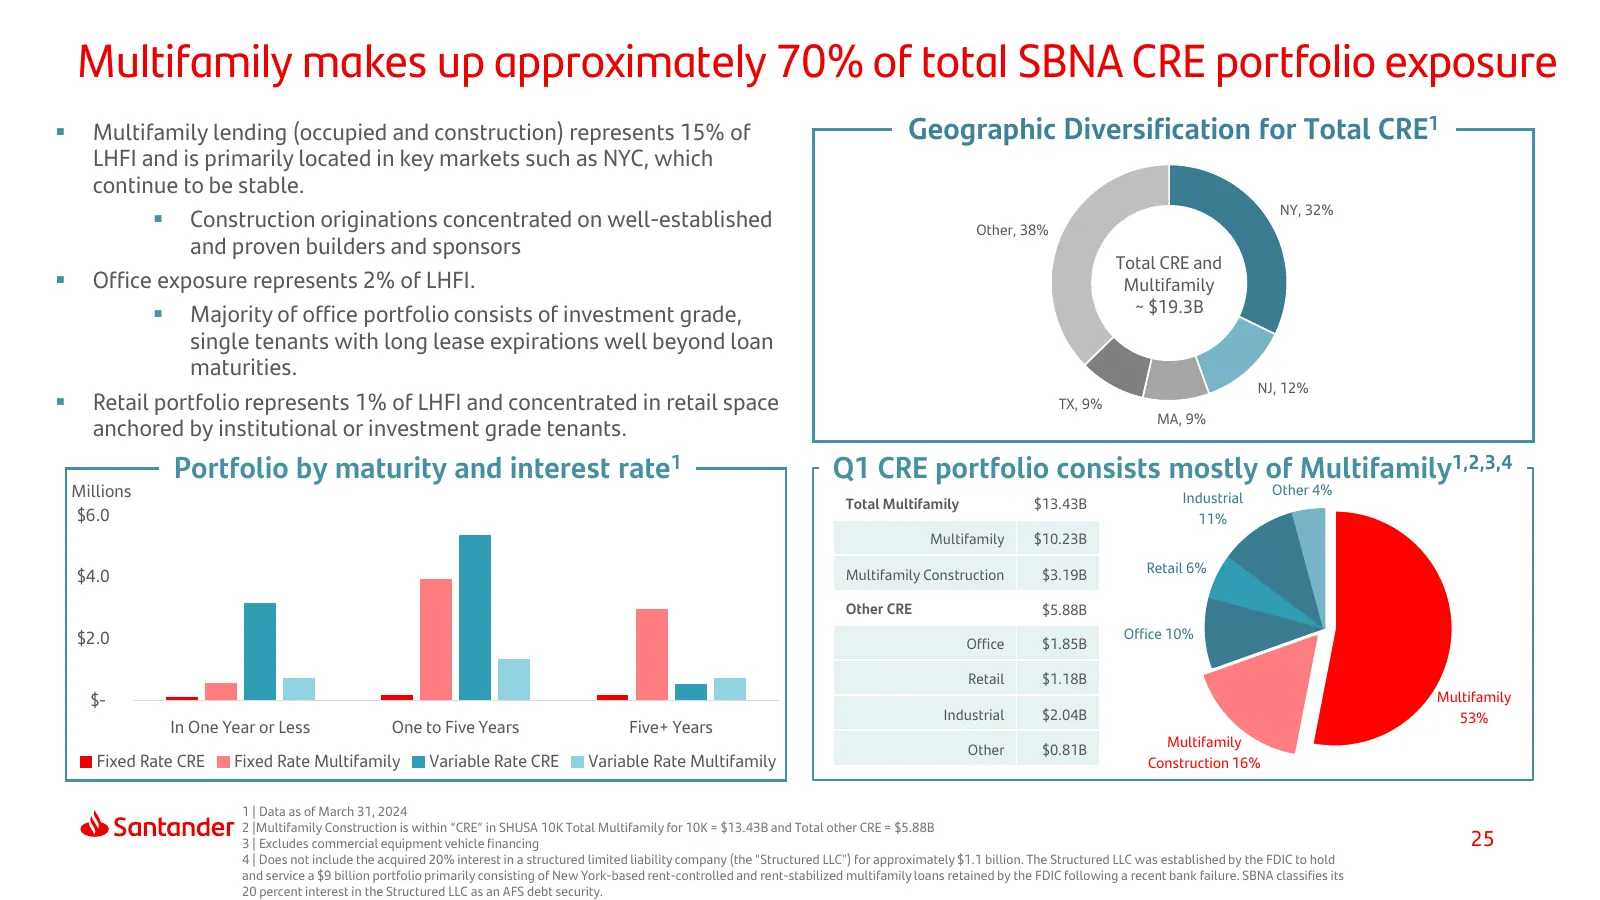
Slide 25: Multifamily makes up approximately 70% of total SBNA CRE portfolio exposure
Multifamily makes up approximately 70% of total SBNA CRE portfolio exposure Multifamily lending (occupied and construction) represents 15% of Geographic Diversification for Total CRE1 LHFI and is primarily located in key markets such as NYC, which continue to be stable. NY, 32% Construction orig
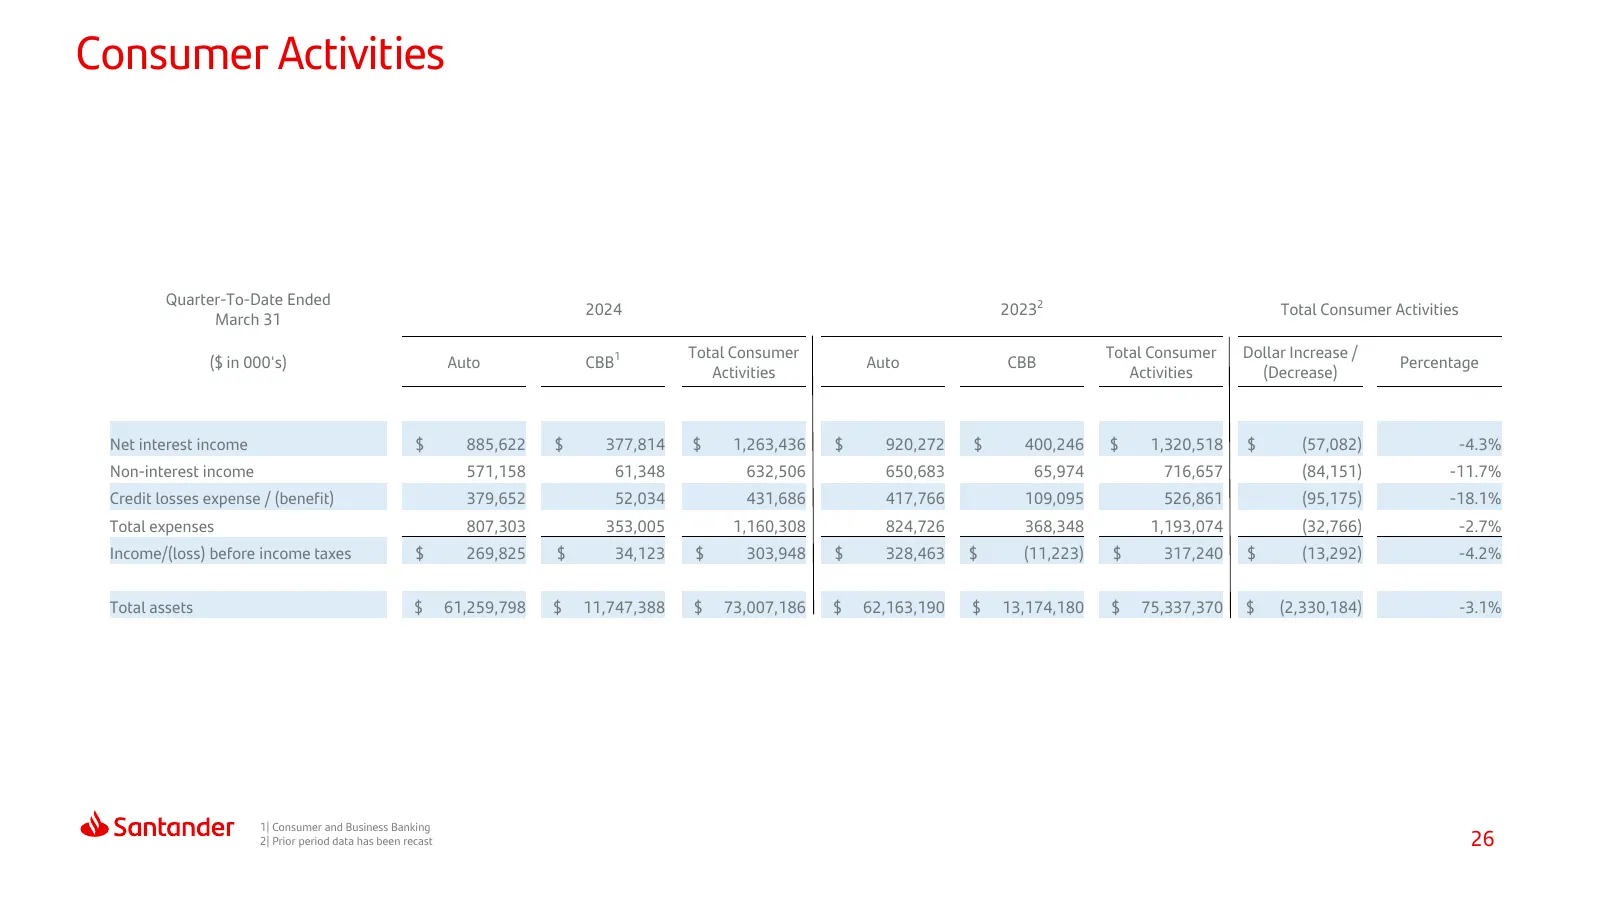
Slide 26: Consumer Activities
Consumer Activities Quarter-To-Date Ended 2024 20232 Total Consumer Activities March 31 Total Consumer Total Consumer Dollar Increase / ($ in 000's) Auto CBB1 Auto CBB Percentage Activities Activities (Decrease) Net interest income $ 885,622 $ 377,814 $ 1,263,436 $ 920,272 $ 400,246 $ 1,320,518 $ (5
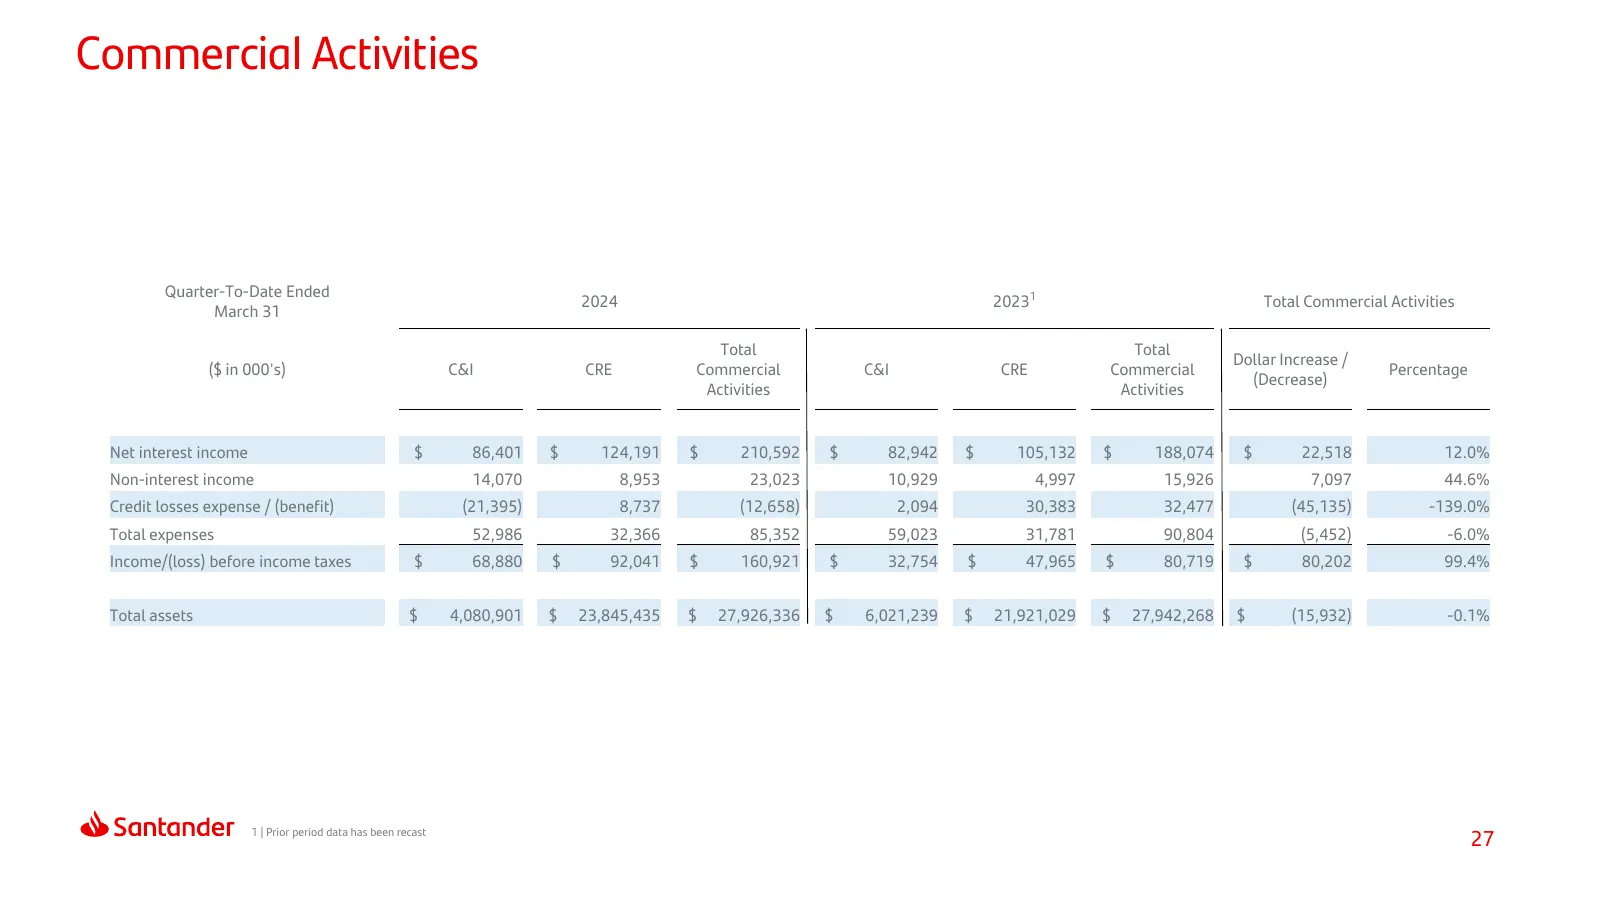
Slide 27: Commercial Activities
Commercial Activities Quarter-To-Date Ended 2024 20231 Total Commercial Activities March 31 Total Total Dollar Increase / ($ in 000's) C&I CRE Commercial C&I CRE Commercial Percentage (Decrease) Activities Activities Net interest income $ 86,401 $ 124,191 $ 210,592 $ 82,942 $ 105,132 $ 188,074 $ 22,
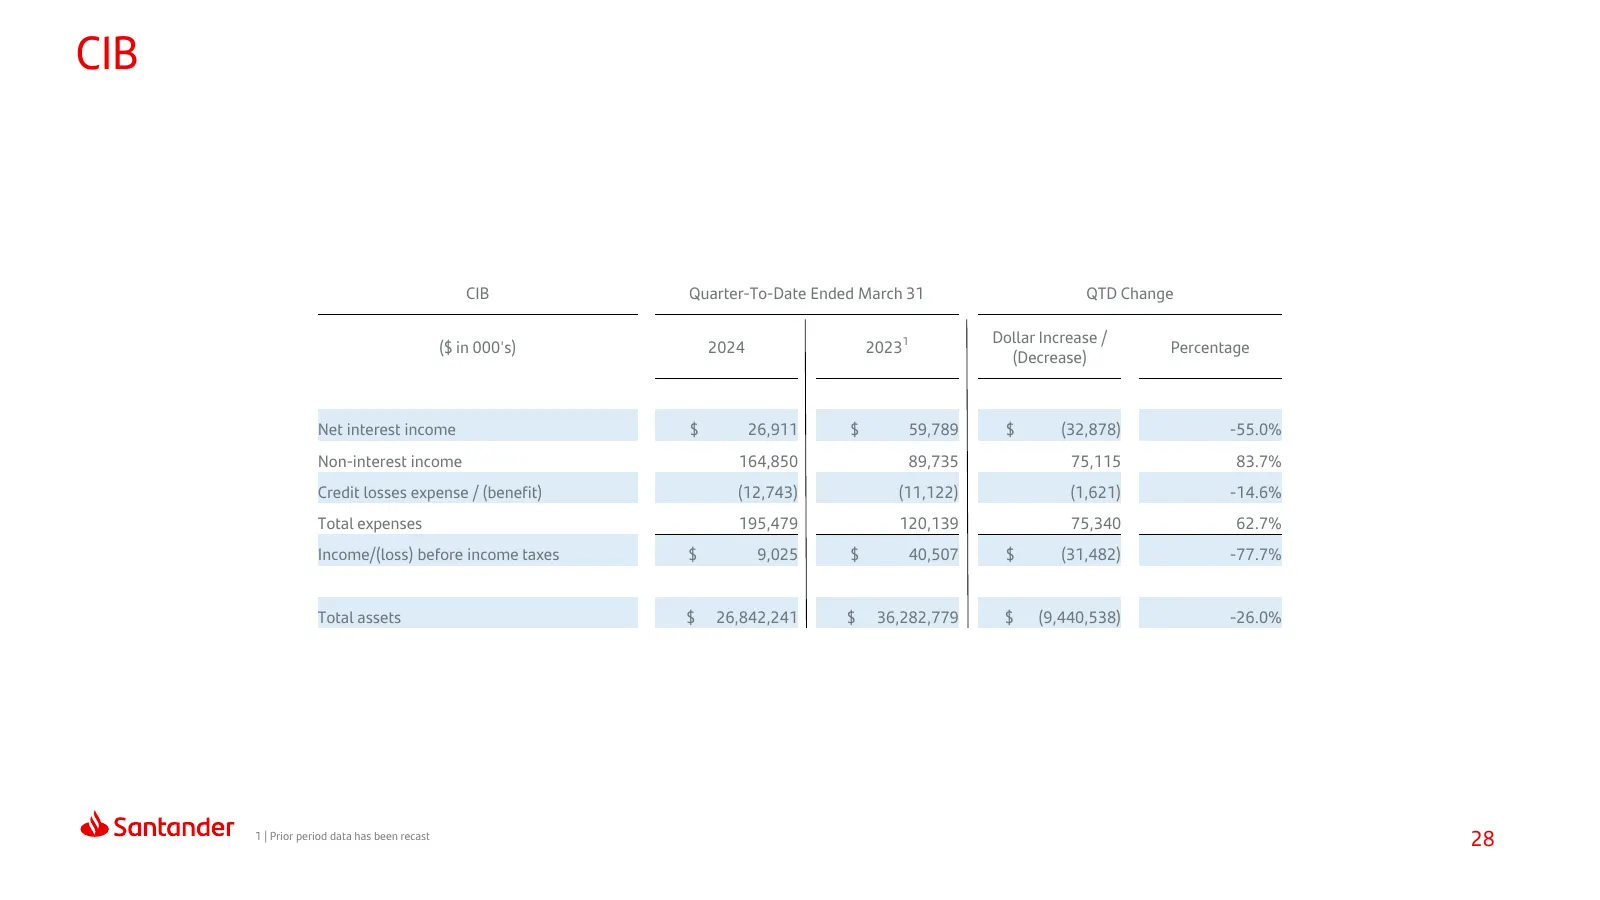
Slide 28: CIB
CIB CIB Quarter-To-Date Ended March 31 QTD Change Dollar Increase / ($ in 000's) 2024 20231 Percentage (Decrease) Net interest income $ 26,911 $ 59,789 $ (32,878) -55.0% Non-interest income 164,850 89,735 75,115 83.7% Credit losses expense / (benefit) (12,743) (11,122) (1,621) -14.6% Total expenses
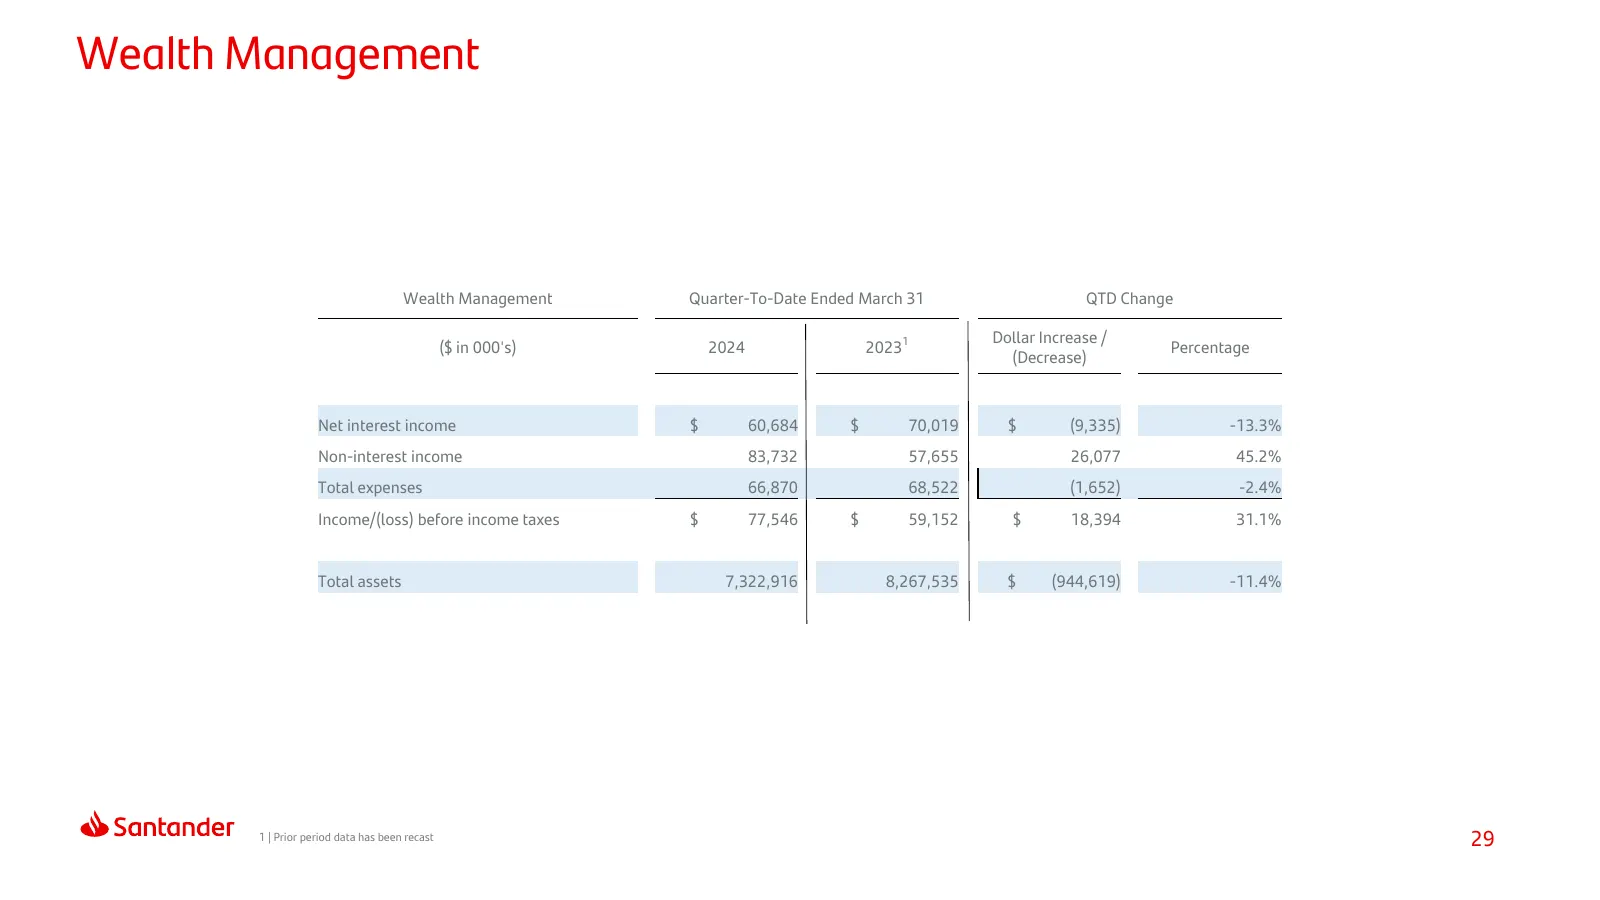
Slide 29: Wealth Management
Wealth Management Wealth Management Quarter-To-Date Ended March 31 QTD Change Dollar Increase / ($ in 000's) 2024 20231 Percentage (Decrease) Net interest income $ 60,684 $ 70,019 $ (9,335) -13.3% Non-interest income 83,732 57,655 26,077 45.2% Total expenses 66,870 68,522 (1,652) -2.4% Income/(loss)
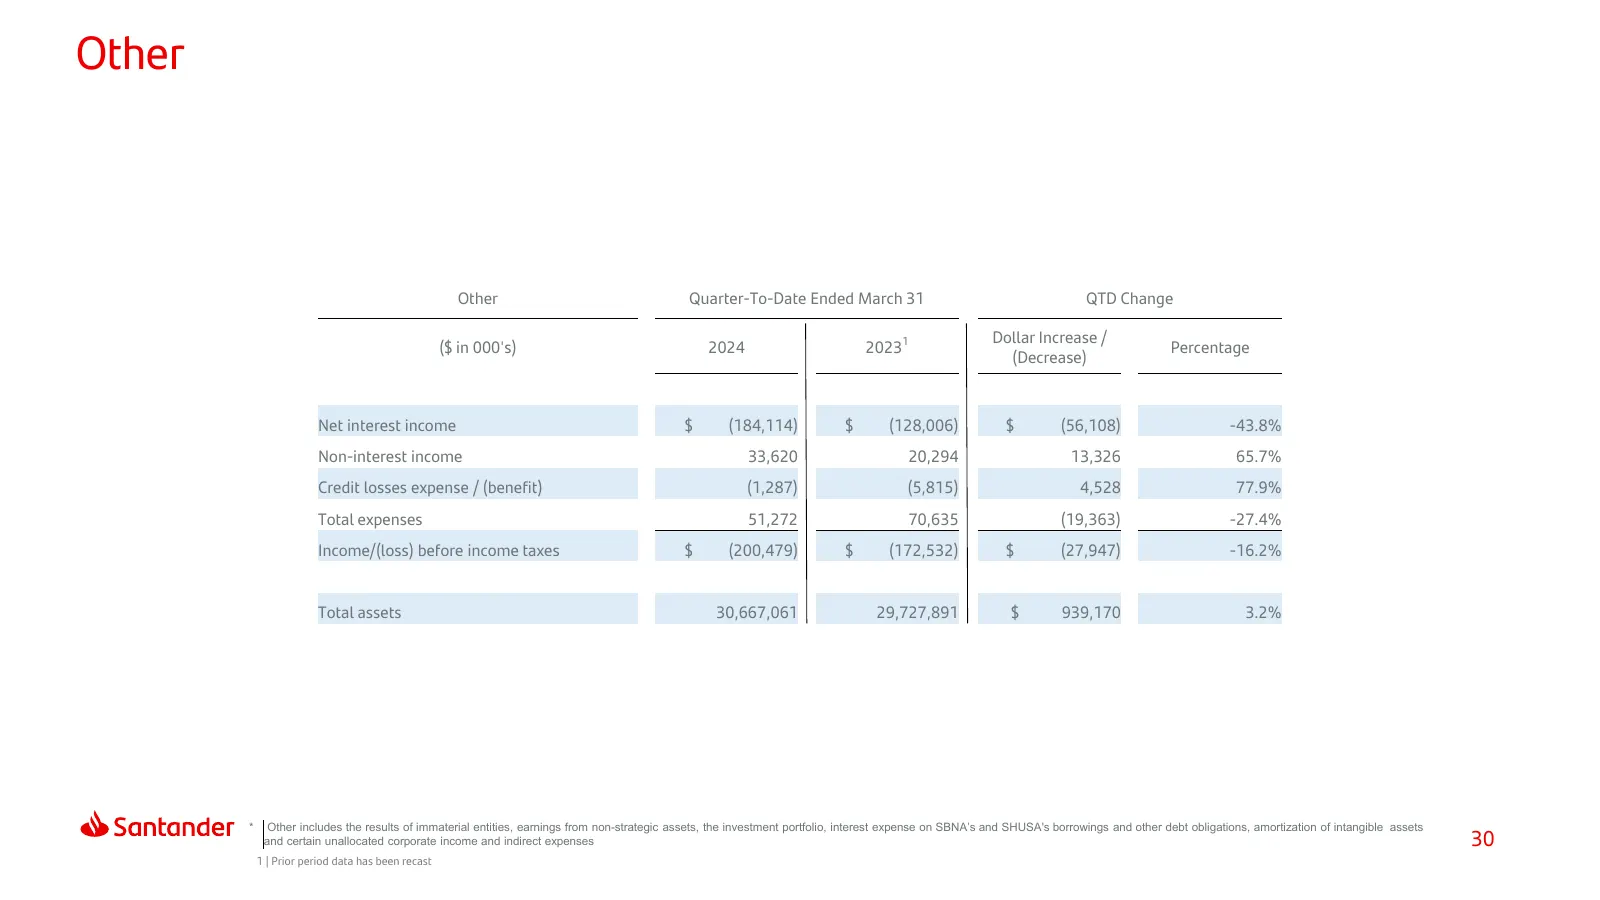
Slide 30: Other
Other Other Quarter-To-Date Ended March 31 QTD Change Dollar Increase / ($ in 000's) 2024 20231 Percentage (Decrease) Net interest income $ (184,114) $ (128,006) $ (56,108) -43.8% Non-interest income 33,620 20,294 13,326 65.7% Credit losses expense / (benefit) (1,287) (5,815) 4,528 77.9% Total expen
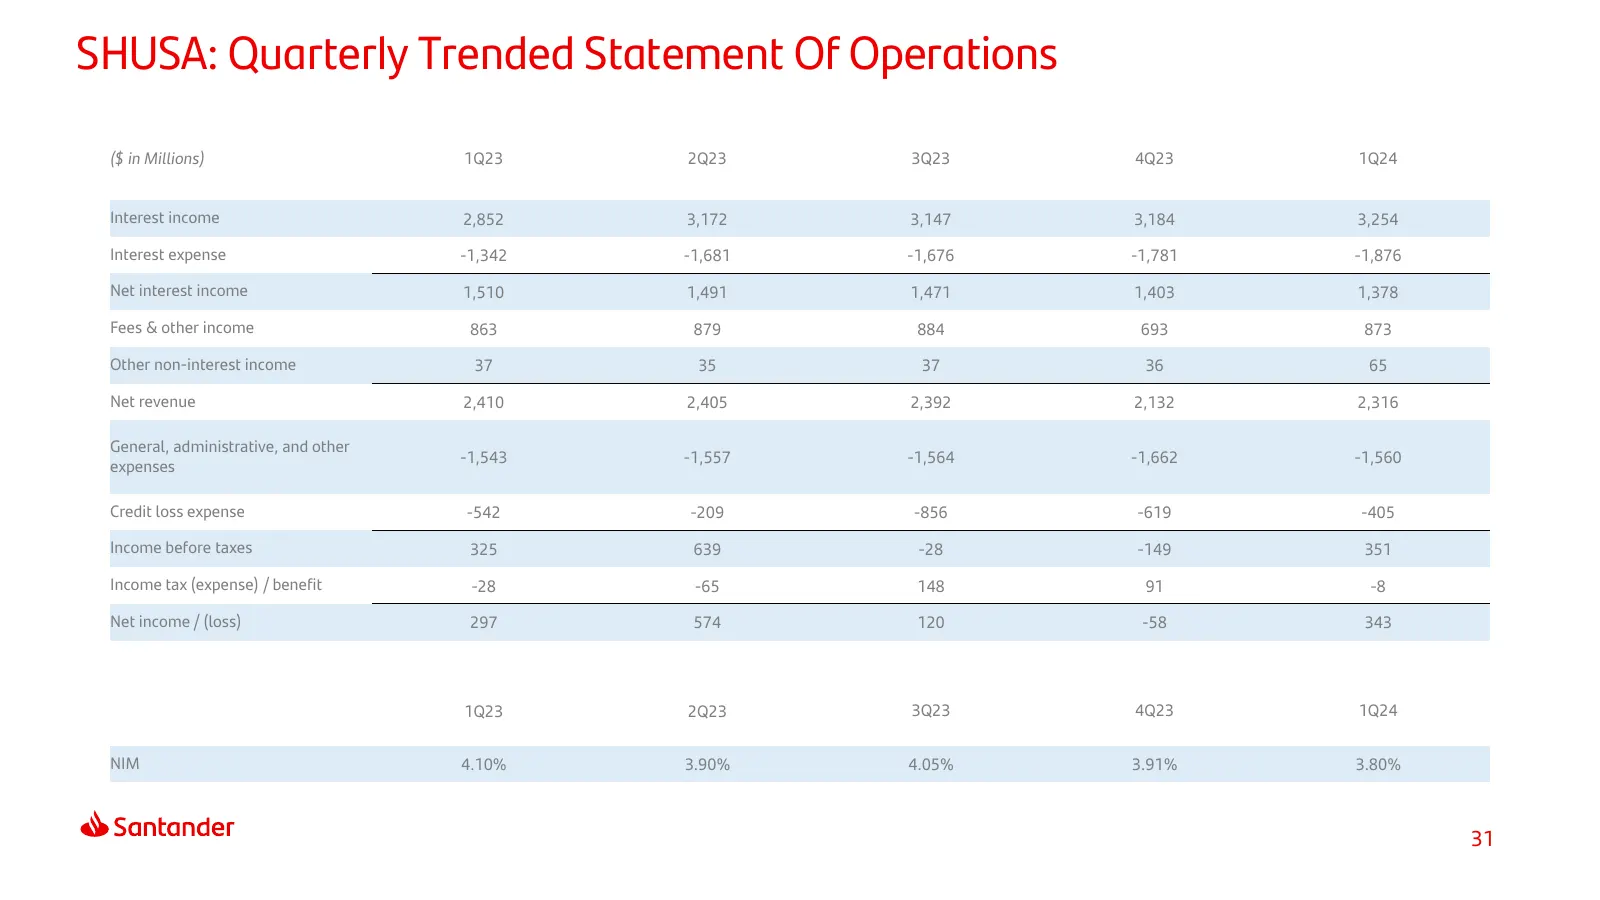
Slide 31: SHUSA: Quarterly Trended Statement Of Operations
SHUSA: Quarterly Trended Statement Of Operations ($ in Millions) 1Q23 2Q23 3Q23 4Q23 1Q24 Interest income 2,852 3,172 3,147 3,184 3,254 Interest expense -1,342 -1,681 -1,676 -1,781 -1,876 Net interest income 1,510 1,491 1,471 1,403 1,378 Fees & other income 863 879 884 693 873 Other non-interest inc
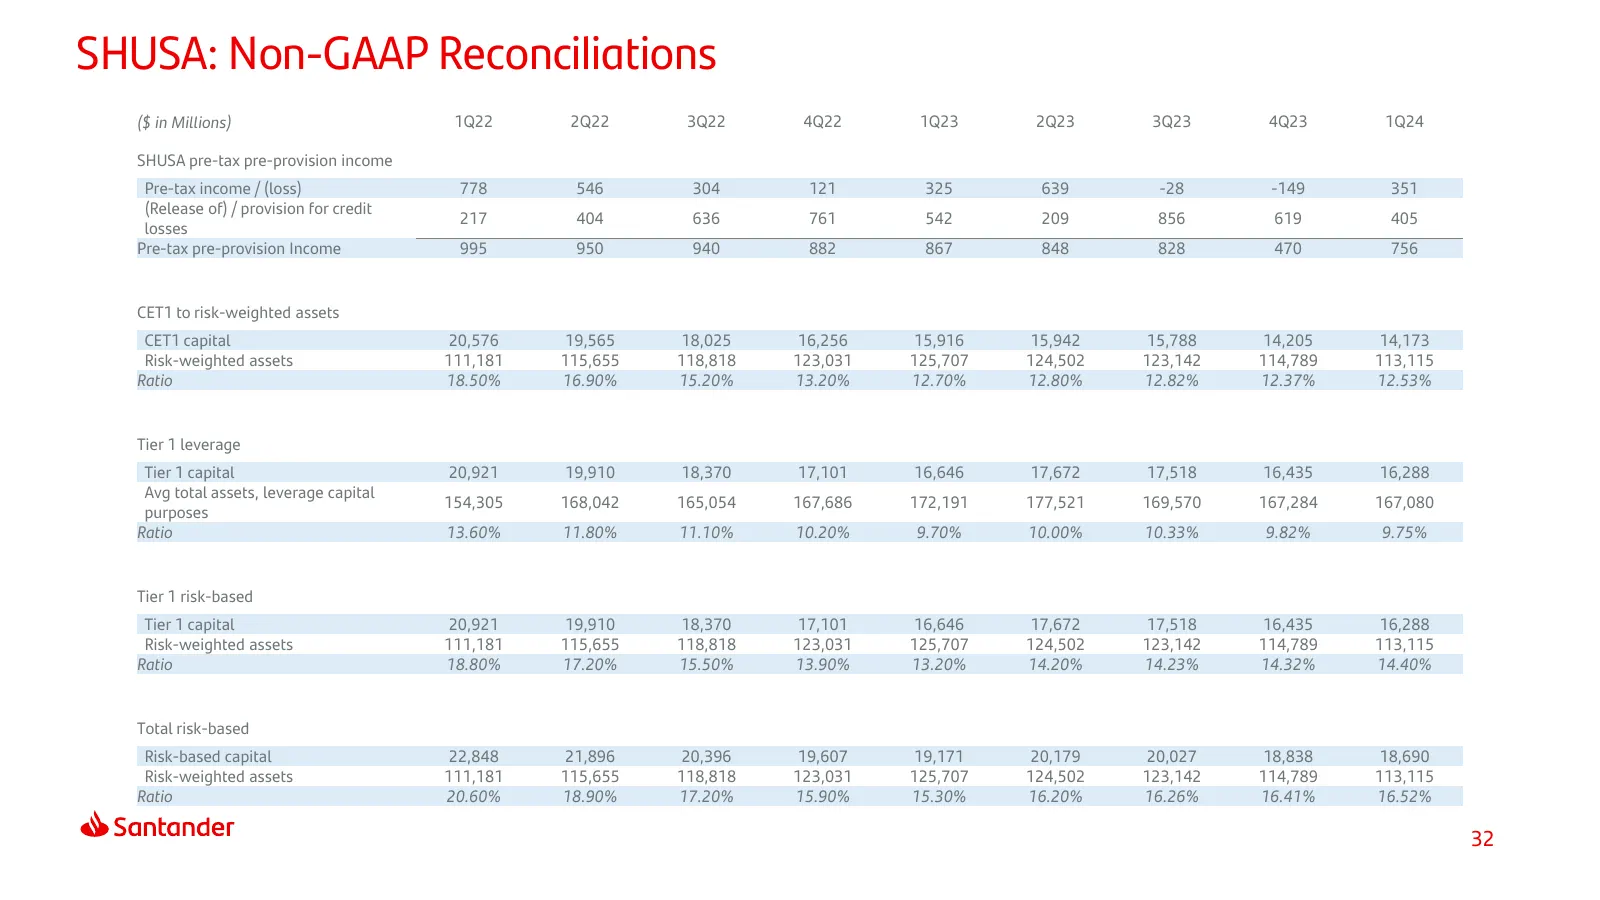
Slide 32: SHUSA: Non-GAAP Reconciliations
SHUSA: Non-GAAP Reconciliations ($ in Millions) 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 SHUSA pre-tax pre-provision income Pre-tax income / (loss) 778 546 304 121 325 639 -28 -149 351 (Release of) / provision for credit 217 404 636 761 542 209 856 619 405 losses Pre-tax pre-provision Income 995
Slide 33: Thank You.
Thank You. Our purpose is to help people and businesses prosper. Our culture is based on believing that everything we do should be:
Source: company website
More decks from Santander Holdings USA Inc
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026