Santander Holdings USA Inc · NYSE:SNUS/PH
Santander Holdings USA — Debt Investor Presentation (August 2021)
37 slides from Santander Holdings USA's debt investor presentation, Aug 3, 2021
Slide 1: Fixed Income Investor Presentation Second Quarter 2021
SANTANDER HOLDINGS USA, INC. Fixed Income Investor Presentation Second Quarter 2021 August 3, 2021
Slide 2: Disclaimer
DISCLAIMER DISCLAIMER This presentation of Santander Holdings USA, Inc. (“SHUSA”) contains “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 regarding the financial condition, results of operations, business plans and future performance of SHUSA.
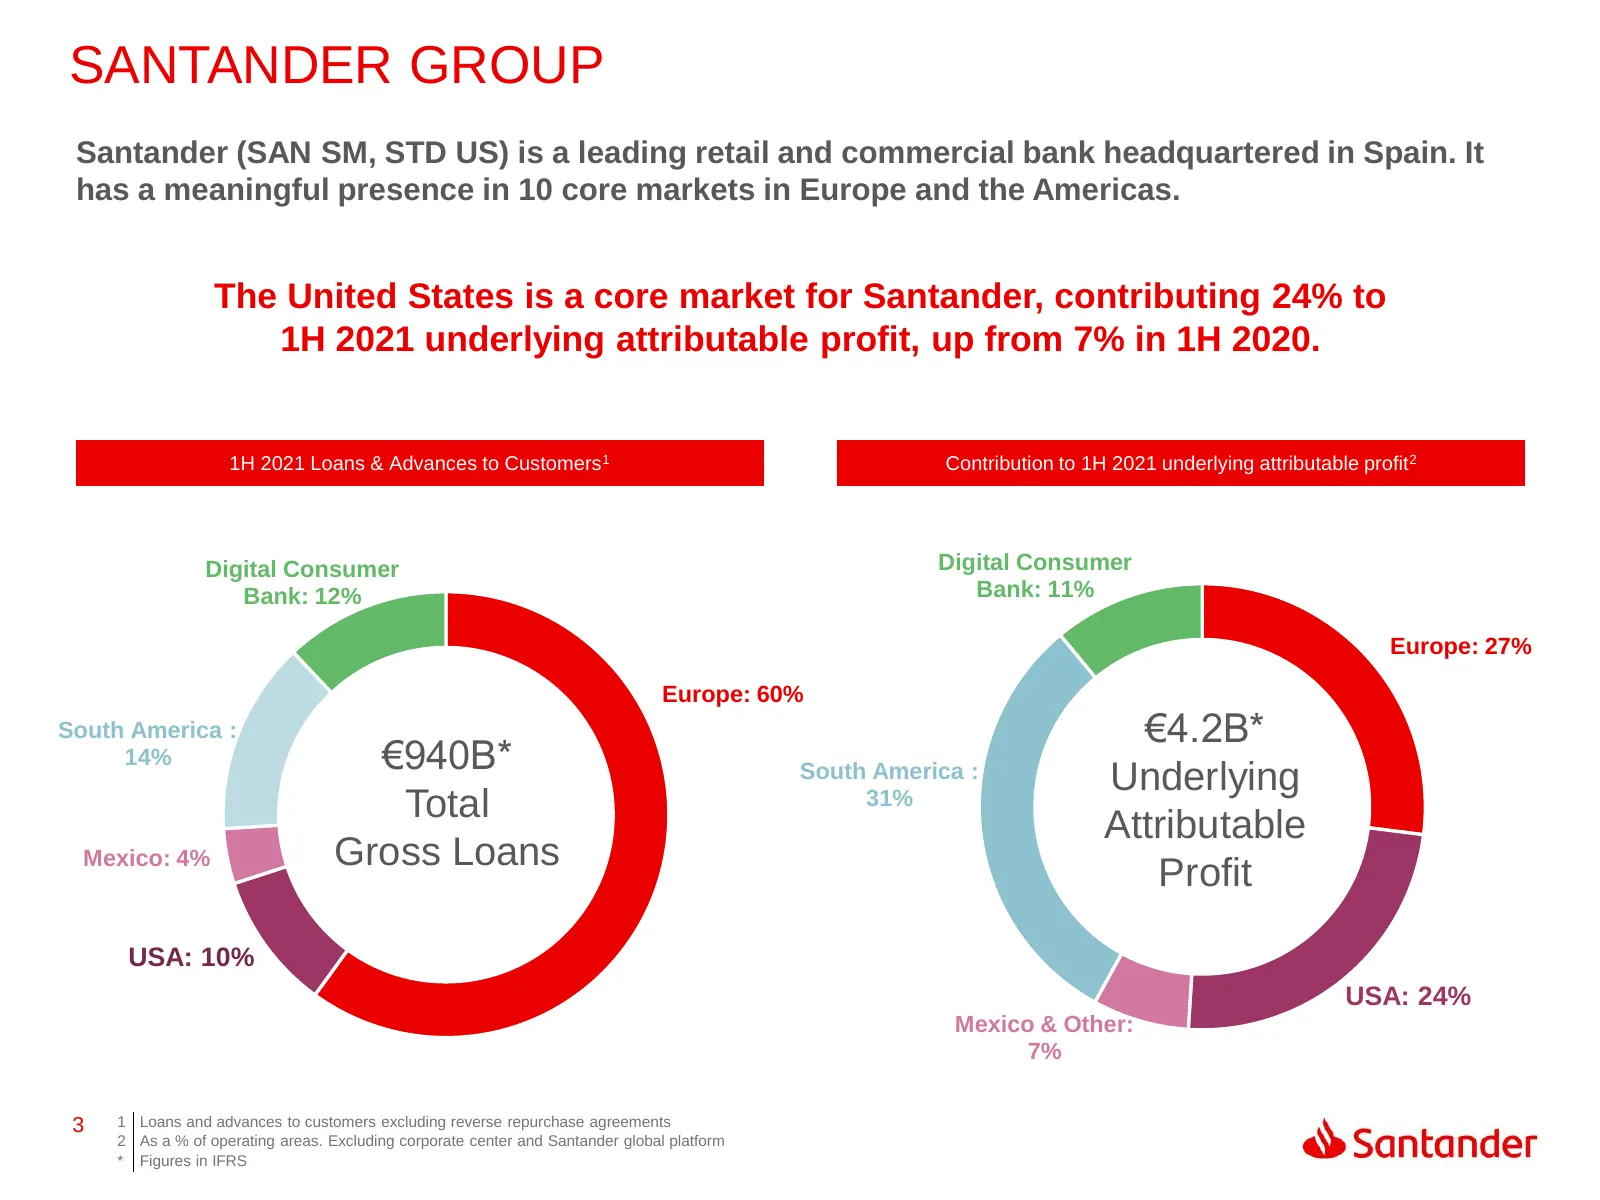
Slide 3: Santander Group
SANTANDER GROUP Santander (SAN SM, STD US) is a leading retail and commercial bank headquartered in Spain. It has a meaningful presence in 10 core markets in Europe and the Americas. The United States is a core market for Santander, contributing 24% to 1H 2021 underlying attributable profit, up from
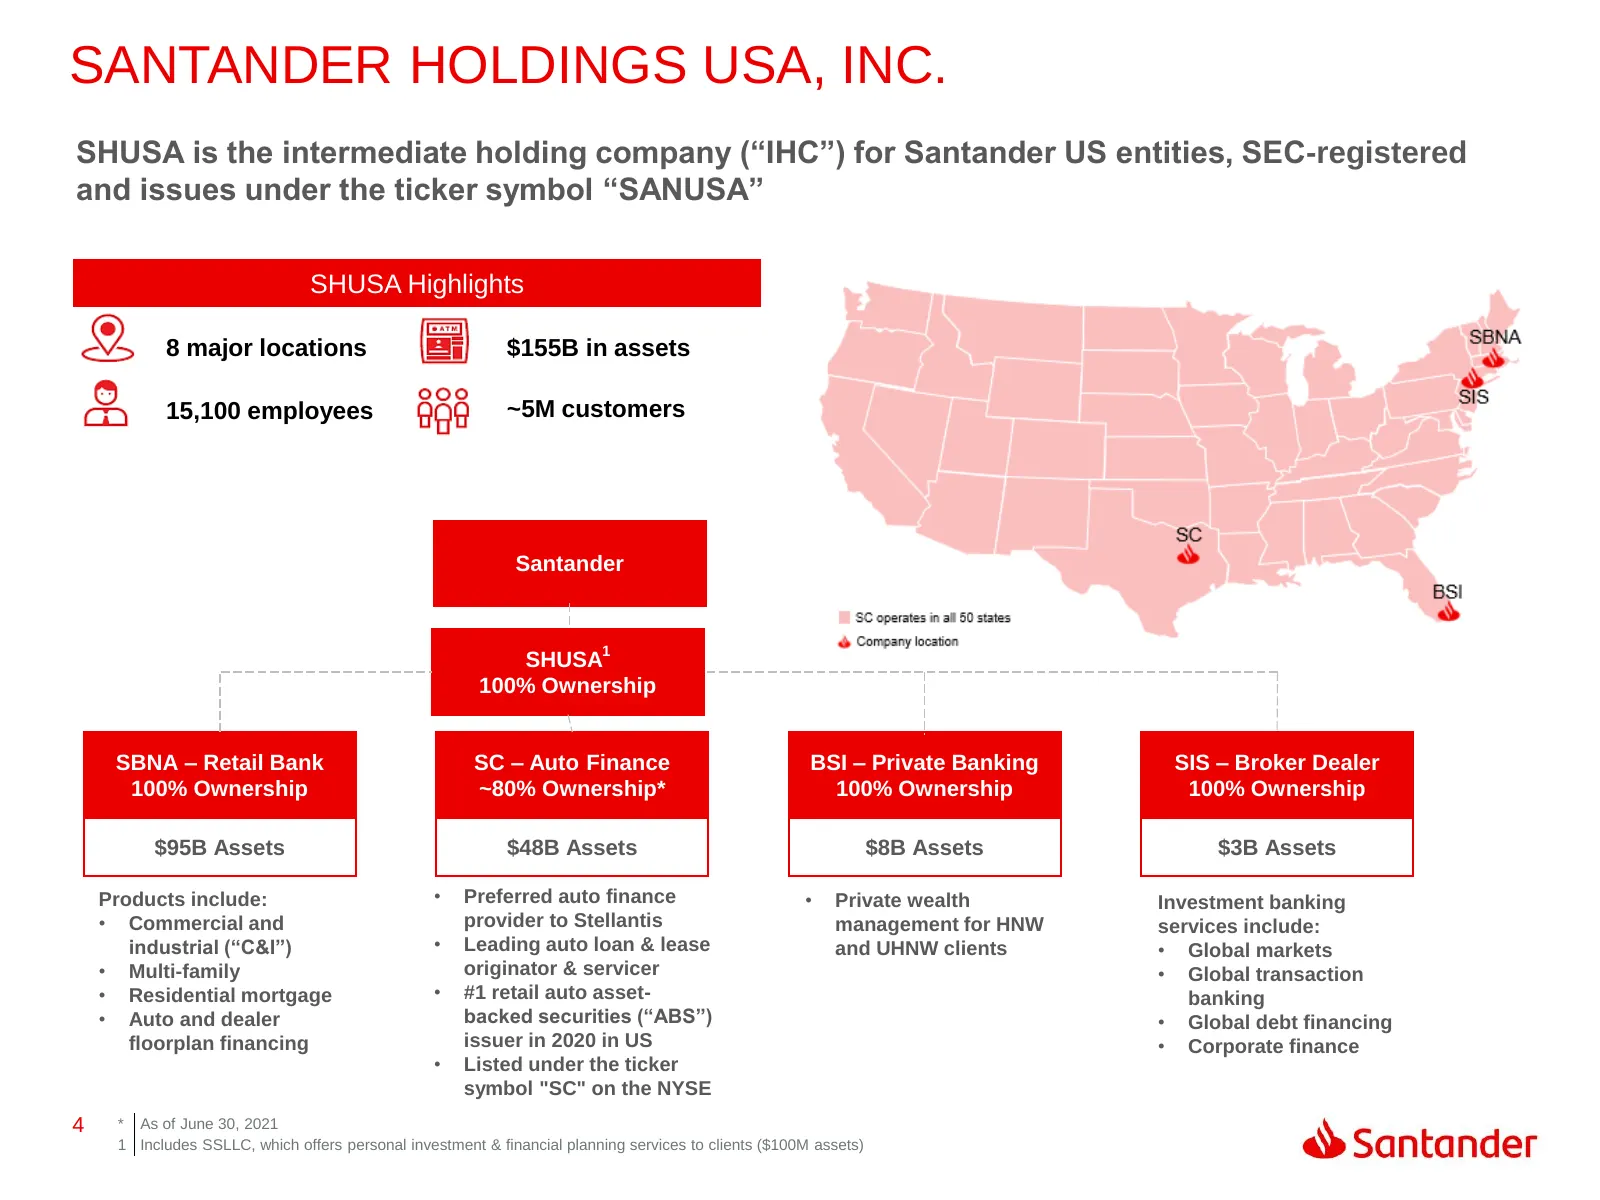
Slide 4: Santander Holdings USA, Inc.
SANTANDER HOLDINGS USA, INC. SHUSA is the intermediate holding company (“IHC”) for Santander US entities, SEC-registered and issues under the ticker symbol “SANUSA” SHUSA Highlights 8 major locations $155B in assets 15,100 employees ~5M customers Santander 1 SHUSA 100% Ownership SBNA – Retail Bank S
Slide 5: Santander Bank
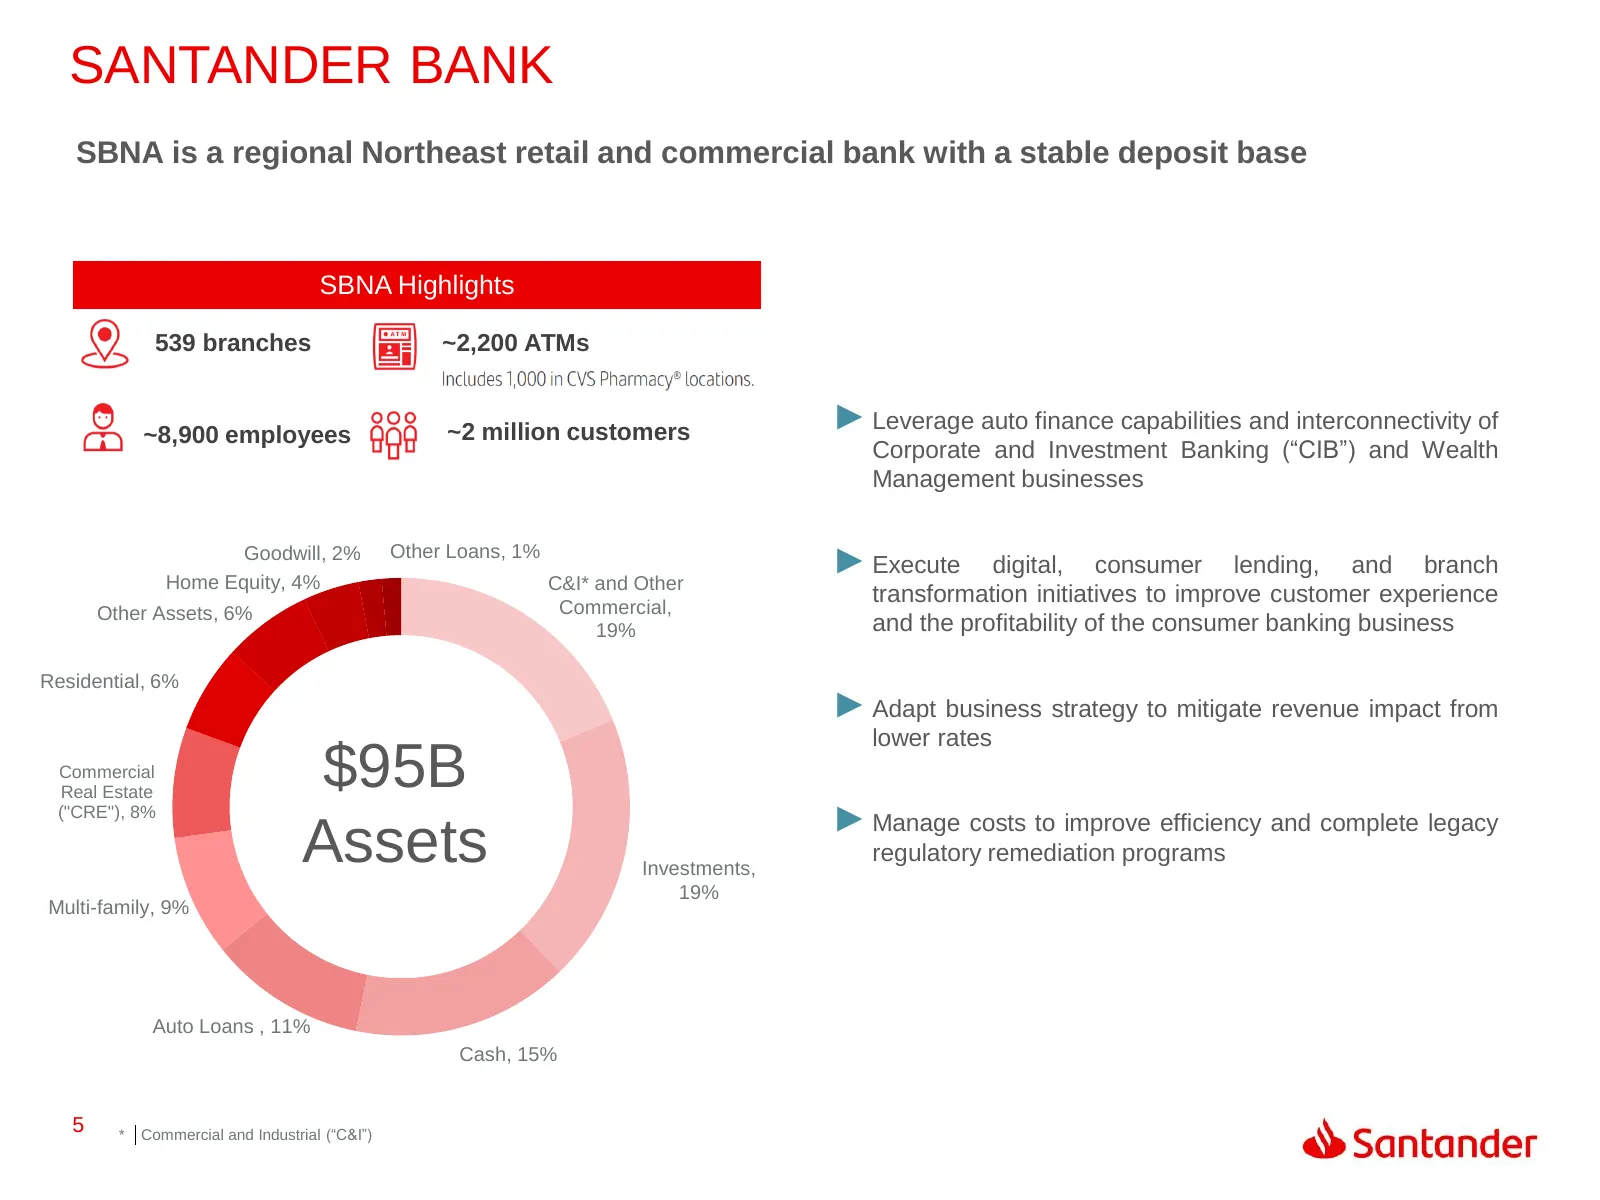
SANTANDER BANK SBNA is a regional Northeast retail and commercial bank with a stable deposit base SBNA Highlights 539 branches ~2,200 ATMs ~8,900 employees ~2 million customers ► Leverage auto finance capabilities and interconnectivity of Corporate and Investment Banking (“CIB”) and Wealth Managemen
Slide 6: Santander Consumer USA
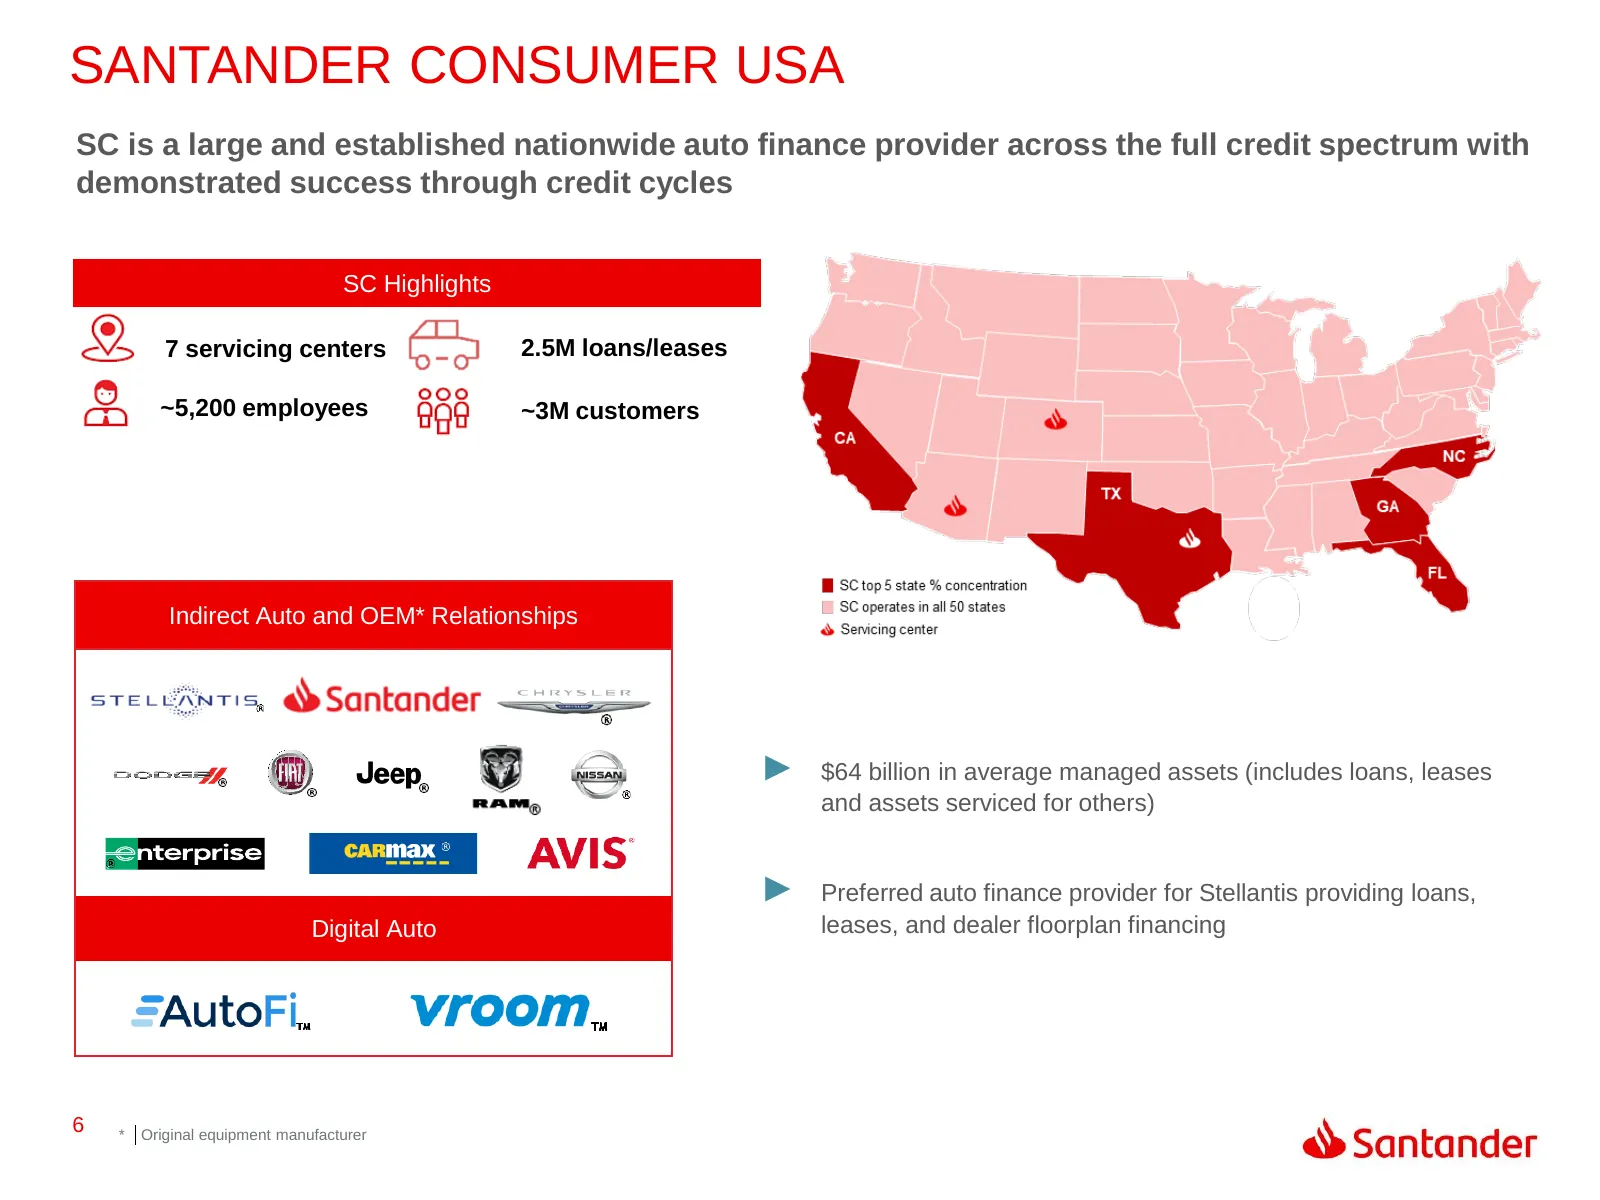
SANTANDER CONSUMER USA SC is a large and established nationwide auto finance provider across the full credit spectrum with demonstrated success through credit cycles SC Highlights 7 servicing centers 2.5M loans/leases ~5,200 employees ~3M customers Indirect Auto and OEM* Relationships ► $64 billion
Slide 7: Q2 2021 Highlights
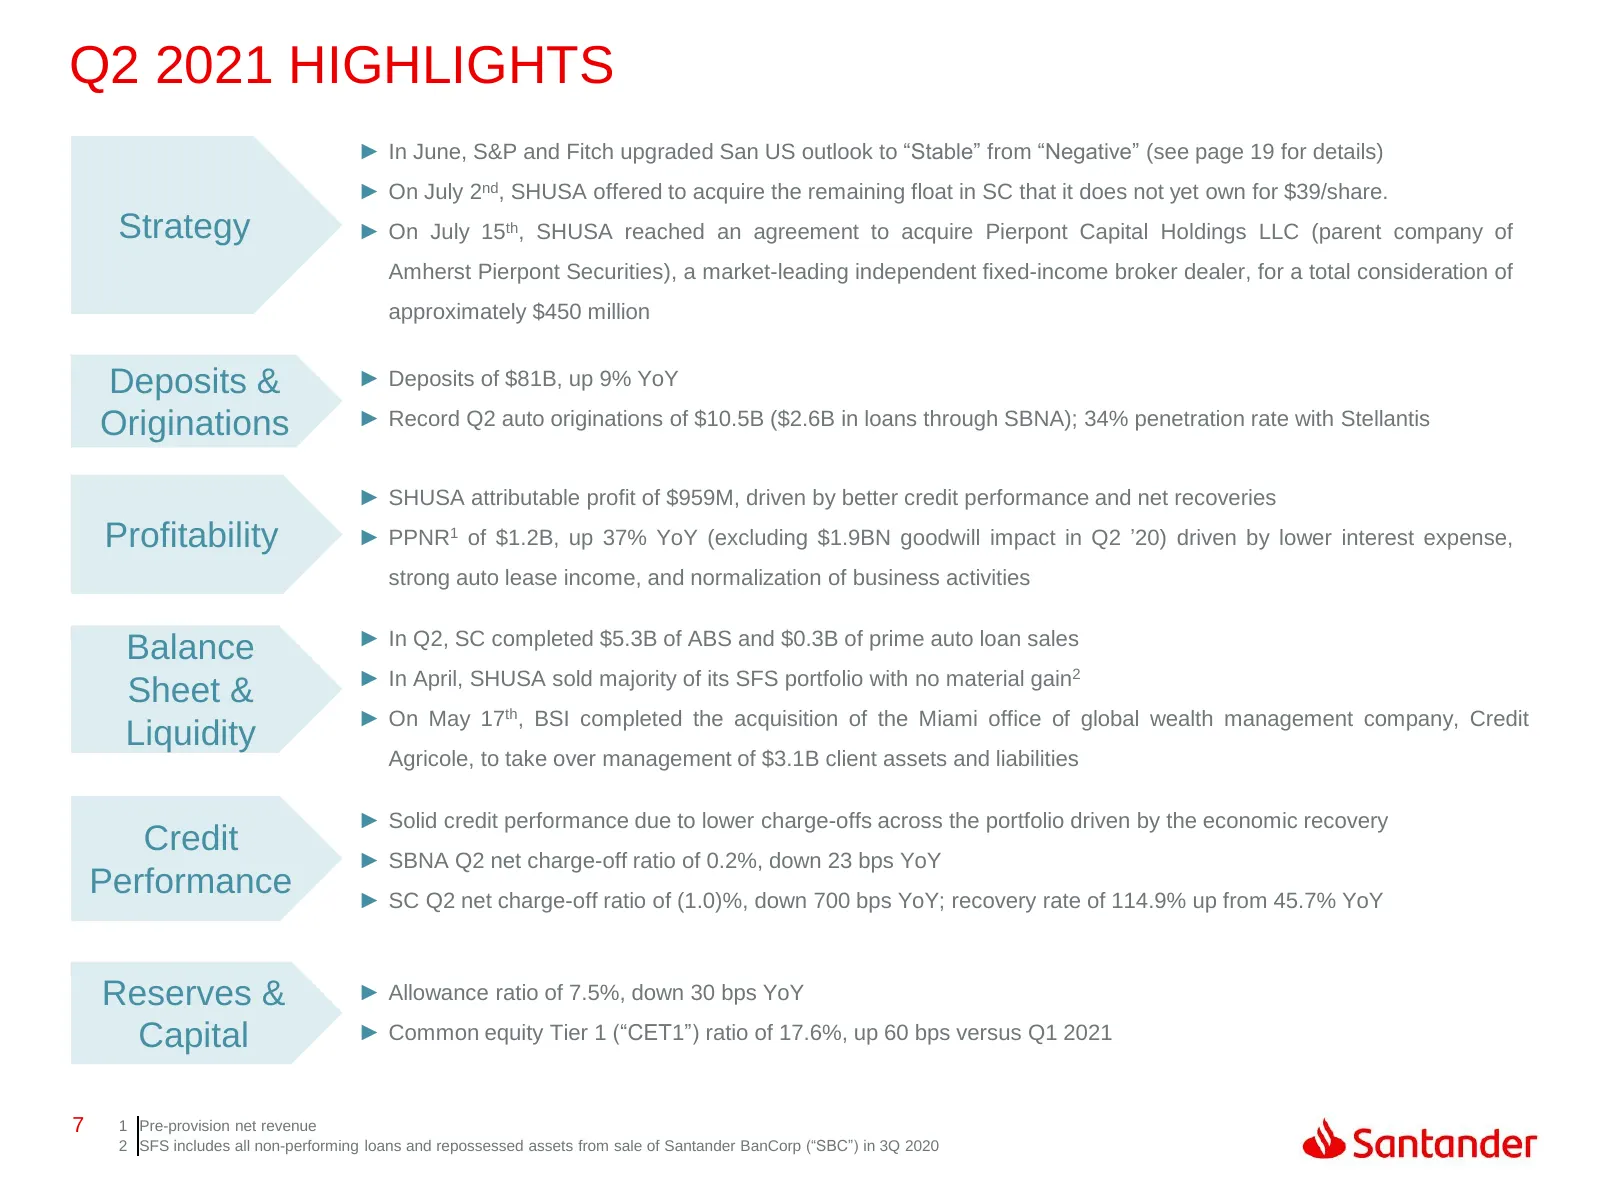
Q2 2021 HIGHLIGHTS ► In June, S&P and Fitch upgraded San US outlook to “Stable” from “Negative” (see page 19 for details) ► On July 2nd, SHUSA offered to acquire the remaining float in SC that it does not yet own for $39/share. Strategy ► On July 15th, SHUSA reached an agreement to acquire Pierpont
Slide 8: Allowance for Credit Losses (ACL)
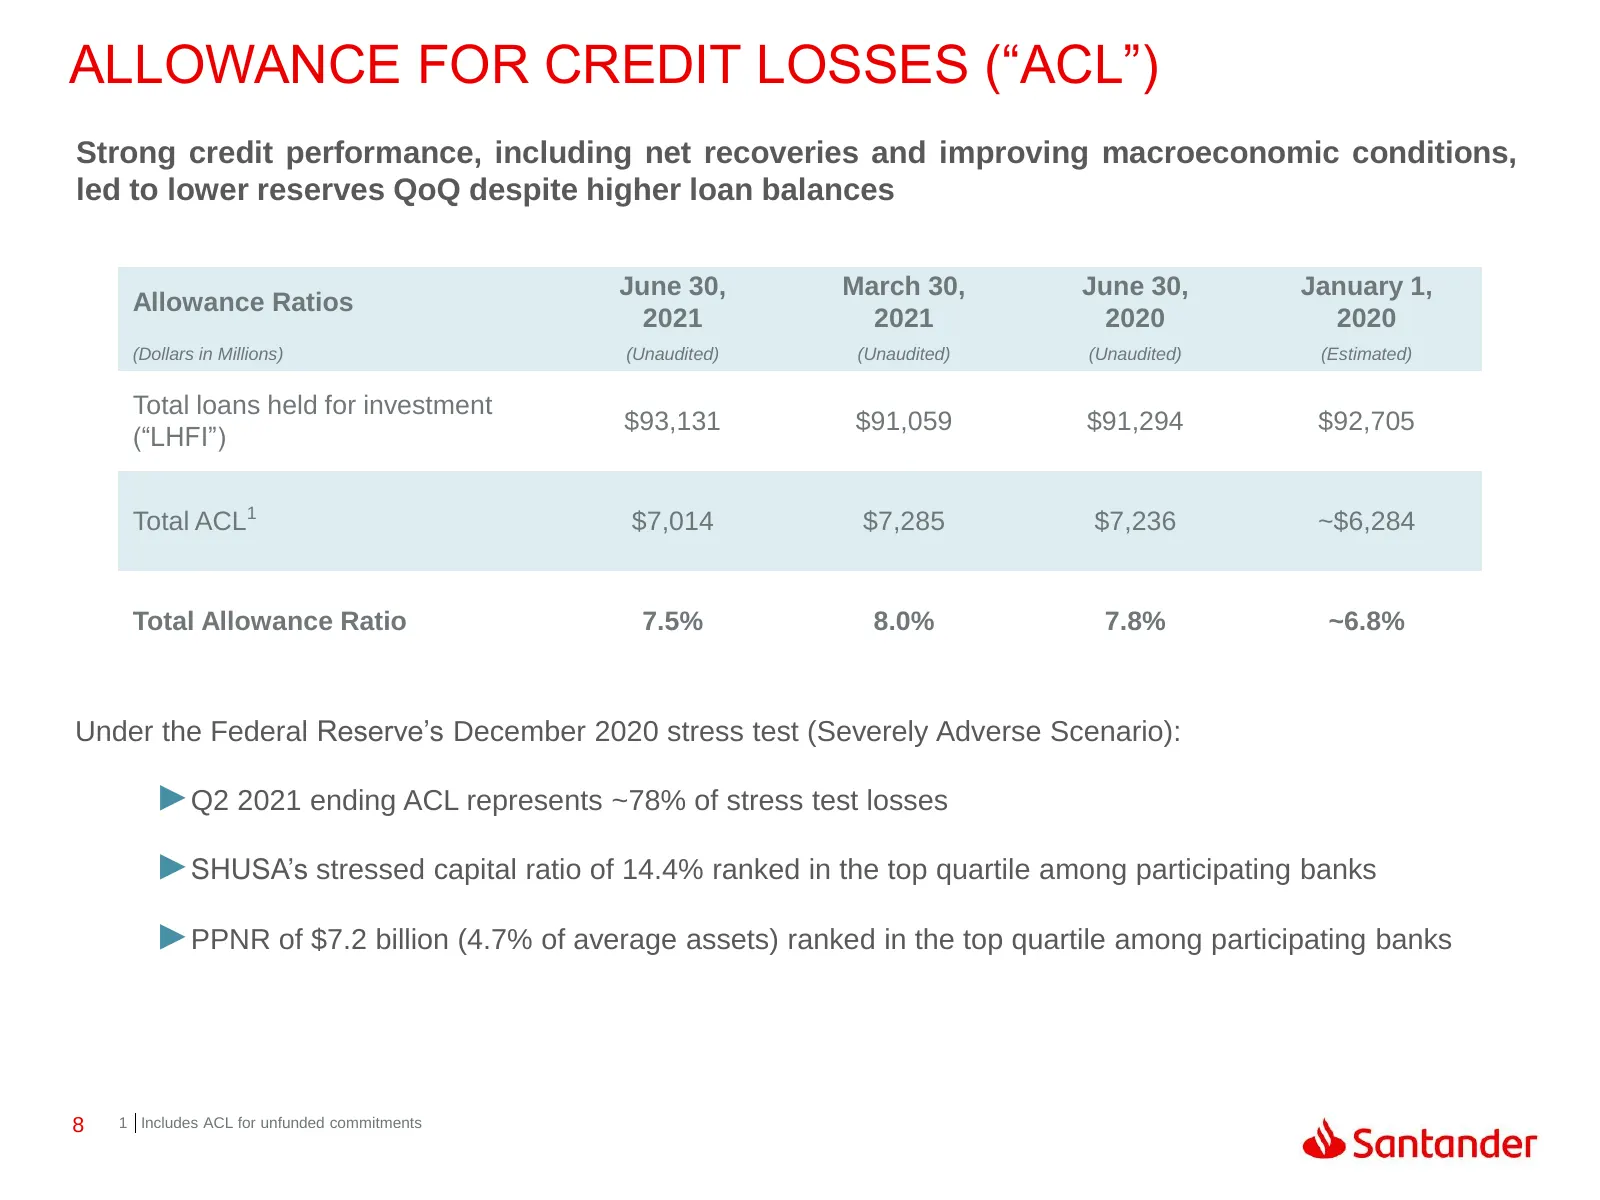
ALLOWANCE FOR CREDIT LOSSES (“ACL”) Strong credit performance, including net recoveries and improving macroeconomic conditions, led to lower reserves QoQ despite higher loan balances June 30, March 30, June 30, January 1, Allowance Ratios 2021 2021 2020 2020 (Dollars in Millions) (Unaudited) (Unaudi
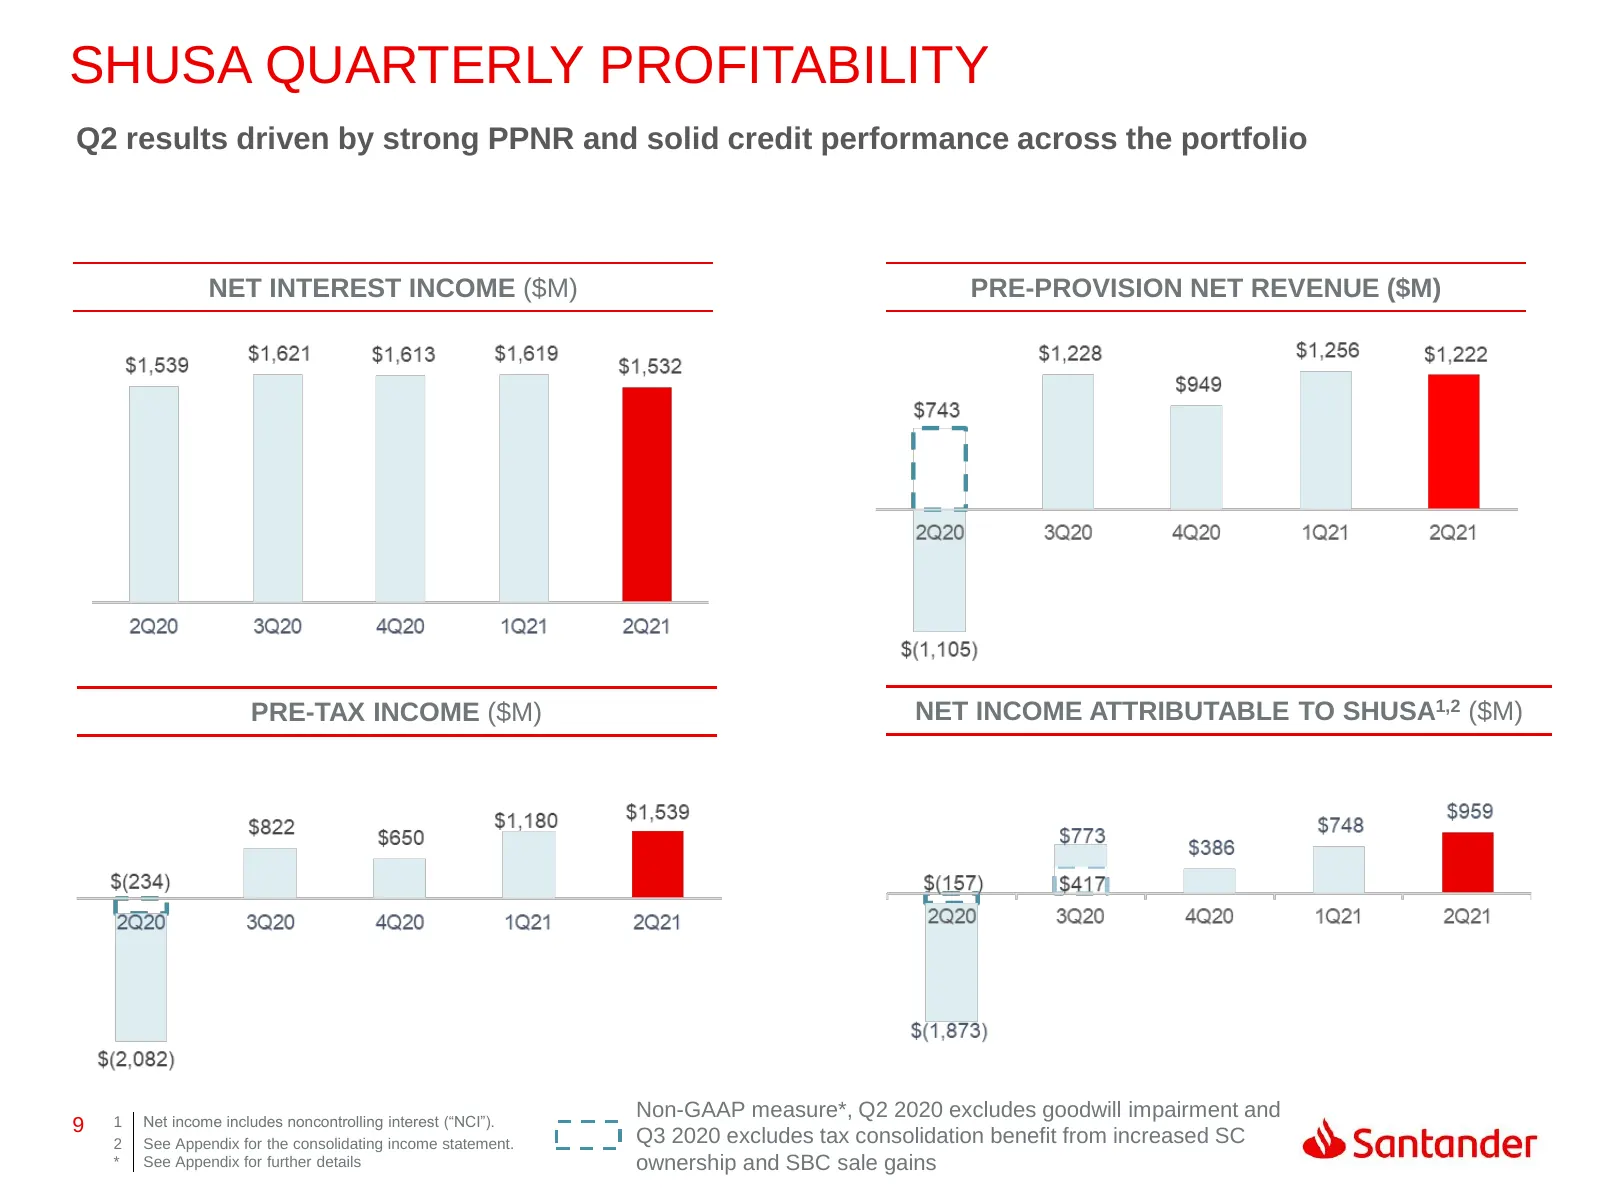
Slide 9: SHUSA Quarterly Profitability
SHUSA QUARTERLY PROFITABILITY Q2 results driven by strong PPNR and solid credit performance across the portfolio NET INTEREST INCOME ($M) PRE-PROVISION NET REVENUE ($M) PRE-TAX INCOME ($M) NET INCOME ATTRIBUTABLE TO SHUSA1,2 ($M) 1 Net income includes noncontrolling interest (“NCI”). Non-GAAP measur
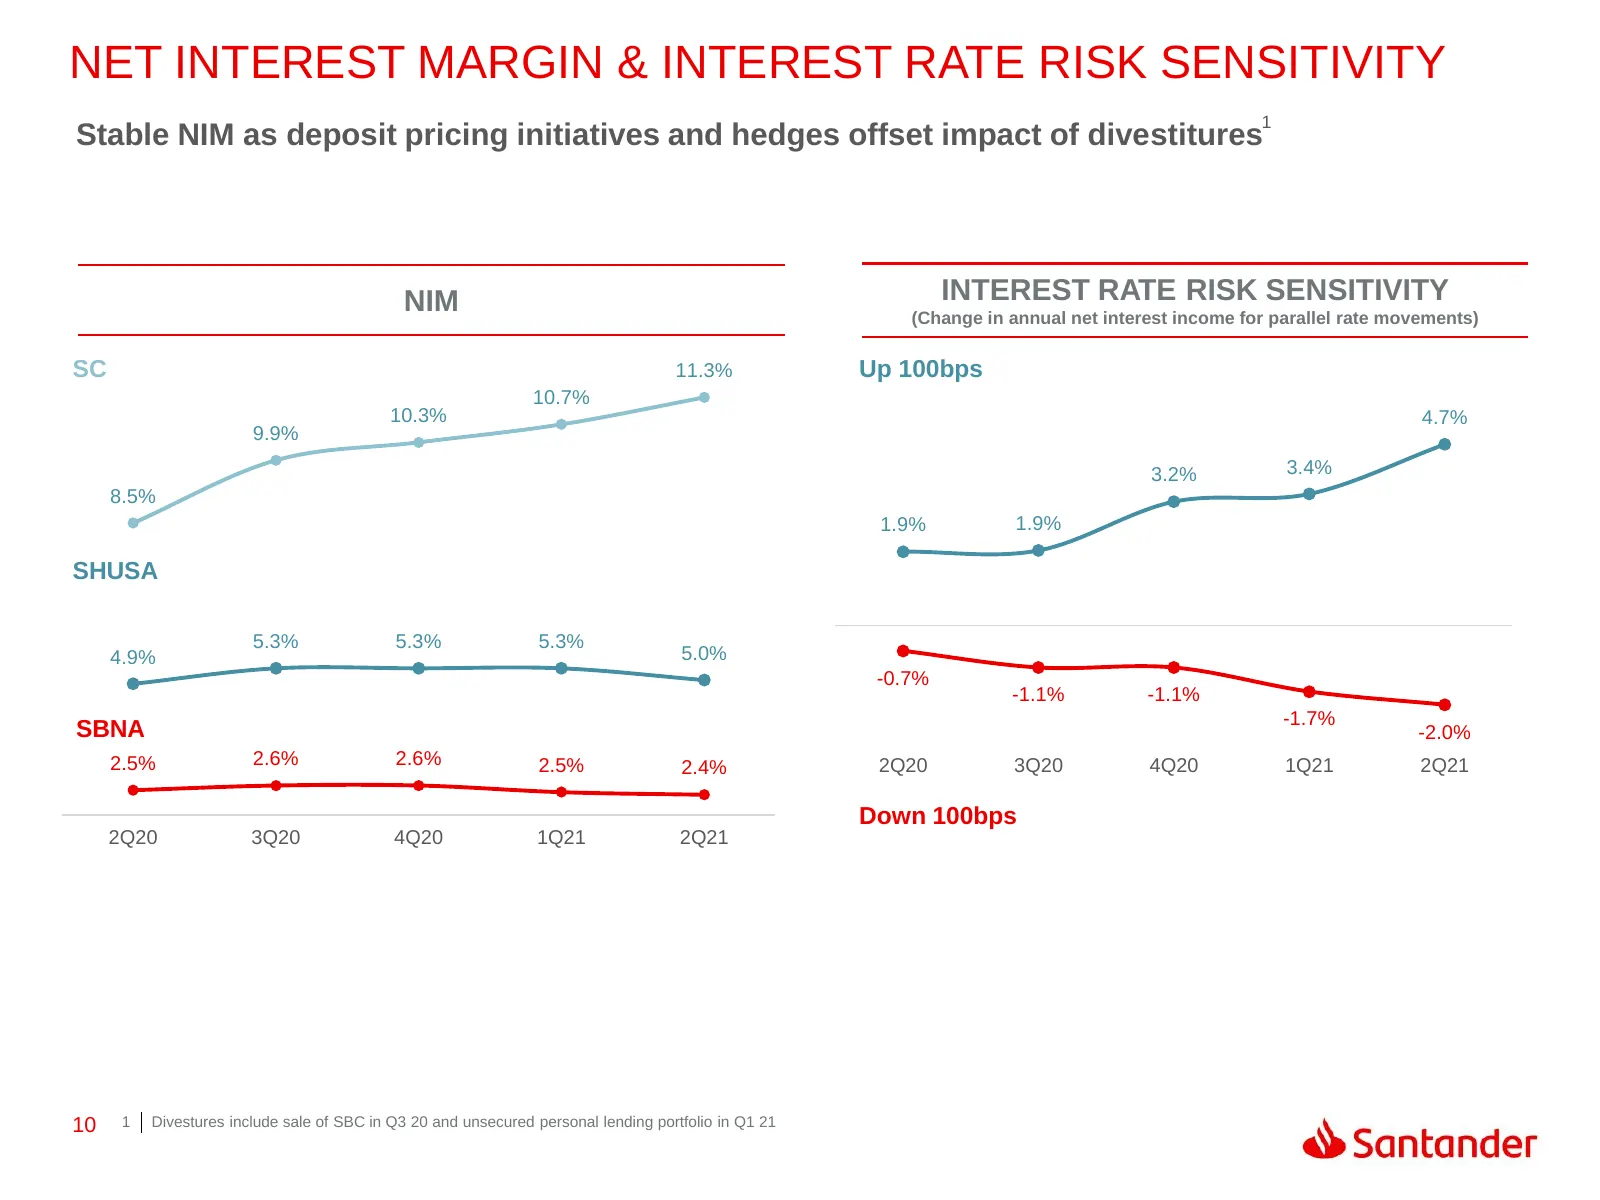
Slide 10: Net Interest Margin & Interest Rate Risk Sensitivity
NET INTEREST MARGIN & INTEREST RATE RISK SENSITIVITY 1 Stable NIM as deposit pricing initiatives and hedges offset impact of divestitures NIM INTEREST RATE RISK SENSITIVITY (Change in annual net interest income for parallel rate movements) SC 11.3% Up 100bps 10.7% 10.3% 4.7% 9.9% 3.2% 3.4% 8.5% 1.9%
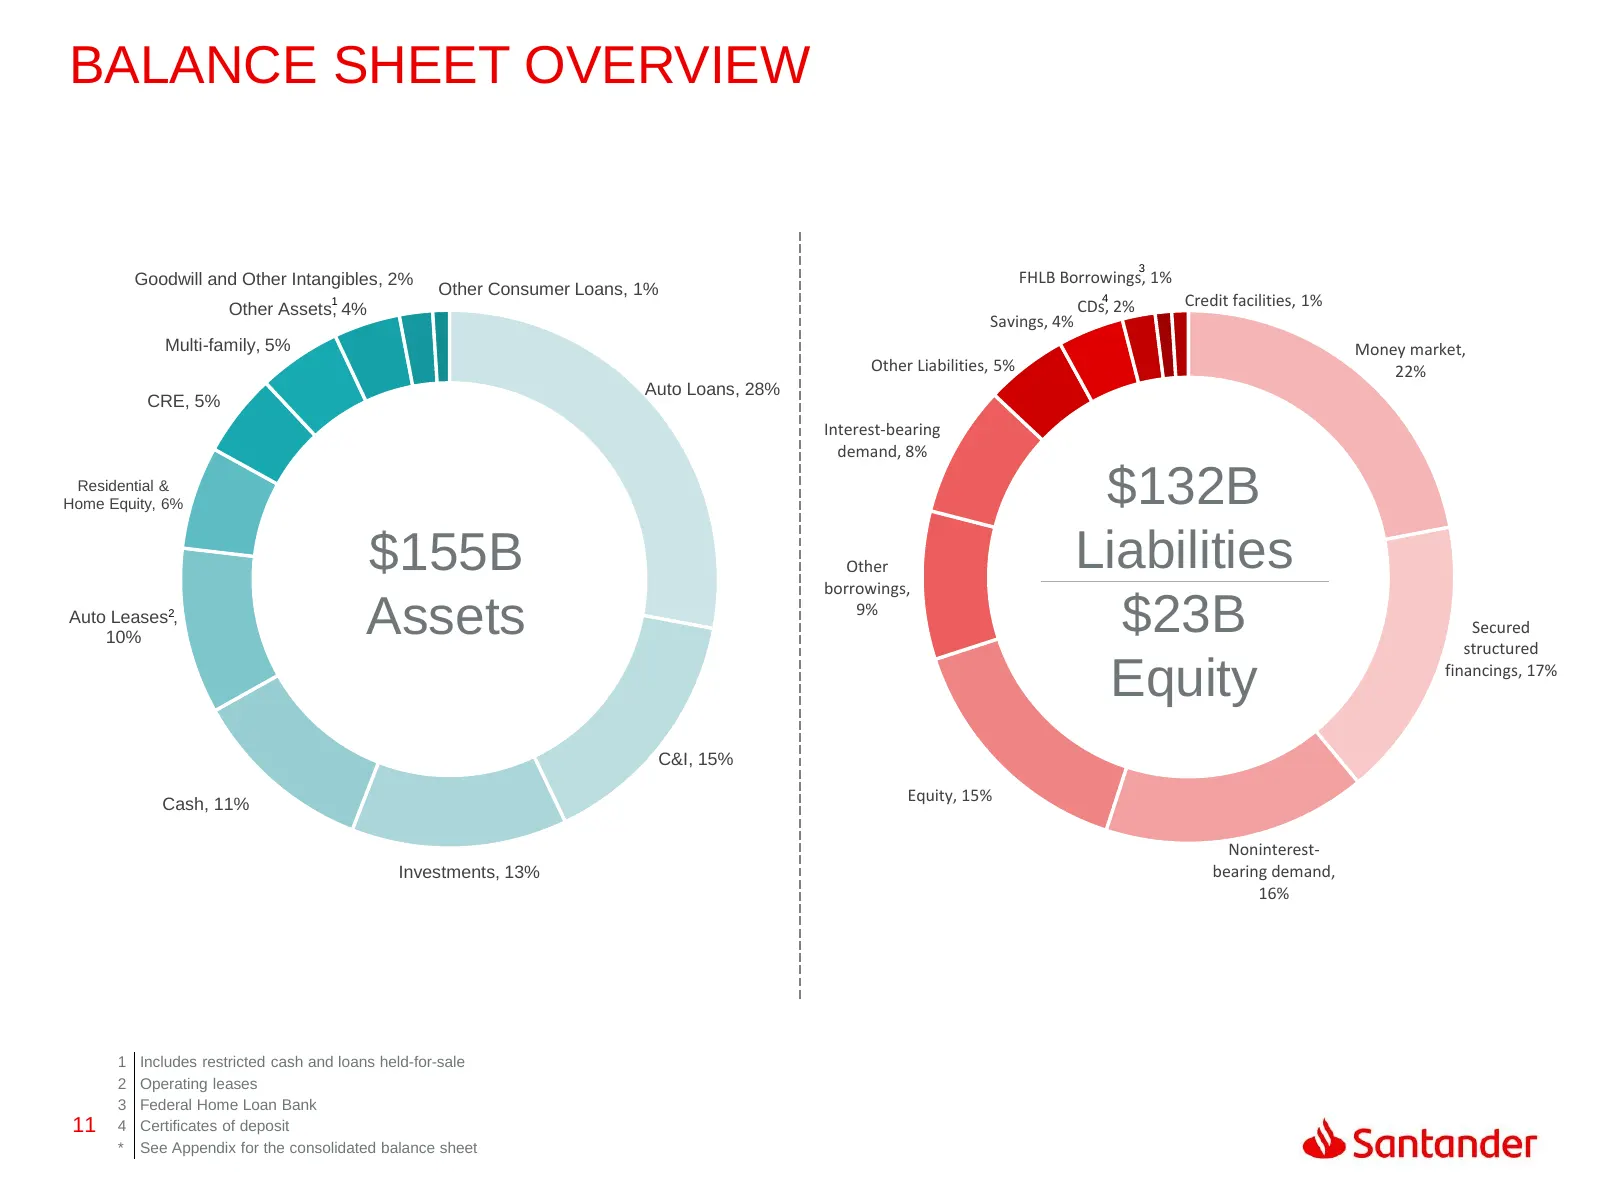
Slide 11: Balance Sheet Overview
BALANCE SHEET OVERVIEW 3 Goodwill and Other Intangibles, 2% FHLB Borrowings, 1% Other Consumer Loans, 1% 1 Other Assets, 4% 4 CDs, 2% Credit facilities, 1% Savings, 4% Multi-family, 5% Money market, Other Liabilities, 5% 22% Auto Loans, 28% CRE, 5% Interest-bearing demand, 8% Residential & Home Equi
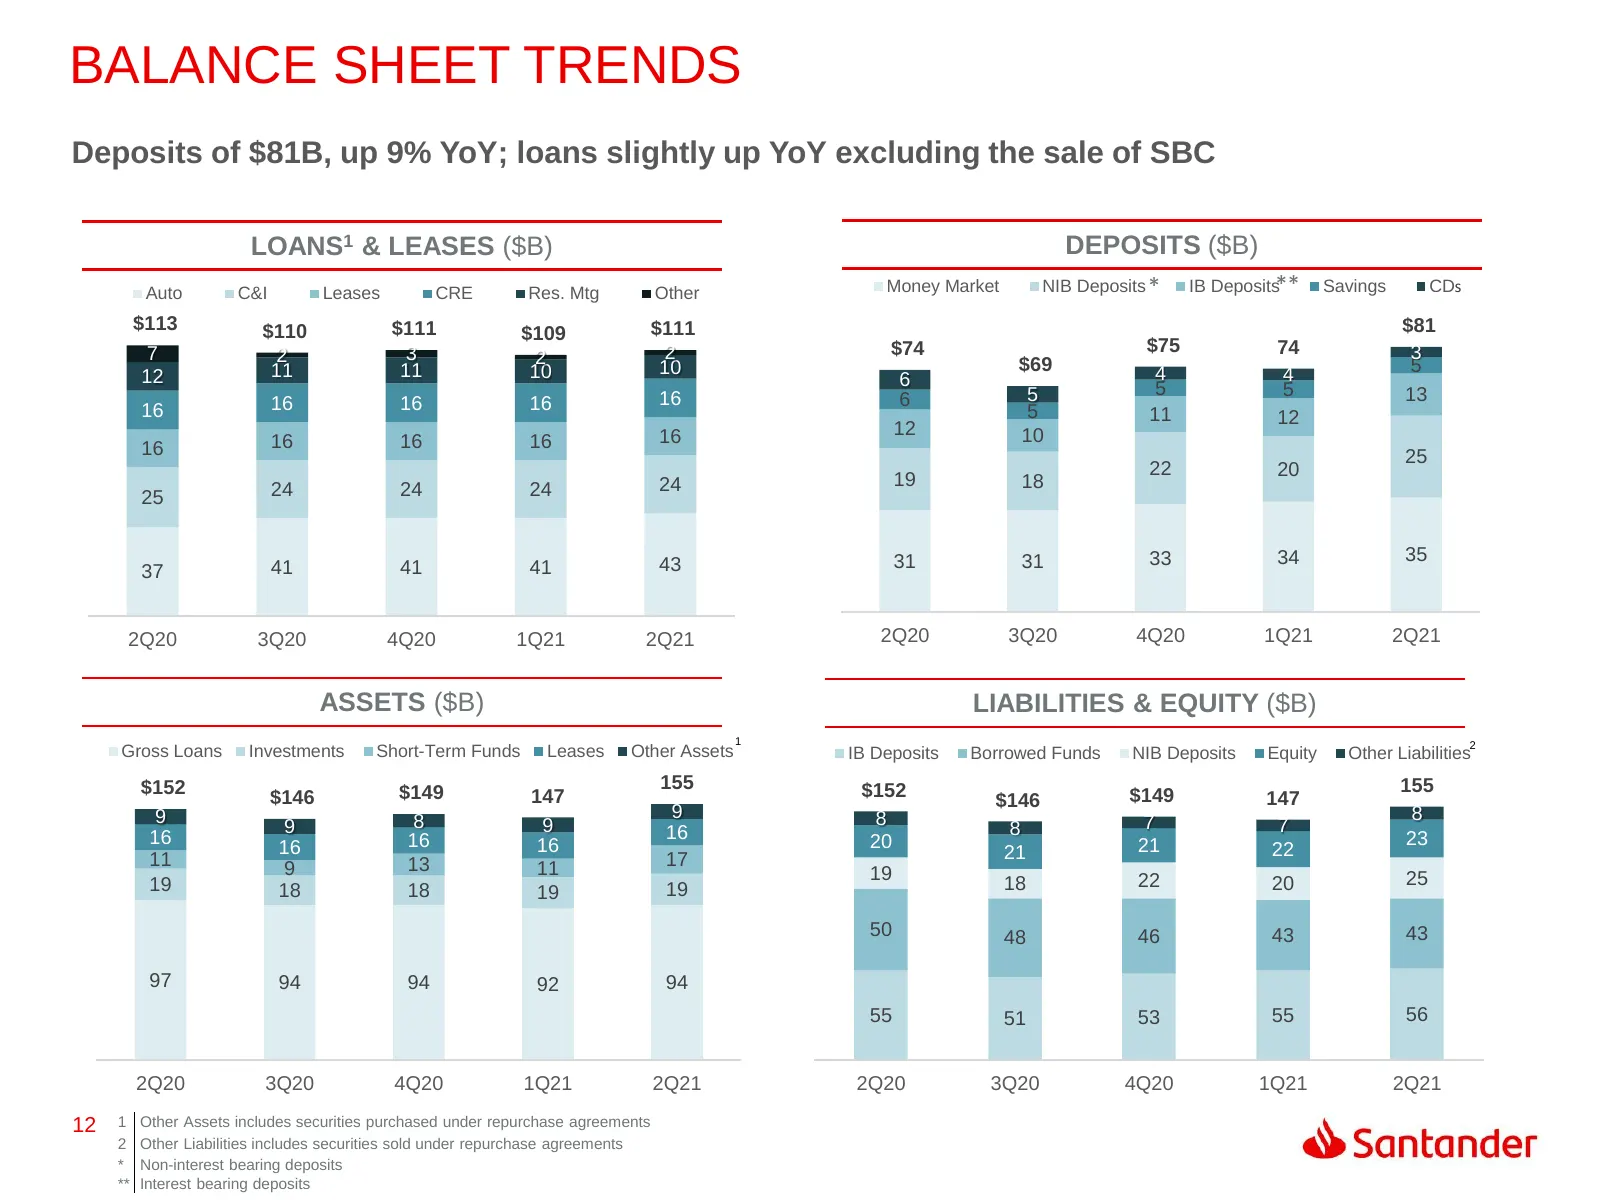
Slide 12: Balance Sheet Trends
BALANCE SHEET TRENDS Deposits of $81B, up 9% YoY; loans slightly up YoY excluding the sale of SBC LOANS1 & LEASES ($B) DEPOSITS ($B) Auto C&I Leases CRE Res. Mtg Other Money Market NIB Deposits * IB Deposits** Savings CDs $113 $110 $111 $109 $111 $81 7 2 3 2 $74 $75 74 3 2 10 $69 5 12 11 11 10 6 4 4
Slide 13: Borrowed Funds Profile
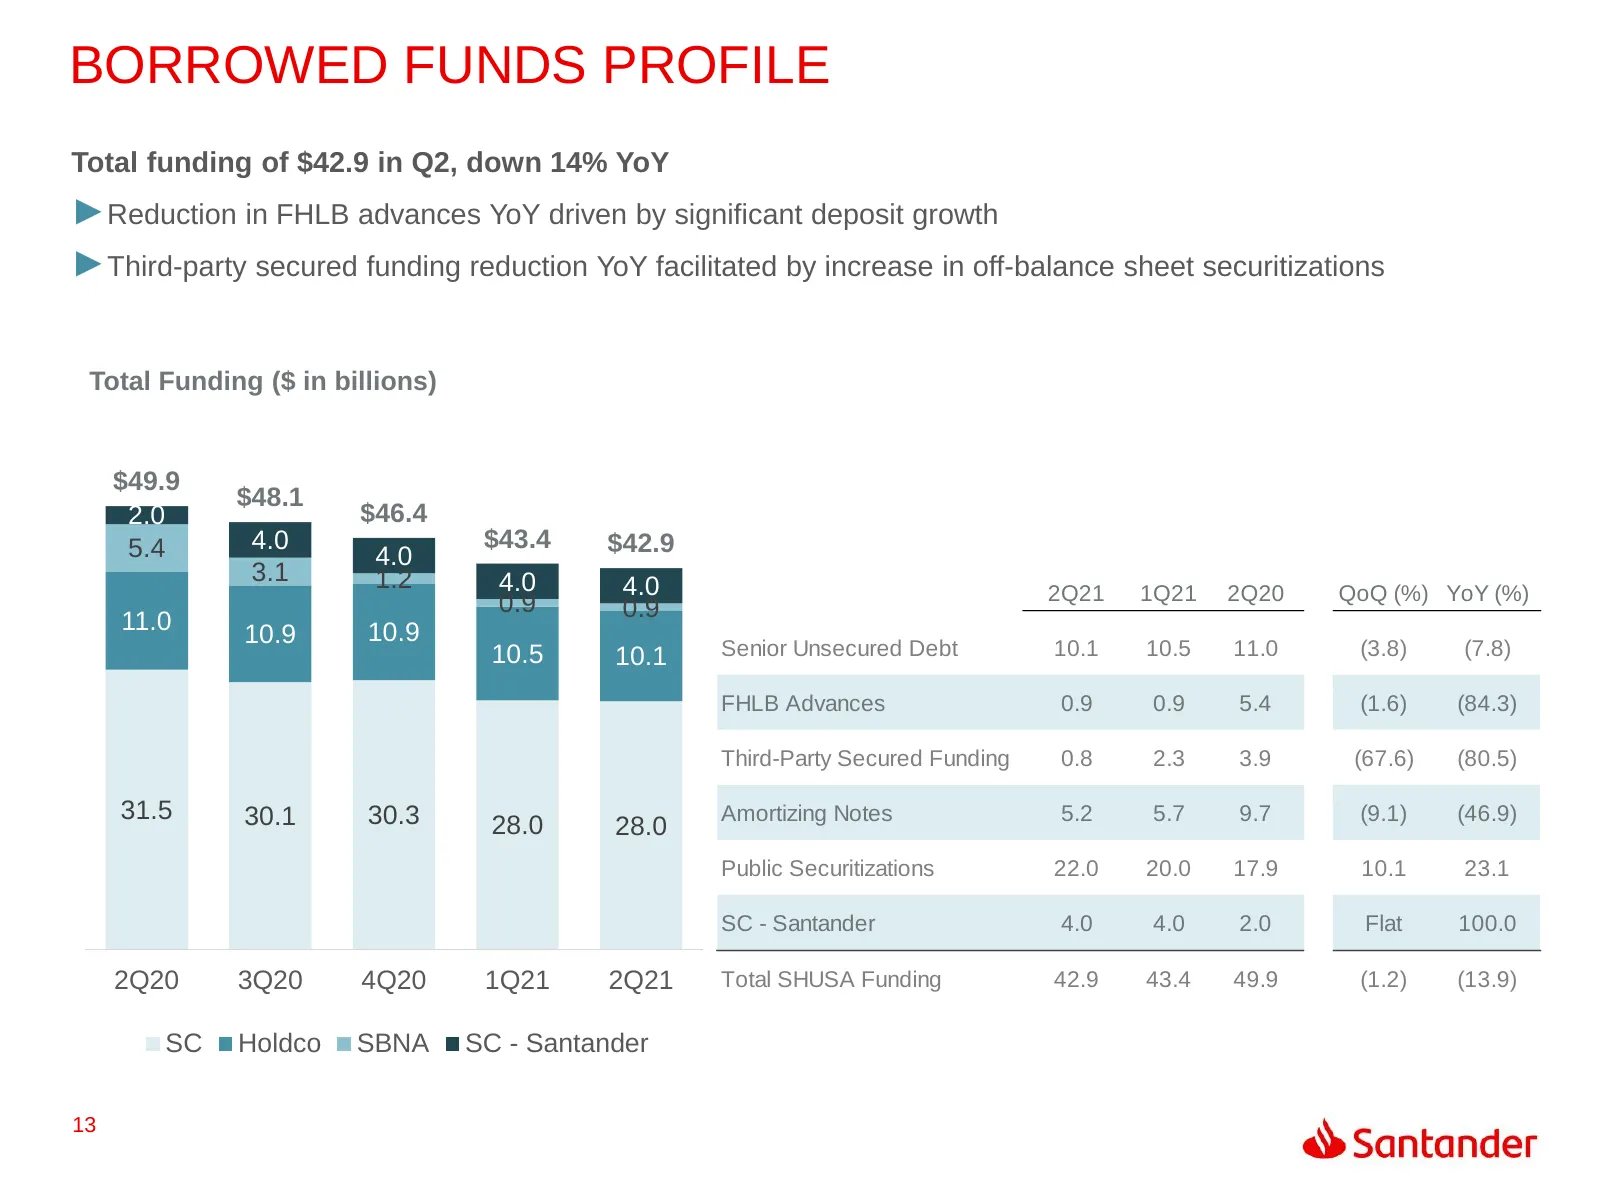
BORROWED FUNDS PROFILE Total funding of $42.9 in Q2, down 14% YoY ►Reduction in FHLB advances YoY driven by significant deposit growth ►Third-party secured funding reduction YoY facilitated by increase in off-balance sheet securitizations Total Funding ($ in billions) $49.9 $48.1 2.0 $46.4 5.4 4.0 $
Slide 14: SHUSA Debt & Total Loss-Absorbing Capacity
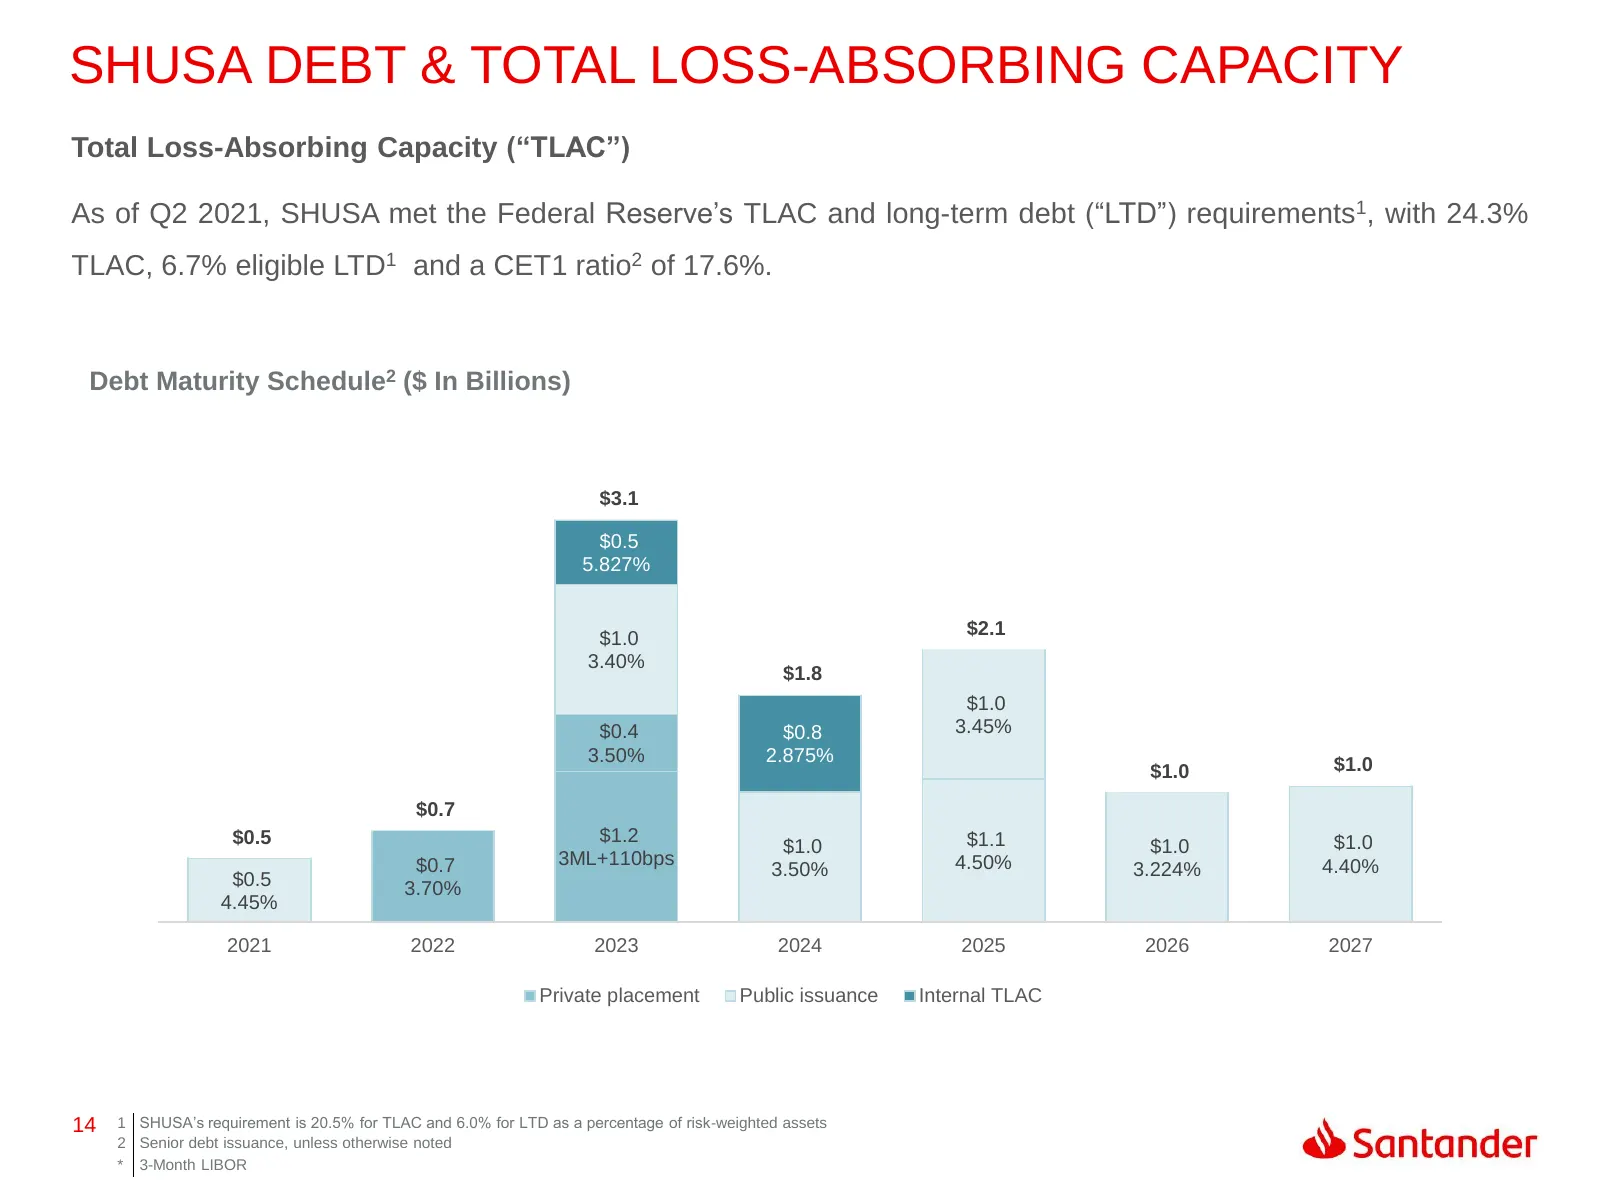
SHUSA DEBT & TOTAL LOSS-ABSORBING CAPACITY Total Loss-Absorbing Capacity (“TLAC”) As of Q2 2021, SHUSA met the Federal Reserve’s TLAC and long-term debt (“LTD”) requirements1, with 24.3% TLAC, 6.7% eligible LTD1 and a CET1 ratio2 of 17.6%. Debt Maturity Schedule2 ($ In Billions) $3.1 $0.5 5.827% $2.
Slide 15: Capital Ratios
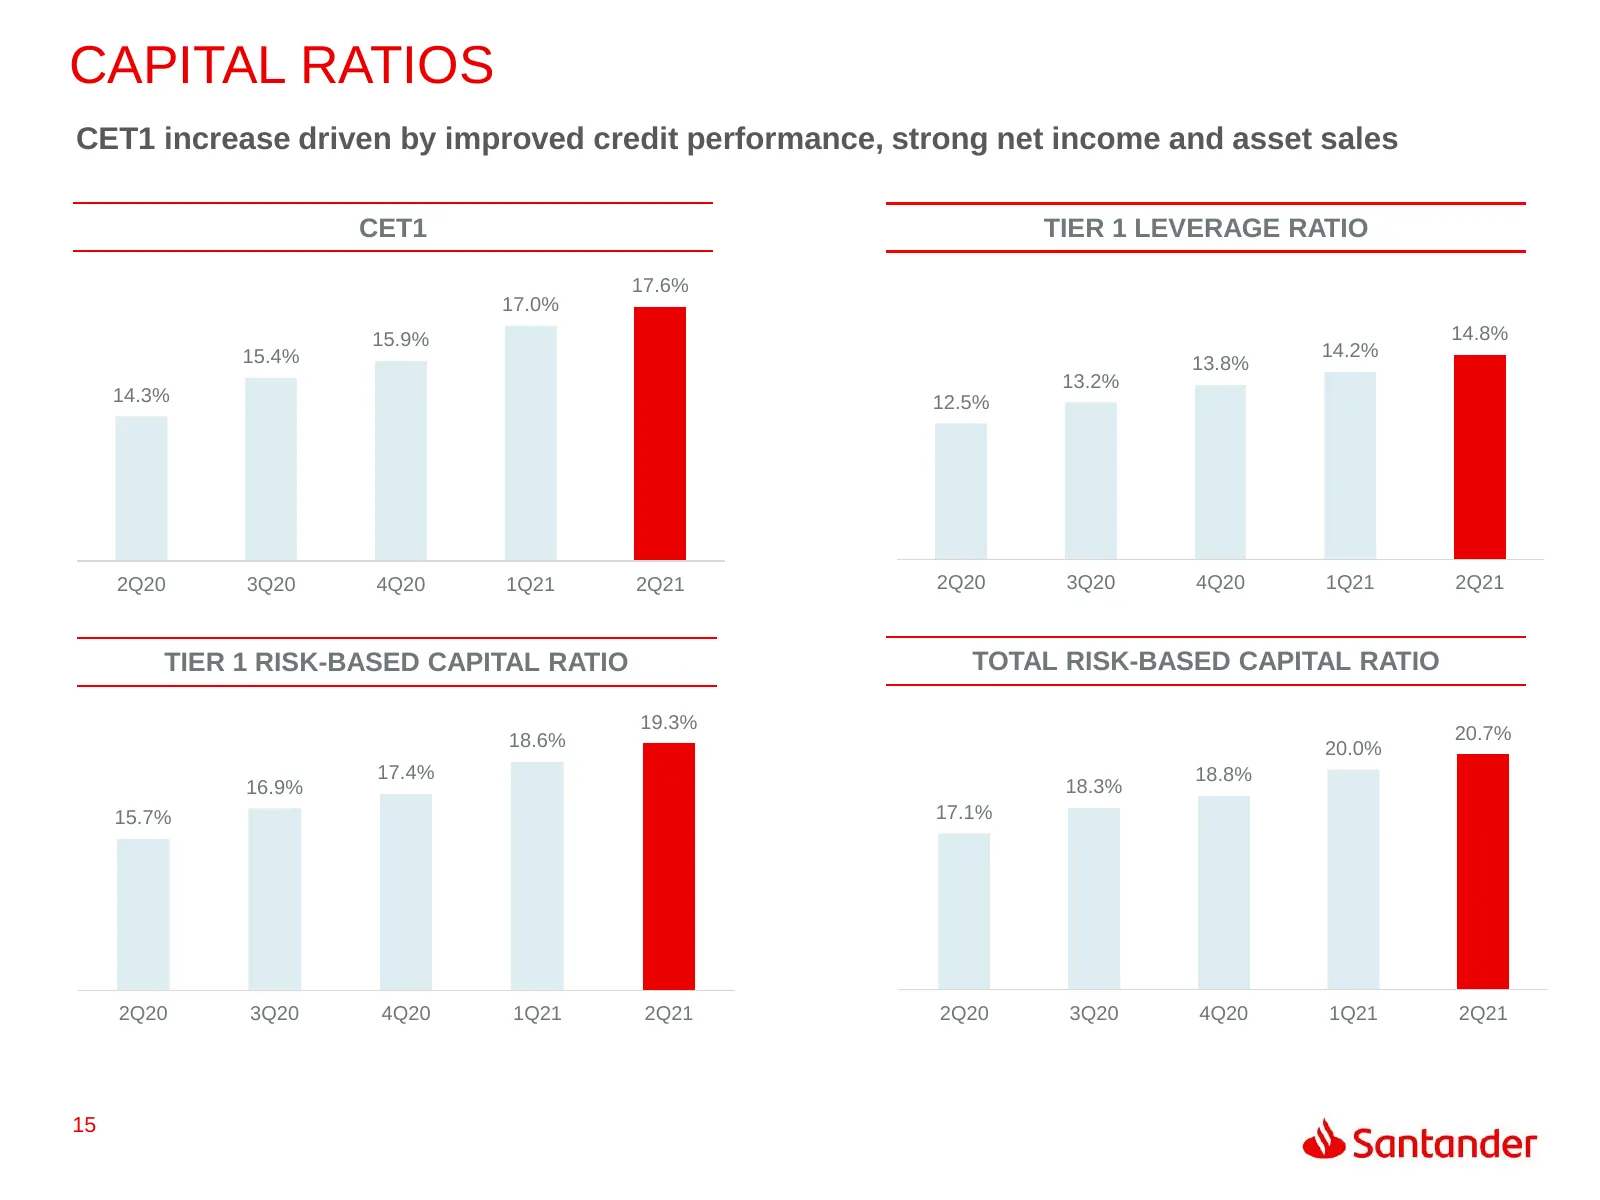
CAPITAL RATIOS CET1 increase driven by improved credit performance, strong net income and asset sales CET1 TIER 1 LEVERAGE RATIO 17.6% 17.0% 15.9% 14.8% 15.4% 14.2% 13.8% 13.2% 14.3% 12.5% 2Q20 3Q20 4Q20 1Q21 2Q21 2Q20 3Q20 4Q20 1Q21 2Q21 TIER 1 RISK-BASED CAPITAL RATIO TOTAL RISK-BASED CAPITAL RATI
Slide 16: SBNA Asset Quality
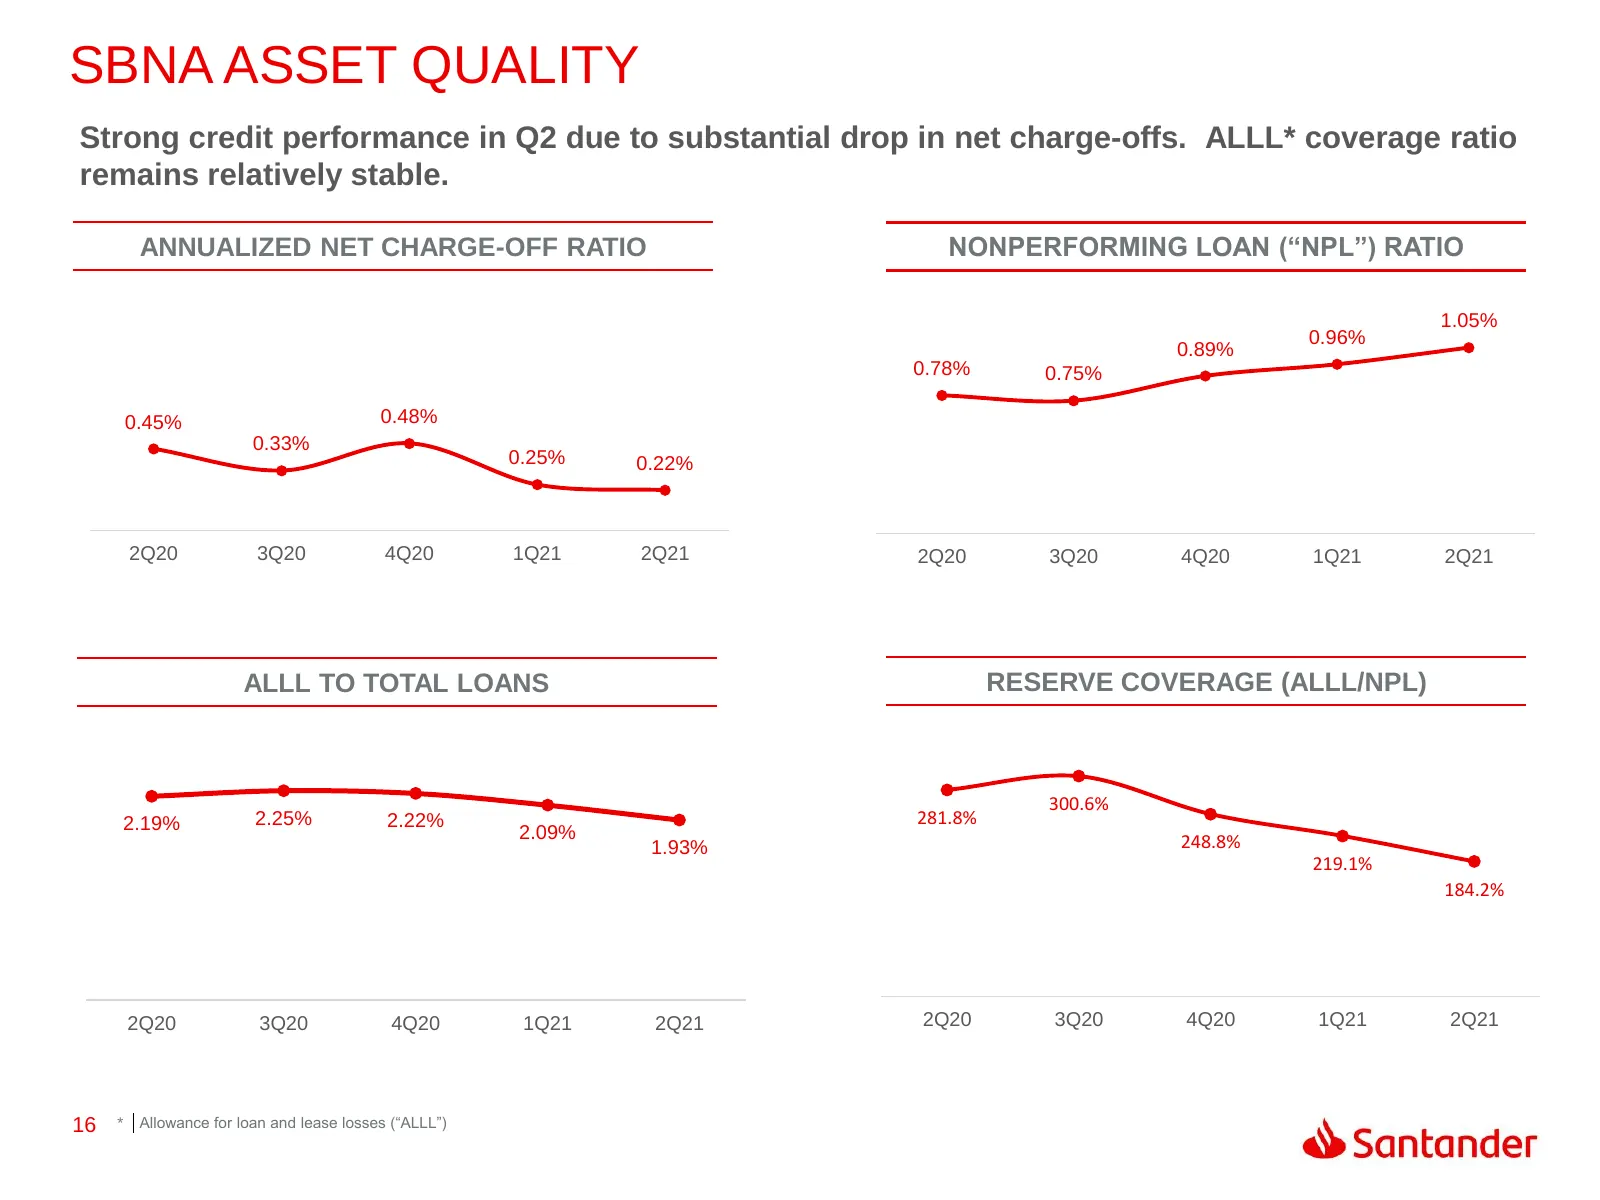
SBNA ASSET QUALITY Strong credit performance in Q2 due to substantial drop in net charge-offs. ALLL* coverage ratio remains relatively stable. ANNUALIZED NET CHARGE-OFF RATIO NONPERFORMING LOAN (“NPL”) RATIO 1.05% 0.96% 0.89% 0.78% 0.75% 0.45% 0.48% 0.33% 0.25% 0.22% 2Q20 3Q20 4Q20 1Q21 2Q21 2Q20 3Q
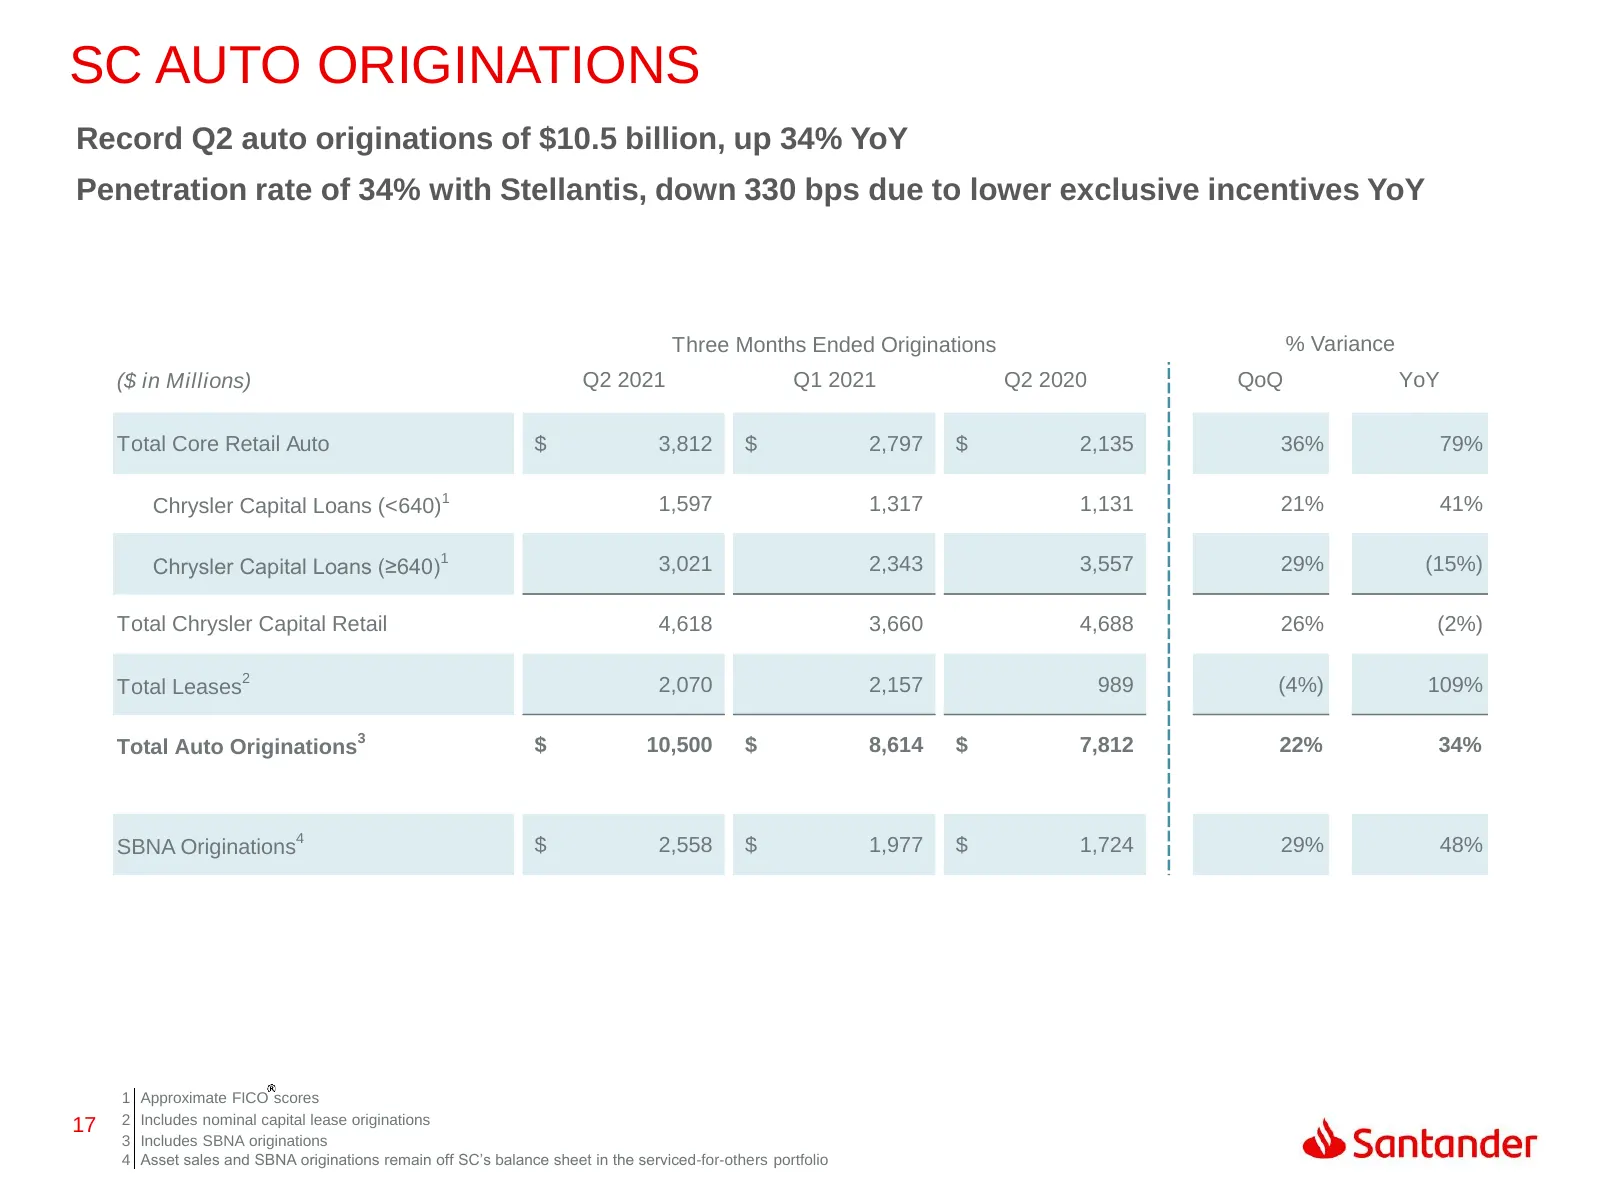
Slide 17: SC Auto Originations
SC AUTO ORIGINATIONS Record Q2 auto originations of $10.5 billion, up 34% YoY Penetration rate of 34% with Stellantis, down 330 bps due to lower exclusive incentives YoY Three Months Ended Originations % Variance ($ in Millions) Q2 2021 Q1 2021 Q2 2020 QoQ YoY Total Core Retail Auto $ 3,812 $ 2,797
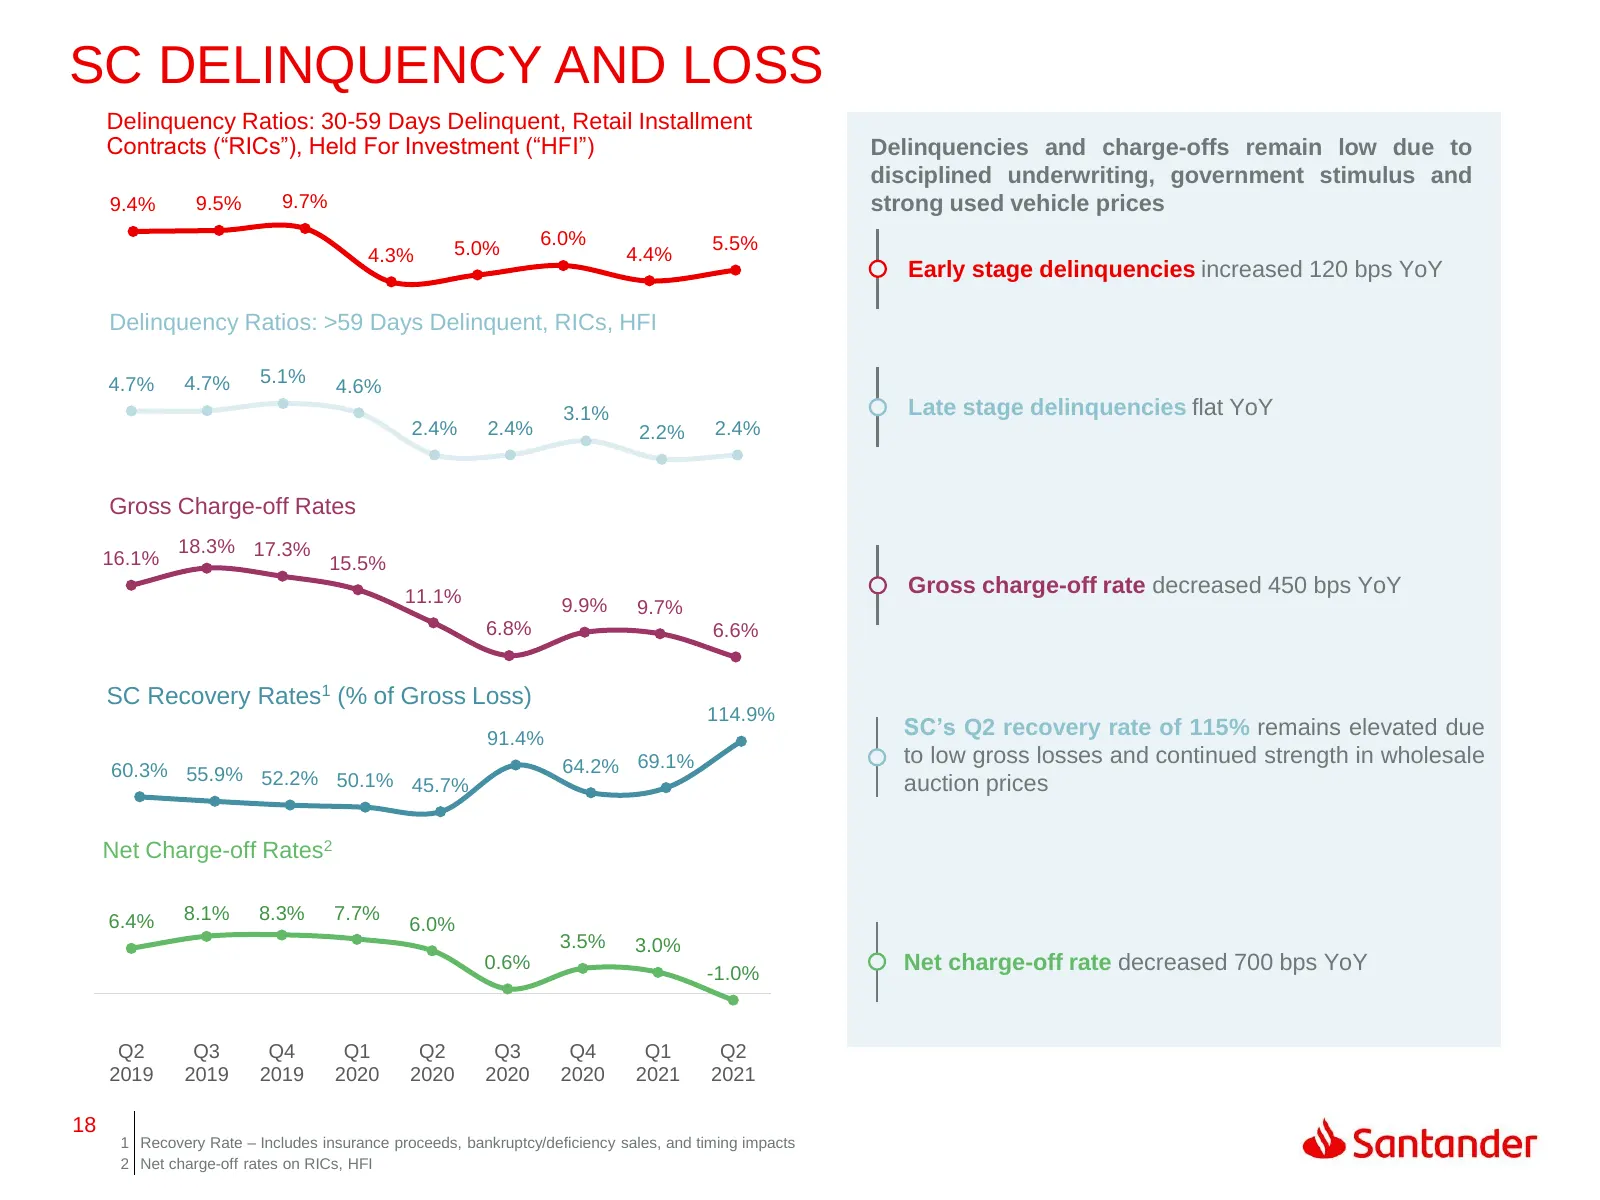
Slide 18: SC Delinquency and Loss
SC DELINQUENCY AND LOSS Delinquency Ratios: 30-59 Days Delinquent, Retail Installment Contracts (“RICs”), Held For Investment (“HFI”) Delinquencies and charge-offs remain low due to disciplined underwriting, government stimulus and 9.4% 9.5% 9.7% strong used vehicle prices 5.0% 6.0% 5.5% 4.3% 4.4% E
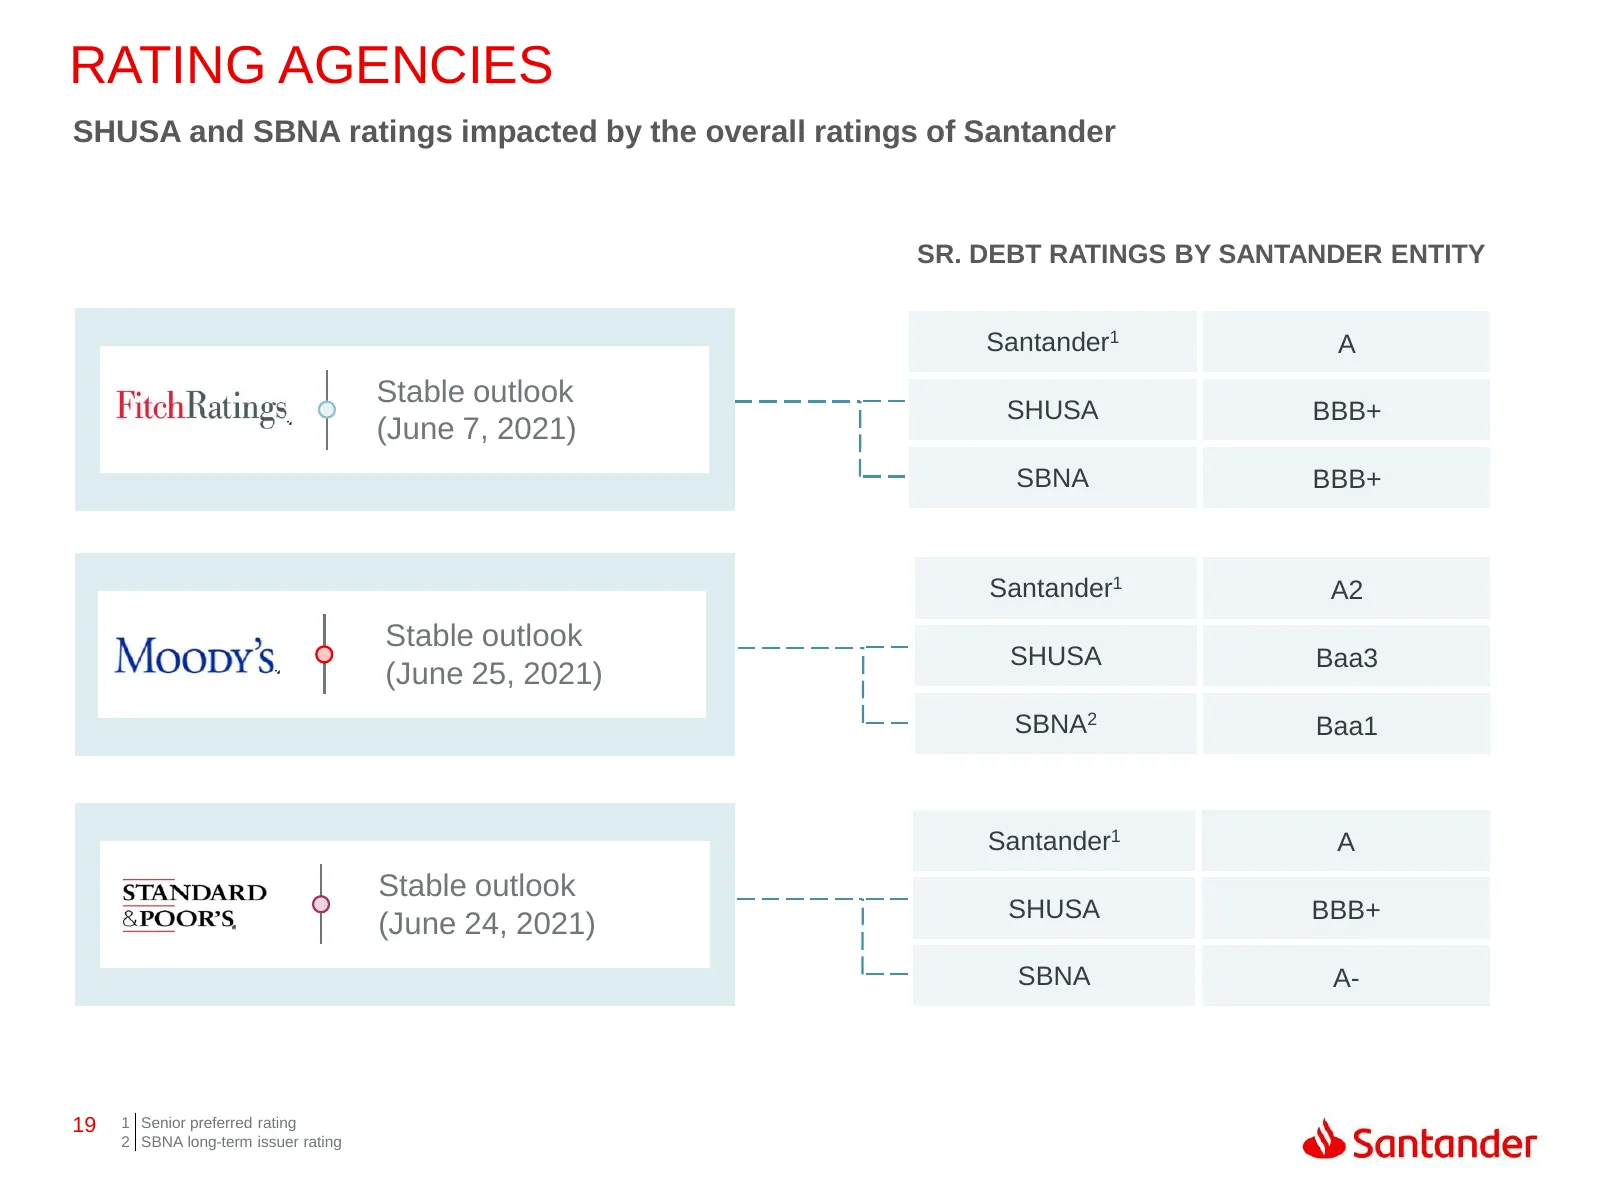
Slide 19: Rating Agencies
RATING AGENCIES SHUSA and SBNA ratings impacted by the overall ratings of Santander SR. DEBT RATINGS BY SANTANDER ENTITY Santander1 A Stable outlook SHUSA BBB+ (June 7, 2021) SBNA BBB+ Santander1 A2 Stable outlook SHUSA Baa3 (June 25, 2021) SBNA2 Baa1 Santander1 A Stable outlook SHUSA BBB+ (June 24,
Slide 20: Appendix
APPENDIX «> Santander
Slide 21: Consolidating Income Statement
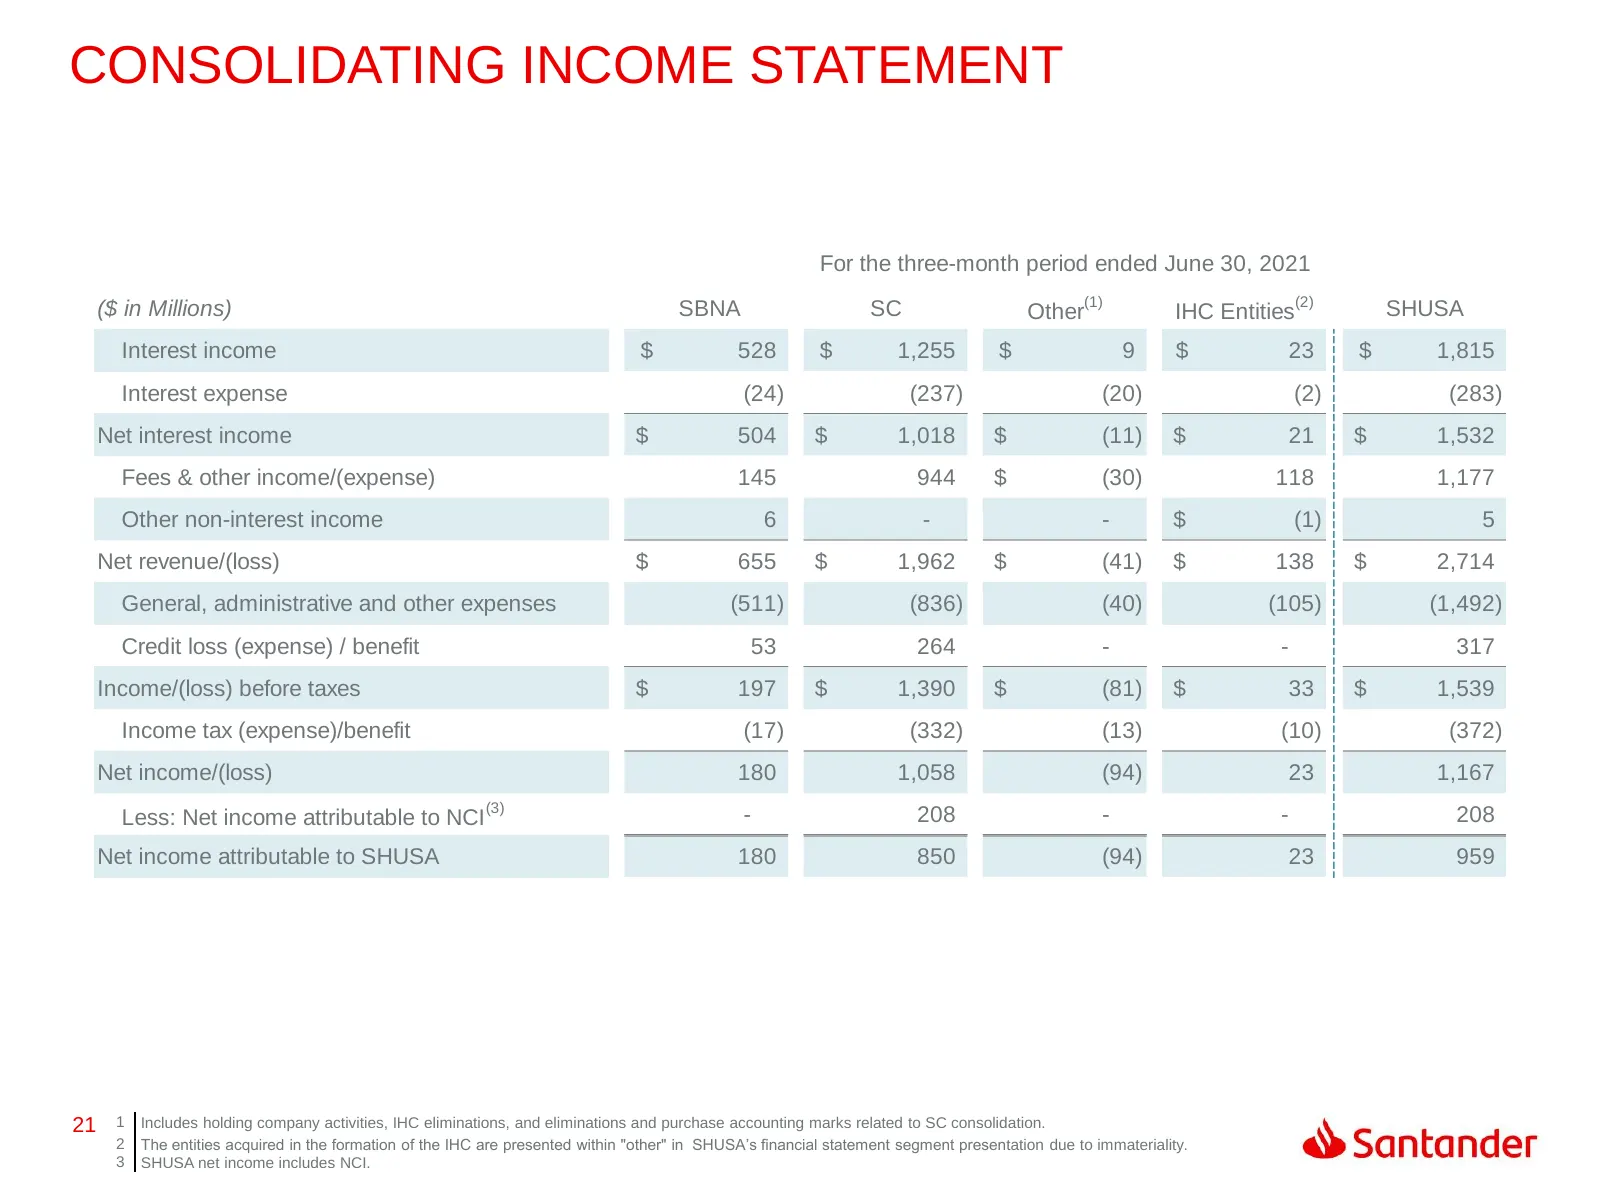
CONSOLIDATING INCOME STATEMENT For the three-month period ended June 30, 2021 ($ in Millions) SBNA SC Other(1) IHC Entities(2) SHUSA Interest income $ 528 $ 1,255 $ 9 $ 23 $ 1,815 Interest expense (24) (237) (20) (2) (283) Net interest income $ 504 $ 1,018 $ (11) $ 21 $ 1,532 Fees & other income/(ex
Slide 22: Consolidating Balance Sheet
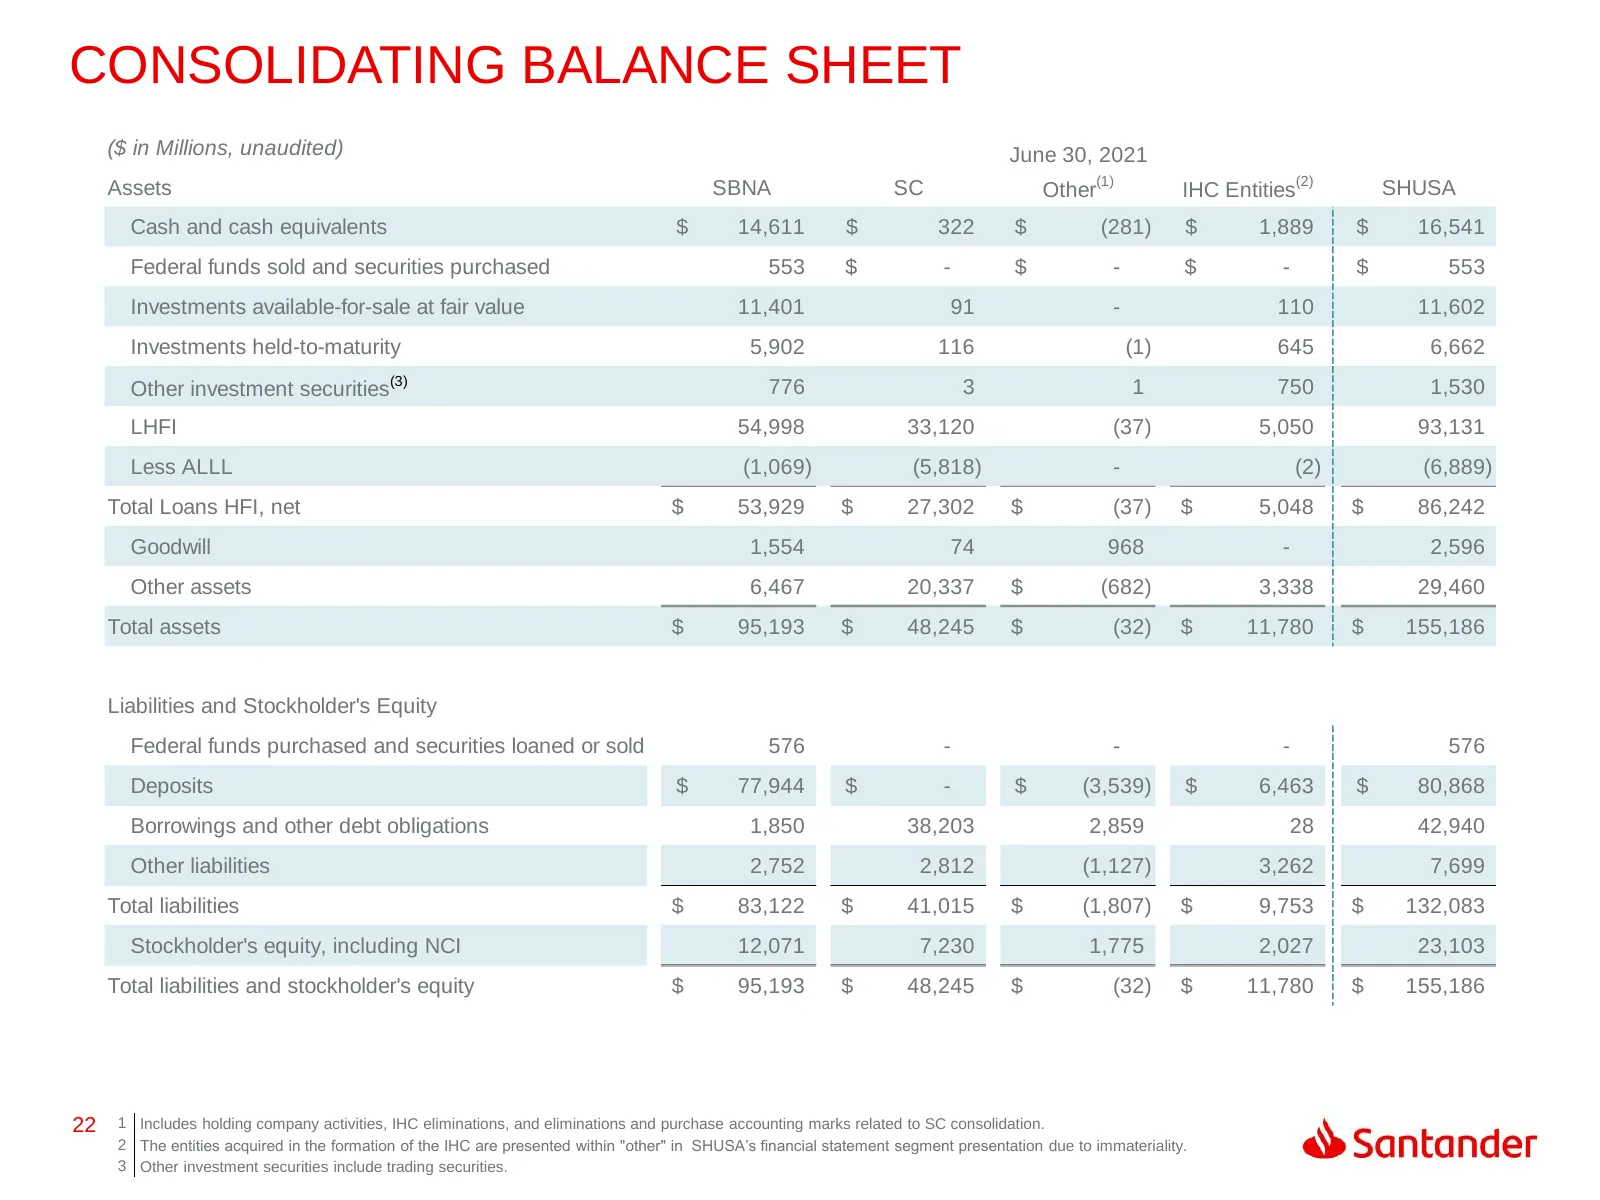
CONSOLIDATING BALANCE SHEET ($ in Millions, unaudited) June 30, 2021 (1) (2) Assets SBNA SC Other IHC Entities SHUSA Cash and cash equivalents $ 14,611 $ 322 $ (281) $ 1,889 $ 16,541 Federal funds sold and securities purchased 553 $ - $ - $ - $ 553 Investments available-for-sale at fair value 11,401
Slide 23: SHUSA: Quarterly Trended Statement of Operations
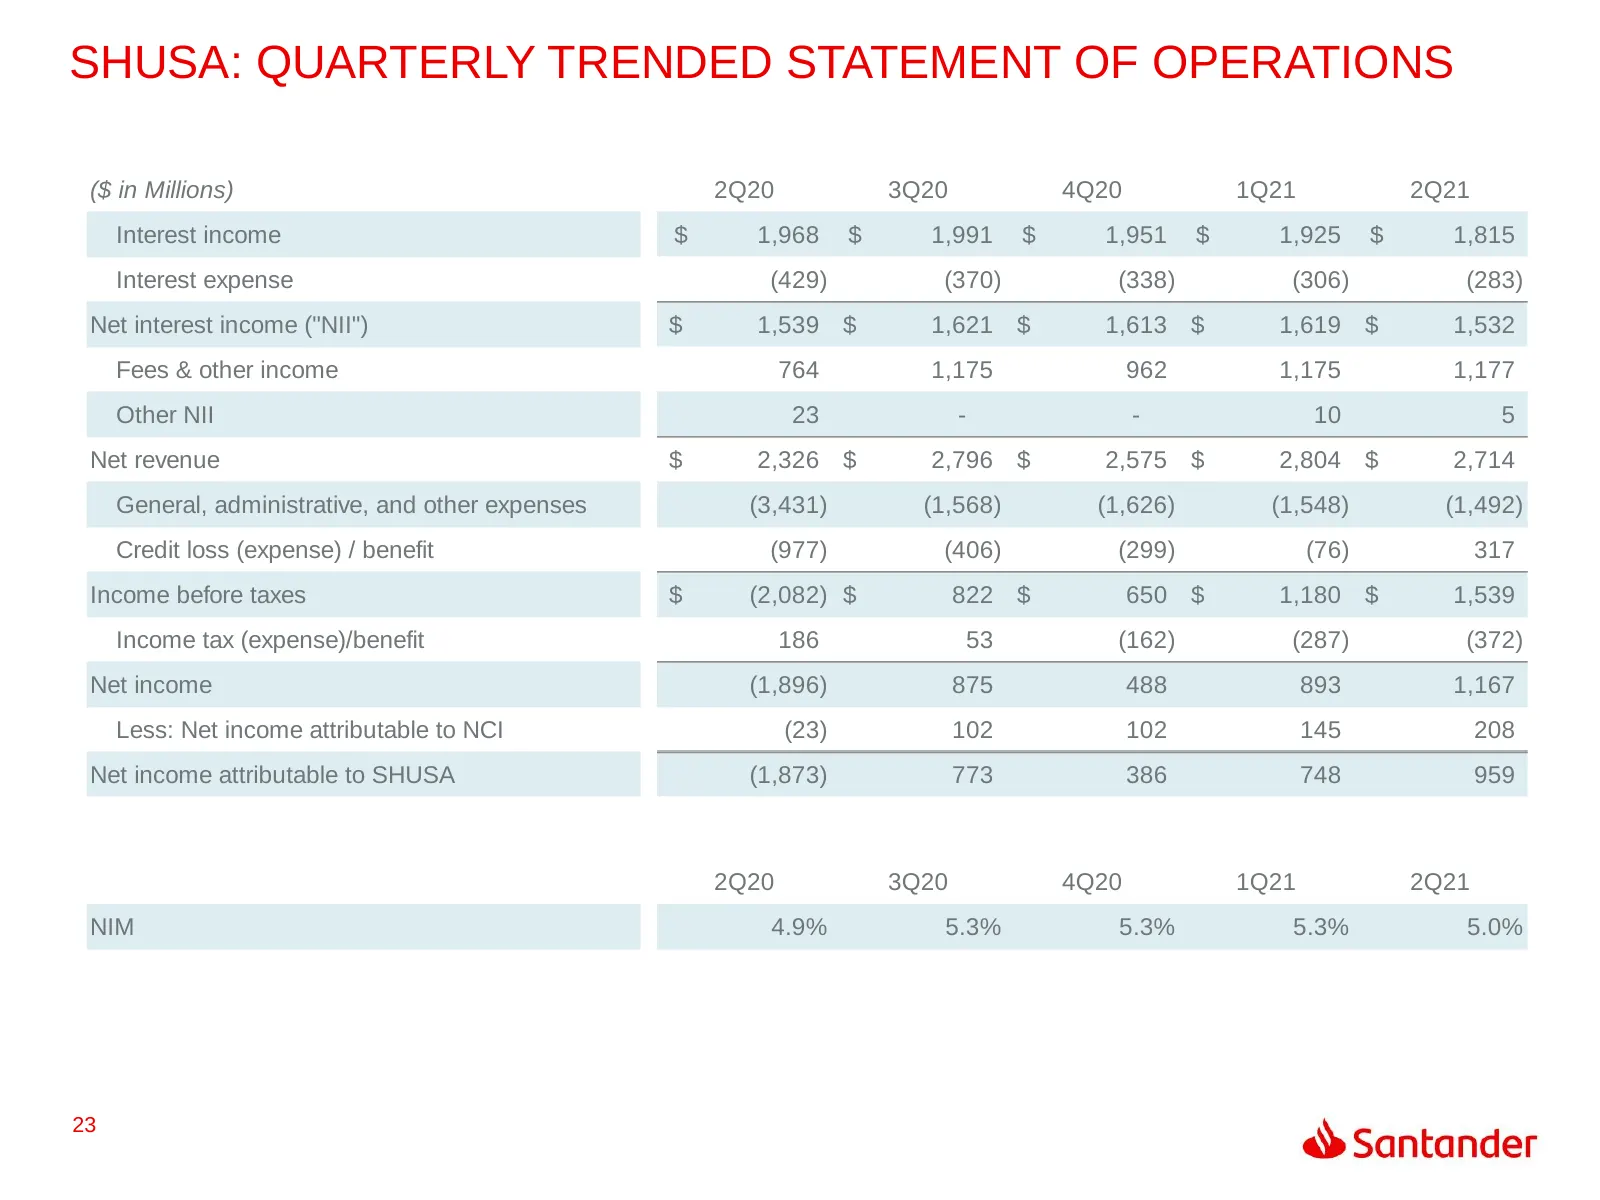
SHUSA: QUARTERLY TRENDED STATEMENT OF OPERATIONS ($ in Millions) 2Q20 3Q20 4Q20 1Q21 2Q21 Interest income $ 1,968 $ 1,991 $ 1,951 $ 1,925 $ 1,815 Interest expense (429) (370) (338) (306) (283) Net interest income ("NII") $ 1,539 $ 1,621 $ 1,613 $ 1,619 $ 1,532 Fees & other income 764 1,175 962 1,175
Slide 24: SHUSA: Non-GAAP Reconciliations
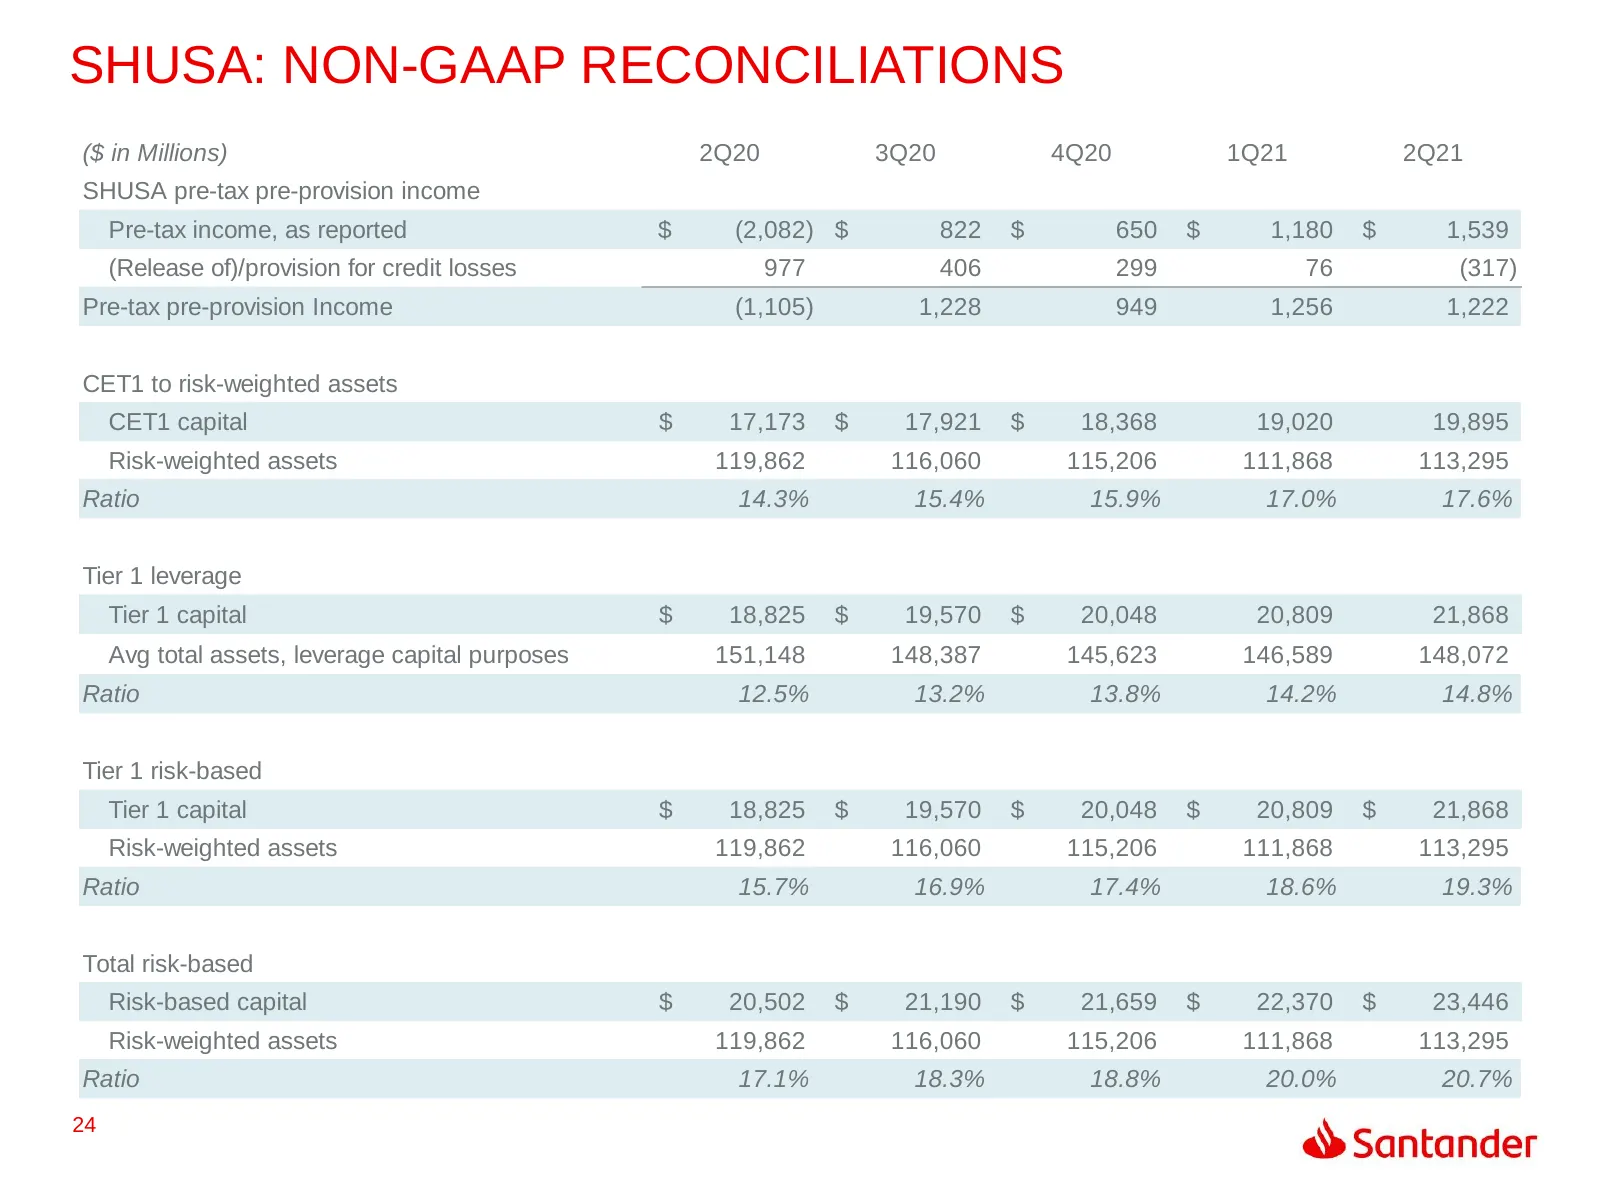
SHUSA: NON-GAAP RECONCILIATIONS ($ in Millions) 2Q20 3Q20 4Q20 1Q21 2Q21 SHUSA pre-tax pre-provision income Pre-tax income, as reported $ (2,082) $ 822 $ 650 $ 1,180 $ 1,539 (Release of)/provision for credit losses 977 406 299 76 (317) Pre-tax pre-provision Income (1,105) 1,228 949 1,256 1,222 CET1
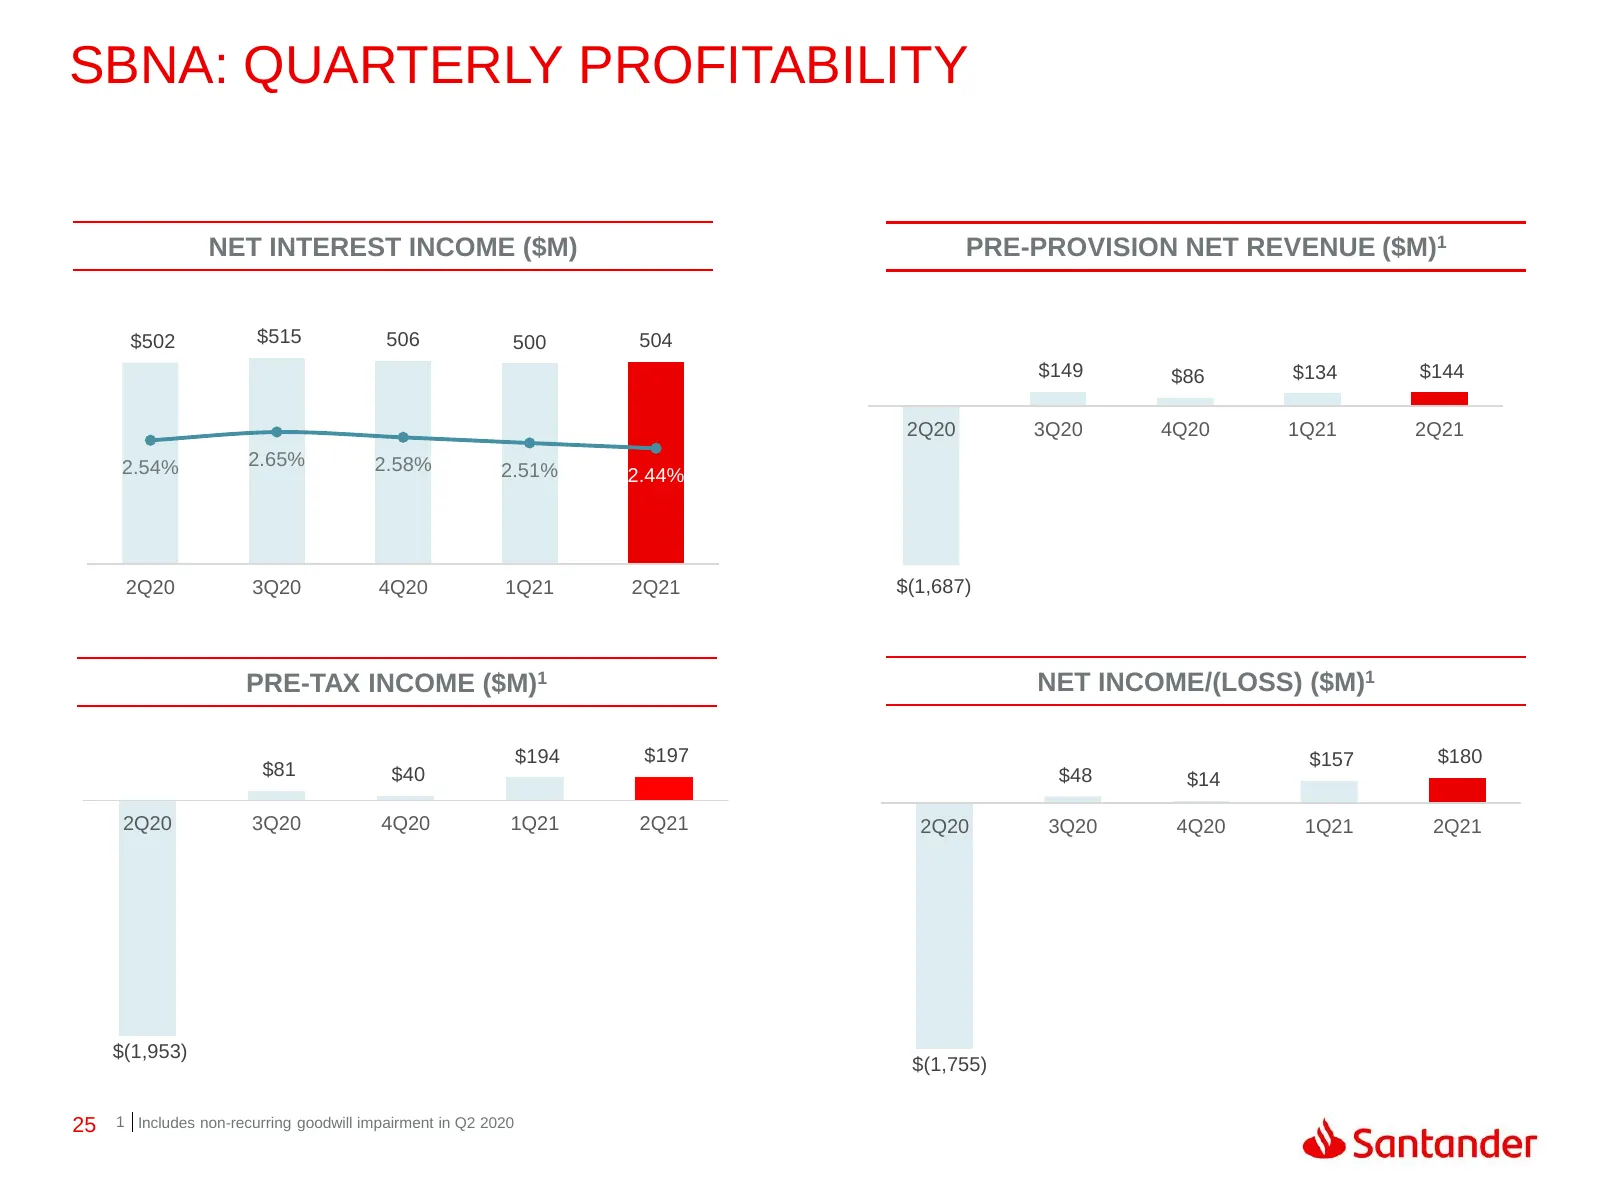
Slide 25: SBNA: Quarterly Profitability
SBNA: QUARTERLY PROFITABILITY NET INTEREST INCOME ($M) PRE-PROVISION NET REVENUE ($M)1 $600 4.00% $502 $515 506 500 504 $500 3.50% $149 $86 $134 $144 $400 3.00% $300 2.50% 2Q20 3Q20 4Q20 1Q21 2Q21 2.54% 2.65% 2.58% $200 2.51% 2.44% 2.00% $100 1.50% $- 1.00% 2Q20 3Q20 4Q20 1Q21 2Q21 $(1,687) PRE-TAX
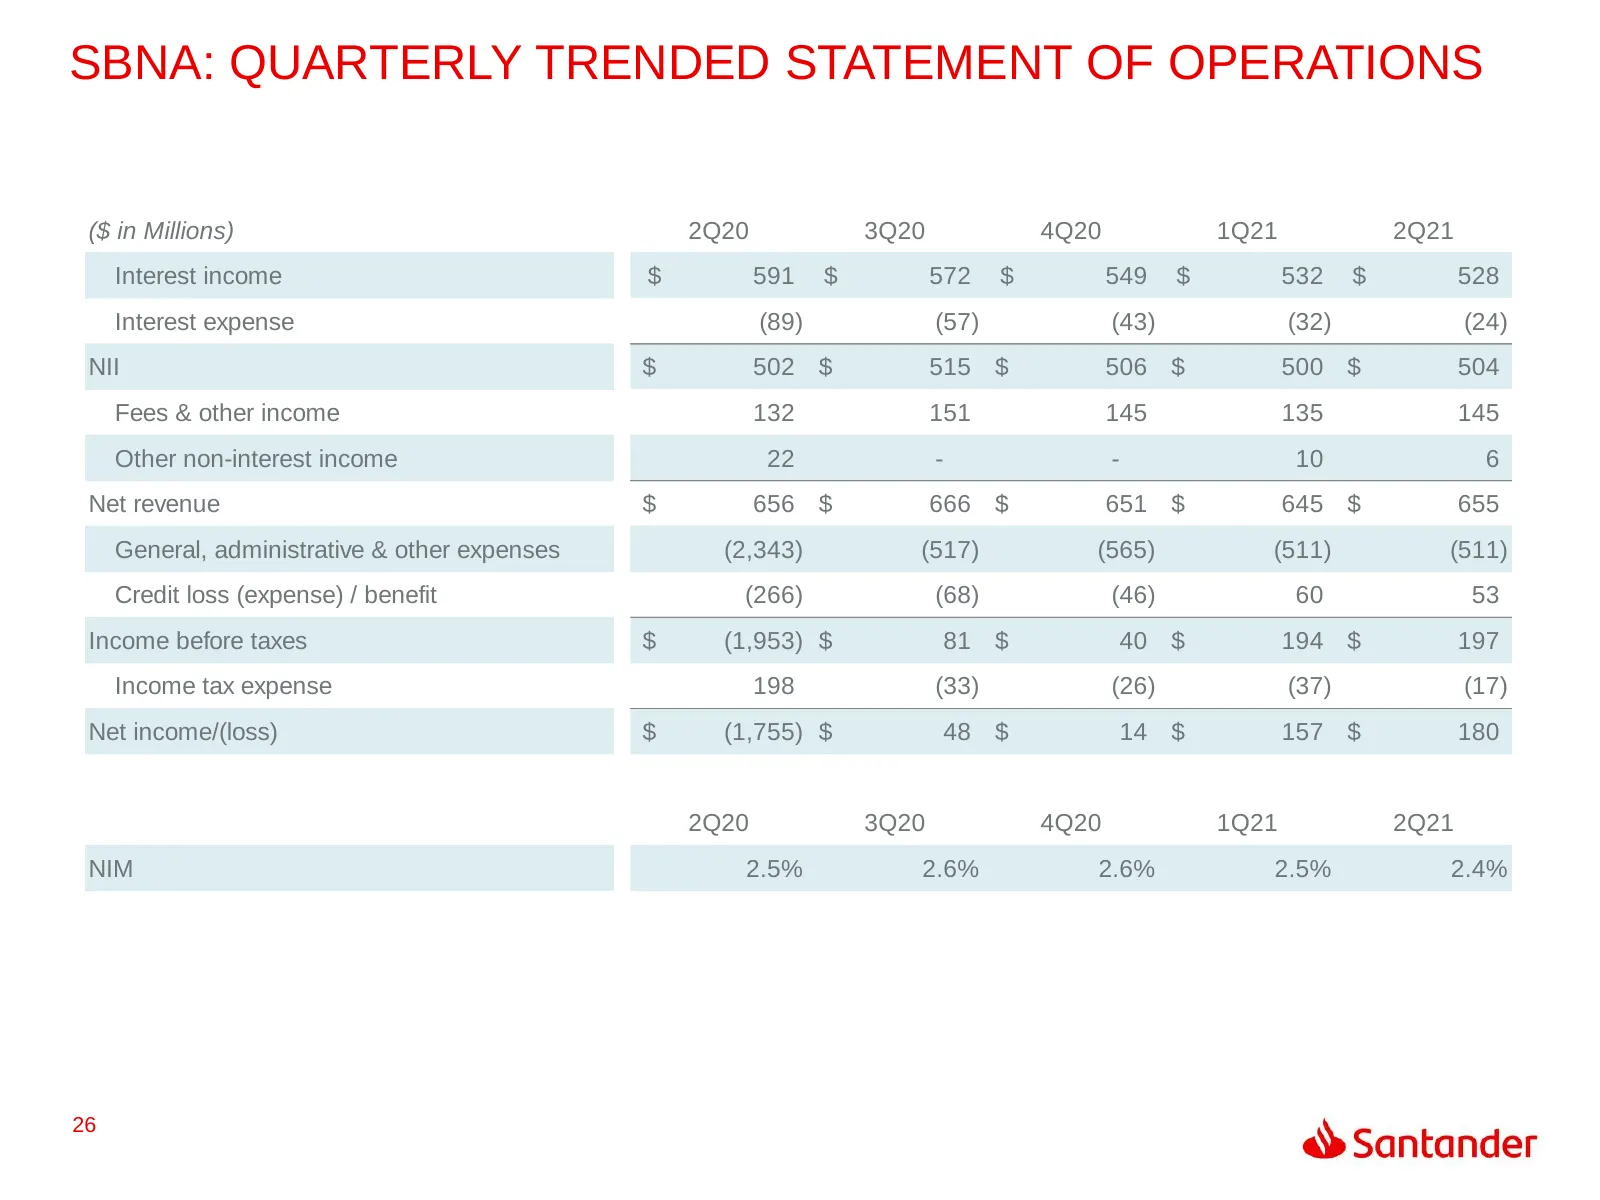
Slide 26: SBNA: Quarterly Trended Statement of Operations
SBNA: QUARTERLY TRENDED STATEMENT OF OPERATIONS ($ in Millions) 2Q20 3Q20 4Q20 1Q21 2Q21 Interest income $ 591 $ 572 $ 549 $ 532 $ 528 Interest expense (89) (57) (43) (32) (24) NII $ 502 $ 515 $ 506 $ 500 $ 504 Fees & other income 132 151 145 135 145 Other non-interest income 22 - - 10 6 Net revenue
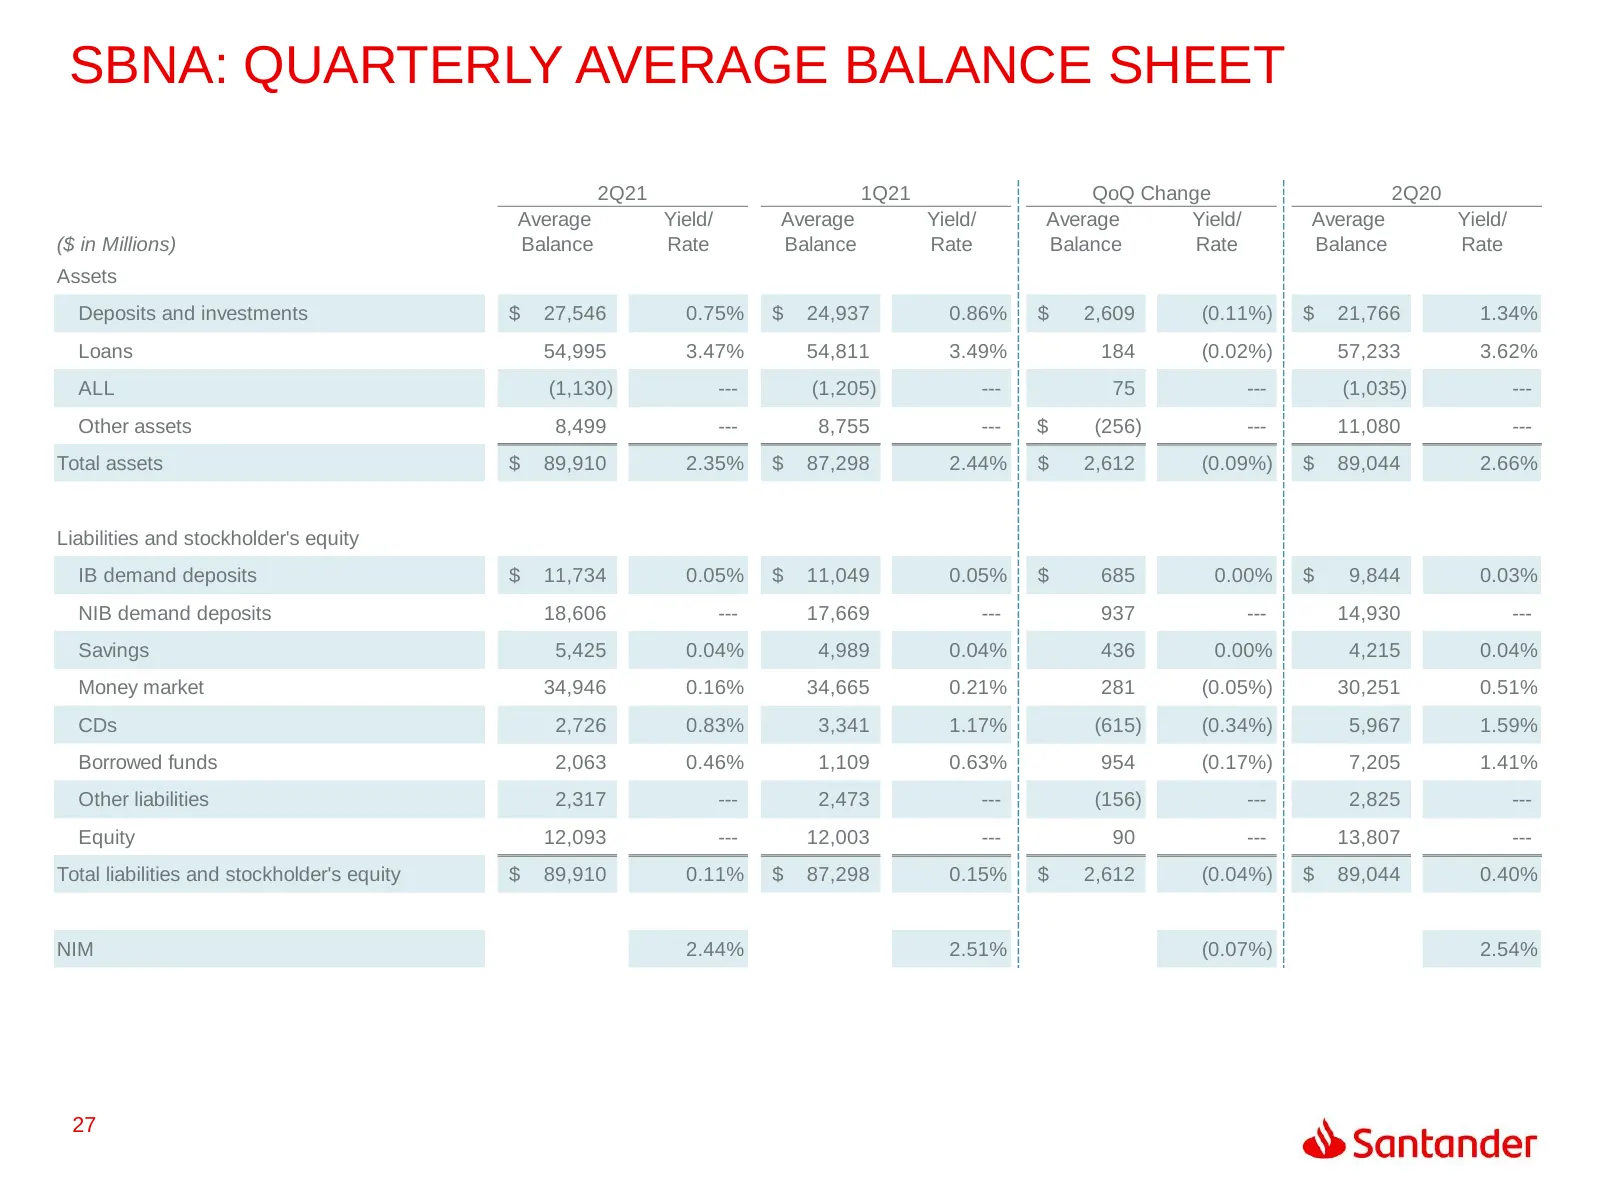
Slide 27: SBNA: Quarterly Average Balance Sheet
SBNA: QUARTERLY AVERAGE BALANCE SHEET 2Q21 1Q21 QoQ Change 2Q20 Average Yield/ Average Yield/ Average Yield/ Average Yield/ ($ in Millions) Balance Rate Balance Rate Balance Rate Balance Rate Assets Deposits and investments $ 27,546 0.75% $ 24,937 0.86% $ 2,609 (0.11%) $ 21,766 1.34% Loans 54,995 3.
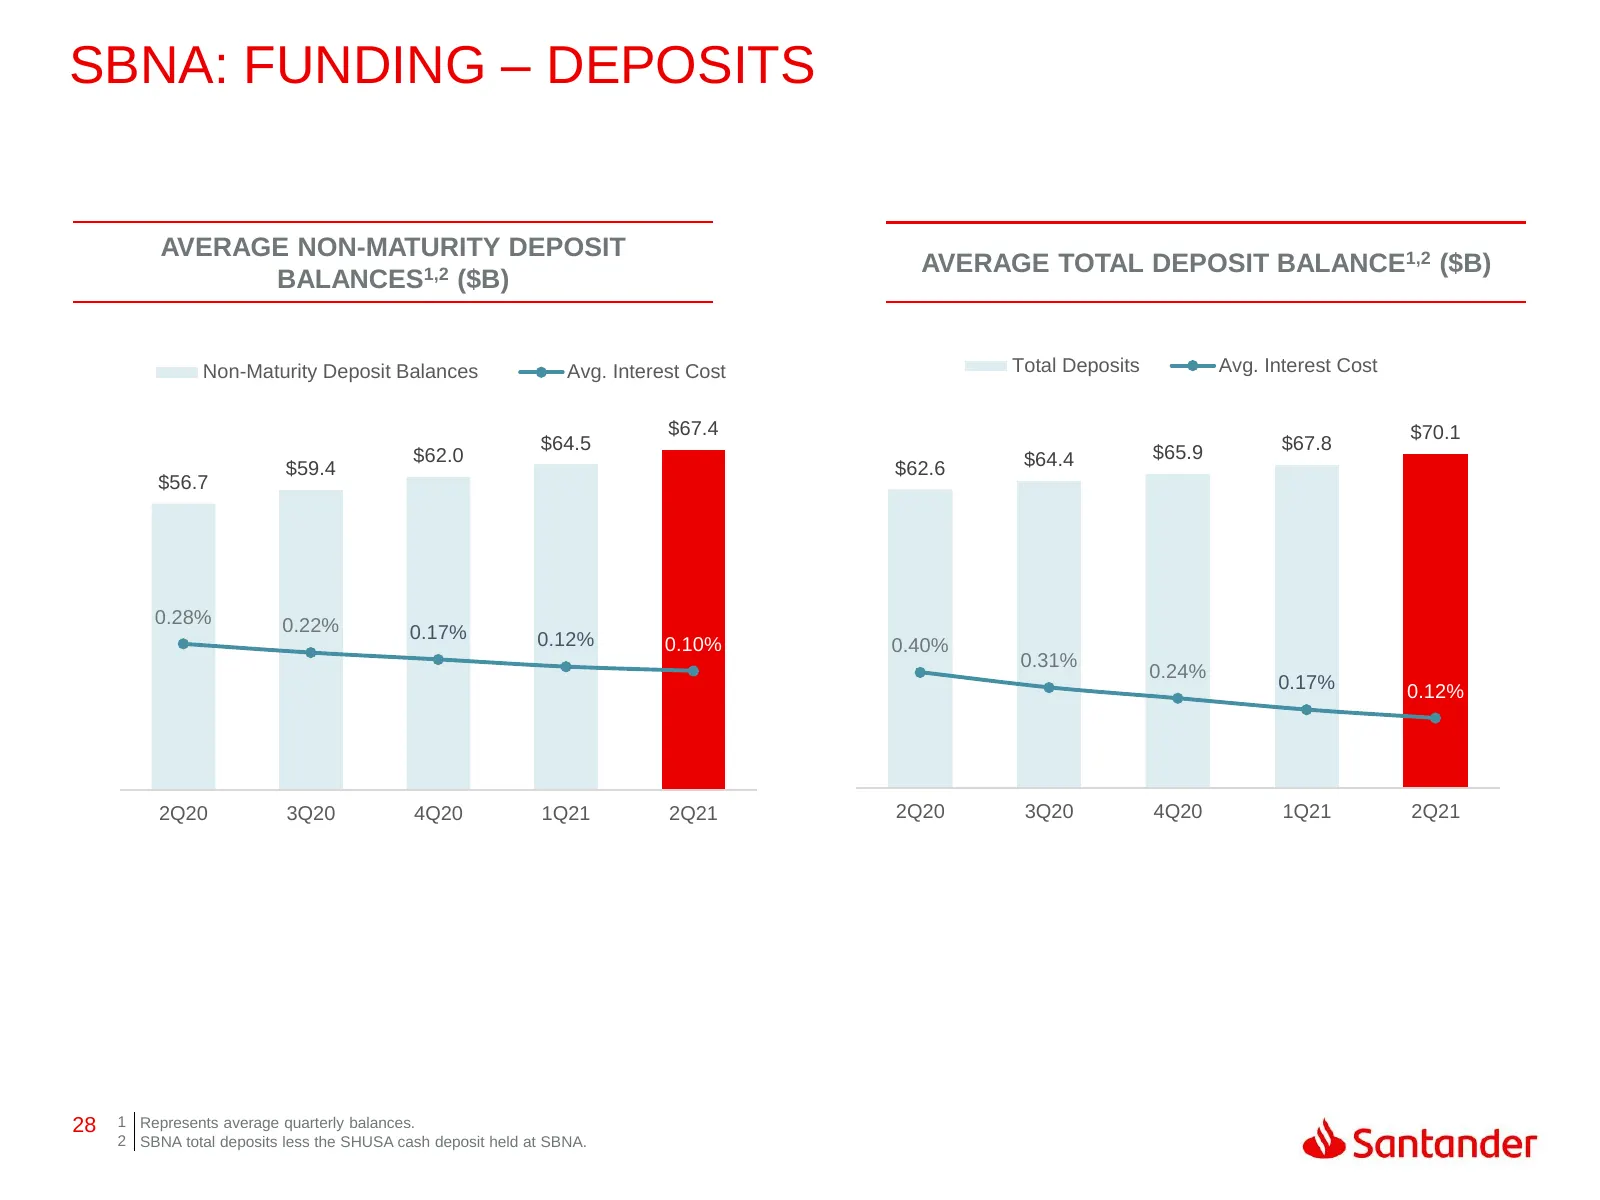
Slide 28: SBNA: Funding – Deposits
SBNA: FUNDING – DEPOSITS AVERAGE NON-MATURITY DEPOSIT AVERAGE TOTAL DEPOSIT BALANCE1,2 ($B) BALANCES1,2 ($B) Non-Maturity Deposit Balances Avg. Interest Cost Total Deposits Avg. Interest Cost 80.0 80.0 1.80% 70.0 $67.4 $70.1 $64.5 $65.9 $67.8 $62.0 70.0 $64.4 1.70% $59.4 $62.6 60.0 $56.7 1.30% 60.0
Slide 29: SBNA: Asset Quality
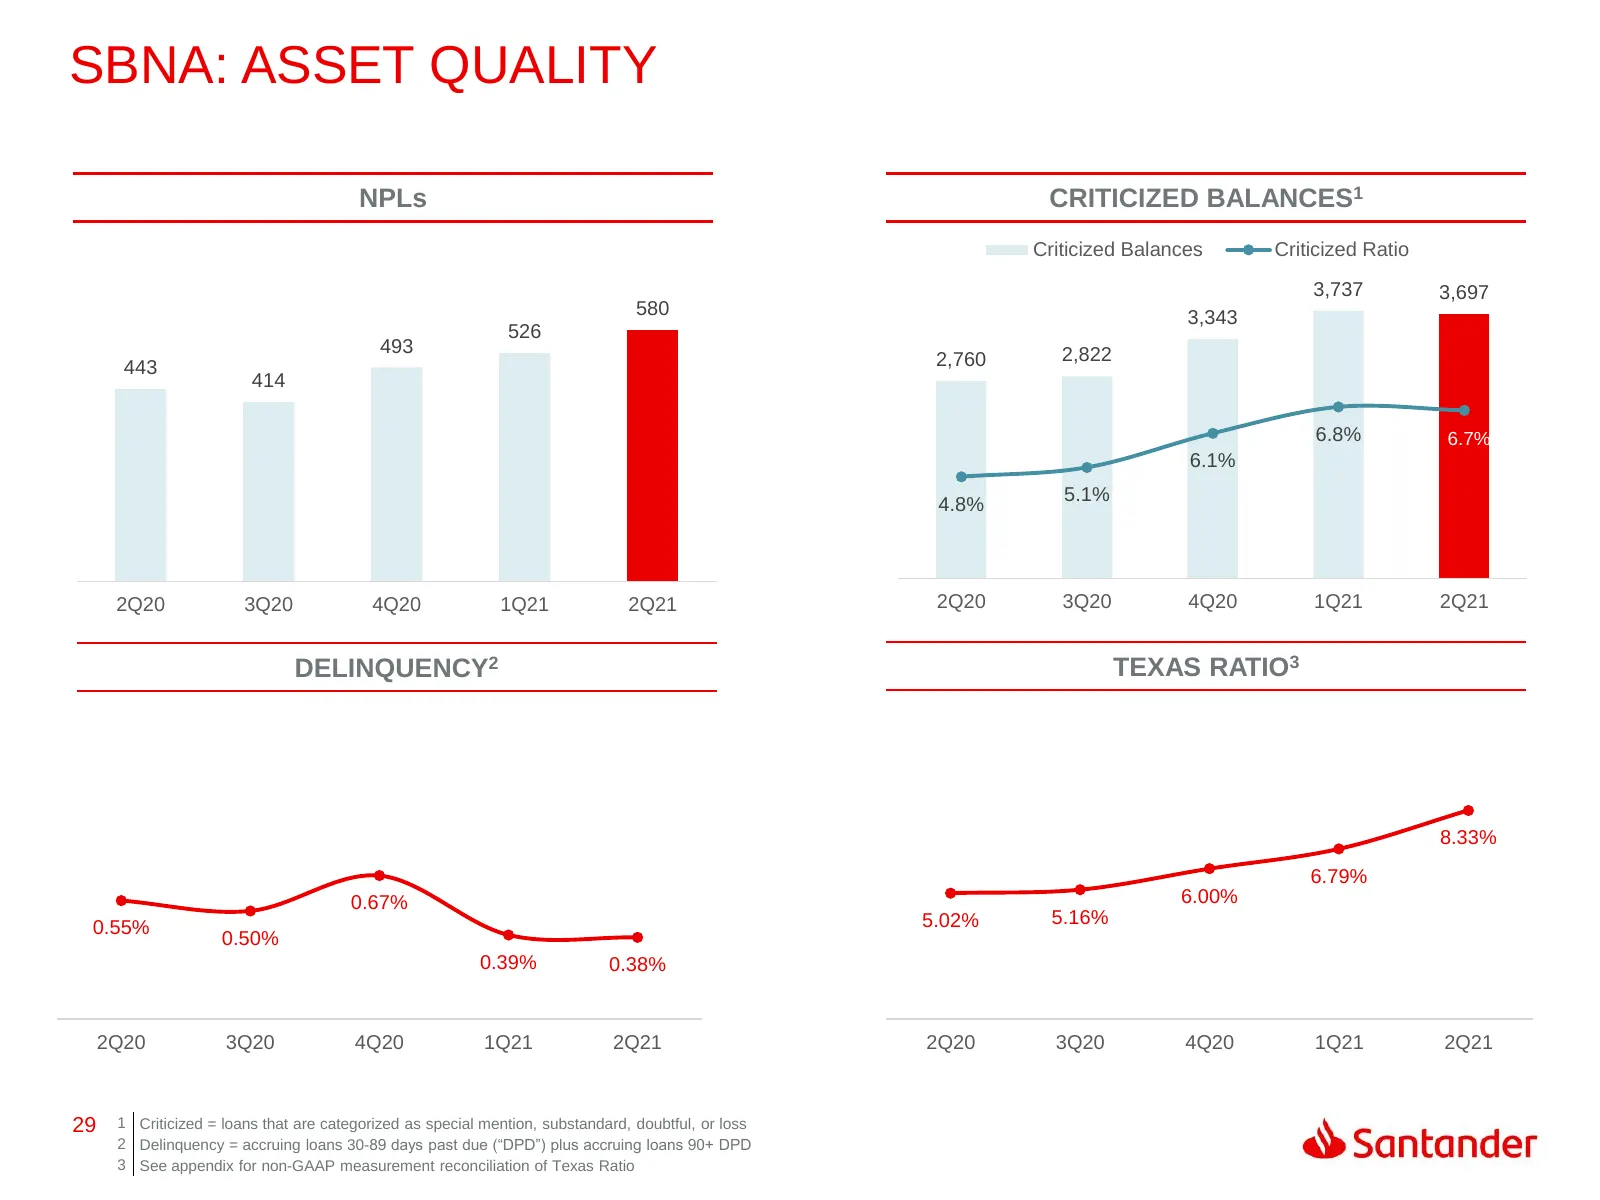
SBNA: ASSET QUALITY NPLs CRITICIZED BALANCES1 Criticized Balances Criticized Ratio 4,000 3,737 3,697 10.00% 580 3,343 526 3,500 9.00% 493 2,822 443 3,000 2,760 8.00% 414 2,500 7.00% 2,000 6.8% 6.7% 6.00% 1,500 6.1% 5.00% 1,000 4.8% 5.1% 4.00% 500 3.00% 0 2.00% 2Q20 3Q20 4Q20 1Q21 2Q21 2Q20 3Q20 4Q20
Slide 30: SBNA: Asset Quality (Continued)
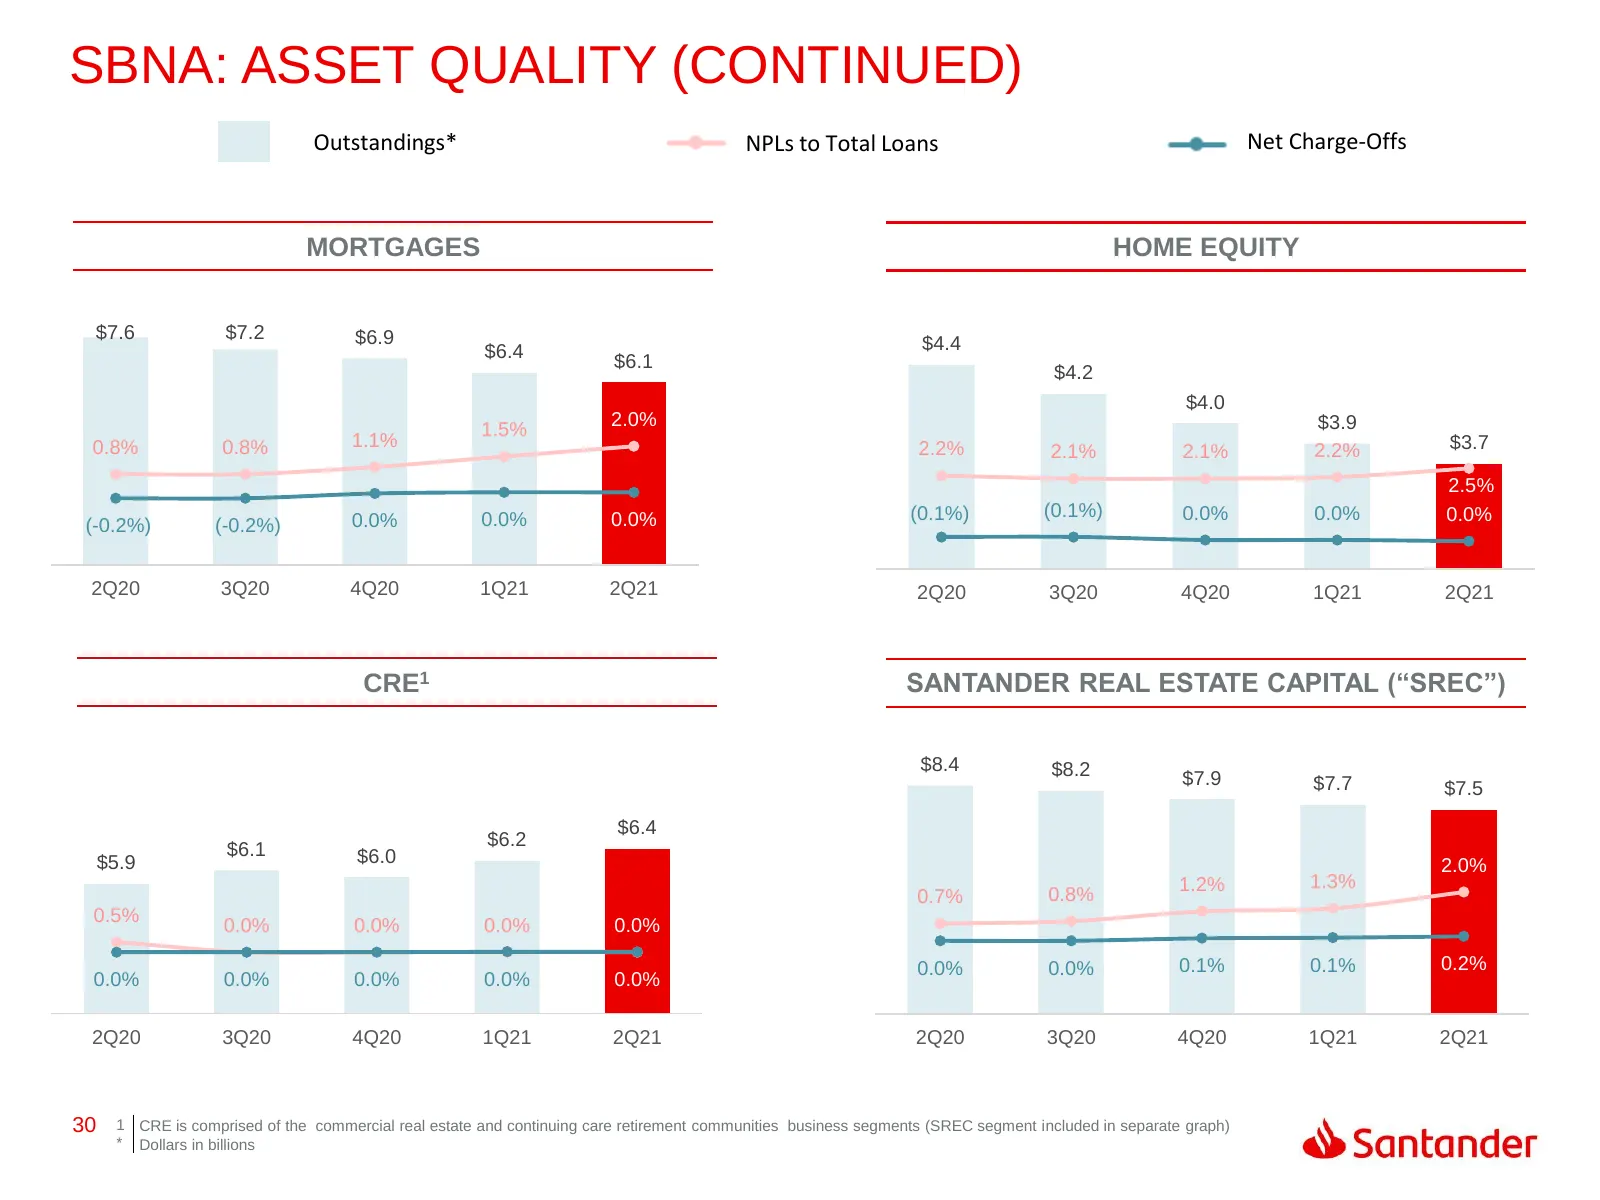
SBNA: ASSET QUALITY (CONTINUED) Outstandings* NPLs to Total Loans Net Charge-Offs MORTGAGES HOME EQUITY $8.0 7.0% $7.6 $7.2 $6.9 $4.6 7.0% $6.4 6.0% $4.4 $6.1 $7.0 $4.4 6.0% $6.0 5.0% $4.2 $4.2 5.0% $4.0 4.0% 2.0% $5.0 1.5% 3.0% $4.0 $3.9 4.0% 0.8% 0.8% 1.1% 2.2% $3.7 2.1% 2.1% 2.2% $4.0 2.0% $3.8 3
Slide 31: SBNA: Asset Quality (Continued)
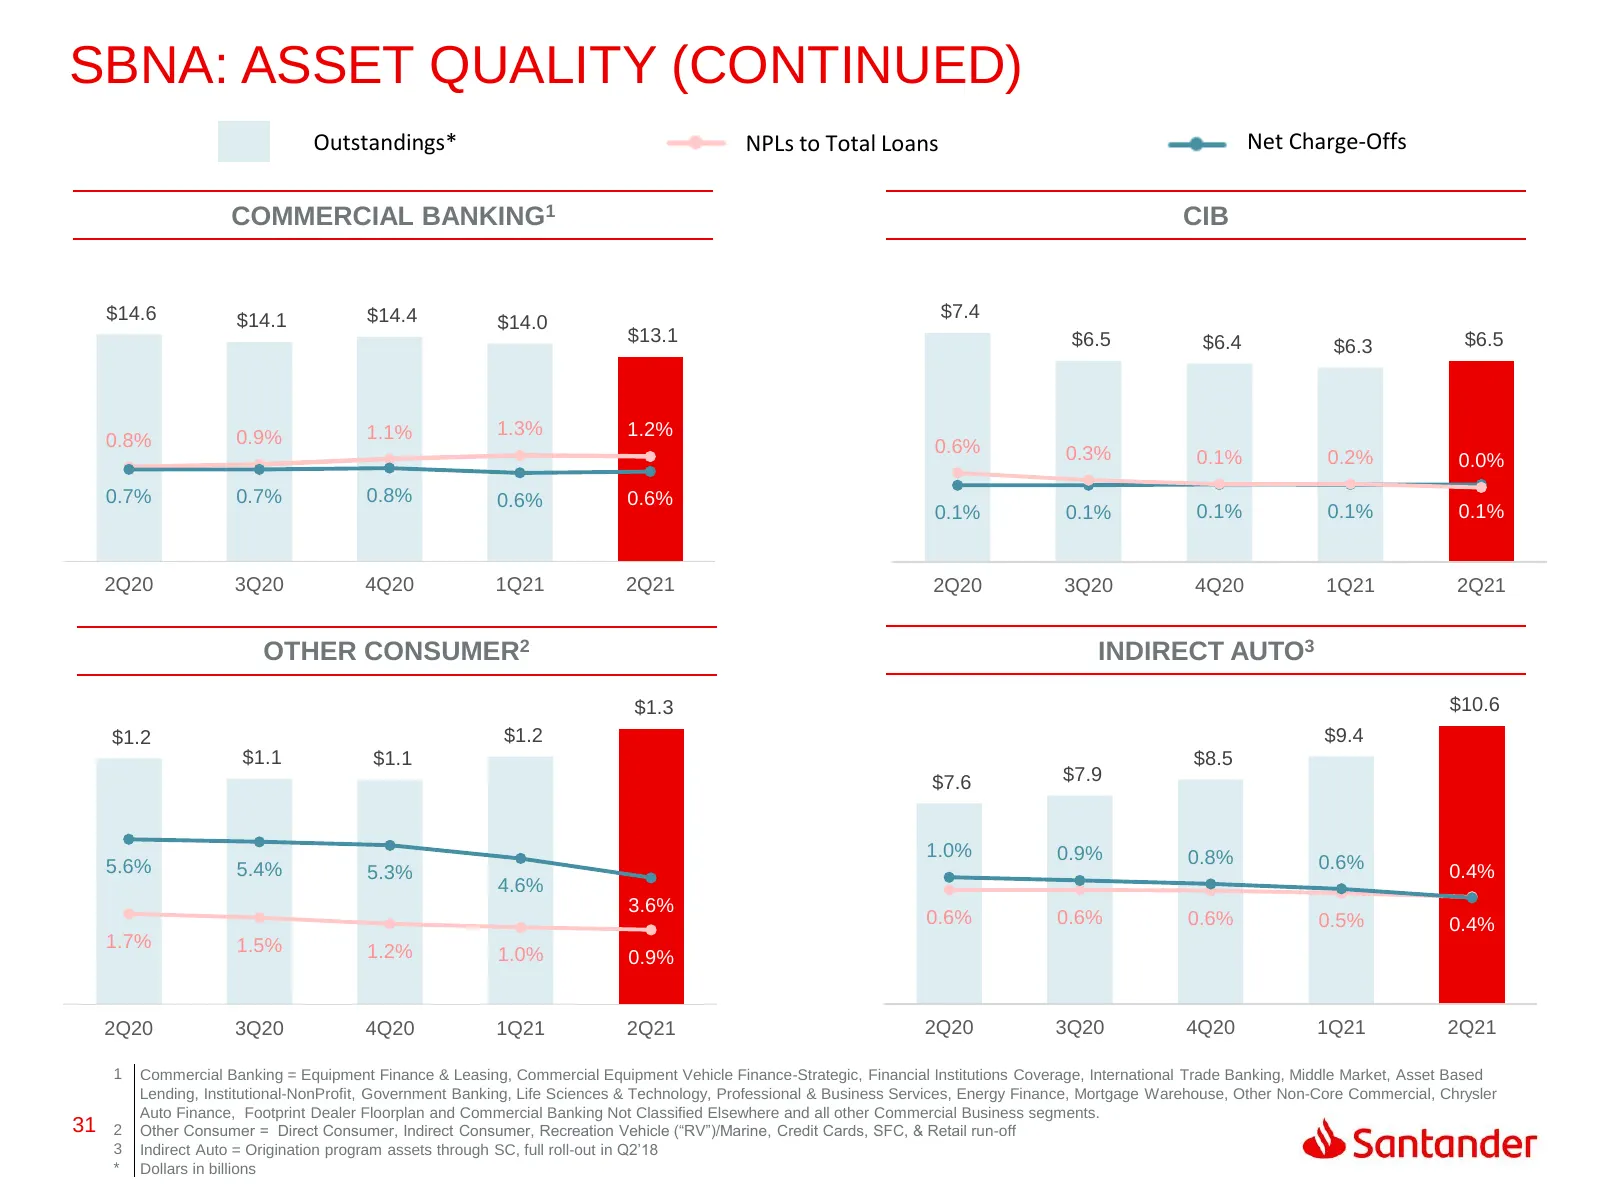
SBNA: ASSET QUALITY (CONTINUED) Outstandings* NPLs to Total Loans Net Charge-Offs COMMERCIAL BANKING1 CIB $16.0 $14.6 $14.1 $14.4 7.0% $8.0 $7.4 7.0% $14.0 $13.1 6.0% $6.5 $6.4 $6.5 6.0% $14.0 $7.0 $6.3 5.0% 5.0% $12.0 $6.0 4.0% 4.0% $10.0 $5.0 3.0% 3.0% 0.9% 1.1% 1.3% 1.2% $8.0 0.8% 2.0% $4.0 0.6%
Slide 32: SBNA: Capital Ratios
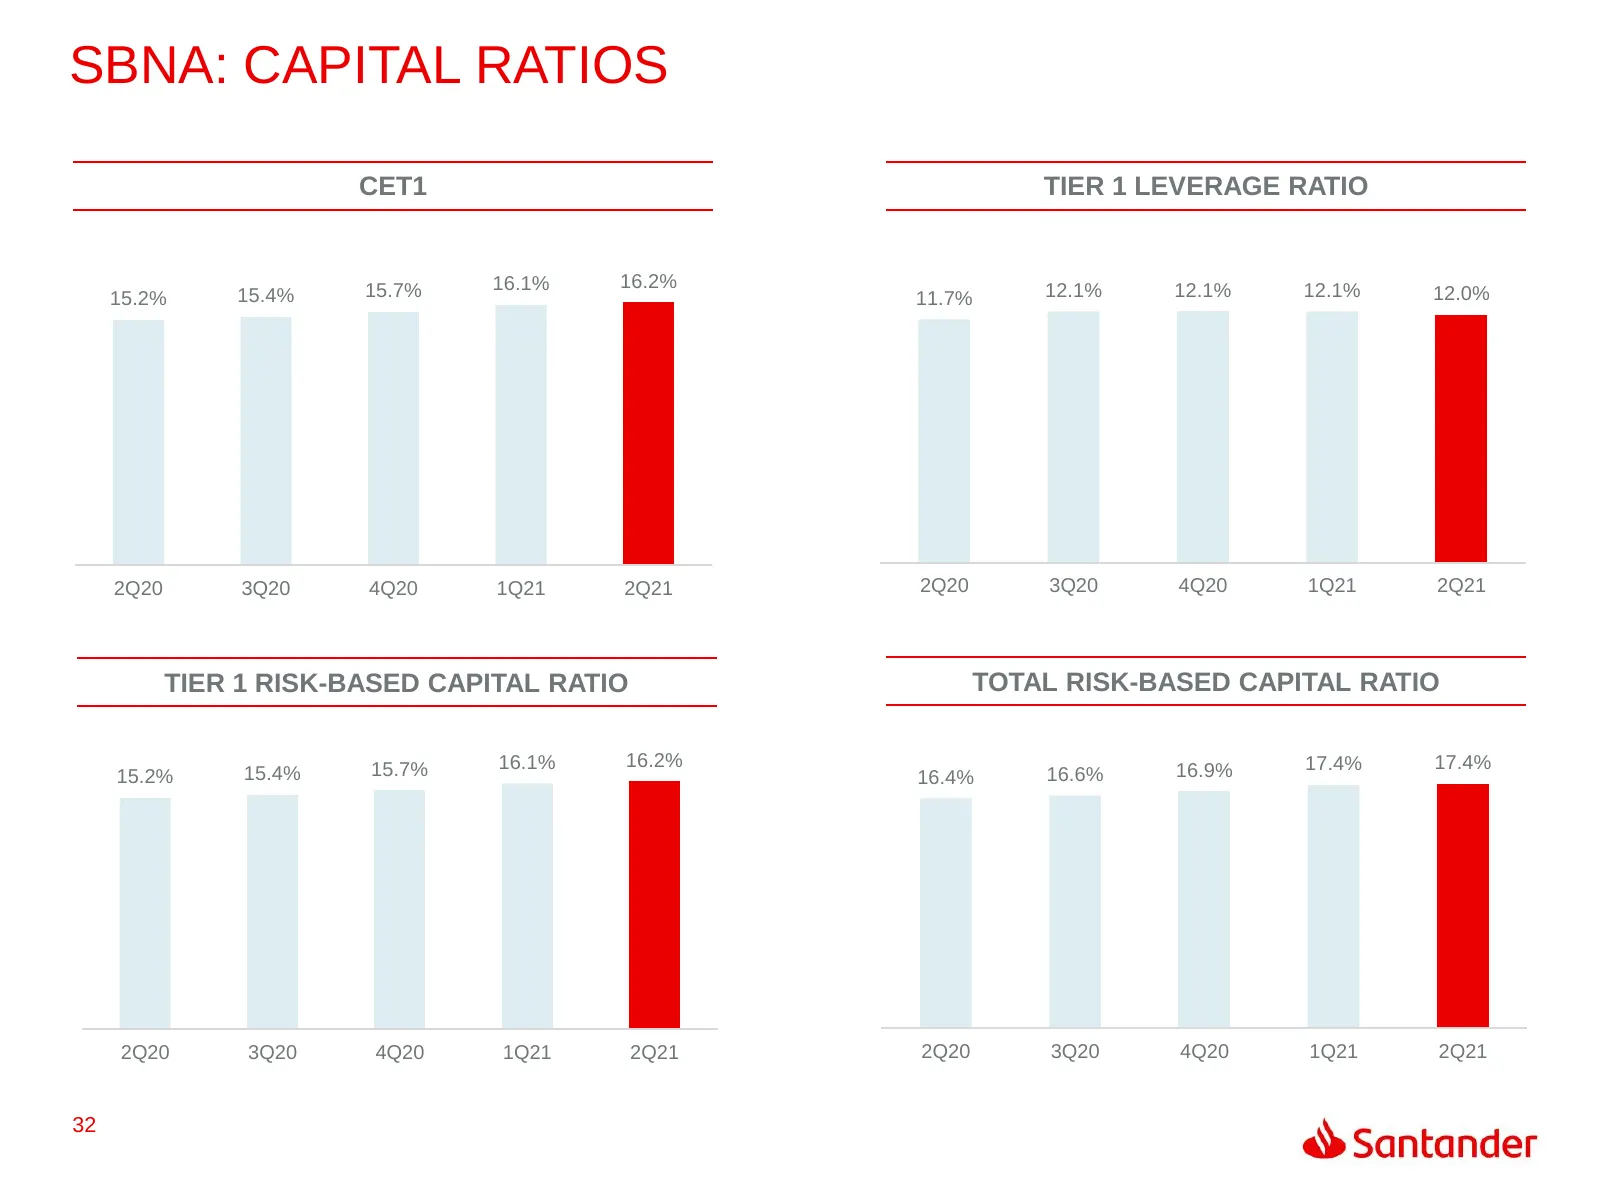
SBNA: CAPITAL RATIOS CET1 TIER 1 LEVERAGE RATIO 15.7% 16.1% 16.2% 12.1% 12.1% 12.1% 15.2% 15.4% 11.7% 12.0% 2Q20 3Q20 4Q20 1Q21 2Q21 2Q20 3Q20 4Q20 1Q21 2Q21 TIER 1 RISK-BASED CAPITAL RATIO TOTAL RISK-BASED CAPITAL RATIO 15.7% 16.1% 16.2% 16.9% 17.4% 17.4% 15.2% 15.4% 16.4% 16.6% 2Q20 3Q20 4Q20 1Q21
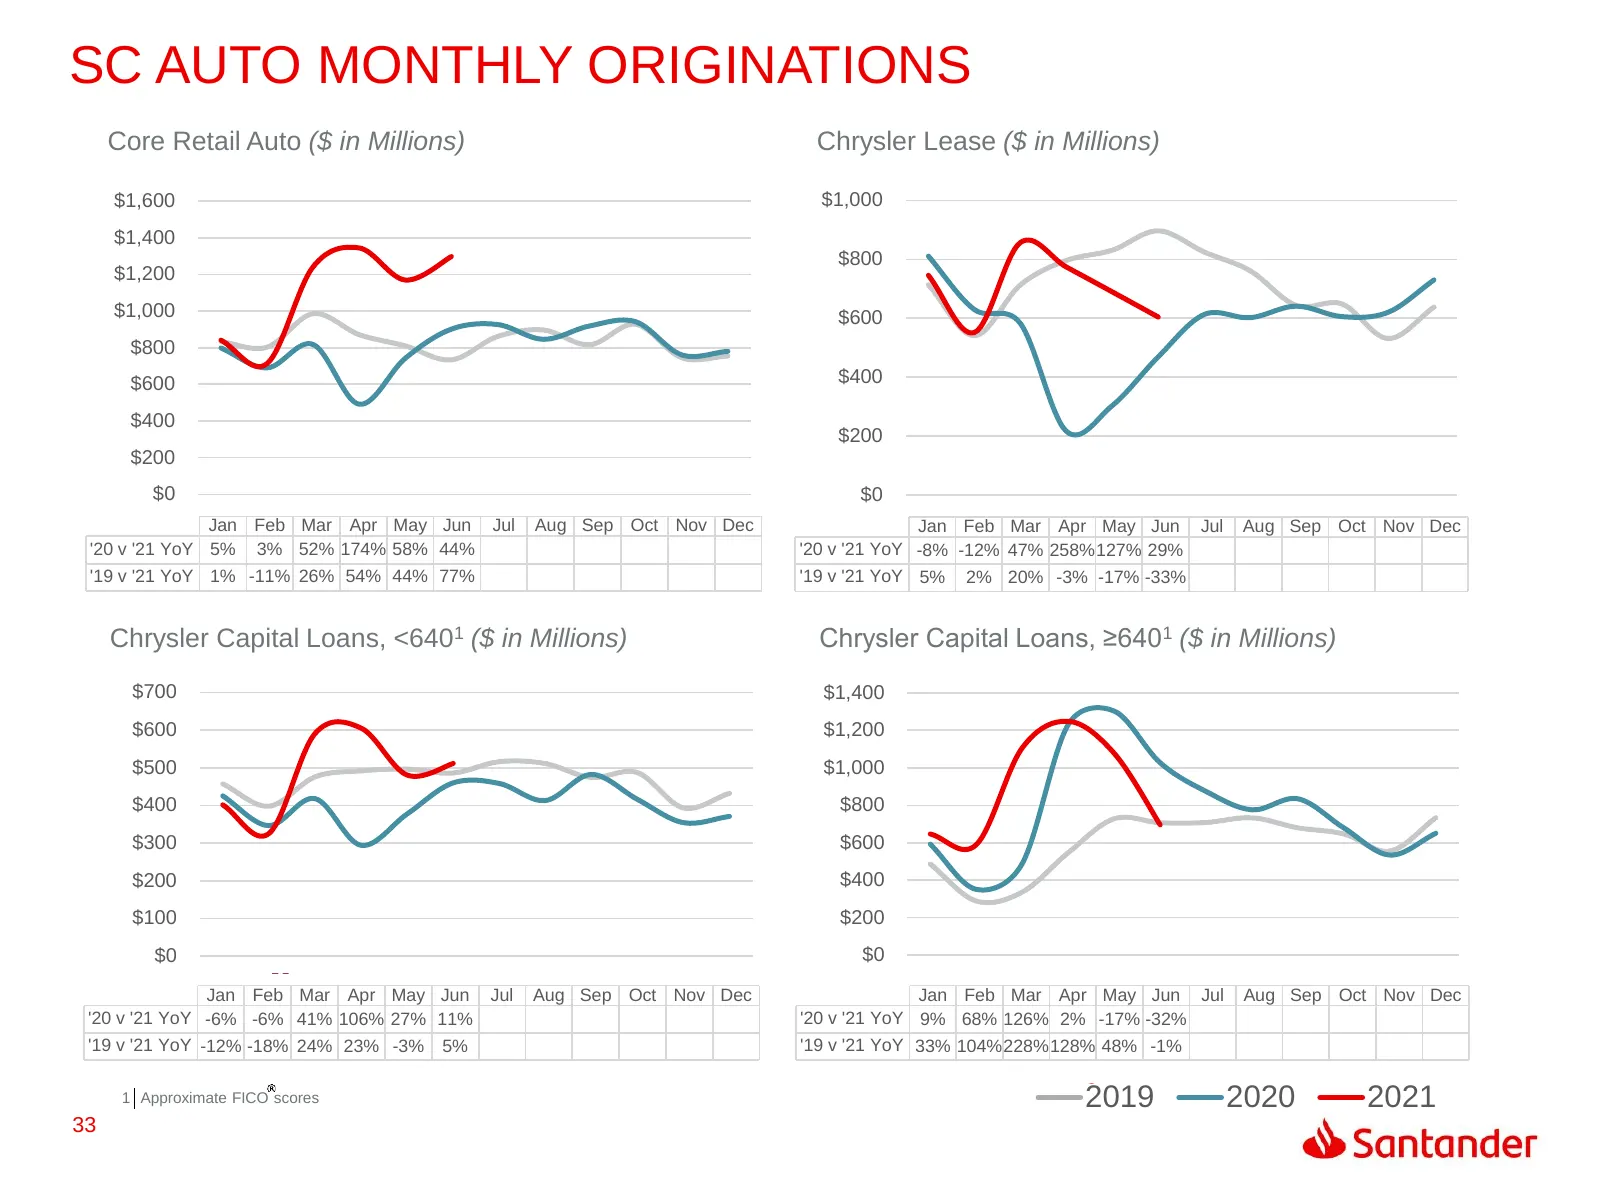
Slide 33: SC Auto Monthly Originations
SC AUTO MONTHLY ORIGINATIONS Core Retail Auto ($ in Millions) Chrysler Lease ($ in Millions) $1,600 $1,000 $1,400 $800 $1,200 $1,000 $600 $800 $600 $400 $400 $200 $200 $0 $0 Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec '20 v '21 YoY 5% 3% 52% 174% 5
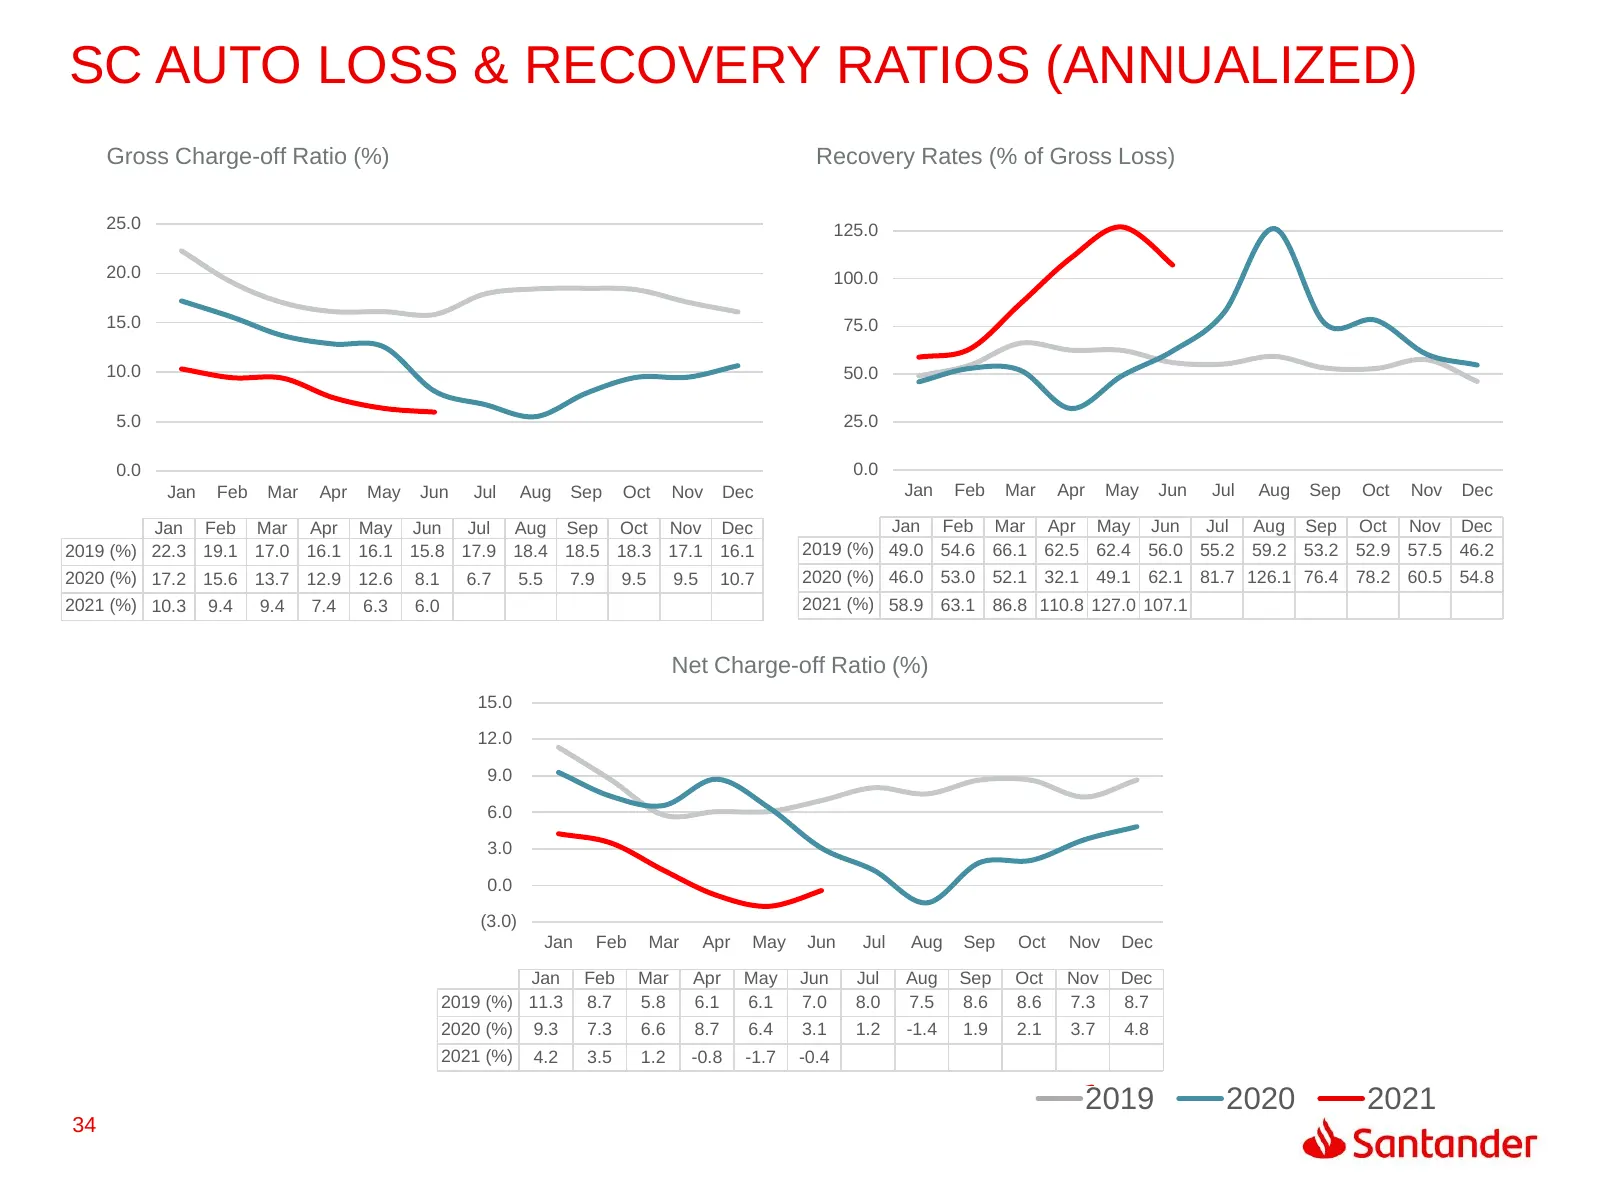
Slide 34: SC Auto Loss & Recovery Ratios (Annualized)
SC AUTO LOSS & RECOVERY RATIOS (ANNUALIZED) Gross Charge-off Ratio (%) Recovery Rates (% of Gross Loss) 25.0 125.0 20.0 100.0 15.0 75.0 10.0 50.0 5.0 25.0 0.0 0.0 Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec Jan Feb Mar Apr May Jun Jul Aug Sep Oct Nov Dec Jan Feb Mar Apr May Jun Jul Aug Sep Oct N
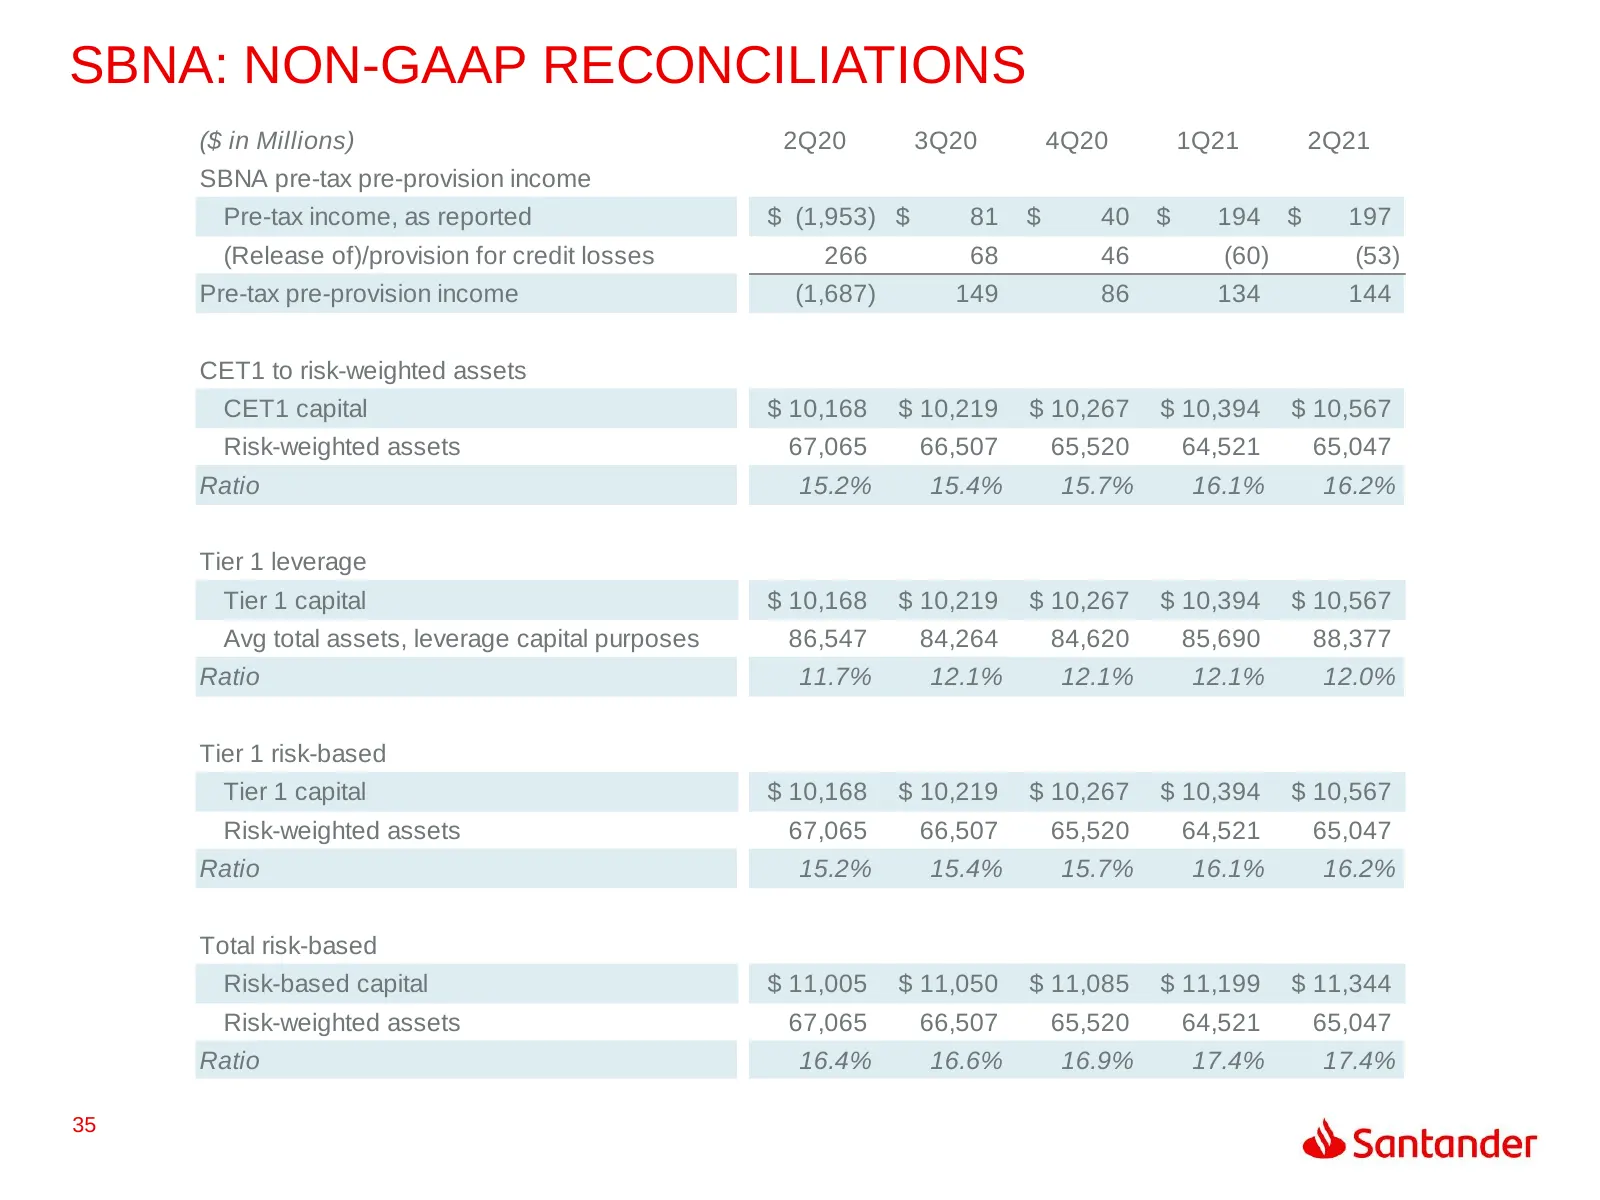
Slide 35: SBNA: Non-GAAP Reconciliations
SBNA: NON-GAAP RECONCILIATIONS ($ in Millions) 2Q20 3Q20 4Q20 1Q21 2Q21 SBNA pre-tax pre-provision income Pre-tax income, as reported $ (1,953) $ 81 $ 40 $ 194 $ 197 (Release of)/provision for credit losses 266 68 46 (60) (53) Pre-tax pre-provision income (1,687) 149 86 134 144 CET1 to risk-weighted
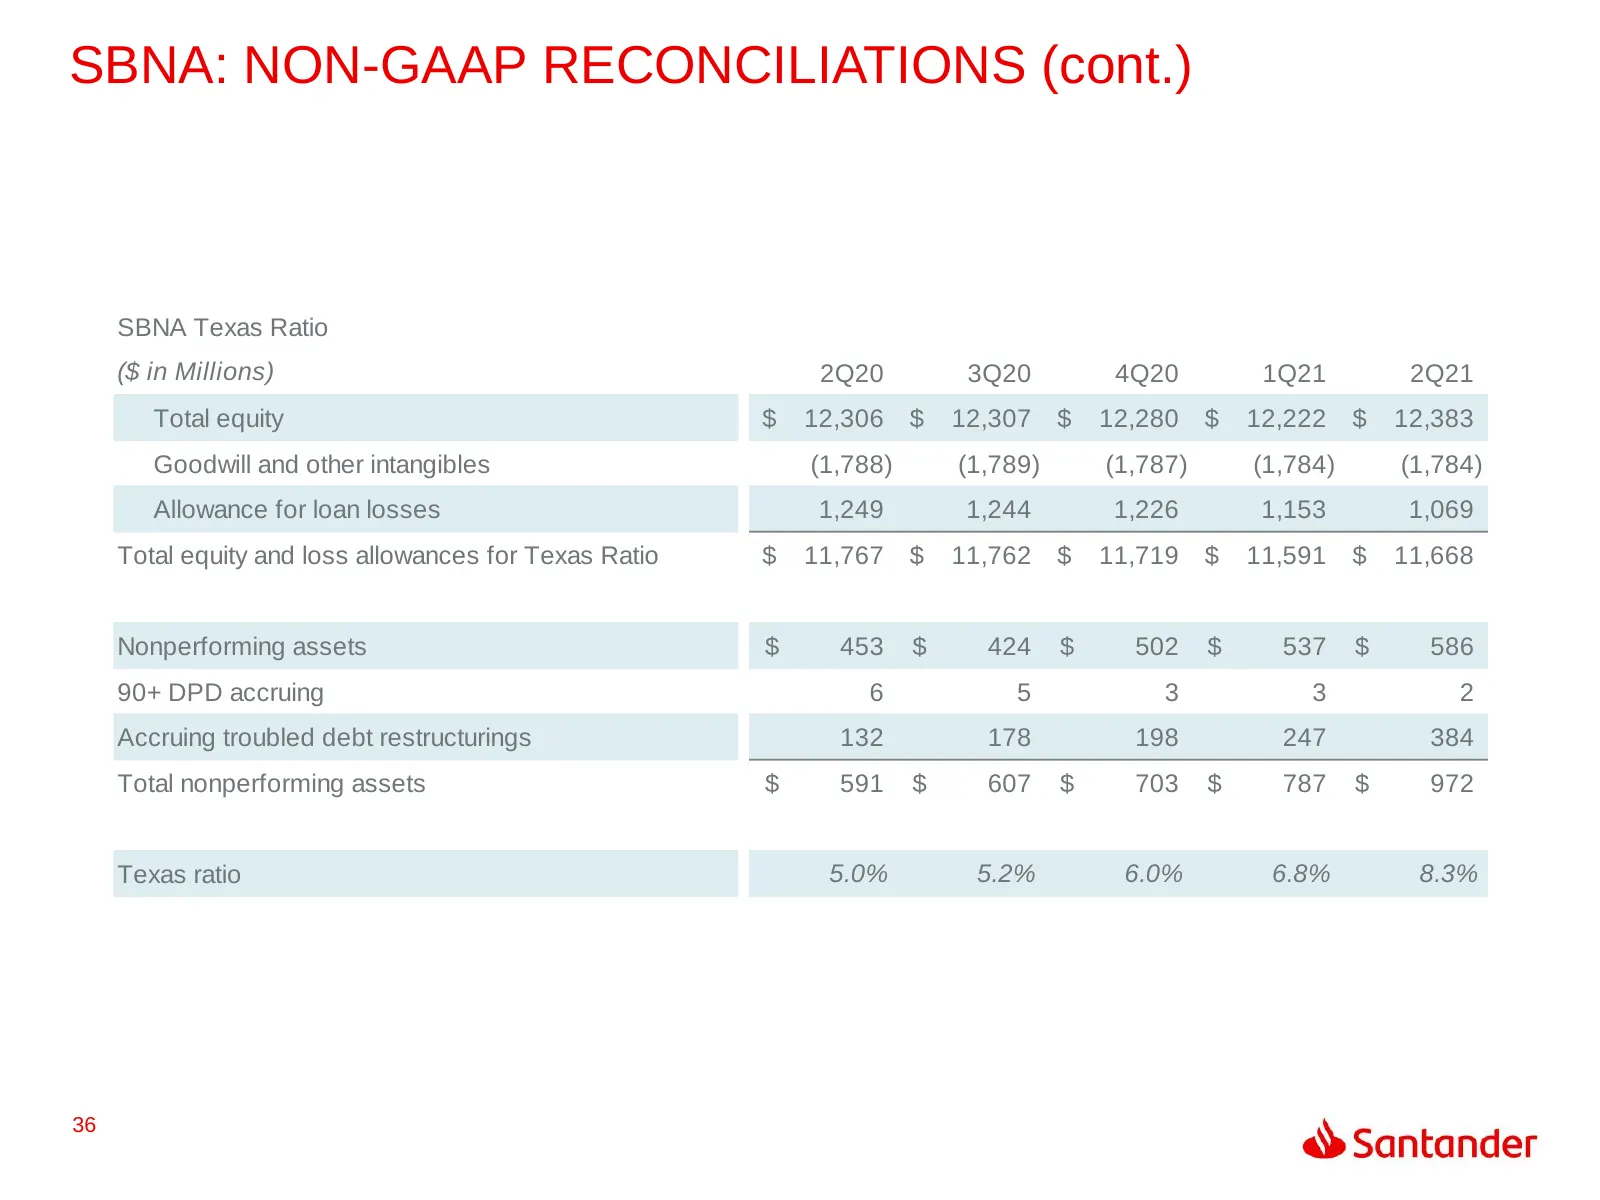
Slide 36: SBNA: Non-GAAP Reconciliations (cont.)
SBNA: NON-GAAP RECONCILIATIONS (cont.) SBNA Texas Ratio ($ in Millions) 2Q20 3Q20 4Q20 1Q21 2Q21 Total equity $ 12,306 $ 12,307 $ 12,280 $ 12,222 $ 12,383 Goodwill and other intangibles (1,788) (1,789) (1,787) (1,784) (1,784) Allowance for loan losses 1,249 1,244 1,226 1,153 1,069 Total equity and l
Slide 37: Thank You
THANK YOU Our purpose is to help people and businesses prosper. Our culture is based on believing that everything we do should be:
Source: company website
More decks from Santander Holdings USA Inc
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (August 2026)30 slides · Aug 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (June 2026)29 slides · Jun 12, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026
 Debt Investor Presentation (March 2026)36 slides · Mar 6, 2026