Metaldyne Performance Group Inc
Metaldyne Performance — Merger or Acquisition (January 2017)
37 slides from Metaldyne Performance's merger presentation, Jan 11, 2017
Slide 1: Forward Looking Statements
Forward Looking Statements Some of the information presented in this document and discussions that follow, including, without limitation, statements with respect to the proposed acquisition of Metaldyne Performance Group, Inc ("MPG") and the anticipated consequences and benefits of the acquisition,
Slide 2: Other Information
Other Information Important Information for Stockholders and Investors This presentation is provided for informational purposes only and is neither an offer to purchase nor a solicitation of an offer to sell shares of AAM or MPG. In connection with the proposed acquisition of MPG, AAM has filed with
Slide 3: Agenda
Agenda 2016 AAM Highlights 2017 AAM Targets AAM's 2017 - 2019 New Business Backlog Technology Leadership Acquisition of MPG Agenda 4
Slide 4: 2016 AAM Highlights
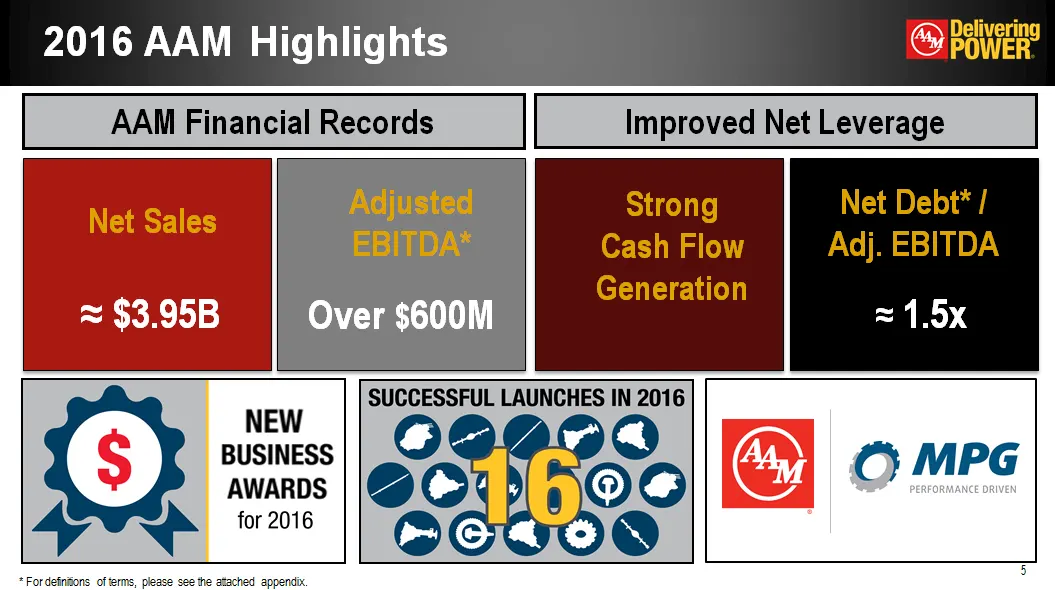
2016 AAM Highlights AAM Financial Records Improved Net Leverage Net Sales = $3.95B Adjusted EBITDA* Over $600M Strong Cash Flow Generation Net Debt* /Adj. EBITDA = 1.5x EW BUSINESS AWARDS for 2016 SUCCESSFUL LAUNCHES IN 2016 * For definitions of terms, please see the attached appendix. 5
Slide 5: 2016 AAM Financial Estimates
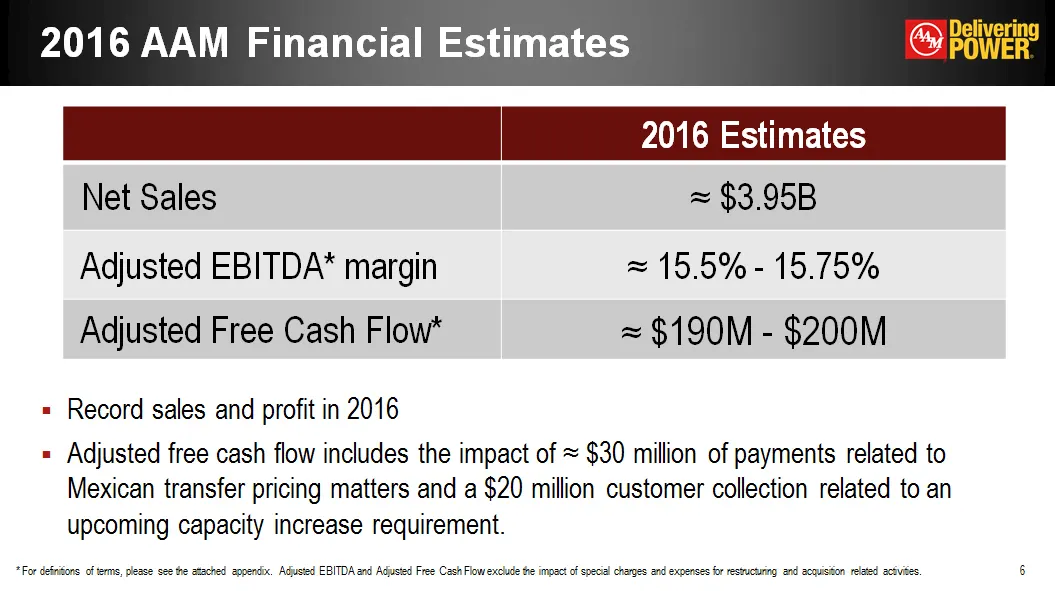
2016 AAM Financial Estimates 2016 Estimates Net Sales = $3.95B Adjusted EBITDA* margin = 15.5% - 15.75% Adjusted Free Cash Flow* = $190M - $200M Record sales and profit in 2016 Adjusted free cash flow includes the impact of = $30 million of payments related to Mexican transfer pricing matters and a
Slide 6: 2017 AAM Financial Targets
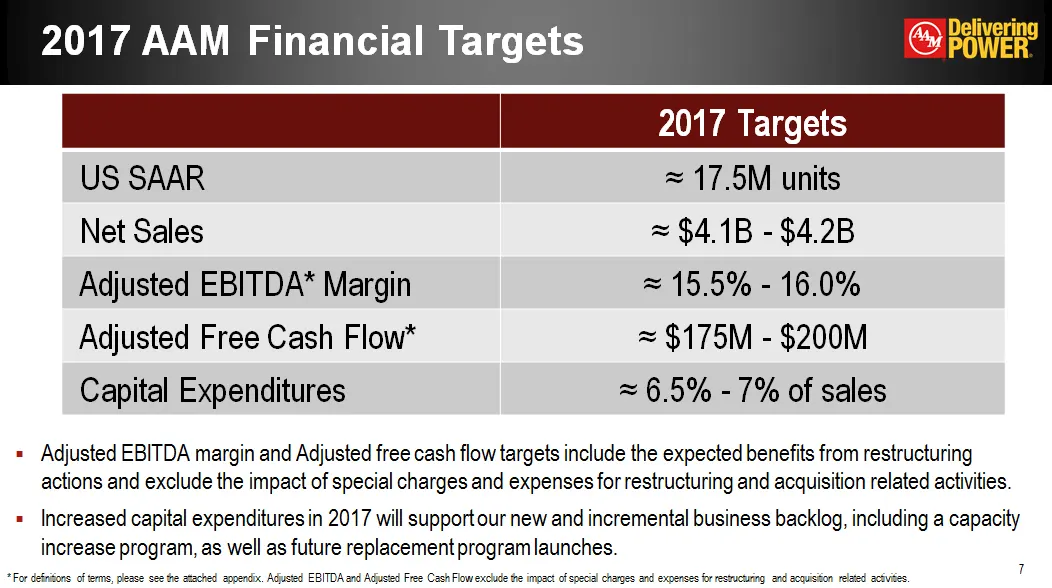
2017 AAM Financial Targets 2017 Targets US SAAR = 17.5M units Net Sales = $4.1B - $4.2B Adjusted EBITDA* Margin = 15.5% - 16.0% Adjusted Free Cash Flow* = $175M - $200M Capital Expenditures = 6.5% - 7% of sales Adjusted EBITDA margin and Adjusted free cash flow targets include the expected benefits
Slide 7: AAM's New and Incremental Business Backlog
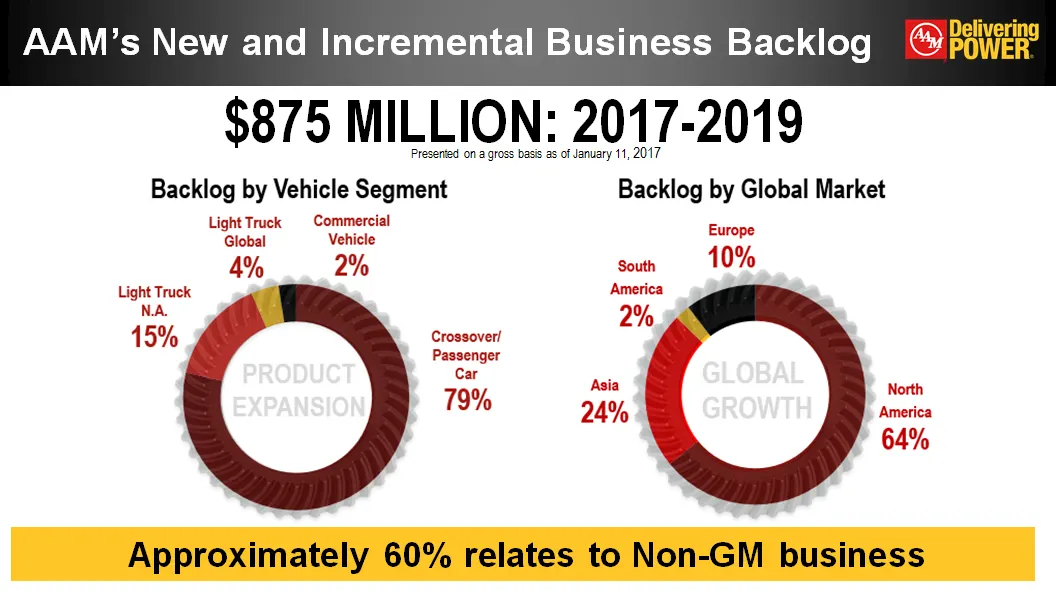
AAM's New and Incremental Business Backlog $875 MILLION: 2017-2019 Presented on a gross basis as of January 11, 2017 Backlog by Vehicle Segment [CATEGORY NAME] [VALUE] [CATEGORY NAME] [VALUE] [CATEGORY NAME] [VALUE] [CATEGORY NAME] [VALUE] Backlog by Global Market [CATEGORY NAME] 24% [CATEGORY NAME]
Slide 8: Backlog and Impact of GM's Sourcing Decision
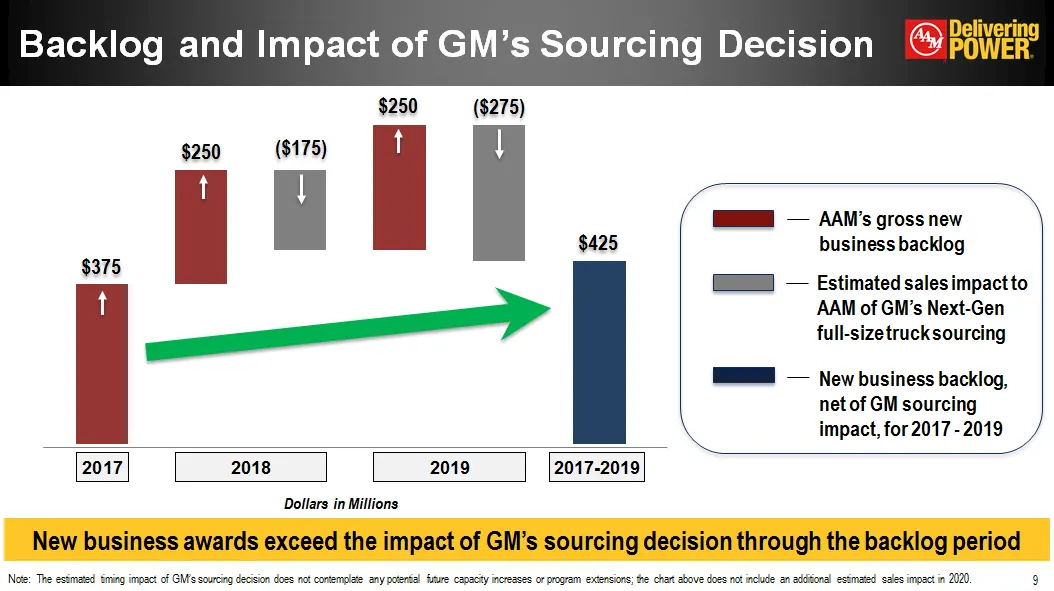
Backlog and Impact of GM's Sourcing Decision $375 $250 ($175) $250 ($275) $425 2017 2018 2019 2017-2019 Dollars in Millions AAM's gross new business backlog Estimated sales impact to AAM of GM's Next-Gen full-size truck sourcing New business backlog, net of GM sourcing impact, for 2017 - 2019 New bu
Slide 9: US SAAR and NA Production Assumptions
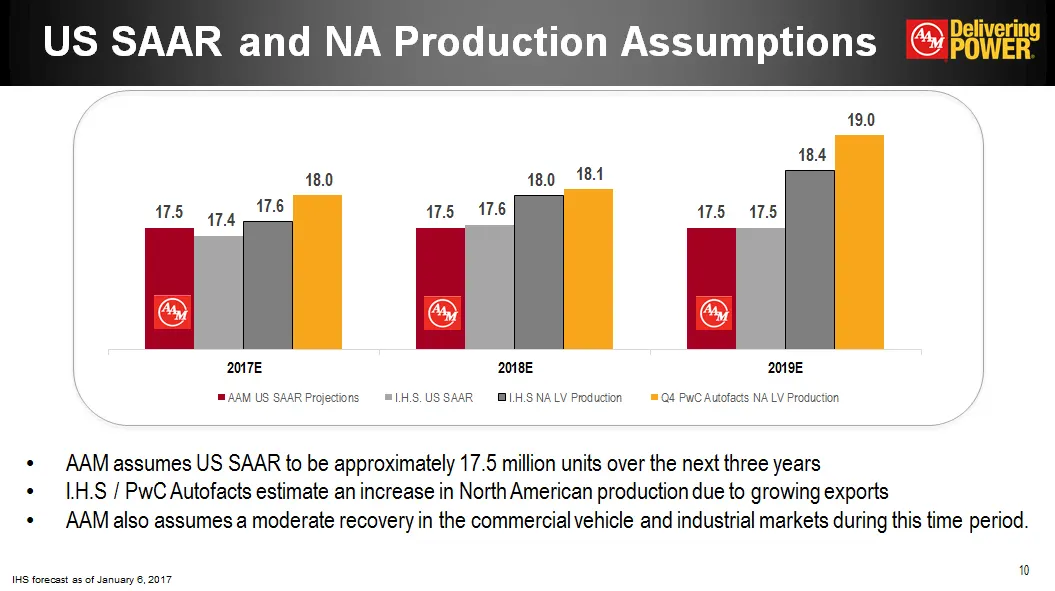
US SAAR and NA Production Assumptions 17.5 17.4 17.6 18.0 2017E 17.5 17.6 18.0 18.1 2018E 17.5 17.5 18.4 19.0 2019E AAM US SAAR Projections I.H.S. US SAAR I.H.S NA LV Productions Q4 PwC Autofacts NA LV Production AAM assumes US SAAR to be approximately 17.5 million units over the next three years I.
Slide 10: North America Light Vehicle Production Mix
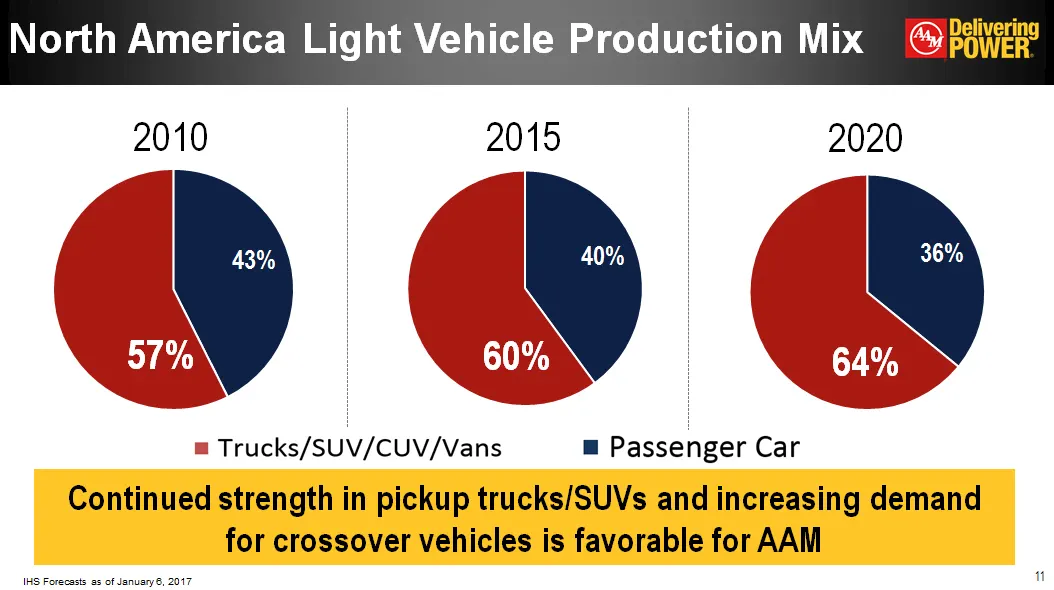
North America Light Vehicle Production Mix 2010 57% 43% 2015 60% 40% 2020 64% 36% Trucks/SUV/CUV/Vans Passenger Car Continued strength in pickup trucks/SUVs and increasing demand for crossover vehicles is favorable for AAM IHS Forecasts as of January 6, 2017 11
Slide 11: North America Light Vehicle Production Mix
North America Light Vehicle Production Mix @ aii? 2010 2015 2020 Trucks/SUV/CUV/Vans m Passenger Car Continued strength in pickup trucks/SUVs and increasing demand for crossover vehicles is favorable for AAM 1
Slide 12: Technology Leadership
Technology Leadership GREEN and EFFICIENT LIGHTWEIGHT AND EFFICIENT QUANTUM(TM) lightweight axles and drive units New component manufacturing processes Advanced materials Lube flow improvements Power density SAFETY and PERFORMANCE AWD TECHNOLOGIES EcoTrac(R) disconnecting AWD system e-AAMTM electric
Slide 13: Powertrain Projections
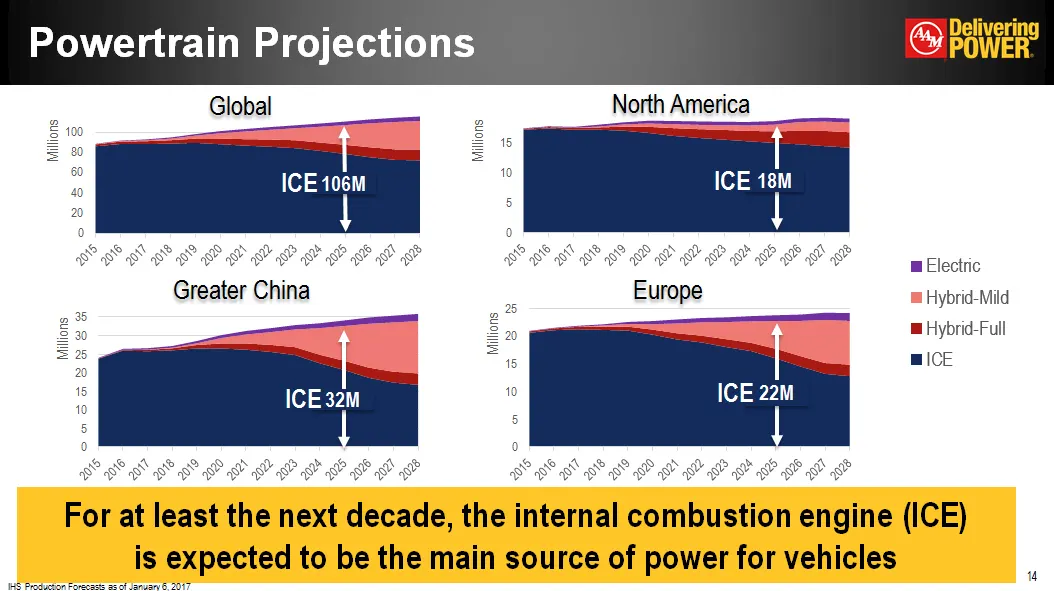
Powertrain Projections Millions Global 100 80 60 40 20 0 ICE 106M 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 Millions North America 15 10 5 0 ICE 18M 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 Millions Greater China 35 30 25 20 15 10 5 0 ICE 32M
Slide 14: EcoTrac Disconnecting AWD Systems
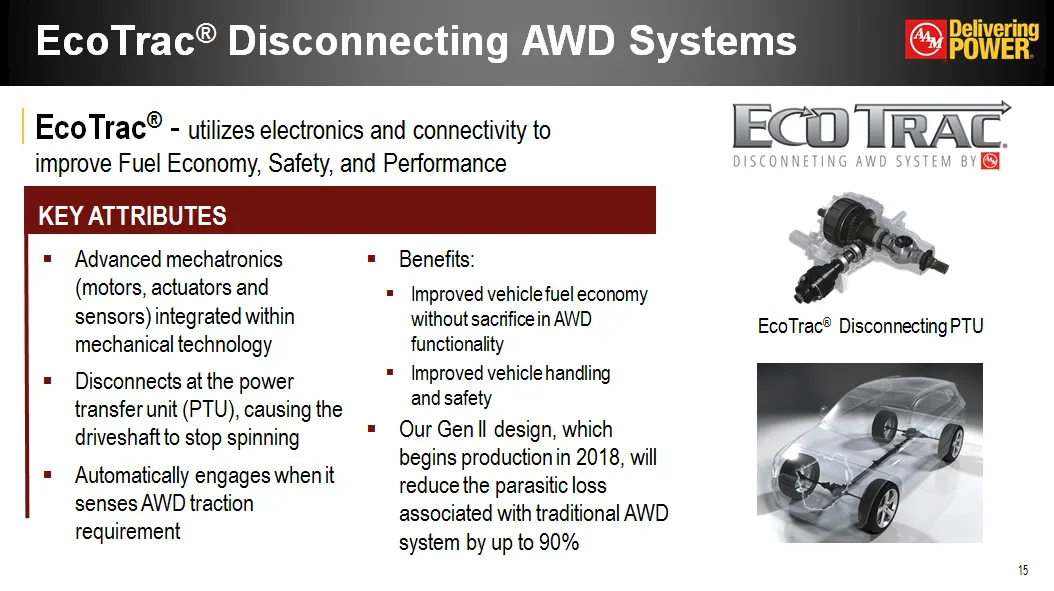
EcoTrac(R) Disconnecting AWD Systems EcoTrac(R) - utilizes electronics and connectivity to improve Fuel Economy, Safety, and Performance KEY ATTRIBUTES Advanced mechatronics (motors, actuators and sensors) integrated within mechanical technology Disconnects at the power transfer unit (PTU), causing
Slide 15: EcoTrac Sales Growth
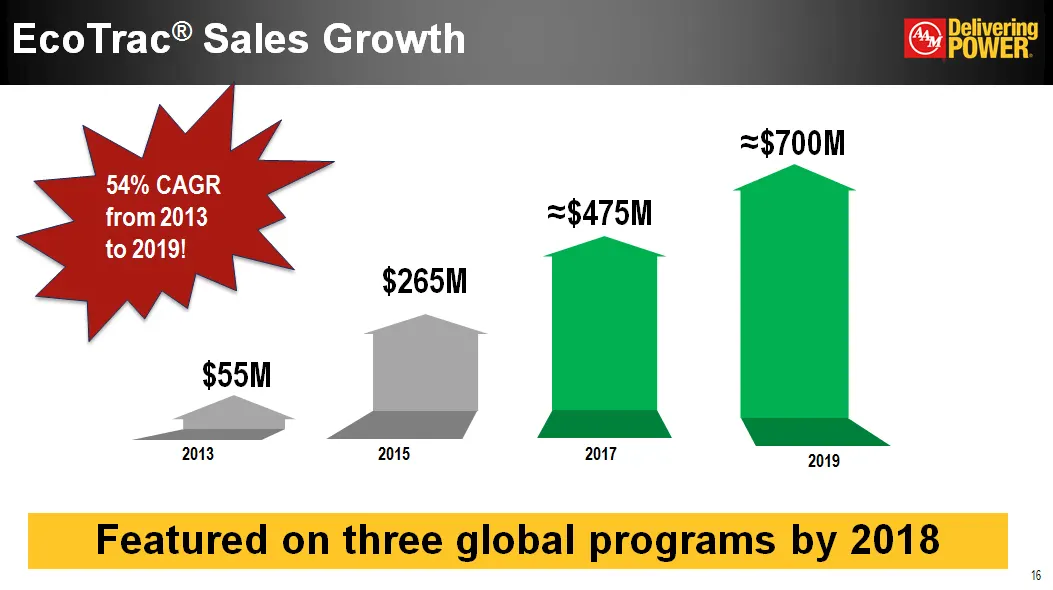
EcoTrac(R) Sales Growth 54% CAGR from 2013 to 2019! $55M $265M =$475M =$700M 2013 2015 2017 2019 Featured on three global programs by 2018 16
Slide 16: e-AAM Hybrid and Electric Drivelines
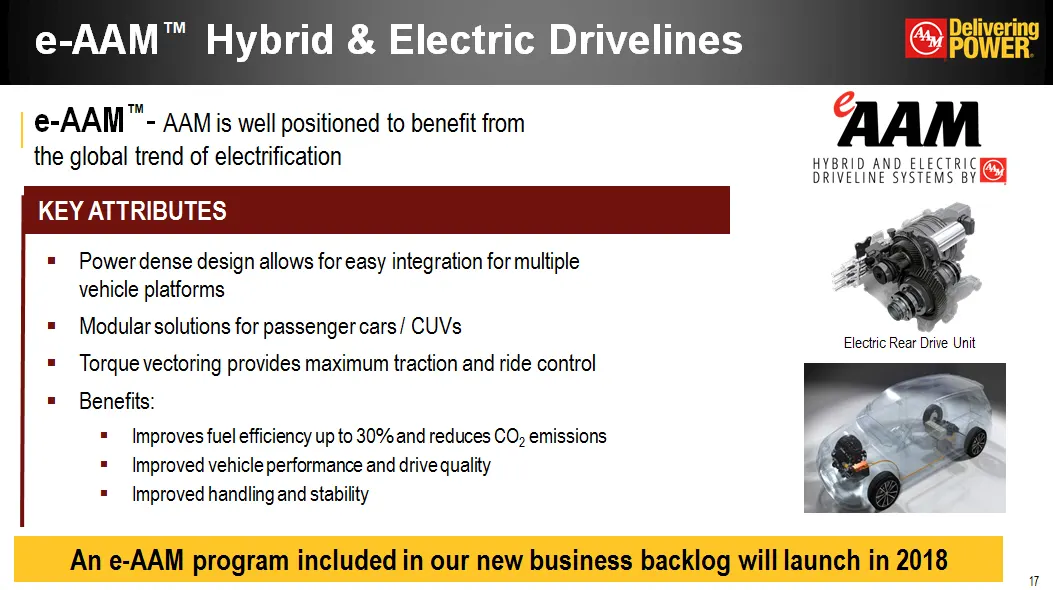
e-AAM(TM) Hybrid and Electric Drivelines e-AAM(TM)- AAM is well positioned to benefit from the global trend of electrification KEY ATTRIBUTES Power dense design allows for easy integration for multiple vehicle platforms Modular solutions for passenger cars / CUVs Torque vectoring provides maximum tr
Slide 17: QUANTUM Technology
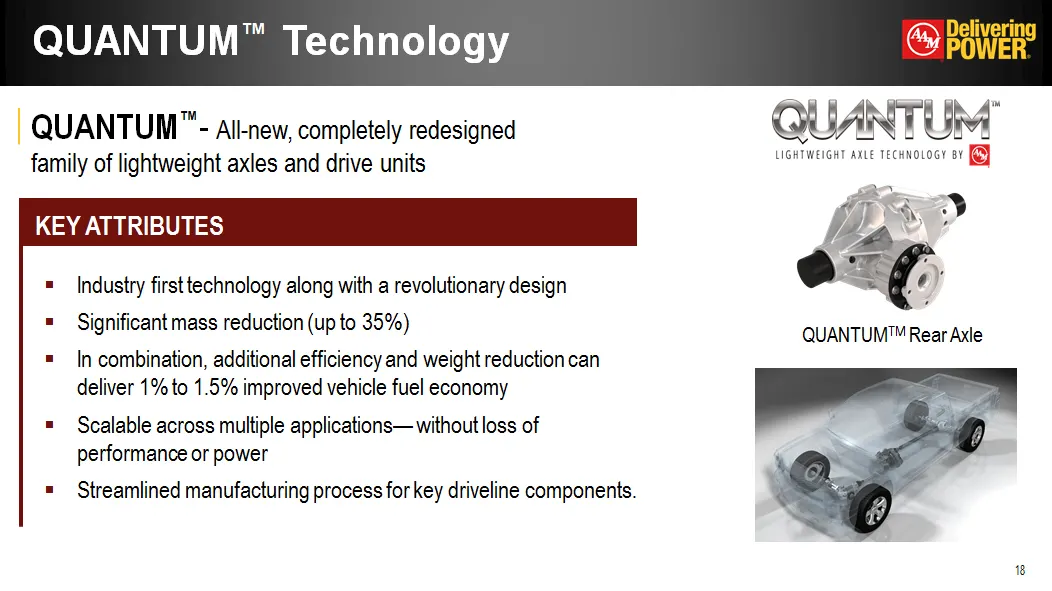
QUANTUM(TM) Technology QUANTUM(TM)- All-new, completely redesigned family of lightweight axles and drive units KEY ATTRIBUTES Industry first technology along with a revolutionary design Significant mass reduction (up to 35%) In combination, additional efficiency and weight reduction can deliver 1% t
Slide 18: Delivering Power: AAM's Acquisition of MPG
Delivering Power AAM'S ACQUISITION OF MPG (Metaldyne Performance Group) Increased Global Scale (light vertical) Expanded Product Portfolio (light vertical) Accelerated Diversification (light vertical) Enhanced Cash Flow Generation
Slide 19: Compelling Strategic Acquisition
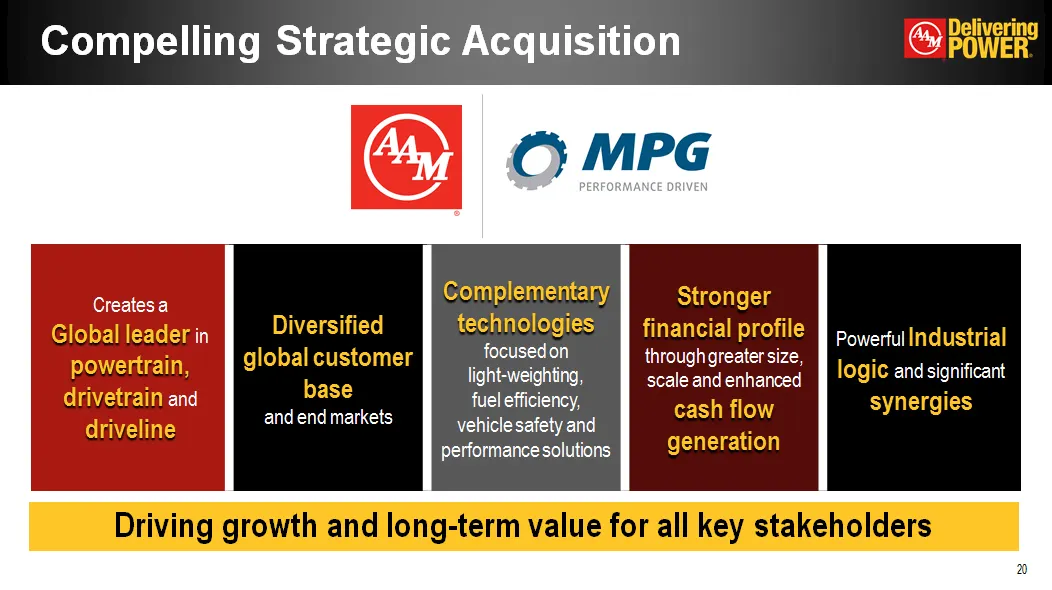
Compelling Strategic Acquisition Creates a Global leader in powertrain, drivetrain and driveline Diversified global customer base and end markets Complementary technologies focused on light-weighting, fuel efficiency, vehicle safety and performance solutions Stronger financial profile through greate
Slide 20: Significantly Enhanced Scale and Profitability
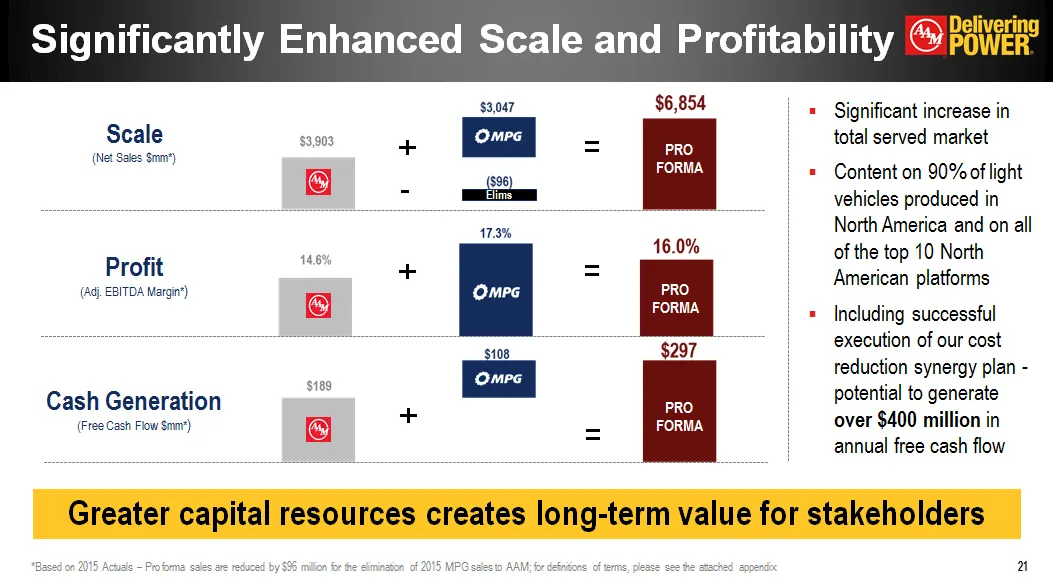
Significantly Enhanced Scale and Profitability Scale (Net Sales $mm*) $3,903 $3,047 $6,854 PRO FORMA Profit (Adj. EBITDA Margin*) 14.6% 17.3% 16.0% PRO FORMA Cash Generation (Free Cash Flow $mm*) $189 $108 $297 PRO FORMA Significant increase in total served market Content on 90% of light vehicles pr
Slide 21: Comprehensive Solutions from Engine to Driveline
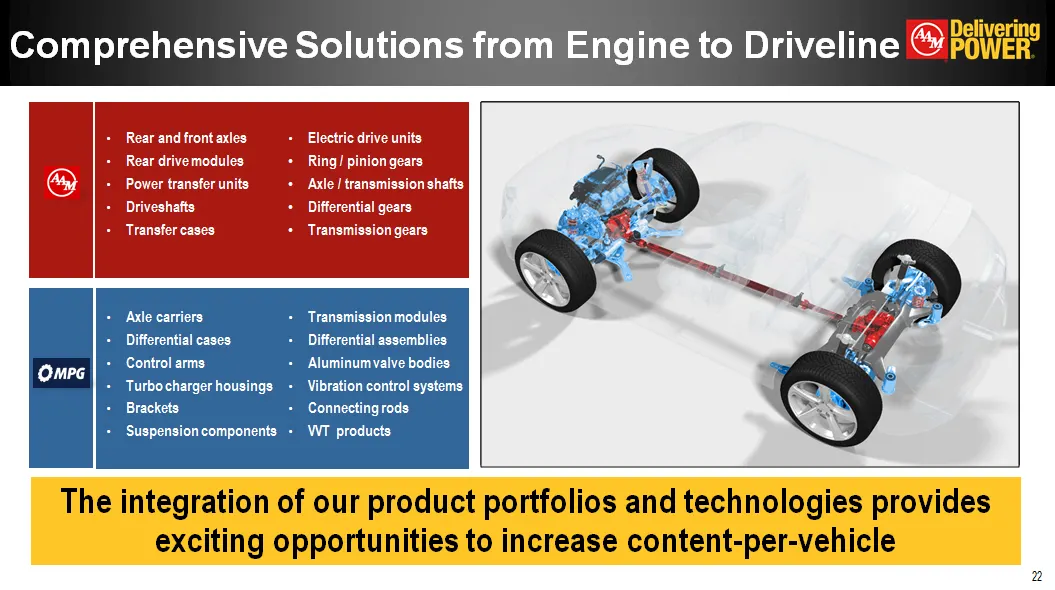
Comprehensive Solutions from Engine to Driveline Rear and front axles Rear drive modules Power transfer units Driveshafts Transfer cases Electric drive units Ring / pinion gears Axle / transmission shafts Differential gears Transmission gears Axle carriers Differential cases Control arms Turbo charg
Slide 22: Expanded Product Portfolio
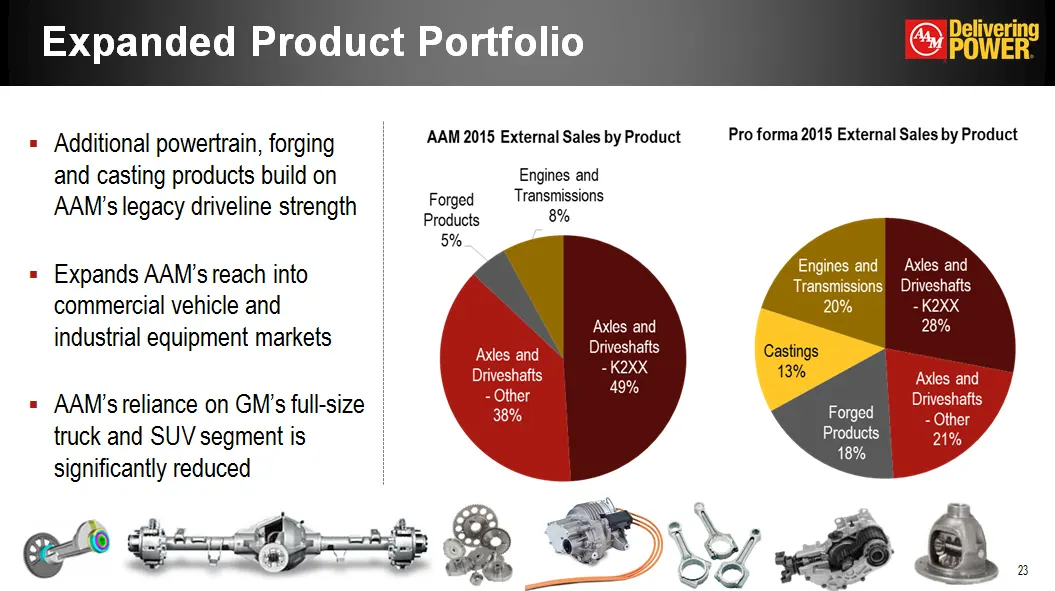
Expanded Product Portfolio Additional powertrain, forging and casting products build on AAM's legacy driveline strength Expands AAM's reach into commercial vehicle and industrial equipment markets AAM's reliance on GM's full-size truck and SUV segment is significantly reduced AAM 2015 External Sales
Slide 23: Accelerated Customer Diversification
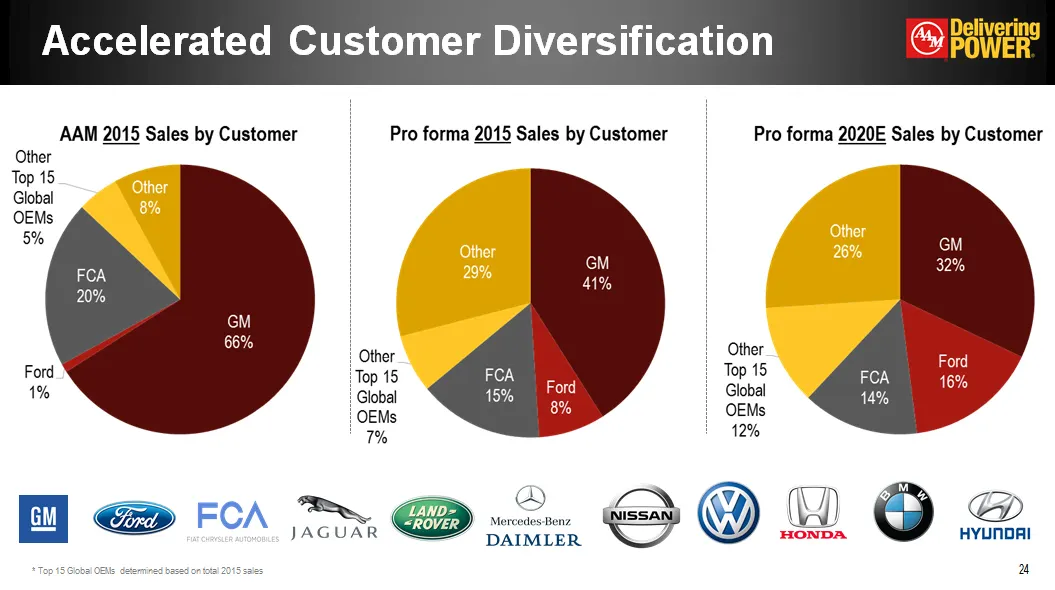
Accelerated Customer Diversification AAM 2015 Sales by Customer GM 66% Ford 1% FCA 20% Other Global Top 15 OEM's 5% Other 8% Pro forma 2015 Sales by Customer GM 41% Ford 8% FCA 15% Other Global Top 15 OEM's 7% Other 29% Pro forma 2020E Sales by Customer GM 32% Ford 16% FCA 14% Other Global Top 15 OE
Slide 24: Integration Management Office (IMO)
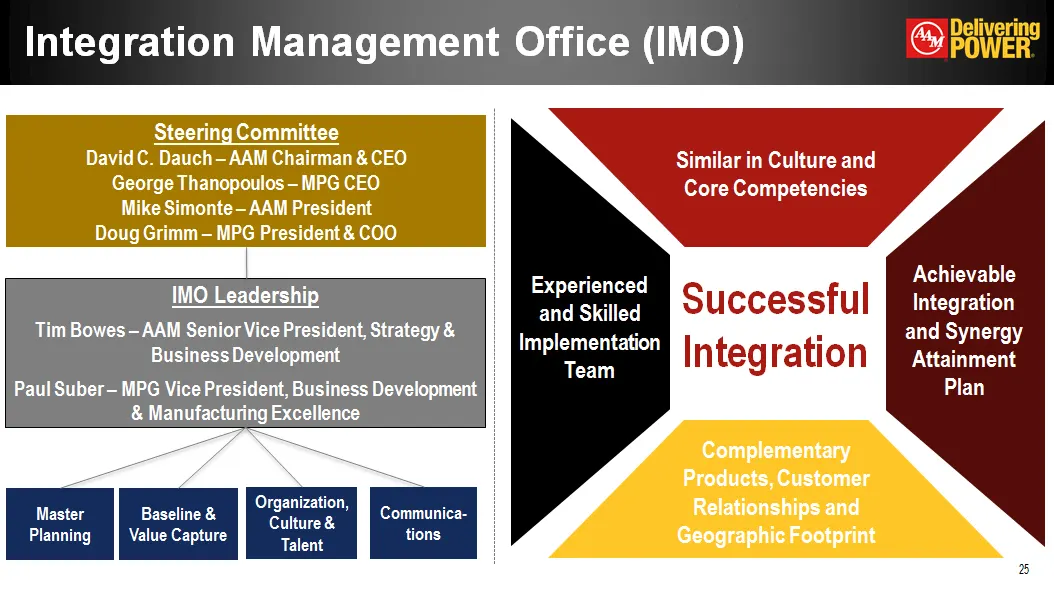
Integration Management Office (IMO) Steering Committee David C. Dauch - AAM Chairman and CEO George Thanopoulos - MPG CEO Mike Simonte - AAM President Doug Grimm - MPG President and COO IMO Leadership Tim Bowes - AAM Senior Vice President, Strategy and Business Development Paul Suber - MPG Vice Pres
Slide 25: Anticipated Synergies
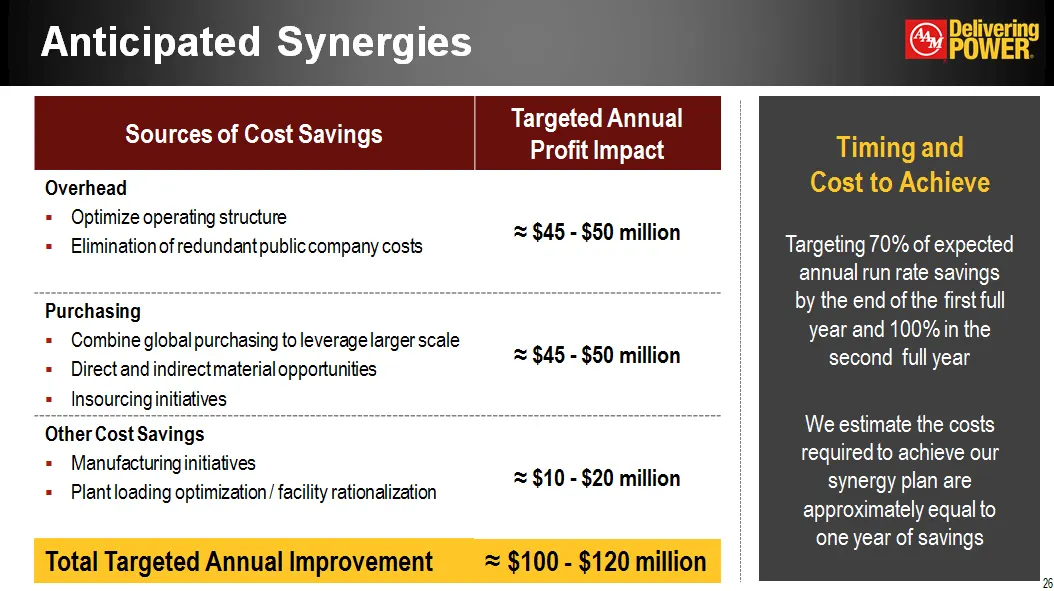
Anticipated Synergies Sources of Cost Savings Targeted Annual Profit Impact Overhead Optimize operating structure Elimination of redundant public company costs = $45 - $50 million Purchasing Combine global purchasing to leverage larger scale Direct and indirect material opportunities Insourcing init
Slide 26: Combined Pro Forma Financial Targets
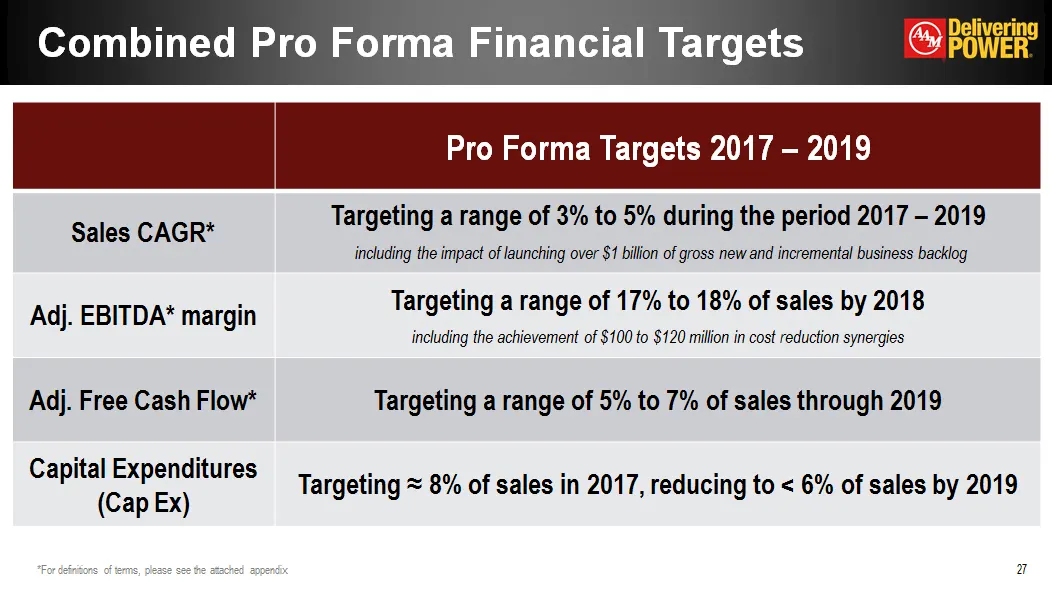
Combined Pro Forma Financial Targets Pro Forma Targets 2017 - 2019 Sales CAGR* Targeting a range of 3% to 5% during the period 2017 - 2019 including the impact of launching over $1 billion of gross new and incremental business backlog Adj. EBITDA* margin Targeting a range of 17% to 18% of sales by 2
Slide 27: Expected Pro Forma EBITDA vs. Cash Payments
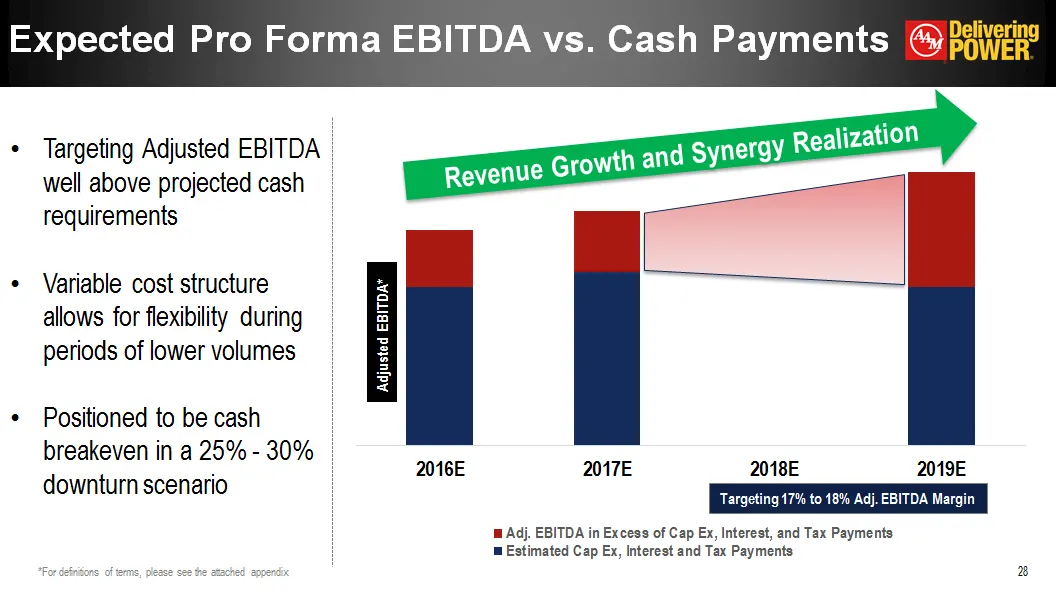
Expected Pro Forma EBITDA vs. Cash Payments Targeting Adjusted EBITDA well above projected cash requirements Variable cost structure allows for flexibility during periods of lower volumes Positioned to be cash breakeven in a 25% - 30% downturn scenario Revenue Growth and Synergy Realization Adjusted
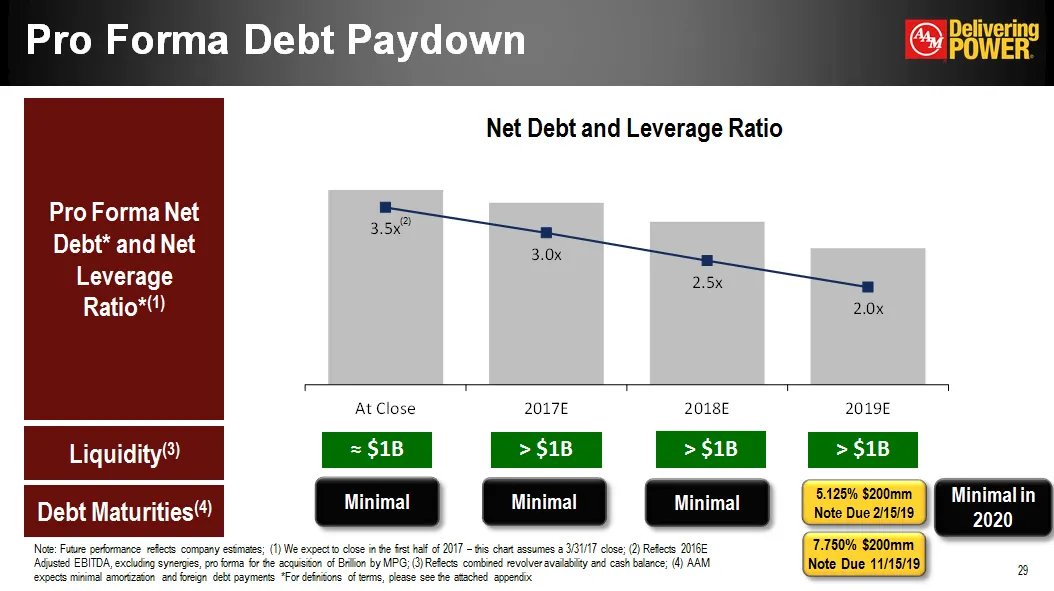
Slide 28: Pro Forma Debt Paydown
Pro Forma Debt Paydown Pro Forma Net Debt* and Net Leverage Ratio*(1) Liquidity(3) Debt Maturities(4) Net Debt and Leverage Ratio 3.5x 3.0x 2.5x 2.0x At Close 2017E 2018E 2019E = $1B > $1B > $1B > $1B Minimal Minimal Minimal 5.125% $200mm Note Due 2/15/19 7.750% $200mm Note Due 11/15/19 Minimal in 2
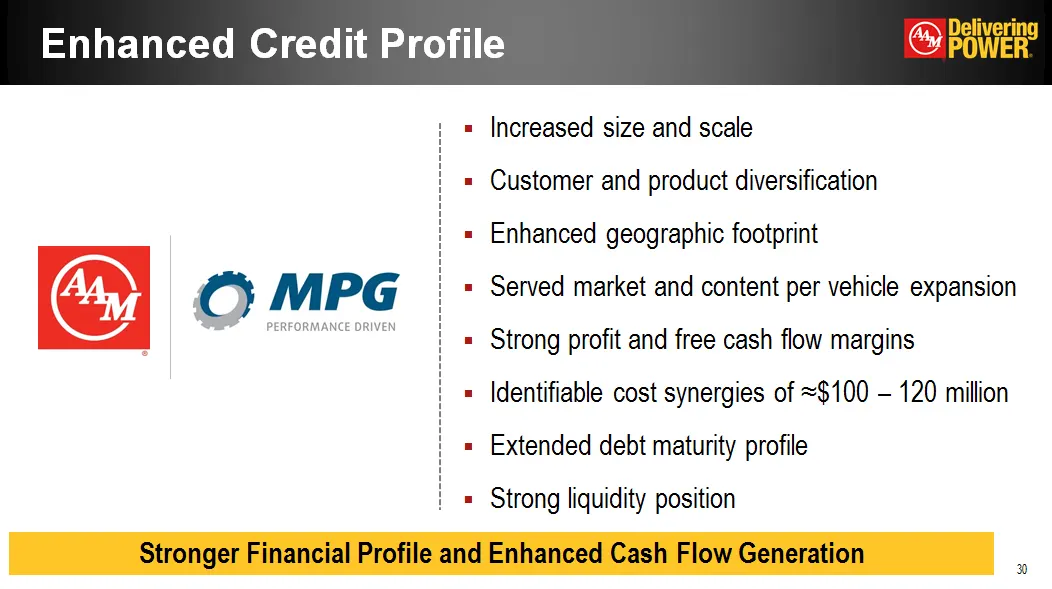
Slide 29: Enhanced Credit Profile
Enhanced Credit Profile Increased size and scale Customer and product diversification Enhanced geographic footprint Served market and content per vehicle expansion Strong profit and free cash flow margins Identifiable cost synergies of (almost equal)$100 - 120 million Extended debt maturity profile
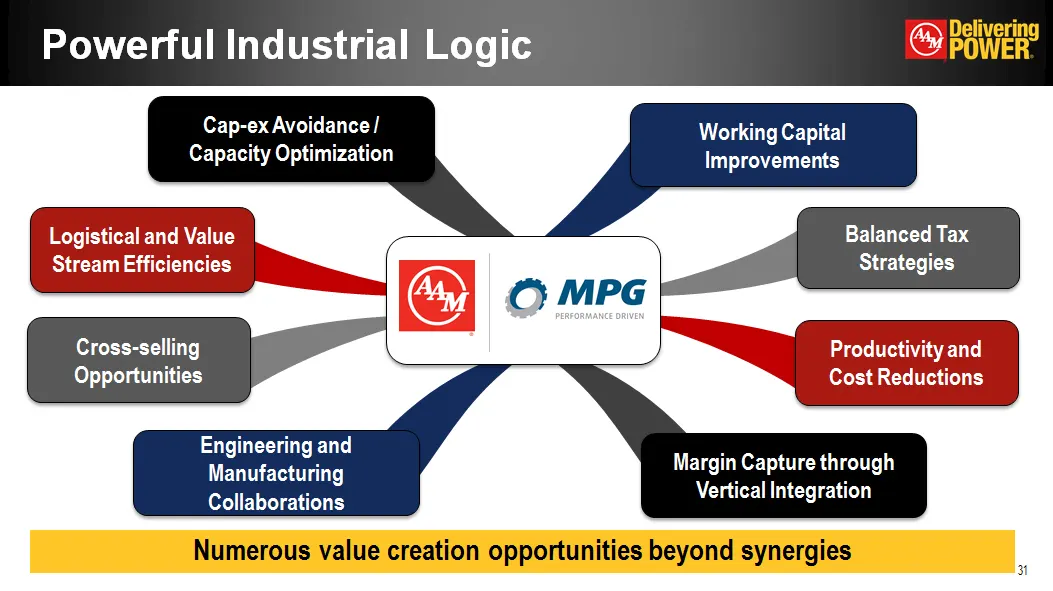
Slide 30: Powerful Industrial Logic
Powerful Industrial Logic Cap-ex Avoidance / Capacity Optimization Logistical and Value Stream Efficiencies Cross-selling Opportunities Engineering and Manufacturing Collaborations Margin Capture through Vertical Integration Productivity and Cost Reductions Balanced Tax Strategies Working Capital Im
Slide 31: Powerful Industrial Logic
Powerful Ind Cap-ex Avoidance / Working Capital Capacity Optimization Improvements Balanced Tax Strategies Cross-selling Opportunities Engineering and Manufacturing Collaborations Margin Capture through Vertical Integration Numerous value creation opportunities beyond synergies aT
Slide 32: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures In addition to the results reported in accordance with accounting principles generally accepted in the United States of America (GAAP) included within this presentation, we have provided certain information, which includes non-GAAP financial measures. Such informa
Slide 33: Reconciliation of Non-GAAP Measures
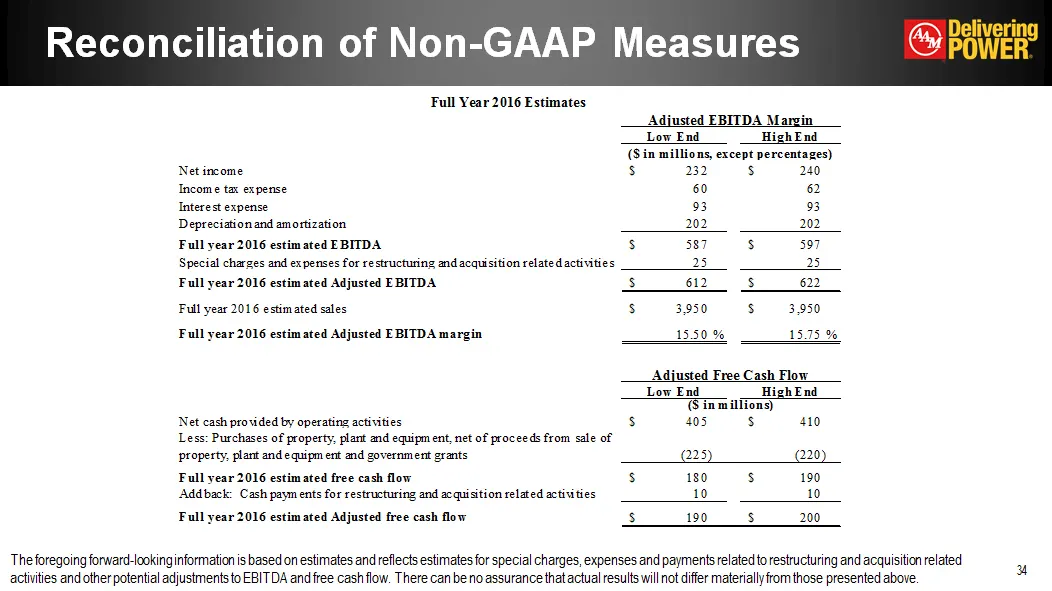
Reconciliation of Non-GAAP Measures Full Year 2016 Estimates Adjusted EBITDA Margin Low End High End ($ in millions, except percentages) Net income $232 $240 Income tax expense 60 62 Interest expense 93 93 Depreciation and amortization 202 202 Full year 2016 estimated EBITDA $587 $597 Special charge
Slide 34: Reconciliation of Non-GAAP Measures
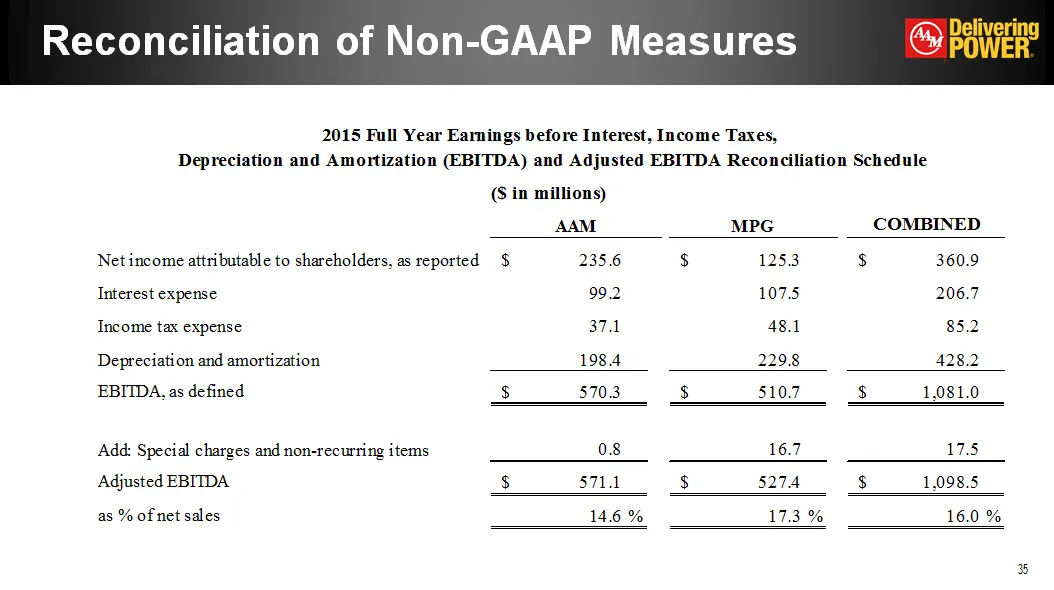
Reconciliation of Non-GAAP Measures 2015 Full Year Earnings before Interest, Income Taxes, Depreciation and Amortization (EBITDA) and Adjusted EBITDA Reconciliation Schedule ($ in millions) AAM MPG COMBINED Net income attributable to shareholders, as reported $235.6 $125.3 $360.9 Interest expense 99
Slide 35: Reconciliation of Non-GAAP Measures
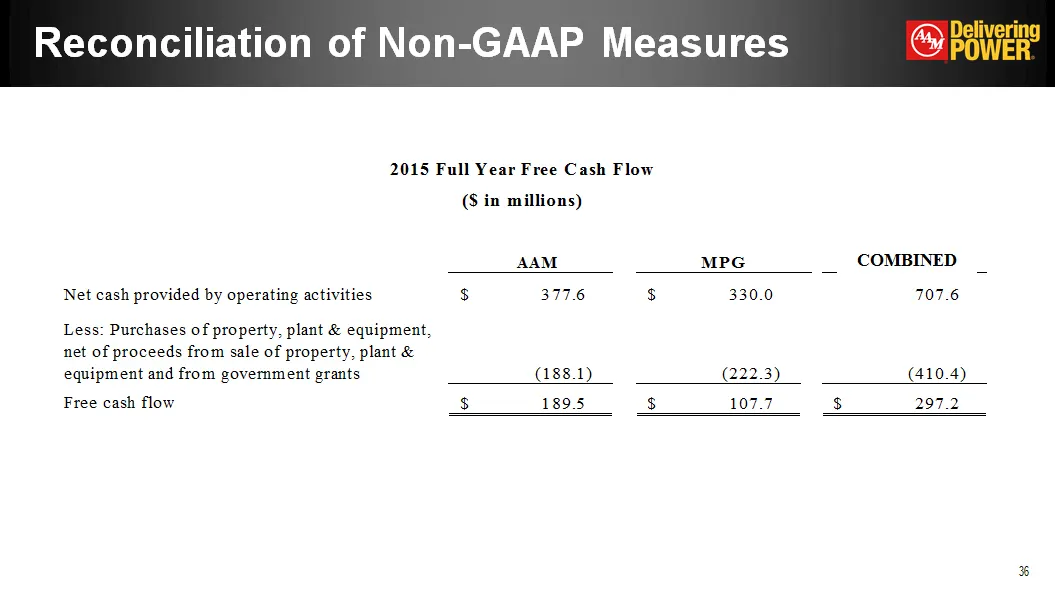
Reconciliation of Non-GAAP Measures 2015 Full Year Free Cash Flow ($ in millions) AAM MPG COMBINED Net cash provided by operating activities $377.6 $330.0 707.6 Less: Purchases of property, plant and equipment, net of proceeds from sale of property, plant and equipment and from government grants (18
Slide 36: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures We define EBITDA to be earnings before interest expense, income taxes, depreciation and amortization. Adjusted EBITDA excludes the impact of special charges and expenses for restructuring and acquisition related activities. We believe EBITDA and Adjusted EBITDA ar
Slide 37: Reconciliation of Non-GAAP Measures
Reconciliation of Non-GAAP Measures @ We define EBITDA to be eamings before interest expense, income taxes, depreciation and amortization. Adjusted EBITDA excludes the impact of special charges and expenses for restructuring and acquisition related activities. We believe EBITDA and Adjusted EBITDA a
Source: SEC EDGAR · 425 filed Jan 11, 2017
More decks from Metaldyne Performance Group Inc
 Debt Investor Presentation (February 2017)55 slides · Feb 23, 2017
 2016 Bank of America Merrill Lynch Leveraged Finance Conference38 slides · Nov 30, 2016
 Merger or Acquisition (November 2016)26 slides · Nov 17, 2016
 Merger or Acquisition (November 2016)25 slides · Nov 3, 2016
 Deutsche Bank Leveraged Finance Conference 201630 slides · Sep 27, 2016
 Goldman Sachs Leveraged Finance Conference 201627 slides · May 17, 2016