Jim Gattoni
President and CEO
Replay available
Landstar System (NASDAQ:LSTR) Q3 2021 earnings call, held 2021-10-21. Watch the replay and read the transcript on 6ix.
On 6ix: 6ix.com/event/landstar-system-inc-lstr-q3-2021-earnings-call
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:00 Good morning and welcome to Landstar System, Inc.'s third quarter 2021 earnings release conference call. All lines will be in a listen-only mode until the formal question-and-answer session. Today's call is being recorded. If you have any objections, you may disconnect at this time. Joining us today from Landstar are Jim Gattoni, President and CEO, Fred Pensati, Vice President and CFO, Rob Brasher, Vice President and Chief Commercial Officer, Joe Beacom, Vice President and Chief Safety and Operations Officer. Now, I would like to turn the call over to Mr. Jim Gattoni. You may now begin.
0:39 Thank you, Missy. Good morning, and welcome to Lesser's 2021 Third Quarter Earnings Commerce Call. Before we begin, let me read the following statement. The following is a safe harbor statement under the Private Securities Litigation Reform Act of 1995. Statements made during this conference call that are not based on historical facts are forward-looking statements. During this conference call, we may make statements that contain forward-looking information that relates to Lannister's business objectives, plans, strategies, and expectations. Such information is by nature subject to uncertainties and risks, included but not limited to the operational, financial, and legal risks detailed in Lannister's Form 10-K for the 2020 fiscal year, described in Section Risk factors and other SEC filings from time to time. These risks and uncertainties could cause actual results or events to differ materially from historical results or those anticipated.
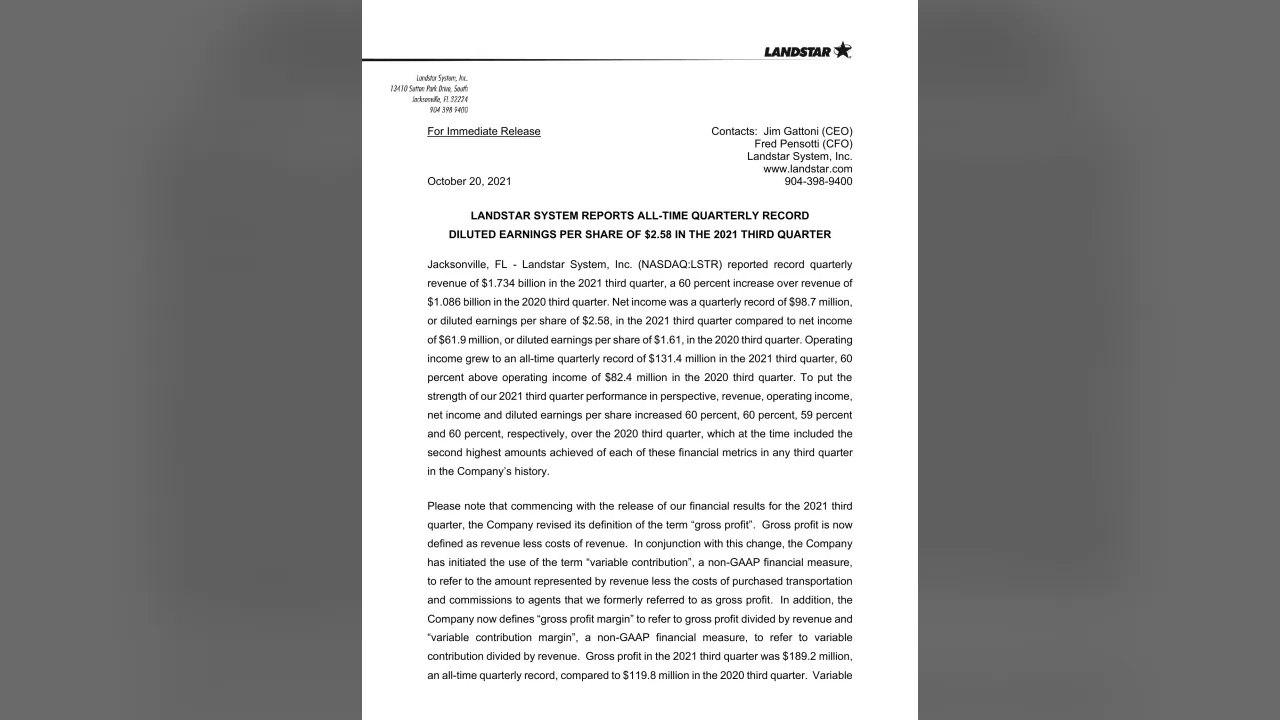
1:27 Investors should not place undue reliance on such forward-looking information, and Landstar undertakes no obligation to publicly update or revise any forward-looking information. Landstar's 2021 third quarter performance was exceptional, extending the record-setting pace that began in the midsummer of 2020. with three more months to go in 2021. Year-to-date 2021 revenue is about equal to revenue from all of physical year 2018, and operating income exceeds the 2018 full physical year amount, which were both record annual financial results. I expect the company's strong performance to continue through the remainder of the year with annual revenue exceeding $6 billion and diluting earnings per share in excess of $9.55. To put the strength of the 2021 performance in perspective, Assuming we achieve our 2021 fourth quarter guidance, full-year 2021 revenue and dilution earnings per share would exceed revenue and dilution earnings per share of our existing physical year records set in 2018 by over 35% and 55%, respectively.
2:29 As it pertains to the 2021 third quarter, revenue, gross profit, variable contribution, operating income, and dilution earnings per share were all-time quarterly records. Additionally, we ended the third quarter with a record number of trucks provided by BCOs and a record number of active truck brokerage carriers representing third-party carriers who have hauled a load of freight for Landstar in the past 180 days. Also, new agents, defined as agents who contracted with Landstar within the last 15 months, contributed $36 million of revenue to the third quarter, the highest quarterly new agent revenue in over 10 years. and considering our financial results and ability to attract agents and truck capacity providers. Revenue in the 2021 third quarter increased 60% over the 2020 third quarter, which at the time was the second highest third quarter revenue in Landstar history.
3:20 Landstar's record 2021 third quarter revenue was driven by strong demand for transportation of consumer doorables, machinery, metals, hazardous materials, building products and automotive parts and supplies and e-commerce services where we provide truckload transportation services between hubs of parcel carriers. Overall revenue hauled via truck in the 2021 third quarter over the 2020 third quarter increased 57%. Truckload revenue hauled via van and unsighted platform increased 54% over the 2020 third quarter. Revenue per load on truckload services increased 29% and the number of truckloads hauled increased 19% over the 2020 period. While Landstar's revenue per load is highly influenced by market conditions, the increased truckload volume of 19% against a relatively strong 2020 third quarter speaks to the ability of the network to flex when demand spikes.
4:13 Truckload revenue hauled via van equipment led the increase at 59% over the 2020 third quarter, while revenue hauled via unsighted platform equipment exceeded prior year by 44%. Other truck transportation revenue, consisting mostly of revenue generated through power only, expedited cargo van, straight truck, and other services almost doubled over the 2020 third quarter. The primary driver of growth in other transportation services was from power-only demand, which contributed 75% of the category in the 2020 third quarter and 63% in the 2020 third quarter. And finally, lessened truckload revenue in the 2021 third quarter, which was 2% of truck transportation revenue, increased 23% over the 2020 third quarter. The number of lows hauled via truck in the 2021 third quarter increased 3.5% compared to the 2021 second quarter, while revenue per load on lows hauled via truck increased 5.8% over the 2021 second quarter. Both growth rates are stronger than normal seasonal trends when comparing the recent second quarter to third quarter results.
5:18 From an end market standpoint, consumer demand for building products, consumer doorables, and small package via e-commerce continue to drive record volume in the 2021 third quarter. The number lowest hauled via unsighted platform equipment also exhibited strong growth in the 2021 third quarter over the 2020 third quarter, mostly due to continuing improvement in the U.S. manufacturing sector that began in March 2020. Revenue per load on trucks hauled via van and unsighted platform equipment increased 29% over 2020 third quarter and 7% over the 2021 second quarter above normal seasonal trends as capacity continues to be constrained across all markets and equipment types. As it relates to the new agent pipeline, we continue to attract qualified agent candidates to the model. As mentioned earlier, revenue from new agents in the 2021 third quarter was the highest quarterly revenue from new agents in over 10 years.
6:06 As to truck capacity, we ended the quarter with 11,746 trucks provided by business capacity owners, 755 more trucks compared to our year-end 2020 count. The increase in our truck count thus far in 2021 is being driven by improved retention, as the number of BCO cancellations through the first three quarters of 2021 was 19% below the number we experienced through the first three quarters of 2020. Year-to-date September, we have recruited almost the same number of BCOs as during the 2020 39-week period. Lows hauled via BCOs increased approximately 5% in the 2021 third quarter over the 2020 third quarter on a 12% increase in average truck count, partially offset by a 6% decrease in BCO truck utilization defined as loads hauled per BCO truck per quarter.
6:57 We ended the third quarter with a record number of approved 30-party carriers in our network, while the number of active third-party carriers, which we define as carriers who have hauled the load in preceding 180 days, increased 42% in the 2021 third quarter. Our network is strong and continues to attract third-party truck capacity. I will now pass it to Fred to comment on additional P&L metrics and a few other third-quarter financial statement items.
7:21 Thanks, Jim. Good morning, everyone, and thanks again for joining us. Jim covered our revenue performance in detail and alluded to our gross profit and variable contribution. I'll make some additional comments about these metrics, as well as other profitability metrics and expenses, and discuss briefly our balance sheet and cash flow performance. I'll start with gross profit. As we disclosed in our earnings release yesterday, effective in the 2021 third quarter, we revised our definition of the term gross profit, which we're now defining as revenue less cost of revenue. Cost of revenue has two categories, variable cost of revenue and other cost of revenue. Variable cost of revenue includes purchase transportation and agent commissions, and other cost of revenue includes numerous costs that vary in different degrees with revenue, including trailer depreciation and maintenance expenses, BCO recruiting, training and qualification costs, insurance-related expenses such as premiums paid and the cost of claims for various freight transportation-related insurance policies, and other costs included in selling, general and administrative in the company's consolidated statements of income such as brokerage commissions and other fees incurred to administer the insurance programs available to BCO independent contractors that are reinsured by the company as well as costs related to our internally developed technology that directly support our revenue as detailed in the reconciliation of gross profit to variable contribution table included in our earnings release. In addition, we now define gross profit margin
8:53 as gross profit divided by revenue. In the 2021 third quarter, gross profit was $189.2 million, an increase of roughly 58% compared to $119.8 million in the 2020 third quarter. Gross profit margin was 10.9% of revenue in the 2021 third quarter, only slightly below 11% gross profit margin in the same period of 2020. In conjunction with the new definition of gross profit, Thank you very much. as variable contribution divided by revenue.
9:52 This measure has always been and continues to be an important one for us since purchase transportation and agent commissions are the primary expenses that are 100% variable with revenue and give us a view into spot market trends in the freight transportation industry on a shipment-by-shipment basis. In the 2021 third quarter, variable contribution increased roughly 51% to $242.3 million compared to $160.9 million in the 2020 third quarter, driven by strong revenue growth. Our variable contribution margin was 14% of revenue this year compared to 14.8% in the same period last year. The decrease in variable contribution margin compared to the 2020 third quarter is mostly attributable to the mix between our BCO independent contractor capacity, the majority of which is fixed margin, and our brokerage capacity, the majority of which has a variable margin. As our brokerage business increased from 44% of total revenue in the 2020 third quarter to 51% of total revenue in the 2021 third quarter.
10:58 The year-over-year growth rate and margin performance of gross profit exceeded that of variable contribution due to the ability of the Landstar model to leverage the mostly semi-variable costs I described earlier that are included in gross profit. Operating income in the 2021 third quarter was $131.4 million, or 69.4% of gross profit compared to $82.4 million, or 68.7% of gross profit in the same period last year. Operating income represented 54.2% of variable contribution in the 2021 third quarter compared to 51.2% in the same period last year. The 300 basis point improvement in operating income as a percent of variable contribution compared to prior year is primarily attributable to the significant growth in variable contribution that drove down insurance and claims expense and depreciation and amortization expense as a percent of variable contribution compared to prior year.
11:55 Getting to a bit more detail on the expenses noted in our consolidated statements of income, purchased transportation grew at a faster pace than our overall revenue growth, which I mentioned earlier was driven by the change and mix of revenue generated by our BCO and brokerage capacity. Other operating costs were $10.6 million in the third quarter this year compared to $7.4 million in the same period last year. This increase came from higher trailing equipment maintenance and tire costs due to a higher trailer count, contractor bad debt, and increased recruiting, qualification, and training costs related to our BCOs compared to last year. Insurance claims costs were $29.6 million in the third quarter this year compared to $21.9 million in the same period last year.
12:43 Total insurance and claims costs represented 4.3% of BCO revenue in the third quarter this Thank you very much. Thank you very much. And lastly, depreciation and amortization was $12.3 million in the 2021 third quarter compared to $11.2 million in the same period last year, primarily due to technology investments and enhancements put into service since last year.
13:56 Our effective income tax rate was 24.4% in the 2021 third quarter compared to 23.9% in the same period last year. Increase in the effective income tax rate was primarily attributable to a higher provision for non-deductible executive compensation during the 2021 period and the impact of excess tax benefits on stock compensation in the 2020 period. Our net income for the 2021 third quarter was $98.7 million, up 59%, $61.9 million in the same period last year. Our diluted earnings per share in the 2021 third quarter was $2.58, up 60%, Thank you for joining us. Business performance has significantly exceeded the expectations I had when I started towards the end of the second quarter. Now, we recognize we're riding an industry wave, but we're also very pleased with how Landstar is performing within the industry, continuing to be a leader with a unique business model with scale and technology that enables entrepreneurial success, and in turn, the company's success.
15:26 I've now had the opportunity to meet some of these entrepreneurs, namely our agents and our BCO independent capacity providers, and the enthusiasm for working with the Landstar Network is very evident, as is the passion our employees put into continuing to make the Landstar Network stronger every day. I've also had the opportunity to meet some of you who are probably on this call today and look forward to getting to know more of you in the future. We look forward to keeping you updated on the business as we make our way through the home stretch of 2021 and start looking ahead to 2022. And I'll turn it back to Jim to discuss our outlook for the fourth quarter and wrap up our prepared remarks.
16:02 Thanks, Fred. That was excellent for job security. Freight demand began to significantly improve in August 2020 from increased consumer spending as the U.S. economy crept from the initial impact of the pandemic. The strength of the freight environment that began in August continued through the end of 2020. As such, year-over-year financial comparisons normalized as we moved through the 2021 third quarter. My expectations are that the strong freight environment Landstar has experienced in 2021 will continue through the fourth quarter. I expect quarter over prior year quarter revenue growth to decelerate from the quarter over prior year quarter growth rate experienced in the 2021 third quarter given that the 2021 fourth quarter compares to a record fourth quarter revenue reported in the 2020 fourth quarter. However, that decelerated growth rate should in no way be viewed as a signal of a change in the very strong freight environment.
16:53 On a year-over-year basis, I expect 2021 fourth quarter load volume to increase in the 13% to 16% range over the 2020 fourth quarter. This is particularly impressive given the strength in business we experienced in the 2020 fourth quarter when the number of loads hauled via truck exceeded the 2019 fourth quarter, that is before the impact of the COVID-19 pandemic, by 13%. This estimate of truck volume for the 2021 fourth quarter would also be in line with what we would consider normal historical volume trends from the third quarter to the fourth quarter of a given year. I expect revenue per load on loads sold via truck in the 2021 fourth quarter to also move in line with what we would consider normal seasonal rate trends based on historical experience.
17:38 As such, I expect revenue per load on loads sold via truck to increase a healthy 15 to 18% over the 2020 fourth quarter. Given those assumptions, I expect total revenue in the 2021 fourth quarter to be within a range of $1.7 billion to $1.75 billion. Assuming insurance and claims costs are 4.3% of estimated BCO revenue in the 2021 fourth quarter. I expect that lunar earnings per share to be in a range of $255 to $265. Overall, I'm extremely pleased with Landstar's 2021 performance. Revenue's 39-week period ended September, was by far the highest ever revenue in the company's history over the period, and increased approximately $1.2 billion, or 34%, compared to the previous record set in the 2018 39-week period. 2021 39-week period, viable contribution, gross profit, operating income, net income, and dilution per share were by far the highest ever achieved in any 39-week period in the company's history, and we expect each of these metrics to significantly exceed the amounts Lansdor achieved during its previously record-setting 2018 fiscal year.
18:37 In our view, the overall environment for Lansdor continues to be as strong as it has been at any point over the last two decades, and Lansdor is positioned to complete the year with tremendous success. We continue to increase our available capacity and remain focused on providing and enhancing technology-based tools for the thousands of small business owners in both the agent and capacity side of our network. I expect 2021 to continue at its record-setting pace as we have to easily surpass $6 billion in annual revenue for the first time in our history. And with that, Missy, we will open for questions. Certainly, sir. We will now begin the question-and-answer sessions. If you would like to ask a question, please press star followed by the number one on your touchtone phone. Once again, that is star one to ask a question. To cancel your request, please press star two.
19:25 We have multiple questions on queue and the first one is from Bascom Majors of Susquehanna. Your line is now open. Yeah, thanks for taking my question and congratulations on another excellent quarter and outlook for the 4Q. Jim, as we look into next year, clearly things are going exceptionally well this year. Could you help us think about what a more normalized base after the incentive comp and stock comp would be on the G&A number as we think about how the model and your margins flex into whatever happens in the trucking market next year? I don't know if that's talking about what this year would look like without the excess comp from that or or just calling out that comp. But anything to help us bridge kind of where we stack on a reset G&A for next year would be really helpful. Thank you.
20:18 Yeah, I would say if you take the 39-week period this year in SG&A and add, we believe we're probably going to be slightly lower than the third quarter. I think the third quarter is about $59 million. I think we'll have a couple million lower than that in the fourth quarter. So if you add that in, you'll have the full year guess of what our SG&A is for the for the full year of 2021. Right now, there's probably 30 to 35 million of variable comp that would not be in next year unless we blow it out again. If we go back to a normalcy where we're not growing revenue 60%, you have a 30 to 35 million tailwind in SG&A related to our variable comp programs. and Jim, does that include both the stock comp and the cash comp?
21:05 Yes, that's both. They kind of move in tandem. The difference between the two is the cash comp is kind of a short term thing. It's an annual target and the stock comp varies based on they invest over a five year period based on growth over that period so it's just a longer tail in the stock comp than it is the cash comp but they kind of tend to move in similar directions. In a great year they kind of elevate and and when things slow down, they pull back. So in a normal year, you know, we're going to probably have a $30-35 million bell wind going in next year in SG&A. Not to put too fine a point to it, it's just a pretty big variance, but do you have a sense of, you know, from hiring and just general wage inflation, what we should think about that base rising?
21:49 Yeah, I would tell you that we have about an $80 and $90 million salary component here, maybe actually a little bit higher than that. And Fred had mentioned that the quarter was impacted by some of that wage inflation. We had made a decision early to actually do 5%. Our increases are July 1 annually for pretty much the entire organization, and we had made a decision based on what we were seeing in the environment as it relates to retaining or recruiting employees that, you know, Thanks for that. And tying it all together, you Even if next year is a normal year and revenues are flat or even down a bit, you have a pretty big cushion here. Do you think that earnings could be flat to up if the market isn't just really challenging on the truck pricing?
23:01 Just any preliminary thoughts on how you guys feel heading into next year?
23:06 Feeling pretty good for the first half. When we were talking at the end of June, it was hard to predict when this thing turns, but with the strength we're seeing, We were saying that sometime first half we might see it start to cycle back. Now we're thinking maybe it's more toward the end of the first half because things still remain very strong coming into the fourth quarter. We don't see anything pulling back. We see no metrics of trucks coming to the system or demand slowing down. Look, do I expect this market to continue? No. Do I expect pricing to stay elevated higher than historical? Yeah, because I think the costs that are now into the in the industry, whether it's driver wages or insurance or things like that, the costs are elevated. So I don't think you're ever going to pull back to where we were back in 16, 17. But, you know, in our cyclical business, you do expect a pullback.
23:53 If we get that pullback, I still think we'll perform well. And can we cover? So I'm talking about the $35 million of variable comp offset by $5 million. So we have that $30 million cushion. I think we can grow earnings, but I want to put a commitment to that. I think there's Thanks for all that. We really appreciate the color. All right. Thanks. Thank you so much. Our next question is from Charles Yukovich of Evercore ISI. Your line is now open.
24:39 Good morning. Thank you for taking my call. I wanted to talk about freight mix across industries and your views on trends that are here to stay versus shifts that may be more temporary in the long term. Clearly, the pandemic continues to result in outside consumer retail, and the chip shortage has really weighed on autos. But when you think about the current mix versus pre-pandemic levels, what sector shifts do you see as permanent, and which ones do you think will eventually reverse? Well, we'll just talk about the consumer side. Look, we're highly affected by the manufacturing sector in the U.S., or at least we used to be. If you go back five, six, seven years, we used to tie our load volumes to the changes in industrial production here in the U.S., right? And when you think about that, if industrial production was growing 3%, we feel we could have grown volume 6% or 7%. If it was down 2%, we'd see volumes go down, right?
25:25 And we tied pretty tightly to that. The strong demand we're seeing now and we've seen for the last two years is really a lot of consumer-driven based, whether it's consumer doorables, building products, stuff like that for home improvement. That's a lot of what's driving us today. But like I said, we go back six or seven years. We've been kind of penetrating a little bit more into consumer before the pandemic hit with some building product stuff and appliance type stuff. So we are slowly getting into that, but it's just really ramped up. You know, it's a difficult question to answer, you know, based on what we're sitting in an environment that really hasn't happened in my lifetime, you know, driven by high consumer demand, the government printing money, and, you know, and supply chain bottlenecks. And you take all that stuff and then you've got to think about what's, you know, when the supply chain bottlenecks start to clear out and that disruption goes away, clearly you'll have an impact on pricing, right? Pricing will come down, trucks will be a little more readily available regardless of whether there's trucks in the, More trucks coming into the marketplace.
26:26 And then you've got the U.S. domestic manufacturing sector on the flatbed side, which we feel still hasn't jumped off. It's still relatively, I don't want to say it's soft, but it's not where we think it should be. So you might see, in my world, I would say you're definitely sooner or later going to see the consumer market pull back. You can only buy so many dryers and washing machines or repair your house, so that will slow down. The consumer will start burning up some of the cash that they're sitting on. and that might balance out with some of the U.S. production coming back and flatbed market coming back. You've got this infrastructure bill that's hung up in the U.S. We've been talking about infrastructure bills for 20 plus years and they've never been able to pull it off but anything there that would help on the flatbed market on the equipment side if the infrastructure bill got signed and they're talking about heavy equipment and building roads and bridges and stuff like that That's very favorable to the market.
27:15 So in summary, sooner or later the consumer is going to pull back. And if you get an infrastructure bill, that will help the flatbed market. And if manufacturing starts to improve better than where it is today, I think eventually we'll see the flip where the van rates start to pull back a little bit, but the flatbed kind of stays strong into maybe the next 12 to 18 months would be in my thoughts. Okay, great. That's really helpful. Would you say that the current environment impacts the way you think about the current trailer fleet at all?
27:47 Well, our trailer fleet is really driven by how many BCOs we have, so it's really more tied to our BCO count and the number of BCOs we have using trailers. We keep a ratio of two to one for every BCO who's using our van trailers. It's a two to one, so if we have... and say 6,000 or 7,000 guys using our trailers in a drop and hook operation. We have 14,000 trailers. So it's really demand driven. It's demand and BCO count. If we get a lot more consumer demand and drop and hook, we'll have more opportunities, it draws more BCOs into the network and we buy more trailers. That's kind of the trailer thing. We generally don't just buy 1,000 trailers and try and put them into the market and get used by third party capacity. That really hasn't been a niche for us. Kind of hard to control the The use of the trailer by a third-party capacity that isn't committed to, I don't say maintaining it, but they pick it up from point A, they drive it to point B, and they disappear. That hasn't really worked in our network, so it's really tied to our BCO count more than it is anything else.
28:45 Okay, great. That's very helpful. Thanks a lot. Yeah. Thank you so much. Our next question is from Jack Adkins of Stevens. Your line is now open. Okay, great. Good morning, everyone. Hey, Jack. Jack, you there? I think we lost Jack. We now have Scott Schneeberger of Oppenheimer. Your line is now open. Thanks. Good morning, everyone. I guess I'm curious, Jim, obviously a very robust demand environment. Could you speak to existing accounts and then growth in new accounts? Where are you seeing new business? Is it predominantly in the... and the consumables or consumer durables.
29:32 I'm just kind of curious where you see that popping up. Thanks.
29:37 From an account standpoint, it's kind of difficult for us to talk. We have over 25,000 accounts and even the top 25 only make up about 30% or 40% of our business. We kind of nickel and dime it. There's a lot of new accounts in our system that are doing $500 to $1 million. When you do a $1.7 billion, it's really hard to talk about where it is. It's really across the board. The truck market right now is so tight that anybody's looking for capacity. When you have 1,200 agents all around the country locally in market, I think that just gives us an advantage. Our guys are hungry to go satisfy customer demand right now. Customer demand is pretty hot regardless of what kind of commodity you're talking. Is it softer in other areas than some? Absolutely. Consumer doorbells is hot. Building products is hot. There are things that are hot. and things that aren't so hot.
30:22 Foodstuffs for us, it's never been a great category. Very big, we have a couple agents specialize it, so the refrigerated market's not really something we play in. But it's kind of across the board. A lot of it's coming from these small shippers who we may not have ever dealt with before, but they see us as a capacity resource. That's kind of what we see happening. Did we add any large customer in the quarter? No, over prior year. It's more nickel and diamond. It's just all these small customers we pull in. Some customers clearly have grown. We talked about the substitute line haul guys. Clearly a lot of growth there from the e-commerce market driving that growth on the sub-line haul, which is primarily just a handful of accounts that we do.
31:08 I would say it's just coming from all different directions. Great, thanks. Appreciate that. And then just kind of delving into the other truck transportation services, that new breakout for your reporting. Of the subcomponents, power only, expedited, straight truck, cargo van, how would you just – you might not give it by percents, but by order of magnitude, what are the – Can you kind of rank order those as in that bucket and then just expectations going forward for what you see from that category? Thanks.
31:47 Yeah, Rob will probably talk about what he sees in that category, but I'll give you the – like I said, power only was 75%. And this is a year to date, so the number I think in the revenue per year to date was like $518 million. So if I break it down, 75% of that is power only where we provide a tractor and there's a loaded trailer somewhere. It's somebody else's trailer. We haul it away. The ground expedite is probably about $70 million, $80 million of that. And then there's container that's in there, maybe $30 million to $40 million. and then there's a bunch of other small categories within there that, you know, almost add to nothing. But really, if you break it down, I'd say power only, then expedite on ground and then some container moves in that order from large to, you know, biggest to smallest and then a bunch of other small stuff that our agents get involved in.
32:38 And then Rob can speak to what he's thinking about the power only future and expedite.
32:44 Yeah, Scott, so this is Rob. The power only basically, as Jim kind of put it, The reason we kind of broke it out is we've seen the consumer spending in e-commerce kind of continue to grow, and we decided it really needed its own category. Again, we do a great deal of, I won't say a great deal, we do a lot of port work, especially now, a lot of dray work, if you will, a lot of chassis, a lot of containers, things like that, not compared to e-commerce. And as the international backlogs continue to happen, we continue to get involved a little bit more in that, but it's mainly driven by the e-commerce and consumer spending. Thanks, Rob. Thanks, Jim. I'll turn it over.
33:21 I think one thing about the power only, too, is if you think about the trailer market right now, carriers don't have any trailers available, so I think the shippers are doing a lot to put stuff into trailers and just waiting for it. Like, if they can access a trailer, they're going to load it, and they're going to try to get a truck to move it. That makes sense. Thank you so much. We now have Jack Atkins back of Stephens. Your line is now open. Okay, great. Guys, good morning. Can you hear me now? We can hear you now. Okay, great. Thanks for taking my question. Sorry about that earlier. I guess just kind of going back to the trailer question a moment ago, as you guys think sort of longer term about the business, I know it's sort of two trailers to one BCO.
34:07 Is it maybe worth considering extending out your trailer program to the third-party broker carriers? Other and other folks in the industry have sort of had success with that. I'm just curious if you guys are looking for ways to maybe expand that because it's been so successful with your BCOs. Just curious if you could maybe talk about that and if that's a consideration. I know trailers are hard to come by right now, but as you look out over the next several years.
34:32 Sure. Yeah, Jack, this is Joe. We have conceptually talked about that some, and Jim alluded to some of the utilization you know, repositioning, some of those things that would be challenges for us. We currently do it on a kind of a case-by-case basis in those situations where we can make sure that we capture the trailers and get the right kind of utilization. It's not like we don't ever do it, it's just that we're pretty selective in how we do it. In order to do it on a larger scale, there'd be some things that we would need to do, I think, internally from a systems perspective that would allow us to make sure that we're tracking and utilizing and so forth. You know, somewhat of a drop-and-hook capacity-constrained environment.
35:32 It tends to come up. But it's on the radar from a tech perspective.
35:36 I think, Jack, one of the things that's actually had us talking about it more now is that the fact that over the last three to five years is trailer tracking has been a lot more efficient right now as opposed to, like, when we used to hook trailer, we didn't really need that much trailer tracking because we had BCOs and agents managing them and watching them, right? So you always knew you could call a BCO and ask them what trailer he's on, stuff like that. It's easier to track. That's hard to do with third-party capacity. But now with all our trailers having reliable trailer tracking devices, it's easy to monitor and it's easy to manage utilization and tracking. So there is clearly more discussion about that third-party capacity usage of trailers today than we would have had five or six years ago here at Landstar. Okay, that makes sense. I guess for my follow-up question, Jim, you touched on it in your prepared comments, but you guys are just experiencing extremely rapid growth here.
36:26 and many more. to the degree that growth continues. How are you thinking about the need to maybe invest in additional headcount? Do you feel like that you've got any areas where you may need to add folks, just as you think about keeping that growth engine going, I guess. I'm just curious if there's some areas of additional investment that may be needed or if you feel like you're in a good spot.
37:08 Absolutely, I think there's going to be additional investment. I'll tell you the scenario that's going on this year is, you know, we came into this year, we had our target for the year coming out, you know, at the end of 2020. You know, we kind of internally here, we have internal budgets, targets for volume, you know, truck volumes and rates and all that kind of stuff. And we kind of base our head count on what we think that's going to be. Because we do, you know, we handle all the payables and receivables and all the transaction processing here. on behalf of the agents. So we do have a decent-sized group of people who are transaction processing. They're all working at home today, and it's working fantastic, actually. I think they like it, and productivity's been fine. But with the volume exceeding what we anticipated, there's clearly been some headcount ads. Early summer this year, we're sitting down with the administrative group going through The throughput of number of calls, revenue, the receivables people make.
38:02 And there's a backlog. So we jumped on it. We quickly approved about 30 people to handle payables and receivables. So yeah, you're going to see some headcount additions that'll drive. So when I talk about that $4 or $5 million just from a year, just from salary increases, you're going to see another couple million or more as we add headcount as the volume increases throughput. But it's not... Clearly, the revenue is going to offset anything we put in the system because we do have efficiency, so it's not anything where you're like, for every 100 loads, you've got to add a head. That's not the kind of way it works here. With the new systems we're putting in and everything like that, new workflows we've put in and they're starting to put in, we'll be able to get more throughput per head, but we're still not going to overburden our people.
38:49 We've got to keep an eye on how hard they're working and if they're doing any overtime or stuff like that. Yeah. There will be more headcount coming in from that standpoint. And we have also enhanced our IT department. If you think back to about four or five years ago, we were pretty much a mainframe company in RPG coding, stuff like that. We didn't have a lot of app developers or website-type people, so we have made a transformation. Rick Coro came on in 2017, and he's kind of transformed the IT organization to move to cloud-based as opposed to just the old mainframe stuff. So we have mainframe people and we've converted now into, we also have groups of people who go into the new world and the new technology, handling it whether it's cloud-based applications or operational data stores and the information highway.
39:37 So there's that stuff. But that's kind of already baked in. Those people are baked in and there might be a few more of those people coming in. But it's more of the transaction processing people that you'll see coming in and some headcount growth. Okay, that's really helpful. Thanks for all the colors, Jim. Appreciate it. Thank you so much. Our next question is from Stephanie Moore of Truist. Your line is now open. Hi, good morning. Morning. I wanted to touch a little bit on the commentary and the release just about that for what you're seeing thus far into October, you're seeing both revenue per load and loads really following normal consistent sequential patterns. So I'm just curious, I think that's kind of an abnormal Abnormal trends that we've just seen throughout 2021 and given all that we're seeing with supply chain disruptions and record low inventory levels, just curious on what you think is driving that return to more sequential trends into the fourth quarter.
40:40 And at the same time, what are your thoughts of going into the first quarter? I think last year we saw an extension of the and many more.
41:09 It's, you're not going to, you know, the supply chain disruption and the demand dynamic has been around now for quite a while, six or seven months, and sooner or later it's going to stabilize. And I think what we're saying is, we're kind of saying that we're seeing some, you know, coming in October that we're, or for the fourth quarter we're actually anticipating some stable, the stable seasonal trend, not necessarily to continue to grow because, you know, you just feel that supply chain disruption, you know, and the lack of capacity has leveled off. Look, it's a very strong freight environment, it's gonna stay very strong, but that doesn't mean it's gonna drive another step up in above seasonal norm. The other thing that you're thinking, so we're seeing that October. The other thing that, you know, there's a lot of talk about, you know, what's going to happen December. I think December's a little unpredictable right now.
41:58 I know there's a lot of ships off the West Coast, and that's probably going to carry into December and all that freight market. But there was talk early on about how everybody pulling all their freight earlier so December's not that backlogged, and they're trying to get people to order their Christmas gifts early. So does December start to pull back a little bit? Now, I don't think that's going to happen, but there is a little bit of talk around here about maybe – Maybe we're going to see this heavy demand and pricing come through December and then maybe it starts pulling back. I don't think that's what happens. But as to the current trends, I think it's really just to do with we're at peaks right now and I'm not sure that we're going to see any change in the capacity tightness or the environment. So stable seasonal is kind of what we're seeing coming into October.
42:44 And as to the first quarter, look, like I said, and many more. but it turned into a full, you know, another nine months of strong consumer demand on building products and appliances and all the other stuff they're buying. Will we see a, look, the first quarter this year was a very good quarter. Comps year over year are going to be tough in the first quarter, even if it's a strong first quarter. That's about all I got on the first quarter.
43:31 I think it's just right now a little hard to predict what's going to happen since the environment we're in is an environment I honestly haven't have been in since my time here at 25 years. No, that's really helpful. Thank you so much.
43:48 All right. Thank you so much. We have two more questions on queue, and the next one is from Bruce Chan of Defo. Your line is now open. Hey, good morning, gents, and thanks for taking the question. Jim, I just want to go back real quick to your comment on BCO utilization. I think you mentioned a 6% decrease is that just vacation and time off like you talked about back in 17 and 18 when great's really good or is there something else going on there?
44:14 Yeah, Bruce, this is Joe. I think it's a few different things that play into that. I think one is, you know, they're making a decent amount of money and I think some percentage of BCOs, they've got a target of earnings they want to make in a given year and once they surpass that target, they tend to slow down a little bit. I think that's part of it. I think there's still, you know, a COVID risk element to some of the utilization and we're starting to hear more recently that, you know, as trucks need repairs. Some of the parts for those trucks are just, you know, what used to be something you could take care of over the weekend. Now it takes a week and a half to get the parts and get the truck back on the road. So I think it's multiple factors that lead to that. And I don't, you know, I don't have specific percentages by, but I mean, those are the kind of things that we're seeing and we're hearing as we talk to our guys that are sitting for any length of time. And it's usually, you know, one of those kind of reasons that they come up with.
45:12 Okay, that's helpful. And, you know, I know everyone's sick of talking about COVID right now, but you mentioned that retention rates for BCOs were good right now. And, Joe, maybe just a follow-up question on the ETS vaccine mandate or potential mandate for drivers. You know, as you're looking at that proposal, is that a concern for you, or is it maybe a benefit given your IC composition? You know, do you think vaccine-related attrition is going to be something that shippers, you know, should be or need to be worried about?
45:40 Well, I think from a federal standpoint, the mandate for federal contractors, of which we are one, I think it's really too early to tell how the impact is going to play out there because the specifics really haven't been determined or released yet. Clearly, we have more than 100 employees, so people in the office or here maybe have a different impact to us than would be others who service government installations. If that's BCOs, does that apply to them or not? I think that customers, as they go about trying to figure out what the mandate means, I think they're right now, from what we've heard from a handful of customers, very exploratory as to if this happens, what happens. We don't have a sense right now as to Thank you for joining us.
46:44 Thank you for joining us. I think it's a little early because they don't have a lot of specifics out of OSHA on the one hand. And then, you know, again, customer by customer depending on how they feel they need to implement on the other side. Okay, great. Thanks for that. And just a real quick point of clarification. You mentioned that you can still grow earnings in a 10% pullback type scenario. Was that specifically demand pullback or was that 10% on total revenue?
47:30 I think I didn't say that we could grow – I thought – I don't think I said I could grow earnings. I think I could, in a 10% pullback scenario, I think we could not grow 10%. In a 10% pullback in the market, I think is what I meant to say, I think we could still either hit or grow earnings a little bit. Okay, super helpful. Just based on the tailwind of the expenses. Got it. Thank you. Thank you so much. Our last question on cue is from Todd Fowler of KeyBank Capital Markets. Your line is now open. Great. Thanks and good morning. Jim, listening to the call, you're almost starting to sound like a little bit more of an optimist, but I'll let that be determined, I guess.
48:14 It's pretty difficult not to be happy today. I tried. Look what it takes, Todd. I thought that. To be a pessimist with these results, it's difficult. So, no, congratulations. So I guess what I wanted to ask about, you know, the strong volume growth, you know, you guys are going to end this year if the fourth quarter comes together over 20%. You know, how do you help us think of or can you help us think about, you know, how much of how sticky some of that volume growth is? I mean, I think that there's a perception that you're much more transactional. but I know that some of your underlying business has some stickiness to it so is there a way to think about how much of that volume is really considered overflow and transactional would go away in a more balanced market or how much of that you really keep on a kind of recurring basis as we move into next year?
49:03 I would think the sticky stuff clearly the drop and hook is 30% of our business about so I mean that's clearly sticky business government I mean we're kind of playing that they're committed to us we're committed to them on the government side Automotive's a little more, you know, that less sticky. You know, when demand's high, we do better. When demand is low on automotive, but supply chain disruption is good for us, which is what you talk about there. Hazardous, you know, if you look at hazmat in the A and E, that hazmat stuff, you know, every one of our BCOs is hazmat certified. So that isn't true for a lot of the carriers out there. So we have 11,000 guys who can haul hazardous materials. So everybody comes to us for that. So if that market's hot, Thank you for joining us. on the drop and hook operations. It's a decent sticky.
50:11 Do I know the exact number? But, you know, it's clearly more than half as sticky. You know, if I were really thinking about the true spot world where people are just calling us, we're moving one load for a guy, and then they're leaving us, that's not a big piece of the business. When we talk about being in the spot world, it's really, you know, from a customer standpoint, not necessarily spot, the rates move up and down, right, for these customers. We're really buying capacity in the spot market. We look at it two different ways. We live in the spot world as it relates to capacity, but a lot of the relationships we have with our customers, is it sticky? Is it guaranteed that we're going to move people's freight? Absolutely not, but I think they're a little bit sticky as it relates to agent relationships and being able to provide capacity in tough times, and they kind of stick with you, especially if we're throwing trailers at them or moving their hazmat or helping them with a situation.
51:01 But putting a percent on it would be difficult. Yeah, no, I understand that it's a tough question, but that context is helpful, and what it sounds like is that just the overall base of the business has moved up pretty substantially, and now going forward, there'll be some cyclicality and some seasonality, but it's off of a higher base, and it's not that we're going to revert back to 2019 levels as soon as things normalize.
51:22 Yeah, I wouldn't expect. The great thing about the agent model is they build the relationships, and it's When people need capacity like this, and it just elevates us. You know, you're going to see us cycle back. I don't think there's any question, but then we launch higher, and you've seen it since our inception. I haven't given a chance to be a pessimist, and you didn't take the bait on that one. So, hey, just my last one, maybe, Fred. You know, in the past, I think that there's been some metrics around, you know, how much cash you want to keep on hand, maybe as a percent of revenue or total assets. As far as cash, we obviously have way more cash than we need to run the business.
52:21 We've deployed it successfully historically with dividends, share buybacks, special dividends. And I think that makes sense going forward. I personally prefer share buybacks to any kind of special dividends, but that's just kind of how I think about it. And so I think we'll continue to do that. And as far as deploying it through other opportunities, we'll keep our eyes open to see if there's any potential M&A kind of opportunities. But we haven't really historically done a lot of that. Thank you. Thank you.
53:14 In an environment we're in, you can see our receivables just grew over a billion dollars for I think the first time in our history. And it's a little bit of, it's not a, we are definitely cash flow positive. But when things start to soften up, we become bigger cash flow, you know, we're collecting more, paying less. So cyclicality, you know, as things, and if things do pull back, we end up actually bringing in more net cash during that period and have more opportunities. So it's the model kind of protects itself in any environment. and like Fred said, if you go back, we haven't borrowed in a long time against our revolver to buy stock, which is, there's two times we've borrowed on the revolver. Once is when I think we were buying stock pre-2010 and the other one was because we had that We had that contract with the FAA where we actually had about $275 million due from the government. They didn't pay until the tasks were done.
54:02 It was all – that's how the contract was written, so we needed to borrow then. But, you know, do we need to keep cash on the balance sheet to run the business? We don't really have a set in mind. I don't see us borrowing to do a buyback program. Some of that cash is collateral for our insurance claims, so what you see on the balance sheet is there's some of it is locked up, but, you know, we – We kind of more look at how much cash do we have and how do we deploy it to shareholders. And that's kind of what we've done historically, as you know. Yeah, yeah. No, that helps. That makes sense. All right, thanks a lot for the time this morning, guys. Congratulations again. Sure, Todd. Thanks. Yep. Speakers, at this point, we do not have any more questions on queue. You may continue.
54:47 Thank you, and I look forward to speaking with you again on our 2021 Fourth Quarter Earnings Conference call currently scheduled for January 27th. Thank you so much everyone and that concludes today's conference. Thank you all for participating. You may disconnect your lines at this time.
Follow Landstar System, Inc. into a list and get an email when it puts out news.
President and CEO
Vice President and CFO
Vice President and Chief Commercial Officer
Vice President and Chief Safety and Operations Officer