Replay available
AMG Critical Materials (Euronext:AMG) Q1 2026 Earnings Call
AMG Critical Materials (Euronext:AMG) Q1 2026 earnings call, held 2026-05-07. Watch the replay and read the transcript on 6ix.
- Company
- Amg Critical Materials N.V. (EURONEXT:AMG)
- Period
- Q1 2026 earnings call
- Date
- Thu, May 7, 2026, 3:00 AM ET
- Replay
- Watch the replay on this page · 35 min
- Results news release
- AMG Announces Results of its 2026 Annual General Meeting · Thu, May 7, 2026
On 6ix: 6ix.com/event/amg-critical-materials-nv-amvmf-q1-2026-earnings-call
Replay
Transcript
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:00 Good morning, everyone, and welcome to today's AMG First Quarter twenty twenty six Earnings Conference Call. At this time, all participants are in a listen only mode. Later, you will have the opportunity to ask questions during the question and answer session. You may register to ask a question at any time by pressing star, then the number one on your telephone keypad. Please note this call is being recorded, and I will be standing by if you should need any assistance. It is now my pleasure to turn the conference over to Thomas Swoboda. Please go ahead. Yes. Good day, everyone, and welcome to our first quarter twenty twenty six earnings call. As usual, joining me on this call is the entire AMG management board, namely Doctor. Heinz Schimmelbusch, the Chairman of the Management Board and Chief Executive Officer Mr. Jackson Bunkel, the Chief Financial Officer and Mr. Michael Conner, the Chief Corporate Development Officer.
1:03 We published our first quarter twenty twenty six earnings press release yesterday along with the presentation for investors, both of which you can find on our website. They include our disclaimers about forward looking statements. Today's call will begin with a review of the first quarter twenty twenty six business highlights by Doctor. Schimmelbusch. Mr. Connor will comment on strategy and Mr. Dunkle will comment on AMG's financial results. At the completion of Mr. Dunkirk's remarks, Doctor. Schimmelbusch will comment on outlook. We will open the line to take your questions thereafter. I will now pass the floor to Doctor. Schimmelbusch, AMG's Chairman of the Management Board and Chief Executive Officer. Doctor. Schimmelbusch? Thank you, Thomas.
1:55 Ladies and gentlemen, our focus on a broad portfolio of critical materials and technologies for the energy transition is increasingly paying off. In Q1, we achieved an adjusted EBITDA of $44,000,000 a 2% improvement compared to $43,000,000 in Q4 twenty twenty five. This is better than expected initially driven by the consolidation of beginning 01/01/2026. Beyond circular molybdenum, our bought recycled tungsten into our Critical Materials portfolio and the tungsten price performance helped their results.
2:41 On April 9, we increased our capital by 10% successfully placing shares at €34 per share. The capital increase was oversubscribed four times. The proceeds of €127,000,000 will be used to finance expansions into lithium, high purity molybdenum and vanadium. These projects have low capital requirement, short implementation times and quick payback. We are laying the groundwork to play a key role in achieving energy and critical materials sovereignty in Europe and The U. S.
3:27 The capital increase makes sure that we can implement the earlier mentioned projects in any given geopolitical environment. I will now hand over to Mike Conner. Mike? Thank you, Heinz. Good morning, everyone. In the first quarter, our markets have remained resilient despite the conflict in The Middle East. While we may see some limited impact from higher energy costs, particularly in Europe, and potential volatility of vanadium feedstock later in the year, the broader effect has been to reinforce the key structural trends already underway: electrification, energy security, supply chain localization, and recycling.
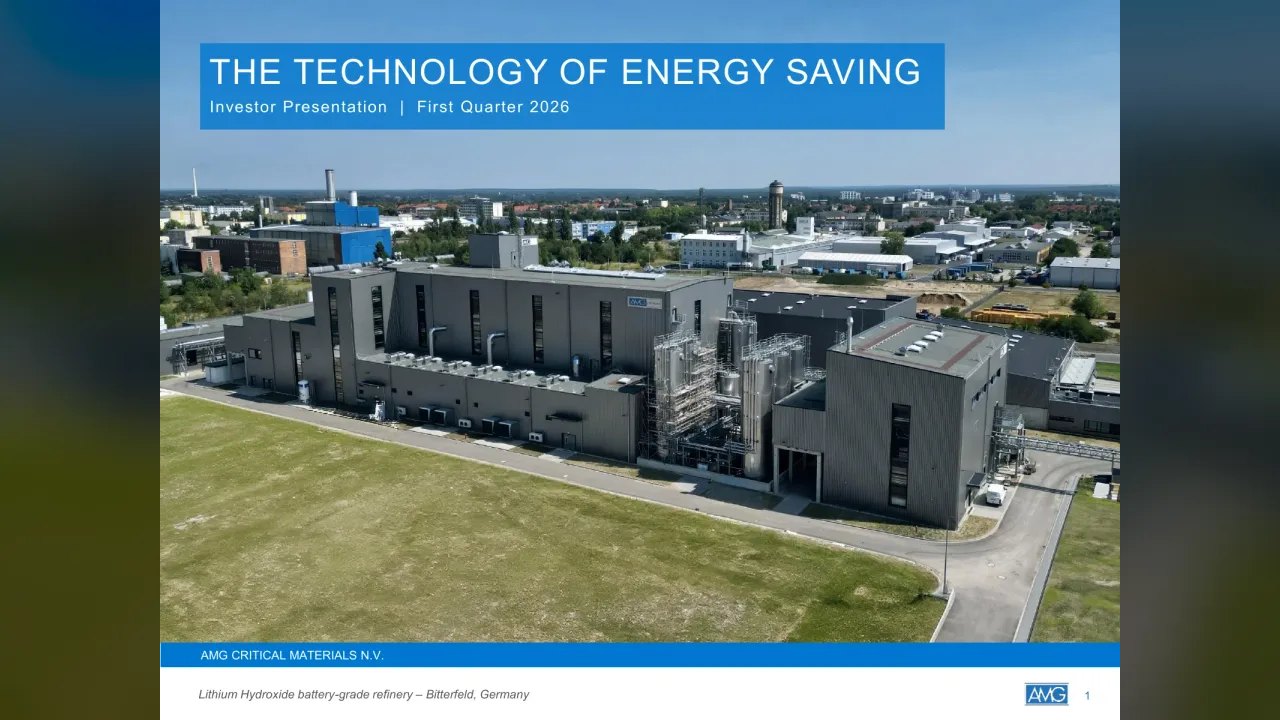
4:14 AMG is uniquely positioned to capitalize on these trends, which remain central to our strategy. And we will continue to aggressively pursue growth opportunities. Pricing across many of our key materials, including lithium, tantalum, and vanadium, improved during the quarter. These gains are supported by structural tailwinds from global trends, underpinning a more resilient and constructive pricing environment over the longer term. In lithium, Brazil delivered production in line with guidance, and we entered the second quarter as we enter the second quarter, higher realized prices and volumes are expected to drive meaningful step up in profitability. At Bitterfeld, we are ramping on plan, consistently producing battery grade lithium hydroxide within specification and generating initial sales and gross profit and early validation as we move toward full commercial production.
5:15 We are also advancing a carbonate to hydroxide conversion plant to process additional recycled feedstock, improving our cost efficiency and flexibility, supported by a German government grant as previously announced. In vanadium, fundamentals remain supported by steel demand and growing interest in grid scale energy storage, particularly for long duration applications. Our recycling and upgrading capabilities position us as a differentiated and sustainable supplier. Strategically, we continue to expand our global footprint. In The Kingdom Of Saudi Arabia, our supercenter project with Shell is progressing on schedule, with engineering complete and key equipment deliveries planned for later this year, positioning us to play a central role in the kingdom's industrial and energy transition strategy.
6:12 In parallel, AMG's LEVA hybrid energy storage system deployment for Aramco further supports the development of an integrated vanadium value chain in the region. In The United States, we are opening our chrome metal facility in New Castle, Pennsylvania, creating domestic production of materials designated as critical for aerospace, defense, and energy applications. The Aura acquisition performed ahead of expectations in the first quarter, driven by strong performance in tungsten markets. This early outperformance highlights the quality and resilience of the business and reinforces the strategic rationale for the acquisition. In addition, HORA provides a strong platform for our expansion into high purity millibile, where we see clear opportunities to leverage our existing recycling and processing expertise to drive further growth and value creation over time.
7:11 During the quarter, we also strengthened our balance sheet through an equity raise and now expect to close the graphite divestiture in the second quarter, sharpening our focus on core energy transition materials. Overall, the first quarter reflected solid execution and building momentum. We entered the second quarter with improving market conditions, expanding capacity, a clear strategic vision, and continued focus on disciplined execution and long term value creation. I will now pass the floor to Jackson Dunckel. Jackson? Thank you, Mike. Starting on Page four of the presentation, you can see that Q1 twenty six adjusted EBITDA decreased 24% versus the same period last year.
7:59 This is primarily due to the exceptionally strong profitability from AMG Antimony in Q1 of last year. On the lower left, can see our net income attributable to shareholder of $12,000,000 during Q1 'twenty six was more than double the $5,000,000 in the first three months of last year, aided by a write up of our lithium inventories. On Page five, you can see the price and volume movements for our key products represented by arrows, which underscore our segmental results. I will cover these price and volume movements for the individual segment comments. AMG Lithium results are shown on Page seven. On the top left, you can see that Q1 twenty six revenues increased 89% versus the prior year, driven by the startup of the Bitterfeld plant, which sold unqualified battery grade lithium hydroxide, as well as higher spodumene volumes and improving lithium and tantalum sales prices.
8:55 Q1 twenty six adjusted EBITDA was $4,000,000 compared to $5,000,000 in Q1 last year. Despite strong production in the current period, sales were impacted by shipping vessel availability and will be realized in the second quarter. Q1 'twenty five was also impacted by nonrecurring costs related to the startup of our spodumene capacity expansion, were added back to EBITDA. AMG vanadium results are shown on Page eight. Revenue for the quarter increased by 18% compared to Q1 'twenty five, due largely to increased volumes of chrome metal and ferrovanadium, as well as higher sales prices in ferrovanadium. Q1 twenty twenty six adjusted EBITDA of $21,000,000 for our vanadium segment was 60% higher than the same period in 2025.
9:46 This is primarily due to the increased volumes driven by improved spent catalyst availability from our North American suppliers, and the higher sales prices in ferrovanadium, which I just noted. The results for AMG Technologies are shown on page nine. The Q1 twenty six revenue of $2.00 $5,000,000 was in line with the $2.00 $2,000,000 in the same period last year, due to significantly higher sales at AMG Engineering, which were offset by lower sales at AMG Antimony. Adjusted EBITDA during Q1 twenty six was $19,000,000 compared to the $39,000,000 in Q1 twenty five. The segment's adjusted EBITDA in the prior period was particularly strong due to high profitability in AMG Antimony. And this quarter on quarter drop was offset in Q1 twenty six by very strong results from AMG Engineering.
10:39 Page 10 of the presentation shows our main income statement items. The key change in this page is regarding our tax expense, which was $4,000,000 for Q1 twenty six, up from $1,000,000 in the same period last year. The increase is largely attributable to an improvement in operating results, partially offset by a deferred tax benefit in Brazil, which resulted from the appreciation of the Brazilian real. Page 11 of the presentation shows our cash flow metrics. The drop in operating cash flow was driven by increased investment into working capital as both volumes and prices increased in all three of our divisions. We ended the quarter with $581,000,000 of net debt. And as of 03/31/2026, we had $2.00 $3,000,000 in cash and cash equivalents and $200,000,000 available on our revolving credit facility.
11:30 The resulting $4.00 $3,000,000 of our total liquidity demonstrates that our balance sheet is in good shape, and crucially, we have no significant near term debt maturities. Dollars 127,000,000 in proceeds from last month's placement of 3,300,000 newly issued ordinary shares will further strengthen our balance sheet. That concludes my remarks. Doctor. Schulbusch. Thank you, Jackson. Prices for many of our sales strengthened in early twenty twenty six and the backlog in our engineering business continues to historical high levels. However, as we noted last quarter, given the lag of the price effect on our profitability, we expect this tailwind to support our adjusted EBITDA in Q2 twenty twenty six.
12:25 We expect Q2 twenty twenty six to approach the level achieved in Q2 twenty twenty five aided by tantalum prices peaking and a very favorable phasing of shipments in AMG Lithium. Despite significantly increased geopolitical headwinds and hence reduced visibility, we reiterate our adjusted EBITDA range for $210,000,000 to $240,000,000 for the full year 2026. Operator, we would now open the line for questions. At this time, we will conduct a question and answer session.
13:22 You may remove yourself from the queue at any time by pressing pound and one. Our first question comes from Stinzinger with ING. Your line is open. Yes, good morning. Thanks for taking my questions. I have a couple of them, and I will ask them one by one, if that's okay. The first one is on AMG Lithium. Can you help us with the amount of spodumene volumes that were shifted from Q1 to Q2 in Brazil due to the shipping delays? Can you also update us on the operational issues in Libra and the target capacity for the full year as well as with the ramp up over the coming quarters? That's the first question.
14:15 Yes. So we had about 12,000 tons that were on the water that we normally would have expected to arrive in the first quarter, which are now arriving in the second quarter. So obviously, that's a big volume shift from Q1 to Q2. So that will impact the profitability. And we tried to one of the reasons we gave the additional guidance on the second quarter earnings relative to the first quarter. In regards to the expansion, the expansion is on track for what we guided to previously, which is that we expect to be able to produce at 130,000 ton capacity by the end of the year. Okay, understood. If you've missed out on 12,000 tons, it means that today you're already at around 100 to 110,000 ton capacity again?
15:06 Correct. Yeah. Okay. The next question is on Bitterfeld. In the press release, you mentioned revenue from unqualified biodegradable lithium hydroxide. It seems to have had a revenue contribution, but not an EBITDA contribution. Is that correct? Yes. And you can see in the EBITDA bridge that there was a positive impact regarding the impact of lithium prices on those sales. So you can see the number there, but we did not include that with our EBITDA. So it was a positive write up of inventory due to improvement in lithium prices related to LCMs that we took last year for Bitterfeld due to the drop in prices in prior year.
15:55 Seeing accounting dictates that we include the sales in our results, but we have excluded the EBITDA, which we're allowed to do. Yeah. The $21,000,000 write up is not entirely due to these volumes? No. We sold about 20 it's unfortunately the exact same number. We sold about $21,000,000 of revenue from Bitterfeld in Q1. Okay. Understood. And then related to Bitterfeld, yes, can you update us on the several qualification processes that are currently ongoing? Because in most of your businesses, you have a guaranteed off taker, for example, glenoprolin, vanadium, etcetera.
16:40 But this doesn't seem the case for Binafel. So how certain are you that you can sell those volumes, I assume, in the second half when the facility ramps up? You know, we are qualifying with several customers. We're highly confident in our ability to sell the material at both. The qualification will occur at different times for different customers, but we're continuing to move those along on schedule and are confident in our ability to place the material. Okay. Okay. And any any sort of quantum that you can commit to for the second half since you're already selling right now?
17:27 Well, it's the nature of the qualification process, but shouldn't be done. Yeah, I mean we'll be producing in spec material at full capacity by the end of the year. Okay, understood. And last one from my end, and I'll put myself in the queue because I have some others. But on vanadium, do you see an impact of the conflict on the supply spent catalysts? And if so, is there any adverse impact on second half EBITDA? Or are you sufficiently supplied from the North America suppliers today? Yeah, I mean, a majority of our feed comes from North America. We do have a certain amount of supply in The Middle East and other places internationally. Shipping globally obviously has been impacted.
18:14 We do not see an impact right now on second quarter earnings. We're running at full capacity today. We can't guarantee that there won't be interruptions later in the year. But as I said, a majority of our fee does come from America. So we're well positioned in that regard. Okay. It means that the supply issues in North America are largely Yes. Resolved Okay, thanks. That's for me. And if there's more, I will ask myself back in the queue. Your next question comes from Michael Kuhn with Deutsche Bank. Your line is open. Good morning. Thanks for taking my question. I'll also ask them one by one. Starting with cash generation, I understood that there were some shipping delays in the quarter and obviously working capital build up still.
19:10 I think 'twenty six was meant to be a year of better cash generation. Does that still hold true? And when would you expect, let's say, working capital effects to normalize and then ideally, cash generation to improve? Yeah. So Q1 is always seasonally low for cash generation. It was exacerbated by the very high volumes we produced across all three of our divisions and the increasing prices. So you can see in our cash flow statement that working capital cost us roughly $68,000,000 in the first quarter. We would expect that to largely be resolved, given that prices have flattened now and volumes have ramped, such that we should be generating cash Q2, Q3 with a much larger percentage in Q4.
20:06 That's reassuring. Thank you. Then on engineering, you mentioned the order intake and the book to bill in the release. If I do the math, I end up with close to $90,000,000 of sales in the first quarter, which I think is unusually high and above the run rate we have seen over recent years. Is that a sustainable level or should we expect some kind of normalization over the upcoming quarters? That is more or less a sustainable level. I mean, is the result of a full backlog that we're working through in 2026. So, okay, sustainable in '26, but not necessarily the years beyond or is the, let's say, client demand continuously high also in terms of, let's say, orders that you would expect?
21:09 Inbound order intake has been extremely strong. And our the basic fundamentals of the engineering business is exceptionally strong compared to some periods in the past. And it's an aerospace related upswing and we believe that to stay, obviously. We would consider today's operating results abnormal from a long term operating perspective. Okay, understood. And maybe one more on antimony. Although it has come down in terms of robust contribution, I think it's still a bigger business than it used to be. I think you were always trying to get a decent premium versus, let's say, the Chinese prices.
22:08 Is the situation evolving here? How do those premiums look like? And what should we expect in terms of results contribution from that business going forward? It is very difficult to predict. However, we believe that the spike after reversal of the spike has settled on a higher margin level related to additional demand drivers for antimony in the solar industry. And that can be seen in a couple of ways, Michael. The price outside of China, inside China has stabilized and equalized. So I think that's an important factor to look at when thinking about shipping restrictions, etcetera.
22:58 And they stabilize at a higher price because of the increased demand domestically in China related to new applications. So we believe that is a sustainable trend. Understood. Thank you. Our next question comes from Frank Clausen with Degroof Petercam. Your line is open. Yes, good morning all. Yeah, most of my questions have already been asked but one question left. Maybe on the equity issue you've done. Should we read into that that for next year CapEx levels will go up again?
23:46 So yes, maybe yes, could you elaborate what are the biggest pockets you think you want to spend, let's say, the raised money on? Could you elaborate on that? Thank you. Yes, broadly, CapEx will increase in 2027. And again, the three main projects will be our lithium carbonate project, our high purity molybdenum project, and our oh, and of course, SARBV. However, SARBV will likely be front loaded in 2026. So that's included in the 70,000,000 to $90,000,000 estimate that we have. So hopefully that helps you. But CapEx will be, you know, slightly higher in 2027 than it was in 'twenty six. I think one important note there is that we will have continued strength in operating cash flows as a result of the other investments that we've made coming online to help fund those investments in addition to the equity raise. So we feel pretty comfortable with the relative cash flow generation overall of the company moving forward.
24:59 Okay. That helps. Thanks. Your next question comes from Usama Tariq with ABN AMRO. Your line is open. Hi, good morning team. Thank you for the opportunity. I have a few set of questions. So I will go one by one. Firstly, on AMG vanadium. So the sales and EBITDA of vanadium was solid despite some disruption from The Middle East. So can we assume going forward that the vanadium is back to normal operation and can fully benefit from the increase in ferrovanadium prices going forward? So that would be my first question. It's more generalistic in nature, I would say. Yes, the answer, I think we covered a little bit earlier. But to expand on it, yes, we're running at full capacity right now. We will see the benefits of the higher pricing in the second quarter.
25:56 The pricing is tailed off a little bit towards the last few weeks. So that will impact later quarters in the year. But we've given some guidance in the second quarter that takes into account those full volumes and higher pricing. Thank you so very much. Thank you. And I'll move to the second question, if I may. That will be on lithium. So you did mention that some of the unqualified lithium hydroxide has been sold, assuming, for instance, for the traders. Can you help us understand the impact of the sales in Q1? And secondly, do you expect to this to occur into the future given the qualification is not yet completed?
26:42 Yes. So I think Jackson quoted $20,000,000 approximately for revenues in the first quarter for Bitterfeld. That number will continue to increase throughout the year as production reaches full commercial levels. Okay. Thank you. That will be just one more question if I may, then I'll go back into the queue and that will be on technologies. So profitability was higher than expected. If you analyze Q1 and deduct the $30,000,000 in EBITDA from engineering, it suggests that the antimony businesses, despite the 30% decline in price, generating annualized EBITDA of 45,000,000 Do I understand correctly from the previous questions that do you see this as more of a normal going forward?
27:33 Or do you still think this is a little bit more optimistic? Well, think as Mike said, we expect antimony profitability to remain where it is. In terms of how you got to your numbers, I think we'd like to take that offline with you. Okay, thank you. Thank you. That will be all. I'll go back in the queue. Thank you. Your next question is a follow-up from Stan Denister with ING. Your line is open. Your line is open, sir. Sorry, I was on mute.
28:21 Apologies. My follow-up is on Aura. Can you help us understand the quantum of the contribution of this acquisition in the Q1 EBITDA? And what kind of EBITDA should we be looking at for the full year from this? A bit of guidance maybe on capacities in molybdenum and Tungsten Health. Thank you. Yeah, the Ora acquisition, the big plus and benefit of it is as a platform for further expansion. As we described previously, it's going to be the platform for high purity molybdenum production in the future, and that's an investment for us over the coming months. The contributions today are not hugely significant, but they did have a decent impact on the first quarter, but relatively small single digits.
29:15 And what kind of volumes are you currently generating? Yeah, we don't disclose the volumes. It's a little complex as far as the production. But it's a small level today. Okay, understood. Thank you. That's it for me. Your next question is a follow-up from Usama Tariq with ABN AMRO. Your line is open. Hi, thank you. Just one or two follow-up questions. So you mentioned that you received R and D tax credits in Germany. I'm sorry if I missed it out. Would you be able to quantify the magnitude of it? Was it low single digit or mid single digit, anything on that?
30:04 It is 20% of the total expenditure, which we have said is $50,000,000 Okay. No, no, sorry. The tax credits Oh, tax credits, not the Low single digits. And please note that that is not included in the EBITDA because it's for Bitterfeld. So our EBITDA was not positively impacted by that number. Okay. Thank you. That will be all from me. Thank you. Thank you. Your next question comes from Martin Burby with WTE Idea. Your line is open. Good morning. It's Martin Burby of DID.
30:50 Firstly, your guide that your adjusted EBITDA of the second quarter will virtually match last year's. Could you more or less indicate what kind of profits of antimony you have to compensate to arrive at that level? Would it be some $25,000,000 Is it a fair assumption? We're not I mean, we haven't given any guidance on antimony profitability up or down. So we can't really bridge you. I will say that approaching last year's profitability will be largely driven by lithium and vanadium prices. So those are the two key items.
31:37 But in terms of bridging the antimony gap, that's not really in our mind. Okay. Secondly, when presenting the full year results, you mentioned that guidance you guided to between $210,000,000 and $240,000,000 And the current price levels of the key products would indicate at the upper end. According to me, those have all edged up even a bit further. So what has hold you back to even sharpen your outlook guidance for the year? We have scenario plannings routinely updated and they come to the conclusion of that range.
32:30 And we are assuming that you when you read that range think that we are conservative and so probably you tend towards the upper number of that range. Martijn, I mean there's certainly a good amount of geopolitical uncertainty in the world today which limits visibility for the latter part of the year. And additionally, you noted prices have creeped up, but that's not true across the entire portfolio. So if you look at vanadium and tantalum, for example, in recent weeks have trended downward, the medium in The United States particularly.
33:15 So it is a little bit of a mixed bag. Lithium continues to strengthen obviously. But as I said, we run multiple scenarios with multiple price environments and are confident in our current guidance. I don't see the delta on this downward trend. It's from a very high level to a less high level, which is an upward trend corrected to a less upward trend. So and it's interesting to note that in March the tantalum price was $200 or higher. And in such a constellation you get our lithium thing for free because breakeven price for lithium at the constellation of 200 tantalum zero, Thank you very much. Which means that we are the lowest cost mine on the world's scale.
34:19 At this time, it appears we have no further questions. I would like to turn the program back to Thomas Swoboda for closing remarks. Yes. Thank you very much for your interest and all the questions. I'm sorry if we couldn't take all the follow ups. We are heading to our AGM today and we will be very busy being on the road. So hopefully, we can catch up with you in person soon. Morgan, thank you very much. Thank you. This does conclude today's AMG first quarter twenty twenty six earnings conference call. Thank you for your participation. You may now disconnect and have a wonderful rest of your day.
Follow Amg Critical Materials N.V. into a list and get an email when it puts out news.
Latest news releases
- Euronext:AMG — AMG Lithium Projects Recognized by European Commission · Fri, Oct 9, 2026
- Euronext:AMG — AMG Critical Materials N.V. Publishes Annex IX Information Document ahead of Listing on the Frankfurt Stock Exchange · Fri, Sep 25, 2026
Companies on this call
More from Amg Critical Materials N.V.
- Jul 30, 2026 AMG Critical Materials (Euronext:AMG) Q2 2026 Earnings Call
- May 07, 2026 AMG Critical Materials (Euronext:AMG) Q1 2026 Earnings Call
- Feb 26, 2026 AMG Critical Materials (Euronext:AMG) Q4 2025 Earnings Call
- Nov 06, 2025 AMG Critical Materials (Euronext:AMG) Q3 2025 Earnings Call
- Jul 30, 2025 AMG Critical Materials (Euronext:AMG) Q2 2025 Earnings Call
- May 30, 2025 AMG Critical Materials (Euronext:AMG) Q1 2025 Earnings Call