Ray Iardella
Head of Investor Relations
Replay available
Accelerant Holdings (NYSE:ARX) Q1 2026 earnings call, held 2026-05-14. Watch the replay and read the transcript on 6ix.
On 6ix: 6ix.com/event/accelerant-holdings-arx-q1-2026-earnings-call
Automated transcript · Written by software from the replay's audio. It can mishear names and figures; the replay is the record.
0:00 Thank you for standing by. My name is Jaylen, and will be your conference operator today. At this time, would like to welcome everyone to the Accelerant First Quarter twenty twenty six Earnings Call. All lines have been placed on mute to prevent any background noise. After the speakers' remarks, there will be a question and answer session. I would now like to turn the conference over to Ray Iardella, Head of Investor Relations. You may begin. Thank you, operator, and welcome everyone to Accelerant's first quarter twenty twenty six earnings conference call. Joining me on today's call are Jeff Radke, Accelerant's Chairman and CEO Linda Hubert, CFO and Ryan Schiller, Head of Strategy.
0:47 The remarks will be followed by a Q and A session. Yesterday, we issued a press release related to our first quarter twenty twenty six financial results, filed our Form 10 Q and have also posted our updated investor presentation. All of these can be found on our IR website at www.investor.accelerant.ai. Before we get started, I'd like to remind you that our remarks today will include forward looking statements, including those regarding our future plans, objectives, expected performance and in particular, guidance for second quarter and full year 2026. Actual results may vary materially from today's statements. Information concerning risks, uncertainties and other factors that could cause these results to differ is included in our SEC filings, including those stated in the Risk Factors section of our funds with the SEC.
1:33 These forward looking statements represent our outlook only as of the date of this call. We undertake no obligation to revise or update any forward looking statements. Additionally, today's discussion will include both GAAP and non GAAP financial measures related to both our consolidated results as well as our operating segments. Reconciliation of any non GAAP financial measures to the most directly comparable GAAP measures is set forth in our earnings release. Non GAAP financial measures should be considered in addition to, not as a substitute for GAAP measures. Finally, today's conference call is being webcast and recorded. Now I'll turn the call over to Jeff. Thanks, Ray, and good morning, everyone. Before we dive into our discussion, I'd like to welcome Linda Huber, our new CFO, to her first earnings call at Accelerant.
2:19 Linda joined us about two months ago and her impact across the finance organization can already be felt. Welcome to the call, Linda. Moving to my comments about the business. We had a fantastic first quarter, reflecting strong momentum across our platform. Once again, we exceeded the midpoint of our quarterly guidance across exchange written premium, third party premium and adjusted EBITDA. We also continued to compound and deepen our data moat during the quarter, adding an additional 22,000,000 rows and 4,000 incremental risk attributes. Our mantra from the very beginning of Accelerant has been no data left behind. We capture and ingest exposure characteristics, price per exposure, policy provisions, geospatial information, public sentiment vectors, and environmental features, just to name a few.
3:14 Today, we have 156,000,000 rows of information across more than 62,000 unique risk attributes, further widening our position as having the largest usable decision ready specialty insurance data set. You might be asking, so what? And I think that's a fair question. The so what for Accelerant is higher growth with better loss ratios and minimal churn from members or risk capital partner. How's that? We leverage this proprietary data through closed loop AI native system to enhance underwriting decisions. The Accelerant Risk Exchange's position in the insurance value chain allows us to quickly link underwriting submission and exposure data with claims outcomes.
4:04 Thus, our underwriting models are updated in very short cycles, nearly continuously. That feedback loop today influences tomorrow's underwriting decisions. When members can out select risk versus the market, it clearly drives profitability, but what's less obvious and more impactful is that better risk selection also drives growth in premium volume across the Accelerant Risk Exchange, and growing profitable and predictable specialty insurance risk is exactly what our risk capital partners are looking for. We discussed with you last quarter how artificial intelligence is the architecture of our business and how its use benefits members and risk capital partners alike.
4:50 Another important benefit of artificial intelligence is the productivity gains Accelerant is generating internally. We are using the latest AI capabilities to augment cumbersome workflows and are already developing beta version solutions that we believe may reduce our reliance or even replace expensive third party software systems. Additionally, we've seen significant improvements from AI within our product and technology team of engineers. They're focused on the core operations of the Accelerant Risk Exchange, and AI has become a meaningful execution enabler for us. This has led to higher output per engineer and a productivity lift of more than 24%.
5:38 We think that being able to do more with less is going to become table stakes in tomorrow's world. The ultimate winners will grow their technical workforce and deploy AI augmented teams to solve the most complex problems. Thus, our higher output allows us to move faster and faster, fund new areas of investment and deliver on our strategic priorities. In 2026, we plan to invest productivity gains into AI enabled teams across priority areas. For example, we endeavor to cut the member onboarding cycle from three months, which we believe is already three to four times faster than the industry to a matter of days.
6:26 Additionally, we will be building 20 fourseven AI enabled claims monitoring, agent driven actuarial support and early profit signals directly into our members' underwriting workflow. We are excited about our AI driven productivity, but as we scale, greater efficiency will lead to more investment and better outcomes as we continue our journey to transform the specialty insurance marketplace. Next, let me move to the six KPIs that track the health of our business. These metrics balance both sides of the Accelerant Risk Exchange, including three on the supply side and three on the demand side. All six of these metrics were in line with or better than we expected for our first quarter.
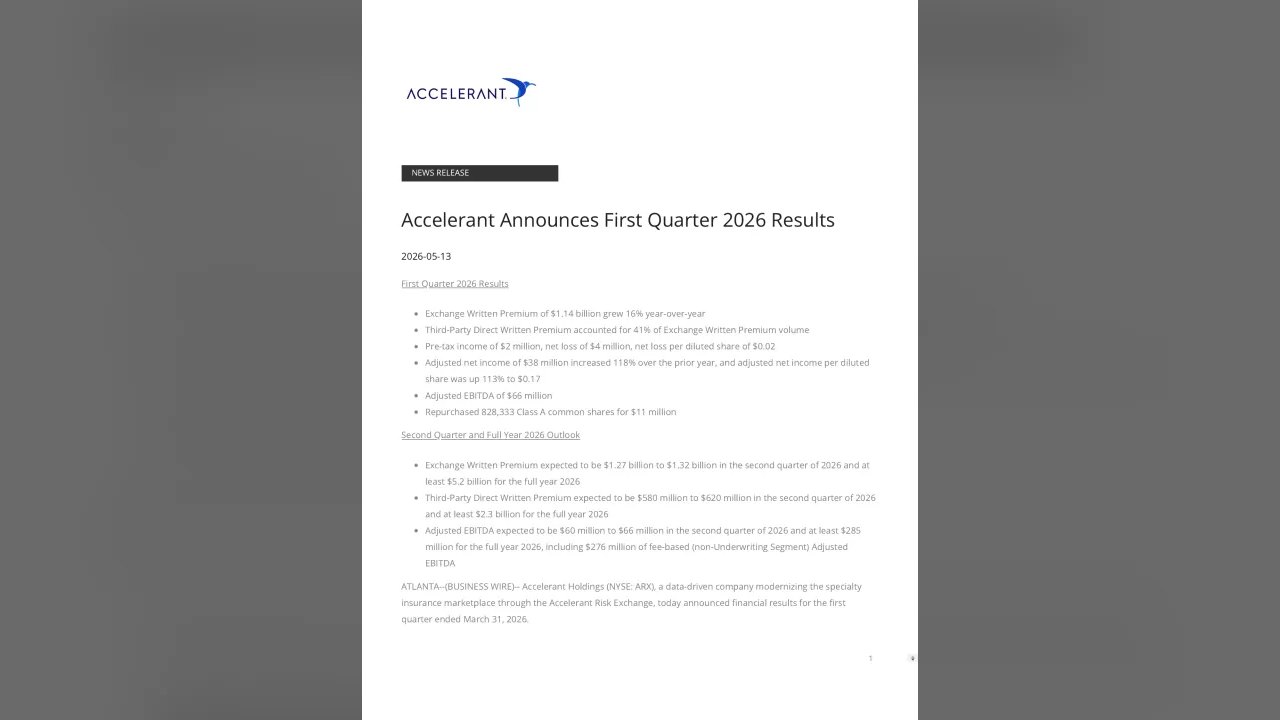
7:13 Beginning with the supply side, exchange written premium was $1,140,000,000 in the first quarter, above the high end of our expectations. This translates to headline year over year growth of 16%. Now importantly, that growth would have been 22%, excluding the large premium, low margin member that we terminated at the end of Q2 last year. Our second KPI is our member count. We added 16 new MGAs during the first quarter, similar to our average over the past four quarters of twenty twenty five. That brings the total to two ninety six member MGAs. These new members were added across numerous geographies, including The U. S, Canada, UK and EU and offer specialty insurance coverages that run the gamut from management liability to captives.
8:12 The third and final supply side KPI is net revenue retention. We define net revenue retention as the trailing twelve month exchange written premium growth of our pre existing members year over year. That includes terminated members. First quarter net revenue retention was 116%. That continues to demonstrate the edge that our proprietary data, tools and platform provide our members. Again, it's worth noting that the net revenue retention would have been 122% if we excluded the one off terminated member. Moving to the other side of the platform, the first of our three demand side KPIs is gross loss ratio.
8:59 The gross loss ratio is a key profitability measure of the business produced for our risk capital partners. For the first quarter of twenty twenty six, the gross loss ratio remained very attractive at 52.1%. That increase of 80 basis points over the full year 2025 figure is primarily due to seasonal differences in business mix. The second demand side KPI is third party direct written premium. This metric measures our ability to attract non Accelerant insurers to participate on the risk exchange. We continued to make progress during the first quarter with 41% of exchange written premium going to third party insurers. That's up from 19% in last year's first quarter and up from 30% for the full year of 2025.
9:53 Over the medium term, our goal is for third party insurers to represent two thirds of the total exchange written premium. Additionally, we continued to mix away from hadron during the quarter. Ryan will comment further on this in his remarks. The third and final KPI on the demand side is our net retention. That's defined as the trailing twelve month ratio of premiums we retain in relation to total exchange written premium. This ratio was 10% for the trailing twelve months, which is in line with our expectations and where we expect to be for the full year of 2026. Our objective is to pass along the favorable underwriting economics to our risk capital partners in exchange for fees, not to grow our share of net premiums.
10:45 In summary, we had an excellent quarter of performance against all six of our KPIs. This continues our positioning to be the rails on which specialty insurance runs and delivering long term value to our shareholders. I'll turn it over to Ryan to cover Accelerant's risk exchange metrics in more detail. Ryan? Thank you, Jeff, and good morning, everyone. Today, I will begin with the demand side of the platform. We ended the first quarter with 96 risk capital partners in line with our strategy of maintaining a diverse group in order to maximize the stability and efficiency of our platform. Total third party written premium this quarter was 462,000,000 versus a 184,000,000 in the first quarter of last year. We currently have eighteen third party insurers and are actively engaging with a range of potential new partners.
11:37 When we grow with third party insurers, we are less dependent on our balance sheets, increasing Accelerant's capital lightness. Additionally, we are continuing to work on reducing the concentration of Hadron within our third party insurers. Consistent with our plan, Hadron's gross written premiums were just 41% of third party premiums in Q1 twenty twenty six, down from 67% in Q1 twenty twenty five. We have executed well on the shift away from hadron, decreasing the percentage of third party premium to 58% in Q2 of twenty twenty five, 54% in Q3, and 47% in Q4. Looking ahead, we continue to expect hadron to mix down further to 35% to 40% of third party premium for full year 2026, including less than a third in the fourth quarter.
12:27 Shifting to the supply side of the platform, we delivered $1,140,000,000 of exchange written premium, a 16% increase from last year's first quarter. And as Jeff noted, year over year growth would have been 22% excluding the terminated member. That's a really strong result, especially considering the low to mid single digit growth of the commercial P and C industry. Existing members represented more than 90% of our growth in the first quarter of twenty twenty six. That's driven by higher premium volume on existing insurance products and incremental products being offered and written with the Accelerant Risk Exchange. Over the past year, existing members have added more than 100 products to the Accelerant Risk Exchange. The balance of the exchange written premium growth was driven by the addition of new members, while rate was not a significant driver of our premium growth at just 1% during the quarter, with greater increases in The US versus our international business.
13:19 Our book of business is not cat exposed and is focused on low limit and low premium specialty policies within the commercial SME space, both admitted and non admitted. The book of business is made up of thousands of policies with 95% of them less than $10 in annual premium. These policies are much smaller than even the CIAB's small business cohort, which is consistently referenced as seeing more stable rates given their size. The bottom line is exchange written premium is not as meaningfully impacted by the insurance pricing cycle, including what you're reading about across E and S property lines. Moving to our member growth. We continue to believe member count is a good leading indicator for future exchange written premium. In the first quarter, we added 16 new members, which was just a bit above our plan. Make no mistake, we are not just looking to add volume for member growth, anyone can do that. Rather, we are undertaking significant due diligence on each new potential member, analyzing their underwriting, and making sure their targeted business aligns with our value proposition to our risk capital partners.
14:21 Looking ahead, we have more than $4,000,000,000 of annualized premium in our member pipeline at the end of the first quarter, which makes us excited about the remainder of 2026 and looking forward to 2027. In summary, Q1 twenty twenty six was another excellent quarter of execution with a stable but increasing diverse group of risk capital partners and continued member growth. The Accelerant Risk Exchange is well positioned to balance the increasing supply and the rising demand across the platform. I'll now turn it over to Linda to discuss our financial performance in more detail. Thanks, Ryan, and good morning, everyone. I'm excited to participate on my first earnings call with Accelerant as CFO. Today, I'll be discussing our quarterly financial performance and will walk you through our guidance for 2026. Now as you heard this morning, we had a great first quarter with continued strong growth in operating revenue and adjusted EBITDA.
15:10 Overall revenue was up 54% over the prior year $273,000,000 Operating revenue, which is before the impact of realized and unrealized investment gains and losses, was up 57. We posted pretax income of $2,000,000 a GAAP net after tax loss of $4,000,000 and adjusted net income of $38,000,000 The reconciliation of our non GAAP adjusted net income can be found in our earnings release. The largest driver of the difference between GAAP and adjusted net income was share based compensation expense. This quarter includes approximately $8,000,000 related to the acceleration of certain awards associated with the CFO transition, so we expect share based compensation expense to be lower in subsequent quarters of 2026.
16:00 Adjusted EBITDA was $66,000,000 for the first quarter compared to $39,000,000 in the comparable quarter last year. Importantly, our fee based operating revenue and adjusted EBITDA, which we define as consolidated results less the underwriting segment, grew 52112% respectively. Remember, our goal is to drive adjusted EBITDA growth within our Exchange Services and MGA operations, while continuing to keep our trailing twelve month underwriting net retention at around the 10% level. Our segment results show that we are successfully executing on that strategy. Consolidated GAAP earnings per diluted share was a loss of $02 while adjusted non GAAP EPS was $0.17 And just a reminder, we updated our non GAAP measures to exclude the impact of net realized and unrealized investment gains and losses.
16:54 We believe these updates improve comparability and better align us with others in the industry. The impact of these changes on our non GAAP results were de minimis this quarter. Now let me move on to some comments on our financial performance by segment. I'll begin with the core of Accelerant, Exchange Services. First quarter Exchange Services operating revenue was $100,000,000 up 41% over last year. That's due to the $1,140,000,000 of Exchange written premium and the 8% plus take rate we make on the premium running through our exchange. We believe the take rate will be in the mid 8% range for the remainder of the year, reflecting the strong value proposition we provide to our risk capital partners. Exchange services adjusted EBITDA was $67,000,000 leading to an adjusted EBITDA margin of 67%.
17:47 We expect adjusted EBITDA margins will be approximately 70% for the remainder of 2026. And moving now to our other fee based segment, MGA operations. This segment represents MGAs we have ownership stakes in, predominantly our Mission MGA incubation business. For the first quarter, operating revenue was $54,000,000 growing 10% year over year. That 10% growth was impacted by a little bit of timing between quarters and leveling for that year over year growth would have been in the high teens. MGA operating adjusted EBITDA was $17,000,000 resulting in a healthy margin of 31%. And shifting to our underwriting segment, which is the home of our own insurance and reinsurance company results.
18:33 In the first quarter of twenty twenty six, we generated operating revenue of $149,000,000 and adjusted EBITDA of $7,000,000 Adjusted EBITDA margin in the mid single digits was driven in part by continued strong performance in the gross loss ratio at 52.1%. Operating cash used in the first quarter was $21,000,000 predominantly reflecting the timing of reinsurance payments within the underwriting segment and to a much lesser extent increases in personnel related payments and other expenses to support our growth. Cash flow can be volatile from quarter to quarter, but importantly, we still expect to convert our 2026 fee based adjusted EBITDA to free cash flow at a level similar to 2025.
19:19 And jumping now to our balance sheet. At March 31, we had about $450,000,000 of unrestricted cash and investments outside the insurance company. That's after our first quarter repurchase of 828,000 Class A shares for $11,000,000 at a weighted average price of $13.11 per share. We find share repurchases very attractive at current levels and have repurchased another $52,000,000 so far in the second quarter. We will continue to evaluate repurchases against a backdrop of valuation, our future expected cash flows and investments back into the business. Within our insurance entities, we had approximately $630,000,000 of capital at the end of the first quarter. We expect minimal capital contributions to these entities during 2026 as we continue to grow with third party insurers.
20:12 And moving now to our financial outlook, we are providing the following financial guidance based on our strong first quarter performance and more favorable outlook for the year. In the second quarter, we expect first exchange written premium of 1,270,000,000 to $1,320,000,000 Second, third party direct written premium of $580,000,000 to $620,000,000 and adjusted EBITDA of $60,000,000 to $66,000,000 For the full year 2026, we expect first exchange written premium of at least $5,200,000,000 secondly, third party direct written premium of at least $2,300,000,000 and finally, adjusted EBITDA of at least $285,000,000 which includes fee based or non underwriting adjusted EBITDA of at least $276,000,000 And two additional comments regarding the second quarter of twenty twenty six. First, our second quarter adjusted EBITDA guidance includes eliminations in the $20,000,000 range, and the second quarter segmental adjusted EBITDA is estimated to be much higher than the consolidated figure.
21:23 Over time, we expect elimination adjustments to decline given the expected increase in the proportion of premiums written by third party insurers. Importantly, we increased our full year guidance given our confidence in continued adjusted EBITDA growth in the second half of twenty twenty six. Second, from time to time, we make strategic investments in financially attractive business partners. And in late April, there were transactions resulting in an observed increase in the fair value of an investment we had made in a third party claims administration business. We participated in the capital transactions, consult a portion of interest, and generated $52,000,000 of cash proceeds. We also expect to recognize both a realized gain on the sale and an unrealized gain on the portion we continue to hold in aggregate of $55,000,000 during the second quarter.
22:15 Our non GAAP metrics will exclude the revenue, EBITDA and net income of this transaction. So in summary, first quarter was further proof of the strength of our business model. Looking ahead, we see continued strong growth in exchange written premium and adjusted EBITDA. That positive momentum is reflected in our increased 2026 financial outlook relative even to eight weeks ago. And with that, I'll turn things back to Jeff. Thanks, Linda. Before we move to your questions, I'd like to welcome our two new independent Board members who were elected at our Annual General Meeting earlier this week, David Talich and Simon Wainwright. Both are skilled and talented executives and bring diverse perspectives, which will be valuable to the Board and the management team as we endeavor to make Accelerant the rails on which specialty insurance runs.
23:09 We are well on our way to realizing that vision. We are actively attracting and growing with the industry's most talented and entrepreneurial underwriters, our MGA members. We are making them even better with our data analytics and increasingly autonomous underwriting tools. We are connecting them to diversified, committed and high quality risk capital that is looking to generate attractive predictable returns. The growth in exchange written premium over the past year is continued affirmation of the value our platform provides to our members and risk capital partners. Operator, we will now open it up for questions. Thank you. The floor is now open for questions.
24:05 Session. Your first question comes from the line of Roland Emmer of RBC Capital Markets. Your line is open. Hi, good morning. I wanted to start on the new adds in the MGA partners in the first quarter. Looks like it was more tilted towards mission and owned MGAs. And was there anything specific that drove that? And are we reaching a point where the majority of quality MGAs are already on your platform? Hi, Roland. It's Ryan. Thanks for the question and and good morning. I so a few few odd things that happened in the quarter. One, we actually had an existing independent member that shifted to be a mission member, which was one of those in the quarter.
25:02 I still think we expect going forward just like we saw last year that the vast majority of new members will be independent members. And I think as suggested by the size of our pipeline, we don't think we're sort of touching or getting anywhere close to the bottom in terms of the opportunity out there and the number of high quality underwriters that we're we're seeing and hopefully being able to partner with. That's help. Maybe one more quick one. Can you on the fee based definition, does that include corporate and eliminations? It does. Alright, thank you. That's all I really had. Your next question comes from the line of Charlie Litterer of BMO Capital Markets. Your line is open.
25:49 Hey, thanks. Good morning. If I take your EBITDA guide as a percentage of premium for 2Q and the full year, it points to that ratio moving lower year over year both in 2Q and for the full year. I appreciate you have a lot of eliminations. You said that, that will go down over time. But given you've lowered the or sorry, increased the percentage of premium coming from third parties year over year, why would that move lower? Can you expand on what's driving that? Thank you. Yes, Charlie, great question. Particularly in Q2, I think we're expecting a higher level of eliminations than would be normal. I think we're expecting very strong segmental results and we'd expect that as you look at the full year guide for both Q3 and Q4 and what that implies, right? Some elevated performance that we expect to come through as the overall platform continues to sing.
26:52 Further, as you'll recall from prior conversations, the more and more business we're riding with those third party insurers, we're shifting more and more towards our fee based segments and away from underwriting, right? That is obviously going to reduce overall revenue, but that's a good thing. And so what we're very focused on is how are we maximizing those fee based segments and having those essentially those eliminations earned through as you write more and more business with third party insurance companies. Thanks. Switching gears, Jeff, the 10 Q, we can see you opened up a new 10b5-one plan. Appreciate you'll still have alignment via holding a significant number of shares, but wondering if you can provide some color or expand on that. Thanks.
27:48 Sure. And thank you for the question. Quite simply, it's to pay a tax bill. And as you said, I just point out to listeners, it's a small percentage of the the position that I and the and the rest of the the senior management team have. Okay, thanks. Maybe just one last one. So you're clearly having success demixing Hadron. As you move closer to that being 33% in the back half of the year, can you share how spread out the exposure from the other 17 carriers on the exchange is going to be? Are there any concentrations there? Any color? Thanks. I think our experience with Hadron, I'm not sure we needed to be taught a lesson, but we are very focused on making sure that there isn't a concentration issue that emerges in the others.
28:47 They're all terrific companies, and they're all growing really, really well. So I don't think that there'll be another concentration thing that emerges that will concern you or us. Your next question comes from the line of Robert Cox of Goldman Sachs. Your line is open. Hey, thanks. Good morning. So just looking at the share buyback, numbers are really strong in the first, call it, few months here relative to your outstanding authorization. But my question is on the cash in the non regulated entities. I think the firm has around $450,000,000 in cash and investments in the non underwriting entities.
29:33 Can you just help us think through your thought process on how that should grow along with the business over the next three years? And any context around what you think might be a floor for those cash levels as we think about capital deployment through the buyback? Yes, sure, Robert. It's Linda. Thank you very much for the question. Focusing just on where we are with the buyback first, on March 18, you'll remember we announced $200,000,000 of authorization and through yesterday, we've repurchased about $63,000,000 of shares. So that leaves us with about $137,000,000 outstanding on our authorization. And we'll continue to look at that and evaluate where we stand with our expectations on cash flow, our views on valuation and thoughts regarding investments back into the business.
30:32 You're right, have about $450,000,000 of cash outside entities. And what we would like to do is maintain a safe cash level across the business. We haven't disclosed what that would be, but we're very optimistic about future cash flows for the business. So we'll continue to update you as we move through the next quarter's earnings call in terms of what we've done with share repurchase, but we're very comfortable with cash situation and the cash flow outlook. Okay, thank you. And then just wanted to follow-up Jeff, thanks for all the helpful comments on how Accelerant is leveraging AI.
31:18 I just wanted to double check, or double click on your comments for reducing reliance or replacing third party software systems. Can you just provide a little more color on what types of functions these systems, are providing that you might be able to bypass and if you think Accelerant is uniquely capable of bypassing these systems due to the company's technology stack? Great great question. Let me set the stage more broadly, and and then I'll eventually I'll get to your question. From our perspective, AI and our team is how we're gonna become a $20,000,000,000 platform. So we're reinventing Accelerant to speed up every critical process inside Accelerant using AI and that terrific team we built.
32:08 And while there are great efficiencies to that, some of that is the third party software that you described, What we're really excited about is the speed and how quickly we can move. The reason that's important is moving faster means we will capture more of that specialty insurance marketplace. And as you know, every every and not every percentage point share that we gain, that means more data, which means a bigger moat. More data means better loss ratios and the ability to grow smarter, faster. So you run that flywheel for a year or two, and the growth potential of the portfolio is really, really extraordinary. So I want I wanna be clear that what the real excitement about reinventing Accelerant with AI comes on the offensive side of the ball.
32:58 Now having said that, what types of what types of software was I talking about? I was talking about the historically very, very tailored insurance and reinsurance software around administration of policies and administration of reinsurance. We're we're having great luck in replacing or reducing the reliance on those pieces of software. I suspect I suspect that other organ well, I can't answer how fast other organizations will be able to do that. I'm pleased with what the team's been achieving week to week over here, though. Thank you. Your next question comes from the line of Paul Newsome of Piper Sandler.
33:49 Your line is open. Good morning. I think at the end of the year, there was a fairly big shift in the costs industry wide fronting. And curious as we have moved towards using other fronts beyond Hadron, has there been a change in the sort of incremental economics because of the competition and change in the fronting business in the last several months? Thanks for the question, Paul. I hope you're doing well. The to do with I don't believe anything to do with Hadron or any of our other risk exchange insurance partners. What I will say is that we have experienced the ability to get better and better unit economics as the portfolio grows, and we're able to become a bigger and bigger and more important partner of our risk exchange insurance partners, we've been able to improve the unit economics, which is a fancy way, Paul, of saying they're charging less to use their balance sheets.
35:05 Sort of a different question. There's a lot of talk in the industry about at the broker level, a ton of MGAs about sort of a war on talent and some my grandmother would say interesting strategies towards approaching people. But does that have any impact on MGA formations for you in any way shape or form because the insanity that's happening to the broker's office? Paul, I'm gonna read that back to you because for me, it was a little hard to hear you. I I think what I heard is that you've there have been a lot of comments about the war for talent and whether that I think you asked, did that, in our view, slow down the formation, pace of MGAs? Did I get that right, Paul?
36:01 Yep. That's the general thought. Yeah. I don't I don't think so. Not not that we felt. We're we're able to add, as Ryan said, predominantly independent MGAs, but we've been able to add MGAs at a pace that's that's very consistent. So I don't think so. Not that we've noticed, Paul. Alright. Appreciate the help. Thank you. Sure. Your next question comes from the line of Andrew Kligerman of TD Cowen. Your line is open. Good morning. I want to follow-up a little bit on the MGAs.
36:46 You had another robust quarter with 16 members. And I'm wondering if you could size the market. How long can you continue to add quality members this kind of a pace? Maybe just along those lines, a lot of the traditional underwriters have been growing mud at MGAs, and I I I'm I'm curious as to what your your thoughts are on that. Sure. Well, first of all, hi, Andrew. Thank you for the question. I guess the only way that Accelerant could really answer that question is based on what we see in front of it.
37:37 The questions about how big is the market or or how long can this continue, we can only talk about, I think, the pipeline ahead of us. And and here's what I'd say. What I would say is in The US, in The UK, and especially in Europe, there continue to be just spectacular opportunities that we're so excited about because of the quality of the underwriting teams that are looking to be able to join of the Accelerant platform that Andrew, I don't know if and when we run out of runway, but I'll tell you the runway is looking longer and larger quarter by quarter instead of shorter. And the other thing, Andrew, sorry, this is Ryan, just hopping in sort of on the first part of your question, particularly at the market sizing.
38:25 Look, a large part of our team was just recently at the Target Markets Conference here in The United States. There was also a MGA conference in Barcelona, I think, earlier this week that a large part of our team was at. And I think we're seeing more and more fervent demand and excitement around the space from within sort of MGAs broadly or focused on MGAs broadly. And I think you could see that also in the Note 19 data about the overall MGA market continuing to take share. When we think about the target market, right, and I think you saw this in our prospectus, etcetera, We've always talked about a $252,000,000,000 market, that MGAs just keep taking share of sort of within our core space. What the you know, in our opinion, the scarce resource is there is truly the specialty underwriting talent, whether it sits in an MGA or whether it sits in what you'd call a direct underwriter at an insurance company. Either way, right, that's the scarce resource, and that scarce resource is gonna continue to find whatever ways make the most sense for it, right, to do and conduct business.
39:31 I think, Jeff, maybe it's worth you commenting on the second part of Andrew's question related to, obviously, I think some folks in the broader market have been throwing stones at MGAs. Yeah. Which is which is pretty standard. If if you've been through enough cycle rotations, this is the time Yeah. For those pithy comments. One one of one of the comments that I read, I thought was great, is the the the speaker said, this is short tail business. The report card comes home pretty quickly. We couldn't agree more, and we love our report card. Right? Well, the gross loss ratio is still terrific. And what's perhaps more important and more comforting, at least to me, is the fact that what we're looking through and seeing in our portfolio is not loss experience. That's a trailing indicator.
40:24 What we're looking through and we're seeing all that exposure characteristics that I described about our data edge, we know the quality of our book and we know the quality of our book of business is getting better. So I'm sure there are lots of different kinds of MGAs out there in the world. We say no to most of the MGAs that wanna join. So I can only speak to the ones that that are Accelerant members, and they're doing terrifically. Yes. That's a great comment. And I do like the report card that we saw this quarter at 52% gross loss ratio. So maybe thinking about that 52%, Jeff, Ryan, team, could you talk a little bit about the pricing by your major product areas that you're seeing in terms of rate? I think you talked about only 2% of last twelve months growth coming from rates. So that was a good sign. But maybe just break down a few of your key product areas.
41:31 What kind of rate were you seeing? And you know, it does that does that allow you to sustain that kind of 52% strike zone for a gross loss ratio over the intermediate term? Sure, Andrew. You you know this, but but for other listeners, as always, it's a mixed bag. Right? Depending on geography and class of business, things rates are moving up or down at different levels. The other thing that's worth knowing wrote noting is the largest, rate increases that we get and every other underwriter gets, is on the worst business sort of by definition.
42:16 Right? Because the market has decided the rates have to go up. So almost by definition, it needs sort of a correction. Here's what I'd say. What I would say is The US market from a rate perspective is much is healthier than, The UK or Europe. However, across all classes of business, we were up 1% this quarter. So we were up 1% this quarter. And, Andrew, I I again, for everyone listening, I just have to remind everyone how atypical our portfolio is with 95% of the business of the policies being really, really small. What we're seeing in this cycle is what we've seen in cycles past over the past several decades, I e, this small business does not suffer or enjoy big rate increases or decreases.
43:12 I said that backwards, but you know what I mean. Yes, that was super helpful. So do you feel like you're still in the strike zone for that 52 ish? I forget guidance, maybe could see 52 to 53 over the longer haul. But do you feel like that strike zone is a good place future? Andrew, I think we're very comfortable saying that we expect the loss ratio in 2026 to be in the low 50s. And and and longer term, you feel like there's, you know, some sustainability there? Absolutely. Absolutely. For the reasons that I described, which are which are and let's just review We're better loss we're better risk selectors because we have better data, and that gets better and better all the time and with every turn to the flywheel. That's the first thing.
44:07 Second thing, small business tends not to have the same rate movements, so we won't have the pressure in on on average across our classes of business that that larger business would show. So with the superior data, the better technology, making making us and our members better risk selectors and operating in the small business segment, we feel we feel really comfortable about continued loss ratio performance. Very helpful. Thank you. Your next question comes from the line of Charlie Litterer of BMO Capital Markets. Hey, thanks. Just a follow-up on Rob's question earlier on cash flows.
44:55 So you guys have said the last couple of quarters, you don't anticipate contributing much capital to your insurance companies going forward. Guess, we can see in the 10 Q that you put in, I think, 59,000,000 into some insurance subs this quarter. Just wondering if you could provide some color around that. Thanks. I think you're referring to my comment, so maybe I should answer it. It's the difference between statutory recognition and gap recognition. I was thinking stat, that that cap that capital contribution counted for 12/3125. And I probably should have gotten given a more complete answer, but that's the that's the answer.
45:40 It's timing difference between GAAP and statutory. Sorry. Thank you. With no further questions, that concludes our Q and A session. I will now turn the conference back over to Jeff Ratke for closing remarks. Thanks very much, operator, and thank you all for participating on our earnings call. We look forward to continuing to execute and speaking to you in a quarter. Thank you. This concludes today's conference call. You may now disconnect.
Follow Accelerant Holdings into a list and get an email when it puts out news.
Head of Investor Relations
Chairman and CEO at Accelerant
CFO
Head of Strategy
at RBC Capital Markets
at BMO Capital Markets
at Goldman Sachs
at Piper Sandler
at TD Cowen