CenterState Bank — CenterState Banks — The Burton Partnership Investor Presentation (March 2016)
30 slides from CenterState Bank's conference presentation, Mar 15, 2016
Slide 1: The Burton Partnership Investor Presentation
The Burton Partnership Investor Presentation Tampa, FL March 16, 2016 Exhibit 99.1
Slide 2: Forward Looking Statement
This presentation contains forward-looking statements, as defined by Federal Securities Laws, relating to present or future trends or factors affecting the operations, markets and products of CenterState Banks, Inc. (CSFL). These statements are provided to assist in the understanding of future finan
Slide 3: Corporate Overview
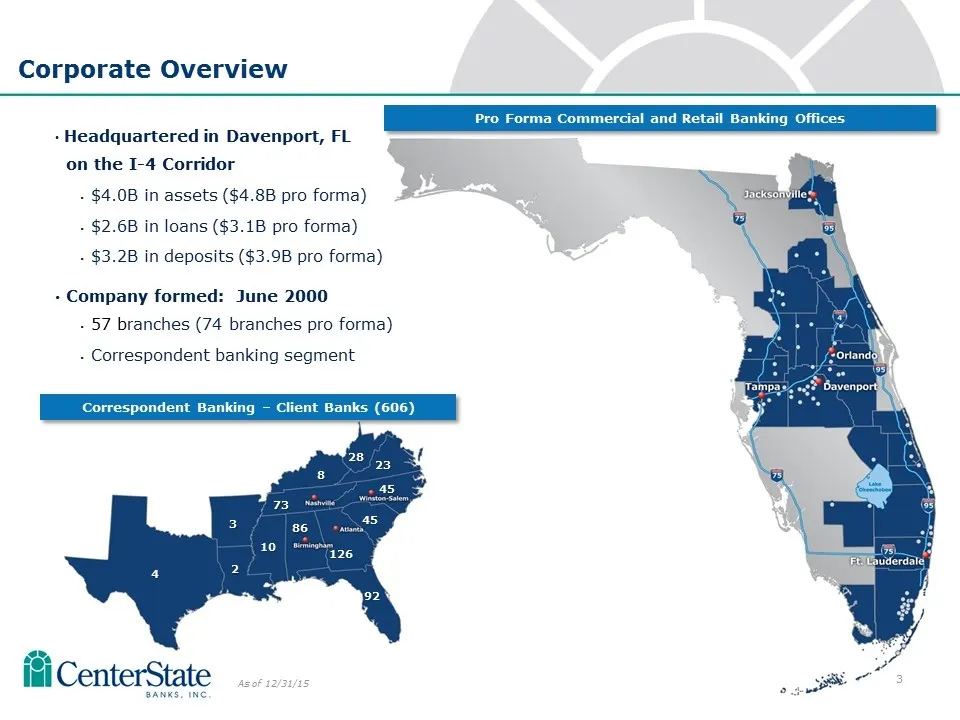
4 3 2 10 86 73 92 126 45 45 8 23 28 As of 12/31/15 Headquartered in Davenport, FL on the I-4 Corridor $4.0B in assets ($4.8B pro forma) $2.6B in loans ($3.1B pro forma) $3.2B in deposits ($3.9B pro forma) Company formed: June 2000 57 branches (74 branches pro forma) Correspondent banking segment Cor
Slide 4: Banking the Sunshine State
Banking the Sunshine State
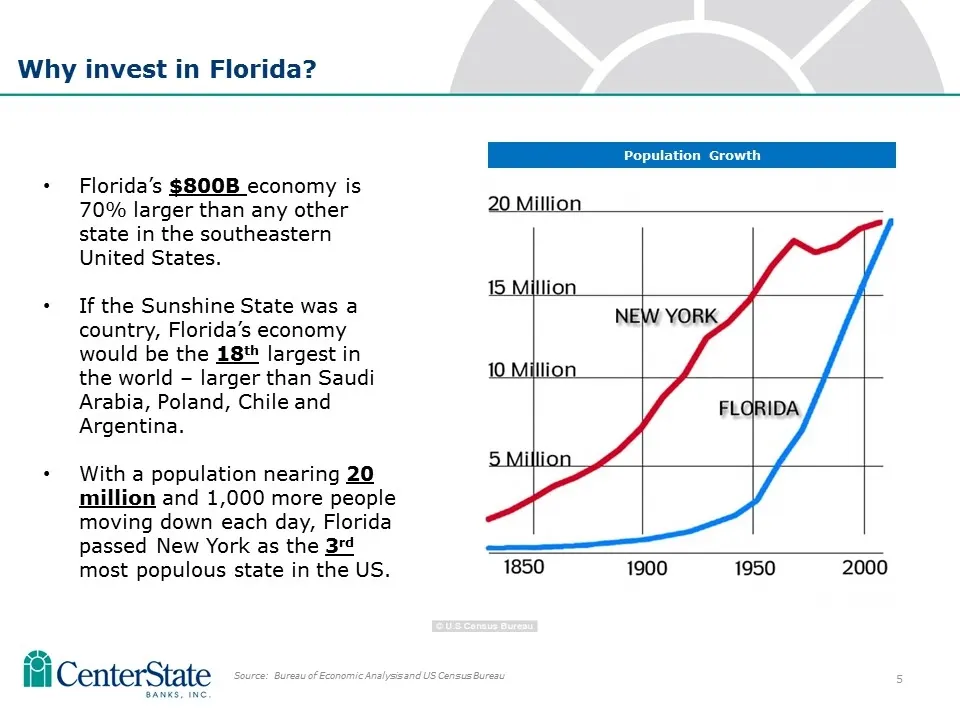
Slide 5: Why invest in Florida? Population Growth
Florida’s $800B economy is 70% larger than any other state in the southeastern United States. If the Sunshine State was a country, Florida’s economy would be the 18th largest in the world – larger than Saudi Arabia, Poland, Chile and Argentina. With a population nearing 20 million and 1,000 more peo
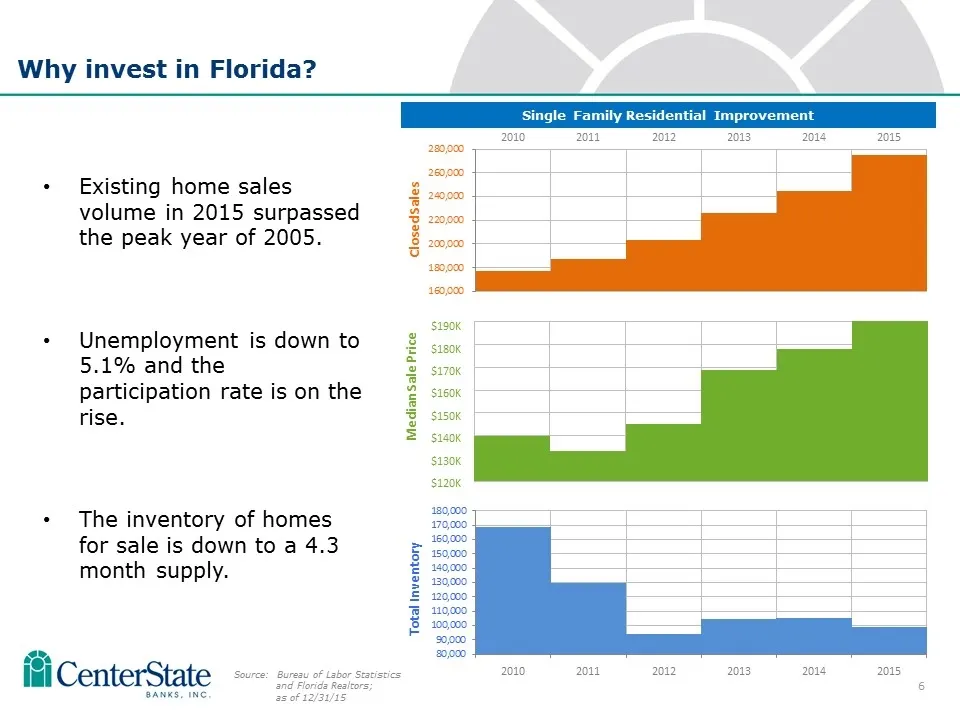
Slide 6: Why invest in Florida? Housing and employment
Existing home sales volume in 2015 surpassed the peak year of 2005. Unemployment is down to 5.1% and the participation rate is on the rise. The inventory of homes for sale is down to a 4.3 month supply. Why invest in Florida? Source: Bureau of Labor Statistics and Florida Realtors; as of 12/31/15 Me
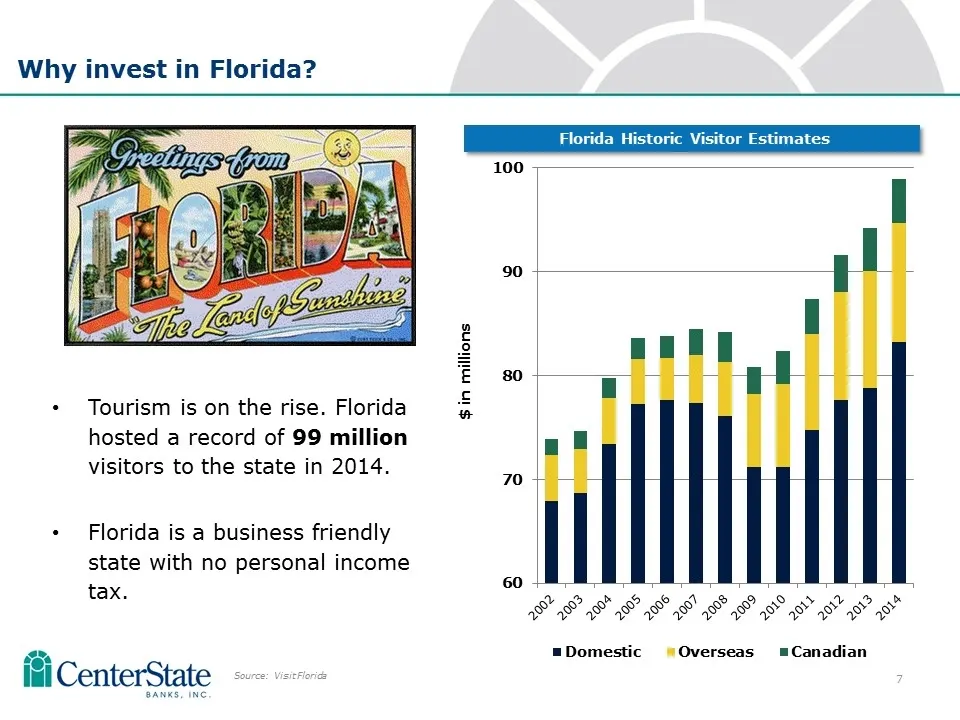
Slide 7: Why invest in Florida? Tourism
Tourism is on the rise. Florida hosted a record of 99 million visitors to the state in 2014. Florida is a business friendly state with no personal income tax. Why invest in Florida? Source: Visit Florida Florida Historic Visitor Estimates
Slide 8: Capital Management
Capital Management
Slide 9: Capital Management
Capital Management Bank acquisitions Support organic growth Stock repurchase plan Dividends
Slide 10: Acquisition History
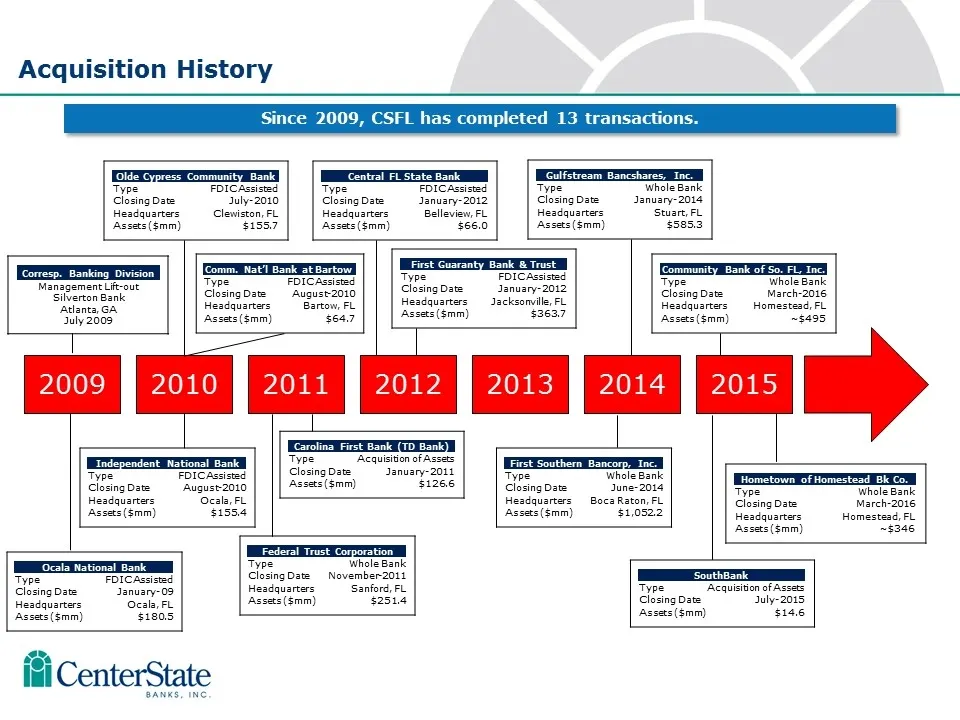
Acquisition History 2009 2010 2011 2012 2013 2014 2015 Corresp. Banking Division Management Lift-out Silverton Bank Atlanta, GA July 2009 Ocala National Bank Type FDIC Assisted Closing Date January-09 Headquarters Ocala, FL Assets ($mm) $180.5 Olde Cypress Community Bank Type FDIC Assisted Closing D
Slide 11: 1Q16 Acquisitions
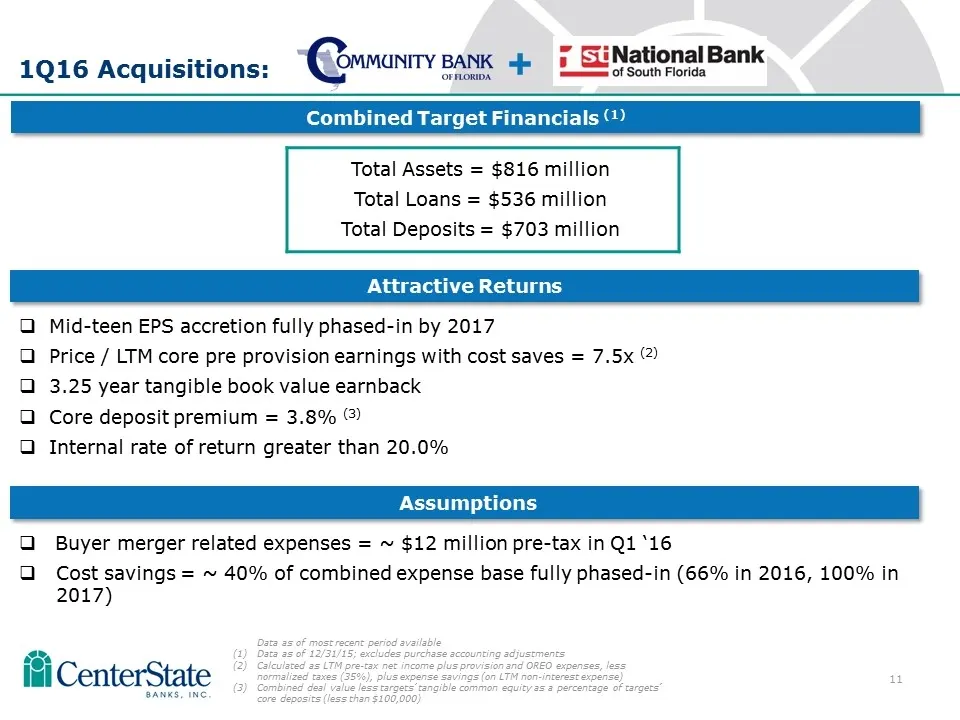
1Q16 Acquisitions: Total Assets = $816 million Total Loans = $536 million Total Deposits = $703 million Assumptions Buyer merger related expenses = ~ $12 million pre-tax in Q1 ‘16 Cost savings = ~ 40% of combined expense base fully phased-in (66% in 2016, 100% in 2017) Combined Target Financials (1)
Slide 12: Overview of Pro Forma Franchise
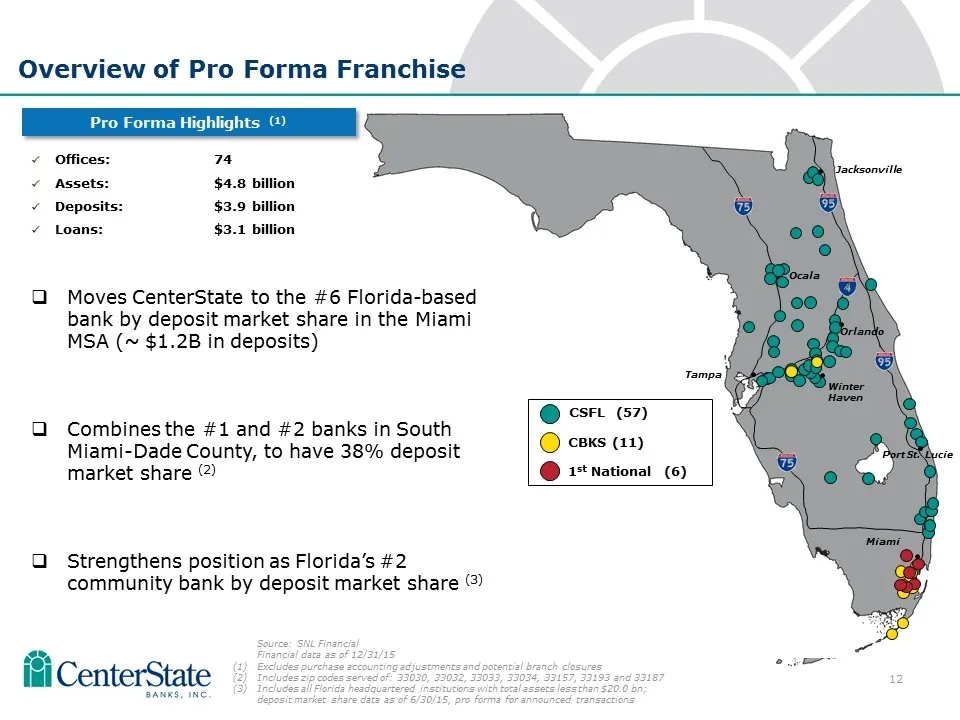
Offices: 74 Assets: $4.8 billion Deposits: $3.9 billion Loans: $3.1 billion CSFL (57) CBKS (11) 1st National (6) Tampa Jacksonville Orlando Winter Haven Miami Port St. Lucie Overview of Pro Forma Franchise Source: SNL Financial Financial data as of 12/31/15 Excludes purchase accounting adjustments a
Slide 13: Significant Branch Overlap Drives Cost Savings
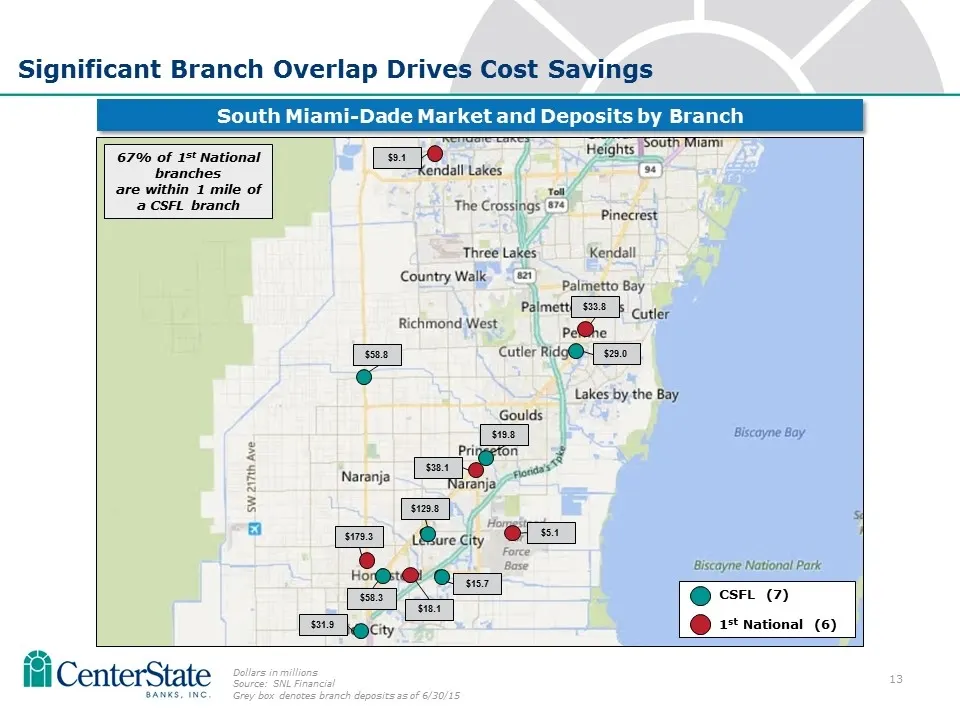
Significant Branch Overlap Drives Cost Savings South Miami-Dade Market and Deposits by Branch Dollars in millions Source: SNL Financial Grey box denotes branch deposits as of 6/30/15 $29.0 $19.8 $31.9 $179.3 67% of 1st National branches are within 1 mile of a CSFL branch CSFL (7) 1st National (6) $5
Slide 14: Earnings
Earnings
Slide 15: ROA (Operating)
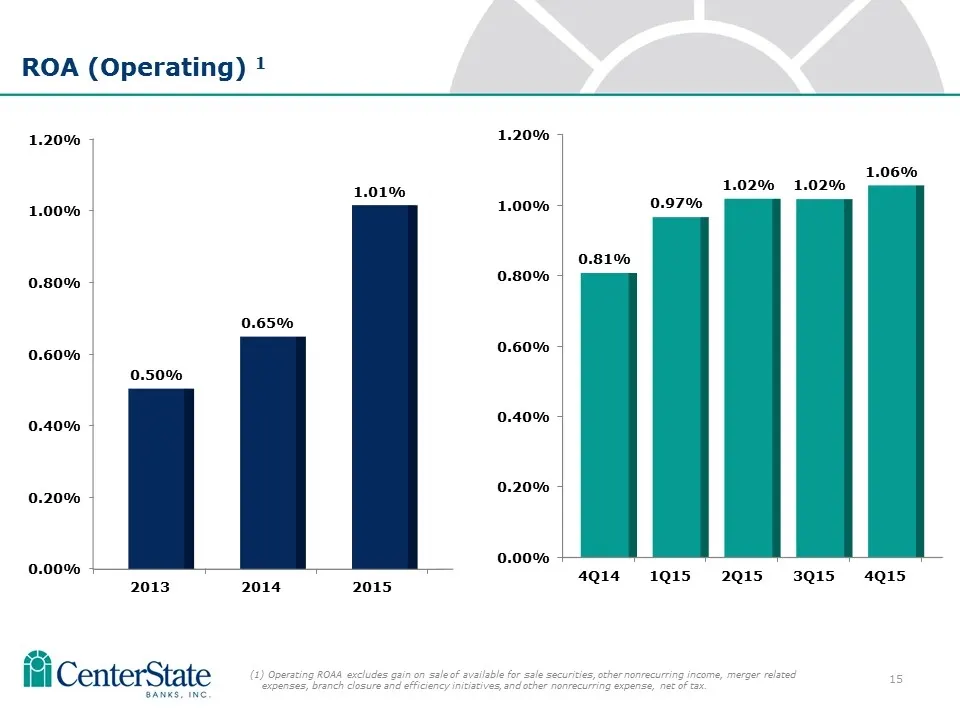
ROA (Operating) 1 (1) Operating ROAA excludes gain on sale of available for sale securities, other nonrecurring income, merger related expenses, branch closure and efficiency initiatives, and other nonrecurring expense, net of tax.
Slide 16: Efficiency Ratio
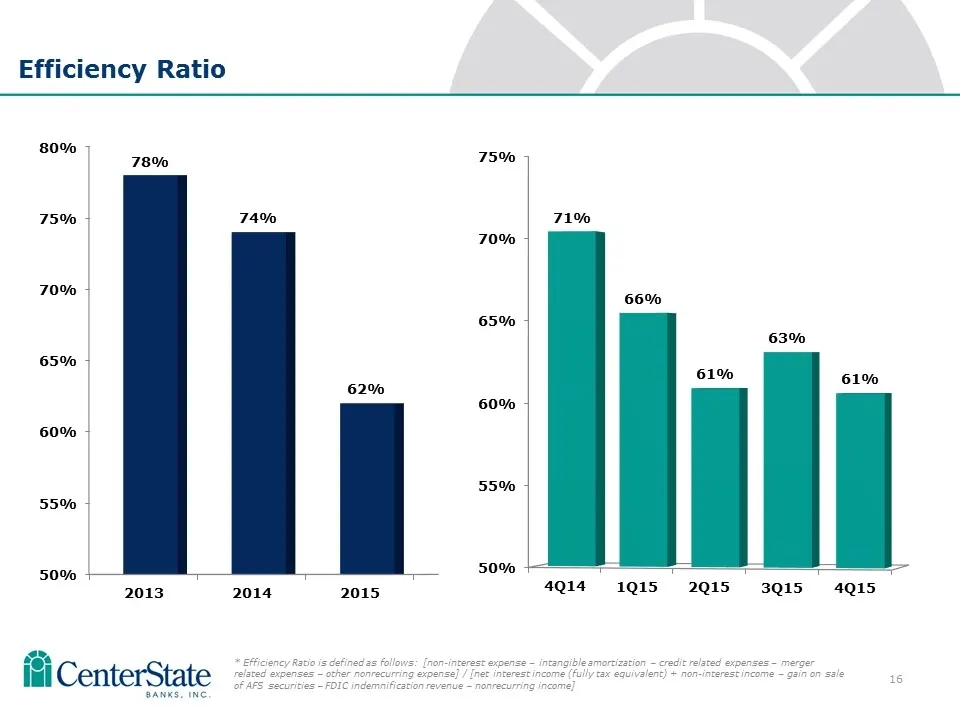
10 Efficiency Ratio * Efficiency Ratio is defined as follows: [non-interest expense – intangible amortization – credit related expenses – merger related expenses – other nonrecurring expense] / [net interest income (fully tax equivalent) + non-interest income – gain on sale of AFS securities – FDIC
Slide 17: Operating Earnings Per Share: Historical and Consensus Forecast
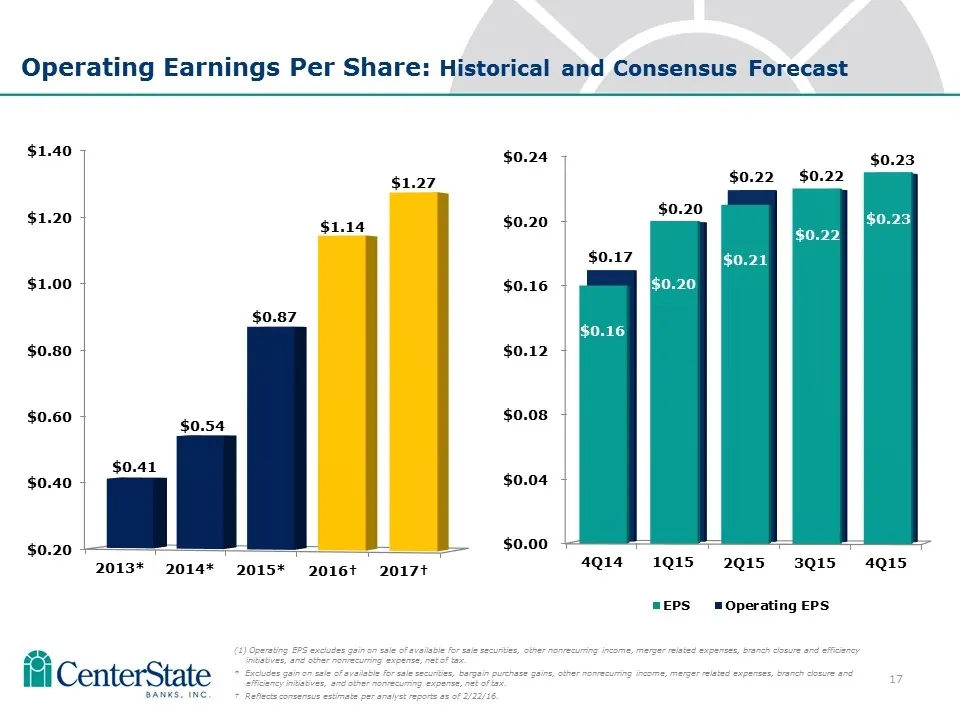
Operating Earnings Per Share: Historical and Consensus Forecast (1) Operating EPS excludes gain on sale of available for sale securities, other nonrecurring income, merger related expenses, branch closure and efficiency initiatives, and other nonrecurring expense, net of tax. * Excludes gain on sale
Slide 18: 2015 Earnings Summary
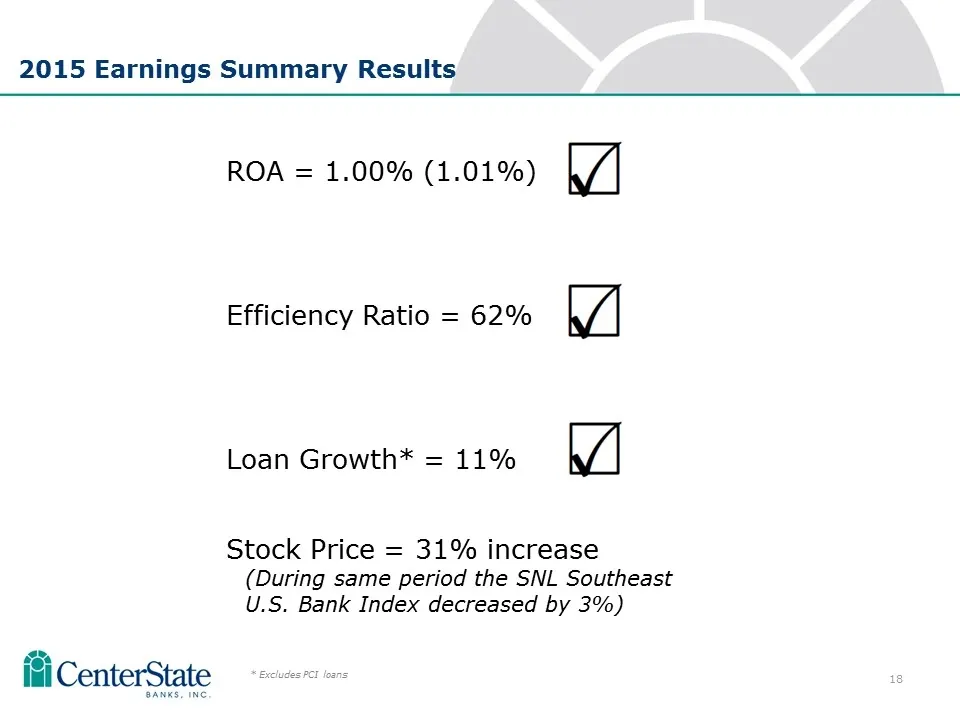
2015 Earnings Summary Results ROA = 1.00% (1.01%) Efficiency Ratio = 62% Loan Growth* = 11% Stock Price = 31% increase (During same period the SNL Southeast U.S. Bank Index decreased by 3%) * Excludes PCI loans
Slide 19: Operating Performance & Efficiency The Catalysts Ahead
Operating Performance & Efficiency The Catalysts Ahead
Slide 20: 4Q15 Highlights
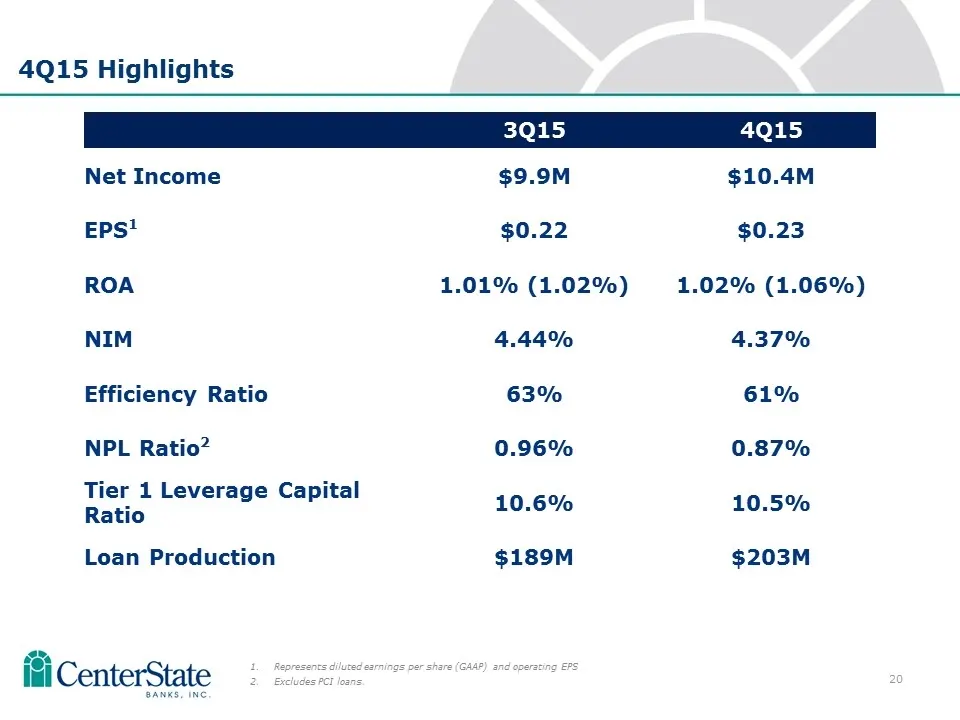
4Q15 Highlights 3Q15 4Q15 Net Income $9.9M $10.4M EPS1 $0.22 $0.23 ROA 1.01% (1.02%) 1.02% (1.06%) NIM 4.44% 4.37% Efficiency Ratio 63% 61% NPL Ratio2 0.96% 0.87% Tier 1 Leverage Capital Ratio 10.6% 10.5% Loan Production $189M $203M Represents diluted earnings per share (GAAP) and operating EPS Excl
Slide 21: Loan Production by Quarter
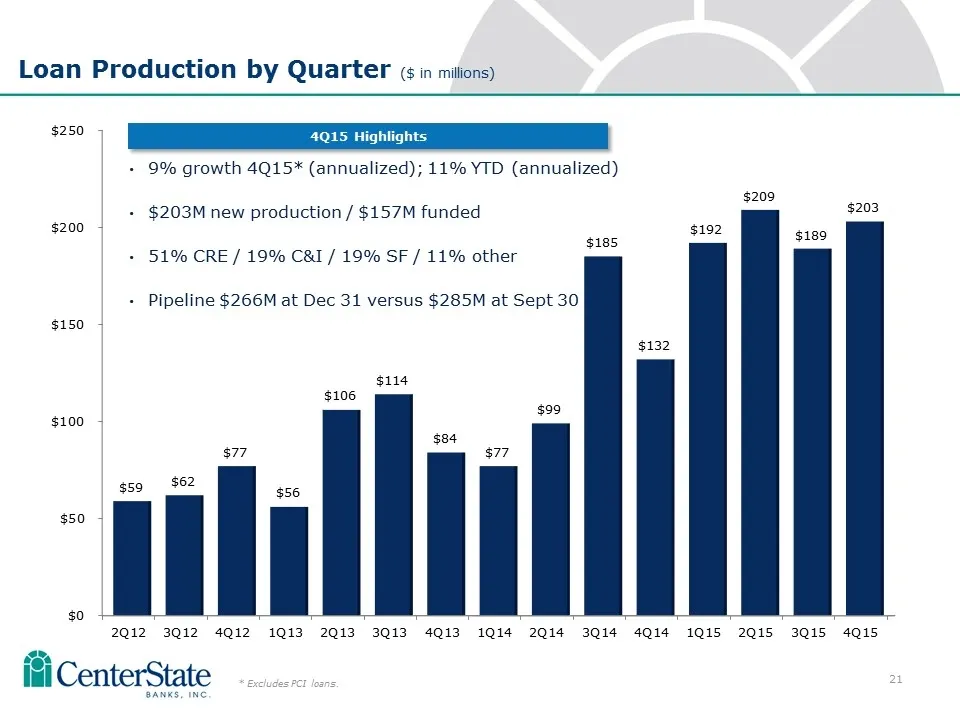
Loan Production by Quarter ($ in millions) 9% growth 4Q15* (annualized); 11% YTD (annualized) $203M new production / $157M funded 51% CRE / 19% C&I / 19% SF / 11% other Pipeline $266M at Dec 31 versus $285M at Sept 30 * Excludes PCI loans. 4Q15 Highlights
Slide 22: Total Loans by Type
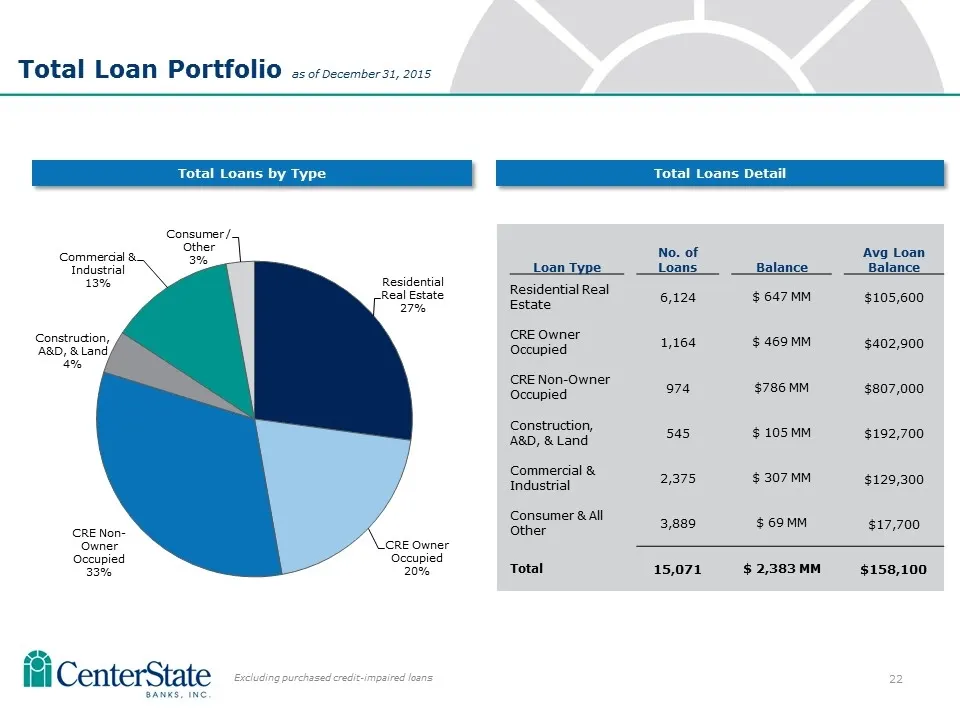
Total Loans by Type Total Loans Detail Loan Type No. of Loans Balance Avg Loan Balance Residential Real Estate 6,124 $ 647 MM $105,600 CRE Owner Occupied 1,164 $ 469 MM $402,900 CRE Non-Owner Occupied 974 $786 MM $807,000 Construction, A&D, & Land 545 $ 105 MM $192,700 Commercial & Industrial 2,375
Slide 23: Net Charge-offs / Average Non PCI Loans
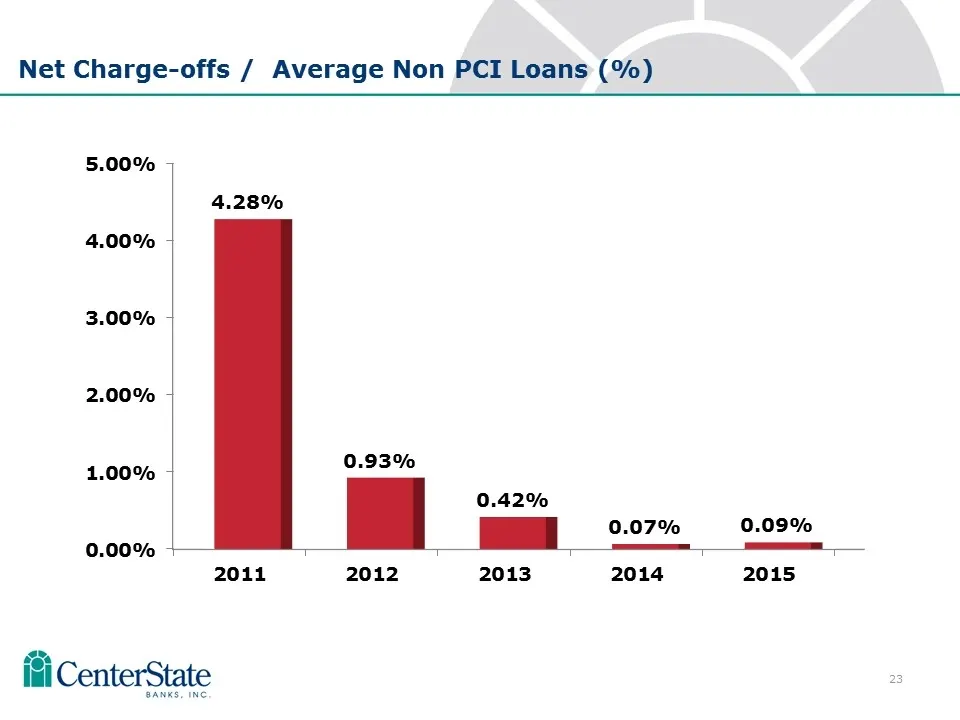
Net Charge-offs / Average Non PCI Loans (%)
Slide 24: Operating Leverage Through Branch Consolidation
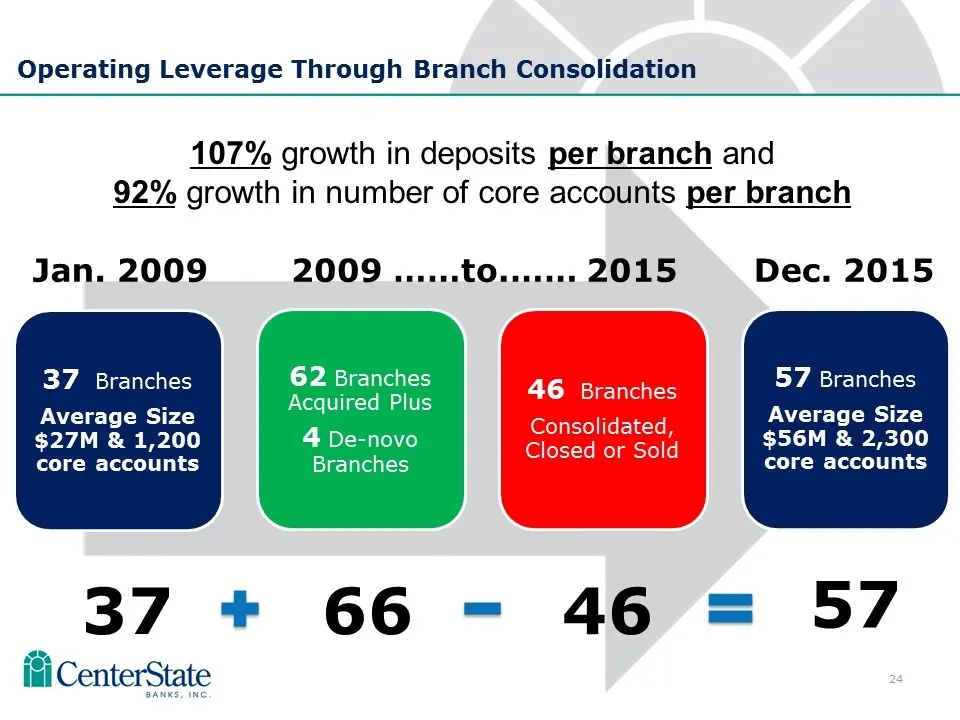
Operating Leverage Through Branch Consolidation 107% growth in deposits per branch and 92% growth in number of core accounts per branch 37 66 46 57 Jan. 2009 2009 ……to.…… 2015 Dec. 2015 37 Branches Average Size $27M & 1,200 core accounts 62 Branches Acquired Plus 4 De-novo Branches 46 Branches Conso
Slide 25: Premium Core Deposit Franchise
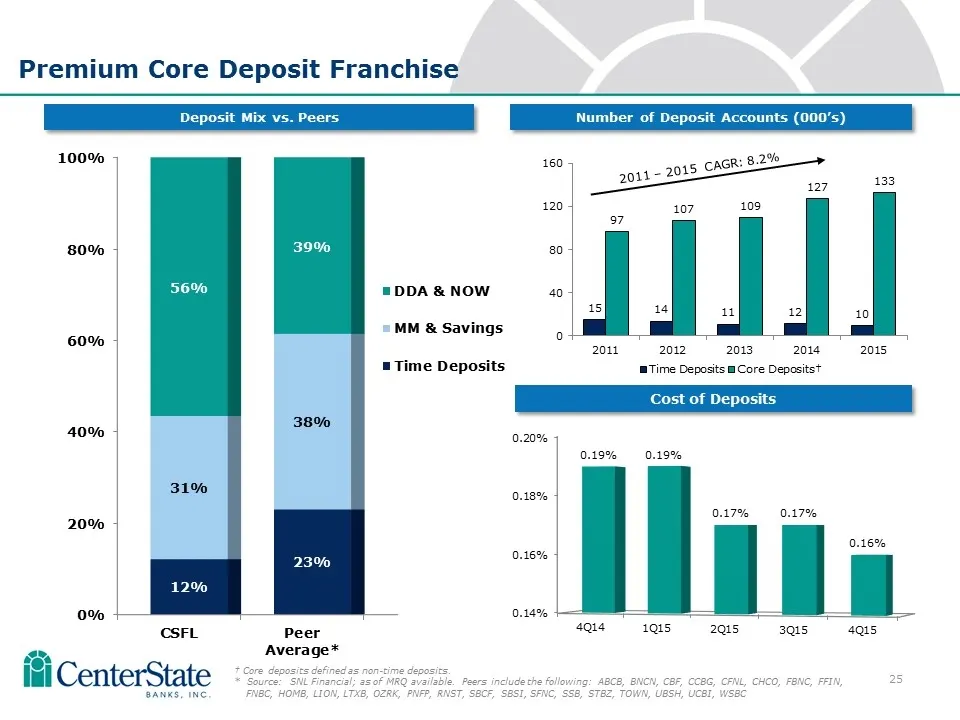
Number of Deposit Accounts (000’s) Premium Core Deposit Franchise Cost of Deposits 2011 – 2015 CAGR: 8.2% Deposit Mix vs. Peers † Core deposits defined as non-time deposits. * Source: SNL Financial; as of MRQ available. Peers include the following: ABCB, BNCN, CBF, CCBG, CFNL, CHCO, FBNC, FFIN, FNBC
Slide 26: The Catalysts Ahead – Year 2016
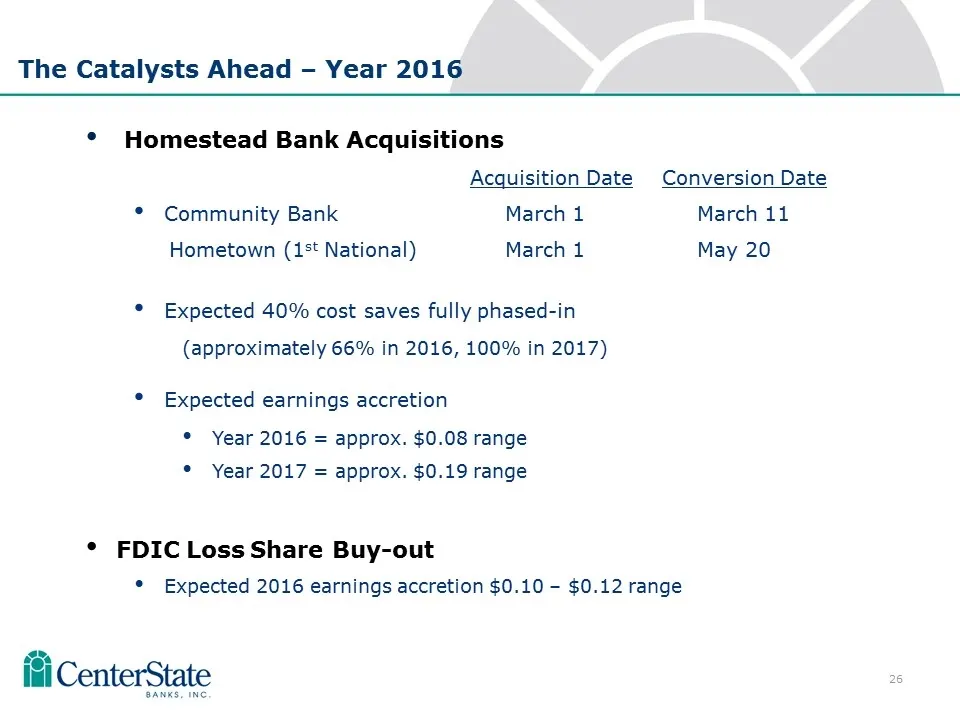
The Catalysts Ahead – Year 2016 Homestead Bank Acquisitions Acquisition Date Conversion Date Community Bank March 1 March 11 Hometown (1st National) March 1 May 20 Expected 40% cost saves fully phased-in (approximately 66% in 2016, 100% in 2017) Expected earnings accretion Year 2016 = approx. $0.08
Slide 27: FDIC Loss Share Termination - Strategic Benefits
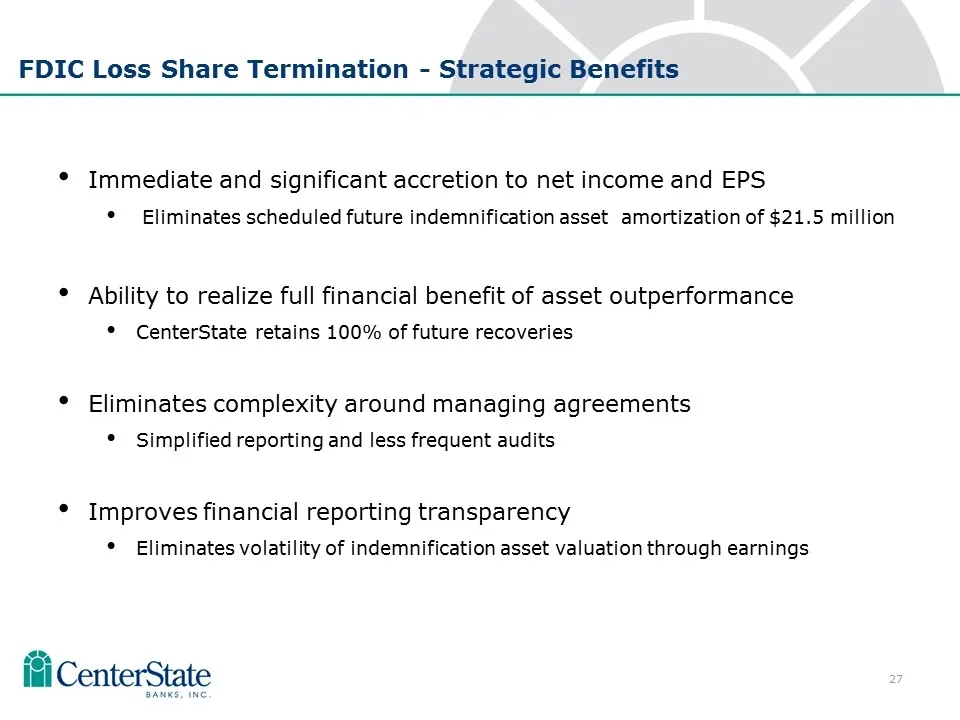
FDIC Loss Share Termination - Strategic Benefits Immediate and significant accretion to net income and EPS Eliminates scheduled future indemnification asset amortization of $21.5 million Ability to realize full financial benefit of asset outperformance CenterState retains 100% of future recoveries E
Slide 28: Summary and Investment Thesis
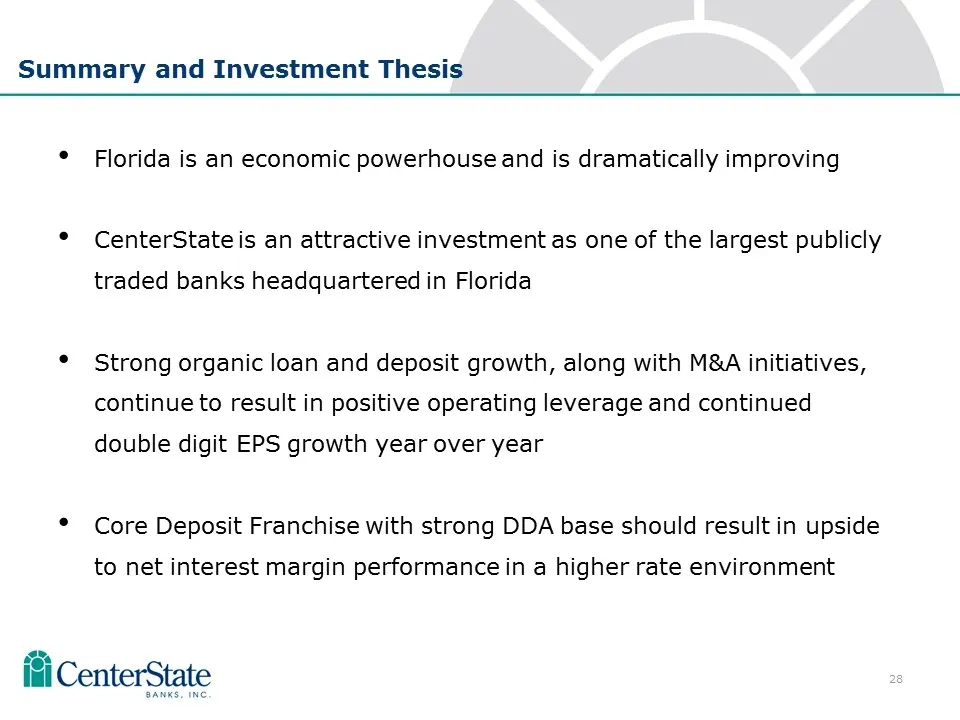
Summary and Investment Thesis Florida is an economic powerhouse and is dramatically improving CenterState is an attractive investment as one of the largest publicly traded banks headquartered in Florida Strong organic loan and deposit growth, along with M&A initiatives, continue to result in positiv
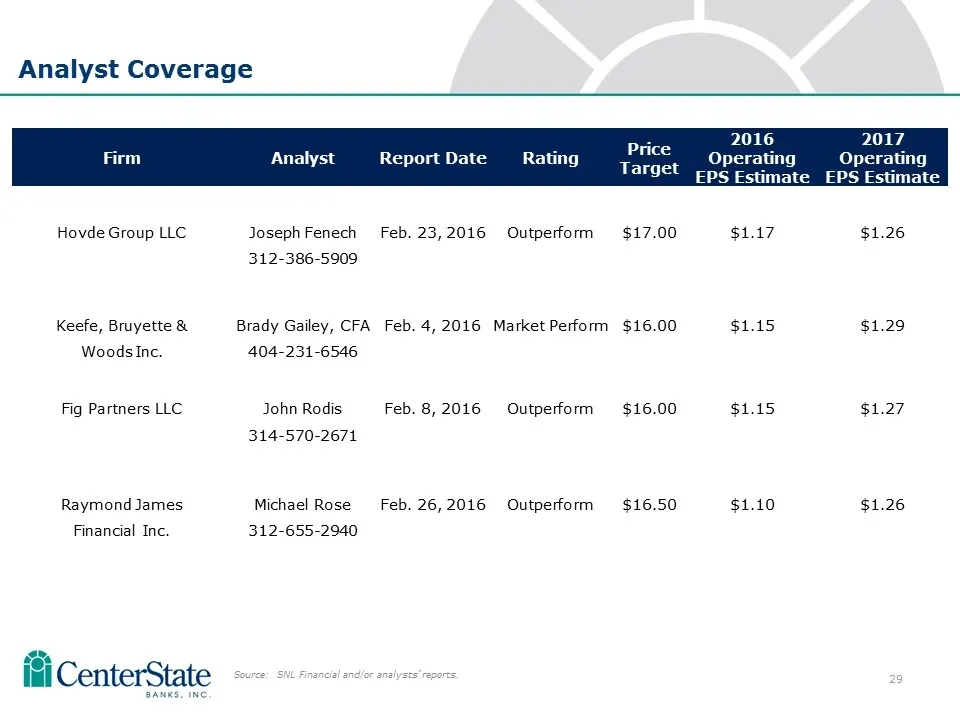
Slide 29: Analyst Coverage
Analyst Coverage Source: SNL Financial and/or analysts’ reports. Firm Analyst Report Date Rating Price Target 2016 Operating EPS Estimate 2017 Operating EPS Estimate Hovde Group LLC Joseph Fenech Feb. 23, 2016 Outperform $17.00 $1.17 $1.26 312-386-5909 Keefe, Bruyette & Brady Gailey, CFA Feb. 4, 201
Slide 30: CenterState
isi CenterState www.centerstatebanks.com
Source: SEC EDGAR · 8-K filed Mar 15, 2016
More decks from CenterState Bank Corporation
 IPO Roadshow (May 2020)42 slides · May 21, 2020
 D.A. Davidson 22nd Annual Financial Institution Virtual Conference (May 2020)25 slides · May 6, 2020
 Q1 2020 Earnings Presentation25 slides · Apr 23, 2020
 Merger or Acquisition (January 2020)24 slides · Jan 27, 2020
 Q3 2019 Earnings Presentation28 slides · Nov 4, 2019
 Investor Presentation (July 2019)28 slides · Jul 30, 2019