United Western Bancorp — Investor Presentation (May 2008)
27 slides from United Western Bancorp's investor presentation, May 6, 2008
Slide 1: May 2008 Investor Presentation
May 2008 Investor Presentation
Slide 2: Safe Harbor Statement
Safe Harbor Statement Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 that are subject to significant risks and uncertainties. Forward- looking statements include information concerning our
Slide 3: Summary - United Western Bancorp, Inc.
Summary - United Western Bancorp, Inc. o NASDAQ: UWBK o $2 Billion Assets o 7.3 Million Shares Outstanding o $17.13 per share* o $124.5 Million Market Capitalization* o Dividend Yield 1.40%* o Holding company for two primary subsidiaries: n United Western Bank - Denver, CO n Sterling Trust Company -
Slide 4: Who we are
Who we are o United Western Bank n One of three publicly traded banks headquartered in the State n Traditional community bank - target businesses first, consumers second n Re-directed in early 2006 from wholesale (mortgage) to community banking o Sterling Trust Company n Nondiscretionary trust compa
Slide 5: United Western Bank - Strategy
United Western Bank - Strategy o Create new independent bank brand in 2006 o Capitalize on dynamic Colorado banking environment and growing economy o Recruit veteran bankers disenfranchised by banking consolidation o Build exceptional “local” banking branches - regional banking model o Combine “priv
Slide 6: United Western Bank - our new "independent" brand
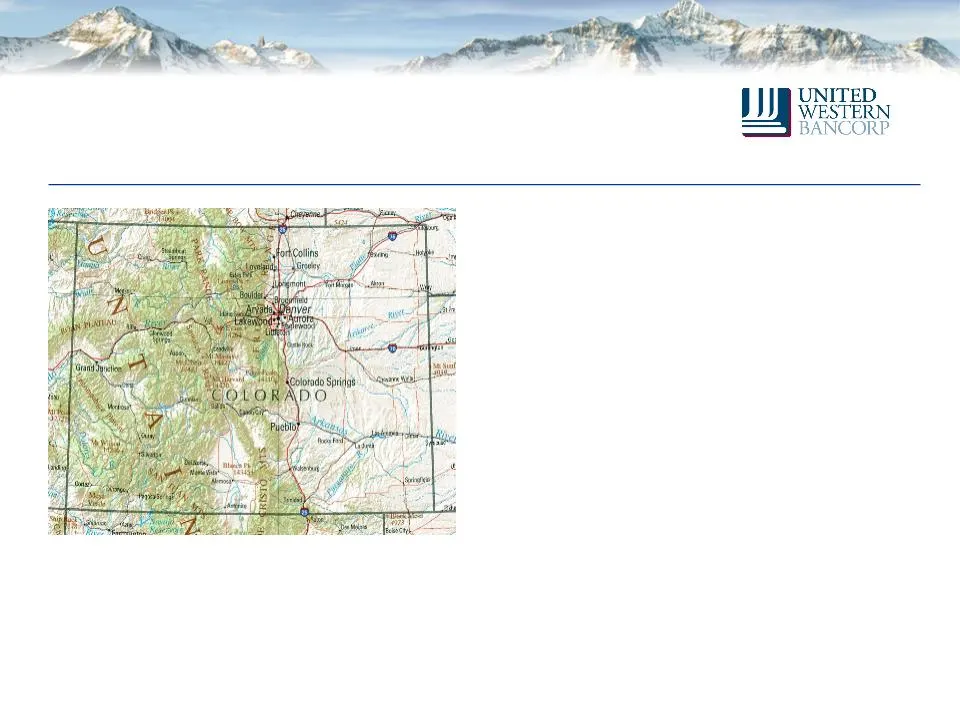
United Western Bank - our new “independent” brand o UWB name launched in 2006 o “United” and “Western” n Two recognizable Colorado community bank names n Consolidated o Branding in population center n 82% of Colorado population in Front Range n 75 miles north and 75 miles south of Denver o New $2 bi
Slide 7: Colorado Economy, Colorado Bank Market
Colorado Economy Colorado Bank Market o Colorado growth metrics n Population growth continues at a steady 2%, ranking 8 th overall in the nation (December 2007) 1 n Job growth - - 60,300 jobs since February 2007 2 o National rankings n 10 th fastest increase in personal income 3 n Ranked 8 th for po
Slide 8: United Western Bank - Recruit the best bankers
United Western Bank - Recruit the best bankers o Bankers looking for new “local” opportunity o Align interests n Make them owners, uncapped incentive plans, pay for performance o Regional presidents - local banking teams, average 20 years in market o Hired 162 “hand-picked” people through 2007 n Sal
Slide 9: United Western Bank - Growing branch network
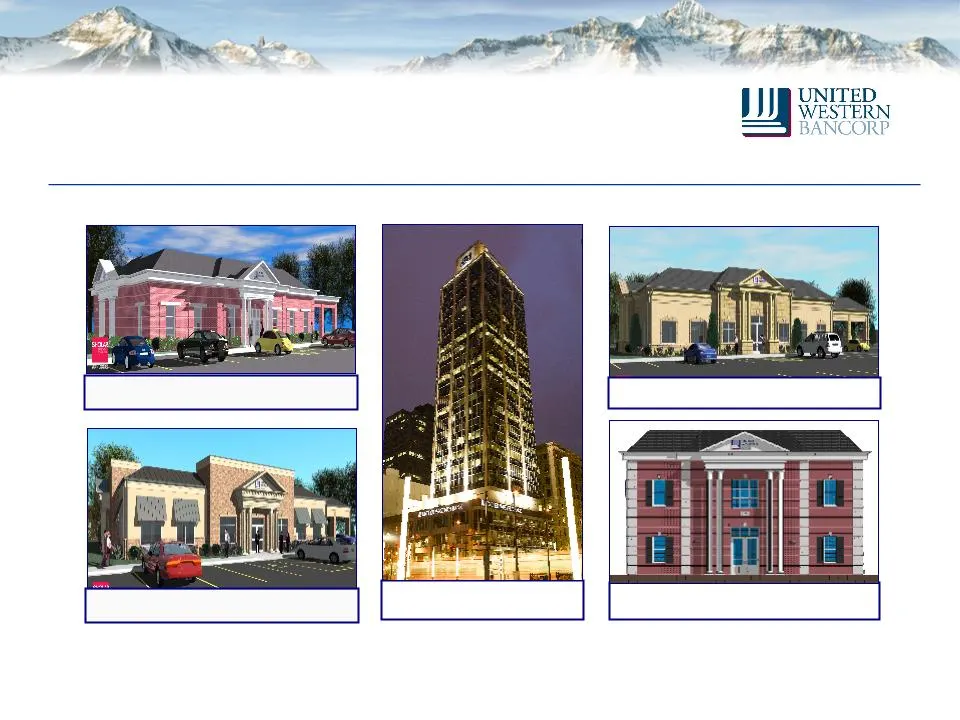
United Western Bank - Growing branch network o “Best” locations - pay premium for location, breakeven target of 14 months o Smaller distribution network - 12, not 100 o High visibility, branding opportunity o Consistent construction theme - regional banking office, not “branch” o Six locations open
Slide 10: Expanded branch locations
Downtown Tower Denver Technological Center Longmont Cherry Creek Fort Collins Expanded branch locations
Slide 11: United Western Bank - Differentiation
United Western Bank - Differentiation o Private banking “feel” coupled with technology o High touch - - regional leadership runs markets, makes local decisions o Invest in local communities - banker and board leadership entrenched o Product & service offerings expanding n Metavante® core processor n
Slide 12: Sterling Trust Company - Core deposits
Sterling Trust Company - Core deposits o Custodian, not asset manager o Primarily self-directed IRAs, non-typical assets (real estate, etc.) o Approximately 61,000 accounts - 11.53% CAGR since December 31, o $4.62 billion under custody - 16.74% CAGR since December 31, 2002 o Accounts maintain liquid
Slide 13: Capital and Financial Strategy
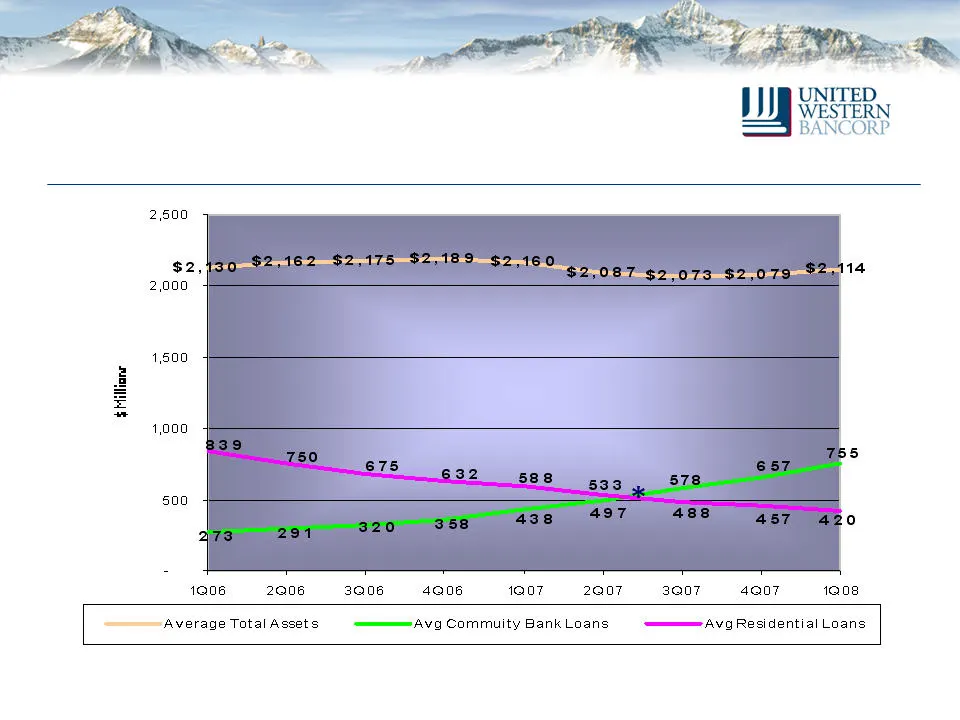
Capital and Financial Strategy o Change mix/shift balance sheet n Wholesale to community banking o Called expensive trust preferred securities ($30 million at 9.81%) o Repurchased 374,100 shares o Initiated payment of quarterly dividend of $0.06 per share o Divested non-core assets (2006) o De-lever
Slide 14: Balance Sheet Transition: Runoff Wholesale Assets
* Balance Sheet Transition: Runoff Wholesale Assets
Slide 15: Quarterly: 2006-2008 Net Interest Margin
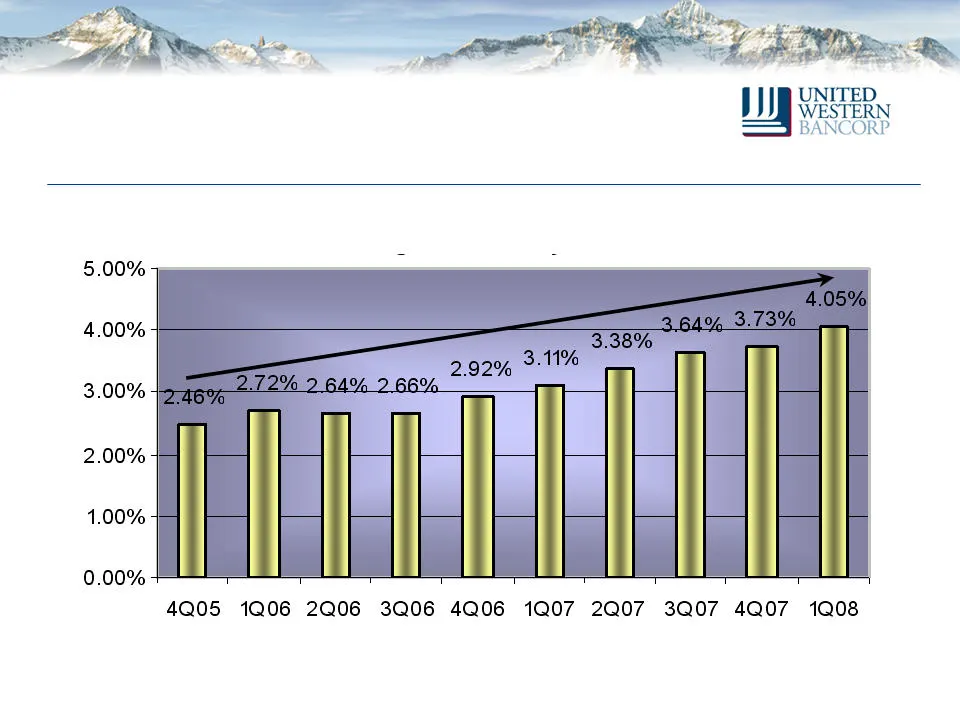
Quarterly: 2006-2008 Net Interest Margin
Slide 16: Q1 2008 results vs. prior year
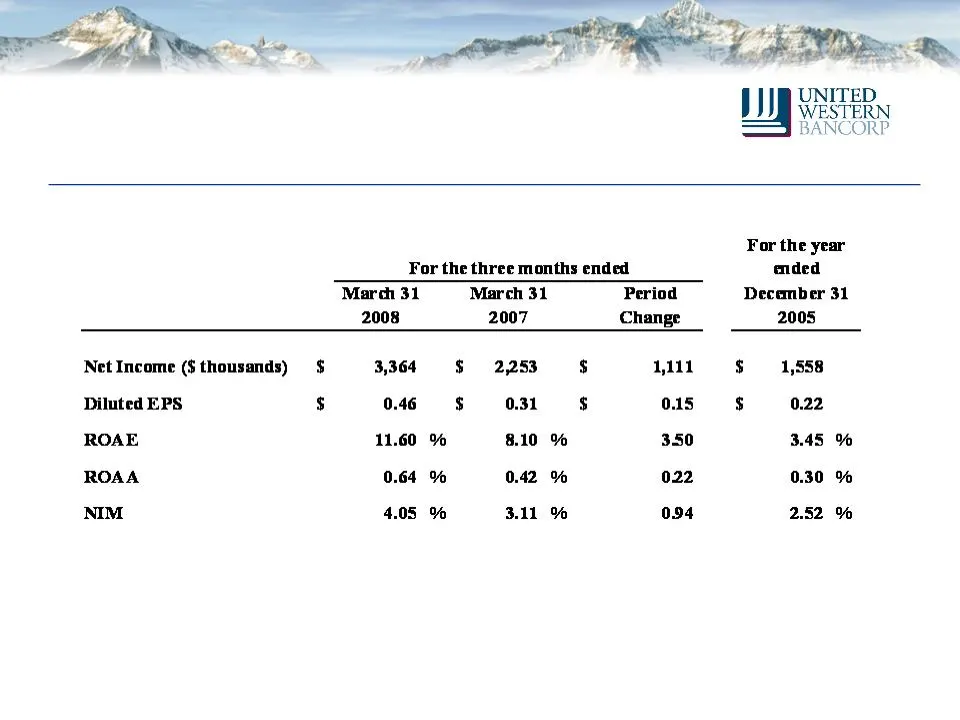
J i} UNITED WESTERN BANCORP For the year For the three months ended ded March 31 March 31 Period December 31 2008 2007 Change 2005 Net Income ($ thousands) $ 3,364 $ 2,253 $ 1111 $ 1,558 Diluted EPS $ 0.46 $ 0.31 $ 0.15 $ 0.22 ROAE 11.60 % 8.10 % 350 3.45 % ROAA 0.64 % 0.42 % 022 0.30 % NIM 4.05 % 3
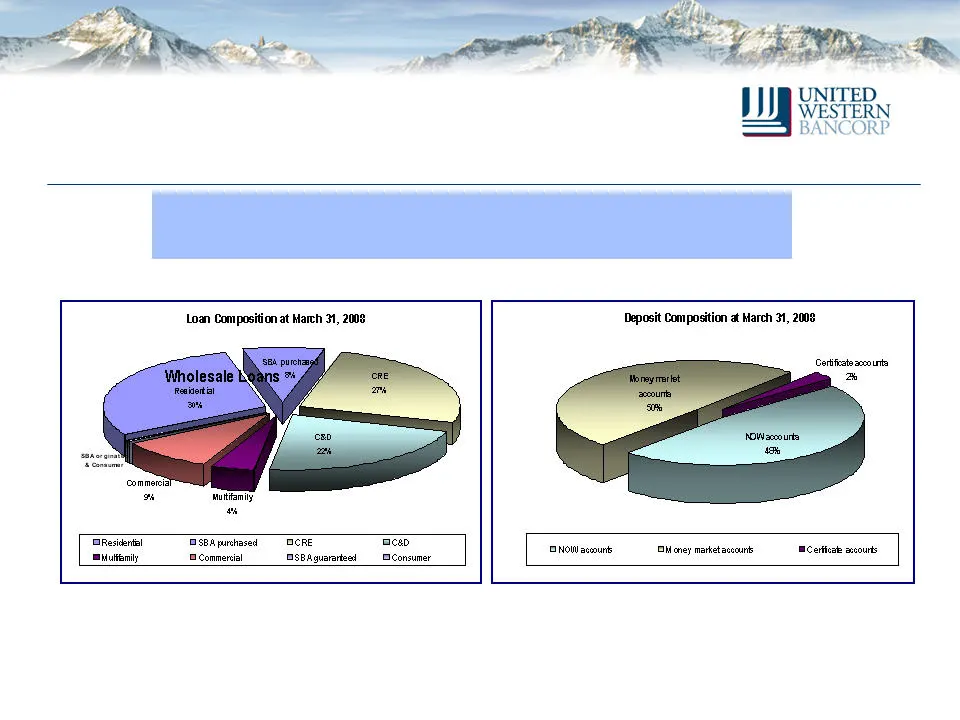
Slide 17: Q4-2007 to Q1-2008: Loan Portfolio & Deposits in Transition
Q4-2007 to Q1-2008: Community Bank Loans Grow 16% - from $706 million to $820 million Deposits Grow 3% - from $1.38 billion to $1.43 billion Loan Portfolio & Deposits in Transition
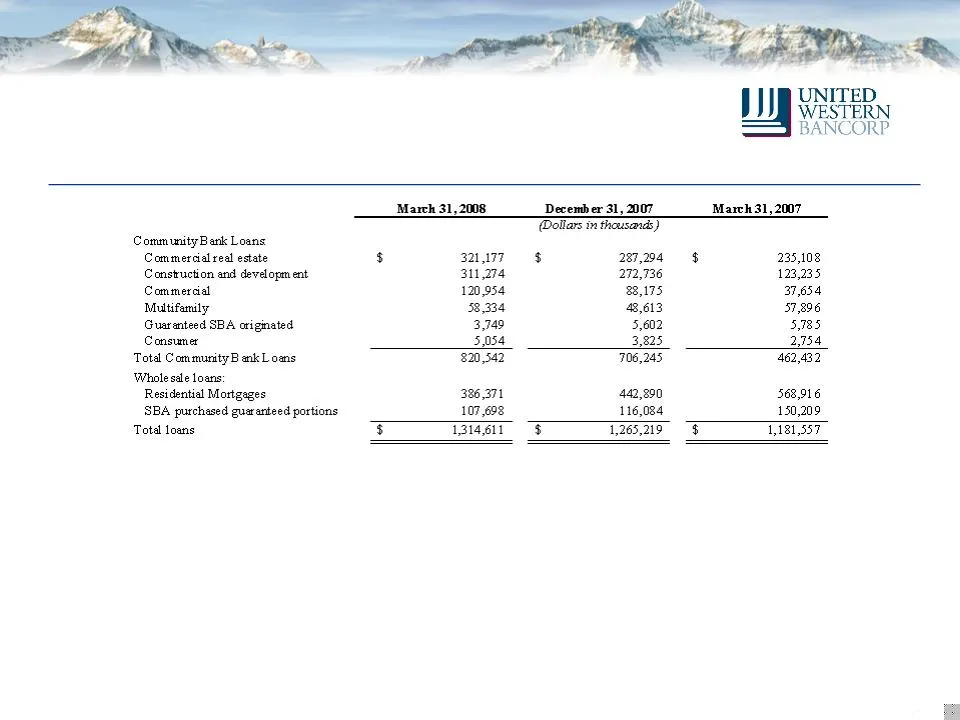
Slide 18: Loan Portfolio
Loan Portfolio o We provide vertical construction financing for local-based residential and commercial real estate developers. o Our construction loans generally do not exceed 18 months in tenure, with the exception of some mountain communities requiring longer building cycles. o We generally do not
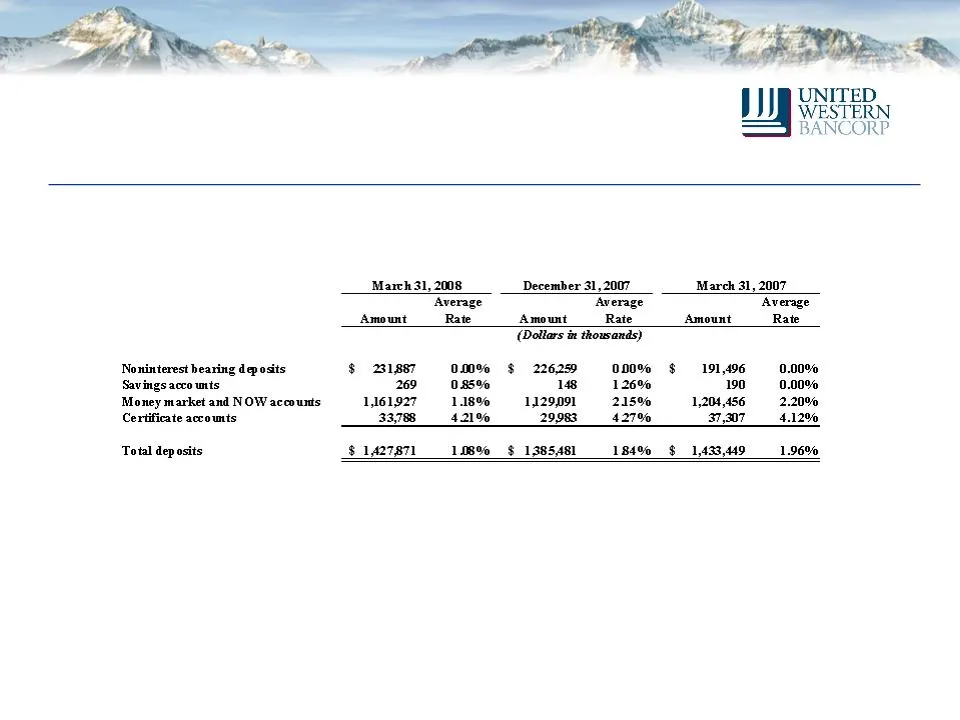
Slide 19: Deposit balances and average rates
J J J UNITED WESTERN BANCORP Mareh31, 2008 December 31,2007 ‘March 31, 2007 “Average “Average ‘Average Amount Rate Amout___ Rate Amount Rate ‘(Dollars ix thowands) Noninterest bearing deposits $ 21887 000% $ 226259 000% $ 191,495 0.00% Savings acco mis 269 0.85% 148 126% 190 0.00% Money market and N
Slide 20: Characteristics of SFR Portfolio
Characteristics of SFR Portfolio o Over 6.5 years seasoned o Average loan size $146,000 o Rigorously underwritten when acquired o Geographically diverse o Average FICO scores over 700 when originated o Reasonable loan-to-values and debt-to-income ratios o Estimate current loan-to-value to be in the
Slide 21: Investment Portfolios
Investment Portfolios o $602 million of MBS securities o At March 31, 2008, approximately 99% AAA and AA rated, and 1% A rated CRA bonds o 88% A collateral and 12% Alt-A
Slide 22: Quarterly: 2006-2008 Allowance for Credit Losses
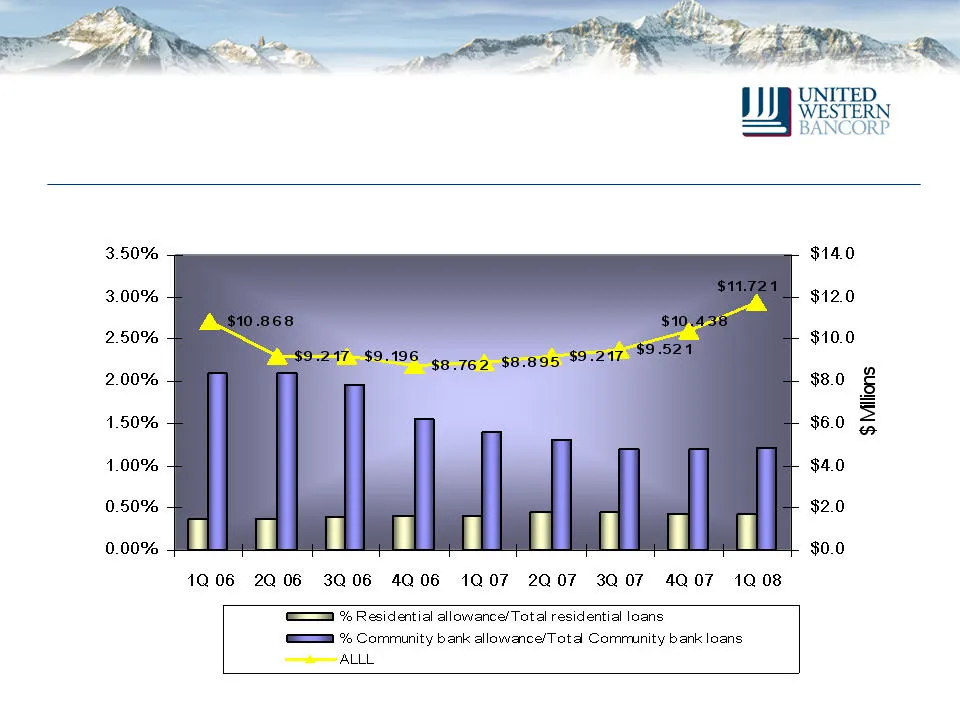
Quarterly: 2006-2008 Allowance for Credit Losses
Slide 23: UWBK Stock Performance
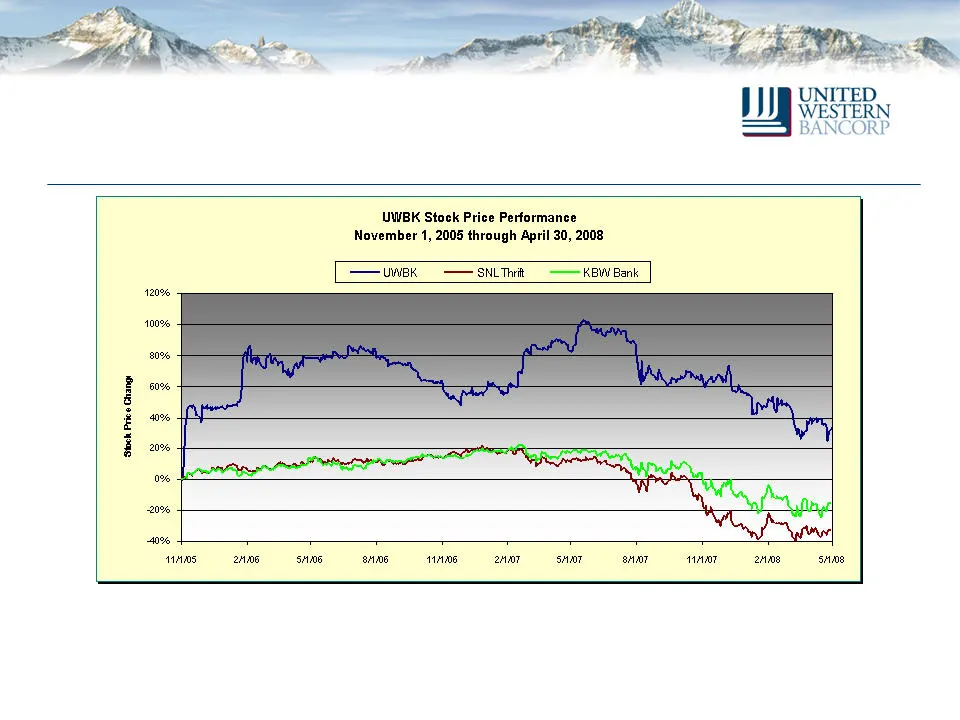
UWBK shareholders experienced a 33.53% growth in total share price since November 1, 2005 - from $12.83 on November 1, 2005 to $17.13 at April 30, 2008, compared to a return on the SNL Thrift Index of (33.47%) and the KBW Bank Index of (16.36%). Stock Performance
Slide 24: UWBK Total Return vs. Colorado Peers
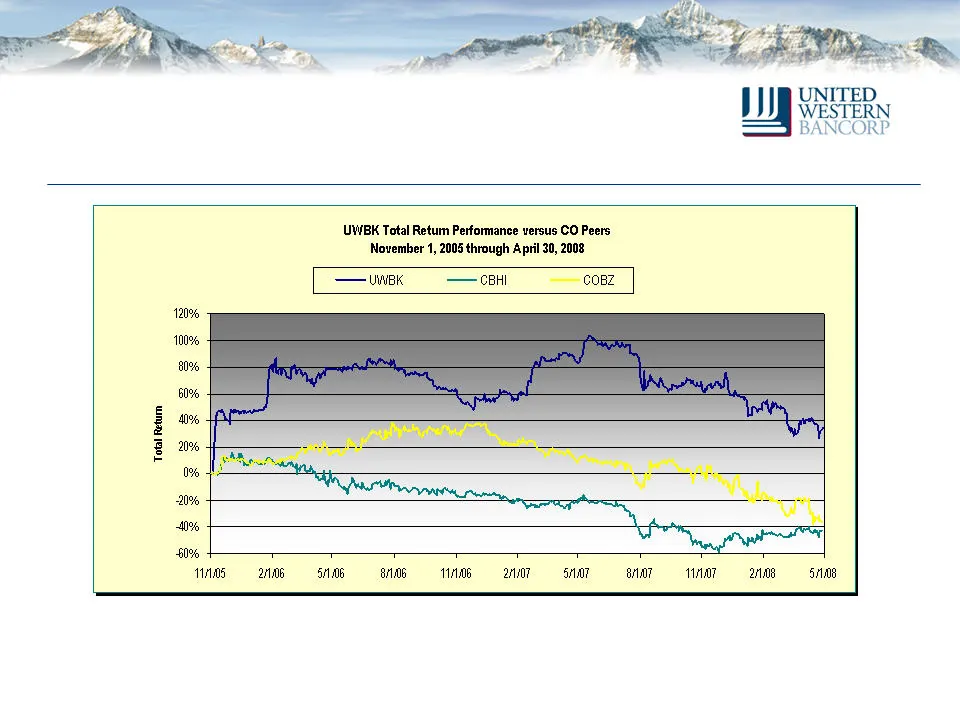
UWBK shareholders experienced a positive 35.38% total return since November 1, 2005 compared to a total return loss on CBHI of (44.06%) and a total return loss on COBZ of (33.44%). UWBK Total Return vs. Colorado Peers
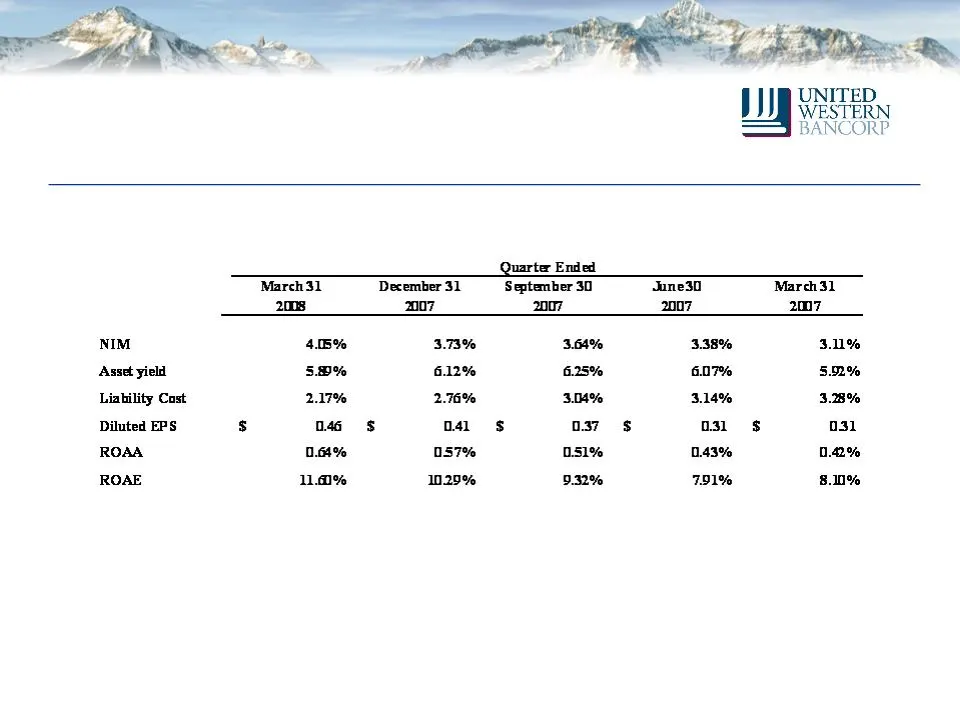
Slide 25: Quarterly NIM, yield, EPS, ROAA, ROAE
UNITED. WESTERN BANCORP Quarter Ended March 31 December 31 ‘September 30 anes March 31 2008 2007 2007 2007 2007 NIM 4B% 3.73% 364% 338% 3.0% Asset yield 5% 6.12% 625% 607% 52% Liability Cost 217% 2.76% 34% 3.14% 3.23% Diluted EPS a4 o4 $s 037 ol $ 031 ROAA 0.64% 057% Ds1% 043% 1.2% ROAE na% 10.20% 9
Slide 26: Promising Future - Growing Value
A Promising Future - Growing Value n Experienced management n Well-established infrastructure n Strong employee base n Attractive demographics n Vibrant marketplace n Solid relationship with regulators n Compelling business model n Proven execution to date
Slide 27: United Western Bancorp
J i} UNITED. WESTERN BANCORP j J UNITED WESTERN BANCORP
Source: SEC EDGAR · 8-K filed May 6, 2008
More decks from United Western Bancorp Inc
 Shareholder Meeting (July 2010)12 slides · Jul 30, 2010
 Merger or Acquisition (June 2010)16 slides · Jun 15, 2010
 Q3 2009 Earnings Presentation29 slides · Nov 10, 2009
 IPO Roadshow (September 2009)38 slides · Sep 8, 2009
 Shareholder Meeting (May 2009)28 slides · May 21, 2009
 Merger or Acquisition (April 2009)6 slides · Apr 10, 2009