United Western Bancorp — Shareholder Meeting (May 2009)
28 slides from United Western Bancorp's shareholder meeting presentation, May 21, 2009
Slide 1: Presentation to Annual Shareholders' Meeting
May 22, 2009 Presentation to Annual Shareholders’ Meeting
Slide 2: Forward looking statement
2 2 Forward looking statement Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 that are subject to significant risks and uncertainties. Forward-looking statements include information concerni
Slide 3: Summary
3 * As of May 12, 2009 Summary o NASDAQ: UWBK o $2.3 Billion Assets o 7.3 Million Shares Outstanding o $9.66 per share* o $70.1 Million Market Capitalization* o Dividend Yield 2.48%* o Holding company for two primary subsidiaries: n United Western Bank ® - Denver, CO n Sterling Trust Company - Waco,
Slide 4: Who we are
4 Who we are o United Western Bank ® n One of three publicly traded banks headquartered in Colorado n Largest federal savings bank in Colorado - $2.2 billion in assets n Fourth largest publicly traded thrift in the western United States n Traditional community bank - target businesses first, consume
Slide 5: United Western Bank - Strategy
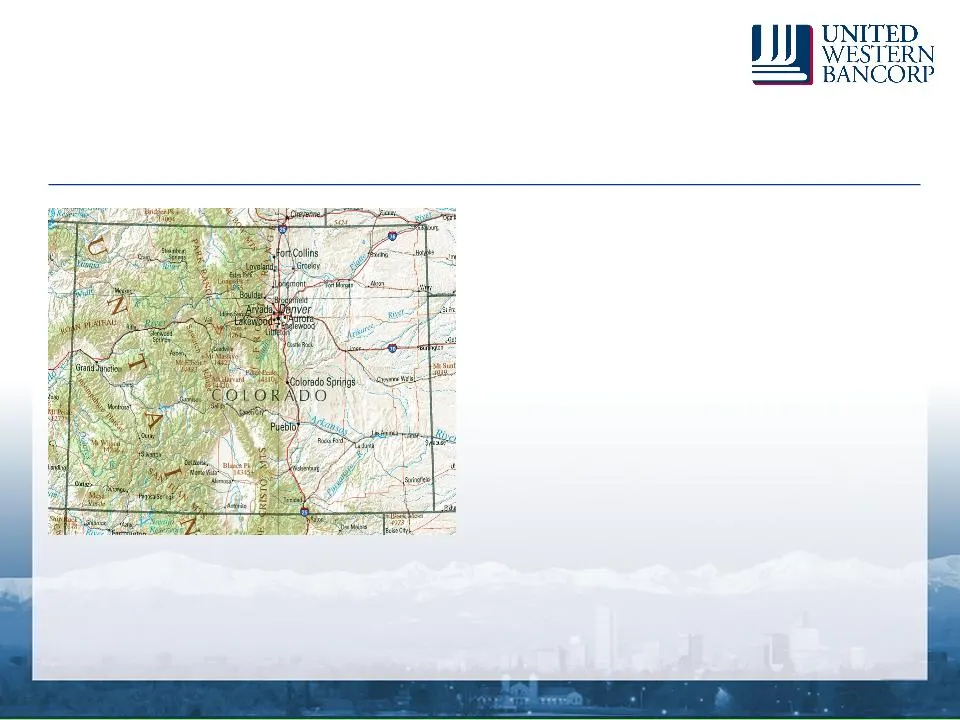
5 5 United Western Bank ® - Strategy o Established community bank business plan in 2006 o Redirected legacy company into community banking o Transition balance sheet → community banking vs. wholesale mortgage business o Capitalize on dynamic Colorado banking environment and growing economy o Recruit
Slide 6: United Western Bank - our new independent brand
6 6 United Western Bank ® - our new “independent” brand o UWB name launched in 2006 o Brand awareness is growing n Distribution expanding - eight full service locations open n First marketing efforts fourth quarter 2008 o Branding in population center n 82% of Colorado population in Front Range n Fr
Slide 7: Colorado Economy and Bank Market
7 7 Colorado Economy Colorado Bank Market o Colorado metrics n Unemployment rate 7.5% at March 31, 2009 compared to 8.5% nationally 1 n Median home price $216,337 2 n SFR foreclosures overstated! n Median household income $71,000 compared to $64,000 nationally 3 o National rankings n Ranked fifth in
Slide 8: Colorado's Front Range
8 8 Colorado’s Front Range o Second largest “megapolitan” area in the Intermountain West (first is the Arizona Sun Corridor) 1 o Average labor productivity 8% higher than national average in 2005 1 o Higher than average per capita wages n $54,994 median in Denver Metro area, 14.2% higher than nation
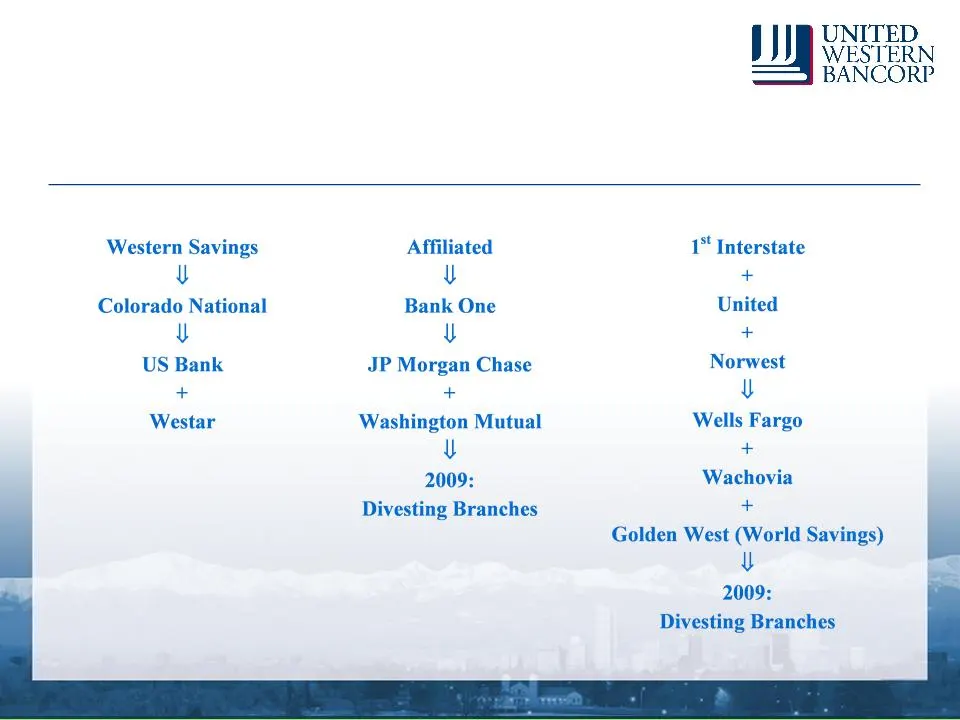
Slide 9: Colorado banks - my banker is ???
9 9 Colorado banks - my banker is ???
Slide 10: United Western Bank - Growing branch network
10 10 United Western Bank ® - Growing branch network o “Best” locations - breakeven target of 14 months o Smaller distribution network - 10-12, not 100, over time o High visibility, branding opportunity o Consistent construction theme - regional banking office, not “branch” o Eight full service loca
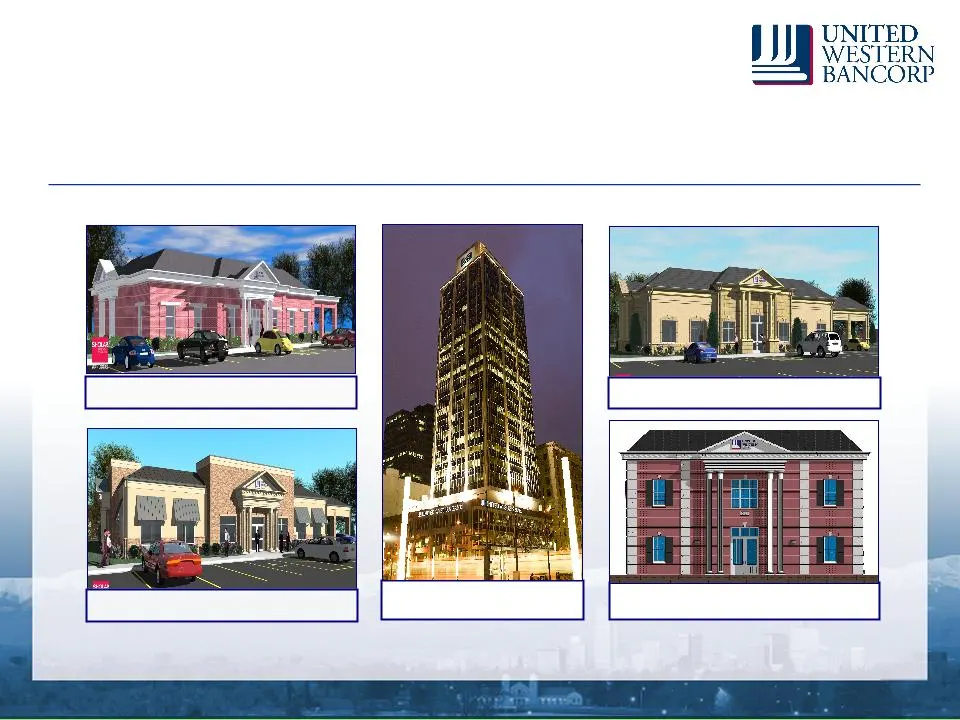
Slide 11: Growing branch network
11 Growing branch network Downtown Tower Centennial Longmont South Denver Fort Collins
Slide 12: United Western Bank - Differentiation
12 United Western Bank ® - Differentiation o Private banking “feel” coupled with technology o High touch - regional leadership runs markets, makes local decisions, speed of execution key o Invest in local communities - banker and local advisory board leadership entrenched o Average tenure of senior
Slide 13: Sterling Trust Company
13 Sterling Trust Company o Custodian, not asset manager o Primarily self-directed IRAs, non-typical assets (real estate, precious metals, etc.) o As of March 31, 2009, approx. 75,200 accounts - 13.37% CAGR since December 31, 2002 o As of March 31, 2009, $4.9 billion under custody - 15.04% CAGR sinc
Slide 14: Sale of Sterling Trust Company Assets
14 Sale of Sterling Trust Company Assets o Equity Trust Company and an affiliate are acquiring certain assets of Sterling Trust in an asset purchase o Sale of Sterling assets - proceeds of (~) $61.2 million o Estimated after-tax gain on sale of (~) $35.6 million o Sterling’s custodial deposits - (~)
Slide 15: Historic Capital and Financial Strategy
15 Historic Capital and Financial Strategy o Change mix/shift balance sheet n Wholesale to community banking o Called expensive trust preferred securities ($30 million at 9.81%) o Repurchased 474,100 shares o Quarterly dividend of $0.06 per share o Divested non-core assets (2006) o De-leverage whole
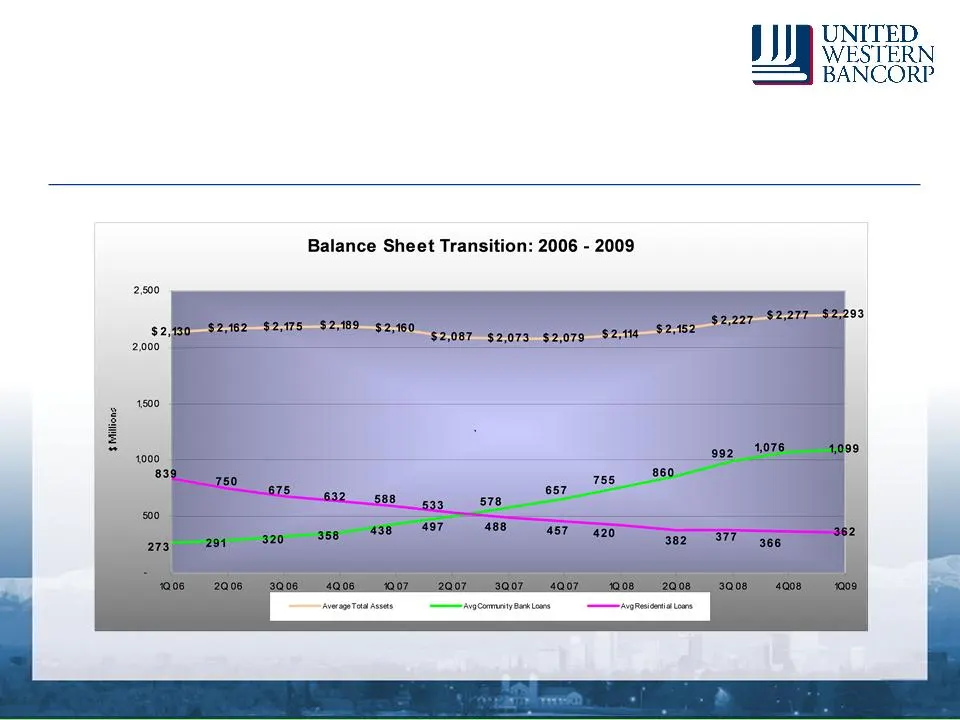
Slide 16: Balance Sheet Transition: Runoff Wholesale Assets
16 Balance Sheet Transition: Runoff Wholesale Assets
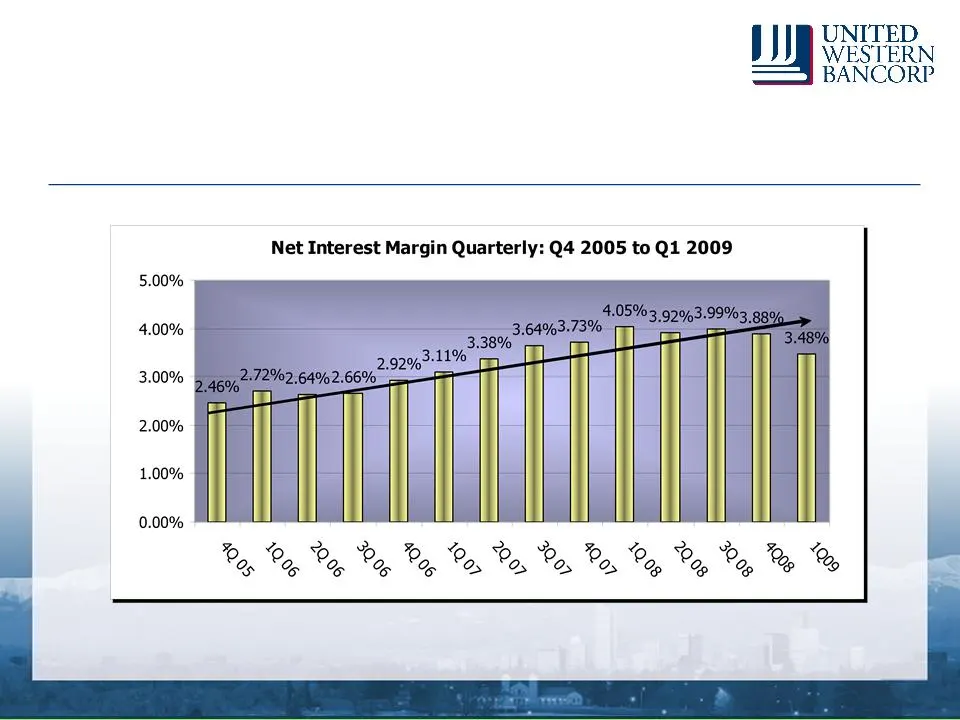
Slide 17: Net Interest Margin Quarterly
Ip yee WESTERN BANCORP Net Interest Margin Quarterly: Q4 2005 to Q1 2009
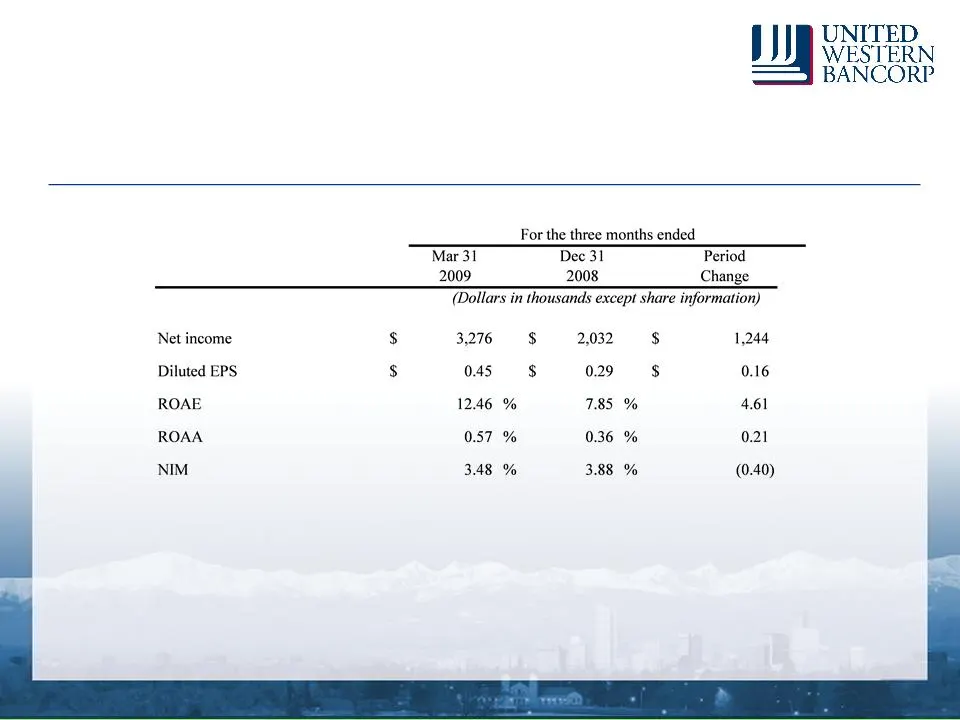
Slide 18: First Quarter Results - 2009
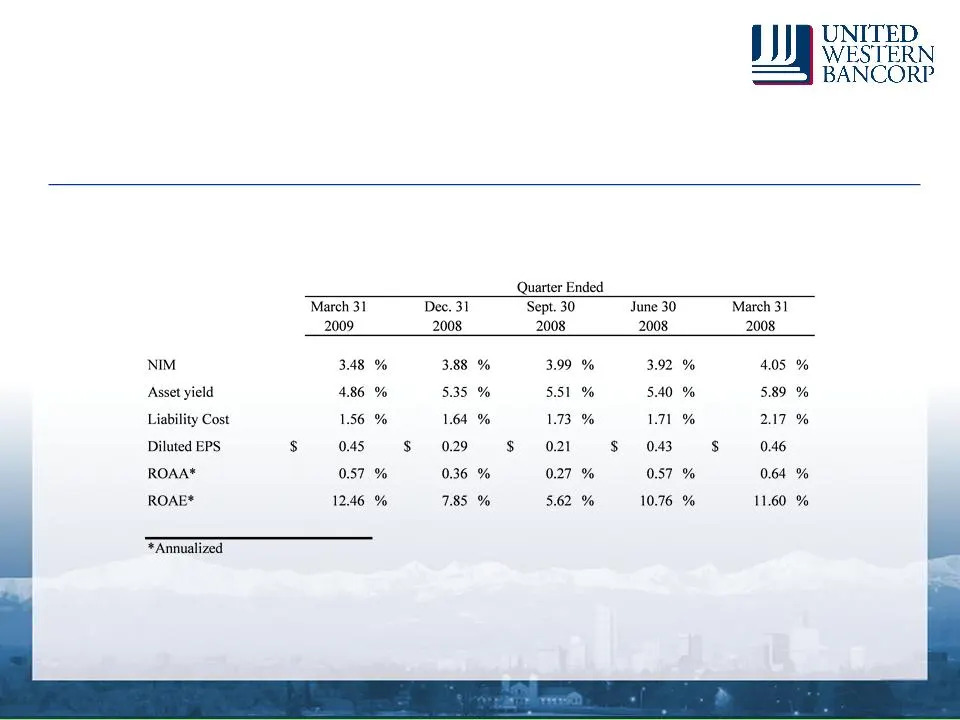
18 First Quarter Results - 2009
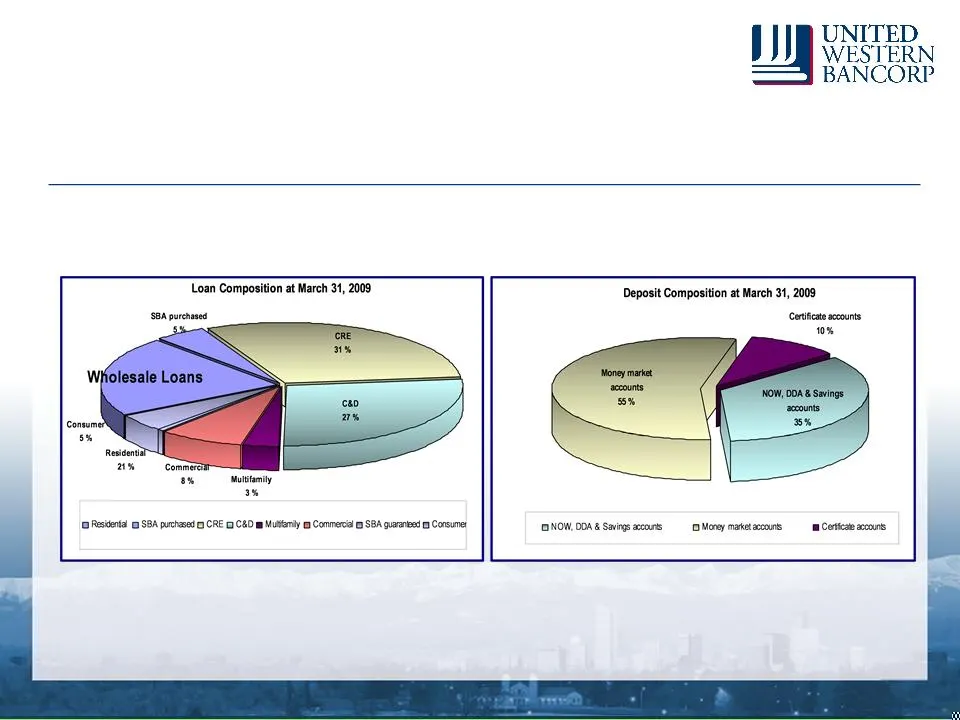
Slide 19: Loan Portfolio & Deposits in Transition
19 Loan Portfolio & Deposits in Transition March 31, 2008 to March 31, 2009: Community Bank Loans Grow 36% - from $821 million to $1.12 billion Deposits Increased 22% - from $1.43 billion to $1.74 billion Community bank deposits attributable to new branches = $234 million at March 31, 2009 vs. $192
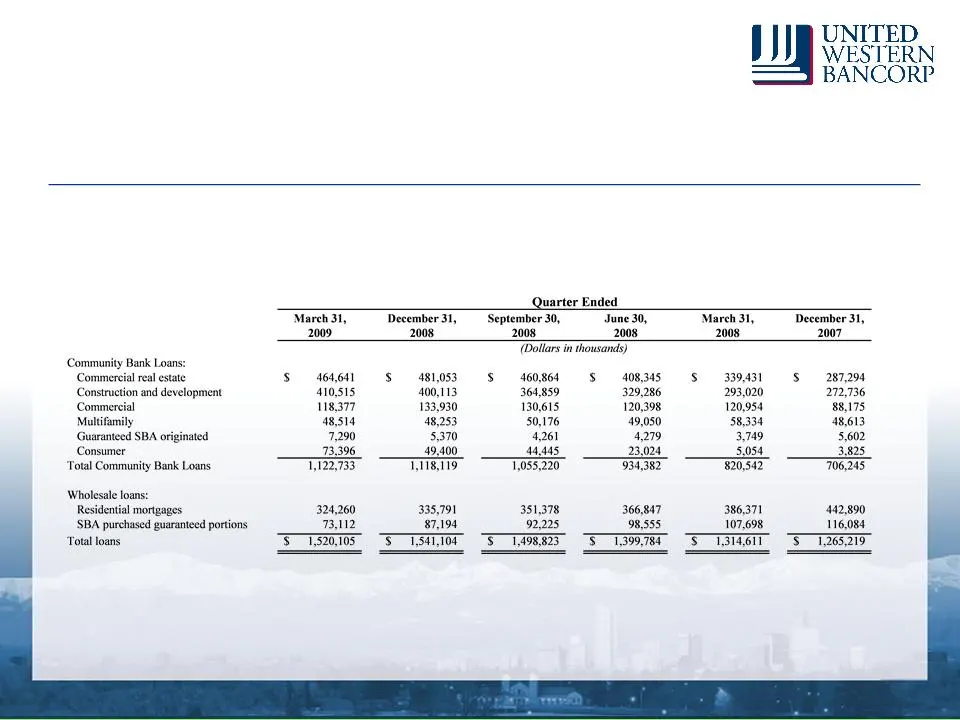
Slide 20: Community Bank Loans table
J J J UNITED WESTERN BANCORP Quarter Ended Mareh3t, December 3, September30, June 30, March 31, December 31, 2009 2008 2008 2008 2008 2007 (Dollars i ousands) Community Bank Loans: Commercial realestate S 46468 $481,053 S$ A60864 SARS «S| 330K31 (287298 Construction and development a10sis 400,113 36
Slide 21: Loans - what we do
21 Loans - what we do o Traditional community bank - business credit focused o Lend to people we know, in our Colorado back-yard o Recourse or co-borrower structures o Tangible collateral lender o Sole banker for our clients - avoid disputes with other banks o We get our terms - structure and pricin
Slide 22: Loans - what we don't do
22 Loans - what we don’t do o No shared national credits - no control / out of touch n Have three credits where borrower outgrew us o No levered cash flow finance / EVA o No auto dealers / manufacturers / auto industry n No floor plan (new or used) n No dealer real estate n No supplier, manufacturin
Slide 23: Characteristics of SFR Portfolio
23 Characteristics of SFR Portfolio o Over 8 years seasoned o Average loan size $135,000 o Rigorously underwritten when acquired o Geographically diverse o Average FICO scores over 700 when originated o Reasonable loan-to-values and debt-to-income ratios at origination o Estimate current loan-to-val
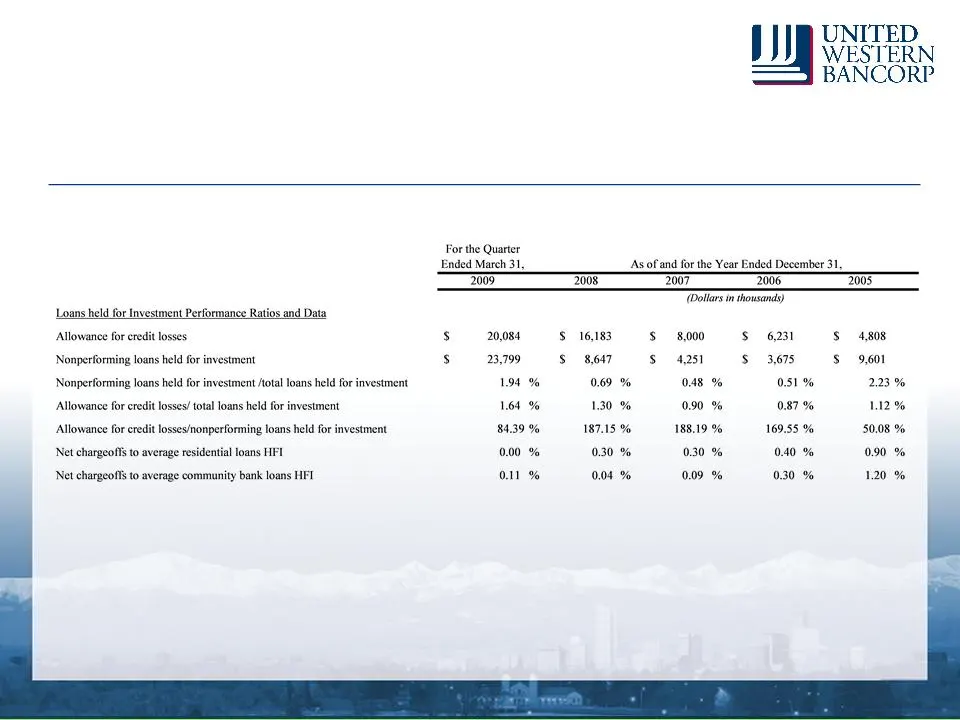
Slide 24: Allowance for Credit Losses & Nonperforming Loans HFI
24 Allowance for Credit Losses & Nonperforming Loans HFI
Slide 25: MBS Portfolio
25 MBS Portfolio o $520 million of Mortgage Backed Securities at March 31, 2009 o At March 31, 2009, based on the carrying value and lowest rating assigned: n 57% are agency securities or A rated and above n Of which 50% of the 57% are AAA and AA rated n 87% A collateral and 13% Alt-A collateral n B
Slide 26: Progress in a difficult environment
26 Progress in a difficult environment Net income to shareholders since December 31, 2005 = $33.3 million
Slide 27: A promising future - growing value
27 A promising future - growing value n Experienced management n Well-established infrastructure n Strong employee base n Attractive demographics n Stable marketplace n Solid relationship with regulators n Compelling business model n Proven execution to date
Slide 28: Ip yee
Ip yee WESTERN BANCORP DB Western BANCORP
Source: SEC EDGAR · 8-K filed May 21, 2009
More decks from United Western Bancorp Inc
 Shareholder Meeting (July 2010)12 slides · Jul 30, 2010
 Merger or Acquisition (June 2010)16 slides · Jun 15, 2010
 Q3 2009 Earnings Presentation29 slides · Nov 10, 2009
 IPO Roadshow (September 2009)38 slides · Sep 8, 2009
 Merger or Acquisition (April 2009)6 slides · Apr 10, 2009
 Investor Presentation (March 2009)31 slides · Mar 3, 2009