Radius Health — JP Morgan Healthcare Conference 2019
31 slides from Radius Health's conference presentation, Jan 7, 2019
Slide 1: Radius Health JP Morgan Healthcare Conference
Radius Health (RDUS) JP Morgan Healthcare Conference JANUARY 7, 2019 Jesper hoeiland Chief Executive Officer Exhibit 99.1
Slide 2: Safe Harbor
Safe Harbor Any statements made in this presentation relating to future financial or business performance, guidance, conditions, plans, prospects, trends or strategies and other financial or business matters, including regarding the commercialization of TYMLOS® (abaloparatide) injection in the U.S.,
Slide 3: An Innovation Leader in Osteoporosis and Breast Cancer to support Women's Health
An Innovation Leader in Osteoporosis and Breast Cancer to support Women’s Health VISION
Slide 4: 2019 and Beyond
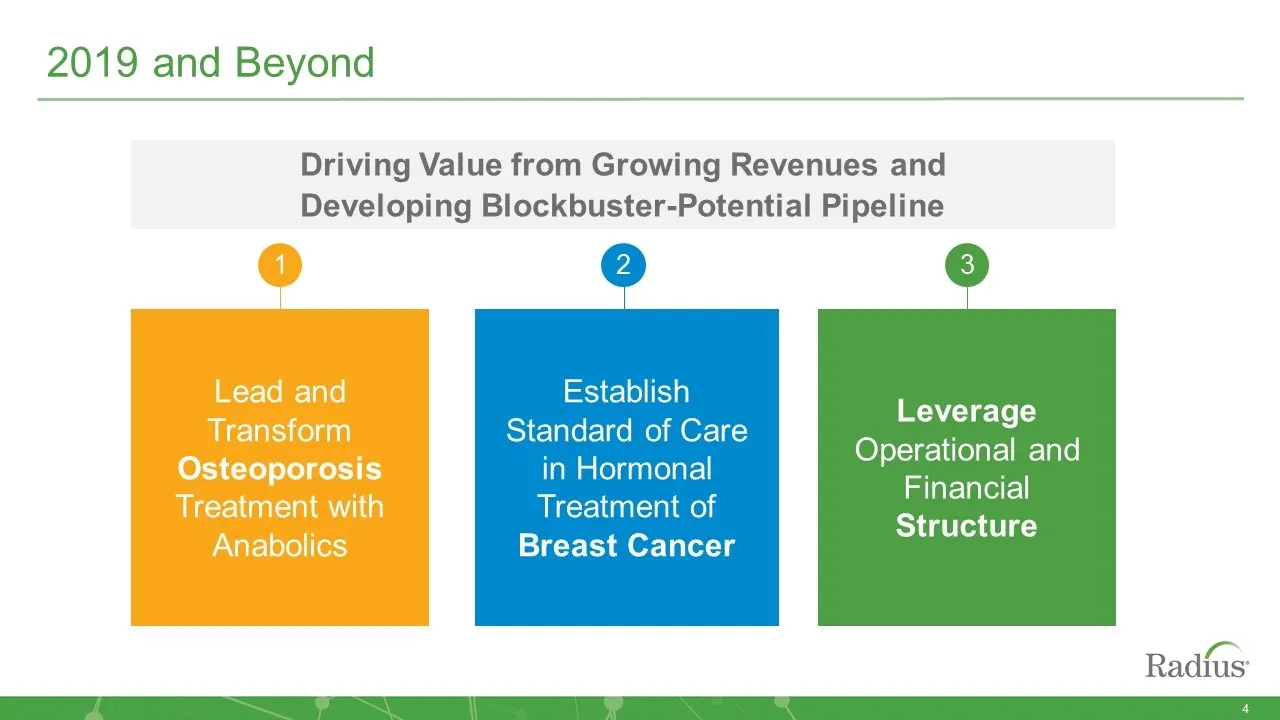
3 2 2019 and Beyond Lead and Transform Osteoporosis Treatment with Anabolics Establish Standard of Care in Hormonal Treatment of Breast Cancer Leverage Operational and Financial Structure 1 Driving Value from Growing Revenues and Developing Blockbuster-Potential Pipeline
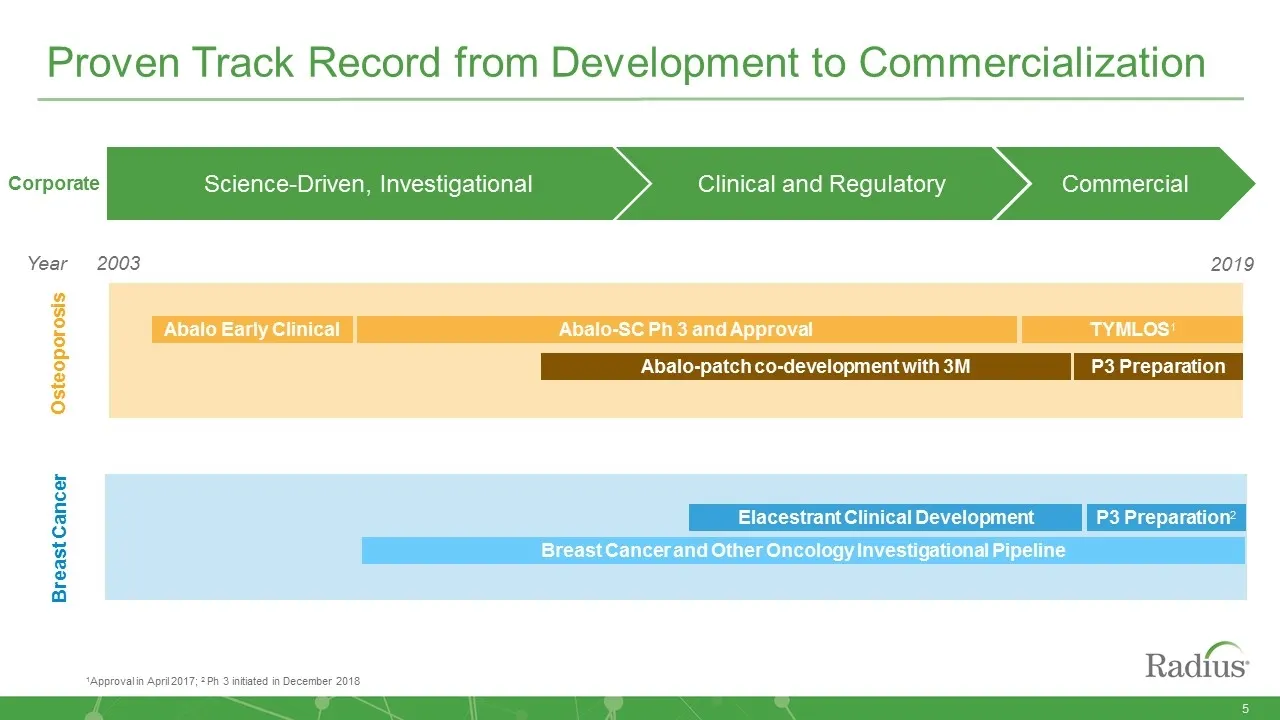
Slide 5: Proven Track Record from Development to Commercialization
Proven Track Record from Development to Commercialization Osteoporosis Breast Cancer Abalo Early Clinical Abalo-SC Ph 3 and Approval TYMLOS1 Abalo-patch co-development with 3M P3 Preparation Elacestrant Clinical Development P3 Preparation2 Breast Cancer and Other Oncology Investigational Pipeline 1A
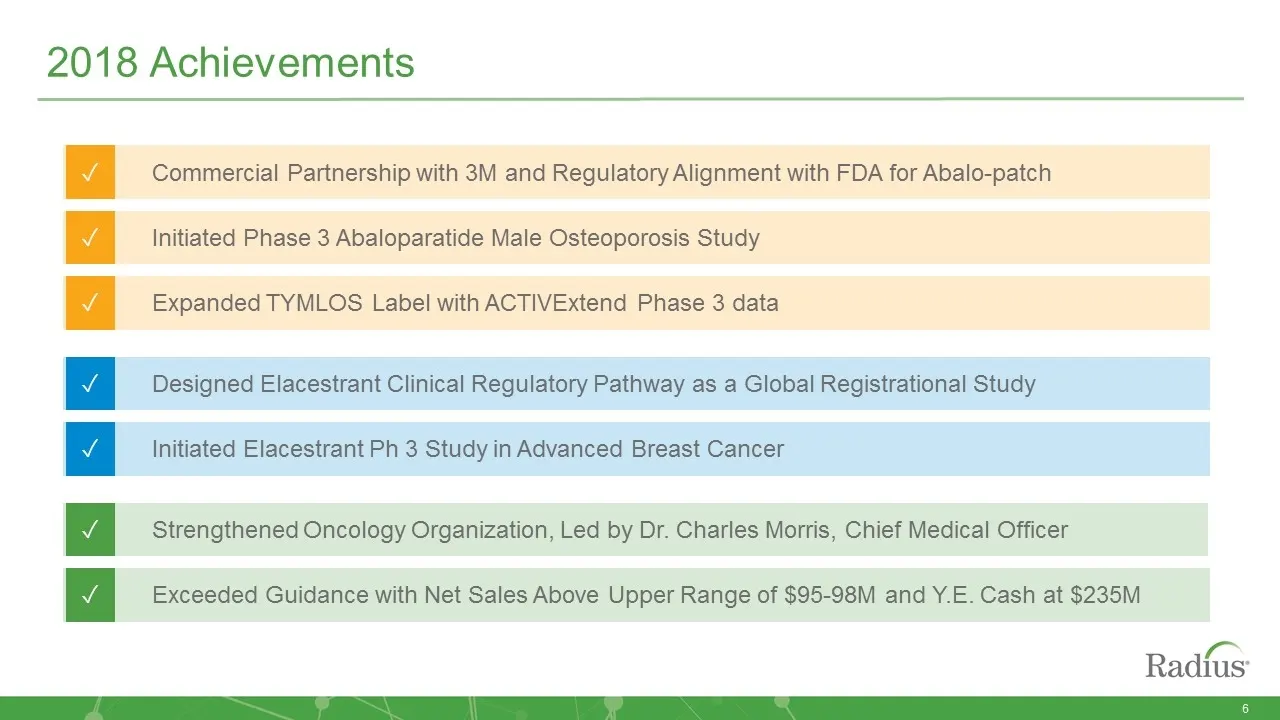
Slide 6: 2018 Achievements
2018 Achievements Strengthened Oncology Organization, Led by Dr. Charles Morris, Chief Medical Officer ✓ Exceeded Guidance with Net Sales Above Upper Range of $95-98M and Y.E. Cash at $235M ✓ Commercial Partnership with 3M and Regulatory Alignment with FDA for Abalo-patch ✓ Expanded TYMLOS Label wit
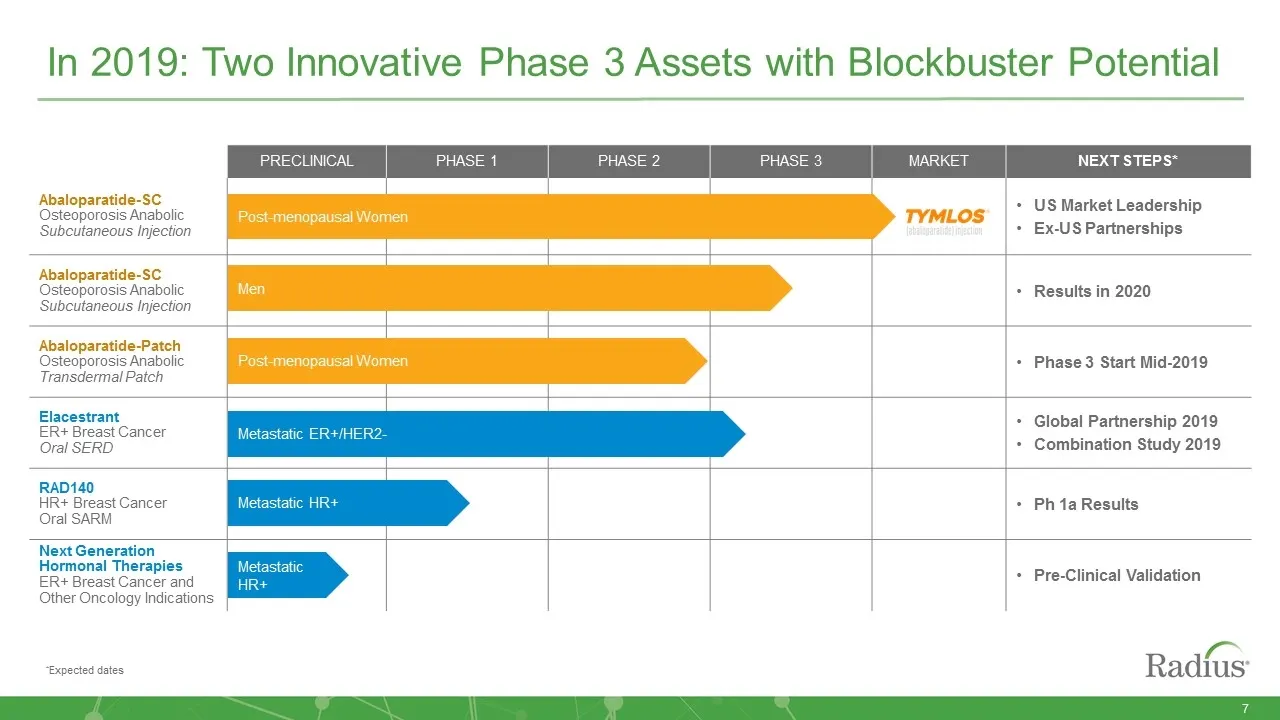
Slide 7: Pipeline
PRECLINICAL PHASE 1 PHASE 2 PHASE 3 MARKET NEXT STEPS* Abaloparatide-SC Osteoporosis Anabolic Subcutaneous Injection US Market Leadership Ex-US Partnerships Abaloparatide-SC Osteoporosis Anabolic Subcutaneous Injection Results in 2020 Abaloparatide-Patch Osteoporosis Anabolic Transdermal Patch Phase
Slide 8: 2019 and Beyond: Osteoporosis
1 3 2 2019 and Beyond: Osteoporosis Lead and Transform Osteoporosis Treatment with Anabolics Establish Standard of Care in Hormonal Treatment of Breast Cancer Leverage Operational and Financial Structure
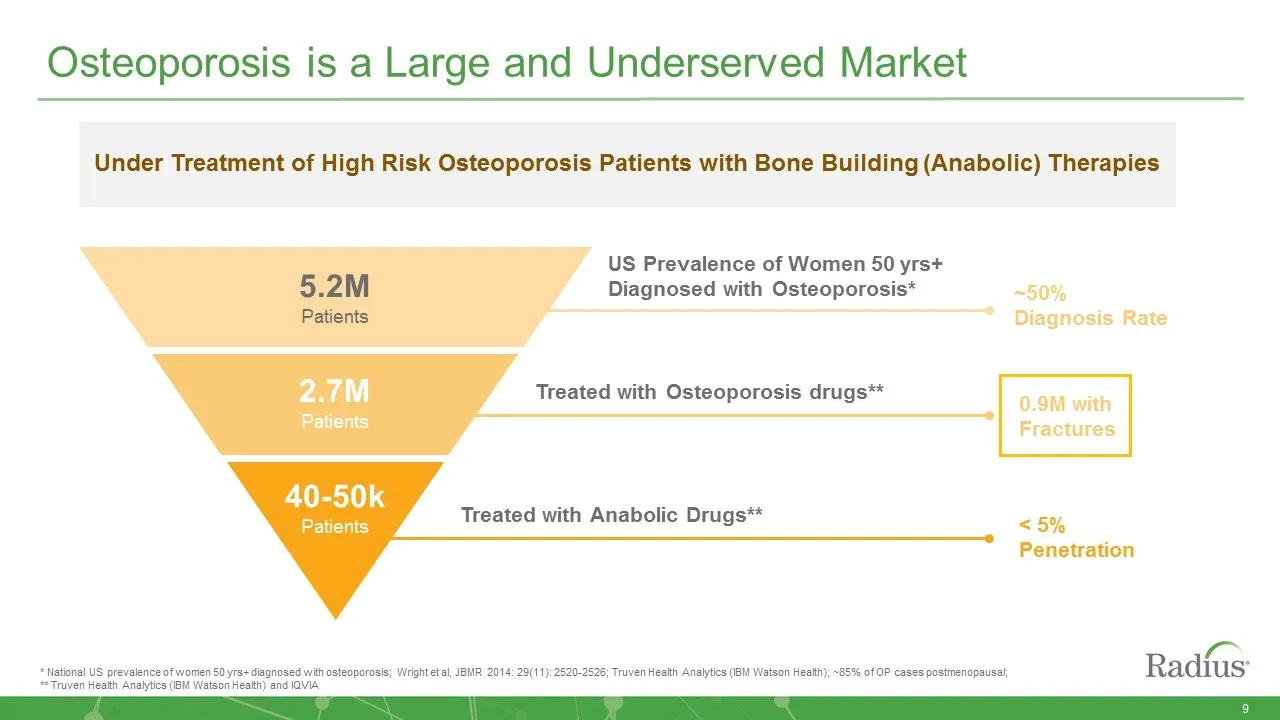
Slide 9: Osteoporosis is a Large and Underserved Market
Osteoporosis is a Large and Underserved Market * National US prevalence of women 50 yrs+ diagnosed with osteoporosis; Wright et al, JBMR 2014: 29(11): 2520-2526; Truven Health Analytics (IBM Watson Health); ~85% of OP cases postmenopausal; ** Truven Health Analytics (IBM Watson Health) and IQVIA 5.2
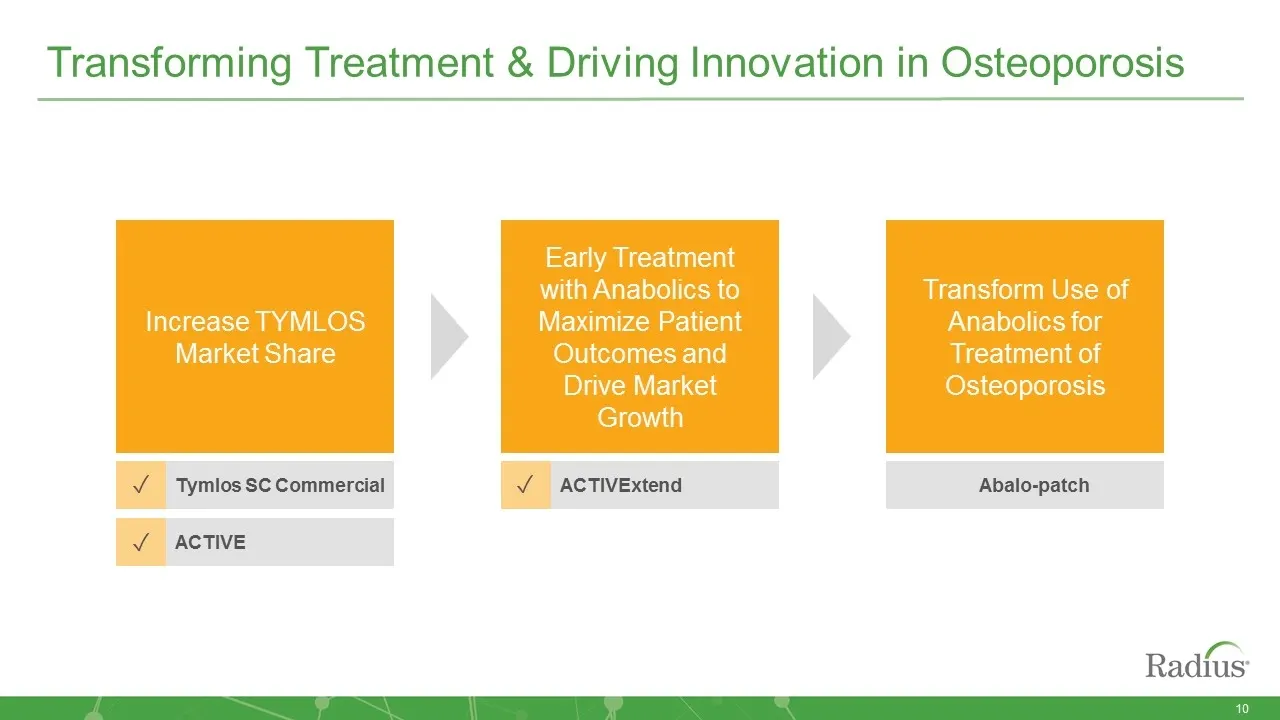
Slide 10: Transforming Treatment & Driving Innovation in Osteoporosis
Transforming Treatment & Driving Innovation in Osteoporosis Early Treatment with Anabolics to Maximize Patient Outcomes and Drive Market Growth Increase TYMLOS Market Share Transform Use of Anabolics for Treatment of Osteoporosis Abalo-patch Tymlos SC Commercial ✓ ACTIVE ✓ ACTIVExtend ✓
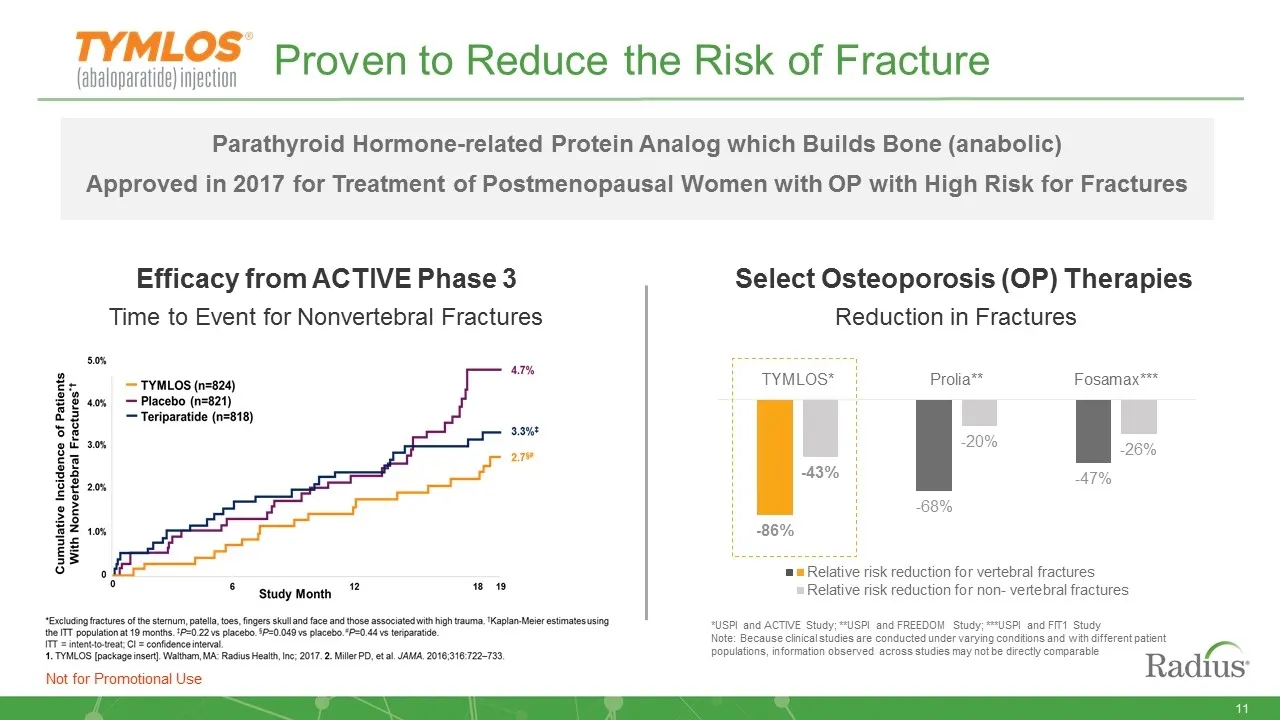
Slide 11: Proven to Reduce the Risk of Fracture
Proven to Reduce the Risk of Fracture Parathyroid Hormone-related Protein Analog which Builds Bone (anabolic) Approved in 2017 for Treatment of Postmenopausal Women with OP with High Risk for Fractures Reduction in Fractures Efficacy from ACTIVE Phase 3 Select Osteoporosis (OP) Therapies Time to Eve
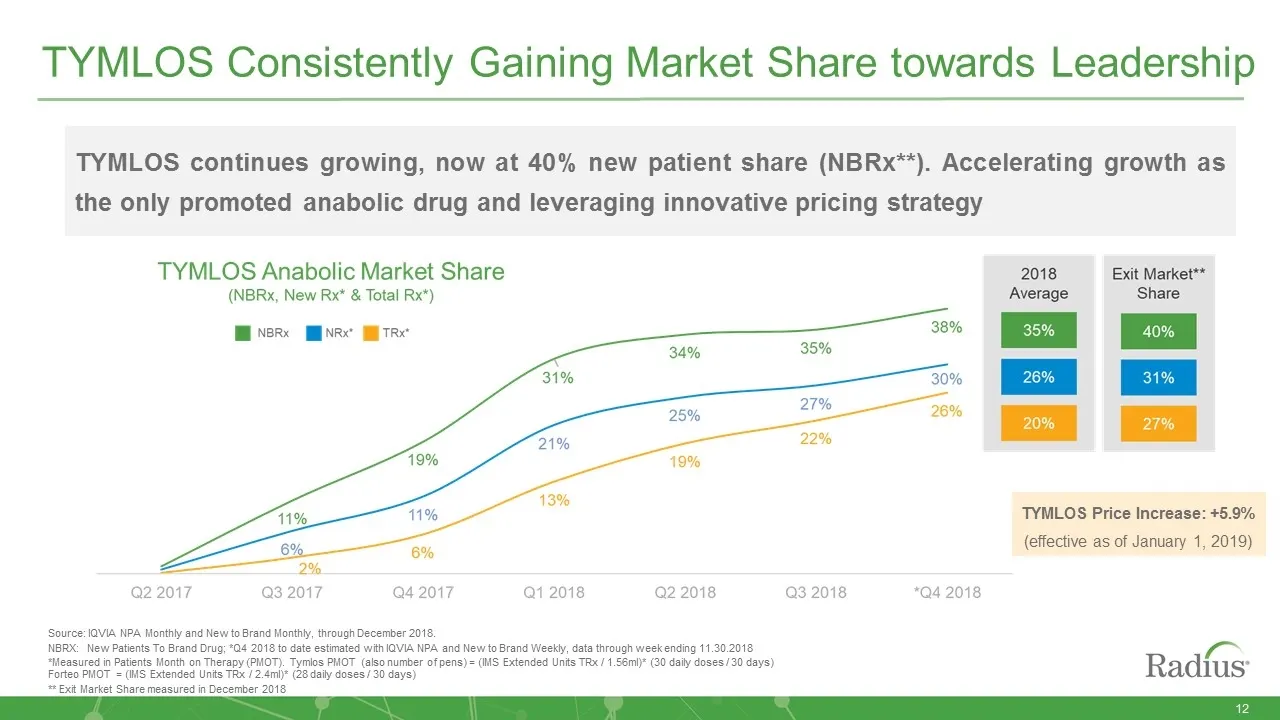
Slide 12: TYMLOS Consistently Gaining Market Share towards Leadership
TYMLOS Consistently Gaining Market Share towards Leadership TYMLOS continues growing, now at 40% new patient share (NBRx**). Accelerating growth as the only promoted anabolic drug and leveraging innovative pricing strategy Source: IQVIA NPA Monthly and New to Brand Monthly, through December 2018. NB
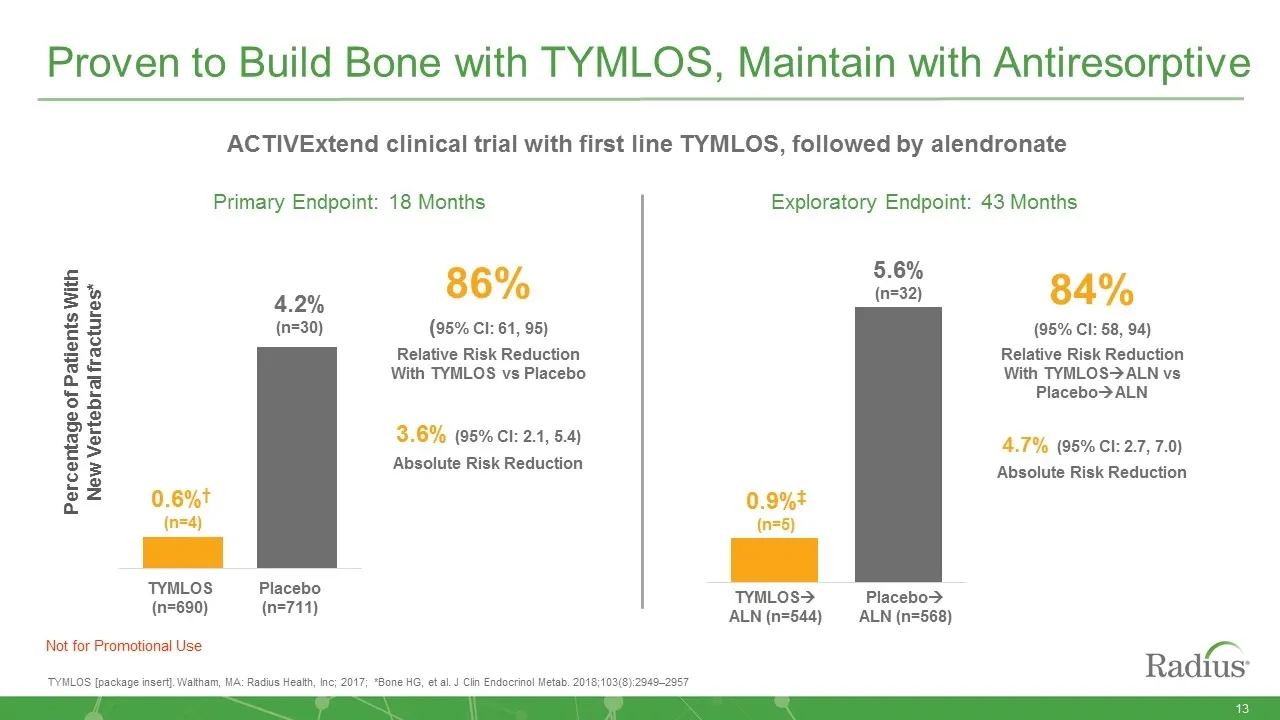
Slide 13: Proven to Build Bone with TYMLOS, Maintain with Antiresorptive
Proven to Build Bone with TYMLOS, Maintain with Antiresorptive ACTIVExtend clinical trial with first line TYMLOS, followed by alendronate Primary Endpoint: 18 Months 84% (95% CI: 58, 94) Relative Risk Reduction With TYMLOSàALN vs PlaceboàALN 4.7% (95% CI: 2.7, 7.0) Absolute Risk Reduction TYMLOSàALN
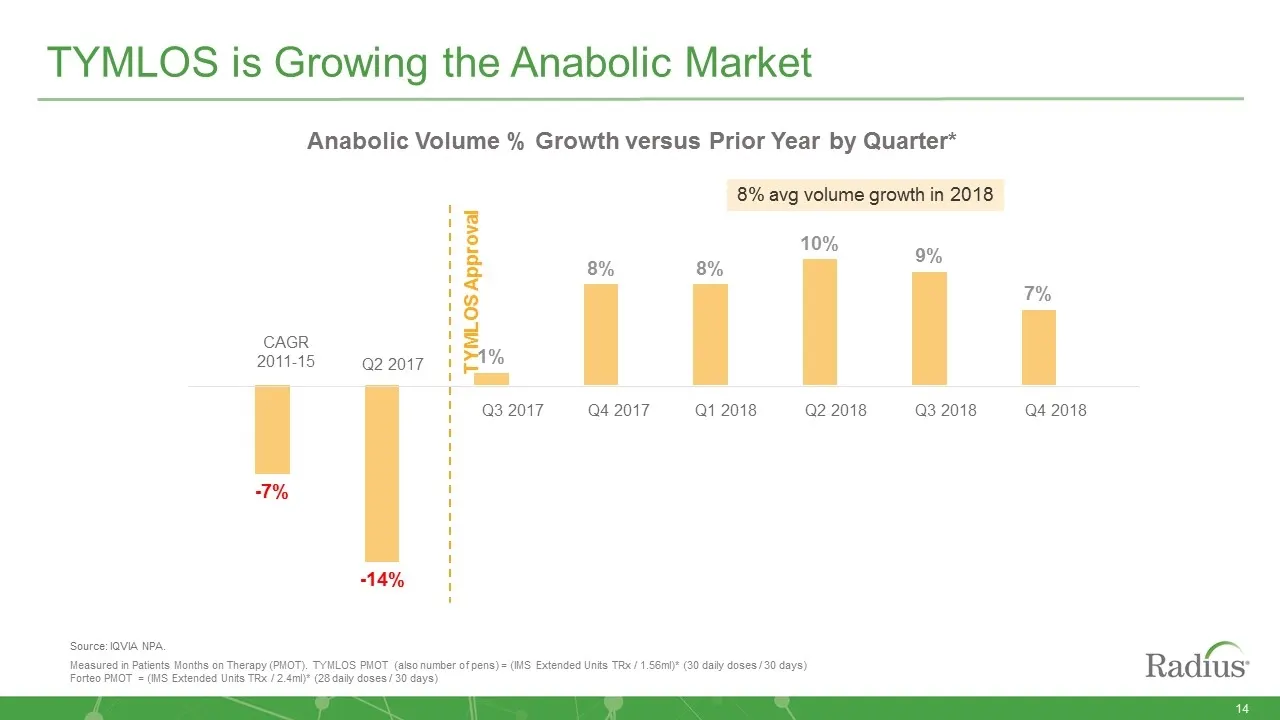
Slide 14: TYMLOS is Growing the Anabolic Market
TYMLOS is Growing the Anabolic Market Source: IQVIA NPA. Measured in Patients Months on Therapy (PMOT). TYMLOS PMOT (also number of pens) = (IMS Extended Units TRx / 1.56ml)* (30 daily doses / 30 days) Forteo PMOT = (IMS Extended Units TRx / 2.4ml)* (28 daily doses / 30 days) Anabolic Volume % Growt
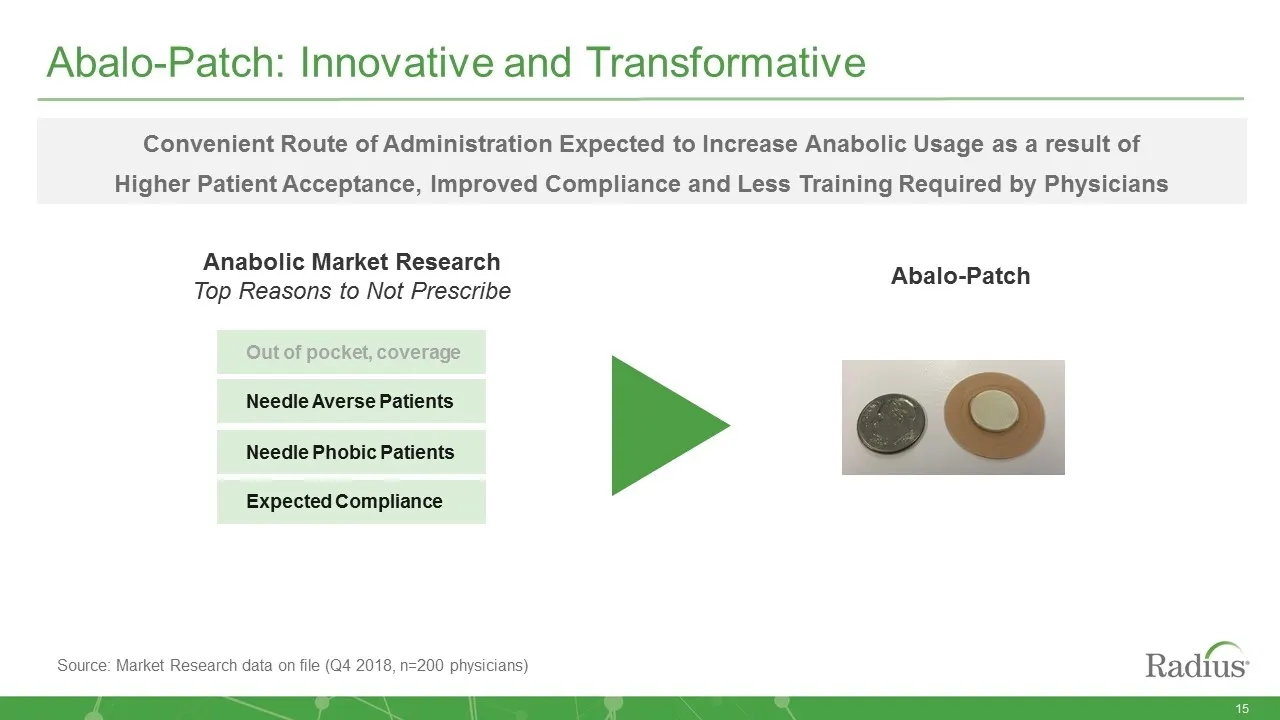
Slide 15: Abalo-Patch: Innovative and Transformative Anabolic
Out of pocket, coverage Abalo-Patch: Innovative and Transformative Anabolic Market Research Top Reasons to Not Prescribe Abalo-Patch Needle Averse Patients Needle Phobic Patients Expected Compliance Convenient Route of Administration Expected to Increase Anabolic Usage as a result of Higher Patient
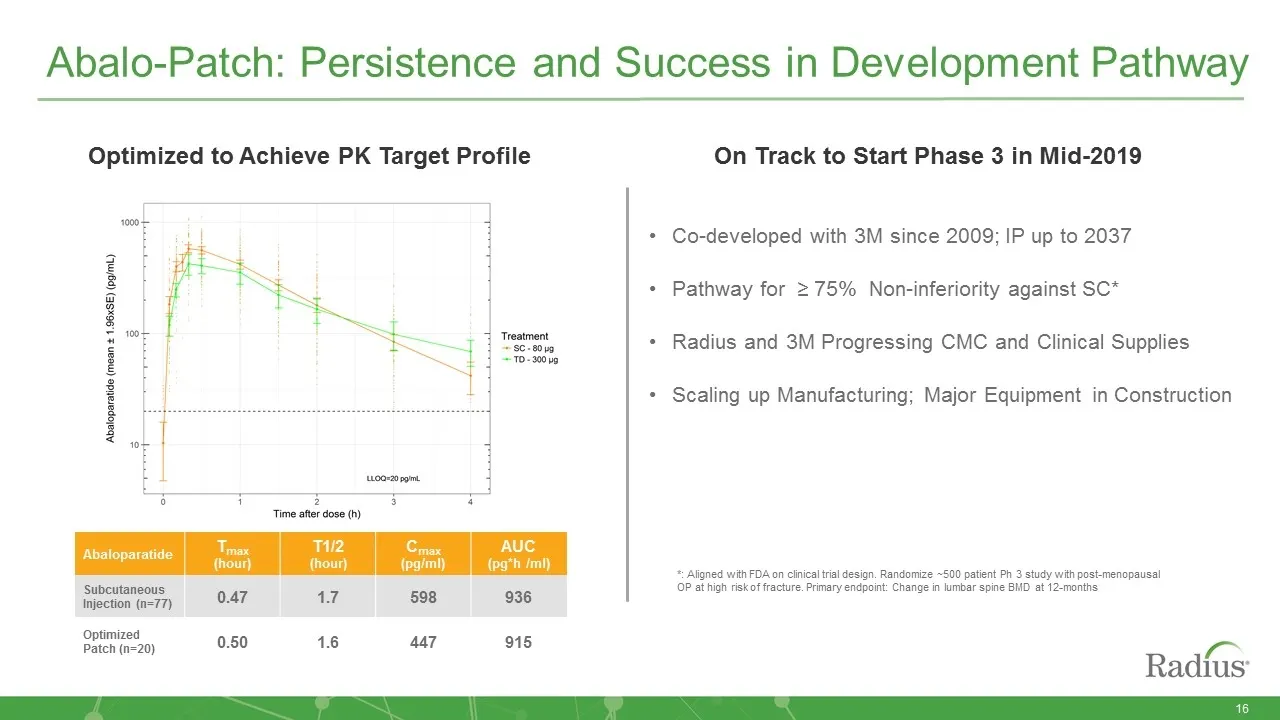
Slide 16: Abalo-Patch: Persistence and Success in Development Pathway
Abalo-Patch: Persistence and Success in Development Pathway Co-developed with 3M since 2009; IP up to 2037 Pathway for ≥ 75% Non-inferiority against SC* Radius and 3M Progressing CMC and Clinical Supplies Scaling up Manufacturing; Major Equipment in Construction Abaloparatide Tmax (hour) T1/2 (hour)
Slide 17: Abalo-Patch Blockbuster Potential in a Tripled Anabolic Market
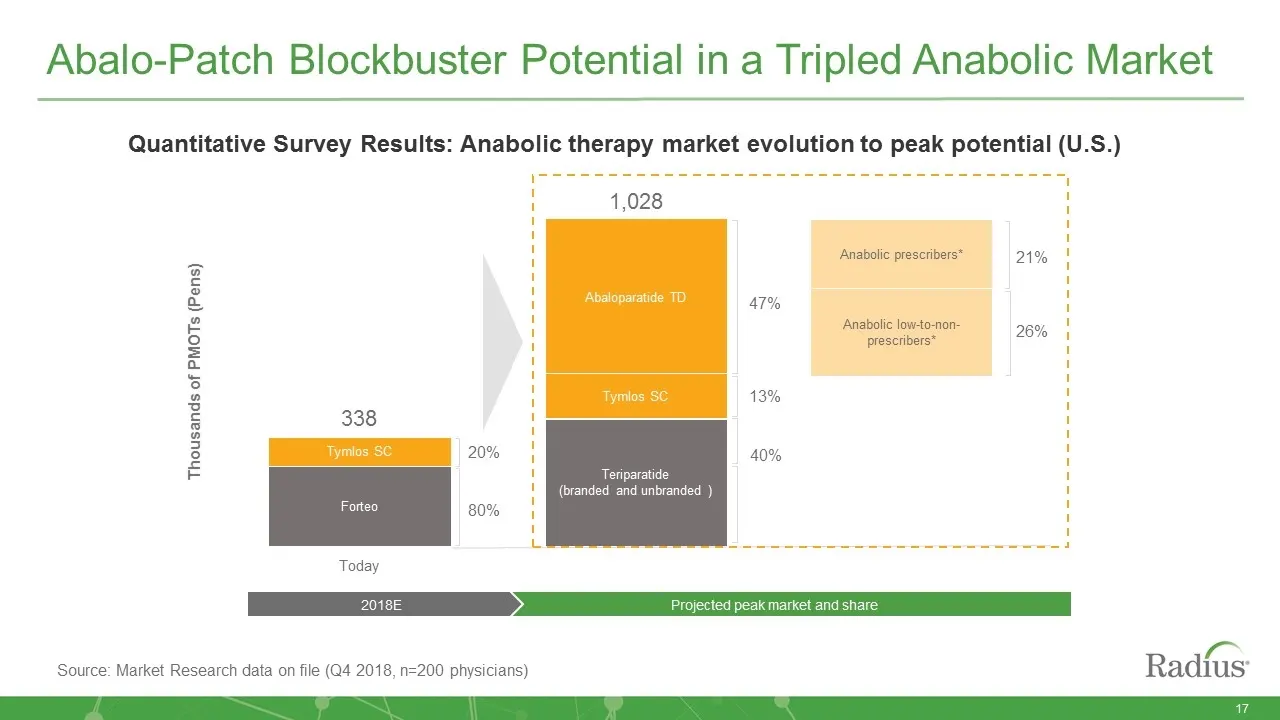
Projected peak market and share Abalo-Patch Blockbuster Potential in a Tripled Anabolic Market Today Tymlos SC Forteo Abaloparatide TD Tymlos SC Teriparatide (branded and unbranded ) Anabolic prescribers* Anabolic low-to-non-prescribers* 2018E 20% 80% 47% 13% 40% 21% 26% Quantitative Survey Results:
Slide 18: 2019 and Beyond: Breast Cancer
1 3 2019 and Beyond: Breast Cancer Lead and Transform Osteoporosis Treatment with Anabolics Establish Standard of Care in Hormonal Treatment of Breast Cancer Leverage Operational and Financial Structure 2
Slide 19: Driving Results in Breast Cancer
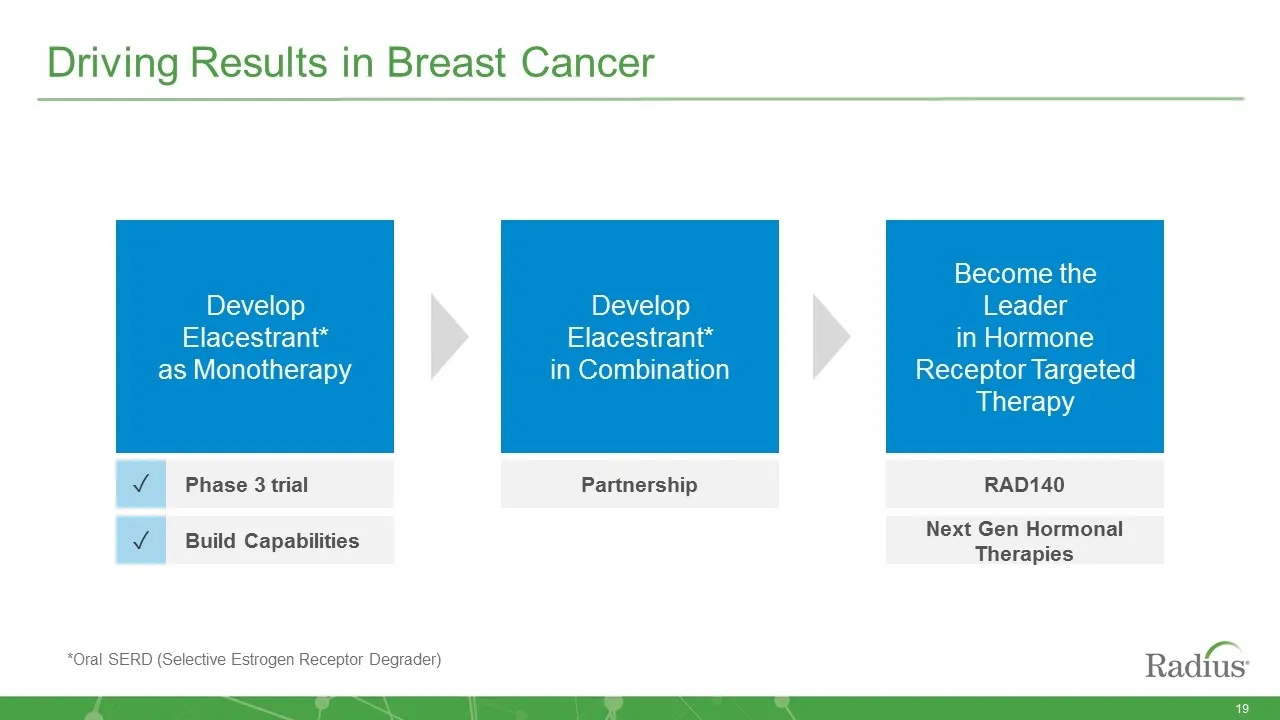
Driving Results in Breast Cancer Develop Elacestrant* in Combination Partnership Develop Elacestrant* as Monotherapy Become the Leader in Hormone Receptor Targeted Therapy RAD140 Next Gen Hormonal Therapies Phase 3 trial ✓ Build Capabilities ✓ *Oral SERD (Selective Estrogen Receptor Degrader)
Slide 20: Elacestrant Blockbuster Sales Potential as Mono and Combo
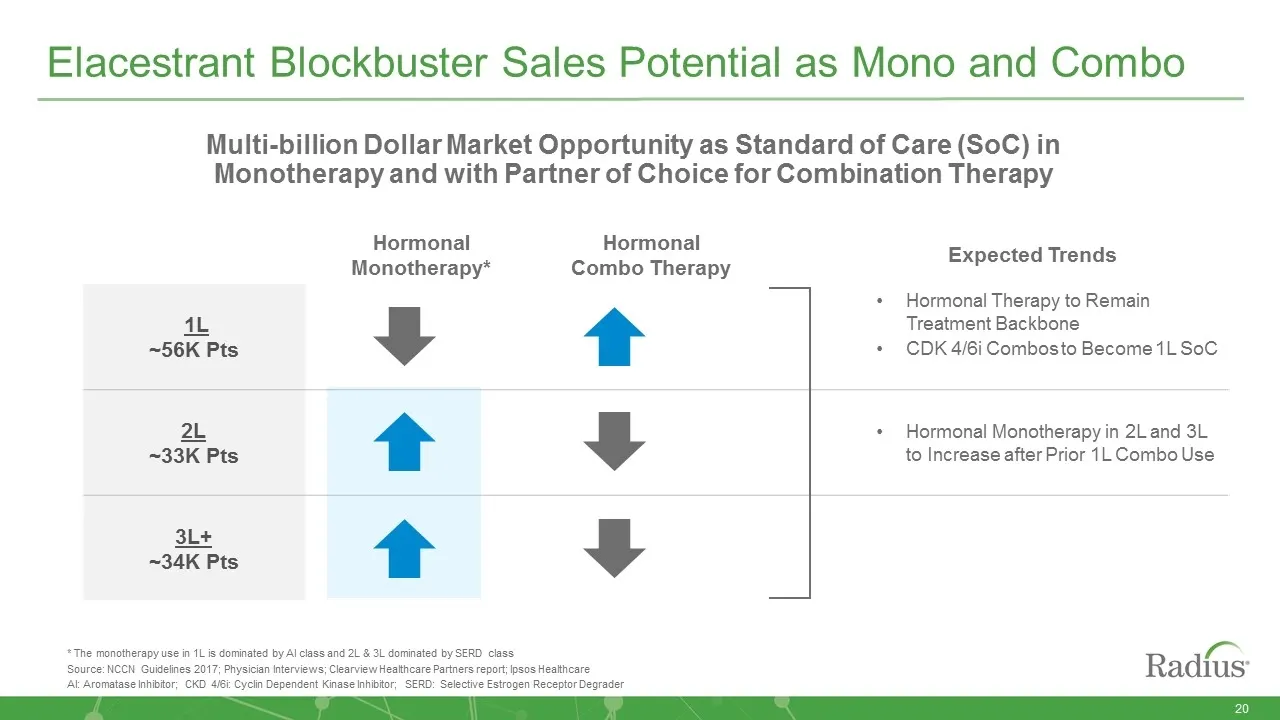
Hormonal Monotherapy* Hormonal Combo Therapy Expected Trends 1L ~56K Pts Hormonal Therapy to Remain Treatment Backbone CDK 4/6i Combos to Become 1L SoC 2L ~33K Pts Hormonal Monotherapy in 2L and 3L to Increase after Prior 1L Combo Use 3L+ ~34K Pts Elacestrant Blockbuster Sales Potential as Mono and
Slide 21: Encouraging Elacestrant Clinical Trial Results
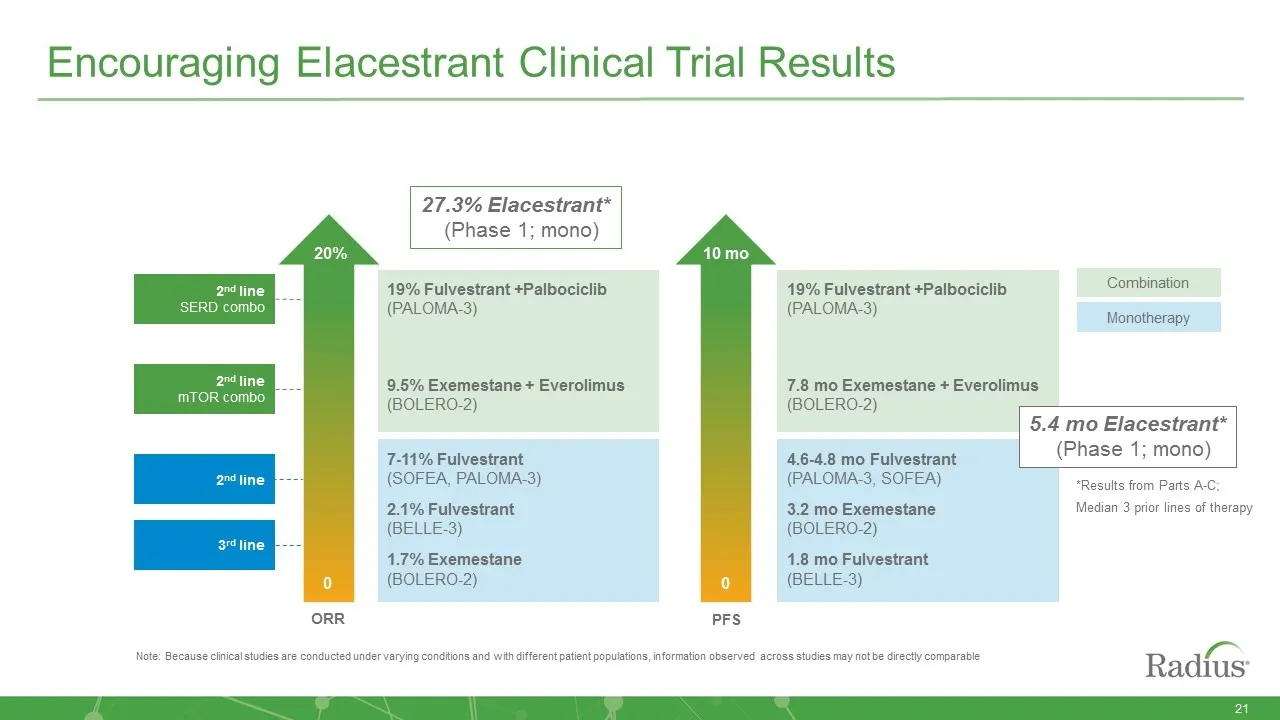
Encouraging Elacestrant Clinical Trial Results *Results from Parts A-C; Median 3 prior lines of therapy ORR 2nd line SERD combo 2nd line mTOR combo 2nd line 3rd line 0 10 mo 19% Fulvestrant +Palbociclib (PALOMA-3) 9.5% Exemestane + Everolimus (BOLERO-2) 7-11% Fulvestrant (SOFEA, PALOMA-3) 2.1% Fulve
Slide 22: Elacestrant Phase 3 Designed to Optimize Likelihood of Success
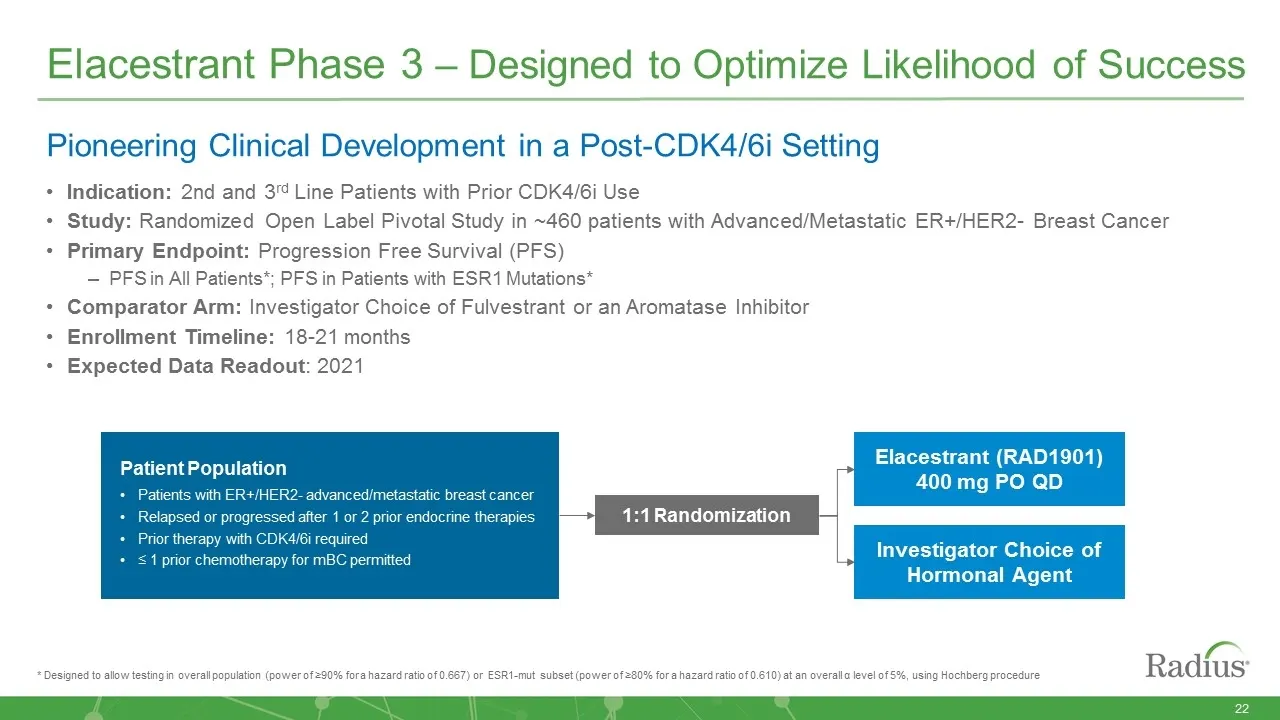
Elacestrant Phase 3 – Designed to Optimize Likelihood of Success Indication: 2nd and 3rd Line Patients with Prior CDK4/6i Use Study: Randomized Open Label Pivotal Study in ~460 patients with Advanced/Metastatic ER+/HER2- Breast Cancer Primary Endpoint: Progression Free Survival (PFS) PFS in All Pati
Slide 23: Elacestrant's Potential to Change Treatment Paradigm
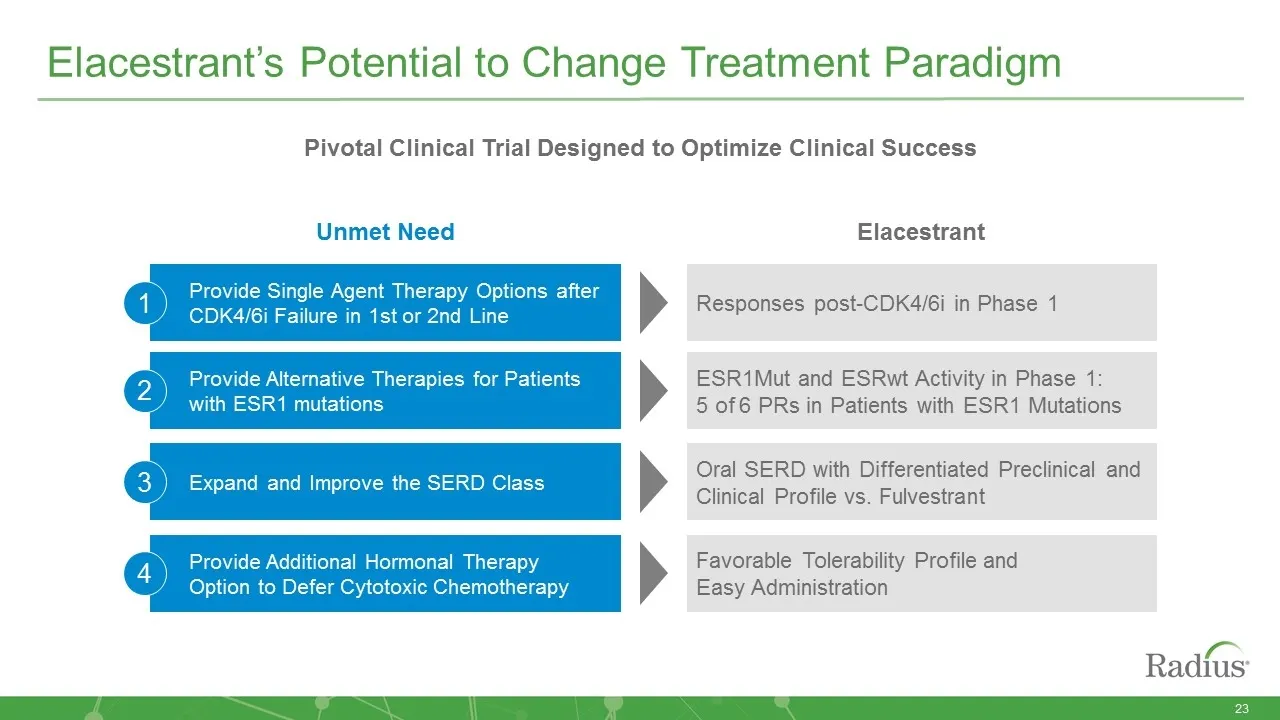
Elacestrant’s Potential to Change Treatment Paradigm Pivotal Clinical Trial Designed to Optimize Clinical Success Unmet Need Provide Single Agent Therapy Options after CDK4/6i Failure in 1st or 2nd Line 1 Responses post-CDK4/6i in Phase 1 Provide Alternative Therapies for Patients with ESR1 mutation
Slide 24: Elacestrant: Only Oral SERD in Phase III
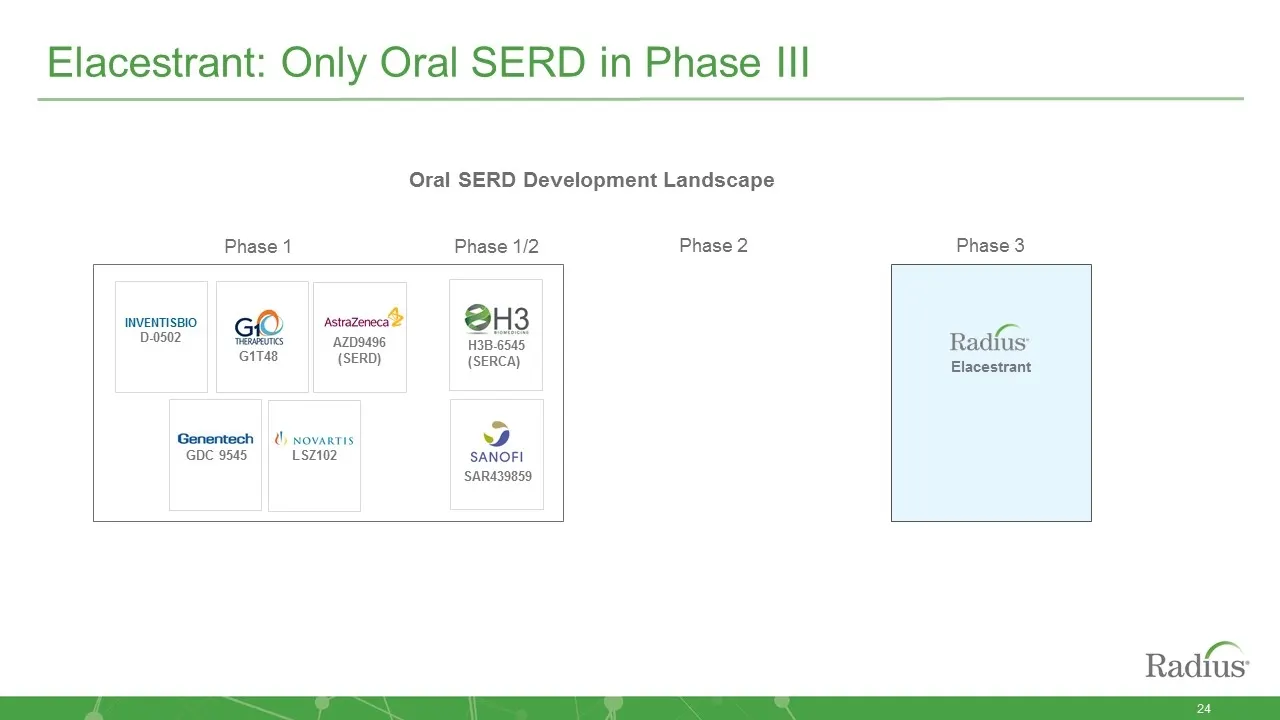
Elacestrant: Only Oral SERD in Phase III Phase 1 G1T48 AZD9496 (SERD) INVENTISBIO D-0502 SAR439859 GDC 9545 LSZ102 Phase 2 Phase 3 Elacestrant Oral SERD Development Landscape H3B-6545 (SERCA) Phase 1/2
Slide 25: Partnership Goals to Achieve Full Potential for Elacestrant
Partnership Goals to Achieve Full Potential for Elacestrant Global Co-Development and Co-Promotion Partnership Seek Partner with a Global Footprint in Oncology Expansion into Earlier Lines and Combination Therapy Retain Strategic Value and Exploit Synergies with De-risked Program Maximize Success of
Slide 26: Active Early Stage Breast Cancer Product Pipeline
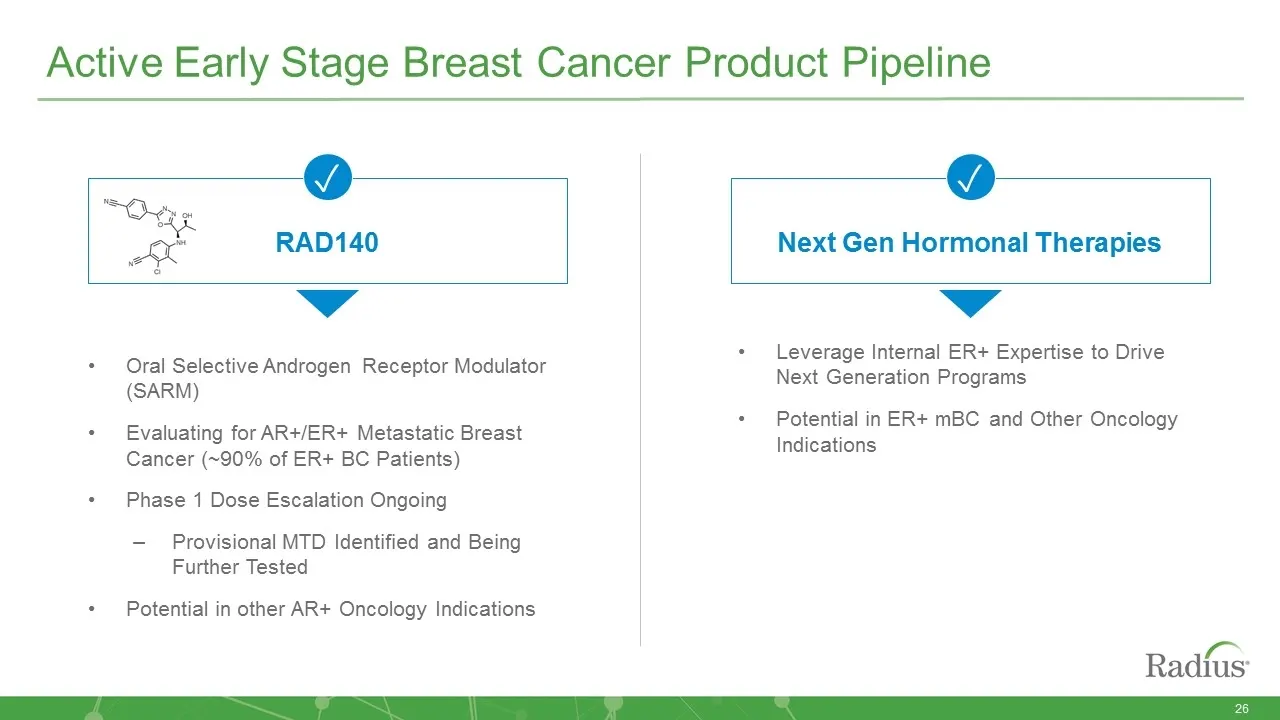
Active Early Stage Breast Cancer Product Pipeline Oral Selective Androgen Receptor Modulator (SARM) Evaluating for AR+/ER+ Metastatic Breast Cancer (~90% of ER+ BC Patients) Phase 1 Dose Escalation Ongoing Provisional MTD Identified and Being Further Tested Potential in other AR+ Oncology Indication
Slide 27: 2019 and Beyond: Corporate Structure
2 1 2019 and Beyond: Corporate Structure Lead and Transform Osteoporosis Treatment with Anabolics Provide Standard of Care in Hormonal Breast Cancer Leverage Operational and Financial Structure 3
Slide 28: Long-term Financial Growth Drives Value Creation
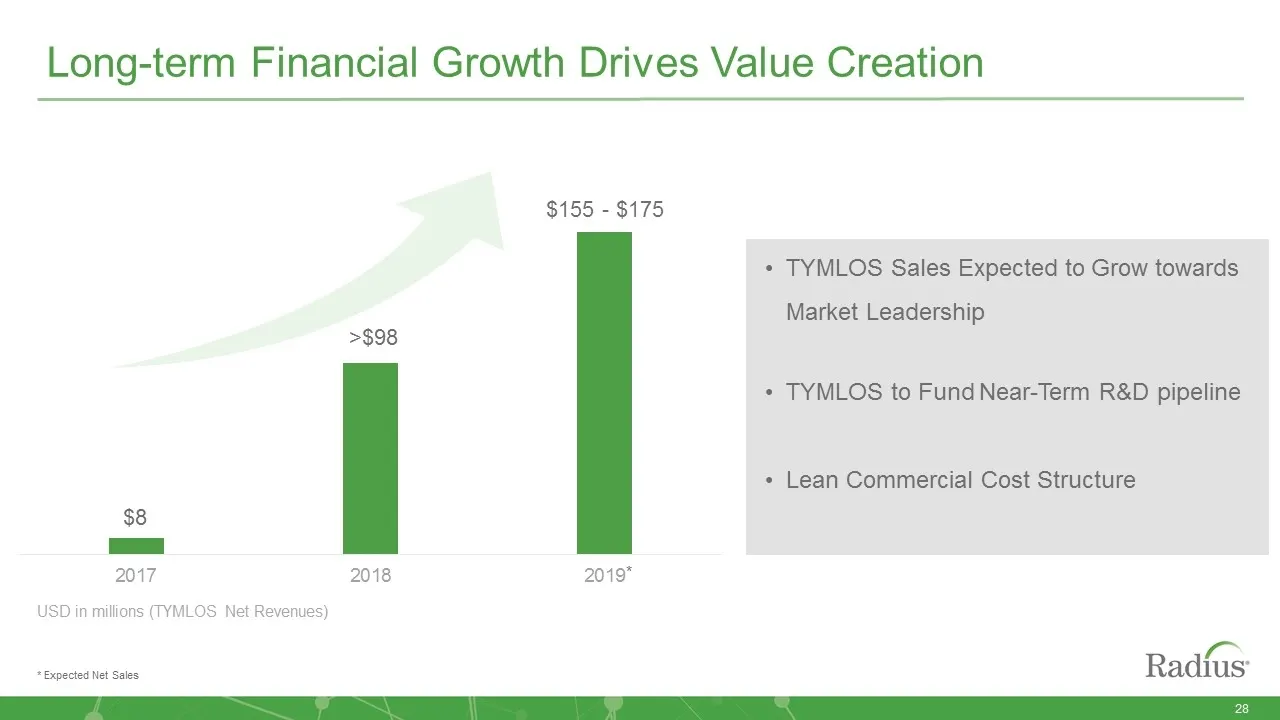
Long-term Financial Growth Drives Value Creation $8 >$98 $155 - $175 USD in millions (TYMLOS Net Revenues) TYMLOS Sales Expected to Grow towards Market Leadership TYMLOS to Fund Near-Term R&D pipeline Lean Commercial Cost Structure * * Expected Net Sales
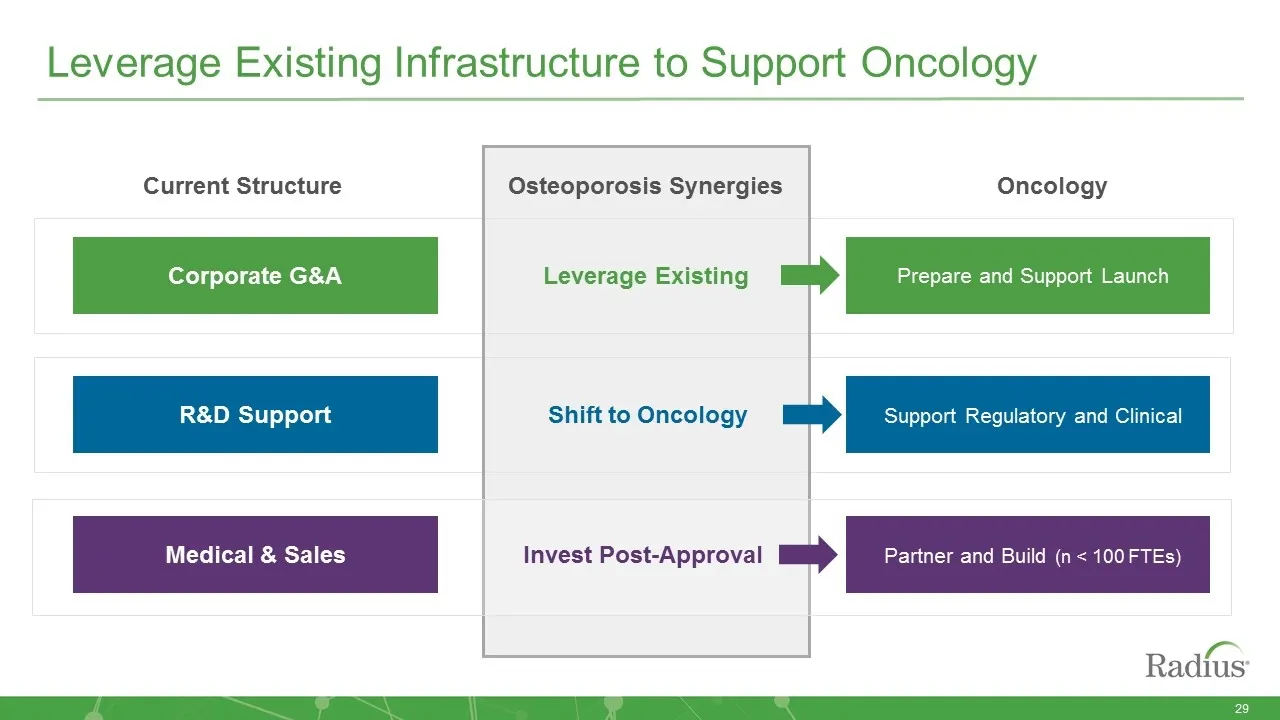
Slide 29: Leverage Existing Infrastructure to Support Oncology
Leverage Existing Infrastructure to Support Oncology Current Structure Oncology Osteoporosis Synergies Support Regulatory and Clinical R&D Support Shift to Oncology Prepare and Support Launch Corporate G&A Leverage Existing Medical & Sales Partner and Build (n < 100 FTEs) Invest Post-Approval
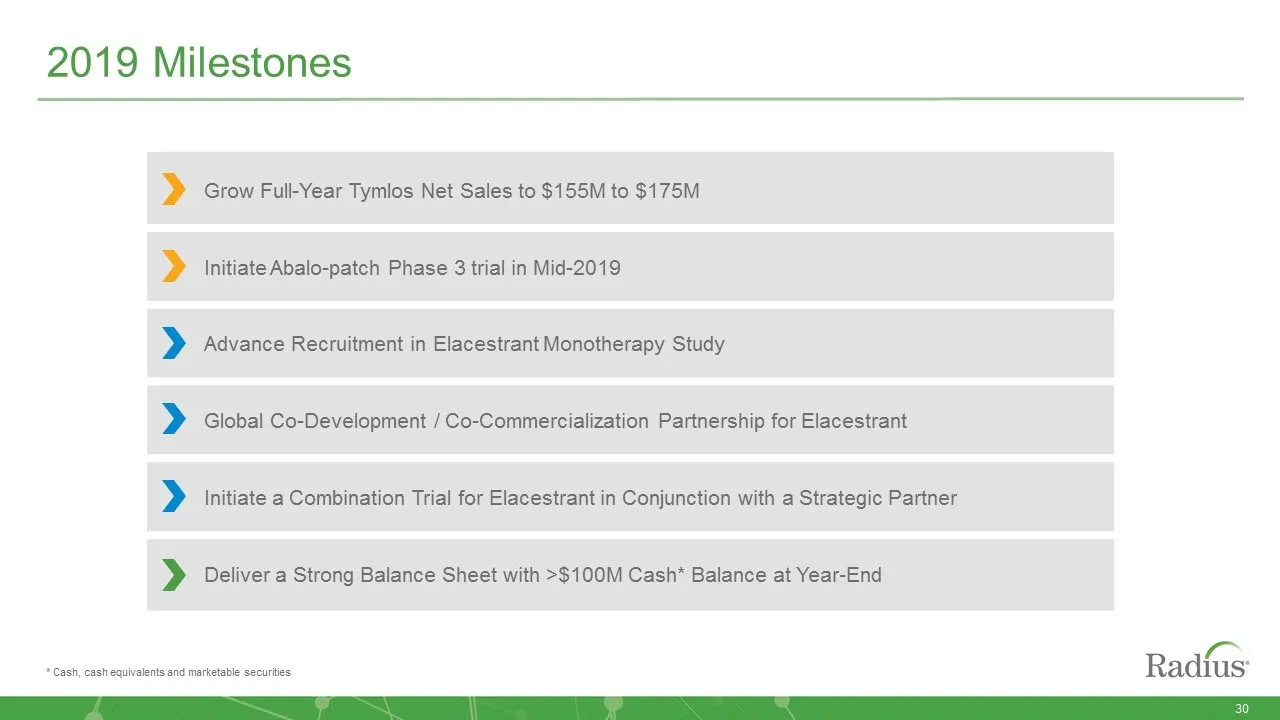
Slide 30: 2019 Milestones
2019 Milestones * Cash, cash equivalents and marketable securities Grow Full-Year Tymlos Net Sales to $155M to $175M Initiate Abalo-patch Phase 3 trial in Mid-2019 Advance Recruitment in Elacestrant Monotherapy Study Global Co-Development / Co-Commercialization Partnership for Elacestrant Initiate a
Slide 31: Q&A Session in the Sussex Room at 2:00pm
Q&A Session in the Sussex Room at 2:00pm
Source: SEC EDGAR · 8-K filed Jan 7, 2019