Stellarone — Virginia Financial Group — SunTrust Robinson Humphrey Sunbelt Community Bank Conference 2004
35 slides from Stellarone's conference presentation, Sep 29, 2004
Slide 1: SunTrust Robinson Humphrey Sunbelt Community Bank Conference
SunTrust Robinson Humphrey Sunbelt Community Bank Conference September 28, 2004
Slide 2: Forward-Looking Statement
Forward-Looking Statement Statements contained in this presentation which are not historical facts are forward-looking statements as defined in Securities Laws. Such forward-looking statements are subject to risks and uncertainties which could cause actual results to differ materially from estimated
Slide 3: Company Overview
Company Overview
Slide 4: Company Overview
Company Overview A $1.4 billion bank holding company headquartered in Culpeper, Virginia. Three bank subsidiaries and one financial service subsidiary. 37 banking offices, two loan production offices and five trust and investment locations. $480 million in trust and managed assets under administrati
Slide 5: Company Overview
Company Overview Landmark transaction was the merger-of-equals of Virginia Commonwealth Financial and Virginia Financial Corp. to form Virginia Financial Group in 2002. Most recent M&A transaction was purchase of eight branches from First Virginia Bank in connection with BBT merger. Traded on the Na
Slide 6: Corporate Structure
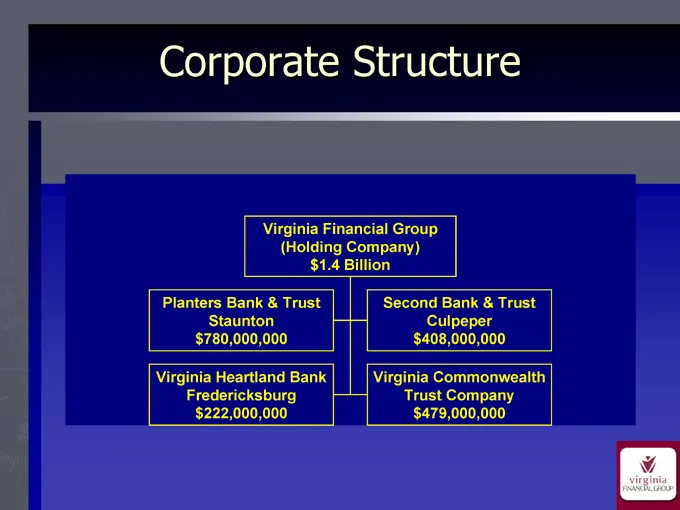
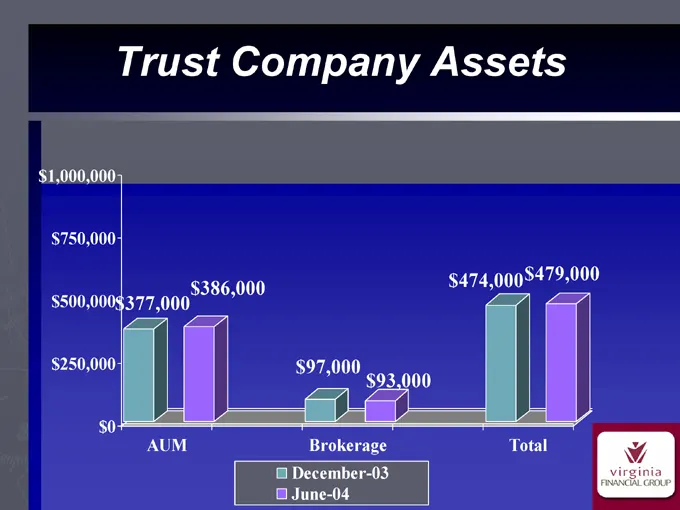
Corporate Structure Virginia Financial Group (Holding Company) $1.4 Billion Planters Bank & Trust Staunton $780,000,000 Virginia Heartland Bank Fredericksburg $222,000,000 Second Bank & Trust Culpeper $408,000,000 Virginia Commonwealth Trust Company $479,000,000
Slide 7: Multi Charter Model
Multi Charter Model – What Changes? Human Resources Marketing Compliance Internal Audit Finance / Treasury Management Credit Review Operations / Information Technology
Slide 8: Markets Served
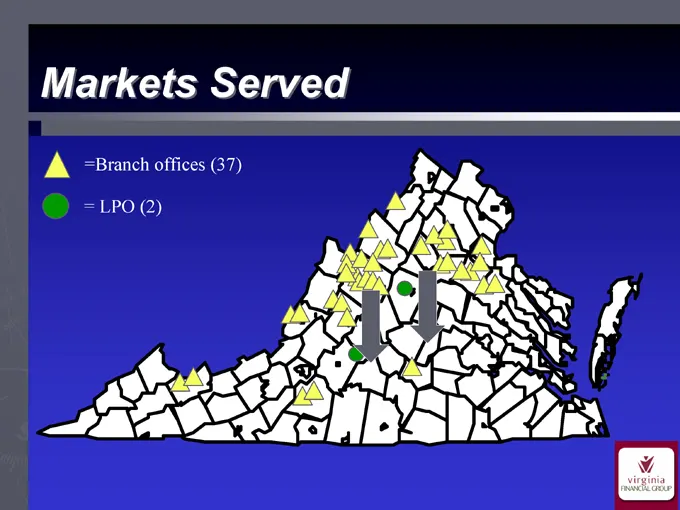
Markets Served = Branch offices (37) = LPO (2)
Slide 9: Market Share by County
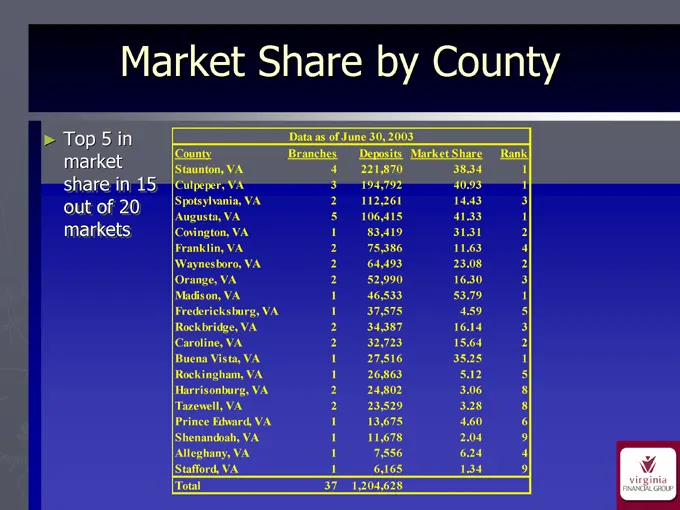
Market Share by County Top 5 in market share in 15 out of 20 markets Data as of June 30, 2003 County Branches Deposits Market Share Rank Staunton, VA 4 221,870 38.34 1 Culpeper, VA 3 194,792 40.93 1 Spotsylvania, VA 2 112,261 14.43 3 Augusta, VA 5 106,415 41.33 1 Covington, VA 1 83,419 31.31 2 Frank
Slide 10: Growth Market Penetration
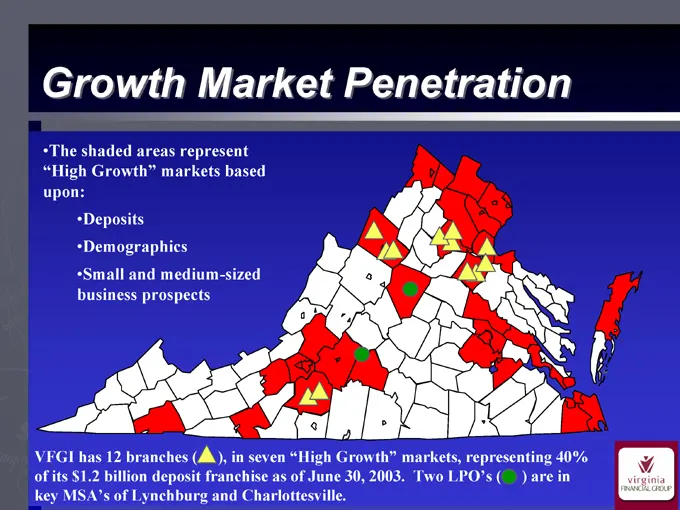
Growth Market Penetration The shaded areas represent “High Growth” markets based upon: Deposits Demographics Small and medium-sized business prospects VFGI has 12 branches ( ), in seven “High Growth” markets, representing 40% of its $1.2 billion deposit franchise as of June 30, 2003. Two LPO’s ( ) a
Slide 11: Strategic Initiatives
\/ virginia FINANCIAL GROUP Strategic Initiatives
Slide 12: Strategic Initiatives
Strategic Initiatives Become the “Community Bank of Choice” in Virginia Become second to none in quality of service Continue to attract and retain the best talent
Slide 13: Strategic Initiatives – Specific Actions/Plans
Strategic Initiatives – Specific Actions/Plans Strengthening of management group: Hiring of Chief Operating Officer Hiring of Chief Credit Officer Hiring of Director of Internal Audit Hiring of New President for Planters affiliate Average age of top four VFG Executives (excluding CEO – 42 years SOX
Slide 14: Strategic Initiatives – Specific Goals/Action Plans
Strategic Initiatives – Specific Goals/Action Plans Common branding for all affiliates: Common logo Common products Bank anywhere within family Maintain distinct identity of the franchise
Slide 15: Strategic Initiatives – Specific Actions/Plans
Strategic Initiatives – Specific Actions/Plans Sale or close non-performing branches Aggressive de novo strategy once BSA issue has been resolved; real estate and site planning well underway Continue M&A discussions with the intent to also grow by acquisition Perfect the multi-bank holding company m
Slide 16: Growth Strategies
Growth Strategies Growth to be driven by acquisition, LPOs and de novo branches Five year growth target: $3 billion in assets Primary growth markets will be Charlottesville and Lynchburg MSAs Continue to focus on legacy markets Build Wealth Management platform organically and through acquisition - P
Slide 17: Financial Overview
virginia FINANCIAL GROUP
Slide 18: Financial Trends – Income Statement
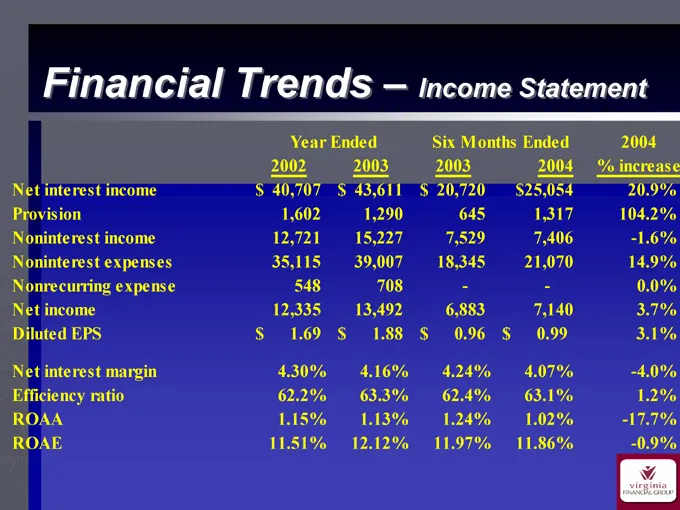
Financial Trends – Income Statement Year Ended Six Months Ended 2004 2002 2003 2003 2004 % increase Net interest income $40,707 $43,611 $20,720 $25,054 20.9% Provision 1,602 1,290 645 1,317 104.2% Noninterest income 12,721 15,227 7,529 7,406 -1.6% Noninterest expenses 35,115 39,007 18,345 21,070 14.
Slide 19: Revenue Growth and Composition
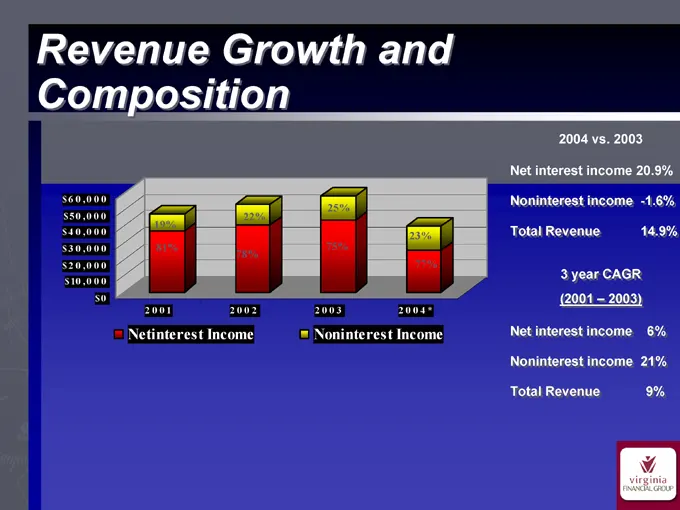
Revenue Growth and Composition $60,000 $50,000 $40,000 $30,000 $20,000 $10,000 $0 25% 22% 19% 23% 81% 75% 78% 77% 2001 2002 2003 2004* Netinterest Income Noninterest Income 2004 vs. 2003 Net interest income 20.9% Noninterest income -1.6% Total Revenue 14.9% 3 year CAGR (2001 – 2003) Net interest inc
Slide 20: Per Share Data – Earnings and Dividends
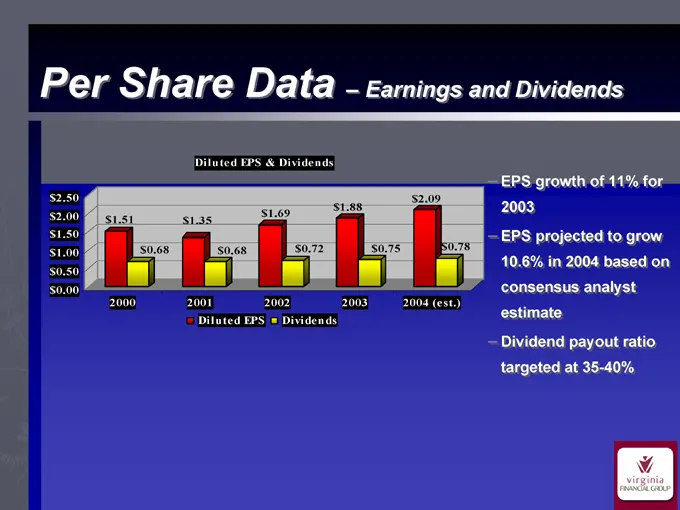
Per Share Data – Earnings and Dividends Diluted EPS & Dividends $2.50 $2.00 $1.50 $1.00 $0.50 $0.00 $2.09 $1.88 $1.69 $1.51 $1.35 $0.68 $0.68 $0.72 $0.75 $0.78 2000 2001 2002 2003 2004 (est.) Diluted EPS Dividends EPS growth of 11% for 2003 EPS projected to grow 10.6% in 2004 based on consensus anal
Slide 21: Trust Company
Trust Company Assets $1,000,000 $750,000 $500,000 $250,000 $0 $377,000 $386,000 $97,000 $93,000 $474,000 $479,000 AUM Brokerage Total December-03 June-04
Slide 22: 2004 Loan Growth
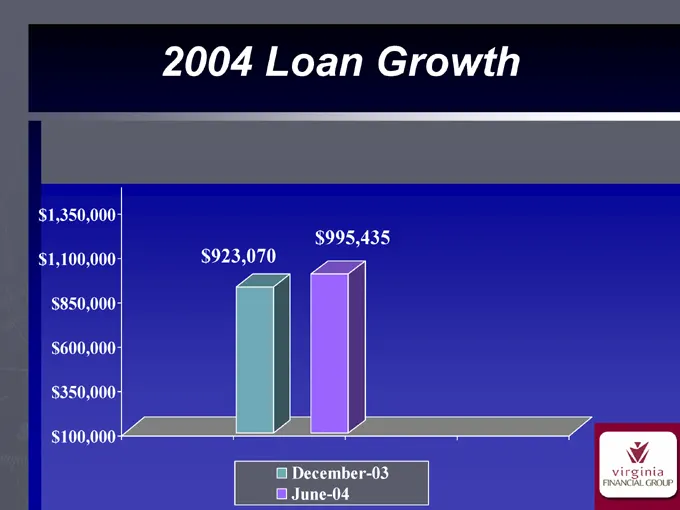
2004 Loan Growth $1,350,000 $1,100,000 $850,000 $600,000 $350,000 $100,000 $995,435 $923,070 December-03 June-04
Slide 23: Loan Portfolio
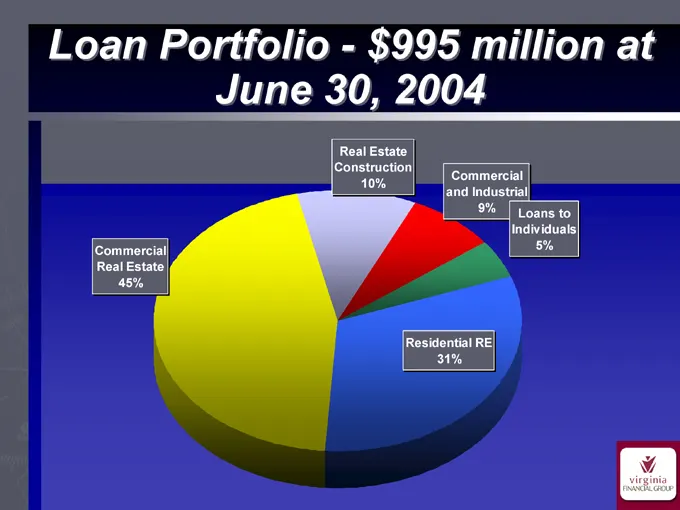
Loan Portfolio - $995 million at June 30, 2004 Commercial Real Estate 45% Real Estate Construction 10% Commercial and Industrial 9% Loans to Individuals 5% Residential RE 31%
Slide 24: Summary of Larger Loans
Summary of Larger Loans Predominately all of VFG’s significant commercial real estate loans are owner occupied with the real estate representing a secondary source of repayment Largest commercial real estate loan is $9 million participated among member banks Lending capacity of $18 million; in-house
Slide 25: Loan Portfolio – Fixed vs. Floating
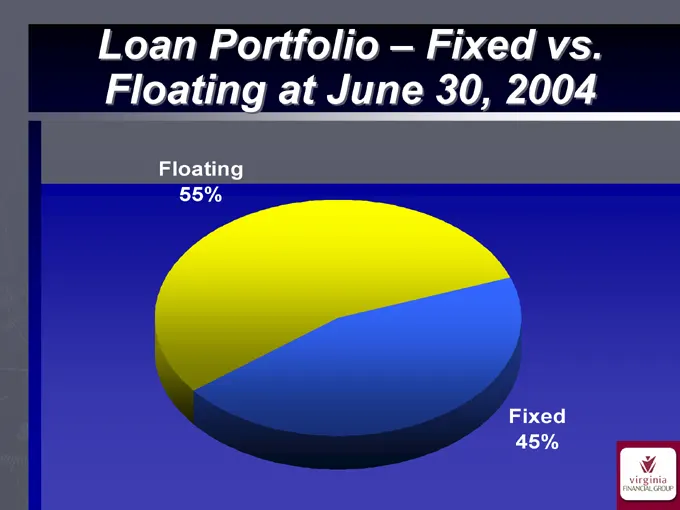
Loan Portfolio – Fixed vs. Floating at June 30, 2004 Floating 55% Fixed 45%
Slide 26: Interest Rate Risk Model
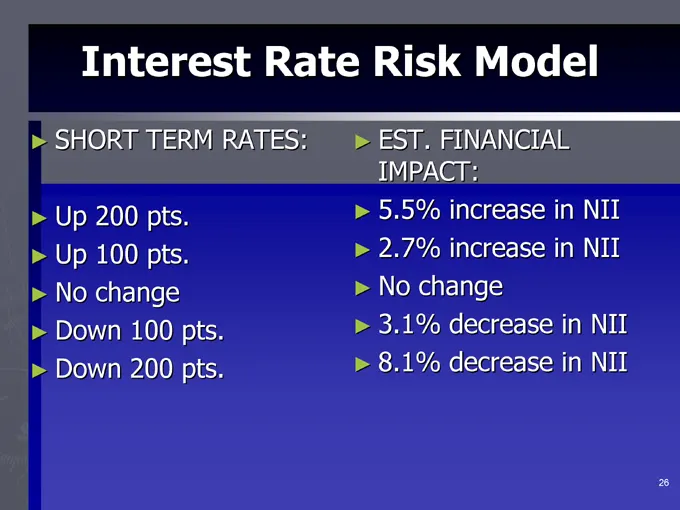
Interest Rate Risk Model SHORT TERM RATES: Up 200 pts. Up 100 pts. No change Down 100 pts. Down 200 pts. EST. FINANCIAL IMPACT: 5.5% increase in NII 2.7% increase in NII No change 3.1% decrease in NII 8.1% decrease in NII
Slide 27: Credit Quality
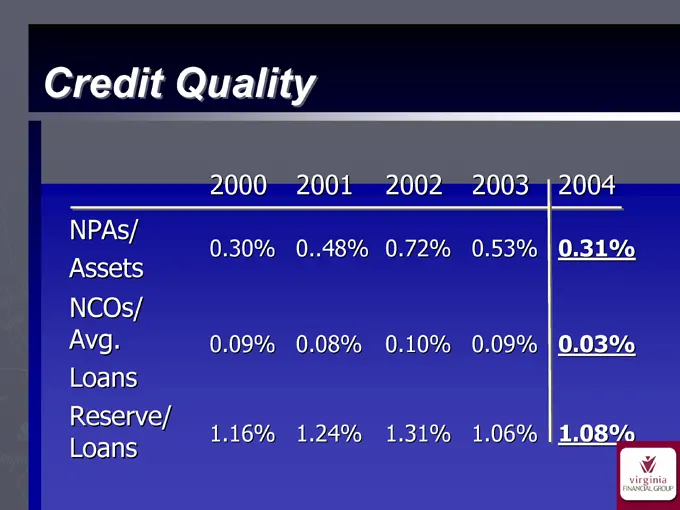
Credit Quality 2000 2001 2002 2003 2004 NPAs/ 0.30% 048% 0.72% 0.53% 0.31% Assets NCOs/ Avg. 0.09% 0.08% 0.10% 0.09% 0.03% Loans Reserve/ Loans 1.16% 1.24% 1.31% 1.06% 1.08%
Slide 28: Non-performing Assets
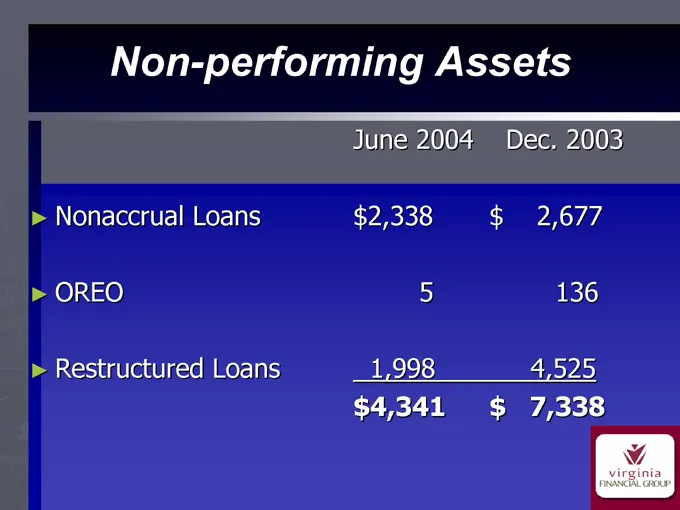
Non-performing Assets June 2004 Dec. 2003 Nonaccrual Loans $2,338 $ 2,677 OREO 5 136 Restructured Loans 1,998 4,525 $4,341 $ 7,338
Slide 29: Average Deposit Growth (YTD June)
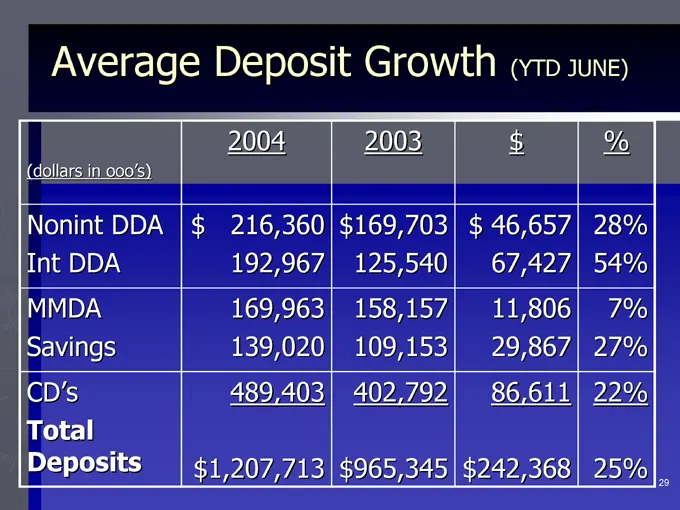
Average Deposit Growth (YTD JUNE) 2004 2003 $ % (dollars in ooo’s) Nonint DDA $216,360 $169,703 $46,657 28% Int DDA 192,967 125,540 67,427 54% MMDA 169,963 158,157 11,806 7% Savings 139,020 109,153 29,867 27% CD’s 489,403 402,792 86,611 22% Total Deposits $1,207,713 $965,345 $242,368 25%
Slide 30: Deposit Base
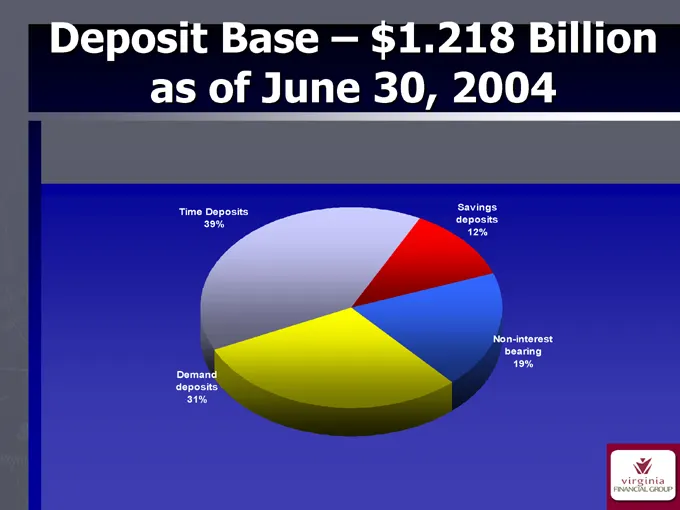
Deposit Base – $1.218 Billion as of June 30, 2004 Time Deposits 39% Demand deposits 31% Savings deposits 12% Non-interest bearing 19%
Slide 31: Capital Ratios
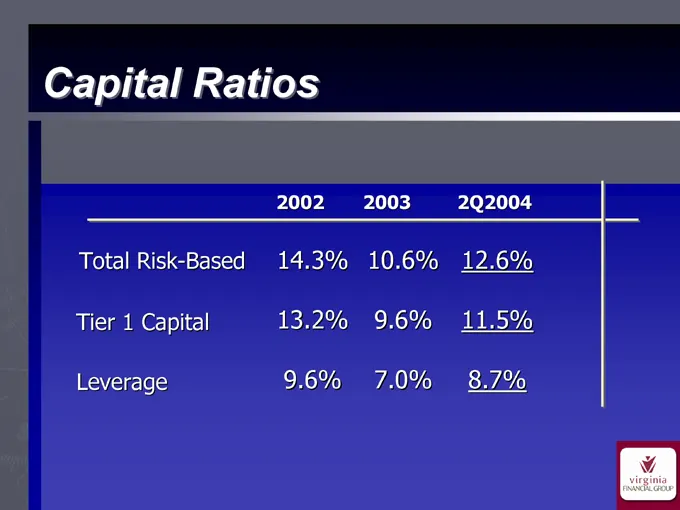
Capital Ratios 2002 2003 2Q2004 Total Risk-Based 14.3% 10.6% 12.6% Tier 1 Capital 13.2% 9.6% 11.5% Leverage 9.6% 7.0% 8.7%
Slide 32: Financial Objectives
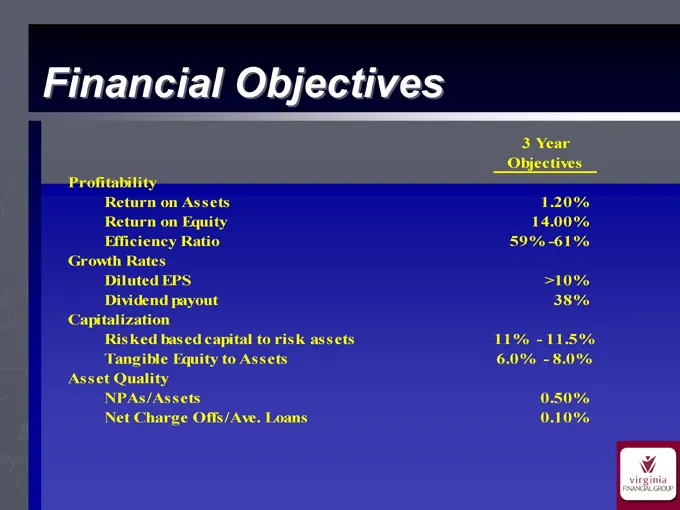
Financial Objectives 3 Year Objectives Profitability Return on Assets 1.20% Return on Equity 14.00% Efficiency Ratio 59% -61% Growth Rates Diluted EPS >10% Dividend payout 38% Capitalization Risked based capital to risk assets 11%—11.5% Tangible Equity to Assets 6.0%—8.0% Asset Quality NPAs/Assets 0
Slide 33: Trading Data
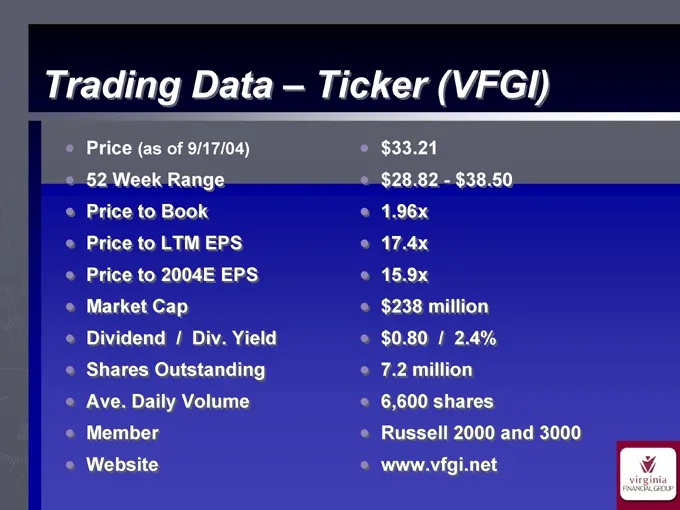
Trading Data – Ticker (VFGI) Price (as of 9/17/04) 52 Week Range Price to Book Price to LTM EPS Price to 2004E EPS Market Cap Dividend // Div. Yield . Shares Outstanding Ave. Daily Volume Member Website $33.21 $28.82—- $38.50 1.96x 17.4x 15.9x $238 million $0.80 // 2.4% 7.2 million 6,600 shares Russ
Slide 34: Why Virginia Financial Group?
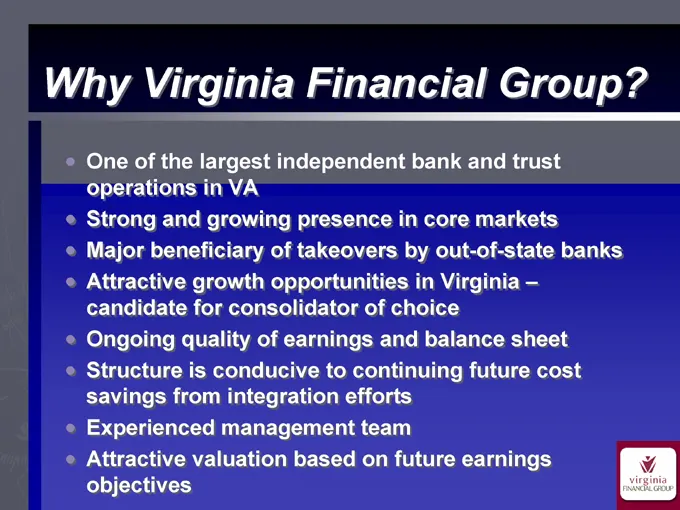
Why Virginia Financial Group? One of the largest independent bank and trust operations in VA Strong and growing presence in core markets Major beneficiary of takeovers by out-of-state banks Attractive growth opportunities in Virginia – candidate for consolidator of choice Ongoing quality of earnings
Slide 35: SunTrust Robinson Humphrey Sunbelt Community Bank Conference
SunTrust Robinson Humphrey Sunbelt Community Bank Conference September 28, 2004
Source: SEC EDGAR · 8-K filed Sep 29, 2004
More decks from Stellarone Corp
 Merger or Acquisition (June 2013)17 slides · Jun 12, 2013
 Merger or Acquisition (June 2013)17 slides · Jun 10, 2013
 Q1 2010 Earnings Presentation23 slides · May 21, 2010
 Shareholder Meeting (April 2010)54 slides · Apr 27, 2010
 Keefe, Bruyette & Woods Community Bank Investor Conference (July 2009)32 slides · Jul 29, 2009
 FNB Corp (VA) — Merger or Acquisition (October 2007)5 slides · Oct 2, 2007