CenterState Bank — CenterState Banks — Gulf South Bank Conference 2014
34 slides from CenterState Bank's conference presentation, May 12, 2014
Slide 1: Gulf South Bank Conference New Orleans
Gulf South Bank Conference New Orleans May 12, 2014 Ernest S. Pinner, Chairman & CEO James J. Antal, Chief Financial Officer Stephen D. Young, Treasurer ( and chief operating officer of subsidiary bank ) Exhibit 99.1
Slide 2: Forward Looking Statement
2 This presentation contains forward-looking statements, as defined by Federal Securities Laws, relating to present or future trends or factors affecting the operations, markets and products of CenterState Banks, Inc. (CSFL). These statements are provided to assist in the understanding of future fin
Slide 3: Company Overview
Company Overview
Slide 4: Corporate Overview
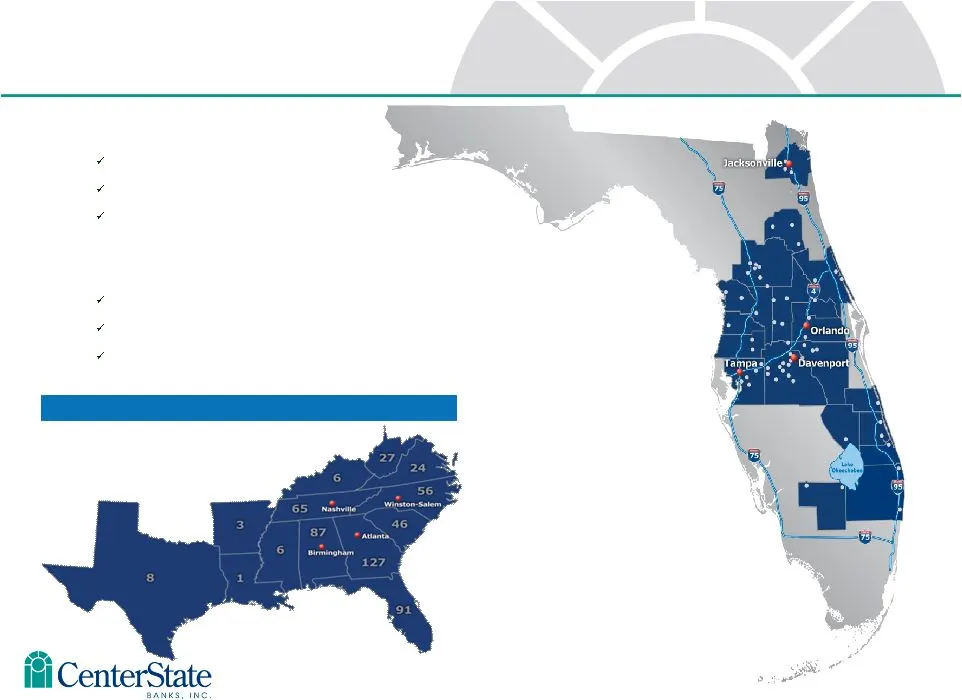
Correspondent Banking Market As of 3/31/14 • Headquartered in Davenport, FL $3.0 billion in assets $1.8 billion in loans $2.6 billion in deposits • Company formed: June 2000 1 Subsidiary Bank 51 Branch banking offices Correspondent Segment Corporate Overview
Slide 5: CSFL – Best Positioned Florida Consolidator
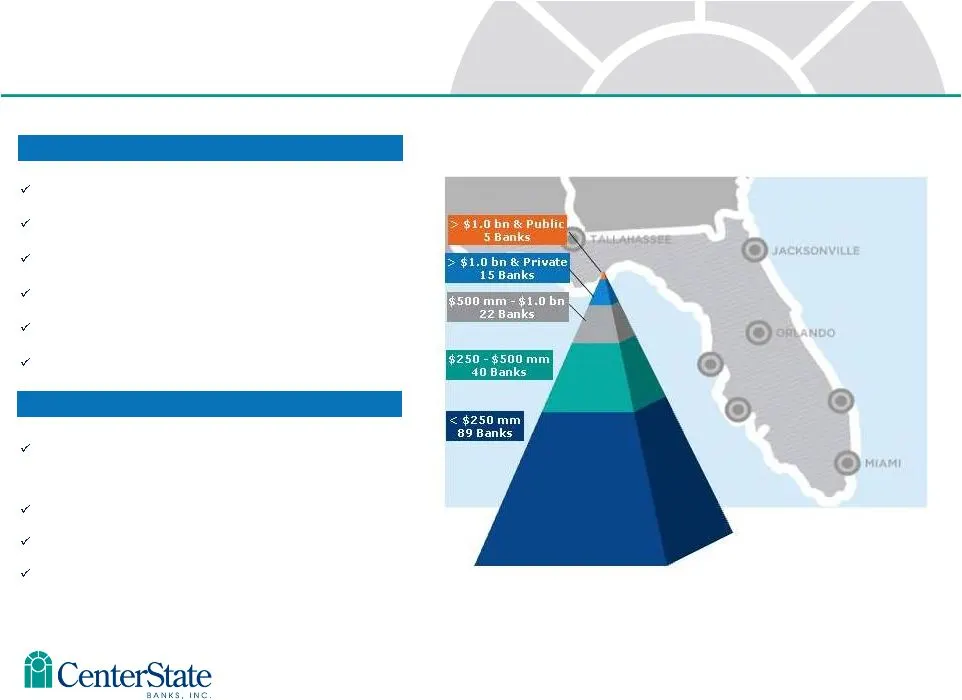
18 FDIC Acquisitions Non-FDIC Acquisitions CSFL – Best Positioned Florida Consolidator Source: SNL Financial Data as of MRQ available Ocala National Bank (Jan 2009) Olde Cypress Community Bank (July 2010) Independent National Bank of Ocala (Aug 2010) Community National Bank of Bartow (Aug 2010) Cent
Slide 6: Gulfstream Highlights
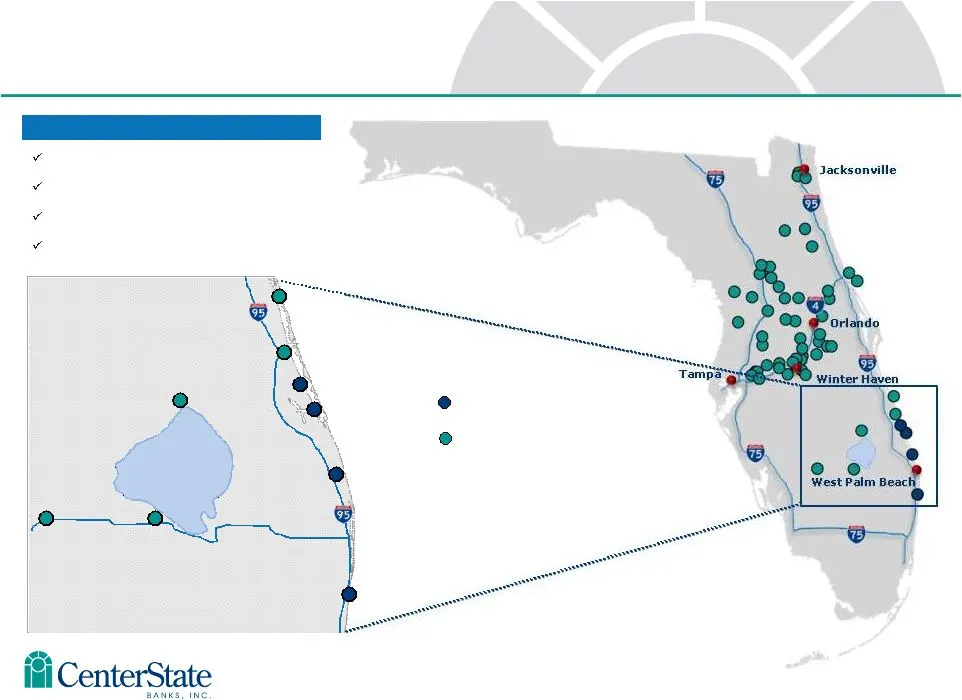
Gulfstream Highlights (1) Gulfstream Business Bank – Closed January 17, 2014 Offices: Assets: $545 million Deposits: $467 million Loans: $376 million (1) Financial data as of 12/31/13 Gulfstream (4 branches) CSFL (55 branches) Port St. Lucie Stuart Jupiter Delray Beach Lake Okeechobee Vero Beach For
Slide 7: Efficiency Initiatives
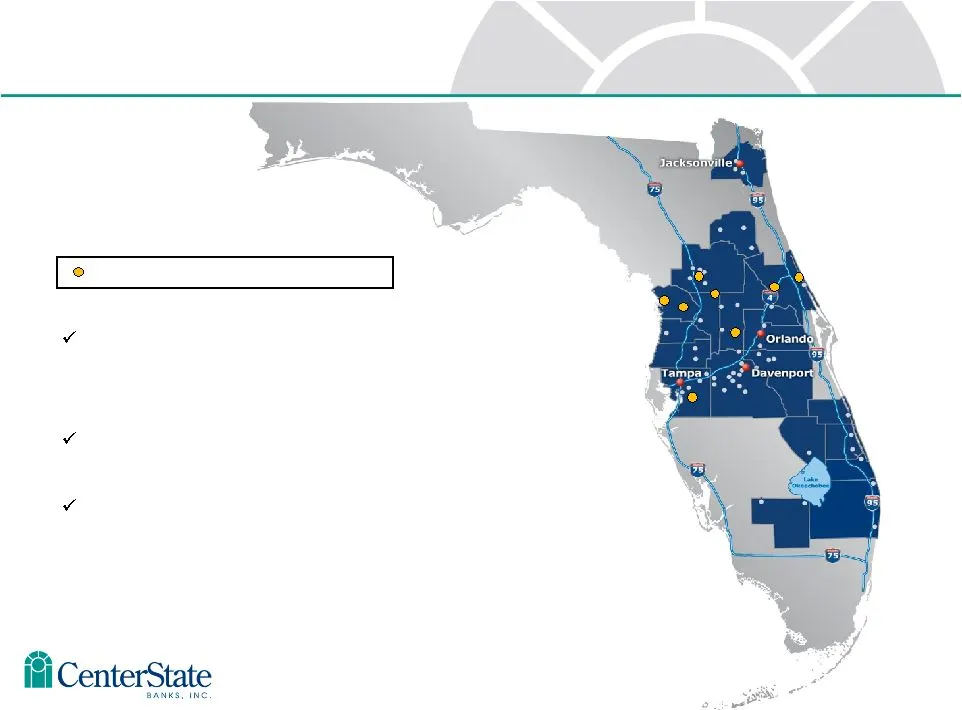
Efficiency Initiatives Total fully phased-in expense reduction – $6 million annually Branch closures – $2.7 million annually Other restructuring and expense reductions – $3.3 million annually 8 branch closings in April 2014
Slide 8: First Southern Highlights
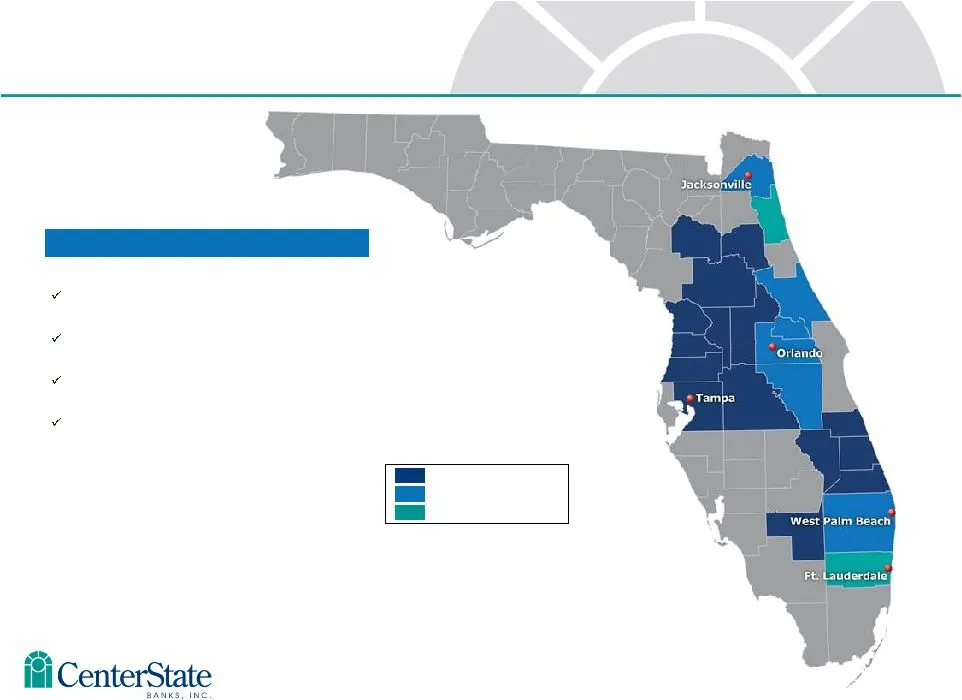
First Southern Highlights (1) (1) Based on financial data as of December 31, 2013 Source: CSFL Management, FSOF Management Offices: Assets: $1,093 million Deposits: $883 million Loans: $635 million CSFL Branches CSFL & FSOF Branches FSOF Branches First Southern Bancorp, Inc. – Expected to close June
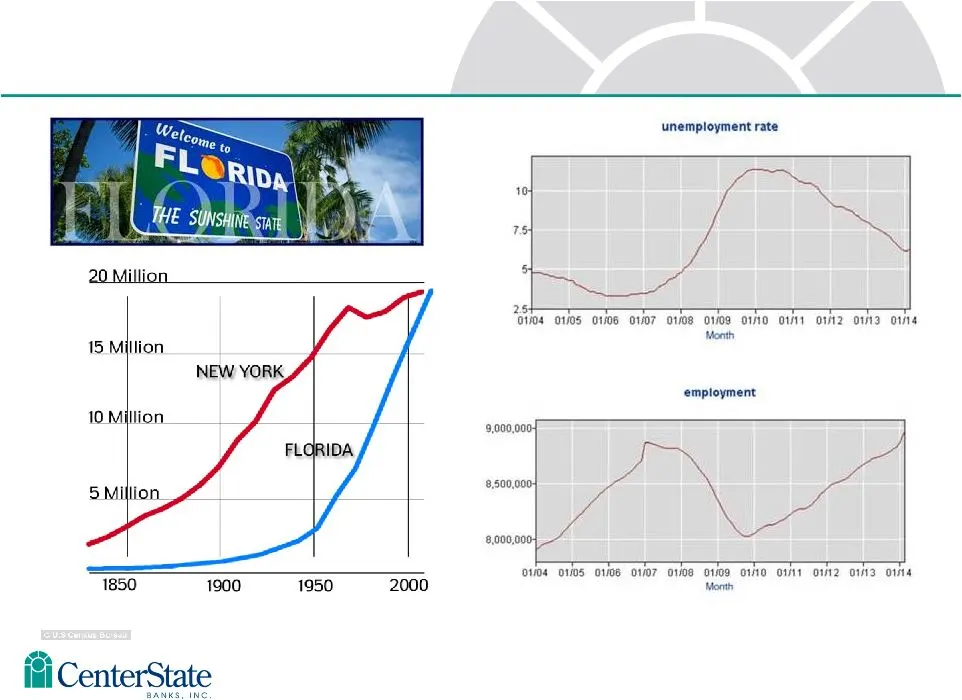
Slide 9: Florida Trends
Florida Trends Source: U.S. Census Bureau and Bureau of Labor Statistics
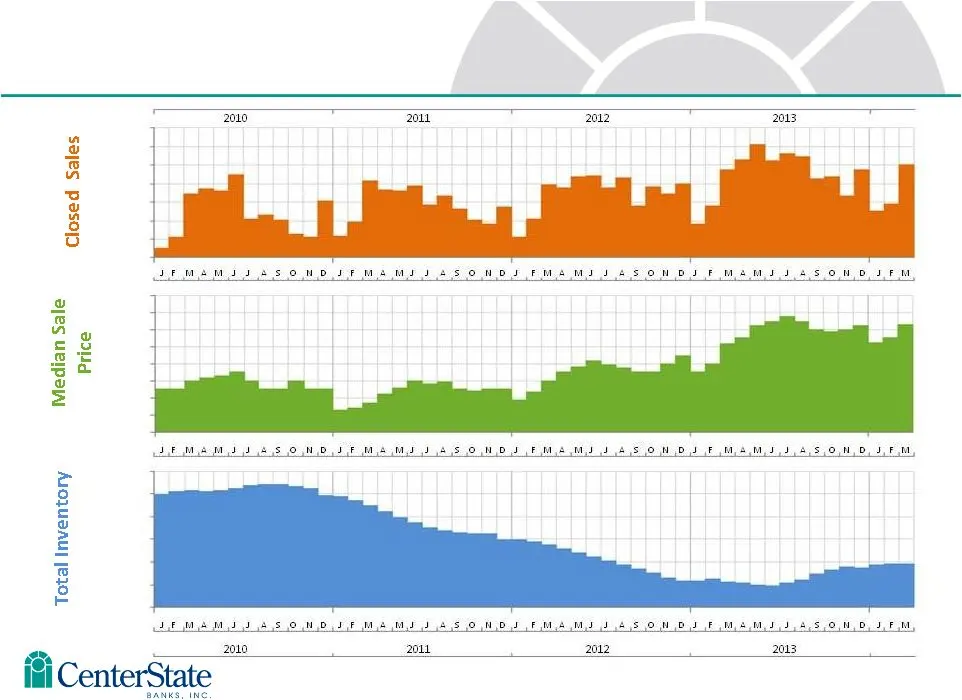
Slide 10: Florida Real Estate – Single Family Homes
10 Source: Florida Realtors Monthly Market Detail (March 2014) – Single Family Homes Florida Real Estate – Single Family Homes 24,000 22,000 20,000 18,000 16,000 14,000 12,000 10,000 $190K $180K $170K $160K $150K $140K $130K $120K $110K 190,000 170,000 150,000 130,000 110,000 90,000 70,000
Slide 11: 1st Quarter Financial Summary
1st Quarter Financial Summary
Slide 12: 1st Quarter Summary of Financial Results
1Q14 4Q13 Current Qtr take-aways 1st Quarter Summary of Financial Results EPS $0.03 $0.06 Operating EPS $0.13 $0.07 • Merger related expenses Gulfstream $2,072 First Southern $275 • Efficiency initiatives- charges Impairment charges $2,653 RIF severance $505 • Efficiency improvements • GSB & Branch
Slide 13: NIM Summary
13 1Q14 4Q13 NIM Summary 1. Interest bearing deposits. Does not include non-interest bearing checking accounts. Average Avg Average Avg Balance Rate Balance Rate Loans $1,513,060 4.75% $1,229,868 4.64% PCI loans 251,587 13.27% 240,804 13.00% Securities 532,046 3.04% 453,658 2.94% Fed funds sold and
Slide 14: Covered Loans – Average Yields and IA Amortization Expense
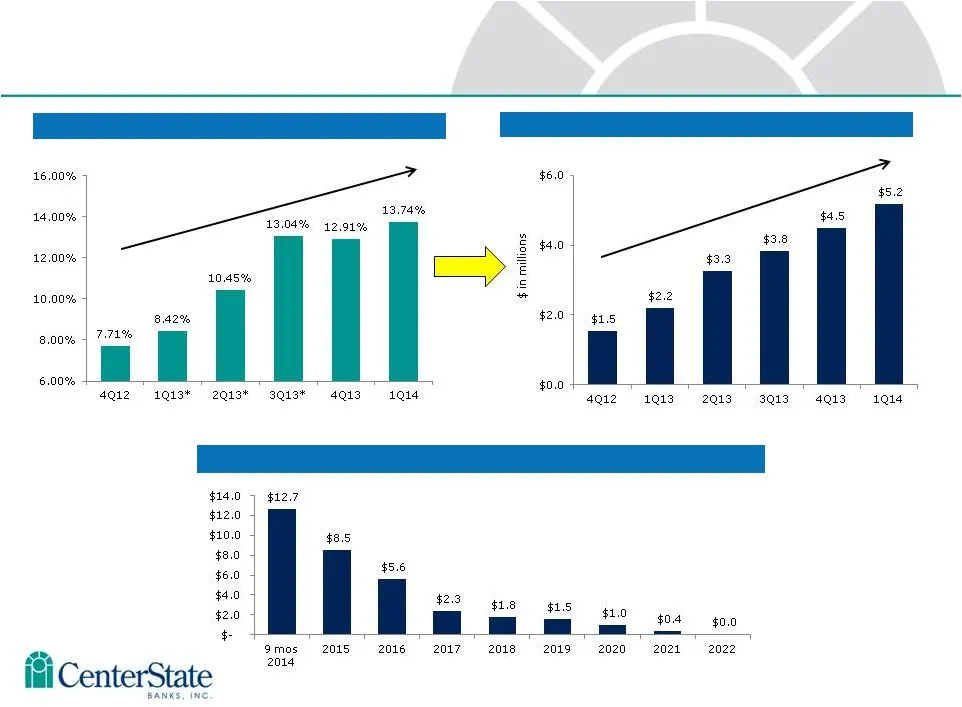
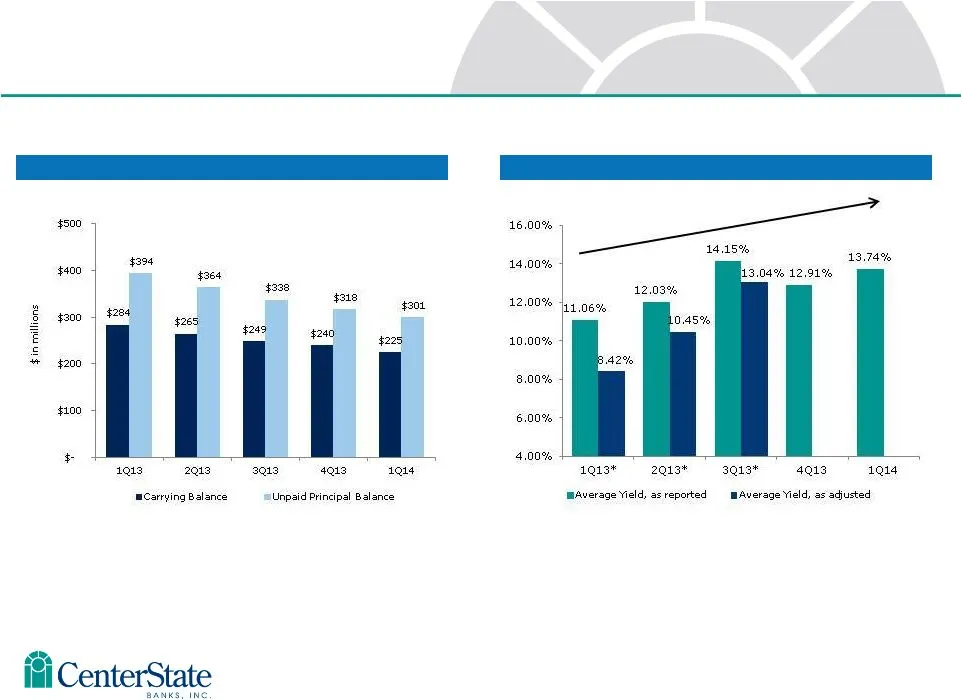
14 Covered Loans – Average Yields* IA Amortization Expense At 3/31/14 remaining projected IA to be amortized ($34M) Relationship between Covered loans and FDIC indemnification asset (IA) * As adjusted, excludes accelerated accretion related to ASC 310-10 loans
Slide 15: Loan Production by Quarter
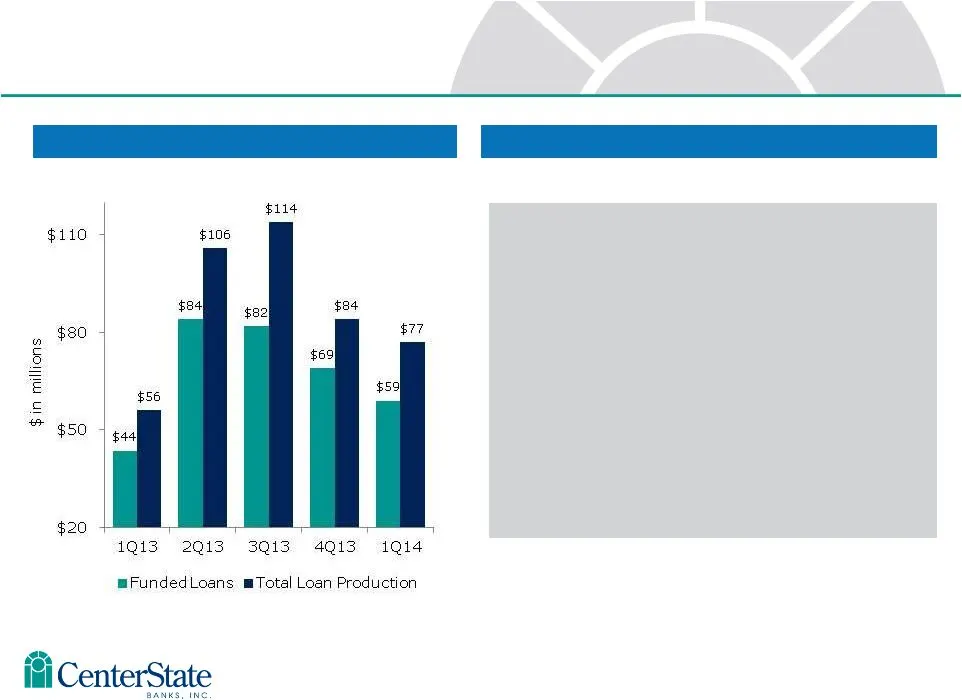
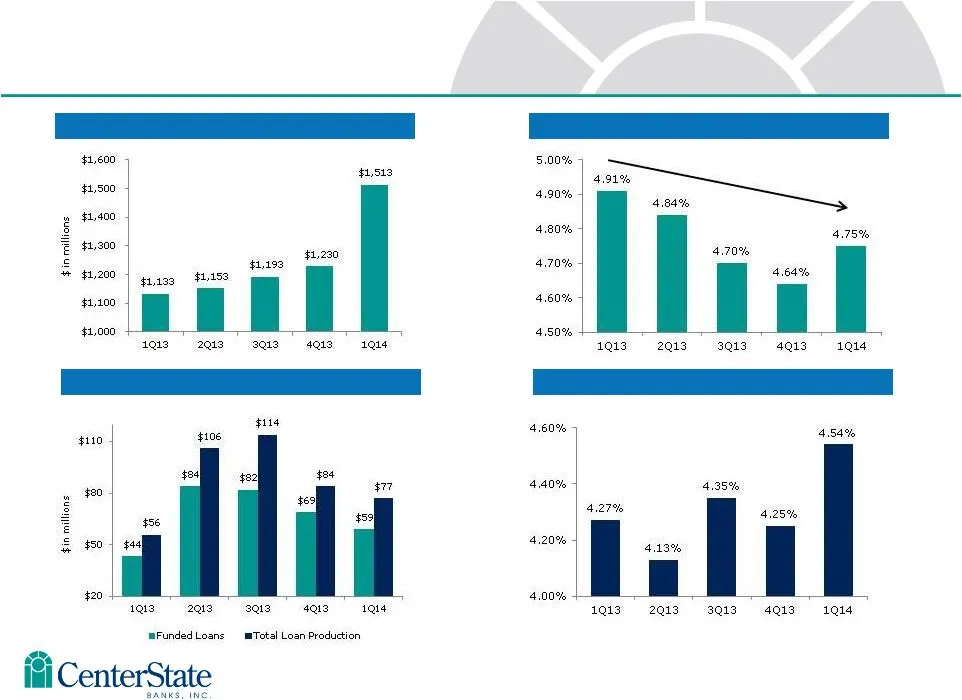
Loan Production by Quarter Current Quarter Loan Production Loan Growth, excludes PCI loans • Avg yld funded loans 4.54% • 27% Resi • 33% CRE • 24% C&I • 16% all other • Loan pipeline: End of 1Q14: $140M End of 4Q13: $114M End of 3Q13: $124M End of 2Q13: $150M End of 1Q13: $175M
Slide 16: ALLL – excluding PCI Loans
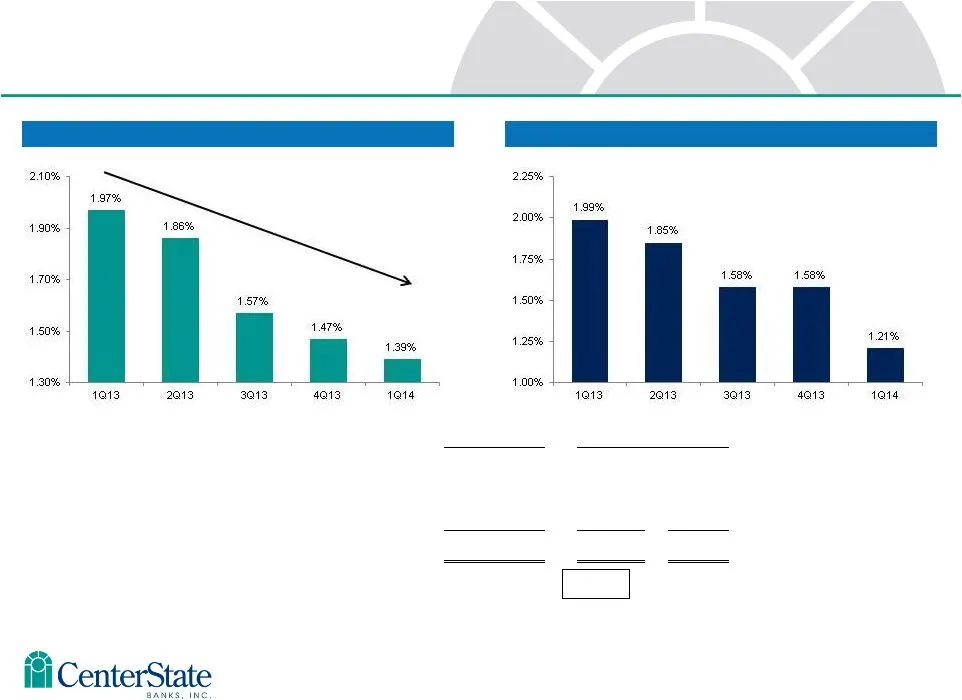
16 FAS 5 Component (excluding Gulfstream) Total ALLL (excluding PCI loans) ALLL – excluding PCI Loans Loan Balance ALLL Loans (Fas 5) $1,218,614 $16,994 1.39% Gulfstream loans 319,665 --- --- Impaired Loans (Fas 114) 26,555 1,919 7.23% Total Non-PCI Loans $1,564,834 $18,913 1.21% ALLL as a % of NPLs
Slide 17: ALLL – PCI loans
17 FDIC Not Total % of Covered Covered PCI Loans Legal Bal ALLL – PCI loans Legal Balance $291,821 $41,540 $333,361 100% Discount Balance (72,088) (10,473) (82,561) (25%) Book Value $219,733 $31,067 $250,800 75% ALLL (1,183) --- (1,183) Total, net of ALLL $218,550 $31,067 $249,617
Slide 18: Credit Metrics
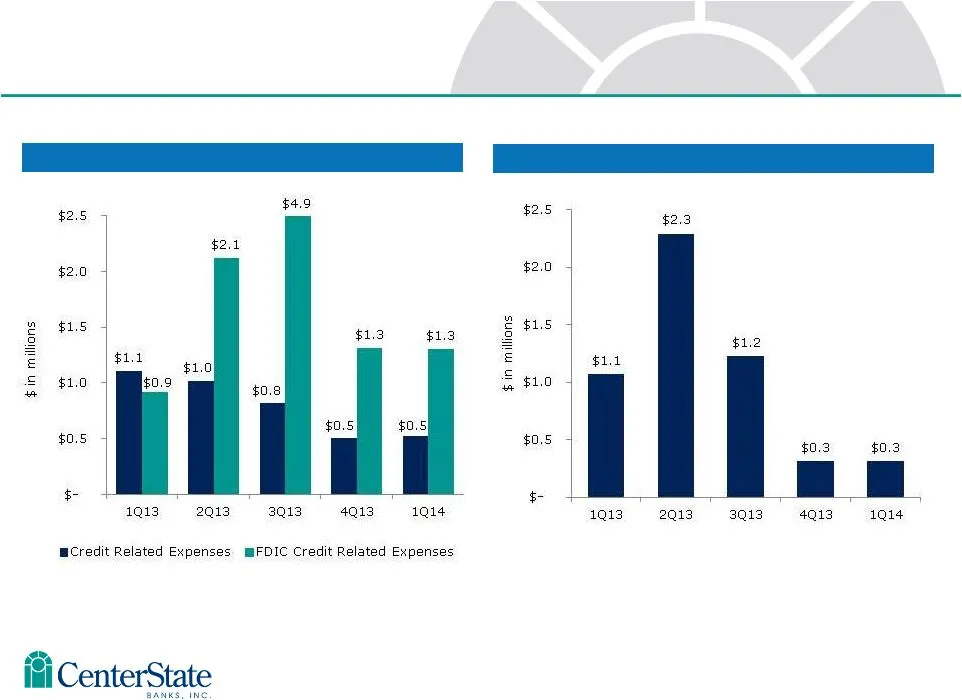
18 Credit Related Expenses Net Charge-offs Credit Metrics
Slide 19: Profitability Metrics
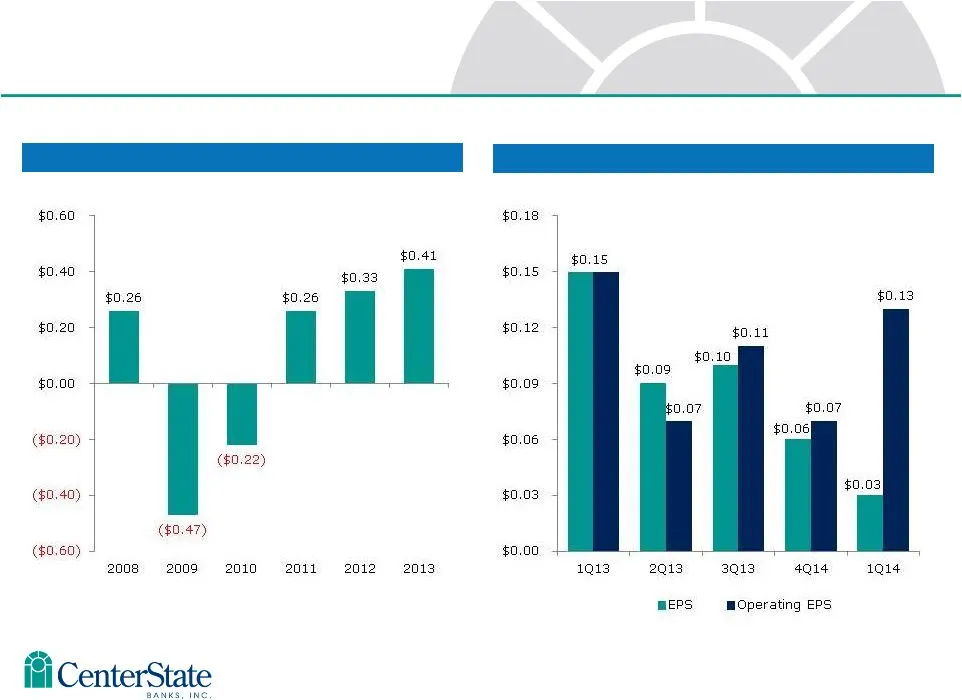
EPS – 6 years EPS & Operating EPS - 5 quarters Profitability Metrics
Slide 20: Operating Efficiencies
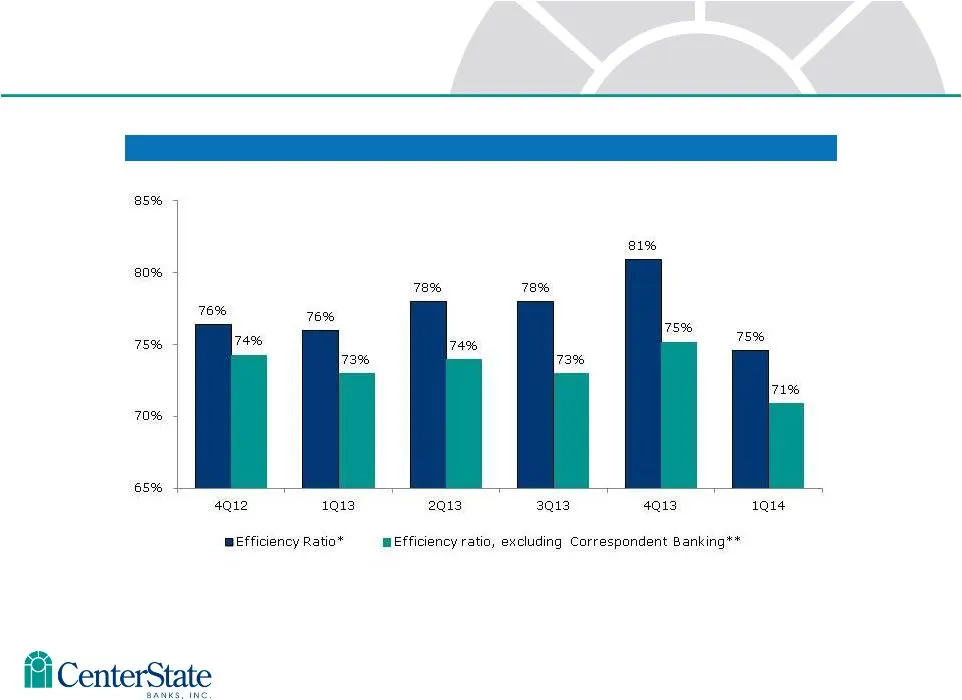
10 Efficiency Ratio Operating Efficiencies * Efficiency Ratio is defined as follows: [non-interest expense – intangible amortization – credit related expenses – merger related expenses – other nonrecurring expense] / [net interest income (fully tax equivalent) + non-interest income – gain on sale of
Slide 21: Loan Portfolio
Loan Portfolio
Slide 22: Total Loans by Type and Detail
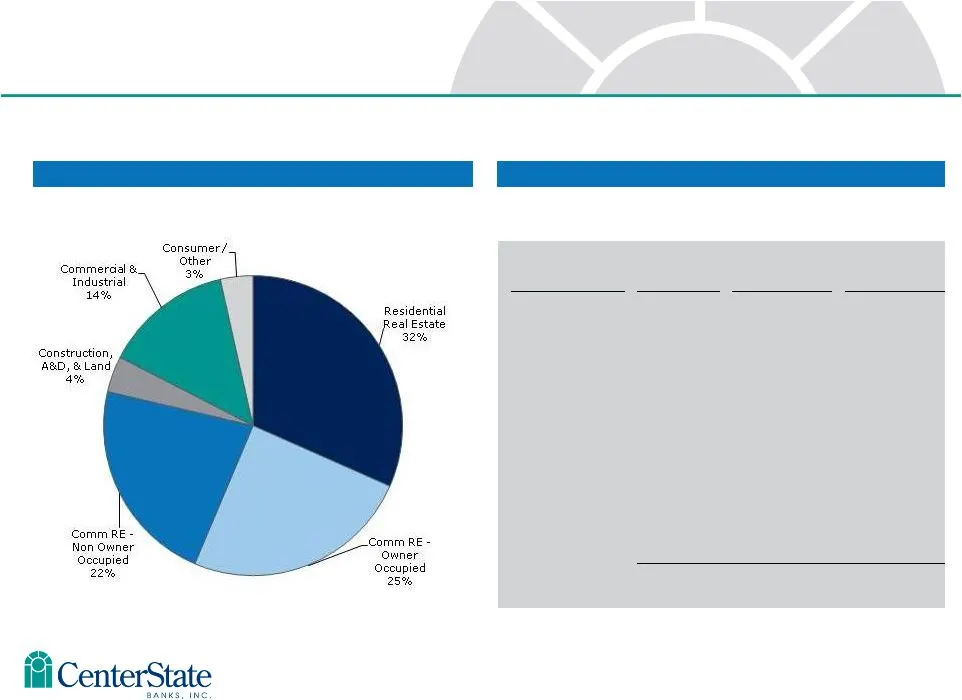
Total Loans by Type Total Loans Detail Loan Type No. of Loans Balance Avg Loan Balance Residential Real Estate 4,715 $ 495 MM $105,000 CRE-Owner Occupied $ 387 MM $404,400 CRE-Non Owner Occupied $ 349 MM $540,200 Construction, A&D, & Land $ 61 MM $131,200 Commercial & Industrial 1,858 $ 218 MM $117,
Slide 23: Yields, Average Balances and New Loan Production
Yields (TEY) Average Balances New Loan Production – Average Yields New Loan Production Loans, excluding PCI loans
Slide 24: Covered Loans – Average Yields and Balances
Covered Loans – Average Yields* Covered Loans – Average Balances Covered Loans, included in total PCI loans * Excluding accelerated accretion related to ASC 310-10 loans
Slide 25: Amortization of Indemnification Asset ($34M)
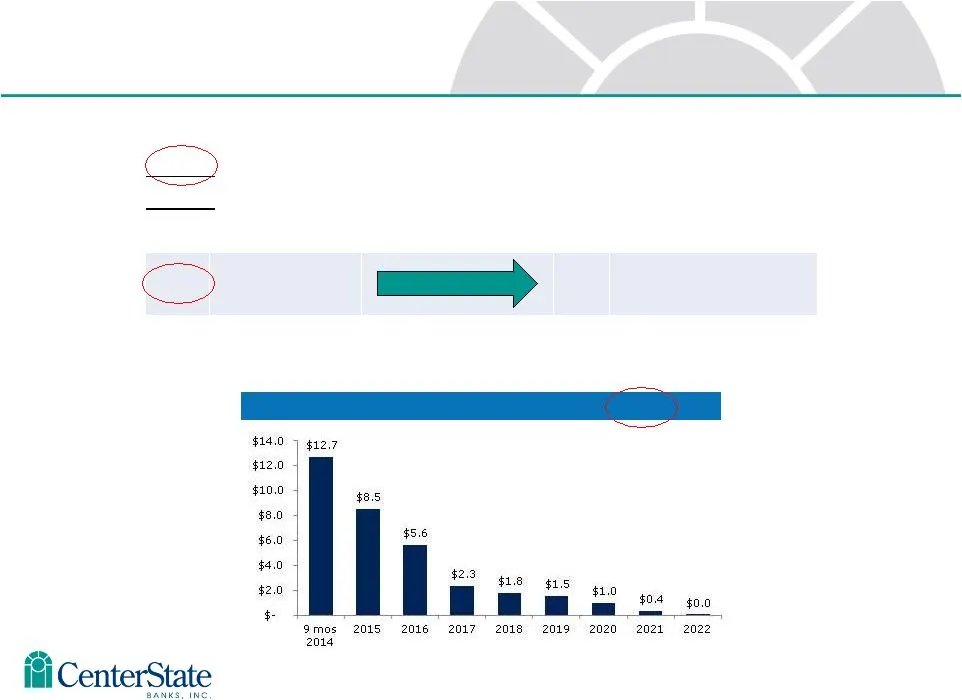
25 Amortization of Indemnification Asset ($34M) FDIC Indemnification Asset $34M FDIC Reimbursement Write-Off $43M Collect from Borrower (or sale of OREO) $31M Expected reimbursements from FDIC for 80% of expected losses $34M Previously expected reimbursements for previously expected losses no longer
Slide 26: Yields on Covered Loans and Indemnification Asset
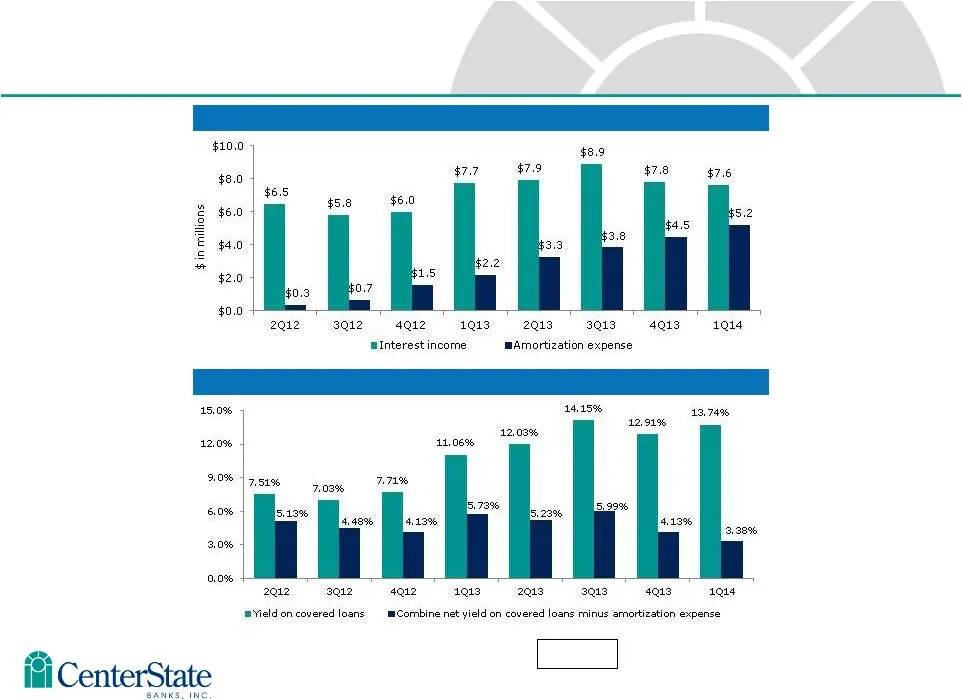
26 Interest Income and Amortization Expense Yields on Covered Loans and Indemnification Asset Indemnification Asset (“IA”) amortization and its relationship with FDIC covered loan interest income accretion 8 Quarter Average = 4.78%
Slide 27: Credit Trends – NPAs / Loans & OREO
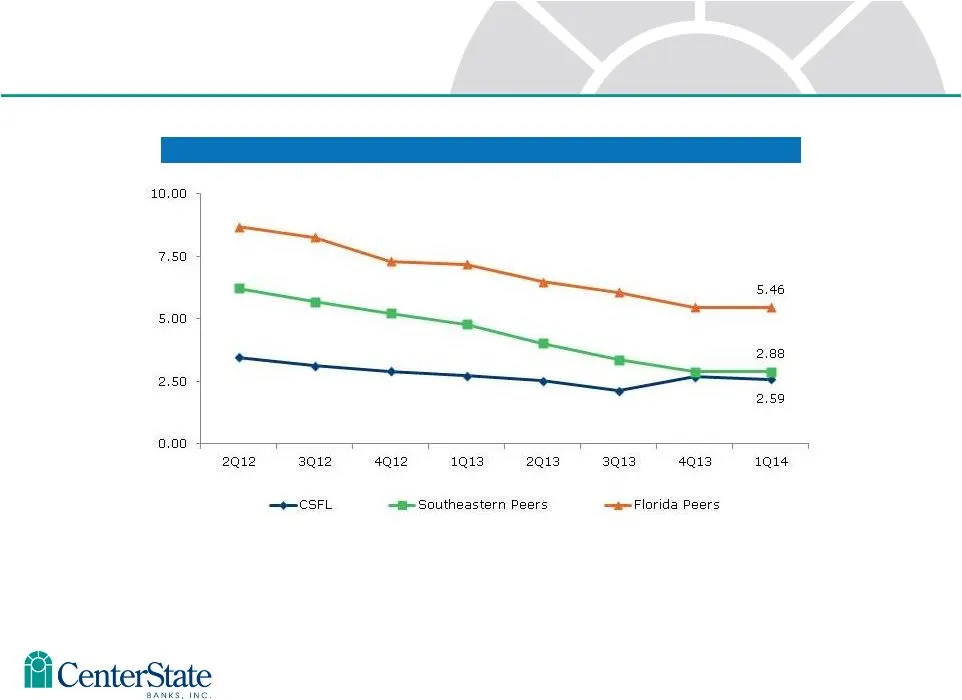
NPAs / Loans & OREO (%) Credit Trends Source: SNL Financial, MRQ presented if current quarter not yet available Nonperforming assets include loans 90 days or more past due, nonaccrual loans, and OREO/ORA; and exclude FDIC covered assets Southeastern peers include ABCB, PNFP, RNST, SCBT, UBSH and UCB
Slide 28: Deposit Portfolio
Deposit Portfolio
Slide 29: Total Deposits by Type and Detail
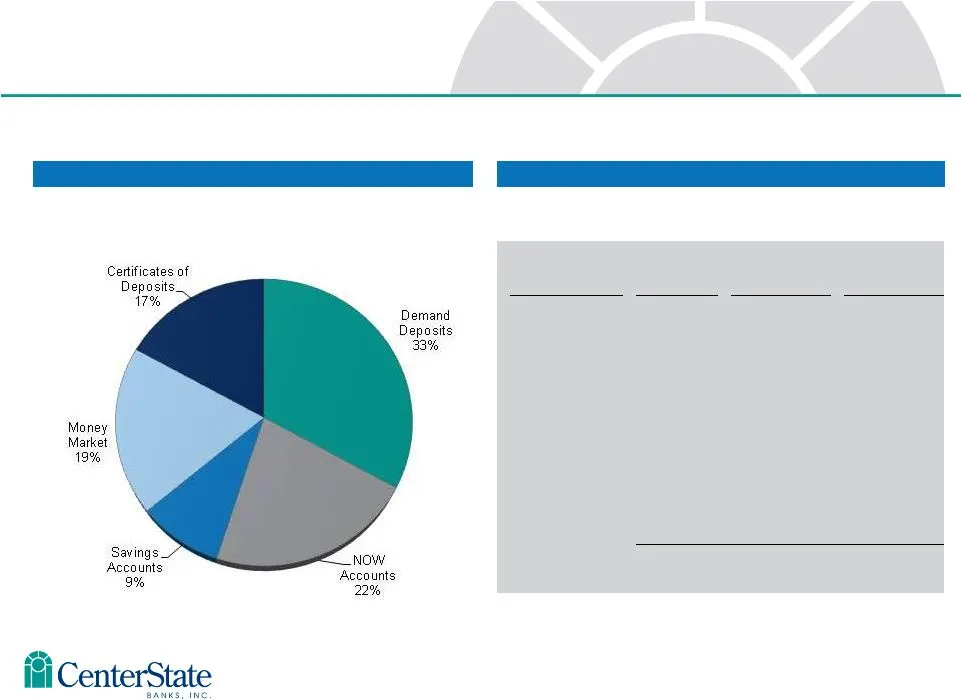
Total Deposits by Type Total Deposits Detail 23 Total Deposit Portfolio as of March 31, Deposit Type No. of Deposits Balance Avg Deposit Balance Demand Deposits 43,283 $ 839 MM $19,400 Now Accounts 50,961 $ 559 MM $11,000 Savings Deposits 17,487 $ 235 MM $13,400 Money Market 4,442 $ 482 MM $108,600
Slide 30: Building Franchise Value with Core Deposits
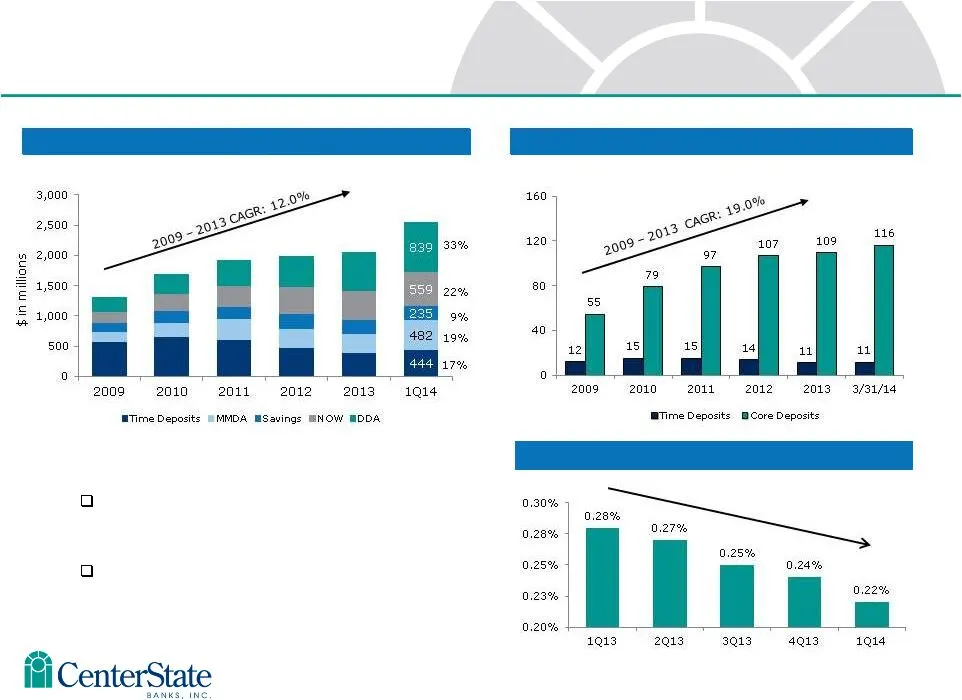
Total Deposits Number of Deposit Accounts (000’s) Cost of Deposits Core deposits defined as non-time deposits. Building Franchise Value with Core Deposits Value of core deposits not fully realized in this low rate environment. Approximately 127,575 total accounts - $20,056 average balance per accoun
Slide 31: CenterState Banks
igi CenterState www.centerstatebaniscom BANKS. INC
Slide 32: Appendix
Appendix
Slide 33: Correspondent Analysis
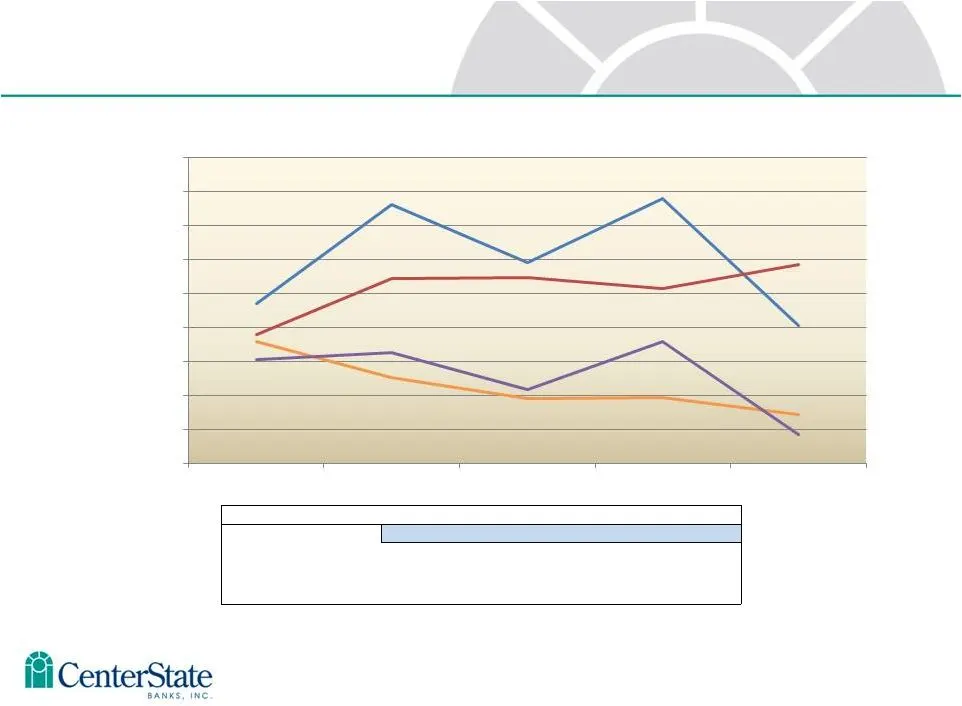
1. Assumes 8% capital allocation. Correspondent Analysis Correspondent Earnings Ratios ROE 38.06% 59.07% 33.14% 58.80% 15.99% ROA 3.04% 4.73% 2.65% 4.70% 1.28% Net Capital Mkt Revenue Fixed Non-Interest Expense Net Interest Income Net Income $0 $2,000,000 $4,000,000 $6,000,000 $8,000,000 $10,000,000
Slide 34: Correspondent Analysis
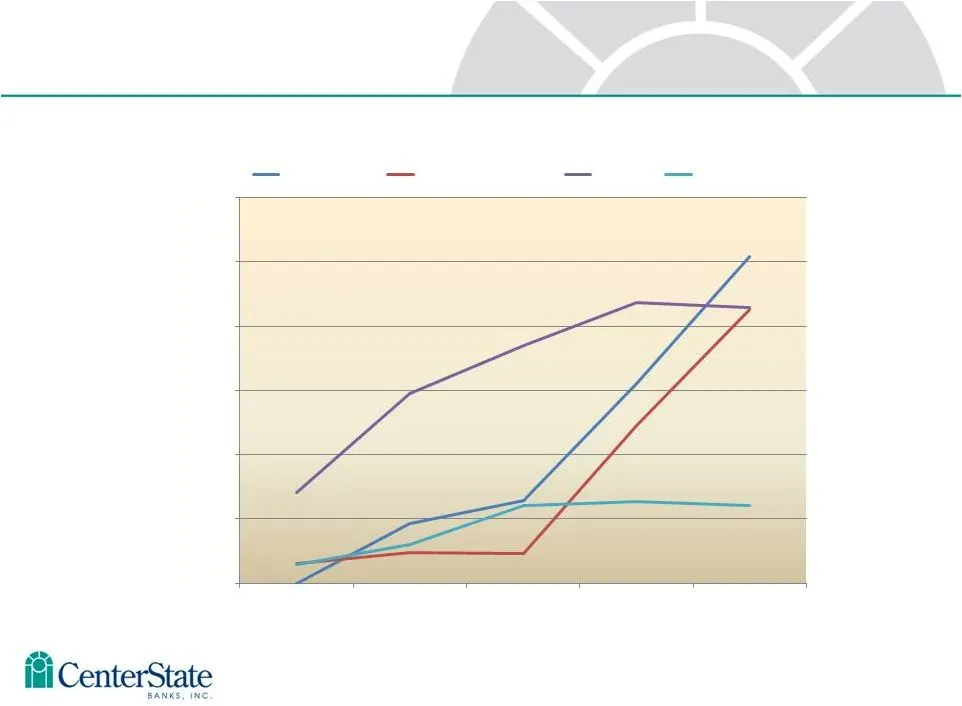
Correspondent Analysis $0 $200,000 $400,000 $600,000 $800,000 $1,000,000 $1,200,000 Recurring Revenue International Clearing/Fed Funds BA / SK Asset Liability
Source: SEC EDGAR · 8-K filed May 12, 2014
More decks from CenterState Bank Corporation
 IPO Roadshow (May 2020)42 slides · May 21, 2020
 D.A. Davidson 22nd Annual Financial Institution Virtual Conference (May 2020)25 slides · May 6, 2020
 Q1 2020 Earnings Presentation25 slides · Apr 23, 2020
 Merger or Acquisition (January 2020)24 slides · Jan 27, 2020
 Q3 2019 Earnings Presentation28 slides · Nov 4, 2019
 Investor Presentation (July 2019)28 slides · Jul 30, 2019