SunTrust Banks — 2017 Bancanalysts Association of Boston Conference
20 slides from SunTrust Banks's conference presentation, Nov 2, 2017
Slide 1: 2017 Bancanalysts Association of Boston Conference
2017 BANCANALYSTS ASSOCIATION OF BOSTON CONFERENCE Mark Chancy, Vice Chairman & Consumer Segment Executive November 2, 2017 © 2017 SunTrust Banks, Inc. SunTrust is a federally registered trademark of SunTrust Banks, Inc.
Slide 2: Important Cautionary Statement
IMPORTANT CAUTIONARY STATEMENT The following should be read in conjunction with the financial statements, notes and other information contained in the Company’s 2016 Annual Report on Form 10-K, Quarterly Reports on Form 10- Q, and Current Reports on Form 8-K. This presentation includes non-GAAP fina
Slide 3: Overview of SunTrust & the Consumer Segment
OVERVIEW OF SUNTRUST & THE CONSUMER SEGMENT Building from a position of strength
Slide 4: SunTrust Overview
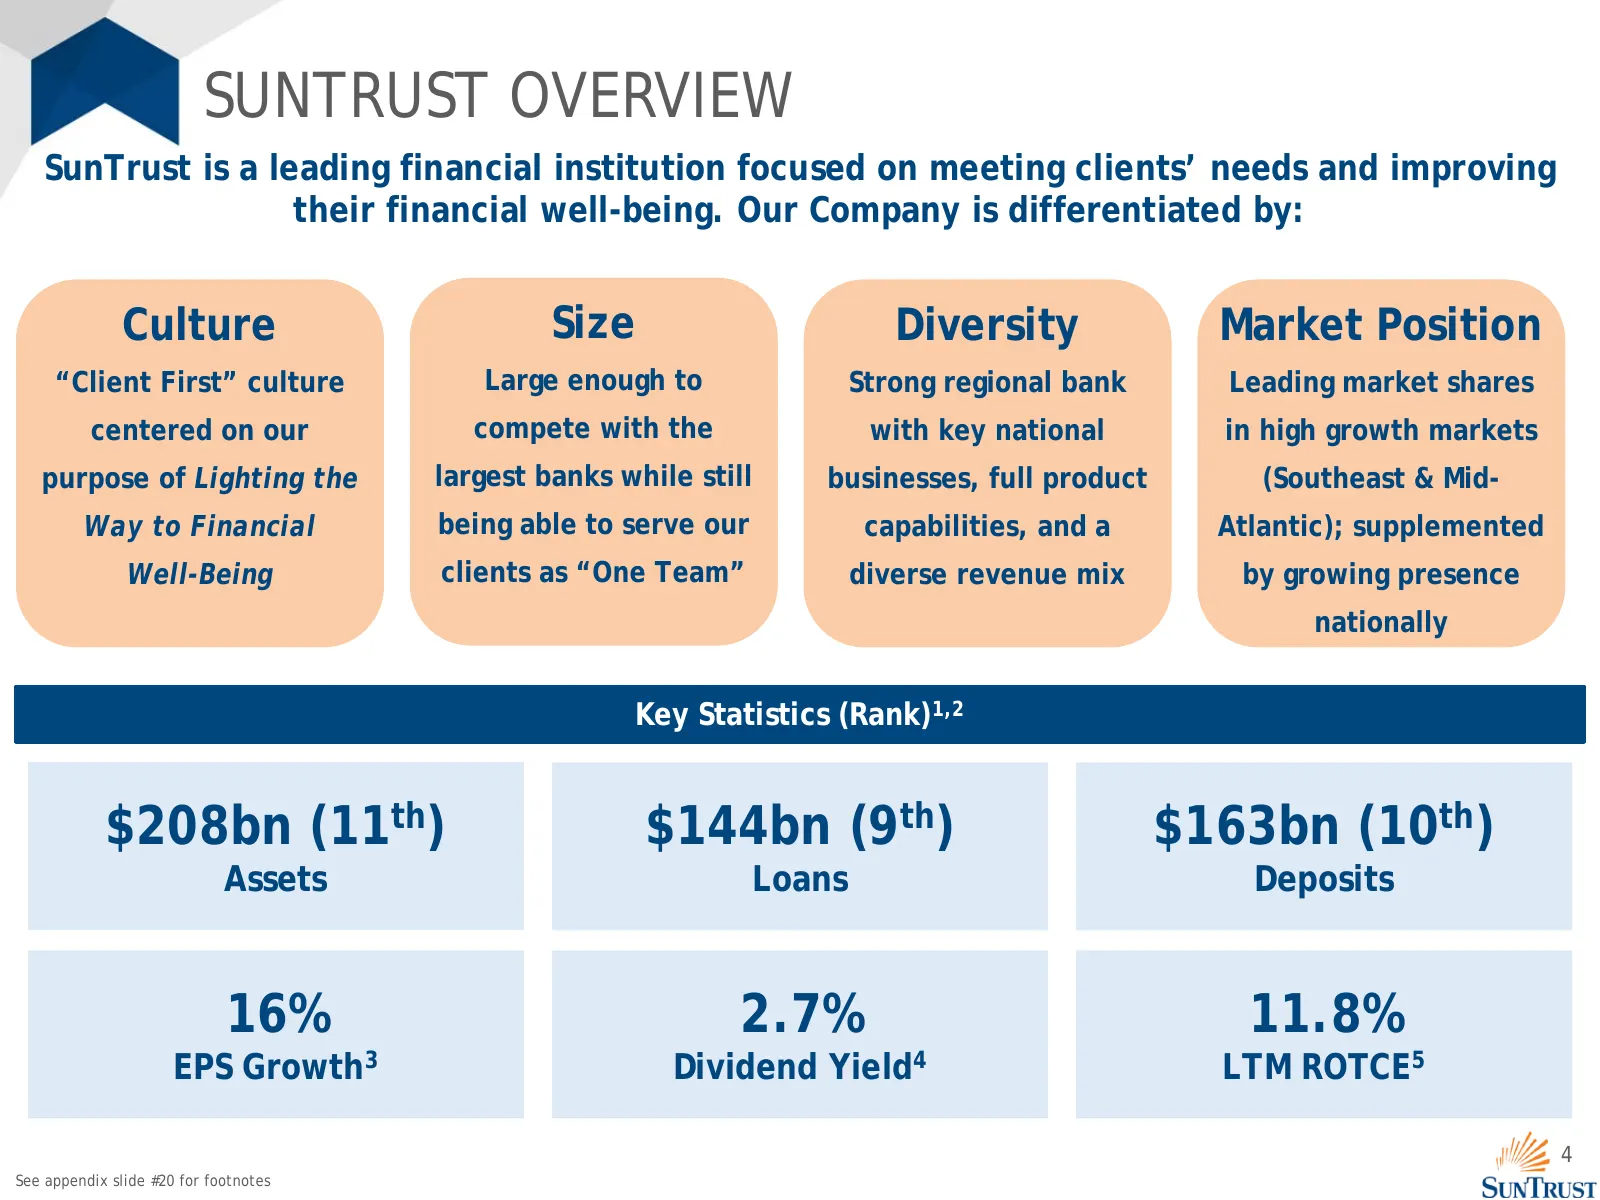
SUNTRUST OVERVIEW SunTrust is a leading financial institution focused on meeting clients’ needs and improving their financial well-being. Our Company is differentiated by: Culture Size Diversity Market Position “Client First” culture Large enough to Strong regional bank Leading market shares centere
Slide 5: Strong Deposit Franchise
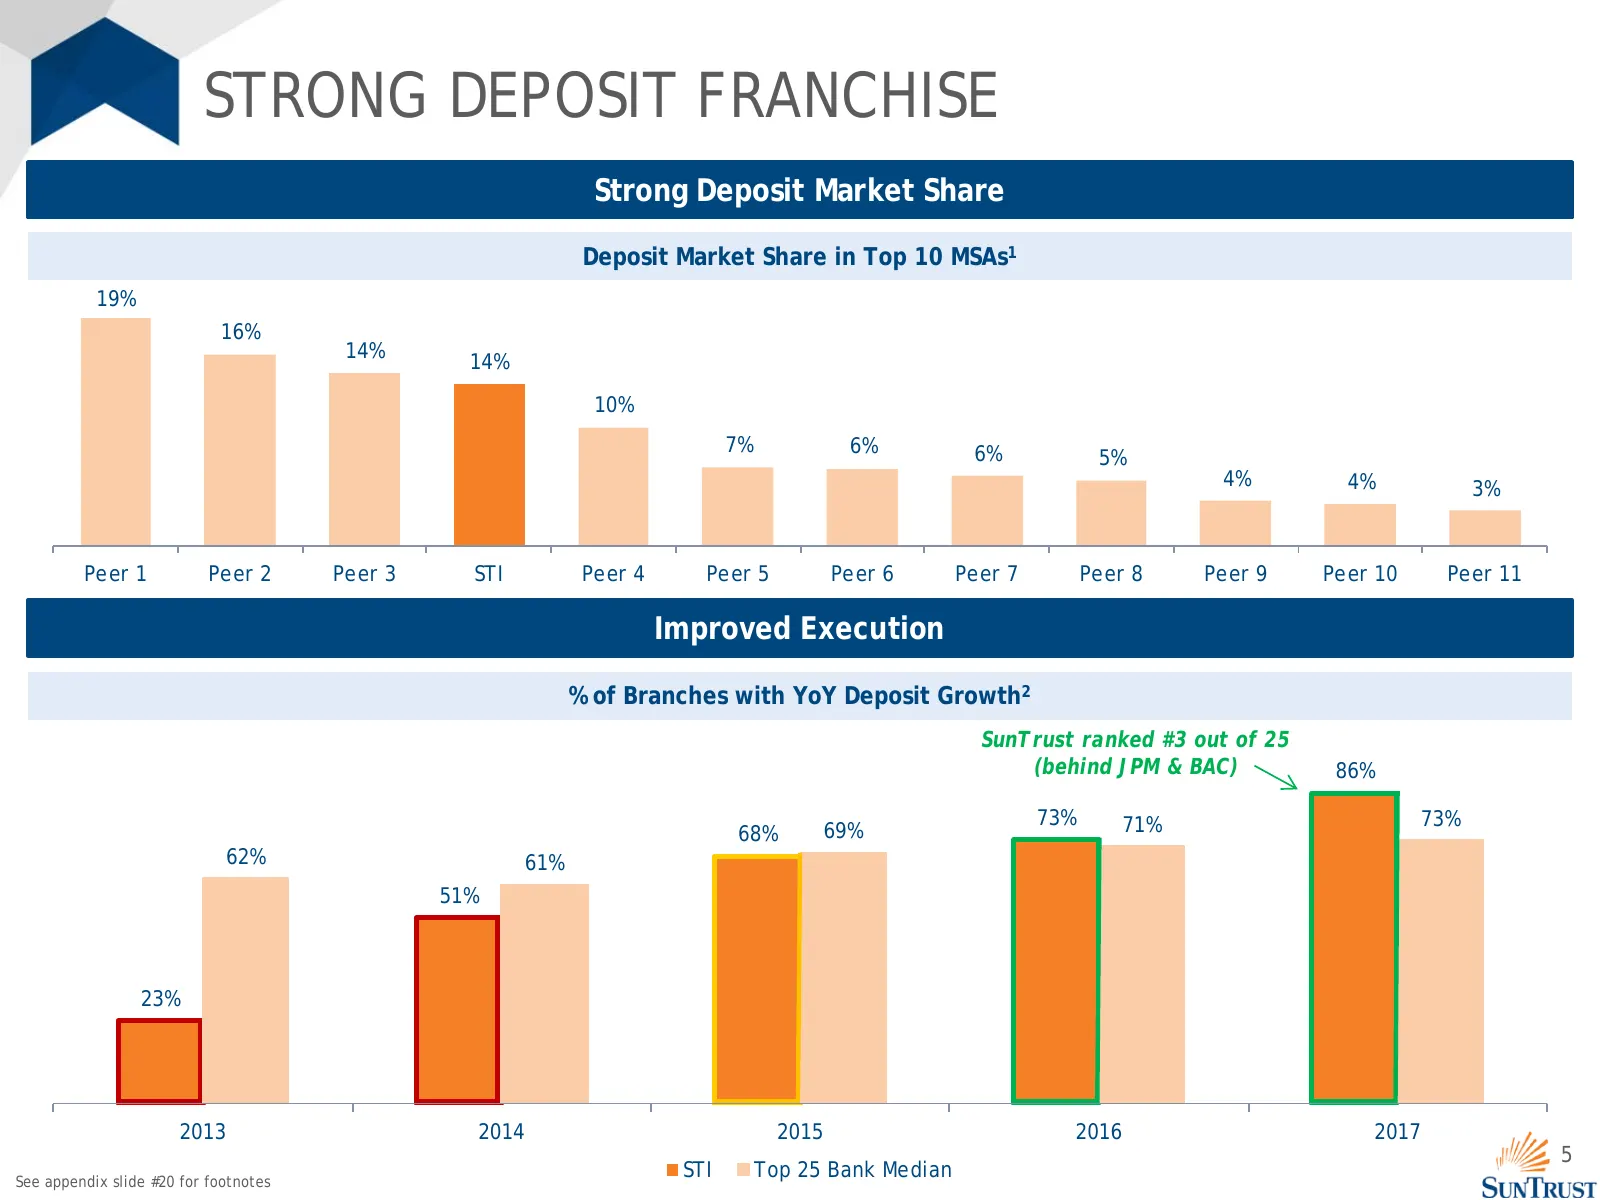
STRONG DEPOSIT FRANCHISE Strong Deposit Market Share Deposit Market Share in Top 10 MSAs1 19% 16% 14% 14% 10% 7% 6% 6% 5% 4% 4% 3% Peer 1 Peer 2 Peer 3 STI Peer 4 Peer 5 Peer 6 Peer 7 Peer 8 Peer 9 Peer 10 Peer 11 Improved Execution % of Branches with YoY Deposit Growth2 SunTrust ranked #3 out of 25
Slide 6: Favorable Market Positioning
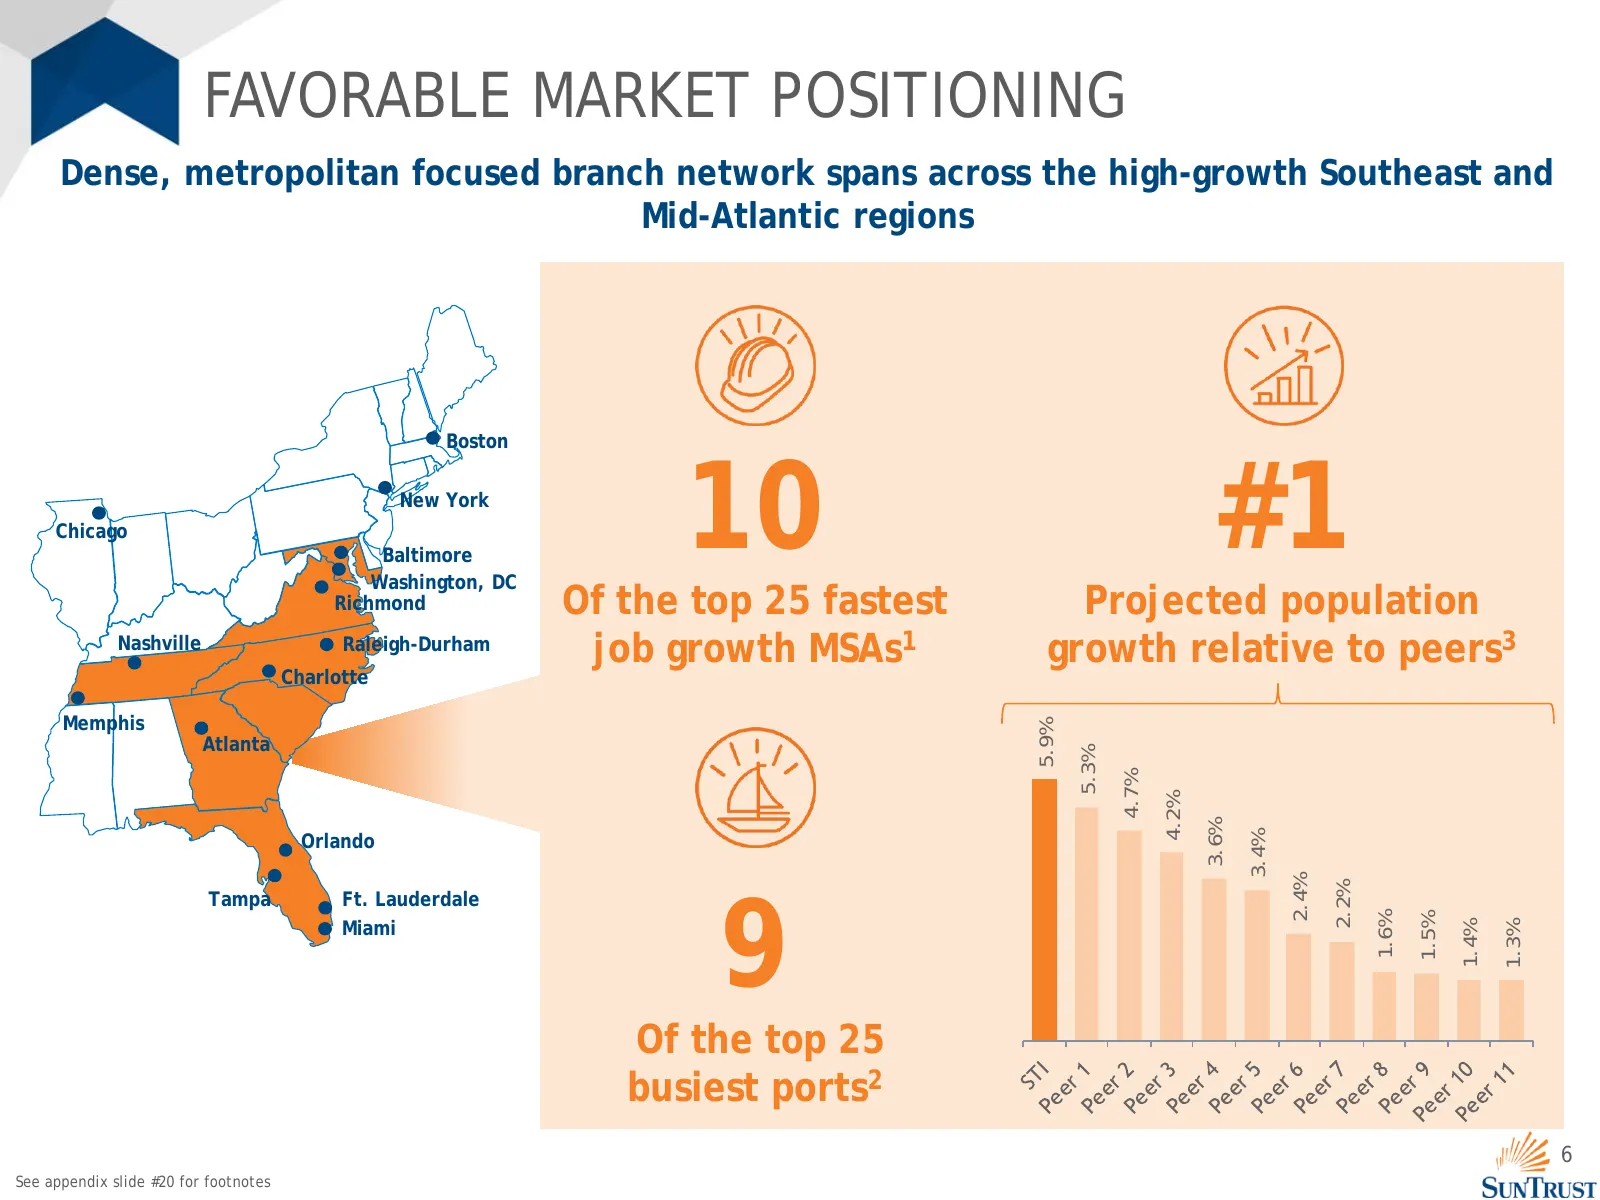
FAVORABLE MARKET POSITIONING Dense, metropolitan focused branch network spans across the high-growth Southeast and Mid-Atlantic regions Boston Chicago New York Baltimore Washington, DC 10 #1 Richmond Of the top 25 fastest Projected population Nashville Raleigh-Durham job growth MSAs1 growth relative
Slide 7: Consumer Segment: Recent Performance
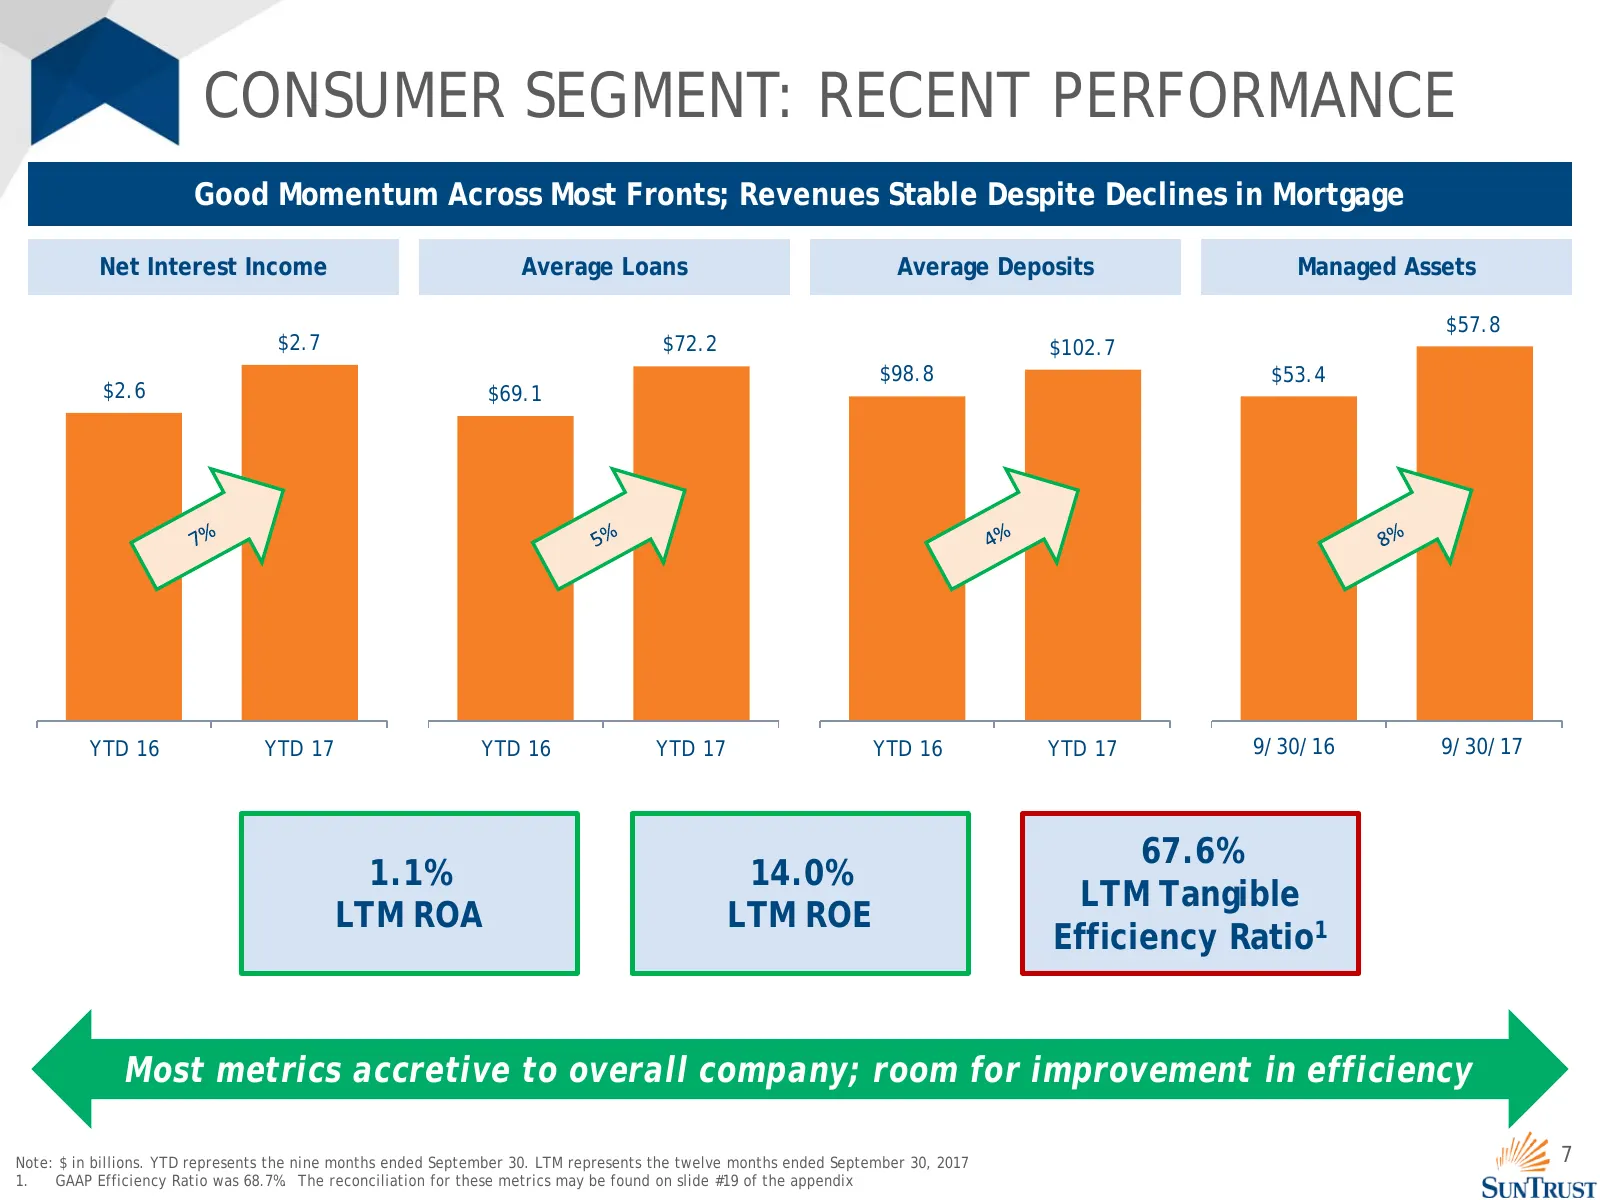
CONSUMER SEGMENT: RECENT PERFORMANCE Good Momentum Across Most Fronts; Revenues Stable Despite Declines in Mortgage Net Interest Income Average Loans Average Deposits Managed Assets $57.8 $2.7 $72.2 $102.7 $98.8 $53.4 $2.6 $69.1 YTD 16 YTD 17 YTD 16 YTD 17 YTD 16 YTD 17 9/30/16 1/1/2016 9/30/17 1/1/
Slide 8: Overview of Consumer Strategy & Growth Opportunities
OVERVIEW OF CONSUMER STRATEGY & GROWTH OPPORTUNITIES
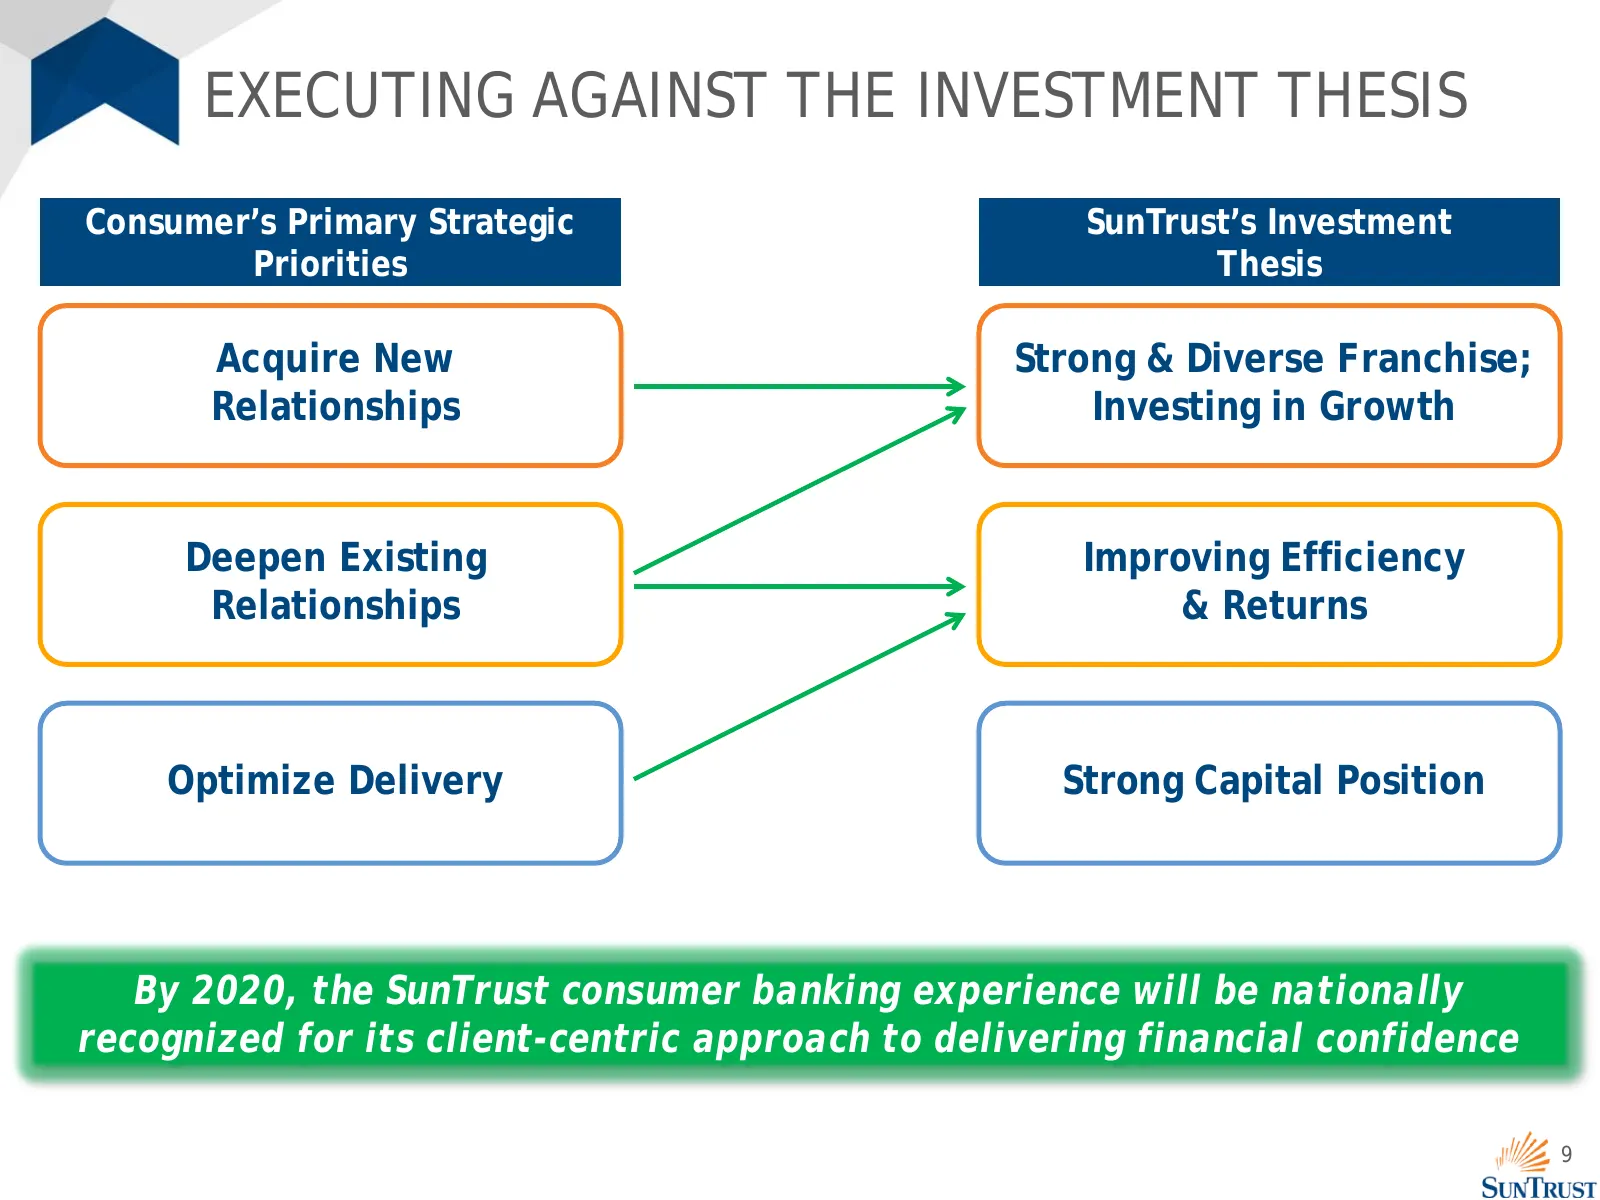
Slide 9: Executing Against the Investment Thesis
EXECUTING AGAINST THE INVESTMENT THESIS Consumer’s Primary Strategic SunTrust’s Investment Priorities Thesis Acquire New Strong & Diverse Franchise; Relationships Investing in Growth Deepen Existing Improving Efficiency Relationships & Returns Optimize Delivery Strong Capital Position By 2020, the S
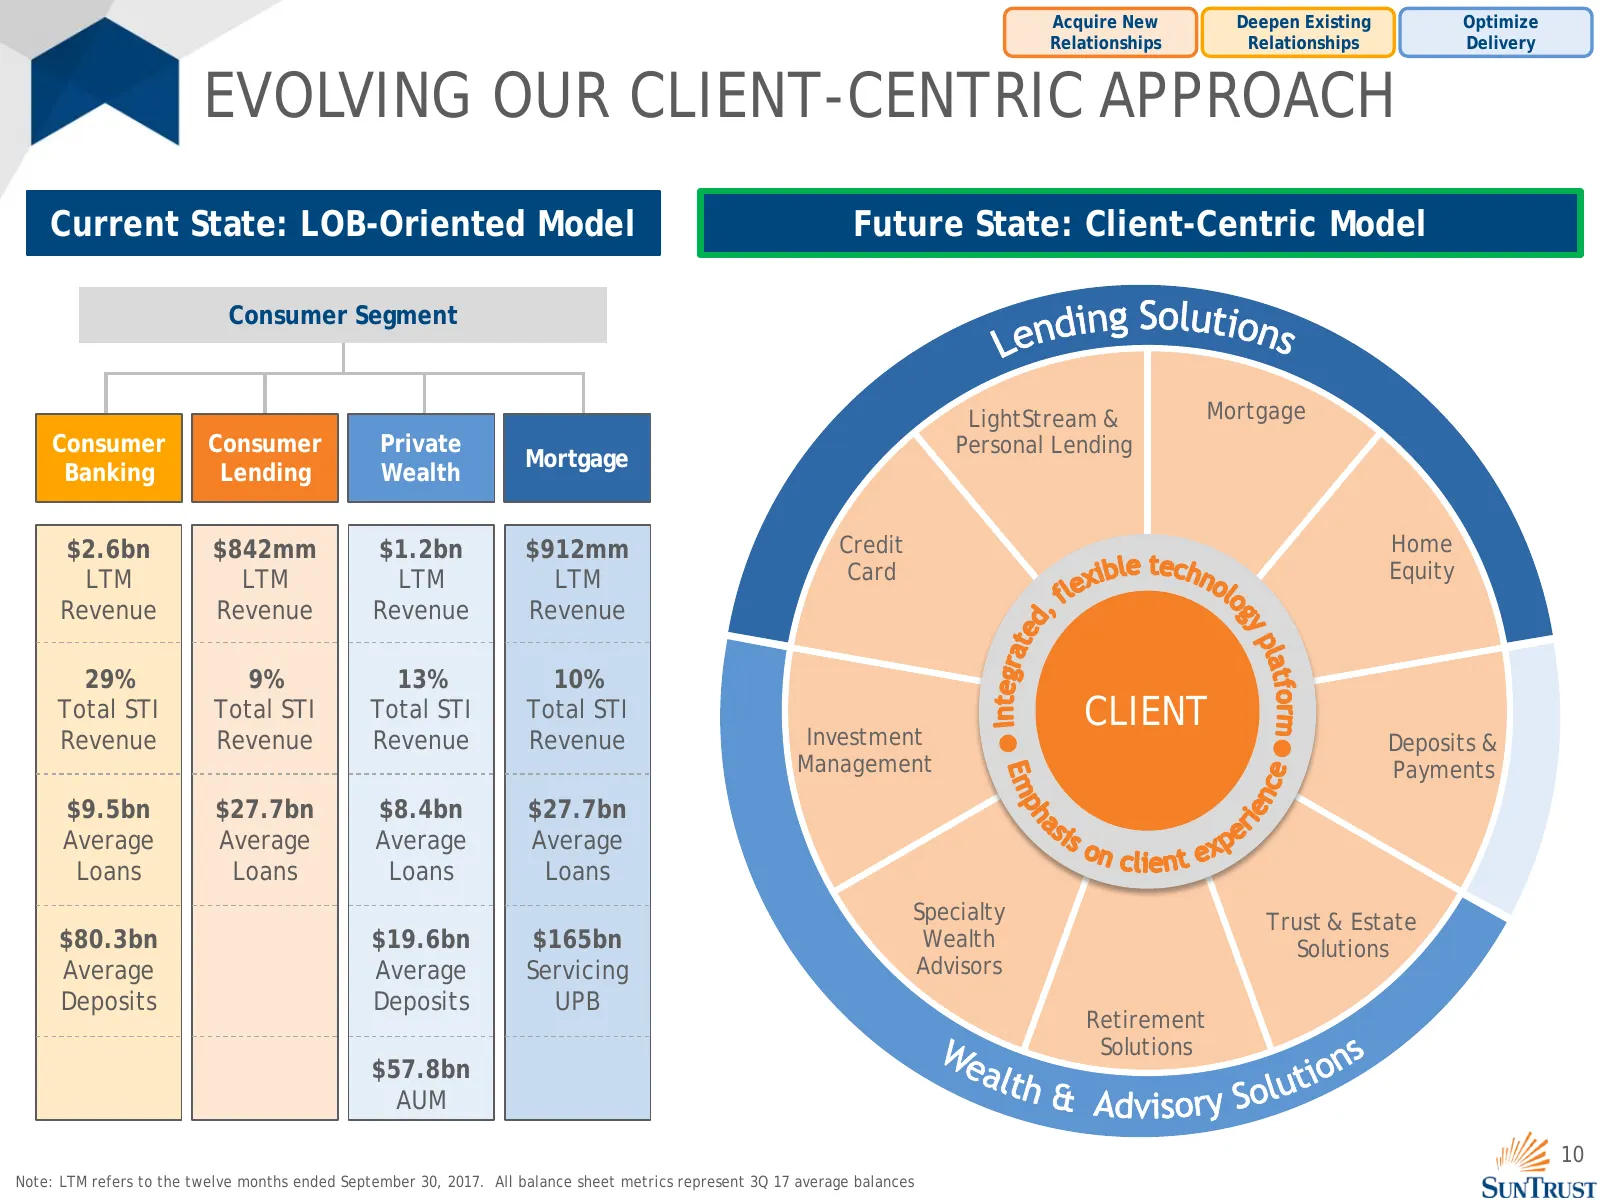
Slide 10: Evolving Our Client-Centric Approach
Acquire New Deepen Existing Optimize Relationships Relationships Delivery EVOLVING OUR CLIENT-CENTRIC APPROACH Current State: LOB-Oriented Model Future State: Client-Centric Model Consumer Segment LightStream & Mortgage Consumer Consumer Private Personal Lending Mortgage Banking Lending Wealth $2.6b
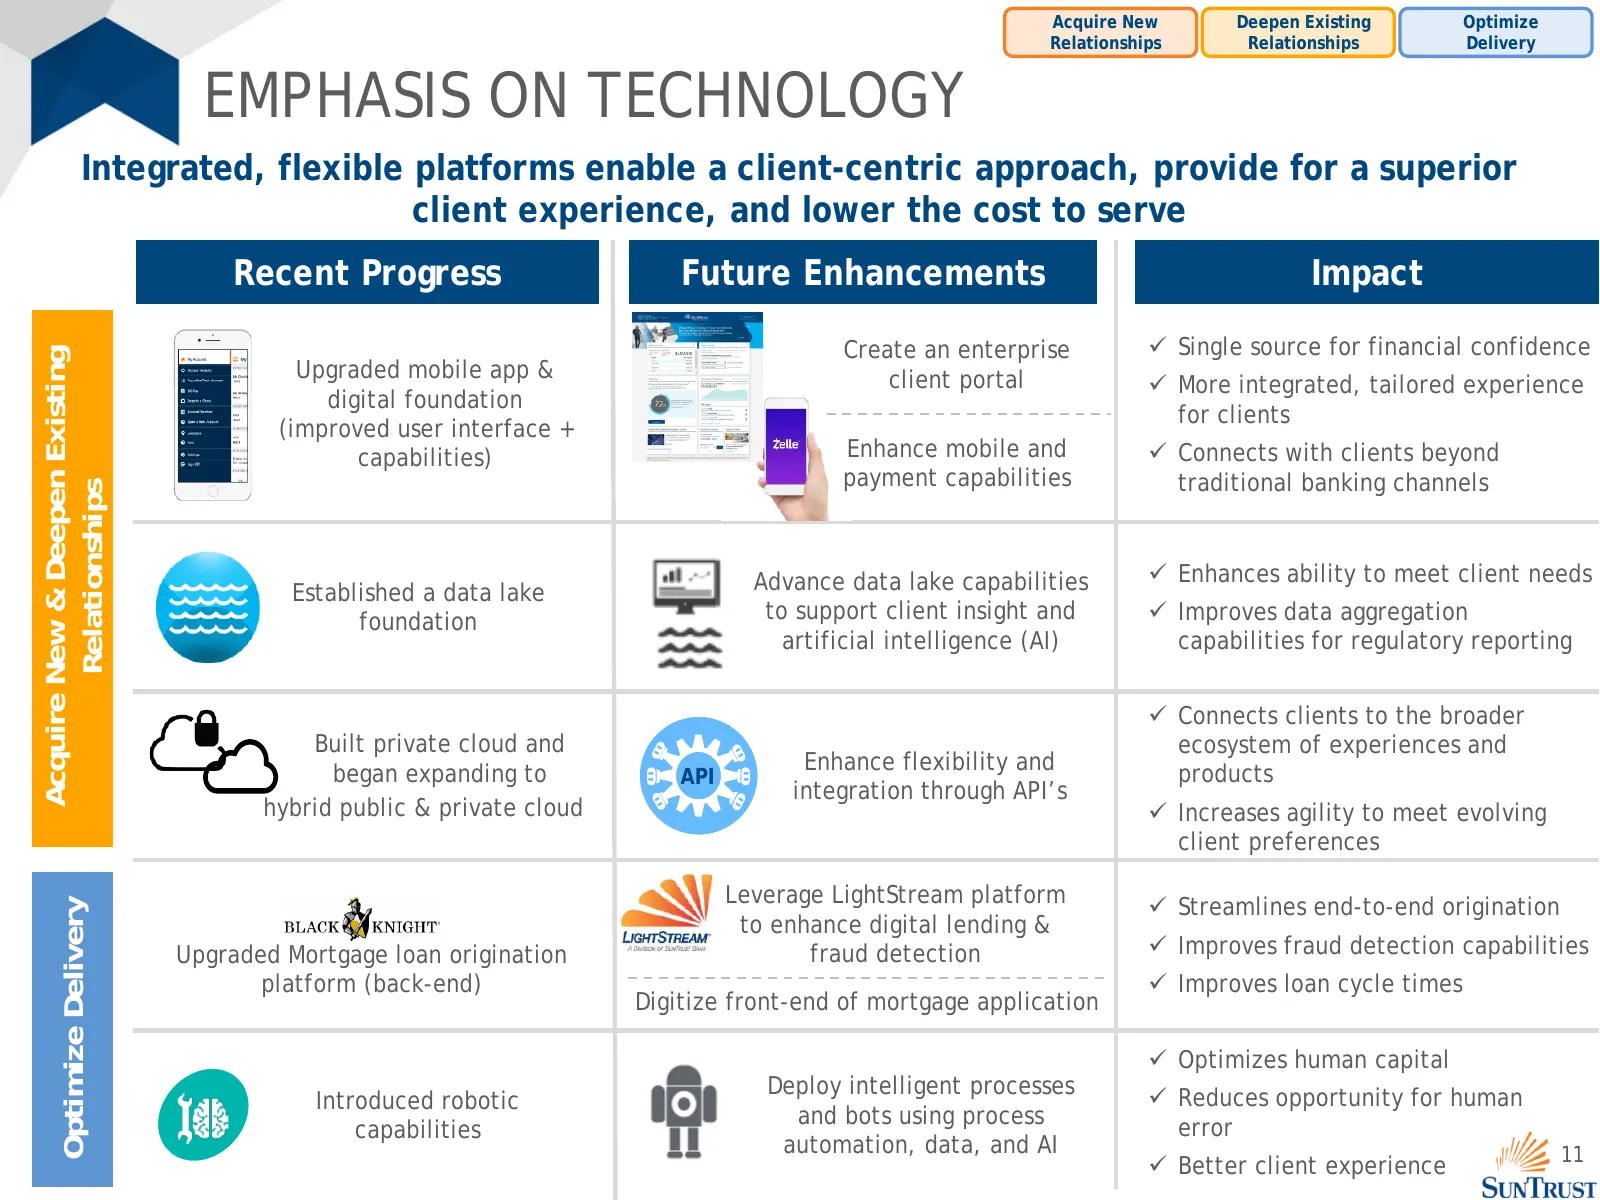
Slide 11: Emphasis on Technology
Acquire New Deepen Existing Optimize Relationships Relationships Delivery EMPHASIS ON TECHNOLOGY Integrated, flexible platforms enable a client-centric approach, provide for a superior client experience, and lower the cost to serve Recent Progress Future Enhancements Impact Create an enterprise Si
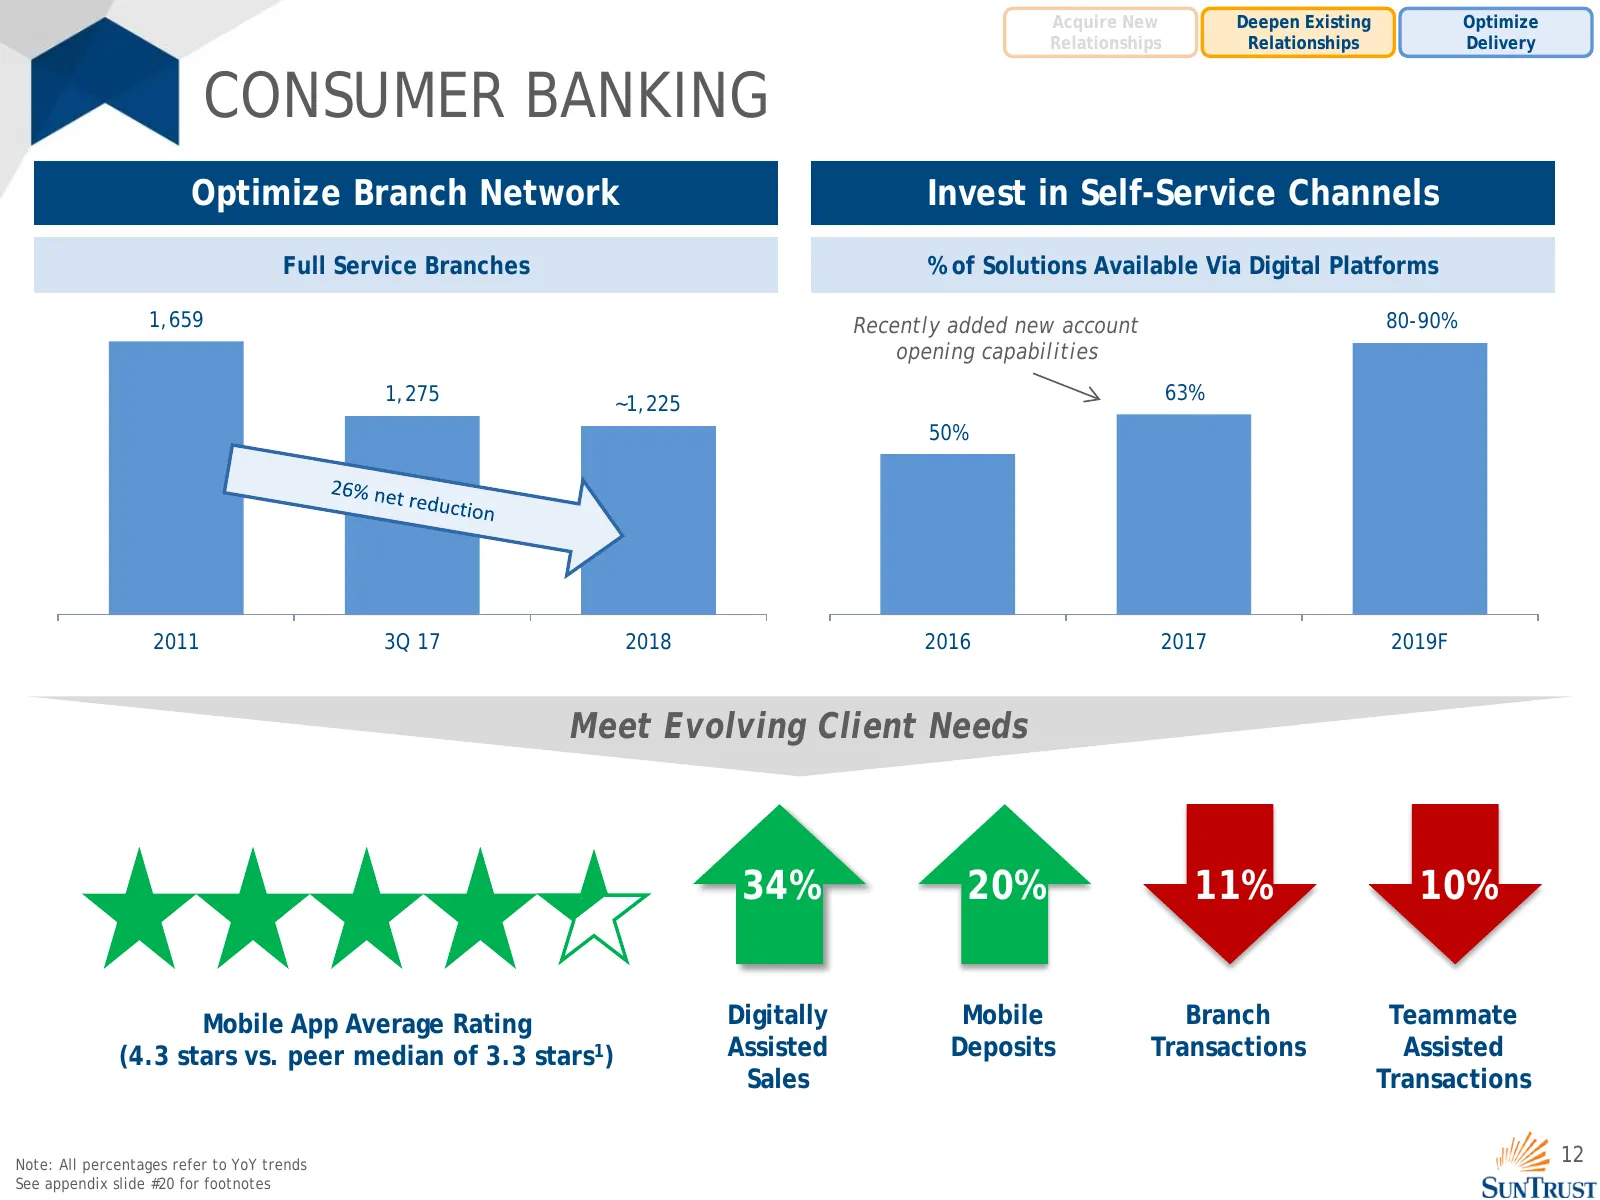
Slide 12: Consumer Banking
Acquire New Deepen Existing Optimize Relationships Relationships Delivery CONSUMER BANKING Optimize Branch Network Invest in Self-Service Channels Full Service Branches % of Solutions Available Via Digital Platforms 1,659 Recently added new account 80-90% opening capabilities 1,275 63% ~1,225 50% 20
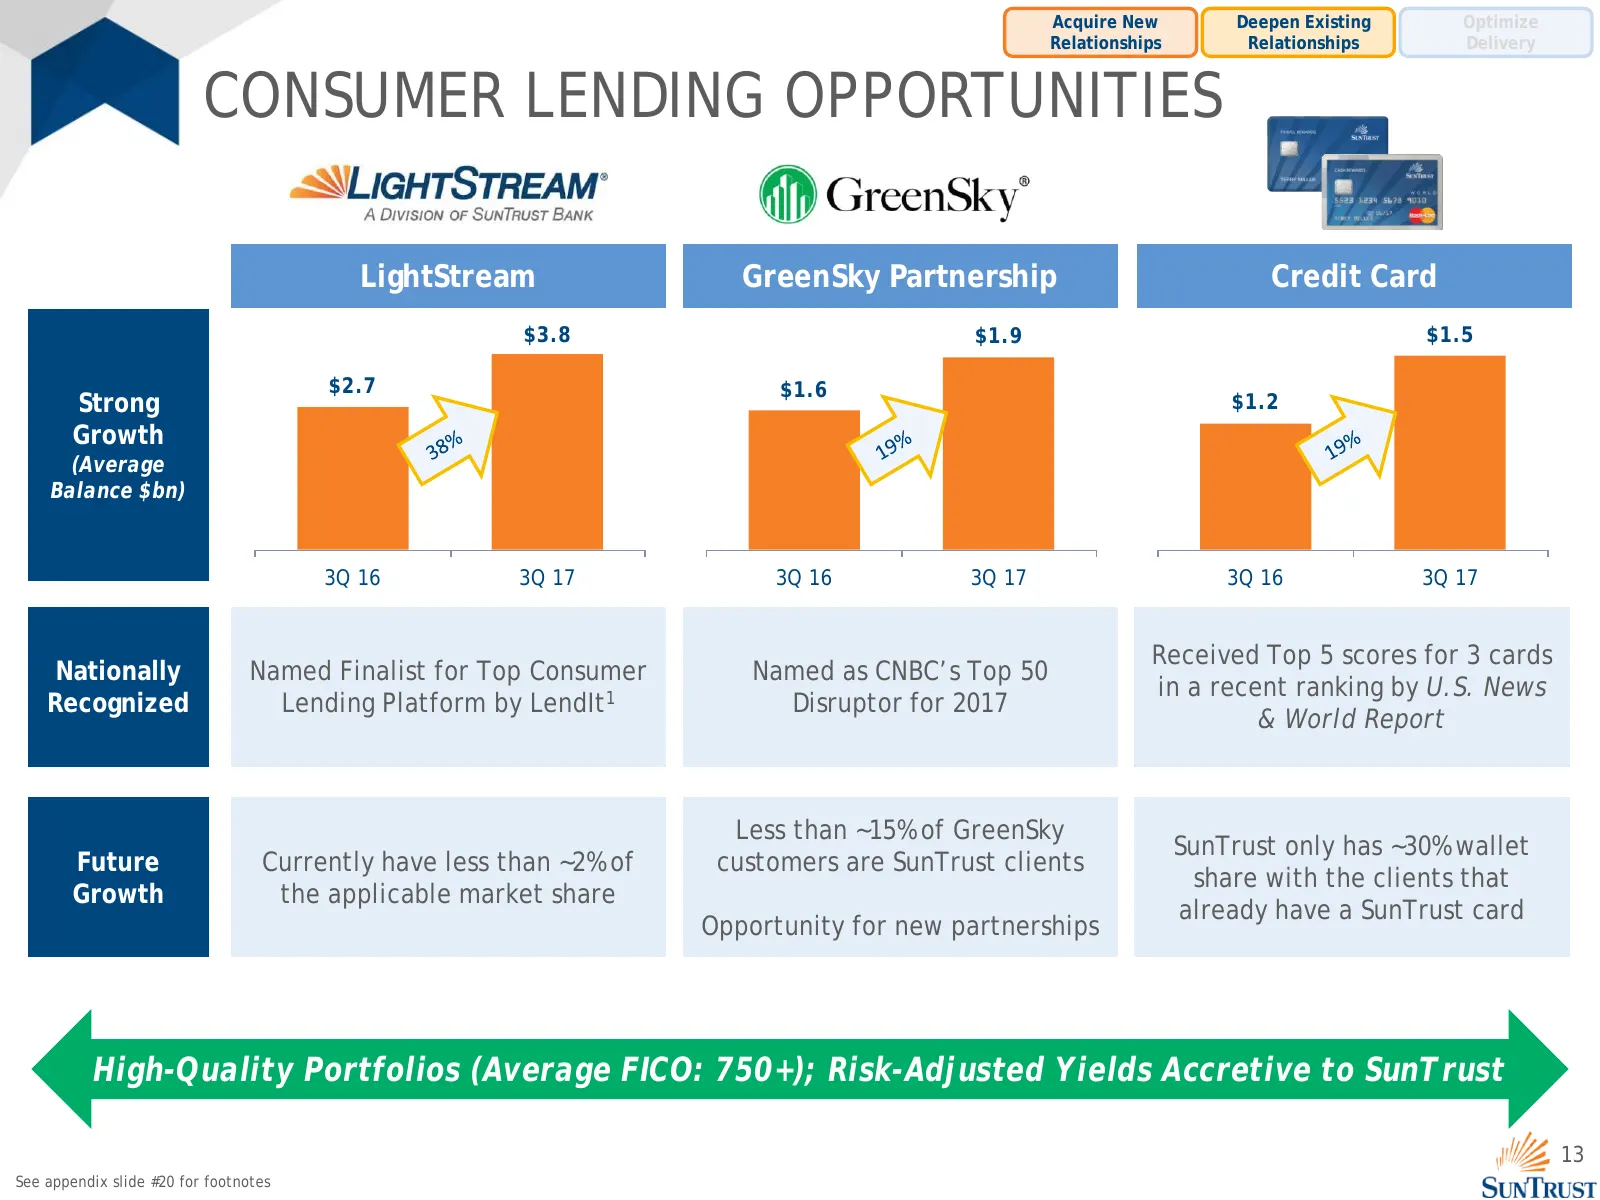
Slide 13: Consumer Lending Opportunities
Acquire New Deepen Existing Optimize Relationships Relationships Delivery CONSUMER LENDING OPPORTUNITIES LightStream GreenSky Partnership Credit Card $3.8 $1.9 $1.5 $2.7 $1.6 Strong $1.2 Growth (Average Balance $bn) 3Q 16 3Q 17 3Q 16 3Q 17 3Q 16 3Q 17 Received Top 5 scores for 3 cards Nationally Nam
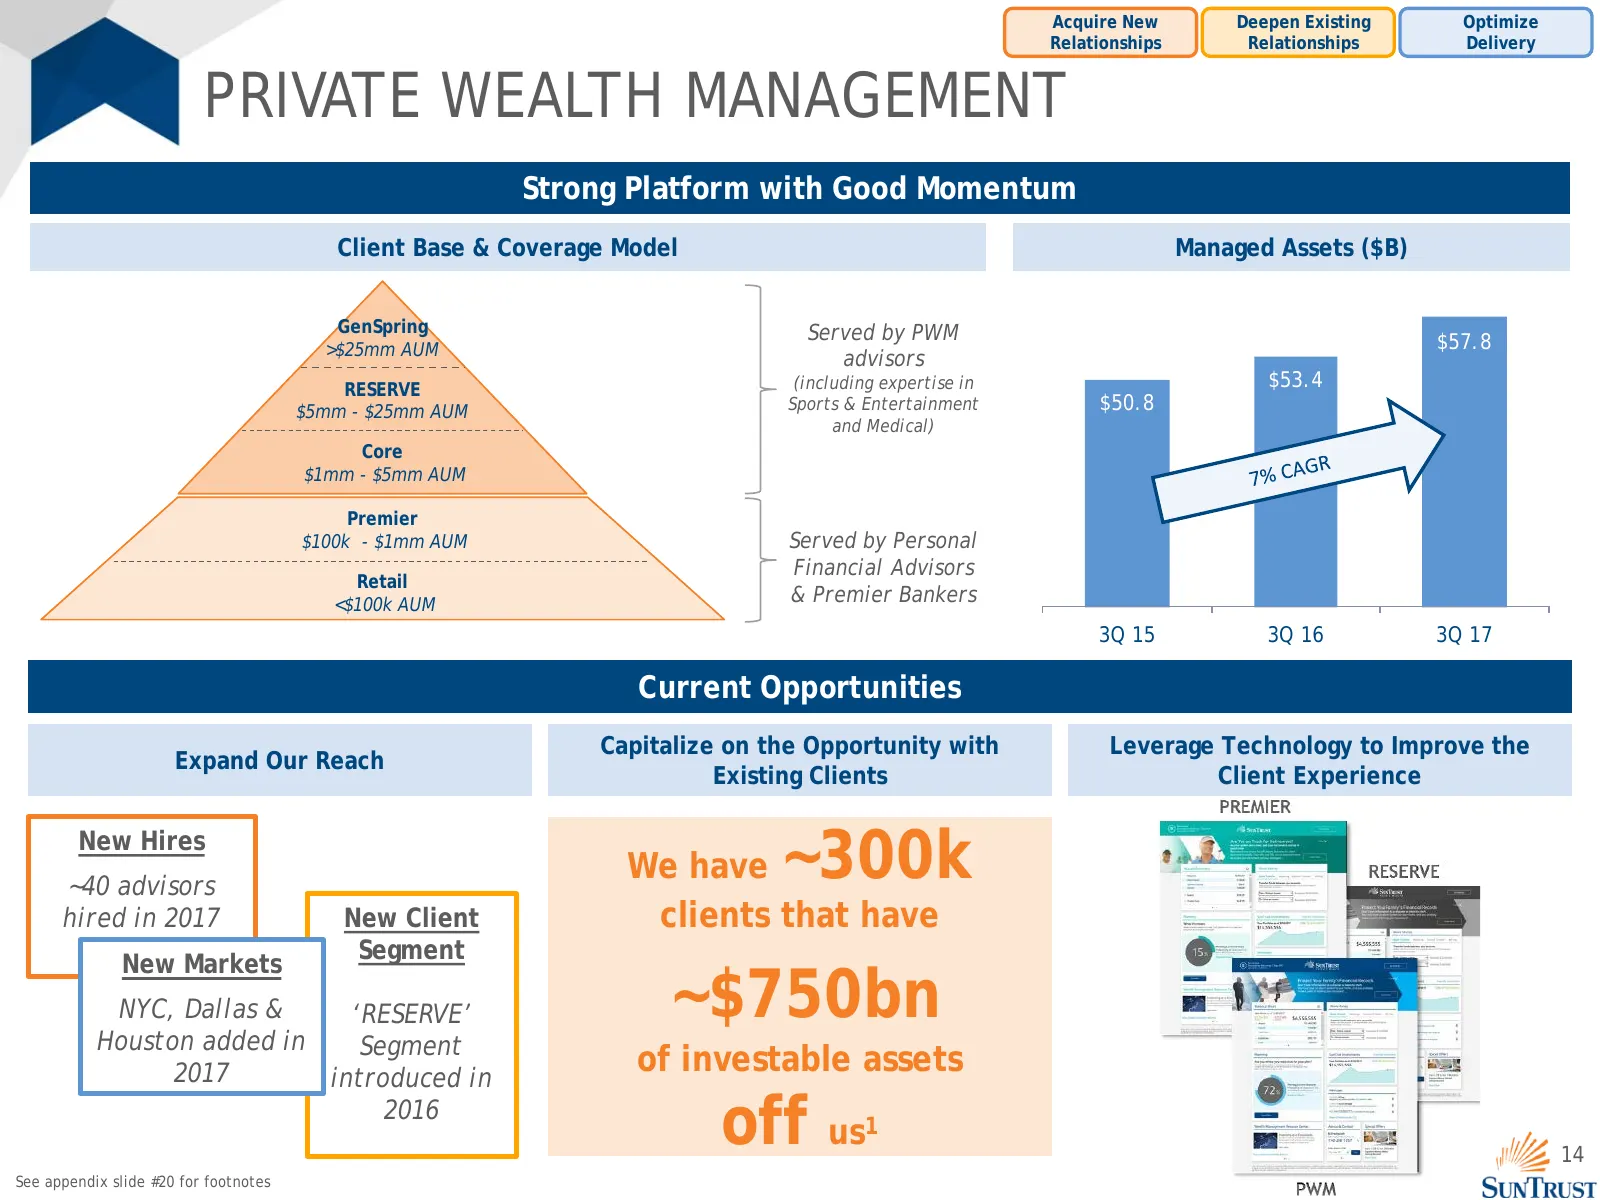
Slide 14: Private Wealth Management
Acquire New Deepen Existing Optimize Relationships Relationships Delivery PRIVATE WEALTH MANAGEMENT Strong Platform with Good Momentum Client Base & Coverage Model Managed Assets ($B) GenSpring Served by PWM >$25mm AUM $57.8 advisors RESERVE (including expertise in $53.4 $5mm - $25mm AUM Sports & En
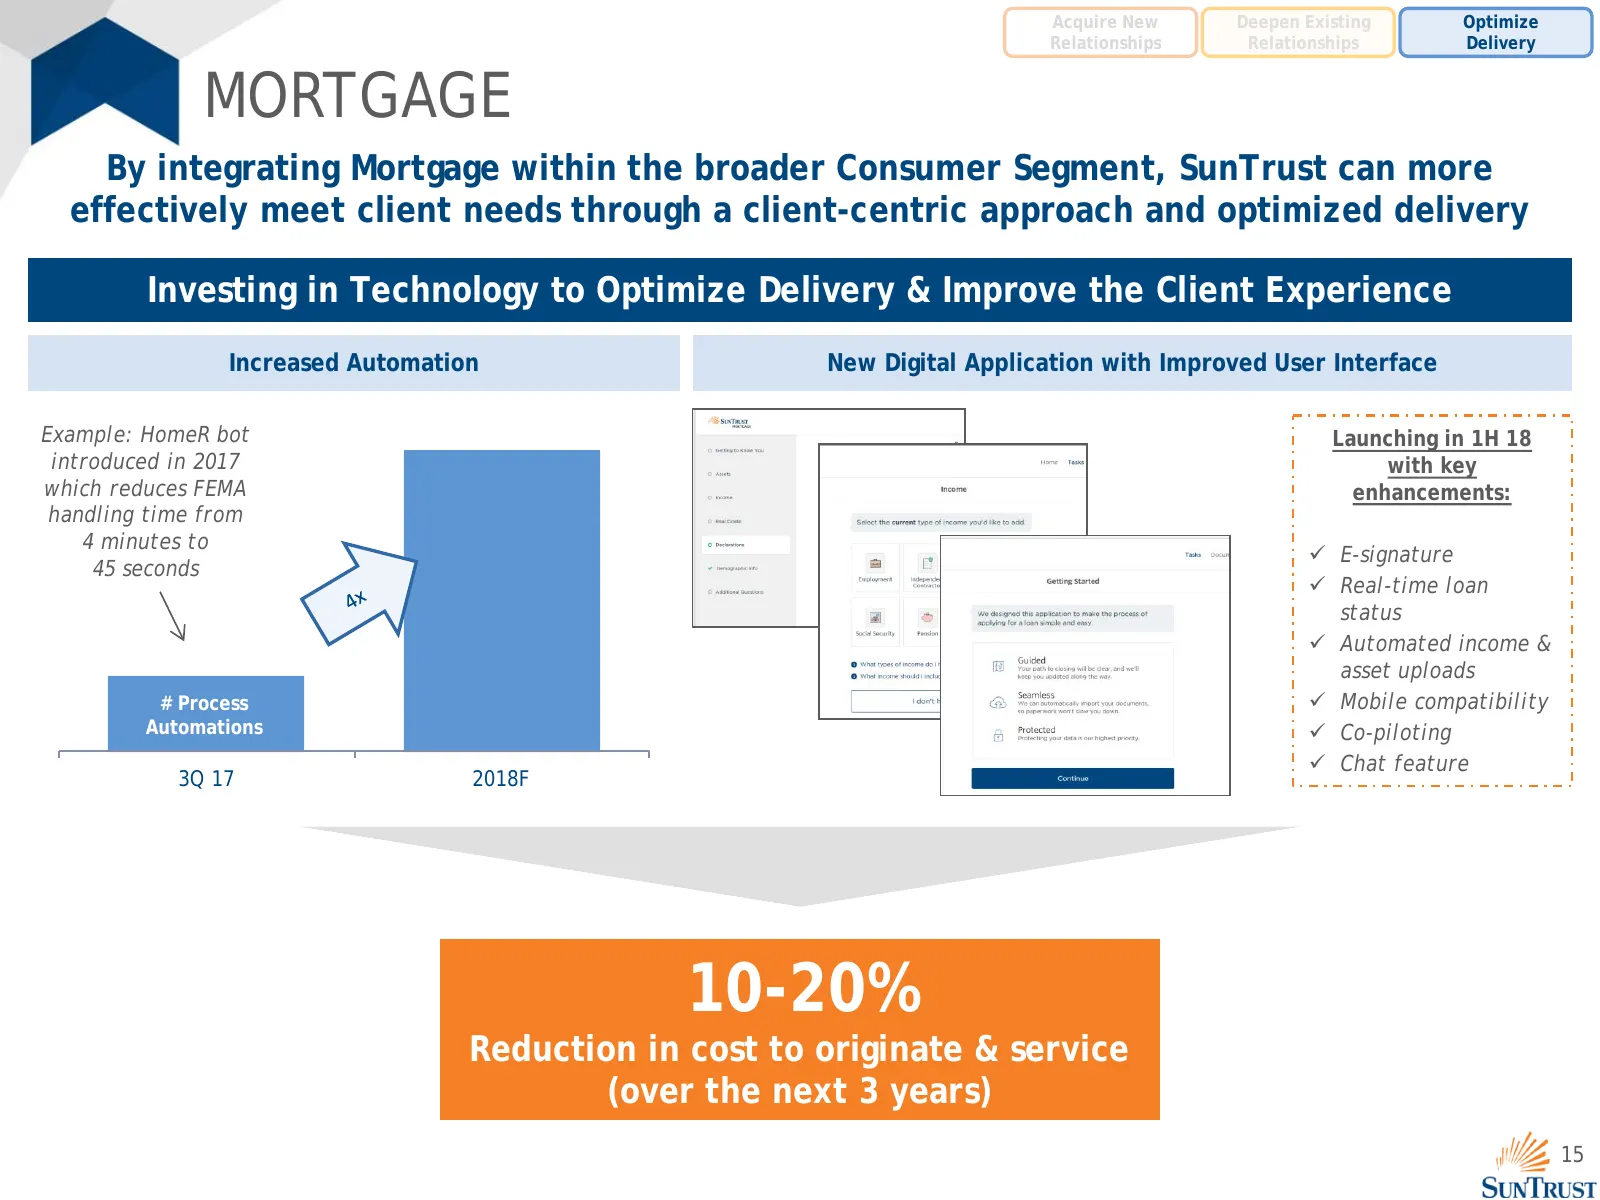
Slide 15: Mortgage
Acquire New Deepen Existing Optimize Relationships Relationships Delivery MORTGAGE By integrating Mortgage within the broader Consumer Segment, SunTrust can more effectively meet client needs through a client-centric approach and optimized delivery Investing in Technology to Optimize Delivery & Impr
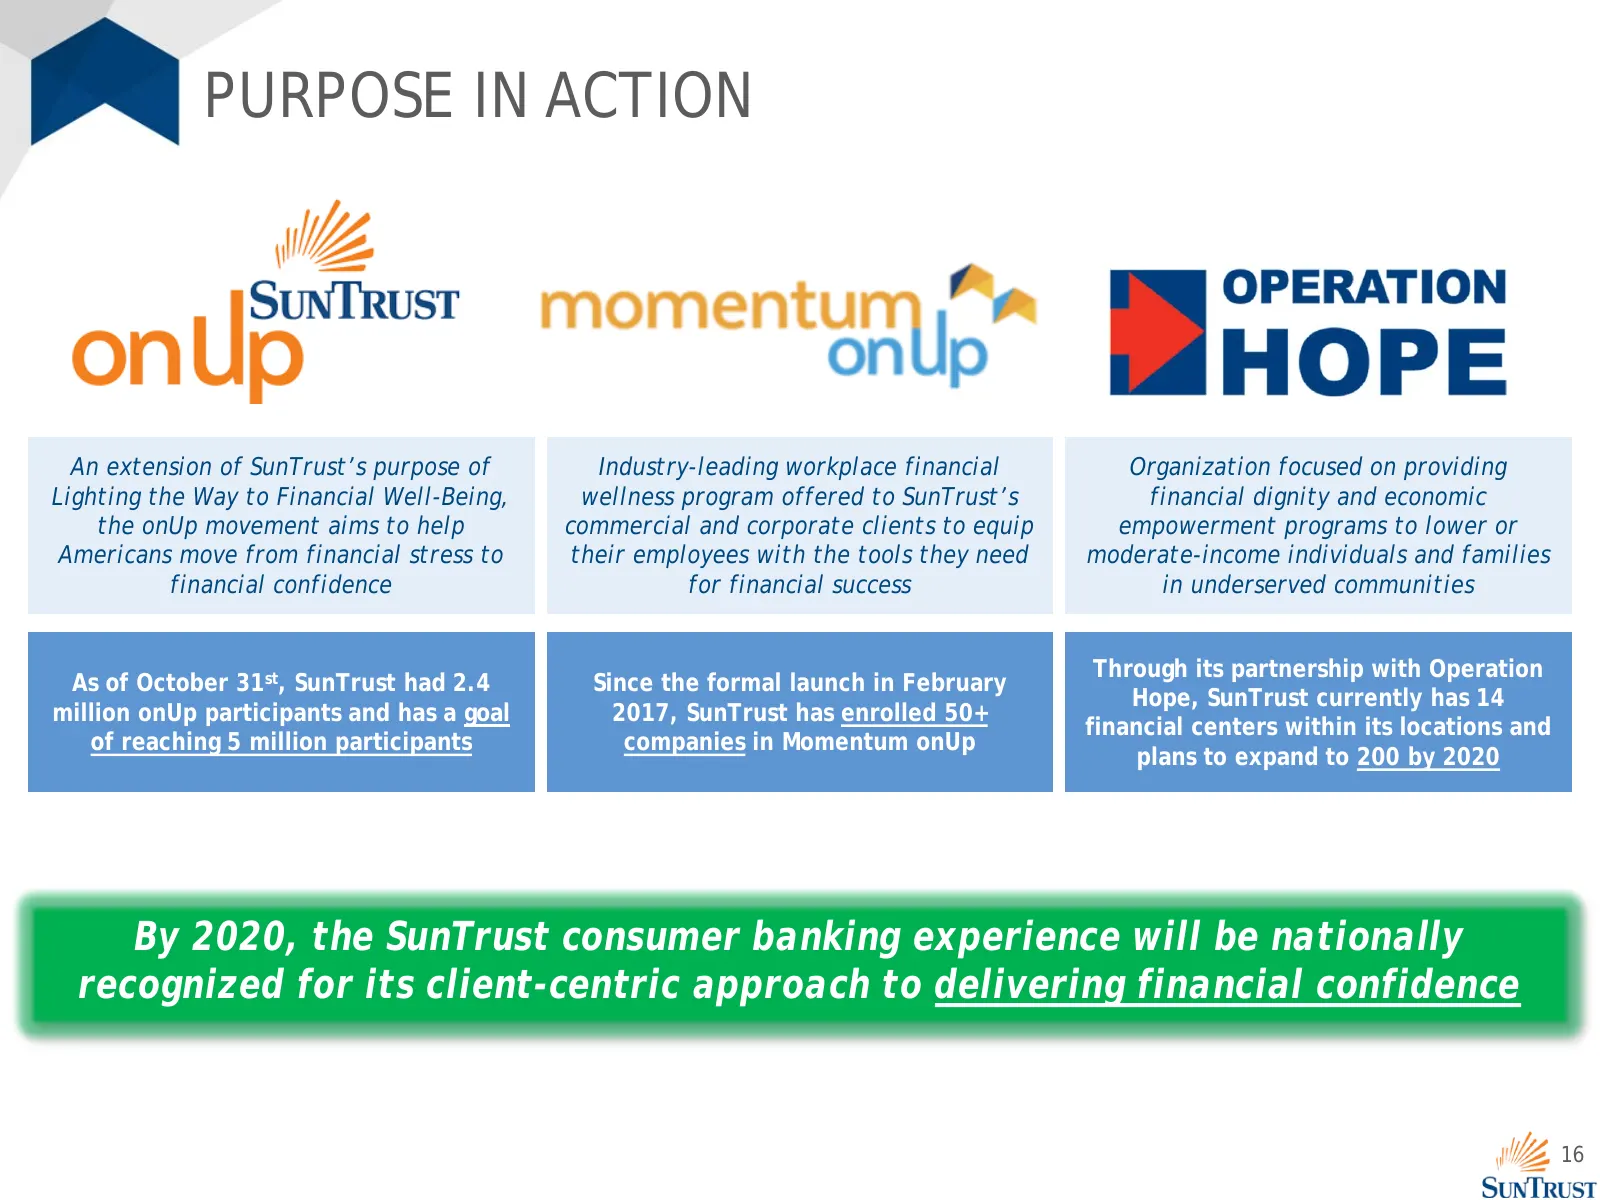
Slide 16: Purpose in Action
PURPOSE IN ACTION An extension of SunTrust’s purpose of Industry-leading workplace financial Organization focused on providing Lighting the Way to Financial Well-Being, wellness program offered to SunTrust’s financial dignity and economic the onUp movement aims to help commercial and corporate clien
Slide 17: Recap: Why Invest in SunTrust?
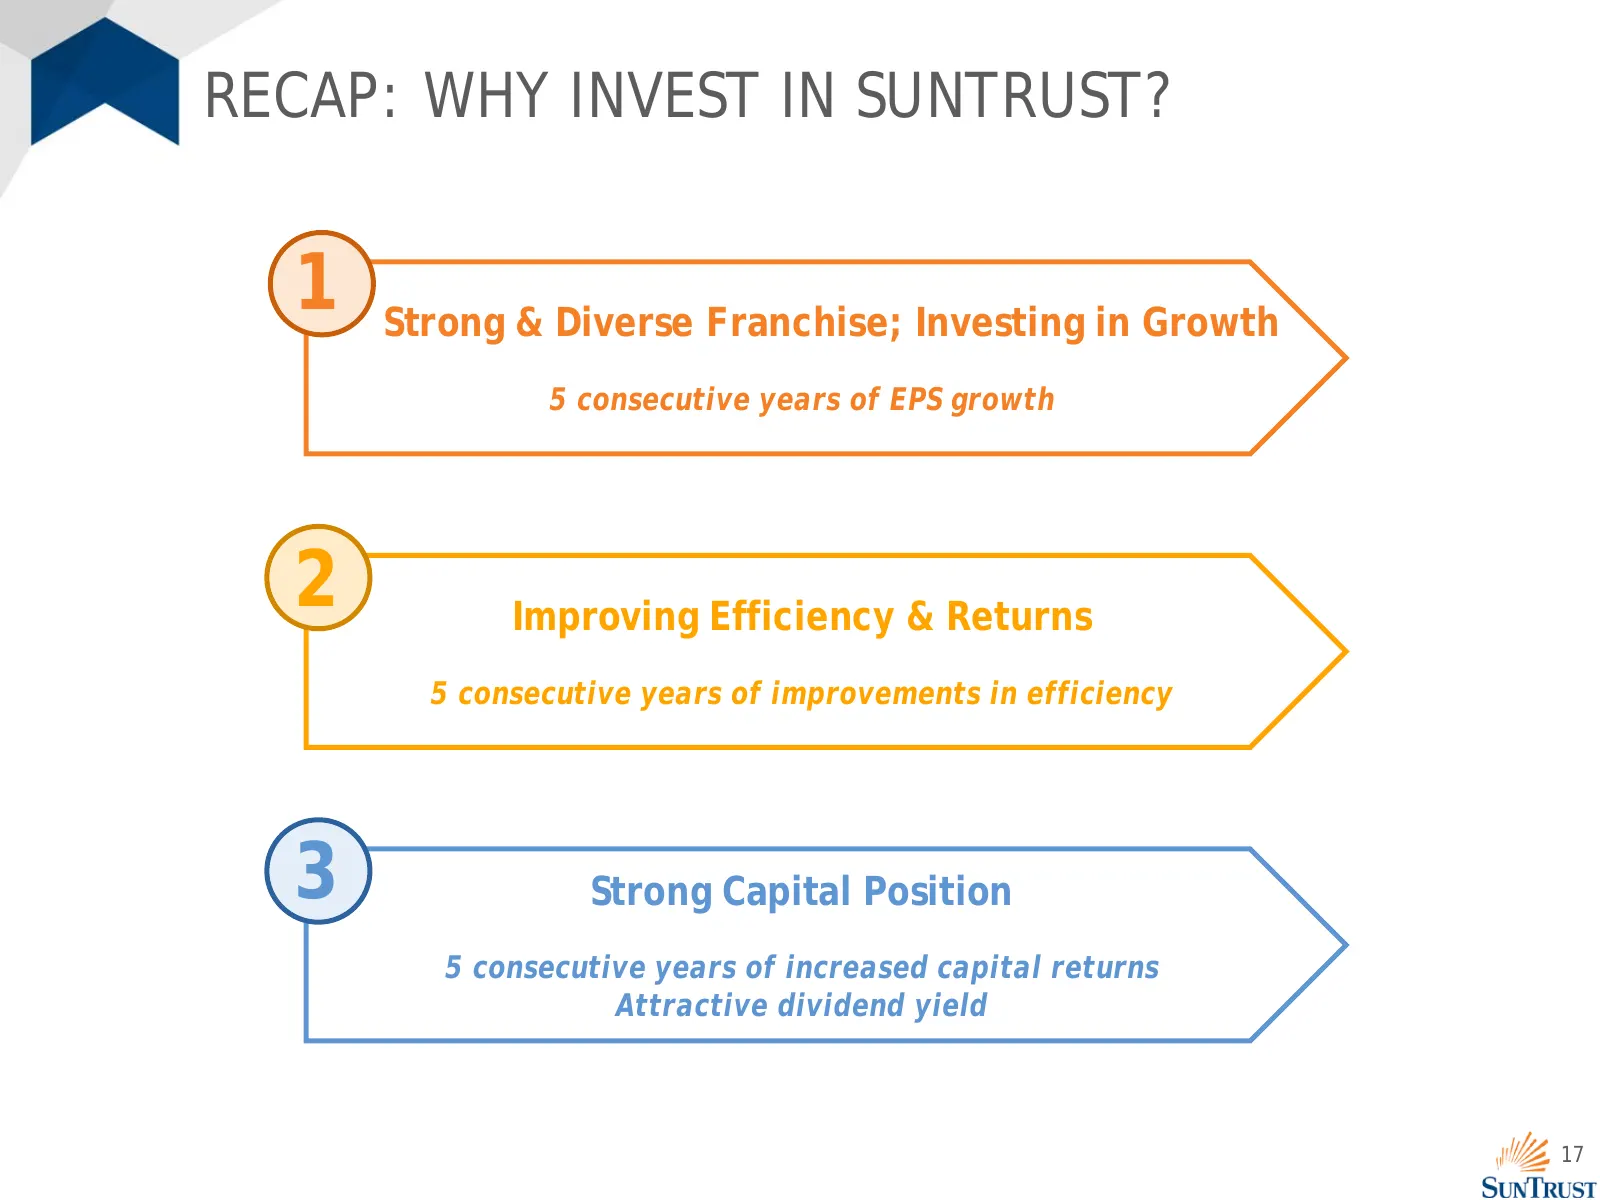
RECAP: WHY INVEST IN SUNTRUST? 1 Strong & Diverse Franchise; Investing in Growth 5 consecutive years of EPS growth 2 Improving Efficiency & Returns 5 consecutive years of improvements in efficiency 3 Strong Capital Position 5 consecutive years of increased capital returns Attractive dividend yield 1
Slide 18: Appendix
APPENDIX SUNTRUST
Slide 19: Reconciliation of Consumer Segment's Tangible Efficiency Ratio
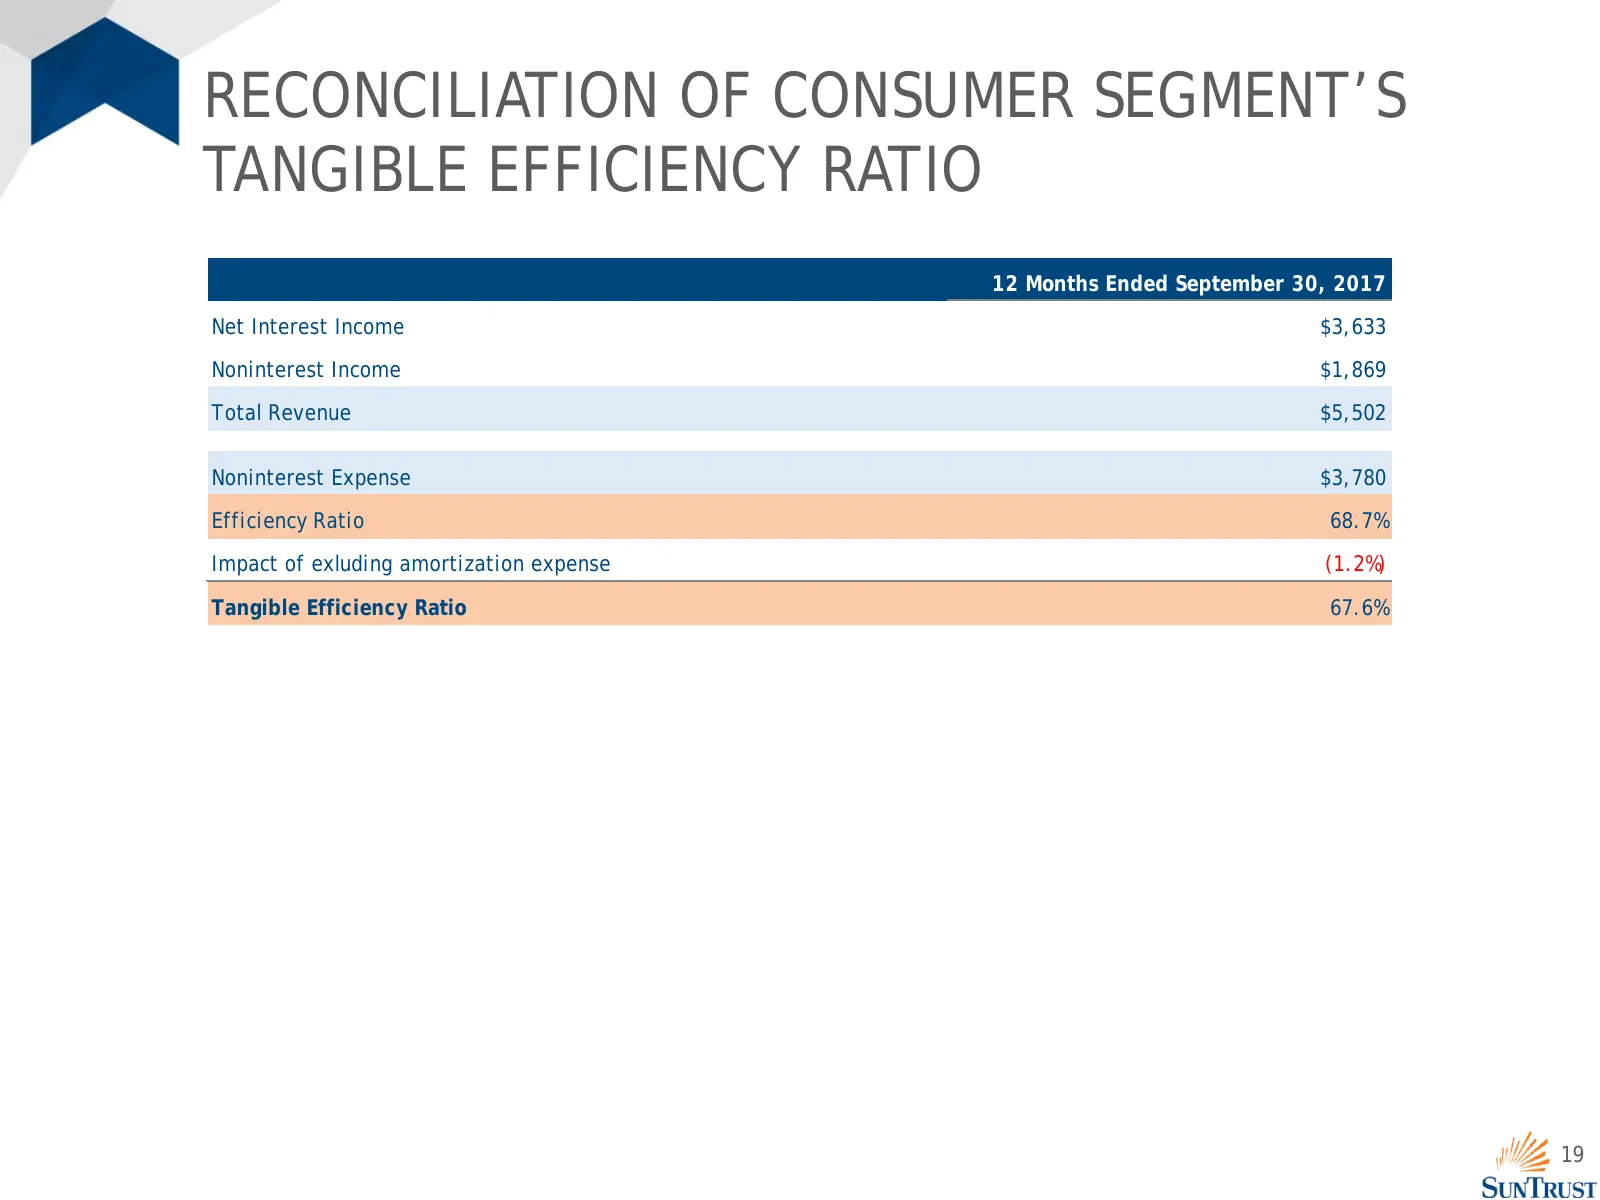
RECONCILIATION OF CONSUMER SEGMENT’S TANGIBLE EFFICIENCY RATIO 12 Months Ended September 30, 2017 Net Interest Income $3,633 Noninterest Income $1,869 Total Revenue $5,502 Noninterest Expense $3,780 Efficiency Ratio 68.7% Impact of exluding amortization expense (1.2%) Tangible Efficiency Ratio 67.6%
Slide 20: Footnotes
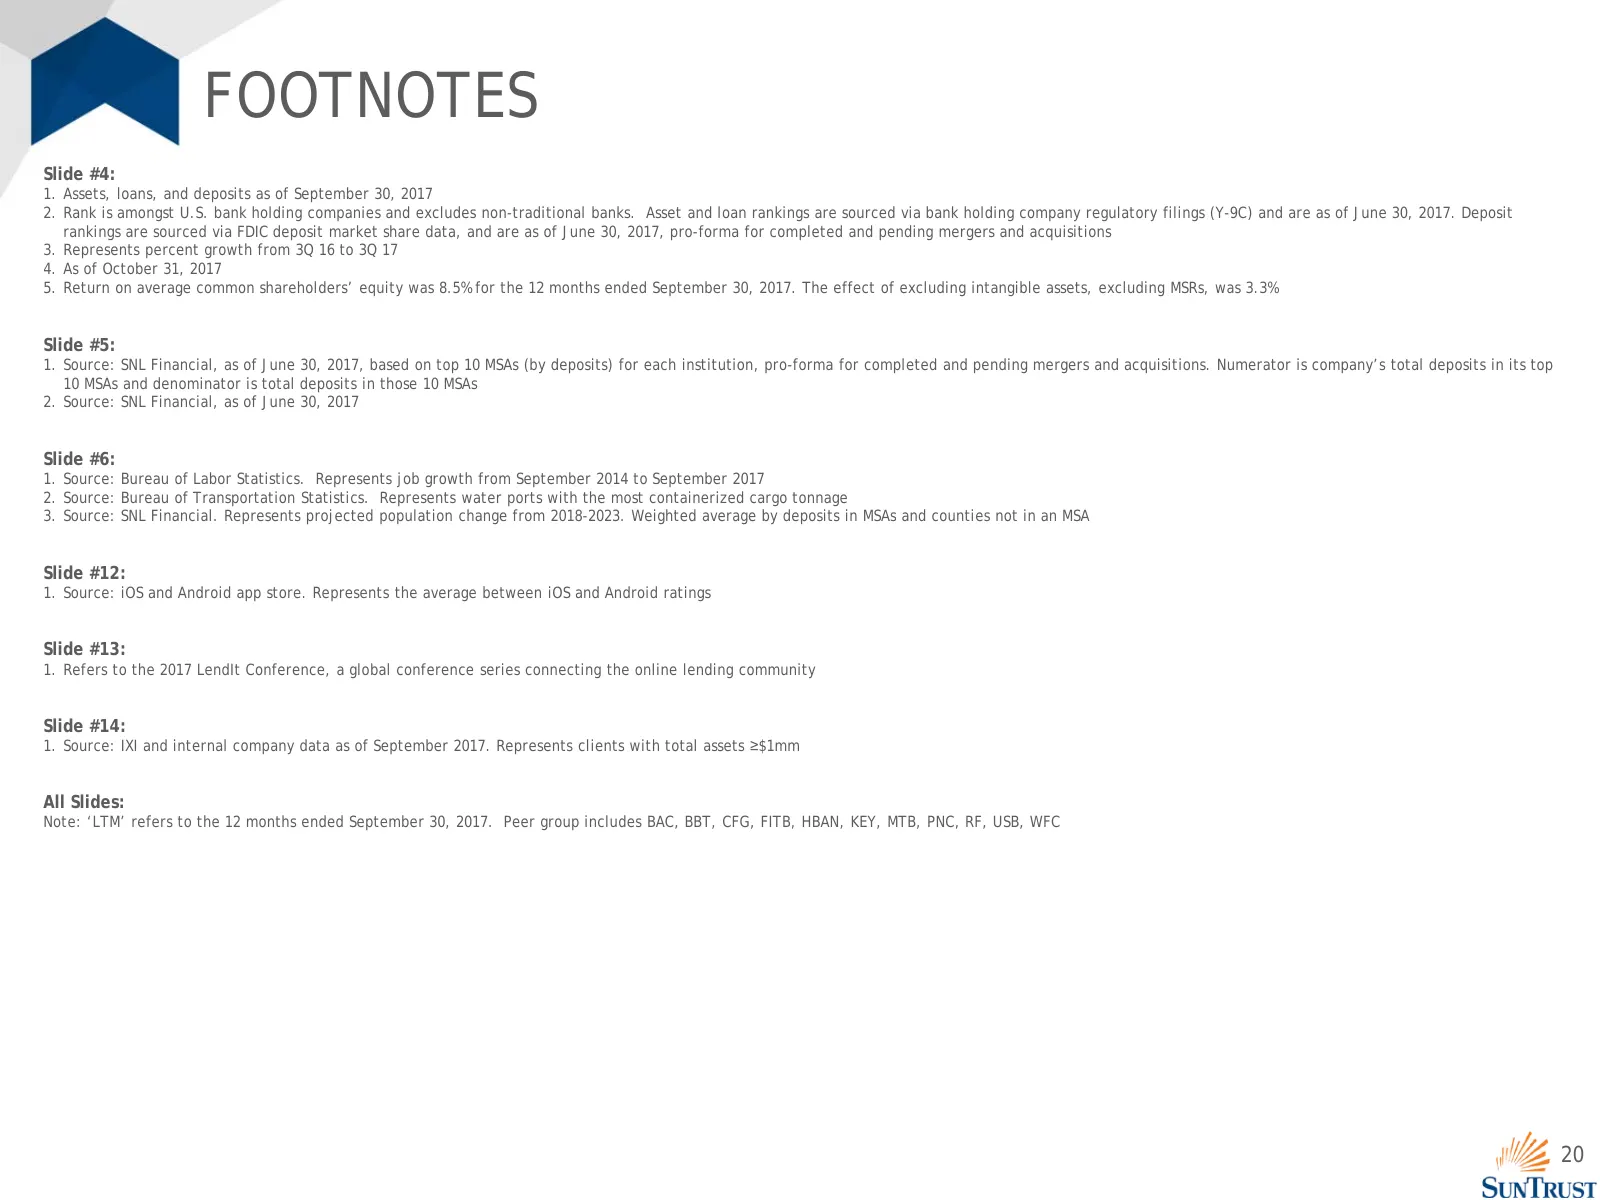
FOOTNOTES Slide #4: 1. Assets, loans, and deposits as of September 30, 2017 2. Rank is amongst U.S. bank holding companies and excludes non-traditional banks. Asset and loan rankings are sourced via bank holding company regulatory filings (Y-9C) and are as of June 30, 2017. Deposit rankings are sour
Source: SEC EDGAR · 8-K filed Nov 2, 2017
More decks from SunTrust Banks Inc
 Q3 2019 Earnings Presentation21 slides · Oct 17, 2019
 Q2 2019 Earnings Presentation22 slides · Jul 18, 2019
 Q1 2019 Earnings Presentation22 slides · Apr 18, 2019
 Merger or Acquisition (February 2019)38 slides · Feb 7, 2019
 Q4 2018 Earnings Presentation23 slides · Jan 18, 2019
 2018 Goldman Sachs US Financial Services Conference30 slides · Dec 4, 2018