Endeavour International — Howard Weil 41st Energy Conference 2013
22 slides from Endeavour International's conference presentation, Mar 20, 2013
Slide 1: Howard Weil 41st Energy Conference
Howard Weil 41 st Energy Conference March 20 – 21, 2013 Exhibit 99.1
Slide 2: Endeavour At A Glance
Key Figures Endeavour At A Glance Near-term growth through lower risk development activities • Rochelle field development in execution phase – U.K. • Bacchus third production well to commence drilling – U.K. • Strategic review process ongoing Balanced Portfolio • Oil and Gas • U.K. and U.S. • Conven
Slide 3: Production Volumes
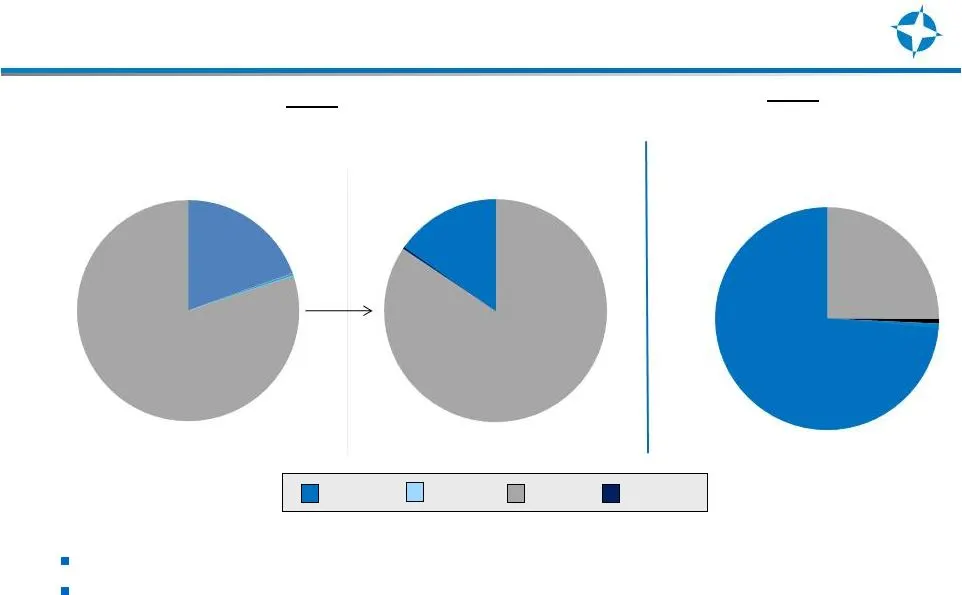
20% 15% 73% Production Volumes (BOE per day) Q3 Sales = 11,006 Q4 Sales = 11,541 Q4 Sales = 4,253 US Gas US Oil UK Oil UK Gas Year-over-year sales volumes up 133% Physical production volume for the fourth quarter averaged 10,300 boepd and 7,873 boepd for the full year of 2012 80% 84% 25%
Slide 4: Our Growing Resource Base
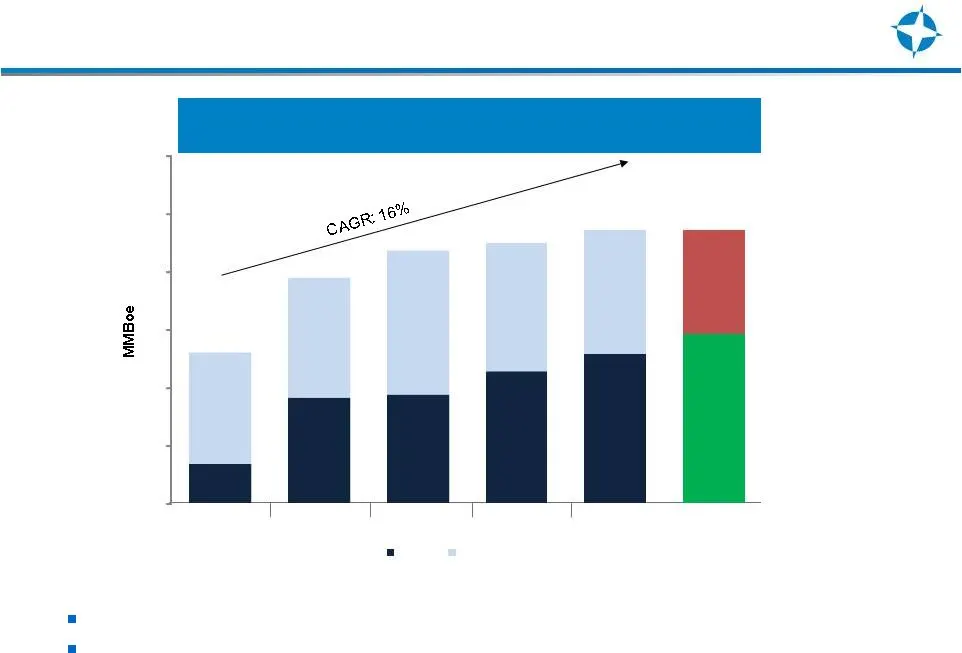
Reserve Growth 6.8 18.2 18.7 22.7 25.7 62% Oil 38% Gas Our Growing Resource Base U.K. proved reserves increased 186% year-over-year Decrease in U.S. proved and probable reserves of 12.1 MMboe during 2012 caused by lower natural gas prices 19.3 20.7 25.0 22.3 21.5 26.1 38.9 43.7 45.1 47.2 100% Proved
Slide 5: Net Asset Valuation
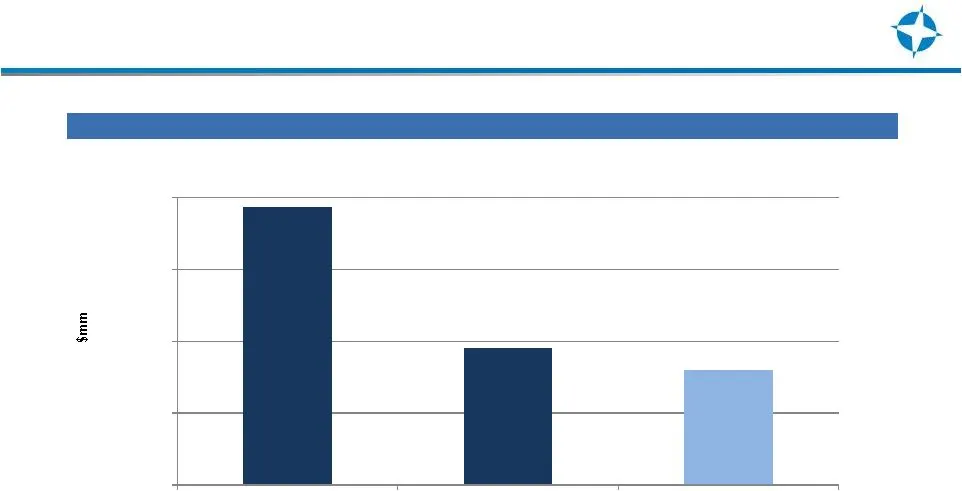
Net Asset Valuation Reserve Valuation (as of 12/31/12) $1,939 $951 $800 $0 $500 $1,000 $1,500 $2,000 2P PV-10 1P PV-10 Net Debt
Slide 6: Reserves Value Make-Up and Migration
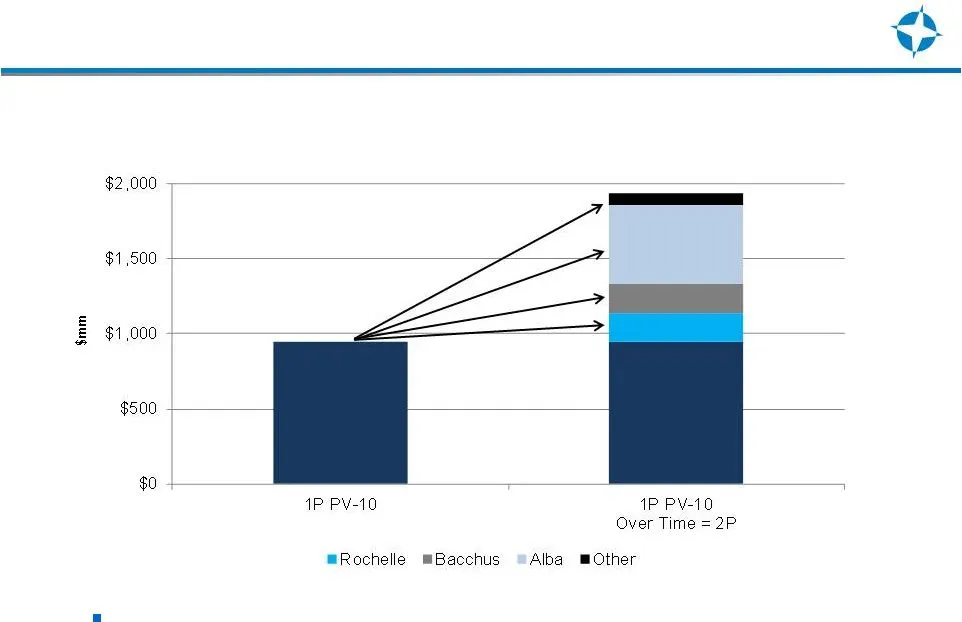
Reserves Value Make-Up and Migration (as of 12/31/12) Low ongoing maintenance capital requirements, after Rochelle and Bacchus fully developed (2013), which should result in a transfer of 2P PV-10 to 1P PV-10 in the near term $951 $1,939
Slide 7: Overview of Endeavour's U.K. Assets
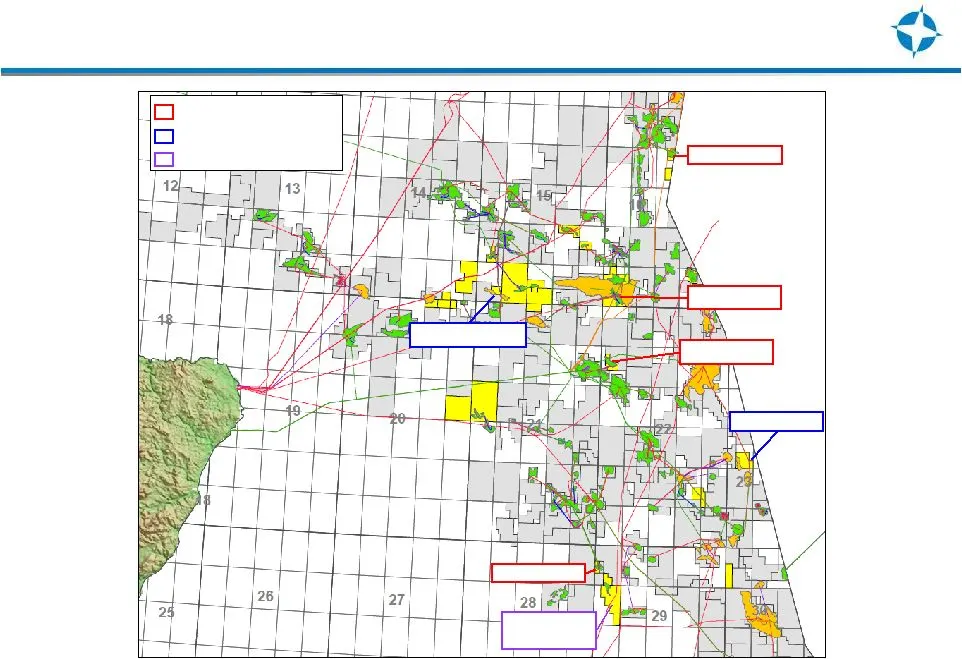
Overview of Endeavour’s U.K. Assets Bacchus Enoch Columbus Bittern Alba Rochelle Current Production Development Projects Exploration Centurion South
Slide 8: Production Sold Into Higher-Valued European Markets
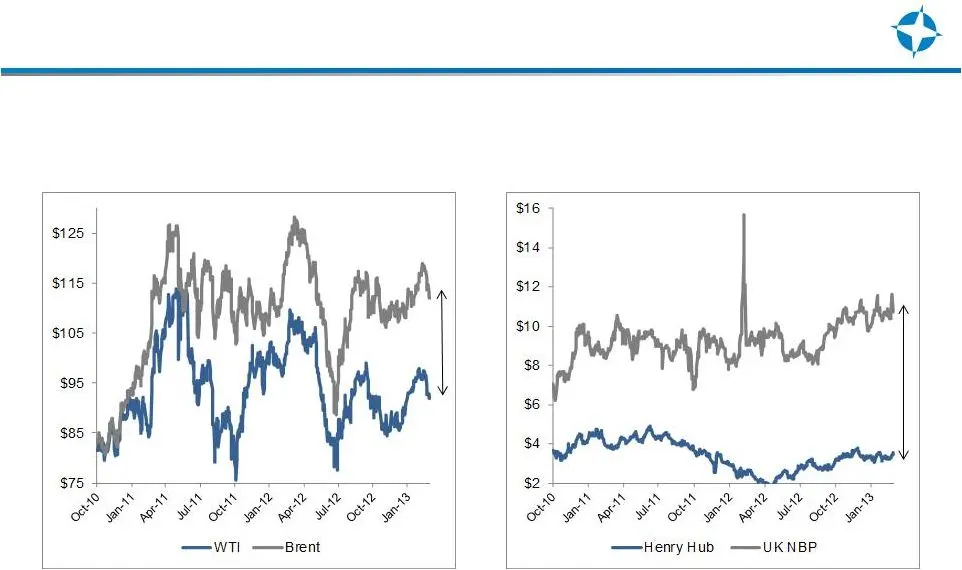
Production Sold Into Higher-Valued European Markets Crude oil Natural gas $20.00 spread $7.17 spread Average spread over the period: $15.16 Average spread over the period: $5.83
Slide 9: Rochelle: Project in execution phase
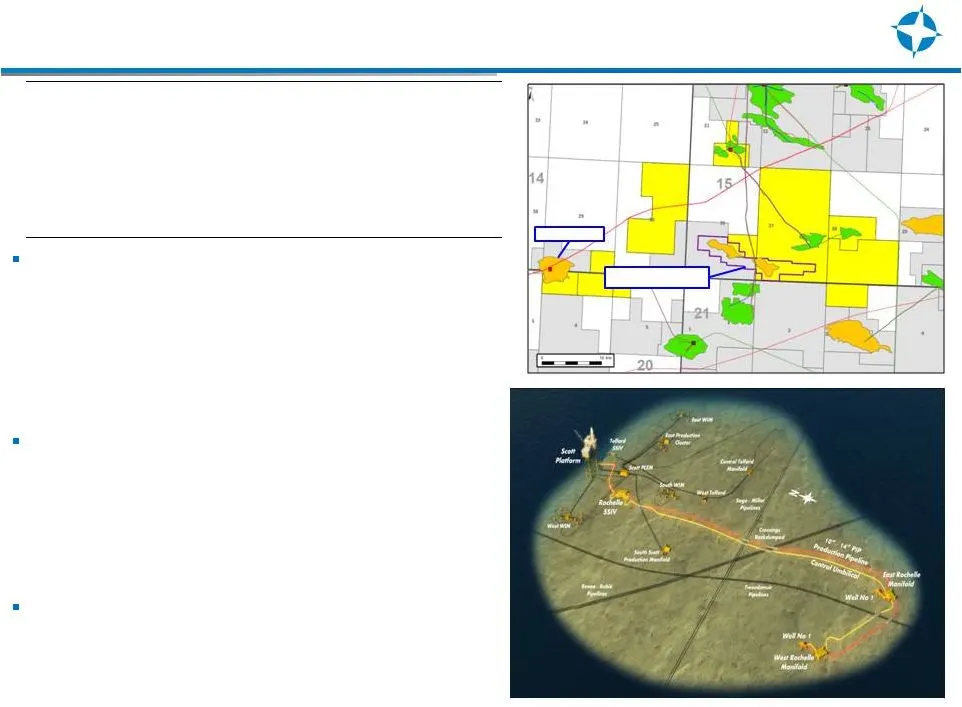
Project in execution phase • Drilling at the West Rochelle well commenced on February 21, 2013 • Pipe laying operations completed • Modifications to Scott platform completed • Evaluating options to return to the East well after the completion of the West well Reservoir development • 2 x 500m horizon
Slide 10: Bacchus - Block 22/06a Central North Sea
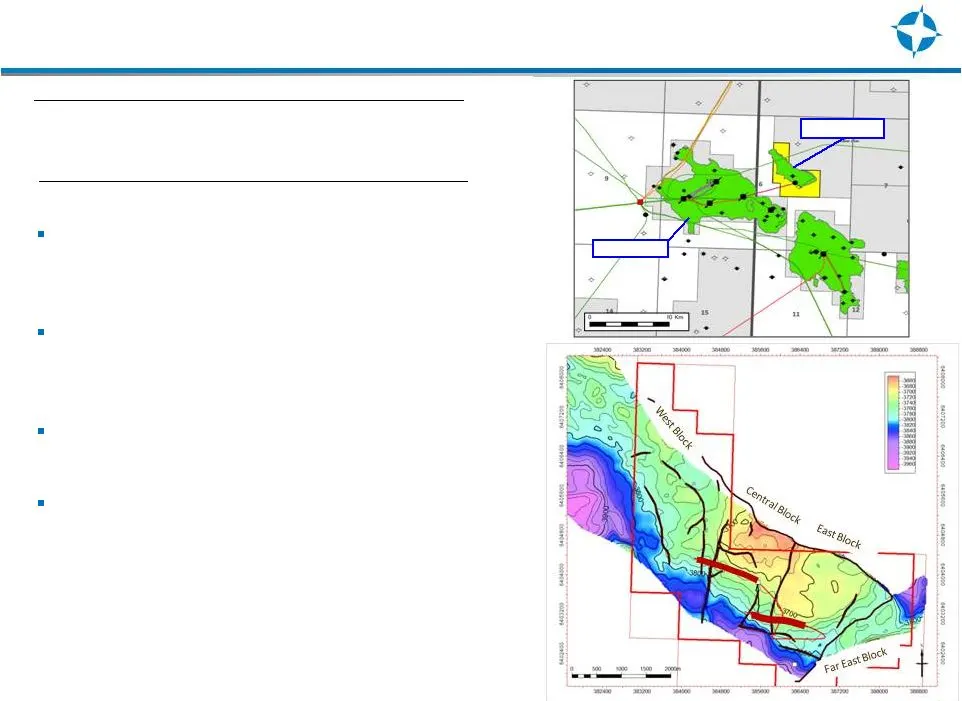
Bacchus - Block 22/06a Central North Sea Reservoir is formed by shallow marine Fulmar sandstones of Upper Jurassic age Current production at the first two wells ~ 10,000 boepd gross Oil exported to Forties Pipeline System Drilling of the third production well scheduled to commence – additional produ
Slide 11: Alba Field Overview
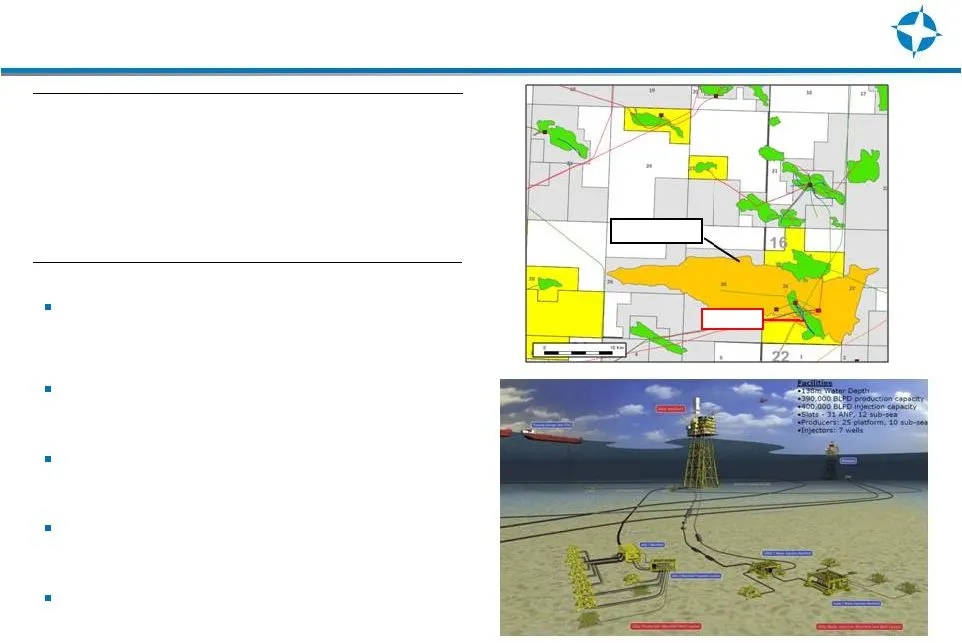
Alba Field Overview - Block 16/26a Late Eocene reservoir at ~6,200ft depth • 600 MMboe in place 450ft water depth 35 Platform and subsea wells Oil exported by tanker Infill drilling plans for 2013 extended from six to nine months • Three – four wells expected Endeavour WI: 25.68% Operator: Chevron (
Slide 12: High Quality Exploration in Core Central North Sea Area
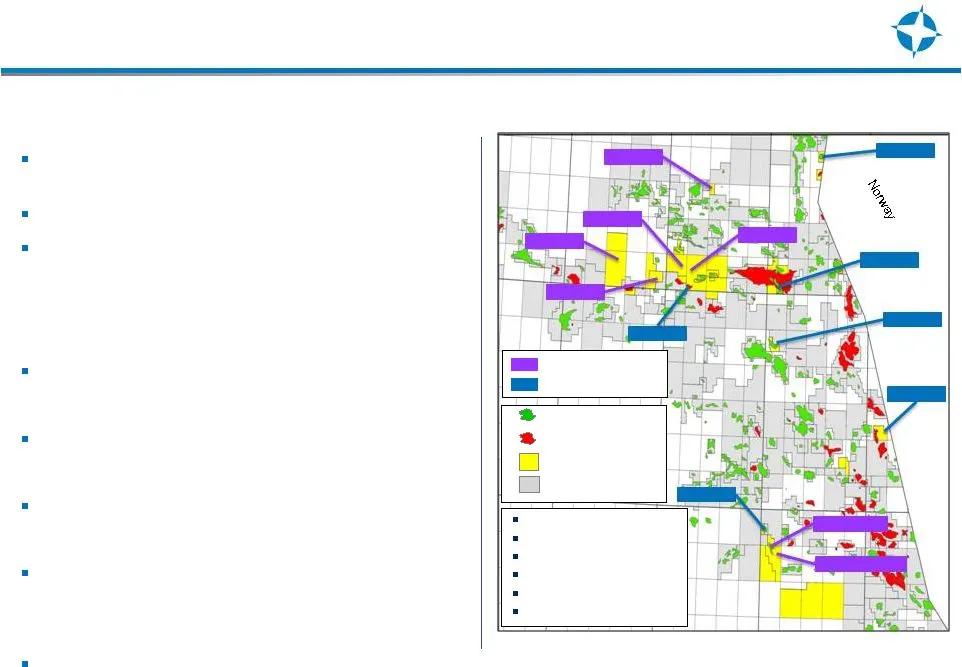
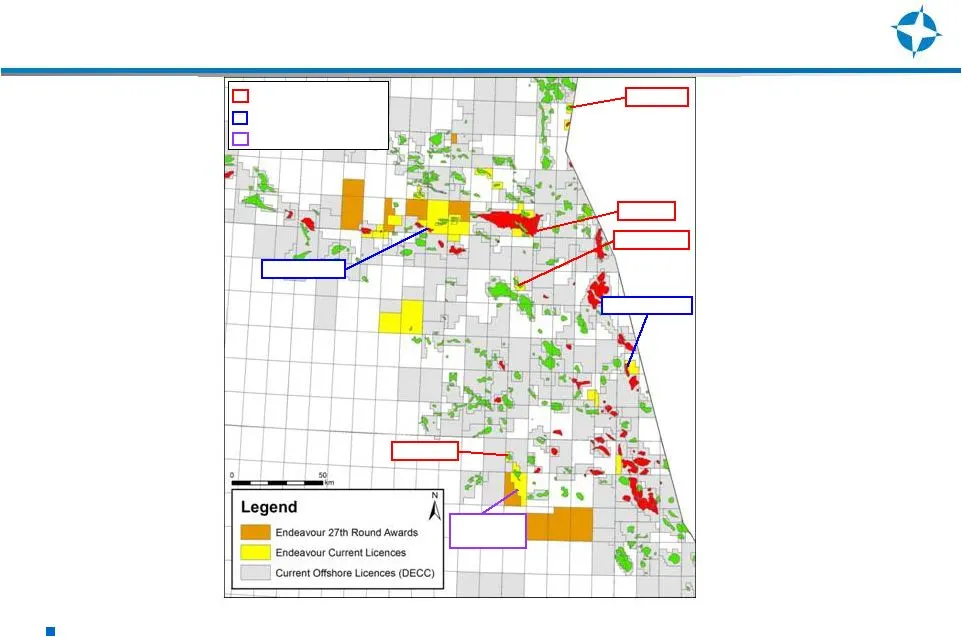
Rochelle Enoch Columbus Bittern Bacchus Alba Buffalo Centurion Mostyn Centurion South Rogers Ravel Mabry High Quality Exploration in Core Central North Sea Area Net Unrisked Contingent Prospective Resources: 376 MMboe 28 Licences (12 Endeavour operated) Successful 27 Licensing Round result with focu
Slide 13: New Blocks Acquired in the 27th Licensing Round
New Blocks Acquired in the th Licensing Round Bacchus Enoch Columbus Bittern Alba Rochelle The new licenses covering ten blocks located in core areas around • The existing Rochelle development and R-blocks • Bittern and the Centurion South appraisal opportunity Centurion South Current Production Dev
Slide 14: Centurion South
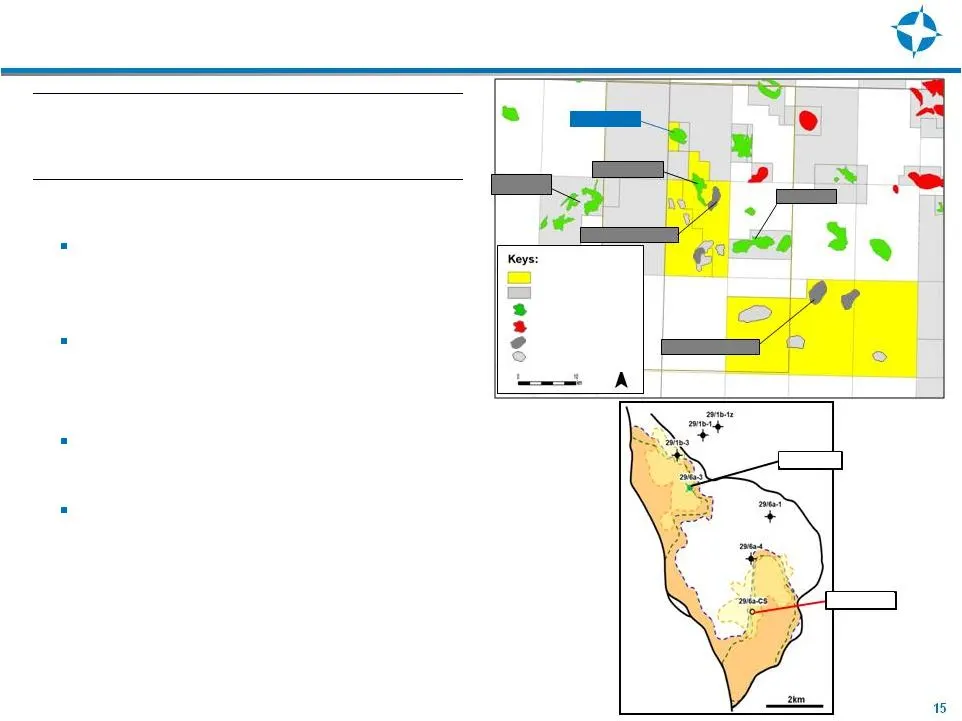
Centurion Bittern Catcher Centurion South 29/13 Fulmar B Curlew Centurion South • Upper Jurassic Fulmar Sandstone Vertical exploration well • ~12,000 feet deep Oil prone Adjacent to Centurion discovery • Well 29/6a-3 flowed at 5,200 bbl/d Centurion South Prospect CENTURION CENTURION SOUTH 29/6a-CS 2
Slide 15: US Onshore Assets
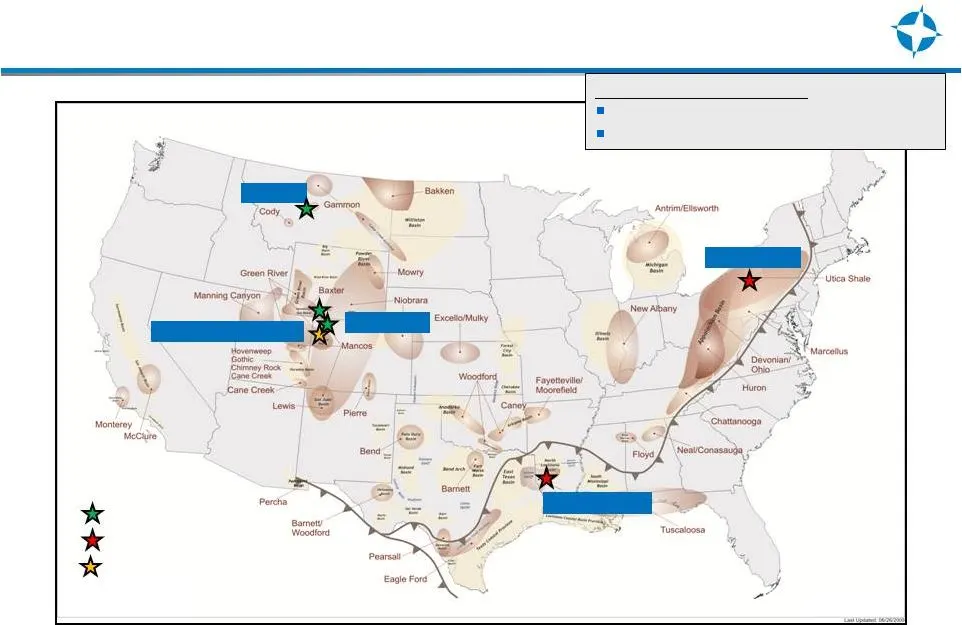
Heath Marcellus Niobrara/Frontier Haynesville Niobrara US Onshore Assets Oil Gas Mixed Building Portfolio US 2012 Year-End Totals 525,000 gross / 154,000 net acres 9.0 MMCFe/D net production
Slide 16: US Onshore Portfolio
US Onshore Portfolio Low-Cost Option on US Gas Futures • Pennsylvania Marcellus position (100% WI) • 31,000 net acres in central PA • 300-500 BCFe net resource potential • 3 wells drilled/cased, waiting on completion in 2013 • 10 MMCF/D take-away capacity available Q4 2013 • Louisiana Haynesville po
Slide 17: US 2013 Strategy
US 2013 Strategy Build on successful Marcellus trade • wells to be completed - MMCF/D take-away capacity Defer/”Hold” Haynesville gas development Grow and test Rockies liquids-rich portfolio • Initial Niobrara pilot planned in Piceance Basin play Evaluate Heath Oil play potential • Leverage learning
Slide 18: Strategic Review
Strategic Review Announced February 14, 2013 • Evaluating a broad range of options to further enhance shareholder value including: • Sale, joint venture or partnership in the U.K. • Sale of specific assets • Sale or merger of the Company • Execute operational plans Objective: To accelerate de-leveri
Slide 19: Direct Capital Expenditures
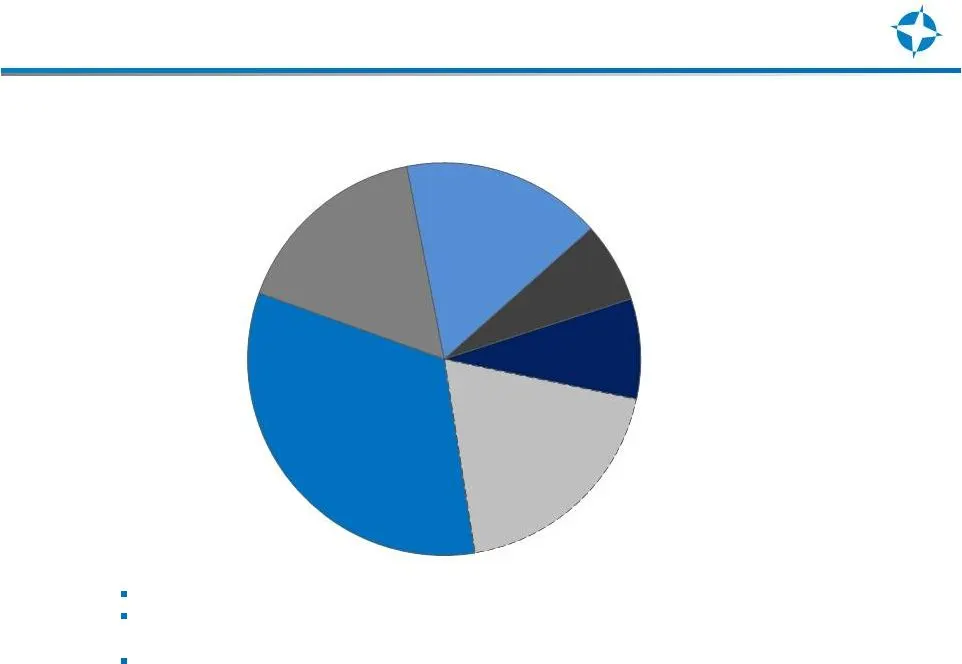
Rochelle Bacchus Alba U.K. Other Centurion South Direct Capital Expenditures Rochelle and Bacchus represent 60% of the planned spend in the U.K. U.S. budget of $30 million - $40 million is largely discretionary and second half of the year weighted Budget is preliminary and dependent on the outcome o
Slide 20: Debt Maturity Schedule
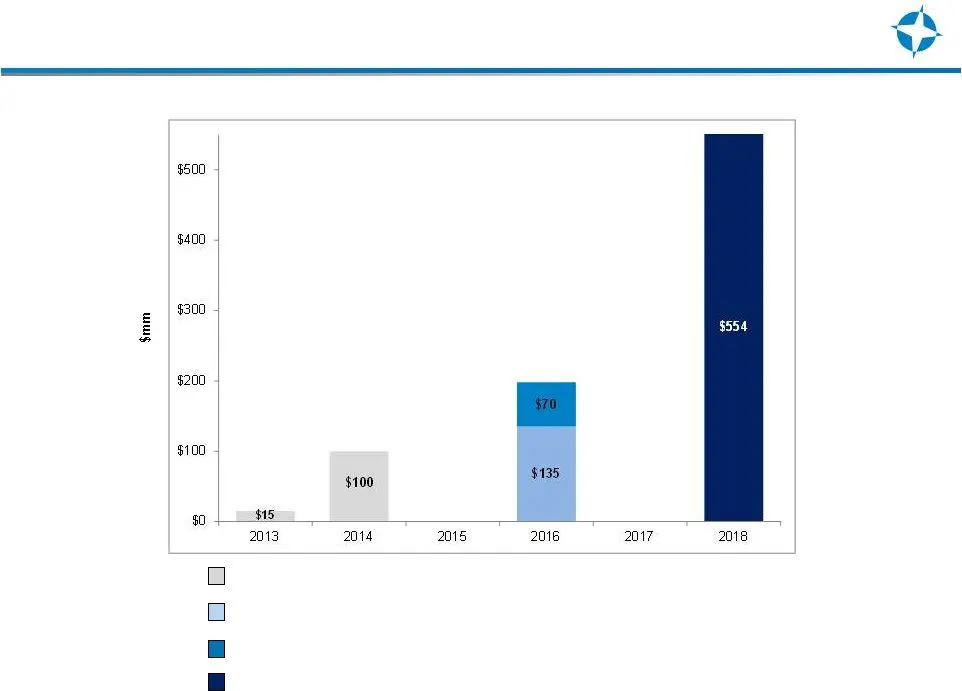
Debt Maturity Schedule Convertible Notes due 2016 ($18.51 per share conversion price) Convertible Bonds due 2016 ($16.52 per share conversion price) Senior Notes due 2018 Revolving Credit Facility due 2013/2014
Slide 21: Corporate Focus for 2013
Corporate Focus for 2013 Rochelle in Execution Phase • Currently drilling the West development well • First gas in mid 2013 Bacchus Development Completed • Third development well to commence drilling Review of Strategic Alternatives • Evaluating a broad range of options to further enhance shareholde
Slide 22: Investor Contact
LSE:ENDV NYSE:END www.endeavourcorp.com Darcey Matthews Director of Investor Relations 713.307.8711 [email protected] INVESTOR CONTACT:
Source: SEC EDGAR · 8-K filed Mar 20, 2013
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014