Endeavour International — IPAA OGIS New York 2009
19 slides from Endeavour International's conference presentation, Apr 21, 2009
Slide 1: IPAA OGIS New York
Exhibit 99.1 IPAA OGIS New York 21 April 2009
Slide 2: Forward-looking statements and SEC reserves notice
This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and potenti
Slide 3: Endeavour at a Glance
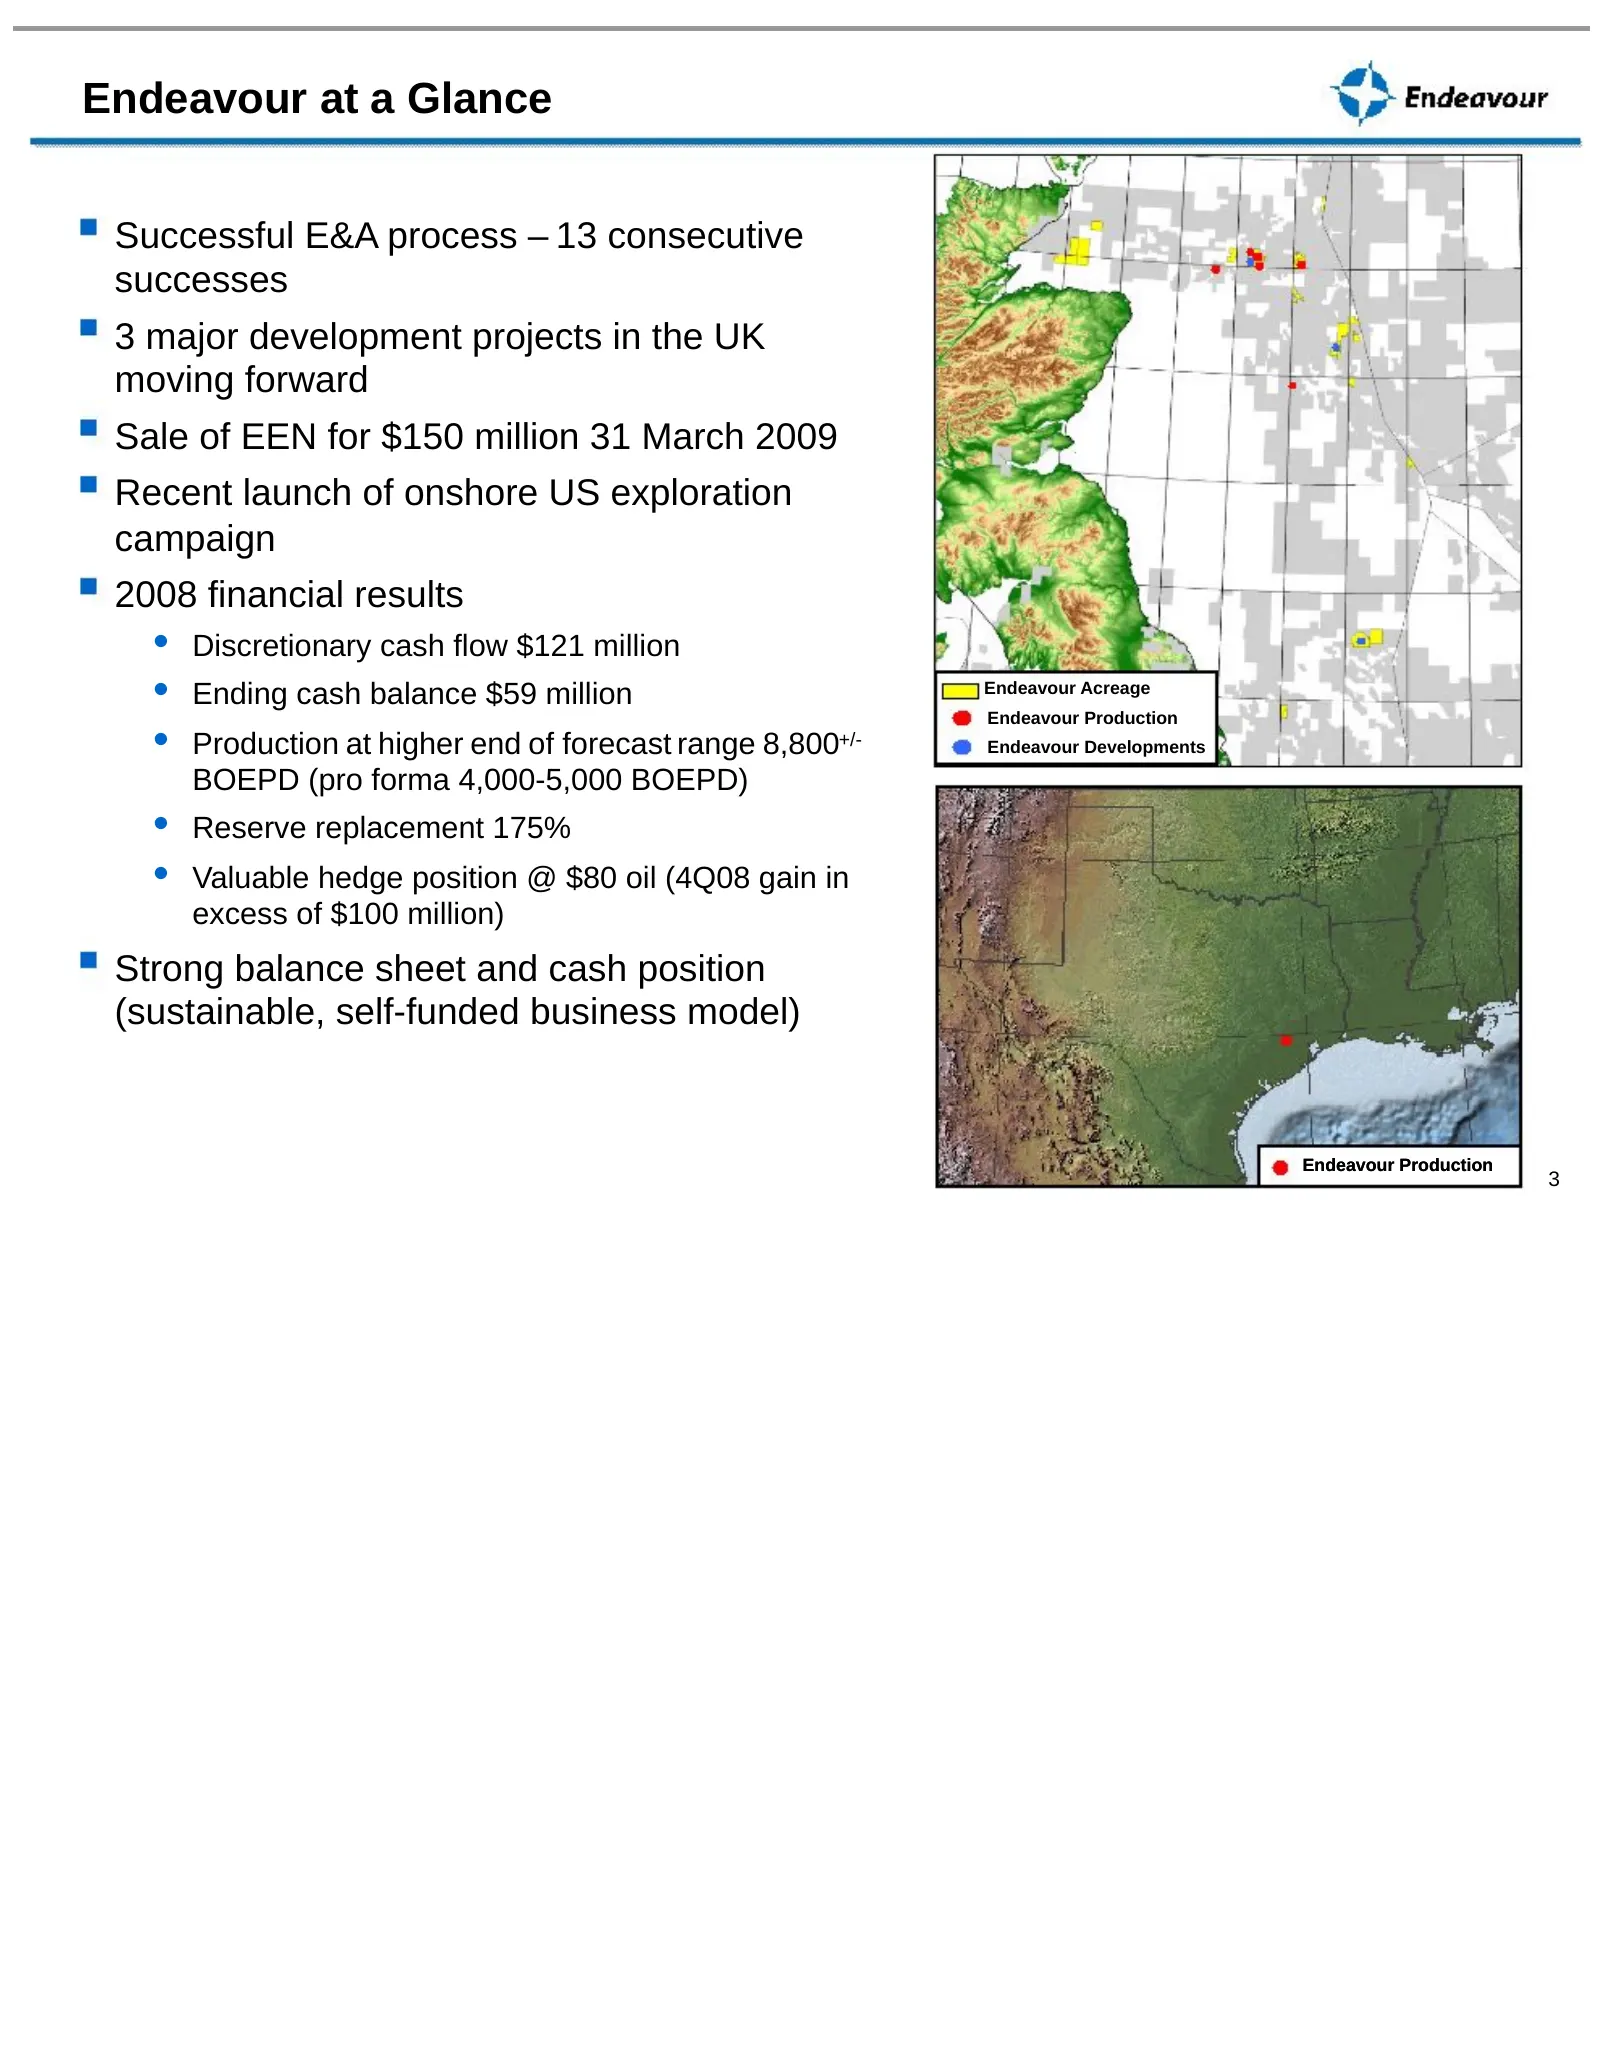
Endeavour at a Glance Successful E&A process – 13 consecutive successes 3 major development projects in the UK moving forward Sale of EEN for $150 million 31 March 2009 Recent launch of onshore US exploration campaign 2008 financial results • Discretionary cash flow $121 million • Ending cash balanc
Slide 4: Sale of Norwegian Subsidiary – Deal at a Glance
Sale of Norwegian Subsidiary – Deal at a Glance Rationale • Made money for investors • Adds financial flexibility and strength • Gives ability to capitalize on drilling successes in United Kingdom • Allows opportunity to actively pursue growth strategy of shorter-cycle, lower cost opportunities in U
Slide 5: Our Strategy – Balanced and Sustainable Growth
Our Strategy – Balanced and Sustainable Growth Production • Portfolio of high-quality producing assets • Upside performance potential Development • Active advancement of multiple projects to assure near-term growth • Strive to operate or have influence in driving performance Exploration • Discipline
Slide 6: Valuation Creation
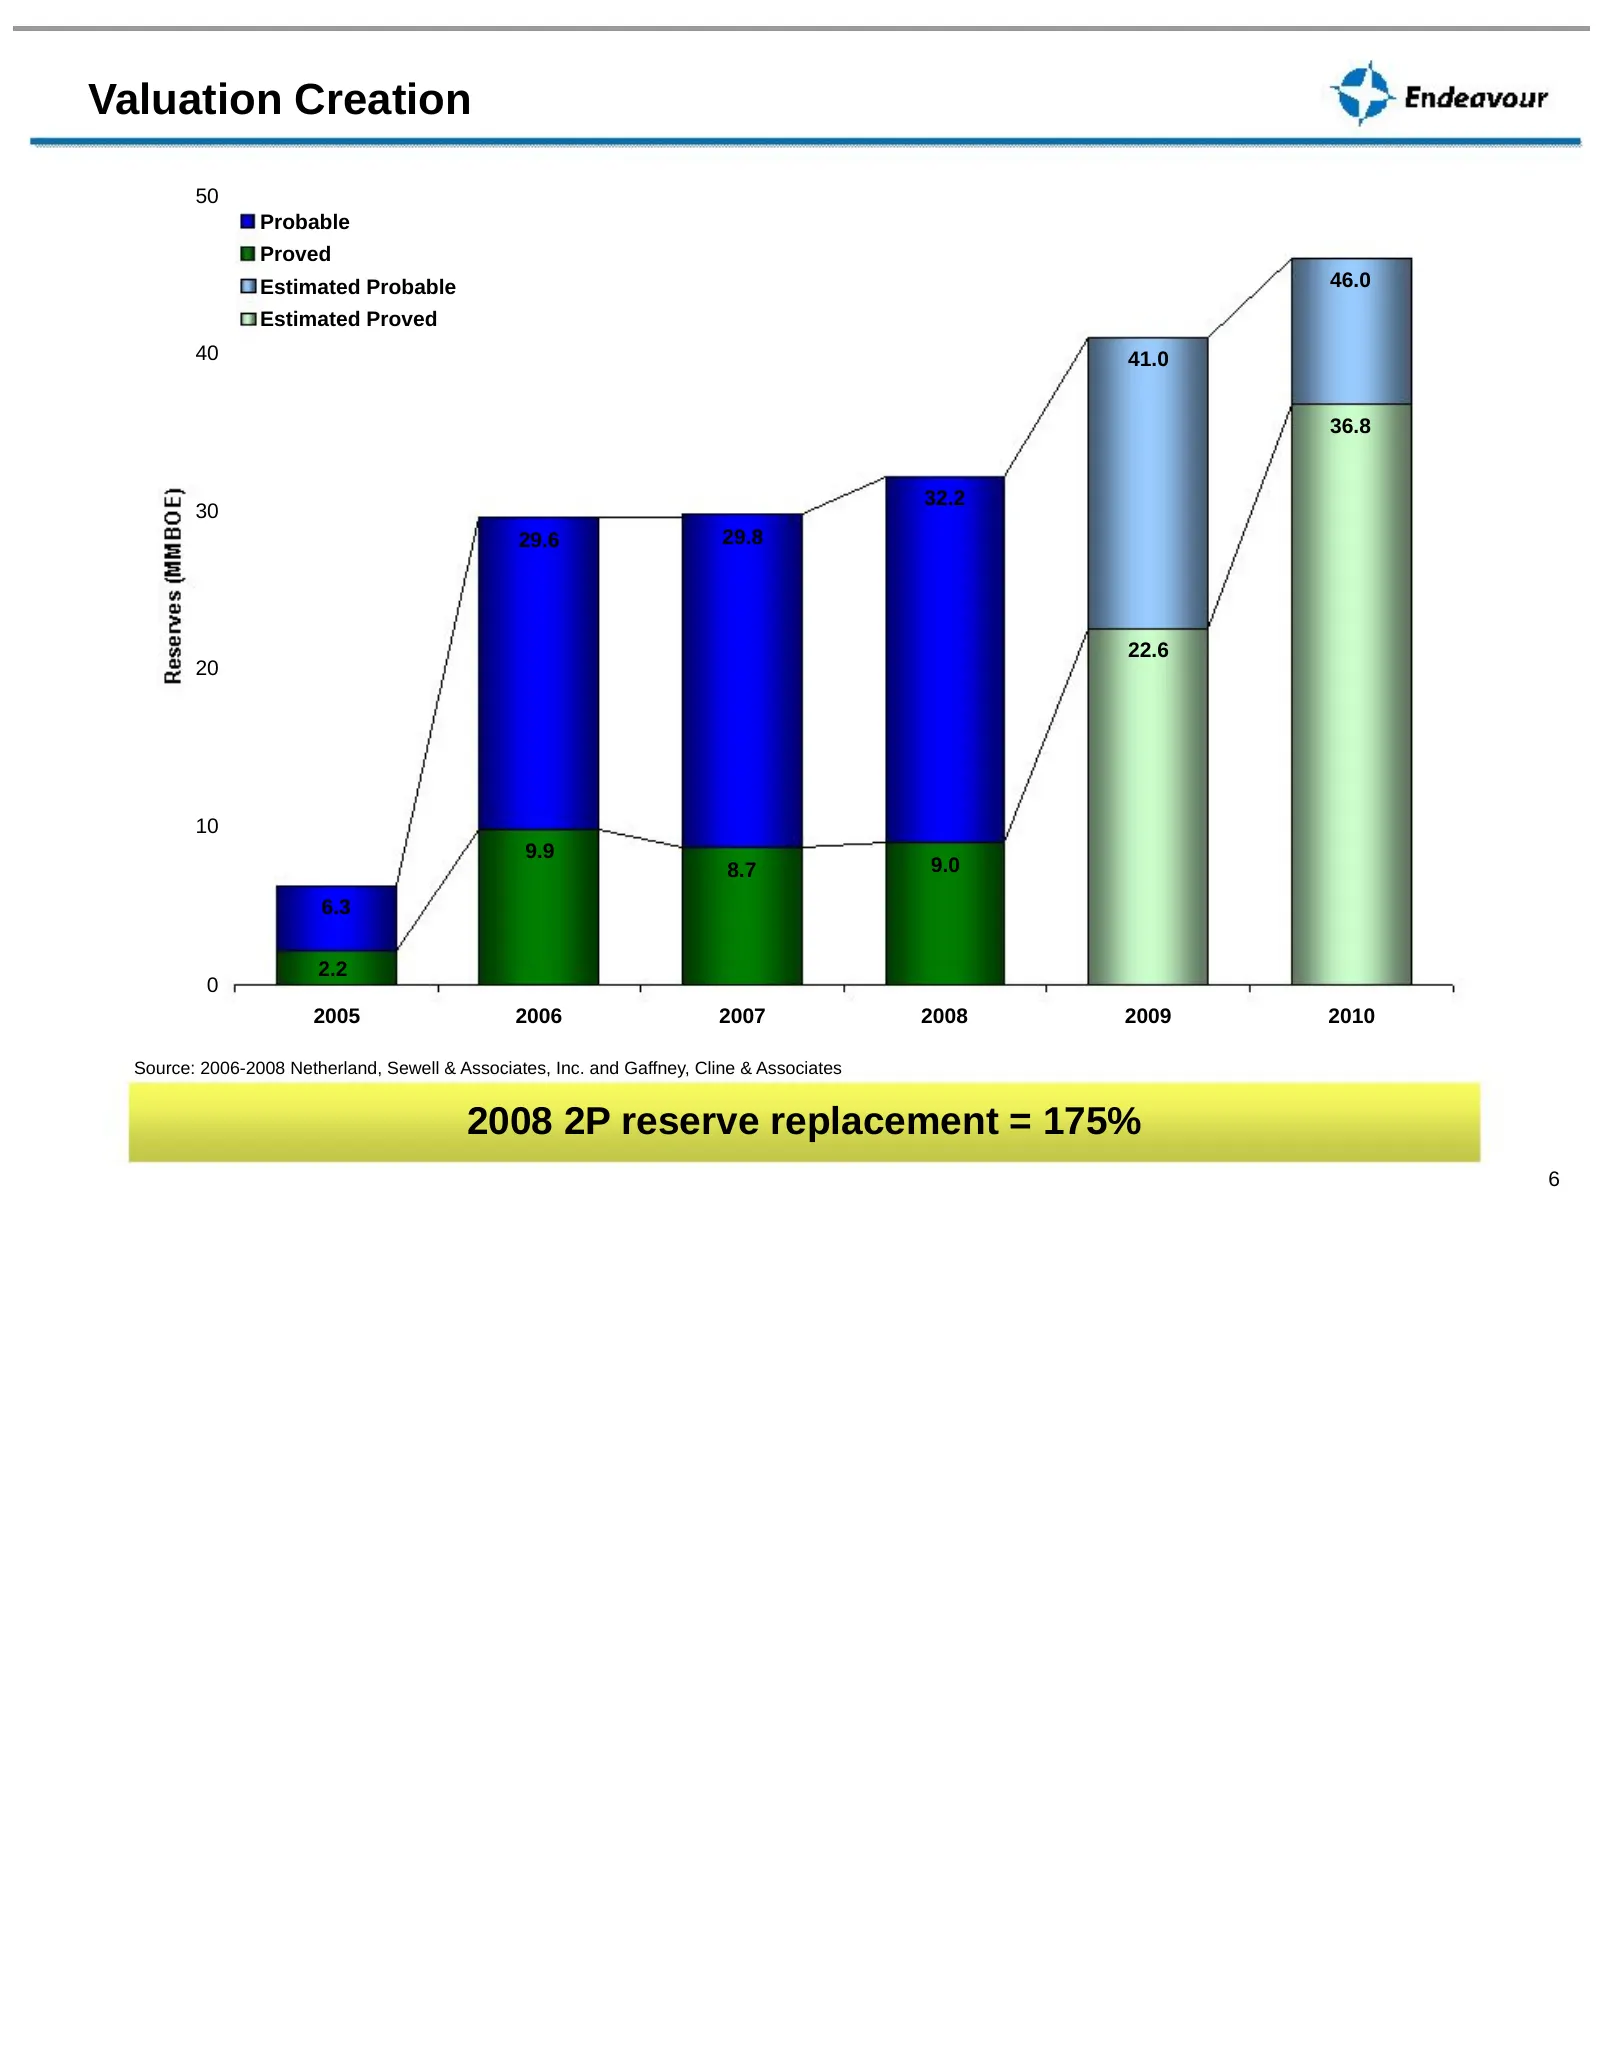
Valuation Creation 50 Probable Proved Estimated Probable 46.0 Estimated Proved 40 41.0 36.8 32.2 30 29.6 29.8 22.6 20 10 9.9 8.7 9.0 6.3 2.2 0 2005 2006 2007 2008 2009 2010 Source: 2006-2008 Netherland, Sewell & Associates, Inc. and Gaffney, Cline & Associates 2008 2P reserve replacement = 175% 6
Slide 7: Potential Production Growth
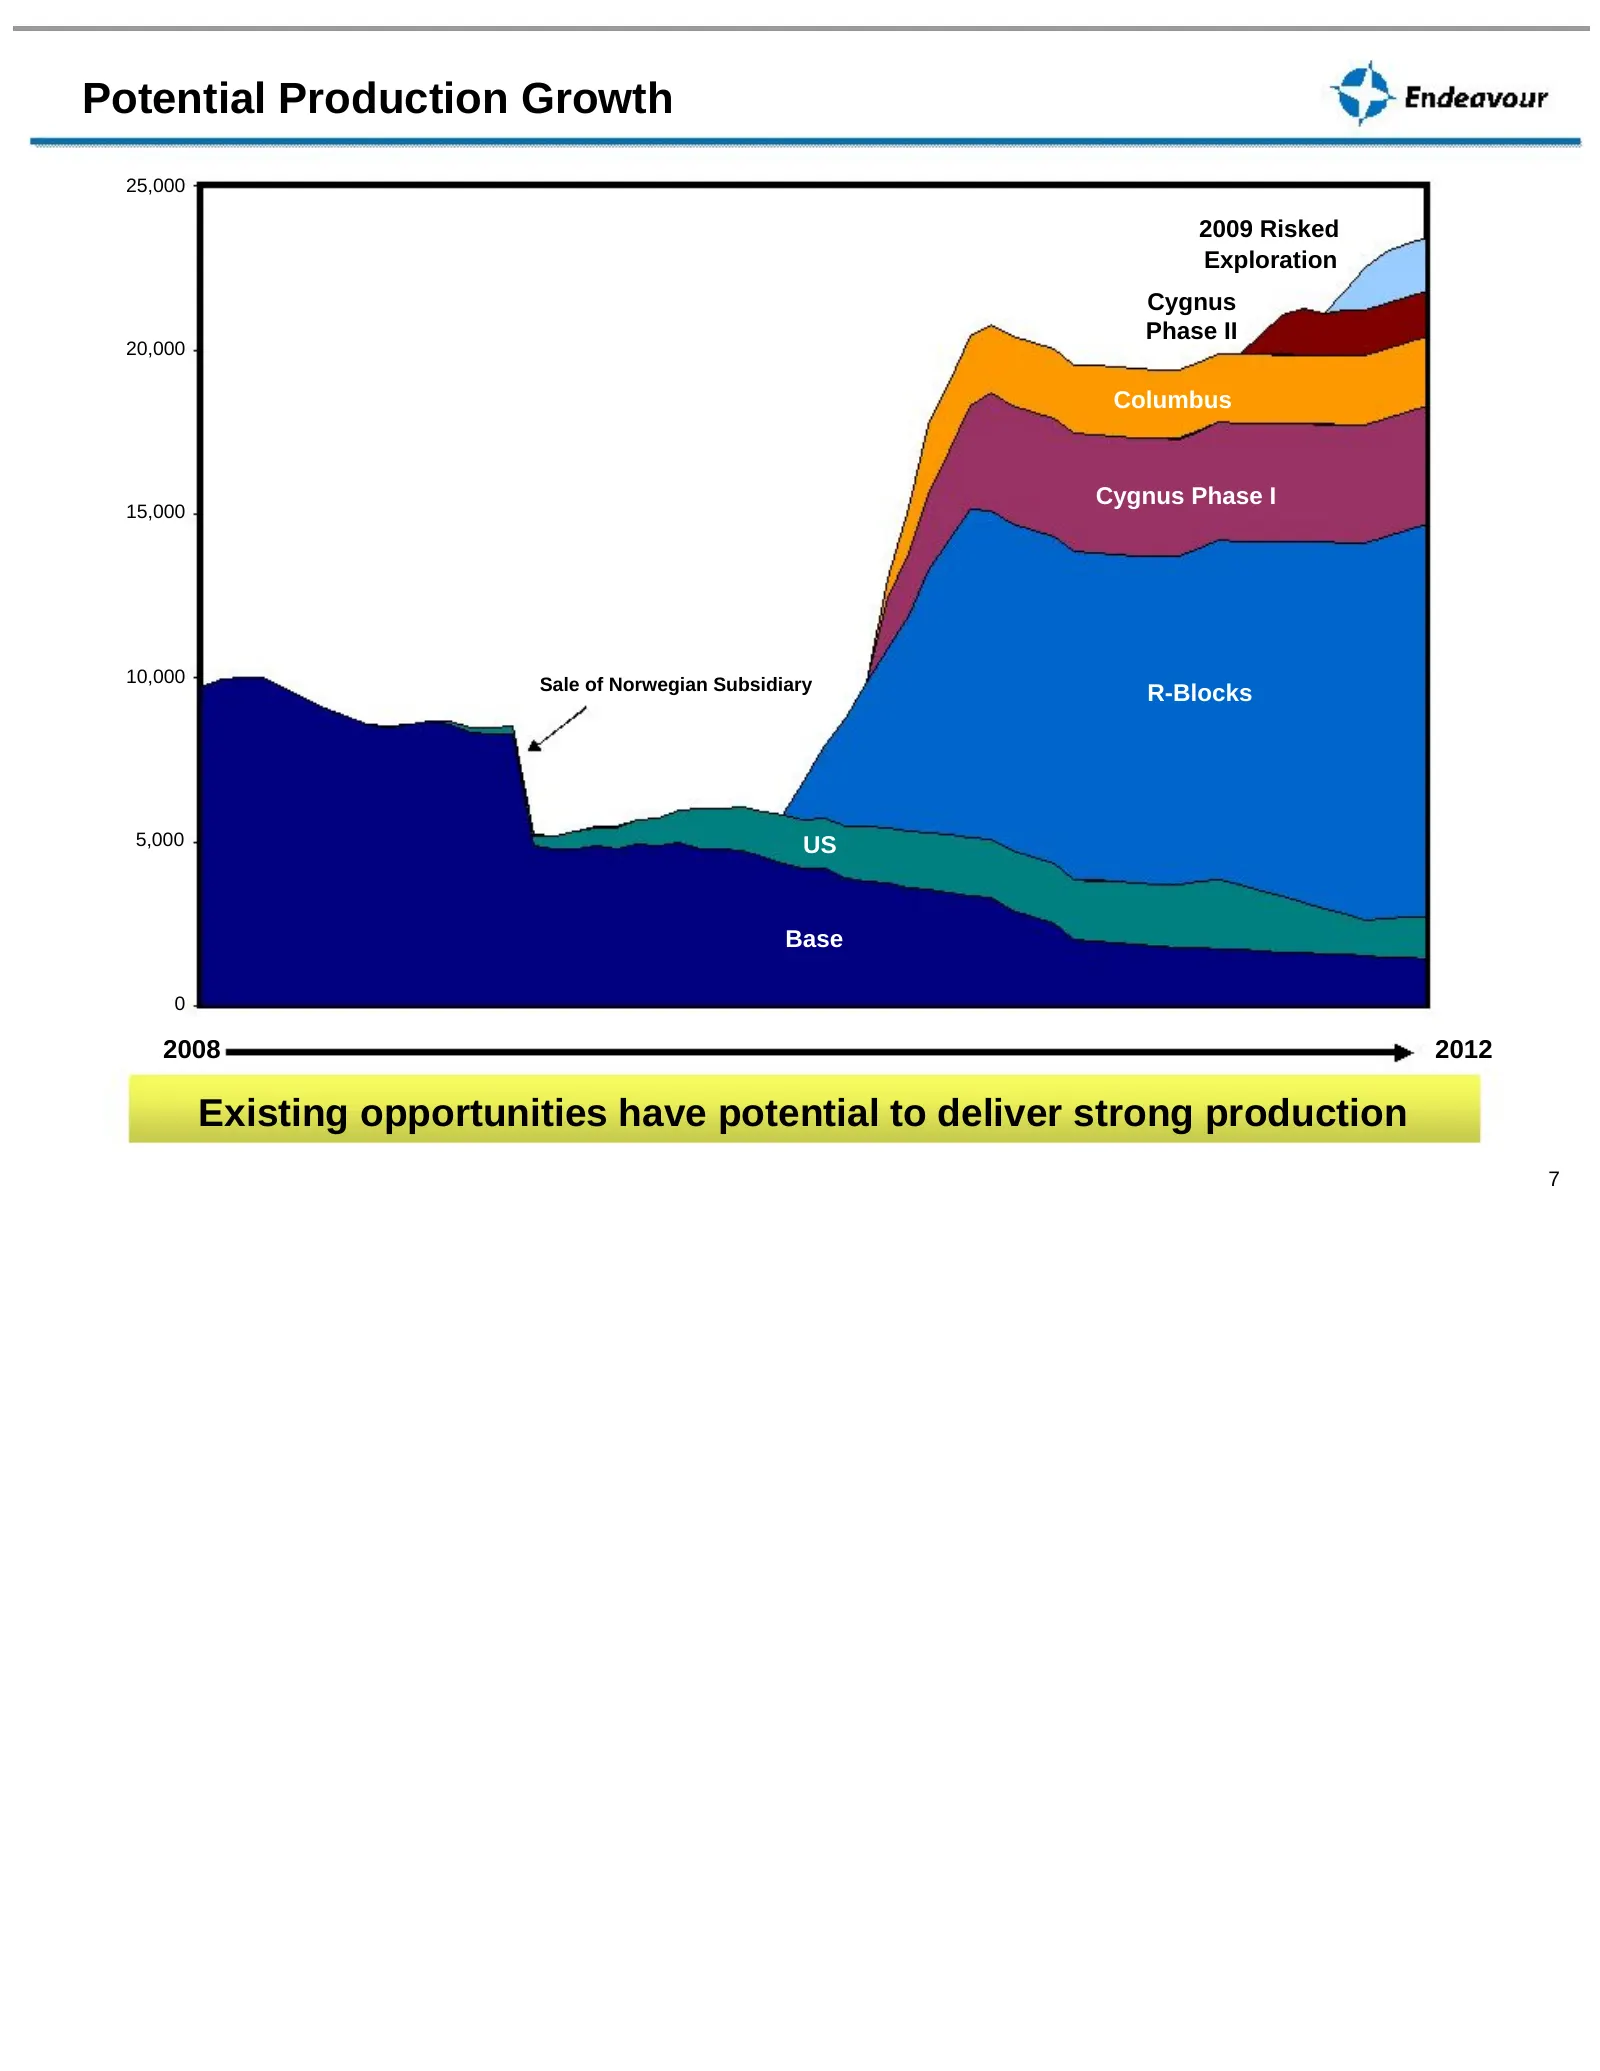
Potential Production Growth 25,000 2009 Risked Exploration Cygnus Phase II 20,000 Columbus Cygnus Phase I 15,000 10,000 Sale of Norwegian Subsidiary R-Blocks 5,000 US Base 0 2008 2012 Existing opportunities have potential to deliver strong production 7
Slide 8: Current North Sea Developments
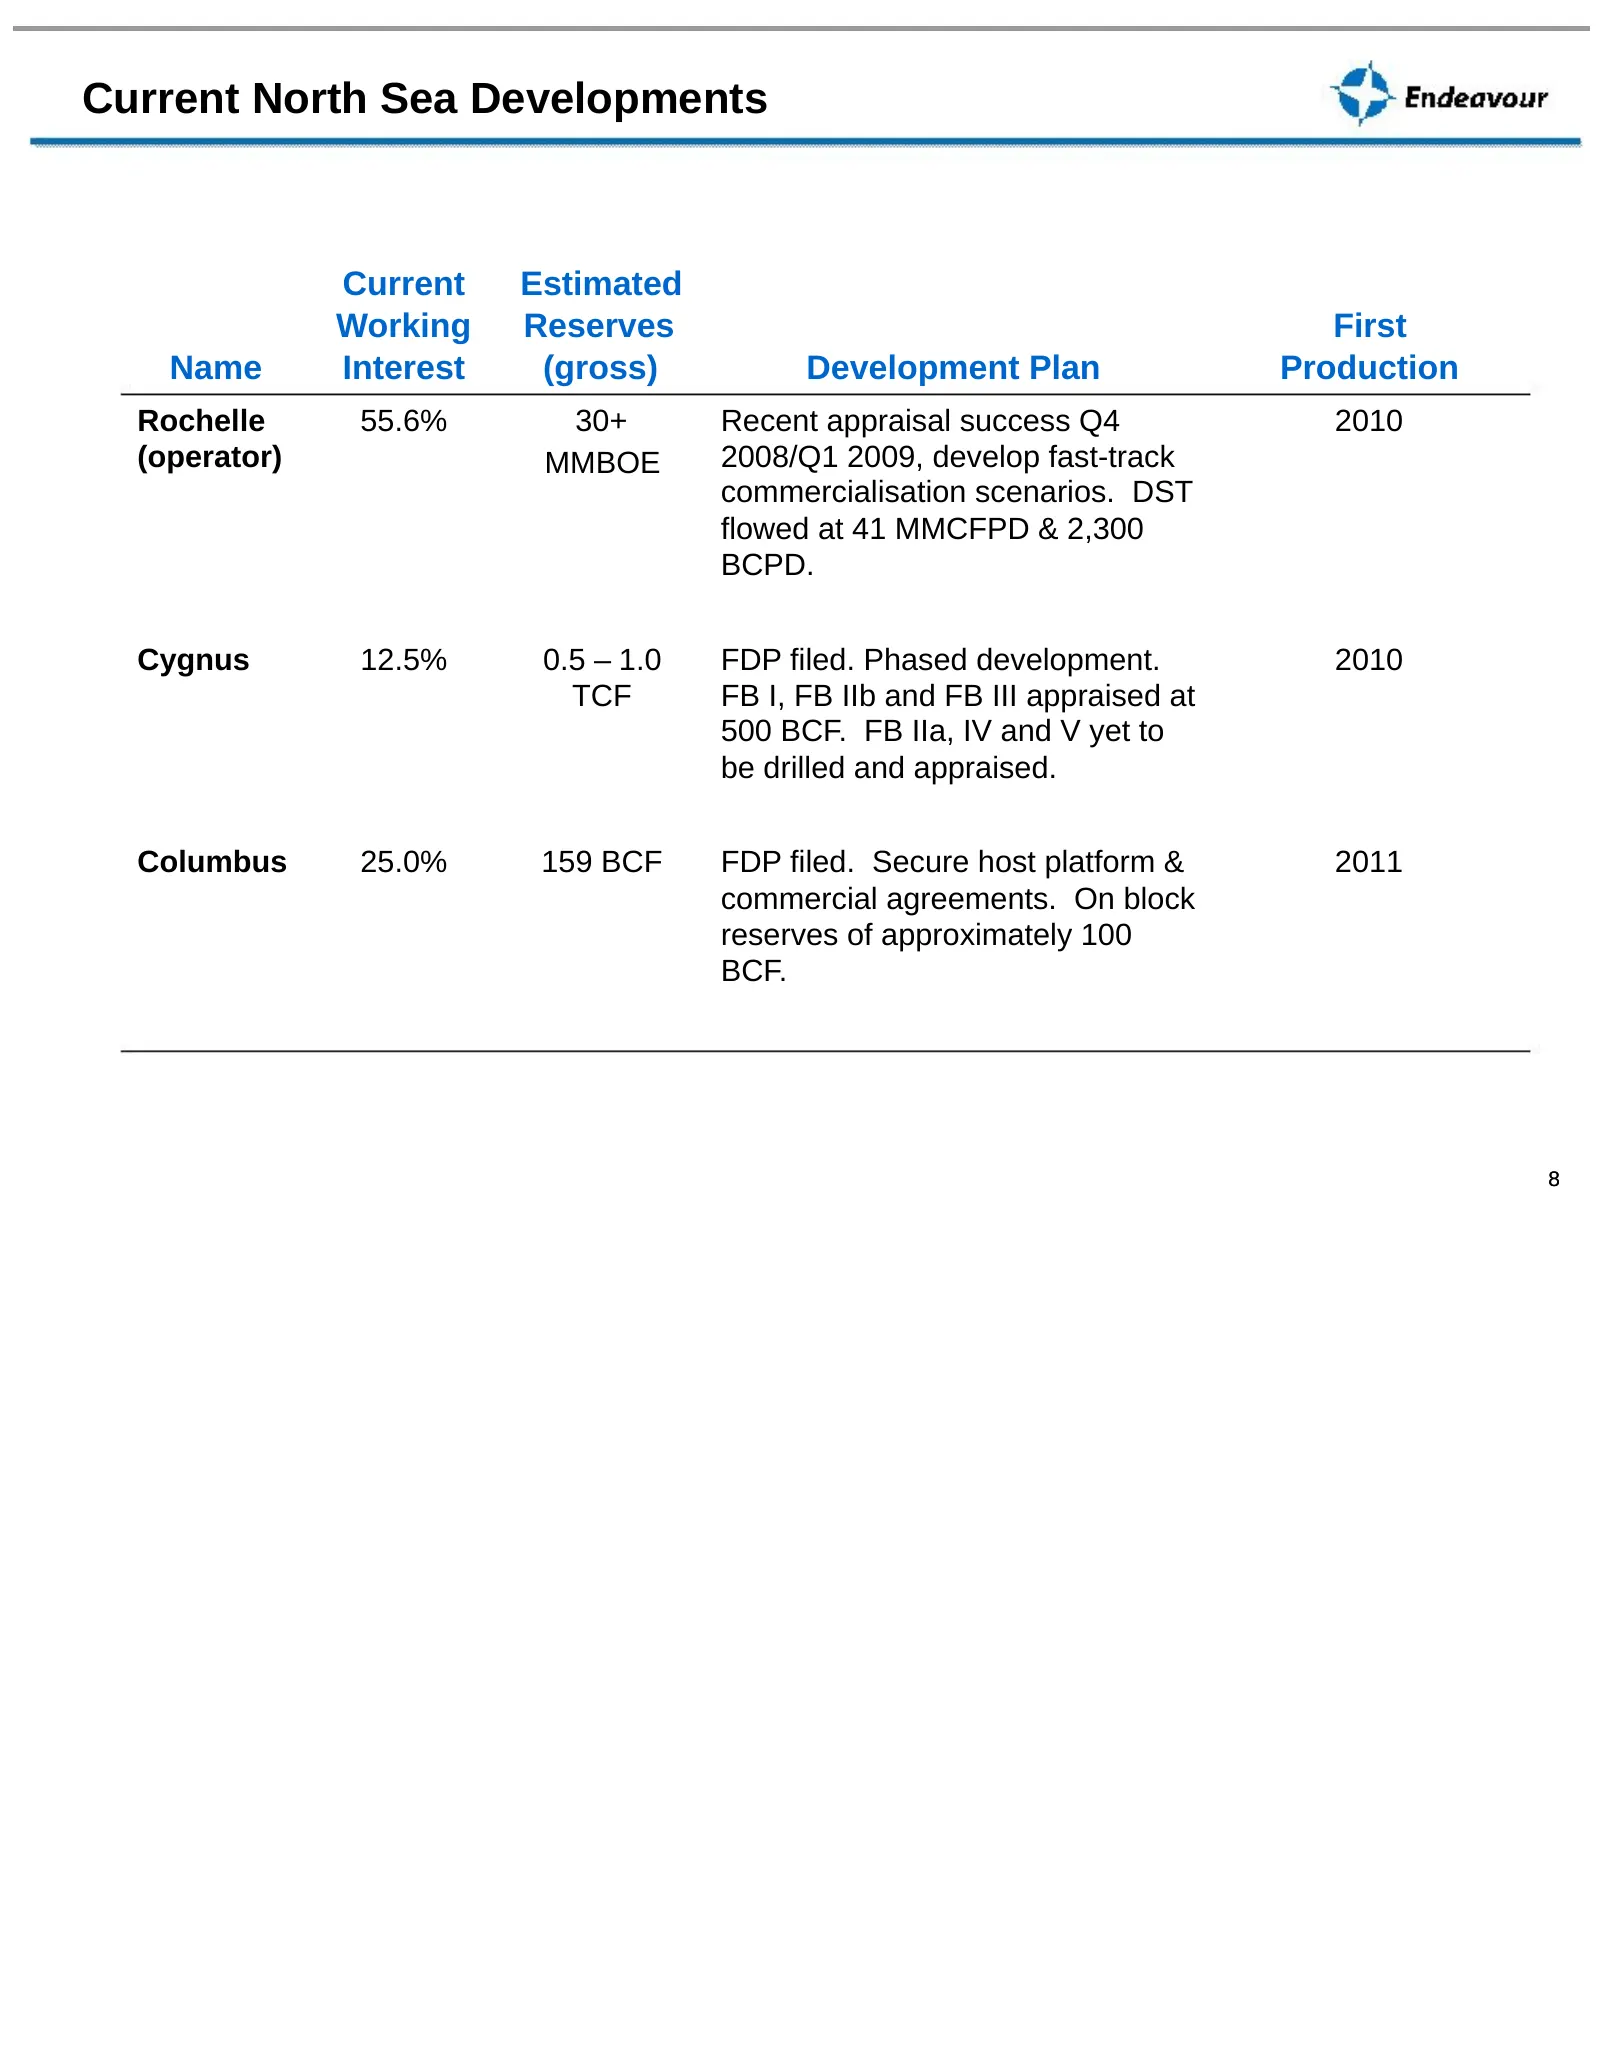
Current North Sea Developments Current Estimated Working Reserves First Name Interest (gross) Development Plan Production Rochelle 55.6% 30+ Recent appraisal success Q4 2010 (operator) MMBOE 2008/Q1 2009, develop fast-track commercialisation scenarios. DST flowed at 41 MMCFPD & 2,300 BCPD. Cygnus 12
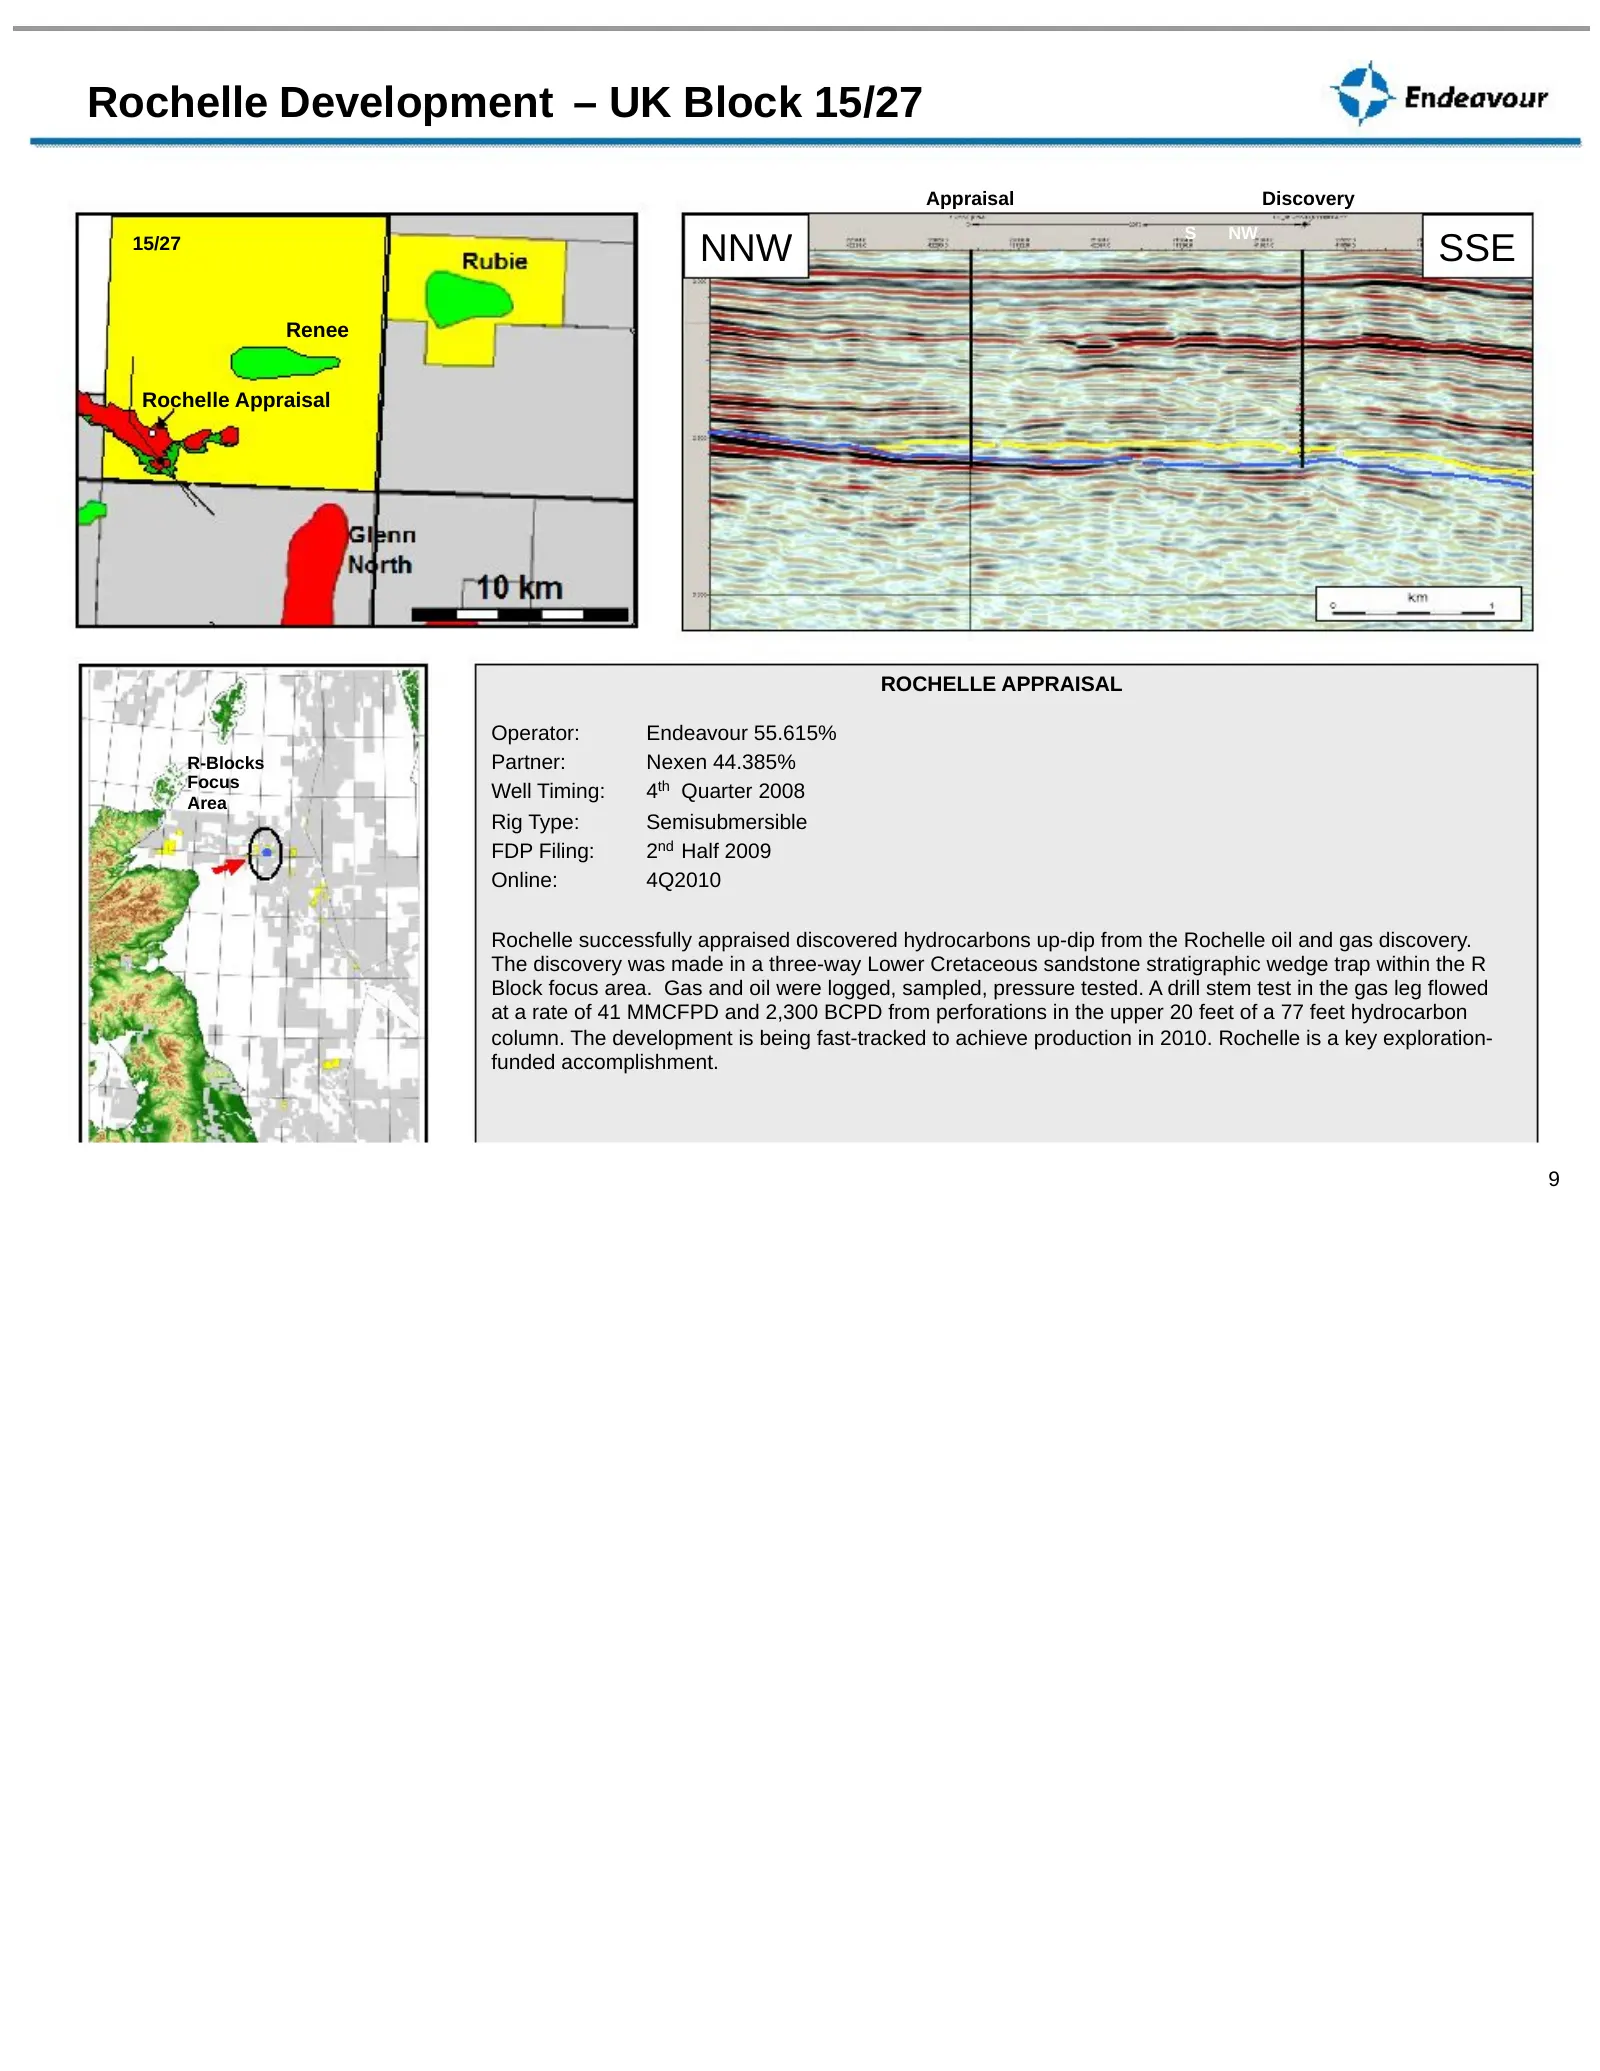
Slide 9: Rochelle Development – UK Block 15/27
Rochelle Development – UK Block 15/27 Appraisal Discovery N S NW SE 15/27 NNW SSE Renee Rochelle Appraisal ROCHELLE APPRAISAL Operator: Endeavour 55.615% R-Blocks Partner: Nexen 44.385% Focus Well Timing: 4th Quarter 2008 Area Rig Type: Semisubmersible FDP Filing: 2nd Half 2009 Online: 4Q2010 Rochel
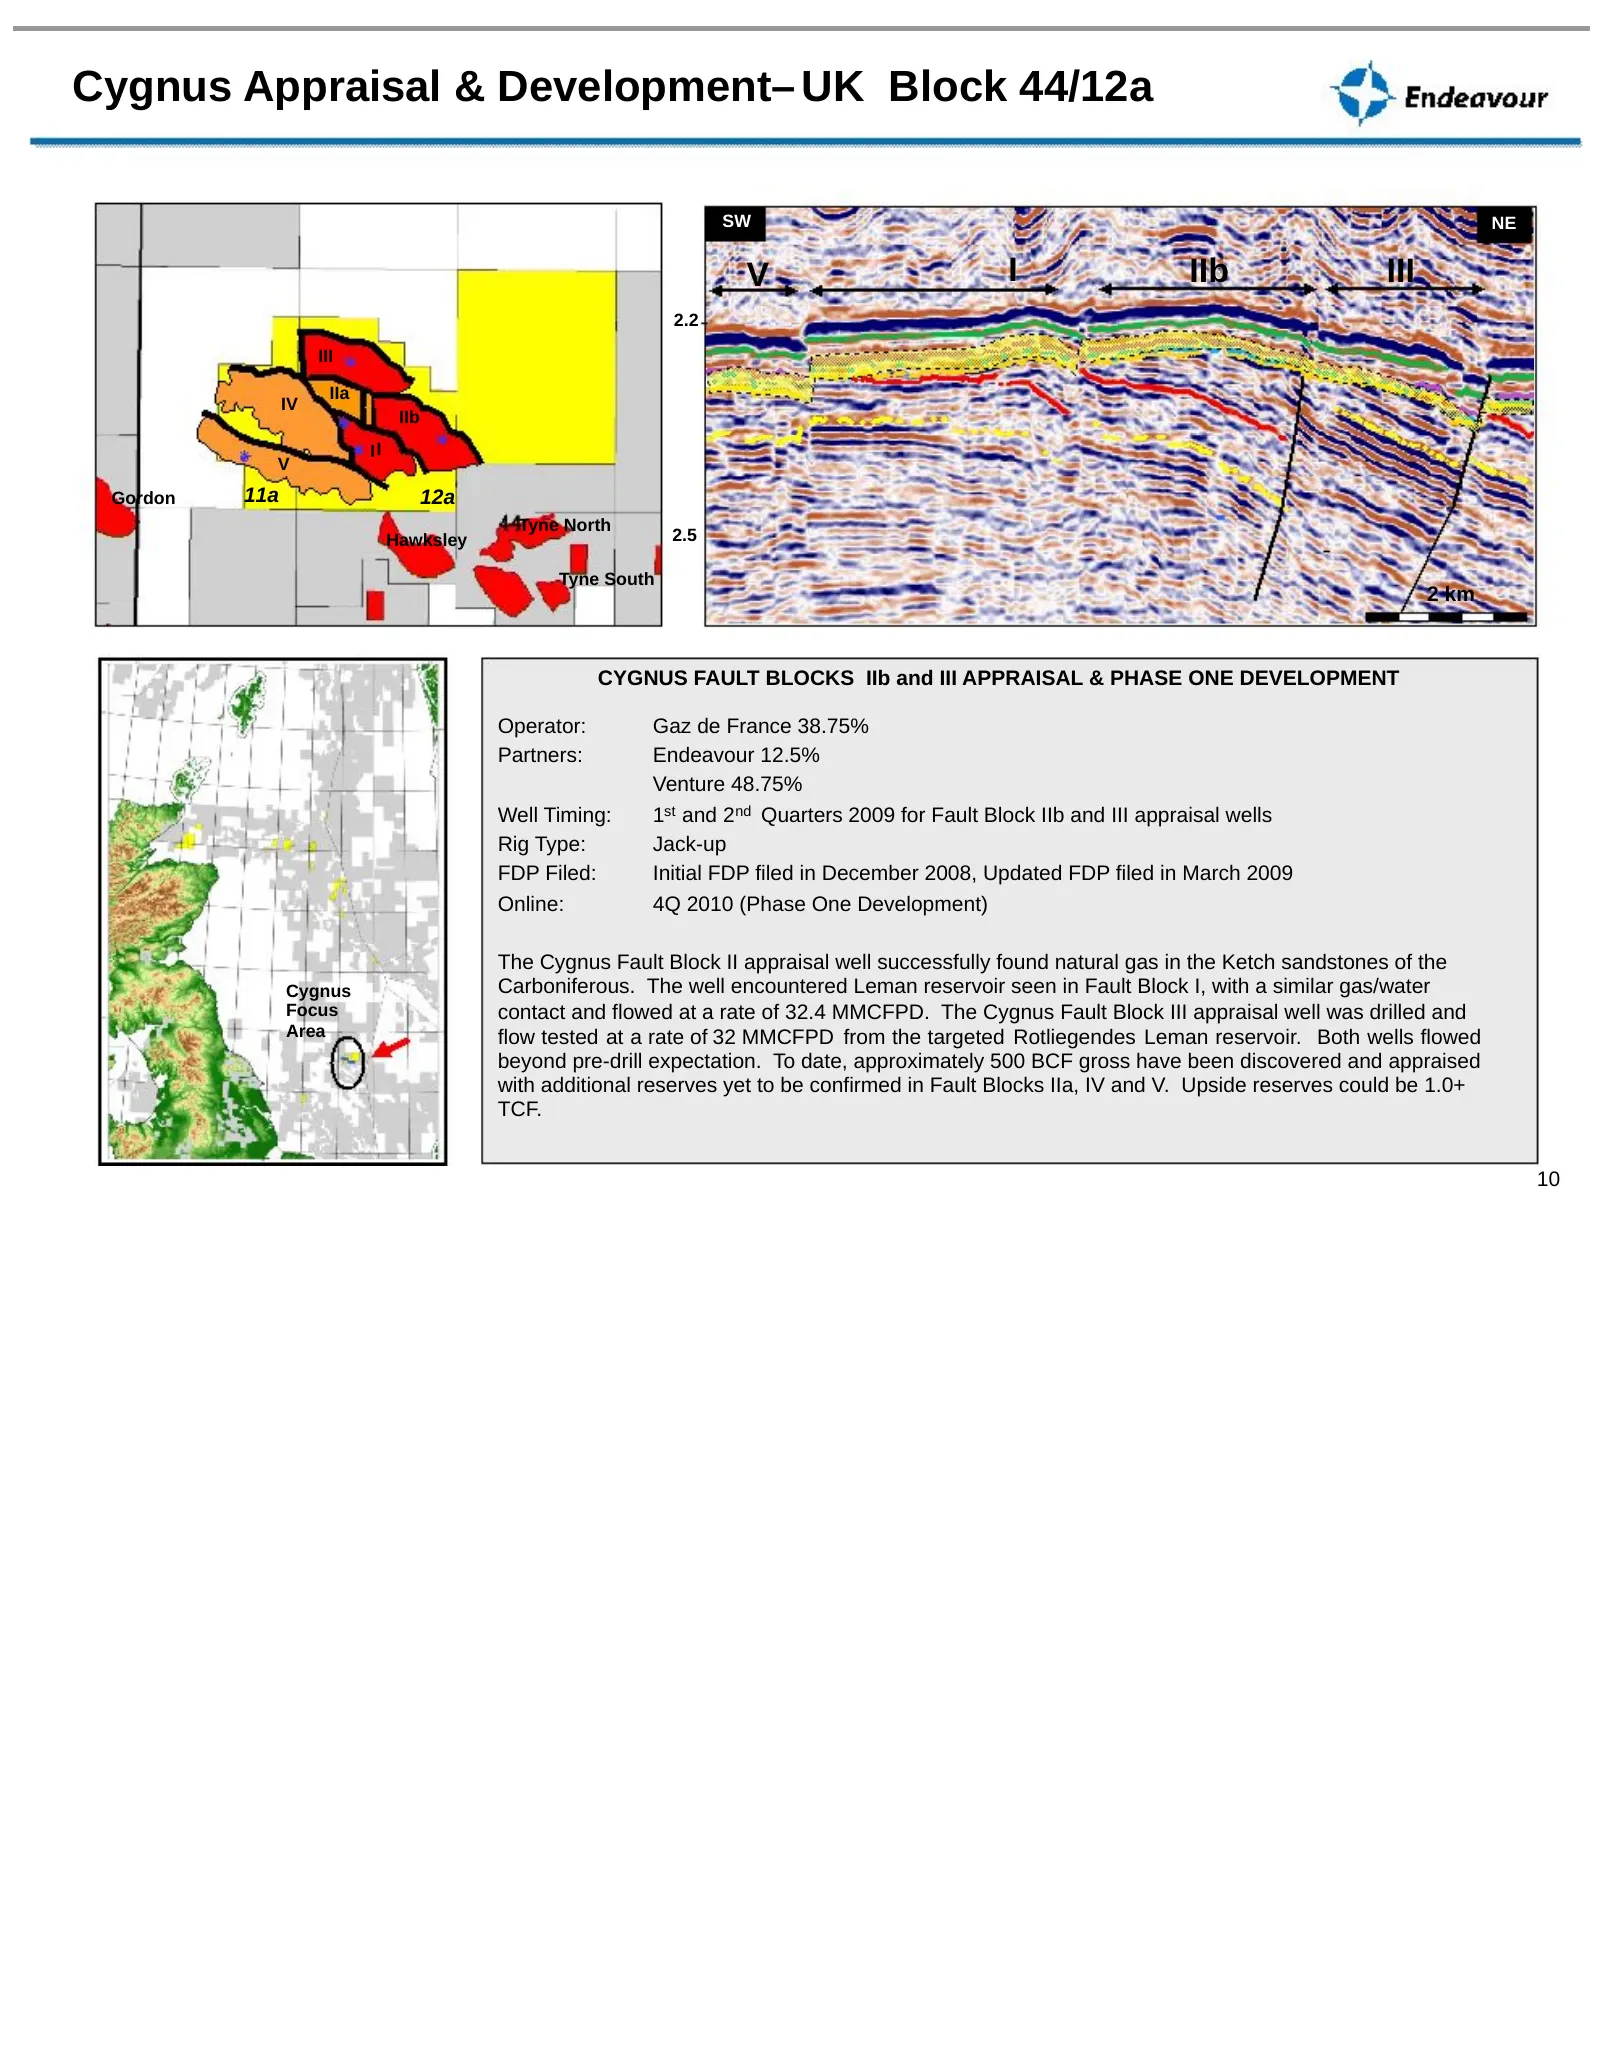
Slide 10: Cygnus Appraisal & Development – UK Block 44/12a
Cygnus Appraisal & Development– UK Block 44/12a SW NE V I IIb III 2.2 III IIa IV IIb II V Gordon 11a 12a Tyne North Hawksley 2.5 Tyne South 2 km CYGNUS FAULT BLOCKS IIb and III APPRAISAL & PHASE ONE DEVELOPMENT Operator: Gaz de France 38.75% Partners: Endeavour 12.5% Venture 48.75% Well Timing: 1st
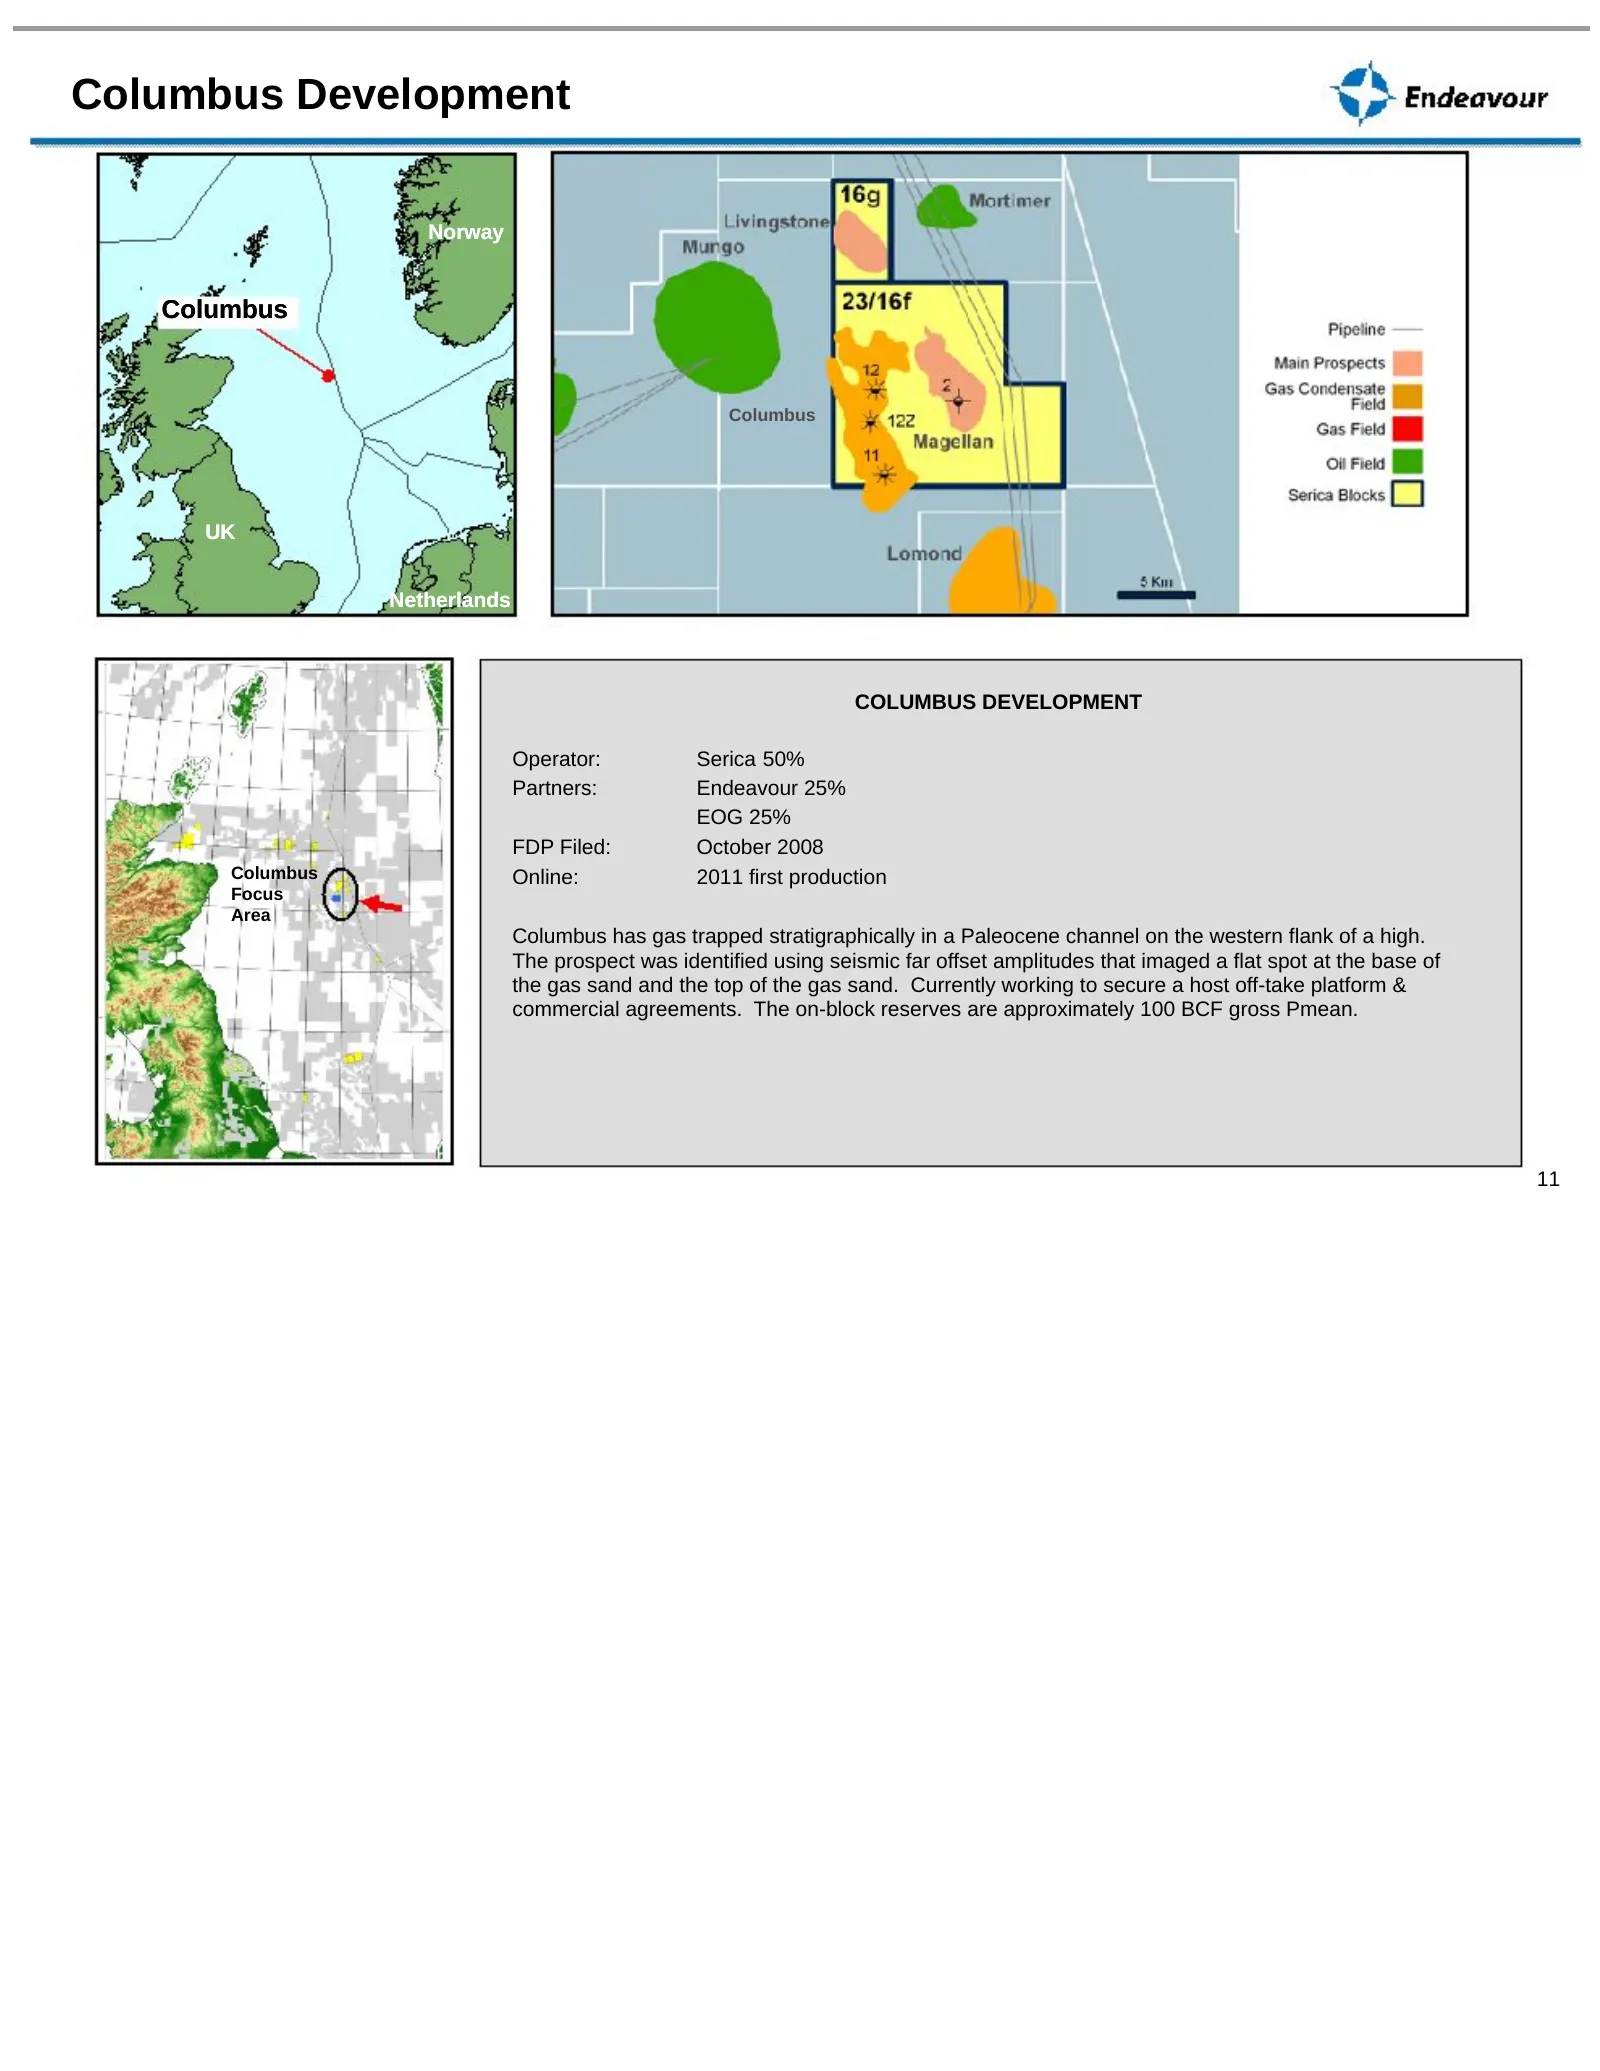
Slide 11: Columbus Development
Columbus Development Norway Columbus Columbus UK Netherlands COLUMBUS DEVELOPMENT Operator: Serica 50% Partners: Endeavour 25% EOG 25% FDP Filed: October 2008 Columbus Online: 2011 first production Focus Area Columbus has gas trapped stratigraphically in a Paleocene channel on the western flank of a
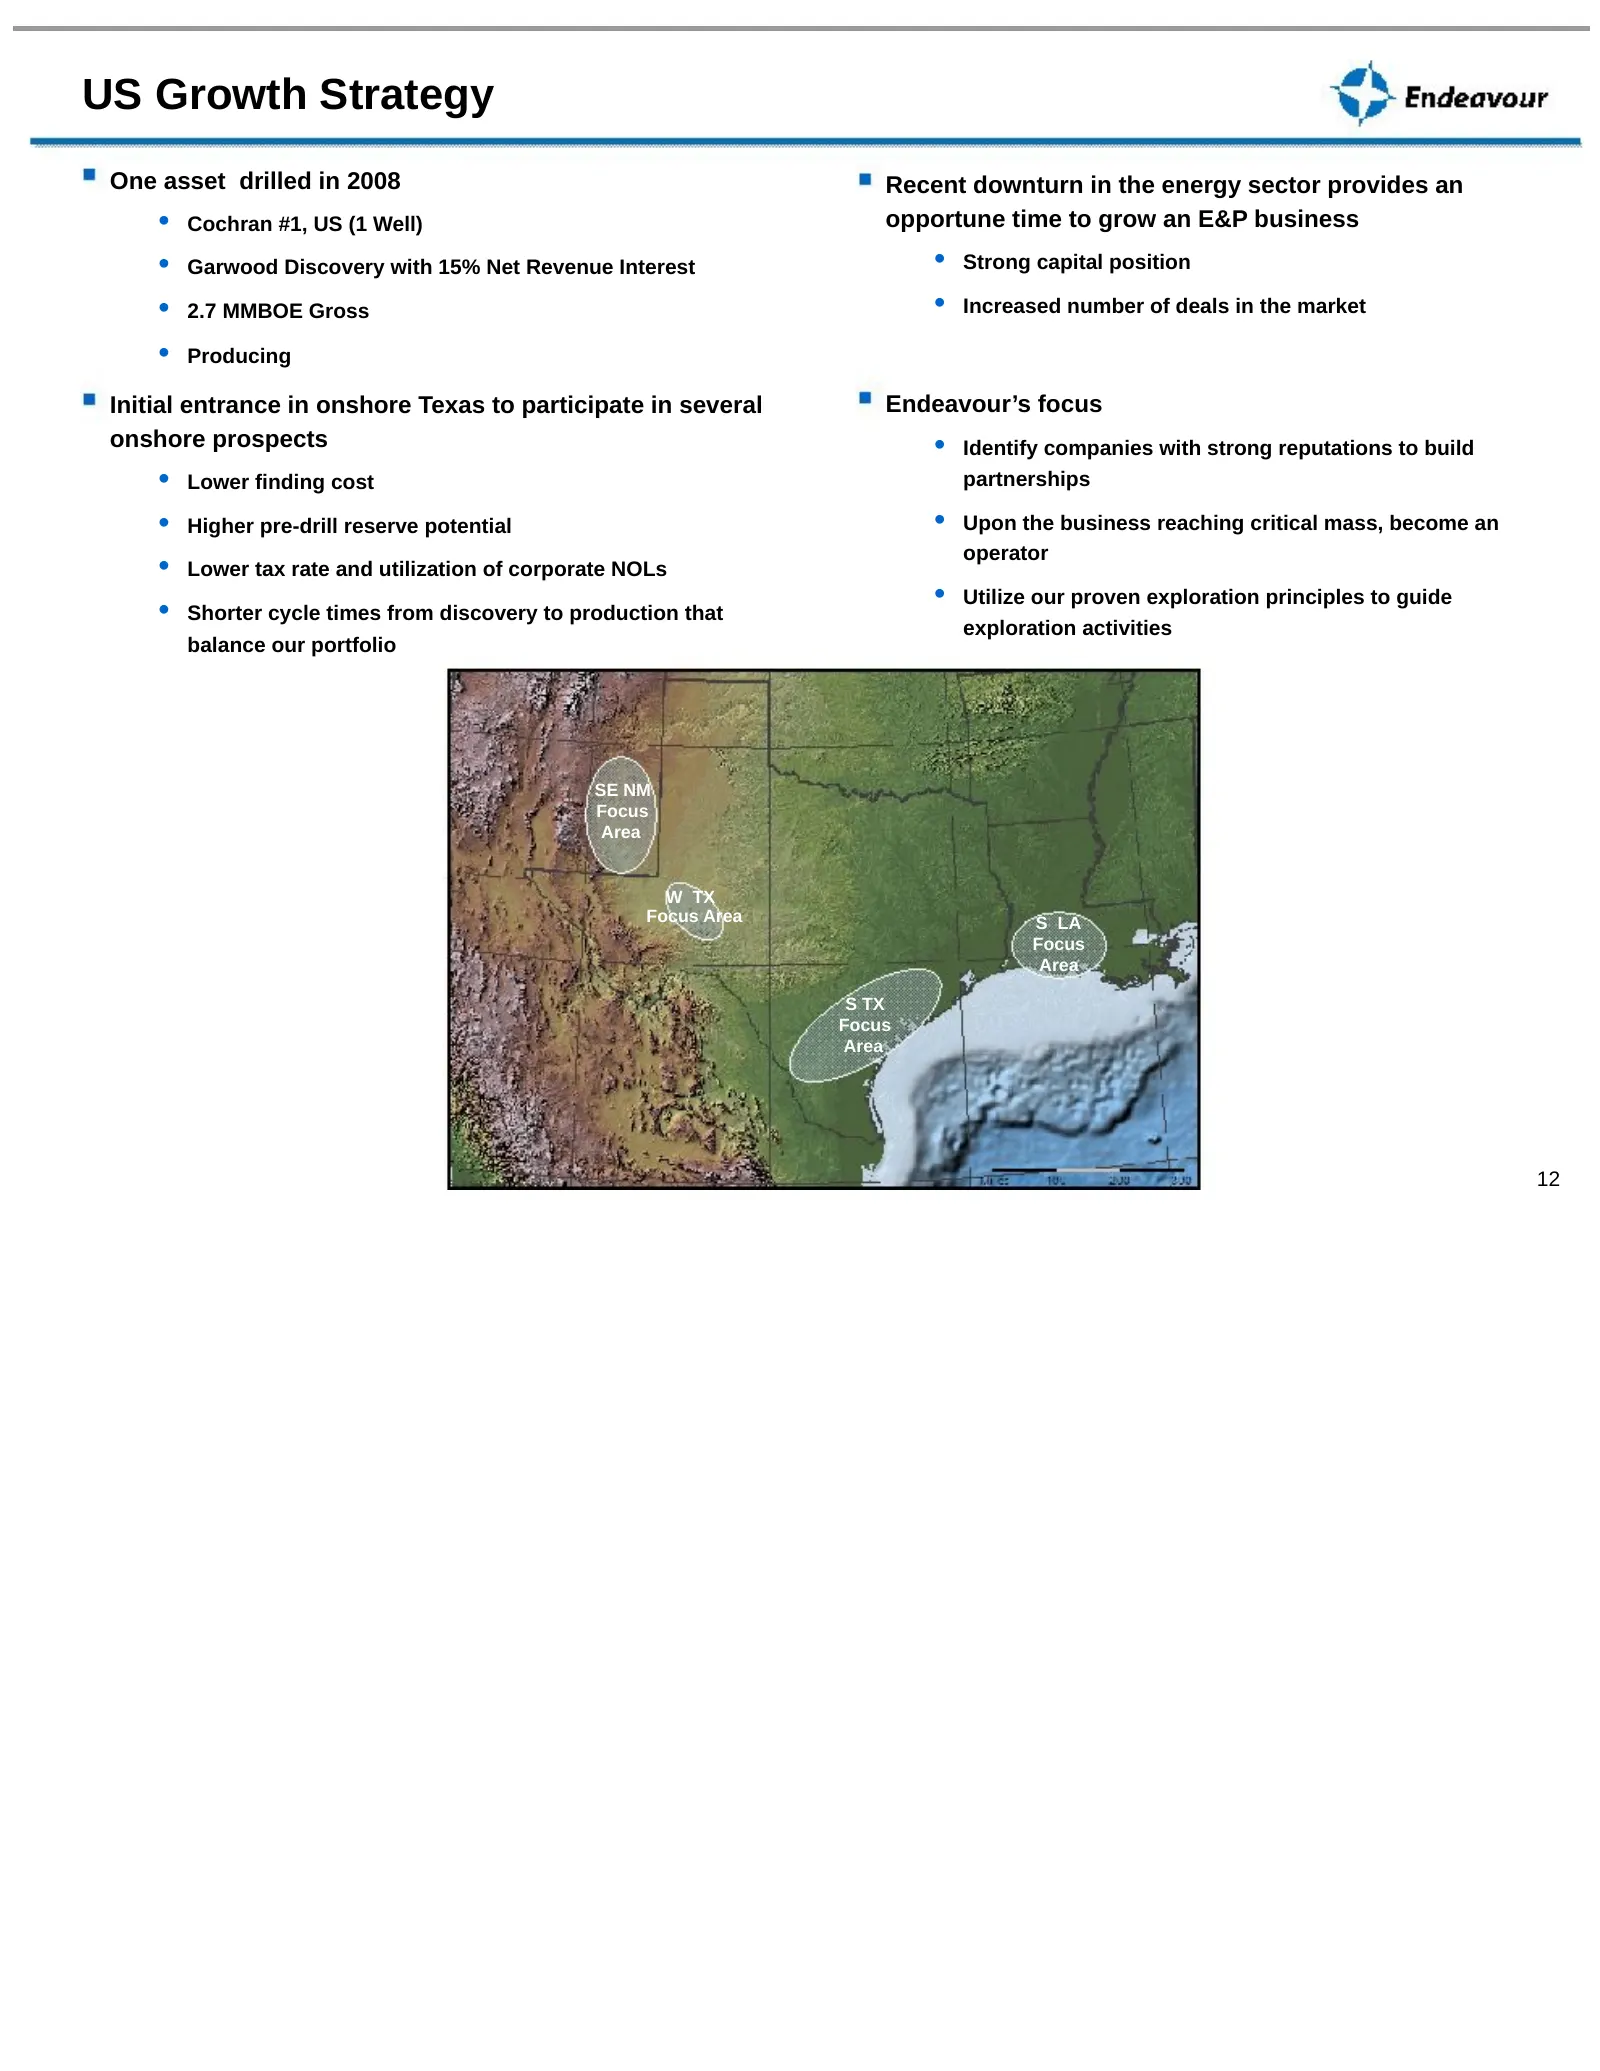
Slide 12: US Growth Strategy
US Growth Strategy One asset drilled in 2008 Recent downturn in the energy sector provides an • Cochran #1, US (1 Well) opportune time to grow an E&P business • Garwood Discovery with 15% Net Revenue Interest • Strong capital position • 2.7 MMBOE Gross • Increased number of deals in the market • Pro
Slide 13: 2009 Exploration and Appraisal Drilling Program
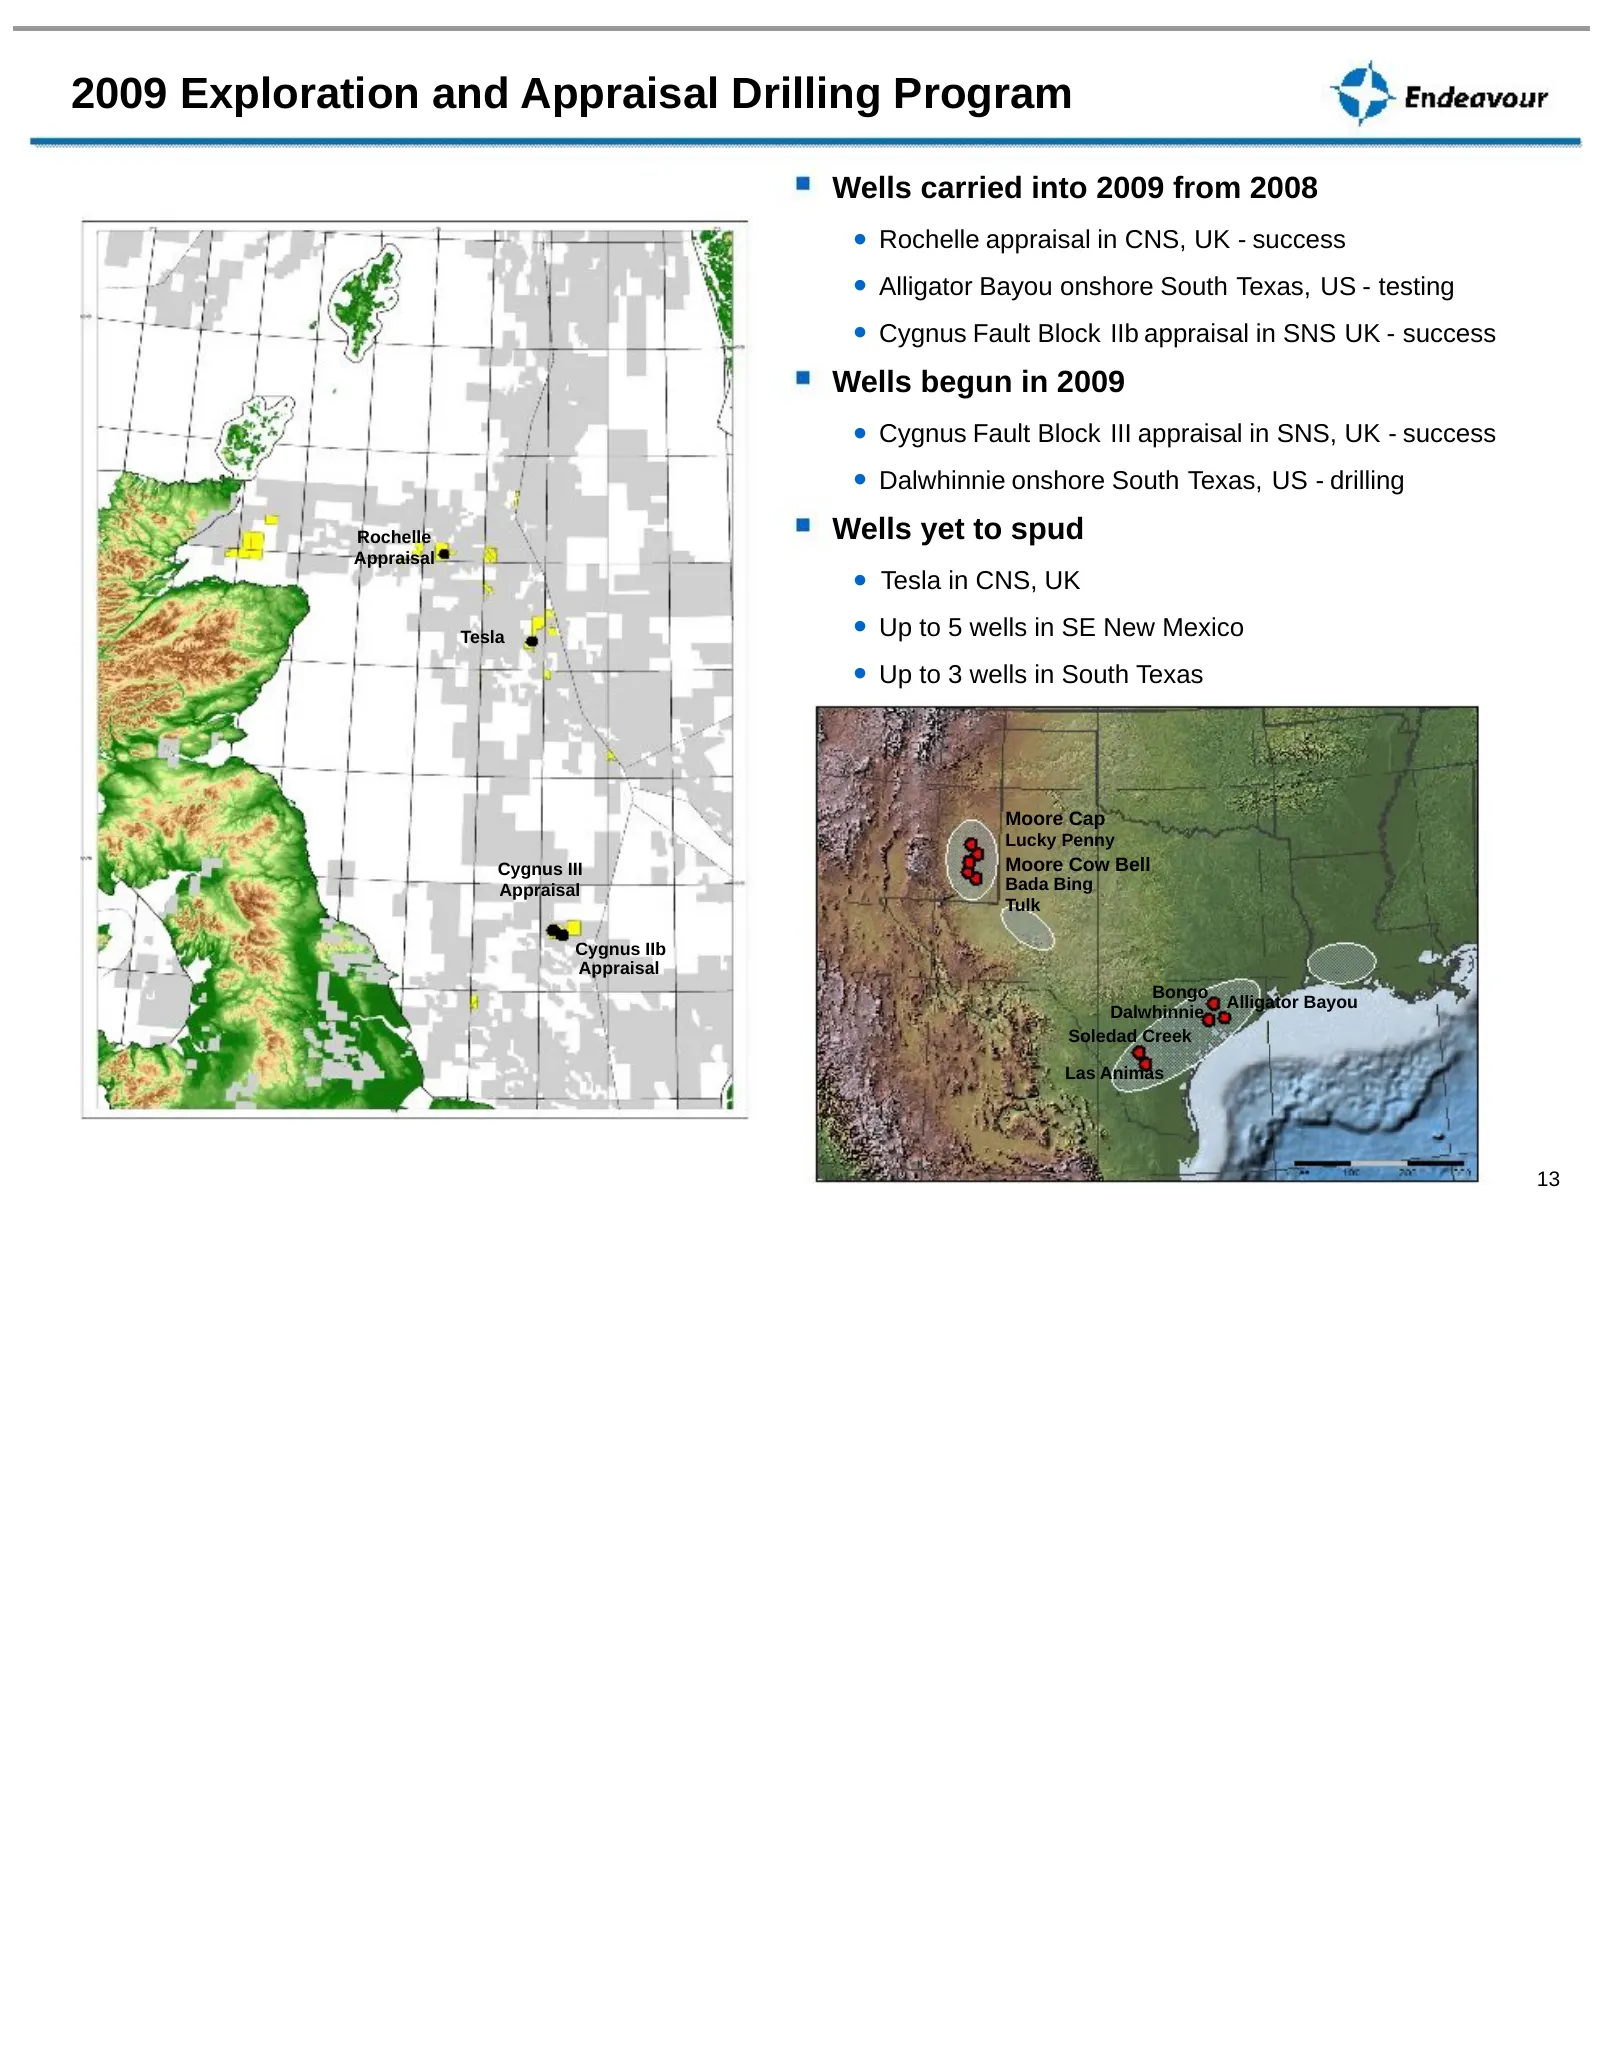
2009 Exploration and Appraisal Drilling Program Wells carried into 2009 from 2008 • Rochelle appraisal in CNS, UK - success • Alligator Bayou onshore South Texas, US - testing • Cygnus Fault Block IIb appraisal in SNS UK - success Wells begun in 2009 • Cygnus Fault Block III appraisal in SNS, UK - s
Slide 14: 2009 Guidance
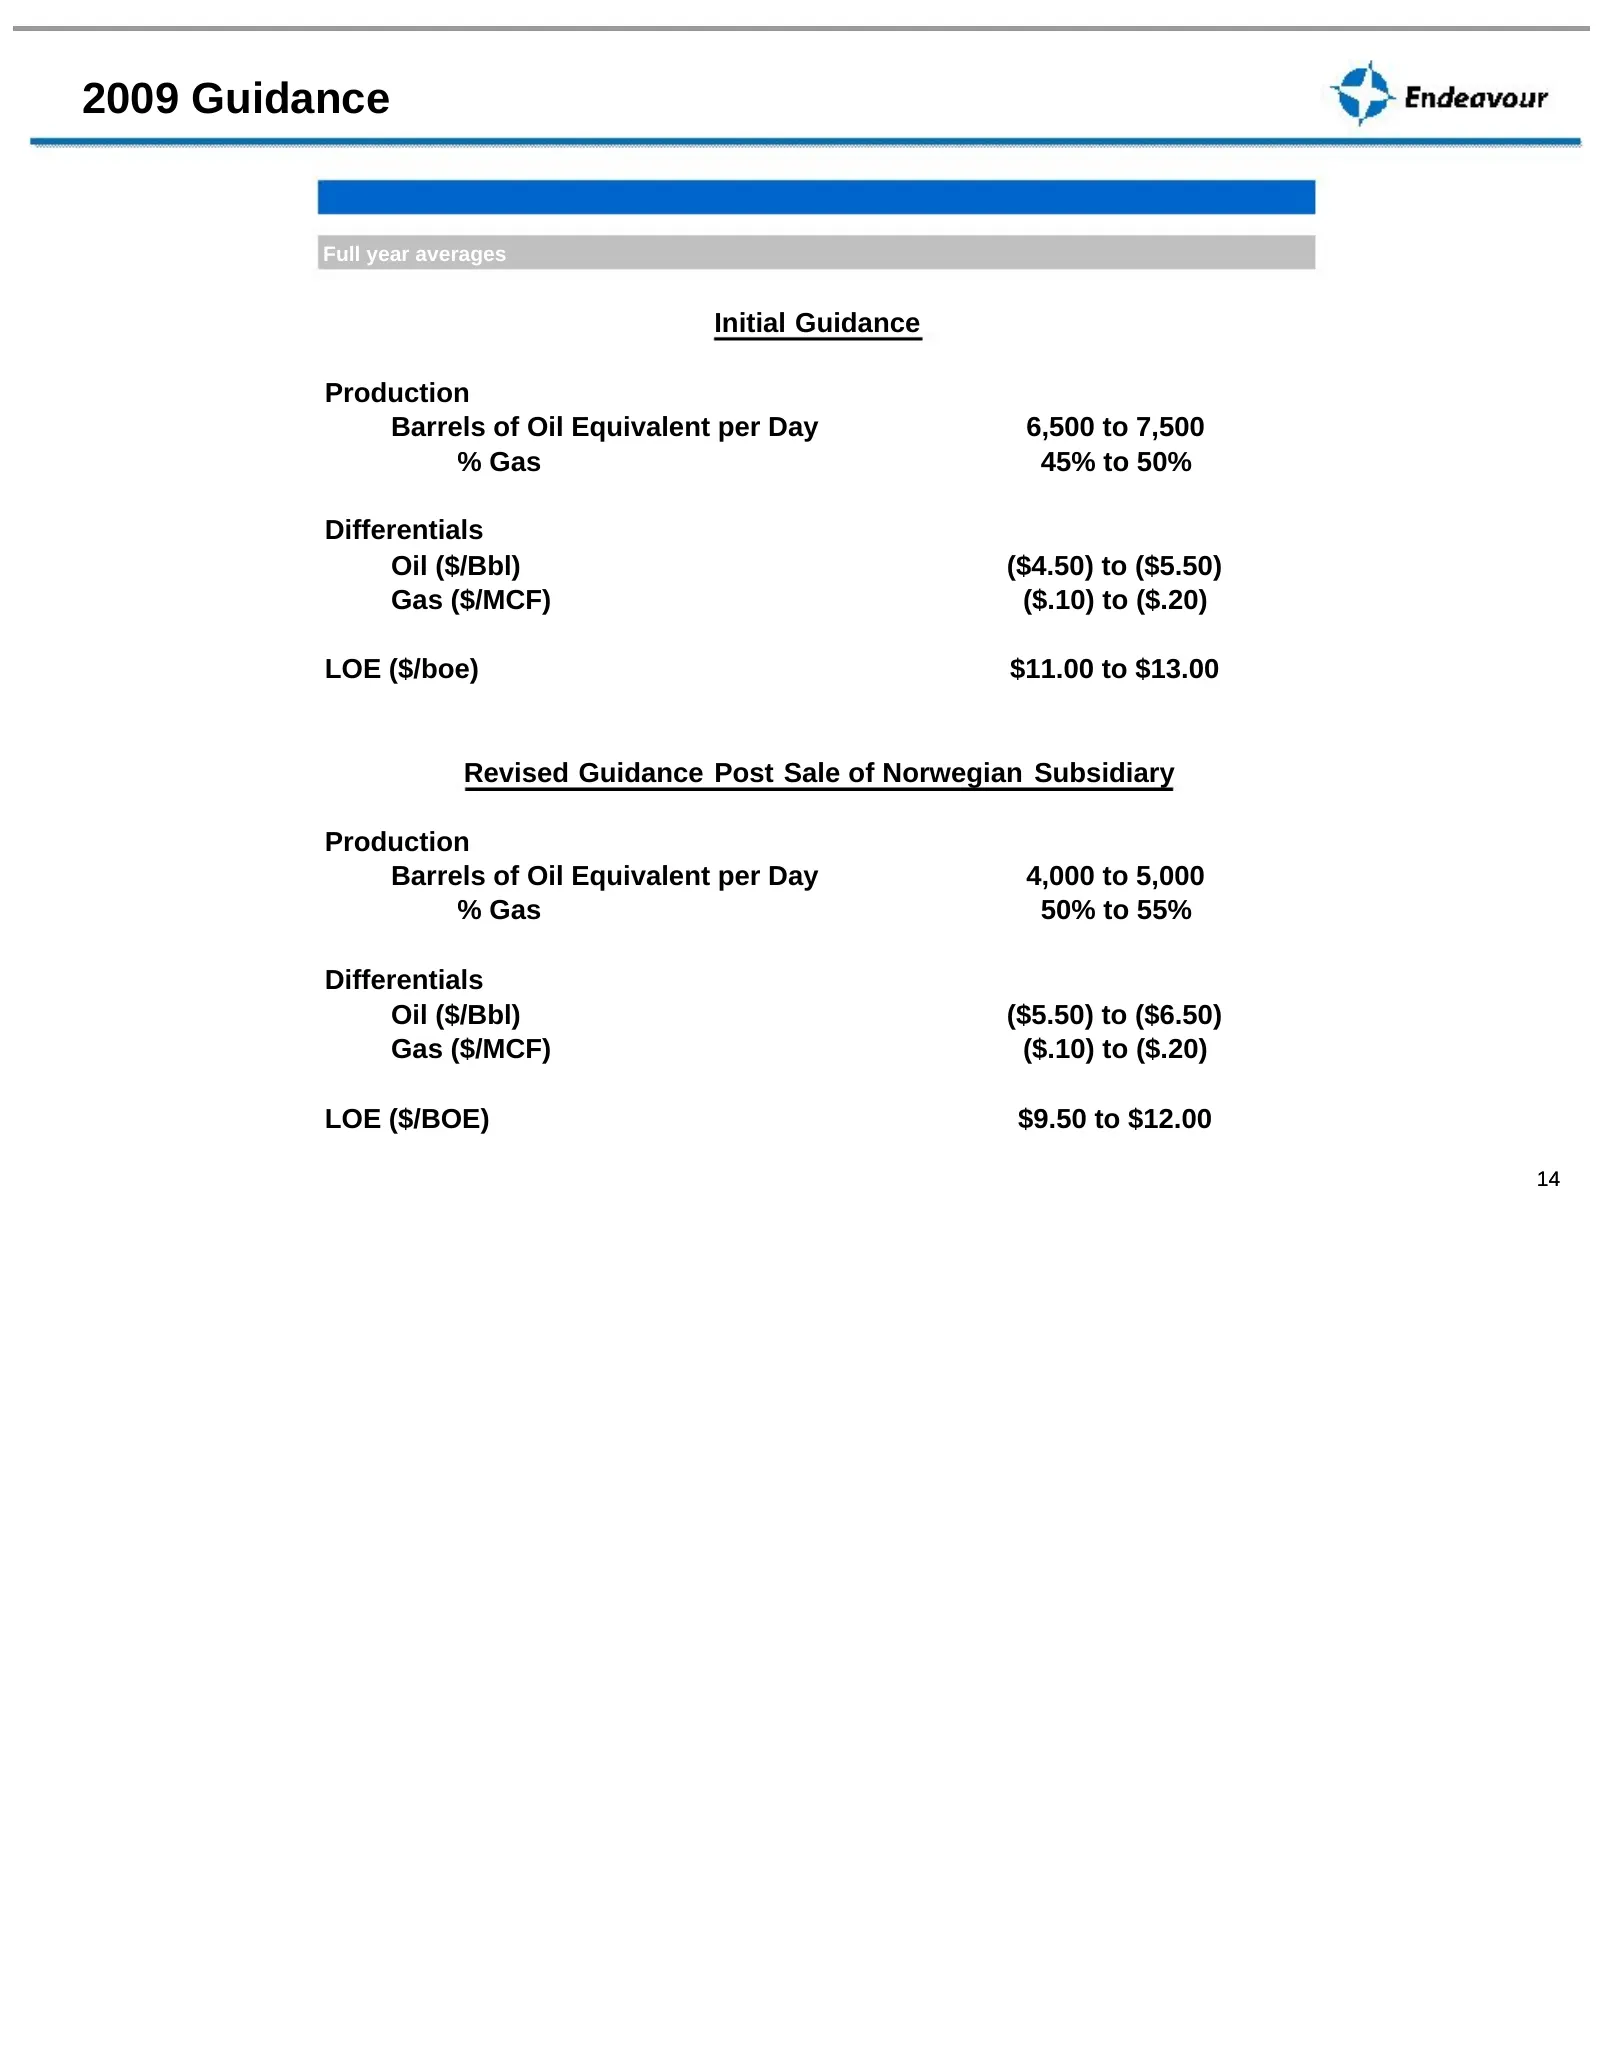
2009 Guidance Full year averages Initial Guidance Production Barrels of Oil Equivalent per Day 6,500 to 7,500 % Gas 45% to 50% Differentials Oil ($/Bbl) ($4.50) to ($5.50) Gas ($/MCF) ($.10) to ($.20) LOE ($/boe) $11.00 to $13.00 Revised Guidance Post Sale of Norwegian Subsidiary Production Barrels
Slide 15: Capital Structure
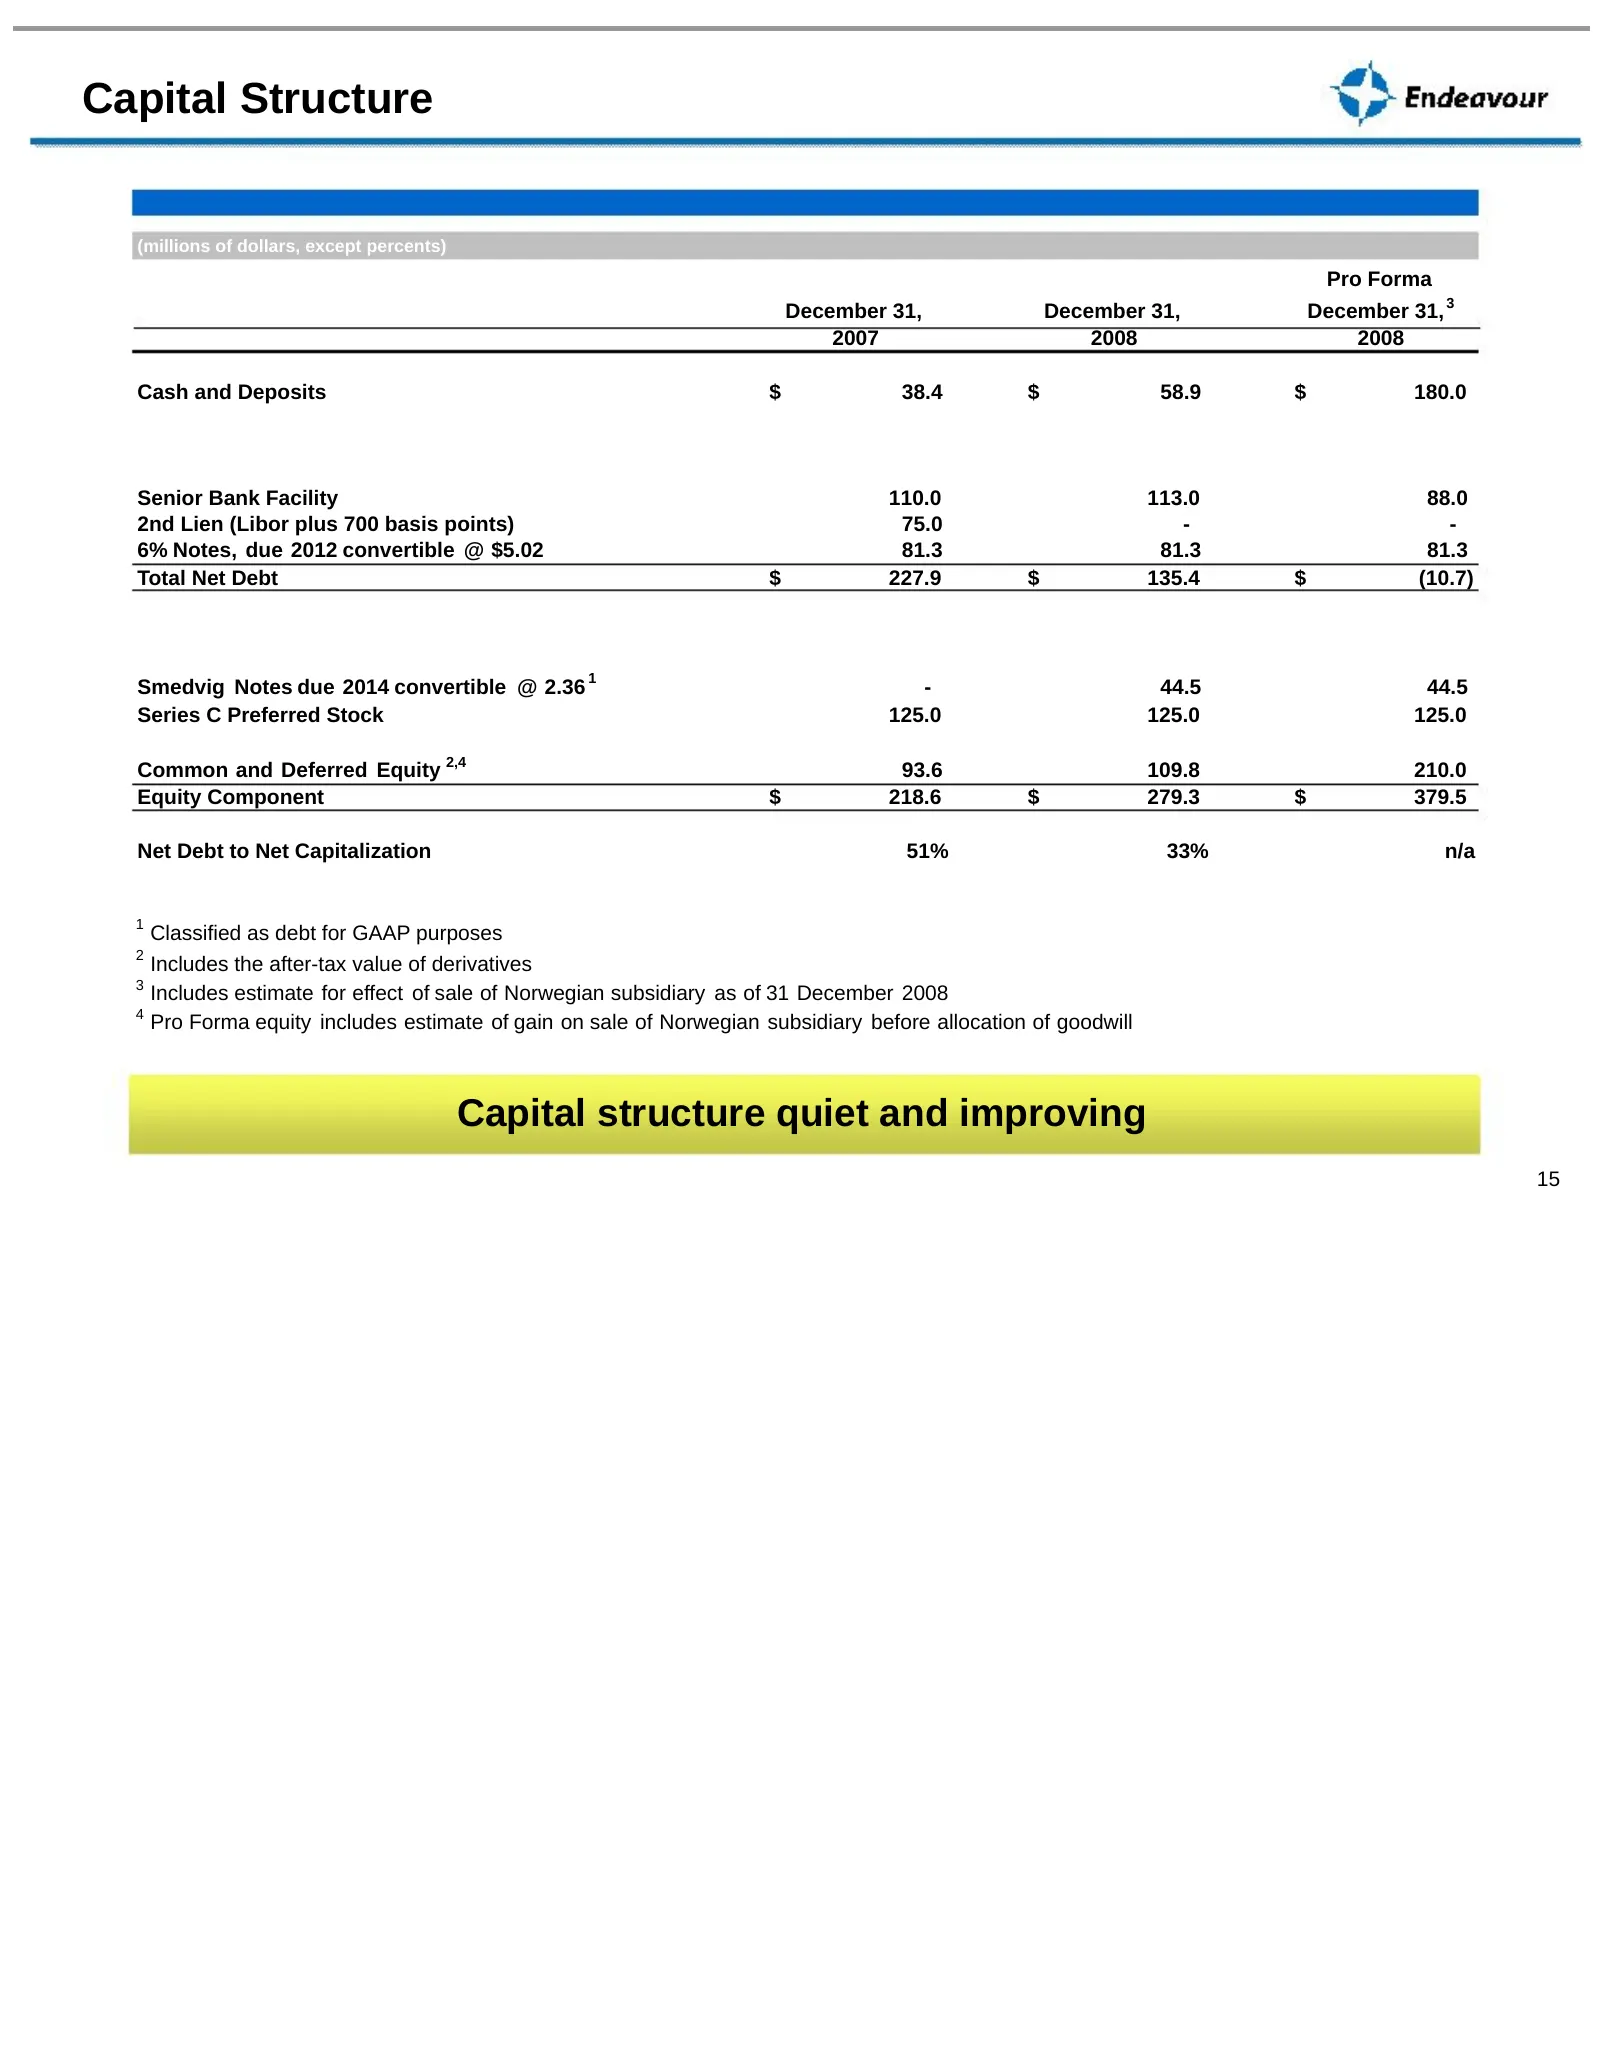
Capital Structure (millions of dollars, except percents) Pro Forma December 31, December 31, December 31, 3 2007 2008 2008 Cash and Deposits $ 38.4 $ 58.9 $ 180.0 Senior Bank Facility 110.0 113.0 88.0 2nd Lien (Libor plus 700 basis points) 75.0 - - 6% Notes, due 2012 convertible @ $5.02 81.3 81.3 81
Slide 16: Results of Operations Metrics
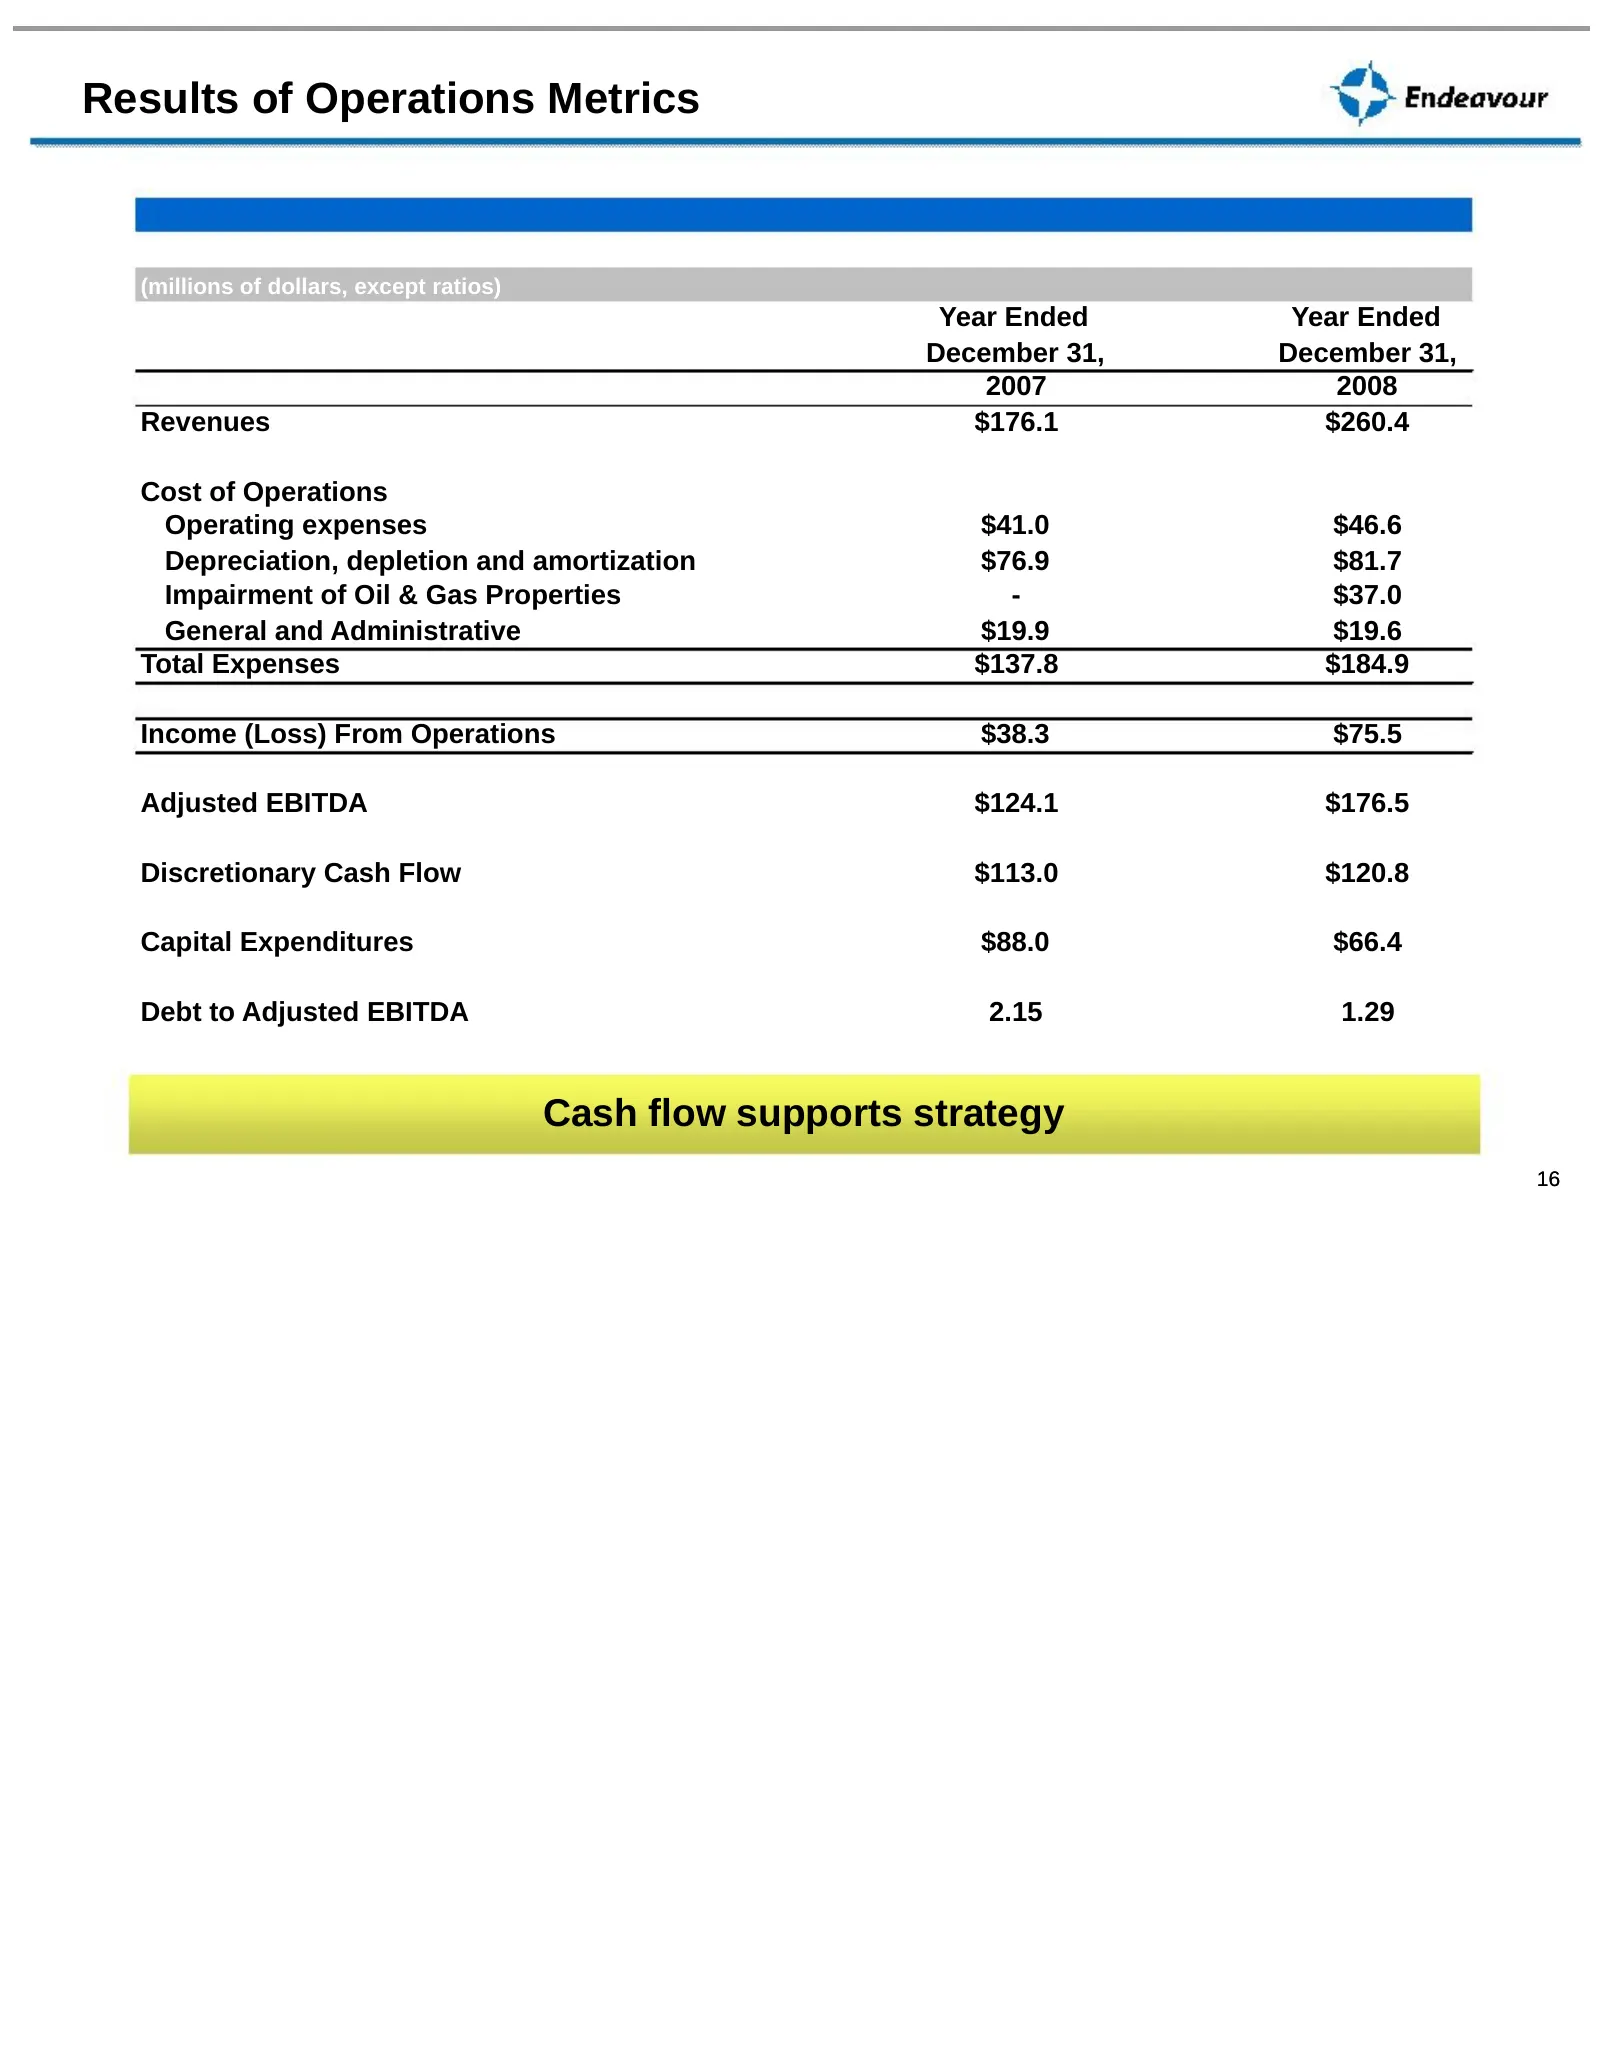
Results of Operations Metrics (millions of dollars, except ratios) Year Ended Year Ended December 31, December 31, 2007 2008 Revenues $176.1 $260.4 Cost of Operations Operating expenses $41.0 $46.6 Depreciation, depletion and amortization $76.9 $81.7 Impairment of Oil & Gas Properties - $37.0 Genera
Slide 17: Acquisitions Show Excellent Returns
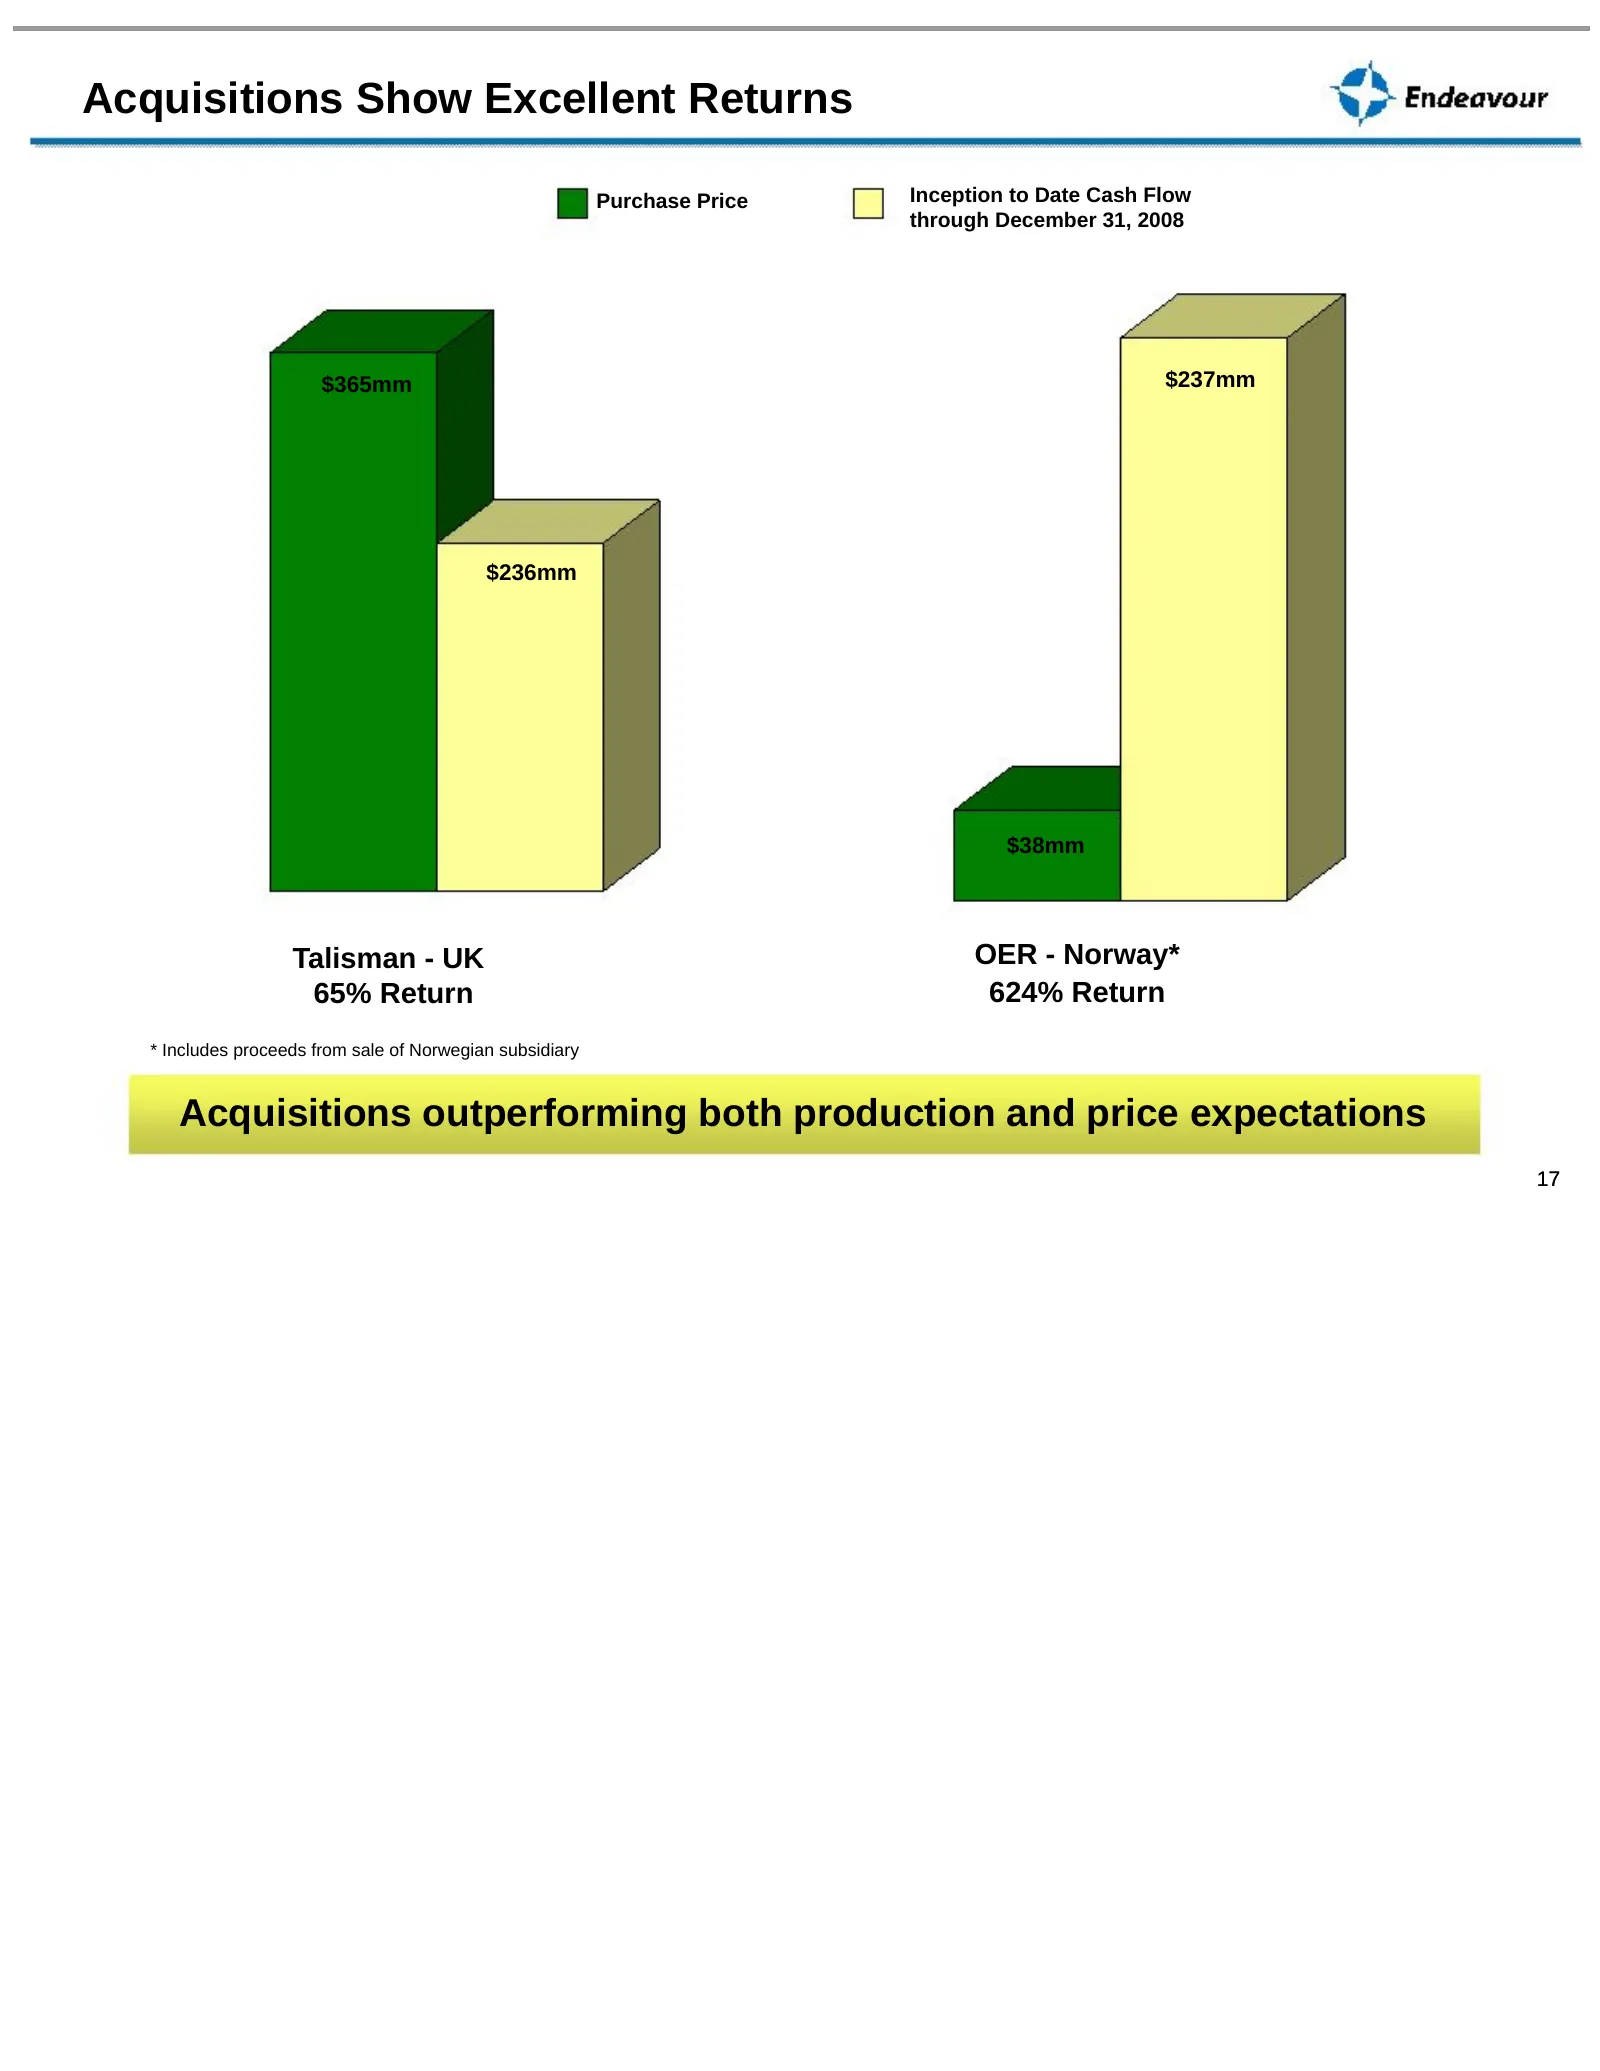
Acquisitions Show Excellent Returns Purchase Price Inception to Date Cash Flow through December 31, 2008 $365mm $237mm $236mm $38mm Talisman - UK OER - Norway* 65% Return 624% Return * Includes proceeds from sale of Norwegian subsidiary Acquisitions outperforming both production and price expectatio
Slide 18: Hedging Statistics
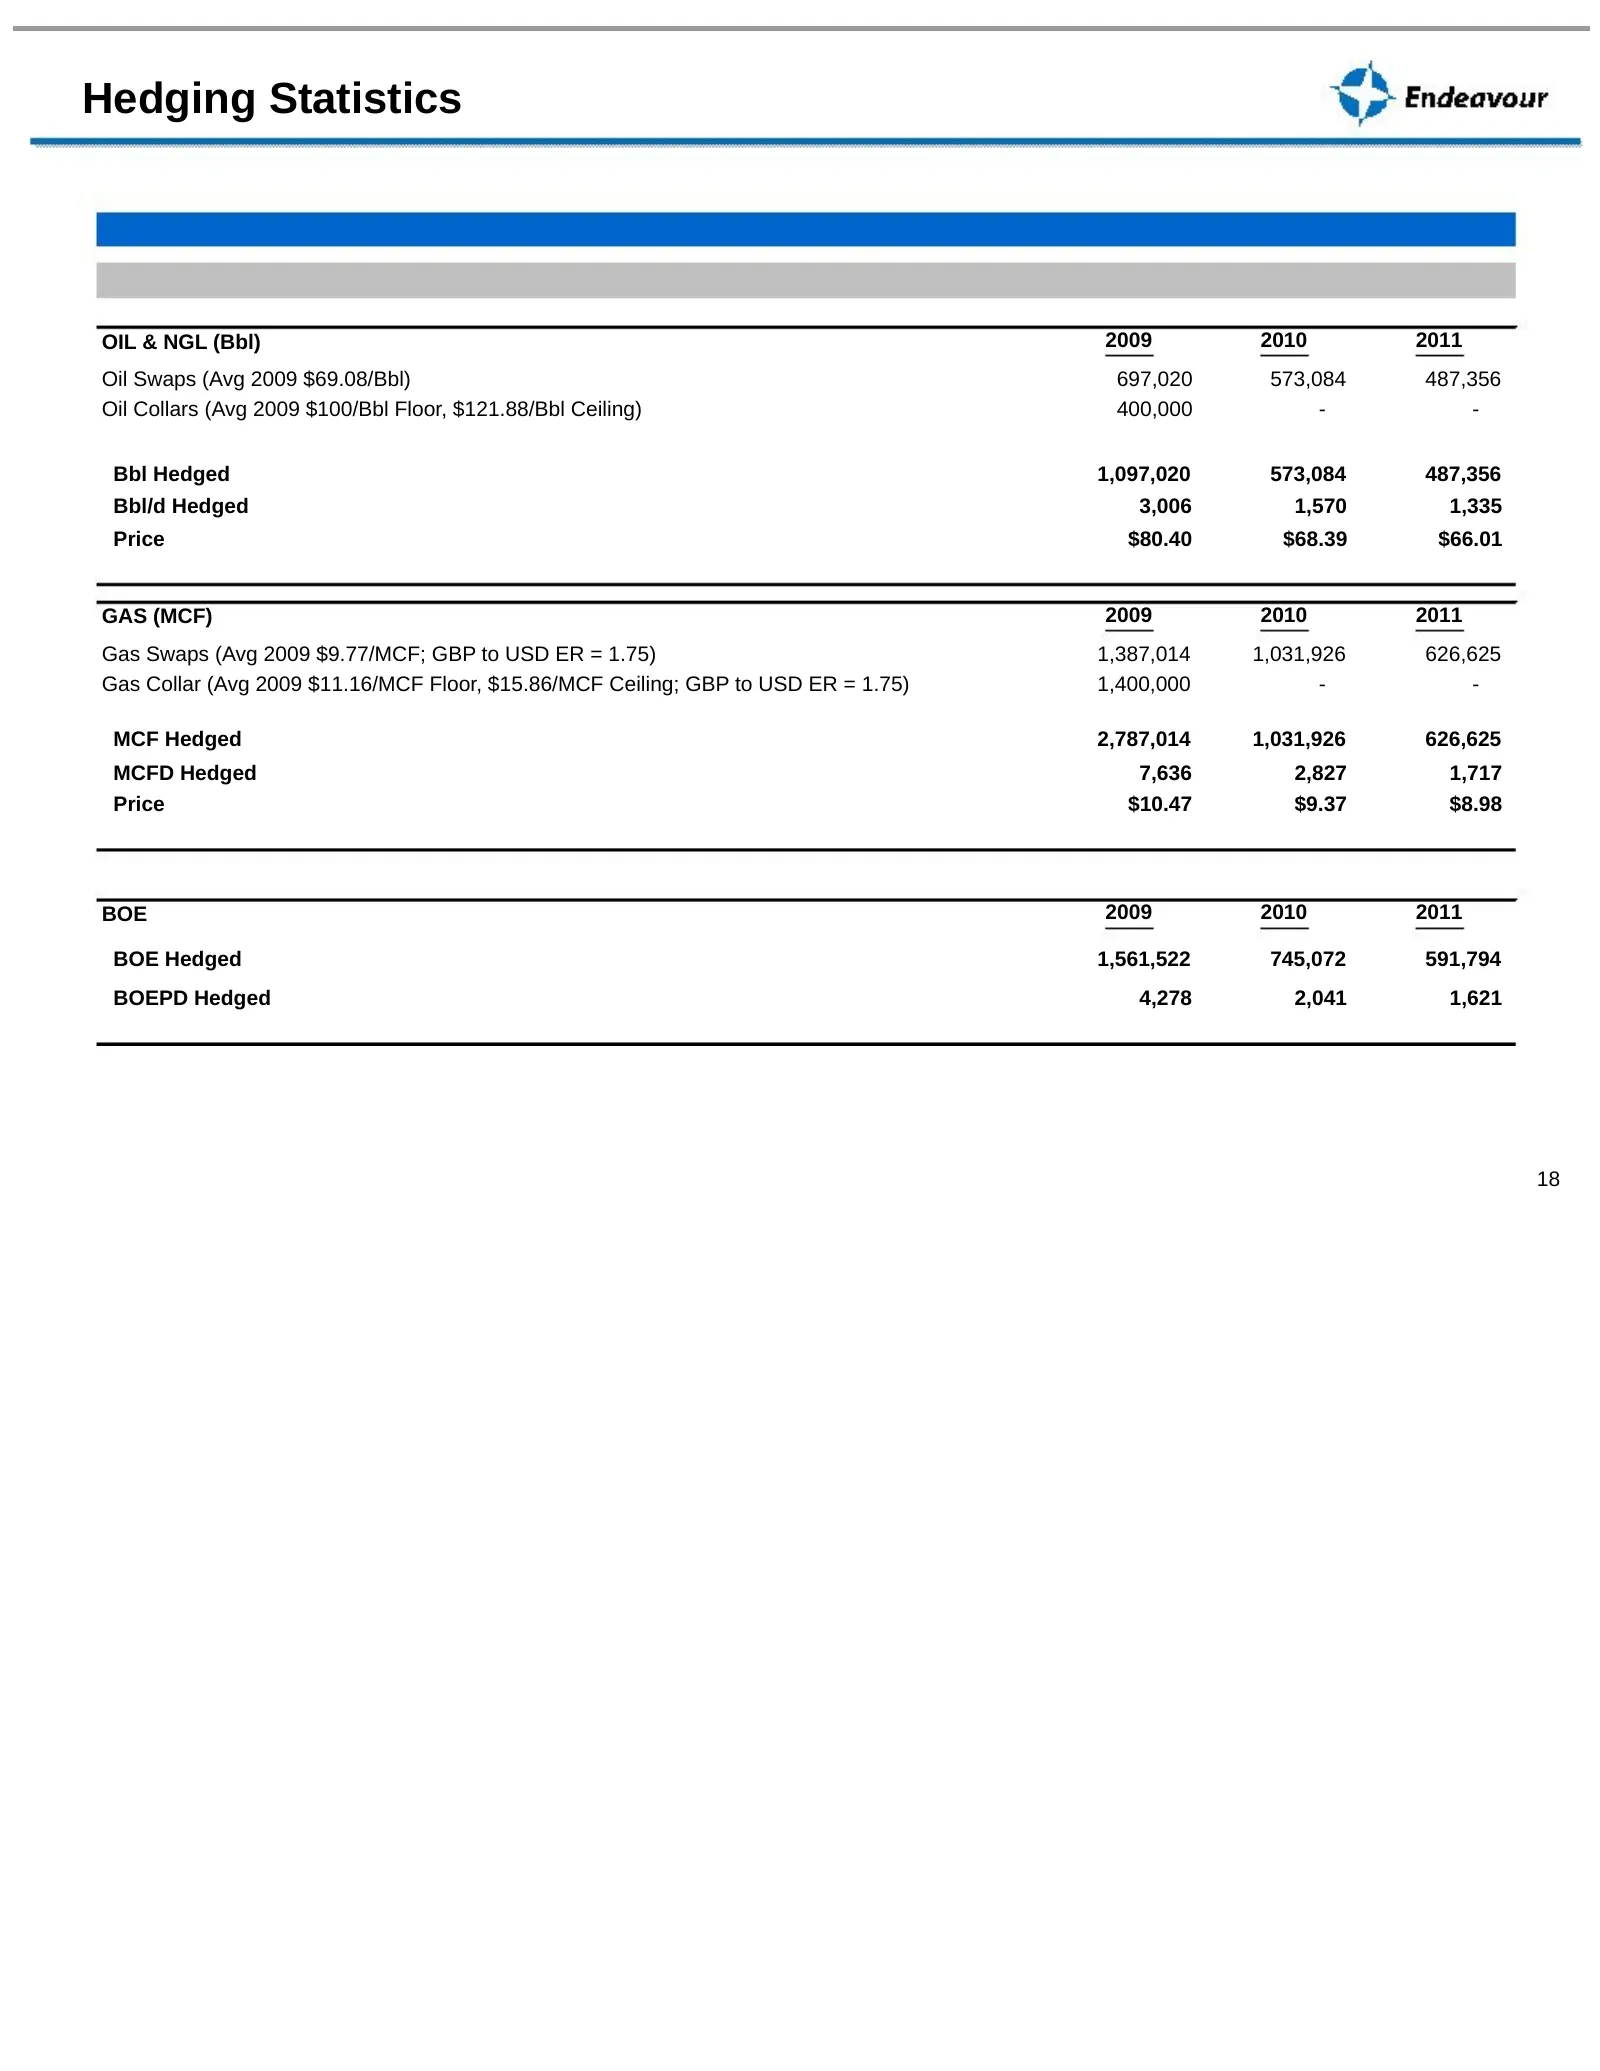
Hedging Statistics OIL & NGL (Bbl) 2009 2010 2011 Oil Swaps (Avg 2009 $69.08/Bbl) 697,020 573,084 487,356 Oil Collars (Avg 2009 $100/Bbl Floor, $121.88/Bbl Ceiling) 400,000 - - Bbl Hedged 1,097,020 573,084 487,356 Bbl/d Hedged 3,006 1,570 1,335 Price $80.40 $68.39 $66.01 GAS (MCF) 2009 2010 2011 Gas
Slide 19: Conclusion
Conclusion Balanced strategy with experienced global team in place - UK North Sea and US Onshore Strong track record of successful drilling (13 straight successes) Significant growth in production by 2010/2011 from UK development projects Multiple growth channels to organically grow company • Develo
Source: SEC EDGAR · 8-K filed Apr 21, 2009
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014