The Pantry — Pantry — 13th Annual ICR XChange Conference (January 2011)
28 slides from The Pantry's conference presentation, Jan 12, 2011
Slide 1: 13th Annual ICR XChange Conference
13 th Annual ICR XChange Conference Mark R. Bierley, SVP and CFO January 12, 2011
Slide 2: Safe Harbor Statement
Safe Harbor Statement Some of the statements in this presentation constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. All statements other than those of historical facts included herein, including those related to the company’s financia
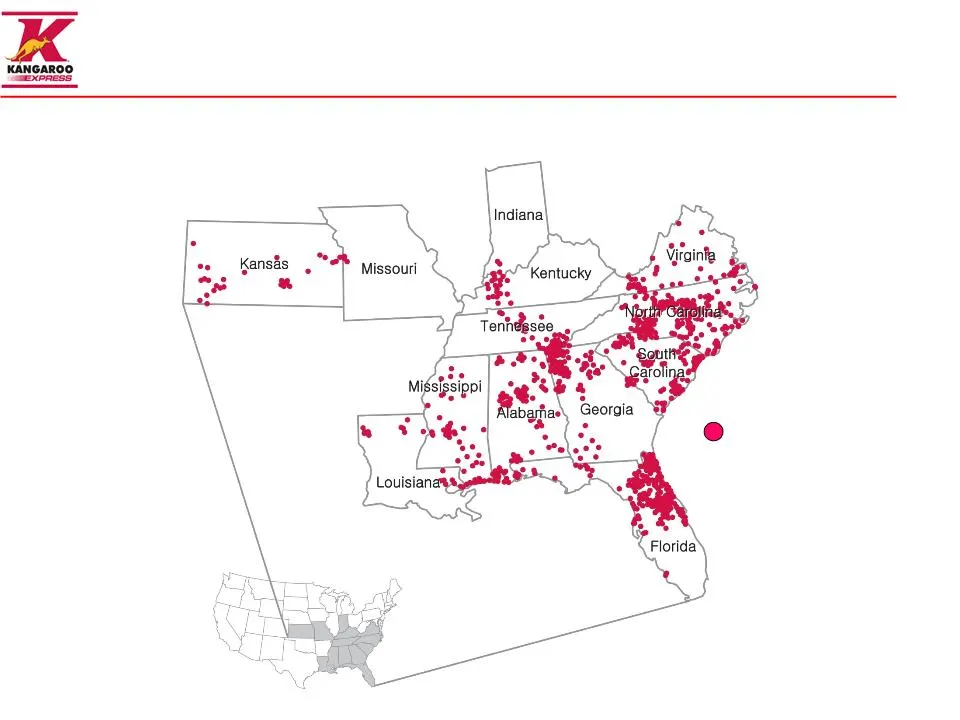
Slide 3: Leading convenience store retailer concentrated in the southeastern United States
Leading convenience store retailer concentrated in the southeastern United States _____________________ Note: Map is illustrative 1,667 Stores Located in Thirteen States as of January 11, 2011 Pantry Store Locations
Slide 4: Key Strategies
Key Strategies n Improve comp sales and merchandise gross margin with focus on Coffee and Meals & Snacks n Invest in technology to drive effectiveness and efficiency n 2% to 4% annual store growth target n Accelerate EBITDA and cash flow growth
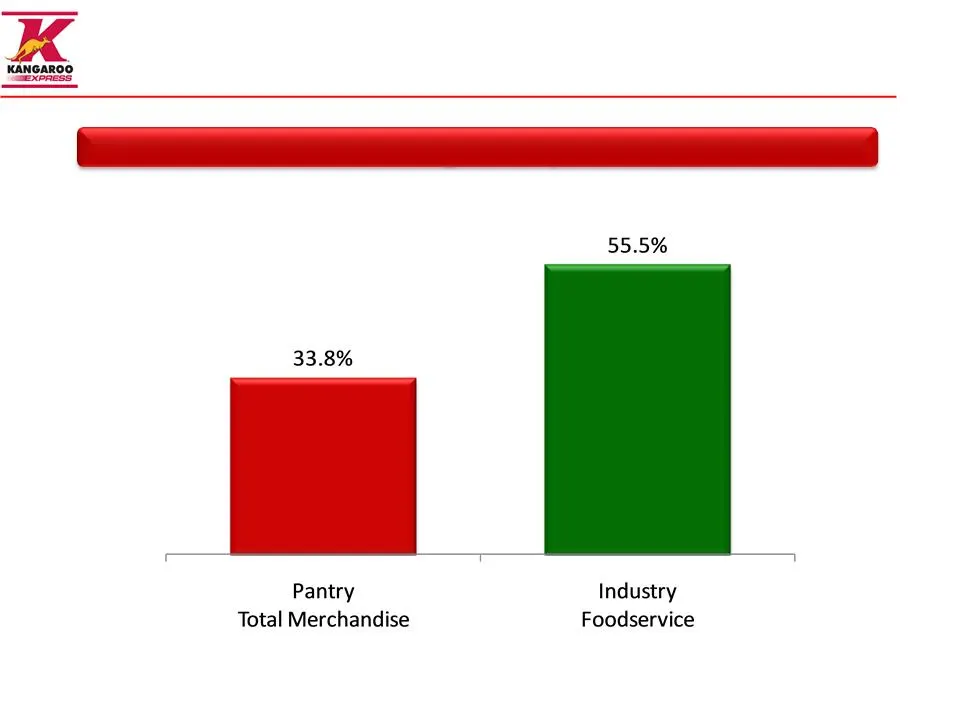
Slide 5: Gross Margin Comparison: Why Meals & Snacks?
Gross Margin Comparison Why Meals & Snacks? _____________________ (1) Represents fiscal year 2010 total merchandise gross margin for The Pantry (2) Industry data is foodservice only for Calendar Year 2009 and Industry source is NACS SOI
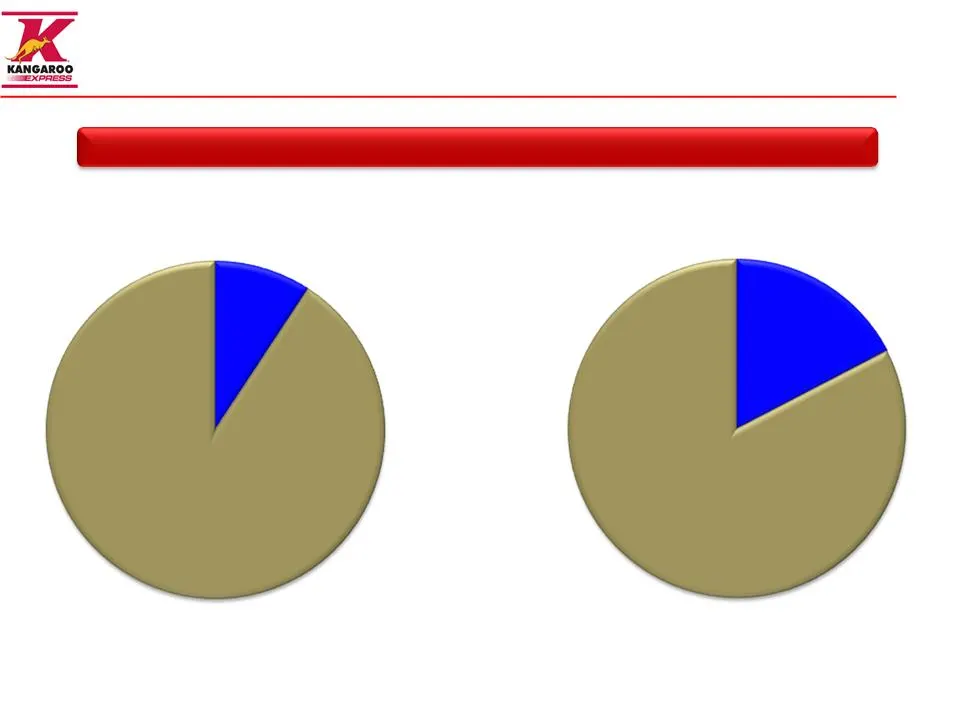
Slide 6: Focused on capturing the foodservice opportunity
17% 9% Foodservice Mix of Total Inside Sales Focused on capturing the foodservice opportunity _____________________ (1) Pantry Foodservice includes Fast Foodservice, Self-Service Fast Foods and Beverages and is for FY2010 (2) Industry Data is for Calendar Year 2009 and Industry source is NACS Indust
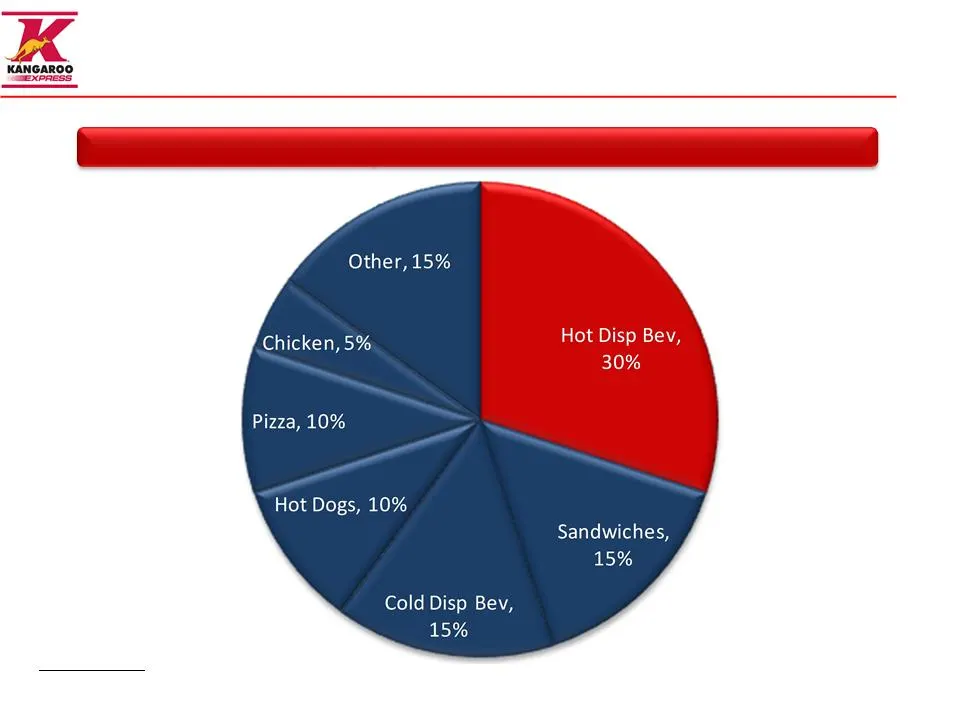
Slide 7: Industry Foodservice Sales Mix: Why Coffee?
Industry Foodservice Sales Mix Why Coffee? Source: Convenience Store News 2009 Extended Foodservice Study. Figures based on annual 2008 average per store sales and rounded to nearest 5% interval
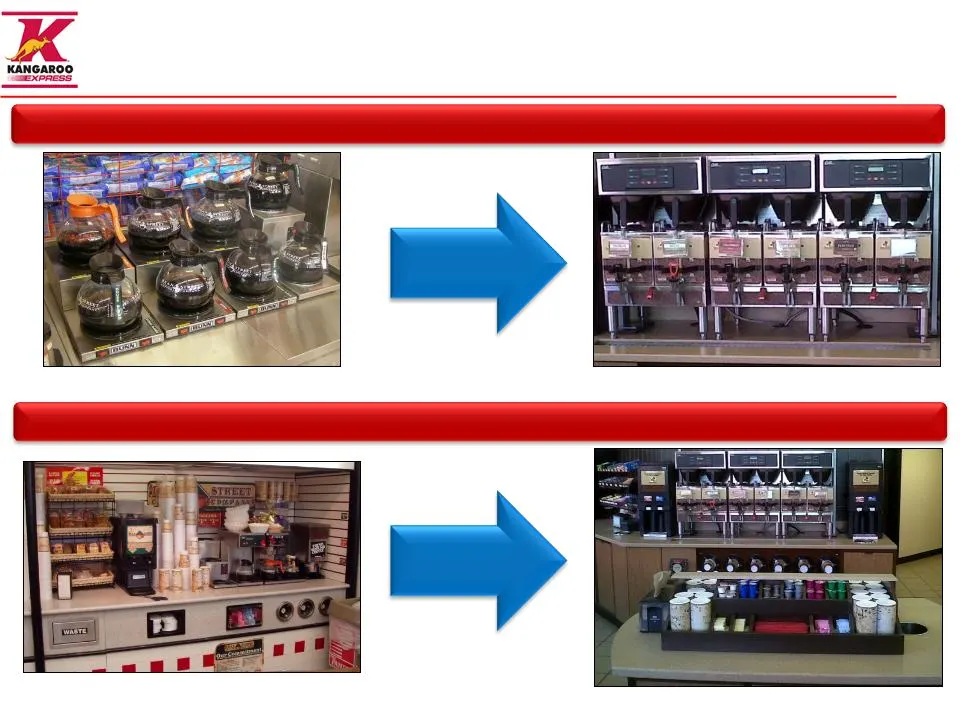
Slide 8: Bean Street Coffee Focus: Dispensing Preparation
DISPENSING PREPARATION Bean Street Coffee Focus
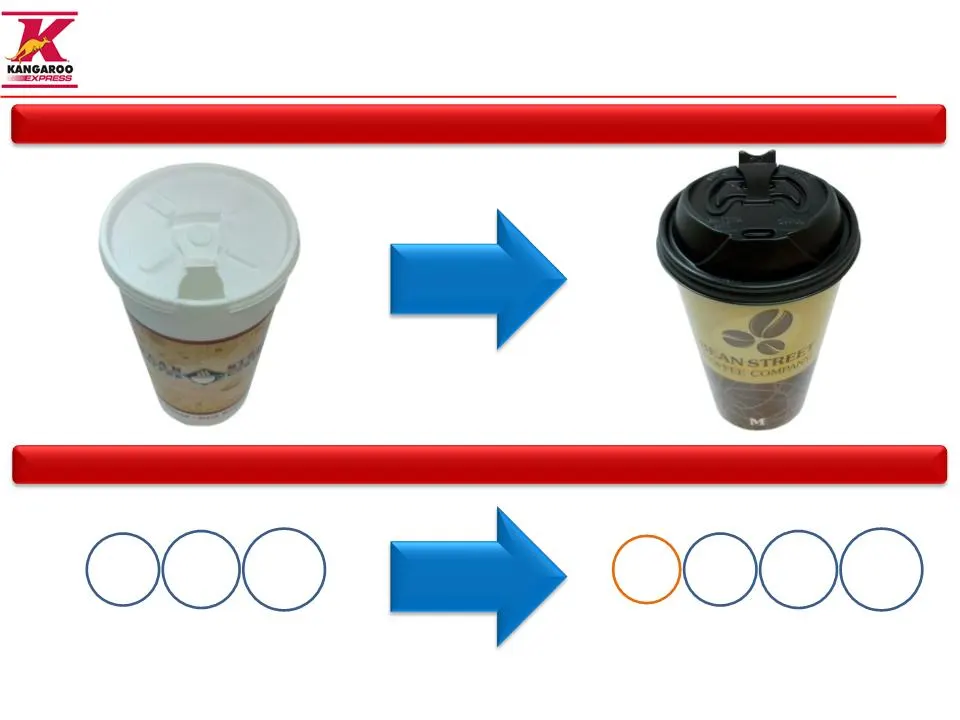
Slide 9: Bean Street Coffee Focus: Cups Assortment
CUPS ASSORTMENT 16oz 20oz 24oz 12oz 16oz 20oz 24oz Bean Street Coffee Focus
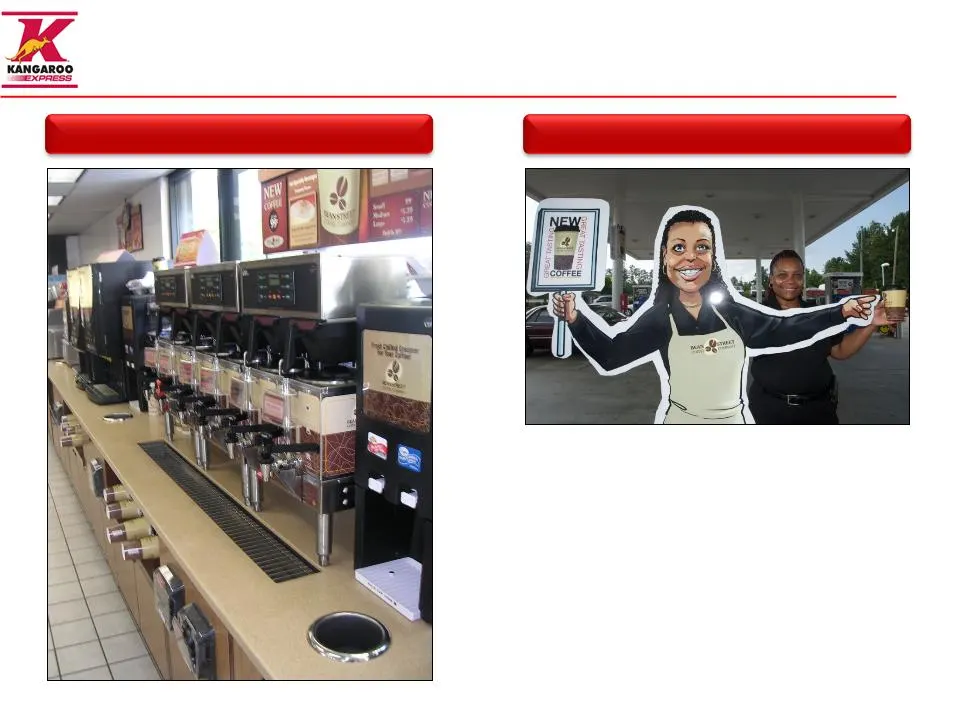
Slide 10: Bean Street Coffee Focus: Coffee Hospitality Host
Coffee Hospitality Host Bean Street Coffee Focus
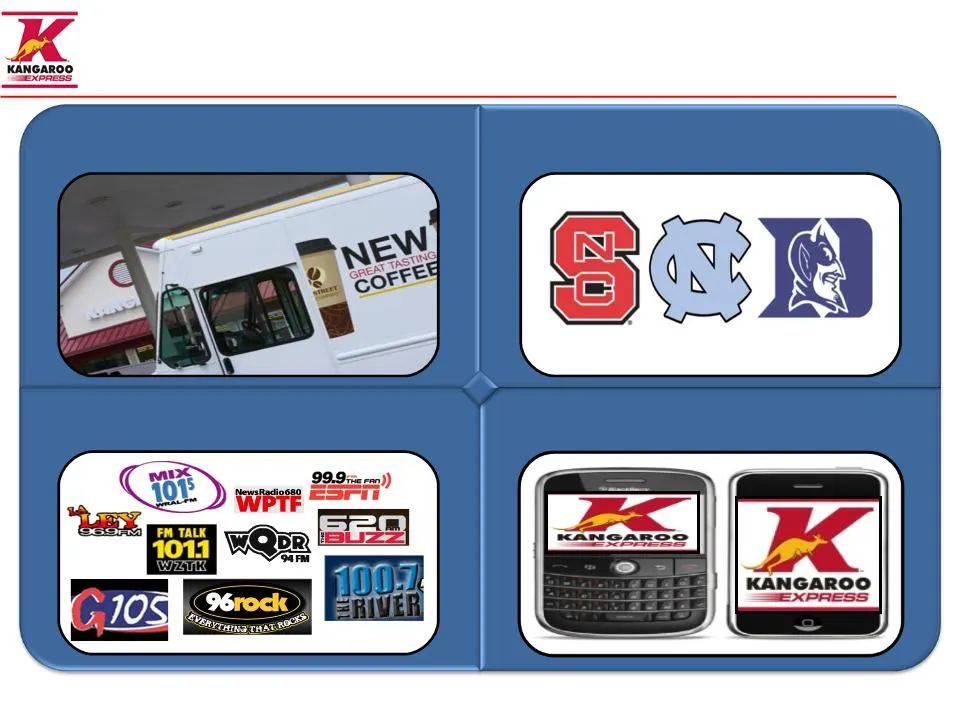
Slide 11: Getting the word out
Sampling Strategic Partnerships Digital Relationship Marketing Radio Getting the word out “Battle for Bean Street”
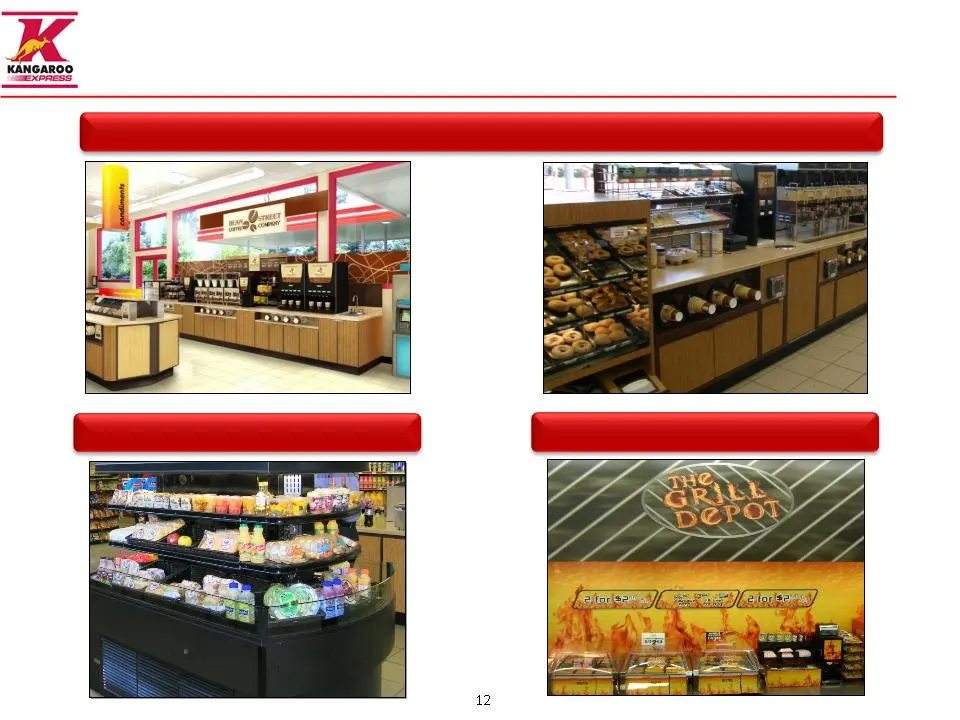
Slide 12: FRESH focus on breakfast, lunch, all day snacks
Lunch Breakfast Snacks FRESH focus on breakfast, lunch, all day snacks
Slide 13: Fast, Friendly and Clean Platform
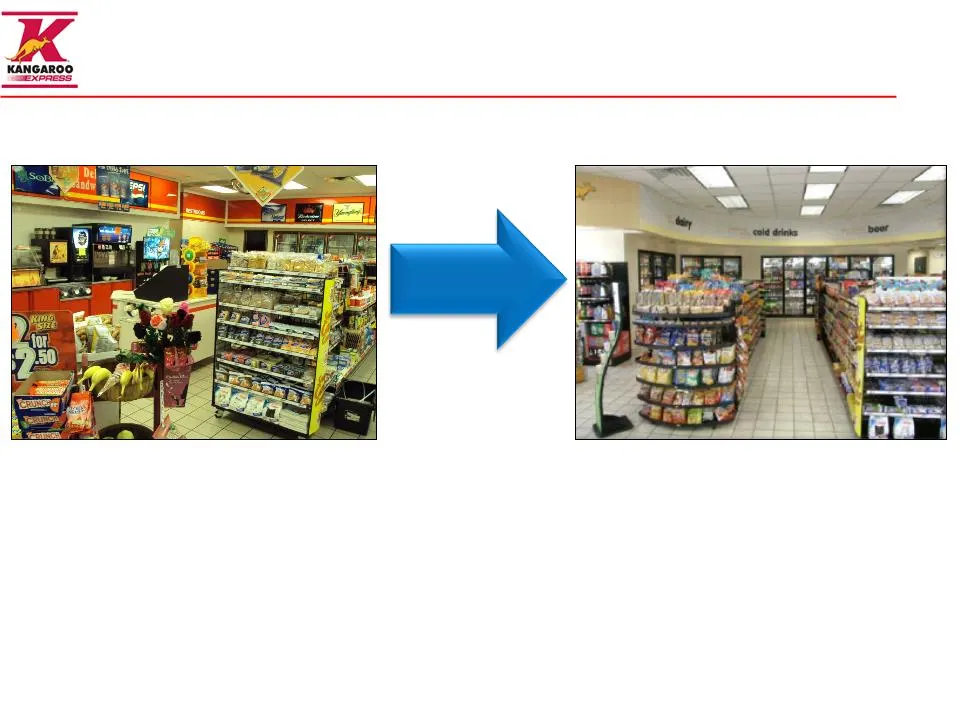
Fast, Friendly and Clean Platform
Slide 14: FRESH Program Highlights
Financials Focus Roll-out FRESH Program Highlights n Estimated $30-45K average investment per store for Fresh elements n Expect 20% cash on cash returns n Coffee is King n Breakfast, lunch and all day snack occasions n Fast, Friendly and Clean foundation n 130 stores completed by end of calendar 201
Slide 15: Systems investment to drive effectiveness and efficiency
KSS Gas Pricing Point of Sale Workforce Management Systems investment to drive effectiveness and efficiency n Site-level optimization n 10 bps = $2 million n Software fully installed across the chain as of January 11, 2011 n PCI Compliant n Promotional flexibility n Capturing transaction level detai
Slide 16: 79% of U.S. Convenience Stores are Single Stores or Small Chains
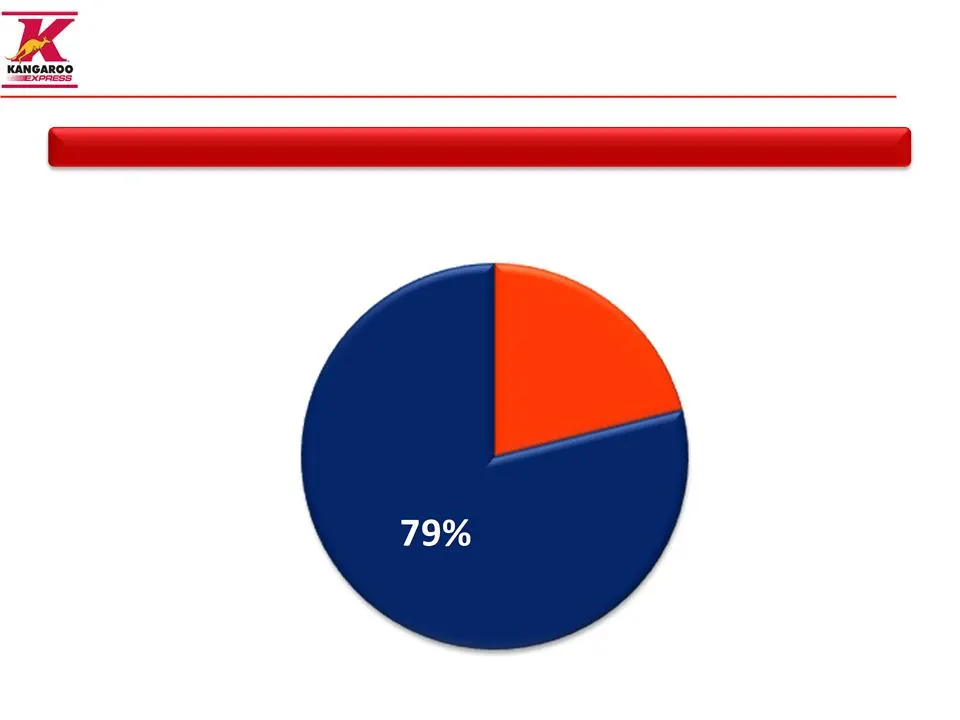
79% of U.S. Convenience Stores are Single Stores or Small Chains High degree of fragmentation presents continued consolidation opportunities 145,000 Total U.S. C-Stores _____________________ Source: U.S. Convenience December 2009 Store Count (Gas and Non-Gas) from NACS/TDLinx
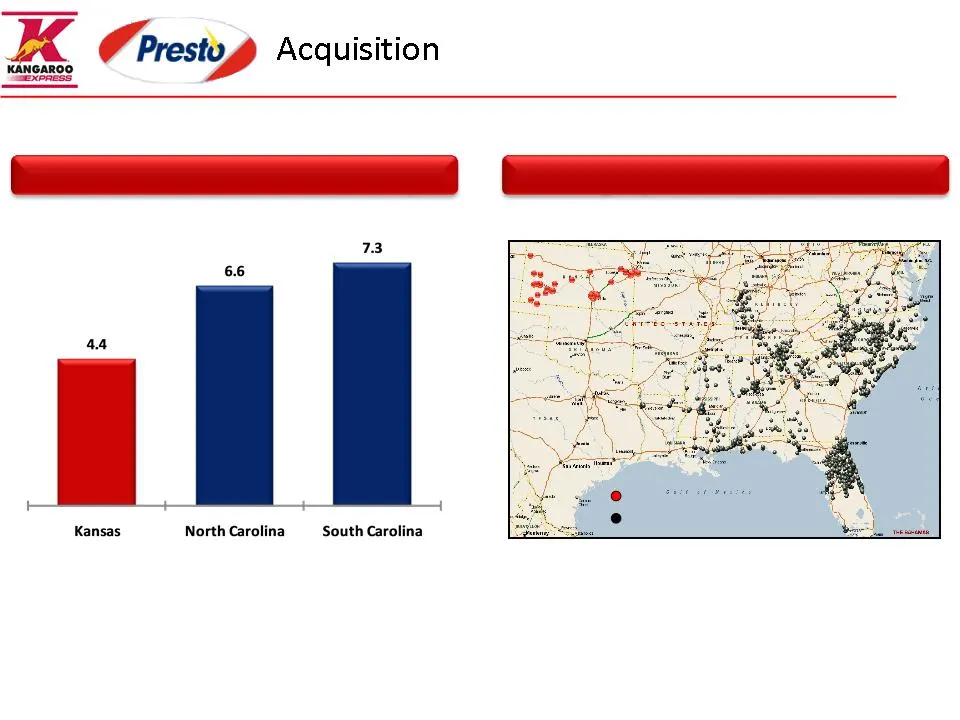
Slide 17: Low C-Store Channel Density, Geographic Diversification
Low C-Store Channel Density 1 Geographic Diversification 2 = Pantry Site = Presto Site _____________________ (1) Stores per 10,000 residents from U.S. Census Bureau 2009 population estimates and U.S. Convenience December 2009 Store Count (Gas and Non-Gas) from NACS/TDLinx (2) Map is illustrative
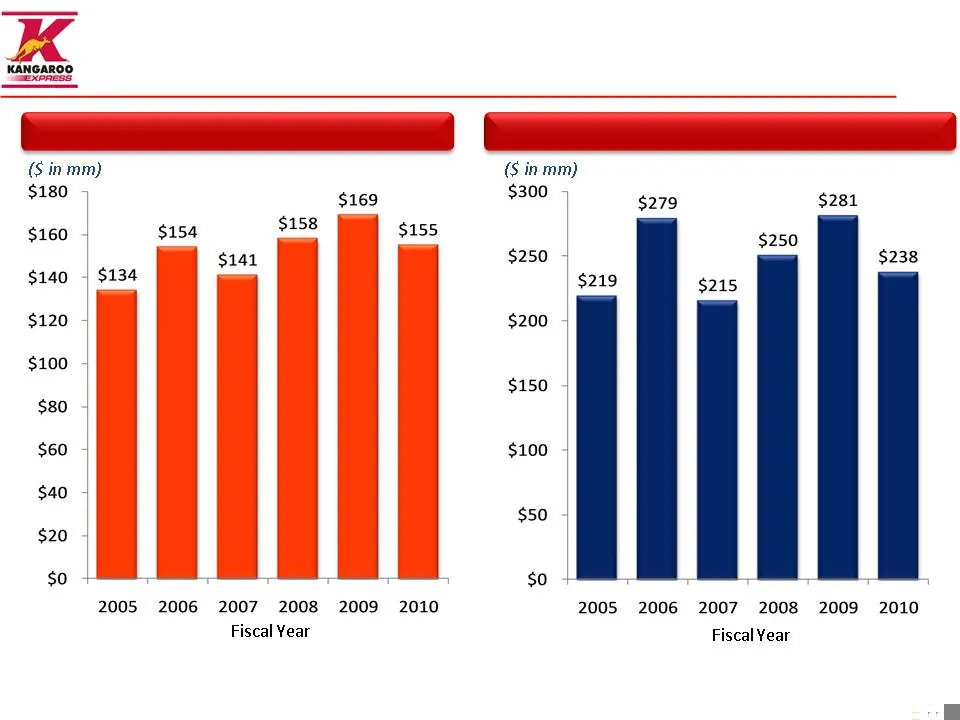
Slide 18: History of consistent cash flows & Adjusted EBITDA
Adjusted EBITDA 2 Operating Cash Flow _____________________ (1) Fiscal year 2010 included 53 weeks (2) We are no longer including lease payments we make under our lease finance obligations as a reduction in our presentation of Adjusted EBITDA. See slides 27 and 28, which include a reconciliation of
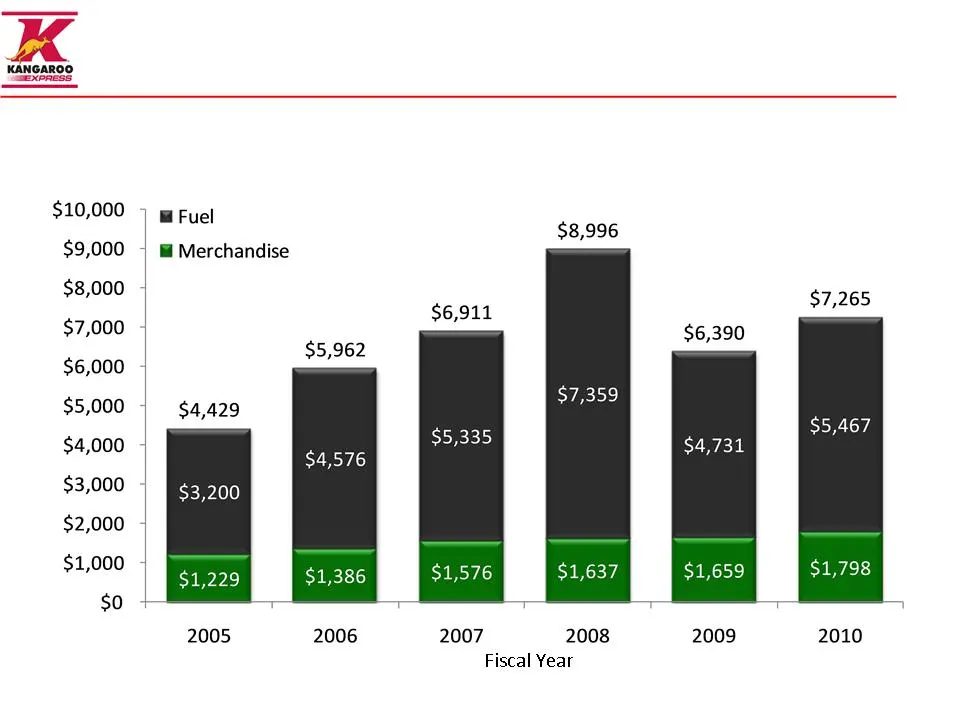
Slide 19: Fuel comprises the majority of revenue
Fuel comprises the majority of revenue Revenue Split: Merchandise vs. Fuel ($ in mm) _____________________ (1) Fiscal year 2010 included 53 weeks
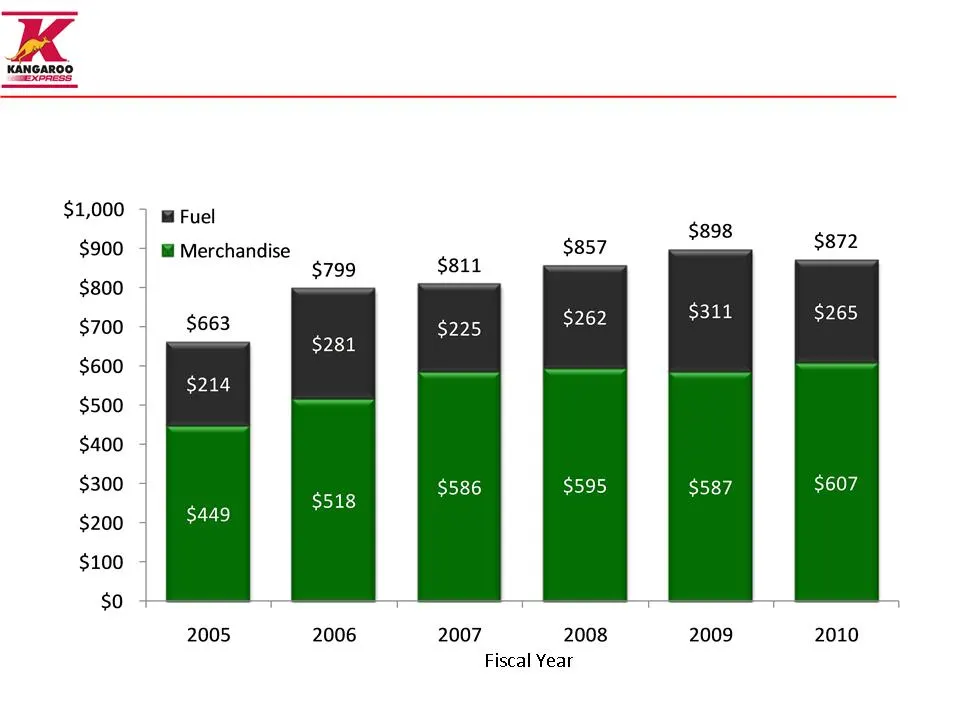
Slide 20: Gross profit is driven by merchandise
Gross profit is driven by merchandise Gross Profit Split: Merchandise vs. Fuel ($ in mm) _____________________ (1) Fiscal year 2010 is 53 weeks
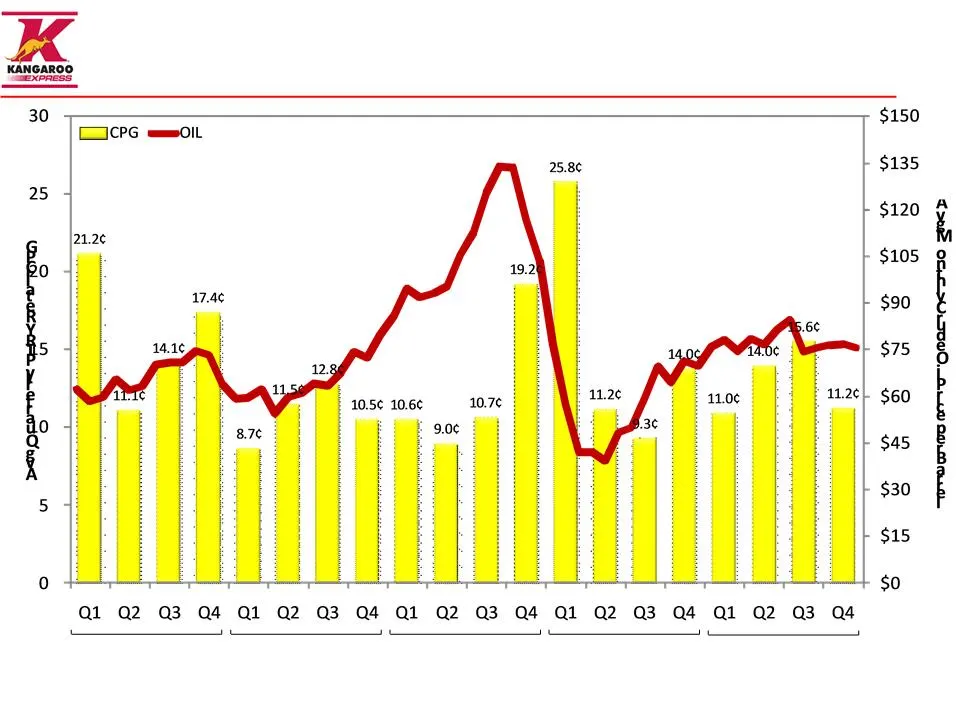
Slide 21: Oil price changes drive volatility in quarterly retail gasoline margins
Oil price changes drive volatility in quarterly retail gasoline margins _____________________ Source: Energy Information Administration. Data represents daily average futures contract price per barrel of light sweet crude (contract 1) and CPG is net of credit card fees and repairs and maintenance FY
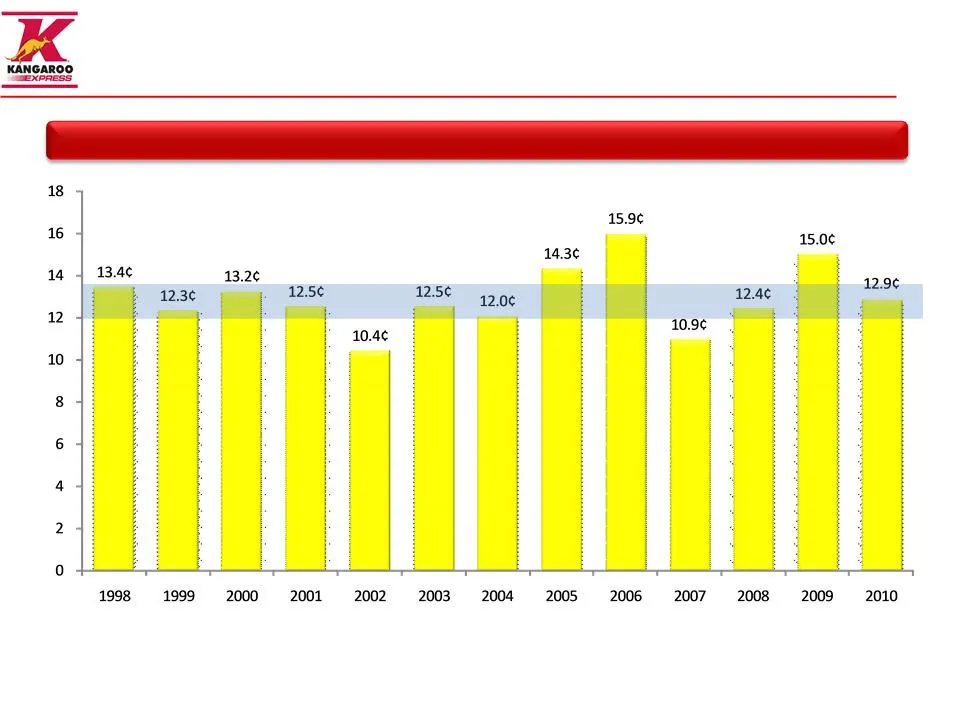
Slide 22: Annual Net CPG Margins Typically Range from 12.0¢ to 13.5¢
Annual Net CPG Margins Typically Range from 12.0¢ to 13.5¢ Annual CPG tends to remain relatively stable Fiscal Year _____________________ Note: Shaded area represents average historical CPG range and CPG is net of credit card fees and repairs and maintenance. ¢ ¢ ¢ ¢ ¢ ¢ ¢ ¢ ¢ ¢
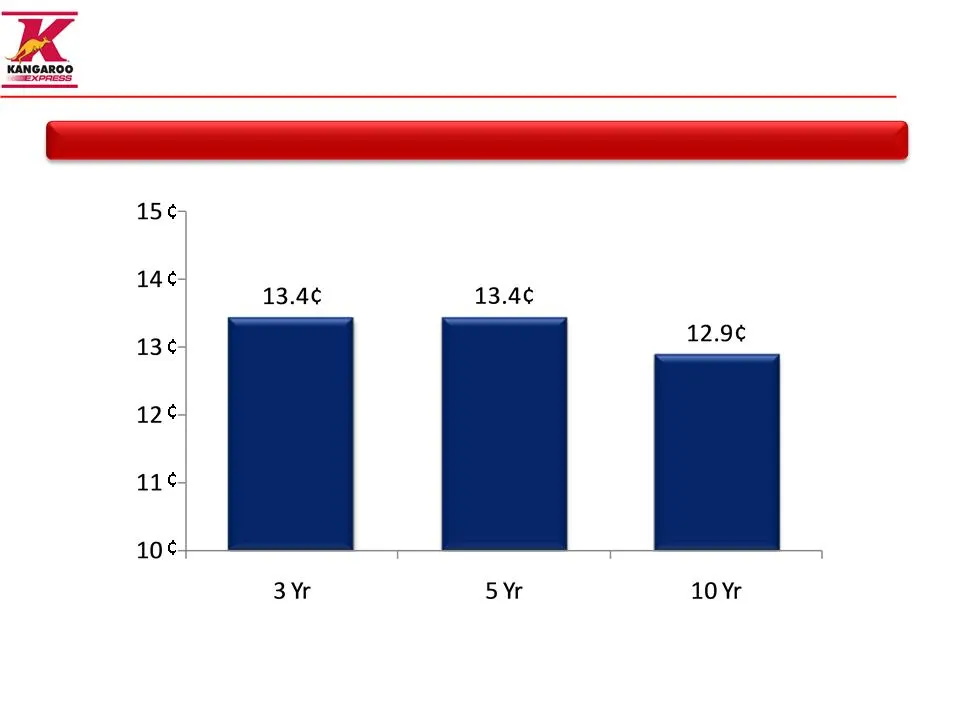
Slide 23: Historical CPG Averages
Historical CPG Averages Historical averages reinforce the stability _____________________ Note: Historical averages are non-weighted averages of each fiscal year. CPG is net of credit card fees and repairs and maintenance
Slide 24: Financial Flexibility
Financial Flexibility n Meaningful liquidity } $201 million in cash-on-hand } $225 million revolver - $0 drawn, approximately $106 million available after LOCs n Long-term debt profile; earliest maturity is the convertible debt in November 2012 n Covenant-light bank facility } 6.25x Adj. Net Debt /
Slide 25: Key Strategies
Key Strategies n Improve comp sales and merchandise gross margin with focus on Coffee and Meals & Snacks n Invest in technology to drive effectiveness and efficiency n 2% to 4% annual store growth target n Accelerate EBITDA and cash flow growth
Slide 26: Appendix
Appendix
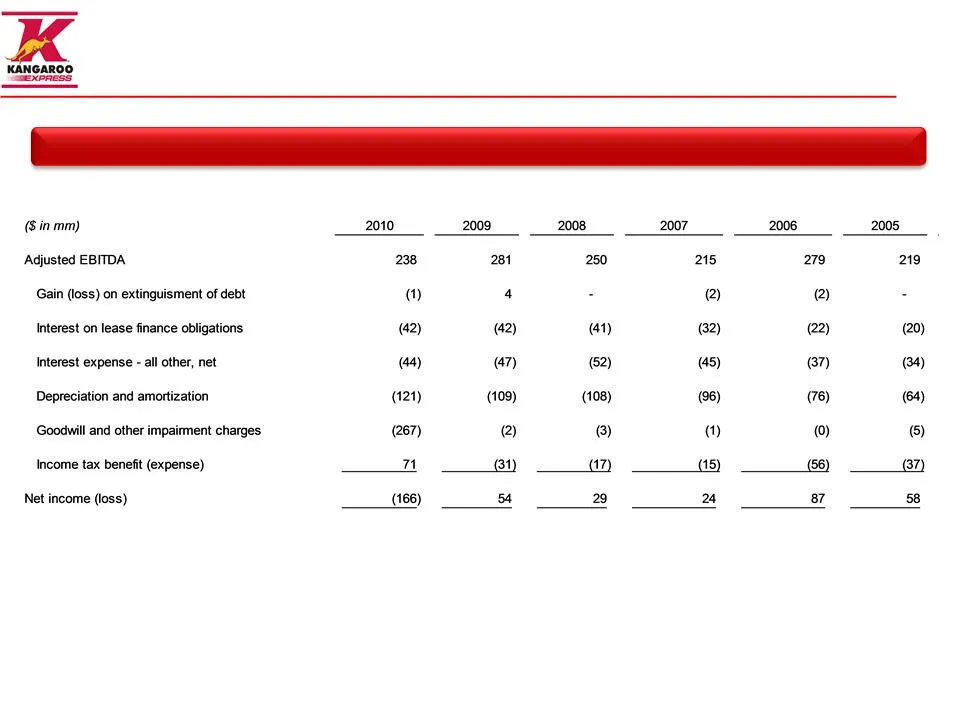
Slide 27: Adjusted EBITDA Reconciled to Net Income/(Loss)
Adjusted EBITDA Reconciled to Net Income/(Loss) Reconciliation of Non-GAAP Measures
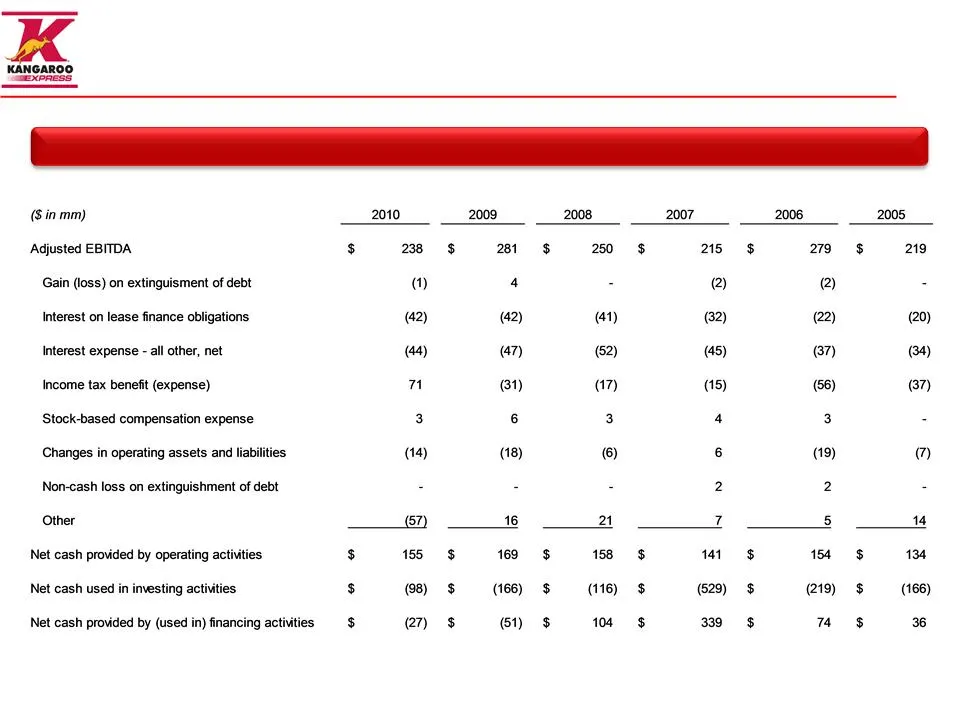
Slide 28: Adjusted EBITDA Reconciled to Cash Flows
Adjusted EBITDA Reconciled to Cash Flows Reconciliation of Non-GAAP Measures
Source: SEC EDGAR · 8-K filed Jan 12, 2011
More decks from The Pantry Inc
 Q4 FY2014 Earnings Presentation25 slides · Dec 9, 2014
 2014 Convenience Store Forum (Wells Fargo Securities)21 slides · Oct 7, 2014
 Q3 FY2014 Earnings Presentation25 slides · Jul 30, 2014
 Q2 FY2014 Earnings Presentation24 slides · May 1, 2014
 Proxy Contest (February 2014)44 slides · Feb 20, 2014
 Proxy Contest (February 2014)49 slides · Feb 19, 2014