Transatlantic — Merger or Acquisition (September 2011)
21 slides from Transatlantic's merger presentation, Sep 19, 2011
Slide 1: Investor Presentation September 2011
Investor Presentation September 2011
Slide 2: Cautionary Note Regarding Forward-Looking Statements
Cautionary Note Regarding Forward-Looking Statements This communication contains forward-looking statements that involve a number of risks and uncertainties. Statements that are not historical facts, including statements about our beliefs and expectations, are forward-looking statements. Such statem
Slide 3: Key Discussion Issues / Questions
Key Discussion Issues / Questions Our assessment of current industry dynamics and their impact on Transatlantic Our strategic review process National Indemnity offer Validus proposal Our path forward 2
Slide 4: Who We Are
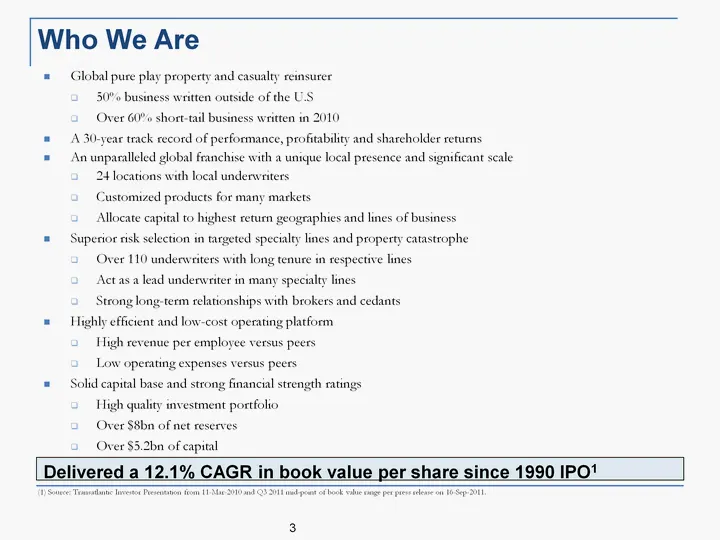
Who We Are 3 Global pure play property and casualty reinsurer 50% business written outside of the U.S Over 60% short-tail business written in 2010 A 30-year track record of performance, profitability and shareholder returns An unparalleled global franchise with a unique local presence and significan
Slide 5: We Have Grown Our BVPS at 12% Annualized Over Multiple Industry Cycles
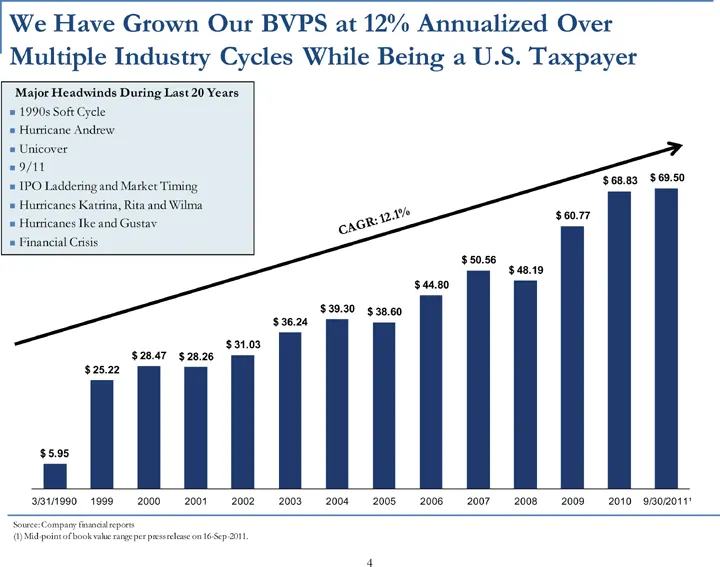
We Have Grown Our BVPS at 12% Annualized Over Multiple Industry Cycles While Being a U.S. Taxpayer 4 CAGR: 12.1% Source: Company financial reports (1) Mid-point of book value range per press release on 16-Sep-2011. Major Headwinds During Last 20 Years 1990s Soft Cycle Hurricane Andrew Unicover 9/11
Slide 6: Industry Landscape
Industry Landscape 5 Industry Dynamics: Primary insurance writers are buying less reinsurance due to higher retained capital, better information, and stronger underwriting results Soft pricing environment Low interest rate environment Recent regulatory requirements have increased the need for local
Slide 7: Summary of P&C Industry Performance
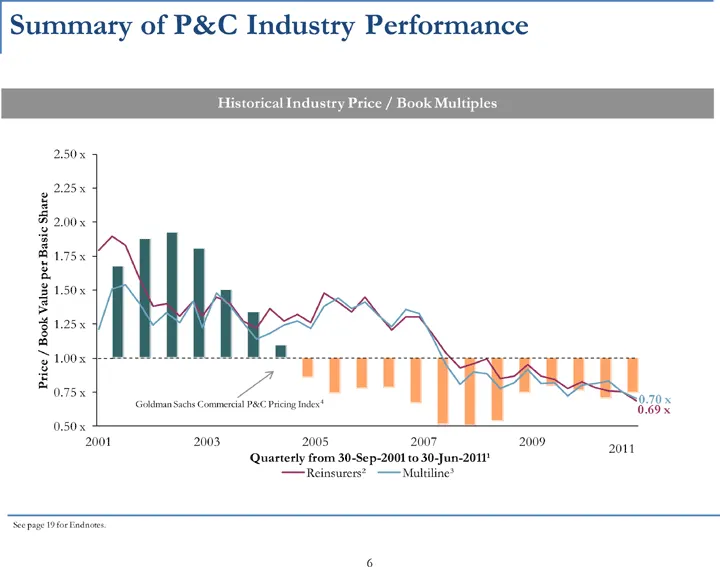
Summary of P&C Industry Performance 6 Historical Industry Price / Book Multiples Goldman Sachs Commercial P&C Pricing Index4 See page 19 for Endnotes.
Slide 8: Our Strategic Objectives to Compete Most Effectively Over Long-Term
Our Strategic Objectives to Compete Most Effectively Over Long-Term 7 Majority owned by AIG 1990-2009 Barriers to re-domicile due to AIG's U.S. domicile Could not expand to primary insurance operations due to potential conflicts with AIG's businesses Maintained legacy branch system Emerged as a full
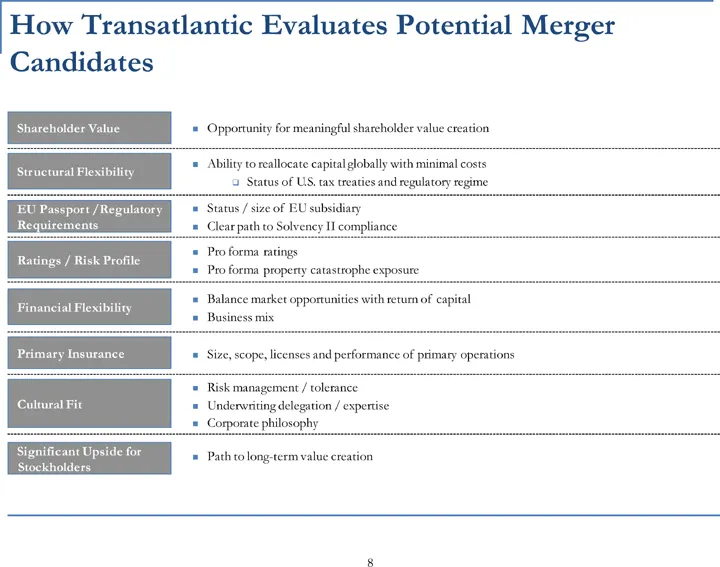
Slide 9: How Transatlantic Evaluates Potential Merger Candidates
Opportunity for meaningful shareholder value creation Ability to reallocate capital globally with minimal costs Status of U.S. tax treaties and regulatory regime Status / size of EU subsidiary Clear path to Solvency II compliance Pro forma ratings Pro forma property catastrophe exposure Balance mark
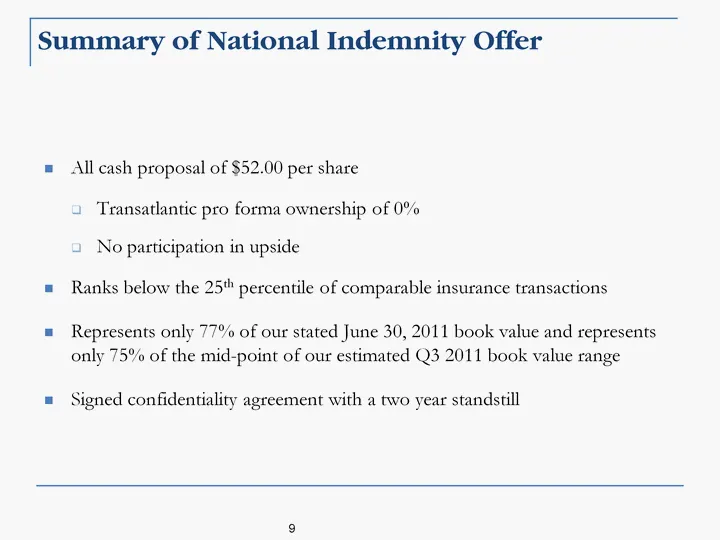
Slide 10: Summary of National Indemnity Offer
Summary of National Indemnity Offer 9 All cash proposal of $52.00 per share Transatlantic pro forma ownership of 0% No participation in upside Ranks below the 25th percentile of comparable insurance transactions Represents only 77% of our stated June 30, 2011 book value and represents only 75% of th
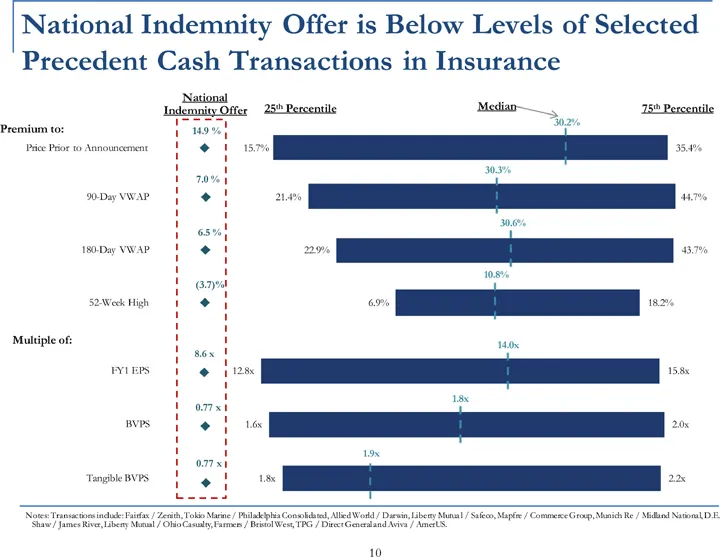
Slide 11: National Indemnity Offer is Below Levels of Selected Precedent Cash Transactions in Insurance
National Indemnity Offer is Below Levels of Selected Precedent Cash Transactions in Insurance 10 Notes: Transactions include: Fairfax / Zenith, Tokio Marine / Philadelphia Consolidated, Allied World / Darwin, Liberty Mutual / Safeco, Mapfre / Commerce Group, Munich Re / Midland National, D.E. Shaw /
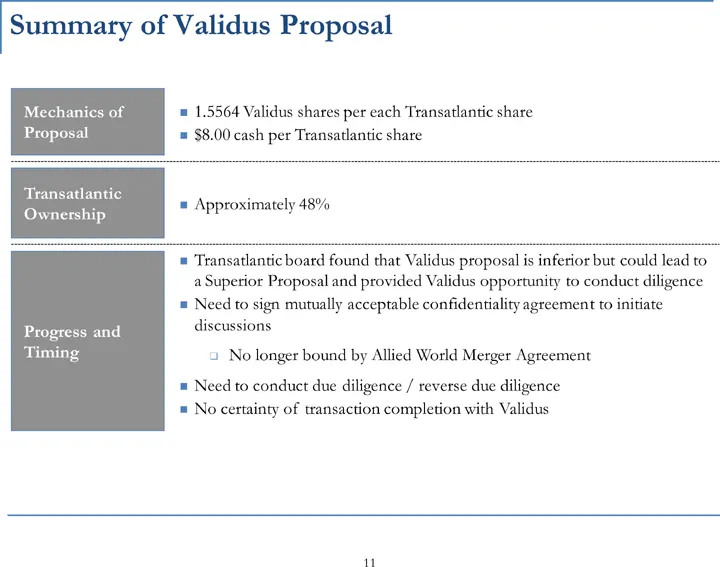
Slide 12: Summary of Validus Proposal
Summary of Validus Proposal 11 1.5564 Validus shares per each Transatlantic share $8.00 cash per Transatlantic share Approximately 48% Transatlantic board found that Validus proposal is inferior but could lead to a Superior Proposal and provided Validus opportunity to conduct diligence Need to sign
Slide 13: Validus Proposal is Not Acceptable on an Absolute Basis
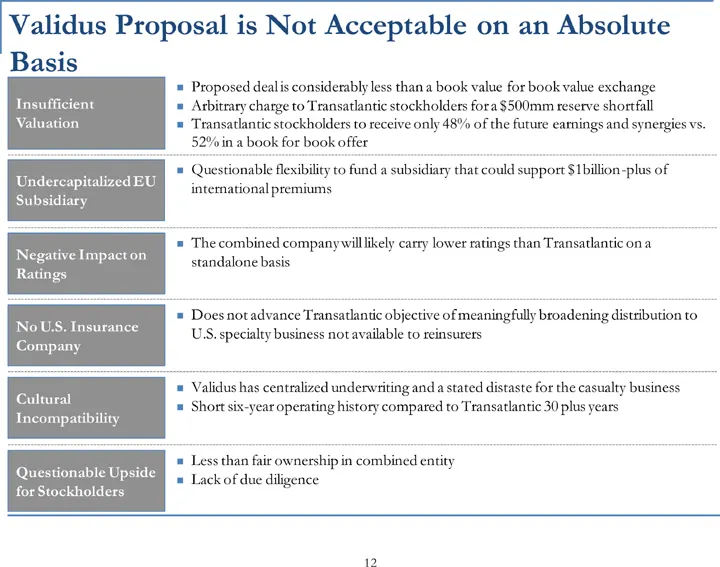
Validus Proposal is Not Acceptable on an Absolute Basis 12 Does not advance Transatlantic objective of meaningfully broadening distribution to U.S. specialty business not available to reinsurers Questionable flexibility to fund a subsidiary that could support $1billion-plus of international premiums
Slide 14: Less Than Book Value-for-Book Value Exchange Ratio
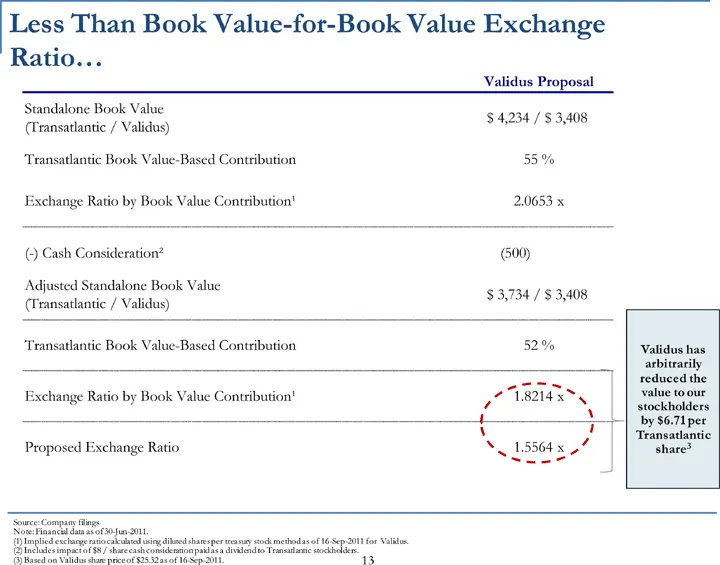
Less Than Book Value-for-Book Value Exchange Ratio... 13 Source: Company filings Note: Financial data as of 30-Jun-2011. (1) Implied exchange ratio calculated using diluted shares per treasury stock method as of 16-Sep-2011 for Validus. (2) Includes impact of $8 / share cash consideration paid as a
Slide 15: Validus Proposal is Not Acceptable on Relative Basis
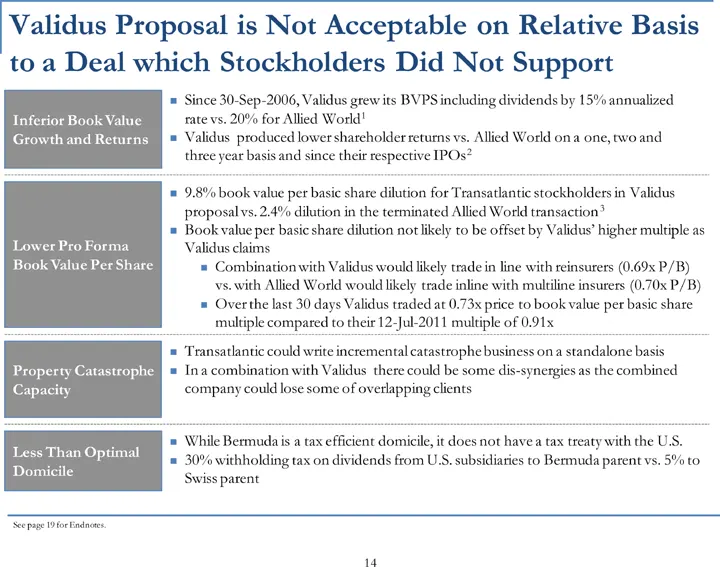
Validus Proposal is Not Acceptable on Relative Basis to a Deal which Stockholders Did Not Support 14 While Bermuda is a tax efficient domicile, it does not have a tax treaty with the U.S. 30% withholding tax on dividends from U.S. subsidiaries to Bermuda parent vs. 5% to Swiss parent 9.8% book value
Slide 16: We Are Taking Specific Actions in Our Path Forward
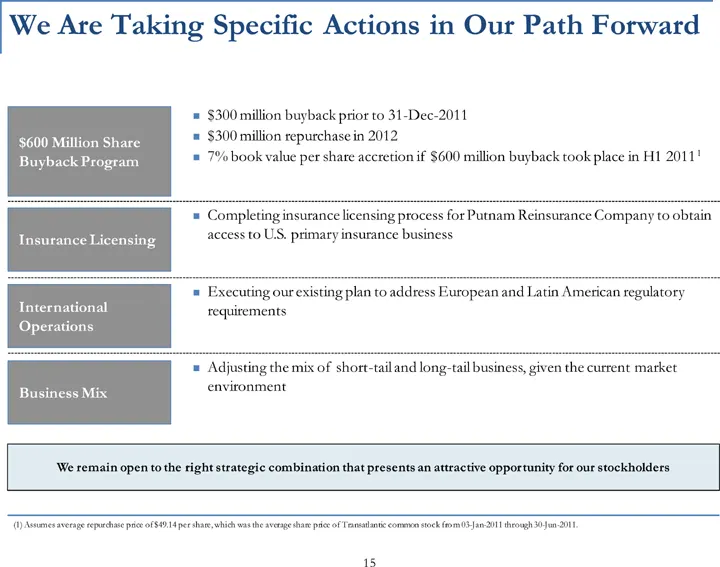
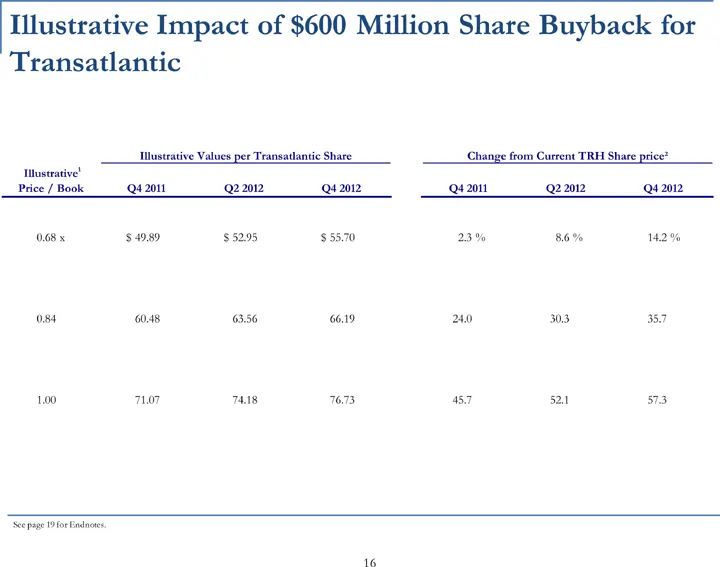
We Are Taking Specific Actions in Our Path Forward 15 $300 million buyback prior to 31-Dec-2011 $300 million repurchase in 2012 7% book value per share accretion if $600 million buyback took place in H1 20111 Completing insurance licensing process for Putnam Reinsurance Company to obtain access to U
Slide 17: Illustrative Impact of $600 Million Share Buyback for Transatlantic
Illustrative Impact of $600 Million Share Buyback for Transatlantic 16 See page 19 for Endnotes. 1
Slide 18: Preliminary Third Quarter Financial Results
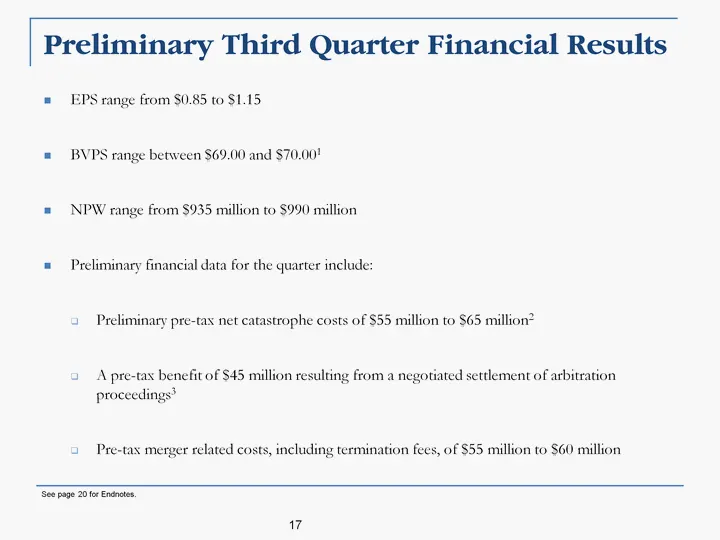
Preliminary Third Quarter Financial Results 17 EPS range from $0.85 to $1.15 BVPS range between $69.00 and $70.001 NPW range from $935 million to $990 million Preliminary financial data for the quarter include: Preliminary pre-tax net catastrophe costs of $55 million to $65 million2 A pre-tax benefi
Slide 19: Conclusions
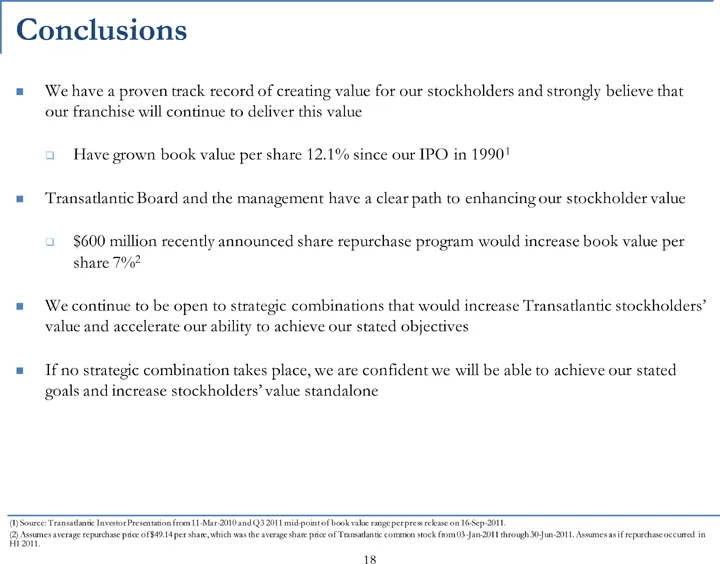
Conclusions 18 We have a proven track record of creating value for our stockholders and strongly believe that our franchise will continue to deliver this value Have grown book value per share 12.1% since our IPO in 19901 Transatlantic Board and the management have a clear path to enhancing our stock
Slide 20: Page Endnotes
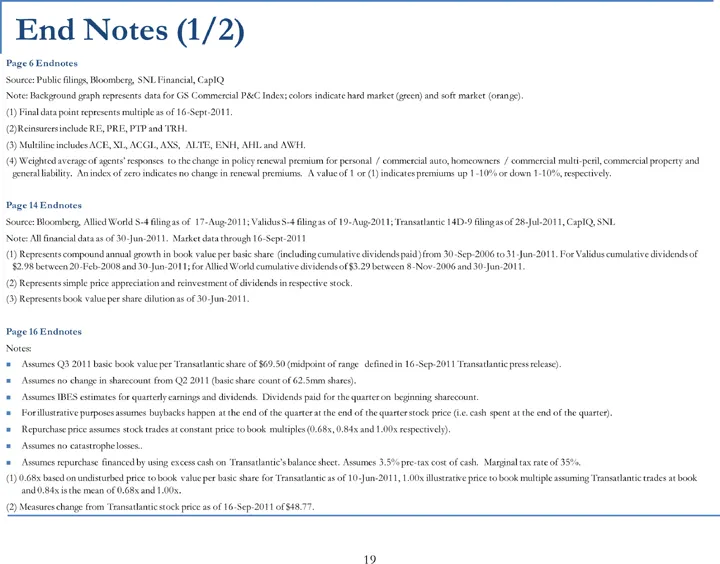
Page 6 Endnotes Source: Public filings, Bloomberg, SNL Financial, CapIQ Note: Background graph represents data for GS Commercial P&C Index; colors indicate hard market (green) and soft market (orange). (1) Final data point represents multiple as of 16-Sept-2011. (2)Reinsurers include RE, PRE, PTP an
Slide 21: Page Endnotes
Page 17 Endnotes Note: Financial data includes estimates using information known at this time. Such financial data do not include any estimate for foreign exchange movement, changes in fair value or other events that could materially affect earnings or book value per share that occur or become known
Source: SEC EDGAR · 8-K filed Sep 19, 2011
More decks from Transatlantic Holdings Inc
 Q3 2012 Earnings Presentation10 slides · Nov 2, 2012
 Merger or Acquisition (December 2011)40 slides · Dec 1, 2011
 Merger or Acquisition (December 2011)39 slides · Dec 1, 2011
 Merger or Acquisition (November 2011)11 slides · Nov 29, 2011
 Merger or Acquisition (November 2011)28 slides · Nov 10, 2011
 Merger or Acquisition (November 2011)41 slides · Nov 4, 2011