Dresser-Rand — Natixis 5th Annual Transatlantic Oil Services Conference (September 2008)
32 slides from Dresser-Rand's conference presentation, Sep 19, 2008
Slide 1: Natixis 5th Annual Transatlantic Oil Services Conference
Natixis 5 th Annual Transatlantic Oil Services Conference Vince Volpe, President & CEO September 22, 2008
Slide 2: Disclosure
Disclosure The Private Securities Litigation Reform Act of 1995 provides a “safe harbor” for certain forward-looking statements so long as such information is identified as forward-looking and is accompanied by meaningful cautionary statements identifying important factors that could cause actual re
Slide 3: Dresser-Rand Investment Highlights
Dresser-Rand Investment Highlights New Units: Strong secular growth / late cycle play Aftermarket: Dependable, non-cyclical growth Sustainable competitive advantages Strong business model Opportunity to amplify growth via acquisitions using free cash flow Attractive Stock on Cash Flow Basis
Slide 4: Dresser-Rand is a Global Supplier of Energy Solutions to a Growing Market
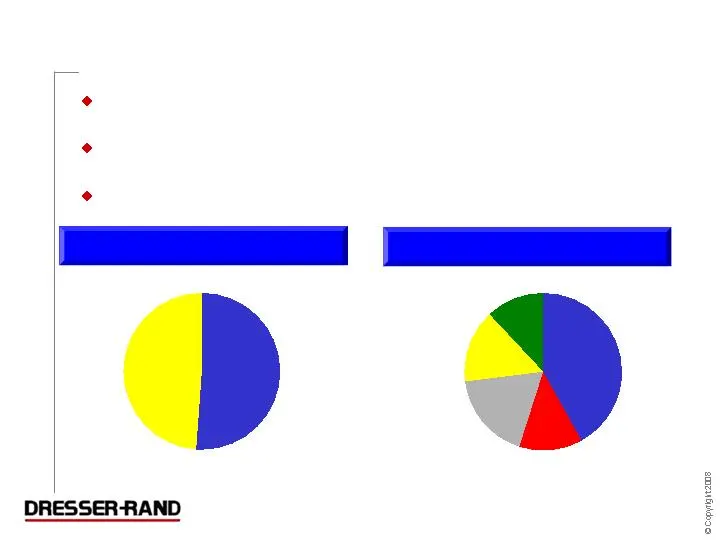
51% 2007 Sales By Business Segment 2007 Revenues By Destination 13% 42% 12% Dresser-Rand is a Global Supplier of Energy Solutions to a Growing Market Over 90% of bookings for the twelve months ended 6/30/08 of $2.2 billion from oil and gas infrastructure spending A leading provider of rotating equip
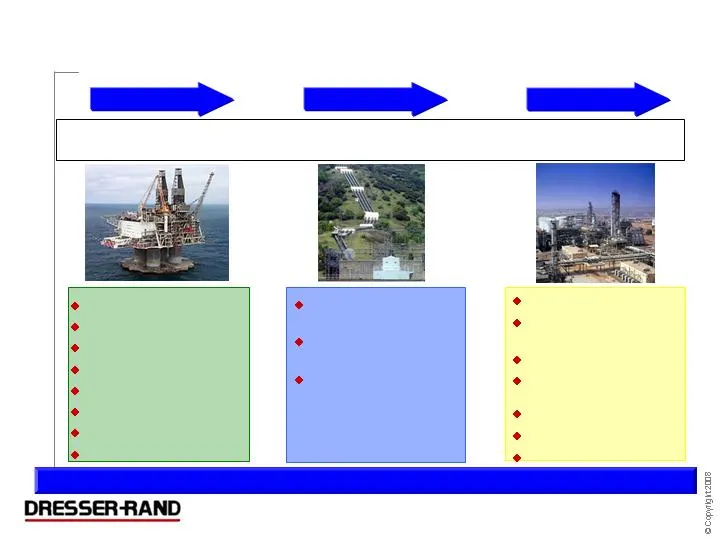
Slide 5: We Serve the Entire Energy Value Chain
Upstream Midstream Downstream We Serve the Entire Energy Value Chain Reinjection Gas lift Gathering Export / sales gas Power generation Fuel gas LNG Gas-to-Liquid Gas pipeline transmission Gas storage / withdrawal Gas processing Hydrocracking Fluid Catalytic Cracking Power generation Hydro treating
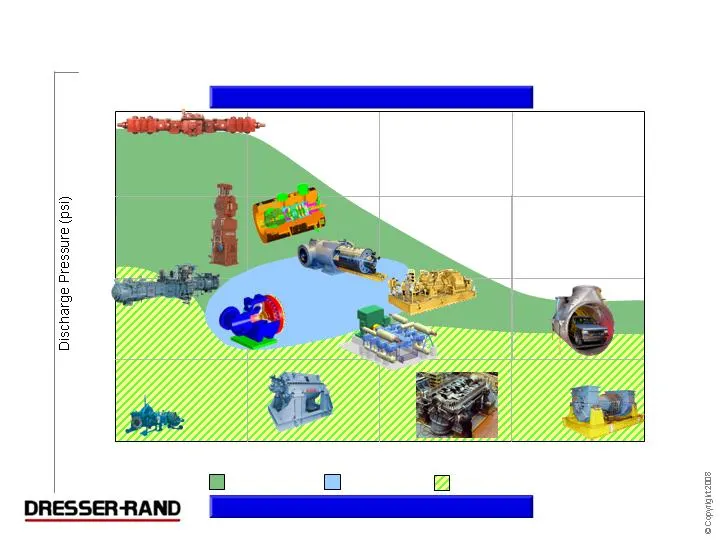
Slide 6: Broadest Rotating Equipment Offering One Stop for Rotating Equipment Solutions
Broadest Rotating Equipment Offering One Stop for Rotating Equipment Solutions Upstream Midstream Downstream Inlet Volume (cfm) 5,000 50,000 500,000 1,500 15,000 75,000 Gas Reinjection LNG Refining Hydrogen Ethylene GTL CNG Axial DATUM Axially Split Pipeline Booster Process & Separable Recip PDI Boi
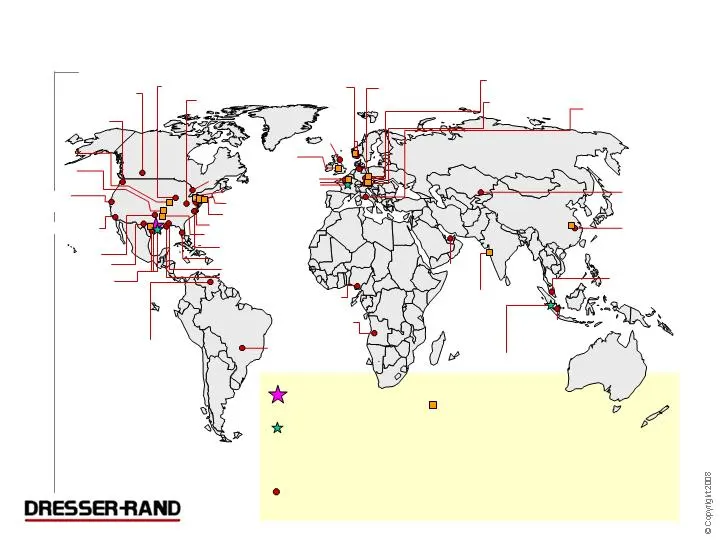
Slide 7: Dresser-Rand's Global Presence
Dresser-Rand’s Global Presence Shanghai, PRC Kemanan, Terengganu, Malaysia Cilegon, Banten, Indonesia Naroda, India Kongsberg, Norway Spijkenisse, The Netherlands Oberhausen, Germany Peterborough Cambridgeshire U.K. Le Havre, France Genoa, Italy Campinas - SP, Brazil Maracaibo, Edo. Zulia Venezuela
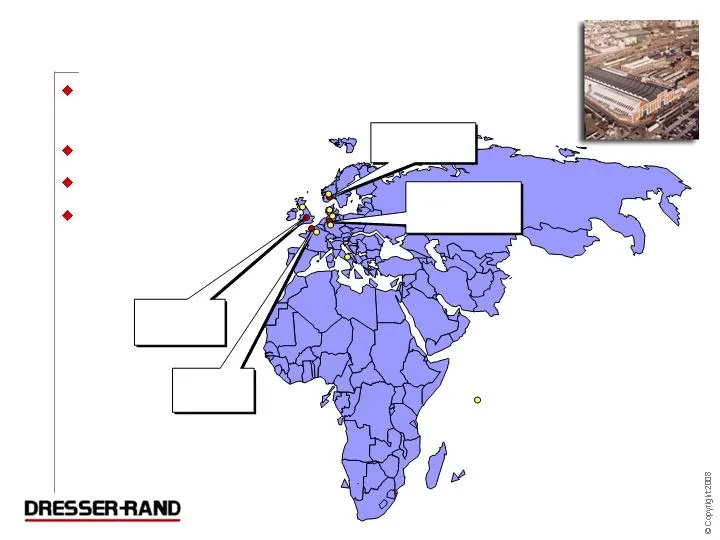
Slide 8: Dresser-Rand's European Presence
Five manufacturing operations Seven service centers 1,300 employees Approximately 40% of total company revenues Dresser-Rand’s European Presence LE HAVRE France KONGSBERG Norway OBERHAUSEN & BIELEFELD Germany Peterbourgh UK Denotes Service Center
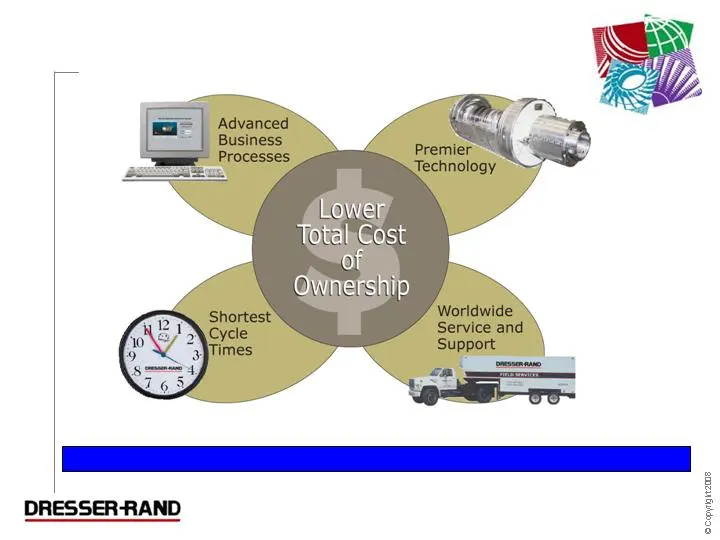
Slide 9: Dresser-Rand's Value Proposition
Dresser-Rand’s Value Proposition Makes our Clients More Competitive in their Markets
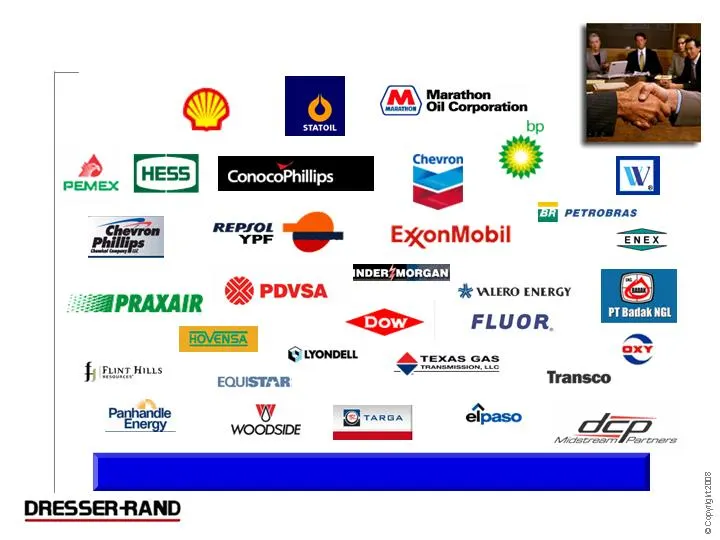
Slide 10: Most Client Alliances in Industry
Most Client Alliances in Industry ~ 50 Validation of Dresser-Rand’s Value Proposition
Slide 11: Dresser-Rand
: DRESSER-RAND
Slide 12: New Units Benefiting from Strong Secular Growth
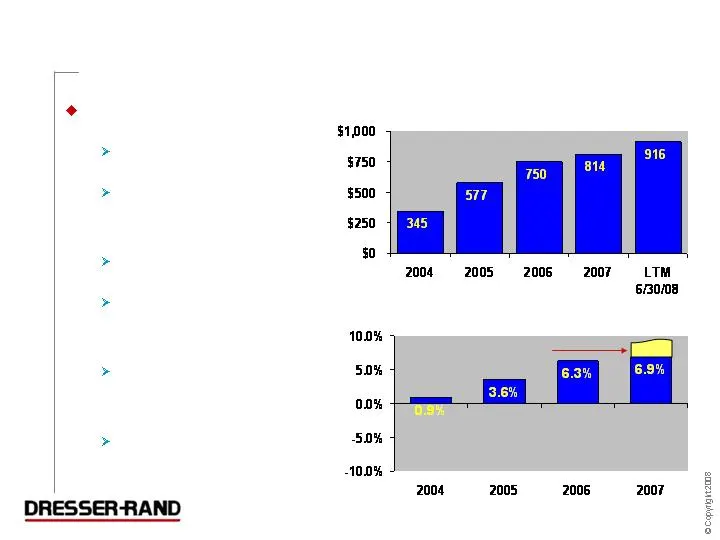
New Units Benefiting from Strong Secular Growth Key Initiatives: Cost Reduction Productivity Improvements Price Increases Technology Leadership New Innovative Products Cycle Times New Unit Margins ($ in Millions) Pro forma 9.0% adjusted for unusual items New Unit Sales ($ in Millions)
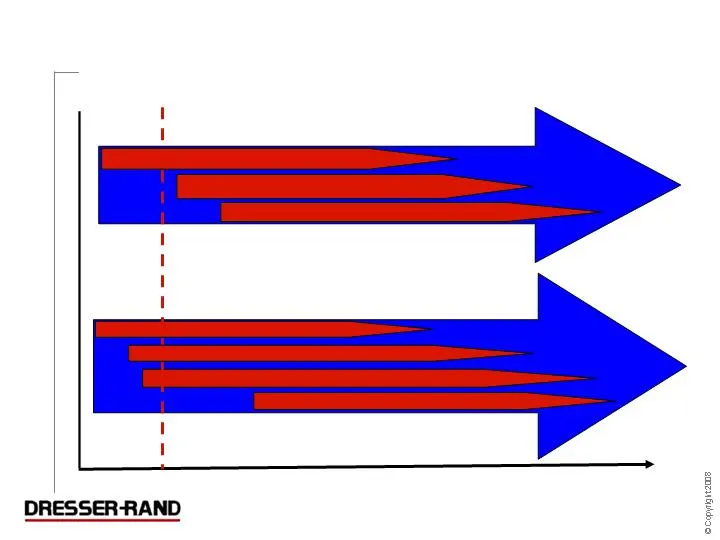
Slide 13: Dresser-Rand – A Late Cycle Play
Dresser-Rand – A Late Cycle Play Time Cycle FPSO Compact Compression (Topside ICS) Subsea Compression (ICS) Refining CO2 Sequestration Compressed Air Energy Storage (CAES) Downstream Upstream LNG
Slide 14: Recent Major New Unit Bookings Reflects Continuing Strong Activity
Recent Major New Unit Bookings Reflects Continuing Strong Activity Across All Markets and Regions (Bookings 6/30/07 to 9/08/08) 3 Offshore Platforms $78 6 Refineries $145 (Abu Daibi, Malaysia & Thailand) (3 US, 2 Spain & 1 India ) 3 FPSO's (2 Angloa; 1 Norh Sea) $85 Methanol (Oman) $15 Gas Gathering
Slide 15: Compressed Air Energy Storage (CAES)
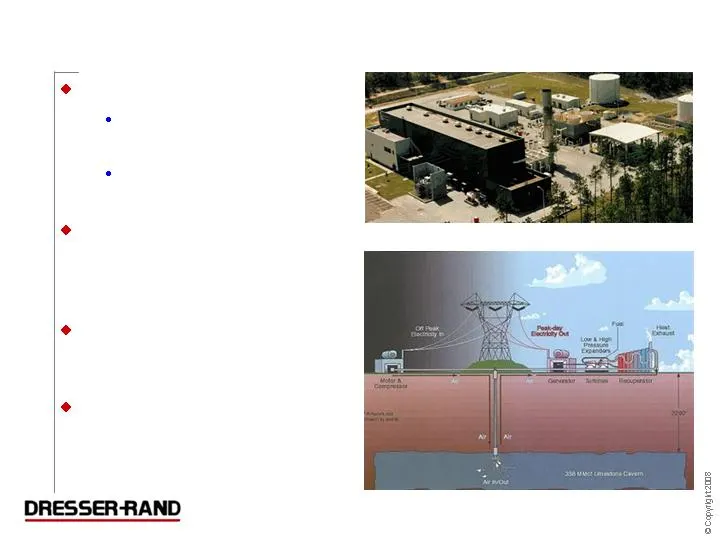
Compressed Air Energy Storage (CAES) Concept: Compress air into cavern at night – use energy Expand air during day – produce energy One plant currently exists in North America - 110 MW unit built in McIntosh, Alabama in 1991 (Built by D-R) More than 15 projects being contemplated over next 5 to 10 y
Slide 16: Liquefied Natural Gas (LNG)
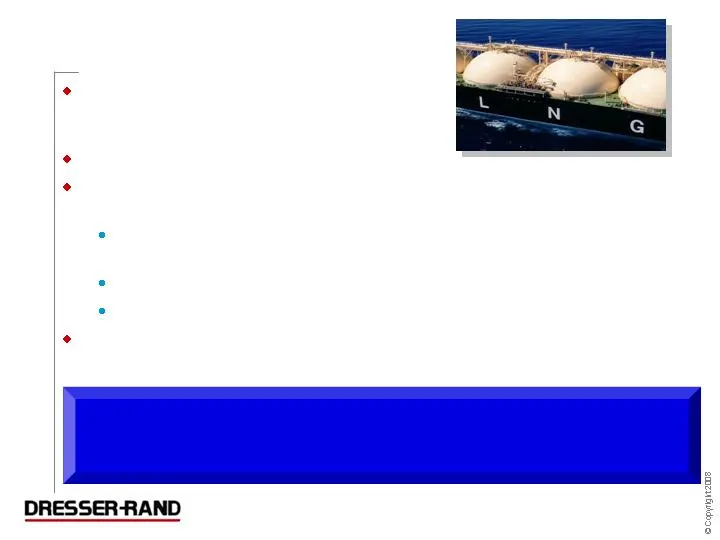
Liquefied Natural Gas (LNG) Worldwide production estimated at ~ 225 MTPA and 25% of it is performed with D-R compressors on liquefaction LNG expected to grow at approximately 10% per year for next 10 years Floating LNG is an emerging market to monetize the stranded gas from small to medium size gas
Slide 17: Floating Production, Storage & Offloading (FPSO) Vessels
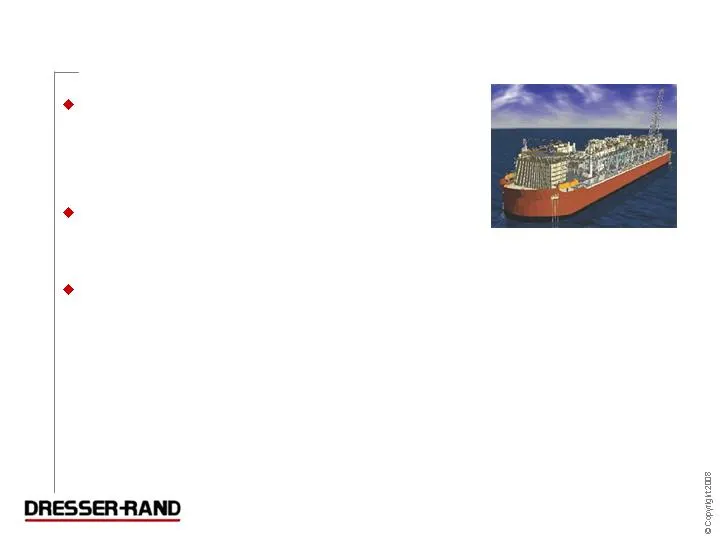
Floating Production, Storage & Offloading (FPSO) Vessels Industry sources estimate that there are over 100 FPSO projects planned over the next 5 years Many of those projects are earmarked for Asia, West Africa and Latin America Opportunity for DRC is approximately $200,000 of equipment per one milli
Slide 18: Refining
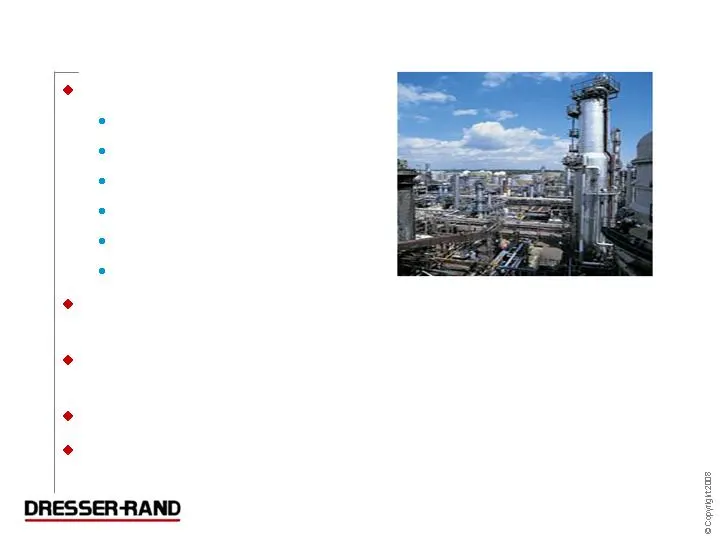
Refining Major Market Drivers Environmental Compliance Capacity Expansion Asset Utilization Energy Conservation Increased Demand (WW) Difficult Crudes In July 2008, the IEA reported that an anticipated 8.8 mb/d of crude distillation capacity will be added to the refinery system by 2013 New capacity
Slide 19: Delivering a Portfolio of Technologies – Today and Tomorrow
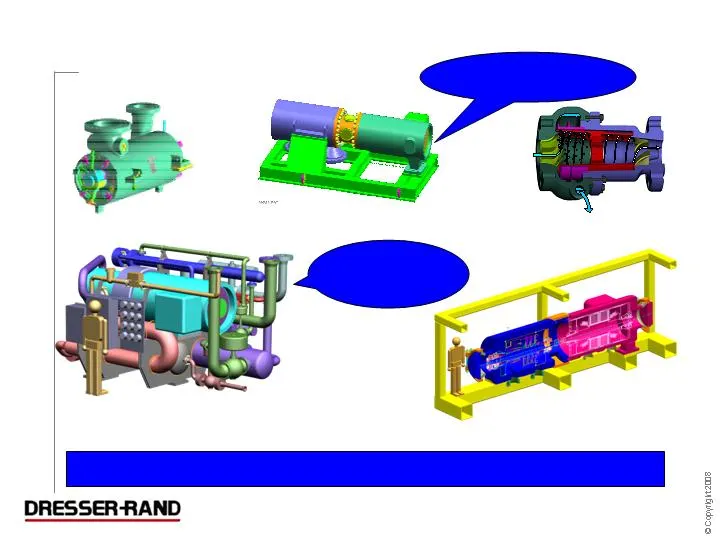
Delivering a Portfolio of Technologies – Today and Tomorrow TOPSIDE ICS Petrobras 1 st Order Deliver 4Q08 U.S. Pipeline Installation Delivered 2Q08 Separator / Compressor Differentiates DRC as “Only” One In-Class DATUM DATUM C MULTI-STAGE SEPARATOR TECHNOLOGIES SUBSEA ICS
Slide 20: Program: ICS
Program: ICS Testing and 4Q08 delivery Production platform service Accelerated marketing Future top-side orders Subsea integration All Fields with Depleting Reservoir Pressures are Candidates for ICS
Slide 21: Dresser-Rand
: DRESSER-RAND
Slide 22: Aftermarket Objective is to Grow Revenues
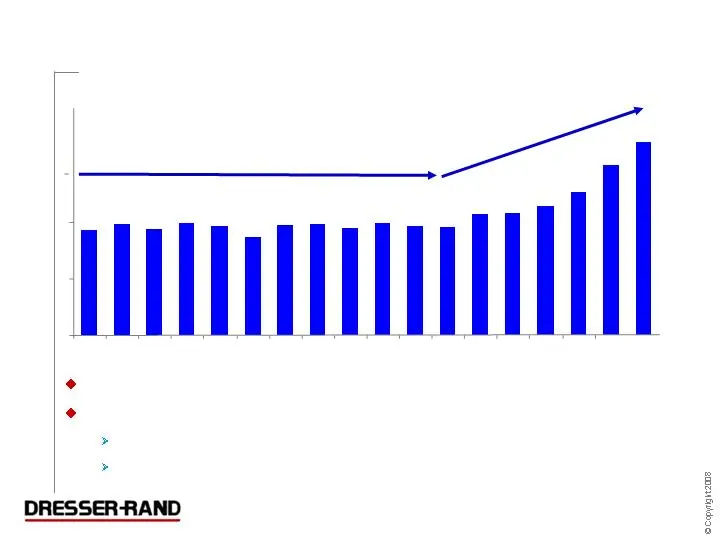
Aftermarket Objective is to Grow Revenues ($ in Millions) Provides recurring, high-margin revenue Largest installed base – approximately 95,000 units worldwide Built through organic sales and acquisitions - difficult to duplicate 30-year service life of units 0.4% CAGR 10.0% CAGR ’90 ’91 ’92 ’93 ’94
Slide 23: Aftermarket Initiatives Drive Revenue Growth
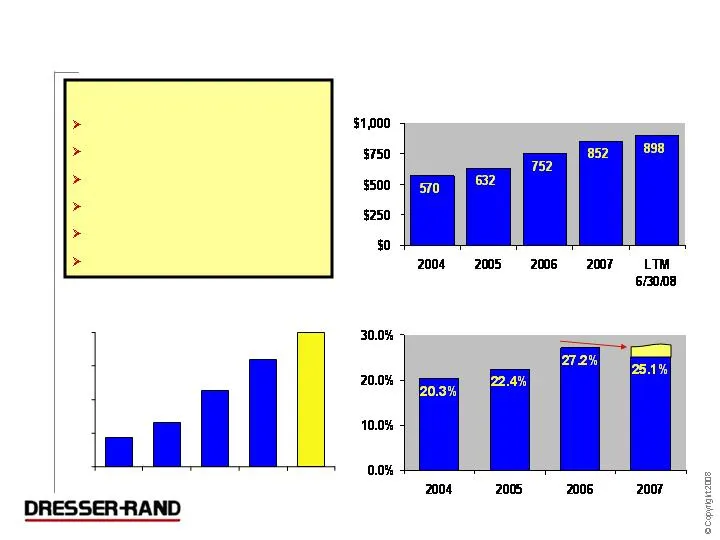
22 33 56 80 Aftermarket Initiatives Drive Revenue Growth Key Initiatives: Sales Entitlement Model Leverage Alliances Expand Service Centers Technology Leadership D-R Avenue Applied Technology Aftermarket Margins ($ in Millions) Pro forma 27.4% adjusted for unusual items Aftermarket Sales ($ in Milli
Slide 24: Aftermarket Growth Opportunity – Tier Approach
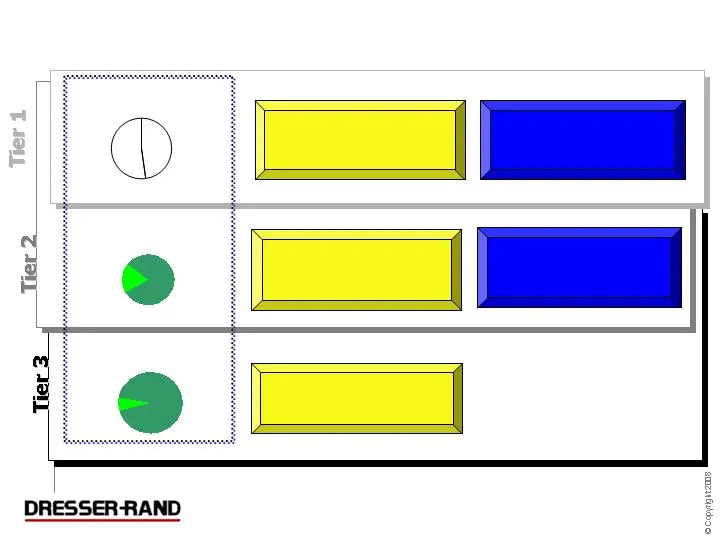
44.4% 77% 47% 53% Aftermarket Growth Opportunity – 3 Tier Approach Total Aftermarket Spend (Supplier & Customer) For All Like Rotating Equipment Total Third Party Supplied Aftermarket For All Like Rotating Equipment DRC Installed Base ~ 95,000 Units Industry-wide Installed Base ~ 225,000 Units Sourc
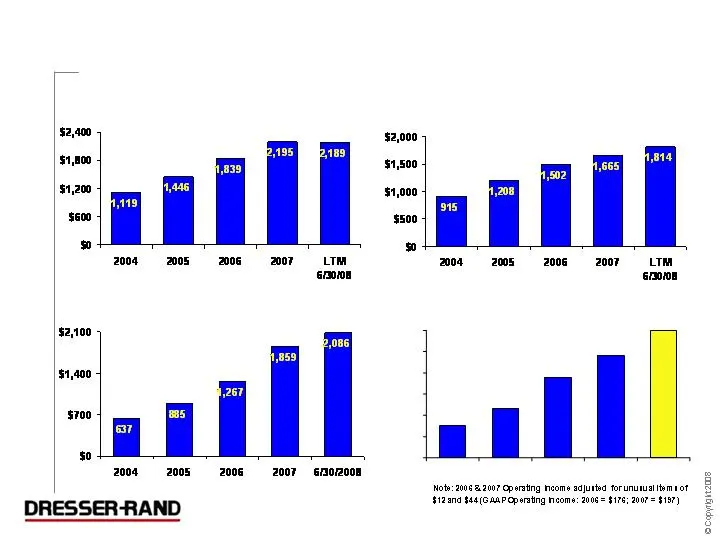
Slide 25: Strong Markets & Operational Excellence Have Led to Solid Revenue and Income Growth
Strong Markets & Operational Excellence Have Led to Solid Revenue and Income Growth Backlog End of Period ($ in Millions) Bookings ($ in Millions) Sales ($ in Millions) Operating Income ($ in Millions) 285- 315 $0 $50 $100 $150 $200 $250 $300 2008E
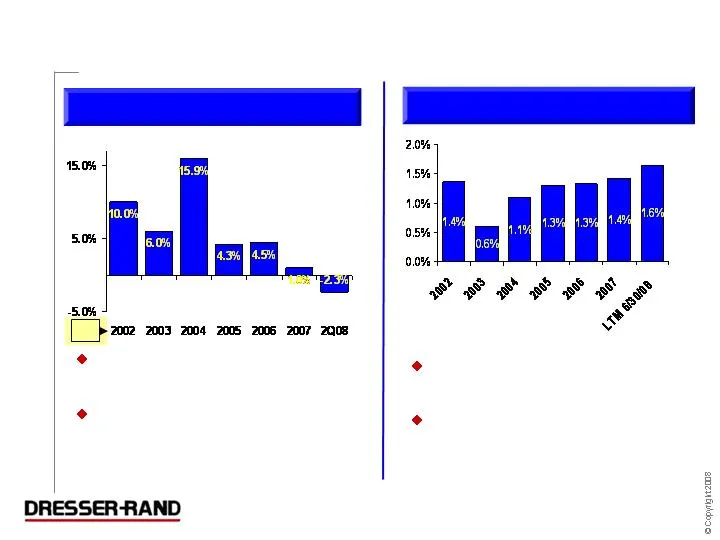
Slide 26: Unique Business Model: Low Capital Intensity
Capex as a % of Sales NWC as a % of LTM Sales Unique Business Model: Low Capital Intensity Modest working capital requirements Customer advance payments and progress payments finance working capital Manufacturing strategy allows for low capital expenditures Aftermarket segment low capital intensity
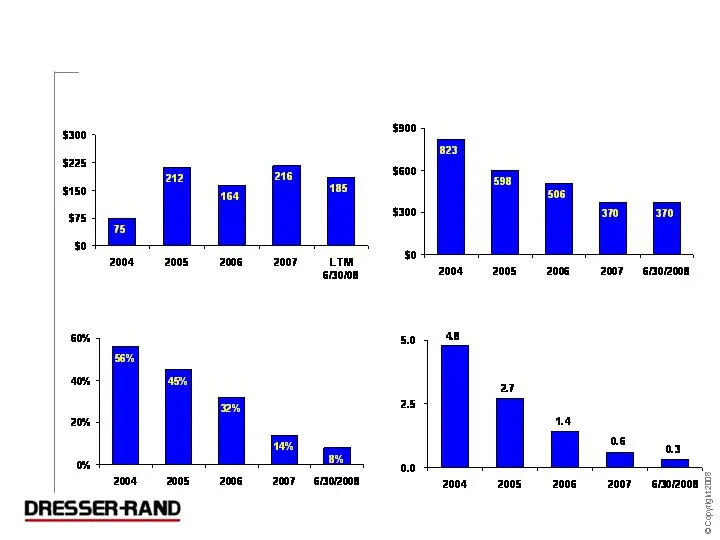
Slide 27: Drives Strong Cash Flow and Capital Structure
Drives Strong Cash Flow and Capital Structure Cash from Operating Activities ($ in Millions) Total Debt ($ in Millions) Net Debt / Adjusted EBITDA Net Debt / Capitalization
Slide 28: 2008 Highlights
2008 Highlights Strong first half performance - 1H08 vs. 1H07: Sales + 20% to $905 million Operating Income + 47% to $122 million Net Income +78% to $74 million Aftermarket bookings + 28% to $508 million Backlog + 29% from 6/30/07 to $2.1 billion $150 million share repurchase program Announced strat
Slide 29: Recent Strategic Acquisitions
Recent Strategic Acquisitions Peter Brotherhood : Manufactures steam turbines, recips, combined heat & power systems (CHP), and gearboxes 2007 sales ~ $100 million / Installed base ~ 755 units Strategic Rationale: Grow aftermarket and new unit business segments Arrow Industries : Premier provider of
Slide 30: Dresser-Rand Investment Highlights
Dresser-Rand Investment Highlights New Units: Strong secular growth / late cycle play Oil production / Refining / LNG / Transmission / CAES / Subsea Aftermarket: Dependable, non-cyclical growth Expanding service footprint / Applied Technology Sustainable competitive advantages Leading technology / I
Slide 31: Oil Services & Equipment Company Valuations
Oil Services & Equipment Company Valuations Source: Natixis September 8, 2008 2008E 2009E 2008E 2009E Dresser-Rand 13.1X 10.1X 8% 10% Average (5 companies*) 36.4X 16.4X 5% 7% * CAM, CBI, EMR, DRQ and FTI EV / FCF FCF Yield
Slide 32: www.dresser-rand.com [email protected]
www.dresser-rand.com [email protected]
Source: SEC EDGAR · 8-K filed Sep 19, 2008
More decks from Dresser-Rand Group Inc
 Merger or Acquisition (September 2014)16 slides · Sep 23, 2014
 Merger or Acquisition (March 2011)32 slides · Mar 7, 2011
 Credit Suisse Energy Summit 201128 slides · Feb 7, 2011
 Investor Day (November 2010)111 slides · Nov 10, 2010
 Howard Weil 2010 Energy Conference24 slides · Mar 19, 2010
 Pritchard Capital Partners – Energize 201022 slides · Jan 5, 2010