Spirit Airlines — Merger or Acquisition (January 2025)
18 slides from Spirit Airlines's merger presentation, Jan 29, 2025
Slide 1: January 2025 Presentation to Spirit
January 2025 Presentation to Spirit
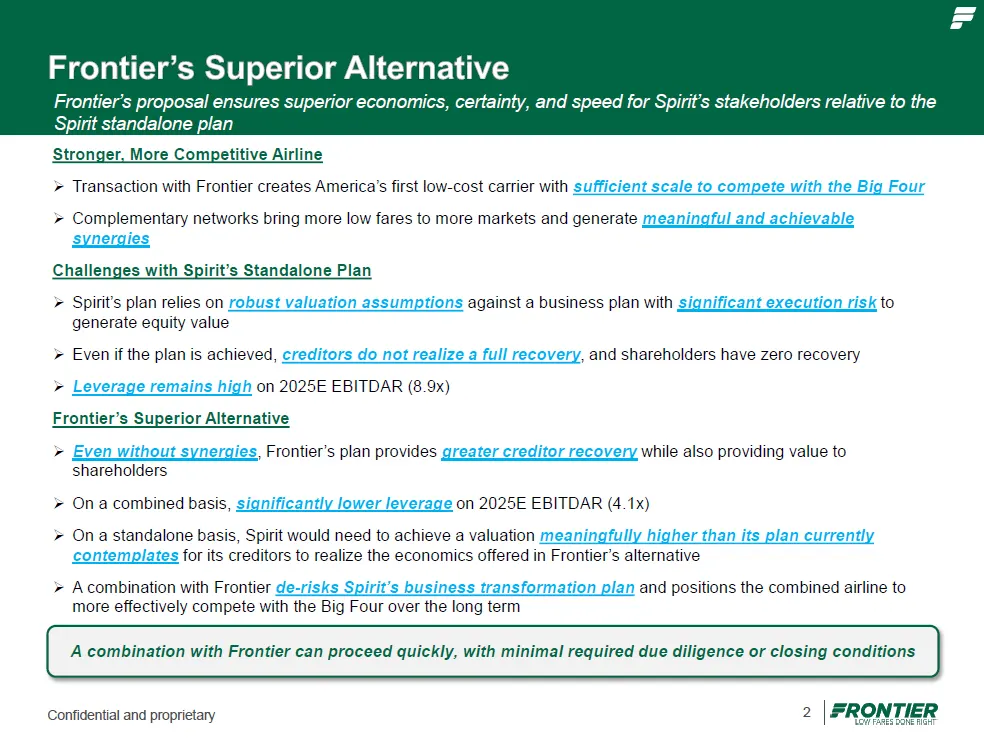
Slide 2: Frontier's proposal ensures superior economics, certainty, and speed for Spirit's stakeholders
2 Confidential and proprietary Frontier’s proposal ensures superior economics, certainty, and speed for Spirit’s stakeholders relative to the Spirit standalone plan Stronger, More Competitive Airline » Transaction with Frontier creates America’s first low - cost carrier with sufficient scale to comp
Slide 3: Strategic Rationale
Strategic Ra ti ona l e • Compelling industrial logic • Creates the first formidable low - cost challenger to the Big Four • Combination benefits all stakeholders
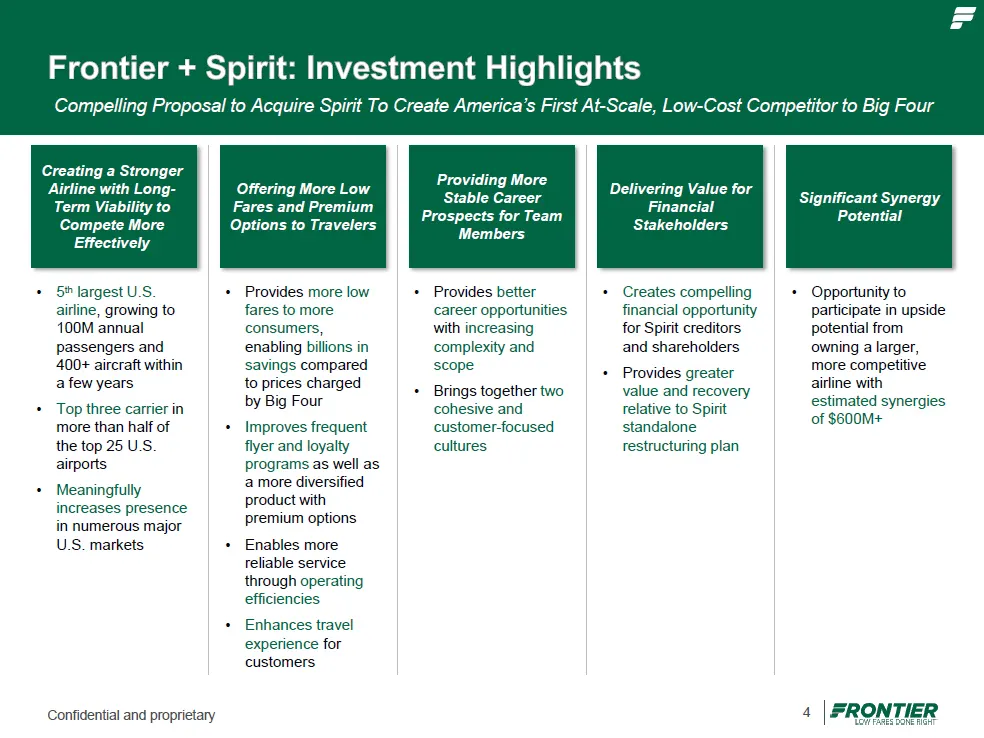
Slide 4: Compelling Proposal to Acquire Spirit
4 Confidential and proprietary Providing More Stable Career Prospects for Team Members • Provides better career opportunities with increasing complexity and scope • Brings together two cohesive and customer - focused cultures Compelling Proposal to Acquire Spirit To Create America’s First At - Scale
Slide 5: Stronger Airline with Long-Term Viability to Compete Against Big Four
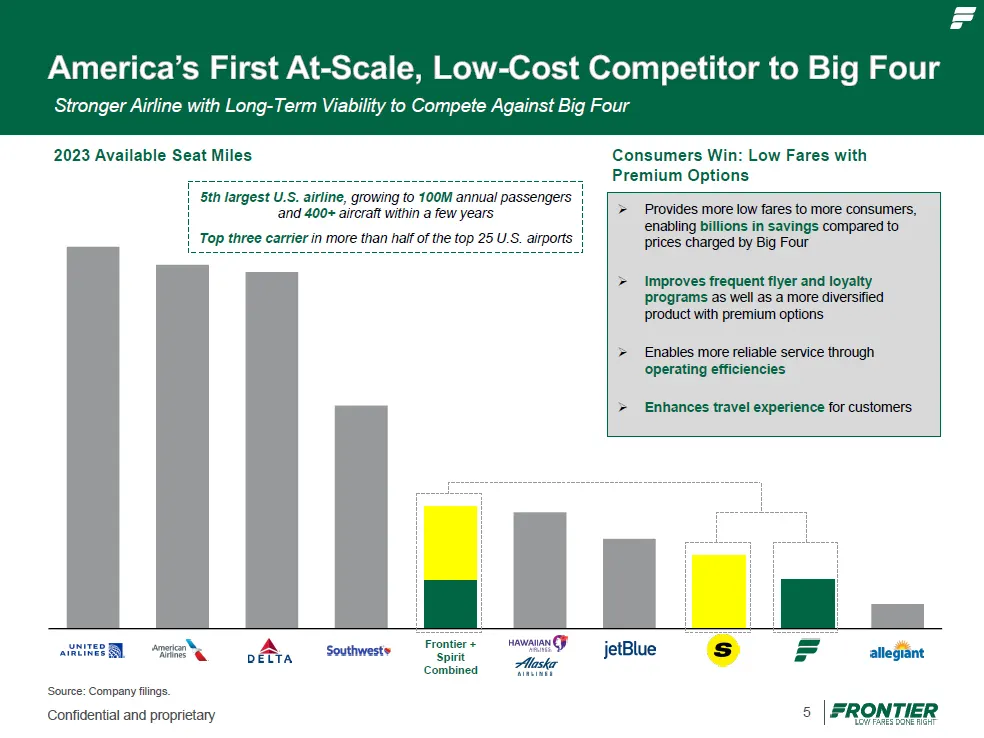
5 Unite d A m eri c a n De lta S o u t hwe s t F ront i e r + S pi r it P F A la s k a / J et B lu e S p i r i t F ront i e r A llegiant Hawaiian Stronger Airline with Long - Term Viability to Compete Against Big Four Frontier + Spirit C o m bin e d 5th largest U.S. airline , growing to 100M annual
Slide 6: Consumers & Communities, Team Members, Stakeholders
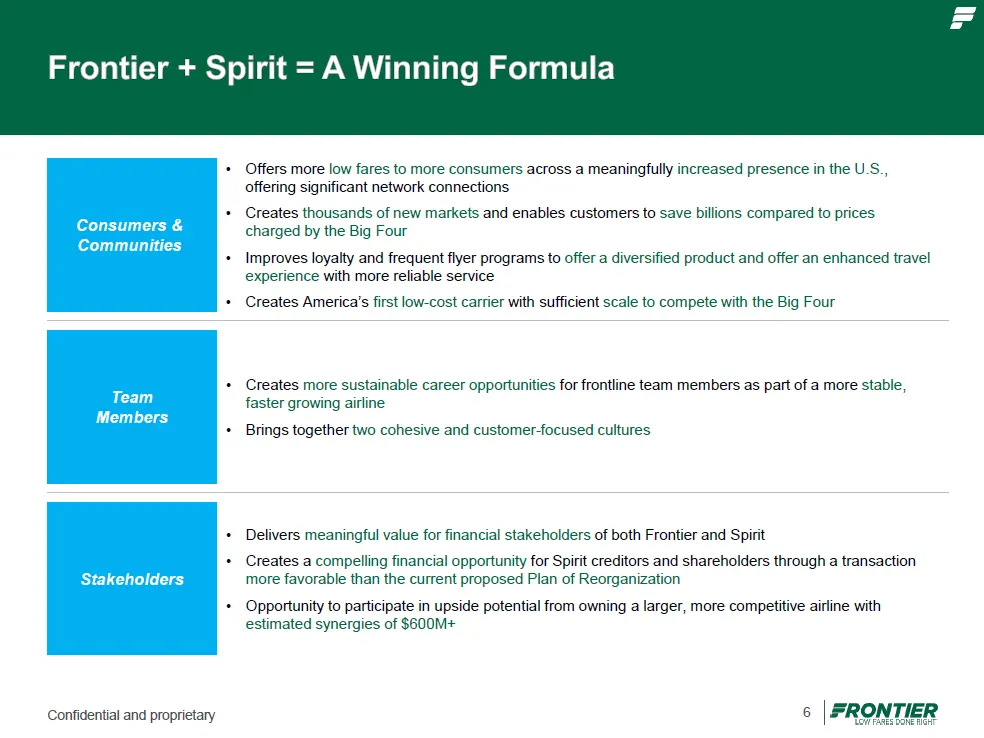
6 Confidential and proprietary Consumers & Communities • Offers more low fares to more consumers across a meaningfully increased presence in the U.S., offering significant network connections • Creates thousands of new markets and enables customers to save billions compared to prices charged by the
Slide 7: Comparing the Plans
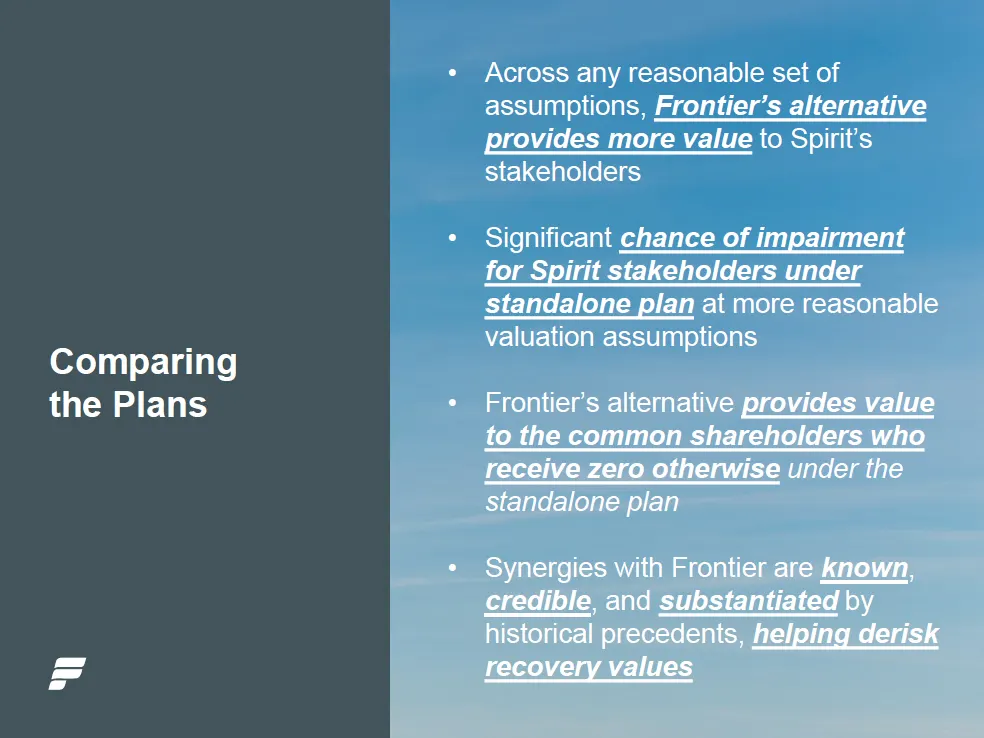
C o m pa ri ng the Plans • Across any reasonable set of assumptions, Frontier’s alternative provides more value to Spirit’s stakeholders • Significant chance of impairment for Spirit stakeholders under standalone plan at more reasonable valuation assumptions • Frontier’s alternative provides value t
Slide 8: Comparison of Spirit RSA and Frontier Proposal
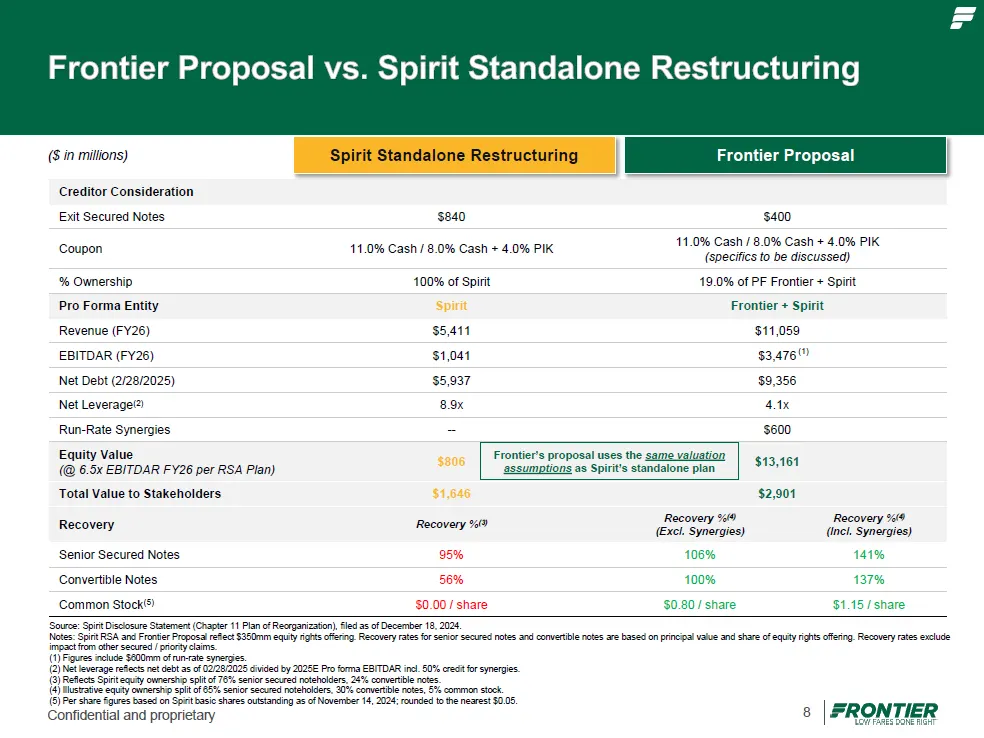
8 Confidential and proprietary Source: Spirit Disclosure Statement (Chapter 11 Plan of Reorganization), filed as of December 18, 2024. Notes: Spirit RSA and Frontier Proposal reflect $350mm equity rights offering. Recovery rates for senior secured notes and convertible notes are based on principal v
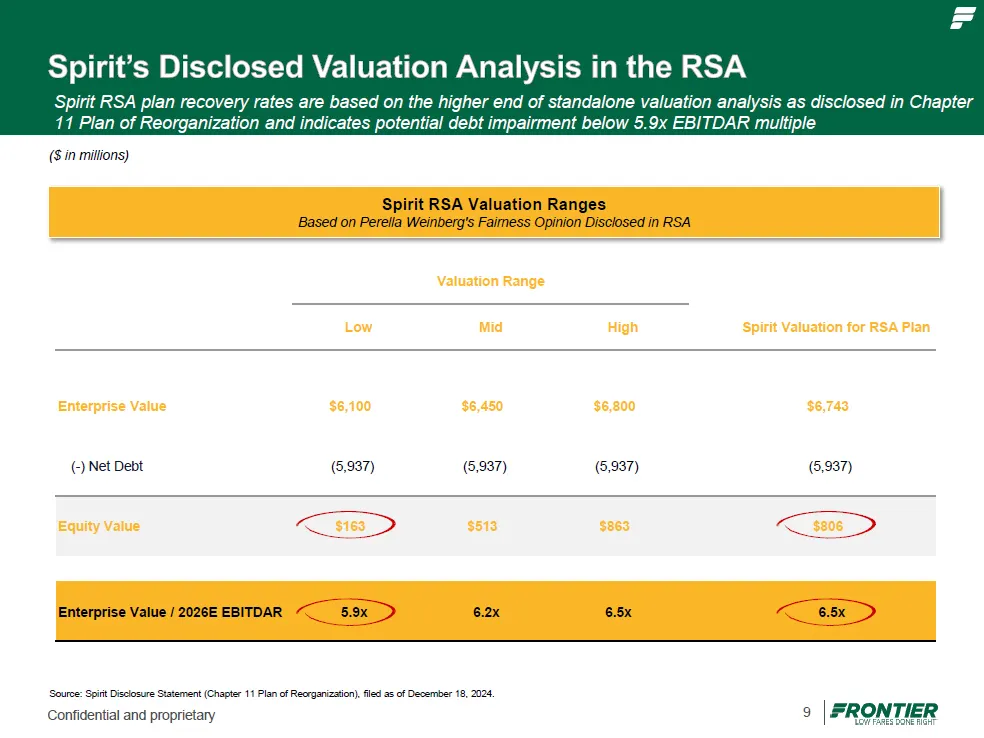
Slide 9: Spirit RSA Valuation Ranges Based on Perella Weinberg's Fairness Opinion
9 Spirit RSA Valuation Ranges Based on Perella Weinberg's Fairness Opinion Disclosed in RSA Spirit RSA plan recovery rates are based on the higher end of standalone valuation analysis as disclosed in Chapter 11 Plan of Reorganization and indicates potential debt impairment below 5.9x EBITDAR multipl
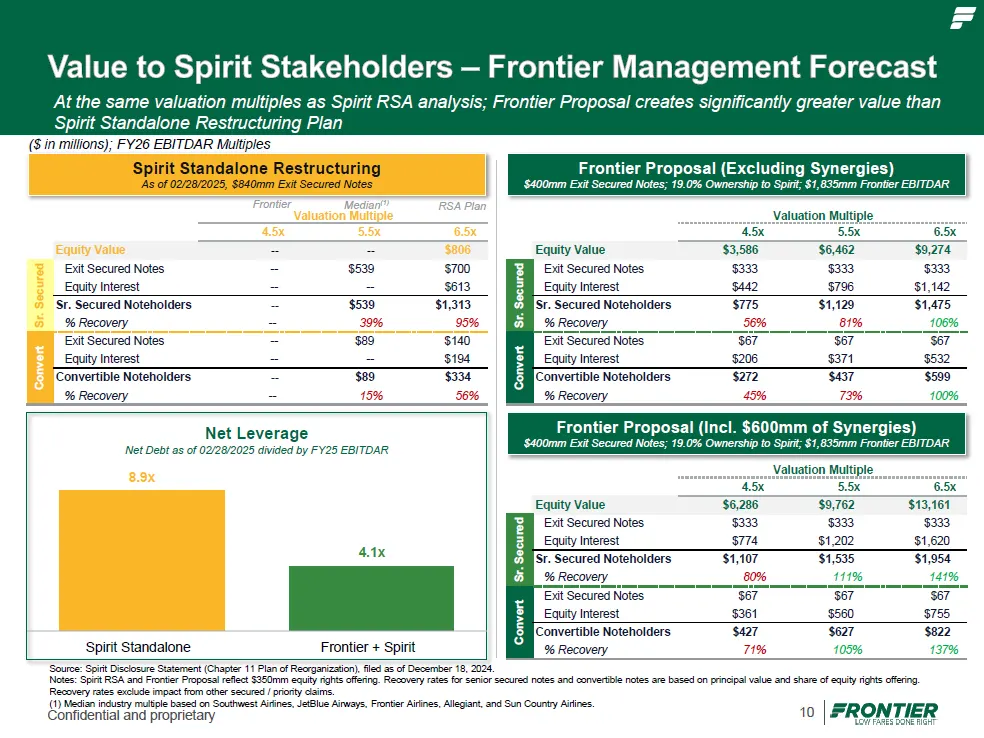
Slide 10: Frontier Proposal vs Spirit Standalone Restructuring
10 Confidential and proprietary Spirit Standalone Restructuring As of 02/28/2025, $840mm Exit Secured Notes Frontier Proposal (Excluding Synergies) $400mm Exit Secured Notes; 19.0% Ownership to Spirit; $1,835mm Frontier EBITDAR Frontier Proposal (Incl. $600mm of Synergies) $400mm Exit Secured Notes;
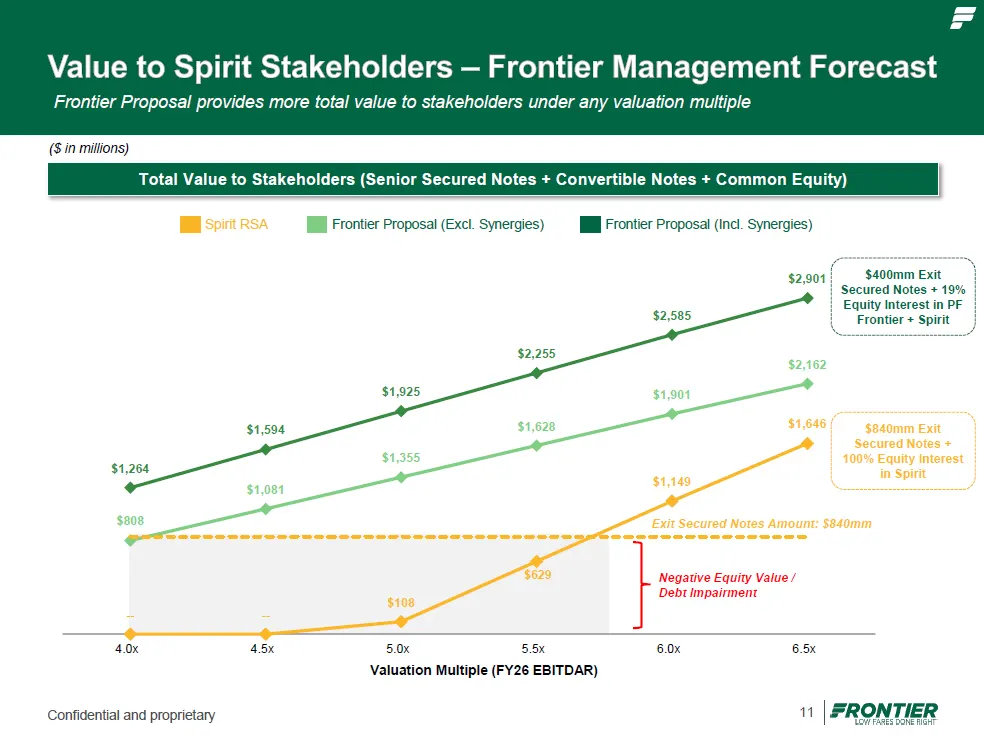
Slide 11: Total Value to Stakeholders by Valuation Multiple
11 Confidential and proprietary Spirit RSA Frontier Proposal (Excl. Synergies) Frontier Proposal (Incl. Synergies) $840mm Exit Secured Notes + 100% Equity Interest in Spirit $400mm Exit Secured Notes + 19% Equity Interest in PF Frontier + Spirit ($ in millions) Total Value to Stakeholders (Senior Se
Slide 12: Analysis Based on Analyst Estimates
Analysis Based on Analyst Es ti ma t es • Even using conservative estimates, the Frontier proposal provides significantly more value than the standalone plan • Net leverage at emergence is 4.2x less for the combined company than standalone (8.9x Standalone vs. 4.7x Pro Forma) • Noteholders have pote
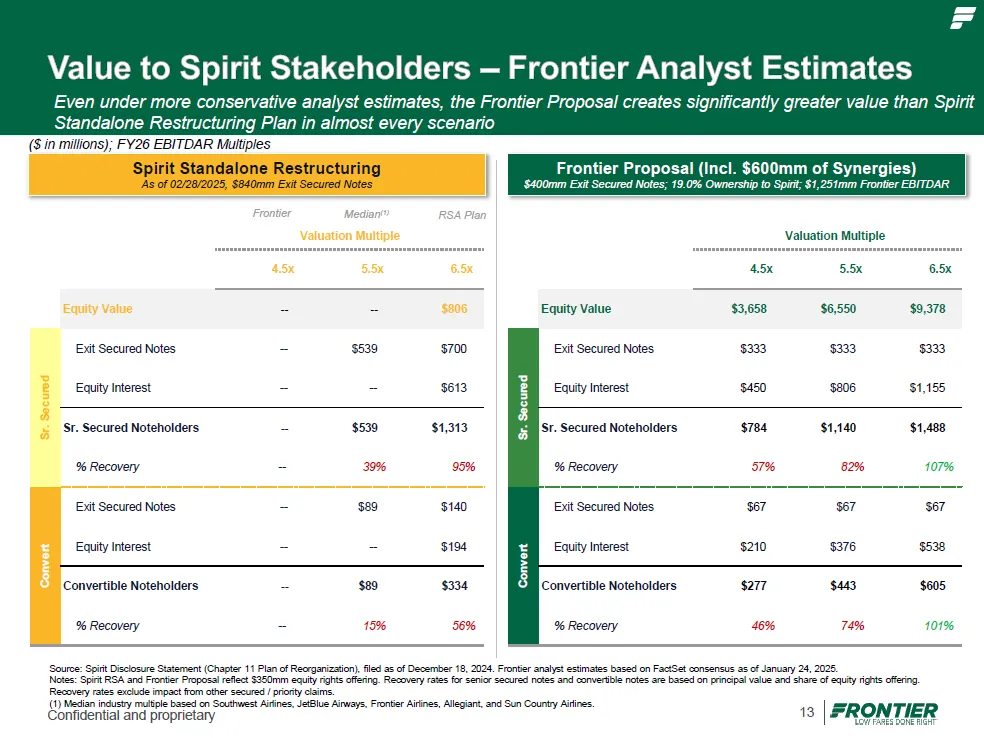
Slide 13: Frontier Proposal vs Standalone under Analyst Estimates
13 Confidential and proprietary Spirit Standalone Restructuring As of 02/28/2025, $840mm Exit Secured Notes Frontier Proposal (Incl. $600mm of Synergies) $400mm Exit Secured Notes; 19.0% Ownership to Spirit; $1,251mm Frontier EBITDAR Even under more conservative analyst estimates, the Frontier Propo
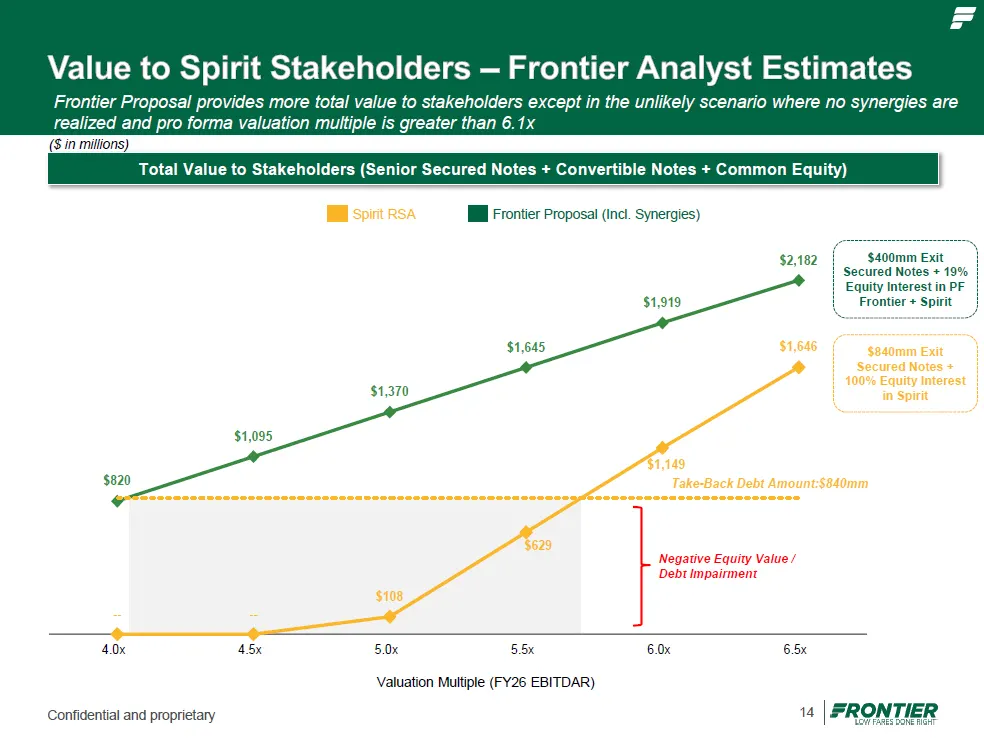
Slide 14: Total Value to Stakeholders under Analyst Estimates
14 Confidential and proprietary $840mm Exit Secured Notes + 100% Equity Interest in Spirit $400mm Exit Secured Notes + 19% Equity Interest in PF Frontier + Spirit Negative Equity Value / Debt Impairment Spirit RSA Frontier Proposal (Incl. Synergies) Frontier Proposal provides more total value to sta
Slide 15: Significant Synergy Potential
S i gn ifi ca n t Synergy Potential • Assumed synergies of $600mm is a conservative metric compared to credible industry consultants’ estimates • Net present value of synergies from combination forecast to be ~$5.7bn based on industry consultants’ assumptions
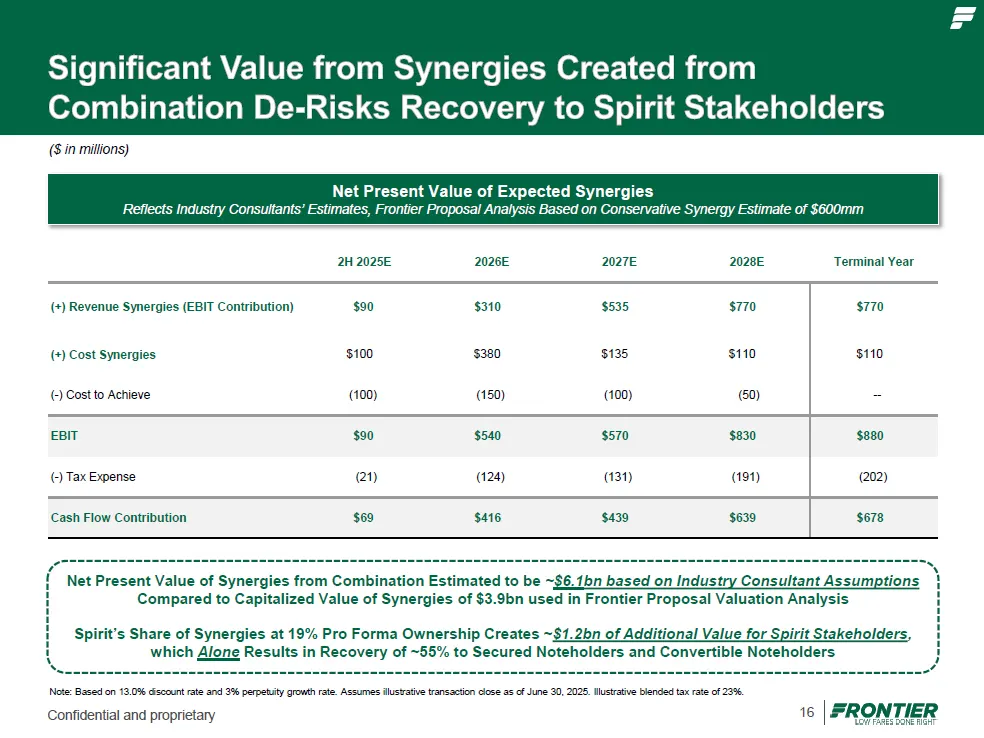
Slide 16: Net Present Value of Expected Synergies
16 Confidential and proprietary ($ in millions) Net Present Value of Expected Synergies Reflects Industry Consultants’ Estimates, Frontier Proposal Analysis Based on Conservative Synergy Estimate of $600mm $770 $770 $535 $310 $90 (+) Revenue Synergies (EBIT Contribution) $110 $110 $135 $380 $100 (+)
Slide 17: Next Steps
Next Steps • Minimal confirmatory due diligence required • Transaction can proceed towards an expedited announcement
Slide 18: Expedited due diligence process and key diligence items
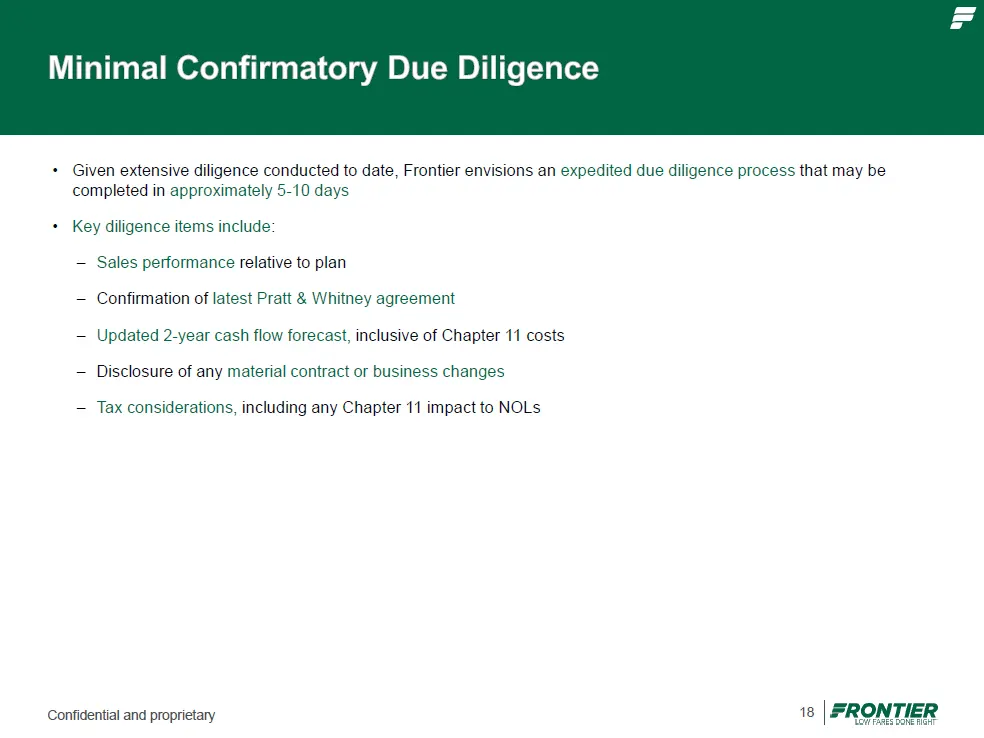
18 Confidential and proprietary • Given extensive diligence conducted to date, Frontier envisions an expedited due diligence process that may be completed in approximately 5 - 10 days • Key diligence items include : – Sales performance relative to plan – Confirmation of latest Pratt & Whitney agreem
Source: SEC EDGAR · 8-K filed Jan 29, 2025
More decks from Spirit Airlines Inc
 Merger or Acquisition (January 2025)8 slides · Jan 29, 2025
 Debt Investor Presentation (November 2024)56 slides · Nov 18, 2024
 Merger or Acquisition (July 2022)43 slides · Jul 28, 2022
 Proxy Contest (June 2022)18 slides · Jun 27, 2022
 Proxy Contest (June 2022)41 slides · Jun 7, 2022
 Proxy Contest (May 2022)30 slides · May 25, 2022