Kraft Foods — Investor Day (September 2012)
74 slides from Kraft Foods's investor day presentation, Sep 7, 2012
Slide 1: The New Kraft Foods Group Investor Day
The New Kraft Foods Group September 7, 2012 Investor Day Exhibit 99.2

Slide 2: Chris Jakubik, Vice President, Investor Relations
Chris Jakubik Vice President, Investor Relations
Slide 3: Forward-Looking Statements
Forward-Looking Statements This presentation contains a number of forward-looking statements. The words “plan,” “drive,” “build,” “focus,” “manage,” “can,” “will,” “expect” and similar expressions are intended to identify our forward-looking statements. Examples of forward-looking statements include
Slide 4: The New Kraft Foods Group
The New Kraft Foods Group Who we are What we’ll do What to expect Meet our team

Slide 5: John Cahill, Executive Chairman
John Cahill Executive Chairman
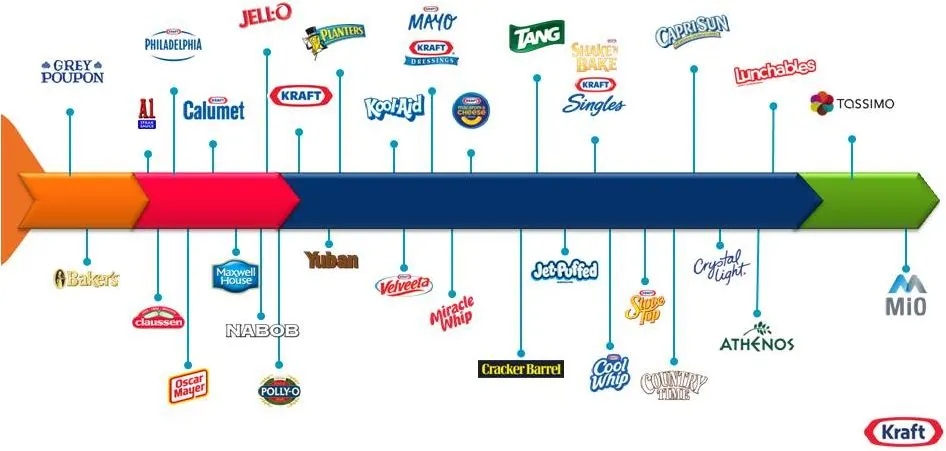
Slide 6: Our Heritage and Our Legacy Lie with Our Iconic Brands
1800 1900 1700 2000 Our Heritage and Our Legacy Lie with Our Iconic Brands Source: Kraft Foods Archives
Slide 7: We have Unparalleled Strength with Our Portfolio
We have Unparalleled Strength with Our Portfolio Household penetration 98% in U.S., 99% in Canada 10 brands with more than $500MM in 2011 annual sales Another 17 brands with 2011 annual sales over $100MM Average of 2x the share of the nearest branded competitor Source: Kraft Foods Group, Nielsen
Slide 8: We are the 4th Largest Player in North American Food and Beverages
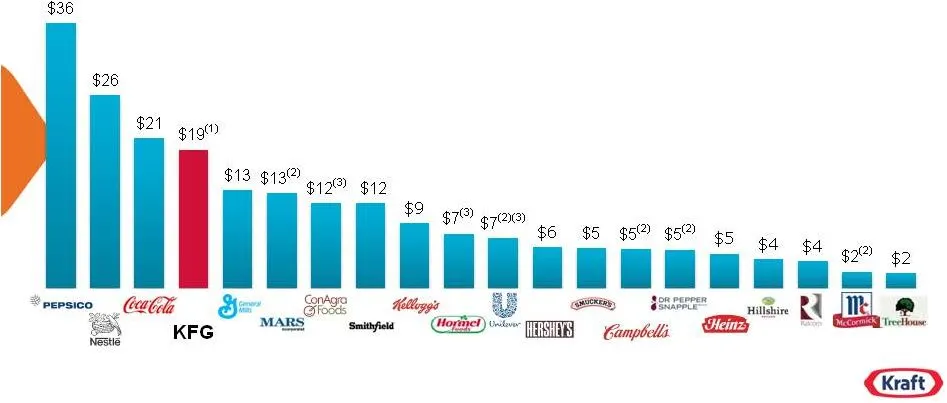
We are the 4th Largest Player in North American Food and Beverages Food & Beverage Net Revenue ($B) North America, Latest Fiscal Year (1) Per Kraft Foods Group Form 10 filing (2) Estimates (3) U.S. figures Source: Public disclosures in press releases or SEC filings, Kraft Foods Group analysis as of
Slide 9: A Huge Opportunity to Improve Profitability
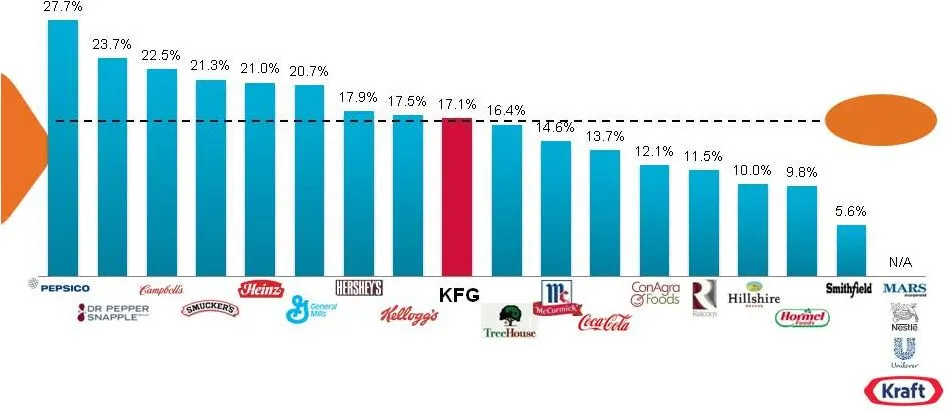
Average 16.6% A Huge Opportunity to Improve Profitability Adjusted Operating Income Margin (1) North America, Latest Fiscal Year (3) (4) (2) (1) Reported Operating Income Margin for the 12 months ended December 31, 2011 was 15.7%. See GAAP to Non-GAAP reconciliation at the end of the presentation. (
Slide 10: An Experienced and Diverse Team with the Right Skills
An Experienced and Diverse Team with the Right Skills CEO: 23 years Johnson & Johnson, 3 years private equity Leadership Team – Evenly split between proven Kraft personnel and external hires – 195 years of combined Kraft experience – 350 years of combined CPG/Industry experience – Drawing experience
Slide 11: Our Mission
Profitable Top-Line Growth Consistent Bottom-Line Growth Superior Dividend Payout Our Mission Make Kraft North American Food & Beverage Company Best Investment in the Industry

Slide 12: Tony Vernon, Chief Executive Officer
Tony Vernon Chief Executive Officer
Slide 13: The New Kraft Foods Group
The New Kraft Foods Group Who we are What we’ll do What to expect Meet our team
Slide 14: The Journey of a $19 Billion Startup
To “Post Office” culture 20-70-10 performance model Limited investment in people and training Best recruiter and developer of industry talent “Peanut-butter spread” resource allocation Strategic resource allocation based on margin, materiality, momentum Inconsistent innovation Best-in-class innovati
Slide 15: We've Made Good Progress
We’ve Made Good Progress… (1) Reported net revenue growth was 3.8%, reported operating income growth was 1.2%, reported operating income margin change was (0.4)pp, all on a trailing four quarter basis ending June 30, 2012, see GAAP to Non-GAAP reconciliation at the end of the presentation; (2) Estim
Slide 16: Operating Environment Remains the Most Difficult in a Generation
… Despite an Operating Environment that Promises to Remain the Most Difficult in a Generation The North American food and beverage market is large, highly profitable but mature and slow growing A weak economy with relatively high commodity volatility is the “new normal” Private label has achieved a
Slide 17: Our Plan will Sustain Our Momentum and Take Performance to the Next Level
Redefine Efficiency Turbocharge Our Iconic Brands Execute with Excellence Make Our People Our Competitive Edge Our Plan will Sustain Our Momentum and Take Our Performance to the Next Level
Slide 18: Make Our People Our Competitive Edge
Make Our People Our Competitive Edge Redefine Efficiency Turbocharge Our Iconic Brands Execute with Excellence Our Plan Aggressively compensate for performance Invest in our people Create a lean, horizontal organization
Slide 19: Aggressively Compensate for Performance
Make Our People Our Competitive Edge Aggressively Compensate for Performance Increasing variable component in compensation programs Adopting 20/70/10 performance model Driving broader, deeper stock compensation and ownership We’ll put more of our pay “at risk”
Slide 20: Invest in Our People
Make Our People Our Competitive Edge Invest in Our People Building Talent Acquisition, University Relations as a competitive advantage Establishing integrated succession planning process to develop next generation of general managers Creating “Kraft University” to assemble world-class capabilities O
Slide 21: Kraft University
ISC Academy Marketing Academy Leadership Development/Management/Diversity & Inclusion Accreditation required for all managers Sales Academy RDQ&I Academy Functional Academies Business Skill Building: Cash Management, Organizational Agility, Compliance, New Hire, etc. Make Our People Our Competitive
Slide 22: Create a Lean, Horizontal Organization
Make Our People Our Competitive Edge Create a Lean, Horizontal Organization Revamping organizational structure to become nimble and non-hierarchical Pushing accountability down to the right levels Transforming headquarters We’re changing how we work and where we work
Slide 23: Execute with Excellence: Our Plan
Redefine Efficiency Turbocharge Our Iconic Brands Make Our People Our Competitive Edge Execute with Excellence Our Plan Strategically allocate resources Leverage our leading sales capability Relentlessly focus on cash generation
Slide 24: Strategically Allocate Resources
Execute with Excellence Strategically Allocate Resources Each of our brands can deliver outstanding returns… but not all need the same resources to reach their potential
Slide 25: Re-allocating Advertising Spend to Power Brands
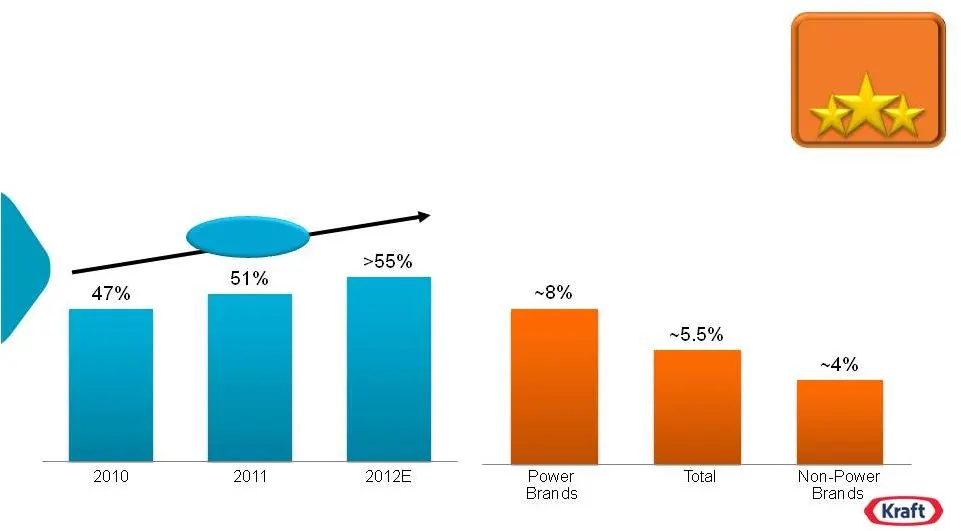
Execute with Excellence CAGR 12.7% Strategically Allocate Resources We’ve already begun to make progress re-allocating advertising spend within businesses % of A&C spend on Power Brands A&C as % of NR (2012E) Power Brands currently include Lunchables, Planters, Velveeta Shells & Cheese, Capri Sun, J
Slide 26: Video: Vernon_BTS_MainStream Reel
Vernon_BTS_MainStream Reel.wmv
Slide 27: Managing and Marketing Our Jewels Entrepreneurially
Execute with Excellence Strategically Allocate Resources Leveraged non-traditional vehicles to create buzz Focused on strategic partnerships Tactically innovated to expand category, generate in-store excitement We’ve managed and marketed our “jewels” more entrepreneurially 2011 Net Revenue Growth 7%
Slide 28: Video: Vernon_BTS_Entrepreneurial Reel
Vernon_BTS_Entrepreneurial Reel v2.wmv
Slide 29: Evaluating the Collective Needs of Our Brands
Execute with Excellence Strategically Allocate Resources Our leadership team now will evaluate the collective needs of our brands and franchises Margin, Materiality, Momentum Power Brands Jewels Price Protect Fix
Slide 30: Allocating Key Resources to Brands and Franchises
Execute with Excellence Strategically Allocate Resources We will strategically allocate a broad set of key resources to brands and franchises Margin, Materiality, Momentum Brand Building Low Cost Advertising Growth R&D & Capex Brand Management & Sales Resources Productivity R&D & Capex Supply Chain
Slide 31: Leverage Our Leading Sales Capability
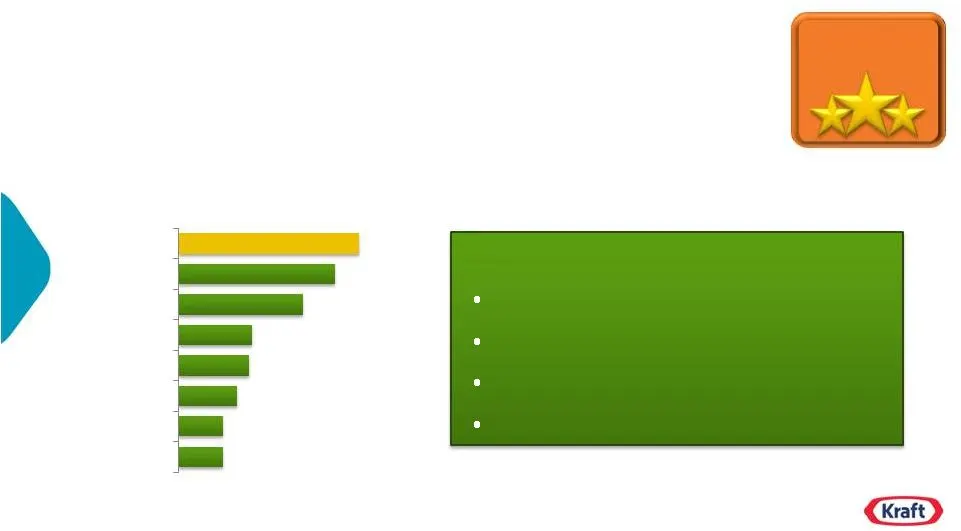
Key Sales Force Attributes Rank Best Sales Force #1 Best Shopper Marketing #2 Best Supply Chain Management #2 Most Helpful Shopper Insights #2 Execute with Excellence Leverage Our Leading Sales Capability Kantar 2011 Power Rankings 2011 Overall Rankings Partnering with Acosta will make us even stron
Slide 32: Initiatives to Generate Higher Returns on Sales Investment
Execute with Excellence Leverage Our Leading Sales Capability Employing a relentless focus on ROI Bringing world-class category leadership to Center Store Building strong, sustainable relationships with our customers Several initiatives will generate higher returns on our investment in sales
Slide 33: Relentlessly Focus on Cash Generation
Execute with Excellence Relentlessly Focus on Cash Generation Building free-cash flow, return-on-capital metrics and targets into business-unit plans Appointed a “Cash Czar,” establish monthly cash reviews by leadership team Institutionalizing disciplined business-process execution and education We’
Slide 34: Turbocharge Our Iconic Brands: Our Plan
Make Our People Our Competitive Edge Execute with Excellence Turbocharge Our Iconic Brands Redefine Efficiency Our Plan Delight the changing consumer Drive “premium-ness” through innovation platforms Differentiate with world-class marketing
Slide 35: Delight the Changing Consumer
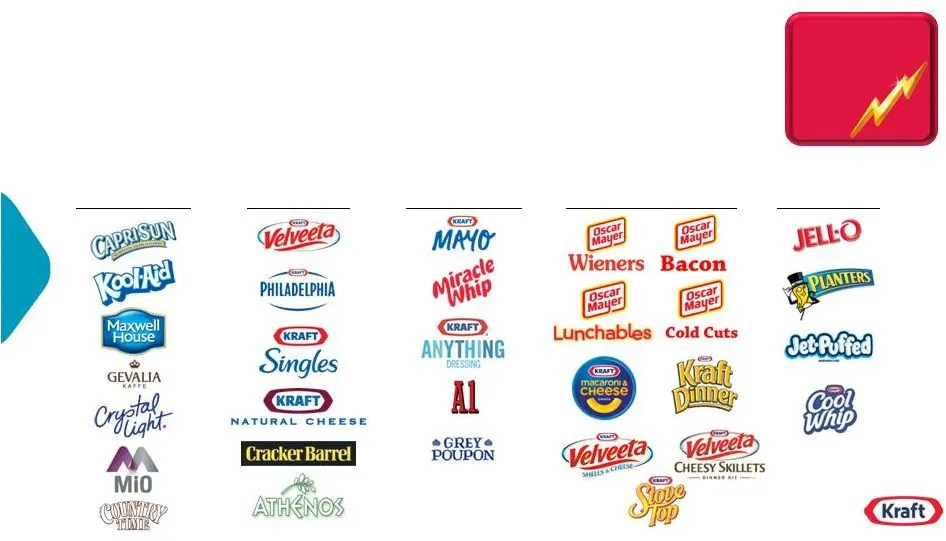
Turbocharge Our Iconic Brands Delight the Changing Consumer We can delight the consumers more ways, on more brands, in more places than any competitor Beverages Cheese Enhancers Convenient Meals Desserts & Snacks
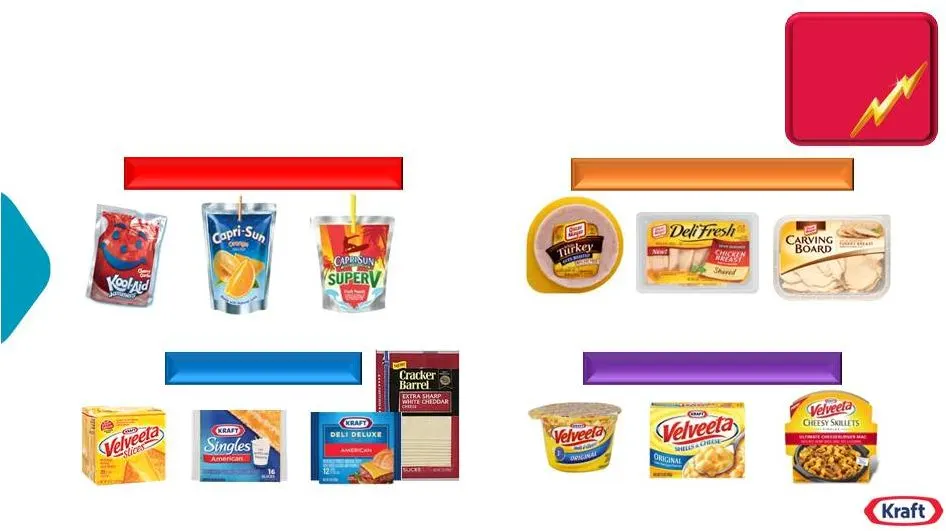
Slide 36: Good, Better, Best
Ready-to-Drink Beverages Cold Cuts Sandwich Cheese Convenient Meals Turbocharge Our Iconic Brands Delight the Changing Consumer Good, Better, Best Delivering the right product at the right price points $1.79 $2.49 $2.99 $1.99 $2.99 $3.99 $1.99 $2.99 $3.99 $0.99 $1.99 $3.49
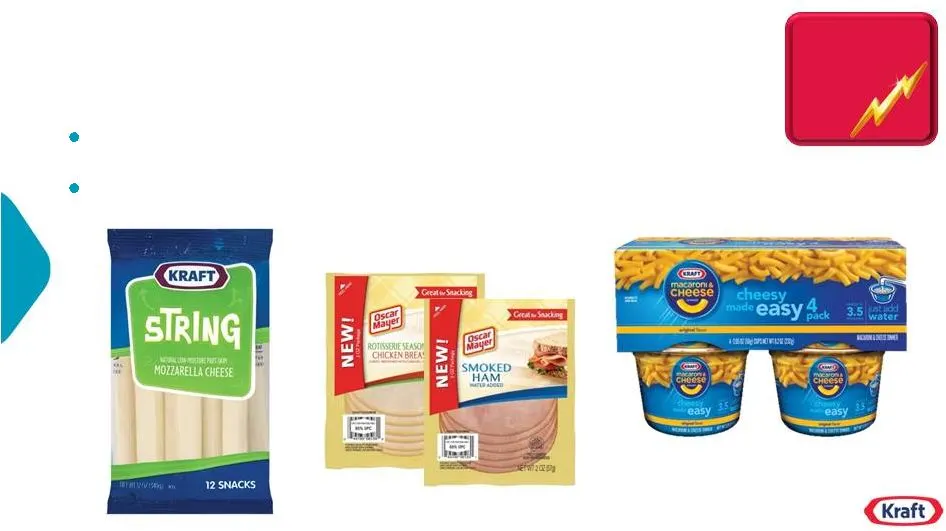
Slide 37: Economically Challenged Consumer Segment
Turbocharge Our Iconic Brands Delight the Changing Consumer Economically challenged consumer segment Dollar stores, drug stores, club Targeted price points for alternate channels
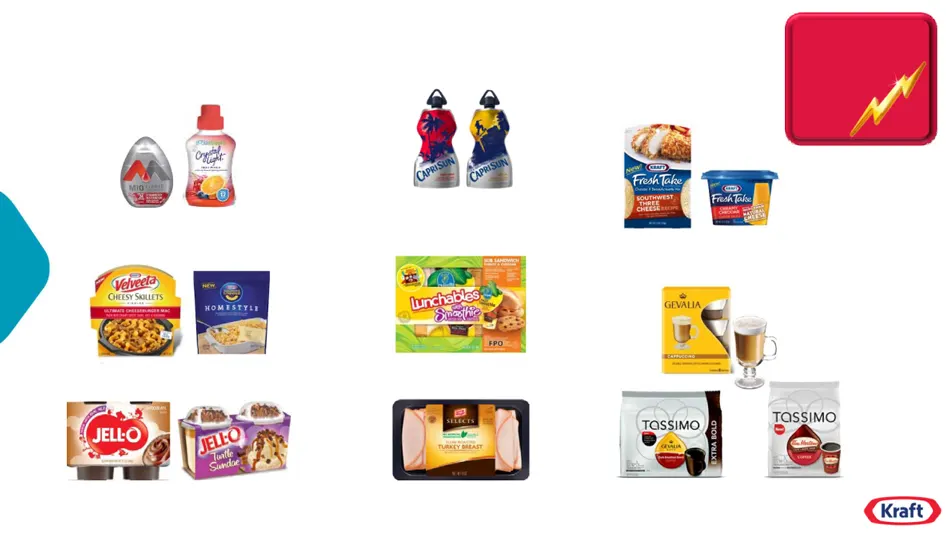
Slide 38: Drive Premium-ness Through Innovation Platforms
Turbocharge Our Iconic Brands Drive “Premium-ness” Through Innovation Platforms Liquid Concentrates Lunchables “With” Premium/One Cup Convenient Meals “Aging Up” Capri Sun Jell-O Reinvention Fresh Take Oscar Mayer Selects
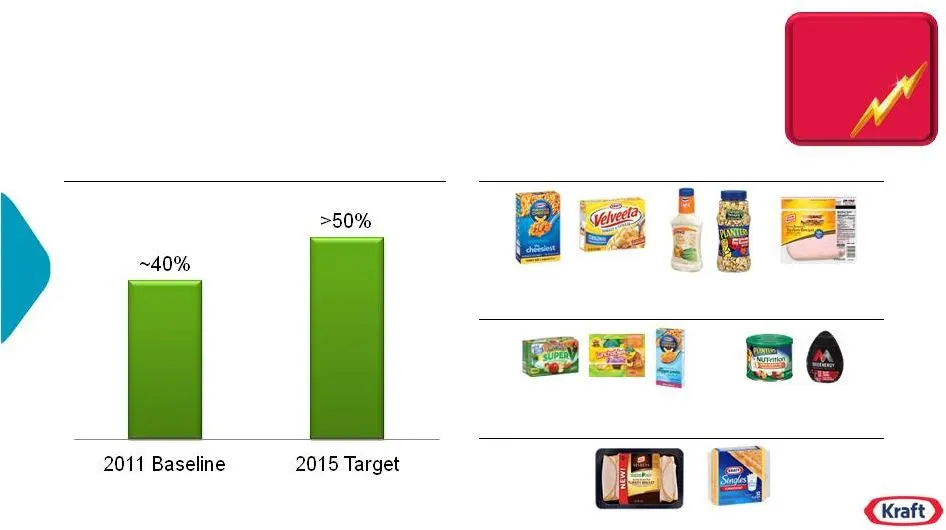
Slide 39: Health & Wellness
Turbocharge Our Iconic Brands Drive “Premium-ness” Through Innovation Platforms Health & Wellness % Revenue from Products That Meet “Better Choices” Criteria Improved Nutritional Profiles Beneficial Ingredients Simplification Sodium Reduction Fruits & Vegetables Vitamin Fortified No Artificial Color
Slide 40: Differentiate with World-Class Marketing
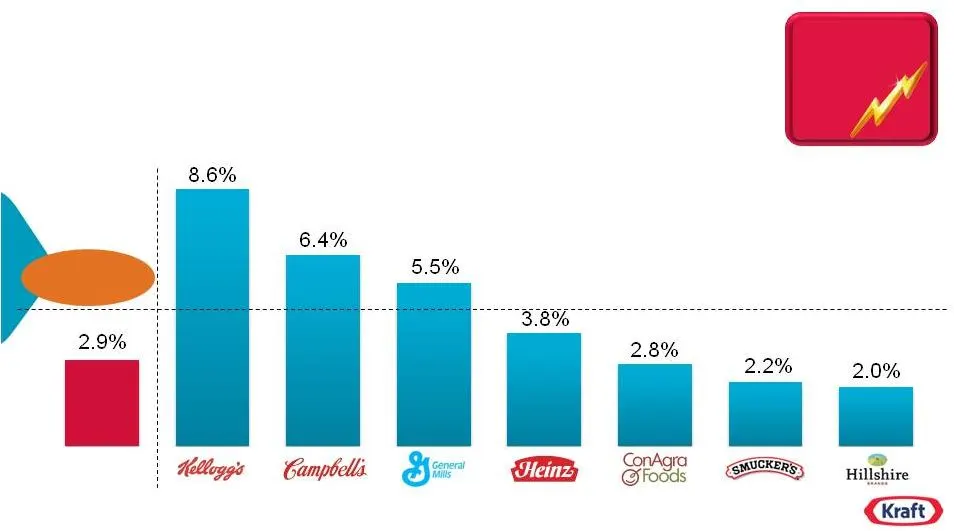
65% of peer avg Turbocharge Our Iconic Brands Differentiate with World-Class Marketing Advertising as % of Net Revenue Latest Fiscal Year Average 4.5% KFG Note: Advertising spend excludes Consumer Promotion spend Source: Company SEC filings, Nielsen 2011 ad spend/US x AOC, Kraft Foods Group analysis
Slide 41: Where We've Spent, It's Had an Impact
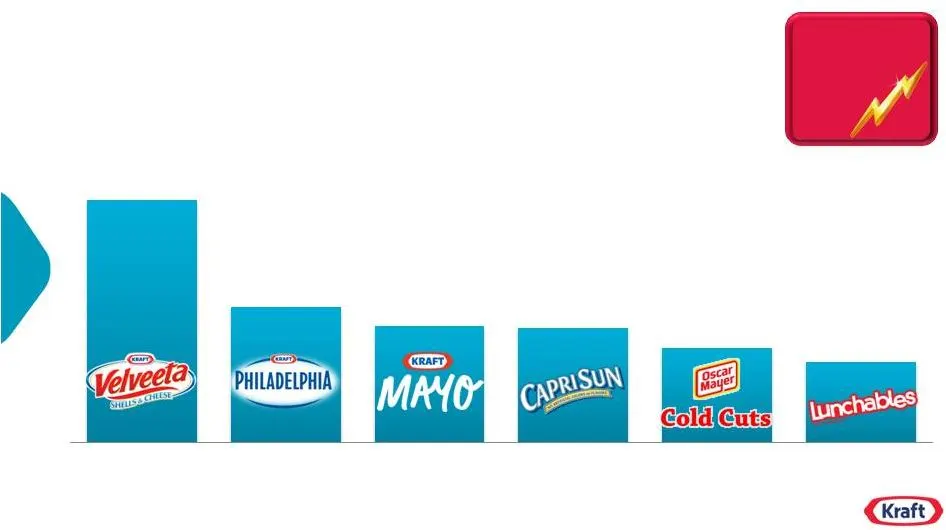
Turbocharge Our Iconic Brands Differentiate with World-Class Marketing 2011 Net Revenue Growth Where we’ve spent, it’s had an impact 20% 11% 10% 9% 8% 7%
Slide 42: Hispanic Marketing Is a Huge Opportunity
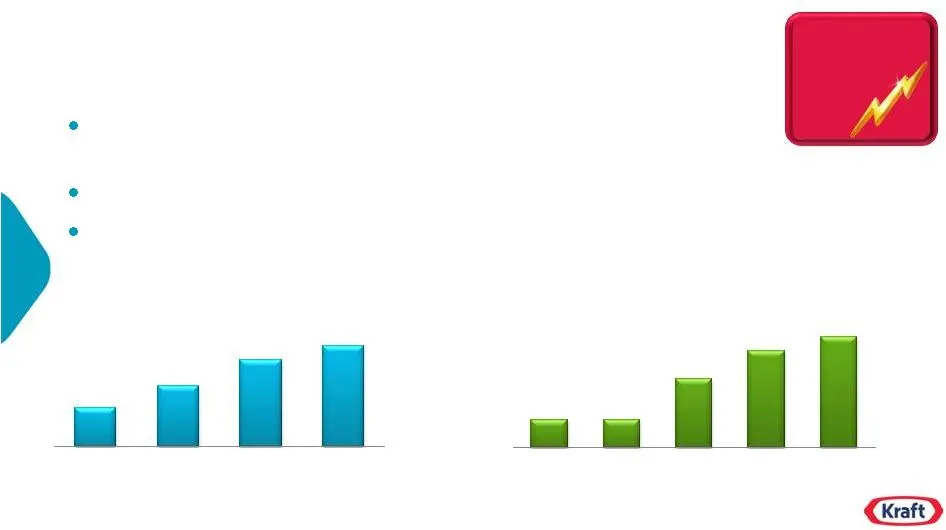
Turbocharge Our Iconic Brands Differentiate with World-Class Marketing U.S. Hispanic Population (MM) KFG Hispanic A&C Index (2011=100) Hispanic marketing is a huge opportunity Our portfolio of family brands are advantaged with Latina moms We have underspent in media and at point of purchase Will be
Slide 43: Video: Vernon_BTS_HispanicReel
Vernon_BTS_HispanicReel.wmv
Slide 44: Redefine Efficiency: Our Plan
Make Our People Our Competitive Edge Execute with Excellence Turbocharge Our Iconic Brands Redefine Efficiency Our Plan Drive industry-leading productivity Realize lowest-cost overheads
Slide 45: Drive Industry-Leading Productivity
Redefine Efficiency Drive Industry-Leading Productivity Lean Six Sigma Strategic-sourcing initiatives Maintenance optimization Simplification across supply chain Business-process excellence Manage labor-cost inflation Streamline and optimize manufacturing networks Raise the return bar for business i
Slide 46: Targeting At Least 2.5% Net Productivity
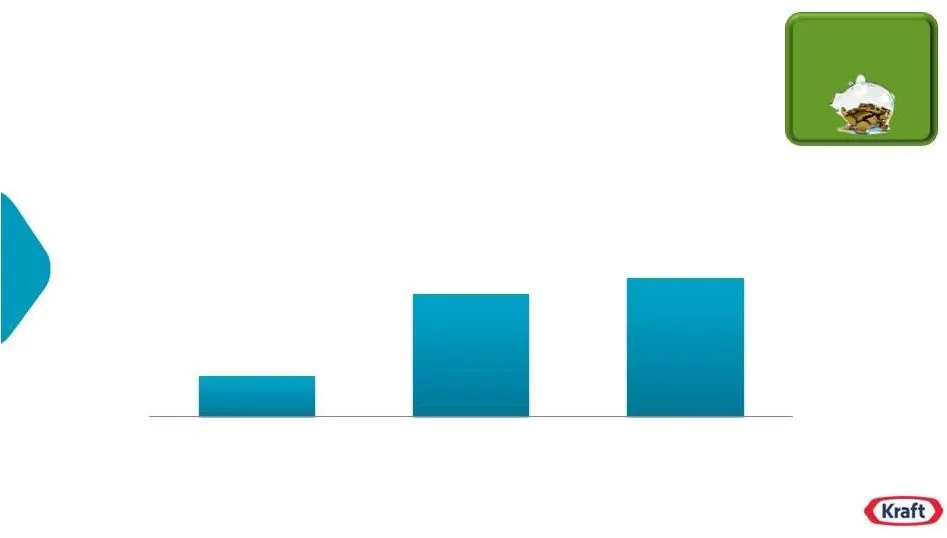
Redefine Efficiency Drive Industry-Leading Productivity We are targeting at least 2.5% net productivity Productivity as a % of COGS 1.5% ~2.5% At least 2.5% 2012E 2013+E
Slide 47: Realize Lowest-Cost Overheads
Realize Lowest-Cost Overheads “Clean sheet” approach to purge complex legacy structures, practices – Business decisions driven by commercial units – Small HQ with efficient shared-service model – Corporate function cost structures to live up to best-in-class external benchmarks Moving to standardize
Slide 48: Our Mission
Redefine Efficiency Turbocharge Our Iconic Brands Make Our People Our Competitive Edge Execute with Excellence Our Mission Make Kraft North American Food & Beverage Company

Slide 49: Tim McLevish, Chief Financial Officer
Tim McLevish Chief Financial Officer
Slide 50: The New Kraft Foods Group
The New Kraft Foods Group Who we are What we’ll do What to expect Meet our team
Slide 51: We have All the Ingredients for Success
We have All the Ingredients for Success A portfolio of the greatest brands in food & beverage Scale to achieve lowest delivered product costs and lowest overheads Strong and diverse management team Operational and financial momentum
Slide 52: Our Financial Targets Must Reflect Several Realities
But Our Financial Targets Must Reflect Several Realities A volatile commodity-price environment is here to stay We must reinvest to deliver sustainable growth We put dollars in shareholders’ pockets… not growth rates, not margins
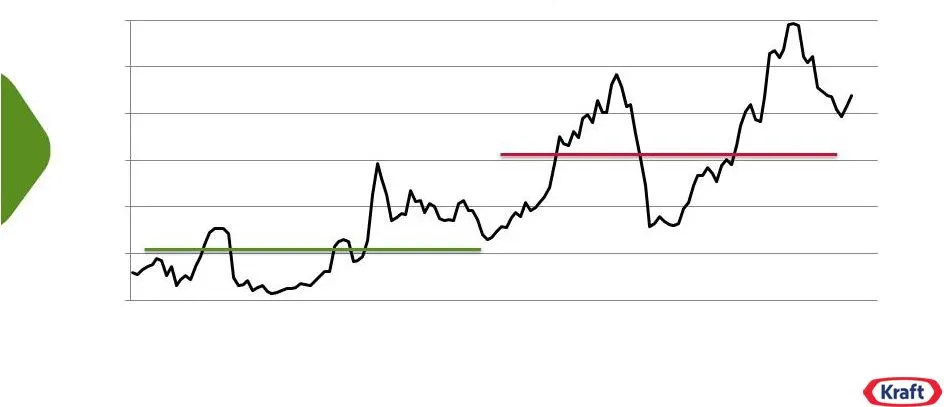
Slide 53: A Volatile Commodity-Price Environment is Here to Stay
A Volatile Commodity-Price Environment is Here to Stay KFG Commodity Price Index (2012E = 100%) Year Note: The index measures a basket of 23 commodities weighted to Kraft Foods Group volumes. Price multiplied by quantity equals total cost. This index holds quantity fixed at expected 2012 volumes and
Slide 54: We Must Reinvest to Deliver Sustainable Growth
We Must Reinvest to Deliver Sustainable Growth Many levers to deliver at least 2.5% net productivity Further opportunity from negative overhead growth (NOG) in the near-term, zero overhead growth (ZOG) long-term Need to be competitive and sustainable on several fronts – People – Brand building – Inn
Slide 55: We Put Dollars in Shareholders' Pockets
To We Put Dollars in Shareholders’ Pockets… Not Growth Rates, Not Margins Inconsistent commitment Key cultural priority Revenue growth and OI margin focus Balanced emphasis on both P&L and Balance Sheet No capital charges ROIC focus from strategic to operating decisions Functional silos, metrics and
Slide 56: Our Long-Term Growth Algorithm is Built to Last
Our Long-Term Growth Algorithm is Built to Last (1) Market defined as the North American Food & Beverage market (2) Free Cash Flow = Cash Flow from Operations, less Capital Expenditures Metric Long-Term Target Organic Revenue Profitable growth at or above market growth (1) Operating Income Consisten
Slide 57: How We Think about Other Drivers
How We Think about Other Drivers Driver Expectation Advertising Spend We expect to hit our Long-Term Targets for consistent growth in Operating Income dollars and Earnings Per Share even as we increase our share of voice Market Share We expect to deliver profitable growth at or above market growth*
Slide 58: Our Ongoing Guidance Policy
Our Ongoing Guidance Policy Will Help Us Focus on Sustainable Long-Term Shareholder Value Our long-term growth algorithm is our ongoing expectation – No point estimates on annual or quarterly P&L line items We will provide quantitative assessments – Material events (e.g., extraordinary pruning, acqu
Slide 59: Using 2012 Reported Financials Will Make Projecting Results Difficult
We Recognize that Using Our 2012 Reported Financials Will Make Projecting Future Results Difficult Expect solid top-line and underlying profit growth, consistent with previous KFT guidance Q1-Q3 presentation based on Form 10 requirements – Carve-out financials below revenue reflect ParentCo charges
Slide 60: 2013 Guidance: Continued Momentum, Clean Base
2013 Guidance: Continued Momentum, Clean Base Organic revenue growth in line with market growth – Including pruning impact of ~(1)pp Productivity, overhead savings to drive ~$2.60 GAAP EPS – Interest expense ~$520MM – Tax rate ~35% – Includes restructuring costs of ~$240MM or $0.26 per share versus
Slide 61: Debt Profile with No Maturities Until June 2015
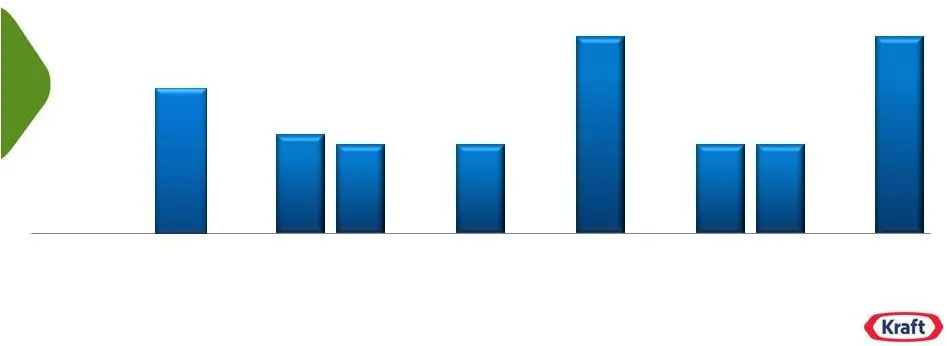
Our Debt Profile is Relatively Fixed at an Average Rate of 5% and No Maturities Until June 2015 ($ Millions) $1,400 $1,000 $900 $900 $2,000 $896 $900 $2,000 Debt Maturity Profile Source: Kraft Foods Group Form 10 filing
Slide 62: Priorities for Free Cash Flow
Priorities for Free Cash Flow Fund a highly competitive dividend Reinvest in the business Acquisitions that quickly achieve EPS accretion and an IRR > risk-adjusted hurdle rate Share repurchase
Slide 63: Well-Positioned to Deliver Predictable Returns
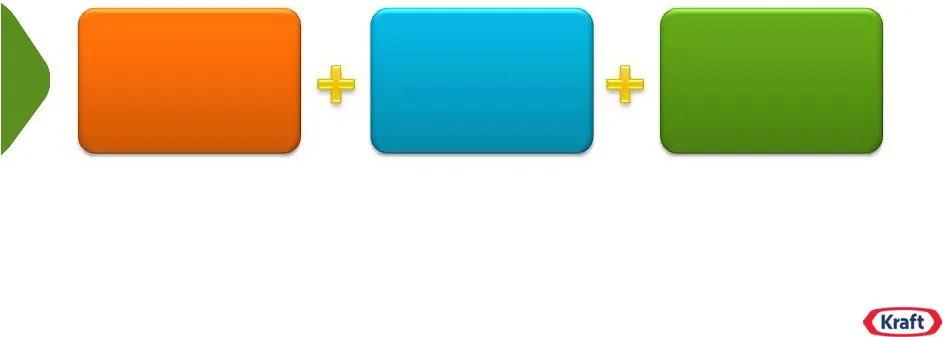
Profitable Top-Line Growth Consistent Bottom-Line Growth Superior Dividend Payout We are Well-Positioned to Deliver Predictable Returns

Slide 64: Tony Vernon, Chief Executive Officer
Tony Vernon Chief Executive Officer
Slide 65: Our Mission
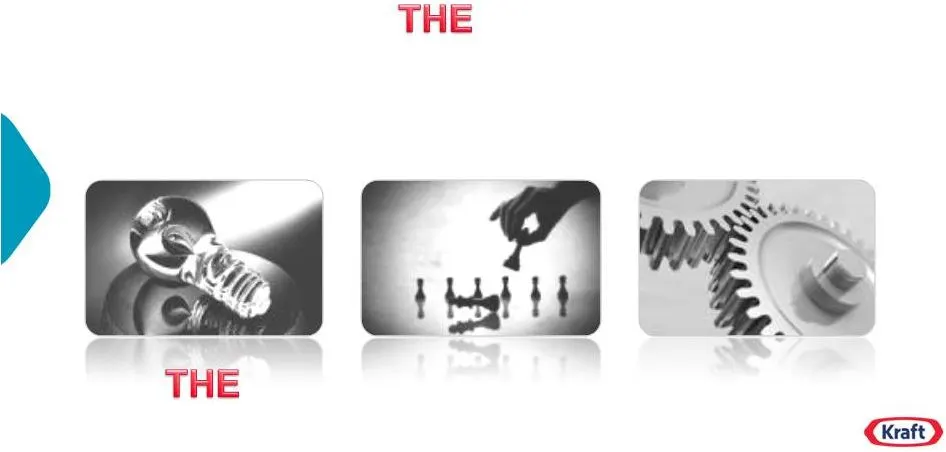
Our Mission THE Innovator THE Strongest Portfolio THE Lowest Cost Producer Make Kraft North American Food & Beverage Company Best Investment in the Industry
Slide 66: The New Kraft Foods Group
The New Kraft Foods Group Who we are What we’ll do What to expect Meet our team
Slide 67: Our Team
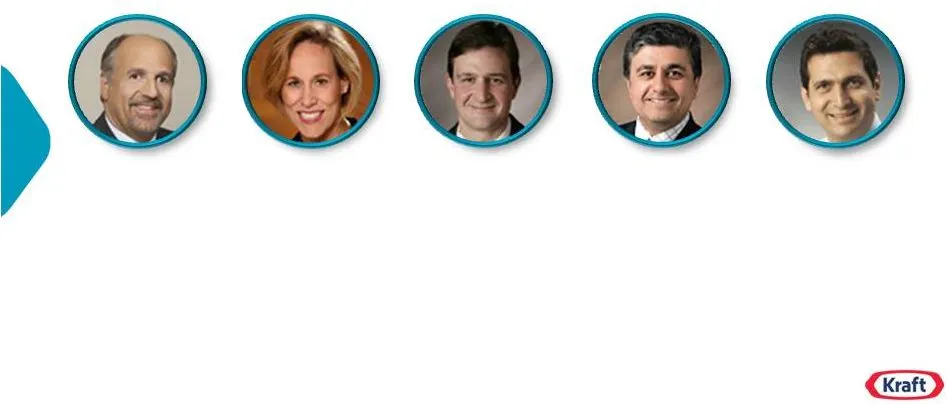
Our Team Deanie Elsner EVP and President, Beverages George Zoghbi EVP and President, Cheese & Dairy Michael Osanloo EVP and President, Grocery Nick Meriggioli EVP and President, Oscar Mayer Dino Bianco EVP and President, National Businesses and Marketing Services *Effective when the spin-off occurs
Slide 68: Our Team
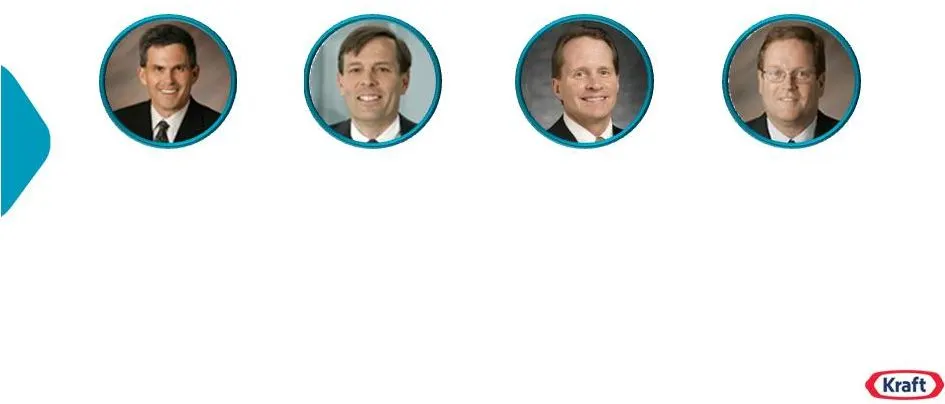
Our Team Chuck Davis EVP, Research, Development, Quality and Innovation Robert Gorski EVP, Integrated Supply Chain Tom Corley EVP and President US Sales Tom Sampson EVP, Business Transformation *Effective when the spin-off occurs
Slide 69: Our Team
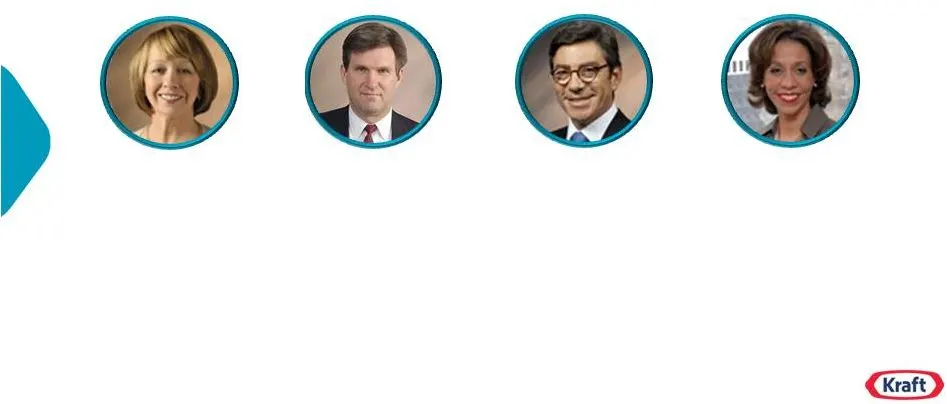
Our Team Kim Rucker EVP, Corporate & Legal Affairs, General Counsel and Corporate Secretary Diane Johnson May EVP, Human Resources Sam Rovit EVP, Strategy President, Planters *Effective when the spin-off occurs Tim McLevish EVP and Chief Financial Officer
Slide 70
Slide 71: GAAP to Non-GAAP Reconciliation
GAAP to Non-GAAP Reconciliation Reported (GAAP) Unrealized G/(L) on Hedging Activities Headquarter Pension Expense General Corporate Expenses Adjusted Operating Income (Non-GAAP) Net Revenue 18,655 $ - $ - $ - $ 18,655 $ Operating Income 2,923 (63) (155) (55) 3,196 Operating Income Margin 15.7% 17.1
Slide 72: GAAP to Non-GAAP Reconciliation
GAAP to Non-GAAP Reconciliation Reported (GAAP) Impact of Divestitures Impact of the 53rd Week of Shipments Impact of Currency Organic (Non-GAAP) Reported (GAAP) Organic (Non-GAAP) Vol / Mix Pricing June 30, 2012 4,786 $ - $ - $ $ 4,811 $ 0.9% 1.5% (1.4)pp 2.9pp June 30, 2011 4,741 - - - 4,741 March
Slide 73: GAAP to Non-GAAP Reconciliation
GAAP to Non-GAAP Reconciliation Reported (GAAP) Restructuring Costs Unrealized G/(L) on Hedging Activities Headquarter Pension Expense General Corporate Expenses Adjusted Operating Income (Non-GAAP) June 30, 2012 2,963 $ (116) $ (26) $ (194) $ (40) $ 3,339 $ June 30, 2011 2,929 - (146) (81) 3,141 Tr
Slide 74: GAAP to Non-GAAP Reconciliation
GAAP to Non-GAAP Reconciliation Reported (GAAP) Restructuring Costs Unrealized G/(L) on Hedging Activities Headquarter Pension Expense General Corporate Expenses Adjusted Operating Income Margin (Non-GAAP) June 30, 2012 15.8% (0.6)pp (0.2)pp (1.0)pp (0.2)pp 17.8% June 30, 2011 16.2% 0.0pp 0.1pp (0.8
Source: SEC EDGAR · 8-K filed Sep 7, 2012
More decks from Kraft Foods Group Inc
 Merger or Acquisition (March 2015)35 slides · Mar 25, 2015
 Merger or Acquisition (March 2015)34 slides · Mar 25, 2015
 Kraft Foods Group Back-to-School Conference 201438 slides · Sep 3, 2014
 CAGE Conference 201436 slides · Mar 17, 2014
 CAGNY Conference 201438 slides · Feb 18, 2014
 Barclays Back-to-School Conference 201339 slides · Sep 4, 2013