SunCoke Energy Partners L.P — NAPTP 2013 MLP Annual Investor Conference
33 slides from SunCoke Energy Partners L.P's conference presentation, May 22, 2013
Slide 1: NAPTP 2013 MLP Annual Investor Conference
Exhibit 99.2 Exhibit NAPTP Investor May 22,99.2 2013 Conference 2013 MLP
Slide 2: Mark Newman, Senior Vice President and Chief Financial Officer
Mark Newman Senior Chief Financial Vice President Officerand
Slide 3: Forward-Looking Statements
Forward-Looking Some 1934, (“SunCoke”) assumptions position, that “will,” Although plans, SunCoke the those included place forward-looking This are 3NAPTP provided Securities are presentation undue expressed as of intentions “should” not 2013 amended. the in potential and management this historical
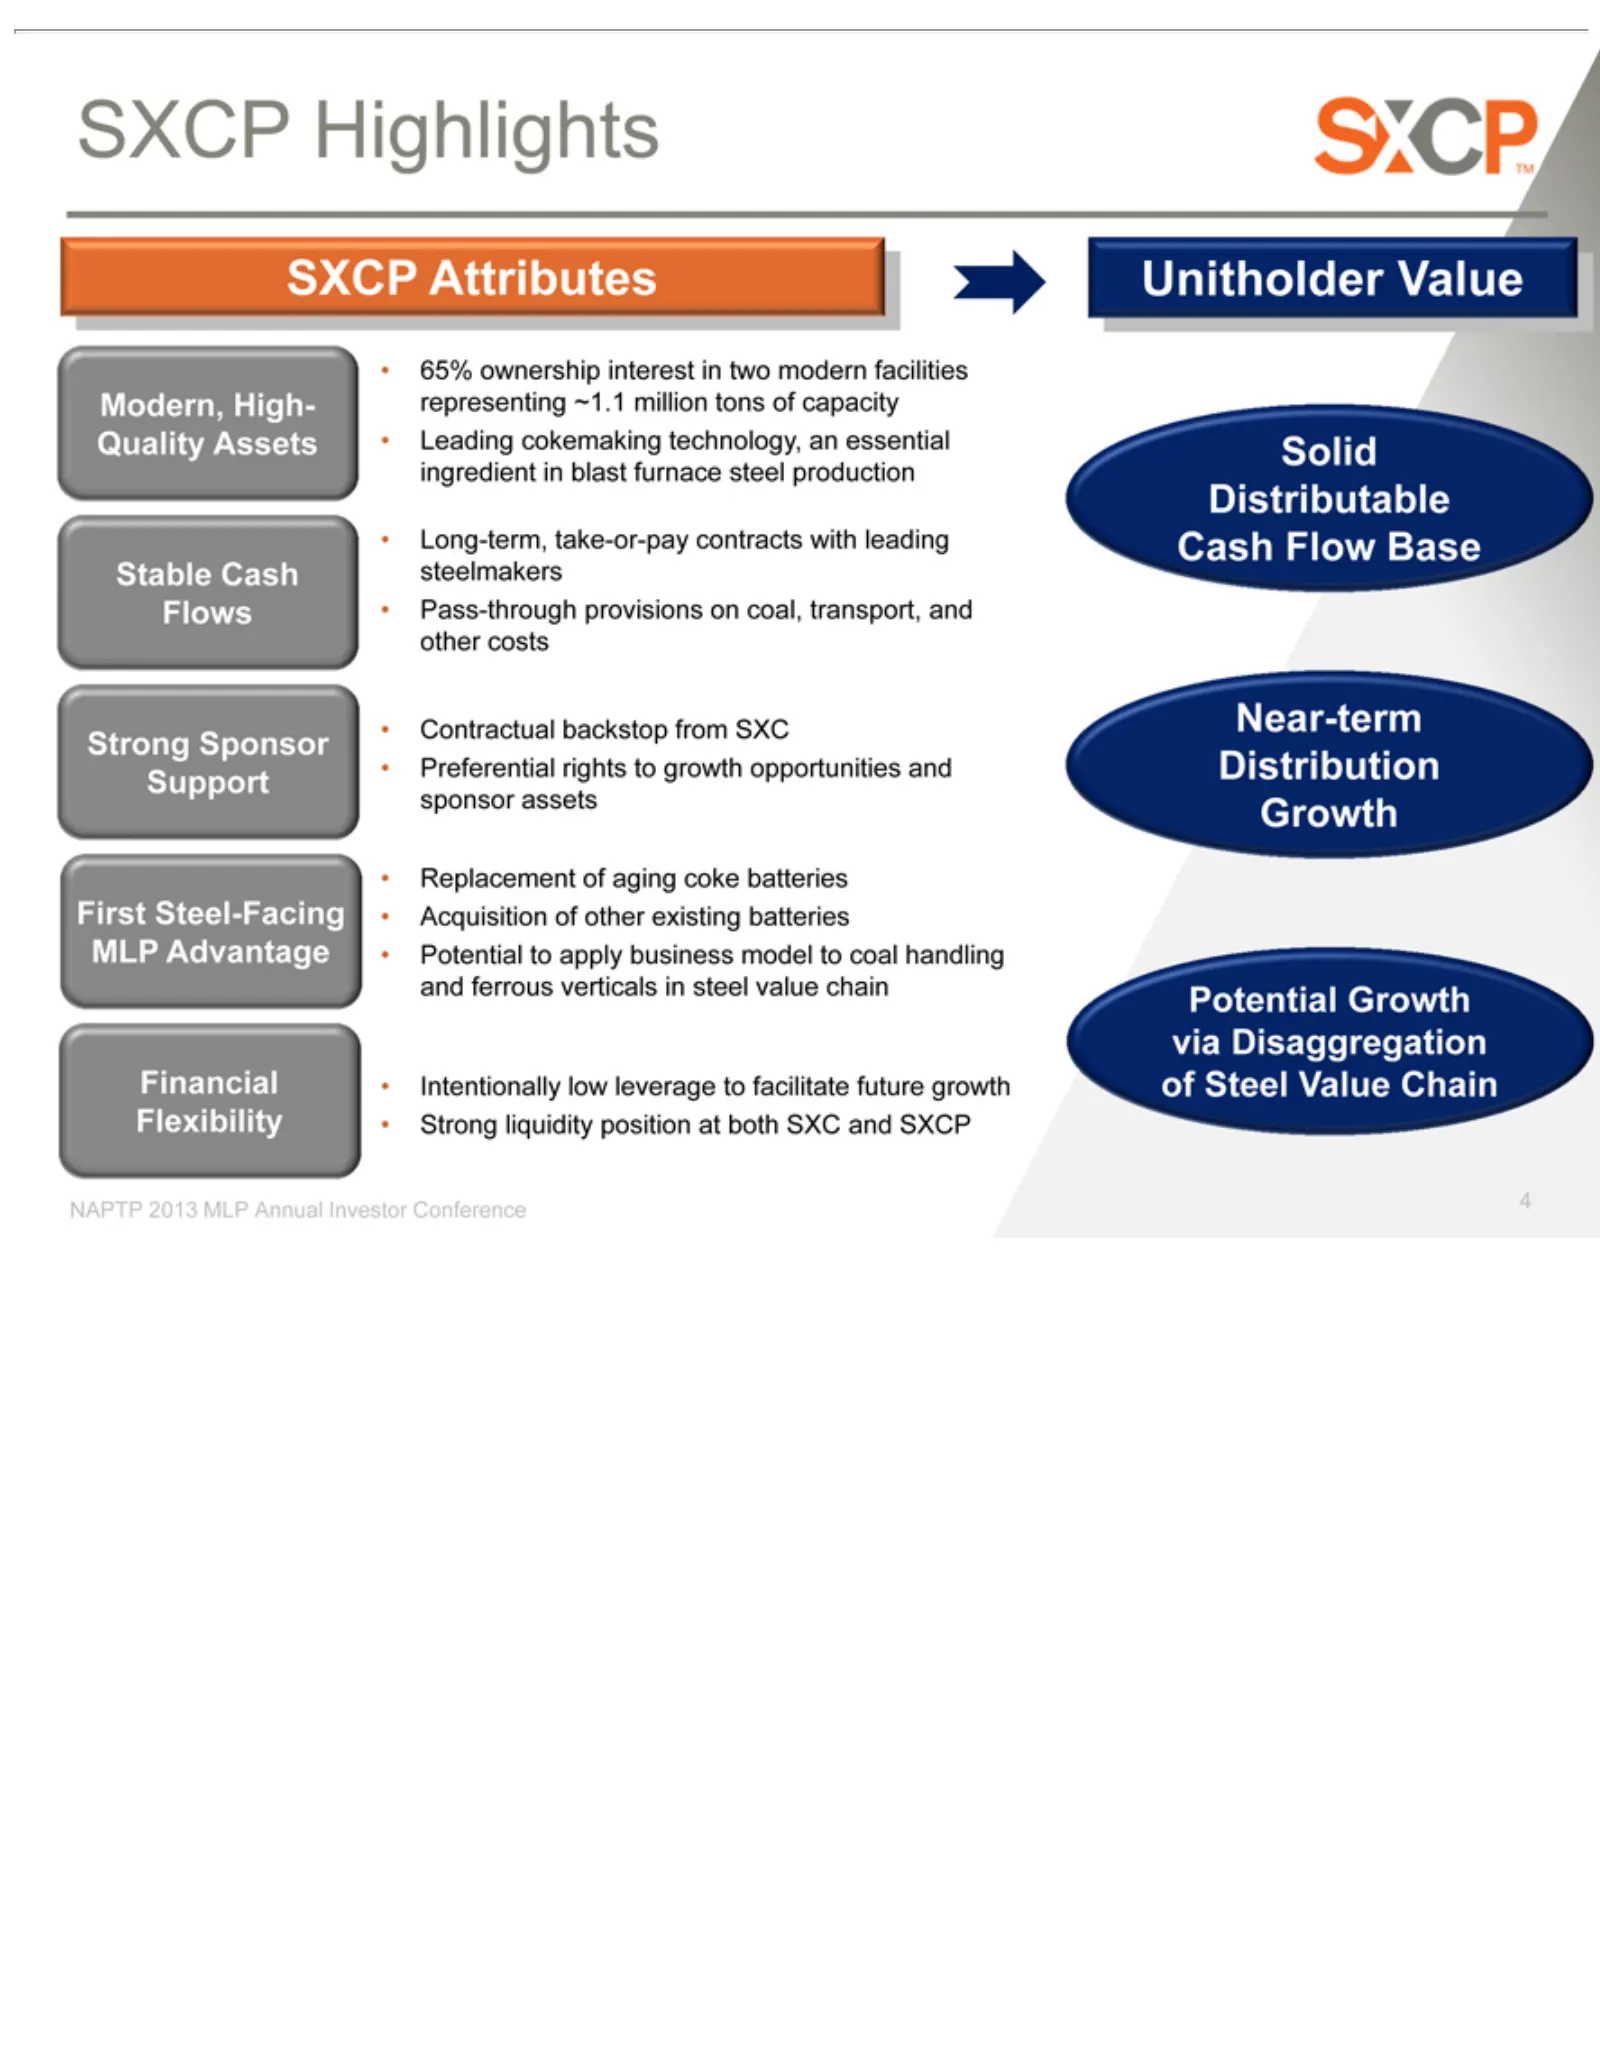
Slide 4: SXCP: Modern, Stable, Long-term cash flows
SXCPownership Modern, Stable First Financial 65% Leading Long-term, Pass-through Contractual Preferential Replacement Acquisition Intentionally Strong Unitholder Solid Near-term Potential 4NAPTPSteel-Facing Distributable Attributes Highlights Cash Sponsor liquidity 2013 cokemaking High-Quality to Gr
Slide 5: Video: This is SXCP
Video: The http://www.sxcpartners.com/phoenix.zhtml 5NAPTP “This This 2013 isisSXCP” MLP SXCPAnnual video isInvestor available Conference for viewing c=251513&p=index on the SunCoke Energy Partners, L.P. website:
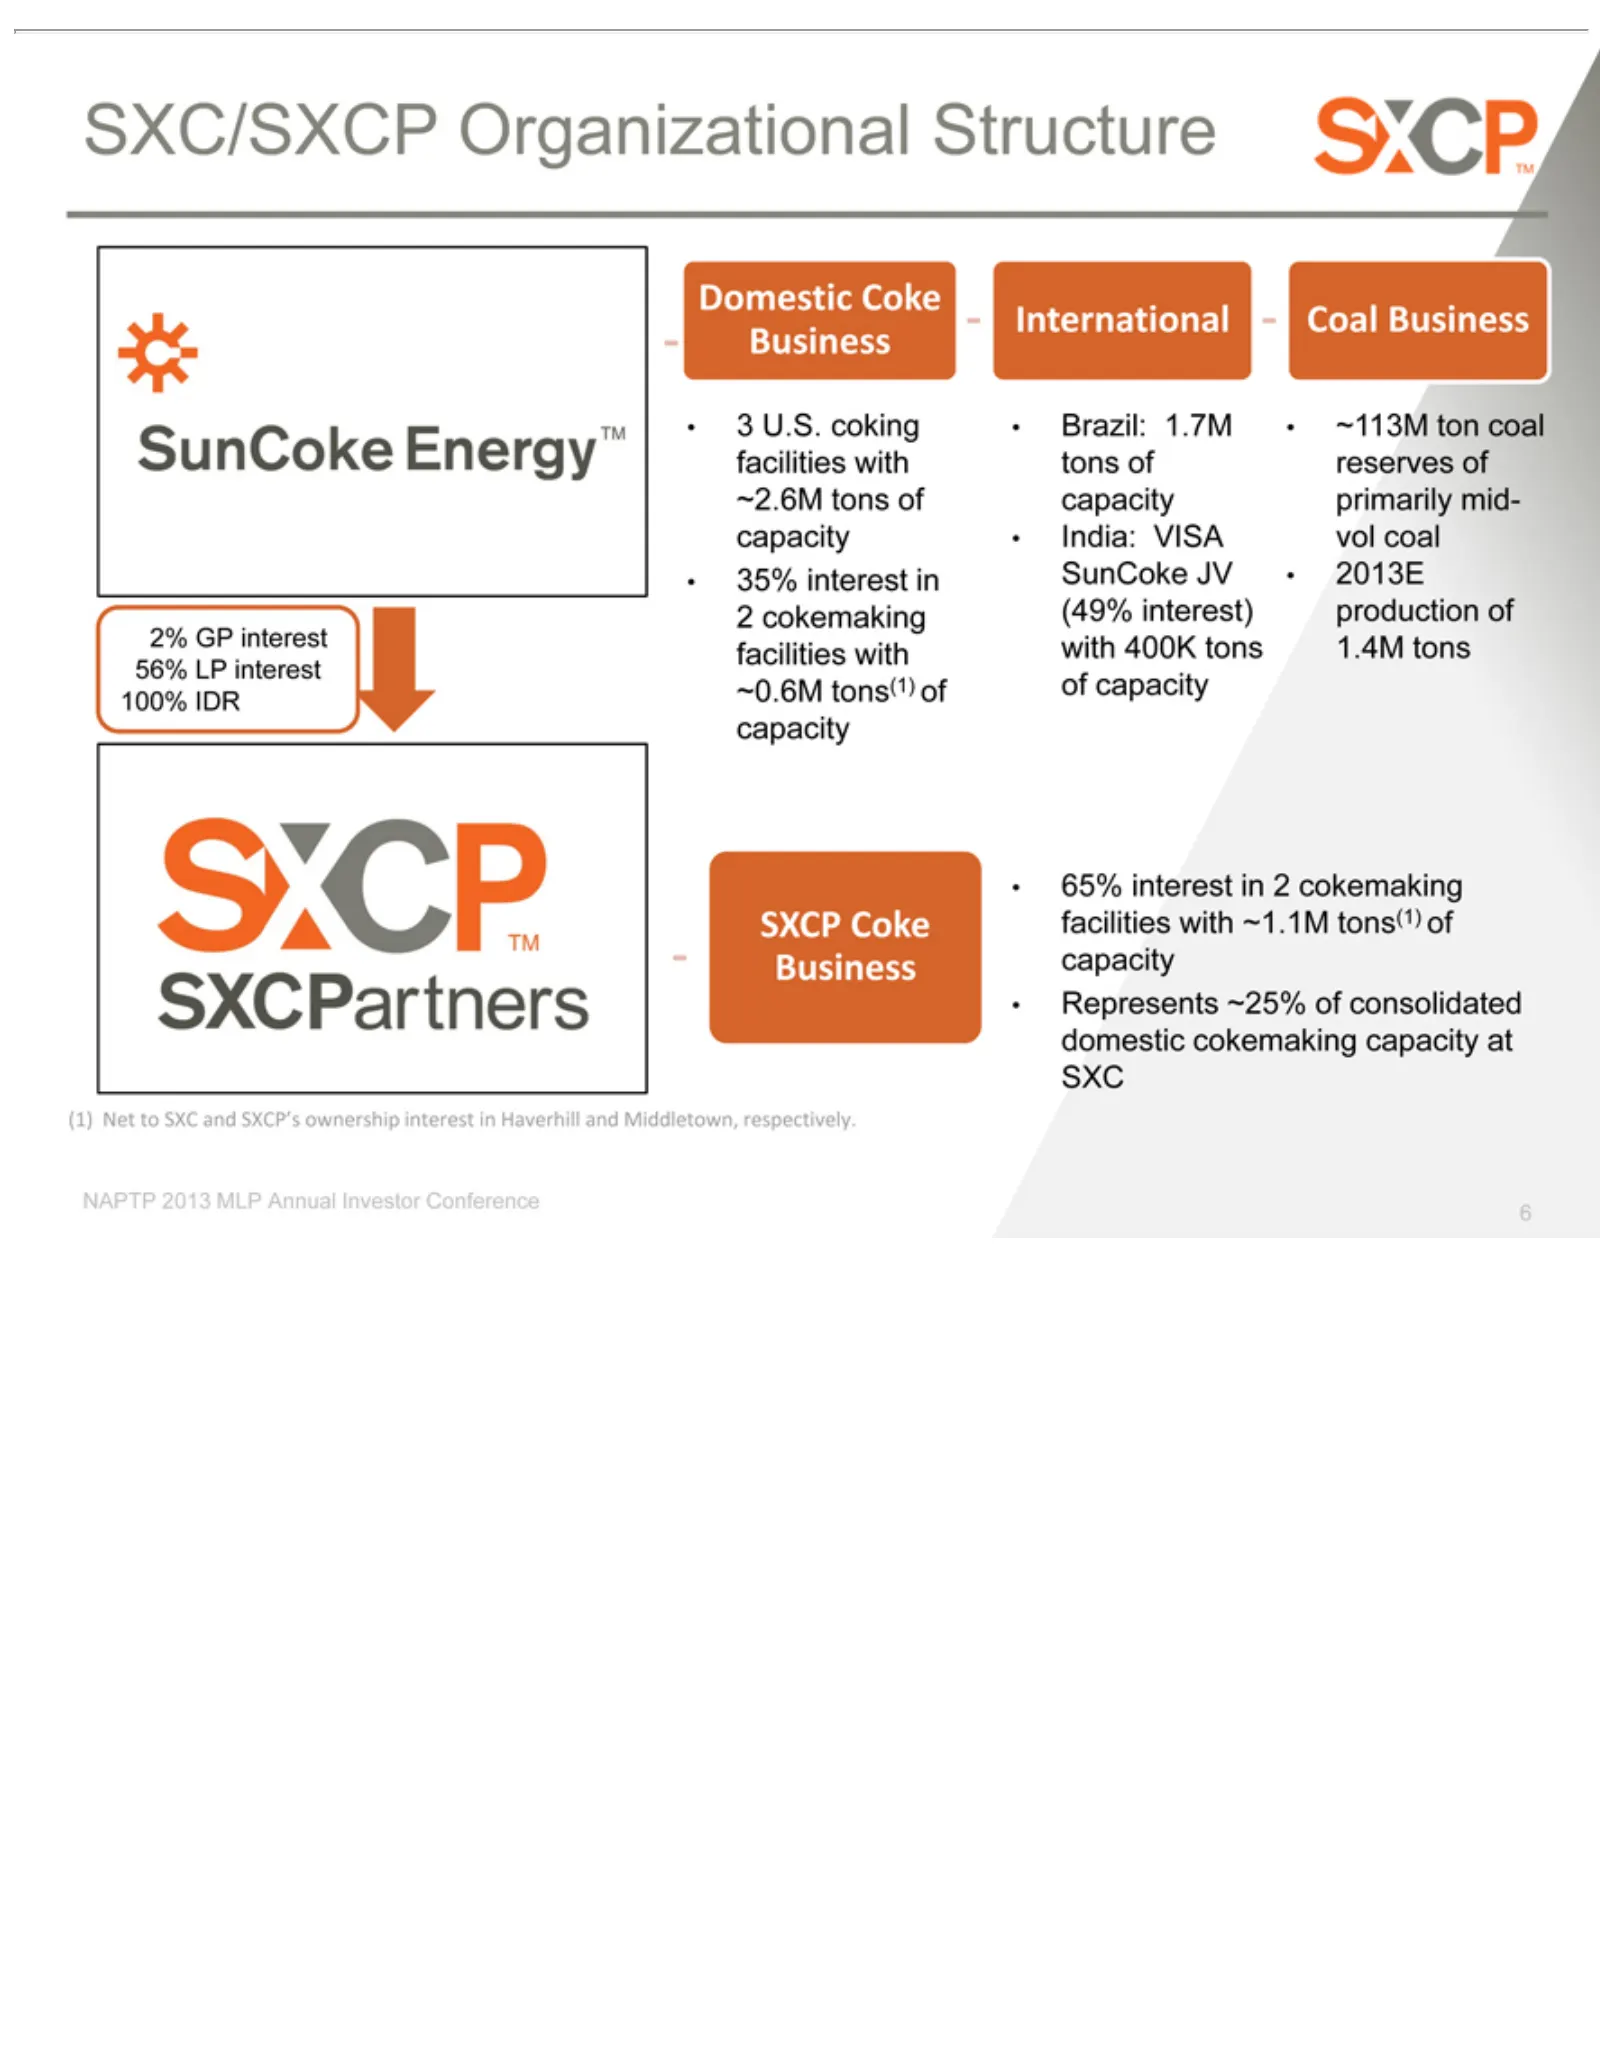
Slide 6: SXC/SXCP Domestic Business
SXC/SXCP 2% Domestic Business 2~2.6M facilities ~0.6M International •tons capacity SunCoke (49% with of Coal ~113M reserves primarily vol production 2013E 1.4M SXCP 65% Represents (1) 6NAPTP 3cokemaking 35% Brazil: India: capacity U.S. Net coal GP of 400K interest Business tons interest) interest Co
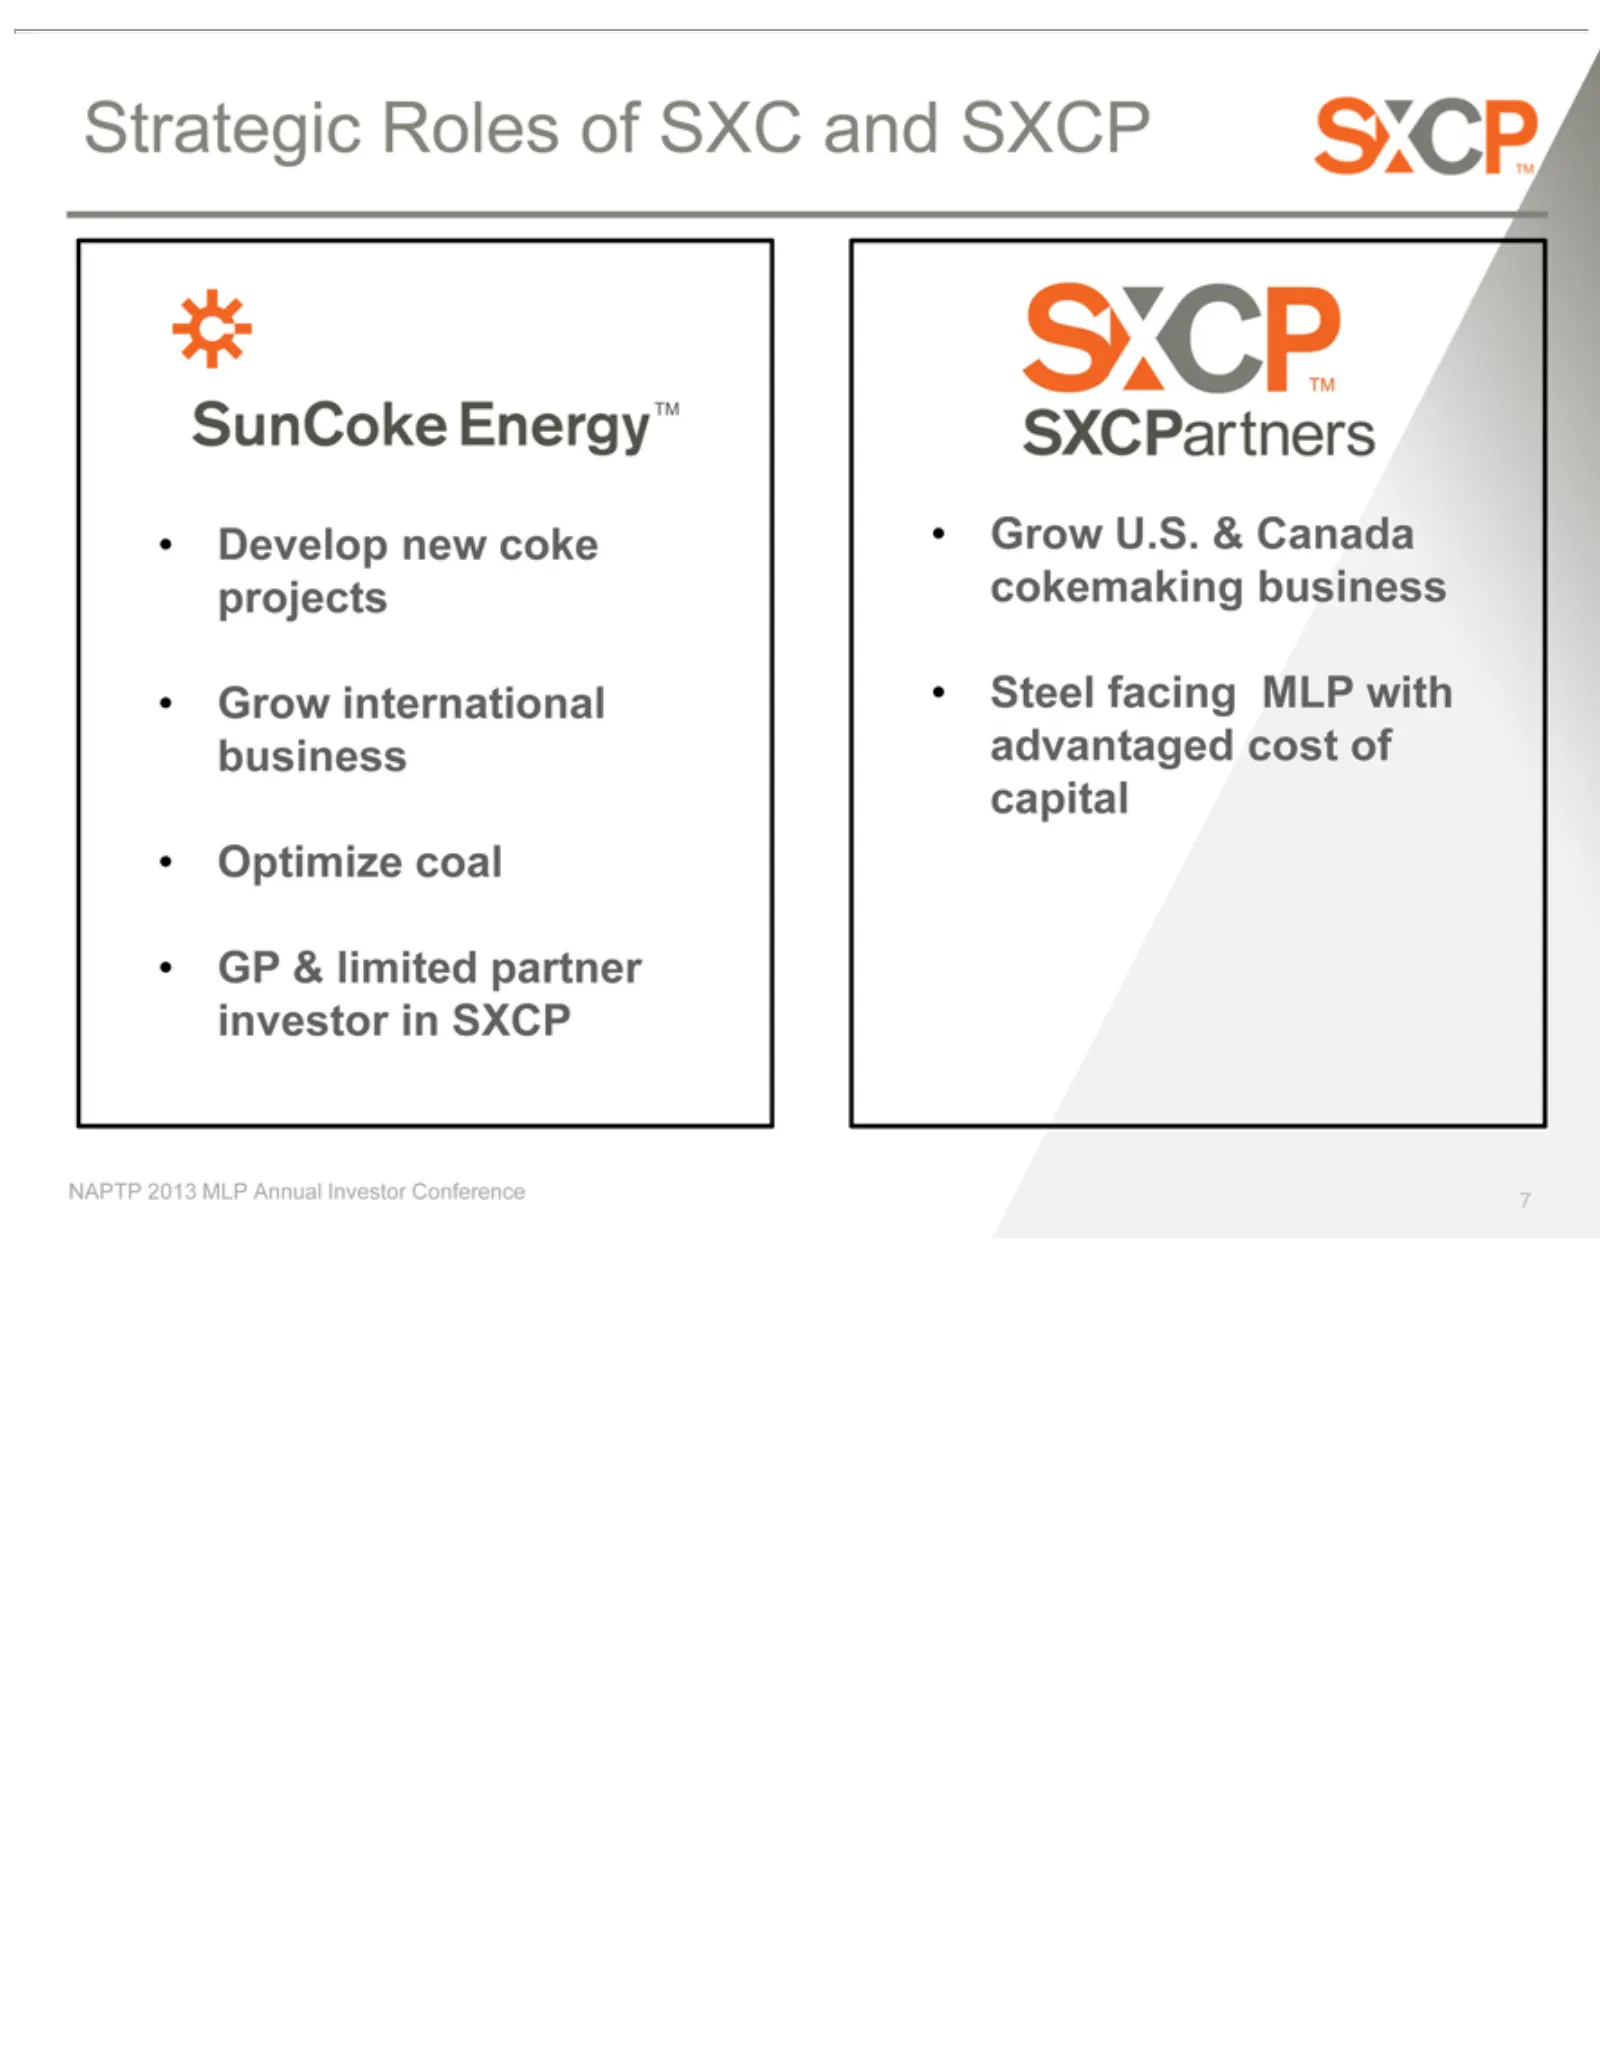
Slide 7: Strategic Roles of SXC and SXCP
Strategic Develop Optimize GP Grow Steel 7NAPTP &facing limited international U.S. 2013 new Roles coal &MLP coke Canada partner MLP of with SXC projects business Annual investor cokemaking advantaged andInvestor SXCP in SXCP business cost Conference of capital
Slide 8: SunCoke's Domestic Cokemaking Business Model and Technology
SUNCOKE’S & 8NAPTP DOMESTIC 2013 MLP COKEMAKING BUSINESS Annual Investor MODEL TECHNOLOGY Conference
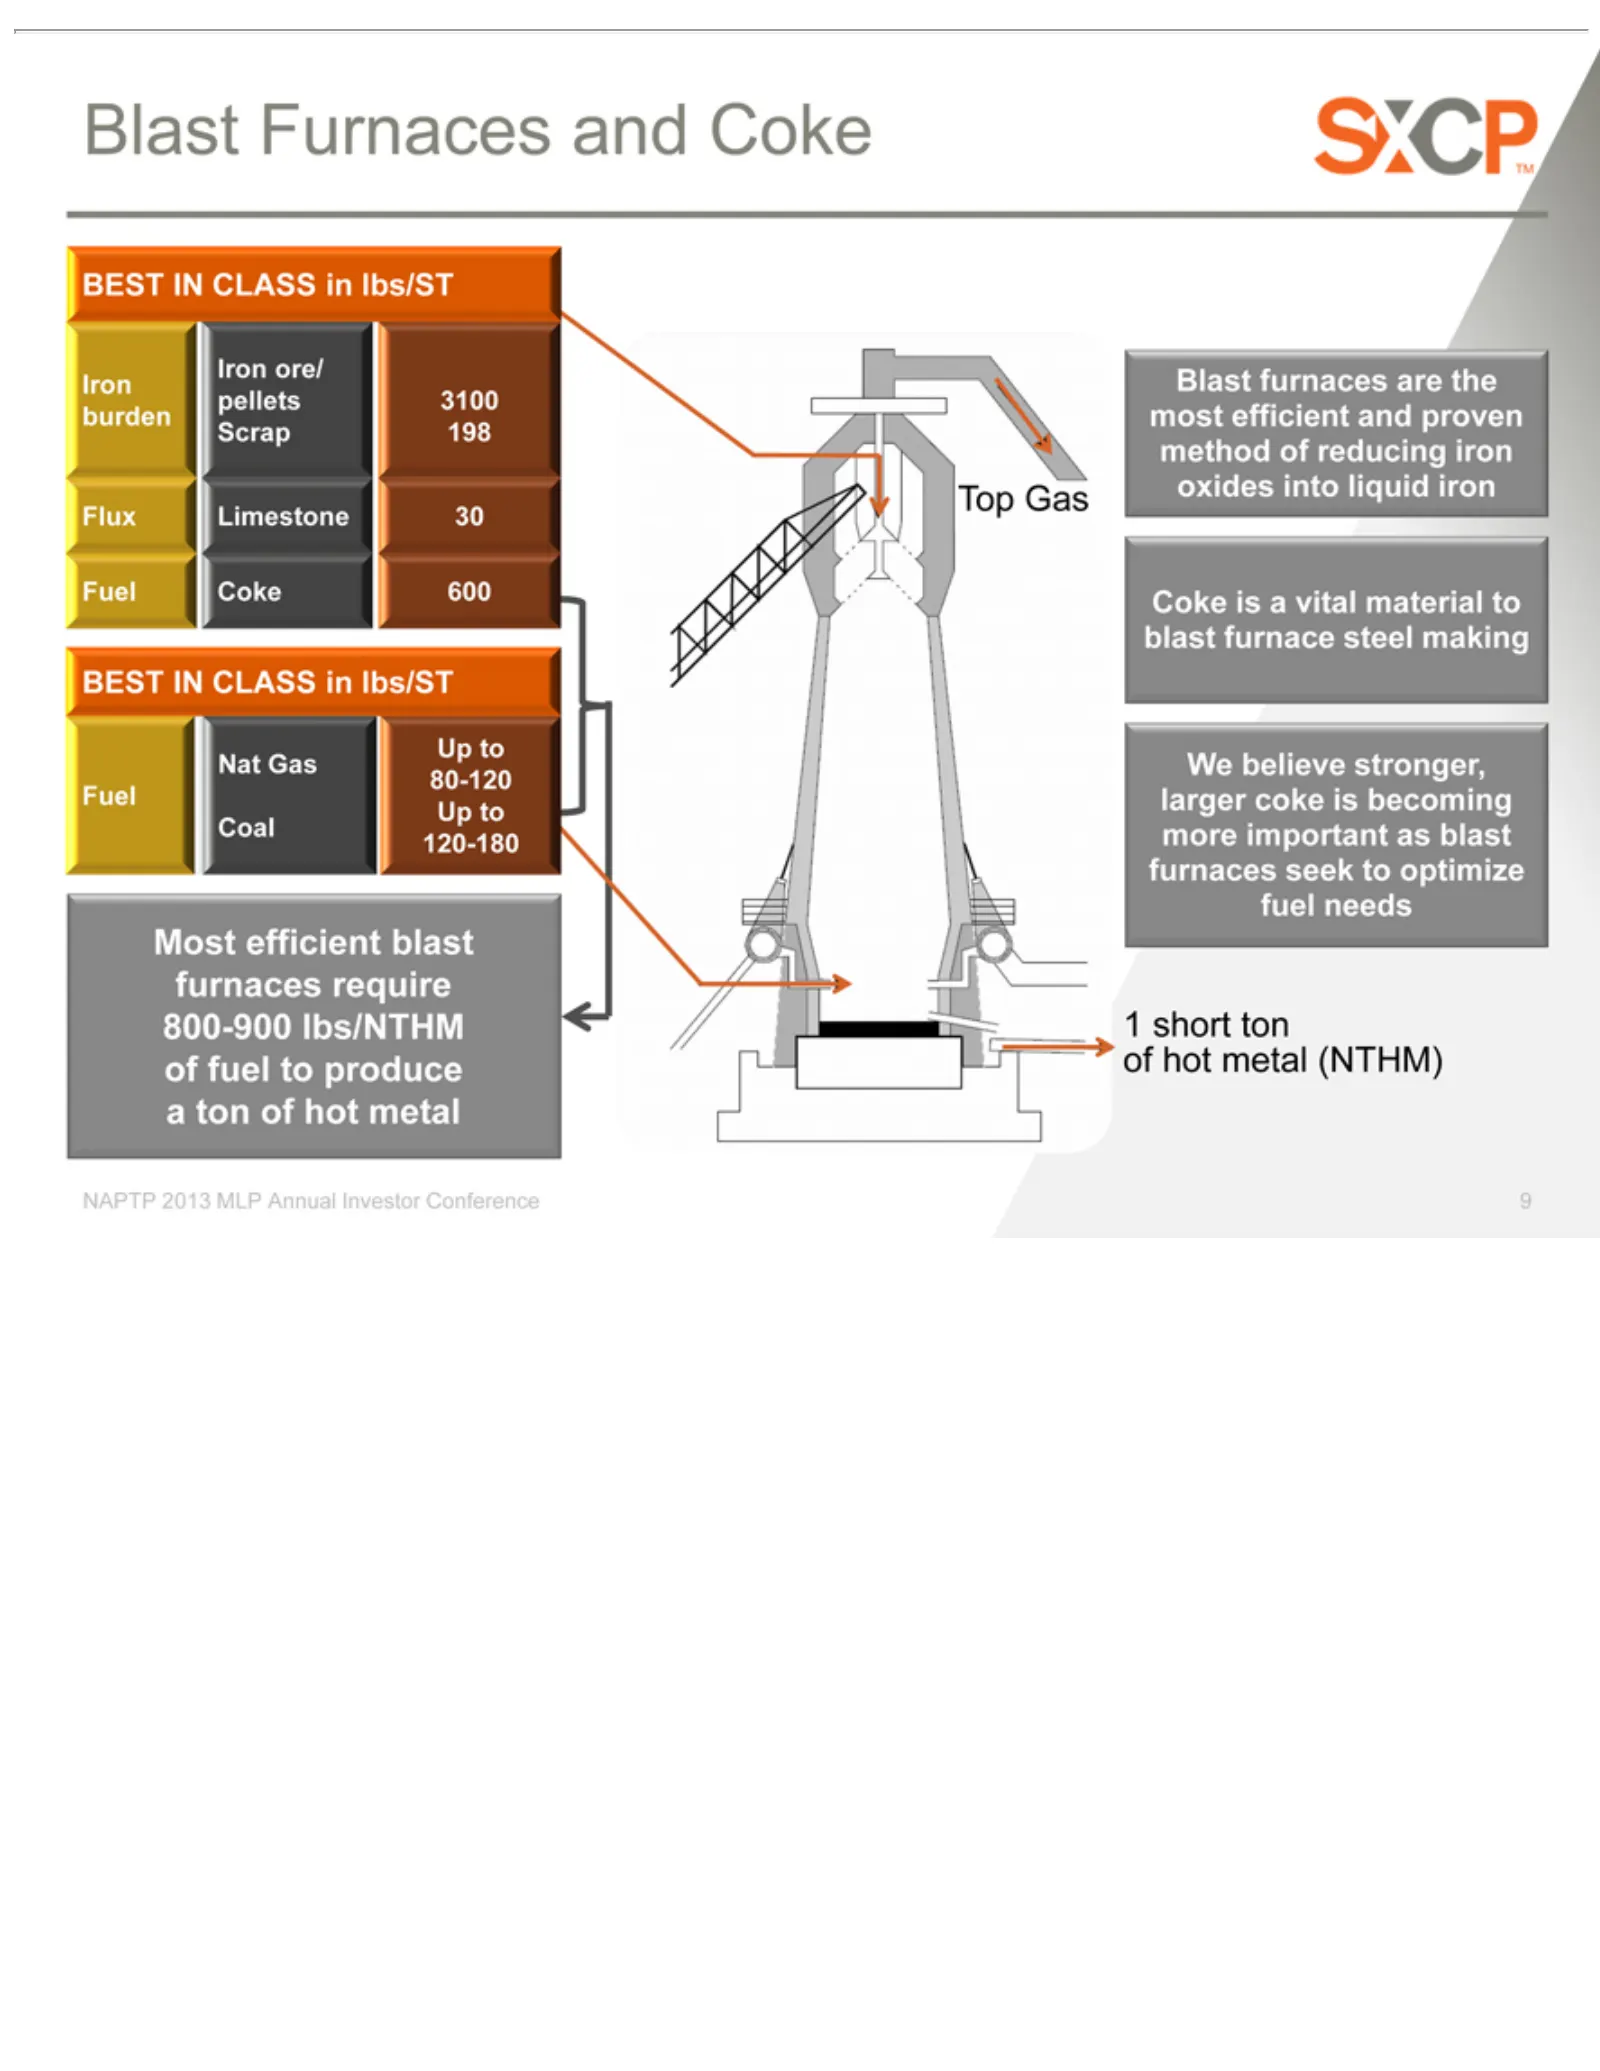
Slide 9: Coke is a vital material in blast furnace steelmaking
Iron burden Flux BEST Nat Fuel Up Coal Most Top Blast Coke 1We 9NAPTP short to believe Gas ore/ pellets okeCoke 80-120 Limestone 120-180 Furnaces furnaces efficient isIN ton Scrap a2013 Up vital CLASS of stronger, 3100 to198 hot MLP 600 blast are material and 30metal in the Annual Coke furnaces lbs/
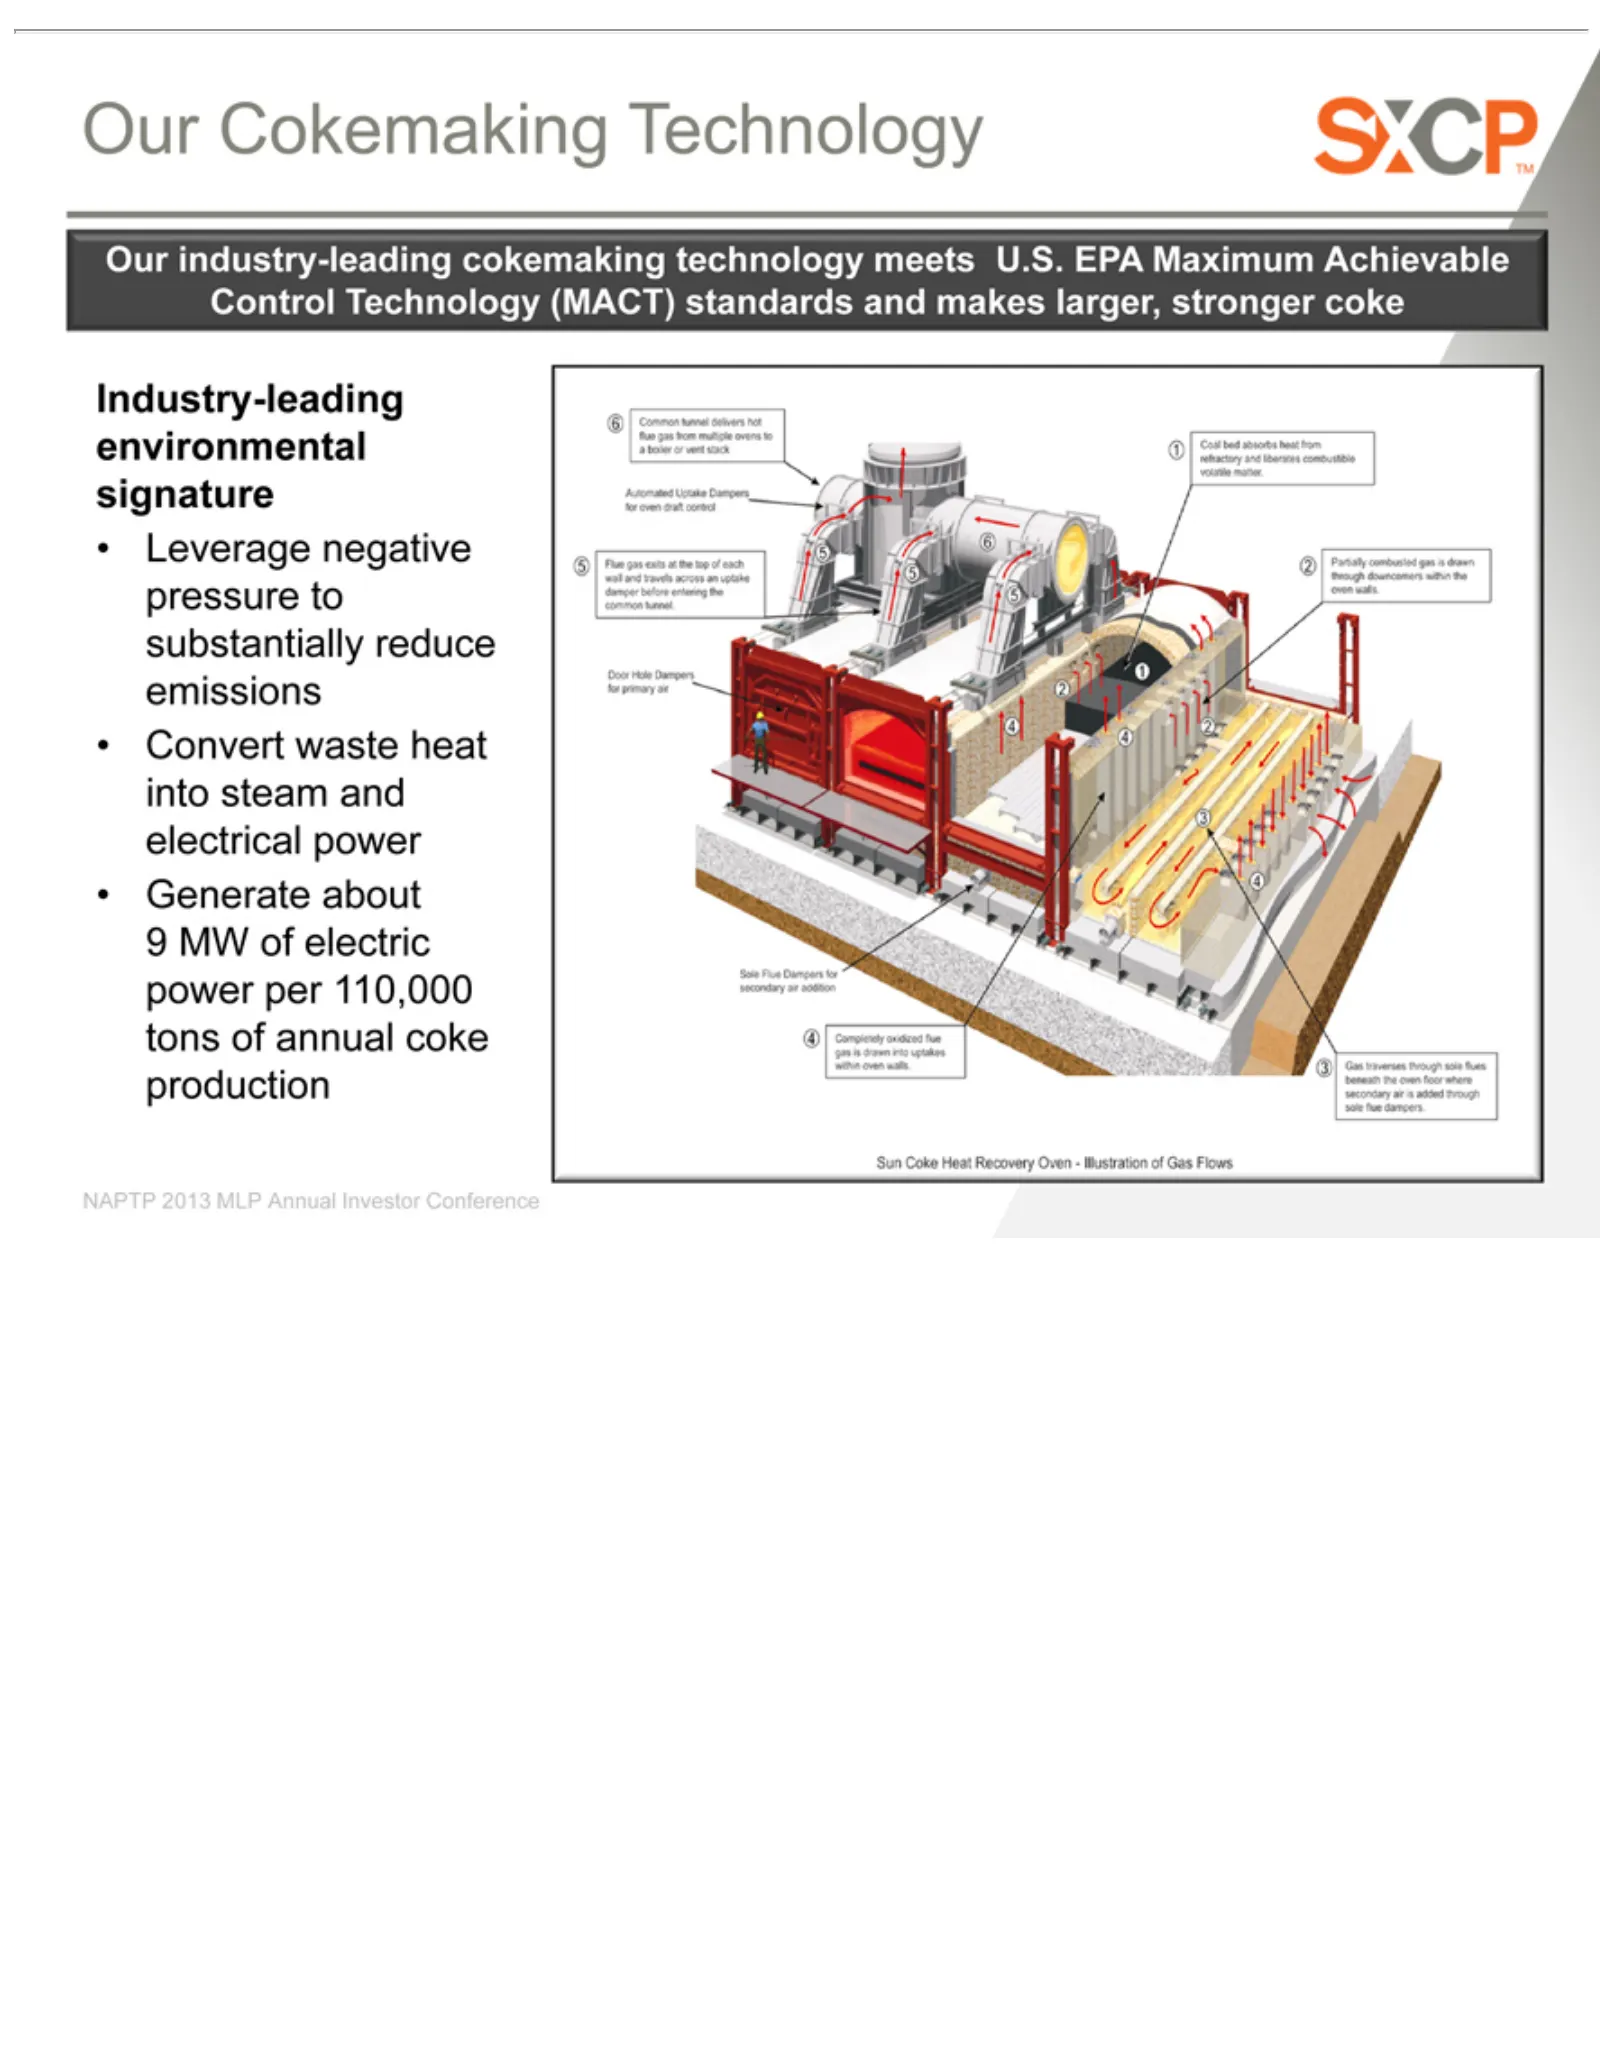
Slide 10: Our signature environmental technology
Our signature environmental Industry-leading pressure substantially emissions into 9•electrical power tons NAPTP production Leverage Convert Generate MW Cokemaking industry-leading steam ofper of annual 2013 toelectric power waste 110,000 and about negative reduce MLP coke heat Technology Annual cok
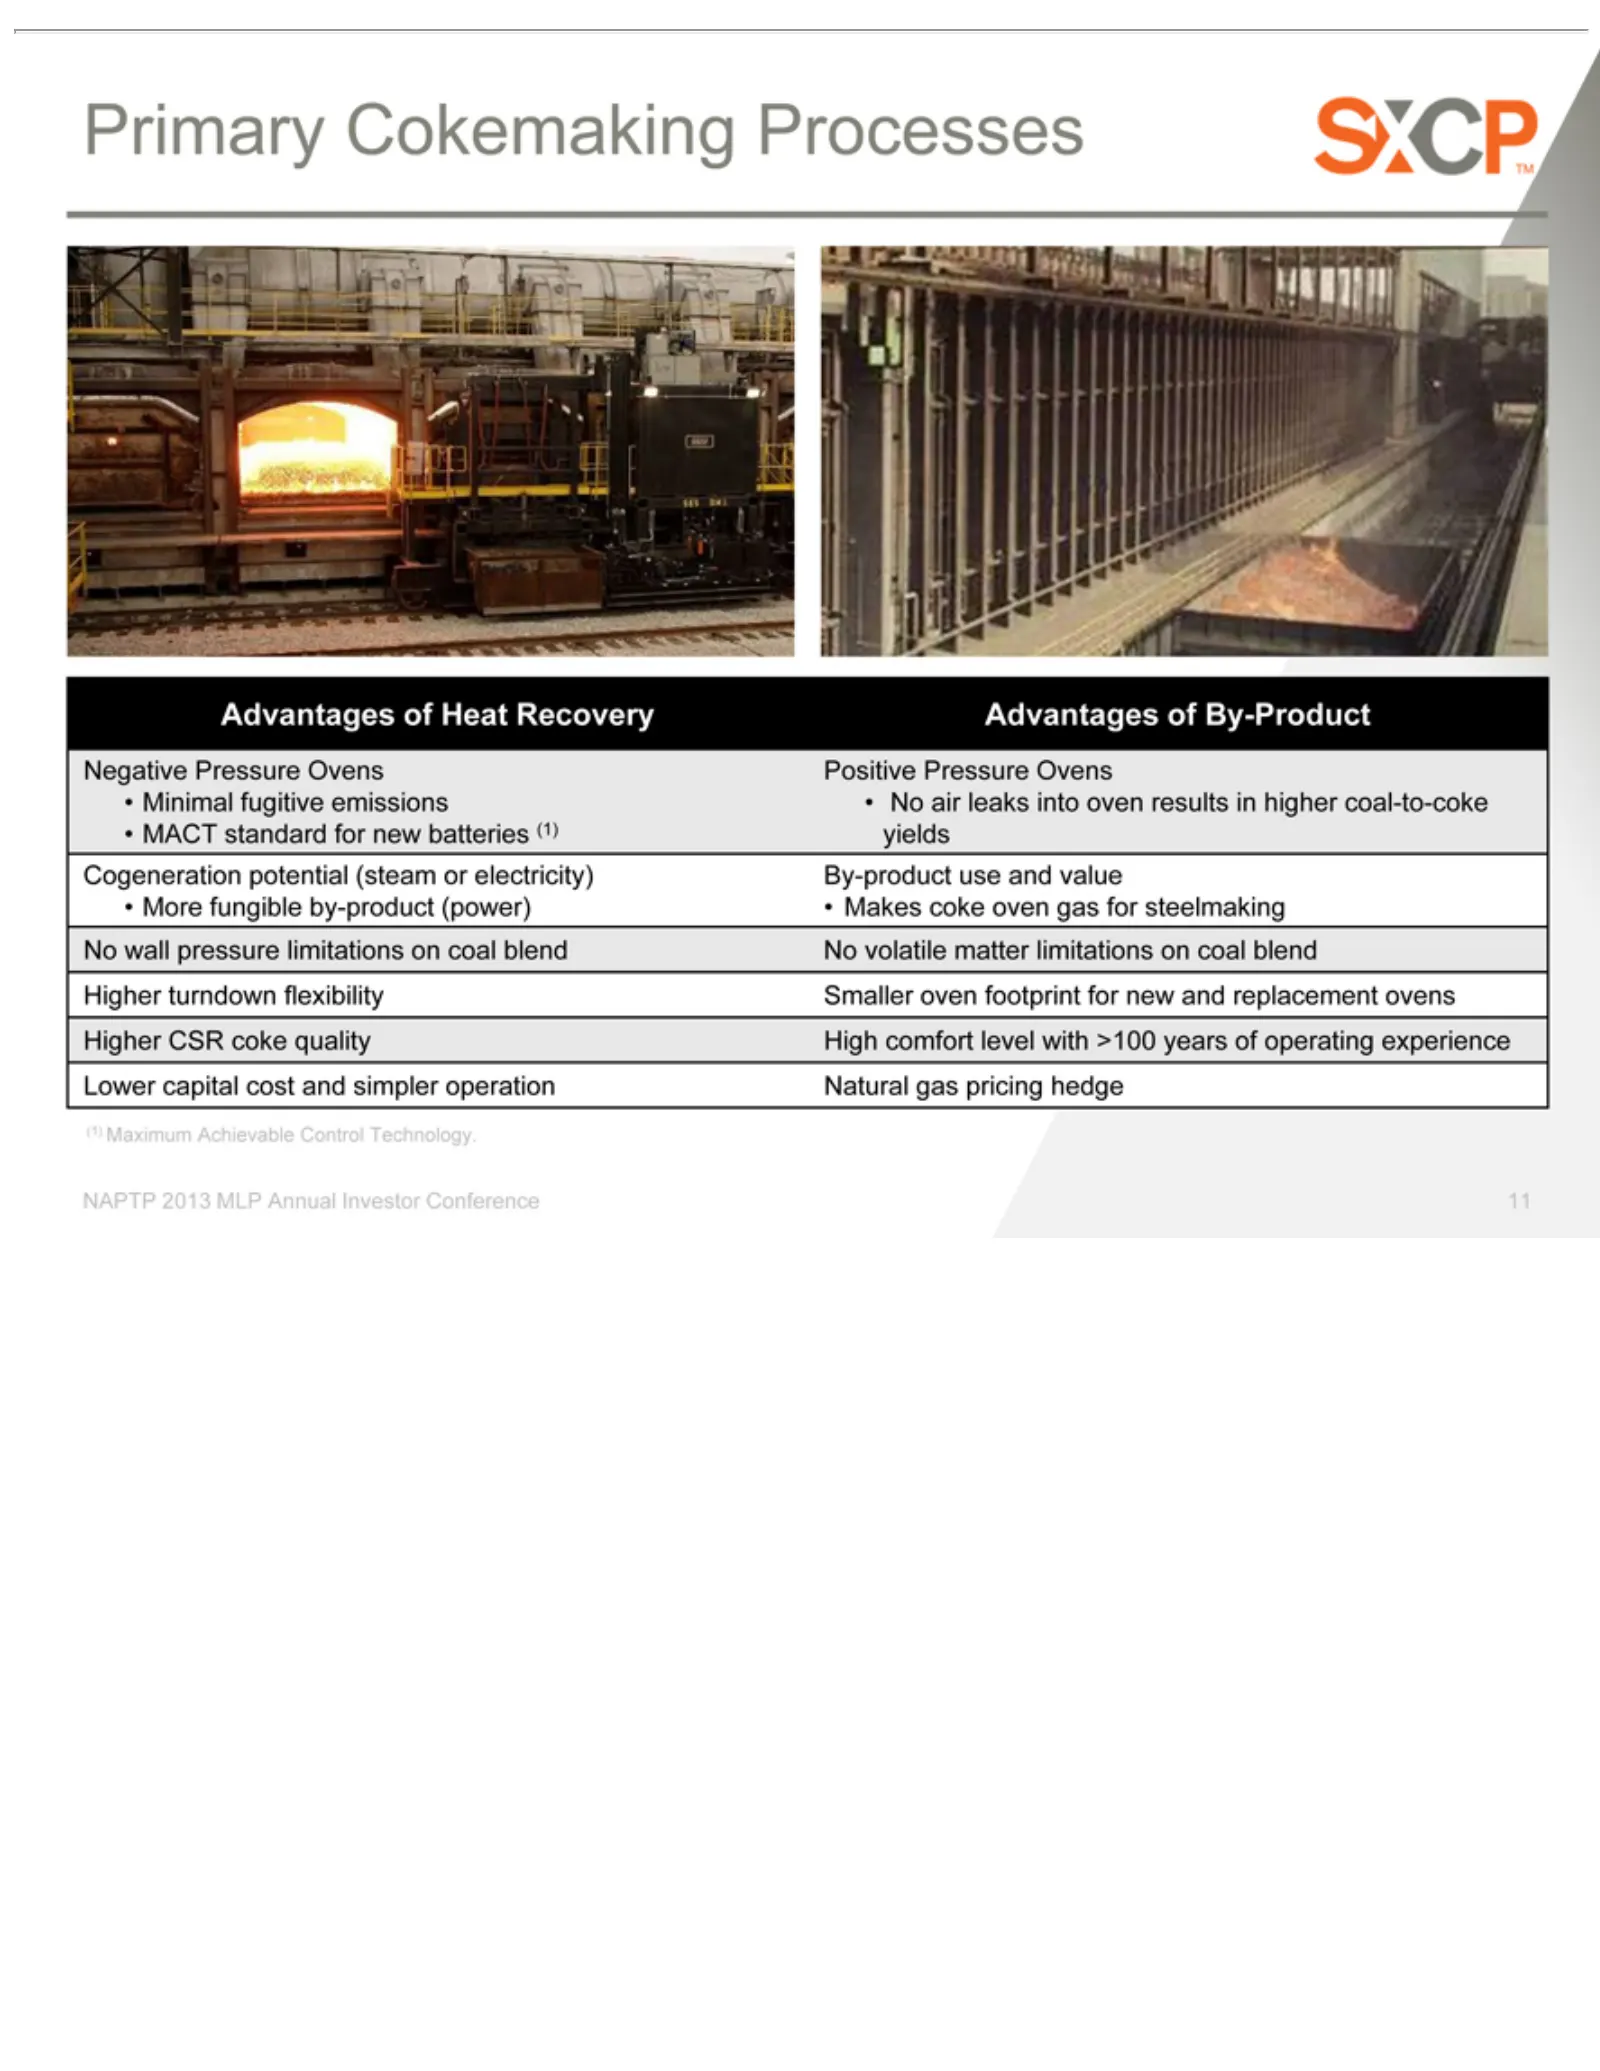
Slide 11: Advantages of Heat Recovery Cokemaking
Primary Negative Cogeneration M Higher Lower Advantages Positive By-product •yields No Smaller High Natural (1) NAPTP 11No Makes inimal ACT ore Maximum wall volatile air comfort fungible capital turndown CSR standard gas oven leaks 2013 pressure Cokemaking Pressure coke fugitive Pressure matter use
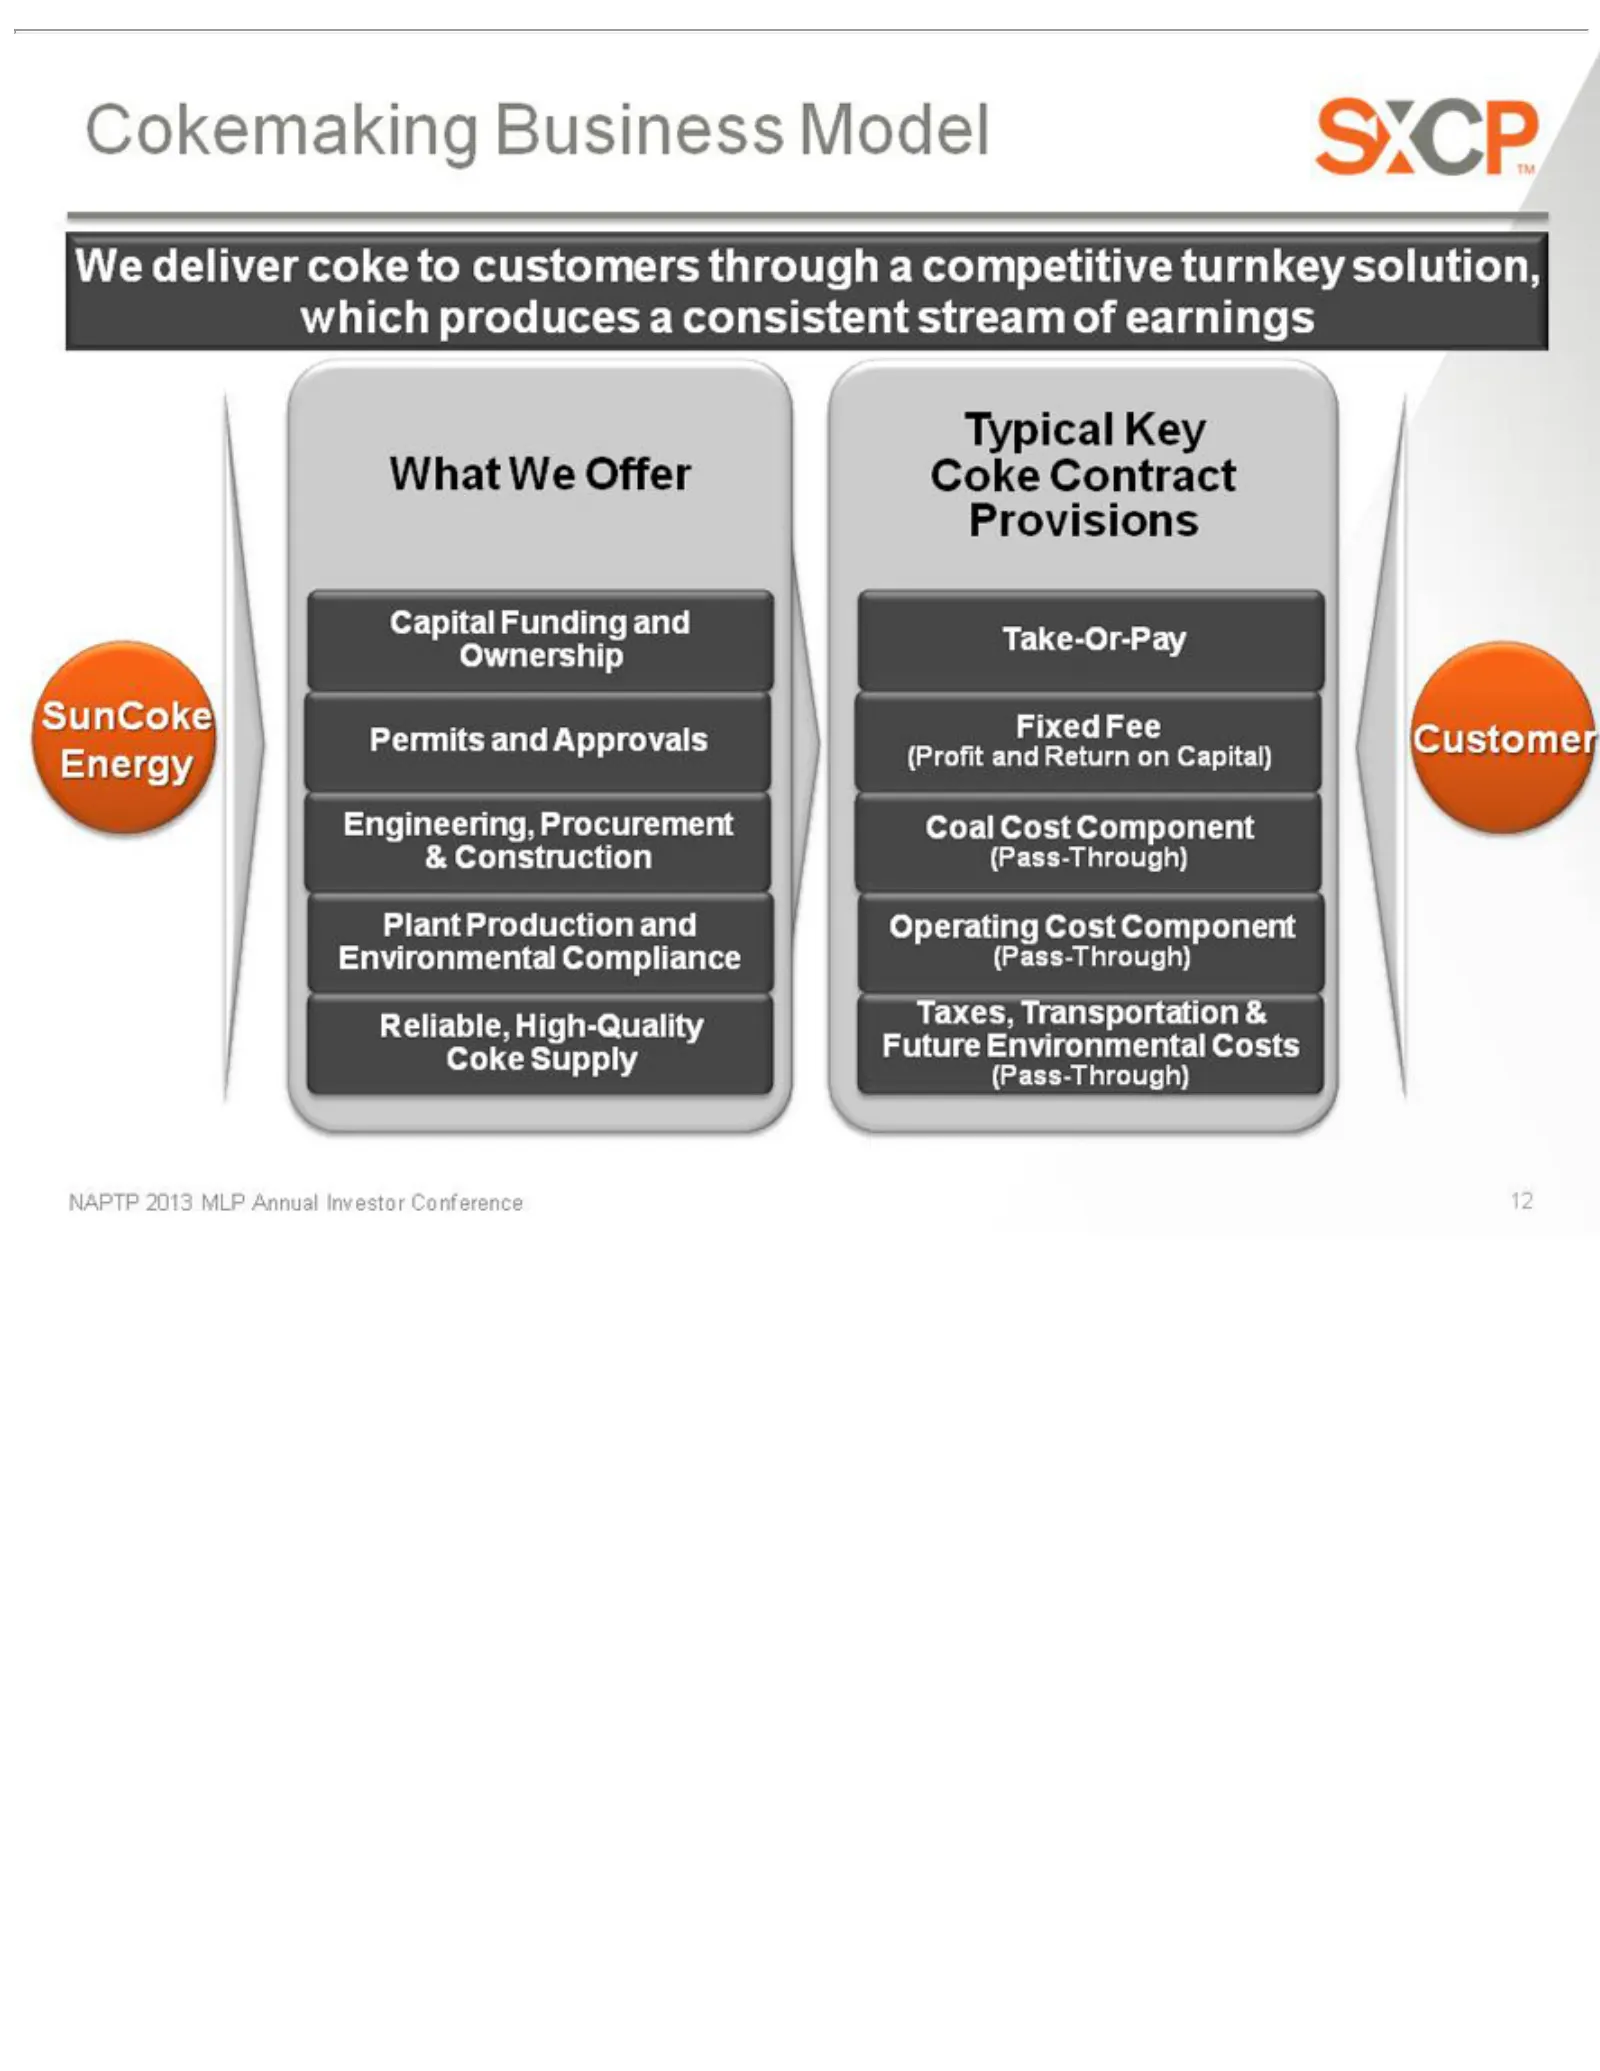
Slide 12: Cokemaking Business Model
Cokemaking We What Capital Permits Ownership Engineering, & Plant Environmental Reliable, Typical Coke Fixed Take-Or-Pay Provisions (Profit Coal Operating Taxes, Future SunCoke (Pass-Through) NAPTP Customer 12 Construction deliver Cost Production Supply Contract We Fee Transportation and Environment
Slide 13: Our Market Opportunity
OUR MARKET NAPTP 13 2013 MLP OPPORTUNITY Annual Investor Conference
Slide 14: SunCoke's Representative Coke Price Based on Market
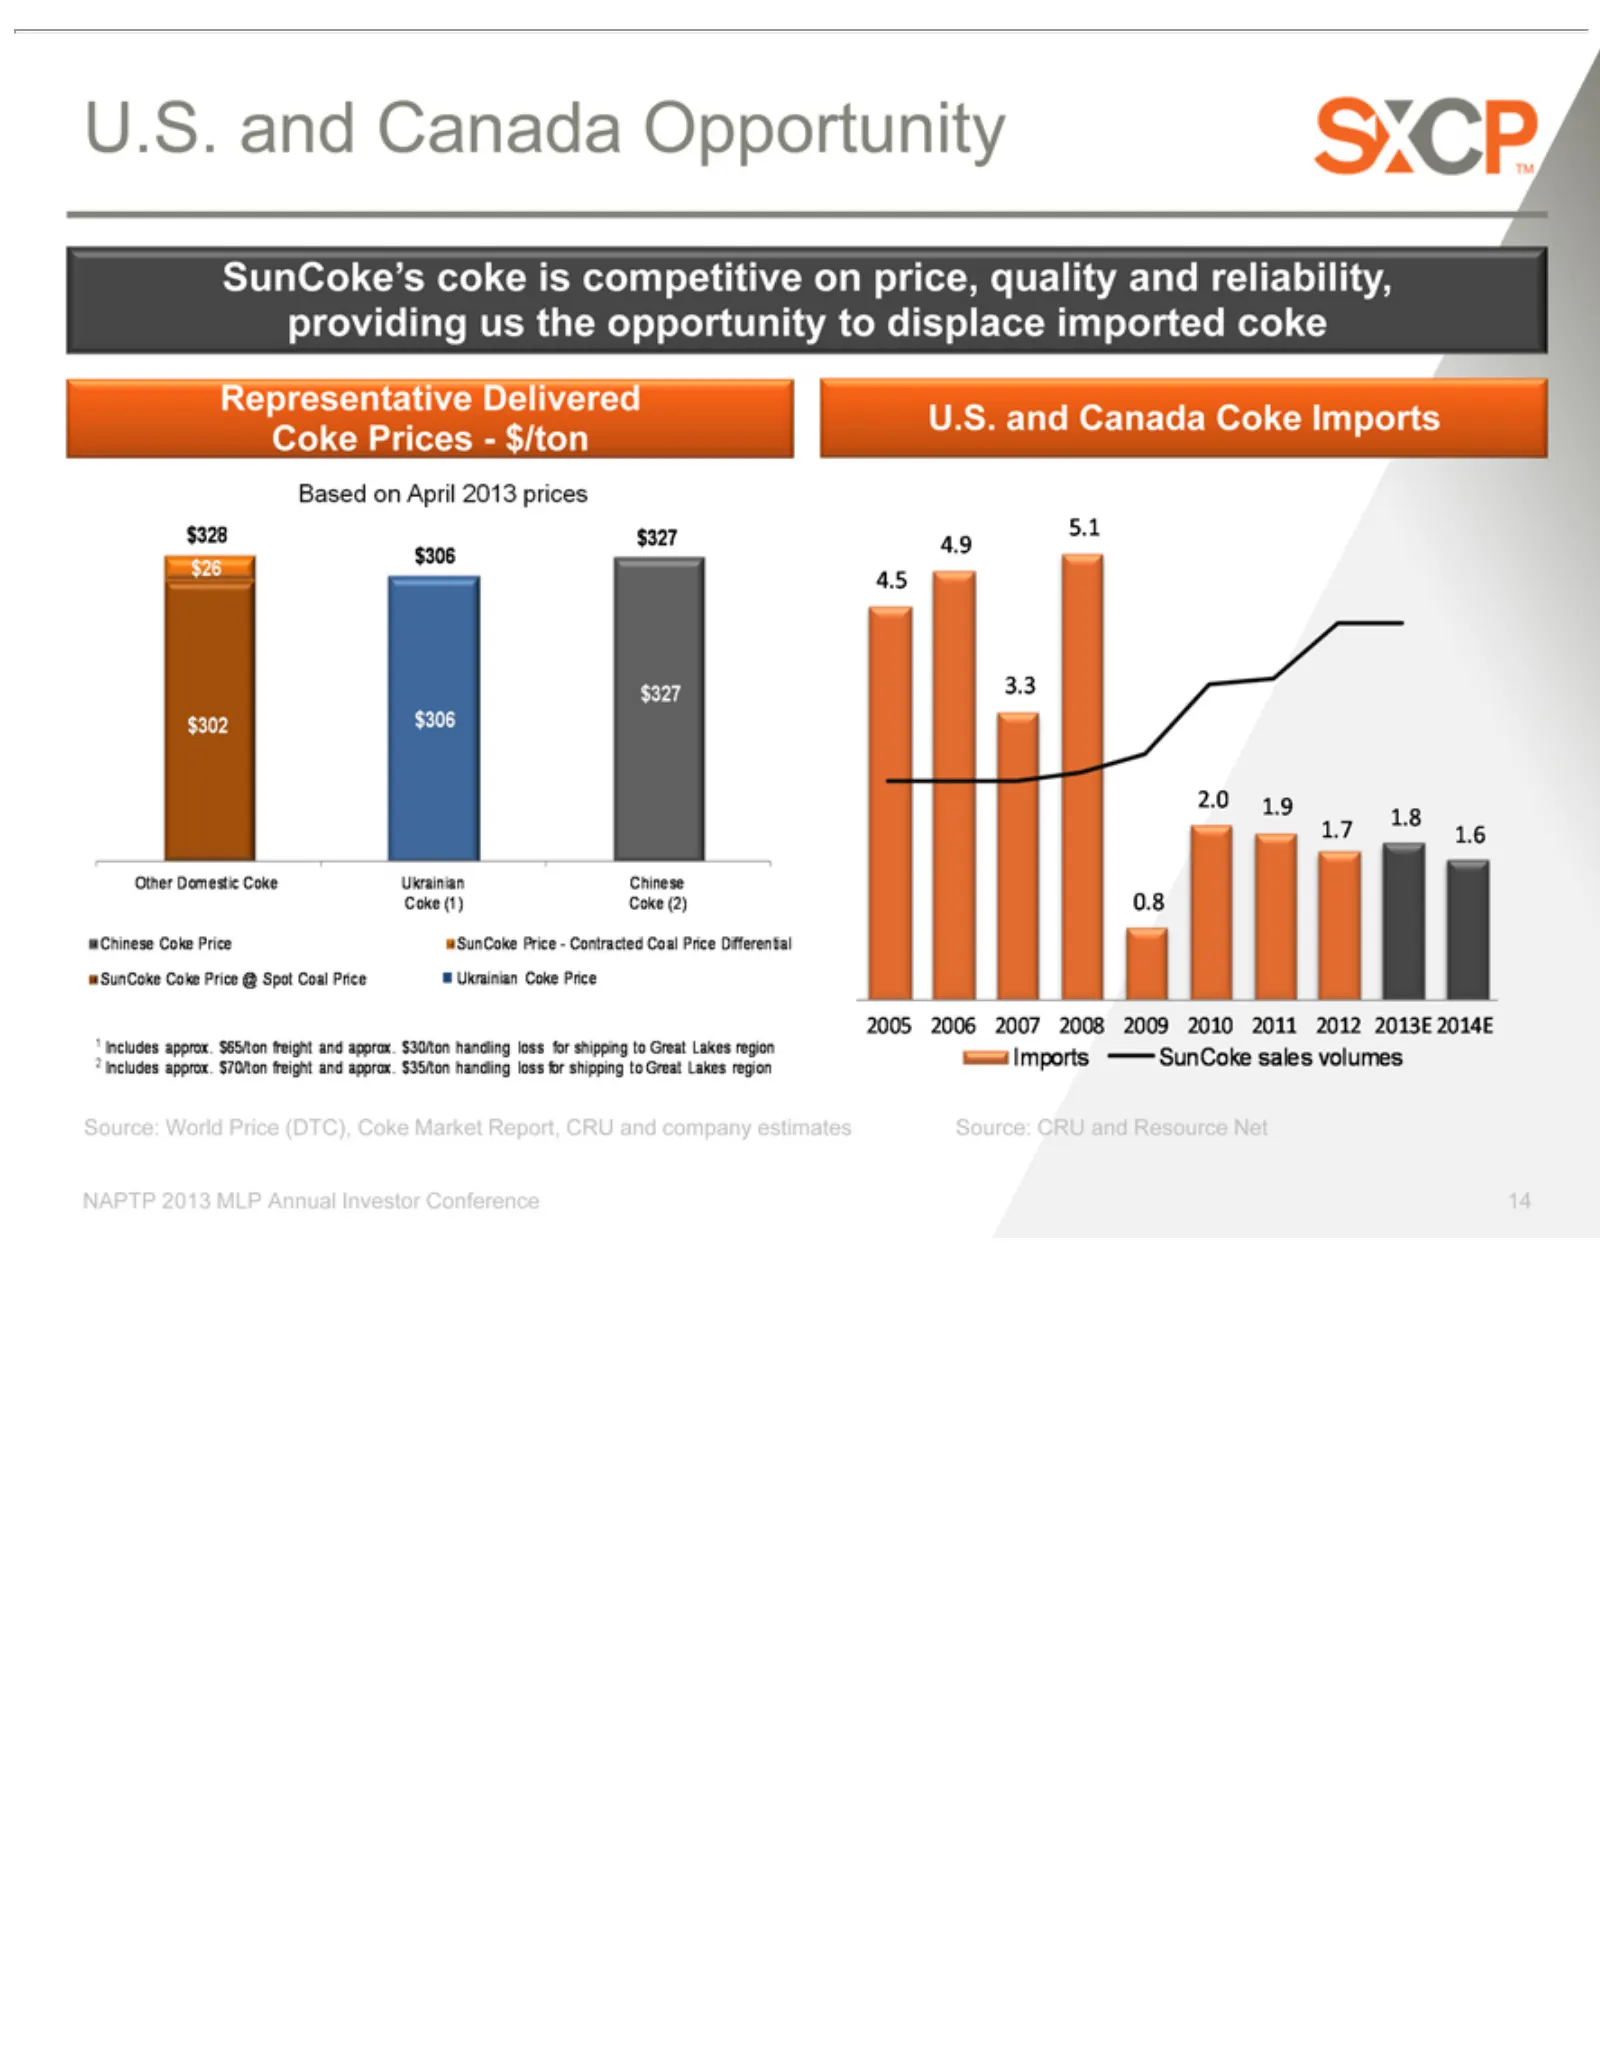
SunCoke’s Representative Based $328 $327 Other Chinese SunCoke Includes U.S. 2.0 3.3 4.5 4.9 5.1 1.7 2005 0.8 Imports Source: NAPTP 14 1.9 1.6 and $327 $302 2006 Domestic on 1.8 World CRU SunCoke 2013 Coke approx. Canada April Coke $306 2007 coke and MLP Price Price Delivered 2013 Price Coke is $26
Slide 15: Replace Aging Coke Batteries
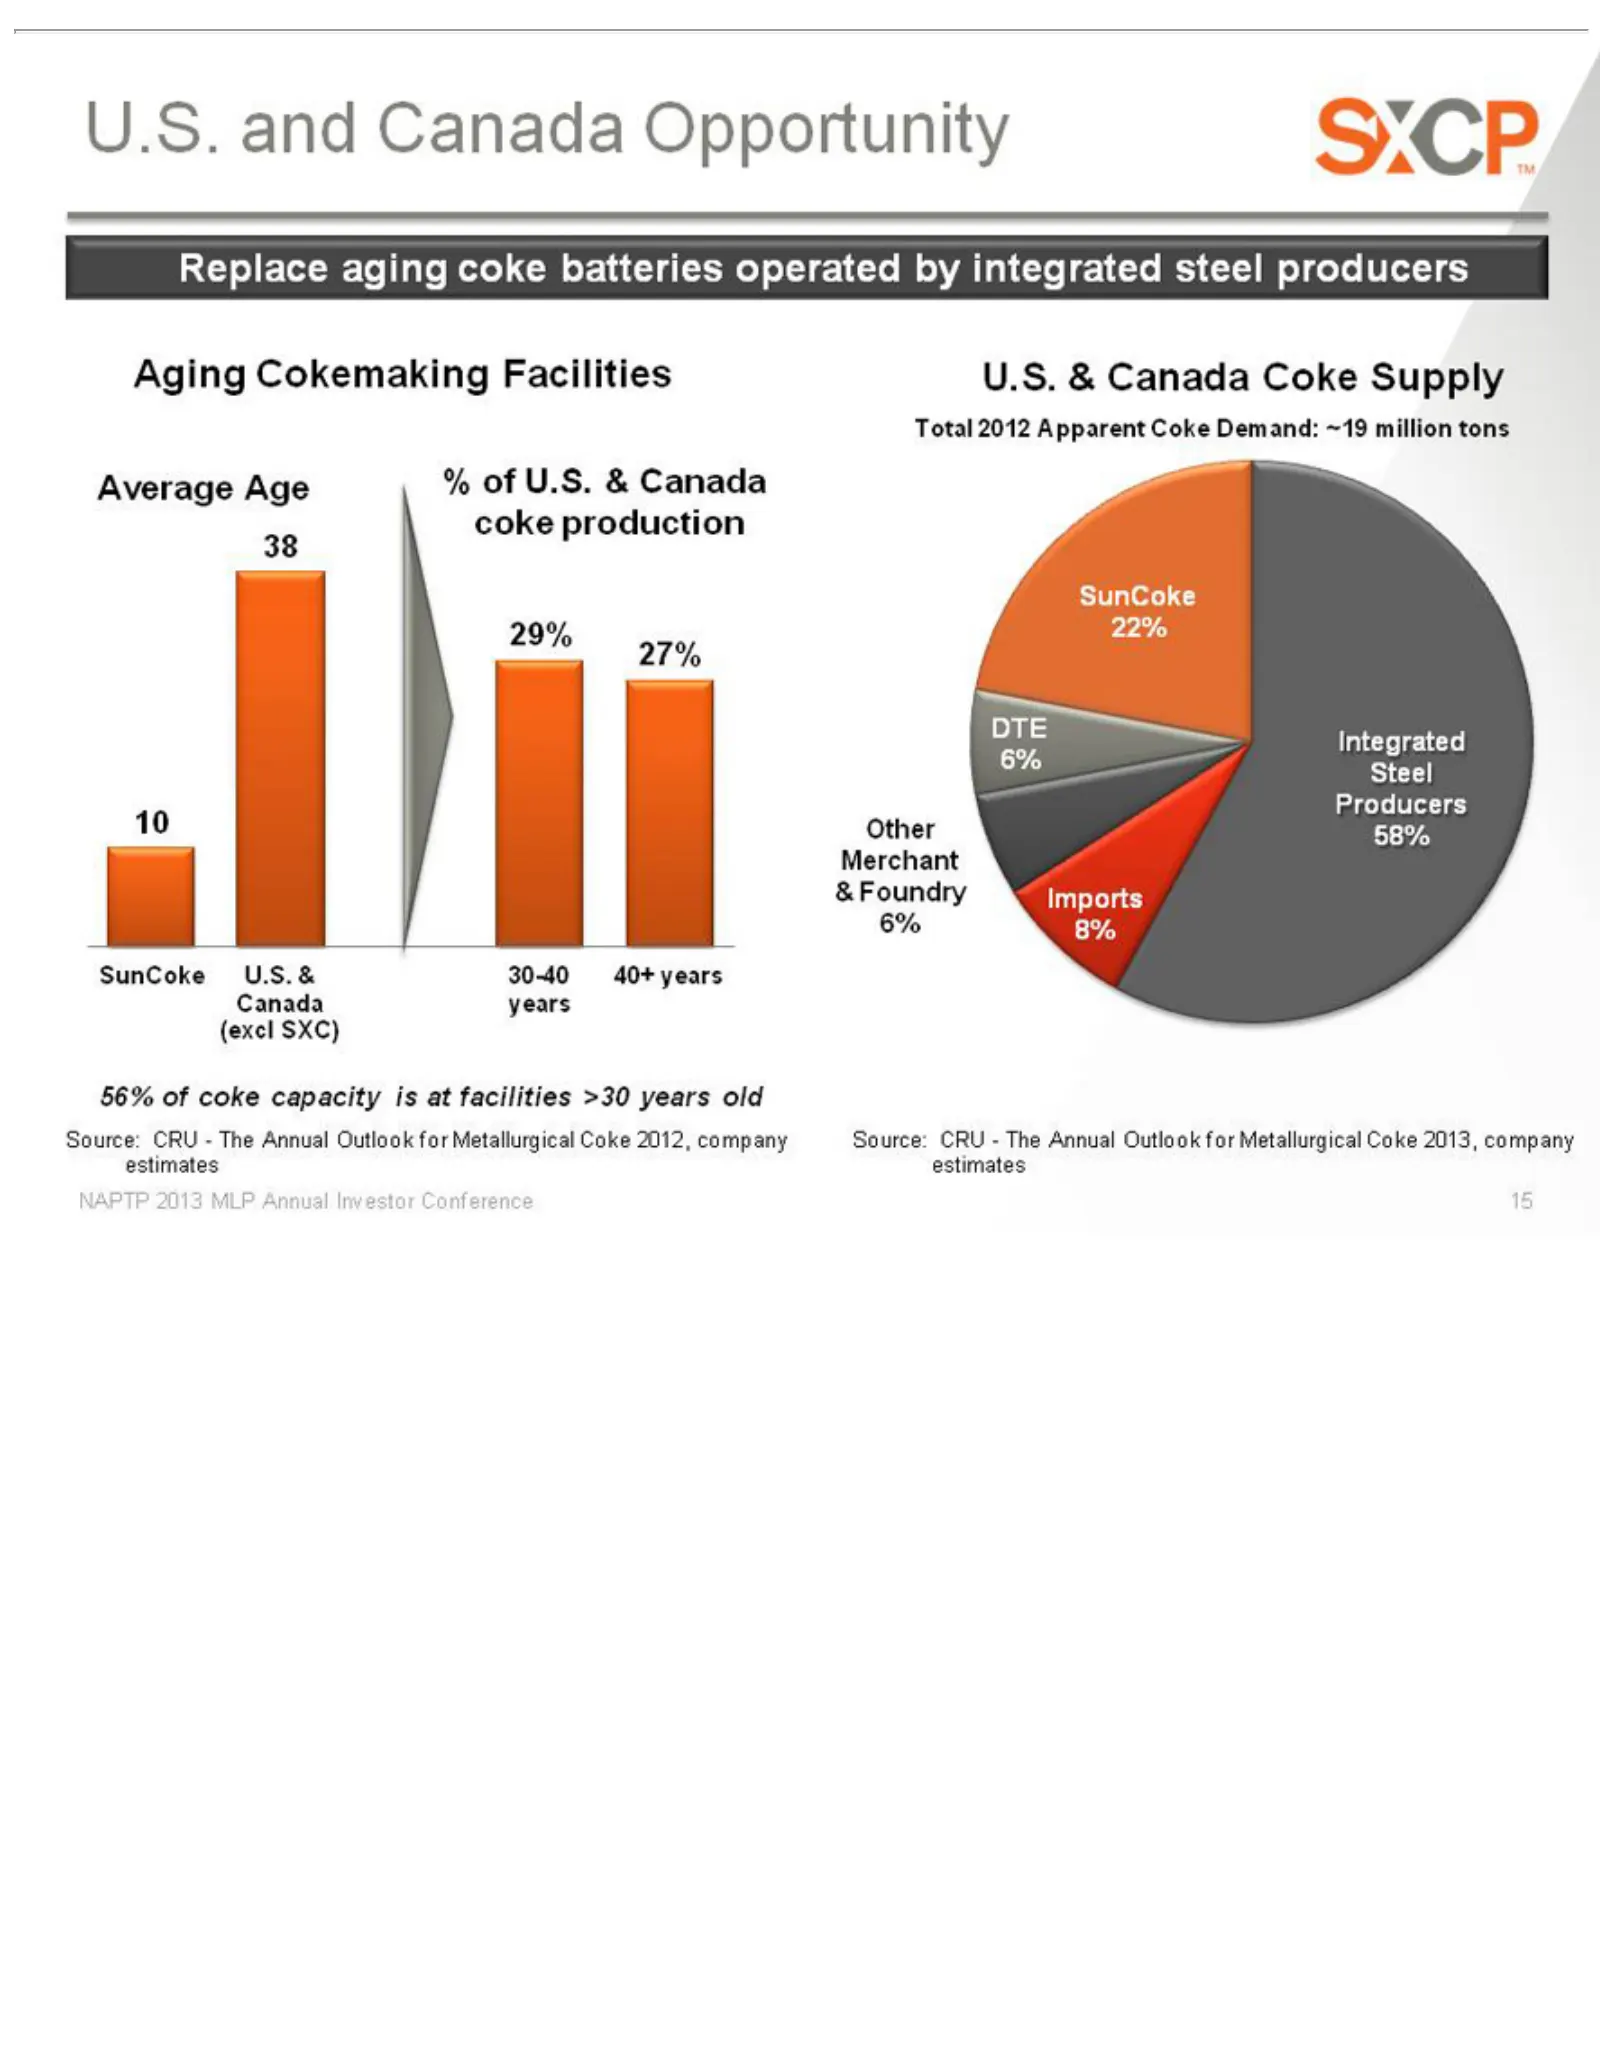
Replace Aging Average % 10 27% 29% 38 56% U.S. Total Other & SunCoke Integrated DTE Imports Source: NAPTP 15 Foundry of & and of U.S. 2012 Merchant Cokemaking Canada coke CRU—The 8% 2013 aging Age Canada U.S. 22% & 6% Apparent 6% Canada capacity MLP Steel coke &Coke Opportunity 30-40 Annual batterie
Slide 16: Coke Facilities Replacement Opportunity
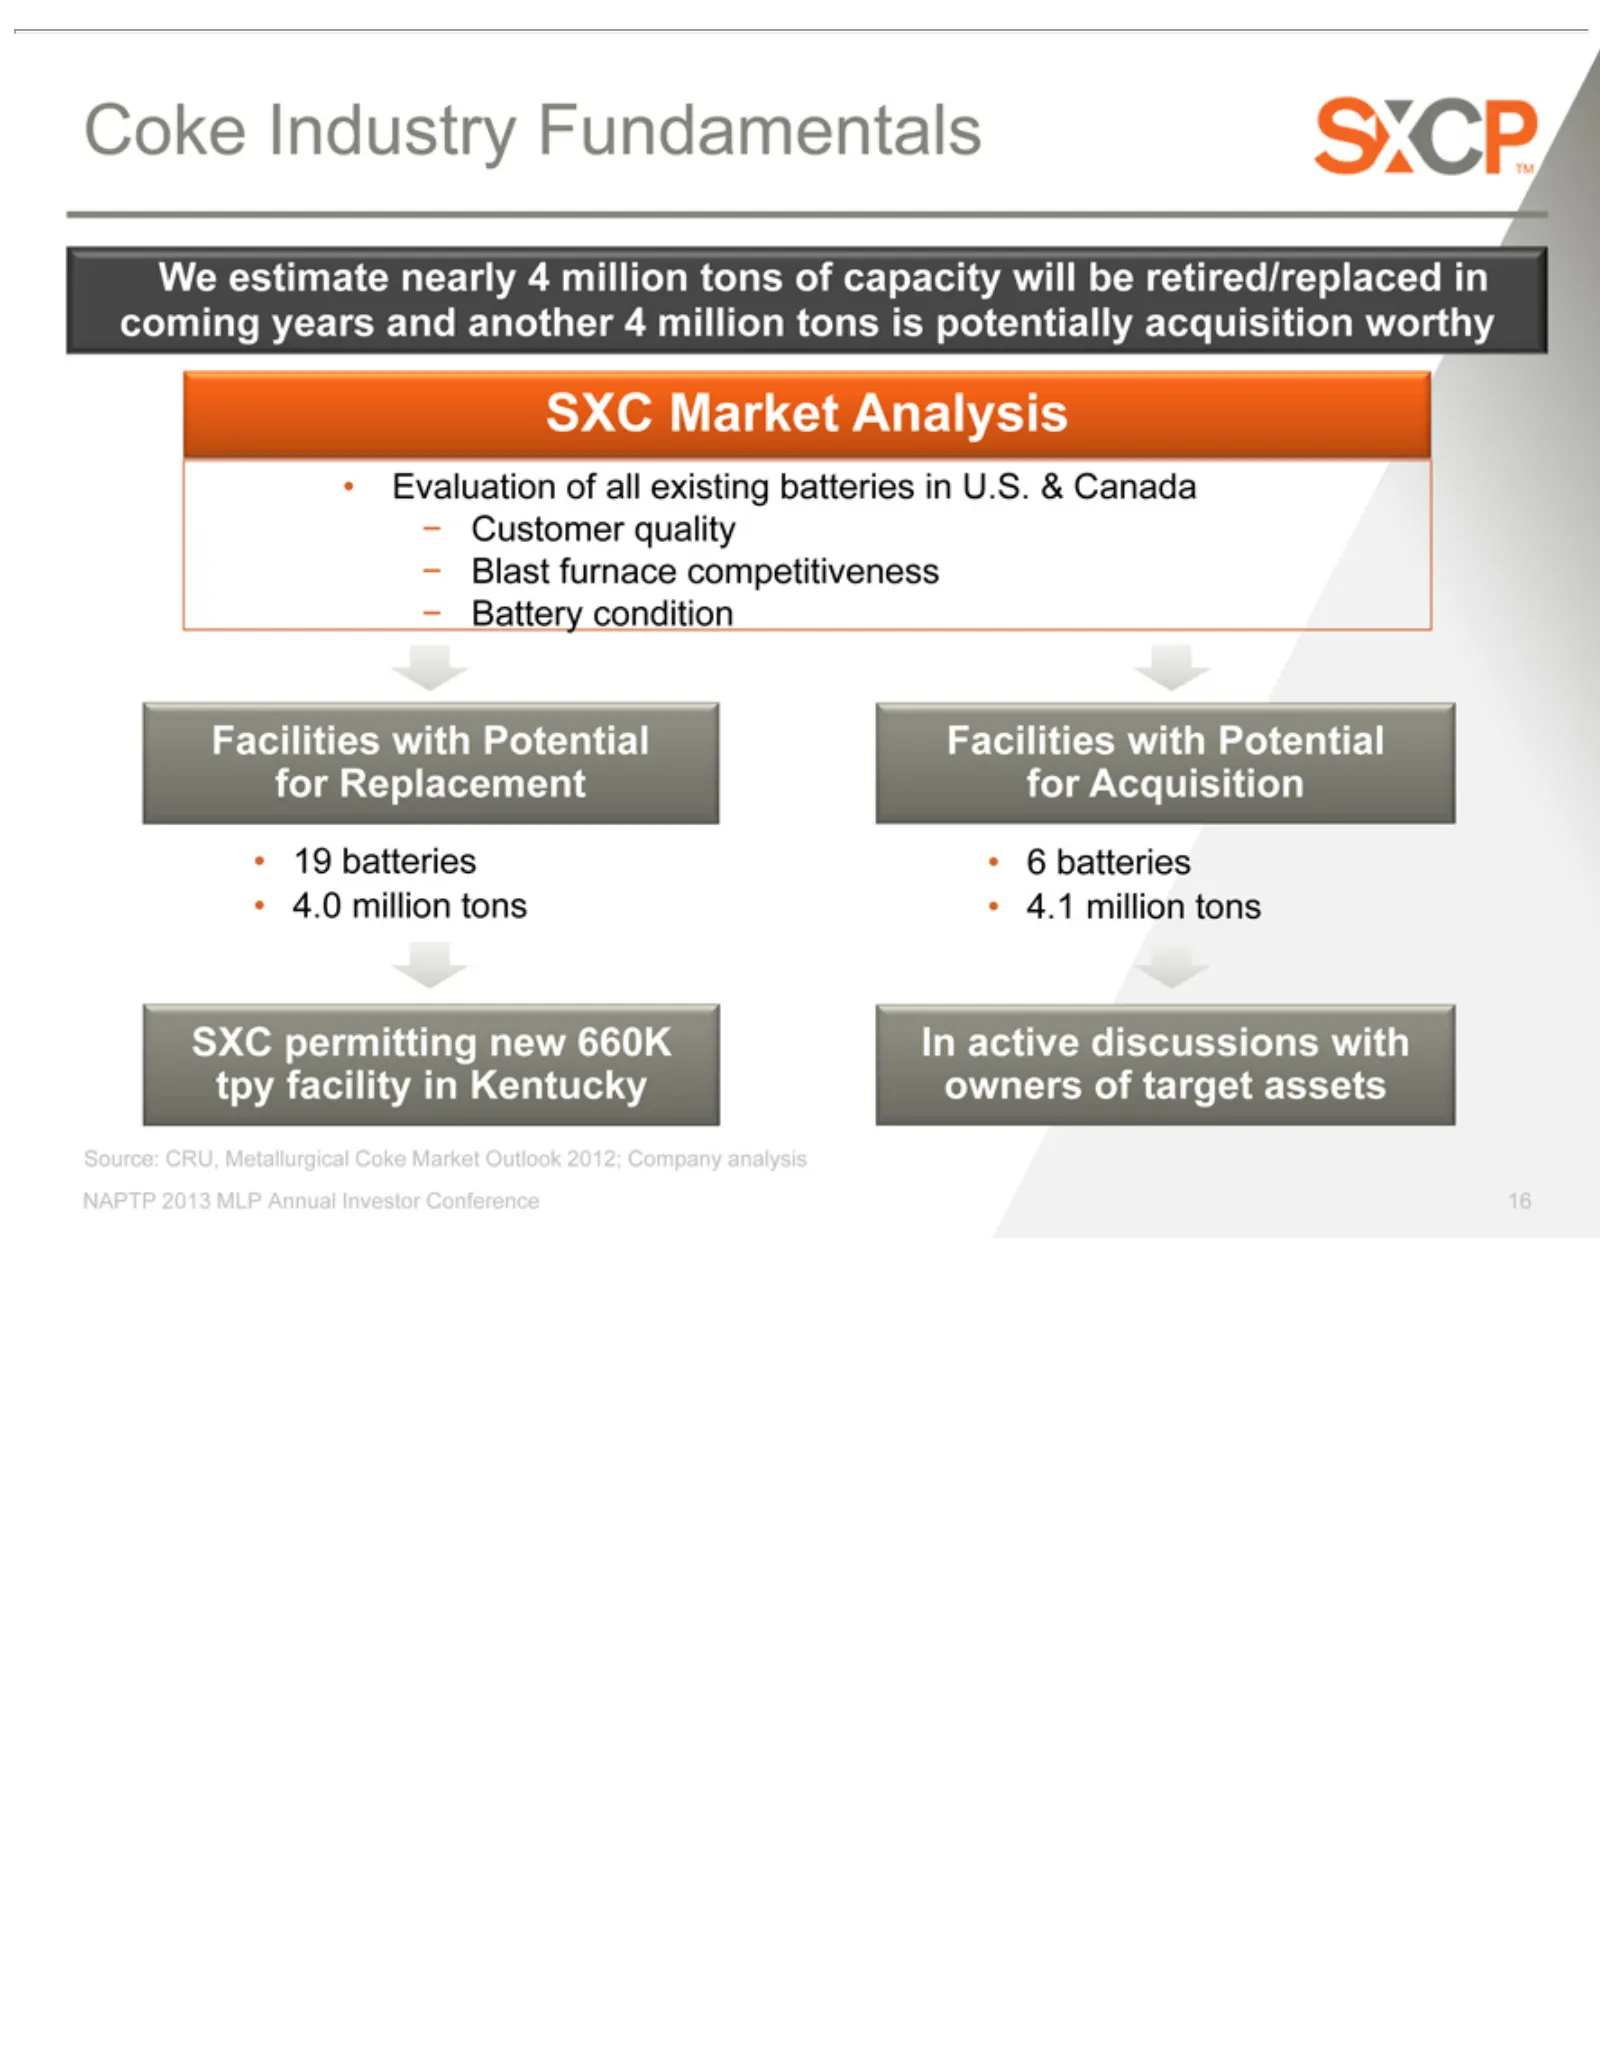
Coke -We •Facilities SXC Source: In 16Customer Blast Battery Evaluation 19 64.0 4.1 active batteries estimate batteries million Market permitting Industry furnace CRU, discussions condition with quality nearly of tons Analysis Metallurgical Fundamentals Potential competitiveness all newexisting 4 wi
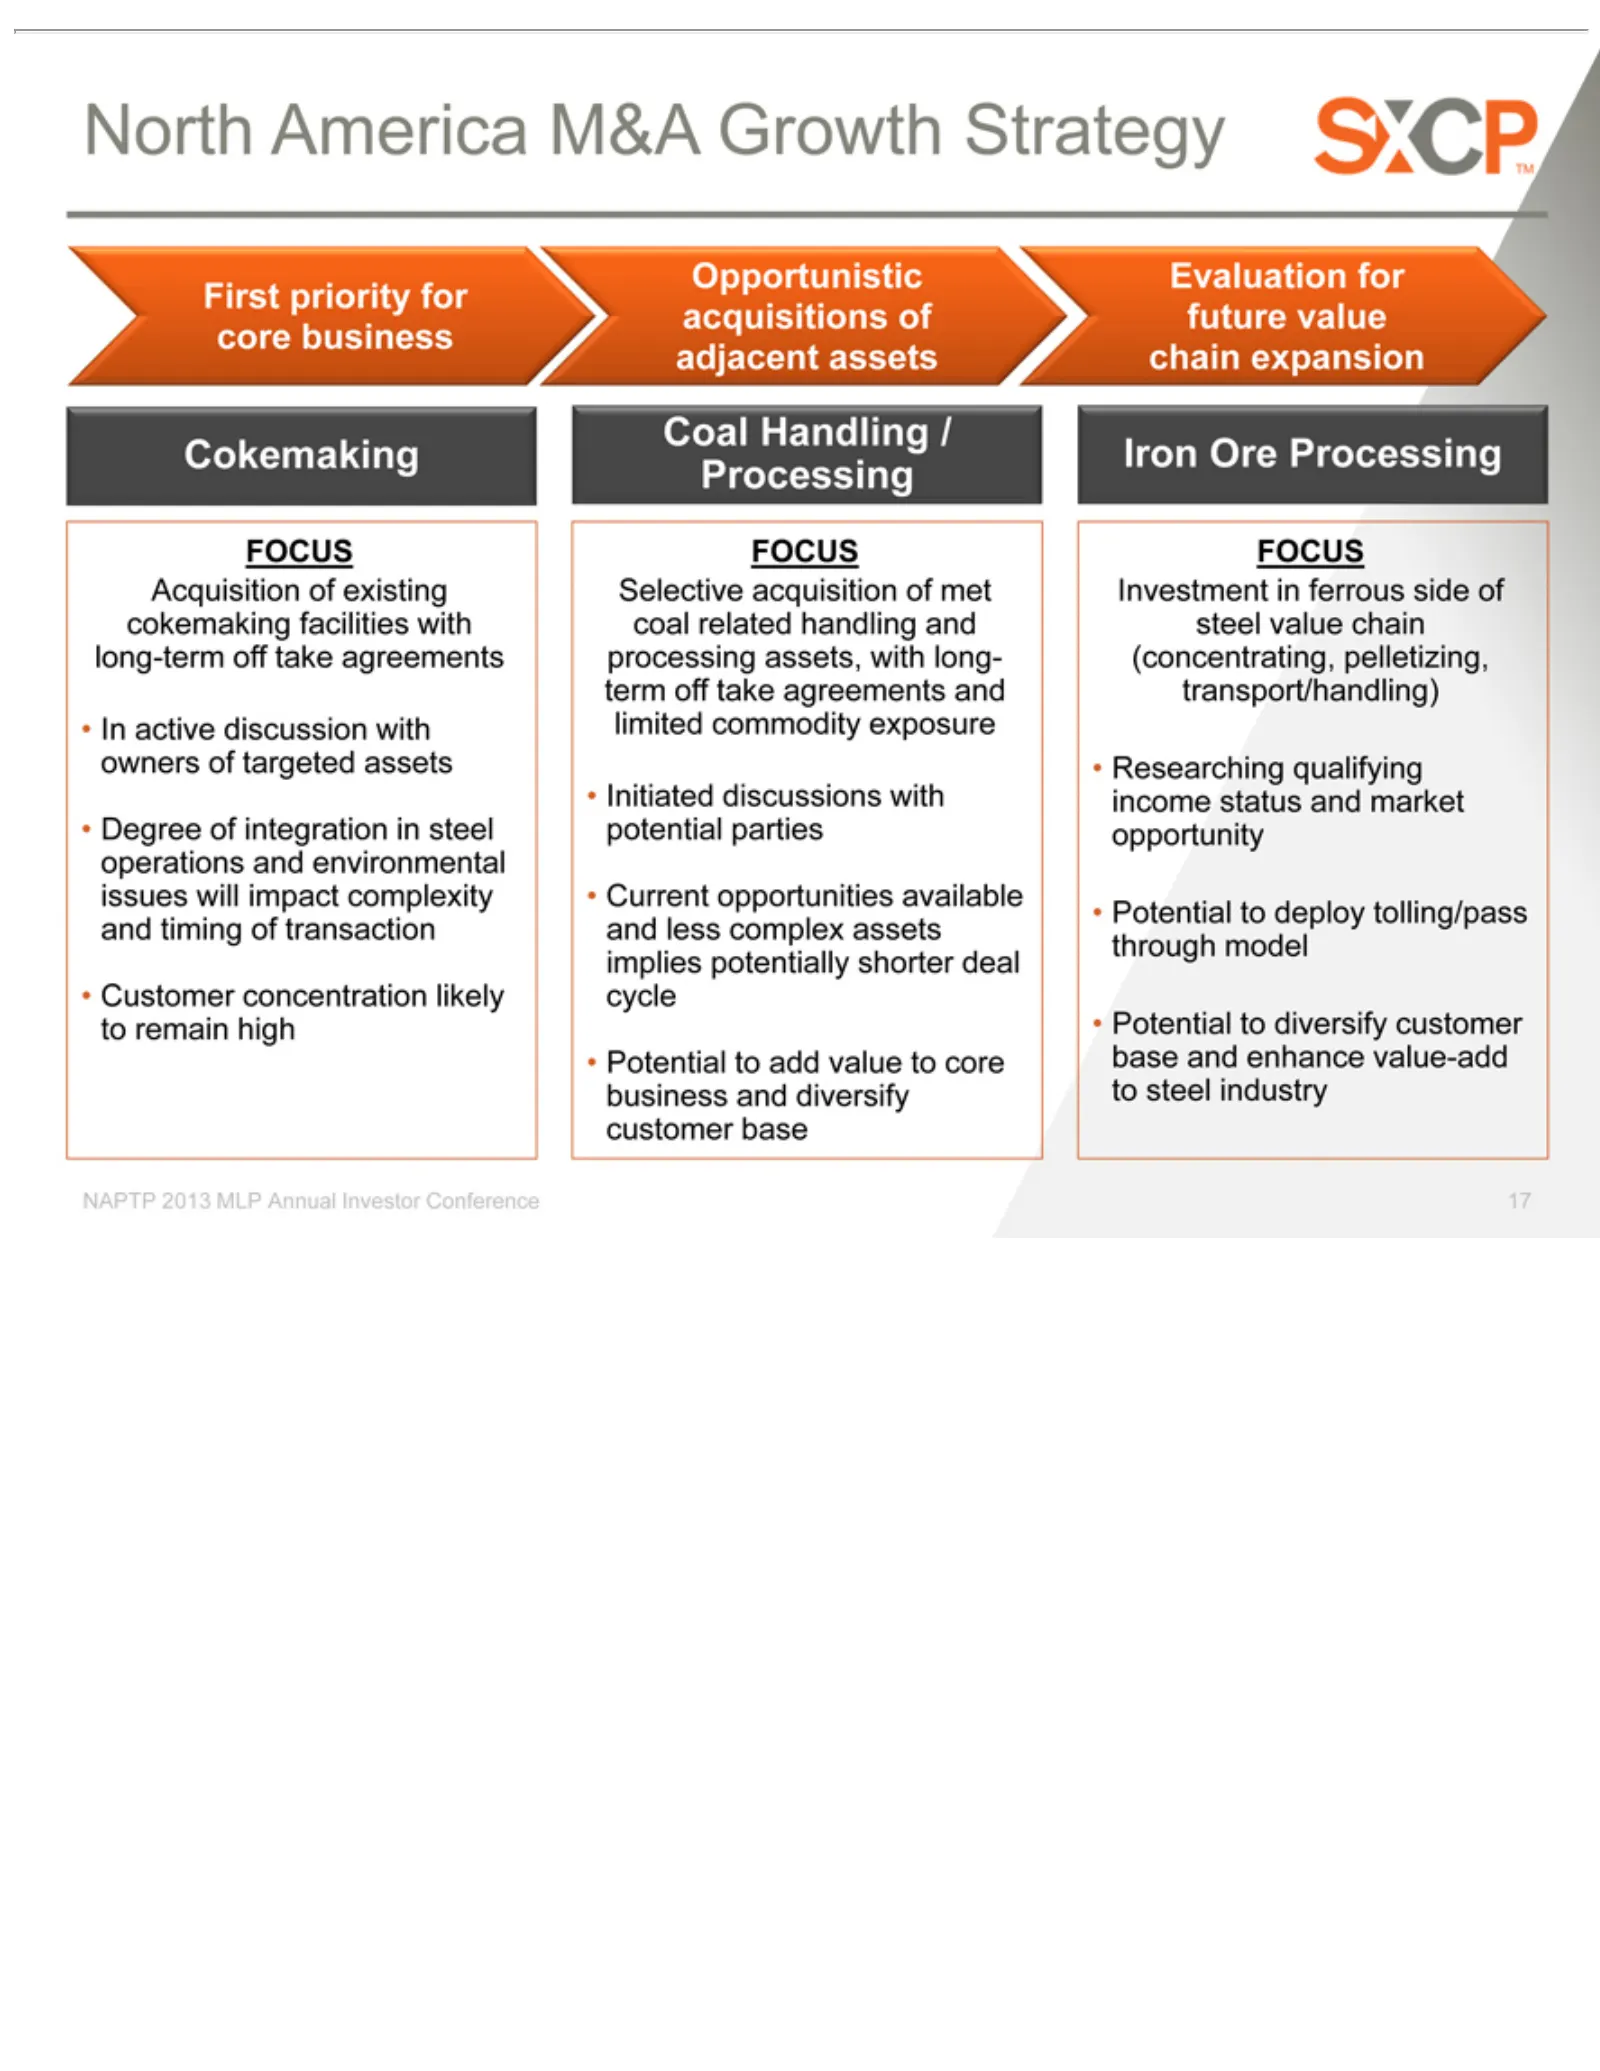
Slide 17: North American Opportunistic Acquisition Focus
North Opportunistic Acquisition Cokemaking In Degree Customer Coal Iron FOCUS Selective commodity Initiated Current Potential NAPTP 17 active Ore Handling America of opportunities 2013 FOCUS discussions Processing discussion to acquisition concentration integration exposure deploy add ofMLP Evaluati
Slide 18: 1Q 2013 Financial Performance and Position
1QFINANCIAL & NAPTP 18 20132013 PERFORMANCE MLP POSITION Annual Investor Conference
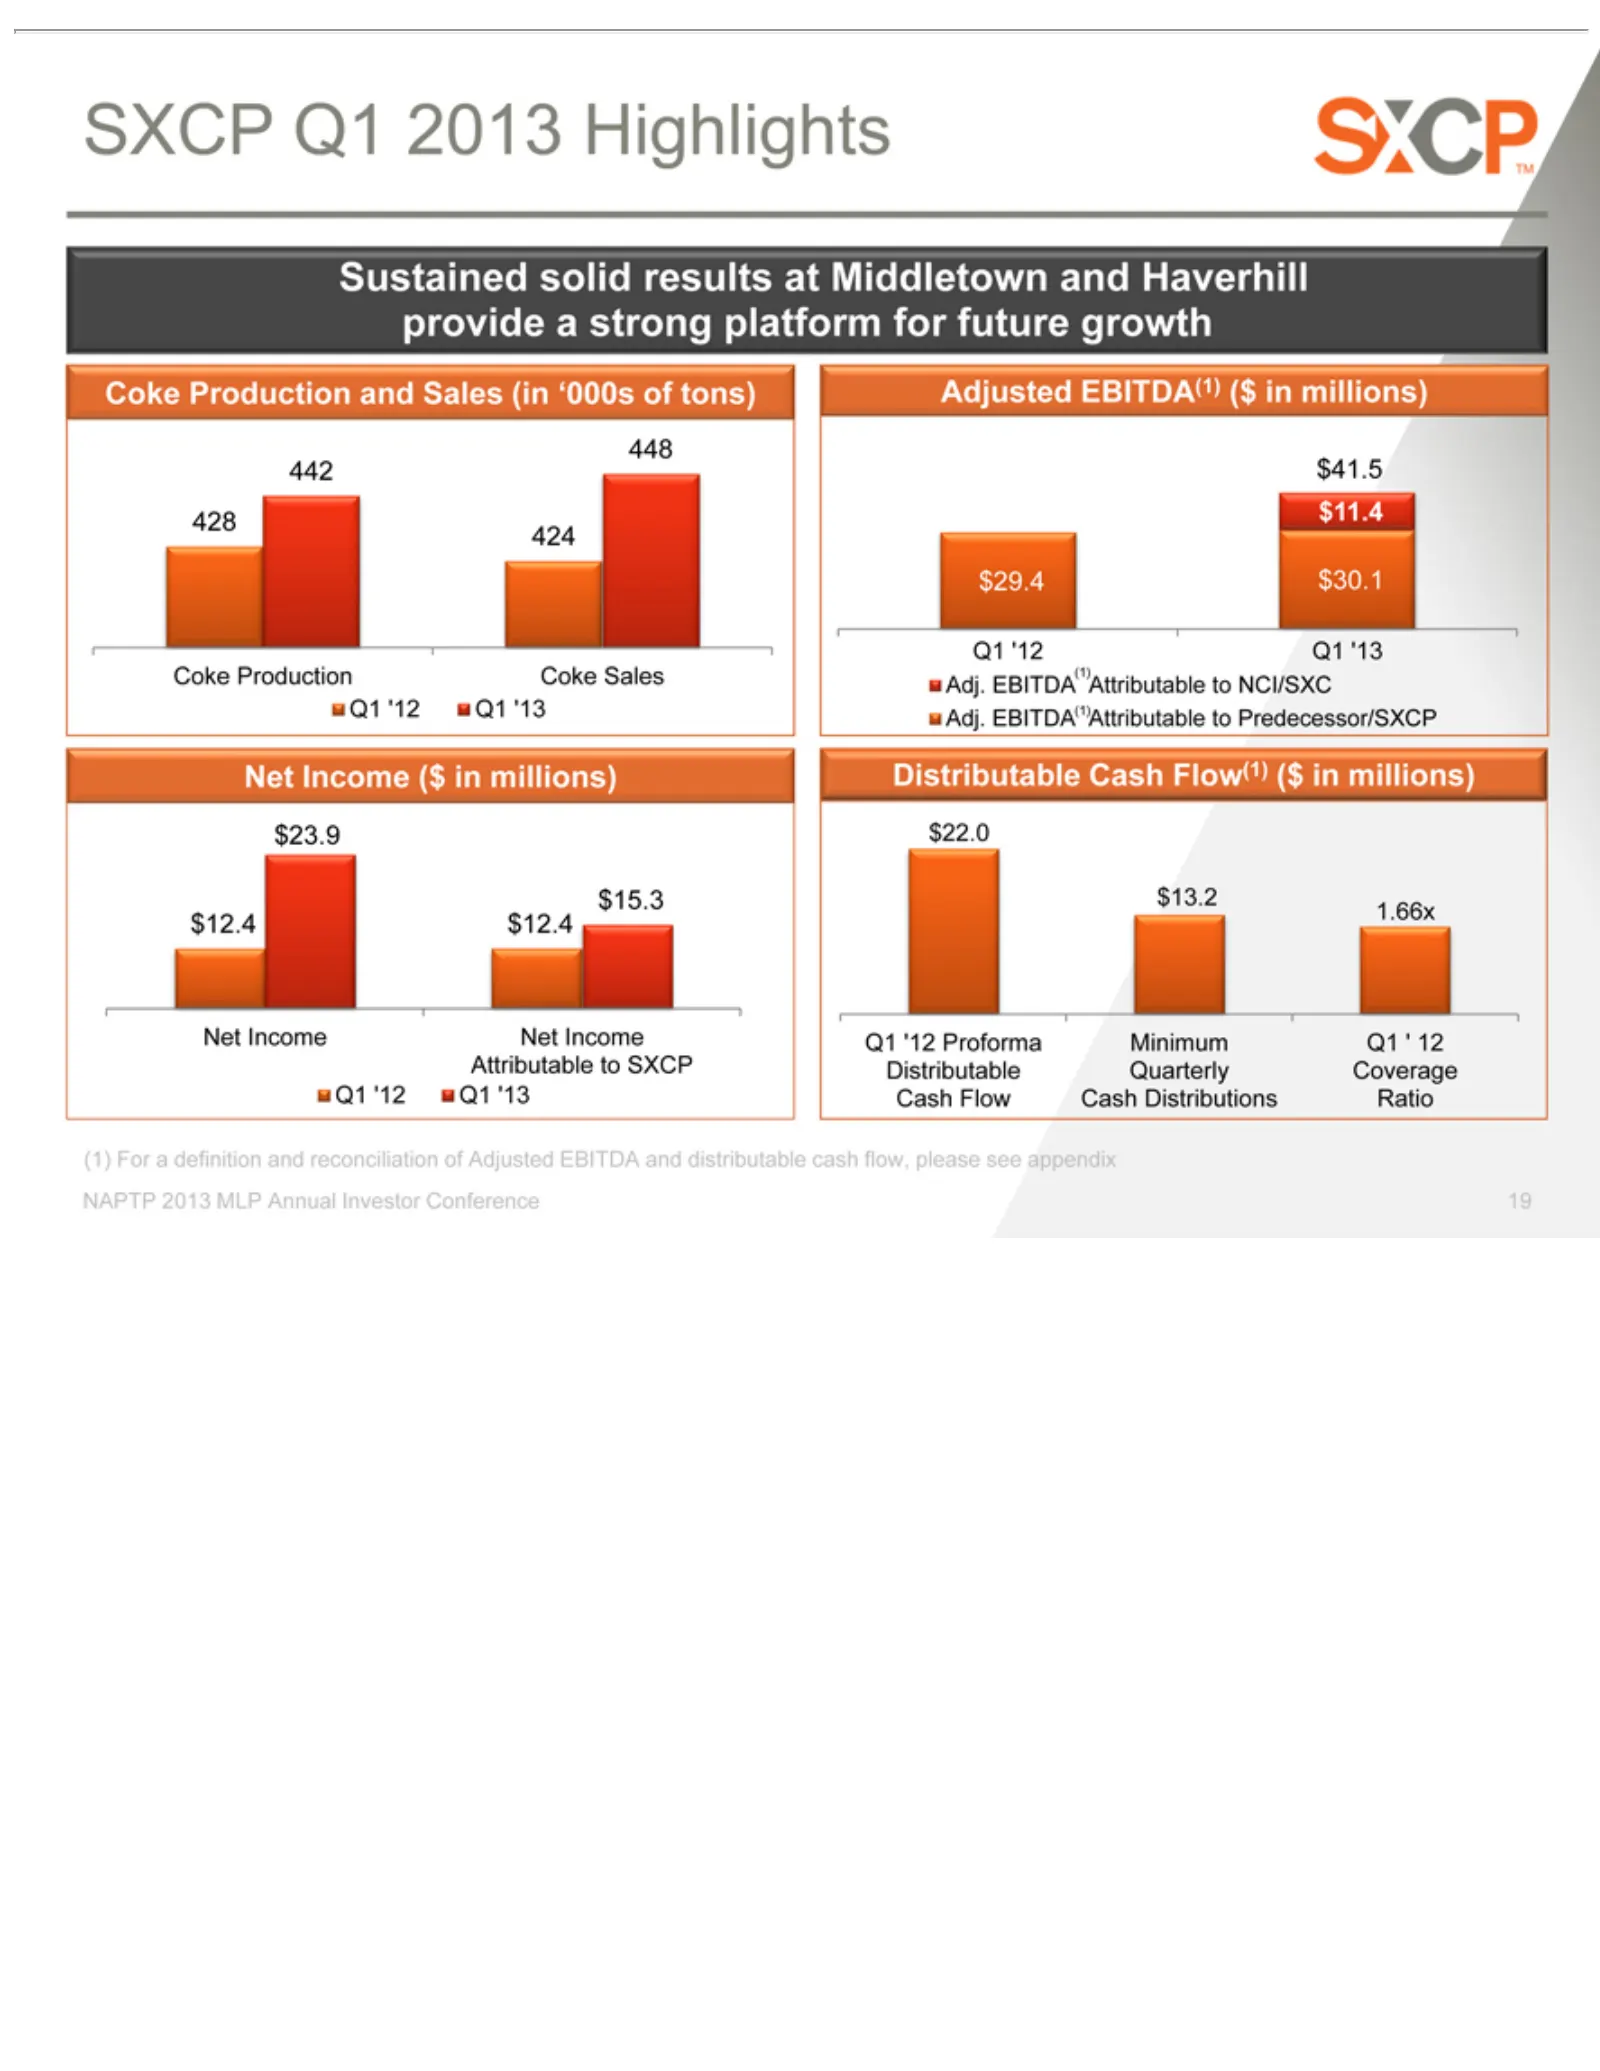
Slide 19: SXCP Sustained Solid Q1 Results
SXCP Sustained 428 442 448 Coke $Adjusted $29.4 $11.4 Adj. $12.4 $15.3 $23.9 Net Attributable $13.2 $22.0 Q1 Distributable Cash (1) NAPTP 1941.5 For ‘12 Income 424 EBITDA(1) EBITDA(1)Attributable Flow Production $30.1 $12.4 1.66x Q1 aProforma Q1 2013 definition EBITDA(1) solid 2013 ‘13 Cash ($ Net t
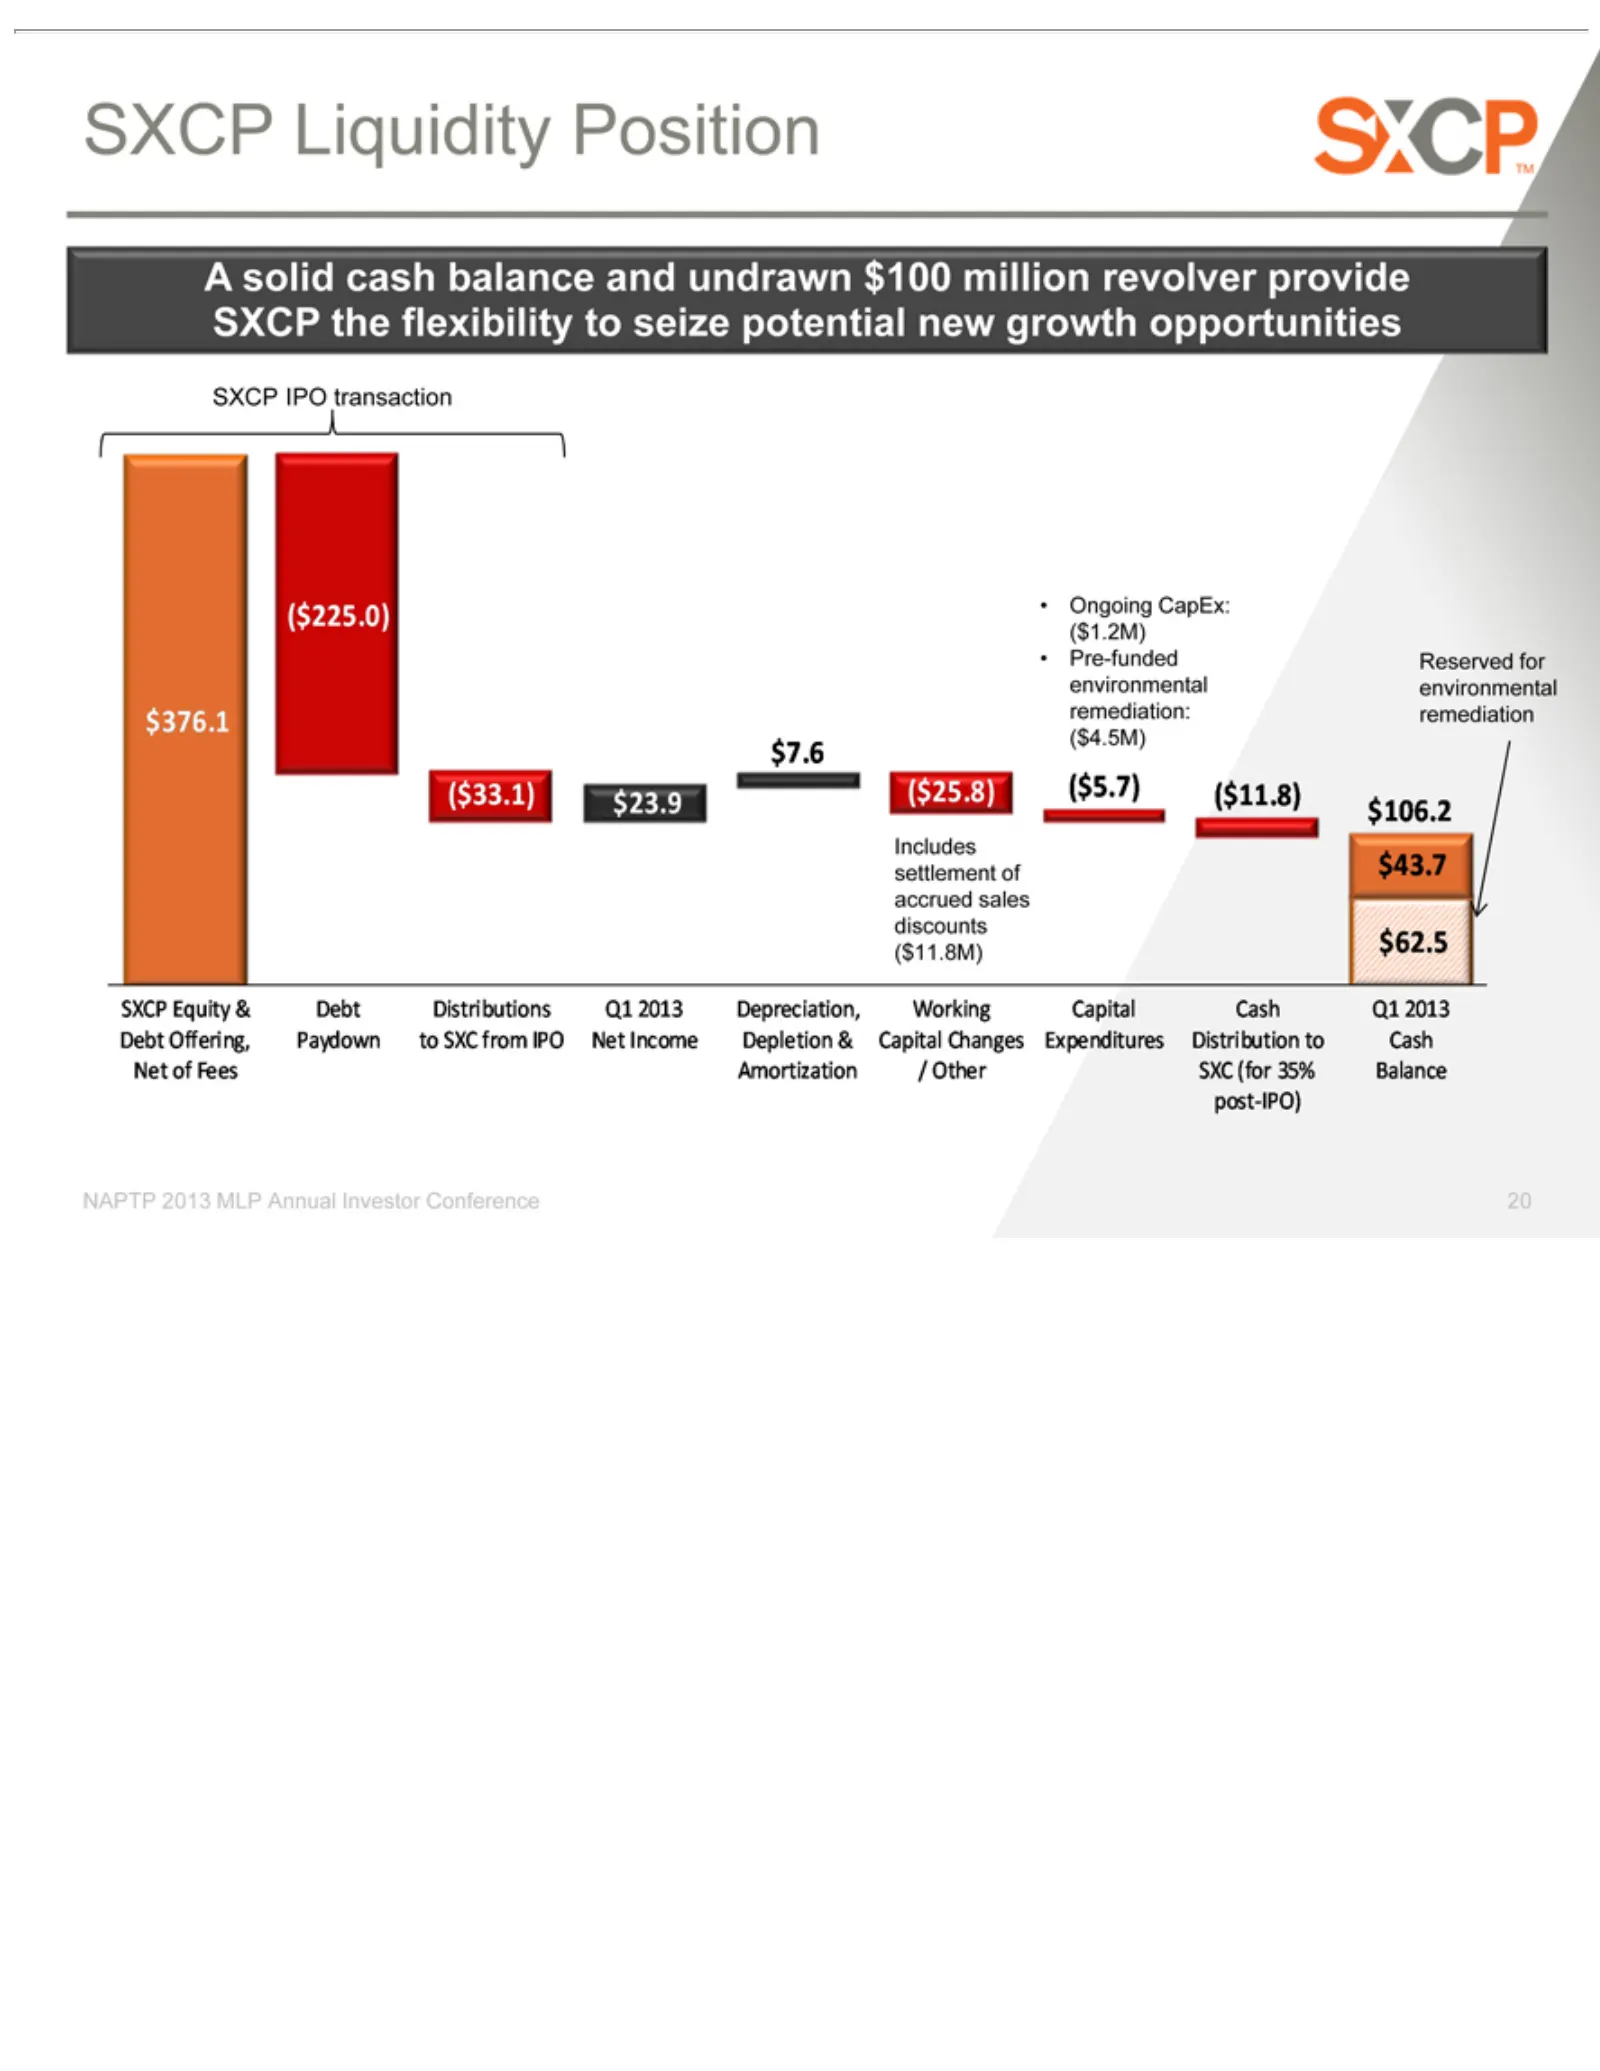
Slide 20: A solid liquidity position
A solid ($225.0) Pre-funded ($1.2M) environmental $376.1 ($33.1) $7.6 ($4.5M) $23.9 settlement Includes accrued ($11.8M) discounts SXCP Debt Net NAPTP 20 ofOffering, $106.2 Liquidity IPO Equity Fees remediation: cash ($25.8) sales 2013 Ongoing $62.5 of transaction Reserved Amortization balance $43.7
Slide 21: Liquidity Position: Both SXC and SXCP Well-Capitalized
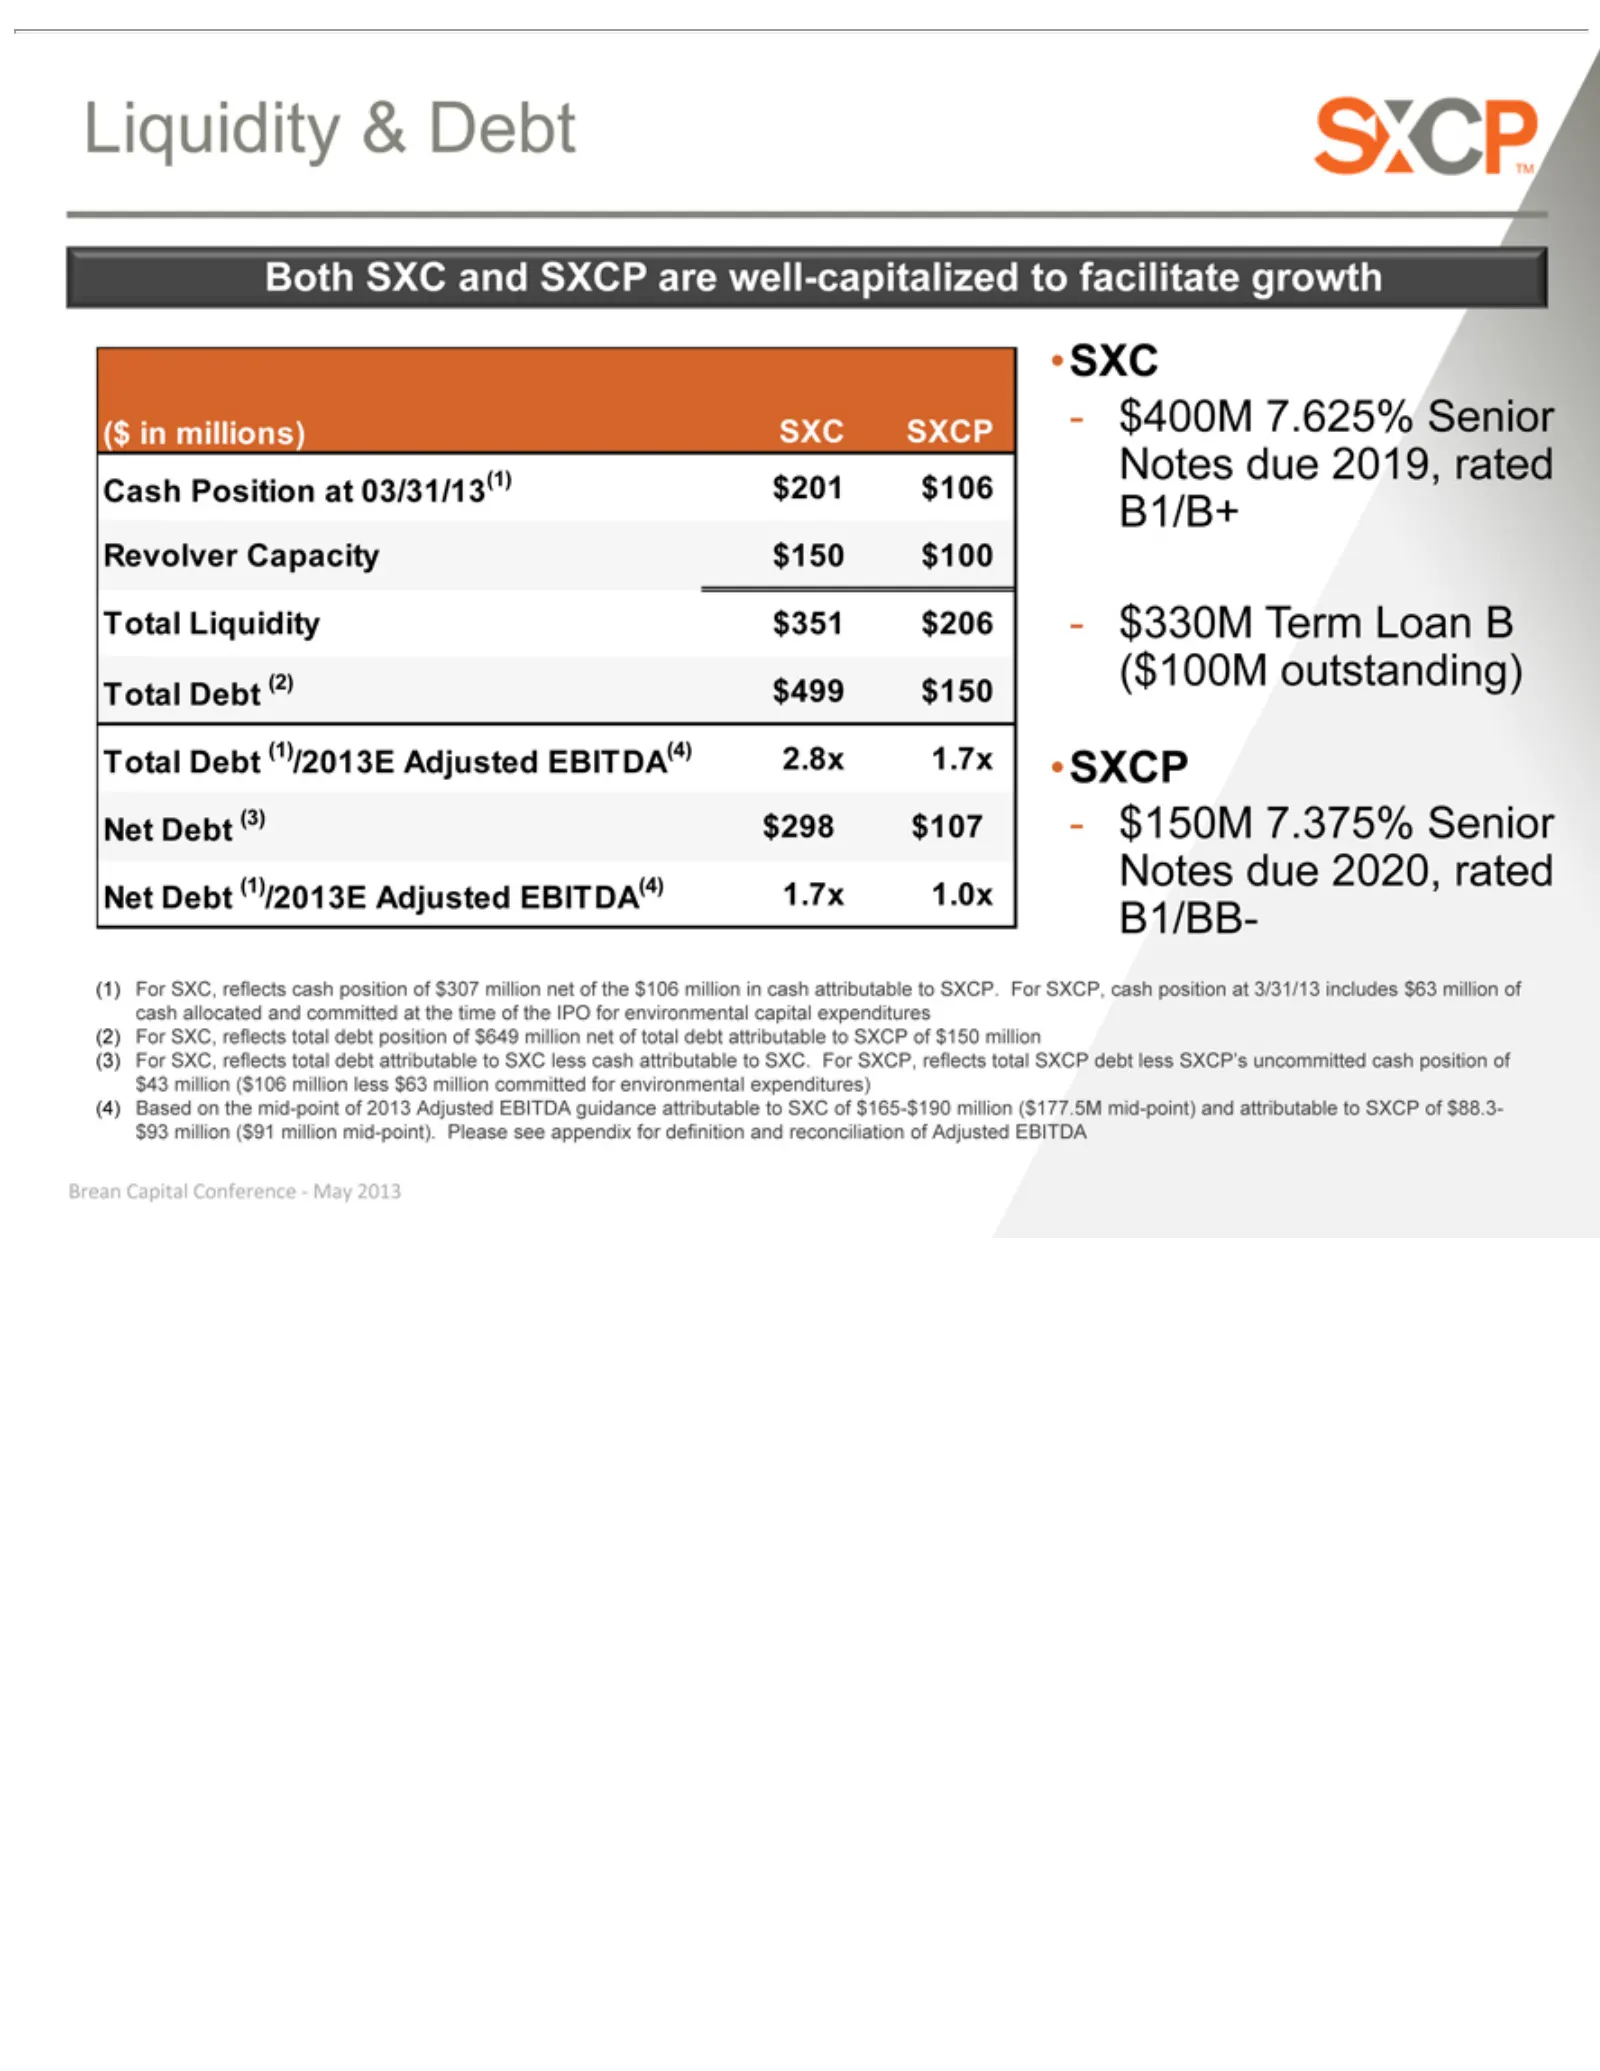
Liquidity Both ($ Cash Revolver Total Net $400M SXC $330M ($100M $150M SXCP (1) for attributable 2013 reconciliation Brean inenvironmental For Debt millions) Adjusted SXC Position Liquidity Debt Capital SXC, Term 7.625% 7.375% outstanding) (3) (1) Capacity &and (2) (1) to Debt $298 /2013E Loan refle
Slide 22: SXCP Outlook Based on Prospectus
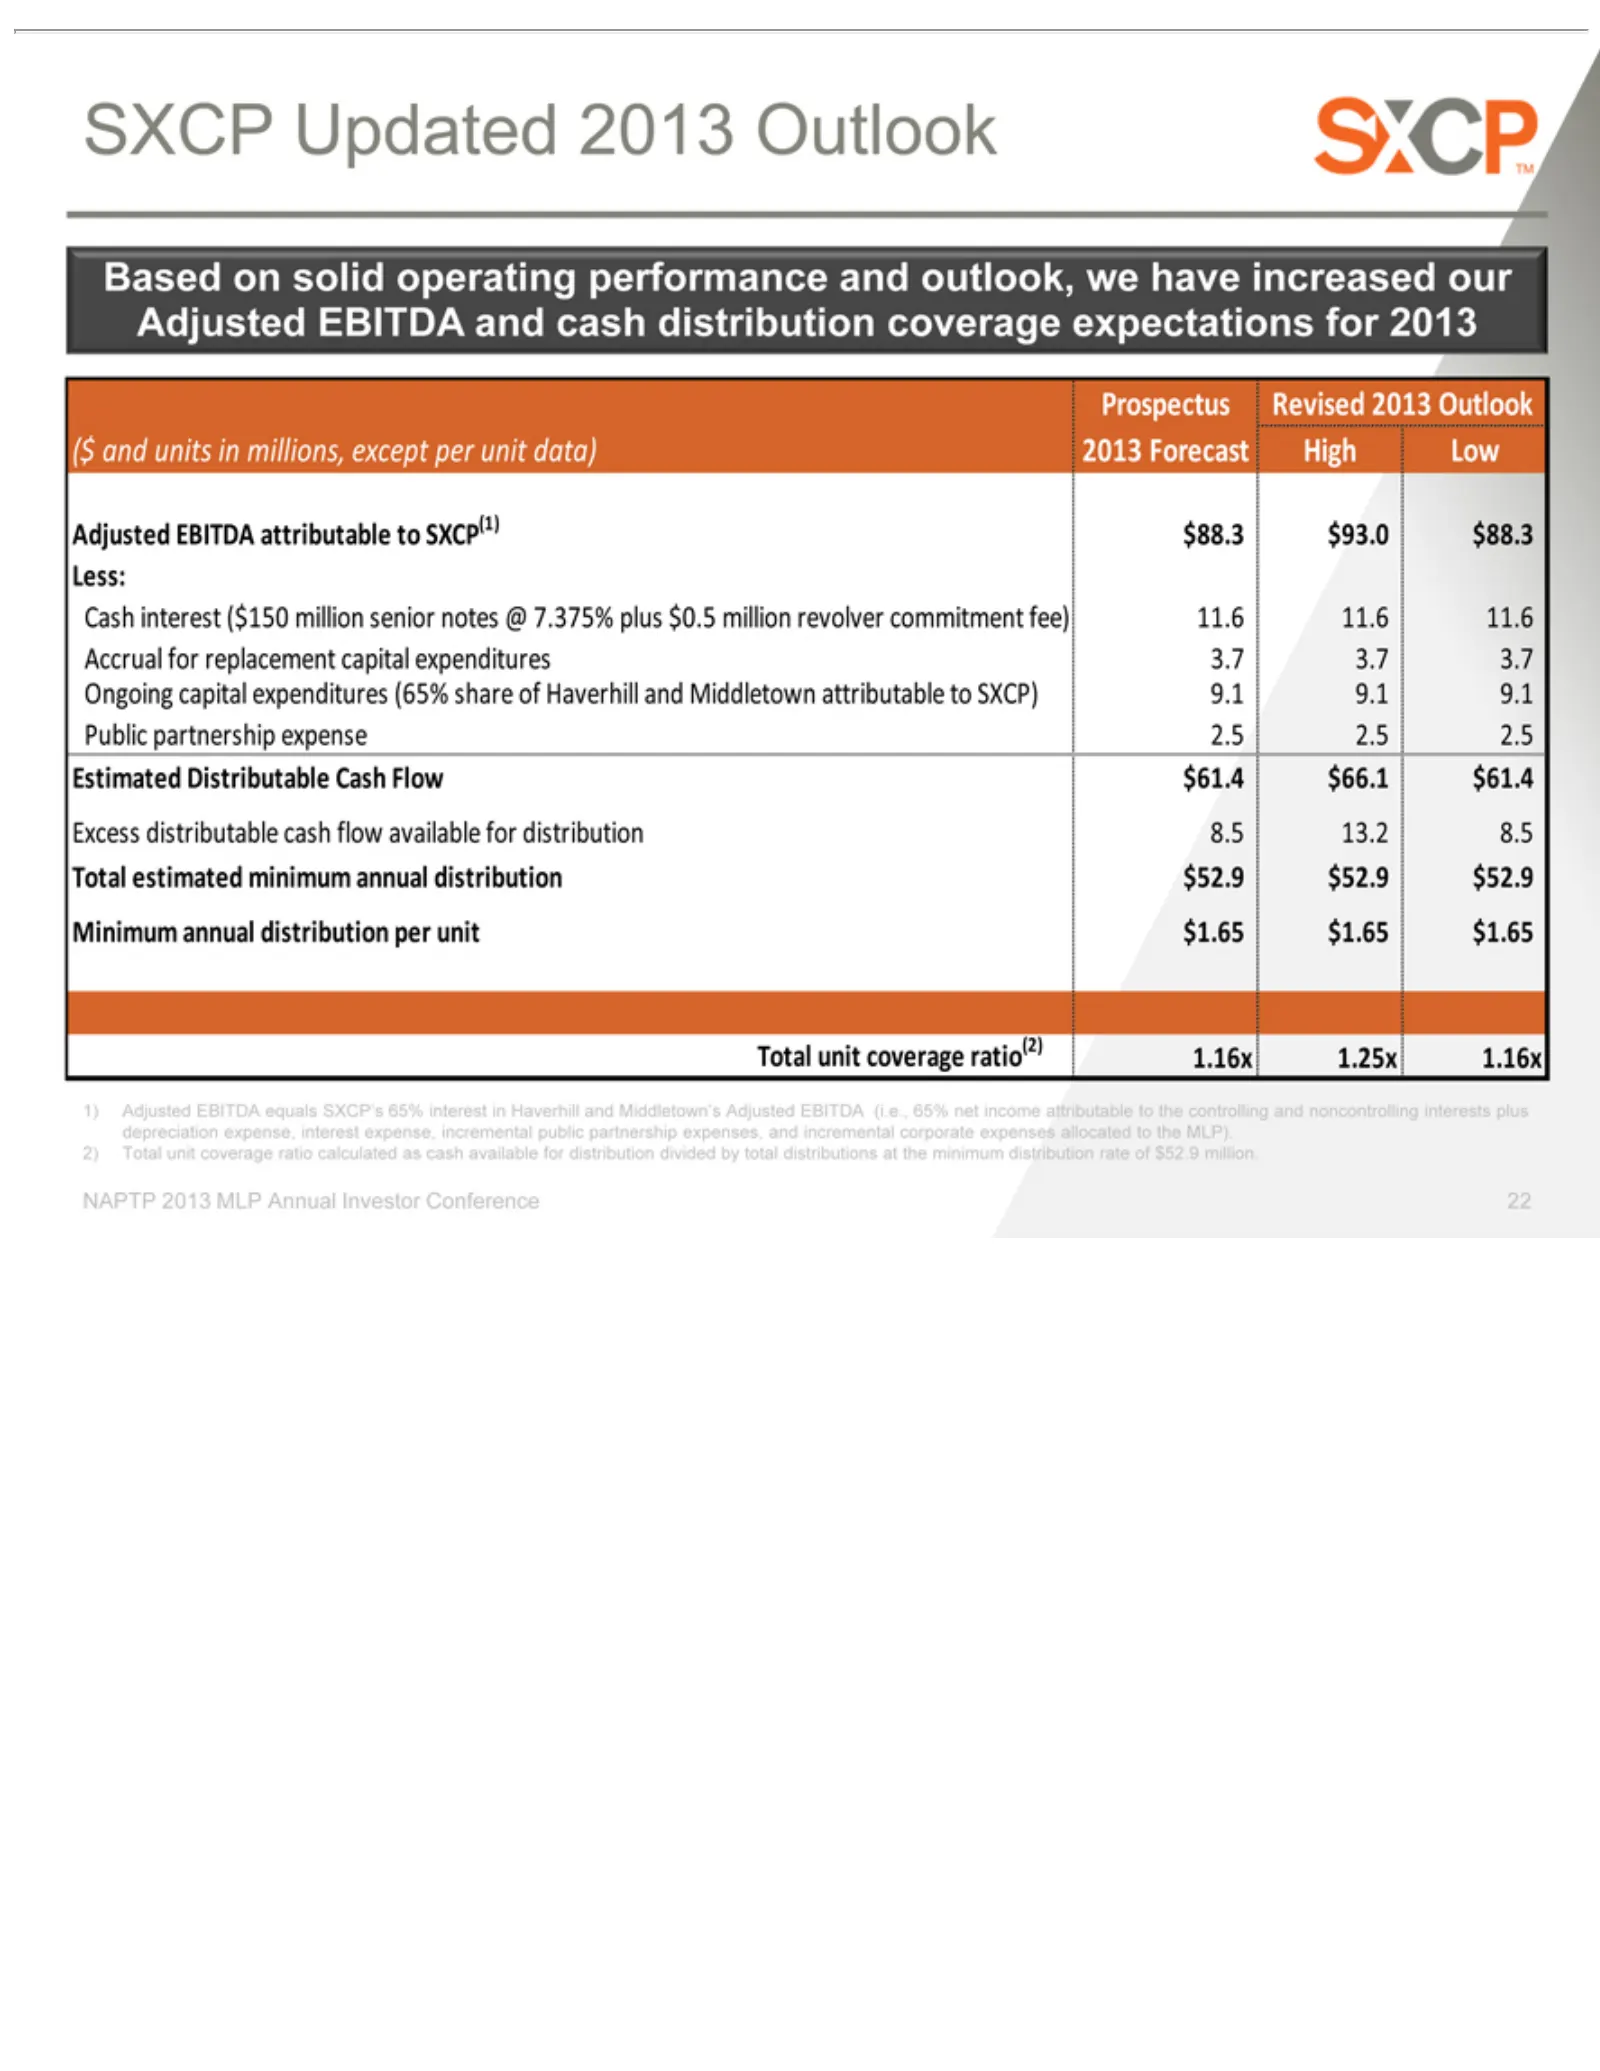
SXCP Based Prospectus ($ Adjusted Cash Less: Accrual Ongoing Public Estimated Excess Minimum Total 1) expense, 2) NAPTP 22 Adjusted Total andinterest estimated unit on Updated units partnership distributable unit 2013 for incremental capital EBITDA solid coverage Distributable annual Revised replace
Slide 23: SXCP Given Outlook, Expect Distribution Increase
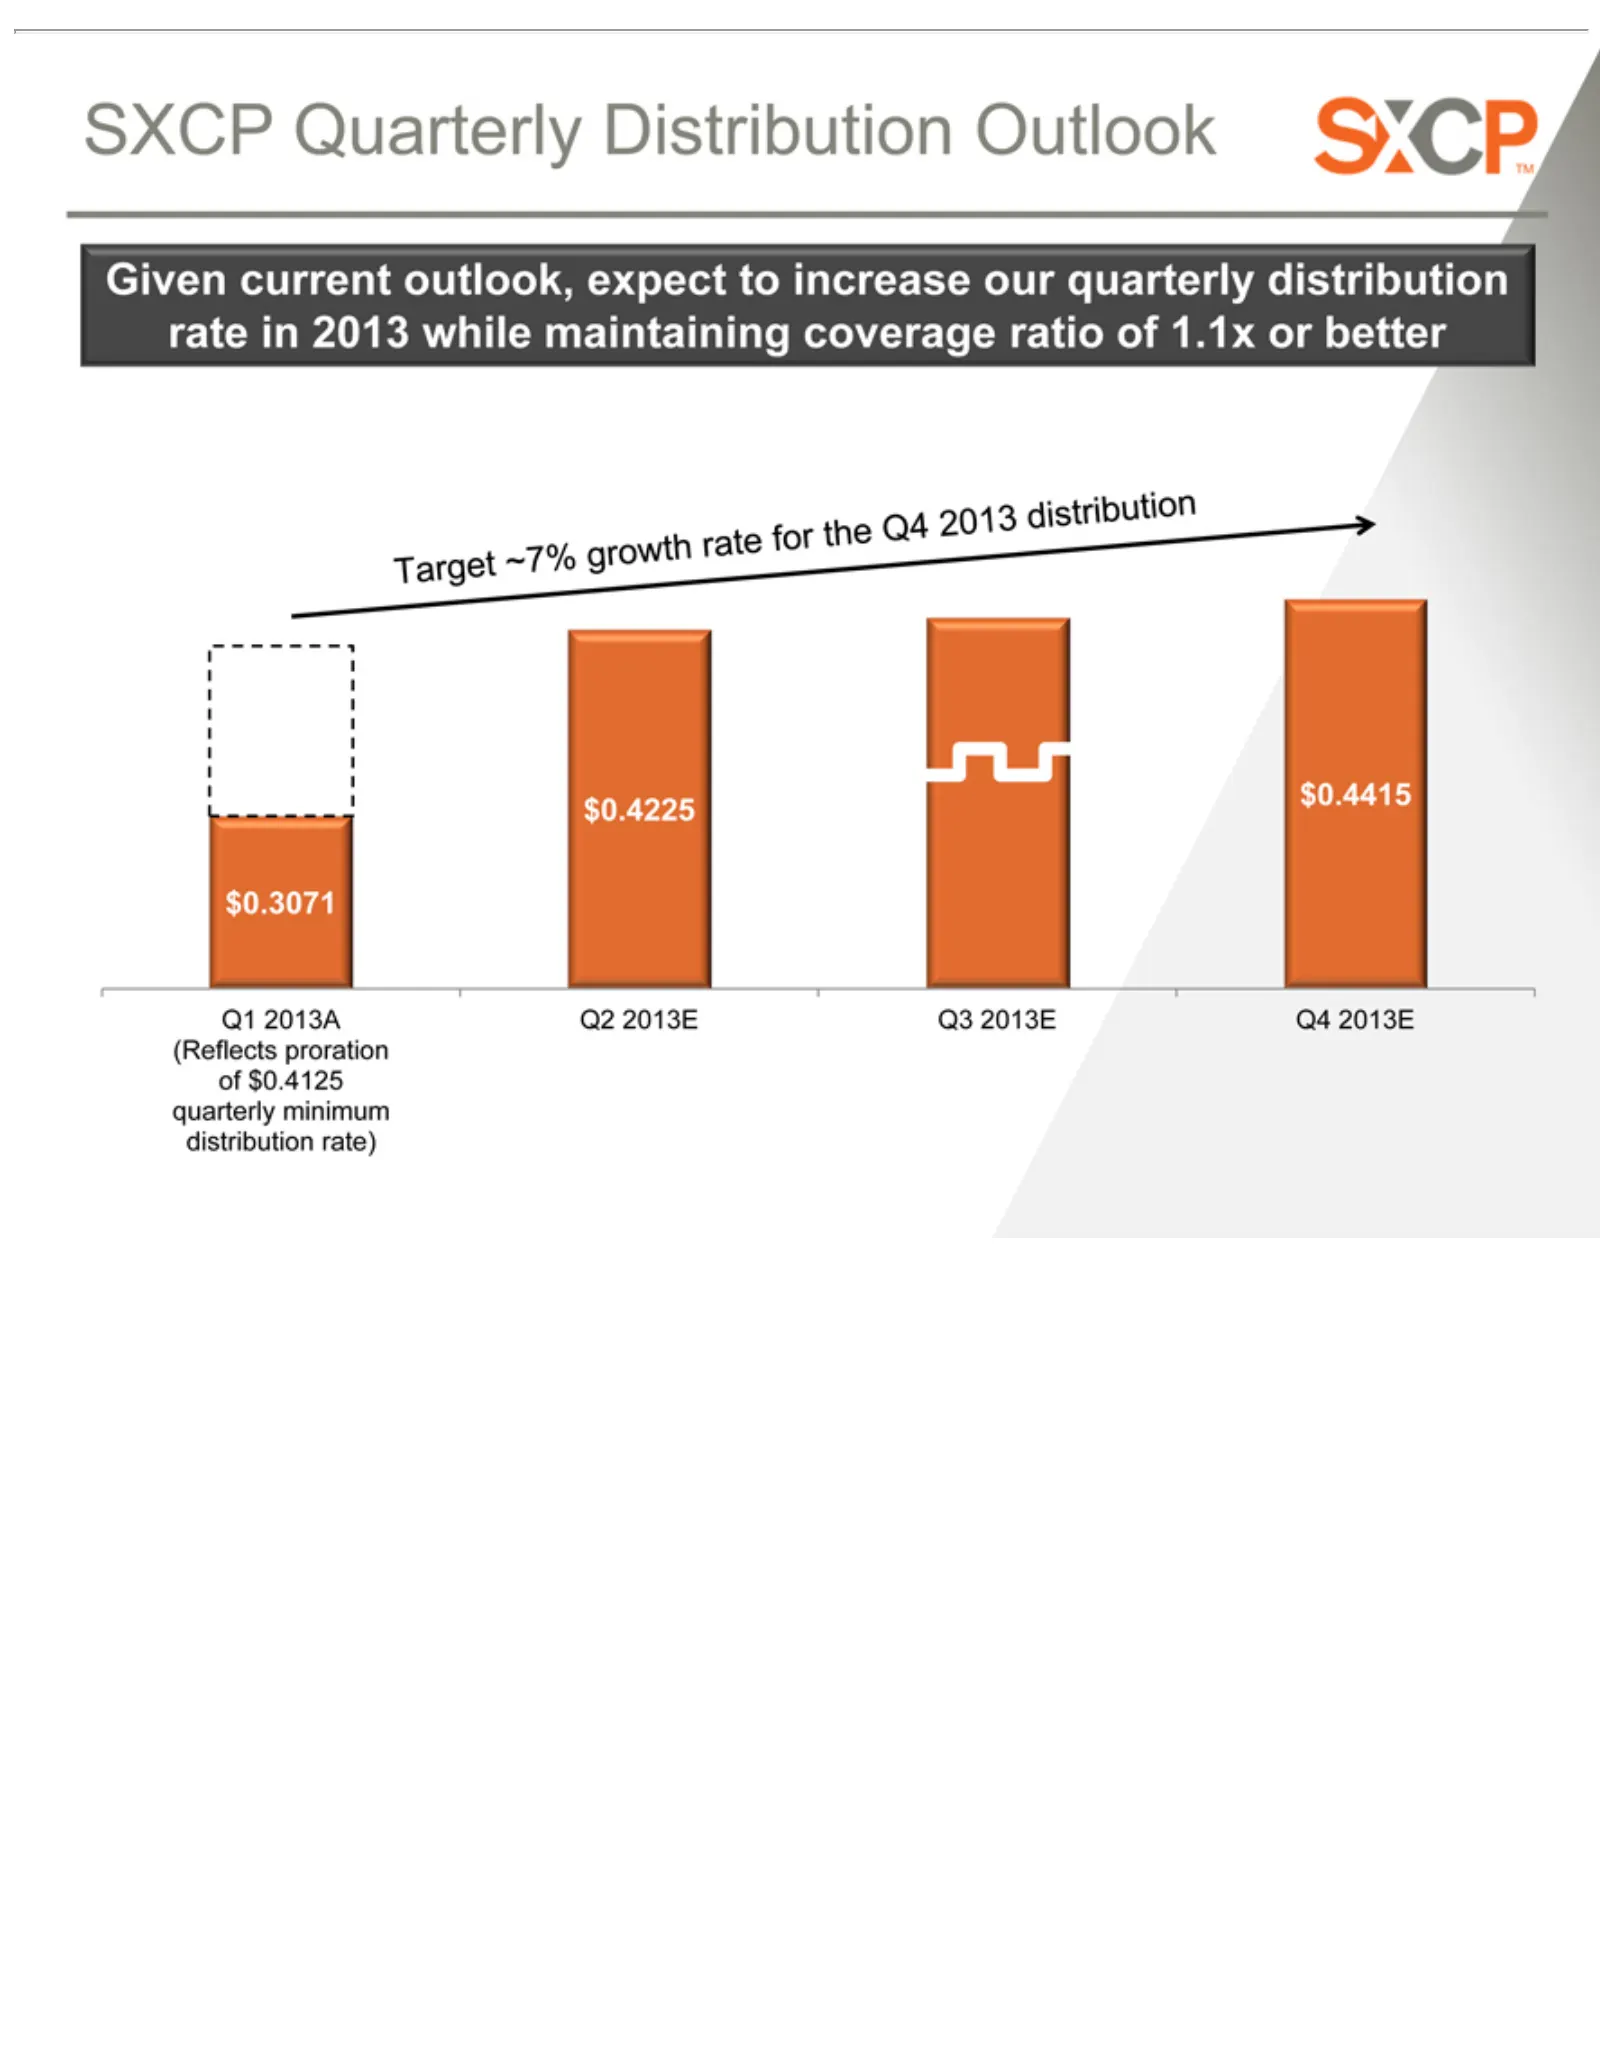
SXCP Given $0.4225 Q1 $0.3071 (Reflects of quarterly distribution $0.4125 2013A current Quarterly $0.4415 minimum proration Q2 rate) outlook, 2013E Distribution Q3expect 2013E Outlook to Q4 increase 2013Eour quarterly distribution rate in 2013 while maintaining coverage ratio of 1.1x or better
Slide 24: SXCP: Long-term, Stable Cash Flows
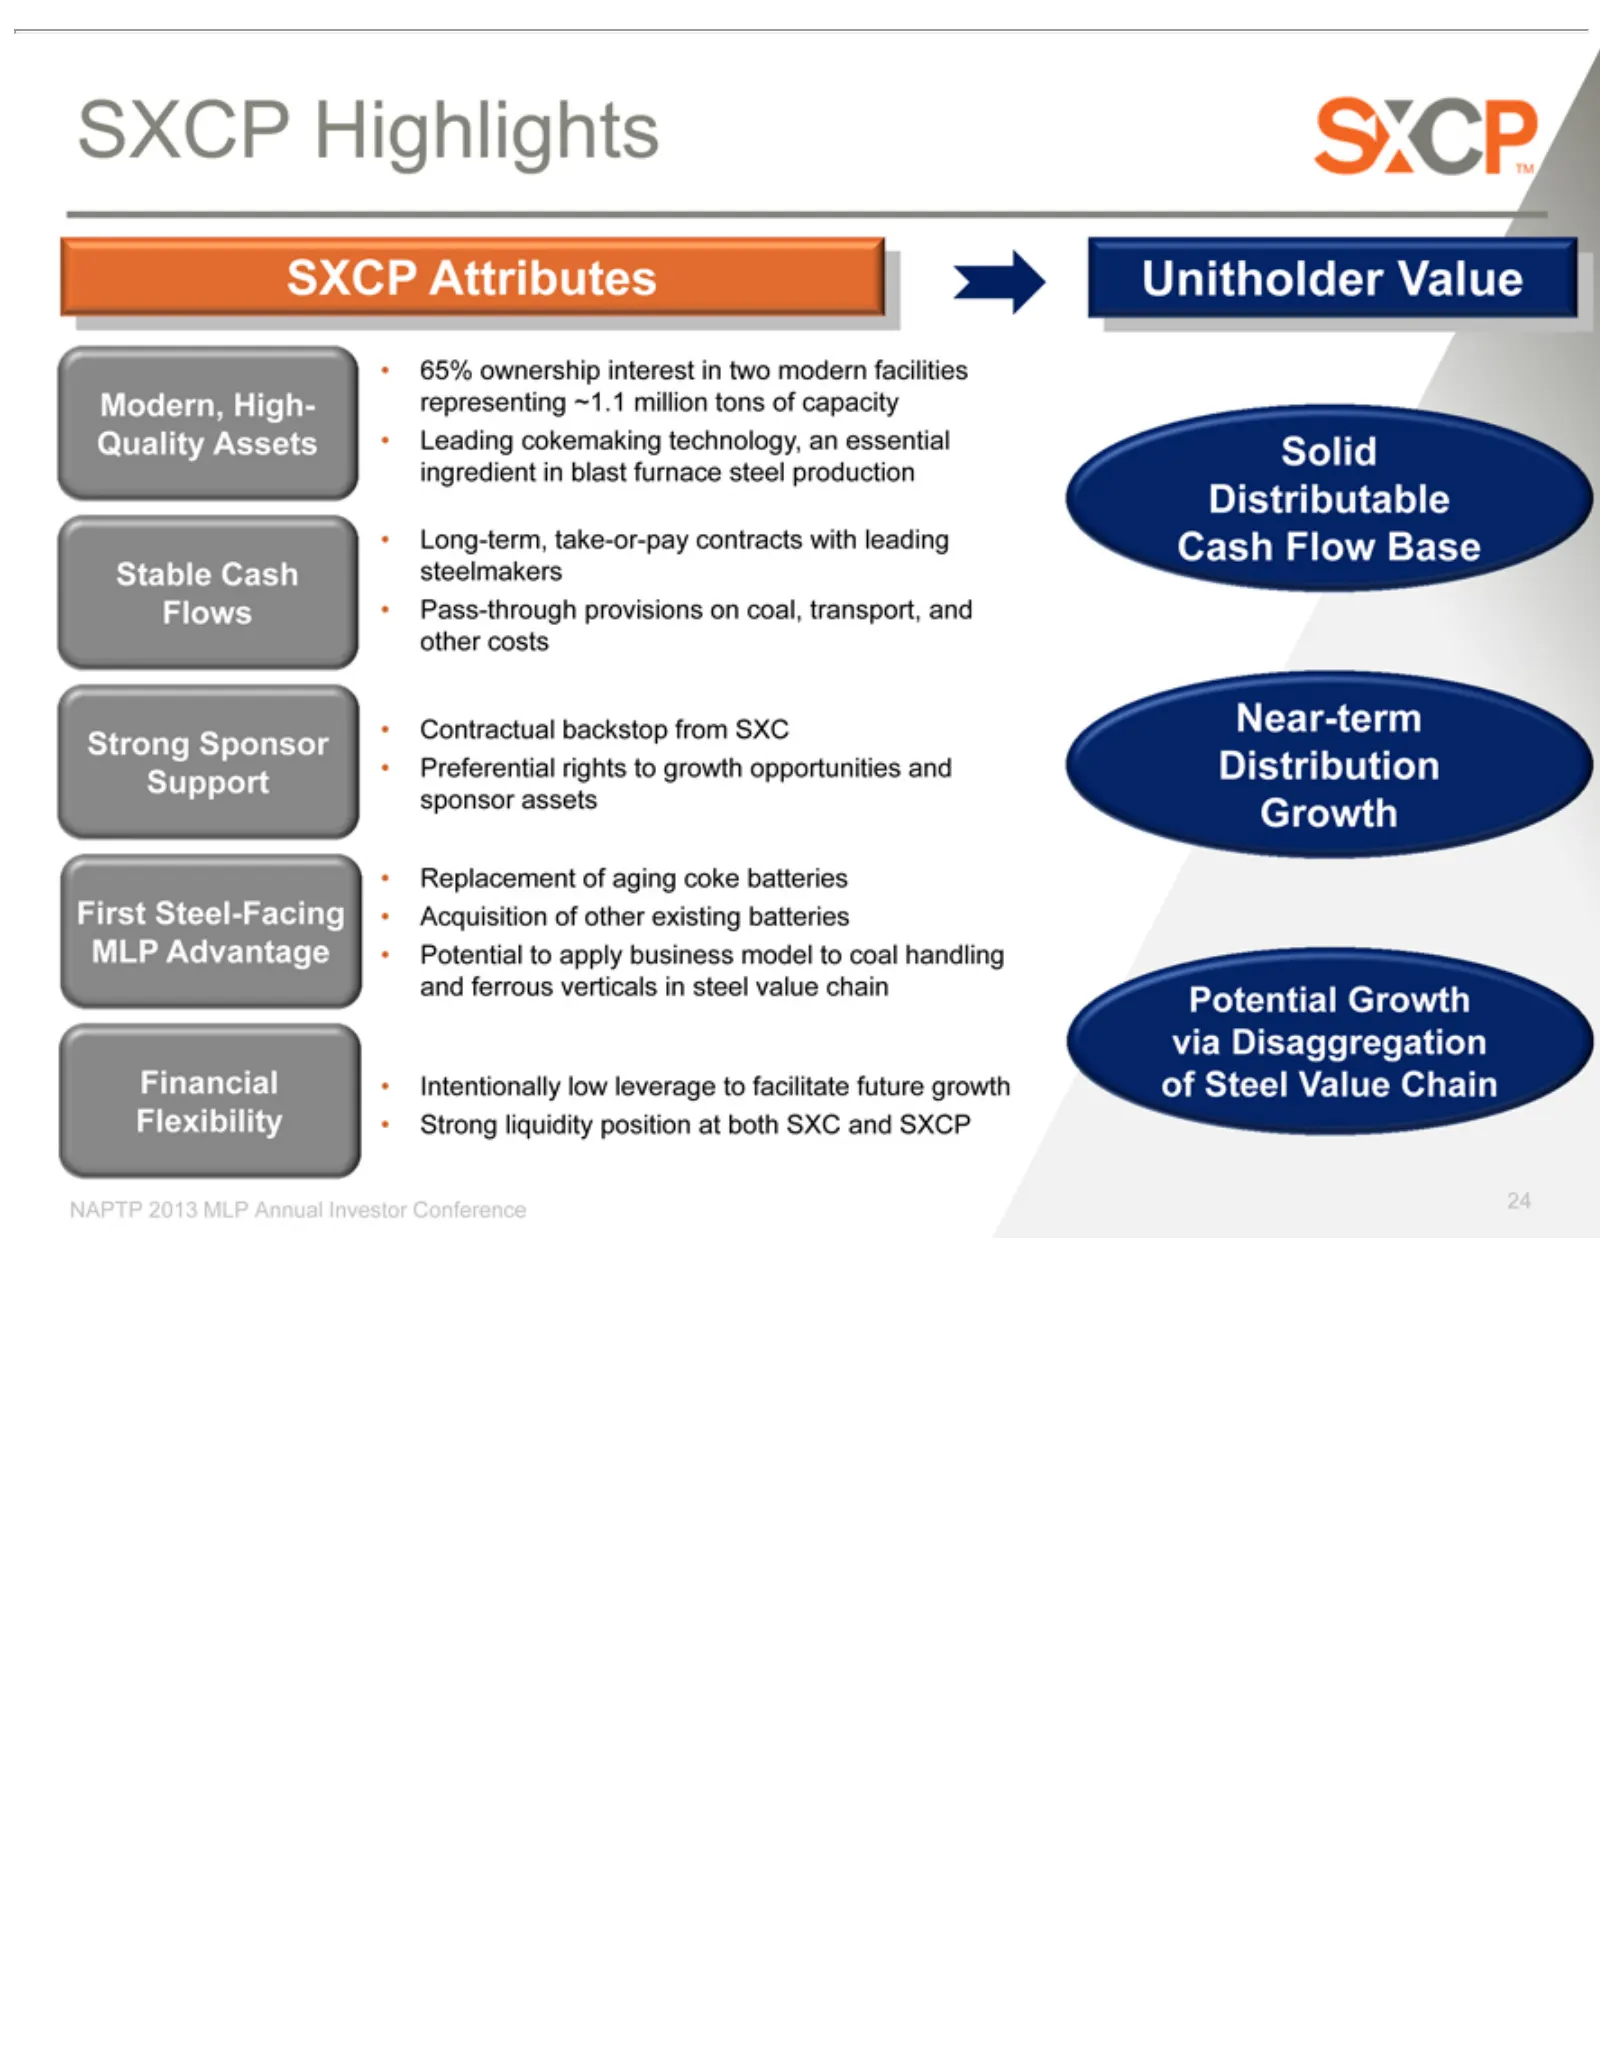
SXCPownership 65% Long-term, Stable Flows Strong Support Replacement MLP Financial Unitholder Solid Near-term Potential NAPTP 24 Advantage Distributable Attributes Pass-through Highlights Cash Sponsor 2013 Preferential Growth Intentionally Distribution Value take-or-pay steelmakers of MLP Contractua
Slide 25: Questions
NAPTP 2013 MLP Annual Investor Conference QUESTIONS 25
Slide 26: Investor Relations
Investor Relations: 630-824-1987 www.suncoke.com
Slide 27: Appendix
NAPTP 2013 MLP Annual Investor Conference APPENDIX 27
Slide 28: Definitions: Adjusted EBITDA
Definitions aattributable EBITDA comparable business performance Adjusted NAPTP 28portion2013 that of since attributable EBITDA to to nonconventional that may MLP equity other those they isnot represents attributable Annual not represent similarly reported earnings to otherwise defined ourInvestor u
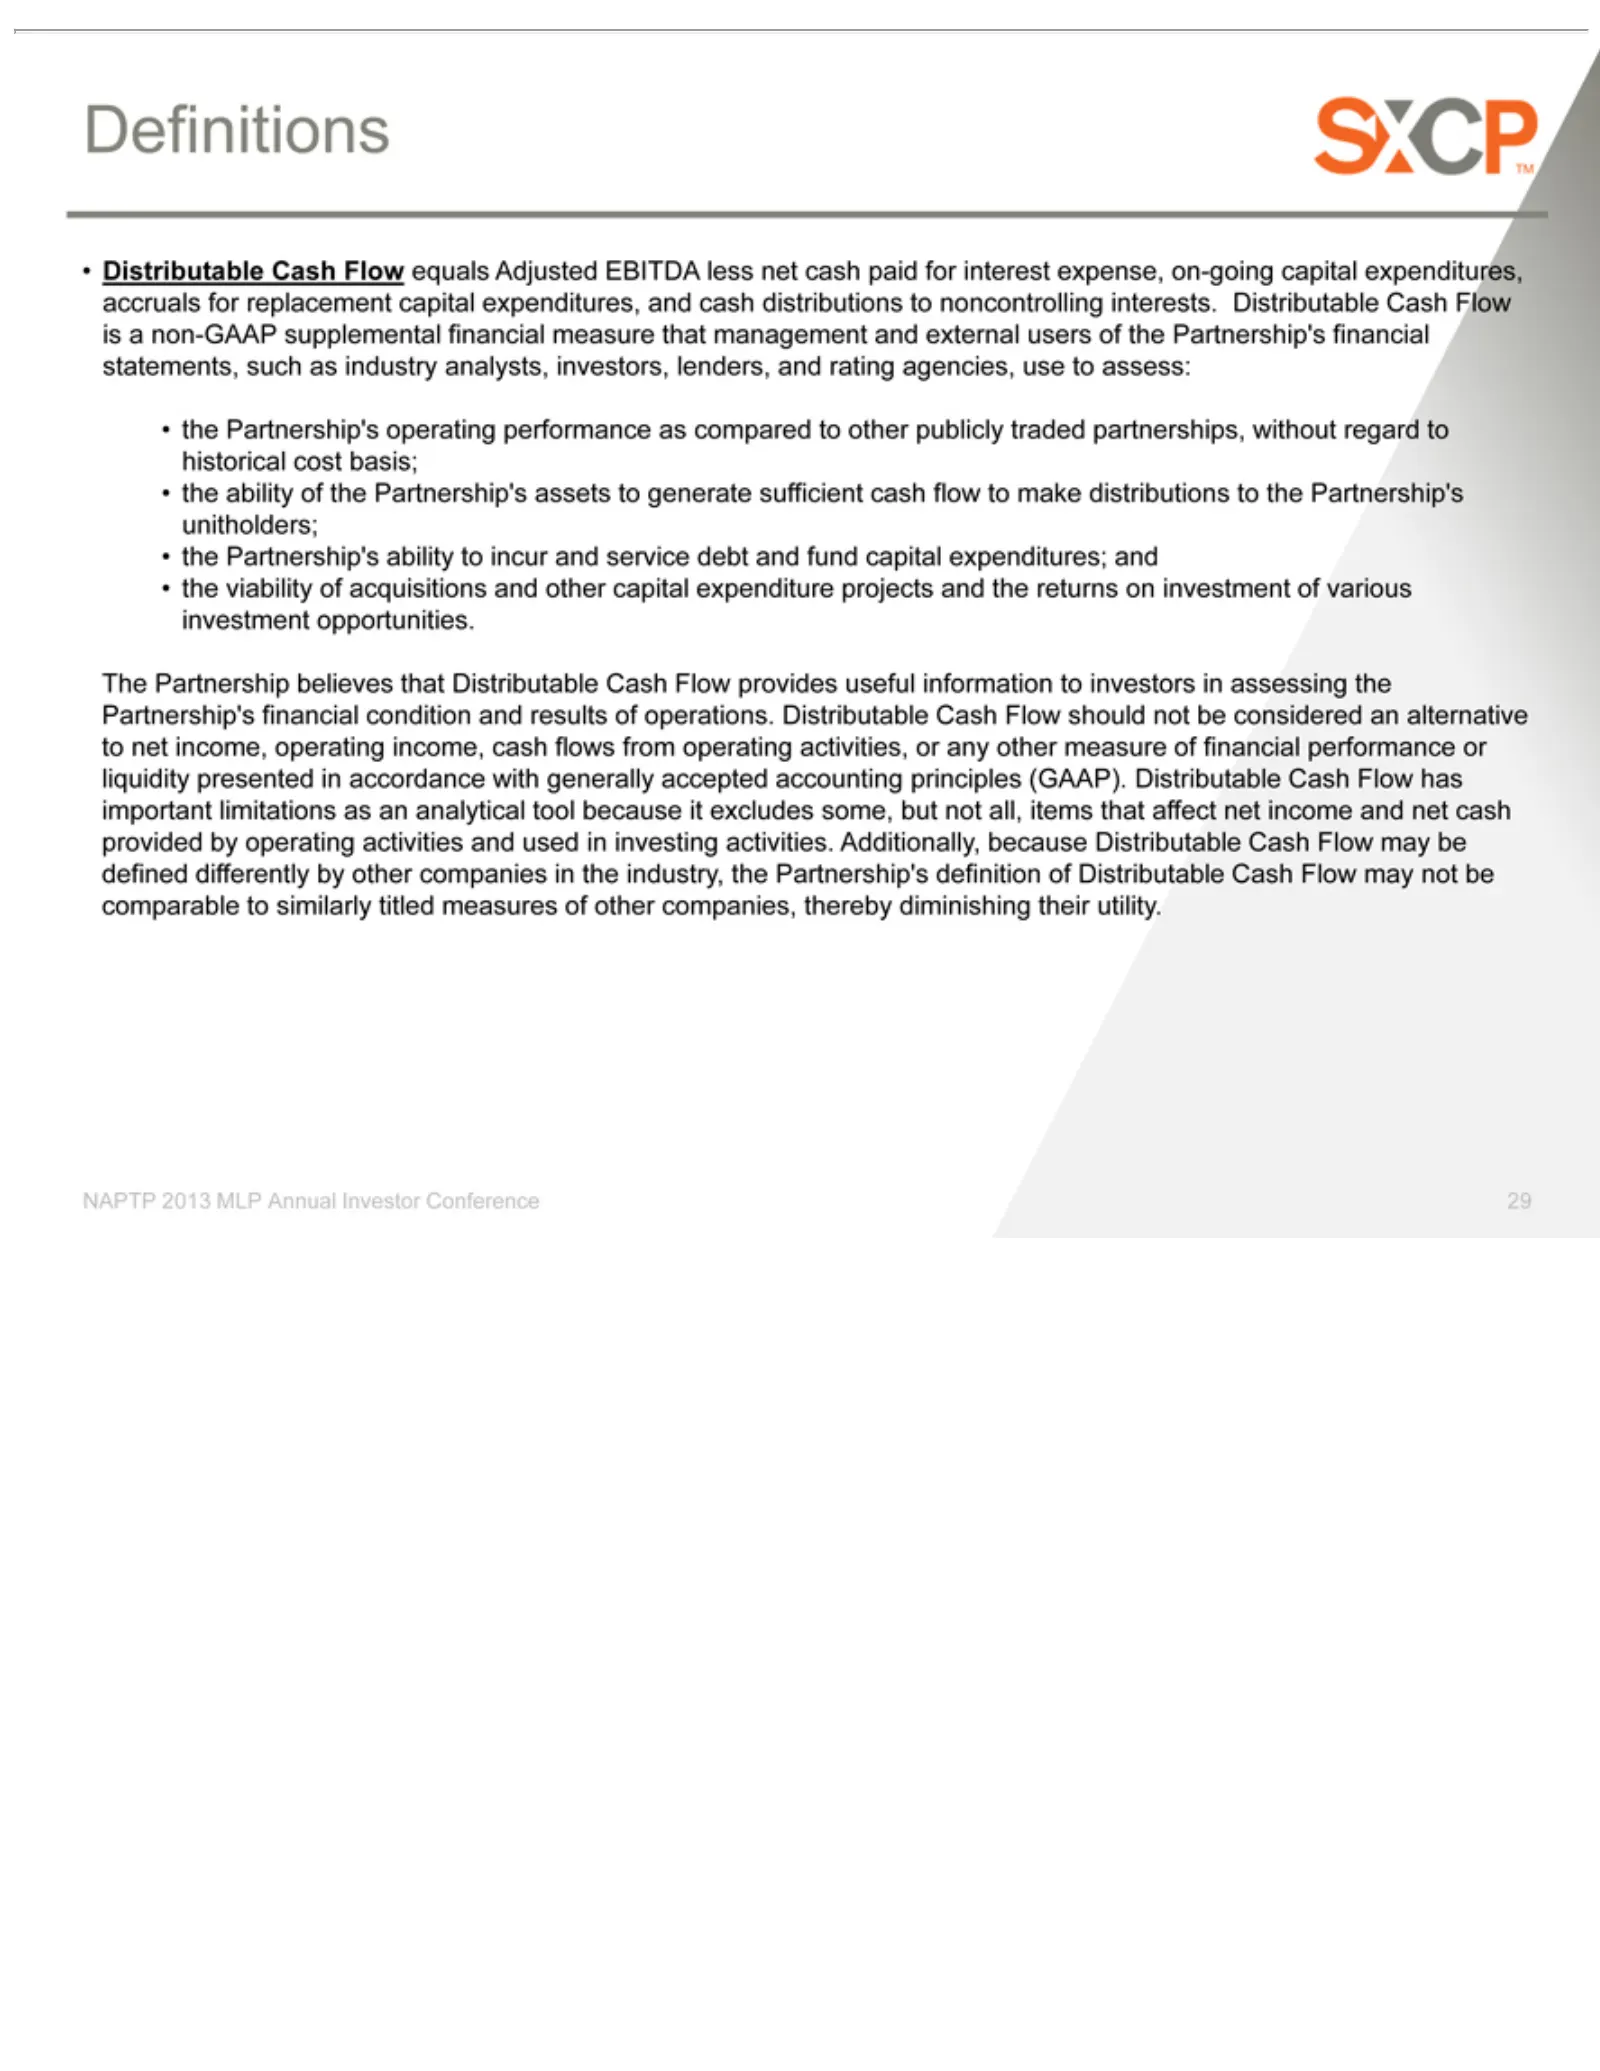
Slide 29: Definitions: Distributable Cash Flow
Definitions Distributable use the distributions investment The Partnership’s financial not industry, NAPTP 29 Partnership’s all, to Partnership assess: items 2013 the performance ofPartnership’s to that Cash financial MLP various the believes operating affect Flow Partnership’s Annual investment or
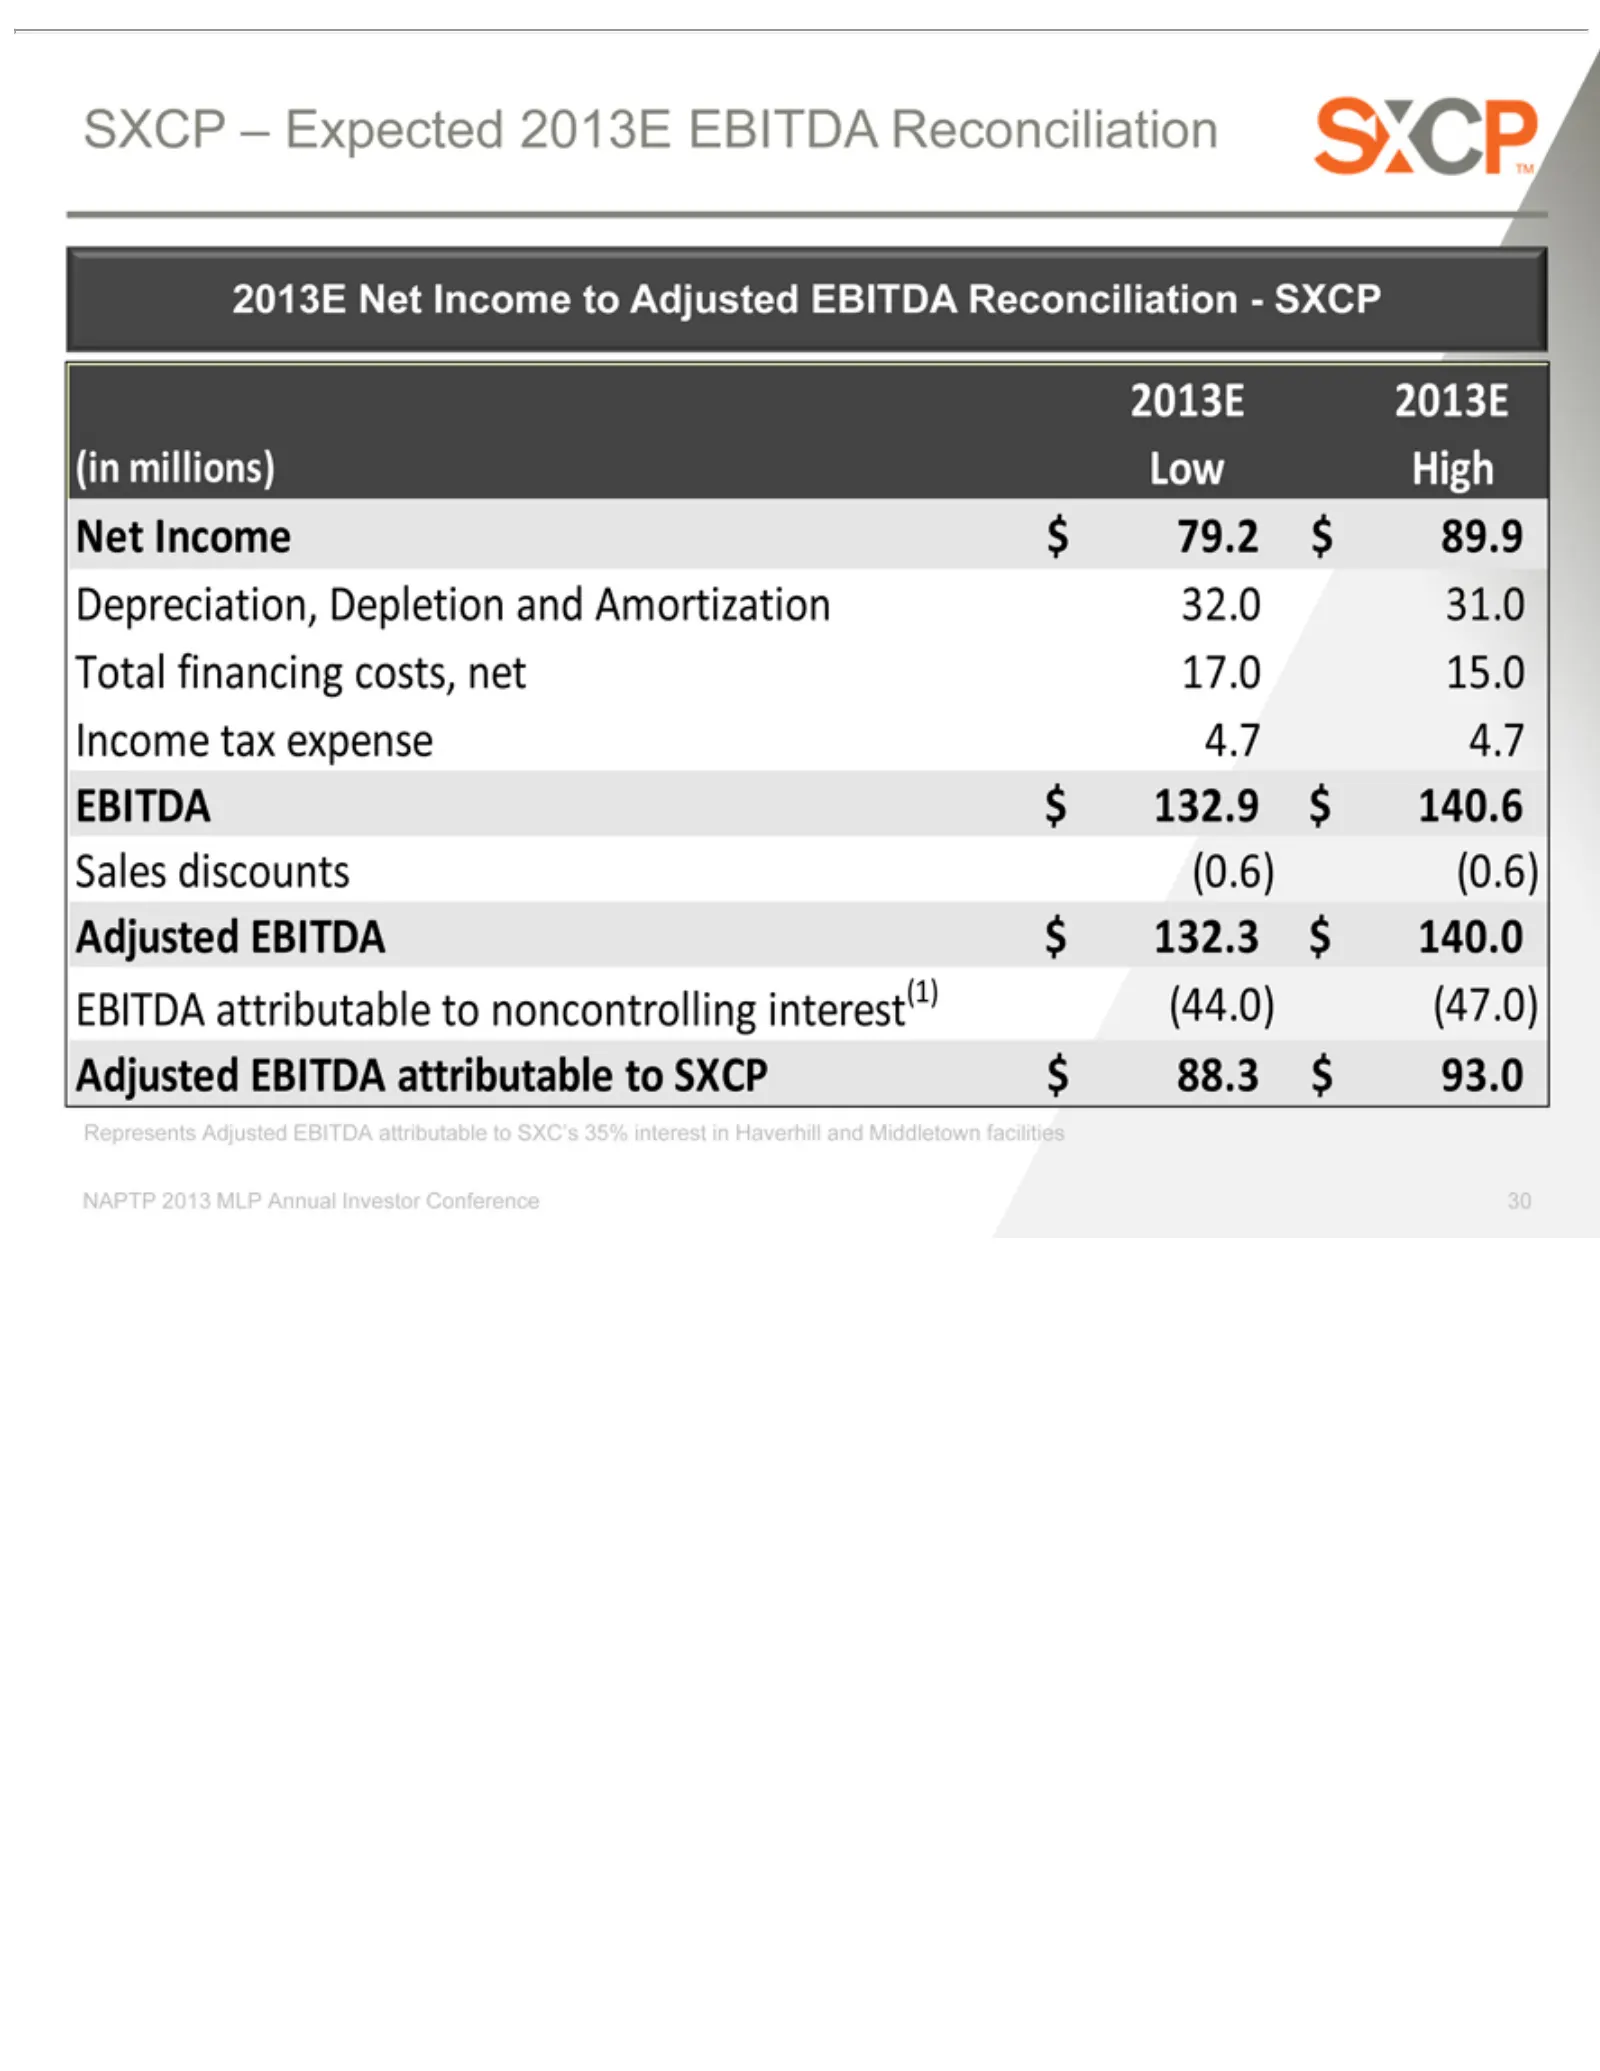
Slide 30: SXCP 2013E Adjusted EBITDA Reconciliation
SXCP 2013E (in Net Depreciation, Total Income Sales EBITDA Adjusted Represents NAPTP 30 millions) Income financing discounts –2013E Net tax 2013 Expected $EBITDA attributable Income Adjusted 132.9 expense $Low MLP Depletion 79.2 costs, (0.6) $High 2013E $attributable to Annual 140.6 4.7 89.9 EBITDA
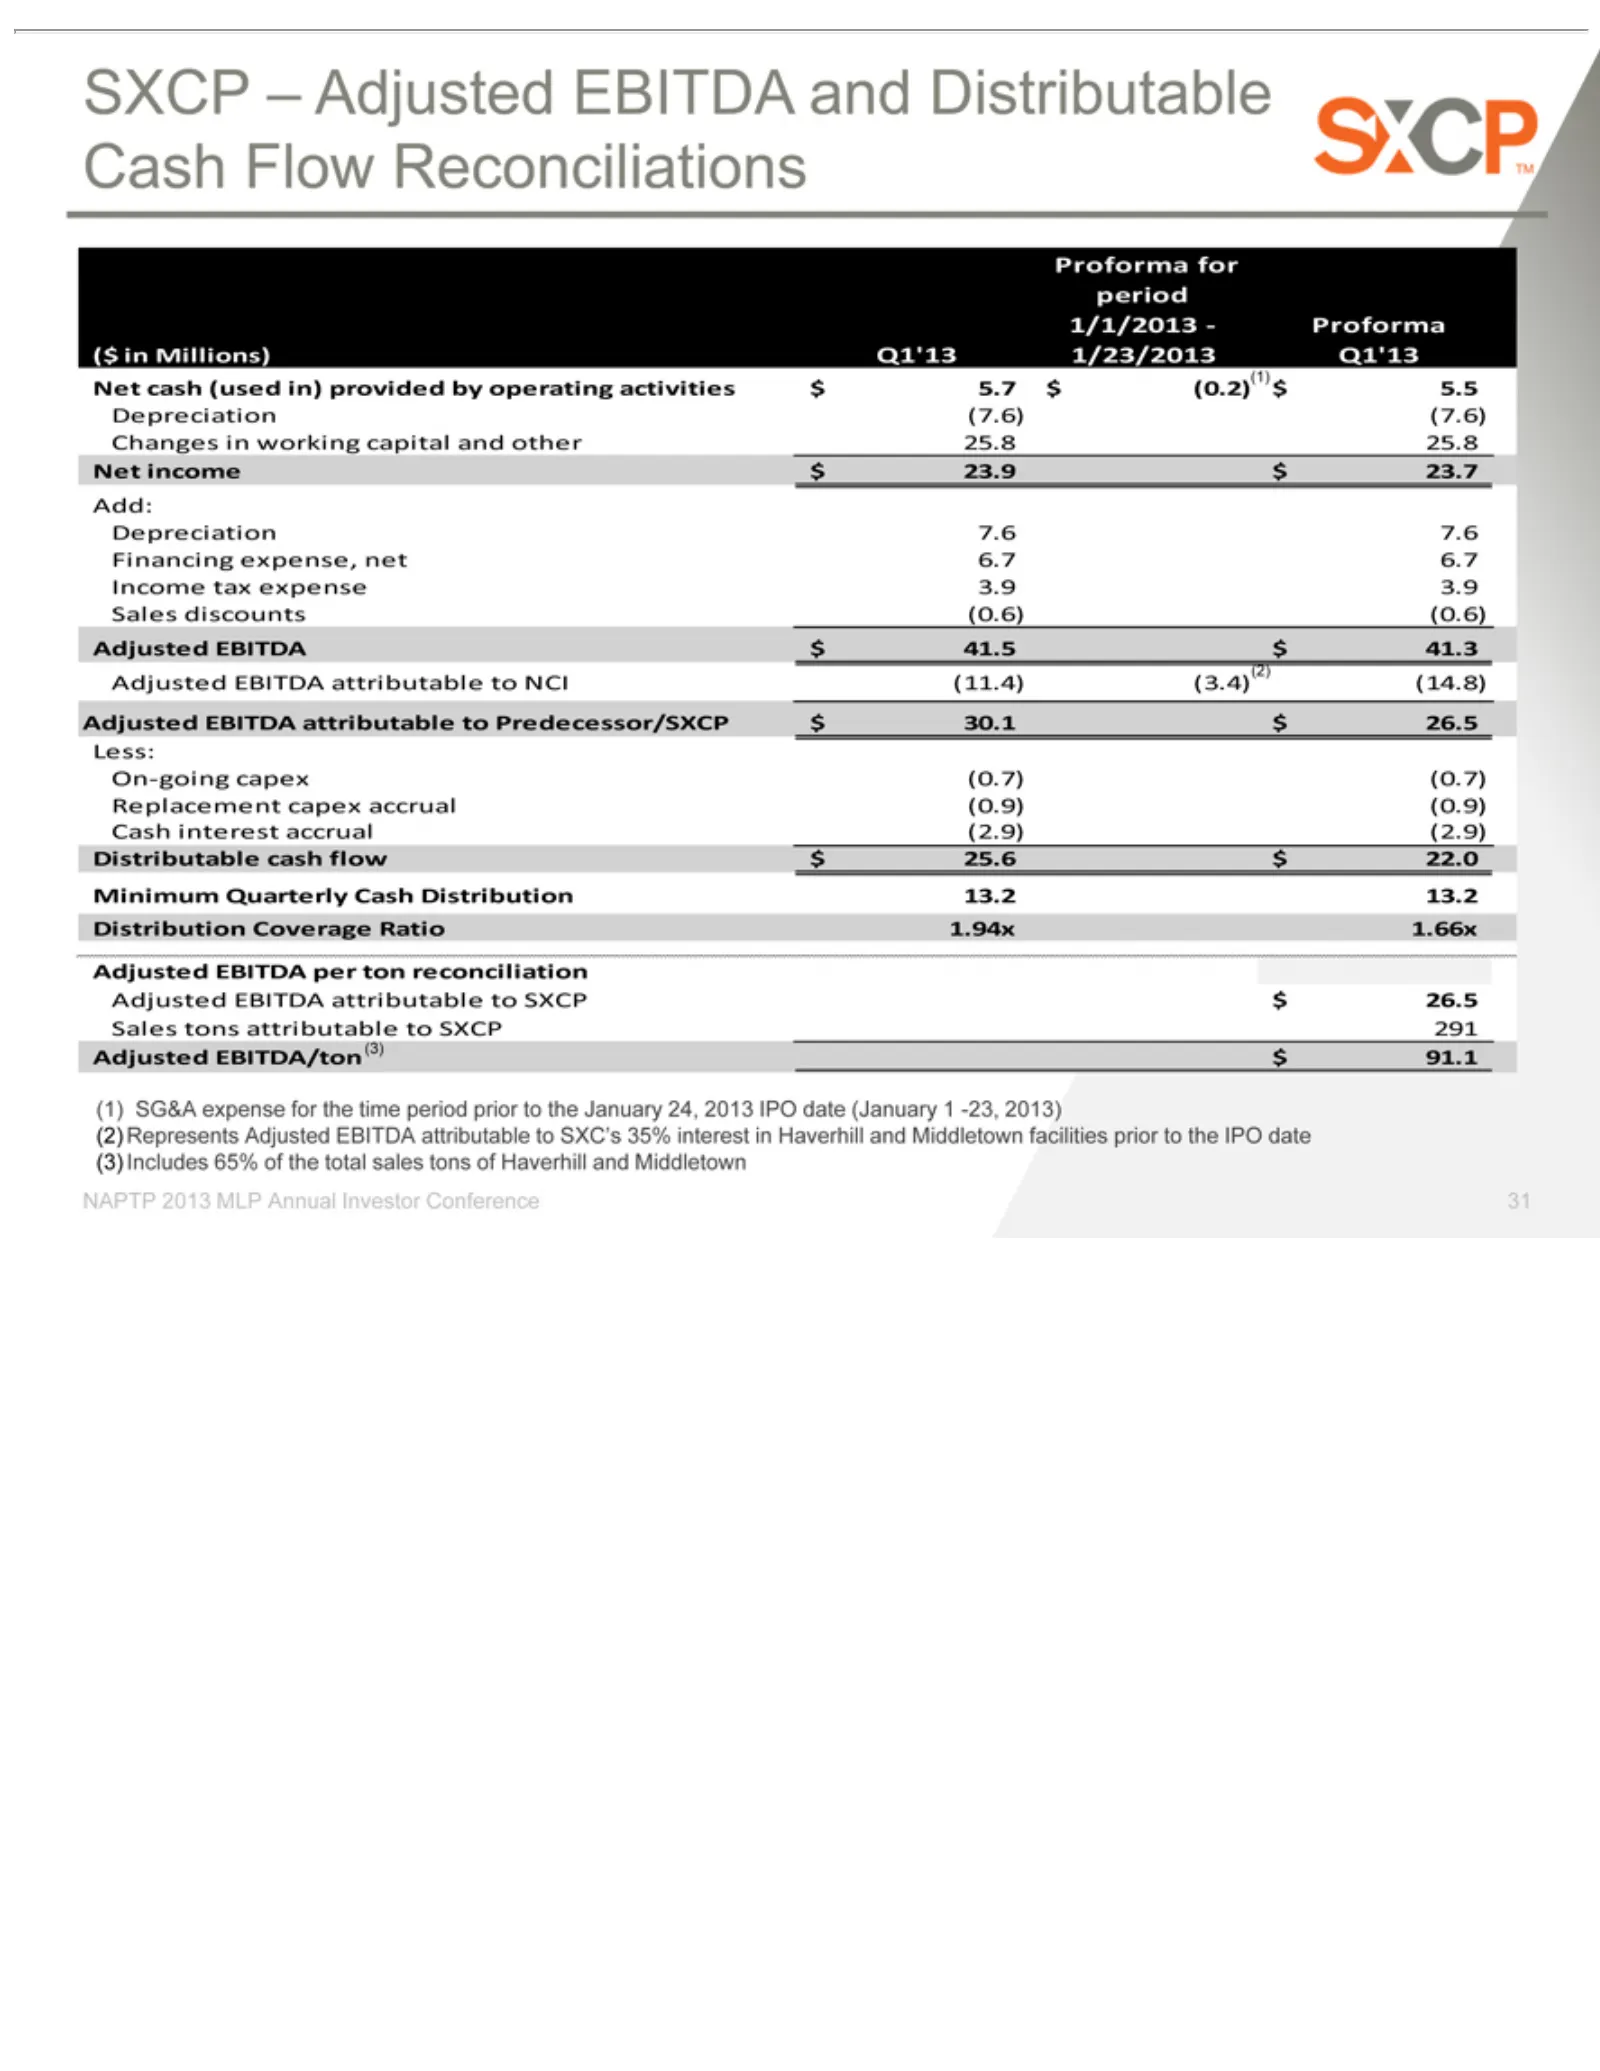
Slide 31: SXCP Proforma Reconciliation
SXCP Proforma 1/1/2013— period ($ Changes Net Depreciation Add: Financing Income On-going Less: Replacement Cash Distributable Minimum Distribution Sales Adjusted (1) (2) (3) NAPTP 31 inIncludes SG&A Represents cash income Millions) interest discounts tons – tax 2013 Adjusted in (used EBITDA EBITDA/
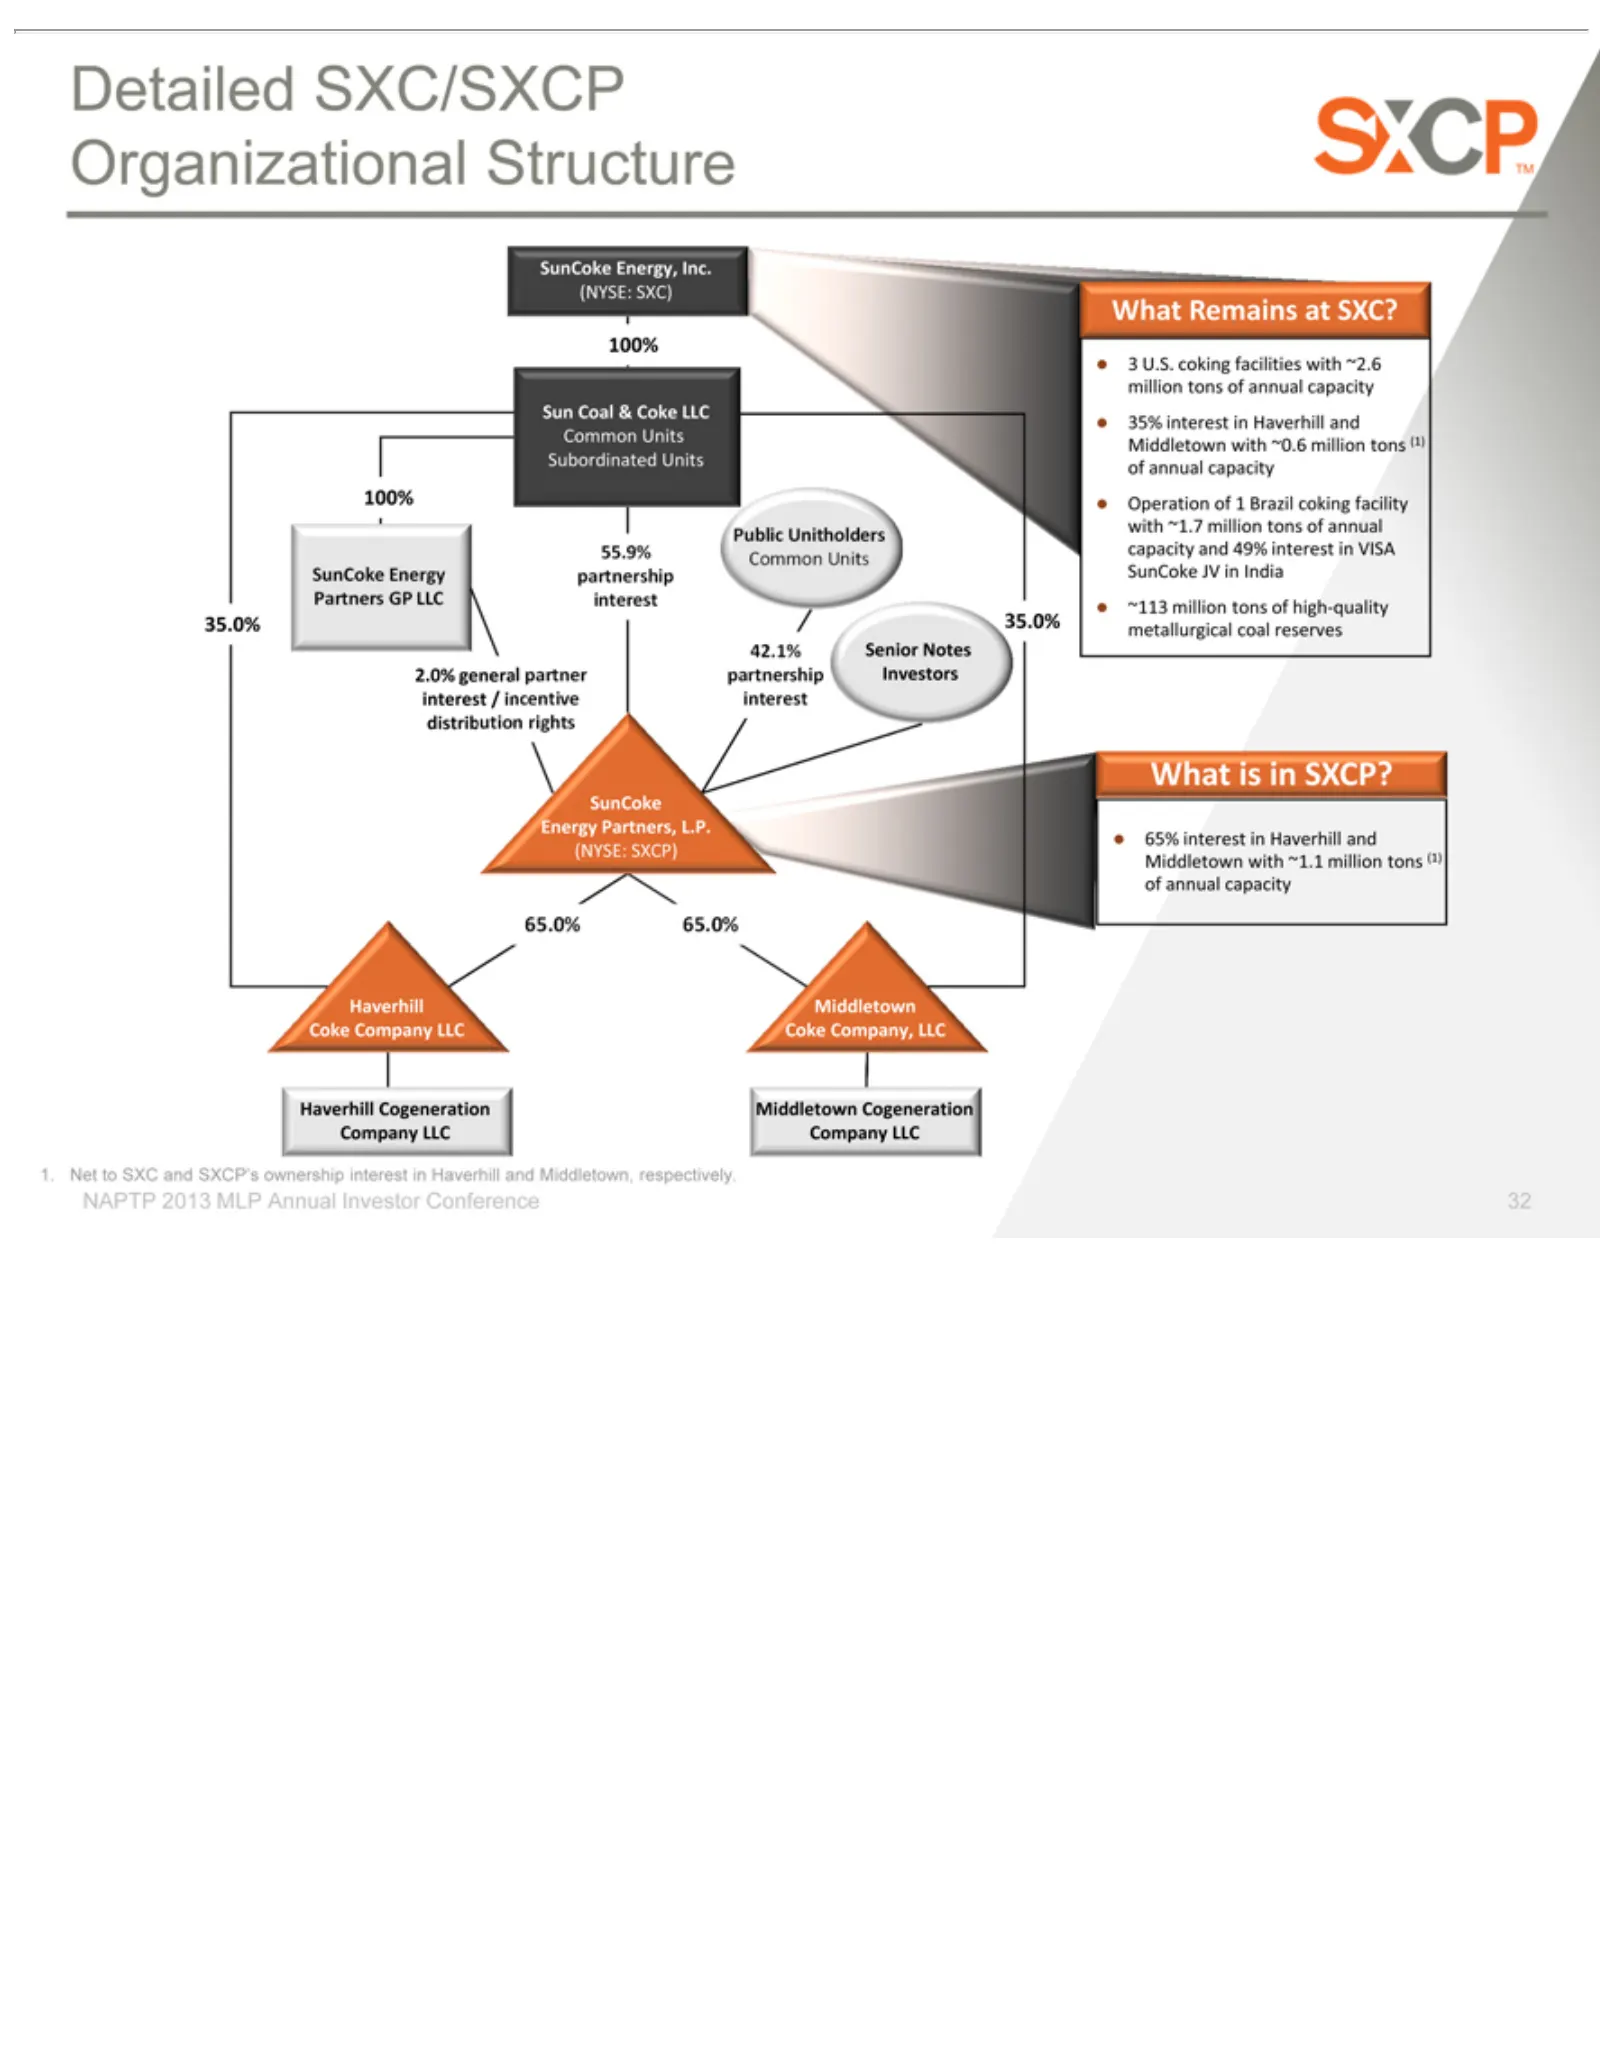
Slide 32: Detailed Organizational Structure
Detailed million Sun Common Subordinated 100% Public 55.9% partnership 35.0% 42.1% 2.0% interest distribution What Energy zSunCoke (NYSE: of 65.0% Coke Haverhill Company 1. NAPTP 323Net 65% annual U.S. Coal general Company Remains is zto interest Unitholders Common 35.0% Senior 65.0% Partners, tons
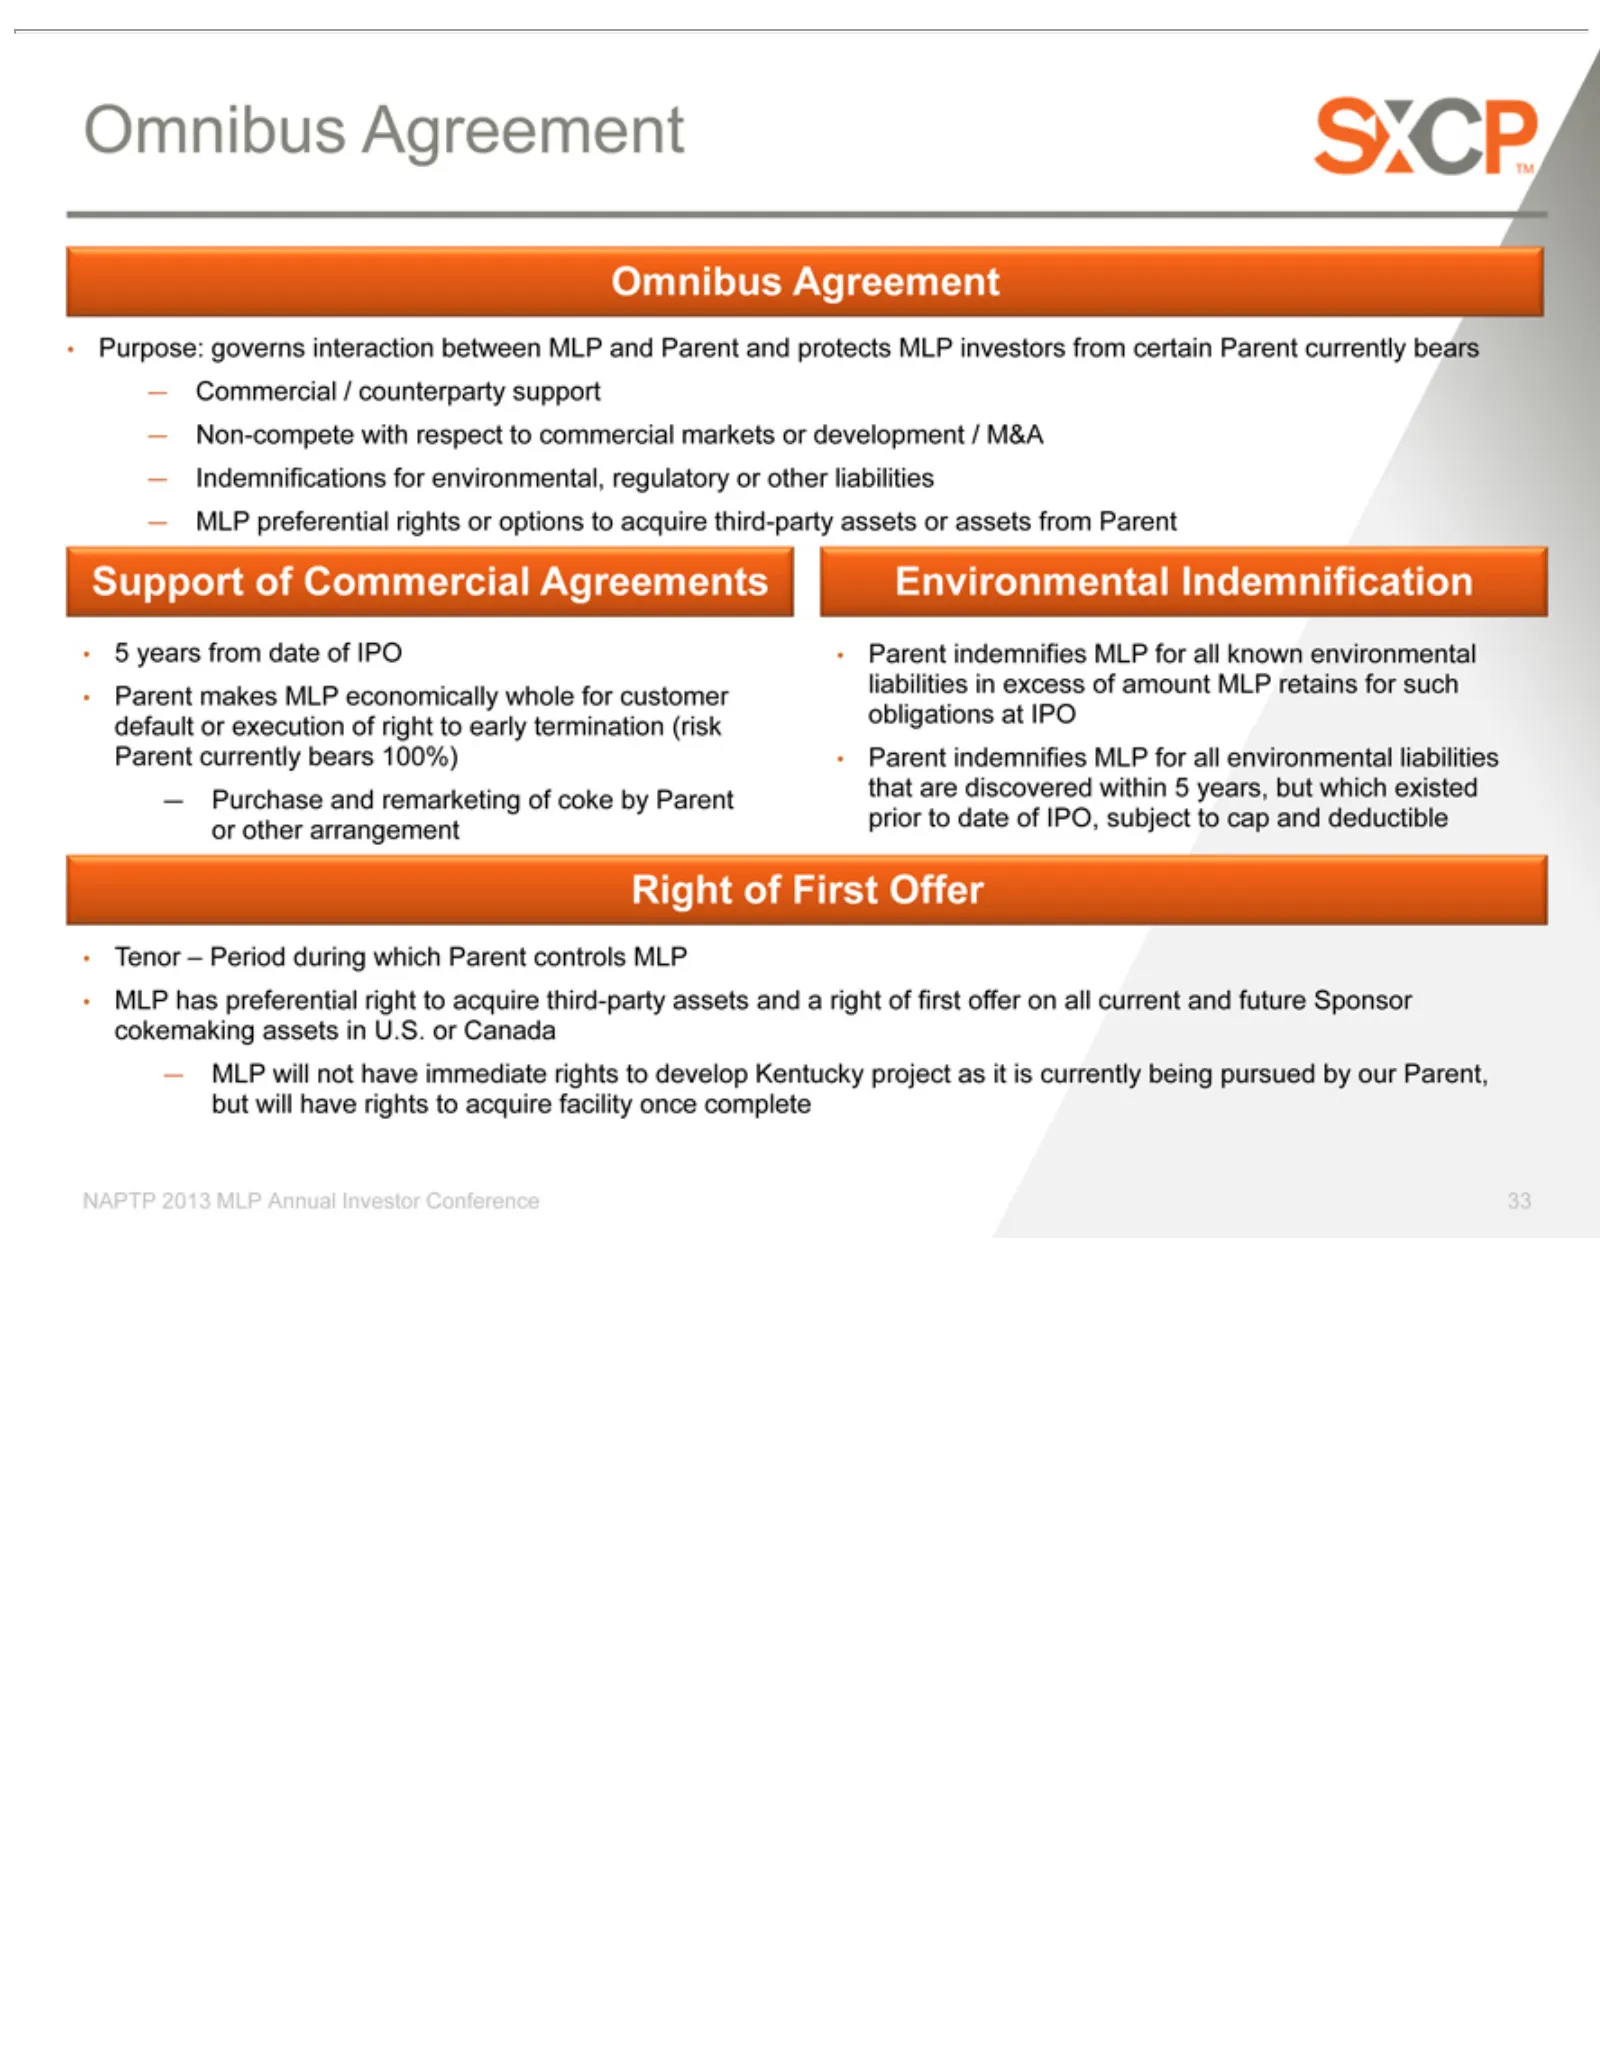
Slide 33: Omnibus Agreement and Commercial Agreements
Omnibus Purpose: Commercial Non-compete Indemnifications 5Support Parent Purchase Right Tenor MLP NAPTP 33years preferential has will of –currently makes from Period 2013 of First governs preferential and Agreement not Commercial /date remarketing have MLP Offer with counterparty during bears for ri
Source: SEC EDGAR · 8-K filed May 22, 2013
More decks from SunCoke Energy Partners L.P
 Merger or Acquisition (May 2019)42 slides · May 22, 2019
 Q1 2019 Earnings Presentation26 slides · Apr 24, 2019
 Merger or Acquisition (February 2019)41 slides · Feb 26, 2019
 FY2018 Earnings Presentation37 slides · Feb 5, 2019
 FY2018 Earnings Presentation36 slides · Feb 5, 2019
 Q3 2018 Earnings Presentation25 slides · Oct 25, 2018