AAC — Investor Presentation (June 2017)
64 slides from AAC's investor presentation, Jun 6, 2017
Slide 1: Company Presentation, Desert Hope Alumni
Exhibit 99.1 COMPANY PRESENTATION DESERT HOPE ALUMNI JUNE 6, 2017
Slide 2: Important Presentation Information
IMPORTANT they be information within “could” disclosure these results, Annual continuously expansions; the economic lender on in statements our no Form acquisitions; provide expectations, assurance forward-looking consent the performance Report or 10-K consequences meaning of the toobtained (v) has
Slide 3: Presenters
•PRESENTERS firm auditor transactions, Started Chief with Moments Financial Ernst including • Founder & ofOfficer Young Change public andLLP, • offerings & Former CEOLifestyle a national ofVice Foundations of Intervention, securities President public accounting Recovery and at two Piper mergers ofJa
Slide 4: Industry Primer
American Addiction Centers Wa Zz > INDUSTRY PRIMER
Slide 5: Significant Unmet Need for Treatment
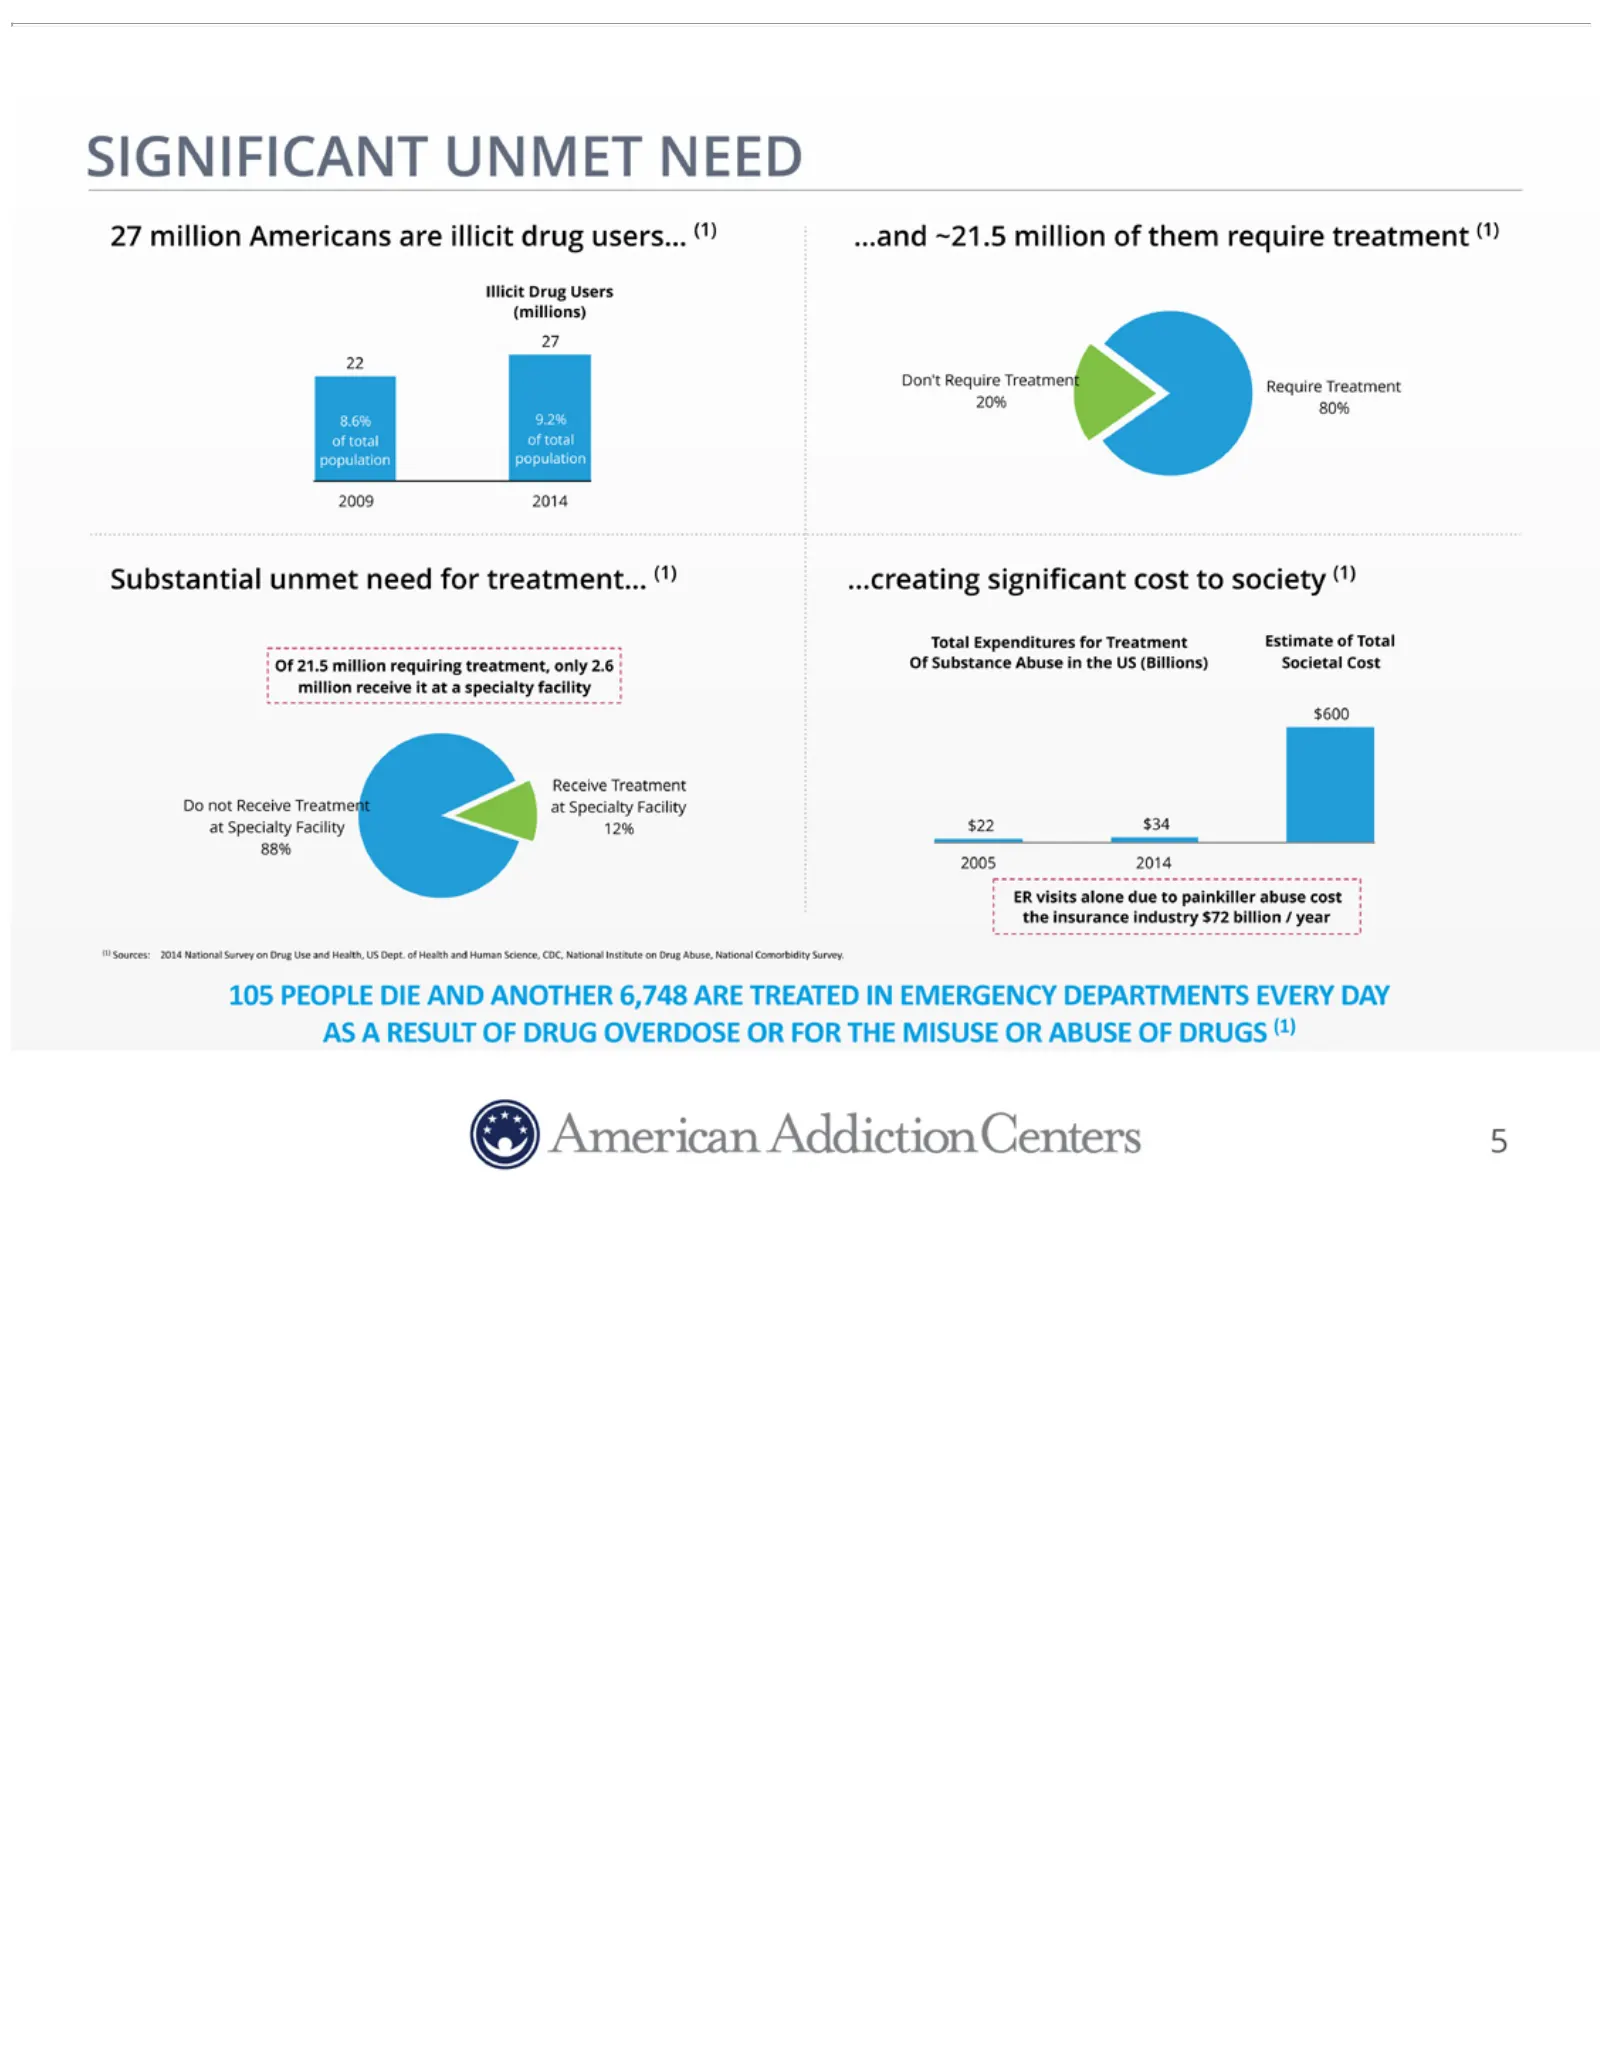
SIGNIFICANT 2014 facility National$Survey$on$Drug$Use$and$Health,$US$Dept.$of$Health$and$Human$Science,$CDC,$National ABUSE Substantial $600 OF DRUGS Receive UNMET unmet (1)Treatment need 5NEED for 27 treatment… Do million not Receive Americans (1) ...creating Treatment are illicit significant at Sp
Slide 6: Current Addiction Headlines
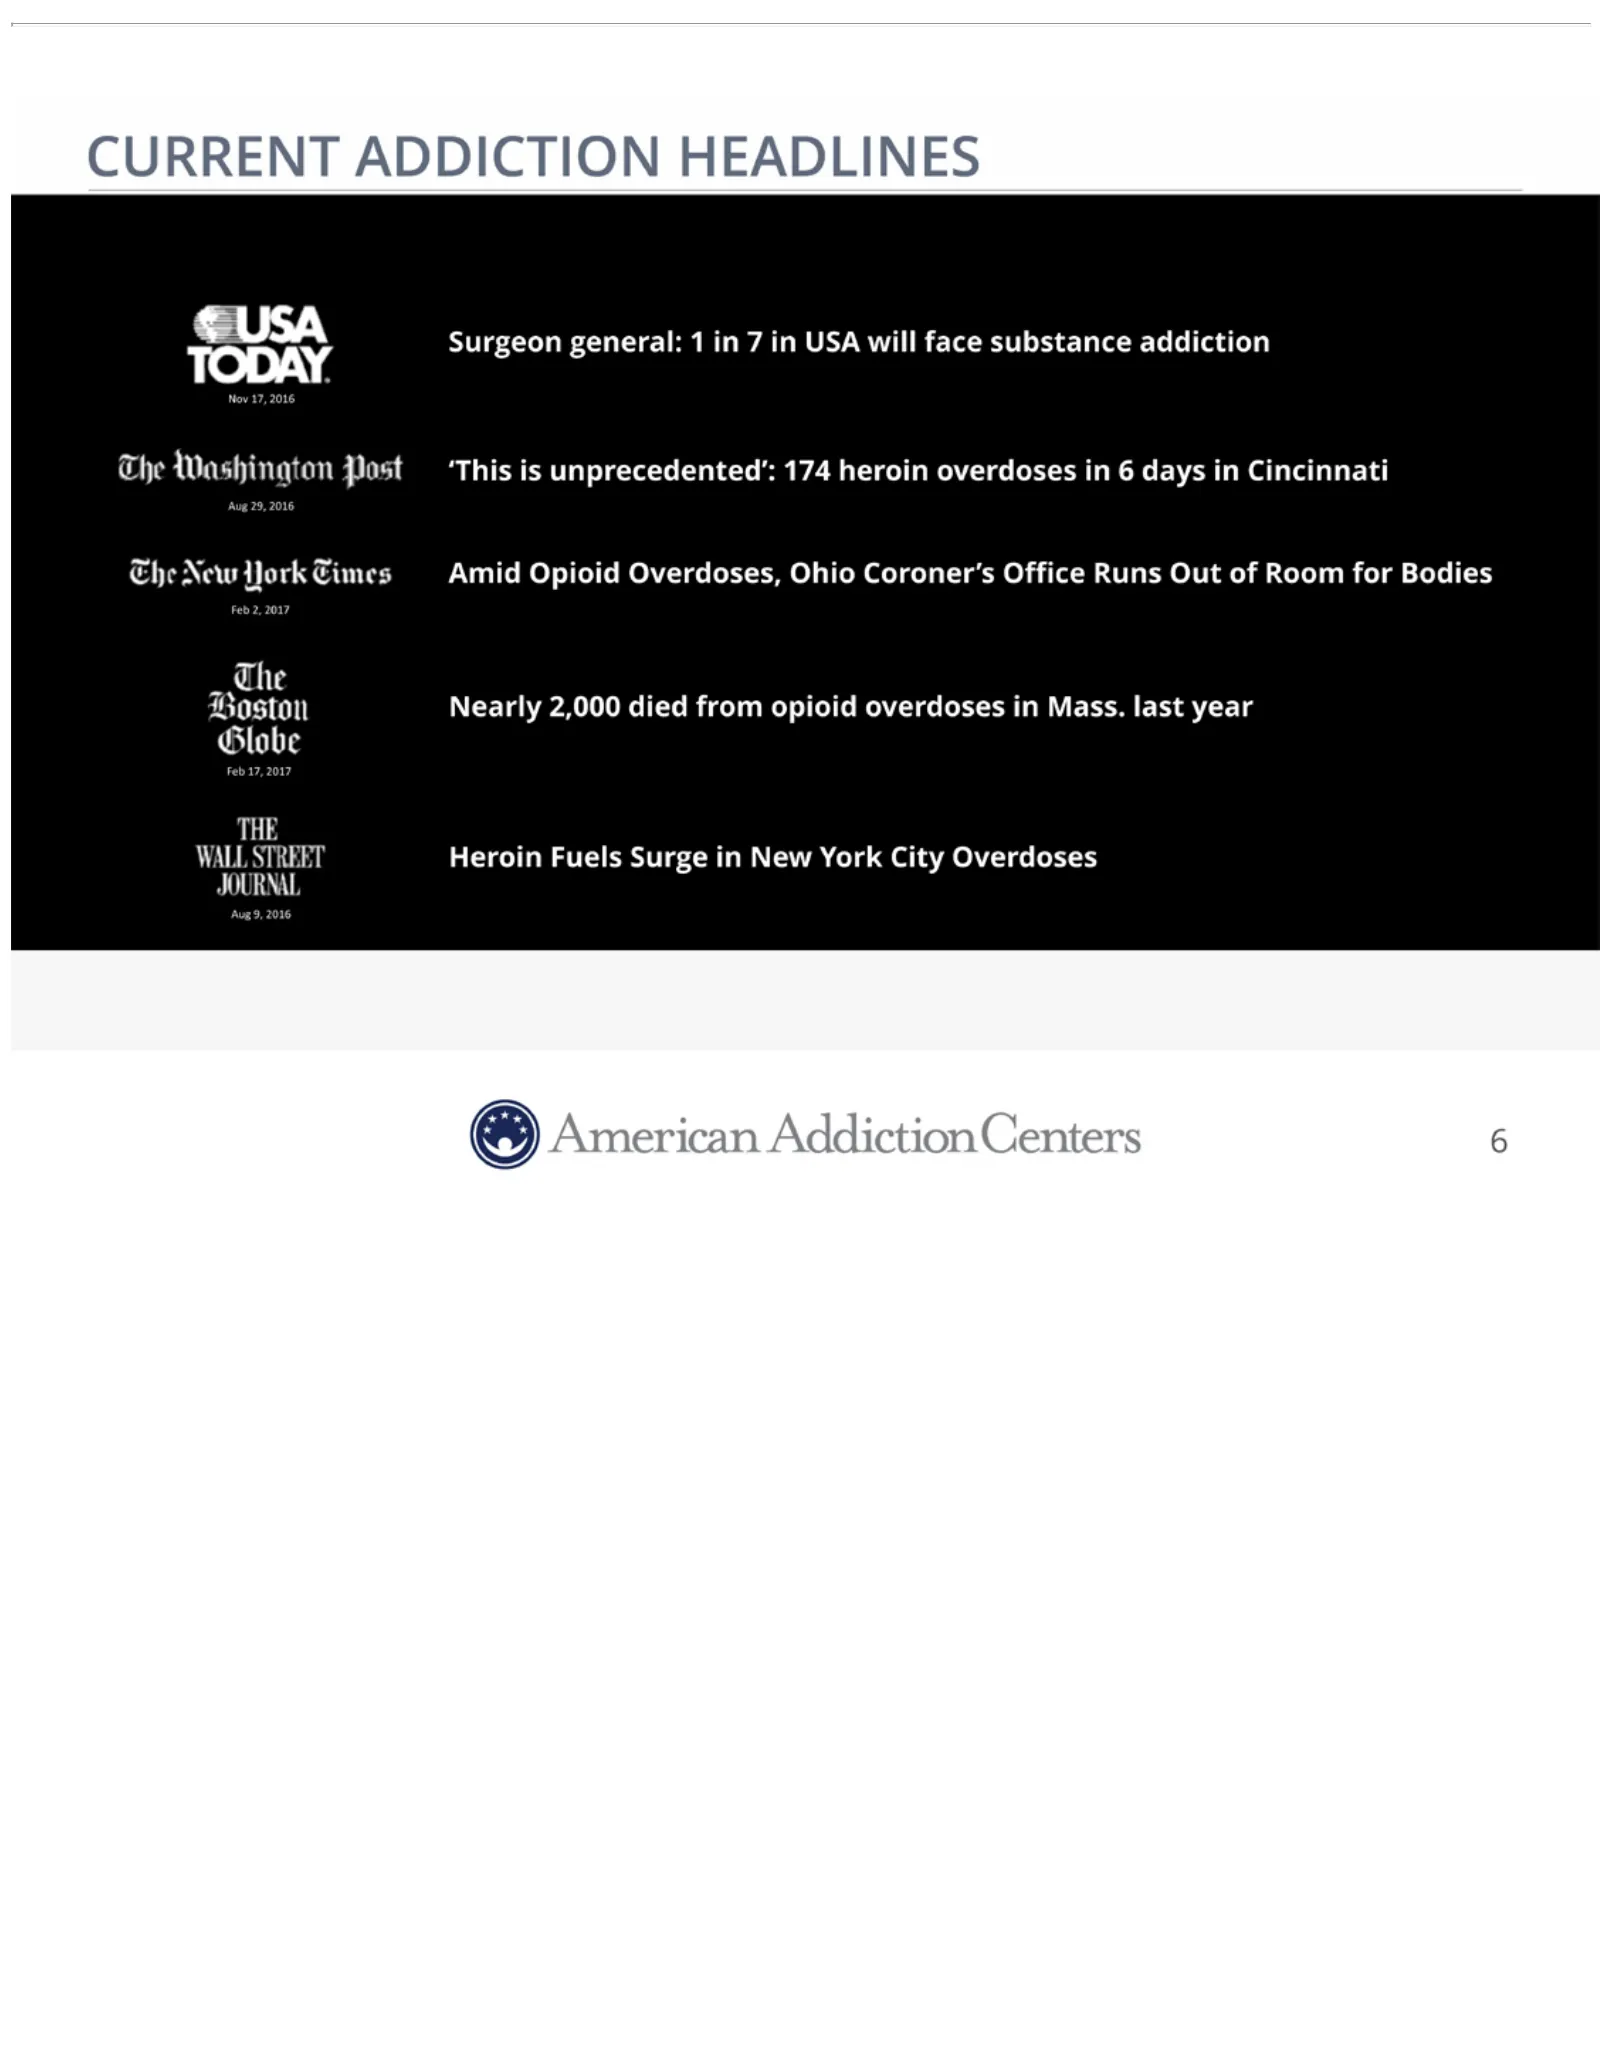
CURRENT Bodies Feb$2,$2017 ADDICTION Nearly HEADLINES 2,000 died from Surgeon opioid general: overdoses 1 in in 7 in Mass. USAlast willyear faceFeb$17,$2017 substance addiction HeroinNov Fuels 17,Surge 2016in‘This NewisYork unprecedented’: City Overdoses 174Aug heroin 9, 2016 overdoses 6 in 6 days i
Slide 7: Types of Treatment Services
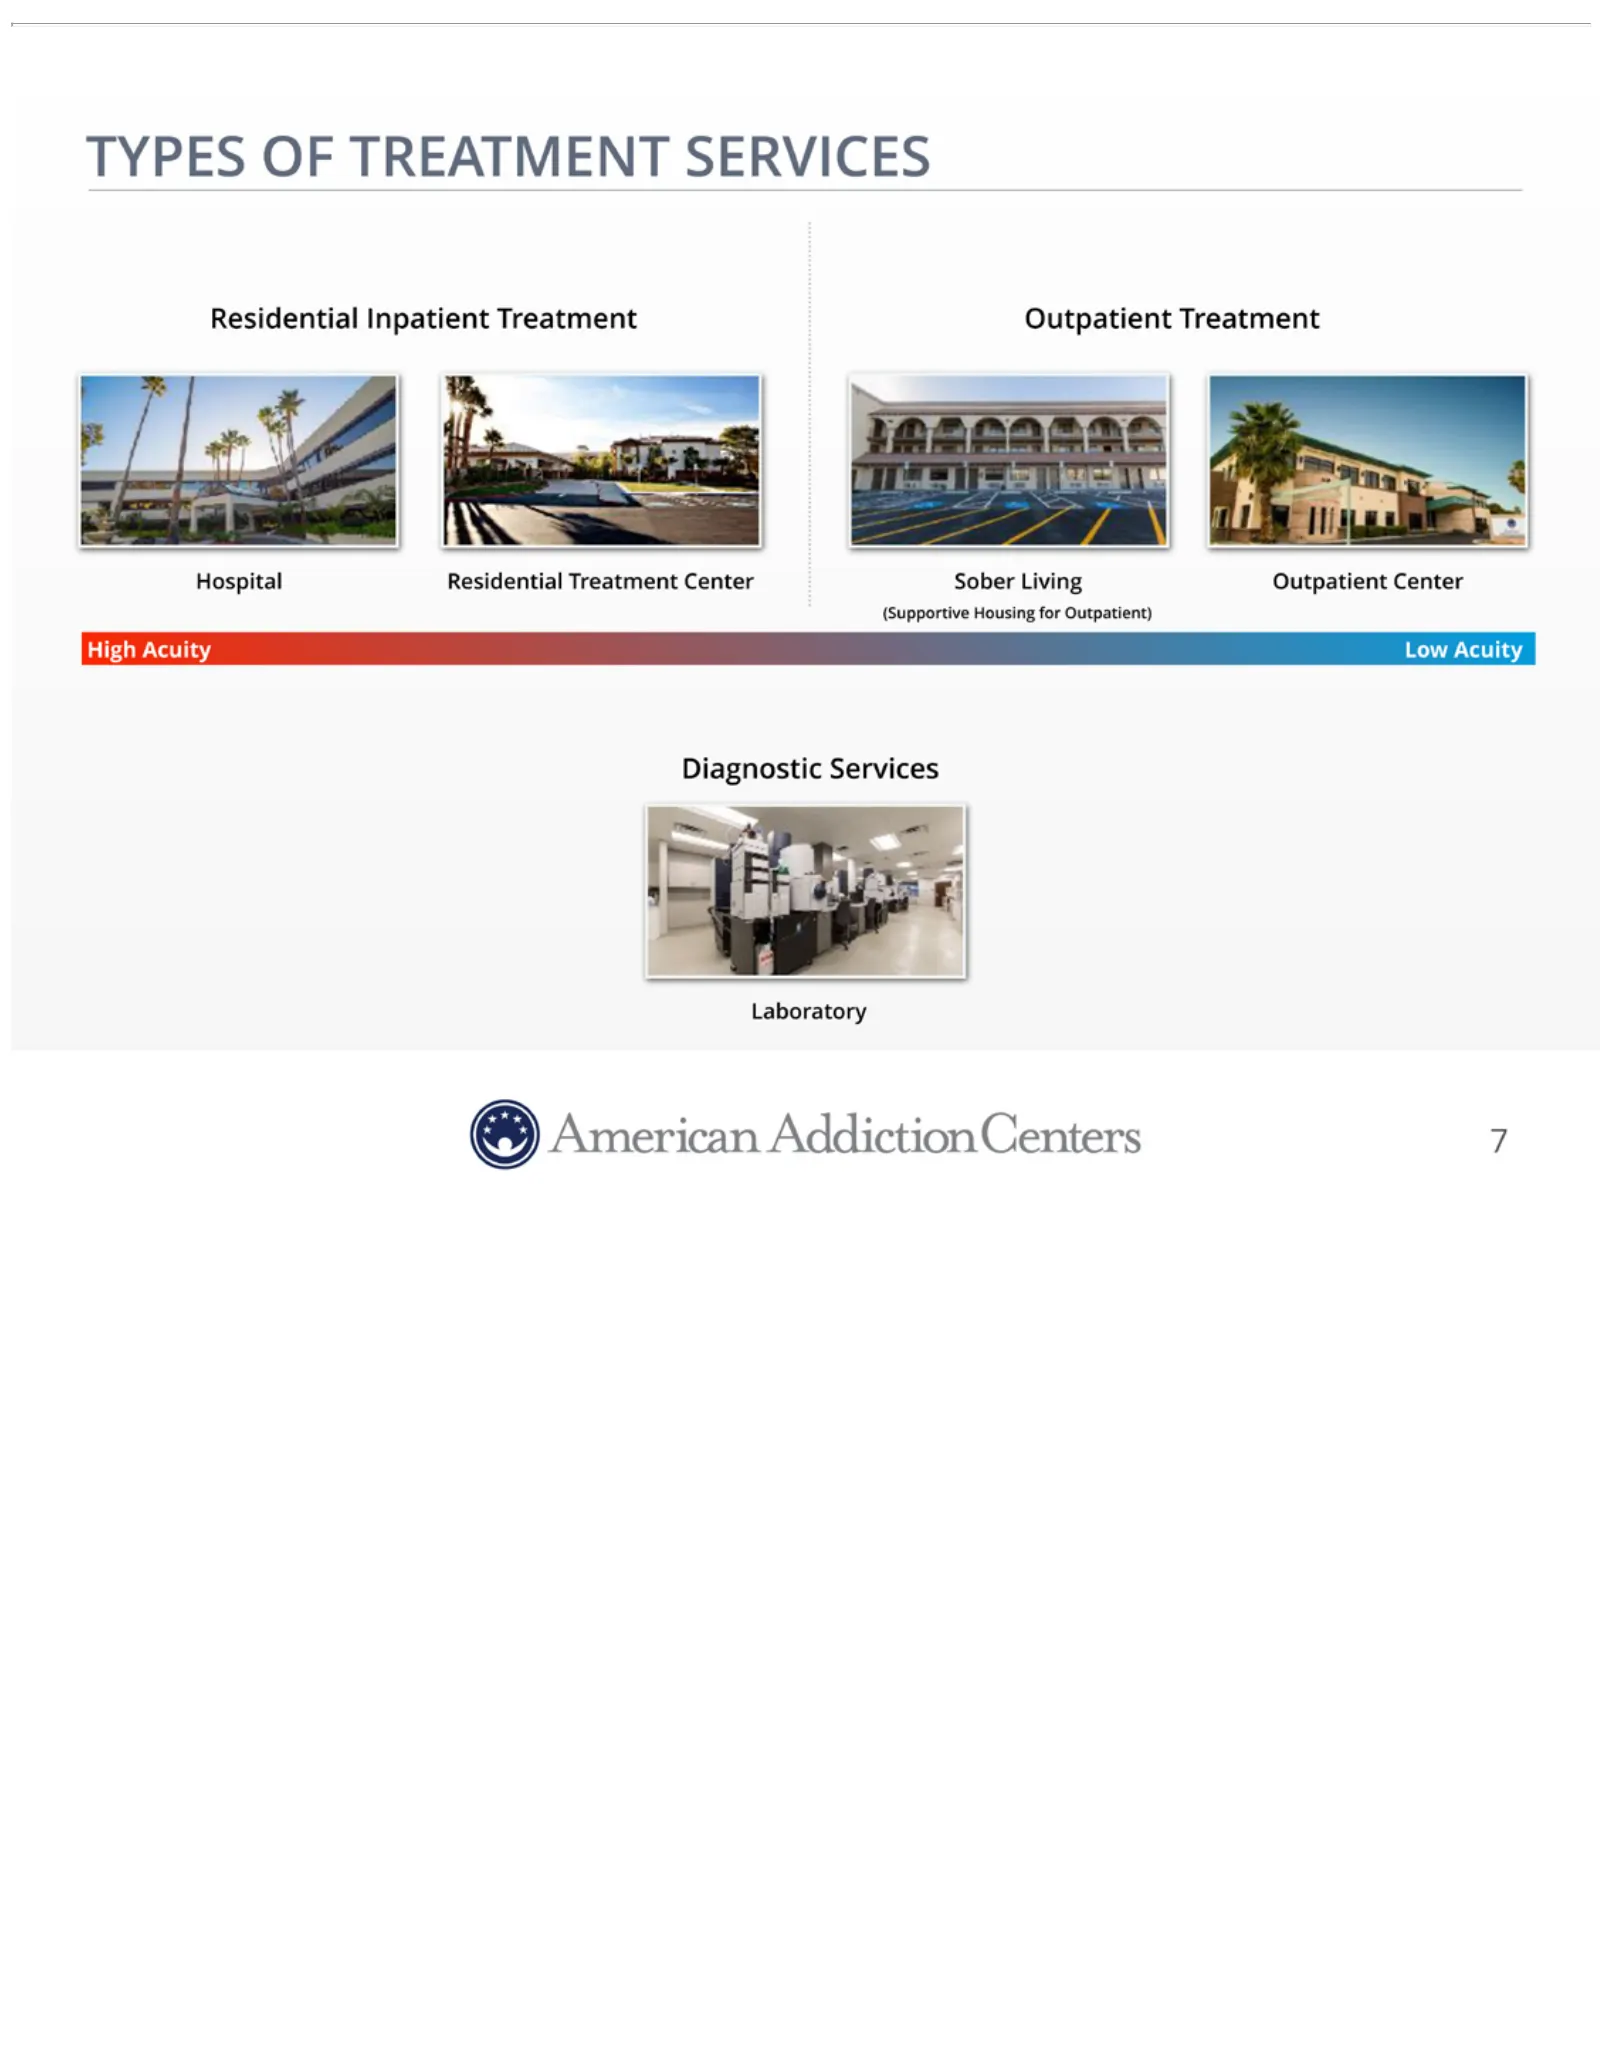
TYPES OF TREATMENT SERVICES Residential Inpatient Treatment Outpatient Treatment Hospital Residential Treatment Center Sober Living Outpatient Center (Supportive Housing for Outpatient) High Acuity Low Acuity Diagnostic Services Laboratory 7
Slide 8: Levels of Care Overview
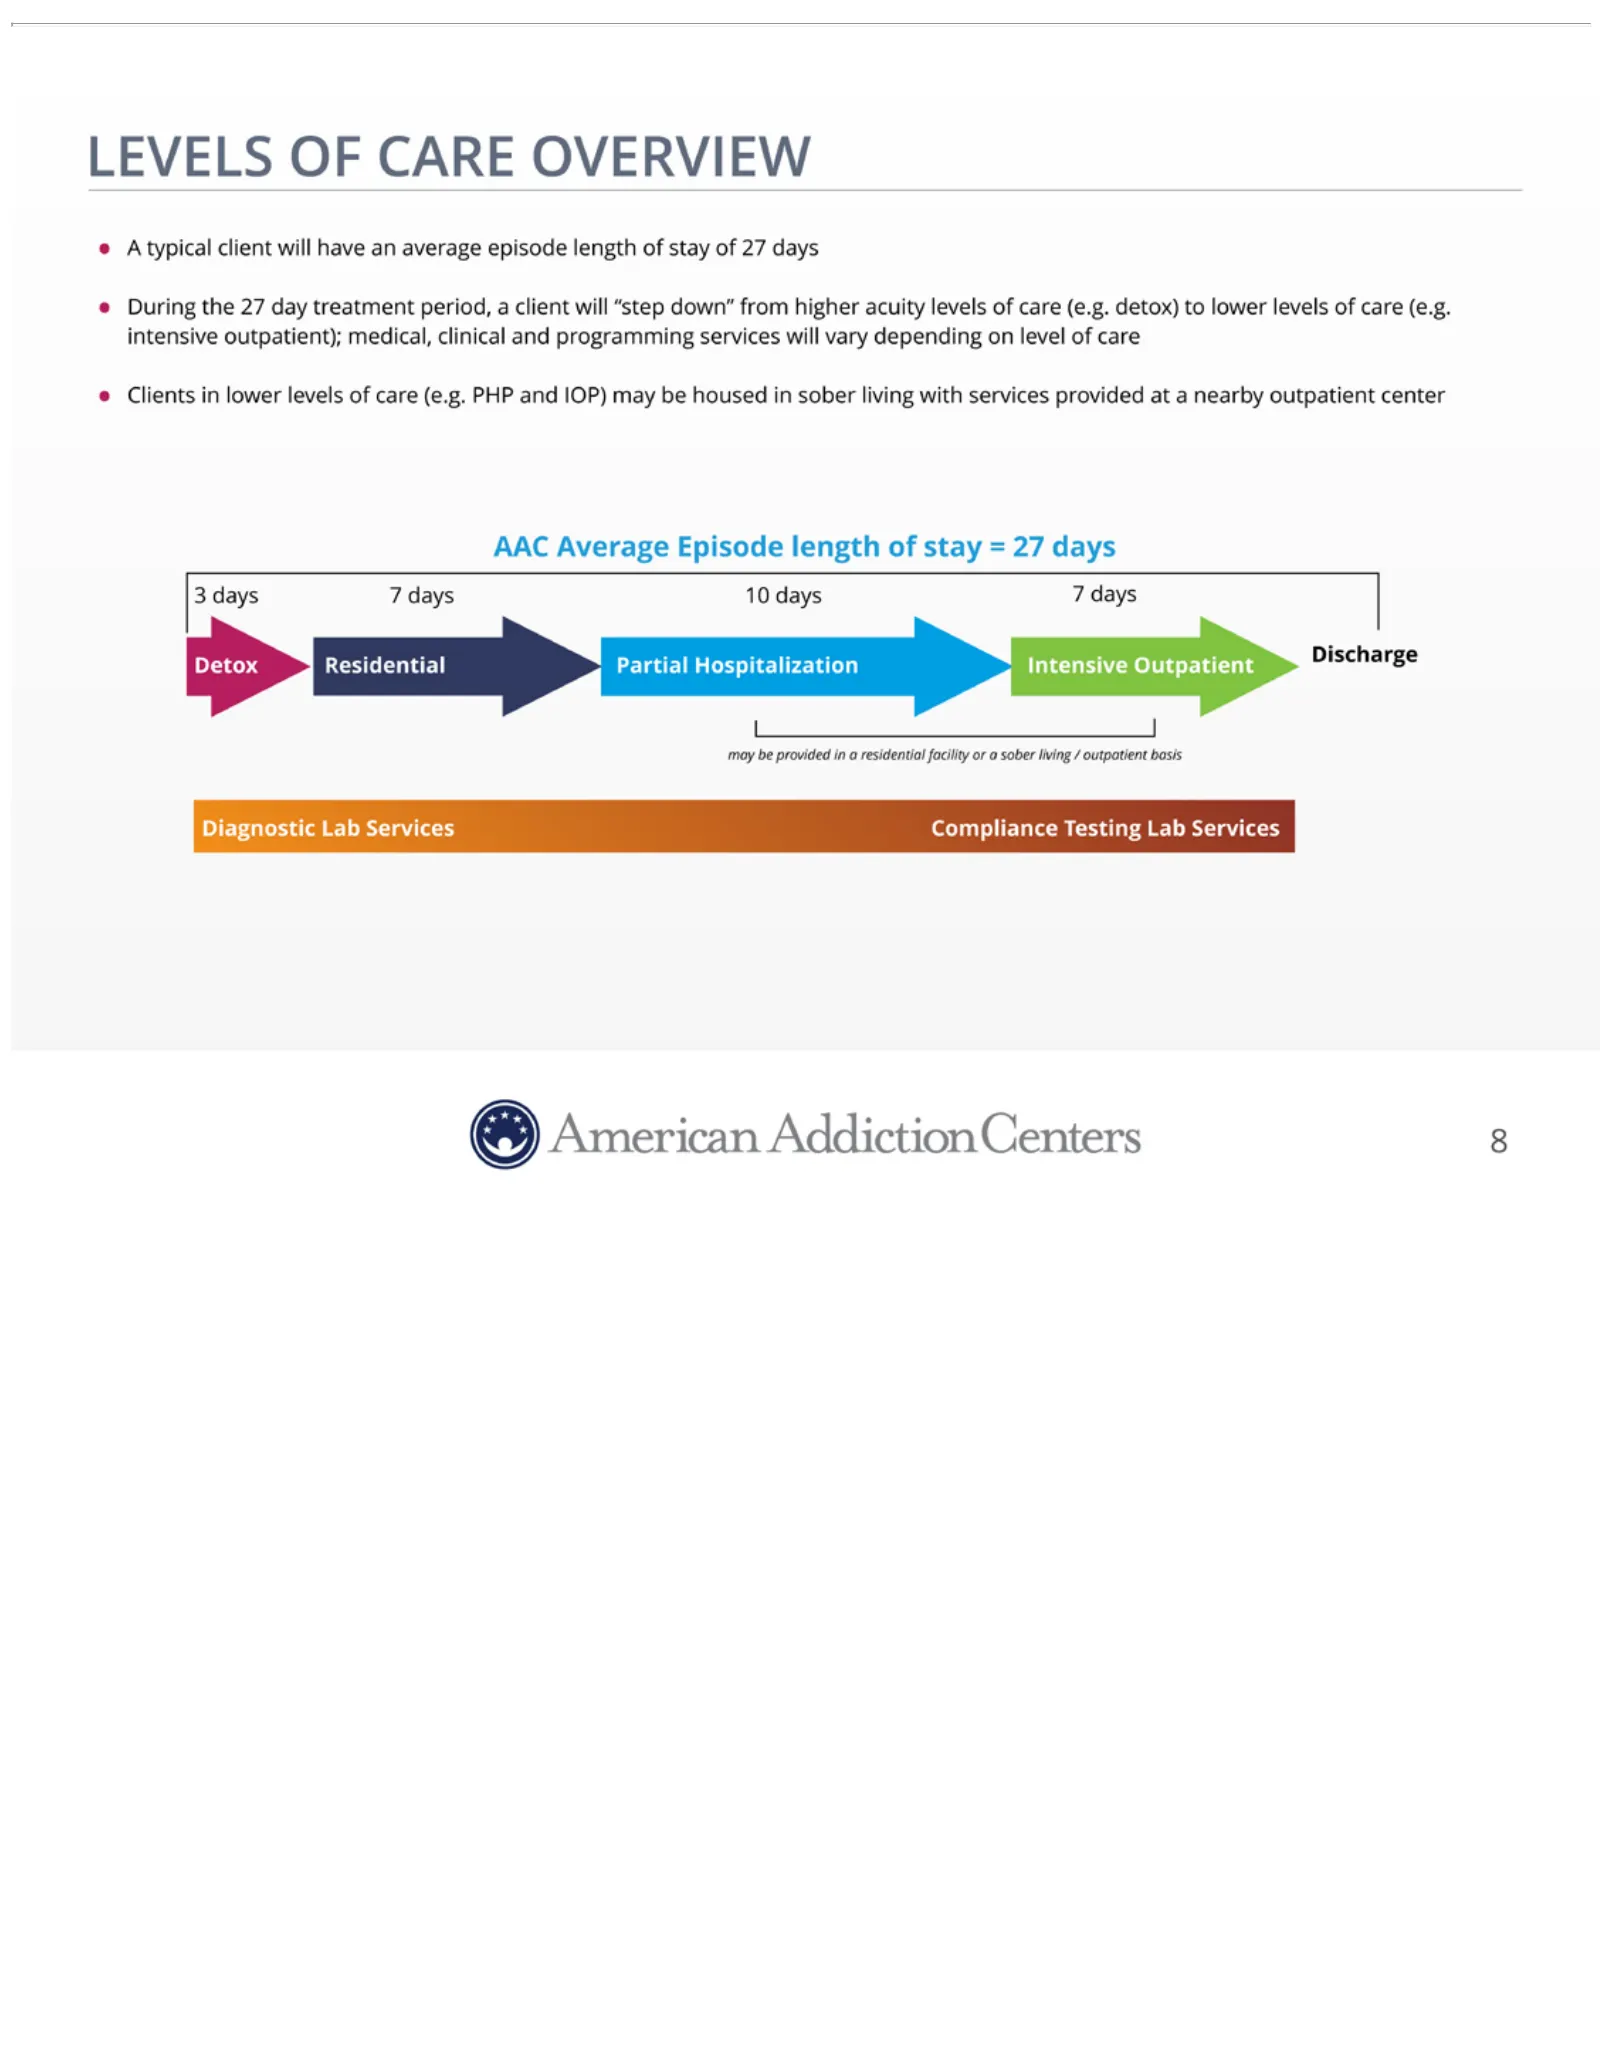
LEVELS 7clinical days Detox and OFprogramming CARE Residential OVERVIEW Partial services Hospitalization •will A typical vary depending client Intensive willon have Outpatient level an of average care Discharge • episode Clientsmay in length lower be provided oflevels stay of ofin 27 care adays resi
Slide 9: Favorable Legislative Tailwinds
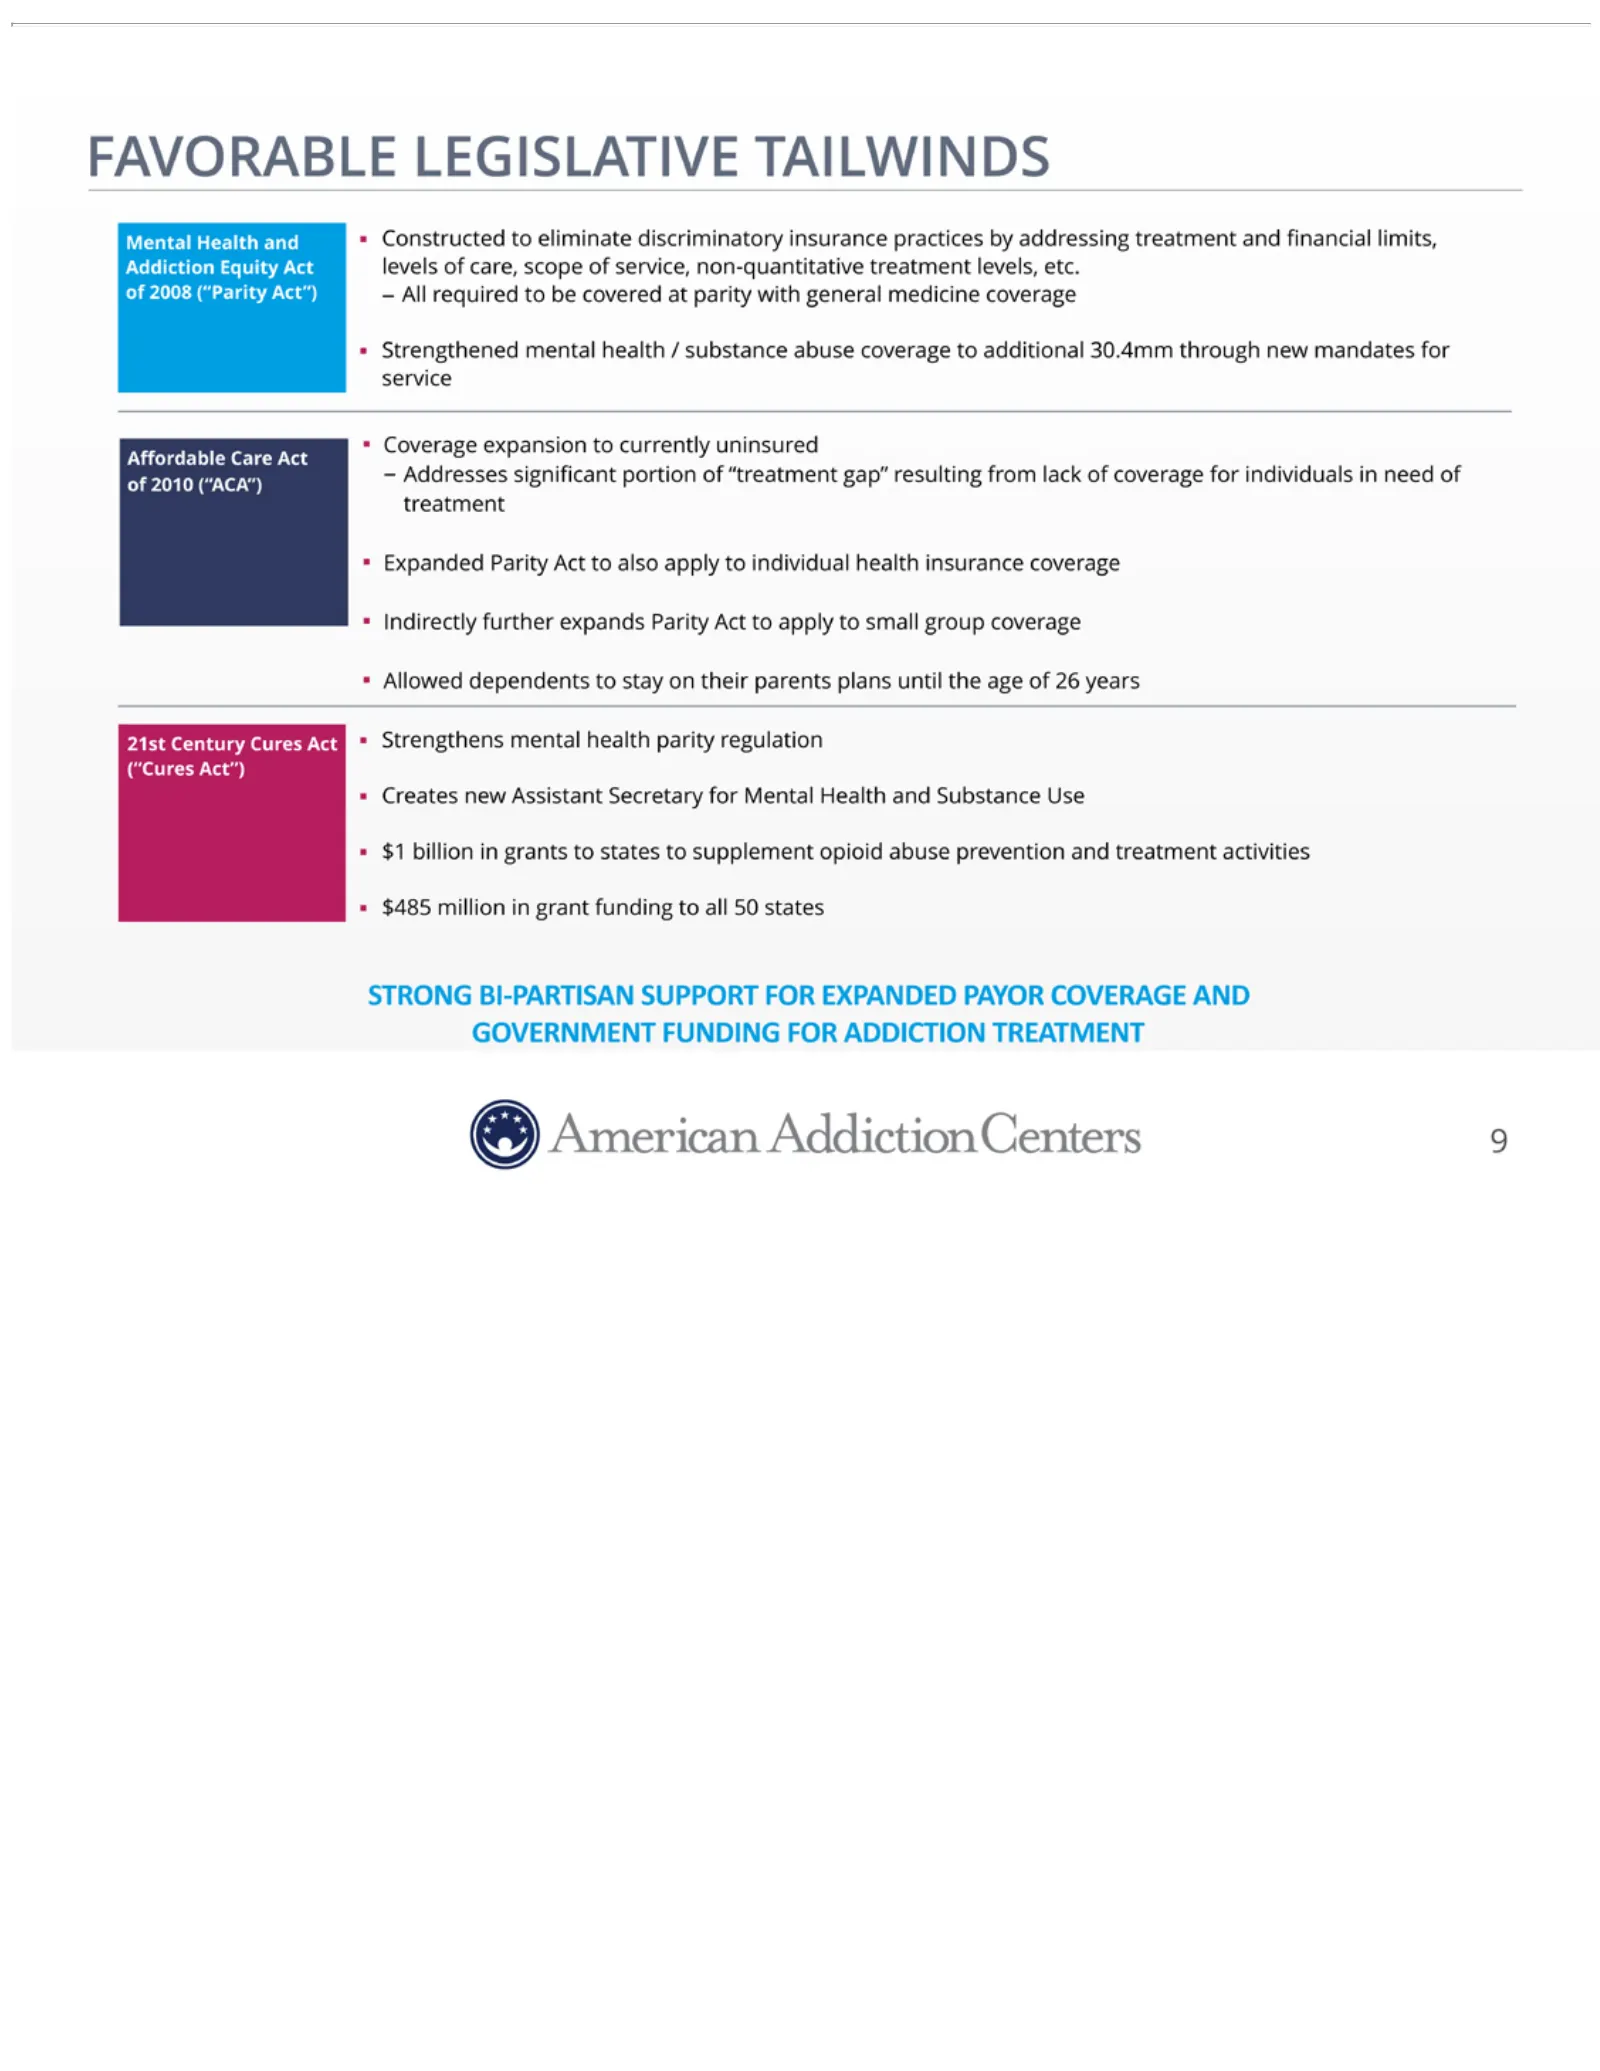
FAVORABLE (“Parity ?(“ACA”) opioid Allowed abuse Act”) - dependents Addresses prevention -LEGISLATIVE All required significant toand stayto treatment onbe TAILWINDS their portion covered parents activities ofat“treatment parity Mental plans ? $485 with until Health gap” million general theresulting
Slide 10: Oxford Center Company Snapshot
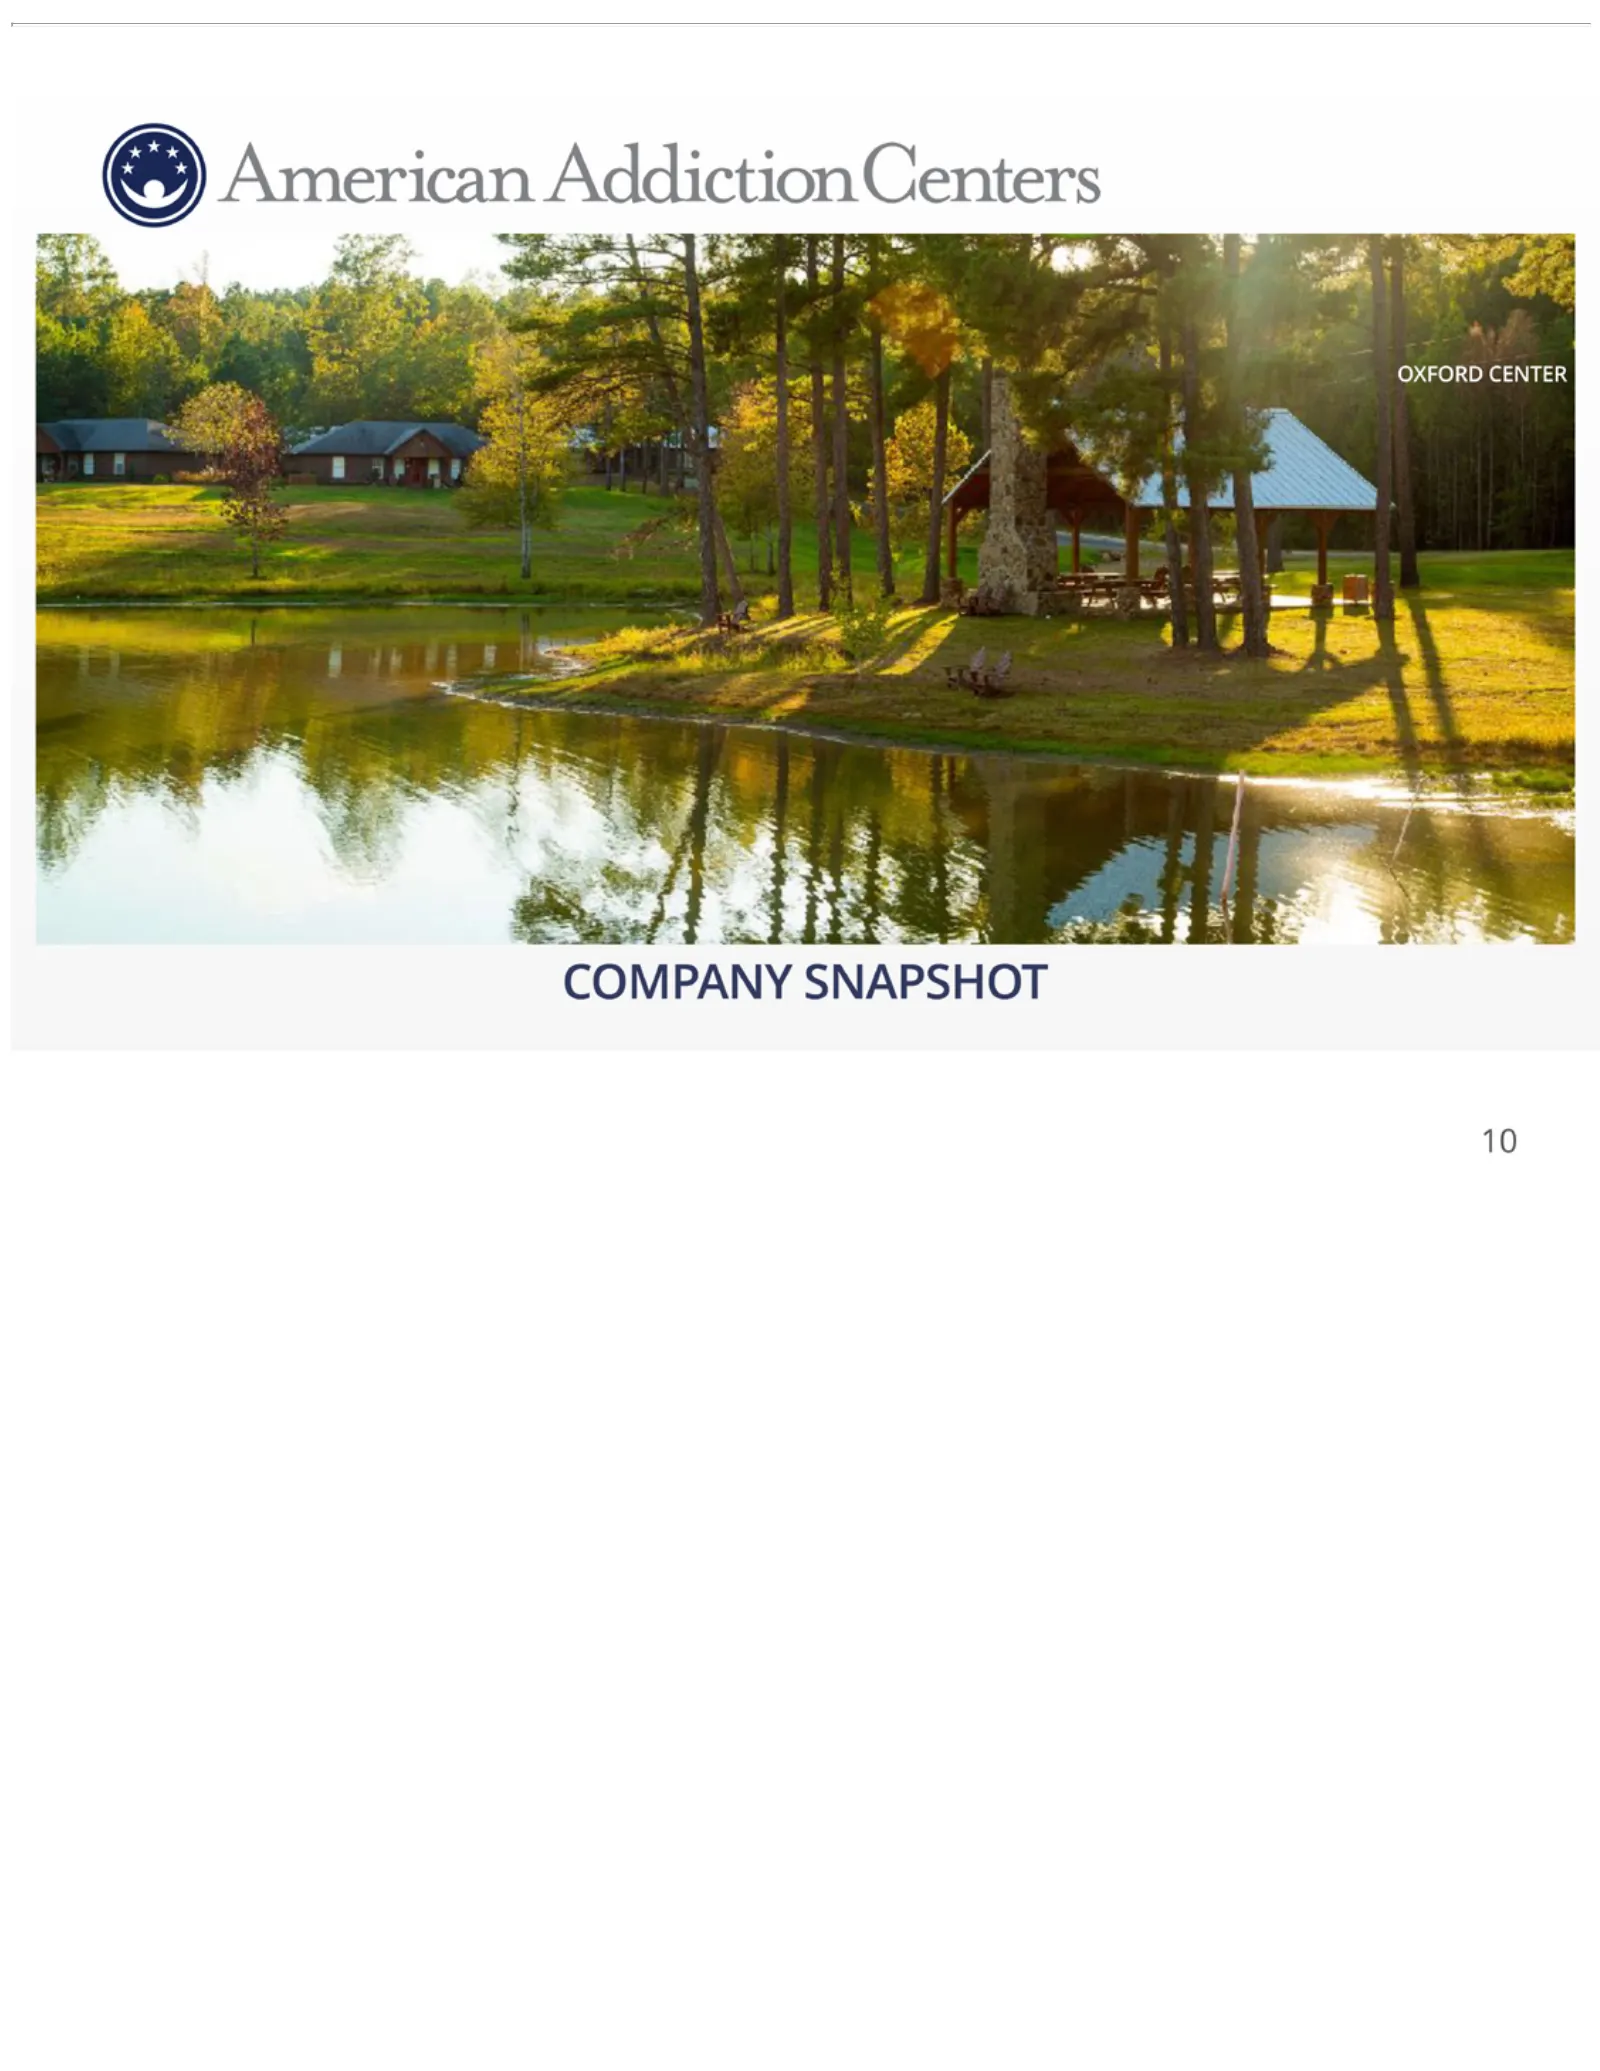
OXFORD CENTER COMPANY SNAPSHOT 10
Slide 11: AAC at a Glance
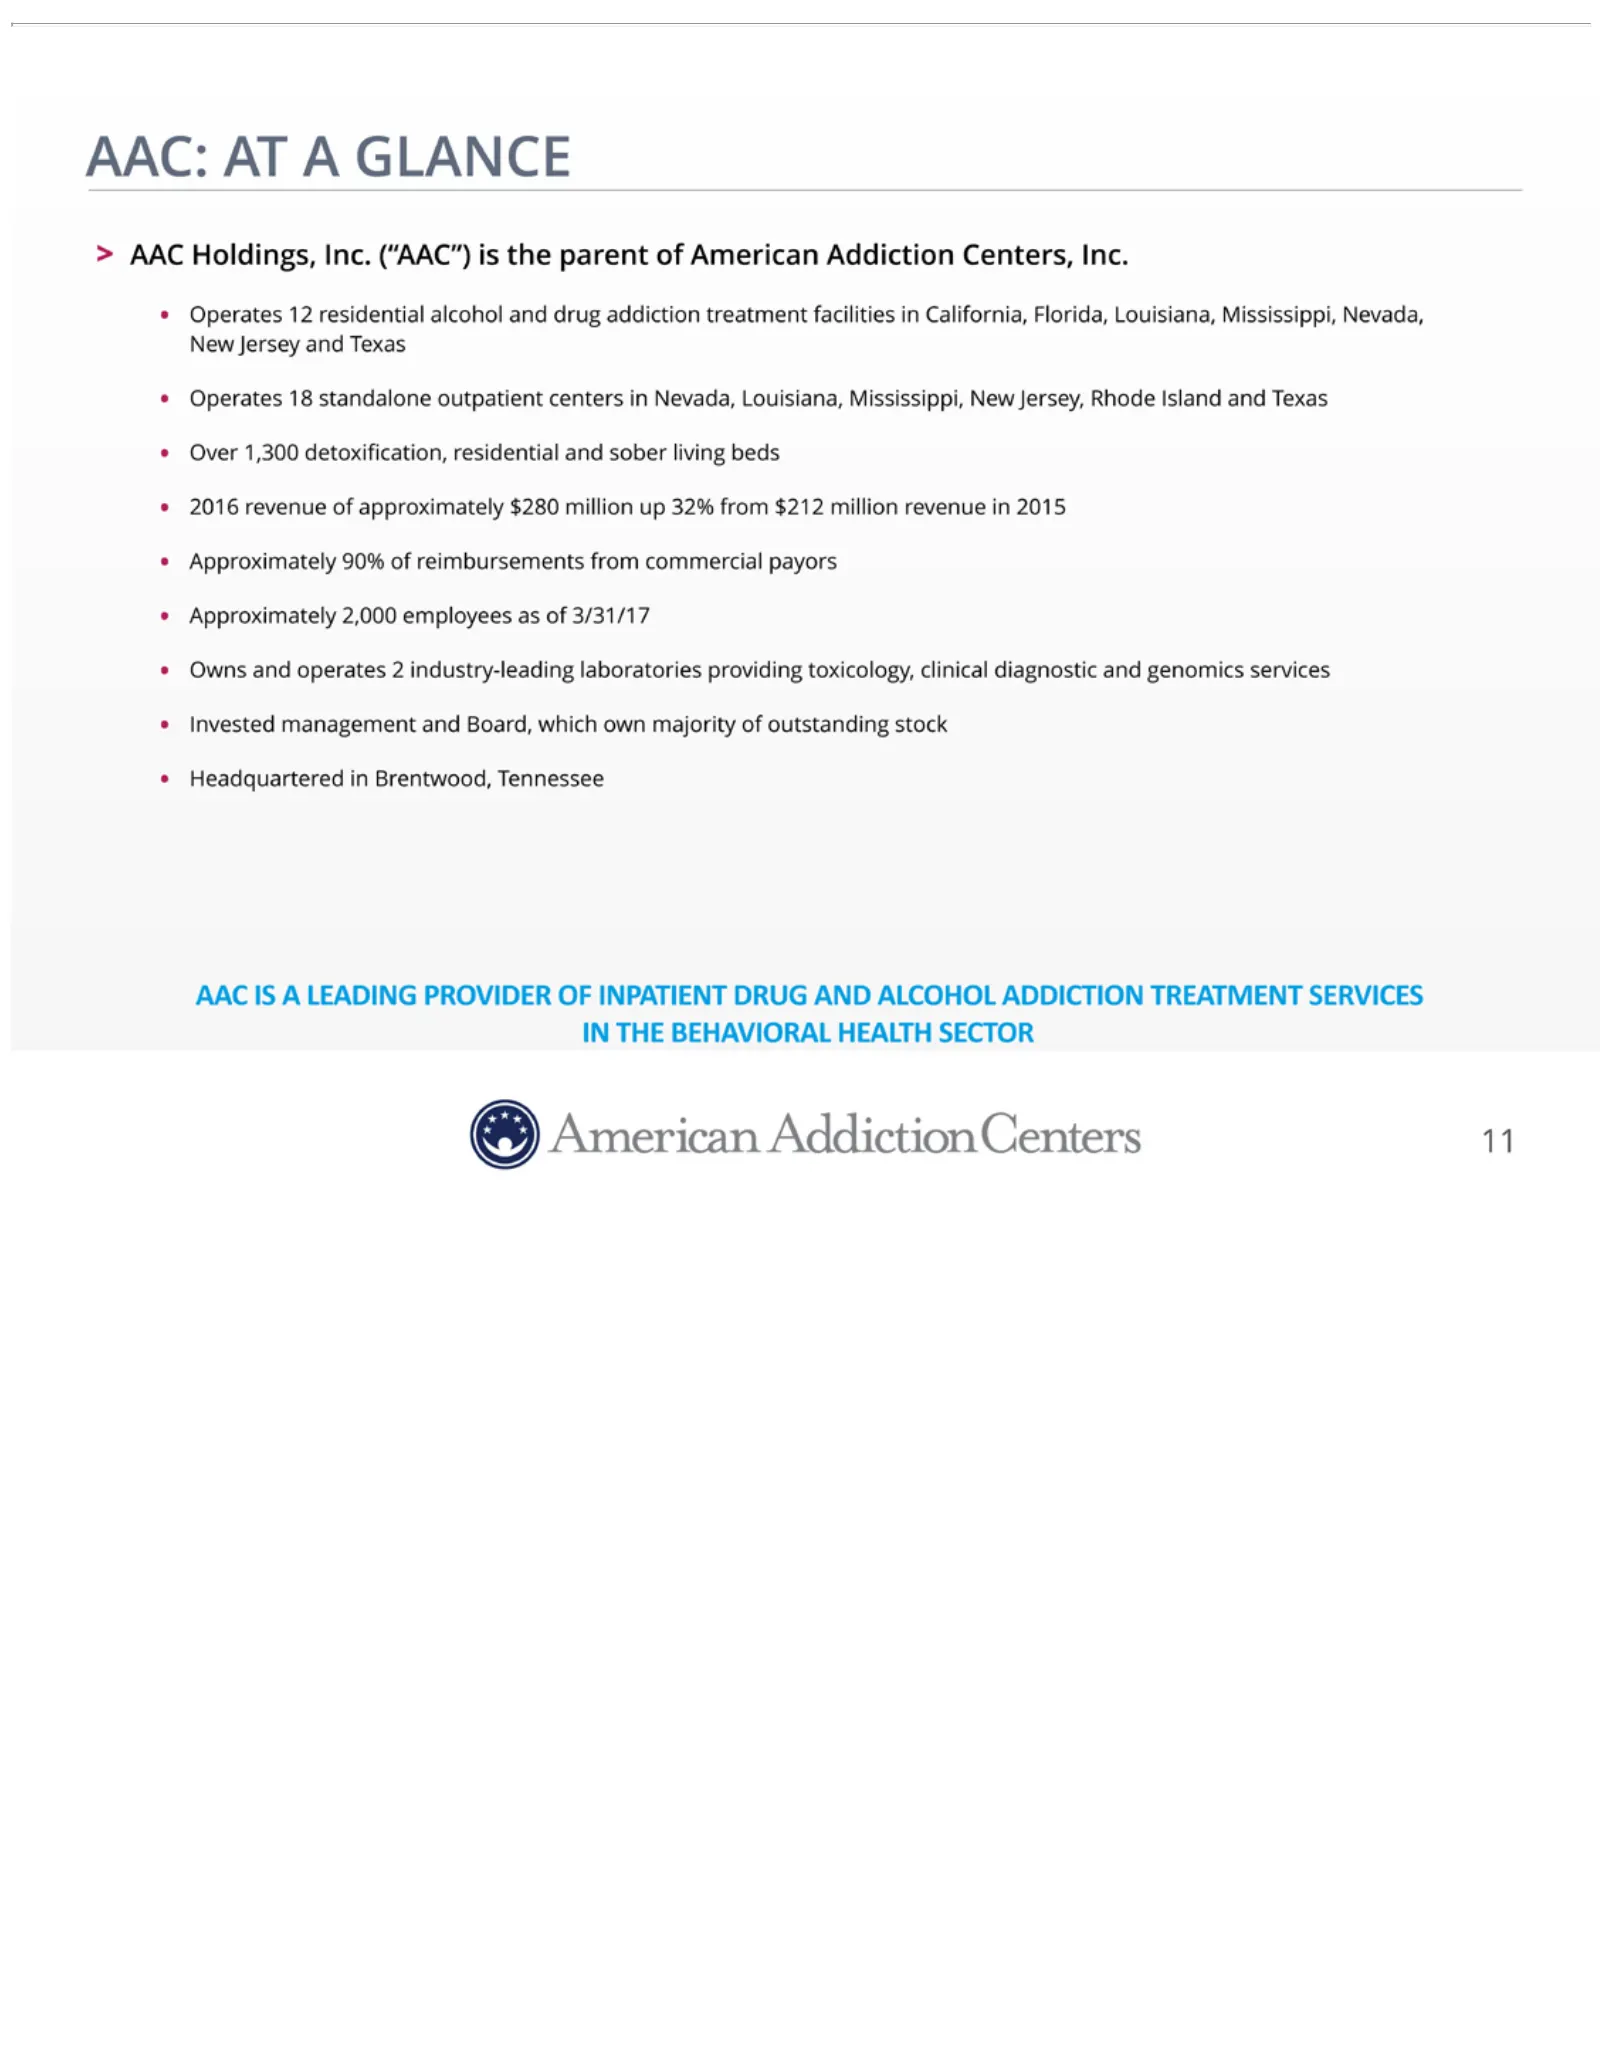
AAC:ofAT standalone 90% outstanding reimbursements Aoutpatient GLANCE stock • Headquartered centers > from AACincommercial Holdings, Nevada, in Brentwood, Louisiana, Inc. payors (“AAC”) •Tennessee Approximately Mississippi, is theAAC parent New IS 2,000 ofAJersey, American LEADING employees Rhode Ad
Slide 12: Market: Types of Treatment Providers
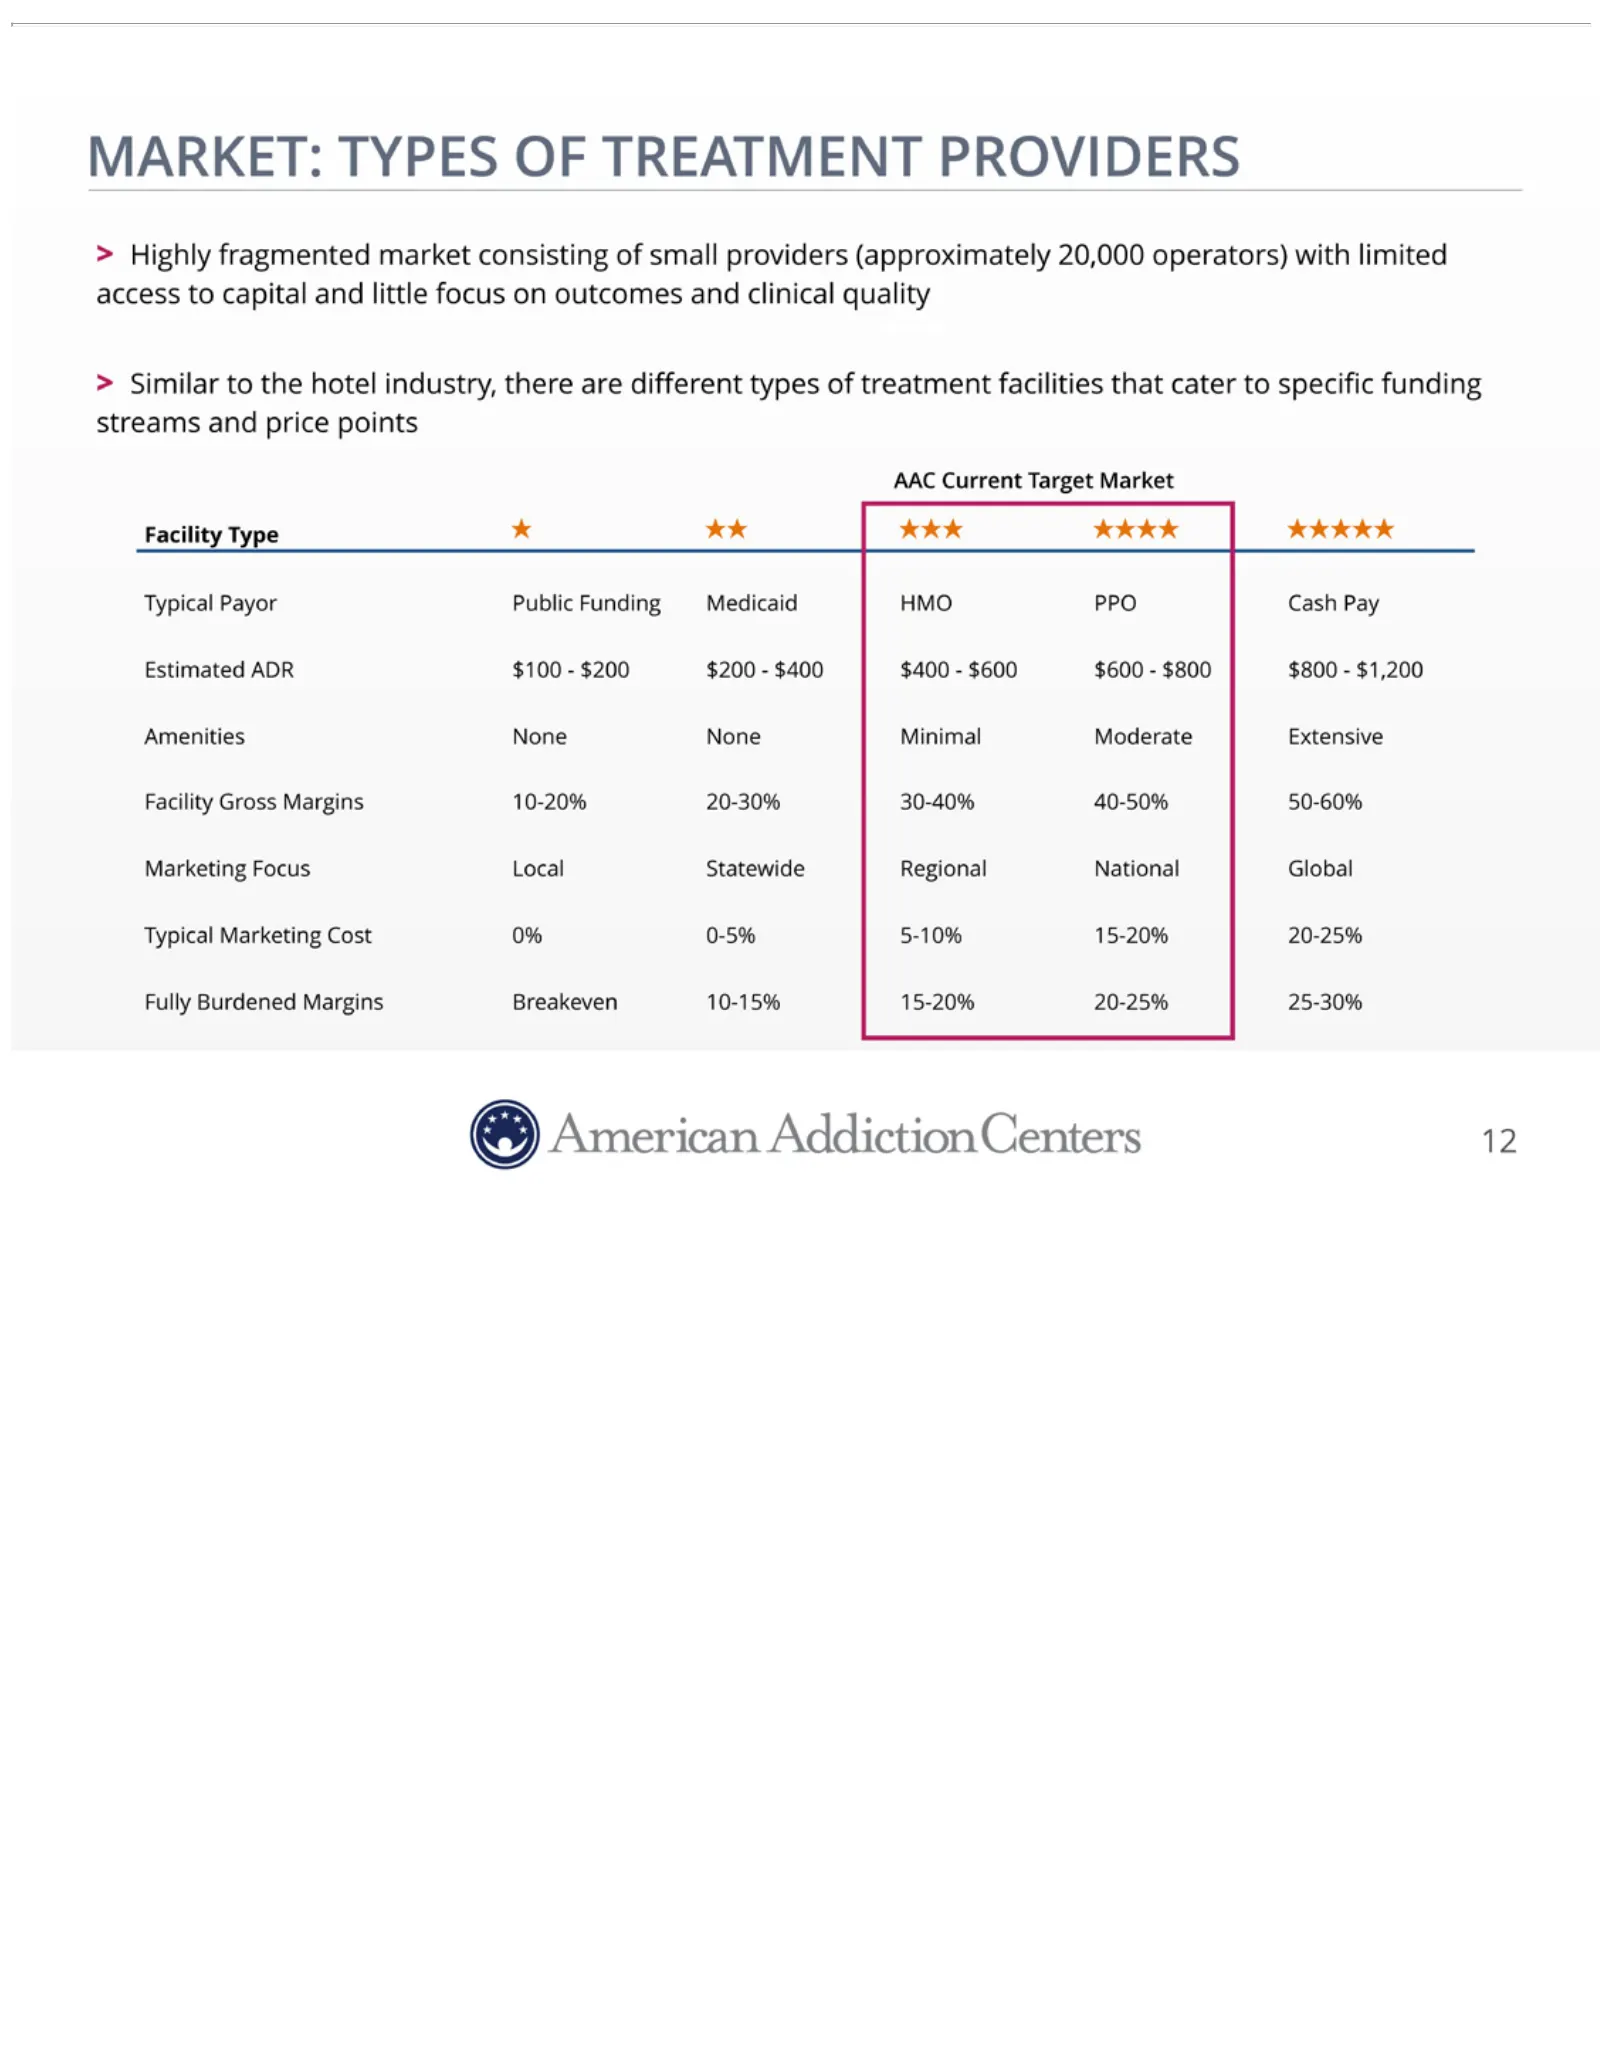
MARKET: types Amenities 10-15%of 15-20% treatment None TYPESNone 20-25% facilities OFMinimal TREATMENT 25-30% that Moderate cater 12 toPROVIDERS specific Extensive funding Facility > Highly streams Gross fragmented andMargins price points market 10-20%AAC consisting 20-30% Current30-40% of Target sm
Slide 13: AAC Differentiation
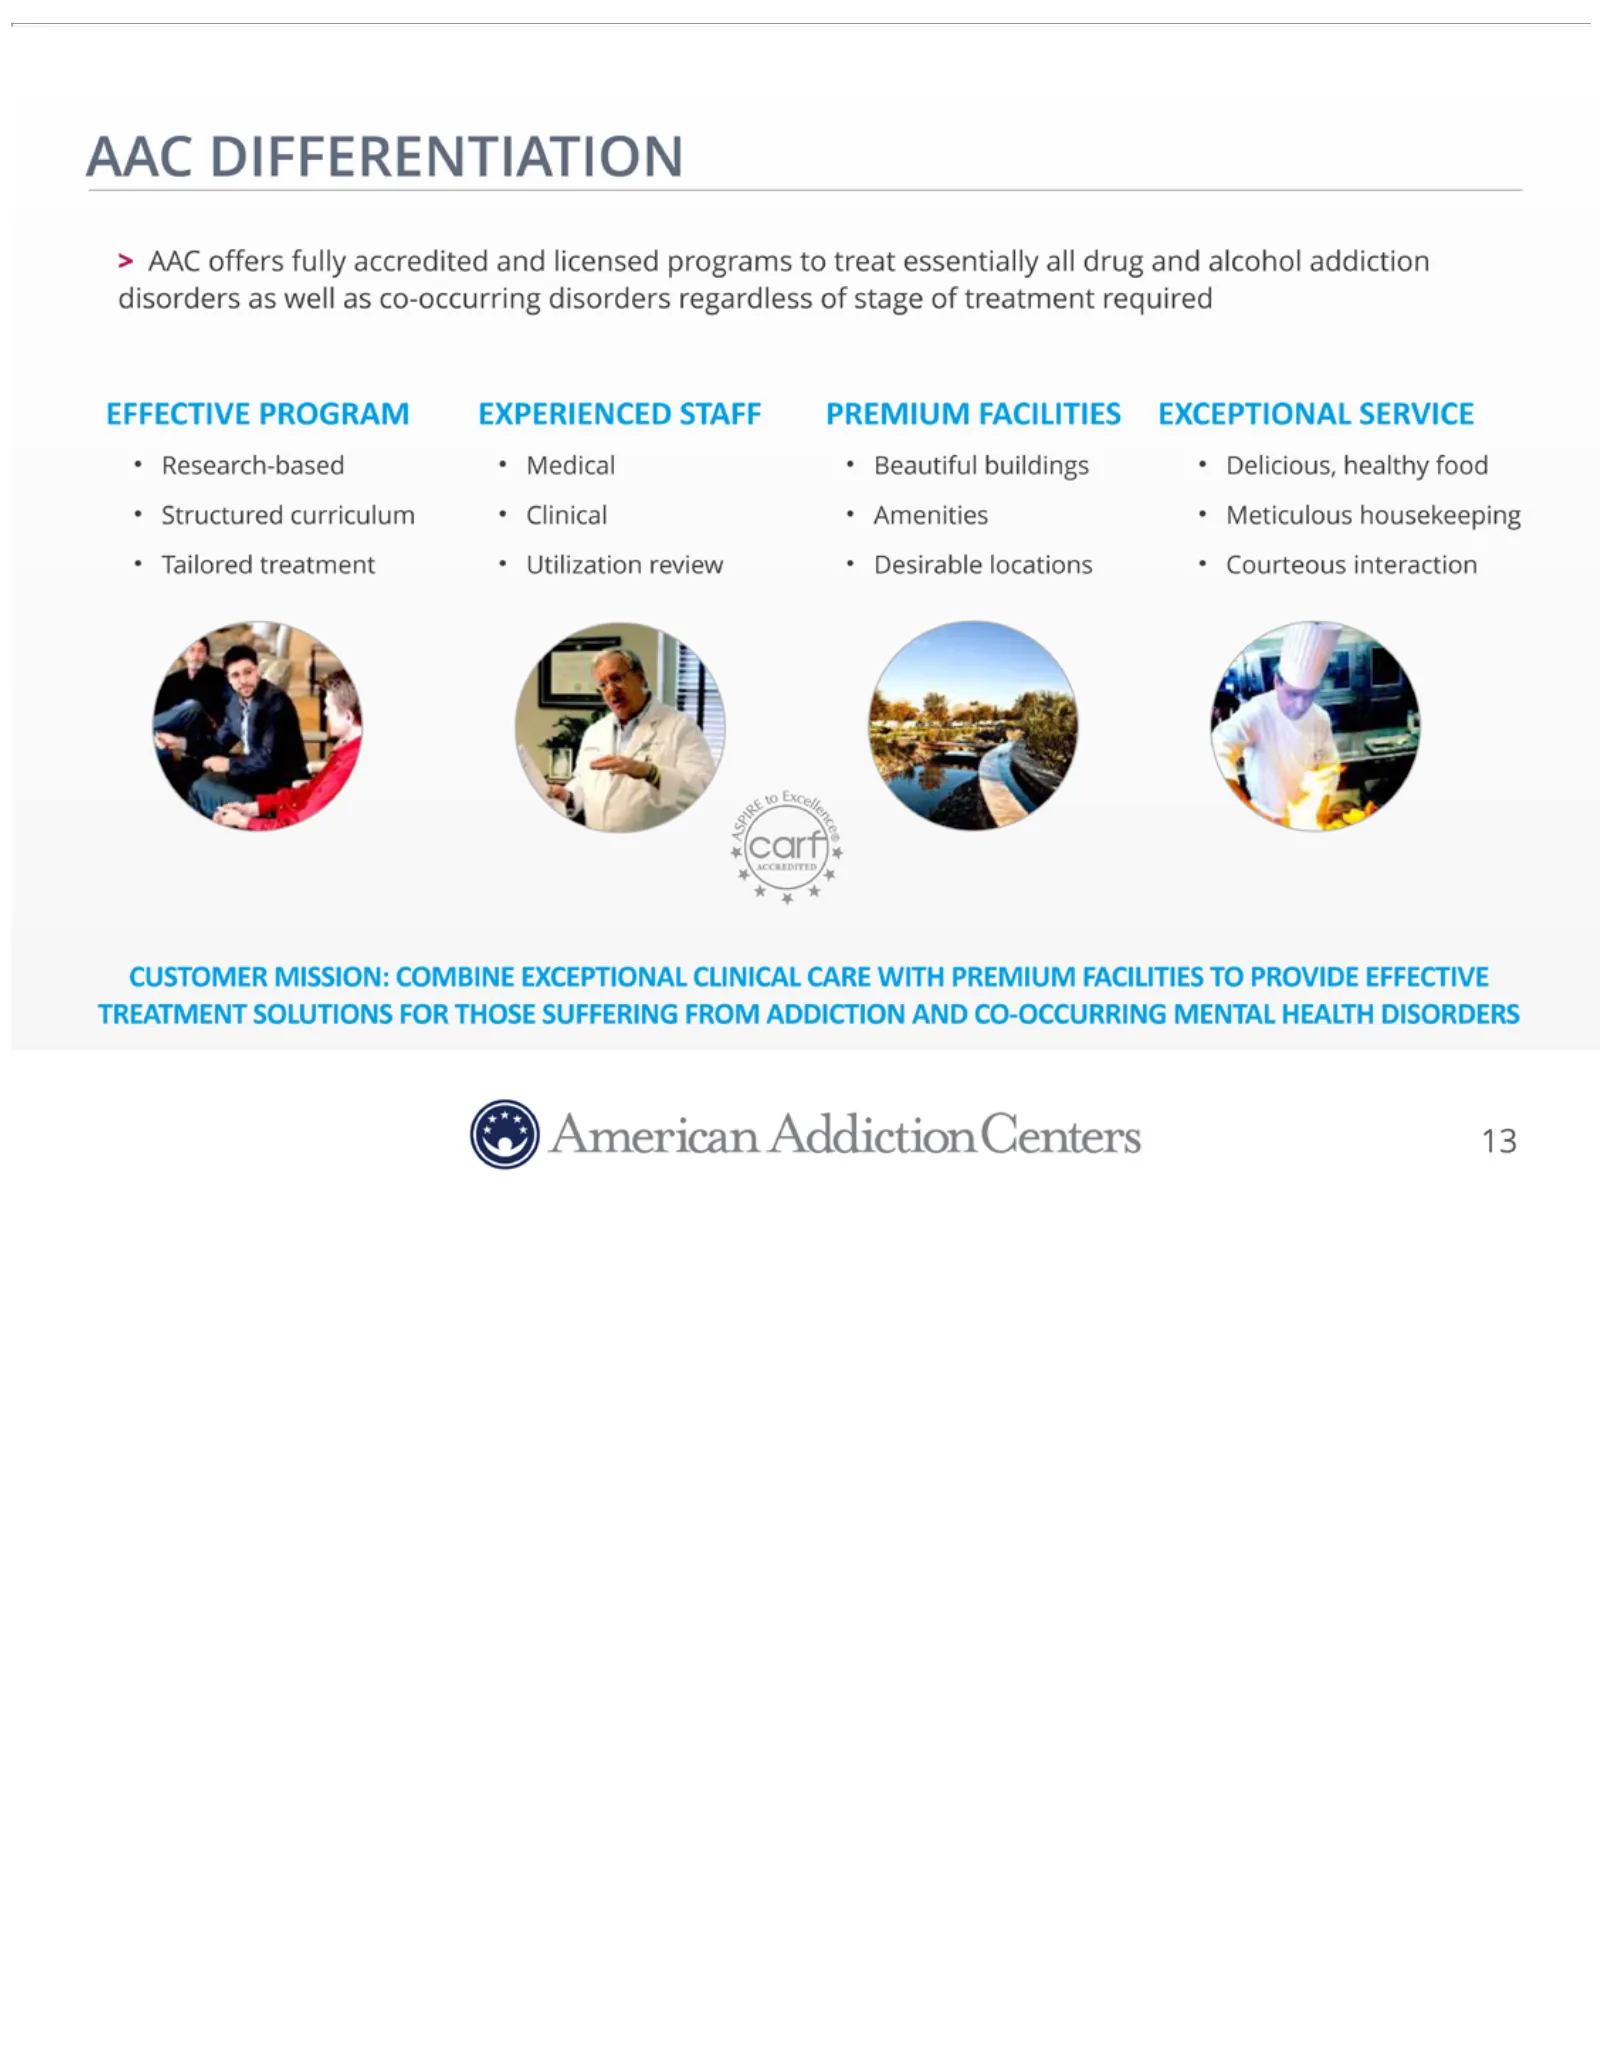
AAC DIFFERENTIATION PREMIUM interaction DISORDERS CUSTOMER FACILITIES 13 MISSION: EXCEPTIONAL > AAC offers COMBINE fully SERVICE accredited EXCEPTIONAL • Research-based and licensed CLINICAL programs • Medical CARE to• Beautiful treat WITHessentially PREMIUM buildings all drug • Delicious, FACILITIE
Slide 14: Commercial Insurance Overview
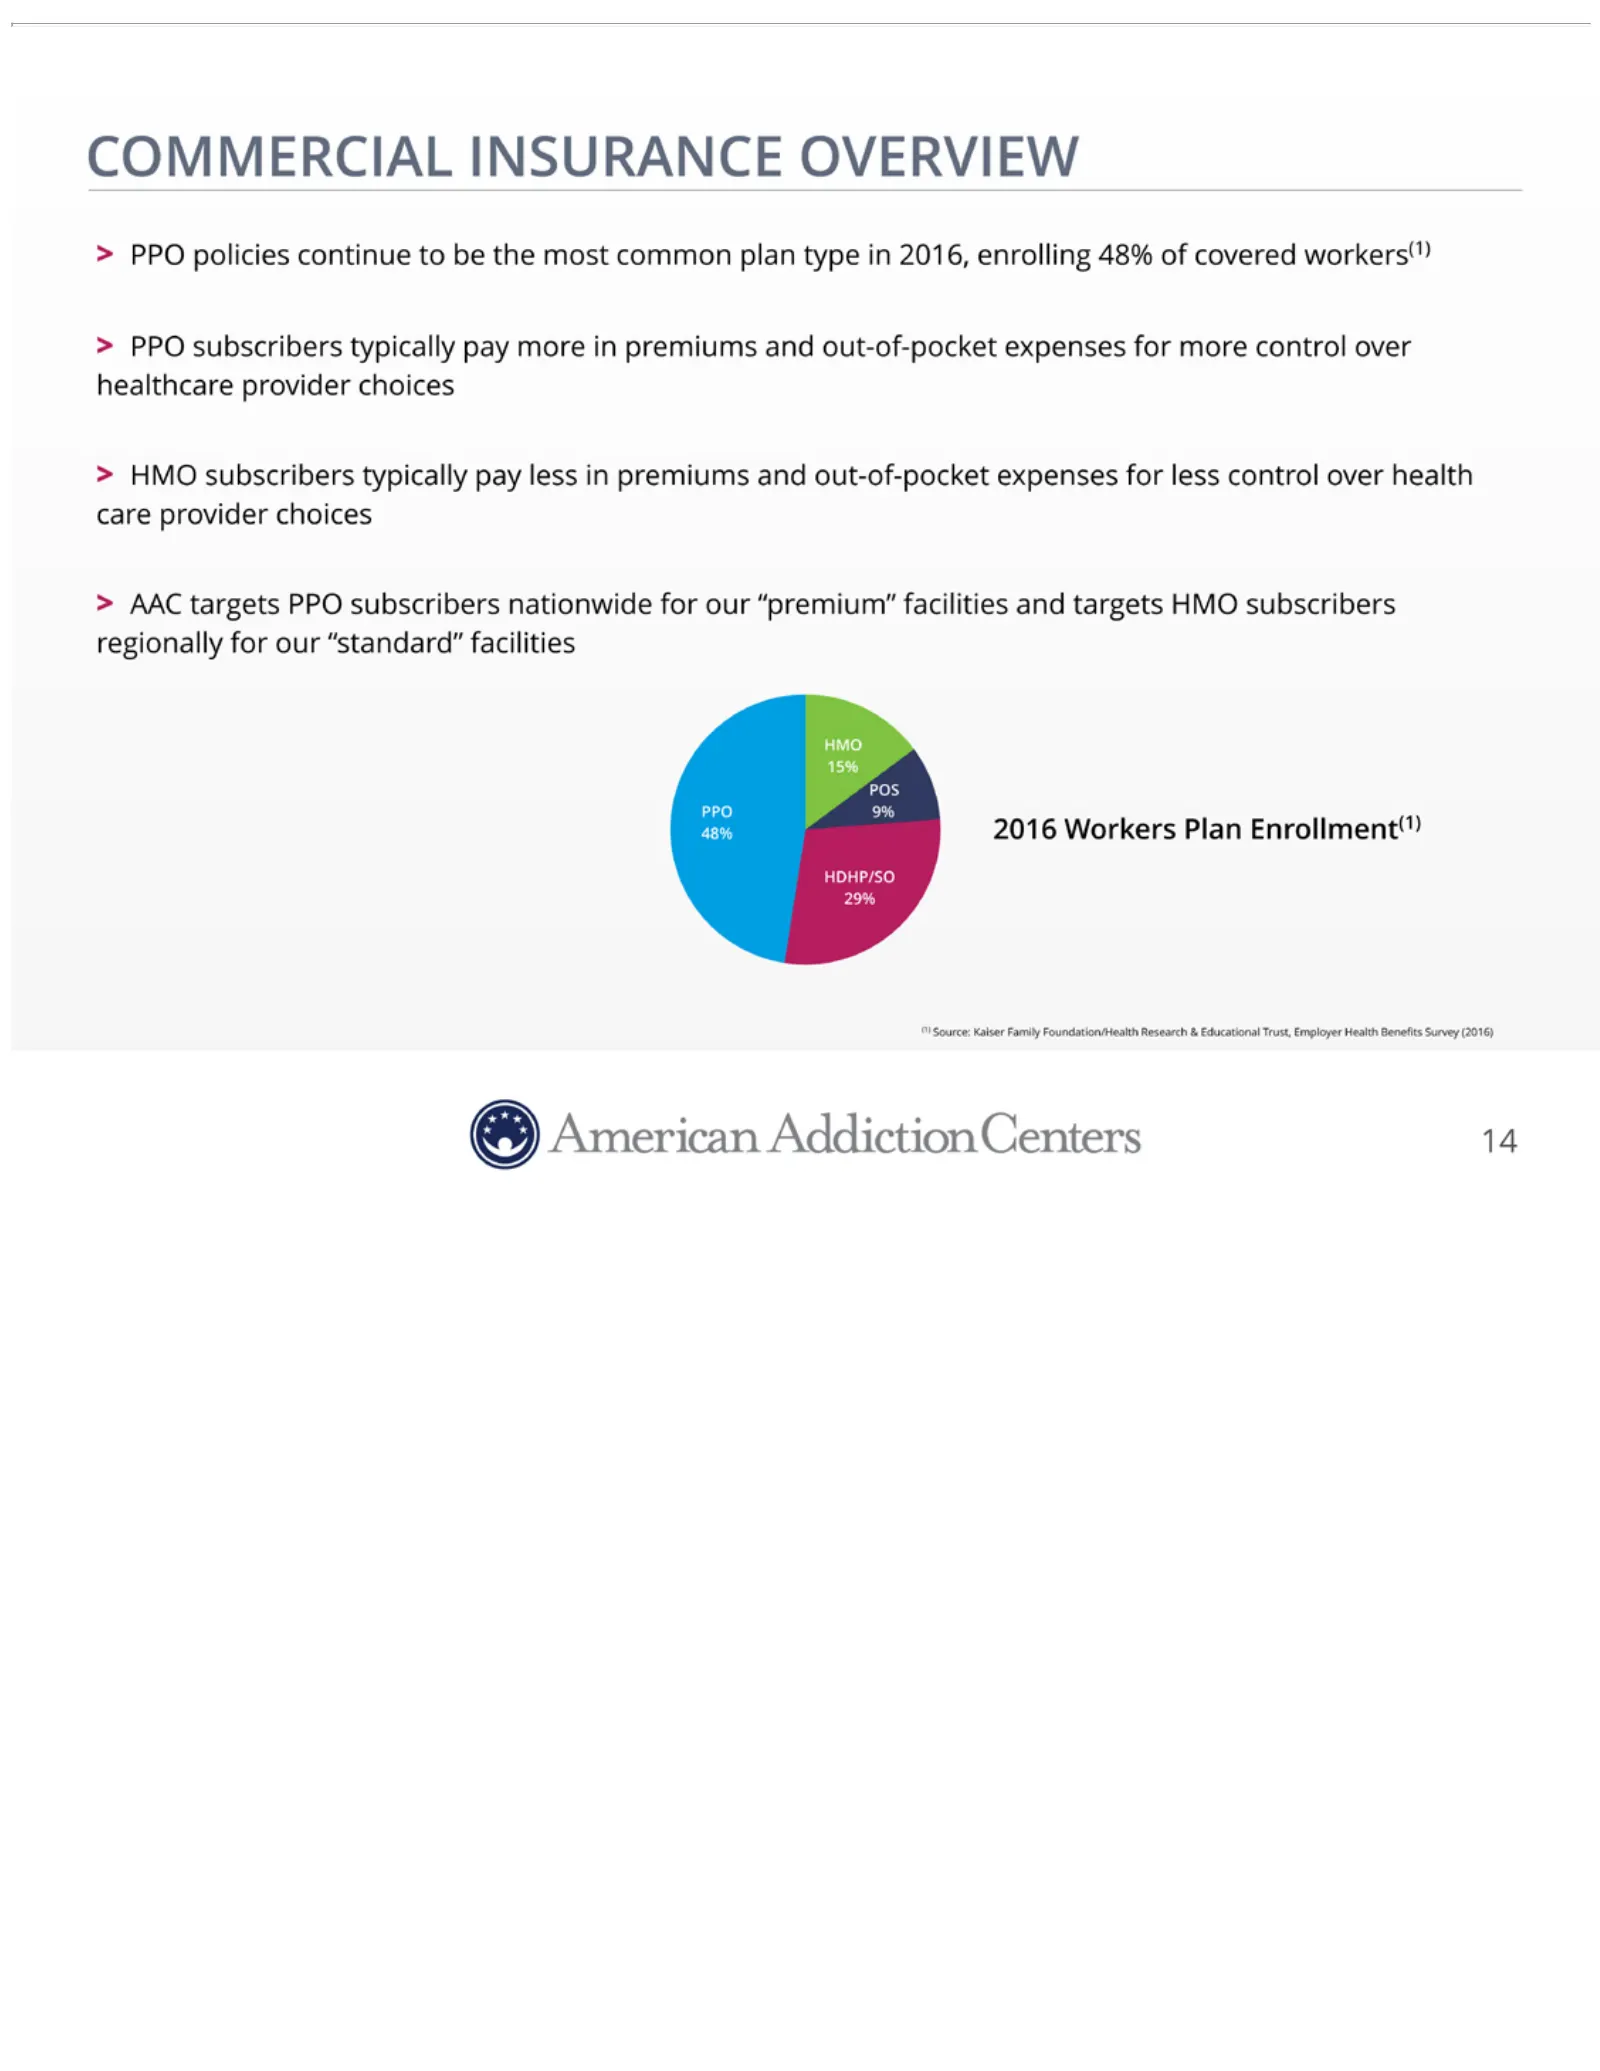
COMMERCIAL choices facilities> HMO HMOsubscribers INSURANCE 15% POS PPOtypically OVERVIEW 9% Enrollment(1) pay less >inPPO premiums 48% policies 2016 and continue Workers out-of-pocket toPlan be the HDHP/SO expenses most common for 29% less (1)plan control Source: typeover in Kaiser 2016, health Fam
Slide 15: AAC Targeted Offerings for Plans
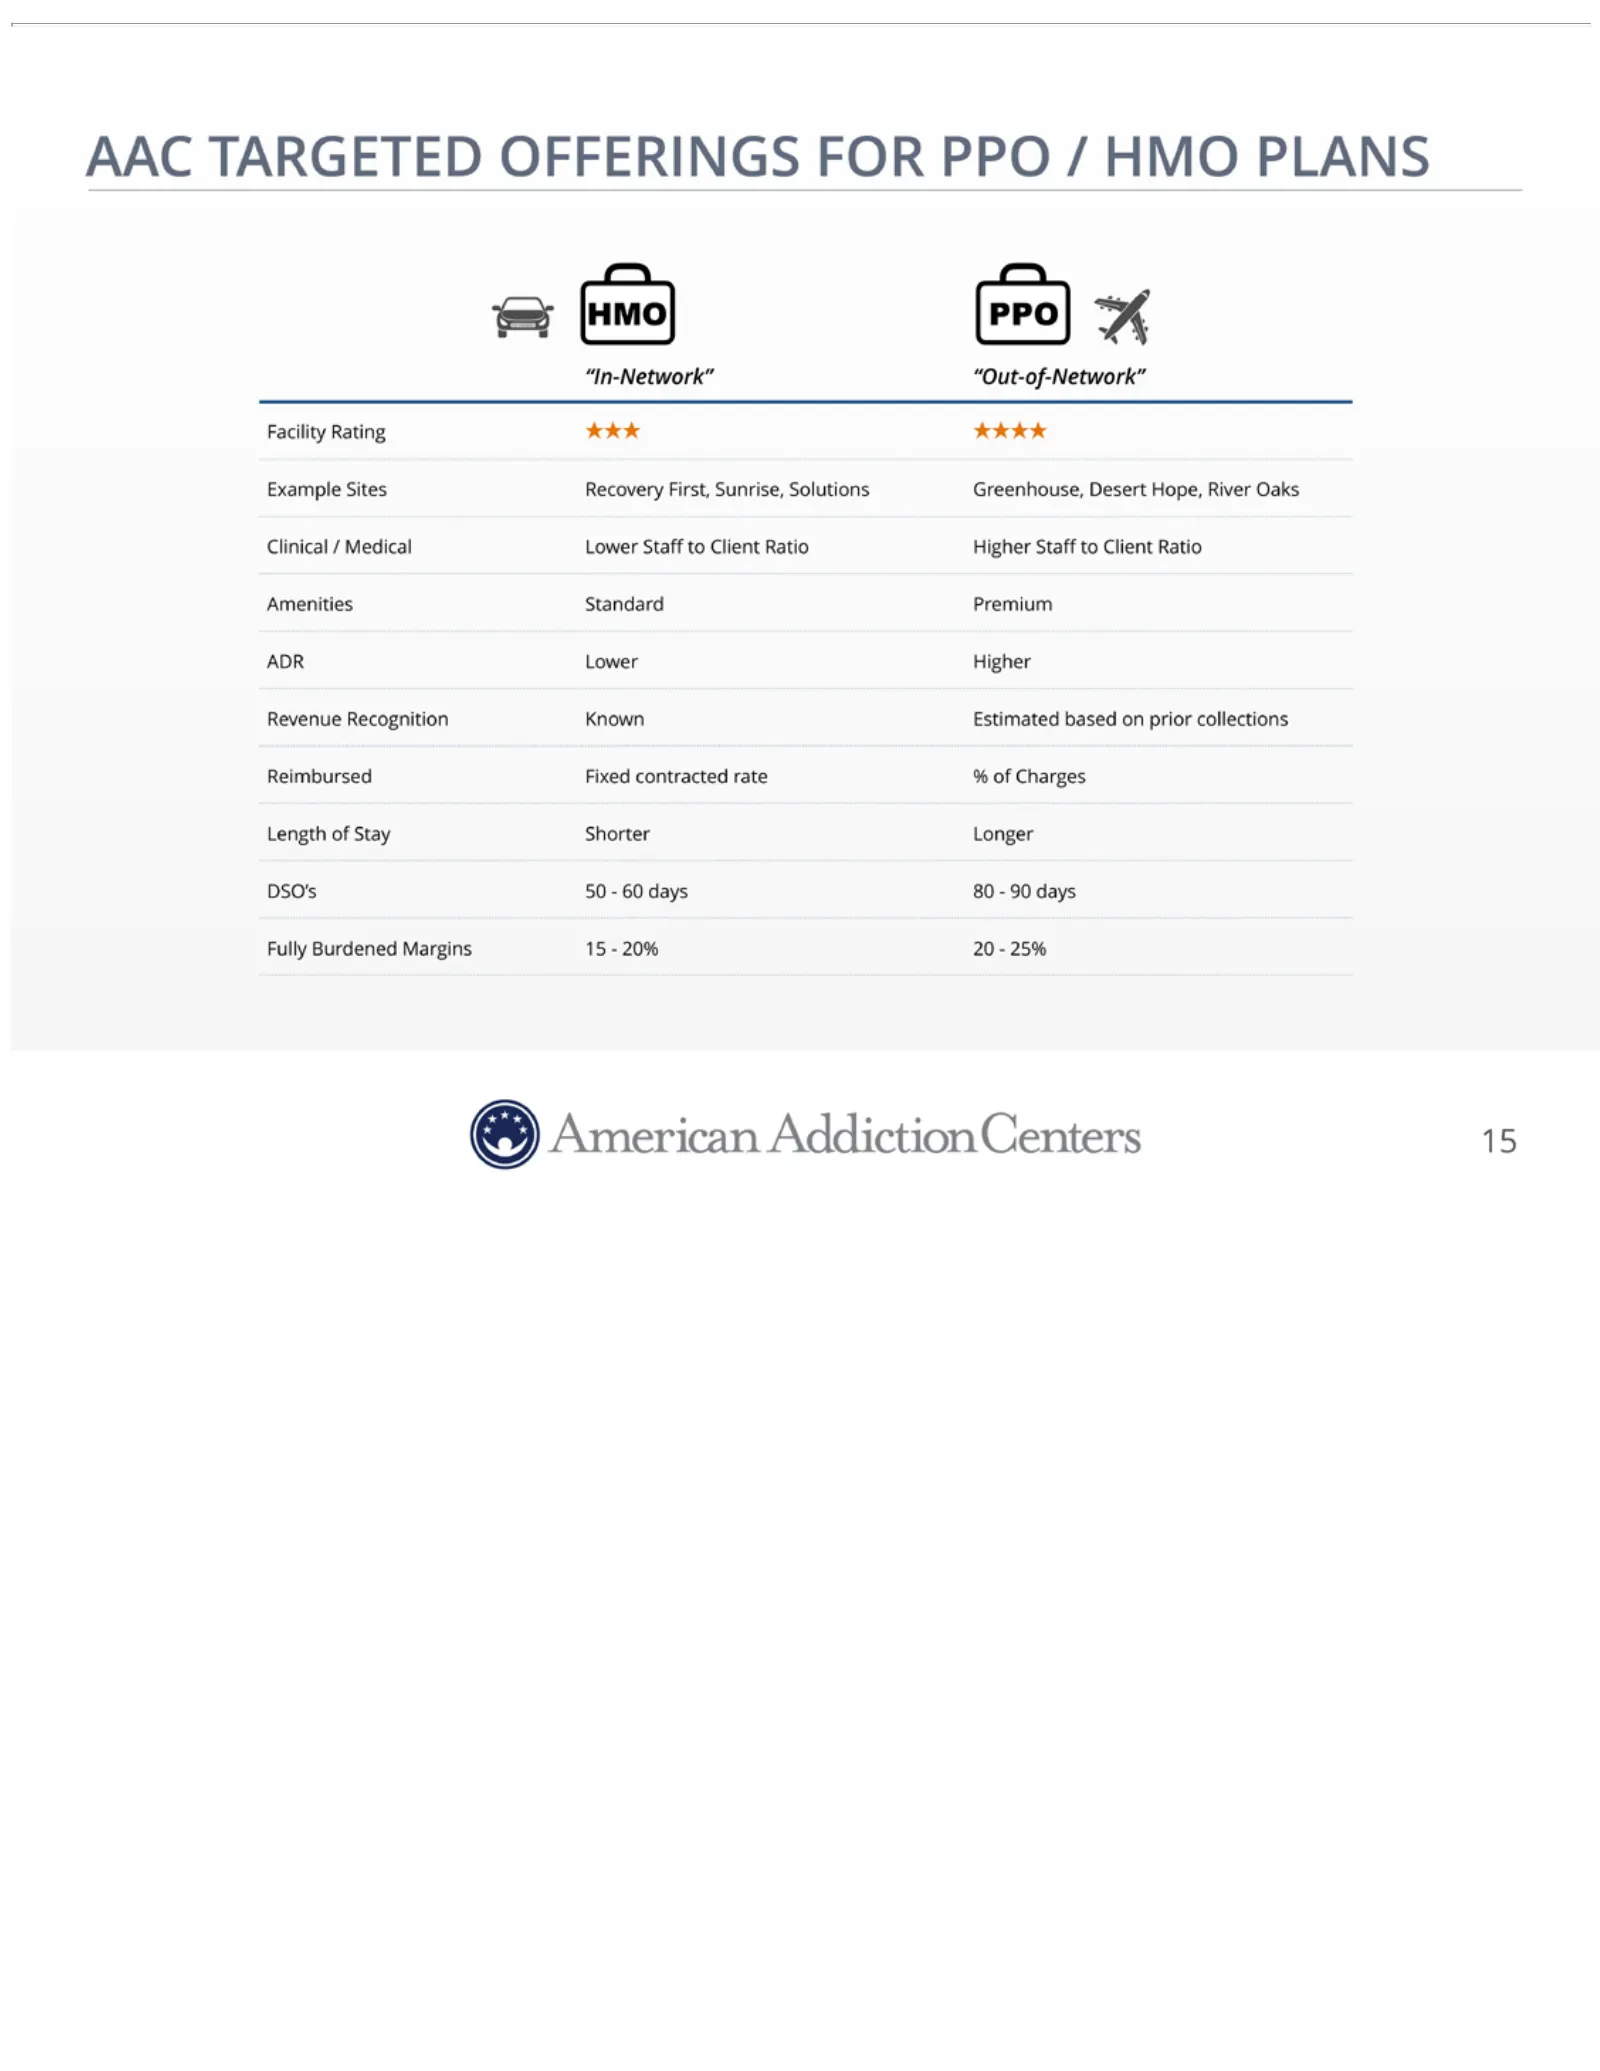
AAC to 20%Client 20—25% TARGETED Ratio Amenities 15 OFFERINGS Standard FOR Premium PPO / ADR HMOLower PLANSHigher HMORevenue PPO “In-Network” Recognition“Out-of-Network” Known EstimatedFacility based onRating prior ??? collections ???? Example Reimbursed Sites Recovery Fixed contracted First, Sunris
Slide 16: Geographic Footprint
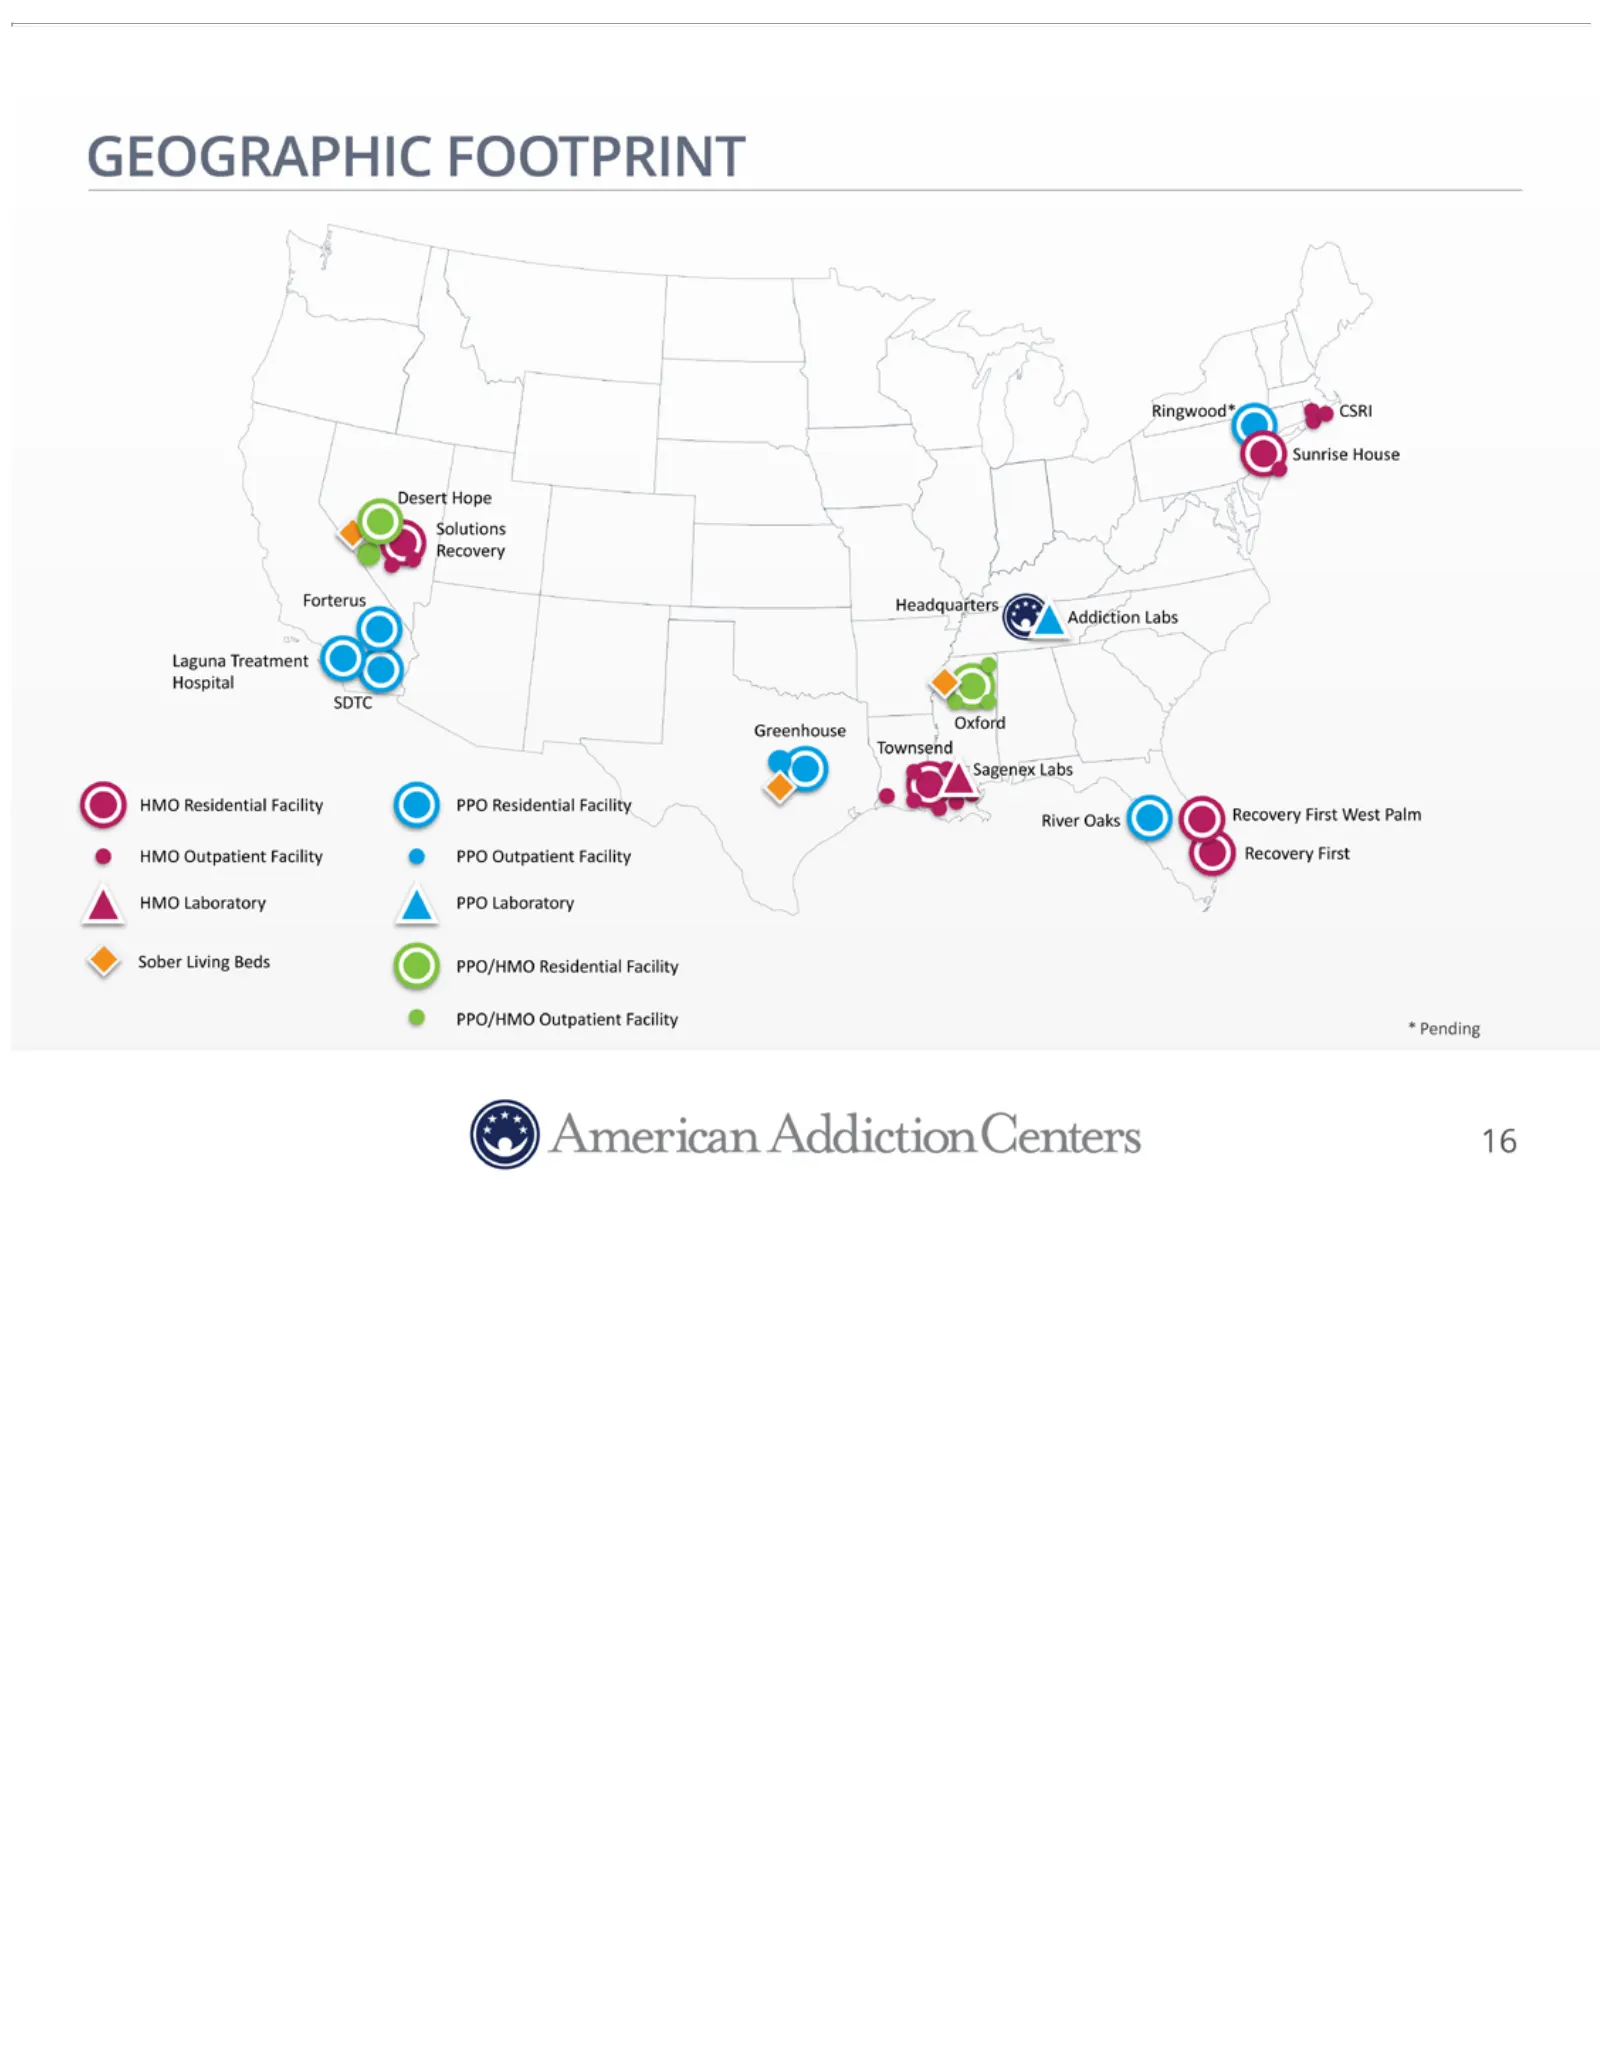
GEOGRAPHIC River$Oaks Recovery$First FOOTPRINT West Ringwood Palm HMO$Outpatient CSRI Sunrise$House Facility Desert PPO$Outpatient Hope Solutions$ Facility Recovery Recovery$First Forterus HMO$Laboratory Headquarters ddiction$Labs PPO$Laboratory LagunaSober Treatment$ LivingHospital Beds PPO/HMO$Res
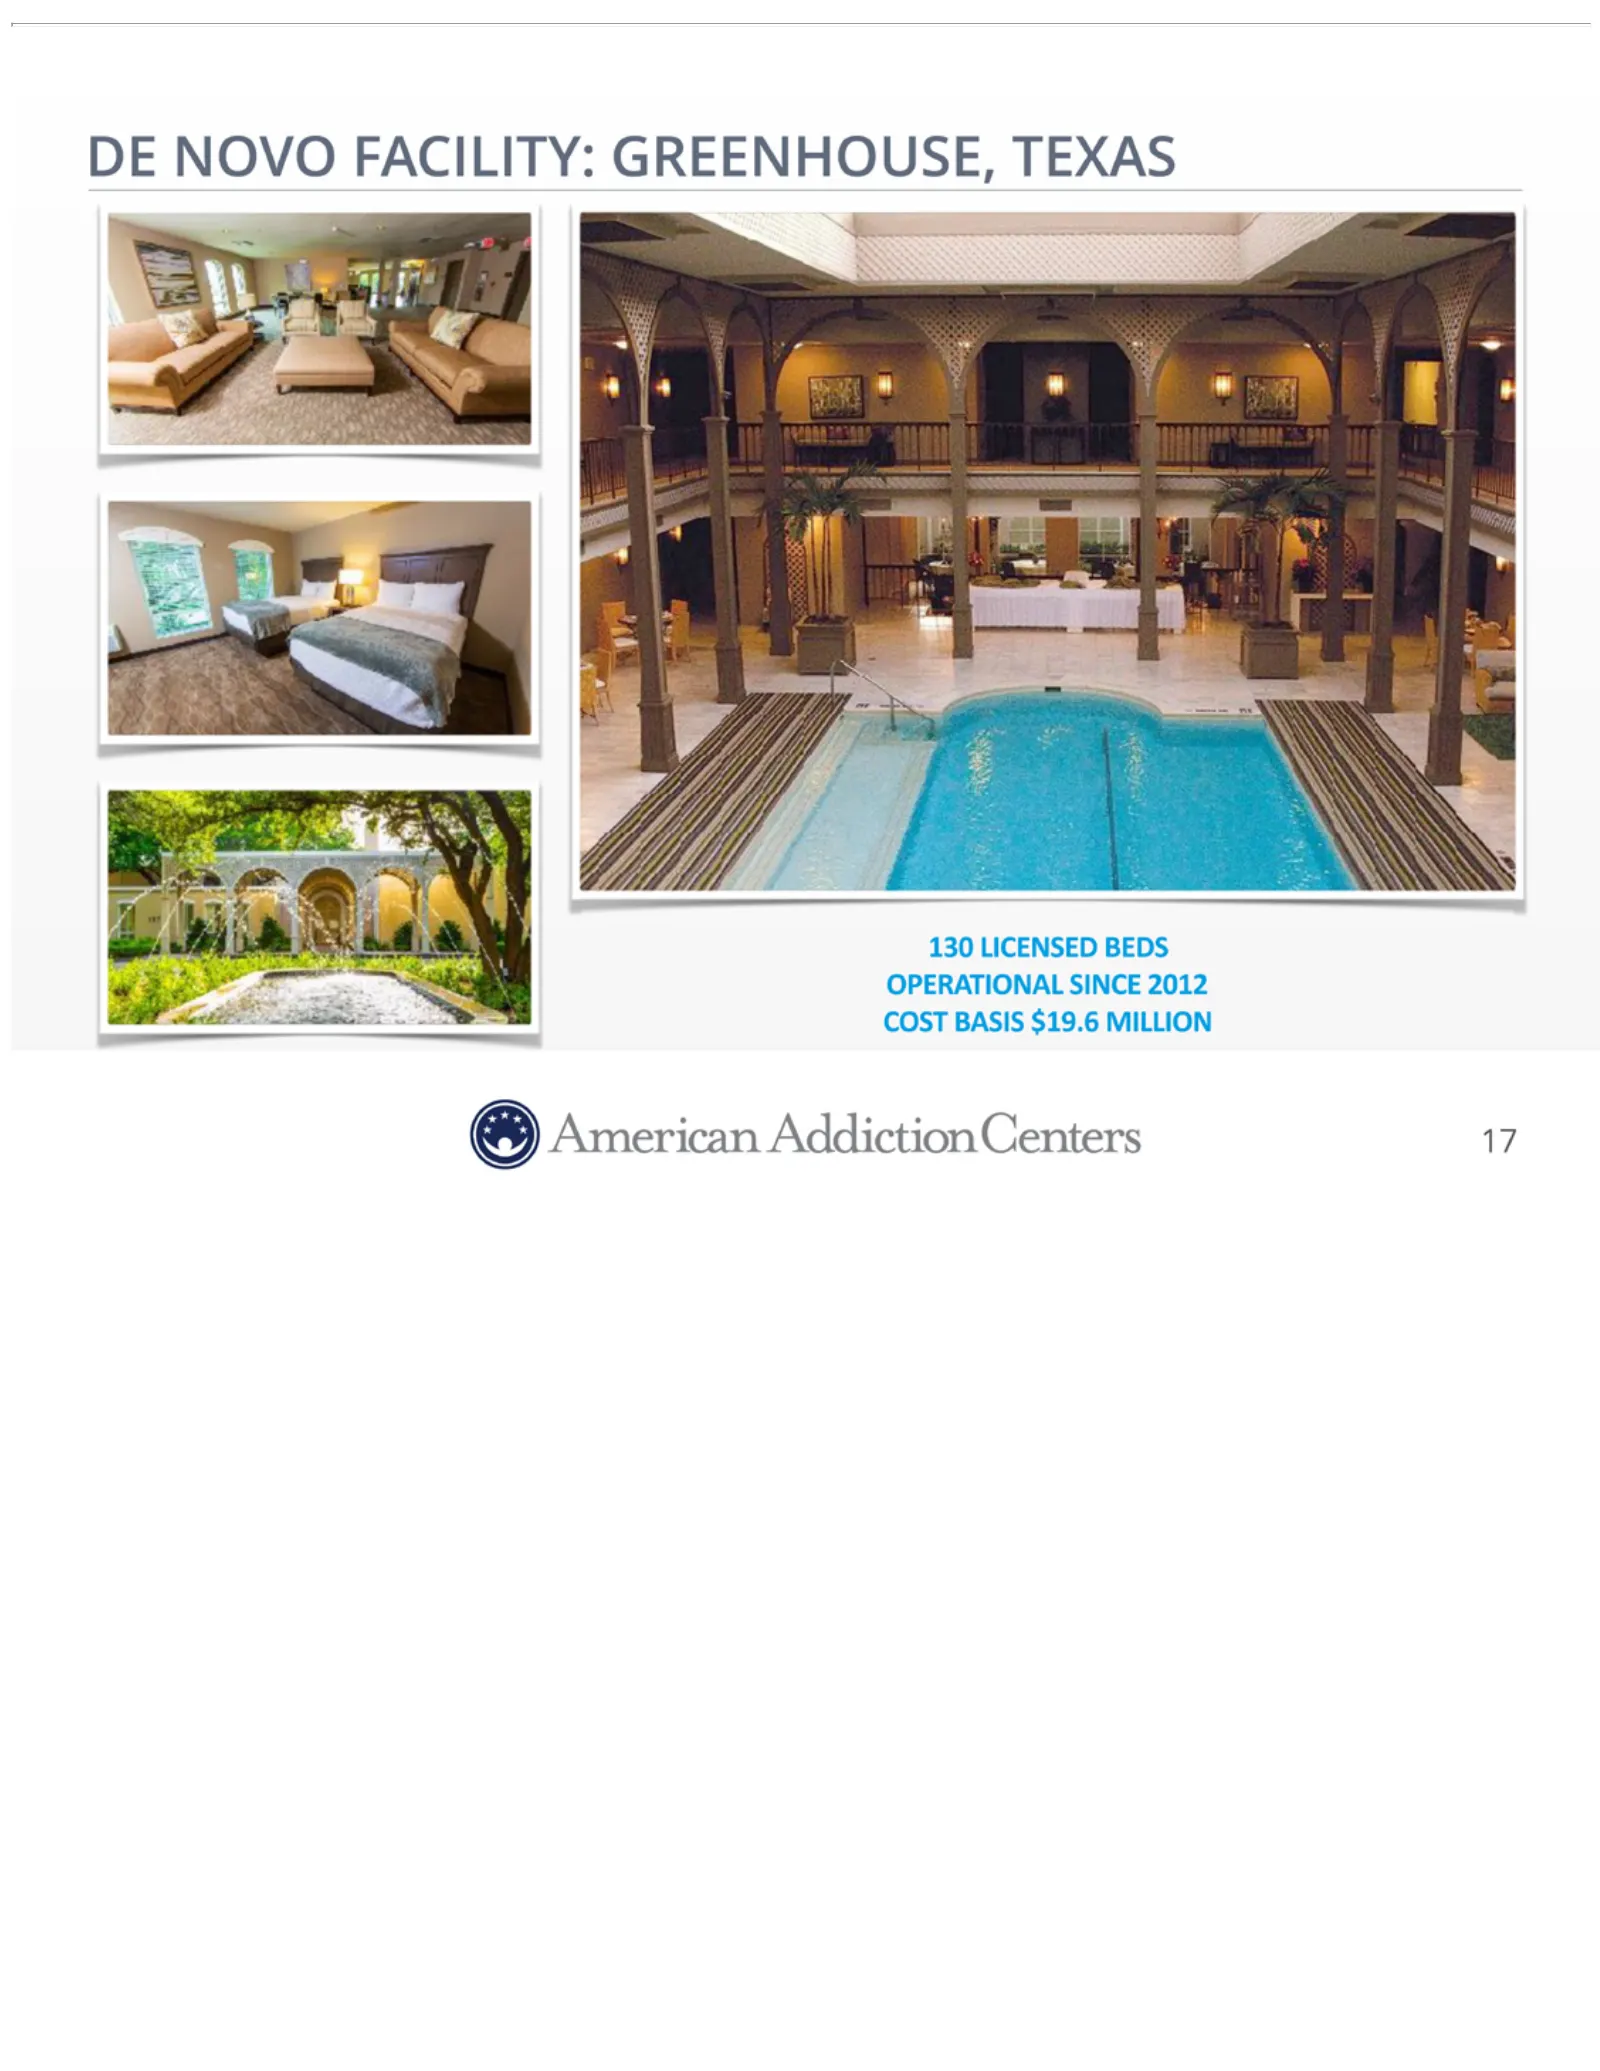
Slide 17: De Novo Facility: Greenhouse, Texas
DE NOVO FACILITY: GREENHOUSE, TEXAS 130 LICENSED BEDS OPERATIONAL SINCE 2012$ COST$BASIS$$19.6$MILLION 17
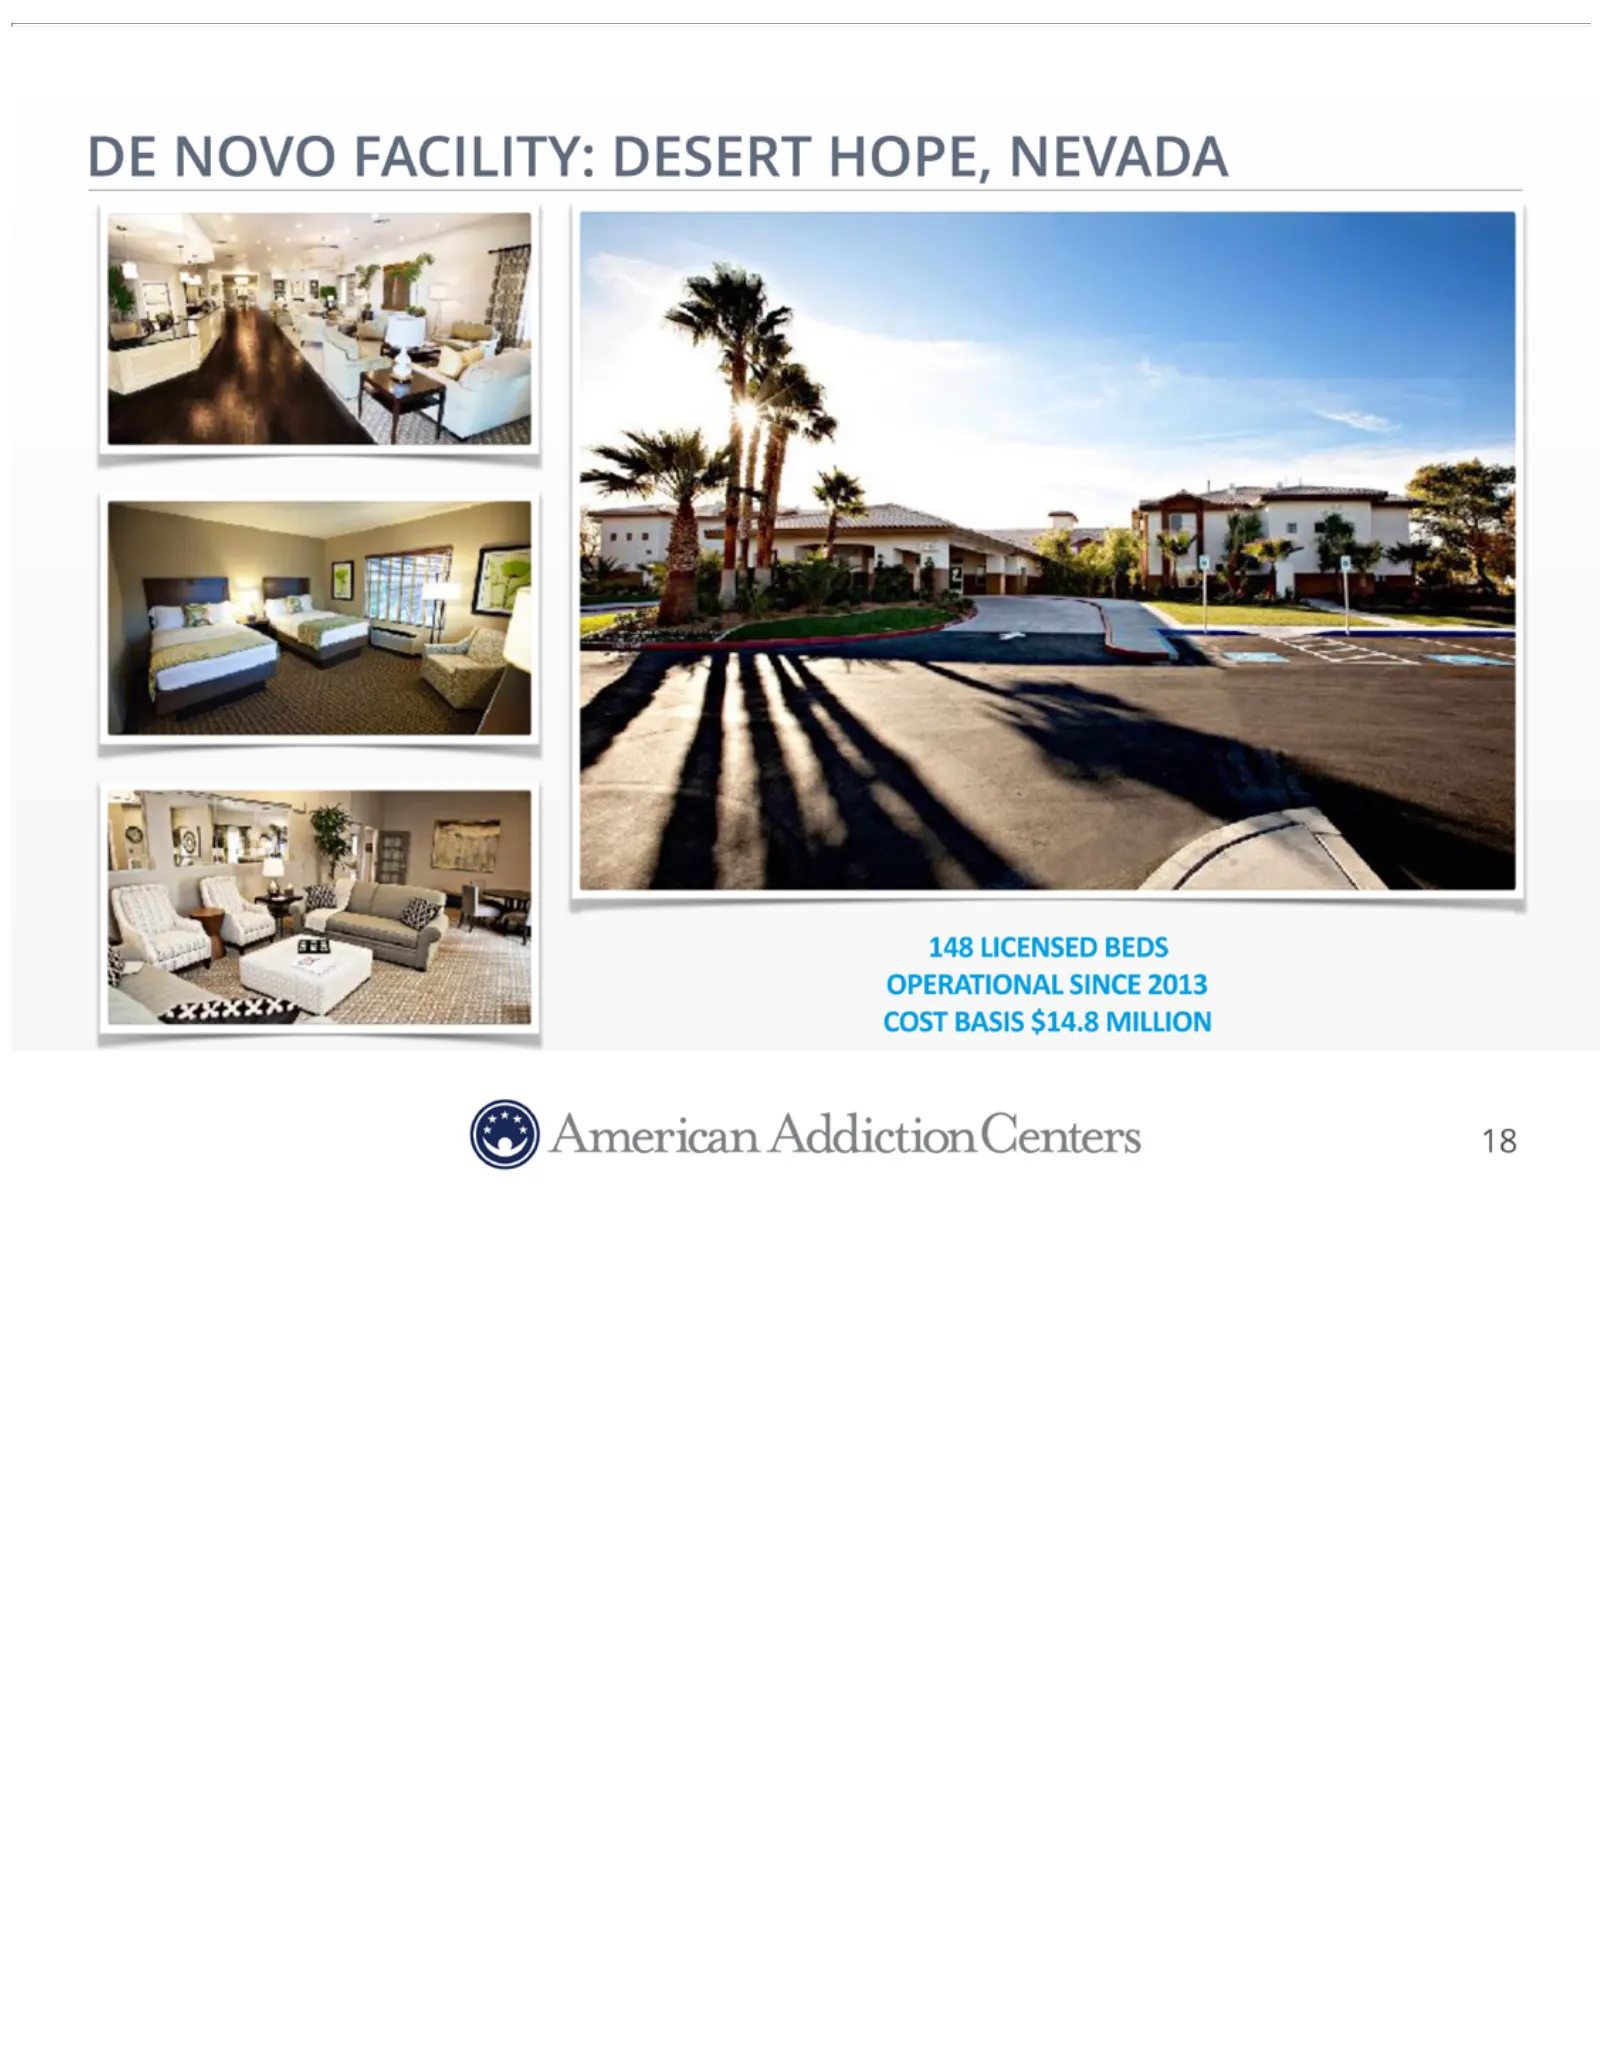
Slide 18: De Novo Facility: Desert Hope, Nevada
DE NOVO FACILITY: DESERT HOPE, NEVADA 148 LICENSED BEDS OPERATIONAL SINCE 2013$ COST$BASIS$$14.8 MILLION 18
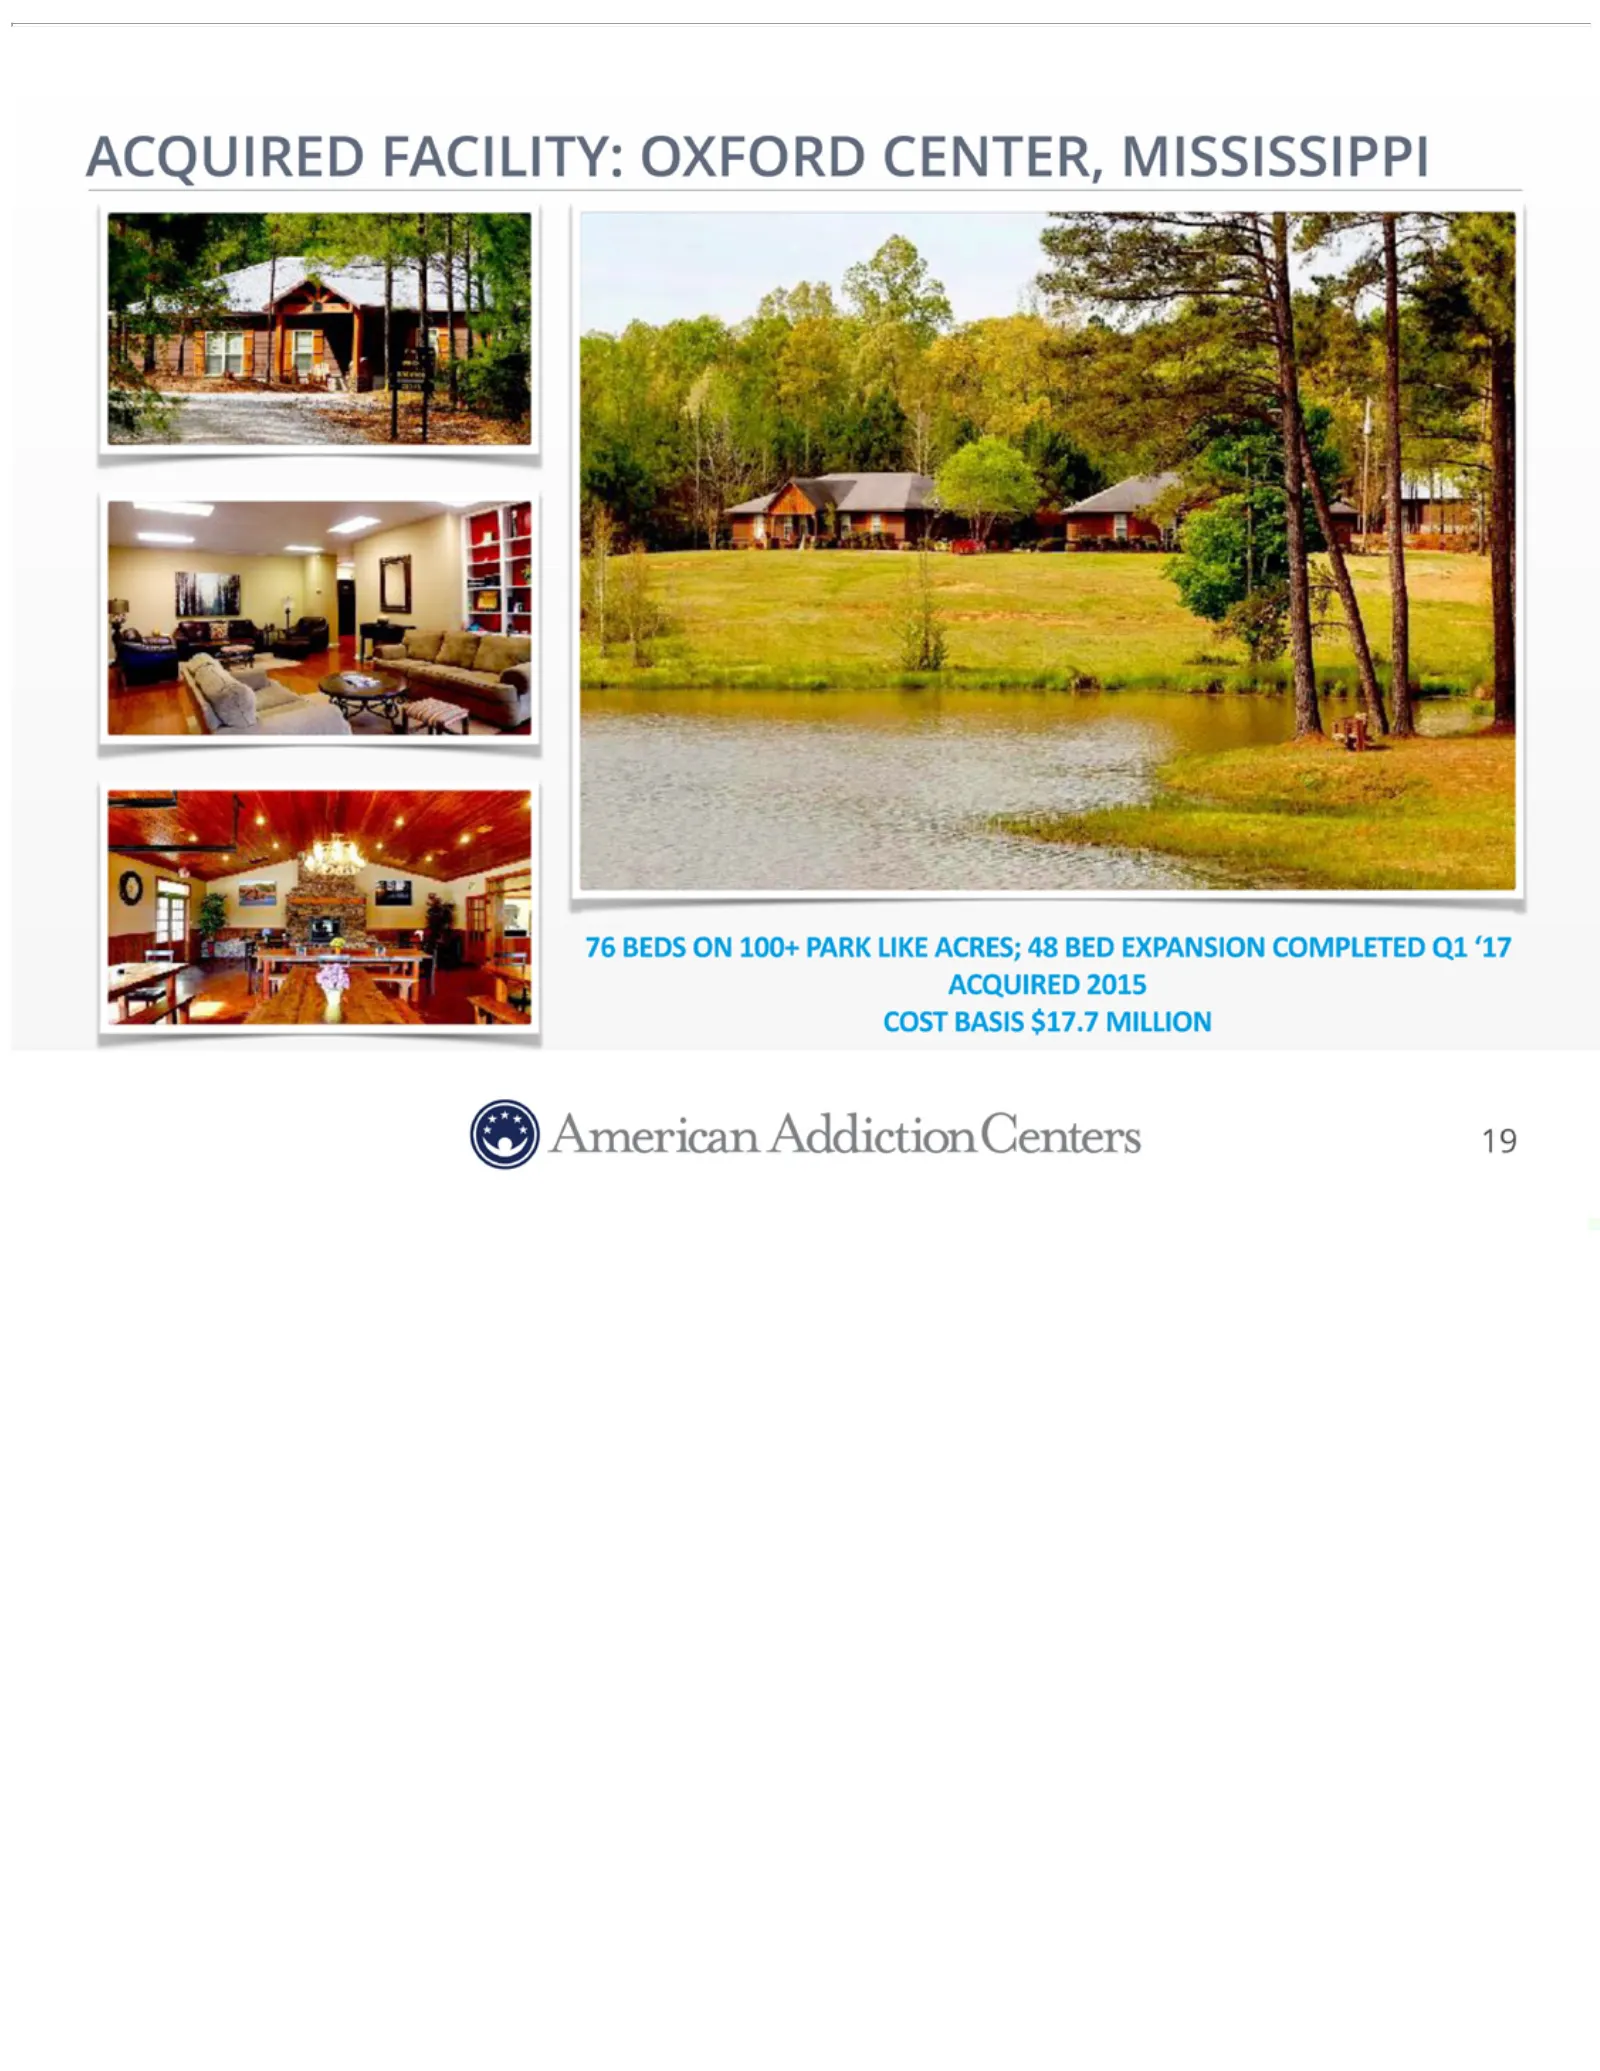
Slide 19: Acquired Facility: Oxford Center, Mississippi
ACQUIRED FACILITY: OXFORD CENTER, MISSISSIPPI 76 BEDS ON 100+ PARK LIKE ACRES; 48 BED EXPANSION COMPLETED Q1 ‘17 ACQUIRED$2015$ COST$BASIS$$17.7 MILLION 19
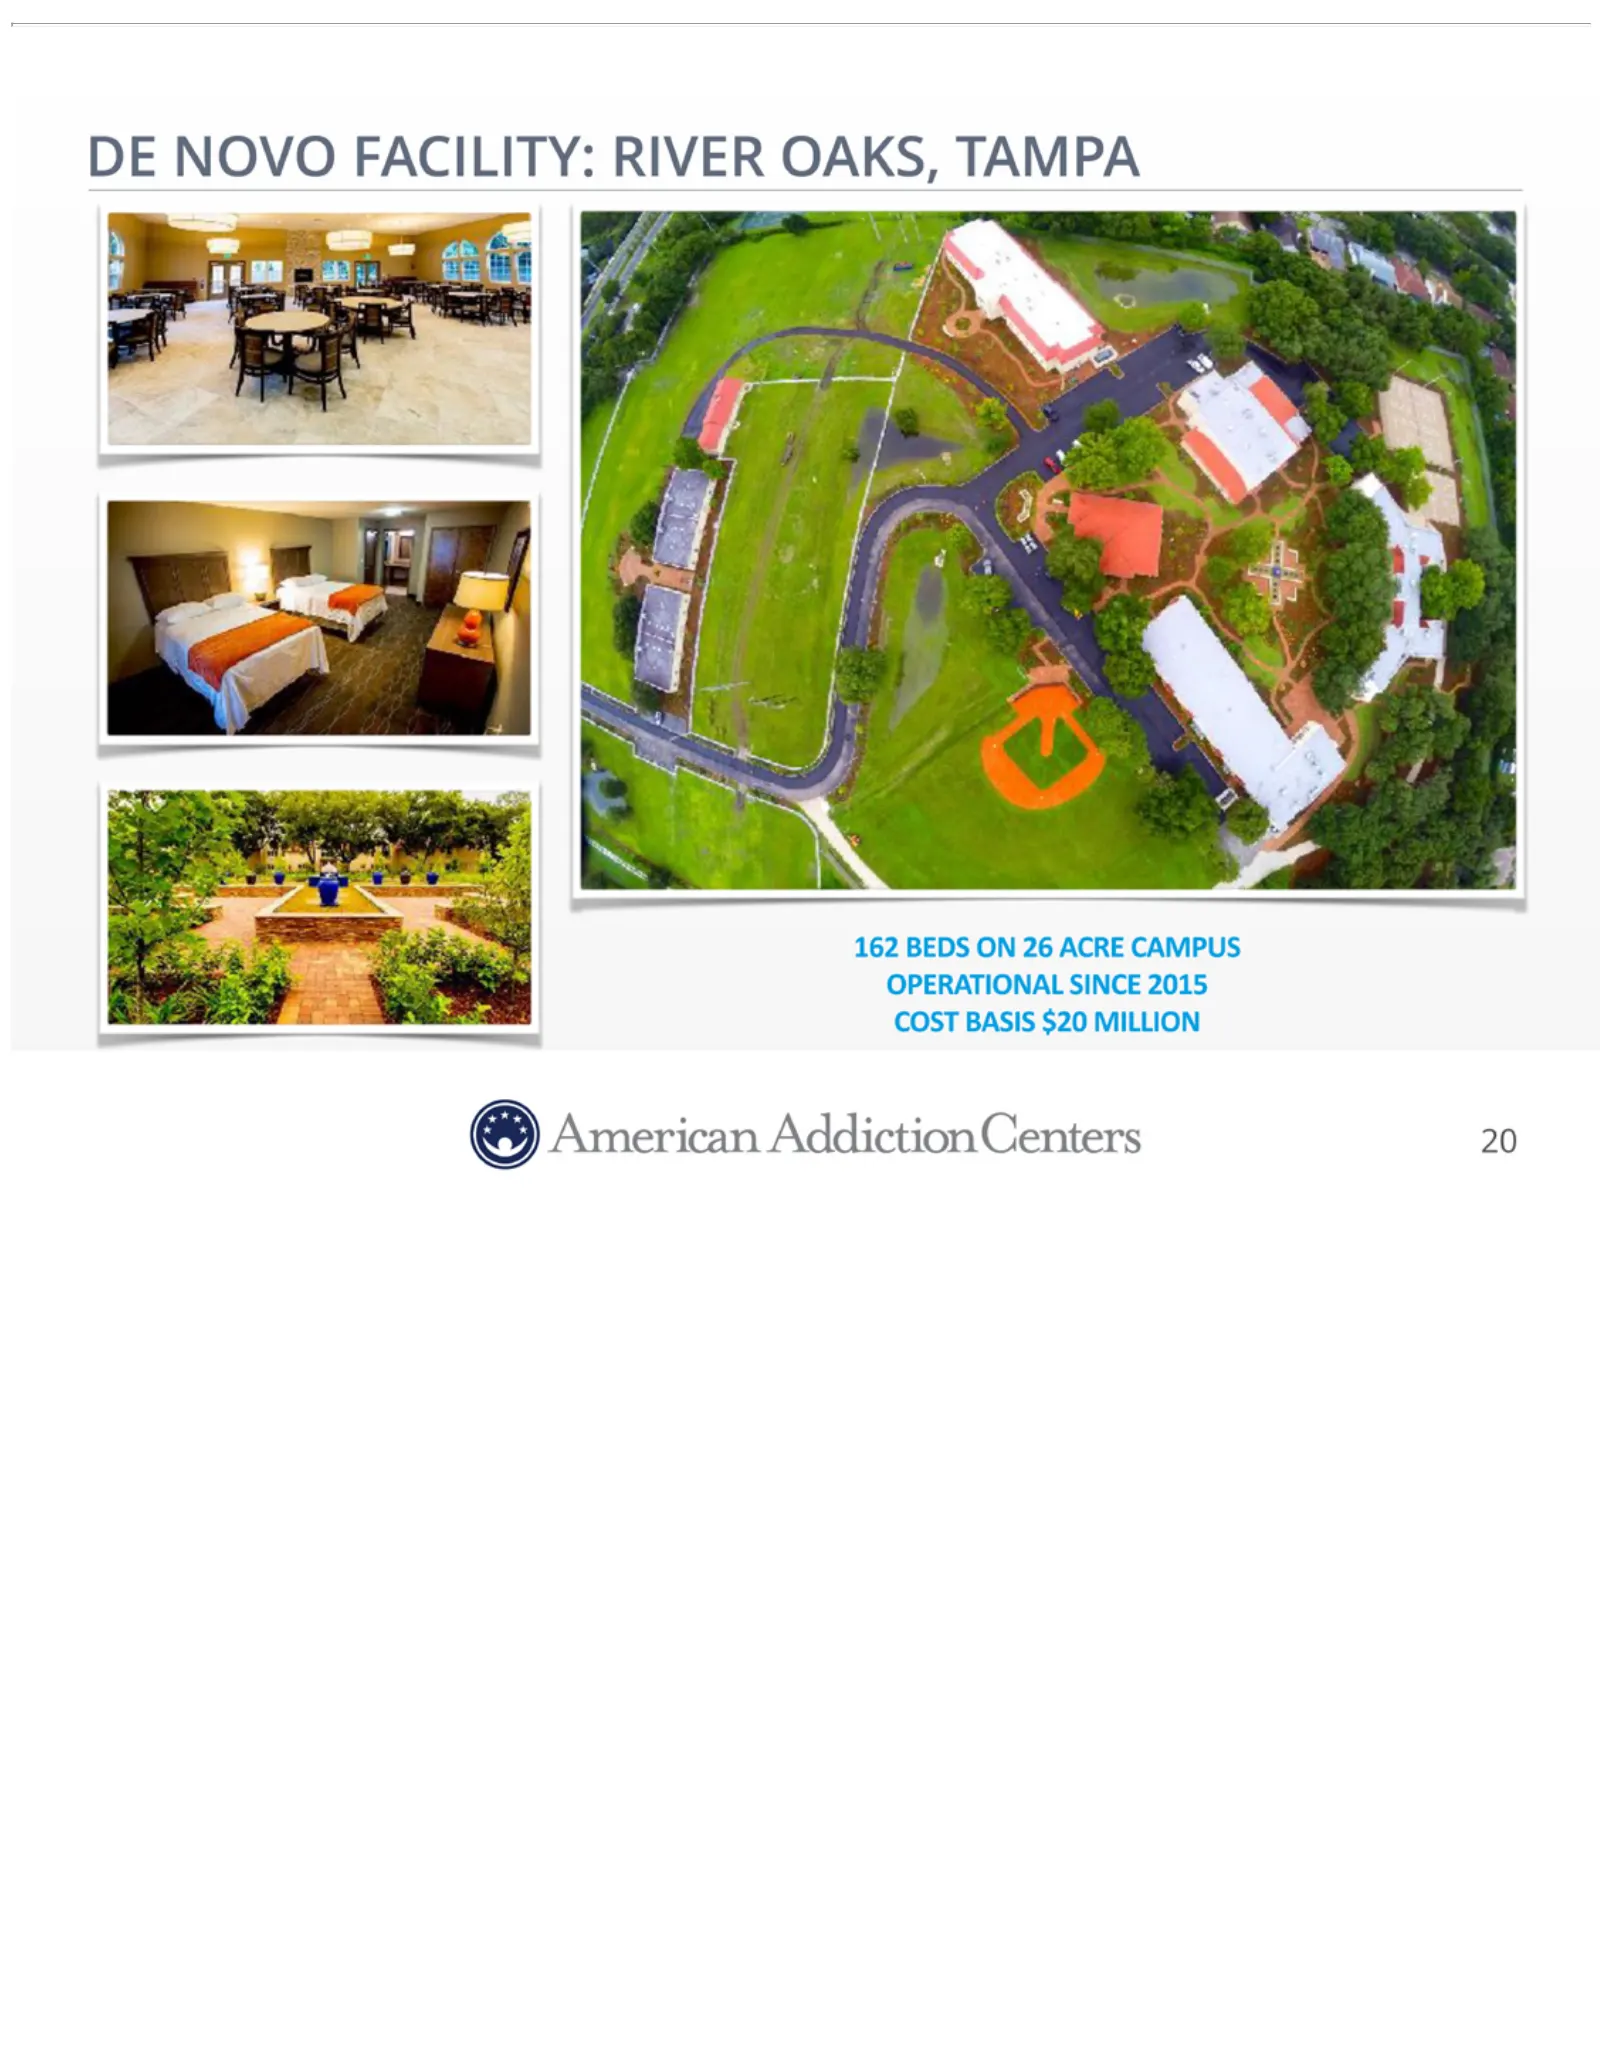
Slide 20: De Novo Facility: River Oaks, Tampa
DE NOVO FACILITY: RIVER OAKS, TAMPA 162 BEDS ON 26 ACRE CAMPUS OPERATIONAL SINCE 2015$ COST$BASIS$$20 MILLION 20
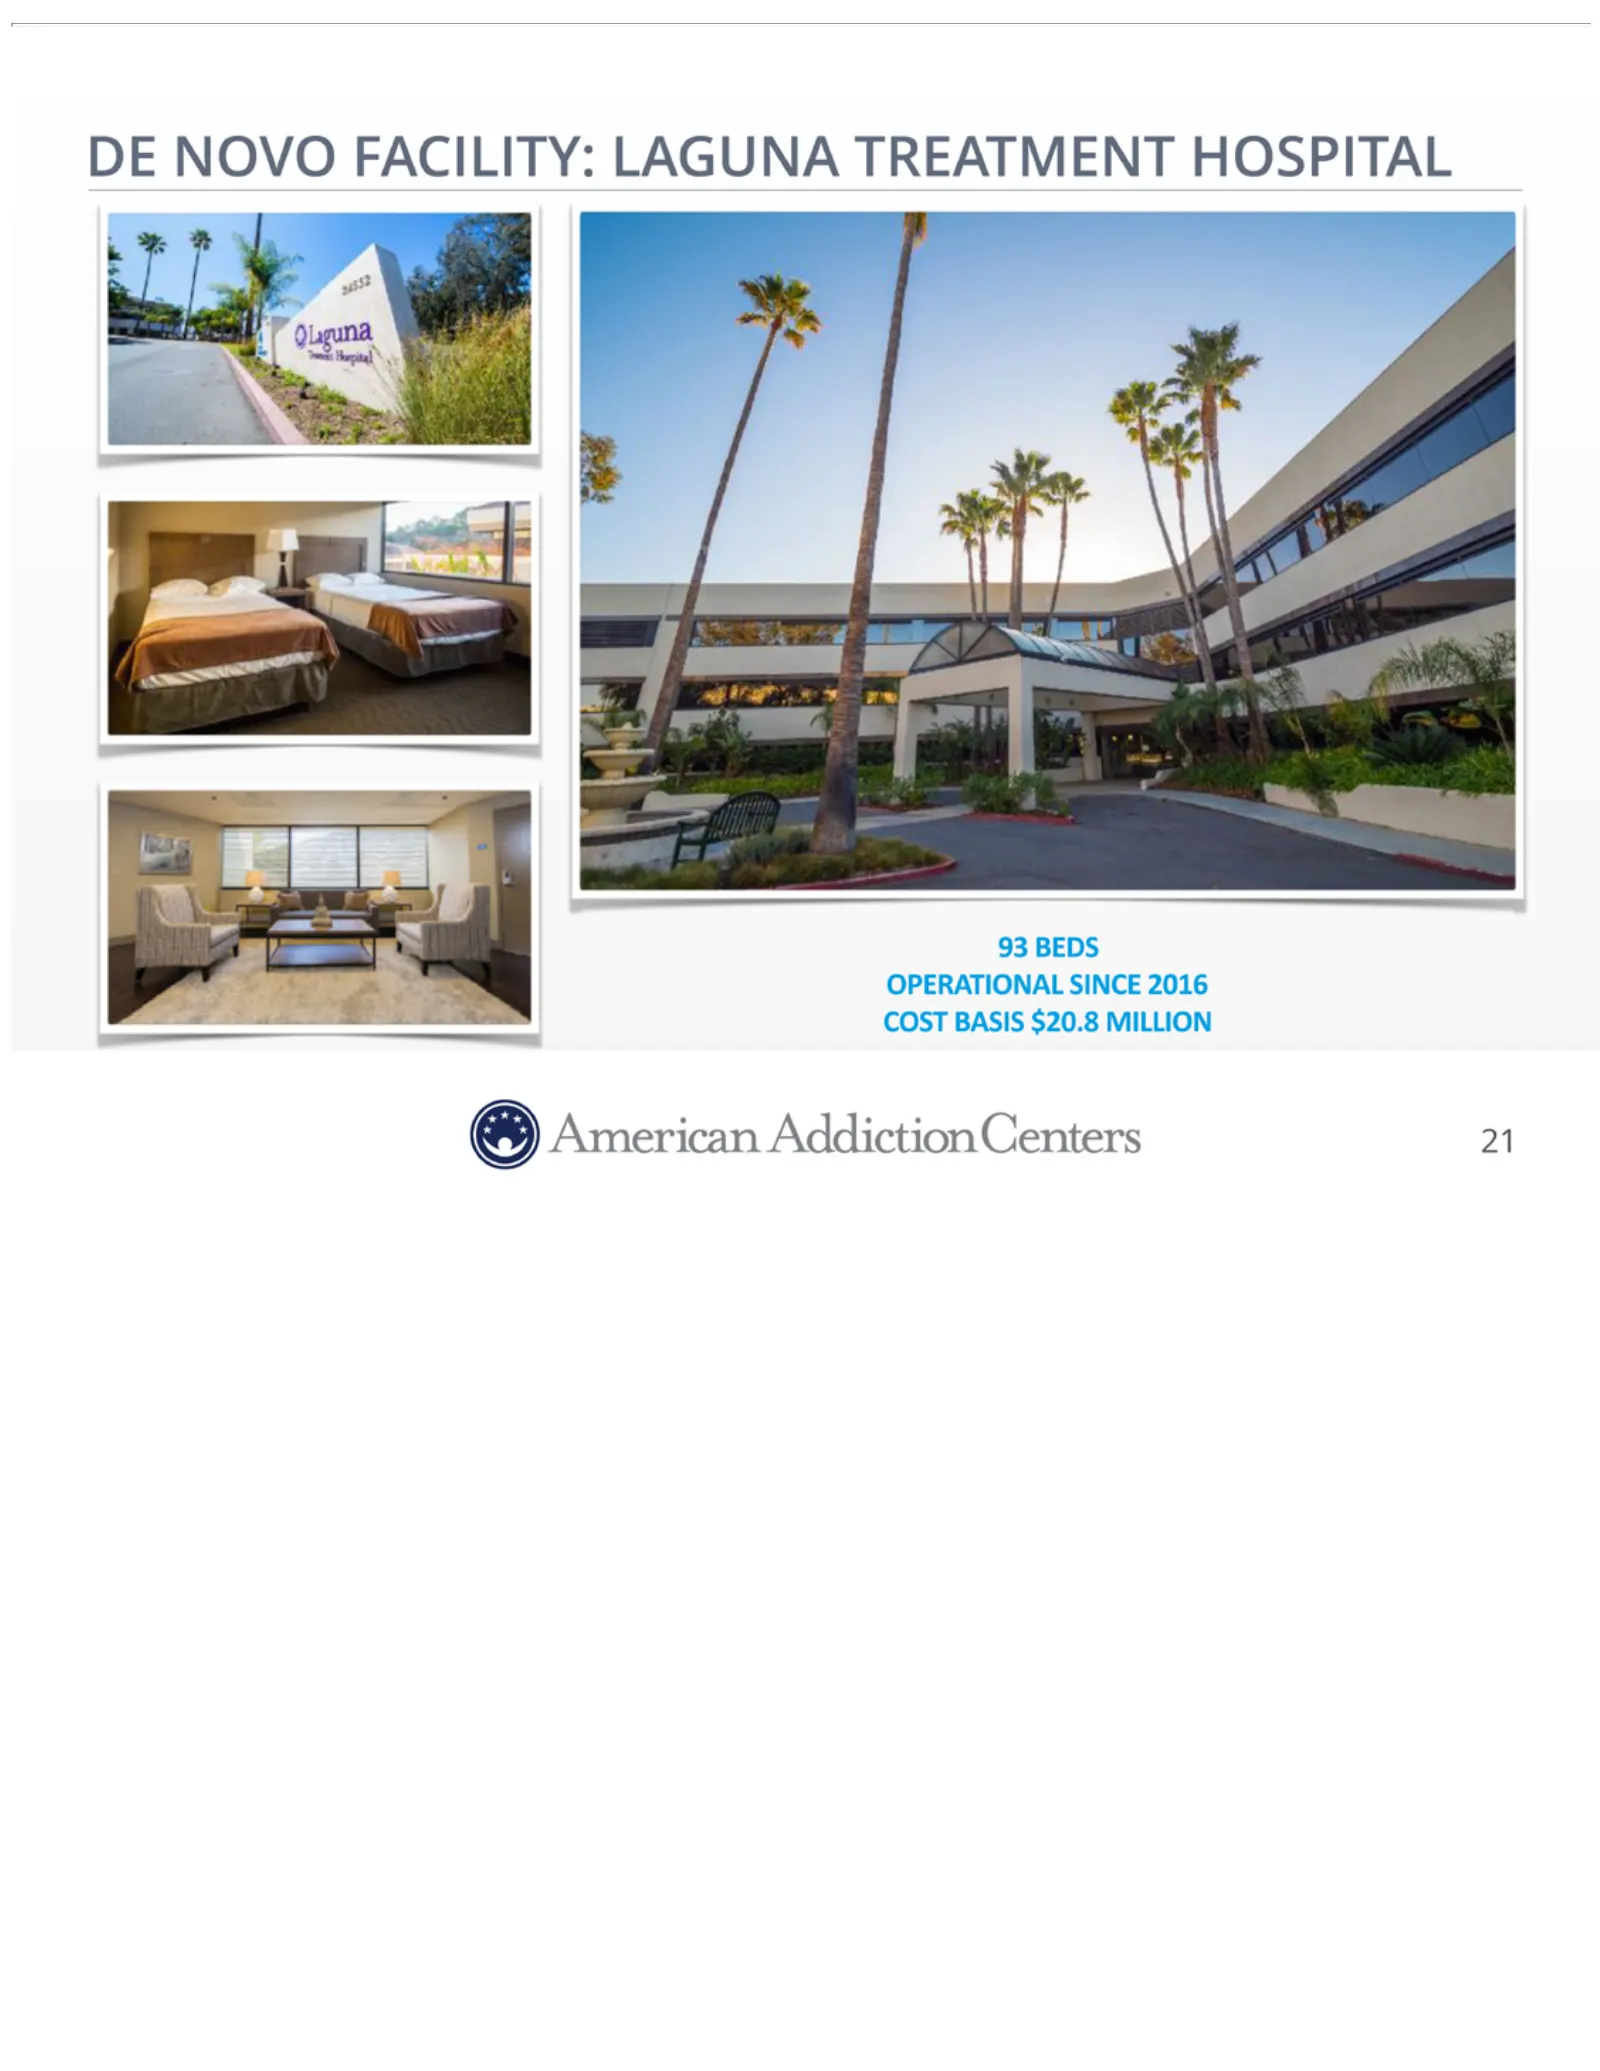
Slide 21: De Novo Facility: Laguna Treatment Hospital
DE NOVO FACILITY: LAGUNA TREATMENT HOSPITAL 93 BEDS OPERATIONAL SINCE 2016$ COST$BASIS$$20.8 MILLION 21
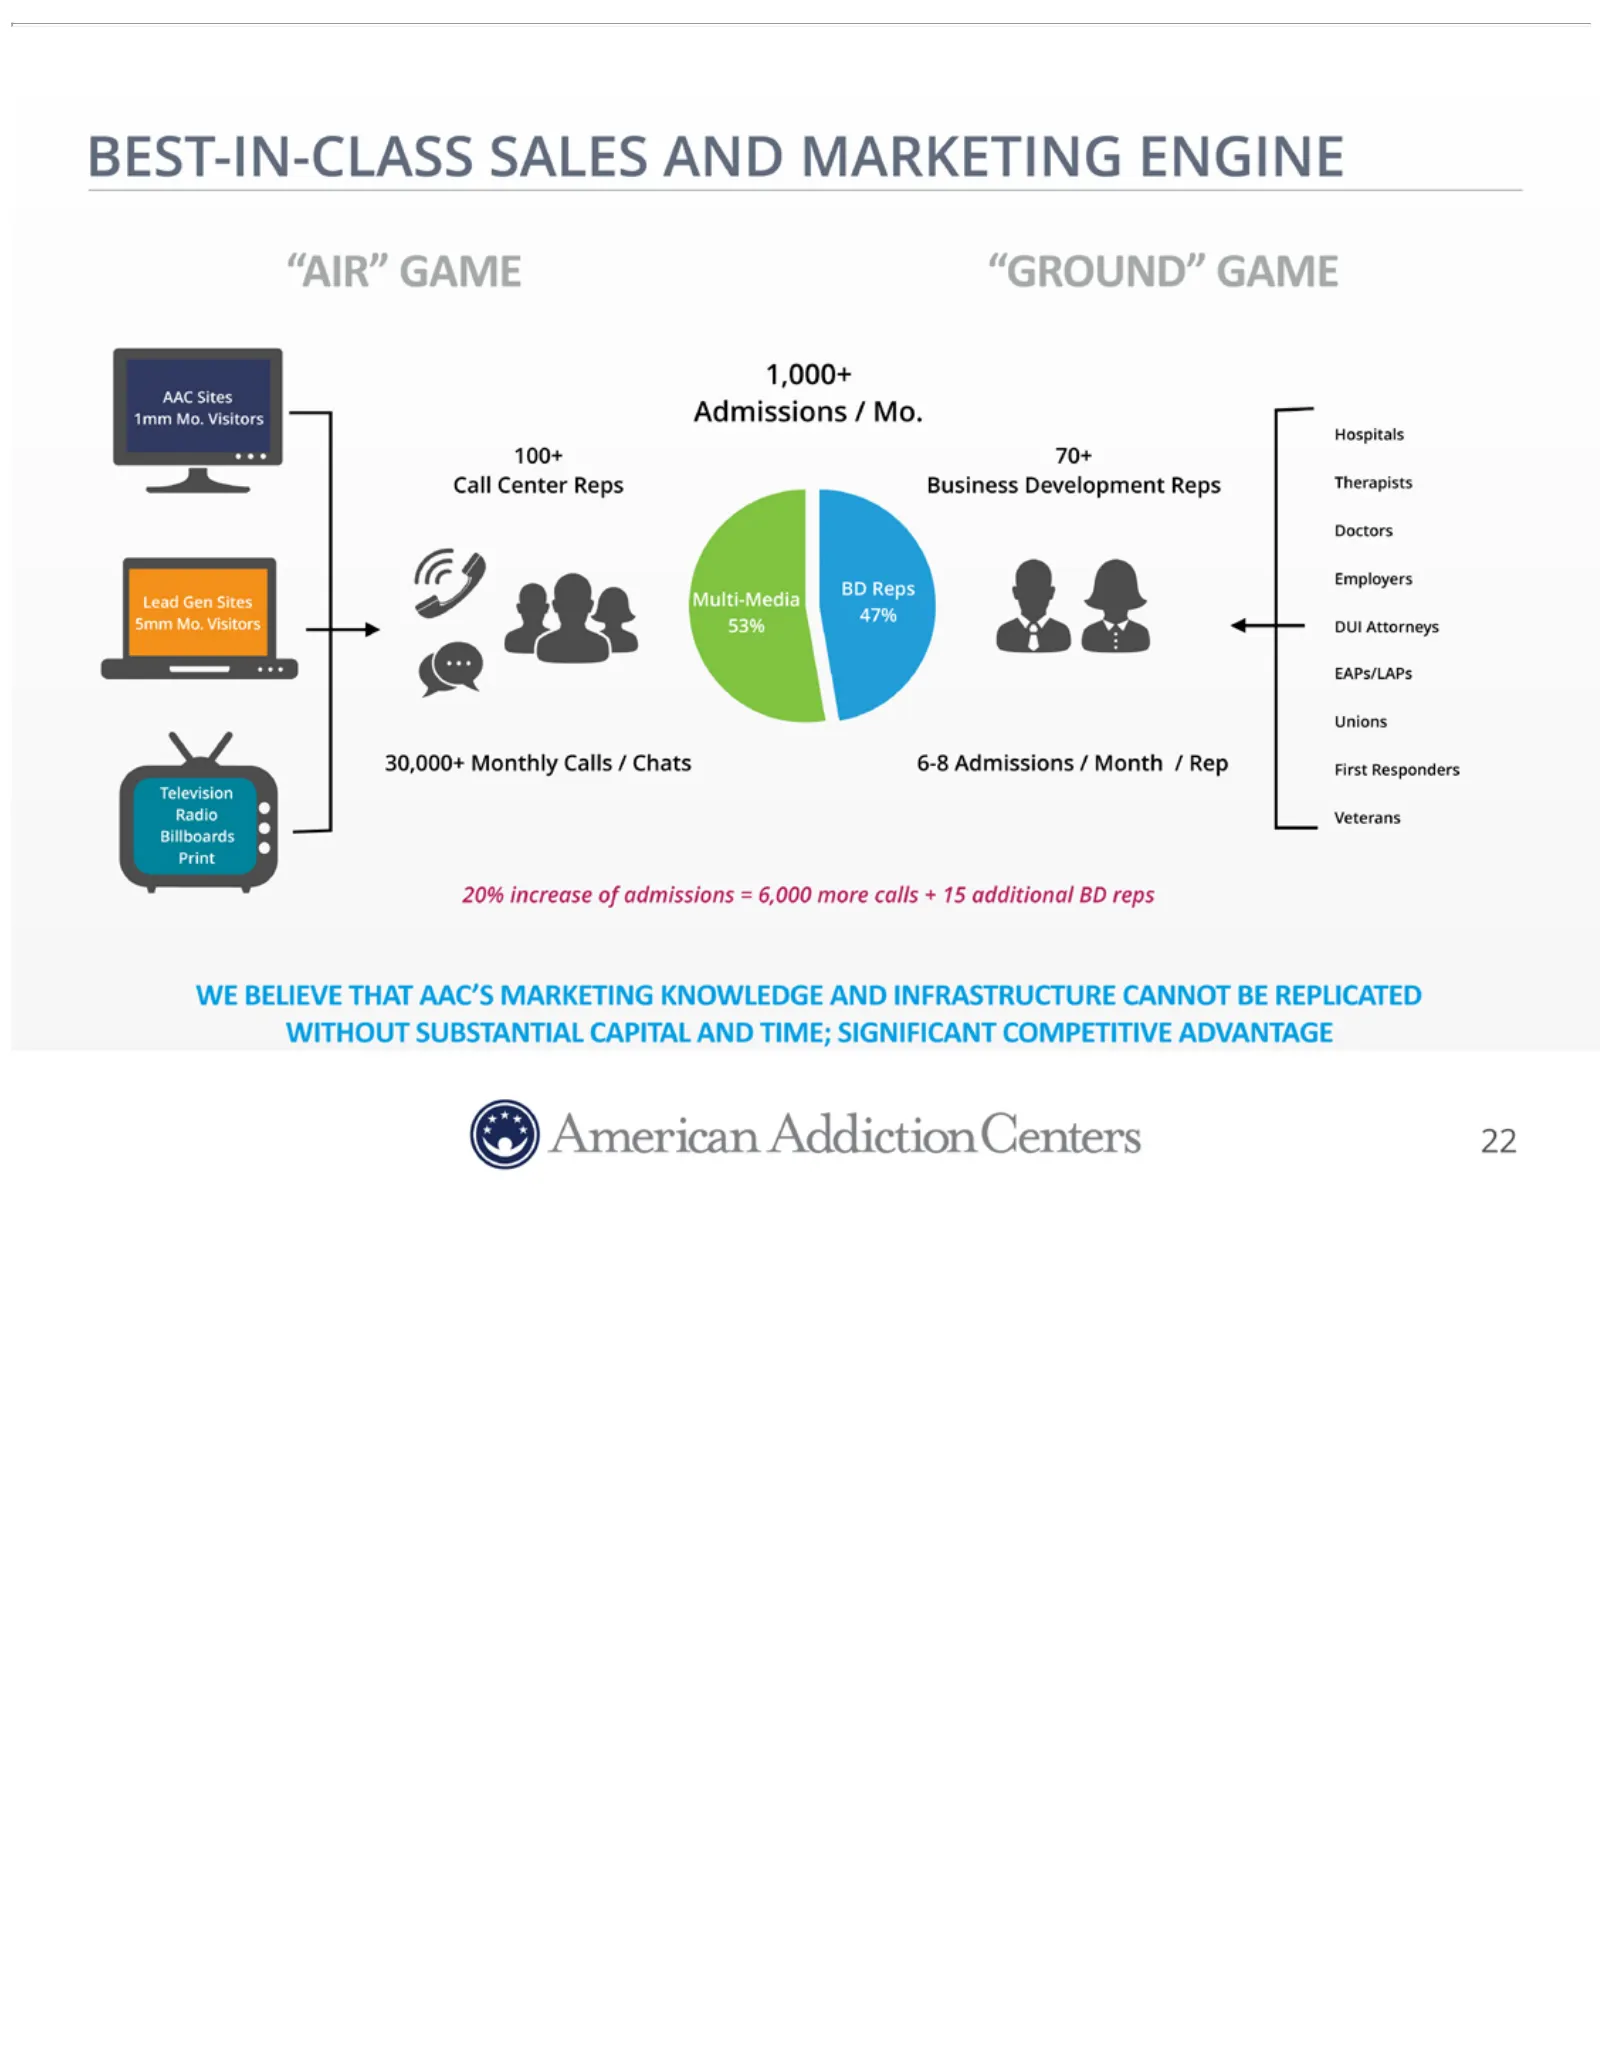
Slide 22: Best-in-Class Sales and Marketing Engine
BEST-IN-CLASS Multi-Media WE BELIEVE 5mm THAT SALES Mo.AAC’S Visitors AND MARKETING 47% MARKETING 53% DUIKNOWLEDGE Attorneys ENGINE EAPs/LAPs “AIR”$GAME AND INFRASTRUCTURE Unions “GROUND”$GAME 30,000+ Monthly CANNOT1,000+ Calls BE / AAC Chats REPLICATED Sites 6-8 Admissions Admissions WITHOUT / /Mon
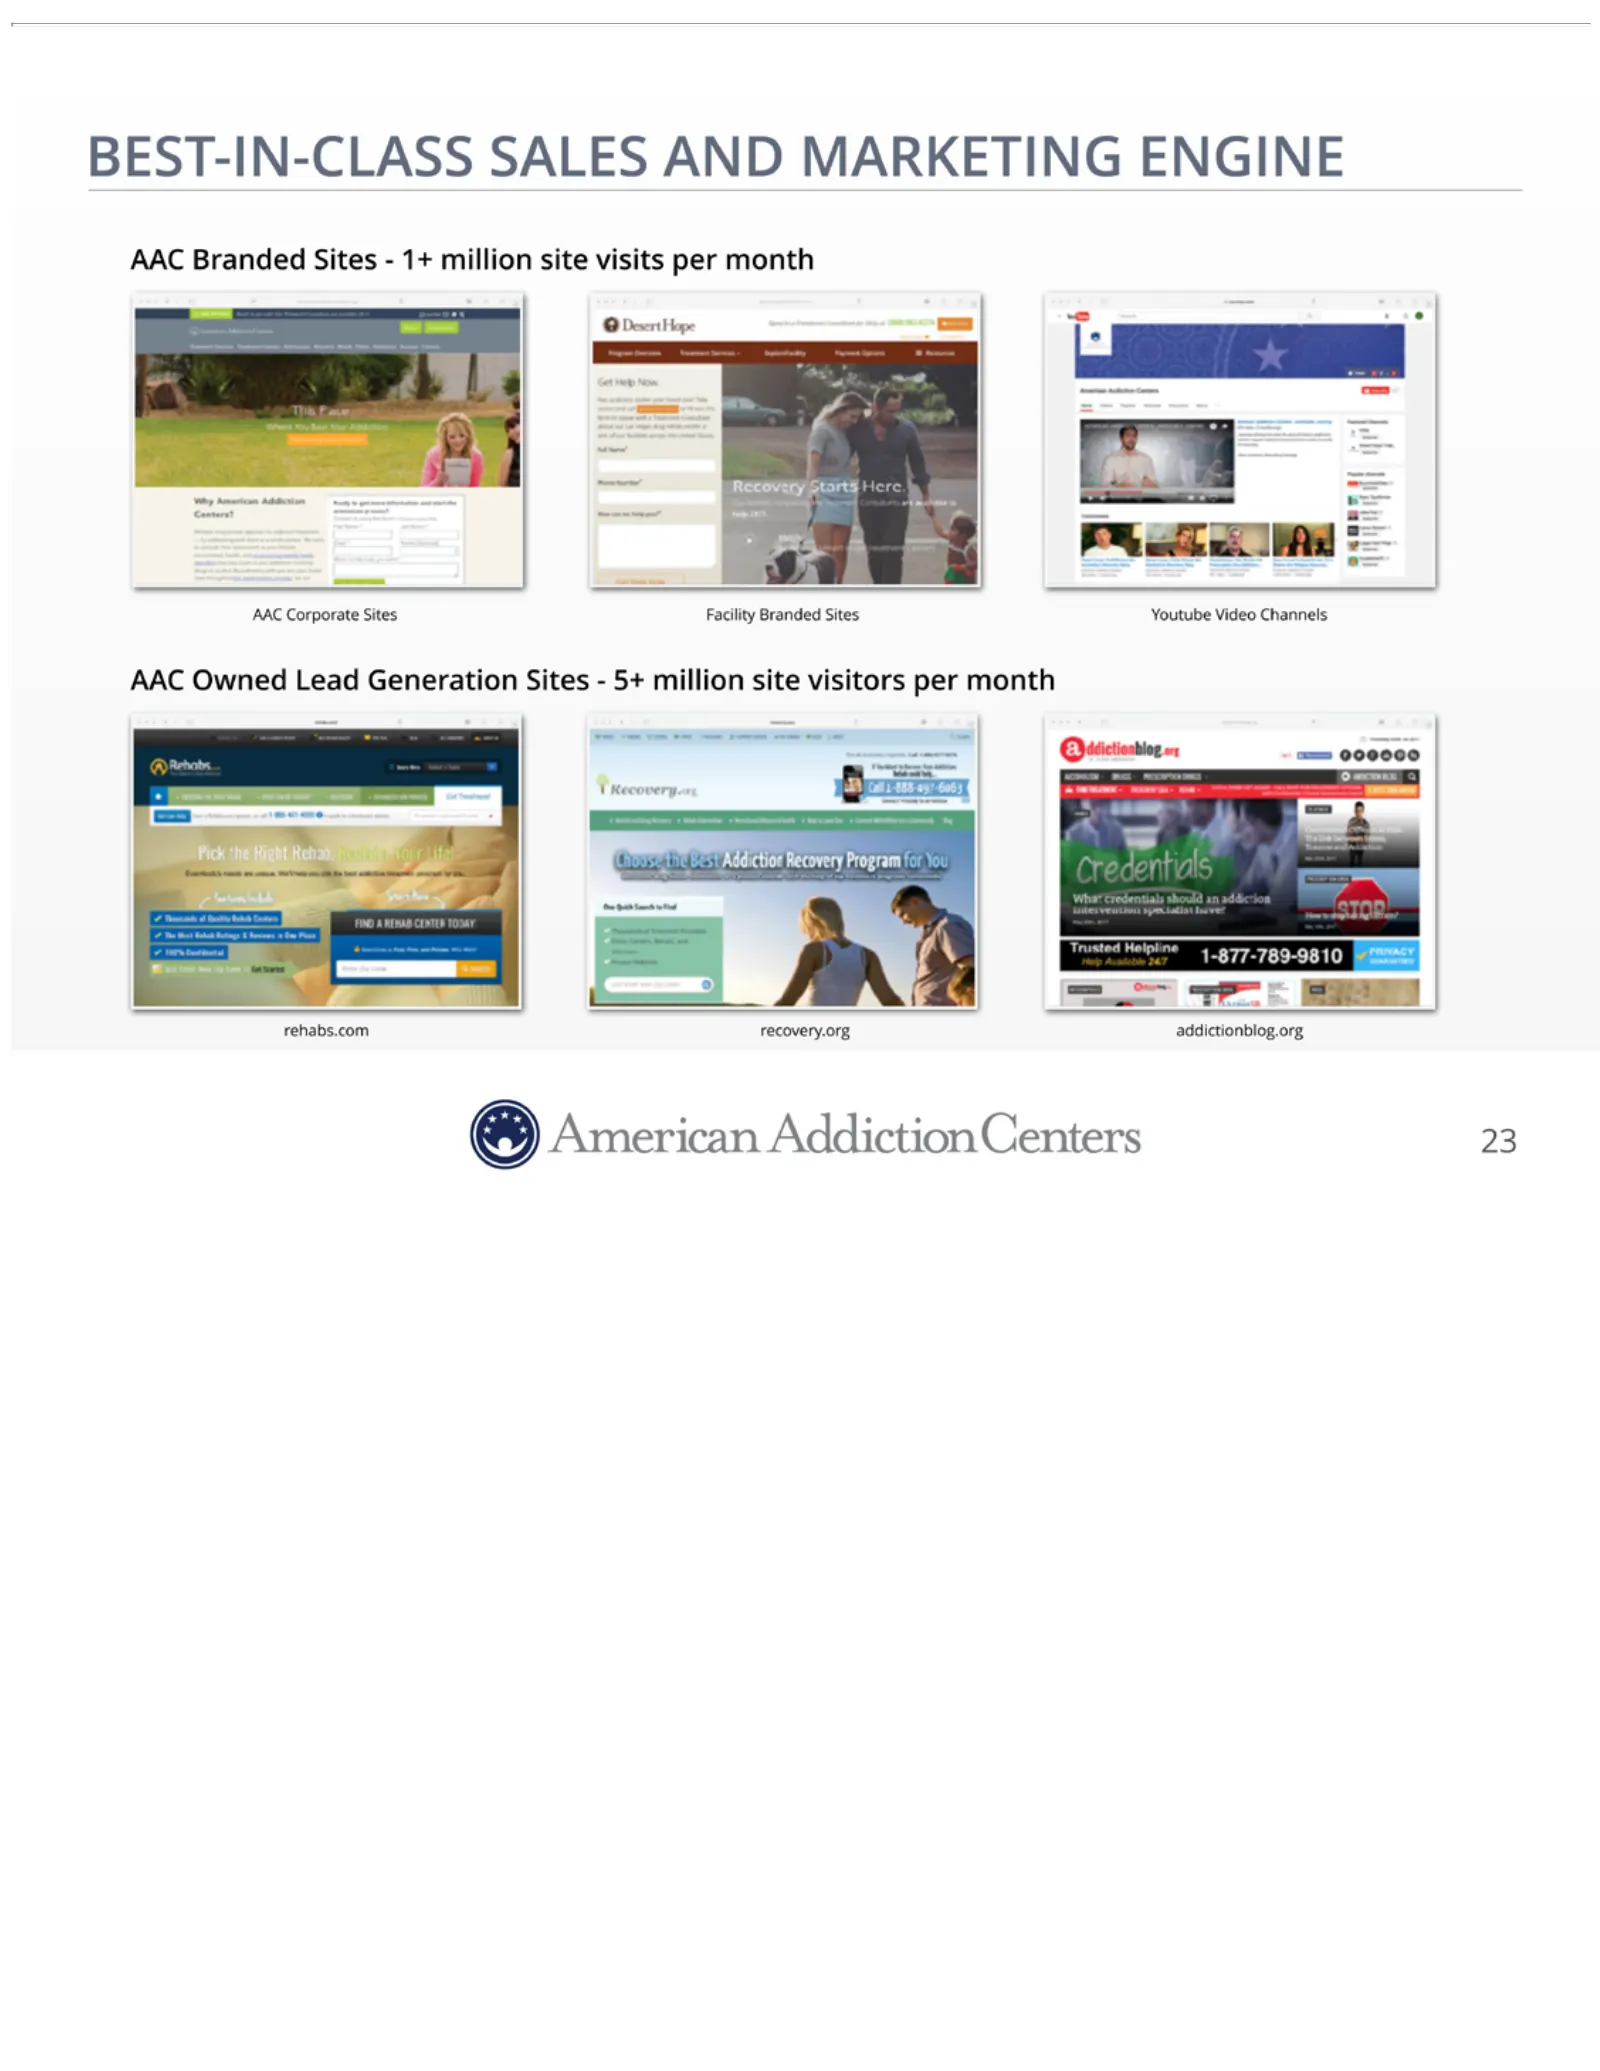
Slide 23: Best-in-Class Sales and Marketing Engine
BEST-IN-CLASS recovery.org addictionblog.org SALES AND MARKETING 23 ENGINE AAC Branded Sites—1+ million site visits per month AAC Corporate Sites Facility Branded Sites Youtube Video Channels AAC Owned Lead Generation Sites—5+ million site visitors per month rehabs.com
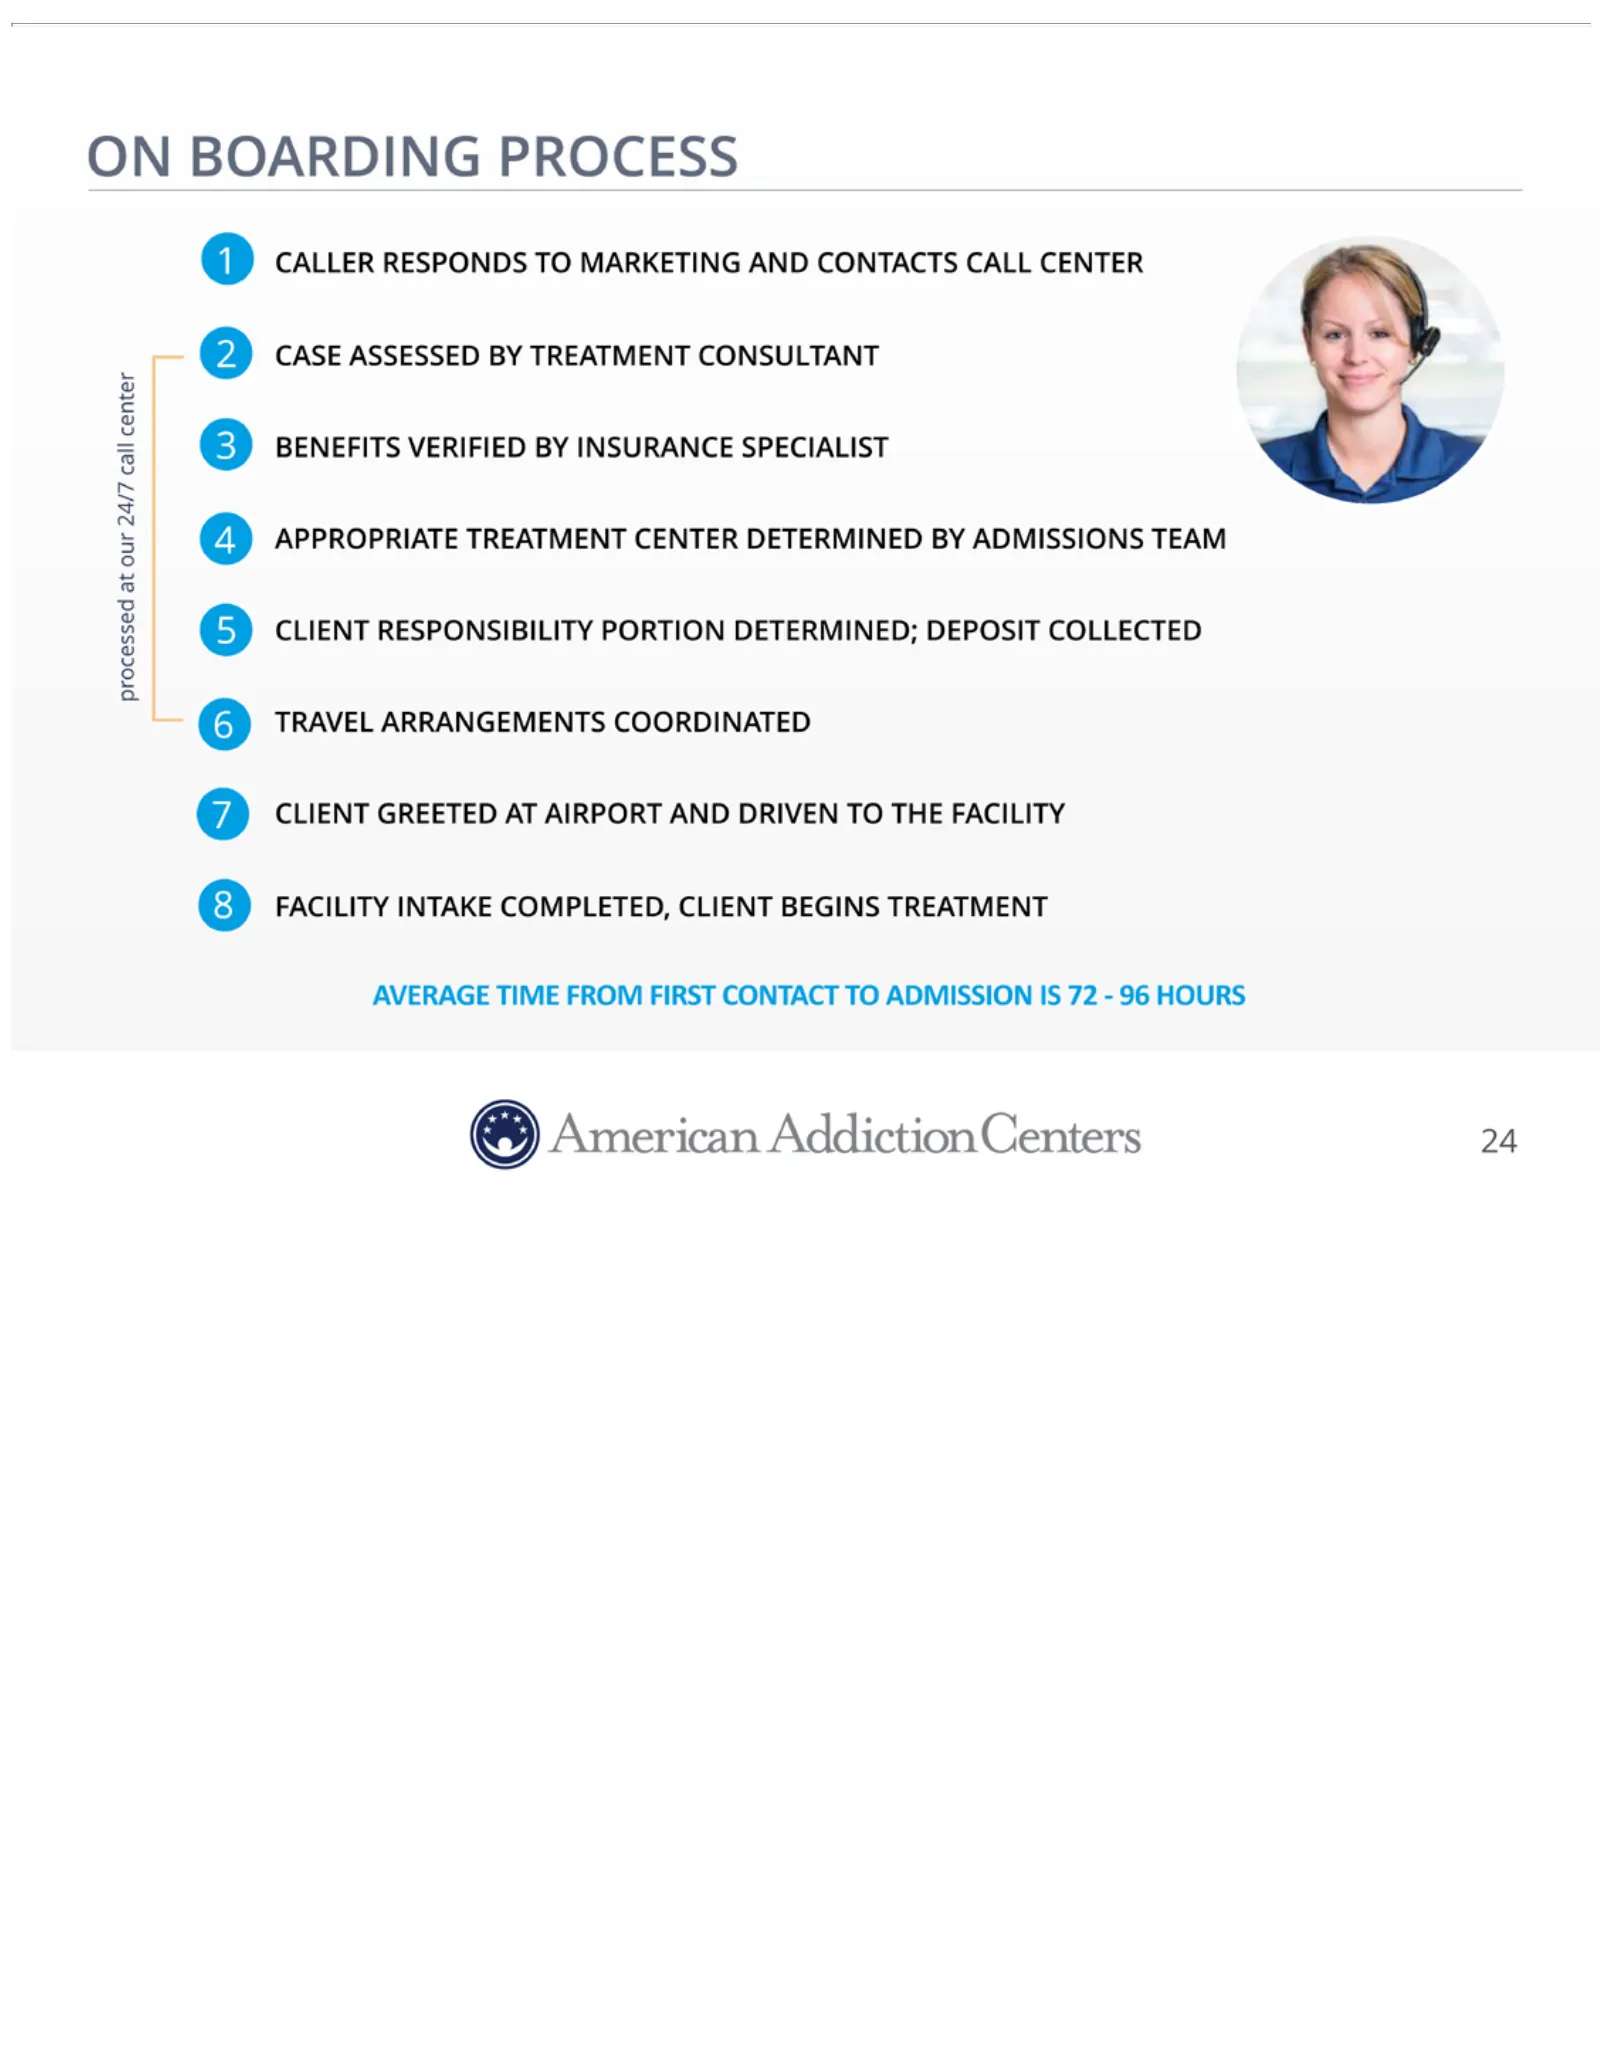
Slide 24: Onboarding Process
ON BOARDING TREATMENT DRIVEN TO THE CENTER PROCESS FACILITY DETERMINED 1 8CALLER FACILITY BY RESPONDS ADMISSIONS INTAKE COMPLETED, TO MARKETING TEAM at CLIENT processed AND BEGINS CONTACTS 5 CLIENT TREATMENT CALL RESPONSIBILITY CENTER AVERAGE$TIME$FROM$FIRST$CONTACT$TO$ADMISSION$IS$72$-$96$HOURS 2 P
Slide 25: Strong National Demand for Services
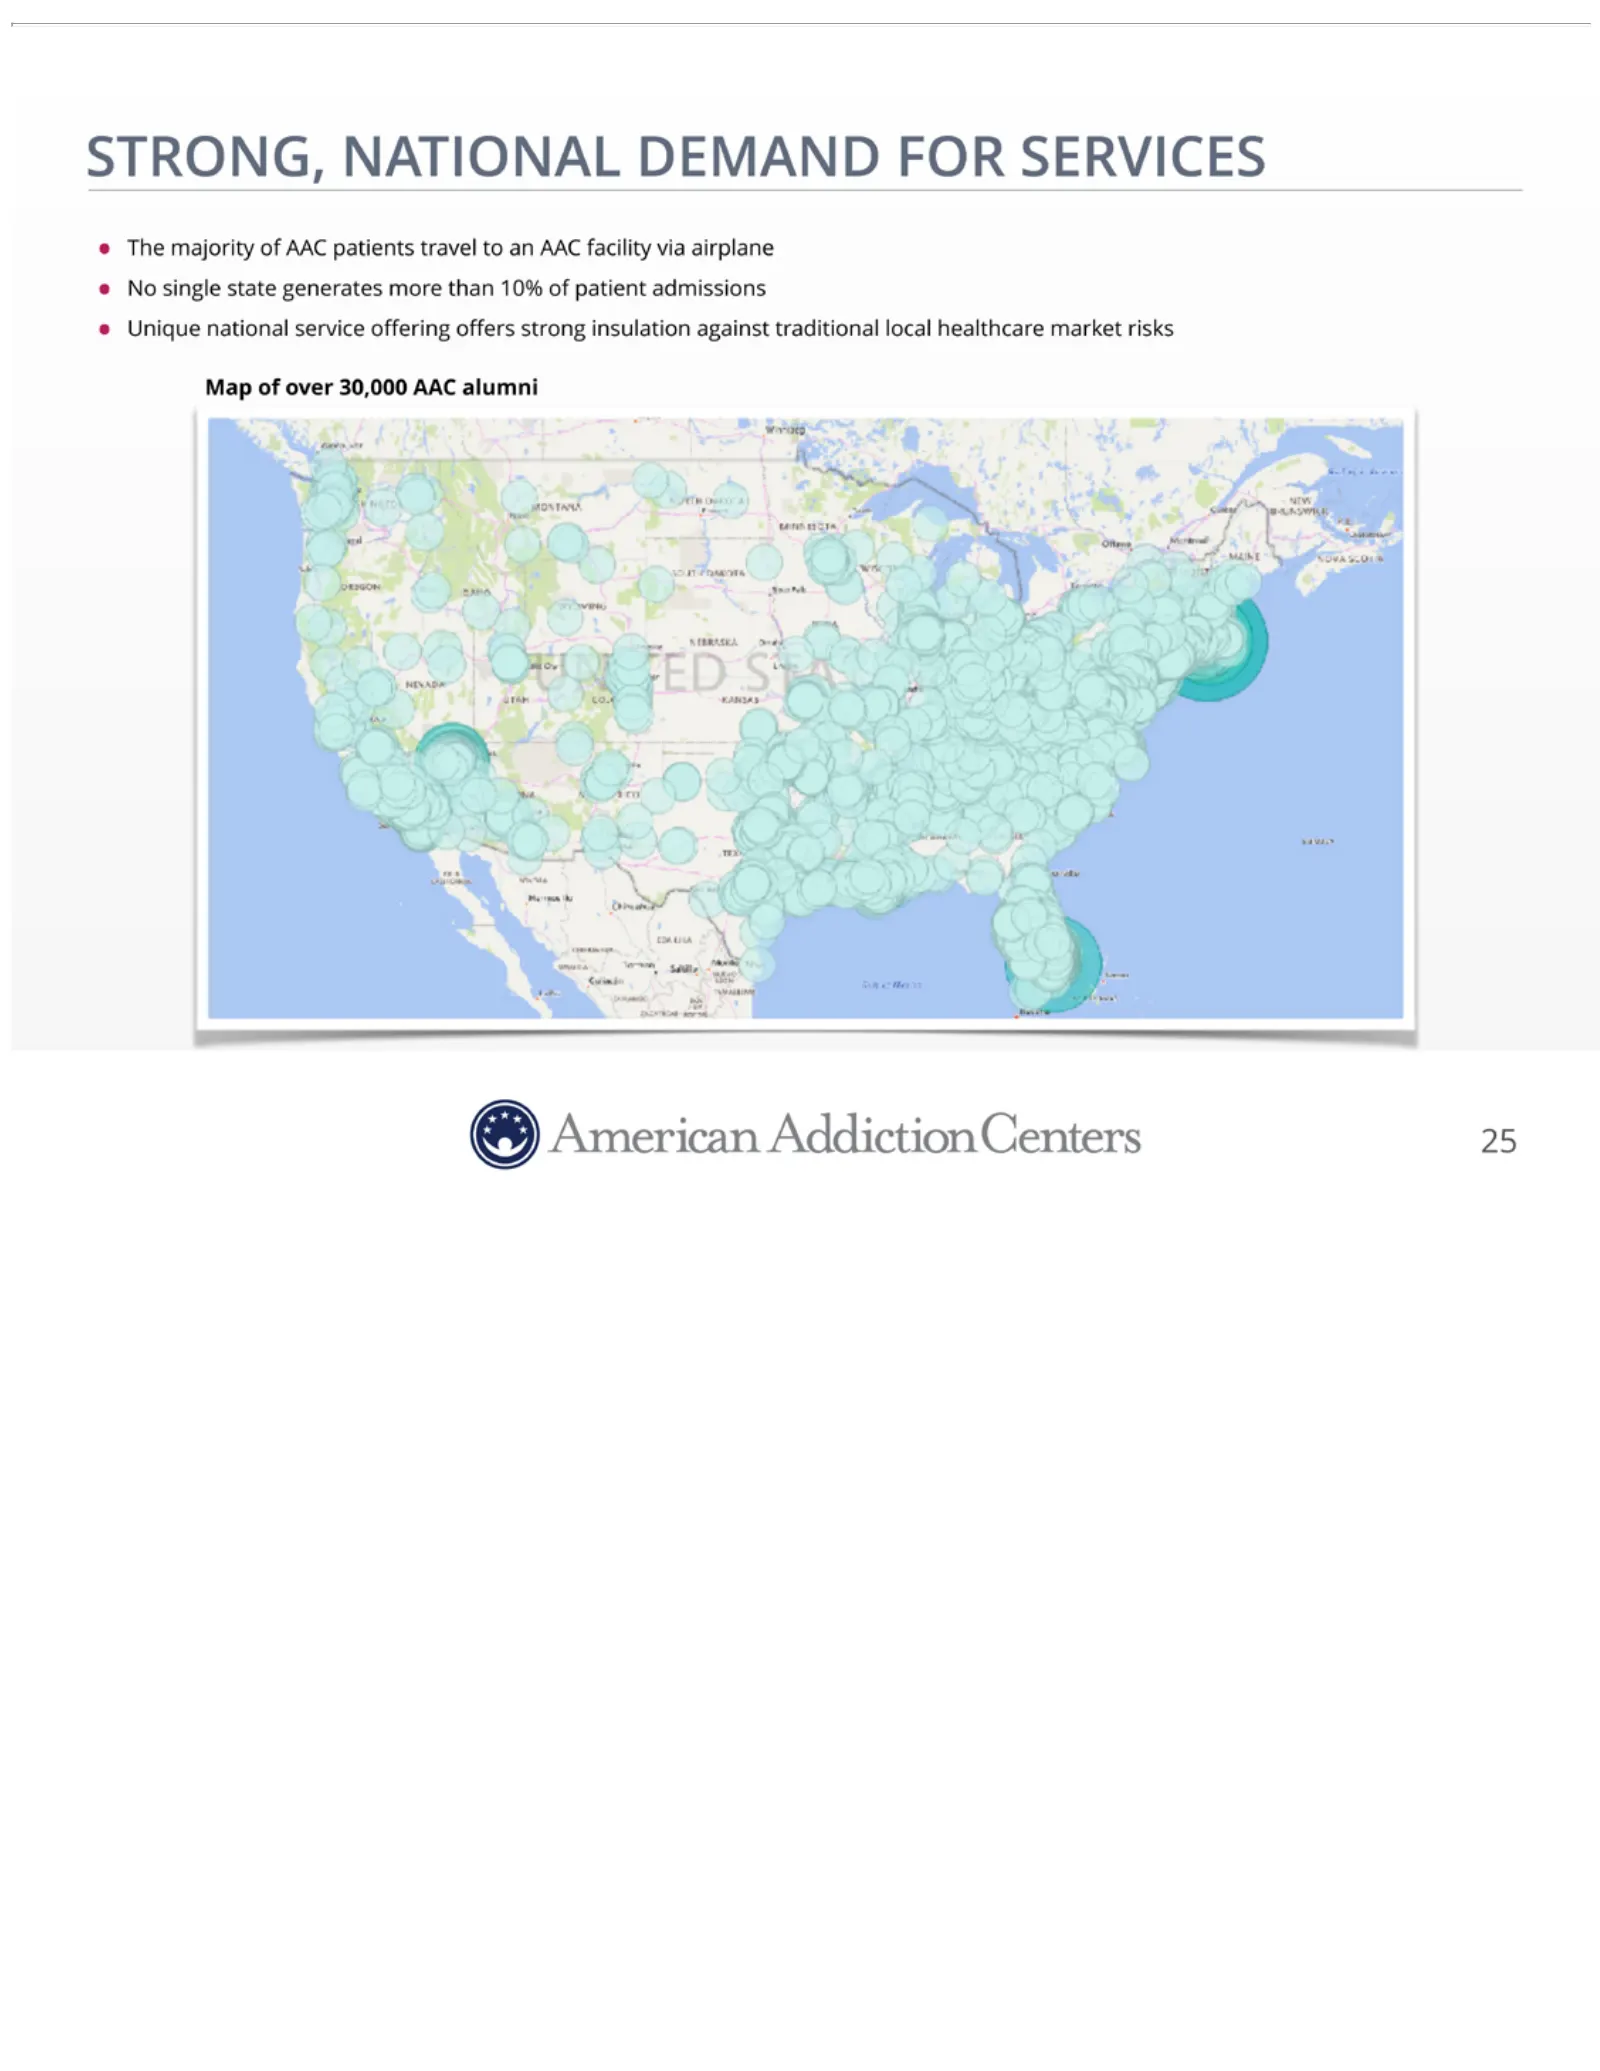
STRONG, market healthcare NATIONAL risks DEMAND Map of over FOR30,000 SERVICES AAC alumni • The majority 25 of AAC patients travel to an AAC facility via airplane • No single state generates more than 10% of patient admissions • Unique national service offering offers strong insulation against tradi
Slide 26: Demographics 2016 Admissions
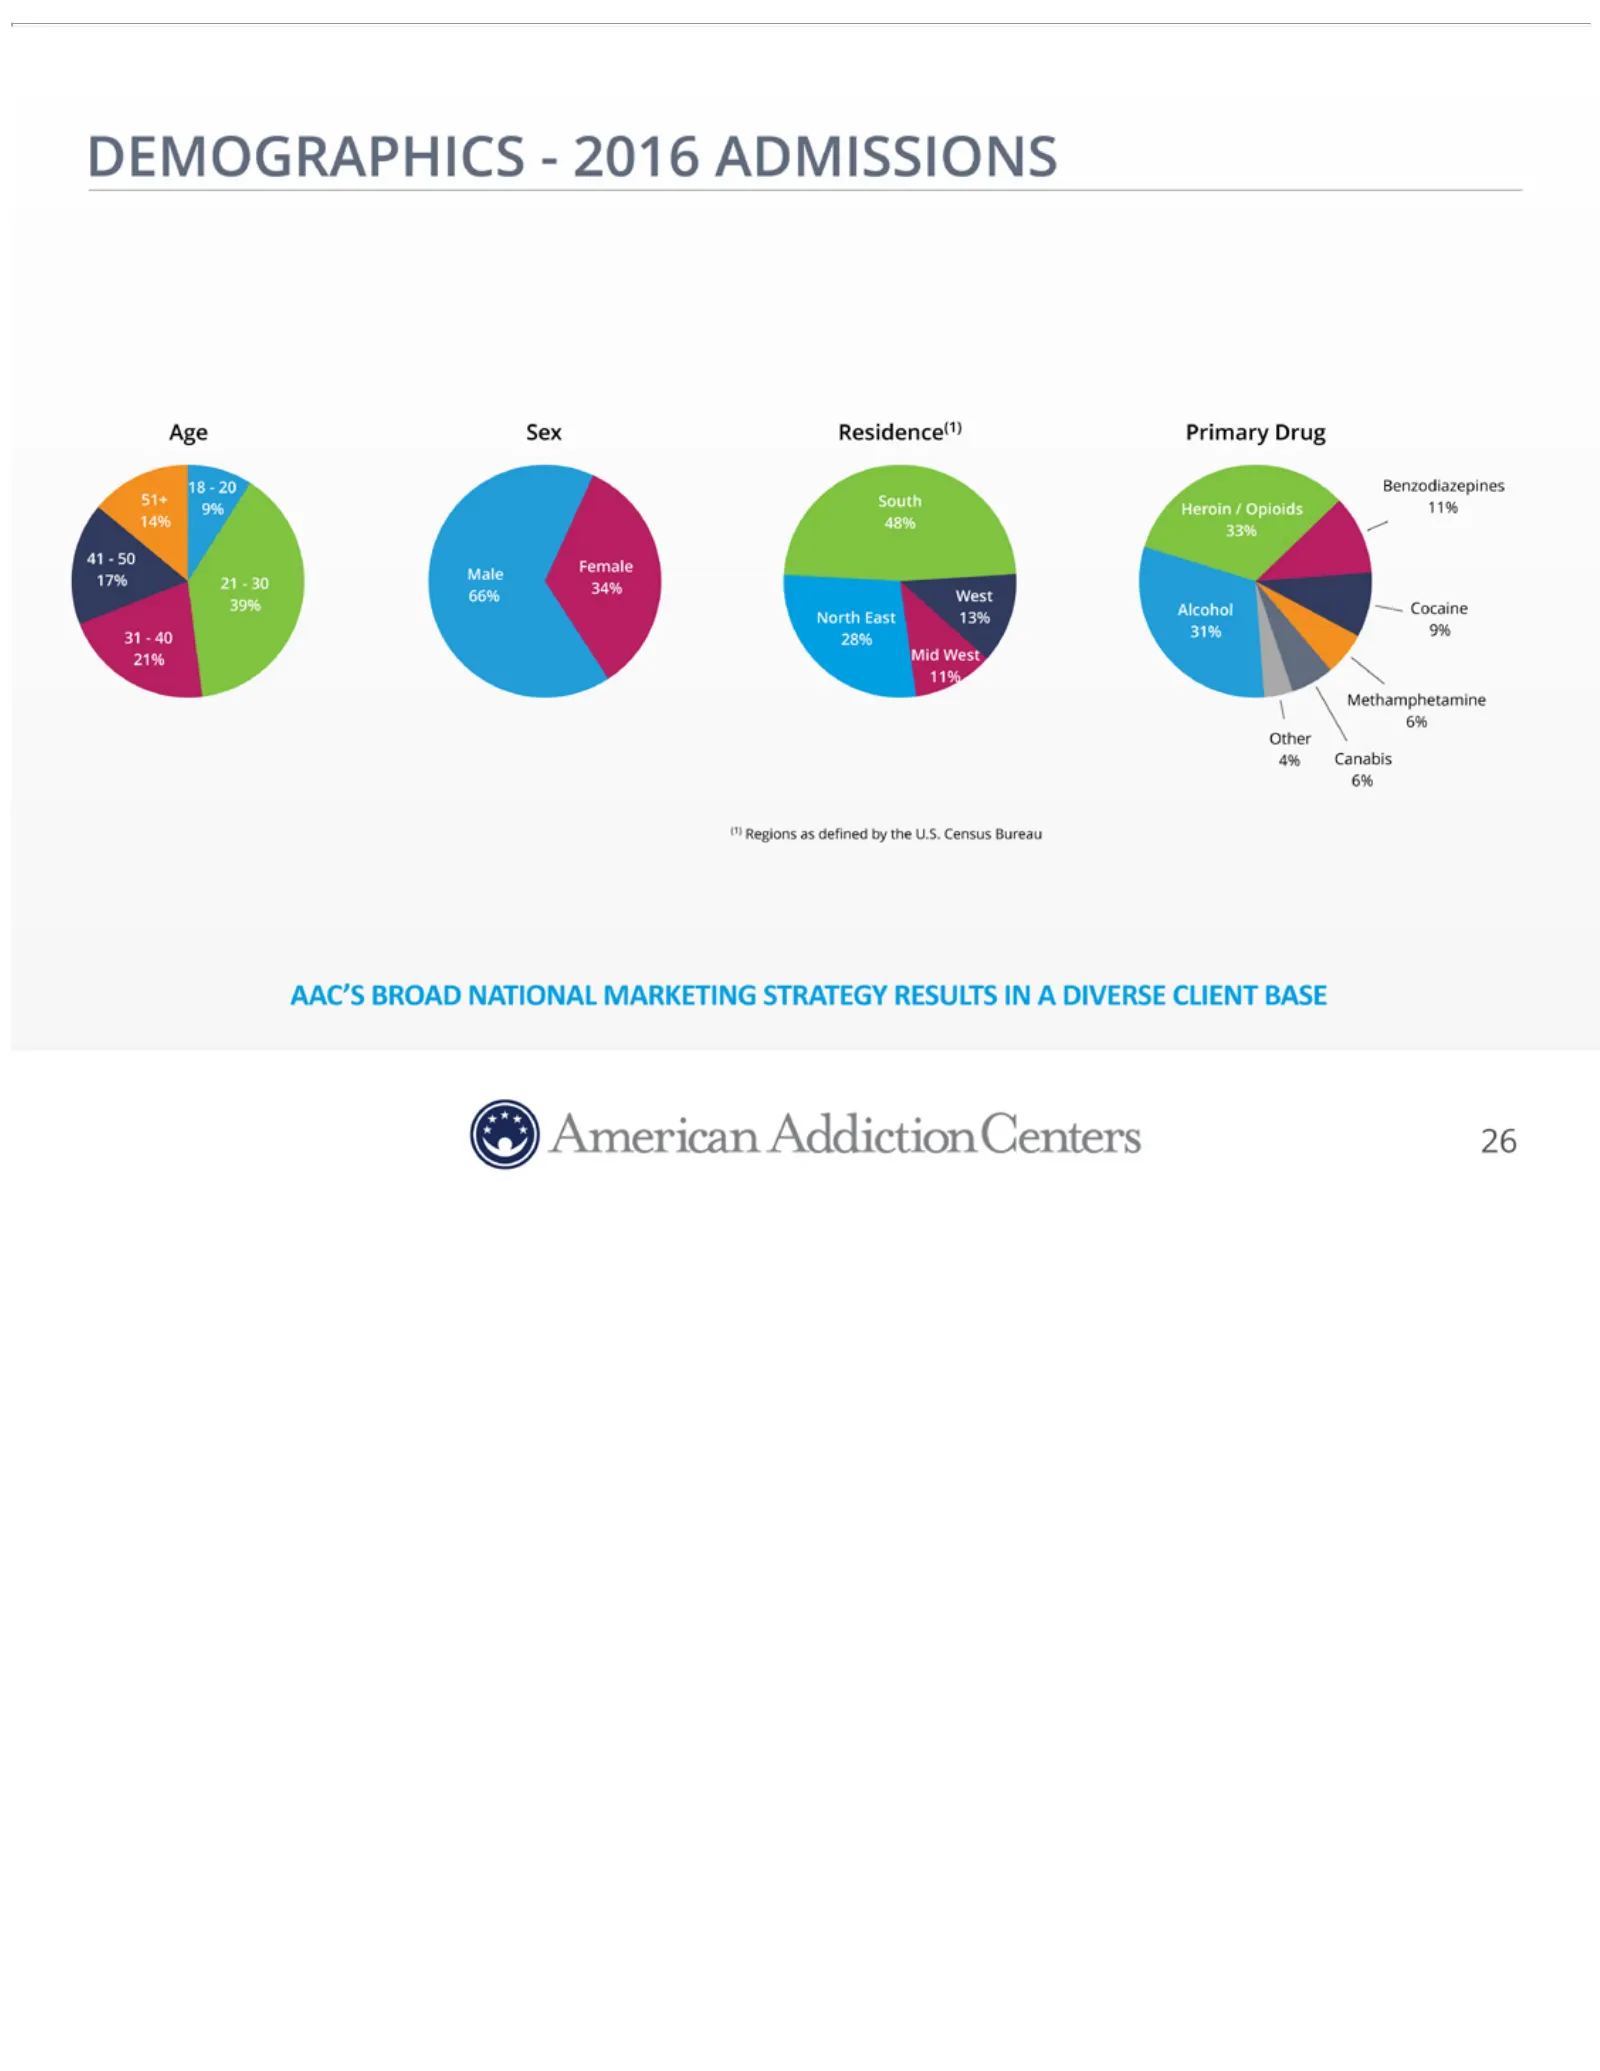
DEMOGRAPHICS—2016 9% 21% Mid West 11% Methamphetamine ADMISSIONS Age 6%Sex Other Residence(1) 4% Canabis18—20 6% (1) RegionsBenzodiazepines as defined by the51+ U.S.9% Census South Bureau Heroin AAC’S / Opioids BROAD11% NATIONAL 14% 48% 33% MARKETING 41—50 Female STRATEGY 17% 21—30 RESULTS MaleIN 34
Slide 27: Proven Improvement in Patient Outcomes
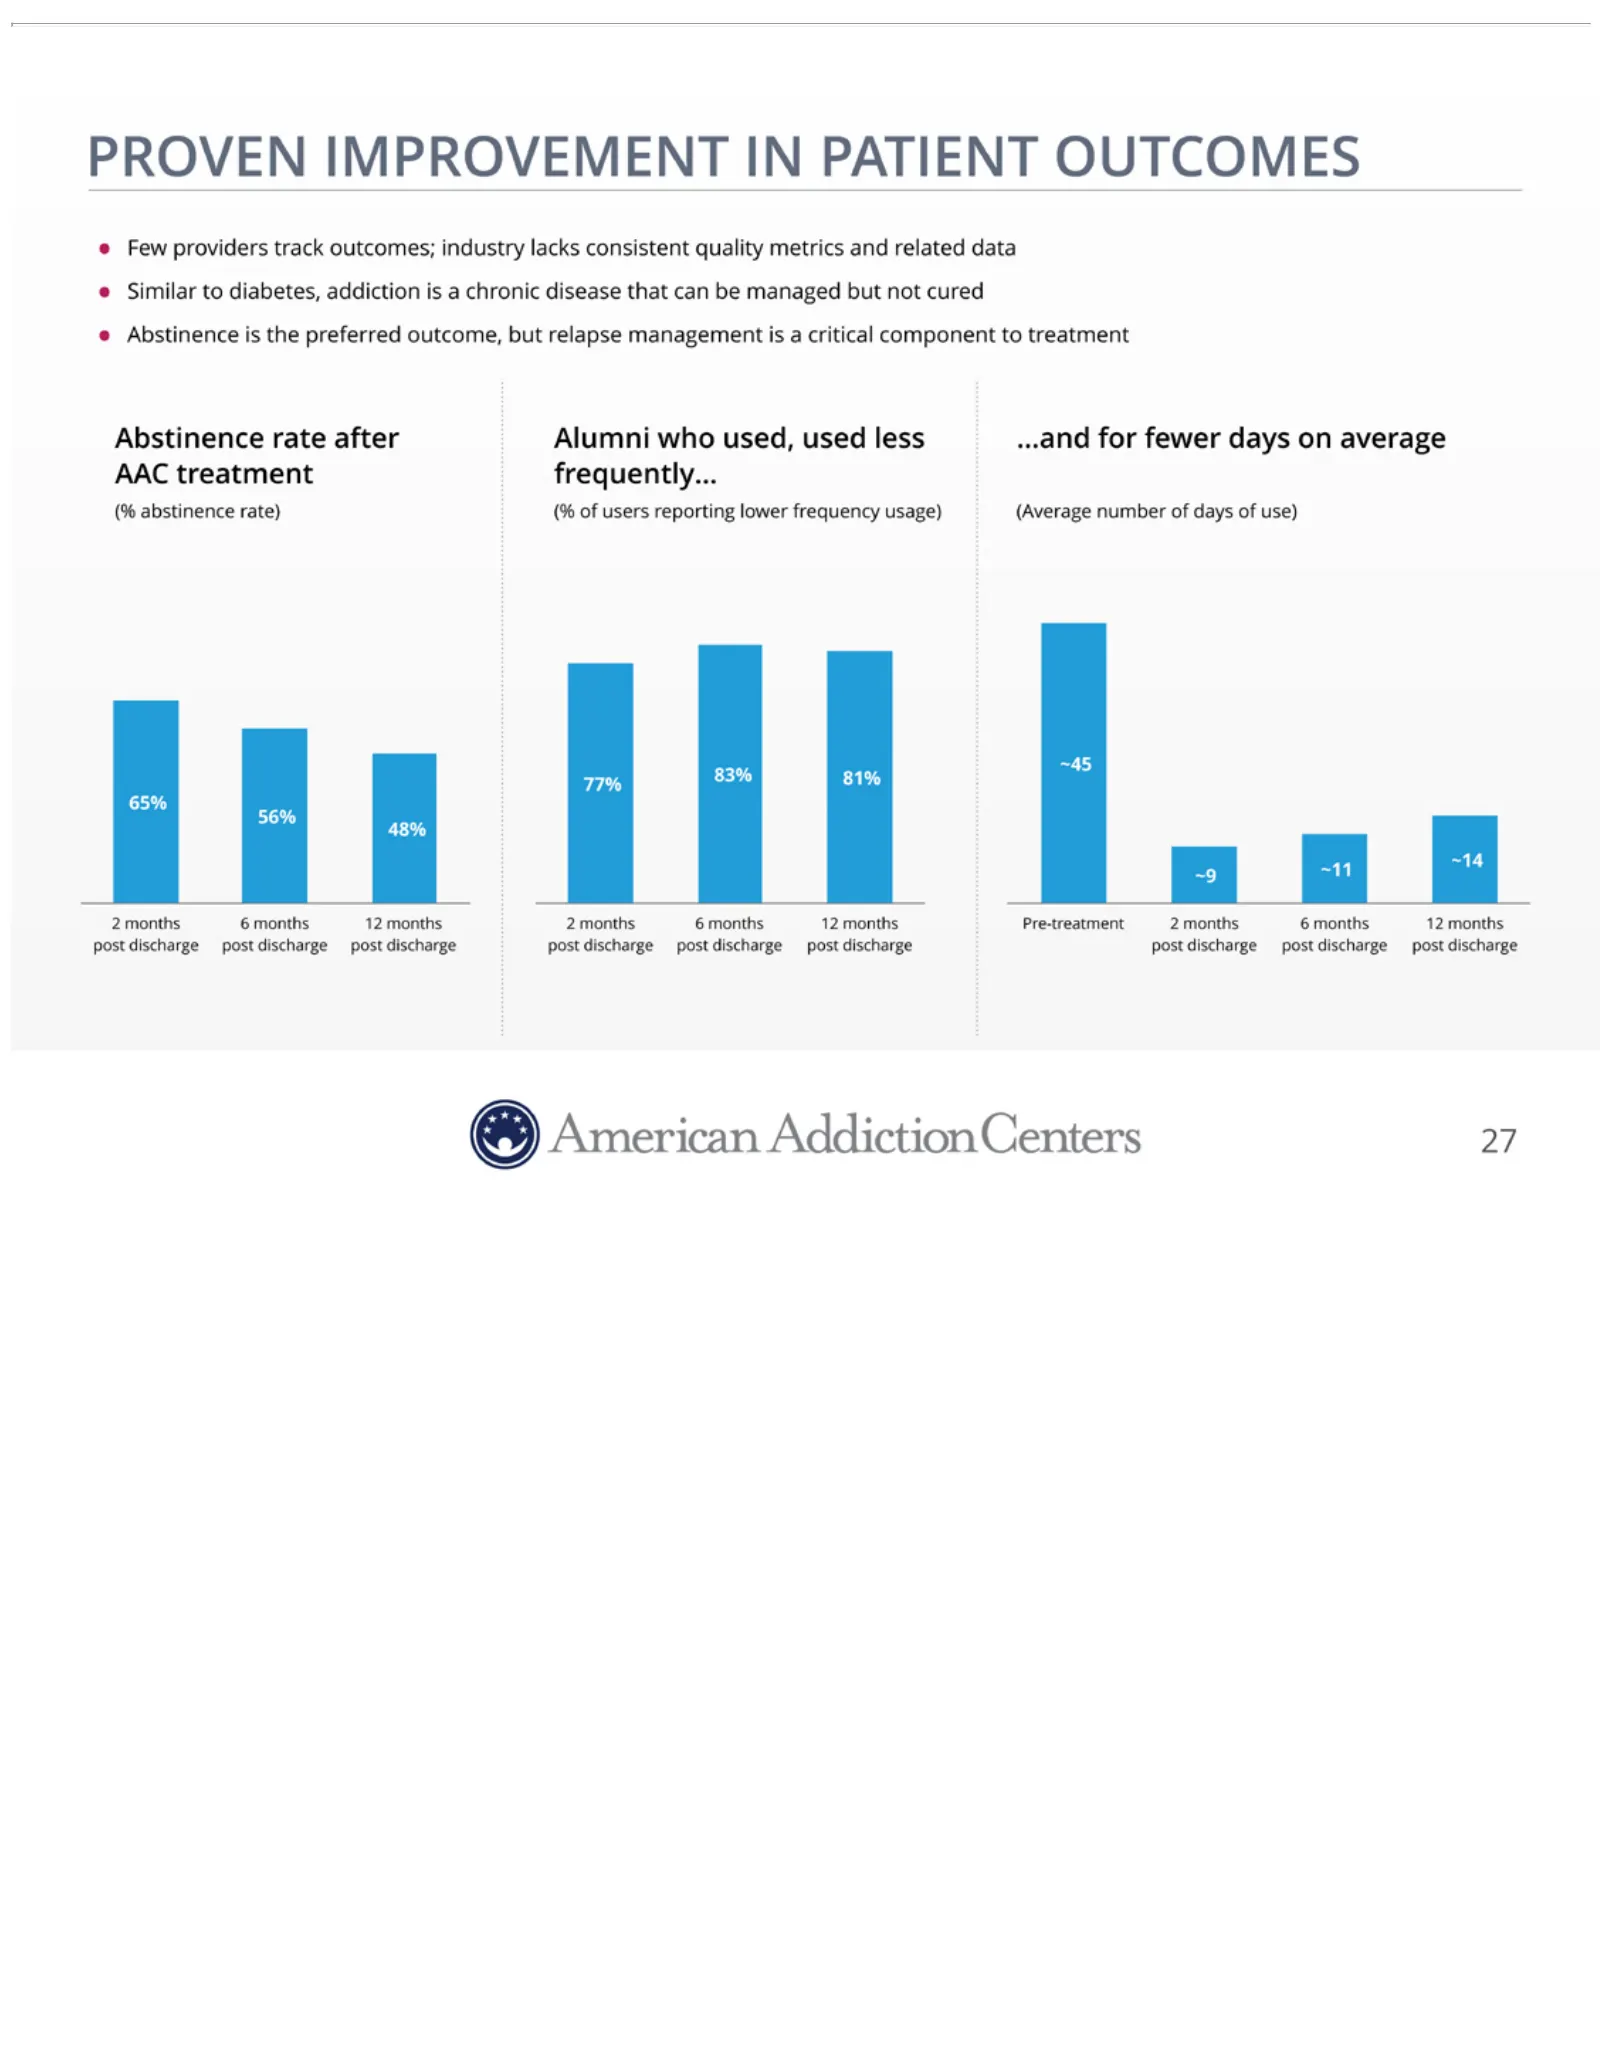
PROVEN but of discharge use) relapsepost IMPROVEMENT management discharge 77% 83% is post a81% critical IN discharge ~45 PATIENT component 65% postOUTCOMES discharge to treatment 56%• 48% FewAbstinence providers 27 ~9 track rate~11 after outcomes; ~14Alumni 2 months industry who6used, months lacks u
Slide 28: Experienced Management Team
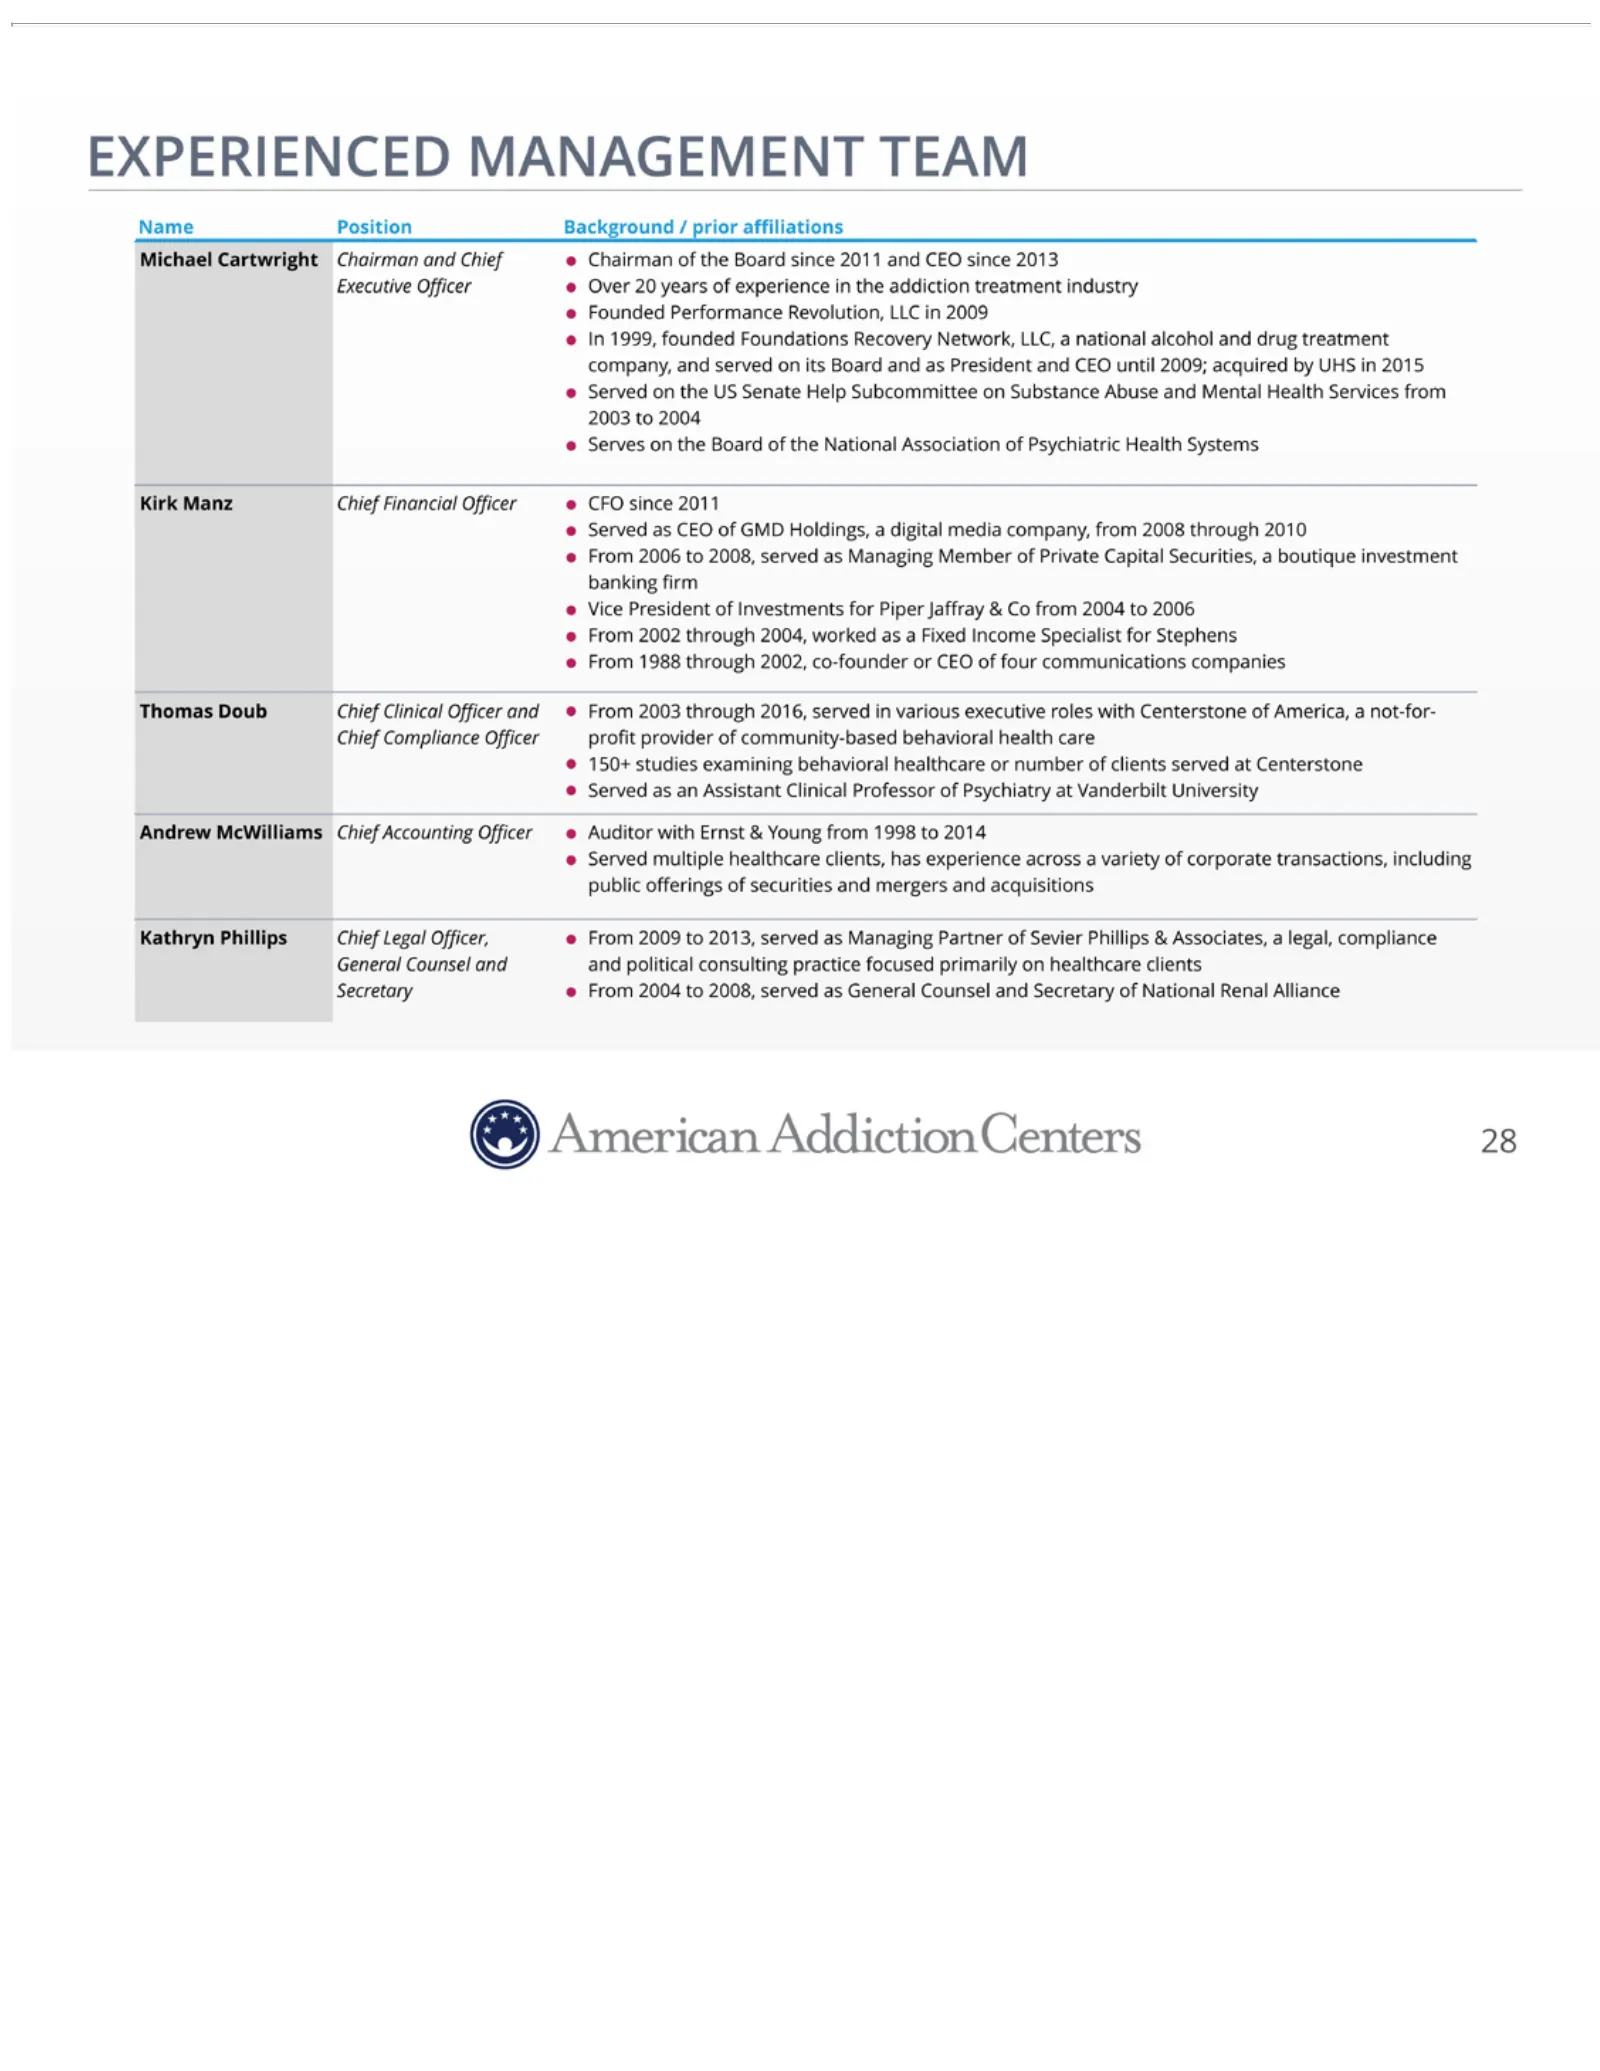
EXPERIENCED Founded Subcommittee company, Income Officer Accounting 2009 Renalto Alliance profit Specialist 2013, Performance from Officer provider served on 28 2008 MANAGEMENT Substance for • through Auditor as Stephens Revolution, ofManaging community-based Abuse 2010 with • From Ernst Partner LLC
Slide 29: Key Credit Strengths
KEY CREDIT platform with significant STRENGTHS operating 1 Growing leveragemarket 5 Proven with treatment significantoutcomes unmet need6 and Strong highfree costcash to society flow generation 2 Significant 7 Highly near-term attractive embedded real estate growthandfrom significant completed colla
Slide 30: Desert Hope Business Overview
DESERT HOPE BUSINESS OVERVIEW 30
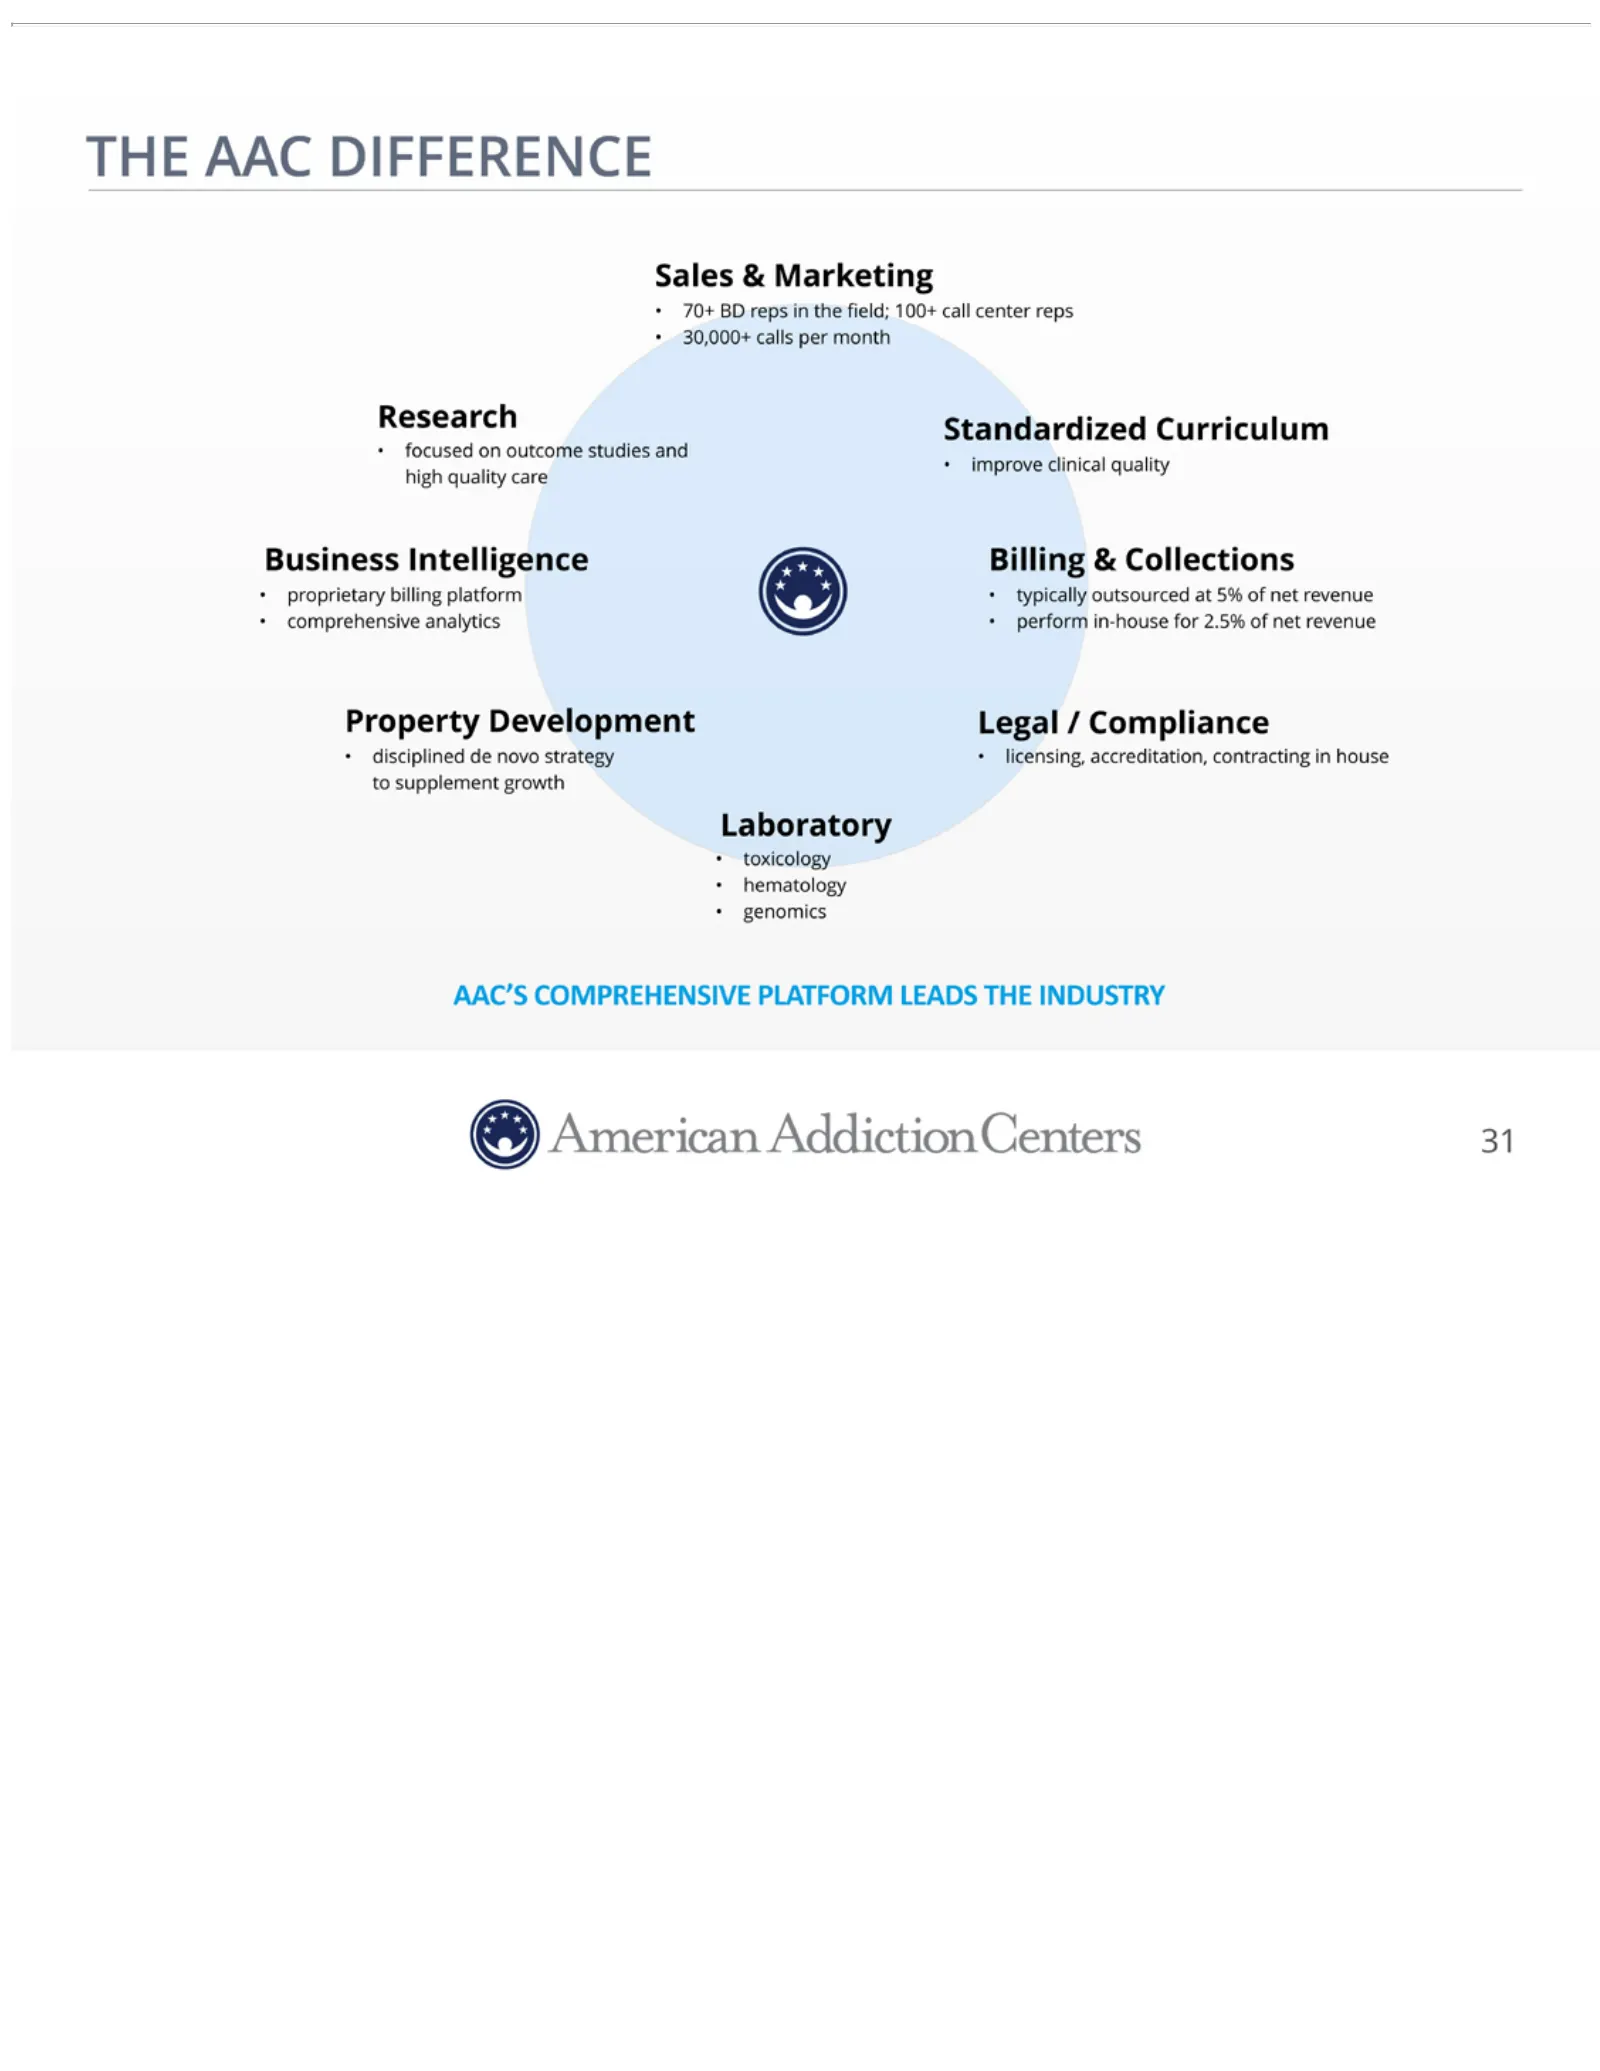
Slide 31: The AAC Difference
THE AAC DIFFERENCE Intelligence accreditation, Billing contracting & Collections in house Sales •toproprietary supplement & Marketing billing growthplatform • 70+ BD• typically reps Laboratory in the outsourced ?eld; 100+at•call 5% toxicology center of net reps revenue • 30,000+ •• comprehensive hem
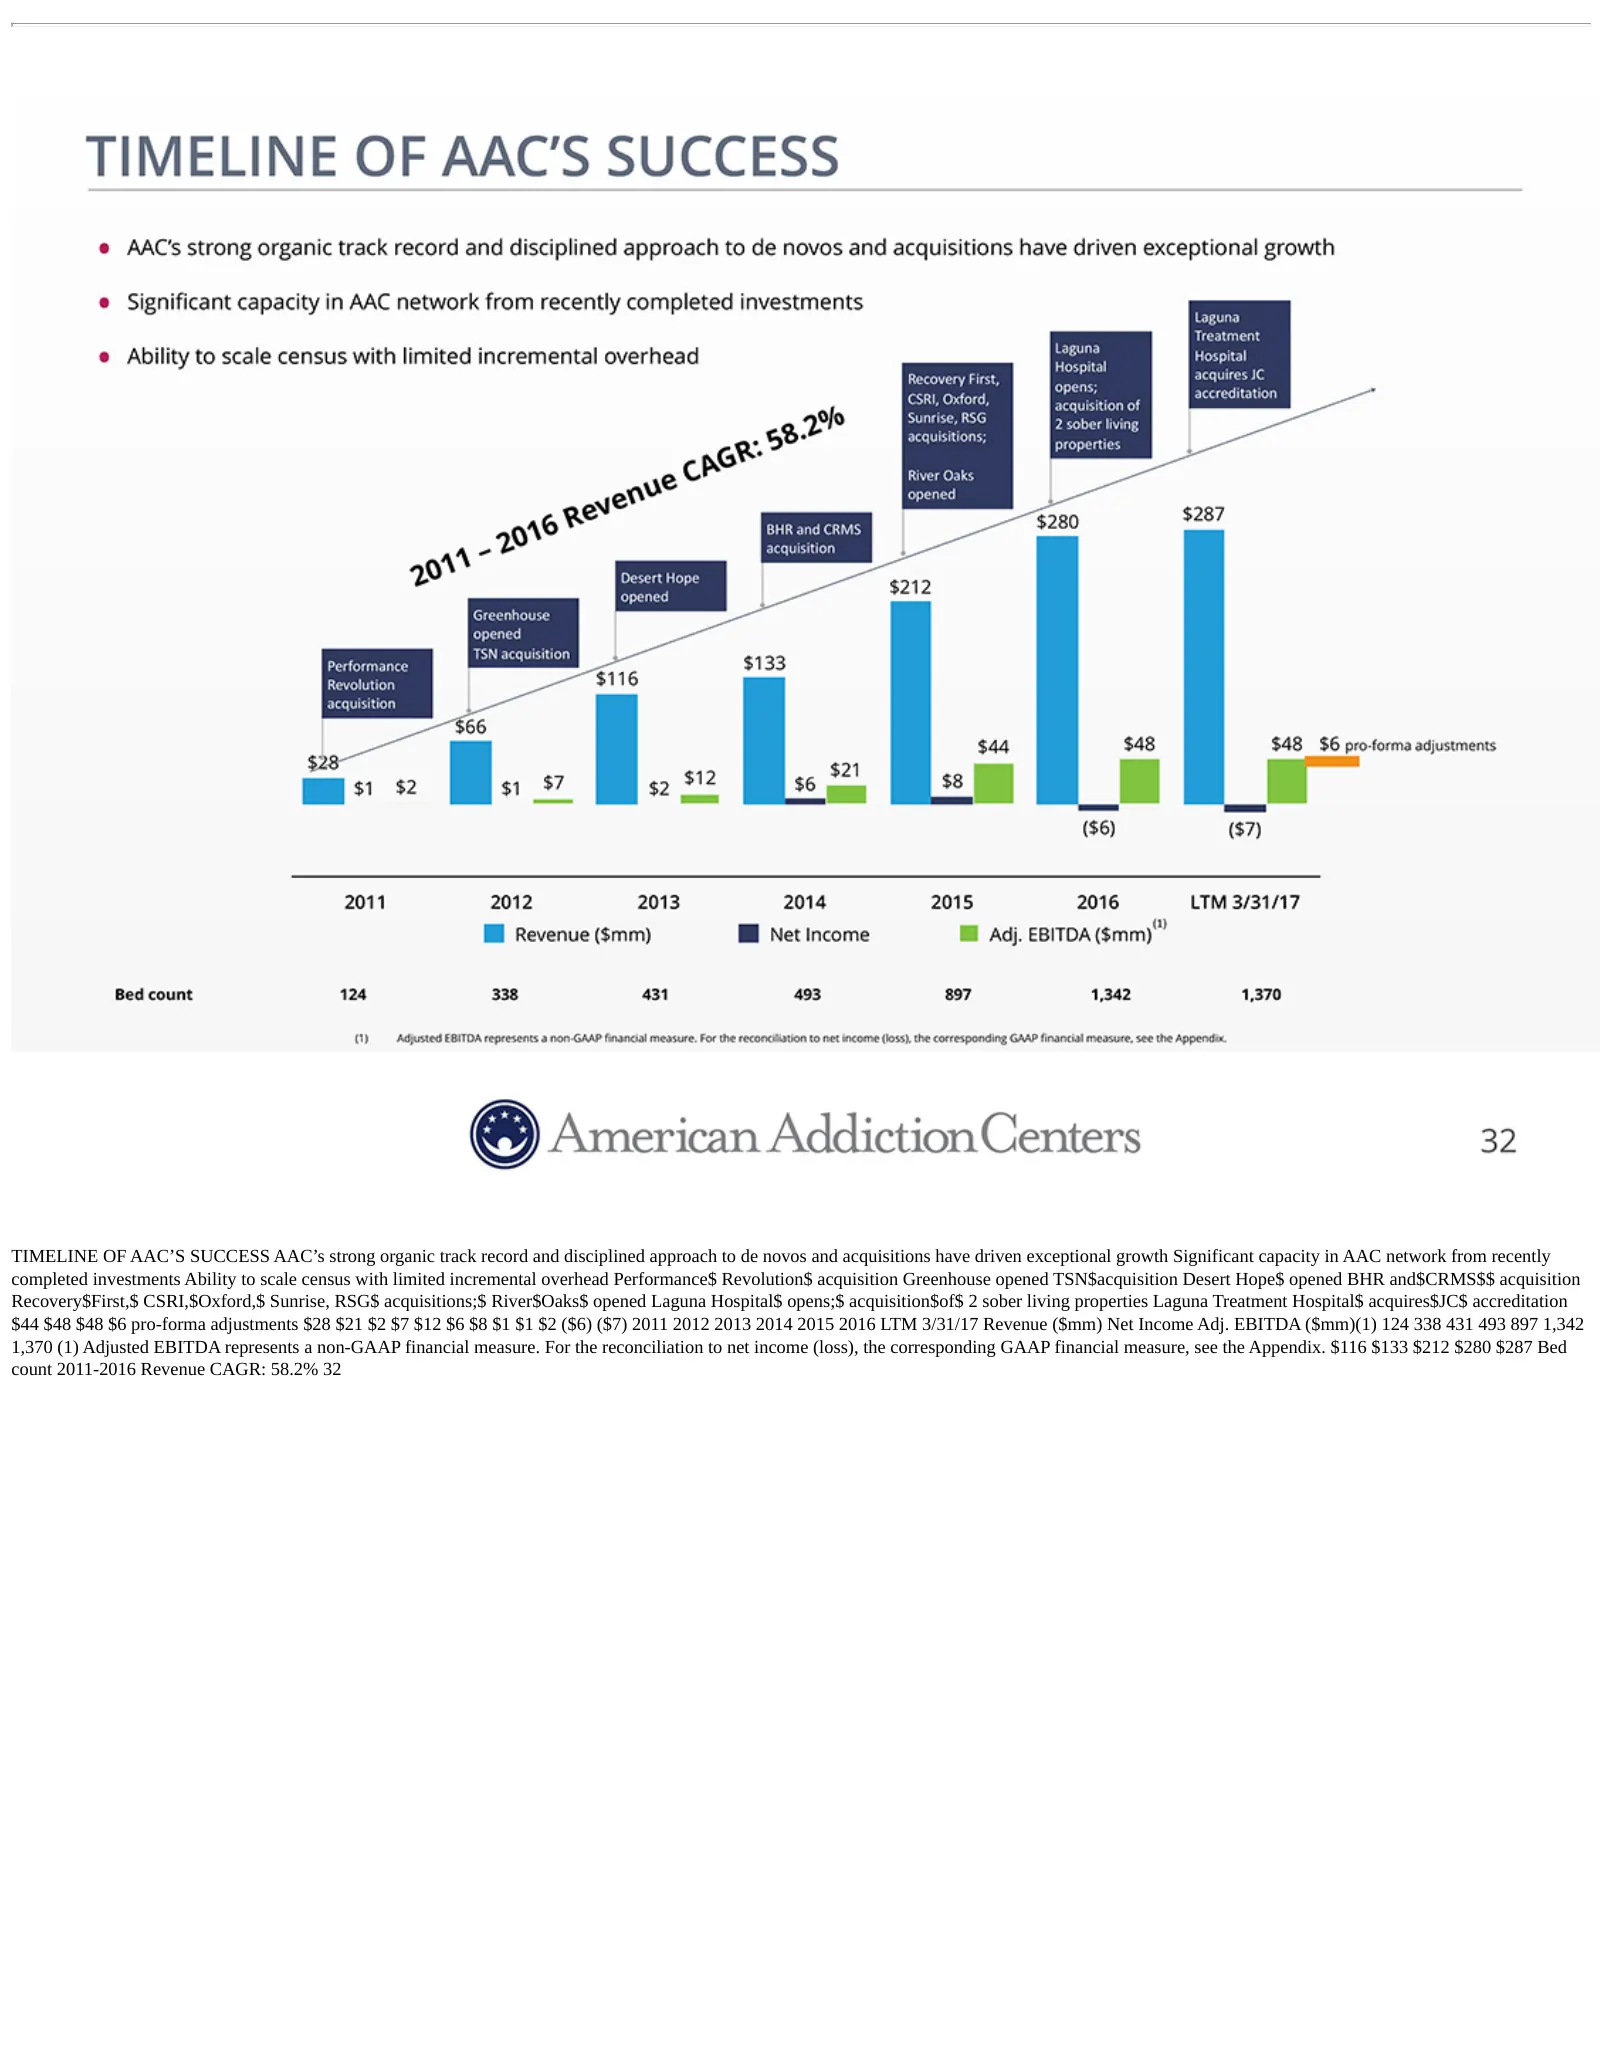
Slide 32: Timeline of AAC's Success
TIMELINE OF AAC’S SUCCESS AAC’s strong organic track record and disciplined approach to de novos and acquisitions have driven exceptional growth Significant capacity in AAC network from recently completed investments Ability to scale census with limited incremental overhead Performance$ Revolution$
Slide 33: De Novo River Oaks Analysis
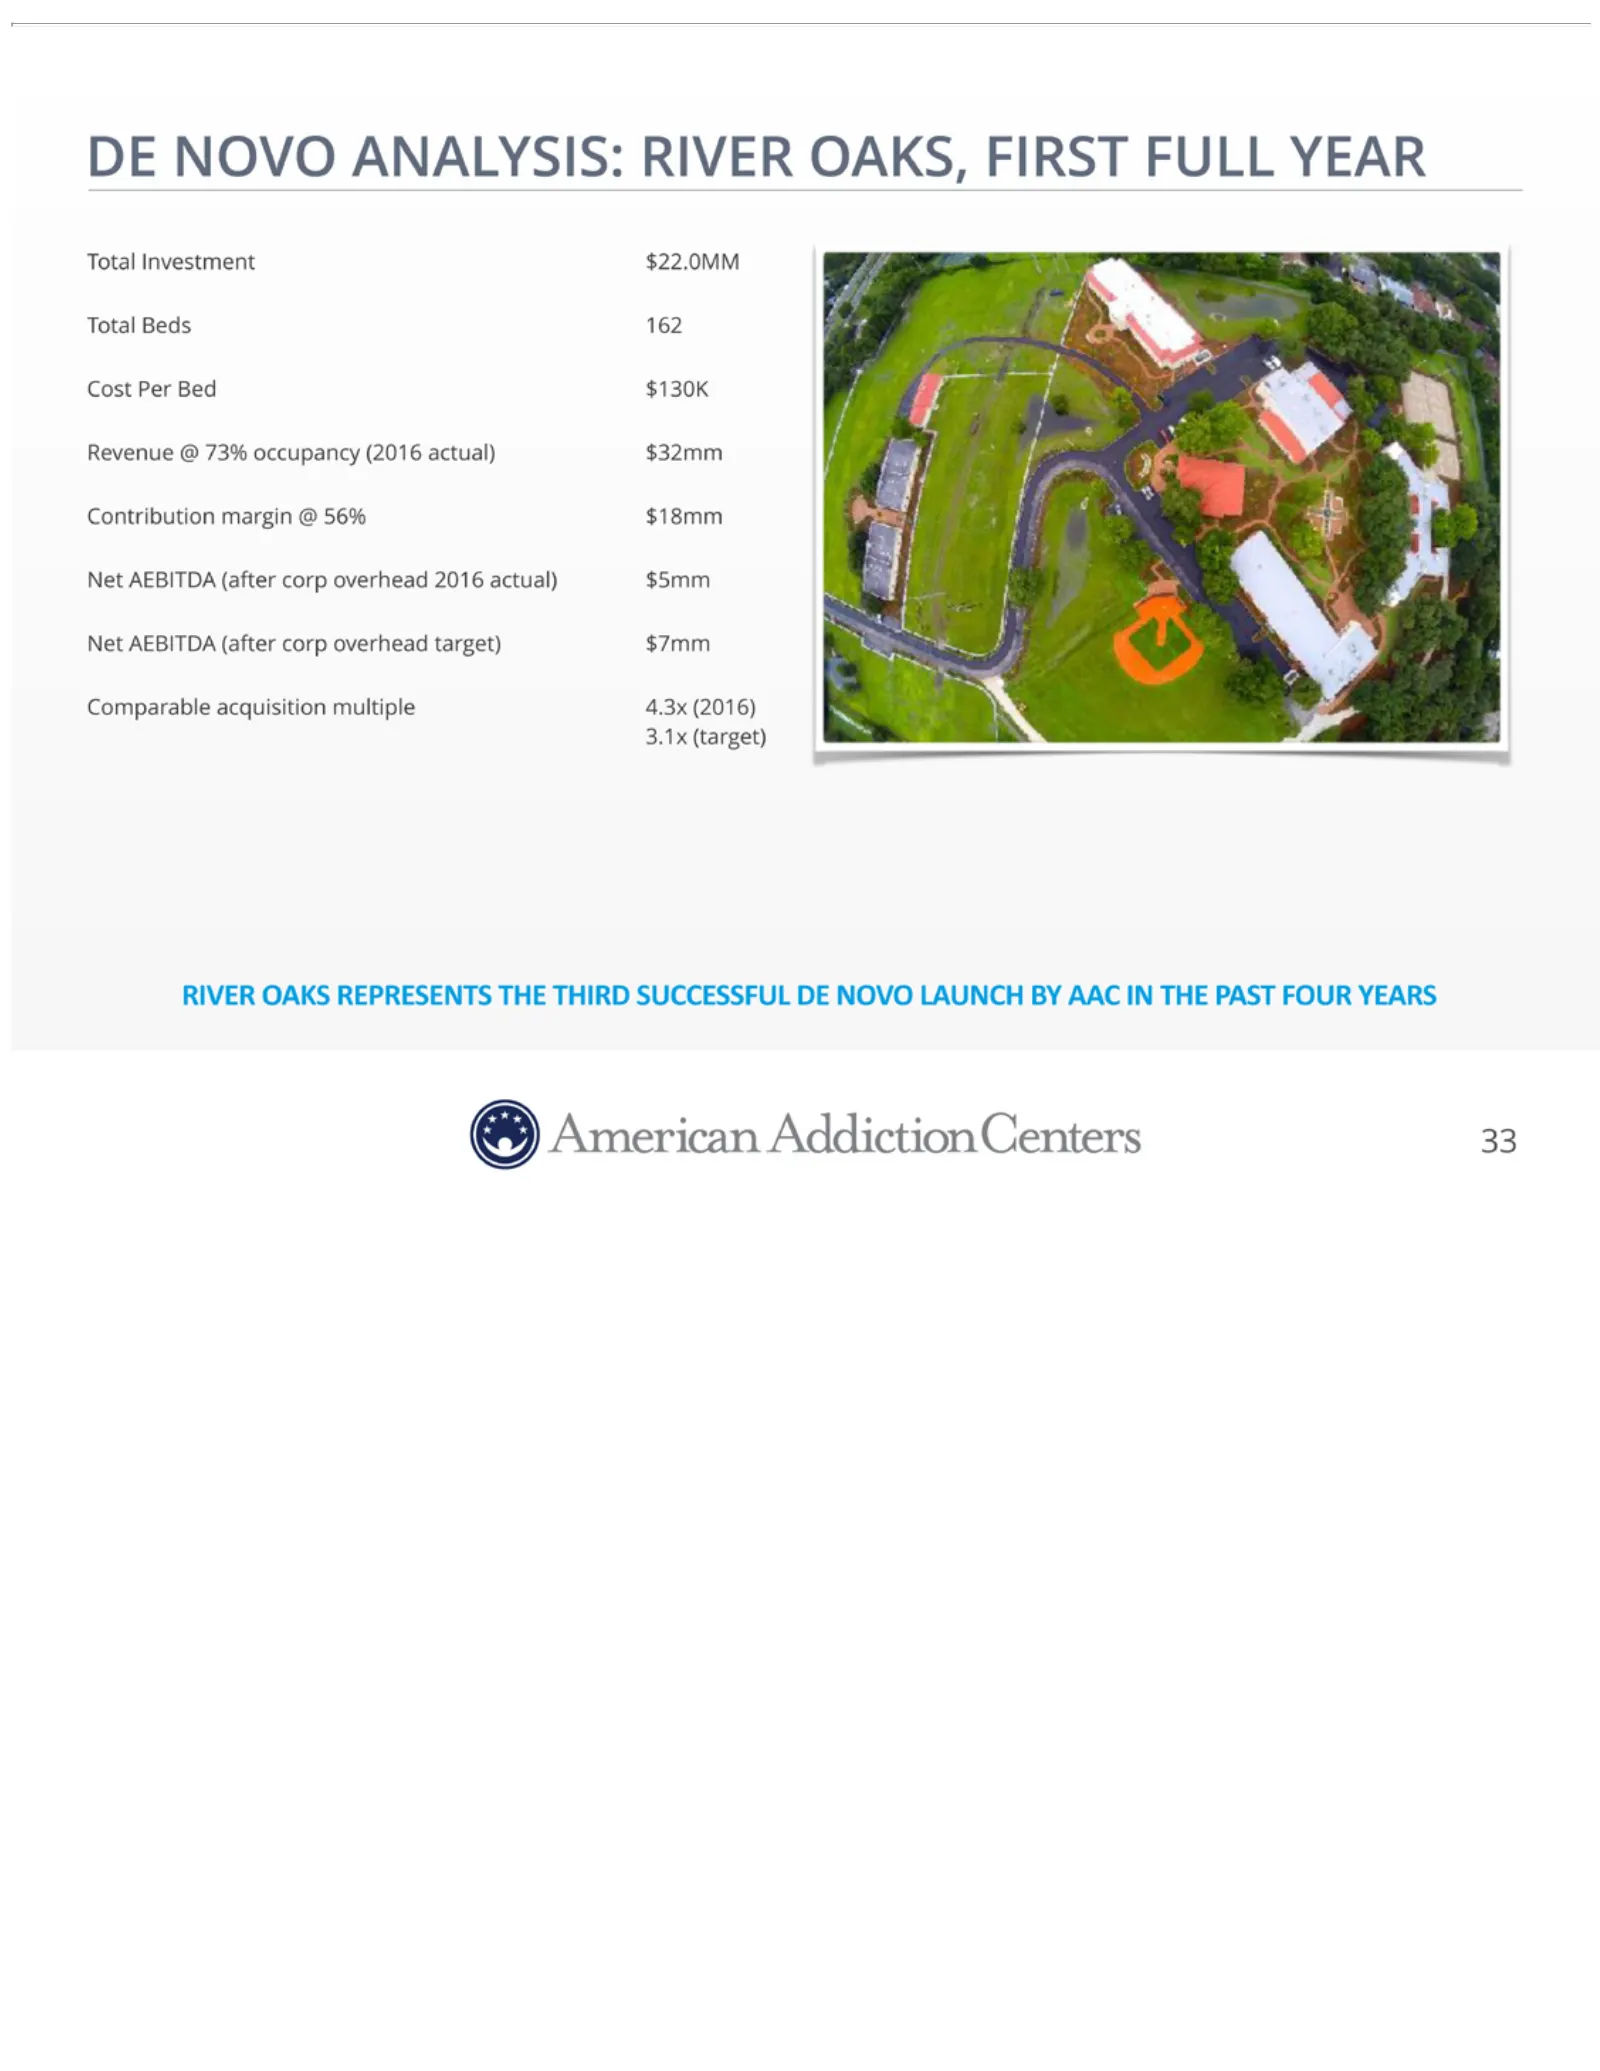
DE NOVO (after AEBITDA ANALYSIS: corp overhead RIVERtarget) OAKS,$7mm FIRST Comparable FULL YEARacquisition Total Investment multiple 4.3x $22.0MM (2016)Total 3.1xBeds (target) 162RIVER Cost Per OAKS Bed $130K REPRESENTS RevenueTHE @ 73% THIRD occupancy SUCCESSFUL (2016 actual) DE NOVO $32mmLAUNCH C
Slide 34: Diversified Payor Base
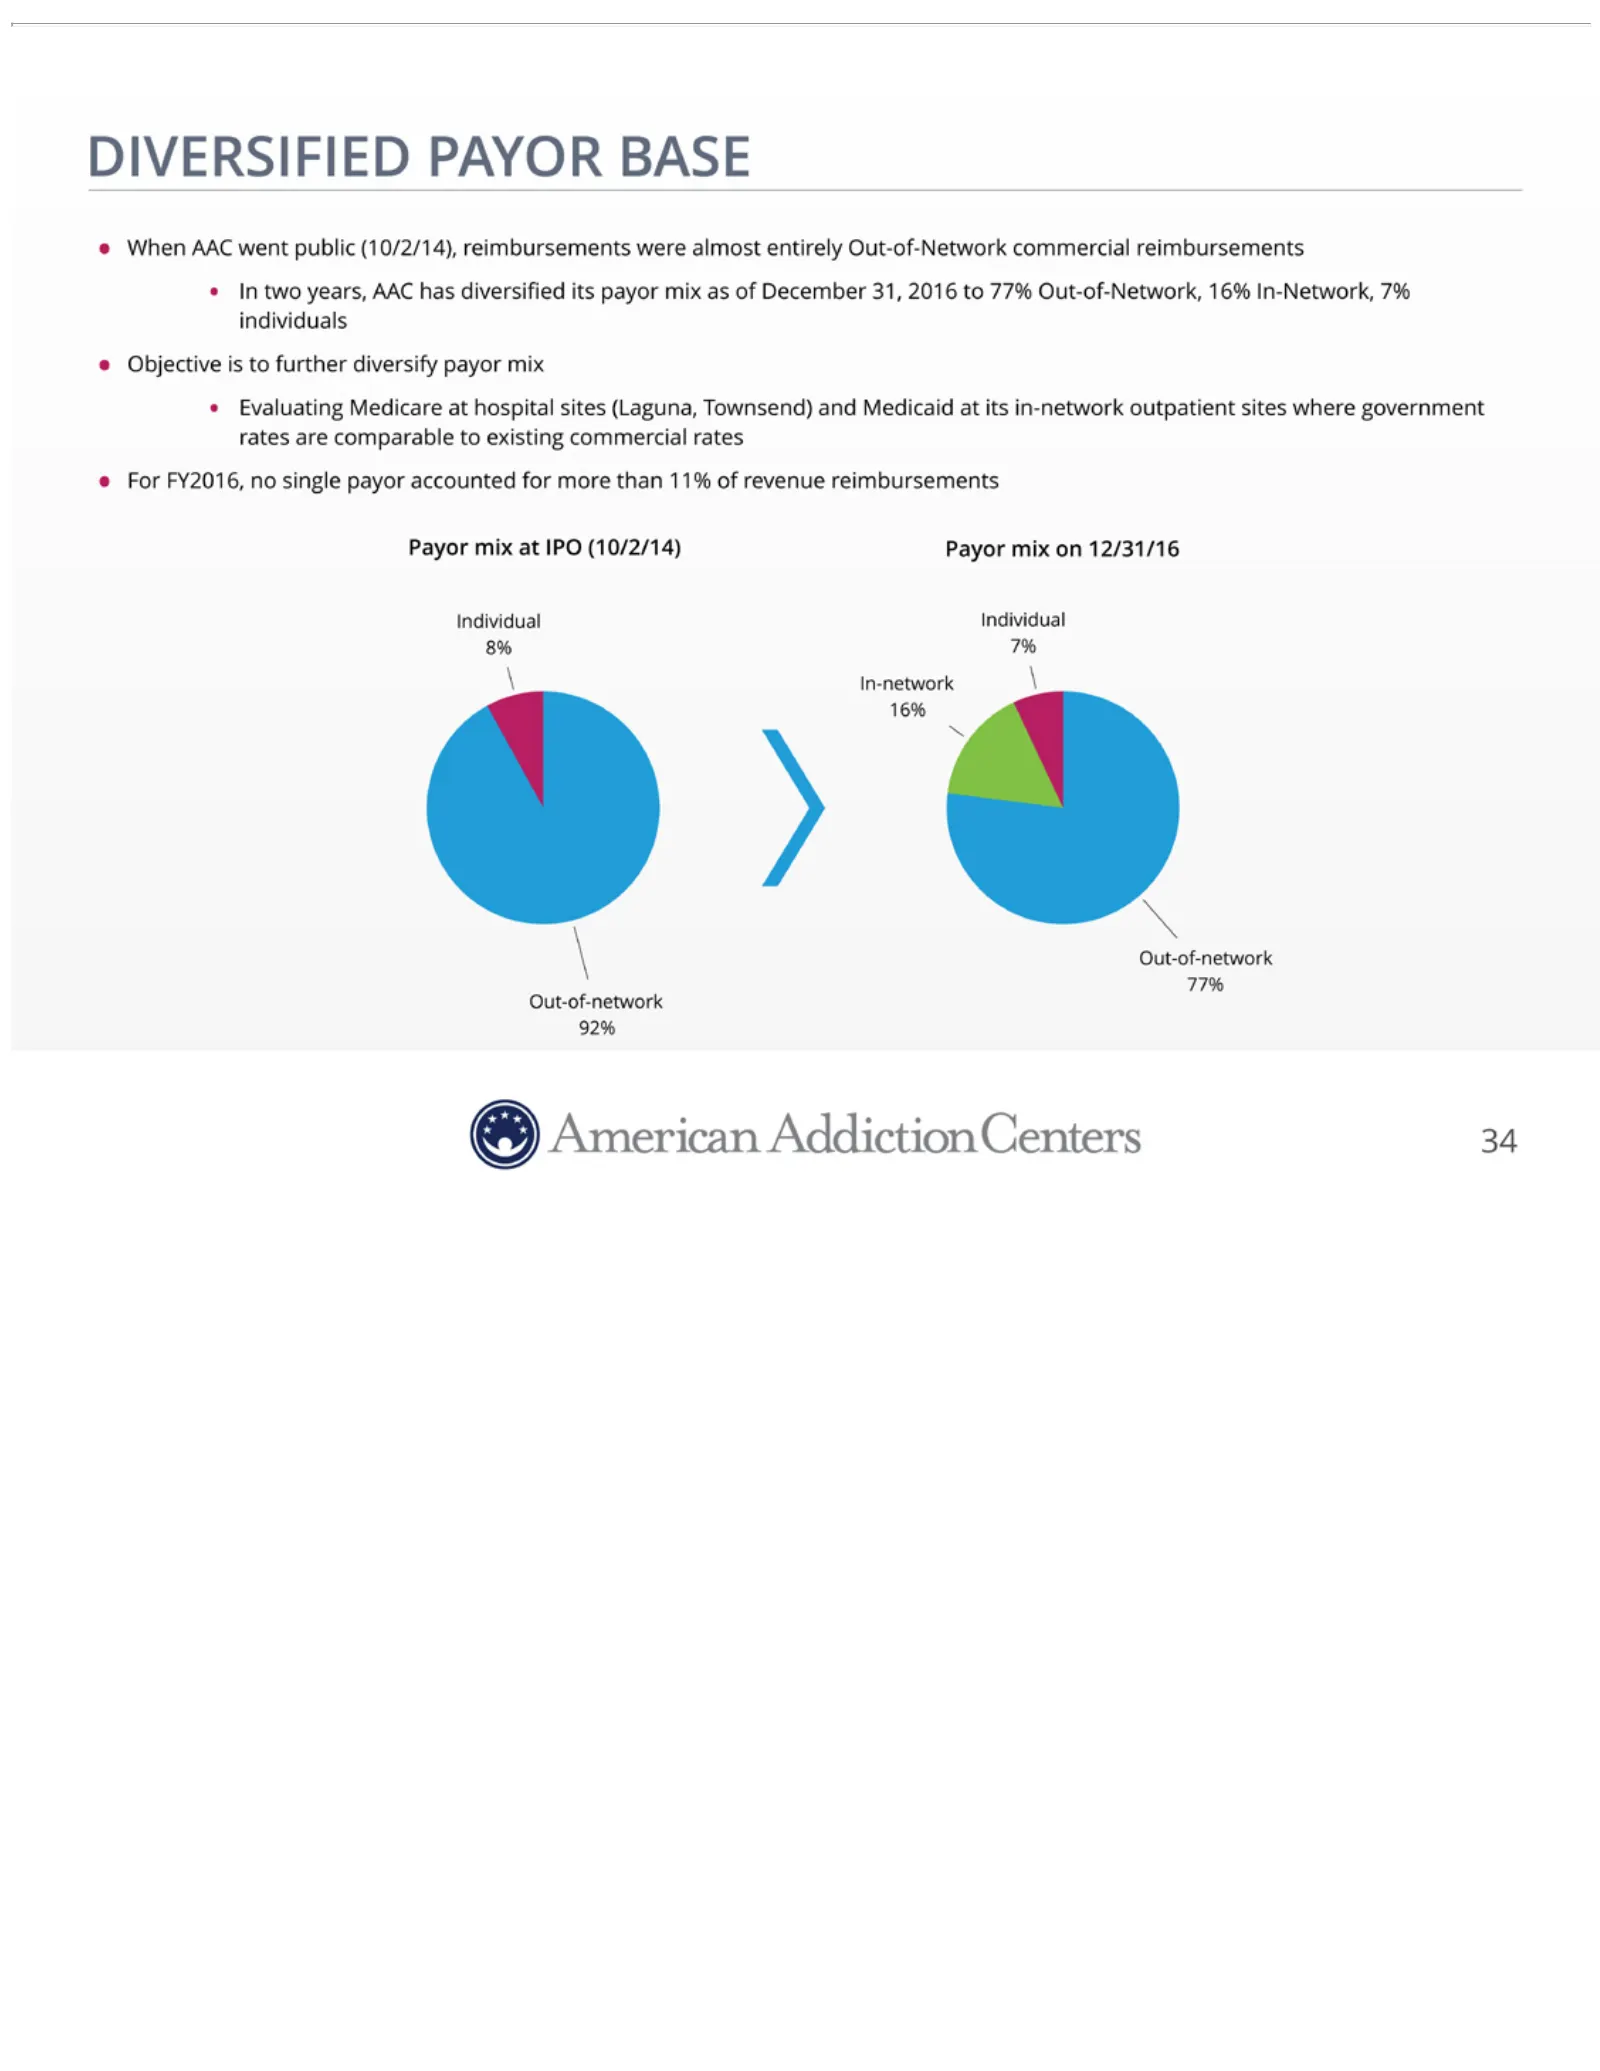
DIVERSIFIED individuals for more than • Objective 11% PAYOR of revenue isBASE to further reimbursements • When diversify AAC payor went Payor public mix mix (10/2/14), •atEvaluating IPO (10/2/14) reimbursements Medicare Payor at mixhospital were on 12/31/16 almost sites (Laguna, entirely Individual
Slide 35: Laboratory and Diagnostics Capabilities
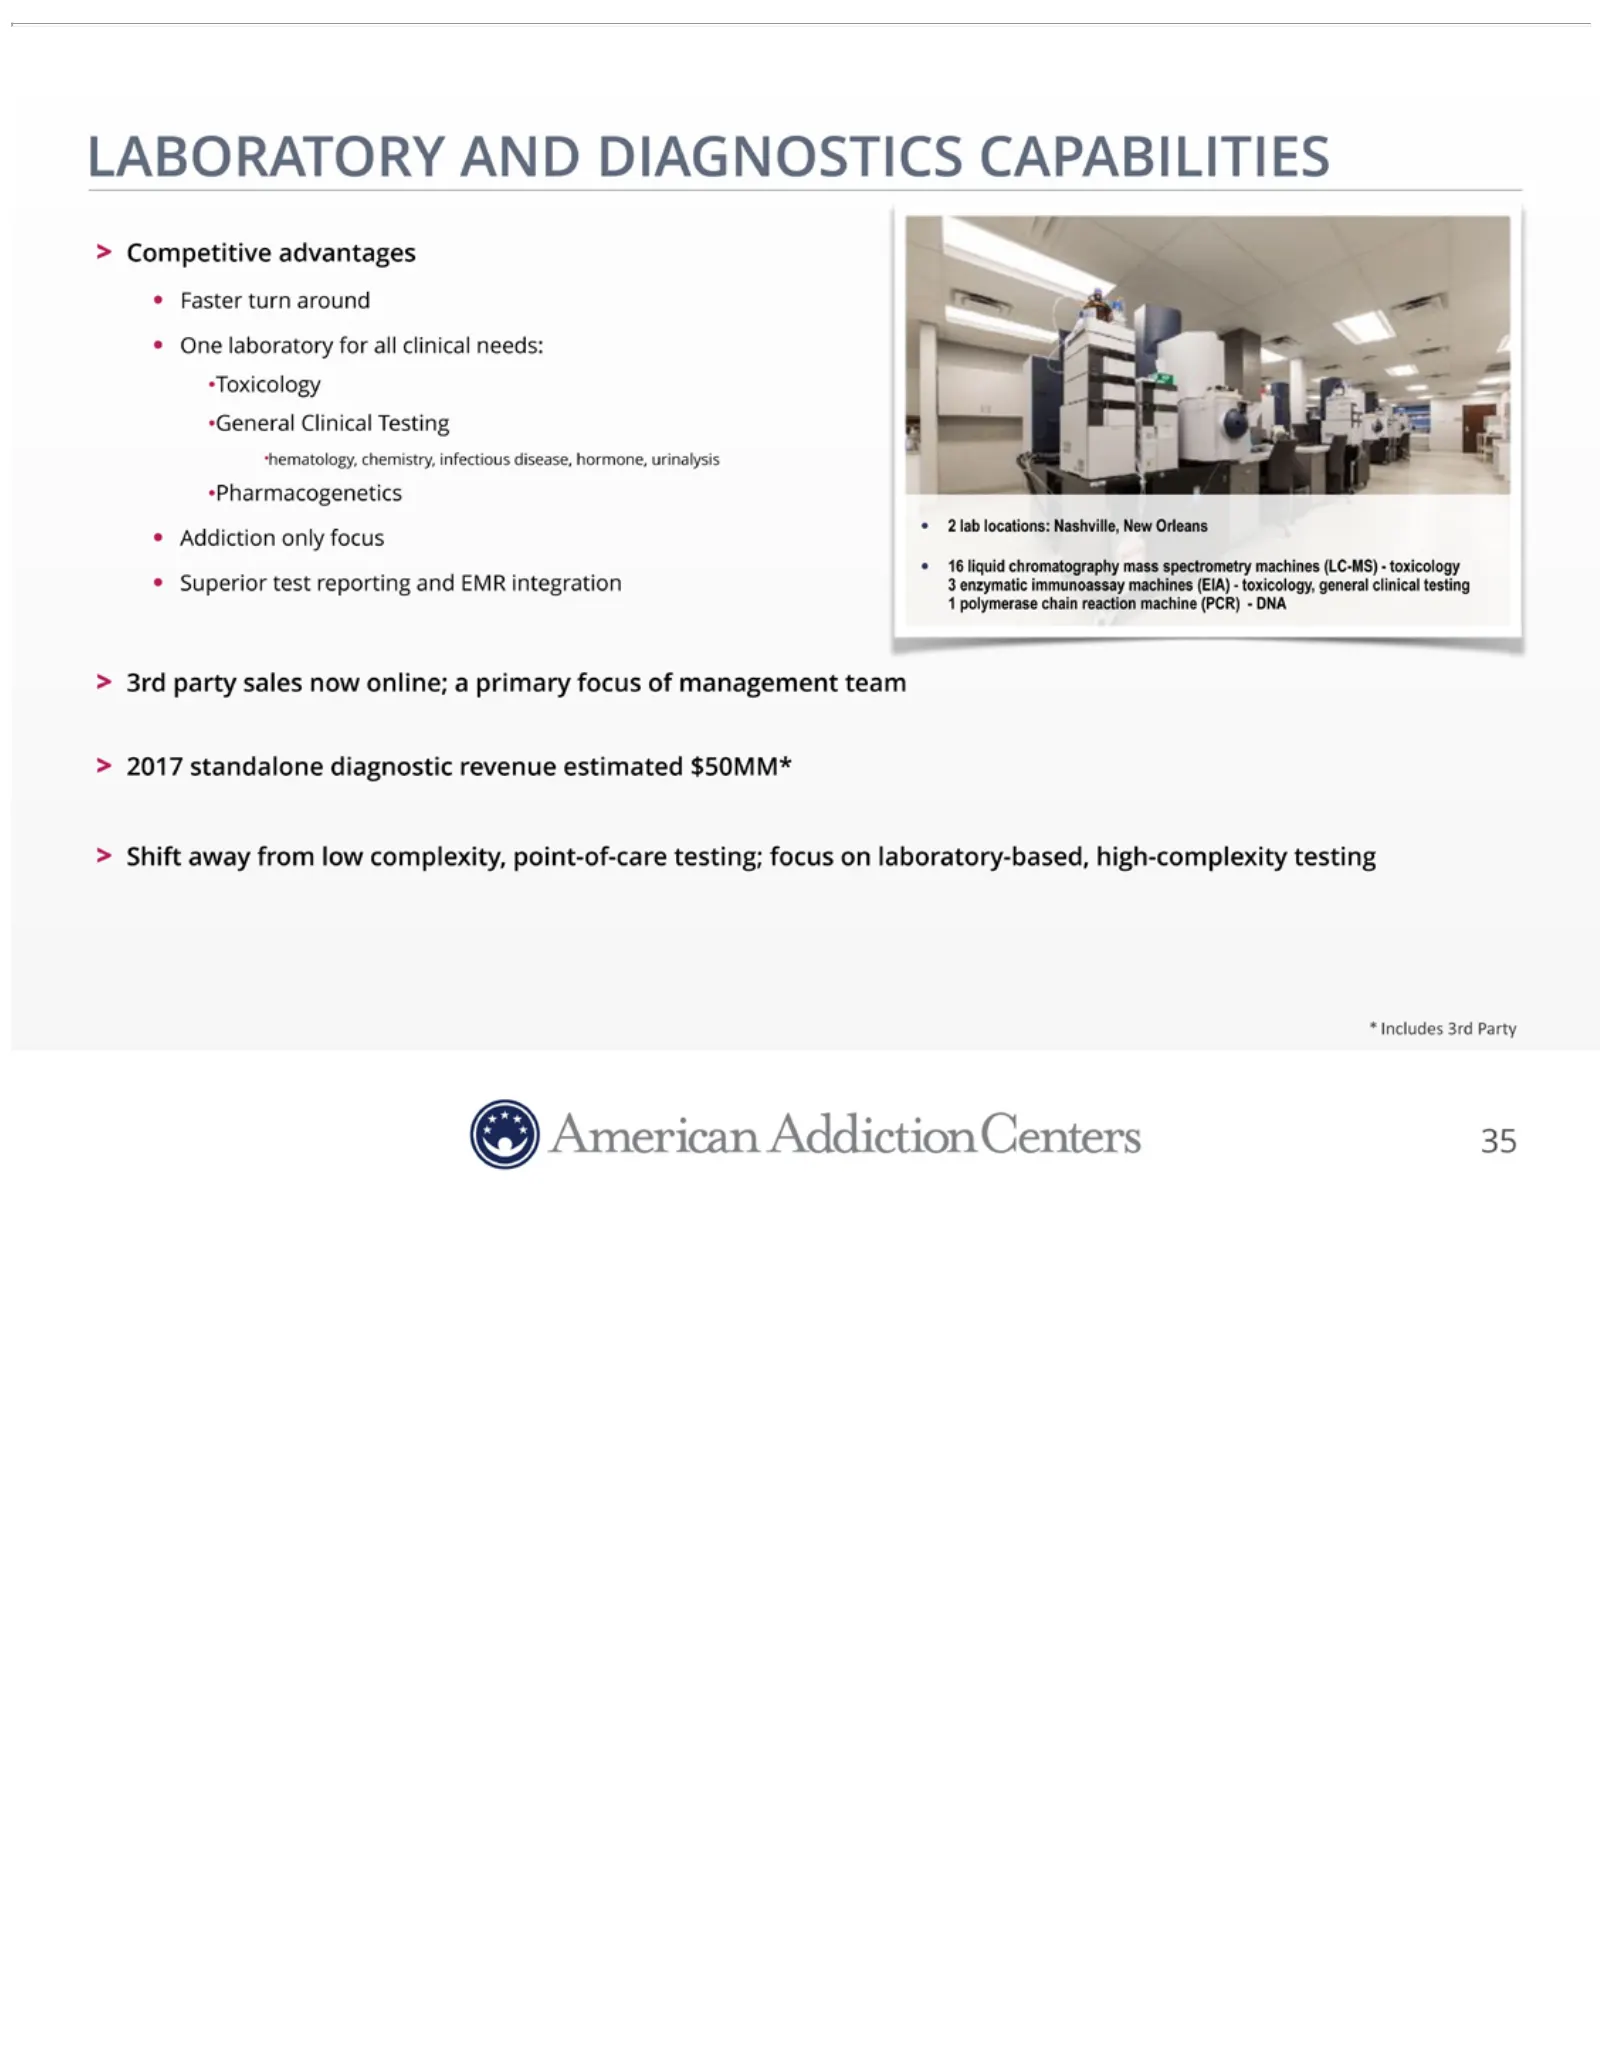
LABORATORY only chain *$Includes$3rd$Party focus reaction • 2 lab machine AND locations: 35 DIAGNOSTICS (PCR)—DNA Nashville,>New CAPABILITIES 3rd party Orleans sales • 16now > liquid Competitive online; chromatography a primary advantages focus mass •ofFaster spectrometry management turn around mach
Slide 36: Employees and Operations
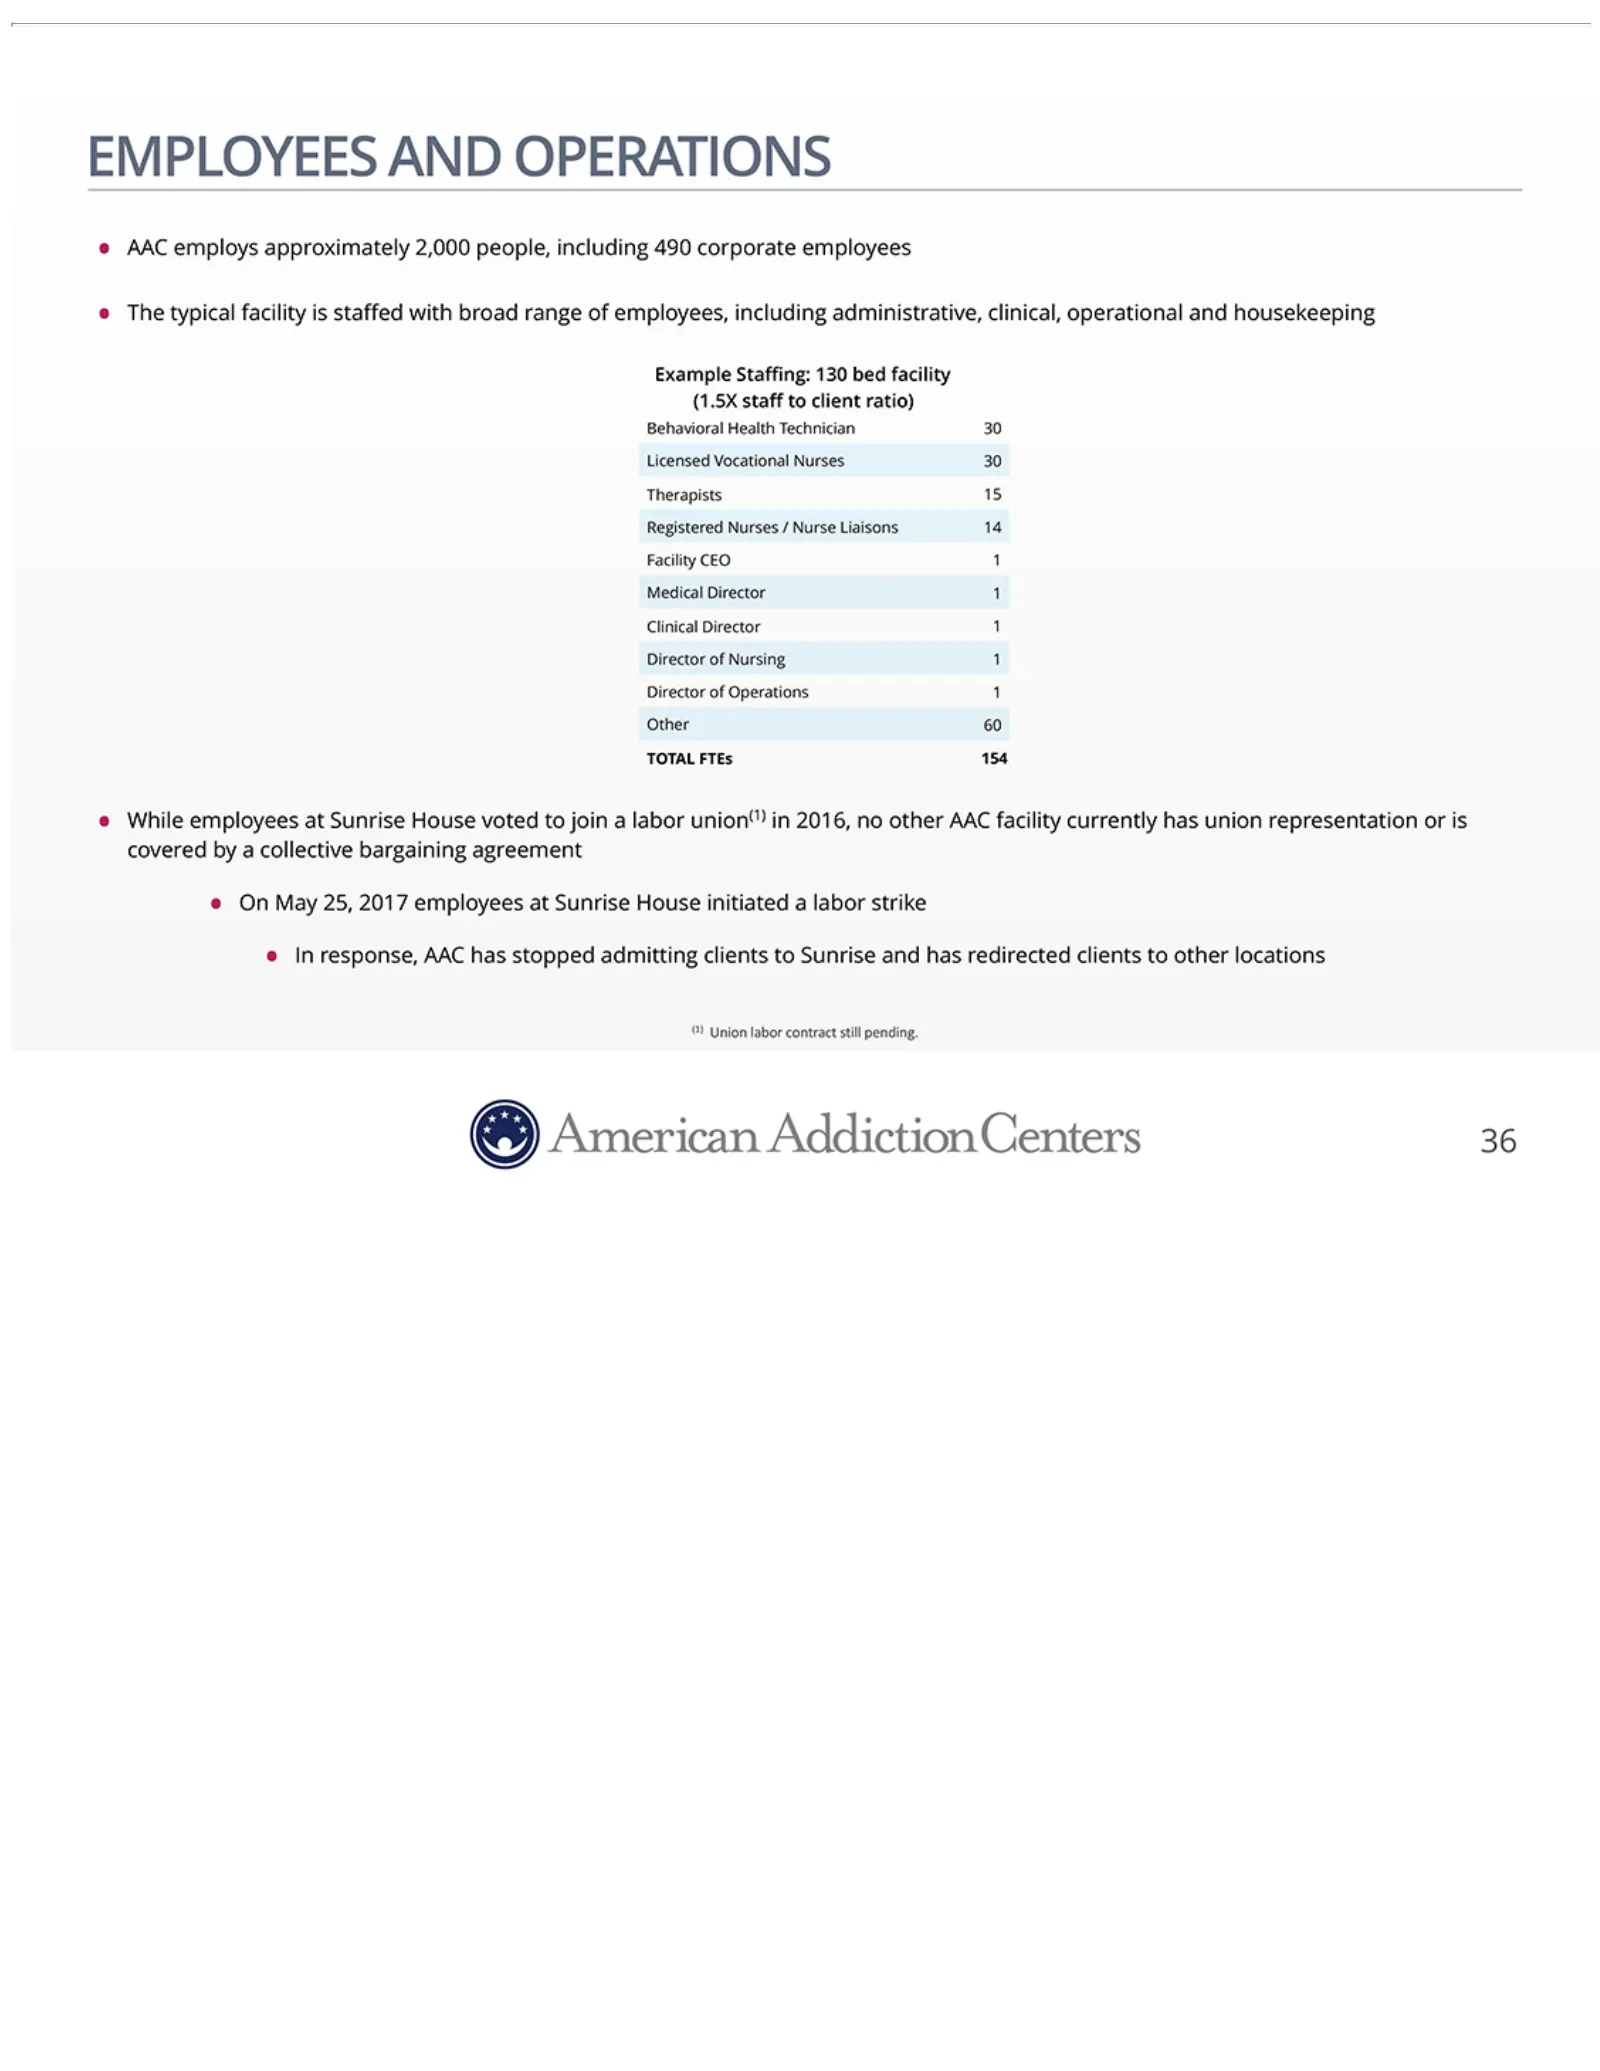
EMPLOYEES (1.5X While stopped staff employees admitting to client ANDatclients ratio) Sunrise OPERATIONS to Behavioral Sunrise House voted and AAC Health has toemploys join redirected Technician a labor approximately clients union(1) 30 Licensed to other in2,000 2016, Vocational locations people, no
Slide 37: Compliance Program
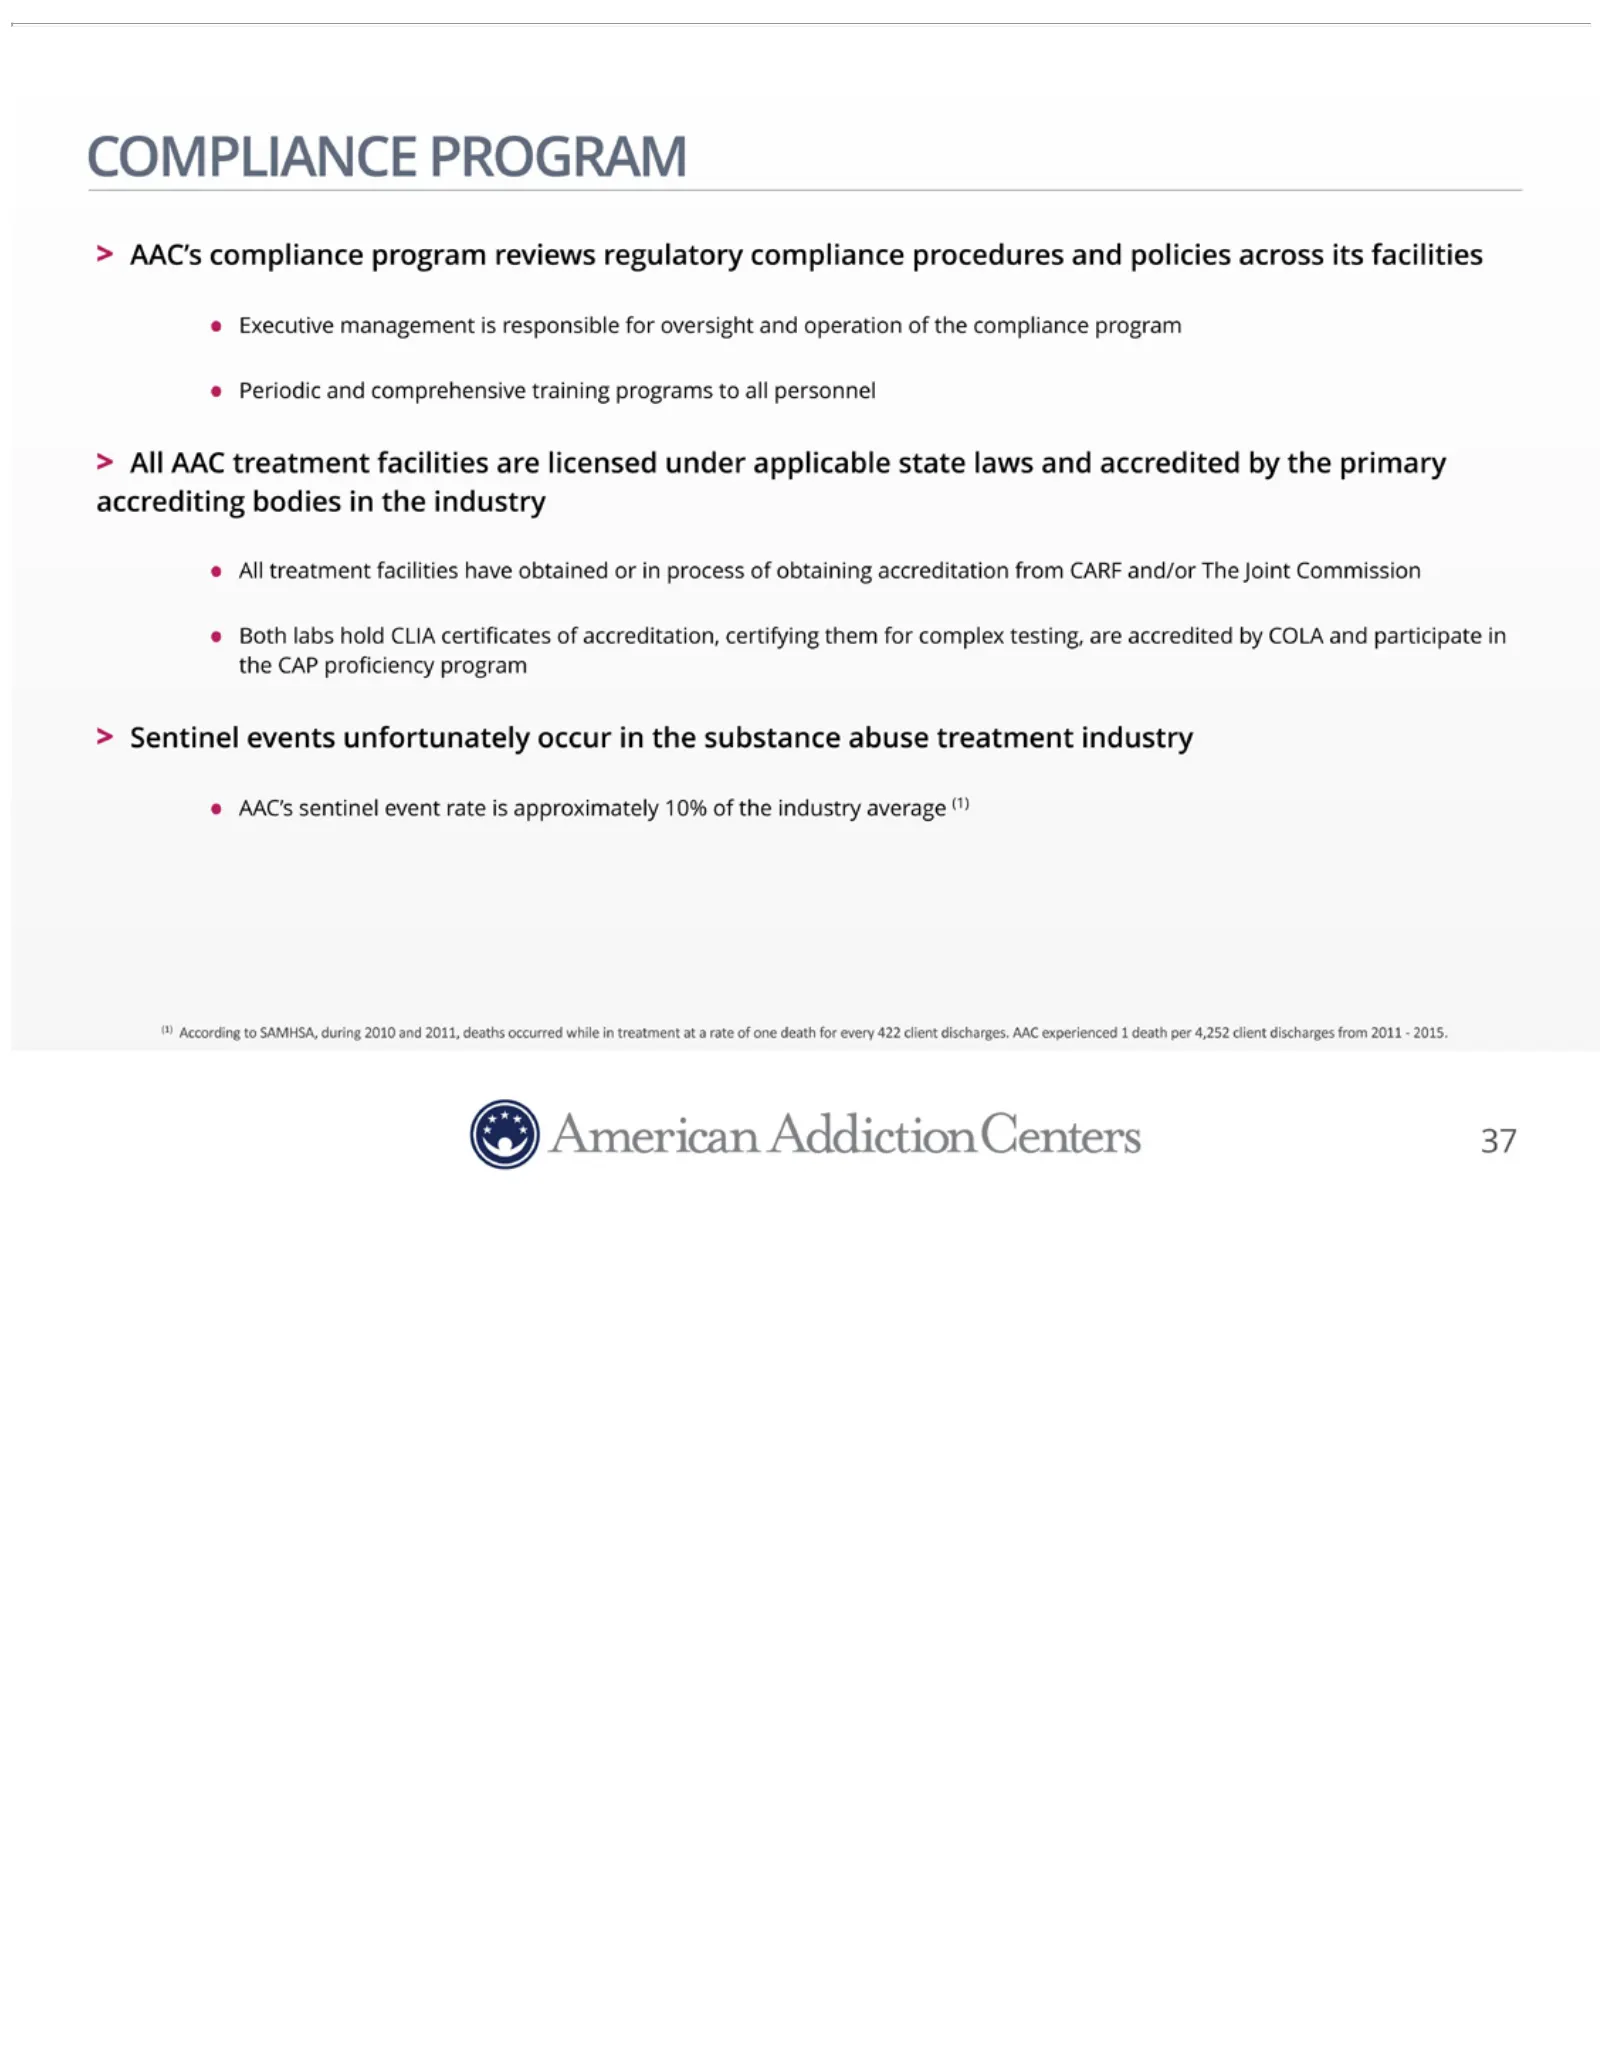
COMPLIANCE programs Commission rate is approximately to all • Both personnel PROGRAM labs 10%hold >ofAll the > CLIA AAC AAC’s industry certificates treatment compliance average facilities of (1) accreditation, program (1)are According licensed reviews certifying to regulatory under SAMHSA, them appl
Slide 38: Recent Developments and Company Updates
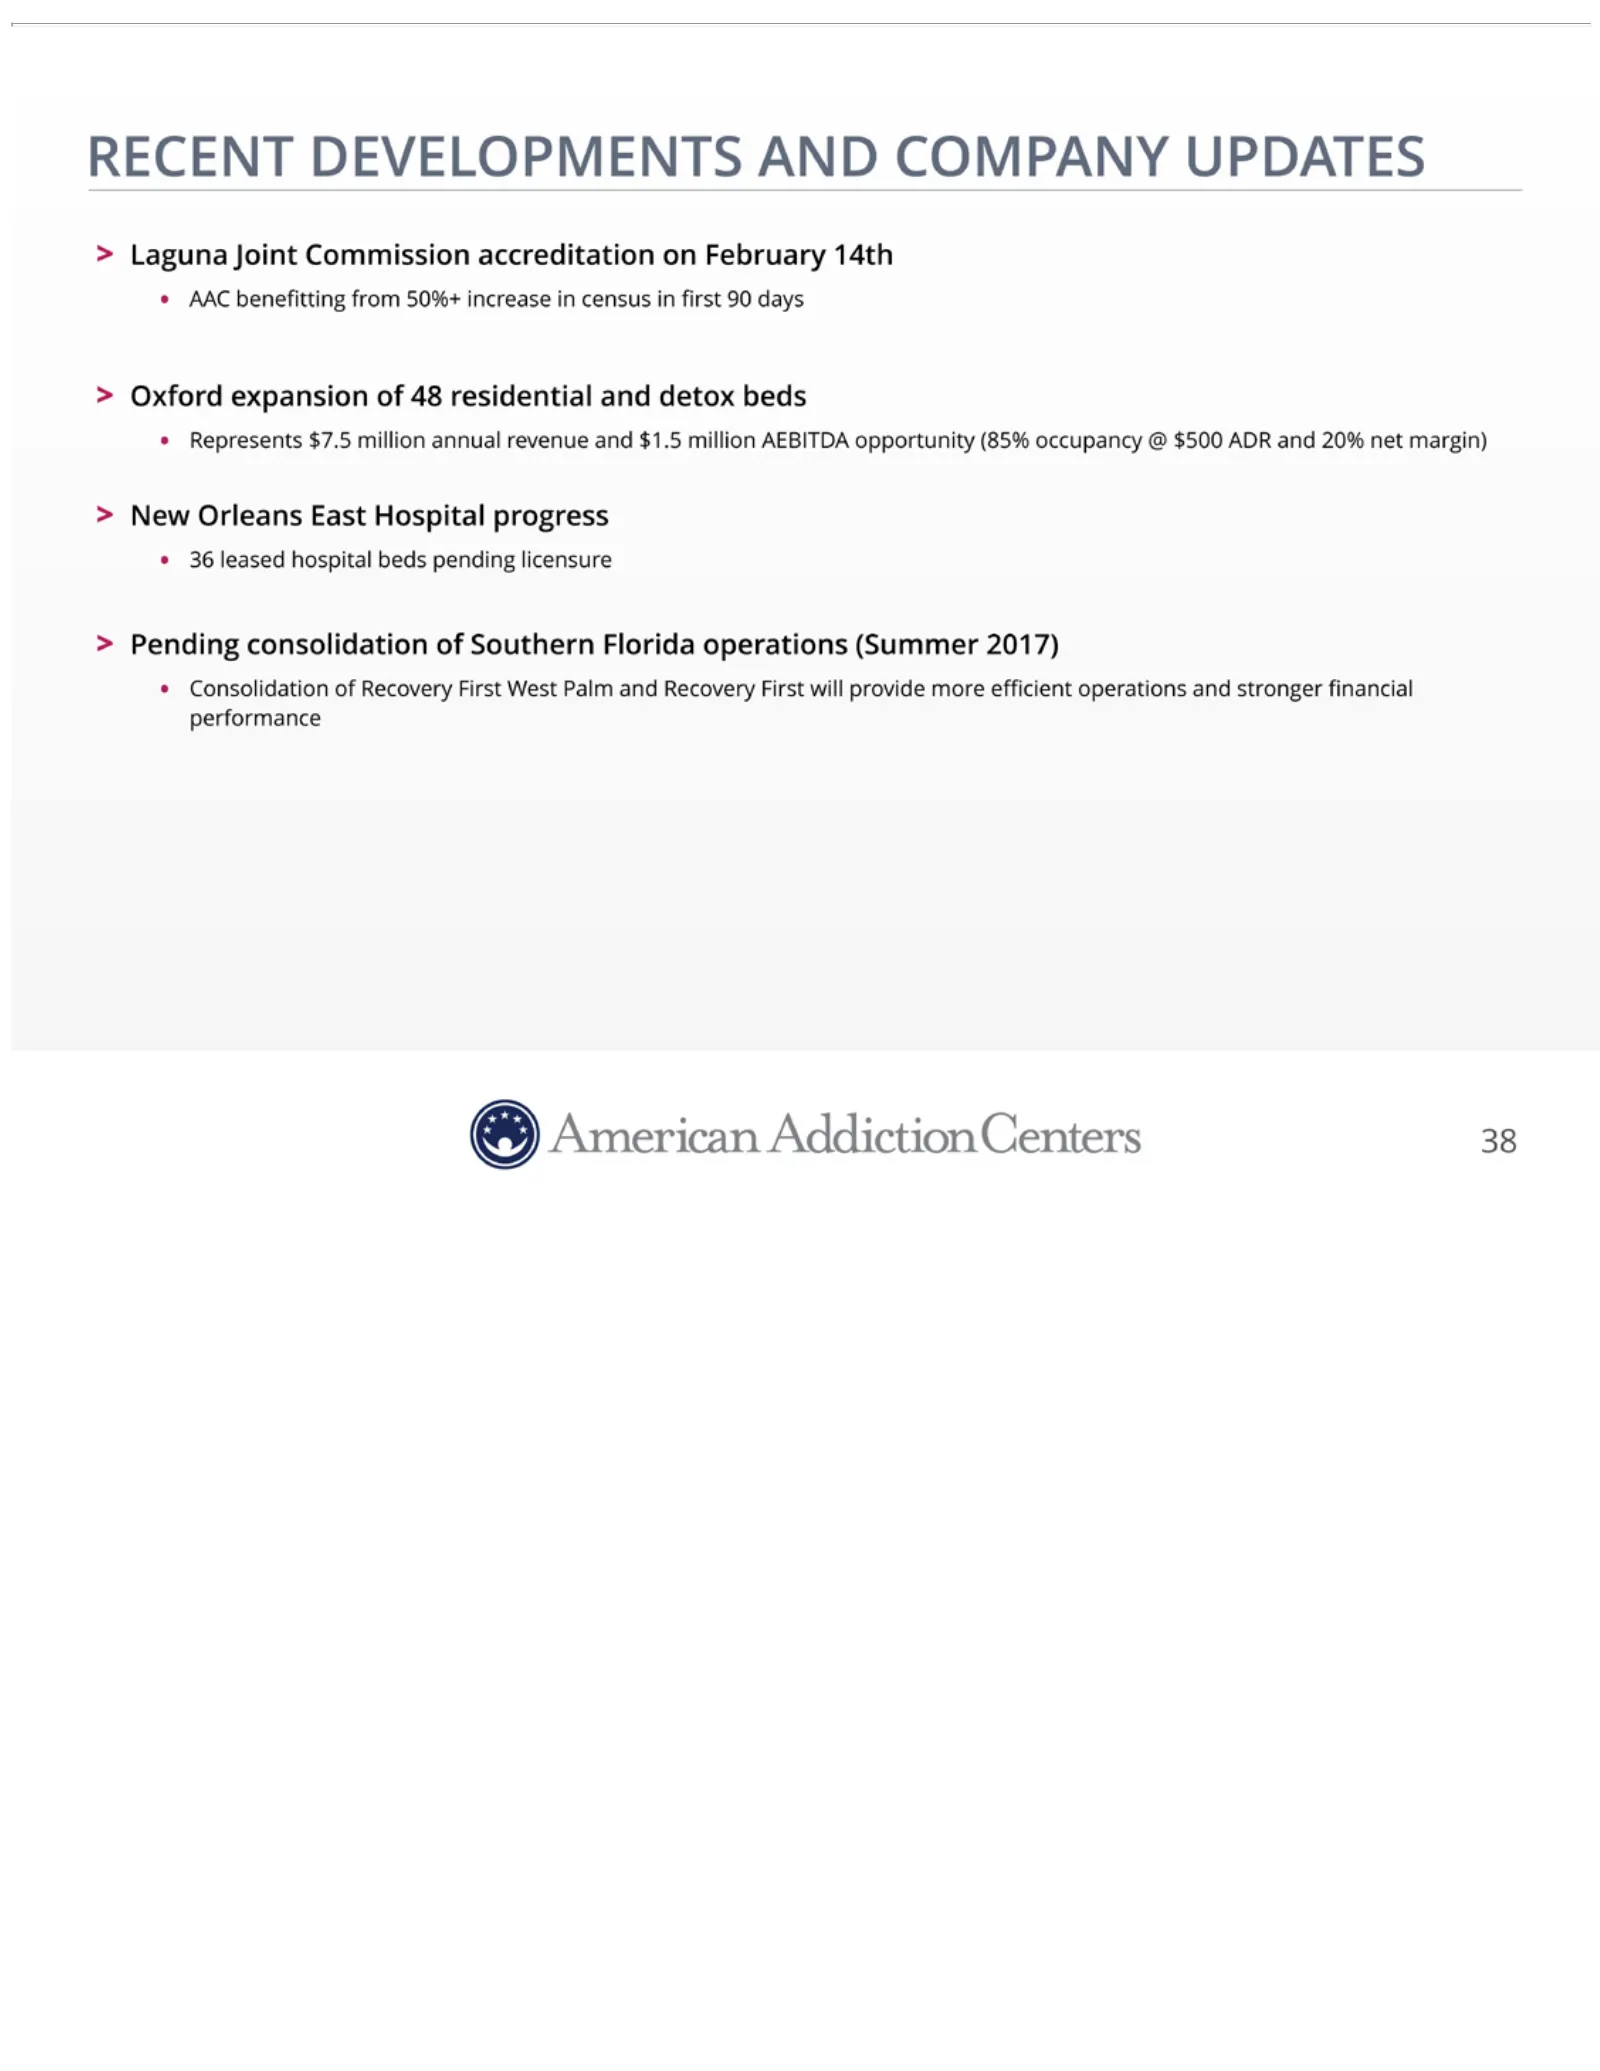
RECENTand revenue Recovery First DEVELOPMENTS $1.5 West million PalmAEBITDA and AND Recovery COMPANY opportunity First will(85% UPDATES provide occupancy more > Laguna efficient @ $500 Joint operations ADR Commission and and 20%stronger accreditation net margin) financial >on NewFebruary performance
Slide 39: River Oaks Key Credit Strengths
RIVER OAKS KEY CREDIT STRENGTHS 39
Slide 40: Embedded Growth from Recent Investments
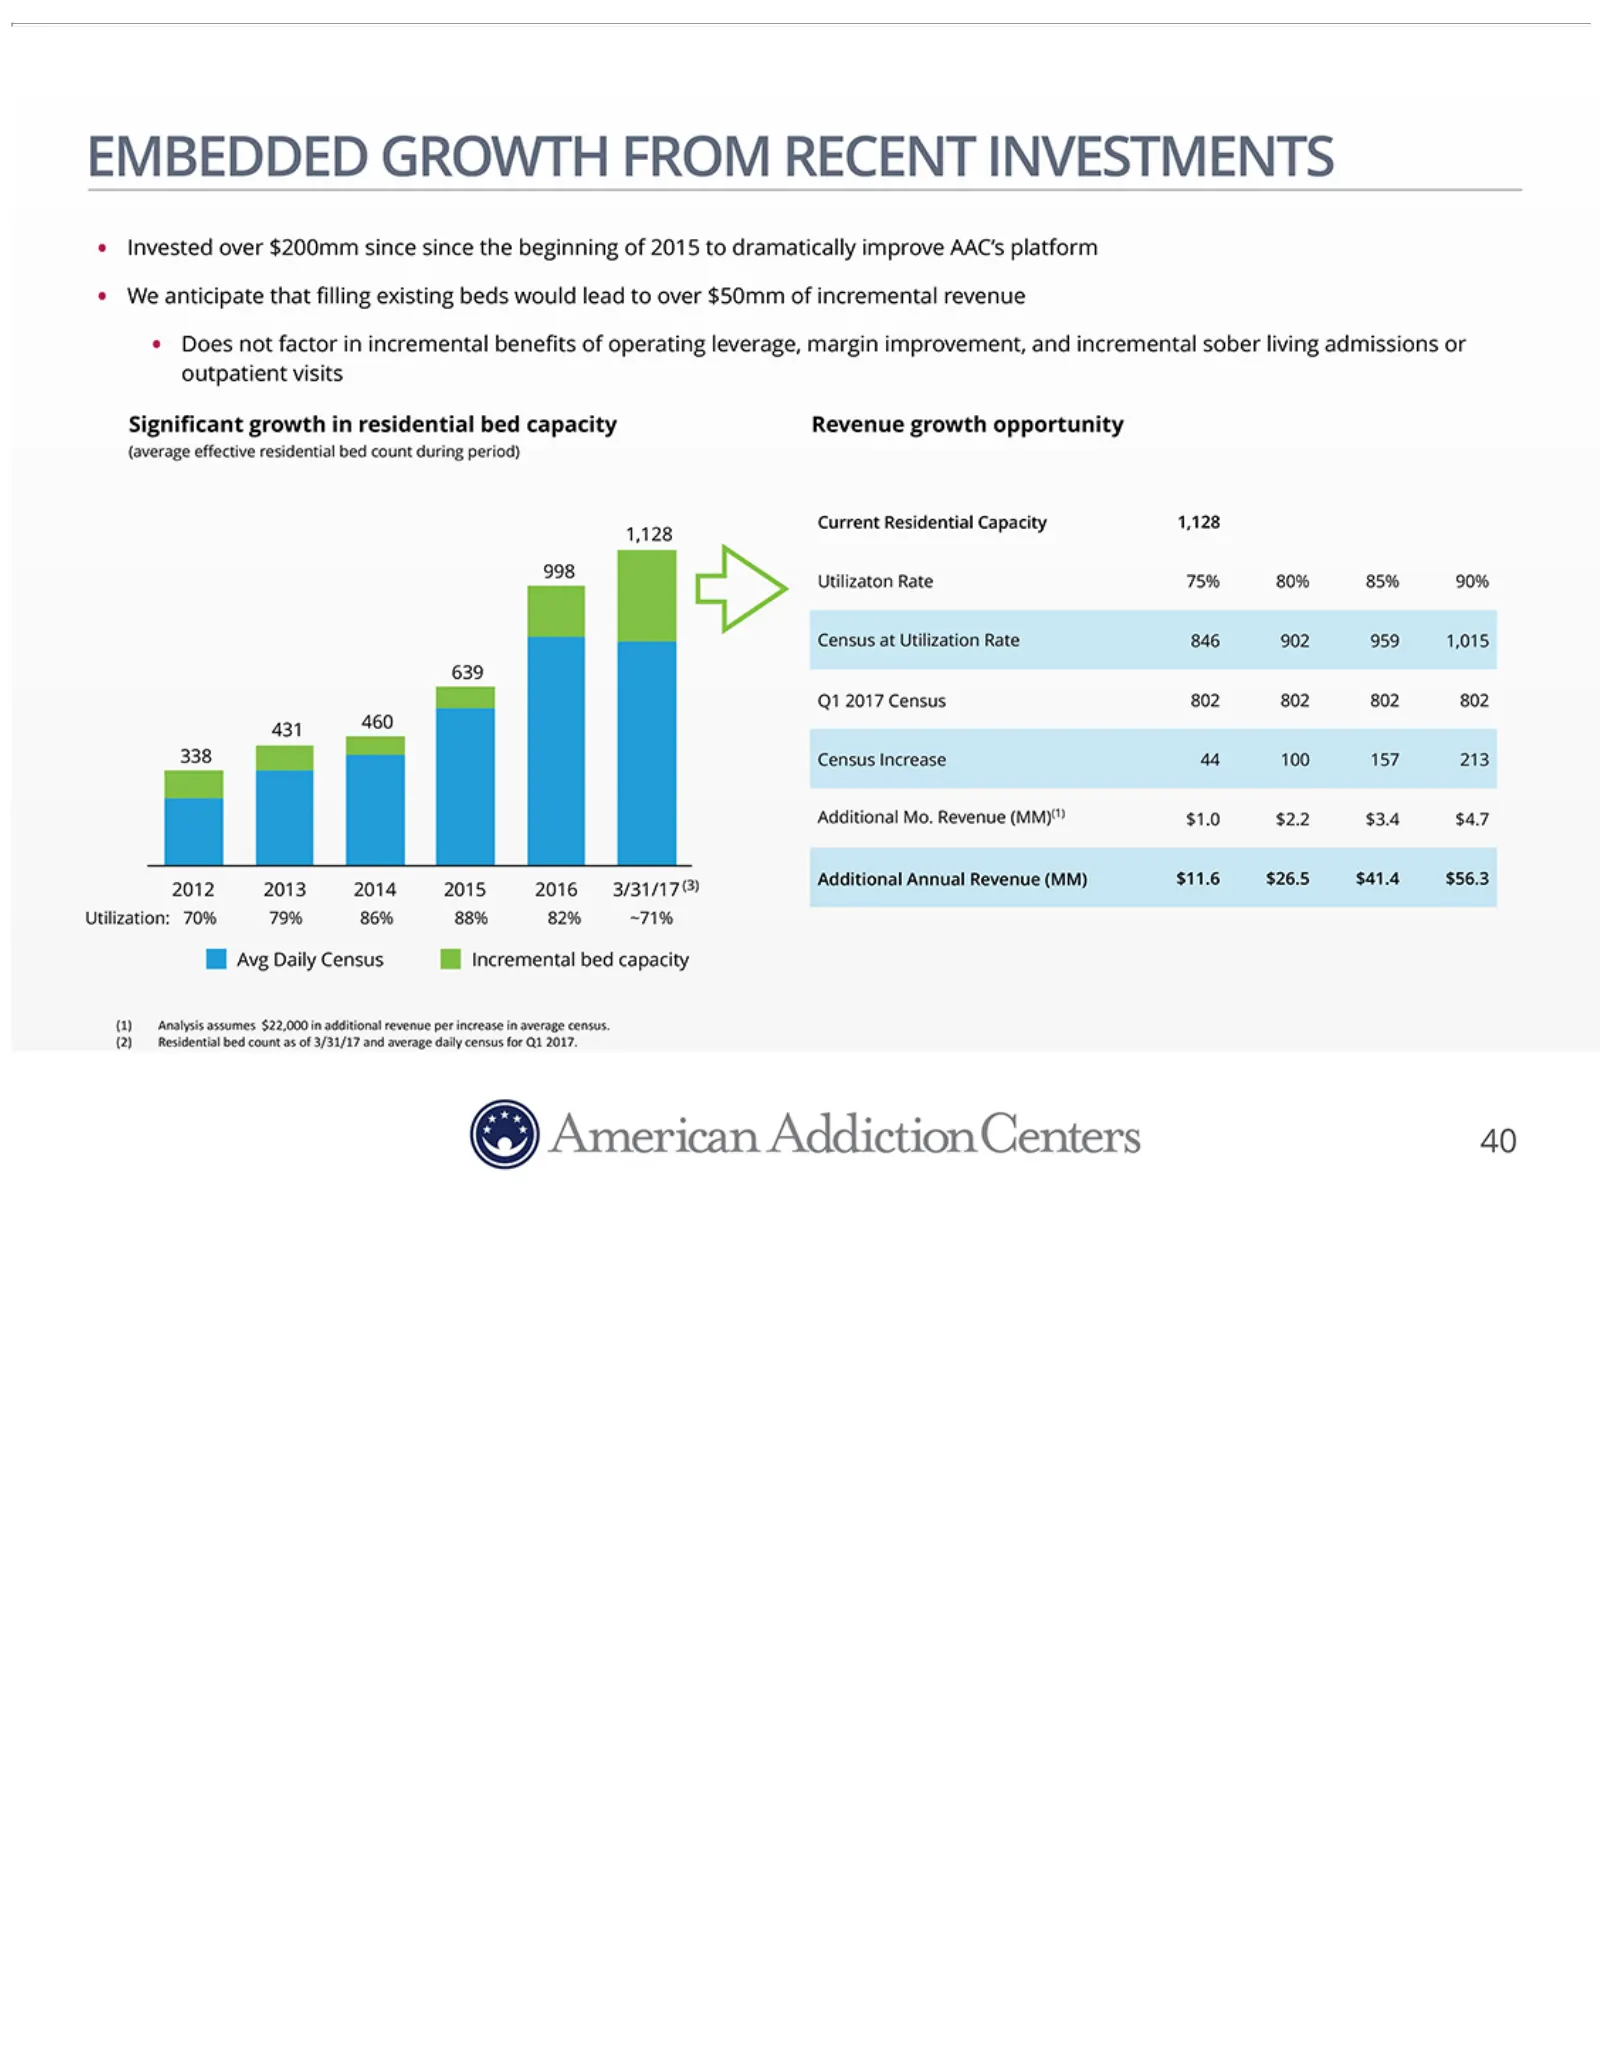
EMBEDDED incremental Capacity Revenue Residential$bed$count (MM) 1,128 benefits GROWTH 1,128 $11.6of998 $26.5 as$of$3/31/17$and$average$daily$census$for$Q1$2017. operating FROM Utilizaton $41.4leverage, RECENT $56.3 Rate2012 75% margin INVESTMENTS 2013 80%improvement, 2014 85% 90% 2015Invested Censu
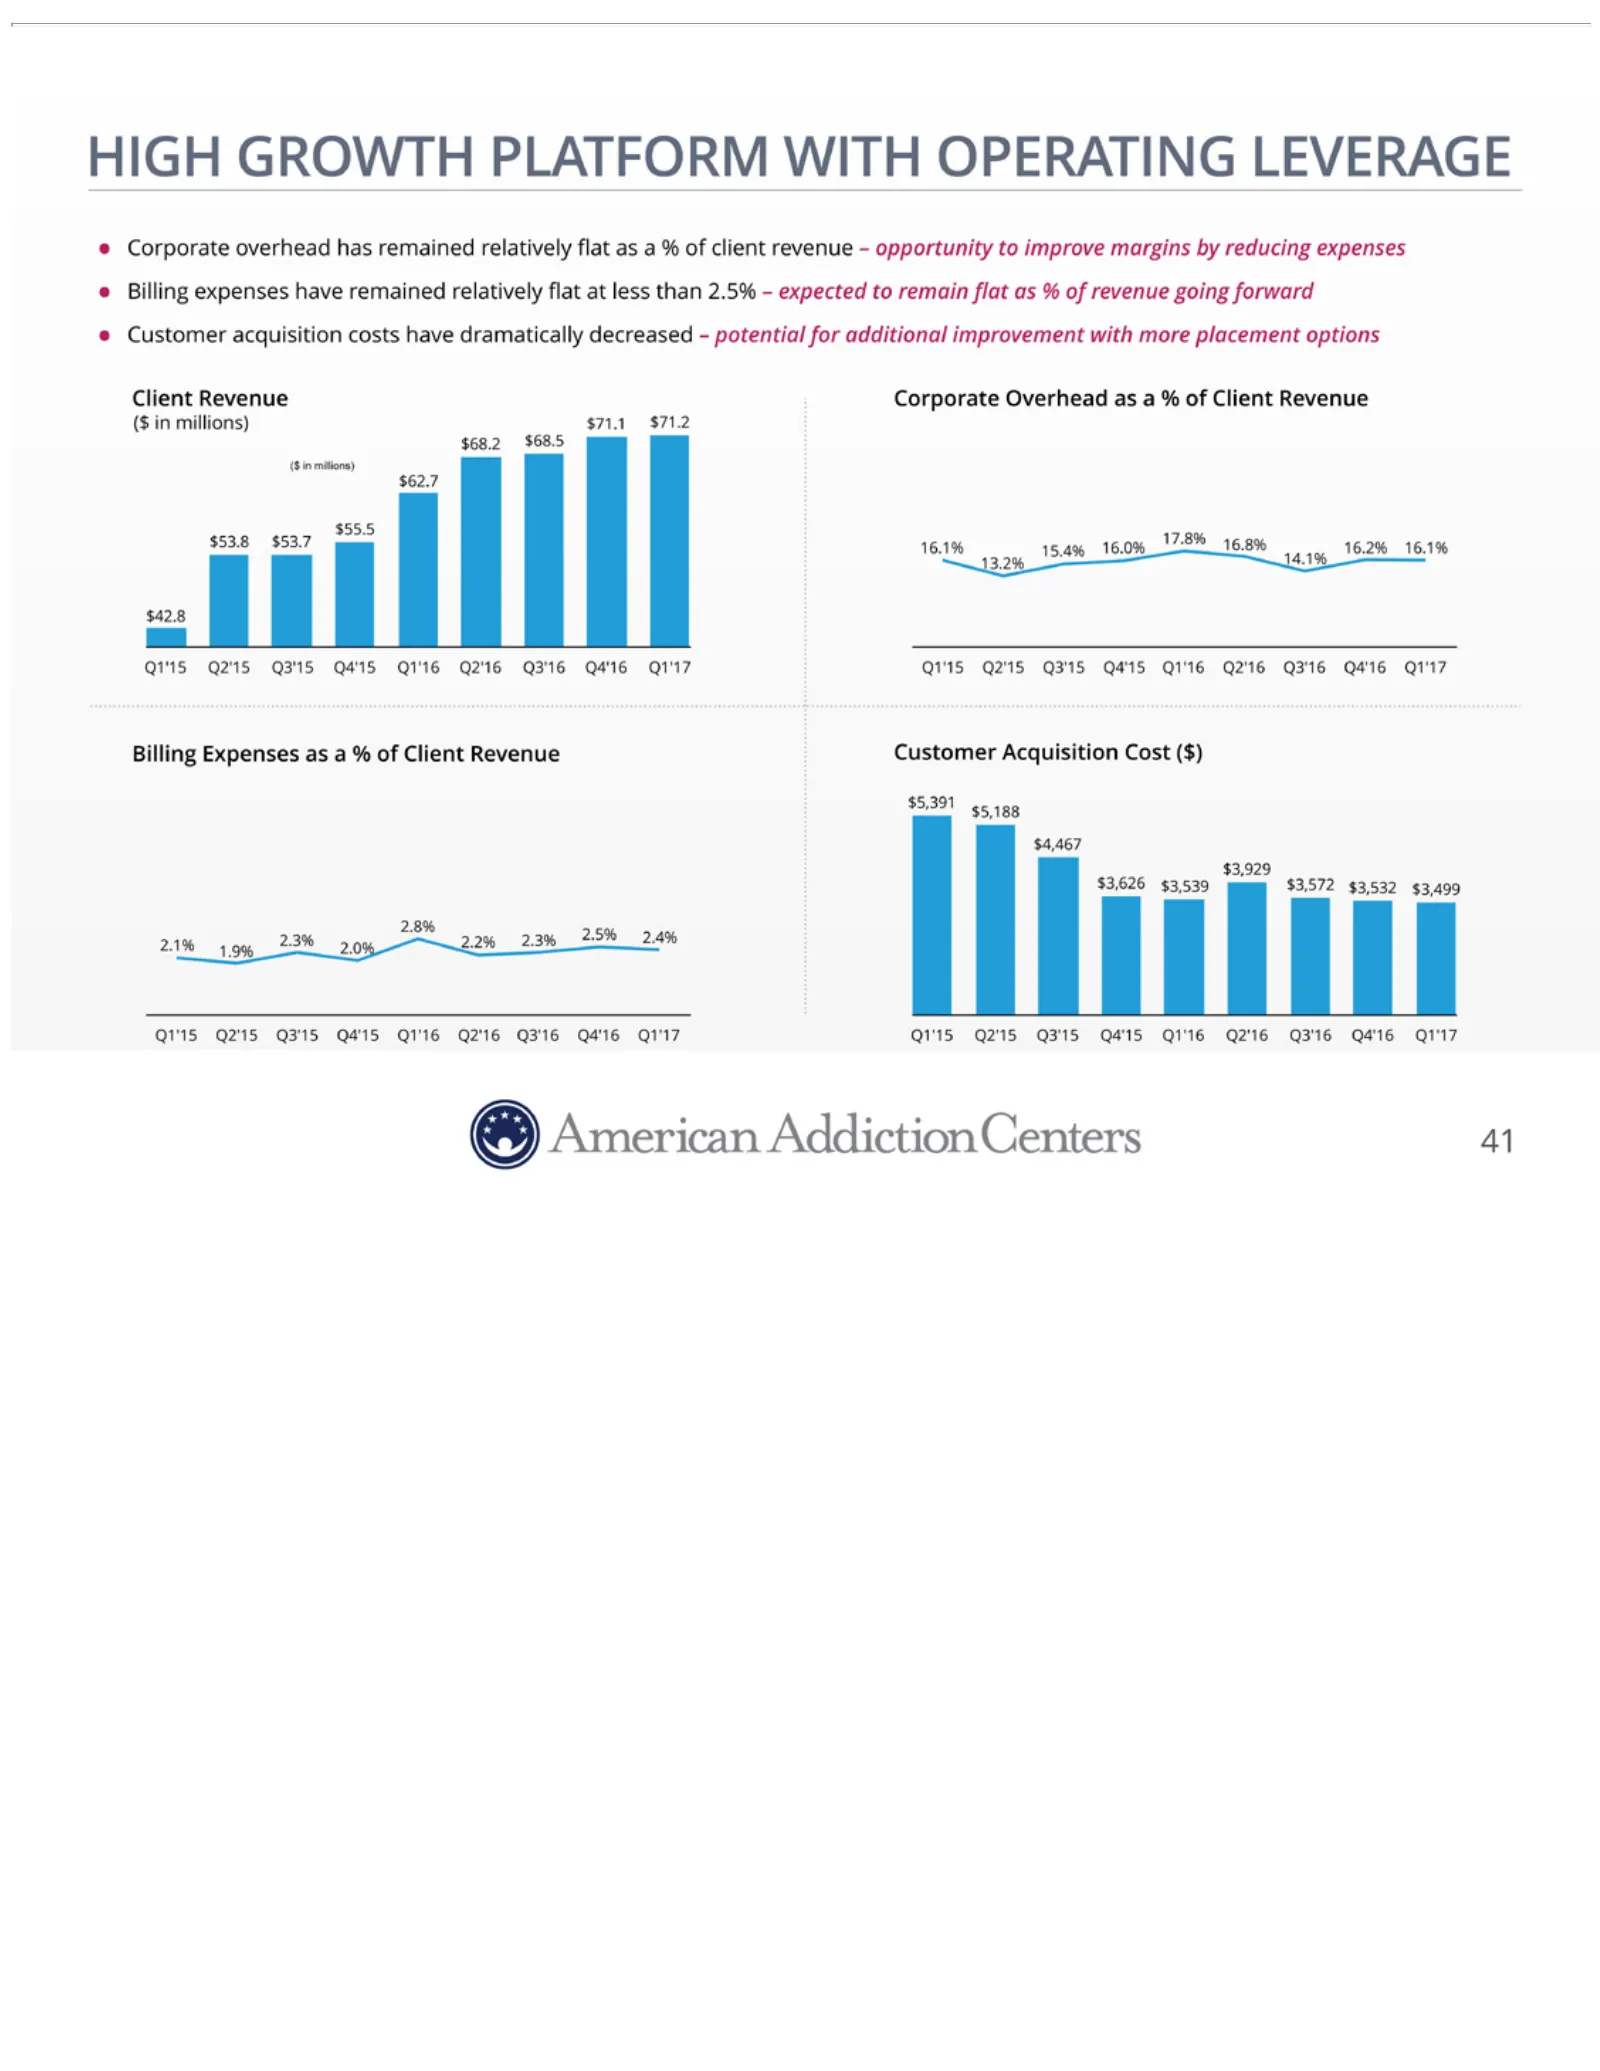
Slide 41: High Growth Platform with Operating Leverage
HIGH GROWTH remain millions) Customer 41 flat$62.7 Acquisition as %$55.5 ofPLATFORM revenue $53.8 Cost ($) going $53.7 $5,391 WITH forward 16.1% $5,188 OPERATING •15.4% Customer $4,467 16.0% $3,929 LEVERAGE acquisition 17.8% $3,626 16.8% costs • $3,539 Corporate 16.2% have$3,572 dramatically 16.1% o
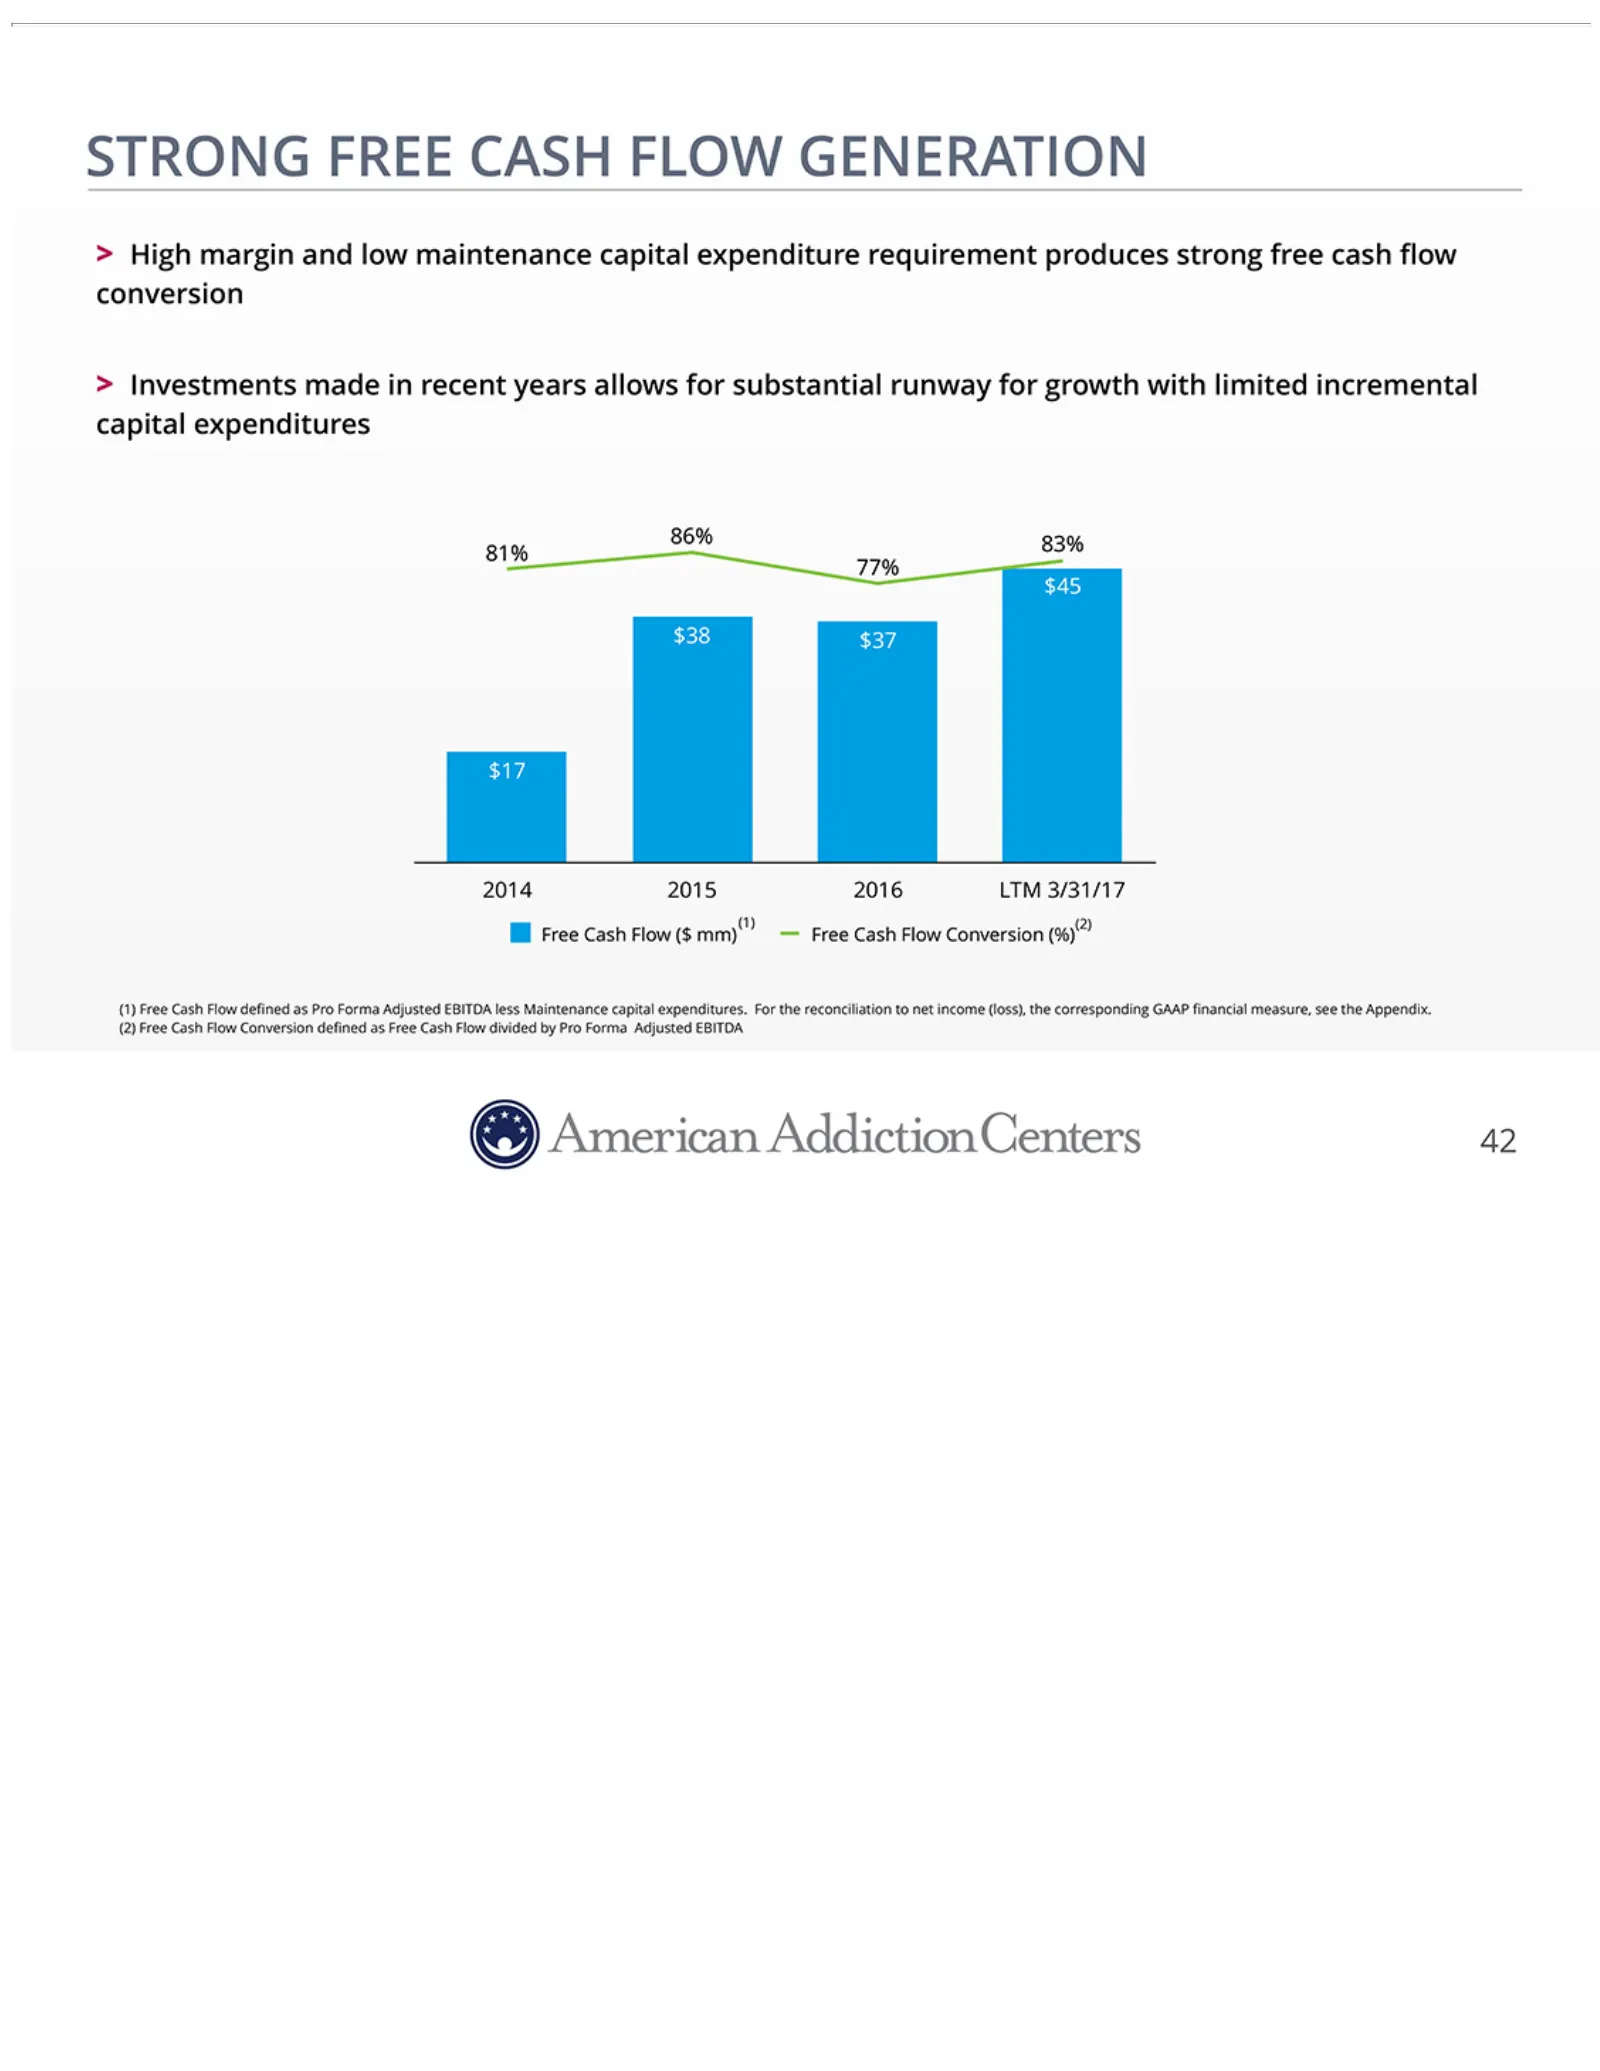
Slide 42: Strong Free Cash Flow Generation
STRONG expenditures (loss), the corresponding FREE 86%CASH 83% 81% FLOW GAAP 77%GENERATION financial $45 $38measure, $37 $17 High see 2014 margin the2015 Appendix. and 2016 low LTM (2) maintenance Free 3/31/17 CashFree capital Flow Cash Conversion expenditure Flow ($ mm) defined requirement FreeasCa
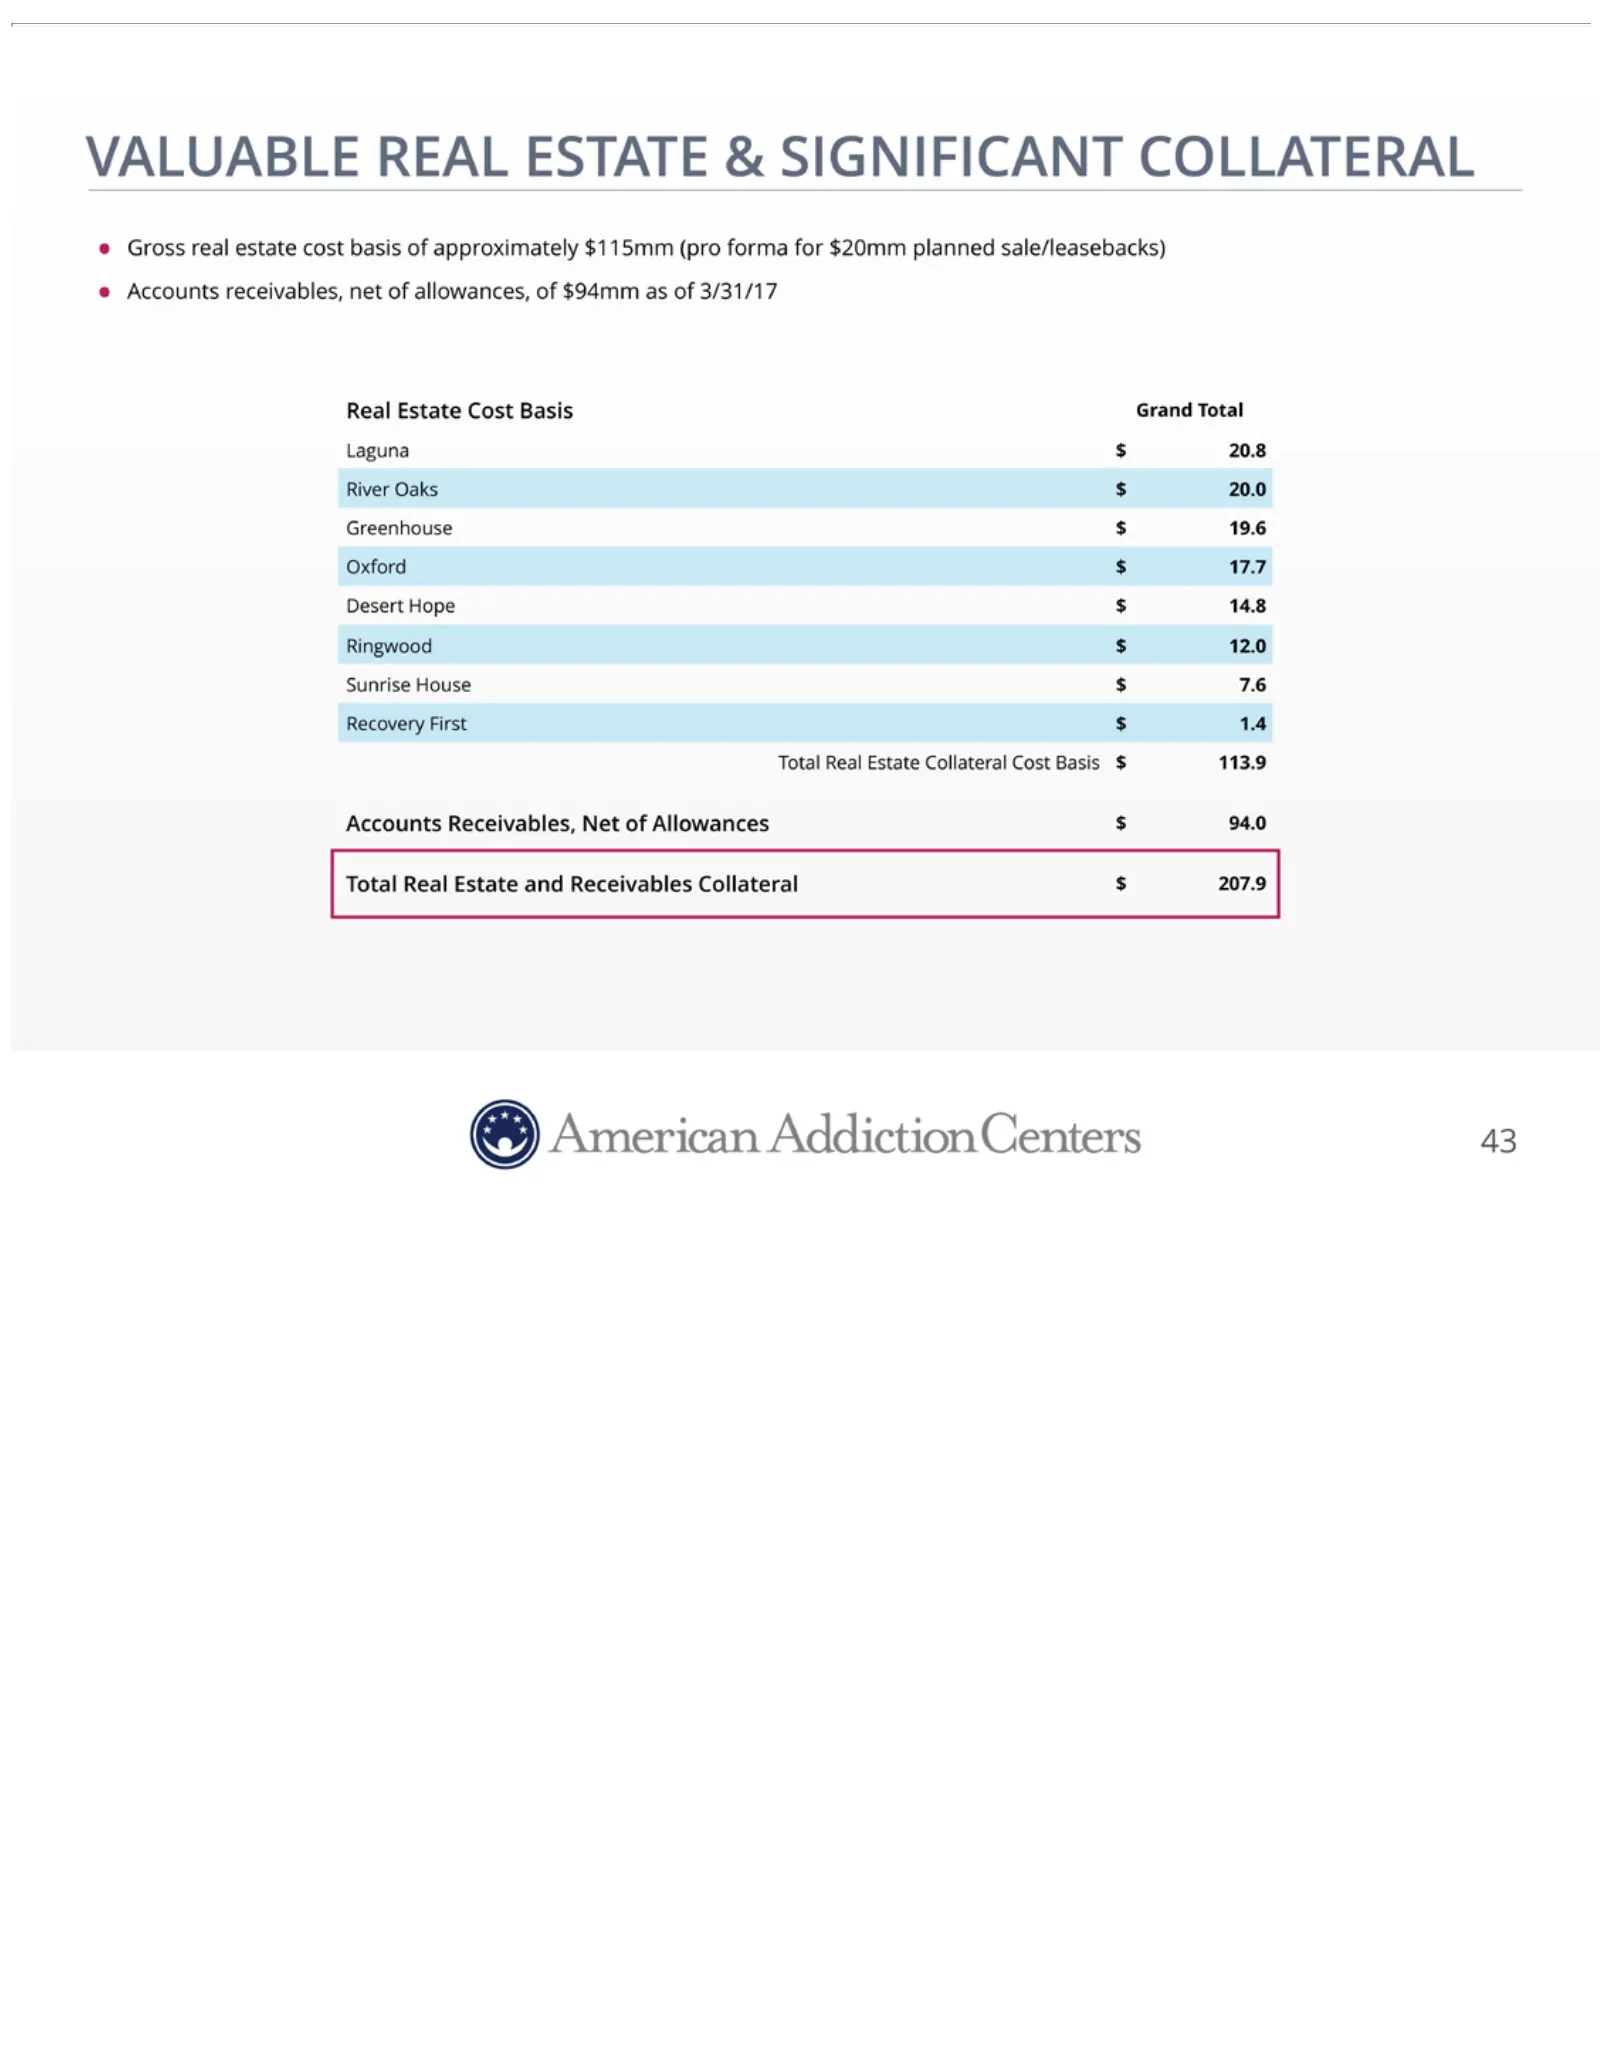
Slide 43: Valuable Real Estate and Significant Collateral
VALUABLE Laguna Receivables $ 20.8 Collateral REAL River ESTATE Oaks $ 207.9 $ 20.0 & SIGNIFICANT Greenhouse $ 19.6 COLLATERAL Oxford $ 17.7 • Gross Desertreal Hope estate $ 14.8 costRingwood basis of approximately $ 12.0 Sunrise$115mm House $(pro 7.6 forma Recovery for $20mm First $ 1.4 planned Tot
Slide 44: Addiction Labs Historical Financials
ADDICTION LABS HISTO RICAL FINANCIALS 44
Slide 45: Operating Metrics
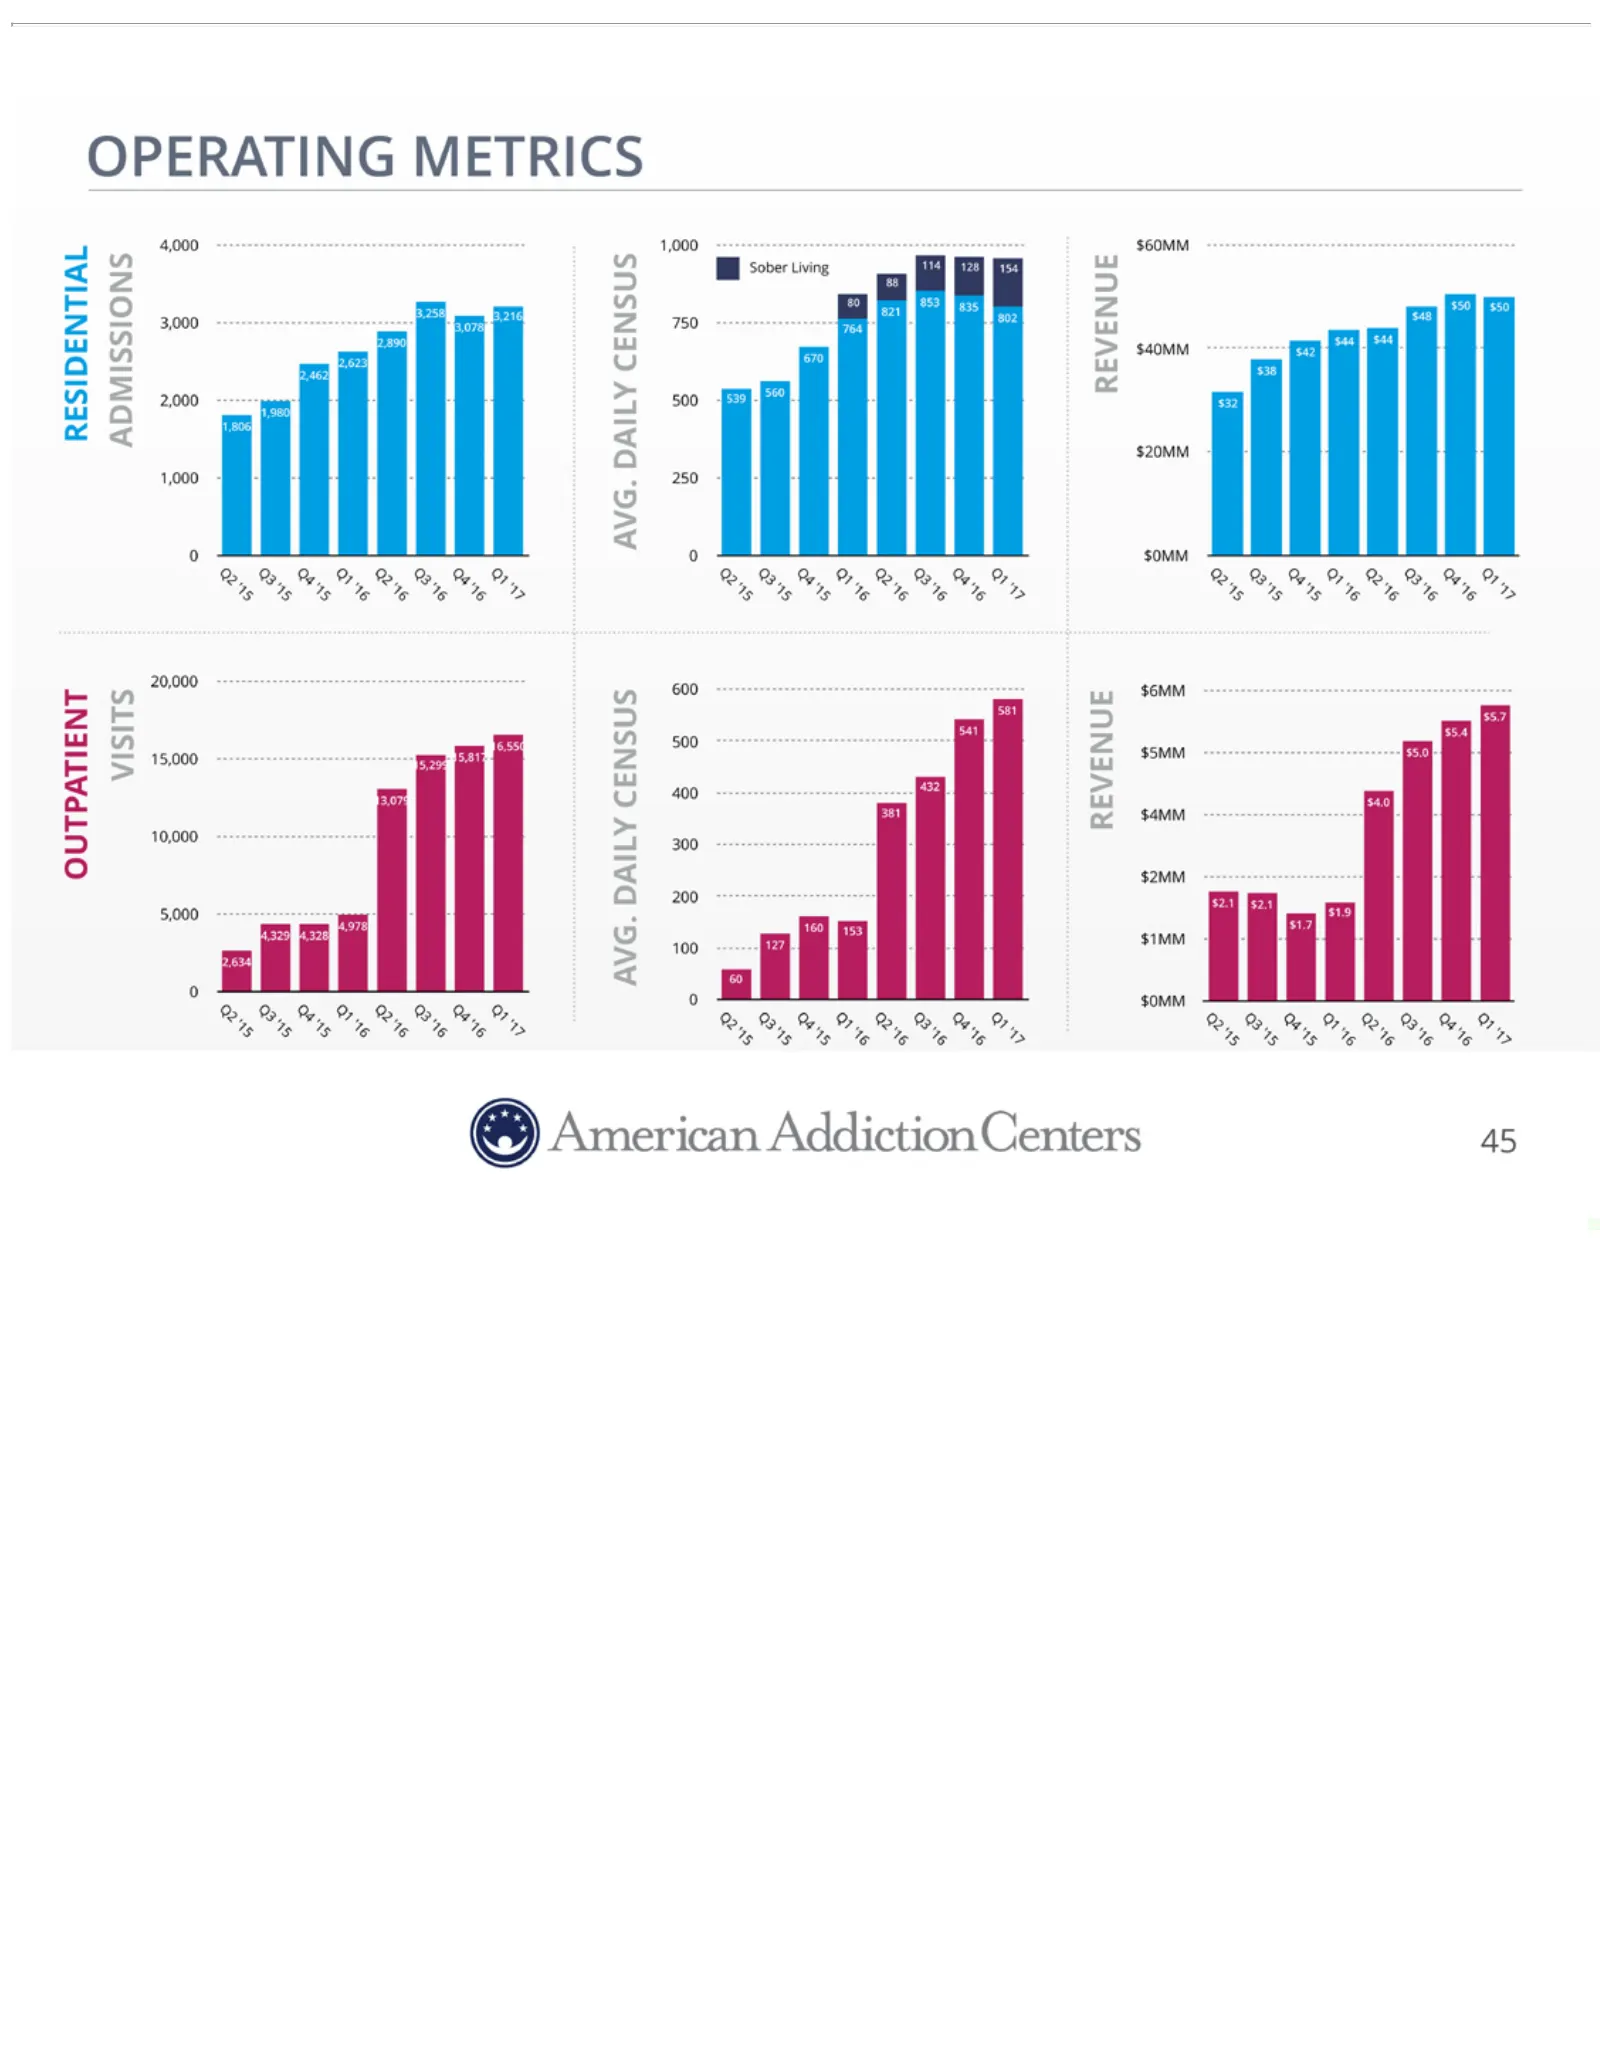
OPERATING 1,980 ‘16 10,000 ‘15 ‘16RESIDENTIAL Q4 ‘15 ‘16 300 Q1 ‘16METRICS ‘16 ‘17Q2’15 ADMISSIONS ‘16 REVENUE ‘15 4,000 Q3‘15 ‘16‘16 1,000 Q4 $2MM ‘16 ‘16 1,806 ‘16 Q1 DAILY CENSUS ‘16 ‘17 ‘17 $60MM 200 Q220,000 Q3 Sober Q4 600 Q1REVENUE $2.1 Living Q2 $2.1 Q3114 Q4 5,000 $6MM 128 DAILY Q1 154 ‘155
Slide 46: Residential Client Economics
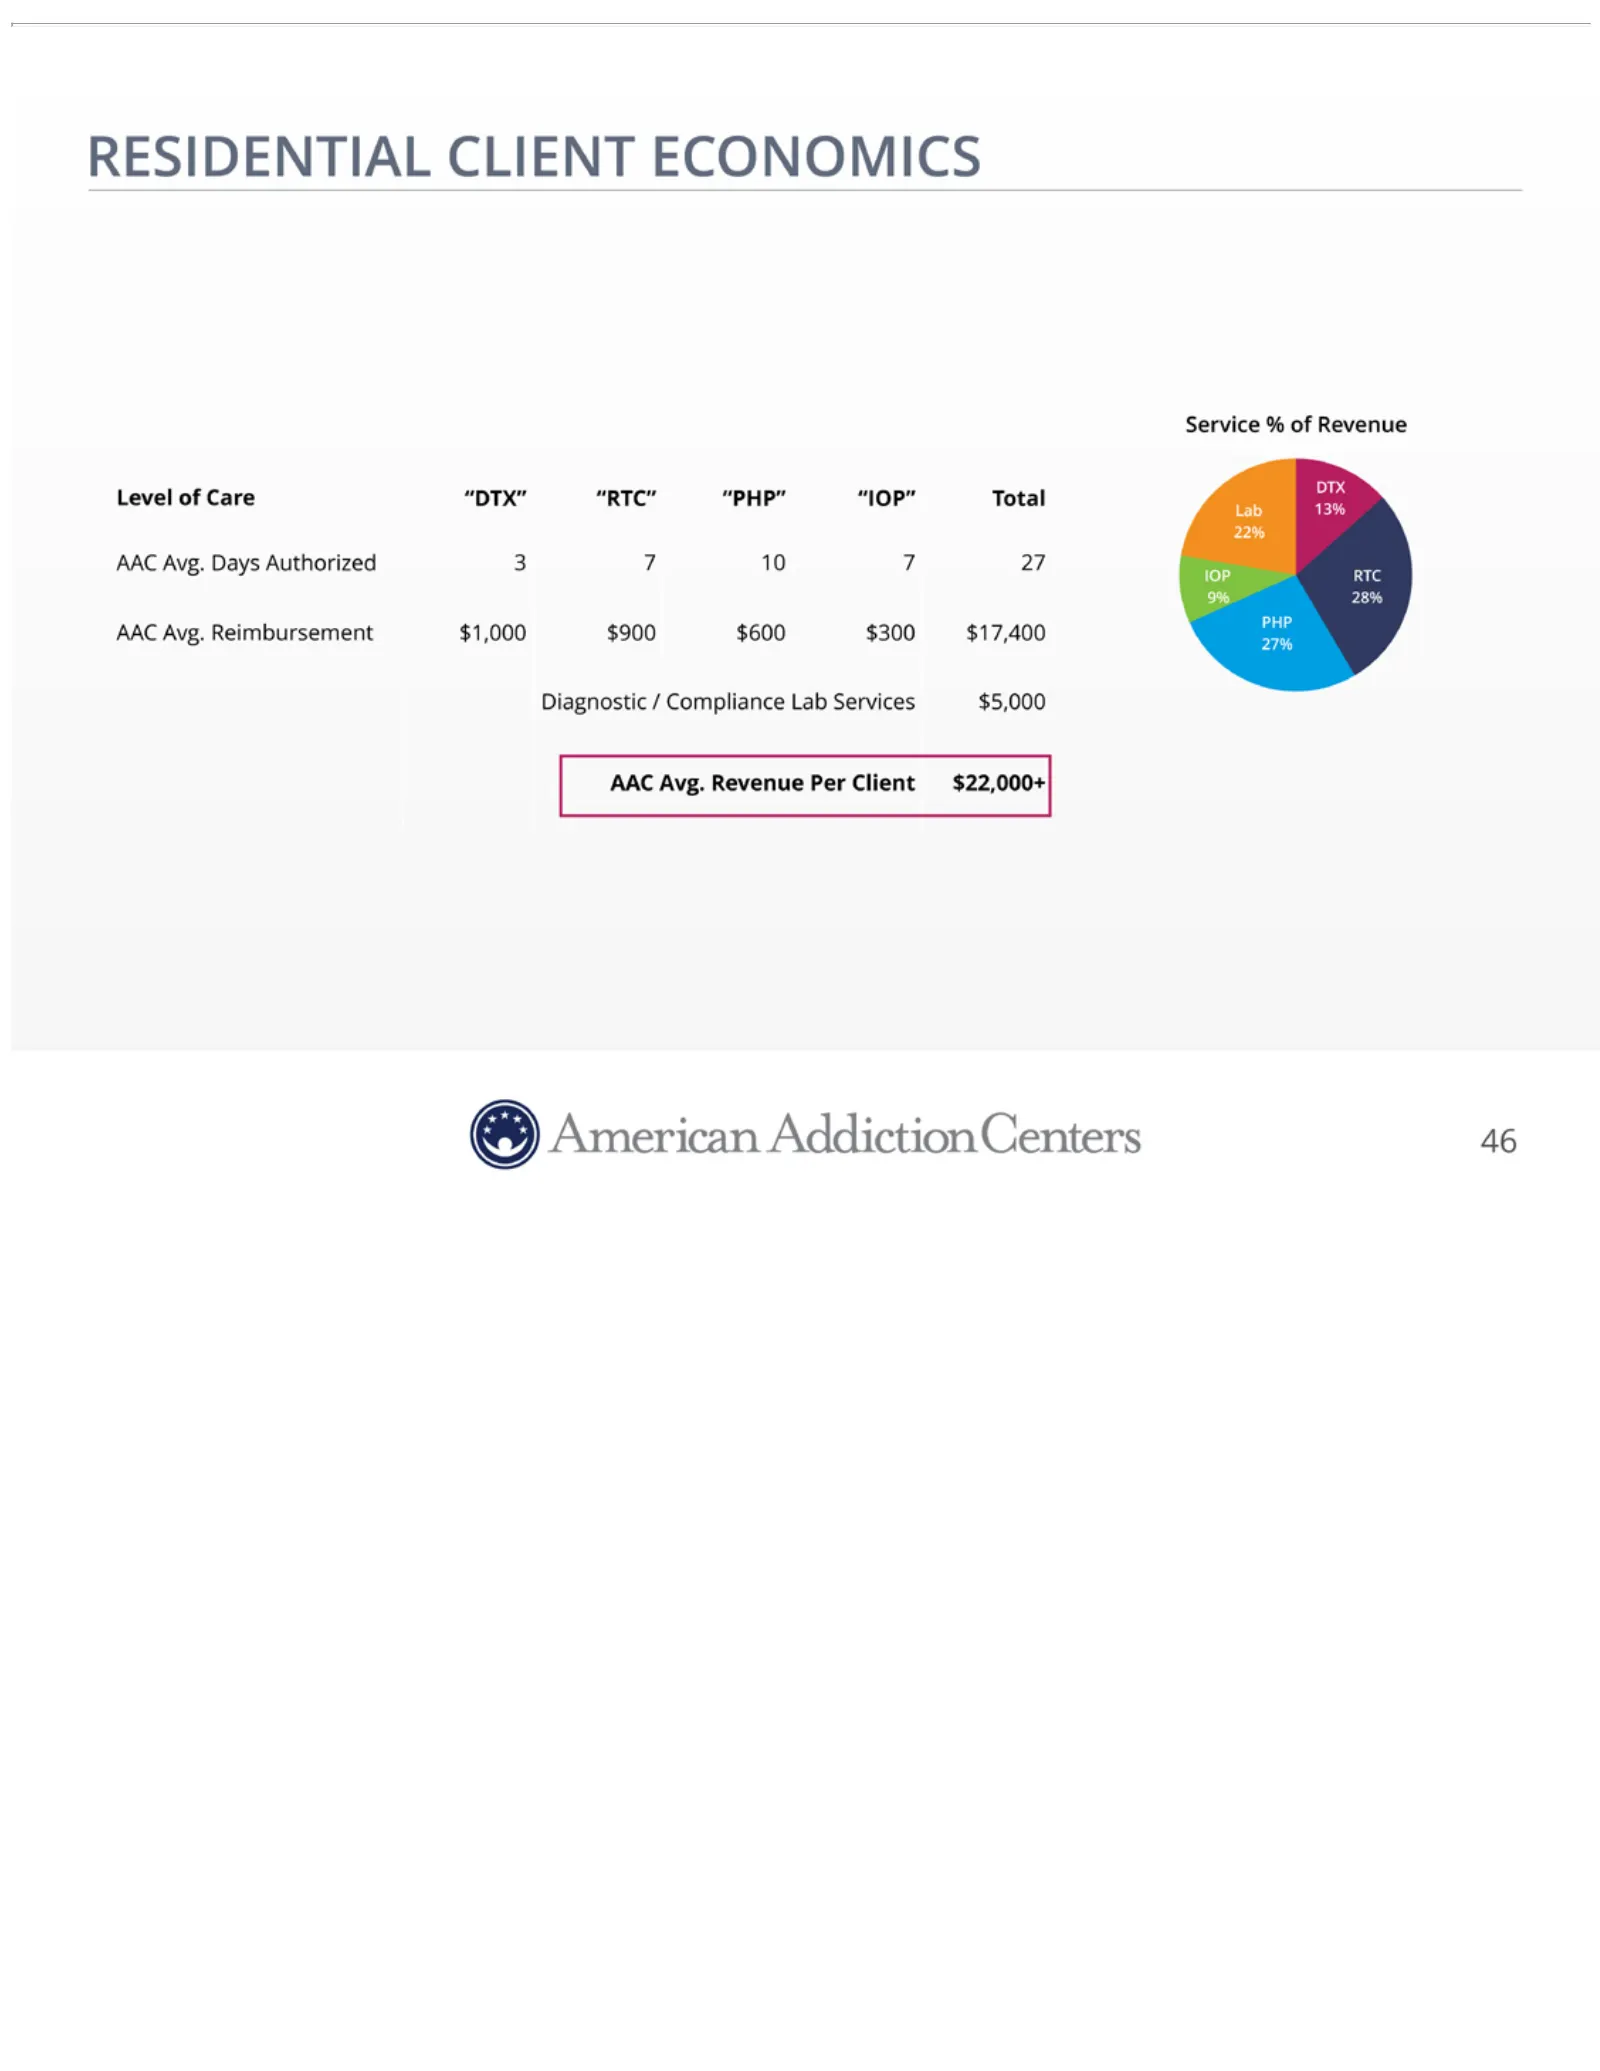
RESIDENTIAL Diagnostic / Compliance CLIENTLab ECONOMICS Services $5,000 Service AAC% Avg. of Revenue Revenue Level Per of Client Care$22,000+ “DTX” “RTC” “PHP” “IOP” Total DTX Lab 13% 22% AAC Avg. Days Authorized 3 7 10 7 27 IOP RTC 9% 28% AAC Avg. Reimbursement $1,000 $900 $600 $300 $17,400 PHP 27%
Slide 47: EBITDA Contribution by Service
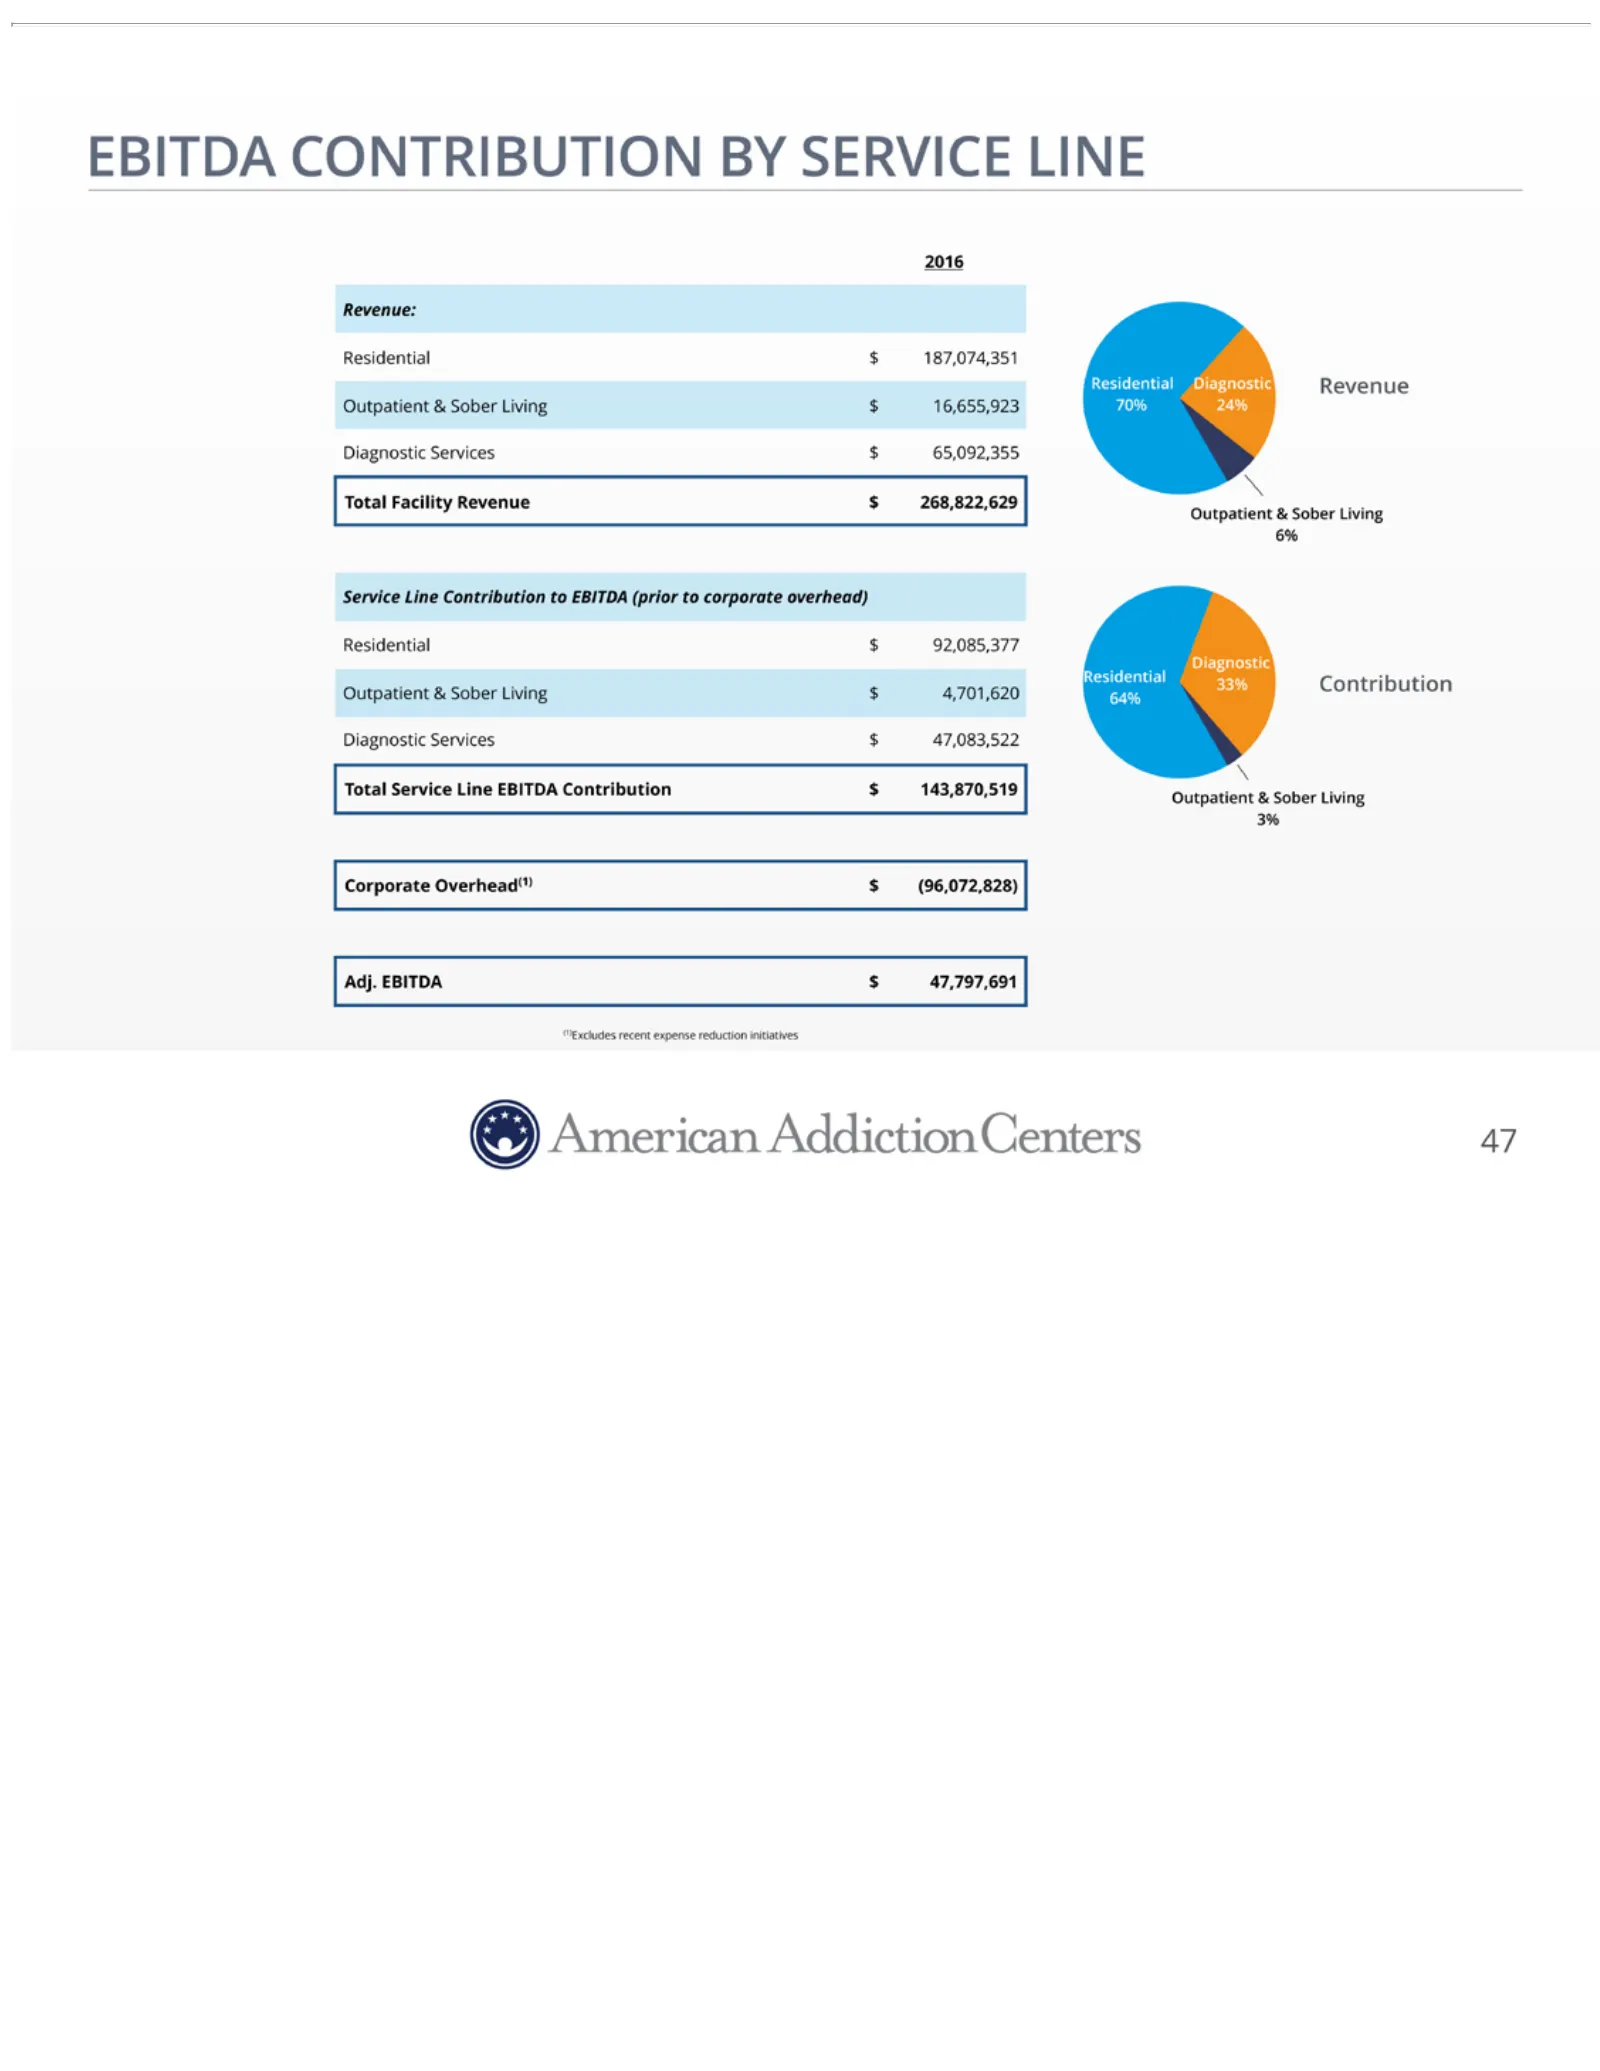
EBITDA CONTRIBUTION Diagnostic initiatives 47 Residential 33% Contribution BY SERVICE Outpatient Revenue:&Residential Sober Living $ Residential $ 64% Diagnostic Diagnostic Services Revenue $ Total Outpatient Service&Line Sober EBITDA Living Contribution $ 70% 24% Diagnostic $ 1 Outpatient Services
Slide 48: Decreasing Diagnostic Services Contribution
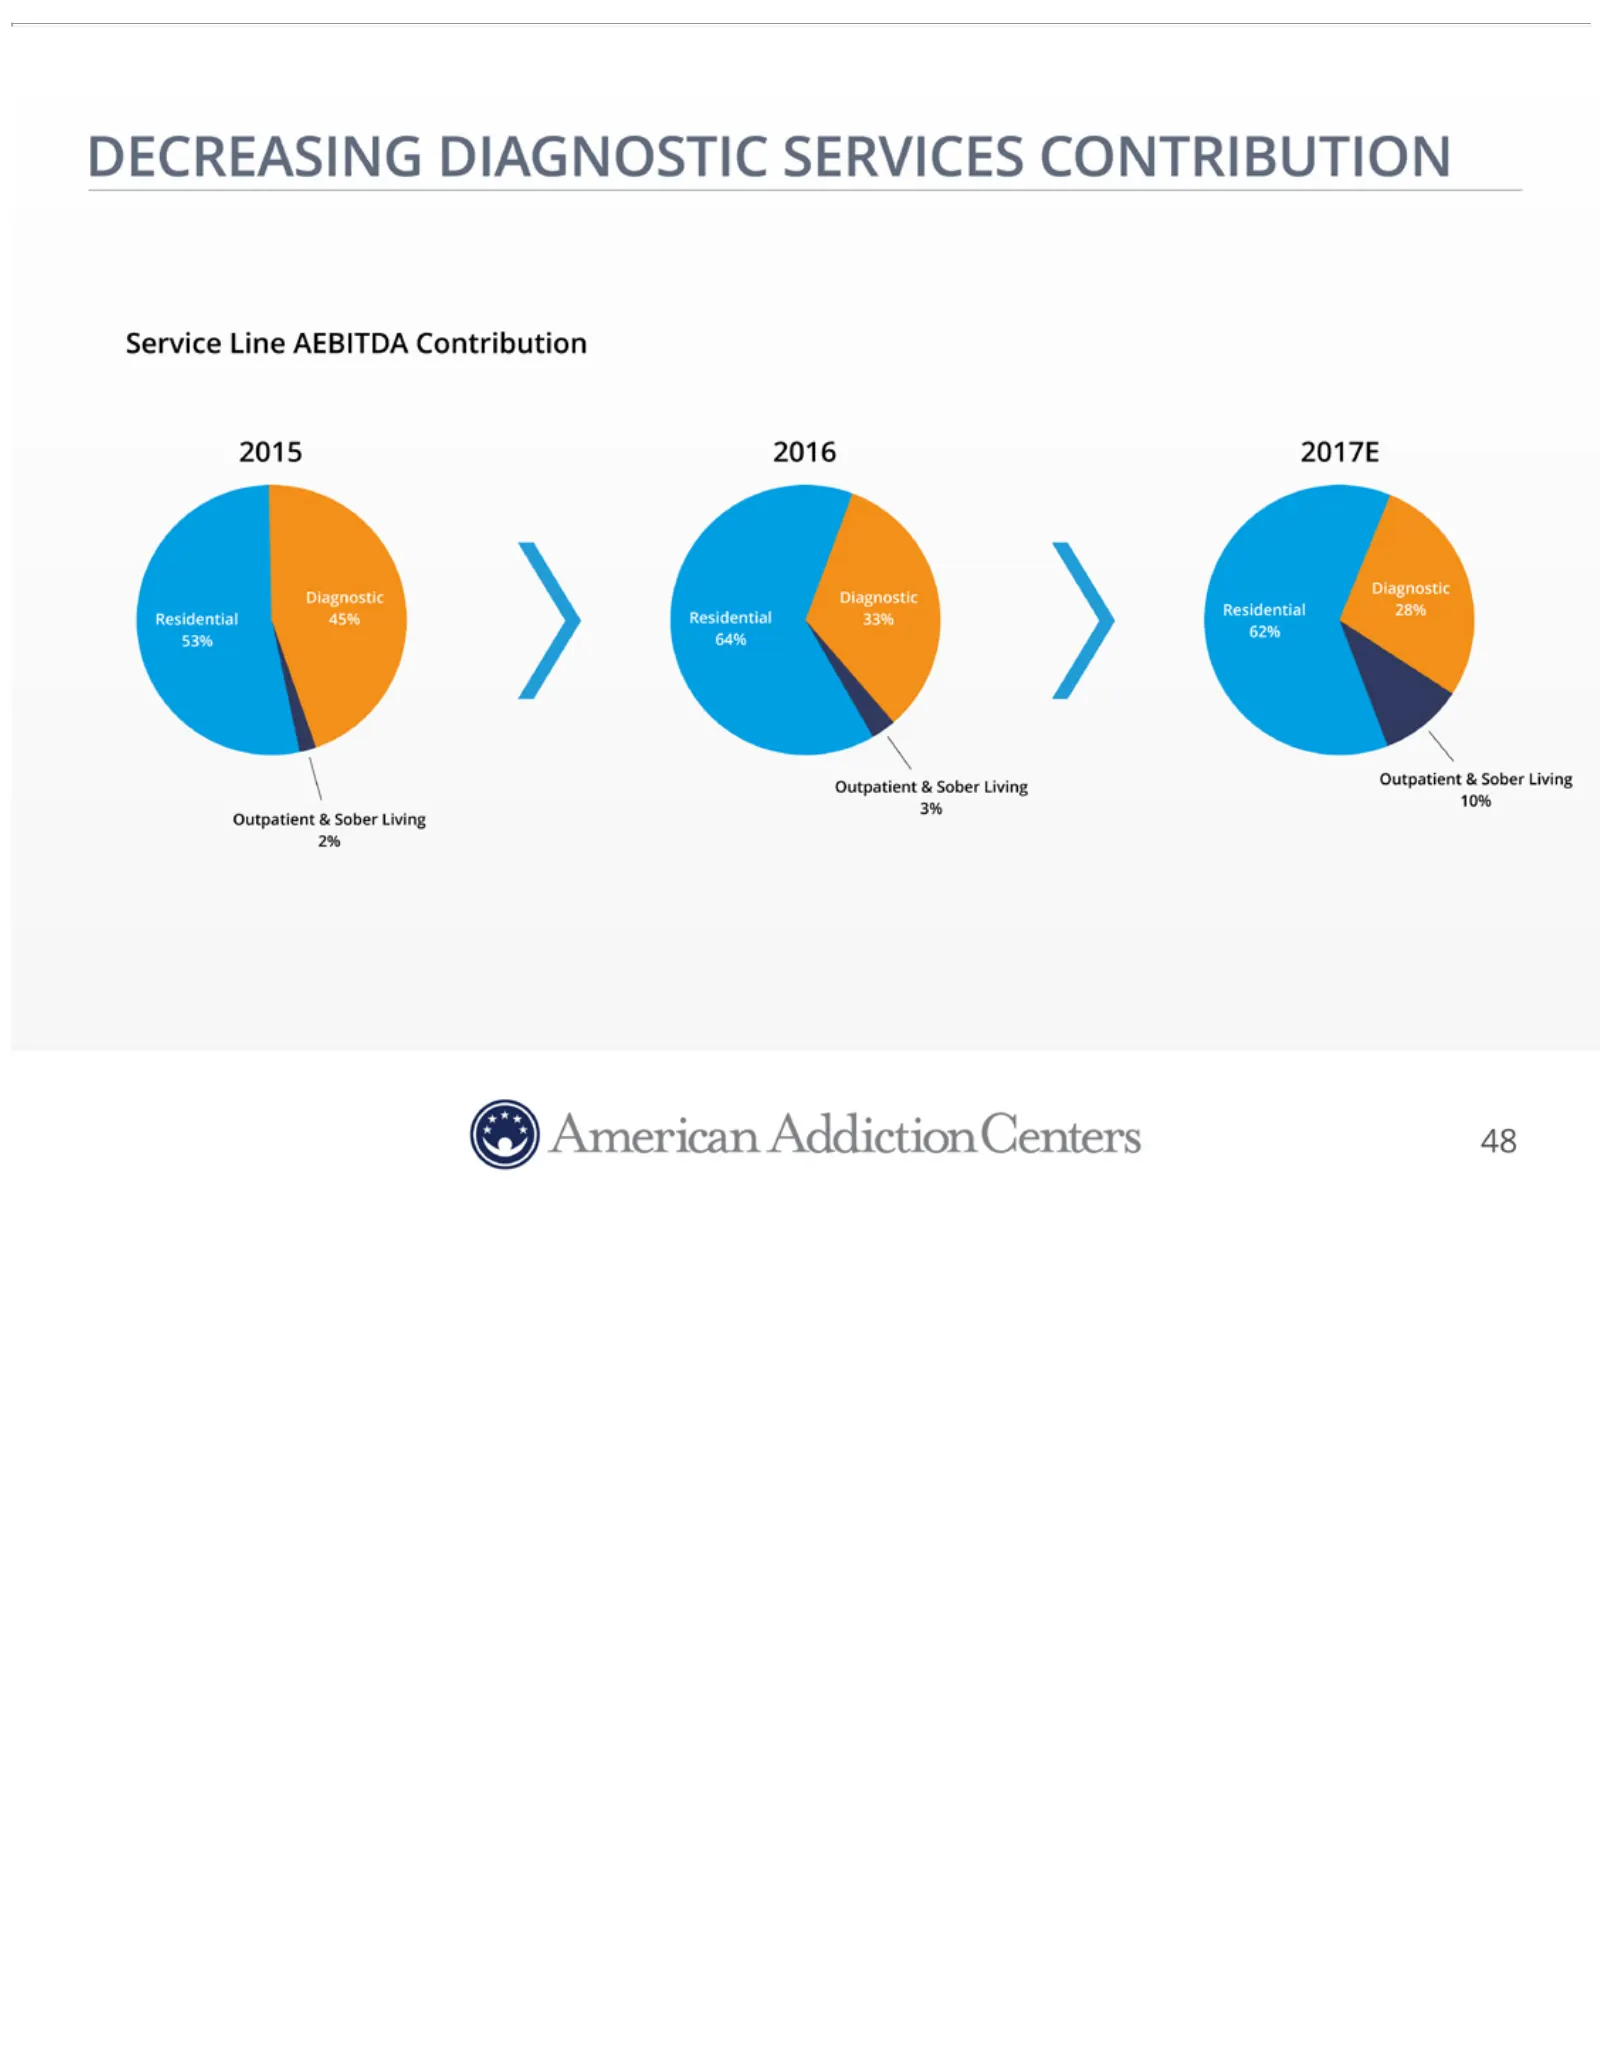
DECREASING 3% 10% Outpatient DIAGNOSTIC & Sober Living SERVICES 2% 48 CONTRIBUTION Service Line AEBITDA Contribution 2015 2016 2017E Diagnostic Diagnostic Diagnostic Residential 45% Residential 33% Residential 28% 53% 64% 62% Outpatient & Sober Living Outpatient & Sober Living
Slide 49: Historical Financial Performance
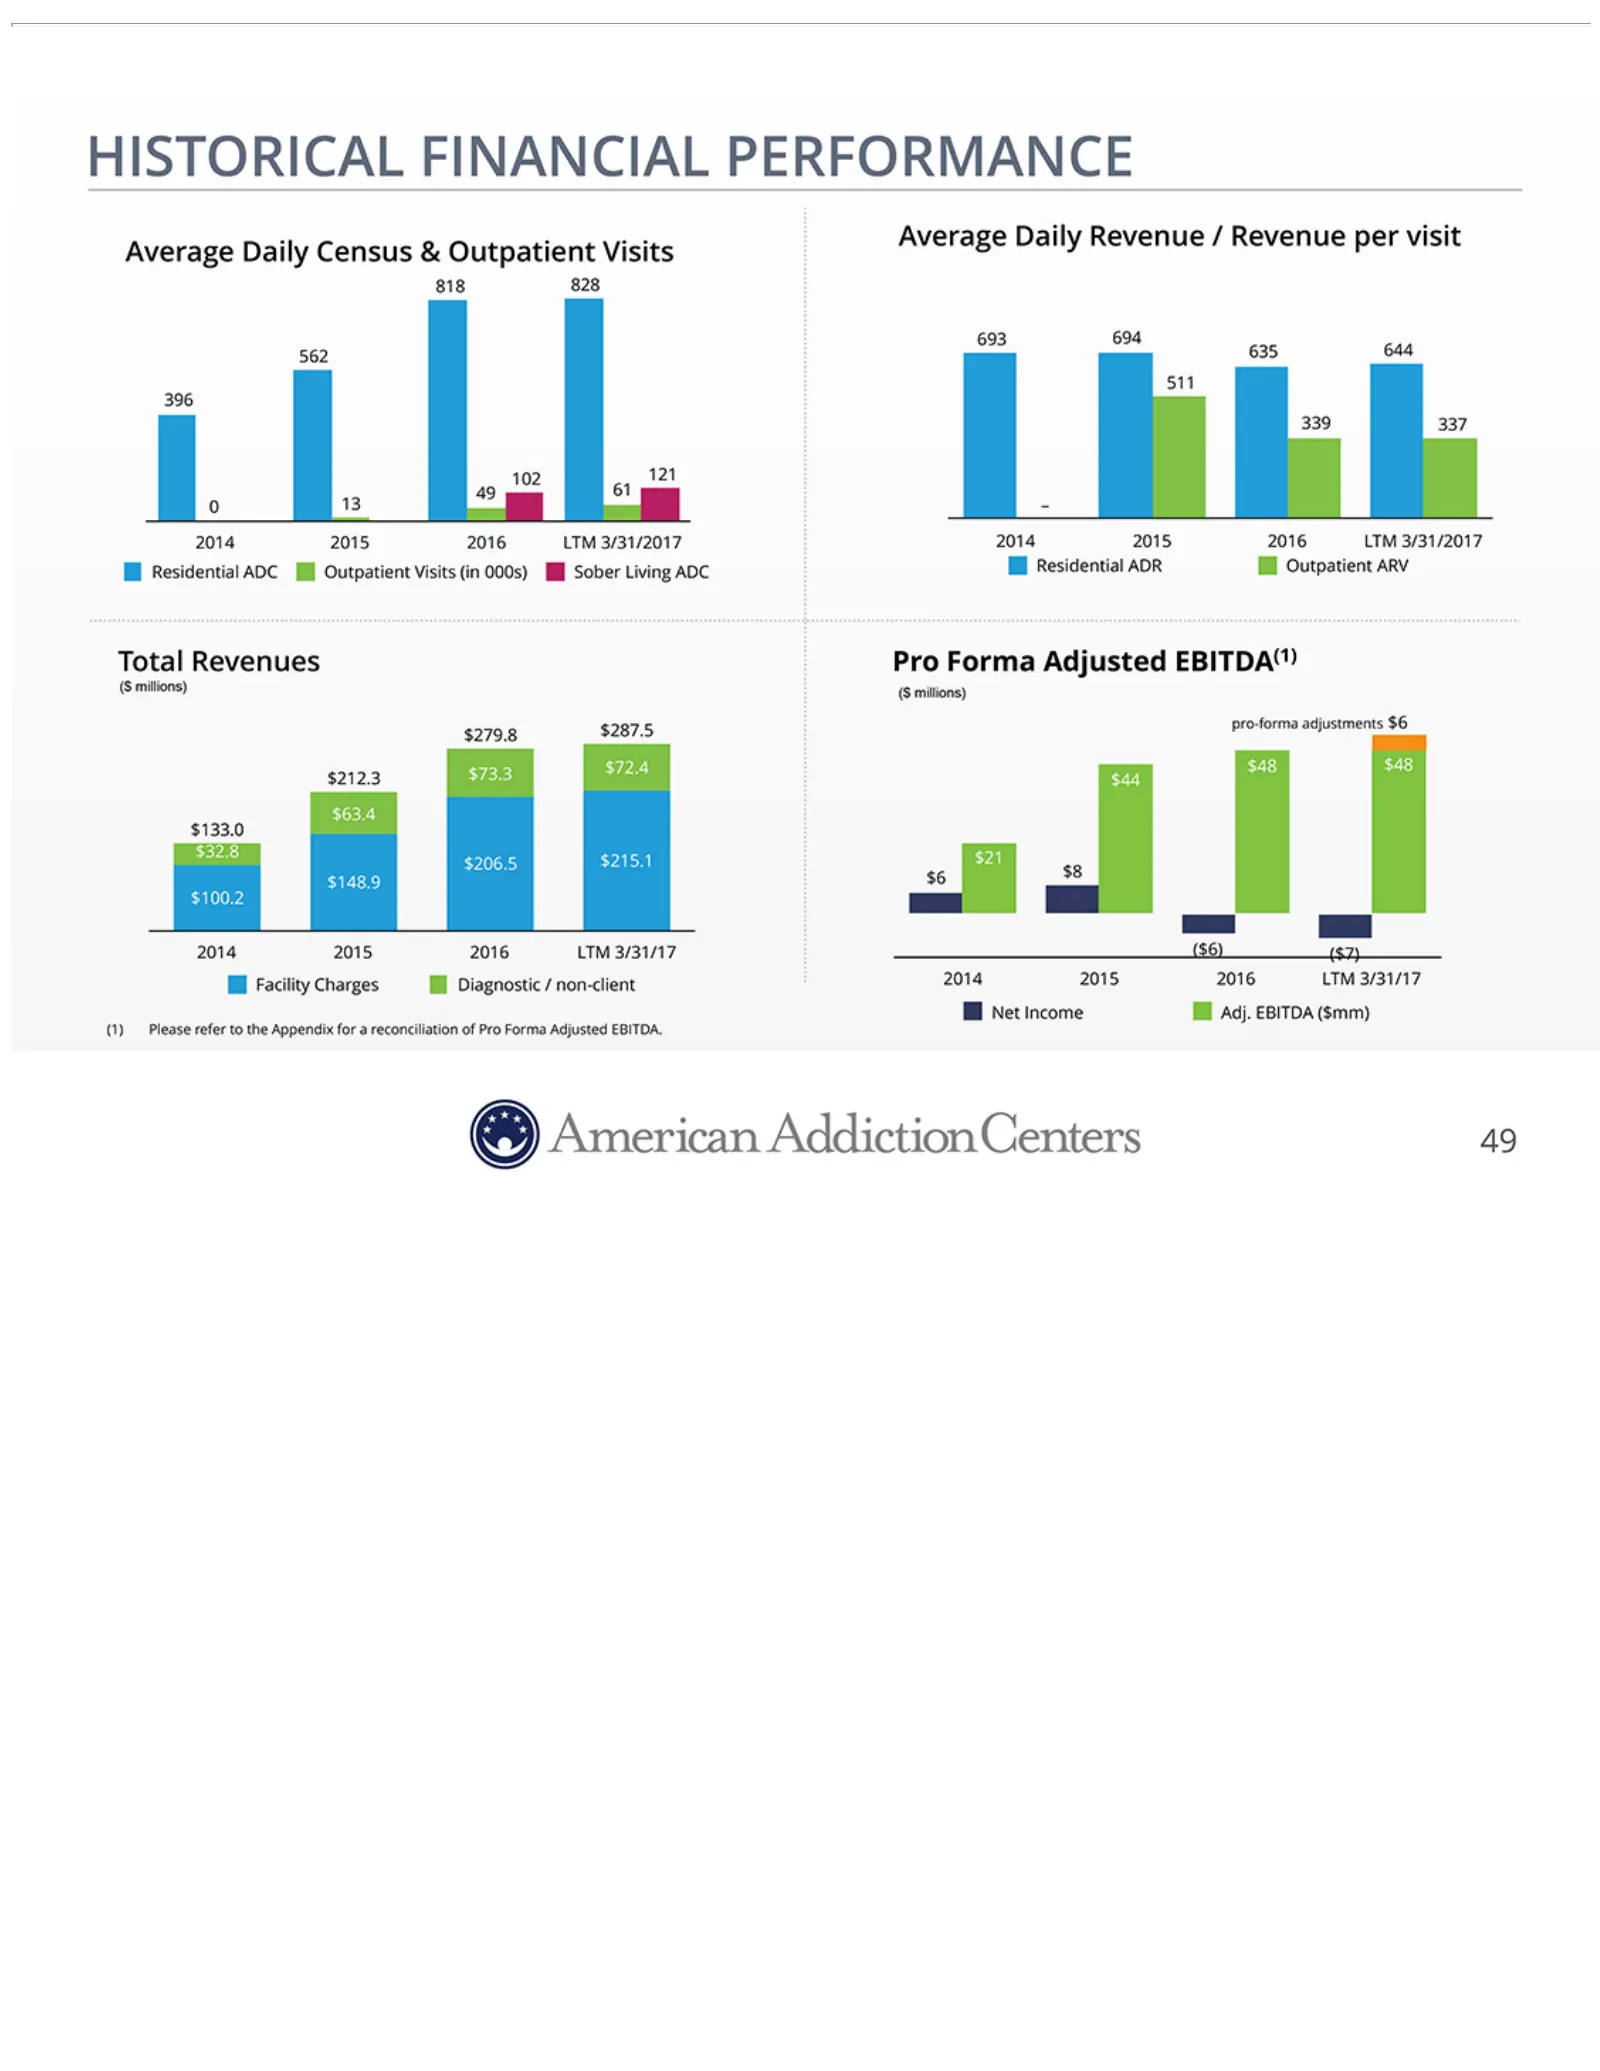
HISTORICAL Residential $206.5 $215.1 ADC $6 FINANCIAL Outpatient $8 $148.9 $100.2 Visits PERFORMANCE (in 2014 000s) 2015 Sober 2016 Average Living LTMDaily ADC 3/31/17 Revenue Residential ($6) ($7) / Revenue ADR Facility Outpatient per Charges visit Average ARV Diagnostic Total Daily Revenues / non-
Slide 50: Facility Revenue Per Admission
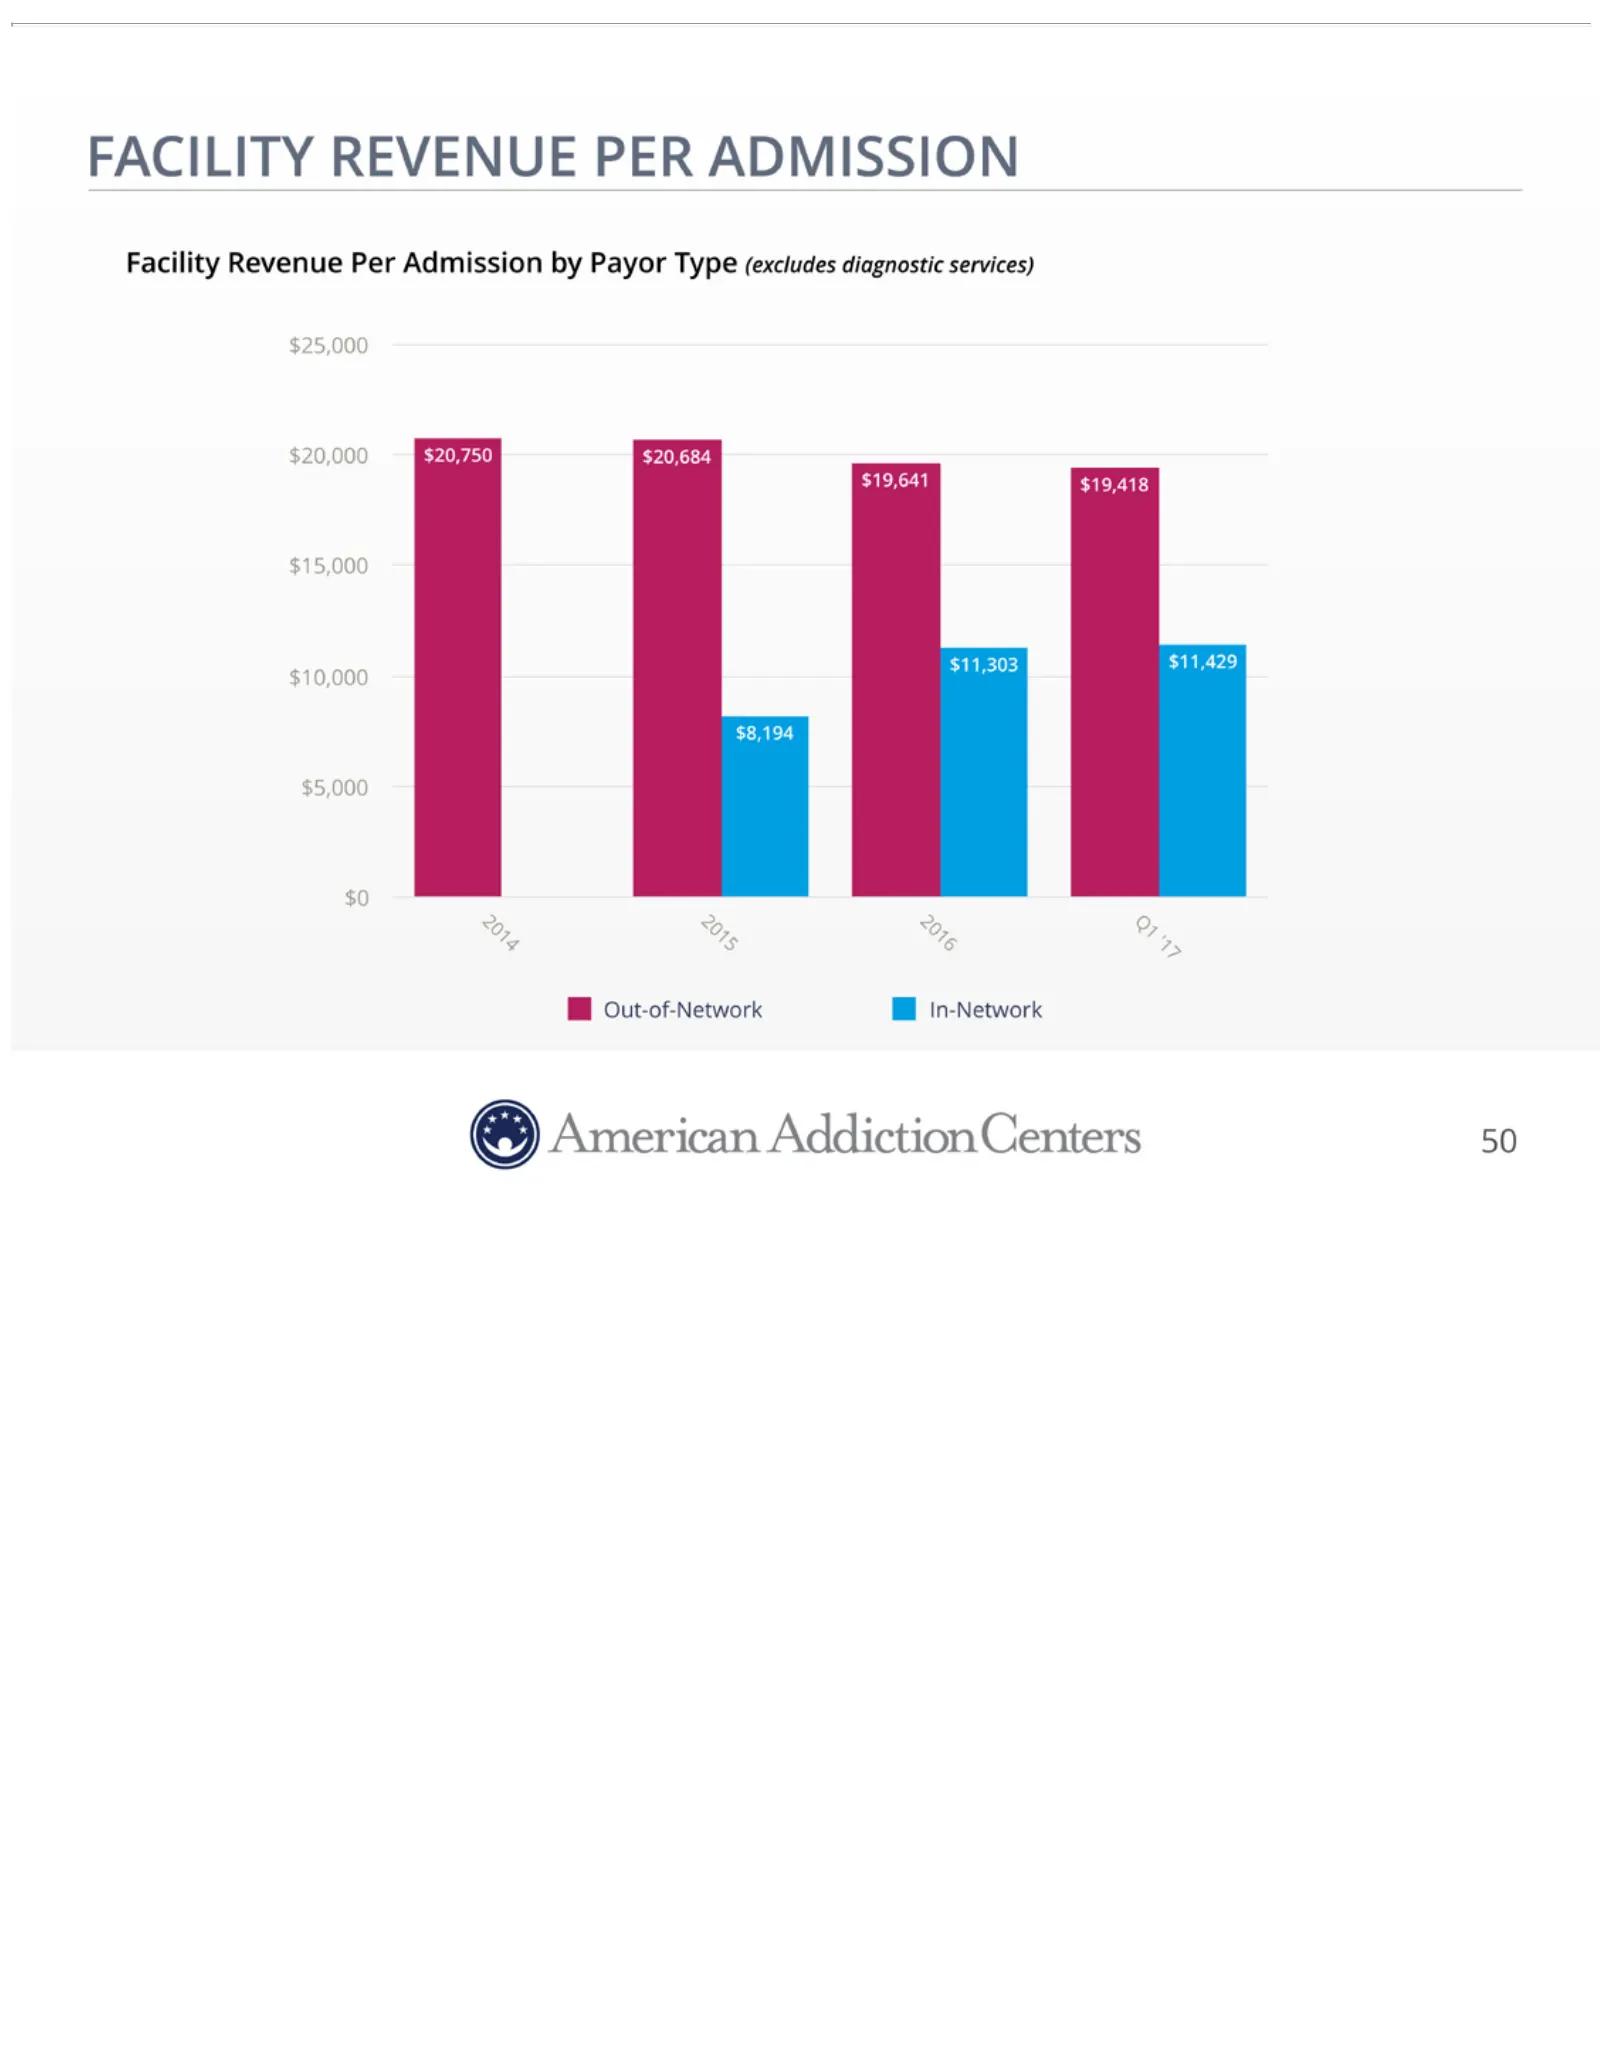
FACILITY REVENUE In-Network 50 PER ADMISSION Facility Revenue Per Admission by Payor Type (excludes diagnostic services) $25,000 $20,000 $20,750 $20,684 $19,641 $19,418 $15,000 $10,000 $11,303 $11,429 $8,194 $5,000 $0 2014 2015 2016 Q1 ‘17 Out-of-Network
Slide 51: Recent Expense Reduction Initiatives
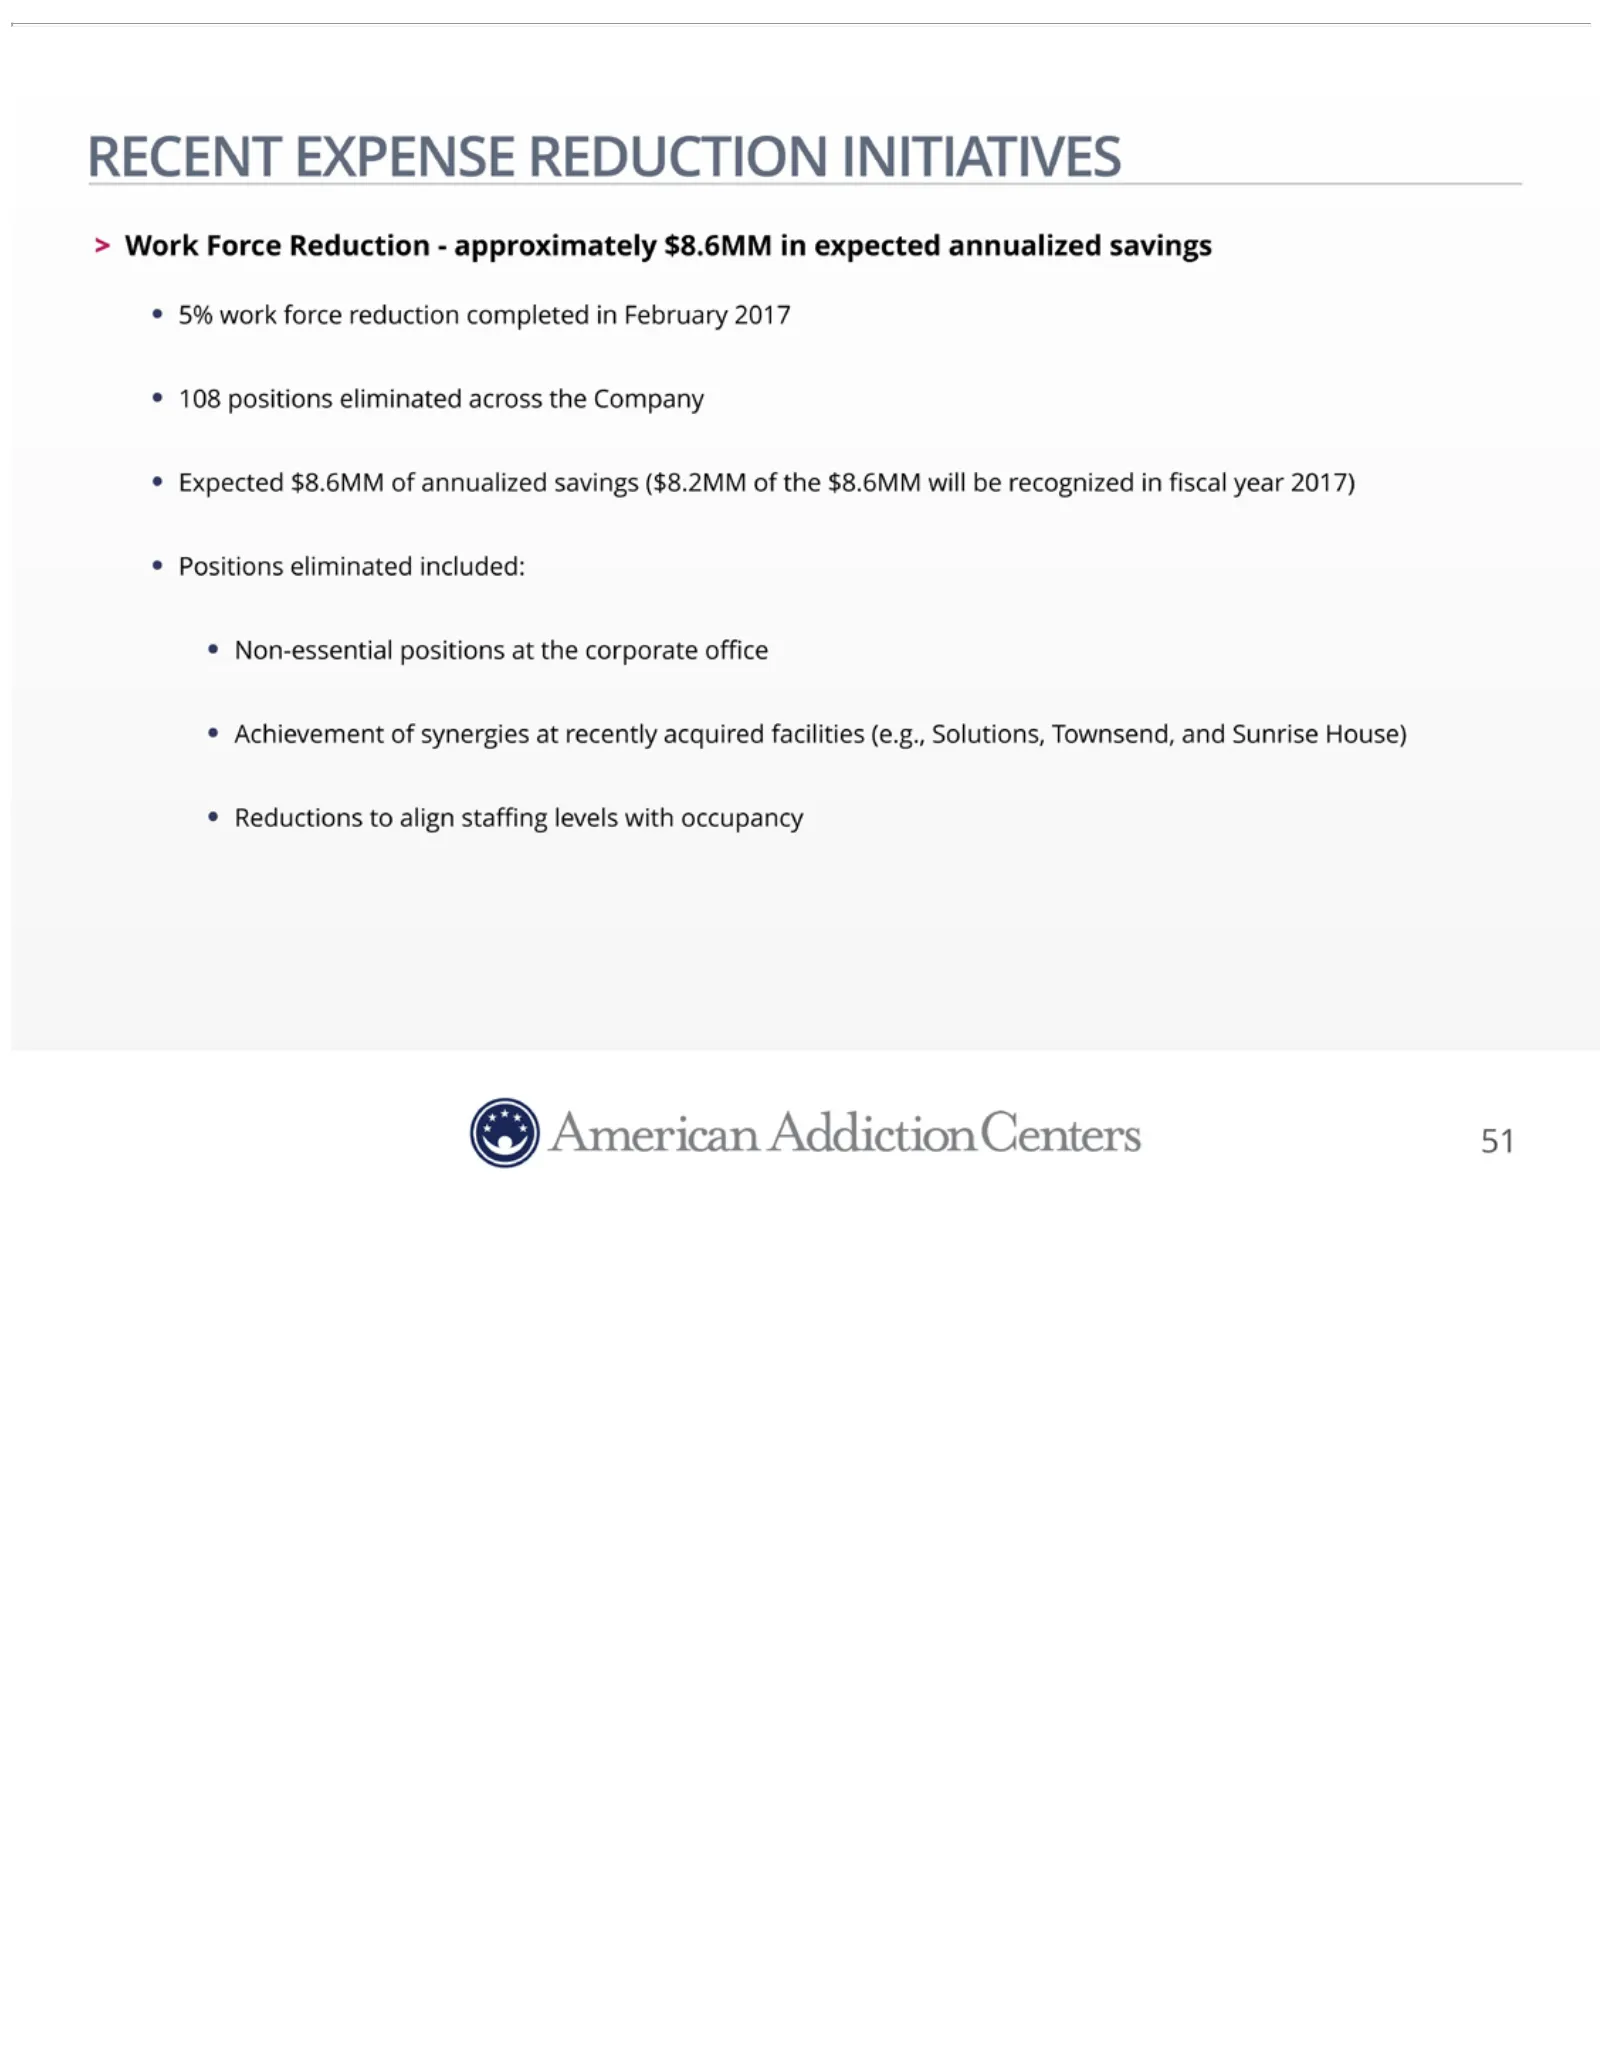
RECENT savings align staffing ($8.2MM EXPENSE levels ofwith the REDUCTION $8.6MM occupancy will 51 INITIATIVES be recognized>inWork fiscalForce year Reduction—approximately 2017) • Positions eliminated$8.6MM included: in•expected Non-essential annualized positions savings at the • 5% corporate work
Slide 52: DSOs Increased, Collections Were Stable
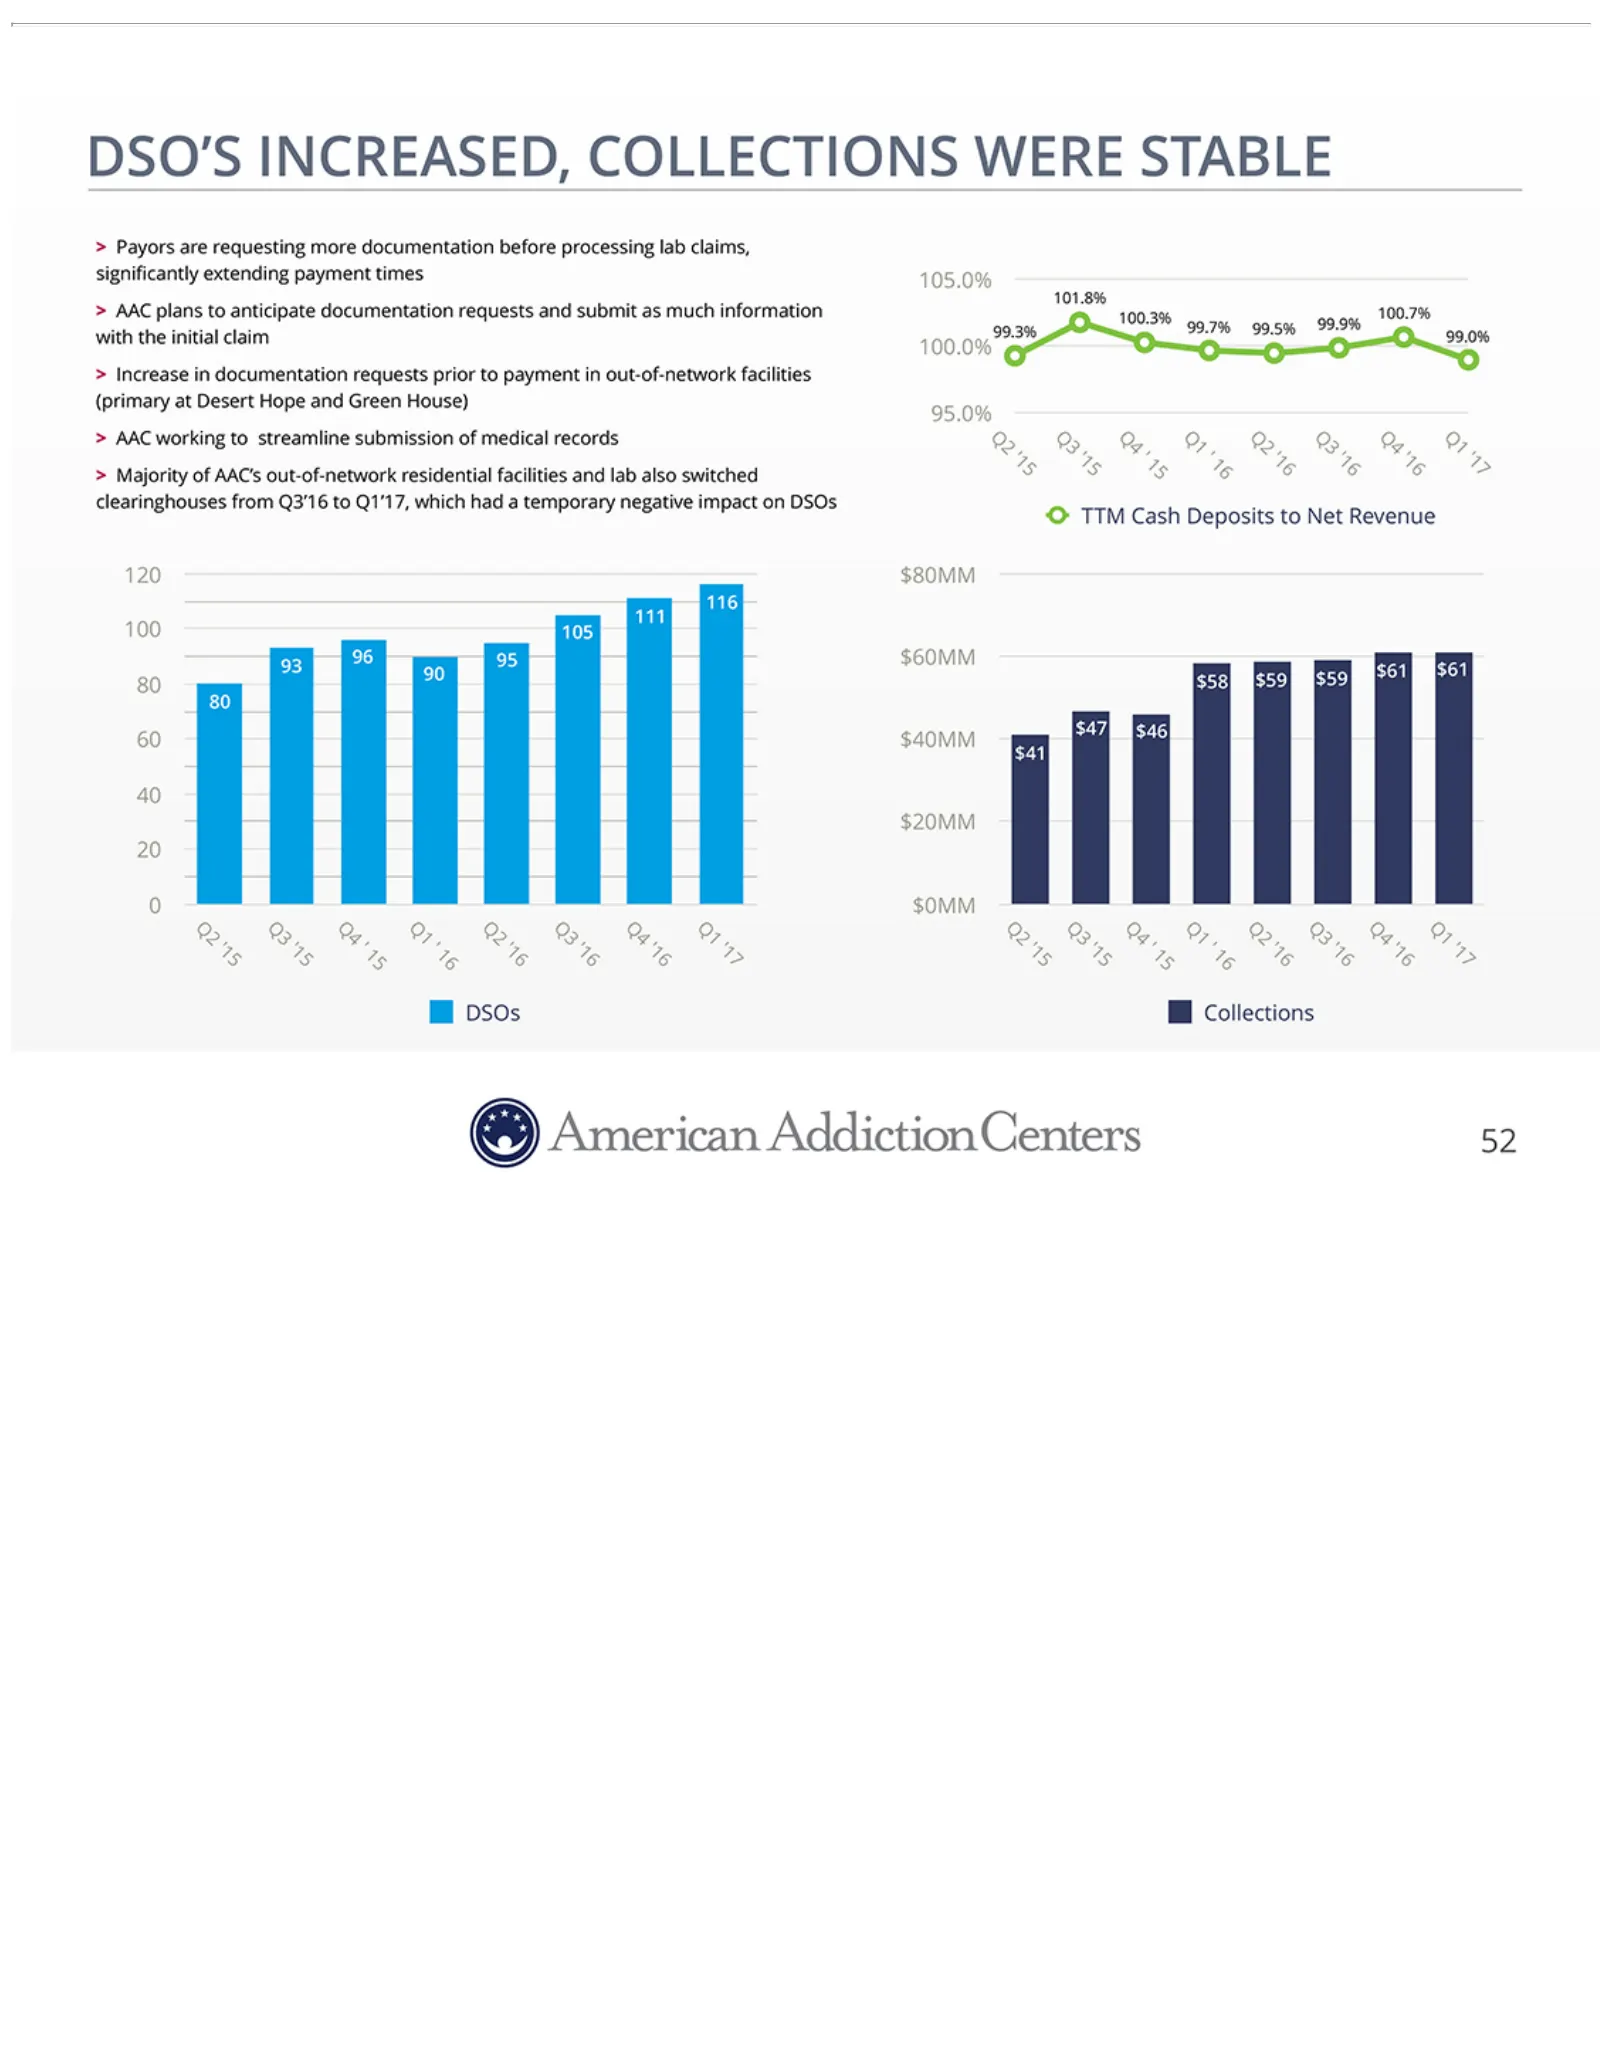
DSO’S 100.3% Q2 116 Q3 111Q4 INCREASED, 100.7% 100Q1 105 Q299.3% 93 Q396Q4 COLLECTIONS 95 99.7% Q1 $60MM ‘15’15’ 99.5% 90‘99.9% $59 ‘16’16’16’17 WERE $61 with $61 STABLE the 80 >initial $58 Majority >$59 claim Payors 80 of 100.0% 60 AAC’s are$40MM requesting out-of-network 99.0% $47>more $46 Increas
Slide 53: 2017 DSO Update
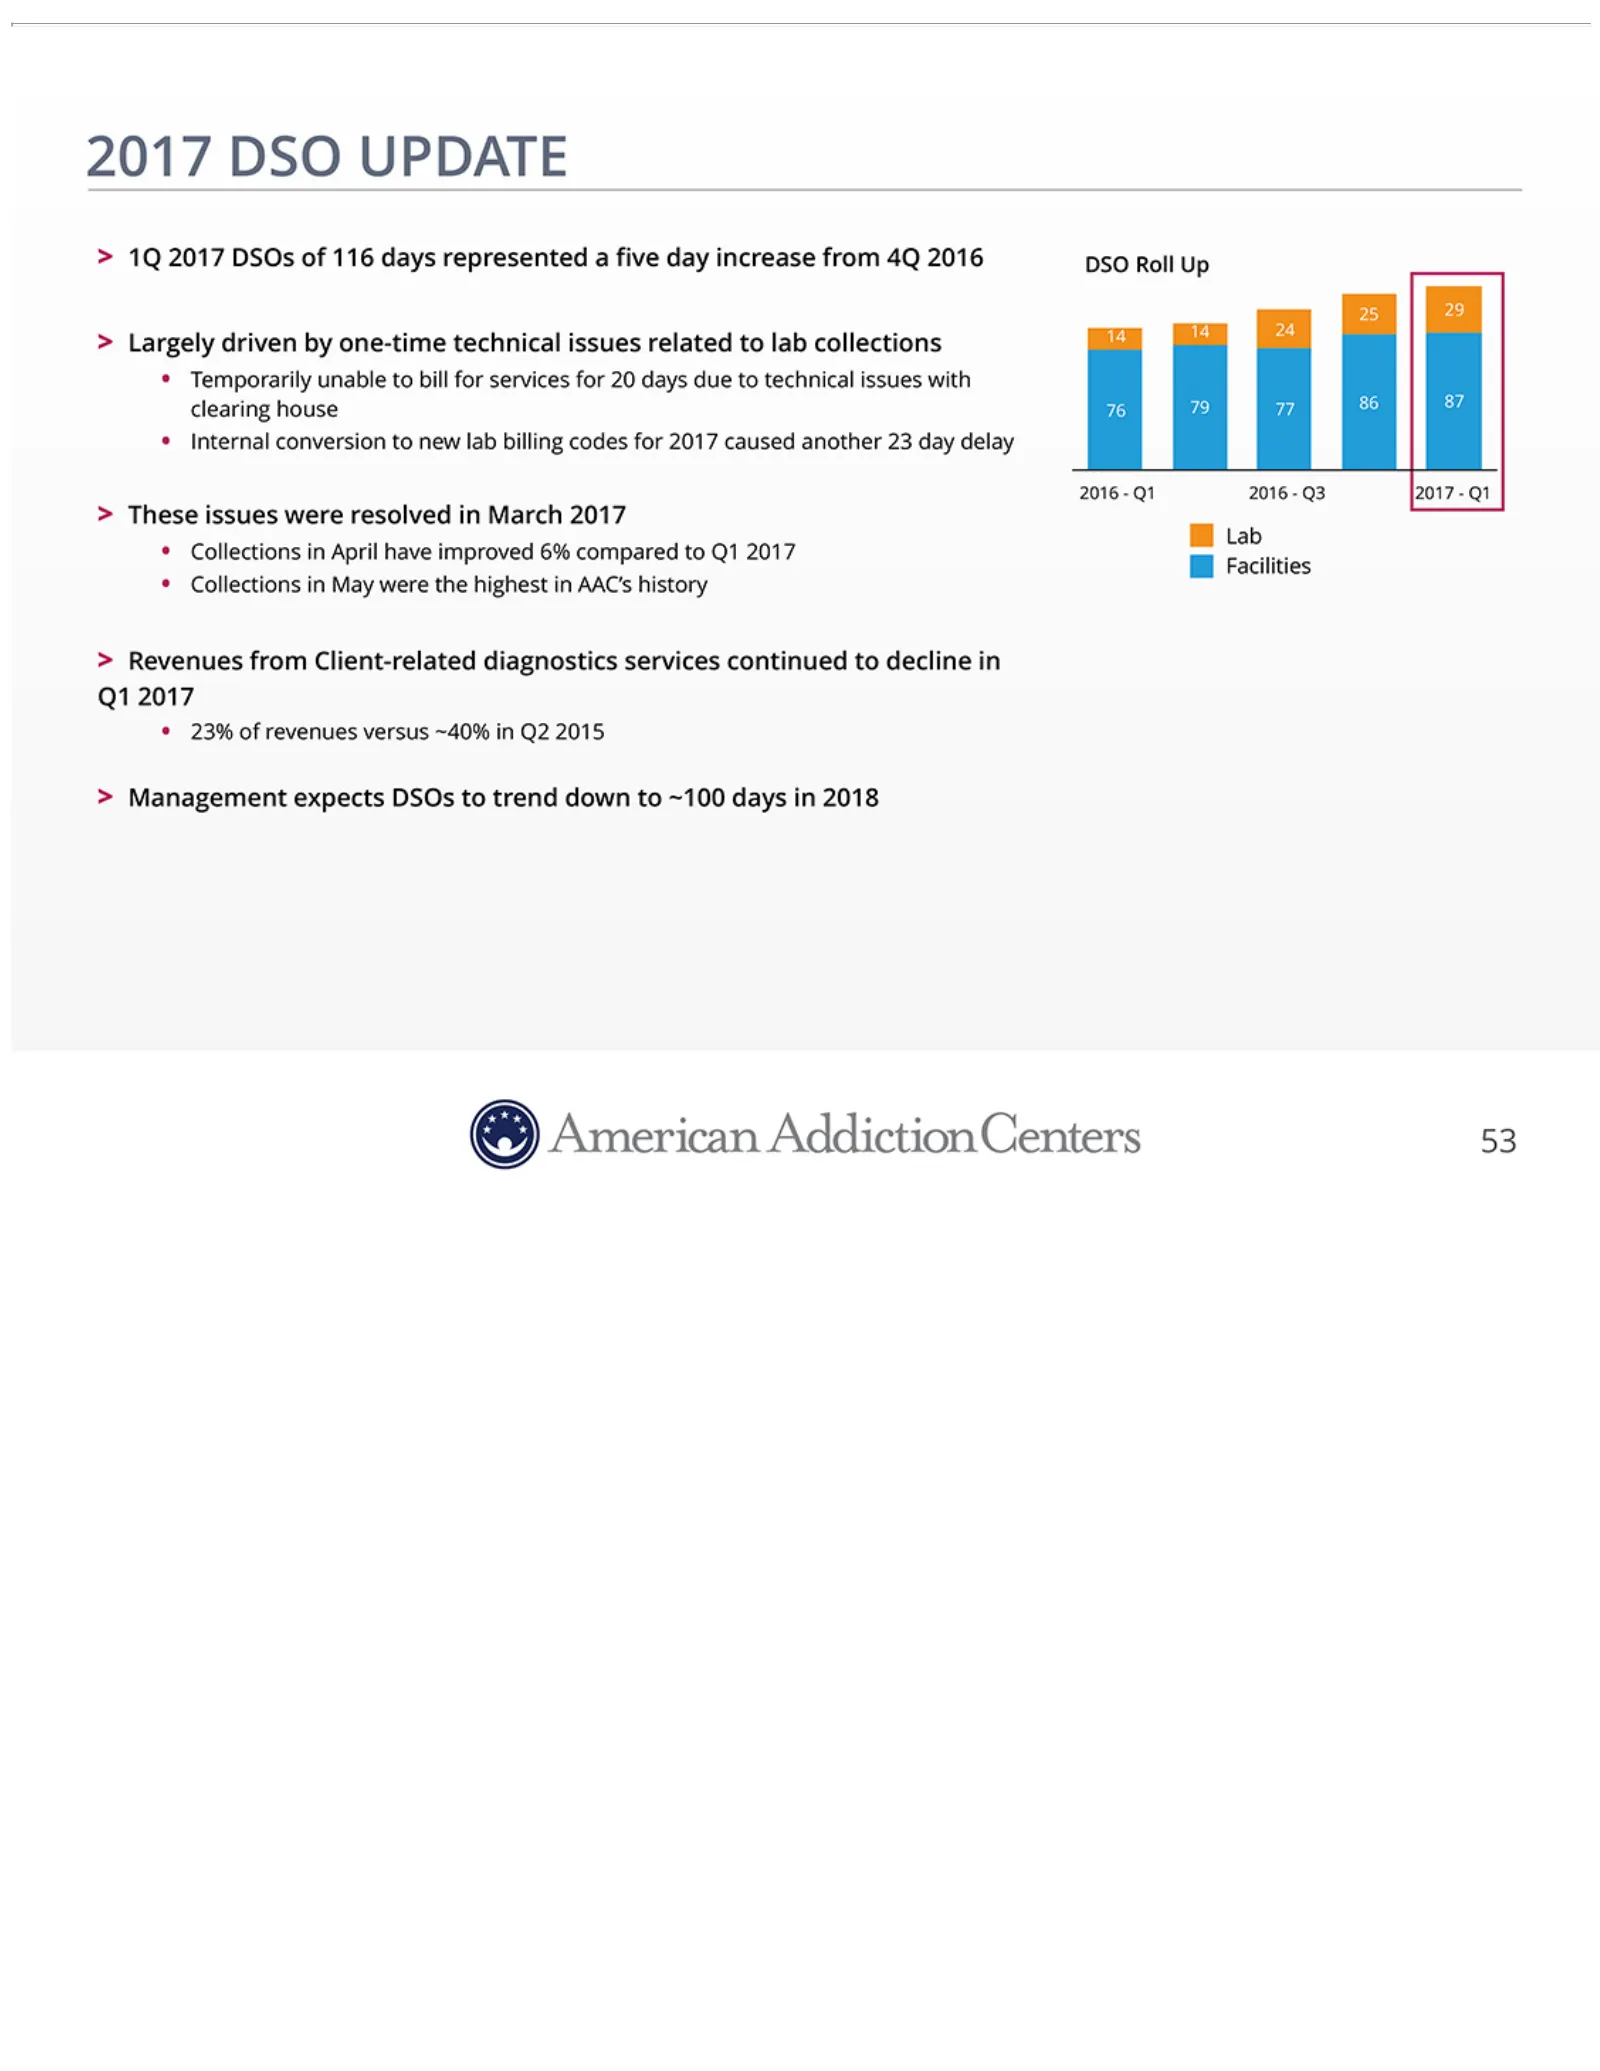
2017 DSO conversion services continued UPDATE to new lab to 1Q decline billing 2017in codes DSOs Q1 2017 for of 2017 116 23%days caused of revenues represented another versus 23 a five day ~40% day delay increase inThese Q2 2015 issues fromManagement 4Q were 2016 resolved Largely expects in driven M
Slide 54: Financial Policy
FINANCIAL leverage > Management POLICY >isFinancial committedpolicy to reducing includesleverage the following by both components: EBITDA expansion • Maintain and ourdebt discipline reduction for >sufficient Intend toliquidity use available and cash cashfor flow operations for attractive • Maintain
Slide 55: Appendix
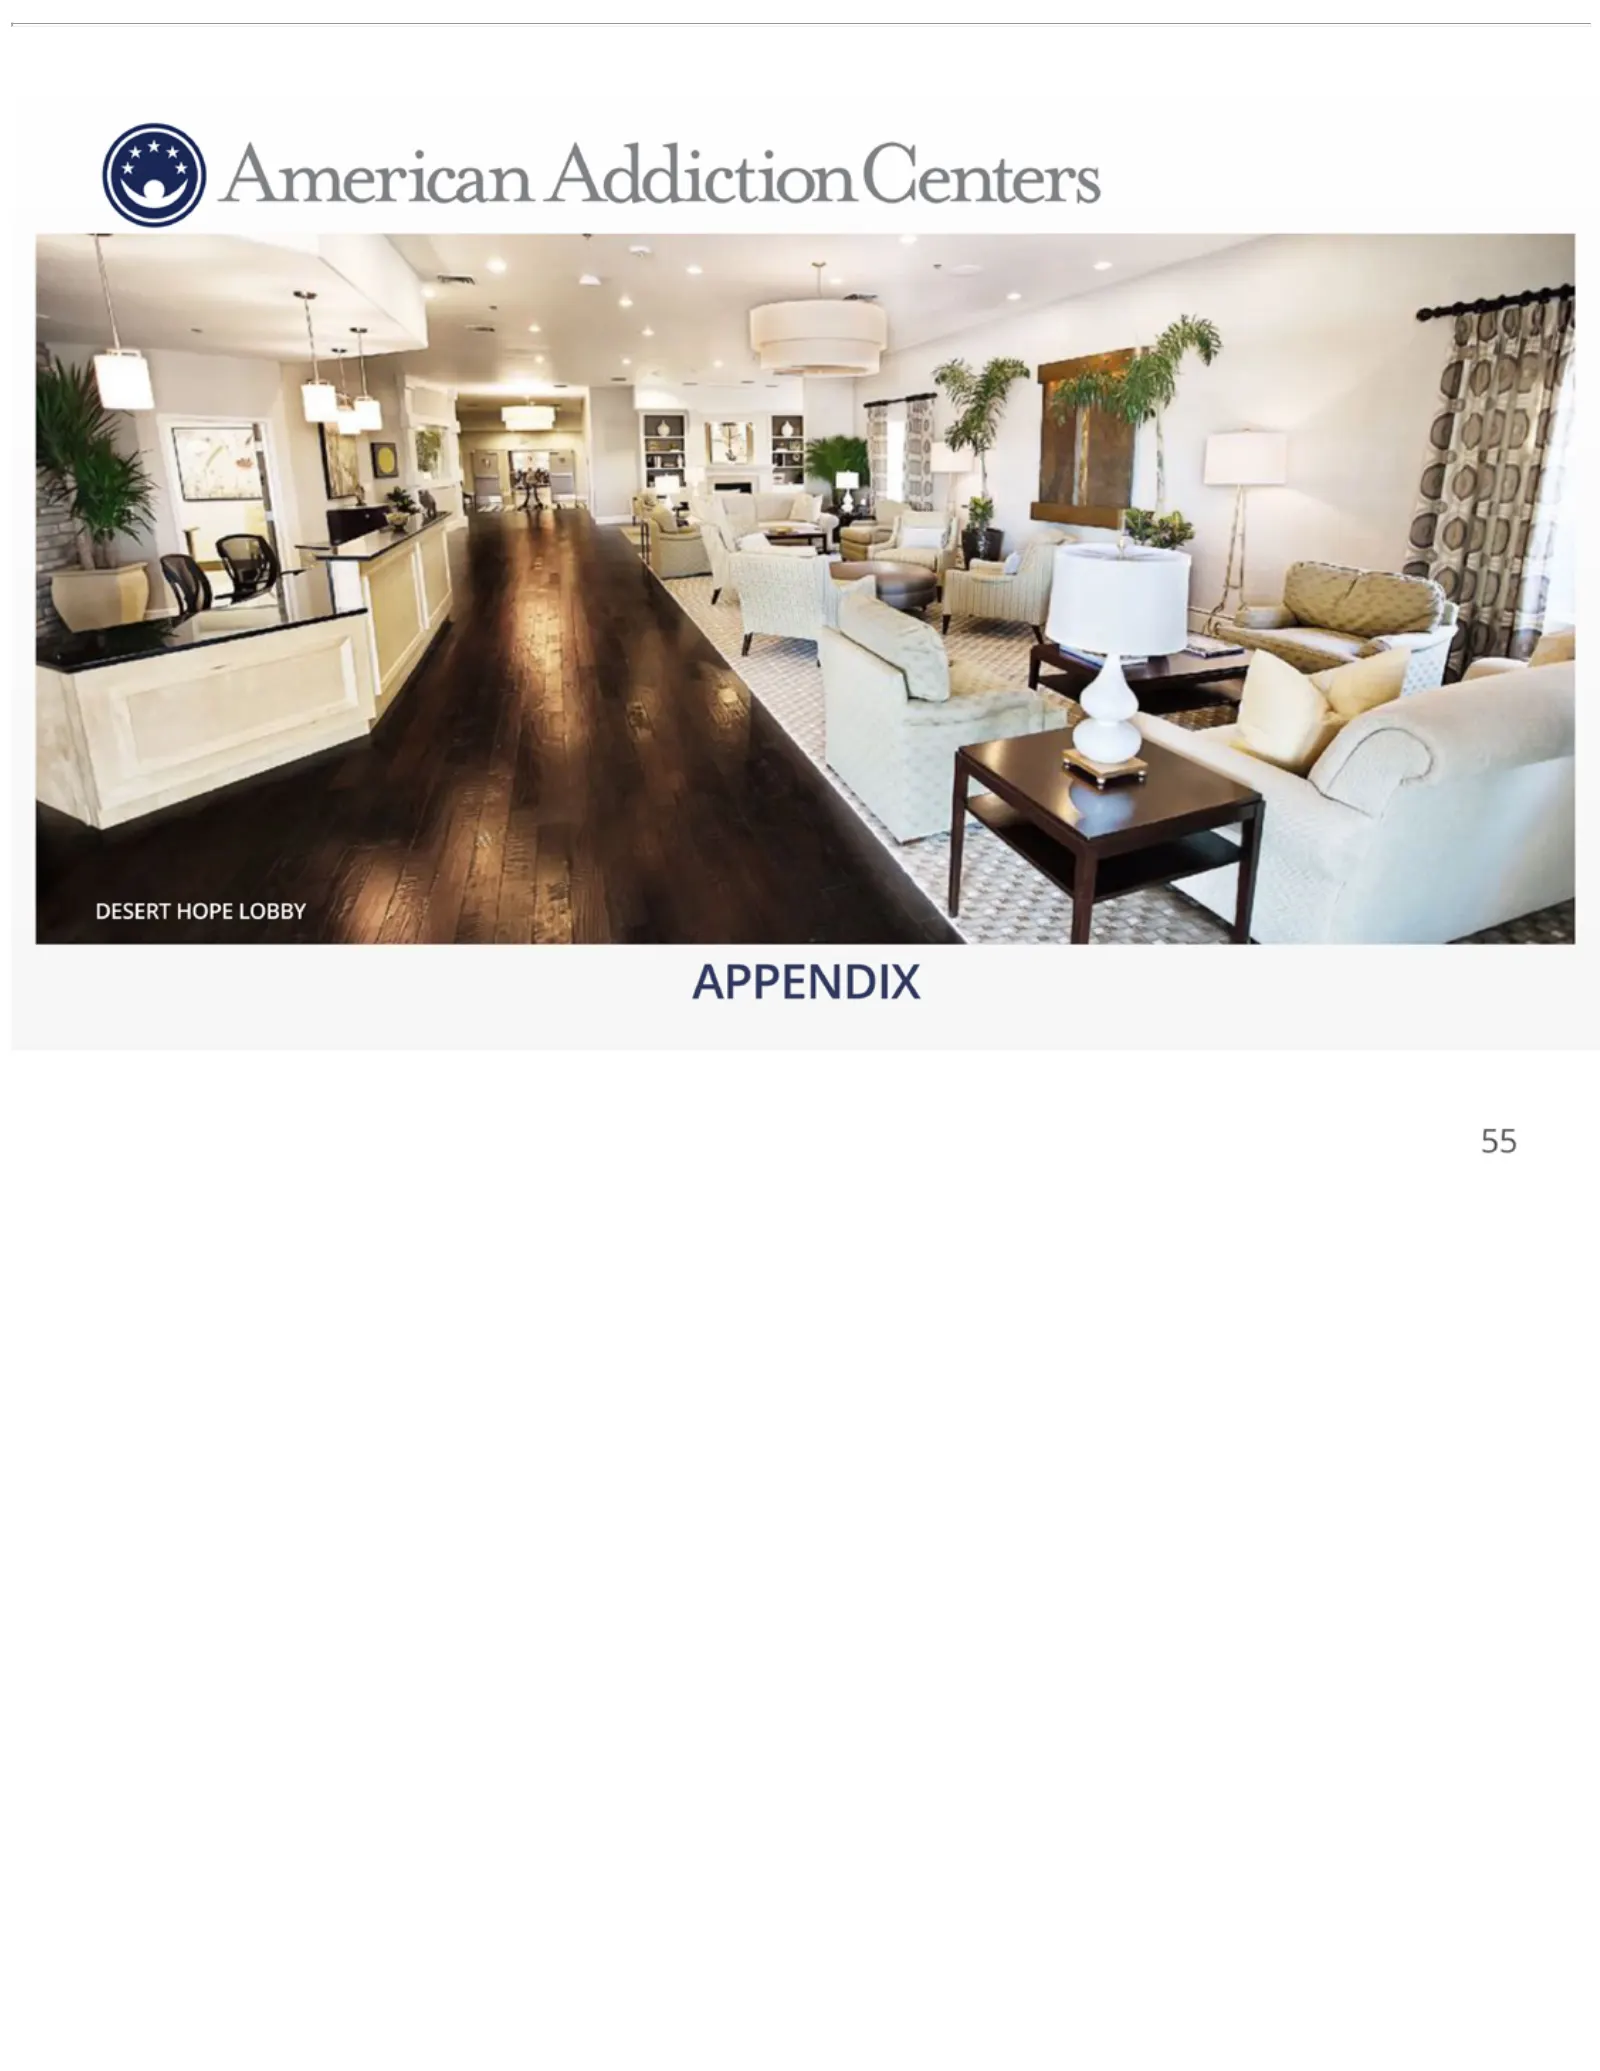
DESERT HOPE LOBBY APPENDIX 55
Slide 56: Appendix: Non-GAAP Financial Measures
APPENDIX: regula when$ be$considered$as$measures$of$financial$performance$under$U.S.$generally$accepted$accoun components$in$understanding$and$assessing$our$financial$performance$and$should$not Non-GAAP$ adjusted$ includes$ considera for$ professional$ on$ of$Q1$2017$workforce$reduc associated$ inte
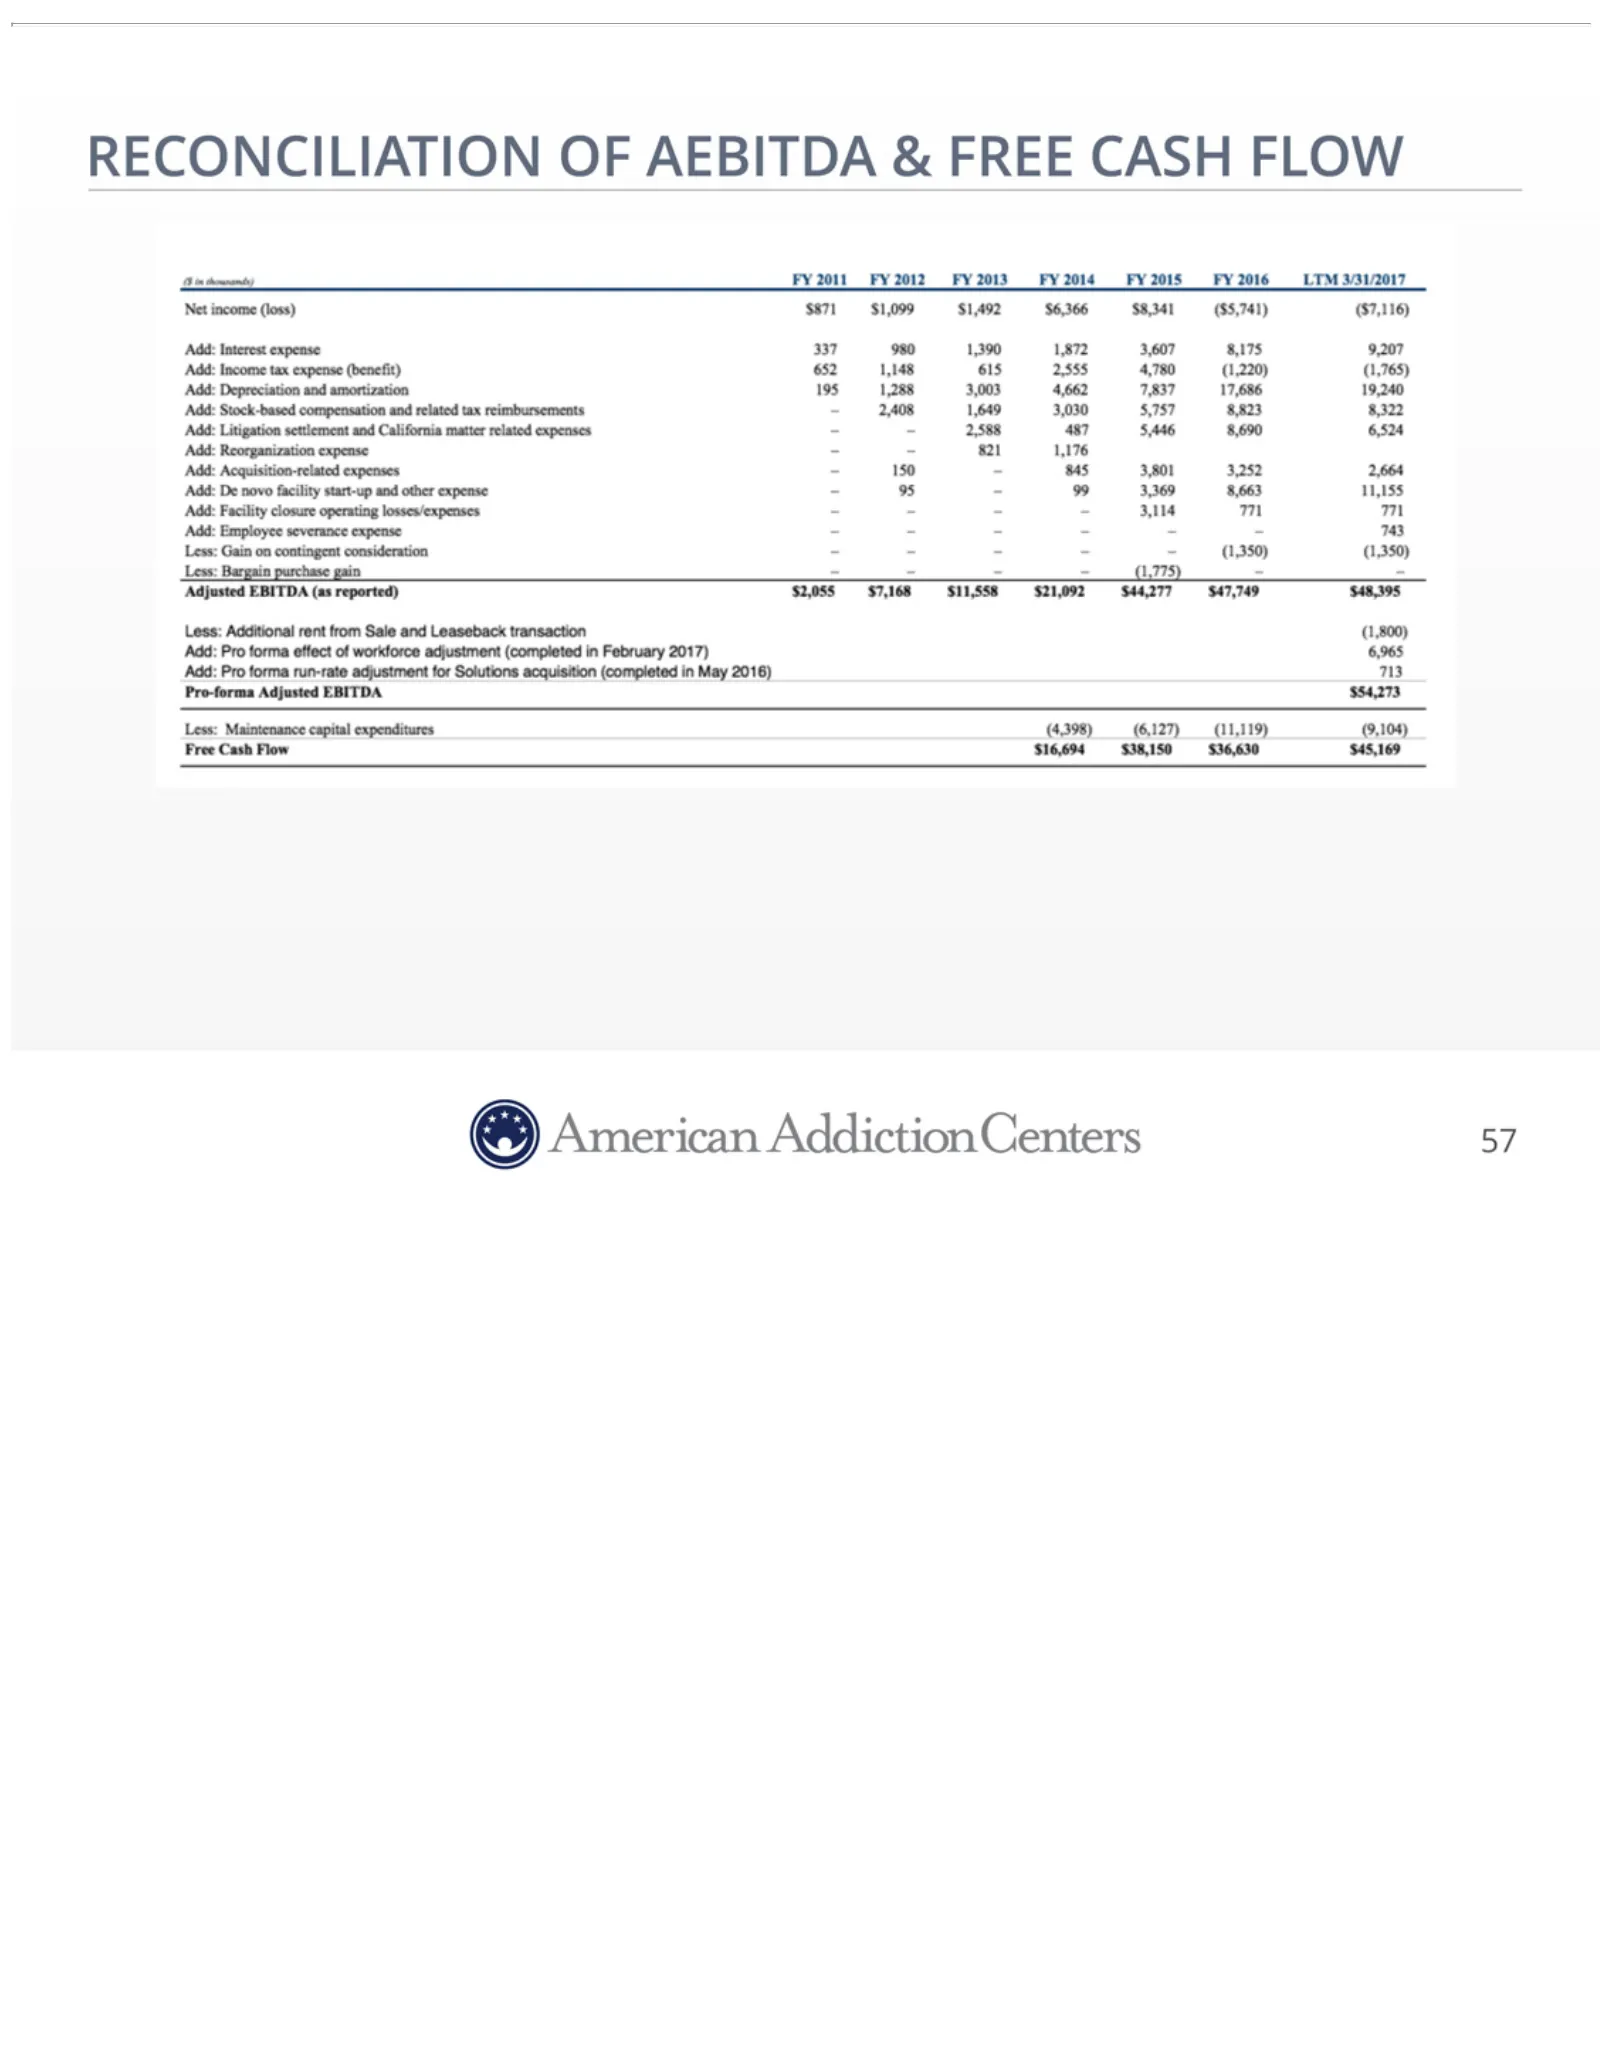
Slide 57: Reconciliation of Adjusted EBITDA
RECONCILIATION Income settlement Facility $11,558 (completed tax closure $21,092 and expense in May California operating $44,277 2016) (benefit) OF ADJUSTED matter $47,749 losses/expenses 652related 1,148 $48,395 713EBITDA Pro-forma expenses 615 –Less: –2,555 – ($ –Additional –3,114 Adjusted in 4,78
Slide 58: Key Terms
KEY TERMS Rehabilitation authorities with>- The licensing Addiction treatment and - Aprogram chronic of chemical brain review ordisease behavioral authority that 58 is addictions, characterized usually by compulsive administereddrug in aseeking residential andsetting use, despite > Rehab harmful - A
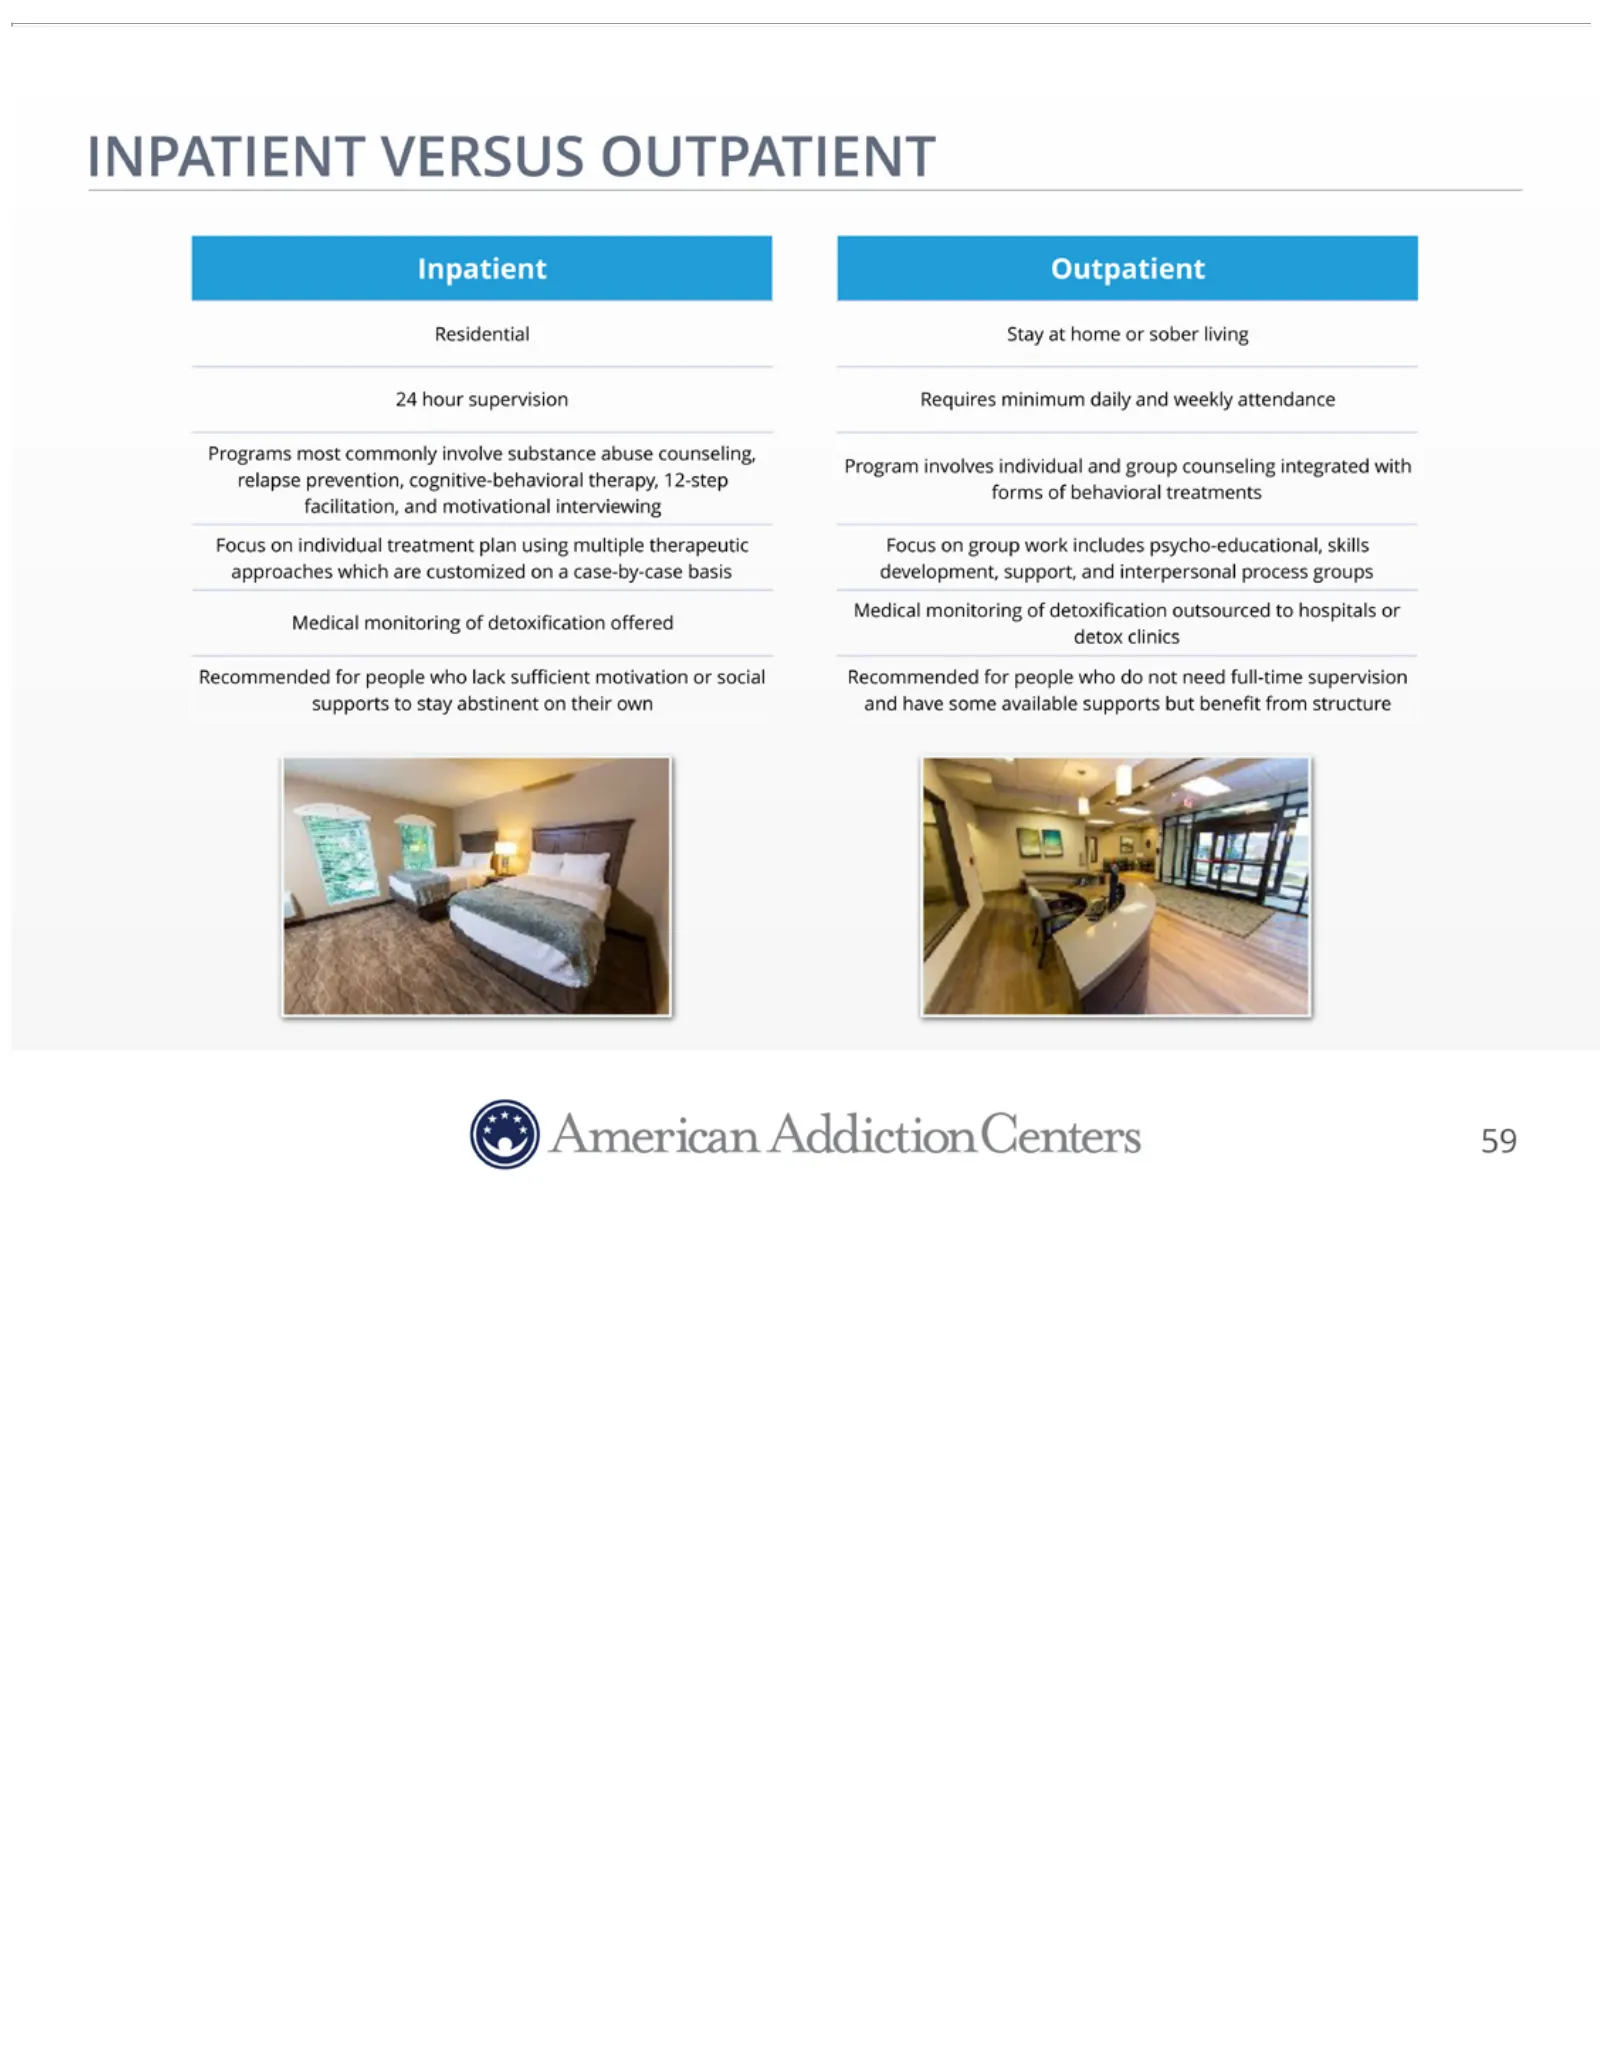
Slide 59: Inpatient Versus Outpatient
INPATIENT counseling skills lack sufficient approaches integrated VERSUS motivation whichwith OUTPATIENT are orrelapse customized socialprevention, Recommended Inpatient on a case-by-case cognitive-behavioral Outpatient for people basis Residential who development, dotherapy, not Stay need at 12-ste
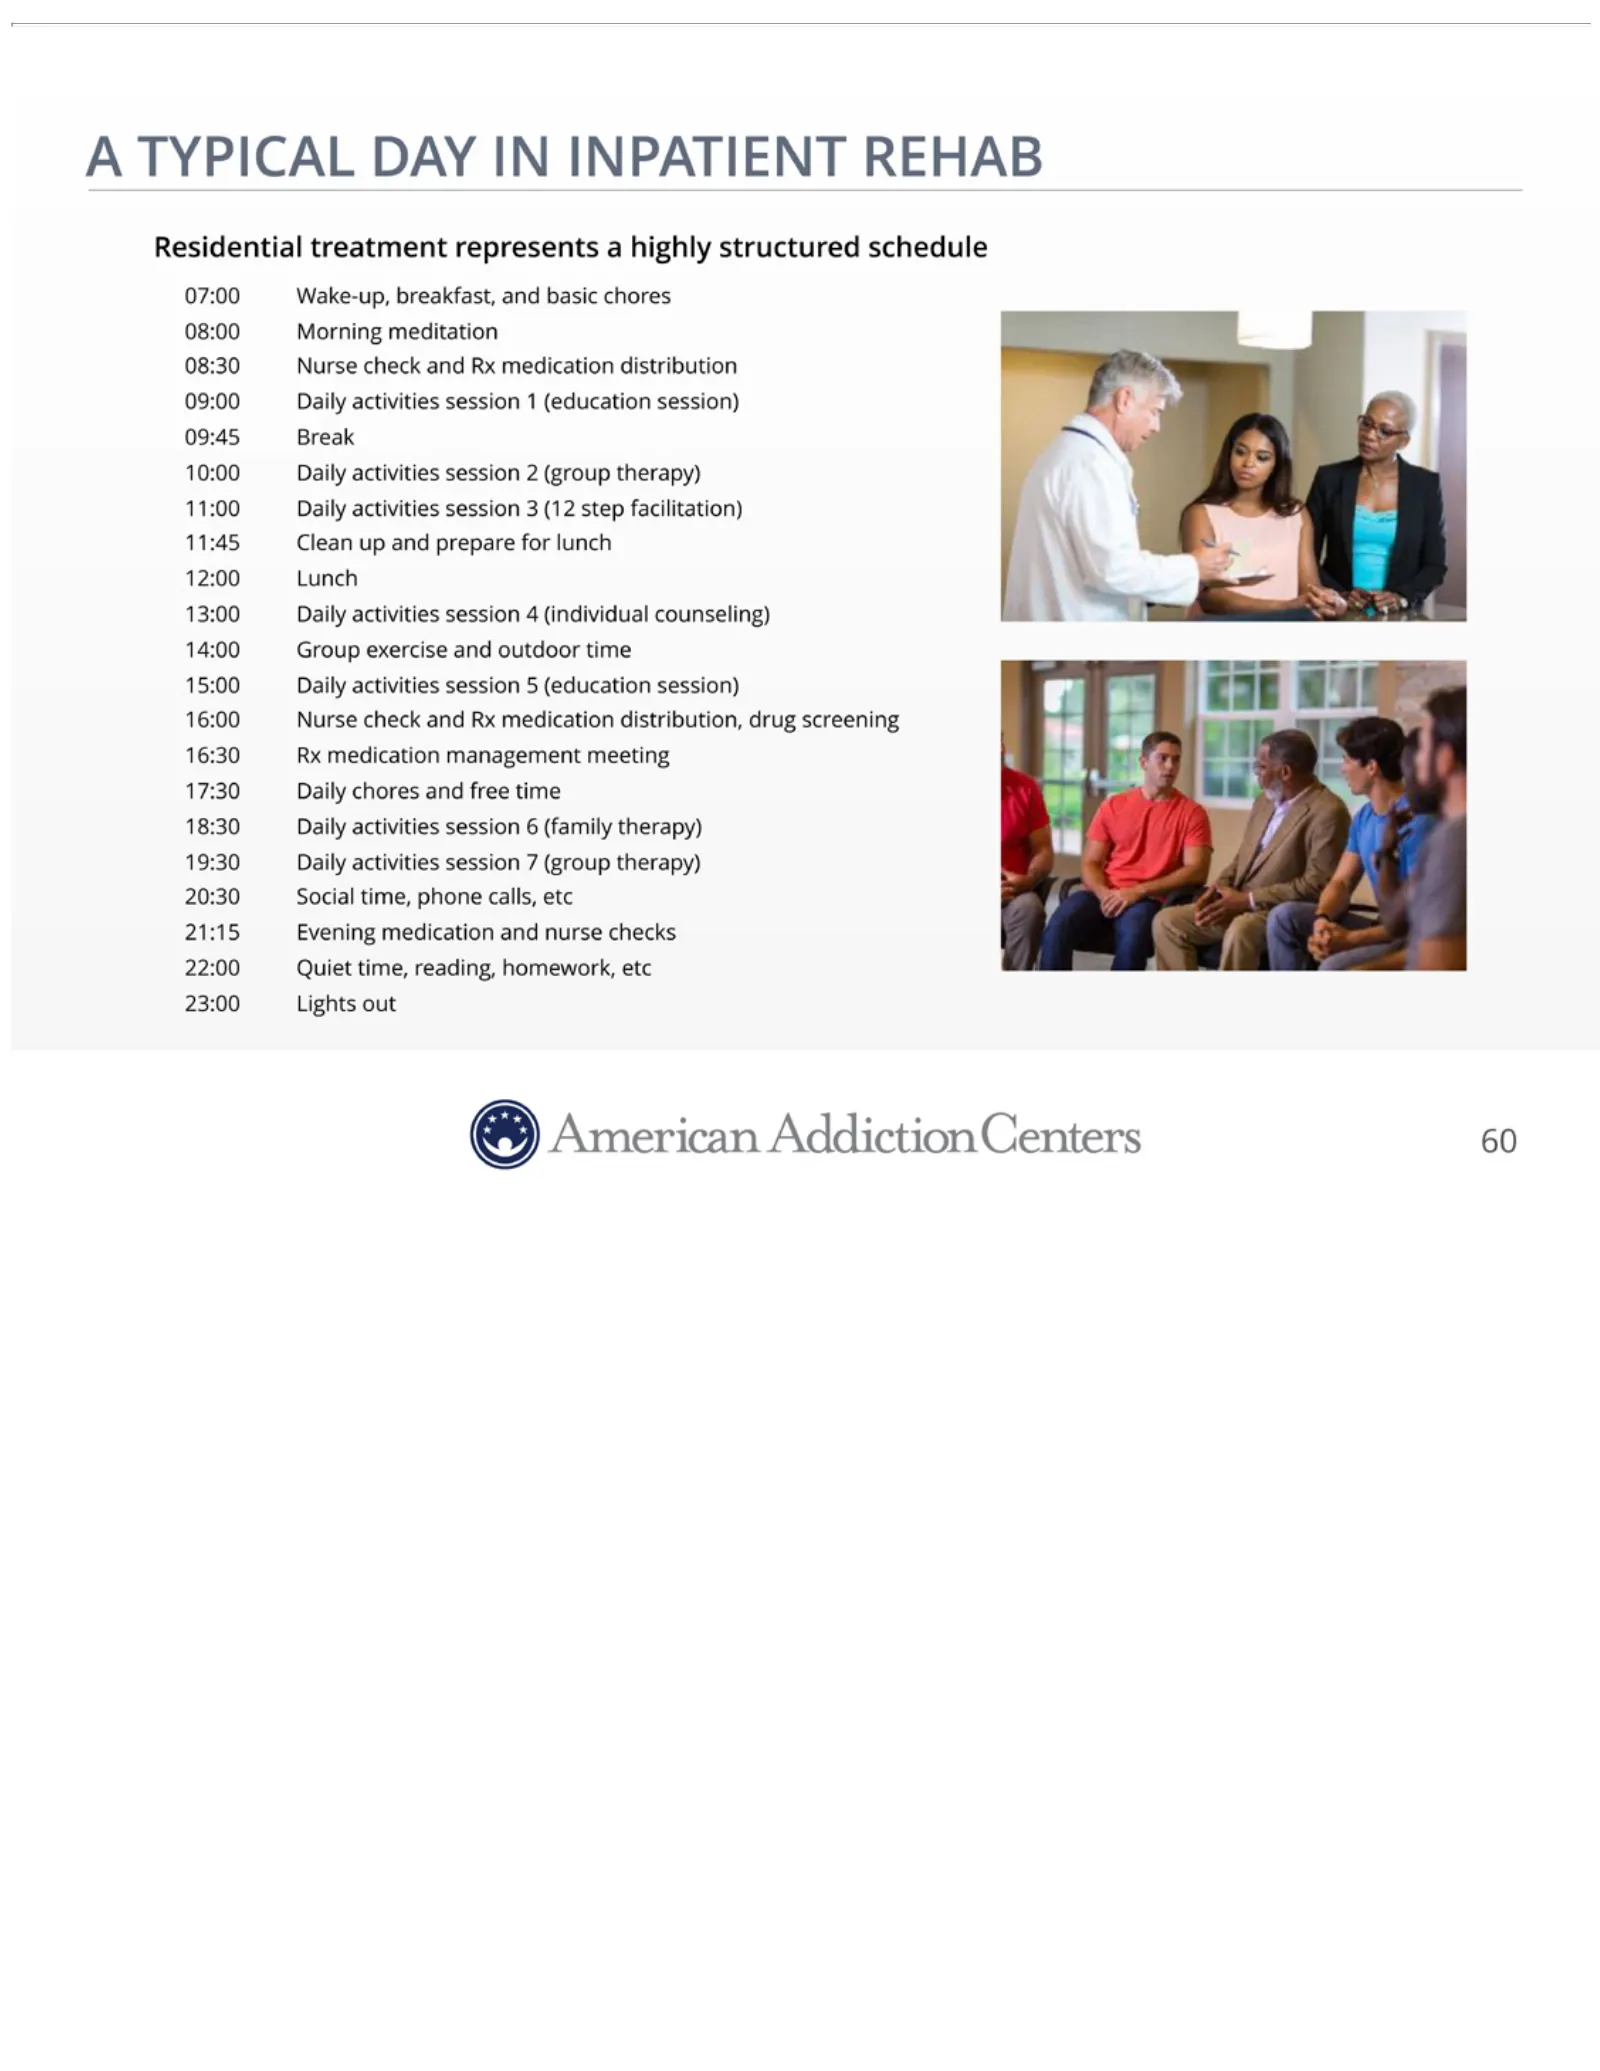
Slide 60: Typical Day in Inpatient Rehab
TYPICAL 09:45 activities therapy) Break 20:30 session DAY 10:00 Social IN 5 Daily (education INPATIENT time, activities phone session) REHAB calls, session 16:00 etcResidential 221:15 (group Nurse Evening therapy) check treatment and medication 11:00 Rx represents medication Daily andactivities anur
Slide 61: Revenue Recognition
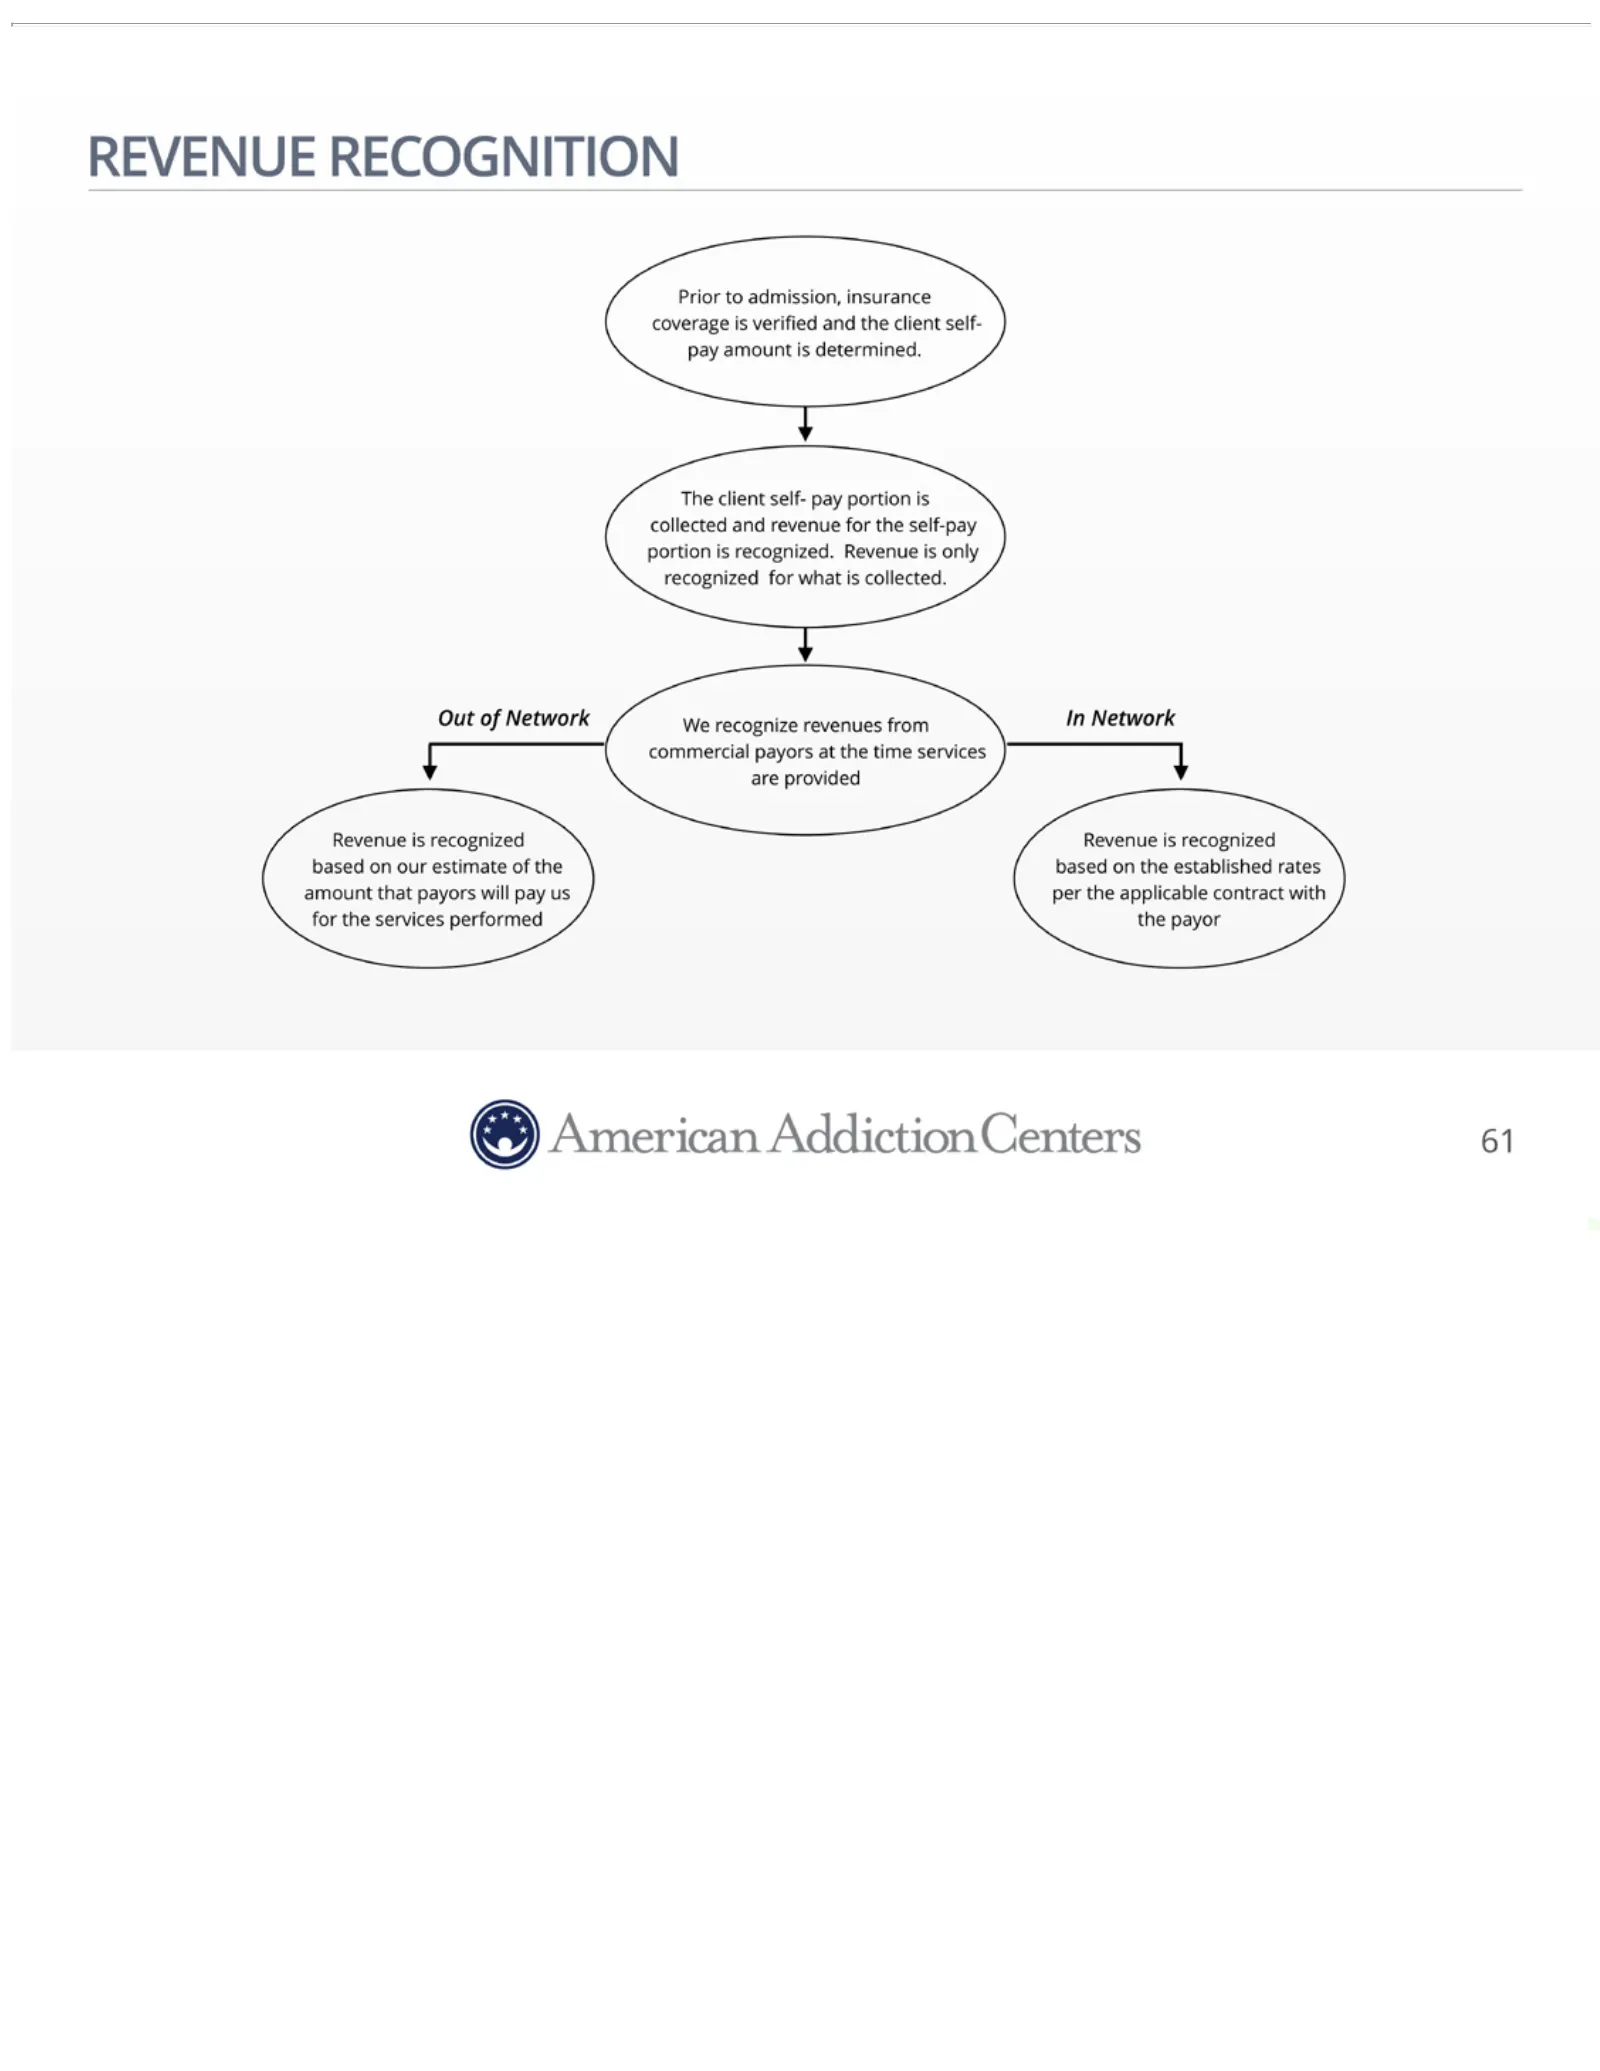
REVENUE Network the services WeRECOGNITION performed recognize the revenues payor Prior from 61to admission, In Networkinsurance commercial coverage payorsisatverified the timeand services the client are provided self- pay Revenue amount isisdetermined. recognized The Revenue clientisself- recognize
Slide 62: Bad Debt Policy
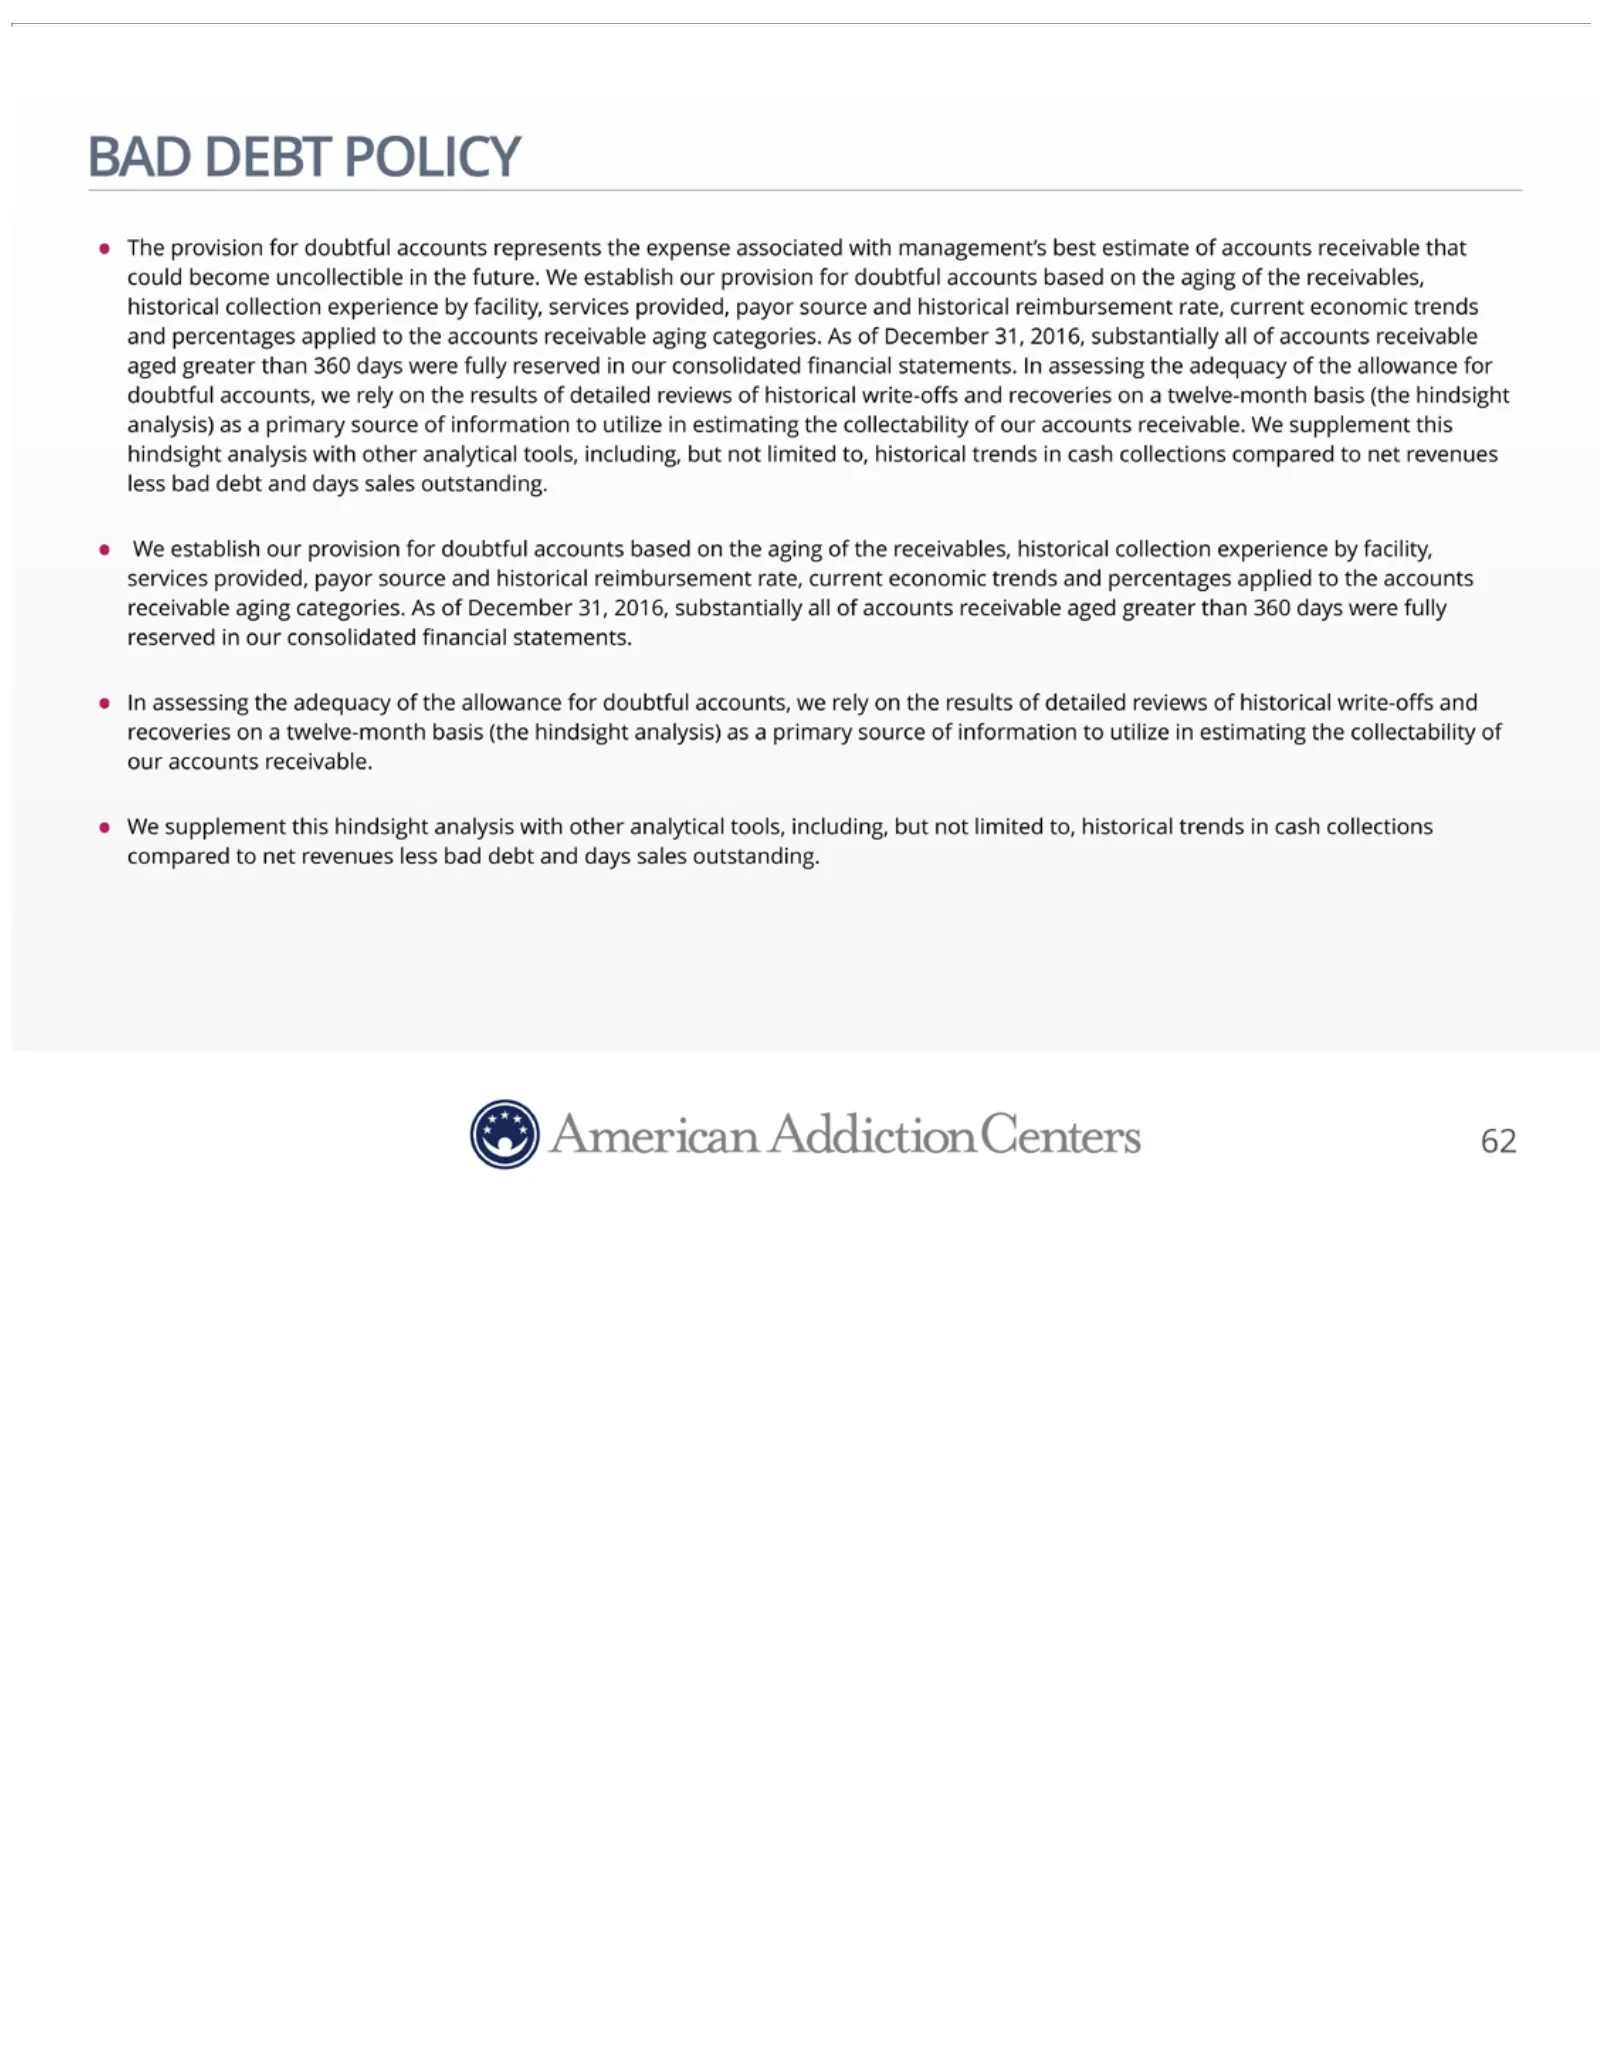
BADpercentages receivables, receivable revenues and doubtful hindsight DEBT accounts, less analysis) analysis aged historical POLICY bad greater applied debt with we as acollection •rely and other than primary The to on the days provision 360 analytical the accounts source sales experience days resu
Slide 63: AAC Current Residential Facility Offerings
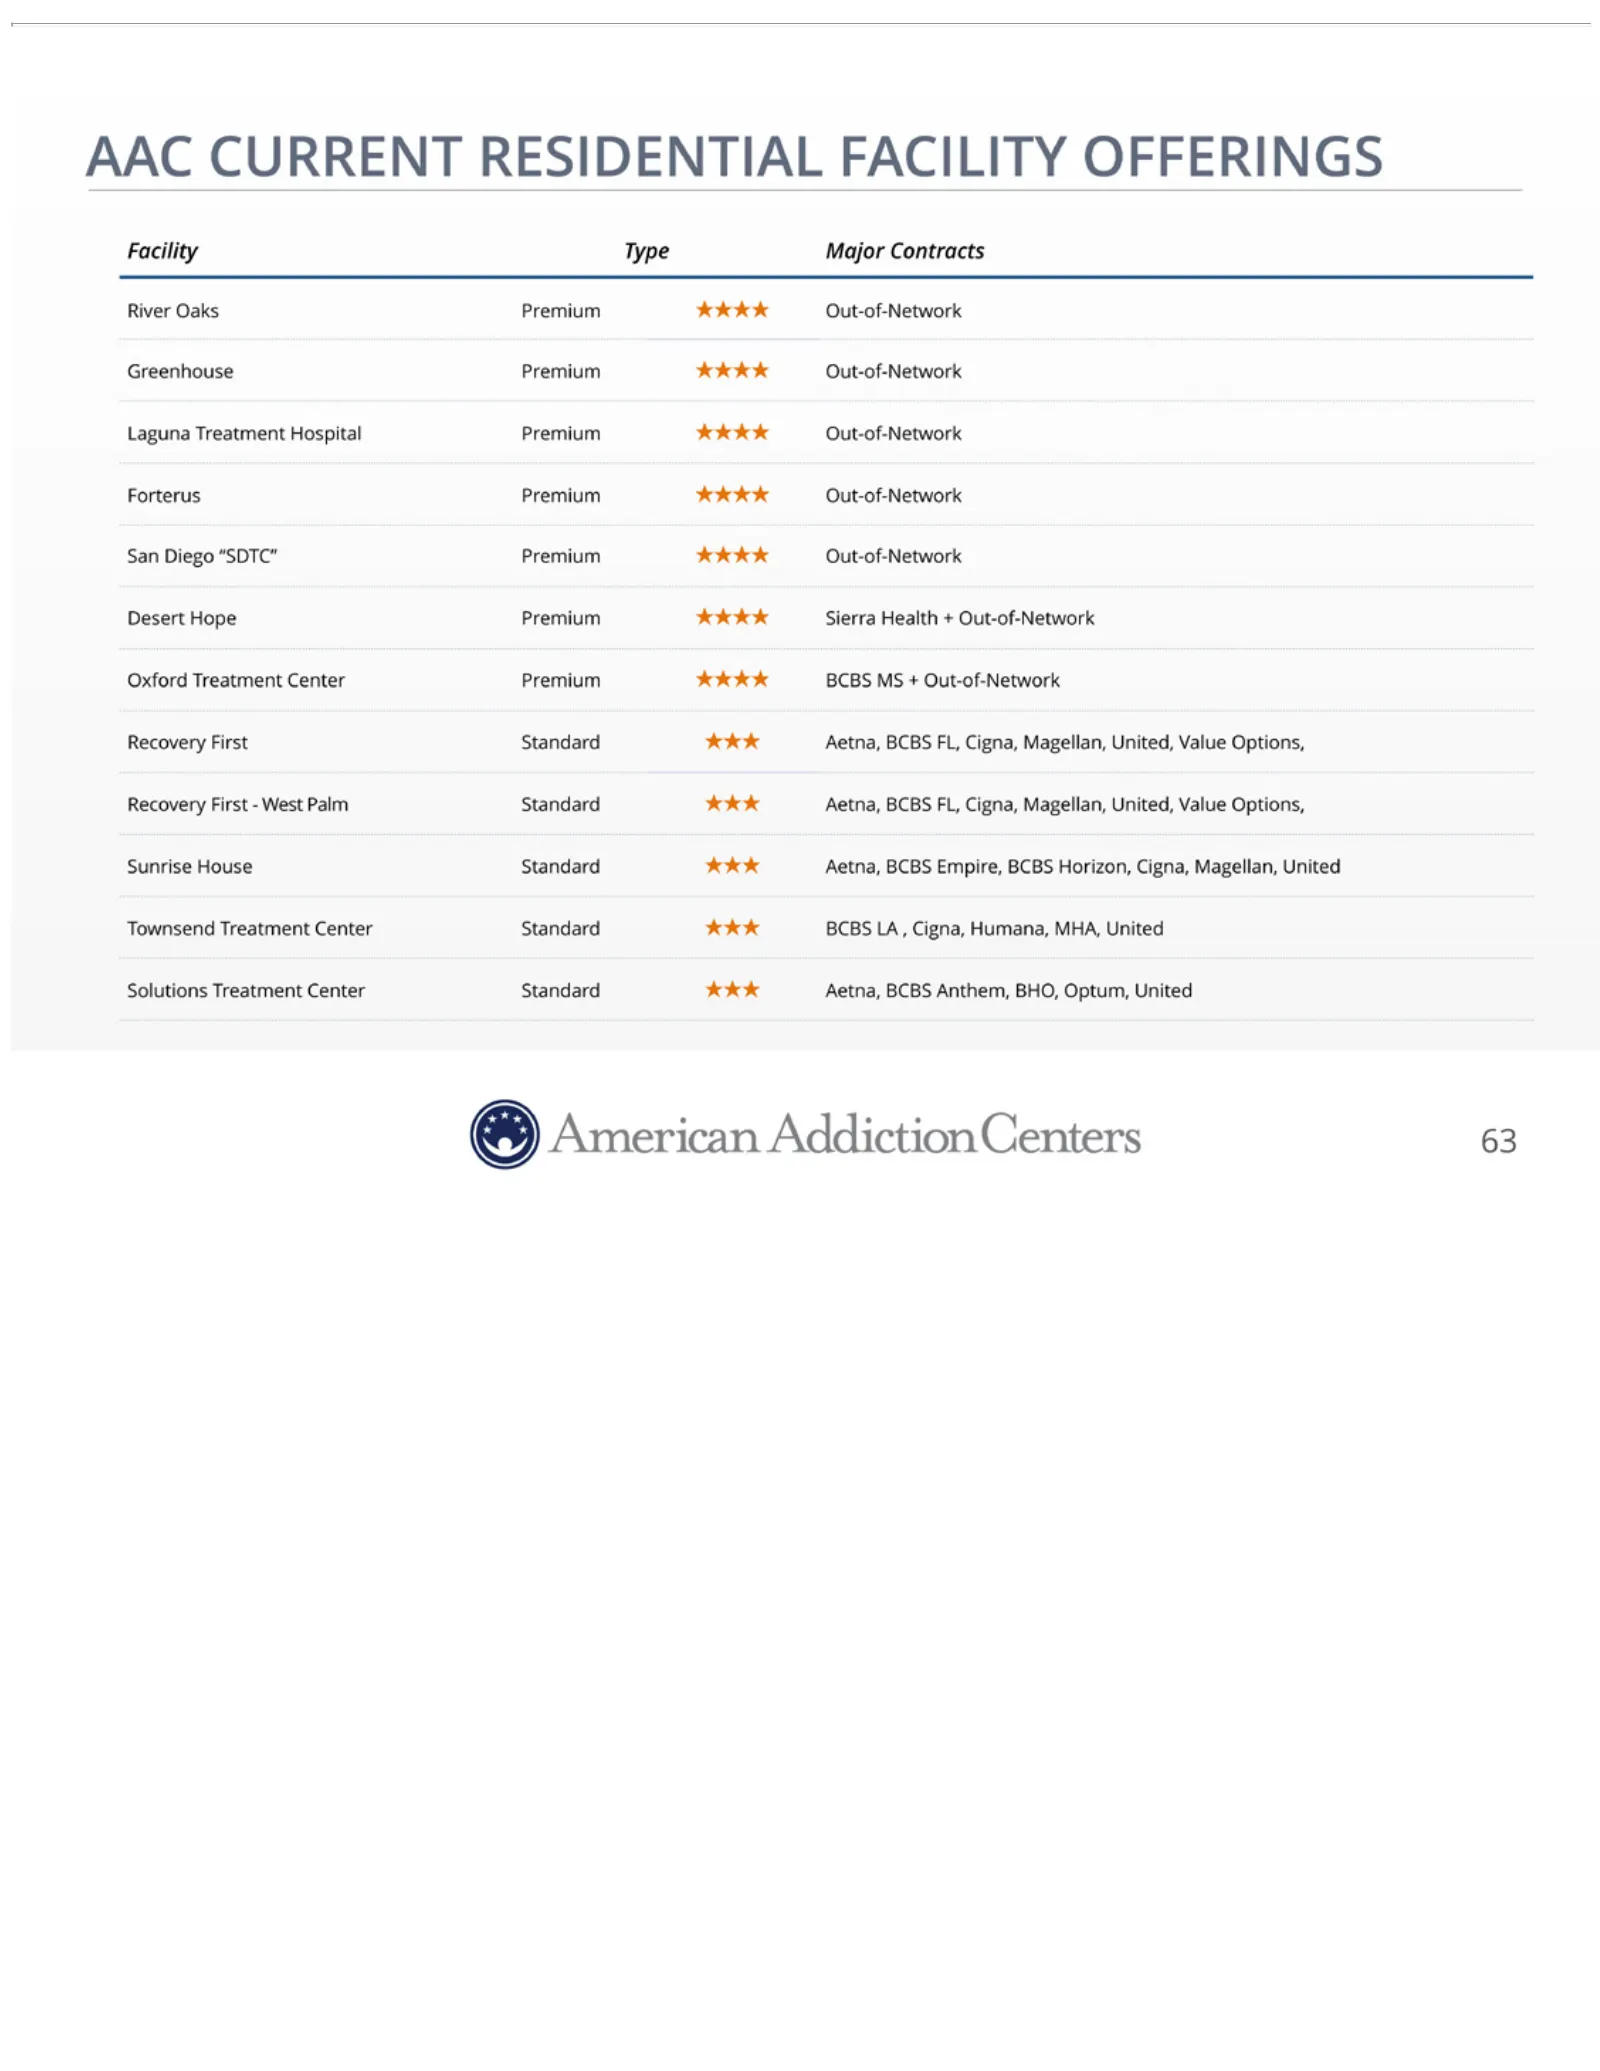
AAC CURRENT Out-of-Network Value Humana, Options, MHA,Recovery United San RESIDENTIAL Diego Solutions First—West “SDTC” Treatment FACILITY Premium Palm Standard Center OFFERINGS ???? Out-of-Network Standard ??? Aetna, Facility ???BCBS Aetna, Desert Type FL, BCBS Major Cigna, Hope Anthem, Contracts P
Slide 64: Current Capacity Overview
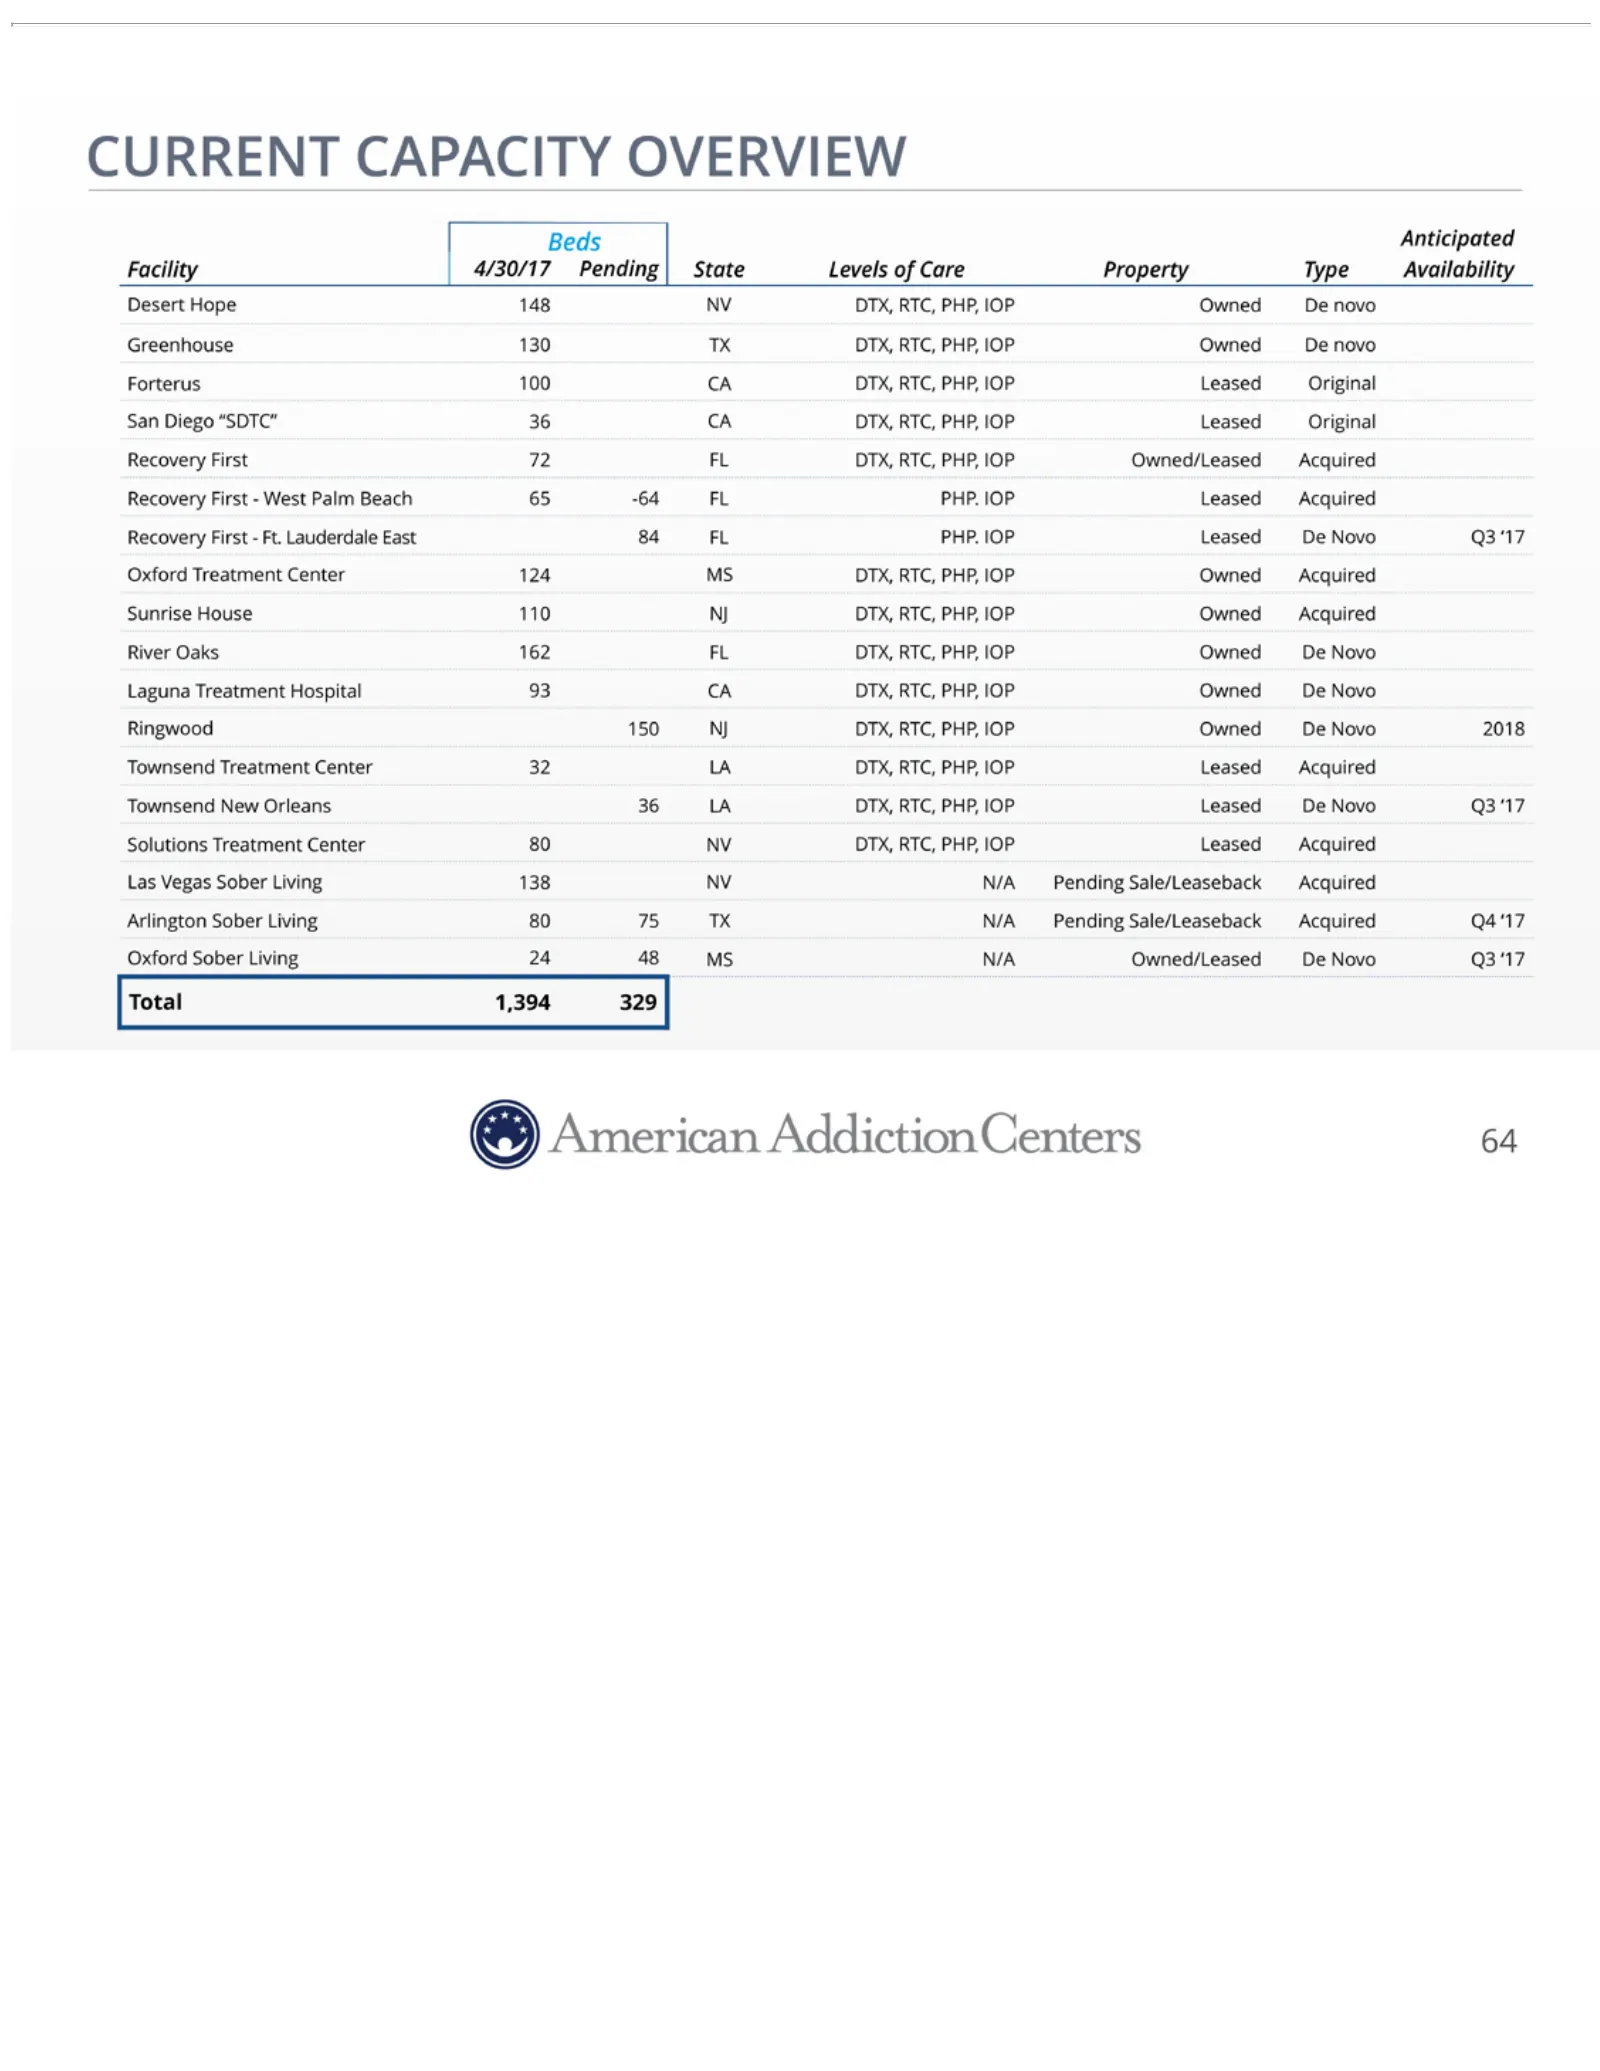
CURRENT RTC, East CA Treatment NovoDTX, 84 PHP, Q3FL‘17 RTC, Center PHP. IOP CAPACITY Total Leased PHP, IOP 801,394 NV Leased IOP Original OVERVIEW DTX, 329 Owned De 64RTC, San Novo DeDiego PHP, Novo Beds Q3 ‘17 IOP “SDTC” Ringwood Anticipated Oxford Leased36Treatment 150 Acquired CAFacility NJ DTX,
Source: SEC EDGAR · 8-K filed Jun 6, 2017