Warren Resources — Pritchard Capital Investors Conference (October 2008)
32 slides from Warren Resources's conference presentation, Oct 7, 2008
Slide 1: Warren Resources, Inc. Pritchard Capital Investors Conference
Warren Resources, Inc. October 8, 2008 Pritchard Capital Investors Conference Pritchard Capital Investors Conference
Slide 2: Disclaimer
Disclaimer Cautionary Note to U.S. Investors: This presentation includes “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The opinions, forecasts, projections or other stateme
Slide 3: Company Profile
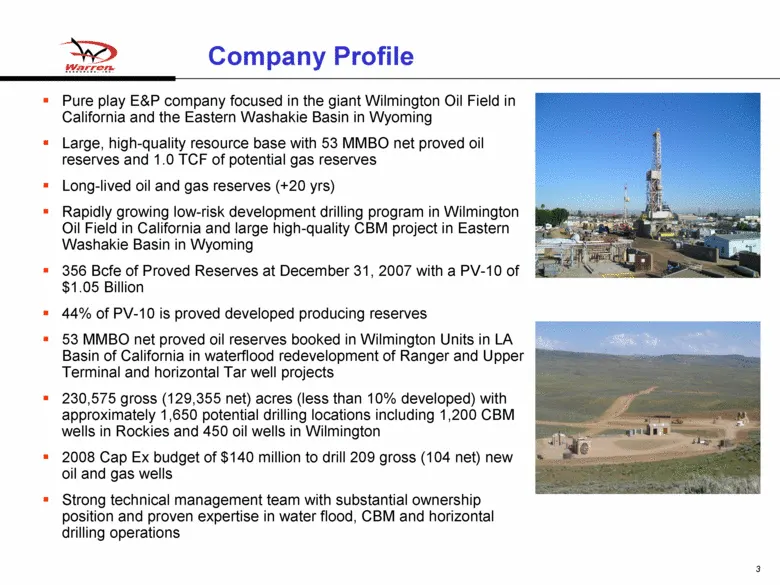
Company Profile Pure play E&P company focused in the giant Wilmington Oil Field in California and the Eastern Washakie Basin in Wyoming Large, high-quality resource base with 53 MMBO net proved oil reserves and 1.0 TCF of potential gas reserves Long-lived oil and gas reserves (+20 yrs) Rapidly growi
Slide 4: Warren Resources Operational Overview
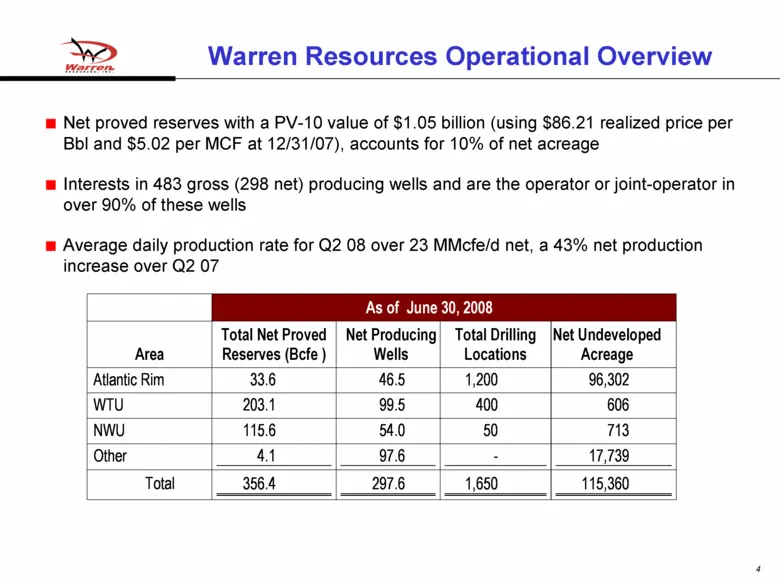
Warren Resources Operational Overview Net proved reserves with a PV-10 value of $1.05 billion (using $86.21 realized price per Bbl and $5.02 per MCF at 12/31/07), accounts for 10% of net acreage Interests in 483 gross (298 net) producing wells and are the operator or joint-operator in over 90% of th
Slide 5: Proved and Unrisked, Unbooked, Potential Reserves
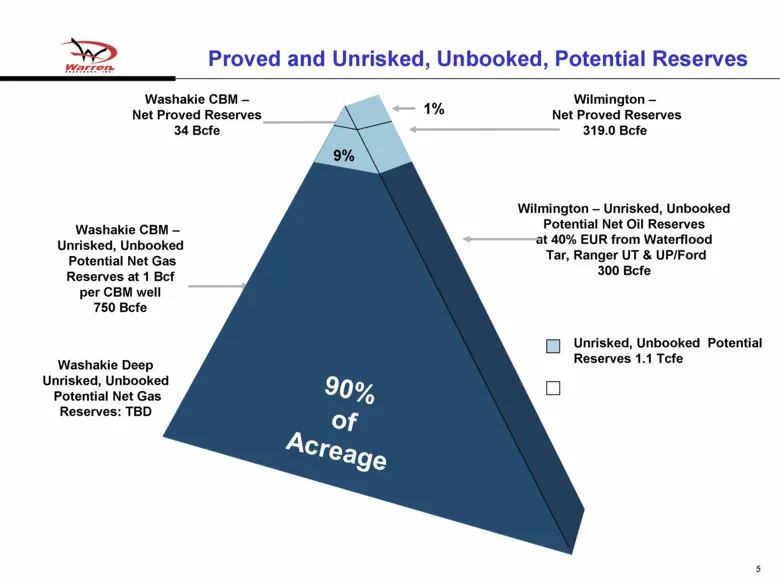
Proved and Unrisked, Unbooked, Potential Reserves Washakie CBM – Net Proved Reserves 34 Bcfe Unrisked, Unbooked Potential Reserves 1.1 Tcfe Washakie CBM – Unrisked, Unbooked Potential Net Gas Reserves at 1 Bcf per CBM well 750 Bcfe Wilmington – Unrisked, Unbooked Potential Net Oil Reserves at 40% EU
Slide 6: Business Strategy
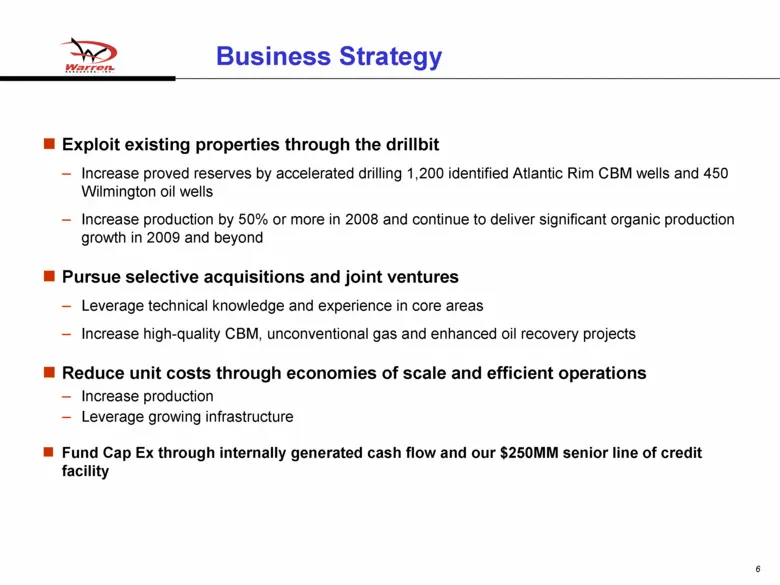
Business Strategy Exploit existing properties through the drillbit – Increase proved reserves by accelerated drilling 1,200 identified Atlantic Rim CBM wells and 450 Wilmington oil wells – Increase production by 50% or more in 2008 and continue to deliver significant organic production growth in 200
Slide 7: Experienced Operating Team
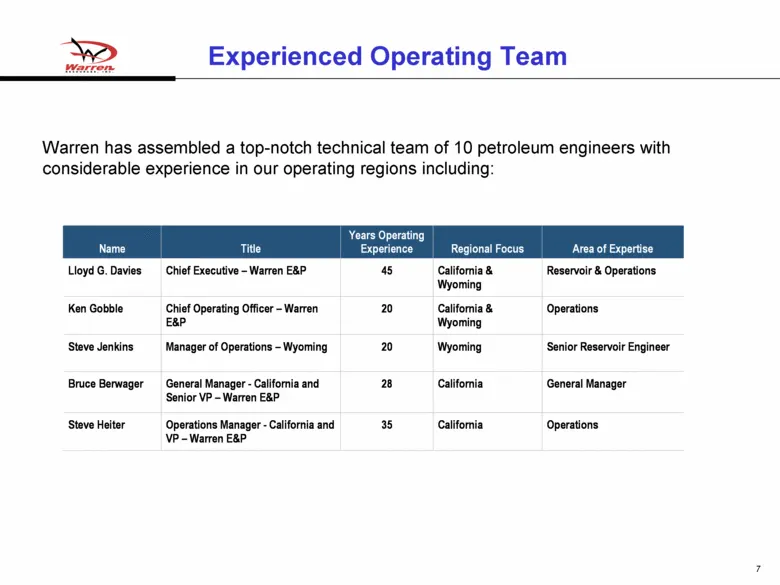
Experienced Operating Team Warren has assembled a top-notch technical team of 10 petroleum engineers with considerable experience in our operating regions including: Name Title Years Operating Experience Regional Focus Area of Expertise Lloyd G. Davies Chief Executive – Warren E&P 45 California & Wy
Slide 8: Focused Operations - Wilmington Oil Field
Focused Operations - Wilmington Oil Field
Slide 9: The Wilmington Oil Field
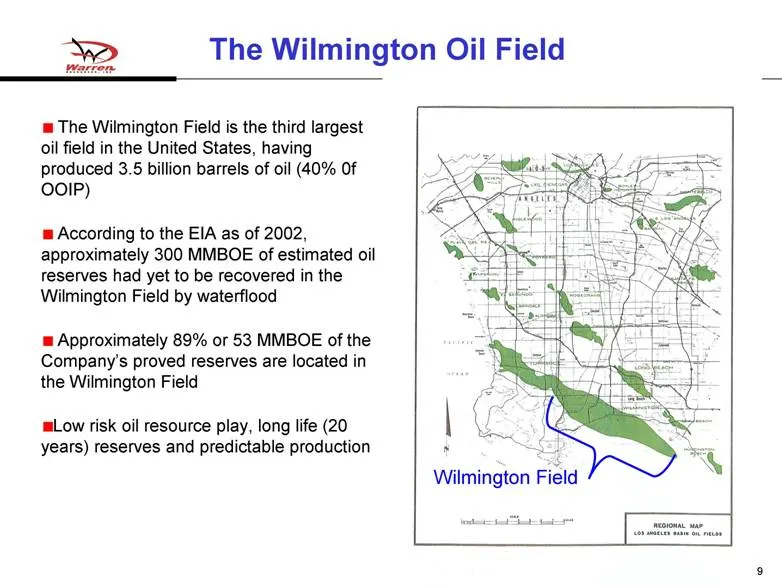
The Wilmington Oil Field The Wilmington Field is the third largest oil field in the United States, having produced 3.5 billion barrels of oil (40% 0f OOIP) According to the EIA as of 2002, approximately 300 MMBOE of estimated oil reserves had yet to be recovered in the Wilmington Field by waterflood
Slide 10: WTU (Warren) Structure
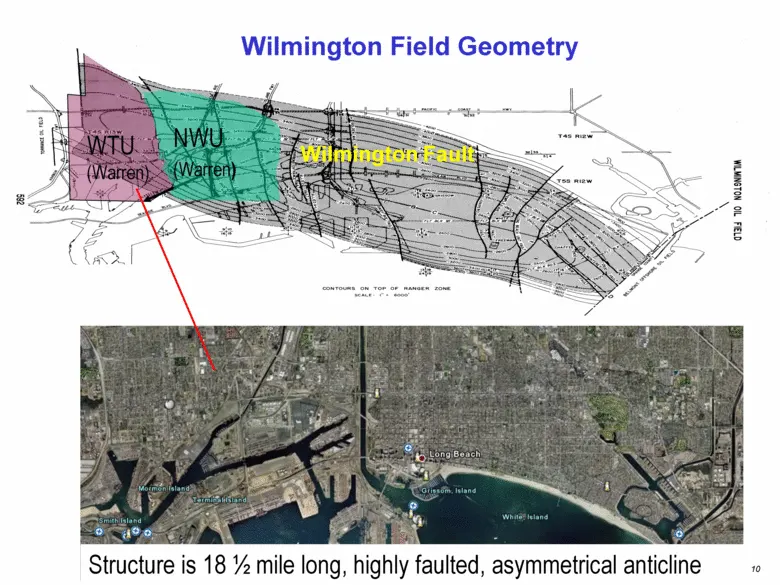
WTU (Warren) Structure is 18 ½ mile long, highly faulted, asymmetrical anticline Wilmington Fault Wilmington Field Geometry NWU (Warren) 10
Slide 11: Wilmington Townlot Unit (WTU)
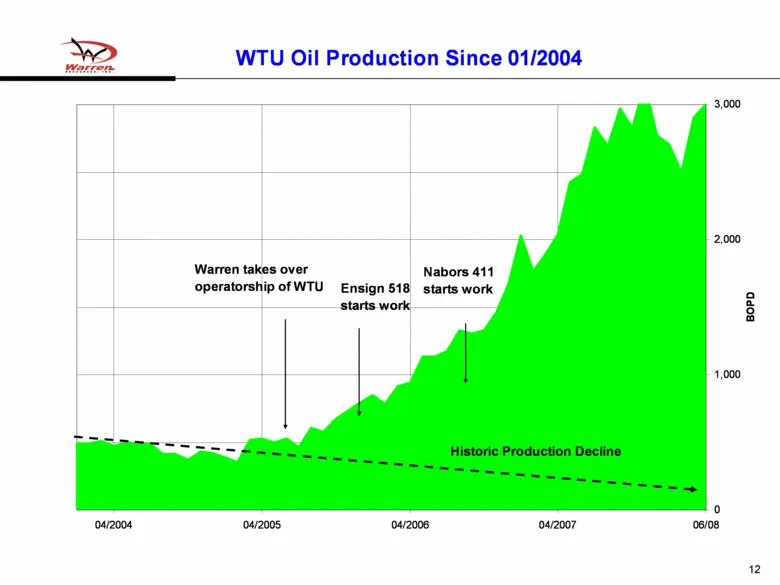
Wilmington Townlot Unit (WTU) Unitized in 1972 by Exxon Warren holds 98.6% WI, 82.3% NRI 34 MMBO net booked proved reserves at 12/31/2007 Enhanced secondary waterflood recovery ASP potential not yet booked Multiple productive sands in reservoirs (Tar, Ranger, Upper Terminal, UP 237, Ford & basement
Slide 12: WTU Oil Production Since 01/2004
WTU Oil Production Since 01/2004 0 1,000 2,000 3,000 06/08 04/2007 04/2006 04/2005 04/2004 BOPD Warren takes over operatorship of WTU Nabors 411 starts work Ensign 518 starts work Historic Production Decline 12
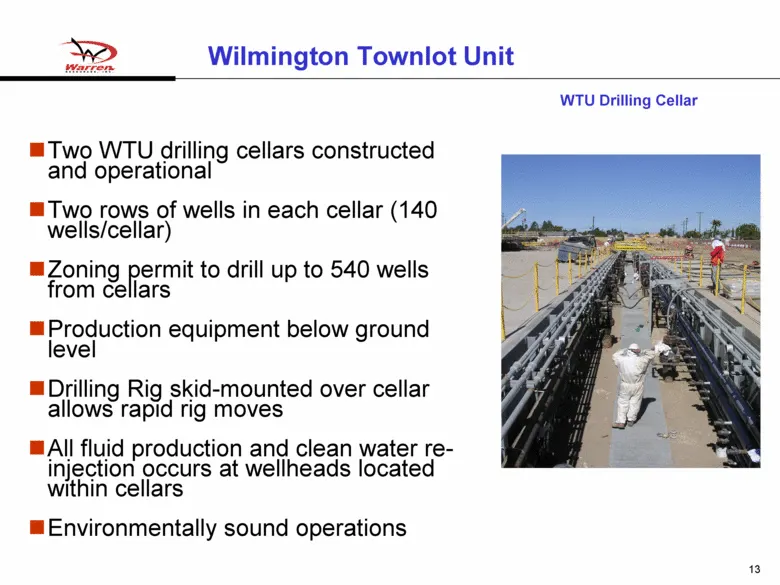
Slide 13: Wilmington Townlot Unit drilling cellars
Wilmington Townlot Unit Two WTU drilling cellars constructed and operational Two rows of wells in each cellar (140 wells/cellar) Zoning permit to drill up to 540 wells from cellars Production equipment below ground level Drilling Rig skid-mounted over cellar allows rapid rig moves All fluid producti
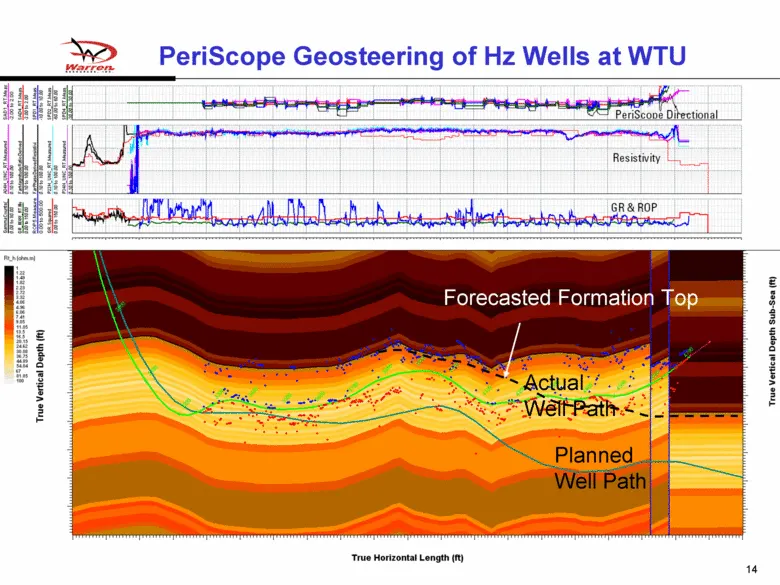
Slide 14: PeriScope Geosteering of Hz Wells at WTU
PeriScope Geosteering of Hz Wells at WTU Planned Well Path Actual Well Path Forecasted Formation Top 14
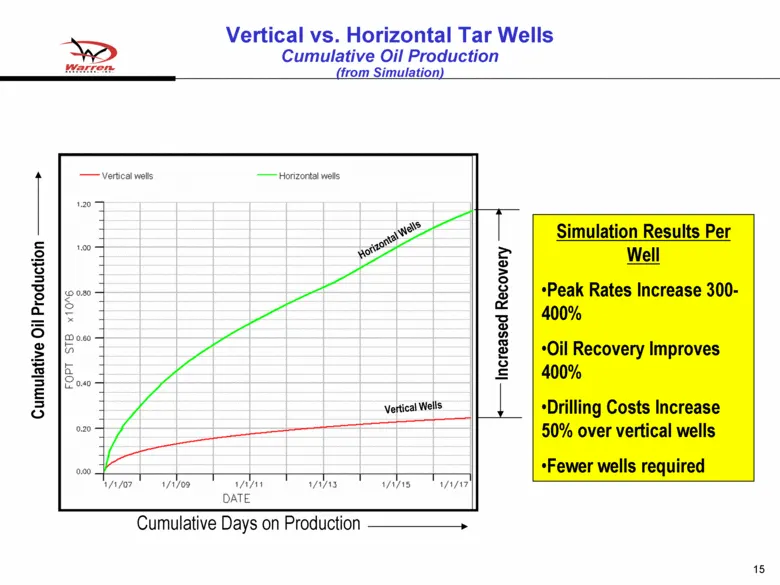
Slide 15: Vertical vs. Horizontal Tar Wells
Vertical vs. Horizontal Tar Wells Cumulative Oil Production (from Simulation) Simulation Results Per Well •Peak Rates Increase 300-400% •Oil Recovery Improves 400% •Drilling Costs Increase 50% over vertical wells •Fewer wells required Cumulative Oil Production Increased Recovery Cumulative Days on P
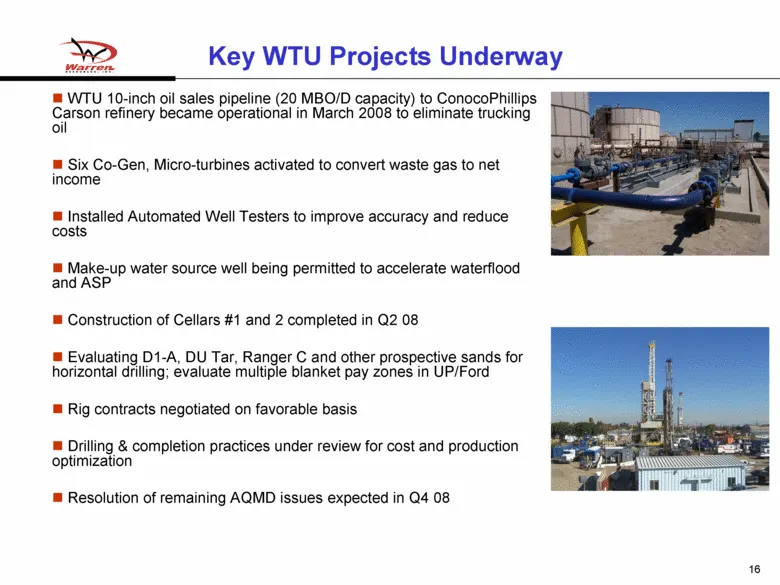
Slide 16: Key WTU Projects Underway
Key WTU Projects Underway WTU 10-inch oil sales pipeline (20 MBO/D capacity) to ConocoPhillips Carson refinery became operational in March 2008 to eliminate trucking oil Six Co-Gen, Micro-turbines activated to convert waste gas to net income Installed Automated Well Testers to improve accuracy and r
Slide 17: North Wilmington Unit
North Wilmington Unit Unitized for Water Flood in 1977 by Sunoco Produced 37 MMBO (24% of OOIP) Net proved reserves remaining of 19 MMBO Warren holds 100% W.I. and 84.6% N.R.I. Warren has focused on operational improvements and returning idle wells to production/injection since acquisition Current p
Slide 18: ASP Flood Basics
ASP Flood Basics WHY USE ASP? WHAT IS ASP? – ASP = Alkaline-Surfactant-Polymer – Alkaline reacts with certain oils to form surfactant in-situ reduces surfactant costs – Surfactant reduces oil/water interfacial tension (IFT) reduces capillary forces that hold oil in pore space – Polymer improves mobi
Slide 19: California Operations Summary
California Operations Summary Quality Assets with huge remaining potential oil-in-place of 550 MMBO Newly proven technologies and high oil prices should enable substantial remaining reserves to be captured economically Construction phase of cellar 1 and 2 completed in Q2 2008 Production volumes have
Slide 20: Washakie Basin – Atlantic Rim CBM
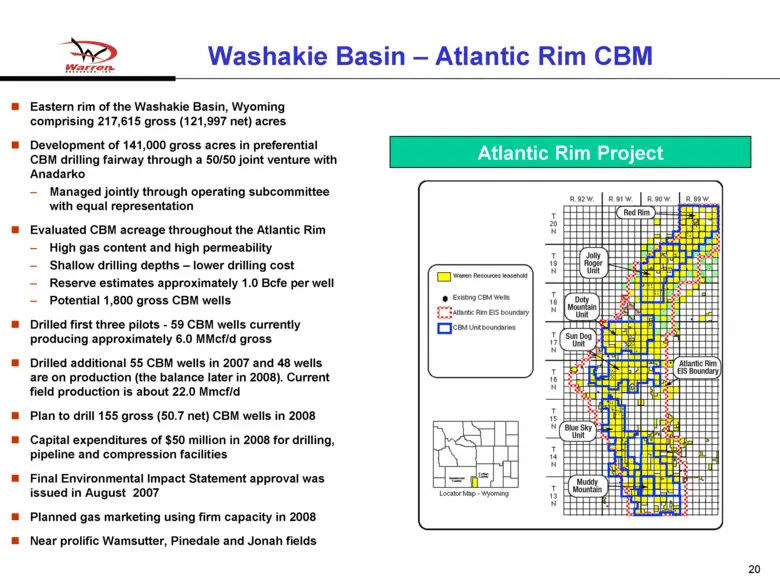
Washakie Basin – Atlantic Rim CBM Eastern rim of the Washakie Basin, Wyoming comprising 217,615 gross (121,997 net) acres Development of 141,000 gross acres in preferential CBM drilling fairway through a 50/50 joint venture with Anadarko – Managed jointly through operating subcommittee with equal re
Slide 21: Atlantic Rim CBM Type Curve
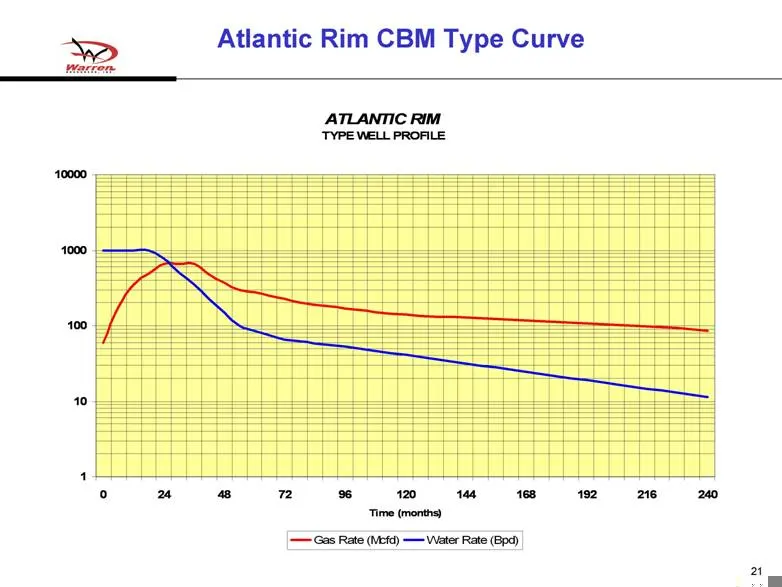
Atlantic Rim CBM Type Curve Cellar 1 ATLANTIC RIM TYPE WELL PROFILE 1 10 100 1000 10000 0 24 48 72 96 120 144 168 192 216 240 Time (months) Gas Rate (Mcfd) Water Rate (Bpd) 21
Slide 22: Atlantic Rim – Sun Dog Unit
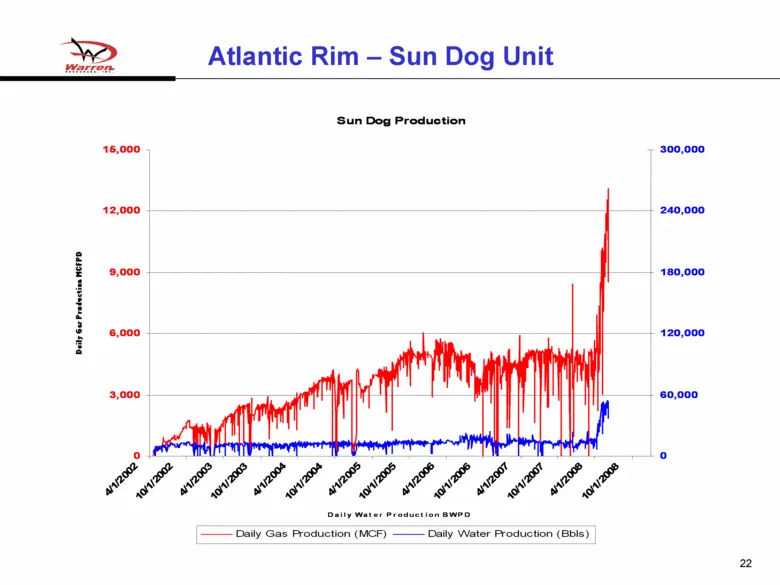
Atlantic Rim – Sun Dog Unit Sun Dog Production 0 3,000 6,000 9,000 12,000 15,000 4/1/2002 10/1/2002 4/1/2003 10/1/2003 4/1/2004 10/1/2004 4/1/2005 10/1/2005 4/1/2006 10/1/2006 4/1/2007 10/1/2007 4/1/2008 10/1/2008 Daily Water Production BWPD 0 60,000 120,000 180,000 240,000 300,000 Daily Gas Product
Slide 23: Rocky Mountain Pipelines
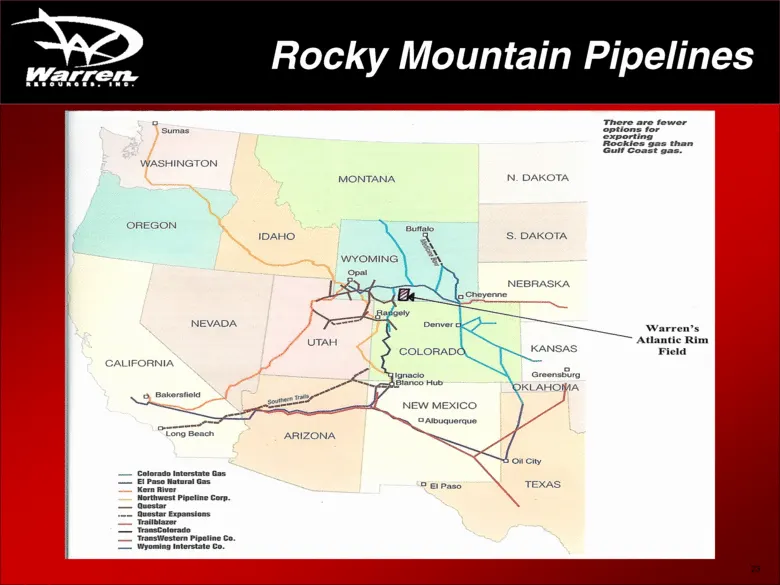
Rocky Mountain Pipelines 23
Slide 24: Financial Overview
Financial Overview 24
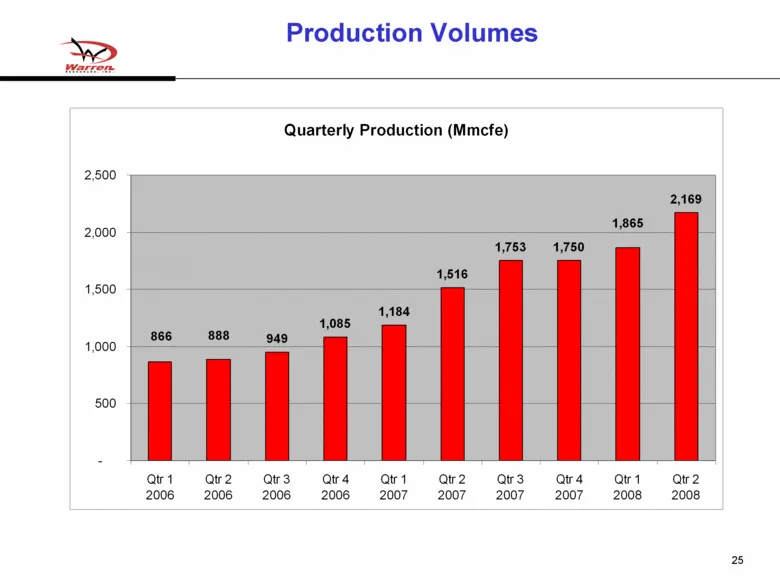
Slide 25: Production Volumes
Production Volumes Quarterly Production (Mmcfe) 949 1,085 1,184 1,516 1,753 1,750 2,169 866 888 1,865 - 500 1,000 1,500 2,000 2,500 Qtr 1 2006 Qtr 2 2006 Qtr 3 2006 Qtr 4 2006 Qtr 1 2007 Qtr 2 2007 Qtr 3 2007 Qtr 4 2007 Qtr 1 2008 Qtr 2 2008 25
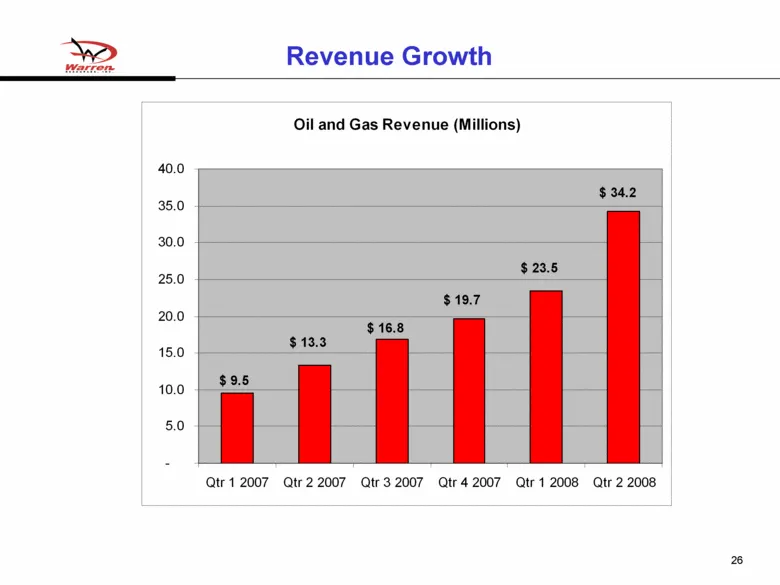
Slide 26: Revenue Growth
Revenue Growth Oil and Gas Revenue (Millions) - 5.0 10.0 15.0 20.0 25.0 30.0 35.0 40.0 Qtr 1 2007 Qtr 2 2007 Qtr 3 2007 Qtr 4 2007 Qtr 1 2008 Qtr 2 2008 $ 9.5 $ 13.3 $ 16.8 $ 19.7 $ 23.5 $ 34.2 26
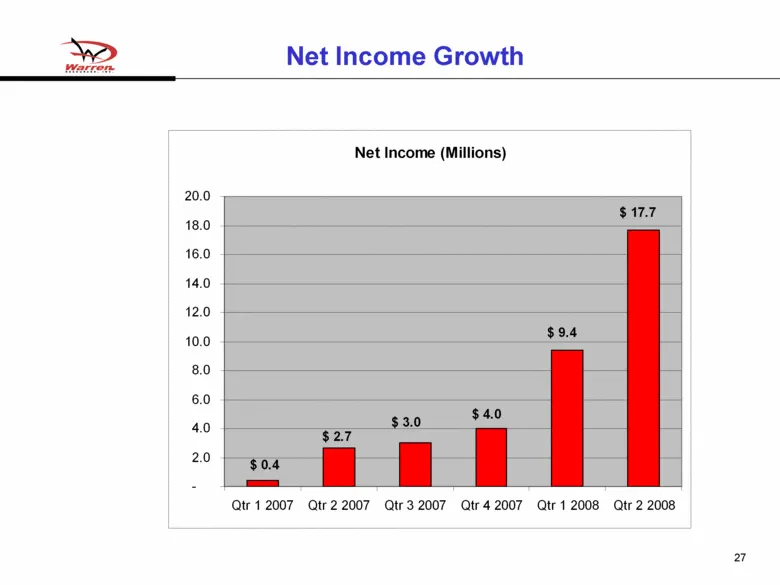
Slide 27: Net Income Growth
Net Income Growth Net Income (Millions) - 2.0 4.0 6.0 8.0 10.0 12.0 14.0 16.0 18.0 20.0 Qtr 1 2007 Qtr 2 2007 Qtr 3 2007 Qtr 4 2007 Qtr 1 2008 Qtr 2 2008 $ 0.4 $ 2.7 $ 3.0 $ 4.0 $ 9.4 $ 17.7 27
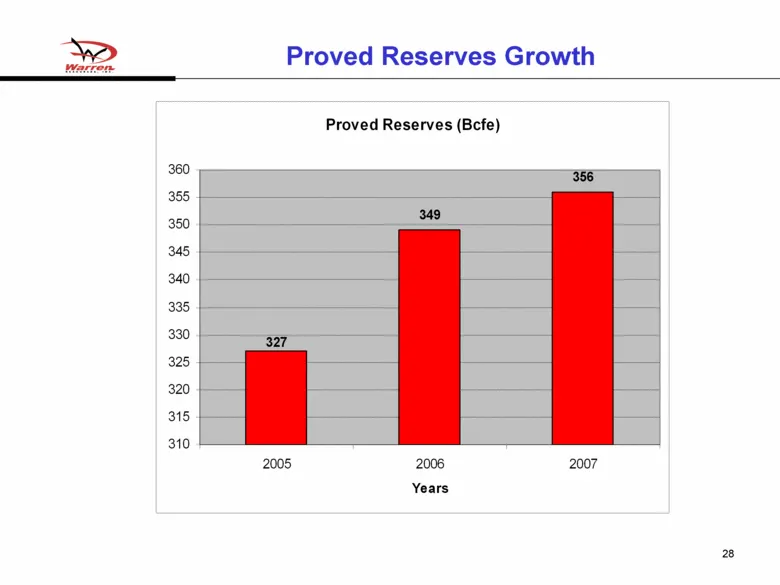
Slide 28: Proved Reserves Growth
Proved Reserves Growth Proved Reserves (Bcfe) 349 356 327 310 315 320 325 330 335 340 345 350 355 360 2005 2006 2007 Years 28
Slide 29: Capitalization
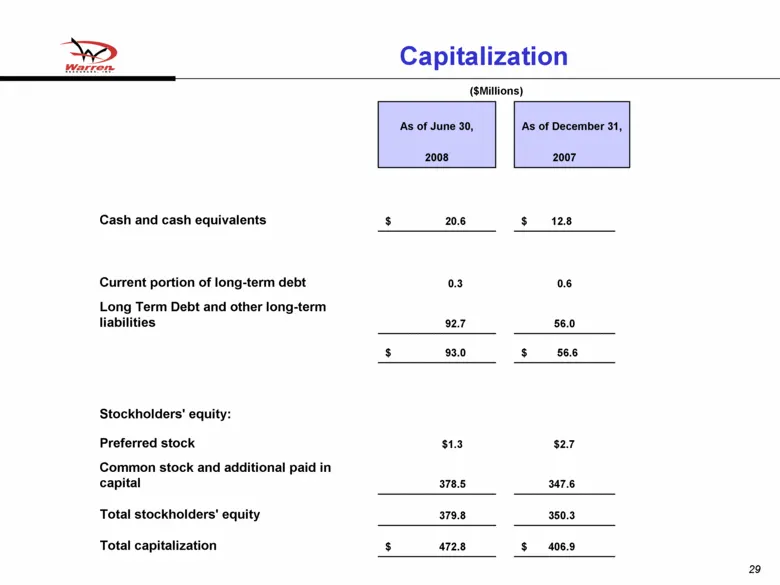
Capitalization ($Millions) 29 $ 406.9 $ 472.8 Total capitalization 350.3 379.8 Total stockholders’ equity 347.6 378.5 Common stock and additional paid in capital $2.7 $1.3 Preferred stock Stockholders’ equity: $ 56.6 $ 93.0 56.0 92.7 Long Term Debt and other long-term liabilities 0.6 0.3 Current por
Slide 30: Historical Financial Performance
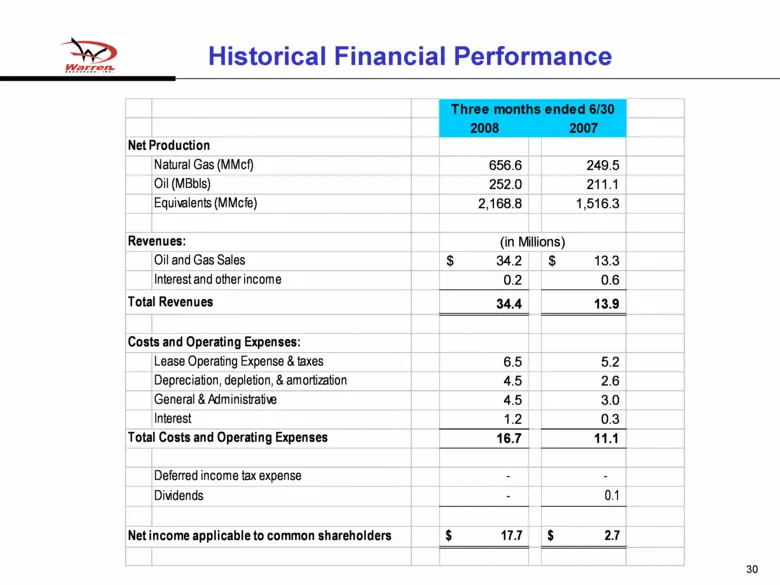
2008 2007 Net Production Natural Gas (MMcf) 656.6 249.5 Oil (MBbls) 252.0 211.1 Equivalents (MMcfe) 2,168.8 1,516.3 Revenues: Oil and Gas Sales $ 34.2 $ 13.3 Interest and other income 0.2 0.6 Total Revenues 34.4 13.9 Costs and Operating Expenses: Lease Operating Expense & taxes 6.5 5.2 Depreciation,
Slide 31: Defined Growth
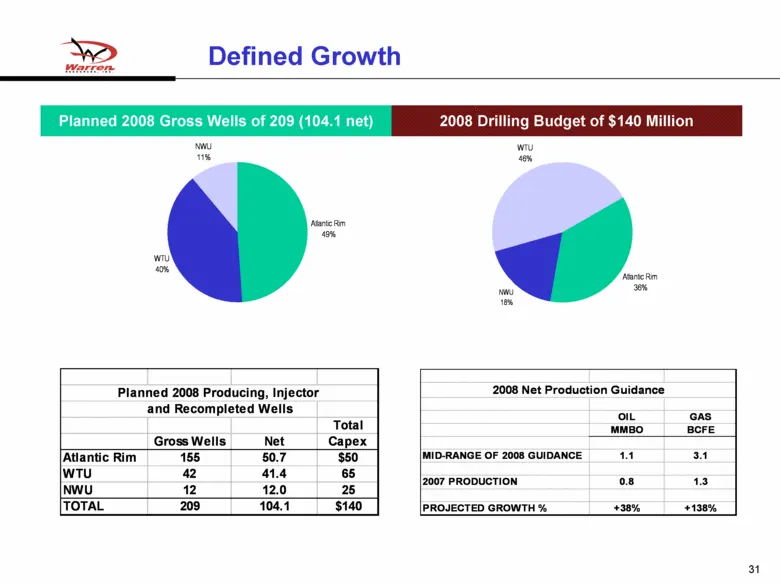
Defined Growth NWU 11% WTU 40% Atlantic Rim 49% WTU 46% Atlantic Rim 36% NWU 18% Planned 2008 Gross Wells of 209 (104.1 net) 2008 Drilling Budget of $140 Million 31 and Recompleted Wells Total Gross Wells Net Capex Atlantic Rim 155 50.7 $50 WTU 42 41.4 65 NWU 12 12.0 25 TOTAL 209 104.1 $140 Planned
Slide 32: Warren Resources
Warremn RESOURCES,
Source: SEC EDGAR · 8-K filed Oct 7, 2008
More decks from Warren Resources Inc
 Debt Investor Presentation (June 2016)18 slides · Jun 3, 2016
 Enercom 2015: The Oil and Gas Conference31 slides · Aug 19, 2015
 GHS 100 Conference 201536 slides · Jun 23, 2015
 Corporate Update (June 2015)7 slides · Jun 16, 2015
 IPAA OGIS New York April 201532 slides · Apr 20, 2015
 Investor Presentation (December 2014)42 slides · Dec 11, 2014