Endeavour International — Rodman & Renshaw Investor Presentation (October 2010)
28 slides from Endeavour International's conference presentation, Oct 4, 2010
Slide 1: Rodman & Renshaw Investor Presentation, New York, October 2010
Rodman & Renshaw Investor Presentation New York, New York October 2010
Slide 2: Forward-looking statements and cautionary notes
2 This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and poten
Slide 3: Endeavour At A Glance
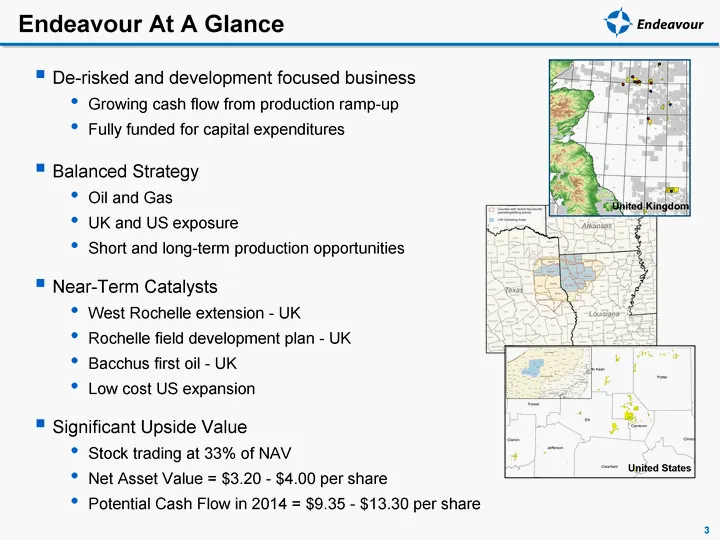
3 Endeavour At A Glance De-risked and development focused business Growing cash flow from production ramp-up Fully funded for capital expenditures Balanced Strategy Oil and Gas UK and US exposure Short and long-term production opportunities Near-Term Catalysts West Rochelle extension - UK Rochelle f
Slide 4: The Endeavour Portfolio of Assets
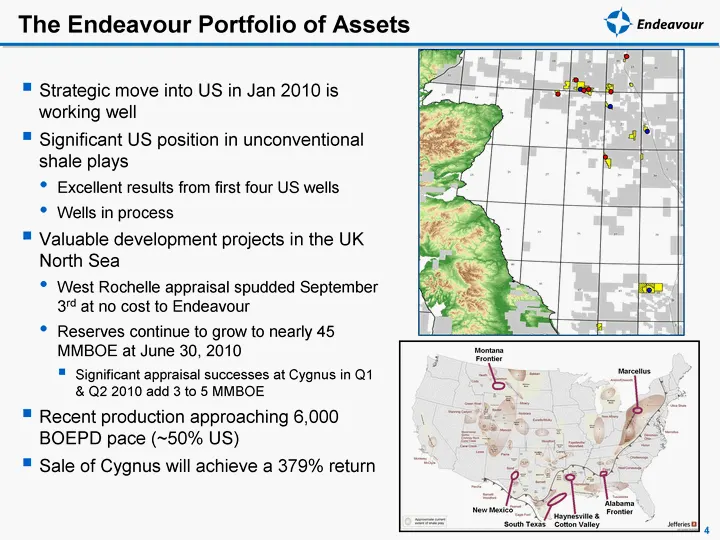
4 The Endeavour Portfolio of Assets Endeavour Acreage Endeavour Production Endeavour Developments Strategic move into US in Jan 2010 is working well Significant US position in unconventional shale plays Excellent results from first four US wells Wells in process Valuable development projects in the
Slide 5: Cygnus Reserves
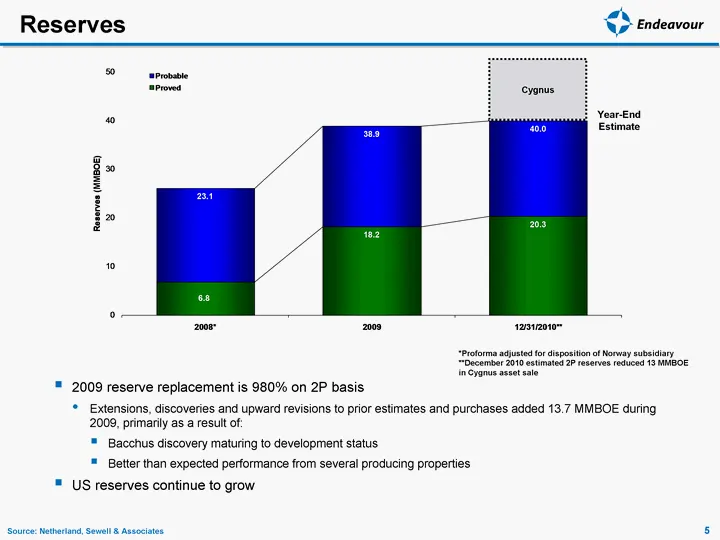
Cygnus 5 Reserves Source: Netherland, Sewell & Associates 2009 reserve replacement is 980% on 2P basis Extensions, discoveries and upward revisions to prior estimates and purchases added 13.7 MMBOE during 2009, primarily as a result of: Bacchus discovery maturing to development status Better than ex
Slide 6: Existing Portfolio Has Potential to Deliver Rapid Production Growth
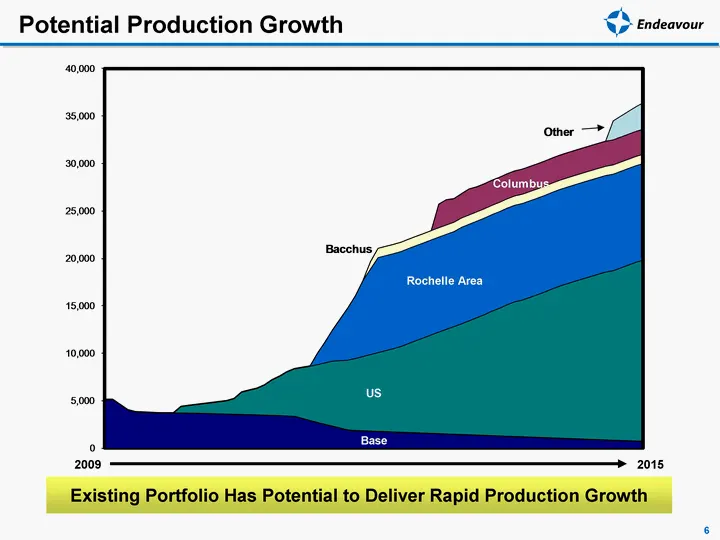
Existing Portfolio Has Potential to Deliver Rapid Production Growth 2009 2015 Potential Production Growth 6
Slide 7: Endeavour Assets - US Portfolio
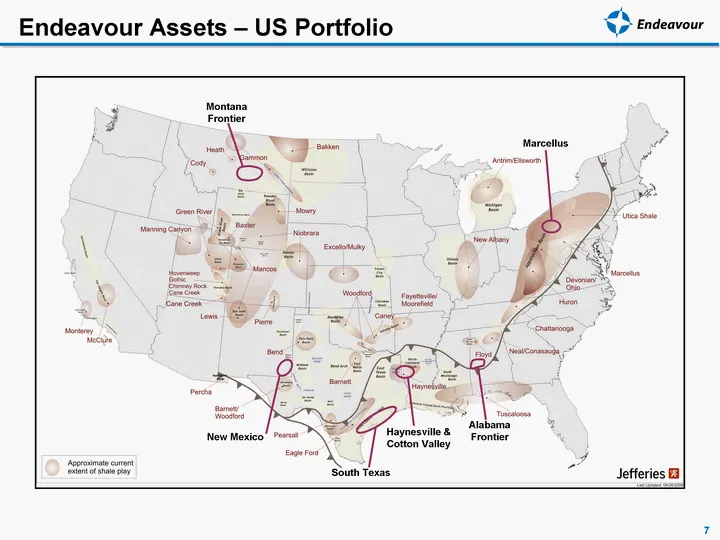
Montana Frontier Marcellus Haynesville & Cotton Valley Alabama Frontier New Mexico South Texas 7 Endeavour Assets - US Portfolio
Slide 8: Shale Gas Plays are lower cost & more sustainable
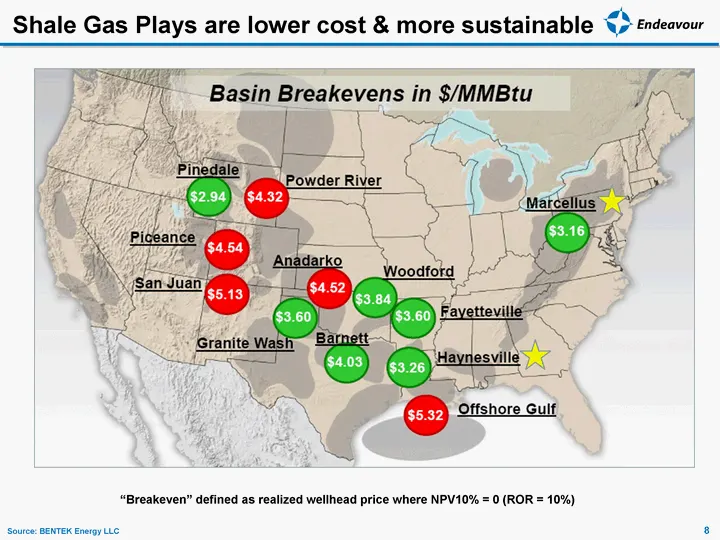
Shale Gas Plays are lower cost & more sustainable 8 "Breakeven" defined as realized wellhead price where NPV10% = 0 (ROR = 10%) Source: BENTEK Energy LLC
Slide 9: The Haynesville Project - Overview
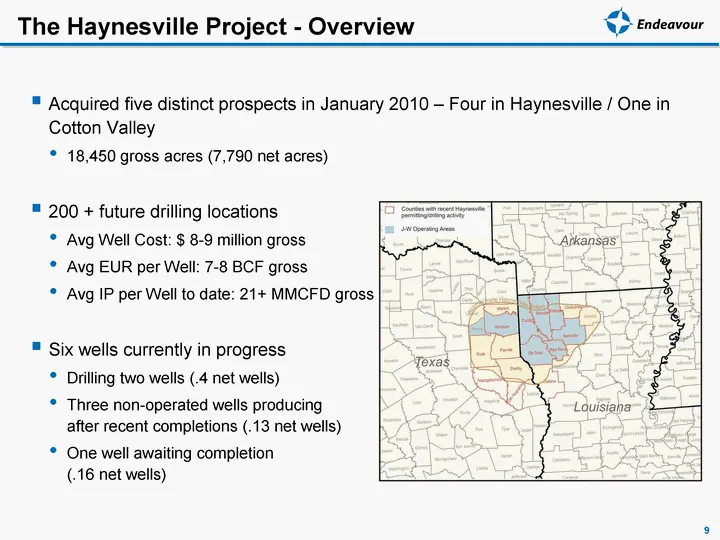
The Haynesville Project - Overview Acquired five distinct prospects in January 2010 - Four in Haynesville / One in Cotton Valley 18,450 gross acres (7,790 net acres) 200 + future drilling locations Avg Well Cost: $ 8-9 million gross Avg EUR per Well: 7-8 BCF gross Avg IP per Well to date: 21+ MMCFD
Slide 10: Haynesville Shale - Louisiana well results
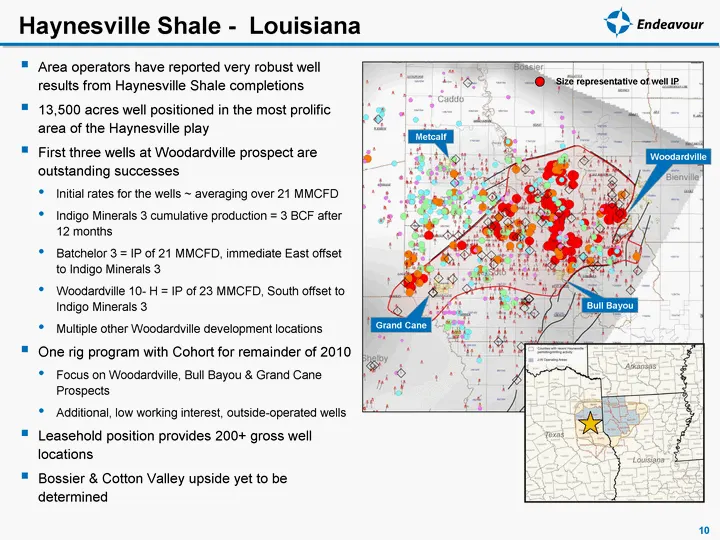
Area operators have reported very robust well results from Haynesville Shale completions 13,500 acres well positioned in the most prolific area of the Haynesville play First three wells at Woodardville prospect are outstanding successes Initial rates for the wells ~ averaging over 21 MMCFD Indigo Mi
Slide 11: Acreage - Haynesville/Bossier Potential
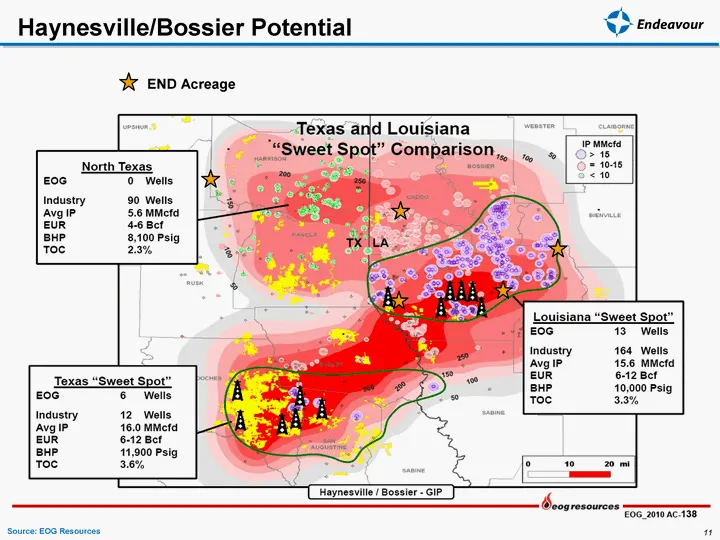
END Acreage 11 Source: EOG Resources Haynesville/Bossier Potential
Slide 12: Distribution of Initial Potential Flow Rates
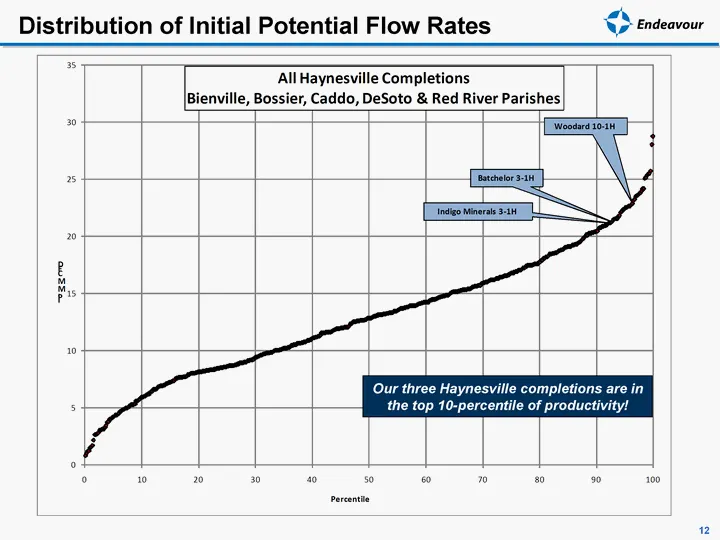
Distribution of Initial Potential Flow Rates 12 Our three Haynesville completions are in the top 10-percentile of productivity!
Slide 13: The Marcellus Project - Overview
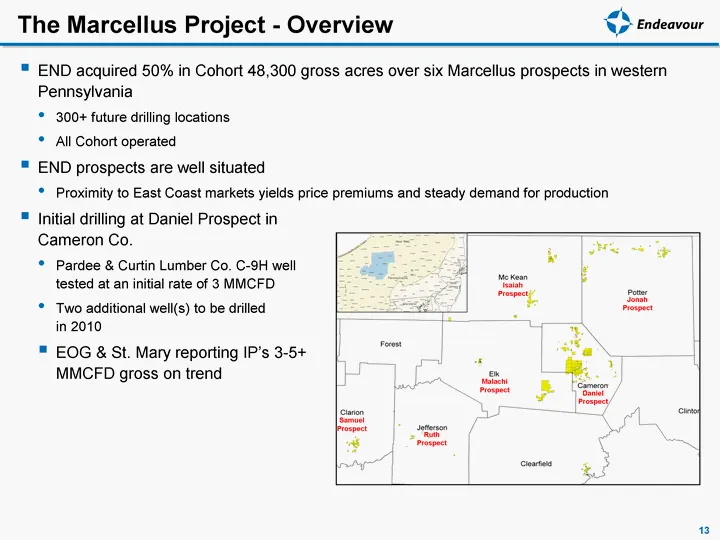
The Marcellus Project - Overview END acquired 50% in Cohort 48,300 gross acres over six Marcellus prospects in western Pennsylvania 300+ future drilling locations All Cohort operated END prospects are well situated Proximity to East Coast markets yields price premiums and steady demand for productio
Slide 14: Western PA Area - Industry Highlights
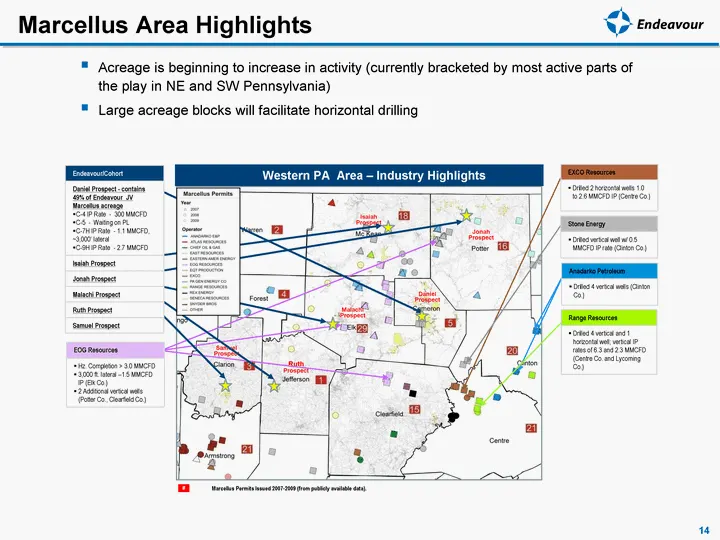
Western PA Area - Industry Highlights Isaiah Prospect Jonah Prospect Daniel Prospect Malachi Prospect Samuel Prospect Ruth Prospect EXCO Resources Drilled 2 horizontal wells 1.0 to 2.6 MMCFD IP (Centre Co.) Acreage is beginning to increase in activity (currently bracketed by most active parts of the
Slide 15: Alabama Frontier Gas Shale Play - Overview
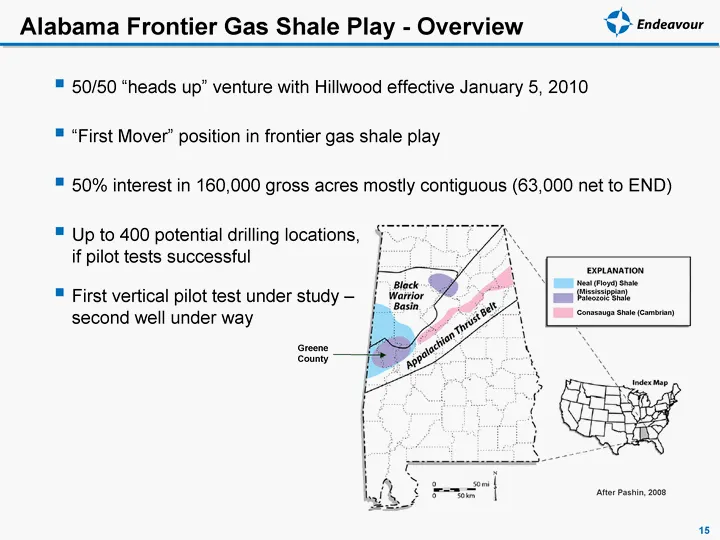
Greene County After Pashin, 2008 Alabama Frontier Gas Shale Play - Overview 15 Paleozoic Shale Conasauga Shale (Cambrian) Neal (Floyd) Shale (Mississippian) 50/50 "heads up" venture with Hillwood effective January 5, 2010 "First Mover" position in frontier gas shale play 50% interest in 160,000 gros
Slide 16: Montana Frontier Oil Shale Play - Overview
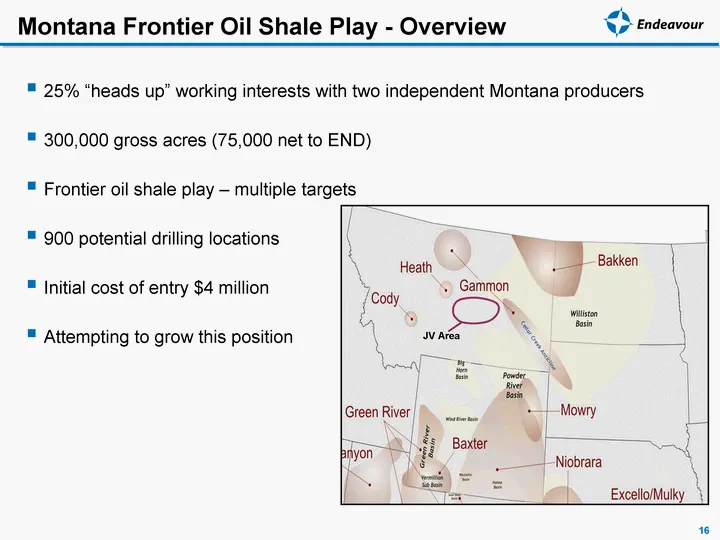
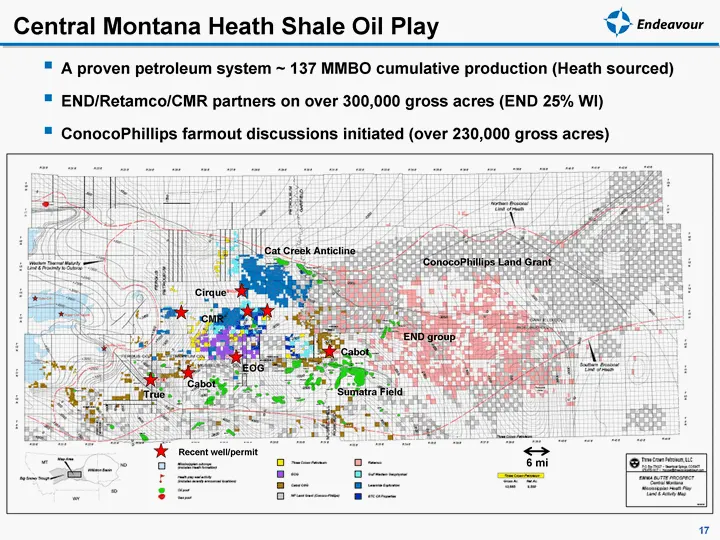
Montana Frontier Oil Shale Play - Overview 25% "heads up" working interests with two independent Montana producers 300,000 gross acres (75,000 net to END) Frontier oil shale play - multiple targets 900 potential drilling locations Initial cost of entry $4 million Attempting to grow this position JV
Slide 17: Central Montana Heath Shale Oil Play
Central Montana Heath Shale Oil Play A proven petroleum system ~ 137 MMBO cumulative production (Heath sourced) END/Retamco/CMR partners on over 300,000 gross acres (END 25% WI) ConocoPhillips farmout discussions initiated (over 230,000 gross acres) 17 Sumatra Field Cat Creek Anticline
Slide 18: Endeavour Assets - UK North Sea
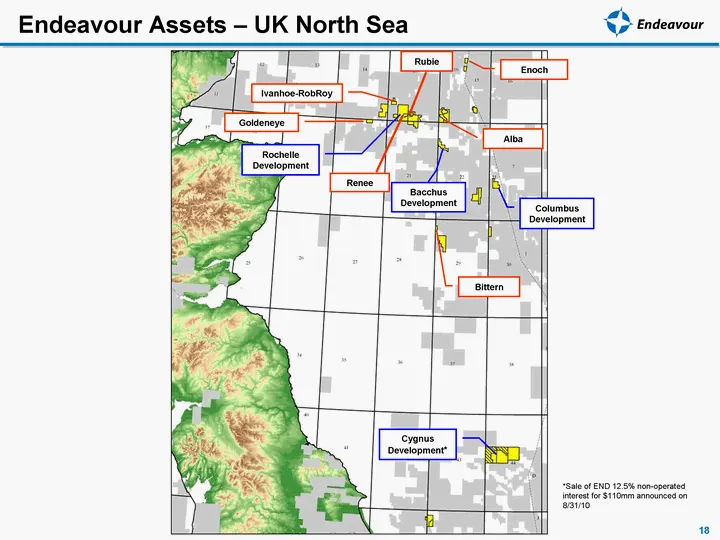
Endeavour Assets - UK North Sea 18 Rubie Renee *Sale of END 12.5% non-operated interest for $110mm announced on 8/31/10
Slide 19: Current North Sea Developments
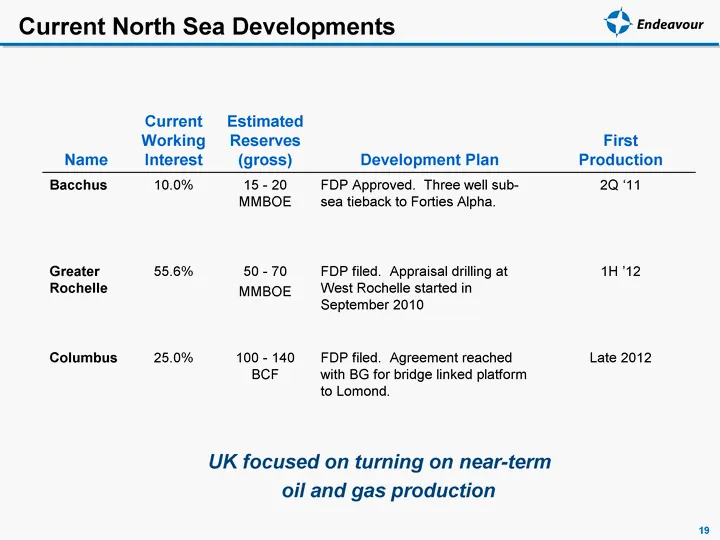
19 Current North Sea Developments Name Current Working Interest Estimated Reserves (gross) Development Plan First Production Bacchus 10.0% 15 - 20 MMBOE FDP Approved. Three well sub-sea tieback to Forties Alpha. 2Q '11 Greater Rochelle 55.6% 50 - 70 MMBOE FDP filed. Appraisal drilling at West Rochel
Slide 20: Bacchus Development
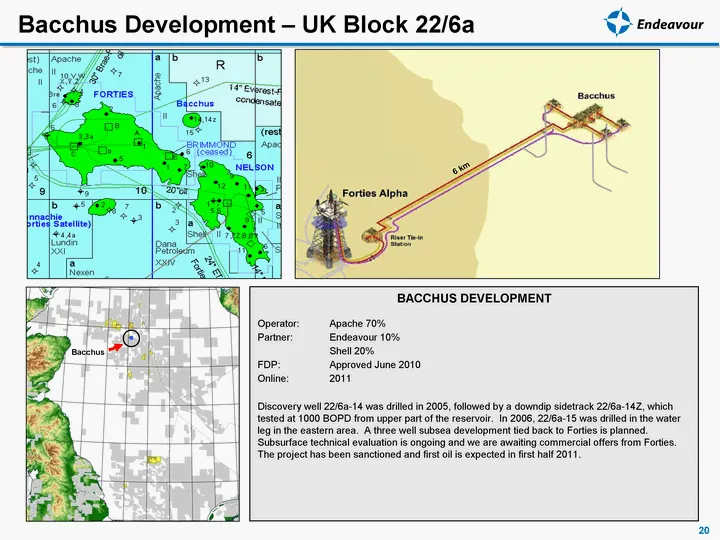
20 BACCHUS DEVELOPMENT Operator: Apache 70% Partner: Endeavour 10% Shell 20% FDP: Approved June 2010 Online: 2011 Discovery well 22/6a-14 was drilled in 2005, followed by a downdip sidetrack 22/6a-14Z, which tested at 1000 BOPD from upper part of the reservoir. In 2006, 22/6a-15 was drilled in the w
Slide 21: Rochelle Development - UK Block 15/27
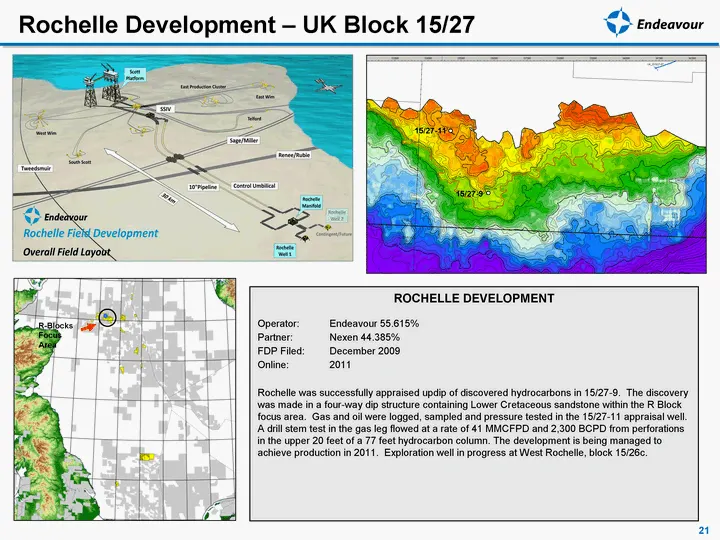
Rochelle Development - UK Block 15/27 15/27-11 15/27-9 21 ROCHELLE DEVELOPMENT Operator: Endeavour 55.615% Partner: Nexen 44.385% FDP Filed: December 2009 Online: 2011 Rochelle was successfully appraised updip of discovered hydrocarbons in 15/27-9. The discovery was made in a four-way dip structure
Slide 22: West Rochelle - Significant Rochelle Expansion Potential
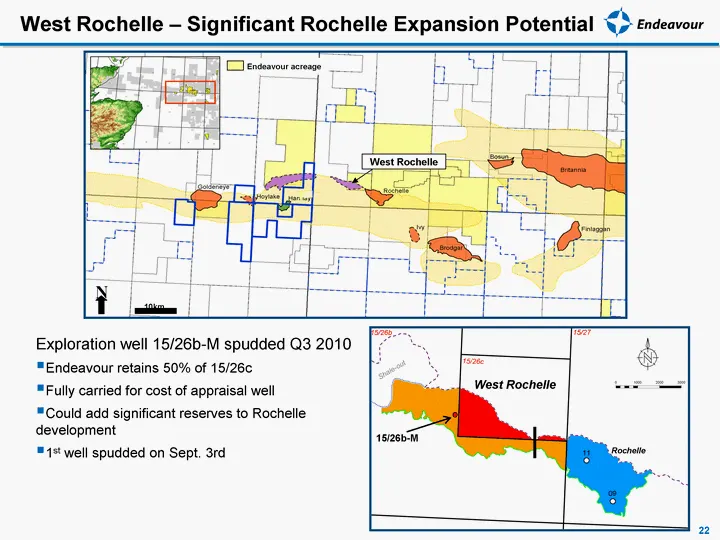
West Rochelle - Significant Rochelle Expansion Potential 10km N West Rochelle 22 Exploration well 15/26b-M spudded Q3 2010 Endeavour retains 50% of 15/26c Fully carried for cost of appraisal well Could add significant reserves to Rochelle development 1st well spudded on Sept. 3rd
Slide 23: Columbus Development - UK Block 23/16f
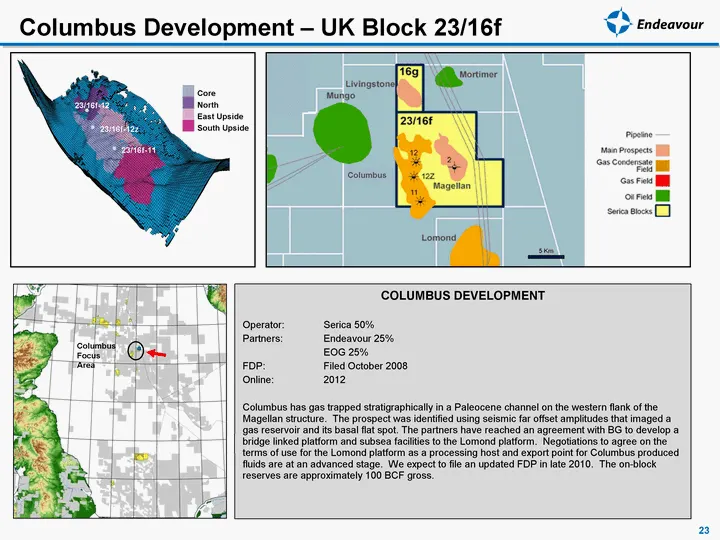
23 Columbus Development - UK Block 23/16f COLUMBUS DEVELOPMENT Operator: Serica 50% Partners: Endeavour 25% EOG 25% FDP: Filed October 2008 Online: 2012 Columbus has gas trapped stratigraphically in a Paleocene channel on the western flank of the Magellan structure. The prospect was identified using
Slide 24: Strong portfolio management - Capital Deployed has Achieved Excellent Returns
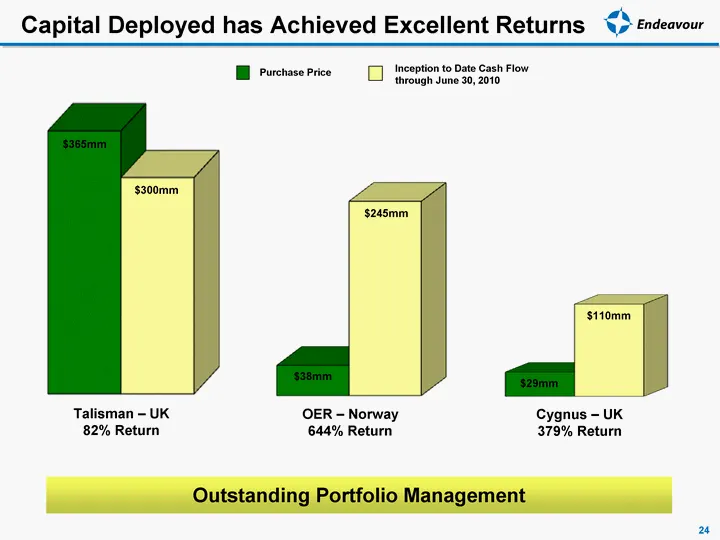
24 Strong portfolio management - outperforming both production and price expectations Inception to Date Cash Flow through June 30, 2010 Purchase Price $365mm $300mm Talisman - UK 82% Return $38mm $245mm OER - Norway 644% Return $110mm $29mm Cygnus - UK 379% Return Capital Deployed has Achieved Excel
Slide 25: Financing Overview
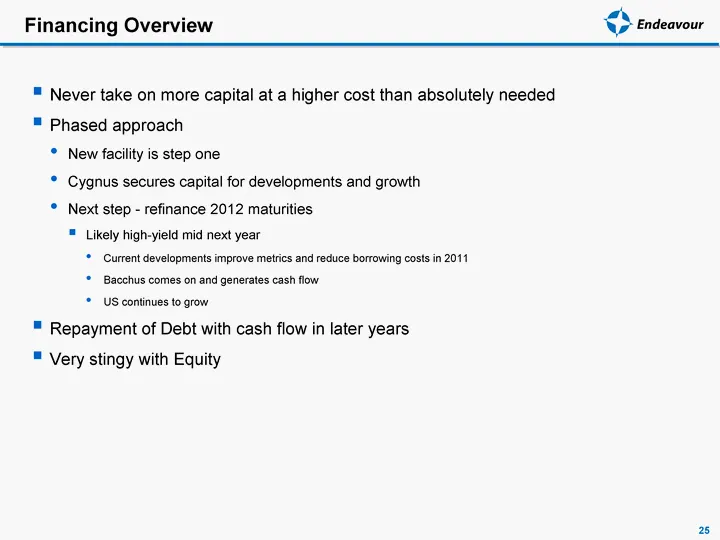
Never take on more capital at a higher cost than absolutely needed Phased approach New facility is step one Cygnus secures capital for developments and growth Next step - refinance 2012 maturities Likely high-yield mid next year Current developments improve metrics and reduce borrowing costs in 2011
Slide 26: Capital Structure
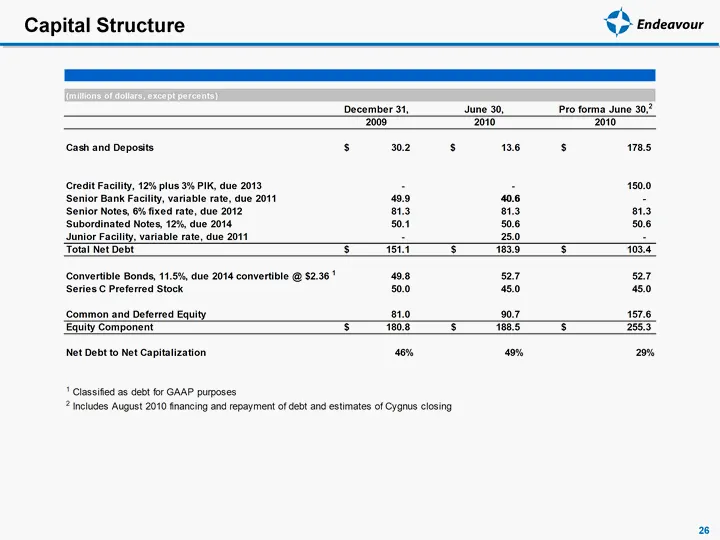
Capital Structure © Endeavour December 31, June 30, ro forma June 30.7 2008 2010 2010 ‘cash and Deposits s w2 $s 138 s 1785 Credit Facility, 12% plus 9% PIK, due 2013 2 2 150.0 ‘Senior Bank Facility, variable rate, due 2011 408 - ‘Senior Notes, 6% fixed rate, due 2012 813 13 ‘Subordinated Notes, 12%
Slide 27: Estimated Valuation Range
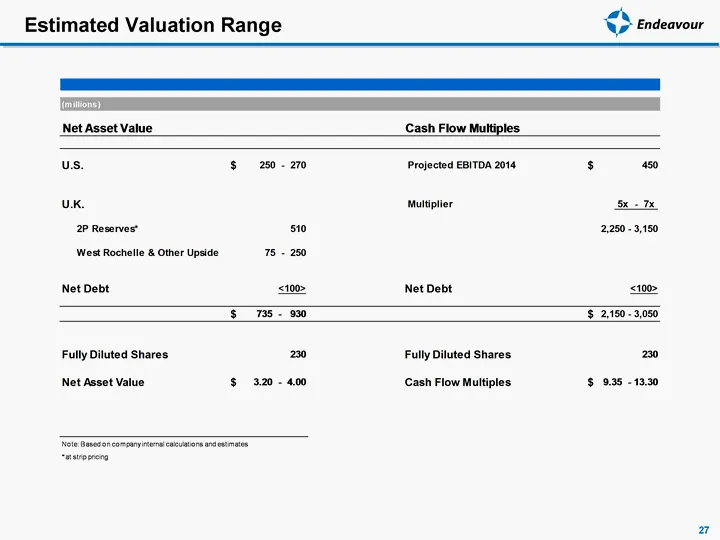
27 Estimated Valuation Range
Slide 28: Key Take Aways
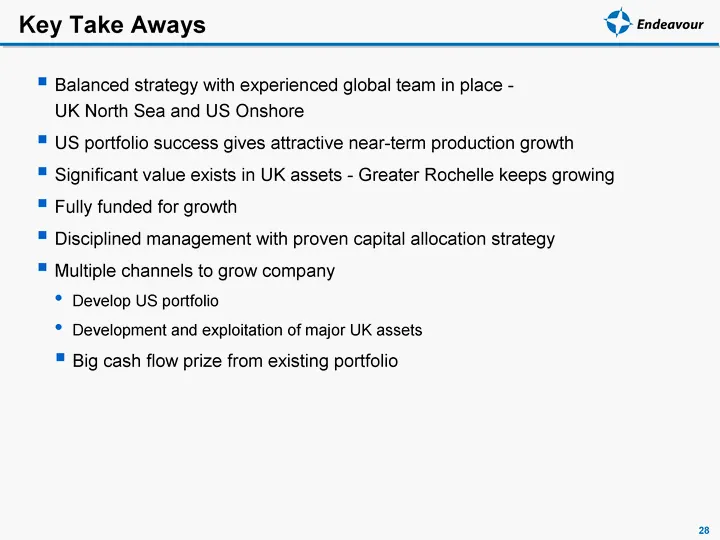
28 Balanced strategy with experienced global team in place - UK North Sea and US Onshore US portfolio success gives attractive near-term production growth Significant value exists in UK assets - Greater Rochelle keeps growing Fully funded for growth Disciplined management with proven capital allocat
Source: SEC EDGAR · 8-K filed Oct 4, 2010
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014